



Category: market research
PW Consulting: Data Center Consulting Market to Reach USD 28,417M in 2025 with 13.45% CAGR
By PW Consulting, 2026-07-13
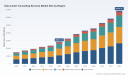
Data Center Consulting Services Market — Strategic Preview for 2026 Decision-Makers
As organizations accelerate digital transformation, artificial intelligence adoption, and hyperscale capacity builds, the global market for data center consulting services has entered a sustained expansion phase. Our new PW Consulting market study — covering historical performance through 2025 and a detailed forecast horizon beginning in 2026 — shows a multi‑year structural growth trajectory with a compound annual growth rate (CAGR) of 13.45% for the forecast period. The market crossed a significant milestone in 2025 and is projected to continue scaling meaningfully into the early 2030s.
Data Center Consulting Services Market
Why this study matters for decisions made in 2026
-
Timing capital allocation: 2026 is a year of discrete windows for committing to new build, modular expansion, or colocation agreements. Our market model translates high-level growth signals into scenario-based demand curves so CFOs and infrastructure owners can align multi-year CAPEX with realistic utilization trajectories and energy cost assumptions.
Data Center Consulting Services Market -
Optimizing operating models: Rapid changes in workload placement and hybrid architectures force choices between managed services, in‑house operations, and co-located models. The report provides TCO frameworks and migration playbooks that surface the critical breakpoints where outsourcing or retaining operations materially alters lifetime cost.
Data Center Consulting Services Market -
Mitigating regulatory and compliance exposure: New privacy laws, sectoral rules for sensitive data handling, and emissions-focused generator regulations are making compliance a design consideration rather than a box checked at the end. The research synthesizes current regulatory developments and models the operational impact on design, staffing, and contingency planning.
-
Sustainability and community license to operate: Environmental, social and governance (ESG) expectations are no longer peripheral. Investors and site hosts increasingly require biodiversity, water management and community engagement strategies embedded in project plans; the report quantifies how these practices affect project timelines and capital needs.
What the PW Consulting report delivers (practical, action-ready content)
-
Integrated market model: A calibrated topline model that links macro demand drivers to near-term capacity needs and consultant service demand across a multi-year forecast horizon. This model is accompanied by transparent assumptions and sensitivity levers for power pricing, server density trends, and utilization efficiency.
-
Decision playbooks: Step-by-step playbooks for build vs buy choices, migration sequencing from brownfield to modernized platforms, and rapid assessment templates for colocation and interconnection strategies.
-
Financial toolkits: TCO calculators, capital planning templates, and scenario-based IRR/NPV illustrations tailored to data center projects under varying energy, labor, and regulatory regimes.
-
Vendor and partner evaluation materials: Due-diligence checklists, contracting red-lines for services and construction management, and a vendor scorecard methodology that balances technical competency, delivery reliability, and sustainability credentials.
-
Operational playbooks: Staffing and skills roadmaps, maintenance and spare-parts optimization, and a practical migration & cutover checklist designed to reduce downtime risk in complex retrofits.
-
Risk register and mitigation matrices: A prioritized enumeration of technical, regulatory, and community risks with recommended mitigation actions and contingency budgets.
Note: the report contains granular segmentation by region, service type and end‑use industry and a comprehensive supplier revenue matrix. To preserve this brief’s role as a strategic preview, those granular splits and company revenue line items are intentionally withheld here — they are available in full in the published study.
Competitive landscape — how the supplier universe is shaping 2026 outcomes
The data center consulting services market remains fragmented: the top three firms account for less than one‑fifth of total market revenue, and the top five remain below 30% concentration. This fragmentation creates divergent strategic options for buyers: engage a wide ecosystem of specialists for best-in-class technical outcomes, or consolidate with a smaller set of large integrators to simplify program management.
-
AECOM and Jacobs (both with major US bases): leaders in site selection, design, and end-to-end project delivery for mission‑critical facilities. Their strengths lie in global program management, heavy civil and MEP engineering, and delivery of complex capital projects at scale.
-
Arup and Ramboll : engineering and sustainability specialists who are frequently engaged on projects where energy efficiency, architectural integration, and biodiversity/ESG outcomes are defining success criteria. Ramboll’s recent partnership to embed biodiversity into a large campus project highlights the growing demand for nature‑positive design approaches.
-
Accenture and IBM Consulting : strategy and IT transformation partners focused on cloud migration, hybrid architectures, and embedding AI into infrastructure operations. Accenture’s recent expansion of capital project delivery capabilities through an acquisition demonstrates the increasing crossover between management consulting, digital tools, and construction management.
-
Deloitte , PwC , and EY : advisory firms that combine risk/compliance, tax, and operational transformation services, and are often selected for program governance, regulatory assurance, and enterprise risk assessments tied to large-scale builds.
-
JLL : a specialist in real estate, site selection, and investment advisory. JLL’s market outlooks and campus-level capacity projections are widely used by corporates and investors to inform site strategy and land acquisition timing.
-
HCL Technologies , TCS , and Kyndryl : providers with strong heritage in managed services and infrastructure operations, positioned for long-term outsourcing contracts and run-books that capture operational knowledge at scale.
-
McKinsey & Company : a strategic advisor for C‑suite decisions around platform strategy, M&A, and large transformation programs where organizational design and future-state operating models are the primary focus.
Recent developments and regulatory dynamics that will shape 2026 playbooks
-
Capital project delivery and digital tools: Significant M&A and capability builds among major consultancies are accelerating the fusion of construction management with AI-driven planning tools. Expect shorter design cycles but greater emphasis on digital twin and construction analytics to manage schedule and cost risk.
-
Workforce and labor: Large-scale training initiatives focused on electrical trades and specialized data center skillsets are beginning to materialize. Organizations that lock in training partnerships now will reduce long-term labor premium risk.
-
Regulatory shifts: New emissions rules for backup generators in some jurisdictions and enhanced federal and state privacy controls have elevated compliance into a core project constraint. Design decisions for redundancy, emissions control, and data handling now have immediate operational and permitting implications.
-
Capacity outlook: Industry forecasts anticipate a step‑up in capacity demand over the next five years, changing the calculus for power procurement, land strategy, and grid interconnection planning. Buyers must integrate capacity scenarios into both short-term resource commitments and long-term siting decisions.
Practical 90‑day action plan for 2026
-
Conduct a regulatory impact scan focused on generator emissions, privacy obligations, and bulk data handling rules; map any near-term project milestones that might be affected.
-
Run an immediate TCO and sensitivity analysis using low/medium/high scenarios for power cost and utilization — prioritize projects where payback is most sensitive to energy price volatility.
-
Initiate or expand workforce partnerships for electrical and critical facilities trades; include apprenticeship metrics and retention KPIs in vendor RFPs.
-
Pilot a modular or prefabricated approach on a single project to compress schedule risk and test vendor integration capabilities.
-
Update procurement templates with ESG and compliance conditions, and issue an RFP to assess market pricing for integrated delivery versus specialist engagements.
Why PW Consulting’s full study is a strategic asset
The full PW Consulting Data Center Consulting Services Market study combines a rigorously validated market model, executive interviews, supplier revenue matrices, and practical implementation toolkits. It is designed to convert market intelligence into executable plans — whether you are an operator sizing next‑generation capacity, an investor evaluating campus plays, or a CISO assessing compliance exposure across a global estate.
This preview intentionally highlights the analytical framework, competitive dynamics, and decision-ready outputs while omitting the report’s granular segmentation and supplier revenue line items. For procurement-ready vendor scorecards, region- and service-level demand curves, and downloadable financial templates, please consult the full report.
PW Consulting stands ready to support your 2026 strategy session with bespoke scenario runs, stress tests of your portfolio under regulatory and energy price shocks, and hands-on workshops to operationalize the report’s playbooks into your capital planning and vendor selection processes.
For detailed analysis of this topic, please visit the official page: Data Center Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gestational Trophoblastic Disease Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the Gestational Trophoblastic Disease (GTD) market designed to frame boardroom and commercial-strategy conversations for 2026. This briefing synthesizes market momentum, clinical and regulatory inflection points, competitor positioning, and the practical intelligence our full report delivers — while deliberately withholding detailed segment tables to encourage direct access to the underlying dataset and model.
Gestational Trophoblastic Disease Market
Why GTD deserves a seat at your 2026 strategy table
-
Clinically driven market growth: The GTD market has grown from a narrow specialty niche into a clearly expanding opportunity. The overall market rose from USD 412.3 Million in 2020 to USD 546.04 Million by the 2025 base year and is forecast to continue expanding, reaching USD 810.26 Million by 2032. This trajectory is supported by a forecast CAGR of 5.81% for 2026–2032, which positions GTD among steadily growing rare-oncology subsegments where incremental clinical advances translate rapidly into commercial uptake.
Gestational Trophoblastic Disease Market -
Actionable clinical levers: Recent guideline updates, new clinical data and the emergence of immunotherapy and targeted repurposing studies are shifting treatment algorithms and referral pathways. For executives, this means that late-stage clinical evidence and guideline adoption timelines — not just first-to-market approvals — will determine commercial outcomes.
Gestational Trophoblastic Disease Market -
Manageable competitive density: The market shows moderate concentration among established oncology and generics players, creating a landscape where well-positioned entrants can scale via partnerships, formulary strategies and guideline adoption without confronting extreme fragmentation or monopolistic incumbency.
Market trajectory and what the headline numbers mean for 2026 choices
From a strategic planning standpoint, the market’s compound growth and absolute scale have immediate implications for resource allocation. The mid-single-digit CAGR through 2032 indicates reliable expansion driven by steady incidence, improved diagnosis/monitoring, and the selective adoption of novel therapeutics and combinations. For 2026 planning cycles, leaders should treat the market as a growth platform that rewards:
- Focused clinical development investments that shorten time-to-guideline inclusion.
- Commercial models that prioritize guideline adoption, center-of-excellence penetration, and payer evidence generation.
- Partnerships with established oncology manufacturers and specialty distributors to bridge supply and access gaps in target geographies.
Clinical and regulatory dynamics shaping near-term commercial outcomes
Three dynamics will most strongly influence commercial trajectories in 2026 and beyond:
-
Guideline-driven uptake. The 2025 international consensus guidance from the EOTTD–ESGO–GCIG–ISSTD consortium has formally recognized avelumab as an option in certain low-risk GTN cases to avoid escalation to multi-agent chemotherapy in select settings. Guideline inclusion accelerates payer consideration and clinician adoption; companies should prioritize real-world evidence and economic modeling to convert guideline statements into on-the-ground utilization.
-
Immuno-oncology and rescue strategies. Checkpoint inhibitors (pembrolizumab, avelumab and others) are increasingly used in chemo-resistant GTN or in trials. While most checkpoint inhibitors lack indication-specific regulatory approvals for GTN as of 2026, NHS England-type recommendations and trial signals create a pragmatic pathway for off-label or directed access programs. This trend opens a practical commercial channel for manufacturers with existing immuno-oncology franchises and necessitates lifecycle strategies for label expansion or formal registration.
-
Novel modalities and repurposing. Early-stage work — such as focused ultrasound research and preclinical studies repurposing statins for choriocarcinoma — suggests potential future adjacencies beyond classic cytotoxic agents. These approaches are not yet commercialized at scale but represent strategic optionality for companies exploring platform technologies or combination regimens.
Competitive landscape: pragmatic positioning and rivalry
The GTD therapeutic environment is populated by multinational originators, established generics manufacturers, and oncology specialist players. From a competitive-mapping perspective:
-
Large originators (e.g., longstanding oncology franchises) currently benefit from brand recognition, distribution reach, and existing guideline-relevant product portfolios. Their muscle is especially pronounced where immunotherapy or branded oncology agents intersect with GTD care pathways.
-
Generics and injectable suppliers control critical access levers for cytotoxic backbones and supportive care. Supply reliability, cost management and hospital formulary relationships are decisive in settings where single-agent chemotherapy remains standard of care.
-
Specialist biopharma and academic spin-outs focusing on rare gynecologic tumors can create outsized clinical and commercial impact by delivering compelling efficacy or tolerability improvements that shift first-line practice or permit de-escalation of multi-agent regimens.
Key corporate archetypes represented among active players include: large multinational originators with immuno-oncology capability, established generic injectables manufacturers, and clinical-stage innovators testing novel combinations. Market concentration metrics indicate that a small group of companies capture a meaningful majority of commercial activity, but not enough to preclude new entrants with differentiated clinical evidence or nimble access strategies.
Recent developments that materially affect 2026 decisions
-
Clinical data — A high-profile analysis presented at the 2026 ESMO Sarcoma & Rare Cancers Congress reported an improvement in complete response rates when first-line avelumab was combined with an 8-day methotrexate schedule versus methotrexate alone in low-risk GTN. This kind of head-to-head and external-control-informed evidence will shape clinicians’ risk/benefit calculus and reimbursement conversations.
-
Guideline updates — The 2025 multi-society consensus that incorporated avelumab as a potential option in certain low-risk cases underscores how guideline language can pivot the market without awaiting conventional regulatory label changes.
-
Policy-level access — NHS England-style recommendations for checkpoint inhibitor use in refractory high-risk GTN establish pathways for targeted access programs and influence global payer evaluations, particularly in countries with centralized decision-making.
Commercial playbook for 2026
Executives should prioritize a triaged set of actions to convert the market’s growth into durable revenue streams and competitive advantage:
-
Clinical evidence acceleration: Invest in pragmatic trials and registries that align tightly with guideline committees’ evidence requirements (comparative effectiveness, hCG normalization metrics, safety in fertility-preserving contexts).
-
Guideline-first market access: Coordinate publication, consensus engagement and payer dossiers to translate guideline mentions into reimbursement pathways rapidly.
-
Supply and specialty channel optimization: For injectable and chemotherapy suppliers, secure hospital-level contracts, stock reliability assurances and educational outreach to key referrers (maternity units, gynecologic oncology centers).
-
Label-extension and lifecycle planning: For companies with checkpoint inhibitors or biologics, map out evidence strategies to move from trial/compassionate use into formal indications or strong place-in-therapy positions.
What PW Consulting's full GTD report delivers
Our complete market study translates the strategic implications above into executable deliverables for 2026 action plans. The full report includes:
-
Proprietary market model with historical (2020–2025) and forecast (2026–2032) line items, sensitivity analyses and scenario outputs you can plug into investment and portfolio models.
-
Regulatory and guideline timelines with jurisdiction-by-jurisdiction access risk scoring and payer-impact matrices.
-
Detailed competitor dossiers and capability maps — from branded immunotherapies to generic injectables — with candidate go-to-market scenarios and partner/opportunity heatmaps.
-
Actionable commercial strategies: three prioritized GTD go-to-market playbooks (originator-led, generics optimizer, and innovator entry) with staffing, evidence, and budget estimates for initial 24-month rollouts.
-
Center-of-excellence and referral network analysis identifying clinical nodes where investments in medical-education and access programs yield highest ROI.
Recommended next steps for 2026 corporate planning
-
Sponsor an evidence-acceleration workshop this quarter to align clinical, HEOR and market-access teams around priority trials and registry designs that can convert into payer-friendly endpoints.
-
Complete a short-list of partnership targets across injectables manufacturers, specialty distributors and academic centers to de-risk supply and speed center penetration.
-
Run a rapid payer-scenario simulation using our forecast model to stress-test pricing and reimbursement assumptions under alternative guideline adoption trajectories.
Closing note
The GTD market is at an inflection where focused clinical evidence and smart access strategies will create disproportionate returns for companies that act this year. PW Consulting’s full report provides the granular segmentation, modeled scenarios, and playbooks required to make those moves with confidence. For executives preparing budgets, M&A screens, or late-stage development plans in 2026, this is a market where timing, evidence design, and partnership selection will decisively shape who leads the next phase of growth.
Access the full dataset and executable appendices on our report page to unlock the segment-level detail and downloadable models that enable immediate implementation.
For detailed analysis of this topic, please visit the official page: Gestational Trophoblastic Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Desktop Refractometers Market to reach USD 641.05M by 2032 at 5.18% CAGR
By PW Consulting, 2026-07-13
Desktop Refractometers Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As laboratory instrumentation budgets tighten and quality-control expectations rise across food, medical and industrial end markets, desktop refractometers have moved from specialist bench-top tools to mission-critical instruments embedded in routine workflows. PW Consulting’s latest market study finds that the global desktop refractometers market reached approximately USD 450 million in the base year (2025) and is positioned to expand at a steady compound annual growth rate (CAGR) of 5.18% through the 2026–2032 forecast horizon, approaching the mid-hundreds of millions by 2032. This briefing summarizes the strategic takeaways our report delivers for executives planning investments, partnerships, and product roadmaps in 2026 — without disclosing the proprietary segment tables and granular breakdowns reserved for the full report.
Desktop Refractometers Market
Why this study matters for 2026 planning
-
Durable demand drivers: Refractometry remains a low-friction measurement method with enduring relevance in QA/QC, clinical diagnostics (where specific reimbursement and coding regimes apply), and research settings. That persistence creates predictable replacement cycles that underpin recurring service, calibration and consumable revenue streams.
Desktop Refractometers Market -
Technology migration and product differentiation: The market shows continued migration toward digital, automated desktop instruments where usability, multi-scale measurement, and temperature control are competitive differentiators. Winning in 2026 will depend on translating measurement accuracy into workflow value (connectivity, LIMS integration, governed user experiences).
Desktop Refractometers Market -
Profitability levers are shifting: Optical components and precision prisms remain a critical cost driver in unit economics, and choices on materials and sourcing materially affect margin profiles and total cost of ownership offered to customers.
What the full PW Consulting report contains (practical, operational tools)
-
Market sizing and validated forecasts (historical 2020–2025 baseline, forward 2026–2032 scenarios) with an integrated financial model you can adapt for board-level planning.
-
Scenario playbooks: three operational scenarios (defensive, base, growth) that map demand, pricing, and supply constraints to measurable KPIs and P&L impacts — designed for rapid sensitivity testing ahead of capital allocation.
-
Go-to-market blueprints: channel strategies for direct vs. distributor models, service and calibration network economics, and a commercialization checklist to accelerate uptake in clinical and industrial accounts.
-
Technology and product roadmaps: feature-prioritization matrices (e.g., multi-wavelength capability, temperature control, touchscreen UX, connectivity standards), recommended R&D staffing mixes, and a pricing ladder to protect ASPs while capturing add-on service revenue.
-
Supply chain and procurement playbook: critical-component risk heatmaps, sourcing strategies for high-value optical elements, and tactical levers (dual-sourcing, strategic inventory, supplier JIT agreements) to reduce lead-time volatility.
-
M&A and partnership targets: a short-list of niche innovators, calibration-service consolidators, and digital-data players whose integration could accelerate platform value — accompanied by estimated deal-sizing frameworks and integration risks.
-
Regulatory and reimbursement navigation: practical guidance for meeting clinical laboratory quality standards, and for positioning products to be compatible with reimbursable workflows where applicable.
Market structure and competitive posture
The market is best described as moderately consolidated: market-leading suppliers command a meaningful share of global revenue, while a mid-tier of regional specialists and OEM suppliers capture the balance. The top-three suppliers together account for a substantial portion of the market, and the top-five extend that concentration further — a dynamic that favors scale players able to sustain R&D and global service networks, while creating openings for agile specialists that focus on verticalized solutions and service-led differentiation.
Competitive landscape — what to watch in 2026
-
Atago Co., Ltd. (Tokyo, Japan) — Strengths: scale in desktop refractometers, strong product portfolio across clinical and industrial lines, recognized for precise Brix and refractive-index offerings. Watch: Atago’s recent RX-5000α-Plus launch (enhanced touchscreen and expanded clinical scales) signals a continued push on user experience and clinical adjacencies. Strategic implication: incumbents must match UX and scale serviceability to defend clinical lab share.
-
Rudolph Research Analytical (New Jersey, USA) — Strengths: laboratory-grade instruments with strict compliance and temperature control; known for USP/EP-capable models. Watch: Certification updates in 2024 reinforce Rudolph’s positioning for regulated pharmaceutical customers. Strategic implication: compliance-oriented features can justify premium pricing in regulated channels but require focused regulatory support and documentation.
-
Anton Paar GmbH (Graz, Austria) — Strengths: premium research-grade refractometers and multi-wavelength instruments for pharmaceutical and chemical QC. Watch: trade show activity and presentation of the Abbemat family at major medical events underscores a demand-driven R&D cadence. Strategic implication: differentiation through measurement breadth (multi-wavelength) is a viable route to higher ASPs in research applications.
-
Mettler Toledo (Greifensee, Switzerland) — Strengths: broad laboratory equipment footprint and strong channel access in clinical and pharmaceutical markets. Strategic implication: integration into broader lab ecosystems (scales, balances, analytics) is a competitive moat; smaller vendors should pursue API and data-standards compatibility to retain customers.
-
Schmidt + Haensch (Berlin, Germany) — Strengths: specialized optical manufacturing and niche laboratory solutions, particularly for diagnostics and beverages. Strategic implication: niche leaders can leverage domain expertise (e.g., beverage analytics) to sustain higher margins and loyal customer bases.
-
Bellingham + Stanley / Xylem Analytics (Tunbridge Wells, UK) — Strengths: industrial and clinical desktop models with an emphasis on accuracy and robustness. Strategic implication: combining industrial-grade reliability with clinical usability is a narrow but effective band for differentiation.
Regulatory, reimbursement and supply considerations
-
Quality frameworks: Desktop refractometers used in clinical settings must align with contemporary laboratory quality standards (for example, ISO 15189), which affects product documentation, validation packages, and post-market surveillance expectations.
-
Reimbursement touchpoints: specific procedural codes exist that cover refractometry in certain clinical workflows; aligning product positioning to those workflows can improve hospital procurement economics and shorten sales cycles.
-
Component risk: high-precision optical components (e.g., prism assemblies) are a non-trivial portion of bill-of-materials cost and require strategic procurement. Manufacturers should evaluate long-term supply agreements, qualification of alternate materials where appropriate, and the total lifecycle cost to customers (durability, sterilizability, warranty).
-
Regulatory limitation on direct use: desktop models are intended for laboratory research and clinical measurement; they are not typically cleared for direct patient contact without appropriate encapsulation and validation — a restraint that shapes product form-factor and service models.
Strategic plays for 2026 — recommended actions
-
Invest selectively in digital differentiation: Prioritize connectivity (secure LIMS integration, cloud-based calibration logs), advanced UI, and automated temperature compensation — features that buyers are increasingly valuing over raw hardware specs.
-
Lockdown optical supply lines: Negotiate multi-year agreements, consider co-investing in supplier capacity, and validate alternative materials to reduce single-source risk on critical prisms and optical assemblies.
-
Service and consumables as recurring revenue: Expand calibrated service networks, subscription calibration plans, and consumable programs to improve customer stickiness and predictability of revenue.
-
Pursue regulatory-first productization: For players targeting clinical labs, invest in validation documentation and post-market support to shorten procurement cycles and position for higher ASPs.
-
Evaluate tuck-in M&A for capability gaps: Acquire niche measurement-tech startups, calibration networks, or software providers to accelerate platform capability and expand routes to market without a multi-year organic R&D timeline.
How to use PW Consulting’s analysis in your 2026 planning cycle
-
Board-level investment cases: use the report’s integrated financial model and scenario outputs to stress-test capex and R&D requests against three demand scenarios.
-
Commercial planning: adopt the go-to-market playbooks to align sales incentives, distributor coverage, and service capacity ahead of product launches.
-
Procurement and supply security: implement the supplier risk matrix and procurement playbook to mitigate optical-component shortages and reduce lead-time exposure.
-
M&A diligence: leverage our short-listed targets and integration checklists to accelerate deal screening and post-merger integration planning.
Conclusion and next steps
The desktop refractometers market offers predictable growth driven by durable use-cases across clinical, food & beverage, and industrial laboratories. Scale players will continue to leverage breadth and service networks, while specialist vendors that tightly couple measurement capability with workflow integration can capture disproportionate value. For executives planning 2026 resource allocation, the strategic priorities are clear: accelerate digital and compliance-enabled differentiation, harden supply chains for optical components, and convert one-time hardware sales into recurring service revenue.
PW Consulting’s full Desktop Refractometers Market report contains the proprietary segmentation, district- and application-level analytics, and downloadable financial models that operational teams and boards need to execute these strategies. Access the complete study and our scenario models at the report landing page to unlock the data-backed, executable intelligence behind this briefing.
For detailed analysis of this topic, please visit the official page: Desktop Refractometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stabilizer Bars Market to reach USD 8,678 Million by 2032 at 4.8% CAGR
By PW Consulting, 2026-07-13
Stabilizer Bars Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
The stabilizer bars market has demonstrated steady expansion through the recent cyclical period and is poised for continued growth across the coming decade. Our consolidated market model shows the global market rising from approximately USD 5.1 billion in 2020 to USD 6.25 billion in the base year 2025, and—under the central scenario—reaching nearly USD 8.68 billion by 2032. The forecast period (2026–2032) carries a compound annual growth rate (CAGR) of 4.8%. These headline figures provide a reliable anchor for capital allocation, product roadmap decisions, and commercial strategies in 2026.
Stabilizer Bars Market
Why this brief matters for 2026 decision-makers
-
Timing capital: With predictable mid-single-digit CAGR, CFOs can size near-term investments (tooling, plant capacity, automation) against a modest but resilient growth backdrop rather than a binary boom-or-bust outlook.
Stabilizer Bars Market -
Product prioritization: OEMs and Tier-1 suppliers face a clear trade-off between legacy solid designs and lightweight hollow or active stabilizer solutions driven by electrification and fuel economy regulations. The market-level growth masks important margin differentials tied to technical complexity — a key input for 2026 R&D budgets.
Stabilizer Bars Market -
Commercial playbooks: Procurement and pricing teams must incorporate raw-material sensitivity and tariff exposure into 2026 agreements. Our analysis illustrates how steel price cycles and policy actions materially affect supplier economics even when end-market demand is steady.
Market dynamics shaping 2026 strategy
Several converging forces will determine winners and losers in the next 12–24 months:
-
Cost-pressure meets technical premium. Volatility in hot-rolled coil pricing (European averages around 650 EUR/mt in late 2023) and enduring trade measures (e.g., US steel tariffs) increase the importance of raw-material hedging, regional sourcing, and design-for-cost. At the same time, lightweight and active stabilizer systems command material and engineering premiums that improve product margins when adopted at scale.
-
Vehicle mix and regulatory drivers. Global passenger car production remains a critical demand lever (roughly 66 million units in 2023), while safety and structural regulations (such as roof-strength standards) continue to reinforce demand for robust, high-quality stabilizer components. OEM platform decisions on electrification and chassis architectures will disproportionately benefit suppliers who can deliver lightweight, integrated modules.
-
Technology substitution and differentiation. Hollow, cold-formed, and active stabilizer architectures offer substantial mass reduction (technical literature cites weight cuts up to ~40% versus traditional solid designs). The adoption curve for these technologies is uneven across vehicle segments and geographies; therefore, strategic bets on tooling and R&D should be calibrated by expected adoption timing rather than purely by headline growth.
-
Supply-chain localization. Geopolitical friction and tariffs are driving OEMs and Tier-1s to accelerate regional sourcing. For 2026, companies with nimble footprint strategies and the ability to reallocate capacity quickly will be best placed to capture near-term share shifts without incurring margin erosion.
Competitive landscape — what to watch in 2026
The sector presents a moderately concentrated topology: the three largest players account for a meaningful but not overwhelming share of global sales, while the top five players approach a plurality. This structure produces a mix of scale-driven competition and technical differentiation.
-
ZF Friedrichshafen AG — Global leader in chassis systems, increasingly positioning active stabilizer technologies (e.g., showcased active systems at industry events). Their scale and OEM relationships make them a strategic partner for OEMs seeking integrated chassis solutions.
-
Magna International Inc. — Offers end-to-end stabilizer systems via multiple divisions, deploying integration capabilities as a competitive moat for body and chassis modules. Their global manufacturing footprint and systems approach are relevant for OEMs consolidating suppliers.
-
Tenneco Inc. — Focused on ride-control components, Tenneco competes on breadth of product portfolio and aftermarket reach. Their exposure to commercial vehicle platforms is a differentiator where product lifecycles and replacement demand matter.
-
Benteler, thyssenkrupp Steel, Mubea — These firms illustrate two complementary strategic vectors: lightweight tubular and hollow-product engineering (Benteler, Mubea) and advanced material supply (thyssenkrupp). Recent product launches targeting electric-vehicle architectures and investments in hollow designs are tactical responses to OEM weight-reduction mandates.
-
Regional specialists (Hyundai WIA, NHK Spring, Chuo Spring, Dura Automotive) — Strong OEM ties and focused manufacturing competence enable them to defend regional share and provide localized design variants; strategic partnerships or M&A could expand their reach into adjacent vehicle segments.
Recent corporate moves underscore the market’s direction: active stabilizer demonstrations by major chassis suppliers signal growing OEM interest in smart chassis control; product launches of lightweight hollow bars targeted at EVs indicate early monetization routes for higher-margin designs; and capacity expansions in North America underscore near-term localization trends. For 2026, these actions foreshadow where competitive pressure and margin opportunities will concentrate.
What the full PW Consulting report provides (practical deliverables)
This research is designed as an operational playbook, not an academic thesis. Key deliverables include:
-
Comprehensive market model (2020–2032): consolidated historicals and forward scenarios with sensitivity to vehicle production, weight-reduction adoption, and raw-material cost trajectories. Headline totals are provided in USD Million; detailed subsegment revenue tables and supplier-level splits are included in the full report.
-
Supplier scorecards: capability maps, capacity footprints, technology investments, and likely OEM affinity. Scorecards enable rapid vendor shortlisting for sourcing and M&A due diligence.
-
Raw-material & tariff impact simulator: pass-through matrix and scenario runs (steel price spikes, tariff changes) to quantify margin pressure and required price adjustments.
-
Product-strategy playbooks: go-to-market approaches for hollow vs. solid vs. active stabilizer offerings, including recommended R&D priorities, localization strategies, and integration opportunities with broader chassis systems.
-
M&A and partnership screening tool: prioritized targets by strategic fit (technology, regional footprint, customer base) with indicative valuation ranges under multiple synergy assumptions.
-
Operational risk heatmap: near-term supply constraints, regulatory exposures, and demand-shock scenarios with mitigation actions and trigger points for senior management.
Note: in keeping with the “preview” purpose of this brief, we intentionally withhold proprietary subsegment tables and supplier revenue splits here. Those detailed datasets are available in the full PW Consulting report and are meant to support direct commercial and investment decisions.
Practical 2026 use cases — how clients are applying these insights
-
Procurement teams create multi-year contracts incorporating steel-price collars and regional escalation clauses to protect margins while ensuring supply continuity.
-
Product planners prioritize hollow/active stabilizer modules on platforms slated for electrification to capture lifecycle cost and efficiency gains.
-
Corporate development groups use our supplier scorecards and M&A screening to fast-track bolt-on acquisitions that add hollow-manufacturing capability or regional capacity.
-
Investors and private-equity sponsors model downside scenarios driven by regulatory or tariff shocks, informed by our raw-material sensitivity simulator and supply-chain localization analysis.
Methodology & data integrity
The analysis is grounded in a triangulation of sources: OEM production and platform roadmaps, supplier financials, industry-standard steel pricing benchmarks, public regulatory texts, targeted interviews with Tier-1 procurement and engineering leads, and event-driven intelligence (product launches, capacity announcements). Our base-year construct uses 2025 as the frame of reference, historical observations cover 2020–2025, and forecasts span 2026–2032 under three bespoke scenarios. Revenue units are presented in USD Million. We perform regular back-testing and sensitivity runs to ensure robustness versus fast-moving inputs such as raw-material cost swings and tariff actions.
Final thought — the strategic inflection point for 2026
For executives planning budgets and strategic moves in 2026, the stabilizer bars market offers a window of opportunity: steady headline growth gives room to pursue structural shifts—lightweighting, active control, and regional manufacturing—without the pressure of hyper-growth competition. The strategic priority is to convert engineering differentiation into sustainable commercial advantage while insulating margins from material and policy volatility.
PW Consulting’s full Stabilizer Bars Market Report delivers the granular, transaction-ready intelligence needed to execute those choices. For access to the complete dataset, supplier revenue splits, and executable playbooks, request the full report via the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page: Stabilizer Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acute Care Telemedicine Market USD 27,450.5M (2025), 14.82% CAGR
By PW Consulting, 2026-07-13
Acute Care Telemedicine Services Market: Strategic Insights for 2026 Decision-Making
As healthcare systems, payers, and technology vendors confront accelerating demand for remote acute care, the Acute Care Telemedicine Services market is transitioning from a disruptive experiment to an operational imperative. Our latest PW Consulting market research frames this evolution with a clear, investment-grade narrative: the market expanded from roughly USD 20.85 billion in 2023 to an estimated USD 27.45 billion in 2025, and is on a trajectory—driven by clinical adoption, platform maturation, and shifting reimbursement—to exceed USD 72.13 billion by 2032 at a compound annual growth rate (CAGR) of 14.82% (USD, revenue in Million). For executives making 2026 strategy choices, this study is designed to convert that trajectory into near-term advantage while protecting the confidential tactical data that drive competitive differentiation.
Acute Care Telemedicine Services Market
Why 2026 Is a Pivotal Inflection Point
-
Policy and payment clarity will shape capital allocation. Temporary reimbursement policies and state-level licensure reforms are converging toward a new baseline in many markets; decisions made in 2026 will lock in network architectures and contract structures for multiple years.
Acute Care Telemedicine Services Market -
Service model experimentation gives way to scale economics. Early adopters who invested behind proof-of-concept programs in 2022–2024 are now facing operational choices—centralized command centers, hybrid hub-and-spoke architectures, or on-demand staffing—that determine margin capture.
Acute Care Telemedicine Services Market -
Talent and technology constraints are now visible operational risks. Physician shortages and specialist sourcing have already elevated staffing costs and will meaningfully affect unit economics unless mitigated by automation, novel contracting, or cross-state licensing strategies.
Market Trajectory – What the Numbers Tell Us
The reported growth path is not academic: rising from approximately USD 20.85B (2023) to USD 27.45B (2025) signals solid commercial validation across multiple acute-care specialties and hospital settings. The forecast CAGR of 14.82% to 2032 encapsulates sustained demand for tele-ICU, tele-stroke, emergency telemedicine, and other acute modalities as hospitals prioritize throughput, specialist access, and cost avoidance. By 2026 the market is projected to accelerate further—an indicator that 2026 investments will be the fulcrum for capturing scale-related benefits.
Strategic Imperatives for 2026
-
Design for interoperability, not lock-in. Buyers should insist on open APIs, standards-aligned streaming and data exchange, and modular contracting to preserve optionality as clinical workflows adapt.
-
Prioritize clinical ROI over tech novelty. Procurement decisions must be driven by measurable improvements in time-to-treatment, transfer avoidance, and length-of-stay deflection rather than feature checklists alone.
-
Build hybrid operational models. A blend of hub-and-spoke command centers for high-acuity coverage plus localized on-demand services for episodic surges balances cost and responsiveness.
-
Lock down workforce strategies now. Given documented staffing pressures and attendant 15–20% increases in clinician cost in certain settings, organizations should pursue a mix of domestic centralized staffing, locum models, and targeted international partnerships where regulatory and quality frameworks permit.
Competitive Landscape — Who Matters and Why
The sector’s commercial dynamics are shaped by a mix of specialist acute-care providers, digital platform vendors, and integrated health systems. Market concentration is moderate: the top three providers account for a meaningful share of supply while the top five control a majority, indicating room for both scale players and focused specialists.
-
Access TeleCare (Dallas, TX; https://accesstelecare.com) has repositioned itself as a multi-specialty acute telemedicine provider and now emphasizes 24/7 coverage across neurology, psychiatry, critical care and ED support—an approach that favors health systems seeking a single-vendor clinical stack.
-
Eagle Telemedicine (Leawood, KS; https://eagletelemedicine.com) focuses on hospitalist and intensivist services for rural and critical-access hospitals, a profile that aligns with providers prioritizing continuity and local integration over broad platform features.
-
Avera eCare (Sioux Falls, SD; https://www.avera.org/ecare) operates one of the largest acute telemedicine networks, offering command-center models and extensive inpatient coordination—an attractive partner for regional systems scaling clinical oversight.
-
Teladoc Health (Purchase, NY; https://www.teladoc.com) and Amwell (Boston, MA; https://business.amwell.com) have leveraged platform capabilities to serve enterprise hospital customers with tele-stroke, tele-ICU, and ED physician support; their strengths lie in technology depth and integration potential.
-
Sound Physicians (Tacoma, WA; https://soundphysicians.com) integrates tele-hospitalist services into broader acute care management programs, offering a blend of clinical management and on-site services that appeals to system-level purchasers.
Recent moves—rebranding, geographic expansion, and partnerships—signal competitive jockeying for scale and specialty depth. Examples include Access TeleCare’s rebrand to emphasize broader capabilities (Nov 2023), Eagle Telemedicine’s regional expansion (Jan 2024), and Avera eCare’s partnership to bolster rural ED coverage (Jun 2024). These maneuvers are early indicators of the consolidation and alliance strategies likely to intensify through 2026.
What This Report Contains — Actionable Frameworks (Not Just Charts)
-
Commercial models and financial templates calibrated to acute care use cases, enabling CFOs to build 36–60 month P&L scenarios tied to utilization, staffing, and reimbursement sensitivity.
-
Buyer’s playbook for technology selection, including an interoperability checklist, security and latency thresholds, and a vendor scorecard tailored to acute workflows.
-
Regulatory and reimbursement maps that translate federal guidance, state licensure nuances, and accreditation requirements into executable compliance steps for 2026 deployments.
-
Operational blueprints for hub-and-spoke and hybrid delivery models, with staffing templates, escalation protocols, and KPI dashboards designed to shorten time-to-value.
-
Vendor landscape analysis with strategic options (partner, build, acquire) and decision trees for hospital systems, payers and technology vendors.
-
Practical risk matrices covering cybersecurity, clinical governance, and workforce fragility—and mitigation playbooks aligned to senior leadership priorities.
Regulatory, Reimbursement and Standards Dynamics
-
Reimbursement momentum has been supportive—but not permanent. For example, Medicare Part B parity for certain acute telemedicine modalities was extended through the end of 2024; future determinations will influence hospital contracting and capital planning.
-
Cross-state licensure remains a gating factor. Compliance options include state licensure, participation in the Interstate Medical Licensure Compact, and targeted MARs—each with implications for speed to scale.
-
Clinical standards matter. Platforms must meet minimum bandwidth and video-resolution standards as defined by clinical societies to be safe and defensible in high-acuity scenarios.
-
Accreditation expectations are rising: The Joint Commission now expects telehealth programs delivering acute care to adhere to validated safety and quality standards—an operational requirement that influences vendor selection and program governance.
Scenarios and Use Cases—How to Translate Insight into Decisions
-
Scenario A—Rapid Scale: For systems aiming to centralize acute coverage, the study provides phased investment schedules, vendor interoperability requirements, and staffing roadmaps that deliver break-even timelines tied to transfer-avoidance and reduced ICU LOS.
-
Scenario B—Targeted Specialty Rollout: For organizations prioritizing tele-stroke and tele-ICU, the research prescribes technology minimums, partner selection criteria, and outcome-linked contracts for specialty groups.
-
Scenario C—Rural Safety Net: For rural hospitals and health systems, the report identifies partnership archetypes and shared-service models that offset specialist scarcity while preserving local governance.
How Senior Leaders Should Use This Research in 2026
-
C-Suite: Use the strategic options and financial templates to set five-year capital and operating budgets that reflect realistic adoption curves and regulatory scenarios.
-
Procurement & IT: Apply the vendor scorecard and interoperability checklist to upcoming RFPs to avoid costly lock-in and to ensure clinical-grade performance.
-
Clinical Leaders: Leverage the KPI dashboards, accreditation playbook and staffing templates to operationalize quality metrics and control clinical risk.
-
Investors & M&A Teams: Use the competitive landscaping and concentration indicators to prioritize targets and bid strategies that capture consolidation upside or defend against it.
Next Steps and Where to Find the Full Intelligence
This introduction outlines the strategic contours that matter most for 2026 planning—market scale, growth dynamics, competitive moves, and the policy landscape. PW Consulting’s full report contains the proprietary segment models, vendor level scorecards, and executable financial templates that operational teams and boards need to move from intent to execution. To access the complete dataset, scenario models, and implementation-ready tools, please refer to the report landing page linked in our release notes.
In 2026, the winners will be those who convert macro momentum into predictable operations—balancing clinician capacity, regulatory certainty, and interoperable technology while preserving the clinical governance that acute care demands. PW Consulting’s Acute Care Telemedicine Services market research is built to accelerate that transition without exposing the granular segmentation that differentiates proprietary strategies.
For detailed analysis of this topic, please visit the official page: Acute Care Telemedicine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Utility Monitoring System Market to Hit USD 16,155.5M by 2032 (14.33% CAGR)
By PW Consulting, 2026-07-13
Water Utility Monitoring System Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, actionable briefing that frames the strategic choices utilities, vendors, and investors must make in 2026. Our full Water Utility Monitoring System Market study provides the data, vendor scorecards, and executable templates behind these conclusions. This article illustrates the market trajectory, the forces shaping competitive advantage, and the practical actions that deliver measurable ROI — while intentionally omitting the granular segmentation tables and proprietary forecasting matrices that drive procurement and M&A plays (those are available in the full report).
Water Utility Monitoring System Market
Market Trajectory — why 2026 is a pivotal inflection point
The global water utility monitoring systems market has moved from an early-adopter phase into a rapid commercial scaling stage. Our model shows the market expanding from roughly USD 3.45 billion in 2020 to about USD 6.33 billion in 2025, and projecting to exceed USD 16.15 billion by 2032. This translates into a robust compound annual growth rate of approximately 14.33% across the 2026–2032 forecast window. For corporate strategists and utility executives, that means the financial and competitive consequences of decisions made in 2026 will compound materially over the next decade.
Water Utility Monitoring System Market
- Demand is driven by a confluence of regulatory pressure, asset renewal cycles, drought and climate adaptation planning, and the imperative to curb non‑revenue water.
- Technology maturation — particularly cloud platforms, digital twins, and edge-sensor analytics — is lowering the marginal cost of actionable monitoring while raising the value of services layered on top of raw telemetry.
- Cybersecurity, spectrum and telecom policy, and workforce shifts are emerging as strategic constraints — not just implementation details.
Practical contents of the PW Consulting study (what you will actually use)
Our report is designed as a decision-support toolkit, not a theoretical treatment. Key deliverables include:
Water Utility Monitoring System Market
- Proprietary market model and scenario engine (base case, accelerated digital adoption, and constrained-capex scenarios) with downloadable inputs you can re-run for your planning.
- Go-to-market playbooks for vendors (product roadmaps, pricing levers, partnership archetypes) and adoption roadmaps for utilities (pilot design, procurement language, and O&M handoffs).
- Vendor risk and capability scorecards with mapped strengths, blind spots, and likely consolidation targets (highly actionable for sourcing teams and corporate development).
- Regulatory-impact matrix and compliance checklist, covering critical infrastructure guidance, data residency, spectrum allocation, and cybersecurity requirements that shape procurement and operations.
- Sample financial models: CapEx-to‑Opex conversion scenarios, life‑cycle TCO templates, and NPV-based ROI thresholds tailored to water utility budgeting windows.
- Implementation playbooks and change-management checklists covering labor reallocation, training, and vendor-managed services contracting.
Competitive landscape — who matters and why (strategic implications)
The vendor ecosystem blends traditional instrumentation and SCADA leaders with metering specialists and software-first entrants. In broad strategic terms:
- Metering specialists with strong AMI/AMR portfolios are doubling down on communications modules and analytics to move up the value chain from devices to outcome-based services. Expect continued investment in leak detection, automated interval reads, and field-hardened wireless nodes.
- Large industrial automation and energy players are leveraging their SCADA, control systems, and cybersecurity capabilities to capture utility-level monitoring and process-control work, particularly in treatment plants and pumping stations.
- Pure-play digital vendors and cloud platform providers are the catalyst for digital twin and GIS-based monitoring adoption; their advantage is rapid feature rollouts and low marginal deployment costs, but they must demonstrate operational resilience in regulated utility environments.
Representative strategic profiles (non-exhaustive):
- Established metering firms are extending into adjacent sensing (e.g., sewer and manhole monitoring) and analytics through M&A and targeted product extensions — a clear signal that meter-plus-service bundles will be a durable commercial model.
- Automation conglomerates are integrating AI-enabled predictive modules and emphasizing cybersecurity features, positioning themselves for large-scale municipal and industrial deals where integration risk is a key buying criterion.
- Regional vendors and network specialists maintain advantage on last-mile communications and regulatory compliance in territories where spectrum policy or telecom regulation governs IoT deployments.
Recent industry moves underscore these dynamics: acquisitions to broaden sensing portfolios, product launches embedding advanced cybersecurity and AI for predictive operations, and strategic partnerships to deploy AMI modernization projects with finer time-series data granularity. Each action suggests vendors are competing on bundled outcomes — not just meters or SCADA systems — which changes procurement evaluation criteria.
Regulatory and operational constraints shaping 2026 choices
- Cybersecurity for water infrastructure has risen to a national-policy priority. Utilities and vendors must design systems with network segmentation, encrypted telemetry, and continuous monitoring as baseline requirements — not premium options.
- Funding pressures and aging assets create competing priorities: replacing physical infrastructure vs. investing in digital overlays. Many jurisdictions face infrastructure funding gaps running into the high hundreds of billions, which will drive phased deployments and creative financing structures.
- Spectrum allocation and telecom policy — from LoRaWAN and NB‑IoT licensing to local data privacy rules — materially affect communications architecture and recurring connectivity costs. Local regulatory constraints will dictate whether private networks, utility-owned radios, or carrier IoT services are practical.
- Labor economics: digital metering reduces manual reading headcount but reallocates spend to cybersecurity, data operations, and vendor service contracts. Workforce transition plans are a non-trivial part of the ROI calculus.
Strategic recommendations for executives — 90-day to 36-month actions
To convert market growth into sustainable advantage in 2026, PW Consulting recommends a layered, risk-aware approach:
- First 90 days — Prepare: Run the scenario engine using your utility-specific inputs; audit telemetry security posture; shortlist two pilot sites with clear performance KPIs (leak reduction, meter-to-cash improvement, or sampling frequency uplift).
- 3–12 months — Pilot and procure: Deploy a time‑phased AMI/monitoring pilot with an incumbent-neutral tender that evaluates device performance, network economics, and vendor SLAs; include clauses for data ownership and cybersecurity audits.
- 12–36 months — Scale and transform: Move from CAPEX-heavy purchases toward hybrid procurement (meter-as-a-service, managed analytics). Invest in digital twins for high‑risk network segments and operationalize predictive maintenance workflows to shift O&M budgets to pre-emptive interventions.
For vendors and investors, the essential moves are:
- Develop outcome-based contracting capabilities (performance guarantees tied to NRW reduction or meter-read accuracy).
- Invest in hardened, certifiable cybersecurity stacks and background compliance artifacts to shorten procurement cycles with regulated buyers.
- Pursue horizontal partnerships (telecoms, cloud providers, local integrators) rather than attempting to own every layer; the winner will be the one that orchestrates a reliable, low-friction stack.
- Use M&A selectively to fill sensing or software gaps, focusing on assets that enable recurring-service revenue rather than one-time hardware sales.
What the full PW Consulting report will enable you to do
Executives who use our full deliverable will be able to:
- Build a defensible, board-ready digital water investment case with detailed TCO and phased payback scenarios;
- Write procurement specifications and KPIs that avoid common traps (vendor lock-in, insufficient cybersecurity, ambiguous data rights);
- Identify high-probability acquisition targets and partnership archetypes based on capability gaps in device, network, or software layers;
- Quantify upside and downside risks across multiple adoption curves and negotiate SLAs that align incentives for long-term network performance.
Final thought — why 2026 decisions compound value
The market’s projected growth trajectory and accelerating technological maturity mean that near-term choices will determine competitive positioning for at least a decade. Suppliers that move from selling hardware to delivering measurable operational outcomes will capture the most durable value. Utilities that treat monitoring systems as strategic infrastructure — integrating cybersecurity, procurement discipline, and workforce transition plans — will realize the fastest, most defensible improvements in service reliability and financial performance.
PW Consulting’s full Water Utility Monitoring System Market report contains the granular forecasts, vendor ratings, procurement templates, and regulatory mappings necessary to act with confidence in 2026. For teams preparing RFPs, planning pilots, or scoping M&A, the report converts market insight into executable programs. Visit our research portal for access to the full dataset and implementation playbooks.
For detailed analysis of this topic, please visit the official page: Water Utility Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Enzymes for Fuel Ethanol market to hit USD 2,175.8M by 2032 at 6.3% CAGR
By PW Consulting, 2026-07-13
Enzymes for Fuel Ethanol: Strategic Outlook for 2026 Decision-Makers
Executive summary
As fuel ethanol producers, enzyme suppliers, investors and policy teams prepare strategic plans for 2026, the enzymatic landscape that underpins conversion efficiency, feedstock diversification and carbon intensity improvement is evolving from process optimization into a competitive axis that determines plant economics and market access. Our market tracking places the global enzymes-for-fuel-ethanol market on a robust growth trajectory from a 2025 base year to 2032, with a multi-year compound annual growth rate (CAGR) of 6.3%. The market’s momentum reflects technology-led yield improvements, regulatory incentives for lower-carbon pathways, and consolidation among upstream enzyme specialists.
Enzymes For Fuel Ethanol Market
Why this analysis matters for decisions made in 2026
Decisions taken in 2026—whether to retrofit plants, commit to multi-year enzyme contracts, invest in cellulosic demonstrations, or pursue M&A—will determine competitive position for the next decade. The commercial levers are now tightly coupled to enzyme strategy: enzymes influence conversion yield, energy use (and therefore operating cost), and carbon intensity scores that feed into tax credits and renewable fuel credit pricing. This report distills the operational, commercial and regulatory signals companies need to convert a rising top-line market into durable margin uplift.
Enzymes For Fuel Ethanol Market
Market trajectory and defining metrics
Using 2025 as the base year, the market is sized and tracked on an annualized basis through 2032. By 2025 the industry reached a substantial market value in USD terms and is forecast to nearly double in value by 2032, in line with the 6.3% CAGR cited above. The trajectory reflects a combination of steady growth in conventional starch-to-ethanol production and faster growth in enzyme demand tied to advanced processes—cellulosic coproducts, corn fiber conversions and enzyme-enabled energy efficiency upgrades.
Enzymes For Fuel Ethanol Market
Market concentration is meaningful: the top three players control a large majority of the commercially available enzyme volume, with the top five representing an even greater share. That concentration creates both supply risk and margin pressure for buyers, but it also creates strategic gateways for entrants who can demonstrate differentiated performance or cost-to-benefit profiles.
Key forces shaping enzyme demand (what to watch in 2026)
- Regulatory incentives and credit mechanisms: Recent regulatory shifts enable co‑production pathways that materially change project economics. A notable example is U.S. guidance permitting corn kernel fiber-based co-production to qualify for cellulosic Renewable Identification Numbers (D3 RINs). In practical terms, this translated to additional revenue opportunities on the order of tenths of a dollar per gallon in 2025 (D3 RINs traded at materially higher levels versus conventional credits), reshaping the ROI calculus for enzyme-enabled upgrades.
- Policy-linked capital structures: Tax credits and clean fuel incentives (including recent modifications connected with the Inflation Reduction Act and the 45Z-style Clean Fuel Production Credit) favor pathways that reduce carbon intensity. Enzyme technologies that enable higher yields, lower process energy, or enable cellulosic coproducts become financeable at different cost of capital—an increasingly important consideration when sizing retrofit CAPEX in 2026.
- Feedstock and conversion efficiency: Corn remains dominant in key producing markets, and enzymatic improvements have incrementally raised ethanol yield-per-bushel over recent seasons. Operational gains—measured in marginal gallons per bushel—compound at scale and quickly translate to plant-level margin expansion.
- Consolidation and scale-up dynamics: The supplier landscape is becoming more concentrated. Strategic acquisitions and alliances are accelerating the integration of enzyme discovery, formulation and industrial-scale supply chains, squeezing out smaller suppliers but also opening partnership pathways for technology integrators.
Competitive landscape: positioning and playbooks
The enzyme supplier set includes global incumbents that combine R&D, process engineering and distribution capability, regional specialists focused on cost-competitive formulations, and enzyme engineering firms delivering bespoke catalysts for cellulosic and low‑temperature processes. Key profiles and strategic implications:
- Novonesis (formerly Novozymes): A global leader with deep product breadth across alpha‑amylases, glucoamylases and cellulases. Their portfolio is optimized for both starch liquefaction and cellulosic conversion. Strategic moves in early 2025 strengthened their feed‑enzyme integration, indicating an intention to expand scope beyond traditional biosolutions into closer industrial collaboration with fuel producers.
- DuPont / IFF (Industrial Biosciences heritage): Offers commercial enzyme brands that prioritize viscosity control and saccharification efficiency in starch-to-ethanol lines. Their playbook centers on field performance data and integrated services to lock in long-term plant relationships.
- dsm-firmenich / AB Enzymes / BASF: Established players with industrial distribution networks and capabilities in formulation and process support. These firms are positioning to serve both conventional grain plants and emerging lignocellulosic projects through licensing, toll manufacturing, or bundled services.
- Codexis, Iogen and select biocatalyst specialists: Focus on engineered enzymes and tailored catalysts for cellulosic feedstocks. Their value proposition is technical differentiation—higher activity at lower dosages or compatibility with novel pretreatment regimes—which matters when margins hinge on incremental conversion gains.
- Regional and niche suppliers (India, China, North America): These firms compete on cost and local service, and are important for feedstock-specific formulations or when buyers seek redundancy in supply.
Noteworthy developments: in February 2025 a strategic acquisition reshuffled incumbency among global leaders, reinforcing the consolidation trend. Separately, new plant-optimization programs announced in early 2025 demonstrate that non-enzyme industrial innovations can still materially increase the addressable enzyme opportunity by enabling higher throughput and lower energy consumption without full-scale equipment replacement.
Strategic imperatives for 2026 planning
Based on our analysis, executives should prioritize five tactical moves in 2026:
- Quantify enzyme economics at the plant level: Move beyond per‑kg enzyme pricing to model marginal gallons, energy delta, and adjusted carbon intensity. Use conservative and upside scenarios tied to credit pricing to stress-test investments.
- Negotiate outcome‑based contracts: Seek performance- or outcome‑based agreements (e.g., yield guarantees, dosage optimization, or uptime warranties) to align supplier incentives with plant economics.
- De‑risk supply via tiered sourcing: Combine incumbents for core volumes with niche suppliers for specialty chemistries; lock options for scale‑up volumes to prevent supply squeezes during peak seasons.
- Invest in pilot demonstrations for cellulosic routes: With policy tailwinds improving economics for cellulosic coproducts, prioritized pilot projects can unlock new revenue streams and justify longer-term enzyme commitments.
- Embed enzyme strategy in financing and M&A diligence: Treat enzyme pathway selection as a value driver for valuation models—adjust synergies to reflect reduced energy use, increased yield and potential access to higher‑value credits.
What the full report delivers (practical contents)
Our full market research product is designed as an operational playbook for 2026 execution. It includes:
- Market sizing and forecast (historical series and forward-looking scenarios through 2032, base year 2025).
- Scenario-driven uptake models for conventional and cellulosic enzyme demand tied to credit prices, feedstock availability and conversion efficiency assumptions.
- Granular segmentation by enzyme class, feedstock pathway and customer type, with commercially actionable recommendations (note: detailed segment tables and regional splits are reserved for the full download).
- Competitive scorecards, supplier risk matrices and supplier selection frameworks to support procurement negotiations.
- Case studies and modeled ROI for retrofit options, pilot projects and full conversions, including sensitivity to RIN and clean fuel credit trajectories.
- M&A and partnership playbooks, including valuation heuristics that capture enzyme-enabled cash flow uplift.
- Operational checklists for implementation: from sampling and assay protocols to dosage optimization and process-control metrics.
How to use this intelligence in 2026
Use the report to compress months of supplier discovery, technical due diligence and scenario modeling into a prioritized action list. Practical uses include:
- Board-level briefings assessing whether to authorize retrofit CAPEX in the next budget cycle.
- Procurement strategy refreshes that move negotiations from price-per-litre to outcome‑based contracting.
- Investor materials demonstrating how enzyme strategies de‑risk carbon-intensity targets and revenue exposure to RIN/credit pricing.
- M&A diligence to validate synergies and integration timelines for enzyme-enabled productivity gains.
Closing perspective
Enzymes for fuel ethanol are no longer a supporting input that is purely technical—by 2026 they are a strategic lever. The intersection of regulatory incentives, consolidation among suppliers, and measurable conversion gains turns enzyme strategy into a value-creation axis. Companies that treat enzymes as part of a holistic operational and commercial plan—tying procurement, process engineering and finance—will capture disproportionate upside as the market grows on the path defined by the 6.3% CAGR and shifting policy economics.
For teams ready to convert these insights into 90‑day to 36‑month action plans, our full study contains the granular segmentation, supplier scorecards and modeled ROIs referenced above. Access to the complete dataset and implementation tools will materially speed decision-making and de-risk execution for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Enzymes For Fuel Ethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryoablation for Cancer Market to Reach USD 902.41M by 2032
By PW Consulting, 2026-07-13
Cryoablation for Cancer: A Strategic Preview for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused market preview designed to orient executive teams, investors, and strategy leaders preparing for 2026. Cryoablation is moving from a niche interventional tool toward a clinically validated, reimbursable modality with clear commercial inflection points. Our full market study drills into the clinical, commercial, and regulatory vectors that will determine winners and losers over the 2026–2032 horizon. This introduction outlines the strategic value of those findings, highlights tactical implications for product, market access, and M&A strategy, and signals where the report hides the granular segmentation data that matter for executable plans.
Cryoablation For Cancer Market
Why 2026 is a Strategic Inflection Point
The cryoablation market has demonstrated sustained expansion through the early 2020s, accelerating into the mid-decade as clinical acceptance and reimbursement pathways matured. After a multi-year growth phase, the market reached a meaningful scale by our 2025 base year and is forecast to maintain a high-single-digit compound annual growth rate (CAGR) across the 2026–2032 forecast window. By 2032 the market is projected to approach roughly double its 2025 size, reflecting a confluence of drivers: guideline evolution, regulatory clearances for new indications, better device ergonomics and imaging integration, and growing adoption by outpatient and community hospital settings.
Cryoablation For Cancer Market
For corporate leadership teams, 2026 is the year to translate proof points into commercial scale. Clinical evidence and coding momentum are creating windows for premium pricing and higher penetration of capital equipment and per-case consumables. But those opportunities come with execution risk: capital intensity for hospital purchasers, uneven global reimbursement environments, and a concentrated competitor set that elevates the importance of differentiated clinical claims and channel strategy.
Cryoablation For Cancer Market
What the PW Consulting Report Delivers (Practical, Executable Content)
- Market sizing and trend architecture: a transparent methodological appendix explains how historical performance (2020–2025) and structural assumptions inform our baseline and forecast through 2032, including sensitivity scenarios tied to reimbursement and guideline adoption.
- Go-to-market playbooks: playbooks for incumbents, scale-up challengers, and niche innovators. Each playbook provides prioritized commercial tactics—key opinion leader (KOL) engagement plans, trial designs that close critical evidence gaps, bundling strategies for capital + disposables, and channel mix recommendations.
- Reimbursement and coding roadmap: pragmatic guidance for engaging payors and national coding bodies, including timing for CPT/HCPCS strategies and how to construct hospital economic models that justify capital purchase under current depreciation and CapEx pressures.
- Clinical and regulatory sequencing: an evidence matrix mapping indication expansion, trial endpoints, and regulatory pathways (e.g., De Novo, PMA equivalents), delineating which investments maximize probability of approval in key markets.
- Transaction playbook and valuation levers: an M&A checklist highlighting what matters to buyers—installed base, service revenue, consumable margins, regulatory clearances, and proprietary probe technologies—alongside model templates for accretive acquisition scenarios.
- Competitive positioning and product gap analysis: a comparative framework that evaluates device systems, probe technologies, imaging integration, multi-needle capability, disposables economics, and manufacturing scale—plus prioritized product development investments.
Market Dynamics: The Forces Shaping 2026 Decisions
Several dynamics will determine the pace and shape of adoption in 2026:
- Clinical validation and guidelines: Recent guideline updates have begun to recognize cryoablation as an option for selected low-risk patients in certain tumor types. These shifts lower the barrier to adoption in community settings and support payer discussions.
- Regulatory momentum: The pathway from single-site feasibility to broad label expansion is shortening for some technologies. Notably, post-marketing study designs and multi-site enrollment commitments will increasingly accompany market authorizations, changing commercialization timelines and investment profiles.
- Reimbursement crystallization: Where explicit facility and device coding exists, per-procedure economics become predictable—enabling hospitals to model throughput and ROI. This predictability fuels device and consumable uptake—but only where codes and coverage decisions align.
- Hospital capital constraints: While hospitals face elevated CapEx pressures—driving selectivity in new capital purchases—there is also pent-up demand to modernize aging interventional suites. Large cryotherapy units are a material capital investment; manufacturers who align financing, service, and utilization guarantees will unlock faster uptake.
- Consolidated supplier structure: Market concentration among established device leaders creates both entry barriers and partnership opportunities. Challengers can win by focusing on niche indications, lower-cost disposables, or differentiated clinical workflows that reduce procedure time and staffing burden.
Competitive Landscape: Strategic Implications for Core Players
The market is anchored by a mix of multinational medtech leaders, specialty cryotech firms, and regional device manufacturers. Across this set, competitive advantage accrues to firms that combine regulatory clarity, broad clinical evidence, and service-enabled consumable revenue models.
- Medtronic —Scale and cross-platform leverage: As a global medtech leader, the company can bundle cryo capabilities with broader surgical and imaging portfolios. Strategy implications: defend installed base through service contracts, expand multi-disciplinary sales targeting urology and interventional radiology, and accelerate label expansions via focused registries.
- Boston Scientific (including Galil technologies) —Imaging integration and multi-needle capability: Strengths include MRI-visible systems and percutaneous multi-needle approaches that address larger or irregular lesions. Strategy implications: exploit imaging visibility claims to pursue higher-acuity centers and partner with imaging OEMs to co-promote integrated solutions.
- IceCure Medical —Regulatory and guideline breakthroughs: Recent successful market authorization and guideline updates have created a first-mover advantage in select breast cancer indications. Strategy implications: convert regulatory momentum into reimbursement and site adoption through a well-resourced post-marketing trial program and robust KOL network; consider licensing or distribution partnerships to scale U.S. adoption rapidly.
- CooperSurgical, AtriCure, Erbe, Sanarus and regional providers —Niche specialization and channel reach: These players have strategic options to extend reach via partnerships, OEM supply, or focusing on gynecologic and soft-tissue niches; they can also compete on cost and service in price-sensitive markets.
- Smaller innovators (METRUM CRYOFLEX, CPSI Biotech, HealthTronics, BVM) —Agility and localized advantage: These firms can win in regional and outpatient markets by offering lower total-cost-of-ownership systems or by targeting indications with under-served clinical needs.
Our full report contains an annotated competitor matrix and decision-tree analysis mapping each company’s probable moves and vulnerabilities. For confidentiality and competitive sensitivity, we do not reproduce proprietary share estimates here; instead, the report provides scenario-based concentration analytics to guide M&A and partnership strategies.
Recent Events that Reframe 2026 Strategy
- Regulatory and guideline progress: Recent approvals and guideline updates have begun to legitimize cryoablation for selected early-stage tumors—events that materially change the adoption calculus for hospital administrators and oncologic surgeons.
- Post-market evidence commitments: For some newly cleared indications, manufacturers will need to deliver confirmatory evidence through multi-site trials; this creates timing pressure and opportunities for competitors to close evidence gaps more quickly.
- Reimbursement clarity for discrete scenarios: Where facility-level billing codes or existing HCPCS descriptors apply, providers can model procedure economics—supporting targeted launches in centers of excellence.
- CapEx and consumables economics: Advanced units require meaningful capital outlay, but the recurring disposables model creates an annuity-like revenue stream. Manufacturers who provide innovative financing or utilization guarantees will secure share faster in the constrained hospital CapEx environment.
Actionable Recommendations for 2026 Planning
- Prioritize indications where clinical evidence and payor recognition intersect. Use focused registries to accelerate label expansions and payor coverage decisions rather than broad uncontrolled trials.
- Bundle capital and disposables with outcome-based contracting for high-volume centers. Offer financing and service plans that reduce the hospital’s adoption hurdle.
- Leverage imaging integration as a discriminator: co-develop or co-market with imaging OEMs to position systems for high-acuity cases and to secure preferred status in tertiary centers.
- Strengthen KOL networks and surgical society engagement to translate guideline shifts into procedural volume. Rapidly operationalize post-market study designs to capture real-world evidence and economic endpoints.
- For investors and M&A teams: prioritize targets with high consumable margins, defensible IP in probe geometry or freezing profiles, and established clinical registries. Beware of carve-outs that lack service infrastructures—these require additional investment to scale.
Conclusion — What PW Consulting Recommends You Do Next
Cryoablation is no longer a purely investigational technology; it is entering a phase where regulatory milestones, reimbursement clarity, and hospital purchasing dynamics converge to create real commercial opportunity. Our market forecast and strategic playbooks are structured to help you convert clinical momentum into sustainable revenue streams while avoiding common execution pitfalls.
This preview intentionally omits the granular regional and application-level splits, competitor share percentages, and certain proprietary financials that are included in the full PW Consulting Cryoablation For Cancer Market report. If your 2026 strategy requires transaction-level insight, competitor share scenarios, or downloadable models and playbooks, please refer to the full report and accompanying data package on our website.
For detailed analysis of this topic, please visit the official page: Cryoablation For Cancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Baby Monitoring Market to Hit USD 3,317.24M by 2032; 8.7% CAGR (2026-2032)
By PW Consulting, 2026-07-13
Baby Monitoring System Market 2026: Strategic Imperatives and What Senior Leaders Need from Market Intelligence
As boards and executive teams prepare for 2026, decisions around product roadmaps, channel investments, M&A, privacy compliance, and talent priorities for the baby monitoring sector will require evidence-led judgment calls. PW Consulting’s latest Baby Monitoring System Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes proprietary primary research, vendor due diligence, and a rigorous bottom‑up financial model to turn industry noise into a clear set of actionable strategies. The market grew from roughly USD 1,260 Million in 2020 to USD 1,850 Million in 2025, and our base-case model projects a compound annual growth rate of 8.7% across the forecast window—reaching a multi‑billion-dollar market by 2032. This briefing highlights the research’s strategic value for 2026 decision-making while intentionally withholding granular subsegment tables and regional breakouts so readers will access the full report for the operational numbers and downloadable models.
Baby Monitoring System Market
Why this research matters for 2026
-
Timing: 2026 will be the first full year that many vendors need to operationalize compliance upgrades driven by new privacy and AI regulations across major markets. Our study identifies which product architectures and go‑to‑market models are best positioned to absorb compliance costs without sacrificing margin.
Baby Monitoring System Market -
Capital allocation: With a mid‑single-digit to high‑single-digit CAGR, executives must choose between investing to capture share in a growing category or prioritizing profitably in core geographies. The report’s scenario analyses quantify payback timelines under alternative investment and pricing strategies.
Baby Monitoring System Market -
Strategic M&A and partnerships: Market concentration metrics in our study show meaningful room for consolidation and strategic alliances. For corporate development teams, the report surfaces high‑priority capability gaps—AI, edge processing, secure cloud architectures—and candidate targets that fill them.
What the report delivers (practical scope)
-
Robust market sizing and forecasts: A transparent, replicable bottom‑up model covering 2020–2032 with base, conservative, and upside scenarios; model variables and sensitivities are provided so teams can stress test assumptions against their internal data.
-
Channel economics and retail playbooks: Unit economics for online vs offline channels, pricing elasticity benchmarks, promotional cadence impact on lifetime value, and retailer negotiation levers for 2026 campaigns.
-
Product and technology roadmaps: Comparative analysis of video, audio, smart/connected, and wearable approaches; tradeoffs between edge compute vs cloud AI; recommendations on battery optimization, camera sensors, and SoC selection aligned to regulatory constraints.
-
Regulatory and security playbook: A prioritized compliance checklist (encryption, authentication, data minimization, consent flows) mapped to likely enforcement outcomes in key jurisdictions, plus incident response templates and certification pathways that reduce time‑to‑market.
-
Vendor scorecards and competitive benchmarking: Qualitative and quantitative assessments of the leading providers—covering product breadth, go‑to‑market strength, service quality, IP, and balance‑sheet health—plus suggested competitive responses for incumbents and challengers.
-
Supply chain and component risk matrix: Identification of single‑source vulnerabilities (camera modules, RF components, specialized sensors), alternative sourcing strategies, and near‑term cost pressure scenarios tied to raw material and logistics outlooks.
-
Investor and M&A intelligence: A shortlist of target archetypes, valuation multiples observed in recent transactions, integration risks, and accretion/dilution analysis templates tailored to the industry’s margin dynamics.
-
Primary research annex: Interview excerpts with channel partners, pediatric clinicians, and end users, together with survey results that illuminate willingness‑to‑pay thresholds and feature prioritization across buyer personas.
Competitive landscape — who matters and why
The sector is diverse: global consumer electronics incumbents, specialized infant‑tech challengers, and security/camera companies converging on the baby monitoring use case. Our analysis evaluates players on three dimensions—product differentiation, trusted brand equity, and technical capability for secure, AI‑enabled features.
-
Large consumer electronics and household brands bring scale and distribution breadth. Their advantage is reach and integration into broader smart‑home ecosystems; their challenge is speed and agility in meeting specialized clinical or privacy requirements.
-
Specialist infant‑tech companies have demonstrated product leadership in either AI sleep analytics or clinically inspired wearables. These firms are attractive targets for large acquirers seeking differentiated IP and sticky subscription models.
-
Security camera vendors and wireless camera platforms provide high‑quality video capabilities and mature cloud infrastructures, offering a fast path to upgrading core monitoring functionality but also raising questions about data governance when children's data are processed in generalized security clouds.
Representative firms profiled in the report include established and emerging names across these categories. Each company profile discusses strategic positioning, recent product and corporate developments, and execution risks—enabling readers to prioritize partnerships, competitive responses, and due diligence targets without wading through marketing claims.
Recent industry moves and regulatory inflection points
Three themes are shaping the competitive and regulatory landscape:
-
Product convergence and specialization: Wearables that provide physiological signals are now routinely paired with high‑resolution video and AI analytics. Product launches in late 2024–2025 demonstrate a clear shift toward integrated solutions that blend vitals monitoring with contextual video feeds.
-
Regulation is driving architectural change: Jurisdictions are increasingly mandating stronger technical controls for internet‑connected baby monitors. Examples include requirements for end‑to‑end encryption, certificate‑based authentication, and prohibitions on unauthenticated access; broader privacy and AI rules emphasize transparency, data minimization, and risk assessments where children’s data are concerned. The practical implications are profound—affecting cost structures, feature design, and time‑to‑market.
-
Security incidents and certification demand: Documented vulnerabilities in consumer Wi‑Fi monitors have accelerated calls for uniform IoT security standards. Vendors that proactively adopt privacy‑by‑design, edge first processing, and certification frameworks will reduce regulatory exposure and win trust premiums.
Strategic recommendations for 2026 (prioritized)
-
Invest in privacy and security as a market differentiator: Treat encryption, authentication, and transparent data practices as product features—not just compliance line items. Early investment reduces remediation costs and shortens sales cycles with large retail partners that demand supplier certifications.
-
Pursue modular product architectures: Separate sensing, compute, and cloud layers to allow incremental upgrades and to support edge processing when required by regulation. This reduces re‑engineering costs and allows flexible monetization (hardware + subscription analytics).
-
Refine channel mix using evidence, not intuition: Rebalance online and offline investments based on a disciplined view of unit economics, promotional ROI, and the premium buyers will pay for trusted, certified devices. The report provides elasticities and break‑even tables to guide these allocations.
-
Prioritize partnerships for capabilities you cannot build economically: For firms lacking AI or security IP, partnerships or tuck‑ins are faster routes to capability, especially where regulatory timelines compress go‑to‑market windows.
-
Scenario‑proof your supply chain: Map single points of failure for critical components and qualify second‑source suppliers now. Include contractual terms that reflect longer lead times and potential rework costs associated with firmware updates and security patches.
How executive teams should use this study in 2026 planning cycles
Boards, strategy teams, product leaders, and M&A professionals can use the study as a playbook and a stress‑testing tool. The downloadable financial model enables CFOs to run sensitivity analyses on price, feature adoption, and regulatory compliance spend. Product teams get a prioritized feature roadmap that balances clinical credibility, parent value, and unit economics. Corporate development uses the vendor briefs and M&A target archetypes to accelerate screening and valuation.
Next steps and how to access the full intelligence
This briefing is intentionally selective—designed to demonstrate analytical depth and signal the strategic pathways we recommend for 2026, while reserving the proprietary subsegment tables, downloadable models, and full competitive scorecards for the complete report. PW Consulting clients and subscribers can access the full Baby Monitoring System Market report to obtain the granular regional, product‑type, and channel revenue series, as well as the primary‑data annex and valuation templates that support the conclusions summarized here.
For executive briefings, scenario workshops, or to receive the complete dataset and models, contact PW Consulting’s industry research desk to schedule a tailored briefing that aligns the study’s insights to your organization’s 2026 planning cycle.
In an industry where trust and safety are the currency, the firms that align product roadmaps with secure architectures and pragmatic commercial strategies will capture both share and margin as the market expands. This report is intended to be the practical intelligence map executives need to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Baby Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultra White Rolled Solar Glass Market to Reach USD 38.2B by 2032
By PW Consulting, 2026-07-13
Ultra White Rolled Solar Glass Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PV glass has moved from a component line item to a strategic lever for module makers, system integrators, and investors. Our PW Consulting Ultra White Rolled Solar Glass Market study—base year 2025, forecasting 2026–2032—shows a market that expanded rapidly through 2020–2025 and is set to grow at a robust compound annual growth rate (CAGR) of 12.84% over the 2026–2032 forecast window. The total market value in 2025 stood at USD 16,400 million and the model projects continued scaling through the forecast period, reflecting both demand-side expansion and supply-side reconfiguration. This briefing explains why the study is strategically valuable for 2026 decisions and what practical outputs clients can deploy immediately.
Ultra White Rolled Solar Glass Market
Why this research matters in 2026
-
Policy and procurement are reshaping demand signals. Recent US policy moves—materially including targeted investment tax credits and financing support—have created first‑mover advantages for domestic producers while changing the calculus for module and component localization.
Ultra White Rolled Solar Glass Market -
Supply‑side reconfiguration is underway. Incumbent global producers and new regional entrants are commissioning lines and furnaces, shifting where and how ultra‑white rolled solar glass is produced, tempered, and coated. These dynamics directly affect availability, lead times, and long‑term pricing trajectories.
Ultra White Rolled Solar Glass Market -
Raw material pressure and downstream efficiency gains are converging. Ultra‑low iron silica sand markets and anti‑reflective coating technologies are now strategic inputs: changes in feedstock pricing or procurement bottlenecks can meaningfully alter module-level performance economics.
What senior leaders can extract from the report
-
Actionable forward views for capacity planning: our demand model translates module deployment scenarios into glass throughput and capital‑intensity requirements, enabling CFOs and plant planners to test capacity timing against financing windows.
-
Procurement playbooks: shortlists, tender structures, price‑indexing templates, quality acceptance criteria and durability testing checklists tailored to rolled/embossed ultra‑white glass versus float alternatives.
-
Regulatory and incentive mapping: a concise matrix linking domestic content rules, tax credits, and loan facilities to supplier selection and site choice for new furnaces or roll forming lines.
-
M&A and partnership frameworks: valuation sensitivity templates, earn‑out structuring options for brownfield acquisitions, and integration checklists for verticalized module manufacturers.
Scope and practical contents of the full study
The report is designed to be a board‑level decision tool that is also directly usable on the plant floor. Deliverables include: a transparent demand model (2020–2032) with scenario toggles; a supply map with existing and commissioned line intelligence; technology assessments comparing rolled, embossed and float routes; techno‑economic models for new line capex/opex; detailed supplier scorecards; a procurement negotiation dossier; and risk heatmaps covering raw materials, logistics and policy. For confidentiality and strategic positioning reasons—consistent with the “trailer” principle used throughout this briefing—we provide high‑certainty aggregate market sizing and growth metrics here, but granular segment allocations by region, thickness and application are reserved for the full dataset available from PW Consulting.
Competitive landscape — where industry power is concentrated
Market concentration is meaningful: the top three manufacturers account for a majority share of global supply, and the top five consolidate roughly three quarters of available capacity. That concentration underpins suppliers’ pricing power in constrained cycles and creates high barriers to rapid commoditization.
-
Xinyi Solar Holdings Limited — a clear technology and scale leader. Its calendering process for ultra‑clear patterned rolled glass and integrated anti‑reflective offerings make it a preferred long‑term partner for high‑efficiency module producers. Xinyi’s large daily melting capacity and recent commissioning of a furnace in Indonesia (Jan 2026) illustrate their strategy of geographic diversification to serve both module fabs and regional demand centers.
-
Established Chinese producers such as Ancai Hi‑Tech, Flat Glass Group, CSG and Qingdao specialists combine technical know‑how with scale and a dense supplier ecosystem. Their strengths lie in cost competitiveness and speed to scale, which remains decisive in price‑sensitive markets.
-
European and Turkish players , led by companies like Şişecam and AGC, are differentiated by patterned glass expertise, AR coating capabilities, and regulatory compliance for markets with stringent material and environmental standards. AGC’s focus on extra‑clear float routes and arsenic/antimony‑free glass is attractive for module makers prioritizing chemical compliance and optical purity.
-
North American entrants such as Stewart Glass and Vitro are redefining local supply economics. Stewart’s new Ohio facility (production start 2026) and Vitro’s Texas expansion (supported by a significant IRS investment tax credit announced in 2025) are practical responses to US localization incentives and supply chain resilience strategies. Stewart’s small‑to‑medium‑scale capacity and Vitro’s large expansion demonstrate two distinct plays: agile local supply versus large industrialized throughput.
Recent developments that matter for 2026
-
Capacity commissioning across geographies: several new furnaces and roll lines came online or were commissioned in late‑2025 and early‑2026, shifting lead times and regional bargaining leverage.
-
Targeted fiscal support has immediate effects: the US allocation of an investment tax credit for domestic patterned glass capacity and a USDA loan guarantee for an Ohio facility are lowering financing costs for new entrants and materially influencing site selection decisions.
-
Feedstock dynamics are rising on corporate radars. The ultra‑low iron silica sand market, a pivotal upstream input, shows its own long‑term scaling (industry estimates value the market in the low‑billions USD by mid‑decade), making long‑term supply contracts and vertical integration legitimate strategic options.
Strategic implications and recommended actions for 2026
-
For module manufacturers: lock differentiated glass supply via multi‑year offtakes tied to quality and performance KPIs (transmittance, AR durability). Negotiate price‑step clauses linked to silica sand indexes and energy inputs to hedge feedstock volatility.
-
For investors and private equity: prioritize assets with flexible tempering and coating capabilities, proximity to logistic hubs, and existing offtake agreements. Use our valuation sensitivities to stress‑test acquisition targets against shifts in WACC and policy incentives.
-
For policymakers and development banks: targeted support—tax credits, loan guarantees, and conditional incentives tied to employment and domestic value capture—can catalyze localized capacity with outsized impact on energy security and industrial resilience.
-
For suppliers and OEMs: accelerate R&D on AR coatings and thinner glass solutions that enable module efficiency gains; prioritize operational excellence to reduce breakage and yield loss in roll‑to‑roll handling.
How to use this study in boardroom and commercial execution
The utility of the PW Consulting study is its dual rigor and operability: quantitative forecasts are directly linked to procurement templates, capex planning schedules, and legal language for offtake and supply contracts. Use the report to populate your 2026 capex approval package, to model the impact of regional content rules on project LCOE, or to structure earn‑outs in a strategic acquisition. For supply chain teams, the supplier scorecards and risk heatmaps provide immediate inputs for supplier rationalization and emergency sourcing plans.
Access to the full dataset
This briefing deliberately presents high‑confidence macro metrics and strategic interpretation while withholding granular segment allocations by region, thickness and application to preserve the commercial value of the underlying dataset and to encourage informed engagement. The full PW Consulting report contains the complete 2020–2032 time series, scenario toggles, and all segment‑level tables and charts required to execute procurement, investment, and policy strategies in 2026. For clients and prospective subscribers seeking the definitive dataset and executable templates, PW Consulting’s Ultra White Rolled Solar Glass Market report page provides secure access to downloads, models and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Ultra White Rolled Solar Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


