



Category: market research
Wood Chippers Market 2026 — Strategic Preview for Executive Decision-Makers
Executive summary
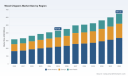
As a capital- and regulation-intensive segment of the broader forestry and biomass equipment market, wood chippers present a distinctive blend of mature demand and tactical disruption. Our 2025-base study shows the global wood chippers market expanded from roughly USD 318 million in 2020 to USD 427.5 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of 6.1% across the 2026–2032 forecast window — reaching an estimated USD 647 million by 2032. For corporate strategists planning capacity, product portfolios, M&A, or go-to-market strategies in 2026, these metrics are the macro scaffold on which more granular choices must be built.
Wood Chippers Market
Why this research matters for 2026 decisions
- Timing matters: 2026 is a hinge year. Regulatory headwinds (Tier 4 Final / EU Stage V) have been internalized by many OEMs and late adopters now face a steeper cost curve for compliant diesel units. Our report quantifies the cost and maintenance implications across machine classes and maps adoption pathways for low-emission alternatives.
- Capital allocation clarity: With mid-term growth at ~6.1% CAGR, executives must reconcile steady market expansion with pockets of disruption (electrification, digital services). The study provides ROI scenarios that help prioritize R&D vs. aftermarket investments.
- Risk-adjusted roadmap: Supply-chain pressure points — from knife and anvil wear rates to after-treatment component scarcity — materially affect TCO. We translate these operational risks into financial sensitivities and procurement safeguards ready for 2026 contracting cycles.
Market trajectory and structural dynamics
The market’s recent compound expansion is driven by converging forces: continued demand from land-clearing, biomass and pulp & paper segments; replacement cycles in municipal and arborist fleets; and technology-driven differentiation among OEMs. However, the headline growth number masks uneven economics across product tiers — low-cost entry machines demonstrate materially higher maintenance intensity and slower throughput, while premium industrial systems trade on uptime, modularity and serviceability.
Wood Chippers Market
Critical structural dynamics that will shape strategic options in 2026 include:
Wood Chippers Market
- Regulation-driven cost inflation: Emission after-treatment (diesel particulate filters, SCR systems) has increased upfront costs and ongoing maintenance for diesel platforms. Compliance timelines and retrofit economics are modeled in the report.
- TCO and maintenance economics: Our benchmarking finds that entry-level machines can incur substantially higher blade and anvil replacement frequencies, with knock-on effects for feed rates and lifecycle cost. Procurement decisions that focus solely on purchase price risk higher lifetime spend.
- Standardization and safety: EN 13525, AS/NZS 4024.1 and ISO 11448 remain binding for machine design and operation. Manufacturers that embed these standards early limit downstream liability and accelerate access to regulated markets.
- Product bifurcation: Demand is bifurcating into high-capacity industrial chippers for biomass and pulp operations, and compact, low-emission or electric solutions for arboriculture and urban applications. Each segment has distinct go-to-market and service requirements.
Competitive landscape — what the majors signal
The competitive map combines legacy OEM strengths (industrial scale, dealer networks) with agile regional specialists focused on niche requirements (compact tracked units, PTO-towed machines, or premium self-propelled designs). Our competitive chapter profiles leading OEMs and identifies the strategic implications of their recent moves without disclosing transaction-level or segment share tables reserved for the full report.
Highlights from company-level patterns:
- Product leadership and differentiation: Firms such as Vermeer emphasize proprietary crushing and feed technologies for throughput and consistency, while others (e.g., Morbark, Terex/CBI) reinforce high-capacity drum and whole-tree solutions tailored for biomass and industrial applications. These technology choices materially affect buyer segments, maintenance regimes and aftermarket opportunities.
- Warranty and service as competitive weapons: Extended warranty programs and parts availability (for example, multi-year or hour-based guarantees) are being used to offset premium pricing and to lock-in fleet operators.
- Geography-driven playbooks: Some manufacturers prioritize road-towable and compact chippers for arborists and municipalities, while others focus on tub grinders and industrial chippers for mills and land-clearing contractors. The report evaluates each player’s manufacturing footprint, channel depth and product roadmap to assess scalability.
- Recent strategic moves worth attention: Product launches of large-capacity whole-tree chippers and compact professional models, an OEM acquisition that consolidates complementary technologies, a contract award for a bespoke drum chipper to a major mill, and supplier appointments for critical wear parts — together, these developments indicate both ongoing product innovation and ecosystem strengthening among incumbents.
From insights to action — what executives can do in 2026
We designed this study as a playbook for the decisions that matter in the coming 12–24 months. Below are the practical outputs and how to use them.
- Portfolio & product decisions: Use our demand segmentation and elasticity models to decide whether to prioritize electrified compact units, invest in high-capacity whole-tree lines, or pursue modular architectures that lower service downtime.
- Pricing & go-to-market: Benchmarks for dealer margins, service revenue potential and replacement-part pricing enable data-driven pricing strategies and subscription models (e.g., knife-management contracts, uptime guarantees).
- Supply chain and sourcing: The report maps critical single-sourced components (after-treatment modules, high-grade steels for knives) and recommends near-term hedging, dual-sourcing, or local manufacturing options aligned with 2026 procurement cycles.
- M&A and partnerships screening: A targeted list of bolt-on opportunities and capability gaps is provided, scoring targets by strategic fit, integration complexity and likely synergies for both OEMs and investors.
- Compliance & safety roadmap: The study translates EN, ISO and national emission frameworks into an actionable compliance timetable and cost schedule so product teams can prioritize design changes ahead of regulatory enforcement windows.
What we do not publish here — and why you should request the full analysis
To preserve the commercial integrity of the intelligence and to encourage direct engagement, this preview intentionally omits the detailed segmentation tables, regional and end-use splits, and the full competitive concentration matrices. The complete report contains:
- Granular segmentation across geography, type and application with modeled revenue paths and elasticities;
- Consolidation metrics and concentration ratios with implication matrices for new entrants vs incumbents;
- Full financial-model workbooks (USD million base, forecasted P&Ls for product lines and scenario-adjusted capex plans);
- Vendor-level SWOTs and an executable 90-day market-entry checklist for OEMs, distributors and private equity investors.
Practical scenario examples (samples from the report)
- Scenario A — Premium industrial focus: A mid-sized OEM redirects 60–70% of R&D to high-capacity drum and whole-tree platforms and pursues a service-first warranty play. Our scenario model shows how this strategy affects utilization thresholds and aftermarket revenue over a 5-year horizon.
- Scenario B — Electrification and urban niche: A distributor pivots toward compact electric and low-emission petrol models for municipal and arborist fleets, pairing machines with battery-as-a-service offerings to reduce operator up-front cost and increase retention.
- Scenario C — Parts and service consolidation: An aftermarket specialist negotiates exclusive supply of knives and wear components to capture recurring revenues; our sensitivity analysis indicates the point at which parts margin begins to offset declining machine sales in a mature market.
Final guidance for 2026 planning
Executives should treat the 2026 planning cycle as an inflection point: the market is not a binary growth story, but a mosaic of stable core demand and fast-evolving subsegments. Strategic clarity requires marrying the macro growth trajectory (6.1% CAGR) with granular insights on regulatory cost, maintenance economics and competing OEM roadmaps. Where to compete, at what price, and how to lock-in aftermarket revenue will determine winners.
To access the full suite of models, segmentation data, competitor concentration metrics, and the executable 12–24 month playbook that underpins these executive recommendations, please consult the complete Wood Chippers Market report from PW Consulting. Our full analysis supplies the confidential line-item breakouts and scenario workbooks that boards and investment committees will need to make rigorous 2026 commitments.
For detailed analysis of this topic, please visit the official page: Wood Chippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Voltage DC Circuit Breaker Market to Reach USD 320.2M by 2032 at 7.0% CAGR
By PW Consulting, 2026-07-12
Low Voltage DC Circuit Breakers: Strategic Outlook for 2026 Decision-Making
Executive preview
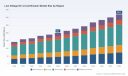
The Low Voltage DC Circuit Breaker market is transitioning from niche engineering challenge to strategic battleground for utilities, inverter makers, balance-of-system vendors and industrial OEMs. Between 2020 and 2025 the market expanded from USD 142.3 Million to USD 200.0 Million (base year 2025), and our forecast projects a continuation of that momentum to approximately USD 320.2 Million by 2032 at a 7.0% CAGR over 2026–2032. That trajectory masks important inflection points: material-cost volatility, standards updates, and rapid product evolution around higher-voltage DC distribution and solid-state protection create both risk and opportunity for firms that need to commit capital in 2026.
Low Voltage DC Circuit Breaker Market
Why this research matters to 2026 corporate plans
-
Capital allocation: With the market expanding meaningfully through the forecast horizon, companies that finalize manufacturing CAPEX, tooling spend or capacity-sharing agreements in 2026 will capture the early-adopter premium in high-growth niches.
Low Voltage DC Circuit Breaker Market -
Product roadmap timing: The convergence of higher-voltage PV strings, energy storage deployments, and faster EV DC charging protocols creates a narrow window where product specification choices made now determine certification cycles and go-to-market readiness into 2027–2028.
Low Voltage DC Circuit Breaker Market -
Supply chain posture: Raw material shocks in 2025 and the cascading cost effects on manufacturing economics mean procurement strategies and hedging approaches decided in 2026 materially affect gross margins into 2028.
Market trajectory and macro drivers
Our historical build (2020–2025) shows steady adoption across renewable and industrial applications—growth accelerated notably as storage and fast-charging use cases matured. The forecast (2026–2032) embeds a 7.0% CAGR that reflects continued end-market expansion as well as gradual migration toward higher-voltage DC topologies and greater electrification of transportation and industrial automation.
Key demand drivers evaluated in the study include the accelerating roll-out of battery energy storage systems (BESS), increasing PV string voltages and inverter architectures, and the mainstreaming of DC fast-charging. Conversely, cost-side pressures—from base commodity shifts to new certification requirements—shape practical pricing and margin outcomes for manufacturers and distributors.
Competitive landscape: who matters and why
The report profiles leading and emerging suppliers, assessing strategic positioning, product portfolios, channel models and near-term capacity moves. Market concentration is moderate: the top three suppliers account for roughly 54% of identifiable market revenue while the top five account for about 65%—enough to influence pricing dynamics but leaving space for regional specialists and innovative entrants.
-
ABB (Switzerland) — A full-spectrum provider with conventional MCBs/MCCBs and solid-state offerings tailored to solar and storage DC distribution. ABB’s portfolio is notable for broad channel reach and system integration capability (link: https://new.abb.com/low-voltage/direct-current-systems).
-
Eaton Corporation (Ireland) — A major global supplier of DC-rated molded case breakers, including solutions designed specifically for PV and BESS applications, with proven designs up to 1000 VDC (link: https://www.eaton.com).
-
Siemens AG (Germany) — Focused on modern low-voltage installations with tried-and-tested series targeting renewables, data centers and industrial use (link: https://www.siemens.com).
-
Mitsubishi Electric (Japan) — Advanced breaking technologies for machinery and electrical equipment; a supplier with deep industrial OEM relationships (link: https://www.mitsubishielectric.com/fa/products/lvd/lvcb/index.html).
-
LS ELECTRIC (South Korea) , Fuji Electric (Japan) , CHINT Group (China) , Hager Group (Germany) , and Chinese OEMs such as Beny and Chinasuntree — each brings distinct advantages, from smart-power integration and cost-competitive manufacturing to specialized enclosures and PV-focused product sets (see company sites cited in report).
Recent tactical moves matter. Fuji Electric’s 2025 investment to expand transmission & distribution capacity—with operations ramping in FY 2026—reshapes regional supply availability. Several OEMs used 2025–2026 trade shows to preview higher-voltage and IP-rated solutions (notably 1500 V capabilities), signaling intent to compete on both performance and system compatibility.
Supply chain and cost dynamics
Material composition and price volatility are no longer secondary issues. Our cost-model deep dives show copper is a dominant raw-material line item—accounting for roughly 45% of material costs in low-voltage electrical equipment—with silver and copper together representing an even larger share of critical metal exposure. Since July 2025, silver prices have surged substantially (well over 400%), while copper has also experienced steep increases (>140%). These moves have immediate margin implications for conventional contact-based breakers and even more pronounced effects for products where precious metals are used in contacts or plating.
For procurement and operations leaders, the combination of concentrated supplier base for certain specialty subcomponents, upward material pressure and long lead times for precision tooling produces three practical levers we quantify in the report: (1) design-for-material-efficiency pathways, (2) alternative contact alloys and coating strategies, and (3) inventory/forward-buy frameworks tailored to hedging costs without overexposure.
Regulatory and standards outlook
Standards evolve rapidly and directly influence product architecture and time-to-market. EN IEC 60898-3:2025 introduces clearer expectations for household DC breakers up to 440V, while industry deployments continue to require compliance with UL 489 B and IEC 60947-2 for solar PV and energy storage systems. Our regulatory risk scenarios examine certification timelines, required lab modifications, and the cost of incremental testing for higher-voltage ratings—all crucial for product managers and compliance teams planning 2026 releases.
Strategic implications and actionable recommendations for 2026
-
Prioritize modularity: Build product roadmaps that allow incremental voltage and interrupting-capacity upgrades without a full redesign. This reduces certification cycles and amortizes test costs across families.
-
Lock targeted capacity early: For companies intending to scale, secure manufacturing slots or partnerships in 2026—especially for enclosures and high-precision contacts—before 2027 demand surges.
-
Hedge raw-material exposure: Combine strategic sourcing with design choices that reduce precious-metal usage, and explore long-term offtake agreements for copper and alternative alloys.
-
Invest in standards readiness: Dedicate a certification roadmap tied to the product launch cadence—missing a standards milestone can delay market entry by quarters and hand share to more agile competitors.
-
M&A and partnership playbooks: Consider bolt-on acquisitions for system integration capabilities (e.g., relays, sensing electronics) or partnerships for manufacturing scale; the report includes diligence templates and valuation sensitivities focused on 2026 timing.
Report content: what you will find inside
The full PW Consulting study is organized to be immediately operational for strategy, product and commercial teams. It contains:
-
Market sizing (USD Million) and historical trend analysis (2020–2025) with a base year of 2025, plus a detailed forecast through 2032 with scenario sensitivity to material prices and standards adoption.
-
Competitive benchmarking across product capabilities, channel strategies, price positioning and near-term capacity events—covering both global leaders and regional specialists.
-
Supply-chain cost models that quantify exposure to copper and silver, and design trade-offs to preserve margin under high-price scenarios.
-
Regulatory and certification timelines, mapped to product architectures and time-to-market impacts.
-
Actionable go-to-market playbooks for OEMs, distributors and EPCs including pricing strategies, channel incentives and systems-integration approaches tailored to 2026 deployment windows.
-
Risk matrices and scenario planning templates designed to support 2026 board-level investment decisions—concisely mapping probabilities, impacts and mitigations.
To preserve commercial value and to respect our clients’ need for proprietary segmentation, this introduction intentionally omits granular regional, type and application splits. The full report contains those segment-level data and the underlying model that powers our forecasts.
How to use this study in 90 days
-
Month 1 — Align: Run the report’s scenario workshop with product, procurement and business leaders to align on which scenario(s) your company will prioritize.
-
Month 2 — Commit: Finalize CAPEX and sourcing decisions for critical-path components, and begin certification scheduling for planned product updates in 2027.
-
Month 3 — Execute: Implement hedging and inventory plans, initiate any targeted M&A or strategic partnership discussions, and deploy the go-to-market testing plans included in the study.
Conclusion and next steps
For firms making binding strategic choices in 2026, the intersection of robust market growth (USD 200.0 Million in 2025 to an expected USD 320.2 Million by 2032 at a 7.0% CAGR), material-cost volatility, and evolving standards creates a compressed set of decision points. The full PW Consulting Low Voltage DC Circuit Breaker Market report provides the granular segmentation, supplier-level intelligence and executable playbooks required to convert market momentum into profitable growth. For access to detailed segment splits, supplier scorecards, and our model workpapers, consult the source report page and schedule a briefing with our industry team.
For detailed analysis of this topic, please visit the official page: Low Voltage DC Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Communications to hit USD 56,800M by 2032 (6.8% CAGR)
By PW Consulting, 2026-07-12
Military Communications Market — Strategic Outlook for 2026 Decision-Makers
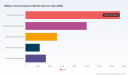
PW Consulting’s latest Military Communications Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) offers an actionable synthesis designed to guide executive decisions in 2026. Anchored in robust bottom‑up modeling, the study traces the market through a period of structural transition and projects continued expansion at a compound annual growth rate (CAGR) of 6.8%. In aggregate terms the market sits comfortably in the multi‑tens of billions (USD, revenue unit: Million) in 2025 and — based on scenario-validated drivers — is forecast to grow materially by 2032. This briefing explains why that trajectory matters, what levers will shape supplier and buyer outcomes over the next 18 months, and how to extract operational advantage from the full report.
Military Communications Market
Why this study matters now
2026 is a decision‑heavy year for stakeholders across defense primes, tiered suppliers, satellite operators, and government procurement offices. Investment cycles are accelerating around three intersecting inflections: the shift toward proliferated and protected small‑satellite architectures; the industry adoption of high‑throughput optical interconnections and anti‑jam technologies; and the tightening nexus between spectrum policy and procurement funding. Our research quantifies the economic implications of these inflections (base year metrics, historical growth patterns, and forecast trajectories are embedded in the report’s models) and translates them into near‑term commercial and programmatic actions.
Military Communications Market
- Macro posture: The market’s mid‑single digit CAGR signals steady demand and encourages capacity investments, but it also requires disciplined portfolio prioritization to avoid misallocated capital.
- Competitive structure: Concentration metrics show the top three firms control a significant portion of market revenue while the top five expand that share further, creating a market where scale matters but niches remain accessible to specialized innovators.
- Program timing: Multiple government programs and IDIQ frameworks initiated in 2024–2026 create procurement windows that favor early movers with validated demonstration assets and partner ecosystems.
Core market dynamics and technology inflection points
Our analysis synthesizes procurement announcements, corporate moves, and regulatory shifts to explain demand and supply evolution.
Military Communications Market
- Proliferation of protected small‑satellite constellations: Program awards and IDIQ pools created in 2025–2026 reinforce a system architecture that prizes distributed resilience and anti‑jamming capabilities. This drives demand across satellite manufacturing, hosted payload services, ground segment anti‑spoofing, and RF hardening.
- Optical and hybrid networking: Progress on optical inter‑satellite links and the acquisition of key optical terminal vendors by launch and integrator players is creating a value chain where photonics expertise materially changes cost and performance equations for long‑haul military comms.
- Hybridization of commercial and dedicated military networks: Operators are increasingly pitching hybrid service models combining commercial constellations with DoD overlays. This trend alters contracting approaches and supports alternative revenue models for satellite operators and service integrators.
- Spectrum policy as a strategic variable: Recent congressional and federal actions are reshaping the spectrum pipeline and reimbursement mechanics; procurement teams must now reconcile auction dynamics, relocation cost recovery frameworks, and the absence of fully documented interagency spectrum‑sharing plans in their risk models.
Competitive landscape — what matters to bidders and partners
Our competitive analysis focuses on a curated set of companies that illustrate three strategic archetypes: prime system integrators, vertically integrated satellite and terminal developers, and specialized subsystem providers. Each archetype faces distinct opportunity and risk profiles.
- Prime integrators (examples reviewed): Firms with legacy systems engineering depth and prime contract experience retain advantage in large‑scale modernization programs. Their ability to package end‑to‑end solutions and to hold critical path responsibility for national continuity and NC3 modernization is a differentiator.
- Platform and operator entrants: Companies building or operating small satellites and hybrid service layers are disrupting traditional supplier relationships. Their advantage lies in rapid iteration, lower per‑unit capital intensity, and service‑level flexibility attractive to both program offices and allied partners.
- Specialist technology providers: Optical terminal vendors, anti‑jam modem manufacturers, and tactical comms hardware suppliers are the innovation engines. Consolidation moves and targeted acquisitions have expanded their industrial reach, enabling them to supply both government programs and new commercial backbones.
Strategically, winners will be those who master systems integration across radiofrequency, photonics, and software layers while navigating multi‑award IDIQs, teaming arrangements, and export/compliance constraints.
What the report contains — practical deliverables
The full study is structured to be immediately operational for commercial strategy teams, M&A investors, and procurement leads. Highlights include:
- Top‑line market sizing and a transparent, reproduceable model (base year 2025; historical window 2020–2025; forecast 2026–2032) with downloadable datasets in USD (Million).
- Scenario‑based forecasts under alternative policy and budget pathways, enabling rapid sensitivity testing of program win rates, pricing pressure, and technology adoption curves.
- Vendor profiles and capability maps that go beyond public press releases to assess program relevance, integration risk, and partnership fit—without exposing confidential commercial splits in the preview.
- Procurement playbooks that translate program timelines and contract vehicle structures into bidding and teaming recommendations, including go‑to‑market approaches for IDIQ pools and prototype opportunities.
- An operator and supplier heatmap that flags where price competition, technical differentiation, or regulatory constraints are likely to compress margins.
- Investment and M&A scoring frameworks with target shortlists and integration red‑flags tailored for investors seeking to enter or expand in military communications supply chains.
- Regulatory and spectrum risk modules that incorporate recent legislative changes, auction mechanics, and reimbursement frameworks—critical for financial planning and program cost‑of‑ownership estimates.
Policy and regulatory context — the unseen constraint
Policy developments in 2024–2026 have elevated spectrum strategy from a technical consideration to a core budgetary and programmatic risk. Recent legislation established a spectrum pipeline and identified bands for reallocation and study. At the same time, federal guidance on spectrum‑sharing mechanisms remains incomplete, and government actors have signaled that auction proceeds must cover federal relocation and sharing costs with defined reimbursement rules. For program planners, this creates two imperatives: model the cost of spectrum transitions conservatively, and engage early with spectrum policy teams to avoid schedule and funding surprises.
Strategic recommendations for 2026
- Prioritize modular, demonstrable capability: Win probability in multi‑award procurements favors teams that can present a demonstrator or flight‑proven subsystem tied to a clear path to scale.
- Build hybrid revenue pathways: Combine service contracts with hardware sales and managed service elements to stabilize cash flow against procurement timing variability.
- Invest in optical and anti‑spoofing competencies: These technologies are gatekeepers to next‑generation architectures and command premium margin in integration phases.
- Calibrate partnership strategies to concentration realities: The market is dominated by a few large primes, but targeted partnerships with incumbents or co‑development with specialist vendors yields differentiated access to program pipelines.
- Embed policy scenario planning: Invest in a small, focused capability to track spectrum policy, auction cues, and reimbursement rules—this reduces bid‑to‑contract timeline risk and protects program margins.
Risk profile — what could derail plans
- Policy uncertainty: Incomplete interagency guidance on spectrum sharing and pipeline timing can create program slips or unanticipated relocation costs.
- Supply chain constraints: Optical terminal production, specialized RF components, and certain semiconductor lines remain chokepoints that can inflate lead times.
- Budget volatility: Shifts in defense appropriation priorities or reallocation to other domains could compress award opportunities in the short term.
- Competitive consolidation: M&A activity among specialist vendors can rapidly change competitive dynamics and create new integration dependencies.
How to use this briefing and next steps
This article is a strategic preview intended to surface the directional forces and practical recommendations that will shape successful plays in 2026. It intentionally omits granular regional and application revenue splits to preserve the commercial incentive for the full dataset. PW Consulting’s full Military Communications Market report contains the detailed segmentation, downloadable financial models in USD (Million), supplier scorecards, and scenario workbooks that allow you to:
- Quantify addressable market share by program and geographies for inclusion in investment memos;
- Create evidence‑based win strategies with sensitivity testing for pricing and program delays;
- Identify mid‑market acquisition targets and model accretive integration paths;
- Build procurement timetables tied to policy milestones and auction outcomes.
For executives mapping 2026 resource allocation, this study provides both the high‑level market architecture and the operational playbooks to convert forecasts into funded programs. To access the complete dataset, segmented forecasts, and supplier playbooks, please refer to the full PW Consulting Military Communications Market report available through our publications portal.
For detailed analysis of this topic, please visit the official page: Military Communications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
IPL Hair Removal Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive snapshot
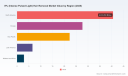
As aesthetic medicine continues to migrate from specialist clinics to multi‑channel delivery models, the IPL (Intense Pulsed Light) hair removal market is moving from niche adoption toward sustained commercial scale. Using 2025 as the base year, PW Consulting projects the global market at roughly USD 100 Million in 2025, expanding at a compound annual growth rate (CAGR) of 8.5% through the forecast horizon (2026–2032). By the end of the forecast period the market is expected to be materially larger, reflecting accelerating adoption in both professional and home‑use contexts and continued technological maturation of IPL platforms.
IPL (Intense Pulsed Light) Hair Removal Market
This briefing outlines why the 2026 planning cycle is pivotal: product roadmaps, regulatory investment, channel partnerships and M&A theses established now will determine competitive position across the next six years. The full PW Consulting IPL Hair Removal Market report contains the detailed datasets, segment breakouts, vendor scorecards and tactical playbooks required to execute—this article intentionally highlights strategic implications while withholding the granular splits that are available in the paid report.
IPL (Intense Pulsed Light) Hair Removal Market
Why this research matters for 2026 strategic planning
- Investment prioritization: The market’s mid‑single‑digit to high‑single‑digit CAGR requires selective capital allocation—knowing which product enhancements and geographies drive outsized returns is essential.
- Regulatory timing: FDA and EU milestones affect time‑to‑market; clearance strategies must be synchronized with commercial launches to avoid revenue leakage.
- Channel transformation: Clinics, med spas and at‑home offerings are converging; manufacturers and service providers must redesign distribution, training and post‑sales models to capture blended demand.
- Competitive differentiation: Leading vendors are shifting from single‑function devices to platform plays that bundle clinical versatility, data capture and consumables—firms that ignore platform economics risk margin compression.
Market dynamics shaping near‑term strategy
The IPL hair removal market is being shaped by four interdependent dynamics that should inform every board‑level discussion in 2026.
IPL (Intense Pulsed Light) Hair Removal Market
- Technology evolution and clinical outcomes: Innovations such as optimized pulse modulation, SHR (super hair removal) techniques, contact cooling and integrated safety sensors are reducing procedure time, minimizing discomfort and expanding treatable skin types. These improvements accelerate in‑clinic throughput and support premium pricing for differentiated platforms.
- Channel convergence and consumer behavior: Demand is shifting from episodic, clinic‑only treatments to hybrid pathways that include professional services and validated home‑use devices. Consumer willingness to pay for convenience and safety is increasing, but providers retain influence through clinical supervision and recurring service revenue.
- Regulatory pressure and safety standards: FDA 510(k) clearances for permanent hair reduction and updated EU MDR requirements have raised the bar for device documentation, electrical safety and clinical evidence. Home‑use devices now face stricter requirements around low‑fluence safety sensors and human factors engineering. Vendors that build regulatory robustness into product design can shorten approval timelines and reduce post‑market risk.
- Competitive intensity and market concentration: The market shows a clear leadership tier of established OEMs and newer entrants leveraging regulatory clearances to scale rapidly. While incumbent brands benefit from installed bases and clinician trust, low‑cost OEMs are increasing price pressure in mature channels and accelerating feature parity in entry segments.
Regulatory and reimbursement context (short, practical takeaways)
- FDA pathways: Professional and home‑use IPL systems intended for permanent hair reduction require careful alignment to 510(k) predicates and radiation safety standards; early engagement with regulators reduces rework risk.
- EU compliance: CE marking under MDR plus a Declaration of Conformity and ISO‑aligned electrical safety testing remain prerequisites for EU commercialization; supply chain documentation and clinical evaluation reports are often the gating factors.
- Reimbursement reality: IPL hair removal is predominantly cosmetic and self‑pay in most jurisdictions; providers must therefore optimize direct‑to‑consumer pricing and financing options rather than relying on third‑party reimbursement codes.
Competitive landscape: how market leaders are positioning
The competitive picture is defined by a handful of globally recognized platforms and a rising cohort of validated new entrants. Key characteristics of the competitive set include platform extensibility, clinical evidence, channel reach and strategic partnerships.
- Lumenis (Yokneam, Israel) — a technology pioneer known for OPT™ (Optimal Pulse Technology) and broad clinical platforms that address multiple aesthetic indications. Lumenis leverages long clinical track records and multi‑indication devices to defend premium positioning.
- Candela (Marlborough, MA, USA) — an incumbent with a deep installed base and FDA‑cleared solutions. Recent partnership activity has demonstrated Candela’s go‑to‑market emphasis on expanding clinic networks and increasing utilization per site.
- Alma Lasers (Caesarea, Israel) — focuses on fast, low‑discomfort SHR approaches and clinic efficiency. Alma’s product packaging is engineered to lower the operator learning curve and maximize throughput.
- Cynosure (Westford, MA, USA) — positions its Xelera platform and laser offerings as integrated tools for multi‑procedure practices, emphasizing workflow integration and training services.
In 2025 and 2026 the market also saw regulatory milestones where multiple new entrants obtained FDA clearances—demonstrating that product entrants with rigorous clinical dossiers can rapidly access the U.S. market. Parallel commercial moves include major clinic networks augmenting fleets with additional platforms, reinforcing the point that partnerships with national providers accelerate adoption curves.
What the PW Consulting report delivers (practical, operational outputs)
The full IPL Hair Removal Market report is designed for direct operational use by product teams, regulatory affairs, corporate development and commercial leadership. Key deliverables include:
- Historical market sizing (2020–2025) and scenario forecasts (2026–2032) with device‑level and channel‑level demand models to support NPV and ROI calculations.
- Competitive vendor scorecards and go‑to‑market playbooks that benchmark product features, clinical evidence, installed base and dealer network strength.
- Regulatory and compliance matrix (FDA 510(k) considerations, EU MDR checklists, human factors testing templates) to accelerate submissions and minimize non‑conformities.
- Commercial strategies tailored to clinics, med spas and home‑use channels—including pricing elasticity analysis, subscription and consumable models, and training/service economics.
- M&A and partnership screening toolsets identifying inorganic targets by capability gaps, geography and regulatory status.
- Practical annexes: sample clinical protocols, risk mitigation checklists, procurement decision trees, and a dataset appendix for integration into internal BI tools.
Note: To preserve the strategic value of this preview we have intentionally withheld the granular regional and application splits, unit price schedules and the full vendor share table. These detailed data products are available in the full PW Consulting report.
Top strategic recommendations for 2026
- Prioritize platform modularity: Build devices that support feature‑bundling (cooling, pulse profiles, software upgrades) to capture upsell and extend product lifecycle without full hardware replacement.
- Invest in a regulatory‑first product development lifecycle: Integrate regulatory, clinical and risk teams from concept to launch. Early human factors testing and predicate mapping shortens 510(k) timelines and reduces post‑market corrective actions.
- Design channel‑specific value propositions: For clinics and med spas emphasize throughput, warranty and consumables economics; for home‑use emphasize safety sensors, UX and data privacy to build consumer trust.
- Move from device sales to recurring revenue models: Consider consumables, service contracts, software subscriptions and training packages to stabilize margin and increase customer lifetime value.
- Execute selective partnerships: Collaborate with major clinic networks and telehealth platforms to create funnel visibility and ensure device utilization at scale—deal structures should align incentives around throughput and repeat visits.
- Monitor low‑cost OEM entries: Maintain a two‑track response: defend premium segments through superior clinical evidence and customer service while evaluating cost reduction or mid‑market product variants.
Decision framework and next steps
To convert market insights into executable plans in 2026, PW Consulting recommends a five‑step decision framework:
- Diagnose: Validate your current addressable market using the report’s demand model and compare to internal forecasting assumptions.
- Prioritize: Identify high‑return product and channel investments using scenario analyses and sensitivity testing provided in the report.
- Prepare: Align R&D, regulatory, clinical and commercial teams on a single product launch roadmap with regulatory milestones mapped to revenue targets.
- Execute: Deploy partnerships, pilot commercial launches, and convert early adopter data into dossier content for accelerated scaling.
- Optimize: Use the report’s performance KPIs and market intelligence to iterate pricing, consumable strategies and service offerings on a quarterly cadence.
PW Consulting’s IPL Hair Removal Market report is built to be the operational backbone of 2026 planning cycles. For executives preparing capital allocation, M&A diligence or product launch strategies, the report provides the quantitative foundation and tactical playbooks necessary to compete effectively.
To access the complete datasets, vendor scorecards and downloadable playbooks, please visit the PW Consulting IPL Hair Removal Market report page where the full intelligence package is available.
For detailed analysis of this topic, please visit the official page: IPL (Intense Pulsed Light) Hair Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ship-to-Shore (STS) Container Cranes Market USD 3,000M in 2025; 5.2% CAGR (2026–32)
By PW Consulting, 2026-07-12
Ship-to-Shore (STS) Container Cranes Market: Strategic Outlook for 2026 Decision-Making
Executive preview
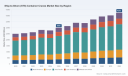
The global Ship-to-Shore (STS) container cranes market has demonstrated steady expansion through the early 2020s and enters 2026 from a position of structural growth and renewed capital intensity. In our base-year assessment (2025) the market reached approximately USD 3,000 Million (revenue, Million USD), up from roughly USD 2,500 Million in 2020. Our model projects a compound annual growth rate (CAGR) of about 5.2% across the 2026–2032 forecast window, driving the market toward an anticipated USD 4,253 Million by 2032 under the baseline scenario.
Ship-to-Shore (STS) Container Cranes Market
This briefing is intended as a strategic “preview”: it captures the data-driven trends, competitive dynamics, and procurement levers that will matter for boardroom decisions in 2026, while intentionally withholding the granular regional and application split tables reserved for the full PW Consulting report and interactive datasheet.
Ship-to-Shore (STS) Container Cranes Market
Why this matters for 2026 purchasers and investors
- Capital allocation and timing: Port terminals, marine investors and OEMs must align crane procurement and retrofit cycles with longer lead-times and rising capital costs. The combination of steady underlying demand and protracted delivery schedules creates windows where early commitment improves access and price certainty.
- Contract design and risk transfer: With stretch in delivery timelines and tariff volatility, contract terms that clearly allocate escalation, delay penalty and scope-change risk are now differentiators in tender outcomes.
- Service and lifetime value: As fleets grow and vessel dimensions increase, lifecycle costs — not only purchase price — determine terminal productivity. Maintenance contracts, digital diagnostics, and spare-parts logistics are elevated priorities.
Key market dynamics shaping 2026 strategies
Three macro dynamics dominate the STS market heading into 2026:
Ship-to-Shore (STS) Container Cranes Market
- Vessel upscaling and operational productivity — The push toward larger vessels and denser yard operations continues to favor higher-capacity cranes, dual-trolley concepts and feature-rich control systems that compress vessel turnaround.
- Supply-chain and manufacturing pressure — Producers and buyers alike grapple with longer manufacturing cycles. Average global delivery schedules extended materially between 2022 and 2024, driven by steel-price and PLC-cost inflation as well as capacity constraints in fabrication and electrical subsystems.
- Regulatory and trade friction — Trade measures and tariff actions introduced noise into sourcing strategies, increasing the premium on diversified procurement footprints and local-assembly options.
Operational evidence underlines these dynamics. Industry surveys reported continued deliveries in the low hundreds of STS units globally in recent years, and trends in lift-class selection and boom outreach reflect how terminal planners are trading capacity for reach. These market signals translate directly into vendor selection criteria: uptime guarantees, anti-sway and automation features, electric-drive options and modularity now outrank simple upfront price in many tenders.
Price and delivery realities: what procurement teams must know
Purchase price ranges remain wide, reflecting model complexity and optionality. STS crane prices typically span from lower-cost Panamax-class units to premium super post-Panamax builds — the variability largely reflects lift capacity, outreach, electrification and automation packages. Importantly, manufacturing lead-times lengthened in the mid-2020s: our analysis cites an extension from roughly 11 months to 15 months on average during 2022–2024, a function of a near-term spike in steel and PLC costs and constrained workshop capacity.
Trade policy can materially change landed cost. Recent Section 301 measures and related import tariffs on certain origins have added a non-trivial incremental cost to some major U.S. terminal projects, forcing re-evaluation of sourcing, value-engineering and potential capital reallocation.
Competitive landscape — who matters and why
The STS market demonstrates concentrated leadership by established OEMs with deep installed bases and broad global service networks. Market concentration metrics indicate that the industry’s top three vendors control a majority share of new-build activity, with the top five extending that dominance further. For procurement teams, this creates a specific dynamic: while a shortlist of incumbents offers scale and predictable delivery, emerging and regional suppliers compete aggressively on price, customization and local support.
- Konecranes (Helsinki, Finland) — Focused on high-reliability STS designs; differentiators include proprietary electric motors, gearing and control systems and a large installed base supporting fast ship turnaround. ( https://www.konecranes.com)
- Liebherr (Bulle, Switzerland) — Premium STS cranes with advanced anti-sway, fully electric variants and dual-trolley options; long-standing manufacturing footprint and recent high-profile deliveries to major European terminals. ( https://www.liebherr.com)
- ZPMC (Shanghai, China) — Global reach with flagship STS deployments across six continents; recognized domestically for manufacturing excellence and sizeable production capacity. ( https://www.zpmc.com)
- SANY Group (Changsha, China) — Competitive pricing and strong Asia-Pacific relationships with increasing emphasis on customization and local support. ( https://www.sanyglobal.com)
- Paceco Corp. (Cypress, California, USA) — Focus on large PORTAINER® STS gantry cranes, emphasizing trolley speed and bespoke designs for North American and select global terminals. ( https://pacecocorp.com)
- Hyundai Samho (South Korea) — Integrated heavy-industry portfolio with STS offerings tied into broader port-equipment supply chains. ( https://www.hyundai-heavy.com)
- Mitsui Engineering & Shipbuilding / PACECO (Tokyo, Japan) — Known for robust PORTAINER® designs with a focus on productivity and lifecycle reliability. ( https://www.mes.co.jp)
- Henan Weihua (Henan Province, China) — Experienced regional manufacturer with multi-decade design and production capability for STS units. ( https://www.henanweihua.com)
- Anupam Industries (India) — Targeting global terminals with competitive, regionally tailored STS solutions. ( https://www.anupamindustries.com)
Recent deal-flow and deliveries illustrate competitive positioning: premium OEMs secured new supply contracts and key deliveries in late 2025 for strategic terminals; flagship projects in emerging markets continue to attract Chinese and regional suppliers. Industry associations’ surveys in 2024 captured unit deliveries and shifting lift-class preferences, reinforcing that the product mix is moving toward higher-capacity, longer-reach equipment.
Practical report takeaways — what PW Consulting delivers
For executives preparing 2026 procurement cycles, the full PW Consulting Ship-to-Shore market study provides five practical outputs designed to inform decisions and accelerate execution:
- Forward-looking demand model: Scenario-based forecasting (2026–2032) with sensitivity to vessel-size trajectories, terminal throughput growth and capex pacing. The model is delivered in an interactive spreadsheet so teams can stress-test assumptions.
- Supplier scorecards and procurement playbooks: Comparative supplier assessment across technical capability, on-time delivery history, service network quality and total cost of ownership (TCO) implications; negotiation templates and contract clauses tailored to mitigate lead-time and tariff risk.
- Unit economics and TCO frameworks: End-to-end cost modelling that captures purchase price, import duty exposures, spare-parts logistics, energy consumption (electric vs diesel/electric hybrid options) and typical maintenance profiles.
- Supply-chain and risk maps: Factory-capacity overlays, single-point-of-failure analysis for critical subsystems, and contingency playbooks for accelerated delivery or local-assembly strategies.
- M&A and Capex screening tools: Valuation benchmarks, integration-risk flags and a shortlist of strategic targets where vertical integration or aftermarket capability could change competitive dynamics.
Note: this preview intentionally omits the full segmentation tables and unit-level pricing ladders (regional splits, application-by-type breakdowns and supplier-by-model price matrices), which are accessible in the full report and accompanying data workbook.
How to apply these insights in 2026 — a short action checklist
- Align procurement windows with current average lead-times; place orders with realistic acceptance dates and incentivize early delivery where needed.
- Build tariff and escalation clauses into contracts; evaluate local assembly or phased delivery if duties materially increase landed cost.
- Prioritize lifecycle uptime through longer service agreements and digital-monitoring add-ons; quantify TCO rather than chasing headline discounts.
- Maintain multi-supplier shot lists for major tenders; use PW Consulting’s supplier scorecards to validate technical claims against historical delivery performance.
- Stress-test capex scenarios against vessel size evolution and terminal throughput; stagger investments to retain flexibility for retrofits and automation upgrades.
Next steps and where to get the full intelligence
This executive preview synthesizes the strategic and operational signals that will shape STS procurement and investment decisions in 2026. The full PW Consulting Ship-to-Shore (STS) Container Cranes Market report includes the complete regional and application segmentation, model assumptions, unit-price ladders, supplier scorecards and an interactive forecast workbook designed for CFOs, procurement leads and terminal operators. To access the comprehensive analysis, data tables and proprietary scenario tools, please follow the link on our report page or contact a PW Consulting advisor for a guided walk-through of the dataset and model outputs.
For detailed analysis of this topic, please visit the official page: Ship-to-Shore (STS) Container Cranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Molecular Beam Epitaxy (MBE) Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
The Molecular Beam Epitaxy (MBE) market is at an inflection point. After steady recovery and consolidation through the early 2020s, the market reached a material scale by the 2025 base year and is projected to grow at a mid-single-digit compound annual growth rate (CAGR) through the early 2030s. This report frames that growth pathway, the structural drivers behind it, and the practical options executives must weigh in 2026 to convert structural trends into competitive advantage.
Molecular Beam Epitaxy (MBE) Market
Why this matters for 2026 strategy
- MBE remains the enabling deposition technology for advanced III‑V semiconductors, optoelectronics, and emerging quantum devices — areas where product roadmaps are advancing from laboratory demonstration to pilot and production scale.
- The market’s projected steady expansion underscores opportunity, but timing and go‑to‑market choices will determine whether firms capture high-margin system sales, recurring services, or downstream device revenue.
- Procurement and policy shifts in key markets are changing how large research and production customers source capital equipment; these shifts alter contract sizes, channel tactics, and service models that vendors must adopt in 2026 and beyond.
Market trajectory and sizing (high level)
Using 2025 as the base year, the MBE market exhibits a predictable, technology‑led growth profile. The market’s baseline scale provides a focused addressable opportunity for suppliers, while the projected mid‑single‑digit CAGR through the forecast period reflects the compound effect of incremental volume growth in production applications, sustained R&D demand, and selective replacement cycles for high‑value systems. For leaders, the strategic implication is clear: growth is real and durable, but concentrated in technologically advanced niches where suppliers that pair equipment innovation with applied services will capture the lion’s share of profitable expansion.
Molecular Beam Epitaxy (MBE) Market
Key demand drivers
- Quantum device commercialization: As quantum photonics and single‑photon emitter programs move from faculty labs into scale pilots, demand for precision MBE platforms optimized for nanostructure repeatability has risen. Research deployments in 2024–2025 underscore the migration from exploratory research to applied device engineering.
- Compound semiconductor and infrared technologies: Advanced detectors and optoelectronic devices—particularly those relying on III‑V materials—continue to anchor MBE demand because of the technique’s atomic‑level control over layer composition and interfaces.
- Dual‑track market dynamics: R&D activity remains a durable revenue base, but production use cases are expanding. The most successful suppliers will demonstrate pathways for customers to transition processes from research platforms to production‑grade systems without compromising yields or wafer throughput.
Supply chain, raw‑material and regulatory considerations
MBE systems are sensitive to components and precursor supply chains. Gallium‑based substrates and arsenide precursors continue to be strategic inputs; their availability and cost volatility materially affect total cost of ownership for users. Separately, procurement policy changes in major buyer jurisdictions are reshaping contract negotiation dynamics—raising thresholds for formal cost disclosures and altering how larger system deals are structured. Vendors should explicitly model these procurement shifts when sizing deals and designing sales incentives in 2026.
Molecular Beam Epitaxy (MBE) Market
Competitive landscape — who matters and why
The MBE supplier ecosystem is a mix of global platform vendors and specialized component or systems houses. Market concentration metrics indicate a market where a small number of tier‑one suppliers capture a sizeable share of the higher end, but a diverse set of regional and niche vendors compete on customization, service and price. For strategic planning, this means incumbents must defend installed base advantages while challengers can win by tightly coupling equipment with application‑specific services.
- Riber S.A. — A European platform vendor with a deep installed base and production‑oriented systems. Recent multi‑system orders and a broad installed fleet emphasize Riber’s strength in production and service continuity. For partners and competitors, Riber’s model underscores the value of combining robust hardware with lifecycle services to lock in production customers.
- Veeco Instruments Inc. — A technology leader with modular R&D and production platforms that has maintained strong engagement with university and research centers. Recent deployments for compound semiconductor and quantum programs illustrate Veeco’s success in securing early‑stage R&D relationships that can translate into production wins over time.
- DCA Instruments, SVT Associates, Dr. Eberl, Eiko Engineering, Omicron Electronics, SKY Technology — These vendors represent the spectrum of specialization: III‑V epitaxy platforms, component suppliers, UHV and tooling specialists, and regional manufacturers. Their strategies vary from focused product differentiation to regionally tuned go‑to‑market models, enabling them to capture niche demand and retrofit opportunities in installed fleets.
Recent market signals to watch
- Academic and spin‑out wins are accelerating: Notable university purchases and commercial deployments in 2024–2025 show that applied research funding is translating into upgraded equipment investments.
- Large production orders remain selectively awarded: There are confirmed instances of multi‑system orders for production platforms—an indicator that certain end markets are moving from pilot to scaled manufacturing.
- Procurement thresholds and contract structures are changing: Updated acquisition rules in some jurisdictions have reduced administrative burdens for mid‑sized procurements, shifting where opportunities lie for both domestic and international vendors.
What the PW Consulting MBE report provides (practical contents)
The full study integrates proprietary demand modeling, supplier inventories, scenario analysis and an action‑oriented playbook for 2026 decision‑makers. Notable deliverables include:
- Top‑down market sizing and a bottom‑up demand model that reconciles installed base dynamics with new system deployments across R&D and production use cases.
- Segment‑level forecasts and sensitivity scenarios (technology shock, raw‑material stress, rapid commercialization) that translate into revenue and margin implications for suppliers and OEMs.
- Supply‑chain mapping and vendor risk scoring, with mitigation actions for critical inputs and long‑lead items.
- Detailed competitive profiles and capability matrices covering system architectures, platform modularity, service offerings and installed‑base monetization strategies.
- An M&A and partnership playbook: valuation heuristics, integration risks, and target archetypes for buyers seeking technology or regional expansion.
- Commercial playbooks for vendors and buyers: pricing frameworks, contract structuring templates that reflect evolving procurement rules, and aftermarket/service revenue accelerators.
Strategic implications and recommended actions for 2026
Executives facing 2026 choices should prioritize clarity on two dimensions: where their core advantage lies (equipment innovation vs. services vs. integration) and how they will manage the transition of customers from R&D to production. The following high‑level recommendations provide a starting point:
- Prioritize platform modularity. Build or acquire modular subsystems that reduce conversion costs when customers scale from research to production; this reduces buyer switching costs and strengthens lifetime revenue.
- Design procurement‑aware commercial models. Given changing procurement thresholds and contract behaviors, create flexible contracting options (lease + service, staged purchases, performance guarantees) tailored to research institutions and production fabs.
- De‑risk critical material supply. Implement diversified sourcing and hedging strategies for gallium and other strategic precursors; where feasible, verticalize or secure long‑term supply agreements to protect uptime for production customers.
- Monetize installed base. Invest in remote diagnostics, upgrade modules and certified refurbishment programs to generate recurring revenue and deepen customer relationships.
- Targeted M&A and partnerships. For suppliers seeking scale, prioritize bolt‑on acquisitions that extend service footprints or add complementary component expertise rather than horizontal hardware duplication.
- Invest in applied R&D partnerships. Secure early access to device roadmaps by partnering with academic centers and corporate research labs; these relationships often convert into multi‑year system and service contracts.
Risks and watchlist for the next 18 months
- Raw‑material shocks that increase operating costs and slow customer purchase cycles.
- Geopolitical and trade policy shifts that alter where customers prefer to source capital equipment.
- Rapid technological substitution in niche applications—if alternative deposition or integration approaches gain parity, the addressable market for certain MBE applications could narrow.
Conclusion — how to use this intelligence in 2026
For leaders making 2026 investment and go‑to‑market decisions, the choice is not whether the MBE market grows—the data indicate a steady, commercially meaningful expansion—but how to position to capture the most valuable portions of that growth. Whether the objective is to win production contracts, expand regional presence, or transition from equipment to lifecycle service models, the playbook must combine technical differentiation with contractual flexibility and supply‑chain resilience. Our full report provides the granular segmentation, company benchmarking and scenario dashboards necessary to convert these strategic priorities into executable 12‑ and 36‑month plans.
Next step
PW Consulting’s full MBE market study contains the detailed datasets, interactive forecasts and vendor scorecards that operational teams require to execute on the recommendations above. Access to the full model and custom briefings will enable tailored scenario runs for procurement, product and M&A teams — contact our research desk to request the complete report and a guided walkthrough of the decision tools referenced here.
For detailed analysis of this topic, please visit the official page: Molecular Beam Epitaxy (MBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mirrors Market at USD 215M in 2025, Poised for 7.82% CAGR to 2032
By PW Consulting, 2026-07-12
Mirrors Market — Strategic Primer for 2026 Decision-Makers
As companies plan product roadmaps, capital allocation and partnerships for 2026, the mirrors sector presents a mix of steady, technology-fueled growth and fragmentation that rewards targeted playbooks. This primer introduces the PW Consulting Mirrors Market study and explains why the research is indispensable for executives who need to convert macro momentum into actionable strategies while avoiding commoditization traps.
Mirrors Market
Snapshot: scale, trajectory and market structure
Measured on a consistent base-year (2025), the mirrors market has shown resilient expansion through the early 2020s and is entering a multi-year growth phase. The total market rose from approximately USD 163 million in 2020 to roughly USD 215 million in 2025. Under our forecast horizon (2026–2032), the market is expected to grow at a compound annual growth rate (CAGR) of 7.82%, reaching an estimated USD 345 million by 2032. These headline dynamics reflect a blend of steady end‑market demand (construction, hospitality, residential retrofit) and rapid adoption of feature-rich products (LED integration, smart displays, safety-laminated architectural glass).
Mirrors Market
Two structural features matter for strategy: first, the market concentration is low — the top 3 players account for under a quarter of the market and the top 5 still capture only slightly more. Second, growth is not uniform across product categories and channels; it is concentrated where technology, regulatory requirements, and high-performance materials intersect. Our study keeps the full set of segment-level numbers and model outputs gated — this primer surfaces the strategic implications while protecting the granular data that will guide operational decisions.
Mirrors Market
What the full report provides (practical, operational content)
- Proprietary demand model (2020–2032) with scenario toggles for raw material inflation, construction cycles, and smart-product penetration; downloadable worksheets allow CFOs to test capital plans under three macro scenarios.
- Go-to-market playbook tailored to five buyer archetypes (architectural/contracting, hospitality FF&E, residential premium, OEMs for appliances/automotive, and high-tech industrial) — each with supplier negotiation levers, margin benchmarks, and channel-mix optimization.
- Detailed supplier scorecards and capability mapping for more than twenty manufacturers and integrators; these include product technology roadmaps, manufacturing lead-time matrices, and recommended partnership types (JV, contract manufacturing, IP licensing).
- Regulatory and standards matrix highlighting current committee activity and anticipated changes in safety, optical performance, and eco-compliance—built to feed procurement and product-engineering roadmaps.
- M&A and partnership playbook with valuation multipliers calibrated to public and private transactions in related glass and smart-fixture markets.
Why this matters for 2026 choices
- Investment Prioritization — With a mid‑single digit-to-low double‑digit growth trajectory, companies must choose where to allocate scarce capex. The report’s scenario-enabled demand model turns headline CAGR into actionable capital timing.
- Product Differentiation — Margin expansion will come from functionality and system integration (embedded lighting, anti-fog, vanishing-display capability), not from basic mirror commodities. Our research shows where to prioritize R&D versus price competition.
- Supply‑chain Resilience — Raw-material costs and processing technologies (e.g., advanced silvering, laminations for safety, and optical coatings) are central to performance. The report maps supplier risk and bargaining power across those nodes.
- Compliance and Standards Exposure — ANSI-accredited U.S. Technical Advisory Groups and ISO-related committees are active in mirror-related standards; early alignment reduces late-stage redesign risk for international projects.
Competitive landscape — positioning and strategic moves
The competitive set is a mosaic of specialist innovators, architectural glass conglomerates, and regional high-volume producers. That fragmentation creates opportunity for targeted consolidation and vertical integration — but not through a one-size-fits-all approach.
- Smart and luxury integrators: Companies focused on illuminated, connected and smart mirrors have a clear premium position. These firms specialize in electronics integration, user experience and hospitality deployments. They typically excel at product design and channel relationships with premium hotel brands and high-end residential specifiers.
- Architectural and industrial glass incumbents: Large glass producers with advanced processing (edge protection, laminates, optical clarity enhancements) have the upstream scale and R&D that matter for large construction or safety‑critical projects. Their strength is materials science and production efficiency for volume or customized architectural panels.
- Local fabricators and decorative specialists: Regional players, artisan makers and mass-volume producers serve distinct niches — from oversized commercial mirrors to decorative framed products — and compete primarily on lead time, customization and local codes compliance.
- Technology disruptors: A small but notable set of firms pursue display‑mirror convergence (switchable mirrors, embedded screens, AR-capable surfaces). These players draw interest from retail, hospitality and experiential signage markets and require partnerships with electronics suppliers and software integrators.
Our company profiles in the report synthesize each player’s strategic footprint: core product offerings, go-to-market channels, geographic strengths, and technology bets. We also catalogue recent moves that matter for partnership and competitive response — product catalog updates from leading LED mirror manufacturers and highly publicized innovation projects (including experimental space-reflection initiatives that signal new demand vectors) are highlighted and analyzed for their strategic ripple effects.
Near-term growth pockets and strategic responses
- Feature-led premiumization: LED lighting, tunable color temperature, anti‑fog systems and integrated controls are now table stakes in premium segments. Suppliers should package optics, electronics and installation as bundled offerings to extract higher margins.
- Commercial retrofit demand: Hospitality and large-scale renovation projects continue to generate steady replacement cycles. Faster lead times and standardized modules reduce project friction.
- Safety and architectural applications: Laminated, distortion‑controlled mirrors for public spaces and institutional projects are growing in importance — driven by both specification standards and insurance considerations.
- High-tech industrial uses: Advanced mirrors for process environments (including sophisticated clean-room applications) require tighter tolerances and specialized coatings; these are higher-margin but require close engineering partnerships with end-users.
Key risks and mitigating actions
- Commoditization risk: Over-reliance on basic glass and commodity silvering squeezes margins. Mitigation: invest selectively in value-added features or lock in long-term supply agreements with premium processors.
- Supply volatility: Raw material shifts and processing capacity constraints can cause lead-time spikes. Mitigation: dual-sourcing strategies, regional buffering, and contract terms that index to validated cost drivers.
- Regulatory shifts: Standards activity can force product changes mid-cycle. Mitigation: engage early in standards committees and maintain a regulatory watch integrated into product development sprints.
- Channel complexity: Varying procurement practices across architectural, hospitality and retail channels increase go-to-market costs. Mitigation: develop channel-specific bundles and a dealer-partner certification program to control brand experience and margins.
Recent developments that affect near‑term strategy
- Market players continue to refresh portfolios — including updated LED and smart mirror lines — creating short windows of opportunity for distributors and installers to capture retrofit projects.
- High-visibility innovation projects (from avant-garde reflector concepts to space-based experiments) are expanding the strategic conversation about non-traditional use cases; companies should track these as potential future demand generators or PR opportunities.
- Standards committees remain active and can materially affect product specifications and procurement requirements. Firms with active standards participation reduce time-to-market friction for regulated projects.
- Operationally, some public accounts of material choices (for example shifts from metal to glass reflectors in specific institutional settings) highlight the importance of monitoring end-user safety and performance preferences — not just price.
How to use the full PW Consulting mirrors study
The full Mirrors Market report is built for busy leaders who need executable plans, not just descriptive analysis. Use it to:
- Stress-test capital projects against three macro scenarios and prioritize rollouts by expected ROI over a 3–5 year horizon.
- Design product roadmaps that assign R&D resources to features with the highest willingness-to-pay in target channels.
- Execute M&A and partnership screening using our calibrated valuation multipliers and supplier scorecards.
- Align procurement and engineering timelines with anticipated standards updates to avoid redesign penalties.
For executives who require the segment-level breakdowns, company scorecards, and the downloadable demand model that underpin these strategic recommendations, the PW Consulting Mirrors Market study provides the complete datasets and scenario tools. Access to those granular outputs is available through the report hub — where clients can also initiate a custom benchmarking or a live model workshop tailored to their portfolio.
PW Consulting has structured this study to be a decision-ready input for 2026 planning cycles. If your 2026 choices include new product investments, channel expansion, or M&A exploration, the right quarter to align strategy and budget is now.
For detailed analysis of this topic, please visit the official page: Mirrors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Remote Proctoring Solutions Market to grow at 15.7% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Remote Proctoring Solutions Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As organizations plan budgets and procurement strategies for 2026, remote proctoring has moved from a tactical response to pandemic-era constraints to a persistent, strategic capability across higher education, professional certification, government testing, and large-scale corporate assessment programs. PW Consulting’s new market study (base year 2025; historical window 2020–2025; forecast 2026–2032) projects continued robust expansion: the market moves from an estimated USD 390 million in 2025 toward a USD 700‑plus million outcome by 2032 under a mid‑teens compound annual growth rate (CAGR 15.7%).
Remote Proctoring Solutions Market
Why this matters for 2026 strategy
- Risk and reputation now sit alongside cost and capacity. High‑stakes assessors must weigh technical integrity, legal defensibility, candidate experience, and geopolitical data constraints when selecting a platform.
- Technology choices made in 2026 will lock in vendor relationships and integration patterns for several years. With a pronounced growth trajectory, procurement windows present both risk (vendor lock) and opportunity (favorable pricing and co‑innovation terms).
- Regulatory and adversarial pressures are tightening concurrently. New rules and sophisticated synthetic‑media threats mean that platform selection should be treated as a strategic architecture decision—not a point purchase.
Market dynamics that will shape vendor and buyer strategies in 2026
Three themes will dominate boardroom conversations and RFPs in 2026.
Remote Proctoring Solutions Market
- Security vs. accessibility tradeoffs. Buyers must reconcile broader access goals (e.g., remote licensing, expanded candidate pools) with increasingly stringent security expectations from regulators and professional bodies.
- AI as both solution and threat. Automated proctoring and behavioral analytics reduce cost per seat, but the same ML advances enable more realistic synthetic attacks. Defenses that combine algorithmic detection with human adjudication become the de‑facto standard for defensibility.
- Regulatory fragmentation and data sovereignty. Major platforms now universally present GDPR/FERPA/CCPA compliance pathways; buyers will prioritize granular data residency controls, encryption standards, and audit trail capabilities when procurement stakes are high.
Selected recent shocks and policy moves
- Policy tightening for high‑stakes professional exams: In April 2026 NCARB announced operational constraints for online delivery of ARE 5.0 that become effective June 1, 2026—most notably, mandatory use of mobile devices as a secondary camera and restrictions on permitted delivery platforms. Such edicts force buyers and vendors to rapidly adapt exam workflows and support toolchains.
- Anti‑spoofing innovations: A May 2026 release of a commercial deepfake detection module that leverages GAN artifact analysis highlights the accelerating arms race between synthetic media and detection systems. Procurement teams must now evaluate not only the presence of AI detectors but their update cadence and transparency.
- Program expansions: Regulatory bodies exploring remote administration of previously in‑person exams (e.g., plans for remote NCLEX testing) signal new addressable demand and stricter acceptance criteria for proctoring evidence.
Competitive landscape — positioning and strategic implications
The market presents a mixed structure: a handful of established providers with specialized capabilities and many niche or regional players. Market concentration remains modest (CR3 ~28.5%; CR5 ~32.8%), indicating room for consolidation and continued opportunity for differentiated entrants.
Remote Proctoring Solutions Market
- Meazure Learning (ProctorU) : A pioneer in live human proctoring focused on high‑stakes certification and licensing. Strengths include robust human review workflows and long experience in defensible chain‑of‑custody practices—important where auditability is paramount.
- Honorlock : Known for hybrid AI + on‑demand live intervention and behavioral analytics tailored to higher education and mid‑stakes assessments. Its model is attractive to institutions seeking a balance between scalability and human oversight.
- PSI Services : Enterprise‑grade portfolio with strong penetration in government and licensing markets. PSI’s platform breadth supports complex delivery modes and testing‑center integration—valuable where exam ecosystem interoperability matters.
- Turnitin / ExamSoft : Focused on academic integrity, coupling assessment delivery with AI‑based cheating indicators and identity verification. Particularly relevant for large universities that emphasize content similarity and learning analytics.
- Proctorio : Automated, high‑volume offering with features such as browser lockdown and eye‑tracking. Suited to cost‑sensitive, scale‑oriented deployments—but buyers should stress test defences against evolving synthetic threats.
- Examity , Talview , Proctor360 , and Proctortrack : Each occupies differentiated niches—ranging from configurable hybrid solutions and enterprise assessment platforms to continuous identity verification and hardware‑assisted environmental security.
- Integrity Advocate : Distinguishes itself with mandatory human review on every AI flag and a no‑install browser approach, positioning for clients that prioritize defensible human adjudication and minimal candidate friction.
What the PW Consulting report provides (practical, action‑oriented content)
This study is structured to support procurement, product, and risk teams as they make near‑term commitments and design multi‑year roadmaps. Highlights include:
- Market sizing, historical tracing (2020–2025), and scenario forecasts (2026–2032) with sensitivity analysis for upside/downside adoption cases.
- Vendor benchmarking matrices: capabilities, deployment footprints, review processes, ML model update cadence, incident response SLAs, and privacy & data‑sovereignty features.
- Use‑case decision trees and procurement scorecards tailored to four archetypal buyers (high‑stakes certification boards, public universities, enterprise talent assessment teams, and government licensing bodies).
- Operational playbooks: pilot design, candidate support models, integrated identity verification flows, and human‑in‑the‑loop escalation protocols.
- Legal & compliance checklist: contract clauses for audit logs, raw footage retention policies, cross‑border transfer risk mitigations, and defensibility standards in the event of contested results.
- M&A and partner landscape: acquisition targets that accelerate capabilities (deepfake detection, secure browsers, hardware accessories), and a short list of potential bolt‑on plays for incumbent platforms.
- ROI and TCO models, including break‑even analyses for live vs. automated proctoring mixes, plus scenario modeling templates to stress test cost/performance tradeoffs.
How buyers should approach procurement in 2026
PW Consulting recommends a three‑track approach for organizations planning decisions in 2026:
- Immediate (0–6 months): Shore up operational controls around identity verification, data residency, and candidate support. Run a focused pilot that stresses synthetic‑media scenarios and multi‑device constraints introduced by new regulatory requirements.
- Medium (6–18 months): Negotiate flexible contracting that preserves pathways for technology swaps and feature upgrades (e.g., module licensing for anti‑deepfake detection). Require transparency on model training data, update frequency, and human review thresholds.
- Strategic (18–36 months): Define a target architecture for assessment delivery across modalities (in‑person, remote hybrid, remote automated) and budget for co‑development with preferred vendors to embed vendor capabilities into broader credentialing ecosystems.
Where vendors will win in 2026
Winning suppliers will demonstrate four competencies:
- Defensible evidence chains—robust, tamper‑resistant audit logs and human review pipelines suitable for legal scrutiny.
- Adaptive detection—rapid ingestion of new threat signatures (including synthetic media) and transparent validation metrics for false‑positive/false‑negative tradeoffs.
- Interoperability—APIs and standards support for LMS, registration systems, and certification platforms to reduce friction and integration costs.
- Customer success at scale—proven operational playbooks for candidate onboarding, accessibility accommodations, and 24/7 support.
What we intentionally withhold in this briefing (and why)
In line with our “trailer” approach: this briefing surfaces directionally important numbers and competitive dynamics but intentionally omits segment‑level tables and region/application share figures. Those granular splits, vendor scorecards, and downloadable financial models are included in the full PW Consulting report and interactive dashboard—materials that procurement and product teams will need to operationalize decisions and contract negotiations.
Next steps and call to action
For teams making FY‑2026 budget allocations, the next step is a short diagnostic: map your assessment portfolio to the four archetypes in our report, run a three‑month synthetic‑threat pilot against your shortlisted vendors, and require each vendor to produce a defensibility dossier (human review logs, model validation results, and data retention practices). PW Consulting’s full market study provides the vendor scorecards, RFP templates, contractual language, and TCO models to convert that diagnostic into procurement decisions with confidence.
Access the full report to obtain the detailed segment analytics, vendor scorecards, risk matrices, and downloadable scenario models that will underpin defensible 2026 decisions.
For detailed analysis of this topic, please visit the official page: Remote Proctoring Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ellagic Acid Market to grow at 6.65% CAGR - USD 275M (2025) to USD 425M (2032)
By PW Consulting, 2026-07-12
Ellagic Acid Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a focused, strategy-first preview of our full Ellagic Acid Market study — a decision-ready briefing tailored for corporate leaders preparing plans for 2026. The market for ellagic acid (USD, revenue unit: Million; base year: 2025) is on a sustained expansion path: our model forecasts growth from the 2025 baseline to the end of the 2032 horizon at a compound annual growth rate (CAGR) of 6.65%. That trajectory reflects evolving end-market demand, shifting supply dynamics, and an intensifying regulatory and certification environment that will shape supplier advantage and commercial returns in the coming 18–36 months.
Ellagic Acid Market
Why this matters for 2026 planning
-
Predictability meets disruption: The underlying growth (mid-single-digit CAGR) affords companies enough runway to invest, but structural supply and regulatory volatility raises execution risk — meaning traditional capacity expansions alone will not guarantee commercial success in 2026.
Ellagic Acid Market -
Premiumization is a margin lever: Higher-purity grades and certification-backed products are capturing buyer preference and commanding meaningful premiums. Firms that can credibly deliver pharma-grade purity or certified organic/Non‑GMO product streams will unlock differentiated pricing power.
Ellagic Acid Market -
Supply resilience is strategic: Raw material concentration and climate exposure are real. Pomegranate peel — the predominant commercial feedstock — varies significantly in active content and has been affected by droughts in key producing regions, which has translated into pronounced cost swings. Securing raw material pathways will be a top procurement priority in 2026.
What the PW Consulting report delivers (practical value)
-
Validated market sizing and a transparent demand model (base year 2025, forecast 2026–2032) that converts macro trends into revenue scenarios and break-even timelines for new investments.
-
Actionable segmentation intelligence across product forms, applications and regional demand pockets — presented as market-weighted demand drivers and opportunity matrices (note: detailed regional/application splits are reserved for the full document).
-
Supplier scorecards and an M&A target shortlist: operational metrics, certification status, quality systems, and integration risk assessments to accelerate buy-side diligence.
-
Commercial playbooks and contract templates for offtake, tolling and captive supply arrangements — enabling rapid deployment of sourcing strategies to mitigate raw-material shocks.
-
Regulatory and quality roadmap: step-by-step requirements to obtain ISO/GMP/Halal certifications and REACH registration considerations for intermediates such as pomegranate extract formulations.
-
Price and margin sensitivity models that tie raw material inflation and purity mix to P&L outcomes under alternative marketing strategies (private label vs. ingredient branding; food-grade vs. pharma-grade focus).
Market dynamics shaping competitive advantage
-
Feedstock concentration and climate risk — operational impact: Pomegranate peel is the primary commercial feedstock and contains high concentrations of ellagitannins that are processed to ellagic acid. Drought-driven yield reductions in several producing countries have materially tightened supplies and created volatility in raw-material pricing. Companies with diversified sourcing or vertical integration into peel processing demonstrate clear first-mover resilience.
-
Certification and quality escalation — commercial impact: International buyers increasingly require ISO, GMP and Halal certifications. Suppliers that invested early in quality management systems now attract longer-term contracts and premium customers in regulated regions.
-
Regulatory overlay — compliance as a gatekeeper: REACH registration and similar regulatory frameworks are non-trivial compliance items for many formulations; treating regulatory readiness as a product feature (and a cost line) is necessary for access to the most valuable buyers.
-
Purity segmentation — margin differentiation: Pharmaceutical-grade material above very-high purity thresholds commands substantial premiums versus lower-grade, food‑industry material. A deliberate product-tier strategy — from research-grade to pharma-grade — is a direct route to improved portfolio margins.
Competitive landscape: positioning and implications
The market is characterized by a mix of specialized botanical-extract houses, regional processors, and global life-science suppliers. A few themes emerge from our company-level review:
-
Specialist extractors and regional scale players: Several established botanical-extract manufacturers offer bulk ellagic acid in multiple grades and leverage low-cost raw material access. These firms compete on cost, certifications and export logistics. Their value lies in scale, supply continuity and price competitiveness for food- and supplement-grade demand.
-
Quality-focused European and US players: A subset of suppliers differentiates through higher-spec products, regulatory compliance (including REACH attention) and technical documentation. These firms are preferred partners for European and North American buyers demanding traceability and SDS/Hazard communication updates.
-
Research- and reagent-grade suppliers: Global life-science distributors offer high-purity ellagic acid for R&D and industrial use, filling a premium niche that supports small-volume, high-margin business lines.
Notable supplier developments illustrate these dynamics: a European producer recently updated safety data and product documentation to reflect evolving regulatory expectations, while multiple Asian manufacturers are expanding organic and GMP-capable production lines to win nutraceutical and pharmaceutical business.
Strategic imperatives for 2026
-
Secure diversified feedstock contracts: Move beyond spot buying. Structured multi-year offtake contracts with staggered delivery, coupled with limited vertical investment in peel-processing capacity, will reduce margin volatility and improve supply predictability.
-
Invest in certification and traceability: Prioritize ISO/GMP/traceability investments — these are market access enablers in key buyer geographies and will convert to higher order sizes and longer contract tenors.
-
Define a purity-tiered commercial strategy: Adopt a two-track approach — protect margins via pharma/high-purity channels while maintaining volume by serving stable supplement/food applications with commodity grades.
-
Operationalize a climate-risk playbook: Implement supplier audits, develop alternate sourcing corridors, and consider feedstock hedging or inventory buffering informed by our supply-stress simulations.
-
Pursue focused M&A or joint ventures: The market concentration indicators show room for consolidation that can deliver procurement synergies and certification-ready capacity. Target companies should add complementary geography, certified capacity or proprietary extraction know-how.
Risk matrix — what keeps CFOs awake
-
Raw-material inflation and availability: Episodic drought and constrained peel supply can raise input costs and compress margins if not hedged or contractually managed.
-
Regulatory non‑compliance: Missing REACH or GMP expectations closes off the most lucrative buyer segments and can lead to retroactive supply interruptions.
-
Product liability and documentation gaps: SDS and technical data currency are now procurement gatekeepers in many advanced markets — lagging updates can disqualify suppliers.
How PW Consulting can accelerate your 2026 agenda
-
Fast-track diagnostics: We offer a bespoke two-week supply-chain stress test and certification gap analysis that translates market benchmarks into an executable 90-day plan.
-
M&A and commercial diligence: Use our proprietary supplier scorecard and valuation overlay to prioritize targets and structure earn-outs tied to certification milestones.
-
Commercial readiness: Access our contract templates, pricing playbooks and go-to-market positioning frameworks tailored for food, nutraceutical and pharmaceutical customers.
Final note — invest with insight
The ellagic acid market presents a classic strategic inflection: a steady top-line growth profile (6.65% CAGR in our 2026–2032 forecast) coupled with elevated execution complexity. Companies that treat quality, regulatory readiness and feedstock resilience as strategic assets — not just operational costs — will capture disproportionate value as the market continues to mature. Our complete report contains the detailed regional and application splits, full supplier profiles, price-curves and the granular scenario models required to operationalize the recommendations above.
Request the full report to obtain the proprietary demand model, supplier scorecards and the granular data that underpins these recommendations. In the current cycle, access to precise segmentation and supplier-level intelligence is the differentiator between cautious participation and market leadership.
For detailed analysis of this topic, please visit the official page: Ellagic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roofing Adhesives Market — Strategic Outlook for 2026 Decision-Makers
Executive preview
As companies plan capital allocation, R&D roadmaps, and go-to-market moves for 2026, the roofing adhesives market presents a blend of steady expansion and regulatory-driven disruption. Our latest PW Consulting study—anchored on a 2025 base year, with historical coverage from 2020–2025 and forecasts through 2026–2032—quantifies this trajectory and translates it into actionable options for manufacturers, distributors, specifiers, and investors.
Roofing Adhesives Market
Why this market matters in 2026
The market has grown from approximately USD 225 million in 2020 to about USD 290 million by 2025, and our forecast implies continued steady expansion at a compound annual growth rate of 5.6% across the upcoming planning horizon. By 2026 the market is projected to pass the USD 300 million threshold and is expected to approach the mid‑hundreds by the end of the 2032 forecast window. That combination of durable size, predictable growth, and ongoing product differentiation makes roofing adhesives a pragmatic arena for strategic investment—even as regulatory momentum and technology shifts reshape specification criteria.
Roofing Adhesives Market
Key structural themes shaping 2026 decisions
- Regulatory and standards acceleration:
Across North America and Europe, tighter VOC limits, updated test standards and more prescriptive ecolabels are raising the bar for formulation and documentation. Notable changes include recent revisions to ecolabel standards for commercial adhesives, stricter regional VOC requirements that many California projects default to, and updated ASTM practices covering time‑to‑failure and uplift testing. These are no longer compliance items only for environmental teams—they materially change product roadmaps, testing budgets, and time‑to‑market for new formulations.
Roofing Adhesives Market - Materials and product innovation:
Expect further acceleration toward low‑VOC, solvent‑free, bio‑based and equipment‑efficient systems. Recent product introductions and plant expansions demonstrate suppliers are prioritizing sprayable canisters, solvent-free hybrids, and adhesives with significant bio‑based content while preserving performance targets such as wind uplift and long‑term creep resistance. Competitive advantage increasingly rests on marrying performance with clear environmental and contractor‑ease attributes.
- Channel and execution economics:
Distribution partnerships and regional production footprint decisions matter more than ever. Manufacturers are optimizing channel partnerships and on‑the‑ground service (training, specification support, and fast shipping) to win fully adhered specifications. Notably, strategic collaborations and capacity expansions are reshaping availability and local cost structures—affecting tender competitiveness and contractor adoption curves.
- Market concentration and consolidation potential:
The roofing adhesives market displays a moderate level of concentration among leading global players. This creates a twofold strategic implication: established players can extract scale benefits from R&D and compliance investments, while well‑targeted acquisitions or partnerships provide a viable route for mid‑tier players and private capital to accelerate capability build‑out and market access.
Competitive dynamics — how the field lines up
The competitive set combines large global chemical and specialty adhesives companies, building‑materials groups, and focused regional players. Global formulators with integrated R&D and broad manufacturing footprints are pushing portfolio strategies that cover single‑ply membranes, modified bitumen and insulation bonding. Technical specialists are differentiating on contractor productivity and sustainability credentials. Regional and system providers emphasize specifier relationships, warranty compatibility and distribution depth.
- Full‑portfolio global players: These firms leverage broad product families across resin classes and roof systems, using global scale to fund testing, certification and localized manufacturing.
- Technical innovators: Suppliers focused on next‑generation application formats (equipment‑free canisters, sprayable, low‑VOC hybrids) are converting specification trials into repeat business by reducing on‑roof labor cost and improving installation reliability.
- System integrators and regional specialists: Companies with deep relationships with membrane and insulation manufacturers or strong contractor networks can command premium positioning through bundled warranties and specification convenience.
Recent market signposts (examples for 2025–early‑2026)
- Product launches emphasizing low‑VOC and solvent‑free chemistries and equipment‑friendly formats signal a near‑term industry tilt toward contractor productivity and environmental compliance.
- Production capacity expansions and strategic distribution partnerships indicate leading firms are reducing lead times and localizing supply to serve large specification markets more reliably.
- Regulatory updates—particularly ecolabel clarifications and regional VOC rules—are forcing reformulation timelines and creating certification costs that will favor players with scale or differentiated technical capabilities.
Concrete implications for 2026 strategy
- For manufacturers:
Prioritize formulation platforms that can be quickly adapted to meet tightened VOC/eco‑label thresholds and maintain mechanical benchmarks (wind uplift, creep). Invest in equipment‑friendly formats that lower contractor labor time and make total installed cost a visible selling point. Consider selective capacity expansions or contract manufacturing in priority regions to shorten lead times and reduce freight and inventory exposure.
- For distributors and channel partners:
Differentiate through specification support and contractor training. Bundled solutions—adhesive + warranty + installation training—will win in competitive bids where performance and compliance are jointly evaluated by owners and specifiers.
- For specifiers and large end users:
Update procurement templates to incorporate both environmental compliance (e.g., updated ecolabels and regional VOC limits) and contractor efficiency metrics. Require documented compliance pathways to new standards and prefer suppliers that offer installation‑ready packaging and warranty support.
- For investors and corporate development teams:
With the market expanding at an approximate mid‑single digit CAGR and moderate concentration among leaders, opportunistic M&A can bring differentiated chemistries or channel access into a larger platform at attractive multiples. Focus targets should combine proprietary, low‑VOC or equipment‑efficient chemistries with established distribution relationships.
Report coverage — what PW Consulting delivers to inform 2026 choices
The full study provides a practical toolkit to turn insight into action. Key deliverables include: a transparent forecasting model spanning 2026–2032; a granular segmentation framework by resin family, application, and geography; a regulatory and standards matrix tied to commercialization timelines; product benchmarking against performance and sustainability KPIs; supply‑chain maps and raw material risk assessments; company profiles with capability heatmaps; and commercial playbooks tailored for manufacturers, distributors, and private equity.
Importantly, while this preview outlines strategic themes and macro trajectories, the report reserves core segmented analytics and proprietary company estimates—data that enable precise prioritization and transactional diligence—for the full publication.
How to use these insights in your 2026 planning cycle
- Update product roadmaps to incorporate low‑VOC/solvent‑free and bio‑content targets with hard milestones tied to certification timelines.
- Stress‑test supply chains for raw materials subject to regulatory scrutiny and identify qualified second‑source partners.
- Quantify the economics of changing packaging and application systems (e.g., canisters, sprayable, pressure‑sensitive) in pilot projects with key contractor partners.
- Make targeted investments in specifier engagement and warranty packages that translate environmental compliance into procurement advantages.
- For acquirers: prioritize targets with both differentiated chemistries and existing distribution linkages in high‑growth end markets.
Closing perspective
The roofing adhesives market in 2026 is neither a high‑risk frontier nor a mature commodity space—it's a pragmatic growth category at the intersection of performance engineering, sustainability regulation, and contractor economics. The projected market expansion and the moderate concentration of leading firms create clear pathways for value creation through product differentiation, targeted capacity decisions, and channel innovation. PW Consulting’s full report turns these strategic pathways into executable plans—complete with the numerical granularity and company‑level diagnostics executives need to commit capital and mobilize teams in 2026.
For access to the full dataset, segmented forecasts, and the detailed competitive and regulatory dossiers that underpin these recommendations, visit PW Consulting’s roofing adhesives market page to license the complete report and modeling tools.
For detailed analysis of this topic, please visit the official page: Roofing Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


