



Category: market research
PW Consulting: Scrap Lifting Magnets Market to Reach USD 290.5 Million by 2032 (5.7% CAGR)
By PW Consulting, 2026-07-12
Scrap Lifting Magnets Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present an executive preview of our new market research on the global scrap lifting magnets sector. This essay highlights the report’s strategic value for corporate leaders making capital-allocation, product, and M&A decisions in 2026. It is written as a professional trailer: we reveal the analytical framework, market trajectory, competitive dynamics, and the pragmatic tools executives need — while preserving the granular, transaction-ready data inside the full report.
Scrap Lifting Magnets Market
Why this study matters in 2026
- Base and scope: Our study uses 2025 as the base year, captures historical trends from 2020–2025, and models multiple scenarios through a 2026–2032 forecast horizon.
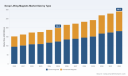
- Market momentum: The market has shown steady growth through the historical period and is forecast to continue expanding at a compound annual growth rate (CAGR) of 5.7% over the forecast window.
- Decision contexts covered: procurement optimization, product roadmap prioritization, capacity planning, aftermarket and service expansion, channel strategy, and transaction screening for strategic or financial buyers.
For procurement teams and asset managers, timing of equipment replacement and the selection of technology (electro-permanent vs. electromagnetic vs. permanent systems) is increasingly value-critical. For corporate development and private equity, the sector’s growth profile, pockets of consolidation, and technology-driven differentiation create specific M&A and partnership opportunities that require precise demand and margin modeling — which our report provides.
Scrap Lifting Magnets Market
Market trajectory at a glance
Readers will find in the full report a rigorous time series that traces market value through the pandemic and recovery years, demonstrating how demand normalized and then accelerated under new regulatory and operational dynamics. To orient strategic thinking: the global market moved from the low hundreds of millions (USD) at the start of the decade to a larger base by 2025, and is projected to grow meaningfully by the early 2030s under our base-case assumptions. The 5.7% CAGR reflects a mix of steady replacement cycles, expanding recycling and scrap-handling activity, and technology-driven conversions in mobile and stationary applications.
Scrap Lifting Magnets Market
Key demand and supply dynamics shaping 2026 choices
- Regulatory pressure and circular-economy mandates. Governments across multiple regions are tightening waste-management and recycling targets, pushing industrial operators to invest in higher-throughput and safer scrap-handling systems.
- Commodity price volatility. Steel scrap pricing has migrated into the mid-hundreds per ton range in recent years, increasing the economic incentive to recover more metal per lift and shorten handling cycles — both of which favor investment in advanced lifting magnets and automation.
- Labor and operating-cost pressures. Rising labor and service costs are accelerating the shift to systems that reduce manual load handling time and deliver higher uptime through modular, battery-assisted, or electro-permanent technologies.
- Energy and operational efficiency. Battery-powered and electro-permanent solutions are gaining share because they combine operational flexibility with lower downtime versus some legacy electrically powered alternatives, influencing total cost of ownership (TCO) calculations.
- Safety and OEM-driven standards. Large end-users — notably automotive and heavy industry OEMs — increasingly specify lifting equipment to meet stringent quality, traceability, and risk-management standards, reinforcing the value of established suppliers with certification and long-term service footprints.
Technology and product trends to prioritize
Technology trends in the sector have clear strategic implications for product development and procurement: modular electromagnets with remote switching, electro-permanent units that maintain magnetic holding without continuous power, battery-operated mobile systems that enable longer operating windows, and sensorized units for predictive maintenance. Each approach carries different CapEx vs. OpEx trade-offs, and the optimal choice depends on rhythm-of-use, maintenance infrastructure, and safety requirements — all modeled in the full report’s TCO and sensitivity tools.
Competitive landscape — what structure means for strategy
The market exhibits moderate concentration: the largest players together account for a substantial share, but meaningful pockets of niche specialist activity remain. That structure has three strategic takeaways:
- Incumbent advantage: Established manufacturers with broad product lines and global service networks can capture premium margins on safety-certified, high-duty-cycle systems and aftermarket service contracts.
- White-space for specialists: Companies that focus on a narrow application (e.g., shovel-mounted units, skid-steer systems, or compact battery-powered lifters) can build defensible niches that remain attractive to consolidators.
- Channel and partnership play: Local service partners, OEM integrators, and distributors continue to be key growth levers for firms seeking to scale penetration in industrial end markets with complex service demands.
Selected companies profiled in our competitive analysis include manufacturers and OEMs that illustrate these strategic archetypes:
- Walker Magnetics (Boyne City, Michigan) — recognized for product breadth across lighter and heavier scrap-handling families designed for steel mills and recycling applications.
- SGM Magnetics (Manerbio, Italy) — an engineering-driven player known for proprietary electro lifting magnet designs that reduce side magnetic attraction and improve handling safety.
- Sinfonia Technology (Japan) — focused on shovel-mounted and integrated systems prioritizing secure load transfer and operational efficiency.
- Gensco Equipment (Canada) — offers hydraulic and skid-steer solutions with strong appeal to demolition and site-level recycling operations.
- DIMET (United States) — producers of a portfolio of electromagnets for scrap and turnings with global sales reach and presence at regional trade shows.
- HVR MAG (China), Bunting Magnetics (United States), and Magnetool, Inc. (United States) — each illustrating different strategic bets: electro-permanent technologies, separation and lifting integration, and mobile battery-powered lifting systems, respectively.
Activity signals in the market reinforce an active product and trade-show calendar, highlighting continued investment in visibility and new-product rollout: recent exhibitor participation and demonstrations by manufacturers in major industry expos underscore the speed of iterative product development and the centrality of field demonstrations to sales cycles.
What the PW Consulting report delivers — practical, actionable outputs
We designed this study to be immediately operational for executives and deal teams. Key deliverables include:
- Robust market sizing and baseline demand curves (2020–2025), plus scenario-based forecasts to 2032 using alternative macroeconomic and commodity assumptions.
- Vendor and product mapping with a decision matrix that links operating profile (lift cycles per hour, duty class, mobility requirement) to recommended technologies and supplier archetypes.
- TCO and sensitivity models that estimate CapEx, energy use, maintenance, and downtime impacts across electrified, electro-permanent, and battery systems.
- Go-to-market playbooks for market entrants and incumbents — channel strategies, pricing frameworks, and aftermarket service bundles that maximize lifetime value.
- M&A screening tools: scorecards, valuation sensitivities, and integration risk checklists customized for both strategic acquirers and financial sponsors.
- Risk matrix and regulatory mapping that align compliance requirements across major jurisdictions with procurement timelines and certification roadmaps.
- Primary interview summaries, expert-opinion synthesis, and a methodology appendix that documents data sources, assumptions, and modeling approaches.
To respect the “trailer” principle, we present the analytical structure and outcomes here, while detailed segment-level splits, regional roll-ups, and the downloadable datasets that underpin our forecasts are available only in the full report package.
How executives should use this intelligence in 2026
- CapEx & procurement: Use the report’s TCO modules to decide between retrofit, replacement, or reconfiguration of fleets — prioritizing projects that shorten payback under plausible scrap-price scenarios.
- Product roadmap and R&D: Prioritize battery management, sensor integration, and modular serviceability where the model shows the highest incremental value per dollar spent.
- Channel strategy: Evaluate partnerships with regional maintenance providers and OEMs to secure long-term service revenue and compliance credentials.
- M&A & JV screening: Identify consolidation targets that offer complementary product capabilities or service footprints; use our M&A scorecards to size integration upside and downside risks.
- Pilot programs: Run targeted field pilots for electro-permanent and battery-assisted platforms to validate productivity uplift and serviceability metrics before full-scale rollouts.
Conclusion — where this report fits in your 2026 playbook
As scrap flows increase and industrial operators pursue higher throughput with lower operating costs, the scrap lifting magnets market sits at the intersection of regulatory demand, energy-efficiency priorities, and technology-driven differentiation. The sector’s steady CAGR and forecasted market expansion create a compelling environment for both incremental investment and selective consolidation. PW Consulting’s full study converts those dynamics into operational guidance — from tactical procurement checklists to strategic M&A screens and validated TCO models.
For teams preparing 2026 budgets, product launch roadmaps, or transactional diligence, the full report provides the granular segmentation, regional demand profiles, and downloadable financial models you will need. Access the complete research package on our site to unlock the datasets and the tactical annexes that make these strategic recommendations executable.
For detailed analysis of this topic, please visit the official page: Scrap Lifting Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UGC Software Market to Hit USD 10.99B by 2032 with 10.6% CAGR — PW Consulting
By PW Consulting, 2026-07-12
User Generated Content (UGC) Software Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Industry Analyst, I present an executive preview of our new market research on the User Generated Content (UGC) Software market. This briefing is designed as a strategic “trailer”: it surfaces the essential macro trends, competitive positions, and actionable levers that should inform enterprise decisions in 2026, while intentionally withholding certain proprietary segment tables and vendor scorecards reserved for the full report.
User Generated Content (UGC) Software Market
Why this research matters for 2026
UGC software is no longer a niche marketing tool — it has become a foundational layer of contemporary commerce, customer experience, and brand trust architecture. Organizations making platform, vendor, and data governance decisions in 2026 must reconcile three concurrent shifts: accelerating AI-driven content collection and personalization, increasing regulatory scrutiny on AI/curated content, and the rising commercial value of shoppable, permissioned visual media.
User Generated Content (UGC) Software Market
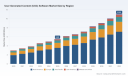
Our modeled market trajectory captures these dynamics. From a clearly observable expansion across 2020–2025, the market reached a material inflection point in 2025 (base year) and is forecast to grow at a 10.6% compound annual growth rate over the 2026–2032 horizon. The outcome is a near-doubling of market scale through the forecast period, underscoring both intensifying vendor activity and expanding buyer demand for integrated UGC capabilities.
User Generated Content (UGC) Software Market
High-level market picture (what leaders need to know)
- Growth profile: The market has expanded steadily through 2020–2025 and transitions into a mature acceleration phase in 2026, driven by enterprise adoption of UGC as a conversion and retention tool.
- Concentration: Market concentration is meaningful but not prohibitive — three vendors account collectively for a majority share of commercial activity, with the top five increasing that footprint. This creates a dual environment of stable incumbency and targeted opportunity for challengers with differentiated capabilities.
- Value drivers: The principal ROI levers for buyers are content authenticity and rights management, shoppable integrations that shorten commerce funnels, and AI-assisted moderation and tagging that reduce operational cost.
Dynamics shaping vendor selection and implementation
- AI as paradox: AI both unlocks scale (automated tagging, sentiment, visual recognition) and introduces new risks (hallucinations, synthetic content). Buyers must evaluate vendor approaches to provenance, explainability, and human-in-the-loop workflows.
- Regulatory noise and compliance priorities: Recent regulatory moves — for example, new rules requiring rapid removal of demonstrably harmful AI-generated content and explicit labeling of AI-curated media in some jurisdictions — elevate compliance from checklist to core capability. Vendors’ content governance, audit trails, and localization support will be decisive.
- Integration tax: UGC value accrues only when tightly integrated with commerce stacks, CDPs, and CX platforms. Procurement assessments should weight API quality, latency SLAs, and headless/rendering options equally with feature lists.
- Rights & moderation economics: Clear, auditable rights acquisition and automated moderation workflows materially affect total cost of ownership and legal exposure—features that have moved from “nice-to-have” to “must-have.”
Competitive landscape — strategic snapshots
The competitive set is diverse: from legacy e-commerce review platforms to AI-first personalization vendors and visual-content specialists. Below are targeted assessments of the primary vendors covered in our study. These snapshots synthesize public positioning, product focus, and strategic implications for enterprise buyers.
- Bazaarvoice (Austin, Texas) — Bazaarvoice is positioned as a robust e-commerce UGC collection and syndication platform. Its strengths are mature review workflows, retailer integrations, and an extensive syndication network. Strategic fit: organizations prioritizing scale of review distribution and cross-retailer consistency. Considerations: evaluate roadmap for AI curation and visual UGC expansion.
- Yotpo (New York, New York) — Yotpo presents an AI-augmented UGC stack covering reviews, social, and visual commerce. Strengths include tight e-commerce UX integrations and marketing automation. Strategic fit: DTC brands seeking embedded loyalty and conversion optimization. Considerations: probe for provenance controls and moderation latency under peak loads.
- Taggbox (Covina, California) — Taggbox emphasizes social feed widgets, reviews, and shoppable content aggregation across platforms. Strengths are flexibility in display formats and channel-agnostic aggregation. Strategic fit: event-driven, campaign-centric use cases and experiential marketing. Considerations: assess enterprise-grade governance and platform SLAs for high-traffic deployments.
- Emplifi (Columbus, Ohio) — Emplifi integrates UGC with social analytics, commerce, and broader CX capabilities. Strengths include an analytics-centric approach and cross-channel orchestration. Strategic fit: enterprises that require UGC insight to feed loyalty, CX, and service functions. Considerations: clarify data ownership models and cross-module interoperability.
- Nosto (Helsinki, Finland) — Nosto is recognized for AI-powered commerce experience and visual UGC personalization. Strengths include recommendation engines and visual merchandising tied to UGC. Strategic fit: retailers investing heavily in personalization at scale. Considerations: request transparency on model training data and regional regulatory compliance readiness.
- PowerReviews (Chicago, Illinois) — PowerReviews focuses on ratings and reviews with conversion optimization and syndication capabilities. Strengths lie in review authenticity features and conversion analytics. Strategic fit: brands focused on review-led conversion strategies with large SKU catalogs. Considerations: understand how visual UGC and influencer-driven content are supported.
- Crowdriff (Toronto, Ontario) — Crowdriff specializes in visual content discovery, management, and publishing, with particular traction in travel, hospitality, and retail. Strengths include visual search and rights-cleared publishing. Strategic fit: destination marketing and retail brands that rely on aspirational imagery. Considerations: evaluate commerce linkage maturity for direct shoppability.
Recent events and regulatory signals to watch in 2026
- Platform innovation: New entrants and product launches continue to change the competitive calculus. For example, early-2026 product introductions aimed at capturing text-based experience data are expanding the types of consumer narratives that can be monetized or moderated.
- Regulatory accelerants: Jurisdictions are moving quickly to impose obligations around AI-generated content — including removal timeframes for harmful content and mandatory labeling of AI-curated media. These measures shift vendor evaluations toward demonstrable auditability and localization features.
- Operational implications: The combined effect of product innovation and regulation increases the premium on vendors that can demonstrate low-latency moderation, strong provenance, and clear rights management across country boundaries.
What the full report delivers (practical, actionable components)
Our full market study is built for practitioners and C-suite decision-makers who need to turn insight into execution in 2026. Deliverables include:
- Comprehensive market sizing and forecast (2020–2032) with sensitivity scenarios and CAGR decomposition by driver.
- Competitive landscaping that pairs vendor capabilities with use-case fit, implementation complexity, and buying signals.
- Go-to-market and procurement playbooks: RFP templates, vendor scorecards, and negotiation levers tailored to enterprise priorities.
- Technical integration blueprints and API evaluation checklists for commerce, CDP, CMS, and moderation pipelines.
- Actionable ROI and TCO models with benchmarked assumptions for content moderation, rights clearance, and shoppable conversion uplift.
- Regulatory compliance annex with jurisdictional heatmaps, sample contractual clauses, and audit trail templates aligned to 2026 regulations.
- Deployment roadmaps and pilot designs to validate value quickly while managing legal and operational risk.
- Curated executive briefs and one-page decision frameworks for board and procurement committees.
How to use this briefing to act in 2026
- Prioritize a rights-first evaluation: Require vendors to demonstrate rights acquisition, verifiable provenance, and chain-of-custody for visual assets as a gating criterion.
- Make AI governance concrete: Insist on explainability, human-in-the-loop review thresholds, and remediation SLAs tied to regulatory timeframes in your contracts.
- Prize integration over point features: Choose vendors that reduce integration lift and offer clear pathways into your commerce and CX ecosystems.
- Pilot for legal and commercial outcomes: Structure initial engagements as limited-scope pilots with measurable conversion and compliance KPIs before rolling out wholesale.
Closing — a strategic prompt
The UGC software market in 2026 sits at an inflection of opportunity and obligation. Growth is robust — reflecting sustained enterprise investment — but the competitive and regulatory environments are evolving rapidly. This briefing surfaces the strategic signposts leaders must use to select vendors, design pilots, and scale responsibly.
For the complete segmentation tables, provider scorecards, and the proprietary appendices that translate these insights into executable procurement and integration artifacts, access the full PW Consulting report. Our research includes the granular data and templates required to turn the market’s projected 10.6% CAGR and the full 2020–2032 sizing into a concrete 12–18 month action plan for your organization.
For detailed analysis of this topic, please visit the official page: User Generated Content (UGC) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SMS Medical Nonwoven Market at USD 402.46M in 2025 — 5.75% CAGR Ahead
By PW Consulting, 2026-07-12
SMS Medical Nonwoven Fabric Market — Strategic Outlook and Decision Playbook for 2026
Executive preview
As healthcare systems, PPE manufacturers, and hospital procurement teams recalibrate for a post‑pandemic steady state, the SMS (spunbond–meltblown–spunbond) medical nonwoven fabric market is entering a phase defined by steady growth, concentrated supply, and a new set of regulatory and sustainability pressures. Our PW Consulting market study — based on a 2025 base year with historical tracking from 2020–2025 and forward projections through 2032 — shows a resilient market trajectory underpinned by a compound annual growth rate (CAGR) of roughly 5.75% over the forecast horizon. Global revenue has expanded meaningfully over the past five years and is expected to continue its upward climb through 2032.
SMS Medical Nonwoven Fabric Market
Why this research matters for 2026 decisions
- Timing: 2026 is the inflection year when incremental demand drivers (elective procedures rebound, routine PPE procurement normalization, and renewed focus on biodegradables) meet the cyclical effects of capacity additions announced in 2024–2025. The study translates those interactions into decision-ready scenarios.
- Capital allocation: Companies considering greenfield lines, capacity upgrades, or converting existing meltblown assets to SMS lines need forward‑looking demand curves and utilization sensitivity models — not just historical size figures. Our model provides scenario-based utilization thresholds tied to price and raw‑material volatility.
- Regulatory readiness: With recent FDA clarifications and 510(k) clearances relevant to SMS constructions, 2026 procurement and compliance strategies must change. The report maps regulatory pathways and the risk/reward of pursuing classification changes or exemptions.
Market trajectory and macro drivers
From a macro standpoint, the SMS medical nonwoven segment has moved from emergency-driven spikes to predictable, healthcare-driven growth. The study quantifies that transition: after the rapid demand shocks of the early 2020s, annual market revenues have expanded and are projected to continue growing at mid-single-digit rates through the end of the decade. This is driven by a confluence of forces:
SMS Medical Nonwoven Fabric Market
- Structural healthcare demand — routine surgeries, outpatient care growth, and expanding access in developing markets.
- Product innovation — manufacturers are introducing SMS variants that balance barrier performance with breathability and comfort, widening the addressable applications beyond traditional gowns and drapes.
- Sustainability and circularity — biodegradable blends and recyclable constructions are becoming procurement differentiators, influencing both OEM selection and premium pricing potential.
- Regulatory de‑risking — clearer FDA guidance on exemptions for certain nonwoven medical devices and recent 510(k) clearances reduce time‑to‑market uncertainty for modification of SMS constructions.
Competitive landscape — what the market structure means for strategy
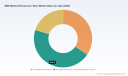
The market exhibits moderate concentration with the top three players controlling a substantial share and the top five an even larger portion. That structure produces distinct competitive dynamics:
SMS Medical Nonwoven Fabric Market
- Scale advantages: Large global producers have the balance-sheet capacity to invest in multi‑regional capacities and sustainability R&D, enabling them to capture enterprise OEM contracts and hospital system frameworks.
- Regional specialist plays: Mid‑sized and local producers compete by offering customization, faster lead times, or lower cost bases in localized markets.
- Collaborative innovation: The trend toward co‑development partnerships and cross‑licensing (notable between multinational material suppliers and performance‑fabric specialists) is accelerating differentiated product launches.
Key players profiled in the study include established global integrators and regional specialists. The report assesses each on dimensions that matter for strategic counterpart selection and competitive response: manufacturing footprint, product portfolio breadth (including SMMS and reinforced laminates), sustainability roadmap, regulatory clearances, and customer segmentation focus.
Recent industry moves and regulatory context — implications for 2026
- Strategic partnerships and product launches: Several strategic collaborations and new product introductions in 2024–2025 signal a shift from capacity‑race tactics to capability‑led competition. Notably, collaborations targeting sustainable SMS formulations and high‑performance barrier fabrics suggest that technical differentiation — not purely price — will drive premium procurement decisions.
- Capacity expansions: Announcements of manufacturing expansions by leading firms point to upcoming capacity additions that will moderate raw‑material inflation pass‑throughs but will also pressure utilization for smaller producers unless demand growth accelerates as forecasted.
- Regulatory clarity: Recent FDA notices and 510(k) activities have reduced some approval risk for specific SMS constructions, while regional certifications (e.g., CE conformity of blood/biological sample collection materials) open adjacent market opportunities for material suppliers. Commercial teams need to align product claims, testing packages, and submission strategies to exploit these windows.
Strategic playbook for 2026
For executives planning actions in 2026, the study translates macro forecasts and competitive intelligence into a set of prioritized strategic moves. Examples include:
- Capacity and footprint decisions: Use our utilization-trigger matrix to decide between incremental capacity (module expansion), asset retrofits (converting meltblown to SMS lines), or contract manufacturing partnerships. The matrix highlights breakpoints where internal capacity becomes accretive versus outsourcing.
- Product portfolio and differentiation: Prioritize investment in SMS variants that offer validated barrier-breathability trade-offs and in biodegradable/polyolefin blends that meet hospital sustainability procurement criteria. The study includes concept-to-commercial timelines and cost implication models.
- Partnerships and M&A targets: Identify targets that fill capability gaps — whether raw‑material resilience (regional polymer supplies), specialty meltblown technology, or validated regulatory dossiers — and use our valuation overlay to size accretive deals under multiple demand scenarios.
- Regulatory and quality readiness: Align R&D and regulatory teams to the simplified entry pathways for select SMS device classes; prepare 510(k) or equivalent dossiers for high‑value product extensions to minimize launch delays.
- Procurement and supply resilience: Rebalance supplier mix and contract tenors to mitigate polymer feedstock volatility; consider vertical integration or strategic long‑term offtakes for meltblown intermediates where scale advantages justify CAPEX.
What’s in the full report (practical, executable content)
The full PW Consulting report is structured to support immediate decision-making and phased strategy execution. Highlights include:
- Bottom‑up market sizing and validated growth scenarios through 2032, including sensitivity to adoption rates for biodegradable and reinforced SMS constructions.
- Utilization and capacity maps incorporating announced expansions and plausible new builds, with breakeven and payback analyses for different capex pathways.
- Competitive benchmarking across manufacturing footprint, product capabilities, regulatory clearances, and sustainability credentials — enabling prioritization of partners and competitors.
- Segment playbooks (go‑to‑market, pricing, and procurement strategies) for hospital systems, OEMs, and national health agencies — presented as executable 90‑, 180‑, and 360‑day plans.
- M&A screening tool: a short list of target archetypes and valuation ranges tied to synergy and integration complexity.
- Regulatory navigators: step‑by‑step guidance for leveraging recent FDA clarifications and CE conformity precedents to accelerate market entry.
Note: To preserve strategic advantage and respect commercial sensitivity, our public executive summary intentionally omits detailed sub‑segment revenue splits, regional share tables, and explicit pricing ladders. These are included in the full dataset and interactive dashboards available on our report portal.
How to use these insights in boardroom conversations
- Frame capital requests with scenario‑tested utilization outcomes: present conservative, central, and aggressive demand cases derived from the study.
- Use competitive profiles to justify partnership versus build decisions: show how capability gaps will impact time‑to‑contract for large health systems.
- Prioritize regulatory investment: align 510(k) and certification timelines to product launch windows where margin recovery is highest.
- Embed sustainability metrics into procurement negotiation: leverage hospital ESG mandates to capture premium pricing for certified biodegradable or recyclable SMS options.
Closing — a call to action for 2026
The SMS medical nonwoven fabric market is no longer a pure-volume play — it has evolved into a multi‑dimensional battleground where technology, sustainability, regulatory positioning, and regional footprint determine who captures value. Our analysis shows a clear path for companies that can synchronize capacity deployment with differentiated product offerings and regulatory readiness. For executives preparing 2026 plans, the immediate priority is to convert market visibility into executable roadmaps: align capex, partner selection, and compliance investments to the demand scenarios that best fit your risk appetite.
For full access to the detailed breakdowns, sub‑segment forecasts, regional demand analytics, and our interactive scenario tools, request the complete PW Consulting SMS Medical Nonwoven Fabric Market report and dataset.
For detailed analysis of this topic, please visit the official page: SMS Medical Nonwoven Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Biotin Market 2026 Strategic Preview — PW Consulting
As companies set strategy for 2026 and beyond, biotin is no longer a niche ingredient story: it is a strategic supply-and-demand battleground with implications across nutrition, pharmaceutical, personal care, and animal-feed value chains. Our PW Consulting Biotin Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes five years of observed dynamics with a seven-year projection to 2032 to give commercial leaders the decision-grade intelligence needed for sourcing, product development, M&A, and regulatory positioning.
Biotin Market
Market trajectory at a glance
The biotin market has expanded rapidly over the past half-decade, growing from approximately USD 1,000 Million in 2020 to USD 1,482 Million in 2025. Our scenario-based forecast anticipates continued momentum: by 2032 the market is projected to reach roughly USD 2,637 Million under the central scenario, reflecting a compound annual growth rate (CAGR) of 8.6% across the 2026–2032 forecast window. That scale and pace make biotin a strategic priority for ingredient buyers, formulators, and investors: demand growth is robust, while supply-side stressors create differentiated margin and risk profiles across product forms and end-markets.
Biotin Market
Why this report matters for your 2026 decisions
-
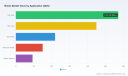
Supply concentration is a strategic risk. Control of D-biotin production capacity is highly concentrated, with a single geographic region accounting for the lion’s share of global output for this critical stereo-specific intermediate. The resulting single-source exposure raises sourcing risk, pricing volatility, and geopolitical sensitivity — issues that need to be addressed explicitly in supplier strategy and contingency planning.
Biotin Market -
Value is shifting toward traceability and specialty formats. Premium buyers are increasingly willing to pay for traceable, pharma-grade and application-optimized biotin. European and specialty suppliers are moving up the value chain with verified traceability, higher-bioavailability formulations, and documented quality systems — creating commercial opportunities that go beyond raw-volume supply.
-
Regulatory and IP signals affect market access and differentiation. Patent disputes, local IP enforcement, and tightened label and claim rules in major markets are reshaping competitive positioning. Recent patent outcomes and regulatory rulings have real commercial impact on manufacturing routes, product claims, and the ability of new entrants to scale internationally.
-
Market concentration is material but not monopolistic. Market concentration metrics indicate a mid-to-high consolidation level among the largest producers, leaving room for nimble mid-tier suppliers and specialty players to capture share through differentiation, vertical integration, or regional partnerships.
What PW Consulting’s report delivers (practical, transaction-ready content)
-
High-fidelity market sizing and methodology. Transparent, auditable sizing from 2020–2025 and an adaptable forecasting model covering 2026–2032. The model includes demand-driver elasticities, scenario switches (supply-shock, premium-adoption, and regulatory tightening), and an interactive input sheet that lets commercial teams stress-test assumptions against price and supply scenarios.
-
Supply-chain mapping and supplier risk heatmap. A mapped universe of active producers and intermediate suppliers, with a supply-risk score combining capacity concentration, quality certification, export compliance, and financial strength. The heatmap highlights single points of failure and recommended hedging strategies for contract and inventory design.
-
Commercial playbooks for buyers and brand owners. Negotiation scorecards, RFP templates tailored to traceability and quality specifications, techniques for securing long-term capacity, and sample contract clauses to mitigate force majeure, price pass-through, and IP exposure.
-
Product and formulation playbooks for R&D and marketing. Guidance on form selection (capsules, gummies, powders, etc.), stability and bioavailability considerations, co-formulation constraints, and claim-substantiation frameworks aligned to major regulatory regimes.
-
Due diligence and M&A toolkits. Commercial and technical red flags for target assessment, integration checklists, unit economics sensitivity analysis, and a shortlist methodology for identifying high-fit acquisition targets — especially useful where supply consolidation or backward-integration is a strategic objective.
-
Regulatory & IP intelligence. A compendium of relevant regulatory thresholds and labeling requirements in key markets, patent landscape mapping, and an assessment of how recent rulings affect freedom-to-operate and process selection.
-
Appendices with raw datasets and interactive files. For subscribers we provide the underlying time-series data, supplier master file, and an adaptable Excel model so internal teams can rerun forecasts using company-specific assumptions.
Competitive landscape — who matters and why
The competitive map in biotin is differentiated by strategic intent. A set of global specialty chemical and ingredient houses compete on quality, traceability, and regulatory reach; a large group of manufacturers in concentrated geographies compete on volume, cost, and scale. Key players profiled in the report include established European ingredient houses that emphasize pharma-grade, traceable products and Chinese manufacturers that offer high-volume synthetic biotin and integrated supply capability.
-
DSM-Firmenich (Kaiseraugst, Switzerland) — Global specialty player with an emphasis on pharmaceutical-grade and traceable branded solutions. Recent activity includes a traceable branded biotin line aimed at clean-label supplement demand, demonstrating how traceability and data-backed quality are being commercialized.
-
BASF SE (Ludwigshafen, Germany) — Supplies biotin ingredients across food, beverage, pharmaceutical and nutrition markets; management commentary shows a resilient business backing continuing investment in bioavailability and regulatory compliance capabilities.
-
Merck KGaA (Darmstadt, Germany) — Offers fine-chemical and diagnostic-grade biotin inputs; strengths lie in application-specific formulations and strict quality systems serving regulated end-markets.
-
Evonik Industries AG (Essen, Germany) — Focuses on specialty derivatives and custom formulations, enabling product differentiation for food and pharma customers.
-
Leading Chinese producers (multiple headquarters) — A cohort of major producers supplies the bulk of synthetic biotin volumes globally. These firms benefit from large-scale integrated production, strong cost positions, and export reach. IP and capacity dynamics among these producers are central to price and availability outcomes.
The report’s company profiles extend beyond public summaries to include capacity estimates, quality certification matrices, export footprint, and a commercial posture assessment (e.g., premium vs. volume play). Where competitive developments have direct market impact — such as new traceable product lines, patent decisions, and public earnings commentary — we flag implications for supplier selection and pricing strategy.
Industry signals you cannot ignore in 2026
-
Geographic concentration of critical production steps raises the probability of supply shocks and trade friction translating to abrupt cost increases or allocation events.
-
Patent and IP developments have real commercial consequences: process patents and stereoselective synthesis rulings affect who can scale and where they can sell.
-
Price volatility and sourcing spreads continue to influence gross margins for downstream manufacturers and private-label brands — necessitating dynamic procurement approaches rather than static spot purchasing.
-
Regulatory scrutiny on labeling and structure/function claims means marketing and claims teams must align early with regulatory counsel and product development to avoid rework or market access loss.
Recommended strategic actions for 2026
-
Stress-test your supply base. Run scenario exercises using the provided model to quantify the P&L impact of allocation events, price spikes, and lead-time elongation. Translate results into prioritized mitigation measures (dual-sourcing, safety-stock policies, strategic inventory hubs).
-
Pursue premiumization where regulatory and traceability demand supports higher ASPs. Invest in branded or co-branded traceability propositions for customers in personal care and high-trust supplement segments.
-
Lock in strategic capacity through blended contracts. Mix long-term offtake for core volumes with indexed short-term arrangements for flexibility; use contract design to balance cost and supply security.
-
Monitor IP and patent developments closely. Legal outcomes can change the attractiveness of certain synthesis routes or acquisition targets; build IP clauses into any acquisition or joint-development deal.
-
Position R&D and regulatory teams early. If your product mix relies on label claims or structure/function messaging, a preemptive regulatory plan reduces launch risk and speeds time to market.
How to use this preview and next steps
This preview surfaces the high-impact signals and recommended actions that corporate leaders must consider in 2026. For procurement leaders, R&D heads, corporate development teams, and private-equity investors, the full PW Consulting Biotin Market report includes the granular, transaction-ready datasets, supplier master files, segment-level forecasts, and commercial templates required to execute. To preserve the strategic value of that intelligence, segment-level market shares and company revenue estimates are provided only within the full report and interactive models.
If your 2026 plan involves supply diversification, product premiumization, M&A in the ingredient space, or stronger regulatory alignment for biotin-containing products, this study is designed to be the operating manual for action. PW Consulting’s diagnostic frameworks and deliverables convert market insight into executable roadmaps — minimizing downside from concentrated supply and maximizing upside from premium offerings.
For access to the full dataset, supplier shortlists, scenario models, and a tailored briefing for your executive team, request the full PW Consulting Biotin Market study.
For detailed analysis of this topic, please visit the official page: Biotin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coated Abrasive Market Poised for 5.97% CAGR Through 2032
By PW Consulting, 2026-07-12
Coated Abrasive Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations prepare 2026 budgets and strategic roadmaps, the coated abrasive market presents a mix of steady expansion, tectonic shifts in product expectations, and pockets of consolidation that demand targeted responses. Our benchmarking shows the global market expanded from roughly USD 8.1 Billion in 2020 to approximately USD 10.93 Billion in 2025, and is projected to continue expanding to about USD 16.44 Billion by 2032 — an underlying compound annual growth rate of 5.97% across the 2026–2032 forecast window. Market concentration is meaningful but not prohibitive: the top three suppliers account for around 38.5% of the market, and the top five for roughly 50.2% — a structure that rewards scale while leaving room for focused innovators and regional challengers.
Coated Abrasive Market
Why this matters for 2026 planning
-
Investment prioritization. Predictable mid-single-digit CAGR supports continued investment in capacity, but success will hinge on capital allocation toward product innovation, sustainability adaptation, and digital customer channels rather than undifferentiated volume expansion.
Coated Abrasive Market -
Supply-chain resilience becomes strategic. Recent and ongoing disruptions to key bonding chemicals and specialty inputs have shortened planning horizons and elevated the value of alternative sourcing, upstream partnerships, and on-shore buffer strategies.
Coated Abrasive Market -
Regulatory and procurement risk. Sustainability mandates and tightening product-compliance requirements are accelerating adoption of bio-based and certifiable product options. Firms that can combine performance with verifiable environmental credentials will unlock premium segments and preferred-supplier status with OEMs.
-
Automation-led demand shifts. Labor shortages and expanded robotic finishing lines are changing product specifications (durability under robotic cycles, dust control, integration with automated tooling). Suppliers who co-develop solutions with systems integrators capture higher-margin, recurring-revenue streams.
Market dynamics — from raw materials to end-use
The coated abrasive value chain is being reconfigured along several vectors simultaneously. On the supply side, intermittent shortages in specialty chemicals and adhesives have increased lead-time volatility and input-cost pass-through complexity. On the demand side, adoption patterns are diverging by end-use: traditional industrial metalworking continues to provide a volume foundation, while newer growth pockets are driven by automation, precision finishing in electronics and semiconductors, and sustainability-led replacement cycles in aftermarket and construction segments.
Regulation and certification are no longer peripheral considerations. Product launches in 2025 that emphasize biodegradability and life-cycle performance reflect an emerging baseline expectation among institutional buyers. Meanwhile, digital procurement and traceability features — exemplified by recent platform rollouts — are migrating from nice-to-have to procurement criteria tied to compliance and supplier rationalization programs.
Competitive landscape — what leading firms are doing
-
Saint‑Gobain Abrasives / Norton brand — A broad portfolio and recent inorganic expansion have reinforced global coverage, particularly in growth geographies. Their strategy appears focused on marrying range breadth with local manufacturing to protect margins against freight and input shocks. For incumbents, the lesson is clear: combine product depth with distribution proximity to remain relevant to industrial OEMs and large distributors.
-
3M — The company has sharpened its sustainability messaging with product innovation (e.g., biodegradable coated abrasives launched in August 2025). 3M’s playbook is to translate material science into brand-differentiated products, then leverage broad channel reach to scale adoption. Competitive response should evaluate where material innovation can create defensible features rather than commodity parity.
-
Norton Abrasives — While Norton remains a major brand within larger groups, recent investments in digital customer experience (new platform launched October 2025) demonstrate a shift to procurement-led value capture. The platform also aligns supplier capabilities with ISO-compliance requirements — a blueprint for suppliers seeking deeper integration into customer procurement workflows.
-
Klingspor — High-quality, application-focused product lines and strong woodworking-industrial finishing credentials make Klingspor a resilient player in premium niches. Their model underlines the commercial advantage of tightly aligned product-development with specific industrial workflows.
-
Mirka — A recognized leader in precision surface finishing, Mirka’s emphasis on systems (abrasives + tools + consumables) highlights how bundling raises switching costs and creates stickier customer relationships — particularly in OEM and high-precision subcontractor segments.
-
sia Abrasives — High output capacity and strong automotive and building-sector focus enable sia to compete on scale for contract manufacturing and large-scale projects. Their capability profile is instructive for firms evaluating contract manufacturing vs. in-house production decisions.
-
Carborundum Universal Limited (CUMI) — A leading regional player with a broad product catalog and strong presence in construction and industrial channels. Recent catalog updates and product portfolio refreshes keep the brand relevant for distribution-led growth in emerging markets.
Recent corporate moves with strategic implications
-
Product launches emphasizing biodegradability and sustainability (notably from a major global player in 2025) signal that product life-cycle attributes will be a point of competitive differentiation in procurement dialogues during 2026.
-
Acquisition activity in Asia by a leading European incumbent underscores the importance of strategic M&A to secure local capacity and reduce exposure to freight and input-price inflation.
-
Digital platform rollouts that embed compliance and procurement workflows are becoming a competitive moat. Expect an acceleration of supplier digitization projects as buyers demand traceability and easier re-ordering.
Strategic playbook for 2026
-
Prioritize product portfolios into three buckets: (1) high-performance systems for automation and precision finishing, (2) sustainability-certified offerings for regulated channels and green procurement, and (3) cost-optimized ranges for high-volume industrial applications. Allocate R&D and capex according to downstream margin potential, not historical volume alone.
-
Invest in supplier diversification and chemical-substitute R&D. A dual approach — securing alternative suppliers for key inputs while developing formulations that reduce dependency on constrained chemistries — materially reduces service-risk in 12–18 month planning horizons.
-
Embed digital procurement and compliance features into customer-facing platforms. Platforms that simplify ISO certification, batch traceability, and automated re-ordering convert technical product advantages into commercial stickiness.
-
Assess M&A and JV targets with an “access-to-technology” and “access-to-market” lens. Regional producers with strong channel relationships or unique material know-how offer faster paths to capability expansion than greenfield investments.
-
Develop partnerships with systems integrators and robotic suppliers. Co-engineering abrasive consumables for robotic finishing lines will be a significant value driver as automation adoption grows.
What the full PW Consulting report delivers (practical, actionable)
-
Transparent market-sizing and growth scenarios with sensitivity analysis that connects macro trends to unit economics and margin outcomes — enabling finance teams to stress-test 2026 capex proposals.
-
Commercial playbooks for supply chain resilience, including a prioritized list of alternative suppliers, suggested inventory buffers by risk-profile, and supplier scorecards tailored to abrasive-specific inputs.
-
Competitive benchmarking across product, price, channel, and service dimensions with go-to-market tactics for defending share or entering adjacent segments.
-
Innovation radar and R&D roadmaps that map material science advances to potential premium features and regulatory-ready product variants.
-
M&A heatmaps that prioritize targets by strategic fit (technology, geography, channel) and modeled synergy ranges to support deal conversations in 2026.
-
Operational playbooks for digitizing the customer interface, including procurement integrations, traceability workflows, and KPIs to measure commercial impact.
How to use this intelligence in boardrooms and procurement meetings
For CEOs and CFOs: use the market trajectory and scenario outputs to stress-test capital allocation between capacity, R&D, and digital transformation. For commercial leaders: adopt the segment-specific playbooks to prioritize sales coverage and channel investments in 2026. For procurement and operations: implement the supply-chain resilience checklist immediately to mitigate near-term input risks and ensure continuity for high-value contracts.
Closing — the strategic choice in 2026
The coated abrasive market offers a predictable growth backdrop combined with disruptive inflection points around sustainability, automation, and digital procurement. Success in 2026 will not be decided by scale alone; it will hinge on the ability to convert material science and digital capabilities into procured value — measurable through reduced total cost of ownership and improved compliance footprints for buyers. PW Consulting’s full Coated Abrasive Market report delivers the granular segmentation, country-level analytics, and downloadable models required to operationalize the strategies outlined here.
For the complete dataset, in-depth segment economics, and executable playbooks referenced in this preview — including the withheld granular splits and customer-level insights — visit our report page to access the full intelligence suite and downloadable decision-support tools.
For detailed analysis of this topic, please visit the official page: Coated Abrasive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LDPE Extrusion Coating to hit USD 344.8M by 2032 at 5.2% CAGR
By PW Consulting, 2026-07-12
LDPE Extrusion Coating Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our new market study on LDPE extrusion coating — a practical intelligence asset designed to inform senior executives, commercial leaders, and investment committees as they set strategy for 2026 and beyond. This briefing summarizes the study’s strategic value, synthesizes the most consequential market forces, and outlines the competitive implications for incumbents and challengers alike. It deliberately signals depth while reserving the granular tables and segmented figures for the full report — the information you will need to operationalize moves in 2026.
LDPE Extrusion Coating Market
Market snapshot — clear, calibrated, and forward-looking
Our work is grounded in a rigorously constructed time series and forecast model with a 2025 base year. The LDPE extrusion coating market demonstrates steady, mid-single-digit growth: the report applies an underpinning compound annual growth rate of 5.2% across the 2026–2032 forecast window. This trajectory reflects continued demand from core packaging end-markets, gradual product premiumization, and selective capacity additions globally. The base-year sizing and the projected terminal values are integrated throughout the report’s commercial scenarios and sensitivity runs to ensure decisions are tested against realistic volumetric and revenue outcomes.
LDPE Extrusion Coating Market
Why this study matters for 2026 strategic choices
- Timing of capacity and contract decisions: 2026 will be a year when several capacity moves and contract roll-offs intersect. Our forecast and scenario engine lets you evaluate the commercial impact of executing or deferring capex, entering long-term off-take agreements, or pursuing tactical spot exposure.
- Risk-aware commercial planning: Feedstock and film price volatility remain the fastest route to margin swings. The study overlays price scenarios and hedging playbooks onto customer and channel segmentation so sales and trading teams can set defensible floor/ceiling pricing.
- Regulatory posture and market access: Recent standards updates and quality control amendments in major markets are reframing acceptance criteria for LDPE extrusion coating grades. Our regulatory consequence matrix helps procurement and regulatory affairs teams prioritize compliance investments and certification timelines.
- M&A and partnership screening: With moderate market concentration among the largest players, there is strategic optionality for bolt-on transactions and JV models. The report provides a prioritized target list and valuation stress-tests consistent with 2026 capital constraints.
Key demand and supply dynamics shaping 2026
- End-market momentum and product mix: Packaging demand, especially in liquid and flexible sectors, continues to underpin LDPE extrusion coating volumes. The report traces substitution risk (incl. barrier films and mono-material formats), customer-spec upgrades, and the commercial premium attached to higher-performance extrusion grades.
- Feedstock and pricing volatility: Raw-material swings remain a dominant short-term earnings driver. Seasonal and regional feedstock dislocations — combined with the introduction of new converting capacity in Southeast Asia and occasional rebounds in major supply hubs — produce a patchwork pricing environment. The full study models these dynamics through probabilistic price paths informed by recent industry observations.
- Regulatory and standard-setting shifts: Policy updates in large consuming countries have tightened quality and testing requirements for extrusion-coating resins. These changes increase the compliance burden for suppliers lacking formal certification pathways and accelerate demand for traceable, quality-assured grades.
- Capacity additions and regional re-balancing: New LDPE and film capacity in select regions has temporarily depressed pricing in those markets, while localized feedstock advantages continue to support higher utilization elsewhere. Our supply-side module maps announced and probable greenfield/expansion projects and assesses their commercial impact under multiple demand scenarios.
Competitive landscape — what differentiates winners
The LDPE extrusion coating market is served by a mix of large integrated petrochemical majors, regional champions, and specialty producers. Market concentration is moderate: the top three players account for roughly one-third of reported market activity, while a broader top-five group expands that share further. This topology produces both scale advantages and niches for targeted differentiation.
LDPE Extrusion Coating Market
- Global integrated majors (e.g., Dow, LyondellBasell, ExxonMobil Chemical): These players leverage feedstock integration, broad product portfolios, and global sales networks. Their advantages are most evident in multi-region supply agreements, custom grade development, and risk management at scale. Expect them to defend share through technology licensing, customer co-development, and bundled commercial offers.
- Regional and national champions (e.g., Sinopec Beijing Yanshan, Braskem, Westlake): Local production footprint and access to favourable feedstock or logistics cost structures enable competitive local pricing and rapid response to domestic regulatory shifts. They often play a crucial role in regional pricing and service benchmarks.
- Specialty and flexible producers (e.g., LG Chem, SABIC, Chevron Phillips, INEOS): These companies compete on product differentiation — higher performance grades, tailored resin properties for extrusion coating, and sustainability credentials. Their commercial playbook emphasizes technical service and conversion support for brand owners seeking premiumized packaging formats.
- Strategic takeaways: For buyers — diversify homologous supply sources across integrated and specialty partners; for suppliers — invest in certification, application support, and selective local capacity to blunt commoditization pressures.
Recent market signals to watch
- Commercial offers from major feedstock producers have recently influenced delivered pricing into key export hubs; these offers have the potential to shift regional competitive dynamics when combined with new converting capacity.
- Regional film prices have shown episodic weakness where capacity additions outpaced demand growth, while other markets have experienced cyclical rebounds after short-term declines — underscoring the need for dynamic pricing playbooks.
- Regulatory updates in sizeable consuming economies have tightened quality-control standards for LDPE extrusion uses. Compliance timelines and audit-readiness will be a differentiator for suppliers seeking to retain or expand market access.
- Public commentary from major integrated producers suggests an expectation of continued supply disruptions in the near term — a signal for buyers and sellers to stress-test 2026 plans against upside and downside supply scenarios.
What PW Consulting’s full report delivers — practical outputs for 2026
The study is designed as an operational toolkit, not an academic exercise. Key deliverables include:
- Granular market sizing and a probabilistic demand-forecast model (2026–2032) with scenario toggles for volume, price, and feedstock pathways.
- Competitive scorecards and capability maps for every major supplier, including product line-up, regional capacity, quality certifications, and go-to-market strength.
- Price-sensitivity and margin impact calculators that tie feedstock trajectories to finished-product margins under multiple contracting assumptions.
- A regulatory impact matrix that translates recent and pending standards into certification costs and market-access timing by jurisdiction.
- Commercial playbooks for buyers and sellers — including recommended contract terms, hedging strategies, and supplier consolidation tactics appropriate to different company profiles.
- Capital projects tracker and M&A screening framework that ranks opportunities by strategic fit, integration complexity, and likely valuation bands under conservative and optimistic market cases.
- Excel-based models and dashboards to run bespoke corporate scenarios and to stress-test strategic choices ahead of board decisions.
Actionable strategic recommendations for 2026
- Lock selective long-term supply while preserving optionality: Negotiate blended contracts that combine a fixed baseline with indexed volumes to protect against short-term price spikes without surrendering upside in favorable price environments.
- Prioritise certification and quality-traceability investments: For suppliers, early compliance to tightened standards will create a barrier to entry for less-prepared rivals and support premium positioning with multinational brand owners.
- Use regional arbitrage for tactical margin capture: For trading desks and commercial teams, opportunistic sourcing from regions where new capacity has depressed pricing can be profitable, provided logistics and quality risks are managed.
- Accelerate product differentiation efforts: Invest in application-specific grades and conversion support to anchor higher-margin relationships with converters and consumer-packaging firms moving toward mono-material and recyclable designs.
- Screen M&A for strategic rather than purely volumetric gains: Targets that bring technical differentiation, downstream channels, or regulatory-certification advantages will deliver superior returns in a moderately concentrated market.
Conclusion — how to use this intelligence in 2026
Decisions in 2026 will be made under the influence of intertwined supply, pricing, and regulatory forces. The PW Consulting LDPE Extrusion Coating study equips decision-makers with the forecast fidelity, scenario tooling, and commercial playbooks required to mobilize capital, renew contracts, and outmaneuver rivals. We have structured the deliverables to be immediately actionable at the board and commercial desk levels — with downloadable models and step-by-step implementation templates in the full report.
For access to the complete dataset, segmented tables, supplier scorecards, and the scenario-enabled Excel model, please consult the full report on our website — the only place where the granular segment splits and price ladders are disclosed in their entirety.
For detailed analysis of this topic, please visit the official page: LDPE Extrusion Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Plastic Gears Market: Strategic Outlook for 2026 — PW Consulting Insights
As companies prepare budgets and capital allocations for 2026, the plastic gears sector presents a clear growth trajectory—and a complex set of strategic choices. PW Consulting’s latest market research (base year 2025) frames that opportunity with a data-driven forecast: after rising from approximately USD 320 Million in 2020 to USD 420 Million in 2025, the market is projected to expand at a compound annual growth rate (CAGR) of 5.8% through the forecast window, reaching roughly USD 617 Million by 2032. That topline growth masks important operational, technological and competitive inflection points that will determine winners and losers in the next 24 months.
Plastic Gears Market
Why this report matters for 2026 decisions
- Prioritization under uncertainty: Executives must decide where to allocate R&D, capital equipment, and commercial resources in an industry experiencing both steady demand growth and episodic supply-side shocks.
- Material strategy and cost control: Volatility in specialty thermoplastic prices and feedstock availability has re-framed procurement as a strategic capability, not a transactional function.
- M&A and partnership timing: Consolidation and capability acquisition are active, making targeted transactions a fast route to capability build-out—but timing and target selection are critical.
- Engineering investments: Advances in simulation, precision molding, and gear design are shifting value from commodity supply to integrated system suppliers who can guarantee noise, vibration and durability performance.
What the research delivers (practical, actionable content)
PW Consulting’s study was designed as a decision-support toolkit for leadership teams, investors, and engineering directors. The report synthesizes quantitative market sizing and scenario forecasts with qualitative, executable intelligence across six core modules:
Plastic Gears Market
- Topline market sizing and validated forecast (2026–2032) with scenario builds that stress raw material, demand shock, and regulatory variables.
- Demand drivers and end-market dynamics: deep narrative on automotive electrification, industrial automation, consumer electronics miniaturization, medical device trends, and emergent mobility (e-bikes, micro-mobility).
- Materials and design playbook: evaluation of engineering plastics (including common high-performance polymers), design-for-manufacture constraints, and trade-offs between injection molding, precision machining, and hybrid assemblies.
- Supply-chain and procurement risk matrix: supplier concentration mapping, alternate sourcing strategies, inventory and payables levers, and contingency scoring against raw-material price volatility.
- Competitive and commercialization playbook: discrete profiles and capability maps of incumbent and emerging suppliers, channel strategies, and aftermarket/service approaches—plus M&A screening criteria.
- Regulatory, standards, and R&D landscape: synthesis of recent conference outputs, standardization tracks, and simulation/validation best practices that shorten development cycles.
To respect the “preview” intent of this brief, we intentionally summarize the structural findings here while retaining detailed regional/application splits, price point analysis and proprietary model outputs for the full report.
Plastic Gears Market
Industry dynamics shaping 2026
- Stability with episodic volatility: The underlying demand base is expanding steadily, but raw-material cost swings—specialty thermoplastics experienced near double-digit percentage variability in 2025—create short-term margin pressure and re-pricing opportunities.
- Engineering intensity rising: Greater emphasis on NVH (noise, vibration, harshness), life-cycle performance, and integration into mechatronic assemblies is favoring suppliers that combine gear expertise with simulation and systems engineering.
- Consolidation and capability M&A: Recent transactions and strategic buys show acquirers seeking immediate access to precision molding and custom-engineering capabilities rather than just volume production.
- Standardization and knowledge diffusion: Conferences and technical committees are accelerating the adoption of advanced simulation methods and design guidelines, reducing barriers to entry for well-funded challengers but raising engineering expectations for OEMs.
Competitive landscape — what incumbents and challengers are doing
The market remains moderately fragmented (CR3 ~25.2%, CR5 ~27.8%), reflecting a mix of specialized precision houses and broader component suppliers. Key participants typify two winning archetypes: engineering-intensive specialists and scale-driven suppliers that offer integrated manufacturing services.
- IMS Gear (Donaueschingen, Germany) — Strong foothold in automotive and industrial planetary and precision gears; positioned to benefit from actuator electrification and robotics partnerships.
- Winzeler Gear (Harwood Heights, IL, USA) — Known for high-precision injection-molded gears serving automotive actuators and medical devices; recently acquired by a strategic buyer, signaling consolidation interest in precision capabilities.
- Gleason Corporation (Rochester, NY, USA) — Expanding thought leadership and customer enablement through training and technical programs; transitioning from pure equipment supplier to solutions partner for high-precision gear systems.
- Designatronics Inc. (Danbury, CT, USA) — Offers both standard and custom catalog options, serving aerospace and medical niches that demand traceability and strict qualification.
- Oechsler AG (Aalen, Germany) — Focuses on reinforced thermoplastics and wear-resistant solutions for industrial robotics and automotive segments—an R&D-led differentiator.
- Rush Gears , AmTech International , Kohara Gear , Essentra plc , Stagnoli T.G. — Each brings localized strengths in precision molding, aftermarket parts, or mobility-specific gearboxes (e.g., e-bike transmissions).
Recent developments underline these dynamics: Gleason’s May 2025 technical training initiative, a July 2025 acquisition that expanded a North American precision player’s footprint, and product unveilings at major trade shows in 2025. These events are not isolated; they reflect a broader market emphasis on capability, knowledge transfer, and rapid commercialization.
Strategic implications for 2026 — a practical playbook
- Hedge and diversify material sourcing: Build dual-sourcing contracts for critical polymers, qualify substitute material families in parallel, and incorporate price-indexed contracts to reduce margin erosion from feedstock swings.
- Prioritize engineering-to-order capabilities: Invest in simulation tools and measurable NVH/ wear testing so you can sell performance guarantees rather than raw component pricing.
- Targeted M&A and partnerships: Use a capability-first acquisition screen—precision molding, materials science, and mechatronics integration—to accelerate entry into higher-margin applications.
- Commercial segmentation and value-based pricing: Move away from unit-cost pricing in segments where life-cycle performance and integration reduce system cost for OEMs; capture aftermarket service and spare-part revenue streams.
- Operational resilience: Reconfigure inventory policy for long-lead resin families, and implement supplier stress-testing and scenario drills to shorten reaction time to supply shocks.
- Sustainability and circularity: Develop material-recovery pathways and validated recycled-content designs for sensitive applications—expected to be a differentiator for regulated medical and consumer channels.
- Skilling and cross-functional teams: Establish cross-disciplinary squads (materials, design, procurement, application engineering) to shorten design cycles and commercialize faster.
How PW Consulting supports execution in 2026
Our full report couples market intelligence with execution tools tailored for 2026 planning cycles:
- Interactive dashboards and scenario models that let you stress-test revenue, margin and working-capital outcomes across multiple raw-material and demand scenarios.
- Supplier and country risk heatmaps to guide nearshoring and dual-sourcing decisions.
- M&A target shortlists and synergy calculators built from proprietary capability assessments and commercial fit analyses.
- Engineering workshops and simulation clinic templates to elevate internal design-for-manufacture competencies.
- Go-to-market playbooks for OEM engagement in electrified mobility, industrial robotics, and medical device sectors.
To maintain the value of this executive preview, detailed regional and application-level splits, price curve series, supplier scorecards, and full model files are reserved for subscribers and licensed clients. These artifacts include the granular inputs we use to produce the topline forecasts summarized above.
Next steps — an offer for a 2026-ready strategy
For leadership teams preparing 2026 budgets, the decision window for capital investment, M&A, and capability upgrades is now. PW Consulting can provide a tailored briefing that overlays your corporate priorities onto the market scenarios in our study, generating a prioritized roadmap and a short list of near-term actions you can operationalize within 90–180 days.
Contact PW Consulting to schedule a confidential executive briefing and receive access to the full dataset, competitor dossiers, and the scenario toolkit that power this market outlook.
For detailed analysis of this topic, please visit the official page: Plastic Gears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Potting Compound Market to hit USD 4,444.96M by 2032 at 3.4% CAGR
By PW Consulting, 2026-07-12
Potting Compound Market — Strategic Preview for 2026 Decision-Making (PW Consulting)
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision-oriented preview of our latest Potting Compound Market study. This briefing synthesizes the market trajectory, competitive positioning and regulatory dynamics that will determine winners and laggards in 2026 — while intentionally withholding the granular segment tables contained in the full report to preserve strategic value and prompt direct engagement for the underlying data.
Potting Compound Market
Market snapshot and trajectory
Using 2025 as our base year, the global potting compound market has shown steady expansion through the last half-decade and remains on a moderate-growth path through our forecast window. Key macro numbers from the study that should shape capital allocation and product strategy in 2026:
Potting Compound Market
- The market grew from approximately USD 2,902.6 Million in 2020 to USD 3,516.0 Million in 2025 (base year).
- Our forecast period spans 2026–2032, during which the market is projected to grow at a compound annual growth rate (CAGR) of about 3.4%.
- By the end of the forecast horizon the global market is modeled to approach USD 4,444.96 Million (2032).
- Market concentration is moderate: the top 3 players account for roughly 38% of industry revenues; the top 5 for about 45% — a structure that enables both scale advantages and opportunities for nimble specialists.
Two subtle but important notes for 2026 planning: our baseline shows a near-term normalization in 2026 versus 2025 (a small adjustment reflecting supply-chain and pricing normalization), followed by steady expansion through the late 2020s. This pattern favors timely, selective investments rather than indiscriminate capacity build-outs.
Potting Compound Market
Why this study matters for 2026 corporate decisions
- Portfolio prioritization: the report quantifies where incremental volume and margin pools are likely to appear and which material types and performance attributes will command premium pricing.
- R&D and product roadmaps: it maps regulatory and application-driven specifications (e.g., flame retardancy, thermal conductivity, low-VOC, UV-curability) to commercial opportunity windows.
- Sourcing and procurement: it offers a cost-sensitivity model calibrated to recent feedstock volatility to inform hedging, supplier diversification and contract structuring.
- M&A and partnership screening: a focused set of acquisition targets and partnership archetypes is identified, with high-level valuation assumptions and integration risks.
- Go-to-market and pricing: the study provides commercial playbooks for OEM engagement, certification strategies and value-based pricing in high-performance niches.
Report contents — practical, action-ready deliverables
- Market sizing and 2020–2032 forecasts (total market and full segmentation — note: detailed split tables are accessible in the paid report).
- Demand-driver analysis across electronics, automotive, aerospace, industrial and adjacent verticals, including scenario-based demand ladders.
- Material technology canvas assessing epoxy, silicone, polyurethane and alternative chemistries against performance and cost vectors.
- Supply-chain heatmap with input-price sensitivity (we quantify the impact of epoxy resin feedstock volatility observed in early 2025).
- Regulatory compliance matrix covering UL 94, IEC family standards, RoHS and REACH, plus VOC restrictions and their commercialization implications.
- Competitive landscape with executive summaries and strategic positioning for leading suppliers.
- Commercial playbooks: channel segmentation, certification roadmaps, OEM sourcing requirements and country-level go-to-market considerations.
- Scenario analysis and three executable strategic playbooks for incumbents, challengers and private-equity-backed roll-ups.
- Practical appendices: technical test protocols, sample procurement contracts, and an interview-log of primary discussions with formulators, OEM engineers and procurement leaders.
Strategic implications and recommended actions for 2026
1) Investment timing & capacity decisions
With a mid-single-digit industry CAGR and a modest near-term flattening, 2026 is not the year for blanket greenfield buildouts unless tied to secured contracts. Recommended actions:
- Pursue modular, flexible capacity expansions (skid-mounted mixing lines, contract manufacturing partnerships) to capture upside without heavy fixed-cost commitments.
- Prioritize investments in finishing/dispensing capabilities (precision metering, vacuum-degassing, thermal management additives) that increase yield and margin on existing volumes.
2) R&D and product roadmap prioritization
Regulatory pressure (low-VOC and heavy-metal restrictions), safety standards (UL 94, IEC), and demanding thermal/flame requirements from electronics and power applications are creating a premium for performance chemistries. Recommended focus areas:
- Low-VOC, low-odor formulations and alternatives to restricted substances to meet RoHS/REACH trends.
- Thermally conductive yet electrically insulative blends; flame-retardant systems that meet UL94 V-0 and equivalent IEC tests.
- UV- and light-curable chemistries for rapid process cycles where application permits — an area of clear differentiation for formulators investing in curing technologies.
3) Procurement strategy and raw-material risk management
Epoxy and other resin feedstock price volatility in early 2025 materially affect margins. For 2026 we recommend:
- Implement multi-tier supplier agreements with indexed pricing bands and minimum-offtake protections.
- Develop strategic inventory buffers for critical monomers while avoiding long-term overexposure to spot pricing.
- Assess backward-integration options for specialty additives where scale and capex profiles make sense.
4) Commercial and channel playbook
Given the industry’s moderate concentration (CR3 ~38%, CR5 ~45%), scale and relationships matter — but there is also room for specialty players. For 2026:
- Win with technical services: invest in application labs and OEM co-development to shift the procurement conversation from price to total cost of ownership.
- Segment pricing by performance attributes (thermal, flame-retardance, cure-profile) and certify technologies to shorten sales cycles in regulated verticals.
- Leverage regional contract manufacturers for faster time-to-market in pockets where high-volume OEM demand is emerging.
5) M&A and partnership themes
Opportunistic M&A remains a key pathway to scale and capability access. Targets that consistently surface in our diligence include specialty formulators, additives providers and regional converters with strong OEM relationships. Due-diligence priorities should emphasize regulatory compliance histories, formulation IP, and customer concentration.
Competitive landscape — who you’ll be competing and collaborating with
The study profiles a set of incumbent and specialized competitors that collectively shape strategic options for suppliers and buyers. Representative players covered in the report include:
- Henkel AG & Co. KGaA (Düsseldorf) — established leader with recognized Loctite STYCAST and Loctite potting portfolios; notable for introducing next-generation polyurethane systems focused on industrial and power-electronics reliability (notably a product launch in January 2026 targeting harsh-environment applications).
- ELANTAS GmbH (Hanau) — specialist supplier of electrically focused potting and casting resins with deep traction in demanding protection applications.
- MG Chemicals (Vancouver) — nimble player recognized for flame retardant, thermally conductive and optically clear formulations.
- 3M Company (St. Paul) — global brand with mature Scotchcast family and strong channel reach into electrical infrastructure and service segments.
- Dymax Corporation (Torrington) — niche leader in UV- and light-curable encapsulants for high-throughput applications.
- Dow Inc. and Momentive Performance Materials — major raw-material and specialty-silicone suppliers whose formulations serve large industrial and electronics use-cases.
- Parker Hannifin / LORD, Electrolube, Aremco, Epic Resins — specialized formulators and performance-material providers that act as both competitors and potential acquisition targets depending on strategic fit.
The competitive map in the full report highlights capability clusters (e.g., UV-curing, high thermal conductivity, flame-retardant epoxies) and identifies white spaces where new entrants can realistically pursue premium positions.
Regulatory and materials dynamics to watch
- Standards and safety: UL 94 and IEC testing continue to be gating factors for adoption in electronics and appliance segments; meeting these standards shortens procurement cycles.
- Environmental compliance: RoHS/REACH and global VOC restrictions are pushing formulators toward lower-VOC systems and substitution of restricted additives.
- Input-price volatility: episodic swings in key resin feedstocks materially alter unit economics for formulators that lack hedging or flexible sourcing approaches.
How to use the full PW Consulting report (and what’s intentionally reserved)
This preview is designed to equip senior leaders with the strategic framing needed for 2026 decisions. The full report contains the granular intelligence that operational teams, M&A advisors and procurement should directly use — including:
- Detailed segmentation tables (by region, type and application) and quarterly demand curves.
- Company-level revenue estimates, product-level share assumptions and pricing curves.
- Raw-material cost models and sensitivity analyses down to specific monomer inputs.
- Supplier scorecards, validated interview transcripts and downloadable technical appendices.
To preserve the commercial value of those deliverables (and to enable confidential briefings), we have intentionally withheld the granular split values in this public preview. PW Consulting offers tailored briefings and bespoke workshops that walk buyers and sellers through the full dataset and its implications for specific strategic options.
Concluding guidance — a short playbook for 2026
In 2026, firms that combine nimble capacity strategies, targeted R&D in compliance-driven performance attributes, and disciplined procurement will outperform peers. The market’s moderate growth and concentration profile reward technical differentiation and smart commercial execution more than scale-alone gambits. Use the data in this preview to set priorities — then engage PW Consulting for the complete dataset and an execution roadmap customized to your risk profile and growth ambitions.
Contact PW Consulting to schedule a confidential briefing or to license the full Potting Compound Market report and its underlying datasets.
For detailed analysis of this topic, please visit the official page: Potting Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mindfulness Apps Market to Grow at 12.6% CAGR — Key Insights
By PW Consulting, 2026-07-12
Mindfulness Meditation Apps Market: Strategic Briefing for 2026 Decision‑Makers
As organizations and investors reassess digital wellbeing priorities for 2026, this briefing synthesizes the strategic implications of PW Consulting’s latest Mindfulness Meditation Apps Market study (base year 2025, forecast 2026–2032). The market has moved from an early-stage wellness play into a commercially significant digital vertical: after growing from under USD 1 billion in 2020, the industry reached roughly USD 1.5 billion in 2025 and is forecast to exceed USD 3.5 billion by 2032, expanding at a compound annual growth rate of approximately 12.6%. This trajectory creates both opportunity and risk — and requires different choices from product, regulatory, partnership and M&A leaders than were necessary even three years ago.
Mindfulness Meditation Apps Market
Why this study matters for 2026 decisions
-
Timing: The market is entering a higher‑growth phase where early investments in AI personalization, immersive experiences, and strategic partnerships can compound value quickly. Decisions made in 2026 will determine whether a company is a category leader or a fast follower by 2028–2030.
Mindfulness Meditation Apps Market -
Complexity: The convergence of consumer wellness expectations, regulatory scrutiny of AI, and new delivery modes (XR and wearables) means simple product pivots are no longer sufficient. Execution requires cross‑functional programs spanning clinical quality, privacy engineering, and device integration.
Mindfulness Meditation Apps Market -
Capital allocation: With predictable, repeatable subscription economics emerging across premium offerings, boards must decide whether to prioritize CAPEX for IP and R&D, M&A to consolidate market share, or partnerships that accelerate distribution.
Data‑driven market picture (high level)
Our market model shows a clear and accelerating revenue curve. Between 2020 and 2025 the market more than doubled, and at a sustained CAGR of ~12.6% the total addressable revenue base is projected to grow substantially through 2032. The inflection points in our forecast correspond to three structural drivers: (1) premiumization and monetization of sleep and therapy-adjacent features; (2) platform extensions into XR and wearables that increase engagement and willingness to pay; and (3) enterprise and clinical channel expansion (employee wellbeing contracts, clinical pilots) that add higher‑ACV revenue streams. These drivers are quantified and stress‑tested across multiple scenarios in the full report.
Competitive landscape — who matters and why
-
Headspace — comprehensive consumer platform with guided sessions, sleep programs, and expanding AI and mixed‑reality experiments. Recent product initiatives include an XR app rollout for immersive meditation on mainstream headsets.
-
Calm — consumer leader known for sleep content, calming soundscapes and a strong brand position for stress reduction and bedtime experiences.
-
Insight Timer — community-driven, freemium model with an extensive library and social features that drive retention without heavy paid conversion spending.
-
Waking Up — niche, teacher‑led approach that emphasizes depth and pedagogy; appealing to users seeking long‑form learning and a subscription willing to pay for thought leadership.
-
Smiling Mind , Medito , and non‑profit/teacher apps — these entrants exert pricing pressure and broaden market reach through entirely free models and community distribution.
-
Isha Foundation — large institutional reach and recent viral uptake for short guided programs through its Miracle of Mind app, demonstrating the power of faith‑and‑teacher‑led networks to scale rapidly.
Collectively, the competitive set reveals two viable strategic archetypes going forward: (a) premium, product‑led platforms that monetize deep personalization and clinical adjacencies; and (b) scale‑and‑engagement players that dominate reach using free or community monetization models. Both archetypes face the same regulatory headwinds and technology opportunities — but they require different operating models, talent mixes and capital plans.
Recent developments that change the playbook
-
Mass adoption signals: Specialist and teacher‑backed apps have demonstrated rapid consumer uptake in 2025, underscoring how content provenance and network effects can drive viral growth.
-
XR and wearables: Major vendors have moved beyond concept demos — immersive meditation apps and consumer wearables with meditation modes are now commercially available, shifting parts of engagement from mobile UI to spatial and biosignal experiences.
-
Device‑adjacent innovation: New consumer wearables promise deeper relaxation states and present opportunities (and risks) for apps to bundle hardware + subscription offerings.
Regulatory and operational dynamics to factor into 2026 plans
-
EU AI Act — personalization engines and conversational agents embedded in meditation apps will become subject to transparency obligations as bulk applicability increases in 2026. Some mental‑health oriented AI features could be classified as higher‑risk and require conformity assessments; companies must map feature-level risk now to avoid slowdowns.
-
Data privacy frameworks — GDPR and CCPA remain front‑and‑center: consent flows, data minimization, and secure processing are table stakes for customer trust and B2B contracts. These are not optional compliance items for market leaders.
-
Healthcare boundary — mindfulness apps remain primarily classified as wellness offerings and therefore outside the strictures of healthcare privacy regimes domestically; however, moving into therapist‑integrated or diagnostic features changes the regulatory posture materially.
-
Talent and operating cost — AI personalization requires sustained investment in ML engineering, ethical review boards and clinical oversight, creating a higher ongoing labor component in cost structure versus a pure content app.
Actionable strategic recommendations for 2026
-
Prioritize compliance‑first product roadmaps: Conduct feature‑level AI risk mapping and privacy impact assessments in Q1–Q2 2026. For any conversational or recommendation engine that touches mental health, build conformity plans early to avoid market access delays in the EU.
-
Define a clear monetization archetype: Decide whether to compete as a premium platform, scaled freemium community, or hybrid. Each requires different investment multipliers — premium platforms must invest more in clinical validation and device integrations; community models must optimize for engagement velocity and alternate monetization (partnerships, donations, ancillary services).
-
Invest selectively in XR and wearables: Run controlled pilots with headset and wearable partners to understand engagement lift and CAC/retention impacts before committing to hardware bundling.
-
Build an enterprise arm as a margin lever: Employee wellbeing contracts and clinical pilots can increase ARPU and reduce churn volatility. Establish a small, cross‑functional enterprise team to pilot two to three employer or clinical partnerships within 12–18 months.
-
Use M&A to accelerate capability gaps: Identify tuck‑ins for AI personalization, clinical assessment, or XR content libraries rather than performing multi‑year internal builds — the report provides a calibrated M&A screen of targets that meet these criteria.
-
Plan for resilient privacy and data engineering: Budget for a privacy‑by‑design stack and third‑party audits; these investments materially reduce deal friction for global enterprise contracts and EU distribution.
What the PW Consulting report delivers (practical contents)
-
Proprietary revenue model with 2020–2025 historicals and scenario forecasts through 2032, including sensitivity runs on pricing, retention and new channel adoption.
-
Competitive playbooks and feature benchmarking for the leading global apps, with differentiated GTM options for premium and freemium strategies.
-
Regulatory thermostat: a feature‑level EU AI Act and privacy impact checklist, plus a regulatory remediation matrix and estimated time‑to‑conformity for high‑risk features.
-
M&A and partnership shortlists with valuation priors, integration risk profiles and example term sheets for strategic and financial buyers.
-
Operational toolkits: consumer research templates, UX/clinical validation protocols, implementation roadmaps for XR and wearable pilots, and an enterprise sales playbook.
-
90/180/365‑day execution plans tailored to investor, incumbent platform, and start‑up use cases to make the strategy operational immediately.
How clients are using this intelligence in 2026
-
CEOs and boards: to set three‑year capital allocation and inorganic growth targets aligned with projected market expansion.
-
Chief Product Officers: to prioritize roadmap items that increase monetization, reduce regulatory risk and improve retention.
-
Investors and corporate development: to identify acquisition targets that close capability gaps (AI, XR, clinical validation) and to model post‑deal synergies.
-
Legal and privacy teams: to operationalize compliance frameworks that enable rapid scaling into EU and enterprise markets.
Closing — what to do next
The mindfulness meditation apps market is no longer an emerging curiosity — it is a tangible commercial category with predictable growth and clear strategic levers. PW Consulting’s full report delivers the granular models, competitive intelligence and operational playbooks required to convert that growth into market‑leading outcomes.
Note: this briefing highlights the study’s strategic value while intentionally omitting granular segmentation tables and proprietary split metrics. Those detailed breakdowns (including regional, type and application splits, and the complete concentration analysis) are available in the full report and are designed to support transaction‑level and operational decisions in 2026.
For boards, investors and product leaders ready to move from insight to implementation, PW Consulting’s market study is designed as a working toolkit — not merely a narrative. Access the full analysis to obtain the data tables, scenario models and executable templates that underpin the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Mindfulness Meditation Apps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Educational Furniture Market to Reach USD 7.07M by 2032 (5.8% CAGR)
By PW Consulting, 2026-07-12
Educational Furniture Market: Strategic Imperatives for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a concise, decision-focused briefing on the educational furniture market that senior leaders must use to calibrate strategy in 2026. This briefing synthesizes long‑run market momentum, competitive posture, regulatory inflection points and raw‑material innovation to surface the practical choices procurement, product and M&A teams will face over the coming 18–36 months. The intent: demonstrate the report’s analytical depth and operational value while preserving the granular segment data and scorecards that are available only in the full PW Consulting study.
Educational Furniture Market
Executive snapshot
The global educational furniture market is on a steady expansion pathway. After a recovery period in the early 2020s, the market reached approximately USD 4.75 Million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of roughly 5.8% over the forecast period (2026–2032), reaching around USD 7.07 Million by 2032. Market concentration is moderate: the top three players account for about 42.5% of revenue and the top five for roughly 52.3%, indicating room for scale consolidation but also significant opportunities for focused product and service differentiation.
Educational Furniture Market
Why this matters for 2026 corporate decisions
-
Timing and resource allocation: With mid‑single‑digit CAGR and steady expansion through 2032, investment choices now should prioritize durable value creation (product differentiation, after‑sales services, and modular platforms) over speculative geographic plays that require extensive local infrastructure.
Educational Furniture Market -
Portfolio positioning: Buyers and specifiers in education environments increasingly demand research‑backed ergonomics, durability under heavy use, and sustainability credentials. Successful 2026 launches will pair validated pedagogy-driven design with lifecycle cost narratives.
-
Competitive dynamics: The market’s moderate concentration signals that scale matters, but so does specialization. Mid‑sized manufacturers can defend and grow by owning distinct product niches (e.g., flexible seating, outdoor learning spaces, STEM furniture) backed by service propositions.
Market dynamics that will drive decisions in 2026
-
Regulatory acceleration and procurement impact: New and updated standards—most notably recent updates to furniture surface guidelines from recognized standards bodies and national school furniture requirements in major markets—are already shifting specifications for safety, durability and ergonomics. These changes affect procurement cycles, product certification timelines and the claims companies can make in RFPs.
-
Sustainability as a procurement filter: Adoption of recycled composites and engineered materials (for example, solid blocks of recycled plastics used for durable table tops) is no longer niche. Buyers increasingly ask for verifiable recycled content, end‑of‑life pathways and embodied carbon reporting. That changes product sourcing and cost modeling.
-
Outdoor and flexible learning spaces: Guidance on outdoor furniture and the growth of hybrid learning programming are expanding the TAM for durable outdoor and multi‑use furniture. Vendors who can demonstrate weather resistance, low maintenance and compliance with new outdoor standards will win incremental tenders.
Competitive landscape — strategic reads on the core players
The report’s competitive module profiles manufacturers and suppliers across scale, channel reach, technical capabilities and R&D orientation. A brief strategic read on marquee players follows to illustrate how different positioning translates into competitive advantage:
-
Virco — A traditionally strong K‑12 manufacturer with deep distribution in North America. Strengths: scale in classroom staples, OEM-level manufacturing. Strategic angle: leverage existing relationships to bundle services (installation, warranties, refresh programs) and explore lifecycle selling to lock recurring revenue.
-
School Specialty — Strong in early childhood and classroom solutions with an emphasis on distribution and integrated offer sets. Strategic angle: expand value-added services and digital specification tools to reduce friction in large tenders and become the default one‑stop vendor for school districts.
-
HNI Corporation (HON) — Durable, scaled production and a reputation for reliability in institutional channels. Strategic angle: invest in modularity and configurable systems to capture higher-margin, specification-led campus renovation work.
-
Herman Miller — Research-driven design and campus solutions orientation give a premium positioning. Strategic angle: continue to monetize knowledge through consulting, design services and evidence‑based product roadmaps for higher education and research facilities.
-
Smith System & VS America — Innovators in flexible seating and movement‑oriented classrooms. Strategic angle: capitalize on ergonomics trends and outdoor line extensions (following recent product launches in durable outdoor furniture) to address new use cases beyond traditional classrooms.
-
Smaller specialists (Allied USA, K‑Log, Artcobell, Columbia, SAFFE, Alumni Educational Solutions) — These firms often compete on craftsmanship, regional service and niche educational use cases. Strategic angle: partnerships or white‑label agreements with larger distributors, or laser focus on high-margin specialty categories such as STEM lab furniture.
Across suppliers, recent industry activity (product launches, trade show innovations and cross‑category exhibitions) demonstrates that market leaders are attacking both product and channel layers to secure specification wins. Firms that combine product innovation with friction‑reducing procurement support will gain share without requiring deep price cuts.
Regulation and materials: the twin engines re‑shaping product roadmaps
-
Standards and procurement compliance: The recent refresh of furniture surface guidelines and outdoor furniture whitepapers create new certification windows. Companies that pre‑emptively test and certify against the updated standards will shorten supply lead times and reduce rework risk in public‑sector tenders.
-
Material innovation: Use of recycled plastics and engineered composites—materials offering impact resistance, waterproofing and lower cost volatility—are entering standard spec sheets. Firms should evaluate supplier partnerships for these materials and adjust BOM (bill of materials) and warranty policies accordingly.
-
Market entry and localization: National standards in large markets (for example, recent requirements in major Asian jurisdictions) create both barriers and opportunities. Localized production or distribution arrangements may be required to meet mandated product features while maintaining cost competitiveness.
Practical playbook for 2026 (five immediate moves)
-
1) Prioritize standards compliance audits now: Run a prioritized gap assessment of your product portfolio against the latest surface and outdoor furniture standards. Fast followers pay certification costs and lose specification windows.
-
2) Re‑engineer BOMs toward recycled composites where lifecycle advantages are clear: Conduct supplier pilots with recycled solid plastics for tabletops and test endurance metrics. Create a pricing premium narrative based on total cost of ownership.
-
3) Build a specification playbook for tenders: Develop templated performance specs, test reports and certificate packages that procurement teams can drop into RFP responses to reduce procurement friction and shorten sales cycles.
-
4) Monetize services: Introduce design consultation, phased refresh plans and extended warranties as bundled offerings to increase recurring revenue and improve customer retention.
-
5) Pursue targeted partnerships rather than broad geographic expansion: Use joint ventures, licensing and distribution agreements to enter markets with stringent local standards instead of building full manufacturing footprints immediately.
What the full PW Consulting report provides (teaser)
Our full Educational Furniture Market report delivers the operational intelligence procurement, product and M&A teams need to act in 2026:
-
Granular demand maps by product family, application and country-level forecasts across 2020–2032 (note: to drive procurement and commercial tactics we deliberately keep these tables in the full report).
-
Vendor scorecards and competitive benchmarking that combine financial strength, product breadth, R&D investments and channel reach to quantify acquisition targets and partnership fits.
-
Pricing elasticity models and tender‑win probability matrices to optimize bid strategies for public and private education procurement.
-
Operational playbooks for material transition (e.g., recycled composites), certification timelines and supply‑chain risk mitigation plans tied to actual lead‑time and cost scenarios.
We intentionally limit the high‑level briefing to maintain strategic signals while steering readers to the full analysis for segment‑level numbers, regional shares and the proprietary vendor scores that will directly drive procurement and investment decisions.
Concluding perspective
For 2026, the educational furniture market presents a mix of predictable growth and accelerated structural change. Macro growth—anchored by a mid‑single‑digit CAGR and steady market expansion—supports investment. Simultaneously, regulatory updates and a shift to recycled, high‑durability materials are compressing time‑to‑market windows for certified products. The companies that will outpace peers next year are those that translate evidence‑based design into procurement‑ready packages, couple product innovation with services, and treat standards and material transitions as strategic assets rather than compliance costs.
PW Consulting’s full report equips executive teams with the granular models, vendor scorecards and tactical playbooks necessary to convert these market dynamics into defensible 2026 plans. For access to the complete dataset and actionable segment-level directives, please consult the report landing page linked in our release materials.
For detailed analysis of this topic, please visit the official page: Educational Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


