



Category: market research
PW Consulting: Petroleum Needle Coke Market Poised for 6.7% CAGR Through 2032
By PW Consulting, 2026-07-12
Petroleum Needle Coke Market — Strategic Outlook for 2026 Decision-Making
Executive trailer
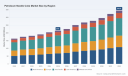
Petroleum needle coke (PNC) sits at the intersection of traditional refining economics and the fast-evolving carbon-materials chains that underpin modern electrification and steelmaking. Our newly completed PW Consulting study, using 2025 as the base year, tracks the market’s journey from historical dynamics (2020–2025) into a rigorous forecast window (2026–2032). The headline: the global market expanded from roughly USD 163.2 million in 2020 to USD 215.0 million in 2025, and is projected to grow at a 6.7% CAGR across 2026–2032, reaching an estimated USD 344.8 million by 2032. For corporate leaders planning investments, offtakes, or restructuring in 2026, this trajectory is both an opportunity and a call for disciplined strategy.
Petroleum Needle Coke Market
Why this study matters in 2026
-
Timing of demand inflection — The convergence of graphite-electrode replacement cycles and accelerating battery-anode capacity expansions creates a near-term window where securing high-quality PNC supply materially affects project economics for both incumbents and new entrants.
Petroleum Needle Coke Market -
Supply-side consolidation and concentration — The market shows meaningful concentration among a small number of integrated producers, shaping pricing power, contract structures, and capacity availability. Our work quantifies concentration and models realistic sourcing scenarios for 2026 procurement.
Petroleum Needle Coke Market -
Regulatory and feedstock uncertainty — Volatile crude and coal-tar derivative markets, combined with tightening environmental rules in several jurisdictions, add execution risk that must be stress-tested in every capital decision made in 2026.
Market trajectory — evidence you can act on
PW Consulting’s base-year analysis documents a steady post-pandemic recovery through 2025, with market value rising from USD 163.15 million in 2020 to USD 215.0 million in 2025. Our scenario-driven forecast then projects the market to continue expanding to USD 225.48 million in 2026, with intermediate milestones at approximately USD 296.4 million by 2030 and USD 344.8 million by 2032 under the central-case assumptions. A 6.7% compound annual growth rate across the forecast period encapsulates technical substitution, capacity additions, and policy-driven share shifts between feedstock routes.
Demand drivers and application dynamics
-
Graphite electrodes remain the backbone of near-term demand, driven by steel industry cycles and capacity rationalization in certain regions. The timing of restocking and electrode replacement schedules creates demand spikes that are highly lumpy and geographically concentrated.
-
Battery anode markets represent the structural growth vector. While battery-grade demand is still a smaller share today, its growth rate outpaces traditional applications and requires higher specification feedstocks and consistent quality over long horizons.
Supply fundamentals and feedstock volatility
PNC supply is fundamentally linked to aromatic-rich refinery residues, predominantly FCC decant oil and other heavy aromatic streams. Price swings in crude, coal tar, and slurry oils propagate quickly into producers’ cost bases; our sensitivity modules quantify how a 10–20% shift in feedstock cost affects cash margins across different plant configurations. Additionally, capacity additions tend to follow investment cycles in delayed-coking and calcination assets — capital-intensive projects that carry long lead times and operating complexity.
Regulation, sustainability, and the low-carbon premium
-
Regulatory tightening in major producing regions has already manifested in material capacity attrition. Notably, environmental enforcement in China led to substantive closures and output restrictions across graphite electrode facilities, creating short-term supply tightness and regional price divergence.
-
At the same time, evolving carbon accounting frameworks in the EU and customer procurement policies in downstream battery and specialty carbon markets are beginning to favor lower life-cycle-emission PNC routes (e.g., petroleum-based vs. coal-based). This creates a bifurcation: product quality remains important, but carbon-intensity profiles are rapidly becoming a second-order commercial requirement.
-
Our report includes an LCA-comparison framework and an EU-alignment heatmap to help buyers and producers quantify the commercial value of low-carbon certification in 2026 contracting rounds.
Competitive landscape — who matters and why
The market is dominated by a handful of integrated and regionally-specialized players whose strategic moves materially shift supply balances. PW Consulting’s competitive chapter profiles leading producers and assesses their strategic postures, investment trajectories, and downstream relationships.
-
Phillips 66 Company (Houston, TX) — An integrated refiner with delayed-coking operations and electrode-grade supply capability. Recent strategic moves include a substantial capacity expansion investment in Louisiana announced in February 2025, aimed at capturing growth from battery-anode demand. They have also concluded long-term supply agreements with anode manufacturers, indicating a vertical-supply strategy that secures demand for expanded output.
-
GrafTech International Ltd. (Brooklyn Heights, OH) — A vertically integrated electrode and specialty-carbon supplier operating petroleum needle coke capacity. GrafTech’s 2025 launch of a lower-carbon “Eco Graphite” product signals the industry’s pivot toward differentiated, sustainability-linked offerings and reflects an R&D and feedstock-diversification approach that de-risks regulatory exposure.
-
ENEOS Corporation (Tokyo) , Seadrift Coke L.P. (Seadrift, TX) , Petrocokes Japan Ltd. (Tokyo) , C-Chem Co., Ltd. (Japan) , and Chinese Petroleum & Chemical Development Company (Taiwan) — These producers combine regional refinery integration with calcination capability or specialized pitch-processing. Their strategic relevance varies by product grade focus (electrode vs. battery) and regional access to feedstocks.
Recent strategic moves—what they reveal
-
Feb 2025: Phillips 66 announced a multi-hundred-million-dollar expansion to increase PNC capacity in Louisiana by approximately 40% — a move explicitly tied to EV battery supply chains.
-
Apr 2025: GrafTech introduced a product produced from a significant recycled-feedstock component, pre-positioning itself for low-CO2 steelmaking contracts and demonstrating how product differentiation can create pricing and offtake advantages.
-
Sep 2025: Phillips 66 signed a long-term supply agreement to support a 30,000 tpa graphite-anode plant in the U.S. — an example of buyers and suppliers seeking to lock-in bilateral arrangements to de-risk critical upstream supply for battery projects.
Strategic implications for 2026 — prioritized actions
-
Secure supply through diversified contracting: For battery-anode projects planned or under construction in 2026, obtain multi-year offtake arrangements with staggered volume and quality clauses. Use price collars and pass-through mechanisms tied to transparent feedstock indices to protect margins.
-
De-risk feedstock exposure: Buyers and producers should model blended-feed scenarios (FCC decant oil, heavy cycle oils, and recycled aromatics) to quantify quality tradeoffs and margin impacts under commodity stress.
-
Invest in qualification pathways: Battery-grade PNC requires rigorous qualification. Allocate resources in 2026 to accelerate lab-to-pilot qualification programs and secure early supply slots with suppliers that have calcination and carbonization capabilities.
-
Pursue low-carbon differentiation: Producers should evaluate retrofits or feedstock blends that reduce cradle-to-gate emissions and develop verifiable LCA dossiers — these can command a commercial premium in tenders and reduce regulatory friction.
-
Prepare scenario-based capital plans: Given the market’s 6.7% CAGR central case and the lumpy nature of demand spikes, treat new greenfield capacity as contingent on confirmed offtake and include modular/capex-light designs where possible.
-
Consider strategic M&A and partnerships: With market concentration favoring a small number of players, targeted acquisitions of feedstock-processing assets or joint ventures with electrode and anode makers can secure margins and reduce exposure to spot volatility.
What PW Consulting’s full report delivers (practical, executable content)
-
Detailed historical and forecast market-sizing (2020–2032) with scenario runs (base, downside, upside) and sensitivity to feedstock and regulatory shocks.
-
Proprietary supply-demand balance models with plant-level capacity, lead times, and utilization assumptions mapped to likely contractual outcomes.
-
Price and margin stress tests linking crude/coal tar/slurry oil dynamics to producer cashflows under different contractual structures.
-
Operator scorecards and supplier capability matrices to support procurement shortlists, including qualification timelines for battery-grade supply.
-
Regulatory risk matrices (China, EU, North America) and a carbon-footprint playbook to help buyers and sellers align capex and procurement strategy with emerging standards.
-
Commercial templates: term-sheet clauses, sample offtake agreements, and negotiation playbooks tailored for 2026 contracting.
How decision-makers should use this study in 2026
Executives should treat the report as both an intelligence brief and a transactional tool. Use the market-sizing and scenario modules to validate internal assumptions; use supplier scorecards to compress qualification timelines; and use the commercial templates to move from intent to executed contracts before mid-2026 when capacity commitments and supply reallocations will crystallize. For investors and M&A teams, our valuation appendices and comparable-transactions analysis provide the levers to translate operational risk into purchase-price adjustments.
Final note — the trailer promise
This article has outlined the strategic contours and actionable directions embedded in PW Consulting’s Petroleum Needle Coke Market study. We have demonstrated the macro trajectory, the major strategic levers, and the competitive moves shaping supply and demand. To preserve the value of our proprietary segment-level models, regional splits, and granular supplier data — the precise inputs that drive deal-level outcomes — those detailed tables, interactive dashboards, and model instances are available exclusively in the full report and via our client portal. For procurement teams, investors, and corporate strategists preparing decisions in 2026, accessing the full dataset and scenario workbooks is the critical next step.
Contact PW Consulting to request the full Petroleum Needle Coke Market report, access the interactive forecast model, or commission a tailored deep-dive aligned to your project timelines and risk appetite.
For detailed analysis of this topic, please visit the official page: Petroleum Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Captioning & Subtitling Market to Hit USD 6,150M in 2025
By PW Consulting, 2026-07-12
Captioning and Subtitling Solutions Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
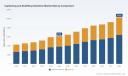
As organizations embed video into every customer, employee and compliance touchpoint, captioning and subtitling moved beyond an accessibility checkbox to become a mission-critical layer of content infrastructure. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps how this transformation is translating into measurable market growth and new buying imperatives. The global market expands from a multi-billion USD base in 2020 to an estimated USD 6,150 Million in 2025, and is forecast to continue on a steady compound annual growth trajectory (CAGR 7.84%) through 2032, when our model projects a market above USD 10 billion (Million USD units throughout).
Captioning and Subtitling Solutions Market
Why this research matters for 2026 strategic planning
- Timing of investment decisions: 2026 is the first full planning cycle after recent regulatory shifts and a visible acceleration of AI-driven live-capabilities. Boards and CIOs who commit to a clear captioning and subtitling strategy this year capture outsized operational and compliance value over the next six years.
- Vendor selection risk-reward: The market shows healthy growth but also distinct specialization: pure-play captioning services, AI-first platforms, and enterprise software suites are coexisting and competing. Choosing the wrong partner risks integration drag, audit exposure, or overspend on bespoke services.
- Operational leverage: Organizations that standardize on cloud-first, auditable captioning pipelines and embed human-in-the-loop QA where it matters will reduce long-run costs while improving accessibility and searchability of video assets.
Macro dynamics shaping the market
Three structural forces are driving the market dynamics that buyers must incorporate into 2026 budgets and vendor roadmaps:
Captioning and Subtitling Solutions Market
- Regulation and standards: Recent regulatory activity—most notably new closed-captioning accessibility rules affecting hardware manufacturers and multichannel programmers—has raised the compliance bar. The regulatory environment now emphasizes developer-accessible display settings and broader obligations for IP-delivered programming. Simultaneously, security and quality certifications (e.g., ISO frameworks) are being positioned as de facto prerequisites for enterprise procurement, particularly for sensitive education, government, and corporate content.
- Real-time AI + human hybrid models: Advances in speech recognition and neural machine translation have made real‑time captioning commercially viable at scale. However, accuracy expectations in broadcast, legal, and academic settings still demand human post-editing or supervised workflows. The winners will be those who operationalize hybrid models that balance latency, accuracy and cost.
- Platformization and verticalization: Buyers are asking for captioning to be embedded within broader media workflows—encoding, OTT publishing, LMS integration, and archival search—rather than treated as a bolt-on. At the same time, vertical-specific feature sets (e.g., verbatim legal transcription, curriculum-aligned subtitle mapping for education, or multi-language dubbing for entertainment) are differentiators in procurement decisions.
Competitive landscape — who matters and why
The competitive field combines specialized captioning houses, AI-driven transcription platforms, and major software/technology vendors. The market’s structure rewards both deep domain expertise and scale of platform reach. Key strategic observations from our vendor analysis:
Captioning and Subtitling Solutions Market
- Specialist live-caption providers (e.g., VITAC, Verbit, Ai‑Media): These firms lead on live and broadcast workflows, low-latency streaming integrations, and service models that mix AI with professional editing. Their strength lies in operational maturity for large-scale events and regulatory compliance for broadcasters.
- AI-native platforms (e.g., Otter.ai, Trint, Amberscript): These vendors excel at developer-friendly APIs, rapid transcription for enterprise use-cases, and scalable cloud deployments. Some emphasize data governance and certification as a procurement differentiator; others trade higher automation for lower per-minute costs.
- Broad media and tech incumbents (e.g., Adobe, Microsoft, IBM): Their advantage is ecosystem integration—captioning as a feature inside creative suites, communication platforms, or cloud AI services. They appeal to customers seeking single-vendor simplicity and deep analytics integration across content pipelines.
- Localization and post-production specialists (e.g., TransPerfect, ZOO Digital, 3Play Media): These players target subtitling, translation and international distribution workflows where linguistic accuracy and quality control are paramount.
- Niche innovators (e.g., SyncWords, AppTek): Focused on specific technical gaps—real-time multi-language live subtitles, voice dubbing, or advanced speech models—these vendors often become tactical partners for broadcasters or event platforms.
Our competitive chapter evaluates each vendor against operational criteria (real-time latency, accuracy/QA model, platform integrations, compliance posture, data governance, pricing transparency, and go-to-market motion). It also maps partnership opportunities—where incumbent broadcasters and OTT platforms can thin-slice vendor capabilities through alliances rather than acquisitions.
Regulatory and standards implications
Regulation is no longer a background risk; it is a leading driver of procurement. Recent rules requiring accessible caption display settings and the expansion of closed-captioning obligations to IP-delivered programming are changing technical spec sheets and RFP checklists. For government and education buyers, the demand for auditable workflows, retention policies and certification-compliant vendors is already influencing vendor shortlists. PW Consulting’s report includes a compliance impact matrix that translates regulatory requirements into technical acceptance criteria and procurement clauses.
Practically useful deliverables inside the full report
This market brief is a trailer. The full PW Consulting study is designed as a hands-on playbook for practitioners and includes:
- Market sizing and a seven-year forecast model (2026–2032) with scenario analyses to stress-test demand drivers under alternative regulatory and technology adoption curves.
- Vendor benchmark framework with scored profiles across technical capabilities, vertical strengths, security posture and commercial terms.
- Procurement toolkit: RFP templates, proof-of-concept (PoC) scripts for live and post workflows, SOW language to protect data privacy and SLAs, and comparative TCO models.
- Implementation blueprints: Integration patterns for common stacks (media asset management, LMS, OTT/CDN), latency optimization playbooks for live events, and QA workflows for hybrid AI/human models.
- M&A and partnership playbook: Valuation multipliers we observe in recent transactions, integration risk checklists, and recommended carve-outs for IP and model licensing.
- Case studies and vendor negotiation guidance that distill lessons from broadcast, education, enterprise and government deployments.
Actionable recommendations for 2026
- Adopt a modular architecture: Treat captioning/subtitling as a callable service (API-first) rather than a standalone vendor tie. This reduces lock-in and makes it easier to apply specialized services where necessary.
- Build hybrid workflows: Standardize on AI-driven first-pass captions, augment with human review only for high-risk content, and instrument quality gates to optimize cost vs. accuracy.
- Prioritize certified providers: For enterprise, education and government use-cases, procurement should require auditable security certifications and contractual commitments on data residency and retention.
- Negotiate outcome-based SLAs: Move beyond uptime clauses to include accuracy bands, latency maximums for live events, and remediation processes to reduce operational disputes.
- Plan for consolidation: Expect an active M&A environment as platform players seek to bolt on live captioning capabilities or as specialists seek scale; prepare data/integration due diligence templates now.
What we intentionally withhold in this preview
Consistent with PW Consulting’s “trailer” approach, this article shares directional insights and the strategic implications of the market’s growth trajectory. We have intentionally not published detailed segment-level tables, regional/application percentage splits, contract-level pricing benchmarks or vendor scorecards here. These proprietary datasets and granular segmentation outputs are available in the full report and underlying models—designed to support procurement negotiations, CapEx approval decks and M&A diligence.
Final note — how to use this intelligence
For senior executives and functional leaders preparing 2026 budgets, the core conclusion is straightforward: captioning and subtitling are transitioning from a compliance/afterthought cost center into a platform-level capability that can unlock reach, discoverability and legal risk mitigation. The market’s projected expansion through 2032 creates both urgency and opportunity—buyers who act with a clear architecture, risk-managed vendor mix and outcome-oriented contracts will realize measurable ROI. PW Consulting’s full study provides the models, vendor intelligence and playbooks to execute that agenda with confidence.
To access the complete segmentation tables, vendor benchmarking, scenario models and procurement toolkits, consult the full PW Consulting report and dataset on the Captioning and Subtitling Solutions Market page.
For detailed analysis of this topic, please visit the official page: Captioning and Subtitling Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diethanol Isopropanolamine (DEIPA) Market Set to Expand at 6.98% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Diethanol Isopropanolamine (DEIPA) Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this briefing is designed to equip senior executives, corporate strategists, and investment committees with the high‑level, decision‑focused intelligence they need entering 2026. Drawing on our 2025 base‑year analysis and our proprietary forecast through 2032, this preview highlights the structural forces, competitive dynamics, and tactical implications that will determine who captures value in the DEIPA market over the next investment cycle. The full study contains the granular segmentation, regional allocations, and vendor scorecards that underpin the conclusions offered here; those detailed datasets are intentionally gated to preserve commercial sensitivity and to direct stakeholders to the full report for transaction‑grade inputs.
Diethanol Isopropanolamine (DEIPA) Market
Snapshot: Market Trajectory and Structural Signal
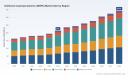
Our consolidated market sizing shows steady expansion over the 2020–2032 horizon. The DEIPA market grew from USD 163.15 Million (USD, Million unit) in 2020 to USD 215.0 Million in the 2025 base year, and our scenario‑validated forecast projects growth to approximately USD 344.8 Million by 2032. The compound annual growth rate (CAGR) implied across the forecast window is 6.98% — a pace that makes DEIPA a mid‑growth specialty chemical segment, attractive to both incumbent producers and adjacent chemical players seeking exposure to construction and performance‑chemicals demand chains.
Diethanol Isopropanolamine (DEIPA) Market
Why This Research Matters for 2026 Decisions
- Capital allocation and capacity planning: The mid‑single‑digit CAGR and predictable end‑market end‑use patterns warrant staged capacity investments and optioning rather than large upfront greenfield builds. Our analysis identifies where flexible, modular expansion will outperform single‑stage scale.
- M&A and partnership screening: A relatively low market concentration (CR3 ≈ 24.6, CR5 ≈ 26.2) signals a fragmented supply base — fertile ground for bolt‑on consolidation and route‑to‑market acquisitions, particularly for firms seeking to pair product portfolios with regional logistics footprints.
- Procurement and price risk management: Raw material volatility and tightening compliance costs mean purchasing strategies (fixed vs floating contracts, indexation, strategic stockpiles) materially affect margin. The report lays out hedging thresholds tied to feedstock price bands and utilization levels.
- Regulatory and sustainability roadmaps: Environmental compliance is a top‑line risk for manufacturers. Operators that invest early in emissions control and VOC mitigation technologies reduce both regulatory risk and future capex dislocation.
Key Market Dynamics Shaping 2026 Strategy
- Demand composition and end‑use resilience: DEIPA remains anchored in construction‑adjacent applications (cement grinding aids, concrete admixtures) while an increasing share of demand is linked to high‑value specialty applications. This demand mix produces a resilient base with episodic acceleration tied to infrastructure cycles and select industrial manufacturing ramps.
- Input cost volatility: The prices of core feedstocks for DEIPA — including isopropanolamine and diethanolamine — have shown periodic volatility linked to upstream energy markets and regional supply disruptions. Firms without disciplined input cost strategies experienced margin compression in 2024–2025; those with active procurement programs maintained spread.
- Regulatory tightening and compliance burden: Our industry outreach indicates increasing pressure in mature markets: over half of manufacturers report environmental compliance issues, with significant shares citing VOC restrictions and difficulty meeting emissions standards. These factors raise the effective cost of production, extend permitting cycles, and in some cases create practical barriers to new capacity.
- Fragmented supply base and specialization: The market structure favors small‑to‑mid sized regional producers and specialist formulators. Low concentration ratios mean national/regional champions can command premium routing advantages in logistics and customer service but lack the scale pricing power of large commodity players.
Competitive Landscape — Strategic Positions and Implications
Our competitive review concentrates on producers and distributors that shape customer choice, technology diffusion, and channel control. Below are strategic syntheses of the core players we evaluated (profiles in the full report include product grades, asset footprints, certifications, and supply‑agreement history):
Diethanol Isopropanolamine (DEIPA) Market
- Nanjing Hongbaoli Group Co., Ltd. (Nanjing, China): A vertically integrated manufacturer with a focused isopropanolamines series. Strengths include localized supply continuity for Chinese construction markets and integration into regional cement additive value chains. Strategic implication: attractive partner for off‑take agreements in Greater China but vulnerable to environmental capex requirements.
- Viswaat Chemicals Limited (India): Positioned as a cost‑competitive producer serving domestic and export construction chemical demand. Strengths include nimble production and existing trade relationships in South Asia; opportunity exists to move up the value chain through performance‑grade product development.
- Amines & Plasticizers Limited (Mumbai, India): One of the larger DEIPA producers in India with established supply to cement grinding aid markets. Strategic implication: potential consolidation target or strategic partner for players seeking scale in South and Southeast Asian markets.
- Bisley International LLC (Houston, USA): A prominent distributor with channel reach into North American industrial and construction segments. Value proposition centers on inventory service, technical support, and regulatory advisement — critical assets where upstream producers lack direct sales presence.
- Hebei InnoNew Material Technology Co., Ltd. and Shandong Inniolamine New Material (China): Both firms emphasize high‑purity DEIPA grades for performance‑critical applications. Their capabilities are strategically important for OEM customers and formulators requiring consistency and traceability.
Collectively, these participants demonstrate a market comprised of national champions, specialty producers, and channel specialists. The balance of bargaining power is situational — procurement teams with diversified supplier lists can command service and price concessions, whereas specialty end‑users depend on a small set of qualified suppliers for consistent quality.
Report Contents — Practical Deliverables
The full PW Consulting DEIPA study includes operationally actionable modules designed for 2026 decision cycles. Key deliverables include:
- Top‑down and bottom‑up market sizing (2020–2032) with scenario overlays and sensitivity bands tied to macroeconomic and construction indices.
- Demand drivers and elasticities by end‑use class, with prioritized use‑case maps for go‑to‑market planning (note: segment‑level tables and regional allocations are proprietary and available in the full report).
- Supply‑side cost models, including feedstock pass‑through mechanics, plant economics at different utilization levels, and margin levers by product grade.
- Regulatory risk matrix with jurisdictional hot spots, compliance capex estimates, and recommended mitigation levers for producers and downstream buyers.
- Vendor benchmarking and procurement due‑diligence checklists — tradeoffs between price, quality, lead time, and compliance.
- Playbooks for M&A screening, JV structuring, and off‑take negotiation templates calibrated to the market’s fragmentation profile.
How to Use This Intelligence in 2026
- For CEOs and corporate development: Use the market concentration and growth assumptions to prioritize inorganic growth in targeted regions or product grades. Pursue smaller, complementary assets that add technical capability and customer access rather than costly multinational platforms.
- For COO and supply chain leads: Implement dynamic purchasing frameworks tied to feedstock indices. Prioritize supplier redundancy in jurisdictions subject to regulatory tightening and build contingency warehousing for critical customers during permit or logistics disruptions.
- For R&D and product management: Invest in formulations and low‑VOC production methods that preempt likely regulation shifts in mature markets and that create differentiation for high‑value end uses.
- For investors and PE teams: Target bolt‑on acquisitions where operational improvement (procurement, quality systems, emissions control) can quickly unlock multiple expansion levers across a fragmented supplier base.
Risk and Scenario Considerations
- Upside scenario: Faster infrastructure spending and nearshoring of construction materials accelerate demand; producers with flexible capacity capture incremental margins.
- Downside scenario: Persistent feedstock price volatility and regulatory closures in mature markets depress capacity utilization and push marginal players to exit, creating short‑term supply squeezes.
- Mitigation levers: Contractual hedging, regulatory certification roadmaps, and strategic inventory layering are pragmatic defenses we recommend for 2026 operational planning.
Conclusion — The Strategic Imperative for 2026
DEIPA is a mid‑growth, structurally important specialty chemical with a clear nexus to construction and select industrial applications. The modestly aggressive CAGR and the fragmented competitive landscape create an environment where disciplined operators can outpace peers through focused product development, regulatory foresight, and targeted consolidation. In 2026, companies that align capital allocation to modular capacity, strengthen procurement governance, and proactively address environmental compliance will capture the outsized margins created by supply disruptions and premiumized product demand.
For transaction‑grade details — full segment breakdowns, regional tables, vendor scorecards, and the proprietary supply‑chain maps that support the recommendations above — please consult the full PW Consulting DEIPA Market report. The report contains the underlying datasets and executable tools necessary to convert these strategic insights into concrete 2026 actions.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Recycling Market to hit USD 5.88B by 2032 at 5.66% CAGR
By PW Consulting, 2026-07-12
Glass Recycling Market — Strategic Briefing for 2026: Why PW Consulting’s Analysis Matters
Executive snapshot
Between 2020 and 2025 the global glass recycling market more than doubled in headline valuation, expanding from approximately USD 2.05 Billion to USD 4.01 Billion (base year 2025). Our forecast through 2032 points to continued, steady expansion — reaching roughly USD 5.88 Billion by 2032 — representing a compound annual growth rate of 5.66% across the 2026–2032 forecast window. These topline dynamics reflect an ecosystem responding simultaneously to policy pressure, energy-and-cost imperatives, and fast-evolving industrial use-cases for recycled glass feedstock.
Glass Recycling Market
As PW Consulting’s lead industry analyst, I prepared this briefing to explain the practical decision-making value of our full Glass Recycling Market study for corporate leadership and investors making choices in 2026. Consider this a high-fidelity preview: we will show the analytical thinking and the risk/return frameworks you need to trust our work, while preserving the tactical segment-level data behind our paywall so that you are incentivized to access the full study for execution.
Glass Recycling Market
Why this report turns 2026 decisions from reactive to strategic
- Investment timing and sizing: The market’s transition from USD ~4.0B in 2025 toward an anticipated ~USD 5.9B in 2032 creates windows for entry, scale-up, and tuck-in acquisitions. Our modelling identifies where near-term capacity constraints and demand pulls create premium spreads for high-quality cullet — critical for capex prioritisation.
- Cost-to-carbon optimization: Each incremental increase in cullet content meaningfully lowers furnace energy consumption (industry evidence shows a near 3% furnace energy drop for every 10% increase in cullet in the batch). The report translates those process efficiencies into EBITDA and capital-return implications for glassmakers and recyclers.
- Regulatory compliance planning: New legislation and target-setting — for example, the Packaging and Packaging Waste Regulation that sets aggressive glass packaging recycling targets — materially alter demand for certified recycled feedstock and create compliance-driven procurement markets. Our scenario maps show timing, likely compliance costs, and procurement options.
- Supply chain and feedstock security: Infrastructure realities, such as the fact that a meaningful share of collected glass is not accepted at material recovery facilities when commingled in single-stream systems, drive a two-track strategy: invest in separations & logistics vs. vertical integration into collection and processing. We quantify trade-offs for both approaches.
- M&A and competitive positioning: The market is consolidating (our concentration metrics place the top three and five players as material influencers on pricing and standards). The full report includes acquisition scorecards and integration playbooks to turn M&A into value creation rather than replacement spending.
What the full report contains — pragmatic, transaction-ready tools
PW Consulting’s Glass Recycling Market study is deliberately practical. It is designed to be used by corporate strategy teams, investors conducting due diligence, operations leaders sizing facilities, and procurement teams negotiating long-term offtake. Below are the core deliverables included in the full study:
Glass Recycling Market
- Bottom-up market sizing and forecast models (2020–2032) that link collection, processing throughput, and end-market demand. The model is provided in an editable workbook so clients can test bespoke scenarios.
- Unit economics and plant-level benchmarks — energy, yields, capex/opex ranges, and payback profiles for common processing routes (municipal MRFs, dedicated glass sorting facilities, cullet beneficiation plants).
- Regulatory impact scenarios that overlay near-term (2026) to medium-term (2032) policy changes on demand and pricing. This includes stress-tests for rising recycled-content mandates and extended producer responsibility (EPR) frameworks.
- Supply-chain playbooks — design options for collection, inbound logistics, and quality control to raise acceptable cullet yields from mixed-stream systems.
- Commercial and go-to-market templates — offtake contracting strategies, indexation recommendations, and quality specifications to reduce basis risk between recyclers and glassmakers.
- Competitive database and M&A playbook — high-level dossiers on strategic participants, capability maps, and an acquisition screening tool calibrated to valuation multiples observed in the sector.
- Risk heatmaps and mitigation plans — covering feedstock availability, contamination, energy price shocks, and litigation/regulatory shifts.
Competitive landscape — who matters and why
The market is shaped by a mix of global miners/processors, glassmakers with closed-loop ambitions, and regional specialist processors. Strategic moves over 2024–2025 illustrate industry intent: capacity investments by independent recyclers, partnerships between glassmakers and recyclers to secure high-quality cullet, and consolidation among larger material suppliers seeking scale and geographic reach.
- Sibelco — a global materials supplier with an established recycling network and many facilities across North America. Their strategic posture is scale plus vertical integration; in late 2025 they completed an acquisition that expands their North American glass recycling footprint and strengthens procurement links into container and fiberglass supply chains.
- Owens-Illinois (O-I) — the container glass giant has operational programmes to increase recycled feedstock utilization and runs corporate recycling initiatives that both reduce scope and create PR/ESG value. Such programmes illustrate how manufacturers can combine procurement discipline with consumer-facing collection efforts.
- Vetropack and Ardagh Group — regional container manufacturers that are leaning into partnerships and localised cullet supply models to insure feedstock quality and reduce transportation intensity.
- Specialist processors (Momentum Recycling, Strategic Materials, and equivalents) — these players supply high-quality cullet and often operate closer to municipal collection systems. Their agility makes them attractive partners or targets for larger manufacturers seeking feedstock security.
- Notable greenfield and expansion signals: recent facility openings and partnerships demonstrate that growth capital is available for projects that meaningfully improve yield and quality — a key signal for investors and corporates assessing timing for brownfield upgrades vs. new builds.
Policy and infrastructure: near-term constraints and long-term tailwinds
Regulation is the accelerant. The recent Packaging and Packaging Waste Regulation sets demanding recycling targets, and several subnational jurisdictions (notably some U.S. states) are already legislating higher recycled content or incentives for recycled-material use. At the same time, structural infrastructure challenges — such as the limited acceptance of glass at many material recovery facilities when commingled — create near-term bottlenecks. These two forces together mean the market’s growth is both policy-driven and engineering-limited: solving the operational constraints unlocks a rapid value uplift.
In practical terms, this creates three actionable priorities for 2026:
- Accelerate pilots that address contamination and separation losses at the collection stage; the delta between collected glass and processed cullet is where immediate margin is created.
- Invest in higher-quality downstream processing where furnace-ready cullet commands premium pricing and reduces energy costs in smelting operations.
- Engage proactively with policymakers and industry coalitions to influence standards for recycled-content verification and logistics incentives — shaping regulation is as valuable as adapting to it.
How to use our study in 2026 planning cycles
Leaders who will make consequential choices in 2026 should view our report as an implementation toolkit rather than a passive desk reference. Use the study to:
- Run multi-scenario investment appraisals that combine plant-level unit economics with policy-triggered demand scenarios.
- Screen acquisition targets using our valuation framework and integration checklist, prioritising targets that close collection-to-process gaps and add furnace-ready cullet capacity.
- Design procurement contracts with built-in quality indices and pass-through mechanisms that align recycler and glassmaker incentives.
- Benchmark operations against a global dataset to identify 6–18 month improvements that materially lower processing costs and raise saleable yield.
- Build stakeholder narratives for investors and regulators that quantify carbon, cost, and circularity benefits from recycled glass adoption.
Final note: what you’ll find behind the paywall
This briefing demonstrates the depth and practical orientation of PW Consulting’s Glass Recycling Market study while adhering to our “trailer” principle: we intentionally withhold the report’s detailed regional, product and application-level splits and the granular financial tables. Those segmented datasets, the editable forecasting workbook, deal comparables, and the facility-level benchmarking dataset are available in the full report and are the elements that deliver execution-ready value to strategy, operations, and M&A teams in 2026.
If your organisation is contemplating capital allocation, partnership selection, or procurement strategies in glass recycling this year, the full study will convert high-level signals into executable roadmaps. Contact PW Consulting to obtain the complete dataset, scenario workbooks, and bespoke advisory support to accelerate your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Glass Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Convenience Store Software to hit USD 251.2M by 2032 at 4.19% CAGR
By PW Consulting, 2026-07-12
Convenience Store Software Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As convenience retail operators confront accelerating margin pressure, evolving consumer expectations, and heavier regulatory burden, software decisions are moving from tactical IT projects to central commercial strategy. PW Consulting’s latest market study — anchored to a 2025 base year and a 2026–2032 forecast window — quantifies that shift and translates it into executable choices for 2026. The global Convenience Store Software market grew from USD 150 million in 2020 to USD 190 million in 2025 and, under current trajectories, is projected to approach roughly USD 251 million by 2032, representing a compound annual growth path consistent with a mid-single-digit expansion (4.19% CAGR for the forecast interval).
Convenience Store Software Market
Why this research matters to executive decision-makers in 2026
-
Timing maturation vs. disruption: The market is no longer nascent. A steady multi-year climb confirms the technology stack for convenience stores is transitioning from pilot-stage capabilities to enterprise-grade platforms. Strategic buyers must decide in 2026 whether to adopt now to capture operational leverage or to defer and risk integration penalties later.
Convenience Store Software Market -
Investment calibration: With a predictable market growth path through 2032, capital planning can shift from ad-hoc modernization budgets to phased digital roadmaps aligned with revenue uplift, cost-to-serve reductions, and compliance risk mitigation.
Convenience Store Software Market -
Vendor differentiation is sharpening: Our analysis shows a field of specialized suppliers and platform-scale incumbents competing on cloud enablement, AI-driven automation, and verticalized workflows (fuel, tobacco, foodservice). Procurement strategies must therefore weigh feature fit, integration cost, and operational change management rather than price alone.
Key market dynamics shaping 2026 choices
-
Cloud adoption and composable architectures: Cloud-first deployments are accelerating replacement cycles for legacy on-premises systems. For most operators, the cloud promises faster feature delivery, lower upfront capital, and simpler compliance updates — especially pertinent where fiscal/tax complexities are endemic.
-
AI and automation moving beyond experimentation: Labor shortages and high turnover in the c-store workforce are pushing operators to adopt AI for scheduling, demand forecasting, and frontline decision support. Expect 2026 to be the year where pilots scale into working controls that materially reduce shrink and labor cost volatility.
-
Regulatory and data-privacy friction: Rising regulatory complexity — from health-safety mandates to regional privacy regimes — is creating product and process requirements that bind vendor choices. Software that embeds compliance-by-design will save operators substantial remediation costs.
-
Integration with fuel, loyalty, and foodservice ecosystems: Convenience stores are multi-proposition environments. Successful platforms are those that unify point-of-sale, inventory, loyalty, and fuel operations into coherent workflows, reducing reconciliation effort and improving basket-level analytics.
-
Moderate market concentration, active innovation: The landscape features both niche specialists and large retail-software providers. Competitive intensity is focused on ease of deployment, vertical feature sets, and partnership networks rather than pure price wars.
What the PW Consulting report delivers (practical, operational content)
-
Executive playbooks: Decision frameworks for selecting between cloud-first, hybrid, and legacy renewals mapped to operator size, site complexity, and risk appetite.
-
Vendor diagnostic and scorecards: Comparative assessments across product maturity, roadmap alignment, total cost of ownership (TCO) modeling, and integration readiness — with guided weighting templates you can reuse in vendor selection.
-
Implementation roadmaps: Phased migration timelines (pilot → regional rollout → enterprise) including realistic cutover windows, staging configurations for multi-site operators, and a catalog of common pitfalls and mitigations.
-
Operational KPIs and ROI levers: A focused set of metrics and short-run experiments that drive measurable improvements in shrink, labor productivity, and incremental sales from loyalty/foodservice upsell.
-
Compliance and data governance guide: Practical templates for privacy-impact assessments, vendor contract clauses for data residency, and employee training checklists tied to regulatory hot spots.
-
Scenario-based financial models: TCO and payback calculators that quantify choices across deployment types and integration complexity — designed for direct insertion into 2026 capex and operating budgets.
Note: In this preview we outline directions and strategic themes. The full report contains granular regional and application splits, vendor scorecards, and downloadable dashboards. We intentionally withhold those tables here to preserve the actionable exclusivity of the full dataset.
Competitive landscape — who to watch in 2026
The competitive field is defined by a mix of focused convenience retail specialists and broader retail-software incumbents. A short guided tour of representative players highlights how different strategies create differentiated value.
-
AccuPOS (US) — positions itself with c-store-tailored POS and inventory modules that appeal to smaller chains and franchise operators seeking rapid deployment and ease of use.
-
SSCS (US) — specialized in inventory accuracy and back-office controls; attractive to operators prioritizing shrink reduction and reconciliation automation.
-
PDI Technologies (US) — leverages deep fuel and back-office domain expertise to serve integrated fuel-and-convenience operations; differentiation stems from fuel-tax logic and retail accounting workflows.
-
POS Nation (US) — brings bundled POS-hardware solutions designed for rapid rollouts at scale where standardization and predictable support models matter.
-
ADD Systems (South Korea) — focused on wholesale inventory and logistics for fuel-centric convenience models, often chosen in regions where vertical integration matters.
-
DataMax (US) & CStorePro Inc. (US) — emphasize reporting, cloud POS, and operational analytics for chains that want quick insights without building internal BI teams.
-
SHENZHEN KEMAI (China) — competes on cost-effective POS hardware and integrated management suites in markets sensitive to price and speed of deployment.
-
Petrosoft (US), Paytronix (US), and GK Software (US) — represent adjacent value propositions: fuel/c-store operations, loyalty/customer engagement, and omnichannel retail systems respectively; each is extending into convenience retail via verticalized modules.
-
NCR Voyix (US), Oracle (US), and Toshiba Global Commerce Solutions (Japan) — global incumbents with enterprise-grade POS and ERP capabilities, attractive to the largest multi-national operators that require scale, SLAs, and global support networks.
-
Tote.ai (US) — notable for rapid innovation in AI-driven POS and kiosk solutions; recent strategic partnerships (announced in early 2026) highlight how AI-enabled front-end automation is moving into mainstream deployments.
Recent market activity underscores two dynamics in particular: (1) partnerships and pilots around AI POS and kiosks are graduating to commercial rollouts, and (2) trade-show demonstrations and provider roadmaps announced throughout 2025 are translating into 2026 procurement decisions. Operators should expect a wave of platform upgrades driven by both competitive necessity and regulatory demand.
Practical recommendations for 2026 strategy and execution
-
Prioritize compliance-first selections: Choose platforms that can demonstrably implement regional privacy and fiscal rules quickly. The cost of retrofitting compliance after deployment is typically higher than incremental premium paid at selection.
-
Adopt a phased modernization path: Start with pilot clusters that capture typical site complexity (fuel, foodservice, loyalty) to validate integration templates before broader rollouts.
-
Design integration around customer journeys: Ensure POS, loyalty, and inventory share a common data model; investments that improve “basket intelligence” yield disproportionately high ROI on marketing and assortment.
-
Factor in total cost and hidden switching costs: Evaluate vendors on migration tools, data migration support, and third-party ecosystem integrations rather than headline licensing fees alone.
-
Treat AI as operational augmentation: Automate routine tasks (scheduling, reorder triggers) first, and phase predictive models (demand forecasting, dynamic pricing) once data hygiene is proven.
-
Use procurement as a lever for partnerships: Negotiate pilot-to-rollout clauses, SLA-based payments, and performance incentives tied to measured shrink/lift impacts.
Methodology and confidence
PW Consulting’s study synthesizes historical market activity (2020–2025), primary interviews with operators, vendors, and systems integrators, quantitative vendor intelligence, and scenario-based forecasting across the 2026–2032 horizon. Our forecast incorporates rate-of-adoption assumptions validated against transaction-level metrics collected from operators across major markets. The resulting view balances near-term disruption risk with medium-term stabilization, reflecting a market that is large enough to matter to executive agendas but still fragmented enough to reward strategic clarity.
To preserve the commercial utility of the full dataset, this preview omits granular regional, type, and application splits — these are provided in interactive form in the full report along with downloadable vendor scorecards, implementation timelines, and TCO models.
Conclusion — the choice for 2026
For 2026, convenience store operators face a clear strategic fork: accelerate modernization now to capture operational uplift and competitive differentiation, or delay and accept higher future switching costs and regulatory exposure. PW Consulting’s research shows that, given a predictable growth trajectory and an increasingly capable vendor ecosystem, early movers who pair cloud-enabled platforms with disciplined integration and change management will realize the greatest economic upside through 2032.
For operators, investors, and solution providers preparing 2026 strategies, the full PW Consulting Convenience Store Software Market report provides the operational tools, vendor diagnostics, and scenario models needed to convert insight into measurable outcomes. Access the full findings and interactive datasets through PW Consulting’s report page to move from strategic intent to executable plans.
For detailed analysis of this topic, please visit the official page: Convenience Store Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Autoclaved Aerated Concrete (AAC) Market: Strategic Imperatives for 2026 — A Preview
Executive snapshot
Autoclaved Aerated Concrete (AAC) sits at an inflection point. Between 2020 and 2025 the global AAC market expanded steadily, rising from roughly USD 178.5 Million to USD 227.8 Million (base year 2025). Our forecast model projects continued momentum through the 2026–2032 horizon, with a compound annual growth rate of approximately 6.98%, driving the market to roughly USD 359.4 Million by 2032 under the base case. These macro dynamics — steady demand growth, evolving regulation, and supply-side stress — create a landscape where near-term choices (capex, supply agreements, product mixes) will materially affect total returns over the next five years.
Autoclaved Aerated Concrete (AAC) Market
Why this preview matters to executives in 2026
- Validate or challenge current investment plans: The market’s mid-single-digit CAGR supports growth-oriented capital allocation, but timing and geography of capacity additions will determine IRR.
- Price and margin protection: Input volatility — notably cement and lime — has already pressured margins episodically; procurement and hedging strategies are now strategic priorities.
- Regulatory-driven demand swings: Energy codes and low-carbon policies are materially shifting specification choices in construction procurement, accelerating adoption in some markets and creating adoption barriers in others.
- M&A and partnership decisions: Moderate-to-high concentration at the top tiers of the industry points to attractive consolidation opportunities — but value capture requires disciplined target screening.
What the full PW Consulting AAC Market Study delivers (practical, transaction-ready outputs)
The full report is designed for commercial leaders, corporate strategy teams, and private equity investors who need executable intelligence, not just descriptive statistics. Key deliverables include:
Autoclaved Aerated Concrete (AAC) Market
- Top-down and bottom-up market sizing with transparent assumptions (historical 2020–2025 calibration and 2026–2032 scenario funnels).
- Demand-driver heatmaps by policy, construction segment, and technology adoption curves to prioritize markets and product formats.
- Supply-side cost models that isolate the impact of cement, lime and supplementary inputs on manufacturing economics, with sensitivity testing for commodity shocks and carbon-pricing scenarios.
- Regulatory impact analysis (building codes, green certification requirements, waste and fly ash policies) translating compliance into unit demand and specification shifts.
- Competitor landscape and capability matrices to support buy/sell-side diligence, including plant-level capacity, licensing models, and route-to-market footprints.
- Deal origination playbook: acquisition screens, valuation multiples observed in comparable transactions, integration risk checklists and quick-win synergies.
- Commercial growth playbook: product bundling, channel partnerships, specification roadmaps for architects and developers, and pilot frameworks for modular construction strategies.
- Risk & resilience framework: supplier concentration analysis, procurement hedges, inventory strategies, and contingency playbooks for seasonal cement price spikes.
Competitive landscape — positioning and strategic takeaways
The market features an assortment of legacy manufacturers, regional champions, licensed-technology providers, and new entrants. A handful of established players account for a majority share at the top end of the market, creating a competitive environment where scale, technology access, and distribution reach matter.
Autoclaved Aerated Concrete (AAC) Market
- Legacy North American producers: Long-tenured manufacturers with deep project references and established distribution channels retain pricing power in their home markets. Their strengths are brand recognition, developer relationships, and operational know-how for blocks and panels.
- Technology licensors: Firms that offer production technology and licensing know-how enable rapid market entry for new plants while monetizing intellectual property. Licensing models reduce upfront capex for entrants but create a dependency on technology partners for process improvements.
- Regional scale players and recent capacity expansions: Recent capacity expansions and new product launches by regional producers have materially changed competitive dynamics in several markets. These moves create near-term pressure on utilization rates but also accelerate market education and specification adoption.
- Distributors and project-focused specialists: A cohort focused on distribution, system integration, and end-user support is expanding the product footprint into retrofit and modular construction segments — areas where specification and logistics add value beyond commodity pricing.
For dealmakers, the implication is clear: targets should be evaluated not only on current volumes, but on their channel access, specification credentials with architects/developers, and the flexibility of their manufacturing footprint to switch between blocks, panels and engineered elements.
Notable recent moves and what they signal
- Capacity expansion by a regional manufacturer completed in late 2024 doubled production capability at a strategic factory, demonstrating operators’ willingness to back demand growth with tangible asset investments.
- New product introductions from a cement producer in 2025 underline the convergence between raw-material suppliers and finished-product manufacturers — signaling vertical integration and product diversification as active strategic paths.
- New green-building regulations and building-code enforcement in several advanced markets are already influencing procurement committees to favor AAC for thermal performance and embodied-carbon considerations.
Material and regulatory dynamics that will shape 2026 decisions
Cement and lime remain the dominant input cost drivers for AAC production. Recent seasonal cement price surges and ongoing volatility have resulted in compressed margins for many producers, particularly where pass-through is delayed by procurement contracts. At the same time, policy levers — from fly ash substitution strategies in some jurisdictions to stricter energy codes in others — are reshaping the inputs mix and the lifecycle emissions profile of AAC.
- In markets where fly ash substitution is enabled, embodied-carbon reductions and raw-material cost relief can materially improve the business case for AAC adoption.
- Green building certification requirements and energy-code compliance (e.g., country-level thermal performance mandates) are increasing AAC specification wins in new construction and certain retrofits.
- Conversely, regions exposed to cement-supply shocks or logistical bottlenecks will see slower margin recovery unless producers adopt hedging, vertical integration, or alternative binders.
Strategic playbook for 2026 — recommended moves for executives
Based on our modelled scenarios and competitive analysis, PW Consulting recommends a tiered action plan for companies and investors entering or scaling in the AAC market in 2026:
- Immediate (0–12 months): Secure long-term raw-material contracts with indexed pricing clauses; prioritize small, high-impact pilots with developers to convert specification inertia into demonstrable performance cases; and run stress tests on working capital under commodity price swings.
- Near-term (12–36 months): Evaluate selective capacity additions aligned with regional demand signals; pursue licensing or JV arrangements to accelerate market entry where green codes are tightening; implement product modularization pilots that reduce onsite labor and logistics costs.
- Mid-term (36+ months): Consider M&A focused on acquiring channel access, specification leadership, or complementary product lines (e.g., engineered panels, lintels, floor/roof elements) to capture higher-margin system sales rather than only commodity blocks.
Decision-support tools included in the complete study
The full PW Consulting report equips decision-makers with practical tools: scenario-based valuation models, plant-level break-even calculators, a supplier-risk heatmap, and a prioritized list of intervention levers (procurement, product, policy engagement) with quantified impact on EBITDA under multiple commodity and policy scenarios.
Closing: what to expect if you act (and what you miss if you don’t)
For market participants who align strategy with the structural drivers highlighted in this preview — regulation, raw-material dynamics, and modular construction trends — the projected growth offers a clear runway for profitable expansion. Those who delay or treat AAC as a purely tactical product risk being outpaced by better-capitalized and more integrated competitors as specifications and supply chains tighten.
This preview is a strategic teaser: it demonstrates the depth of analysis and the practical tools PW Consulting provides, while reserving detailed segmentation, plant-level economics, and the full competitor scorecards for the comprehensive report. For executives preparing 2026 budgets, M&A pipelines, or procurement strategies, the full study will convert the high-level signals above into concrete, executable decisions.
Next steps
- Request the full report to access the granular segmentation models, regional demand curves, and downloadable valuation and scenario tools.
- Set up a 60–90 minute strategic briefing with our industry team to map these insights onto your specific portfolio or investment thesis.
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrofusion Fittings Market to grow 6.99% CAGR to USD 2,182.4M by 2032
By PW Consulting, 2026-07-12
Electrofusion Fittings Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new Electrofusion Fittings Market study is designed as an operational playbook for companies making strategic choices in 2026. Built on a 2025 base year and a detailed 2020–2025 historical reconstruction, the report projects the market through 2032. At the macro level, the market has expanded from under USD 1 billion in 2020 to roughly USD 1.36 billion in 2025 and, under our central assumptions, is forecast to exceed USD 2.18 billion by 2032 — a compound annual growth rate of approximately 6.99% across the 2026–2032 forecast window. That trajectory reflects persistent infrastructure investment, accelerating adoption in new applications, and steady product and process innovation.
Electrofusion Fittings Market
Why this matters for 2026 strategy
- Timing of investment: The market growth profile and forecasted CAGR identify 2026 as a pivotal year to move from pilot investments to scale deployment of product variants, automation, or channel expansion.
- Unit economics focus: As raw material volatility and labour constraints compress margins, firms must refresh sourcing strategies and productivity benchmarks now to sustain returns across the forecast period.
- Regulatory and standards alignment: Recent standard-setting activity and procedural updates are shifting procurement and installation specifications — creating both compliance risk and differentiation opportunities for early adopters.
Market trajectory: what the numbers imply (without giving away the granular map)
The topline expansion visible in the historical series and forecast underscores three structural dynamics. First, core utility renewal and new-build programs continue to underpin steady baseline demand. Second, engineering and process innovations are shortening cycle times and enabling electrofusion solutions to compete more broadly against mechanical and welded alternatives. Third, the net effect of raw material cost swings and labour challenges is to widen dispersion in profitability across participants — favoring firms that can control feedstock exposure or achieve higher field productivity.
Electrofusion Fittings Market
For executives, the headline CAGR provides a frame for portfolio sizing and long‑term capacity planning. But our research goes beyond the headline: it quantifies sensitivity to resin price shocks, models labour availability scenarios, and maps product‑level operating margins under different adoption curves. These are the inputs that turn a growth percentage into executable capex, procurement, and go‑to‑market decisions.
Electrofusion Fittings Market
Competitive landscape — what the report will enable you to do
Our competitive analysis combines primary interviews, product audits, and recent corporate announcements to create vendor scorecards that are decision-ready. Highlights:
- Plasson Ltd. (Israel): Strong catalogue management and tooling support; recent catalog releases reinforce focus on product continuity and installer enablement. The report evaluates how this approach translates into channel resilience and specification wins.
- Georg Fischer Central Plastics Company (United States): Institutional strength in standards‑compliant fittings and training materials; recognized for automatic parameter-setting features. We analyze how compliance-led differentiation affects specification selection by large utilities.
- Integrity Fusion Products (United States): Depth in large-diameter, pressure-rated couplers under the IntegriFuse brand. Our assessment models the economics of scaling large-diameter production versus subcontracting strategies.
- Radius Systems Limited (United Kingdom): Integrated offering of fittings and welding equipment for municipal customers. The report quantifies cross-sell advantages when equipment and consumables are bundled.
- Pipelife International (Finland): Product innovation focused on reduced-cycle fittings and demonstrated deployment scale in Europe. We interrogate the time-to-profitability trade-offs of cycle-time reductions versus higher unit pricing.
- Agru Kunststofftechnik GmbH (Austria), Egeplast (Turkey), Strongbridge Inc. (United States), Kimplas/NORMA Group (India): Each profile covers manufacturing depth, regional go‑to‑market models, and niche strengths (e.g., high-pressure classes, large-diameter capability, or mass deployment experience). The report also flags likely partnership, M&A, and distribution plays for each.
Recent market developments and operational implications
- MAB-1 (Third Edition, November 2025) — Municipal Advisory Board: The approval of a uniform electrofusion field-joining procedure materially raises the bar for installer qualifications and auditability. Our operational playbook includes a gap analysis for contractors and vendors to meet the updated procedural controls.
- ISO 12176‑2:2025: New performance requirements for electrofusion control units mean procurement specs must be updated to avoid obsolescence. The report supplies a compliance matrix and a supplier assessment checklist to streamline RFPs.
- Labour availability: In 2025 a significant majority of utility contractors reported difficulty sourcing qualified electrofusion technicians, driving project delays. We provide labor productivity benchmarks and a staffing optimization model that quantifies training and automation investments required to protect schedule and margin.
- Raw material volatility: Polyethylene resin prices have shown large swings, with manufacturers citing significant volatility. Our sensitivity scenarios translate feedstock price movements into unit-cost impacts and suggest hedging and sourcing strategies appropriate to different firm sizes.
- New application signals: Events such as industry exhibitions and targeted product launches indicate growing interest in hydrogen distribution and transition couplings. The report contains a practical assessment of hydrogen compatibility and the R&D or certification steps required to enter that segment.
What’s inside the report — actionable, not academic
We designed the study for immediate use by strategy, product, operations, and commercial teams. Key operational deliverables include:
- Market sizing and forward-looking demand curves (2026–2032) with scenario variants reflecting high/low infrastructure spend, labour constraints, and feedstock volatility.
- Vendor scorecards and a procurement decision matrix that tie product features (e.g., cycle time, pressure class, diameter range) to utility specs and installer economics.
- Installation productivity benchmarks and a field quality checklist aligned to MAB‑1 and ISO guidance, enabling contractors to reduce rework and inspection time.
- Raw-material sensitivity dashboards and recommended hedging/contract strategies by firm archetype.
- Go‑to‑market playbooks for incumbent manufacturers and new entrants — channel selection, pricing levers, and partnership mapping.
- M&A and alliance screening: diagnostic criteria for target selection and commercial due diligence templates tailored to the electrofusion value chain.
Key uncertainties and trigger events to monitor in 2026
- Standards and procedure rollouts: Wider adoption of MAB‑1 and national uptake of ISO 12176‑2 could reshape procurement specs within months, not years.
- Labour market shifts: Any material easing or tightening in trained appliance availability will alter the economics of design-for-installation investments.
- Feedstock shocks: Large polyethylene price moves remain a primary margin risk; monitoring resin contract windows and inventory strategies is essential.
- New end-use markets: Early movers into hydrogen or other specialty gases can gain specification advantages, but must validate material compatibility and regulatory approvals first.
How executives should use this study in 2026
Use the report as a decision engine rather than a desk reference. Recommended actions include:
- Run the contained sensitivity models against your P&L to identify the minimum productivity or price improvement needed to hit margin targets under adverse feedstock or labour scenarios.
- Update procurement specifications to align with ISO 12176‑2 and MAB‑1 where applicable; use our supplier assessment templates during Q2 vendor reviews.
- Pilot reduced-cycle-time fittings and track end-to-end installed cost per joint; the report includes a template for a 90‑day pilot that isolates installation time, inspection cost, and failure rates.
- Map potential partners in regions where you lack scale; our competitive profiles and distribution maps provide shortlists and negotiation levers.
What we intentionally leave out here — and why you’ll want the full study
In this executive preview we surface strategic conclusions, vendor positioning, standards impacts, and operational playbooks — but we deliberately omit the detailed segment-by-segment revenue breakdowns, regional and application-level percentage splits, and granular company market-share tables that constitute the core intelligence asset in the full report. Those datasets are the proprietary drivers of Go/No-Go capital allocations, tender bid modeling, and territory planning; they are provided in the full deliverable to paying subscribers and enterprise clients only.
Next steps
If your 2026 roadmap includes capacity investments, product launches, or major procurement re‑specifications, PW Consulting’s full Electrofusion Fittings Market report will convert the strategic direction above into executable plans — including downloadable models, RFP templates, and supplier scorecards. Contact our industry team to request the full dataset, tailored briefings for your executive leadership, or a workshop to run the sensitivity and procurement exercises with your finance and operations teams.
For detailed analysis of this topic, please visit the official page: Electrofusion Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air & Water Pollution Control Market to Reach USD 209.3M by 2032 (5.5% CAGR)
By PW Consulting, 2026-07-12
Air & Water Pollution Control Equipment Market — Strategic Outlook for 2026 Decision-Making
Executive summary
As organizations finalize capital allocation and product roadmaps for 2026, the Air & Water Pollution Control Equipment market is entering a period of steady, investment‑grade growth underpinned by steady regulatory pressure, aging installed bases, and technology-driven replacement cycles. Our PW Consulting model — built on primary interviews, supplier financials, and installed‑base analytics — estimates the market at approximately USD 143.5 Million in the base year (2025) and projects growth to roughly USD 209.3 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.5% over the forecast horizon. Historical momentum from 2020–2025 shows consistent expansion driven by retrofit demand and municipal infrastructure renewal; the 2026 planning year is pivotal for firms seeking to translate this trajectory into defensible revenue and margin gains.
Air & Water Pollution Control Equipment Market
Why this study matters for 2026 decisions
- Allocation of scarce CAPEX: Our analysis helps prioritize retrofit versus green‑field projects based on total cost of ownership, permitting timelines, and expected payback under near‑term regulatory scenarios.
- M&A and portfolio pruning: With market concentration measured at CR3 = 28.5% and CR5 = 35.2%, the competitive field is fragmented — presenting targeted bolt‑on acquisition opportunities for medium‑sized incumbents and private equity.
- Product and service strategy: The market is bifurcated between equipment suppliers and aftermarket/service providers; success in 2026 will depend on moving up the lifecycle curve into long‑term service contracts and digital monitoring.
- Supply chain and input risk management: Raw material volatility (notably polymer and resin inputs affected by shipping disruptions) requires procurement hedges and alternate sourcing strategies.
- Regulatory compliance planning: Even as broad national emissions inventories show multi‑decadal declines, station‑specific and sectoral rules continue to create pockets of urgent retrofit demand — our regulatory scenario mapping turns those pockets into actionable sales pipelines.
Market dynamics and near‑term catalysts
Three forces will shape decisions in 2026:
Air & Water Pollution Control Equipment Market
- Regulatory evolution and enforcement concentration: Long‑term reductions in criteria pollutant totals (as recorded in recent U.S. EPA inventories) coexist with tighter local and sectoral limits for industrial VOCs, SOx/NOx and particulate matter. This creates persistent demand for both air and water treatment equipment across specific stationary sources even when national totals trend down.
- Technology maturation and modularization: Vendors are increasingly offering modular, skid‑mounted systems and digital monitoring to reduce installation lead times and enable performance‑guarantee contracts. Buyers in 2026 must weigh modular capex vs. bespoke engineering for lifetime economics.
- Input cost and logistics volatility: The May 2026 resin price shock — traced to shipping disruptions — is a timely reminder that polymer‑based components (filters, gaskets, lining materials) can materially affect BOM inflation and project scheduling. Scenario planning for raw material spikes is now a core procurement requirement.
Competitive landscape — what to watch
The space remains populated by a mix of specialized air equipment manufacturers, water technology leaders, and multi‑domain suppliers. Key players profiled in the study include CECO Environmental, Ducon Environmental Systems, Airnord, Thermax, KC Cottrell, Pentair, and HUBER Group. Our strategic read of these firms yields the following implications for 2026 positioning:
Air & Water Pollution Control Equipment Market
- CECO Environmental (Addison, TX) — Strength: diversified filtration and emissions control portfolio (scrubbers, cyclones, biofiltration, thermal oxidizers) combined with aftermarket capabilities. Strategic emphasis should be on converting project wins into longer‑term service streams and on cross‑selling to adjacent end‑markets.
- Ducon Environmental Systems (Farmingdale, NY) — Strength: wet electrostatic precipitators, baghouses and activated carbon systems for industrial stacks. 2026 opportunity: leverage deep application expertise to expand turnkey delivery for refining and petrochemical clients seeking single‑vendor accountability.
- Airnord (Copenhagen) — Background: emerged from a divestment transaction (FLSmidth’s Air Pollution Control business) and retains established tech and customer relationships. Strategic focus: stabilize after transition and exploit European retrofit pipelines where emissions enforcement is most active.
- Thermax (Pune) — Strength: strong presence in industrial air pollution control in high‑growth Asian markets. Competitive pathway: bundle finance and long‑term service agreements to overcome price competition on equipment.
- KC Cottrell (Seoul) — Strength: power‑sector‑grade ESPs, fabric filters, FGD and DeNOx systems. For 2026: target utilities with aging units that face near‑term tightening of emission limits and a need for phased upgrades.
- Pentair (London) — Strength: broad water and wastewater treatment platform with global aftermarket reach. Strategic lever: integrate digital water monitoring and remote service into pricing models to convert municipal and industrial customers to subscription‑like revenue.
- HUBER Group (Berching) — Strength: mechanical and process equipment for municipal/industrial water and sludge treatment. 2026 opportunity: scale into emerging markets with packaged treatment plants that reduce engineering complexity and tender risk.
Recent industry signals — such as demonstrator activity at IE Expo China and forum appearances by Anguil at SESHA — confirm that trade shows remain high‑value deal origination venues. The divestment and rebranding of legacy portfolios are creating windows for agile players to capture market share.
Report contents — practical chapters and tools
PW Consulting’s full report is designed as an operational playbook for executives and includes:
- A comprehensive market model (2020–2025 historical, 2026–2032 forecast) with scenario toggles for regulatory tightening, raw material shocks, and slower capex cycles.
- Segment and regional demand drivers, with end‑user behaviors modeled at the plant‑level (note: detailed segment tables and granular splits are included in the full report and intentionally withheld from this summary).
- Competitive benchmarking: product matrix, installed‑base analysis, win/loss patterns, and aftermarket exposure for the leading vendors profiled above.
- M&A and partnership playbook: valuation multiples observed, integration risk checklists, and a shortlist of acquisition targets by strategic fit.
- Procurement and supply‑chain risk tools: raw material sensitivity analyses, alternative supplier maps, and contracting templates to hedge resin and specialty chemical exposure.
- Practical commercial templates: RFP scorecards, test & commissioning checklists, and KPI frameworks for O&M and performance guarantees.
Strategic implications and recommended actions for 2026
- Implement modular-first product strategies for quick wins: prioritize skid-based systems where permitting and schedule pressure dominate.
- Lock in long‑term service and remote-monitoring contracts to convert one‑time equipment revenue into recurring streams; align incentives through availability-based SLAs.
- Hedge raw material risk: secure secondary polymer sources and include indexation clauses in long‑lead supplier contracts to mitigate sudden resin price moves.
- Pursue targeted bolt‑on M&A where service capability or regional presence can be rapidly combined to improve CR margins; use the CR3/CR5 concentration data to identify consolidation gaps.
- Adopt regulatory scenario planning: build three regulatory tracks (status quo, moderate tightening, aggressive tightening) to stress test procurement and sales pipelines.
- Invest in demonstration projects and local certifications in priority markets to lower vendor switching costs for prospective customers.
- Leverage trade shows and technical workshops — these remain high‑impact channels for lead generation and for shaping procurement specification language.
How PW Consulting can support your 2026 plan
Our consulting engagement is structured to move from insight to execution in 90–120 days: baseline diagnostic (installed‑base, customers, and supplier map), scenario modelling workshops with executive stakeholders, and delivery of transaction‑grade diligence packs or a commercial playbook. For teams preparing capital cycles in 2026, our work translates market forecasts and supplier intelligence into specific project prioritization and a defensible investment thesis.
Next steps — where to get the full data
This article highlights the strategic implications and capabilities contained in PW Consulting’s full research. For the granular market tables, segmented forecasts by region/type/application, supplier financial matrices, and downloadable procurement templates, please consult the full Air & Water Pollution Control Equipment Market report. The executive access version includes the complete datasets and interactive scenario tools that are deliberately withheld from this summary to preserve the actionable value of the primary research.
For detailed analysis of this topic, please visit the official page: Air & Water Pollution Control Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Mixers Market at USD 6.2B in 2025, Poised for 4.5% CAGR to 2032
By PW Consulting, 2026-07-12
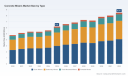
Concrete Mixers Market — Strategic Briefing for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our new Concrete Mixers Market study — a forward-looking, decision-oriented intelligence product built to inform capital allocation, R&D prioritization, fleet strategy, and M&A activity through the pivotal year of 2026 and beyond. Grounded in a 2020–2025 historical reconstruction and a 2026–2032 forecast horizon, the study translates raw market movement into operational choices. Our base-year framework (2025) and modeled trajectories capture a market that grew from a global size of approximately USD 4.78 Billion in 2020 to an estimated USD 6.20 Billion in 2025, with projections pointing to roughly USD 8.51 Billion by 2032 at a compound annual growth rate of 4.5% (USD, Billion).
Concrete Mixers Market
Why this study matters in 2026
-
Timing: 2026 is a turning point. Post-pandemic construction rebound, shifting infrastructure priorities, and early electrification pilots are conflating to reshape demand and fleet composition. Decisions made in 2026 will lock in fleets and supplier relationships that shape operational costs for the rest of the decade.
Concrete Mixers Market -
Margin pressure & input volatility: Volatile steel and commodity prices are raising production costs for drums, chassis and batching systems. Procurement and design choices taken now — from material substitution strategies to supplier risk-sharing — will protect margins as volumes normalize.
Concrete Mixers Market -
Technology acceleration: Real-time monitoring, telematics and hybrid powertrains have moved from pilots to commercially visible launches. Early adopters can harvest productivity gains and new service revenues in maintenance and data-driven route optimization.
-
Regulatory and ESG vectors: While full zero-emission concrete mixer trucks are not yet commercially available in some leading markets as of 2026, regulatory focus on emissions and job-site pollution is increasing capital and operating constraints for fleet operators and OEMs.
What PW Consulting’s Concrete Mixers Market report delivers
-
Market sizing and forecasts: A transparent, bottom-up market model covering 2020–2025 historical performance and a 2026–2032 forecast (CAGR 4.5%). We provide scenario runs that stress-test demand against three adoption curves for electrification and volumetric solutions.
-
Segmentation analysis: Discrete breakdowns by product type, application and region to reveal where margin pools and growth pockets reside (note: this executive brief omits detailed subsegment tables; the full report contains the granular splits and proprietary market-share mapping).
-
Competitive landscaping and vendor benchmarking: Strategic profiles, capability matrices, and a partner/competitor heatmap covering OEMs and niche innovators across continuous, volumetric, stationary and truck-mounted mix solutions.
-
Technology and product roadmaps: Assessment of electrification, hybridization, telematics, in-drum monitoring and mobile batching innovations — with lifecycle and TCO implications for fleet operators.
-
Supply chain, cost modeling and procurement playbooks: Practical mitigations for raw-material volatility (steel, hydraulic components) and guidance on contractual arrangements to lock in capacity and cost certainty.
-
Commercial and service strategies: Aftermarket revenue levers, digital subscription models for monitoring systems, and dealer network optimization to increase uptime and lifetime value.
-
M&A/partnership screens: A prioritized list of strategic acquisition and JV targets informed by capability gaps, market concentration (CR3 ~45%, CR5 ~60%) and regional footprint objectives.
Key market dynamics and strategic implications
-
Demand composition and resilience: The market’s recovery path through 2020–2025 demonstrates resilient underlying demand from residential, commercial and infrastructure projects. Growth to 2032 is steady but non-linear — episodic public infrastructure spend and localized construction booms create concentrated windows of high utilization.
-
Product strategy: Manufacturers of continuous and volumetric systems are diverging on go-to-market paths. Volumetric mixers emphasize just-in-time, on-site blending flexibility and reduced waste, while drum and truck-mounted solutions prioritize payload efficiency and scale. OEMs should map product roadmaps to customer segments that value flexibility versus scale.
-
Electrification and hybridization: 2026 has seen the first commercialized hybrid mixers and greater in-drum intelligence. These developments lower operating emissions and improve asset utilization. However, full battery-electric heavy mixers remain constrained by energy density, charging infrastructure and regulatory timelines—meaning pragmatic transition strategies (hybrid pilots, retrofit programs) will win the near term.
-
Telematics and data-as-service: Real-time in-drum monitoring and integrated telematics are maturing into monetizable services — enabling route optimization, quality assurance and SLA-based maintenance. Early adopters can convert telemetry into recurring revenue while differentiating on uptime guarantees.
-
Supply-side fragility: Component concentration and material price swings necessitate multi-sourcing, long-term contracts and design tolerances for alternative materials to preserve margins.
Competitive landscape — who matters and why
-
Established global OEMs: Players with integrated batching, truck-mounted and truck-chassis capabilities continue to dominate on large infrastructure projects due to scale, service networks and product breadth. These firms compete on durability, payload optimization and dealer reach.
-
Volumetric and mobile innovators: Companies focused on volumetric and portable solutions appeal to contractors seeking flexibility, lower waste and minimal dependence on central ready-mix plants. This segment is fertile ground for partnerships with regional contractors and rental chains.
-
Niche disruptors and digital leaders: Startups and specialist manufacturers are differentiating on electrification, lightweight designs, and embedded sensors for asset management. Their ability to iterate quickly and pilot novel business models (e.g., telemetry subscriptions) presents an acquisition or white-label opportunity for larger OEMs.
Representative company positioning captured in our report (illustrative, not exhaustive): Graco with continuous in-plant systems; Zimmerman and ProAll in volumetric/on-site delivery; Vince Hagan and Columbia Machine serving mobile batching and ready-mix producers; Schwing, Putzmeister, CIFA and SANY shaping heavy-duty truck-mounted and batching solutions; Mack and International offering vocational truck platforms; MudMixer, Mix Right and other portable specialists enabling site-level flexibility; Revolution, Chaney and a handful of innovators pushing electrification and in-drum monitoring. Recent 2026 activity validates these dynamics: Chaney’s production-proven hybrid mixer launch (April 2026), Revolution’s in-drum xBOLT™ temperature monitoring integrated with INSIGHT™ (May 2026), Mack Trucks’ expanded concrete mixer lineup showcased at World of Concrete 2026 (January 2026) and ProAll’s new lightweight volumetric L20R (May 2026).
Methodology and scenarios underpinning our forecasts
-
Data foundations: The market model combines public financials, OEM shipment data, dealer inventories, tender pipelines, and primary interviews with fleet operators and construction contractors across the 2020–2025 historical window. Base-year normalization is anchored in 2025.
-
Forecast approach: We apply a blended demand model decomposing volume growth, replacement cycles and equipment intensity per application and region. Forecast sensitivity focuses on three levers: infrastructure spend variance, steel/commodity cost shocks, and pace of electrification adoption.
-
Concentration and competition: Market concentration metrics (CR3 ~45%, CR5 ~60%) inform competitive dynamics — indicating a moderately consolidated market in which large OEMs set technical and commercial standards while smaller specialists maintain pockets of influence.
Actionable recommendations for 2026
-
Refine fleet mix decisions: Run a TCO vs. flexibility assessment to determine the optimal ratio of drum, volumetric and portable assets by project type. Prioritize volumetric pilots where labor scarcity and waste reduction are critical.
-
Pilot hybrid and telemetry programs: Initiate limited fleet trials of hybrid drivetrains and in-drum monitoring to quantify fuel savings, emissions reduction and quality control benefits before scaling.
-
Hedge input risk: Negotiate multi-year agreements with key component suppliers, consider inventory buffers for critical items (drums, hydraulic parts), and review design alternatives to reduce steel dependency where feasible.
-
Build aftermarket revenue: Commercialize telematics, predictive maintenance and performance guarantees as recurring-revenue products. These services materially improve unit economics and customer stickiness.
-
Pursue targeted M&A and partnerships: Use our M&A screens to identify bolt-on acquisitions that close capability gaps (e.g., telematics, volumetric designs) or extend regional distribution.
Next steps and how to access the full intelligence
This brief highlights the strategic frame and core implications from PW Consulting’s Concrete Mixers Market report. The full study contains proprietary subsegment tables, granular regional and application splits, vendor market shares, price curves, and executable playbooks (procurement templates, integration checklists and an M&A target prioritization matrix). If your 2026 planning depends on accurate fleet sizing, supplier selection, technology investment sequencing or M&A screening, the complete report provides the operational detail and datasets required to convert insight into action.
For executives calibrating strategy in 2026: treat this market as structurally steady but tactically volatile. Growth to 2032 is positive, but value capture will be decided by those who manage supply risk, adopt the right mix of electrification and telematics, and convert product differentiation into service-based revenue. PW Consulting’s full-market dossier contains the playbooks you need to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Concrete Mixers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Tubing Set Market to Reach USD 1,370.0M by 2032 at 4.12% CAGR
By PW Consulting, 2026-07-12
Blood Tubing Set Market — Strategic Preview for 2026 Decision-Makers
As healthcare providers, device manufacturers, and investors prepare plans for 2026, the Blood Tubing Set market is entering a phase where modest compound growth masks structurally important shifts in concentration, regulation, and procurement behavior. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — identifies the commercially actionable inflection points that will determine winners and laggards over the coming investment cycle. Our high-level findings: the market expanded from a steady baseline in the early 2020s to exceed USD 1 billion in the 2025 base year and is projected to approach roughly USD 1.37 billion by 2032 under a 4.12% compound annual growth trajectory. That trajectory coexists with a high degree of supplier concentration, making strategic partner selection and operational resilience central to 2026 planning.
Blood Tubing Set Market
Why this analysis matters in 2026
- Decision clarity for capital allocation: The market is growing steadily but not explosively. Firms deciding whether to invest in new manufacturing capacity, automation, or M&A need forward-looking margin and volume scenarios — not just historical growth rates.
- Regulatory and reimbursement alignment: Blood tubing sets remain Class II devices under FDA 510(k) pathways and are embedded in dialysis reimbursement regimes. Regulatory readiness and coding strategy materially affect time-to-revenue and capture rates in tendered contracts.
- Supplier and product risk management: High market concentration raises counterparty risk; a single device correction or supply shock can ripple through procurement networks and contracts.
- Commercial segmentation playbooks: Differences between procurement in dialysis centers vs. hospital systems, product compatibility across dialysis machines, and single-use sterilization logistics create pathways for premium positioning or cost competition.
Report composition — what you get (practical and deployable)
- Concise executive summary with strategic imperatives tailored for manufacturers, contract manufacturers, large buyers (dialysis networks), and private equity.
- Validated market sizing and a transparent forecast model (2026–2032) with scenario and sensitivity modules you can run for alternate price, volume, and raw material scenarios.
- Demand-side analysis covering clinical drivers (CKD prevalence, modality mix), procurement cycles, and pricing dynamics across care settings.
- Supply-side diagnostics: capacity maps, technology footprints (materials, connector systems, airless/low-volume designs), and a supplier risk heatmap.
- Regulatory and reimbursement dossier: FDA pathways, ISO biocompatibility expectations, sterilization validation protocols, and implications for market access timelines and cost-of-goods.
- Competitive intelligence: company profiles, go-to-market archetypes, contract structures, and a playbook to win tenders and long-term supply agreements.
- Actionable commercial plans: pricing levers, tender strategies, cross-sell opportunities, and sample contracting clauses to de-risk supply continuity.
- Strategic M&A and partnership targets, plus diligence checklists focused on manufacturing quality, sterile supply chain, and regulatory histories.
Macro takeaways and near-term dynamics
The forecasted CAGR of approximately 4.12% conceals heterogeneity that matters. Growth is underpinned by stable demand from hemodialysis programs coupled with incremental value capture from product innovation (e.g., airless systems, low-volume tubing, and machine-specific bundles). At the same time, the market exhibits high concentration among a handful of global suppliers, producing clear advantages for incumbent manufacturers but also exposing buyers to supplier-side disruptions. Our concentration analysis shows that the top three suppliers command a substantial share of the market, with the top five even more dominant — a structural fact that tightens competition for smaller players and elevates consolidation as an effective route to scale.
Blood Tubing Set Market
Cost dynamics are pragmatic: manufacturing economics are driven by medical-grade polymer supply and customization levels (connector types, lengths, and machine compatibility). Material unit economics are modest at the per-set level, but they compound across volume and customization complexity; even small changes in raw-material pricing, sterilization method selection, or yield can swing margins materially. All blood tubing sets in the market are single-use and require validated sterilization prior to release (gamma irradiation and ethylene oxide are the mainstream methods), and biocompatibility testing consistent with ISO 10993 is a gating requirement for market entry.
Blood Tubing Set Market
Regulatory and reimbursement context
- FDA: Hemodialysis blood tubing sets are regulated as Class II devices requiring 510(k) submissions demonstrating substantial equivalence. Post-market vigilance and labeling accuracy are increasingly scrutinized.
- ISO: Compliance with ISO 10993 biocompatibility standards is essential for blood-contacting devices; sterilization validation and leachables testing create non-trivial time and cost hurdles.
- Reimbursement: Dialysis procedures are reimbursed under established outpatient codes in major markets. Manufacturers should align pricing models to procedure-level economics and bundle strategies where possible.
Competitive landscape — profiles and strategic implications
- Nipro Corporation (Osaka, Japan) — Nipro offers machine-specific blood tubing solutions designed for close integration with hemodialysis platforms. Their strategy emphasizes component validation and machine compatibility, which supports long-term OEM relationships and replacement part sales. For incumbents and challengers alike, Nipro’s approach underlines the commercial value of device compatibility and OEM certification pathways. ( https://www.nipro-group.com/en)
- B. Braun Melsungen AG (Melsungen, Germany) — B. Braun’s Streamline Airless System and DiaStream product families highlight differentiation through safety and handling features. However, recent events require careful monitoring: in April 2026, an Urgent Medical Device Correction was issued for certain Streamline Airless System and Low Volume bloodlines due to potential microbubble and leakage risks, illustrating how product quality events can create immediate reputational and supply disruptions. ( https://www.bbraun.com)
- Fresenius Medical Care AG (Bad Homburg, Germany) — Fresenius groups product and service strategies, offering integrated blood tubing solutions like the CombiSet SMARTECH, and often bundles disposables with machine sales and service agreements. Their playbook demonstrates how vertical integration and service contracts can create stickiness in buyer relationships. ( https://freseniusmedicalcare.com/en)
Implications: product differentiation (safety, air elimination, low priming volume), machine interoperability, and field support are decisive commercial levers. Quality incidents — even when resolved quickly — can shift procurement toward alternate suppliers or longer qualification processes, amplifying the importance of robust post-market surveillance and rapid field corrective action capability.
Strategic playbook for 2026
- Supply resilience and cost control: Diversify polymer and connector sources, qualify secondary sterilization partners, and build safety stock for critical SKUs. Use the forecast model to stress-test gross margin under raw-material shocks and sterilization pricing changes.
- Regulatory-first product development: Prioritize designs that reduce microbubble risk, ease of priming, and simplified labeling to shorten 510(k) cycles. Invest early in biocompatibility and sterilization validation to avoid costly post-market actions.
- Commercial packaging and contracting: Design bundled offers that tie bloodline sales to service, warranties, or training for dialysis staff — emphasizing total cost-of-use rather than per-set price alone.
- Tender and regional go-to-market: Tailor contract terms by buyer type (chain dialysis centers vs. independent hospitals) and incorporate supply assurance clauses and rapid field-replacement commitments into bids.
- M&A and partnerships: Target niche technology providers (e.g., microbubble mitigation, smart sensors), regional CMOs with validated sterile capacity, or distributors with deep access to dialysis clinic networks.
- Quality and communications: Strengthen post-market surveillance and communications protocols. The April 2026 corrective action by a major supplier underscores how quickly public trust and procurement patterns can pivot following a safety advisory.
How PW Consulting helps execute
Our deliverable is more than a slide deck. We provide an integrated toolkit: an editable financial model with baseline and alternate scenarios; a supplier map with qualification checklists; tender-play templates; a regulatory timeline with required testing and documentation; and a prioritized action matrix for immediate (0–6 months), medium (6–18 months), and strategic (18–36 months) initiatives. All findings are backed by primary interviews with procurement leads, OEM engineers, and sterilization specialists, cross-checked against regulatory filings and publicly available alerts.
Closing — the strategic choice for 2026
For executives planning resource allocation in 2026, the choice is not binary between cost leadership and product innovation. In a market with modest topline growth, concentrated supplier dynamics, and strict regulatory gates, winning strategies will blend disciplined cost engineering with clear, verifiable safety differentiation and supply resilience. PW Consulting’s full Blood Tubing Set Market report provides the granular segmentation, contract templates, supplier risk scores, and model outputs that enable those strategic choices. We have intentionally withheld the detailed segment-by-region and application-level breakdowns from this preview; those granular insights and the downloadable forecast workbook are available in the full report on our portal.
To move from competitive awareness to operational readiness in 2026, stakeholders need a playbook that connects regulatory timelines, procurement cycles, and manufacturing levers — exactly what our study delivers. Contact PW Consulting or visit the full report page to access the complete dataset, scenario models, and supplier diligence materials.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


