



Category: market research
PW Consulting: Global Pharmaceutical Dyes Market to Reach $1.23B by 2032 Amid 5.52% CAGR
By PW Consulting, 2026-09-17
Strategic Color: Navigating the Pharmaceutical Dyes Market Through 2032
In the highly regulated and technically demanding pharmaceutical industry, colorants are far more than aesthetic additions. They serve as critical quality identifiers, aid in patient compliance, and play a vital role in brand differentiation and counterfeit prevention. As the global pharmaceutical landscape shifts toward more complex drug delivery systems and heightened regulatory scrutiny, the market for pharmaceutical dyes has entered a new phase of strategic importance. PW Consulting's latest Worldwide Pharmaceutical Dyes Market research provides a comprehensive evaluation of this evolving sector, offering actionable intelligence for stakeholders looking to optimize supply chains, innovate product portfolios, and capture growth opportunities from 2026 through 2032.
This report serves as an essential compass for pharmaceutical manufacturers, excipient suppliers, contract development and manufacturing organizations (CDMOs), and investors. By synthesizing historical performance data with forward-looking forecasts, it highlights the intersection of technological innovation, regulatory changes, and shifting consumer preferences that will define market dynamics over the next decade.
Historical Trajectory and Forecasted Growth
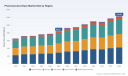
Understanding where the market has been is crucial to anticipating where it is headed. Analysis of historical data from 2020 to 2025 reveals a period of steady expansion, driven by increasing demand for orally administered medications and a growing emphasis on patient-centric drug design. The global market reached a valuation of approximately 844.47 million USD in the base year of 2025, marking significant progress from levels observed just five years prior.
Looking ahead, the forecast period from 2026 to 2032 projects continued momentum. The market is expected to surpass the 900 million USD threshold in 2026, reflecting an accelerating pace of adoption in emerging therapeutic areas. By the end of the forecast window in 2032, revenue is projected to approach 1.23 billion USD. This growth path corresponds with a compound annual growth rate of 5.52 percent, signaling a resilient demand structure that is somewhat insulated from broader macroeconomic volatility. For strategic planners, this trajectory suggests that pharmaceutical colorants represent a stable, growth-oriented segment within the broader chemical and healthcare values chain.
Material Diversification: Synthetic versus Natural Solutions
The composition of the market reflects a complex balancing act between performance, cost, and regulatory compliance. Synthetic dyes remain the dominant force, leveraging their consistency, intensity, and well-established compatibility with various manufacturing processes. These materials are particularly critical for applications requiring precise color matching and stability under stringent processing conditions, such as high-shear tablet coating.
However, the segment analysis indicates a notable and accelerating shift toward natural alternatives. As clean-label initiatives expand beyond food and beverage into pharmaceutical formulations, manufacturers are increasingly seeking pigments derived from fruits, vegetables, and other natural sources. This trend is not merely a marketing preference; it is increasingly driven by regulatory expectations in key markets like Europe and the United States, where origin transparency and perceived safety are becoming key differentiators. Pigments and lakes also maintain a significant presence, particularly in specialized applications where solubility characteristics dictate formulation choices. The interplay between these material categories will define competitive positioning, as suppliers invest in R&D to enhance the stability and performance profiles of natural options to rival their synthetic counterparts.
Application Drivers Across Dosage Forms
The demand for pharmaceutical dyes is heavily influenced by the mode of drug administration. Oral solid dosage forms continue to represent the largest application segment, underscoring the enduring dominance of tablets and capsules in global pharmacotherapy. In this context, dyes are indispensable for coating technologies that protect active ingredients, control release profiles, and enhance swallowability and visual identification.
Beyond solids, liquid and semi-solid formulations maintain a substantial share, catering to pediatric, geriatric, and dysphagia populations where ease of administration is paramount. Topical and ophthalmic preparations represent a specialized but high-value niche, where purity standards and light stability are particularly critical. The variation in application requirements means that a one-size-fits-all supply strategy is rarely viable. Successful market participants must align their production capabilities with the specific technical demands of each dosage form, ensuring compliance with monographs such as USP, NF, and Ph. Eur. across all product lines.
Regional Dynamics and Supply Chain Considerations
Geographically, the market exhibits distinct characteristics shaped by local manufacturing capabilities, regulatory environments, and healthcare infrastructure. North America remains a primary revenue contributor, supported by a robust domestic pharmaceutical industry and stringent quality expectations that favor established, compliant suppliers. Europe follows closely, with demand driven by strong generic drug markets and a regulatory framework that increasingly emphasizes sustainability and natural ingredients.
Asia Pacific represents a dynamic growth engine, characterized by expanding manufacturing bases and rising domestic consumption. Latin America and the Middle East and Africa collectively form an emerging frontier, where healthcare access improvements and localized production initiatives are gradually increasing volume demand. For multinational corporations, these regional nuances necessitate a flexible supply chain approach. Recent industry observations highlight that geopolitical factors and raw material availability can introduce significant volatility. For instance, fluctuations in key feedstock prices, such as aniline, have impacted cost structures for azo dye production, while regulatory adjustments in major markets have forced rapid compliance adaptations. Companies that maintain diversified sourcing strategies and invest in regional inventory buffers are better positioned to navigate these disruptions.
Competitive Landscape and Consolidation Trends
The market structure reflects a moderate level of concentration, with leading players holding significant share through technical expertise, regulatory certifications, and long-standing relationships with pharmaceutical clients. The competitive environment is characterized by a mix of large, diversified chemical corporations and specialized niche manufacturers. Key entities such as Sensient Technologies Corporation, Clariant AG, BASF SE, GNT Group, Kolor Jet Chemical Pvt Ltd, and Sun Chemical Corporation illustrate the breadth of capabilities present in the sector.
Sensient Technologies Corporation, based in Milwaukee, USA, continues to strengthen its position through product innovation, recently introducing advanced color dispersions designed to enhance stability in demanding coating processes. Clariant AG, headquartered in Switzerland, has focused on expanding its certification footprint, achieving Halal certification for expanded ranges of iron oxide pigments to access broader international markets. BASF SE, a major player from Germany, has invested in capacity expansion at key sites to meet rising demand for pharmaceutical-grade iron oxides and other colorants certified across global pharmacopeias. Meanwhile, GNT Group from the Netherlands has carved out a distinctive niche by specializing in natural dyes derived from fruits and vegetables, catering to the growing clean-label trend in both Europe and the USA. Manufacturers like Kolor Jet Chemical in India and Sun Chemical in the USA further diversify the landscape by providing compliant dyes and lakes with global certifications, including Halal and Kosher options, to serve varied market requirements.
Recent corporate activities underscore the strategic priorities shaping the landscape. Product launches focusing on enhanced stability and performance, certification updates to meet religious and cultural standards, and capacity expansions to secure supply continuity are recurrent themes. The competitive intensity is further amplified by the fact that market concentration, as measured by leading firms, reflects a market where differentiation through quality, compliance, and innovation is essential to maintaining margins.
Regulatory Pressures and Technical Standards
Regulatory compliance is not a static backdrop; it is an active driver of market evolution. Pharmaceutical dyes operate within a tightly controlled framework governed by pharmacopeial monographs and regional regulations. Recent updates have raised the bar for quality and safety. The European Union's regulation lowering permitted lead levels in pharmaceutical iron oxide dyes required manufacturers to rapidly adjust sourcing and purification processes. Similarly, updates to USP monographs introduced stricter light stability testing for aluminum lake dyes, compelling formulators and suppliers to validate performance under more rigorous conditions.
Worldwide Pharmaceutical Dyes Market
Textile Dyes Market
Beyond product specifications, regulatory enforcement actions also influence market behavior. Increased scrutiny by US FDA on import compliance for certain dyes has led to higher rejection rates for non-conforming shipments, reinforcing the importance of supplier qualification and quality assurance systems. For pharmaceutical companies, these dynamics mean that the dye supply chain must be treated as a critical quality attribute component. Risk mitigation requires deep vetting of suppliers, rigorous testing protocols, and agile responsiveness to regulatory change. This environment favors established players with robust compliance infrastructures and creates barriers to entry for less equipped competitors.
How PW Consulting's Report Supports Strategic Decision-Making
In a market defined by technical complexity, regulatory flux, and shifting consumer expectations, generic industry summaries are insufficient for high-stakes planning. PW Consulting's Worldwide Pharmaceutical Dyes Market research is designed to provide the depth and specificity required for confident decision-making. The report offers a granular examination of segmentation structures, enabling readers to assess the relative attractiveness of different material types and application areas without relying on broad averages. It provides detailed regional analysis that accounts for local regulatory nuances, manufacturing capabilities, and demand drivers, allowing for more precise geographic strategy formulation.
Competitive profiling extends beyond basic company descriptions to include an analysis of strategic moves, product portfolios, and positioning tactics. By examining recent developments such as product launches, certification achievements, and capacity investments, the report reveals the operational priorities of key market participants. This intelligence helps clients identify gaps in their own offerings, anticipate competitor responses, and evaluate partnership or acquisition opportunities. Furthermore, the integration of market dynamics data, including raw material cost trends and regulatory updates, ensures that strategic plans are grounded in the realities of the current operating environment.
Stakeholders will find value in the report's focus on actionable insights. Whether the objective is to refine a product development roadmap, optimize procurement strategies, enter new geographic markets, or assess investment potential, the research provides a structured framework for evaluating options. The combination of historical data, forecast projections, and qualitative analysis creates a holistic view that supports both short-term tactical adjustments and long-term strategic positioning.
Conclusion
The pharmaceutical dyes market is poised for sustained growth, underpinned by the enduring need for effective, compliant, and patient-friendly drug formulations. The projected expansion from 2026 through 2032 offers significant opportunities for companies that can navigate the interplay of material innovation, application-specific requirements, regional differences, and regulatory demands. Success will depend on strategic agility, technical excellence, and a deep understanding of the forces shaping the competitive landscape.
PW Consulting's comprehensive analysis equips industry leaders with the intelligence necessary to anticipate change and capitalize on emerging trends. To access the full dataset, detailed segmentation breakdowns, and complete competitive profiles that underpin this overview, professional stakeholders are encouraged to consult the complete report. This document represents a vital investment in informed strategy, ensuring that your organization is prepared to thrive in a market where color, compliance, and innovation converge.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 3D Microscope Market Hits $1.21B in 2025, Projected to Reach $2.12B by 2032
By PW Consulting, 2026-09-17
Navigating the Next Decade: Strategic Intelligence Behind the Worldwide Super Depth of Field 3D Microscope Market Forecast
The transition from conventional optical inspection to super depth of field 3D microscopy is no longer a niche engineering preference. It has become a structural shift across semiconductors, healthcare, automotive, and advanced materials. As laboratories and manufacturing lines demand simultaneous high-resolution surface inspection and extended focal coverage, the market has entered a phase of sustained, compounding expansion. At PW Consulting, we have dedicated extensive primary and secondary research to map this trajectory in our latest Worldwide Super Depth of Field 3D Microscope Market study. This article outlines the strategic architecture of the report, demonstrates why it matters for 2026 capital allocation and product planning, and explains how executive teams can convert macro-level momentum into defensible market positions.
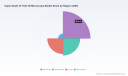
The quantitative foundation is robust. Drawing on a verified historical window from 2020 through 2025 and extending the forecast horizon to 2032, our analysis captures a market that has repeatedly outperformed early-cycle expectations. Measured in millions of USD, the sector has climbed from approximately 815.42 in 2020 to 1213.75 in the base year of 2025. The forward curve remains firmly upward, with 2026 projected at 1345.12 and continued expansion through 2120.95 by 2032. The overall compound annual growth rate settles at 8.3 percent across the forecast period. These are not abstract indicators; they are the scaffolding for capacity planning, R&D prioritization, and partner selection. But numbers alone do not translate into strategy. What separates a useful dataset from an execution-ready intelligence asset is the way those numbers are contextualized across product architectures, end-use demand drivers, regional deployment patterns, and the competitive behaviors shaping pricing, differentiation, and channel access.
Why 2026 Decision-Makers Need This Report Now
2026 is a pivotal planning year. Capital budgets are being finalized, technology roadmaps are being stress-tested against new imaging requirements, and procurement cycles are lengthening as organizations seek platforms that can serve both inspection and documentation workflows. In this environment, a market study must do more than describe what happened. It must anticipate where capability gaps, regulatory shifts, and procurement behaviors will create winners and laggards. Our report was built for that purpose. It connects the macro growth curve to the operational realities of buying, integrating, and deploying super depth of field 3D microscopes in real facilities.
Worldwide Augmented Reality Microscope Market
The strategic value begins with clarity on demand composition. The market is not growing uniformly; it is being pulled by distinct application engines that prioritize different performance attributes. In semiconductors and electronics, the emphasis falls on repeatable measurement accuracy, contamination control, and throughput. Automotive and aerospace buyers prioritize ruggedized workflows, large-field imaging, and traceability for quality systems. Healthcare and life sciences demand ergonomic, high-depth visualization that integrates with surgical or laboratory procedures. Material science and research teams require extreme flexibility, multi-modal illumination, and precise Z-axis control for 3D reconstruction. Understanding how these application segments interact with product architectures is essential for anyone evaluating entry, expansion, or partnership opportunities.
Equally important is the geographic dispersion of demand. The market's regional footprint influences not only volume but also service intensity, support expectations, and the speed at which new features migrate from premium to broader user bases. Our analysis integrates these regional dynamics without reducing them to simplistic rankings, because the real insight lies in how local procurement structures, distribution networks, and application density combine to shape addressable opportunity. For a 2026 planning team, the practical question is not simply which region is larger, but where the next wave of upgrades, replacements, and greenfield installations will concentrate, and what that concentration implies for service coverage, inventory positioning, and channel strategy.
What the Report Delivers: An Operational Anatomy
PW Consulting's study is designed to convert market intelligence into decision-ready workflows. Rather than stopping at headline figures, the report decomposes the landscape into actionable dimensions that align with corporate planning processes. The content architecture reflects the needs of strategy, R&D, sales leadership, and procurement teams simultaneously.
Scope, Methodology, and Forecast Discipline
The report is anchored in a transparent historical baseline and a forward-looking framework that clarifies assumptions, sensitivities, and extension paths. The historical record from 2020 to 2025 provides a credible basis for trend validation, while the forecast window from 2026 through 2032 enables multi-cycle planning. We structure projections with disciplined scenario thinking so that leadership can test how shifts in adoption timing, product mix, or application demand affect outcomes. This approach matters because microscopy purchasing is rarely a one-time transaction. It is a sequence of evaluations, validations, and phased deployments that respond to both technical requirements and budget rhythm.
Segmentation That Maps to Commercial Reality
The study segments the market along axes that match how buyers actually evaluate solutions. Product-type distinctions separate benchtop 3D digital microscopes from portable 3D digital microscopes, recognizing that performance requirements, deployment settings, and user profiles differ sharply between fixed laboratory or production environments and mobile inspection workflows. Application segmentation isolates the demand logic of semiconductors and electronics, automotive and aerospace, healthcare and life sciences, and material science and research. Each segment is treated not as a static slice of revenue, but as a distinct adoption environment with its own buying committee, qualification path, and performance threshold. This framing helps teams identify where to concentrate applications engineering support, where to package service agreements, and where to design entry-level versus premium feature sets.
Worldwide Super Depth of Field 3D Microscope Market
Regional and Structural Context
Regional analysis is integrated as a strategic variable rather than a descriptive sidebar. Distribution maturity, end-user density, and the pace of digital transformation vary across markets, affecting how quickly advanced depth-of-field capabilities move from early adopters to broader procurement programs. The report also examines market concentration and competitive structure, giving readers a realistic view of how supply-side dynamics influence pricing behavior, innovation cadence, and negotiation leverage. In a market with meaningful concentration among leading participants, understanding the relationship between incumbency, feature leadership, and channel reach is critical for assessing both partnership opportunities and competitive threats.
Competitive Landscape: Innovation Patterns and Positioning Pressures
The worldwide super depth of field 3D microscope market is shaped by a blend of established optics and instrumentation leaders, surgical visualization specialists, and a growing field of regional and application-focused manufacturers. The competitive picture is not simply a matter of brand presence; it is a story of differentiated engineering philosophies, targeted application claims, and periodic product events that reset buyer expectations.
Among the firms setting the pace, Keyence Corporation stands out for its emphasis on digital microscopy platforms that integrate focus stacking and real-time 3D measurement into industrial inspection workflows. Its VHX series exemplifies the convergence of super depth-of-field imaging with practical measurement utility, and its influence extends beyond traditional inspection into medical device manufacturing and quality control environments. ZEISS Group brings a parallel but distinct emphasis through surgical and visualization systems. Products such as the PENTERO 800 S with Depth+ mode and the ARTEVO family demonstrate how enhanced depth of field, 4K 3D visualization, and heads-up workflow design are being fused for ophthalmic and neurosurgical procedures. These platforms reflect a broader institutional push toward ergonomics, precision, and digital integration in complex clinical settings. Leica Microsystems contributes a strongly differentiated technological approach through FusionOptics, which combines two beam paths to preserve high resolution while substantially increasing depth of field. Its surgical microscope portfolio, including M530 OHX, PROvido, and Proveo 8x, is aimed at neurosurgery, ophthalmology, and multidisciplinary procedures where 3D perception and visualization clarity directly affect workflow quality.
On the industrial and cost-sensitive side, several manufacturers are expanding the accessible range of super depth of field systems. BestScope, for instance, offers the BSDM-500 3D Super-Depth Digital Microscope with high-magnification objectives, motorized stage capabilities, and advanced 2D/3D measurement tools, illustrating how feature-rich configurations are becoming available beyond the top tier of the market. Other active participants, including OUMIT Optical Instruments, ES-ray, Teelen, Peentech Precision Machinery, and MNT, are competing with configurations tuned for cost-effective deployment, precision inspection, research use, or metrology-oriented workflows. Hirox rounds out the landscape with high-resolution 3D digital microscopes that emphasize stitching capabilities for detailed surface and depth imaging, reinforcing the importance of workflow integration in demanding inspection contexts.
Recent product activity underscores how quickly expectations are evolving. In April 2025, Leica Microsystems launched the Proveo 8x 3D digital microscope for ophthalmology, featuring real-time 3D imaging with improved depth-of-field control, higher resolution, and immersive visualization. Earlier, in October 2024, ZEISS showcased the ARTEVO 850 3D heads-up ophthalmic microscope with true color imaging and a meaningful increase in depth of field. These developments are not isolated product launches; they are signals that depth of field, 3D perception, and digital heads-up workflows are becoming central purchase criteria rather than optional enhancements. For 2026 planning, such moves matter because they recalibrate the baseline for what buyers in clinical and high-value inspection environments expect from a modern platform.
Market Dynamics Shaping 2026 and Beyond
The market's trajectory is being shaped by a set of interlocking forces that extend beyond pure device sales. Technology integration is a defining theme. In surgical microscopy, for example, the combination of enhanced 3D visualization and extended depth of field is supporting hospital adoption of digital heads-up displays and robotic visualization systems. The result is a shift in value creation from optics alone to integrated workflows that improve ergonomics and precision in complex procedures. This integration is broadening the relevance of super depth of field capabilities, because the question is no longer only what a microscope can resolve, but how well it fits into a digitally enabled procedural environment.
Regulatory and clearance pathways further influence commercial velocity. Systems with strong clinical or industrial validation profiles benefit from smoother market access in major regions, especially where CE marking and FDA clearance create confidence for deployment at scale. The presence of such clearances for advanced 3D visualization platforms reduces adoption friction for cautious buyers and strengthens the commercial case for upgrading existing installations. At the same time, product-feature evolution continues to push the practical frontier. Motorized Z-axis precision, telecentric optics, multiple illumination modes, and high magnification ranges are enabling more reliable 3D reconstruction and measurement, particularly in inspection-heavy environments where repeatability and documentation are essential.
Taken together, these dynamics create a market in which feature leadership, workflow compatibility, and service reliability matter as much as headline specifications. Buyers are increasingly evaluating total cost of ownership, integration effort, and the ability to support multidisciplinary use cases. That is why our report devotes attention not only to what is being sold, but to why it is being bought, how adoption decisions are made, and which capabilities are becoming table stakes versus differentiators.
How to Use This Research in 2026 Planning
The most valuable market studies are those that help organizations ask better questions and make safer bets. This report is structured to support that outcome across several common 2026 priorities. For product and R&D teams, it provides a comparative view of application requirements and product architectures, helping prioritize which performance attributes deserve sustained investment. For commercial leaders, it clarifies where demand is concentrated by application logic and where regional deployment patterns may create 보다 favorable entry or expansion conditions. For procurement and operations stakeholders, it frames purchasing behavior in terms of qualification cycles, replacement timing, and the growing importance of service and integration capabilities.
The report is also built to support scenario-based planning. Because the forecast period extends well beyond the immediate budget cycle, leadership teams can use it to test how changes in adoption pace, product mix, or competitive intensity would affect strategic assumptions. That flexibility is especially important in a market where technological differentiation can shift buyer expectations quickly and where a single product event can alter the evaluation criteria for an entire segment.
Conclusion: From Market Size to Market Position
The worldwide super depth of field 3D microscope market is expanding against a backdrop of rising precision requirements, expanding clinical and industrial digital workflows, and intensifying competition across both premium and value-oriented tiers. The headline growth path tells part of the story, but the strategic insight lies in the structure beneath it: which applications are driving sustained demand, how product types are diverging in functionality and deployment context, where regional buyers are most likely to upgrade, and how leading competitors are positioning innovation to reshape purchase criteria.
PW Consulting's full study goes further than this overview can. It provides the detailed segmentation context, competitive profiles, application-level demand logic, regional deployment dynamics, and forward-looking scenarios that turn macro momentum into operational clarity. For organizations planning 2026 investments, the complete report is the difference between knowing the market is growing and knowing where to act. Readers seeking the full intelligence set, including segment-level breakdowns, competitive assessments, and forecast scenarios, are encouraged to access the complete study directly on the PW Consulting website. The macro evidence is strong; the detailed roadmap to capitalize on it is available in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Super Depth of Field 3D Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Rubella Treatment Market to Reach $1.60B by 2032, Growing at 3.62% CAGR
By PW Consulting, 2026-09-17
Strategic Horizons: Navigating the Global Rubella Treatment Landscape Through 2032
Executive Overview
The global landscape for rubella treatment and prevention is undergoing a subtle but significant transformation. As public health priorities shift towards strengthening immunization infrastructure and addressing regional coverage gaps, understanding the commercial dynamics of this market is critical for stakeholders across the pharmaceutical value chain. Our latest research, the Worldwide Rubella Treatment Market analysis, offers a comprehensive examination of the sector, projecting trends from the base year 2025 through 2032. This article serves as an strategic preview, outlining the macro-economic forces and competitive intelligence that will define decision-making in the coming years.
For industry leaders, investors, and public health partners, the sheer volume of data can be overwhelming. The key is not just access to numbers, but the contextual interpretation of what those numbers mean for supply chain resilience, regulatory strategy, and product development pipelines. This report is designed to bridge that gap, moving beyond surface-level statistics to provide actionable intelligence on how the market evolves amidst varying healthcare policies and manufacturing capabilities.
Market Trajectory and Growth Dynamics
The historical trajectory of the rubella treatment market reflects the broader success of global vaccination initiatives. From 2020 to 2025, the market demonstrated resilience, with revenue climbing from approximately $1045.2 million to $1251.0 million. This growth underscores the sustained demand for both prophylactic vaccines and supportive care medications necessitated by routine immunization schedules and outbreak management protocols.
Looking forward to the forecast period of 2026 to 2032, the market is expected to maintain a steady upward trajectory. Analysts project the overall market size to grow at a Compound Annual Growth Rate (CAGR) of 3.62%. By 2032, the total revenue is anticipated to reach $1604.6 million. This growth is not merely a continuation of past trends but is driven by specific structural factors, including the expansion of public health programs in emerging economies and the introduction of technologically advanced vaccine delivery systems.
However, growth is not linear. The forecast period accounts for potential fluctuations based on supply chain stability and regulatory milestones. For instance, the market size is projected to experience slight adjustments in the near term, stabilizing before accelerating again towards the end of the decade. This nuanced projection allows strategists to model cash flows and investment returns with greater accuracy, accounting for both the steady demand in mature markets and the higher volatility in developing regions.
Strategic Implications of Market Concentration
Understanding the competitive intensity is vital for new entrants and established players alike. The market exhibits a moderate to high level of concentration. Data indicates that the top three companies command a significant portion of the market share, while the top five firms collectively hold a substantial majority of the revenue. This concentration suggests that while the market is accessible, competitive barriers exist in terms of regulatory approval, manufacturing scale, and established distribution networks.
For companies looking to penetrate this space, the strategy often involves differentiation through delivery technology or targeting specific underserved geographic segments. For incumbents, the focus remains on maintaining coverage rates and navigating the complex landscape of public procurement and reimbursement policies.
Segmentation Analysis: Treatment Modalities and Channels
The market is fundamentally segmented by treatment type, end-user, and region. While specific percentage splits are detailed in the full report, the broader categories reveal where value is being generated.
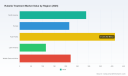
- Treatment Types: The landscape is dominated by preventive measures, specifically MMR (Measles, Mumps, and Rubella) and MMRV vaccines. These combination vaccines represent the largest share of revenue, reflecting their status as the primary tool for rubella eradication. Supportive medications constitute a secondary but essential segment, addressing symptom management when infection occurs. Hyperimmune globulins represent a specialized, smaller segment utilized in specific high-risk scenarios.
- End-User Channels: Distribution flows primarily through institutional channels. Hospitals and public health centers are the predominant recipients of rubella-related products, driven by national immunization programs and outbreak response protocols. Retail pharmacies play a supporting role, often handling follow-up doses or private sector vaccinations. The balance between public procurement and private consumption varies significantly by region.
The interplay between these segments is critical. For example, advancements in vaccine thermostability could reduce cold-chain reliance, thereby impacting the cost structures for public health centers in regions with logistical challenges. Similarly, shifts in reimbursement policies regarding supportive medications can alter demand patterns within hospital versus retail segments.
Competitive Landscape and Key Players
The rubella treatment market features a mix of global pharmaceutical giants and specialized biotechnology firms. The competitive environment is shaped by intellectual property, manufacturing capacity, and regulatory approvals in key markets such as the United States, Europe, and Asia Pacific.
Worldwide Buruli Ulcer Treatment Market
Merck & Co., Inc., based in the United States, remains a cornerstone of the market with its M-M-R II vaccine, a live attenuated virus vaccine widely used for active immunization. Their portfolio strength lies in established distribution networks and long-term safety data. GlaxoSmithKline (GSK), headquartered in the United Kingdom, is another major force, offering Priorix for MMR prevention. GSK has recently been active in regulatory engagements, securing FDA approvals for Priorix formulations, which reinforces their position in the Western market.
Sanofi Pasteur, headquartered in France, supplies MMR vaccines including Trimovax, contributing to combination formulations used in various national schedules. In the emerging market space, the Serum Institute of India stands out as a major producer of affordable MMR vaccines like Tresivac, playing a pivotal role in global prevention programs where cost is a primary constraint. Similarly, PT Bio Farma in Indonesia manufactures rubella-containing vaccines for domestic use and export, supporting national immunization efforts in Southeast Asia. The Shanghai Institute of Biological Products in China develops and produces local MMR formulations, catering to the large domestic demand.
A notable innovation dynamic comes from Micron Biomedical Inc. in the United States. Their focus on needle-free delivery technology represents a potential shift in how measles and rubella vaccines are administered, aiming to improve coverage in global immunization programs by overcoming needle-stick injuries and reducing waste.
Recent Regulatory and Development Activity
Recent developments highlight the pace of innovation and regulatory activity in this sector. In March 2026, GlaxoSmithKline received FDA approval for Priorix (Measles, Mumps and Rubella Vaccine, Live) for active immunization against rubella in individuals 12 months of age and older. This follows earlier regulatory updates in November 2025, signaling continuous optimization of their portfolio.
Additionally, while not a direct rubella treatment, the broader antiviral landscape is seeing activity. In February 2026, NanoViricides, Inc. filed an Orphan Drug Designation application with the FDA for NV-387 as a potential treatment for measles. While this targets a related paramyxovirus context, it holds exploratory antiviral research relevance for rubella-like infections, indicating a potential long-term shift towards therapeutic options beyond vaccination, though currently, no specific antivirals are approved for rubella.
Industry Dynamics: Regulation, Reimbursement, and Manufacturing
The operational environment for rubella treatment is heavily influenced by regulatory frameworks and public health policies. Currently, there are no specific antiviral drugs approved for the treatment of rubella infection. Management relies primarily on supportive care, including rest, hydration, and symptom relief with antipyretics such as acetaminophen. This clinical reality cements the importance of the vaccine segment over the therapeutic drug segment.
Research into broad-spectrum antivirals continues. Peer-reviewed studies have noted that nitazoxanide has demonstrated in vitro inhibition of rubella virus replication. However, these findings remain exploratory, and the compound is not approved for this indication. This gap between research potential and clinical approval defines a key risk and opportunity area for future R&D investment.
Reimbursement structures are heavily tied to public health mandates. MMR vaccines targeting rubella are included in routine childhood immunization schedules supported by public health programs globally. High coverage targets are set by the WHO and national governments, ensuring a stable baseline demand. However, changes in public funding or shifts in policy prioritization could impact procurement volumes for manufacturers reliant on government contracts.
Manufacturing complexities also pose strategic challenges. The production of live attenuated rubella vaccines requires specific cell culture systems and strict cold-chain logistics to maintain viability during distribution. These requirements are particularly challenging during global immunization campaigns in regions with infrastructure limitations. Innovations that improve thermal stability or simplify logistics are therefore highly valued strategic assets.
Regional Dynamics and Strategic Focus
Regional variations define the opportunity set for the forecast period. The Asia Pacific region represents a significant volume of activity, driven by large populations and ongoing immunization expansion efforts. North America and Europe maintain steady demand driven by mature healthcare systems and booster programs, while the Middle East, Africa, and Latin America offer growth potential linked to international aid and regional health infrastructure development.
Strategists must consider that while overall market size grows, the velocity of growth differs by region. Factors such as local manufacturing capabilities, reliance on imported vaccines, and the stability of public health funding play crucial roles. For instance, regions with strong domestic manufacturing may see different margin structures compared to those reliant on global supply chains.
Strategic Value of the Full Report
While this overview provides a high-level snapshot of the market's direction, the full Worldwide Rubella Treatment Market report offers the granular intelligence required for precise planning. Decision-makers need access to detailed segmentation splits, historical data correlations, and proprietary forecasts that go beyond aggregated statements.
The complete study delves into specific regional revenue contributions, detailed treatment type breakdowns, and end-user distribution metrics that are essential for market entry strategies and capacity planning. It also provides deep-dive profiles of key competitors, analyzing their recent developments, strategic moves, and potential vulnerabilities.
Worldwide Rubella Treatment Market
Furthermore, the full report contextualizes the regulatory noise into actionable insights. It analyzes how recent FDA approvals, orphan drug filings, and international health guidelines interplay to create both barriers and openings for business development. Understanding the nuances of cold-chain requirements versus emerging needle-free technologies, for example, requires the detailed technical analysis provided in the full document.
For organizations aiming to optimize their portfolio, secure supply chains, or identify partnership opportunities in the rubella treatment space, the comprehensive data set is indispensable. It transforms macro trends into micro-level tactics, enabling stakeholders to navigate the 2026-2032 period with confidence.
We invite industry leaders and strategic planners to access the full report to unlock these critical insights. The landscape is evolving, and the margin between success and missed opportunity lies in the depth of understanding. Let the data guide your next strategic move.
For detailed analysis of this topic, please visit the official page: Worldwide Rubella Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Non-Invasive Bilirubin Meter Market Hits $234.6M in 2025, 5.78% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Decade: Inside the Global Non-invasive Bilirubin Meter Market
The landscape of neonatal care is undergoing a subtle but critical transformation, driven by the imperative to reduce clinical invasiveness while maintaining diagnostic precision. As healthcare systems globally prioritize patient comfort and cost-efficiency, the demand for transcutaneous bilirubinometers has moved from a niche convenience to a standard of care in newborn jaundice screening. Our latest comprehensive study, the Worldwide Non-invasive Bilirubin Meter Market report, offers a definitive roadmap for stakeholders navigating this evolving sector from 2026 through 2032.
For executives, investors, and strategic planners, understanding the trajectory of this market is not merely about tracking device sales. It is about anticipating shifts in regulatory frameworks, reimbursement policies, and competitive maneuvers in a consolidated industry. This article serves as a strategic preview, outlining the core dynamics and structural elements contained within the full research dossier, designed to empower high-level decision-making in 2026 and beyond.
The Macro Trajectory: Growth Anchored in Clinical Value
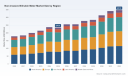
The global market for non-invasive bilirubin meters has demonstrated resilient growth over the past half-decade, reflecting broader trends in digital health adoption and neonatal care optimization. Historical data from 2020 to 2025 indicates a steady expansion in revenue, with the market establishing a robust foundation despite global supply chain fluctuations. As we look toward the forecast period of 2026 to 2032, the narrative shifts toward sustained acceleration.
Current projections suggest a compound annual growth rate (CAGR) that underscores the long-term viability of non-invasive screening technologies. The market value is expected to scale significantly by the end of the forecast window, driven by the replacement of invasive blood testing protocols with optical screening methods. This growth is not linear; it is punctuated by regulatory milestones and the adoption of new technologies that lower the barrier to entry for various healthcare settings. Our report dissects these revenue streams meticulously, providing a clear view of how value accumulates across different time horizons without exposing the specific sensitive forecasts available only in the full document.
Segmentation Dynamics: Product, User, and Regional Insights
A superficial analysis of market size is insufficient for strategic positioning. The true value of our research lies in the granular segmentation analysis that reveals where value is generated and consumed. The market is broadly categorized by product type, end-user environment, and geographic region, each presenting unique opportunities and challenges.
- Product Architecture: The market is dominated by handheld devices, which offer portability and point-of-care flexibility, essential for busy maternity wards and pediatric clinics. However, benchtop systems retain significance in high-throughput settings. The report analyzes the revenue contribution and strategic importance of each form factor.
- End-User Ecosystems: Hospitals remain the primary revenue anchors, utilizing these devices for repeated testing protocols where the lack of disposable probes offers long-term cost advantages. Clinics and pediatric centers represent a high-volume secondary segment, while home care settings are emerging as a frontier for expanded screening access.
- Geographic Distribution: Revenue is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct regulatory and reimbursement landscapes that influence adoption rates. Our analysis maps these regional revenue contributions to help strategists prioritize market entry or expansion efforts.
By understanding the interplay between these segments, organizations can identify high-growth niches. For instance, the shift toward handheld units in outpatient clinics versus the stability of benchtop systems in large hospital networks requires different product strategies and sales approaches. The full report provides the exact revenue splits and growth trajectories for each segment to guide these investments.
Competitive Landscape: Consolidation and Innovation
The competitive environment in the non-invasive bilirubin meter sector is characterized by a moderate to high degree of concentration. With top players commanding a significant share of the market revenue, barriers to entry exist, primarily driven by regulatory clearance and established clinical trust. However, innovation continues to disrupt the status quo, particularly through strategic collaborations and technological integration.
Our research profiles key industry participants, ranging from established medical giants to specialized device manufacturers. Companies such as Drägerwerk AG & Co. KGaA, Konica Minolta, Inc., and Philips represent the forefront of technological capability, often collaborating with partners to expand reach. Regional players like Beijing M&B Electronic Instruments Co., Ltd., AVI Healthcare, and Xuzhou Kejian Hi-tech Co., Ltd. highlight the growing manufacturing capacity and distribution networks in Asia. Meanwhile, companies like Hutchison Medical, Natus Medical Incorporated, and Mennen Medical Ltd. contribute to a diverse ecosystem of solutions.
Worldwide Non-invasive Bilirubin Meter Market
A critical development highlighted in our recent industry monitoring involves strategic alliances aimed at enhancing screening solutions. For example, recent collaborations combining traditional transcutaneous meters with smartphone-based tools indicate a shift toward integrated digital health ecosystems. This trend suggests that future market leaders will not just sell hardware but will offer connected solutions that facilitate data tracking and remote management.
The report details the specific product portfolios, including models like the Jaundice Meter JM-105 and the MBJ20, analyzing their positioning against competitors. It also evaluates the impact of manufacturing hubs in China and Europe on global pricing and supply stability. Understanding who holds the market share and how they are evolving is crucial for competitive benchmarking.
Regulatory and Reimbursement Drivers
Market growth in medical devices is inextricably linked to regulatory validation and financial viability. In the context of non-invasive bilirubin meters, regulatory clearance serves as a key differentiator. Certain devices have achieved specific FDA 510(k) clearances that allow for use in newborns as young as 35 weeks gestational age, setting a high bar for clinical safety and efficacy. Such certifications not only validate the technology but also influence procurement decisions in regulated markets like the United States.
Furthermore, alignment with clinical guidelines, such as those from the American Academy of Pediatrics (AAP), reinforces the utility of these devices. Objective measurements provided by transcutaneous bilirubinometers help identify at-risk infants accurately, supporting standardized care protocols. This clinical alignment is a strong selling point for hospital administrators seeking to reduce variability in care.
From a financial perspective, reimbursement policies and health economic data play a pivotal role. Evidence suggests that transcutaneous screening can lead to a reduction in hospital readmissions for light therapy, thereby lowering overall healthcare costs. Additionally, the capital equipment nature of these meters, which do not require disposable probes for repeated testing, offers a compelling total cost of ownership argument compared to invasive blood tests. Our report synthesizes these regulatory and economic factors, analyzing how they impact market penetration rates in different regions.
Strategic Implications for 2026 Decision Makers
As organizations plan their strategies for 2026, several key questions arise. How will the consolidation of market share among top players affect pricing power? Where are the untapped opportunities in emerging regions? What role will digital integration play in the next generation of devices? The Worldwide Non-invasive Bilirubin Meter Market report addresses these questions with data-backed answers.
For product managers, the segmentation analysis offers insights into where to focus R&D resources—whether on enhancing handheld ergonomics or improving optical sensor sensitivity. For market access teams, the regulatory and reimbursement section provides the evidence needed to negotiate with payers and hospital procurement committees. For investors, the market concentration data and growth forecasts help assess the attractiveness of potential targets or entry points.
The report also contextualizes the market within the broader neonatal care ecosystem. By understanding how bilirubinometers fit into the workflow of hospitals and clinics, stakeholders can better position their solutions to meet the practical needs of clinicians. This includes considerations for training, maintenance, and integration with existing electronic health records.
Worldwide Handheld Jaundice Detector Market
Conclusion: Access the Full Intelligence
The non-invasive bilirubin meter market stands at a pivotal juncture, balancing established clinical practices with emerging technological innovations. The data indicates a clear upward trajectory, supported by favorable clinical outcomes and economic efficiencies. However, navigating this market requires more than general trends; it requires precise intelligence on revenue splits, regional dynamics, and competitor strategies.
This overview provides a glimpse into the depth of analysis available in our full market research publication. To leverage these insights for your strategic planning, we invite you to access the complete report. Inside, you will find detailed forecasts, comprehensive competitor profiles, and actionable recommendations tailored to maximize your competitive advantage in the coming years.
Equip your leadership team with the knowledge needed to make informed decisions. Download the full Worldwide Non-invasive Bilirubin Meter Market report today to secure a comprehensive understanding of the opportunities shaping the future of neonatal screening.
For detailed analysis of this topic, please visit the official page: Worldwide Non-invasive Bilirubin Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: World Industrial Control Automation Small PLC Market Hits $4.52B in 2025, Set to Reach $6.73B by 2032 at 5.85% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for the 2026 Industrial Automation Landscape: Unlocking the Small PLC Market Opportunity
As industrial enterprises navigate the complex transition toward smart manufacturing, the decisions made in 2026 regarding control architecture will define operational competitiveness for the next decade. The Worldwide Industrial Control Automation Small PLC Market research report provides the foundational intelligence required to navigate this critical juncture. This analysis serves as a strategic preview of the comprehensive market study, highlighting the macro-economic trajectories, competitive pressures, and technological shifts that are reshaping the small programmable logic controller sector. For decision-makers in procurement, strategic planning, and engineering leadership, this report offers more than statistical hindsight; it delivers a forward-looking roadmap calibrated for the forecast period extending through 2032.
The Macro Trajectory: A Market in Structural Growth
The historical data from 2020 through 2025 establishes a clear baseline of resilience and expansion for the small PLC segment. The market has demonstrated consistent appreciation in revenue terms, moving from a foundational value of 3420.5 million USD in 2020 to 4520.0 million USD by 2025. This growth trajectory reflects the broader industrial adoption of compact automation solutions that balance functionality with spatial and budgetary constraints. Looking ahead to 2026, the market is projected to breach the 4919.83 million USD threshold, signaling an acceleration that underscores the sector's vitality.
The forward-looking assessment indicates a sustained compound annual growth rate of 5.85% throughout the forecast period ending in 2032. This growth is not merely linear; it represents an expansion driven by the integration of advanced connectivity features, the transition toward modular small PLC architectures, and the increasing reliance on compact PLCs for small to medium machine automation. By 2032, the market valuation is expected to reach 6729.37 million USD, a figure that highlights the enduring demand for scalable automation controls. Importantly, this macro growth masks varying regional and vertical dynamics that are explored in depth within the full research document, providing the granularity necessary to identify high-priority expansion zones without revealing the segmented percentages prematurely.
Competitive Dynamics and Architectural Shifts
The landscape of the small PLC market is characterized by a mix of established global conglomerates and specialized innovators, with market concentration indicating a moderate level of consolidation. The combined market share of the top three players stands at 48.5%, while the top five firms control 62.4%. This concentration suggests that while incumbent dominance is significant, there remains substantial room for differentiation through technology innovation and niche application targeting.
Plc Software Market
Key industry participants are actively reshaping their offerings to capture this growth. Siemens AG continues to lead with significant momentum, having recently delivered the new SIMATIC S7-1200 G2 compact PLC generation, which emphasizes space-saving design, increased communication capabilities, and enhanced performance scalability. In March 2026, Siemens unveiled the LOGO! 9, a next-generation intelligent logic controller featuring doubled function blocks up to 800, expanded I/O, a color touchscreen, and robust security enhancements including Secure Boot and user management. These developments target both basic automation tasks and small-scale industrial and building automation projects.
Rockwell Automation has expanded its Micro800 family with the introduction of Allen-Bradley Micro820 L20E controllers, offering faster performance, USB-C connectivity, and Class 1 implicit messaging to improve smart machine integration. Mitsubishi Electric Corporation supplies the MELSEC iQ-F and FX series, delivering high-speed processing, built-in Ethernet, and motion control for small to medium applications. Schneider Electric delivers Modicon M241 and M221 micro and compact PLCs that support advanced machine control with embedded Ethernet, CANopen, and Industry 4.0 connectivity.
Omron Corporation offers CP, NX, and NJ series, including the NX1P2 compact machine controller with built-in EtherCAT for precise motion control. ABB Ltd. provides compact PLC solutions often integrated with drives and robotics, while Beckhoff Automation showcases high-performance compact PLCs and PC-based control systems with TwinCAT for real-time automation in setups ranging from small to complex. Eaton Corporation offers XC150/XC152 series compact PLCs with SmartWire-DT connectivity for flexible automation tasks. Delta Electronics manufactures cost-effective compact PLCs with integrated motion and communication features, and WAGO Kontakttechnik provides PFC series compact controllers and I/O systems programmable as small PLCs using open standards.
Specialized players further diversify the ecosystem. Unitronics specializes in all-in-one PLC and HMI compact units, while Horner Automation offers X4 and other compact PLCs with integrated HMI. ifm efector supplies mini PLCs and compact controllers for sensor-integrated automation, Phoenix Contact provides compact solutions including Axioline and PLCnext, and IDEC Corporation manufactures micro and compact PLCs for machine and process automation. Each of these players contributes to the architectural dichotomy within the market, where the Compact PLC segment and the Modular Small PLC segment represent distinct value propositions tailored to different deployment complexities and scalability requirements.
Structural Segmentation: Decoding the Value Chains
The market segmentation reveals that the architecture of small PLCs is evolving to meet diverse industrial needs. The split between Compact PLC and Modular Small PLC architectures reflects a strategic choice for manufacturers: whether to prioritize a unified, space-efficient form factor or a modular approach that allows for incremental expansion. The report details these segments with specific revenue valuations and growth trends, enabling readers to assess which architecture aligns best with emerging industrial infrastructure trends. This analysis covers the underlying demand drivers for each architectural type and how they are influenced by raw material availability and technological constraints.
Industry vertical analysis provides equally critical insights. The report dissects the contributions of key sectors such as Packaging, Food and Beverage, Electronics and Semiconductor, Automotive, Pharmaceuticals, and Others. Each vertical presents unique automation challenges and regulatory requirements that influence PLC selection. For instance, the Electronics and Semiconductor vertical is heavily influenced by the availability and performance of semiconductors, particularly microcontrollers and industrial-grade ICs, which serve as the core component in small PLCs. The global industrial microcontroller market is valued at 10.2 billion USD in 2025 and is projected to reach 20.6 billion USD by 2035 at a 7.4% CAGR, driven largely by automation demand. This upstream dynamic creates a favorable environment for PLC manufacturers, though supply chain resilience remains a focus given that global semiconductor supply chain investments exceed 1.5 trillion USD from 2024 to 2030 to diversify production away from dominant Asian sources.
By examining these vertical splits and regional distributions in the full report, procurement and strategy teams can identify concentrated demand clusters and evaluate the relative maturity of automation adoption across different geographies without relying on high-level averages that obscure actionable regional nuances.
Macro Drivers and Regulatory Pressures Shaping 2026 Dynamics
Several concurrent macro trends are accelerating the adoption of small PLC-based automation. Labor shortages in manufacturing are compelling enterprises to invest in automation solutions that enhance productivity, enable predictive maintenance, and optimize energy usage. Industry 4.0 and 5.0 initiatives are increasingly emphasizing human-centric and sustainable control systems, pushing small PLCs to evolve beyond simple logic execution toward integrated intelligence. The push for sustainability is further reinforced by increasing focus on energy efficiency mandates and sustainability regulations in industrial automation. These pressures are driving small PLCs toward integrated motion control and power management features designed to reduce carbon emissions in factories.
However, the drive toward connectivity and advanced functionality introduces new risk vectors. Cybersecurity vulnerabilities have been identified in multiple small PLC series, including advisories regarding Mitsubishi MELSEC iQ-F units and security notifications concerning Schneider Modicon M241 and M251 series. These incidents are driving requirements for secure boot mechanisms, encrypted communication protocols, and regular firmware updates in industrial control systems. Manufacturers must now balance the benefits of open standards and Industry 4.0 connectivity with rigorous security postures. The full report analyzes how these regulatory and security dynamics affect procurement criteria, vendor evaluation, and long-term asset lifecycle management.
Furthermore, raw material dynamics, particularly the semiconductor supply chain, play a pivotal role in market stability. While the substantial investments in semiconductor production support resilient manufacturing of chips essential for PLC controllers, geopolitical efforts to diversify from dominant Asian sources introduce complexity into the supply landscape. This context influences lead times, cost structures, and the strategic positioning of players with robust supply chain management capabilities.
Latest Industry Developments: Innovation Signals for 2025-2026
Recent product launches and trade show showcases provide tangible evidence of the rapid innovation cycle characterizing this market. In addition to the previously mentioned Siemens and Rockwell releases, Beckhoff Automation showcased innovations at SPS 2025, including TwinCAT PLC++, new multi-touch panels, compact industrial PCs, and AI-integrated automation solutions. Siemens also presented its S7-1200 G2 and other automation solutions at the same event, focusing on digital transformation and basic automation enhancements. These developments signal a market that is not only growing in size but also evolving in sophistication, with AI integration and advanced human-machine interfaces becoming increasingly prevalent even in compact control forms.
Worldwide Industrial Control Automation Small PLC Market
For enterprises evaluating their 2026 automation strategy, these signals are critical. They indicate that the window for leveraging legacy compact PLC installations is narrowing, and that future-proofing investments requires alignment with vendors who are actively deploying secure, connected, and performant next-generation controllers. The report's competitive profiling and recent developments section allows readers to benchmark their current supplier relationships against the innovation velocity of the market leaders and challengers, ensuring that strategic partnerships are aligned with long-term technological roadmaps.
Why This Report is Essential for 2026 Decision-Making
The strategic value of the Worldwide Industrial Control Automation Small PLC Market report lies in its ability to synthesize macro growth indicators, segmentation precision, competitive intelligence, and regulatory context into a cohesive decision-support framework. For executives planning capital expenditure for 2026 and beyond, the report answers critical questions: Which architectural approach is gaining share in specific industrial contexts? How are regional demand patterns evolving relative to global averages? What are the implications of cybersecurity mandates on vendor selection? How do raw material supply chain dynamics affect total cost of ownership?
The report provides the actionable detail necessary to move beyond generalizations. It dissects the growth contributions of regions such as Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, and quantifies the revenue associated with each industry vertical. While this preview establishes the market's direction and scale, the complete dataset reveals the specific growth rates, value distributions, and competitive positioning metrics that are essential for granular strategy formulation. Readers seeking to validate market entry opportunities, optimize procurement portfolios, or assess the risk exposure of their current automation vendors will find the full segmentation and company-level analysis indispensable.
In an environment where the total market is projected to expand significantly through 2032, the ability to discern the drivers behind that growth separates reactive organizations from proactive market leaders. This report equips decision-makers with the intelligence to anticipate shifts, mitigate risks related to security and supply, and capitalize on the opportunities presented by labor constraints and sustainability mandates.
From Insight to Action: Accessing the Full Intelligence
The analysis presented here offers a high-level view of the market's structural health and strategic importance. However, the depth required to execute a winning strategy in 2026 demands access to the complete market research. The full report contains detailed revenue breakdowns for every region and industry vertical, precise architectural segment valuations, comprehensive company profiles with strategic assessments, and a thorough examination of market concentration dynamics. It also incorporates a robust methodology that ensures data reliability across the historical and forecast periods.
To obtain the specific growth rates, regional share percentages, vertical revenue figures, and competitive benchmarking data that will inform your organization's 2026 planning, we invite you to access the complete Worldwide Industrial Control Automation Small PLC Market report. The full document transforms the macro trends and competitive signals highlighted in this preview into a precise instrument for strategic advantage, allowing your team to navigate the small PLC market with confidence and clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Control Automation Small PLC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Smart Carry-on Bags Market Hits $1.45B in 2025 with 13.42% CAGR to 2032
By PW Consulting, 2026-09-17
Global Smart Carry-on Bags Market: Strategic Intelligence for 2026 and Beyond
The global travel accessories industry is undergoing a profound technological transformation, driven by the convergence of mobility, connectivity, and stringent safety regulations. At the forefront of this evolution is the smart carry-on bag segment, a category that has rapidly shifted from a niche novelty to a mainstream necessity for the modern traveler. As businesses navigate an increasingly complex landscape defined by fluctuating consumer preferences, evolving aviation safety standards, and intense competitive pressure, access to precise, forward-looking market intelligence is no longer optional—it is a strategic imperative.
PW Consulting is pleased to introduce our comprehensive Worldwide Smart Carry-on Bags Market research report, a definitive resource designed to equip executives, product strategists, and investors with the actionable insights needed to capitalize on the opportunities emerging in 2026 and throughout the forecast period ending in 2032. This article serves as a strategic preview of the report's depth, outlining the macroeconomic trajectory, competitive dynamics, and regulatory forces shaping this high-growth market.
Macroeconomic Trajectory: Sustained Expansion Through 2032
The smart carry-on bags market has demonstrated remarkable resilience and growth acceleration over the past half-decade. Our analysis tracks historical performance from 2020 through the base year of 2025, revealing a consistent upward trajectory that underscores the segment's maturation. Market revenue has expanded substantially over this period, reflecting the broader integration of technology into travel goods and the rising disposable income of frequent flyers worldwide.
Looking ahead, the market is projected to maintain robust momentum. The compound annual growth rate (CAGR) for the forecast period spanning 2026 to 2032 is estimated at 13.42%, signaling a period of sustained double-digit expansion. This growth rate is supported by multiple reinforcing factors, including the post-pandemic recovery of business and leisure travel, the increasing sophistication of smart hardware, and the growing consumer willingness to pay a premium for convenience-centric travel solutions. Revenue valuations across the forecast horizon indicate a clear pathway toward significant market valuation by the early 2030s, presenting a compelling window for stakeholders to position themselves advantageously.
Worldwide Smart Carry-on Bags Market
However, raw growth figures only tell part of the story. The true strategic value lies in understanding the underlying drivers, the shifts in regional demand patterns, and the technological adoption curves that will dictate market share distribution. Our report deconstructs these macro trends with granular precision, offering a roadmap that aligns corporate strategy with foreseeable market realities.
Report Contents: A Framework for Actionable Decision-Making
The Worldwide Smart Carry-on Bags Market report is structured to provide a holistic yet focused analysis of the industry ecosystem. Beyond high-level sizing, the study delivers a multi-dimensional perspective that addresses the critical variables influencing commercial success. Readers will gain access to detailed segmentation analysis that dissects the market across key dimensions, including technology integration, sales channel performance, and regional demand characteristics.
The technology landscape within smart carry-on bags is particularly dynamic. Our report evaluates the adoption and commercial impact of features such as GPS and Bluetooth tracking, USB charging capabilities coupled with integrated power bank pockets, digital weight sensors, and advanced biometric or remote locking systems. Understanding the relative market penetration and consumer valuation of each technology cluster is essential for product development teams prioritizing feature roadmaps and for marketing divisions crafting value propositions. The report further examines how these technologies interplay with airline compliance requirements, a critical consideration that directly affects product design and market accessibility.
In addition to technological segmentation, the study provides an in-depth assessment of sales channel dynamics. The shift toward online e-commerce platforms has reshaped how smart luggage is distributed and discovered, yet specialty stores and duty-free retail environments continue to play strategic roles in specific consumer segments. By analyzing the revenue contributions and growth trajectories associated with each channel, the report enables stakeholders to optimize their go-to-market strategies and allocate resources toward the most effective distribution pathways.
Geographically, the report offers a nuanced view of regional market landscapes, highlighting the distinct growth rates, consumer behaviors, and competitive intensities that characterize different territories. This regional granularity allows multinational corporations to tailor their market entry or expansion strategies with precision, while regional players can benchmark their performance against global trends.
Competitive Landscape: Navigating an Evolving Roster of Innovators
The smart carry-on bags market is characterized by a diverse array of established luggage manufacturers, premium lifestyle brands, and technology-forward startups, each pursuing distinct value propositions and business models. Our report provides detailed company profiles and competitive assessments for key industry participants, offering stakeholders a clear view of the strategic positioning and product innovations that define the current market phase.
Leading the premium segment are firms such as Samsonite International S.A. and TUMI Holdings, Inc., which have leveraged their brand heritage to introduce smart lines that blend connectivity, security, and durability. Samsonite's EVOA TECH series, for example, integrates built-in weighing scales, fingerprint TSA locks, Bluetooth proximity trackers, and USB charging capabilities, reflecting a comprehensive approach to traveler convenience. TUMI continues to target the business traveler demographic with offerings that emphasize connectivity and charging functionality within a sophisticated design language.
Direct-to-consumer and premium lifestyle brands have also made significant inroads. Away Travel Inc. has built a strong market presence through durable polycarbonate designs and smart features like removable batteries for USB charging, coupled with an organized interior ecosystem that appeals to both functionality and aesthetics. Similarly, Arlo Skye Inc. and Delsey Paris have focused on delivering airline-compliant smart carry-ons, with Delsey notably expanding into lithium-free connected options such as its Pluggage line, a strategic response to tightening battery regulations.
Other notable players include Travelpro International, Inc., whose Platinum Elite series features external USB A and C fast-charging ports and dedicated patent-pending battery compartments designed for FAA compliance, and Heys, which markets its SmartLuggage series of hardside spinner carry-ons with integrated smart features tailored to airline-approved travel. European innovation is represented by Horizn Studios GmbH and Rimowa, the latter combining high-end aluminum construction with integrated smart elements that cater to the luxury segment. Meanwhile, Samsara Luggage, Inc. specializes in aluminum smart suitcases with app-based connectivity features, including movement alerts and opening notifications, appealing to security-conscious consumers.
At the intersection of mobility and luggage, Airwheel Holding Ltd. has pursued a differentiated path by developing rideable and motorized smart carry-on suitcases that incorporate smart mobility features, pushing the boundaries of what a carry-on can achieve. This diversity of approaches underscores the importance of strategic clarity: companies must decide whether to compete on premium luxury, technological integration, regulatory compliance, affordability, or mobility innovation, and our report provides the analytical framework to evaluate these strategic choices against market realities.
Industry Dynamics: Regulation, Innovation, and the Road Ahead
The smart carry-on bags market does not operate in a vacuum; it is deeply influenced by regulatory environments, industry events, and shifting safety protocols. One of the most critical dynamic factors shaping product design and market viability is the regulatory treatment of lithium-ion batteries. Guidelines from the International Air Transport Association (IATA) and various aviation authorities mandate that lithium-ion batteries in smart luggage must be removable for checked baggage acceptance. Non-removable batteries restrict bags to carry-on only, with capacity limits typically capped at 100 Wh. These requirements have compelled manufacturers to engineer battery compartments and connectivity solutions that align with safety standards without compromising user experience.
These regulatory pressures intensified further with effective updates to dangerous goods regulations in 2026, which tightened rules for lithium batteries and power banks in smart luggage across multiple aviation authorities. In parallel, individual carriers have moved to enforce stricter policies; airlines such as Frontier and Spirit have explicitly prohibited smart luggage with non-removable lithium batteries as either carry-on or checked baggage due to safety risks. These regulatory developments have direct implications for product portfolios, requiring ongoing compliance monitoring and, in some cases, product redesigns or the introduction of alternative battery chemistries.
Beyond regulation, industry events continue to signal the pace of innovation. The 2025 Travel Goods Show, organized by the Travel Goods Association, featured record-breaking new product launches and innovations from luggage brands, with a notable emphasis on smart and tech-enabled carry-ons. Such gatherings highlight the industry's commitment to pushing technological boundaries while responding to consumer demand for smarter, more secure, and more convenient travel gear.
Consumer media and review platforms also play a vital role in shaping market perception and purchasing decisions. In March 2026, Travel & Leisure published updated testing and recommendations for smart luggage pieces, highlighting products such as the Heys SmartLuggage, the Aotos L2 rideable suitcase, and the July Carry On with CaseSafe. These independent evaluations help refine consumer expectations and influence brand visibility, making real-time awareness of media narratives an important component of market strategy.
Strategic Imperatives for 2026 and the Forecast Horizon
As the market moves through its forecast period spanning 2026 to 2032, executives and strategists must address several foundational questions. How will regulatory evolution reshape the competitive balance between brands that have already embraced removable battery architectures and those that lag? Which technology features will deliver the strongest return on investment as consumers become more discerning about their smart luggage purchases? How will channel strategies adapt as e-commerce continues to capture share while specialty and duty-free retail maintain relevance in specific contexts? And how should companies position themselves regionally to maximize growth in markets with differing travel behaviors and purchasing power?
The Worldwide Smart Carry-on Bags Market report is designed to answer these questions with rigor and clarity. It provides the data-driven foundation necessary to evaluate investment priorities, align product development with emerging standards, and anticipate shifts in competitive dynamics before they become apparent in public market signals. The study also examines market concentration metrics, offering context on the degree of consolidation and the strategic implications of competitive density within the industry.
Luggage Bags Market
Market leaders and challengers alike will find value in the report's structured approach to forecasting, segmentation, and competitive benchmarking. Whether the objective is to identify white-space opportunities, refine pricing and feature strategies, optimize distribution networks, or assess the viability of new market entries, the intelligence contained within this study is calibrated to support decisive action.
Access the Complete Intelligence
This overview provides a high-level perspective on the growth trajectory, competitive dynamics, and regulatory forces defining the worldwide smart carry-on bags market. However, the full strategic value of this research lies in its detailed segmentation analysis, proprietary forecasts, regional breakdowns, and in-depth company evaluations—elements that are essential for translating market awareness into executable strategy.
We invite industry executives, product leaders, investors, and analysts to access the complete report for a comprehensive exploration of the data, insights, and recommendations that will shape decision-making throughout 2026 and the forecast period extending to 2032. PW Consulting remains committed to delivering the analytical precision and strategic clarity necessary to navigate complex markets with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Carry-on Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FPSO Market to Hit $21.1B by 2032, Powered by 7.34% CAGR and Deepwater Growth
By PW Consulting, 2026-09-17
Strategic Imperatives in the Global FPSO Market: Navigating Growth Through 2032
The global offshore energy landscape is undergoing a structural transformation, driven by the interplay of deepwater resource development, evolving service delivery models, and shifting macroeconomic conditions. As operators seek to maximize asset utilization while managing capital expenditure, Floating Production Storage and Offloading (FPSO) equipment has emerged as a critical enabler of offshore field development. The Worldwide Floating Production Storage and Offloading Equipment Market study provides a comprehensive lens into this evolving ecosystem, offering decision-makers the analytical rigor required to navigate the forecast period from 2026 through 2032.
Our latest market research captures the momentum building across the sector. The overall market valuation expanded from approximately US$9.0 billion in 2020 to an estimated US$12.9 billion in 2025, reflecting sustained demand across multiple offshore basins. Looking ahead, the market is projected to follow a compound annual growth rate of 7.34 percent, reaching a substantial valuation by the end of the forecast window. This trajectory underscores a sector that is not merely recovering from cyclical downturns but is being reshaped by structural demand drivers, technological standardization, and changing commercial arrangements.
The strategic value of this analysis lies in its ability to translate macroeconomic and project-level signals into actionable intelligence. For executives evaluating capacity allocation, supply chain partnerships, or fleet expansion strategies, the report delineates where value pools are forming, which commercial models are gaining traction, and how competitive dynamics are consolidating around a set of capable, globally positioned players. Rather than offering static snapshots, the study maps the interplay between equipment categories, water depth classifications, and regional project pipelines, enabling stakeholders to anticipate shifts in procurement timing, scope definition, and risk allocation.
Market Trajectory and Core Dynamics
The growth path reflected in the data is neither linear nor uniform. Market expansion between 2020 and 2025 was characterized by incremental gains punctuated by project sequencing decisions, contract negotiation cycles, and the influence of input cost dynamics. Going forward, the forecast period reveals a more pronounced acceleration, with yearly valuations climbing steadily as project awards translate into fabrication, conversion, and installation activity. This pattern highlights the importance of understanding lead-time sensitivity and the cascading effects of final investment decisions on equipment demand.
Worldwide Floating Production Storage and Offloading Equipment Market
Several structural dynamics are reshaping how FPSO projects are conceived and executed. Lease-and-operate contracts have gained considerable share in recent award cycles, reflecting a broader industry preference for models that reduce upfront operator capital exposure while transferring operational responsibility to specialized providers. This shift toward turn-key, lease-based arrangements is altering the risk-reward calculus for both operators and equipment suppliers, favoring entities with strong execution track records, financial flexibility, and the ability to manage long-duration charters.
Regional content requirements and local supply chain development continue to influence project economics in key basins. In certain jurisdictions, regulatory frameworks designed to foster domestic industrial capacity can increase project budgets while simultaneously expanding the pool of trained personnel and supporting suppliers. Understanding these trade-offs is essential for bidders and investors evaluating entry strategies, as compliance costs and schedule implications can materially affect bid competitiveness and margin structures.
Macro energy pricing and supply environment conditions further modulate investment decisions. Variations in benchmark crude pricing and gas market dynamics influence the economic viability of offshore development schemes, particularly for projects with higher breakeven thresholds. At the same time, the push toward decarbonized operations is starting to inform equipment specification decisions, with operators increasingly favoring concepts that reduce greenhouse gas emissions intensity through electrification, process optimization, and integrated subsea-to-topsides design. These considerations are becoming embedded in procurement criteria and are reshaping the competitive differentiation of equipment and service providers.
Equipment Segmentation, Water Depth, and Geographic Distribution
The FPSO equipment market is inherently multi-dimensional, spanning process equipment, mooring and marine systems, power generation and distribution, and safety and control systems. Each category carries distinct technology requirements, supply chain dependencies, and margin profiles. Process equipment typically anchors the scope definition of an FPSO, reflecting the central role of separation, treatment, and process control in field development plans. Mooring and marine systems remain critical to station-keeping reliability and operational safety, particularly in exposed environments and ultra-deepwater settings. Power generation and distribution systems, alongside safety and control architectures, are increasingly scrutinized for their contribution to overall energy efficiency and compliance with evolving operational standards.
Water depth classification further differentiates demand patterns and engineering complexity. Shallow water projects continue to support a meaningful share of activity, often leveraging mature designs and established fabrication pathways. Deepwater deployments represent the largest demand concentration, reflecting the migration of development activity into more challenging environments where FPSO flexibility offers distinct logistical and economic advantages. Ultra-deepwater applications, while smaller in relative terms, are characterized by higher technical barriers, customized engineering, and longer execution cycles, making them focal points for specialized contractors and technology leaders.
Geographic distribution of demand is similarly varied, with activity concentrated across multiple offshore basins. Latin America remains a dominant demand center, supported by extensive pre-salt programs and ongoing fleet expansion. Asia Pacific continues to contribute a significant share, driven by regional field developments and conversion activity. Africa maintains a steady presence as operators advance new projects and extend the life of existing facilities. Europe and the Middle East and North America region also represent relevant demand pockets, often associated with specific field developments, conversion opportunities, and technology demonstration projects. Importantly, the relative weight of these regions is not static; it evolves with the timing of final investment decisions, the pace of regulatory approvals, and the competitive dynamics of local content and supply chain readiness.
Worldwide Subsea Well Access And BOP System Market
Commercial Models and Project Delivery Evolution
The way FPSO capacity is procured and operated has become as strategically important as the equipment itself. Operators are increasingly evaluating total cost of ownership, schedule certainty, and operational flexibility when selecting between newbuilds, conversions, and lease-based arrangements. Conversion programs offer potential schedule and cost advantages by repurposing existing hull structures, while newbuilds provide design freedom andthe ability to incorporate latest-generation process and decarbonization features. The choice between these pathways often hinges on fleet availability, yard capacity, hull integrity assessments, and the specific production profile of the target field.
Standardization initiatives are beginning to influence procurement efficiency. The emergence of standardized hull concepts and modular delivery approaches is reducing engineering redundancy, compressing cycle times, and improving predictability for repeated project types. For suppliers and operators alike, standardization can unlock economies of repetition, simplify spare parts management, and enhance the bankability of lease-and-operate structures by reducing performance uncertainty across multiple units.
At the same time, the industry is witnessing the continued maturation of integrated delivery models. Engineering, procurement, construction, installation, and commissioning scope is increasingly bundled across multiple disciplines, including subsea systems, topsides, hull fabrication, and marine operations. Such integration can reduce interface risk, improve schedule alignment, and facilitate single-point accountability, but it also demands robust project controls, supply chain coordination, and commercial structuring. Stakeholders evaluating partnership strategies should assess not only technical capability but also the commercial architecture through which risks and rewards are shared across the project lifecycle.
Competitive Landscape and Key Players
The FPSO market is defined by a mix of specialized offshore service companies, major shipbuilders, and operator-driven project constituencies. A consolidated set of firms commands a significant share of activity, with the top three participants accounting for roughly 38.4 percent of market revenue and the top five reaching approximately 52.15 percent. This concentration reflects the capital intensity, technical complexity, and execution risk associated with FPSO projects, which tend to favor organizations with established fleet management capabilities, strong balance sheets, and long-term operator relationships.
SBM Offshore stands out for its global leadership in FPSO design, engineering, construction, installation, and lease/operate models, supported by standardized hull concepts and a substantial backlog anchored in deepwater projects across Guyana and Brazil. MODEC has built a strong reputation in EPCI and charter/operate arrangements, particularly for ultra-deepwater and harsh environment applications, with multiple active units and recent contract wins in Brazil pre-salt and Guyana. BW Offshore continues to provide FPSO ownership, leasing, and operations, with an active footprint across Brazil, Africa, and advancing projects such as Bay du Nord, while Yinson Holdings has expanded its leasing and operations portfolio with recent Brazilian deployments including Anna Nery and Maria Quiteria units.
Bumi Armada contributes design, construction, and operations capabilities with a focus on Southeast Asia and international markets, and Bluewater Energy Services delivers specialized turret mooring systems and FPSO/FSO units with expertise in harsh environments and marginal field developments. On the engineering and integration side, Saipem offers integrated EPCI services spanning subsea and topsides across multiple offshore basins, while TechnipFMC provides subsea and topside integration often in partnership with hull specialists. Keppel Offshore & Marine and Samsung Heavy Industries represent major shipyard capabilities in FPSO construction and conversions, supporting Asian and global projects, and HD Hyundai Heavy Industries adds significant capacity for deepwater hull and topsides fabrication.
The operator side is equally influential. Petrobras remains a major charterer and operator of FPSOs in Brazil's pre-salt fields, with an extensive fleet and an ongoing newbuild program, including recent final investment decisions on SEAP-scheme units awarded to SBM Offshore under build-operate-transfer arrangements. ExxonMobil continues to drive significant demand through multiple FPSO developments in the Guyana Stabroek block. These operator-led programs not only shape demand volumes but also influence technology specifications, procurement timing, and the competitive positioning of equipment and service providers.
Recent Project Developments and Demand Signals
Recent milestones illustrate the pace and direction of market activity. In early 2026, Petrobras reached a final investment decision on the SEAP scheme, awarding SBM Offshore the P-81 and P-87 FPSOs under a build-operate-transfer model, reinforcing the continued expansion of Brazil's pre-salt fleet and the preference for collaborative delivery structures. Around the same time, Hunting secured a significant equipment supply contract for an FPSO offshore Guyana, highlighting the breadth of demand across different equipment categories and the continued inflow of fabrication and supply awards tied to major operator programs.
In the second half of 2025, MODEC received an award for the FPSO Hammerhead for ExxonMobil in Guyana, contributing to a notable surge in order activity and underscoring the strength of ultra-deepwater demand in the region. BW Offshore advanced its Bay du Nord FPSO project with Equinor, completing pre-FEED activities and initiating long-lead equipment ordering, a signal that new project fronts are moving into execution-ready phases. Separately, the BW Opal FPSO arrived at the Barossa gas field and progressed through hookup and final commissioning activities ahead of first gas, demonstrating the operational transition from construction to production that characterizes mature project cycles.
Collectively, these developments point to a market where demand is being driven by multiple concurrent programs, with Brazil and Guyana acting as focal points, while additional basins contribute incremental but strategically relevant activity. For market participants, the implication is clear: visibility into award timing, scope composition, and delivery sequencing is essential for aligning capacity, securing contracts, and managing cycle-time risk.
Strategic Takeaways for 2026 Decision-Making
As organizations formulate their strategies for the 2026 to 2032 horizon, several priorities emerge. First, demand visibility should be anchored in a disciplined view of final investment decision timing, project award cycles, and the lag between contract execution and equipment fabrication. Second, commercial model selection is increasingly consequential, with lease-and-operate structures reshaping capital allocation and risk transfer; stakeholders should evaluate the implications for balance sheet exposure, operational control, and long-term profitability. Third, supply chain resilience and yard capacity must be assessed against the backdrop of concentrated demand in specific regions and water-depth segments, where competition for engineering talent, hull slots, and long-lead equipment can create bottlenecks.
Fourth, technological differentiation is becoming a decisive competitive factor. Standardization, electrification concepts, process efficiency improvements, and integrated subsea-to-topsides design are not merely engineering optimizations; they are becoming commercial differentiators that influence operator preferences and lease economics. Fifth, regulatory and local content environments require careful navigation, particularly in markets where compliance costs and domestic supply chain development intersect with project economics and schedule risk.
Finally, the concentration of market revenue among a limited set of players suggests that partnership strategy matters. Whether through joint ventures, EPCI alliances, charter structures, or technology partnerships, the ability to assemble credible, execution-ready consortia will be central to securing a position in a market where trust, track record, and financial strength are heavily weighted in award decisions.
The Worldwide Floating Production Storage and Offloading Equipment Market report is designed to provide the analytical foundation for these decisions. It integrates macro market size and growth trajectory with granular segmentation, competitive profiling, recent project developments, and sector-specific dynamics, enabling stakeholders to move from high-level awareness to targeted strategic action. By mapping where demand is forming, how it is being structured, and which organizations are positioned to capture it, the study equips executives, investors, and project planners with the intelligence needed to allocate resources, shape partnerships, and anticipate the next wave of market opportunity.
For detailed analysis of this topic, please visit the official page: Worldwide Floating Production Storage and Offloading Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trading to $2.3B by 2032: PW Consulting Notes 6.92% CAGR in Global Topical Dispenser Market
By PW Consulting, 2026-09-17
Strategic Intelligence for the Global Topical Dispenser Market: Navigating Growth and Precision in 2026 and Beyond
The worldwide topical dispenser market stands at a critical inflection point. As healthcare systems increasingly prioritize precise drug delivery, infection control, and patient-centric formulation design, the mechanisms that govern how creams, gels, lotions, and topical adhesives reach their intended site of action have evolved from simple packaging components into indispensable clinical enablers. For executives, procurement leaders, and R&D strategists operating across pharmaceutical, dermatology, cosmetics, and personal care value chains, understanding the structural forces shaping this segment is no longer optional. It is a core determinant of competitive positioning, supply chain resilience, and regulatory readiness through the end of the decade.
This article outlines the strategic rationale behind PW Consulting’s latest worldwide topical dispenser market study, a comprehensive intelligence framework designed specifically to equip decision-makers with actionable clarity for 2026 planning. Rather than offering static snapshots, the research maps the interplay of demand fragmentation, manufacturing precision, regulatory scrutiny, and competitive consolidation that will define the next seven years of market evolution.
The Macro Trajectory: Mapping a Seven-Year Expansion Cycle
Over the historical window from 2020 through 2025, the topical dispenser market demonstrated consistent upward momentum, reflecting cumulative shifts in compounding pharmacy workflows, hospital formulary modernization, and consumer-facing skincare innovation. That trajectory sets the stage for the forecast period spanning 2026 to 2032, during which the global market is projected to expand at a compound annual growth rate of 6.92 percent. By the close of the forecast horizon, total revenue is expected to surpass the two-billion-dollar threshold in USD terms, underscoring a market that has matured beyond niche clinical applications into a broadly integrated distribution ecosystem.
For strategic planners, the significance of these headline figures lies not in the numbers themselves but in what they reveal about underlying demand elasticity. Growth is being distributed across multiple innovation vectors: the continued adoption of airless pump architectures that protect sensitive active ingredients from oxidation and microbial contamination, the steady utilization of metered-dose tubes and click-dosing mechanisms that standardize compound preparation, and the expanding role of dual-chamber systems that maintain ingredient separation until point-of-use. Jar dispensers, droppers, and ancillary accessories continue to serve specialized workflows, but the center of gravity is clearly shifting toward dispensing technologies that deliver repeatable, dose-controlled output across varied base formulations.
The forecast window also exposes the market’s structural sensitivity to broader healthcare and industrial trends. Supply chain localization efforts, evolving pharmacopeial expectations for dose uniformity, and the growing intersection of human and veterinary compounding are all reshaping procurement calendars, manufacturing scale-up timelines, and regional distribution footprints. A rigorously segmented view of these dynamics is essential for distinguishing transient demand spikes from durable shifts in application mix, and for forecasting capital allocation with greater precision.
From Volume to Value: Why Strategic Precision Matters in 2026
Leadership teams operating in this space are increasingly asked to reconcile two competing imperatives: capturing volume growth while defending margin integrity through higher-value dispensing architectures. The transition is not merely technological; it is commercial, regulatory, and operational. As formulators and compounding organizations demand greater consistency in active-ingredient delivery, the economic premium associated with precision dispensing mechanisms becomes more pronounced. Simultaneously, the cost of non-compliance—whether through dose variability, inadequate sterile-barrier performance, or misalignment with quality management expectations—continues to rise.
A research framework built for 2026 decision-making must therefore move beyond aggregate sizing. It needs to isolate the operational drivers that determine which dispensing platforms gain traction in institutional versus decentralized compounding environments, how reimbursement structures influence formulary inclusion of topical agents paired with specific applicators, and which geographic corridors are experiencing the fastest reconfiguration of supply and demand balances. The strategic value lies in mapping the trigger points where product design, regulatory classification, and procurement economics intersect.
In practice, this means equipping regional managers with the context needed to evaluate whether a shift toward metered-dose or airless architectures aligns with local clinical workflows and sterilization capacity, helping product developers anticipate which formulation characteristics will require dispenser redesign, and enabling sourcing leaders to stress-test supplier qualification pipelines against evolving quality-system expectations. Without a clear view of these intersections, organizations risk over-indexing on legacy container strategies or underinvesting in the precision components that will define competitive differentiation as the market matures.
Inside the Research: Operational Intelligence for Cross-Functional Teams
The newly released PW Consulting study is structured to convert macro trends into practical decision support across multiple functional domains. Rather than functioning as a single-volume market summary, the report is designed as an operational intelligence toolkit that can be deployed by commercial, R&D, regulatory, and supply chain teams in parallel.
At its core, the research provides a detailed breakdown of the global market across its primary segmentation axes, mapping revenue distribution by geographic corridor and by dispensing technology category. The regional view captures divergent adoption patterns, procurement maturity, and the varying intensity of institutional demand, while the technology-level analysis isolates the relative positioning of airless pump dispensers, metered-dose tubes, dual-chamber systems, jar dispensers, and dropper-based accessories. This dual-lens approach enables readers to cross-reference where specific dispensing formats are gaining structural advantage and how regional demand profiles influence product-mix planning.
A parallel segmentation by end-use application situates the compounding and healthcare context within the broader commercial landscape. Pharmaceutical and dermatology applications, cosmetics and skincare workflows, and personal care utilization all draw on the same underlying dispensing infrastructure, yet they impose distinct requirements on dose accuracy, barrier performance, manufacturability, and end-user experience. Clarifying how these segments interact with the overall revenue base allows organizations to anticipate cross-segment demand spillover, identify adjacent market entry opportunities, and calibrate investment priorities with a realistic view of where growth is being generated and where it is merely ornamental.
The study also integrates a dedicated competitive landscape analysis, profiling organizations that are actively shaping product architecture, manufacturing capability, and go-to-market positioning. These profiles are paired with a chronological account of recent corporate developments, including new product introductions and regulatory milestones that signal shifts in the competitive baseline. For strategists evaluating partnership opportunities, supplier transitions, or competitive response scenarios, this timeline provides the context needed to distinguish one-off announcements from sustained positioning moves.
To support scenario planning, the research addresses the regulatory and reimbursement environment with applied granularity. Coverage spans device classification expectations for topical applicators and skin adhesives, quality management standards relevant to design and production, and the practical implications of dose-uniformity evaluations for dispenser selection in compounding workflows. Reimbursement considerations are also mapped, particularly where topical agents and associated applicators intersect with coverage policies that affect downstream demand. These elements are presented as decision variables rather than background noise, enabling teams to factor compliance and coverage risk directly into product and market strategy.
Finally, the report is built to support executive-level synthesis. It provides the connective tissue needed to translate data points into actionable conclusions: where concentration dynamics suggest platform-level competition, where regional variance indicates the need for localized supply strategies, and where technological differentiation is likely to become a determinant of customer retention and pricing power.
Competitive Architecture: Incumbents, Specialists, and the Push Toward Precision Manufacturing
The competitive landscape in the topical dispenser market is defined by a blend of established packaging and dispensing specialists, medical-device-oriented manufacturers, and niche players concentrated on compounding and clinical workflow optimization. This mix creates a market structure in which scale advantages in component supply and global distribution coexist with highly differentiated clinical engineering capabilities. Understanding how these tiers interact is essential for anticipating pricing behavior, partnership structures, and technology adoption cycles.
Among the profiled organizations, several illustrate the market’s direction of travel. Companies developing metered dosing applicators for creams, gels, and lotions are increasingly emphasizing dose uniformity and workflow integration for both human and veterinary compounding pharmacy applications. The focus on pharmacist and patient experience signals a broader shift from purely mechanical dispensing toward solutions that reduce preparation variability and streamline operational throughput. In parallel, suppliers of airless and semi-solid dispensing systems continue to highlight product protection, hygiene, and metered output as core value propositions for pharmaceutical skin treatments, reinforcing the clinical premium attached to containers that preserve formulation integrity.
The competitive field also includes providers of click-dosing and metered pump dispensers designed for both non-sterile and sterile compounded preparations, alongside manufacturers supplying airless metered dose pumps and lidded applicators tailored to compounding workflows. These product lines reflect the market’s sensitivity to dosing accuracy across different cream bases and the growing expectation that dispensing hardware should be evaluated for consistency rather than convenience alone. Supporting this ecosystem are porous plastic and fiber component manufacturers that engineer drug delivery reservoirs and applicator components for medical device integration, as well as organizations developing precision healthcare dispensing solutions for dermal applications and controlled-dosing devices for topical gels and creams.
Dispenser Pump Market
Contract manufacturing capability further shapes the landscape. FDA-registered, ISO 13485-certified manufacturers of injection-molded pharmaceutical and medical applicators provide the production discipline required to support Class I and Class II device supply chains. Their presence underscores the market’s dependence on quality-system maturity as a competitive differentiator, particularly as demand for precision applicators grows across regulated healthcare channels.
Worldwide Topical Dispenser Market
Recent corporate activity reinforces these structural themes. A notable product launch introduced a metered-dose topical applicator optimized for in-container automated compounding, with design choices explicitly oriented toward improving pharmacist workflow and patient experience. In parallel, regulatory activity surrounding topical skin adhesives—classified as Class II medical devices requiring premarket notification—illustrates the broader device-ecosystem context within which topical dispensers and applicators operate. These developments are more than isolated milestones; they indicate how product architecture, regulatory expectations, and workflow efficiency are converging into a new competitive baseline.
Concentration dynamics within the market suggest a landscape that is neither fully fragmented nor tightly consolidated. A meaningful share of revenue is captured by a defined tier of leading participants, while substantial remaining share is distributed across specialists and regional suppliers. For strategy teams, this implies that competitive advantage will increasingly depend on the ability to combine component reliability, dosing precision, and workflow compatibility, rather than competing on container cost alone.
Regulatory and Reimbursement Fault Lines as Strategic Variables
As the topical dispenser market matures, regulatory and reimbursement variables are moving from peripheral considerations to central strategic inputs. Device classification frameworks, quality management requirements, and dose-uniformity expectations directly influence which dispensing architectures can scale efficiently and which require additional validation investment. At the same time, reimbursement treatment for certain topical agents and their associated application methods can shape formulary decisions, compounding volume, and downstream demand for specific applicator types.
For manufacturers and distributors, the implication is clear: product strategy cannot be decoupled from compliance strategy. ISO-aligned quality systems, documentation discipline, and design controls are increasingly treated as market-access prerequisites rather than operational overhead. Similarly, understanding dose-accuracy performance across formulation types is becoming relevant not only for clinical outcomes but also for procurement justification in regulated environments. The market’s most agile participants are those that integrate regulatory foresight into product roadmaps early, allowing them to align dispensing capabilities with evolving expectations before compliance gaps become market barriers.
2026 Positioning: How to Use This Intelligence
The strategic utility of this research lies in its ability to convert a rapidly evolving market into a structured set of decision levers. For commercial leaders, the segmentation views clarify where demand is concentrated and where regional variance calls for differentiated go-to-market models. For R&D and product management teams, the technology- and application-level analysis identifies the performance attributes that will command premium positioning as compounding and clinical workflows demand greater consistency. For supply chain and procurement functions, the competitive profiles and manufacturing context support more disciplined supplier evaluation and risk allocation. For regulatory and market-access teams, the coverage of device classification, quality standards, and reimbursement dynamics provides the context needed to anticipate friction points before they affect launch timing or adoption.
To move from overview to operational advantage, organizations need the full analytical layer behind these themes: the detailed segmentation splits, the regional revenue architecture, the application-level demand mapping, and the competitive-event timeline that together form the study’s core intelligence spine. These components transform strategic narrative into precise planning inputs, allowing leadership teams to size opportunity, calibrate investment, and stress-test assumptions with confidence.
Access the Full Strategic Framework
The complete PW Consulting Worldwide Topical Dispenser Market study provides the detailed data architecture and cross-segment analysis required to translate market direction into executable strategy. For decision-makers responsible for portfolio planning, supply chain positioning, competitive benchmarking, and regulatory readiness through 2032, the full report delivers the granularity needed to move from observation to action. Readers seeking the precise segmentation values, regional revenue distributions, application-level demand breakdowns, and extended competitive intelligence should consult the full research release, where the underlying dataset and analyst commentary are available in complete form.
For detailed analysis of this topic, please visit the official page: Worldwide Topical Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Occlusion Spray Sales Hit USD 115.45M in 2025, Projected 5.28% CAGR Till 2032
By PW Consulting, 2026-09-17
Unlocking Precision: Strategic Intelligence for the Worldwide Occlusion Spray Market (2026-2032)
In the rapidly evolving landscape of digital dentistry and industrial 3D scanning, occlusion sprays have transitioned from simple diagnostic aids to critical enablers of precision manufacturing and clinical accuracy. As we step into 2026, the Worldwide Occlusion Spray Market stands at a pivotal juncture, characterized by steady growth, evolving regulatory standards, and a competitive landscape dominated by specialized dental innovation leaders. Our latest comprehensive market research study, "Worldwide Occlusion Spray Market," offers stakeholders a granular view of the opportunities, challenges, and strategic imperatives defining this sector over the forecast period from 2026 to 2032.
Worldwide Occlusion Spray Market
This article serves as a strategic preview, outlining the macroeconomic trajectory, competitive contours, and the actionable intelligence embedded within our full report. We invite industry executives, investors, and procurement leaders to explore how this analysis can sharpen decision-making in an environment where precision, compliance, and cost-efficiency are paramount.
Market Trajectory: Steady Expansion Driven by Clinical and Industrial Demand
The occlusion spray market has demonstrated resilient growth over the past five years, and our analysis projects this momentum to continue through the end of the decade. Valued at approximately 115.45 million USD in 2025, the market is poised to reach 121.57 million USD in 2026, reflecting a consistent upward curve. Over the full forecast window, the market is expected to expand at a Compound Annual Growth Rate (CAGR) of 5.28 percent, culminating in a projected revenue of 165.72 million USD by 2032.
This growth is underpinned by a confluence of factors. The global shift toward digital dentistry, including CAD/CAM workflows and intraoral scanning, demands highly accurate marking and scanning aids that reduce errors in prosthetic fabrication. Simultaneously, the industrial 3D scanning segment is increasingly adopting occlusion spray technologies for enhanced surface contrast and measurement precision. While the market base remains rooted in dental applications, the diversification of use cases and the ongoing modernization of dental laboratory and clinical workflows provide a robust foundation for sustained expansion.
It is important to note that while the headline growth figures are compelling, the true strategic value for decision-makers lies in understanding the velocity of growth across different operational contexts, the nuances of regional demand dynamics, and the shifting preferences in product specifications. Our full report dissects these layers, providing a roadmap for capitalizing on high-growth vectors without exposing the organization to unquantified risks.
Strategic Segments and Application Dynamics: Where Value Is Concentrated
Occlusion sprays are not a monolithic category. The market is segmented by type, application, and region, each with distinct performance characteristics and demand drivers. Our research identifies clear patterns in how these segments perform relative to one another, offering insights into where competitive advantages can be cultivated.
From a product type perspective, certain color variants have established dominant positions, reflecting their alignment with specific clinical and scanning requirements. Green-color sprays, for instance, have captured a significant share of the market, driven by their high visibility and widespread acceptance in both dental and scanning workflows. Red-color sprays follow closely, offering complementary contrast properties. White scanning sprays represent a specialized but growing niche, particularly relevant for digital surface preparation. Other color variants and specialized formulations continue to address niche performance needs, allowing manufacturers to differentiate through formulation innovation and packaging flexibility.
In terms of end-use applications, the market is primarily anchored in dental laboratories, which account for the largest share of demand. This dominance reflects the intensive use of occlusion sprays in the evaluation, adjustment, and finishing of crowns, bridges, dentures, and other restorations. Dental clinics represent a substantial secondary segment, where rapid in-office marking and occlusal verification drive consistent consumption. Meanwhile, the industrial 3D scanning application segment, though smaller in relative terms, is emerging as a strategic growth area, reflecting the crossover of dental-grade marking technologies into broader precision scanning environments.
Regional demand patterns further illustrate the market's structural characteristics. Europe currently commands the largest share of global revenue, supported by a mature dental infrastructure, stringent quality standards, and a strong presence of established manufacturers. North America follows, driven by high adoption rates of digital dentistry and a competitive procurement environment. The Asia Pacific region presents a dynamic growth story, with expanding healthcare access, increasing dental tourism, and growing investments in dental technology infrastructure. LAMEA markets, while smaller in absolute terms, offer long-term potential as awareness of advanced dental diagnostics and scanning aids increases.
The detailed segmentation analysis in our report goes beyond identifying who leads and who follows. It explores the interplay between product attributes, application requirements, and regional procurement behaviors, enabling stakeholders to pinpoint the most attractive entry points, expansion strategies, and product positioning tactics. However, the precise numerical allocations and region-specific revenue contributions are reserved for the full dataset, where stakeholders can conduct tailored scenario modeling and sensitivity analysis.
Competitive Landscape: A Concentrated Arena of Specialized Innovators
The occlusion spray market exhibits a moderately concentrated competitive structure, with the top three players collectively holding a significant share of total market revenue. The top five companies extend this influence further, underscoring the importance of brand reputation, product quality, and regulatory compliance in capturing and retaining market share. This concentration does not imply stagnation; rather, it reflects a market where incumbents have built strong technical moats through formulation expertise, clinical validation, and distribution partnerships. At the same time, the presence of multiple credible players creates opportunities for differentiation through innovation, customer service, and value-added solutions.
Among the leading companies, Pascal International, Inc. has established itself as a trusted provider of occlusion sprays designed for precise occlusal contact marking across a range of restorative applications. Its aerosol indicator marking spray is approved for intra-oral use, a critical credential in a market where safety and regulatory alignment are non-negotiable. The company's focus on both wet and dry field applicability demonstrates an understanding of the practical demands faced by dental professionals.
Bausch (Dr. Jean Bausch GmbH & Co. KG) brings a strong European heritage to the market, with its Arti-Spray occlusion articulating spray available in multiple colors and formulated to leave a thin, removable film. The product's compliance with the European Council Directive 93/42/EEC for medical devices, along with its use of physiologically safe ingredients and environmentally neutral propellants, positions it favorably in markets where sustainability and regulatory rigor are increasingly valued. This alignment with environmental and safety standards is not merely a compliance checkbox; it is a strategic asset that resonates with procurement teams and clinical stakeholders alike.
Renfert GmbH contributes to the competitive mix with its Occlutec occlusion spray, offered in green and red variants for clear, detailed marking of high spots and trouble areas on model castings, crowns, and bridges. The emphasis on clarity and diagnostic precision aligns with the needs of dental technicians and laboratory professionals who rely on consistent, interpretable markings to refine prosthetic fit. YETI Dentalprodukte GmbH complements this offering with its intense occlusal spray, which is water-soluble and adheres to a variety of surfaces, providing versatility in both clinical and laboratory settings.
DFS Diamon GmbH differentiates itself with Okklean occlusion spray, which is formulated to mark contact points without discoloring plaster models and without dissolving in water or alcohol. This characteristic addresses a specific pain point in dental laboratory workflows, where model integrity and long-term usability are critical. Vacalon, operating in the USA market, provides Quickcheck indicating spray that serves dual purposes: detecting high spots and evaluating contacts, while also functioning as a digital scan spray. This hybrid functionality reflects the broader industry trend toward multi-purpose solutions that streamline procurement and reduce workflow complexity. Indenco Dental Products rounds out the competitive field with contact-indicating occlusal sprays available in multiple colors and sizes, catering to the need for flexibility in marking high spots and occlusal contacts across diverse practice settings.
The competitive dynamics in this market are shaped not only by product performance but also by the ability to navigate regulatory frameworks, maintain supply chain reliability, and respond to shifting user preferences. Our report provides a deep-dive analysis of each key player's positioning, product portfolio breadth, and strategic moves, enabling stakeholders to benchmark their own capabilities and identify potential partnership or acquisition opportunities. The full competitive intelligence section includes proprietary assessments and strategic groupings that are not disclosed in this preview.
Regulatory and Market Dynamics: Navigating Compliance as a Competitive Advantage
Regulatory compliance is a defining feature of the occlusion spray market, particularly given the intra-oral application of many products. In the United States, occlusion spray products such as Reveal Occlusion Spray are permitted for intra-oral use under FDA guidelines for dental articulating materials, establishing a clear regulatory pathway for manufacturers seeking to serve the US market. This framework emphasizes safety, biocompatibility, and appropriate labeling, setting a baseline that all credible entrants must meet.
In Europe, the regulatory landscape adds an additional layer of scrutiny. Arti-Spray occlusion spray, for example, meets the requirements of the European Council Directive 93/42/EEC for medical devices and utilizes physiologically safe ingredients with environmentally neutral propellants. This compliance is a strategic differentiator, as European procurement decisions increasingly factor in environmental impact and ingredient safety alongside clinical performance. The trend toward greener propellants and non-toxic formulations is not confined to Europe; it is emerging as a global expectation, particularly among forward-looking dental laboratories and clinics that prioritize sustainability in their supply chains.
Beyond regulatory compliance, market dynamics are influenced by packaging norms and user preferences. Occlusion sprays are typically packaged in 75 ml aerosol cans, with some variants available in 23 g or 200 ml sizes. The availability of multiple sizes allows manufacturers to serve both high-volume laboratory users and smaller clinic-based consumers, while the range of colors green, red, blue, and white ensures that professionals can select the visibility profile that best matches their diagnostic or scanning needs. These seemingly granular details have strategic implications for inventory planning, distribution design, and product line optimization, all of which are addressed in the operational recommendations section of our report.
Report Capabilities: Actionable Intelligence for 2026 Decision-Making
Our Worldwide Occlusion Spray Market research is designed to be more than a static data repository. It is a decision-support tool that translates market complexity into actionable strategy. The full report includes a comprehensive suite of analyses and datasets, structured to support a wide range of strategic planning activities.
- Historical and forecast revenue data spanning 2020 through 2032, enabling robust trend analysis and forward-looking scenario modeling. The data is presented in a consistent currency framework and revenue unit structure, facilitating accurate aggregation and comparison across segments and regions.
- Deep-dive segmentation analysis by region, type, and application, with methodological rigor that allows stakeholders to evaluate growth drivers, demand elasticity, and competitive intensity within each segment. While this preview highlights directional trends, the complete dataset contains the precise numerical breakdowns necessary for financial planning and market entry assessments.
- Competitive landscape profiling of key companies, including headquarters location, product portfolio summaries, and strategic positioning insights. This section is structured to support benchmarking, partnership evaluation, and competitive response planning.
- Regulatory and compliance review, mapping FDA and European directive requirements to product attributes and market access implications. This component helps stakeholders assess regulatory risk and align product development or procurement strategies with evolving standards.
- Packaging, formulation, and application detail analysis, drawing on manufacturer catalogs and industry documentation to inform product specification decisions and user preference alignment.
- Strategic implications and recommendations tailored to different stakeholder roles, including market incumbents, new entrants, investors, and procurement leaders.
The report also incorporates a structured approach to market concentration analysis, providing context on how revenue is distributed among leading players and what this means for competitive strategy. By combining quantitative data with qualitative industry insights, the study offers a holistic view of the market that supports both operational planning and long-term strategic positioning.
Looking Ahead: Precision, Compliance, and Growth in the Occlusion Spray Market
As the Worldwide Occlusion Spray Market moves through the 2026-2032 forecast period, stakeholders face a landscape defined by steady expansion, regulatory sophistication, and a competitive environment that rewards precision and compliance. The projected growth trajectory, supported by a CAGR of 5.28 percent and a market size expected to exceed 165 million USD by 2032, signals that occlusion sprays will remain an essential component of dental and scanning workflows. However, realizing value in this market requires more than awareness of aggregate trends. It demands a nuanced understanding of segment performance, regional dynamics, competitive positioning, and the operational implications of regulatory and packaging norms.
Our full market research study provides the depth, structure, and actionable insight necessary to navigate this complexity. For executives evaluating market entry, product portfolio adjustments, or partnership strategies, the report offers a rigorous foundation for decision-making. For procurement leaders and clinical stakeholders, it delivers clarity on the product attributes and compliance credentials that matter most in a competitive bidding environment. And for investors seeking to understand the growth vectors and concentration risks within the sector, the study presents a comprehensive analytical framework.
Worldwide Micro Spray System Market
The occlusion spray market is not a commodity space. It is a specialized domain where formulation quality, regulatory alignment, and user-centric design determine long-term success. Our research is built to help stakeholders distinguish between incremental trends and transformative opportunities, ensuring that strategic decisions in 2026 and beyond are grounded in reliable, detailed, and forward-looking intelligence.
To access the complete dataset, segment-level analysis, competitive profiles, and strategic recommendations, we invite you to explore the full Worldwide Occlusion Spray Market report. The detailed intelligence within is designed to support confident, informed action in a market where precision is not just a product feature but a business imperative.
For detailed analysis of this topic, please visit the official page: Worldwide Occlusion Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RF Chip Inductors Market Hits $1.79B in 2025, 7.5% CAGR to 2032
By PW Consulting, 2026-09-17
Navigating the RF Chip Inductors Landscape: Strategic Intelligence for the 2026–2032 Cycle
Executive Perspective
The RF chip inductor market is entering a phase of disciplined expansion where volume growth, technological specificity, and supply chain resilience must be managed simultaneously. Based on our Worldwide RF Chip Inductors Market research, the sector is projected to move from approximately USD 1,794.5 million in 2025 to around USD 2,977.2 million by 2032, reflecting a compound annual growth rate of 7.5 percent. This trajectory is not merely a function of broader electronics demand. It is being redefined by high-frequency communication architectures, vehicle intelligence mandates, and the material and geopolitical pressures that now shape component sourcing decisions.
For senior leaders, procurement heads, product strategists, and investors, the market story is no longer about whether RF chip inductors matter. The question is where value will concentrate, how competitive positioning will shift, and which decisions made in 2026 will determine margin and optionality through the end of the decade. This article previews the strategic logic behind our latest study and explains how its structure supports high-stakes planning without exposing the granular intelligence that gives competitive advantage to paying stakeholders.
Why 2026 Is a Defining Planning Year
A Market Framework Built for Decision-Making
Any useful market study for 2026 must do more than present a forward revenue curve. It needs to connect historical behavior, structural demand drivers, and near-term market friction into a single operational lens. Our research framework was designed with that intent. The historical base from 2020 through 2025 provides a migration path that shows how the RF chip inductor market has consistently expanded across technology cycles, product generations, and regional manufacturing shifts. That history is valuable precisely because it exposes the pattern of acceleration and consolidation that often repeats in passive component markets when new communications standards and automotive electronics requirements converge.
From a planning perspective, the forecast window from 2026 through 2032 is where early decisions compound. Because the sector is moving toward roughly a USD 2.98 billion revenue envelope by 2032, even modest changes in sourcing strategy, qualification lead times, or technology mix can translate into meaningfully different cost positions and time-to-market outcomes. Our report translates that macro path into a structured environment where leadership teams can test assumptions around demand timing, component allocation, and portfolio prioritization rather than reacting to market signals after they have already reshaped the supply base.
Importantly, this study is built to support decisions at multiple levels of granularity. Executives can use it to validate top-down market direction, while operations and engineering teams can use its segmentation logic to think through technology choice, application exposure, and regional sourcing implications. The objective is not simply to describe the market, but to provide a reusable analytical scaffold that can inform product roadmaps, supplier negotiations, and capital allocation conversations throughout the forecast period.
What the Study Covers: From Market Structure to Execution
Segmentation Logic That Maps to Operational Reality
The research is organized around the dimensions that matter most to actual sourcing, design, and commercialization decisions. Rather than offering a single aggregate narrative, the report breaks the market into type, application, and region in a way that reflects how buyers evaluate trade-offs among performance, form factor, qualification burden, and cost.
On the product side, the study examines how wire-wound, multilayer, and thin-film chip inductor technologies differ in the contexts where they are most relevant. Each technology pathway carries distinct implications for high-frequency performance, miniaturization, manufacturing complexity, and qualification requirements. Instead of treating these categories as static labels, the report ties them to application needs and supply characteristics so that engineering and procurement teams can interpret them as strategic choices rather than catalog options.
The application perspective is equally practical. Communication-related devices, automotive electronics, industrial and IoT systems, and consumer electronics plus other end-use contexts each place different demands on RF chip inductors. Some prioritize high-frequency stability and noise management, others prioritize durability under vehicle-grade qualification regimes, and still others depend on cost-compressed volume delivery. By analyzing the market through application lenses, the study helps readers understand where demand intensity is structurally stronger and what that means for capacity planning, supplier dependencies, and launch timing.
RF Inductors Market
Regional analysis completes the picture by linking market size distribution to sourcing architecture and manufacturing footprint considerations. In practice, geography is inseparable from risk, lead time, logistics, and qualification strategy. The report situates regional dynamics within the broader supply chain environment so that decision-makers can assess not just where demand is concentrated, but where production, trade exposure, and input vulnerabilities intersect.
Competitive Positioning and the Shape of the Supply Base
Concentration, Differentiation, and the Players That Matter
Market structure is one of the most actionable elements of the study because it reveals where bargaining power, innovation tempo, and qualification advantage tend to reside. The RF chip inductor sector is characterized by a moderately concentrated competitive field, with the top five participants accounting for a substantial share of activity and the top three representing nearly half of the market. That level of concentration is significant. It suggests that while multiple suppliers remain available, strategic relationships, technical differentiation, and reliability credentials increasingly shape sourcing outcomes.
The report profiles a broad set of established and region-specific participants whose product footprints illustrate the competitive logic of the market. Japanese manufacturers such as Murata Manufacturing, TDK Corporation, and Taiyo Yuden continue to occupy prominent positions in multilayer and high-frequency RF inductor offerings, with product development emphasis on high-Q performance, miniaturization, and communication- and vehicle-relevant use cases. Murata, for example, commercialized its LQP02HQ_Z2 high-Q RF chip inductor series in a very compact form factor for in-vehicle communication devices, bringing AEC-Q200 qualification into mass production.
In the United States, suppliers including Bourns, Coilcraft, Vishay Intertechnology, Gowanda Electronics, and API Delevan illustrate the range of specialization available in the market. Bourns has advanced multiple multilayer chip inductor series built around advanced multilayer technology and monolithic construction, targeting high-frequency performance, compact size, and strong self-resonant frequency characteristics for RF and mobile applications. Coilcraft contributes high-performance RF inductor and magnetic component expertise oriented toward RF, microwave, and high-frequency signal processing environments. Vishay and Gowanda extend the competitive field with multilayer and wire-wound approaches as well as ceramic core solutions aimed at demanding RF, power, military, and medical requirements. API Delevan rounds out this group with RF inductors tuned for high-frequency analog circuits, signal processing, RFID, GPS, and radar applications, including qualified and custom options.
Worldwide RF Chip Inductors Market
European participation is represented by Würth Elektronik, whose RF inductor and passive component portfolio supports signal and communications applications across high-frequency chip inductor designs. Meanwhile, Taiwan-based suppliers such as Walsin Technology, ABC ATEC, and Chilisin Electronics, along with Shenzhen Sunlord Electronics in China, reflect the increasingly important role of regional manufacturers in RF inductor supply, spanning wire-wound ceramic chips, multilayer RF inductors, LTCC-based products, and broader communications-related components.
These company profiles are not included as marketing directories. They are used to show how product strategy, application targeting, and technology selection differentiate suppliers in a market where specifications, qualification records, and delivery reliability often matter as much as headline price. The report also tracks recent company-level moves so readers can connect competitor actions to broader market momentum. The recent product launches and commercialization milestones captured in the study demonstrate how the competitive field is actively responding to miniaturization, high-frequency performance, and automotive-grade requirements in parallel.
Market Dynamics: Materials, Regulation, and Risk Asymmetry
Why Structural Pressures Are Now Central to Strategy
No market study for 2026 can treat pricing and supply as background variables. In the RF chip inductor space, raw material behavior and regulatory direction are becoming core drivers of cost structure and availability. Early 2026 has already seen rising silver and copper costs interacting with strong AI, electric vehicle, and industrial demand, producing structural price adjustments across multilayer chip inductors and related passive components. Copper price movement on the London Metal Exchange has moved materially above late-2025 averages, feeding directly into inductor production economics. At the same time, ferrite core supply has tightened, extending delivery cycles for certain models and slowing inductive component production in some contexts.
These pressures create a risk asymmetry that decision-makers cannot afford to overlook. When input costs rise and lead times elongate, the cost of late planning increases as well. Buyers that rely on reactive sourcing are more exposed to allocation constraints, spot pricing, and qualification delays. Organizations that anticipate these dynamics can protect margins through design flexibility, dual qualification, inventory policy adjustment, and more deliberate supplier coordination. The report integrates these material and supply dynamics so that procurement and engineering teams can evaluate not only what the market size trajectory implies, but also what it will cost to access supply reliably.
Regulatory direction adds another layer of strategic relevance. EU RoHS and WEEE directives continue to influence the adoption of recyclable and low-toxicity materials in chip inductor production, reinforcing the idea that compliance is increasingly tied to material selection and manufacturing process choices. At a geopolitical level, Europe’s dependence on China for rare earth elements and high-purity ferrites remains a critical vulnerability, with export controls on materials such as gallium and certain rare earths classified as high supply risk. This context matters for any organization evaluating regional sourcing strategies or long-term supply resilience because it shows that component availability is no longer determined by factory output alone. It is also shaped by trade policy, material concentration, and the broader regulatory environment.
Strategic Applications of the Research for 2026 Decision-Making
From Intelligence to Action
The real value of this study lies in the decisions it helps organizations make more confidently. The report is intended to support:
- Portfolio and technology roadmapping decisions by linking RF chip inductor types to application requirements and future demand trajectories
- Sourcing and supplier strategy by clarifying where competitive concentration, specialization, and regional dynamics shape access and negotiation leverage
- Cost and risk planning by incorporating material price behavior, supply tightness, and regulatory shifts into scenario-based thinking
- Market entry, expansion, or partnership evaluation by identifying where demand intensity and technology needs are most pronounced
- Investment and capability prioritization by showing how market growth is distributed across application and technology pathways rather than treating growth as a monolith
In practice, these applications often converge. A product team may need to decide whether a design should emphasize one inductor technology over another; a sourcing leader may need to assess whether current supplier coverage is sufficient under tightening material availability; and a strategy group may need to evaluate whether regional exposure creates unacceptable risk in the context of trade and material controls. The study is structured to support all three discussions with a consistent evidence base.
How to Use This Intelligence Without Guesswork
Accessing the Full Analytical Depth
The preview above reflects the strategic architecture of the report, but many of the most useful analytical outputs are designed for users who need full segmentation context, competitive benchmarking, and forward-looking scenario support. The complete study goes beyond narrative to provide the structured detail that teams require for supplier scoring, demand modeling, risk assessment, and executive alignment.
Because the RF chip inductor market is being shaped simultaneously by technology differentiation, application growth, material cost pressure, and geopolitical supply exposure, the margin between good planning and reactive planning is widening. Organizations that understand the direction of travel early can align product development, procurement, and investment decisions before the market redistributes advantage.
To benefit from the complete assessment, including the detailed segmentation findings, company-level competitive analysis, and forecast-supported planning tools, we invite you to access the full Worldwide RF Chip Inductors Market research. The published report is designed to give leadership teams the depth they need to act with precision in 2026 and to build resilience through the 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide RF Chip Inductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


