



Category: market research
PW Consulting: Soft Touch Laminating Films Market to Hit $1.725B by 2032 at 6.8% CAGR
By PW Consulting, 2026-09-16
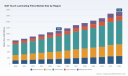
Strategic Foresight in a Billion-Dollar Tactile Economy: Why the Soft Touch Laminating Films Market Report Is Your 2026 Decision-Making Blueprint
In an era where consumer attention is measured in milliseconds and premium brand perception is increasingly tactile, the soft touch laminating films sector has graduated from a niche finishing option to a strategic growth vector. PW Consulting’s newly released market study arrives precisely when executives need to recalibrate portfolios, align sourcing strategies, and anticipate regulatory shifts. Spanning historical baselines through 2025 and projecting forward through 2032, this research translates granular supply-demand mechanics into actionable intelligence. For leadership teams navigating capital allocation, product development roadmaps, or regional expansion plans in 2026, the report functions less as a retrospective snapshot and more as a forward-looking compass.
The macroeconomic architecture of the market tells a clear story of compounding relevance. Measuring in the billions of U.S. dollars across the evaluation window, the trajectory reflects sustained expansion anchored by a forecast compound annual growth rate that underscores structural rather than cyclical momentum. Historical movement from the early 2020s through the 2025 baseline demonstrates consistent uplift, while the 2026 inflection and subsequent multi-year projections signal that demand generation is diversifying across value chains. Executives evaluating 2026 investments must recognize that this growth is not uniformly distributed across end-users or material architectures; rather, it is being shaped by intersecting forces of sustainability mandates, digital printing adoption, premiumization in branded packaging, and raw material volatility. Understanding where capital should be deployed, which product formats will command pricing power, and which geographic corridors will accelerate adoption requires the kind of layered analysis embedded in this study.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market research is structured for decision utility. Rather than aggregating high-level summaries, the study maps the commercial ecosystem across multiple analytical dimensions, enabling strategy, procurement, and R&D teams to cross-reference assumptions against validated market mechanics. The report’s architecture is designed to answer the questions that typically stall executive planning: which material families are gaining share and why, how application-specific demand is reconfiguring supply expectations, where regional manufacturing and consumption patterns are diverging, and what macroeconomic or regulatory triggers will reshape margin structures in the next planning cycle.
Soft Touch Laminating Films Market
- Forward-looking sizing and trajectory modeling that tracks the transition from historical baselines to the 2026 jump-off point and extends through the end of the decade, giving portfolio planners a quantified window for capacity allocation and scenario testing.
- Material-type evaluation that distinguishes performance characteristics, processing requirements, and end-market suitability across the dominant film architectures, allowing engineering and sourcing leaders to map technical trade-offs against commercial viability.
- Application-level demand mapping that surfaces how premium finishing, commercial print workflows, publishing, branded consumer packaging, and stationery are each shaping volume expectations and specification shifts.
- Regional corridor assessment that contextualizes consumption intensity, manufacturing footprint dynamics, and import-export considerations without overstating any single geography’s role, letting strategy teams prioritize where to focus commercial execution.
- Competitive benchmarking and strategic activity tracking that connects company-level moves to broader market positioning, highlighting how innovation, partnership models, and consolidation patterns are redefining competitive thresholds.
- Regulation and sustainability influence analysis that translates policy trajectories into operational implications, helping compliance, product stewardship, and innovation teams anticipate formulation requirements and material transition timelines.
Each analytical layer is built to interlock. Procurement leaders can trace how raw material cost exposure intersects with type-specific demand; product managers can evaluate how application preferences drive specification selection; and executive strategists can align long-range forecasts with near-term investment gates. The study deliberately avoids superficial rankings or static snapshots, focusing instead on dynamic relationships between technology readiness, demand behavior, and market structure.
Competitive Dynamics and the 2025–2026 Innovation Wave
The competitive landscape in this segment is defined less by sheer scale and more by targeted differentiation. A concentrated set of multinational and specialized manufacturers is competing on performance consistency, sustainability credentials, print compatibility, and application engineering. The study profiles a cross-section of firms whose recent strategic actions illustrate the direction of travel for the entire category.
3M has reinforced its focus on eco-friendly, UV-curable soft touch laminating films engineered for high-speed digital printing, aligning product development with the broader shift toward short-run, variable-data, and on-demand production workflows. Avery Dennison has leaned into integrated solution design, announcing a strategic partnership with a leading digital printing equipment manufacturer to synchronize digitally printable soft touch films with personalized packaging systems targeting luxury and premium-brand environments. LG Chem expanded its formulation capabilities through the acquisition of a niche startup specializing in bio-based coating technologies, signaling that sustainable surface engineering is becoming a core competency rather than a peripheral compliance exercise. Nobelus continues to anchor its position around specialized tactile films for labels and flexible packaging, while Dunmore Corporation’s DUN-SOFT engineered laminate portfolio emphasizes adjustable durability and scuff resistance for demanding application contexts. Cosmo Films and YIDU SAILS reflect the breadth of the supply base, offering versatile lamination options with an emphasis on graphic arts, packaging, and thermal lamination execution. On the application and conversion side, Remington Laminations, Binding101, and Presco UK demonstrate how pressure-sensitive characteristics, extreme-bond performance, and strong-adhesive premium finishes are being tailored to custom packaging, book covering, and commercial print requirements.
Laminating Machine Market
These company trajectories matter because they reveal where competitive edges are being built. Innovation is increasingly tied to compatibility with digital print engines, the ability to deliver consistent tactile quality across high-speed runs, and formulation pathways that reduce dependence on conventional petrochemical inputs. Strategic partnerships and targeted acquisitions are accelerating capability building in sustainability, coating science, and integrated packaging solutions. For 2026 planning, the implication is clear: differentiation will be judged not only by finish quality but also by environmental compliance readiness, printing workflow integration, and the capacity to support customized, premium-brand experiences at commercial scale.
Regulatory and Sustainability Pressures as Market Catalysts
The sector is operating under an intensifying regulatory backdrop that is actively reshaping formulation priorities and end-market adoption. European frameworks, including packaging waste directives and food-contact substance requirements, are pushing manufacturers toward advanced sustainable film technologies. Parallel legislation across multiple jurisdictions is raising compliance expectations and favoring material architectures that support recyclability, compostability, or reduced environmental burden. These regulatory dynamics are not merely constraints; they are becoming demand catalysts for next-generation soft touch laminates that can meet performance expectations while satisfying stewardship criteria.
At the same time, raw material economics remain a central variable in margin planning and pricing strategy. Exposure to petrochemical-linked cycles affecting polypropylene, polyester, nylon, EVA, and coating additives introduces cost variability that can influence both product architecture decisions and commercial terms. Organizations that map cost exposure to material type, application, and regional sourcing options will be better positioned to manage volatility without sacrificing performance. The study integrates these forces so executives can assess not just where the market is heading, but where sensitivity points exist within value chains and how strategic sourcing or formulation investment can mitigate risk.
What the Report Withholds—and Why That Is Strategically Useful
This preview is intentionally high-resolution on methodology, scope, and directional insight, while reserving the granular segmentation breakdowns for the full research document. Detailed regional, application, and type-level splits, along with precise revenue unit distributions, are embedded in the complete study to preserve analytical integrity and ensure that decision-makers rely on validated numbers rather than approximations. The strategic purpose of this structure is straightforward: enable executives to understand the market’s architecture and the logic behind its growth dynamics, while directing commercial and investment decisions to the source intelligence where the full evidence base, sensitivity considerations, and cross-segment interactions are presented.
In practice, this means the report functions as both a trust-building introduction and a decision funnel. Readers gain enough depth to assess relevance to their own portfolios, identify where further diligence is required, and recognize the commercial implications of recent moves by leading manufacturers. At the same time, the most granular intelligence remains accessible within the complete study, where it can be used for targeted sourcing reviews, product roadmap alignment, competitive positioning checks, and investment committee materials.
Positioning for 2026: Three Strategic Imperatives
As leadership teams convert market intelligence into action, three imperatives stand out. First, build formulation and sourcing strategies that treat sustainability not as a compliance add-on but as a commercial differentiator, especially where regulatory pressure is converging with brand-owner expectations for premium, responsible finishes. Second, evaluate digital-print compatibility and process reliability as core purchasing criteria, since high-speed printing adoption is reshaping volume expectations and performance thresholds across multiple applications. Third, use the multi-year forecast window to test scenario assumptions around capacity deployment, regional focus, and product-mix evolution, rather than relying on a single-point projection for long-range planning.
The soft touch laminating films market is expanding within a context where premium tactile experience, sustainability requirements, and production agility are becoming inseparable. PW Consulting’s study provides the analytical foundation to navigate that convergence with discipline. For executives preparing decisions in 2026, the full research document offers the segmented evidence, company-level benchmarks, and market-mechanics detail needed to convert direction into execution.
For detailed analysis of this topic, please visit the official page: Soft Touch Laminating Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Furniture Hardware Market Hits $195M in 2025, 3.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Global Furniture Hardware Market 2026–2032
The global furniture hardware market stands at a critical inflection point. As manufacturing ecosystems recalibrate and consumer expectations evolve, the components that quietly enable furniture functionality are becoming strategic differentiators rather than commodity inputs. For executives, procurement leaders, and product development teams operating in 2026, understanding where this market is heading is not a matter of curiosity—it is a prerequisite for resilient supply chain design, portfolio positioning, and capital allocation. The newly released Furniture Hardware Market research study delivers precisely that clarity, translating multi-year historical performance, forward-looking projections, and granular competitive intelligence into an actionable decision framework.
This article serves as a strategic preview of the full report. It outlines the macro trajectory, highlights the structural forces reshaping supply and demand, maps the competitive architecture, and details the operational contents that make this study a practical tool for 2026 planning cycles. What follows is designed to demonstrate the analytical rigor and corporate relevance embedded in the research—while deliberately reserving the exact segment breakdowns, revenue figures, and regional allocations for the complete publication. To secure the full dataset and execute targeted planning, stakeholders are encouraged to access the source portal directly.
Market Trajectory and the Case for Forward-Looking Intelligence
Over the past half-decade, the furniture hardware sector has demonstrated steady expansion, recovering from minor cyclical adjustments and building momentum through sustained demand for upgraded cabinetry, kitchen systems, and commercial furnishings. Historical tracking from 2020 through 2025 reveals a consistent upward arc, with market valuation rising into the range of 195 million USD by the base year. This trajectory sets the foundation for a forecast period extending to 2032, during which the market is projected to continue its measured expansion at a compound annual growth rate of 3.5 percent.
For strategic planners, these numbers are more than a historical recap—they signal durability. The projected valuation progression through 2032 reflects both volume retention in mature markets and incremental growth in regions undergoing densification, renovation cycles, and modernization of commercial interiors. Importantly, the forecast horizon captures the compounding effects of product innovation, regulatory alignment, and shifting procurement preferences. Because hardware is integrated early in the furniture design and sourcing lifecycle, market-side intelligence with a multi-year view gives manufacturers, distributors, and component specifiers the foresight needed to align production capacity, pricing strategy, and SKU rationalization before demand signals become visible at the retail or project level.
The report’s full publication preserves detailed regional and application-level allocations, enabling readers to identify where growth is most concentrated and which end-use environments are creating the strongest pull for specific hardware categories. Those precise figures are essential for scenario modeling and are therefore reserved within the complete study, ensuring that decision-makers can calibrate their strategic assumptions against verified baselines rather than approximations.
Structural Forces Redefining the Competitive Landscape
Behind the headline growth numbers lie several operational and structural dynamics that are actively reshaping how hardware is designed, manufactured, and specified. A dominant material reality continues to anchor the sector: steel remains the primary raw material for drawer slides, hinges, and runners, with supply trends holding stable amid broad-based manufacturing demand. This material continuity provides a predictable cost backbone, but it also means that sourcing strategy, supplier diversification, and quality assurance now matter more than ever in differentiating margins and protecting delivery reliability.
Simultaneously, regulatory frameworks are tightening the floor for acceptable performance. ISO 9001 certification has become a baseline requirement for manufacturers seeking to operate across international markets, reinforcing the need for documented quality management and consistent production controls. Complementing this, BIFMA and ANSI standards govern safety and performance expectations for furniture fittings, including hinges and slides intended for consumer use. Compliance is no longer a peripheral consideration; it is a market-access condition that influences supplier selection, export readiness, and risk exposure. The study details how these standards intersect with supply chain qualification processes and what they mean for long-term vendor relationships.
On the demand side, a clear innovation vector is pulling the market toward enhanced user experience and sustainability. Soft-close mechanisms and a growing preference for sustainable materials are driving product development, reinforced by energy-efficiency mandates and broader environmental expectations in both household and commercial settings. This shift is not cosmetic. It alters design requirements, testing protocols, and the value proposition that leading suppliers must articulate to design teams and end customers alike.
Cost pressures are also part of the equation. Skilled labor shortages in precision manufacturing for furniture hardware components are contributing to production cost increases in key regions. As tolerances tighten and functional complexity rises, the labor dimension of manufacturing becomes a strategic variable, influencing where capacity is expanded, how automation is prioritized, and which supplier profiles remain competitive over time. These dynamics are explored in depth within the report’s market dynamics section, where qualitative drivers are linked to the quantitative forecast to show how structural pressures translate into market outcomes.
Competitive Architecture and Strategic Positioning
The furniture hardware market is characterized by a concentrated yet diverse competitive field. Top-tier players hold a meaningful share of consolidated revenue, with the three largest firms accounting for approximately 54 percent of the market and the five largest reaching around 58 percent. This level of concentration indicates that scale, brand trust, and comprehensive product ecosystems play a decisive role in capturing specification share. At the same time, a broader set of specialized manufacturers competes on innovation, regional reach, and niche system solutions, making the landscape dynamic rather than static.
Among the leading organizations, several European and Italian manufacturers anchor the premium and mid-premium segments with broad portfolios spanning drawer runners, hinges, lift systems, sliding mechanisms, and interior accessories. Austria-based Blum stands out as a leading manufacturer of drawer runners, hinges, lift systems, and box systems for furniture, while Germany’s Hettich covers hinges, drawer systems, runner systems, sliding door systems, and folding door systems. Germany’s Häfele extends beyond fittings into architectural hardware, electronic locking systems, and kitchen appliances, reflecting a broader systems orientation. Italy’s Salice focuses on hinges, runners, and sliding systems; GRASS produces movement systems including hinges, drawer slides, flaps, and interior accessories; and FGV delivers hinges, drawer slides, drawer systems, hanging brackets, and sliding systems. Kesseböhmer contributes kitchen interior fittings, steel processing, and storage solutions, and Vauth-Sagel specializes in storage solutions, base cabinets, corner solutions, and pull-out systems. Italy’s Titus rounds out the European contingent with connectors, dowels, drawer and cabinet hardware, dampers, and levelers.
Furniture Hardware Market
Cabinet Hardware Market
On the Asia side, Taiwan’s King Slide manufactures drawer slides, undermount slides, ball bearing slides, and furniture fittings, while China hosts a strengthening cohort of producers. DTC is a leading manufacturer of hinges, drawer slides, drawer systems, and lifting systems; Taiming is recognized as a world-leading manufacturer of drawer slides and innovative opening and closing mechanisms; Jusen operates as an active manufacturer of furniture hardware components and systems; and Hi-Gold produces home hardware including kitchen and wardrobe fittings. ADAMS serves as an active provider of furniture fittings and hardware solutions. This geographic diversification underscores the market’s dual reliance on established European engineering heritage and expanding Asian manufacturing capacity.
Recent corporate and product developments make the competitive dynamics even more tangible. In January 2024, Hettich completed a merger with FGV, expanding its product portfolio in furniture fittings and strengthening its system-level offering. In May 2025, King Slide opened a new manufacturing facility in Houston, Texas to support U.S. market growth—an indicator of how critical regional capacity has become for serving near-term demand and reducing logistical friction. At the trade level, Vauth-Sagel introduced new VS ENVI waste bin systems and VS COR corner solutions at the interzum fair in November 2025, highlighting how product launches are increasingly focused on space optimization, functionality, and integrated storage.
Looking ahead, the industry calendar reinforces the pace of innovation diffusion. The 11th–12th March 2026 edition of the Furniture Component Expo in Telford, UK, showcased the latest furniture hardware innovations, while the 8th–11th September 2026 Furniture China Expo in Shanghai is set to feature new furniture hardware models and systems. These gatherings do more than display products; they reveal where specification trends are moving, which functional promises are gaining traction, and how quickly new mechanisms are reaching commercial readiness. The report integrates these corporate milestones and event signals into a competitive assessment that goes beyond headcount and revenue, examining portfolio breadth, regional footprint, and the strategic logic behind recent expansion and consolidation moves.
What the Full Report Delivers: A Practical Toolkit for 2026 Decisions
This study was constructed with execution in mind. Rather than stopping at high-level projections, it assembles a modular set of analyses that can be applied directly to sourcing strategy, product planning, market entry evaluation, and competitive benchmarking. The full report includes:
- A comprehensive market overview that frames current size, historical behavior, and forecast direction within a single, decision-ready narrative.
- Segmentation analyses that break down the market by type, application, and region, allowing readers to isolate the categories and geographies most relevant to their operations.
- Historical and forecast data tables covering the 2020–2032 window, providing a consistent basis for modeling volume assumptions, pricing scenarios, and capacity planning.
- A detailed competitive landscape section profiling the key companies, their headquarters, product focus, and strategic posture, along with an assessment of market concentration and positioning logic.
- Recent developments tracking covering product launches, mergers and acquisitions, facility expansions, and major trade events, so that planners can connect external movements to internal decision timelines.
- A market dynamics chapter that examines raw material conditions, regulatory requirements, macro trends, and labor cost pressures, linking these forces to procurement and production implications.
- Forward-looking insight on innovation directions, sustainability expectations, and specification trends, helping teams anticipate near-term shifts in demand before they become widespread.
Why This Research Matters for 2026 Corporate Strategy
The strategic value of this study lies in its ability to connect high-level market behavior with the operational realities that executives face on a daily basis. For procurement and supply chain leaders, the combination of material stability, regulatory requirements, and labor-driven cost pressure calls for a deliberate approach to supplier qualification, dual sourcing, and quality assurance. For product development teams, the momentum behind soft-close solutions, sustainable materials, and integrated storage mechanisms indicates where differentiation is most likely to pay off in both household and commercial projects. For executive planners and investors, the forecast trajectory and concentration profile provide a structured basis for evaluating growth potential, competitive vulnerability, and the timing of capacity or portfolio investments.
Equally important, the report is designed to support scenario-based thinking. Because the forecast extends through 2032 and is anchored in a detailed historical record, readers can test assumptions about regional expansion, application mix, and category substitution against a consistent analytical baseline. That capability matters in 2026, when supply chain restructuring, specification changes, and competitive realignment can materially affect margins and market share within a single planning cycle. The full report preserves the exact regional and application-level allocations, type-specific revenue context, and concentration details that make such scenario work precise rather than speculative.
Conclusion: Turn Market Intelligence into Action
The Furniture Hardware Market research study offers more than a snapshot of current conditions. It provides a structured, forward-looking view of a sector defined by stable material foundations, rising performance expectations, concentrated yet competitive supplier dynamics, and a forecast path that supports multi-year planning. For organizations operating in 2026, the difference between reactive sourcing and strategic advantage often comes down to access to the right level of detail at the right time.
The preview above highlights the scope, methodology, and strategic relevance of the study. To leverage the full set of quantitative tables, segment splits, regional allocations, and company-level insight, readers are invited to access the complete report through the source webpage. There, the data is presented in a format built for direct integration into budgeting models, sourcing reviews, and strategic planning sessions—enabling teams to move from awareness to action with confidence.
For detailed analysis of this topic, please visit the official page: Furniture Hardware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting ETRM Market to Hit $349.79M by 2032, Growing at 4.8% CAGR from 2026-2032
By PW Consulting, 2026-09-16
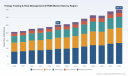
Navigating the 2026 Energy Trading and Risk Management Landscape: Strategic Imperatives for Enterprise Leaders
The global energy markets are undergoing a structural transformation defined by regulatory complexity, accelerated digital adoption, and an unrelenting demand for real-time risk intelligence. As organizations transition from legacy spreadsheet-based workflows to enterprise-grade Energy Trading and Risk Management (ETRM) ecosystems, the strategic stakes for technology investment have never been higher. Our latest market intelligence study on the ETRM sector provides a rigorous, forward-looking blueprint for executives who must align technology strategy with operational resilience, compliance obligations, and commercial growth. Drawing on historical performance from 2020 through 2025 and extending our forecast horizon to 2032, this research translates macroeconomic signals into actionable decision frameworks for procurement leaders, risk officers, and enterprise architects.
The Post-2025 Market Arc: Scale, Momentum, and Structural Shifts
The commercial trajectory of the ETRM market through the mid-2020s confirms a sustained expansion cycle that is reshaping procurement priorities across commodity trading houses, utilities, financial institutions, and diversified energy portfolios. Historical revenue performance between 2020 and 2025 reflects the compounding effect of compliance-driven modernization, the migration to cloud-native architectures, and the operational necessity of consolidating fragmented trade lifecycles into unified risk platforms. The market crossed a critical inflection point as adoption rates accelerated sharply, driven by both regulatory pressure and the tangible return on investment that centralized analytics deliver for position management, margin optimization, and counterparty exposure assessment.
Looking toward the forecast period of 2026 to 2032, the expansion trajectory remains firmly positive, anchored by a compound annual growth rate that underscores durable demand even as broader macroeconomic conditions fluctuate. The forward revenue envelope indicates a clear upward path, with the total market size projected to scale meaningfully over the next several years. For enterprise buyers, this growth environment carries two strategic implications. First, it signals that ETRM investments will remain central to competitive differentiation, particularly for organizations managing complex physical and financial commodity portfolios. Second, it highlights that procurement timelines and platform selection windows are compressing, as vendors release more sophisticated analytics, automation features, and integration capabilities at a faster cadence. Decision-makers who delay platform evaluation or remain tethered to legacy, on-premise configurations risk falling behind peers who are standardizing on modern workflows capable of supporting real-time risk calculation, automated compliance reporting, and multi-commodity visibility.
Importantly, the growth dynamic is not uniform across every operational segment or geography. While the overall revenue trend is robust, procurement teams must interpret the broader figures in the context of their own portfolio complexity, trade volumes, and regional compliance obligations. The market expansion reflects a convergence of multiple underlying drivers, including sustained hedging activity, increasing volumes in renewable and transition-fuel trading, and the modernization imperative triggered by years of fragmented system landscapes. Understanding how these drivers interact requires deeper segmentation intelligence that goes beyond headline totals and examines where demand intensity is concentrated, which asset classes are generating the fastest workflow transformation, and how vendor capabilities are evolving to capture new use cases.
Sector Dynamics Redefining Platform Requirements
The modernization imperative in ETRM adoption has moved rapidly from a best-practice discussion to an operational baseline. During the recent reporting period, the proportion of organizations actively deploying or modernizing ETRM and CTRM systems climbed dramatically, signaling that automation, transparency, and integrated analytics are no longer optional enhancements. This acceleration is being reinforced by a dense regulatory environment in which firms must continuously satisfy obligations under frameworks such as EMIR for derivatives reporting, MiFID II market conduct requirements, REMIT transparency mandates, and emerging sustainability directives. In practice, these obligations affect every stage of the trade lifecycle, from initial capture and confirmation to settlement, risk aggregation, and auditable emissions or origin tracking. Platforms that cannot deliver automated compliance workflows, traceable audit trails, and configurable reporting structures quickly become liabilities rather than enablers.
Energy Trading & Risk Management (ETRM) Market
At the same time, the compliance landscape is expanding beyond traditional market supervision. Evolving ESG and carbon reporting mandates are placing new responsibilities on trading and risk operations, requiring systems to support emissions calculations, carbon intensity attribution, and verifiable documentation for sustainability disclosures. The integration of these requirements into daily trading and risk workflows is driving demand for platforms that can unify financial risk management with environmental and operational data without sacrificing speed or accuracy. As firms face stricter position reporting expectations in Europe and derivatives regulation in North America, the ability to compute risk metrics, exposure concentrations, and margin implications in near real time has become a critical differentiator. ETRM solutions that support these capabilities are increasingly viewed as foundational infrastructure rather than standalone trading tools.
A parallel shift is occurring in the deployment architecture itself. Cloud-native ETRM platforms are enabling organizations to scale compute capacity on demand, lower the capital expenditure burden associated with legacy hardware, and accelerate access to advanced analytics for position monitoring and value-at-risk calculations. The move toward cloud delivery is also reshaping vendor roadmaps, as providers release managed cloud offerings, expand integration flexibility, and improve user workflows to reduce operational friction. Recent product developments illustrate the pace of this evolution: vendors are introducing AI-assisted trade capture modules that reduce manual input errors, updating risk visualization dashboards for faster decision-making, and releasing new platform versions optimized for evolving liquid hydrocarbon and renewable fuel markets. Some providers have also secured growth capital to fund further expansion of cloud-based capabilities, while others have established partnerships to deliver their ETRM solutions as fully managed cloud services. These developments collectively indicate that the competitive frontier is moving from basic trade recording toward intelligent, continuously updated operating environments.
Competitive Landscape: Ecosystem Architecture and Strategic Positioning
The ETRM vendor landscape is characterized by a high degree of concentration at the top tiers, with a small group of major providers accounting for a substantial share of total market revenue. This concentration reflects both the scale required to sustain comprehensive trade lifecycle coverage and the specialized expertise needed to serve complex energy and commodity workflows. Nonetheless, the market remains structurally diverse, encompassing dedicated ETRM specialists, broader enterprise software players, and service-led organizations that offer managed platforms or consulting-intensive implementations. For procurement leaders, the strategic challenge is not simply comparing feature lists but evaluating how each vendor aligns with the operational, regulatory, and integration requirements of a particular portfolio.
At one end of the spectrum are platforms focused deeply on end-to-end energy trading, risk management, and settlement across physical and financial commodities. These solutions emphasize full lifecycle support, portfolio analytics, and multi-commodity operations, often serving organizations with sophisticated trading desks and substantial risk aggregation requirements. Other providers concentrate on commodity trading, risk analysis, and portfolio management with flexible configuration for different asset classes, while additional vendors specialize in enterprise risk management for energy and commodities with strong emphasis on compliance workflows and regulatory reporting. On the enterprise software side, large platform vendors extend their broader ERP and analytics ecosystems by offering ETRM modules that integrate trading, risk, and compliance activity into unified corporate systems. This provides a distinct value proposition for organizations seeking tighter alignment between trading operations and back-office or corporate finance processes.
A notable competitive trend is the rise of cloud-native entrants and the accelerated modernization of established platforms. Several providers are positioning their offerings around real-time risk and trading capabilities, cloud-first deployment models, and rapid scalability. Others continue to strengthen core strengths in electronic trading, logistics management, bid-to-bill operations, scheduling, and wholesale energy lifecycle management. Regional specialization also remains relevant, with some platforms optimized for multi-commodity trading and risk in specific international markets. Service-oriented participants complement the software ecosystem by delivering implementation, integration, and managed operations support, enabling firms to accelerate modernization without assuming all implementation risk internally.
Recent product and commercial moves underscore how this competitive field is evolving in practice. Vendors are introducing AI-assisted trade capture to reduce error rates and improve operational speed, releasing updated versions calibrated for shifting hydrocarbon and renewable fuel dynamics, and rolling out enhanced risk visualization and cloud deployment options to improve analytics performance and user workflows. Partnerships aimed at delivering fully managed cloud services, alongside funding rounds that expand cloud-based platform development, indicate a strategic race to combine regulatory-grade functionality with the speed, flexibility, and total cost of ownership advantages that modern deployment models can provide. For buyers, these developments create both opportunity and complexity: the expanding feature frontier can materially improve risk oversight and compliance readiness, but it also demands disciplined evaluation of integration complexity, vendor stability, and long-term roadmap alignment.
Evaluating this landscape effectively requires multi-dimensional assessment criteria. Procurement teams should weigh trade lifecycle coverage against the specific commodities and markets they operate in, examine the depth and speed of risk analytics and compliance automation, and assess the flexibility of deployment and integration paths. Equally important is the organizational fit: some firms benefit from highly configurable specialist platforms, while others gain more from integrated enterprise modules or managed service arrangements that reduce internal delivery burden. The concentrated nature of the top-tier market does not eliminate choice; rather, it raises the importance of understanding which provider can support the firm's regulatory footprint, portfolio complexity, and transformation timeline with the least operational friction.
Translating Intelligence into 2026 Decision Architecture
For enterprise leaders planning ETRM investments in 2026, the most valuable insights are not abstract market totals but the operational implications embedded within them. The current environment rewards a structured decision architecture that connects platform selection to measurable business outcomes: faster exposure visibility, reduced compliance leakage, improved trade workflow efficiency, and better alignment between trading strategy and risk appetite. Organizations that approach procurement as a strategic capability upgrade rather than a software replacement exercise are better positioned to capture the value of modern platforms. This means defining clear evaluation criteria around trade capture accuracy, risk calculation latency, reporting automation, integration breadth, and operational support model, then testing those criteria against realistic usage scenarios rather than scripted demonstrations.
Procurement teams should also pressure-test the total cost and risk profile of each option. Cloud-native offerings can reduce upfront capital requirements and improve scalability, but they require careful assessment of data governance, migration effort, and ongoing service economics. Enterprise-integrated modules can simplify broader system alignment, but they may require trade-offs in commodity-specific depth. Specialist platforms can deliver advanced functionality for targeted use cases, but they may demand more extensive integration work with ERP, scheduling, logistics, or settlement systems. The right answer depends on portfolio composition, regulatory exposure, internal capability, and the pace at which the organization expects its trading and risk operations to evolve. What is consistent across all scenarios is that delaying evaluation tends to increase future retrofit costs, especially as vendors continue to raise the bar on automation, analytics, and regulatory readiness.
Our full market study goes further than these directional insights by providing the segmentation depth, vendor positioning detail, and quantitative forecasts needed to support formal sourcing decisions, budget planning, and risk investment prioritization. The report examines regional revenue distributions, type-based market structures, and application-level demand patterns that reveal where procurement pressure is most intense and which workflows are driving the fastest transformation. It also maps competitive dynamics more precisely, giving buyers a framework to compare platform families, assess recent product movements, and anticipate where vendor roadmaps are likely to converge or diverge. This level of detail is essential for organizations that must justify investment, sequence modernization phases, and select technology partners with confidence.
Worldwide Electricity Trading Platform Market
Accessing the Complete Strategic Intelligence
The energy trading and risk management sector is moving quickly, and the difference between reactive technology spending and deliberate strategic investment is widening. Organizations that build their 2026 decisions on rigorous market intelligence will be better equipped to balance compliance obligations, operational efficiency, and competitive agility. The complete study provides the segmentation data, forecast trajectories, competitive profiles, and industry dynamics required to move from high-level awareness to executable strategy. To review the full quantitative findings, vendor comparisons, and segmentation breakdowns that underpin this analysis, access the complete report and secure the intelligence your team needs to make informed ETRM investment decisions in the year ahead.
For detailed analysis of this topic, please visit the official page: Energy Trading & Risk Management (ETRM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Budesonide Market: Navigating the 2026 Decision Landscape
The global pharmaceutical landscape is undergoing a period of significant transformation, driven by evolving therapeutic indications, complex regulatory approvals, and shifting competitive dynamics. For stakeholders invested in respiratory and gastrointestinal therapies, Budesonide remains a cornerstone molecule with enduring clinical relevance. As we move deeper into the forecast period spanning 2026 through 2032, understanding the trajectory of this market is not merely an academic exercise but a critical component of strategic planning. This article serves as an executive preview of our latest comprehensive market research, designed to equip leadership teams with the contextual intelligence necessary to make informed decisions in a rapidly changing environment.
Our analysis indicates a steady upward trajectory for the sector. Based on historical performance from 2020 through 2025, the market has demonstrated resilience and consistent growth. The revenue scale has expanded from approximately 4,758.5 million USD in 2020 to an estimated 5,855.2 million USD in 2025. Looking forward, the forecast period projects continued expansion, with revenues expected to reach 6,158.54 million USD in 2026 and climbing to 8,670.5 million USD by 2032. This growth is underpinned by a compound annual growth rate of 6.0 percent. Such macro-level indicators suggest that while the market is mature, it retains sufficient momentum to offer viable opportunities for manufacturers, distributors, and investors who can navigate the nuances of supply chain dynamics and therapeutic innovation.
Decoding the Market Structure and Segmentation Nuances
A superficial glance at top-line numbers often obscures the strategic realities hidden within specific segments. Our research delves deep into the structural composition of the market to reveal where value is truly being generated. The market is fragmented across various dimensions including product type, dosage form, strength, indication, and distribution channels. While the aggregate data paints a picture of growth, the real strategic value lies in understanding the relative weight and performance of these distinct categories.
Mesalamine Market
For instance, the split between inhalants and nebulizer products reveals different usage patterns and supply chain requirements. Similarly, the variation across dosage forms such as aerosols, dry powder, suspensions, and sprays indicates diverse manufacturing capabilities and patient preference trends. Strength variations ranging from 0.25 mg to 1.0 mg further complicate the procurement and formulation strategies for generic manufacturers and branded innovators alike. The indication landscape, balancing between Asthma and Chronic Obstructive Pulmonary Disease, alongside emerging uses in eosinophilic esophagitis, dictates the volume drivers for the coming years. Furthermore, the distribution channel ecosystem, spanning hospital pharmacies, retail pharmacies, and online pharmacies, highlights the critical importance of market access and formulary positioning.
Rather than presenting static percentage splits that may age quickly, our full report provides a dynamic analysis of how these segments interact. We examine how regulatory shifts impact specific dosage forms and how reimbursement policies influence distribution channel preferences. This granular understanding is essential for companies aiming to align their production capacities with actual demand signals rather than relying on generalized industry assumptions.
Budesonide Market
Competitive Intensity and Key Player Strategies
The competitive landscape for Budesonide is characterized by a mix of established multinational corporations and specialized generic manufacturers. Our research identifies a concentrated market environment where strategic positioning is key to maintaining market share. The concentration ratios indicate a significant level of consolidation among top players, suggesting that scale and regulatory compliance are major barriers to entry.
Key companies analyzed in our report include major entities such as Takeda Pharmaceutical Company Limited, AstraZeneca AB, Sun Pharmaceutical Industries Ltd., and Teva Pharmaceutical Industries. These organizations are not merely selling products; they are actively shaping the therapeutic standards through innovation and regulatory engagement. For example, Takeda has made significant strides in expanding the indication profile of Budesonide oral suspension, securing approval for eosinophilic esophagitis, thereby opening a new therapeutic avenue beyond traditional respiratory uses. AstraZeneca continues to leverage its portfolio leadership in inhalation therapies, pursuing label expansions and new combination therapies that enhance the value proposition of Budesonide-containing products.
On the generic side, manufacturers like Aurobindo Pharma USA, Zydus Pharma, and Amneal Pharmaceuticals play a crucial role in ensuring accessibility and price competition. Their ability to navigate FDA approvals and maintain supply chain integrity for delayed-release capsules and inhalation suspensions is vital for the market's overall health. Additionally, API specialists such as Minakem Dunkerque Production S.A.S., Axplora, and Caesar & Loretz GmbH ensure that the foundational supply of Active Pharmaceutical Ingredients remains robust and compliant with global cGMP standards. The interplay between API suppliers and finished dosage form manufacturers creates a complex dependency chain that our report maps in detail.
Recent developments highlight the pace of change. In early 2024, regulatory approvals opened new doors for oral treatments in niche indications. By late 2025 and into 2026, label expansions and new approvals for combination inhalers have further consolidated the position of Budesonide in maintenance and rescue therapies. These moves are not isolated incidents but part of a broader strategy by key players to extend product lifecycles and defend market share against emerging competitors. Our analysis tracks these movements to help clients anticipate competitive responses and adjust their own strategies accordingly.
Regulatory and Reimbursement Dynamics Shaping the Future
Market growth does not occur in a vacuum. It is heavily influenced by the regulatory framework and reimbursement landscape. Our research incorporates critical intelligence on how policy changes impact market access and profitability. The approval history of specific formulations, such as the recent recognitions for oral suspensions and combination inhalers, signals regulatory willingness to support innovative delivery mechanisms and new indications.
Reimbursement policies are equally critical. The inclusion of various Budesonide formulations in national preferred formularies as covered alternatives to branded therapies influences prescribing behavior and patient uptake. These formulary placements can make or break the commercial potential of a specific product variant. Furthermore, patent certification activities regarding enteric-coated capsules indicate ongoing generic availability, which sustains competition but also pressures pricing structures. Understanding the timing and implications of these regulatory milestones is essential for forecasting revenue streams and planning product launches.
The industry context also involves safety and efficacy data that support these regulatory decisions. Randomized studies demonstrating histologic remission rates or reductions in severe exacerbations provide the evidence base that regulators and payers rely on. Our report synthesizes this clinical context with commercial data to provide a holistic view of what drives adoption. This is particularly important for stakeholders evaluating the long-term viability of specific indications or dosage forms in the face of evolving clinical guidelines.
Strategic Implications for 2026 and Beyond
Why does this detailed analysis matter for your organization in 2026? The answer lies in the ability to move from reactive positioning to proactive strategy. With the market projected to grow from 6,158.54 million USD in 2026 to over 8,670.5 million USD by 2032, the absolute opportunity is significant. However, capturing value requires knowing where to allocate resources. Whether it is investing in specific manufacturing capabilities, pursuing regulatory approvals for new indications, or optimizing distribution partnerships, decisions must be grounded in robust data.
The concentration of market power among top players suggests that collaboration or differentiation is necessary for smaller entities. For generic manufacturers, the focus may shift towards optimizing supply chains and navigating patent landscapes to ensure timely market entry. For innovators, the opportunity lies in combination therapies and novel delivery systems that command premium positioning. For investors, understanding the segmentation splits and regional dynamics is crucial for assessing risk and return profiles.
Our full market research report goes beyond these high-level insights to provide the actionable intelligence needed to execute these strategies. It offers a detailed examination of the segmentation splits across regions, product types, dosage forms, strengths, indications, and distribution channels, providing the specific data points required for micro-level planning. It also includes comprehensive profiles of key companies, analyzing their strategic moves, recent developments, and market positioning.
Accessing Complete Market Intelligence
While this article provides a strategic overview and highlights the macro trends shaping the Budesonide market, it is only a prelude to the depth of information available in our full study. The nuances of regional performance, the specific valuation of different dosage forms, and the detailed competitive landscaping require a more comprehensive dataset than can be summarized here. Strategic decisions in the pharmaceutical sector demand precision, and relying on partial information can lead to misallocated capital and missed opportunities.
We invite you to access the complete market research report to gain the full advantage. The detailed segmentation analysis, coupled with our expert commentary on regulatory trajectories and competitive responses, will provide the clarity needed to navigate the 2026 to 2032 forecast period with confidence. The data presented in the preview points to a market with solid fundamentals and evolving opportunities, but the specific pathways to success are detailed within the full intelligence package.
In an industry where timing and accuracy are paramount, having access to validated forecasts and deep competitive analysis is a distinct strategic asset. Our team has compiled this research to serve as a definitive guide for stakeholders committed to excellence in the Budesonide sector. We encourage you to review the full findings to ensure your organization is fully equipped to capitalize on the growth trajectory outlined in our forecast. The market is moving forward, and the detailed insights within our report will help ensure you are moving with it, strategically and profitably.
For detailed analysis of this topic, please visit the official page: Budesonide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass-to-metal Seals Market to Reach $1.74B by 2032 with 4.34% CAGR
By PW Consulting, 2026-09-16
Inside the Glass-to-Metal Seals Market: A Strategic Intelligence Brief for 2026 Enterprise Decisions
The glass-to-metal seals market has entered a defining phase in 2026. After navigating a period of pronounced volatility through 2023 and 2024, the sector is now stabilizing around a clearer growth trajectory. Our latest research assessment, built on a comprehensive historical baseline spanning 2020 through 2025 and extended through a forecast window that reaches to 2032, offers decision-makers a structured view of how this critical hermetic sealing ecosystem is evolving. Rather than presenting a static snapshot, the study maps the interplay of material science, defense and aerospace procurement cycles, medical device miniaturization, and the broader push toward harsh-environment electronics. For executives evaluating capital allocation, supply chain resilience, or technology roadmaps, the report functions as a diagnostic instrument designed to separate durable growth signals from short-term market noise.
At the macro level, the market has demonstrated a compound annual growth rate of approximately 4.34 percent across the forward forecast period. This trajectory reflects a sector that is neither in a speculative boom nor in structural decline, but rather in a phase of disciplined, application-driven expansion. Revenue movements across the historical window reveal the kind of cyclical sensitivity that procurement and engineering leaders must now price into their planning. The 2020 baseline established a market size of roughly 1,254.4 million USD. Subsequent years recorded incremental gains, with 2021 reaching 1,337.89 million USD and 2022 climbing to 1,456.88 million USD. A meaningful contraction followed in 2023, when revenue pulled back to 1,420.93 million USD, before a sharp rebound in 2024 pushed the market to 1,578.11 million USD. The 2025 figure settled at 1,295.6 million USD, reflecting the kind of post-peak rationalization that commonly reshapes vendor strategies and customer buying patterns. Looking ahead, the forecast window traces a measured ascent: 1,329.88 million USD in 2026, progressing toward 1,444.75 million USD in 2027, holding near 1,442.17 million USD in 2028, then gaining momentum again to 1,530.31 million USD in 2029, 1,626.75 million USD in 2030, 1,666.82 million USD in 2031, and ultimately 1,743.89 million USD in 2032.
These numbers matter, but they are only the beginning. What separates a useful market assessment from a simple data table is the ability to translate revenue movement into operational consequences. For a VP of procurement, the historical swing between 2023 and 2024 is not merely a statistical blip; it is a reminder that glass-to-metal sealing supply Chains can tighten quickly when specific end-use sectors accelerate procurement. For a CTO evaluating next-generation packaging, the projected 2032 ceiling is less important than the intermediate inflection points that will determine when capacity expansions, glass formulation investments, or custom tooling decisions become financially justified. Our report is structured precisely around that translation challenge.
Why the 2026 Decision Window Demands This Level of Intelligence
The current year presents a distinctive set of strategic conditions. On one side, demand for hermetic glass-to-metal seals continues to be anchored by sectors where failure is not an option. Military and defense programs, aerospace platforms, and high-reliability medical devices depend on sealing solutions that can withstand thermal cycling, pressure differentials, chemical exposure, and long service lives. On the other side, the supply base is undergoing subtle but important adjustments in capability, geography, and specialization. Some manufacturers are broadening their preform and glass formulation portfolios; others are refining compression and matched seal architectures for increasingly demanding custom geometries. Meanwhile, the broader electronics and energy storage landscape is pushing seal designers to think beyond conventional configurations and toward hybrid, oxide-free, and high-durability solutions.
In that environment, a decision made without granular market visibility can create three types of risk. The first is timing risk: committing to a supplier relationship, internal capacity investment, or long-term procurement contract at a point in the cycle that does not align with actual demand momentum. The second is specification risk: over-indexing on a seal type or material class because it appears dominant in a headline figure, while missing the more nuanced fit between application requirements and seal architecture. The third is concentration risk: underestimating how fragmented or consolidated the competitive field truly is, and therefore misreading the bargaining power available to buyers or the vulnerability of incumbents. Our research is designed to reduce all three.
The report's forecast framework is deliberately built to support near-term execution while preserving long-range optionality. By anchoring the analysis to a 2025 base year and running the outlook through 2032, the study enables readers to test multiple strategic scenarios. A component manufacturer can examine how early-cycle demand in 2026 and 2027 might affect tooling schedules and glass preform inventory. A systems integrator can assess whether anticipated revenue progression through the end of the decade justifies qualification investments in a new seal material or a second-source supplier. A strategic planner can use the trajectory to distinguish between temporary price relief and a genuine shift in market structure. The goal is not to provide a single predicted path, but to make the range of plausible paths explicit and operationally actionable.
Glass-to-Metal Connectors Market
What the Report Delivers: Operational Content, Not Just Aggregates
A high-quality market study should function as a working document for cross-functional teams. Our glass-to-metal seals research is organized to support that expectation. It combines macro revenue tracking with the kind of structural decomposition that engineering, sourcing, and strategy groups need when they translate market conditions into commercial choices.
At the core of the report is a detailed segmentation architecture. The analysis breaks the market down by type, by application, and by region, allowing readers to see where demand is concentrated and where it is emerging. This decomposition is essential because revenue aggregates can conceal very different operational realities. A market that appears stable in total can still contain a segment that is contracting while another is accelerating, and those internal shifts often determine which suppliers thrive and which lose relevance. The report treats segmentation not as a decorative breakdown, but as the lens through which buyers can evaluate specification fit, supplier breadth, and regional sourcing logic.
Just as important, the study examines the boundaries of each segment. In practice, many sealing decisions are not made by broad category alone. They are driven by specific operating conditions: temperature ranges, pressure environments, electrical requirements, chemical exposure, miniaturization constraints, and qualification cycles. The report maps these application-dependent requirements to the relevant seal typologies and material considerations, giving readers a clearer sense of where matched seals, compression seals, and other configurations are typically positioned. That mapping is a practical aid for teams comparing vendor offerings or evaluating whether an existing supply base can support a next-generation design.
The research also includes forward-looking commentary on market dynamics that are likely to shape procurement and production decisions through the forecast period. Rather than relying on generic speculation, the analysis ties observed revenue behavior to underlying drivers such as program timing in defense and aerospace, the scaling of medical device platforms, and the broader adoption of harsh-environment electronics. By connecting the numbers to the conditions that generate them, the report helps organizations avoid the common mistake of interpreting a single year's revenue figure as a permanent signal.
- Detailed segmentation by type, application, and region, with enough granularity to support specification and sourcing decisions
- Historical revenue tracking from 2020 through 2025, enabling cycle-aware planning rather than point-in-time assumptions
- A forecast trajectory through 2032 that supports scenario modeling for capacity, qualification, and supplier strategy
- Competitive profiling of the leading participants shaping hermetic sealing capability across multiple end markets
- Practical interpretation of market concentration and what it implies for buyer leverage, supplier resilience, and entry dynamics
Competitive Landscape: Who Shapes the Market and How
The glass-to-metal seals market is characterized by a blend of established multinational players, specialized U.S. manufacturers, and focused European and Italian producers, each with distinct strengths in materials, process control, and application know-how. Our competitive analysis evaluates the companies that materially influence pricing, capability benchmarks, and supply availability. The study does not simply list participants; it assesses the strategic posture of each, including their positioning across seal types, their depth in critical applications, and the extent to which they control the upstream components of the value chain.
SCHOTT AG remains a central reference point in the global landscape. Headquartered in Mainz, Germany, the company is recognized as a world leader in hermetic glass-to-metal seals, with an unusually complete internal footprint that spans in-house glass formulation, preform production, and full process control. That breadth is strategically significant because it allows tighter integration across matched and compression seal architectures for electronic packaging, medical implants, aerospace, and high-temperature applications. For buyers, the relevance of a fully integrated supplier is not just quality assurance; it is the ability to respond to demanding custom requirements without depending on a fragmented chain of external material and component sources.
Electronic Products Industries, based in Newburyport, Massachusetts, represents a more specialized but equally important profile. The company focuses on custom glass-to-metal hermetic seals and TO headers for microelectronic packages, supporting both compression and matched seals across sensors, batteries, and harsh-environment electronics. Its value proposition is rooted in tailored packaging solutions rather than broad commodity supply, which makes it particularly relevant for programs where header and seal design directly affect reliability and form factor.
Concept Group LLC, operating from Florida, illustrates another distinct niche. The company manufactures oxide-free hermetic glass-to-metal compression seals using stainless steel and titanium, targeting high-temperature and high-pressure feedthroughs and connectors. In applications where material compatibility and long-term integrity under stress are decisive, this kind of specialization can become a differentiator that is not captured by headline revenue figures alone.
Elan Technology, headquartered in New York, contributes a different layer of market capability. The company supplies glass preforms and composite materials, including ceramic glass formulations such as Elan 46, for matched and compression hermetic seals. Its emphasis on high chemical durability and custom geometries underscores an important point: in many sealing challenges, the material and preform stage is not a commodity input but a strategic variable that determines whether the final assembly can meet the required specification.
Other firms extend the competitive field into targeted application areas and specialized production approaches. Hermetic Seal Technology, in Cincinnati, Ohio, produces custom hermetic glass-to-metal seals and feedthroughs for lithium batteries, aerospace, military, and oil exploration applications, aligning its capabilities with sectors where environmental severity and energy storage demands intersect. Legacy Technologies LLC, based in Mission, Kansas, specializes in precision quartz crystal and hermetic glass-to-metal seals for aerospace, medical, automotive, and sensor use, highlighting the connection between frequency-critical components and sealing precision. Dietze Group, in Switzerland, develops and manufactures glass-ceramic-to-metal feedthroughs with copper conductors and stainless-steel housings for interconnection solutions, reflecting a structural focus on reliable interfaces in complex assemblies.
The field also includes players whose relevance lies in specialty glass formulation and high-reliability execution. STC Material Solutions, operating from California, formulates and produces specialty glass for matched and compression seals, including challenging custom applications where standard material libraries are insufficient. Sintermetalglass, a long-established producer based in Opera, Italy, is known for high-quality hermetic compression glass-to-metal seals with a strong emphasis on reliability, while progressively expanding into advanced lines. SGA Technologies, located in Uttlesford, United Kingdom, is recognized for high-reliability glass-to-metal seals serving satellite communications, medical, and harsh-environment systems, reinforcing the importance of qualification-intensive markets in shaping supply capability.
Taken together, these companies illustrate a market that is diversified in capability but not uniformly concentrated. The report quantifies that structural reality, noting that the top three firms account for approximately 25.0 percent of market revenue, while the top five reach roughly 35.0 percent. Those concentration levels carry practical implications. For buyers, they indicate meaningful but not overwhelming supplier consolidation, which shapes negotiation strategy, qualification risk, and the value of maintaining alternative sources. For suppliers, they highlight the distance between being a recognized specialist and being a market-defining scale player. The analysis unpacks these dynamics without reducing them to simplistic rankings, because in a market driven by reliability and custom engineering, scale is only one dimension of competitive advantage.
Reading the Numbers Strategically: What the Report Reveals Without Giving Everything Away
One of the intentional design choices behind this study is to demonstrate analytic depth while preserving the full decision-grade detail for the complete report. Readers of this overview will see enough to evaluate the research's relevance and to understand the strategic questions it answers. They will also see why the complete dataset, regional breakdowns, application-level splits, and supplier-level detail matter when a company moves from general market awareness to an actual sourcing, investment, or expansion decision.
Glass-to-metal Seals Market
This approach reflects a realistic view of how enterprise intelligence is used. A C-suite audience may need the narrative logic and the strategic implications first. A sourcing team may need the segmentation logic and supplier profiles to assess alternative sources. An R&D group may need the material, preform, and seal-type framing to determine whether current internal capabilities align with anticipated application demands. By presenting the scaffold of the analysis here and reserving the full operational detail for the complete report, we make it possible for different functions to recognize the specific value that the study can deliver to them.
The report's treatment of the competitive and demand environment is particularly important at a moment when several long-cycle industries are revising their expectations for durability, miniaturization, and environmental resistance. Hermetic glass-to-metal seals sit at the intersection of those expectations. They are often invisible in the final product, yet they frequently determine whether the product can survive the conditions it was designed for. That dependence makes the market less sensitive to short-lived consumer trends and more sensitive to engineering requirements, qualification cycles, and program-level procurement behavior. The report reflects that reality by emphasizing structural drivers over speculative hype.
How to Use This Research in a 2026 Planning Cycle
The most effective use of this study is to embed it in a multi-step decision process rather than treating it as a one-time reference document. Early in the planning cycle, executives can use the forecast trajectory and historical behavior to stress-test assumptions about near-term demand and medium-term growth. Mid-cycle, engineering and sourcing teams can use the segmentation and competitive content to evaluate supplier fit, second-source options, and specification alignment. Later in the cycle, strategy groups can use the concentration data and capability profiles to assess whether the market structure supports current procurement policies or whether a change in sourcing posture is warranted.
The report is also designed to support conversations across functions. A market assessment that can be read by procurement, engineering, finance, and strategy without losing analytic rigor is more likely to produce aligned decisions. Accordingly, the study avoids unnecessary jargon while preserving technical accuracy. It translates revenue movements into operational context, and it frames competitive dynamics in terms of capability, reliability, and strategic positioning rather than simple market share rhetoric.
Access the Full Intelligence
This overview provides the strategic context and analytic framing that underpin the complete study. It is intended to show why the research is relevant to 2026 decision-making and how it connects market behavior to operational consequences. The full report extends this foundation with the detailed segmentation values, regional and application-level breakdowns, and the complete competitive profiles needed to convert insight into action. For teams that are preparing sourcing strategies, qualification roadmaps, capacity plans, or investment cases, that additional depth is where the practical advantage lies.
The glass-to-metal seals market is moving through a period in which disciplined analysis matters more than ever. Historical volatility, application-specific demand, and a competitive field defined by both scale and specialization all point to the same conclusion: enterprises that rely on broad generalizations will miss the nuances that determine sourcing resilience and technical fit. Our research is built to close that gap. The complete version is available through our market research portal, where decision-makers can access the full dataset, the detailed segmentation, and the supplier analyses that support the scenarios discussed here.
For detailed analysis of this topic, please visit the official page: Glass-to-metal Seals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Embedded Computing Market Hits $215M in 2025, Projects 7.02% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Merchant Embedded Computing Market (2026–2032)
The global landscape for merchant embedded computing is undergoing a structural transformation. As industries accelerate digitalization and edge intelligence becomes embedded in everyday operations, the demand for specialized, robust, and standards-compliant computing platforms has moved from niche infrastructure to strategic enterprise priority. Our latest market research, The Merchant Embedded Computing Market, delivers a comprehensive, data-grounded forecast designed to equip executives, procurement leaders, and technology strategists with the actionable intelligence required to make confident decisions throughout 2026 and beyond.
Drawing on historical performance data from 2020 through 2025 and extending through a detailed forecast period to 2032, this study maps the trajectory of a market that is expanding at a measured yet sustained pace. The analysis is built on rigorous primary and secondary research, cross-validated industry modeling, and transparent methodological frameworks. The result is a strategic reference that goes beyond surface-level projections to uncover the operational, competitive, and regulatory forces shaping procurement cycles, product roadmaps, and market entry decisions.
A Market Poised for Sustained Expansion
Historical data reveals a market that navigated volatility with resilience. After reaching a baseline of approximately 163.15 million USD in 2020, the sector demonstrated consistent growth momentum, peaking at 215.0 million USD by 2025. This trajectory reflects more than cyclical upturns; it signals a fundamental shift in how enterprises deploy computing at the edge, particularly where reliability, real-time processing, and integration with digital payment or industrial automation ecosystems are non-negotiable.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to reach 344.8 million USD by the close of the decade. The compound annual growth rate of 7.02 percent underscores a steady, compounding trajectory rather than speculative spikes. For enterprise decision-makers, this growth profile presents a clear strategic implication: merchant embedded computing is no longer a supplementary technology layer. It is becoming a foundational component of operational architecture, particularly for organizations scaling IoT deployments, modernizing factory automation, and integrating secure transaction platforms.
Decoding the Report’s Architecture: From Macro Trends to Tactical Playbooks
This research is structured to serve multiple strategic functions. Rather than offering a single aggregated view, the report dissects market dynamics across applied dimensions that matter to procurement, R&D, and competitive positioning teams. The analytical architecture includes:
- Historical baseline and forward modeling: A granular reconstruction of market performance from 2020 through 2025, paired with a decade-long forecast extending to 2032, allows stakeholders to benchmark current investments against projected trajectories.
- Technology and product-type evaluation: The study maps the competitive and functional relevance of segment categories, highlighting where innovation cycles are accelerating, where integration complexity persists, and which platforms are attracting the highest enterprise demand.
- Application-driven demand mapping: The report disaggregates adoption across high-impact verticals, revealing where merchant embedded computing platforms are resolving latency, reliability, and compliance bottlenecks, and where emerging use cases are reshaping procurement criteria.
- Regional demand dynamics: Geographic analysis identifies where infrastructure investment, industrial digitization, and regulatory environments are creating localized pull factors, helping multinational teams align supply strategies with regional procurement realities.
- Competitive positioning and company profiling: Detailed assessments of market participants include operational footprints, product portfolios, and strategic focus areas, providing context for partnership selection, benchmarking, and market entry planning.
- Industry context and constraint analysis: The research incorporates real-world friction points, from certification requirements and interoperability gaps to workforce and component cost pressures, ensuring that strategic planning reflects on-the-ground realities.
By integrating these dimensions into a unified analytical framework, the report enables decision-makers to move from broad market awareness to precise allocation strategies. The emphasis is on clarity, comparability, and operational relevance, ensuring that every section translates into a decision-enabling insight.
The Merchant Embedded Computing Market
Competitive Landscape: Who Is Shaping the Next Cycle?
The merchant embedded computing market is defined by a diverse mix of established industrial suppliers, edge-computing specialists, and defense-grade technology integrators. Market concentration data indicates a moderately fragmented environment, with the top three players holding a combined share of 24.6 percent and the top five reaching 26.2 percent. This distribution suggests that while incumbents maintain strong positioning, differentiation through application-specific engineering, certification readiness, and edge AI integration remains a viable path for competitive advantage.
Several companies stand out for their strategic alignment with the market’s evolving demands:
Embedded Computer Market
- Advantech Co., Ltd. continues to anchor its portfolio around industrial-grade merchant embedded computing platforms and systems, with a clear focus on digital payment solutions and rugged applications. Its January 2025 announcement of a new line of AI-enabled embedded systems for industrial automation, delivering 20 percent faster processing speeds, signals a deliberate push toward higher-throughput edge intelligence.
- ADLINK Technology Inc. has positioned itself at the intersection of edge processing and real-time industrial automation. Its November 2025 launch of the i-MX95 Modules for Edge AI Systems reflects an emphasis on enhancing edge computing capabilities in commercial and industrial environments, reinforcing the broader industry shift toward localized inference and faster decision cycles.
- Kontron AG delivers commercial off-the-shelf embedded computing solutions designed for merchant and industrial use cases, emphasizing rapid deployment and integration flexibility.
- Curtiss-Wright Corporation supplies rugged merchant embedded computing systems tailored for mission-critical and payment applications, where reliability under demanding conditions is a defining procurement criterion.
- Mercury Systems, Inc. manufactures high-performance merchant embedded computing boards and modules for defense and industrial integration, bringing ruggedized performance and specialized engineering to sectors with stringent operational requirements.
- ARBO R Technology Corporation provides compact merchant embedded computing solutions tailored for edge and payment systems, addressing the need for space-efficient, high-density deployments.
- AAEON Technology Inc. sells fanless and rugged merchant embedded computing platforms for industrial and commercial deployments, aligning product design with thermal management and environmental resilience demands.
- Avalue Technology Inc. offers ready-to-integrate merchant embedded computing systems for digital payment and automation applications, reducing time-to-deployment for enterprises seeking streamlined integration paths.
- IEI Integration Corp. delivers specialized merchant embedded computing hardware for payment and edge computing platforms, reflecting a focused approach to transaction-adjacent and edge processing workloads.
- DFI Inc. manufactures merchant embedded computing solutions integrated into retail and industrial devices, underscoring the convergence of embedded platforms with end-device ecosystems.
The competitive picture is not static. Recent product launches illustrate a market where edge AI capabilities, processing speed, and ruggedization are becoming baseline expectations rather than differentiators. Companies that can harmonize performance with compliance readiness, interoperability, and integration ease are likely to capture disproportionate value as procurement teams prioritize total cost of ownership and deployment certainty over raw specification comparisons.
Market Dynamics and Operating Realities in 2026
Strategic planning for merchant embedded computing cannot rely on growth projections alone. Several industry dynamics are actively reshaping procurement criteria, product design, and deployment economics:
- Regulatory and certification pressure: The EU AI Act and CE marking requirements under the EU Green Deal are tightening energy-efficiency and safety-certification standards for embedded systems. Simultaneously, PCI DSS compliance is required for all merchant embedded computing platforms integrated into digital payment solutions. These requirements are elevating the importance of pre-certified platforms, documented compliance trails, and engineering partnerships with demonstrated regulatory fluency.
- Cost and supply constraints: Rising chip costs and a shortage of skilled professionals have impacted a significant share of SMEs operating in the merchant embedded computing sector. For larger enterprises, this environment increases the value of supply chain resilience, component availability guarantees, and design-in support that reduces integration risk.
- Standardization and interoperability gaps: Limited standardization and interoperability among embedded computing systems continues to pose a major challenge. Enterprises seeking to scale deployments across sites or integrate with legacy equipment must account for integration friction, custom bridging costs, and long-term maintenance implications.
- Application concentration and demand signals: Industrial and factory automation applications represent close to 36 percent of total demand for merchant embedded computing platforms, reinforcing the centrality of operational technology environments in market growth. This concentration also highlights where performance, durability, and real-time processing requirements are most acute.
Together, these dynamics create a more demanding procurement environment. Enterprise buyers are increasingly evaluating platforms not only on technical capability, but on compliance readiness, integration predictability, lifecycle support, and alignment with regional regulatory frameworks. The companies that succeed in this environment will be those that can reduce deployment uncertainty while delivering performance that matches mission-critical expectations.
Why This Research Matters for 2026 Decision-Making
The merchant embedded computing market is entering a phase where strategic foresight directly affects competitive positioning. Growth is steady, but the path to capturing value is becoming more nuanced. Procurement leaders must navigate certification requirements, component cost volatility, interoperability constraints, and a competitive field where product launches increasingly emphasize edge AI and higher-throughput processing. In this environment, high-level market awareness is insufficient. Decision-makers need structured, scenario-ready intelligence that connects market size and growth trajectory to application demand, regional dynamics, technology evolution, and competitor behavior.
This research is designed to fill that gap. By grounding its analysis in verified historical data, transparent forecasting methodology, and detailed competitive and regulatory context, the report provides a practical foundation for:
- Aligning capital allocation and procurement cycles with credible growth trajectories rather than optimistic assumptions.
- Evaluating product portfolios and integration strategies against application-specific demand concentration and deployment constraints.
- Anticipating regulatory and certification impacts on platform selection, particularly in payment-adjacent and energy-sensitive environments.
- Mapping competitive positioning to identify where incumbents hold scale advantages and where emerging capabilities may reshape procurement preferences.
- Structuring partnership, sourcing, and market-entry decisions around interoperability, lifecycle support, and regional demand realities.
Access the Full Strategic Blueprint
The merchant embedded computing market is expanding with discipline, but the complexity beneath the headline numbers is where strategic advantage is won or lost. From technology-type differentiation and application-driven demand patterns to regional deployment dynamics and competitive maneuvers, the full report provides the depth required to make informed, forward-looking decisions in 2026 and across the forecast horizon to 2032.
To move from directional awareness to execution-ready intelligence, we invite you to access the complete study. The full market research includes detailed segmentation analysis, comprehensive company profiling, scenario-driven forecasts, and operational context that equips enterprises to translate market growth into concrete strategic action.
For detailed analysis of this topic, please visit the official page: The Merchant Embedded Computing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Benefits Admin Software Market Hits $200M in 2025, Forecasts 10.23% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Modern Benefits Administration Software Market: A 2026 Outlook
The benefits administration software market is undergoing a structural transformation driven by regulatory complexity, workforce expectations, and the rapid infusion of artificial intelligence into core HR technology stacks. As organizations navigate post-pandemic benefits redesign, rising healthcare inflation, and evolving compliance requirements, the strategic function of benefits administration software has expanded far beyond enrollment and payroll reconciliation. It now sits at the intersection of employee experience, financial stewardship, and risk management. Our latest Benefits Administration Software Market research was commissioned to cut through the noise and provide enterprise decision-makers with a rigorous, forward-looking framework for evaluating vendor selection, technology investment, and competitive positioning through 2032.
This article previews the strategic architecture of that study. Rather than offering surface-level vendor lists or incremental trend commentary, the report delivers a disciplined market model, competitive intelligence, and operational benchmarking designed to inform capital allocation, digital transformation roadmaps, and compliance strategy. What follows is a guided introduction to the market forces, segmentation logic, competitive dynamics, and content architecture embedded in the full research package. The core quantitative estimates, granular regional and application splits, and detailed company scoring matrices are intentionally reserved for the complete deliverable, ensuring that executives who engage with the source report receive actionable, decision-grade intelligence rather than recycled summary data.
The Macro Trajectory: Why Benefits Administration Software Is Entering a New Growth Cycle
The global benefits administration software market has demonstrated durable expansion over the past half-decade, with total revenue climbing steadily as enterprises migrated from manual, spreadsheet-driven processes to integrated, cloud-enabled platforms. Looking across the historical tracking window and forward forecast horizon, the market has entered a phase of accelerated monetization tied to digital transformation mandates, compliance automation, and payroll-to-HR system consolidation. The research models a compound annual growth rate of 10.23 percent across the forecast period, reflecting sustained demand for platforms that can simultaneously manage enrollment, eligibility verification, carrier connectivity, and regulatory reporting at enterprise scale.
Several structural drivers underpin this trajectory. First, regulatory complexity continues to raise the cost of non-compliance. Employers face escalating exposure to penalties tied to minimum essential coverage, HIPAA-mandated data security controls, and state-level continuation coverage requirements. These obligations are not static; they intensify with inflation indexing and evolving enforcement expectations, creating a persistent need for software that can automate compliance logic rather than rely on manual interpretation. Second, the financial burden of administering benefits through generalized HRIS platforms has prompted organizations to evaluate dedicated benefits solutions that deliver greater workflow precision, carrier integration depth, and ROI clarity. Third, employee expectations around self-service, mobile accessibility, and personalized benefit selection have shifted administrative software from a back-office utility into a frontline retention and engagement tool.
Within the forecast timeline, market expansion is projected to accelerate in the latter years, with total revenue expected to surpass the 300 million threshold by the close of the decade and approach the 400 million mark by 2032. This growth path reflects more than incremental adoption. It signals a maturation cycle in which mid-market and large enterprise buyers are consolidating fragmented vendor relationships, upgrading legacy systems, and embedding benefits workflows into broader workforce management architectures. The strategic implication for 2026 decision-makers is clear: the window for optimizing benefits technology is narrowing, and the cost of deferred modernization is rising in both compliance risk and operational friction.
Market Segmentation Logic and Strategic Dimensions
Effective vendor evaluation and investment planning require a segmentation framework that aligns with how buyers actually purchase, deploy, and scale benefits technology. The research structures the market across multiple strategic axes, each designed to illuminate distinct purchasing behaviors, technology adoption patterns, and operational priorities.
- Organizational scale continues to be a defining determinant of technology strategy. Large enterprises typically prioritize comprehensive integration, multi-carrier connectivity, and advanced compliance automation, while small and medium enterprises often seek streamlined onboarding, predictable pricing, and packaged self-service capabilities. The division of revenue between these segments reflects contrasting purchasing velocity, implementation complexity, and vendor preference.
- Deployment architecture remains a critical selection factor as buyers weigh agility against control. Cloud-based platforms dominate contemporary procurement decisions because they reduce infrastructure burden, accelerate feature updates, and enable broader user accessibility. However, on-premises and hybrid configurations retain relevance for organizations with stringent data governance requirements, legacy system dependencies, or specialized security protocols.
- Geographic distribution shapes both vendor strategy and buyer expectations. Regional dynamics influence compliance regimes, carrier ecosystems, compensation structures, and the maturity of digital benefits adoption. The research captures these variations to help organizations assess market opportunity, competitive intensity, and localization requirements across major economic zones.
Rather than presenting segmentation as a static data table, the report analyzes how these dimensions intersect. For example, it examines how cloud adoption compounds differently across organization sizes, how regional compliance burdens reshape feature prioritization, and how buyers typically sequence implementation priorities when migrating from HRIS-embedded benefits to dedicated administration platforms. This layered approach enables buyers to map their own operating profiles against broader market behavior and identify where their deployment strategy may expose them to inefficiency or competitive lag.
Competitive Dynamics and the Battle for Platform Relevance
The competitive landscape is concentrated yet diverse, with a mix of large HCM incumbents, specialized benefits administration providers, and emerging all-in-one workforce platforms competing on integration depth, compliance automation, user experience, and intelligent feature sets. The research provides detailed company profiles, capability assessments, and strategic positioning analysis to help buyers distinguish between vendors that offer genuine differentiation and those that rely primarily on brand recognition or bundled pricing.
Benefits Administration Software Market
Several established players anchor the market through broad HCM ecosystems that embed benefits administration within wider payroll, time, talent, and HR workflows. These platforms appeal to organizations seeking operational consolidation and unified data models. Their value proposition centers on end-to-end continuity, carrier integrations at scale, and compliance workflows designed to reduce manual oversight. At the same time, dedicated benefits administration specialists compete by emphasizing enrollment optimization, eligibility precision, member-facing self-service, and regulatory reporting rigor. Their advantage often lies in workflow specificity, carrier connectivity breadth, and the ability to tailor benefits experiences without forcing buyers into a full HCM replacement cycle.
A third competitive current is being shaped by platform companies that treat benefits as one module within a broader operational stack spanning IT provisioning, workforce management, and employee services. These offerings attract organizations pursuing operational simplification and unified dashboards, particularly when benefits administration must connect tightly to payroll, devices, access management, and cross-functional employee data flows. The strategic question for buyers is not whether a platform is broad or specialized, but whether its architecture aligns with the organization's implementation capacity, compliance risk profile, and long-term system consolidation plans.
The report also incorporates competitive intelligence around recent product momentum and innovation signals. For instance, the market has seen heightened activity around AI-driven personalization, mobile self-service enhancements, billing visibility improvements, and expanded carrier and partner connectivity. Recent updates from leading providers underscore a shift toward smarter administrative guidance, more transparent financial tracking, and conversational or recommendation-based tools that help employees navigate complex plan options. Separately, new market entrants and adjacent platform launches announced in early 2026 extend the competitive perimeter, particularly around AI-powered benefits administration targeting insurance agencies and healthcare operations contexts. These developments matter because they indicate where vendors are placing bets on differentiation and where buyers should expect feature escalation in the next procurement cycle.
Market concentration remains notable, with a substantial share of revenue held by a limited set of leading providers. This concentration has practical implications for negotiation leverage, integration roadmaps, and platform switching costs. Buyers must assess not only current capability but also the likelihood that a vendor will continue to invest in the specific workflows, compliance logic, and data interoperability their organization requires. The research addresses these issues through structured evaluation criteria that go beyond feature checklists and into strategic fit, scalability, and innovation cadence.
Regulatory Pressure, Cost Economics, and Operational Reality
No benefits administration technology evaluation is complete without a clear view of the regulatory and economic forces that shape both platform requirements and total cost of ownership. The research treats compliance not as a feature footnote but as a core design constraint that influences product architecture, implementation effort, and long-term administrative burden.
On the regulatory side, employers must contend with overlapping obligations that vary by organization size, workforce composition, and jurisdiction. Compliance workflows increasingly demand automated tracking for coverage adequacy, secure handling of protected health information, encryption standards, role-based access controls, and ongoing reporting for continuation coverage mandates at the state level. For applicable large employers, the financial stakes of coverage noncompliance can be substantial and are subject to inflation-indexed adjustments. These realities elevate the importance of software that embeds regulatory logic directly into enrollment, eligibility, and reconciliation processes rather than requiring manual monitoring outside the platform.
Worldwide Financial Wellness Benefits Market
On the cost side, the operational economics of benefits administration are prompting organizations to reassess how much administrative overhead is acceptable when benefits are processed through generalized HRIS environments. Dedicated benefits solutions are increasingly evaluated on their ability to reduce manual intervention, streamline carrier billing reconciliation, and improve the accuracy of deductions and eligibility determinations. The research incorporates this economic dimension by examining how buyers justify technology investment through efficiency gains, risk reduction, and improved employee experience outcomes, rather than treating software spend as an isolated administrative expense.
Together, these dynamics shape a market in which buyers are less interested in incremental feature expansion than in platforms that deliver measurable operational improvement, compliance assurance, and scalable employee engagement. The report's analysis reflects that shift, positioning benefits administration software as a strategic system rather than a tactical utility.
What the Report Delivers: A Framework for 2026 Decision-Making
The full Benefits Administration Software Market research was constructed to support concrete executive and procurement decisions. Its contents are organized to move from market structure to competitive reality to implementation planning, providing a comprehensive basis for investment strategy, vendor comparison, and digital roadmapping.
- Executive market overview and growth trajectory analysis that situates current market size within a multi-year forecast, giving leadership a calibrated view of where the market is heading and how quickly adoption is expected to evolve.
- Segmentation analysis across organization size, deployment model, and regional dynamics, designed to help buyers benchmark their own profile against market behavior and identify where their procurement priorities align with broader demand patterns.
- Competitive landscape assessment covering core providers, platform positioning, capability emphasis, and recent product developments, enabling side-by-side evaluation without relying on marketing narratives.
- Regulatory and operational context that frames compliance obligations, data security expectations, and cost-efficiency pressures as central selection criteria rather than peripheral considerations.
- Practical intelligence for vendor evaluation, including the types of workflow, integration, and automation capabilities that distinguish leading platforms in real implementation settings.
Throughout the report, data is used to support judgment rather than replace it. The analysis emphasizes where market momentum is strongest, which capabilities are becoming table stakes, and how competitive differentiation is increasingly tied to personalization, mobile usability, carrier connectivity, and AI-assisted administration. This framing helps organizations prioritize what to evaluate, what to negotiate, and what to validate during proof-of-concept or implementation planning.
Why 2026 Is a Pivotal Year for Benefits Technology Strategy
For 2026 planning cycles, benefits administration software decisions carry heightened strategic weight. The convergence of regulatory exposure, employee experience expectations, and platform consolidation economics means that organizations can no longer treat benefits technology as a static purchase. The market's growth trajectory, competitive intensity, and innovation cadence are all pointing toward a smaller number of platforms achieving outsized relevance for enterprises seeking efficiency, compliance assurance, and differentiated employee engagement.
At the same time, the abundance of vendor claims makes disciplined evaluation more important than ever. Buyers need a clear framework for separating integrated convenience from genuine benefits administration depth, for understanding where deployment architecture affects long-term cost, and for anticipating how regulatory and cost pressures will influence platform requirements over the forecast horizon. The research was designed to provide that framework.
The preview above outlines the analytical orientation, market logic, and competitive context embedded in the study. The full report expands on these themes with detailed market sizing, segmentation evaluation, vendor profiling, and forward-looking scenario analysis intended to support procurement strategy, budgeting, and enterprise technology planning. For decision-makers seeking a precise, evidence-based basis for allocating benefits technology investment in 2026 and beyond, the complete research offers the depth required to move from general awareness to confident action.
For detailed analysis of this topic, please visit the official page: Benefits Administration Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tape Measures Market Hits USD 215M in 2025, Projected 4.75% CAGR Through 2032
By PW Consulting, 2026-09-16
Beyond the Blade: Strategic Intelligence for the 2026 Tape Measures Market
The global tape measure industry is a deceptively complex sector where incremental engineering, material science, and compliance considerations converge to shape purchasing decisions across construction, woodworking, and industrial trade ecosystems. What appears at the surface as a simple hand tool is in reality a performance-critical instrument calibrated to exacting tolerances, evolving material standards, and regional compliance frameworks. For executives, procurement leaders, and market strategists navigating the 2026 landscape, understanding the underlying mechanics of demand, competitive positioning, and regulatory influence is no longer optional. It is a strategic imperative.
As organizations recalibrate their go-to-market strategies and supply chain investments for the coming decade, this market intelligence briefing offers a structured, forward-looking view of the tape measures industry. Drawing on rigorous historical analysis and calibrated forecasting through 2032, our latest research unpacks the forces that will determine volume trajectories, category rotation, and competitive intensity across mature and emerging trading environments. The findings are designed to inform product road-mapping, channel prioritization, compliance readiness, and merger or acquisition screening with a level of precision that generic industry summaries cannot deliver.
Market Trajectory and Structural Momentum
The tape measures market has evolved through a period of disciplined expansion, shaped by steady reconstruction activity, sustained professional trade demand, and gradual material substitution trends that reward durability and measurement reliability. Historical data spanning the past half-decade reveals a resilient revenue base that has absorbed cyclical fluctuations while maintaining a consistent upward trajectory. From a global revenue perspective measured in USD millions, the industry recorded sequential growth through 2020 to 2025, with 2025 closing at approximately 215.0 million. Looking ahead, the forecast window from 2026 through 2032 projects continued expansion, with 2026 establishing an opening baseline of roughly 225.5 million and forward estimates extending well past the 290 million threshold by the close of the decade.
This growth profile is underpinned by a compound annual growth rate projected at 4.75 percent across the 2026–2032 horizon. Such a rate signals more than steady-state expansion; it reflects shifting adoption patterns, incremental premiumization in professional-grade tooling, and expanding commercial and industrial measurement requirements that reward precision-engineered products. The forecast environment also reflects a market that is neither purely commodity-driven nor fully insulated from price competition. Instead, it is a segment where differentiated blade technology, ergonomic design, reinforced housings, and certification-backed accuracy create defensible positioning for brands that can consistently deliver on job-site performance standards.
Importantly, the structural momentum observed in the historical series does not guarantee uniform distribution across the forecast period. Cyclical construction activity, raw material cost dynamics, and regulatory refreshes can alter the pace of demand migration between product categories and end-use channels. Our analysis accounts for these variables by mapping growth drivers against material constraints and compliance milestones, enabling decision-makers to anticipate where volume concentration and margin exposure are likely to intensify.
Competitive Architecture and Strategic Positioning
The competitive landscape of the tape measures market is defined by a concentrated group of established tool manufacturers alongside specialized producers that compete on precision, material innovation, and professional-grade durability. Industry concentration metrics indicate that the top three participants command approximately 34.5 percent of total market revenue, while the top five extend their combined share to roughly 45.2 percent. This level of concentration suggests meaningful brand equity, established distribution relationships, and sustained investment in product differentiation, but it also leaves considerable room for regional specialists and performance-focused entrants to capture share through targeted engineering or niche application alignment.
At the center of this arena, Stanley Black & Decker operates as a foundational force, leveraging its LEVERLOCK platform and NIST-traceable certifications to anchor professional trade credibility. Its DeWalt portfolio extends this positioning through durable standout-blade designs built for construction and trade environments where visibility, reliability, and ruggedization drive repeat purchase behavior. Milwaukee Electric Tool reinforces the professional segment with its STUD series and wide-blade formats, pairing reinforced bodies with job-site durability that appeals to contractors seeking reduced failure rates under demanding use conditions.
Tape Measures Market
Parallel to these global-scale players, a second tier of competitive differentiation emerges from firms that emphasize material-specific advantages and ergonomic control. Crescent Lufkin has built a distinctive identity around its Shockforce series, incorporating diamond-coated hooks and high-contrast blades to improve grip, hook retention, and reading clarity under variable site conditions. Tajima Tool Corporation advances its GS-LOCK and GS-25 offerings with SIGMA STOP functionality and compatible clip systems, expanding accessory interoperability and user consistency across structured measuring workflows. Komelon USA contributes to this ecosystem through fiberglass and True Control tape measures, emphasizing dual-sided printing and intuitive retraction behavior that supports faster, more accurate field use.
Irwin Tools enters the conversation with Strait-Line tape measures that utilize finger-brake retraction for more controlled blade management, addressing the fine motor requirements of precision layout work. Keson Industries supplies open-reel and professional fiberglass formats tailored to industrial and construction applications where extended reach and durability intersect. Ullman Devices Corporation focuses on precision measuring tools for trades and survey-oriented workflows, reinforcing the market’s dependence on accuracy assurance beyond basic consumer applications. Great Wall Precision Industrial Co., Ltd. supports broader segment needs with steel tape measures and measuring tools aligned to ISO 9001 and CE standards, reflecting the growing relevance of standardized manufacturing discipline in globally sourced tooling. Stabila Measuring Tools contributes ergonomic BM series and professional-grade formats designed to maintain measurement fidelity while reducing user fatigue. The Perfect Measuring Tape Company, with assembly heritage dating back to 1912, continues to serve surveyor and construction segments through precision-focused domestic manufacturing. Hoechstmass adds a complementary dimension through flexible and roller tape measures, including digital options for tailoring and industrial contexts. Empire Level rounds out the competitive mosaic with reinforced safety and underground tape measures integrated into broader hand-tool assortments.
Recent commercial activity underscores how competition is intensifying through product refreshes, catalog expansion, and performance benchmarking. Tajima Tool Corporation released its E-Catalog 2026, highlighting GS-LOCK compatible clips and SIGMA STOP tape measures, signaling continued investment in accessory interoperability. Crescent Lufkin introduced second-generation Shockforce series tape measures with 360-degree diamond-coated hooks, demonstrating a clear focus on hook durability and field usability. Komelon USA launched its True Control tape measure, assigning emphasis to an intuitive retraction disc and a compact case form factor. Meanwhile, Pro Tool Reviews published a head-to-head evaluation of leading 2026 tape measures spanning Milwaukee, DeWalt, Stanley, Irwin, Tajima, Komelon, and Crescent Lufkin, reinforcing the market’s increasing reliance on comparative performance validation as a purchasing influence.
Regulatory Forces Shaping the Demand Environment
Regulatory specifications are becoming a more visible filter in the tape measures market, especially where measurement accuracy intersects with commercial transactions and professional trade standards. NIST Handbook 44-2026, approved in December 2025, establishes specifications and tolerances for weighing and measuring devices used in commerce, extending the compliance conversation beyond industrial metrology into everyday trade tooling. Within this framework, a 1.82-meter tape used for buying and selling goods must meet accuracy requirements of within 0.79 millimeters, equivalent to 1/32 inch, and maintain that tolerance as a baseline for commercial use.
For manufacturers, distributors, and procurement teams, these specifications are more than technical footnotes. They influence claim substantiation, product positioning, and the perceived risk profile of lower-cost alternatives that may struggle to consistently meet tolerance thresholds under field conditions. As buyers become more attentive to certification, traceability, and measurement reliability, products with documented accuracy alignment can command stronger positioning in professional and compliance-sensitive channels. At the same time, regulatory evolution introduces a dual dynamic: it can consolidate demand for certified, repeatable products while pressuring manufacturers to validate design choices, quality control processes, and labeling claims across regional market entry points.
In parallel, raw material composition remains central to product differentiation and cost structure. Steel and fiberglass continue to serve as the primary raw materials for tape measures, with each material pathway carrying distinct trade-offs in flexibility, ruggedness, weight, and application suitability. Steel-dominant formats typically reinforce durability and blade rigidity for construction and heavy-duty use cases, while fiberglass alternatives address corrosion-sensitive environments and extended-reach scenarios where non-conductive or lighter-weight properties matter. The interplay between these material choices and end-user requirements continues to shape segment preferences and influences how manufacturers balance performance claims against input cost volatility.
What the Full Study Delivers for 2026 Decision-Making
This market research goes beyond headline sizing and top-line forecasts to build an operational intelligence framework for companies making investment, sourcing, and product strategy decisions in 2026 and beyond. The study is structured to help leadership teams answer practical questions about where demand is expanding, which product attributes are gaining commercial weight, and how competitive forces are likely to shift under evolving compliance and material conditions.
At the analytical core, the report combines historical market reconstruction with a forecast model stretching from 2026 to 2032. It situates the overall revenue progression within a broader set of segmentation lenses, enabling readers to understand how growth is distributed across product types, application environments, and regional markets without reducing the analysis to static averages. This framing is essential because aggregate growth can obscure important variance: one segment may be consolidating around premium features, another may be responding to material substitution, and another may be expanding based on construction activity or industrial maintenance cycles.
Equally important, the study examines the competitive field through company-level profiling and recent commercial moves, allowing readers to assess not only who competes but how they compete. Product architecture, certification posture, blade engineering, retraction control, hook design, case durability, and accessory compatibility are treated as strategic variables rather than marketing claims. By connecting these product-level attributes to broader market concentration patterns, the report helps executives evaluate where brand strength is likely to persist and where disruption opportunities may emerge for new entrants or channel-focused challengers.
The research also integrates regulatory and material context into the demand narrative, so that strategic planning reflects the compliance environment as a market force rather than a separate legal consideration. Readers will find structured assessment of how tolerance expectations, commercial-use requirements, and material inputs interact with product positioning, market entry, and buyer decision criteria. This integrated approach is particularly valuable for companies evaluating new product introductions or regional expansion, where misalignment with compliance expectations or material demand realities can quickly erode anticipated returns.
From an operational standpoint, the report is designed to support:
Measuring Tape Market
- Product portfolio decisions that align engineering priorities with segment-level demand signals and competitive gaps
- Commercial planning that anticipates where professional trade buyers and industrial purchasers are likely to prioritize durability, accuracy, and certification-backed confidence
- Supply chain and sourcing review informed by material dependency patterns and the broader raw material mix shaping cost and performance differentiation
- Competitive benchmarking grounded in product launches, catalog activity, and performance evaluations that influence buyer perception in 2026
- Strategic scenario planning that translates forecast trends into practical considerations for capacity, assortment, and channel emphasis
Every section is built to function as a decision-support asset rather than a static market description. The objective is to give executives, category leaders, and strategy teams a clearer line of sight into where value is being created, what attributes are paying off in the field, and how the market is likely to evolve under the combined influence of construction activity, trade professionalism, compliance tightening, and product innovation.
Why This Intelligence Matters Now
The tape measures market is entering a period in which performance differentiation, certification awareness, and material-driven value propositions will increasingly determine competitive outcomes. A 4.75 percent CAGR across the forecast period indicates sustained expansion, but the strategic value lies in understanding which sub-segments, product attributes, and commercial channels will absorb that growth most effectively. For suppliers and distributors operating in 2026, the difference between average execution and superior positioning will often come down to insight: knowing where precision matters most, where hook and blade engineering drives loyalty, and where regulatory expectations are reshaping buyer preferences.
This is precisely the space the full study is designed to fill. It converts historical momentum, forecast trajectory, competitive activity, and regulatory context into a coherent strategic map for the years ahead. The report does not simply describe the market; it equips decision-makers with the analytical structure needed to interpret change before it becomes visible in quarterly results.
For those responsible for product strategy, channel development, competitive positioning, or regional expansion, the complete findings provide the depth required to move from observation to action. The detailed segmentation analysis, company profiles, and market dynamics assessment are available through the full market research report. Accessed in its entirety, the study offers the comprehensive intelligence needed to plan with confidence in a market where small differences in measurement performance can translate into measurable differences in commercial outcomes.
For detailed analysis of this topic, please visit the official page: Tape Measures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Textiles Market to Hit $1,366.98M by 2032 at 19.3% CAGR
By PW Consulting, 2026-09-16
The Fabric of the Future: Why Electronic Textiles Demand Immediate Strategic Attention
The convergence of textile engineering and advanced electronics is no longer a speculative vision. It is a measurable commercial reality that is reshaping supply chains, product roadmaps, and consumer expectations across multiple industries. At PW Consulting, we have recognized that electronic textiles represent one of the most structurally transformative material categories of this decade. Our newly released Electronic Textiles Market research report is designed to help executives, product leaders, and investors navigate this complexity with clarity, precision, and actionable foresight.
This article serves as a strategic preview of the full study. It outlines the market trajectory, the operational and regulatory forces shaping development, the competitive architecture defining the space, and the specific analytical content readers will gain access to when they download the complete report. The objective is straightforward: to demonstrate why this intelligence matters for 2026 decision-making, while preserving the granular segmentation, pricing models, and operator-level benchmarking that form the core of the full publication.
A Market Compressing at an Unusual Velocity
The electronic textiles sector has transitioned from experimental prototyping to commercial scaling in a remarkably short window. Historical revenue data from 2020 through 2025 shows a consistent upward curve, with overall market size climbing from approximately 163 million USD at the start of the period to around 395 million USD by the base year. That trajectory reflects more than incremental growth; it signals a structural shift in how fabrics are being designed, manufactured, and integrated with electronic functionality. The forecast window extending through 2032 points toward a total addressable market approaching 1.37 billion USD, with a compound annual growth rate of 19.3 percent.
Worldwide Smart Medical Textiles Market
These figures are not merely headline numbers. They reflect the compounding effect of several intersecting forces: the miniaturization of electronic components, the proliferation of low-cost wireless sensor networks, and the growing demand for garments and surfaces that can monitor, communicate, regulate temperature, or deliver haptic feedback. The pace of expansion suggests that organizations delaying strategic engagement risk being structurally disadvantaged as integration standards solidify, supply chains mature, and customer expectations normalize around intelligent textiles.
What deserves particular attention is the manner in which growth is being distributed across innovation pathways. The market is not expanding uniformly. Certain product architectures and application domains are advancing faster than others, and the divergence between early commercializers and late followers is already visible in inventory positioning, partnership structures, and manufacturing readiness. Understanding which pathways are accelerating, which are plateauing, and why requires a level of granularity that only a dedicated, data-rich study can provide.
Structural Forces Reshaping the Electronic Textiles Landscape
The current market environment is defined by a tension between rapid innovation and the incomplete infrastructure required to support widespread commercial deployment. Several dynamics are particularly consequential for 2026 planning.
On the technology side, the miniaturization of electronic components and the spread of affordable smart wireless sensor networks are accelerating adoption across wearables, automotive interiors, and performance-facing smart surfaces. These enablers lower the physical and economic barriers to embedding functionality directly into fabrics. At the same time, advanced conductive yarns and specialized printing equipment remain primary bottlenecks for scalable, washable e-textile production. The gap between laboratory-grade prototypes and durable, repeatable manufacturing at commercial volumes is still a defining constraint, and companies that fail to account for it in their sourcing and product-development strategies will face consistent quality variance and margin pressure.
Regulatory and standardization activity is also entering a more mature phase. The IPC has established IPC-8921A as the primary standard for woven and knitted e-textiles integrated with conductive fibers and yarns, creating a clearer technical baseline for manufacturers and integration partners. In parallel, the Smart Textile Alliance launched an E-textile Connectivity taskforce in early 2026 to define industry connectivity standards for sustainable e-textiles. These developments are constructive, but the sector still faces a broader lack of comprehensive global standards and regulations, which continues to hinder consistent quality and safety across markets. For firms operating across regions or planning to scale internationally, navigating this fragmentation will be a critical competency.
Taken together, these forces create both urgency and optionality. Companies that act early can shape product architecture around emerging standards, secure access to constrained material inputs, and position themselves as preferred partners in ecosystems that are still forming. Those that wait will inevitably confront higher integration friction, narrower supplier choice, and more expensive compliance pathways.
The Competitive Architecture: Who Is Building the Value Chain
The electronic textiles market is not dominated by a single archetype of player. It is a multi-layered ecosystem in which material innovators, garment integrators, sensor developers, and contract manufacturers each occupy distinct positions along the value chain. Understanding this architecture is essential for evaluating partnership opportunities, acquisition targets, and competitive vulnerability.
On the materials and component side, several established and specialized firms are supplying the foundational inputs that make electronic textiles viable. Bekaert produces conductive fibers and yarns designed specifically for embedding electronics into textiles, enabling durable smart fabric solutions. Volt Smart Yarns supplies innovative conductive yarns and e-textiles for flexible, washable applications. Mitsufuji Corp and Toray Industries contribute advanced functional fibers and conductive yarns that support both durability and integration in smart garments. DuPont supplies advanced materials, silver nanowire solutions, and conductive technologies for flexible e-textiles, EMI shielding, and smart surfaces. Statex Production and Sales develops and supplies conductive and smart textile technologies for wearable electronics and industrial integration. Bally Ribbon Mills manufactures E-WEBBINGS conductive smart fabrics optimized for IoT integration in wearable and industrial applications. These material and component suppliers are often the quiet enablers of downstream product differentiation, and their capability sets frequently determine how far a downstream designer can push performance, washability, and production scalability.
A second cluster of players is focused on turning materials into finished or semi-finished intelligent products. AiQ Smart Clothing develops and commercializes AI-powered smart clothing and e-textiles with integrated sensors and connectivity for health monitoring, sports, and daily use. Hexoskin creates wearable smart shirts with embedded sensors for continuous health monitoring of heart rate, respiration, and activity. Sensoria manufactures smart socks and apparel with embedded sensors for running, training, and health analytics. EXO2 designs and produces smart fabrics with integrated electronics for health monitoring, performance tracking, and functional apparel. Xenoma creates hybrid smart textiles with embedded electronics for medical, military, and consumer uses. Interactive Wear specializes in fully integrated smart textiles for military, healthcare, and industrial applications. Ohmatex ApS focuses on printed smart textiles with conductive patterns for fashion, healthcare, and industrial uses. Sensing Tex develops e-textiles and smart fabrics with sensors for sports, healthcare, and lifestyle applications. These companies illustrate how rapidly the product frontier is expanding beyond niche fitness wear into clinical monitoring, defense, and lifestyle applications.
Performance apparel and lifestyle brands are also shaping the market through high-visibility integration and consumer-facing validation. Nike produces connected sportswear and smart textiles with embedded sensors for performance tracking and athlete feedback. Adidas offers performance sportswear and smart textiles with embedded sensors, heat regulation, and connectivity features for athletic applications. Schoeller Textil produces high-performance smart fabrics with enhanced durability and functionality for outdoor and technical applications. Textronics pioneers conductive yarns and e-textiles for athletic performance, healthcare monitoring, and embedded electronics. Their involvement signals that electronic textiles are increasingly judged not only on technical capability but also on wearability, aesthetics, and brand trust.
Thermal, haptic, and comfort-focused applications represent another distinct value-creation path. Gentherm develops heated and smart textiles using thermoelectric and conductive elements for automotive, medical, and consumer applications. Loomia develops smart fabric panels for heat, touch, haptic feedback, and wellness in apparel and automotive interiors. ThermoSoft International focuses on heated smart textiles for comfort, therapy, and functional apparel. These applications are particularly relevant where user experience, thermal management, and human-machine interaction intersect.
Finally, the manufacturing and integration layer remains critical. Jabil provides contract manufacturing and assembly for electronic components embedded in smart textiles and wearables, bridging the gap between design intent and repeatable production. The presence of capable contract manufacturers reduces the barrier for brands and startups that lack in-house assembly expertise, but it also concentrates valuable process knowledge in a smaller set of suppliers.
Recent activity underscores how quickly the ecosystem is formalizing. In March 2026, the Smart Textile Alliance launched an E-textile Connectivity taskforce to shape industry connectivity standards for sustainable e-textiles. In April 2026, Loomia released smart fabric panels for heat, touch, and haptic feedback integrated with e-textiles. Also in April 2026, IPC introduced new standards IPC-8921A and related requirements for woven and knitted electronic textiles integrated with conductive fibers. These milestones are not isolated news items; they are indicators of an industry moving from fragmented experimentation toward coordinated development. For strategists, they mark the moment when timing, alignment, and standards readiness begin to separate winners from followers.
How the Market Is Structured Across Types, Applications, and Regions
The electronic textiles market cannot be understood through a single lens. It is simultaneously a materials story, a product-design story, a use-case story, and a regional deployment story. The report maps these dimensions in detail, but a few structural observations are worth surfacing at the strategic level.
By product architecture, the market spans passive, active, and ultra categories. This classification is more than a taxonomy; it reflects different levels of embedded functionality, power requirements, integration complexity, and cost structures. The balance among these categories is shifting as designers choose between simpler sensing or conductive functions and more advanced, computation-enabled textiles. Understanding where value accrues along this spectrum, and which architectures command premium positioning, is central to product strategy.
By application, the market extends across military uses, civil uses, healthcare uses, and other segments. Each application domain carries distinct procurement rhythms, performance requirements, regulatory expectations, and durability thresholds. Military deployments often prioritize robustness and mission-critical reliability. Healthcare applications emphasize measurement accuracy, biocompatibility, and clinical workflow integration. Civil uses span a broader consumer and industrial spectrum where comfort, aesthetics, and cost compete with functionality. The relative size and growth profile of these application pools determine where companies should concentrate go-to-market effort and where they can expect longer sales cycles or higher entry barriers.
Regionally, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Regional divergence matters because manufacturing footprints, supplier density, standards adoption, and end-customer preferences differ substantially. Companies evaluating expansion, sourcing, or partnership strategies need a region-by-region view that connects market size to operational reality rather than relying on aggregate numbers alone. The report provides that regional mapping without reducing it to simplistic share percentages, because strategic nuance is lost when complex markets are flattened into a single ranking.
Concentration data also offers an important strategic signal. The market currently exhibits a moderate level of concentration, with the top three players accounting for a meaningful combined share and the top five extending that footprint further. This structure suggests that while the field is still broad enough for new entrants and specialized innovators, scale, integration capability, and standards alignment are beginning to reward the most complete value-chain players. For competitors and investors alike, this is a moment when portfolio positioning and partnership strategy can meaningfully influence long-term market standing.
What the Full Report Delivers for 2026 Decision-Making
The complete PW Consulting Electronic Textiles Market study is built for practitioners who need more than narrative overview. It is structured to support concrete decisions in product planning, sourcing, partnership evaluation, market entry, and investment prioritization. The analysis integrates historical context, forward-looking projections, and operator-level detail so that readers can benchmark assumptions rather than rely on generic industry commentary.
The report begins with market sizing and trajectory analysis across the full forecast horizon, anchored in a base year of 2025 and extending through 2032. It translates historical performance into a credible growth pathway while identifying the assumptions, sensitivities, and demand drivers that shape the outlook. Rather than presenting numbers in isolation, the study places them in the context of component miniaturization, sensor proliferation, material constraints, and standardization progress, so that leadership teams can test how changes in any one factor might alter their own planning.
A major portion of the research is devoted to segmentation and segment dynamics. Readers will find structured analysis of the market by type, by application, and by region, with attention to the operational and commercial implications of each split. The objective is not to produce a static table of shares, but to explain where different architectures and use cases are gaining traction, where manufacturing or regulatory friction is slowing deployment, and how regional conditions influence both opportunity and execution risk.
Competitive intelligence is another core pillar. The report profiles the key companies shaping the market, including material suppliers, product developers, performance-apparel brands, thermal and haptic specialists, and contract manufacturers. Each profile is tied to the company’s specific offering in electronic textiles, allowing readers to assess where competitors are building capabilities, where gaps remain, and how the value chain may consolidate or reconfigure over time. This company-level detail supports benchmarking, partnership screening, and competitive positioning in a way that high-level market summaries cannot.
The study also integrates the most consequential recent developments and structural dynamics. It addresses the establishment of IPC-8921A as a primary standard for woven and knitted e-textiles integrated with conductive fibers and yarns, the launch of the Smart Textile Alliance E-textile Connectivity taskforce, and the practical implications of product launches such as Loomia’s smart fabric panels for heat, touch, and haptic feedback. These events are analyzed not as headlines but as inputs to strategic timing, compliance planning, and ecosystem alignment.
In addition, the report examines the persistent bottlenecks that shape commercial viability, including the limitations of advanced conductive yarns and specialized printing equipment for scalable, washable production, and the broader absence of comprehensive global standards and regulations for e-textiles, which continues to complicate consistent quality and safety across markets. By linking these constraints to real operating decisions, the study helps teams anticipate sourcing challenges, design-for-manufacturing requirements, and the compliance effort likely to be needed as standards mature.
Throughout, the emphasis is on actionable insight. The report is designed to help executives answer questions such as where to allocate R&D focus, which supplier relationships are likely to matter most, how different application domains compare in payback profile and execution complexity, and what a credible entry or expansion strategy should look like in a market that is growing quickly but still maturing in critical ways.
Electronic Textiles Market
Why This Intelligence Matters Now
Electronic textiles are crossing a threshold from promising technology to strategically unavoidable category. The combination of strong growth momentum, expanding application breadth, and the gradual formalization of standards is creating a window in which early, informed decisions can compound into durable advantage. Companies that treat the market as a peripheral innovation experiment risk being surprised by how quickly integration expectations, supplier dependencies, and customer requirements solidify.
At the same time, the market’s complexity demands discipline. Growth alone does not reveal where profitability will concentrate, which material inputs will become constrained, how regional conditions will shape execution, or which competitor moves will redefine competitive positions. Those questions require detailed segmentation, operator-level benchmarking, and a clear view of the forces that can accelerate or disrupt adoption.
This is precisely the gap the PW Consulting Electronic Textiles Market report is built to fill. It provides the macro trajectory, the structural analysis, the competitive mapping, and the current dynamic context that leadership teams need to make 2026 decisions with confidence. The preview above illustrates the scope and tone of the study, but the full report contains the depth, segmentation, and company-level intelligence that turn market awareness into operational advantage.
For executives, strategists, and investors ready to move beyond surface-level trends, the complete research offers a disciplined foundation for product planning, sourcing strategy, partnership selection, and market-entry design. The electronic textiles opportunity is real, but its value will be captured by those who understand it in detail. The full report is the instrument for that understanding.
For detailed analysis of this topic, please visit the official page: Electronic Textiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: USV Market Hits $1.125B in 2025, Projected 12.45% CAGR to $2.556B by 2032
By PW Consulting, 2026-09-16
Navigating the Autonomous Horizon: Strategic Imperatives in the 2026 USV Market
Executive Summary
The maritime domain is undergoing a profound transformation, shifting from crewed dominance to a hybrid ecosystem where Unmanned Surface Vehicles (USVs) play a pivotal role in defense, commercial efficiency, and scientific exploration. As we move through 2026, the strategic importance of understanding this market cannot be overstated. PW Consulting's latest comprehensive study on the Unmanned Surface Vehicles Market offers a critical roadmap for stakeholders aiming to navigate this rapidly evolving landscape. This report is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, product development, and partnership strategies in an environment defined by technological acceleration and geopolitical tension.
The transition from experimental prototypes to operational deployment is now complete. The market has matured beyond the proof-of-concept phase, entering a period of sustained growth driven by tangible operational requirements. For enterprise leaders, defense contractors, and investment firms, the window to establish market position is narrowing. This analysis serves as the introduction to our full market intelligence package, highlighting the macro-economic trajectories and competitive forces that will define the next seven years.
Market Trajectory: From Niche to Mainstream
Historical Growth and Future Outlook
The USV market has demonstrated exceptional resilience and expansion over the past half-decade. Our analysis tracks revenue performance from 2020 through the base year of 2025, revealing a consistent upward trajectory that outperforms many adjacent technology sectors. In 2020, the global market revenue stood at USD 520.0 Million. By 2025, this figure had more than doubled, reaching USD 1125.0 Million. This growth underscores the rapid adoption rates across both governmental and commercial sectors, validated by sustained investment streams.
Unmanned Surface Vehicles (USV) Market
Looking forward, the forecast period from 2026 to 2032 suggests that this momentum is not only maintained but accelerated. The market is projected to reach USD 1225.21 Million in 2026 immediately, climbing steadily to USD 2556.18 Million by 2032. This trajectory indicates a Compound Annual Growth Rate (CAGR) of 12.45 percent over the forecast period. Such growth rates signal a maturing industry where standardized platforms are beginning to replace bespoke solutions, allowing for scalability and broader market penetration.
Value Chain and Economic Drivers
The economic expansion is underpinned by several key drivers. Operational cost reductions in maritime surveillance, increased risk tolerance in hazardous zones, and the strategic necessity of distributed maritime operations are primary catalysts. Furthermore, technological advancements in sensor fusion and autonomous navigation are reducing the barrier to entry for commercial entities. The revenue unit across all analyses is tracked in USD Million, providing a standardized benchmark for comparing investment potential against other defense and maritime technology sectors.
Underwater Drone Market
Investors and strategists must note that the growth is not linear. There are inflection points associated with regulatory approvals and technological breakthroughs. The period between 2024 and 2025 saw a significant jump in valuation, suggesting a tipping point in market acceptance. As we enter the forecast period, the focus shifts from capability demonstration to reliability and endurance. The market size projections for 2027 through 2032 reflect the cumulative effect of new entrants and the expansion of existing product lines into broader operational domains.
Segmentation and Functional Deployment
To understand where the value lies, one must look at how the market is structured. Our report dissects the industry across three primary dimensions: Type, Application, and Region. While specific quantitative breakdowns are reserved for the full dataset to preserve proprietary depth, the qualitative structure reveals where innovation is concentrated.
Classification by Vehicle Type
The market is categorized by the level of autonomy and control mechanisms employed. The segments include Autonomous Surface Vehicles, Remotely Operated Surface Vehicles, and Hybrid Surface Vehicles. Autonomous systems are gaining significant traction due to advancements in AI-driven decision-making, allowing for prolonged missions without direct human intervention. Remotely Operated systems remain critical for tasks requiring precise human oversight, particularly in complex littoral environments. Hybrid systems offer a flexible middle ground, adapting to mission requirements dynamically. Understanding the adoption rates and technological maturity within each of these types is essential for manufacturers deciding where to focus R&D resources.
Application Verticals
Deployment scenarios drive demand. The primary applications analyzed include Defense and Security, Commercial operations, and Scientific Research and Environmental Monitoring. Defense and Security remains a dominant force, driven by naval modernization programs and border security needs. However, the Commercial segment is expanding rapidly, encompassing sectors such as offshore energy inspection, hydrographic surveying, and logistics support. Scientific Research continues to be a steady growth area, leveraging USVs for oceanographic data collection that was previously cost-prohibitive or too dangerous for crewed vessels. Each vertical presents unique procurement cycles and regulatory hurdles that are detailed extensively in the full report.
Regional Distribution
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Regional dynamics are heavily influenced by local defense spending, maritime trade volumes, and environmental regulations. North America and Europe currently show strong adoption rates linked to established defense budgets and advanced maritime industries. Meanwhile, the Asia Pacific region represents a high-growth frontier, driven by increasing naval capabilities and commercial shipping expansion. A localized strategy is required for each region, as regulatory frameworks and operational requirements vary significantly.
Competitive Landscape and Strategic Positioning
Market Concentration and Key Players
The USV market exhibits a moderate to high level of concentration, indicative of an industry where barriers to entry include significant R&D investment and certification hurdles. Our analysis indicates that the top three companies hold a substantial market share, with the top five firms controlling a significant majority of the industry revenue. This concentration suggests that partnerships, acquisitions, or niche specialization are viable strategies for new entrants looking to gain foothold without competing directly on volume.
Several key enterprises define the current competitive landscape. Teledyne Marine, based in Redondo Beach, California, maintains a strong focus on specific offerings tailored to the USV sector, leveraging their broader sensor and instrumentation capabilities. Maritime Robotics, headquartered in Norway, is recognized for its robust autonomous solutions designed for harsh maritime environments. OceanAlpha, located in Zhuhai, China, represents the growing manufacturing capacity and innovation coming from the Asian market, focusing on cost-effective unmanned platforms.
In the United States, Saildrone, headquartered in Richmond, California, has become synonymous with long-endurance solar-powered vessels, pushing the boundaries of persistence in data collection. Textron Systems, based in Boston, Massachusetts, is a major defense contractor contributing significant engineering resources and proven military-grade platforms. L3Harris Technologies, also in Florida, brings extensive integration capabilities for communication and payload systems. Sea Machines, another Boston-based firm, is notable for its focus on autonomous control systems that can be retrofitted onto existing vessels, lowering the barrier for commercial adoption.
European defense and technology firms also play a critical role. Elbit Systems, based in Haifa, Israel, contributes advanced defense electronics and unmanned capabilities. Exail Technologies, in Paris, France, focuses on specialized naval technologies and robotics. Kongsberg Gruppen, in Kongens Lyngby, Norway, is a longstanding leader in maritime autonomy and precision systems. These companies are not just vendors; they are setting the standards for interoperability and reliability.
Recent Developments and Strategic Moves
The competitive landscape is dynamic, with recent developments highlighting the shift towards operational deployment. In May 2026, the US Navy selected seven companies to advance Medium Unmanned Surface Vessel (MUSV) designs to the at-sea prototype evaluation and testing phase. This selection process is a critical filter, separating conceptual designs from those ready for integration into naval operations.
Furthering this momentum, HII advanced its Romulus USV design into the MUSV prototype phase for Navy evaluation in February 2026. This move signals a commitment to scalable unmanned logistics and combat support. Meanwhile, Textron Systems was awarded a contract in June 2026 to deploy multiple Tsunami USVs for Navy FLEX exercises and SOUTHCOM operations, demonstrating the immediate utility of these systems in real-world scenarios.
Historical context also validates the technology. In November 2025, a US Navy-sponsored Lightfish solar-powered USV completed the fastest transatlantic crossing in over two months. This achievement underscores the viability of renewable energy integration for extended range missions, a key consideration for long-duration autonomous operations.
Industry Dynamics and Technological Enablers
Propulsion and Material Science
The physical capabilities of USVs are being enhanced by breakthroughs in raw materials and energy storage. In 2024, Lithium-iron-phosphate batteries delivered 25 percent higher energy density. This improvement enables smaller USV craft to carry reserves for complex sensor operation at extended range, directly impacting mission profiles and payload capacity. This technological leap allows designers to optimize hull sizes without sacrificing endurance, a critical factor for commercial viability.
Furthermore, hull construction materials are standardized around high-performance options. USV hulls primarily use aluminum and composite materials, including fiberglass and carbon fiber. These materials are selected for their high strength-to-weight ratios, corrosion resistance, and reduced maintenance needs. The choice of material affects not only the operational lifespan but also the total cost of ownership, making material science a key consideration in procurement decisions.
Regulatory and Operational Requirements
Regulatory frameworks are tightening alongside technological capabilities. The US Navy currently requires operational demonstrations of not less than 720 continuous hours without any form of repair or maintenance on the main propulsion system, electrical generation, and distribution systems for large USV programs. This stringent requirement sets a high bar for reliability and influences vendor selection heavily. It implies that software autonomy is only half the battle; hardware durability and energy management are equally critical.
Compliance with these standards requires rigorous testing protocols and quality assurance processes. Companies that can demonstrate adherence to these operational tempos will gain a competitive advantage in defense contracting. For commercial entities, similar reliability standards are emerging as insurance and liability concerns come into play. The intersection of regulation and technology creates a moat for established players who have the resources to meet these demanding specifications.
Strategic Value for 2026 Decision-Making
Why This Research Matters Now
The data presented in our full market study provides more than just hindsight; it offers foresight. The convergence of defense modernization, commercial automation, and environmental monitoring needs creates a unique investment environment. However, the complexity of the supply chain, the nuance of regulatory compliance, and the velocity of technological change make intuition insufficient for strategic planning. Accessing detailed segmentation data, competitor profiling, and scenario analysis is essential.
Our report provides the granularity needed to answer specific questions: Which application vertical offers the highest margin potential? How do regional tariffs impact material costs? What is the adoption curve for hybrid versus fully autonomous systems? These insights are critical for positioning products and services effectively.
Actionable Intelligence
Stakeholders utilizing this research can expect to gain clarity on market entry barriers, partnership opportunities, and risk mitigation strategies. The analysis of key companies and recent contract awards provides a benchmark for assessing competitive strength. Understanding the material and energy trends allows for better product planning and supply chain management. Ultimately, the goal is to move from reactive adaptation to proactive strategy.
The market is moving toward a future where unmanned systems are integral to maritime operations. Those who understand the trajectory today will define the standards of tomorrow. PW Consulting's USV Market study is designed to equip leaders with the intelligence required to make those defining decisions with confidence.
For detailed segmentation data, comprehensive competitor financial analysis, and region-specific forecasts, we invite you to access the full report. The insights within go beyond the macro trends to provide the specific intelligence necessary for tactical execution in the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Unmanned Surface Vehicles (USV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


