



Category: market research
PW Consulting: Messaging Platform Market Hits $89.65M in 2025, Projected 5.7% CAGR Through 2032
By PW Consulting, 2026-09-16
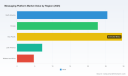
Beyond the Inbox: Strategic Intelligence for the Messaging Platform Market 2026–2032
The enterprise communication landscape is undergoing a structural transformation. What was once a utility layer for internal coordination has evolved into a critical orchestration engine for customer engagement, operational resilience, and cross-border data exchange. As organizations navigate an era defined by AI-augmented workflows, fragmented regulatory mandates, and accelerating cloud migration, the ability to separate signal from noise in the messaging platform ecosystem has become a decisive competitive advantage. Our latest research release, Messaging Platform Market 2026–2032: Strategic Intelligence & Forecast , is engineered to provide executives, product leaders, and procurement strategists with the analytical rigor required to allocate capital, position technology stacks, and anticipate market shifts with precision.
The Macro Trajectory: Compound Growth Meets Structural Inflection
Drawing on a comprehensive historical baseline spanning 2020 through 2025, the market has demonstrated consistent upward momentum, with total industry revenue climbing steadily as enterprises embed messaging infrastructure into core operational workflows. The trajectory projects into a robust forecast window through 2032, anchored by a compound annual growth rate of 5.7 percent. This growth is not merely linear expansion; it reflects a market in the midst of platform consolidation, feature compression, and heightened demand for interoperable, secure, and scalable communication architectures. Revenue progression across the forecast horizon signals sustained institutional investment in messaging as a strategic layer rather than a tactical add-on.
The implications for enterprise decision-makers are clear: budgeting for messaging infrastructure must now account for multi-year capability roadmaps, not just license renewals. Organizations that treat messaging as a static utility will find themselves outpaced by competitors who leverage platform elasticity, API-driven integration, and intelligent routing to compress response cycles and improve engagement quality.
Market Architecture: Why Segmentation Matters Without the Noise
Understanding where value concentrates requires more than top-line figures. The research dissects the market across multiple structural dimensions to reveal how demand, capability, and pricing dynamics diverge by segment type, deployment context, and end-user application. Rather than presenting isolated percentages, the analysis contextualizes how each segment interacts with broader enterprise priorities, such as digital transformation maturity, compliance readiness, and channel diversification.
Historical and projected sizing across regional and application categories is examined through a demand-pull lens, highlighting where infrastructure investments are being prioritized and where platform vendors are differentiating on reliability, localization, and integration depth. The report deliberately avoids superficial metric dumping, instead mapping how segment-level behaviors influence procurement cycles, vendor evaluation criteria, and total cost of ownership over the forecast period.
Competitive Dynamics: incumbents, challengers, and the shifting center of gravity
The messaging platform arena is characterized by a tightly concentrated competitive field, with a small group of established players commanding a substantial share of enterprise and provider-facing deployments. The research profiles a curated set of organizations that shape pricing norms, feature expectations, and integration standards across the ecosystem. These include platform providers targeting communication service providers and enterprise buyers, technology conglomerates embedding messaging into broader productivity suites, and specialized vendors offering secure collaboration hubs, API-driven messaging services, and multi-channel engagement platforms.
Messaging Platform Market
Several strategic archetypes emerge from the competitive mapping. Legacy-heavy vendors are accelerating modernization to retain enterprise accounts that demand tighter application integration and compliance assurance. Cloud-native and API-first players are expanding into carrier-grade and business messaging use cases, leveraging developer ecosystems to drive adoption. Meanwhile, regional specialists continue to compete on localization, data residency, and domain-specific workflow support. The report details how these positioning strategies intersect with procurement timelines, risk tolerances, and internal IT capacity, enabling readers to benchmark their vendor shortlists against realistic deployment scenarios.
Recent Momentum: Cross-Industry Signals Reshaping the Landscape
The market does not move in isolation. Recent developments across product launches, regulatory milestones, and infrastructure requirements are actively reshaping how organizations evaluate messaging platforms. In early-to-mid 2026, multiple product and approval milestones captured industry attention. An AI-powered messaging platform secured approval for RCS Business Messaging in the United States, signaling heightened regulatory and carrier readiness for richer, interactive enterprise messaging flows. Simultaneously, enterprise-focused communications providers launched self-healing voice resiliency technology and carrier-grade out-of-band messaging capabilities enhanced with AI and productivity features, underscoring a broader push toward reliability, continuity, and intelligent routing in mission-critical deployments.
At the same time, major exhibition showcases highlighted the emergence of autonomous, AI-enabled messaging architectures, reinforcing the industry's trajectory toward low-friction, context-aware communication layers. These announcements are not isolated product news; they reflect a market-wide shift toward platforms that can operate with greater autonomy, resilience, and cross-channel coherence.
Worldwide Mobile Application Development Platform Market
Regulatory and Infrastructure Undercurrents: The Hidden Cost of Non-Alignment
Beyond product cycles, structural forces are redefining evaluation criteria. The global financial community's completion of the transition to the ISO 20022 messaging standard has established a new baseline for cross-border payment speed, data richness, and interoperability. This shift reverberates beyond banking, influencing how enterprises design message schemas, audit trails, and integration pathways across partners and service providers. Concurrently, financial institutions have finalized critical architecture adjustments to achieve ISO 20022 compliance for 2026 implementation, reinforcing the expectation that messaging standards will increasingly shape vendor requirements and data governance expectations.
On the regulatory front, enterprise messaging platforms are operating under intensifying obligations. Compliance frameworks including GDPR, DORA, and the NIS2 Directives now shape how organizations manage data privacy, incident reporting, and record retention within communication workflows. Procurement teams can no longer treat compliance as an afterthought; platform selection must account for data handling boundaries, logging granularity, regional residency constraints, and auditability. Additionally, infrastructure considerations are gaining prominence. Scalable cloud architectures and specialized materials in hardware components are becoming relevant to reliable data transmission and energy efficiency, particularly as messaging workloads intensify and uptime expectations rise. Strategic buyers are beginning to factor these operational realities into vendor scoring, recognizing that platform endurance is inseparable from underlying infrastructure quality.
What the Report Delivers: Operational Intelligence, Not Just Forecasts
This research is built for execution, not just observation. The full study is structured to translate market complexity into decision-ready frameworks. Readers will find a detailed competitive landscape assessment that maps vendor positioning, capability emphasis, and ecosystem reach across major players. The report examines product and service architectures across the principal platform categories, providing context on how each category serves distinct operational needs and buyer profiles.
Forecast modeling extends across the 2026–2032 horizon, supported by historical trend analysis and scenario-aware projections that help organizations stress-test investment assumptions. The study includes use-case orientation across enterprise and personal communication contexts, highlighting where platform selection criteria diverge and where convergence is accelerating. In addition, the report integrates regulatory, standards-based, and infrastructure developments into a cohesive market dynamics narrative, enabling readers to anticipate compliance burdens, architectural expectations, and procurement risk factors before they become contractual blockers.
To support practical application, the analysis is paired with vendor evaluation considerations, deployment readiness markers, and strategic guidance for aligning messaging investments with broader digital transformation objectives. The goal is to equip teams with a structured lens for comparing platforms, sequencing adoption, and avoiding overinvestment in capabilities that do not match future operating conditions.
Strategic Implications for 2026 Decision-Makers
For leadership teams planning 2026 budgets and technology roadmaps, the messaging platform market presents both opportunity and complexity. The steady growth trajectory indicates durable demand, but the real strategic question is not whether to invest, but how to invest intelligently. Organizations should assess whether their current messaging stack can absorb AI-driven routing, multi-channel orchestration, and resilience requirements without fragmented point solutions. They should evaluate vendor commitments against compliance mandates, data governance expectations, and integration depth rather than feature checklists alone.
Procurement strategies must also account for concentration dynamics. In markets where a limited set of providers dominate enterprise and provider-facing deployments, negotiation leverage, transition risk, and roadmap alignment become central considerations. The research clarifies where competitive intensity is likely to drive differentiation, where pricing pressure may emerge, and where consolidation could reshape available options over the forecast window.
Access the Full Intelligence: Directed Next Steps
The messaging platform market is not a monolith; it is a set of interlocking demand streams, compliance pressures, infrastructure constraints, and competitive maneuvers. Capturing the strategic value of this environment requires a research foundation that goes beyond headline figures and connects market structure to operational decision-making. Our complete report delivers the granular segmentation, vendor profiling, forecast breakdowns, and dynamics mapping necessary to build confidence in 2026 planning and beyond.
For executives seeking the full segmented data, competitive benchmarking, and forecast detail that underpin this analysis, the complete study is available through our market research portal. The full edition provides the structured intelligence required to validate assumptions, narrow vendor shortlists, and align messaging platform strategy with enterprise objectives through 2032.
For detailed analysis of this topic, please visit the official page: Messaging Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sawmill Market Hits $93.5M in 2025, Projects 3.23% CAGR Through 2032
By PW Consulting, 2026-09-16
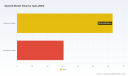
Navigating the Sawmill Market: Strategic Intelligence for 2026 Decision-Making
The global sawmill industry stands at a critical inflection point. As we move through 2026, timber processors, investors, and supply chain strategists face a complex matrix of shifting trade policies, evolving raw material economics, and structural changes in how wood products are sourced and manufactured. Understanding where this market is headed requires more than surface-level trend watching. It demands rigorous, data-grounded analysis that connects macroeconomic signals to operational realities.
Our newly released Sawmill Market Research report delivers precisely that level of insight. Spanning historical performance from 2020 through 2025 and extending forward across the 2026 to 2032 forecast horizon, this study provides the foundational intelligence enterprise leaders need to allocate capital, plan capacity, and position for sustainable growth. This article offers a strategic preview of the report's scope, methodology, and decision-ready frameworks, demonstrating why it has become an essential reference for senior executives navigating the timber sector.
Why 2026 Demands a Fresh Market Assessment
The sawmill sector has demonstrated remarkable resilience over the past half-decade, but resilience is not the same as predictability. Between 2020 and 2025, the global market expanded from approximately 79.55 million USD to 93.5 million USD, reflecting a compound trajectory shaped by post-pandemic construction rebounds, shifting housing demand, and supply chain recalibration. Looking ahead, the market is projected to reach 94.16 million USD in 2026, with growth accelerating toward 116.5 million USD by 2032. This forward path implies a compound annual growth rate of 3.23 percent, a figure that underscores both steady expansion and the nuanced volatility that defines industry cycles.
What makes the 2026 landscape particularly consequential is the convergence of several disruptive forces. Import tariff structures have tightened considerably, reshaping cost dynamics for cross-border lumber flows. Labor availability, natural gas pricing, and insurance premiums continue to pressure operating margins. At the same time, policy interventions are opening new financing channels for mill modernization and capacity restoration. For enterprises evaluating expansion, acquisition, or portfolio optimization, the margin for strategic error has narrowed. Informed decisions now depend on granular visibility into how these intersecting factors will play out across different market segments and regional contexts.
Report Architecture: What Decision-Makers Will Find Inside
This research was designed with practitioner needs at its core. Rather than offering abstract commentary, the report delivers a structured, actionable intelligence framework that translates market data into executable strategies. The following components illustrate the depth and practical orientation of the analysis.
Historical Baseline and Forward Projection
The report anchors its forecasts in a rigorously verified historical dataset covering 2020 through 2025. By examining year-over-year shifts, demand inflection points, and the impact of external shocks, readers gain a clear picture of the structural trends that will carry into the forecast period. The 2026 to 2032 projection window applies scenario-based modeling to map plausible growth pathways, enabling leadership teams to stress-test plans against multiple macroeconomic conditions.
Revenue Composition and Segment Breakdown
Understanding how revenue is distributed across product categories, application areas, and geographic regions is essential for identifying where competitive advantages can be built. The report provides a detailed segmentation analysis that illuminates the relative weight of softwood and hardwood lumber streams, the demand pull from construction and furniture manufacturing, and the contribution of packaging, joinery, and ancillary applications. Geographic distribution patterns are examined to reveal which markets exhibit the strongest momentum and which face structural headwinds.
Competitive Landscape and Enterprise Profiles
Market concentration remains a defining feature of the sawmill sector. The report evaluates the competitive positioning of leading producers, analyzing how scale, geographic footprint, and product specialization influence market share. Detailed profiles cover major North American operators, European forest products firms, and specialized equipment manufacturers, offering a panoramic view of the organizations shaping industry output. These profiles examine operational focus, production capabilities, and strategic orientations, giving readers a reliable reference for benchmarking and partnership evaluation.
Industry Dynamics and Policy Environment
Beyond pure market mechanics, the research integrates an analysis of the forces that are actively reshaping competitive conditions. Tariff escalations, stumpage price movements, log supply constraints, and labor cost inflation are examined in the context of their operational impact. The report also tracks legislative and financing developments that affect capital deployment, including rural development loan programs and proposed legislation aimed at sustaining sawmill infrastructure. This policy-aware perspective ensures that strategic plans account for both market-driven and regulatory-driven change.
Sawmill Market
The Competitive Arena: Key Players and Strategic Positioning
The sawmill market features a blend of large-scale integrated producers, regionally focused operators, and specialized equipment providers. Several organizations stand out for their influence on supply, innovation, and market signaling.
In North America, prominent producers such as West Fraser Timber Co., Weyerhaeuser Company, Canfor Corporation, Interfor Corporation, and Sierra Pacific Industries anchor substantial portions of softwood and hardwood output. These firms operate extensive sawmill networks and have pursued expansion and modernization initiatives that influence regional capacity dynamics. Georgia-Pacific LLC and Hampton Affiliates contribute additional scale within the building products and lumber segments, while Tolko Industries Ltd. and Arauco extend production reach across North American and international markets.
European operations are led by established forest products enterprises including Stora Enso, Södra, SCA, and Moelven Industrier ASA, each bringing distinct capabilities in sawn timber and engineered wood production. The Pfeifer Group, Holzindustrie Schweighofer, Klausner Holz Thüringen, and Ante-holz GmbH represent Germany and Austria's strong hardwood and sawn timber tradition, reflecting the region's emphasis on quality-grade lumber and industrial processing.
Beyond integrated producers, the market includes specialized equipment manufacturers such as Wood-Mizer LLC and Peterson Sawmills, which serve on-site and portable milling needs for agricultural, construction, and decentralized wood processing applications. These companies illustrate the breadth of the ecosystem, where machinery innovation intersects with changing patterns of timber utilization.
Competitive dynamics are not static. Capacity adjustments, asset sales, and operational curtailments are actively reshaping the field. Recent industry activity includes strategic divestitures, facility disruptions, and product demonstrations that signal shifting priorities. For decision-makers, tracking these movements is essential to understanding where supply flexibility is increasing, where consolidation pressure is building, and how rivals are recalibrating their portfolios.
Forces Reshaping the Market: Dynamics That Cannot Be Ignored
No strategic assessment of the sawmill market is complete without a clear accounting of the external forces that drive cost structures, demand patterns, and investment timing. Several developments have emerged as particularly influential.
Trade policy remains a dominant variable. Import duty levels on key cross-border lumber flows have risen substantially, altering the cost calculus for domestic producers and changing the competitive balance between regional supply sources. These shifts affect pricing strategies, margin expectations, and the economics of export-oriented production.
Raw material economics present a mixed picture. While stumpage and delivered log prices have experienced declines in certain regions, other cost inputs, including logging, trucking, labor, natural gas, and insurance, continue to exert upward pressure. The resulting squeeze on operating margins has prompted closer scrutiny of residual sales revenue, processing efficiency, and input procurement strategies. Understanding how these opposing trends interact is vital for projecting profitability under different supply scenarios.
Buttermilk Market
Policy and financing interventions are introducing new variables into the capital landscape. Government-backed loan programs have been deployed to support the reopening, expansion, and modernization of sawmill facilities, particularly those processing byproducts from federal land restoration activities. Proposed legislation aims to make such programs permanent, signaling a longer-term policy interest in sustaining domestic sawmill infrastructure. For enterprises considering facility investment or modernization, these programs can meaningfully affect project economics and timing.
Operational disruptions also warrant attention. Facility damage events, log supply constraints, and market-driven curtailments have intersected to create pockets of capacity tightness alongside broader demand uncertainty. These episodes remind industry participants that resilience planning, supply diversification, and contingency modeling are no longer optional enhancements but core components of operational strategy.
Translating Insight Into Action: How the Report Supports Strategic Decisions
The value of this research lies in its ability to convert complex market signals into clear strategic implications. Executives can use the report to address several high-priority questions.
- Which product segments and application areas are most likely to drive revenue growth over the forecast period, and how should production portfolios be aligned accordingly?
- How are regional demand patterns evolving, and where do the most favorable conditions exist for capacity investment, market entry, or partnership development?
- What competitive moves are leading producers making, and how should organizations interpret expansions, divestments, and operational adjustments when planning their own responses?
- How should enterprises model the impact of tariff changes, input cost volatility, and financing availability on project feasibility and margin projections?
- Which structural trends indicate durable shifts in demand, and which reflect cyclical fluctuations that require differentiated strategic treatment?
By addressing these questions within a unified analytical framework, the report helps leadership teams move from observation to action. Whether the objective is to prioritize capital projects, refine market targeting, assess competitor behavior, or build more resilient supply strategies, the research provides the evidence base needed to support confident decision-making.
Conclusion: Strategic Clarity for an Evolving Market
The sawmill market is neither static nor easy to navigate. Growth is real, but it is uneven. Opportunity is present, but it is accompanied by cost pressures, policy uncertainty, and competitive repositioning. In such an environment, strategic advantage belongs to organizations that ground their decisions in comprehensive, forward-looking intelligence rather than fragmented signals.
This report offers that foundation. It combines verified historical data, carefully constructed forecasts, detailed competitive profiling, and nuanced analysis of the forces shaping industry dynamics. For executives, investors, and strategic planners, it provides the clarity required to act with precision in 2026 and beyond.
To access the complete dataset, full segmentation breakdowns, detailed company profiles, and the complete forecast model, visit the source page for the Sawmill Market Research report. The full intelligence package is available for teams ready to translate market understanding into strategic execution.
For detailed analysis of this topic, please visit the official page: Sawmill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
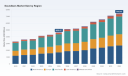
Strategic Intelligence for the Soundbars Market: Navigating Growth from 2026 to 2032
The global home entertainment landscape is undergoing a profound transformation, driven by the convergence of high-fidelity audio, smart home integration, and the enduring demand for immersive content consumption. As the market transitions from a phase of pandemic-fueled expansion into a period of structured, technology-led growth, stakeholders require precise, forward-looking intelligence to inform capital allocation, product roadmap planning, and competitive positioning. Our latest comprehensive Soundbars Market research report offers exactly that: a rigorously constructed, data-driven strategic roadmap spanning the forecast period from 2026 through 2032. This article outlines the foundational market trajectory, the structural forces currently reshaping competitive dynamics, and the actionable intelligence embedded within the full study to equip enterprise decision-makers with the clarity needed for 2026 and beyond.
The Macro Trajectory: A Sustained Growth Arc Validated by Historical Momentum
Market evolution is rarely linear, yet the historical record for the soundbars sector during the base period of 2020 to 2025 demonstrates a remarkably consistent upward curve, underscoring the category's transition from a peripheral accessory to an essential component of modern living spaces. Revenue expanded steadily from 3,300 million USD in 2020 to 4,650.87 million USD by the close of 2025. This trajectory reflects not merely volume growth but a fundamental shift in consumer willingness to invest in dedicated audio experiences that complement large-format television displays and streaming platforms.
Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with market valuation anticipated to climb from an estimated 5,144.89 million USD in 2026 to approximately 7,442.45 million USD by the terminal year of the study. This progression translates into a compound annual growth rate of 7.08 percent, a figure that signals healthy, sustainable momentum rather than speculative hype. For executive teams and investors, this CAGR serves as a critical benchmark: it validates the category's resilience against macroeconomic headwinds while highlighting the necessity of strategic agility. The market is not expanding uniformly across all vectors, and the firms that thrive will be those that align product development, pricing architecture, and channel strategy with the underlying structural shifts identified in our full analysis. The detailed forecasting models, scenario planning matrices, and sensitivity parameters that underpin these projections are explored comprehensively in the complete report, offering a transparent view of the assumptions and variables that will dictate performance across different operational horizons.
Structural Segmentation: Where Growth Converges and Diverges
Revenue is generated across multiple dimensions, each carrying distinct growth drivers, margin profiles, and deployment architectures. The historical and projected sizing across these axes reveals how form factor preferences, connectivity standards, application environments, and regional infrastructure maturity are collectively steering the medium-term trajectory. Understanding these structural splits is essential for manufacturers calibrating SKU portfolios, for distributors optimizing inventory depth, and for private equity or corporate venture teams evaluating market entry or consolidation opportunities.
- Form factor architecture continues to dictate acoustic performance trade-offs and installation complexity. The distribution between tabletop configurations, wall-mounted systems, and specialized variants reflects shifting consumer priorities around aesthetics, room acoustics, and integration with existing television mounts and entertainment centers.
- Connectivity protocols have fundamentally redefined the user experience and purchasing decision matrix. The balance between Wi-Fi-enabled ecosystems, Bluetooth-dominant streaming setups, and emerging or niche connectivity standards highlights the tension between local wireless convenience, multi-room synchronization, and high-bandwidth lossless audio expectations.
- Application environments segment the market into residential audio enhancement, commercial deployment scenarios, and specialized or emerging use cases. Each vertical carries unique procurement cycles, performance requirements, and replacement rhythms that influence both top-line volume and aftermarket service strategies.
- Geographic distribution reveals how mature entertainment markets, rapidly digitizing economies, and price-sensitive regions each contribute differently to aggregate growth. Infrastructure readiness, content localization, and brand perception heavily influence how product portfolios must be adapted to capture share in each territory.
The precise valuation breakdowns, share allocations, and forward-looking sensitivity adjustments across these segmentation dimensions are detailed extensively within the full research document. Accessing the complete study provides the granular visibility required to identify white-space opportunities, anticipate substitution effects, and model portfolio performance under varying demand scenarios.
Competitive Dynamics and the 2026 Strategic Reset
The competitive architecture of the soundbars market in 2026 is characterized by concentrated leadership, rapid product cycle acceleration, and a clear divergence between mass-market integration strategies and specialized audiophile-grade interventions. Strategic groupings shaped by headquarters and ecosystem depth illustrate how incumbents and challengers are simultaneously competing on sound quality, spatial processing, and smart-home interoperability.
Ecosystem Leaders and Premium Positioning
At the top of the competitive hierarchy, firms such as Samsung Electronics, LG Electronics, Sony Corporation, and Bose Corporation continue to anchor the market through aggressive premiumization, advanced spatial audio marketing, and deep television or consumer electronics integration. Samsung's Q-Series portfolio leverages multi-channel Dolby Atmos architectures, Q-Symphony synchronization with compatible displays, and expanding multi-device audio ecosystems to reinforce the living-room entertainment anchor. LG has emphasized modular flexibility, utilizing its Sound Suite design philosophy to allow adaptable speaker and subwoofer placement while deploying proprietary processing to refine spatial rendering and dialogue clarity. Sony maintains its traditional home-cinema heritage by pairing accessible entry performers with flagship Atmos-capable models tuned for cinematic reference listening and high-fidelity playback. Bose continues to compete at the intersection of acoustic refinement and convenience, aligning immersive processing with smart-home interoperability and simplified user onboarding.
Platform Players and Ecosystem Scale
Parallel to the traditional consumer electronics leaders, platform-centric players are expanding their footprint through integrated multi-room capabilities and subscription-adjacent ecosystem lock-in. Sonos has extended its architectural approach into the soundbar category, coupling waveguide-based acoustic engineering with wireless multi-room orchestration and enhanced low-frequency extension through dedicated woofer technologies. Harman International, operating through its JBL brand, continues to leverage broad audio ecosystem reach, offering immersive channel configurations and wireless subwoofer options designed to slot into broader Harman-connected environments. These players benefit from network effects, recurring engagement, and cross-device compatibility, but must also navigate the pressure of hardware margins, platform differentiation, and consumer fatigue around ecosystem fragmentation.
Late Entrants and Niche Audio Specialists
A notable strategic development in the current cycle is the consistent movement of specialized high-fidelity and pro-audio-adjacent brands into the soundbar category, targeting consumers willing to pay a premium for acoustic accuracy, calibrated calibration, and scalable home-theater configurations. SVS entered the space with its first soundbar platform, emphasizing onboard room correction, Dolby Atmos support, wireless subwoofer pairing, and expandable channel architectures intended for enthusiasts seeking serious home-theater performance. KEF introduced a single-enclosure approach built around coaxial driver technology, prioritizing spatial coherence and musicality within a compact installation footprint. Yamaha continues to serve the broader upgrade-to-quality segment with compact, balanced entries that emphasize high-resolution audio handling and approachable everyday performance. The arrival of these specialists intensifies the performance arms race and pressures incumbents to justify premium pricing through demonstrable acoustic differentiation rather than brand heritage alone.
Worldwide Sound Cards Market
January 2026 Product Cycle: Strategic Implications
The opening months of 2026 already reflect the acceleration described above. Multiple major manufacturers deployed new product initiatives within a compressed timeframe, signaling that 2026 will be defined by rapid refresh cycles rather than incremental updates. LG's introduction of a modular sound system combining a central soundbar, dedicated subwoofer, and wireless surround elements highlighted a push toward placement flexibility and adaptive tuning. Samsung's simultaneous expansion of its Q-Series lineup, including higher-channel-count configurations and dialogue-shifting processing features, reinforced the ongoing premiumization of mainstream living-room audio. SVS's first-ever soundbar reveal underscored the continued blurring of lines between traditional home-theater subwoofer specialists and integrated soundbar form factors. KEF's compact coaxial-driver soundbar further demonstrated that acoustic accuracy and form-factor restraint can serve as decisive differentiators in crowded retail environments. Collectively, these movements indicate that competitive advantage in 2026 will increasingly depend on the speed of architectural innovation, the credibility of spatial audio claims, and the ability to simplify complex installations without sacrificing performance.
Soundbars Market
Input Constraints, Supply Realities, and Market Resilience
Growth narratives must be evaluated alongside the operational frictions that govern manufacturing, component sourcing, and regulatory exposure. Two intersecting themes are particularly relevant to strategic planning for the 2026 to 2032 horizon.
First, the rare earth supply picture remains a structural variable for audio hardware manufacturers. With the twelve-month suspension of China's expanded rare earth export controls set to expire in November 2026, current supply conditions indicate limited progress in reducing global dependence on concentrated sourcing channels. For soundbars and related audio electronics, rare earth elements influence magnet design, transducer performance, and miniaturization efficiency. Firms that have not diversified supplier relationships, secured forward inventory positions, or engineered component substitutions may face margin compression or delayed product cycles if export conditions tighten.
Second, the broader industrial context around critical minerals continues to reshape input-cost expectations across consumer electronics and adjacent device categories. Lithium's role in the energy transition has intensified attention on both primary extraction and recycled sourcing pathways, and while soundbars are not direct battery-dependent devices in the same sense as portable electronics or electric vehicles, the macroeconomic attention on critical mineral resilience influences component pricing norms, supplier negotiating leverage, and strategic procurement frameworks across the broader electronics value chain. Companies that embed supply-chain scenario modeling into product planning will be better positioned to absorb volatility than those that treat component sourcing as a static cost line.
These dynamics do not negate the sector's growth outlook, but they reframe how leadership teams should approach manufacturing footprints, bill-of-materials strategy, and long-term cost modeling. The complete market study incorporates supply-side sensitivity analysis, sourcing risk assessments, and procurement strategy recommendations that allow organizations to stress-test plans against realistic input-cost and regulatory scenarios.
The soundbars market entering 2026 presents a compelling combination of validated growth, architectural innovation, and intensifying competitive differentiation. Historical momentum through 2025, a projected trajectory toward 2032, and the early-2026 product cycle collectively point to an environment where strategic advantage will be earned through precise segmentation targeting, credible acoustic engineering, ecosystem interoperability, and resilient supply-chain design. Organizations that align product strategy with the structural insights outlined here will be best positioned to capture disproportionate share in a market that is expanding steadily but rewarding only those who execute with discipline.
To translate this high-level intelligence into actionable commercial strategy, we encourage stakeholders to access the full Soundbars Market research report. The complete study provides detailed segmentation valuations, competitive benchmarking, supply-chain scenario modeling, regional deployment analysis, and forward-looking demand indicators calibrated to support board-level planning, product portfolio decisions, and investment prioritization throughout the 2026 to 2032 forecast period.
For detailed analysis of this topic, please visit the official page: Soundbars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Law Enforcement Software Market to Reach $30B by 2032 with 10% CAGR
By PW Consulting, 2026-09-16
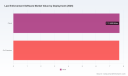
Navigating the Next Wave: Strategic Intelligence in the Law Enforcement Software Market 2026–2032
A Market at the Crossroads of Technology and Public Safety
The global law enforcement software market stands at a defining inflection point. Between 2020 and 2025, the sector expanded from 9.5 billion USD to 15.4 billion USD, reflecting a decade of sustained investment in digital policing, records modernization, and dispatch automation. Our latest research projects this momentum to accelerate through 2032, with the market reaching 30.02 billion USD and a compound annual growth rate of 10.0 percent over the 2026–2032 forecast period. These are not merely trailing indicators; they are structural signals that public safety agencies, technology vendors, and institutional investors must interpret with precision.
For enterprise decision-makers, the strategic question has shifted from whether to digitize law enforcement workflows to how to architect integrated, compliant, and scalable platforms that can withstand regulatory scrutiny, labor constraints, and evolving threat landscapes. This report delivers the analytical framework required to navigate that complexity. It translates macroeconomic trajectory into actionable intelligence, mapping the pathways through which cloud migration, records management modernization, and AI-enabled digital policing are reshaping procurement, partnership, and competitive positioning.
Why 2026 Demands a Fresh Strategic Lens
The 2026 landscape is shaped by converging pressures that traditional planning cycles rarely capture in unison. Persistent staffing shortages across police departments, federal and state agencies, and municipal correctional facilities are driving rapid automation of routine workflows. Simultaneously, regulatory frameworks continue to tighten around criminal justice information handling, with CJIS compliance, sovereign-data requirements, and regional hosting expectations becoming non-negotiable design constraints for any prospective deployment. These dynamics are not isolated; they reinforce one another. Agencies seeking to do more with fewer personnel are prioritizing platforms that unify dispatch, records, case management, and evidence workflows, while vendors must engineer architectures that satisfy both operational efficiency and jurisdiction-specific privacy mandates.
Our analysis situates these forces within a broader competitive reality: market concentration remains pronounced, with the top three players collectively commanding a significant share and the top five exceeding three-quarters of total revenue. This concentration does not imply stagnation. Rather, it signals a market where incumbents are expanding platform breadth while specialized entrants are carving defensible niches through cloud-native RMS/CAD integration, digital evidence workflows, and real-time intelligence tooling. Understanding where each competitor is vulnerable, where integration gaps persist, and which capability bundles are resonating with end users is essential for any organization seeking to enter, expand, or partner within this ecosystem.
Police Law Enforcement Recorder Market
What This Report Delivers: Operational Intelligence, Not Abstract Projections
This study is designed for practitioners who require granular, decision-ready intelligence rather than high-level summaries. Beyond the headline trajectory, the report dissects the market across deployment models, solution categories, and end-use segments, providing a multidimensional view of where adoption is accelerating and where legacy dependencies still constrain modernization. Readers will gain access to a structured competitive profiling framework covering leading vendors, their core offerings, and the strategic implications of their positioning. Each profile is assessed for product architecture, compliance posture, integration capabilities, and the operational realities of agency adoption.
The report also integrates recent market developments that illustrate how platform functionality is evolving in near-real time. For example, recent feature updates in records management systems have targeted faster pricing decisions and streamlined approval workflows, reflecting a broader industry push to reduce administrative friction and accelerate operational responsiveness. Such updates may appear incremental in isolation, but when mapped against broader deployment trends and end-use priorities, they reveal meaningful shifts in how agencies value speed, transparency, and workflow continuity. Our analysis connects these signals to longer-term adoption patterns, helping readers distinguish tactical enhancements from strategic repositioning.
Mapping the Competitive Field
The vendor landscape is anchored by organizations that have built reputations across the full spectrum of public safety software. Caliber Public Safety provides comprehensive CAD, RMS, mobile solutions, and NIBRS-compliant records management with CJIS-secure cloud hosting, positioning it as a full-stack provider for agencies prioritizing compliance and continuity. Vector Solutions contributes records management, CAD integration, and agency readiness software, emphasizing operational preparedness alongside core records functions. Motorola Solutions brings Spillman Flex CAD and RMS suites tailored for law enforcement records management, dispatch, and multi-agency coordination, leveraging deep domain expertise in dispatch-centric workflows.
Tyler Technologies offers an Enterprise Public Safety software suite encompassing CAD, law enforcement records management, mobile access, and analytics for policing operations, appealing to agencies seeking a unified analytics-enabled platform. Flock Safety has introduced cloud-based Flock Nova public safety software that integrates RMS, CAD, LPR video, and AI tools for real-time crime intelligence and investigations, reflecting the growing convergence of sensor data, video analytics, and records workflows. Axon Enterprise provides Axon Records and Evidence management software with direct CAD integration for digital evidence storage, chain of custody, and officer workflows, targeting the evidentiary and investigative demands that increasingly define modern case handling.
Versaterm contributes cloud-based CAD, RMS, and CommunityConnect solutions for dispatch, reporting, and public safety operations, with a footprint that spans North American deployment models. CODY Systems has developed Pathfinder cloud RMS/CAD software with NIBRS native support, mobile RMS, and cross-platform data sharing, addressing interoperability and compliance requirements that remain central to multi-jurisdictional operations. EIS provides core CAD, RMS, jail, and mobile public safety software solutions, reinforcing the enduring importance of end-to-end coverage across detention and field operations. PsPortal supplies CJIS-compliant cloud software for secure NCIC/NLETS database access and law enforcement records management, highlighting the critical role of secure information exchange in integrated platforms.
Verint focuses on public safety software for emergency call handling, recording, and operational efficiency in law enforcement dispatch and response, complementing broader CAD/RMS ecosystems with specialized communications and recording capabilities. Oracle has developed a Public Safety Suite with CAD, RMS, and jail management systems integrated for secure law enforcement data management, bringing enterprise-scale infrastructure and integration depth to a sector that increasingly values platform durability and data governance. Together, these players illustrate a market where differentiation is no longer defined solely by feature count, but by compliance assurance, interoperability, evidence lifecycle management, and the ability to support multi-agency coordination under constrained staffing conditions.
Market Dynamics Shaping Adoption Trajectories
Several structural dynamics are reshaping how agencies evaluate, procure, and deploy law enforcement software. Cloud adoption continues to gain traction, supported by the promise of scalable infrastructure, reduced on-premises maintenance burdens, and faster access to updated functionality. At the same time, cloud deployment in this sector is not a simple lift-and-shift decision. Agencies and vendors must navigate regional hosting options that satisfy both CJIS sovereign-data requirements and localization expectations, making architecture decisions highly jurisdiction-sensitive. This reality elevates the strategic importance of deployment flexibility, data residency controls, and transparent compliance documentation.
Labor economics are equally influential. Persistent staffing shortages are accelerating the adoption of integrated platforms that automate routine processes, reduce manual data entry, and improve cross-functional visibility. In parallel, federal funding mechanisms such as the Byrne Justice Assistance Grants are helping agencies justify investments in workflow automation and modern records infrastructure. These funding and labor dynamics create a favorable environment for platforms that can demonstrably reduce administrative load while improving response coordination and investigative throughput. Decision-makers should therefore assess vendors not only on feature breadth, but on measurable operational efficiency gains and integration readiness with existing agency ecosystems.
Regulation remains a defining constraint and enabler. CJIS compliance is foundational for any platform handling criminal justice information, and integrated software environments must preserve data sharing integrity, privacy safeguards, and auditability across modules. As platforms become more interconnected, the compliance surface area expands, making it essential for buyers to evaluate end-to-end governance rather than isolated module certifications. The reports framework helps readers map these requirements to vendor capabilities, ensuring that procurement decisions align with both operational ambition and regulatory reality.
How to Use This Research for 2026 Decision-Making
This report is structured to support multiple decision pathways. For technology vendors and aspiring market entrants, it provides a competitive terrain map that clarifies where concentration is highest, where integration gaps create entry opportunities, and which solution categories are gaining relative momentum. For public safety agencies and municipal decision-makers, it offers a structured basis for comparing deployment models, evaluating compliance posture, and aligning platform selection with staffing constraints and funding timelines. For investors and strategic partners, it delivers a forward-looking view of market scale, growth cadence, and the competitive dynamics that will determine which platforms achieve durable share as the market approaches 30.02 billion USD by 2032.
Throughout the analysis, the emphasis is on actionable clarity. Readers will find segmentation discussions that illuminate how deployment preferences, solution adoption, and end-use demand interact across the forecast horizon, without reducing the market to oversimplified ratios. The competitive profiles are designed to support side-by-side evaluation, while the dynamics section connects near-term developments to longer-term structural shifts. By linking macro trajectory to micro decision criteria, the report enables organizations to build strategies that are resilient to regulatory change, staffing volatility, and evolving technology expectations.
Conclusion: Turning Market Scale Into Strategic Advantage
The law enforcement software market is expanding with clarity and conviction, but growth alone does not guarantee advantage. The organizations that will capture value in 2026 and beyond are those that can translate macro momentum into disciplined choices about deployment architecture, compliance readiness, integration depth, and workflow automation. This report provides the intelligence infrastructure required to make those choices with confidence. It combines top-down market trajectory with bottom-up competitive and operational analysis, giving readers a comprehensive vantage point on where the market is headed and how to position within it.
Law Enforcement Software Market
The full study contains the detailed segmentation analysis, competitive benchmarking, deployment and solution-level insights, and forward-looking scenario context needed to move from strategic awareness to execution. For decision-makers ready to align their planning with the realities of a 10.0 percent CAGR market on a path from 17.34 billion USD in 2026 to 30.02 billion USD in 2032, the complete report offers the depth required to act decisively.
For detailed analysis of this topic, please visit the official page: Law Enforcement Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Amplifier Market Hits $386.3M in 2025, Forecast 7% CAGR to $620.9M by 2032
By PW Consulting, 2026-09-16
Car Amplifiers Market 2026-2032: Strategic Intelligence for Automotive Audio Decision-Makers
The automotive audio sector is undergoing a structural transformation driven by electrification, premiumization, and standardized performance measurement. For executives evaluating capital allocation, product roadmaps, or supply chain resilience, the Car Amplifiers Market demands a clear-eyed view of where growth premiums are forming and how competitive dynamics are consolidating. Our latest market research publication delivers a comprehensive, data-grounded assessment of this landscape, translating historical momentum and forward-looking projections into actionable intelligence for 2026 and beyond.
Over the 2020-2025 historical window, the global car amplifiers market expanded from approximately 302.5 million USD to 386.3 million USD, reflecting a compound trajectory that has consistently outpaced broader automotive accessory growth. This momentum is projected to sustain through the 2026-2032 forecast horizon, with the market advancing toward a six-hundred-million-dollar revenue threshold by the end of the period. The forecast implies a steady CAGR of 7.0 percent, signaling that amplifier demand will remain resilient even as vehicle architectures evolve and consumer spending patterns recalibrate. For strategy teams, this trajectory is not merely a top-line projection; it is a signal that underlying demand drivers—enhanced cabin acoustics, integrated multimedia systems, and the aftermarket pursuit of differentiated audio experiences—continue to compound.
The strategic value of this research lies in its ability to convert macro growth into operational clarity. While headline figures establish the scale of opportunity, the real decision-making leverage emerges when leaders understand how that growth distributes across amplifier architectures, deployment channels, and regional ecosystems. The report maps these dimensions with precision, enabling organizations to calibrate portfolio focus, pricing strategy, and geographic prioritization without relying on fragmented anecdote or outdated benchmarks. Readers will find that the analysis deliberately isolates structural drivers rather than surface-level fluctuations, ensuring that resource allocation decisions are anchored in durable market mechanics.
Report Scope and Operational Utility
This publication is engineered for practitioners who need more than a market snapshot. It functions as a planning instrument, aligning commercial strategy with technical and regulatory realities that shape the amplifier competitive arena. The report architecture is built around several interlocking components that translate directly into business decision support.
- Comprehensive market sizing and forecast modeling that extends from the 2020 baseline through 2032, providing continuity between observed historical performance and projected market expansion.
- Granular segmentation analysis covering amplifier types, application pathways, and regional demand structures, allowing stakeholders to identify where volume concentration and value premiums diverge.
- Competitive positioning frameworks that evaluate leading manufacturers across product philosophy, channel integration, and innovation cadence, rather than relying on generic brand recognition.
- Regulatory and standards context that clarifies how measurement protocols and certification benchmarks influence performance claims, buyer trust, and competitive differentiation.
- Supply chain and production dynamics that detail manufacturing footprints, labor intensity, and integration patterns affecting cost structures and time-to-market.
- Recent corporate developments, including product catalog updates, trade show showcases, and technology unveilings, offering near-real-time signals on where incumbents are directing engineering and marketing energy.
Each section is designed to feed directly into strategic workstreams such as go-to-market planning, M&A screening, partnership evaluation, and portfolio rebalancing. By embedding macro and micro perspectives within a unified analytical structure, the report reduces the friction between market intelligence and execution planning.
Competitive Landscape: Concentration, Capabilities, and Positioning Signals
The car amplifiers market is characterized by a pronounced concentration of share among established audio and automotive electronics players. The top three firms collectively account for 62.0 percent of market revenue, while the top five extend that share to 75.0 percent. For strategic planners, this concentration pattern matters because it shapes pricing power, channel access, and the feasibility of disruptive entry. It also indicates that innovation leadership and brand equity remain highly correlated with scale advantages in component sourcing, testing infrastructure, and OEM integration relationships.
Incumbents span a diverse set of corporate lineages, from dedicated audio specialists to global consumer electronics groups with automotive divisions. JL Audio, headquartered in Miramar, Florida, anchors its offering in premium car audio amplifiers and extends into marine-rated models that support vehicle integration scenarios where environmental durability intersects with acoustic performance. Rockford Fosgate, based in Tempe, Arizona, emphasizes high-performance amplifiers and mobile audio systems designed for demanding aftermarket and automotive applications. Kicker, operating from Stillwater, Oklahoma, delivers high-performance car audio amplifiers and vehicle-specific audio solutions that align closely with targeted retrofit and performance upgrade segments.
The Japanese cohort—Alpine, Clarion, Kenwood, Pioneer, and Sony—maintains a strong presence across both aftermarket and OEM channels, with product philosophies that blend in-dash integration, amplifier architecture, and cabin audio system design. Alpine and Pioneer, for example, continue to position amplifiers as part of broader vehicle audio ecosystems, while Clarion and Kenwood emphasize compatibility and integration flexibility for both installed and replacement use cases. Sony contributes premium-grade amplifier models intended for automotive audio systems where brand perception and acoustic refinement intersect.
European premiumization efforts are represented by Audison in Italy, which focuses on premium DSP car amplifiers and audio processors that target reference-level performance and advanced signal processing. This emphasis on digital signal processing reflects a broader industry movement in which amplifier value is increasingly tied to tuning capability, integration intelligence, and acoustic customization rather than raw power output alone. On the OEM and luxury integration side, Harman, based in the United States, extends its amplifier footprint through Harman Kardon and Infinity brand portfolios for both OEM and aftermarket vehicles. Bose similarly concentrates on OEM car audio amplifiers embedded within vehicle sound systems, where performance is engineered around manufacturer-specific cabin acoustics and system constraints. Yamaha rounds out the competitive field with amplifier offerings for automotive and OEM applications, reinforcing the breadth of participating lineages.
Strategic observers should note that competitive differentiation in this market is not simply a function of wattage or price point. It increasingly depends on verified performance claims, integration readiness, system-level tuning expertise, and the ability to serve both factory-installed and aftermarket ecosystems. Recent corporate activity underscores this dynamic. In April 2026, Audison released its 2026 catalog, providing detailed documentation of updated technologies, integration solutions, and reference-level audio performance for modern car audio systems. That release was followed in May 2026 by Audison’s participation in Motor Valley Fest in Modena, where the company showcased premium sound systems on a Ferrari 360 Modena demonstration vehicle, combining exclusive listening sessions with a live discussion on lifestyle mobility. These events signal a deliberate emphasis on experiential positioning and high-end integration narratives.
Around the same period, Rockford Fosgate used SEMA to unveil a new amplifier positioned as among the most powerful car audio amplifiers ever produced for aftermarket 12V applications. This showcase highlights the continued relevance of performance escalation in the aftermarket segment, where enthusiasts and installers seek demonstrable gains in output, thermal management, and system reliability. Taken together, these developments illustrate a market in which premium audio specialists and performance-oriented brands are actively redefining the ceiling of what consumers and integrators expect from an amplifier subsystem.
Market Dynamics: Standards, Certification, and Structural Forces
Regulatory conventions and measurement standards have become increasingly consequential in shaping buyer confidence and competitive signaling. The Consumer Technology Association approved the updated CEA-2006 standard for testing and measurement methods of mobile audio amplifiers, and voluntary compliance remains a relevant benchmark across the industry. The standard specifies uniform testing at 14.4 volts into a 4-ohm impedance at 1 percent THD plus noise, with a frequency range of 20 Hz to 20,000 Hz for general-purpose car amplifiers. For manufacturers and buyers alike, this framework helps anchor RMS power ratings and signal-to-noise ratios in a comparable format, reducing ambiguity in product evaluation and making performance claims more defensible across channel touchpoints.
Certification has emerged as an additional lever for differentiating credible performance. Rockford Fosgate became the first company to achieve Klippel Verified certification for an amplifier, a milestone that supports verified power handling and performance in car audio products. This type of verification matters strategically because it ties engineering claims to independent measurement methodology, giving integrators, retailers, and end users a clearer basis for evaluating product integrity. As the market grows, such certification pathways may increasingly influence purchasing decisions in segments where acoustic expectations and system reliability carry premium value.
Beyond standards and certification, structural production dynamics continue to influence cost architecture and scaling capacity. Regional manufacturing footprints remain important, with significant labor deployment in facilities that produce car amplifiers and related automotive audio systems. For instance, Chinese manufacturing operations supporting Harman’s automotive audio production reportedly employ more than 1,200 workers at a Suzhou plant, highlighting the scale of labor-intensive assembly and integration work that underpins certain supply chains. This dimension is particularly relevant for organizations assessing lead-time stability, cost competitiveness, and exposure to regional production shifts.
Market structure also reflects a clear divergence between OEM installation and aftermarket replacement pathways. The OEM axis is tightly linked to vehicle program cycles, manufacturer brand partnerships, and system-level audio integration, while the aftermarket axis is shaped by installer networks, enthusiast demand, retrofit compatibility, and performance expectations. The interplay between these pathways defines how amplifiers move through the market and where competitive advantage is most durable. Organizations evaluating entry, expansion, or partnership opportunities must account for the fact that these channels operate with distinct purchasing logic, margin profiles, and performance assurance requirements.
Guitar Amplifier Market
Why This Research Matters for 2026 Decision-Making
The forecast period beginning in 2026 presents both opportunity and uncertainty. Demand is expected to keep expanding, but the distribution of that growth will not be uniform across segments, geographies, or product categories. Organizations that treat the car amplifiers market as a monolithic category risk misallocating resources, misreading channel priorities, or underestimating the importance of verified performance and integration readiness. Our report is designed to counter those risks by offering a structured, evidence-based view of where value is accumulating and how the competitive field is evolving.
Car Amplifiers Market
For strategy teams, the practical payoff is threefold. First, the report supports portfolio decisions by clarifying how amplifier types and application pathways interact with demand patterns, enabling sharper segmentation focus without overexposing the organization to low-yield categories. Second, it provides competitive context that maps manufacturer positioning, recent innovation signals, and certification or standards developments into a single decision-relevant framework. Third, it connects market growth to operational considerations such as production scale, regional manufacturing dynamics, and channel-specific purchasing behavior, helping leaders translate macro projections into execution assumptions.
The research also serves as a reference point for partnership and sourcing evaluation. In a market where concentration is high and performance credibility is increasingly scrutinized, understanding the distinction between brand visibility and verifiable engineering advantage is essential. Recent events—such as updated product catalogs, premium showcase demonstrations, and landmark certification achievements—provide useful leading indicators of where incumbents are investing and how they intend to defend or expand their positions. By placing these signals into a longer historical and forecast context, the report enables decision-makers to separate short-term momentum from durable strategic shifts.
Access the Full Strategic Assessment
This article serves as an introduction to the full Car Amplifiers Market research publication, which contains the complete segmentation breakdown, regional demand structures, application-level analysis, manufacturer profiles, and forecast detail required for thorough strategic planning. The macro trajectory and competitive themes outlined here establish the analytical foundation, but the complete dataset is necessary for precise market sizing, segment prioritization, and scenario modeling.
Organizations preparing for 2026 planning cycles should treat this intelligence as a prerequisite for informed investment and positioning decisions. The full report provides the depth needed to move from directional insight to operational action, including the segmentation detail and competitor specificity that cannot be fully reproduced here. To obtain the complete forecast, segmentation data, and competitive analysis, access the full market research report on our source page.
For detailed analysis of this topic, please visit the official page: Car Amplifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydraulic Power Unit Market to Reach $18.2B by 2032, Growing at 5.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Next Decade: Navigating the Hydraulic Power Unit Market
The global industrial landscape is undergoing a profound transformation. As machinery becomes increasingly sophisticated and energy efficiency mandates tighten, the Hydraulic Power Unit (HPU) market stands at a critical inflection point. For executives, investors, and strategic planners, understanding the trajectory of this sector is not merely an academic exercise but a prerequisite for capitalizing on emerging opportunities. PW Consulting has prepared a comprehensive market research report designed to equip decision-makers with the actionable intelligence needed to navigate the period from 2026 through 2032.
This analysis serves as a strategic compass. It moves beyond superficial market summaries to deliver a granular understanding of revenue streams, competitive positioning, and the operational dynamics that will define success in the coming years. By synthesizing historical performance data with forward-looking projections, this report offers a robust framework for assessing risk and identifying high-growth vectors within the hydraulic power ecosystem.
Macro Growth Trajectory and Economic Context
The financial narrative of the Hydraulic Power Unit market is characterized by steady expansion and resilience. Based on rigorous analysis of historical data from 2020 to 2025, the market has demonstrated a consistent upward trend, overcoming various supply chain challenges and economic fluctuations. The baseline year of 2025 establishes a solid foundation, with the total market revenue reflecting the accumulated demand from key industrial sectors.
Looking forward, the forecast period spanning 2026 to 2032 indicates a favorable growth environment. The Compound Annual Growth Rate (CAGR) is projected to remain robust, driven by modernization efforts in legacy infrastructure and the adoption of advanced hydraulic systems in new applications. Throughout this forecast horizon, the market is expected to witness a significant increase in total valuation, reaching new milestones by 2032. This growth is not linear; it is punctuated by periods of acceleration linked to technological breakthroughs and regulatory shifts.
It is crucial for stakeholders to recognize that while the aggregate numbers suggest stability, the underlying composition of this growth varies significantly across different vectors. The total revenue figures mask the divergent performance of specific technology types and application verticals. Our full report dissects these layers to reveal where the true value is being generated, ensuring that your strategic investments are aligned with the highest potential segments rather than the average market performance.
Market Dynamics and Operational Pressures
Success in the HPU market requires a sophisticated understanding of the external forces shaping production and procurement. Several key dynamics are currently influencing the sector, creating both headwinds and tailwinds for market participants.
-
Regulatory Frameworks: Compliance is no longer optional. Standards such as ISO 4413:2010 specify general rules and safety requirements for hydraulic fluid power systems and components used on machinery. Furthermore, the Harmonised Standard EN ISO 12100:2010 is utilized for guidance in hydraulic power unit risk assessments. Adherence to these protocols affects design cycles, certification costs, and market access, particularly in regions with stringent safety enforcement.
-
Raw Material Volatility: The cost structure of HPU manufacturing is sensitive to commodity markets. Volatility in steel and copper prices can shift HPU production costs by up to 20%. This level of fluctuation demands agile procurement strategies and robust hedging mechanisms to protect margins. Companies that fail to account for this volatility in their pricing models risk eroding profitability during periods of supply tightness.
-
Technology Shift: There is a marked transition toward electrification and efficiency. The industry is gradually moving away from purely combustion-based solutions in favor of systems that offer reduced energy consumption and lower operational footprints. This shift is reshaping the product roadmap for manufacturers and altering the procurement criteria for end-users who are under pressure to meet sustainability targets.
These dynamics create a complex operating environment. The report provides a detailed examination of how these factors interact with regional supply chains and pricing strategies, offering scenarios that help leaders prepare for various economic conditions.
Hydraulic Power Unit Market
Diverse Offerings and Technology Segmentation
The competitive arena is defined by a wide array of product technologies. The market is not monolithic; it is split between distinct power sources and delivery mechanisms, each catering to specific operational needs.
On one hand, electric hydraulic power units represent a significant portion of the market, driven by the demand for cleaner, more efficient solutions suitable for indoor and precision applications. On the other hand, diesel and gasoline hydraulic power units retain strong relevance in mobile and remote settings where grid power is unavailable or reliability in harsh conditions is paramount.
Similarly, application segmentation reveals distinct demand profiles. Industrial settings continue to be a primary driver, utilizing HPUs for stationary machinery and process control. Mobile applications represent another critical pillar, supporting construction, agriculture, and transportation equipment. There is also a category of specialized uses that fall under other applications, often requiring custom configurations.
Understanding the revenue contribution and growth rate of each of these segments is vital. While the overall market size is important, the strategic value lies in knowing which technology type is gaining share, which application vertical is saturating, and where the white space for innovation exists. Our detailed segmentation analysis provides this breakdown without exposing the numbers prematurely, ensuring that clients gain a clear view of where to allocate resources for maximum return.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with a handful of key players commanding a significant share of total revenue. The CR3 and CR5 metrics indicate that while there are dominant forces, there is still ample room for specialized players to compete on niche capabilities, customization, and regional service excellence.
Major corporations are actively shaping the market through product innovation and strategic focus.
-
Bosch Rexroth AG: Maintains a diverse portfolio of hydraulic power units, emphasizing efficient compact and project-specific models tailored to precise customer requirements.
-
Parker-Hannifin Corp.: Focuses on eco-friendly hydraulic power units designed to reduce energy consumption, aligning with broader sustainability goals in the industrial sector.
-
Eaton Corporation plc: Provides comprehensive industrial hydraulic power solutions, leveraging its scale to serve large-scale manufacturing and infrastructure projects.
-
Danfoss Power Solutions A/S: Specializes in hydraulic power and motion control systems, integrating advanced electronics with traditional hydraulic mechanics.
-
HYDAC International GmbH: Offers hydraulic filtration and power unit solutions, addressing the critical need for fluid cleanliness and system longevity.
Beyond these industry giants, a robust ecosystem of specialized manufacturers adds depth to the market. Companies like Nachi-Fujikoshi, Dana Incorporated, and Atlas Copco contribute specific strengths, ranging from industrial precision to integrated system capabilities. Regional specialists such as Weber Hydraulik, Brevini Fluid Power, and Bucher Hydraulics provide localized expertise and custom engineering that larger conglomerates may not prioritize.
Recent activity highlights the pace of innovation. In August 2025, Parker-Hannifin announced a new line of eco-friendly hydraulic power units designed to reduce energy consumption by up to 30%, signaling a aggressive push toward efficiency. Similarly, in July 2025, Guorui Hydraulics launched a Permanent Magnet Synchronous Hydraulic Drive Integrated Power Unit featuring high-efficiency permanent magnet synchronous motors, wide speed range hydraulic pumps, and CAN bus control. These moves illustrate the competitive pressure to modernize product lines and capture value through technological differentiation.
The report includes a comprehensive profiling of all key competitors, analyzing their headquarters, strategic focus, and recent developments to help you benchmark your position and identify potential partnership or acquisition targets.
Regional Nuances and Global Reach
Geographically, the market exhibits distinct characteristics. Demand is not distributed evenly, reflecting the industrial maturity and economic priorities of different regions.
Hydraulic Pumps Market
North America represents a significant market, driven by strong manufacturing bases and infrastructure investment. Europe follows with a focus on high-precision engineering and regulatory compliance. The Asia Pacific region stands out as a dynamic growth engine, fueled by industrialization and expanding construction sectors. Latin America and the Middle East and Africa also contribute to the global total, each with unique demand patterns linked to local resource extraction and development projects.
However, relying solely on regional aggregate data can be misleading. Within each geography, the mix of electric versus diesel units, or industrial versus mobile applications, varies considerably. A strategy that works in one region may fail in another due to differences in labor costs, energy availability, and local content requirements. Our geographical analysis goes beyond surface-level numbers to explore the specific drivers and barriers within each territory, enabling a more nuanced international strategy.
Report Content and Operational Utility
This market research report is designed as a practical tool for strategic execution. It is not merely a collection of data points but a structured analysis intended to support specific business functions.
-
Market Sizing and Forecasting: Detailed revenue projections for the forecast period, allowing for budget planning and investment appraisal.
-
Segmentation Analysis: Deep dives into type, application, and regional splits to identify high-growth niches.
-
Company Profiles: Comprehensive assessments of key players, including their offerings, strategic focus, and recent moves.
-
Dynamics Assessment: Evaluation of regulatory, raw material, and technological factors impacting the supply and demand balance.
By integrating these elements, the report enables users to construct robust market entry strategies, optimize product portfolios, and anticipate competitor moves. Whether you are a manufacturer looking to expand your footprint, a supplier seeking to understand end-user demand, or an investor evaluating the sector's potential, this document provides the foundational intelligence required to make informed decisions.
Conclusion: The Imperative for Informed Strategy
The Hydraulic Power Unit market offers substantial opportunities for those equipped with the right information. The projected growth from 2026 to 2032 suggests a expanding pie, but the distribution of that growth will favor players who understand the nuances of technology shifts, regulatory compliance, and regional dynamics.
Superficial market summaries are insufficient for the complexities of today's industrial environment. To truly capitalize on the trends outlined here, stakeholders need access to the complete dataset, including the specific revenue splits, detailed competitive benchmarks, and granular regional forecasts that we have reserved for this full report.
PW Consulting invites you to leverage this research to secure a competitive advantage. We encourage you to access the full source webpage to download the complete study. There you will find the detailed intelligence necessary to transform these high-level insights into concrete operational success. The future of hydraulic power is being written now, and the decisions you make in 2026 will define your position for the rest of the decade.
For detailed analysis of this topic, please visit the official page: Hydraulic Power Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hemp Seeds Market Hits USD 500 Million in 2025, Projects 7.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: Navigating the Hemp Seeds Market Outlook 2026-2032
As the global functional food and wellness ingredients sector accelerates, hemp seeds have emerged as a cornerstone commodity bridging consumer nutrition, industrial utility, and sustainable agriculture. PW Consulting’s newly released Hemp Seeds Market research delivers a comprehensive, data-grounded assessment of this evolving landscape, designed specifically to equip executive leadership, product development teams, and supply chain strategists with the clarity required for high-stakes 2026 decision-making. Unlike broad industry summaries that rely on delayed indicators or superficial trend-spotting, this study maps the structural drivers, competitive fault lines, and regulatory inflection points that will define commercial viability over the next seven years. The following overview outlines the strategic framework, methodological rigor, and actionable intelligence contained within the full report, while preserving the granular segmentation required for precise corporate planning.
The Trajectory and Structural Signals of a Maturing Commodity Market
The hemp seeds sector has transitioned from a niche, regulation-constrained niche to a mainstream ingredient pipeline with measurable macroeconomic traction. Historical performance from 2020 through 2025 demonstrates a consistent upward arc, with annual revenue milestones reflecting sustained demand absorption across food formulation, personal care, and industrial applications. Building on this foundation, the 2026 base-year valuation establishes a clear inflection point, followed by a forecast period extending through 2032 that projects compounded annual growth at 7.5 percent. This trajectory is not merely a linear extrapolation; it reflects converging supply chain maturation, shifting consumer preference toward plant-based complete proteins, and expanding regulatory clarity that has reduced market entry friction for ingredient suppliers and branded manufacturers alike.
Strategists evaluating capital allocation, capacity expansion, or M&A targets will recognize that sustained double-digit absolute growth over a multi-year horizon signals a market moving past early adoption cycles. The compound growth rate indicates that while the category is no longer in its experimental phase, it remains far from saturation. Demand is being pulled by formulation innovation in nutritional supplements and beverage platforms, while simultaneously being pushed by agricultural processors optimizing yield, extraction efficiency, and downstream fractionation capabilities. The full study contextualizes these macro trends against historical volatility, delineating which growth phases are cyclical versus structural, and identifying the specific institutional triggers that will accelerate or constrain regional deployment.
Regulatory Architecture and the New Operational Baselines
Market velocity in hemp-derived ingredients has historically been constrained by legal ambiguity. Recent legislative and administrative actions have materially altered that landscape. The amendment enacted through Pub. L. No. 119-37 on November 12, 2025, clarified the federal definition of hemp by establishing a total THC concentration limit of not more than 0.3 percent on a dry weight basis, while explicitly excluding viable seeds from any parent plant exceeding that threshold. This provision reduces compliance uncertainty for seed-focused growers, processors, and ingredient distributors, enabling more predictable sourcing contracts and downstream certification pathways.
Parallel to statutory clarification, USDA mechanisms continue to provide structured importation pathways for hemp seeds into the United States following their removal from DEA jurisdictional authority under the 2018 Farm Bill framework. These administrative routes have streamlined cross-border supply chains, particularly for processors integrating North American grain with European and Asian finishing capacity. On the formulation side, the FDA’s 2018 GRAS evaluation, which issued no objections to hulled hemp seeds, hemp seed protein powder, and hemp seed oil as food ingredients, remains a critical benchmark. It has enabled rapid incorporation into baked goods, dairy alternatives, snack matrices, and beverage systems without requiring case-by-case premarket approval. The full report maps how these regulatory pillars interact with regional compliance variations, quality assurance protocols, and audit readiness requirements, providing operations leaders with a practical compliance roadmap rather than a theoretical legal summary.
Report Architecture: Operational Intelligence for Executive Deployment
The study is structured to translate market complexity into executable strategy. Readers will find a delineation of product architecture across whole seeds, hulled formats, extracted oils, and protein powders, with each category assessed for processing intensity, margin profiles, storage and logistics constraints, and formulation compatibility. Application pathways are examined through the lens of commercial adoption velocity, highlighting where food and beverage integration drives volume, where nutritional supplement positioning commands premium pricing, where personal care formulations leverage fatty acid and antioxidant profiles, where industrial applications utilize structural and chemical properties, and where animal feed channels absorb byproducts and lower-grade fractions. Regional demand distribution, supply chain nodes, and trade flow patterns are analyzed to identify where processing capacity aligns with consumption growth, and where infrastructural bottlenecks may create pricing dislocations or delay time-to-market for new product launches.
Beyond structural mapping, the report delivers quantitative baselines, forward-looking scenario modeling, and sensitivity analysis that allow strategy teams to stress-test assumptions around yield variability, input cost fluctuations, regulatory enforcement intensity, and competitive entry timelines. The analytical framework is calibrated for 2026 planning cycles, meaning that forecasts are anchored to current capacity utilization, recent processing line expansions, and observable shifts in procurement behavior among large-scale food manufacturers and ingredient distributors. By consolidating historical performance, base-year positioning, and multi-year projections into a single decision-ready format, the study eliminates the need for internal teams to piece together fragmented data sources or rely on outdated secondary references.
Competitive Landscape: Strategic Positioning and Recent Capacity Shifts
The market exhibits moderate concentration, with the top three participants accounting for approximately 45 percent of total revenue and the top five collectively representing roughly 55 percent. This concentration profile indicates a landscape where established processors and vertically integrated ingredient suppliers hold meaningful scale advantages, yet sufficient fragmentation remains to allow specialized entrants, regional growers, and formulation-focused brands to capture differentiated value. The competitive field spans North American grain originators, European fractionation specialists, and global distributors that bridge organic certification, bulk procurement, and retail-ready packaging.
Manitoba Harvest Hemp Foods operates as the largest hemp foods manufacturer in the category, producing and selling raw shelled hemp seeds and hemp seed oil from North American-grown and processed grain, positioning itself as a scale anchor for both retail and ingredient channels. Victory Hemp Foods has recently reinforced its processing leadership by launching North America’s largest hemp heart protein and oil processing line in April 2025, utilizing patented solvent-free fractionation to deliver allergen-free V-70 protein and V-ONE oil, an expansion that directly strengthens its value proposition for plant-based food, baking, and beverage formulators. Navitas Organics and Nutiva maintain strong consumer-facing and wholesale positions by offering organic, non-GMO, gluten-free, and vegan-certified shelled hemp seeds tailored for smoothies, baking, and superfood applications. Green Source Organics and Harvest Hemp Foods supply organic and derived hemp products across food and ingredient markets, while Canah International and Hempflax BV focus on processing and distributing seeds and oils for food and industrial ingredient applications. BAFA neu GmbH emphasizes certified organic seed production for food and animal feed, and Kanda Hemp supplies certified industrial hemp seeds for commercial grain and fiber production. Bulk Hemp Warehouse serves the raw grain and fiber segment with bulk viable whole seeds, whereas Allive and North Central Company address wholesale and snack/baking demand through bulk unhulled, hulled, and organic-compliant supply options.
Hemp Market
The strategic implication for 2026 is clear: scale processors are investing in fractionation and allergen-free certification to capture premium ingredient contracts, while mid-tier and regional players are competing on organic certification, supply reliability, and application-specific formatting. The full study evaluates these players across capacity positioning, product architecture, distribution reach, and recent operational developments, providing a comparative lens that helps procurement and partnership teams identify where scale, where specialization, and where geographic proximity deliver the highest strategic return.
Strategic Imperatives for 2026 Planning Cycles
Executives entering 2026 must treat hemp seeds not as a single commodity line but as a multi-format ingredient ecosystem with distinct margin structures, regulatory touchpoints, and formulation barriers. The most effective strategies will align procurement and capacity decisions with application-specific demand rather than aggregate volume alone. Formulators seeking clean-label protein and lipid profiles will continue to favor hulled seeds, protein powders, and oils that carry GRAS status and organic or allergen-free certifications, which means supplier qualification, batch consistency, and documentation readiness will become as critical as unit pricing.
Supply chain leaders should assess whether existing grain contracts, storage configurations, and finishing capacity match the forecast distribution of whole versus hulled demand, particularly as processors expand fractionation lines and seek to minimize solvent exposure while maintaining throughput. Market entrants and investors will benefit from understanding where regional demand concentration intersects with processing density, and where logistics costs or certification lag may create temporary arbitrage opportunities. Brand managers and innovation teams should monitor how recent legislative clarifications and administrative importation pathways reduce lead-time uncertainty, enabling faster launch cadences for hemp-integrated food, beverage, personal care, and supplement portfolios. The report provides the scenario scaffolding required to evaluate these decisions quantitatively, rather than relying on directional intuition.
Conclusion: From Market Awareness to Decisive Action
The hemp seeds market in 2026 stands at the intersection of regulatory stabilization, processing innovation, and broadening application adoption. Sustained compound growth through 2032 signals that the category has moved beyond experimental positioning into a structured ingredient pipeline with measurable economic gravity. Yet the opportunity is not uniformly distributed across formats, applications, or regions, and the firms that outperform will be those that can translate macro momentum into precise procurement, capacity, and partnership decisions. PW Consulting’s full Hemp Seeds Market research report delivers the segmented baselines, competitive mapping, regulatory context, and forward-looking scenario analysis necessary to make those decisions with confidence. Complete segmentation values, regional deployment detail, application-level revenue splits, and additional processing-line and competitive developments are available in the full study, providing the depth required for board-level planning, product roadmapping, and supply chain optimization.
Hemp Seeds Market
For detailed analysis of this topic, please visit the official page: Hemp Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 22.4% CAGR for Chargeable Flexible Battery Market to Reach $932M by 2032
By PW Consulting, 2026-09-16
The Bendable Power Paradigm: Strategic Intelligence for the Chargeable Flexible Battery Market in 2026 and Beyond
The transition from rigid power sources to conformable energy solutions is no longer a conceptual novelty in electronics design. It is an engineering imperative. As product architectures grow more complex, ergonomically demanding, and spatially constrained, manufacturers across medical technology, consumer wearables, and industrial IoT are actively seeking power systems that can bend, twist, and integrate seamlessly into unconventional form factors. PW Consulting has published a comprehensive market research study on the Chargeable Flexible Battery Market, offering executives a data-driven foundation for technology sourcing, partnership selection, and geographic expansion in the critical 2026 through 2032 horizon.
This strategic briefing introduces the scope and analytical rigor of the study. While we outline the structural dynamics and competitive forces shaping the sector, readers should note that granular segmentation metrics, pricing models, and regional revenue splits are reserved for the full report. The following analysis is designed to demonstrate the depth of our methodology and establish the commercial rationale for acquiring the complete dataset.
Market Trajectory: From Steady Growth to an Accelerating Curve
Historical tracking across the 2020 to 2025 period reveals a market that moved from incremental adoption to a structural inflection point. Revenue expanded from approximately 93.15 million USD in 2020 to an estimated 115.5 million USD by 2024, reflecting steady but measured progression driven by early-stage pilot deployments and niche product integration. The trajectory shifted noticeably in 2025, with market revenue reaching an estimated 226.52 million USD, marking a step-change that signals broader commercialization readiness across multiple end-use verticals.
The forward outlook reinforces this acceleration. Forecast modeling projects the market to reach approximately 282.97 million USD in 2026, with continued expansion through 342.56 million USD in 2027, 403.09 million USD in 2028, and 512.58 million USD in 2029. The trajectory extends toward 605.34 million USD by 2030, climbing further to 764.37 million USD in 2031 and an estimated 932.34 million USD by 2032. This progression translates to a forecast compound annual growth rate of 22.4 percent throughout the 2026 to 2032 period, indicating that flexible rechargeable power is transitioning from a supporting technology to a strategically critical component category.
Such a growth profile demands more than headline recognition. For corporate strategists, the operative question is not whether the market is expanding, but where the growth concentrates, which technology families are gaining share, and how regulatory and supply-chain dynamics will alter competitive positioning. The full report maps these variables in granular detail, with segmentation dimensions structured to support product roadmap planning, investment allocation, and market-entry timing.
Core Report Scope: An Execution-Oriented Intelligence Framework
A market study is only as valuable as its applicability to operating decisions. This report is designed to function as a practical decision-support tool rather than a high-level survey. It integrates historical performance analysis, forward-looking demand drivers, technology maturity assessment, and competitive benchmarking into a single coherent framework. The research structure enables users to evaluate both the commercial opportunity and the execution risks associated with flexible rechargeable battery adoption.
The report’s analytical coverage includes the following operational components:
- Market sizing and trajectory modeling grounded in historical data covering the 2020 to 2025 period, extended through the 2026 to 2032 forecast window.
- Technology-family evaluation distinguishing thin-film architectures from printed flexible battery formats, with emphasis on performance trade-offs, manufacturing readiness, and application fit.
- Application-side analysis examining how wearable electronics, medical devices, and consumer electronics are influencing volume demand, specification requirements, and procurement behavior.
- Regional market structure assessment designed to inform expansion planning and channel strategy without relying on publicly available approximation.
- Competitive profiling of major participants, including product focus, technological specialization, geographic footprint, and strategic posture within the flexible battery value chain.
- Regulatory and standards context, including evolving compliance expectations in key markets and their implications for product design, sourcing, and market access.
- Demand-driver mapping that connects product innovation trends, form-factor requirements, and functional performance needs to battery specification priorities.
By organizing the intelligence around these dimensions, the report supports a range of corporate functions. R&D leaders can use the technology assessment to benchmark architectural choices. Commercial teams can align product positioning with the most attractive application segments. Supply-chain and procurement stakeholders can evaluate vendor profiles with greater clarity. Executive leadership can use the forecast structure to test investment scenarios and set internal growth targets that reflect market reality rather than extrapolated assumptions.
Competitive Landscape: Differentiation in a Fragmented, Innovation-Driven Market
The chargeable flexible battery sector is characterized by a broad set of active participants, many of which compete on technological specialization, application-specific engineering, and regional manufacturing relationships rather than on scale alone. Market concentration data indicates a relatively distributed structure, with the combined share of the top three firms estimated at 25.0 percent and the top five firms at 32.0 percent. This level of dispersion signals that there is meaningful room for differentiation, and that competitive advantage will increasingly depend on proprietary cell design, integration capability, reliability under mechanical stress, and the ability to meet application-specific certification or compliance requirements.
Several established and emerging players illustrate the breadth of approaches shaping the market. Samsung SDI manufactures flexible lithium-ion rechargeable batteries targeted at wearables, smartcards, and IoT devices, reinforcing the relevance of flexible power in high-volume consumer and connected-device categories. LG Chem develops and supplies flexible rechargeable batteries optimized for wearable and flexible electronics applications, aligning product development with the mechanical and energy-density demands of next-generation form factors. Panasonic produces flexible lithium-ion rechargeable batteries engineered to withstand repeated bending and twisting, addressing durability as a core adoption barrier in wearables and smart devices.
Alongside these larger-scale participants, a number of specialized firms are advancing distinct technology positions. Blue Spark Technologies develops thin, flexible printed batteries integrated into continuous vital sign monitoring wearables, highlighting the medical and health-monitoring application pathway. Enfucell specializes in printed flexible power sources for wireless sensors and IoT, offering lithium-polymer rechargeable options that support low-power distributed sensing use cases. BrightVolt manufactures ultra-thin solid-state lithium-polymer rechargeable batteries for IoT and wearable devices, leveraging solid-state design as a potential differentiator in safety and form-factor flexibility.
Imprint Energy produces ultrathin flexible rechargeable zinc batteries for IoT smart labels and integrated electronics, expanding the material choice set available to designers seeking cost-effective or application-tailored alternatives. Cymbet develops solid-state rechargeable thin-film batteries with energy harvesting compatibility for embedded IoT and wearable applications, combining energy storage with broader system-level power strategies. Jenax manufactures J.Flex solid-state flexible lithium-ion rechargeable batteries intended for wearables and fast-charging applications, reflecting ongoing efforts to combine mechanical flexibility with improved charging performance. FlexEl offers custom thin flexible rechargeable batteries for specialized medical and industrial wearable uses, underscoring the role of bespoke engineering in high-value, lower-volume market segments.
Chargeable Flexible Battery Market
The strategic implication is clear. Buyers and competitors are not navigating a market with a single dominant solution. Instead, they are evaluating a multi-technology, multi-application space in which design strategy determines commercial success as much as manufacturing capacity does. The full report provides deeper comparative profiling and trend analysis that helps organizations identify which vendors, technology families, and partnership models are most aligned with their product architecture and market ambitions.
Market Dynamics: Technology Push, Regulatory Pressure, and Application Pull
Flexible battery adoption is advancing through a combination of simultaneous forces. On the technology side, progress in thin-film deposition, printed battery manufacturing, material flexibility, and solid-state chemistry is expanding the range of applications that can use conformable power without sacrificing reliability. On the demand side, wearables and other compact electronic devices continue to push for slimmer profiles, ergonomic integration, and uninterrupted operation, all of which increase the relevance of rechargeable flexible power sources. Medical devices and industrial IoT applications further broaden the opportunity by requiring specialized characteristics such as continuous monitoring capability, low-power efficiency, or custom form factors for embedded use.
At the same time, regulatory and standardization activity is becoming a more prominent market dynamic. The EU Battery Regulation establishes mandates affecting carbon footprint declarations, due diligence obligations, labeling, recyclability expectations, and removability considerations across rechargeable battery products. For flexible battery producers and downstream manufacturers, these requirements influence sourcing, documentation, product design, and compliance timelines. Recent developments underscore that regulatory readiness is shifting from a planning issue to an active operating constraint. European Commission industrial carbon footprint reporting for rechargeable batteries exceeding 2 kWh capacity became mandatory in February 2026. In parallel, Intertek moved toward Notified Body status under the EU Battery Regulation for flexible battery compliance, reflecting the growing institutional infrastructure needed to assess and certify flexible battery products against evolving standards.
Flexible PV Cell Market
Beyond regulatory pressure, recent patent activity illustrates how manufacturers are reinforcing their technological claims. Volt Carbon issued a second U.S. patent supporting high-cycle lithium-metal pouch cells suitable for flexible battery formats, a development that points toward improved cycle life and application versatility in next-generation cell designs. Beam Global filed a U.S. patent for a scalable flexible smart battery system intended to enhance power efficiency, indicating continued interest in system-level optimization rather than cell performance alone. These developments, while individual in scope, collectively suggest that innovation in the flexible battery field is increasingly focused on cycle durability, integration intelligence, and efficiency improvement.
A full market study must therefore account not only for what is being built, but also for what regulation, certification, and patent positioning will allow in the market ahead. The report integrates these dynamics to help organizations anticipate compliance costs, identify possible sourcing shifts, and assess whether specific technology paths offer durable advantage or merely temporary differentiation.
Strategic Value for 2026 Decision-Making
For executives making decisions in 2026, the chargeable flexible battery market presents both opportunity and complexity. Growth is strong, but the market is not uniform. Technology choices differ substantially in maturity, manufacturability, and application compatibility. Regional demand structures are not interchangeable. Regulatory expectations are evolving. Competitive positioning is shaped as much by specialized engineering as by scale. In this environment, organizations need intelligence that is detailed enough to support action, yet structured clearly enough to support prioritization.
The PW Consulting study is built for that purpose. It provides a consolidated view of historical performance, short-term momentum, and long-term expansion, with segmentation and competitive analysis calibrated to support real operating decisions. Readers seeking a broad overview may find the macro trajectory useful, but organizations that intend to source materials, select partners, enter new geographies, or justify R&D investment will need the complete segmentation detail, regional breakdowns, application-level drivers, and competitive profiles that the full report contains.
This article has outlined the analytical framework and strategic themes that define the study. It has not disclosed the core segmented data that underpin those themes. That is intentional. In a market moving at this pace, the most valuable insights are the ones that enable precise action. The full chargeable flexible battery market research report is designed to deliver that precision, supporting decision-makers who need to move from market awareness to market execution.
For detailed analysis of this topic, please visit the official page: Chargeable Flexible Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micronized Rubber Powder Market to Hit $279.34M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
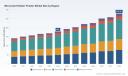
Strategic Intelligence Brief: The Micronized Rubber Powder Market Outlook 2026-2032
Executive Summary: A Market Poised for Structural Transformation
The global micronized rubber powder (MRP) industry is navigating a pivotal inflection point. As sustainability mandates intensify and circular economy principles transition from regulatory ideal to commercial necessity, the demand for high-performance recycled rubber solutions has accelerated. Our latest comprehensive research publication provides a granular analysis of this dynamic landscape, offering decision-makers the clarity required to navigate market volatility, supply chain constraints, and competitive disruptions across the forecast period of 2026 to 2032.
For strategic planners, procurement leaders, and investment committees, the window to secure advantageous positioning is narrowing. This article serves as a foundational overview of the market mechanics, growth trajectories, and competitive architectures detailed in our full report. It is designed to demonstrate the analytical rigor and operational relevance of our research while preserving the proprietary data necessary for precise strategic modeling. To access the complete segmentation matrices, pricing elasticity curves, and forecast scenario models, readers are invited to consult the full market brief directly.
The market has demonstrated consistent resilience over the past half-decade, evolving from a niche recycling byproduct segment into a specialized materials market characterized by technological differentiation and stringent performance standards. Understanding the forces propelling this evolution is essential for any organization seeking to capitalize on the opportunities embedded within end-of-life tire valorization and advanced polymer modification.
Historical Trajectory and Baseline Valuation (2020-2025)
Our retrospective analysis covering the period from 2020 through 2025 reveals a market that has steadily expanded despite macroeconomic headwinds, supply chain uncertainties, and fluctuating raw material costs. Over this six-year horizon, the industry consolidated its foundation, driven by increasing adoption of MRP in high-value applications and growing acceptance of recycled content mandates across key industrial sectors. The baseline valuation at the end of the historical period stands at a recorded level, reflecting a mature and increasingly sophisticated market ecosystem.
This historical growth was not uniform. It was shaped by diverging regional adoption rates, varying degrees of regulatory enforcement on tire disposal, and the gradual maturation of processing technologies. The data indicates a clear trajectory of value accumulation, with early adopters of fine-particle processing technologies capturing disproportionate margins compared to producers relying on conventional ambient grinding methods. The historical record establishes a credible foundation for forward-looking projections and underscores the importance of timing in capacity expansion and technology investment decisions.
Forward Outlook: Growth Catalysts for 2026-2032
Looking ahead, the forecast period anticipates a robust compound annual growth rate that outpaces many traditional industrial materials segments. This growth is underpinned by a convergence of structural drivers that are likely to persist throughout the decade. Regulatory frameworks worldwide are tightening requirements for tire recycling, mandating higher recovery rates and penalizing landfill disposal. Simultaneously, infrastructure spending programs in multiple economies are creating immediate demand pull for asphalt modifiers and construction additives derived from recycled rubber.
Technological advances are also reshaping the supply side. Improvements in cryogenic processing efficiency have progressively reduced energy intensity, mitigating one of the historically significant cost burdens associated with fine-particle production. At the same time, the industrial preference for powders with superior surface area and morphology is elevating the commercial relevance of specialized grades, creating pricing tiers that reward producers with advanced milling and classification capabilities. These dynamics suggest that the market of 2032 will look materially different from the market of 2026, with greater emphasis on product specification, traceability, and environmental certification.
Market Structure, Segmentation, and Value Migration
The Particle Size Dimension: Technical Differentiation as a Margin Driver
Particle size is not merely a physical specification; it is a fundamental determinant of end-use eligibility and pricing power. The market segmentation by particle size reveals a clear hierarchy of value, with finer fractions commanding preferential positioning in applications that demand intimate polymer interaction, uniform dispersion, and enhanced mechanical performance. Coarser fractions continue to serve bulk-modification roles, but the margin differential between fine and coarse grades has become increasingly pronounced as downstream formulators optimize formulations for performance and sustainability credentials.
Worldwide Micronized Silica Market
This technical segmentation has strategic implications for capacity planners. Investment in fine-grinding capability requires higher capital intensity and more complex operational control, but it opens access to application segments with lower price elasticity and stronger competitive moats. Our full report dissects the capacity allocation trade-offs across these size categories and provides scenario analysis on how shifting application preferences may alter relative demand shares over the forecast horizon.
Application Ecosystems: Where Demand Converges and Diverges
The application landscape of MRP spans multiple industrial domains, each with distinct procurement cycles, specification requirements, and growth trajectories. The automotive sector has historically represented the largest demand pool, leveraging MRP for vibration damping, component lightweighting, and recycled content integration. Construction-related applications, particularly asphalt modification and paving compounds, have emerged as a high-growth vector, supported by public-sector sustainability procurement and the demonstrated performance benefits of rubber-modified surfaces.
Industrial manufacturing, coatings, and specialty uses constitute additional demand pillars, each responding to different drivers such as polymer compounding trends, adhesive formulation requirements, and consumer-facing sustainability messaging. The interplay between these application segments creates a diversified demand base that can buffer the market against sector-specific downturns, but it also complicates forecasting, as relative demand shares shift with technological substitution, raw material pricing, and regulatory emphasis. Our detailed analysis maps these interdependencies and identifies the segments most likely to generate incremental volume growth in the coming years.
Micronized Rubber Powder Market
Regional Dynamics and Geographic Arbitrage
Geographic distribution of demand and production capacity reflects a complex interplay of regulatory environments, tire generation rates, processing infrastructure density, and logistics economics. Different regions exhibit markedly different adoption curves, with some markets leading in per-capita recycled content integration while others remain in earlier stages of capacity development. Understanding these regional asymmetries is critical for companies evaluating export opportunities, local processing investments, or strategic partnerships.
The full research publication provides a comprehensive geographic breakdown that maps demand intensity against supply availability, identifies logistics bottlenecks, and evaluates the economic viability of regional trade flows. This geographic intelligence is essential for optimizing footprint strategy and for anticipating where regulatory or infrastructure developments may create the next wave of regional demand spikes.
Competitive Architecture and Strategic Positioning
Market Concentration and the Scale Advantage
The MRP industry exhibits a moderate concentration profile, with a defined set of leading producers holding meaningful shares of global output. Competitive positioning is increasingly determined by technology tenure, processing capability, and the ability to supply certified, specification-grade materials at scale. Producers that have invested in proprietary milling technologies, integrated recycling loops, or advanced quality assurance systems are better positioned to capture premium segments and defend against commoditization pressure.
Market leaders such as Lehigh Technologies, a Michelin Group subsidiary operating from Tucker, Georgia, exemplify the integration of advanced cryogenic turbo mill technology with a diversified application portfolio spanning tires, plastics, asphalt, and construction materials. Their emphasis on lifecycle assessment and circular economy messaging aligns with the credentialing demands of downstream customers. Genan Holding A/S, headquartered in Denmark and recognized as a leading global end-of-life tire recycler, has built a reputation around ultra-fine powder production and ambient granulates, with recent product certifications reinforcing the environmental value proposition of their asphalt premix offerings.
Tinna Rubber & Infrastructure Limited, based in India, has established itself as a large-scale producer with deep integration from radial truck and bus tire feedstock through to crumb rubber modifiers, reclaim rubber, and polymer applications. Their scale and vertical integration illustrate a distinct competitive model centered on feedstock control and cost-efficient processing. Entech Inc., operating from Middlebury, Indiana, brings long operational tenure dating back to the mid-1990s, offering a broad size range of MRP and crumb rubber products complemented by integrated hauling, processing, and compounding services.
The Rubberjet Group, based in Italy, represents a different technological pathway, utilizing proprietary high-pressure water-jet technology to produce micronized rubber powder and granules from medium and large end-of-life tires and rubber tracks. Their approach underscores the ongoing innovation in processing methods and the differentiation potential that alternative milling technologies can create.
Recent Competitive Signals and Industry Developments
Recent announcements from key players illustrate the intensifying focus on environmental credentialing and product certification. In late 2025, Lehigh Technologies released a lifecycle assessment study quantifying CO2 reduction and circular economy benefits associated with their micronized powders used in asphalt modification, signaling a strategic emphasis on evidence-based sustainability claims. Concurrently, Genan Holding A/S secured Environmental Product Declaration certification for its GENAN ROAD+ PREMIXED asphalt premix, reinforcing the market trend toward third-party verified environmental performance in construction applications.
These developments are not isolated marketing events; they reflect a structural shift in procurement decision-making, where environmental documentation and performance validation are becoming prerequisites for entry into premium application segments. Companies that invest early in measurement, certification, and transparent reporting are likely to gain preferential access to specification-driven demand.
Structural Dynamics Shaping Margin and Viability
Cost Architecture and the Cryogenic Premium
The economics of MRP production are heavily influenced by process technology choice and the associated variable cost structure. For cryogenic producers, liquid nitrogen represents a significant share of variable production costs, making energy efficiency and nitrogen consumption management critical levers for margin protection. Over the past five years, improvements in cryogenic processing efficiency have materially reduced per-ton nitrogen consumption, easing a persistent cost pressure and enhancing the competitiveness of fine-grade output.
At the same time, the market has demonstrated willingness to pay a meaningful price premium for cryogenic-grade material, reflecting the functional benefits associated with superior particle morphology and surface area. This premium creates a clear economic rationale for producers to invest in or maintain cryogenic capability, but it also raises the stakes for operational execution. Cost mismanagement in the cryogenic process can quickly erode the margin advantage that the premium is meant to deliver.
Regulatory Tailwinds and Circular Economy Alignment
Policy frameworks continue to play a decisive role in shaping demand. The inclusion of natural rubber on the European Commission list of critical raw materials has heightened attention on alternative material sourcing and recycling pathways. Simultaneously, recycling regulations targeting end-of-life tires are reinforcing demand for high-value MRP as a compliant, value-adding circular economy solution. These regulatory signals are not uniform across jurisdictions, but the overall trajectory favors increased recovery, higher-value reuse, and greater documentation of environmental impact.
Organizations seeking to align their strategies with these regulatory currents must look beyond headline compliance requirements and understand the specification expectations, certification pathways, and procurement preferences emerging in regulated markets. Our report provides the detailed regulatory mapping and interpretation needed to translate policy signals into actionable commercial strategy.
Strategic Implications for 2026 Decision-Making
For executives planning allocations, capacity decisions, partnership structures, and competitive positioning in 2026, the MRP market offers both opportunity and complexity. The growth trajectory is favorable, but the distribution of value is increasingly concentrated among producers with advanced technology, certified product portfolios, and the ability to serve specification-driven applications. Companies that treat MRP as a commoditized byproduct risk ceding margin and market access to competitors who have built differentiation into their operational and commercial models.
Our full market research publication delivers the depth and granularity required to execute informed strategy. It includes detailed segmentation analysis, forward-looking volume and value projections, competitive benchmarking, cost structure evaluation, regulatory interpretation, and scenario modeling across multiple demand and supply variables. The complete dataset, including regional breakdowns, application-level demand shares, particle size valuations, and concentration metrics, is available in the full report and forms the analytical backbone for strategic planning.
To explore the full research suite, access detailed segmentation data, and obtain the complete forecast models for 2026 through 2032, request the complete Micronized Rubber Powder Market research publication. The insights within are structured to support immediate strategic action and long-range planning in a market that is rapidly redefining the value of recycled rubber materials.
For detailed analysis of this topic, please visit the official page: Micronized Rubber Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coal Tar Pitch Market to Hit $3,044.1 Million by 2032, 4.85% CAGR
By PW Consulting, 2026-09-16
Navigating the Carbon Binders Landscape: Strategic Imperatives for the Coal Tar Pitch Market Through 2032
The global coal tar pitch market stands at a critical inflection point. As foundational carbon binders underpin both primary aluminum production and advanced graphite manufacturing, industry participants must reconcile steady demand growth with tightening environmental regulations and evolving feedstock dynamics. Our latest research evaluates the market across a comprehensive 2026 through 2032 forecast window, building on a rigorously validated historical baseline spanning 2020 to 2025. This analysis is designed to equip procurement leaders, strategy executives, and investment committees with the structural clarity required to allocate capital, secure supply corridors, and align product portfolios with long-term industrial trajectories.
Over the historical period, revenue patterns reflected a combination of cyclical demand recovery, capacity rationalization in mature regions, and gradual migration toward higher-performance grades. The market advanced from a baseline of 1,765.2 million USD in 2020 to 2,185.5 million USD in 2025, with the trajectory demonstrating both resilience and episodic volatility driven by downstream construction cycles and metallurgical output adjustments. Looking forward, the forecast horizon projects sustained expansion, positioning total market revenue near 3,044.1 million USD by 2032. This growth is anchored by a compound annual growth rate of 4.85 percent, signaling a mature yet persistently expanding addressable market rather than a speculative surge. For corporate planners, this trajectory underscores the importance of modeling demandelasticity against macro industrial indicators, rather than relying on static volume assumptions.
Market Framework and Structural Segmentation
A rigorous understanding of coal tar pitch requires disaggregating the market across both product architecture and end-use demand profiles. The report maps the landscape across multiple type categories, capturing the distinct operational requirements that separate aluminum-grade binders from impregnation and specialty variants. Aluminum-grade pitch continues to represent the dominant share of revenue, reflecting its indispensable role in carbon anode formulation for primary smelting operations. Binder and impregnation grades serve a more specialized set of downstream applications, where softening points, coking values, and rheological characteristics dictate procurement specifications. Special-grade formulations address niche performance thresholds in advanced carbon materials and refractory systems, creating a higher-margin yet technically demanding segment for producers with differentiated processing capabilities.
Coal Tar Pitch For Graphite Electrodes Market
Demand concentration across applications follows a similarly hierarchical pattern. Aluminum smelting remains the foundational consumption pillar, while graphite electrode manufacturing sustains a substantial secondary channel tied to electric-arc furnace steelmaking and industrial carbon processing. Additional application channels, including roofing formulations and specialty industrial uses, provide supplementary revenue streams that help balance cyclical volatility in the core metallurgical segments. The report examines how these application pathways interact with regional processing capacity, logistics constraints, and customer specification requirements, enabling readers to identify where supply-demand balance is most likely to tighten or loosen over the forecast period.
Regional analysis in the study is structured to highlight where manufacturing footprints, trade flows, and regulatory environments shape competitive positioning. The market is not uniformly distributed; instead, it concentrates around established carbon-processing clusters and emerging refining hubs that can offer both scale and grade flexibility. The research details how regional pricing differentials, freight exposure, and local compliance requirements influence buyer-seller dynamics, helping strategists evaluate which geographies present durable advantages and which are more susceptible to regulatory friction or feedstock disruption.
Competitive Landscape and Enterprise Positioning
The coal tar pitch sector remains moderately concentrated, with established producers leveraging integrated distillation assets, long-term customer relationships, and technical service capabilities to defend market positions. Our analysis identifies the core enterprise cohort shaping competitive dynamics, including Koppers Holdings Inc., Rain Carbon Inc., Himadri Speciality Chemical Ltd., Deza, a.s., and Shree Shyam Chemicals. Each occupies a distinct strategic niche shaped by feedstock access, geographic footprint, and grade specialization.
Coal Tar Pitch Market
Koppers Holdings Inc., headquartered in Pittsburgh, Pennsylvania, operates as an integrated producer of carbon pitch derived from coal tar distillation, with primary offerings focused on binding agents for carbon anodes serving aluminum smelters and for graphite electrodes used by electric-arc furnace steel producers. Rain Carbon Inc., based in Stamford, Connecticut, has established itself as a global leader in coal tar and petroleum distillation, manufacturing coal tar pitch with varying softening points for carbon anodes, graphite electrodes, specialty graphite, and refractory materials. Himadri Speciality Chemical Ltd., operating from Kolkata, India, stands out as a vertically integrated producer with annual pitch capacity exceeding 600,000 metric tons, offering coal tar pitch grades for aluminum, graphite electrode, and carbon black sectors, including liquid and export variants. Deza, a.s., in the Czech Republic, produces coal tar pitch and related distillation products, supplying binder-grade and impregnating grades for carbon and specialty applications. Shree Shyam Chemicals, based in Bhilai, Chhattisgarh, manufactures coal tar pitch, coal tar, and related chemicals, serving industrial-grade requirements across aluminum, graphite, chemical, and pharmaceutical sectors.
Recent Developments Shaping Supply and Corridor Strategy
Beyond structural positioning, the report tracks recent operational moves that reveal where capital is flowing and how supply arrangements are evolving. In January 2025, Rain Carbon Inc. announced a new coal tar distillation and pitch processing facility in APSEZ, Anakapalli, Andhra Pradesh, India. The initial phase targets 50,000 metric tons per year and addresses graphite, battery, and aluminum markets, with further expansion planned, signaling a deliberate push to diversify processing geography and capture demand growth in South Asia. In November 2025, Epsilon Carbon Private Limited signed a non-binding MoU with Aluminium Bahrain for the long-term supply of liquid coal tar pitch, aimed at supporting aluminum smelting demand and strengthening export security for a key downstream customer. In December 2025, Himadri Speciality Chemical Ltd. executed its first-ever liquid coal tar pitch export of 3,600 tonnes to the Middle East from the New Mangalore Port terminal, establishing a new supply corridor and demonstrating the increasing importance of logistics-enabled grade differentiation.
These developments are not isolated events. Collectively, they point to a market in which supply reliability, grade customization, and corridor diversification are becoming as strategically consequential as raw production volume. The report examines how such moves reshape competitive pressure, influence customer negotiation leverage, and alter regional import-dependency profiles for buyers seeking to de-risk procurement.
Regulatory Dynamics and the Compliance Premium
Regulatory scrutiny represents one of the most consequential variables for coal tar pitch strategy, particularly where polycyclic aromatic hydrocarbon exposure intersects with pavement applications, industrial emissions standards, and chemical handling requirements. The analysis incorporates multiple regulatory signals that are reshaping demand quality and compliance economics. Minnesota prohibits the sale and use of coal tar sealant products containing coal tar, coal tar pitch volatiles, or CAS 65996-93-2/65996-89-6 on asphalt-paved surfaces, effective January 1, 2014. New York State has proposed legislation, Senate Bill 2025-S3179A, to tighten the PAH limit in the state's coal tar ban for pavement products. Under the EU REACH framework and related directives, strict PAH controls apply to coal tar pitch production and use, with compliance costs rising for legacy grades. Tightening PAH emission and wastewater norms in Canada and New York State continue to drive compliance-driven capacity considerations and low-PAH grade development.
These regulatory threads matter because they create a structural divergence between commodity-grade volumes and specification-driven demand. As jurisdictions tighten limits on certain applications and emissions profiles, producers and buyers alike must navigate higher compliance burdens, reformulation requirements, and potential substitution pressure in affected end-use channels. The report assesses how these dynamics influence grade architecture, regional demand elasticity, and the relative attractiveness of processing investments that can accommodate tighter specifications without sacrificing cost competitiveness.
Feedstock Volatility and Industrial Demand Shifts
In addition to regulation, market participants must contend with raw material uncertainty. Coal tar feedstock volatility and shifts toward electric-arc furnace steel production continue to constrain coal tar availability for pitch distillation. This constraint is significant because it links the coal tar pitch market not only to aluminum and graphite demand, but also to broader metallurgical technology transitions and upstream coke and tar supply conditions. Where tar availability tightens, grade allocation, pricing behavior, and customer qualification timelines can all become more volatile, making supply-chain visibility and flexible contracting models increasingly valuable. The study evaluates how these pressures interact with regional availability, refining capacity utilization, and downstream qualification cycles, helping stakeholders anticipate where bottlenecks may emerge and which procurement strategies are best suited to mitigate them.
What the Full Study Delivers
This executive overview highlights the strategic contours of the coal tar pitch market, but the full research provides the operational depth that decision-makers need to convert insight into action. Our report delivers a comprehensive market sizing and forecasting framework covering historical performance and forward projections through 2032. It includes detailed segmentation analysis by type and application, together with regional evaluation that situates demand growth within local regulatory and logistical realities. The study maps the competitive landscape across key producers, examining capacity structures, product orientation, and recent developments that signal changing market power. It also assesses the regulatory and raw-material environment shaping compliance costs, feedstock constraints, and demand quality.
For executives responsible for procurement, production planning, or market entry assessments, the research is structured to answer practical questions: which grade families offer the most durable growth under tightening compliance regimes, where regional demand expansion is likely to be most consistent, how supply corridor development may affect import dependency, and what operational factors distinguish resilient producers in a concentrated market. The analysis avoids superficial generalizations in favor of scenario-aware interpretation, allowing readers to integrate findings into internal forecasting models, sourcing strategies, and investment evaluations.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is unlikely to resolve into a single dominant trend. Instead, leaders will need to manage multiple overlapping forces: steady structural demand growth, a moderately concentrated producer base, regulatory tightening across key jurisdictions, and feedstock availability linked to broader metallurgical transitions. In that environment, strategic advantage will accrue to organizations that can distinguish durable growth from temporary cyclical noise, align grade portfolios with shifting specification requirements, and secure supply access before capacity reallocations intensify.
Our coal tar pitch market research is designed to support that process by combining macro market visibility with segment-level interpretation. It provides the evidence base needed to evaluate whether to expand supply relationships, pursue qualification in higher-specification grades, or reassess exposure to applications facing heightened regulatory scrutiny. Just as importantly, it offers a structured competitive lens for interpreting the significance of recent capacity expansions, supply agreements, and corridor developments that may reshape buyer leverage over the coming planning cycles.
The full report contains the detailed regional, type, and application breakdowns, the extended competitive profiles, and the scenario discussion that decision-makers require for rigorous 2026 and beyond planning. Readers seeking the complete dataset and analysis are encouraged to access the full study page, where the comprehensive market intelligence is available in a format designed for strategic integration and executive review.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


