



Category: market research
PW Consulting: Automobile Cylinder Sleeve Market Hits USD 6.18 Billion in 2025, Projects 5.2% CAGR to 2032
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Automobile Cylinder Sleeve Market 2026–2032
The global automotive powertrain component landscape is undergoing a structural transformation. For procurement leaders, engineering directors, and corporate strategists, the automobile cylinder sleeve market represents far more than a steady replacement cycle. It is a bellwether for material innovation, regulatory compliance, and the shifting center of gravity in global engine manufacturing. PW Consulting’s latest comprehensive research on this segment delivers the granular intelligence required to navigate the 2026–2032 forecast horizon with precision.
Worldwide Isolated RTD Input Module Market
As the industry transitions toward stricter emission standards, hybridized powertrains, and aggressive lightweighting mandates, cylinder sleeve specification has evolved from a commodity purchasing decision into a strategic engineering lever. Understanding where value will concentrate, which material technologies will gain commercial traction, and how the competitive hierarchy is crystallizing around proprietary casting methods requires a market study built on verified primary research and scenario-driven forecasting. This research preview outlines the analytical architecture of our full report, demonstrates how macroeconomic signals translate into actionable decision frameworks, and highlights the competitive dynamics that will separate market leaders from followers.
Hairdressing Training Heads Market
Readers will encounter a synthesis of historical performance data, forward-looking volume projections, and operational intelligence on the firms actively reshaping the supply base. No isolated percentages or region-by-region revenue tables are disclosed here; those granular breakdowns are preserved for the complete deliverable, where they are cross-referenced with capacity utilization rates, pricing architectures, and distributor network mappings. The objective of this preview is to establish the strategic terrain, clarify why disciplined intelligence consumption matters for 2026 planning cycles, and demonstrate the depth of analysis embedded in our methodology.
Worldwide Smart Grammar Editor Market
Market Trajectory: From Recovery Momentum to Sustained Expansion
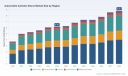
The automobile cylinder sleeve market has demonstrated remarkable resilience through a volatile decade of post-pandemic supply recalibration, fluctuating raw material costs, and divergent regional demand patterns. Historical tracking from 2020 through 2025 reveals a clear upward trajectory, with total market revenue climbing from approximately $3.71 billion to $6.18 billion. That growth arc reflects not only the restoration of global vehicle production volumes but also a structural shift in how engine builders approach cylinder bore durability, thermal management, and lifecycle cost optimization.
Looking toward the forecast window, the trajectory continues upward with measured confidence. Market valuations are projected to reach $6.29 billion in 2026, expanding steadily toward the $8.82 billion mark by 2032. This progression translates to a compound annual growth rate of 5.2 percent, a figure that signals sustainable expansion rather than speculative inflation. Growth of this nature is typically anchored by fundamental demand drivers: rising commercial vehicle utilization in developing economies, sustained passenger car fleet refreshes in mature markets, and the persistent need for upgraded sleeve solutions as internal combustion platforms are refined for efficiency and longevity.
For corporate decision-makers, a 5.2 percent CAGR carries strategic implications beyond top-line projections. It indicates a market where share gains are earned through technical differentiation and supply reliability rather than price compression alone. It also suggests that capacity planning, tooling investment, and material sourcing agreements negotiated in 2026 will have multi-year payoff horizons. Companies that treat the forecast period as a static backdrop risk underinvesting in advanced casting capabilities or misallocating working capital toward segments where margin compression is most acute. The full report decomposes this trajectory by volume-to-value ratios, regional capacity shifts, and application-specific growth vectors, enabling leadership teams to align capital deployment with the most defensible pockets of expansion.
Segmentation Architecture: Where Material, Design, and Application Intersect
Cylinder sleeve demand does not behave uniformly across the automotive ecosystem. The segment is shaped by intersecting technical requirements, cost structures, and manufacturing footprints that determine which product architecture wins in a given application. The research framework dissects the market through three primary segmentation lenses, each carrying distinct strategic implications for suppliers, OEMs, and tier-one integrators.
Material Technology Divergence
Material selection remains the foundational decision point in cylinder sleeve engineering. The historical dominance of traditional cast iron reflects its proven wear resistance, thermal stability, and cost-effectiveness in high-volume applications. Yet the landscape is increasingly textured by the emergence of aluminum alloy formulations and specialized steel variants designed to meet tighter dimensional tolerances and reduced component mass. The interplay between these material categories is not a simple substitution dynamic; rather, it represents a portfolio optimization challenge.
Cast iron continues to anchor a substantial portion of the installed base, particularly where durability under high thermal loads and long service intervals are non-negotiable. Simultaneously, industry trajectory analysis points toward sustained growth in lightweight aluminum and composite alloy architectures, driven by fuel economy targets and the broader regulatory push for vehicle weight reduction. Aluminum-based sleeves, often paired with specialized coatings and surface treatments, enable thermal transfer optimization while contributing to overall engine mass savings. Steel variants occupy a more specialized position, typically deployed where specific load profiles or mating surface requirements demand superior tensile characteristics.
Strategic buyers evaluating material roadmap alignment must look beyond headline performance claims. The research delves into how alloy formulations interact with casting methodologies, how surface finishing tolerances influence runout and friction behavior, and how material supply chains are being restructured to mitigate volatility in metallurgical input pricing. By isolating the value pools within each material category, the report equips engineering and procurement teams with the criteria needed to negotiate supply agreements that balance performance assurance with cost predictability.
Liner Configuration and Application Mapping
Beyond material chemistry, the physical configuration of the sleeve—whether dry, wet, or finned—fundamentally alters the thermal management and assembly architecture of the engine block. Dry liners, seated directly into the cylinder block and relying on the block material for coolant isolation, remain prevalent in applications where structural rigidity and simplified assembly are prioritized. Wet liners, which interface directly with the cooling jacket, offer superior heat extraction but introduce sealing and corrosion management complexities that demand higher precision manufacturing. Finned configurations occupy niche positions where enhanced surface area for thermal dissipation is required under extreme operating conditions.
Application segmentation further differentiates demand intensity and specification requirements. Passenger car platforms account for the largest concentration of sleeve consumption, reflecting the sheer multiplicity of global vehicle platforms and the ongoing refresh cycles required to meet evolving emission norms. Commercial vehicle segments—both light and heavy—present different engineering constraints, with heavy-duty applications emphasizing extended service life, resistance to particulate-induced abrasion, and tolerance for sustained high-load operation. Two-wheeler platforms, while representing a smaller revenue footprint, demand cost-optimized solutions that can be produced at high velocity with minimal tolerance variability.
The full report maps these configuration and application intersections against regional manufacturing footprints, revealing where production localization incentives, logistics cost structures, and OEM sourcing strategies are reshaping supply routes. Rather than presenting static regional shares, the analysis emphasizes the flow of capability: which manufacturing clusters are expanding advanced centrifugal casting capacity, which regions are seeing increased local content requirements, and how tier-one suppliers are repositioning their plant networks to serve emerging platform allocations. This dynamic view allows strategists to anticipate sourcing friction points and identify partnership opportunities before capacity constraints become pricing leverage for incumbents.
Regulatory Pressure and Engineering Imperatives
Regulatory frameworks are no longer peripheral compliance costs; they are primary drivers of material specification and dimensional precision in cylinder sleeve design. The progressive tightening of emission standards across major automotive markets has cascading effects on combustion chamber tolerances, piston ring dynamics, and the thermal fatigue characteristics expected of cylinder liners over extended service intervals.
Standards such as Euro 6d and Bharat Stage VI mandate tighter combustion chamber tolerances and longer service intervals, directly elevating the requirement for cylinder liners that exhibit superior thermal fatigue resistance and dimensional stability under repeated heating and cooling cycles. A sleeve that distorts under thermal load compromises combustion efficiency, increases oil consumption, and accelerates wear across reciprocating components. These pressures push material and coating innovation from optional enhancement to baseline requirement.
Complementing emissions mandates, engineering standards such as SAE J2236 define material specifications for engine cylinder liners, providing a formalized reference for metallurgical composition, casting integrity, and surface performance criteria. Adherence to such standards not only mitigates liability in warranty and quality dispute scenarios but also streamlines the validation process when introducing new sleeve architectures to engine platforms that must satisfy multiple regulatory jurisdictions.
The research integrates these regulatory and standards-driven dynamics into a forward-looking risk matrix. Rather than treating compliance as a static checkpoint, the analysis examines how evolving test protocols, extended durability expectations, and cross-market alignment of emission thresholds are reshaping the acceptable performance envelope for cylinder sleeves. This perspective is critical for organizations that must justify tooling investments or material transitions to internal stakeholders, as it anchors engineering decisions in verifiable regulatory trajectories rather than speculative assumptions.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The automobile cylinder sleeve market exhibits a moderate concentration structure, with leading firms commanding disproportionate influence through proprietary casting technology, long-standing OEM qualifications, and globally distributed production footprints. The competitive hierarchy is not defined solely by scale; it is increasingly shaped by the ability to deliver application-specific liner architectures that satisfy stringent performance criteria while maintaining cost competitiveness across high-volume and specialty segments.
Incumbent Profiles and Capability Positioning
Several established manufacturers anchor the competitive landscape, each leveraging distinct technical strengths and geographic reach. MAHLE GmbH, headquartered in Stuttgart, operates a vertically integrated approach to centrifugal cast cylinder liners, producing in-house solutions for passenger cars, commercial vehicles, and engines extending up to 460 mm piston diameter. Their emphasis on high-strength materials and low-wear running surfaces positions them as a supplier of choice for applications where dimensional consistency and durability under sustained load are critical.
Tenneco Inc., based in Ann Arbor, Michigan, has built its cylinder sleeve portfolio around advanced material optimization, coating engineering, and design precision aimed at enhancing running surfaces, heat transfer efficiency, and friction reduction. Their capability spans light-duty, heavy-duty, and large-bore engines, reflecting a breadth of application expertise that aligns with diverse OEM performance targets.
In the Japanese market, TPR Co., Ltd. has differentiated itself through cast-in liners utilizing patented AsLock® technology delivered via centrifugal casting, alongside thin-wall and wet liner configurations engineered for compatibility with aluminum engine blocks. Their solutions serve Japanese OEMs across gasoline and diesel applications, illustrating how localized technical differentiation can secure long-term supply relationships within concentrated OEM ecosystems.
Kolbenschmidt GmbH, operating from Frankfurt, integrates cylinder liners into broader piston system offerings for passenger cars and commercial vehicles, emphasizing high-quality construction aligned with original equipment specifications. This systems-oriented approach enables coordinated engineering across reciprocating components, reducing interface variability and simplifying validation workflows for engine manufacturers.
The competitive field also includes regionally significant players such as Zhongyuan Cylinder Liner Company Limited in China, which supplies the GKNZ-branded portfolio for automotive and industrial engines, and Aichi Machine Industry Co., Ltd. in Aichi, Japan, whose cylinder liner production supports a range of engine applications. These firms illustrate the importance of regional manufacturing depth and localized engineering responsiveness in markets where supply chain proximity, cost structures, and OEM relationship dynamics diverge from globalized procurement models.
Recent Developments and Industry Reconfiguration
Market structure is not static; it evolves through product introductions, corporate restructuring, and shifts in technology emphasis. Recent industry activity signals ongoing realignment in how cylinder sleeve capabilities are packaged and delivered. In early 2025, Federal-Mogul Powertrain released a new silicon-aluminum alloy composite cylinder liner designed to meet evolving engine demands, reflecting the broader industry exploration of composite formulations that balance thermal performance with weight efficiency.
In parallel, Nippon Piston Ring Co., Ltd. announced plans to merge with Riken, forming NPR-RIKEN Corporation to enhance combined capabilities in piston rings and cylinder liners. This consolidation underscores a recurring theme in component manufacturing: the increasing value of integrated reciprocating system expertise, where liner, ring, and piston dynamics are engineered as a synchronized performance package rather than isolated parts.
The research evaluates these developments not as isolated news items but as structural indicators of where technical investment and M&A activity are concentrating. By examining the interplay between product launches, corporate consolidation, and capability expansion, the report enables strategists to anticipate shifts in supplier bargaining power, identify potential disruptions in established supply routes, and assess which firms are likely to strengthen their qualification positions with major OEMs over the forecast horizon.
What the Full Report Delivers: Analytical Structure and Decision Utility
The complete PW Consulting research deliverable is structured to move from strategic context to operational detail, ensuring that every analytical layer connects to a concrete decision application. The report combines historical reconstruction, multi-variable forecasting, segmentation cross-analysis, and competitive profiling into a cohesive intelligence asset designed for executive planning, engineering roadmap alignment, and procurement strategy refinement.
Core Report Components
- Comprehensive market size reconstruction spanning the 2020–2025 historical window, with methodological transparency on data sourcing, triangulation approaches, and revision history to establish a credible baseline for forecasting.
- Scenario-based projections through 2032 that account for base-case, accelerated, and constrained growth pathways, allowing leadership teams to stress-test capacity planning and sourcing commitments against alternative macroeconomic and industry volume outcomes.
- Detailed segmentation analysis across material type, liner configuration, vehicle type, and geographic production distribution, with volume-to-value mapping that clarifies where revenue intensity diverges from unit volume and how pricing architectures differ across application categories.
- Competitive benchmarking that evaluates firm positioning through technology differentiation, capacity footprint, OEM qualification breadth, and recent strategic moves, providing a comparative lens for partnership evaluation and competitive response planning.
- Regulatory and standards impact assessment that translates emission mandates, material specification frameworks, and durability expectations into actionable engineering and procurement criteria.
- Supply chain and raw material dynamics review that examines casting feedstock availability, alloy pricing volatility, and logistics considerations influencing regional sourcing decisions.
- Identification of high-growth subsegments and emerging application vectors, supported by qualitative indicators that signal where demand intensity is likely to outpace incumbent capacity or where new material architectures may create displacement opportunities.
Intended Audience and Use Cases
This research is designed for multiple functional stakeholders who require synthesized intelligence rather than raw data tables. Corporate strategists can use the segmentation and competitive frameworks to evaluate market entry potential, partnership suitability, and portfolio alignment. Procurement and supply chain leaders can leverage the material and configuration analysis to structure sourcing negotiations that balance performance assurance with cost management across multi-year agreements. Engineering and product development teams benefit from the regulatory and standards mapping, which clarifies which technical thresholds are likely to become baseline requirements and where innovation headroom remains available. Investors and market analysts can utilize the forecast architecture and competitive positioning assessment to evaluate sector attractiveness, margin sustainability, and consolidation probability.
Connecting Intelligence to 2026 Decision Cycles
The strategic value of market intelligence is realized not through passive consumption but through active integration into planning cycles. As organizations finalize 2026 capital allocations, sourcing strategies, and engineering roadmaps, the automobile cylinder sleeve market presents a landscape where disciplined analysis directly informs competitive positioning. The 5.2 percent CAGR trajectory signals a market large enough to support multiple specialized players yet concentrated enough that capability gaps translate quickly into lost qualification opportunities. Material innovation, particularly around lightweight aluminum and composite formulations, is reshaping specification conversations, while regulatory tightening continues to elevate the importance of dimensional stability and thermal fatigue performance.
Companies that embed granular segmentation understanding, competitive capability mapping, and regulatory trajectory awareness into their 2026 decision frameworks will be better positioned to negotiate from a place of informed confidence. They will be able to identify which supplier relationships merit long-term commitment, which material transitions warrant accelerated validation investment, and which regional capacity shifts may alter logistics cost structures or lead-time reliability. The full research report preserves the detailed regional revenue distributions, application-specific growth vectors, and competitive share constructs required to execute these judgments with precision, ensuring that strategic conclusions rest on verified data rather than approximation.
Accessing the Complete Intelligence Asset
This preview has outlined the analytical terrain, demonstrated the interplay between macro trajectory and micro engineering requirements, and highlighted the competitive dynamics that will define the market structure through 2032. The complete PW Consulting Automobile Cylinder Sleeve Market research report builds on this foundation with granular segmentation data, regional capacity and revenue distributions, pricing and margin analysis, detailed company profiles, and forward-looking scenario modeling. All core tables, regional breakdowns, application-level growth vectors, and material segment revenue constructs are presented in the full deliverable to support rigorous strategic review.
For organizations preparing 2026 sourcing strategies, capacity plans, or technology investment roadmaps, the complete report provides the evidentiary depth needed to convert market observation into executable strategy. Readers seeking the full segmentation matrices, regional production and consumption distributions, competitive share constructs, and scenario-based forecast tables are encouraged to access the complete report at the source webpage, where the complete dataset and accompanying analytical commentary are available for download and internal distribution.
For detailed analysis of this topic, please visit the official page: Automobile Cylinder Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: In-Building Wireless Market to Hit $49.3M by 2032, 11.8% CAGR
By PW Consulting, 2026-09-07
The 2026 In-Building Wireless Market: Strategic Imperatives for Enterprise Decision-Makers
The Connectivity Imperative Driving Next-Generation Infrastructure
The modern enterprise operates on a foundation of seamless, high-capacity connectivity. As organizations continue to digitize operations, deploy dense IoT ecosystems, and expect uninterrupted wireless performance from staff and visitors alike, the physical and operational architecture of in-building wireless (IBW) networks has transitioned from a tactical facility requirement to a core strategic asset. The trajectory of the IBW market through 2026 confirms that institutional attention is well placed. Following a sustained expansion cycle between 2020 and 2025, the sector reached a valuation of approximately 22.58 million USD at the close of the base year. From that starting point, the market is projected to advance through the 2026–2032 forecast horizon, with 2026 opening at an estimated 25.35 million USD and climbing steadily toward 49.3 million USD by 2032. This progression reflects a compound annual growth rate of 11.8 percent, signaling that infrastructure planners and corporate decision-makers must treat IBW investment as a long-term capability rather than a periodic refresh cycle. The acceleration is not merely a reflection of incremental demand. It is driven by structural shifts in how facilities consume wireless spectrum, how operators monetize indoor coverage, and how enterprises balance performance requirements against operational complexity. Understanding the forces shaping this expansion requires moving beyond headline valuations and examining the architecture of demand, the competitive dynamics defining supply, and the regulatory and technical environment that determines deployment feasibility. Our latest In-Building Wireless Market research is designed precisely for that purpose. It translates macroeconomic momentum into actionable positioning, enabling technology buyers, network architects, and commercial strategy teams to align capital allocation with the specific conditions that will govern the next several years of deployment.
Automatic Sealing and Packing Machine Market
Market Trajectory and the Structural Forces Behind the Growth Curve
The expansion recorded between 2020 and 2025 established a clear baseline for understanding today’s demand environment. Over that five-year span, the market moved from 12.93 million USD to 22.58 million USD, demonstrating resilience through shifting macroeconomic conditions and growing comfort with advanced indoor wireless architectures. The current forecast period extends that trend into the late 2020s and early 2030s, with the market expected to reach 28.19 million USD in 2027, 32.51 million USD in 2028, and continued appreciation through 34.5 million USD in 2029, 39.42 million USD in 2030, 44.38 million USD in 2031, and 49.3 million USD in 2032. These figures illustrate a market that is not simply rebounding but compounding, with each forecast interval building on prior capacity gains, technology maturity, and broadened enterprise adoption. The 11.8 percent CAGR embeds several underlying drivers that our research unpacks in detail. First, the shift toward higher-density wireless environments is accelerating across sectors that historically underinvested in indoor coverage optimization. Second, the operational case for distributed wireless architectures is becoming more compelling as facilities seek to support simultaneous high-throughput applications, real-time analytics, and massive device connectivity without degrading performance. Third, the commercial logic of shared and neutral host deployment models is reducing the friction that previously constrained enterprise adoption, particularly in properties where multiple stakeholders or carriers must coexist on a single infrastructure footprint. Our report situates these trends within a rigorous analytical framework. It tracks revenue progression across the historical and forecast windows, isolates the variables that materially influence deployment velocity, and identifies where market participants stand to capture value as architectural preferences evolve. Importantly, the analysis is structured to support decision-making at the procurement, investment, and competitive positioning levels. By understanding how the overall revenue curve behaves and what conditions sustain it, strategic teams can forecast infrastructure spend with greater precision and avoid the common pitfall of reacting to technology hype rather than deploying resources against verified demand patterns.
Electronic Contract Management Market
Core Segmentation Dynamics Reshaping Deployment Architecture
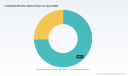
The composition of market growth reveals a landscape in which technology type and application environment interact to create distinct deployment priorities. Our research examines technology segmentation across Distributed Antenna Systems, Small Cell architectures, and Distributed Radio Systems, along with application segmentation spanning Commercial Campuses, Hospitality, Transportation and Logistics, Entertainment and Sports Venues, Industrial Manufacturing, Education, Government, and Healthcare. These categories are not isolated demand pools. They form a set of interdependent considerations that determine which architecture, deployment model, and vendor capability set will deliver the strongest return for a given facility profile. Technology choices increasingly reflect the need to reconcile coverage breadth with capacity granularity. Some environments favor centralized distribution approaches that simplify signal management across large footprints, while others rely on more granular deployment nodes that offer rapid scaling and localized performance control. The report details the circumstances in which each architecture delivers the most favorable balance of capital efficiency, maintenance burden, and performance reliability. On the application side, the demand profile is equally varied. Hospitality and entertainment venues continue to prioritize seamless connectivity as a core guest experience and operational enabler. Transportation and logistics environments demand robust wireless performance in spaces with challenging propagation characteristics and high equipment density. Industrial manufacturing contexts emphasize mission-critical reliability and integration with operational technology ecosystems. Education, government, and healthcare facilities face their own combinations of capacity requirements, regulatory considerations, and multi-stakeholder coordination demands. The commercial campus segment sits at the intersection of multiple use cases, often requiring a flexible architecture that can support both enterprise productivity and visitor-facing service expectations. Our segmentation analysis goes further than descriptive classification. It evaluates how these demand categories map to deployment economics, where architectural choices influence total cost of ownership, and how facility characteristics shape the relative attractiveness of different vendor offerings. Decision-makers who rely on generic wireless assumptions often underestimate the importance of environment-specific design. This research corrects that gap by providing a structured view of how application profiles influence both short-term deployment decisions and longer-term network evolution. By focusing on the practical relationships between segment characteristics and architectural viability, the report enables teams to prioritize investment where it produces the most durable operational outcomes.
Worldwide Milling Automation Market
Competitive Dynamics and the Strategic Positioning of Leading Providers
The IBW market is characterized by a concentration of capability among a defined group of established and emerging providers, and understanding their strategic behavior is essential for procurement planning and competitive assessment. Our research includes detailed profiles of key participants, with particular attention to companies whose recent product and positioning moves signal where the market is heading. Moso Networks, based in the United States, has built a profile around private 5G and neutral host solutions for in-building wireless. Its offering emphasizes plug-and-play indoor and outdoor radios designed to function as rapid DAS replacements, supported by CBRS capability and cloud-based management. This positioning reflects a broader movement toward reducing deployment friction while preserving flexibility in operator and enterprise use cases. In January 2026, Moso Networks advanced this direction by launching the Chorus P5G solution in partnership with Ataya, an initiative intended to simplify private 5G deployment to a 5G radio and secure cloud connection for indoor and outdoor use. The move underscores an emerging expectation that private wireless deployments must be manageable without requiring extensive integration overhead. ANDREW, operating under Amphenol Corporation and also headquartered in the United States, provides a complementary but distinct set of capabilities. Its portfolio spans ERA digital DAS, ONECELL small cells, and in-building wireless solutions oriented toward 5G coverage, multi-operator connectivity, and mission-critical private networking. The company’s focus on multi-operator and neutral host models positions it within the infrastructure layer that serves venues and enterprises seeking shared access arrangements rather than single-operator exclusivity. In January 2026, ANDREW received honors at the Small Cell Forum awards for innovation in indoor and outdoor wireless solutions and neutral host and multi-operator models. The recognition highlighted a world’s first DAS deployment with full direct digital connectivity to three leading RAN vendors in a live stadium, an achievement that illustrates the increasing feasibility of high-performance, multi-vendor indoor environments. SOLiD, based in South Korea, contributes another strategic angle through modular and scalable DAS and in-building wireless solutions designed for venues and enterprises that must deliver 5G coverage and capacity in challenging environments. Its emphasis on modularity aligns with the broader market push toward architectures that can expand incrementally as coverage or capacity requirements change. These company profiles do not exist in isolation. They reflect a competitive environment in which vendors are differentiating through deployment simplicity, multi-operator enablement, modularity, and cloud management maturity. Our report maps these differentiators against the conditions that matter most to buyers, including integration complexity, operational overhead, and the ability to support evolving spectrum and service requirements. In parallel, the analysis tracks wider industry signals that shape competitive dynamics. The Wireless Infrastructure Association highlighted Nextivity Inc. in January 2026 as a key player in in-building wireless networks, with emphasis on ROI measurement and unified network approaches for schools and enterprises. Such visibility indicates that competitive positioning is increasingly tied to measurable outcomes and cross-environment network unification, not solely to hardware capability. The market concentration context further reinforces the importance of strategic supplier evaluation. With a CR3 of 52.6 percent and a CR5 of 67.0 percent, the landscape is concentrated enough that vendor selection has meaningful implications for negotiation leverage, integration risk, and long-term support continuity. Our research supports more disciplined supplier assessment by aligning provider capabilities with the deployment scenarios in which they are most likely to succeed.
Inside the Report: Operational Content Designed for Execution
Strategic Decision Support Across the Investment Lifecycle
A market study earns its place in an enterprise workflow only if it supports concrete actions. This report is built around that expectation. It provides a structured foundation for evaluating where in-building wireless investment should be prioritized, how deployment architecture should be selected, and what vendor and partnership strategies are most likely to deliver value across the forecast horizon. The content is organized so that readers can move from high-level market context to operational considerations without losing analytical discipline. Rather than offering generic technology overviews, the report ties market behavior to procurement and planning decisions that matter in 2026 and beyond.
Detailed Architecture and Deployment Considerations
The report examines the physical and operational realities that determine whether an in-building wireless investment performs as intended. Topics include the integration requirements associated with existing fiber optic networks and signal sources, with emphasis on practical factors such as PIM mitigation and power optimization. These details are not ancillary. They directly affect deployment reliability, long-term maintenance burden, and the feasibility of achieving consistent coverage in environments where signal propagation is constrained by structure, density, or interference. The analysis also addresses how different architectural approaches influence integration effort and operational control, enabling teams to anticipate both the capital and operational implications of design choices before commitments are made.
Application, Technology, and Regional Demand Context
Demand does not distribute evenly across sectors or deployment environments. The report maps how application profiles shape performance expectations, investment urgency, and architectural suitability. At the same time, it provides regional context that helps decision-makers understand where demand intensity, infrastructure readiness, and competitive activity converge. Rather than presenting narrow percentage breakdowns or isolated submarket figures, the research integrates regional and application context into a broader narrative of where growth is accelerating and why. This approach is deliberate. It allows readers to grasp the relative importance of different demand pools and geographic environments without reducing the analysis to a static table of splits. The result is a market map that is useful for strategy formulation, sales targeting, investment prioritization, and competitive positioning.
Regulatory, Spectrum, and Operational Environment Factors
Technology selection cannot be separated from the regulatory and spectrum context in which it operates. The report incorporates the January 2026 FCC action through FCC 26-1, which enabled more flexible operation of low-power indoor unlicensed devices in the 6 GHz band, including building loss considerations within automated frequency coordination. This development matters because it affects how unlicensed and lightly licensed spectrum can be used to complement licensed deployments and how automation tools influence indoor frequency management. The report also addresses broader FCC activity in 2026 related to spectrum abundance in space operations and the modernization of sharing rules for satellite broadband, both of which carry implications for spectrum access and the wider environment in which in-building wireless enhancements are planned. In addition, the analysis notes compliance and procurement realities relevant to public-sector and infrastructure buyers, including alignment with Build America Buy America requirements for certain products as of early 2026. These regulatory and operational inputs are not treated as isolated news items. They are integrated into the practical side of deployment planning, helping readers assess where flexibility is increasing, where constraints remain, and how those conditions influence vendor selection, architecture design, and total project risk.
Why This Research Matters for 2026 Strategy
Translating Market Momentum into Capital and Vendor Strategy
Organizations evaluating in-building wireless investment face a common challenge: market momentum is visible, but the path from growth headline to deployment decision is not. The market’s expansion from 12.93 million USD in 2020 to 22.58 million USD in 2025, and its projected rise through the forecast window toward 49.3 million USD by 2032 at an 11.8 percent CAGR, provides a strong signal that indoor wireless infrastructure is moving up the priority stack. But signal strength alone does not define strategy. Decision-makers still need clarity on which application contexts justify accelerated investment, which technology profiles align with specific facility conditions, and how competitive and regulatory developments alter the risk and reward calculus of different deployment approaches. This report is designed to answer those questions with enough depth to guide action. It helps procurement and network teams compare architectural options against real operating conditions, supports executive teams in communicating why indoor wireless investment deserves sustained attention, and equips strategy functions with the context needed to evaluate vendor promises against market reality. In an environment marked by concentration, rapid product iteration, and evolving spectrum possibilities, disciplined research is not a luxury. It is the mechanism that separates informed planning from reactive purchasing.
What the Report Enables Decision-Makers to Do
The research is structured to support a set of recurring strategic tasks. It helps organizations benchmark current infrastructure assumptions against the market direction reflected in the 2026–2032 forecast. It supports vendor evaluation by connecting provider profiles and recent developments to the operational requirements that buyers are likely to face. It clarifies how application environments differ in their connectivity demands and what that means for architecture, timing, and budget sequencing. It also gives leadership teams a shared analytical baseline for discussions about capital planning, partnership strategy, and long-term network evolution. By focusing on usable intelligence rather than exhaustive disclosure of every submarket figure, the report preserves analytical depth while directing readers to the full dataset and supporting detail where they can refine their own models and internal assumptions.
A Strategic Entry Point for Deeper Intelligence
In-building wireless is no longer a niche infrastructure category. It is a strategically significant layer of enterprise connectivity that intersects with private networking, multi-operator access, venue experience, industrial digitization, and facility modernization. The research presented here is intended for teams that need to understand the market well enough to act with confidence in 2026 and to plan for the changes expected through 2032. The macro trajectory, segmentation dynamics, vendor movements, and regulatory context described in this article establish the foundation. The full report extends that foundation into a more granular analytical environment, providing the detailed data, segmentation detail, and scenario-based interpretation that decision-makers need to convert market insight into execution. For organizations seeking to align infrastructure strategy with where the IBW market is actually heading, this research offers the evidence base and interpretive framework required to move forward with precision.
For detailed analysis of this topic, please visit the official page: In-Building Wireless Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Light Gauge Steel Market to Hit USD 42.7B in 2025, Grow at 5.73% CAGR to USD 63.02B by 2032
By PW Consulting, 2026-09-07
Navigating the Light Gauge Steel Market: A Strategic Intelligence Brief for 2026 Decision-Makers
The construction materials landscape is undergoing a structural recalibration. As decarbonization mandates tighten, labor constraints persist, and prefabrication demands accelerate, Light Gauge Steel (LGS) has moved from a niche alternative to a strategic core component in modern building systems. For executives, investors, and procurement leaders operating in 2026, the question is no longer whether LGS will gain traction but how to position portfolios, supply chains, and go-to-market strategies against a rapidly consolidating and innovation-driven market.
Worldwide Constant Temperature Electric Blanket Market
PW Consulting's latest Light Gauge Steel Market research study is engineered to translate macro trajectories into executable intelligence. Rather than offering static snapshots, this report maps the operational, regulatory, and competitive forces that will define market behavior between 2026 and 2032. The brief below outlines the strategic architecture of the study, demonstrates how macro indicators contextualize today's decisions, and highlights the competitive and regulatory signals that are already reshaping the field. Complete segmentation breakdowns, regional deployment matrices, and company-level performance metrics are reserved for the full report, where they can be cross-referenced against your internal benchmarks and growth models.
Worldwide Dry Suit Market
Why 2026 Imposes a Different Decision Rhythm
The post-pandemic construction cycle has matured into a phase defined by cost discipline, material traceability, and engineered efficiencies. Organizations can no longer rely on historical volume growth alone to justify capacity expansion or product development. Instead, they must interpret how demand shifts across building types, how regional procurement ecosystems evolve, and how standard-setting bodies influence specification behavior.
Worldwide Natural Creatine Market
Our research window opens from a 2025 base year that captures the market at a meaningful inflection point. Historical tracking from 2020 through 2025 demonstrates a sustained upward trajectory, with the overall market expanding from approximately 29.0 billion USD in 2020 to 42.71 billion USD in 2025. That progression reflects more than cyclical recovery; it indicates structural adoption across multiple construction verticals, supported by lighter material handling, faster erection timelines, and increasing compatibility with off-site manufacturing workflows.
Looking forward, the forecast horizon through 2032 projects continued expansion at a CAGR of 5.73 percent, with the market advancing from 44.71 billion USD in 2026 toward 63.02 billion USD by 2032. These headline numbers matter because they reframe the scale of opportunity relative to capital allocation cycles. A mid-single-digit compound trajectory in a materials sector typically signals durable demand rather than speculative surges, which means firms that invest early in manufacturing precision, engineering partnerships, and specification capture can compound advantages over multiple budget cycles.
Crucially, the macro path only becomes actionable when tied to segmentation behavior, pricing architecture, and competitive response patterns. That is where the full study adds differentiated value: it disaggregates the trajectory into the operational dimensions that determine which players capture share, which applications become margin leaders, and which geographies transition from emerging interest to sustained deployment.
Decoding the Market Architecture
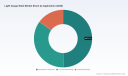
The LGS market is not a single demand pool. It is a matrix of framing solutions, application requirements, and regional procurement cultures that reward different capabilities. Our research unpacks this matrix through three analytical lenses: type, application, and region. Rather than presenting these as isolated charts, the study evaluates how they interact to shape pricing power, specification risk, and distribution priorities.
Type-Level Dynamics
The framing category encompasses wall-bearing systems, skeleton framing, long-span solutions, and other specialized types. Each carries distinct engineering requirements, installation workflows, and end-user expectations. Wall-bearing systems tend to align with repetitive structural layouts and faster envelope completion. Skeleton framing supports flexible interior configurations and load distribution strategies. Long-span applications address larger clear-height requirements and specialized architectural programs. The report examines how these type segments differ in specification drivers, fabrication tolerances, and competitive positioning, helping manufacturers and distributors decide where to concentrate engineering resources and sales specialization.
Application Pathways
Residential construction, commercial buildings, and industrial buildings represent the principal application pathways. Their demand profiles diverge significantly in procurement cadence, volume consistency, and tolerance for design customization. Residential demand is shaped by housing velocity, build-system standardization, and regional labor availability. Commercial demand responds to tenant improvement cycles, office and hospitality renovation activity, and the push toward modular interiors. Industrial demand is influenced by warehouse expansion, logistics infrastructure, and light-manufacturing facility construction. The report maps how these application segments interact with framing type preferences and regional procurement habits, providing a basis for prioritization in product roadmaps and channel strategy.
Regional Realities
Regional markets operate under different code environments, sourcing expectations, and competitive densities. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The research avoids superficial regional comparisons and instead evaluates how local specification culture, trade dynamics, and adoption maturity influence market behavior. Decision-makers receive context on where distribution networks need strengthening, where engineering partnerships accelerate specification, and where local manufacturing or assembly capabilities create defensibility.
By weaving type, application, and region together, the study reveals where growth is most concentrated, where substitution risk is highest, and where strategic entry or expansion would yield the strongest return on effort. The complete segmentation analysis in the full report provides the quantified foundation for those decisions without exposing the underlying splits in advance, preserving the integrity of the intelligence for clients who need to benchmark against their own pipeline and capacity assumptions.
Competitive Landscape and Strategic Positioning
One of the strongest features of this research is its structured evaluation of the companies actively defining LGS market behavior. The competitive field spans established framing manufacturers, structural component suppliers, cold-formed steel specialists, and broader steel ecosystems that extend into LGS applications. Rather than treating these players as a simple roster, the study assesses them through the lens of capability depth, geographic reach, and strategic posture.
The market structure reflects meaningful concentration. The top three firms collectively account for approximately 55.0 percent of market share, while the top five reach around 65.0 percent. This concentration pattern signals that scale, specification relationships, and manufacturing consistency are becoming decisive advantages. At the same time, the presence of multiple regional specialists and product-focused innovators indicates that differentiation remains possible for firms that excel in installation precision, engineering support, or targeted application expertise.
The competitive analysis profiles a broad cross-section of organizations, including ClarkDietrich Building Systems LLC, WARE Industries, Inc., CEMCO, Hadley Industries PLC, Genesis Manazil Steel Framing, Scottsdale Construction Systems Ltd, Nucor Building Systems, Studco Building Systems, Tata BlueScope Steel, The Steel Network, Inc., ArcelorMittal S.A., Precision Walls Inc., FRAMECAD Limited, MiTek Industries, Inc., Stratus Steel, EPACK Prefab, MBA Building Supplies, Aegis Metal Framing, Radius Track Corporation, and Steel Frame Solutions Ltd.
Each profile is evaluated for its operating footprint, product system orientation, and relevance to specific application or regional contexts. For example, firms headquartered in the United States and United Kingdom often reflect mature framing ecosystems with strong specification channels, while entities operating in Australia, the Middle East, India, and New Zealand illustrate how LGS is gaining traction in markets seeking faster construction cycles, material consistency, or prefabricated system adoption. The study does not merely list these companies; it situates them within competitive clusters, assesses where they are likely to compete on price versus value, and identifies which organizational profiles are best positioned to benefit from the forecast trajectory.
This competitive layer is essential for 2026 strategy because the market is not expanding in a vacuum. Growth will be allocated according to who can execute on installation reliability, engineering support, supply continuity, and specification influence. The report provides the framework needed to determine whether your organization should compete through scale, specialization, regional depth, system integration, or partnership-led distribution.
Regulatory Signals and Industry Dynamics Reshaping Deployment
Materials markets do not move solely on demand; they move on the standards, certifications, and technical updates that govern specification and liability. In 2026, several developments are already reshaping how engineers, contractors, and manufacturers approach cold-formed steel and light gauge steel systems. The report integrates these dynamics into its forward-looking analysis so that strategic recommendations reflect not just market size but also the rules of engagement.
A notable technical milestone is the publication of CFSEI Tech Note J200-26 on the vibration of cold-formed steel joist framed floors. Updates of this nature matter because they influence floor system design assumptions, acoustic and serviceability considerations, and the confidence with which engineers specify LGS assemblies in multi-unit and commercial projects. When technical guidance evolves, specification behavior evolves with it, and manufacturers that align product documentation, engineering support, and training to the new expectations can strengthen their position in the specification pipeline.
Alongside the technical update, the CFSEI 2026 Expo in Long Beach, California brought together more than 250 engineers to discuss resilience and real-world solutions for cold-formed steel framing. Events of this scale are more than industry gatherings; they are indicators of where professional attention is concentrating, which performance themes are gaining prominence, and how knowledge transfer is shaping adoption. The research interprets these gatherings as signals of specification momentum and workforce readiness, both of which affect the speed at which LGS solutions move from consideration to repeatable deployment.
Innovation in installation precision is another dynamic shaping the market. The Steel Network's introduction of NotchTrak in April 2026 reflects an industry-wide emphasis on improving accuracy and efficiency in LGS framing installation. Products and systems that reduce field variability, shorten assembly time, or improve alignment can influence contractor preference and repeat procurement. The study evaluates how such launches alter competitive differentiation and what they imply for manufacturers seeking to compete on total installed value rather than component price alone.
Talent development is also part of the market's future readiness. CFSEI's announcement of 2026 Student Competition winners and stipend recipients highlights continued investment in the next generation of cold-formed steel design talent. For long-term market planning, this matters because specification ecosystems depend on engineers who understand LGS behavior, design constraints, and system integration. The report frames talent pipelines as an underappreciated but real driver of sustainable demand, especially in markets where engineering capacity can either accelerate or bottleneck adoption.
By embedding these regulatory and industry dynamics into the broader forecast, the research ensures that strategic recommendations are grounded in how the market actually changes, not just how it grows. The complete dynamic analysis in the full report connects these developments to regional specification environments, competitive responses, and application-level implications.
What Decision-Makers Can Expect Inside the Full Study
This market research is built for practical use. It is structured to support capital planning, product strategy, channel expansion, competitive benchmarking, and specification positioning. The full study translates the macro and competitive framework into a detailed operational reference that can be aligned with internal planning cycles.
Inside the report, readers will find:
- A comprehensive market sizing and forecast architecture that links historical performance to forward trajectory across the 2026 to 2032 window.
- Segmentation analysis that evaluates framing types, application pathways, and regional demand behavior in a manner designed for prioritization and resource allocation.
- Competitive profiles that place key companies in context, highlighting operating footprints, product system orientations, and strategic positioning.
- Market concentration analysis that clarifies where scale advantages matter and where differentiation remains viable.
- Industry dynamics coverage that ties technical standards, product launches, exhibition activity, and talent development to specification and deployment behavior.
- Strategic implications tailored for manufacturers, distributors, engineering-focused suppliers, and construction-system integrators seeking to act in 2026 and beyond.
The study does not stop at describing the market. It provides the analytical scaffolding needed to interpret where opportunity is most durable, where competitive pressure will intensify, and how to sequence investments for maximum impact. Detailed quantitative splits, company-level benchmarking, and region-specific deployment insights are presented in full within the report so that they can be used for internal modeling and board-level discussion with complete confidence.
How This Research Supports 2026 Strategy
In a market expanding from 44.71 billion USD in 2026 toward 63.02 billion USD by 2032, the strategic question is not simply how large the opportunity is, but how to capture the right portion of it with the right capabilities. The report is designed to help organizations answer that question with precision.
For manufacturers, the research clarifies where product development and fabrication investments are likely to generate the strongest returns, based on application demand and competitive positioning. For distributors and building-system suppliers, it highlights where regional coverage, specification support, and installation reliability can create durable advantage. For engineering-led organizations and component innovators, it identifies where technical updates and precision-focused product launches are reshaping preference and procurement. For investors and corporate strategists, it provides a structured view of concentration, growth dispersion, and competitive dynamics that can inform entry, expansion, or partnership decisions.
The deliberate emphasis on strategic context over raw data exposure reflects the reality that market intelligence is most valuable when it helps leaders decide, not just when it helps them observe. By integrating macro trajectory, segmentation logic, competitive structure, and regulatory momentum into one coherent framework, the study gives executives a way to stress-test assumptions, prioritize initiatives, and align 2026 actions with the market's longer-term architecture.
Conclusion: Turn Forecast Confidence into Executable Strategy
The Light Gauge Steel market is entering a phase where growth is supported by structural adoption, technical refinement, and competitive consolidation. That combination rewards organizations that act with informed discipline rather than broad speculation. PW Consulting's Light Gauge Steel Market research delivers the depth, structure, and strategic framing needed to make those decisions with confidence.
The full report contains the complete segmentation analysis, detailed company evaluations, concentration data interpretation, and regional deployment insights that turn high-level trajectory into operational direction. For teams preparing capital plans, product roadmaps, channel strategies, or competitive responses for 2026 and beyond, the study offers a rigorous intelligence base to guide execution.
Access the full Light Gauge Steel Market research to retrieve the complete data architecture, segmentation detail, and strategic recommendations designed for immediate decision use.
For detailed analysis of this topic, please visit the official page: Light Gauge Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheelbarrows Market to Hit $880M by 2032, Growing at 4.3% CAGR: PW Consulting
By PW Consulting, 2026-09-07
Strategic Horizon 2026: Unlocking Value in the Global Wheelbarrows Market
The industrial tools sector is rarely characterized by glamour, yet few categories embody the fundamentals of global economic activity quite like the wheelbarrow. From the sprawling infrastructure projects reshaping emerging economies to the quiet corners of residential renovation, this humble equipment category serves as a critical linchpin in material handling logistics. As we move through 2026, the wheelbarrows market presents a complex landscape of steady growth, material innovation, and shifting regulatory pressures. Understanding these dynamics is not merely an academic exercise; it is a strategic imperative for manufacturers, suppliers, and investors aiming to capitalize on the sustained demand projected over the coming years.
Database Management Platform Market
Our latest comprehensive market research report offers an unprecedented look into the mechanisms driving this sector. By analyzing historical data from 2020 through 2025 and projecting forward to 2032, we have identified the key vectors of growth and risk. This article serves as an executive preview of those findings, highlighting the strategic value embedded in the data without divulging the granular intelligence reserved for our full subscribers. In an environment where supply chain volatility and raw material costs can erase margins overnight, access to precise market forecasting is the difference between reactive scrambling and proactive planning.
Pen Making Market
Market Trajectory and Macro Economic Insights
The financial narrative of the wheelbarrows market over the past half-decade tells a story of resilience and incremental expansion. Starting from a consolidated base in 2020, the market has navigated post-pandemic recovery phases, supply chain disruptions, and shifting labor dynamics to reach a stabilized revenue base in 2025. Our analysis indicates that the compound annual growth rate (CAGR) for the forecast period extending to 2032 is positioned at 4.3 percent. While this figure may appear moderate compared to high-growth technology sectors, it represents a robust, underlying demand curve driven by essential industries rather than speculative hype.
Engineering Plastics Grade Nylon 66 Resin Market
The revenue progression from 2020 to the forecast horizon suggests a market that is maturing but not stagnant. Key inflection points in the forecast period, particularly around the late 2020s, highlight where demand spikes are anticipated based on current infrastructure commitments and construction cycles. For decision-makers, this trajectory offers a blueprint for capacity planning and inventory management. Investors looking at long-term asset allocation in the industrial manufacturing space will find that the stability of this growth curve provides a hedge against more volatile market segments. However, the aggregate numbers only tell part of the story. The real strategy lies in understanding where this value is generated and how the composition of that value is shifting over time.
Notably, the market size projections indicate periods of acceleration followed by consolidation. This pattern reflects the broader economic cycles affecting construction and agriculture, the two primary pillars supporting demand. For a business leader, recognizing these cycles allows for the timing of product launches and the negotiation of long-term supply contracts. Our report details the specific revenue milestones expected across the forecast horizon, providing the granularity needed to align operational budgets with market realities. The goal is to move beyond simple top-line growth expectations and understand the volume and value dynamics that underpin them.
Competitive Landscape and Strategic Positioning
The competitive environment in the wheelbarrows market is defined by a mix of established multinational manufacturers and specialized regional players. Our analysis of market concentration reveals a fragmented landscape where the top three players hold a combined share of approximately 32.5 percent, while the top five control around 47.8 percent. This concentration level suggests that while there are dominant incumbents, there remains significant room for niche players to differentiate through specialization, material innovation, or regional service networks.
Key companies such as Tramontina, Walsall Wheelbarrow Company, Ames True Temper, and Gorilla Carts illustrate the diverse approaches to capturing market share. Tramontina, based in Brazil, exemplifies a strategy focused on versatility and sustainability. Their recent launch of the 200-liter Extraforte da Agricultura model, featuring dual solid recycled rubber tires, signals a strong alignment with agricultural endurance needs and circular economy principles. This move is not just about product utility; it is a statement on material sourcing and brand responsibility that resonates with modern procurement standards in the agriculture sector.
In contrast, manufacturers like Walsall Wheelbarrow Company in the UK are doubling down on professional certification and regional prestige. Their recent membership in the EURO CRAFT European buying group and recognition as Family Business of the Year highlight a strategy built on collaboration, quality assurance, and local economic integration. Similarly, Ames True Temper and Brentwood Industries in the USA continue to dominate the construction end of the spectrum with heavy-duty steel trays and wooden handles designed for the rigors of professional building sites. These companies rely on brand legacy and proven durability to maintain loyalty among contractors who cannot afford equipment failure on the job.
Emerging technologies are also reshaping the competitive field. Husqvarna AB from Sweden is pioneering the electrification of material handling. By developing battery-powered wheelbarrows with smart sensors and long runtime, they are addressing labor shortages and ergonomic concerns in professional landscaping and construction. This represents a potential disruptive vector in the market. Companies that rely solely on traditional steel and plastic mechanisms may find themselves overtaken by electrified alternatives if labor costs continue to rise or if regulations push for reduced manual strain in the workplace. Our full report provides a detailed competitive analysis matrix, evaluating each key company's product portfolio, geographic reach, and recent strategic developments to help you benchmark your position against the market leaders.
Market Dynamics: Materials, Regulations, and Demand Drivers
The operational environment for wheelbarrow manufacturers is currently shaped by a triad of forces: raw material volatility, regulatory intervention, and shifting consumer habits. Steel remains the primary raw material for the majority of heavy-duty wheelbarrows, and its price stability is directly correlated with production margins. Post-pandemic recovery in the US steel industry has led to fluctuating prices, creating a challenging environment for cost management. Manufacturers must navigate these fluctuations without alienating price-sensitive consumers or eroding their own profitability. The industry context data we have gathered highlights how sensitive the market is to these raw material shifts, and our report offers strategies for hedging against steel price volatility through design optimization or material substitution.
Regulatory factors are also coming into sharper focus. In April 2025, the UK Steel Industry (Special Measures) Bill addressed primary steelmaking challenges with direct government intervention on raw material purchases. While this legislation is specific to the UK, it sets a precedent for how governments might intervene in industrial supply chains to ensure security of supply. For global manufacturers, such regulatory moves can alter the competitive balance between regions with subsidized steel production and those relying on open markets. Understanding the regulatory landscape in key export and import territories is crucial for compliance and for anticipating shifts in material availability.
Demand-side dynamics are equally transformative. Infrastructure and construction development remain the primary drivers of demand for material handling equipment. As governments worldwide continue to invest in public works, the need for reliable wheelbarrows on job sites remains constant. However, beyond the professional sector, there is a noticeable shift in consumer behavior. Rising DIY and home improvement trends are increasing consumer preference for durable and lightweight options. This segment often prioritizes ease of use and maneuverability over raw load capacity, creating a distinct product requirement profile compared to the construction segment. Manufacturers that can effectively bridge the gap between heavy-duty durability and consumer-friendly ergonomics stand to capture value in both the professional and retail channels.
Sustainability is no longer a peripheral concern but a core component of product value. The incorporation of recycled industrial rubber from tires for durability, as seen in recent product launches, reduces environmental impact and appeals to eco-conscious procurement officers. This trend intersects with the broader push for green construction and sustainable agriculture. Our research delves deep into how sustainability metrics are becoming a differentiator in tenders and large-scale contracts, influencing which suppliers win business in the public sector.
Segmentation Strategies and Growth Opportunities
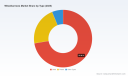
While the aggregate market data provides the macroeconomic view, the true strategic opportunities lie in the segmentation of the market. The division between material types, applications, and geographies creates distinct battlegrounds for competition. Steel continues to hold a dominant position in terms of revenue share, reflecting its preference in heavy-duty construction and industrial applications. However, plastic and other composite types offer specific advantages in terms of weight reduction and corrosion resistance, making them vital for specific agricultural or chemical handling use cases. The balance between these material types is shifting as manufacturing technologies evolve and as customers seek lighter loads for manual handling.
Application-wise, construction remains the largest driver of value, but agriculture represents a significant and resilient revenue stream. The agricultural sector requires equipment that can withstand harsh environments, mud, and heavy loads of produce or feed. The recent product innovations in this space, such as specialized agricultural models with recycled rubber tires, indicate that stakeholders in this segment are actively innovating to meet these specific needs. The third segment, comprising various other applications, often includes landscaping, gardening, and utility tasks. Growth in this area is closely tied to consumer discretionary spending and urban greening projects.
Regionally, the market is distributed across North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique challenges and opportunities. Developed markets in North America and Europe are characterized by high standards for safety and durability, alongside a mature competitive landscape. In contrast, Asia Pacific and emerging regions offer volume growth potential driven by infrastructure expansion and urbanization. However, these markets may also present challenges regarding price sensitivity and distribution logistics. Our report breaks down these regional dynamics without exposing the specific revenue splits, allowing clients to assess where their current footprint aligns with the highest growth potential before making capital allocation decisions.
For businesses looking to expand, the strategic question is not just where the market is growing, but where their specific value proposition fits best. A manufacturer specializing in heavy steel construction tools may find limited synergy in the consumer DIY segment, whereas a company with flexible molding capabilities might find significant growth in the lightweight plastic segment for landscaping. The interplay between type, application, and region creates a matrix of opportunities that requires careful analysis to navigate effectively. Our full segmentation analysis provides the detailed breakdowns necessary to identify these high-yield pockets of demand.
Conclusion and Call to Action
The wheelbarrows market in 2026 is at a crossroads of tradition and innovation. While the fundamental need for manual material handling equipment remains unchanged, the methods of production, the materials used, and the regulatory environment are evolving rapidly. For industry stakeholders, the margin for error is shrinking. The ability to anticipate steel price fluctuations, adapt to new sustainability requirements, and cater to both professional and DIY demand streams will define the winners of the next decade. The projected CAGR of 4.3 percent offers a reason for optimism, but realizing that growth requires more than passive observation.
Our comprehensive market research report goes beyond the high-level trends discussed here. It contains the proprietary data, detailed segmentation splits, and deep-dive competitor profiles necessary to build a robust strategic plan. We invite industry leaders, investors, and strategists to access the full report to gain the complete intelligence picture. By leveraging these insights, your organization can make informed decisions on product development, market entry, and supply chain optimization, ensuring that you are not just participating in the market but leading within it. The tools are simple, but the strategy required to master their market is complex. Let us help you navigate that complexity.
For detailed analysis of this topic, please visit the official page: Wheelbarrows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thermal Management Market Hits $13.8B in 2025, 8.1% CAGR to $23.8B by 2032
By PW Consulting, 2026-09-07
The Thermal Management Imperative: Strategic Intelligence for the 2026 Market Landscape
As we navigate the complex technological shifts of the mid-2020s, thermal management has ceased to be merely a supporting engineering function. It has become a critical bottleneck and a primary enabler of innovation across multiple high-growth sectors. From the exponential heat loads generated by artificial intelligence workloads in data centers to the stringent reliability requirements of next-generation automotive systems, controlling temperature is now synonymous with controlling performance. PW Consulting is proud to unveil our latest comprehensive study on the Thermal Management Market, a report designed not just to map the terrain, but to provide the strategic compass necessary for enterprise decision-making in 2026 and beyond.
Water-Washable Resin-Based Ribbon Market
This article serves as an executive preview of the depth and utility embedded within our full research publication. Our objective is to highlight why this intelligence is vital for your strategic planning cycles, investment committees, and operational roadmaps. While we will outline the macro trajectory and the critical dynamics reshaping the industry, the granular segmentation data and proprietary competitive profiles contained in the full report are reserved for our clients. This approach ensures that the strategic advantage derived from deep data remains exclusive to those who invest in comprehensive intelligence.
Worldwide Chemical Resistant Fiber Market
Market Trajectory: A Decade of Accelerated Growth
The thermal management sector is currently riding a wave of demand that shows no signs of abating. Our historical analysis covers the period from 2020 through 2025, establishing a robust baseline of resilience and growth despite global supply chain fluctuations. The market has demonstrated consistent upward momentum, evolving from a valuation of approximately 9.35 billion USD in 2020 to an estimated 13.8 billion USD by 2025. This historical performance sets the stage for a forecast period that extends through 2032, where we project the market valuation to reach nearly 23.8 billion USD.
Worldwide Construction Vehicle Axle Market
Such growth is not linear; it is propelled by structural shifts in how technology is deployed and cooled. The compound annual growth rate observed during our forecast horizon underscores the intensity of this expansion. For stakeholders, this trajectory suggests that thermal management is no longer a mature, stagnant market but a dynamic field ripe with investment opportunities and partnership potential. However, understanding the aggregate numbers is only the first step. The real value lies in dissecting how this growth is distributed across technologies, applications, and geographies, which is where our full report provides unparalleled granularity.
The Shift from Traditional to Advanced Cooling
The historical growth from 2020 to 2025 was largely driven by incremental improvements in existing technologies. However, the forecast period from 2026 to 2032 marks a transition point. We are witnessing a decisive shift away from conventional air-cooling methods toward more sophisticated hybrid and liquid cooling solutions. This is not merely a technological preference but a physical necessity driven by higher power densities. As electronic components become more compact and powerful, the ability to dissipate heat efficiently determines the viability of the entire system.
Regional and Segment Nuances
While the global aggregate figures are impressive, the regional disparities tell a more complex story about where the opportunities lie. North America and Europe have historically held significant shares of the market, driven by established infrastructure and early adoption of high-density computing. Meanwhile, the Asia Pacific region continues to be a critical engine for growth, fueled by manufacturing capacity and rapid technological adoption. In our full report, we break down these regional contributions with specific revenue valuations for each territory, allowing you to assess market entry barriers and localization strategies with precision.
Similarly, the segmentation by type reveals a reshuffling of the portfolio. Convection cooling devices have traditionally held a large portion of the market, but the demand for conduction and hybrid cooling devices is accelerating. The full study quantifies these splits, providing exact revenue figures for each technology type, enabling you to identify which technological bets are likely to yield the highest returns in the coming years.
Key Drivers and Industry Dynamics
To make informed decisions in 2026, one must understand the underlying forces pushing the market. Our report dedicates significant attention to the dynamics section, where we analyze the interplay of regulations, standards, and macro trends. These factors are not background noise; they are active variables that will influence cost structures, compliance requirements, and technology lifecycles.
Regulatory Pressures and Environmental Standards
One of the most critical dynamics identified involves regulatory changes regarding refrigerants. With the EPA governing high global warming potential refrigerants effective January 2027, companies must prepare for a transition in their cooling fluid portfolios. This regulatory shift impacts not only data centers but any industrial application relying on traditional cooling agents. Our analysis details the timeline and the potential market impact of these regulations, helping compliance teams and procurement officers anticipate supply chain adjustments.
Furthermore, the establishment of ISO thermal management standards for data center cooling is bringing a new level of uniformity to the industry. Announced in mid-2025, these standards aim to optimize energy efficiency and interoperability. For enterprises, adhering to these standards may become a prerequisite for partnerships and certifications. The full report contextualizes these standards within the broader competitive landscape, explaining how they might consolidate the market around compliant leaders.
The AI and Liquid Cooling Nexus
A macro trend that cannot be overlooked is the increased demand for liquid cooling in AI data centers. As artificial intelligence models grow in complexity, the power consumption of training and inference hardware has skyrocketed. Air cooling is increasingly reaching its physical limits in high-density environments. This has spurred a surge in demand for direct-to-chip and immersion cooling technologies. Our industry context analysis highlights this shift as a primary growth catalyst for the forecast period. Understanding the specific adoption rates and capacity requirements of this trend is essential for suppliers of liquid cooling components and for data center operators planning capacity expansions.
Competitive Landscape: Consolidation and Innovation
The competitive environment in thermal management is characterized by a mix of specialized innovators and large conglomerates seeking to expand their footprint. Our report provides detailed profiles of key companies, but beyond the profiles, we analyze the recent movements that signal the direction of the market. The last few months of 2025 and early 2026 have been particularly active, with significant mergers and acquisitions reshaping the buyer landscape.
Strategic Acquisitions Defining the Future
In a move completed in March 2026, Eaton finalized the acquisition of the Boyd Thermal business. This integration brings advanced liquid cooling and grid-to-chip solutions under the Eaton umbrella, signaling a strong commitment to electrified thermal solutions. Just prior to this, in February 2026, Johnson Controls signed an agreement to acquire Alloy Enterprises. This deal is focused on strengthening their data center thermal management platform, adding specialized capabilities to their existing YORK chiller and Silent-Aire hyperscale cooling portfolio.
These acquisitions are not isolated events; they represent a broader strategy among market leaders to secure supply chains and integrate complementary technologies. Vertiv, Schneider Electric, Johnson Controls, and other major players are actively positioning themselves to capture the value chain from component manufacturing to system-level integration. By examining these moves in our full report, clients can gauge which partnerships are likely to strengthen and where potential gaps might emerge in the supply market.
Key Players and Their Focus Areas
The market includes a diverse set of players, each dominating specific niches. Vertiv, headquartered in Atlanta, continues to focus on adaptive air, liquid, and hybrid cooling systems specifically tailored for data centers and high-density thermal management. Schneider Electric, based in Paris, is heavily invested in EcoStruxure data center software and modular liquid cooling solutions designed for HPC and AI workloads. Johnson Controls, from Charlotte, leverages its YORK chillers and Silent-Aire solutions to provide integrated thermal management for massive data center operations.
On the component and material side, Boyd Corporation has long been known for advanced liquid cooling plates and extruded heat sinks. CoolIT Systems, from Victoria, focuses on high-performance liquid cooling systems for CPUs and servers. Meanwhile, companies like Calyos in Paris are pushing the boundaries with micro-channel heat pipes and direct-to-chip cooling. In the materials sector, Dow is focusing on thermal gels, fluids, and coolant management, while Gates Corporation provides high-capacity MegaFlex hoses essential for liquid cooling systems. Indium Corporation rounds out this competitive view with a focus on high-performance metal thermal interface materials, crucial for semiconductor packaging.
Our full report not only lists these companies but analyzes their relative market positions, strategic focus areas, and recent developments such as Indium Corporation's featured presence at TestConX 2026. This depth allows you to benchmark your own capabilities or identify potential partners and competitors with accuracy.
Segmentation Deep Dive: Applications and Technologies
While we have avoided specific percentage breakdowns in this preview, it is important to understand the application diversity driving the market. The automotive sector undoubtedly represents a massive portion of the demand, driven by the electrification of vehicles and the need for battery thermal management. Data centers remain the hotbed of innovation, particularly with the shift to liquid cooling. Consumer electronics, aerospace, and defense also contribute significant shares, each with unique thermal challenges.
The full report provides exact revenue valuations for each application segment. This allows you to answer critical questions: How much revenue is attributable to automotive versus data centers? Which application segment is growing faster? What is the specific market size for aerospace and defense thermal solutions? Having these numbers allows for precise market sizing for your specific product offerings.
Similarly, the technology segmentation is nuanced. Conduction cooling devices, convection cooling devices, hybrid cooling devices, and others each cater to different thermal requirements. The forecast data shows how the balance between these technologies is expected to shift. For instance, as hybrid cooling devices gain traction, the revenue mix will change. Our report provides the exact valuation for each technology type for the base year and forecast years, enabling a detailed technology road mapping exercise.
Strategic Value for 2026 Decision Making
Why should your organization invest in this level of detail? In 2026, the margin for error is narrowing. The combination of regulatory deadlines, rapid technological obsolescence, and intense competition means that decisions must be data-backed. Guessing market size or competitor strength is a strategy that leads to lost market share.
Investment and Capacity Planning
For investors and CAPEX managers, the forecast period through 2032 offers a long-term view of opportunity. Knowing which segments will grow allows for targeted capital allocation. Whether you are expanding a manufacturing line for heat sinks or investing in a startup focused on thermal fluids, the data in this report provides the quantitative backing needed to justify the investment. The high demand for high-performance TIMs in semiconductor packaging, identified as a raw material trend in our analysis, suggests specific supply chain opportunities that might be missed without granular data.
Operational and Compliance Strategy
For operations leaders, the report details the implications of the EPA refrigerant regulations and ISO standards. Understanding the timeline helps in planning for retrofitting or new installations. Ignoring these dynamics could lead to stranded assets or compliance penalties. The competitive analysis also helps in negotiating with suppliers. If you know the market concentration levels—with the top three companies holding a CR3 of 25.5 percent and the top five at 32.8 percent—you can better understand supplier power and negotiate contracts with leverage.
Market Entry and Expansion
For companies looking to enter new geographic markets or application verticals, the regional and application segmentation data is indispensable. You can identify which regions offer the highest revenue potential relative to competition. You can assess whether the automotive sector in a specific region is a viable entry point compared to data centers. The detailed breakdown prevents the costly mistake of entering a saturated segment or overlooking a high-growth niche.
Conclusion: Access the Complete Intelligence
The thermal management market is at a inflection point. The convergence of AI demand, regulatory changes, and technological innovation is creating a landscape where strategic foresight is the primary differentiator. This preview has outlined the macro trends, the competitive movements, and the regulatory pressures that define the environment. However, the true power of this research lies in the data that supports these conclusions.
To make the most informed decisions for 2026 and the forecast period ahead, you need access to the specific revenue figures, segmentation splits, and detailed company profiles that we have reserved for the full report. PW Consulting's Thermal Management Market study is designed to be a cornerstone of your strategic planning. We invite you to visit our source webpage to access the complete intelligence. Equip your team with the data required to navigate the heat of competition and secure a leadership position in the market of tomorrow.
The insights provided here are just the surface. The depth of analysis required to outmaneuver competitors and capitalize on the 8.1 percent growth trajectory awaits you in the full publication. Do not rely on generalities in a market this specialized. Secure the detailed intelligence that will drive your successful strategy.
For detailed analysis of this topic, please visit the official page: Thermal Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sheet Molding Compound Market Projected to Reach $2.3B by 2032, Growing at 4.22% CAGR
By PW Consulting, 2026-09-07
Strategic Horizons in the Sheet Molding Compound Market: Navigating Growth and Complexity Through 2032
The structural landscape of the Sheet Molding Compound (SMC) market is undergoing a quiet but significant transformation. What was once viewed primarily as a cost-effective alternative for complex geometries is now emerging as a critical enabler for weight reduction, design flexibility, and chemical resistance across multiple industrial verticals. For supply chain leaders, procurement strategists, and corporate development teams, this shift carries profound implications for 2026 and beyond. The market is not merely expanding; it is rebalancing around new formulation technologies, capacity realignments, and application-driven demand that reward early visibility and strategic positioning.
Worldwide Gas Powered Cold Water Pressure Washer Market
This article introduces our latest comprehensive market research on the SMC sector, designed to equip decision-makers with the analytical depth required to navigate the forecast period from 2026 through 2032. Rather than offering surface-level aggregates, the study dissects the operational, competitive, and macroeconomic forces shaping the industry, providing a roadmap for capacity planning, product portfolio optimization, and partnership development. The following overview previews the strategic architecture of the research, demonstrating how granular insights can be converted into actionable intelligence.
Frameless Resolvers Market
Market Size Evolution and the Trajectory Anchored for 2026
The SMC market has demonstrated resilience through periods of raw material volatility, shifting end-use demand, and incremental capacity adjustments. Drawing on historical data spanning 2020 through 2025, the industry has experienced a series of nuanced fluctuations that reflect both cyclical pressures and structural shifts in downstream consumption. The base year of 2025 establishes a critical reference point, capturing the market's positioning as it enters a new phase of forecast-driven growth.
Home Theater Recliner Market
Looking forward, the projected trajectory through 2032 reveals a steady, compounding expansion that underscores the material's enduring relevance. The compound annual growth rate underscores a market that is not experiencing explosive disruption but rather a disciplined, application-led ascent. This steady climb is supported by ongoing substitutions in sectors where metal and unreinforced thermoplastics face cost, performance, or weight penalties. The forecast window captures the cumulative effect of incremental capacity additions, formulation refinements, and the gradual penetration of SMC into higher-specification applications that were previously considered marginal.
It is important to recognize that absolute market size alone does not tell the story that matters to 2026 decision-makers. The real value lies in understanding how growth is distributed across formulation types, downstream sectors, and geographic corridors, and how those distributions interact with supply constraints, pricing dynamics, and competitive capacity shifts. Our research isolates these layers, allowing executives to distinguish between headline growth and the underlying drivers that will dictate margin stability, sourcing strategy, and regional investment priorities.
Segmentation: Where Growth Actually Originates
A market of this scale only becomes actionable when its internal architecture is understood. The SMC industry is not a monolith; it is a constellation of formulation families, application verticals, and regional supply ecosystems that each follow distinct logic. The research breaks down the market across these dimensions, mapping how different product categories and end-use sectors contribute to overall momentum and where performance diverges from broad trends.
Formulation Families and Their Differentiated Roles
The composition of SMC demand is shaped by the performance requirements of downstream applications and the cost-performance tradeoffs accepted by manufacturers. Unsaturated polyester formulations continue to anchor a substantial portion of the market, reflecting their versatility, established processing infrastructure, and favorable economics for high-volume structural and cosmetic parts. Vinyl ester-based variants occupy a distinct niche, particularly where enhanced chemical resistance or improved thermal stability is required, making them relevant to demanding industrial and electrical contexts. Epoxy and phenolic systems, while representing smaller shares of the broader mix, are gaining attention in specialized applications where mechanical stiffness, flame performance, or adhesion characteristics justify the premium.
Understanding these formulation dynamics is essential for companies evaluating product roadmap decisions. A supplier expanding its unsaturated polyester capacity, for example, is making a fundamentally different strategic bet than a producer investing in flame-retardant or epoxy-based grades. The research examines how these formulation categories evolve in response to raw material availability, processing improvements, and specification changes in end markets, enabling readers to identify which segments offer the strongest alignment with their own technical capabilities and customer portfolios.
Application Verticals and Demand Velocity
The dispersion of SMC consumption across applications reveals where demand is most resilient and where it is most sensitive to macro conditions. Automotive remains a central pillar of the market, driven by ongoing lightweighting initiatives, the need for corrosion-resistant components, and the growing use of composite materials in both structural and exterior applications. Within this vertical, the rise of electric vehicle architectures has introduced new considerations around panel design, underbody protection, and enclosure materials, prompting both material suppliers and molders to refine formulations for specific performance targets.
Electrical and electronics applications represent another significant channel, where SMC's electrical insulation properties, dimensional stability, and ability to meet flame and tracking requirements support its use in enclosures, components, and infrastructure-adjacent hardware. Building and construction demand is anchored by the material's durability, weatherability, and suitability for molded panels, profiles, and specialty components that must balance aesthetics with long-term performance. Beyond these core verticals, a diverse set of industrial and specialty applications contributes additional demand, often driven by custom engineering requirements and lower-volume, higher-value production runs.
The research profiles these application streams with attention to demand drivers, specification trends, and the interaction between material performance and total cost of ownership. This perspective helps readers assess which verticals offer the most attractive growth profiles for their capabilities, and where competitive intensity or specification barriers may limit rapid share gains.
Regional Supply and Demand Architectures
Geography shapes the SMC market in ways that go beyond simple volume distribution. Regional demand patterns reflect local industrial bases, automotive production footprints, construction activity levels, and the maturity of composite processing ecosystems. At the same time, regional supply dynamics are influenced by the location of resin manufacturers, compounders, and molders, as well as by logistics costs and local regulatory environments.
North American demand has been supported by a combination of automotive production, industrial manufacturing, and building product applications, alongside a relatively mature compounding and molding infrastructure. European markets reflect strong demand from automotive suppliers, electrical component manufacturers, and construction-related applications, with an emphasis on engineered formulations and compliance-driven specifications. Asia Pacific represents an important growth axis, shaped by expanding manufacturing capacity, vehicle production, and infrastructure development, though the region's market structure is more fragmented and increasingly influenced by localized formulation strategies. Latin America and the Middle East and Africa contribute smaller but strategically relevant volumes, often tied to specific industrial projects, export-driven manufacturing, or niche applications where SMC's performance profile offers a clear advantage.
Rather than presenting static regional snapshots, the study examines how these geographies interact with formulation availability, lead-time considerations, and competitive capacity. For companies evaluating export opportunities, sourcing diversification, or local production investments, this regional layer is essential for distinguishing between apparent demand and commercially viable demand.
Competitive Landscape: Capacity, Formulation, and Strategic Positioning
The SMC market is characterized by a mix of compounders, resin suppliers, and engineered materials producers, with a notable concentration among the largest participants. The research profiles the companies that shape market dynamics through capacity decisions, formulation innovation, vertical integration, and customer-facing technical support. Understanding this landscape is critical for assessing supplier reliability, partnership opportunities, and the risk of capacity constraints in key segments.
Key Companies and Their Strategic Footprints
IDI Composite International, based in Noblesville, Indiana, operates as a custom-formulated SMC and BMC manufacturer with dedicated production lines and tailored solutions spanning automotive, industrial, and electrical applications. The company's recent expansion underscores the importance of flexible capacity in serving both high-volume and lower-volume runs. In January 2026, IDI Composite International launched a third SMC production line at its new Noblesville facility, reducing lead times to approximately three to four weeks and enabling smaller batch sizes that broaden its appeal for custom and specialized programs.
Core Molding Technologies, headquartered in Columbus, Ohio, is an engineered materials company specializing in compression molding of SMC for automotive, building products, and aerospace applications, relying on proprietary formulations to differentiate its offerings. By March 2026, the company was installing two 4,500-ton presses in Matamoros, Mexico, to expand its SMC production footprint. This capacity expansion coincided with new business wins, including proprietary SMC formulations for building products, signaling the value of combining equipment scale with formulation IP.
In Europe, Menzolit Kunststoffwerk GmbH has established itself as a specialist in high-performance SMC for automotive, electrical, and demanding structural applications, emphasizing part quality and formulation precision. Polynt S.p.A., based in Italy, produces SMC and flame-retardant SMC grades that serve automotive, electrical, and power applications, reflecting the importance of regulatory and performance-driven grades in certain downstream markets.
Japan's Teijin Limited manufactures advanced SMC and carbon-fiber-reinforced SMC for automotive and EV exterior panels, illustrating how reinforcement strategy and panel-specific engineering can create differentiated positions in the mobility sector. LyondellBasell Industries Ltd., operating from the Netherlands, supplies unsaturated polyester and vinyl ester systems for SMC compounding, representing the upstream resin supply layer that directly affects formulation economics and availability. Toray Industries, Inc., also based in Tokyo, provides advanced fibers and resins used in SMC formulations for high-performance composites, reinforcing the link between fiber technology and SMC performance ceilings.
In the United States, AOC Resins formulates resins and additives for SMC production, contributing to the broader ecosystem of compounding inputs. Premix Inc. operates as an SMC compounder offering engineered materials for automotive and industrial use, while Molding Products LLC, based in South Bend, Indiana, serves as a custom SMC and BMC formulator and producer with technical support spanning R&D to production. Together, these companies illustrate a competitive field in which formulation capability, capacity responsiveness, and technical service differentiate participants more than scale alone.
Concentration, Capacity, and the Nature of Competition
Market concentration among the leading participants creates a landscape where strategic moves by a small number of players can influence pricing, lead times, and the availability of specialized grades. At the same time, the presence of regional compounders and custom formulators ensures that niche applications and lower-volume programs can still access tailored solutions. The research evaluates how this concentration interacts with capacity expansion patterns, acquisition activity, and formulation differentiation, providing context for assessing supplier risk and partnership strategy.
For buyers, the key question is not simply which companies are largest, but which are expanding capacity in the right geographies, investing in formulations aligned with upcoming application requirements, and maintaining the technical support infrastructure needed to move programs from development to production. For competitors, the strategic challenge is to identify where scale, where specialization, and where regional presence create defensible positions in a market that rewards both consistency and customization.
Market Dynamics and Operational Realities
Beyond size, segmentation, and competition, the SMC market is shaped by operational dynamics that directly influence profitability, planning certainty, and sourcing decisions. Raw material price volatility remains a significant challenge for manufacturers, particularly in unsaturated polyester resins and fiberglass. Fluctuations driven by oil prices and supply imbalances can compress margins, disrupt quoting accuracy, and complicate long-term planning. The research addresses these dynamics not as abstract risks but as practical factors that shape formulation choices, inventory strategies, and the timing of capacity commitments.
Processing infrastructure also plays a decisive role. The number, tonnage, and flexibility of compression molding presses, together with the availability of skilled technical support, determine how quickly programs can be scaled and how effectively custom formulations can be commercialized. Companies that combine formulation expertise with responsive production capacity are better positioned to win lower-volume, higher-specification work, while those reliant on rigid high-volume lines may face challenges when demand patterns shift toward more customized or region-specific programs.
Regulatory and specification requirements further influence market behavior. Flame performance, electrical properties, weathering resistance, and structural durability are increasingly important in automotive, electrical, and building applications. These requirements create both barriers and opportunities: they raise the technical bar for entry into certain segments, but they also reward suppliers that can demonstrate consistent performance and provide validated grades aligned with end-use standards.
Our study integrates these dynamics into a coherent framework, showing how raw material exposure, processing capacity, specification demands, and regional logistics combine to shape commercial outcomes. This integrated view is essential for companies that need to evaluate not only where the market is growing, but where growth can be captured profitably and reliably.
What the Research Delivers for 2026 Decision-Making
The SMC Market research is structured to move beyond descriptive trends and provide the operational intelligence needed for concrete decisions in 2026 and the forecast period that follows. It is designed for executives, planners, and technical leaders who must reconcile market opportunity with supply reality, specification requirements, and competitive constraints.
The study offers a detailed segmentation architecture that maps formulation types, application verticals, and regional demand patterns, allowing readers to identify which combinations of material, application, and geography offer the strongest strategic alignment. This is not a superficial split of broad categories; it is a working framework for evaluating product portfolios, sourcing strategies, and investment priorities.
The competitive analysis profiles the companies that matter most to market dynamics, examining their capacity footprints, formulation strengths, geographic presence, and recent operational moves. By linking company actions to market implications, the research helps readers assess supplier stability, partnership potential, and the likely direction of capacity and price trends in key segments.
The report also incorporates market dynamics that influence commercial outcomes, including raw material volatility, processing infrastructure considerations, specification drivers, and the interaction between regional demand and local supply. This contextual layer is essential for translating growth forecasts into practical planning, whether the objective is to secure reliable supply, enter a new application, expand into a new region, or evaluate whether a competitor's capacity move affects your own positioning.
For corporate strategy teams, the research provides a basis for scenario planning, helping to frame decisions about capacity investment, product development, and market entry in light of the forecast period's growth curve and the structural forces shaping demand. For procurement and supply chain leaders, it offers context on where concentration, formulation specificity, and raw material exposure may affect lead times, pricing stability, and supplier diversification options. For technical and product leaders, it connects downstream application requirements with formulation characteristics, supporting more informed decisions about material selection and program feasibility.
Why 2026 Is the Pivot Year for SMC Strategy
The SMC market in 2026 sits at a point where multiple forces converge. Capacity expansions are coming online, formulation differentiation is intensifying, and end-use sectors are refining their material requirements in response to product architecture changes, regulatory expectations, and total-cost considerations. At the same time, raw material volatility and regional supply constraints continue to test the resilience of supply chains and the accuracy of long-range planning.
In this environment, decision-makers benefit most from intelligence that connects growth potential with operational reality. Headline market size and CAGR provide necessary orientation, but they do not reveal which formulations are gaining specification traction, which applications are driving durable demand, which regions offer the most commercially viable opportunities, or which competitors are reshaping the supply landscape through capacity and formulation investment. Those are the questions that determine whether a company can act with confidence in 2026 and sustain its position through the rest of the forecast window.
The full report provides the detail, segmentation depth, competitive profiles, and dynamic analysis required to answer those questions. It is built for readers who need to move from general market awareness to specific, defensible decisions about sourcing, product strategy, regional focus, and partnership development.
For leaders who are evaluating SMC as a strategic material, assessing the competitive field, or planning capacity and formulation investments, this research offers the analytical foundation to act with precision. The market is expanding in a disciplined, application-led manner, and the companies that succeed in 2026 will be those that understand where growth originates, how it flows through the value chain, and which operational choices convert opportunity into durable advantage.
To access the complete segmentation architecture, competitive profiles, regional demand analysis, and dynamic assessment that underpin the forecast, we invite you to explore the full report. The detailed intelligence within is designed to support the decisions that matter most in the months and years ahead.
For detailed analysis of this topic, please visit the official page: Sheet Molding Compound (SMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bluetooth Speaker Market to Hit $64B by 2032, 19.65% CAGR
By PW Consulting, 2026-09-07
The Bluetooth Speaker Market in 2026: Strategic Intelligence for Enterprise Decision-Makers
The consumer audio landscape is undergoing a structural acceleration, and few product categories illustrate this momentum more clearly than Bluetooth speakers. After a decade of steady consumer adoption, the market has entered a phase where growth is no longer driven solely by baseline demand. It is now shaped by product segmentation, supply chain recalibration, regulatory pressures, and the strategic positioning of dominant manufacturers. For executives who operate in audio hardware, consumer electronics, retail distribution, or connected lifestyle ecosystems, understanding where this category is heading is no longer optional. It is a prerequisite for portfolio planning, pricing strategy, and regional expansion.
Worldwide Water-based Fire Retardant Coating Market
PW Consulting has just released a comprehensive Bluetooth Speaker Market research study that maps the trajectory of this category from the 2020-2025 historical window through the 2026-2032 forecast period. This article introduces the strategic rationale behind the report, outlines the scope of the analysis, and explains how the findings are designed to support high-stakes corporate decisions in 2026 and beyond. The objective is not to repeat every figure available in the full document. It is to show why the research matters, what kind of insight it contains, and how decision-makers can convert that intelligence into competitive advantage.
Automobile Hub Spindle Oil Seal Market
Why the 2026 Market Inflection Demands a Fresh Research Lens
The market’s recent trajectory signals a category that has moved well beyond early growth volatility. Between 2020 and 2025, revenue expanded from roughly 7.47 billion USD to 18.32 billion USD, reflecting both recovering consumer spending and the broadening role of portable and fixed audio systems in residential and commercial environments. In 2026, the market is projected to reach approximately 22.52 billion USD, with continued expansion ahead. Over the full forecast horizon to 2032, the study applies a CAGR of 19.65 percent, underscoring a market that is compounding at a pace far above many adjacent consumer electronics segments.
Worldwide Syringe Filling System Market
That headline growth narrative is useful, but it is only the starting point for strategy. The more important question for leadership teams is what is underneath the top-line escalation. Which product and usage configurations are absorbing the majority of incremental demand. Where regional concentration is intensifying or diversifying. How the competitive field is consolidating around a relatively small group of influential players. And, crucially, how external shocks, especially tariff policy, raw material costs, and export controls, are reshaping cost structures, sourcing logic, and go-to-market timing.
The PW Consulting study is built to answer those questions. It treats the market as a system rather than a single number line. That means combining historical performance, forward estimates, segmentation logic, competitive behaviors, and regulatory context into one integrated analytical framework. For any organization that needs to make sourcing decisions, launch cadence choices, channel investment calls, or product roadmap commitments in 2026, this type of integrated view is far more actionable than a standalone size estimate.
What the Report Covers: An Integrated View of Growth, Structure, and Competitive Pressure
The research is designed as a practical decision-support tool. Rather than functioning as a generic overview, it maps the market across the dimensions that most influence operational and strategic planning. The analysis blends quantitative modeling with qualitative industry intelligence, so readers can move from broad market direction to the specific segments and competitive dynamics most relevant to their business.
At the core of the study is a time-based revenue framework covering the historical period from 2020 to 2025 and the forecast period from 2026 to 2032. This structure allows users to evaluate not only where the market has been, but also how the pace and composition of growth are expected to evolve. The forecast is constructed to support scenario thinking, giving leadership teams a basis for investment planning, capacity decisions, and product prioritization.
The report also builds out the market architecture through multiple segmentation lenses. These include geographic breakdowns, portability distinctions, and application contexts. Each segmentation dimension is examined not as an isolated statistic, but as a strategic variable: which segments are becoming structural growth engines, which are likely to remain niche or value-driven, and where demand concentration is likely to influence pricing power, channel strategy, and inventory planning.
Beyond segmentation, the study incorporates competitive analysis centered on the major manufacturers shaping category direction. These profiles are not limited to corporate descriptions. They address positioning, product philosophy, and the strategic implications of each player’s approach to audio performance, portability, durability, and brand identity. The report also integrates recent company-level activity, including product launches and feature upgrades that signal where leading manufacturers are betting on the next wave of consumer value.
Equally important, the research embeds market dynamics and structural pressures that influence profitability and execution risk. Tariff exposure, component cost volatility, and supply chain dependencies are treated as active variables rather than background noise. These factors are especially relevant for companies that source components across borders, manufacture in cost-sensitive environments, or rely heavily on battery and magnet-intensive production processes.
Growth Trajectory and the Strategic Meaning of the Forecast
Any credible market study must anchor its conclusions in a defensible growth narrative. Here, the numbers point to sustained expansion with a clear upward curve. The historical data shows a market that has grown consistently, while the forecast suggests that momentum will persist through the end of the decade and beyond. From 2020 through 2025, the category’s revenue increased from 7.47 billion USD to 18.32 billion USD. The forecast period then extends that arc, with projected revenue reaching approximately 22.52 billion USD in 2026, followed by continued gains through 2032.
For executives, the strategic message is not simply that the market is getting larger. It is that the timing and shape of growth are likely to create allocation choices. Some years in the forecast window show especially pronounced expansion, which means product launches, inventory positioning, and channel commitments made at the right moment can have disproportionate returns. Conversely, a rapidly expanding market can also intensify competition, attract new entrants, and compress margins if pricing power is not defended through differentiation or brand strength.
The forecast also provides a useful reference for long-horizon capital decisions. Organizations evaluating retail expansion, manufacturing commitments, product roadmap investments, or partnerships can use the time-based model to test whether their assumptions are aligned with the market’s expected direction. In that sense, the study functions as a planning anchor: not a guarantee, but a structured basis for internal forecasts and strategic scenarios.
Segmentation Dynamics: Portability, Application, and Regional Structure
One of the most practical parts of the report is its segmentation analysis. Growth is rarely uniform across a category, and the Bluetooth speaker market is a strong example of how product design choices and usage contexts can separate winners from laggards. The study examines how portability, application type, and geography interact to shape demand patterns.
Portability remains a defining feature of the category, but the report does not treat it as a single homogeneous block. Instead, it explores how portable products differ from fixed systems in terms of product architecture, battery dependency, consumer behavior, and channel dynamics. The analysis highlights the scale advantage enjoyed by the portable segment and examines why that segment continues to attract a large share of consumer attention and incremental demand. At the same time, fixed speaker configurations remain important in certain usage scenarios, and the report explores where stationary products may offer complementary strategic value, especially in settings that prioritize continuous playback, integration, or higher-end audio experiences.
On the application side, the study considers how residential and commercial environments create distinct purchasing behaviors. Residential demand is shaped by lifestyle preferences, home audio integration, and personal mobility, while commercial usage often depends on practicality, robustness, deployment scale, and total cost of ownership. By distinguishing these contexts, the report helps organizations understand which product attributes matter most to each audience and how messaging, distribution, and feature investment should differ accordingly.
The geographic dimension is equally important. The report evaluates regional demand patterns to identify where the category is most mature, where growth is emerging, and where distribution complexity or competitive intensity may differ. Rather than presenting regional data as a static ranking, the analysis is framed around operational implications: which markets may require localized product strategies, which may be more sensitive to pricing or channel availability, and where regulatory or sourcing exposures can influence execution.
Across all three segmentation dimensions, the study maintains a consistent logic. It identifies where volume and value are concentrating, how those concentrations are likely to evolve, and what that means for product planning, marketing, and supply strategy. This is the kind of segmentation insight that supports better portfolio choices than a single market total ever could.
Competitive Landscape: Ten Key Players and What Their Strategies Reveal
The Bluetooth speaker market is not only shaped by demand trends. It is also defined by a competitive set whose product philosophies, launch cadence, and brand strategies influence consumer expectations and category standards. The report profiles ten important companies whose approaches range from premium audio craftsmanship to value-oriented portability and rugged outdoor performance.
Bose Corporation continues to emphasize premium sound quality and portability through its SoundLink series, reinforcing a consumer audio identity built around performance and travel-friendly design. Harman International Industries, through its JBL and Harman Kardon lines, maintains a broad footprint across popular portable formats, including Flip, Charge, and Go + Play models, and has consistently used iterative product refreshes to sustain market relevance. Sony Group Corporation contributes a distinct angle with its ULT Field and portable lines, combining advanced audio processing with durability and, in recent launches, enhanced wireless party features.
Ultimate Ears has built recognition around portable speakers optimized for outdoor and party environments, with products such as Hyperboom and Wonderboom reflecting a focus on durability, volume, and social use cases. Anker Innovations has expanded its reach through the Soundcore brand, offering affordable Bluetooth speakers in the Boom and Motion series, an approach that targets volume-conscious consumers without abandoning practical feature sets. Marshall Amplification brings a different appeal with retro-styled products like Emberton and Middleton, emphasizing design identity alongside audio performance. Tribit addresses rugged portable applications with its Stormbox series, catering to users who prioritize high-volume outdoor performance and durability.
Klipsch Audio Technologies supports advanced audio formats through lines such as The One and Music City, positioning itself in a part of the market where sound quality and format support matter. Sonos focuses on Bluetooth-enabled home audio ecosystems, including Era and Roam lines, with an emphasis on multi-room integration and system-level convenience. Guangzhou Deyin Electronics Co., Ltd. rounds out the competitive set with high-fidelity Bluetooth speakers that emphasize sound quality and long battery life, illustrating how focused engineering strategies can compete in a crowded category.
The report does not treat these profiles as static company summaries. It connects them to recent product activity and broader competitive logic. Recent moves illustrate how competitive intensity is being maintained through continual refreshes and feature differentiation. For instance, Sony advanced its second-generation ULT Power Sound series, including ULT Field 5 and ULT Field 3 portable Bluetooth speakers with enhanced wireless party features. Harman’s JBL released next-generation portable Bluetooth speakers with improved sound and durability. Klipsch teased next-generation Music City Series II Bluetooth speakers with Auracast broadcast audio support. Marshall released a portable Bluetooth speaker with IP67 rating and equalizer controls. Anker introduced a compact Bluetooth speaker with extended battery life and a high IP rating.
These developments matter because they show that leading players are not simply riding a growing market. They are using product updates, durability claims, battery performance, wireless features, and design differentiation to defend share and shape consumer preference. The study interprets these moves as signals: where companies are investing, what attributes they believe will win, and how fast the category is likely to keep evolving.
Pricing, Tariffs, and Margin Pressure: The 2026 Operational Reality
Market growth does not automatically translate into margin expansion. In the current environment, one of the most strategically important parts of the report is its treatment of cost, regulatory, and supply chain pressures. The Bluetooth speaker category sits at the intersection of consumer demand and manufacturing exposure, which means pricing strategy and sourcing decisions are increasingly intertwined.
By mid-2025, tariff policy had become a significant factor for U.S. importers of Chinese electronics. Reports indicated that importers paid substantial tariff costs, contributing to broader price and cost pressures across consumer technology. At the same time, certain components central to Bluetooth speaker production faced heightened cost exposure. Semiconductors and lithium-ion batteries became particularly relevant as tariff dynamics evolved into 2026. Combined with rising costs for neodymium magnets and lithium cells, these pressures have placed strain on margins for manufacturers that depend on such inputs.
Export controls have also contributed to the complexity. Restrictions on key rare earth elements have introduced additional uncertainty for manufacturers that rely on specialized materials and cross-border supply chains. In parallel, some audio brands have already moved to adjust pricing in response to tariff tensions, signaling that cost pass-through is becoming part of the competitive reality rather than a theoretical risk.
For decision-makers, the implication is clear. Even in a rapidly growing market, execution risk and margin management deserve as much attention as demand forecasting. Companies need to evaluate sourcing footprints, component exposure, pricing flexibility, and channel strategy in light of regulatory and input cost volatility. The report integrates these dynamics so that users can align growth assumptions with operational feasibility. In other words, it helps answer not only how large the market may become, but also how hard it may be to capture value profitably.
Why This Research Is a Strategic Input for 2026 Decisions
The value of this study lies in its ability to connect market scale with market structure. A top-line forecast can tell leadership that the category is expanding quickly, but it cannot by itself explain which segments are driving expansion, which competitive players are shaping standards, or which cost and regulatory factors may limit margin capture. The PW Consulting report is designed to bridge those gaps.
For product teams, the segmentation analysis supports roadmap choices by identifying where portable, fixed, residential, and commercial demand patterns differ. For commercial and channel leaders, the geographic and application insights help frame distribution priorities and localized positioning strategies. For executive teams, the competitive profiles and recent product developments provide a basis for benchmarking and for anticipating where category expectations may shift next. And for operations and sourcing leaders, the integrated treatment of tariffs, component costs, and supply chain pressures creates a more realistic foundation for pricing and planning than growth figures alone.
The report is also intended to support scenario-based thinking. Because it covers both historical performance and a long forecast window, organizations can use it to test assumptions about launch timing, inventory commitments, regional focus, and investment intensity. Rather than relying on a single prediction, leadership teams can use the study as a structured reference point for internal planning and strategic debate.
Who Should Use This Report and How to Turn Insight into Action
This research is most useful for organizations that need to make decisions where market direction, competitive behavior, and cost risk interact. That includes companies developing Bluetooth speaker products, retailers and distributors evaluating category allocation, audio accessory makers considering adjacent expansion, and strategic teams monitoring consumer electronics trends for portfolio implications.
To get maximum value, readers should approach the report as a planning instrument rather than a static summary. The recommended use is to begin with the growth trajectory to align internal forecasting assumptions, then move into segmentation to identify the most relevant demand pools, and finally review competitive and regulatory dynamics to assess execution risk. In practice, that means using the study to answer questions such as:
- Which product segments are likely to offer the most durable growth opportunities over the forecast period?
- Where do regional demand differences affect distribution, pricing, or product adaptation decisions?
- How are leading competitors using product launches, features, and brand identity to shape consumer expectations?
- What sourcing and pricing sensitivities should be factored into 2026 planning given tariff and component cost pressure?
By treating the report as a framework for decision-making, organizations can convert industry intelligence into concrete choices about product emphasis, market focus, and operational preparedness.
Conclusion: A Market Moving Fast Enough to Reward Prepared Organizations
The Bluetooth speaker market in 2026 is defined by more than rapid top-line growth. It is defined by a combination of strong demand momentum, clear segmentation dynamics, a competitive set that is continually refreshing its product logic, and supply-side pressures that make margin strategy as important as volume strategy. That combination creates both opportunity and risk, and it rewards organizations that prepare with a clear, evidence-based view of the landscape.
The PW Consulting Bluetooth Speaker Market research study was developed to provide exactly that view. It combines historical context, forward estimates, segmentation insight, competitive profiling, and regulatory and cost dynamics in a single integrated analysis. For decision-makers planning product, channel, sourcing, or portfolio moves in 2026, the report offers the kind of structured intelligence that can reduce uncertainty and improve strategic timing.
Full segmentation detail, company-level depth, regional breakdowns, and scenario-ready forecast materials are available in the complete report. For teams that need to move from market awareness to informed action, the full study is the next logical step.
For detailed analysis of this topic, please visit the official page: Bluetooth Speaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rigid Endoscopes Market Hits $1.25B in 2025, Poised for 5.5% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Horizons: Navigating the Rigid Endoscopes Market in 2026 and Beyond
The landscape of minimally invasive surgery is undergoing a profound transformation, driven by technological innovation, stringent regulatory frameworks, and shifting reimbursement models. As organizations plan their capital allocation and product development strategies for 2026, the need for precise, actionable intelligence regarding rigid endoscopes has never been more critical. This article serves as a strategic primer, outlining the broader market trajectory and the key dynamics that will define the competitive landscape. It is designed to equip executive leadership with the contextual awareness necessary to interpret complex market signals, while underscoring the necessity of deeper granular analysis for final decision-making.
Worldwide RF Needles Market
Our latest comprehensive market research offers a detailed roadmap through this evolving ecosystem. The data indicates a resilient growth trajectory, with the global market valuation reaching significant benchmarks in the base year of 2025. Looking forward, the forecast period extending to 2032 suggests a sustained compounding growth rate that outpaces many traditional medtech segments. This momentum is not merely a function of volume but is deeply rooted in the value proposition of improved patient outcomes, reduced hospital stays, and the integration of advanced imaging technologies into standard surgical workflows.
Worldwide Smoke Mechanical Damper Market
Market Trajectory and Macro Economic Indicators
Migraine Wearables Market
Understanding the top-line growth is essential, but interpreting the underlying velocity is where strategic value is generated. Historical data from 2020 through 2025 demonstrates a consistent upward trend, recovering from global supply chain disruptions and emerging stronger with renewed investment in surgical infrastructure. The market revenue unit is tracked in USD Million, providing a standardized metric for cross-border comparison and investment appraisal.
For the forecast period spanning 2026 to 2032, the projected growth curve indicates a steady acceleration. The Compound Annual Growth Rate (CAGR) is estimated to sustain momentum over this seven-year horizon, suggesting that demand drivers are structural rather than cyclical. By the end of the forecast window, the total market size is anticipated to reach new heights, reflecting the cumulative effect of adoption in emerging economies and the premiumization of devices in mature markets. This macro view provides the boundary conditions for any strategic plan, setting the stage for more nuanced segmentation analysis.
Segmentation Dynamics: Type and Application Interplay
While the aggregate numbers provide the horizon, the true strategic opportunities lie within the segmentation splits. The market is categorized by distinct device types, each serving specific clinical needs. Laparoscopes continue to represent a substantial portion of the revenue mix, reflecting their ubiquity in general surgical procedures. Arthroscopes maintain a strong foothold, particularly driven by the sports medicine and orthopedic sectors. Cystoscopes and gynecological endoscopes form critical niches, often tied to specific reimbursement codes and procedural volumes.
Beyond device classification, the application landscape reveals where value is being captured. General surgery remains a dominant application area, absorbing a significant share of procedural usage. Orthopedics and pulmonology represent high-growth vectors, leveraging advanced visualization for complex interventions. Urology and gynecology continue to be steady contributors, with innovation focused on ergonomics and durability.
It is crucial for stakeholders to recognize that these segments do not grow in isolation. Cross-segment synergies, such as the adoption of 4K imaging across both laparoscopes and arthroscopes, create platform opportunities for manufacturers. However, detailed revenue breakdowns for each specific type and application segment are complex and subject to regional variations. To obtain the precise valuation figures for each sub-segment and understand the internal share distribution, stakeholders are encouraged to consult the full dataset available in our complete market report.
Competitive Landscape and Key Players
The rigid endoscopes market is characterized by a moderately concentrated competitive environment. The presence of established multinational corporations alongside specialized niche players creates a dynamic ecosystem where innovation speed and regulatory compliance are key differentiators. Market concentration metrics suggest that a handful of major entities command a significant portion of the market share, indicating high barriers to entry and strong brand loyalty among healthcare providers.
Key Market Participants
- KARL STORZ SE & Co. KG : Based in Tuttlingen, Germany, this organization remains a cornerstone of the industry. Their portfolio encompasses a wide range of rigid endoscopes, including HOPKINS® telescopes, cystoscopes, and laparoscopes. They serve diverse applications spanning gynecology, ENT, and general surgery, maintaining a reputation for optical quality and system integration.
- Stryker Corporation : Headquartered in Kalamazoo, Michigan, United States, Stryker leverages its Endoscopy and Surgical Visualization portfolio to deliver rigid endoscopes and hysteroscopes. Their focus extends to laparoscopic, urologic, and gynecologic procedures, often integrating visualization towers that enhance the utility of the scopes themselves.
- Olympus Corporation : Operating out of Tokyo, Japan, Olympus provides critical rigid endoscopy solutions including ENDOEYE® and rigid laparoscopes. Their strength lies in endoscopic surgery and minimally invasive procedures, benefiting from a global distribution network and a strong heritage in optical engineering.
- Smith & Nephew plc : With headquarters in London, United Kingdom, Smith & Nephew specializes in orthopedic and sports medicine applications. They offer rigid arthroscopes and 4K optimized scopes, targeting high-precision environments where visual fidelity directly impacts surgical outcomes.
- B. Braun Melsungen AG : Based in Melsungen, Germany, this company produces Aesculap-branded rigid endoscopes. Their focus on laparoscopy and minimally invasive surgery aligns with the broader trend toward standardizing instrument quality across hospital networks.
These companies are not merely selling hardware; they are selling ecosystems. The competition is increasingly shifting toward service models, training, and compatibility with digital operating room infrastructure. Understanding the specific market share percentages and the growth rates of each individual player requires a depth of analysis that goes beyond corporate profiles. Our full report details the competitive positioning, recent strategic moves, and financial health indicators that allow for a granular competitive benchmarking exercise.
Industry Dynamics and Regulatory Pressures
One of the most significant factors influencing cost structures and procurement strategies in 2026 is the regulatory environment surrounding reprocessing and sterilization. The days of simple cleaning protocols are evolving into complex, validated processes that add substantial operational costs to healthcare facilities.
Reprocessing and Compliance Costs
The ANSI/AAMI ST91:2021 standard for flexible and semi-rigid endoscope processing has implications that extend to rigid endoscopes as well. This standard increases the rigor of reprocessing requirements, directly impacting the total cost of ownership for hospitals. Industry analysis suggests that these enhanced reprocessing requirements increase costs to approximately 216 USD per procedure. This figure is a critical input for hospital administrators evaluating the switch between reusable and disposable options, and for manufacturers designing scopes that must withstand more aggressive sterilization cycles.
Furthermore, regulatory bodies continue to issue updated recommendations. In 2024, the FDA recommended that for reusable endoscopes, organizations transition to more robust reprocessing methods. Techniques such as ethylene oxide sterilization or gas plasma are becoming preferred standards to mitigate infection risks. These mandates drive demand for scopes made from materials compatible with harsher sterilization methods, potentially altering the material science roadmap for device manufacturers.
Strategic Implications of Regulation
- Cost Structure Reassessment : Procurement teams must factor in the recurring cost of sterilization per procedure when calculating the lifetime value of reusable rigid endoscopes.
- Product Design Innovation : Manufacturers are incentivized to develop scopes that are durable enough to withstand frequent gas plasma or ethylene oxide exposure without degradation of optical quality.
- Disposable vs. Reusable Debate : As reprocessing costs rise, the economic break-even point between single-use and reusable devices shifts, opening new market segments for disposable rigid endoscopes in specific high-turnover settings.
These dynamics create a complex web of operational constraints that influence market growth. While the regulatory environment poses cost challenges, it also drives standardization and safety, which can fuel long-term adoption confidence. Detailed analysis of how these regulatory costs impact specific regions and hospital types is available within the regional and dynamics sections of our comprehensive study.
Regional Growth Vectors
Geographically, the market exhibits distinct maturity levels and growth potentials. North America continues to represent a substantial revenue base, driven by high procedure volumes and advanced healthcare infrastructure. Europe maintains a steady demand, influenced by public healthcare funding models and regulatory harmonization. Asia Pacific presents a compelling growth story, fueled by expanding surgical capacity and increasing access to minimally invasive techniques in developing economies.
Latin America and the Middle East and Africa regions, while smaller in absolute volume compared to the major three, offer niche opportunities for market penetration. Success in these regions often depends on local partnerships, pricing strategies tailored to diverse economic conditions, and training programs that build surgical competency.
It is important to note that regional revenue splits are sensitive to currency fluctuations, local reimbursement policies, and the pace of technology adoption. A high-level view confirms that the global market is diversifying, but the specific contribution of each region to the total market size varies year over year. For precise regional valuations and forecasts, our full report provides the necessary granularity to support market entry strategies or capacity expansion plans.
Strategic Imperatives for 2026 Decision Makers
As we move deeper into the forecast period, several strategic imperatives emerge for stakeholders operating in the rigid endoscopes market.
1. Portfolio Optimization and Technology Integration
Companies must evaluate whether their product portfolios are aligned with the shifting application demands. The integration of 4K and potentially 3D visualization capabilities is no longer a differentiator but a baseline expectation in many orthopedic and general surgery settings. Investment decisions should focus on platforms that can evolve with software upgrades, extending the lifecycle of hardware assets.
2. Cost Management and Value Proposition
With reprocessing costs becoming a visible line item for healthcare providers, manufacturers have an opportunity to demonstrate value beyond the purchase price. Offering comprehensive service contracts, sterilization compatibility guarantees, and efficiency tools can differentiate a brand in a concentrated market. The ability to prove total cost of ownership savings will be a key sales enabler.
3. Navigating Concentration and Competition
Given the market concentration levels, new entrants or smaller players must identify underserved niches or innovate significantly to capture share from the incumbents. Strategic partnerships, licensing agreements, or acquisitions may be viable paths to accelerate market presence. Understanding the exact market share distribution among the top five players is vital for assessing the feasibility of competitive moves.
4. Regulatory Agility
Proactive engagement with regulatory standards regarding reprocessing and sterilization will mitigate risk. Companies that design for compliance with the latest FDA recommendations and AAMI standards will reduce friction in the procurement process for their customers. This agility can serve as a trust signal in tenders and contract negotiations.
Conclusion: The Value of Deep Intelligence
The rigid endoscopes market in 2026 is defined by a confluence of steady macroeconomic growth, technological maturation, and evolving operational constraints. The projected growth rate of 5.5 percent over the forecast period underscores a healthy demand environment, but realizing success within this environment requires more than just acknowledging the top-line numbers.
Stakeholders need to understand the interplay between segmentation splits, regional nuances, and the specific financial positions of key competitors like KARL STORZ, Stryker, Olympus, Smith & Nephew, and B. Braun. They need to quantify the impact of reprocessing regulations on their specific cost models and identify which application segments offer the highest margin potential.
This article has outlined the strategic landscape, highlighting the critical areas of focus. However, to build a robust business plan or investment thesis, one requires the specific revenue figures, detailed segmentation splits, and precise regional data that underpin these trends. The macro narrative provides direction, but the micro data provides the map.
PW Consulting's full market research report delivers this granular intelligence. It dissects the market size from 2020 through the forecast horizon to 2032, offering detailed breakdowns by type, application, and region. It analyzes the competitive intensity and provides the data necessary to validate strategic assumptions.
For organizations ready to move from general awareness to precise execution, accessing the complete dataset is the logical next step. The depth of insight required to navigate the complexities of the rigid endoscopes market is available in our comprehensive publication.
For detailed analysis of this topic, please visit the official page: Rigid Endoscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Instant Adhesive Market to Hit $344.8M by 2032, 6.58% CAGR Amid 2025's $215M Growth
By PW Consulting, 2026-09-07
Projecting the Instant Adhesive Market: A Strategic Blueprint for 2026 and Beyond
Introduction: The Adhesive Imperative in Modern Manufacturing
In the contemporary industrial landscape, bonding technologies have evolved from simple assembly aids to critical engineering components that dictate product performance, durability, and design flexibility. The instant adhesive market stands at the forefront of this transformation, serving as an essential enabler across sectors ranging from high-precision electronics to heavy-duty transportation manufacturing. As organizations navigate an increasingly complex global environment characterized by supply chain recalibrations, stringent environmental regulations, and shifting consumer expectations, the ability to make informed, data-driven decisions regarding adhesive procurement and investment has never been more vital.
Escape Door Control Unit Market
This comprehensive market research study examines the historical trajectory and future projections of the instant adhesive industry, offering a rigorous analytical framework designed to support executive decision-making through 2032. By synthesizing macroeconomic trends, competitive intelligence, raw material dynamics, and regulatory pressures, this report provides stakeholders with the actionable intelligence needed to position their organizations advantageously in a market projected to experience sustained growth.
Gasket Structure Keyboard Market
Market Trajectory: Navigating Growth Amid Volatility
The instant adhesive market has demonstrated remarkable resilience and expansion over the past half-decade, establishing a robust foundation for continued momentum. Historical data from 2020 through 2025 reveals a market that has not only recovered from disruptions but has accelerated its growth trajectory, reaching approximately 215.0 Million USD in the base year of 2025. This represents a significant evolution from the 163.15 Million USD recorded in 2020, underscoring the compound annual growth rate that has characterized the industry's maturation.
Worldwide Switch Expansion Joints (SEJ) Market
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 6.58 percent, a figure that reflects both steady demand expansion and the industry's capacity to adapt to emerging technological and regulatory requirements. By 2026, market revenue is anticipated to reach 230.33 Million USD, climbing progressively to 344.8 Million USD by the close of the forecast horizon in 2032. This upward trajectory signals more than mere volume growth; it indicates a maturing market where value creation is increasingly tied to product innovation, application-specific formulations, and strategic geographic expansion.
Several structural factors underpin this growth outlook. The ongoing transition toward lightweight materials in transportation and automotive manufacturing continues to drive demand for high-performance bonding solutions that can replace traditional mechanical fasteners. Simultaneously, the electronics industry's relentless miniaturization and the medical sector's push for biocompatible, rapid-curing adhesion technologies create sustained pull factors across multiple end-use verticals. Companies that recognize these cross-industry demand signals and align their product development pipelines accordingly will be best positioned to capture disproportionate market share in the coming years.
Structural Composition: Demand Drivers Across Key Verticals
Understanding where instant adhesive demand concentrates is essential for strategic resource allocation and market entry timing. The application landscape reveals a diverse but clearly hierarchical set of consumption patterns that reflect broader industrial trends. Electronics represents a dominant consumption segment, driven by the sector's need for precise, high-speed bonding in component assembly, consumer devices, and increasingly sophisticated wearable technologies. The woodworking sector, while historically associated with slower-curing formulations, has embraced instant adhesive solutions for applications requiring rapid turnaround and strong initial tack in furniture manufacturing and cabinetry production.
Transportation applications continue to expand as original equipment manufacturers seek weight-reduction strategies and design flexibility that instant adhesives facilitate. This includes both traditional automotive manufacturing and the rapidly growing electric vehicle segment, where battery assembly and lightweight structural components demand specialized bonding chemistries. The medical sector represents another critical growth vector, with demand fueled by surgical device assembly, wound closure applications, and the development of increasingly sophisticated diagnostic equipment. Industrial applications broadly encompass manufacturing assembly, maintenance repair operations, and specialty bonding tasks that require rapid setting times without compromising ultimate bond strength.
From a product type perspective, the market is anchored by two principal categories. Cyanoacrylate-based instant adhesives command the largest share of the product landscape, reflecting their widespread adoption across consumer, industrial, and medical end uses due to their rapid curing characteristics and strong bonding performance on a variety of substrates. Epoxy-based instant adhesive formulations constitute a complementary segment, particularly valued in applications requiring higher temperature resistance, greater structural integrity, or specialized chemical resistance profiles. The interplay between these product categories creates a dynamic where formulators must continuously innovate to meet the diverging requirements of performance, safety, and cost-efficiency.
Geographic Distribution and Regional Dynamics
The geographic footprint of instant adhesive consumption reflects both established industrial bases and emerging growth corridors. North America represents a substantial revenue contributor, supported by mature manufacturing sectors, a strong electronics industry presence, and a healthcare market that demands advanced bonding solutions. Europe maintains a parallel position of significance, driven by its robust automotive and industrial manufacturing ecosystems, alongside increasing regulatory emphasis on environmental compliance that shapes product formulation strategies across the region.
Asia Pacific emerges as a particularly notable region in terms of market scale, reflecting the concentration of electronics manufacturing, rapid industrialization, and growing consumer markets across multiple economies. The region's expansive production capacity and increasing domestic consumption create a complex competitive environment where both multinational formulators and regional players vie for share. Latin America and the Middle East and Africa represent additional geographic dimensions, with growth potential tied to infrastructure development, industrial modernization initiatives, and gradually expanding manufacturing bases in select economies.
Regional dynamics are further complicated by divergent regulatory environments, varying raw material access, and differing labor cost structures that influence both product pricing and formulation priorities. Strategic market entry or expansion decisions require nuanced understanding of these regional characteristics rather than one-size-fits-all approaches. Companies that develop region-specific product portfolios and distribution strategies will find themselves better equipped to navigate the heterogeneous demands of global instant adhesive markets.
Competitive Landscape: Architects of Market Evolution
The instant adhesive market operates within a moderately concentrated competitive structure. Analysis of the competitive landscape reveals a market environment where the top three players command approximately 19.4 percent of total revenue, while the top five collectively account for roughly 22.5 percent. This concentration profile suggests a market that accommodates both established multinational corporations with extensive research and development capabilities and smaller, specialized formulators that compete through niche application expertise, regional distribution strength, or proprietary formulation technologies.
Among the prominent organizations shaping this landscape, Henkel AG and Co KGaA stands as a defining presence through its Loctite-branded instant adhesive and cyanoacrylate portfolio, which serves industrial, medical, and automotive applications with a reputation for performance reliability. The company's global distribution network and sustained investment in application-specific product development reinforce its position as a benchmark competitor. 3M Company maintains a parallel stature through its Scotch-Weld and Super-Fast instant adhesive lines, catering to electronics, industrial bonding, and medical use cases with a portfolio that emphasizes both performance and accessibility across diverse customer segments.
Huntsman Corporation contributes to the competitive ecosystem by supplying instant adhesive resins and solutions tailored for general industrial and construction bonding applications, leveraging its broader materials science expertise to support large-scale manufacturing customers. H.B. Fuller Company markets a diversified portfolio of instant adhesives designed for quick-bonding industrial and specialty applications, with recent strategic moves underscoring its commitment to capacity expansion and regional market servicing. Bostik SA, operating under the Arkema Group umbrella, develops and supplies instant engineering adhesives including the Born2Bond series, positioning its offerings for demanding environments that require robust performance under stress or temperature variation.
Toagosei Co Ltd brings specialized expertise in cyanoacrylate instant adhesives through its Aron Alpha brand, targeting industrial manufacturing markets with formulations optimized for production-line efficiency. Pidilite Industries Limited extends its reach across consumer, industrial, and craft bonding segments through the Fevikwik instant adhesive line, demonstrating the brand strength that can emerge from effective product positioning in both professional and retail channels. Permabond LLC, with its North American operations anchored from a UK base, specializes in high-performance instant adhesives designed for engineering and industrial use cases where bond reliability is paramount. Dymax Corporation rounds out the competitive array with its focus on UV and light-cure instant adhesives, particularly serving electronics and medical assembly applications where curing precision and speed are critical operational requirements.
Recent corporate developments highlight the strategic dynamism within this competitive field. In May 2026, H.B. Fuller Company executed significant capacity expansion initiatives, opening a new state-of-the-art facility in Cairo, Egypt, that adds manufacturing capacity for pressure-sensitive and non-pressure-sensitive adhesives serving over thirty market segments, including industrial adhesives. Concurrently, the company expanded its site in the United Arab Emirates to enhance manufacturing capabilities for waterproofing, woodworking, and industrial adhesives. These investments signal a deliberate strategy to strengthen regional manufacturing presence, reduce supply chain vulnerabilities, and position the company to capture growth in emerging markets with localized production capabilities.
The competitive dynamics extend beyond corporate strategy to encompass the broader forces that shape market access and product differentiation. Formulators must balance the imperative to innovate with the practical constraints of cost management and regulatory compliance, creating an environment where competitive advantage is increasingly derived from integrated solutions rather than commodity product offerings alone.
Raw Material Dynamics and Cost Structure Considerations
The economics of instant adhesive production are fundamentally shaped by raw material cost structures and supply chain volatility. Industry data indicates that raw material prices account for approximately 86 percent of the final instant adhesive product price, a proportion that makes feedstock cost management a central concern for profitability and pricing strategy. Monomer cost swings, in particular, exert significant influence on pack pricing, requiring manufacturers to maintain agile procurement strategies and, where feasible, hedging mechanisms to mitigate exposure to commodity price fluctuations.
During March 2026, stable but firm feedstock costs, particularly for methanol and acetone, contributed to steady firm pricing of cyanoacrylate in the USA market. This pricing environment reflects the interplay between raw material availability, production capacity utilization, and demand strength, creating conditions where margin preservation depends on operational efficiency and value-added product positioning rather than simple volume expansion. Companies that have invested in vertical integration, long-term supplier agreements, or alternative feedstock sourcing strategies are better insulated against the periodic cost pressures that characterize this segment of the materials market.
The sensitivity of final product pricing to raw material inputs also shapes competitive dynamics in meaningful ways. Larger, well-capitalized manufacturers may possess advantages in procurement scale and supply chain diversification, while smaller players may need to compete through service differentiation, specialized technical support, or regional market focus. Understanding these cost structure dynamics is essential for competitive analysis, pricing strategy development, and investment planning across the instant adhesive value chain.
Regulatory Pressures and Formulation Evolution
The instant adhesive industry operates within an increasingly complex regulatory environment that influences product formulation, market access, and compliance cost structures across multiple geographies. In the United States, Canada, and Australia, strict volatile organic compound regulations and occupational-health requirements compel formulators to develop low-VOC and low-odor instant adhesives, raising compliance costs while simultaneously creating opportunities for companies that can deliver compliant products without sacrificing performance. These regulatory pressures are not static; they evolve as governments and regulatory bodies refine their approaches to chemical safety, emissions control, and workplace health protection.
Across global markets, formulators are shifting toward low-VOC and REACH-compliant instant adhesives to meet tightening environmental standards. This shift represents more than a compliance exercise; it reflects a broader industry movement toward sustainable chemistry and environmentally responsible manufacturing practices that resonate with downstream customers and end consumers alike. Companies that proactively invest in compliant formulation development and maintain robust regulatory monitoring capabilities will find themselves with competitive advantages in markets where environmental compliance is increasingly a prerequisite for supply chain participation.
The medical sector introduces an additional regulatory dimension. New medical-grade cyanoacrylate formulations are being developed without CMR ingredients to comply with safety requirements for heat-resistant medical device applications. This formulation evolution addresses the stringent biocompatibility and safety standards that govern medical device manufacturing, creating specialized product opportunities for formulators with the technical expertise and regulatory documentation capabilities to serve this demanding segment. The intersection of regulatory compliance and product performance in medical applications underscores the value of specialized knowledge and the premium that sophisticated customers place on reliably compliant solutions.
These regulatory trends have strategic implications beyond product development. They influence market entry timing, geographic expansion feasibility, and the competitive positioning of companies with varying levels of regulatory infrastructure and expertise. Organizations that treat regulatory compliance as a strategic capability rather than a peripheral concern will be better equipped to navigate the evolving landscape and capitalize on the opportunities created by regulatory-driven product differentiation.
What This Report Delivers: Analytical Depth and Strategic Utility
This market research study is structured to provide executives, strategic planners, and industry analysts with a comprehensive yet actionable understanding of the instant adhesive market's current state and future trajectory. The report integrates macroeconomic market sizing and growth projections with detailed segmentation analysis, competitive intelligence, and an examination of the regulatory and raw material dynamics that shape market conditions. By situating quantitative data within a qualitative framework of industry forces, the study enables readers to move beyond surface-level market observations toward a nuanced grasp of the strategic factors that will drive performance over the forecast period.
The report's segmentation analysis provides visibility into how revenue distributes across product types, application verticals, and geographic regions, enabling readers to identify where demand concentration creates opportunities and where fragmentation requires targeted strategies. The competitive landscape assessment goes beyond company profiles to examine strategic positioning, recent corporate developments, and the structural characteristics of market concentration that influence competitive behavior and market access. The inclusion of raw material dynamics and regulatory trend analysis ensures that readers understand the cost and compliance environments that underpin product economics and market entry feasibility.
Importantly, this report is designed to support decision-making rather than merely describe market conditions. The analytical framework presented enables stakeholders to assess growth opportunities, evaluate competitive threats, plan capacity investments, and develop product strategies aligned with market realities. Readers seeking a comprehensive understanding of the instant adhesive market's opportunities and challenges will find the full report's detailed data sets, segmentation breakdowns, company profiles, and forward-looking analysis essential to formulating informed strategic responses.
Positioning for 2026 and the Decade Ahead
The instant adhesive market enters the 2026 to 2032 forecast period with a foundation of established growth, evolving competitive dynamics, and a regulatory and cost environment that demands strategic agility. The projected compound annual growth rate of 6.58 percent reflects sustained demand across multiple industrial sectors, but realizing the benefits of this growth requires more than passive market participation. Organizations must actively monitor raw material cost trajectories, adapt product portfolios to meet regulatory and performance requirements, and position themselves within the competitive landscape in ways that leverage their specific capabilities and market access advantages.
The companies that thrive in this environment will be those that treat market intelligence as a strategic asset, integrating deep understanding of segmentation trends, regional dynamics, raw material economics, and regulatory developments into coherent decision-making frameworks. Whether evaluating market entry opportunities, assessing competitive threats, planning capacity investments, or developing product innovation pipelines, access to comprehensive and timely market intelligence proves indispensable. This report is designed to provide exactly that foundation, offering the analytical rigor and strategic perspective needed to navigate the instant adhesive market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Instant Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Golf GPS Market Valued at USD 215M in 2025, Projected to Grow at 6.98% CAGR Through 2032
By PW Consulting, 2026-09-07
The 2026 Golf GPS Market: Strategic Intelligence for Corporate Decision-Making
The global golf GPS and rangefinder sector stands at a inflection point. As course layouts become increasingly digitized, consumer expectations shift toward real-time analytics, and regulatory frameworks tighten around device certification, enterprises operating in this space must navigate a landscape defined by both opportunity and operational complexity. Our latest comprehensive market research on the Golf GPS Market delivers the analytical rigor required to transform uncertainty into actionable strategy for 2026 and beyond.
Shaving Pen Market
This report is not merely a retrospective on past sales figures or a generic projection of industry growth. It is a decision-grade intelligence asset designed for executive teams, product strategists, supply chain planners, and market entry analysts who require a clear line of sight into demand trajectories, competitive positioning, and structural market shifts. By synthesizing historical performance patterns, forward-looking demand signals, and granular product-category dynamics, the study constructs a multidimensional view of where value will be created, consolidated, or disrupted over the coming forecast horizon.
Online File-Sharing Platforms Market
Macro Trajectory and Structural Market Signals
Over the assessment window from 2020 through 2025, the global Golf GPS Market demonstrated consistent expansion, with revenue scales maturing across successive annual cycles. The trajectory reflects a market that has moved past early adoption volatility and entered a phase of stabilized growth driven by broader participation in golf, technological refinement in navigation hardware, and increasing integration of performance analytics into consumer devices. Looking ahead to the 2026-2032 forecast period, the research models a compound annual growth rate of 6.98%, anchored in baseline valuations established at the close of the historical review window. Revenue projections for the opening forecast year indicate continued upward momentum, with subsequent annual milestones reflecting an accelerating expansion curve as hardware ecosystems mature and software-enabled value propositions gain traction across diverse user segments.
Worldwide Proxy Server Reporting Software Market
The forecast architecture within the study isolates key inflection variables that will shape mid-decade performance. These include shifts in hardware form-factor preferences, the monetization pathways of companion applications, course-level data licensing models, and the pacing of professional versus recreational adoption cycles. By mapping these variables against regional demand intensity and competitive supply dynamics, the report enables stakeholders to anticipate revenue concentration patterns, evaluate the timing of category saturation, and calibrate investment horizons accordingly.
Importantly, the research treats market size not as a static endpoint but as a dynamic function of ecosystem readiness. High consumer spending environments have historically supported sustained expansion in golf technology categories, and the study isolates the demand-side conditions that will determine whether growth remains linear or accelerates through cross-category bundling, subscription-enabled analytics, and course-operator partnerships. The resulting analytical framework equips decision-makers with scenario-ready inputs rather than rigid single-point predictions.
Operational and Regulatory Dynamics Shaping the Competitive Field
The operating environment for golf GPS manufacturers and distributors has grown increasingly multifaceted. On the demand side, durable consumer spending capacity has underpinned category resilience through recent assessment years, allowing manufacturers to sustain launch cadences, expand accessory ecosystems, and invest in elevated data-capture capabilities without sacrificing margin stability. However, the supply and compliance pathway is undergoing structural adjustment. Recent regulatory developments require heightened attention from importers, assemblers, and channel partners. Beginning mid-2026, consumer product imports, including golf GPS devices, must electronically file certificates of compliance with U.S. Customs and Border Protection. This procedural shift introduces new administrative obligations that will affect lead times, customs clearance workflows, and cost structures for companies with cross-border supply chains.
Simultaneously, the regulatory footprint of established manufacturers continues to expand. Public registration data indicates that more than 1,200 GPS device models from a leading hardware manufacturer have been recorded for U.S. compliance, including specialized golf GPS configurations. This concentration of registered intellectual property and certified product variants underscores a broader industry reality: scale players are not only competing on feature sets and brand equity but also on the institutional capacity to navigate certification pipelines at volume. For smaller entrants and regional distributors, understanding compliance architecture is increasingly a strategic prerequisite rather than a back-office administrative task.
These dynamics interact with product strategy in meaningful ways. Manufacturers that integrate compliance readiness into early-stage design, localization, and channel planning will gain speed advantages in market entry and product refresh cycles. Conversely, organizations that treat regulatory filing as an afterthought may encounter friction in inventory turnover, regional rollout sequencing, and partnership negotiations with course operators who increasingly demand certified, auditable equipment for course management applications.
Research Architecture and Decision-Ready Content
The study is constructed to translate raw market intelligence into operational clarity. Readers will encounter a layered analytical structure that moves from overarching demand modeling to category-level differentiation, from regional intensity mapping to firm-level competitive positioning. Each section is designed to answer a specific strategic question that executives face when allocating capital, prioritizing product roadmaps, or evaluating partnership and distribution opportunities.
The report delivers detailed segmentation analysis across device categories, usage contexts, and geographic demand zones. Rather than presenting abstract totals, the research isolates the structural drivers behind each segment, including feature preferences, price-point elasticity, adoption barriers, and the role of accompanying software or analytics services. This approach allows readers to identify which sub-categories are experiencing incremental maturation, which are being reshaped by technological substitution, and where latent demand remains under-served by current product portfolios.
Competitive profiling is embedded within the analytical framework rather than appended as a standalone directory. The report examines how leading manufacturers position their offerings across precision distance measurement, on-course navigation, swing and shot analytics, and pace-of-play management. It evaluates product architecture choices, ecosystem lock-in strategies, content partnerships with course databases, and the extent to which brands leverage tradition, performance credibility, or digital convenience as differentiation levers.
Additionally, the study incorporates recent corporate activity to illustrate how strategy is being executed in near-real time. Product launches, display presentations at industry events, and brand campaign shifts are analyzed not as isolated news items but as indicators of strategic intent. By mapping these developments against broader category trends, the report helps readers distinguish between tactical promotions and genuine portfolio pivots.
Competitive Landscape: Positioning, Differentiation, and Strategic Signaling
The competitive field in golf GPS and related precision navigation hardware reflects a blend of established outdoor technology brands, specialized golf-performance companies, and regional specialists expanding their footprint through feature innovation and channel development. Several firms illustrate the dominant strategic archetypes shaping market evolution.
Garmin Ltd. continues to extend its footprint through integrated GPS ecosystems that span wearable devices, handheld units, and application-linked analytics. Recent product activity underscores a dual focus: advancing performance telemetry for engaged players while broadening accessibility for younger or entry-level users. The introduction of a touchscreen-enabled GPS handheld with expanded radar metrics and putting features signals investment in richer on-course data capture. At the same time, a junior-oriented GPS watch emphasizing skill-based tee positioning and pace management reflects a strategic interest in cultivating long-term user relationships and addressing slow-play concerns that affect course throughput and player experience.
Bushnell Corporation, operating through its golf division, maintains a strong association with precision distance measurement and performance compensation features. Its recent rangefinder introduction highlights continued emphasis on slope processing and display modernization, reinforcing the brand's positioning around accuracy, course management utility, and tournament-adjacent credibility. The firm's portfolio approach blends handheld optics, GPS-enabled wearables, and tracking devices, allowing it to address both traditional rangefinder buyers and users migrating toward multi-function performance tools.
Voice Caddie and Shot Scope Technologies exemplify the analytics-forward segment of the market, where hardware serves as a conduit for deeper performance insights. Voice Caddie's emphasis on OLED touchscreen interfaces and advanced swing analytics indicates a product philosophy that prioritizes on-device readability and post-round performance interpretation. Shot Scope Technologies has pursued a similarly data-centric direction, combining GPS hardware with app-linked performance tracking and AI-informed analytics. Its recent launch monitor collaboration and global brand campaign signal an effort to translate performance data into narrative-driven consumer engagement while expanding visibility in key demand regions.
Other participants reflect the breadth of specialization within the category. TecTecTec and Canmore Electronics focus on portable distance measurement and on-course navigation tools, serving users who prioritize compact form factors and straightforward distance feedback. iGolf Solutions contributes embedded GPS and Doppler-based solutions relevant to simulation environments and handheld applications, illustrating the convergence between on-course navigation and off-course practice technology. Precision Pro Golf's emphasis on audible guidance and speaker-integrated navigation highlights an alternative interaction model for players who prefer voice-assisted course management. Tagmarshal's cart-based GPS systems and pace-of-play software represent the course-operator side of the market, where device intelligence is leveraged to manage flow, scheduling, and operational efficiency rather than individual shot data alone.
Collectively, these profiles reveal a market in which differentiation is increasingly multidimensional. Hardware precision remains essential, but competitive advantage is now shaped by ecosystem integration, analytics usability, course database coverage, certification capacity, and the ability to address both recreational and operational stakeholder needs. The report's competitive analysis maps these dimensions systematically, enabling readers to evaluate where incumbents have structural advantages and where emerging players may find viable entry or disruption pathways.
Strategic Implications for 2026 Decision-Makers
For enterprises formulating 2026 strategies, the Golf GPS Market research provides several actionable implications. First, growth planning must account for the interaction between hardware refresh cycles and software-enabled value creation. Devices are no longer isolated purchase events; they are entry points into broader data, analytics, and course-commerce ecosystems. Companies that design roadmaps around companion services, subscription potential, and data interoperability will be better positioned to capture recurring value and extend product lifecycles.
Second, distribution and compliance strategy require proactive design. With evolving import-certification requirements and a heavily registered compliance landscape among scale players, market entrants and expanders must evaluate supply chain architectures for resilience, documentation readiness, and regional clearance efficiency. Organizations that integrate compliance planning into product localization and inventory sequencing will reduce operational friction and protect launch timing.
Third, competitive positioning should be evaluated through the lens of stakeholder coverage. The market now spans individual players seeking distance and performance insights, training-focused users seeking swing and strategy improvement, tournament-adjacent environments demanding precision and reliability, and course operators seeking flow management and operational visibility. Firms that align product features, communication narratives, and channel partnerships with the specific priorities of each stakeholder group will differentiate more effectively than those competing solely on generic navigation functionality.
Fourth, regional demand intensity and segment maturity patterns should inform market entry sequencing. The research isolates where demand is concentrated, where adoption curves are steepening, and where product-category preferences indicate preference for handheld devices, wearables, or application-based solutions. These insights help strategists prioritize geographic rollout, tailor product-mix decisions, and allocate marketing investment toward the most receptive demand environments.
Finally, the study supports risk-aware scenario planning. By connecting historical demand behavior, forecast trajectory, competitive concentration, and regulatory shifts, it provides decision-makers with a structured basis for stress-testing assumptions about pricing, channel access, product substitution, and compliance cost exposure. This is particularly valuable in a market where major players hold substantial concentration, making new entry or portfolio expansion dependent on clear strategic differentiation and operational preparedness.
Why This Research Is Built for Action
The report is intended to serve as a working reference for strategy formulation, not merely a one-time read. It combines macro market modeling with segment-level interpretation, competitive profiling with recent corporate event analysis, and regulatory context with supply-chain relevance. By maintaining a consistent focus on decision applicability, the study ensures that every analytical component ties back to a practical strategic question.
Readers will find structured coverage of market size evolution, forecast progression, segmentation behavior across device types, usage contexts, and regional demand, as well as detailed profiles of key companies and their strategic offerings. The integration of recent product launches, campaign activity, and compliance dynamics enables a near-term view of how competitive momentum is being generated and where operational friction may emerge.
Access the Complete Intelligence Package
The narrative above previews the analytical orientation and strategic relevance of the full study. To support precise planning, the complete research provides the underlying segmentation detail, competitive benchmarking, regional demand patterns, and forecast structures necessary for rigorous decision-making. These components are designed to be referenced during product planning cycles, market entry evaluations, partnership assessments, and capital allocation reviews.
For executive teams seeking a comprehensive, decision-grade view of the Golf GPS Market through 2026 and across the extended forecast horizon, the full report delivers the depth, structure, and strategic context required to move from observation to action.
Discover the complete market research and access detailed segmentation, competitive analysis, and forecast intelligence tailored for strategic planning.
For detailed analysis of this topic, please visit the official page: Golf GPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


