



PW Consulting: Food Grade Calcium Chloride Market to Hit USD 760M by 2032, 6.8% CAGR
By PW Consulting, 2026-09-16
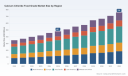
Navigating the Calcium Chloride Food Grade Market: Strategic Intelligence for 2026 Decision Makers
The global food ingredient supply chain is entering a phase of structural recalibration, and calcium chloride food grade sits at a critical intersection of regulatory compliance, processing efficiency, and consumer-driven quality standards. As manufacturers, distributors, and strategic investors map their roadmaps for 2026 and beyond, understanding the underlying market architecture is no longer optional—it is a competitive necessity. Our newly released Calcium Chloride Food Grade Market research report delivers the granular intelligence required to navigate this evolving landscape with confidence.
Worldwide Food Grade Ammonium Chloride Market
Drawing on a rigorous historical analysis spanning 2020 through 2025 and a forward-looking forecast window extending to 2032, this report provides a comprehensive baseline for strategic planning. The market has demonstrated consistent momentum over the review period, with total revenue expanding steadily from a baseline in 2020 to a projected trajectory that crosses the half-billion USD threshold in 2026. The compound annual growth rate across the forecast horizon is positioned at 6.8 percent, reflecting a market that is maturing but still capable of meaningful expansion. By the end of the forecast window in 2032, overall revenue is projected to approach the 760 million USD mark, underscoring the sustained commercial relevance of this essential food additive.
What distinguishes this analysis is not merely the macro trajectory, but the depth of operational and competitive context layered beneath it. The following sections outline the strategic architecture of the report and explain why it serves as an indispensable decision-support tool for executives operating in food processing, ingredient supply, procurement, and market development.
The Strategic Imperative for 2026 Planning
Corporate strategy in the food ingredients sector has shifted decisively toward proactive scenario planning. Regulatory frameworks, raw material sourcing constraints, certification requirements, and regional demand shifts are no longer peripheral concerns; they are central drivers of margin structure, supply continuity, and market positioning. For organizations that rely on or distribute food-grade calcium chloride—whether as a firming agent, preservative, texture modifier, or processing aid—the 2026 decision window demands clarity on three fronts: where growth is structurally concentrated, how competitive dynamics are evolving, and which operational levers will determine long-term resilience.
This report is designed explicitly to answer those questions. Rather than presenting a static snapshot, it maps the interplay between historical performance patterns and forward-looking demand signals. The forecast period, running from 2026 through 2032, is structured to support capacity planning, market entry evaluations, and portfolio allocation decisions. By anchoring analysis in a detailed historical baseline and extending it through a disciplined projection methodology, the report enables stakeholders to stress-test strategic assumptions against multiple market trajectories.
Importantly, the research avoids the trap of oversimplified aggregation. Instead, it dissects the market through multiple analytical lenses—type, application, and region—while maintaining strict attention to the certification, compliance, and quality-assurance requirements that govern food-grade supply chains. The result is a decision-ready intelligence framework that can be integrated directly into commercial planning, procurement strategy, and competitive benchmarking.
Inside the Report: Operational Depth and Executive Relevance
The research is built around a structured, multi-dimensional analytical model that translates market data into actionable strategy. Below is a preview of the core components included in the full report:
- Historical and Forecast Revenue Architecture: A year-by-year reconstruction of market revenue from 2020 through 2025, followed by a projected trajectory through 2032. This framework supports growth benchmarking, market-share modeling, and investment timing analysis.
- Type-Based Market Segmentation: A detailed breakdown separating the market into calcium chloride dihydrate and anhydrous forms. The analysis examines how form-specific demand patterns, processing requirements, and application preferences shape revenue distribution and supply-chain priorities.
- Application-Driven Demand Mapping: A thorough examination of how calcium chloride food grade is deployed across beverage production, dairy processing, meat processing, bakery and confectionery operations, and fruits and vegetables. The report evaluates adoption drivers, formulation considerations, and end-use growth dynamics without reducing the analysis to superficial category labels.
- Regional Market Structure: A geographic assessment that positions demand, supply capacity, and strategic opportunity across major global regions. The segmentation provides context for sourcing decisions, distribution planning, and market-entry prioritization.
- Competitive Landscape and Company Profiles: In-depth profiles of leading producers and distributors, including operational focus, product certifications, jurisdictional strengths, and recent strategic moves. The report also evaluates market concentration indicators to clarify the balance between established incumbents and emerging suppliers.
- Regulatory and Certification Framework: A practical synthesis of the compliance environment governing food-grade calcium chloride, including GRAS status under U.S. FDA regulations, EU food additive ordinance alignment, FCC and USP/EP specifications, and kosher/halal certification expectations. This section serves as a reference for procurement, quality assurance, and export strategy.
- Raw Material and Supply Chain Dynamics: An assessment of feedstock considerations, particularly the role of natural brine sourcing in high-purity production, and how supply-side factors influence cost structure, availability, and regional production advantages.
Each section is structured to provide both strategic context and operational specificity. The goal is to equip readers with a clear understanding of not only where the market is moving, but also what it takes to participate effectively in that movement.
Competitive Landscape: Who Is Shaping the Market
The food-grade calcium chloride sector is characterized by a mix of specialized chemical manufacturers, broad-line industrial suppliers, and regionally focused producers. Market concentration metrics indicate that a relatively small group of major players commands a significant share of total revenue, while a wider field of regional and product-focused companies competes through certification differentiation, application specialization, and supply reliability.
Several leading organizations define the current competitive shape of the market. TETRA Technologies, Inc., based in Houston, Texas, produces and supplies NSF-certified, kosher food-grade calcium chloride in anhydrous flakes and liquid formats, aligned with Food Chemicals Codex and E509 standards for food processing, brewing, and dairy applications. In 2025, the company completed a production expansion at its El Dorado, Arkansas facility to support increased demand across industrial and municipal applications, including specialized food-grade grades.
OxyChem, headquartered in Dallas, Texas, offers a recognized portfolio of food-grade calcium chloride products, including BRINERS CHOICE® Food Grade Anhydrous 94-97% Pellets and Liquidow® food-grade calcium chloride solution. Its offerings are kosher and halal certified for food additive use in canning, meat processing, and preservation. In mid-2025, OxyChem launched anhydrous calcium chloride 96% ultra-pellets designed for fast-acting performance across de-icing, dust control, and industrial applications, reflecting continued investment in purity and solubility optimization.
In Europe, nedMag B.V., based in Venlo, Netherlands, supplies nedMag Ca® food-grade calcium chloride in liquid 34% and prill forms, certified to EU Food Additive Ordinance 231/2012 for cheese production, vegetable processing, and food ingredient applications. Solvay S.A., headquartered in Brussels, Belgium, manufactures food-grade and pharmaceutical-grade calcium chloride dihydrate certified to EN 233, BP/USP pharmacopoeia, and E509 standards. In early 2025, Solvay commercially launched an expanded food-grade and pharmaceutical-grade calcium chloride dihydrate line from its Rheinberg facility, targeting dairy processors and excipient buyers.
North American distribution and specialty supply also play a significant role. Hill Brothers Chemical Co., based in Atlanta, Georgia, produces and supplies 77-80% food-grade calcium chloride flakes meeting FCC and USP specifications for food processing and preservation. Hawkins, Inc., headquartered in Minneapolis, Minnesota, distributes food-grade calcium chloride solutions at 30% and 32% concentrations under FDA CFR Title 21 §184.1193, with kosher and halal certification. CoreChem Inc., located in Knoxville, Tennessee, supplies mini-pellet food-grade calcium chloride in FCC grade for turkey processing, vegetable canning, and food additive applications.
On the global supply side, several Chinese manufacturers contribute significantly to export-oriented supply. Weifang Bell Chemical Co., Ltd. and Weifang Haibin Chemical Co., Ltd., both based in Shandong Province, produce food-grade calcium chloride flakes and granular forms meeting FCC and E509 standards for international food processing markets. Qingdao Huadong Calcium Chloride Co., Ltd. produces food-grade calcium chloride under international purity specifications, while Jiangsu Kolod Food Ingredients Co., Ltd. supplies food-grade calcium chloride at high purity levels for food additives and processing.
This competitive mosaic matters because procurement decisions in food-grade markets are rarely driven by price alone. Certification breadth, supply consistency, regional proximity, application expertise, and regulatory alignment often determine supplier selection. The report examines these dynamics in greater detail, providing a structured basis for supplier evaluation and competitive positioning.
Regulatory, Quality, and Supply Chain Dynamics
Food-grade calcium chloride operates within a tightly governed compliance environment. In the United States, it is generally recognized as safe for food use under the FDA Code of Federal Regulation Title 21, Section §184.1193, with conditions of use specified for food processing and additive applications. It is also recognized under USDA organic regulations without annotation for certain non-synthetic uses in food processing. These regulatory foundations create a stable but stringent operating environment in which product specifications, certification documentation, and batch consistency carry direct commercial weight.
For international markets, alignment with Food Chemicals Codex standards, EU food additive ordinance requirements such as E509 under Ordinance 231/2012, and kosher/halal certification is often essential. In North America and Europe, USP/EP and NSF certifications are commonly mandatory for liquid and anhydrous food-grade calcium chloride sold for pharmaceutical and food applications. The report integrates these regulatory parameters into the broader market analysis so that readers can assess how compliance requirements influence market access, supplier qualification, and regional demand patterns.
Supply-side considerations are equally important. Natural brine feedstock sourced from Michigan brines remains the dominant raw material basis for high-purity food-grade calcium chloride production, supporting operations by major producers and contributing to regional supply advantages. This feedstock reality shapes cost structures, production geography, and the strategic positioning of suppliers with access to consistent brine resources. Understanding these material flows is critical for organizations evaluating sourcing resilience, price sensitivity, and long-term supply security.
Why This Research Matters for 2026 and Beyond
Market research in the food ingredients space is most valuable when it connects high-level trends to operational reality. This report is designed with that principle in mind. It does more than report historical numbers or project future totals; it frames the market in terms that executives, planners, and analysts can use immediately.
Calcium Chloride Food Grade Market
For procurement and supply-chain leaders, the research provides context on certification pathways, supplier differentiation, and feedstock dynamics that influence purchasing strategy. For commercial and business-development teams, it offers a structured view of application demand patterns and regional opportunity sets. For investors and corporate strategists, it supplies the kind of disciplined market sizing, concentration context, and competitive mapping needed to evaluate entry points, expansion timing, and portfolio risk.
The forecast horizon through 2032 is particularly relevant for organizations making multi-year commitments. Capacity planning, product-line decisions, regional distribution investments, and supplier partnerships all benefit from a forward-looking view that is grounded in verifiable historical performance and clearly articulated projection logic. By integrating macro market sizing with segmentation structure and competitive context, the report enables readers to move from awareness to action.
Access the Full Intelligence Framework
This overview provides a strategic preview of the market environment and the analytical scope of the full report. However, the complete research deliverable contains the detailed segmentation data, regional breakdowns, company-level benchmarking, and forward-looking scenario structures that decision-makers need to translate insight into execution.
The full report offers a comprehensive, decision-ready dataset and interpretive analysis designed for professional use across procurement, commercial strategy, competitive intelligence, and investment planning. For teams operating in 2026 and beyond, access to this level of structured market intelligence can meaningfully improve strategic clarity and reduce uncertainty in high-stakes planning processes.
To explore the complete findings, detailed segmentation, competitive profiles, and forecast architecture, access the full report and equip your organization with the market intelligence needed to act decisively in the evolving calcium chloride food grade landscape.
For detailed analysis of this topic, please visit the official page: Calcium Chloride Food Grade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tray Sealing Machines Market to Reach $214M by 2032 with 4.36% CAGR
By PW Consulting, 2026-09-16
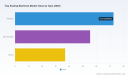
Strategic Intelligence for 2026: Navigating the Tray Sealing Machines Market
As global food supply chains accelerate towards greater efficiency and sustainability, the machinery underpinning primary packaging has entered a phase of critical transformation. For strategic planners, procurement leaders, and capital investment committees, the Tray Sealing Machines Market represents more than a routine equipment upgrade. It is a leverage point for operational resilience, regulatory compliance, and margin optimization in an era defined by volatile input costs and tightening environmental mandates. Our latest market research study, covering historical performance from 2020 through 2025 and delivering a forward-looking forecast from 2026 to 2032, is designed to convert this complexity into actionable boardroom intelligence.
The precision of 2026 decision-making depends on a clear-eyed view of where the market has been, where it is structurally heading, and which competitive forces are actively reshaping the pricing, capability, and technology landscape. This article outlines the strategic architecture of our analysis and demonstrates why a disciplined, data-anchored approach to tray sealing equipment strategy is indispensable for the year ahead.
Mapping the Macro Trajectory: Growth, Cycles, and Structural Shifts
Over the past half-decade, the global tray sealing equipment sector has demonstrated steady, compounding expansion. Revenue generated across the market moved from 135.75 million USD in 2020 to 165.0 million USD by 2025, reflecting an environment where food processors, fresh produce suppliers, and ready-meal manufacturers have consistently prioritized throughput, hygiene, and packaging integrity. Looking forward, the market is projected to advance to 169.06 million USD in 2026 and continue its upward trajectory toward 214.0 million USD by 2032. This path is underpinned by a forecast compound annual growth rate of 4.36 percent, a figure that signals durable demand rather than a temporary cyclical spike.
For executives evaluating capex pipelines, this macro trajectory carries several implications. First, it confirms that demand for tray sealing technology is not confined to a single geography or a narrow application vertical. Growth is being distributed across mature industrial markets and high-velocity emerging production hubs, creating a diversified opportunity set that rewards manufacturers and end-users who can align capacity investments with regional demand signals. Second, the gradual but consistent climb in revenue highlights an industry that is absorbing new automation layers, tighter inline integration, and higher-specification materials processing without sacrificing accessibility for mid-tier operations.
It is important to recognize that forward forecasts are not linear extrapolations. The years ahead will be shaped by the interaction of equipment capability, film and material innovation, compliance timelines, and competitive intensity. Our research isolates these drivers and maps them against demand scenarios so that leadership teams can distinguish between baseline growth and high-leverage investment windows.
Industry Dynamics and the Regulatory-Operational Interface
The operational context surrounding tray sealing equipment has become materially more complex. Food safety compliance is no longer a static checklist; it is an evolving framework that directly influences equipment specification. Alignment with HACCP principles, FDA expectations, and EU food safety standards requires machinery that meets defined hygiene, material compatibility, and performance criteria. At the same time, the FDA Food Traceability Rule compliance date established at January 20, 2026 has sharpened the focus on equipment and processes that support accurate lot handling, line traceability, and data integrity across packaging operations.
On the sustainability and materials side, EU single-use plastics and extended producer responsibility regulations have accelerated collaboration between machine manufacturers, film suppliers, and food processors. This collaboration is pressing equipment designers to accommodate a broader range of substrates, seal formats, and environmental profiles without compromising line speed or package reliability. Complementing this, the EU Food Contact Materials Regulation continues to mandate migration limits and Good Manufacturing Practices for all packaging materials, reinforcing the need for sealing systems that can consistently deliver repeatable performance across variable material inputs.
The industry response to these dynamics is visible in the trade floor. At PPMA Total 2025, thirteen percent of exhibitor visitors identified tray-sealing equipment as their primary interest area, a clear indication that packaging engineering teams are reallocating attention and budget toward sealing technology as a core enabler of compliance, throughput, and waste reduction. This shift is not cosmetic; it reflects a structural re-prioritization in how food manufacturers think about primary packaging as a control point for quality, cost, and regulatory readiness.
Competitive Architecture and Recent Market Activity
The competitive set in the tray sealing equipment market is defined by a balance of scale, specialization, and regional operational strengths. Market concentration reflects a moderately consolidated environment, with the top three players holding a combined share of 42.8 percent and the top five reaching 48.2 percent. This structure creates a landscape where large incumbents provide broad platforms and integration depth, while focused competitors compete on speed, energy efficiency, format flexibility, and application-specific performance.
Leadership teams evaluating vendor selection or benchmarking their current installed base should pay close attention to how different manufacturers are positioning their offerings. Packaging Automation Ltd has advanced a fully electric high-speed automatic REV5 tray sealer engineered to deliver a 20 percent speed increase and 50 percent energy savings, a combination that speaks directly to the dual pressures of throughput and operating cost. JBT Marel has focused on automatic tray sealers suited to burgers, patties, and medium-capacity production lines, and further underscored this direction with the unveiling of the Proseal XTP automatic tray sealer for smart automation in medium-sized production. Reepack S.R.L. has emphasized automatic and semi-automatic tray sealers with snap-on lids and high-speed vacuum skin pack capability, while also showcasing the ReeMaster NextGen series for fresh food performance.
In the retail food packaging segment, ILPRA S.p.A. continues to advance the Speedy series for modified atmosphere packaging and skin pack operations. In volume-driven environments, Ishida Co. Ltd. has demonstrated the QX-800 and QX-500 high-throughput tray sealers, including a live demonstration of the QX-800 at PPMA Total 2025 centered on production efficiency. German engineering has remained highly relevant through Webomatic Maschinenfabrik GmbH, with automatic tray sealers that integrate weighing and packaging systems, and Multivac Sepp Haggenmüller GmbH & Co. KG, with automatic tray sealers built for fresh food and meat processing at high volume. In North America, Form Plastics, Inc. offers HHA600 and automatic and semi-automatic tray sealers for food packaging, while Cima-Pak provides the CiMatic automatic tray sealer for cost-effective small-to-large production runs, and Starview Packaging Machinery Inc. supports inline automatic and manual shuttle configurations through its AITS series.
Specialty and compact-format innovation remains active as well. Gruppo Fabbri Vignola S.p.A. has progressed its Magic 2.0 compact automatic tray-sealing machines with automatic format recognition, supporting changeover efficiency in mixed-SKU environments. Y-Fang Sealing Machine Ltd. rounds out the competitive field with tray sealing machines incorporating vacuum, gas flushing, and auto-dropping piston functionality for food packaging. Collectively, these developments illustrate a market in which incremental technology gains, application-specific engineering, and integration readiness are becoming the primary differentiators.
Inside the Research: What Strategic Buyers Will Gain
Our study is structured to function as an operational decision tool rather than a static market snapshot. It combines a rigorously constructed revenue timeline with a segmentation architecture that isolates how demand is distributed across machine type, application, and region. Executives will be able to use this framework to test capacity plans against realistic demand patterns, identify where automation upgrades are likely to yield the strongest return, and understand which application segments are driving the most intensive equipment specification.
The report also translates market dynamics into procurement and planning relevance. It examines the regulatory and compliance overlay that shapes equipment requirements, connects those requirements to real operational consequences, and maps them against the competitive offerings that are actively entering the market. Recent product launches and exhibition activity are integrated as leading indicators of where technology investment is flowing, enabling readers to anticipate feature migration, pricing pressure, and capability spillover across the competitive set.
Importantly, the study preserves analytical discipline by separating signal from noise. It does not merely aggregate announcements; it interprets them in the context of demand structure, buyer priorities, and installation economics. This makes it possible to identify where the market is genuinely expanding, where growth is concentrated, and where vendor positioning is creating new opportunities for end-users to renegotiate specifications, service terms, and total cost of ownership.
Why 2026 Demands a Disciplined Market View
The current moment rewards preparation over reaction. With compliance dates now active, sustainability and material regulations reshaping supplier relationships, and a competitive field continuously upgrading speed, automation, and energy performance, the window for strategic equipment planning is narrowing. Organizations that rely on fragmented sourcing intelligence or outdated cost assumptions risk under-specifying critical lines, overpaying for capabilities they do not use, or missing the appropriate moment to modernize before throughput and compliance pressures intensify.
Tray Sealing Machines Market
Bag Heat Sealing Equipment Market
Our analysis is built to reduce that uncertainty. It provides the quantitative backbone needed to size the market, the segmentation clarity needed to prioritize use cases, and the competitive context needed to evaluate vendors with greater confidence. By aligning these elements, the research supports decisions on whether to standardize across lines, where to invest in automation, how to assess regional supply dynamics, and which performance attributes should carry the most weight in a purchase or upgrade cycle.
How to Use This Intelligence
For leadership teams preparing 2026 capex reviews, plant modernization plans, and sourcing strategies, the value of this study lies in its ability to connect market structure to operational choice. The macro revenue path and growth rate provide a baseline for demand confidence. The segmentation framework allows teams to test where their product portfolio, production volume, and geographic footprint intersect with the strongest market pull. The competitive and regulatory overlay helps translate those intersections into specification priorities, vendor shortlists, and negotiation parameters.
To move from high-level direction to operational precision, decision-makers need access to the full segmentation detail, regional demand patterns, and application-level revenue splits that form the analytical core of the study. Those elements are essential for building investment cases, sizing line configurations, and benchmarking total cost of ownership across competing equipment pathways.
Accessing the Full Strategic Picture
This article is intended as a strategic primer, not the complete intelligence package. The full research report delivers the granular segmentation, detailed forecast tables, company-level competitive profiling, and regulatory-impact analysis required to make defensible 2026 and 2027 equipment decisions. For executives and planning teams who need to convert market direction into procurement action, the complete study provides the structured evidence base necessary to justify capital allocation, prioritize automation roadmaps, and align sourcing strategy with where the tray sealing equipment market is genuinely heading.
The market is expanding with discipline, the competitive field is advancing with purpose, and the compliance environment is raising the stakes for equipment selection. In that context, informed market intelligence is not optional. It is the foundation for choosing the right technology, the right partners, and the right timing.
For detailed analysis of this topic, please visit the official page: Tray Sealing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Recycling Market to Hit $5.88B by 2032 with 5.66% CAGR
By PW Consulting, 2026-09-16
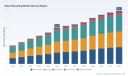
Strategic Intelligence for the Circular Economy: Unlocking Value in the Global Glass Recycling Market 2026–2032
The global transition toward circular economic models is no longer a theoretical ambition; it is a operational imperative reshaping supply chains, regulatory compliance, and capital allocation across the materials sector. For executives navigating the glass manufacturing and waste management landscapes, the coming years present a complex matrix of opportunity and risk. PW Consulting's latest comprehensive study on the Glass Recycling Market is designed to convert this complexity into actionable strategic clarity. As organizations prepare their capital plans and operational roadmaps for the 2026 fiscal year and beyond, understanding the granular mechanics of this market is essential to securing competitive advantage.
Plastic Recycling Market
This market research report serves as a critical decision-support tool, offering a data-rich examination of an industry poised for steady expansion. The underlying narrative is one of maturation. Drawing on historical data from 2020 through 2025, the analysis establishes a baseline of robust growth that continues into the forecast period extending to 2032. In 2020, the global market valuation stood at approximately 2.05 billion USD. By the base year of 2025, this figure had climbed to 4.01 billion USD, reflecting a compound annual growth rate of 5.66 percent over the analyzed historical window. Looking forward, the trajectory suggests continued momentum, with projected revenues reaching 4.2 billion USD in 2026 and advancing toward 5.88 billion USD by 2032. These figures are not merely statistics; they represent the scale of investment required, the volume of feedstock in motion, and the financial magnitude of the opportunity awaiting stakeholders who can navigate the technical and regulatory nuances of glass recovery.
Navigating the Core Dynamics and Operational Challenges
While the headline numbers indicate growth, the strategic value of this research lies in its dissection of the underlying dynamics. The glass recycling ecosystem is not a monolith; it is a fragmented network of collection infrastructure, processing technology, and end-market demand, all influenced by a tightening regulatory environment. A primary focus of the report is the infrastructure bottleneck that currently limits the efficiency of material recovery. Industry data indicates that only 40 percent of glass recycling is accepted at material recovery facilities, largely due to commingling in single-stream systems. This infrastructure constraint creates significant variance in feedstock quality and availability, directly impacting the economics of downstream manufacturers.
Simultaneously, the regulatory landscape is accelerating the demand for recycled content. In Europe, the Packaging and Packaging Waste Regulation 2025/40 entered into force on 11 February 2025 and is generally applicable from 12 August 2026, mandating glass packaging recycling targets at 70 percent by 2025. Such mandates force a reevaluation of procurement strategies for packaging firms, making reliable access to high-quality cullet a critical compliance and operational requirement. In the United States, the glass container recycling rate was recorded at 31.3 percent in 2018, with 3.1 million tons recycled from 12.3 million tons generated. While legislative efforts in states like California have supported increased recycled glass use in packaging, the gap between generation and recovery remains a key area of strategic focus. Furthermore, the economic case for recycling is reinforced by operational efficiencies; for every 10 percent increase in cullet in the batch, furnace energy needs drop by nearly 3 percent. This energy dynamic is a crucial lever for margin improvement in an era of volatile energy prices, and the report deep-dives into how this variable influences regional competitiveness.
Glass Recycling Market
Segmentation and Application Realities
To deploy capital effectively, leaders must understand where value is generated within the value chain. The report provides a rigorous breakdown of the market by product and application, revealing the dominance of specific segments while highlighting the emerging potential of niche applications. Recycled glass cullet remains the cornerstone of the industry, commanding a significant share of the market revenue due to its direct application in container and fiberglass manufacturing. The processing of glass into powder and crushed glass forms represents additional vectors of value creation, catering to specialized industrial needs ranging from abrasives to fillers.
On the demand side, glass containers continue to be the primary driver of recycled material consumption, reflecting the packaging sector's reliance on sustainable inputs. However, the analysis also scrutinizes other critical applications, including flat glass for construction and automotive sectors, and fiber glass for insulation and reinforcement. Smaller but strategically distinct segments such as highway beads, abrasives, and fillers offer diversification opportunities for processors looking to optimize yield and reduce waste. The report avoids superficial aggregation, instead offering a detailed view of how volume flows through these different channels, helping clients identify which applications offer the highest margins, the most stable demand, and the best alignment with their existing operational capabilities. It is important to note that while the report quantifies these market shares with precision, the full depth of regional and application-specific revenue data is reserved for the complete deliverable to ensure stakeholders derive maximum value from the proprietary analysis.
Competitive Landscape and Strategic Consolidation
The competitive architecture of the glass recycling market is characterized by a mix of established multinational players, specialized regional processors, and vertically integrated manufacturers. The market concentration metrics indicate that the top three companies hold a combined share of 42 percent, while the top five account for 51 percent of the market. This level of concentration suggests a mature industry where scale and network density are significant barriers to entry, yet sufficient fragmentation remains for strategic M&A and partnership activity to reshape the landscape.
Key players are actively positioning themselves to capture this growth through expansion, partnerships, and acquisitions. Sibelco, headquartered in Houston, Texas, stands as a dominant force, producing and supplying high-quality recycled glass cullet with a global capacity exceeding 5 million tons annually, including 2 million tons in North America, supported by over 60 facilities. In a significant move to expand its footprint, Sibelco acquired Strategic Materials, Inc. in December 2025, a transaction designed to expand the glass recycling network across North America. Strategic Materials itself is a critical node in the ecosystem, processing and supplying recycled glass cullet as high-quality feedstock for container and fiberglass production.
Other major entities are pursuing parallel strategies to secure their supply chains and enhance sustainability credentials. Owens-Illinois, Inc., based in Toledo, Ohio, operates the Glass4Good program, which recycled 392 metric tons in 2025, representing a 24 percent increase, with cullet processed into new glass bottles and jars. Vetropack Holding AG, headquartered in Meyrin, Switzerland, processes and supplies recycled glass cullet for container manufacturing and other glass applications, reinforcing the European supply base. Ardagh Group, based in Dublin, Ireland, has focused on partnerships for glass recycling services and cullet supply in container production. In April 2025, Ardagh Glass Packaging partnered with CAP Glass to establish advanced glass recycling services across the U.S. for high-quality cullet supply, signaling a strong push into the North American market. Momentum Recycling, LLC, operating out of Utah, processes glass recycling with a focus on cullet production for manufacturing and aggregates, illustrating the role of specialized regional players in optimizing local loops.
Recent developments further underscore the dynamic nature of this competitive field. In March 2025, Glass Half Full opened a new 10,000-square-foot recycling facility in Chalmette, Louisiana, with a capacity of 300,000 pounds per day, marking a 30-fold increase in processing capability. Such expansions demonstrate the rapid scaling potential in regions where infrastructure has been lacking, and the report analyzes the implications of these capacity additions for regional pricing and supply stability.
The 2026 Decision Framework
As organizations finalize their strategies for 2026, the insights contained in this report provide a framework for addressing the most pressing questions facing industry leaders. How should procurement teams structure contracts to mitigate the risk of cullet shortages driven by regulatory targets and infrastructure limitations? Where do the highest growth opportunities lie for processors looking to invest in new fractionation or processing technologies? How does the energy efficiency gain from cullet substitution translate into competitive pricing power in the container and flat glass markets? And perhaps most critically, how should companies evaluate the strategic fit of potential acquisitions or partnerships in a market where consolidation is accelerating, as evidenced by recent moves from major players?
The report equips decision-makers with the analytical tools to answer these questions. It moves beyond generic industry commentary to provide specific, data-backed assessments of market drivers, restraints, and opportunities. By integrating historical performance with forward-looking forecasts, it allows for scenario planning that accounts for regulatory shifts, energy price volatility, and changing consumer preferences. The analysis also highlights the interplay between regional dynamics and global market forces, ensuring that strategies are robust whether they are deployed in mature markets with high recycling rates or emerging regions where infrastructure is being built out.
Conclusion: A Catalyst for Sustainable Growth
The glass recycling market is at an inflection point. The convergence of regulatory pressure, energy economics, and corporate sustainability commitments is driving demand for recycled glass at a pace that outstrips the current capacity of many supply chains. For companies operating in this space, the margin for error is narrowing. Success in 2026 and beyond will belong to those who can secure reliable feedstock, optimize processing efficiency, and align their product portfolios with the most value-intensive applications.
PW Consulting's in-depth Glass Recycling Market research is more than a data repository; it is a strategic asset designed to inform high-stakes decisions. By revealing the structural forces shaping the market and profiling the competitive maneuvers of key players, the report empowers stakeholders to act with confidence. To access the full spectrum of analysis, including detailed segmentation data, regional breakdowns, and comprehensive competitor profiling, stakeholders are encouraged to explore the complete report. The intelligence contained within is essential for turning the challenges of the circular transition into a durable source of growth and resilience.
For detailed analysis of this topic, please visit the official page: Glass Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Portable Kayaks Revenue Hits $896M in 2025, Projected CAGR 4.2% Through 2032
By PW Consulting, 2026-09-16
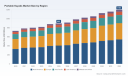
Navigating the Currents: Strategic Insights into the Portable Kayaks Market Through 2032
The portable kayak sector has evolved from a niche recreational corner into a structurally resilient segment of the broader paddlesports industry. Driven by urban densification, the democratization of waterfront access, and a sustained consumer preference for compact, transport-friendly outdoor gear, the market is entering a phase of steady, technology-led expansion. Our latest Portable Kayaks Market research translates this momentum into a decision-ready intelligence framework, designed specifically for executives, product strategists, and channel developers navigating the 2026–2032 horizon.
Worldwide Canoe-Kayak Accessories Market
For decision-makers operating in 2026, the imperative is no longer whether portable kayaks represent an attractive adjacency, but how to position portfolios, pricing architectures, and distribution models against a landscape defined by material innovation, shifting usage patterns, and increasingly concentrated competitive dynamics. This report provides the structural clarity required to separate cyclical noise from durable growth vectors.
Market Trajectory: From Recovery to Sustained Expansion
The historical record from 2020 through 2025 reveals a market that absorbed pandemic-era demand shocks, corrected pricing expectations, and recalibrated around quality and repeatability. By 2025, the sector had stabilized at a revenue base reflecting matured supply chains and a broader consumer base that now treats portable watercraft as a mainstream outdoor accessory rather than a specialist purchase.
Looking forward, the forecast period through 2032 outlines a consistent growth trajectory. The market is projected to expand at a compound annual growth rate of 4.2 percent, reaching a valuation of just under one billion dollars by 2026 and progressing steadily toward a materially larger valuation by the end of the forecast window. This pace of expansion is neither explosive nor speculative; it reflects the compounding effect of product iteration, incremental adoption in emerging usage contexts, and the ongoing substitution of bulky, non-portable alternatives with designs that prioritize on-road convenience and quick deployment.
For strategy teams, the implication is clear. Growth in this segment will be captured by organizations that align product roadmaps with durability expectations, optimize cost-to-volume ratios, and anticipate where portability intersects with performance. The data underscores a market that rewards precision over hype, and our research supplies the dimensional rigor needed to make those judgments with confidence.
Structural Segmentation: Where Demand Actually Concentrates
Portable kayaks are not a monolithic category. The segment decomposes into distinct architectures that serve different performance thresholds, storage constraints, and demographic profiles. Understanding which configuration dominates, why it dominates, and where secondary formats are gaining traction is essential for product planning, inventory strategy, and marketing positioning.
Type-based segmentation reveals a clear preference hierarchy. Inflatable designs command the largest share of overall revenue, reflecting their balance of transport simplicity, storage efficiency, and broad consumer acceptance. Folding constructions occupy a significant but narrower footprint, appealing to buyers who prioritize folding mechanics, assembly speed, and a compromise between rigidity and portability. Rigid portable formats represent a smaller portion of the market, typically serving specialized use cases where weight and trailering constraints are balanced against higher performance expectations. Each architecture carries its own manufacturing complexity, quality assurance requirements, and aftermarket considerations.
Application segmentation further clarifies where commercial energy should be directed. Recreational use remains the dominant demand driver, consistent with the category’s origins and its alignment with casual paddling, weekend excursions, and accessible outdoor leisure. Fishing applications form a meaningful secondary channel, supported by anglers’ need for stable, compact platforms that can be deployed without extensive logistics. Whitewater and other specialized applications occupy more focused niches, often demanding higher material tolerances, tailored hull characteristics, and targeted distribution partnerships.
Geographic distribution adds another layer of strategic context. Consumption patterns vary materially across regions, shaped by local waterway culture, retail infrastructure, seasonal usage cycles, and the pace of outdoor recreation adoption. The research isolates these regional dynamics without reducing them to simplistic rankings, enabling clients to identify where to intensify go-to-market efforts, where to test localized product variants, and where channel consolidation may create near-term barriers or opportunities.
Competitive Landscape: Concentration, Differentiation, and the Innovator’s Edge
The portable kayak market is not a diffusely competitive field. It operates with a meaningful degree of concentration, where leading participants capture disproportionate share through design IP, specialized materials, brand credibility, and tightly managed product ecosystems. This concentration has strategic consequences. It raises the barrier to entry for undifferentiated newcomers, while simultaneously rewarding incumbents that can iterate rapidly, protect performance claims, and reinforce distribution moats.
Among the companies shaping the category, Tucktec Folding Kayaks has built a reputation around hard-shell folding designs that emphasize rapid assembly and road-ready portability without reliance on roof racks or trailers. Their positioning reflects a pragmatic, performance-first approach that addresses the everyday friction points of transport and launch. Oru Kayak, by contrast, has leaned into lightweight construction and space-efficient packaging, utilizing origami-inspired polypropylene architectures designed to withstand extensive repeated folding while maintaining compact storage dimensions. Their product philosophy appeals to urban buyers, apartment dwellers, and users who treat portability as a primary purchasing criterion.
TRAK Kayaks occupies a premium, expedition-oriented tier. Their focus on adjustable rocker, reinforced frame systems, and advanced skin materials positions them at the intersection of portability and serious paddling performance. This higher-spec orientation supports a distinct price architecture and a customer base willing to pay for durability, maneuverability, and expedition-grade reliability. Noisy River Outdoors contributes a different structural answer to portability, developing patented catamaran-style platforms that emphasize stability and integrated functionality for sportsmen and users operating across varied water conditions.
Recent developments in the sector illustrate how product communication and model-level refinement continue to shape market perception. In mid-2025, Tucktec refreshed its product catalog and pricing visibility around its Pro and Jr. models, aligning promotional activity with updated availability and seasonal purchasing cycles. Around the same period, TRAK highlighted its next-generation construction approach through paddling media recognition, reinforcing its positioning around high-performance foldable design and expedition-grade build quality. These moves are not isolated product announcements; they are signals of how leading participants are managing portfolio clarity, performance narrative, and consumer trust in a market where claims must be backed by repeatable user experience.
For clients evaluating partnership, acquisition, or competitive positioning strategies, the research maps these dynamics into actionable intelligence. Concentration levels, brand differentiation levers, and development cadence are all examined in sufficient depth to support scenario planning and risk assessment.
Portable Kayaks Market
Operational Intelligence Embedded in the Report
Market size and trajectory figures are necessary, but they are not sufficient for 2026 decision-making. This research is built around operational usability. It moves beyond high-level estimates to provide a structured view of the levers that actually affect commercial outcomes.
Readers will find detailed analysis covering product type economics, application-specific demand drivers, and regional consumption contexts that inform where to allocate sales effort and marketing investment. The report examines supply-side considerations relevant to manufacturing complexity, material selection, durability expectations, and after-sales support implications. It also addresses channel dynamics, including how specialty retailers, direct-to-consumer models, and seasonal distribution windows interact with product architecture and pricing strategy.
Beyond segmentation, the research integrates competitive profiling that connects company positioning to broader market behavior, helping clients understand not just who occupies which part of the category, but why certain design philosophies and go-to-market approaches succeed or stall. The result is a reference document that can be used for portfolio planning, target market prioritization, pricing architecture reviews, and new product introduction scoping.
Strategic Takeaways for 2026 Decision-Makers
The portable kayaks market in 2026 sits at an inflection where steady growth, design maturity, and competitive concentration intersect. Several strategic conclusions emerge for organizations operating in or adjacent to the category.
- Portability is no longer an accessory feature; it is a primary purchase driver. Consumers increasingly weigh transport friction, storage footprint, and deployment speed alongside on-water performance. Products that reduce everyday friction without sacrificing durability are best positioned for sustained adoption.
- Material and construction choices define brand ceilings and pricing pathways. The divergence between lightweight foldable systems, hard-shell folding designs, and premium expedition-grade builds reflects more than aesthetics. It defines downstream economics, warranty exposure, and the customer segments each product can credibly serve.
- Concentration rewards differentiation, not imitation. With a meaningful share held by established participants, new entrants and expanding incumbents must articulate a defensible performance or convenience claim. Generic portability messaging is unlikely to overcome the trust and repeat-use thresholds already established by leading designs.
- Regional and application context determines execution speed. Demand intensity varies across geographies and usage settings. Strategy teams should avoid one-size market entry assumptions and instead align product variants, channel support, and promotional timing with the specific waterway culture and retail dynamics of each target market.
Why This Research Matters Now
As organizations set priorities for the remainder of the decade, the portable kayak segment offers a rare combination of accessible growth, clear usage rationale, and expanding design sophistication. That combination creates both opportunity and execution risk. The opportunity lies in capturing sustained demand from buyers who want water access without logistical friction. The risk lies in misreading segmentation, overcommitting to undifferentiated product variants, or underestimating how material durability and performance claims shape brand trust over time.
Our Portable Kayaks Market research is designed to reduce that uncertainty. It translates macro trajectory into segment-level logic, clarifies competitive positioning, and maps the operational considerations that determine whether a product, channel, or partnership strategy will hold up under real-world conditions. For executives planning 2026 investments and beyond, the report offers a disciplined foundation for decisions about product architecture, market entry sequencing, pricing strategy, and competitive response.
The full intelligence package provides the detailed segmentation data, regional analysis, competitive profiling, and scenario-based interpretation required to convert broad market momentum into precise commercial action. We invite strategy, product, and commercial teams to consult the complete report for the full analytical depth behind these findings and to apply its structure to their own planning cycles.
For detailed analysis of this topic, please visit the official page: Portable Kayaks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Fused Alumina Market Hits $200M in 2025, Projects 4.01% CAGR Through 2032
By PW Consulting, 2026-09-16
White Fused Alumina Market 2026: Strategic Intelligence for Industrial Decision-Makers
As industrial manufacturing enters a new cycle of material optimization and cost discipline, White Fused Alumina has emerged as a critical component across abrasives, refractories, and technical ceramics. The global market has demonstrated consistent expansion over the past five years, growing from 150.0 Million USD in 2020 to 200.0 Million USD in 2025, with revenue projections indicating a continued upward trajectory through the end of the decade. Our latest White Fused Alumina Market research is built to translate this trajectory into executable strategy, giving procurement leaders, product developers, and market planners a precise, evidence-based view of where value is being created and where competitive pressure is intensifying.
This analysis is not a static snapshot. It is a forward-looking strategic instrument calibrated for the 2026 decision window. By combining historical performance from 2020 through 2025 with a structured forecast spanning 2026 to 2032, the report enables stakeholders to test assumptions, align supply commitments, and prepare for shifting demand patterns without relying on fragmented secondary sources or outdated industry narratives.
Market Trajectory and the Strategic Meaning of the Growth Curve
The market's evolution reflects more than incremental volume growth. The progression from 159.67 Million USD in 2021 to 170.69 Million USD in 2022, followed by acceleration toward 185.97 Million USD in 2023 and a measured 187.12 Million USD in 2024, shows a sector that has absorbed supply disruptions, raw material volatility, and regional demand rebalancing while still advancing ahead of broader industrial benchmarks. The 200.0 Million USD baseline in 2025 reinforces a market that has stabilized around quality differentiation, application-specific grading, and more disciplined inventory management.
From a strategic planning perspective, the forecast period tells its own story. Revenue is expected to reach 215.16 Million USD in 2026, followed by 217.06 Million USD in 2027 and 229.1 Million USD in 2028. The projection continues into 2029 at 231.99 Million USD, approaches 248.89 Million USD by 2030, and then moves toward 245.29 Million USD in 2031 before reaching 263.29 Million USD in 2032. These are not arbitrary numbers. They are planning inputs that help organizations gauge capacity timing, contracting windows, and the pace at which high-performance grades may capture additional share as downstream users demand better wear resistance, thermal stability, and polished surface outcomes.
The overall growth profile supports a compound annual growth rate of 4.01 percent across the forecast horizon, indicating a market that rewards companies able to align product specifications with end-use performance requirements rather than competing solely on commoditized volume. For 2026 planning, this means the strategic question is less about whether demand will advance and more about how to position specifications, supply agreements, and regional sourcing decisions to capture margin in a market where performance credibility increasingly determines customer retention.
Report Architecture: What Decision-Makers Will Find Inside
The study is organized to convert market complexity into operational clarity. Rather than offering a high-level overview alone, the report maps the market across type, application, and regional demand structures so that readers can align internal assumptions with external evidence. The segmentation logic is designed for practical use: it helps teams understand where white fused alumina is being specified, which grade structures are gaining emphasis, and how application requirements are reshaping procurement priorities.
Fused Magnesia Market
Inside the report, stakeholders will find:
- A full market size reconstruction from 2020 through 2025, providing a verifiable historical baseline for internal forecasting and board-level review.
- A detailed 2026 to 2032 outlook that translates growth momentum into planning-relevant signals for capacity, sourcing, and product roadmap decisions.
- Type-level analysis that distinguishes among refractory, abrasive, and ceramic-grade demand patterns, supporting product positioning and specification strategy.
- Application-level evaluation that examines how refractories, abrasives, and ceramics usage shapes volume flows and customer requirements.
- Regional demand mapping that reveals where consumption is concentrated and how geographic dynamics influence pricing, logistics, and sourcing strategy.
- Competitive profile coverage of the leading producers, including operational focus, product offerings, and strategic positioning within the white fused alumina value chain.
- Synthesis of industry dynamics that connects supply-side realities with downstream performance expectations, giving readers context for scenario planning and risk assessment.
The report is intended for teams that need more than directional commentary. It provides a structured foundation for budgeting, segment prioritization, customer strategy, and competitive positioning in a market where small specification advantages can translate into long-term contract value.
Competitive Landscape: Who Shapes the Market and How
The white fused alumina market is defined by a mix of established industrial suppliers and regionally influential producers, each bringing a different balance of purity, scale, application focus, and geographic reach. Our analysis examines the companies that materially influence pricing behavior, grade availability, and supply reliability, allowing readers to benchmark their own positioning against the actors most likely to affect purchasing decisions in 2026 and beyond.
Washington Mills operates with a clear emphasis on high-purity output, manufacturing white fused alumina grains, powders, and bubbles via electric arc fusion of Bayer-processed alumina. With material purity exceeding 99 percent Al2O3, the company supports demanding uses in refractories, ceramics, abrasives, and polishing applications. For customers where consistency and purity are non-negotiable, this profile signals a supplier orientation toward performance-sensitive segments rather than volume-only competition.
Imerys brings a broad, globally distributed production footprint to the market. With 12 global production sites, the company produces fused alumina, including white fused alumina, under the Alodur brand for abrasives, refractories, and technical ceramics. That scale and brand architecture matter in procurement environments where supply continuity, multi-region coverage, and application versatility are weighed alongside price.
Rusal contributes to the landscape through large-scale electric arc furnace production of white fused alumina from pure alumina at its Boksitogorsk Alumina Refinery. The company's integration with upstream alumina resources gives it a distinct supply-chain posture, which can influence cost structure, volume reliability, and the ability to serve industrial users seeking stable baseline supply.
U.S. Electrofused Minerals positions white fused alumina within a broader fused oxides portfolio for industrial applications. Its approach reflects a practical, application-oriented supply model in which white fused alumina is part of a wider materials offering, allowing customers to consolidate sourcing across related oxide products where specification alignment is possible.
MOTIM Electrocorundum provides another important European reference point, producing high-quality white fused alumina for refractories and abrasives. Its specialization reinforces the market's split between performance-driven and cost-sensitive purchasing channels, as well as the continued relevance of regional manufacturers that combine technical consistency with proximity to key industrial users.
In the Asia-Pacific supply structure, Zhengzhou Yufa Group stands out as a large-scale producer with a strong emphasis on cost-efficient supply for global abrasives and refractories. Henan Ruishi Renewable Resources Group similarly supplies white fused alumina grains and powders for industrial use, adding to the region's manufacturing depth and reinforcing the competitive importance of volume capability, logistics efficiency, and pricing agility.
Together, these players illustrate a market where concentration creates both opportunity and caution. The sector's structure indicates that a limited number of producers account for a substantial share of revenue, while still leaving room for specialized suppliers to compete on grade, purity, and service. For 2026 strategy, that means competitive intelligence cannot stop at product specs; it must also address supplier reliability, regional coverage, and the ability to respond to application-specific demand shifts.
Industry Context and Strategic Implications for 2026
The market intelligence in this study is grounded in current industrial realities. White fused alumina demand does not evolve in isolation. It is shaped by how abrasives manufacturers balance surface-finishing performance against cost, how refractory producers evaluate thermal endurance and service life, and how ceramics users align material characteristics with component requirements. At the same time, supply-side considerations such as energy intensity, raw alumina availability, furnace operation efficiency, and logistics constraints influence how reliably producers can meet specification-sensitive orders.
For 2026 planning, these dynamics create several strategic priorities. Companies need to evaluate whether their product and sourcing strategies are aligned with the growing importance of high-consistency grades. Procurement teams must weigh whether multi-supplier structures or consolidated partnerships better serve their risk and performance requirements. Market leaders need to determine where differentiation is sustainable, particularly in applications where wear life, polish quality, and thermal behavior directly affect downstream economics.
The report also supports scenario-based thinking. Because the forecast extends through 2032, organizations can use it to test how changes in regional demand strength, application mix, or grade adoption might alter revenue potential and competitive intensity. That forward visibility is especially valuable for capital planning, long-term contracts, and product development roadmaps where premature commitments can erode flexibility and delayed moves can cede share to more responsive competitors.
White Fused Alumina Market
Why This Research Matters Now
The white fused alumina market is entering a phase where informed decisions will separate resilient operators from those forced to react to supply and pricing shifts after the fact. With a 2025 baseline of 200.0 Million USD and a forecast that points toward 263.29 Million USD by 2032, the market offers meaningful expansion, but it also demands sharper segmentation insight, supplier benchmarking, and application-level understanding. Organizations that enter 2026 with only generic market narratives will be at a disadvantage when negotiating with producers, specifying grades for sensitive applications, or deciding where to invest in capability and coverage.
This White Fused Alumina Market research is designed to close that gap. It translates verified historical data, forward projections, and competitive profiling into a usable strategic framework for 2026 decision-making. The full intelligence set, including deeper segmentation detail, regional demand analysis, and complete company profiles, is available through the complete report. For teams that need precise market estimates, actionable segmentation, and a clear view of who is shaping the competitive environment, the full study provides the depth required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laboratory Animal Housing Cage Market to Reach $307.5M in 2025, Grow at 4.45% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for Decision-Makers: The Global Laboratory Animal Housing Cage Market in 2026
The laboratory animal housing cage market sits at the intersection of biopharma innovation, regulatory evolution, and operational efficiency. For executives, procurement leaders, and R&D strategists, understanding the trajectory of this specialized infrastructure market is not merely an operational concern—it is a strategic imperative. Our latest comprehensive market research on the Laboratory Animal Housing Cage Market provides a rigorous, data-driven foundation for 2026 decision-making, mapping historical performance, forecasting growth through 2032, and dissecting the competitive, regulatory, and technological forces that will shape procurement strategies, facility investments, and partnership opportunities in the coming years.
This article serves as a strategic preview of the full study. It outlines the analytical architecture, highlights the macro market trajectory, contextualizes the regulatory and competitive landscape, and demonstrates how the complete report translates complex intelligence into actionable frameworks for enterprise planning.
Market Trajectory: From Baseline to Forecast Horizon
The market has demonstrated resilient, structurally supported growth over the historical reference period, reflecting sustained demand from research institutions, contract research organizations, and pharmaceutical developers. Our analysis establishes a clear baseline trajectory, with market revenue climbing from approximately 247.8 million USD in 2020 to 307.5 million USD in 2025. This progression underscores a market that has absorbed operational disruptions, adapted to evolving husbandry standards, and continued to expand in line with broader life sciences investment cycles.
Looking ahead, the forecast window from 2026 through 2032 projects continued expansion, with an estimated CAGR of 4.45 percent. The forward curve suggests that demand will be driven by a combination of facility modernization, heightened emphasis on animal welfare and reproducibility, and the gradual uptake of advanced housing architectures across regions and research applications. By 2032, the market is positioned to cross 400 million USD in annual revenue, a threshold that signals both mature adoption in established markets and meaningful growth momentum in emerging research ecosystems.
Importantly, this trajectory is not uniform. The interplay of regional research intensity, species-specific housing requirements, and material-technology preferences introduces structural variation across market segments. The complete report quantifies these variations with disciplined granularity, allowing decision-makers to align procurement roadmaps and capital allocation with the most relevant demand vectors for their operational footprint.
Report Architecture: From Macro Trends to Operational Playbooks
The full study is designed to function as a decision-support instrument rather than a static data repository. Its architecture moves from macro market structure to segment-level dynamics, then to competitive positioning, regulatory mapping, and forward-looking scenario analysis. Each section is anchored by customizable modeling inputs, enabling clients to stress-test assumptions against their own facility portfolios, geographic exposure, and research pipelines.
Key analytical components of the report include:
- Macro market sizing and forecast modeling across the 2020–2032 horizon, with explicit base-year calibration and scenario sensitivity around adoption velocity and capital expenditure cycles.
- Segment-level demand mapping that distinguishes between housing material architectures, species and application categories, and regional research infrastructure profiles, allowing organizations to isolate the demand pools most relevant to their product or service strategy.
- Competitive landscape assessment covering ten leading suppliers, with company profiles, product-system specializations, and a timeline of recent commercial and strategic moves that signal where the market is heading.
- Regulatory and compliance mapping that translates directives, accreditation requirements, and institutional guidance into operational implications for cage design, ventilation standards, sanitation schedules, and environmental control.
- Inventory of industry dynamics and ecosystem signals, including trade engagement, educational program expansion, partnership activity, and product-introduction cadence, that together reveal the cadence of innovation and market entry.
By structuring the analysis in this way, the report enables executives to answer practical questions: where is demand most concentrated, which housing platforms are gaining traction, how do compliance requirements translate into procurement specifications, and which supplier capabilities are becoming differentiators rather than table stakes.
Regulatory Dynamics as a Demand Catalyst
Regulatory and accreditation frameworks are not peripheral constraints; they are structural drivers of housing specification, replacement cycles, and facility upgrade spending. Across major research jurisdictions, animal welfare standards, environmental control expectations, and reproducibility mandates are progressively tightening, compelling institutions and service providers to align infrastructure with documented compliance requirements.
The complete report synthesizes multiple layers of regulatory context into an actionable dynamics section. This includes how requirements for environmental enrichment, temperature stability, humidity control, and minimum cage dimensions influence housing system design and procurement specifications. It also addresses how accreditation frameworks and institutional oversight create consistent demand for certified housing solutions that support animal welfare, biosecurity, and research reproducibility. Furthermore, the analysis maps sanitation frequency expectations and microenvironmental monitoring protocols, showing how modern individually ventilated cage architectures can align with operational efficiency targets while maintaining compliance.
For strategic planners, the regulatory dimension is best understood as a forcing function. As institutions seek to harmonize welfare standards with throughput goals and environmental control precision, investment flows toward housing systems that integrate ventilation performance, sanitation durability, and compatibility with monitoring or tracking technologies. The report quantifies the magnitude of these influences and maps them to realistic procurement and capital planning horizons.
Competitive Landscape: Ten Anchors and a Shifting Innovation Frontier
The market is characterized by meaningful concentration among established suppliers, with a closely contested field of specialized manufacturers competing on system architecture, durability, compliance alignment, and digital integration. The report profiles ten core companies, each with distinct positioning across plastic and metal housing platforms, individually ventilated cage systems, large-animal housing solutions, and specialty accessories or environmental control equipment.
Laboratory Animal Housing Cage Market
Several competitive themes emerge from the profile set. First, a growing emphasis on modular, reusable, and high-density housing platforms reflects the pressure to optimize facility space while maintaining throughput and welfare standards. Second, the integration of RFID census compatibility, ergonomic handling features, and digital ventilation control points toward an operational shift from static housing to data-enabled environment management. Third, durability claims around repeated autoclave cycling and multi-species versatility are becoming material evaluation criteria for procurement teams weighing lifecycle cost against upfront specification.
The full report situates these profiles within a structured competitive analysis, including concentration metrics that illustrate the degree of market consolidation and the strategic implications for sourcing strategy, supplier diversification, and partnership development. Rather than presenting company information in isolation, the study maps competitive capabilities against the demand segments they serve, helping clients identify where incumbents hold structural advantages and where whitespace may exist for differentiated offerings or specialized contracting models.
Worldwide Animal Workstation Market
Recent Commercial and Strategic Signals
Competitive dynamics are not static; they are continuously reshaped by trade engagement, partnership formation, product introductions, and educational outreach. The report captures a curated set of recent developments that reveal how leading suppliers are positioning themselves for the next phase of market growth.
Several patterns stand out in the recent activity set. Trade-show participation and conference presence continue to function as core visibility channels, with leading firms showcasing next-generation housing systems, ventilation platforms, and husbandry-integrated equipment to research and facility audiences. At the same time, educational programming is increasingly used not only for brand visibility but also to deepen engagement around husbandry best practices and housing equipment integration, reinforcing long-term relationships with research communities.
On the product and partnership side, recent moves indicate a strategic pivot toward AI-enabled monitoring integrations, ergonomic and reusable housing designs, and RFID-compatible census systems. These developments suggest that suppliers are responding to facility-level pressures around space utilization, operational consistency, and data-driven animal management. For procurement and R&D leaders, the signal is clear: housing decisions are increasingly inseparable from broader facility technology strategies.
The complete report integrates these developments into a timeline and competitive-context framework, allowing clients to interpret commercial activity not as isolated announcements but as indicators of strategic direction, capability investment, and likely future specification trends.
Implications for 2026 Enterprise Decision-Making
As organizations plan for 2026 and beyond, the Laboratory Animal Housing Cage Market presents both operational leverage points and strategic choices. The forecast trajectory implies sustained demand, but the value of the market research lies in its ability to convert that broad expectation into segment-specific, regulation-aware, and competition-grounded guidance.
For facility operators and institutional buyers, the report informs specification decisions, replacement-cycle planning, and supplier evaluation by linking compliance requirements and welfare expectations to housing architecture choices. For equipment and system suppliers, it clarifies where differentiation is accruing—whether through ventilation performance, durability, digital integration, or multi-species versatility—and how competitive concentration shapes go-to-market positioning. For investors and strategic partners, the study provides a structured view of demand geography, material and application preferences, and the cadence of innovation activity that underpins near-term commercial opportunities.
The analysis also supports scenario planning. Because the market is shaped by research funding cycles, regulatory interpretation, and facility modernization timing, decision-makers benefit from models that test how changes in adoption velocity, compliance stringency, or regional research intensity alter demand outcomes. The full report embeds this flexibility into its forecasting and segmentation structure.
Why the Complete Study Matters
A preview can establish direction, but operational decisions require specificity. The complete Laboratory Animal Housing Cage Market research delivers the detailed segment breakdowns, regional demand context, application-level sizing, material-technology splits, and supplier-level competitive inputs that executives need to move from directional confidence to precise planning. It pairs quantitative rigor with qualitative insight, ensuring that forecasts are grounded in observable market structure and that competitive interpretation is tied to documented product, partnership, and event activity.
Most critically, the study is built to be used. Its segmentation logic, competitive mapping, and regulatory-context synthesis are designed to inform procurement specs, sourcing diversification, capital planning, and product strategy. For organizations operating in biomedical research, contract services, or laboratory infrastructure, the report transforms a complex, regulation-shaped market into a navigable strategic map.
Access the Full Intelligence
This preview has outlined the analytical scope, the macro trajectory, the regulatory and competitive context, and the decision-making value of the study. The full report extends this foundation into detailed segment breakdowns, supplier-level competitive analysis, and customizable forecasting frameworks that allow your organization to align strategy with the most relevant demand signals.
To access the complete dataset, segment-level intelligence, and competitive profiles that underpin this analysis, request the full report through our official research portal. The complete study provides the depth, granularity, and applied frameworks required to support confident 2026 planning and multi-year capital and sourcing decisions.
For detailed analysis of this topic, please visit the official page: Laboratory Animal Housing Cage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Titanium Diboride Market Hits $44.1M in 2025, Set to Grow at 4.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Titanium Diboride Market: Strategic Intelligence for 2026 Decision-Makers
The global landscape for advanced ceramics is undergoing a quiet but fundamental transformation. At the center of this shift lies titanium diboride (TiB2), a material whose unique combination of hardness, electrical conductivity, and thermal stability is reshaping demand patterns across defense, semiconductor, and industrial manufacturing sectors. As organizations finalize their capital allocation and product roadmaps for 2026 and beyond, access to granular, forward-looking intelligence is no longer a luxury—it is a prerequisite for sustainable competitive advantage.
Our latest Titanium Diboride Market study, published by PW Consulting, is designed to meet this imperative. Spanning a historical analysis from 2020 through 2025 and a comprehensive forecast extending to 2032, this research translates complex market signals into an actionable strategic framework. Below, we outline the core architecture of the analysis, highlight the competitive dynamics currently reshaping the value chain, and explain why deepening your understanding of this niche—but rapidly evolving—market is a critical exercise for executive teams planning their next phase of growth.
Market Trajectory: From Steady Expansion to Strategic Inflection
The titanium diboride market has demonstrated resilient, compounding growth over the past half-decade. In 2020, total global market revenue stood at approximately 32.0 million USD. By 2025, that figure had climbed to 44.1 million USD—a trajectory that reflects both organic industrial adoption and the material's successful penetration into high-performance end-use segments. Looking ahead, our baseline forecast projects continued expansion, with market revenue expected to reach 45.28 million USD in 2026 and advance steadily toward 60.2 million USD by 2032. This long-view projection is anchored by an anticipated compound annual growth rate (CAGR) of 4.5 percent across the 2026-to-2032 forecast horizon.
These macroeconomic figures tell an important story, but they are only the starting point. The real strategic value lies in understanding how this growth is distributed across product types, application verticals, and geographic corridors—exactly the dimensions where competitive positioning can be won or lost. Market analysis at this level must move beyond headline numbers to examine the structural drivers: the maturation of bulk-grade production against the accelerating uptake of nanostructured formulations, the shifting allocation of demand across cutting tools, wear-resistant coatings, armor materials, refractory applications, electrodes and electrical contacts, composite materials, thermal barrier coatings, nuclear applications, and aerospace components, as well as the divergent growth tempos across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each of these segments carries its own pricing logic, supply constraints, and technology adoption curves, and our study maps them with precision.
Importantly, the market's growth profile is not uniformly distributed, and concentration patterns underscore this reality. The top three participants command a combined market share of 62.0 percent, while the top five extend that figure to 76.0 percent. This level of consolidation signals a market where scale, technology moats, and long-term customer relationships carry disproportionate weight—and where new entrants or expanding players must navigate an already crowded field with clear differentiation strategies.
Inside the Report: An Operational Playbook, Not a Static Snapshot
PW Consulting's Titanium Diboride Market study is structured to serve as a working reference for strategy, procurement, product development, and investment teams. Rather than offering a single trajectory, the report builds a multi-dimensional view of the market that connects demand fundamentals with supply-side realities, competitive behavior, and the broader industrial environment.
Key components of the analysis include:
- Segment-level deep dives: Detailed evaluation of how each product type and application category is evolving in terms of volume, value, technology requirements, and end-user adoption incentives. The analysis highlights where premium-grade materials are unlocking higher margins and where cost-optimized bulk supplies remain the dominant commercial vehicle.
- Regional market architecture: A geographically disaggregated assessment that examines demand intensity, manufacturing presence, trade flows, and localized supply constraints across all major regions. This section is designed to inform capacity siting decisions, partnership targeting, and market-entry prioritization.
- Competitive profiling and strategic positioning: In-depth company assessments that go beyond corporate descriptions to evaluate each player's product focus, geographic footprint, technology emphasis, and apparent strategic direction. The report contextualizes how established specialists and emerging capacity additions are reshaping share dynamics.
- Supply chain and input cost context: Examination of the material ecosystem that underpins titanium diboride production, including the role of boron-based feedstocks, energy intensity, and the operational impact of logistics and freight conditions on cost structures.
- Regulatory and environmental overlay: Analysis of how environmental considerations, mining and processing constraints, and compliance dynamics influence both upstream feedstock availability and downstream manufacturing economics.
- Technology and application horizon scanning: Identification of emerging use cases—such as additive manufacturing grades, advanced electronic sputtering targets, and next-generation armor and aerospace ceramics—that are expanding the addressable market and creating new value pools.
- Forecast scenarios and decision frameworks: Structured projections through 2032 that allow readers to stress-test assumptions around demand growth, competitive intensity, and input cost evolution, supporting both short-term operational planning and longer-range investment evaluation.
This integrated approach ensures that the study functions as more than a data repository. It is built to help decision-makers translate market signals into concrete actions: whether that means prioritizing a specific application vertical for product development, evaluating a potential partnership or acquisition, calibrating pricing strategy in a consolidating market, or assessing the viability of new capacity in a specific geographic corridor.
Competitive Dynamics: Specialists, Subscale Disruption, and Strategic Consolidation
The titanium diboride market is defined by a set of specialized producers whose capabilities are tightly aligned with specific end-use requirements. Understanding who these players are—and how they are positioning themselves—offers essential context for any strategic assessment of the market.
Europe remains home to several high-purity, technology-focused producers. Treibacher Industrie AG, based in Althofen, Austria, stands as a leading European source of high-purity titanium diboride powders and related hard material powders, serving industrial, aerospace, and electronics applications. Alongside it, H.C. Starck GmbH, part of the Mitsubishi Materials Group and headquartered in Goslar, Germany, is a prominent European producer of high-purity TiB2 powders and sputtering targets, with a strong presence in semiconductor, aerospace, and specialty chemistry markets. In a recent strategic move, H.C. Starck launched a new grade of titanium diboride powder tailored for additive manufacturing applications, with improved properties aimed at aerospace and automotive end-use sectors—a development that underscores the growing intersection between advanced materials and next-generation manufacturing processes.
In North America, the competitive picture blends established industrial material strength with specialized high-performance applications. 3M Company, through its Ceradyne subsidiary based in St. Paul, Minnesota, operates as a dominant supplier of TiB2-based defense armor, aerospace ceramics, and advanced materials, supported by long-standing military procurement relationships. Materion Corporation, headquartered in Mayfield Heights, Ohio, concentrates on high-purity TiB2 sputtering targets and specialty powders for semiconductor and thin-film deposition markets across North America and Europe—an application space where purity specifications and consistent quality are critical differentiators.
Japan continues to play a central role in specialty-grade material supply. Japan New Metals Co., Ltd., based in Toyonaka, Osaka, supplies specialty-grade TiB2 powders designed for electronics, precision tooling, semiconductor, and other high-value-added applications, with both domestic demand and export markets in scope.
China's manufacturing base adds significant volume and breadth to the global supply picture. Shandong Pengcheng Advanced Ceramics Co., Ltd., located in Zibo, Shandong, operates as a major Chinese producer of TiB2 ceramics, powders, and conductive ceramics, with applications spanning aluminum smelting cathodes, industrial cutting tools, and armor protection. Dandong Chemical Engineering Institute Co., Ltd. (DCEI), based in Dandong, Liaoning, produces titanium diboride alongside hexagonal boron nitride and amorphous boron powders, leveraging advanced processing technologies for a range of industrial applications. Together, these producers illustrate the dual nature of the market: a high-value, purity-sensitive segment driven by electronics, aerospace, and defense requirements, and a volume-oriented segment anchored in industrial tooling, wear applications, and cathode materials.
Worldwide Military Grade Titanium Disilicide Powder Market
Capacity and geographic expansion are already reshaping the competitive landscape. In July 2025, Kyocera Corporation acquired a titanium diboride ceramics manufacturing facility in South Korea, a move aimed at expanding production capacity and strengthening its market presence in the region. Such initiatives signal that established materials manufacturers are actively investing in geographic diversification and production scale, reinforcing the market's growth trajectory while simultaneously raising the bar for competitive differentiation.
Input Costs, Logistics, and Regulatory Currents: The Forces Shaping Margins
No strategic assessment of the titanium diboride market is complete without examining the upstream and environmental forces that influence both cost structures and supply reliability. Boron-based feedstocks sit at the heart of TiB2 production economics, and recent market intelligence points to several interconnected dynamics that buyers and producers alike must monitor.
Global boric acid prices exhibited a slightly declining trend in the first quarter of 2026, with spot prices in China recorded at 1,146 USD per metric ton in December 2025 amid relatively stable supply conditions. While a softening in feedstock pricing can ease input cost pressure in the near term, it does not eliminate the structural sensitivities that define this supply chain. Environmental regulations and mining costs continue to shape boric acid supply-side conditions for boron-based materials, introducing a persistent layer of uncertainty into cost forecasting. At the same time, supply chain disruptions and logistical challenges have influenced boric acid price movements across North America, Asia Pacific, and Europe, while environmental restrictions and freight rate fluctuations remain key factors affecting the overall cost structure of boron feedstock destined for TiB2 production.
For market participants, these dynamics carry direct strategic implications. Procurement teams must evaluate supplier resilience, inventory buffers, and geographic sourcing diversification in light of freight volatility and regulatory constraints. Producers need to factor energy intensity, environmental compliance, and logistics exposure into capital planning and pricing architecture. And executives designing market-entry or capacity-expansion strategies must account not only for demand momentum but also for the evolving complexity of the input cost environment that will ultimately determine margin sustainability.
Why This Research Matters for 2026 Strategy
As organizations move from planning cycles into execution, the titanium diboride market presents a clear case for informed, data-grounded decision-making. The combination of a consolidated competitive structure, differentiated application demand, evolving manufacturing technologies, and a feedstock environment shaped by logistics and regulatory pressures creates a setting where strategic clarity matters more than ever.
This study is designed to give executives, analysts, and operational leaders the kind of market visibility that supports confident action. It connects high-level growth trajectories with the granular segment and competitive intelligence required to build realistic scenarios, identify priority opportunities, and anticipate the shifts that will redefine value creation through 2032. Whether your focus is on expanding product portfolios, securing supply, evaluating partnership or acquisition targets, or positioning for geographic growth, the report offers the structured insight needed to move forward with precision.
For a complete view of the market size, segment dynamics, competitive profiles, and forward-looking forecasts underpinning this analysis, we invite you to access the full Titanium Diboride Market research. The detailed intelligence within is built to support the decisions that will define your organization's trajectory in the years ahead.
Titanium Diboride Market
For detailed analysis of this topic, please visit the official page: Titanium Diboride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Tubing Set Market Hits $1,027.5M in 2025 with 4.12% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Blood Tubing Set Market: Navigating Growth and Regulation in 2026
The global medical device landscape is undergoing a period of nuanced transformation, and few segments illustrate this complexity better than the Blood Tubing Set Market. As healthcare systems worldwide grapple with aging demographics, rising prevalence of chronic kidney disease, and increasingly stringent regulatory frameworks, the demand for reliable, high-performance extracorporeal blood circuits has never been more critical. For executives, procurement leaders, and investment analysts, understanding the trajectory of this market is not merely an academic exercise—it is a foundational requirement for strategic planning in 2026 and beyond.
At PW Consulting, we have released a comprehensive new study designed to cut through the noise and provide actionable intelligence. This article serves as an introduction to those findings, highlighting the strategic value the research offers to enterprises operating within or adjacent to the dialysis and blood transfusion ecosystems. While we preview the macro trends and competitive dynamics here, the full depth of segment-level analysis, regional breakdowns, and proprietary forecasts is reserved for our detailed report. Readers seeking to benchmark their position or identify high-yield opportunities are encouraged to consult the complete intelligence package.
Blood Collection Tubes Market
Market Trajectory and Core Financial Indicators
The Blood Tubing Set Market has demonstrated steady, predictable growth over the past half-decade, reflecting the essential nature of the products involved. Analysis of historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, moving from a baseline of approximately 812.35 million USD in 2020 to 1,027.5 million USD by 2025. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Blood Tubing Set Market
Our forecast models indicate that the market will continue to expand, driven by volume growth in dialysis procedures and incremental improvements in tubing set durability and biocompatibility. The projected compounding annual growth rate (CAGR) for the forecast period stands at 4.12 percent. This rate suggests a mature but resilient market environment, where growth is less about explosive disruption and more about steady volume expansion, technological refinement, and strategic consolidation. By the end of the forecast horizon in 2032, total market revenue is anticipated to reach significant new thresholds, offering clear pathways for stakeholders who can navigate supply chain complexities and regulatory compliance effectively.
For decision-makers in 2026, this trajectory implies several strategic imperatives. First, the market is not poised for volatile spikes but rather for sustained, manageable growth, requiring long-term capacity planning rather than short-term speculation. Second, the financial metrics underscore the importance of cost efficiency in manufacturing and procurement, particularly given the material cost dynamics inherent in medical-grade production.
Product Segmentation and Clinical Applications
Understanding where value is generated within the Blood Tubing Set Market is critical for targeted strategy. The market is broadly segmented by patient demographics, distinguishing between adult and pediatric applications. Given the higher prevalence of end-stage renal disease in adult populations, the adult segment naturally commands the majority of revenue share. However, the pediatric segment, while smaller in volume, often commands different specifications regarding priming volume, biocompatibility, and safety features. A successful product portfolio must address both segments with appropriate engineering and positioning.
Application-wise, the market is anchored by two primary channels: dialysis centers and hospitals & clinics. Dialysis centers represent the dominant setting for blood tubing set utilization, reflecting the chronic nature of hemodialysis treatments and the high frequency of disposable circuit replacement required per patient per week. Hospital and clinic environments also constitute a vital channel, particularly for acute dialysis scenarios, surgical procedures requiring extracorporeal circulation, and specialized care units. Each channel presents distinct procurement cycles, reimbursement pathways, and regulatory oversight requirements.
Our report provides granular analysis of these segmentation splits, helping organizations identify which sub-segments offer the best alignment with their manufacturing capabilities or distribution strengths. Rather than applying a one-size-fits-all strategy, the data suggests that tailored approaches based on application setting and patient age group yield significantly better margins and customer retention.
Competitive Landscape: Key Players and Strategic Moves
The Blood Tubing Set Market is characterized by a concentrated competitive environment where established medical device manufacturers leverage specialized product portfolios and regulatory expertise to maintain market share. Several key companies define the landscape, offering machine-specific and system-agnostic solutions that cater to the diverse needs of hemodialysis providers.
Nipro Corporation, headquartered in Osaka, Japan, has established a strong presence through its NiproSet blood tubing sets. These products are notable for being machine-specific for hemodialysis, featuring FDA-tested components that emphasize compatibility and safety. Nipro’s strategy highlights the value of close integration with dialysis equipment manufacturers, ensuring that tubing sets perform optimally within specific system configurations.
B. Braun Melsungen AG, based in Melsungen, Germany, offers the Streamline Airless System Hemodialysis Bloodlines and DiaStream bloodline systems. These solutions focus on reducing air embolism risks and improving hemodynamic stability during treatment. B. Braun’s approach underscores the importance of engineering innovations that directly reduce clinical risks, a key selling point in procurement decisions made by hospital administrators and nephrology directors.
Fresenius Medical Care AG, with headquarters in Bad Homburg vor der Höhe, Germany, provides the CombiSet SMARTECH and other blood tubing sets tailored for hemodialysis machines. As a global leader in dialysis care, Fresenius leverages its extensive clinical network and integrated service model to promote its consumables, reinforcing brand loyalty and standard-setting within care facilities.
Recent developments in the competitive and regulatory space underscore the need for vigilance. In April 2026, B. Braun Medical Inc. issued an urgent medical device correction regarding the Streamline Airless System Hemodialysis Bloodlines and B3 Low Volume Bloodlines. The correction addressed potential microbubble and leakage risks, with updates issued following FDA MedWatch alerts. Such events serve as a stark reminder that even mature products require continuous quality monitoring, rapid response protocols, and transparent communication with the regulatory community. For competitors and customers alike, these corrections influence purchasing confidence and may shift volume toward alternative suppliers who can demonstrate robust quality management systems.
Regulatory Environment and Clinical Compliance
The Blood Tubing Set Market operates within a tightly regulated framework that shapes product development, market entry, and ongoing compliance. Hemodialysis blood tubing sets are classified as Class II devices, subject to FDA 510(k) requirements for demonstrating substantial equivalence to existing predicates. This regulatory pathway demands rigorous documentation, clinical performance data, and quality system adherence, creating barriers to entry that protect established players while ensuring patient safety.
Reimbursement dynamics also play a pivotal role in market behavior. Hemodialysis blood tubing sets are covered under Medicare Part B reimbursement codes for dialysis procedures, linking device utilization directly to federal payment structures. Changes in coverage policies or coding updates can ripple through demand patterns, affecting volume projections and pricing strategies. Stakeholders must stay attuned to Centers for Medicare & Medicaid Services (CMS) national coverage determinations, which remain active and influential throughout 2026.
International standards further complicate the compliance landscape. Blood tubing sets must comply with ISO 10993 biocompatibility standards for blood contact, ensuring that materials do not induce adverse immune or thrombotic responses. Additionally, all blood tubing sets are single-use devices sterilized via gamma irradiation or ethylene oxide prior to market release, as mandated by FDA premarket notification guidance. These sterilization requirements impact production logistics, facility design, and cost structures, particularly regarding the medical-grade PVC tubing that forms the core of many sets. Unit costs for such tubing can vary between 5 and 15 USD per set depending on volume and customization, adding a layer of financial sensitivity that procurement teams must manage carefully.
Strategic Insights for 2026 Decision-Making
The intersection of market growth, competitive dynamics, and regulatory requirements creates a complex environment where strategic foresight is paramount. For manufacturers, the key challenge lies in balancing innovation with compliance, ensuring that new product features do not inadvertently trigger additional regulatory scrutiny or quality issues. For distributors and healthcare providers, the focus shifts to supply chain resilience, vendor reliability, and cost optimization without compromising patient safety.
Several actionable themes emerge for 2026:
- Portfolio Optimization: Companies should assess whether their tubing set offerings adequately address the divergent needs of adult versus pediatric patients and the specific requirements of dialysis centers versus hospital settings. Consolidating around high-performing, compliant products while phasing out underperforming SKUs can sharpen competitive positioning.
- Regulatory Preparedness: With Class II classification and ISO 10993 compliance as baseline requirements, organizations must maintain robust documentation and quality management systems. Proactive engagement with regulators and continuous monitoring of safety alerts, such as the 2026 B. Braun correction, can mitigate reputational risk and inform product improvement cycles.
- Cost and Supply Chain Management: Given the material cost variability in medical-grade PVC and the sterilization requirements, procurement strategies should factor in volume commitments, supplier diversification, and logistics stability. Long-term contracts with reliable raw material suppliers can help smooth out unit cost fluctuations.
- Reimbursement Alignment: Understanding how Medicare Part B codes and CMS determinations affect demand is essential for revenue forecasting. Aligning product features with reimbursable procedure codes can enhance market access and encourage adoption in cost-sensitive care settings.
What the Full PW Consulting Study Delivers
The insights outlined above represent only the opening chapter of our comprehensive Blood Tubing Set Market research. The full report goes much deeper, offering a level of granularity that enables precise strategic planning and investment analysis. Readers who access the complete study will find detailed segmentation breakdowns by region and type, forward-looking revenue forecasts through 2032, and a thorough examination of market concentration metrics. The report also includes analysis of industry context, covering regulatory shifts, reimbursement updates, material cost trends, and sterilization practices that impact total cost of ownership.
Furthermore, the study provides an in-depth competitive benchmarking section, profiling key players, their product specifications, recent developments, and strategic positioning. This allows companies to benchmark their own offerings, identify gaps in their portfolios, and anticipate competitor moves with greater accuracy. The research is designed to serve a wide range of stakeholders, from product managers and supply chain directors to investors and policy analysts, delivering a cohesive narrative backed by rigorous data analysis.
Conclusion
The Blood Tubing Set Market in 2026 is a landscape of steady growth, concentrated competition, and rigorous compliance demands. For organizations operating in this space, the ability to interpret market signals, anticipate regulatory changes, and align product strategies with clinical and reimbursement realities will determine long-term success. PW Consulting’s latest market research provides the strategic intelligence needed to navigate this environment with confidence, transforming raw data into clear, actionable directions. To unlock the full spectrum of insights, segmentation details, and competitive analysis, we invite you to explore the complete report and integrate its findings into your 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


