



PW Consulting: Karaoke Machines Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Unlocking the Rhythm of Growth: Strategic Insights from the 2026 Karaoke Machines Market Intelligence Report
The global karaoke machine market is currently undergoing a significant transformation, driven by shifting consumer habits, technological integration, and evolving entertainment preferences. As we move through the 2025-2032 forecast period, the industry is poised for steady expansion, presenting both opportunities and challenges for stakeholders across the entertainment hardware value chain. This executive summary outlines the strategic landscape of the karaoke machines market, derived from a comprehensive market research study designed to inform high-level decision-making in 2026 and beyond.
For business leaders, understanding the trajectory of this market is no longer optional; it is a prerequisite for capital allocation, product development, and competitive positioning. The following analysis leverages historical data and forward-looking projections to frame the current state of play. However, to maintain the integrity of proprietary forecasting models, specific granular breakdowns regarding regional revenue shares and segment-specific dollar values are reserved for the full report. Here, we focus on the strategic implications of the broad trends reshaping the industry.
Market Trajectory and Historical Context
The market has demonstrated resilience and consistent growth over the past half-decade. Historical data from 2020 through 2025 indicates a clear upward trend in revenue generation. Starting from a base of USD 163.15 million in 2020, the market scaled gradually each year, reaching USD 194.68 million by 2024. This growth trajectory accelerated in 2025, with valuations hitting USD 215.0 million. Such performance underscores a robust demand environment that has outlasted initial pandemic-induced fluctuations, transitioning from a recovery phase to a growth phase.
Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion. Projections indicate the market value will climb to USD 230.86 million in 2026 and further escalate to USD 344.8 million by 2032. This long-term outlook is supported by a Compound Annual Growth Rate (CAGR) of 6.98 percent. This rate of growth implies that the market is outpacing many traditional consumer electronics segments, fueled by innovations in wireless connectivity and portable form factors. For investors and manufacturers, this CAGR serves as a benchmark for evaluating potential returns on investment in manufacturing capacity or marketing spend.
Competitive Landscape and Key Players
The competitive environment is characterized by a fragmented yet dynamic mix of established manufacturers and agile tech innovators. The market concentration remains relatively moderate, with the top three companies holding a CR3 of 24.6 percent and the top five firms accounting for a CR5 of 26.2 percent. This indicates that while there are dominant players, a significant portion of market share is distributed among smaller or regional entities, leaving room for disruption.
Several key companies are defining the current standards of product quality and innovation. The Singing Machine Company, Inc., headquartered in Fort Lauderdale, Florida, remains a pivotal player. They manufacture a wide range of all-in-one karaoke machines, portable systems, and microphones. Their recent strategic moves include the launch of the Carpool Karaoke Mic 2.0 in June 2026, featuring dual microphones and improved wireless connectivity. This product launch highlights their focus on leveraging brand partnerships and enhancing user experience through hardware refinements.
Ikarao, based in New York, distinguishes itself through portable smart karaoke machines with built-in screens and KaraFun integration. Their presence at CES 2025, where they dazzled audiences with all-in-one karaoke technology, signals a strong commitment to integrating software ecosystems with hardware. Meanwhile, Tonor, headquartered in Hong Kong, focuses on wireless karaoke machines with LED lights and Bluetooth connectivity. Their release of the K20 Wireless Karaoke Machine in March 2026, which offered enhanced mood lighting and portable design, demonstrates an emphasis on aesthetic appeal and party functionality.
JYX, also based in Hong Kong, competes directly in the portable speaker and karaoke machine segment. Their introduction of the T17T and S8 models in November 2025, which boasted improved sound quality and longer battery life, reflects the industry-wide push towards mobility and endurance. These companies collectively illustrate the divergence in strategy, from premium branded partnerships to budget-friendly, feature-rich portable units. Understanding the specific strengths and go-to-market strategies of these competitors is essential for any firm looking to gain share in this ecosystem.
Market Segmentation and Demand Drivers
The market is segmented by type, application, and region, each offering distinct growth vectors. In terms of product type, the landscape is divided among portable, desktop, and other variants. The breadth of segmentation suggests that manufacturers cannot rely on a single form factor to capture the total market. Portable devices, in particular, have seen significant shipment increases, with data indicating an 18 percent rise in the first half of 2026 driven by demand for on-the-go entertainment.
Application-wise, the usage patterns have shifted noticeably. While commercial use remains a steady revenue stream, the share of karaoke machines used for home family gatherings surged in 2026. Internal data points to an increase from 52 percent in 2025 to 68 percent in 2026. This shift implies that product design and marketing should increasingly target home entertainment ecosystems rather than solely relying on commercial venue contracts. Portability, ease of setup, and aesthetic integration into home environments are becoming critical decision factors for consumers.
Regional dynamics also play a crucial role. The market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments and consumer preferences. For instance, regulatory bodies such as the US Federal Communications Commission issued updated guidelines in April 2026 for Bluetooth karaoke devices to ensure safer audio output levels. Compliance with such regulations is a non-negotiable aspect of market entry and product certification in key jurisdictions. Ignoring these dynamics can lead to significant delays in product launches or recall risks.
Industry Dynamics and Operational Challenges
Navig 2026 requires a keen awareness of external pressures affecting supply chains and operations. One notable challenge is the cost volatility of raw materials. In the first quarter of 2026, prices for plastic and electronic components used in portable karaoke machines saw a 12 percent increase due to global semiconductor shortages. This cost pressure impacts margins for manufacturers who have not secured long-term supply contracts or diversified their supplier base. Strategic sourcing and inventory management are now critical components of operational planning.
Furthermore, the regulatory landscape is evolving. Beyond the FCC guidelines on audio output, manufacturers must stay abreast of varying safety standards and import-export regulations across different geographies. The fragmentation of regulations means that a product compliant in one region may require significant modification for another, impacting time-to-market and overall profitability.
Karaoke Machines Market
Slot Machines Market
Consumer habits continue to evolve alongside technology. The integration of wireless connectivity and app-based song libraries is no longer a luxury but an expectation. Devices that lack seamless connectivity or a robust library integration risk obsolescence. The trend towards smart features, as seen in recent product launches by key players, suggests that hardware specifications alone are insufficient to drive sales. The user experience, including interface design and library access, is becoming a primary differentiator.
Strategic Value of Comprehensive Market Intelligence
Given the complexity of these dynamics, relying on anecdotal evidence or outdated reports is a strategic risk. A dedicated market research report provides the granularity needed to make informed decisions. The full version of this study offers deep dives into segmentation splits, detailed company profiles with financial and operational highlights, and precise forecast models.
Access to the complete data allows stakeholders to identify high-growth niches within the broader market. For example, while aggregate numbers show growth, understanding the specific revenue contribution of portable versus desktop units, or the exact revenue distribution across regions, enables targeted marketing and production planning. It also allows for a more accurate assessment of competitor moves. While public announcements indicate product launches, the full report contextualizes these moves within market share shifts and pricing strategies.
Moreover, the report includes an in-depth analysis of industry barriers to entry, regulatory compliance checklists, and supply chain risk assessments. These operational insights complement the financial forecasts, providing a holistic view of the market environment. For investors, this translates to better risk-adjusted return profiles. For manufacturers, it means optimized product roadmaps. For distributors, it ensures inventory alignment with regional demand patterns.
The strategic value lies in the ability to anticipate rather than react. With the market projected to reach USD 344.8 million by 2032, the window for establishing a dominant position is open but narrowing. Companies that leverage detailed intelligence to navigate raw material cost fluctuations, comply with emerging regulations, and align product features with the 68 percent home-usage trend will be best positioned to capture value.
In conclusion, the karaoke machines market offers a compelling growth story backed by solid fundamentals and evolving consumer preferences. However, realizing the potential requires more than just observing the upward trend. It demands a nuanced understanding of the forces driving that trend, from semiconductor availability to FCC guidelines, and from competitive product launches to shifts in home entertainment habits. The roadmap to 2032 is clear, but the path to success depends on the quality of intelligence guiding your next move. To access the complete dataset, detailed segmentation analysis, and proprietary forecasts that underpin these insights, we invite you to explore the full report.
For detailed analysis of this topic, please visit the official page: Karaoke Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Next Wave: Strategic Intelligence for the Autoclaved Aerated Concrete Market (2026–2032)
The built environment is undergoing a structural realignment. Decarbonization mandates, shifting material cost dynamics, and an accelerating preference for lightweight, high-thermal-performance solutions have propelled Autoclaved Aerated Concrete (AAC) from a niche alternative to a mainstream strategic consideration. As corporate decision-makers plan capital allocation, supply chain positioning, and geographic expansion for 2026 and beyond, the AAC market has emerged as a critical intersection of construction demand, regulatory tailwinds, and operational efficiency gains. Our latest research publication provides a comprehensive, decision-grade mapping of this trajectory across the forecast horizon through 2032.
The foundation of this outlook is built on a clear historical arc. From a base of USD 178.5 Million in 2020, the market progressed to USD 227.8 Million by 2025, reflecting compounding annual growth even amid intermittent supply chain friction and raw material price volatility. Moving into the forecast period, the trajectory accelerates into a robust growth corridor, with the market expected to cross the USD 244.0 Million threshold in 2026, continue upward through the mid-to-late 2020s, and approach USD 359.4 Million by 2032. Underlying this expansion is a forecast-period CAGR of 6.98 percent, a figure that signals sustained, structurally supported demand rather than a short-lived cyclical spike. For executives evaluating capacity planning, technology licensing, distributor partnerships, or regional entry strategies, these macro indicators establish the baseline for scenario modeling and investment prioritization.
Yet macroeconomic aggregates alone do not dictate competitive success. The strategic value of this research lies in its translational architecture: rather than presenting abstract totals, the study decomposes growth drivers into actionable dimensions that align with corporate planning cycles. Decision-makers are guided through a structured evaluation of how market momentum bifurcates across product formats, end-use applications, and regional ecosystems, enabling targeted positioning instead of broad, unfocused exposure. The report is designed to bridge the gap between market observation and execution, translating demand signals into procurement roadmaps, capacity expansion logic, and partnership criteria.
What the Report Delivers: Actionable Intelligence for 2026 Decisions
This publication is structured as an operational toolkit rather than a passive market summary. The analytical framework is engineered to support cross-functional teams—strategy, operations, supply chain, and business development—in validating assumptions and stress-testing strategic initiatives. Key components include:
- Historical Reconstruction and Baseline Calibration: A granular review of market evolution from 2020 through 2025, isolating inflection points, recovery patterns, and the structural factors that shaped volume and value trends. This retrospective anchors all forward-looking estimates and establishes the credibility of the forecast model.
- Forecasting Architecture for 2026–2032: A multi-variable projection framework that incorporates demand-side drivers, supply-side capacity dynamics, and regulatory pacing. The forecast does not rely on linear extrapolation; instead, it integrates sector-specific momentum to map a realistic growth corridor for the next seven years.
- Segment-Level Strategic Decomposition: Detailed analysis across product categories and application verticals, enabling readers to identify where value creation is concentrating, which formats are scaling most efficiently, and how end-use demand patterns are shifting in response to construction practices and building performance expectations.
- Regional Ecosystem Mapping: An assessment of how geographic markets differ in maturity, adoption intensity, regulatory influence, and competitive saturation. The analysis clarifies where demand is emergent, where it is consolidating, and where strategic entry or expansion may yield disproportionate returns.
- Competitive Positioning and Capability Benchmarking: A panoramic view of the operating landscape, including established manufacturers, technology providers, licensed plant operators, and distribution-focused players. Profiles are evaluated against production tenure, geographic footprint, product breadth, and strategic moves that signal future competitive intent.
- Industry Dynamics and Vulnerability Mapping: Targeted examination of the forces shaping margins and operational resilience, including raw material pricing behavior, policy interventions, and certification-driven procurement shifts. These insights allow organizations to anticipate cost pressure, evaluate substitution trends, and align sourcing strategies accordingly.
Collectively, these elements form a decision-support ecosystem. Rather than leaving readers with isolated data points, the report constructs a continuous logic chain: from historical evidence, through structural drivers, to competitive reality, and finally to strategic implication. The objective is to enable leaders to ask sharper questions—about capacity timing, product mix optimization, distributor alignment, and regional prioritization—and to answer them with evidence that withstands scrutiny.
Market Dynamics: Regulatory Acceleration, Material Realities, and Demand Reconfiguration
The AAC market's expansion is not occurring in a vacuum. It is being reshaped by intersecting forces that alter both the demand curve and the cost structure of production. One of the most consequential shifts involves regulatory and certification environments. In several advanced construction markets, green building certification frameworks have increasingly favored materials that combine structural utility with lightweight characteristics and thermal insulation performance. This has translated into higher procurement visibility for AAC within project specification processes, particularly where energy efficiency targets are tightening and where building envelopes must satisfy stricter performance thresholds. Parallel policy mechanisms in parts of Europe have further reinforced this trajectory, as energy codes and retrofit mandates effectively position AAC as a pragmatic solution for both new builds and renovation programs seeking measurable thermal gains.
At the same time, material-side dynamics are introducing a more complex operating environment. The core input architecture of AAC manufacturing—dependent on cement and lime as primary binding agents—remains exposed to pricing volatility. Seasonal fluctuations, regional supply constraints, and broader commodity cycles have periodically pressured input costs, affecting margin stability across block and panel producers. This has elevated the importance of sourcing strategy, formulation flexibility, and vertical coordination for manufacturers seeking to protect unit economics. In certain markets, policy-driven substitution initiatives have begun reshaping input dependency by encouraging alternative material pathways, lowering embodied carbon intensity and altering the traditional cost equation for AAC production. These regulatory and material intersections are not peripheral concerns; they are central to understanding where competitive advantage will be earned or eroded over the forecast period.
Autoclaved Aerated Concrete (AAC) Market
On the demand side, the configuration of end-use adoption is evolving as construction priorities shift. Residential applications continue to reflect substantial demand, supported by housing activity cycles and the material's suitability for efficient wall systems. Commercial development contributes a distinct demand layer, where speed of assembly, weight reduction, and building performance specifications influence material selection. Infrastructure and industrial applications, while representing smaller share tiers in aggregate, introduce specialized requirements that reward product consistency, durability, and tailored engineering profiles. The report evaluates these demand streams not merely as volume contributors, but as strategic segments where specification influence, purchasing behavior, and competitive differentiation diverge meaningfully.
Competitive Landscape: Established Players, Regional Expansion, and Strategic Signaling
The competitive architecture of the AAC market reflects a blend of long-entrenched manufacturers, technology-and-licensing operators, distribution-centric participants, and newer entrants expanding capacity to capture demand momentum. In North America, the landscape is anchored by producers with substantial operational tenure and established supply relationships. One of the region's oldest manufacturers has built a multi-decade presence in AAC blocks and panels, reinforcing channel depth and regional familiarity. Alongside it, another significant North American supplier has sustained production and market participation for over two decades, contributing to a competitive base that values reliability and specification acceptance. More recent activity has also brought newer manufacturing capacity into the region, with production commencing in 2022, signaling that market growth is attracting additional investment rather than consolidation alone.
In Europe, the competitive picture is shaped by a mix of manufacturers, structural system suppliers, and technology providers operating through licensed plant networks. A major Northern European producer has established scale across Estonia and Latvia, positioning itself as a leading regional manufacturer of blocks and panels. In Poland and broader Eastern Europe, additional producers are reinforcing regional supply, while in the UK, a manufacturer and supplier continues to extend structural wall system offerings across domestic and international channels. Technology-and-licensing operators also play an important role, enabling production capacity beyond the boundaries of vertically integrated manufacturers and expanding the market's geographic reach through partnership-based models.
Asia introduces a different dynamic, characterized by capacity expansion and diversified participation. In India, the sector has seen meaningful manufacturing scale-up, with one major producer completing a phased capacity expansion to a substantial annualized volume for blocks, bricks, and panels. Another significant player has moved into AAC production through a dedicated product line launched in 2025, reflecting the strategic use of broader cement and building materials portfolios to enter or deepen participation in lightweight concrete segments. Additional Indian manufacturers continue to build out block and panel output, underscoring the region's role as a focal point for both volume growth and operational scaling.
Distribution-focused participants further complicate and enrich the competitive fabric. In several markets, distributors act as critical intermediaries, sourcing and supplying AAC blocks and panels to construction projects where manufacturing presence may be limited or where project-specific procurement logistics favor intermediary scale. This dual structure—manufacturers building capacity and distributors extending reach—creates multiple pathways for market participation and complicates simplistic views of competitive intensity. The report evaluates these roles in context, highlighting where manufacturing control, technology licensing, or distribution capability constitutes the more decisive strategic asset.
Strategic Implications for 2026 Planning
For organizations entering 2026 with AAC exposure or considering it, the strategic implications fall into several priority areas. First, the growth trajectory justifies disciplined capacity and supply chain planning, but only when paired with segment-specific demand intelligence. Broad market growth does not automatically translate into uniform opportunity across product types or application verticals. Decisions regarding which formats to prioritize, which applications to target, and where to locate or expand production should be informed by the segmentation patterns revealed in the full study.
Second, competitive positioning will increasingly depend on how well firms manage the tension between demand tailwinds and input cost variability. Companies that can stabilize cost structures, optimize formulation strategies, or align sourcing with regional pricing behavior will be better positioned to preserve margins while scaling. Similarly, firms that understand where regulatory and certification pressures are converting into procurement preference will be able to align product specifications and marketing positioning more effectively.
Third, the competitive landscape suggests that market access is not uniform. In some regions, established manufacturing presence, specification history, and channel relationships create meaningful barriers. In others, licensed production models, distributor networks, and new capacity additions are loosening those barriers and opening room for strategic entry. Evaluating which pathway is most viable—direct manufacturing, technology partnership, or distribution alignment—requires a clear view of regional saturation, demand cadence, and incumbent behavior, all of which are examined in depth in the complete report.
Closing Perspective: The Case for Full Intelligence
The AAC market is entering a phase in which strategic advantage will belong to those who can interpret momentum with precision rather than approximation. The headline growth path outlines an attractive opportunity, but the real decision architecture lies beneath it: in the interplay of segment concentration, regional heterogeneity, regulatory pacing, input cost volatility, and competitive maneuvering. This research is built to expose those layers systematically, giving leadership teams a structured basis for planning capital, refining product strategy, and choosing where to commit operational resources.
The analysis presented here is intended as a strategic preview. It establishes the scale, direction, and structural logic of the market, and it highlights the operational realities that will shape execution in 2026 and beyond. For the full segmentation breakdown, regional demand mapping, competitive benchmarking detail, and the complete forecast tables that support internal modeling, we invite you to access the full report. The complete study provides the depth required to convert market visibility into concrete, defensible action.
Worldwide Cellular Concrete Market
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrofusion Fittings Market to Reach $2.18B by 2032, 6.99% CAGR
By PW Consulting, 2026-09-16
Strategic Intel: Why the Electrofusion Fittings Market Outlook Matters for 2026 Decision-Makers
As infrastructure priorities shift toward resilience, safety, and faster deployment, the electrofusion fittings market is entering a decisive phase for capital allocation and product strategy. Our latest market research unpacks the commercial dynamics shaping polyethylene (PE) joining systems across water, gas, industrial, and emerging energy applications. This overview frames the strategic value of the study for executives planning 2026 investments, while pointing toward the full report for the granular intelligence needed to act with precision.
From Recovery to Sustained Expansion: Quantifying the Opportunity
The global electrofusion fittings market has moved beyond post-pandemic normalization into a structured growth trajectory. Revenue climbed steadily from 2020 through 2025, reaching a base of approximately 1,360.0 million USD, and our forecast model projects continued expansion at a compound annual growth rate of 6.99 percent through 2032. The trajectory is not uniform: near-term growth reflects catch-up installation activity, infrastructure replacement programs, and steady procurement cycles, while the later forecast years indicate a compounding effect driven by material substitution, stricter leakage standards, and expanding utility networks.
For corporate planners, this shape matters. It signals that the market is large enough to justify dedicated go-to-market investment, yet segmented enough that broad-brusf strategies will leave margin on the table. The study maps where value is accumulating, how growth is distributed across product families and end uses, and which regions are converting demand into durable procurement patterns. Rather than presenting static snapshots, the analysis connects historical momentum to forward-looking scenarios so leadership teams can pressure-test revenue assumptions against realistic adoption curves.
What the Study Delivers: Operational Intelligence, Not Just Headlines
A market overview can confirm direction; only a structured research product can translate direction into operational choices. This report is built around decision-ready modules that cover the full electrofusion fittings value chain and the commercial environment surrounding it.
- Market sizing and forecast framework covering historical performance through 2025 and a detailed outlook from 2026 to 2032, expressed in consistent USD million terms for executive modeling.
- Segment-level analysis across fitting types and application categories, identifying where demand concentrates, where substitution risk is higher, and which product families show the strongest pricing and volume dynamics.
- Regional evaluation that distinguishes mature distribution markets from high-growth territories, highlighting procurement habits, channel structures, and local compliance influences.
- Competitive landscape profiling of leading manufacturers and suppliers, with attention to product ranges, certification positioning, equipment ecosystems, and recent commercial moves.
- Industry dynamics including regulatory updates, labor availability pressures, raw material volatility, standardization activity, and application-level installation trends that shape both cost structures and project timelines.
The report also integrates recent developments that can alter short-term competitive positioning. These include refreshed product catalogs, updated generic joining procedures, new fitting launches with transition couplings and threaded options, and exhibition-level visibility around hydrogen distribution use cases. By placing such events inside the broader market framework, the study helps teams separate signal from noise and anticipate which developments are likely to affect procurement, specification, or channel behavior in 2026 and beyond.
Competitive Landscape: How Leading Players Are Shaping the Field
The electrofusion fittings market is not dominated by a single universal solution provider; it is shaped by a set of specialists, regional strongholds, and application-focused suppliers. The research profiles companies that are actively influencing specification, availability, and quality expectations across water, gas, and industrial piping systems.
Electrofusion Fittings Market
Plasson Ltd. continues to reinforce its position through PE100 electrofusion fittings and related fusion equipment for water, gas, and industrial piping, alongside an updated 2026 catalog and tooling listings. This kind of catalog refresh matters because it signals active product stewardship and keeps specifiers current on couplers, tees, elbows, and saddles. Georg Fischer Central Plastics Company remains relevant for pressure applications by supplying HDPE electrofusion fittings aligned with ASTM F1055, supported by training materials and large-diameter options that appeal to processors seeking repeatable parameter setting. Integrity Fusion Products has carved out a recognizable niche with its IntegriFuse brand HDPE electrofusion couplers across multiple diameter ranges and SDR options, emphasizing injection-molded, pressure-rated construction and controlled quality standards.
International and regional suppliers add further differentiation. Radius Systems Limited specializes in electrofusion fittings and welding equipment for PE pipe systems and supports generic fusion procedures for municipal and industrial work. Pipelife International has expanded visibility for its GeoFusion couplers and fittings, including reduced-cycle-time models with substantial deployment in Europe, an indicator of how installation speed can become a competitive differentiator. Agru Kunststofftechnik GmbH supplies couplers and saddles for pressure and drainage applications, while Egeplast focuses on pressure-rated HDPE electrofusion products for water and gas distribution. Strongbridge Inc. emphasizes large-diameter capability with offerings up to 63 inches and high-pressure classes, targeting projects where fitting performance under demanding service conditions is critical. Kimplas Piping Systems Private Ltd., operating within NORMA Group, demonstrates how electrofusion fittings can become integral to large-scale gas distribution supply chains, with significant annual unit volumes supporting British gas distribution projects.
Recent corporate and sector developments reinforce the strategic relevance of these profiles. Updated catalog releases, the approval of revised generic electrofusion joining procedures, new product introductions featuring steel-PE transition couplings and thread options, and high-profile exhibition activity around hydrogen distribution all point to a market where product specifications, installation standards, and application expansion are evolving together. The full study examines how such developments influence competitive positioning rather than treating them as isolated news items.
Market Dynamics: The Forces That Will Define 2026 Execution
Growth rates and market size are necessary context, but the practical challenges of 2026 will be determined by the environment in which fittings are specified, manufactured, and installed. The research integrates multiple dynamic factors that affect cost, speed, compliance, and competitive differentiation.
Installation discipline is receiving renewed attention. The approval of the third edition of MAB-1 in late 2025 establishes a more uniform electrofusion joining procedure for PE pipe installations in the field, which can reduce variability across contractors and improve specification confidence for utilities and engineering teams. At the same time, standardization activity continues to shape equipment and process expectations, including updated performance requirements for electrofusion control units used with polyethylene fittings. These moves do not simply adjust paperwork; they influence which products are easier to specify, which installation crews can work more efficiently, and how manufacturers position training and support.
Labor constraints remain a practical brake on project execution. In 2025, a significant share of utility contractors reported difficulty finding qualified workers for specialized processes such as electrofusion, contributing to project delays. This environment raises the strategic value of fittings and equipment that reduce installation complexity, support faster cycle times, and fit more cleanly into trained workforces. Suppliers that align product design with field usability can convert labor scarcity into a competitive advantage rather than treating it as an external inconvenience.
Input cost volatility also demands attention. Polyethylene resin price fluctuations have been material, with manufacturers reporting substantial variability that affects electrofusion fittings production economics. When resin costs move sharply, pricing discipline, inventory strategy, and product mix decisions become more important than headline volume growth. The study places these cost dynamics alongside segment and regional data so planners can evaluate where margin resilience is strongest and where exposure needs active management.
Application-level momentum further shapes the outlook. In Europe, gas distribution projects installed a markedly higher number of electrofusion joints in 2024 compared with the prior year, reflecting continued investment in pipeline infrastructure and replacement activity. Equally notable is the growing visibility of electrofusion solutions in emerging energy contexts, where distribution-focused projects are beginning to explore PE-based joining for new fluid transport needs. These trends broaden the conversation beyond traditional water and gas pipelines and invite suppliers to think in terms of application expansion rather than static category boundaries.
What Is Held Back—and Why Full Access Changes the Decision
The executive preview above establishes direction, but it deliberately omits the precise splits that conversion planning requires. The full report provides the detailed segmentation data across fitting types, application categories, and regions, along with the numerical market values that support forecasting, channel planning, and scenario modeling. It also includes the structured competitive profiles and recent-devaluation timeline needed to benchmark positioning, anticipate specification shifts, and assess where supplier moves are likely to influence procurement behavior.
Electro-fusion Coupler Market
This design is intentional. High-level growth narratives can inform strategy, but they cannot replace the segmented intelligence required to answer questions such as where demand is most durable, which product families show the strongest pricing power, how regional procurement differs in practice, and which competitor actions warrant a response in 2026. By offering the framework in this preview and reserving the detailed numbers and segmentation for the complete study, we create a clear path from awareness to action.
How to Use This Research for 2026 Planning
For product leaders, the study supports portfolio decisions by connecting segment dynamics to realistic demand patterns and competitive responses. For commercial teams, it helps prioritize regions and channels where procurement behavior is most likely to reward focused investment. For operations and supply chain planners, it frames the impact of resin volatility, labor constraints, and installation standardization on cost and delivery assumptions. For corporate development and investor relations, it provides a defensible market structure that links historical performance to forward projections through 2032.
The report is not intended as a passive reference document. It is structured to support scenario testing: what happens if installation standardization accelerates adoption in one region, if labor scarcity pushes buyers toward faster-cycle products, if resin volatility reshapes margin expectations, or if new application areas expand the addressable market beyond current boundaries. Each of these questions benefits from the segmentation and competitive context held in the full study.
Accessing the Complete Intelligence
If your 2026 planning depends on knowing not just that the market is growing, but where the value is accumulating and how competitors are positioning themselves, the full Electrofusion Fittings Market research provides the detail required to move from strategy to execution. The complete report contains the segmentation figures, regional evaluations, company profiles, and dynamic-factor analysis needed to build more precise forecasts, allocation plans, and competitive responses. The overview presented here is designed to establish credibility and context; the full intelligence is where confident decisions are made.
For detailed analysis of this topic, please visit the official page: Electrofusion Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air Source Heat Pumps Market Hits $49.2B in 2025, Forecast 7.2% CAGR to 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value in the Air Source Heat Pumps Market: Why 2026 Decisions Require Premium Intelligence
The global air source heat pumps market is entering a decisive growth phase, with total industry revenue projected to surpass USD 51.64 billion in 2026 and continue its upward trajectory toward an estimated USD 80.45 billion by 2032. This sustained expansion, driven by a compound annual growth rate of 7.2 percent across the forecast horizon, reflects a structural pivot in building decarbonization, energy security imperatives, and rapid electrification of thermal systems. For executives, investors, and market strategists, navigating this landscape requires more than headline figures. It demands precise, forward-looking intelligence that translates macroeconomic momentum into actionable market positioning.
Our latest comprehensive study on the air source heat pumps market is purpose-built for that reality. Serving as both a baseline diagnostic and a strategic roadmap, the report equips leadership teams with the analytical rigor necessary to allocate capital, refine product portfolios, anticipate regulatory inflection points, and outperform in an increasingly competitive manufacturing and distribution ecosystem. This overview demonstrates how the study translates complex market signals into operational intelligence, while preserving the granular breakdowns that only the full publication delivers.
The Macro Trajectory: Translating Historical Momentum into 2026–2032 Decision Frameworks
The market has evolved from an estimated USD 34.25 billion in 2020 to USD 49.2 billion in 2025, demonstrating consistent year-over-year expansion across a period marked by volatile energy pricing, tightening carbon mandates, and early-stage electrification incentives. The forecast period from 2026 through 2032 maps a deliberate acceleration curve, with annual revenue crossing USD 60.96 billion by 2028 and reaching USD 71.25 billion by 2030. Such progression is not uniform across product architectures, application segments, or geographic territories. Rather, it emerges from converging technology maturation, regional policy differentiation, and supply chain realignment.
Strategic decision-making in 2026 hinges on recognizing that historical growth is not merely descriptive; it is diagnostic. The baseline trajectory reveals how capacity investments, refrigerant transitions, and installer ecosystem readiness have compounded over the past half-decade. Our report contextualizes these dynamics within a structured analytical framework, enabling clients to identify where volume expansion will be concentrated, which technological pathways will command pricing premiums, and how regional policy cycles will influence uptake velocity. The full publication contains the detailed decomposition required to align corporate roadmaps with these shifting demand vectors.
Regulatory and Technology Inflection Points Reshaping Competitive Positioning
Market expansion is being simultaneously accelerated and recalibrated by a wave of regulatory and technological shifts. The EU F-Gas regulation mandates a global warming potential below 150 for new split air conditioning and heat pump equipment starting in 2027, compelling manufacturers to accelerate migration toward low-GWP refrigerants such as R32 and R290. In the United States, the Department of Energy finalized amended energy conservation standards for air-cooled commercial package air conditioners and heat pumps, with compliance becoming effective January 1, 2029. Meanwhile, Japan revised its HFC quota management framework in 2025, pushing R-410A costs upward by more than three times relative to R-32, fundamentally altering regional cost structures and product planning.
These regulatory vectors are intersecting with proactive industrial initiatives. Mitsubishi Electric Corporation committed USD 143.5 million to retrofit a U.S. manufacturing facility for variable-speed compressor production, targeting an October 2027 operational start. Simultaneously, the New England Heat Pump Accelerator introduced a USD 450 million program designed to supercharge cold-climate air source heat pump adoption through midstream incentives, reducing per-unit deployment costs by USD 500 to USD 700. In the Northeast high-performance HVAC market, air source heat pumps now account for 32 percent of residential HVAC equipment demand, underscoring how regional specialization is reshaping equipment mix and channel economics.
Our report dissects how these interventions alter competitive advantage. It evaluates the timing of compliance deadlines against product development cycles, assesses the commercial implications of midstream incentive architectures, and projects how refrigerant pathway decisions will influence long-term serviceability, component sourcing, and after-market economics. Executives seeking to prioritize R&D investments, align capacity additions, or restructure commercial partnerships will find the regulatory impact mapping essential to avoiding stranded investments and capturing first-mover advantage in transitioning segments.
Competitive Landscape: Consolidation Dynamics and Strategic Differentiation
The market exhibits meaningful concentration, with the top three participants collectively commanding approximately 45.2 percent of industry revenue and the top five holding an estimated 62.8 percent share. Such concentration reflects decades of engineering heritage, cold-climate performance differentiation, inverter technology leadership, and global distribution scale. Yet concentration also masks rapid competitive evolution, as regional champions, technology specialists, and vertically integrated appliance manufacturers expand their footprint through targeted product launches and strategic capacity investments.
Prominent market participants include Daikin Industries, Ltd., recognized for high-efficiency inverter platforms and cold-climate monobloc and split solutions spanning residential and commercial applications; Mitsubishi Electric Corporation, distinguished by ductless and multi-split systems with Hyper-Heating technology and variable refrigerant flow architectures; and Carrier Global Corporation, offering residential and commercial platforms built around Infinity and Greenspeed inverter technology. Trane Technologies plc delivers broad split-system and packaged offerings with high-efficiency inverter configurations. From the Asian manufacturing corridor, LG Electronics, Inc. and Samsung Electronics Co., Ltd. contribute air-to-air and air-to-water lines emphasizing high coefficient of performance and residential-to-light-commercial versatility. Gree Electric Appliances Co., Ltd. and Fujitsu General Limited reinforce efficiency-focused residential and commercial portfolios, while Hitachi, Ltd. and Panasonic Corporation maintain established residential and light-commercial heat pump lines. In Europe, Bosch Thermotechnology GmbH markets air-to-air and air-to-water platforms under multiple brand architectures, and NIBE Industrier AB specializes in cold-climate residential heating and domestic hot water systems.
The competitive analysis within our report goes beyond corporate profiling. It evaluates how product architecture focus, refrigerant strategy, cold-climate engineering capability, and regional manufacturing footprint translate into share resilience or vulnerability under evolving standards. The full document provides the comparative benchmarking, segment positioning matrices, and strategic response scenarios required to assess partnership opportunities, potential acquisition targets, and defensive positioning in high-growth sub-segments.
What the Full Study Delivers: Operational Intelligence for Strategy, Capital, and Execution
This market research is engineered to support end-to-end strategic execution. It combines quantitative forecasting, structural segmentation, regulatory mapping, and competitive intelligence into a unified analytical platform. The publication is structured to help leadership teams answer the questions that determine 2026 success: where demand growth will be most durable, which technology pathways will attract premium pricing, how regulatory timelines will reshape product economics, and which competitive moves will determine market access.
Key analytical dimensions include a comprehensive historical-to-forecast revenue trajectory, enabling clients to benchmark internal performance against market momentum and identify inflection points in demand expansion. The study presents rigorously defined segmentation architecture, allowing teams to isolate the segments with the strongest growth elasticity, highest margin potential, and most favorable policy tailwinds. Regional demand mapping clarifies where capacity deployment, distributor expansion, and service infrastructure investment will generate the highest strategic return. Competitive profiling and concentration analysis equip strategists with the intelligence required to anticipate share shifts, evaluate barrier-to-entry dynamics, and refine go-to-market positioning.
Worldwide Absorption Heat Pumps Market
Beyond structural analysis, the report integrates forward-looking operational considerations. It assesses how midstream incentive frameworks alter installed-cost economics and influence buyer behavior. It maps the timing and commercial implications of refrigerant transitions relative to product lifecycles and component supply chains. It examines how efficiency standard revisions will affect competitive parity across residential and commercial equipment categories. These elements are synthesized into scenario-based guidance, enabling decision-makers to test strategic assumptions against plausible regulatory and market pathways rather than relying on static projections.
The full study also provides the detailed quantitative backing necessary for internal validation. Executive teams can use the underlying decomposition to align sales forecasting, production planning, channel investment, and R&D prioritization with verified market trajectories. Investors and corporate development professionals gain a structured basis for evaluating segment attractiveness, competitive durability, and capital allocation efficiency across the forecast horizon.
Strategic Imperatives for 2026: Aligning Decision-Making with Market Reality
As the market advances toward the 2026 revenue milestone and continues its expansion through the early 2030s, several strategic imperatives will separate resilient players from reactive competitors. First, product planning must integrate refrigerant pathway decisions with long-term compliance timelines, ensuring that portfolio architectures are aligned with low-GWP migration without sacrificing performance or service economics. Second, capacity and manufacturing investments need to account for variable-speed compressor demand, cold-climate performance requirements, and regional standards timelines, particularly as major industrial retrofits reshape supply availability. Third, commercial strategy should recognize that incentive structures and regional policy momentum create uneven demand curves, requiring differentiated market entry, pricing, and channel approaches rather than uniform global execution.
Fourth, competitive positioning must reflect the reality that concentration masks rapid product-level and segment-level disruption. Organizations that depend solely on historical share as a proxy for future resilience risk underestimating the impact of efficiency standards, cold-climate performance differentiation, and regional technology convergence. The companies that will capture disproportionate value are those that combine engineering discipline with proactive regulatory anticipation and flexible commercial architecture.
Our report is designed to support each of these imperatives. It provides the analytical scaffolding necessary to convert high-level market growth into detailed strategic action, while preserving the proprietary breakdowns, comparative matrices, and scenario analyses that require full access to the publication. Readers evaluating the air source heat pumps opportunity for capital deployment, product planning, M&A assessment, or channel expansion will find the complete study essential for informed, forward-looking decision-making.
Air Source Heat Pumps Market
Next Steps: Accessing the Full Intelligence Architecture
The macro trajectory, regulatory shifts, competitive concentration, and incentive dynamics described here represent only the entry point to a far more granular analytical framework. The complete market study delivers the segment-level resolution, regional demand mapping, competitive benchmarking, and scenario-based forecasting required to translate market momentum into executable strategy. For organizations preparing 2026 investment decisions, portfolio adjustments, or market-entry plans, the full report provides the evidence base needed to prioritize with confidence and act ahead of inflection points.
Access the complete analysis to obtain the detailed market size decomposition, strategic segmentation insights, competitive positioning frameworks, and forward-looking regulatory impact assessments that will shape your 2026–2032 decision architecture.
For detailed analysis of this topic, please visit the official page: Air Source Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Tourism Hits $267B in 2025, Projects 6.5% CAGR to $414.6B by 2032
By PW Consulting, 2026-09-16
The Blue Horizon: Strategic Intelligence for the Marine Tourism Market in 2026
The global marine tourism sector stands at a critical inflection point. As we navigate the economic landscape of 2026, the industry is not merely recovering from past disruptions but is fundamentally reshaping its operational DNA. For stakeholders, investors, and enterprise leaders, understanding the nuance of this transformation is no longer optional—it is a prerequisite for survival and growth. PW Consulting's latest Market Research Report on the Marine Tourism Market offers a comprehensive lens through which to view these shifting tides, providing the granular intelligence necessary to steer strategic decisions through 2032.
This analysis serves as a strategic overview of the market dynamics, competitive forces, and regulatory pressures defining the sector. While we highlight the magnitude of the opportunity here, the full depth of our proprietary data—down to the specific growth vectors and regional nuances—is reserved for our detailed report. The following insights set the stage for why immediate access to this intelligence is vital for your 2026 planning cycle.
Market Trajectory: Navigating the Growth Curve
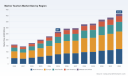
The marine tourism industry has demonstrated remarkable resilience and expansion over the last half-decade. Our longitudinal analysis tracks the market's evolution from 2020 through the base year of 2025, revealing a robust trajectory that defies broader economic volatility. In 2020, the market valuation stood at approximately 160.5 billion USD. Despite the headwinds of that period, the sector rebounded sharply, recording a valuation of 172.9 billion USD in 2022 and surging to 201.14 billion USD by 2023.
By the base year of 2025, the overall market size reached a significant milestone of 267.0 billion USD. This growth underscores a renewed consumer appetite for experiential travel and coastal leisure activities. Looking forward, the forecast period from 2026 to 2032 projects a continued upward climb. We estimate the market will value at 292.75 billion USD in 2026, eventually reaching 414.6 billion USD by 2032.
This expansion is driven by a Compound Annual Growth Rate (CAGR) of 6.5 percent. For enterprise strategists, this figure represents more than just numerical growth; it indicates a sustained period of investment opportunity and market consolidation. The steady rise from 2024's 228.87 billion USD to 2025's 267.0 billion USD suggests that the baseline for future projections is stronger than previously anticipated. However, capturing this value requires more than general optimism; it demands precise alignment with the high-growth segments identified in our full report.
Segmentation Insights: Where Value Converges
While the aggregate numbers are compelling, the true strategic value lies in understanding how value is distributed across different operational types and application streams. The market is not a monolith; it is a complex ecosystem where revenue concentration varies significantly by activity and service delivery.
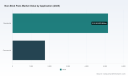
Our segmentation analysis breaks down the market by type, revealing distinct performance tiers among activities such as Yachting and Sailing Tourism, Cruise Tourism, Water Sports, and Other Types. Similarly, revenue generation is dissected by application, including Passenger Ticket Sales, On-board Services and Amenities, and Other Revenue Sources. The disparity in revenue volumes across these categories highlights where the current capital flow is concentrated and where emerging opportunities may lie dormant.
Furthermore, geographic segmentation provides a heatmap of global demand. The market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents unique regulatory environments, consumer behaviors, and infrastructural capabilities. For a multinational operator, understanding the relative weight of these regions is crucial for resource allocation. Our report details these regional splits without relying on broad assumptions, offering instead specific data points that correlate regional performance with local economic indicators.
To fully leverage these segmentation splits, stakeholders must look beyond the totals. The interplay between specific types and applications often reveals hidden efficiencies or untapped markets. We encourage readers to consult the complete segmentation tables in the full study to identify the specific niches that align with their core competencies.
Marine Tourism Market
Competitive Landscape: The Titans and the Challengers
The marine tourism market is characterized by a high degree of concentration, with a few dominant players exerting significant influence over pricing, standards, and consumer expectations. Our analysis identifies a core group of key companies that define the competitive perimeter. Understanding their strategic positioning is essential for any new entrant or existing player looking to expand market share.
In the cruise sector, major operators headquartered in Miami, Florida, United States, hold substantial sway. Carnival Corporation, through its multiple cruise lines including Carnival Cruise Line, provides large-scale marine-based passenger tourism experiences that cater to mass markets. Similarly, Royal Caribbean Group delivers contemporary marine tourism with a strong emphasis on family and adventure voyages, while Norwegian Cruise Line Holdings Ltd. distinguishes itself through Freestyle cruising and large ocean cruises. Across the Atlantic, MSC Cruises S.A., based in Geneva, Switzerland, operates Mediterranean and ocean cruises focused on marine tourism, leveraging its strong presence in European waters.
Contrasting the mass-market cruise giants are the specialized charter providers who cater to the high-end and recreational segments. Dream Yacht Worldwide, based in the United Kingdom, stands as a leading provider of yacht and boat chartering for recreational marine tourism and private charters. The Moorings, headquartered in the United States, supplies catamaran and yacht charters for specific marine tourism experiences. Complementing this landscape is Sunsail, also based in the United Kingdom, which provides sailing yacht and catamaran rentals. These companies illustrate the bifurcation in the market between volume-driven cruise operations and experience-driven charter services.
Worldwide Marine Interiors Market
The concentration of market power is notable. Data indicates a high level of consolidation among the top players, suggesting that barriers to entry remain significant for smaller operators unless they can carve out specialized niches. Our report provides a detailed profile of these companies, examining their recent moves, capacity expansions, and strategic pivots. Understanding the specific offerings and strategic focus of these entities allows competitors to identify gaps in the market offerings.
Industry Dynamics: Regulation, Sustainability, and Policy
The operational environment for marine tourism in 2026 is heavily influenced by regulatory frameworks and sustainability mandates. The industry is no longer operating in a vacuum; it is subject to intensifying scrutiny regarding its environmental footprint and its impact on coastal communities. This dynamic creates both compliance costs and strategic opportunities for leaders who can pivot early.
On the regulatory front, the FuelEU Maritime Regulation requires cruise ships to reduce greenhouse gas emissions by 2 percent in 2025 and aims for an 80 percent reduction by 2050. Crucially, this mandates LNG and shore-side electricity for new vessels starting 2026. This regulation directly impacts capital expenditure planning for fleet operators. Simultaneously, the EU Strategy for Coastal Communities, announced in February 2026, seeks to boost economic growth, competitiveness, resilience, and adaptation for coastal tourism through energy independence and nature restoration. These policies signal a shift where sustainability is becoming a license to operate rather than a optional marketing feature.
Beyond Europe, global initiatives are gaining traction. In June 2025, organizations including the World Sustainable Hospitality Alliance, World Travel and Tourism Council, Travalyst, and UN Tourism launched the Ocean Tourism Pact to protect ocean ecosystems and promote sustainable coastal and marine tourism. This multi-stakeholder approach indicates a growing consensus on the need for standardized sustainability practices across the industry.
Regional governments are also stepping up. In January 2026, the Saudi Red Sea Authority launched the Introductory Guide to Coastal Tourism Activities, a digital gateway streamlining regulations and procedures for the sector. This move aims to reduce bureaucracy and encourage investment in one of the region's key growth areas. Earlier, in May 2025, the Sri Lanka Tourism Development Authority launched the Marine Tourism Roadmap to promote sustainable coastal and marine tourism development. These policy launches suggest that emerging markets are actively seeking to structure their marine tourism sectors to attract responsible investment.
Furthermore, the EU Blue Economy Observatory notes that climate change poses profound impacts on coastal tourism, requiring strengthened environmental standards under the Blue Growth strategy. For strategists, this means risk assessment must now include climate resilience modeling. Our report integrates these regulatory and policy developments into a broader dynamics section, helping firms anticipate compliance costs and identify regions where policy support favors growth.
Strategic Imperatives for 2026 Decision Makers
As we move through 2026, the convergence of market growth, competitive pressure, and regulatory change creates a complex decision matrix. Leaders must balance the pursuit of the projected 6.5 percent CAGR with the realities of emission mandates and shifting consumer preferences.
First, investment decisions must be data-backed. With the market moving from 292.75 billion USD in 2026 toward 414.6 billion USD in 2032, capital deployment needs to be targeted. Blind expansion into high-concentration segments may yield diminishing returns. Our report provides the segmentation granularity required to identify high-yield avenues without exposing firms to unnecessary risk.
Second, competitive positioning must be re-evaluated. With the top five players holding a significant share of the market, smaller firms must leverage agility and specialization. Whether through niche charter services or focused regional operations, differentiation is key. Understanding the specific profiles of competitors like Carnival Corporation or Dream Yacht Worldwide allows for strategic positioning that avoids direct head-on collisions where possible.
Third, sustainability is now a strategic pillar. The regulatory timeline set by FuelEU Maritime and the EU Strategy for Coastal Communities means that environmental compliance is a medium-term financial imperative. Firms that integrate these requirements into their 2026 planning will secure a competitive advantage in terms of operational continuity and brand reputation. The Ocean Tourism Pact and various national roadmaps further indicate that partnerships and adherence to global standards will become increasingly valuable.
Conclusion: Accessing the Full Intelligence
The marine tourism market offers substantial rewards for those equipped with the right intelligence. The trajectory from 160.5 billion USD in 2020 to a projected 414.6 billion USD in 2032 demonstrates the sector's potential. However, realizing this potential requires more than surface-level understanding. It demands a deep dive into regional splits, application-specific revenue streams, and the intricate competitive dynamics defined by key industry players.
PW Consulting's Marine Tourism Market Report is designed to provide this depth. It moves beyond aggregate numbers to offer actionable insights on segmentation, competitive profiling, and regulatory impact. The summary provided here outlines the strategic landscape, but the specific data points—regional percentages, application splits, and detailed company analysis—are critical for formulating precise business strategies.
For decision makers aiming to secure a advantageous position in this evolving market, accessing the full report is the next logical step. We invite you to explore the complete dataset and strategic recommendations available on our platform. In a market defined by wave-like volatility and clear long-term growth, ensure your ship is steered by the best possible navigation tools.
For detailed analysis of this topic, please visit the official page: Marine Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Non-Stick Pans Market to Hit $11.9B by 2032 with 8.27% CAGR
By PW Consulting, 2026-09-16
Navigating the Non-Stick Pans Market: Strategic Intelligence for 2026 and Beyond
The global cookware industry stands at a critical inflection point. As consumer preferences shift toward healthier living, regulatory frameworks tighten around chemical safety, and material innovation accelerates, the non-stick pans market has emerged as a dynamic battleground for established manufacturers and emerging disruptors alike. This comprehensive market research report serves as an indispensable strategic compass for executives, product managers, and investors seeking to navigate the complexities of this evolving landscape through 2032.
Our analysis reveals a market characterized by robust growth trajectories, intensifying competitive pressures, and transformative supply chain dynamics. With a projected Compound Annual Growth Rate of 8.27 percent over the forecast period, the sector presents significant opportunities for stakeholders who can align their strategies with emerging consumer demands and regulatory realities. However, capturing these opportunities requires more than surface-level understanding. It demands deep, granular intelligence that only this report delivers.
Market Trajectory: From Recovery to Sustained Expansion
The historical data tells a compelling story of resilience and acceleration. Following a period of market stabilization between 2020 and 2025, the non-stick pans industry has demonstrated consistent revenue growth, building from approximately 4718.44 million USD in 2020 to an estimated 6915.35 million USD in 2025. This upward trajectory reflects not merely post-pandemic recovery patterns but fundamentally shifting consumer behaviors around home cooking, health consciousness, and premiumization trends.
Looking forward, our forecasts indicate that revenue will continue climbing through 2032, with the market expanding from an estimated 7576.05 million USD in 2026 toward the 11900.0 million USD range by the end of the forecast window. This growth is not distributed evenly across all segments or geographies. Premium segments featuring advanced coating technologies are outpacing traditional offerings, while certain regional markets exhibit faster adoption curves driven by urbanization, rising disposable incomes, and evolving culinary preferences. The report deconstructs these growth vectors with precision, enabling decision-makers to identify high-potential pockets of value creation.
Importantly, the research does not merely project numbers. It contextualizes them within broader macroeconomic indicators, raw material cost volatilities, and channel dynamics that will shape actual realized revenues. Stakeholders who rely on top-line projections alone risk making suboptimal allocation decisions. Our granular analysis illuminates the underlying drivers that will determine which companies capture disproportionate share of the expanding pie.
Segmentation Intelligence: Technology, Application, and Geography
One of the most valuable contributions of this report lies in its detailed segmentation framework. The market divides across multiple axes, each carrying distinct strategic implications for positioning, pricing, and channel strategy.
Non-stick Coatings Market
-
Coating Technology: The competitive landscape is shaped by divergent technology pathways, including traditional PTFE-based formulations, anodized aluminum surfaces, ceramic alternatives, and enameled iron options. Each technology carries unique cost structures, performance characteristics, regulatory exposure, and consumer perception profiles. Understanding the relative positioning and trajectory of each category is essential for R&D prioritization and portfolio optimization.
-
Application End-Use: Demand patterns vary considerably between residential and commercial users. Residential consumers prioritize aesthetics, ease of use, and health considerations, while commercial operators focus on durability, heat distribution, and total cost of ownership. The report quantifies these divergent demand drivers and maps them to actionable go-to-market strategies.
-
Geographic Distribution: Regional dynamics play a decisive role in shaping competitive advantage. Markets in North America, Europe, and Asia Pacific each present distinct regulatory environments, retail channel structures, brand loyalty patterns, and price sensitivities. The research unpacks these regional nuances without reducing them to simplistic rankings, offering instead a nuanced view of where and how to compete effectively.
To preserve the competitive advantage our clients derive from this intelligence, we deliberately withhold granular percentage splits and absolute revenue figures for individual segments in this preview. These details are reserved for the full report, where they are presented alongside cross-tabulated analysis, scenario modeling, and sensitivity assessments that reveal the full strategic picture.
Competitive Dynamics: A Fragmented Yet Concentrated Landscape
The non-stick pans market exhibits a fascinating duality. On one hand, market concentration metrics indicate that the top three players command approximately 35.0 percent of total revenue, while the top five firms control roughly 50.0 percent. This concentration suggests meaningful barriers to entry in certain segments and the presence of established brands with strong distribution networks and consumer recognition. On the other hand, the market remains sufficiently fragmented that nimble, innovation-driven challengers can carve out significant niches, particularly in premium and health-focused categories.
Several leading companies exemplify the strategic directions shaping the market. All-Clad, headquartered in Canonsburg, Pennsylvania, has reinforced its premium positioning through offerings like the NS Pro Ceramic line, which combines ceramic interiors with hard-anodized bodies and an EvenPro base designed for consistent everyday performance. Calphalon, based in St. Louis, Missouri, continues to leverage its reputation for hard-anodized non-stick surfaces that deliver even heating and durability across both sets and individual pan offerings. T-Fal, operating in North America as part of Groupe SEB, maintains a broad portfolio spanning hard-anodized and ceramic non-stick pans and pots engineered for easy food release and quick cleanup.
The competitive field also includes influential players pushing the boundaries of non-toxic offerings. GreenPan, with headquarters in the Netherlands and global operations, has built its brand around PFAS-free ceramic non-stick cookware, including the Valencia Pro and Dover series, positioning itself as a leader in toxin-free performance. Caraway, based in New York, markets ceramic-coated cookware sets explicitly framed as non-toxic alternatives to traditional coatings, appealing to health-conscious consumers. OXO, also headquartered in New York, offers ceramic professional non-stick pans such as the OXO Ceramic Professional Nonstick 10-inch Frying Pan, emphasizing scratch-resistant functionality. Additional brands like Anolon, Our Place, and HexClad contribute to a rich ecosystem of innovation, with the Always Pan from Our Place becoming a notable example of versatile non-stick cookware marketed with ceramic or innovative coatings, while HexClad pursues a hybrid approach blending non-stick coating with distinctive surface architectures.
Recent developments underscore the pace of strategic activity. In December 2025, All-Clad launched its NS Pro Ceramic non-stick cookware line, marking a deliberate push toward cleaner everyday cooking solutions. By April 2026, GreenPan expanded the retail availability of its ceramic non-stick cookware, including the GreenPan Dover and Bobby Flay Chef Series lines, signaling a concerted effort to broaden consumer access to PFAS-free options. These moves, among others detailed in the full report, illustrate how companies are actively responding to shifting demand signals and regulatory currents.
Non-Stick Pans Market
Regulatory and Consumer Tailwinds Reshaping the Industry
No strategic assessment of the non-stick pans market can overlook the profound impact of regulatory and consumer trends. The landscape has been fundamentally altered by actions targeting per- and polyfluoroalkyl substances, commonly known as PFAS, which have been used in various non-stick coatings. Minnesota became the first U.S. state to ban the sale of cookware coated with PFAS chemicals as of January 2025, with California, New York, and Connecticut following with similar legislative actions. These regulatory developments are not isolated events but part of an accelerating trend that will increasingly influence product formulation, labeling, and market access across multiple jurisdictions.
Consumer awareness of chemical exposure risks has risen sharply in parallel. A study from the University of North Carolina released in October 2025 linked cookware use to PFAS exposure while highlighting a retail shift toward PFAS-free ceramic non-stick options. This research, alongside updated testing by Consumer Reports in January 2026 showing that worn or scratched non-stick coatings can release PFAS chemicals into food, has intensified consumer scrutiny and reinforced demand for safer alternatives. Retailers, in turn, have responded by expanding PFAS-free non-stick options to meet growing consumer demand for safer cookware.
Regulatory concerns extend beyond PFAS. The FDA issued a warning in December 2025 regarding imported cookware that may potentially leach lead, a development particularly relevant to aluminum-based non-stick products. This alert underscores the importance of rigorous supply chain oversight and quality assurance for manufacturers sourcing materials and finished goods across international borders.
Raw material economics also factor heavily into competitive strategy. Sector analysis on retail pricing trends from 2026 indicates that ceramic non-stick coatings cost approximately twice as much as traditional PTFE-based non-stick coatings. For instance, an 8-inch GreenPan model priced at 19.96 USD compares against a 9.96 USD standard nonstick alternative. This cost differential shapes margin structures, retail pricing strategies, and the value proposition communicated to consumers. Companies must navigate these economics carefully, balancing premium positioning against affordability thresholds in their target segments.
What This Report Delivers: Actionable Intelligence for Decision-Makers
This market research report goes beyond high-level summaries to provide the depth and specificity required for confident strategic decision-making. The following elements represent core components of the analysis:
-
Comprehensive Market Sizing and Forecasting: Historical revenue data from 2020 through 2025 forms the foundation for detailed forecasts extending through 2032. Projections are built using robust methodology that accounts for historical trends, macroeconomic assumptions, regulatory impacts, and technology adoption curves.
-
Segment-Level Deep Dives: The report disaggregates market performance across coating types, application categories, and geographic regions. Cross-sectional analysis reveals interdependencies and migration patterns that inform product development roadmaps and resource allocation decisions.
-
Competitive Profiling and Benchmarking: Detailed profiles of key market participants, including their strategic positioning, product innovations, and recent developments, enable benchmarking against peer activities. Recent events such as product launches, retail expansions, and research-driven market shifts are integrated into the competitive analysis.
-
Regulatory and Compliance Landscape: An examination of current and emerging regulatory frameworks affecting non-stick cookware, including PFAS restrictions, lead leaching concerns, and import requirements. This section helps organizations anticipate compliance costs and adapt product formulations proactively rather than reactively.
-
Consumer Trend Analysis: Insights into shifting consumer preferences around health, sustainability, aesthetics, and performance. These trends inform packaging, branding, and marketing strategies that resonate with target audiences in different segments and geographies.
-
Supply Chain and Raw Material Considerations: Analysis of input cost dynamics, sourcing complexities, and manufacturing considerations that influence margin potential and competitive positioning. Understanding these factors is essential for pricing strategy and profitability planning.
-
Strategic Recommendations: Synthesized insights translated into actionable guidance for product strategy, market entry, expansion planning, and competitive response. These recommendations are grounded in the data and tailored to the specific challenges and opportunities facing stakeholders in this market.
Why This Intelligence Matters Now
The strategic stakes for 2026 and the years ahead have never been higher. Companies that enter this period with a clear, data-backed understanding of market dynamics will be better positioned to allocate capital efficiently, prioritize R&D investments, refine go-to-market strategies, and respond agility to regulatory and competitive shifts. Those that rely on outdated assumptions or incomplete data risk misallocating resources, missing emerging opportunities, or exposing themselves to compliance vulnerabilities.
The non-stick pans market is not a static arena. It is being reshaped by converging forces: technological innovation in coating materials, regulatory pressure on chemical safety, consumer demand for healthier and more sustainable products, and competitive intensity across both established and emerging brands. Success in this environment requires more than intuition. It requires rigorous analysis, forward-looking scenario planning, and a willingness to act on evidence rather than assumption.
This report is designed to equip stakeholders with precisely that capability. It provides the depth, context, and strategic framing necessary to make informed decisions that align with both near-term market realities and long-term growth trajectories. The full report contains the detailed data, segment breakdowns, regional analyses, and competitive assessments that form the foundation for confident strategic planning.
For executives and analysts seeking to position their organizations advantageously in the non-stick pans market, the insights contained in this research represent a critical resource. The complete analysis, including granular segmentation data, detailed company profiles, scenario models, and strategic recommendations, is available through our comprehensive report. We invite you to access the full document to gain the complete strategic intelligence needed to navigate the opportunities and challenges of this dynamic market landscape.
For detailed analysis of this topic, please visit the official page: Non-Stick Pans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Petroleum Needle Coke Market Hits $215M in 2025 With 6.7% CAGR Through 2032
By PW Consulting, 2026-09-16
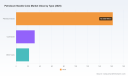
Navigating the Carbon Matrix: Strategic Imperatives in the Petroleum Needle Coke Market Through 2032
The global petroleum needle coke sector stands at a critical inflection point. As graphite electrode demand aligns with grid-scale steelmaking and lithium-ion battery supply chains accelerate, the underlying feedstock architecture is undergoing a structural realignment. For executives, procurement leaders, and capital allocators, the 2026–2032 horizon presents both margin compression risks and premium positioning opportunities. This guide synthesizes the core market architecture, competitive vectors, and operational dynamics that will shape strategic decision-making in the coming cycle. It is designed to function as a strategic compass—grounded in verified market trajectories, yet deliberately scoped to preserve the granular intelligence required for enterprise-grade execution.
Macro Trajectory: Navigating a 6.7% CAGR Across a Reshaped Demand Base
Over the 2020–2025 historical window, the petroleum needle coke market expanded from approximately 163.15 million USD to 215.0 million USD, reflecting a compound trajectory driven by electrode manufacturing intensification and the early-stage integration of battery-grade carbon materials. The forward arc, projected through 2032, extends this momentum with a steady CAGR of 6.7 percent, carrying the aggregate valuation toward the mid-340 million USD range by the close of the forecast period. This growth is not merely linear accumulation; it is structurally uneven, shaped by feedstock pricing volatility, regional capacity recalibration, and a widening divergence between traditional graphite electrode applications and emerging energy storage pathways.
The base year of 2025 serves as a calibration anchor, capturing post-restriction market normalization and the initial absorption of environmental compliance investments. From 2026 onward, the expansion curve reflects compounding capacity additions, qualification cycles for lower-carbon coke variants, and the gradual migration of high-performance anode materials into mainstream battery architectures. Decision-makers evaluating capex timing, supplier diversification, or vertical integration must anchor their models to this trajectory while recognizing that the underlying segmentation shifts will dictate where value actually accrues.
Importantly, the market’s concentration profile underscores a highly consolidated supply environment. A small cohort of integrated producers commands the majority of electrode-grade and battery-grade output, creating both pricing discipline and vulnerability to localized operational disruptions. Understanding how this concentration interacts with regional regulatory acceleration and feedstock availability is essential for anyone mapping supply chain resilience or negotiating long-term tolling and offtake arrangements.
Segmentation Architecture: Where Volume Meets Value
The market’s structural composition reveals three interlocking dimensions that collectively determine margin exposure and growth velocity. The type split highlights the dominance of petroleum-derived needle coke relative to coal-based and other variants, with petroleum routes capturing the bulk of premium-grade electrode and anode production. This hierarchy is not static; it is being actively reshaped by lifecycle emissions considerations, feedstock accessibility, and processing maturity.
Application-wise, graphite electrodes continue to anchor the largest share of consumption, reflecting their entrenched role in electric arc furnace steelmaking and specialty carbon applications. Simultaneously, lithium-ion battery usage represents a smaller but rapidly scaling segment, driven by anode material innovation and the push for higher energy density and faster charge cycles. The remaining application pool serves niche industrial and composite manufacturing requirements.
Regional dispersion further complicates the picture. Supply and demand nodes span North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, each exhibiting distinct consumption intensity, regulatory posture, and feedstock logistics. Capacity additions, export flows, and localized compliance requirements interact to create pockets of tightness and surplus that rarely align with headline aggregates. For strategic planning, this means that aggregate sizing alone is insufficient; the actionable intelligence lies in how segment dynamics intersect with regional supply constraints, qualification lead times, and downstream manufacturing capacity pipelines.
Competitive Landscape: Integrated Producers, Strategic Moves, and Positioning Vectors
The competitive field is defined by a mix of refinery-integrated operators, specialty coke producers, and regionally anchored suppliers whose processing capabilities and customer qualification networks determine market access. Several entities stand out for their operational footprint, product-grade versatility, and recent strategic interventions.
- Phillips 66 Company (Houston, Texas, United States) operates through integrated delayed-coking infrastructure, including its Lake Charles refinery complex, delivering both electrode-grade and battery-grade material. Its recent trajectory reflects a deliberate alignment with energy storage demand, underscored by a multi-hundred-million-dollar capacity expansion in Louisiana and a long-term supply agreement supporting a large-scale graphite-anode plant in North Carolina.
- GrafTech International Ltd. (Brooklyn Heights, Ohio, United States) maintains a vertically integrated supply position via its Seadrift facility, serving ultra-high-power graphite electrode and specialty carbon markets. Its product portfolio expansion into lower-carbon needle coke variants signals a strategic response to demand-side environmental qualification requirements.
- ENEOS Corporation (Tokyo, Japan) leverages Japanese refining and coking assets to produce premium petroleum-based needle coke, supplying graphite electrode and battery anode manufacturers with a focus on consistent grade quality and reliability.
- Seadrift Coke L.P. (Seadrift, Texas, United States) converts Gulf Coast refinery residues into petroleum needle coke, supported by calcination capability for anode-grade material and a logistics profile aligned with North American downstream demand.
- Petrocokes Japan Ltd. (Tokyo, Japan) operates within the Sumitomo Corporation group ecosystem, concentrating on electrode and specialty applications with a regional supply orientation.
- C-Chem Co., Ltd. (Japan) serves regional electrode manufacturers, maintaining a focused production profile aligned with Asian downstream manufacturing needs.
- Chinese Petroleum & Chemical Development Company (CPCDC) (Taiwan) supports regional graphite electrode supply chains, positioning itself within East Asian demand networks that continue to scale electrode consumption.
Beyond individual profiles, the competitive vector is increasingly shaped by three operational levers: capacity expansion timing, feedstock flexibility, and product qualification for lower-emission or recycled-feedstock routes. Recent industry developments illustrate this shift. Capacity investments are being directed toward battery-grade output streams; product launches are emphasizing reduced lifecycle carbon intensity through alternative feedstock blending; and long-term supply agreements are locking in offtake for anode-scale manufacturing footprints. These moves are not isolated. They signal a market where incumbent positioning will be tested by the ability to secure consistent aromatic-rich feedstocks, navigate qualification cycles, and align with downstream decarbonization mandates.
Market Dynamics: Feedstock Volatility, Regulatory Pressure, and the Petroleum Advantage
The operating environment is defined by a set of interacting forces that repeatedly reshape cost structures, capacity utilization, and product-grade competitiveness.
- Feedstock volatility remains a primary margin variable. Petroleum needle coke production depends on highly aromatic decant oil and pitch feedstocks, and the price behavior of these streams is closely tied to crude oil and coal tar market fluctuations. FCC decant oil, derived from slurry oil after particle removal, serves as the primary aromatic-rich feedstock, making refinery throughput patterns and slurry handling economics directly relevant to coke cost curves.
- Environmental regulation is actively restructuring supply geography. Stricter regulatory frameworks in China have constrained a meaningful share of graphite electrode capacity and restricted output across multiple provinces, tightening regional availability and redirecting procurement patterns. At the same time, tightening EU carbon-footprint rules increasingly favor petroleum-based needle coke with lower lifecycle emissions relative to coal-tar routes, altering competitive dynamics in export-sensitive and compliance-driven markets.
- Qualification and downstream alignment are becoming gating factors. As battery-grade applications scale, supplier qualification cycles, consistency requirements, and traceability expectations are increasingly influential. Producers that can demonstrate stable grade performance, auditable feedstock provenance, and alignment with low-carbon or recycled-feedstock pathways are gaining preferential access to long-term agreements and premium pricing tiers.
Collectively, these dynamics create a market where cost leadership alone is no longer sufficient. Competitive advantage is increasingly a function of feedstock security, regulatory adaptation, and the ability to deliver qualified product into both traditional electrode and emerging battery value chains.
The Report: What Decision-Makers Will Find Inside
The complete Petroleum Needle Coke Market study is structured to convert high-level trajectory awareness into executable strategy. Rather than presenting static sizing alone, the report maps the operational and commercial levers that determine where growth, margin, and risk concentrate across the 2026–2032 period.
- Market sizing and forward modeling that anchor planning to verified historical baselines and forecast trajectories, enabling scenario testing around feedstock cost shifts, capacity additions, and application mix evolution.
- Segment-level structure analysis covering type partitions, application channels, and regional dispersion patterns, with emphasis on how volume distribution translates into pricing power, supply security, and qualification risk.
- Competitive profiling and strategic event tracking that examine capacity expansions, product launches, supply agreements, and regional positioning moves, highlighting how incumbents are reallocating capital and reorienting product portfolios.
- Dynamic context integration that connects raw material volatility, regulatory interventions, and carbon-intensity qualification trends to practical procurement, sourcing, and capacity-planning implications.
- Actionable framing for commercial and operational teams seeking to evaluate supplier resilience, entry timing, vertical integration logic, and long-term offtake strategy in a market where concentration and qualification barriers increasingly shape access.
The report is designed for executives who need to move beyond headline aggregates and understand the structural drivers that will determine competitive outcomes in the next investment cycle. It provides the evidentiary scaffolding required to test assumptions, pressure-test supply strategies, and align portfolio decisions with the most consequential market shifts.
Strategic Takeaway for 2026 Planning
As the petroleum needle coke market advances through its 6.7 percent CAGR window, the strategic question is no longer whether demand will expand, but where value will be captured and which supply chains will be rewarded with preferential access, premium pricing, and durable contracting relationships. The convergence of feedstock economics, regulatory recalibration, capacity concentration, and battery-grade qualification is creating a market in which operational precision and forward positioning matter more than ever.
This research study is built to help leadership teams navigate that complexity. It preserves the analytical depth required for credible strategy formulation while guiding readers toward the full dataset, segment architecture, and competitive intelligence needed for enterprise-level execution. For organizations preparing 2026 sourcing strategies, capacity commitments, or market-entry evaluations, the complete report provides the structured intelligence necessary to convert market trajectory into defensible commercial advantage.
Petroleum Needle Coke Market
Needle Coke Market
For detailed analysis of this topic, please visit the official page: Petroleum Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogenated DLC Coating Market to Hit $217.9M by 2032, 5.85% CAGR
By PW Consulting, 2026-09-16
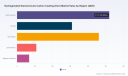
Navigating the Future of Surface Engineering: Strategic Insights into the Hydrogenated Diamond-Like Carbon Coating Market
The landscape of industrial surface engineering is undergoing a profound transformation, driven by the relentless demand for durability, efficiency, and performance across critical sectors. At the forefront of this evolution is the Hydrogenated Diamond-Like Carbon (DLC) Coating market, a niche yet pivotal segment within the broader advanced materials industry. As we move deeper into the decade, understanding the trajectory of this market is no longer optional for industry leaders; it is a strategic imperative. This article serves as a precursor to our comprehensive market research study, designed to equip stakeholders with the intelligence needed to navigate the complexities of the 2026 to 2032 forecast period.
Our latest analysis provides a rigorous examination of the market dynamics, offering a clear view of where value is being created and where challenges lie. By integrating historical data from 2020 through 2025 with robust forward-looking projections, we illuminate the path ahead. The following insights highlight the strategic value embedded in our full report, outlining why this intelligence is critical for decision-making in the current fiscal landscape.
Market Trajectory and Financial Outlook
The financial health of the Hydrogenated DLC Coating market reveals a story of steady resilience and measured growth. Our research indicates that the global market reached approximately 146.8 million USD in 2025, building upon a recovery trajectory that began after the volatility experienced in the early 2020s. Looking ahead, the market is projected to expand to 150.73 million USD in 2026, signaling a continued positive momentum as industries resume full-scale operations and invest in longevity-enhancing technologies.
The long-term forecast suggests a compelling value proposition for investors and manufacturers alike. By 2032, the market is expected to reach 217.9 million USD. This expansion reflects a Compound Annual Growth Rate (CAGR) of 5.85 percent over the forecast period. Such growth is not accidental; it is underpinned by the increasing adoption of DLC technologies in applications where friction reduction and wear resistance are paramount. For corporate strategists, this growth rate represents a stable opportunity for capital allocation, provided that entry strategies and product positioning are informed by granular data.
It is crucial to note that while the aggregate numbers provide a macroeconomic view, the real strategic advantage lies in understanding the velocity of adoption across different segments. Our report dissects these movements without relying on superficial averages, ensuring that stakeholders understand the specific drivers contributing to the 5.85 percent CAGR. This level of detail allows for precise budgeting and capacity planning over the next seven years.
Segmentation and Application Drivers
The versatility of hydrogenated DLC coatings is evidenced by their widespread application across diverse industrial verticals. Our analysis categorizes the market into key types and application areas, revealing where the highest demand intensity resides. In terms of coating type, the market is divided among hydrogenated variants, non-hydrogenated variants, and other coating solutions. The dominance of specific types in the current landscape underscores the preference for hydrogenated amorphous carbon structures in scenarios requiring superior tribological performance.
On the application front, the demand is distributed across Automotive Components, Tools and Dies, Medical Devices, and other specialized uses. The automotive sector remains a primary engine of growth, driven by the need for enhanced component longevity and fuel efficiency. Similarly, the tooling industry continues to rely on these coatings to extend tool life and maintain precision in manufacturing processes. Medical device manufacturers are also increasingly integrating these coatings to ensure biocompatibility and wear resistance in implantable and surgical instruments.
However, the relative weighting of these segments shifts over time based on technological breakthroughs and regulatory changes. Our full report provides a detailed breakdown of these segmentation splits, allowing clients to identify high-growth niches. Instead of relying on broad industry assumptions, stakeholders can leverage our data to pinpoint which application areas are poised for the most significant expansion in the 2026 to 2032 window. This granularity is essential for R&D prioritization and marketing strategy formulation.
Geographical Distribution and Regional Dynamics
Geographic diversification is a key consideration for any company operating in the global coatings market. Our study maps the revenue distribution across major regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of opportunities and regulatory environments that influence market penetration and growth rates.
Currently, North America and Europe hold significant shares of the market, reflecting established industrial bases and high adoption rates of advanced surface technologies. Asia Pacific represents a dynamic growth zone, fueled by expanding manufacturing capabilities and increasing local demand for high-performance components. Emerging markets in Latin America and the Middle East and Africa also contribute to the global revenue pool, albeit at different scales.
Understanding the regional nuances is vital for supply chain optimization and market entry strategies. Our report avoids generic regional summaries, instead offering specific insights into the revenue contributions and growth trajectories of each area. This enables multinational corporations to tailor their regional strategies effectively, ensuring resources are allocated to markets with the highest potential return on investment. Stakeholders seeking to expand their footprint will find the regional analysis within our full study indispensable for mitigating risk and maximizing reach.
Competitive Landscape and Key Players
The market is characterized by a mix of established industrial giants and specialized coating providers. Our analysis profiles the key companies shaping the competitive environment, assessing their technological capabilities, market presence, and strategic positioning. The competitive landscape is moderately concentrated, with the top three players holding a significant portion of the market share, while the top five collectively control a larger fraction. This structure suggests a competitive environment where differentiation through technology and service quality is paramount.
Prominent players such as Oerlikon Balzers and IHI Group / Ionbond are recognized for their robust portfolios in PVD and PACVD-based coating solutions. Oerlikon Balzers, headquartered in Liechtenstein, provides hydrogenated amorphous carbon coatings essential for automotive and aerospace wear resistance. Similarly, IHI Group and Ionbond, operating across Switzerland and Japan, offer comprehensive DLC solutions for tools and precision components. These companies set the benchmark for quality and technological integration.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
In the United States, companies like Calico Coatings, IBC Coatings Technologies, and Acree Technologies specialize in hydrogenated a-C:H coatings for commercial, industrial, and medical applications. Calico's CERTESS CARBON line and IBC's Ceratough D coating exemplify the focus on specific industrial needs, including military and testing compliance. Meanwhile, European entities like Miba Group / Teer Coatings in Austria and CemeCon in Germany continue to supply advanced coatings for engines, transmissions, and toolmaking. The presence of these diverse players ensures a dynamic competitive environment where innovation is continuously driven by the need to outperform rivals in wear resistance and coating durability.
Our report goes beyond simple company profiles. It analyzes the strategic moves, technological pipelines, and market influence of these key entities. By understanding the strengths and weaknesses of competitors, businesses can identify gaps in the market and formulate strategies to capture untapped value. This competitive intelligence is a cornerstone of our research offering.
Report Scope and Operational Content
To support informed decision-making, our comprehensive study offers a deep dive into operational and strategic content. The report is structured to provide actionable intelligence rather than just theoretical data. It includes a detailed examination of the industry chain, covering raw material suppliers, coating service providers, and end-user integration. This value chain analysis helps stakeholders identify bottlenecks and opportunities for vertical integration or partnership.
Furthermore, the report addresses the technological landscape, detailing the processes involved in depositing hydrogenated DLC coatings and the parameters that influence coating performance. This technical depth is crucial for R&D teams looking to optimize production or develop next-generation coating solutions. We also explore the regulatory environment and standardization requirements that govern the use of these coatings in sensitive sectors like medical and aerospace.
Cost structure analysis is another critical component. By understanding the cost drivers associated with production and application, managers can better control expenses and improve margins. The report also includes scenarios and sensitivity analysis, allowing clients to test their strategic assumptions against various market conditions. This holistic approach ensures that the final deliverable is a practical tool for strategic planning, not just an academic exercise.
Strategic Imperative for 2026 Decision-Making
As we enter 2026, the decisions made today will define competitive positioning for the remainder of the decade. The Hydrogenated DLC Coating market offers a stable growth environment, but success requires more than just observing the headline numbers. It demands a nuanced understanding of where the growth is coming from, who is driving it, and how external factors might influence the trajectory.
Diamond-Like Carbon Coating Market
Investing in surface engineering technologies without accurate market intelligence is akin to navigating without a map. Our research provides the necessary coordinates. Whether the goal is to enter a new geographic market, launch a specialized coating product, or optimize an existing supply chain, the data within our full report serves as the foundation for evidence-based strategy. The 5.85 percent CAGR is an invitation to grow, but capturing that growth requires precise execution informed by detailed insights.
We invite industry leaders, investors, and strategic planners to review the full findings of our Hydrogenated Diamond-Like Carbon Coating Market Report. The executive summary provided here offers a glimpse into the depth of analysis available, but the complete study contains the specific data points, regional breakdowns, and competitive assessments necessary to finalize your strategic roadmap. Accessing the full intelligence will ensure your organization is prepared to capitalize on the opportunities within the 2026 to 2032 forecast period.
For detailed analysis of this topic, please visit the official page: Hydrogenated Diamond-Like Carbon Coating (DLC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


