



Navigating the Paper Pallet Market: Strategic Intelligence for 2026 Decision-Makers
As global supply chains recalibrate around sustainability mandates and regulatory pressures, the packaging sector stands at a pivotal inflection point. The paper pallet market, once a niche alternative to traditional wooden and plastic logistics solutions, has matured into a strategic imperative for enterprises managing high-volume freight across international borders. PW Consulting's latest comprehensive study on the Paper Pallet Market delivers actionable intelligence designed to inform capital allocation, supplier partnerships, and regional expansion strategies throughout the 2026–2032 horizon.
This introduction outlines the strategic architecture of our research, demonstrates how macroeconomic indicators translate into operational foresight, and illustrates why forward-looking organizations are treating paper-based palletization as a core component of their supply chain resilience playbook.
The Macro Trajectory: Growth Signals and Structural Shifts
Between 2020 and 2025, the global paper pallet market demonstrated consistent revenue expansion, reflecting a steady migration away from conventional wood-based packaging. Initial valuation benchmarks in the early 2020s established a foundation that subsequent years reinforced through accelerated adoption across logistics-intensive sectors. The market's progression through 2024 and 2025 reflects an ecosystem that has moved beyond early-adopter experimentation into mainstream procurement considerations.
Our forecast model projects continued revenue growth across the 2026–2032 period, with compound annual growth rates indicating a durable expansion path. This trajectory is not merely a reflection of volume displacement; it captures fundamental shifts in how multinational corporations evaluate total cost of ownership, customs compliance, and environmental reporting. Decision-makers who understand the drivers behind this upward curve position themselves to capture margin advantages before commoditization erodes early-mover benefits.
The scale of the opportunity underscores why organizations cannot rely on fragmented industry anecdotes. A structured, data-anchored view of revenue pathways, demand elasticity, and competitive intensity allows procurement leaders and supply chain executives to evaluate whether paper pallet integration belongs in their near-term roadmap or longer-term sustainability pipeline.
Regulatory Tailwinds and the ISPM-15 Advantage
One of the most consequential dynamics shaping the market involves international phytosanitary regulations. Wooden packaging materials entering cross-border trade corridors must comply with ISPM-15 treatment requirements, which mandate heat treatment or fumigation protocols to mitigate pest transmission risks. Paper pallets, by contrast, fall outside these treatment mandates, eliminating a layer of compliance complexity that has historically slowed freight movement and increased administrative overhead.
This regulatory distinction creates measurable operational advantages for shippers managing high-frequency transatlantic, transpacific, and intra-Asia logistics flows. Paper alternatives reduce dwell time at inspection points, lower the risk of shipment rejection, and simplify documentation workflows. As customs enforcement protocols become more stringent in 2026 and beyond, organizations that standardize paper pallet utilization across export lanes can expect smoother clearance cycles and reduced contingency costs.
Wood Pallet Market
The regulatory environment also intersects with corporate sustainability commitments. Enterprises tracking Scope 3 emissions and packaging circularity targets find that paper-based solutions offer clearer end-of-life pathways when paired with recycling infrastructure, reinforcing the business case beyond mere compliance convenience.
Competitive Architecture: Who Shapes the Market and How
Market leadership in the paper pallet sector is defined not by raw production capacity alone but by proprietary engineering, material science capabilities, and the ability to integrate pallet solutions into broader transit and storage ecosystems. Several organizations have emerged as influential players, each pursuing distinct value propositions that appeal to specific supply chain profiles.
Smurfit Kappa Group, headquartered in Dublin, has built a recognizable presence through engineered paper pallet offerings such as PaPillOn strong paper pallet and TOPPSafe™ pallet top systems. Their approach emphasizes load-bearing performance combined with compatibility into existing corrugated supply networks. DS Smith Plc, based in London, advances a complementary yet differentiated position with its patented fibre-based pallet technology, targeting organizations that prioritize structural consistency and manufacturability at scale.
International Paper Company brings extensive raw material and converting infrastructure to the market, offering corrugated and molded paper pallet formats that leverage decades of industrial packaging expertise. Sonoco Products Company, operating from Hartsville, South Carolina, focuses on integrated paper pallet systems designed for specialized transit requirements and operational durability. PALLITE Limited, headquartered in the United Kingdom, has carved a distinct niche through honeycomb paper pallet designs and PIX® storage solutions that appeal to organizations seeking lightweight yet structurally reliable storage and transport alternatives.
Signode, based in Illinois, has positioned itself around paper pallet options designed for transit environments with ISPM-15 compliance considerations, aligning its portfolio with cross-border shippers seeking regulatory simplicity. ATTA Pallet, located in Hungary, emphasizes production and assembly capabilities tailored to paper pallet manufacturing workflows, while EcoDuro Inc., operating in Canada, contributes molded pulp and paper-based pallet options that broaden the material palette available to sustainability-focused procurement teams.
The competitive field reflects a mosaic of engineering priorities, regional strengths, and integration strategies. Understanding which players are expanding capacity, which are locking in proprietary formulations, and which are building partnerships with logistics integrators is essential for organizations evaluating supplier resilience and pricing stability over multi-year contracting cycles.
Recent Developments Reshaping Product Expectations
The pace of product-level innovation has accelerated markedly in recent months, signaling that incumbents are actively responding to shifting procurement criteria. In September 2025, Smurfit Westrock introduced a recyclable paper pallet wrap engineered as a direct replacement for single-use plastic pallet wraps in shipment applications. This launch reflects a growing emphasis on eliminating plastic wrapping without compromising load containment, a concern that has become increasingly prominent among shippers tracking packaging waste reduction targets.
Earlier, in March 2024, Seaman Paper expanded the functional scope of paper-based transit solutions with the launch of SeaStretch™, a patented lightweight paper alternative designed for shipping and storage loads. This development reinforced the viability of paper as a performance-competitive material in contexts where plastic film had previously dominated, particularly when weight reduction and recyclability are weighted heavily in procurement evaluation frameworks.
These launches matter because they illustrate a market trend moving beyond pallet boards alone. The broader product ecosystem now includes wrapping solutions, load stabilization approaches, and storage geometries that collectively influence total logistics cost. Buyers evaluating paper pallet adoption must consider how compatible wrapping, cushioning, and handling practices affect throughput, damage rates, and downstream recycling feasibility.
What the Report Delivers: Operational Intelligence Beyond Headline Figures
PW Consulting's Paper Pallet Market research is structured to support decision-making at multiple organizational levels. Rather than presenting a static snapshot, the study maps revenue evolution, segment dynamics, and competitive interventions across historical and forecast periods, enabling readers to test assumptions against evidence-based scenarios.
The report examines the structural composition of market demand, identifying how different product types and application categories contribute to overall revenue behavior. It explores regional demand patterns without reducing complexity to oversimplified ratios, offering instead a nuanced view of where adoption momentum is strongest and what local regulatory or logistics conditions amplify or constrain growth.
Detailed company profiles analyze strategic positioning, product differentiation, and recent developmental activity across key participants. This competitive mapping is paired with an assessment of concentration dynamics, helping stakeholders gauge pricing influence, supplier dependency risk, and the likelihood of consolidation pressure in the years ahead.
Operational considerations are addressed through analysis of material developments, product launches, and regulatory alignments that affect procurement planning. Readers gain insight into how transit compliance frameworks, sustainability reporting expectations, and packaging innovation cycles intersect with supplier selection and contract structuring. The research also contextualizes supply chain decision points such as total cost comparisons, damage-risk trade-offs, customs efficiency, and recyclability infrastructure readiness.
Because the study spans a defined historical baseline and extends across a multi-year forecast window, it supports scenario-based evaluation. Organizations can assess how shifts in freight volume, regulatory enforcement intensity, or material cost dynamics may alter adoption timing and budget allocation. This forward-looking structure is particularly valuable for teams planning capital-intensive logistics improvements or evaluating multi-year supplier partnerships.
Why 2026 Is a Defining Year for Strategic Action
The convergence of regulatory clarity, product innovation, and expanding adoption creates a window in which strategic choices carry disproportionate long-term effects. Organizations that delay evaluation risk entering supplier negotiations after pricing structures adjust to heightened demand visibility, while those that assess options prematurely may overlook rapid product improvements that reshape performance comparisons.
In 2026, procurement and supply chain leaders must determine whether paper pallet integration belongs within tactical cost-reduction programs or within broader transformation initiatives tied to compliance, sustainability reporting, and international freight efficiency. Answering that question requires a granular understanding of market direction, competitive behavior, and application-specific demand behavior, all of which our research is designed to clarify.
Firms operating across multiple regions face additional complexity. Regional demand intensity varies, and local regulatory expectations, recycling infrastructure availability, and logistics partner capabilities influence whether paper pallet adoption generates the anticipated benefits. A market-level view must therefore be paired with operational realism about implementation readiness, supplier reliability, and internal change management requirements.
The report enables this level of discernment by connecting macro growth signals with actionable procurement implications. Readers can evaluate whether current supplier options align with their technical specifications, whether product innovation timelines match their implementation horizons, and whether market concentration trends suggest a need for diversification or long-term contracting.
From Insight to Execution
Deep market intelligence becomes valuable only when it informs concrete decisions. PW Consulting's Paper Pallet Market study is built to support that translation. It equips strategy teams with evidence-based context, helps procurement groups benchmark supplier claims against market-wide patterns, and gives executive stakeholders the framing needed to prioritize packaging logistics investments alongside other transformation initiatives.
For organizations preparing for the 2026 decision cycle, the critical task is not simply recognizing that the market is expanding. The strategic value lies in understanding which forces are structural rather than cyclical, which supplier capabilities are likely to endure, and where adoption timing will most strongly affect cost and operational outcomes. Our research is designed to illuminate those distinctions without leaving decision-makers to infer them from partial data.
Paper Pallet Market
The complete analysis provides the depth, segmentation clarity, competitive mapping, and scenario-aware forecasting required to move from awareness to action. For teams tasked with evaluating paper pallet integration as part of broader supply chain strategy, the full report offers the intelligence foundation necessary to make informed, timely, and defensible decisions.
For detailed analysis of this topic, please visit the official page: Paper Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Meal Kit Market Hits $39.44B in 2025, Forecast 8.4% CAGR to $69.37B by 2032
By PW Consulting, 2026-09-16
Strategic Compass for the Meal Kit Delivery Services Market: Navigating the 2026–2032 Growth Cycle
The global meal kit delivery services market is entering a decisive phase. As consumer habits around convenience, nutrition, and sustainability continue to reshape home cooking, market participants face a complex matrix of expansion opportunities, cost pressures, and compliance risks. This analysis frames the commercial landscape that will define enterprise strategy through the end of the decade, drawing on a comprehensive market research study designed to support high-stakes decision-making in 2026 and beyond.
Why 2026 Demands a Refined Market View
Meal kit delivery services are no longer an experimental convenience category. They have matured into a structural alternative to traditional grocery and dining-out behaviors. The sector is expanding against a backdrop of shifting household budgets, evolving dietary preferences, and increasing scrutiny of food safety and supply chain resilience. For executives, the central challenge is no longer whether demand exists, but how to position operations, pricing, and portfolio strategy amid volatility.
The most recent market data underscores the scale and momentum of this environment. The global meal kit delivery services market generated approximately USD 39.44 billion in revenue in 2025, up from roughly USD 19.61 billion in 2020. Over that same historical window, the market advanced through a sustained growth trajectory that carried valuations from USD 23.12 billion in 2021 to USD 35.4 billion in 2024, reflecting the category’s deepening penetration across consumer segments. Looking forward, the forecast period from 2026 to 2032 points to continued expansion, with the market projected to reach USD 42.87 billion in 2026 and advance toward USD 69.37 billion by 2032. The implied compound annual growth rate across the forecast horizon is 8.4 percent.
These headline figures matter because they frame the stakes. Growth at this pace is strong enough to justify bold investment, yet not so automatic that it absorbs operational missteps. A company that treats meal kits as a purely transactional offering risks losing share to competitors who integrate brand trust, recipe innovation, and supply chain discipline into a cohesive value proposition. Conversely, operators that align their roadmap to the structural drivers behind this expansion can convert category growth into durable competitive advantage.
Worldwide Pet Food Delivery Market
Macro Signals Shaping the Competitive Terrain
The market’s trajectory is being influenced by more than consumer sentiment alone. Inflationary pressure on raw materials, regulatory scrutiny around food safety, and heightened expectations for quality and transparency are reshaping the operating environment. These forces are not peripheral concerns; they directly affect margin structures, product design, and the credibility of brands that depend on recurring subscription behavior.
On the supply side, farm-level vegetable prices are predicted to increase 20.5 percent in 2026, with a prediction interval ranging from 3.6 percent to 42.7 percent. This degree of uncertainty complicates ingredient planning for providers that rely on fresh produce as a core component of their value proposition. Compounding this, retail fresh vegetable prices increased by 3.1 percent from March 2026 to April 2026 and were 11.5 percent higher in April 2026 than in April 2025. For meal kit companies, the implication is clear: input cost variability can quickly translate into pricing tension, recipe reformulation, or margin erosion if sourcing and hedging strategies are not built for volatility.
At the same time, food safety remains a defining trust factor. A multistate Salmonella outbreak linked to home delivery meals from Metabolic Meals resulted in 16 illnesses and 7 hospitalizations, with the CDC investigation closing after the outbreak was resolved. In a separate event, cheese ingredients included in certain HelloFresh brand meal kits were recalled in Canada due to Listeria monocytogenes contamination. These incidents illustrate how quickly a compliance or quality failure can disrupt brand perception and operational continuity. In a category built on recurring delivery and household trust, such events are not merely reputational setbacks; they are strategic risk signals that should inform vendor oversight, traceability investments, and recall readiness.
What the Research Report Delivers
This market research study is structured to move beyond broad narrative and into actionable intelligence. It is designed for strategy, product, sales, and investor teams that need a shared fact base for planning, prioritization, and external communication. The report brings together market sizing, segmentation logic, competitive profiling, and industry context in a format that supports both internal alignment and external stakeholder engagement.
The analysis covers historical performance from 2020 through 2025 and extends forecast perspective across 2026 to 2032. This dual lens helps organizations distinguish between cyclical fluctuations and structural trends, enabling more disciplined scenario planning. Rather than treating growth as a single line item, the report unpacks the categories, offerings, and meal types that constitute the market’s underlying architecture, allowing decision-makers to identify where demand is concentrated and where variance is likely to emerge.
Throughout the study, attention is given to the practical implications of the data. Market size is presented with the context needed to interpret momentum, while segmentation insights are framed to support portfolio decisions, market-entry logic, and resource allocation. The report also examines market concentration to illuminate the balance between established players and the room available for differentiation. The objective is to provide a stable analytical foundation on which operational strategy can be built.
How the Market Is Structured
The meal kit delivery services market is shaped by multiple overlapping demand drivers. Some consumers prioritize the experience of cooking from scratch with guided recipes and pre-portioned ingredients, while others seek speed and simplicity with minimal preparation. Dietary identity also plays a significant role, with a meaningful portion of demand oriented toward plant-based and vegetarian options, and a larger share anchored in non-vegetarian meals. These preferences influence not only product design, but also customer acquisition messaging, retention dynamics, and the cost profiles of different service models.
Offering formats split the market between services that emphasize cooking from ingredients and those oriented toward quicker, more immediate consumption. The balance between these approaches affects logistics, packaging, customer expectations, and margin potential. Meal type segmentation further differentiates demand, creating distinct strategic paths for brands that compete on variety, culinary authenticity, convenience, or health and sustainability credentials. Regionally, the market reflects varying levels of adoption, with differing consumer expectations around price sensitivity, distribution reach, and brand trust.
In concentrated markets, the behavior of leading providers often sets pace and expectations for the broader field. Concentration patterns can inform how aggressively new entrants can pursue differentiation, how incumbents defend share, and where partnerships or niche positioning may create viable openings. The report contextualizes these structural relationships without reducing them to oversimplified rankings, because competitive advantage in meal kits often depends on execution details that numbers alone cannot capture.
Competitive Landscape: Ten Profiles, Multiple Strategic Playbooks
The competitive field includes a diverse set of operators, each pursuing a distinct interpretation of what consumers should receive from a meal kit service. The companies profiled in the research represent a cross-section of business models, recipe philosophies, and distribution approaches that together define the current market rhythm.
- HelloFresh SE, headquartered in Berlin, Germany, provides meal kit delivery services with more than 100 weekly recipes, alongside add-ons, seasonal boxes, premium meals, and vending machine distribution. Its breadth of format and recipe volume points to a scale-oriented strategy that seeks to serve a wide range of household needs under one brand umbrella.
- Marley Spoon, based in Sydney, Australia, offers meal kit delivery services featuring gourmet recipes, budget plans, and collaborations such as with Martha Stewart. Its profile suggests a dual focus on elevated culinary appeal and accessible price points, using partnerships to extend brand reach and recipe credibility.
- Purple Carrot, headquartered in Santa Barbara, California, specializes in meal kit delivery services focused on plant-based and vegetarian options. Its narrower dietary emphasis positions it within a segment where mission alignment and ingredient storytelling can support loyalty and differentiation.
- Hungryroot, based in Chicago, Illinois, provides fresh meal kit delivery services with customizable recipes and ingredient sourcing. Customization and sourcing transparency indicate a model built around flexibility and consumer control, which can be especially relevant for households balancing dietary preferences with convenience.
- Sunbasket, located in Burlingame, California, delivers organic meal kit services with nutrient-dense recipes and sustainable ingredients. Its emphasis on organic and sustainability attributes aligns with consumers who treat food quality and sourcing as central purchase drivers.
- Gobble, headquartered in Columbus, Ohio, offers meal kit delivery services emphasizing quick and easy home cooking recipes. Its value proposition leans toward time savings and usability, appealing to consumers who want cooking engagement without extended prep burden.
- Freshly Inc., based in New York, New York, provides meal kit delivery services with fresh, pre-portioned ingredients for at-home meals. Its approach reinforces convenience and freshness as core purchase triggers, positioning the service as a practical bridge between groceries and ready-made dining.
- Dinnerly, headquartered in Denver, Colorado, delivers budget-friendly meal kit services with simplified recipes for everyday use. The focus on affordability and simplicity targets cost-conscious households and those seeking repeatable, low-friction meal routines.
- Green Chef, also based in Denver, Colorado, specializes in organic and plant-based meal kit delivery services. By combining organic positioning with plant-centric offerings, it operates at the intersection of health, dietary preference, and ingredient quality.
- Home Chef, located in Chicago, Illinois, offers meal kit delivery services with chef-created recipes and value options. Its combination of culinary identity and value-tiered choices reflects an effort to serve both experience-seeking and price-sensitive consumers.
- Tovala, headquartered in San Francisco, California, provides scan-to-cook meal kit delivery services with smart oven integration for precise heating. This model blends meal kits with connected appliance functionality, illustrating how hardware, software, and food service can converge around convenience and repeatability.
These profiles matter because they show that the market is not converging on a single formula. Some providers compete through scale, recipe variety, and multi-format distribution. Others compete through dietary specialization, sustainability claims, customization, or appliance-linked convenience. For a company planning its next move, the strategic question is less about which model is universally best and more about which combination of audience, operational capability, and brand promise can be sustained at scale.
From Consumer Preference to Operating Risk
Market growth does not happen in a vacuum. The same forces that expand demand can also expose weak points in execution. Ingredient inflation, for example, is not only a cost issue; it is a design issue. If farm-level input prices can swing materially within a single year, then menus, portion sizing, sourcing partnerships, and pricing architecture must be flexible enough to absorb change without eroding consumer trust. Brands that lock themselves into rigid recipes or uncompetitive price points may find themselves squeezed from both sides.
Food safety adds another layer of strategic urgency. The recall events involving HelloFresh and the Salmonella outbreak associated with Metabolic Meals demonstrate that meal kit providers operate in an environment where quality failures can become public quickly and carry both health and business consequences. In this context, operational discipline is a competitive asset. Traceability, supplier vetting, testing protocols, and recall procedures should be treated as part of the core value proposition, not as back-office compliance functions. Companies that institutionalize these practices are better positioned to protect retention and reduce the likelihood that a single incident derails growth momentum.
These dynamics also intersect with customer acquisition and retention economics. Meal kit services depend heavily on recurring engagement, which means the cost of disappointing a customer is multiplied over time. Quality, reliability, and transparent communication can therefore be viewed as retention investments with direct financial returns. In a market projected to grow from USD 42.87 billion in 2026 toward nearly USD 70 billion by 2032, the winners are likely to be those who combine expansion with consistency.
Using the Study to Inform 2026 Decisions
For organizations active in or entering this market, the study functions as a strategic decision-support tool. It helps leadership teams answer questions that are otherwise difficult to resolve with fragmented public information: where demand is accumulating, which segments carry the strongest growth logic, how competitive intensity varies across formats, and what external pressures may shape margin and operational planning in the near term.
The report’s historical and forecast structure supports a range of applications. Strategy teams can use it to evaluate expansion timing and geographic or segment prioritization. Product and operations teams can use it to frame menu architecture, sourcing resilience, and service-model trade-offs. Marketing and brand teams can use the segmentation context to sharpen positioning without relying on broad assumptions. Investors and advisors can use the concentration and growth outlook to assess market maturity and the durability of competitive claims.
Importantly, the study is designed to be actionable without being over-specified at the summary level. It provides the analytical scaffolding needed to make informed choices while leaving room for company-specific interpretation. The most valuable insights often emerge when broad market direction is combined with internal capabilities, customer data, and operational constraints. That is where the research is intended to be most useful: as a reliable base layer for strategic judgment.
What Remains in the Full Analysis
The overview above outlines the strategic context and structural themes that shape the meal kit delivery services market. It also demonstrates why 2026 is a pivotal year for planning: input-cost uncertainty, food safety scrutiny, and continued category expansion are all active at once. Yet the full report contains a deeper level of segmentation value, competitive benchmarking, and scenario-ready detail that cannot be fully reproduced in an executive summary.
Meal Kit Delivery Services Market
For teams that need to move from general market awareness to specific planning assumptions, the complete study provides the granularity required to support concrete decisions. The full analysis examines how the market breaks down across regions, offerings, and meal types, and it contextualizes those splits within the broader growth trajectory. It also expands the competitive and operational picture in ways that help organizations identify where to concentrate resources, where to defend position, and where to experiment responsibly.
If your objective is to align 2026 strategy with a market projected to grow at 8.4 percent through 2032, the complete research offers the evidence base needed to make that alignment precise rather than approximate. The full report is available on the PW Consulting market research page, where the detailed segmentation, competitive profiles, and supporting market context can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Meal Kit Delivery Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Manufacturing Market Hits $215B in 2025, Projected 13.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Intelligent Factory: Strategic Imperatives for the Smart Manufacturing Market in 2026
The industrial landscape is undergoing a fundamental reset. As enterprises transition from pilot projects to enterprise-wide deployment, smart manufacturing has moved from a competitive advantage to an operational necessity. For executives planning capital allocation, technology roadmaps, and supply chain resilience in 2026, the window for strategic action is narrowing. This introduction outlines the strategic framework embedded in our latest market research, designed to equip decision-makers with the analytical rigor required to navigate an increasingly complex ecosystem.
A Market in Accelerated Expansion
The smart manufacturing sector has demonstrated consistent momentum over the past half-decade, evolving from incremental automation to integrated, data-driven production environments. Our analysis tracks this trajectory from 2020 through the base year of 2025, establishing a clear upward curve that sets the stage for the forecast window extending to 2032. The compound annual growth rate of 13.5 percent across the projection period signals more than incremental uptake; it reflects a structural shift in how manufacturers invest in infrastructure, software, and operational intelligence.
Revenue expansion tells a parallel story. The market crossed the two hundred billion dollar threshold in 2024 and reached approximately two hundred fifteen billion dollars by 2025. Forward momentum carries this trajectory through the mid-to-late 2020s, with valuations climbing steadily toward the three hundred forty billion dollar range by 2032. These figures are not abstract metrics; they represent capital deployment patterns, procurement cycles, and technology prioritization decisions that will define competitive positioning for the remainder of the decade.
Yet macro-level growth is only the starting point. The real strategic challenge lies in understanding how capital flows across technology stacks, how regional supply chains are reconfiguring under policy pressures, and which operational models will prove sustainable as deployment scales. This report is built to answer those questions with precision.
Report Architecture and Operational Utility
A market study earns its value only when it translates into actionable strategy. Our research is structured to serve multiple stakeholder functions simultaneously, from executive briefing to operational planning. The core of the analysis is built around four interconnected pillars:
- Technology segmentation analysis that dissects adoption patterns across control systems, execution platforms, and programmable logic architectures, revealing where investment is concentrating and which capabilities are becoming baseline expectations.
- Component-level evaluation distinguishing hardware procurement cycles from software licensing and services integration, helping procurement and IT leaders align budgeting rhythms with deployment realities.
- End-use industry mapping that highlights how automotive, electronics, aerospace, and defense organizations are tailoring smart manufacturing investments to their specific throughput, compliance, and precision requirements.
- Geographic distribution insights that contextualize regional demand intensity, policy acceleration, and supply chain localization trends without reducing complex dynamics to simplistic rankings.
Beyond segmentation, the report delivers competitor profiling, partnership mapping, and a regulatory watch module that tracks how industrial policy is reshaping procurement and localization mandates. Each section is designed to feed directly into scenario planning, vendor evaluation, and capacity expansion decisions. Readers will find executive dashboards, adoption maturity curves, and investment prioritization matrices that convert raw analysis into boardroom-ready narrative.
Competitive Dynamics Among Market Leaders
The smart manufacturing arena is defined by a concentrated but heterogeneous group of players, each anchoring its strategy around distinct value propositions. Our competitive assessment examines how these organizations position themselves across automation, digital factory platforms, and industrial connectivity.
Smart Factory Market
Siemens AG continues to anchor its offering around integrated digital factory ecosystems, bundling automation, production operations, and Industry 4.0 platforms into a unified deployment model. ABB Ltd has carved a parallel path with a focus on robotics, automation, and AI-driven optimization, positioning intelligent control as a differentiator rather than a feature. Rockwell Automation, Inc. emphasizes industrial automation platforms, MES systems, and digital twin technologies, reflecting a growing enterprise appetite for simulation-led process refinement before physical deployment.
Schneider Electric SE brings an energy-centric lens to the market, developing eco-adaptive infrastructure and smart grid solutions that integrate directly into manufacturing environments. Honeywell International Inc. contributes a connective enterprise perspective, pairing industrial cybersecurity with IIoT platforms to address the operational risk dimension that becomes more acute as factories digitize. Emerson Electric Co. reinforces this momentum with automation solutions, digital twins, and smart equipment designed to streamline industrial operations at scale.
GE has maintained leadership in advanced manufacturing technologies, particularly through industrial IoT and predictive maintenance systems that extend asset life and reduce unplanned downtime. Mitsubishi Electric Corporation complements the field with factory automation, robotics, and IoT-enabled smart factory systems, while Robert Bosch GmbH focuses on industrial automation, IoT, and digital transformation solutions that support smart production across diverse manufacturing modalities.
The competitive field also includes specialized and adjacent players that shape niche but high-impact segments. Applied Materials, Inc. delivers semiconductor equipment and smart manufacturing platforms purpose-built for chip production, an industry where precision and process control carry outsized strategic weight. Cimatron Ltd. supplies CAM software and integrated workflow solutions that bridge design and shop-floor execution. HighByte Inc. addresses the data plumbing challenge directly, providing industrial data management and connectivity software that underpins effective smart factory integration.
Together, these players illustrate a market where differentiation is increasingly tied to integration depth, data interoperability, and sector-specific expertise rather than hardware specifications alone. Understanding these positioning strategies is essential for procurement leaders evaluating vendor roadmaps and for operators assessing which ecosystems are most likely to support long-term scalability.
Policy, Regulation, and Regional Dynamics
Market growth does not occur in a policy vacuum. Industrial strategy, trade dynamics, and regulatory frameworks are actively reshaping where and how smart manufacturing investments are deployed. Recent developments provide a clear signal that governments and standards bodies are accelerating their focus on manufacturing modernization.
China's industrial upgrading program continues to influence global supply chain architecture. By mid-2025, assessments documented substantial progress in localization rates across key sectors, including agricultural machinery and basic materials. At the same time, high-performance computing segments have shown more uneven progress, with import dependency remaining elevated in certain categories. The nine implementation paths associated with the initiative prioritize digitalization of manufacturing equipment, intelligent process design, and green standards aimed at reducing resource consumption. These priorities intersect directly with smart manufacturing adoption, especially in energy-intensive sectors where China already holds dominant production share in lithium-ion batteries and solar modules.
On the other side of the Pacific, policy incentives are reinforcing domestic investment. Analysis released in late 2025 highlighted U.S. government incentives and OEM-led digital transformation efforts as key drivers of smart manufacturing adoption, alongside state-level support mechanisms for pilot programs. This alignment between federal encouragement and corporate deployment is creating a more structured pathway for scaling intelligent manufacturing capabilities.
Standards development is also gaining momentum. India's telecommunications engineering framework introduced a technical report in mid-2025 establishing standards for Industry 4.0 and smart manufacturing integration, reflecting a broader international push to harmonize interoperability expectations and reduce fragmentation in connected factory environments.
Meanwhile, industry events and conference agendas are increasingly centered on autonomy, agentic AI integration, and advanced packaging in semiconductor manufacturing, signaling where practitioner attention and R&D emphasis are converging. These developments do not merely contextualize the market; they shape procurement timelines, compliance strategies, and cross-border investment decisions.
Why This Research Matters for 2026 Decision-Making
Executive teams entering 2026 face a set of interlocking decisions: which technology layers to standardize, how to sequence capital deployment, which vendor ecosystems to align with, and how to hedge against regulatory and supply chain volatility. High-level growth projections can inform optimism, but they cannot replace granular intelligence about adoption bottlenecks, segment-specific demand intensity, and competitive maneuvering.
This report is designed to close that gap. It converts market scale into strategic context, situates competitor moves within broader technology trends, and embeds policy developments into operational planning assumptions. For organizations evaluating factory modernization, capacity expansion, or digital transformation roadmaps, the analysis provides a structured reference point for scenario modeling and risk assessment.
The full study goes further than what an introduction can capture. It contains segment-specific adoption trajectories, regional intensity mapping, detailed competitor positioning tables, procurement cycle insights, and scenario-based forecasts that allow leadership teams to test assumptions against multiple future states. Those elements are essential for converting directional awareness into precise investment logic.
Accessing the Complete Intelligence
The smart manufacturing market is expanding at a pace that rewards disciplined analysis. With a sustained growth trajectory, intensifying competition among established and specialized players, and an evolving policy environment that directly affects localization and standards, the cost of incomplete information is rising. Organizations that enter 2026 with a clear view of technology segmentation, competitive positioning, and regulatory direction will be better positioned to allocate capital efficiently, negotiate from an informed stance, and build manufacturing capabilities that remain resilient as the landscape shifts.
Smart Manufacturing Market
To explore the complete dataset, segmentation breakdowns, and competitor profiles in full detail, download the full report. The complete analysis provides the depth required to move from strategic awareness to execution-ready decision-making.
For detailed analysis of this topic, please visit the official page: Smart Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Structural Steel Pipe Market to Hit $489.1M by 2032, 3.45% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Structural Steel Pipe Market: Navigating the 2026-2032 Cycle
The structural steel pipe industry stands at a critical juncture as it moves through the 2026 fiscal year. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient supply chain design and capital allocation. Our latest market research delivers a comprehensive examination of the forces shaping demand, pricing, and competitive positioning across the global structural steel pipe landscape. This introduction outlines the strategic value embedded in the full report, highlights the macro trends that demand attention, and explains how data-driven foresight can convert market volatility into competitive advantage.
The Macro Trajectory: Recovery, Expansion, and Measured Growth
Historical data reveals a market that has steadily climbed out of the pandemic-era disruptions and into a phase of structured expansion. Between 2020 and 2025, total market revenue moved from approximately 298.45 million USD to 386.5 million USD, reflecting a compound annual growth rate that underscores the sector's underlying resilience. The upward momentum carries into the forecast window: 2026 opens at an estimated 399.37 million USD, and the trajectory advances toward 489.1 million USD by 2032, supported by a projected CAGR of 3.45 percent.
While these aggregate figures establish the baseline, the real strategic insight lies in understanding why growth is unfolding at this pace and where the inflection points will emerge. The forecast period through 2032 does not imply a straight line. Year-over-year movement shows nuanced fluctuations that reward stakeholders who look beyond headline numbers. Readers who engage with the full report will find a detailed quarter-by-quarter and year-by-year narrative that connects macroeconomic signals—such as interest rate environments, infrastructure appropriations, and industrial construction cycles—to the demand patterns driving pipe procurement across multiple downstream sectors.
Diversified Demand Centers and the Changing Application Mix
Structural steel pipe is no longer a single-purpose commodity. Its deployment spans oil and gas infrastructure, commercial and civil construction, water and wastewater systems, and an expanding set of industrial applications that rely on high-integrity tubular products. The market's breadth means that shifts in any one vertical can materially alter procurement strategies, inventory planning, and pricing negotiations.
Our research dissects the application landscape without reducing it to simplistic rankings. The full report maps how project pipelines, regulatory mandates, and regional infrastructure spending are redistributing demand across use cases. It also examines the degree to which certain applications are becoming more cyclical while others exhibit steadier, policy-driven consumption. For executives planning multi-year supply agreements or evaluating capacity investments, this granularity matters. It allows organizations to anticipate which segments will tighten during downturns and which will remain robust, enabling more precise hedging of procurement exposure.
Equally important is the interplay between application demand and product type. Seamless pipes, welded pipes, and spiral welded variants each serve distinct performance and cost profiles. The report analyzes how engineering requirements, cost pressures, and manufacturing capabilities are shaping the adoption mix across these categories. Decision-makers who understand these dynamics can better align sourcing strategies with technical specifications, avoiding over-specification in cost-sensitive programs or under-specification in high-stress applications.
Geographies in Motion: Regional Dynamics That Reshape Sourcing
No market analysis is complete without a rigorous view of regional performance. The structural steel pipe market reflects divergent economic conditions, trade policies, and construction cycles across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each geography carries its own set of demand drivers, supply constraints, and policy risks that directly influence landed costs and availability.
In the full report, we avoid surface-level regional snapshots. Instead, we provide an integrated assessment of how cross-border trade flows, local production capacity, and infrastructure investment programs interact to create pricing divergence and availability gaps. This regional lens is especially valuable for multinational operators and distributors who must coordinate procurement across multiple markets. The analysis identifies where local supply is tightening, where import dependency creates exposure, and where domestic production is gaining strategic importance. Readers will see how these regional conditions translate into actionable sourcing recommendations rather than abstract market commentary.
Competitive Landscape: Vertically Integrated Leaders and the Battleground for Share
The competitive structure of the structural steel pipe market is defined by a mix of large, globally integrated steelmakers and specialized domestic producers with strong regional footprints. Market concentration remains moderate, with the top three firms holding approximately 25.8 percent of revenue and the top five reaching 32.4 percent. This structure suggests that while scale confers advantages, there is meaningful space for regional specialists to compete on service, lead times, and product specificity.
Nucor, headquartered in Charlotte, North Carolina, exemplifies the vertically integrated approach. As an electric arc furnace producer of domestic hollow structural sections and tested steel pipe—covering ASTM A500, A135/A795, and A53 specifications—Nucor has positioned itself around low-embodied carbon certification and domestic supply reliability. That positioning has translated into conspicuous pricing activity: in October 2025, the company announced a 50 USD per ton increase across tube steel, HSS, mechanical, and piping products, followed by a further 60 USD per ton increase implemented in February 2026. These moves signal not only cost pass-through but also a deliberate effort to protect margin in an environment where input costs and demand are both elevated.
ArcelorMittal, based in Luxembourg City, remains a global force in tubular products, producing high-strength structural steel pipe and welded pipes for infrastructure and energy applications. Its recent product development activity highlights the innovation dimension of competition: by May 2026, ArcelorMittal Nippon Steel India had commenced commercial production of EQ70 grade high-strength welded steel pipes with a 690 MPa yield at its Hazira mill, enabling weight savings in structural applications. Such advances illustrate how competitors are using grade differentiation and performance improvements to capture premium segments, rather than competing solely on volume.
Structural Steel Pipe Market
United States Steel Corporation, headquartered in Pittsburgh, continues to supply welded and structural steel pipe and tubing critical to construction and infrastructure programs. Meanwhile, California Steel Industries, based in Fontana, serves the western United States with ERW structural steel pipe and tubing for load-bearing and low-pressure applications. These regional specialists matter because they shape localized availability and lead time dynamics. In February 2026, structural tubing mills broadly extended lead times to 6–8 weeks amid rising pricing and demand—an industry-wide signal that procurement planning horizons must lengthen and inventory buffers may need recalibration.
The full report goes deeper into how these players—and the broader field—compete on pricing, product certification, lead time reliability, and sustainability credentials. It evaluates where vertical integration provides genuine insulation from input volatility and where it may create rigidity. It also examines how low-embodied carbon positioning is becoming a differentiator in bids where procurement teams are weighing total cost of ownership against decarbonization commitments.
Forces Reshaping Cost Structures and Pricing Power
Pricing in the structural steel pipe market is being influenced by a convergence of cost pressures, trade policy, and demand timing. Raw material and labor dynamics remain central. In the first quarter of 2026, steel scrap prices stayed firm to upward, with China pricing at 347.20 USD per metric ton and India at 397.20 USD per metric ton. These levels were supported by tight supply and higher freight costs, reinforcing the upward bias in producer input costs and constraining the ability of mills to absorb cost shocks without passing them downstream.
Trade policy has added another layer of complexity. Section 232 tariffs on steel imports were raised to 50 percent in June 2025 and affirmed in April 2026, applying directly to steel pipe and structural products. In parallel, Section 301 tariffs on steel pipe, tube, and structural shapes from excess-capacity countries continued to impact import costs as of May 2026. Together, these measures have altered the relative attractiveness of imported versus domestic supply, tightened available sourcing channels, and strengthened the pricing hand of domestic producers in certain markets.
The price environment has responded accordingly. Steel pipe and tube prices rose 12.5 percent year-over-year in spring 2026, with the producer price index for metals reaching 354.9 in March 2026. These movements matter for budgeting, bidding, and contract structuring. For buyers, they raise the stakes of contract timing, escalation clauses, and inventory strategy. For producers and distributors, they create opportunities to defend margins but also increase the reputational and operational risks associated with lead time reliability and service continuity.
The report provides a structured framework for interpreting these dynamics. It connects raw material indices, tariff timelines, and demand seasonality to practical forecasting tools that help organizations model price scenarios, evaluate make-versus-buy trade-offs, and design procurement contracts that share risk more intelligently. Rather than simply documenting that prices have risen, it explains the mechanisms behind the increases and the conditions under which they may ease or intensify.
What the Full Report Delivers: Operational Intelligence for 2026 and Beyond
This introduction provides the strategic framing; the complete report delivers the operational intelligence required to act on it. Designed for executives, category managers, supply chain planners, and investors, the study translates market data into decision-ready formats. Key content includes a detailed historical reconstruction from 2020 through 2025, a forward-looking forecast spanning 2026 to 2032, and scenario analyses that stress-test assumptions around input costs, tariffs, and demand cycles.
Readers will find a robust segmentation evaluation covering product types and application verticals, along with a regional assessment that connects local supply conditions to cross-border trade realities. The competitive section profiles major players and analyzes recent moves—including price actions, grade launches, and lead time shifts—that signal where market power is being exercised and where vulnerabilities are emerging. The regulatory and cost environment is examined not as background noise but as an integral input to procurement and investment decisions.
Structural Steel Market
Equally important, the report emphasizes practical application. It outlines how to interpret lead time extensions, how to evaluate the implications of tariff structures on total landed cost, and how to incorporate sustainability credentials into sourcing criteria without losing sight of cost and performance. It also provides the analytical scaffolding needed to anticipate where the market is likely to tighten or loosen over the forecast horizon, giving stakeholders a basis for proactive rather than reactive planning.
Why This Research Matters Now
The structural steel pipe market in 2026 is defined by strong but uneven growth, elevated input costs, shifting trade policy, and a competitive field in which both global scale and regional agility matter. Organizations that treat these conditions as isolated events risk mispricing risk and misaligning supply strategies. Those that integrate them into a coherent, data-backed view can make better decisions on contracting, inventory, capacity, and market entry.
The complete report is built to support that integration. It combines the macro trajectory—moving from 386.5 million USD in 2025 toward 489.1 million USD by 2032 at a 3.45 percent CAGR—with the granular, decision-level detail that turns numbers into strategy. For teams responsible for procurement, planning, or investment in structural steel pipe, the difference between reacting to price spikes and anticipating them can be material.
To access the full segmentation analysis, regional assessments, competitive profiles, and scenario-based forecasts, request the complete market research. The methodology, data tables, and actionable recommendations are structured to give your organization a clear line of sight from market intelligence to executive decision-making in 2026 and across the forecast period to 2032.
For detailed analysis of this topic, please visit the official page: Structural Steel Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting ESWL Market Hits $381.96M in 2025, Projects 5.5% CAGR to $552.74M by 2032
By PW Consulting, 2026-09-16
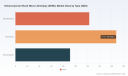
Strategic Horizons in Extracorporeal Shock Wave Lithotripsy: A 2026 Market Perspective
The global landscape for Extracorporeal Shock Wave Lithotripsy (ESWL) is entering a decisive phase of transformation. As healthcare systems worldwide balance cost containment with the demand for minimally invasive urological interventions, understanding the trajectory of this market is no longer optional for strategic planners—it is imperative. This article serves as an executive overview of our latest comprehensive market research, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the market is on a steady upward path. Following historical growth patterns observed between 2020 and 2025, where revenue climbed from approximately 294.62 Million USD to 381.96 Million USD, the momentum is expected to continue. The forecast period projects a compound annual growth rate (CAGR) of 5.5 percent. By 2032, the market volume is anticipated to reach significant maturity, driven by technological advancements and shifting clinical preferences. However, raw figures only tell part of the story. The real value lies in understanding the underlying dynamics that will dictate profitability, market share, and operational feasibility for providers and manufacturers alike.
Market Dynamics and Operational Realities
The ESWL sector does not operate in a vacuum. It is influenced by a complex interplay of regulatory frameworks, reimbursement structures, and capital expenditure constraints. Our report dives deep into these friction points to provide a realistic view of market entry and expansion opportunities.
Regulatory and Clearance Milestones
Recent regulatory activities highlight the pace of innovation and the hurdles remaining for new entrants. For instance, recent clearance events have validated new devices under specific federal classifications, signaling both opportunity and heightened scrutiny. The approval of specific lithotripters under Class II regulations demonstrates that while the pathway is established, the bar for clinical efficacy and safety documentation remains high. Companies aiming to launch new units must navigate these regulatory corridors with precision. Our research details the specific implications of these clearances for future product pipelines and competitive barriers.
Reimbursement and Economic Viability
Financial sustainability for ESWL procedures relies heavily on reimbursement codes. The economic environment for 2026 suggests varied payment structures depending on the care setting. National average Medicare payments differ significantly between ambulatory surgical centers and hospital outpatient departments. This disparity influences where providers choose to locate their services and how they structure their billing practices. Understanding the nuances of Current Procedural Terminology codes and their associated payment rates is critical for forecasting net revenue. Our report dissects these reimbursement landscapes to help stakeholders model accurate financial projections.
Capital Investment Considerations
The barrier to entry for ESWL technology remains substantial. Initial capital investment for systems varies widely, ranging from mobile units to stationary configurations. The cost differential between these options impacts hospital budgeting cycles and procurement strategies. Mobile units offer flexibility but may limit throughput, while stationary systems provide stability at a higher upfront cost. Strategic decision-makers must weigh these capital costs against expected utilization rates and maintenance expenses. We provide a granular breakdown of cost structures to assist in capital allocation decisions.
Technology Segmentation and Clinical Application
The market is segmented by technology type and clinical application, each presenting distinct growth vectors. While the overall market expands, specific technologies are gaining traction due to improved precision and reduced complications. Similarly, the prevalence of different stone types dictates where demand will concentrate.
Technology Evolution
Different shock wave generation technologies compete on efficacy, durability, and cost. The market includes electrohydraulic, piezoelectric, and electromagnetic systems. Each type carries different implications for maintenance, energy consumption, and patient outcomes. Our analysis evaluates the maturity and adoption rates of these technologies across different healthcare settings. We examine how technological shifts are influencing purchasing decisions among major healthcare providers.
Application Diversity
While kidney stones remain the primary driver of demand, other applications are contributing to market expansion. Ureteral stones, pancreatic stones, and salivary stones represent additional revenue streams that are often overlooked in broader analyses. The clinical protocols for these conditions vary, influencing the type of equipment required and the specialist involved. Our report maps the volume and growth potential across these applications, providing a clear picture of where niche opportunities exist.
The competitive landscape is moderately concentrated, with a few key players holding significant market share. This concentration suggests that while there is room for innovation, competitive pressure on pricing and service levels is intense. Our report provides a detailed competitive intelligence section that profiles the strategies of leading manufacturers.
Key Players and Strategic Moves
Several companies are defining the current market standards. German engineering firms have historically held strong positions, leveraging reputation for durability and precision. Simultaneously, manufacturers from emerging manufacturing hubs are increasing their presence through aggressive pricing and rapid innovation cycles.
-
Dornier MedTech: A longstanding participant known for establishing clinical benchmarks in shock wave technology. Their strategy focuses on maintaining high clinical efficacy standards.
-
Karl Storz GmbH & Co. KG: Integrates ESWL solutions within broader endoscopic and urological portfolios, offering bundled solutions that appeal to comprehensive care centers.
-
Siemens Healthineers: Leverages extensive imaging and diagnostic capabilities to enhance the precision of lithotripsy procedures, positioning technology as a integrated diagnostic-therapeutic solution.
-
Shenzhen Wikkon Precision Technologies Co., Ltd.: Represents the growing influence of manufacturers from the Asia-Pacific region. Recent activities indicate a push towards global regulatory approval and branding.
Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Recent Developments and Market Shifts
Recent actions by key competitors signal shifting strategies. In mid-2025, Shenzhen Wikkon Precision Technologies Co., Ltd. achieved a significant regulatory milestone with FDA 510(k) clearance for their U200 Extracorporeal Shock Wave Lithotripter, specifically indicated for kidney stone treatment. This clearance under 21 CFR 876.5990 opens the US market to this specific device. Following this, in late 2025, the company launched a new brand identity and announced global expansion plans during a meeting of the Chinese Urological Association. These moves suggest a deliberate strategy to scale presence in Western markets while consolidating strength in home regions.
However, competition is not limited to these profiled entities. The market concentration metrics indicate that the top three players hold over half of the market revenue, and the top five control approximately 65 percent. This structure implies that market entry for new players requires significant differentiation, either through cost leadership or proprietary technology. Our report analyzes the strategic postures of these leaders to identify potential vulnerabilities and partnership opportunities.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast period, several key strategic imperatives emerge for stakeholders involved in the ESWL market. Success will depend on the ability to align technology procurement with reimbursement realities, manage capital expenditures efficiently, and adapt to a competitive landscape that is both concentrated and dynamic.
Optimizing Procurement and Deployment
Healthcare providers must look beyond the sticker price of ESWL systems. The total cost of ownership, including maintenance, disposable components, and energy consumption, must be factored into procurement decisions. With capital costs ranging significantly based on system type, facilities need to model their expected patient volume to justify the investment. Our research provides frameworks for calculating return on investment based on procedure volumes and reimbursement rates specific to different care settings.
Navigating Regulatory Pathways
For manufacturers and distributors, the regulatory environment remains a critical gatekeeper. Recent clearances demonstrate that compliance is achievable, but the process requires robust clinical data. Companies planning product launches must anticipate regulatory timelines and prepare corresponding quality management systems. The report outlines the specific regulatory requirements and recent precedents that will shape future approval processes.
Capitalizing on Regional Variances
Market growth is not uniform across geographies. Different regions exhibit varying levels of adoption based on healthcare infrastructure, reimbursement policies, and disease prevalence. While some regions show higher immediate revenue potential, others may offer faster growth rates due to developing healthcare access. Strategic expansion plans should be tailored to these regional characteristics rather than applying a one-size-fits-all approach. Our report includes detailed regional analysis to guide market entry and resource allocation.
Conclusion
The Extracorporeal Shock Wave Lithotripsy market presents a landscape of steady growth tempered by complex operational challenges. With a projected CAGR of 5.5 percent leading into the next decade, the opportunity for value creation is substantial. However, realizing this potential requires more than superficial market knowledge. It demands a deep understanding of reimbursement mechanics, capital constraints, regulatory pathways, and competitive strategies.
This article has provided a high-level overview of the forces shaping the ESWL market. Yet, the true depth of intelligence lies in the data points, specific segmentation values, and detailed company profiles contained within our full report. For executives and investors who need to make precise decisions regarding market entry, product development, or investment allocation, the granular details are essential. We invite you to access the full market research report to uncover the specific data driving these trends. The complete analysis offers the actionable intelligence required to turn market insight into strategic advantage.
Extracorporeal Shock Wave Therapy Device Market
For detailed analysis of this topic, please visit the official page: Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
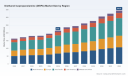
Unlocking Growth Trajectories in the Diethanol Isopropanolamine Market: A Strategic Imperative for 2026
The global chemical landscape is undergoing a quiet but decisive transformation, and at the center of this shift lies Diethanol Isopropanolamine, commonly known as DEIPA. Once confined to niche industrial applications, DEIPA has evolved into a critical enabler across construction chemistry, advanced materials, and precision manufacturing. As organizations navigate an era defined by supply chain recalibration, regulatory tightening, and demand concentration in high-value sectors, understanding the DEIPA market is no longer optional. It is a strategic necessity. Our latest comprehensive market study delivers exactly that clarity, providing enterprise leaders with the analytical rigor required to make informed capital allocation, sourcing, and expansion decisions throughout the forecast window.
The narrative arc of this market is compelling. Drawing from historical data spanning 2020 through 2025, the industry has demonstrated consistent expansion, culminating in a robust baseline valuation that sets the stage for an accelerated growth trajectory. The report projects a compound annual growth rate of 6.98 percent across the 2026 to 2032 period, pushing the market toward a multi-hundred-million-dollar valuation by the end of the forecast horizon. These macro indicators are not merely statistical artifacts. They reflect underlying structural shifts in how industrial chemicals are sourced, formulated, and deployed across increasingly specialized end-use environments. For corporate strategists, procurement directors, and market entry teams, this growth vector signals both opportunity and complexity. The challenge lies in translating broad market momentum into actionable, segmented intelligence that aligns with organizational capability and risk tolerance.
This is precisely where executive decision-makers encounter friction. Aggregate market size and headline growth rates offer direction, but they rarely provide the granularity required to model capacity expansion, pricing strategy, or regional prioritization. Our research framework is designed to bridge that gap. By dissecting demand drivers, supply chain dynamics, regulatory pressure points, and competitive positioning, the study equips stakeholders with a multidimensional view of where value is being created, where bottlenecks are emerging, and how incumbents and newcomers are positioning themselves for the next cycle. The objective is not to overwhelm with volume, but to deliver precision. Every analytical layer serves a practical purpose: reducing uncertainty, sharpening scenario planning, and enabling faster, more confident execution.
Diethanol Isopropanolamine (DEIPA) Market
Decoding the Structural Architecture of DEIPA Demand
DEIPA's growth story is fundamentally tied to its functional versatility. As a specialized chemical intermediate and performance additive, it serves applications where consistency, purity, and formulation compatibility are non-negotiable. The market's demand architecture reflects this reality, with certain application verticals commanding disproportionate share due to their sensitivity to chemical performance and their growth momentum in high-tech and infrastructure sectors. Understanding which verticals are expanding, which are consolidating, and how feedstock volatility influences pricing behavior is essential for any organization operating in or adjacent to this space.
From a supply-side perspective, the DEIPA ecosystem is characterized by a concentrated but strategically active manufacturing base. The report examines how leading producers are navigating raw material fluctuations, particularly around isopropanolamine and diethanolamine, whose pricing can swing sharply in response to global market instability. These input cost dynamics are not abstract concerns. They directly impact margin structures, inventory strategies, and long-term contract positioning. Organizations that integrate feedstock risk modeling into their procurement and production planning gain a measurable advantage, especially when competing in price-sensitive or specification-driven segments.
Equally critical is the role of product differentiation. Within the DEIPA market, performance tiers and purity specifications increasingly dictate commercial outcomes. The study maps how different product configurations align with specific industrial requirements, revealing where premium positioning can sustain pricing power and where volume-driven strategies may be necessary to capture scale. This segmentation lens allows companies to avoid the common trap of treating DEIPA as a homogeneous commodity, and instead approach it as a portfolio of distinct value propositions with varying margin profiles, customer retention characteristics, and entry barriers.
Navigating Regulatory Friction and Cost Dynamics
Growth in the DEIPA market does not occur in a vacuum. Environmental and compliance frameworks are reshaping production economics, particularly in mature markets where regulatory scrutiny has intensified. The research highlights a clear pattern: stringent environmental requirements in North America and Europe are elevating production costs for DEIPA manufacturers, forcing a strategic recalibration of operating models. Compliance is no longer a peripheral consideration. It is a core determinant of competitive positioning, capacity utilization, and regional sourcing strategy.
The operational reality on the ground is stark. A significant portion of global producers are encountering environmental compliance hurdles that affect throughput, capital planning, and time-to-market for new formulations. Nearly half of surveyed manufacturers report restrictions related to volatile organic compounds as a meaningful restraint, while more than half cite broader compliance challenges as direct pressure points on their operational footprint. These figures underscore a market where regulatory agility is becoming a differentiator. Companies that proactively invest in emission control, process optimization, and documentation readiness are better positioned to sustain production continuity, while those that treat compliance as reactive overhead risk margin erosion and supply disruption.
Worldwide N-Methyl Diethanolamine (MDEA) Market
Raw material volatility further compounds this environment. Because DEIPA production depends on precursor chemicals that are exposed to global pricing instability, manufacturers must balance cost pass-through mechanisms with customer retention strategies. The report explores how leading firms are structuring hedging approaches, renegotiating supply agreements, and adjusting formulation strategies to preserve competitiveness without sacrificing compliance standards. For procurement and commercial teams, these insights are vital. They reveal where pricing negotiations are likely to face resistance, where long-term contracts can create structural advantage, and where regional regulatory divergence may open arbitrage opportunities for organizations with multilateral sourcing capabilities.
Competitive Positioning and the Landscape of Strategic Operators
The DEIPA market is not dominated by a single monolithic player. Instead, it features a coalition of specialized producers, regional manufacturers, and distribution networks that collectively shape supply availability, technical service expectations, and market access. The research profiles a set of core companies whose operational footprint and strategic focus provide a clear window into how the market is being contested. These include established producers such as Nanjing Hongbaoli Group Co., Ltd. and Shandong Inniolamine New Material, which anchor significant production capacity around high-purity DEIPA grades for cement grinding aids and concrete admixtures. Their positioning reflects a broader trend in Asian manufacturing ecosystems, where scale, export orientation, and specification refinement are converging to support both domestic infrastructure demand and international supply channels.
India's chemical manufacturing base also features prominently, with organizations like Viswaat Chemicals Limited and Amines & Plasticizers Limited operating as influential contributors to the DEIPA supply chain. Their focus on construction chemicals and cement applications aligns with the region's ongoing infrastructure expansion and the increasing adoption of chemical admixtures to improve performance efficiency. Meanwhile, distribution and trading specialists such as Bisley International LLC play a critical intermediary role, ensuring that industrial and construction end-users can access DEIPA with reduced friction across geographies and specification requirements. This diversified competitive architecture means that market access is rarely about securing a single supplier relationship. It is about understanding how manufacturers, formulators, and distributors interact to create reliability, technical support, and pricing stability.
The report also examines market concentration as a structural indicator of competitive intensity. With a CR3 near 24.6 percent and CR5 at approximately 26.2 percent, the market displays a moderately fragmented profile. This concentration pattern suggests that while leading players hold meaningful influence, there remains substantial room for regional specialists, product-focused innovators, and service-oriented distributors to capture share through differentiation rather than scale alone. For companies evaluating partnerships, acquisitions, or greenfield capacity, this landscape offers multiple entry and expansion pathways, each with distinct risk-reward profiles depending on target segment, geographic exposure, and technical capability requirements.
Translating Market Intelligence into 2026 Execution
What separates useful market research from strategically actionable intelligence is relevance to decision cycles. Our DEIPA study is built around that principle. Rather than stopping at descriptive analysis, the report integrates practical frameworks that help organizations align market signals with internal planning processes. This includes scenario-based forecasting approaches that account for feedstock volatility, regulatory escalation, and demand concentration shifts. It also encompasses supplier evaluation criteria, regional cost-structure comparisons, and application-level demand sensitivity mapping that supports more precise commercial targeting.
For product and R&D teams, the research provides a structured view of specification trends and performance expectations across end-use environments. This enables formulation teams to anticipate where purity thresholds, compatibility requirements, or additive performance benchmarks are moving, reducing the lag between market demand and product readiness. For manufacturing and operations leaders, the study highlights where process efficiency, compliance readiness, and feedstock procurement strategy intersect, offering a basis for capital prioritization and capacity optimization. For commercial and go-to-market teams, the segmentation and competitive analyses clarify where pricing stability is most achievable, where technical service differentiation can protect share, and where geographic expansion may yield disproportionate returns.
The report's design reflects a commitment to operational utility. It organizes complex market dynamics into decision-ready components, allowing executive teams to extract relevant insights without navigating irrelevant detail. Whether the objective is to reassess sourcing strategy, evaluate expansion into adjacent application areas, benchmark competitive positioning, or stress-test margin assumptions under regulatory and raw material pressure, the study provides a coherent foundation for those conversations. In a market where misreading a single variable can compound into inventory imbalance, pricing misalignment, or missed entry windows, that coherence has direct financial and strategic value.
The Strategic Edge in an Accelerating Market
DEIPA is no longer a peripheral chemical story. It is a market where demand growth, regulatory pressure, raw material dynamics, and competitive differentiation intersect in ways that reward informed, anticipatory decision-making. The projected growth trajectory through 2032 signals that the window for strategic positioning is open, but it will not remain frictionless. Companies that treat DEIPA as a static procurement line item risk falling behind organizations that approach it as a strategic capability area, integrating market intelligence into sourcing, product development, compliance planning, and commercial execution.
Our full market study goes deeper into every dimension that matters for 2026 planning and beyond. It unpacks regional demand architectures, application-level growth drivers, competitive movement patterns, and regulatory impact pathways with the level of detail required for credible strategic action. The executive summary provided here is intended to demonstrate analytical depth and establish confidence in the methodology, while preserving the precise segmentation data, detailed company assessments, and scenario modeling frameworks for the complete report. For decision-makers who need more than directional insight, accessing the full study is the logical next step. The market is moving, and the organizations that move with it most effectively will be those that invest in intelligence before they invest in execution.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Virtual Training Market Hits $24.8 Billion in 2025, Projected 10.8% CAGR to $50.78 Billion by 2032
By PW Consulting, 2026-09-16
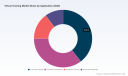
Navigating the Virtual Training Revolution: Strategic Imperatives for 2026 and Beyond
The corporate learning landscape is undergoing a seismic shift. As organizations grapple with hybrid workforces, skill gaps, and the demand for safer, more scalable training environments, Virtual Training has moved from a novelty to a necessity. At PW Consulting, we have synthesized extensive primary and secondary research to deliver a comprehensive view of this transformative market. This article serves as a strategic preview of our latest market research, highlighting the critical intelligence decision-makers need to navigate the forecast period from 2026 to 2032.
Market Trajectory: A Decade of Accelerated Growth
The numbers tell a compelling story of adoption and investment. The virtual training market has demonstrated robust expansion over the historical period. Revenues climbed from 14.85 billion USD in 2020 to 24.8 billion USD in 2025, reflecting a compound annual growth rate that underscores the sector's resilience and strategic importance. As we look toward the forecast horizon, the trajectory accelerates further. Projected revenues are set to reach 27.16 billion USD in 2026, growing steadily to 34.24 billion USD by 2028, and ultimately approaching 50.78 billion USD by 2032.
This growth is not merely linear; it is driven by a sustained CAGR of 10.8 percent across the forecast period. For enterprise leaders, this signals that virtual training is becoming a core infrastructure component rather than a discretionary spend. The expansion reflects broader macroeconomic trends, including the digitization of workflows, the need for remote capability building, and the integration of immersive technologies into standard operational procedures. This report dissects the drivers behind these figures, offering a granular understanding of where capital is flowing and which segments are poised for the most significant upside.
Segmentation Dynamics: Where Value Is Concentrated
Understanding the architecture of the market is essential for allocating resources effectively. Our analysis breaks down the ecosystem into distinct categories, revealing how different technologies and applications are capturing value. In the technology domain, VR and AR training simulations dominate the revenue landscape, reflecting the high-impact nature of immersive learning experiences. This is complemented by a growing market for dedicated training software platforms that manage content delivery, learner analytics, and compliance tracking. Hardware components, while a smaller share of the total revenue mix, remain a critical enabler, particularly as standalone devices become more affordable and powerful.
Application-wise, the market is diversified but shows clear leaders. Corporate training represents a substantial portion of demand, driven by the need for upskilling employees in soft skills, safety protocols, and operational procedures. Educational institutions form another major pillar, leveraging virtual environments for remote labs, vocational training, and accessible learning modalities. Healthcare training is emerging as a high-growth vertical, utilizing immersive simulations for clinical practice and patient interaction scenarios. Government agencies are also increasingly adopting these solutions for defense, public safety, and civil service preparation. The report provides a detailed examination of these application verticals, analyzing adoption rates, key use cases, and the specific value propositions that resonate with each stakeholder group.
Geographically, the market exhibits distinct regional characteristics. North America continues to lead in revenue contribution, supported by high enterprise spending on digital transformation and a mature technology ecosystem. The Asia Pacific region shows dynamic growth potential, fueled by expanding manufacturing bases and increasing investment in workforce development. Europe maintains a strong presence, particularly in sectors requiring strict regulatory compliance and high-fidelity simulations. Latin America and the Middle East and Africa represent emerging opportunities, where infrastructure development and cost-effective training solutions are driving adoption. The full report delves into regional nuances, including local regulatory environments, competitive intensity, and growth catalysts specific to each geography.
Competitive Landscape: Innovators and Incumbents
The virtual training market is characterized by a mix of specialized innovators and established players expanding into immersive technologies. Our report profiles key companies that are shaping the industry, analyzing their strategic positioning, technological capabilities, and target markets.
Several firms are focusing on enterprise-grade solutions for industrial and safety applications. VR Vision, based in Australia, specializes in CGI and 360-degree VR training simulations for sectors such as energy, manufacturing, and utilities, integrating scalable learning management systems. Strivr, headquartered in the United States, has established a strong footprint by deploying custom XR training platforms at Fortune 500 scale, offering centralized headset management and content spanning soft skills, safety, and operations. Humulo addresses the need for compliant safety training with OSHA-aligned industrial VR simulations for manufacturing, warehousing, and government clients, utilizing a one-time licensing model. Transfr focuses on workforce development and credentialing, mapping VR simulations to industry standards like MSSC, OSHA, and NCCER to support career pathway initiatives.
Technical skills training is another area of intense activity. Interplay Learning targets skilled trades with VR training for HVAC, electrical, plumbing, and solar applications, bridging the gap between theoretical knowledge and hands-on practice. PIXO VR operates a safety training marketplace that leverages AI-assisted content creation, enabling enterprise and industrial users to develop customized training modules efficiently. In the healthcare domain, UbiSim provides immersive VR training simulations featuring interactive virtual patients, supporting nursing and clinical education with realistic scenario-based learning.
Broader simulation expertise also plays a role. CAE Inc., based in Canada, delivers high-fidelity simulation training systems for military, defense, and aviation sectors, bringing decades of simulation heritage to the virtual training space. YORD Studio, located in Australia, offers custom XR and AI-powered immersive training solutions across healthcare, manufacturing, and corporate sectors, emphasizing tailored experiences and advanced integration capabilities.
Recent developments highlight the pace of innovation and the increasing focus on trust and compliance. In February 2026, Facilitate confirmed full GDPR compliance for its no-code VR creation platform, which powers immersive training across energy, manufacturing, aviation, mining, healthcare, and higher education. This milestone strengthens data privacy protections for global customers. Concurrently, Facilitate achieved SOC 2 Type II certification, affirming the highest standards of data security, availability, and privacy for its VR training platform. These certifications build on earlier achievements, including SOC 2 Type I certification in May 2025, signaling a maturing ecosystem where security and regulatory adherence are becoming competitive differentiators.
Virtual Training Market
Product innovation continues to expand accessibility and functionality. In October 2025, Virtra introduced the V-One portable simulator, a compact all-in-one design for field-deployable VR training without the need for external screens. This reflects a trend toward hardware solutions that reduce logistical barriers and enable training in diverse environments. Meanwhile, industry analysis from YORD Studio in April 2026 notes that custom enterprise VR training deployments can scale with cloud-based environments, reducing overall training costs by up to 50 percent while maintaining consistent quality. Such insights underscore the economic rationale for adopting virtual training at scale.
Industry Dynamics: Navigating Evolving Pressures
The market is not static; it is shaped by regulatory, operational, and technological dynamics that require strategic attention. Data privacy and security are increasingly central to enterprise procurement decisions. The recent certifications by Facilitate illustrate how vendors are responding to the demand for robust data handling practices. As virtual training platforms collect sensitive learner data and integrate with corporate systems, compliance with frameworks such as GDPR and SOC 2 standards becomes a prerequisite for global deployment. Organizations must evaluate vendors not only on pedagogical effectiveness but also on their ability to safeguard data across borders and use cases.
Regulatory compliance within specific verticals also influences adoption patterns. For instance, OSHA-aligned VR safety training platforms require qualified evaluators for hands-on assessment components, even as they replace formal instruction and practice elements. This nuance highlights the hybrid nature of modern training programs, where virtual simulations augment rather than entirely replace human oversight in regulated environments. Decision-makers need to understand these compliance nuances to design programs that meet legal requirements while maximizing efficiency.
Infrastructure and cost dynamics are shifting the value proposition. Cloud-based environments enable scalable deployments that reduce per-learner costs and ensure consistent training quality across dispersed teams. Labor cost pressures and the need for rapid onboarding further amplify the appeal of virtual training solutions that can be updated quickly and delivered without geographic constraints. However, successful implementation requires careful planning around content development, hardware procurement, change management, and integration with existing learning ecosystems.
Strategic Applications: Turning Insight into Action
This market research is designed to be a practical tool for strategic decision-making. It goes beyond high-level trends to provide actionable intelligence across multiple dimensions. For C-suite executives and strategy leaders, the report offers a clear assessment of market size, growth trajectories, and investment priorities, helping to justify capital allocation and align training initiatives with broader business objectives.
For product and technology teams, the segmentation analysis and competitive profiling provide a blueprint for differentiation. Understanding which technology types and applications are gaining traction allows organizations to refine their roadmaps, prioritize feature development, and identify gaps in the current offering landscape. The profiles of key companies reveal diverse go-to-market strategies, from marketplace models and AI-assisted content creation to specialized vertical solutions and enterprise platform deployments.
Procurement and compliance officers will find value in the detailed examination of regulatory dynamics and vendor certifications. As data security and privacy become critical selection criteria, the report's coverage of certifications, compliance standards, and data handling practices supports informed vendor evaluation. The analysis of regional variations also aids in navigating local requirements and tailoring deployment strategies to specific markets.
Worldwide Virtual Networking Market
Operational leaders can leverage the insights on cost dynamics, scalability, and implementation best practices. The report explores how cloud-based environments, portable hardware, and modular content strategies contribute to cost efficiency and training consistency. It also addresses the practical challenges of integrating virtual training into existing workflows, managing change resistance, and measuring learning outcomes against business metrics.
Conclusion: Positioning for the Future
The virtual training market is entering a phase of sustained expansion, driven by technological maturity, economic incentives, and evolving workforce needs. With revenues projected to grow from 27.16 billion USD in 2026 to nearly 51 billion USD by 2032, the opportunity for organizations that act strategically is substantial. However, capturing this value requires more than simply adopting new tools; it demands a deep understanding of market structure, competitive dynamics, regulatory requirements, and operational realities.
This report from PW Consulting provides that understanding. It synthesizes macro-level data with micro-level analysis, offering a comprehensive view of where the market is headed and how leaders can position themselves for success. From segmentation trends and regional insights to company profiles and recent developments, the research is structured to support informed decision-making at every level of the organization.
For those ready to move beyond surface-level observations and gain access to the full intelligence suite, we invite you to explore the complete report. The detailed findings, including granular segmentation data, competitive benchmarking, and forward-looking scenarios, are available through our source webpage. Equip your strategy with the depth and precision needed to lead in the virtual training era.
For detailed analysis of this topic, please visit the official page: Virtual Training Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive EPS Market to Hit $397M by 2032, 5.57% CAGR Forecasted
By PW Consulting, 2026-09-16
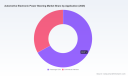
Navigating the Torque Shift: Strategic Imperatives in the Global Automotive Electronic Power Steering Market Through 2032
The automotive industry is currently undergoing one of the most significant paradigm shifts in steering technology since the invention of the rack-and-pinion system. The transition from hydraulic power steering (HPS) to Electronic Power Steering (EPS) is no longer merely an incremental improvement in energy efficiency; it is the foundational enabler for modern Advanced Driver Assistance Systems (ADAS), autonomous driving capabilities, and rigorous emissions compliance. For original equipment manufacturers (OEMs) and tier-one suppliers alike, understanding the trajectory of the EPS market is not optional—it is a prerequisite for strategic resilience.
PW Consulting's latest comprehensive market research report offers a granular examination of the Automotive Electronic Power Steering sector, providing stakeholders with the intelligence necessary to navigate the forecast period from 2026 to 2032. This article serves as a strategic overview of the market landscape, highlighting the macro-economic trends, regulatory pressures, and competitive dynamics that define this critical automotive subsystem.
Market Trajectory and Macroeconomic Environment
The global demand for electronic power steering systems has demonstrated robust growth over the past half-decade, driven by consumer preference for lighter steering feel, improved fuel economy, and the increasing electronic content in vehicles. Historical data from 2020 through 2025 indicates a consistent upward trend in revenue, reflecting the widespread adoption of EPS across various vehicle segments. As the industry moves into the forecast period, the market is projected to sustain a healthy compound annual growth rate, signaling continued investment opportunities in manufacturing capacity and R&D.
By the base year 2025, the aggregate market revenue had reached substantial levels in millions of USD, establishing a strong platform for the forecast years. The projected figures for 2026 and beyond suggest that while the pace of electrification may fluctuate based on regional economic conditions, the underlying demand for steering assist technology remains inelastic. This stability is underpinned by the fact that EPS is now the standard for nearly all new passenger vehicle platforms, displacing legacy hydraulic systems that carry parasitic energy losses.
It is crucial for decision-makers to recognize that the market size expansion is not uniform across all years. Forecasts indicate a gradual acceleration as newer vehicle architectures mature and as regulatory mandates fully take effect in key markets. Understanding the specific revenue projections for each forecast horizon is essential for capacity planning and supply chain optimization, details of which are extensively mapped out in the full report.
Regulatory Catalysts and Technology Dynamics
Regulatory frameworks are acting as potent accelerants for the adoption of EPS technologies. In Europe, the Union's commitment to reducing carbon emissions has directly impacted steering system specifications. With the Euro 7 regulation applicable to new type approvals from 2025, hydraulic power steering has effectively been eliminated from new passenger car specifications due to the parasitic CO2 penalty calculations associated with engine-driven pumps. This regulatory hard line forces manufacturers to prioritize electric solutions that decouple steering power from engine load.
Furthermore, safety standards are evolving to require active intervention rather than passive assistance. The Euro NCAP 2026 protocol now requires lane-keeping assistance as a rated safety feature. This mandate necessitates EPS torque overlay capability across all new passenger vehicle platforms seeking five-star ratings. Consequently, the EPS system is no longer just a comfort feature; it is a critical safety component that must integrate seamlessly with camera and radar inputs to execute corrective steering maneuvers.
Parallel to regulatory pressure, technological innovations are reshaping the competitive landscape. The development of solid-state and sensor-based EPS technologies is improving reliability while reducing system complexity. Modern EPS gearboxes are being engineered with high-strength materials and precision manufacturing techniques that not only improve durability but also reduce noise, vibration, and harshness (NVH)—a key differentiator in premium vehicle segments. Additionally, the shift toward steer-by-wire systems represents the next frontier, removing the mechanical connection between the steering wheel and the wheels entirely, offering unparalleled flexibility in vehicle packaging and human-machine interface design.
Competitive Landscape and Key Player Strategies
The market structure is characterized by high concentration, with a few dominant players holding significant sway over pricing, technology standards, and supply chain dynamics. The top three companies command a substantial share of the market revenue, while the top five entities collectively control an even larger portion of the industry output. This oligopolistic structure suggests that collaboration, strategic partnerships, and first-mover advantages in new technology segments are critical for maintaining market position.
Several key manufacturers are driving these trends through targeted product launches and strategic expansions:
-
Nexteer Automotive , based in Auburn Hills, Michigan, continues to diversify its portfolio beyond traditional column and pinion assist systems. Recently, they initiated series production of a steer-by-wire system as part of a full drive-by-wire chassis program for a leading Chinese New Energy Vehicle (NEV) manufacturer. This move signifies a strategic pivot toward next-generation architectures where steering is fully integrated into the software-defined vehicle ecosystem.
-
China Automotive Systems, Inc. has been aggressively expanding its geographic footprint. Following the award of its first South American C-EPS contract for a new vehicle platform from a leading local manufacturer, the company began volume shipments of EPS systems to a global automaker's European division for two new vehicle models. This demonstrates the increasing competitiveness of Chinese suppliers in established Western markets.
-
JTEKT Corporation confirmed the installation of next-generation steer-by-wire backup power and components in the Lexus RZ production BEV. This validation by a premium brand underscores the reliability challenges inherent in steer-by-wire technology and highlights the importance of redundancy systems in ensuring consumer trust.
-
Other major players such as Robert Bosch GmbH , ZF Friedrichshafen AG , N SK Ltd. , and Denso Corporation continue to refine integrated EPS solutions, focusing on energy-efficient designs and ADAS integration capabilities. Meanwhile, regional champions like Mando Corporation and Hyundai Mobis Co., Ltd. are leveraging their positions within Korean conglomerates to supply premium and volume vehicle platforms with rack-type and column-type systems.
The interplay between these companies involves a complex mix of patent licensing, joint development agreements, and vertical integration strategies. Understanding the specific supply relationships and technology ownership claims among these entities is vital for assessing supply chain risk.
Strategic Segmentation and Application Insights
While the overall market figures provide a top-down view, the true value lies in understanding the dynamics of specific segments. The market is broadly categorized by type, region, and application, each with unique growth drivers and constraints.
In terms of technology type, the market includes Column Assist EPS, Pinion Assist EPS, and Rack Assist EPS systems. Each configuration offers distinct advantages regarding packaging space, steering feel, and cost profile. Rack Assist systems often dominate in terms of revenue volume due to their prevalence in larger vehicles and trucks where higher torque assistance is required. However, Column Assist systems remain prevalent in smaller, cost-sensitive passenger cars. The choice of technology often depends on the vehicle class and the required integration with ADAS features.
Geographically, the market is diversified with significant contributions from North America, Europe, and Asia Pacific. Asia Pacific typically leads in volume due to the high production rates of passenger cars and commercial vehicles in the region. Europe remains a critical market driven by stringent emissions regulations and a strong presence of premium OEMs demanding high-performance steering solutions. North America continues to be a hub for innovation, particularly in steer-by-wire development. Latin America and the Middle East & Africa represent emerging growth areas, often driven by cost-effective manufacturing hubs and increasing vehicle ownership rates.
By application, the market is primarily split between Passenger Cars and Commercial Vehicles. Passenger cars account for the majority of the revenue share, reflecting the sheer volume of production and the mandatory nature of EPS in modern sedans, SUVs, and hatchbacks. Commercial vehicles, including heavy-duty trucks and buses, represent a high-growth niche. As fleet operators seek to reduce operational costs and comply with urban emissions zones, the electrification of steering systems in commercial vehicles is gaining momentum. The specific revenue splits and volume distributions between these applications are detailed in the full dataset, providing precise guidance for segment-specific targeting.
Automotive Electronic Power Steering Market
Implications for 2026 and Beyond
As we move deeper into the forecast period, several strategic implications stand out for industry participants. First, the integration of EPS with vehicle-wide electronic architectures will become a key differentiator. Suppliers who can offer scalable steering solutions that integrate seamlessly with autonomous driving stacks will capture greater value than those offering standalone components.
Second, supply chain resilience is paramount. The reliance on specific electronic components, sensors, and high-strength materials means that disruptions in semiconductor or raw material markets can have outsized impacts on EPS production. Companies must evaluate their supplier diversification strategies and consider localized manufacturing to mitigate geopolitical risks.
Worldwide Automotive Power Steering Market
Third, the rise of Chinese suppliers in European and South American markets suggests that cost competitiveness will remain a primary battleground. Western manufacturers must innovate not just in performance but also in manufacturing efficiency to maintain margins amidst intensifying competition.
Finally, the transition toward steer-by-wire technology, while still in its early stages relative to traditional EPS, will likely accelerate as regulatory approvals streamline and consumer acceptance grows. Early movers in this space have the opportunity to define the standards and interfaces that will govern steering systems for the next decade.
Unlocking the Full Intelligence
This overview provides a high-level synthesis of the Automotive Electronic Power Steering market dynamics, highlighting the critical intersection of regulation, technology, and competition. However, for executives and analysts who need to make precise investment decisions, allocate marketing budgets, or formulate sourcing strategies, a higher resolution of data is required.
PW Consulting's full market research report contains detailed quantitative forecasts, end-user consumption analysis, and granular segmentation data that remain essential for tactical planning. The complete report delves into specific revenue projections for each year through 2032, breaks down market share estimates by region and type with precision, and provides in-depth company profiles that include financial health assessments and product pipeline analyses.
To access the comprehensive intelligence needed to navigate the complexities of the EPS market, stakeholders are encouraged to refer to the full publication. Understanding the exact magnitude of growth, the competitive intensity in specific niches, and the timing of regulatory impacts will be the difference between leading the market and reacting to it.
The road ahead for automotive steering is electric, integrated, and increasingly autonomous. Armed with the right data, industry leaders can steer their organizations toward sustainable growth and technological leadership in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Automotive Electronic Power Steering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


