



PW Consulting: Hemodialysis Concentrates Market to Reach $3.56B by 2032, 6.2% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Hemodialysis Concentrates Market: A 2026 Decision-Maker's Guide
The global landscape for hemodialysis concentrates is undergoing a decisive transformation. As chronic kidney disease prevalence rises and dialysis delivery models evolve, stakeholders across the value chain require more than surface-level market data. They need actionable intelligence grounded in rigorous historical analysis and forward-looking forecasting. PW Consulting's latest Hemodialysis Concentrates Market research report delivers precisely that: a comprehensive, data-driven roadmap designed to inform strategic planning, capital allocation, and competitive positioning through 2032 and beyond. Built on a foundation spanning 2020 to 2025 historical performance and projecting through the 2026 to 2032 forecast horizon, this study equips executives, investors, and operational leaders with the insights necessary to navigate an increasingly complex and regulated marketplace.
The Macro Trajectory: Market Sizing and Growth Dynamics
Understanding where the market stands today and where it is headed requires a clear view of its cumulative growth story. Between 2020 and 2025, the global hemodialysis concentrates market demonstrated consistent expansion, with revenue climbing from approximately 1,800 million USD to an estimated 2,350 million USD by the base year of 2025. This trajectory reflects the compounding effect of rising dialysis patient volumes, evolving clinical preferences, and sustained investment in dialysis infrastructure across multiple continents. Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.2 percent, signaling a market that will continue to expand at a meaningful pace rather than plateauing. By the close of the forecast window in 2032, total market revenue is projected to approach 3,560 million USD.
For enterprise decision-makers, these figures are not merely academic benchmarks. They represent the scale of opportunity and the urgency of strategic preparation. A projected 6.2 percent CAGR over a seven-year horizon implies that companies entering or expanding within this space must align their capacity planning, supply chain resilience, and commercial strategies with a market that will be substantially larger than the one operating today. The report contextualizes this growth within historical volatility, regional infrastructure development cycles, and shifting procurement patterns, ensuring that leadership teams can distinguish between temporary fluctuations and structural trends.
Hemodialysis Concentrates Market
Dissecting the Segmentation Architecture
Effective strategy in the hemodialysis concentrates sector demands a granular understanding of how demand is distributed across product types, end-use applications, and geographic territories. Our analysis examines the market through multiple segmentation lenses, revealing where value concentrates, where growth is most pronounced, and where competitive pressure is intensifying.
Product Type Dynamics
The market is anchored by two principal concentrate categories: acid concentrates and bicarbonate concentrates. Both play indispensable roles in dialysate preparation, yet they serve distinct clinical and operational functions and are subject to different supply chain considerations. The report evaluates the relative market contribution of each type, tracing how formulation preferences, manufacturing complexity, and regulatory scrutiny shape demand patterns. Acid concentrates, which form the foundational component of dialysate chemistry, carry their own set of handling requirements and cost drivers. Bicarbonate concentrates, meanwhile, have seen evolving adoption as clinic and home-care operators seek optimized buffering solutions that align with modern dialysis machine specifications. By mapping historical revenue distribution and projecting forward shifts, the study highlights where manufacturers should prioritize formulation innovation, production scalability, and customer education.
Application and Care Setting Shifts
Beyond product chemistry, the channel through which concentrates reach end users is a critical strategic variable. Dialysis centers remain the dominant consumption environment, benefiting from centralized procurement, standardized dosing protocols, and high-volume utilization. At the same time, home care represents a structurally important and increasingly visible segment. As healthcare systems worldwide explore decentralized treatment models and patient preference shifts toward greater independence, home dialysis programs are gaining policy support and operational investment. The report disentangles these application-level dynamics, examining how procurement cycles, reimbursement environments, and equipment compatibility influence concentrate selection in each setting. This dual-lens approach enables suppliers to tailor their commercial outreach, packaging formats, and technical support resources to the distinct needs of institutional and residential users.
Regional Commercial Landscapes
Geographic diversification is a defining feature of the hemodialysis concentrates market. Demand patterns are shaped by local disease epidemiology, healthcare financing models, dialysis center density, and the maturity of domestic manufacturing capabilities. The report evaluates market conditions across major regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than treating these territories as monolithic blocks, the analysis considers subregional infrastructure gaps, import dependency levels, and the pace of local production ramp-ups. For multinational suppliers, this regional granularity is essential for prioritizing market entry sequencing, localizing supply chains, and calibrating pricing strategies to reflect purchasing power and reimbursement realities in each territory.
Competitive Landscape: Who Shapes the Market and How
The hemodialysis concentrates sector is characterized by a concentrated competitive structure, with a handful of established players accounting for a substantial share of total industry revenue. The report profiles the leading manufacturers whose product portfolios, manufacturing footprints, and commercial strategies define the current market equilibrium. Understanding these companies is not an academic exercise; it is a prerequisite for assessing partnership opportunities, anticipating competitive responses, and identifying white-space opportunities that incumbents may overlook.
Leading Manufacturers and Strategic Positioning
Fresenius Medical Care, headquartered in Bad Homburg, Germany, stands as a major force in the sector, manufacturing Citrasate and a broad range of liquid and dry acid and bicarbonate hemodialysis concentrates for both clinic and home dialysis applications. Its scale and integration with broader dialysis service networks give it a distinctive competitive posture. B. Braun Melsungen, based in Melsungen, Germany, has built its position around the Dialog-plus platform and premixed dialysis concentrates that integrate seamlessly into its full dialysis systems portfolio, emphasizing interoperability and clinician workflow optimization. Nipro Corporation, operating from Osaka, Japan, supplies MedicaPure liquid acid and MedicaLyte bicarbonate concentrates designed for compatibility with hemodialysis machines, reflecting a focus on precision formulation and equipment alignment.
In the United States, Rockwell Medical, headquartered in Wixom, Michigan, has carved out a recognized presence through its CitraPure, Dri-Sate, RenalPure, and SteriLyte product lines, offering both liquid and dry acid and bicarbonate concentrates. Renacon Pharma Limited, based in Karachi, Pakistan, has been manufacturing RENACIT citrate hemodialysis concentrates and related formulations since 1996, representing a long-standing commitment to specialized concentrate production. In Turkey, Farmasol, located in Kayseri, produces acid and bicarbonate concentrates as part of the broader Pollet Medical Group dialysis portfolio. Meanwhile, Pollet Medical Group, operating from Belgium, functions both as a producer of concentrate production systems and as a supplier of acid concentrate solutions for hemodialysis, positioning itself at the intersection of equipment and consumable supply.
Strategic Implications of Competitive Concentration
The market's concentration profile means that strategic moves by top-tier players can ripple across pricing, supply availability, and clinical adoption patterns. The report examines how these manufacturers compete on dimensions such as formulation performance, single-use convenience, digital integration, and geographic reach. By mapping the competitive field, the study helps emerging entrants and mid-tier suppliers identify where they can differentiate effectively, whether through niche formulations, regional partnerships, cost-efficient manufacturing, or service-oriented value propositions that larger incumbents may not fully address.
Recent Industry Developments: Accelerating Change
The competitive and operational landscape is not static. Recent corporate actions and product innovations underscore the speed at which the hemodialysis concentrates market is evolving. In January 2025, Farmasol became part of Pollet Medical Group through an acquisition that expanded in-house production of hemodialysis acid concentrates, illustrating a broader trend toward vertical integration and consolidated manufacturing capabilities. Just weeks later, in February 2025, Rockwell Medical added single-use bicarbonate cartridges to its hemodialysis concentrates portfolio, responding to growing demand for simplified handling, reduced preparation variability, and enhanced infection-control workflows. In July 2025, Fresenius Medical Care launched the kinexus unified digital platform, a move designed to support the integration of hemodialysis concentrates into broader connected care ecosystems, signaling the increasing convergence of consumable supply and digital clinical management. By October 2025, Rockwell Medical further reinforced its commercial visibility by exhibiting its concentrates portfolio at ASN Kidney Week 2025, underscoring the importance of professional conferences as platforms for product education and partnership development.
These developments are not isolated events. They reflect a market in which manufacturers are actively reshaping their portfolios, exploring integration opportunities, and investing in user-centric formats. For buyers and investors, tracking such moves is essential for anticipating supply shifts, evaluating vendor reliability, and understanding where innovation is likely to create new purchasing criteria.
Regulatory, Reimbursement, and Cost Pressures: The Operational Reality
No strategic assessment of the hemodialysis concentrates market is complete without addressing the regulatory and economic forces that shape day-to-day operations. In 2025, the sector faced heightened regulatory attention, including a Class 2 device recall issued by the FDA on May 28, 2025, concerning premixed dialysate for hemodialysis due to potential perimeter seal issues. Later in the year, on December 23, 2025, the FDA issued another Class 2 device recall related to Diasol liquid concentrate, focusing on the safety and efficacy of dialysis acid concentrates. These actions followed earlier quality monitoring measures, including the termination of a Class 2 device recall for dialysate concentrate for hemodialysis on July 11, 2024. Collectively, these regulatory events highlight the critical importance of quality assurance, packaging integrity, and documentation rigor throughout the concentrate supply chain.
Hemodialyzer Market
Reimbursement dynamics add another layer of complexity. Reimbursement for hemodialysis concentrates varies by jurisdiction, with standard CPT codes covering dialysis fluid preparation in major markets. While this framework provides a baseline for cost recovery, differences in coding practices, payer policies, and regional healthcare financing mean that margin structures and purchasing behaviors can diverge significantly across territories. The report contextualizes these reimbursement patterns, helping commercial teams forecast uptake sensitivity to policy changes and design pricing strategies that align with local payment environments.
On the cost side, medical-grade material inputs—including purified water, electrolytes, and acids—are subject to fluctuations driven by supply chain infrastructure and manufacturing logistics. The study examines how input cost variability interacts with production scale, inventory management, and contractual arrangements, providing practical guidance for operators seeking to stabilize margins without compromising product quality or service reliability.
What the Report Delivers: Operational Intelligence for Decision-Makers
PW Consulting's Hemodialysis Concentrates Market report is built to translate market complexity into executable strategy. Its content is organized to support a range of decision-making needs, from long-range capacity planning to near-term commercial execution. The report includes:
- Historical market sizing and growth analysis spanning 2020 through 2025, establishing a reliable baseline against which future performance can be measured.
- A seven-year forecast for 2026 through 2032, projecting revenue evolution at a market level and across key segmentation dimensions, with methodology transparent enough to support internal validation and sensitivity testing.
- Detailed segmentation analysis covering product type, application setting, and regional demand patterns, enabling targeted go-to-market planning and resource allocation.
- Comprehensive company profiles of leading manufacturers, including organizational background, product offerings, and strategic positioning, alongside an assessment of competitive concentration and market share dynamics.
- A curated review of recent industry developments, including acquisitions, product launches, and conference visibility, to help stakeholders track the pace and direction of competitive change.
- An in-depth examination of regulatory events, reimbursement structures, and material cost drivers, providing the operational context needed to interpret market data in practical terms.
- Strategic recommendations and scenario considerations designed to help leaders evaluate entry timing, partnership options, capacity investments, and portfolio emphasis in light of evolving market conditions.
Each section is crafted to avoid generic commentary and instead deliver specific, decision-oriented insight. The report connects quantitative trends with qualitative industry dynamics, ensuring that readers can interpret numbers within the broader operational and regulatory environment in which they will be applied.
Why This Research Matters for 2026 Strategy
As organizations plan their 2026 agendas, the hemodialysis concentrates market presents both opportunity and complexity. Demand is projected to continue its upward trajectory, competitive intensity is being reshaped by consolidation and product innovation, and regulatory scrutiny is reinforcing the importance of quality and supply chain transparency. In this environment, decisions made without comprehensive market intelligence carry heightened risk. Investment timing, geographic prioritization, product portfolio emphasis, and vendor selection all benefit from a clear, evidence-based view of where the market is headed and why.
This report is designed to serve as that reference point. It does not merely describe market size; it explains the forces behind size, the segmentation patterns that determine where growth will be realized, and the competitive and regulatory developments that will shape execution. For executives, procurement leaders, investors, and strategy teams, the study offers a structured basis for evaluating options, challenging assumptions, and aligning internal planning with external realities.
Access the Full Intelligence
While this overview highlights the scope and strategic relevance of the research, the complete report contains the detailed segmentation data, competitive assessments, regional breakdowns, and forward-looking analysis that decision-makers need to act with confidence. For a thorough examination of market trajectories, company positioning, and the operational dynamics influencing hemodialysis concentrates supply and demand, we invite you to explore the full study. Accessing the complete report will provide the depth and specificity required to translate high-level trends into precise, actionable strategy for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Leather Market Hits $732M in 2025, Forecasts 6.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Leather Market in 2026: Strategic Intelligence for Enterprise Decision-Making
The global leather industry stands at a critical inflection point. As we move through 2026, enterprise leaders across apparel, footwear, automotive, and furniture sectors face a complex matrix of regulatory shifts, supply chain realignments, and evolving consumer expectations. The Leather Market research publication from PW Consulting delivers the analytical rigor required to navigate this landscape with confidence. This article previews the strategic framework embedded within our latest market study, illustrating why timely, data-rich intelligence is no longer optional for organizations seeking sustainable growth.
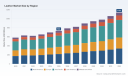
Analyzing historical performance from 2020 through 2025 reveals a sector that has demonstrated notable resilience. The global market expanded from approximately 583.0 million USD in 2020 to an estimated 732.0 million USD by 2025. This trajectory reflects more than post-pandemic recovery; it underscores the enduring value of leather as a material synonymous with durability, premium positioning, and craftsmanship. Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5 percent, with valuations expected to reach 787.79 million USD in 2026 and scale toward 1.138 billion USD by 2032. These figures establish a foundation for substantive strategic planning, but the true value of our study lies in unpacking the structural forces that will drive or constrain this expansion.
Decoding the Structural Growth Architecture
Growth at this scale does not happen uniformly. Enterprise strategists must understand which end-use applications are absorbing capacity, how regional demand centers are shifting, and where material preferences are diverging. The research examines how footwear continues to anchor demand while apparel, furniture, automotive interiors, and miscellaneous applications each contribute to a multifaceted consumption pattern. Rather than presenting static allocation percentages, the study maps the underlying purchase drivers, seasonal inventory cycles, and substitution dynamics that influence volume flows across these categories.
Material segmentation introduces another layer of strategic complexity. The market accommodates both genuine leather and synthetic alternatives, with each pathway serving distinct performance, cost, and sustainability requirements. Our analysis dissects the pricing architectures, manufacturing footprints, and quality certification pathways associated with these material streams, equipping procurement and product development teams with the context needed to make informed sourcing decisions. Regional consumption patterns further complicate the picture. North American, European, Asia-Pacific, Latin American, and Middle East and African markets each present unique demand rhythms, regulatory environments, and distribution infrastructure. The report provides directional intelligence on where capacity is tightening, where new sourcing hubs are gaining credibility, and how trade friction is reshaping traditional supply corridors. Executives seeking precise allocation figures will find them within the full dataset, but the strategic signal here is clear: regional diversification and scenario planning are becoming operational necessities.
The Competitive Landscape: Positioning in a Fragmented Ecosystem
Market concentration metrics indicate a relatively distributed competitive field. With a CR3 of 24.0 percent and a CR5 of 28.0 percent, no single cluster dominates the value chain, leaving substantial room for differentiated strategies. The study profiles a cross-section of organizations that illustrate the breadth of market participation. Horween Leather Company, headquartered in Chicago, has built its reputation on premium full-grain and exotic leathers serving fashion, footwear, furniture, and automotive applications. Wolverine Worldwide, based in Rockford, Michigan, continues to produce genuine leather footwear and apparel under established brand portfolios that emphasize quality and durability. Weinheimer Leder in Freudenberg, Germany, maintains traditional tannery processes to manufacture finished leather for shoes, handbags, and leather goods.
Leather Market
The competitive mosaic extends well beyond legacy North American and European players. Saddleback Leather Co. offers high-quality full-grain and top-grain goods, including bags, wallets, and briefcases, backed by a distinctive long-warranty positioning that reinforces brand trust. American Leather Holdings focuses on custom handcrafted American-made furniture and upholstery products, capitalizing on domestic production narratives. In India, A.V. Thomas Leather & Allied Products Pvt. Ltd. operates as a leading manufacturer of small leather goods with a global export orientation, while Bhartiya International Limited produces leather apparel, accessories, and fashion products across manufacturing bases in India and China. These profiles are not merely corporate summaries; they are strategic reference points for evaluating partnership opportunities, competitive threats, and white-space opportunities in specific product categories and geographies.
Regulatory & Environmental Dynamics: Compliance as Competitive Advantage
Regulatory momentum in 2026 is reshaping the operational baseline for leather manufacturers, traders, and brand owners. The European Commission submitted a report in March 2026 on the scope of the EU Deforestation Regulation (EUDR), addressing cattle hides and prepared leather to mitigate deforestation impacts. Effective December 2026, EUDR requires proof of legality and deforestation-free origin for relevant HS codes, with industry submissions actively seeking the inclusion of leather to close supply chain gaps. This regulatory trajectory is reinforced by OEKO-TEX LEATHER STANDARD, which mandates transparent supply chain disclosure and origin proof for cattle and calf hides, including delivery documentation from slaughterhouses, ahead of EUDR implementation.
In parallel, the U.S. Federal Register published revised REACH restrictions on the import, distribution, and use of leather treated with specific chemicals, effective June 1, 2026. Compliance teams must therefore anticipate chemical management updates alongside traceability requirements. India's Bureau of Indian Standards has also solicited industry comments on draft standards under CHD-17 (Leather, Tanning Materials and Allied Products) and CHD-19 (Footwear), signaling continued standardization efforts in a major production hub. Meanwhile, macroeconomic pressures are materializing in trade flows. U.S. leather exports slipped 1.6 percent in FY26 due to West Asia tensions and tariffs, prompting the Leather & Hide Council of America to secure USDA funding for expanded promotional activities in key markets. These developments are not peripheral; they directly influence sourcing costs, shipment viability, and brand reputation.
Market Intelligence That Drives Actionable Strategy
The research is structured to convert complexity into executable insight. It delivers a comprehensive examination of value chain architecture, from raw hide procurement and tanning processes through finishing, garmenting, and end-market distribution. The analysis integrates demand-side drivers, capacity utilization indicators, and pricing sensitivity across major application verticals. It also evaluates the operational implications of recent industry events that signal where attention is concentrated. The 4th Edition of the RLSD Africa Talent Leather Design Showcase, launched by the Africa Leather and Leather Products Institute in January 2026, highlights the growing emphasis on responsible, design-led leather products in African markets. The 39th India International Leather Fair held at the Chennai Trade Centre in February 2026 showcased the scale and diversity of Indian leather industry output, while the ILM Offenbach 2026 fair reinforced the strategic importance of premium leather goods, bags, and fashion categories in European trade networks. Additionally, a national webinar and outreach initiative under the Pradhan Mantri Viksit Bharat Rozgar Yojana, coordinated by the Council for Leather Exports in February 2026, underscored workforce development and sectoral expansion priorities in India.
Leather Goods Market
Beyond these events, the study examines cross-cutting themes that influence long-term positioning. Traceability infrastructure, chemical compliance readiness, and sustainability narrative alignment are assessed as strategic capabilities rather than checkbox exercises. The report also evaluates how trade policy volatility, regional demand elasticity, and raw material availability interact to shape margin profiles across different participant archetypes. For enterprise decision-makers, this translates into a clearer view of where to invest in supply chain resilience, where to pursue geographic expansion, and where to defend share through product differentiation.
Why This Research Matters for 2026 Decision-Making
Enterprises operating in or adjacent to the leather market face a narrower window for reactive strategy. Regulatory timelines are compressing, trade routes are recalibrating, and consumer expectations around provenance and environmental impact are intensifying. Organizations that wait for disruption to crystallize before acting risk margin erosion, compliance exposure, and brand integrity challenges. Our market study provides the forward-looking framework needed to anticipate rather than merely respond. It supports scenario planning by mapping how regulatory, macroeconomic, and competitive variables could interact across the forecast horizon. It enables procurement and sourcing leaders to evaluate supplier landscapes with greater granularity, identifying partners whose compliance posture, production capability, and geographic footprint align with enterprise risk tolerances. It equips strategy and corporate development teams with the context required to assess M&A targets, partnership structures, and category entry decisions.
The 6.5 percent CAGR projected through 2032 signals that growth is attainable, but the distribution of that growth will favor organizations that act on precise intelligence rather than broad assumptions. This research is designed to close the gap between high-level market awareness and operational readiness. By integrating historical performance, forward-looking projections, competitive profiling, regulatory tracking, and event-driven industry signals, it delivers a single-source reference for cross-functional decision-making.
How to Access the Full Intelligence Package
The preview above distills the analytical lens and strategic relevance of the study, but the detailed segmentation values, regional demand breakdowns, application-level revenue allocations, and company-level competitive assessments are reserved for the complete publication. These granular data points are essential for building sourcing models, setting growth targets, and validating market entry assumptions. PW Consulting's Leather Market research provides the depth required to move from directional understanding to quantified planning. Enterprise teams seeking to align 2026 strategy with rigorous market evidence are encouraged to access the full report for comprehensive figures, scenario tables, and executive-ready synthesis. In a market defined by regulatory acceleration and shifting demand centers, the organizations that secure actionable intelligence first will define the next phase of competitive advantage.
For detailed analysis of this topic, please visit the official page: Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fatigue Machine Market to Hit USD 731.77M by 2032, 6.2% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Fatigue Machine Market: Navigating Growth and Competition Through 2032
The global landscape for fatigue testing equipment is entering a decisive phase of evolution. As manufacturing sectors face mounting pressure to ensure material durability, lifecycle reliability, and compliance with rigorous safety standards, the demand for precision fatigue machines has become a critical enabler of industrial resilience. PW Consulting’s latest market research on the Fatigue Machine Market offers a comprehensive, data-rich foundation for strategic planning in 2026 and beyond. This report is not merely a retrospective analysis; it is a forward-looking decision-support tool designed to help executives, procurement leaders, engineers, and investors navigate a market undergoing steady expansion, technological refinement, and intensifying competitive dynamics.
The fatigue machine market has demonstrated consistent upward momentum over the past half-decade. Historical valuation data from 2020 through 2025 reveals a clear trajectory of growth, with the market expanding from approximately $360 million to $483 million. This progression reflects sustained capital allocation toward materials testing infrastructure, driven by the needs of automotive validation, aerospace certification, civil engineering assessment, and advanced research applications. Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to reach roughly $732 million by the end of the decade. The implied compound annual growth rate of 6.2 percent underscores a market that is not experiencing volatility-driven spikes, but rather a methodological, demand-led expansion rooted in engineering requirements and regulatory expectations. For enterprise decision-makers, this steady growth curve signals a market where long-term capacity planning, technology investment, and supply chain alignment can yield compounding strategic advantages.
Why This Research Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the fatigue testing ecosystem face a conjunction of forces that make high-quality market intelligence indispensable. On the demand side, industries are pushing harder against the boundaries of material performance. Lightweight composites, additively manufactured components, and next-generation battery structures are redefining validation protocols. On the supply side, input cost volatility and competitive pricing pressure are constraining margin expansion for equipment manufacturers, placing a premium on scale, integrated supply chains, and differentiated service capabilities. Simultaneously, evolving regulatory and quality standards are steering procurement decisions toward certified, specification-compliant fatigue testing equipment, making compliance architecture a core competitive variable rather than a back-office function.
In this environment, strategic choices made in 2026 will shape competitive positioning for years. Whether a manufacturer is evaluating capacity expansion, a laboratory is planning capital procurement, an automotive or aerospace supplier is defining testing partnerships, or an investor is assessing market entry and consolidation opportunities, the cost of incomplete intelligence is high. The PW Consulting study is structured to reduce that uncertainty. It provides a granular view of market sizing, segmentation behavior, competitive positioning, and the regulatory and technological currents shaping procurement patterns. By aligning these dimensions into a single analytical framework, the report enables leaders to move from reactive market observation to proactive portfolio and investment strategy.
What the Report Delivers: Operational Content and Analytical Depth
This market research is designed for execution, not just awareness. The report systematically unpacks the Fatigue Machine Market across multiple analytical layers, giving readers a clear map of where value is created, where competition is intensifying, and where strategic openings exist. Core components include:
Fatigue Machine Market
- A detailed historical and forecast revenue analysis covering the base year 2025 and extending through the 2026 to 2032 forecast horizon, allowing readers to benchmark current market conditions against projected growth pathways.
- Segmentation analysis that breaks down demand patterns by technology type, application domain, and geographic footprint, helping stakeholders identify which subsegments are accelerating, which are maturing, and where resource allocation should be prioritized.
- Competitive landscape profiling that examines the strategic posture, product capabilities, geographic presence, and recent activity of leading manufacturers, enabling readers to assess relative market strength and potential partnership or competitive threats.
- Market concentration insights that clarify the share structure among top performers, offering perspective on the balance between established scale players and emerging regional contenders.
- Industry dynamics coverage that integrates regulatory developments, standards symposia, product launches, and major test milestones into a cohesive view of the forces shaping purchasing behavior and technology roadmaps.
Each section is built to translate data into action. Rather than presenting isolated figures, the report contextualizes numbers within operational realities: how different frequency ranges align with specific testing requirements, how application segments differ in procurement cycles and specification sensitivity, and how regional demand profiles interact with local manufacturing capacity and certification ecosystems. For teams responsible for market entry, product positioning, pricing strategy, or long-term capacity planning, this structure provides a practical scaffold for decision-making.
Competitive Landscape: Scale, Specialization, and Strategic Moves
The fatigue machine market is characterized by a blend of globally established testing equipment manufacturers and regionally focused producers that compete on specialization, responsiveness, and cost architecture. Market concentration data indicates that the top three players hold approximately 38 percent of total revenue, while the top five account for roughly 50 percent. This distribution suggests a market where leadership is meaningful but not absolute, leaving substantial room for differentiated positioning by mid-tier and regional suppliers. In practical terms, this means competitive advantage often derives from technology focus, application expertise, service networks, and the ability to meet localized compliance requirements rather than from scale alone.
Several companies illustrate the strategic diversity shaping the market. MTS Systems Corporation, based in Eden Prairie, Minnesota, manufactures servohydraulic and electrodynamic fatigue and fracture testing systems for high-cycle, low-cycle, and thermo-mechanical fatigue applications across aerospace, automotive, and civil engineering. Its breadth of application coverage positions it as a comprehensive solutions provider for sectors where multi-axis and multi-environment validation is essential. ADMET, Inc., headquartered in Norwood, Massachusetts, develops expert and modular fatigue testing systems supporting high-cycle and low-cycle testing compliant with ASTM and ISO standards, emphasizing modularity and standards alignment that appeal to laboratories and industrial users seeking configurable setups. ZwickRoell Group, located in Ulm, Germany, offers dynamic fatigue testing machines, vibrophores, and automated systems for materials including metals, composites, and elastomers, with a clear focus on advanced material categories that are increasingly central to electrification and lightweighting strategies.
Instron, also based in Norwood, Massachusetts, provides fully integrated dynamic and fatigue testing systems using servohydraulic, servo-electric, and linear motor technologies for cyclic loading evaluation. Its technology versatility supports a wide range of test configurations, making it a strong reference point for organizations that prioritize integrated hardware and software ecosystems. Shimadzu Corporation, based in Kyoto, Japan, manufactures hydraulic and electromagnetic fatigue testing machines and servopulser systems for durability assessment under cyclic and sudden loads, reflecting a long-standing capability in precision mechanical testing instrumentation. On the regional side, Testron Group in Guangzhou, China, sells servo-hydraulic anchorage and industrial fatigue testing machines with advanced sensors for cyclic stress and vibration measurement, while Laryee Technology Co., Ltd., in Weifang, Shandong, provides computer-controlled servo-hydraulic and electronic fatigue testing machines for dynamic and static universal testing applications. Shanghai Bairoe Test Instrument Co., Ltd., also in Shanghai, manufactures fatigue testing machines including PLW-series systems for tension, compression, and cyclic loading on metals and non-metals. Together, these companies highlight a market where global technology leadership and regional manufacturing agility coexist, and where procurement decisions increasingly weigh both specification compliance and total cost of ownership.
Recent Developments Shaping Market Dynamics
Current market momentum is being reinforced by a series of high-visibility industrial and standards-related events. In December 2025, ASTM International held its Sixth Symposium on Evaluation of Existing and New Sensor Technologies for Fatigue, Fracture, and Mechanical Testing, inviting papers for related events and signaling sustained attention to the sensor and measurement layer that underpins reliable fatigue data. Earlier that year, in November 2025, the 23rd International ASTM/ESIS Symposium on Fatigue and Fracture Mechanics convened with invited presentations, further reinforcing the role of standards bodies in defining best practices and testing rigor. These gatherings matter because they shape the technical expectations that procurement teams ultimately translate into equipment specifications.
On the product and application front, ZwickRoell Group launched a next-generation biaxial testing system in February 2026, featuring enhanced load capacity for composite materials used in electric vehicle batteries. This launch is strategically significant because it aligns equipment capability with one of the fastest-evolving application demands in the market: the validation of battery-adjacent composite structures. In the aerospace domain, General Atomics Aeronautical Systems, Inc. completed full-scale fatigue testing of the MQ-9B Remotely Piloted Aircraft in January 2026, equivalent to 40,000 operating hours. Such milestones demonstrate the high-stakes nature of fatigue validation in certification-critical programs and reinforce the need for robust, traceable testing infrastructure. Meanwhile, MTS Systems Corporation exhibited at the SAE Japan exhibition in Yokohama in May 2025, showcasing materials testing solutions and underscoring the importance of regional engagement in technology demonstration and customer development.
Hardness Testing Machine Market
Market Dynamics: Standards, Cost Pressures, and Procurement Direction
The fatigue machine market does not evolve in a vacuum. Several structural dynamics are shaping how demand forms and how suppliers compete. First, evolving regulatory and quality standards are structuring procurement toward certified, specification-compliant fatigue testing equipment. As organizations face greater scrutiny on material reliability and component lifecycle performance, the compliance credentials of testing systems have become a decisive factor in purchasing decisions. This trend benefits manufacturers that can clearly demonstrate alignment with recognized standards and provide the documentation, calibration support, and validation traceability that regulated industries require.
Second, input cost volatility and competitive pricing pressure are constraining margin expansion for fatigue testing machine manufacturers. In this environment, scale manufacturers with integrated supply chains hold a structural advantage, since they can better absorb cost fluctuations, manage component availability, and maintain consistent delivery performance. For smaller or more fragmented producers, the strategic response often lies in focused application expertise, faster customization cycles, or regional service advantages that justify price differentials through total value rather than unit cost alone.
Third, the technical standards landscape continues to deepen. Guidance such as NASA-HDBK-5026, finalized in August 2024, provides direction for fatigue and fracture control requirements in additive manufactured parts. As additive manufacturing moves from prototyping into production-critical roles, testing protocols for these components are becoming more formalized. This has direct implications for fatigue machine demand, since additively manufactured parts often require specialized evaluation approaches that differ from conventional wrought or machined components. Markets that embrace advanced manufacturing are therefore likely to drive demand for testing systems capable of handling new geometries, material behaviors, and validation regimes.
Strategic Implications for 2026 and Beyond
For organizations planning their next moves, the strategic implications of this market are clear. Growth is projected to be durable rather than speculative, with the market moving from $504.79 million in 2026 toward $731.77 million by 2032. This trajectory rewards players that can align product portfolios with the most resilient demand drivers, particularly where regulatory expectations, advanced material adoption, and high-cycle validation requirements intersect. At the same time, the concentration structure of the market suggests that while leading firms command meaningful share, there is still substantial competitive space for companies that can differentiate through technology specificity, application focus, or regional execution.
Procurement teams should treat compliance and traceability as strategic procurement criteria, not optional features. Manufacturers and service providers should assess where margin pressure is most intense and where integrated supply chain strength can protect profitability. Investors and entry strategists should pay close attention to the application segments and technology types that are expanding fastest, since the aggregate growth figure alone does not reveal where the most attractive risk-adjusted opportunities reside. In all cases, the ability to connect market data to operational choices will separate informed strategy from generic positioning.
Conclusion: Turn Market Intelligence into Strategic Advantage
The Fatigue Machine Market is entering a period in which disciplined analysis can translate directly into competitive advantage. The combination of steady macroeconomic growth, evolving testing requirements, standards-driven procurement, and cost-side pressure on manufacturers creates a landscape where the right strategic moves can compound over time. PW Consulting’s latest market research provides the depth, structure, and forward-looking context needed to make those moves with confidence. To access the complete analysis, including detailed segmentation insights, company-level evaluations, and full forecast data, readers are encouraged to explore the full report through the source page. In a market defined by durability, precision, and long-cycle decision-making, comprehensive intelligence is the foundation of durable strategy.
For detailed analysis of this topic, please visit the official page: Fatigue Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Patrol Boats Market Set to Rebound to $63.83 Million by 2032 With 6.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Wake: Strategic Insights for the 2026 Patrol Boats Market
The global security landscape is undergoing a profound transformation, driven by evolving threats, maritime boundary complexities, and an intensified focus on rapid response capabilities. For defense contractors, law enforcement administrators, and maritime security stakeholders, understanding the trajectory of the patrol boats market is not merely an exercise in data consumption but a critical component of strategic planning. As we move through 2026, the industry stands at a pivotal inflection point. Following a period of contraction from 2020 to 2025, where global revenue dipped from approximately 56.07 million USD to 40.54 million USD, the market is now signaling a robust recovery. Our latest research indicates that the sector is poised for renewed growth, with projections estimating a climb to 63.83 million USD by 2032.
This shift is not accidental. It reflects a recalibration of procurement priorities, the modernization of aging fleets, and the increasing demand for versatile watercraft that can serve dual roles in military and civil security contexts. However, navigating this resurgence requires more than a superficial glance at top-line numbers. It demands a granular understanding of regional disparities, technological differentiators, and the competitive maneuvers of key players who are reshaping the supply chain. This report serves as a comprehensive guide for executives who need to make informed capital allocation and procurement decisions in this dynamic environment.
Market Trajectory and Growth Dynamics
The historical data from 2020 through 2025 reveals a period of consolidation and adjustment. While the overall market size experienced a downward trend during these years, the forecast period from 2026 to 2032 tells a different story. The market is expected to accelerate, supported by a compound annual growth rate that underscores the renewed confidence in maritime patrol investments. This growth is not uniform across the board; it is concentrated in areas where technological innovation meets urgent operational needs.
Our analysis highlights that the recovery is underpinned by specific demand drivers that vary significantly by application and vessel type. While specific regional revenue figures and detailed segmentation percentages are reserved for the full dataset to maintain the integrity of our proprietary intelligence, the broader trends are clear. The market concentration remains high, with the top three competitors holding a significant share of the landscape, indicating an industry where scale and established relationships play a crucial role. Furthermore, the top five players dominate the majority of the market, suggesting that barriers to entry remain substantial for new manufacturers lacking specialized capabilities or government contracts.
For decision-makers, this structure implies that partnership opportunities may be more viable than attempting to disrupt the market from outside. The projected growth from 41.89 million USD in 2026 to over 57.91 million USD by 2030 suggests a widening window of opportunity for suppliers who can align their offerings with the specific technical and operational requirements of end-users. The forecast extends through 2032, providing a long-term view that accounts for budget cycles, procurement lead times, and the lifespan of existing fleets.
Competitive Landscape and Key Players
The patrol boats market is characterized by a diverse yet concentrated group of manufacturers who specialize in distinct niches ranging from high-speed interceptors to armored surveillance craft. Understanding the strategic positioning of these companies is essential for benchmarking and identifying potential collaborators or competitors. Our report provides detailed profiles of several industry leaders who are currently defining the standards for performance and reliability.
Metal Shark Boats, based in Jeanerette, Louisiana, remains a dominant force with a focus on custom aluminum patrol vessels and near-coastal patrol vessels. Their recent activity underscores their commitment to expanding capabilities and securing high-profile contracts. In April 2026, Metal Shark completed the delivery of a 55-foot patrol vessel to the Massachusetts State Police Marine Unit, demonstrating their penetration into domestic law enforcement sectors. Simultaneously, they completed the U.S. Navy 40PB Flight 1 program for 40-foot patrol boats, reinforcing their position in military supply chains. Further expanding their global footprint, Metal Shark appointed Pacific Manufacturing as its Australian manufacturing partner in May 2026. Additionally, in May 2026, the company delivered eight high-speed interceptors to the Jamaica Defence Force, highlighting their international reach.
MetalCraft Marine, headquartered in Watertown, New York, specializes in high-speed aluminum patrol boats and interceptor models tailored for fire, rescue, and patrol missions. Their product innovations, such as patented rapid-hinging mast technology that allows for one-man deployment in under 10 seconds, address the critical need for rapid response times in emergency scenarios. Moose Boats, located in Vallejo, California, offers custom aluminum catamaran and monohull patrol boats designed for law enforcement and harbor security. Their M1 diesel-waterjet catamaran patrol boats achieve maximum speeds over 40 knots and are certified on the GSA contract for U.S. government law enforcement use, making them a preferred vendor for federal agencies requiring high-performance platforms.
International manufacturers also play a significant role. Swiftships, based in Morgan City, Louisiana, produces steel, aluminum, and composite patrol boats and coastal patrol craft with configurations suitable for both commercial and military applications. Zodiac Milpro, from Paris, France, manufactures Sea RIB and inflatable patrol and responder boats with modular designs for intervention and security. Their Sea RIB Responders patrol boats include detachable stabilizing collars for operation in rough seas up to 11 meters in length, showcasing engineering solutions for challenging maritime environments. Aresa Shipyard, located in Arenys de Mar, Spain, builds military and surveillance patrol boats including armored models for special forces and coastal operations. Their 1700 Black Falcon armored patrol boat is designed for special forces missions with shock mitigation and crew capacity for five personnel, catering to niche high-risk operational requirements.
Offshore Patrol Vessels Market
Operational Requirements and Technical Specifications
The demands placed on modern patrol boats extend far beyond basic transportation. Agencies require platforms that can sustain multi-day patrols, maintain high speeds in varying sea states, and support specialized equipment deployments. The U.S. Coast Guard 87-foot Marine Protector class patrol boats, for instance, operate with a top speed around 25 knots, support multi-day patrols, and feature stern-launch systems for RHIBs in coastal enforcement missions. These operational parameters set a benchmark for what procurement officers expect from new acquisitions.
Speed, durability, and deployability are key differentiators. The ability to launch quickly, navigate rough waters, and operate with minimal crew is increasingly valued as budgets tighten and manpower constraints persist. Manufacturers are responding with innovations that reduce deployment time and enhance crew safety. For example, the integration of rapid-hinging mast technology allows for faster setup, while modular designs enable vessels to be reconfigured for different mission profiles without extensive retrofitting. Armored models with shock mitigation systems are becoming essential for units involved in high-risk interdiction or special forces support. These technical nuances are critical for procurement teams evaluating bids, as the total cost of ownership includes not just the purchase price but also operational efficiency and maintenance requirements over the vessel's lifecycle.
Strategic Value of Detailed Market Intelligence
In an industry where margins are tight and competition is fierce, having access to detailed segmentation data and competitive analysis provides a distinct advantage. This report goes beyond aggregate market size to explore the intricacies of demand by region, vessel type, and application. While we have highlighted the overarching growth trends and key industry players here, the full report contains specific revenue data and percentage splits that allow for precise market sizing and opportunity identification.
Understanding which regions are driving growth, which vessel sizes are seeing increased adoption, and which applications are prioritizing procurement can inform everything from sales strategy to R&D investment. For example, knowing the relative market strength of small versus large patrol boats can help manufacturers prioritize production lines. Similarly, understanding the balance between military and police patrol demands can guide marketing messaging and partnership development. The report also delves into the regulatory environment, examining how standards and operational requirements influence procurement decisions and vendor selection.
Patrol Boats Market
The high market concentration indicates that established players have significant leverage, but it also highlights gaps where specialized solutions can find traction. By analyzing recent developments, such as new partnerships, contract completions, and delivery milestones, stakeholders can anticipate shifts in supplier capabilities and availability. This intelligence is vital for organizations looking to secure supply chains, negotiate contracts, or enter new geographic markets. The forecast period through 2032 allows for long-term planning, helping organizations align their capital expenditure with anticipated market conditions.
Conclusion: Preparing for the Next Decade of Maritime Security
As the patrol boats market emerges from a period of consolidation into a phase of projected growth, the strategic importance of accurate, timely market intelligence cannot be overstated. The data suggests that demand will expand steadily, driven by a combination of fleet renewal, modernization efforts, and the increasing complexity of maritime security challenges. Organizations that invest in understanding the nuances of this market will be better positioned to capitalize on emerging opportunities and mitigate risks associated with procurement and operational planning.
This report is designed to equip leaders with the insights needed to navigate this landscape with confidence. From detailed company profiles and recent development tracking to an analysis of technical trends and regulatory impacts, the content provides a holistic view of the industry. We invite you to explore the full findings to access the specific data points, segmentation breakdowns, and strategic recommendations that will inform your 2026 and beyond decision-making. The waters ahead are complex, but with the right intelligence, your organization can chart a course for success.
For detailed analysis of this topic, please visit the official page: Patrol Boats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fabric Reinforcement Rubber Diaphragm Market to Hit $368.39M by 2032 at 5.6% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Fabric Reinforcement Rubber Diaphragm Market: A 2026 Outlook
The global industrial landscape is undergoing a period of recalibration, where sealing integrity, pressure control precision, and material resilience have moved from operational afterthoughts to core strategic priorities. At the intersection of elastomer science and mechanical engineering lies the fabric reinforcement rubber diaphragm market, a specialized component ecosystem that enables reliable performance across automotive powertrains, aerospace actuation systems, industrial process controls, and fluid management infrastructure. As manufacturing complexity increases and regulatory expectations tighten, decision-makers require more than generic market narratives. They need granular, forward-looking intelligence that connects material-grade selection, application-specific demand cycles, and competitive positioning into actionable strategy. The latest market research from PW Consulting is designed precisely for that purpose, offering a structured 2026 decision framework built on historical validation and forecast discipline.
Why 2026 Is a Defining Inflection Point
Over the past half-decade, the fabric reinforcement rubber diaphragm sector has demonstrated steady expansion, moving from a baseline of approximately USD 190.0 million in 2020 to an estimated USD 252.0 million in 2025. This trajectory reflects more than cyclical recovery; it signals a structural broadening of end-use requirements. Forecasting through 2032, the market is projected to reach USD 368.39 million, supported by a compound annual growth rate of 5.6 percent over the forecast period. These figures are not abstract statistics. They translate into procurement planning, capacity allocation, product roadmap prioritization, and M&A screening. For executives navigating 2026, the strategic question is no longer whether demand will grow, but where the highest-value growth will concentrate, which material platforms will command premium positioning, and how competitive intensity will reshape margin structures.
The base year of 2025 provides a stable reference point for this analysis, anchored by historical data spanning 2020 through 2025. That retrospective clarity matters because it allows organizations to separate temporary price fluctuations from durable adoption trends. The forecast window from 2026 to 2032 then extends the lens into the operational decisions that will define competitive advantage: capital deployment for elastomer compounding, qualification timelines for aerospace and defense-grade components, and supply chain alignment for high-integrity diaphragm assemblies in pressurized fluid systems.
Rubber Diaphragm Market
Market Size Trajectory and What It Reveals for Planning
The upward movement in market size is best understood as a composite of multiple demand vectors rather than a single driver. Historical progression shows consistent year-over-year expansion, with notable acceleration as industrial automation, infrastructure modernization, and performance-based procurement standards gained momentum. By 2026, the market’s estimated scale reflects an environment in which component reliability directly influences system uptime, emission compliance, and safety certification outcomes.
From a strategic planning standpoint, this trajectory has three practical implications. First, organizations must anticipate multi-year demand visibility rather than treating diaphragm procurement as a transactional purchase category. Second, the forecast horizon through 2032 underscores the importance of material and design roadmaps that can withstand shifting regulatory baselines, especially in sectors where performance certification cycles extend well beyond a single budget year. Third, pricing and margin strategy should be informed by an understanding of how value migrates between commodity-grade sealing elements and engineered, fabric-reinforced solutions designed for demanding pressure and temperature profiles.
Application-Specific Demand Signals and Segment Dynamics
Demand for fabric reinforcement rubber diaphragms is distributed across a diversified application base, with each vertical carrying its own performance thresholds, qualification requirements, and replacement cycles. Automotive systems continue to represent a substantial share of consumption, driven by fuel regulation, pneumatic actuation, and sealing architectures that must endure vibration, thermal cycling, and chemical exposure. Aerospace and defense applications impose an even more rigorous standard, where fatigue life, certification compliance, and failure-mode predictability are non-negotiable. Industrial environments contribute sustained volume through pump, valve, and pressure-regulation assemblies, while oil and gas installations increasingly prioritize high-integrity diaphragms in response to fugitive emission expectations. Medical instrumentation and fluid-handling systems, though smaller in absolute scale, reward precision sealing and material consistency.
Fabric Reinforcement Rubber Diaphragm Market
Alongside application demand, material-type segmentation shapes both cost architecture and performance differentiation. Natural rubber, nitrile rubber, EPDM, silicone, and other specialty compounds each occupy distinct niches defined by chemical compatibility, temperature tolerance, elongation behavior, and service environment. EPDM compounds, for example, have gained prominence in fabric reinforcement rubber diaphragm production because of their strong chemical resistance and broad operating temperature range, making them especially relevant for industrial and outdoor-exposed installations. Nitrile-based formulations continue to serve fuel-adjacent and oil-resistant applications, while silicone and fluorocarbon variants support specialized sealing requirements where thermal stability or aggressive media resistance is paramount. The strategic takeaway for 2026 is that material selection is no longer a linear trade-off between cost and durability; it is a value-engineering decision that must align with application duty cycles, certification pathways, and total cost of ownership.
Regulatory Pressure, Infrastructure Spending, and Elasticity of Demand
Market momentum is being reinforced by a combination of regulatory tightening and capital investment programs. In oil and gas, fugitive emission rules are accelerating the adoption of high-integrity fabric-reinforced diaphragms within pressure regulators and valve assemblies, effectively raising the performance floor for sealing components in process environments. In aerospace and defense, mandates requiring stringent fatigue-life performance and formal certification standards are constraining the use of unverified material systems and rewarding manufacturers capable of documented qualification. At the same time, ISO standards and ASME specifications continue to govern material selection and performance testing, providing a common technical language that influences procurement benchmarks across multiple industries.
Infrastructure activity adds another layer of demand support. Large-scale spending initiatives in the United States and Europe are helping to accelerate pneumatic actuator installations and broader fluid-control modernization efforts, which in turn increase consumption of fabric-reinforced diaphragms in automation and process control configurations. These developments do not simply expand volume; they shift the procurement emphasis toward components that can deliver longer service life, lower maintenance frequency, and more predictable failure behavior under load. For strategic planners, the implication is clear: regulatory and infrastructure tailwinds are reinforcing demand for engineered solutions rather than commoditized replacements, creating a more favorable environment for suppliers that can demonstrate validated performance and technical differentiation.
Competitive Landscape and Strategic Positioning
The market’s competitive architecture is moderately consolidated, with a limited number of high-profile manufacturers commanding meaningful share while a broader supplier base serves specialized applications and regional demand pockets. Concentration metrics indicate that the top three competitors account for approximately 24.6 percent of market revenue, and the top five together represent roughly 26.2 percent. This level of concentration suggests that scale, technical reputation, and qualification depth still matter enormously, but it also leaves room for capability-driven differentiation among mid-tier and application-focused producers.
Several established players illustrate the range of competitive approaches shaping the market. Freudenberg Sealing Technologies GmbH and Co. KG operates from Weinheim, Germany, with a global footprint in fabric reinforcement rubber diaphragms for valves, actuators, and pressure control across automotive, aerospace, and industrial environments. Trelleborg AB, headquartered in Trelleborg, Sweden, contributes integrated sealing and pressure regulation systems tailored to industrial and marine applications, emphasizing durability and system-level performance. Parker Hannifin Corporation, based in Cleveland, Ohio, supplies fabric-reinforced rubber diaphragms for pneumatic actuators, fuel regulators, and high-performance sealing in aerospace and industrial equipment, leveraging broad distribution and engineering support. EagleBurgmann Germany GmbH and Co. KG, located in Füssen, Germany, focuses on custom fabric-reinforced rubber diaphragms for demanding mechanical shaft sealing and pressure management in process industries. Bellofram Elastomers, operating from New Hampshire in the United States, specializes in fabric-reinforced single-coat diaphragms for precise pressure regulation and sealing in automation, aerospace, and medical fluid systems.
Additional suppliers extend the competitive field with strong application or regional emphasis. Techno Ad Ltd., based in the United Kingdom, engineers fabric-reinforced diaphragms from NBR, EPDM, and fluorocarbon compounds for medical, food processing, and aerospace pressure applications, highlighting material versatility and compliance-sensitive use cases. Rain Bird Corporation, located in Glendora, California, supplies fabric-reinforced rubber diaphragms for irrigation valves, where long-term tear and stretch resistance are central to commercial and residential performance. In India, Western Polyrub India Private Limited in Mumbai and Cyma Rubber Products in Kolkata manufacture fabric-reinforced rubber diaphragms for industrial valve and pump sealing needs, serving cost-conscious yet performance-critical applications. Across China, Tianjin King Seal Co., Ltd. in Tianjin provides OEM fabric-reinforced rubber diaphragms for valves and pumps with custom tooling and high-volume production capability, while Lindas Rubber Products Co., Ltd. delivers fabric-reinforced rubber diaphragms using polyester or nylon reinforcement across various elastomers for industrial applications.
This competitive mix matters for strategic planning because it reveals where value is created and captured. Large, globally integrated suppliers compete on qualification portfolios, supply reliability, and cross-industry engineering expertise. Specialized producers compete on precision manufacturing, compound customization, and responsiveness to certification-driven requirements. Regionally concentrated manufacturers often compete on cost structure, production flexibility, and local service proximity. In 2026, successful positioning will depend on understanding not just who the players are, but how each competitor’s strengths align with the segments most likely to expand under current regulatory and infrastructure conditions.
What the Research Delivers for 2026 Decision-Making
This market research is structured to move beyond macro summaries and into the operational detail that strategic teams actually use. The report opens with a validated historical baseline and a forecast model that connects demand drivers, material adoption patterns, and application growth pathways into a coherent forward view. It then examines segmentation logic across region, type, and application, providing decision-makers with the context needed to evaluate where opportunity is accumulating and where competitive pressure is most intense. Rather than presenting isolated figures, the analysis integrates these dimensions so that procurement, product development, and commercial strategy teams can compare implications across scenarios.
A central feature of the research is its focus on practical intelligence for sourcing and roadmap decisions. The report assesses how material platforms such as EPDM, nitrile, silicone, and other compounds are positioned relative to performance requirements, chemical exposure profiles, and temperature ranges. It also explores the operational impact of regulatory developments, including fugitive emission expectations in oil and gas and fatigue-life and certification mandates in aerospace and defense. Infrastructure-related demand catalysts are examined alongside these dynamics to show how spending momentum interacts with component specifications and replacement cycles. For organizations evaluating supplier partnerships, the research provides a structured basis for comparing capabilities, identifying qualification gaps, and anticipating where consolidation or regional expansion may alter sourcing options.
The competitive section goes further by mapping the strategic posture of key companies, not merely listing them. By situating each organization within its core application strengths, geographic footprint, and engineering orientation, the report helps readers interpret where rivalry is intensifying and where differentiation remains achievable. Combined with the broader market trajectory, this competitive context enables more disciplined decisions about capacity investment, product mix, pricing strategy, and market entry or expansion timing.
Why This Report Matters Now
In a market defined by technical specialization and evolving compliance expectations, intuition alone is insufficient. The fabric reinforcement rubber diaphragm market sits at the convergence of material performance, system reliability, and regulatory influence, which means that even small differences in specification, compound choice, or supplier qualification can have outsized operational consequences. The 2026 to 2032 forecast horizon amplifies this challenge by extending the payoff period for today’s decisions. Organizations that act with incomplete information risk misallocating development resources, underestimating qualification lead times, or entering competitive segments without a clear value proposition.
PW Consulting’s analysis is designed to reduce that uncertainty. It provides a disciplined, data-informed foundation for evaluating growth vectors, understanding competitive exposure, and aligning product and sourcing strategies with the segments where performance requirements and demand momentum are most aligned. The report does not simply describe the market; it frames it in a way that supports concrete choices about where to invest, what to qualify, and how to position for durable share in a market that is expanding but increasingly performance-driven.
Access the Full Strategic Intelligence
The insights outlined here offer a high-level view of market direction and competitive structure, but the full strategic value lies in the underlying detail: segment-level demand logic, material adoption patterns, application-specific qualification pathways, regulatory impact scenarios, and competitor capability mapping. For executives, engineers, and commercial leaders preparing 2026 plans, those details are the difference between a directional narrative and an executable strategy. To explore the complete forecast model, segmentation analysis, and competitive evaluation, access the full report and secure the intelligence needed to make informed, forward-looking decisions in the fabric reinforcement rubber diaphragm market.
For detailed analysis of this topic, please visit the official page: Fabric Reinforcement Rubber Diaphragm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pw Consulting: Torsional Vibration Damper Market Hits $1.8B in 2025, Projects 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Global Torsional Vibration Damper Market (2026–2032)
Executive Perspective: Why This Study Matters for 2026 Decision-Making
As industrial engines, powertrains, and heavy-duty drivelines face tighter NVH mandates and more aggressive downsizing roadmaps, the torsional vibration damper market has entered a phase of structural acceleration. This study is designed as a decision-grade intelligence asset for executives, product planners, and supply-chain leaders who must align capital allocation, R&D roadmaps, and commercial positioning with the realities of the 2026–2032 forecast window. Rather than offering a static snapshot, the analysis is built to support scenario planning, pricing strategy, and competitive positioning in a market where technological differentiation increasingly determines margin survival.
The global revenue trajectory reflects a market that has moved beyond post-pandemic normalization and is now being shaped by powertrain hybridization, emission-driven crankshaft protection requirements, and the cost dynamics of engineered elastomers and silicone-based fluids. From a historical base of approximately 1.2 billion USD in 2020, the market expanded to roughly 1.8 billion USD by 2025, with momentum carrying into a projected 1.95 billion USD in 2026. Over the full forecast horizon, the market is expected to advance at a compound annual growth rate of 5.5 percent, reaching approximately 2.8 billion USD by 2032. These headline figures establish the scale of opportunity, but the strategic value of this research lies in how that growth is distributed across product architectures, application-driven demand, regional maturity curves, and the competitive responses of incumbents and challengers.
Market Dynamics: Forces Shaping Demand, Cost, and Margin Structure
The growth path is not uniform. Several interlocking dynamics are reshaping both the demand side and the cost structure for damper manufacturers, and the study unpacks each of them with operational granularity.
- Regulatory and NVH pressure is becoming a primary demand catalyst. Stricter emission and noise regulations continue to tighten at a pace that is increasing certification and testing protocols for damper manufacturers in many mature markets. Because torsional vibration dampers protect crankshaft integrity and reduce NVH-related emissions impact, compliance-driven design cycles are extending the lifecycle relevance of dampers even as powertrain architectures evolve.
- Powertrain evolution is changing the technical spec window. Downsized high-torque internal combustion engines, hybrid system integration, and higher-performance stationary power applications are creating new vibration profiles that legacy single-stage designs do not always address efficiently. This is driving interest in multi-stage elastomer solutions, viscous systems suited to severe-duty cycles, and tuned steel spring geometries that balance performance with cost of ownership.
- Raw material volatility is reshaping cost assumptions. Fluctuations in petrochemical markets have raised input costs for engineered elastomers and silicone-based fluids used in damper production. For suppliers, this creates a margin environment where material strategy, formulation innovation, and supplier diversification are no longer support functions but core commercial levers.
- OEM pricing pressure is rewarding differentiated scale. Sustained OEM price-reduction programs in high-volume automotive contracts compress margins for suppliers lacking differentiated technology or scale advantages. This means competitive positioning increasingly depends on the ability to offer validated performance, integration-ready designs, and cost-efficient manufacturing footprints rather than commoditized component supply.
These dynamics do not operate in isolation. They interact with product architecture choices, application mix, and regional demand maturity, producing a market in which growth is real but uneven. The report maps these interactions so decision-makers can distinguish between structural expansion and transient demand spikes, and align their strategies accordingly.
What the Study Delivers: Operational Content for Commercial and Technical Leaders
This research is structured to serve multiple internal audiences. For strategy and corporate development teams, it provides a macro-to-micro framework that links market size evolution to the drivers behind it. For product and engineering leaders, it translates demand-side requirements into technology roadmaps, supplier selection criteria, and integration considerations. For commercial and sales leadership, it outlines where demand intensity is building, which application segments are expanding most reliably, and how competitive intensity varies by type and geography.
The core analytical sections include:
- Market sizing and forward modeling. A detailed historical reconstruction and forecast engine covering 2020 through 2032, anchored in the latest observed base-year data and projected through the forecast period with scenario-sensitive CAGR logic.
- Segment-level demand architecture. A structured breakdown by product type, application, and region that reveals where concentration is high, where growth is broadening, and which sub-markets are likely to become decisive for capacity and portfolio planning. The report deliberately avoids publishing the granular split values in this preview; those figures, along with their growth velocities and share trajectories, are embedded in the full dataset and accessible through the complete study.
- Competitive positioning and capability mapping. Profiles of the companies that define the market’s technical and commercial frontier, with attention to product families, end-market coverage, and the types of innovation each player is advancing.
- Recent corporate activity and signal analysis. A curated review of product unveilings, technical webinars, trade-show showcases, and aftermarket expansions that indicate where incumbents are placing bets and how fast commercialization cycles are moving.
- Risk, margin, and sourcing considerations. An integrated discussion of raw material cost exposure, certification burden, OEM price dynamics, and the operational choices that determine whether suppliers capture value or merely participate in volume growth.
Throughout, the study emphasizes actionable inference over descriptive enumeration. The aim is to help teams answer questions such as: Which technology families are likely to command premium positioning? Where do certification and integration requirements make supplier switching costly? Which regional markets offer durable growth rather than short-cycle fluctuations? And how should organizations interpret recent corporate moves as leading indicators rather than isolated events?
Competitive Landscape: Who Is Shaping the Market and How
The torsional vibration damper market is defined by a diverse but concentrated set of players, spanning European engineering heritage, North American heavy-duty and performance expertise, Japanese manufacturing scale, and global Tier-1 integration capability. The study examines the companies that are most influential in setting technical expectations, securing OEM relationships, and expanding aftermarket reach.
A central theme is the coexistence of multiple damper architectures, each with distinct performance and cost profiles. Elastomer-based solutions remain foundational, particularly where multi-stage rubber engineering is advancing beyond traditional single-stage layouts. Viscous shear-type dampers continue to hold strategic importance in severe-duty and reciprocating compressor applications, where reliability and controlled damping characteristics are paramount. At the same time, tuned steel spring configurations and integrated dual-mass flywheel approaches are gaining attention for their ability to decouple torsional vibrations within transmission and driveline systems. Companies operating across these families are increasingly competing on integration readiness, validation depth, and the ability to adapt designs to hybrid and downsized engine environments.
The competitive field includes firms with specialized viscous damper leadership, organizations building on centrifugal pendulum-type absorbers and arc spring dampers for powertrain systems, and suppliers extending torsional damping into transmission, clutch, and driveline integration. There are also players focused on aftermarket and heavy-duty components, as well as manufacturers that provide elastomeric and specialized vibration control components for broader NVH portfolios. Across this landscape, the report assesses not only who is present, but where each company is positioning for the next cycle of demand.
Recent activity reinforces that positioning is moving quickly. In late 2025, a major industry webinar addressed next-generation viscous torsional vibration dampers for downsized high-torque internal combustion engines and hybrid systems, signaling a clear technical focal point for the coming years. In early 2026, a milestone advancement in elastomer engineering was unveiled for multi-stage rubber torsional vibration dampers, accelerating commercialization over traditional single-stage layouts. Around the same period, severe-duty independent aftermarket portfolios were expanded with advanced heavy-duty damping components and belt tensioners optimized for specific high-output engines, while reciprocating compressor applications saw new damper solutions showcased and ordered through established OEM channels. These moves are not isolated product updates; they are indicators of where engineering attention, certification effort, and commercial resources are being concentrated.
Strategic Imperatives for 2026 and Beyond
For organizations operating in, supplying, or investing alongside this market, the 2026–2032 period will reward clarity of posture. The study translates the market’s trajectory into several decision-relevant imperatives.
First, technology selection is becoming a margin decision as much as a performance decision. As OEMs face tighter NVH and emissions standards and run sustained price-reduction programs, suppliers that can deliver validated damping performance with scalable, cost-efficient architectures are better positioned to preserve margins. The report examines how elastomer, viscous, and tuned mechanical approaches compare in the context of these pressures, and where differentiation is most defensible.
Second, application mix matters more than headline growth. The automotive segment remains a dominant share of demand, but industrial machinery and other applications are shaping a broader growth base that can reduce dependency on any single cycle. Understanding which applications expand through compliance-driven replacement, which grow through new powertrain designs, and which depend on severe-duty durability is essential for demand planning and capacity strategy.
Worldwide Automotive Torsional Vibrational Damper Market
Third, regional maturity is uneven, and growth leadership can shift as local regulations, fleet turnover, and industrial demand evolve. The full study maps these regional patterns without reducing them to simplistic rankings, allowing readers to evaluate where near-term volume is coming from and where longer-term expansion is building.
Fourth, recent corporate signals should be read as forward indicators. Technical webinars, elastomer engineering unveilings, aftermarket expansions, and compressor-focused showcases all point to a market in which the next wave of value capture will go to firms that can move from proven concept to commercialized, validated, and integration-ready solution with speed and scale.
How to Use This Preview and Where the Full Intelligence Resides
This article is intentionally structured as a strategic preview. It establishes the scale of the market, the drivers behind the 5.5 percent compound growth path, the competitive logic shaping the field, and the operational questions that executives should be asking in 2026. What it does not do is expose the granular segmentation values, region-by-region revenue splits, type-level share distributions, or application-level market figures that form the analytical backbone of the complete study.
Those detailed figures are not omitted for stylistic reasons. They are reserved for the full report because they are precisely the data points that enable precise capacity planning, pricing strategy, segment entry evaluation, and competitive benchmarking. Once published in a preview setting, they lose their value as decision-grade intelligence and can be used by competitors before a company has completed its own internal assessment.
The complete study provides access to the underlying segmentation structure, forecast sensitivity, company-by-company positioning context, and the recent-deviation analysis needed to interpret raw material, regulatory, and OEM pricing dynamics with confidence. It is designed to support board-level review, product roadmap decisions, sourcing strategy, and market-entry evaluation without forcing teams to reconstruct conclusions from public signals alone.
Closing Case for the Study
The torsional vibration damper market is entering a period in which growth is supported by regulatory pressure, powertrain evolution, and durable industrial demand, but profitability will depend on technical differentiation, cost discipline, and the ability to interpret competitive signals early. This research translates that environment into a structured, forward-looking framework for 2026 decision-making. It offers enough analytical depth to confirm the study’s rigor, while preserving the detailed segmentation and company-level figures that make the full report a practical tool rather than a general overview.
Torsional Vibration Damper Market
For leaders who need to move from market awareness to concrete action, the complete study delivers the depth required to convert a 5.5 percent CAGR trajectory and a 2.8 billion USD 2032 outlook into targeted strategy. The preview makes the case for the study; the full report provides the intelligence to act on it.
For detailed analysis of this topic, please visit the official page: Torsional Vibration Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Circuit Breaker Market Set for 5% CAGR Growth to $10,835M by 2032
By PW Consulting, 2026-09-16
Navigating the Electronic Circuit Breaker Market: Strategic Intelligence for 2026 and Beyond
The global electronic circuit breaker market stands at a critical inflection point. As industries accelerate digital transformation, electrification initiatives redefine power distribution, and regulatory frameworks evolve to accommodate new technologies, decision-makers require more than surface-level market data. They need contextualized intelligence that connects macroeconomic trends, competitive maneuvers, supply chain realities, and application-specific demand shifts. Our latest Electronic Circuit Breaker Market research report delivers precisely that. Built on a rigorous analytical framework spanning 2020 through 2032, this study equips corporate strategists, product leaders, and investment planners with the foresight required to navigate the 2026 decision cycle confidently.
Macro Trajectory: A Market Defined by Sustained Expansion
Over the past half-decade, the electronic circuit breaker sector has demonstrated consistent revenue growth, reflecting broader industrial electrification trends and the ongoing replacement of legacy mechanical protection systems with intelligent, digitally integrated alternatives. The market crossed the 6.1 billion USD threshold in 2020 and has since followed a steady upward trajectory, reaching approximately 7.7 billion USD by 2025. This expansion is not incidental; it is structurally anchored in the proliferation of DC power architectures, the modernization of industrial automation infrastructure, and the accelerating integration of renewable energy sources into commercial and residential grids.
Looking ahead, the forecast window from 2026 to 2032 signals continued momentum, with the market projected to approach 10.8 billion USD by the close of the period. The underlying compound annual growth rate of roughly 5.0 percent reflects a mature yet dynamically evolving landscape. Growth is not uniform across all segments, and that is precisely where strategic nuance becomes indispensable. Leaders who treat this market as a monolithic growth curve risk misallocating capital, overlooking regional procurement behavioral shifts, or misreading the pace at which specific voltage architectures and application verticals will absorb next-generation protection solutions.
Our report dissects this trajectory without reducing it to simplistic top-line projections. Instead, it maps the drivers, constraints, and inflection points that will shape demand realization across the forecast horizon. For executives planning capacity, pricing, or market entry strategies in 2026, understanding the cadence of adoption across industrial, residential, transport, and specialized application segments is not a luxury; it is a prerequisite for resource optimization.
Competitive Architecture: Incumbents, Differentiation, and Strategic Posture
The electronic circuit breaker landscape is characterized by a moderately concentrated competitive field, where a handful of engineering-led multinationals command significant market share while mid-tier and regional players compete on specialization, certification agility, and integration versatility. The industry's CR3 and CR5 concentration metrics underscore the presence of established players who have invested heavily in solid-state protection technology, digital communication protocols, and modular system architectures. Yet concentration alone does not dictate strategy. The real competitive advantage lies in how these firms translate technological capability into vertical-specific value propositions.
Several key organizations define the current strategic baseline. Phoenix Contact continues to strengthen its position in DC distribution environments through modular electronic breaker platforms designed for 12-24V applications, with recent enhancements focused on communication interoperability and monitoring granularity. Siemens has pushed the performance envelope with fully electronic solid-state solutions engineered for microsecond-level interruption, positioning its portfolio at the intersection of industrial automation and renewable energy protection. Eaton's SENTRON family reflects a broader commitment to smart grid readiness and low-voltage protection ecosystems that align with industrial digitalization roadmaps. Schneider Electric has leaned into the convergence of monitoring, automation, and energy management, offering digital breaker solutions that bridge commercial, industrial, and renewable use cases. ABB rounds out the competitive core with a portfolio oriented toward electrification, automation, and DC application integration, emphasizing smart manufacturing compatibility and renewable integration pathways.
These players are not merely competing on component specifications. They are competing on system-level integration, communication standards, certification readiness, and the ability to align with evolving installation codes. Recent product updates and launch activity illustrate this trajectory. In mid-2025, one major manufacturer extended its electronic breaker ecosystem with a feed-in module equipped with Modbus/TCP capabilities, explicitly targeting enhanced communication and monitoring in DC distribution environments. More recently, another global engineering firm introduced a fully electronic solid-state breaker optimized for DC systems, highlighting microsecond-fast switch-off performance at a major industrial trade event. These developments are not isolated product announcements; they are signals of where the market is heading in terms of responsiveness, interoperability, and protection precision.
Our report evaluates these competitive moves within a structured framework that maps product architecture, application alignment, regional compliance positioning, and strategic partnership potential. For procurement leaders and competitive intelligence teams, this analysis clarifies where substitution risk is highest, which vendors are most likely to expand into adjacent application verticals, and how technology roadmaps may reshape purchasing criteria over the next several years.
Structural Dynamics: Supply Chain, Regulation, and the Cost of Compliance
Market growth does not occur in a vacuum. The electronic circuit breaker sector is subject to a layered set of operational and regulatory dynamics that directly influence pricing, availability, product design cycles, and go-to-market timelines. One of the most consequential factors in recent periods has been supply chain stability for electronic components. DC-oriented circuit breakers depend heavily on specialized semiconductors, control modules, and precision sensing elements. Disruptions in these upstream inputs have had measurable effects on production costs and lead-time predictability, forcing manufacturers and buyers alike to recalibrate inventory strategies and long-term sourcing commitments.
On the regulatory front, compliance requirements continue to shape product architecture and market access. In North America, safety certification remains a non-negotiable gate for market entry, with established standards driving ongoing design validation, testing cycles, and documentation rigor. This compliance burden is not merely a cost center; it is a competitive differentiator for organizations that have built robust certification infrastructure and can bring compliant products to market with shorter lead times. At the same time, regulatory frameworks in other territories continue to evolve, with installation codes and electrical safety guidelines influencing how DC protection solutions are specified and integrated into broader power systems.
Trade policy dynamics have also introduced new considerations for sourcing and pricing. Recent tariff implementations in the United States have had a pronounced effect on the DC electronic circuit breaker supply chain, altering cost structures and prompting both manufacturers and distributors to reassess procurement routing, inventory positioning, and customer pricing strategies. For multinational organizations operating across multiple procurement hubs, these policy-driven shifts require scenario planning that accounts for both near-term cost pressure and longer-term supply chain reconfiguration.
Our report integrates these dynamics into a cohesive market environment analysis. Rather than treating regulation, raw material dependency, and trade policy as isolated risk factors, we examine how they interact with product design priorities, segment-level demand elasticity, and regional procurement behavior. This holistic view is essential for organizations that need to forecast total cost of ownership, assess supplier resilience, or evaluate the feasibility of entering new geographic or application markets in 2026 and beyond.
What the Report Delivers: Actionable Intelligence for Strategic Decision-Making
A market overview alone cannot support complex enterprise decisions. That is why this research is constructed as an operational reference tool rather than a static snapshot. The report is designed to help strategists, engineering leaders, procurement teams, and investors answer specific, high-stakes questions about where the market is going and how to position for it.
Electronic Circuit Breaker Market
The study begins with a comprehensive historical and forecast revenue analysis, grounding decision-makers in verified baseline data before extending into forward-looking scenario modeling. It then moves into segmentation analysis that examines how demand distributes across voltage architectures, application verticals, and regional markets. The segmentation framework is built to reveal relative emphasis patterns, adoption pacing, and structural drivers rather than mere numerical splits. This enables readers to identify which voltage categories and application contexts are likely to command disproportionate attention from manufacturers and specifiers, and where growth may be constrained by technical, regulatory, or economic headwinds.
The competitive assessment section goes beyond corporate profiling. It maps product families to application requirements, evaluates differentiation levers such as communication protocols, interruption speed, modular integration, and certification alignment, and situates recent product developments within broader strategic intent. This is paired with an analysis of market concentration dynamics, helping readers understand the balance between incumbent influence and the room available for specialized entrants or collaborative partnerships.
Beyond competitive positioning, the report delivers a structured examination of market drivers and restraints. The analysis covers electrification momentum, industrial automation expansion, renewable energy integration, DC system adoption, and the replacement cycle of legacy protection equipment. It also addresses limiting factors such as component supply volatility, compliance and certification lead times, pricing sensitivity in cost-constrained segments, and the complexity of integrating advanced electronic protection into legacy infrastructure. By weighing these forces together, the report provides a balanced view of where growth is durable and where it is conditional.
Strategic decision-makers will also find value in the report's treatment of regional market environments, application-specific procurement patterns, and the evolving role of digital monitoring and automation in breaker selection. The study is organized to support multiple use cases: entry-point evaluation for new product lines, competitive benchmarking for existing portfolios, supply chain resilience planning, and long-range capital allocation modeling. Each section is written to standalone where necessary while maintaining a consistent analytical thread across the full document.
Why This Research Matters for 2026 Executive Decisions
2026 is not simply another year in a forecast window. It is a planning anchor for organizations that must align product roadmaps, procurement strategies, pricing models, and market expansion priorities with a market that is maturing but still accelerating. The electronic circuit breaker sector is being reshaped by the convergence of DC architecture adoption, digital communication expectations, safety and compliance demands, and supply chain recalibration. Companies that treat these forces as separate issues will miss the cumulative strategic signal. Companies that understand how they interact will be better positioned to allocate resources, time product launches, negotiate supplier relationships, and anticipate specification shifts.
This report is built for that level of strategic clarity. It does not overwhelm readers with undifferentiated data volume. Instead, it curates the insights that matter for executive judgment: where demand is structurally anchored, which competitive moves indicate longer-term positioning, how regulatory and supply chain realities shape market access, and what segmentation dynamics suggest about near-term opportunity concentration. By integrating historical validation with forward-looking analysis, the study helps organizations move from reactive market monitoring to proactive strategy formation.
For leaders evaluating investment priorities, product portfolios, or regional expansion in the electronic circuit breaker space, the difference between informed strategy and assumption-driven planning is measurable. This research is designed to close that gap.
DC Circuit Breaker Market
Access the Full Strategic Intelligence
Market summaries provide direction. Comprehensive research delivers the precision required to act with confidence. The complete Electronic Circuit Breaker Market report expands on every dimension outlined here, offering detailed segmentation context, competitive mapping, regulatory and supply chain scenarios, and forecast modeling that supports decision-making across multiple functional teams.
To access the full report, including detailed market sizing, segmentation analysis, competitive profiles, and forward-looking strategic implications, visit our research portal and download the complete study. Equip your team with the intelligence needed to navigate 2026 and the years ahead with clarity, speed, and strategic advantage.
For detailed analysis of this topic, please visit the official page: Electronic Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plating Equipment Market Hits $182M in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Opportunities in the Plating Equipment Market: A 2026 Outlook
The global industrial landscape is undergoing a profound transformation driven by technological advancement and stringent regulatory frameworks. Within this shifting environment, the plating equipment sector stands as a critical enabler for manufacturing excellence across multiple high-value industries. Our latest comprehensive market research provides a definitive guide for stakeholders navigating the complexities of this evolving landscape through 2032. For enterprise leaders and investors seeking to capitalize on emerging trends, understanding the trajectory of this market is not merely an option but a strategic imperative.
This analysis delves into the macro-economic drivers, technological shifts, and competitive dynamics shaping the industry. By examining the convergence of automation, sustainability mandates, and supply chain resilience, we uncover the pathways to growth that will define the next decade. The following insights are drawn from our extensive data modeling and industry expertise, offering a preview of the deep intelligence contained within our full report.
Market Trajectory and Growth Drivers
The market for plating equipment has demonstrated resilient growth over the past half-decade, reflecting the underlying demand for surface finishing solutions in key manufacturing sectors. Historical data indicates a steady expansion in revenue, with the market valuation climbing consistently from 2020 through 2025. This upward trend is projected to accelerate as we move into the forecast period extending to 2032. The compounded annual growth rate suggests a robust expansion phase, signaling strong confidence in the sector's ability to sustain momentum despite macroeconomic headwinds.
Several core drivers are fueling this expansion. First, the proliferation of electric vehicles and renewable energy infrastructure has intensified the need for high-performance plating solutions in battery components and power distribution systems. Second, the electronics industry continues to demand miniaturization and enhanced conductivity, pushing the boundaries of plating technology. Third, regulatory pressures regarding environmental compliance are forcing manufacturers to upgrade legacy systems with newer, more efficient equipment that minimizes waste and energy consumption. These factors combine to create a fertile ground for capital investment in modern plating infrastructure.
Our forecast models project the market to reach significant valuation milestones by the end of the decade. This growth is not linear but is influenced by specific regional developments and technological breakthroughs. Understanding the timing and magnitude of these shifts is crucial for capacity planning and strategic positioning. The data underscores a clear transition from traditional manual processes to automated, integrated systems that offer higher precision and lower operational costs.
Plating for Microelectronics Market
Segmentation and Technology Trends
The landscape of plating equipment is diverse, encompassing various technologies tailored to specific application requirements. The industry categorizes equipment based on the method of plating, the target application, and the geographic deployment. Each segment offers distinct value propositions and faces unique challenges regarding adoption rates and technological maturity.
In terms of equipment type, the market is dominated by systems designed for high-volume production and specialized finishing tasks. Rack plating systems remain a cornerstone for many industrial applications due to their versatility and ability to handle large components. However, there is a noticeable shift towards continuous plating equipment in sectors requiring high throughput and consistency. Barrel plating continues to hold relevance for smaller components, particularly in jewelry and small electronic parts, while emerging categories address niche requirements. The choice of technology often depends on the specific geometry of the substrate and the desired coating properties.
Application-wise, the automotive sector represents a substantial portion of demand, driven by the need for corrosion resistance and aesthetic finishing in both traditional and electric vehicles. The electrical and electronics industry is another major contributor, leveraging plating for connectivity and circuitry protection. Aerospace and defense applications demand high-reliability plating for critical components, often commanding premium pricing. Other sectors, including jewelry and general industrial manufacturing, also contribute to the overall ecosystem, though their relative share varies based on economic conditions and consumer demand.
A key trend observed across all segments is the integration of automation. Labor shortages and the need for consistent quality are driving manufacturers to adopt robotic integration within plating lines. This shift not only improves throughput but also enhances worker safety by reducing exposure to hazardous chemicals. Furthermore, the push for sustainability is influencing equipment design, with a focus on closed-loop systems and low-waste chemistry. These technological advancements are redefining the competitive benchmarks for equipment suppliers.
Regional Insights and Supply Chain Dynamics
Geographic distribution plays a pivotal role in the market's structure. Different regions exhibit varying levels of maturity and growth potential based on local industrial policies, manufacturing bases, and economic conditions. North America and Europe remain significant markets, characterized by high regulatory standards and a focus on high-tech applications. These regions are seeing renewed investment in domestic manufacturing capabilities, which in turn drives demand for advanced equipment.
Plating Equipment Market
The Asia Pacific region represents a substantial volume of activity, fueled by a robust manufacturing base and rapid industrialization. However, recent geopolitical developments have introduced complexity into the supply chain. Restrictions on the export of critical materials, such as rare earth elements, have impacted the availability of components for plating equipment. This has prompted manufacturers to diversify their supply sources and consider localized production strategies to mitigate risk. The interplay between global trade policies and local manufacturing goals creates a dynamic environment for equipment providers.
Emerging markets in Latin America and the Middle East & Africa are also showing signs of growth, albeit from a smaller base. These regions are increasingly adopting modern surface finishing technologies to upgrade their industrial output and meet export quality standards. However, infrastructure challenges and capital constraints can affect the pace of adoption. Strategic entry into these markets requires a nuanced understanding of local economic drivers and partnership ecosystems.
Competitive Landscape and Key Players
The market is characterized by a mix of established global players and specialized niche providers. While the concentration ratio indicates a moderate level of consolidation, there is still room for innovation and differentiation. Leading companies are leveraging their expertise in chemistry, automation, and service to secure a competitive edge.
Atotech, headquartered in Berlin, stands out as a leading provider of integrated plating chemicals and turnkey equipment. Their recent activities highlight a focus on both advanced packaging and sustainable solutions. At JPCA 2026, they emphasized integrated PCB and advanced packaging solutions alongside laser systems. Simultaneously, at SUR/FIN 2026, they presented sustainable surface finishing solutions for automotive and power distribution. Additionally, earlier in 2025, Atotech announced a new eco-friendly electroplating line featuring low waste chemistry, signaling a strong commitment to environmental compliance.
Technic Inc., based in Cranston, USA, maintains its position as a global leader in specialty chemistry and selective electroplating equipment. Their portfolio covers industrial and decorative applications, providing essential tools for precise surface enhancement. SIFCO ASC, located in Cleveland, specializes in selective brush plating equipment, catering specifically to on-site repairs and component enhancement. This niche focus allows them to address critical maintenance needs in heavy industry and aerospace.
KOCH Finishing Systems, based in Chicago, provides turnkey automated plating equipment and surface finishing systems. In July 2025, they launched innovative Hex Barrels designed for enhanced plating performance, demonstrating a commitment to product innovation. Becker Industries Corp., also in the United States, supplies brush plating kits and gold plating systems, serving both jewelry and industrial segments with specialized solutions.
Other notable entities include Allied Plating Supplies, Inc., which offers a wide range of equipment and chemicals for anodizing and metal finishing processes. A Brite Company operates as a one-stop provider for plating line projects and technical services, particularly for nickel and chrome systems. International Plating Technology (IPT LLC) manufactures and supplies electroplating equipment and automated plating lines, contributing to the breadth of options available to manufacturers. The interplay between these companies defines the availability of solutions and drives the pace of technological adoption.
Regulatory and Economic Headwinds
Operating in this sector requires navigating a complex web of regulations and economic factors. The US Environmental Protection Agency updated effluent limitations for electroplating industry wastewater treatment requirements effective 2025. This regulatory change necessitates significant investment in wastewater treatment capabilities and may render older equipment non-compliant. Companies must factor these compliance costs into their capital expenditure plans.
Raw material volatility also poses a challenge. Industrial market data reports indicate that copper anode prices hit record highs in 2026 due to heightened demand from EV battery production. This increase affects the cost structure of plating operations and may influence the pricing of equipment and consumables. Manufacturers are increasingly looking for equipment that optimizes material usage to mitigate these cost pressures.
Furthermore, the sector analysis indicates that automation labor shortages are driving demand for robotic integration in plating systems. This labor dynamic pushes companies towards higher levels of automation, not just for efficiency but for operational continuity. These external pressures create a compelling case for upgrading to modern, compliant, and automated equipment solutions.
Strategic Recommendations for Stakeholders
For businesses operating in or entering the plating equipment market, a proactive strategy is essential. The data suggests that growth will be concentrated in segments that align with sustainability and automation trends. Investors and manufacturers should focus on the following areas to maximize value.
- Invest in Compliance-Ready Technology: Given the tightening regulatory environment, prioritizing equipment that meets the latest wastewater and emission standards is crucial. Non-compliance risks operational shutdowns and reputational damage.
- Embrace Automation: With labor shortages affecting the sector, integrating robotic solutions can ensure consistent output and reduce dependency on manual labor. This also aligns with the broader industry shift towards Industry 4.0.
- Monitor Supply Chain Resilience: Recent export controls and material shortages highlight the need for diversified supply chains. Engaging with suppliers who offer robust logistics and local support can mitigate disruption risks.
- Focus on High-Growth Applications: While overall market growth is positive, specific applications like EV components and advanced electronics offer higher margins and faster growth rates. Tailoring equipment capabilities to these needs can provide a competitive advantage.
Conclusion: The Value of Deep Intelligence
The plating equipment market is at a inflection point where technology, regulation, and demand converge to create new opportunities. Success in this environment requires more than just surface-level knowledge; it demands a granular understanding of market sizing, segmentation dynamics, and competitive moves. Our full market research report provides the detailed data and strategic frameworks necessary to make informed decisions.
We have outlined the macro trends, key players, and regulatory context in this overview, but the complete picture involves detailed segmentation data, regional deep dives, and specific financial projections. Accessing the full intelligence allows stakeholders to benchmark their position, identify gaps in their strategy, and uncover untapped market potential. For those ready to navigate the complexities of the 2026-2032 landscape, comprehensive data is the most valuable asset.
To obtain the complete analysis, including precise market valuations, detailed segmentation splits, and proprietary competitive assessments, we invite you to access our full report. Equip your organization with the insights needed to lead in the next era of industrial surface finishing.
For detailed analysis of this topic, please visit the official page: Plating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


