



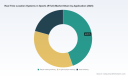
The On-Field Revolution: Strategic Intelligence in the Real Time Location Systems in Sports Market 2026–2032
The intersection of sports performance and digital tracking has crossed a critical threshold. What began as a niche application for elite athletic monitoring has evolved into a scaled operational infrastructure, driven by demands for precision, safety, and revenue optimization in modern stadiums. Our latest market research on Real Time Location Systems in Sports (RTLS) maps this transformation across a seven-year forecast window, providing enterprise leaders with the structural clarity required for capital allocation, supply chain planning, and competitive positioning. The analysis is grounded in observed historical trajectories and forward-looking market mechanics, emphasizing the operational realities that will shape procurement decisions, partnership strategies, and technology roadmaps through the end of the decade.
Building on five years of documented market activity, the sector has demonstrated sustained expansion as venue operators, training facilities, and sports franchises integrate location intelligence into daily routines. The transition from experimental deployments to standardized implementations reflects a maturing technology stack and growing organizational familiarity with real-time spatial data. As the industry moves past early adoption curves, decision-makers are no longer asking whether to implement tracking infrastructure, but how to structure it for durability, interoperability, and measurable return. This report is designed to move leadership teams past vendor narratives and toward evidence-based strategic planning.
Macro Trajectory: Contextualizing Growth for 2026 Decision-Making
Historical revenue data from 2020 through 2025 reveals a consistent upward curve, reflecting the gradual normalization of location-based tracking within sports operations. What started as a modest initial valuation in 2020 has progressed through successive years of expansion, reaching a documented market size of 9.59 million USD by 2025. This progression was not linear nor accidental; it was shaped by successive waves of facility upgrades, performance analytics adoption, and operational digitization across professional and recreational sports ecosystems.
Real-time Location System (RTLS) (Real Time Location Systems) Market
The forecast period spanning 2026 through 2032 projects continued acceleration, with an overall compound annual growth rate of 26.4 percent. By the close of the forecast window, market valuation is expected to reach 49.44 million USD, a trajectory that underscores both the scale of opportunity and the velocity at which deployment patterns are shifting. For executives planning investment cycles in 2026, this expansion rate carries direct implications. Procurement teams must weigh infrastructure durability against rapid technology iteration. Product managers need to anticipate integration requirements as venues layer location data onto existing analytics platforms. Investors and venture stakeholders require a calibrated view of where consolidation pressures will emerge and which operational niches will remain fragmented.
The underlying growth mechanics are anchored in the compounding benefits of precise spatial intelligence. Training facilities use continuous location data to refine conditioning protocols and reduce injury exposure. Competition venues deploy tracking to manage crowd flow, coordinate staff movement, and secure high-value equipment. The convergence of these use cases within a single technology category means that market expansion is not reliant on a single driver, but on the simultaneous maturation of multiple operational demands. Understanding this multi-vector growth structure is essential for leaders who must justify budget commitments to non-technical stakeholders and sequence implementation roadmaps across fiscal years.
Report Architecture: Translating Market Intelligence into Executable Strategy
This study is structured to bridge the gap between high-level market observation and field-level implementation planning. Rather than offering abstract trend commentary, the report organizes findings around decision-making frameworks that executive teams, procurement departments, and product strategists can apply directly to operational planning. The document is divided into functional modules that move from market structure to competitive positioning, then into deployment economics and technology pathway analysis.
The segmentation analysis examines how different tracking technologies, application environments, and regional implementation patterns interact to shape procurement requirements. Instead of presenting static breakdowns, the report contextualizes each segment within adoption drivers, integration complexity, vendor capability maturity, and venue-specific constraints. This allows leaders to evaluate which technology pathways align with their facility profiles, performance objectives, and operational budgets. Application-focused chapters detail how tracking functions are being embedded into player development workflows, competition-day operations, and venue asset management, highlighting where integration friction is most likely to occur and where standardization is beginning to take hold.
Competitor evaluation is presented through a functional lens rather than a purely financial one. Each profiled organization is assessed on technology architecture, deployment model, geographic reach, and compatibility with existing sports analytics ecosystems. Recent product and compatibility developments are incorporated where they signal meaningful shifts in cost structures, scalability, or interoperability. The report also maps concentration dynamics to help readers understand how market share distribution influences negotiation leverage, vendor dependency risk, and long-term sourcing flexibility.
To support practical execution, the study includes operating environment assessments that cover installation requirements, calibration cycles, data integration pathways, maintenance expectations, and staff training considerations. These elements are frequently underestimated during procurement decisions, yet they determine whether a deployment delivers sustained value or becomes a costly maintenance burden. Leaders using this report will be able to construct more realistic total cost models, anticipate operational bottlenecks, and design implementation timelines that account for facility downtime, seasonal usage patterns, and staff readiness.
Real Time Location Systems in Sports (RTLS) Market
Competitive Landscape: Positioning, Differentiation, and Consolidation Signals
The RTLS market in sports has developed a competitive mosaic in which technology origin, deployment philosophy, and ecosystem compatibility determine differentiation more than brand visibility alone. Global participants span multiple regions and technical approaches, and their strategic positioning reflects the broader tension between precision, scalability, and integration simplicity. Understanding these distinctions is critical for organizations evaluating vendor partnerships or assessing where competitive pressure is likely to intensify.
Among the companies examined, Catapult Sports has built recognition through athlete monitoring systems that integrate GPS and local positioning infrastructure for real-time tracking across indoor and outdoor environments. Its profile reflects a strong foothold in performance-oriented deployments where quantitative feedback plays a central role in training and competition preparation. Quuppa Oy has pursued a different axis of differentiation, developing an intelligent locating framework based on Bluetooth angle-of-arrival technology for high-precision tracking of athletes, staff, and assets in venues and stadiums. Recent compatibility announcements and product introductions through early 2026 indicate an active effort to broaden cost-efficient, high-volume positioning options, particularly for applications that require scalable tag ecosystems and venue-level deployment flexibility.
Blueiot has concentrated on Bluetooth-based location solutions that support stadium navigation, crowd management, staff coordination, and visitor tracking, positioning its offering around operational flow and venue experience rather than solely on performance analytics. Eliko and WISER both work within ultra-wideband-based platforms, with Eliko emphasizing high-precision monitoring in indoor sports facilities and WISER extending ultra-wideband applications into player tracking, sports analytics, and stadium operations that include crowd and guidance management at major venues. Sewio Networks offers a broader positioning portfolio spanning ultra-wideband, Bluetooth, and GPS technologies, with use cases that reach into sports facilities through asset, employee, and efficiency-focused tracking configurations. Litum approaches the market with hybrid platform strategies that combine multiple radio technologies for venue and stadium tracking of athletes, equipment, and personnel, reflecting the growing demand for adaptable deployment architectures.
The competitive structure is further shaped by concentration patterns that indicate meaningful share aggregation among leading participants. This concentration matters for procurement planning because it influences technology standardization, integration pathways, and the negotiating power available to facility operators and sports organizations. At the same time, the presence of multiple technology approaches and geographically distributed providers suggests that competition will remain multidimensional, with differentiation emerging through accuracy thresholds, integration compatibility, total deployment cost, and venue-specific scalability. Recent compatibility announcements and product introductions reinforce the likelihood that interoperability and ecosystem alignment will become increasingly decisive factors in vendor selection.
Strategic Implications for Enterprise Decision-Making in 2026
For organizations evaluating RTLS investments in 2026, the market trajectory points toward a clear strategic imperative: location intelligence is transitioning from optional enhancement to foundational operational infrastructure. This shift carries several practical consequences for executive planning. First, procurement decisions must be assessed against long-term integration requirements rather than immediate deployment cost alone. Systems that appear economical at the point of purchase may generate friction if they cannot interface cleanly with existing analytics environments, facility management platforms, or staff workflows.
Second, the diversity of technology approaches means that one-size procurement models are increasingly misaligned with real operating conditions. Venues with heavy indoor usage patterns, for example, face different precision, calibration, and infrastructure requirements than training centers operating primarily in open environments. Leaders need to evaluate candidate technologies against their specific operational topology, seasonal venue usage, and the data ecosystems that surround them. A mismatch at this stage often results in underused hardware, redundant data silos, and extended realization timelines for expected returns.
Third, the competitive landscape suggests that vendor selection should be treated as strategic partnership design rather than transaction procurement. Concentration among leading providers increases the importance of compatibility roadmaps, support structures, and long-term upgrade pathways. At the same time, the presence of multiple regional and technology-focused participants creates opportunities for tailored deployments, provided organizations have the internal capability to manage integration and operational alignment. Companies that treat vendor evaluation as a static comparison of features risk overlooking durability factors that will shape total value over the deployment lifecycle.
Finally, the growth rate projected for the forecast period signals that delay carries its own cost. Market maturation is not only increasing availability and operational familiarity, but also accelerating the pace at which integration standards, staff expertise, and venue expectations evolve. Organizations that postpone evaluation may find themselves entering a more competitive procurement environment with fewer opportunities to shape implementation design on their own terms. Strategic timing, internal readiness planning, and early ecosystem alignment are becoming differentiators in how effectively organizations convert location technology into measurable operational advantage.
Conclusion: The Case for Full Intelligence Access
The Real Time Location Systems in Sports market is entering a phase in which scale, precision, and operational integration will determine which organizations capture sustained value and which are left managing fragmented deployments. This report has been built to support leaders who need more than directional insight. It is designed to clarify where growth is accumulating, how technology choices shape total cost and performance outcomes, and how competitive dynamics influence sourcing and partnership strategy. The strategic decisions made in 2026 will define deployment quality, integration flexibility, and competitive positioning well into the end of the decade.
To support that decision process, the complete study provides detailed segmentation evaluation, competitive profiles, concentration analysis, deployment considerations, and forward-looking scenario frameworks that extend beyond the summary presented here. Readers seeking to align capital planning, procurement strategy, and technology roadmaps with the underlying market structure will find the full report essential for constructing defensible, evidence-based decisions. The complete market intelligence, including granular breakdowns and implementation-level analysis, is available through the source page, where enterprise teams can access the data and frameworks required to move from strategic awareness to execution-ready planning.
For detailed analysis of this topic, please visit the official page: Real Time Location Systems in Sports (RTLS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
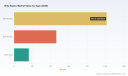
Strategic Intelligence in Motion: Navigating the Global Bike Racks Market Through 2032
The transportation of bicycles has evolved from a niche logistical consideration into a critical component of broader mobility, urban planning, and recreational infrastructure strategies. As cycling gains sustained momentum across commuter corridors, adventure tourism routes, and institutional facilities, the hardware designed to safely secure and transport these assets has become a focal point for manufacturers, distributors, and public-sector procurement teams alike. Our latest market research publication examines the structural trajectories, competitive pressures, and regulatory inflection points shaping the global bike racks market, offering a decision-ready framework for executives who must allocate capital, refine product portfolios, and position for sustained growth through the end of the decade.
Market Trajectory and the 2026 Decision Window
Historical valuation patterns through the base year demonstrate a consistent upward arc, with market revenue expanding steadily from just above twelve hundred million USD in the early 2020s to a projected 1,720.23 million USD in 2026. The forecast horizon extending to 2032 indicates that this momentum is neither anomalous nor cyclical; rather, it reflects entrenched shifts in consumer transportation preferences, municipal infrastructure investments, and the ongoing normalization of multi-modal travel. A compound annual growth rate of 6.2 percent across the evaluation window underscores a market that is maturing with predictable velocity, even as regional demand centers and application-specific monetization strategies diverge in meaningful ways.
Bike Locks Market
For strategic planners operating in 2026, this trajectory carries several operational implications. First, the growth baseline is sufficiently stable to validate mid-cycle capacity investments, but precision in timing matters. Second, the divergence between macroeconomic expansion and segment-level absorption rates means that top-line projections must be calibrated against channel readiness, distribution density, and regulatory compliance costs. Third, the market’s structural resilience creates an environment where differentiation, rather than volume alone, becomes the primary lever for margin preservation. Our analysis isolates these dynamics with forward-looking scenarios that stress-test demand elasticity, supply chain responsiveness, and competitive pricing behavior under varying economic assumptions.
Report Architecture and Actionable Intelligence
This publication is structured to move beyond descriptive market sizing and into the operational mechanics of value creation. The analytical framework integrates baseline demand mapping, segmentation interrogation, competitive benchmarking, and regulatory durability assessments into a single decision-support instrument. Readers will encounter practical tools designed to translate market signals into procurement, R&D, and channel strategy actions:
- Comprehensive segmentation mapping that dissects revenue concentration across mounting configurations, vehicle-class applications, and end-use environments, revealing where adoption curves are steepening and where saturation thresholds are approaching.
- Competitive positioning matrices that evaluate incumbents across product architecture, geographic footprint, distribution agility, and service-model differentiation, enabling benchmarking against peers that have successfully converted product innovation into share gains.
- Regulatory and compliance sensitivity analysis that tracks certification requirements, recall exposure, and fatigue-testing standards, providing risk-adjusted context for product launches and production planning.
- Scenario-based forecasting modules that model revenue pathways under alternative penetration rates, pricing architectures, and policy-support assumptions, helping teams stress-test investment theses before committing capital.
- Channel and procurement pathway reviews that examine how public-sector grant programs, institutional purchasing cycles, and retail ecosystem dynamics shape order velocity and lifecycle revenue capture.
Each section is calibrated for executive utility rather than academic completeness. The objective is to equip strategy, product management, and commercial leadership teams with a defensible basis for prioritizing development pipelines, allocating marketing resources, and negotiating supplier or distribution agreements with awareness of where structural advantages are forming.
Competitive Landscape and Strategic Positioning
The competitive architecture of the market is defined by a relatively fragmented but increasingly specialized participant base, with leadership concentration remaining disciplined. Industry concentration metrics indicate that the top three enterprises command approximately 30 percent of aggregate revenue, while the top five collectively hold roughly 35 percent. This structure suggests that scale advantages exist without creating insurmountable barriers for focused specialists who can differentiate through engineering, application fit, or regional service intensity.
Within this ecosystem, firms are pursuing divergent value propositions aligned to distinct customer priorities. Commercial and institutional-oriented manufacturers concentrate on durable mounting systems, post and ring configurations, and lift-assisted storage solutions designed for high-traffic public and facility environments. These players emphasize longevity, vandalism resistance, and integration with municipal or campus infrastructure specifications. Vehicle-transport specialists, by contrast, optimize for hitch compatibility, aerodynamic clearance, load stability, and ease of deployment, often aligning product architecture with specific vehicle platforms and recreational use cases. A third cohort explores modular storage and wall-mounted solutions that address space-constrained residential and indoor environments, leveraging pivoting or tiered mechanics to maximize utility within limited footprints.
Strategic positioning increasingly hinges on the ability to bridge engineering rigor with user experience. Companies that have built recognizable reputations in this space typically anchor their portfolios around a core mounting philosophy while extending into adjacent application lanes where channel relationships and service assurance can compound advantage. Product development cadence, warranty architecture, and compatibility assurance have become as commercially significant as raw manufacturing scale. For entrants or incumbents evaluating partnership, acquisition, or geographic expansion opportunities, the market rewards clarity of application focus and disciplined go-to-market execution over broad, undifferentiated product proliferation.
Regulatory, Technical, and Operational Undercurrents
Hardware reliability and compliance performance are no longer peripheral concerns; they are central to brand durability and procurement eligibility. Certification expectations and dynamic fatigue testing standards require manufacturers to validate vertical load resistance and long-cycle structural integrity under realistic stress conditions. These technical mandates influence material selection, assembly tolerances, and validation costs, and they increasingly shape the competitive baseline for any firm seeking institutional contracts or retail placement in regulated channels.
The compliance environment has also been shaped by recent recall activity affecting specific hitch-mounted and carrier product lines. Investigations into pivot-cam engagement integrity, latch-mechanism wear, and service requirements on particular models have highlighted how design validation, production consistency, and post-market service responsiveness can directly influence market standing. These episodes are instructive for procurement teams and product developers alike, reinforcing the importance of supplier due diligence, documentation traceability, and proactive field-service planning when integrating third-party components or scaling production across model years.
Beyond compliance, recent program-level developments signal how public-sector incentives and product-cycle timing can accelerate adoption in targeted segments. Grant programs supporting safer school routes and institutional cycling infrastructure have expanded procurement pathways for commercial-grade parking and storage hardware, creating demand pockets that reward readiness, specification alignment, and reliable fulfillment capacity. At the same time, spring and summer product introductions from established manufacturers indicate an ongoing commitment to refinement in hitch, roof, and trunk-mounted configurations, sustaining consumer-facing innovation even as the broader market shifts toward more normalized demand patterns. The interplay between policy-supported procurement and consumer-product refreshes adds a layer of temporal complexity to demand forecasting, one that our research models explicitly address.
Bike Racks Market
2026 Strategic Priorities for Market Participants
Executing effectively in this environment requires a disciplined balance of investment, compliance readiness, and channel alignment. Organizations that treat the market as a single homogeneous opportunity tend to over-index on volume assumptions and under-allocate to the application-specific requirements that actually drive conversion and retention. The research suggests several priorities that should shape executive agendas in 2026:
- Clarify application focus before expanding SKU breadth. Revenue concentration across mounting styles and vehicle-class applications indicates that adjacency expansion works best when anchored by proven channel demand and engineering compatibility rather than speculative diversification.
- Integrate compliance and durability validation into product roadmaps. Certification expectations and recall precedents make structural testing and quality assurance not just technical concerns but commercial differentiators that influence procurement trust and retail shelf performance.
- Align capacity and service planning with procurement cycles. Public-sector grant timing, institutional purchasing calendars, and seasonal product launches create demand pulses that reward flexible fulfillment and proactive field support rather than static inventory assumptions.
- Benchmark competitive advantage through ecosystem strength. Distribution relationships, installation support, warranty responsiveness, and compatibility assurance increasingly determine share movement, especially in a market where leadership concentration remains moderate and specialization is viable.
- Adopt scenario-based capital allocation. Because segment-level absorption and regional readiness can diverge from aggregate growth signals, investment decisions should be tested against multiple penetration and pricing pathways rather than a single baseline forecast.
Conclusion: Why This Research Matters Now
The global bike racks market is not simply expanding; it is reorganizing around clearer application boundaries, more demanding reliability expectations, and a competitive field that rewards focused differentiation. The 6.2 percent compound annual growth trajectory through 2032 provides a credible macro foundation, but the operational decisions that determine who captures disproportionate value will be made at the level of product architecture, compliance readiness, channel execution, and procurement timing. Our full research publication delivers the segmentation resolution, competitive mapping, regulatory context, and scenario modeling required to move from awareness to action. For executives responsible for product strategy, commercial planning, and investment allocation in 2026 and beyond, the detailed intelligence within this report is designed to sharpen judgment and reduce exposure to assumption-driven decisions.
For detailed analysis of this topic, please visit the official page: Bike Racks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Monofilament Line Market Reaches $427M in 2025, Set for 4.2% CAGR Through 2032
By PW Consulting, 2026-09-16
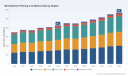
The Monofilament Fishing Line Market in 2026: Strategic Imperatives Amid Regulatory Shifts and Material Volatility
The global outdoor recreation sector continues to evolve under the influence of shifting consumer preferences, tightening environmental regulations, and volatile raw material economics. Within this landscape, the monofilament fishing line industry occupies a critical niche where durability, cost-efficiency, and compliance increasingly dictate competitive positioning. As we move through 2026, enterprises operating across manufacturing, distribution, retail, and specialty retail channels must navigate a complex matrix of demand drivers, formulation constraints, and supply chain dynamics. Our latest market research report delivers a comprehensive, decision-ready analysis of this industry, structured to inform product strategy, capacity planning, sourcing decisions, and competitive positioning for the 2026–2032 horizon.
This article serves as a strategic preview of the full study. It outlines the structural forces shaping market trajectories, highlights the operational content embedded in the report, and demonstrates why forward-looking enterprises require granular, multi-dimensional intelligence rather than high-level aggregates. The underlying research combines historical reconstruction, forward-looking forecasting, competitive profiling, and regulatory impact mapping to produce a cohesive intelligence framework. Readers seeking precise regional valuations, segment-level revenue splits, and application-specific penetration metrics will find those details reserved for the complete publication, where they are presented alongside demand elasticity models, supplier concentration analysis, and scenario-based forecasting tools.
Macro Trajectory: Structural Growth and the 2026–2032 Outlook
The market has demonstrated consistent expansion over the past half-decade, with total industry revenue progressing from approximately USD 350.0 million in 2020 to an estimated USD 427.0 million in 2025. This historical arc reflects steady demand from recreational anglers, commercial operators, and specialty retail channels, supported by product innovation and gradual market maturation. Looking ahead, the forecast period spans 2026 through 2032 and is anchored by a projected compound annual growth rate of 4.2 percent. Under this trajectory, industry revenue is expected to reach roughly USD 450.72 million in 2026 and continue its upward progression toward approximately USD 568.0 million by 2032.
Several structural factors underpin this growth path. First, recreational fishing participation in key markets has stabilized above pre-pandemic levels, with anglers increasingly investing in higher-quality line systems that balance tensile strength, knot integrity, and abrasion resistance. Second, the broader outdoor equipment ecosystem is benefiting from sustained consumer spending on leisure activities, which indirectly supports accessory categories such as monofilament lines, leaders, and replacement spools. Third, ongoing improvements in polymer processing and extrusion consistency have enabled manufacturers to deliver more predictable performance characteristics, reinforcing brand loyalty and repeat purchases.
At the same time, the forecast is not linear. The 2026–2032 window includes years where supply-side pressures, regulatory transitions, and material cost fluctuations may compress margins or shift demand toward alternative formulations. The full report models these inflection points explicitly, separating baseline growth from sensitivity scenarios that account for crude oil-driven resin pricing, regional compliance deadlines, and competitive product launches. Rather than presenting a single deterministic curve, the analysis maps a range of plausible outcomes, giving decision-makers the ability to stress-test capacity plans, inventory strategies, and pricing models against multiple external conditions.
Raw Material Volatility and Formulation Realities
Monofilament fishing line production is inherently tied to petrochemical feedstock economics. Crude oil price movements since early 2022 have introduced pronounced cost variability for nylon polymer resins, which remain the dominant feedstock for the category. Prices reached a 14-year peak near USD 140 per barrel in March 2022 before retreating to a low of approximately USD 75 per barrel in March 2023, and this volatility has directly influenced input costs throughout the manufacturing chain. Even as feedstock curves stabilize, producers must manage the indirect effects on energy usage, logistics, and downstream pricing expectations.
Within this material environment, nylon-based monofilament continues to command the largest share of industry demand, reflecting its balance of durability, versatility, and cost-effectiveness. Its strength-to-flexibility profile makes it suitable for a wide range of fishing conditions, from freshwater angling to targeted saltwater applications. The category’s performance characteristics have also facilitated steady adoption among both novice and experienced users, reinforcing its central position in product portfolios and retail assortments.
However, material selection is no longer determined by performance and cost alone. Environmental scrutiny of per- and polyfluoroalkyl substances has accelerated reformulation efforts across the industry. Several jurisdictions have already imposed restrictions on PFAS-containing products, prompting manufacturers to evaluate alternative coatings, surface treatments, and polymer blends. The full report examines how these formulation shifts affect production economics, quality assurance protocols, and time-to-market for compliant product lines. It also maps the interaction between raw material volatility and regulatory compliance, helping enterprises anticipate where cost pressures may intensify and where reformulation investments may yield long-term differentiation.
Regulatory Dynamics and Compliance Trajectories
Regulatory developments are reshaping the competitive baseline for monofilament fishing line suppliers and downstream distributors. In the United States, the Environmental Protection Agency adopted a one-time reporting requirement covering per- and polyfluoroalkyl substances manufactured or imported between January 1, 2011, and December 31, 2022, including imported articles that contain these substances. This reporting framework increases transparency across supply chains and encourages manufacturers to document material inputs with greater precision. Beyond reporting, state-level actions are introducing direct market constraints. California prohibits the manufacture, distribution, sale, and offer for sale of PFAS-containing textile articles, including fishing line, beginning January 1, 2025. In parallel, the Minnesota Pollution Control Agency banned the sale of PFAS-containing products, including fishing line, starting January 1, 2026.
These measures affect both product availability and formulation strategy. Manufacturers with broad multi-state distribution must now navigate heterogeneous compliance timelines, assess legacy inventory exposure, and determine whether to accelerate regional reformulation or consolidate around compliant product families. Distributors and retailers face parallel responsibilities, particularly around assortment planning, shelf-life management, and customer communication. The full report breaks down these obligations by jurisdiction, mapping the operational implications for sourcing, inventory rotation, labeling, and channel strategy. It also evaluates how proposed federal adjustments to broader environmental standards may indirectly influence feedstock availability and production scheduling.
Importantly, regulatory pressure is not purely a compliance burden; it is also a catalyst for innovation. Companies that proactively invest in non-PFAS formulations and recycled-content options can convert regulatory risk into market differentiation. The report evaluates this dynamic in detail, linking compliance pathways to brand positioning, customer segmentation, and retail partner expectations. Readers who require precise regional compliance calendars and product-category coverage will find those specifics in the full analysis, where they are integrated with sourcing recommendations and reformulation feasibility frameworks.
Competitive Landscape and Strategic Positioning
The industry features a concentrated set of active manufacturers that compete across product performance, brand recognition, distribution reach, and increasingly, sustainability credentials. Berkley Fishing, headquartered in Columbia, South Carolina, remains a prominent producer of monofilament lines, with its Trilene series serving as a widely recognized reference point for reliability and broad application coverage. Sufix Fishing Line, based in Minnetonka, Minnesota, continues to expand its monofilament offerings while responding to sustainability-driven demand through product innovation. Momoi Fishing Line, operating from Kobe, Japan, is known for specialized series such as Hi-Catch and Diamond, which emphasize consistent performance characteristics for targeted angling use cases.
Other notable participants include Seaguar, with headquarters in Louisville, Kentucky, and a product lineup that encompasses monofilament options alongside its broader line portfolio; Spiderwire, also based in Columbia, South Carolina, which markets monofilament variants such as Ultracast Ultimate within its broader product ecosystem; Sunline Fishing Line, operating from Torrance, California, with monofilament products positioned for both retail and specialty channels; and Daiwa Corporation, headquartered in Foothill Ranch, California, which integrates monofilament lines into a wider range of fishing equipment offerings. Together, these firms illustrate a market where brand heritage, product consistency, and channel access remain central to competitive success.
Monofilament Fishing Line Market
Market concentration metrics indicate that the top three companies collectively account for approximately 35 percent of industry revenue, while the top five firms reach roughly 50 percent. This concentration suggests that scale advantages in production, distribution, and brand investment continue to matter, but it also leaves meaningful room for specialization, regional strength, and niche positioning. The full report profiles each core company’s product architecture, geographic footprint, recent strategic moves, and competitive vulnerabilities. It also assesses how product launches, reformulation initiatives, and distribution partnerships are reshaping share dynamics across retail and specialty channels.
Recent activity underscores the strategic importance of sustainability-aligned innovation. In June 2026, Sufix Fishing Line launched the Sufix Recycline brand, featuring 100 percent recycled fishing line, including monofilament options, targeting sustainability-focused consumers. This move highlights how environmental messaging, material circularity, and product performance must be integrated to resonate with modern buyers. The report situates such launches within broader competitive trends, evaluating how sustainability claims influence retailer assortment decisions, customer perception, and long-term portfolio strategy.
Report Architecture and Operational Utility
The full market research report is designed as a decision-support toolkit rather than a static summary. It opens with market sizing and forecasting, presenting total industry revenue across historical and forecast periods, along with growth decomposition that isolates the contributions of volume dynamics, pricing behavior, and product-mix evolution. From there, the analysis transitions into segmentation structures that organize demand by geography, product type, and application, enabling readers to identify where growth concentrates, where performance differs, and where strategic investment is most likely to generate returns.
The competitive section provides company-level profiles, recent development tracking, and concentration analysis. It explores how leading manufacturers differentiate through product architecture, brand positioning, and channel strategy, while also mapping the operational impact of regulatory and material conditions on production planning. In parallel, the report examines market dynamics such as supply chain dependencies, raw material pricing exposure, and compliance-driven reformulation requirements. These sections are linked so that readers can trace how upstream cost shifts and regulatory changes propagate through product design, pricing, and competitive response.
To support practical decision-making, the study includes forward-looking scenario analysis, demand sensitivity considerations, and strategic recommendations tailored to manufacturers, distributors, and retail operators. It identifies where capacity expansion, portfolio rebalancing, supplier diversification, and compliance investment are likely to create the strongest strategic advantage. The full publication also includes detailed regional and segment-level data that are not disclosed in this preview, allowing clients to build localized plans with confidence. Readers who require direct access to those figures, along with the underlying methodology and forecasting assumptions, are encouraged to consult the complete report.
Why This Research Matters for 2026 Decision-Making
Enterprises operating in the monofilament fishing line market face a rare combination of challenges and opportunities in 2026. Raw material volatility continues to complicate cost planning, while regulatory timelines are compressing the window for formulation adjustments and inventory transitions. At the same time, consumer interest in durable, high-performance lines remains solid, and sustainability-oriented innovation is creating new avenues for differentiation. In this environment, strategic decisions cannot rely on broad trends alone. They require a clear view of where demand is strengthening, how regulatory obligations differ by market, which competitive moves are reshaping share, and how material conditions will influence margin structures over the forecast period.
The full report delivers that view. It connects macro growth patterns with segment-level demand behavior, links regulatory developments to operational consequences, and places competitive activity in the context of shifting customer expectations. For manufacturers, it supports product roadmap planning, sourcing strategy, and compliance investment prioritization. For distributors and retailers, it informs assortment decisions, inventory forecasting, and regional merchandising approaches. For investors and strategic partners, it provides a structured basis for evaluating growth potential, concentration risk, and the durability of competitive advantages.
Monofilament Market
This preview has outlined the strategic logic behind the study and the categories of insight it contains. The complete publication expands each area with detailed data, scenario modeling, and actionable recommendations designed for 2026 planning cycles and beyond. Organizations that integrate this intelligence into their decision processes will be better positioned to manage volatility, meet compliance expectations, and capture growth in a market that rewards both operational discipline and forward-looking innovation. The full report is available through the source page, where readers can access the complete dataset, methodology notes, and executive recommendations needed to translate market intelligence into concrete strategic action.
For detailed analysis of this topic, please visit the official page: Monofilament Fishing Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E-Liquids Market Hits $1.125B in 2025, Projects 12.58% CAGR Through 2032
By PW Consulting, 2026-09-16
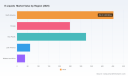
Navigating the Vapor Shift: Strategic Intelligence for the 2026 E-Liquids Market
The global e-liquids market stands at a critical inflection point. As regulatory frameworks tighten and consumer preferences evolve, understanding the precise trajectory of this sector is no longer optional—it is a prerequisite for sustainable growth. Our latest market research publication offers a comprehensive roadmap for navigating the complexities of the e-liquids landscape from 2026 through 2032. This report is designed not merely as a data repository, but as a strategic asset for decision-makers who need to anticipate shifts rather than react to them.
For industry stakeholders, the difference between market participation and market leadership often comes down to the quality of intelligence available at the point of decision. The following analysis outlines the macro-economic environment, the competitive architecture, and the regulatory currents shaping the sector, demonstrating why deep-dive research is essential for capital allocation, product development, and market entry strategies in the coming year.
Macro-Economic Trajectory and Growth Fundamentals
The historical performance of the e-liquids market demonstrates a robust upward trend, reflecting the continued shift away from traditional combustion products toward vaporized nicotine delivery systems. Between 2020 and 2025, the sector experienced consistent expansion, building a substantial revenue base that sets the stage for the forecast period. Current estimates place the total market valuation at USD 1,125.0 Million in 2025, marking a significant increase from the 2020 baseline.
Looking forward, the growth momentum is projected to accelerate. Our forecast models indicate that the market will reach USD 1,265.53 Million in 2026, continuing to climb steadily toward a projected valuation of USD 2,470.0 Million by 2032. This trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 12.58 percent during the 2026-2032 forecast period. Such a rate suggests that the e-liquids sector will continue to outpace many traditional consumer goods categories, driven by innovation in device compatibility, flavor profiling, and evolving regulatory approvals that legitimize specific product categories.
For strategic planners, these figures represent more than just top-line growth; they indicate a maturing market where consolidation and specialization are becoming key drivers. The sheer scale of the projected revenue unit expansion over the next six years implies significant opportunities for players who can secure supply chain stability and navigate the varying compliance landscapes across different jurisdictions.
Market Structure and Concentration Dynamics
One of the most critical aspects of strategic planning in this sector is understanding the competitive density. The market is not uniformly distributed; rather, it exhibits a high degree of concentration among key players. Current analysis reveals a CR3 (Concentration Ratio of the top three firms) of 62.0 percent, while the CR5 extends to 78.0 percent. This level of concentration highlights the dominance of established tobacco giants and specialized nicotine technology firms that have secured significant market share through brand recognition, regulatory approvals, and distribution networks.
This concentration has profound implications for new entrants and existing mid-sized players. It suggests that while the total addressable market is growing, the pathway to capturing share requires distinct differentiation. Companies cannot simply rely on volume; they must offer unique value propositions, whether through proprietary flavor technologies, superior hardware integration, or specialized OEM/ODM manufacturing capabilities. The gap between the top-tier concentrated firms and the long tail of the market is where strategic agility becomes most valuable.
Our research delves into the specific structural dynamics that allow certain entities to maintain these high concentration levels while others struggle to gain footholds. Understanding the barriers to entry, the cost structures of compliant manufacturing, and the distribution leverage held by incumbents is vital for any organization considering M&A activity or organic expansion.
Competitive Landscape and Key Players
The competitive environment is a mix of established multinational tobacco corporations and specialized e-liquid manufacturers. This duality creates a complex ecosystem where traditional smoke-free portfolios intersect with agile, niche liquid producers. Our report profiles the strategies and operational focuses of the industry's pivotal companies.
Major multinational entities such as Philip Morris International Inc., British American Tobacco PLC, Imperial Brands PLC, and Japan Tobacco International are heavily invested in the e-vapor space. These companies integrate e-liquids into broader smoke-free business portfolios, leveraging their existing distribution channels and regulatory expertise to maintain market presence. Their approach often focuses on standardized, compliant products that align with global regulatory trends.
On the other side of the spectrum are specialized manufacturers and technology developers. JUUL Labs Inc. and Logic Technology Development LLC have historically focused on specific delivery systems and cartridge formats, emphasizing authorized variants and specific flavor profiles. NJOY LLC continues to push pod formats designed for ease of use and nicotine delivery efficiency. Meanwhile, specialized manufacturers like Hangsen have carved out a significant role as world-leading OEM/ODM partners, providing solutions to markets across over 86 countries. This highlights a crucial supply-side dynamic: the reliance of many brands on specialized manufacturing partners to scale production while adhering to quality guidelines.
Independent premium brands such as Ruthless Vapor, Mister-E-Liquid, and Vape Base Ltd also play a crucial role in shaping consumer preferences, particularly in the flavored e-liquid segment. These companies often lead in flavor innovation and community engagement, setting trends that larger conglomerates may later adopt or regulate around. Our analysis examines how these different tiers of competitors interact, compete for shelf space, and navigate the varying regulatory requirements that define their respective operational zones.
Regulatory Environment and Industry Dynamics
No strategic discussion of the e-liquids market is complete without addressing the regulatory environment, which remains the single most significant variable affecting market access and profitability. As of May 2026, the regulatory landscape is characterized by a patchwork of authorizations and duties that vary significantly by region.
In the United States, the FDA continues to be the gatekeeper. As of May 2026, the FDA has authorized 45 ENDS products, representing the only ones legally marketed in the United States. This tight control over market entry creates a high barrier for new products but provides stability for those who secure authorization. Recent developments underscore this reality; in June 2025, the FDA granted premarket authorizations to Swedish Match North America, Inc. for tobacco-flavored e-liquid products. Furthermore, in May 2026, the FDA authorized the marketing of four Glas ENDS products featuring e-liquid pods with non-tobacco and non-menthol flavors. This authorization is particularly significant as it signals a potential pathway for flavor diversity under strict compliance conditions, a key area of interest for consumer growth.
Across the Atlantic, the UK has introduced new fiscal measures. On 01 April 2026, the UK HMRC opened applications for the Vaping Products Duty of £2.20 per 10ml on all vaping liquids. This duty imposes a direct cost on production and distribution, which will inevitably influence pricing strategies and margin structures for companies operating in or exporting to the UK market. Strategic budgeting for 2026 and beyond must account for these duty implications to avoid margin erosion.
State-level actions also contribute to the complexity. The Virginia Annual Report on Liquid Nicotine and Nicotine Vapor Products, published in February 2026, records 13 manufacturers certified and $380,000 in revenue collected, indicating active state-level monitoring and taxation. Similarly, Arkansas requires manufacturers to certify compliance with directory rules for vapor products and e-liquid products, with penalties for non-compliance starting November 2025. These fragmented regulatory requirements necessitate a robust compliance infrastructure that our report details extensively.
Industry Activity and Capacity Expansion
Despite regulatory headwinds, industry activity remains vigorous. Corporate strategies reflect a commitment to growth and capacity building. In February 2026, VPZ announced a multi-million-pound investment to expand e-liquid manufacturing capacity and launch new retail locations. This move signals confidence in the long-term demand for compliant vaping products and highlights the importance of physical retail presence alongside manufacturing scalability.
Trade activity also continues to facilitate commercial connections. The Total Product Expo in April 2026 featured a dedicated e-liquids and vapes category with significant commercial activity for independent retailers. Such events are critical nodes in the supply chain, where manufacturers connect with distributors and retailers to secure shelf space and negotiate terms for the upcoming fiscal year. Our market research captures the sentiment and transaction trends observed at these key industry gatherings, providing qualitative context to the quantitative data.
E-cigarette Market
Strategic Value of the 2026 Market Research
Given the interplay of high market concentration, rapid growth projections, and a shifting regulatory moat, generic market data is insufficient for high-stakes decision-making. This report provides the granular intelligence required to transform uncertainty into strategy.
Our analysis goes beyond surface-level metrics to explore the segmentation splits that drive revenue. We examine the performance of different product types, including Pre-Filled and Bottled E-Liquids, and analyze how application preferences such as Tobacco, Fruit, and Menthol flavors influence purchasing behavior in different regions. However, the specific weightings and regional revenue distributions are detailed within the full report to maintain competitive confidentiality and ensure that subscribers receive the most actionable, non-public insights.
The core value of this research lies in its operational applicability. For investors, it offers a clear view of where capital is flowing and which segments offer the highest risk-adjusted returns. For manufacturers, it identifies gaps in the supply chain and opportunities for OEM/ODM expansion. For distributors and retailers, it highlights the flavor profiles and product formats that are gaining traction in compliant markets.
Readers are encouraged to access the full source webpage to retrieve the complete segmentation data, detailed company profiles, and specific regional forecasts. Only through the comprehensive dataset can organizations build the precise financial models and market entry plans required to succeed in this high-growth, high-regulation environment. The summary provided here establishes the strategic necessity of the research; the full document delivers the executional intelligence.
Conclusion
The e-liquids market is poised for substantial expansion over the next six years, but the path to capturing this value is fraught with regulatory and competitive challenges. With a projected market size nearing USD 2,470.0 Million by 2032 and a CAGR of 12.58 percent, the opportunity is significant. However, success will belong to those who can navigate the FDA authorization landscape, adapt to duties like the UK Vaping Products Duty, and compete effectively within a market where the top five players already control 78.0 percent of the share.
E-Liquids Market
PW Consulting's latest market research equips stakeholders with the necessary tools to make informed decisions. By integrating historical performance data, current regulatory facts, and competitive profiles, this report serves as a foundational document for strategic planning in 2026. We invite you to review the complete findings on our website to fully leverage this intelligence for your organization's growth objectives.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Calcium Sulfate Market Hits $288.9M in 2025, Poised for 4.2% CAGR Growth to 2032
By PW Consulting, 2026-09-16
Strategic Outlook: Navigating the Calcium Sulfate Market Through 2026 and Beyond
The global industrial landscape for calcium sulfate is undergoing a nuanced transformation, driven by shifting construction demands, evolving regulatory frameworks, and the strategic repositioning of key material suppliers. For executives and portfolio managers operating within the industrial minerals, agriculture, and specialty chemicals sectors, 2026 represents a pivotal inflection point. Decisions made today regarding supply chain diversification, grade-specific sourcing, and regional expansion will directly determine competitive positioning through the end of the decade. Our latest research initiative examines the structural forces shaping this market, providing a decision-ready architecture for navigating both near-term volatility and long-term growth trajectories.
Market Architecture and Macro Trajectory
Calcium sulfate continues to anchor a multifaceted value chain that spans construction infrastructure, agricultural soil management, food and pharmaceutical formulation, and broad industrial processing. Historical movement from 2020 through 2025 illustrates a market that has demonstrated steady resilience despite macroeconomic headwinds, raw material supply constraints, and regional policy realignments. Revenue expanded from approximately 235.18 Million USD in 2020, reached 246.45 Million by 2021, fluctuated marginally at 246.44 Million in 2022, and then accelerated to 269.81 Million in 2023 as construction and industrial activity rebounded across major economies. By 2024, the figure climbed to 278.75 Million, and the current baseline for 2025 sits at 288.90 Million USD.
Magnesium Sulfate Market
These sequential expansions reflect more than incremental demand; they signal the maturation of application ecosystems and the gradual integration of calcium sulfate into higher-value manufacturing and processing workflows. Looking forward, the forecast window extending to 2032 maps a clear upward pathway. Revenue is projected to advance toward 302.82 Million in 2026, followed by sustained growth across subsequent years, ultimately approaching 385.32 Million by the close of the decade. This trajectory corresponds to a compound annual growth rate of 4.2 percent, a figure that underscores moderate but structurally reliable expansion.
For strategic planners, this pace of growth carries distinct implications. A 4.2 percent CAGR suggests a market that is neither volatile nor speculative, but rather characterized by methodical procurement cycles, grade-driven pricing premiums, and regional supply-demand mismatches. Companies that align procurement calendars with forecast inflection points, rather than reacting to annual spot fluctuations, will be better positioned to manage working capital and secure favorable contract terms. The underlying forecast also reveals where capacity planning, inventory optimization, and downstream application development will yield the highest returns, and our full report isolates those leverage points with granular timeline mapping.
Segmentation Dynamics and Application Realities
The calcium sulfate market is inherently multi-dimensional, spanning variations in mineral forms, grade specifications, and end-use applications. Gypsum and anhydrite represent the two foundational product categories, each with distinct handling characteristics, processing requirements, and downstream suitability. Technical-grade, food-grade, and pharmaceutical-grade specifications further fragment procurement strategies, as material purity, trace element limits, and certification pathways vary significantly across industries. The construction sector remains the dominant application anchor, drawing substantial volume for wallboard manufacturing, cement conditioning, and specialty finishing products. Agricultural applications constitute another meaningful demand stream, particularly where calcium sulfate serves as a soil amendment and secondary nutrient carrier. Food and beverage formulation, pharmaceutical and personal care manufacturing, and broader industrial processing round out a diversified application matrix.
Understanding how these segments interact is essential. Industrial buyers do not simply purchase a homogenous material; they navigate a tiered landscape where grade purity, origin traceability, moisture content, and particle morphology directly influence processing efficiency and final product quality. The construction industry's volume requirements often create baseline demand floors, while food-grade and pharmaceutical-grade channels operate on tighter specification windows and command differentiated pricing structures. Agricultural demand, meanwhile, fluctuates with planting cycles, regional soil conditions, and the availability of competing amendments. Our detailed analysis dissects these interdependencies and maps where procurement teams should prioritize grade flexibility versus specification rigidity, but the exact volume distributions, regional consumption allocations, and application-level revenue splits are reserved for the complete intelligence package. The objective of this overview is to establish the structural logic; the report delivers the operational quantification needed to act on it.
Competitive Landscape and Strategic Postures
The competitive environment in calcium sulfate is defined by a blend of industrial mineral processors, regional suppliers, and specialized formulators who serve distinct end markets. Several established players illustrate the strategic diversity within this space. One prominent supplier headquartered in Mamaroneck, New York, offers calcium sulfate in dihydrate, hemihydrate, and anhydrous forms, sourcing from both domestic and international origins while targeting industrial and agricultural buyers. Another U.S.-based processor, operating out of Mentor, Ohio, functions as a supplier and industrial mineral extender, distributing anhydrous and dihydrate forms for additive and formulation applications. In China, a manufacturer and exporter based in Xingtai, Hebei, processes food-grade, anhydrous, and specialized calcium sulfate products used in baking ingredients, tofu coagulation, and pharmaceutical contexts. Separately, a U.S. operation headquartered in Illinois has focused on granular calcium sulfate fertilizer blends designed to deliver secondary nutrients such as calcium and sulfur for agricultural use.
The strategic postures of these companies reveal broader market dynamics. Some entrants emphasize multi-origin sourcing to mitigate supply disruptions and maintain price competitiveness, while others concentrate on grade specialization to capture higher-margin formulation and food-adjacent channels. Agricultural-focused producers increasingly differentiate through nutrient delivery formats and soil-health positioning. These approaches reflect a market where scale alone is insufficient; sourcing reliability, specification consistency, regulatory compliance, and application-specific technical support increasingly determine purchasing decisions. The report includes a structured competitive assessment that maps these differentiation vectors across the leading participants, including recent operational milestones such as new facility openings and capacity expansions that reshape regional supply availability. Full competitor benchmarking, sourcing footprints, and strategic capability comparisons are available within the published intelligence, enabling procurement and strategy teams to calibrate vendor selection with precision.
Regulatory, Supply-Side, and Operational Headwinds
Beyond demand-side growth, calcium sulfate markets are being shaped by regulatory evolution and supply-side constraints that carry direct operational consequences. Government agencies in key regions have begun issuing handling and management guidance for by-product gypsum derived from flue gas desulfurization processes, aiming to facilitate agricultural and industrial reuse while strengthening environmental compliance standards. These guidance frameworks influence how secondary calcium sulfate streams can be processed, certified, and commercialized, adding both opportunity and compliance complexity for processors and end users.
Simultaneously, the raw material environment is experiencing structural adjustments. Synthetic gypsum production has declined as coal-fired power facilities continue to close, reducing the availability of a historically important secondary feedstock for calcium sulfate processing. This shift affects cost structures, supply continuity, and regional sourcing strategies, particularly for industrial buyers who have relied on recovered gypsum streams to balance procurement economics. The intersection of cleaner environmental standards and reduced synthetic feedstock availability is prompting a recalibration of primary versus secondary sourcing mixes. Organizations that anticipate these supply-side transitions, evaluate primary deposit access, and build qualification pathways for alternative feedstocks will face less disruption than those depending on legacy synthetic supply networks. The complete report examines these regulatory and supply dynamics in context, including their projected impact on pricing behavior, processing investments, and regional availability throughout the forecast window.
Strategic Implications for Corporate Decision-Making
For executives evaluating market entry, capacity investment, sourcing strategy, or product portfolio development, the calcium sulfate landscape offers both predictable growth and targeted risk. The 4.2 percent CAGR indicates that expansion will be driven by steady industrial and agricultural demand rather than speculative cycles, which favors disciplined long-term planning. However, the segmentation complexity means that growth opportunities are uneven across grades, applications, and geographies. Companies that treat calcium sulfate as a single commodity risk missed margin opportunities in higher-specification channels, while organizations that over-specialize without securing diversified supply may face cost volatility when regulatory or feedstock conditions shift.
Effective positioning requires a multi-layered strategy. Procurement teams must evaluate supplier qualification frameworks that account for both origin traceability and grade reliability. Operations leaders should assess whether existing facilities can accommodate shifts in feedstock composition and specification requirements as synthetic gypsum volumes change. Market development teams need to identify where food-grade and pharmaceutical-grade applications offer margin premiums and where agricultural channels provide volume stability. Regulatory affairs functions should monitor handling and reuse guidance that may expand downstream utilization of by-product streams while introducing new compliance obligations. Each of these considerations carries distinct return profiles and implementation timelines, and our research isolates where strategic capital and operational attention will generate the strongest outcomes.
Calcium Sulfate Market
How the Full Report Supports Your Next Move
This overview establishes the strategic contours of the calcium sulfate market and the rationale for informed, forward-looking decision-making in 2026. The complete market research publication extends this foundation into a fully operational intelligence framework. It delivers a detailed segmentation analysis across product types, grade specifications, and application channels, alongside regional market sizing and consumption trajectories. It maps the competitive landscape with structured company profiles, recent operational developments, and capability comparisons that help procurement and strategy teams evaluate vendor alignment. It integrates regulatory and supply-side developments into scenario-based implications, allowing decision-makers to test sourcing and pricing assumptions under changing feedstock and compliance conditions.
Most importantly, the report translates market structure into actionable milestones. It identifies where demand acceleration is most likely, which grade channels merit specification investment, and where sourcing diversification will provide the greatest resilience. For leaders responsible for capital allocation, supply chain design, or market expansion, the publication functions as a single-source reference for aligning commercial strategy with market reality. To access the complete segmentation data, regional breakdowns, competitive benchmarking, and forecast pathways, readers are invited to explore the full research publication. The detailed intelligence contained within is designed to support precise, confident decisions as the calcium sulfate market continues its measured ascent through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Calcium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Dairy Market to Hit $344.8M by 2032 with 6.6% CAGR
By PW Consulting, 2026-09-16
Navigating the Dairy Ingredients Horizon: Strategic Imperatives for 2026 and Beyond
The global dairy ingredients sector stands at a critical inflection point as it moves through the mid-2020s. For executives, procurement leaders, and strategic planners, the decisions made in 2026 will define competitive positioning throughout the decade. Understanding where the market has been, where it is heading, and who is shaping its trajectory is no longer a matter of routine monitoring. It requires a rigorous, forward-looking intelligence framework. PW Consulting’s latest Dairy Ingredients Market study delivers that framework, translating complex supply dynamics, shifting demand patterns, and rapidly evolving trade conditions into actionable strategy.
Dairy Ingredients Market
Over the past five years, the industry has experienced a period of measured expansion punctuated by supply chain recalibration, regulatory shifts, and changing end-user expectations. Total industry revenue climbed from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting steady consolidation of demand across multiple application verticals. The trajectory points toward continued growth, with market valuation projected to reach 237.36 million USD in 2026 and advance to 344.8 million USD by 2032. This progression corresponds to a compound annual growth rate of 6.6 percent across the 2026 through 2032 forecast window. Such a macro outlook signals a fundamentally resilient category, but the real strategic value lies beneath the headline figures: in how value is distributed across ingredient types, how regional supply balances interact with trade policy, and which application segments are generating the strongest margin discipline.
Why 2026 Demands a Recalibrated Strategic View
The year 2026 is not a simple continuation of recent patterns. Several structural forces are converging to reshape how dairy ingredients are sourced, formulated, priced, and distributed. On the regulatory front, the Food and Drug Administration’s July 2025 proposal to revoke 18 standards of identity for dairy products, including multiple cheese and milk variants, has introduced new considerations around labeling, formulation compliance, and ingredient substitution. For manufacturers and formulators, this creates both flexibility and ambiguity, requiring closer coordination between regulatory affairs, R&D, and procurement teams.
At the same time, trade dynamics are shifting quickly. Recent reporting from the International Dairy Foods Association in February 2026 highlighted landmark new trade agreements with Taiwan that fully eliminate dairy tariffs, materially expanding U.S. dairy ingredients market access. The same reporting noted additional accords with Argentina, El Salvador, Guatemala, Bangladesh, and North Macedonia, collectively boosting export potential. These developments are unfolding alongside U.S. Dairy Export Council data from January 2026 showing that 2024 U.S. dairy exports recorded increased volumes on a milk-fat basis while experiencing declines on a skim-solids basis. The divergence underscores a nuanced export environment where composition, destination, and commodity mix matter as much as total shipment volume.
On the demand side, a McKinsey dairy industry survey from April 2026 found rising demand for dairy ingredients even as cost pressures and margin challenges persist across the value chain. This combination of resilient demand and compressed profitability is precisely the environment in which granular market intelligence becomes indispensable. Executives cannot rely on aggregate growth narratives alone; they must understand which ingredient categories are absorbing volume, which applications are commanding premium positioning, and how competitive intensity is evolving among established producers and specialized suppliers.
Inside the Research: What This Study Delivers
PW Consulting’s Dairy Ingredients Market report is structured to move beyond surface-level forecasts and into the operational detail that decision-makers actually use. The study is built around several core analytical pillars:
- Historical reconstruction and forward modeling covering the 2020 to 2025 historical window and a detailed 2026 to 2032 forecast period, with revenue expressed in million USD and a documented 6.6 percent CAGR.
- Segment-level analysis across ingredient types, end-use applications, and regional markets, designed to reveal where growth is concentrated and where competitive saturation is most pronounced.
- Competitive landscape assessment profiling leading producers and suppliers, evaluating their product portfolios, geographic reach, formulation capabilities, and strategic positioning within the broader ingredients ecosystem.
- Market structure evaluation examining concentration metrics and the balance between diversified global players and specialized regional operators, helping buyers and investors gauge pricing power, supply resilience, and partnership options.
- Regulatory, trade, and standards context integrating developments such as FDA identity standard revisions, ADPI-maintained industry standards for U.S.-produced dairy ingredients including whey, lactose, and milk proteins, and the latest trade agreement outcomes that affect market access and cost structures.
- Recent industry milestones capturing events such as the April 2026 ADPI Annual Conference in Chicago and other sector gatherings that shape innovation direction, foodservice application trends, and cross-functional collaboration across the ingredients community.
The report is deliberately built for practical use. Rather than stopping at high-level trends, it connects demand signals to ingredient functionality, links regional supply dynamics to trade policy outcomes, and frames competitive moves within the context of margin discipline and formulation innovation. This integrated approach allows readers to assess not only where the market is going, but how their own sourcing strategies, product development roadmaps, and partnership decisions should adapt in response.
Competitive Landscape: Who Is Shaping the Market
The dairy ingredients arena is populated by a mix of large, globally active dairy organizations and focused ingredient specialists. The competitive field spans North American producers with strong domestic supply chains, European exporters with broad international distribution, and formulation-oriented companies that provide custom concentrates and blended powders tailored to specific food and beverage applications. Rather than a single dominant architecture, the market operates as a layered ecosystem in which scale, specialization, and application expertise create distinct competitive advantages.
Several organizations stand out through the breadth of their ingredient portfolios and their presence across multiple end markets. Agropur, headquartered in Montreal, Canada, focuses on dairy ingredient production including whey, milk protein, and casein for food and beverage applications. Arla Foods, based in Viby J, Denmark, provides dairy ingredients such as milk powders, whey proteins, and lactose for global food and nutrition markets. Lactalis, located in Bourgbarre, France, offers dairy ingredients including milk powders, whey, and casein for global food and beverage industries. Saputo Cheese USA, with operations linked to Montreal, Canada, supplies whey powders, milk proteins, and other dairy ingredients for food production. These organizations illustrate how major dairy groups leverage ingredient divisions to serve a wide range of industrial and consumer-facing applications.
Alongside these broader players, a set of specialized suppliers adds critical depth to the market. Bluegrass Ingredients, Inc., based in Kentucky, United States, specializes in custom dairy concentrates, blended powders, and whey-based ingredients for food formulation. California Dairies, Inc., in Tulare, California, produces and supplies milk powders, whey products, and other dairy ingredients for industrial and food applications. Dairy Farmers of America, headquartered in Roseville, Illinois, supplies milk powder, whey, casein, and other dairy ingredients for dairy products, food manufacturing, and nutrition. Glanbia Nutritionals, located in La Crosse, Wisconsin, manufactures whey protein isolates, concentrates, and other dairy protein ingredients for sports nutrition and food products. Land O’Lakes, based in Arden Hills, Minnesota, provides milk powders, whey products, and functional dairy ingredients for food processing and nutrition. Leprino Foods, in Denver, Colorado, produces cheese powders, whey, and other dairy ingredients used in food manufacturing and baked goods. MCT Dairies, based in Millburn, New Jersey, distributes and supplies dairy ingredients across global markets for food and beverage applications. Proliant Dairy Ingredients, in Ames, Iowa, specializes in dairy protein ingredients, whey products, and milk proteins for food and industrial use. Schreiber Foods, headquartered in Green Bay, Wisconsin, manufactures dairy ingredients such as milk powders, whey, and casein for beverage and food industries.
Together, these companies represent the operational core of an industry that must continuously balance scale efficiency with formulation precision. Their product ranges, application focus, and geographic footprints shape how buyers evaluate supply reliability, technical support, and long-term partnership potential. The full report provides a more detailed competitive mapping, assessing how these organizations are positioned relative to one another across ingredient types, end-use segments, and regional markets, while preserving the analytical depth needed to support sourcing strategy, partnership evaluation, and competitive benchmarking.
Market Dynamics: Regulation, Trade, and Demand Signals
A durable understanding of dairy ingredients requires attention to the forces that alter cost structures, market access, and formulation choices. The July 2025 FDA proposal to revoke 18 standards of identity for dairy products has introduced a meaningful regulatory variable. For ingredient suppliers and end-product manufacturers alike, changes to identity standards can affect labeling requirements, ingredient substitution pathways, and the competitive positioning of specific product forms. The strategic implication is not simply compliance; it is the opportunity to reconsider formulation architectures and ingredient blending strategies in light of broadened flexibility.
Worldwide Infant Dairy Ingredients Market
Trade policy is equally consequential. The February 2026 announcement of new agreements with Taiwan, alongside expanded collaboration with Argentina, El Salvador, Guatemala, Bangladesh, and North Macedonia, signals a widening aperture for export-oriented growth. These agreements can reduce tariff barriers, improve destination-market competitiveness, and reshape the relative attractiveness of different sourcing origins. At the same time, the U.S. Dairy Export Council’s January 2026 data reminds the market that export performance is not uniform. Increased milk-fat basis volumes alongside skim-solids declines indicate that commodity composition, end-use demand, and pricing dynamics differ significantly by product stream. Organizations that treat dairy ingredients as a single homogeneous category risk misreading both opportunity and exposure.
On the demand side, the April 2026 McKinsey survey’s finding of rising ingredient demand amid cost and margin pressure captures the current tension. Buyers are seeking functional reliability, consistent supply, and formulation versatility, while suppliers are navigating input volatility and the need to protect profitability. In this environment, industry standards maintained by organizations such as the American Dairy Products Institute play an important role in anchoring quality expectations for U.S.-produced dairy ingredients including whey, lactose, and milk proteins. The June 2026 reinforcement of those standards, alongside the April 2026 ADPI Annual Conference’s focus on innovation and foodservice applications, suggests that technology, consistency, and application performance remain central competitive differentiators.
What Strategic Decision-Makers Need to Know Next
The macro picture is clear enough to establish confidence in continued growth, but the strategic decisions that matter most are segmental, operational, and partnership-driven. Which ingredient categories are expanding fastest in value terms? Where are application segments generating the strongest demand pull, and which are facing substitution risk or margin compression? How do regional supply balances interact with the new trade agreements to alter sourcing geography? Which competitors are building advantage through formulation capability, and which are competing primarily on scale and distribution?
These are the questions that determine whether an organization simply rides broad market growth or actively captures disproportionate value from it. The answers require a detailed view of segmentation splits, regional performance patterns, application-level demand intensity, and competitive positioning that cannot be responsibly compressed into a single summary. PW Consulting’s full Dairy Ingredients Market study is built to provide exactly that depth, enabling procurement teams, R&D leaders, and corporate strategists to align their plans with the most current structural reality of the market.
For executives preparing 2026 initiatives and longer-range plans through 2032, the study offers a structured intelligence base: historical trajectory, forward projections anchored to a 6.6 percent CAGR, segment and regional breakdowns, competitive profiling, and dynamic context drawn from the latest regulatory, trade, and industry developments. The objective is not to overwhelm with data, but to give decision-makers the clarity needed to prioritize investments, manage supply risk, and position products where demand and margin discipline intersect.
The full report is available for review and acquisition through PW Consulting’s market research portal. Readers seeking a complete segment-by-segment view, detailed competitive mapping, and region-specific growth pathways are encouraged to access the source page for the complete intelligence package. In a market where aggregate growth can mask important local and segmental shifts, that level of detail is what turns insight into advantage.
For detailed analysis of this topic, please visit the official page: Dairy Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epoxidized Soybean Oil Market to Hit $825M by 2032 Growing at 7.58% CAGR
By PW Consulting, 2026-09-16
Navigating the Epoxidized Soybean Oil Market: Strategic Intelligence for 2026 and Beyond
The global chemical landscape is undergoing a structural shift where sustainability, regulatory compliance, and supply chain resilience converge. For stakeholders in the polymer additives sector, Epoxidized Soybean Oil (ESBO) has emerged as a critical component, bridging the gap between performance requirements in PVC formulations and the escalating demand for bio-based alternatives. As we enter 2026, the market stands at a pivotal juncture. PW Consulting's latest comprehensive study on the Epoxidized Soybean Oil Market is designed not merely as a data repository, but as a strategic compass for executive decision-making in this evolving environment.
This research provides a granular look at the forces shaping revenue trajectories from the base year of 2025 through the forecast period extending to 2032. By synthesizing historical performance with forward-looking indicators, this report equips leadership teams with the insights necessary to navigate volatility, capitalize on regional opportunities, and understand the competitive intensity defining the sector.
Market Trajectory and Growth Dynamics
Understanding the macroeconomic pulse of the ESBO market is the foundational step for any strategic planning process. The historical data from 2020 to 2025 reveals a consistent upward trend, reflecting the material's entrenched role in various industrial applications. The market valuation witnessed steady expansion, moving from approximately 392.15 million USD in 2020 to an estimated 496.5 million USD in 2025. This historical resilience sets the stage for the forecast period, where growth is projected to accelerate.
Our analysis indicates that the market is poised to reach significant milestones by the end of the forecast window. Starting from a projected 534.71 million USD in 2026, the trajectory points toward a valuation of 825.27 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 7.58 percent. Such growth is not accidental; it is driven by the dual engines of increasing PVC demand in emerging economies and the regulatory push away from phthalate-based plasticizers in developed markets.
However, raw growth figures only tell part of the story. The strategic value lies in understanding the velocity of this growth across different horizons. Early forecast years suggest a period of consolidation and capacity adjustment, while the latter half of the decade indicates a potential surge driven by downstream industry adoption. Decision-makers must distinguish between short-term cyclical fluctuations and long-term secular trends to allocate capital effectively.
Competitive Landscape and Strategic Positioning
The ESBO market is characterized by a moderately concentrated competitive environment. Our concentration analysis reveals that the top three players hold a combined market share of 55.0 percent, while the top five entities command 65.0 percent. This structure suggests that while market leaders possess significant influence over pricing and supply standards, there remains sufficient fragmentation to allow for niche specialization and regional agility.
Waterborne Epoxy Resin Market
Several key corporations define the current operational landscape, each leveraging distinct strategic advantages:
- Cargill, Incorporated (Minneapolis, Minnesota, United States): A dominant force leveraging scale and integration. Cargill produces Vikoflex and Vikoflex High IV grades, positioning them as primary plasticizers and co-stabilizers for flexible and semi-rigid PVC formulations. Their recent capacity expansion and modernization of the facility in Sidney, Ohio, demonstrates a commitment to scaling production to meet growing demand.
- Valtris Specialty Chemicals (Chicago, Illinois, United States): Focuses on specialized grades such as Plas-Chek and Lankroflex. Their value proposition heavily emphasizes compliance, offering secondary heat stabilizers and plasticizers with food-contact and Kosher certifications. This focus was reinforced in late 2024 when they promoted these grades for flexible PVC, highlighting renewable and food-safe features.
- Galata Chemicals LLC (Ewing, New Jersey, United States): Competes on performance metrics, manufacturing plasticizers that emphasize heat stability. Their February 2024 product launch of an advanced ESBO plasticizer with superior heat stability targets high-performance PVC applications, signaling a strategy focused on technical differentiation.
- CHS Inc. (Inver Grove Heights, Minnesota, United States): Utilizes vertical integration as a competitive moat. By leveraging soybean crushing operations, CHS secures a cost-effective supply chain for PVC and polymer markets, insulating themselves somewhat from upstream commodity volatility.
- ADEKA Corporation (Tokyo, Japan): Operates as a global supplier, ensuring geographic diversification and serving PVC stabilization needs across international markets.
- Acme-Hardesty (New Haven, Connecticut, United States): Supplies Jenkinol 680 grades, catering to specific PVC production requirements as both plasticizer and stabilizer.
- ChemCeed (Cary, North Carolina, United States): Plays a crucial role in distribution, offering technical-grade ESO in various quantities from drums to bulk, facilitating accessibility for smaller-scale or specialized users.
- Interstate Chemical Company (Hermitage, Pennsylvania, United States): Manufactures Interflex ESO for general PVC and plastics formulations, maintaining a steady presence in the domestic manufacturing sphere.
Beyond the incumbents, the landscape is dynamic. Recent developments indicate ongoing innovation and market entry. For instance, J-Oil Mills launched an enhanced liquid epoxidized soybean oil variant in March 2025 with improved compatibility for PVC stabilizers. Such moves highlight that the barrier to entry relies heavily on technical formulation capabilities and certification compliance rather than just raw production capacity. Understanding the specific strategic moves of these players—from capacity expansion to product promotion—is essential for benchmarking one's own market position.
Segmentation Insights and Demand Drivers
A core strength of this research lies in its detailed segmentation analysis. While aggregate numbers provide the trend line, the real strategic opportunities are often hidden within specific application and end-use verticals. The market revenue is distributed across several key applications, with Plasticizers representing the largest share of consumption. This is followed by significant contributions from Pigment Dispersion Agents and other specialized uses. Fuel Additives also constitute a notable segment, reflecting the versatility of ESBO beyond traditional polymer stabilization.
From an end-use industry perspective, the Food & Beverages sector emerges as a critical demand driver, largely due to stringent safety regulations requiring non-toxic additives. Adhesives & Sealants and Automotive industries also represent substantial consumption bases. The Automotive sector, in particular, faces pressure to reduce weight and improve interior air quality, driving the adoption of non-phthalate plasticizers like ESBO.
It is important to note that while regional dynamics vary, the interplay between local manufacturing capabilities and import dependencies creates unique market structures in different geographies. North America, Europe, and Asia Pacific represent major hubs of activity, each with distinct regulatory frameworks and supply chain characteristics. Latin America and the Mideast and Africa regions, while smaller in current valuation, offer growth potential as industrialization accelerates. Our report dissects these regional nuances without exposing the specific revenue splits, ensuring that clients uncover the precise opportunity magnitudes through the full analysis.
Industry Context and External Volatility Factors
Strategic planning in the chemical sector cannot occur in a vacuum. External factors regarding raw materials and regulation exert profound influence on profitability and supply security. One of the most significant cost drivers is soybean oil, which accounts for approximately 58.6 percent of the raw material share in epoxidized soybean oil production. Fluctuations in soybean oil prices directly impact production margins. According to recent USDA forecasts, soybean oil season-average prices are projected at 0.59 per lb for the 2025/26 marketing year. Furthermore, USDA economic data suggests soybean crush demand is forecast to reach a record 2.75 billion bushels, with soybean oil used as feedstock in biomass-based diesel production. This competition for feedstock between the biodiesel and chemical sectors introduces a layer of complexity to supply forecasting.
Regulatory developments also pose both risks and opportunities. In September 2024, Mexico launched an antidumping probe into ESBO imports from Brazil and China covering 85–99 percent pure content. Such trade measures can disrupt established supply chains, alter cost structures, and shift sourcing strategies for manufacturers operating in or exporting to the Latin American market. Additionally, global trends favoring bio-based and renewable materials continue to tighten regulations around traditional phthalates, effectively creating a protective moat for ESBO producers who can certify compliance with food-contact and safety standards.
These externalities require a proactive rather than reactive stance. Companies must model scenarios where raw material costs spike due to biodiesel demand or where trade barriers redirect flow volumes. Our report integrates these macroeconomic and regulatory variables into the forecast model to provide a robust range of outcomes.
Tactical Applications of the Research
PW Consulting's Epoxidized Soybean Oil Market report is structured to support diverse strategic functions within an organization. For strategic planners, the historical and forecast data provides the baseline for long-term capacity planning and investment appraisal. For sales and marketing teams, the segmentation breakdown offers insights into which application verticals are growing fastest, allowing for targeted promotional efforts.
Epoxidized Soybean Oil Market
Supply chain managers will find value in the analysis of raw material dependencies and regional supply dynamics, enabling better negotiation strategies with suppliers and logistics partners. Competitive intelligence teams can utilize the company profiles and recent developments sections to track rival maneuvers, such as new product launches or capacity expansions, and adjust positioning accordingly.
The report also serves as a vital tool for risk management. By highlighting regulatory probes and commodity price forecasts, it allows leadership to stress-test their operational models against potential disruptions. Whether the goal is to enter a new geographic market, launch a specialized grade, or consolidate market share through acquisition, the data herein provides the evidentiary support needed to justify initiatives to stakeholders.
Conclusion: The Imperative for Deep Intelligence
As the Epoxidized Soybean Oil market moves toward a valuation exceeding 825 million USD by 2032, the window for strategic advantage is open but narrowing. The convergence of regulatory tailwinds, raw material volatility, and competitive intensification means that generic market knowledge is no longer sufficient. Organizations need precise, data-backed intelligence to navigate the complexities of this sector.
This overview has highlighted the macroeconomic trajectory, the key players defining the competitive space, and the external factors influencing market dynamics. However, the specific revenue splits by region, the detailed growth rates per application segment, and the granular competitive benchmarking data are reserved for the full report. These details are the levers that drive specific tactical decisions.
To access the complete dataset, including detailed segmentation splits, proprietary competitive analysis, and comprehensive regional forecasts, we invite you to explore the full study. Equip your organization with the depth of insight required to lead in the Epoxidized Soybean Oil market throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Guitar Amp Market Hits $142M in 2025, 2.11% CAGR to $182.7M by 2032
By PW Consulting, 2026-09-16
Guitar Amplifier Market Outlook 2026: Strategic Insights for Industry Leaders
The global guitar amplifier market stands at a critical inflection point as it moves through the 2026–2032 forecast period. Characterized by steady expansion, evolving technological paradigms, and a shifting regulatory landscape, the sector demands rigorous strategic planning from manufacturers, distributors, and investors alike. This article outlines the foundational dynamics captured in our latest market research, demonstrating why actionable intelligence is no longer optional for competitive positioning. Readers seeking granular segmentation matrices, regional deployment forecasts, and proprietary competitive scoring frameworks are encouraged to access the full report at our source webpage, where complete analytical datasets are available.
Market Trajectory and Historical Momentum
Understanding the trajectory of the guitar amplifier market begins with a clear assessment of its historical performance and forward-looking projections. Over the past five years, the industry has navigated supply chain recalibrations, shifting consumer preferences, and incremental technological adoption. Our analysis tracks consolidated revenue performance from 2020 through 2025, establishing a baseline that informed our 2026–2032 forecast model. The market demonstrated resilient top-line growth through the early part of the decade, with consolidated revenue reflecting both post-pandemic consumption patterns and sustained demand from professional audio ecosystems.
As we enter 2026, the market is positioned to reach an estimated consolidated revenue threshold of approximately 147.85 million USD. This figure represents a deliberate continuation of an upward arc, though the pace of growth reflects a more measured annualized rate of 2.11 percent across the entire forecast window. Rather than signaling stagnation, this moderated expansion underscores a maturing industry where value creation increasingly stems from product differentiation, channel optimization, and premium tier positioning rather than pure volume acceleration. Stakeholders who anchor their planning to this nuanced growth profile will be better equipped to allocate capital efficiently, time product launches strategically, and manage inventory risk across volatile macroeconomic cycles.
Guitar Effects Market
Our forecast model further maps the revenue pathway through 2032, with projected figures advancing steadily toward a terminal value near 182.7 million USD. This horizon provides decision-makers with a multi-year planning framework that aligns product roadmaps, capacity investments, and market entry strategies. The full report dissects the inflection points, demand catalysts, and potential headwinds that could alter this trajectory, enabling scenario-based planning that goes beyond single-point estimates.
Structural Dynamics Shaping Competitive Posture
The contemporary guitar amplifier market is influenced by a confluence of structural forces that redefine how manufacturers approach product design, sourcing, and geographic positioning. At the forefront of these dynamics are regulatory adjustments that directly impact landed costs and margin structures. Recent trade policy shifts have introduced heightened tariffs on imported components and finished units, with certain cross-border flows now subject to additional surcharges that reverberate through boutique and professional-grade amplifier segments. These policy-driven cost structures are not uniform; their impact varies by origin, classification, and end-market destination, making tariff-aware sourcing strategies essential for maintaining price competitiveness.
Guitar Amplifier Market
Simultaneously, the European market has seen the application of targeted duties on specific amplifier-related components, adding another layer of complexity for firms with transatlantic supply chains. Companies that fail to model these cost layers into their pricing architecture risk margin compression or, conversely, alienating price-sensitive downstream buyers. Our research evaluates how leading manufacturers are reconfiguring their manufacturing footprints and distribution strategies in response to these regulatory realities.
Beyond trade policy, raw material and component availability has become a defining constraint. Transformer pricing for power and output units has experienced substantial escalation, with lead times for high-voltage models stretching considerably longer than historical norms. This bottleneck affects everything from boutique hand-wired builds to higher-volume production lines, forcing manufacturers to balance inventory commitments against working capital efficiency. The report assesses how different operational models are absorbing these constraints and which procurement strategies are proving most resilient under extended lead-time conditions.
Competitive Landscape and Innovation Vectors
The market's competitive architecture is anchored by a mix of legacy brands, technology-first manufacturers, and boutique specialists, each pursuing distinct value propositions. Fender Musical Instruments Corporation continues to leverage its comprehensive amplifier portfolio, spanning tube, modeling, and digital platforms, including recognized series that have long defined professional and semi-professional reference points. Recent product announcements have reinforced its commitment to heritage positioning while integrating modern enhancements, such as limited-edition commemorative releases that capitalize on brand equity and collector demand.
Gibson Brands, Inc. brings a historically rooted amplifier lineage to the market, complemented by contributions through affiliated product lines. With announced revitalization plans for amplifier offerings, the company is signaling renewed emphasis on this category, an approach that could reshape competitive dynamics in segments where brand heritage and tonal familiarity remain decisive purchase drivers. Marshall Amplification, headquartered in the United Kingdom, maintains its reputation for high-gain tube and hybrid designs that continue to influence professional stage and studio setups. Its product philosophy emphasizes tonal character and stage-ready durability, reinforcing its position within a segment where performance consistency carries outsized brand value.
PRS Guitars contributes to the competitive mix through signature and combo amplifier models that align with its broader instrument ecosystem. Its recent activity, including collaborations with performing artists, highlights a strategy of leveraging performer credibility to differentiate within a crowded product landscape. Friedman Amplification represents the boutique tier with hand-crafted tube and hybrid amplifiers, where limited production runs and signature partnerships create premium positioning. Its launch of compact-wattage designs incorporating modern load technology demonstrates how boutique manufacturers are integrating digital-ready features without abandoning analog-centric identities.
BOSS Corporation’s modeling and tube-logic amplifier offerings illustrate the growing relevance of versatile, technology-forward platforms, including compact formats that appeal to mobile players and content creators. Orange Amplification reinforces the British-style tube and solid-state lineage, catering to players who prioritize distinct voicing and aesthetic identity. Peavey Electronics Corporation continues to serve professional-grade requirements while expanding production capacity in key regions to improve supply reliability and cost structure. Benson Amps focuses on hand-wired all-tube designs that appeal to discerning buyers seeking artisanal construction and tonal specificity. Hammond Manufacturing occupies a specialized niche by supplying replacement transformers for tube amplifiers, an essential enablement role that supports the broader repair, customization, and longevity ecosystem.
The full report provides a detailed competitive assessment covering market concentration indicators, strategic positioning, and relative execution patterns across these players. By mapping how each organization balances heritage, innovation, and cost structure, the analysis supports benchmarking exercises and competitive response planning.
Product Architecture and Application-Driven Demand
Guitar amplifier demand is shaped by a diverse set of use cases, from professional performance and studio recording to educational environments and home practice. The market's product architecture divides along lines that reflect both functional requirements and buyer preferences. Combo amplifiers continue to hold substantial relevance given their integrated convenience and broad accessibility across skill levels. Head amplifier configurations remain important for professional workflows where separate cabinet selection and system modularity are valued. The interplay between these configurations influences channel strategies, SKU rationalization, and accessory ecosystems.
Demand patterns also vary by application context. Commercial environments, including venues, studios, rental operations, and educational programs, sustain consistent procurement cycles driven by equipment aging, replacement cycles, and performance reliability standards. Household demand reflects a different set of purchase triggers, including entry-level learning, home recording setups, and hobbyist engagement. The research examines how these application streams interact with regional purchasing behaviors, retail channel dynamics, and seasonal demand fluctuations, providing planners with a practical view of where volume concentrates and where premium positioning may yield stronger returns.
Rather than presenting static allocation figures, the report translates these structural patterns into decision-ready implications. This includes guidance on portfolio balancing, pricing architectures, and channel mix adjustments that align with the distinct economics of each demand stream.
Strategic Implications for 2026 Decision-Makers
For executives and strategy teams operating in or adjacent to the guitar amplifier market, the 2026 landscape calls for disciplined positioning across several dimensions. First, product planning must reconcile tonal heritage with modern convenience features. Players increasingly expect flexible signal paths, improved connectivity, and formats that adapt to both stage and content-creation workflows. Companies that can integrate these features without diluting core tonal identity are likely to capture share in premium categories.
Second, supply chain strategy requires active restructuring. The combination of tariff exposure, component cost escalation, and extended lead times means that sourcing diversification, inventory segmentation, and regional production planning are now strategic imperatives rather than operational afterthoughts. Organizations that model cost pass-through scenarios and stress-test margin resilience will be better prepared to maintain pricing integrity under volatile conditions.
Third, competitive differentiation is increasingly achieved through ecosystem thinking. Amplifier purchases often intersect with instrument branding, accessories, digital signal tools, and after-sales service. Strategic partnerships, signature product lines, and integrated support offerings can strengthen retention and expand wallet share within target customer groups. The report evaluates which ecosystem strategies are generating measurable traction and where white space remains for new entrants or incumbents seeking reinvigoration.
Finally, scenario planning should incorporate regulatory and macroeconomic variables as dynamic inputs rather than static assumptions. Tariff regimes, component availability, and regional demand shifts can alter the relative attractiveness of specific geographies or segments over short time horizons. A flexible planning framework allows organizations to reallocate resources quickly when conditions change, preserving optionality in uncertain environments.
What the Full Report Delivers
Beyond the strategic overview presented here, the complete market research provides a comprehensive analytical toolkit designed for operational and executive use. The report integrates consolidated market sizing, forward-looking projections, and structural segmentation analysis that connects product types, application contexts, and regional dynamics to actionable planning parameters. It includes competitive profiling that maps strategic positioning, recent product activity, and operational emphasis for key market participants, along with an assessment of market concentration indicators that contextualize rivalry intensity and consolidation risk.
The research also examines demand-side patterns, channel considerations, and pricing architecture implications, offering guidance on how to interpret evolving buyer priorities and translate them into portfolio and commercial strategy. In addition, the report assesses regulatory and supply-side developments, including trade policy effects and component cost dynamics, presenting their strategic implications in a format that supports risk assessment and scenario planning. To ensure practical usability, the study is structured around clear analytical sections, comparative frameworks, and decision-oriented commentary that allows readers to extract relevant insights without navigating unstructured data.
Granular segmentation data, detailed regional breakdowns, and full quantitative matrices are available in the complete version of the study. These components are intentionally reserved for the full report to provide subscribing organizations with a differentiated intelligence advantage and to support precise internal modeling, investment evaluation, and competitive benchmarking.
Accessing the Complete Intelligence Package
For teams that require detailed segmentation values, regional demand pathways, and proprietary competitive scoring to support 2026 planning cycles, the full report offers the depth necessary for confident execution. The complete study is available through our source webpage, where decision-makers can review the full dataset, access supporting analytical frameworks, and integrate the findings directly into strategic planning processes. In a market defined by steady growth, evolving product expectations, and an increasingly complex operating environment, access to comprehensive, decision-ready intelligence is a critical enabler of sustainable advantage.
For detailed analysis of this topic, please visit the official page: Guitar Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


