



Ice Cream Market 2026: Why 7.23% CAGR and Regional Shifts Redefine Growth
By PW Consulting, 2026-09-21
The Frozen Dessert Pivot: Strategic Trends and Commercial Opportunities in the Global Ice Cream Market
The global ice cream market is undergoing a structural recalibration. Valued at approximately USD 88.68 million in the base year, the sector has tracked a compound annual growth rate of 7.23 percent across the forecast horizon, expanding toward a projected valuation near USD 144.56 million by the terminal year of the outlook period. This trajectory reflects more than seasonal demand or discretionary spending cycles. The 2020 to 2025 historical window, during which the market advanced from USD 62.15 million to USD 88.68 million, established a clear inflection point. The subsequent decade will be defined by competitive realignment, regulatory pressure, and supply chain readjustment rather than simple volume expansion.
Ice Cream Machine Market
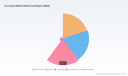
Market concentration remains pronounced, with the top three players commanding roughly 65 percent of total share and the top five consolidating approximately 78 percent. Such concentration signals a landscape where scale advantages in distribution, brand equity, and cost management create durable moats. At the same time, the persistent mid-tier fragmentation leaves room for targeted entrants and regional specialists who can exploit niche positioning. The market is not uniformly expanding; it is stratifying.
Structural Inflection Points
Three structural tensions are reshaping competitive dynamics. First, ingredient and input cost volatility has compressed operating margins across trophic layers of the value chain, forcing manufacturers to reconsider formulation architecture and pricing strategies. Second, regulatory mandates targeting nutritional transparency and labeling thresholds are accelerating product reformulation, creating both compliance costs and differentiation opportunities for brands that act early. Third, the divergence between impulse purchasing channels and at-home consumption patterns is widening the strategic gap between foodservice operators and retail formulations, demanding channel-specific market planning rather than unified product roadmaps. These tensions are not temporary headwinds. They are redefining how value is captured across the category.
Key Drivers Reshaping Commercial Value
Understanding where growth will materialize requires looking beyond aggregate figures and examining the mechanisms that are actively redistributing demand, cost structures, and competitive advantage. Four drivers stand out.
Technological and Formulation Innovation
Advances in texture modification, fat-reduction architectures, and alternative sweetening systems are enabling manufacturers to respond to nutritional scrutiny without abandoning sensory expectations. The category is moving from incremental recipe tweaks to engineered reformulations that address sugar, calorie, and fat thresholds while preserving mouthfeel and melt behavior. This shift is most visible among premium brands that treat formulation as a core competency rather than a compliance exercise. Companies that pair R&D agility with rapid commercialization cycles are beginning to capture shelf attention that slower-moving incumbents surrender. The implication for operators is clear: formulation capability is becoming a barrier to entry and a source of margin protection.
Regulatory Pressure and Labeling Transparency
The introduction of mandatory warning labeling for packaged frozen desserts exceeding defined sugar and calorie thresholds, effective January 2026, has triggered a wave of reformulation across global portfolios. This regulatory shift is not a one-time compliance event. It establishes a new baseline for consumer-facing nutritional claims and shelf eligibility in key export and domestic markets. Early movers are using the transition to reposition legacy SKUs, retire underperforming variants, and introduce reduced-sugar lines that maintain the indulgence narrative consumers expect. Brands that treat regulatory change as a design constraint rather than a cost center are gaining a first-mover advantage in shelf visibility and consumer trust. For strategic planners, the critical question is not whether reformulation will continue, but whether the pipeline is aligned with regional thresholds and channel expectations.
Consumer Behavior and Channel Realignment
Purchasing behavior is bifurcating. Impulse consumption remains the dominant share driver, anchored in convenience outlets, dedicated scooping locations, and quick-service environments where immediate gratification and visual merchandising drive conversion. Simultaneously, take-home formats continue to strengthen in households seeking planned consumption, bulk value, and flexibility in serving occasions. This divergence is producing distinct competitive requirements: impulse channels reward speed-to-shelf, promotional agility, and localized flavor rotations, while take-home segments reward packaging efficiency, stable supply continuity, and consistent flavor profiles. Artisanal and specialty formats, though smaller in overall share, command premium pricing and intense loyalty, making them attractive for brand-building and margin enhancement. Operators that map product architecture and go-to-market plans to these behavioral segments outperform those that rely on a single platform strategy.
Supply Chain and Input Cost Dynamics
Cost pressure from dairy inputs remains a persistent factor. Wholesale milk prices rose sharply in 2023 due to feed cost escalation and labor constraints, and the impact continued to flow through production economics in 2025 and 2026. In parallel, US production of ice cream and other frozen dairy products declined by approximately 10 percent between 2000 and 2024, reaching around 1,386 million gallons in 2024, with regular ice cream still accounting for the majority of output. By 2025, total production rebounded to roughly 1.23 billion gallons, reflecting operational stabilization but also underscoring the ongoing consolidation of domestic capacity. These dynamics are reshaping supplier negotiations, inventory planning, and regional sourcing strategies. Operators that invest in supply visibility, contractual flexibility, and formulation efficiency are better positioned to absorb input volatility without sacrificing margin or availability.
Competitive Landscape and Strategic Positioning
The market is anchored by a concentrated group of multinational and regional players, each pursuing distinct strategic postures. Unilever PLC leverages a premium portfolio, including Ben & Jerry's and Magnum, to anchor global brand equity and reinforce distribution reach across both retail and foodservice. The Magnum Ice Cream Company operates a complementary global portfolio spanning Magnum, Ben & Jerry's, Cornetto, and Wall's, using broad brand coverage to serve retail and foodservice channels with differentiated flavor architectures and occasion-based positioning. General Mills, Inc. focuses on North American retail and convenience through Häagen-Dazs and adjacent frozen dessert products, emphasizing channel density and premium shelf presence. Nestlé S.A. maintains worldwide reach with Häagen-Dazs, Drumstick, and other branded products, drawing on scale in manufacturing, brand management, and multi-market distribution to sustain category leadership.
A second tier of players illustrates the range of strategic options available to mid-sized and regionally focused operators. Blue Bell Creameries, Inc. concentrates on super-premium and high-protein offerings for retail and foodservice, using flavor specialization and nutritional positioning to differentiate within a crowded premium space. Baskin-Robbins, LLC sustains relevance through a parlor chain model that blends scooping services with retail formats, leveraging experiential consumption and flavor variety to drive repeat visits. Dairy Queen, LLC extends soft-serve and ice cream availability through 7-Eleven partnerships and retail outlets, using convenience-channel density to capture impulse demand. Amul, operating under cooperative branding in India, distributes dairy-based ice cream and frozen desserts at scale, demonstrating how regional brand trust and supply integration can support broad market penetration. Wells Enterprises, Inc. and Straus Family Creamery round out the landscape with retail and foodservice distribution; the latter's focus on organic super-premium positioning highlights the premiumization pathway available to smaller, values-driven producers.
Dry Ice Market
Concentration, Differentiation, and Emerging Entrants
With three players holding roughly two-thirds of share and five controlling more than three-quarters, the category displays strong consolidation characteristics. Yet this concentration does not eliminate competitive dynamism. Instead, it pushes differentiation toward brand identity, formulation novelty, channel specialization, and regional trust. Leading incumbents protect share through brand heritage, distribution depth, and reformulated portfolios aligned with labeling requirements. Mid-tier players compete by narrowing focus to premium, protein-enhanced, organic, or geographically anchored products that larger portfolios treat as secondary. Regional cooperatives and artisanal specialists use provenance, local sourcing, and experiential retail to build loyalty and command price premiums.
The entry landscape is also evolving. Recent trade shows such as the Ice Cream and Artisan Food Show in Birmingham and Conecon 2026 in Palm Springs illustrate sustained supplier engagement, with high average order values and concentrated attention on innovation showcases. These events signal that buyer interest remains active and that supplier pipelines are being refreshed around flavor innovation, packaging efficiency, and compliance-ready formulations. At the same time, product launches from major players continue to expand flavor complexity and cross-brand collaboration, reinforcing the premium and indulgence narrative even as nutritional reformulations progress. Such activity suggests that new entrants and expanding regional players will find opportunity not in unseating incumbents directly, but in serving underserved segments, launching compliance-aligned premium variants, or building channel-specific platforms that larger portfolios do not prioritize. A recent voluntary recall affecting select organic flavors from a specialty producer also underscores the operational risk dimension: quality assurance, traceability, and recall readiness are becoming competitive differentiators as regulatory and consumer scrutiny intensify.
Forward Outlook: Trends and Commercial Implications
Looking across the 2026 to 2032 horizon, three trends are likely to define where value is created and where risk accumulates.
Reformulation as a Growth Lever, Not a Compliance Cost
As labeling mandates and consumer expectations converge, reformulation will increasingly function as a growth strategy. Brands that reduce sugar and calorie intensity without eroding sensory appeal can expand addressable occasions, improve shelf eligibility in regulated markets, and reposition legacy lines that face declining repeat purchase. The commercial upside lies in launching reduced-indulgence variants that preserve the emotional and taste associations consumers seek, while also extending portfolio life cycles. The risk is execution: reformulations that misread texture, melt, or flavor balance will accelerate trade-down behavior rather than retain basket share. Success will depend on disciplined sensory testing, regional threshold mapping, and phased rollout strategies that protect brand equity.
Channel-Specific Architecture Becomes Non-Negotiable
The widening gap between impulse and take-home consumption will push operators toward channel-specific product and packaging strategies. Impulse channels will continue to demand rapid flavor rotations, promotional visibility, and formats optimized for immediate consumption, while take-home segments will prioritize packaging efficiency, consistent availability, and family- or household-oriented sizing. Artisanal and specialty channels will sustain as premium brand-building environments where smaller batches, provenance narratives, and experiential retail drive loyalty and margin. Operators that maintain a single platform across all channels will lose relevance. Those that design distinct SKUs, pricing architectures, and supply plans for each behavioral segment will capture a larger share of differentiated demand. The risk is complexity: channel-specific portfolios require stronger demand forecasting, inventory segmentation, and trade execution capabilities to avoid service gaps.
PW Consulting Health Care Research Center
Supply Chain Resilience and Input Diversification
Input volatility and shifting production footprints will make supply visibility and formulation efficiency central to margin protection. As domestic production patterns adjust and wholesale dairy costs remain sensitive to feed and labor dynamics, manufacturers will increasingly rely on sourcing flexibility, inventory buffering, and recipe engineering to manage cost exposure. Suppliers that offer traceability, consistent quality, and contractual adaptability will gain negotiating leverage with larger buyers. For operators, the strategic imperative is to treat supply chain resilience as a commercial asset rather than a back-office function. Diversifying supplier relationships, investing in formulation that tolerates input variation, and aligning procurement with regional demand cycles will reduce earnings volatility. The uncertainty lies in the pace and severity of input cost swings, which can outstrip hedging and forecasting assumptions if not continuously monitored.
Strategic Recommendations for Decision-Makers
For manufacturers and brand owners, the priority is to align formulation pipelines with labeling thresholds and channel expectations while protecting sensory appeal. This means reviewing legacy SKUs against regulatory baselines, retiring variants that face shelf-eligibility risk, and investing in reduced-sugar and reduced-calorie lines that maintain mouthfeel and melt behavior. Premium and super-premium portfolios should be refreshed around flavor complexity and occasion-based positioning to sustain indulgence narratives even as nutritional profiles shift. At the same time, supply contracts and inventory strategies should be stress-tested against input volatility, with flexibility built into specifications and delivery terms to protect continuity and margin.
For investors and strategic planners, the actionable focus is to distinguish between scale-driven stability and segment-driven growth. Concentrated incumbents offer distribution depth and reformulation capacity, but the most dynamic value creation is likely in targeted premium niches, regional brand-led formats, and channel-specific platforms that serve impulse and take-home behaviors differently. Due diligence should emphasize formulation agility, channel alignment, compliance readiness, and quality assurance infrastructure, including recall preparedness and traceability systems. Portfolios that combine brand equity with operational discipline and clear nutritional positioning are better positioned to compound across the forecast period.
For procurement and supply chain leaders, the emphasis should be on resilience through visibility and flexibility. This includes mapping dairy and ingredient exposure to regional cost dynamics, diversifying supplier relationships to reduce concentration risk, and aligning procurement cycles with anticipated reformulation and packaging changes. Negotiating for contractual adaptability, consistent quality standards, and rapid response to specification changes will help absorb input volatility while supporting product continuity. Investing in data-driven demand planning across impulse, take-home, and specialty channels will also reduce service failures and protect promotional execution.
The strategic horizon for the ice cream category is defined by the intersection of regulatory change, input economics, and behavioral divergence. Operators that treat these forces as design inputs rather than external shocks will find clearer paths to margin protection and share gains. Those that continue to rely on unified platforms, reactive reformulation, and undifferentiated channel strategies will face increasing pressure as concentration tightens and consumer expectations rise. For decision-makers seeking deeper segmentation data, regional breakdowns, and tailored go-to-market recommendations, proprietary research reports from PW Consulting provide the granular intelligence needed to translate these trends into measurable execution plans.
For detailed analysis of this topic, please visit the official page: Ice Cream Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Phosphate Ester Market 2026: Beyond the 5.4% CAGR Story, Mapping the 3.3B Shift to Flame Retardants and Asia Pacific
By PW Consulting, 2026-09-21
The Phosphate Ester Market: Strategic Shifts and Commercial Opportunities Beyond the Baseline
Market Context and the Pressures Reshaping the Industry
The global phosphate ester market has entered a phase of steady expansion, with total revenue reaching approximately USD 2.29 billion in 2025 and projected to climb toward USD 3.30 billion by 2032. Over the 2020-2025 historical window, the segment demonstrated a resilient upward trajectory, reflecting the incremental replacement of legacy additives and the persistent demand for high-performance fluids, flame-retardant formulations, and surfactant systems across industrial and consumer applications. The forward-looking forecast horizon points to a compound annual growth rate of around 5.4 percent, which suggests that the market will outpace many broad chemical categories but will do so under a fundamentally different operating environment than the one that characterized the early 2020s. Growth is no longer a straightforward function of volume expansion; it is increasingly tied to formulation differentiation, regulatory navigation, and the ability to secure stable, cost-competitive feedstock access.
The current industry landscape is defined less by explosive demand pull and more by structural tension between performance requirements, compliance costs, and margin compression. Three intersecting pressures are reshaping how producers, formulators, and end-users approach the market.
First, feedstock volatility continues to inject uncertainty into cost structures and pricing strategies. Phosphate esters rely on a combination of phosphoric acid derivatives and organic alcohols that are subject to regional supply disruptions, energy cost swings, and shifting trade flows. Price movements in key precursors have remained pronounced over recent years, forcing manufacturers to balance inventory positioning, contract structures, and formulation flexibility. Companies that treat feedstock exposure as a static procurement issue are finding that they lose competitiveness to firms that integrate cost risk into product design and go-to-market strategy.
Second, regulatory scrutiny is becoming more granular and more consequential. Phosphate ester applications sit at the intersection of environmental, health, and safety considerations, while specific grades are tied to dual-use export controls in advanced economies. At the same time, trade remedies and countervailing determinations have begun to affect pricing dynamics in certain alkyl phosphate ester flows. These developments are not merely administrative; they alter the economics of sourcing, the risk profile of specific customer segments, and the relative attractiveness of regional production footprints. In practice, this means that compliance capability is evolving from a cost center into a differentiator that can protect market access and shape customer trust.
Third, the demand environment is fragmenting. The most visible growth vectors are shifting toward specialized applications where performance thresholds are high and substitution is difficult, while commoditized end-uses face margin pressure and reformulation pressure from alternative chemistries. This divergence rewards producers who can supply application-specific solutions rather than generic intermediates, but it also raises the bar for technical service, validation cycles, and customer-level customization. The net effect is a market that continues to grow, but increasingly through value-added segments rather than broad-based volume expansion.
The Forces Driving the Next Phase of Growth
Despite the pressures, the market is being pushed forward by several reinforcing dynamics that are likely to define competitive outcomes over the next several years. These drivers are not independent; they interact in ways that create both margin opportunities and execution risks.
Technology and formulation differentiation
Technical innovation is moving from incremental improvement to application-specific engineering. Leading suppliers are not simply expanding capacity; they are tailoring phosphate ester architectures to meet the requirements of electric vehicle thermal management, advanced lubricants, fire-resistant industrial fluids, and lower-impact consumer formulations. The recent direction of partnership activity underscores this shift. For example, Eastman Chemical Company announced a collaboration with a leading automotive manufacturer in 2025 to develop phosphate esters designed for electric vehicle applications, signaling that the next wave of differentiation is coming from co-engineering with end-users rather than standalone product launches. Similarly, BASF SE’s introduction of a bio-based phosphate ester line reflects a broader industry push to align performance attributes with lower-carbon sourcing narratives, which is increasingly relevant for customers facing their own emissions and procurement targets.
For manufacturers, the implication is that formulation IP, application testing, and close customer integration are becoming central to value capture. For investors, the companies that can demonstrate a repeatable model for translating technical service into premium positioning are likely to earn disproportionate share in high-margin niches.
Policy, trade, and compliance as competitive levers
Regulatory and trade conditions are reshaping where and how phosphate esters are produced and sold. Recent trade-related determinations involving alkyl phosphate ester producers and exporters from China have highlighted how policy can alter cost competitiveness in specific segments and redirect sourcing strategies. At the same time, dual-use export controls on certain grades tied to nuclear applications continue to add complexity for cross-border trade and for customers who depend on globally integrated supply chains. The practical result is a more fragmented sourcing environment in which regional availability, documentation rigor, and qualification speed matter as much as unit cost.
Phosphonate Market
This environment favors firms that can provide predictable supply within defined compliance boundaries and that can support customers through qualification and documentation requirements. It also creates an opportunity for regional producers and integrated downstream formulators who can reduce exposure to cross-border friction while maintaining technical performance.
Demand-side shifts in industrial and consumer applications
Demand is being reshaped by changes in end-use priorities rather than by a single macro driver. Flame retardants continue to represent a substantial share of phosphate ester consumption, but the surrounding pressure toward sustainability and reformulation is encouraging formulators to seek grades that combine performance with improved environmental profiles. Lubricants and hydraulic fluids remain important, yet the growth emphasis is moving toward specialized fluids where fire resistance, thermal stability, and compatibility with advanced machinery and electric vehicle systems justify higher specification thresholds. Plasticizers and surfactants are evolving as well, with some applications shifting toward alternatives that meet stricter regulatory expectations while retaining functional performance.
PW Consulting
In parallel, customer procurement behavior is changing. Large industrial buyers increasingly evaluate suppliers on a broader set of criteria that includes reliability, documentation, sustainability attributes, and regional supply security. This shifts the value proposition from price per unit to total cost of ownership and risk mitigation, rewarding suppliers that can demonstrate consistent quality and proactive technical support.
Supply chain reconfiguration and regional dynamics
Supply chain strategy is becoming a strategic asset rather than a back-office function. Recent corporate activity points to a deliberate effort to strengthen regional production capabilities, particularly in Asia-Pacific, where demand is significant and competitive intensity is rising. The acquisition completed by Huntsman Corporation in mid-2025, which expanded production capabilities in the region, reflects a broader industry tendency to secure closer proximity to demand, reduce logistical exposure, and improve responsiveness to local customers.
At the same time, raw material pricing remains a salient factor. Recorded prices for tributyl phosphate in Asia reached approximately USD 2,600 per metric ton in December 2025, while precursor movements such as n-butanol have exhibited wide swings over the 2022-2025 period. These conditions reinforce the importance of integrated feedstock planning, hedging where appropriate, and flexible manufacturing footprints that can adapt to regional cost advantages. Companies that can coordinate feedstock procurement, production location, and application mix are better positioned to absorb volatility without sacrificing competitiveness.
Worldwide Phosphating Agent Market
Competitive Landscape and How Leaders Are Positioning
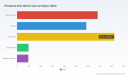
The phosphate ester market is moderately concentrated, with the top three firms accounting for roughly 35.8 percent of revenue and the top five reaching approximately 52.4 percent. This structure suggests that scale and portfolio breadth matter, but it also leaves substantial space for specialized players to compete on application fit, technical capability, and regional presence. The competitive dynamics are increasingly less about who produces the most volume and more about who can reliably deliver the right grade, with the right documentation, to the right customer at the right total cost.
Several patterns emerge when looking at how leading companies are differentiating themselves.
Clariant has emphasized specialty phosphoric acid esters through its Hordaphos™ offering, with production tied to its Knapsack site and focused on cleaning products, antistatic and anti-foaming functions in detergents, and multifunctional additives in inks, paints, and coatings. This positioning reflects a strategy rooted in formulation utility and downstream integration rather than commodity volume.
Stepan Company has concentrated on customized phosphate esters built on tridecyl alcohol ethoxylate and tristylylphenol ethoxylate chemistry, targeting agricultural compatibility aids, metalworking lubricants, gear oils, hydraulic fluids, and plasticizers. The emphasis on customization and application breadth allows the company to serve segments where formulation fit is a key purchase criterion.
Eastman Chemical Company has built recognition around fire-resistant phosphate ester hydraulic fluids, notably through its Skydrol™ line for aviation and industrial use. This heritage in high-performance, safety-critical fluids gives the company a strong platform in applications where qualification and reliability are paramount. The recent automotive partnership for electric vehicle applications extends this logic into new high-value demand pools.
LANXESS has developed a presence through Reofos® phosphate ester products aimed at fire-resistant hydraulic fluids and broader industrial applications. The product framing highlights performance in demanding operating environments, which aligns with customers seeking alternatives to conventional fluids in challenging conditions.
Solvay has positioned phosphate ester solutions across flame retardants, lubricants, and specialty chemical applications, suggesting a multi-segment approach that can benefit from cross-portfolio technical leverage. Dow has similarly maintained a foothold in phosphate ester additives and intermediates for lubricants, flame retardants, and industrial fluids, reflecting an integrated chemical supplier model that can connect feedstock capability with downstream application support.
AkzoNobel and Croda International represent a more sustainability- and specialty-oriented orientation. AkzoNobel’s emphasis on eco-friendly phosphate esters for industrial and consumer applications, and Croda’s focus on phosphate ester surfactants and additives for personal care, industrial, and specialty uses, both illustrate how formulation narratives and end-use fit can support premium positioning in segments where customer expectations are shifting.
ExxonMobil and Ashland contribute additional scale and application breadth, with ExxonMobil active in flame retardants, lubricants, and high-performance fluids, and Ashland focused on phosphate ester-based solutions for industrial additives and performance chemicals. Evonik Industries rounds out the landscape with specialty phosphate esters oriented toward flame retardancy, coatings, and sustainable applications, reinforcing the trend toward higher-value, application-specific positioning.
Taken together, these profiles show a market in which competitive advantage is increasingly constructed through a combination of technical service, application credibility, regional supply capability, and alignment with evolving sustainability expectations. The most differentiated players are those that can connect product chemistry to specific operating outcomes for customers, rather than positioning phosphate esters as interchangeable inputs.
The landscape is also evolving through consolidation and targeted expansion. The mid-2025 acquisition in Asia-Pacific illustrates how incumbents are seeking to strengthen regional capability where demand growth and competitive pressure are most acute. At the same time, regional differentiation and trade complexity may encourage further fragmentation in some niches, particularly where qualification requirements and local compliance expectations create natural barriers to rapid redistribution of share. New entrants are likely to find the most traction not by competing head-on in established volume segments, but by addressing unmet formulation needs, sustainability-linked specifications, or regional supply gaps.
Forward Outlook: Trends and Commercial Opportunities
Looking toward the 2026-2032 window, several trends are likely to shape both the direction of the market and the opportunities available to well-positioned players.
Trend 1: Application-led premiumization will outpace generic volume growth
The most durable growth is expected to come from applications where phosphate esters solve specific performance problems, particularly in fire-resistant fluids, high-performance lubricants, and specialized formulation functions. As end-use industries adopt more demanding operating conditions and as electric vehicle and advanced industrial ecosystems expand, the value pool will shift toward grades that are validated for specific requirements and supported by strong technical service. This creates opportunities for suppliers that can shorten qualification cycles, provide clear performance documentation, and maintain consistency across batches. It also raises the stakes for producers that depend on undifferentiated volume without a clear application link.
Trend 2: Sustainability and trade compliance will become inseparable from sourcing decisions
Customers are increasingly evaluating phosphate esters through a dual lens of environmental impact and supply reliability. Bio-based and lower-carbon formulations, such as the bio-based line introduced by BASF SE, are likely to gain relevance in segments where procurement teams must balance performance with emissions goals and customer-facing sustainability commitments. In parallel, trade measures, countervailing determinations, and dual-use export controls will continue to complicate cross-border sourcing for certain grades. The commercial opportunity here lies in building credible, documented supply pathways that reduce customer risk. Suppliers that can combine technical performance with transparent compliance and sustainability credentials will be better placed to secure long-term supply agreements and higher-margin relationships.
Trend 3: Regional supply control and feedstock integration will determine cost resilience
Because price volatility in key precursors remains a defining feature of the market, companies that can manage feedstock exposure through integration, flexible procurement, and regionally aligned production will have a structural advantage. The combination of regional demand growth, trade friction, and raw material swings makes it increasingly important to view manufacturing location, inventory policy, and customer concentration as interconnected strategic choices. Producers with the ability to shift mix, serve regional demand efficiently, and protect margins through intelligent cost management will be more resilient in fluctuating conditions and more attractive to risk-conscious buyers.
These trends carry risks as well. Formulation substitution pressure could intensify if alternative chemistries improve on cost or regulatory ease in specific applications. Trade policy could shift again, altering competitive dynamics in alkyl phosphate ester flows and other sensitive segments. Feedstock volatility may persist, making margin planning more difficult for firms that lack flexibility. Finally, if demand in certain specialized segments develops more slowly than anticipated, premium positioning may prove harder to sustain without clear differentiation.
What This Means for Decision-Makers
For manufacturers, the priority is to move beyond treating phosphate esters as a volume commodity and toward building capability in application-specific value creation. That means sharpening formulation expertise, strengthening technical service around customer use cases, and aligning product portfolios with segments where performance and compliance justify differentiated pricing. It also means treating feedstock and trade exposure as part of the product strategy, not just procurement. Companies that can show consistent performance, reliable documentation, and credible sustainability alignment will be better positioned to defend margins and deepen customer relationships.
For investors, the signal is to look for firms that demonstrate a repeatable connection between technical differentiation and commercial outcomes. Scale alone is less informative than the ability to capture premium segments, manage feedstock and trade risk, and expand in regions where demand growth and local capability reinforce each other. Attention should also be paid to partnership activity and product launches that indicate traction in emerging applications, as these often precede broader share movement in specialized niches.
For procurement and sourcing leaders, the practical imperative is to diversify risk intelligently while maintaining qualification discipline. That includes evaluating suppliers on total cost of ownership and supply security rather than headline price alone, ensuring documentation readiness for regulated or dual-use-relevant grades, and considering regional supply options where they reduce exposure to trade friction or feedstock volatility. In environments where certain alkyl phosphate ester flows are affected by trade determinations or export controls, traceability and supplier qualification become especially important.
Given the pace of change across formulation, regulation, trade, and demand, decision-makers benefit from access to detailed, segment-level intelligence that can translate broad trends into specific sourcing, investment, and product decisions. The interaction between regional dynamics, precursor pricing, application mix, and competitive moves creates a landscape where timely, granular information can materially improve the quality of strategic choices. Organizations that stay close to the shifting detail in this market will be better equipped to identify where to compete, how to structure supply, and which segments offer the most resilient opportunities.
For detailed analysis of this topic, please visit the official page: Phosphate Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hexanoic Acid Market: How a 6.5% CAGR Trajectory and Fragmented Supply Chain Redefine Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Hexanoic Acid Market
The hexanoic acid market is navigating a phase of steady expansion amid shifting regulatory expectations and evolving supply chain priorities. Valued at 255.0 million USD in 2025, the market has grown from 200.0 million USD in 2020, reflecting a compound annual growth rate of approximately 6.5 percent through the forecast period extending to 2032. Projections indicate revenue will reach 396.32 million USD by the end of the forecast horizon, with 2031 and 2032 marking particularly notable steps upward. This trajectory signals more than incremental growth; it reflects structural changes in how manufacturers source feedstocks, design formulations, and align production with regional compliance frameworks.
Yet the expansion path is not uniformly smooth. Three cross-cutting challenges define the current inflection point. First, feedstock dependency on palm kernel oil and coconut oil creates cost volatility that directly pressures operating margins, given that these raw materials typically account for a substantial share of total production expenses. Second, regulatory divergence across key markets is reshaping purity expectations and documentation requirements, which in turn influences which product grades can be commercialized where. Third, capacity and specification alignment are becoming strategic differentiators as downstream industries demand more consistent quality for pharmaceutical, food, and personal care applications. These factors collectively separate suppliers that treat hexanoic acid as a commodity from those that position it as a specification-driven specialty chemical.
For executives and investors, the implication is straightforward: top-line growth is real, but margin resilience and market access will be determined by how well organizations manage feedstock exposure, regulatory compliance, and application-specific quality requirements.
Key Drivers Reshaping Market Dynamics
Feedstock Economics and Cost Structure Sensitivity
The production of hexanoic acid remains closely tied to bio-derived feedstocks, particularly palm kernel oil and coconut oil. This linkage is not merely a sourcing preference; it is a structural cost driver that shapes pricing behavior, regional competitiveness, and margin sensitivity. When feedstock prices move, operating expenses follow quickly, which explains why price adjustments in oxo-chemical portfolios often coincide with broader raw material cycles. The sensitivity is especially pronounced for manufacturers that rely heavily on these oil-based inputs without diversified supply options or hedging mechanisms.
The commercial consequence is twofold. Suppliers that can secure stable feedstock access, negotiate long-term contracts, or incorporate regional sourcing flexibility gain a meaningful cost advantage. At the same time, downstream buyers are increasingly attentive to origin documentation and purity certification, particularly when sourcing for food-grade or pharmaceutical-grade applications. This creates a dual pressure: cost management must be paired with traceability and specification integrity. In practice, the manufacturers most likely to sustain margins are those that treat feedstock procurement as a strategic function rather than a transactional purchase.
Regulatory Frameworks and Purity Differentiation
Regulatory conditions are actively influencing which grades of hexanoic acid gain traction in specific markets. In Europe, stringent REACH and CLP requirements have encouraged broader adoption of higher-purity grades, reinforcing a market environment where specification consistency is a competitive asset. This regulatory backdrop does not simply raise compliance costs; it redirects demand toward products that can demonstrate reliable purity profiles and robust documentation. For European customers, the choice of supplier is increasingly tied to the ability to meet these expectations without supply disruption.
Meanwhile, in the United States, hexanoic acid holds GRAS designation under FDA 21 CFR 172.515 for use as a flavoring agent and adjuvant, which supports its continued presence in food and beverage formulations. In parallel, EU Regulation 1334/2008 recognizes hexanoic acid as a flavoring agent with approved Codex Alimentarius standards, further reinforcing its role in flavor and fragrance applications. These regulatory anchors provide market stability, but they also raise the bar for suppliers that must maintain compliance across multiple jurisdictions. Bio-based variants derived from palm kernel oil have also gained food-grade certifications and are shipped to EU markets under strict purity and origin documentation requirements. The net effect is a market where regulatory acceptance supports demand, but regulatory complexity rewards suppliers with strong quality systems and transparent supply chains.
Application-Side Demand and Formulation Preferences
Demand for hexanoic acid is not growing uniformly across end-use segments. Food and beverage applications continue to represent a significant share of market activity, supported by the compound's role in flavor profiles and its regulatory acceptance in key jurisdictions. Personal care formulations also contribute meaningfully, where the acid's functional properties and compatibility with specialty product development make it relevant for niche but value-conscious applications. Pharmaceutical use cases further reinforce demand for higher-purity grades, particularly where consistency and documentation are non-negotiable. Industrial chemical applications add additional volume, though they often emphasize cost efficiency and broader specification tolerances.
What matters for strategy is the direction of travel within these segments. In food and personal care, buyers increasingly favor suppliers that can provide stable purity, reliable availability, and clear origin documentation. In pharmaceutical and premium applications, the emphasis shifts toward specification control and audit-ready supply chains. This divergence is creating a market in which application-specific value propositions matter more than generic volume positioning. Companies that align their product grades, technical support, and compliance documentation with the expectations of specific end-use sectors are better placed to capture premium demand and reduce exposure to price-based competition.
Supply Chain Reconfiguration and Regional Capacity Responses
Supply chain dynamics are increasingly shaped by localized capacity decisions and regional sourcing strategies. Recent announcements indicate that some producers are expanding specialty carboxylic acid capacity in locations designed to serve pharmaceutical and premium personal care segments more directly. Such moves reflect a broader industry trend: rather than treating hexanoic acid as a globally interchangeable bulk chemical, suppliers are building or adjusting capacity to better match application requirements, reduce lead-time risk, and strengthen regional service levels.
At the same time, price actions across oxo-chemical portfolios have underscored the importance of cost-feedstock alignment. When producers implement price increases for derivatives and related products, downstream customers reassess sourcing alternatives, inventory strategies, and specification trade-offs. This environment favors suppliers that can justify pricing through consistent quality, regulatory readiness, and reliable delivery, rather than competing purely on cost. For buyers, the practical response is to evaluate total cost of ownership, including compliance risk, specification fit, and supply continuity, instead of focusing narrowly on unit price.
Competitive Landscape and Leadership Strategies
Differentiated Positioning Among Leading Suppliers
The competitive field includes a mix of integrated chemical producers, oxo-chemical specialists, and oleochemical manufacturers. Perstorp Holding AB stands out as a leading producer of oxo-chemicals and specialty carboxylic acids, with hexanoic acid serving pharmaceutical, food, personal care, and industrial applications. Its profile suggests a strategy centered on specialty positioning rather than commodity volume, reinforced by recent capacity expansion targeting pharmaceutical and premium personal care segments, as well as periodic price adjustments across oxo-chemical portfolios. This combination indicates a focus on margin quality, specification control, and application-aligned service.
Eastman Chemical Company operates as a major manufacturer of carboxylic acids and oxo derivatives, with hexanoic acid included in its food additives, flavors, and industrial uses portfolio. Its scale and application breadth provide a broad market reach, which can be advantageous where customers value integrated supply and multi-segment capability. OXEA GmbH specializes in oxo-chemicals and produces n-hexanoic acid for European industrial chemicals, food ingredients, and pharmaceutical-grade markets. Its European orientation and grade-specific focus align well with regional regulatory expectations and purity demands.
BASF SE contributes through an integrated production approach, supplying hexanoic acid and caproic acid via its Verbund network for flavor esters, polyamides, and other chemical applications. That integrated structure can support cost efficiency and supply reliability for customers embedded in broader chemical value chains. Tokyo Chemical Industry Co., Ltd. serves research, flavor, and fragrance markets with high-purity organic chemicals, positioning itself where specification precision and product variety matter more than bulk volume. In the oleochemical segment, KLK OLEO and IOI OLEO produce palm kernel-derived caproic acid and hexanoic acid for food-grade, cosmetic, and lubricant applications, highlighting the importance of bio-based feedstock expertise and food-grade certification pathways.
Strategic Themes Across the Competitive Set
Several strategic patterns emerge when these players are viewed together. One is the tension between scale and specialization. Larger integrated producers can leverage broad networks and multi-product portfolios, while specialists can compete by offering grade precision, regional compliance readiness, and targeted application support. Another theme is the growing importance of documentation and certification. In markets where purity expectations and origin requirements are rising, suppliers with established quality systems and clear traceability gain an advantage in securing premium segments. A third theme is capacity alignment. Recent expansion moves suggest that producers are investing where demand is expected to be most specification-sensitive, especially in pharmaceutical and premium personal care applications.
The market is not necessarily moving toward full consolidation. Instead, it appears to be reorganizing around differentiated value propositions. Some customers will continue to prioritize broad availability and price competitiveness, while others will pay for consistency, certification, and technical support. This creates room for multiple business models to coexist, provided each is clearly aligned with a defined customer base and application profile.
Forward-Looking Trends and Strategic Risks
Trend One: Purity and Specification as Commercial Currency
Over the next three to five years, higher-purity grades are likely to capture disproportionate attention in markets where regulatory expectations and downstream formulation requirements are most demanding. The trend is already visible in European markets, where strict regulatory frameworks have strengthened adoption of 0.99 purity grades. As pharmaceutical and personal care formulations become more exacting, specification reliability will increasingly influence supplier selection. For commercial strategy, this suggests that investments in quality control, analytical consistency, and documentation rigor can translate directly into market access and pricing resilience.
Trend Two: Feedstock-Linked Cost Cycles Will Keep Shaping Pricing Power
Because production depends heavily on palm kernel oil and coconut oil, the market will remain sensitive to feedstock cost cycles. This does not mean prices will move in lockstep with raw materials at all times, but it does mean that margin management will continue to hinge on procurement strategy, product mix, and the ability to pass through cost changes with credible value justification. Suppliers with diversified sourcing options or stronger application-based differentiation are better positioned to manage these cycles. Buyers, in turn, will need to balance cost optimization against supply continuity and specification security.
Isononanoic Acid Market
Trend Three: Regional Compliance Will Drive Sourcing Configuration
As regulatory and documentation requirements diverge across regions, sourcing configurations are likely to become more regionally attuned. Food-grade certifications, origin documentation, and purity standards can determine whether a product is acceptable in a given market. This favors suppliers that can provide market-specific assurance and buyers that avoid over-reliance on a single supply route for specification-sensitive applications. The commercial opportunity lies in matching supply to regulatory context, rather than assuming global interchangeability.
Risks and Uncertainties
Several risks merit attention. Feedstock price volatility can compress margins quickly if not managed through contract structure, product mix, or pass-through mechanisms. Regulatory shifts, while currently supportive in many respects, could raise compliance burdens or change documentation expectations, especially for cross-border trade. Competition from alternative ingredients or substitute formulation approaches may pressure demand in particular applications, especially where cost sensitivity is high. Finally, capacity expansions that are well-aligned with premium segments may still face execution risk if demand timing, feedstock availability, or regional acceptance does not evolve as expected.
Actionable Guidance for Decision Makers
For Manufacturers and Producers
Position product portfolios around specification differentiation rather than volume alone. Higher-purity grades, robust documentation, and application-specific technical support can support stronger margin profiles, especially in pharmaceutical and premium personal care segments. Feedstock strategy should be treated as a core competitive lever, with emphasis on supply continuity, cost visibility, and flexibility across oil-based inputs. Where possible, align capacity and service models with the regions and applications most likely to value consistency and compliance.
PW Consulting
For Investors and Strategic Planners
Evaluate exposure to feedstock-linked cost cycles when assessing business models in this market. Companies with strong specialty positioning, clear regulatory readiness, and the ability to serve specification-sensitive segments may offer more resilient value creation paths than pure volume players. When comparing opportunities, consider how well a company's product grades, certifications, and regional reach match the markets where purity and documentation requirements are tightening. Also monitor capacity announcements and price actions as indicators of where suppliers expect margin and demand to be strongest.
2-Ethylhexanoic Acid Market
For Procurement and Sourcing Leaders
Expand evaluation criteria beyond unit price. Total cost of ownership should include purity consistency, regulatory documentation, origin traceability, and delivery reliability, especially for food, pharmaceutical, and personal care applications. Diversifying sourcing options can reduce exposure to feedstock-driven price swings and regional compliance interruptions. Where formulations allow, establish clear specification thresholds and audit expectations so that suppliers understand the quality and compliance standards required for ongoing supply.
The hexanoic acid market is entering a period in which growth is increasingly tied to how well participants manage feedstock economics, regulatory expectations, and application-specific specification demands. Organizations that can combine cost discipline with quality assurance and regional compliance readiness are best positioned to convert market expansion into durable commercial advantage.
Detailed segmentation data, company-level estimates, and region-specific demand profiles can help refine these strategic choices further. For decision makers seeking deeper granularity on grade-level dynamics, application trends, and competitive positioning across key markets, PW Consulting's full research report provides the additional detail needed to support tailored planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Hexanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Glycated Albumin Market: Strategic Trends and Commercial Opportunities in Diabetes Monitoring
The glycated albumin market has emerged as a critical niche within the broader diabetes diagnostics landscape, offering a complementary alternative to traditional glycated hemoglobin testing. With total market revenue reaching approximately 243.1 million USD in 2025 and projected to climb to 425.6 million USD by 2032, the sector is tracking a compound annual growth rate of 8.4 percent over the 2026-2032 forecast period. This trajectory reflects a market that has moved past its early adoption phase and is now experiencing structural expansion driven by clinical validation, regulatory clarity, and shifting demand for intermediate-term glycemic markers. For executives, investors, and strategic planners, the question is no longer whether glycated albumin testing will gain traction, but how to position portfolios, partnerships, and capital allocations to capture value as the market matures.
Market Landscape and Core Challenges
A Market in Transition: From Niche Assay to Mainstream Complement
The glycated albumin market passed 163.15 million USD in 2020 and has expanded consistently through 2025, reflecting a decade of steady adoption across clinical and laboratory settings. By 2025, the market had crossed the 240 million USD threshold, and the forward curve points to acceleration as reimbursement pathways stabilize and automated chemistry platforms broaden assay compatibility. The growth is not uniform across all channels, however. Hospitals and diabetic care centers continue to anchor demand, while diagnostic laboratories and research-oriented users represent segments with distinct purchasing dynamics and validation requirements.
Despite the positive trajectory, the market faces several structural challenges that will shape competitive outcomes over the next five years. First, clinical adoption remains tied to the strength of comparative evidence against glycated hemoglobin. While glycated albumin offers a shorter reflection window of glycemic control—typically two to three weeks versus two to three months for HbA1c—clinicians and payers require robust head-to-head data demonstrating improved outcomes in specific populations, such as patients with hemoglobin variants, renal disease, or rapid glycemic fluctuations. Without broader clinical consensus, glycated albumin testing risks remaining a supplementary tool rather than a standard-of-care component.
Second, reimbursement fragmentation continues to create uneven access across providers and regions. Glycated hemoglobin and glycated protein testing is reimbursed under CPT codes 82985 and 83036 when billed with approved ICD-10-CM diagnosis codes, and some payers have issued policies addressing outpatient glycated hemoglobin and glycated serum protein testing for monitoring glycemic control. Yet coverage policies vary by insurer and geography, and glycated albumin specifically must navigate payer-specific determinations that can slow volume growth in cost-sensitive settings. This reimbursement variability affects hospital economics, laboratory testing mix, and the willingness of manufacturers to invest in broader commercialization efforts.
Third, the market must contend with supply chain and cost-structure pressures that influence assay affordability and availability. Enzymatic assay kits and reagent systems depend on consistent raw material inputs, manufacturing scale, and compatibility with automated chemistry analyzers. As demand grows, suppliers must balance quality control, regulatory compliance, and unit-cost optimization. Any disruption in reagent availability or analyzer compatibility can create localized shortages or pricing volatility, particularly in emerging markets where procurement cycles and import dependencies add complexity.
Key Drivers Shaping Market Trajectory
Technology Innovation and Assay Standardization
Technological progress is one of the most tangible drivers of market expansion. The availability of enzymatic glycated albumin assay kits designed for automated chemistry analyzers has reduced manual workflow burden and improved reproducibility across laboratory settings. These assay systems enable quantitative measurement of glycated albumin as a percentage of total albumin, providing a standardized output that clinicians can interpret alongside other glycemic markers. The trend toward analyzer-compatible, kit-based formats is lowering the barrier to integration for hospitals and diagnostic laboratories that already operate established chemistry platforms.
In addition, reagent and antibody suppliers are supporting assay development and validation by offering specialized components that improve sensitivity and consistency. This ecosystem of enabling products is helping both established manufacturers and new entrants refine their offerings, which in turn supports broader market credibility. As assay performance becomes more uniform across vendors, clinicians can adopt glycated albumin testing with greater confidence that results will be comparable across institutions and over time.
Regulatory Progress and Market Access Clarity
Regulatory milestones are reshaping market expectations by reducing uncertainty around test availability and commercialization pathways. Diazyme Laboratories received FDA 510(k) clearance for its GlycoGap enzymatic glycated albumin assay kit in March 2026, a development that reinforces the role of enzymatic assays in the U.S. market and signals ongoing regulatory openness to new entrants. Similarly, Asahi Kasei Pharma’s Lucica Glycated Albumin-L assay received FDA 510(k) clearance in 2017 and has CE marking for use in Europe, demonstrating that multi-region regulatory approval is achievable and can support international distribution strategies.
These regulatory events matter because they create clearer routes to market for manufacturers and more predictable purchasing decisions for laboratories. FDA clearance and CE marking reduce the burden of proof for clinical buyers and can accelerate procurement cycles, especially in hospital systems that require documented regulatory status before adding a new assay to their menu. At the same time, regulatory progress does not automatically translate into volume growth; it must be paired with reimbursement alignment, clinical education, and workflow integration to realize commercial impact.
Demand-Side Shifts in Diabetes Management
The demand environment is evolving as clinicians and health systems look for more granular tools to manage glycemic control. Glycated albumin testing is particularly relevant for patients whose HbA1c readings may be less reliable or who require more frequent monitoring of short-term glycemic changes. This includes individuals with hemoglobinopathies, certain renal conditions, or rapidly changing treatment regimens. As personalized diabetes management gains emphasis, providers are increasingly interested in complementary markers that can inform medication adjustments, lifestyle interventions, and closer follow-up intervals.
Consumer and patient awareness is also indirectly influencing demand. As diabetes screening and monitoring become more visible in public health discourse, providers face greater pressure to offer precise, timely, and actionable testing options. In practice, this means laboratories and care centers are evaluating assay menus not only on clinical performance but also on the ability to support broader chronic disease management programs. Glycated albumin testing can fit into that model when positioned as part of a coherent monitoring strategy rather than as an isolated test.
Supply Chain Dynamics and Cost Optimization
Supply chain considerations are becoming more prominent as the market scales. Manufacturers of assay kits and reagent systems must manage the trade-offs between regional sourcing, production consistency, and cost competitiveness. In laboratory diagnostics, even modest changes in reagent pricing or lead times can influence testing volume, especially in high-throughput settings where cost per test directly affects margin. Suppliers that can demonstrate reliable supply, scalable production, and compatibility with widely used analyzers are better positioned to secure long-term contracts and defend volume share.
HbA1c Testing Device Market
At the same time, cost structures are being shaped by the degree of automation and integration. Assays that fit into existing chemistry workflows reduce the need for additional instrumentation and staff training, which can improve adoption economics. Conversely, products that require specialized handling or separate processing may face slower uptake unless they offer a compelling performance advantage. As the market matures, cost-per-test efficiency and operational simplicity will increasingly influence purchasing decisions alongside clinical performance.
Competitive Landscape and Leading Strategies
Positioning Among Established Manufacturers
The competitive field includes manufacturers with distinctive regulatory footprints, geographic reach, and product focus. Asahi Kasei Pharma Corporation, based in Tokyo, Japan, has built recognition around its Lucica GA-L and Lucica GA-LA enzymatic assay kits for quantitative percent glycated albumin measurement on automated chemistry analyzers. The company’s established regulatory status and assay design for automated platforms give it a recognizable position in the market, particularly where hospitals and laboratories prioritize compatibility with existing instrumentation.
Albumin Market
Diazyme Laboratories Inc., headquartered in Poway, California, offers the GlycoGap enzymatic glycated albumin assay kit, which is FDA 510(k) cleared and designed for use on Roche cobas analyzers and most automated chemistry systems. This positioning illustrates a strategy centered on analyzer compatibility and regulatory clearance, two factors that can materially reduce adoption friction in U.S. laboratory settings. By aligning its product with widely used platforms, Diazyme is seeking to make glycated albumin testing easier to integrate into routine workflows.
EKF Diagnostics Holdings plc, based in Cardiff, United Kingdom, participates through distribution and availability of FDA-cleared Lucica Glycated Albumin-L test kits. This distribution-oriented approach highlights the importance of channel access and regional market presence, especially in settings where procurement decisions depend on established supplier relationships and service support. Rather than competing solely on assay innovation, this model emphasizes reach, logistics, and customer support.
Diverse Entrants and Enabling Players
Beyond the more visible assay manufacturers, the market includes companies with different roles in the value chain. Abbexa Ltd., located in Cambridge, United Kingdom, offers glycated albumin assay kits for research and clinical use, reflecting a dual-market strategy that can support both laboratory adoption and scientific validation. Laboratory Corporation of America, headquartered in Burlington, North Carolina, provides in-house laboratory offering of glycated albumin testing under CPT 123030, demonstrating how large reference laboratories can drive test volume through existing patient networks and service capabilities.
Other participants contribute through specialized reagents, research-grade kits, and laboratory diagnostic offerings. LifeSpan BioSciences Inc., in Seattle, Washington, supplies antibodies and reagents that support development and validation of glycated albumin assay kits, an enabling role that can influence downstream product quality and time-to-market for new assays. Maccura Biotechnology Co., Ltd., in Chengdu, Sichuan, China, provides glycated albumin assay kits for diabetes management and clinical diagnostics, illustrating regional manufacturing activity that may support cost-competitive offerings in Asia Pacific and beyond. Abnova Corporation, in Taipei, Taiwan, offers a glycated albumin assay kit for quantitative measurement, while Biocompare, in San Diego, California, aggregates customized and standard glycated albumin assay kits from multiple suppliers, serving as a sourcing interface for laboratories and researchers. Geno Technology Inc., in St. Louis, Missouri, provides glycated albumin assay kits for laboratory diagnostics, adding further optionality in the supplier base.
Strategic Differentiation and Market Evolution
The competitive landscape is evolving along several axes. One is regulatory and geographic reach: companies with multi-region clearance and established distribution can pursue broader volume opportunities, while others may focus on specific markets or customer types. Another is workflow integration: assay kits compatible with common automated chemistry analyzers have a structural advantage in hospital and laboratory settings where instrumentation already exists. A third is channel strategy: some players aim to sell directly into laboratories and hospitals, while others rely on distribution partnerships or reference laboratory adoption to build volume.
Market concentration suggests room for both consolidation and differentiation. CR3 stands at 38.5 percent and CR5 at 47.8 percent, indicating a moderately fragmented environment in which leading participants hold meaningful share but no single player dominates the entire market. This structure leaves space for regional specialists, niche entrants, and enabling suppliers to compete on specific value propositions. Over time, consolidation may accelerate as larger players seek geographic expansion, broader analyzer compatibility, or strengthened distribution networks, while smaller firms may differentiate through specialized reagents, research support, or cost-efficient manufacturing. The likely outcome is a layered competitive environment where assay manufacturers, distributors, and reference laboratories each capture value in different ways.
Future Trends and Commercial Implications
Trend 1: Broader Integration of Glycated Albumin as a Complementary Marker
Over the next three to five years, glycated albumin testing is likely to become more firmly embedded as a complementary marker in diabetes management, especially where clinicians need short-term glycemic insight or where HbA1c interpretation is limited. This trend will create opportunities for assay manufacturers and laboratories that can position glycated albumin testing within broader monitoring programs rather than as a standalone test. Commercial value will accrue to those who can align assay offerings with clinical workflows, patient populations, and decision-making intervals that benefit from intermediate-term glycemic data.
The opportunity is not simply to sell more tests, but to support adoption in contexts where glycated albumin adds clear value. That may include developing educational materials for clinicians, supporting validation studies in relevant subpopulations, and ensuring that assay results can be interpreted consistently across settings. Providers that invest in these enabling activities are more likely to see sustained volume growth than those relying on test availability alone.
Trend 2: Regulatory and Reimbursement Maturation as Adoption Accelerators
Regulatory activity and reimbursement policies are expected to remain central to market trajectory. The FDA clearance environment has shown willingness to clear enzymatic glycated albumin assays, and continued regulatory activity could further normalize the test category. At the same time, reimbursement coverage will influence the pace of adoption in cost-sensitive settings. Payers’ policies on outpatient glycated hemoglobin and glycated serum protein testing for monitoring glycemic control suggest that coverage is possible, but the operational reality is that labs and hospitals must still navigate payer-specific rules and documentation requirements.
For commercial teams, this means market access strategy matters as much as product quality. Manufacturers and laboratories that actively monitor coverage policies, support coding and billing clarity, and provide documentation that facilitates reimbursement are better positioned to convert test availability into routine use. In regions where reimbursement pathways are still developing, early engagement with payers and providers can create differentiation and lock in adoption before the category becomes more crowded.
Trend 3: Regional Expansion With Localized Value Propositions
Regional dynamics will continue to shape demand and competition. North America and Europe represent established markets with regulatory and reimbursement structures that influence adoption speed, while Asia Pacific reflects a large and growing patient population with diverse healthcare delivery models. Latin America and the Middle East and Africa, though smaller in current value, may present incremental opportunities as diagnostic infrastructure expands and diabetes prevalence rises.
The commercial implication is that a single global strategy will rarely be optimal. In some regions, analyzer compatibility and regulatory clearance may be the primary adoption drivers. In others, cost efficiency, supply reliability, or distribution partnerships may matter more. Companies that tailor their value proposition to regional purchasing criteria—rather than assuming uniform global demand—will have a better chance of converting market growth into share gains. At the same time, regional expansion carries execution risk, including regulatory timelines, import and procurement constraints, and variability in laboratory capabilities.
Risk Factors and Uncertainties
Several uncertainties could alter the pace or shape of market growth. If clinical evidence does not strengthen sufficiently, glycated albumin testing may remain a secondary option rather than achieving broader standard-of-care status. Reimbursement policies could also become more restrictive in certain markets, particularly if payers question incremental clinical benefit relative to cost. Supply chain volatility, regulatory delays, and competitive pricing pressure may further complicate expansion plans for manufacturers and laboratories. Finally, if glycated hemoglobin testing continues to improve in accessibility and performance, the incremental advantage of glycated albumin testing may be scrutinized more closely, making differentiation increasingly important.
PW Consulting
Strategic Implications for Decision Makers
For Assay Manufacturers and Diagnostics Suppliers
Manufacturers should prioritize analyzer compatibility, regulatory readiness, and supply reliability as core commercial pillars. In a market where workflow integration strongly influences adoption, products that fit existing automated chemistry systems and demonstrate consistent performance are more likely to secure long-term contracts. At the same time, firms should consider where they can differentiate beyond the assay itself—through regional distribution strength, clinical education support, or specialized reagents that improve validation and quality control. Companies that treat approval as the finish line rather than the starting point risk underinvesting in the market access and support activities that convert clearance into volume.
For Investors and Strategic Capital Allocators
Investors should evaluate opportunities based on the interplay of regulatory status, reimbursement exposure, and adoption economics rather than on global headline growth alone. The moderate market concentration suggests that there are multiple viable business models, but not all will scale equally. Assets with strong analyzer compatibility, established distribution, or access to large reference laboratory networks may offer more predictable pathways to volume than undifferentiated kit offerings. At the same time, investors should monitor clinical evidence development and payer policy, since these factors can shift adoption curves faster than product availability alone. A useful lens is to assess whether a company’s strategy is resilient across reimbursement scenarios and capable of capturing value if glycated albumin testing becomes more standardized in routine care.
For Hospitals, Laboratories, and Procurement Teams
Procurement and laboratory leaders should evaluate glycated albumin testing as part of a broader diabetes monitoring strategy. The decision to add or expand testing should consider analyzer compatibility, reagent supply reliability, total cost per test, and the clinical populations most likely to benefit. Laboratories that can integrate glycated albumin testing into existing workflows and support clear clinical use cases are better positioned to realize operational and patient-management value. It is also important to track reimbursement documentation requirements and payer policies, since these influence whether testing can be sustained at scale. Where possible, labs should seek supplier partnerships that provide consistent availability, support staff training, and reduce the operational burden of introducing a new assay.
Why Detailed Market Intelligence Matters Now
The glycated albumin market is entering a phase where broad growth signals are increasingly shaped by company-specific execution, regional access conditions, and payer dynamics. For decision makers, this means that high-level trends are necessary but not sufficient. Understanding which analyzer platforms are gaining traction, how reimbursement policies are evolving by market, where regulatory milestones are likely to open or close opportunities, and which competitors are strengthening distribution or cost positions can materially affect strategic choices.
The detailed segmentation, company-level benchmarks, and scenario analysis contained in PW Consulting’s full research report provide a deeper view of these dynamics, including differentiated volume projections, regional adoption drivers, and competitive positioning across the assay, distribution, and reference laboratory segments. For teams evaluating product strategy, capital deployment, or procurement planning, that level of detail can help convert market momentum into targeted action rather than relying on aggregate growth figures alone.
As the market moves from early adoption toward broader integration, the firms and institutions that act earliest on robust, granular intelligence will be best positioned to capture value and manage risk. The opportunity is real, but its shape will be defined by who understands the details fastest.
For detailed analysis of this topic, please visit the official page: Glycated Albumin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ski Apparel Market: Strategic Trends and Commercial Opportunities Through 2032
The ski apparel market has entered a phase of measured but steady expansion, shaped by evolving consumer expectations, material science breakthroughs, and a reconfiguration of global trade flows. From 2020 through 2025, the sector moved from $1.95 billion to approximately $2.55 billion in annual revenue, reflecting consistent year-over-year growth even as global supply chains navigated volatility. Projections for the 2026–2032 window point to a compound annual growth rate of 5.51 percent, with the market expected to cross the $3.7 billion threshold by the end of the forecast period. This trajectory signals more than cyclical demand; it reflects structural shifts in how cold-weather performance gear is designed, manufactured, and commercialized.
Yet the growth path is not without friction. The industry is navigating a set of interconnected challenges that will separate adaptive operators from those relying on legacy models. Trade policy uncertainty has introduced material cost variability, particularly for brands sourcing specialized membranes, zippers, and insulation across multiple jurisdictions. At the same time, climate variability is reshaping ski season reliability in traditional gateways, forcing retailers and brands to reconsider inventory timing, product mix, and regional allocation. A third pressure sits in the mid-market: consumers increasingly expect genuine technical performance paired with recognizable sustainability credentials, but the cost of authenticity in both domains continues to rise.
Market Context and the Shape of Demand
The revenue base has shown durable expansion, with the 2024–2025 period demonstrating resilience after a period of post-pandemic normalization. Jackets continue to anchor the category, reflecting their dual role as a core performance item and a visible brand statement. Pants and one-piece suits represent smaller but strategically important slices of the portfolio, with one-piece garments gaining renewed attention among freeride and backcountry participants who prioritize streamlined mobility and weather protection in a single layer.
Ski Apparel Market
应用需求-side patterns reveal a market that is increasingly democratized. The amateur segment remains the volume driver, but its purchasing behavior is no longer defined solely by price sensitivity. Recreational skiers and snowboarders are investing more in durability, weatherproofing, and fit precision, often treating ski apparel as an annual upgrade rather than a multi-season purchase. Professional athletes and specialized operators represent a smaller but highly visible segment that influences design credibility and fabric validation, while the remaining demand pool spans resort staff, guides, and specialty outdoor users whose requirements push manufacturers toward modular layering and extended-service-life construction.
Key Drivers Shaping the Market
Technique-Led Material Innovation
Performance apparel is being re-engineered around three overlapping priorities: weight reduction, weather adaptability, and longer useful life. Advanced weatherproof membranes and engineered knit-weather barrier hybrids are enabling thinner profiles without sacrificing protection, which matters increasingly for resort skiers who value agility and for backcountry users managing fatigue over longer tours. Insulation strategies are shifting toward modular, compressible options that can be layered or replaced depending on temperature swings, rather than relying on single-thickness fixed systems.
Fabric durability is also becoming a differentiator in a market where extended product lifecycles are both a consumer expectation and a sustainability objective. Brands are investing in seam reinforcement, abrasion-resistant face fabrics, and coatings that hold performance after repeated wash and repair cycles. The commercial implication is clear: materials strategy is no longer a backend engineering function. It directly shapes pricing architecture, return rates, and brand positioning in a crowded performance category.
Policy and Tariff Dynamics
Trade policy has moved from a background risk to a core planning variable. A range of tariff adjustments affecting apparel and related inputs has increased landed-cost variability for ski gear, with reported price increases in the 5–20 percent range for certain categories. These shifts are not uniform across destinations or product codes, and they interact with supplier geography, sourcing concentration, and logistics routing. For ski apparel specifically, tariff exposure on relevant suit and outerwear classifications varies by market, which means margin planning cannot rely on a single global assumption.
Beyond immediate cost effects, the regulatory environment is shaping how brands structure sourcing commitments. Importers are increasingly evaluating multi-origin strategies, near-term buffer inventory for critical hardware and membranes, and more granular landed-cost modeling by region. The broader takeaway for decision-makers is that trade policy now influences not only cost but also product rollout timing and assortment logic.
Demand-Side Evolution and Experience Economics
Consumer behavior is being reshaped by experience-led purchasing and a stronger preference for products that perform across a wider range of conditions. Skiing is increasingly treated as a lifestyle and travel experience rather than a purely seasonal sport, which raises the value of versatile garments that can transition between resort days, travel days, and varying mountain conditions. Fit expectations are also rising: consumers are paying closer attention to mobilization, layering compatibility, and weather-specific zoning within a garment.
This shift has consequences for product architecture. Brands that can offer coherent layered systems—where jackets, pants, and base/mid components are designed to work together—tend to capture more basket value and reduce the friction of piecemeal purchasing. At the same time, the amateur buyer is demanding clearer value communication. Technical claims must be paired with tangible benefits in warmth, dryness, durability, and care, because the premium for performance is increasingly scrutinized.
Supply Chain and Cost Structure Realignment
Cost structures are being re-evaluated in response to labor, logistics, and material availability pressures. Specialized inputs such as technical zippers, performance shells, and engineered insulation remain concentrated among a limited set of suppliers, which creates both quality assurance benefits and dependency risks. As a result, leading operators are balancing efficiency with resilience by diversifying critical-input sourcing and by designing products with substitute-friendly material architectures where possible.
Worldwide Ski Touring Apparel Market
Service and repair infrastructure is also becoming part of the cost-and-value equation. Garments that can be maintained, re-sealed, or reinforced extend usable life and reduce replacement frequency, which is increasingly important for both cost-conscious buyers and sustainability-oriented positioning. This creates an opportunity for brands to build post-purchase value pathways that reinforce product credibility while supporting margin defensibility.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with a handful of established players holding meaningful share and a broader field of regional and specialty brands competing on fit, performance narrative, and lifestyle alignment. The leadership group is not converging on a single formula; rather, it is diverging into distinct strategic identities that appeal to different buyer profiles.
Differentiated Strategic Identities
Helly Hansen continues to emphasize premium technical outdoor ski apparel, including jackets, pants, and layered systems built for both resort and freeride use. Its positioning leans into weather-ready construction and broad resort relevance, which makes it a practical reference point for buyers seeking reliable cold-weather performance without narrow specialization. Arc'teryx has carved a space around high-performance technical apparel with a strong focus on performance fabrics and minimalist design. Its appeal rests on precise engineering and a restrained aesthetic that resonates with users who value function-first construction and clean silhouettes.
Black Diamond Equipment anchors its offering in alpine ski-specific apparel and layered systems designed for technical mountain skiing. This orientation supports a more performance-intensive narrative, appealing to users who prioritize mobility and mountain conditions over resort fashion cues. Columbia Sportswear Company competes with a broader outdoor ski apparel line that includes jackets, pants, and insulated layers for cold-weather performance. Its scale and distribution breadth give it a strong presence in accessibility-oriented segments where insulation, ease of care, and value clarity matter. Patagonia Inc. has built a recognizable position around sustainable ski apparel, using recycled materials and eco-friendly technical layers to align performance with environmental credentials.
PW Consulting
How the Field Is Evolving
The landscape is not simply consolidating; it is stratifying. At the premium and technical end, differentiation is increasingly tied to fabric specificity, design restraint, and repairability narratives. At the accessible end, competition centers on insulation performance, fit consistency, and distribution reach. In parallel, regional and niche specialists continue to enter or re-enter with focused product stories, often targeting backcountry, freeride, or lifestyle crossover demand that larger portfolios may under-serve.
This stratification has two practical implications. First, broad-based brands must decide whether to compete across all segments with a unified line or to create clearer sub-architectures that separate resort, recreational, and technical use cases. Second, smaller specialists can win by owning a narrowly defined performance or lifestyle position rather than attempting to match the full assortment breadth of larger competitors.
Forward Trends and Commercial Implications
Trend One: Product Architecture Will Shift Toward Modular Layering
Over the next three to five years, garments are likely to be engineered less as isolated items and more as interoperable components within a layered system. This will matter for both design and commercial execution. Modular layering supports more precise temperature regulation, easier mix-and-match purchasing, and clearer product storytelling around use cases. For manufacturers, this creates opportunities to expand basket size while reducing the risk of overcommitting to a single hero product in a volatile season. The risk is complexity: systems only work commercially if fit, closure, and weather protection are coordinated across categories.
Trend Two: Sustainability Will Be Judged on Durability and Service, Not Only Materials
Eco-oriented positioning is becoming table stakes, but the more decisive competition will increasingly revolve around proof of durability, repair pathways, and lifecycle communication. Consumers and retail partners are likely to reward products that demonstrate extended service life and transparent care options more than those relying on material claims alone. For brands, this opens a path to defend premium pricing through service, warranty, and repair offerings. The uncertainty lies in execution: sustainability programs that are not supported by product robustness can quickly become credibility risks.
Trend Three: Regional Diversification Will Replace Single-Path Sourcing as a Baseline
Given tariff variability and input concentration, sourcing diversification is likely to become standard practice rather than a contingency measure. Expect more multi-region supplier strategies for critical components, more deliberate buffer planning for hardware and membrane materials, and more region-specific pricing and assortment logic. This trend creates speed and resilience advantages for operators who invest early in scenario planning, but it raises overhead for those that continue to rely on single-path sourcing for core inputs.
Strategic Actions for Decision-Makers
For Manufacturers and Brand Operators
Product architecture should be evaluated through a systems lens rather than a single-product lens. Align jackets, pants, and layering components so they reinforce one another in fit, weather protection, and care requirements. This reduces internal cannibalization and strengthens the value proposition for buyers who want coherent cold-weather kits. At the same time, invest in repairability and post-purchase support as a margin and brand-trust lever. Products that are easier to maintain can support higher lifetime value and reduce sensitivity to upfront price comparisons.
Sourcing strategy should be stress-tested against tariff scenarios and input availability, especially for specialized hardware and weatherproof materials. Where possible, design substitute pathways into product platforms so that a change in one input does not force a full redesign. This dual focus on design flexibility and sourcing diversification improves resilience without sacrificing performance consistency.
For Investors and Portfolio Strategists
Performance in this market will increasingly depend on how well companies translate technical differentiation into commercial outcomes: repeat purchase, lower return rates, and clear positioning that can command premium pricing without relying on vague performance claims. Evaluate portfolio exposure not only by brand recognition but also by product-system maturity, repair and service capability, and the flexibility of the sourcing model. Companies that are structurally better at modular design and post-purchase value creation are likely to show more stable margins as input costs and trade conditions fluctuate.
It is also worth distinguishing between brands competing on lifestyle reach and those competing on technical specialization. Both can be viable, but they require different operating assumptions, channel strategies, and margin models. Portfolio decisions should reflect which path a company is truly built to win, rather than treating premium performance and accessible volume as interchangeable growth levers.
For Procurement and Channel Leaders
Buying decisions should place greater weight on total usable life and system compatibility than on unit price alone. Garments that integrate cleanly into existing layered setups and withstand repeated use can lower replacement frequency and improve end-user satisfaction. Where possible, prioritize suppliers that offer clear care guidance, repair support, and consistent fit across related categories, because these attributes reduce downstream friction for both retailers and end users.
Regional assortment planning should also account for trade and tariff variability rather than assuming uniform landed cost across markets. Aligning product mix, timing, and inventory depth to regional cost exposure can protect margin while maintaining availability in key demand windows. This is especially relevant for categories where weather conditions, season length, and travel patterns influence selling cycles.
The Strategic Bottom Line
The ski apparel market is expanding steadily, but the real competition is shifting from headline growth to execution quality. Winning is increasingly defined by how effectively a company integrates material innovation, sourcing resilience, product-system coherence, and authentic durability claims into a single commercial model. Brands that treat ski apparel as a set of interoperable performance layers, supported by clear service pathways and region-aware cost planning, are better positioned to convert market growth into durable share and margin stability.
For executives and investors navigating this landscape, the most valuable next step is to move from broad market awareness to a more precise view of where growth is concentrating, which product architectures are winning, and how sourcing and tariff exposure will shape profitability by market. A fuller segmentation view, company-level comparisons, and scenario-based planning data can sharpen those decisions considerably. Detailed breakdowns of regional dynamics, type-level performance, application-side demand, and competitive positioning are available in the complete Ski Apparel Market research suite from PW Consulting, where the analysis can be tailored to specific product categories, channels, and sourcing footprints.
For detailed analysis of this topic, please visit the official page: Ski Apparel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Train Seat Market 2026: Why 5.2% CAGR and High-Speed Demand Reshape Growth
By PW Consulting, 2026-09-21
The Train Seat Market: Strategic Shifts and Commercial Opportunities (2025–2032)
The global train seat market has entered a phase of steady expansion, underpinned by renewed investment in rail infrastructure and a structural shift toward higher passenger comfort. Valued at approximately 146.8 million USD in 2025, the market is projected to grow at a compound annual rate of 5.2 percent through 2032, reaching an estimated 207.6 million USD. Historical progression from 2020 through 2025 reflects a consistent upward trajectory, with growth accelerating as operators prioritize fleet modernization and passenger experience. This expansion is not merely a function of rising ridership; it reflects deeper changes in how rail operators configure interiors, how manufacturers respond to regulatory and material constraints, and how seating has evolved from a commodity component to a strategic differentiator.
Despite the favorable growth outlook, the industry faces several structural challenges that will shape competitive outcomes over the next decade. First, stringent safety and fire-resistance regulations for railway interiors continue to lengthen production cycles and increase compliance costs, compressing margins for manufacturers that lack scalable certification processes. Second, material cost volatility remains a persistent pressure point. Prices for aluminum, high-density foam, and composite materials fluctuate in response to broader industrial demand and supply chain disruptions, directly affecting the economics of advanced seating systems. Third, pricing dynamics on the operator side are reshaping procurement behavior. In regions where rail market liberalization has driven ticket prices downward, operators face tighter capital allocation for cabin upgrades, forcing manufacturers to justify seating investments through lifecycle cost reductions, durability, and modularity rather than upfront premium pricing. These intersecting pressures create a market where value engineering, regulatory agility, and total-cost positioning matter as much as raw product performance.
Key Demand and Supply Drivers
The market’s growth is not uniform; it is being pulled forward by a combination of technological, regulatory, and behavioral forces. Understanding these drivers is essential for operators, manufacturers, and investors evaluating where to allocate resources.
Technology and Material Innovation
Seating design is increasingly converging with automotive-era engineering practices. Lightweight construction, ergonomic optimization, and modular architectures are becoming standard expectations rather than niche differentiators. Manufacturers are adapting automotive-derived seating technologies to rail applications, reducing weight while maintaining structural integrity and passenger comfort. Monomaterial frames and recyclable fabric systems are gaining traction, particularly in segments where operators seek to streamline maintenance and align with sustainability targets. These innovations reduce assembly complexity and improve component interchangeability, which in turn lowers long-term service costs. The shift toward flexible, high-tech fabric and recyclable structures also supports faster retrimming cycles and simplifies compliance with evolving fire-safety requirements, though the upfront engineering investment remains substantial.
Regulatory and Policy Environment
Policy frameworks continue to act as both a catalyst and a constraint. On the demand side, expansion of railway infrastructure and urban transit systems globally is generating a steady pipeline of new and replacement seating orders. Public investment in intercity corridors, high-speed networks, and modernized commuter fleets creates volume that supports manufacturing capacity utilization. On the constraint side, interior safety regulations mandate rigorous fire-resistance, durability, and vandalism-resistant performance standards. These requirements increase testing, documentation, and production overhead, particularly for manufacturers serving multiple jurisdictions with divergent approval processes. The regulatory environment also indirectly shapes procurement pacing. Where competition in the rail market has intensified, operators have reduced ticket prices and recalibrated capital spending, which can slow large-scale seat replacement programs unless the value proposition is clearly tied to operational efficiency or passenger retention.
Demand-Side Behavior and Operator Priorities
Passenger expectations are shifting the internal economics of rail seating. Modern travelers increasingly equate cabin comfort, cleanliness, and ergonomic support with overall service quality, especially on intercity and high-speed routes where competition from air and road transport remains intense. Operators are responding by prioritizing seating that supports higher occupancy flexibility, improved accessibility, and easier maintenance. The introduction of double-deck and next-generation high-speed trains illustrates this shift: interior layouts are being redesigned to maximize capacity without sacrificing comfort, and seating packages are selected with step-free boarding, weight distribution, and cabin modularity in mind. For manufacturers, this means that the sale is no longer just about the seat itself; it is about how the seating system integrates into broader fleet performance objectives, including turnaround time, cleaning cycles, and passenger satisfaction metrics.
PW Consulting Health Care Research Center
Cost Structure and Supply Chain Realities
The economics of train seat production are increasingly tied to material sourcing and manufacturing footprint decisions. Volatility in the cost of aluminum, foam, and composites directly impacts margins, particularly for suppliers that rely on fixed-price contracts or operate with thin manufacturing buffers. In response, several manufacturers have expanded or relocated production capacity to improve cost competitiveness and reduce lead times. New facility investments in regions with favorable labor and input economics are enabling suppliers to scale modular platforms more efficiently while maintaining regional compliance capabilities. At the same time, high manufacturing and material costs associated with advanced seating systems continue to act as a restraint on rapid adoption, especially for operators with constrained capital budgets. This tension is pushing the market toward platform-based seating solutions that balance performance, weight, and lifecycle cost, rather than bespoke designs for every order.
Toilet Seat Market
Competitive Landscape and Leader Strategies
The competitive structure of the train seat market is moderately concentrated, with leading players collectively holding a significant share of regional and segment demand. This concentration reflects the technical barriers to entry, the importance of regulatory certification, and the long qualification cycles that rail operators typically impose on interior suppliers. Within this structure, companies are differentiating themselves through product architecture, regional alignment, and the ability to pair seating with broader engineering and manufacturing services.
German and European suppliers remain prominent across multiple rail segments, offering full-line passenger and driver seating for city, regional, intercity, and high-speed applications. Their advantage lies in broad portfolio coverage and established relationships with operators running mixed fleets. Several of these manufacturers have emphasized modular, ergonomic, and vandalism-resistant designs tailored to local, regional, and intercity use cases, where durability and ease of maintenance are central procurement criteria. Others have focused on comfort-optimized seating for intercity, regional, and metro applications, with high degrees of individualization and durability that appeal to operators seeking brand consistency across routes.
In North America, suppliers are concentrated on commuter rail, light rail, subway, and regional passenger vehicles, where robustness, turnaround efficiency, and compliance with regional safety standards are paramount. These providers have built strong positions by aligning product designs with the operational realities of high-frequency urban services. Meanwhile, manufacturers leveraging automotive-derived technologies are gaining relevance in segments that demand lightweight construction, ergonomic refinement, and durable materials. Their cross-industry expertise allows them to accelerate material and cushioning innovation while maintaining the structural requirements specific to rail use. Specialist firms in France and Spain have carved out a distinct role in high-speed train seating, emphasizing ergonomic and modular solutions that suit premium intercity travel and operator customization needs. In parallel, engineering-focused providers offer design, engineering, and manufacturing services for rail seating systems, including lightweight and modular options, positioning themselves as partners in cabin integration rather than solely as component suppliers.
Recent developments illustrate how these players are translating strategy into market action. One European manufacturer launched a new regional seating platform featuring flexible high-tech fabric and a recyclable monomaterial frame, signaling a push toward sustainability-aligned modular design and simplified material handling. That same company inaugurated a new production plant to expand rail seating capacity, reflecting a deliberate move to strengthen manufacturing throughput and regional responsiveness. On the operator side, major rail systems have introduced new fleets with updated seating configurations: double-deck trains with modern seating packages, next-generation high-speed trains with refreshed passenger seating, and high-speed models featuring step-free boarding and enhanced interior seating. These introductions are not isolated product updates; they represent broader fleet strategies where seating is integral to accessibility, capacity optimization, and passenger experience.
The market structure is evolving along a dual path. On one hand, consolidation pressure exists where scale, certification capability, and multi-segment coverage create advantages for larger full-line suppliers. On the other hand, segmentation remains pronounced, with specialized players competing in high-speed, commuter, and metro niches by offering tailored ergonomic, modular, and durability-focused solutions. New entry is difficult but not impossible, particularly for firms that bring differentiated material technology, lightweight engineering, or integrated cabin-design capabilities that reduce operator integration risk. The overall trend points toward a landscape where breadth of coverage and platform commonality are increasingly valuable, but segment-specific expertise still commands premium positioning in demanding applications.
Worldwide Non-recliner Train Seat Market
Future Outlook: Trends Shaping 2026–2032
Looking ahead, several trends are likely to define the market’s trajectory and determine where commercial value concentrates.
Platform-Based Seating and Modular Standardization
The industry is moving toward platform-based seating architectures that allow operators to standardize components across train families while retaining flexibility for route-specific configurations. Modular frames, interchangeable cushioning, and adaptable fabric systems reduce inventory complexity and shorten refit cycles. This trend benefits manufacturers that can offer a coherent platform with proven compliance, predictable maintenance, and lower total cost of ownership. For operators, the opportunity lies in reducing lifecycle costs and improving cabin turnaround without sacrificing passenger comfort. The risk is that over-standardization may limit differentiation in premium segments, making it harder to distinguish services on high-margin routes.
Sustainability-Linked Design and Material Circularity
Sustainability is becoming a procurement consideration rather than a secondary attribute. Recyclable monomaterial frames, durable fabric systems, and designs that facilitate disassembly are increasingly relevant as operators align fleet upgrades with broader environmental goals and regulatory expectations. Manufacturers that can demonstrate lower end-of-life disposal impact, reduced material waste, and easier retrimming will have stronger positioning in bids where total lifecycle cost and compliance are evaluated together. The uncertainty here is material availability and cost consistency; recycled and monomaterial solutions must prove they can meet fire-resistance, durability, and vandalism-resistance standards at scale before they become default choices across all segments.
Fleet Modernization as a Persistent Demand Engine
Infrastructure expansion and urban transit upgrades will continue to drive demand for both new and replacement seating, but the pace will vary by region and operator budget. High-speed and intercity modernization programs are likely to sustain premium seating demand, while commuter and metro operators will focus on durable, high-throughput designs that withstand heavy usage. The key opportunity is to align product roadmaps with fleet renewal cycles, anticipating where replacement programs intersect with accessibility upgrades and interior redesigns. The principal risk is budget compression: if operator capital remains limited, large-scale upgrades may be deferred, shifting demand toward incremental replacement rather than full cabin overhauls.
Strategic Implications for Decision Makers
For manufacturers, the priority is to balance platform scale with segment specificity. Expanding modular seating platforms can improve production efficiency and strengthen compliance repeatability, but winning in high-speed, commuter, or metro niches still requires targeted ergonomic, durability, and customization capabilities. Manufacturers should accelerate certification agility across jurisdictions, stabilize material sourcing through long-term agreements or diversified supply channels, and position seating as part of a broader cabin-integration value proposition that reduces operator downtime and maintenance complexity.
For investors, the market offers exposure to recurring demand tied to infrastructure expansion and fleet modernization, but returns will depend on identifying suppliers with durable differentiators. The most attractive profiles combine certification capability, modular platform economics, and proven relationships across multiple rail segments. Investors should monitor capacity expansion decisions, material cost management, and the ability to convert sustainability trends into commercially viable product lines rather than treating them as isolated marketing claims.
For procurement teams and rail operators, the strategic task is to evaluate seating decisions through total-cost and operational-impact lenses rather than upfront price alone. Seating that reduces cleaning time, supports faster turnaround, improves accessibility, and maintains performance under heavy usage can deliver meaningful operating savings over a fleet lifecycle. Procurement should require evidence of fire-resistance compliance, durability under vandalism-prone conditions, and modularity that enables component-level replacement instead of full-unit swaps. Where operators are balancing ticket-price pressures with service-quality expectations, seating investments should be tied to measurable passenger experience and maintenance outcomes.
Detailed segmentation data, regional nuance, and company-level trajectory analysis can materially improve planning accuracy and risk assessment. For organizations seeking deeper granularity on demand splits, competitive positioning, and scenario-based forecasts across the forecast period, the full market research report provides expanded breakdowns and customized guidance tailored to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: Train Seat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Cyclotron Market: How 6.9% CAGR and Diagnostic Imaging Demand Reshape Growth by 2032
By PW Consulting, 2026-09-21
Medical Cyclotron Market: Strategic Trends and Commercial Opportunities
The medical cyclotron sector is entering a period of structural expansion. Historical data shows a steady rise from approximately $189 million in 2020 to $252 million in 2025, with a projected compound annual growth rate of 6.9 percent through 2032, pushing the market toward $398 million. This trajectory is not merely a reflection of steady capital equipment demand; it signals a shift in how radiopharmaceuticals are produced, distributed, and integrated into clinical pathways. For executives and investors, the market is moving from a niche imaging-support segment to a foundational component of precision diagnostics and targeted therapy ecosystems. Understanding why growth is accelerating, where competition is concentrating, and how demand-side behavior is reshaping procurement decisions will determine which organizations capture durable value.
Market Snapshot and Structural Shifts
The revenue trend over the 2020-2025 period demonstrates resilience through clinical adoption cycles and supply chain volatility. Demand has broadened beyond traditional PET tracer production, with oncology therapies and specialized diagnostic protocols expanding the addressable base for on-site isotope generation. The forecast period through 2032 suggests continued expansion, but not uniformly across use cases. Growth is being steered by applications that tie imaging to therapeutic decision-making, as well as by production models that favor localized isotope generation over centralized distribution. This structural shift is altering demand patterns, vendor selection criteria, and capital planning timelines.
Three challenges define the current inflection point. First, the industry is navigating a policy environment that is becoming more explicit about production traceability, quality documentation, and reimbursement coding for cyclotron-dependent isotopes. Regulatory attention to process validation and isotope sourcing is raising the bar for operators and suppliers alike. Second, the market remains concentrated, with a small group of manufacturers commanding the majority of share. Concentration creates short-term stability but also intensifies competition around product differentiation, service models, and installation flexibility. Third, demand is being reshaped by clinical adoption of theranostic protocols, which require reliable isotope supply and production capacity aligned to treatment schedules rather than episodic imaging volumes. These pressures are forcing vendors and buyers to rethink operating models rather than simply adding units.
Worldwide Positron Emission Tomography Devices Market
Key Drivers Shaping the Market
Technology innovation remains the clearest catalyst for change. Manufacturers are increasingly focusing on compact designs, higher output efficiency, and dedicated configurations for specific isotope families. Recent product launches illustrate this direction, including instruments engineered for routine production of alpha-emitter isotopes with automated irradiation control and reduced operator exposure. At the same time, high-output platforms continue to evolve for PET and SPECT applications, expanding the range of clinical sites that can support localized production. The strategic implication is straightforward: performance differentiation is moving from raw beam capability to workflow integration, footprint constraints, and compliance-ready operation.
Regulatory and reimbursement dynamics are reinforcing that shift. Authorities have been clarifying pathways for cyclotron-based isotope production in both diagnostic and therapeutic settings, with notable approvals and coding decisions that tie production methods to billing and clinical use. Examples include cleared production processes for Ga-68-based diagnostics, PDUFA action dates for cyclotron-prepared diagnostic kits, and therapy approvals that depend on reliable isotope production for radioligand treatments. These developments are not abstract regulatory milestones; they affect commercialization timelines, reimbursement certainty, and the economics of on-site production versus generator or centralized supply.
Demand-side behavior is changing as well. Hospitals, research centers, and specialized radiopharmacies are seeking more control over supply continuity and production timing, especially where therapeutic workflows depend on synchronized imaging and treatment. On-site cyclotron capability is increasingly viewed as a strategic asset for centers building out precision medicine programs. At the same time, expansion projects are being planned around manufacturing capacity and service responsiveness. New dedicated production facilities, installation milestones at academic and clinical sites, and multi-unit setups at manufacturing locations all point to a market where deployment speed, local support, and operational reliability are becoming as important as instrument performance.
Cost structure and supply chain considerations are also influencing purchasing strategy. Capital expenditure decisions are being evaluated against total cost of ownership, including servicing, consumables, staffing requirements, and regulatory compliance burdens. Suppliers that reduce installation complexity, streamline operational training, and provide clearer service coverage gain an advantage in procurement discussions. For buyers, the question is no longer only whether a cyclotron can produce a required isotope, but whether the broader operating model supports predictable uptime, qualified personnel, and integration with existing radiopharmacy workflows.
Competitive Landscape and Strategic Positioning
The market is led by a set of globally positioned manufacturers with distinct strategic angles. One established leader continues to emphasize breadth across medical cyclotron families and targeted alpha therapy production, including configurations designed for routine isotope output with minimized operator exposure. Another large diversified player anchors its offering around PETtrace platforms, linking on-site isotope production to diagnostic and therapy-related applications through hospital and research installations. A specialist manufacturer focused on high-output systems has been expanding its footprint, including investments in production capacity to support global nuclear medicine demand. A compact superconducting cyclotron developer is positioning around smaller footprints and integrated radiopharmaceutical manufacturing solutions. A Japanese industrial producer continues to compete with compact HM-series systems, emphasizing reliable support and delivery for PET tracer production. These profiles reveal a landscape where scale, specialization, and application focus coexist.
PW Consulting
The strategic differentiation among leaders is becoming clearer along three lines. First, product architecture matters: dedicated high-energy configurations for specific isotope families compete alongside flexible general-purpose platforms, and buyers increasingly evaluate which architecture best fits their isotope roadmap. Second, service and deployment models are a growing battleground, with vendors competing on installation speed, site readiness, commissioning support, and ongoing operational reliability. Third, application breadth is being used as a positioning lever, with some suppliers emphasizing alpha therapy production, others emphasizing PET and SPECT output, and still others connecting cyclotron capability to broader radiopharmaceutical manufacturing services. In practice, this means competitive advantage is less about a single specification and more about how well a vendor aligns instrument design with clinical workflow, compliance, and supply chain expectations.
Market structure is evolving through both consolidation pressure and fragmentation risk. Concentration in the hands of a few incumbents creates a high barrier to entry for general-purpose platforms, but it also opens space for specialized entrants in compact systems, superconducting architectures, or application-specific production lines. At the same time, recent installation activity by both manufacturers and end users reflects a pattern where multi-vendor environments and site-specific procurement choices are becoming more common. Some leading radiopharmaceutical operations are installing instruments from different suppliers to diversify production capability and support parallel diagnostic and therapeutic pipelines. This suggests the competitive battleground is shifting toward ecosystem value: how effectively equipment, isotope workflows, service coverage, and regulatory alignment fit together in a real operating environment.
Worldwide Negative Ion Cyclotron Market
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is continued specialization around isotope families that connect diagnostics with therapy, particularly where production reliability directly affects treatment scheduling and clinical throughput. This trend favors vendors and operators that can demonstrate consistent output, documented quality processes, and flexible configurations for specific therapeutic and imaging isotopes. The commercial opportunity lies in aligning equipment selection with isotope roadmaps, not just current production needs.
The second trend is greater emphasis on site-integrated deployment. As more centers invest in precision medicine infrastructure, the value proposition of a cyclotron is increasingly tied to facility planning, staffing, and workflow integration rather than standalone instrument performance. Suppliers that offer simpler siting requirements, clearer commissioning pathways, and stronger local service coverage will have an advantage in competitive procurement processes. For operators, the opportunity is to plan capital investments as part of a broader production and service model, reducing downtime risk and improving utilization.
The third trend is regulatory and reimbursement clarity continuing to influence adoption velocity. As more production processes, diagnostic kits, and therapy pathways become explicitly linked to cyclotron-based isotope supply and billing codes, procurement decisions will be more directly connected to commercialization risk and operational compliance. This creates both opportunity and uncertainty. Where coding and approval pathways stabilize, demand can accelerate around established isotope families. Where regulatory timelines or reimbursement changes remain fluid, adoption may pause while buyers await clearer economics. Organizations that monitor policy milestones and reimbursement updates will be better positioned to time investments and avoid overcommitting to supply models that depend on uncertain coding outcomes.
Actionable Guidance for Decision-Makers
The market is expanding, but value capture will depend on how well organizations align strategy with isotope production realities, regulatory direction, and procurement dynamics. For manufacturers, the priority is to strengthen differentiation beyond instrument specifications by tightening the link between platform design, service coverage, and compliance-ready workflows. Product roadmaps should reflect the growing importance of specific isotope families, installation flexibility, and operational support, especially as centers plan multi-unit or multi-isotope environments. Competitive advantage will increasingly belong to suppliers that can demonstrate not only output capability but also reduced operational friction and reliable site readiness.
For investors, the practical question is where durable demand is forming and which segments are most exposed to rapid adoption or policy-driven uncertainty. Growth is strongest where production reliability supports both diagnostic imaging and therapeutic protocols, and where sites are willing to invest in localized isotope generation. At the same time, reimbursement coding and regulatory approvals can accelerate or delay commercialization timelines for specific isotopes and kits. Due diligence should focus on product fit to likely isotope roadmaps, the strength of service and deployment models, and the sensitivity of demand to policy milestones. Portfolio exposure should account for both the upside from theranostic adoption and the timing risk from evolving approval and billing pathways.
For procurement teams and radiopharmacy operators, the decision calculus is shifting from instrument capability alone to total operating suitability. Evaluating vendors now requires attention to siting constraints, staffing demands, commissioning support, service responsiveness, and alignment with planned isotope mixes. Multi-vendor environments and parallel production lines are becoming more relevant where organizations need flexibility across diagnostics and therapeutics. Procurement planning should also incorporate the impact of regulatory and reimbursement changes on isotope economics, since production method and coding status can materially affect the business case for on-site cyclotron investment.
Strategic decisions in this market carry long lead times and depend on details that are not always visible in high-level market sizing. Segment-level demand patterns, vendor-specific deployment metrics, policy timelines, and reimbursement developments will shape which opportunities convert into durable advantage. For teams that need a sharper view of these factors, the full research report provides deeper segmentation data, regional and application-level context, and customized guidance tied to specific operating model and investment objectives.
For detailed analysis of this topic, please visit the official page: Medical Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Ferulic Acid Market: Strategic Trends and Commercial Opportunities in a Growing Antioxidant Economy
Market Landscape and Core Challenges
The ferulic acid market has entered a phase of sustained expansion, driven by the compound's dual role as a potent antioxidant and a functional ingredient across multiple end-use sectors. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenue climbing from approximately 100 million USD at the start of the decade to around 130 million USD by 2025. This trajectory reflects a compound annual growth rate of roughly 7 percent over the base period, a pace that signals healthy demand absorption rather than speculative hype. Forecasts extending through 2032 project the market to surpass the 205 million USD threshold, indicating that the growth runway remains intact even as the base widens.
Such figures, however, only tell part of the story. Behind the headline growth lies a market that is structurally evolving, with shifting cost dynamics, regulatory clarifications, and changing buyer expectations reshaping how value is created and captured. The expansion is not uniform across all value chains; it is concentrated in specific purity grades, sourcing paradigms, and application verticals that command premium pricing or faster volume growth. At the same time, the market exhibits moderate concentration, with the top three players accounting for approximately 45 percent of revenue and the top five reaching around 50 percent. This level of concentration suggests that incumbents possess meaningful scale and distribution advantages, yet it also leaves room for specialized challengers to carve out niches through differentiation in purity, sourcing origin, or regulatory positioning.
Natural Ferulic Acid (CAS 1135-24-6) Market
Several core challenges and inflection points are testing the industry's resilience. First, raw material volatility is exerting persistent pressure on production economics. Rice bran and wheat bran serve as the primary upstream feedstocks for ferulic acid extraction and refining, and the prices of these agricultural inputs fluctuate in response to harvest cycles, weather patterns, and competing demand from food and feed industries. When feedstock costs spike, manufacturers face difficult margin calculations, especially for price-sensitive segments that cannot easily pass through cost increases. Over time, this dynamic favors players with integrated sourcing arrangements, long-term supply contracts, or access to byproduct streams that lower effective input costs.
Second, regulatory clarity is both a catalyst and a constraint. Food-grade ferulic acid must meet quality standards approved by bodies such as the FDA, which increases compliance costs for manufacturers but also raises barriers to entry for less rigorous competitors. At the same time, the FDA's approval of ferulic acid usage in pharmaceutical formulations up to certain levels provides manufacturers with legal protection and stimulates product development in higher-margin therapeutic and nutraceutical contexts. The net effect is a bifurcated market where compliance capability becomes a competitive asset rather than a mere overhead expense. Companies that invest early in documentation, testing protocols, and quality management systems are better positioned to access premium channels, while those treating compliance as an afterthought risk exclusion from regulated supply chains.
Third, the market is experiencing a sourcing and purity divergence that is reshaping procurement behavior. Natural ferulic acid derived from agricultural byproducts is gaining traction in cosmetics and nutraceuticals, where clean-label positioning and traceable sourcing resonate with end consumers. Synthetic variants continue to serve applications where consistency, cost efficiency, and scalable supply are paramount. On the purity axis, high-purity material at 98 percent and above commands a disproportionate share of revenue compared with lower-purity grades, reflecting the premium that formulators place on performance reliability, color stability, and regulatory acceptability. This split creates strategic tension: producers must decide whether to compete on volume and cost in lower-purity tiers or to invest in purification capability, certification, and technical service to capture value in higher-purity segments.
Key Drivers Shaping the Market
Technological Innovation and Process Breakthroughs
Process innovation is a critical lever for expanding margins and unlocking new application potential. Extraction and purification technologies that improve yield from rice bran and wheat bran feedstocks directly reduce unit costs and improve the economic viability of natural ferulic acid. Advanced purification methods, including refined crystallization and chromatography-based approaches, enable manufacturers to consistently achieve high-purity specifications, which in turn opens doors to pharmaceutical and sensitive cosmetic formulations. These technical advances are not merely incremental; they alter the cost curve of the entire value chain, allowing producers to offer premium grades at prices that remain attractive to buyers who previously faced trade-offs between quality and affordability.
PW Consulting
In parallel, formulation science is expanding the functional scope of ferulic acid. Its antioxidant synergy with other ingredients, such as vitamins and UV filters, enhances product efficacy in personal care and cosmetics, reinforcing its appeal to brand owners seeking substantiated performance claims. As research continues to clarify stability profiles and delivery mechanisms, the compound's value proposition in topical applications strengthens, creating a virtuous cycle where better formulation outcomes drive greater demand, which in turn justifies further investment in supply quality.
Policy and Regulatory Environment
The regulatory landscape is moving from ambiguity toward structured acceptance, with meaningful implications for market participants. The FDA's stance on ferulic acid in pharmaceutical formulations, including approval for use up to specified levels, provides a clearer pathway for developers and reduces the regulatory risk associated with incorporating the ingredient into drug products. This legal certainty encourages research and development teams to explore ferulic acid in new therapeutic contexts, knowing that compliant use is definable and defensible. For manufacturers, this translates into a more predictable demand environment in the pharmaceutical segment, where formulation cycles are long but contract value and margin profiles can be substantial once approved products reach commercialization.
Simultaneously, food-grade regulations are raising the floor for quality. Meeting FDA-recognized quality standards for food applications increases compliance costs, but it also filters out under-resourced entrants and consolidates supply relationships around manufacturers with robust quality systems. The result is a market where regulation functions as a competitive filter: it adds cost, yes, but it also rewards those who treat quality infrastructure as strategic capability. Over the next several years, as regulatory expectations continue to crystallize across regions, the ability to provide traceable, well-documented material will become a prerequisite for access to premium buyers rather than a differentiator reserved for a few.
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, the most visible shift is the accelerating emphasis on clean-label and plant-derived ingredients in personal care and cosmetics. Consumers and brand owners alike are increasingly scrutinizing ingredient origin, sustainability credentials, and transparency. Ferulic acid sourced from rice bran and similar agricultural byproducts aligns well with these preferences, offering a narrative of upcycling and natural efficacy that resonates in marketing and product positioning. This demand-side pressure is not cosmetic; it influences procurement decisions, as formulators seek ingredients that support brand claims without compromising performance.
A parallel shift is occurring in pharmaceuticals and nutraceuticals, where the focus on antioxidant support, skin health, and metabolic wellness continues to expand the functional ingredient pipeline. In this context, ferulic acid's established antioxidant properties and growing body of application research make it a candidate for inclusion in formulations that target specific health and wellness outcomes. The demand here is less about consumer-facing branding and more about evidence-based functionality, which places a premium on purity, consistency, and regulatory compliance. Together, these demand-side trends are pulling the market in two complementary directions: one emphasizing natural origin and storytelling in cosmetics, the other emphasizing specification reliability and compliance in pharmaceutical and nutraceutical channels.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are reshaping where value accrues. Because rice bran and wheat bran are the primary upstream feedstocks, the economics of ferulic acid production are tied to agricultural commodity markets and the logistics of bran collection, storage, and processing. Volatility in these inputs affects production costs, but it also creates opportunities for players who can secure stable, cost-effective feedstock through regional partnerships, integrated processing facilities, or access to milling byproducts that would otherwise be underutilized. In effect, feedstock advantage is becoming a strategic moat, not just a procurement detail.
Cost structures are also evolving as manufacturers invest in higher-purity output and compliance infrastructure. The revenue skew toward 98 percent and above purity grades indicates that buyers are willing to pay for assurance, and that premium pricing can offset some of the cost burden associated with advanced purification and quality systems. For suppliers, the strategic question is whether to absorb these costs to gain access to higher-margin channels or to remain in lower-spec tiers where competition is more price-driven. The answer increasingly favors those who can couple technical capability with customer-facing service, such as formulation support, documentation packages, and reliable batch-to-batch consistency, because these elements turn a commodity ingredient into a value-added partnership.
Competitive Landscape and Leading Strategies
The competitive field in ferulic acid reflects a mix of regional specialization, sourcing heritage, and regulatory positioning. Tsuno Rice Fine Chemicals Co., Ltd., based in Wakayama, Japan, anchors its offering in rice bran-derived natural ferulic acid and related rice bran products used as source material for extraction into antioxidant ingredients for cosmetics and nutraceuticals. This positioning leverages a clear sourcing narrative and a heritage in rice bran processing, which can be compelling for buyers seeking traceable natural origin and a well-defined upstream story. The strategic implication is that Tsuno competes on provenance and specialty sourcing rather than on pure commodity scale, making its value proposition strongest in applications where ingredient origin carries commercial weight.
Vigon International, located in East Stroudsburg, Pennsylvania, USA, focuses on natural ferulic acid supplied for cosmetic formulations at greater than 98 percent purity. This combination of natural sourcing and high-purity specification targets a premium segment where formulators demand both clean-label alignment and performance reliability. The strategic logic is clear: by pairing natural origin with high purity, Vigon addresses a buyer need that sits at the intersection of marketing and functionality, allowing it to command attention in cosmetic supply chains that are increasingly discerning about both claims and specifications.
Spectrum Chemical Manufacturing Corp., based in Gardena, California, USA, offers ferulic acid powder meeting cGMP standards for pharmaceutical and research use. This positioning emphasizes quality systems and regulatory alignment, which are critical in pharmaceutical and research contexts where documentation, consistency, and compliant manufacturing practices are non-negotiable. Spectrum's strategy illustrates how compliance capability can serve as a market access key, enabling participation in higher-value channels where trust in quality is a prerequisite rather than a nice-to-have.
Indofine Chemical Company, situated in Belle Mead, New Jersey, USA, supplies ferulic acid for pharmaceutical, agricultural, and life science industries. This multi-sector orientation suggests a diversification strategy that spreads demand exposure across related verticals, reducing dependence on any single end-market while leveraging common quality and supply capabilities. Such diversification can stabilize revenue streams during cyclical shifts in any one sector, though it also requires the operational flexibility to serve differing specification and documentation requirements across industries.
On the natural ingredient side, Shaanxi LonierHerb Bio-Technology Co., Ltd., based in Xi'an, Shaanxi, China, provides natural ferulic acid as a herbal extract for food additives, cosmetics, and functional ingredients. This offering aligns with the broader trend of plant-derived ingredient demand and positions the company to serve buyers looking for herbal extract framing across multiple application categories. Similarly, Sichuan Benepure Pharmaceutical Co., Ltd., in Chengdu, Sichuan, China, offers ferulic acid as a botanical extract and active pharmaceutical ingredient for pharmaceutical, cosmetic, and nutraceutical applications. Benepure's dual framing as both botanical extract and API reflects an intent to span the gap between nutraceutical and pharmaceutical demand, which can be a powerful positioning if supported by appropriate quality and regulatory infrastructure.
Taken together, these players illustrate several patterns in the competitive landscape. First, sourcing origin and purity specification are central axes of differentiation. Companies that combine natural sourcing with high purity, or that pair compliance certifications with reliable supply, create defensible positions that are not easily replicated by generic producers. Second, there is a geographic spread that includes both established players in Japan and the United States and growing capabilities in China. This dispersion suggests that supply is not monolithically concentrated in one region, and that buyers have options based on their requirements for origin, certification, scale, and technical service. Third, the market is showing signs of both integration and specialization: larger or more diversified players can span multiple sectors and purity grades, while specialists can thrive by owning a narrow but valuable niche, such as cosmetic-grade natural ferulic acid at high purity or cGMP-compliant material for pharmaceutical use.
The evolution of the landscape is likely to continue along these lines. Incumbents with scale, certification, and long-standing customer relationships will seek to protect share by reinforcing quality credentials and expanding application support. New entrants and regional challengers will look for gaps where specific sourcing narratives, purity capabilities, or regulatory alignments can create entry points. Consolidation may occur where scale and compliance become increasingly decisive, particularly in pharmaceutical and food-grade channels, while fragmentation may persist in cosmetics and nutraceuticals where branding, origin, and specialized grades create room for multiple viable suppliers. The strategic winners are likely to be those who can articulate a clear value proposition along one or more of these axes and back it with consistent execution.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are poised to shape the ferulic acid market and create actionable commercial opportunities. The first trend is the deepening of high-purity demand as formulators across cosmetics and pharmaceuticals increasingly prioritize specification reliability. As products become more complex and claims more scrutinized, the tolerance for batch variability diminishes. Suppliers that can reliably deliver 98 percent and above purity, supported by robust documentation and consistent quality, will find expanded opportunities to serve as preferred partners rather than interchangeable sources. For businesses, this means that investments in purification capability, quality systems, and customer-facing technical support can translate into longer-term contracts and improved margin profiles.
Fumaric Acid Market
The second trend is the continued rise of natural and plant-derived positioning in cosmetics and nutraceuticals, amplified by clean-label consumer preferences and brand differentiation strategies. Ferulic acid sourced from rice bran and wheat bran is well placed to benefit from this trajectory, particularly where suppliers can provide traceable origin stories and substantiate sustainability or upcycling narratives. The commercial opportunity here lies not only in selling the molecule but in enabling brand owners to communicate value to end consumers. Suppliers that can package origin, purity, and technical performance into a coherent offering will be better positioned to capture premium demand than those competing solely on price.
The third trend is the gradual formalization of regulatory acceptance across applications, which is likely to reduce uncertainty and encourage product development in pharmaceutical and food contexts. The FDA's approval of ferulic acid usage in pharmaceutical formulations up to certain levels, alongside ongoing quality standard expectations for food-grade material, points toward a more structured environment where compliance capability becomes a market access determinant. For forward-looking businesses, this trend suggests that early investment in regulatory documentation, quality management, and application-specific testing can create a timing advantage as new formulations move from research to commercialization. The opportunity is to be an established, trusted supplier when demand materializes, rather than scrambling to qualify during a product launch window.
These trends are not without risks and uncertainties. Raw material volatility in agricultural feedstocks remains a persistent threat to cost stability, and any prolonged spike in bran prices could compress margins or trigger price resistance in sensitive segments. Regulatory environments can also shift, and while current signals are favorable, changes in quality expectations or jurisdictional requirements could raise compliance burdens unexpectedly. In addition, the growing interest in ferulic acid could attract new entrants, intensifying competition in specific grades or regions and pressuring pricing where differentiation is weak. Companies that rely on a single feedstock source, a single application channel, or a single geographic market may find themselves more exposed to these dynamics than those with diversified supply and demand bases.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to clarify which value axis to own and to invest accordingly. If the strategy is to compete in premium cosmetic or pharmaceutical channels, then high-purity capability, compliance infrastructure, and technical service should be treated as core assets rather than optional enhancements. If the strategy is to serve volume-driven segments, then securing stable, cost-effective feedstock through integrated or long-term supply relationships becomes the critical lever. In either case, it is advisable to avoid undifferentiated commodity positioning, because the market's revenue skew toward higher-purity grades and its increasing regulatory selectivity reward specificity. Manufacturers should also stress-test their cost models against raw material volatility and consider hedging strategies, regional diversification of feedstock sources, or byproduct integration to reduce exposure.
For investors evaluating opportunities in this space, the key is to distinguish between structural growth and cyclical pricing noise. The market's projected expansion through 2032, supported by demand in cosmetics, pharmaceuticals, and food and beverages, indicates a foundational growth trend rather than a transient surge. However, value creation will be uneven, and returns are likely to concentrate among players with clear differentiation in sourcing origin, purity, or compliance capability. Due diligence should therefore focus on the durability of a company's positioning: whether its sourcing advantages are defensible, whether its quality and regulatory infrastructure can support premium channels, and whether its customer relationships are based on specification and service rather than price alone. Monitoring regulatory developments, particularly around food-grade standards and pharmaceutical usage approvals, will also be important, as these factors can accelerate or constrain demand in specific segments.
For procurement and R&D leaders in cosmetics, pharmaceutical, and food and beverage companies, the strategic imperative is to treat ferulic acid sourcing as a partnership decision rather than a transactional purchase. Given the divergence between natural and synthetic offerings, and between lower- and higher-purity grades, procurement teams should align ingredient selection with product positioning, regulatory requirements, and performance needs. This means specifying not only the molecule but also the origin, purity, documentation package, and supply reliability that matter for the end application. Building relationships with suppliers that can provide consistent quality, clear traceability, and formulation support reduces the risk of downstream issues and strengthens the ability to make credible claims in marketing and regulatory contexts. It also pays to qualify multiple suppliers across different sourcing and purity profiles, so that supply strategies can adapt if feedstock costs shift or if application requirements evolve.
Across all these roles, timely access to detailed market intelligence remains a decisive advantage. The ferulic acid market is moving on multiple fronts at once, from feedstock economics and purification technology to regulatory acceptance and clean-label demand. Decisions made without a clear view of how these forces interact risk being reactive rather than proactive. More granular data on segment dynamics, purity-grade revenue splits, sourcing cost structures, and company-level positioning can sharpen strategy and reveal where to commit resources for the highest return. For those seeking a deeper, more customized view of the market, an expanded research report can provide the segmentation detail, competitive benchmarking, and scenario analysis needed to translate these high-level trends into concrete action plans.
For detailed analysis of this topic, please visit the official page: Ferulic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


