



Fuel Cell Electric Vehicles Market: Decoding 26.6% CAGR Growth Trajectory to 2032
By PW Consulting, 2026-09-21
Strategic Horizons: Navigating Commercial Opportunities in the Fuel Cell Electric Vehicle Market
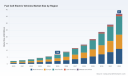
The fuel cell electric vehicle (FCEV) sector is entering a phase of accelerated expansion, driven by technological maturation and targeted policy support. Market valuation in the base year of 2025 reached 7.08 million USD, reflecting a compound annualized growth rate of 26.6 percent across the forecast horizon extending to 2032. This growth trajectory marks a decisive shift from early-niche adoption toward broader commercial deployment, with revenue projections scaling toward 37 million USD by the end of the decade. While passenger segments continue to refine hydrogen integration for range and efficiency, heavy-duty and logistics applications are increasingly anchoring demand, creating asymmetric opportunities across vehicle classes and operational profiles.
PW Consulting Automotive & Machinery Research Center
Defining the Competitive Arena
Market structure currently reflects moderate concentration, with the top three participants capturing roughly 48 percent of total activity and the leading five firms accounting for approximately 52 percent. This distribution suggests room for specialized entrants and regional specialists, particularly where localized infrastructure development or vertical integration creates defensible positions. Leadership is increasingly defined not by aggregate volume but by the ability to align fuel cell architecture, hydrogen sourcing, and operational economics around specific use cases. Companies that treat the stack as a modular component rather than a proprietary black box are gaining flexibility in scaling across passenger, commercial, and stationary applications.
Critical Inflection Points
Three structural challenges are reshaping how stakeholders should evaluate opportunity and risk in this space. The first concerns the pace of refueling network expansion relative to vehicle rollout. Without coordinated station development, adoption patterns risk becoming fragmented, limiting total addressable demand even as vehicle supply improves. The second challenge sits in cost parity, particularly for fuel cell stacks, balance-of-plant systems, and hydrogen procurement contracts. Progress is visible, but sustained reductions depend on manufacturing scale, material innovation, and standardized maintenance models that lower lifetime operating expenses. The third challenge relates to demand-side framing: buyers are weighing total cost of ownership, uptime reliability, and regulatory compliance rather than technology credentials alone, meaning that value propositions must be expressed in operational terms rather than technical specifications.
Key Drivers Reshaping the FCEV Opportunity Set
Technology Pathways and Performance Gains
Advances in stack durability, power density, and cold-start behavior are expanding the practical operating envelope for hydrogen vehicles. Integrated designs that pair fuel cells with buffer batteries are improving transient response and enabling short zero-emission electric ranges, which is particularly valuable for urban delivery, off-road cycles, and environments with access restrictions. These architectures also reduce the burden on hydrogen fueling during stop-start duty cycles, helping operators manage downtime and energy costs.
Recent product activity illustrates how manufacturers are translating these gains into customer-facing value. Honda began customer leasing of the 2025 CR-V e:FCEV through select California dealerships, combining a domestically produced fuel cell module with plug-in battery capability that delivers up to 29 miles of electric range alongside hydrogen refueling. This approach positions the vehicle as a flexible tool for fleets that need both emissions performance and operational resilience. Hyundai reinforced its passenger lineage by debuting an all-new NEXO at the 2025 Japan Mobility Show, previewing a production model that builds on more than two decades of fuel cell development. Meanwhile, BMW has signaled a series-production timeline targeted for 2028, indicating growing confidence in scaling fuel cell platforms beyond demonstration fleets.
Policy Architecture and Regulatory Tailwinds
Regulatory frameworks are increasingly used to channel investment toward specific decarbonization outcomes rather than blanket technology support. In California, the Air Resources Board's 2025 annual evaluation reported 14,128 FCEVs registered as of April 2025, alongside a first recorded year-over-year decline of 291 units. This inflection underscores the sector's transition from early growth momentum to a more measured phase where infrastructure readiness, vehicle availability, and buyer economics must align. At the same time, the evaluation projects a network of up to 112 stations capable of supporting as many as 16,210 FCEVs by 2028, framing the policy task as one of synchronized build-out rather than unconstrained expansion.
Broader industry coordination is reinforcing this direction. The 2025 Hydrogen and Fuel Cell Seminar highlighted commercialization strategies and latest FCEV products, with a notable emphasis on heavy-duty applications where emissions intensity and duty cycles make hydrogen particularly relevant. Policy alignment with decarbonization targets is encouraging fleet operators and equipment manufacturers to experiment with hydrogen in segments where battery-only configurations face practical constraints. The implication for decision-makers is that incentives and mandates are becoming more targeted, and success will depend on matching vehicle deployment to the specific regulatory and operational context of each market.
Demand-Side Behavior and Fleet Economics
Buyers are increasingly evaluating FCEVs through the lens of operational continuity, refueling time, payload capability, and total cost of ownership. In commercial settings, hydrogen's appeal lies in its ability to support long ranges and rapid replenishment without the charging downtime associated with battery-only vehicles, which is especially relevant for heavy-duty trucking, regional logistics, and high-utilization routes. Passenger buyers are weighing similar trade-offs, though their decisions are more sensitive to fuel availability, residual value, and the perceived convenience of the energy pathway. This divergence means that demand creation is uneven: some segments require infrastructure confidence before volume scales, while others can move faster where refueling access and fleet incentives are already in place.
Electric Vehicles and Fuel Cell Vehicles Market
Supply Chain and Cost Dynamics
Cost structures are evolving through a combination of manufacturing scale, component standardization, and hydrogen supply contracts. As fuel cell stacks and related subsystems move from bespoke engineering toward repeatable production, the economics of per-unit cost and service intervals improve. Hydrogen supply is equally important: long-term sourcing agreements, on-site generation where feasible, and logistics optimization can materially affect operating expenses. Companies that vertically coordinate stack production, vehicle integration, and fuel supply are better positioned to manage variability in input costs and to offer predictable service arrangements. Conversely, reliance on fragmented supply chains can expose operators to price swings and availability risk, particularly in early-adopter regions where demand spikes may outpace supply flexibility.
Competitive Landscape and Strategic Positioning
Differentiation Strategies Among Leading Players
Leadership in this market is increasingly articulated through platform strategy, application focus, and ecosystem partnerships rather than headline vehicle counts. Toyota continues to advance its Mirai passenger FCEV, emphasizing integrated hydrogen fuel cell technology and a refined passenger experience. The company's positioning reflects confidence in hydrogen for segments where range, refueling speed, and technology credibility matter, even as it navigates the realities of limited refueling access in some markets. Hyundai has expanded its footprint across both passenger and commercial domains, with the Xcient heavy-duty FCEV and the Nexo passenger vehicle illustrating a dual-track strategy that targets high-utilization commercial demand alongside consumer adoption. This breadth allows Hyundai to apply learning from one segment to another, particularly where stack durability and operational data can be cross-leveraged.
Honda has adopted a modular and flexible approach by combining a U.S.-made fuel cell module with plug-in battery capability in the CR-V e:FCEV, supporting both hydrogen refueling and short electric range. This dual-energy configuration broadens the vehicle's usability and reduces dependence on any single refueling event, which is attractive for early adopters in areas where hydrogen availability is still developing. BMW's focus on series production targeted for 2028 signals an emphasis on manufacturing discipline and product readiness, suggesting a strategy built around scalable architecture rather than limited demonstration runs. Collectively, these positions point to a market in which differentiation is increasingly about how well a company integrates technology, supply, and customer use cases.
Market Evolution and Consolidation Dynamics
The competitive field is likely to evolve through a mix of consolidation, specialization, and selective entry. Established automakers are strengthening their positions through platform investments and product cadence, while component suppliers and hydrogen-focused companies are exploring opportunities to enter at the system, fueling, or service layer. In commercial applications, there is growing potential for partnerships that bundle vehicles, hydrogen supply, and maintenance into integrated offerings, reducing friction for fleet buyers and improving lifetime economics. At the same time, regional disparities in infrastructure and policy create natural fragmentation, where local champions may emerge around specific corridors, ports, or logistics hubs. The result is a landscape where broad scale and localized execution both matter, and where successful players will need to manage multiple business models simultaneously.
Recent events reinforce this multi-speed environment. California's latest evaluation highlights both the maturity of the current registration base and the urgency of expanding the station network to sustain further growth. The FCEV seminar circuit continues to serve as a venue for sharing commercialization strategies and product developments, indicating that the industry is moving from concept discussion to deployment detail. As these dynamics mature, companies that can align product timing with infrastructure milestones and customer readiness will gain an advantage over those that rely solely on technology leadership without considering the operating environment.
Forward Outlook: Trends and Risk Factors for 2026-2030
Trend One: Application-Led Growth in Commercial Heavy-Duty Segments
Heavy-duty and commercial applications are expected to play an outsized role in shaping demand over the next several years. The operational characteristics of long-haul routes, port operations, and high-utilization delivery cycles make refueling time, payload retention, and range reliability especially valuable, which aligns well with hydrogen's strengths. This trend suggests that commercial segments will not only drive volume but also provide the utilization data and service models needed to lower costs and refine stack design. For businesses, the opportunity lies in identifying routes and duty cycles where hydrogen offers a clear total-cost advantage and in structuring supply and maintenance arrangements that reduce operational uncertainty.
Trend Two: Infrastructure Synchronization as a Growth Determinant
Vehicle availability will increasingly need to be matched with station expansion and hydrogen supply reliability. As deployment scales, operators and buyers will scrutinize station uptime, geographic coverage, and pricing consistency, since these factors directly affect fleet planning and consumer confidence. Regions that coordinate station planning with vehicle rollouts and fleet incentives are likely to see faster adoption and more stable economics, while areas where supply and demand develop unevenly may experience slower momentum. This trend elevates the strategic importance of partnerships between vehicle manufacturers, fuel suppliers, and infrastructure developers, as well as the value of standardized operating practices that improve reliability across sites.
Trend Three: Modular Architectures and Dual-Energy Configurations
The integration of fuel cells with buffer batteries and plug-in capability is likely to become more common, offering flexibility in how energy is used across different driving conditions. Such architectures can improve transient performance, support short electric-only operation, and reduce dependence on frequent hydrogen refueling in mixed-use scenarios. This trend also opens the door to more adaptable business models, where vehicles can be configured for specific routes or customer preferences without sacrificing core fuel cell performance. The trade-off is complexity in design and service, so the winners will be those who manage modularity without compromising durability or maintenance simplicity.
Risk Considerations
Several uncertainties could shape the pace and distribution of growth. Infrastructure expansion may lag vehicle availability in some markets, constraining demand even where technology and policy support are strong. Hydrogen pricing and supply reliability remain sensitive to production methods, transport logistics, and contract structures, which can affect operating economics for both fleets and individual buyers. Policy environments may also shift as jurisdictions refine incentives and compliance mechanisms, creating variability in the timing and scale of demand. Finally, competition from battery-electric alternatives in chosen segments could pressure hydrogen's role in passenger applications, making it more important to anchor the value proposition in use cases where hydrogen offers clear differentiation.
Actionable Strategic Recommendations for Decision-Makers
For Vehicle Manufacturers and System Suppliers
Align product planning with the rhythms of infrastructure development and fleet readiness rather than pursuing volume in isolation. Prioritize applications where refueling time, range, and uptime translate into measurable operational advantages, and use those deployments to gather durability data and refine service models. Consider modular or dual-energy architectures that broaden customer appeal in early-adopter markets while preserving a clear core fuel cell value proposition. Build partnerships that connect stack production, vehicle integration, and hydrogen supply, since coordinated offerings can improve economics and reduce buyer friction. Monitor regions where station networks and policy frameworks are converging, and stage product introductions to coincide with practical refueling access rather than projected but unverified capacity.
Hydrogen Vehicle Market
For Investors and Capital Allocators
Evaluate exposure across the value chain with a focus on segments where utilization and total cost of ownership most favor hydrogen. Commercial heavy-duty applications, regional logistics corridors, and integrated fuel-and-service models present opportunities where operating economics can be validated more quickly than in broad passenger markets. Assess companies on the strength of their supply agreements, manufacturing scalability, and ability to manage service intervals, since these factors increasingly determine margin stability and customer retention. Be attentive to policy timing and infrastructure milestones, because demand in early markets can be highly sensitive to station availability and incentive structures. Diversify across complementary positions, including component suppliers, fuel logistics providers, and application-focused integrators, to capture value from different layers of the ecosystem.
For Fleet Operators and Procurement Leaders
Structure procurement around operational confidence and total cost rather than vehicle specifications alone. Prioritize routes and duty cycles where hydrogen's refueling speed, range, and payload characteristics deliver measurable benefits, and pilot deployments in areas with reliable fueling access. Negotiate long-term hydrogen supply terms and service arrangements that reduce variability in operating expenses and downtime. Use early deployments to collect data on fuel consumption, maintenance needs, and vehicle availability, then feed those insights into broader fleet planning. Where feasible, coordinate with multiple stakeholders to strengthen local station coverage and supply reliability, since improved infrastructure benefits not only a single fleet but the entire demand environment.
The Value of Targeted Intelligence
Success in this market depends on reading the interaction between technology, policy, infrastructure, and buyer economics in real time. Broad trends provide direction, but the details that matter most—station rollout timing, supply contract structures, stack durability outcomes, and application-specific economics—require focused analysis. Decision-makers benefit from access to segmented data and scenario-based guidance that connects market movement to operational choices, whether that means sizing a commercial pilot, sequencing product launches, or evaluating where capital will be most efficiently deployed. As the landscape continues to evolve, timely and granular intelligence becomes a practical tool for reducing uncertainty and improving execution.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stabilizer Bar Market 2032 Outlook: How 5.3% CAGR and Asia Pacific Demand Are Reshaping Competition
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Automotive Stabilizer Bar Market
The global automotive stabilizer bar market has demonstrated sustained expansion over the past half-decade, transitioning from a mature commodity component space into a strategically sensitive segment where weight, durability, and active damping performance directly influence vehicle platform competitiveness. Revenue crossed the $3.6 billion threshold in 2025 and is projected to reach $5.2 billion by 2032, reflecting a compound annual growth rate of 5.3 percent. The trajectory is not a straight line; it is shaped by platform electrification, tightening safety and emissions standards, raw material volatility, and a fragmented yet consolidating supplier landscape. For executives and investors, the market is no longer about volume alone. It is about aligning product architecture, sourcing strategy, and regional manufacturing footprint with where vehicle architectures are heading.
The growth profile shows a steady climb through 2025, followed by a noticeable inflection after 2028 as electrification and lightweighting programs mature across multiple vehicle segments. A brief plateau in 2030 hints at pricing pressure, platform transitions, or regional demand normalization, before acceleration resumes through 2032. This pattern underscores a market that is cyclical but structurally expanding, where short-term turbulence masks long-term demand shifts tied to vehicle mix and regulatory endpoints.
Market Status and Core Challenges
The stabilizer bar market today operates at the intersection of cost discipline and performance differentiation. Suppliers compete on material grade, hollow versus solid architecture, surface treatments, and integration with active or semi-active damping systems. The component itself is well understood, yet the value pool is shifting toward engineered variants that help OEMs meet stricter rollover and handling targets without adding mass or sacrificing durability.
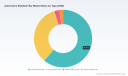
Three challenges define the current turning point. First, the transition to electric vehicle platforms is changing suspension loading patterns and component packaging constraints. Battery weight alters roll dynamics, which increases the importance of stabilizer bar geometry, material selection, and joint design, but it also compresses available packaging space and introduces new durability targets for continuous high-torque scenarios. Second, raw material exposure remains a persistent margin risk. Steel stabilizer links and related components continue to hold a dominant share of the material mix at 72.1 percent in 2025, reflecting mature manufacturing processes and broad applicability. At the same time, aluminum-based solutions are gaining traction in lightweight programs, yet aluminum prices fluctuate 15 to 25 percent annually based on global supply-demand dynamics and geopolitical factors affecting mining and refining operations. This volatility complicates multi-year sourcing agreements and pressures cost planning for both solid and hollow designs.
Third, regulatory pressure is rewriting component priorities. European Euro 7 regulations drive continuous suspension system innovation, including lightweight and smart stabilizer link designs, while EU emissions regulations targeting 93.5 g CO2/km average fleet emissions by 2025 accelerate the adoption of lightweight suspension components. The result is not a regulatory burden in isolation; it is a design constraint that rewards suppliers capable of delivering weight reduction without compromising NVH, corrosion resistance, or fatigue life. Companies unable to engineer around these constraints face margin compression or displacement by more adaptive competitors.
Key Drivers of Market Change
The market is being reshaped by four interconnected drivers: technology innovation, regulatory direction, demand-side behavior, and supply chain cost structures. Each driver influences not just volume, but where margin and differentiation are created.
Technology innovation is moving the segment beyond generic passive bars. Active damping variants, hollow architectures for weight savings, and high-strength steel or aluminum grades are becoming standard expectations for premium and performance platforms. Recent product activity illustrates this shift. In March 2025, thyssenkrupp Automotive Technology launched a new high-strength aluminum stabilizer bar series designed specifically for electric vehicles, signaling a direct response to the weight and packaging demands of electrified powertrains. In April 2025, Federal-Mogul LLC introduced a new line of corrosion-resistant stabilizer bars with advanced surface treatment for harsh climates, addressing durability concerns in markets where road salt, humidity, and extreme temperatures shorten service life. These launches show that value is shifting toward application-specific engineering rather than commodity production.
Stabilizer Bars Market
Policy and regulation amplify the need for engineered solutions. Euro 7 and fleet CO2 targets are not one-time compliance events; they are continuous pressure points that encourage lightweighting, smarter link designs, and improved suspension tuning to reduce emissions indirectly through weight savings and efficiency gains. In practical terms, regulations reward designs that lower unsprung mass, improve handling without additional energy consumption, and extend component life to reduce replacement frequency. Suppliers that align their roadmaps with these requirements can position themselves as enablers of compliance rather than victims of it.
On the demand side, consumer and fleet behavior is bifurcating. Passenger vehicles continue to represent the larger share of demand, but commercial vehicles remain strategically important because stabilizer durability, corrosion resistance, and load capacity matter more heavily in sustained-duty applications. The broader trend is that automakers are increasing model variant complexity while tightening platform commonality, which means stabilizer bar programs must be flexible enough to serve multiple derivatives without incurring redundant tooling costs. Meanwhile, performance-oriented buyers and aftermarket channels continue to reward reinforced or specialized bars, creating parallel demand streams that do not always track OEM cycles.
Supply chain and cost structure changes are the fourth driver. The combination of steel’s continued dominance and aluminum’s price volatility creates a strategic sourcing dilemma: lean into mature steel processes for reliability and cost predictability, or move toward aluminum and hybrid designs for weight and performance at the risk of exposure to price swings. The answer increasingly depends on region, vehicle segment, and program volume. Geopolitical factors affecting mining and refining operations add another layer of uncertainty, making dual sourcing, localized production, and inventory buffers more relevant for long-cycle programs.
Competition Dynamics and Leader Strategies
The competitive field is moderately concentrated, with the top three firms holding roughly 32.5 percent and the top five holding 45.2 percent of the market. This concentration suggests a landscape where scale and regional presence matter, but specialization and application expertise can still create defensible niches. The leading players are not merely selling bars and links; they are competing on integration capability, material engineering, and proximity to OEM development cycles.
ZF Friedrichshafen AG stands out for integrated offerings spanning solid and hollow stabilizer bars and links, including active damping variants for passenger and commercial vehicles. Its strategic move to form a joint venture with Wolong Electric Group Co., Ltd. to manufacture electric motors for driveline and stabilizer systems indicates an intention to embed stabilizer technology deeper into electrified platform architecture. The signal is clear: stabilizer systems are increasingly connected to driveline and energy management strategies, and suppliers that can bridge mechanical and electromechanical domains may capture more value.
Mubea Group continues to emphasize precision manufacturing across passenger cars, light trucks, and commercial vehicles, a positioning that suits customers seeking consistent tolerances and reliability across diverse vehicle types. Kongsberg Automotive and Sogefi Group both serve OEM integration in passenger cars and light commercial vehicles, with Sogefi extending into heavy-duty applications where durability and load capacity carry greater weight. These profiles illustrate a broader split between generalists with integrated portfolios and specialists with deep segment knowledge.
thyssenkrupp AG adds a differentiated angle through lightweight aluminum and high-strength steel variants, targeting OEMs that need weight reduction without sacrificing strength. ADDCO Manufacturing Company and SwayTec focus on performance-oriented and aftermarket applications in the U.S., where polymer bushings and reinforced designs address durability and handling in both standard and specialty use cases. Tinsley Bridge Group rounds out the landscape by serving OEM and aftermarket passenger and commercial vehicle suspension, showing that dual-channel strategies can buffer against OEM cycle volatility.
Worldwide Automotive Stabilizer Bar Link Market
Recent developments reinforce the directions already visible in product roadmaps. The JV between ZF and Wolong in November 2025 points toward electrification-driven integration, while the U.S. Defense Logistics Agency procurement solicitation in December 2025 for stabilizer bars under a fleet sustainment set-aside signals that durable, serviceable components remain relevant in government and specialty fleet contexts. These events show that the market is not only commercial; it also includes institutional demand channels where specification, traceability, and longevity matter as much as price.
Strategic implications differ by positioning. Integrated players are leveraging cross-component engineering and electrification partnerships to capture more system value. Lightweight specialists are betting that aluminum and high-strength steel will become more central as emissions and efficiency targets tighten. Aftermarket and performance-focused companies are differentiating through application tuning, corrosion resistance, and reinforcement, where brand trust and fitment accuracy can command premiums. The broader trend is a mix of consolidation among players seeking scale and platform leverage, alongside fragmentation in niches where specialized materials, regional service needs, or performance characteristics create barriers to generic competition.
Future Outlook and Commercial Opportunities
Over the next three to five years, three trends are likely to shape where value concentrates. The first is the accelerating integration of lightweight materials with suspension architecture, especially in electric and hybrid platforms. As battery mass and packaging constraints continue to reshape vehicle dynamics, hollow stabilizer bars, aluminum variants, and high-strength steel grades will see increased adoption in programs where weight savings directly support range, handling, and packaging goals. The commercial opportunity lies in offering modular designs that can be tuned across derivatives without excessive tooling duplication, allowing OEMs to scale lightweight solutions across multiple nameplates.
PW Consulting
The second trend is rising demand for corrosion-resistant and climate-adapted components. Advanced surface treatments and material selections that withstand harsh climates are becoming differentiators not only for durability but also for warranty costs and brand reputation. For suppliers, this creates an opening in regions with severe winter conditions, coastal environments, or heavy-duty service cycles, where premium coatings and treatment processes can command higher margins and reduce total cost of ownership for fleets and consumers alike.
The third trend is the gradual move toward smarter and more integrated suspension components, particularly in higher-tier platforms. Active damping variants and parametrically tuned links are unlikely to become universal, but they will expand in premium passenger cars and selected commercial applications where handling precision and occupant experience are central to positioning. The opportunity here is for suppliers that can integrate stabilizer technology with electronic control strategies, sensor feedback, or modular linkage designs, provided they can manage increased complexity and validation costs.
These trends come with risks. Aluminum price swings can erode the economics of lightweight designs if hedging, sourcing, or design flexibility is insufficient. Regulatory endpoints may shift, altering the pace of lightweighting mandates and the relative attractiveness of certain material choices. Platform consolidation by automakers can reduce the number of discrete programs, making volume concentration a double-edged sword. Finally, electrification introduces durability unknowns for components under continuous high-torque and altered load patterns, which can surface late in a program if validation and testing are rushed. Companies that treat these risks as design and sourcing parameters rather than external shocks will be better positioned to protect margins.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align material and architecture roadmaps with where vehicle platforms are moving. That means investing in hollow and aluminum-capable processes where volume and program mix justify them, while maintaining strong steel-based offerings for cost-sensitive and heavy-duty applications. It also means building corrosion-resistant and climate-adapted variants as standard options rather than custom exceptions, since durability expectations are rising across regions. Developing integration capabilities, including active or semi-active damping elements and link designs that support modular platforms, will help capture more value from OEMs seeking to reduce component count and simplify assembly.
For investors, the most relevant signal is that growth is shifting toward engineered differentiation rather than pure volume expansion. Companies with strong material engineering, regional manufacturing flexibility, and evidence of integration into electrified or lightweight platform programs are better placed to defend margins through raw material volatility and regulatory change. Attention should also be paid to dual-channel players that balance OEM programs with aftermarket or specialty fleet demand, since these channels can cushion program concentration risk. Monitoring recent strategic moves such as electrification-linked partnerships and procurement activity in institutional channels can provide early indications of where demand will intensify.
For procurement and sourcing leaders, the key is to treat stabilizer bar sourcing as a risk-managed engineering decision rather than a commodity purchase. Evaluating suppliers on corrosion resistance, tolerance consistency, material flexibility, and regional production capability can reduce downstream warranty and service issues. Where programs are exposed to aluminum price volatility, structured sourcing with hedging options, dual material strategies, or configurable designs can preserve cost predictability without sacrificing performance targets. In fleet and institutional contexts, durability, traceability, and sustainment support may outweigh lowest initial price, making total lifecycle cost the more relevant evaluation frame.
The market’s next phase will reward companies that can translate regulatory pressure, electrification-driven packaging constraints, and material volatility into practical product architectures and sourcing strategies. Detailed segment data, regional demand patterns, material mix modeling, and customized company benchmarking can sharpen those decisions further. PW Consulting’s full research report provides a deeper breakdown of regional demand trends, type and application dynamics, and supplier positioning to support more precise planning and investment choices.
For detailed analysis of this topic, please visit the official page: Automotive Stabilizer Bar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheel Balancer Market: How 4.1% CAGR and Regional Shifts Redefine Competition
By PW Consulting, 2026-09-21
Wheel Balancer Market: Strategic Trends and Commercial Opportunities in a Maturing Industry
The global wheel balancer market has entered a phase of steady, structurally supported expansion. Between 2020 and 2025, industry revenue climbed from approximately $183.0 million to $242.0 million, reflecting consistent demand across aftermarket service networks, fleet maintenance operations, and dealership service bays. Looking ahead to 2032, the market is projected to reach roughly $320.0 million, translating to a compound annual growth rate of approximately 4.1 percent over the forecast period. While the trajectory is unspectacular in headline terms, the underlying dynamics reveal a sector undergoing meaningful technological and operational transformation. For executives, investors, and procurement leaders, the opportunity lies not in chasing volume growth alone, but in understanding where efficiency, precision, and regulatory alignment are reshaping competitive positioning.
The current landscape reflects a mature but evolving equipment category. Wheel balancing has transitioned from a purely mechanical calibration task to a digitally assisted, automation-friendly process that directly impacts service throughput, tire longevity, and vehicle safety compliance. Producers and service operators alike are responding to tighter workshop margins, skilled labor constraints, and rising customer expectations for faster, repeatable results. At the same time, the market is not immune to friction points. Supply chain volatility for precision components, uneven adoption of advanced balancing technologies across regions, and the cost of integrating new automation features create real barriers for mid-tier manufacturers and independent shops. These pressures are not temporary disruptions; they are structural conditions that will define which players capture margin expansion and which remain trapped in price competition.
One of the most pressing challenges is the tension between automation momentum and workforce realities. Service centers face persistent technician shortages and rising labor costs, yet retrofitting older balancing equipment or training staff on hands-off systems requires capital and change management that many operators delay. A second challenge centers on standardization and compliance complexity. Workshop equipment must navigate overlapping safety and quality frameworks, and balancing accuracy is increasingly tied to mandatory periodic technical inspections in multiple jurisdictions. Operators that treat balancing as a discretionary service risk losing credibility with fleet buyers and inspection-dependent customers. A third challenge lies in product differentiation. As baseline balancing performance becomes table stakes, manufacturers must demonstrate measurable gains in changeover speed, error reduction, or fleet-level vibration control without pushing prices beyond what service operators can justify through labor savings. These challenges create a clear inflection point: the next cycle of growth will reward companies that align product design, service workflows, and compliance readiness rather than those that compete solely on unit price.
Key Drivers Reshaping the Wheel Balancer Market
Technology Innovation and Precision Automation
The most visible driver of market evolution is the shift toward automation and sensor-enhanced precision. Modern wheel balancers are increasingly designed to reduce manual intervention, compress cycle times, and standardize results across operators with varying experience levels. Hands-off inflation, automatic weight detection, and integrated tire-changing workflows are no longer niche 프리미엄 features; they are becoming central to high-volume service economics. Recent product introductions illustrate this direction. In October 2025, Hunter Engineering Company introduced a Road Force WalkAway wheel balancer with an automatic hands-off inflation system that reduced four-tire changeover times by up to 45 percent, and the same platform was demonstrated alongside an integrated Revolution tire changer at SEMA Show 2025. Around the same period, ARI-Hetra launched a heavy-duty line featuring Tri-Sensor Technology and LCD displays aimed at improving workshop precision. These developments signal a broader industry move toward closed-loop balancing processes where measurement, correction, and verification are tightly integrated.
For service operators and equipment buyers, the strategic implication is straightforward: automation is being evaluated less as a convenience and more as a labor multiplier. Shops that can standardize balancing output while reducing technician fatigue gain advantages in throughput, consistency, and customer trust. For manufacturers, the challenge is to ensure that advanced features translate into demonstrable operational savings rather than added complexity or maintenance burden. The market is therefore rewarding platforms that combine intuitive interfaces, reliable sensor performance, and seamless integration with adjacent tire service equipment.
Policy and Regulatory Environment
Regulatory and safety standards are increasingly shaping purchasing decisions and equipment design. Workshop equipment, including wheel balancers, operates under a framework of occupational safety, product certification, and quality management expectations that vary by region but converge on the same principle: balancing accuracy and operator protection are non-negotiable. Mandatory periodic technical inspections under systems such as TÜV and MoT regulations reinforce the need for accurate wheel balancing as part of vehicle safety compliance. At the same time, OSHA, CE, and ISO standards continue to influence how tire handling equipment is specified, installed, and maintained in professional environments.
This regulatory layer is not merely a compliance checkbox; it is a market filter. Fleet managers, dealership groups, and regional service chains are more likely to standardize on equipment that aligns with recognized safety and quality expectations because it reduces audit exposure, simplifies technician training, and supports consistent inspection outcomes. For manufacturers, regulatory alignment has become a competitive differentiator, especially in markets where inspection regimes are tightening and where service providers must demonstrate repeatable, documented balancing performance.
Wheel Weight Market
Demand-Side Shifts in Aftermarket and Fleet Service
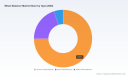
Demand for wheel balancing is being reshaped by changes in how vehicles are maintained and how service time is valued. Passenger vehicle segments continue to represent the largest application share, driven by high vehicle parc, frequent tire rotations, and consumer sensitivity to ride quality and tire wear. Commercial vehicle operations, while smaller in volume terms, are expanding their reliance on advanced balancing solutions because fleet downtime, fuel efficiency, and vibration-related component wear carry direct operational costs. In both segments, the value proposition is shifting from balancing as a standalone service to balancing as part of a broader efficiency and safety workflow.
Fleet adoption is particularly telling. IMI Products received approval from UPS for its Equal FLEXX wheel balancer under the 2026 Tire Solutions Program following a two-year field evaluation with over 10,000 assemblies. This type of endorsement matters because it moves balancing technology from theoretical benefit to validated operational performance in a high-mileage, cost-sensitive environment. Fleet buyers are increasingly willing to evaluate internal adaptive balancing systems and other specialized solutions when they can tie them to measurable outcomes such as vibration reduction and fuel efficiency improvements. The broader lesson for the market is that demand is becoming more evidence-driven, and suppliers that can document real-world performance will have an advantage in both fleet and high-volume aftermarket channels.
Supply Chain and Cost Structure Dynamics
Cost structure and supply chain resilience remain critical underlying drivers. Precision balancing equipment depends on reliable sourcing of sensors, electronics, machining components, and durable mechanical assemblies. Inflationary pressure on materials, lead-time variability, and the cost of integrating digital features can compress margins for manufacturers and raise total cost of ownership for buyers. At the same time, rising labor intensity in service environments is changing how total costs are evaluated. Service operators are increasingly comparing the upfront price of a balancer against its impact on technician utilization, rework rates, and service cycle time.
This shift is pushing both sides of the market toward more holistic cost assessments. Manufacturers that can stabilize production, reduce dependency on fragile component pathways, and design equipment that is easier to service and calibrate gain credibility with buyers who are managing both capex and opex constraints. For purchasers, the decision framework is moving toward lifecycle value: equipment that lowers labor intensity, reduces error-related rework, and supports faster turnaround can justify a higher initial investment. In a market where labor shortages and throughput demands are persistent, cost discussions are increasingly anchored in operational efficiency rather than sticker price alone.
Competitive Landscape and Leading Strategies
The wheel balancer market is characterized by a moderately concentrated competitive structure, with the top three players holding roughly 45 percent of market share and the top five accounting for about 55 percent. This concentration suggests that established manufacturers retain significant influence over product standards, channel relationships, and customer expectations, while still leaving meaningful space for regional specialists and integrated equipment providers. The leadership group reflects a mix of long-standing diagnostic and heavy-duty balancer expertise, broad tool and equipment portfolios, and manufacturers that emphasize vibration analysis, alignment compatibility, or fleet-specific internal balancing technologies.
PW Consulting
Hunter Engineering Company continues to reinforce a leadership position centered on diagnostic-grade balancing and workflow integration. Its focus on automatic inflation, hands-off procedures, and integrated tire changer demonstrations points to a strategy built around reducing changeover time and standardizing results in high-throughput environments. Coats Company LLC has carved a strong position in heavy-duty direct drive balancing, targeting high-volume tire service operations where durability, speed, and repeatability are paramount. Snap-on Incorporated leverages its broader professional tool footprint to serve high-volume shop use, aligning wheel balancers with a wider ecosystem of workshop equipment and service reliability expectations. CEMB S.p.A. brings a garage and truck-oriented perspective, with product emphasis on vibration analysis integration and touchless alignment compatibility, which positions it well in markets where multi-function workshop efficiency matters. IMI Products differentiates through internal adaptive balancing systems designed for fleet truck tires, focusing on vibration reduction and fuel efficiency improvements rather than conventional external balancing alone. Balance Group represents a more integrated equipment approach, offering wheel balancers within a broader tyre service equipment lineup that spans car, motorcycle, truck, and heavy-duty wheels, appealing to operators seeking unified sourcing and service compatibility.
These differing strategic positions reveal how the market is fragmenting by use case while still rewarding clear differentiation. Leadership is no longer defined solely by balancing accuracy in isolation; it is increasingly defined by how well a product fits into a specific operating model. Heavy-duty commercial service providers value durability and throughput. Fleet operators value documented operational outcomes. Dealership and high-volume aftermarket shops value speed, consistency, and integration. Manufacturers that can articulate and deliver a distinct workflow advantage are better positioned than those offering generic balancing capability.
The competitive landscape is also evolving through a combination of consolidation pressure and targeted new entry. Larger players benefit from scale, channel reach, and the ability to invest in automation and compliance-driven design, but they must navigate the complexity of serving diverse segments without diluting their value proposition. Smaller or regional manufacturers can compete by focusing on specific vehicle classes, localized service support, or integrated equipment bundles that reduce procurement friction. At the same time, new entrants that bring novel sensor architectures, improved display and user-interface design, or fleet-validated internal balancing concepts can gain traction if they address a clearly defined operational pain point. The overall trend points toward a market where differentiation is increasingly tied to workflow fit, validated performance, and total cost of ownership rather than brand familiarity alone.
Future Trends and Strategic Implications
Over the next three to five years, the wheel balancer market is likely to be shaped by three interconnected trends. The first is the deepening integration of automation and workflow standardization. As service operators continue to face labor constraints and throughput pressure, equipment that minimizes manual steps, reduces changeover variability, and supports repeatable results will become increasingly central to shop economics. This trend will likely accelerate the adoption of hands-off balancing features, integrated tire service workflows, and easier calibration routines, especially in high-volume environments. The commercial opportunity here lies in equipment and service models that help operators quantify labor savings, reduce error-related rework, and maintain consistent output across different technicians and shifts.
The second trend is the growing importance of fleet-validated and application-specific solutions. As fleet managers and commercial operators look for tangible gains in vibration control, tire life, and fuel efficiency, internal adaptive balancing and heavy-duty precision systems are likely to receive stronger evaluation and adoption in targeted segments. This creates an opportunity for manufacturers to build credibility through field trials, documented performance data, and partnerships with large fleet programs. It also suggests that generic balancing claims will face greater scrutiny, while solutions backed by operational evidence will command stronger consideration in commercial and high-mileage applications.
The third trend is the continued alignment of equipment purchasing with regulatory and inspection-driven compliance expectations. As periodic technical inspection regimes and workshop safety standards remain influential, balancing accuracy and equipment reliability will stay closely tied to service credibility and operational risk management. Manufacturers and service providers that proactively design for compliance, documentation, and consistent performance will be better positioned to win standardized contracts, dealership network agreements, and fleet maintenance programs. The related risk is that operators who underinvest in balancing quality or rely on outdated equipment may face growing inconsistency in inspection outcomes, technician training burdens, and customer trust.
These trends carry both opportunity and uncertainty. On the opportunity side, the market is moving toward clearer value metrics: cycle-time reduction, labor efficiency, vibration-related performance, and compliance readiness. Providers that can connect product capabilities to these outcomes are more likely to capture premium positioning and repeat business. On the risk side, adoption pace may vary by region and shop size, and the cost of upgrading equipment or retraining staff can slow momentum for smaller operators. Additionally, if automation features become widespread without meaningful differentiation, competition could shift back toward price, squeezing margins for manufacturers that fail to sustain a distinct workflow advantage. The most resilient strategies will therefore combine technological relevance with practical evidence, clear segmentation, and a credible pathway to total cost reduction for the buyer.
Worldwide Wheel Balancer With Touchscreen Market
Actionable Recommendations for Decision Makers
For manufacturers and product strategists, the priority is to sharpen differentiation around workflow outcomes rather than balancing performance alone. This means designing for measurable labor savings, integrating balancing with adjacent tire service steps where it improves throughput, and ensuring that automation features are easy to adopt, maintain, and calibrate. Companies should also invest in field-validated documentation, especially for commercial and fleet applications, because evidence of vibration reduction, fuel efficiency improvement, or assembly-level consistency can become a decisive factor in procurement decisions. Finally, maintaining regulatory and safety alignment as a core design principle will help reduce friction in inspection-heavy markets and in standardized service networks.
For investors and strategic planners, the most relevant signal is that growth in this market is likely to be earned through efficiency and application fit rather than broad-based volume expansion. Opportunities may be strongest in companies that serve high-volume aftermarket and fleet workflows, offer clear automation advantages, and have product lines aligned with commercial vehicle and heavy-duty needs. At the same time, caution is warranted where product portfolios lack segmentation clarity, where automation claims are not tied to operational savings, or where supply chain and service support are weak. Evaluating total cost of ownership, channel strength, and the credibility of field performance data will be more informative than relying on headline market growth alone.
For procurement leaders and service operators, the practical imperative is to evaluate balancing equipment as a productivity investment rather than a commodity purchase. Selection criteria should include changeover speed, repeatability across technicians, integration with existing tire service workflows, and the availability of service support and calibration resources. Where fleet or commercial vehicle use is significant, internal adaptive systems and heavy-duty solutions deserve structured evaluation against documented operational outcomes. Operators should also consider how equipment choices affect inspection readiness, technician training burden, and long-term service consistency, since these factors increasingly influence overall workshop economics.
For decision makers seeking a deeper understanding of segment-level demand patterns, regional variations, pricing dynamics, and company-specific competitive positioning, the full research report provides the detailed breakdown needed to support planning and procurement decisions. It offers a more granular view of how product types, application segments, and regional markets interact, along with customized guidance for aligning equipment strategy with operational goals. Accessing that level of detail can help teams move from broad market awareness to targeted action, especially when evaluating new product roadmaps, fleet adoption programs, or service-shop upgrade cycles.
For detailed analysis of this topic, please visit the official page: Wheel Balancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isononyl Alcohol Market: Why 5.55% CAGR Changes Everything Through 2032
By PW Consulting, 2026-09-21
Isononyl Alcohol Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The isononyl alcohol market has matured into a cornerstone of specialty chemical supply chains, anchored by consistent growth in plasticizer and surfactant applications. Valued at approximately $1.5 billion in 2025, the market has expanded steadily over the past half-decade, with historical revenues climbing from $1.2 billion in 2020 to current levels. Forecasts indicate a continued upward trajectory, projecting revenues to surpass $2.1 billion by 2032 at a compound annual growth rate of 5.55 percent. This growth pattern reflects both cyclical demand recovery and structural shifts toward higher-performance, non-phthalate intermediates.
Behind the headline figures, the industry confronts several pivotal challenges that will shape competitive positioning over the next decade. The first is the tension between cost efficiency and sustainability compliance. As regulatory frameworks tighten and end-use customers demand verified circular sourcing, producers must justify capital expenditures for bio-based feedstocks, traceable supply chains, and certified manufacturing processes without sacrificing margin performance.
The second challenge lies in demand concentration and substitutability risk. A significant share of isononyl alcohol consumption flows into plasticizer formulations, where formulation engineers continuously evaluate alternatives such as alternative oxo alcohols, bio-derived esters, and phosphate-based systems. Suppliers cannot rely on legacy volume assumptions; they must demonstrate differentiated performance, regulatory readiness, and supply reliability to retain share in evolving formulations.
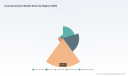
The third challenge is geographic and capacity imbalance. Production capacity remains clustered among a handful of integrated manufacturers, while demand growth is accelerating in regions with expanding PVC processing, personal care manufacturing, and industrial lubricant consumption. New capacity additions in East Asia and Southeast Asia are reshaping supply dynamics, but they also intensify competition for feedstock access, logistics optimization, and customer qualification. These pressures create a market where incumbents must defend margins through operational excellence and sustainability credentials, while newer entrants seek footholds through technology licensing, strategic partnerships, and targeted application specialization.
Key Demand Drivers
Several interconnected forces are steering the market’s direction, and each carries distinct implications for sourcing strategies, capacity planning, and product development.
Technological Innovation and Process Differentiation
Advancements in oxo synthesis and hydroformylation continue to redefine quality parameters and cost structures. Modern catalyst systems, improved isomer control, and integrated downstream purification enable producers to deliver higher-purity grades suitable for sensitive applications, including specialty esters and electronics-adjacent formulations. Process refinements also support narrower specification ranges, which matter for downstream formulators seeking consistent plasticizer performance and reduced variability in surfactant blends. Manufacturers that pair process reliability with flexible grade portfolios are best positioned to capture premium segments and reduce the cost of customer qualification.
A parallel wave of innovation centers on sustainability-linked production. Certification frameworks and circular sourcing commitments are moving from optional differentiators to operational requirements. Recent certification activity at major production sites signals that sustainable sourcing and circular economy compliance are becoming embedded in commercial offerings rather than remaining aspirational. For buyers and partners, this shifts the conversation from whether a supplier can provide certified material to how consistently it can do so across volumes and geographies.
Regulatory and Compliance Evolution
Regulatory oversight remains a decisive factor in formulation choices and supply chain design. Registration and compliance documentation for isononyl alcohol underpin its continued use in plasticizers and related applications, giving formulators confidence in long-term availability. At the same time, the broader regulatory environment is nudging the market away from traditional phthalate architectures and toward alternatives that preserve performance while meeting evolving safety and environmental expectations. This does not eliminate isononyl alcohol’s role; rather, it reinforces its position as a versatile intermediate when paired with compliant manufacturing practices and transparent documentation.
The practical impact is twofold. First, compliance readiness becomes a competitive asset, particularly for suppliers serving multiple jurisdictions with differing registration and traceability requirements. Second, the regulatory trajectory encourages investment in grades and processes that can adapt to reformulated end products, reducing the risk of stranded capacity as customer specifications change.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by formulation trends in plastics, personal care, and industrial lubricants. In plasticizer applications, the push toward non-phthalate and high-performance alternatives sustains interest in isononyl alcohol as a building block for DINP and related systems, especially where flexibility, durability, and processing characteristics remain critical. In personal care and fragrance-adjacent uses, formulators are seeking emollient ingredients that offer consistent skinfeel and stability, driving niche but high-value demand for specialty grades. Lubricant applications add another layer of demand resilience, as industrial and automotive segments pursue formulations that balance performance with extended drain intervals and efficiency goals.
These demand-side shifts reward suppliers that can offer application-specific grades, technical support, and reliable lead times. The market is increasingly less about commodity volume alone and more about the ability to match grade attributes to formulation requirements, which in turn supports more stable pricing and deeper customer relationships.
Supply Chain and Cost Structure Dynamics
Cost structures are influenced by feedstock availability, energy pricing, and the geographic distribution of production assets. Integrated producers with access to reliable olefin streams and efficient hydroformylation operations hold a structural advantage in managing input cost volatility. At the same time, regional capacity additions are altering logistics patterns, with new facilities positioned to serve fast-growing demand centers and reduce freight exposure for local customers.
Capacity expansion announcements, including large-scale projects utilizing established technology licenses, indicate that supply will continue to broaden in key regions. These developments can improve availability and create competitive price tension, but they also place a premium on qualification speed, supply consistency, and technical service. In practical terms, the cost equation is no longer determined solely by feedstock prices; it increasingly reflects the value of certified continuity, grade flexibility, and regional proximity to demand.
Competitive Landscape and Leading Strategies
The market features a concentrated group of global manufacturers alongside regional specialists and new capacity entrants. Leading firms differentiate through a combination of process technology, grade breadth, certification readiness, and application-focused commercial support. Their strategic positioning offers a useful lens for understanding where value is being created and how the landscape is likely to evolve.
Strategic Positioning of Core Players
German-based producers have strengthened their standing by combining integrated oxo alcohol capabilities with a focus on sustainability certification and application breadth. One major manufacturer operates isononyl alcohol production tied to its C4 chemicals platform, supplying plasticizer and surfactant grades through hydroformylation of C8 olefins, and has reinforced its sustainability positioning through certification valid through mid-2026. Another industry leader leverages partnership structures and its own facilities to serve plasticizer applications at scale, supported by ongoing regulatory compliance documentation that facilitates use across multiple markets.
Specialty oxo intermediates producers have built reputation on grade consistency and global distribution, offering both plasticizer and specialty chemical grades that serve diverse formulation needs. In the United States, large chemical companies provide isononyl alcohol through established oxo processes at major complexes, with emphasis on DINP and high-purity plasticizer applications. One North American supplier focuses on specialty esters and non-phthalate plasticizer supply, aligning its offering with shifting formulation preferences. In Asia, integrated producers with large complexes supply PVC plasticizer grades for domestic and export markets, benefiting from regional demand growth and logistics advantages.
Additional players contribute to the landscape through portfolio breadth and targeted application focus. A Swedish producer offers isononyl alcohol within a broader C8-C10 oxo alcohol portfolio for plasticizers and lubricants, while a Japanese manufacturer supports high-purity grades for electronics and automotive uses through licensed oxo processes. A South African producer supplies the chemical within its oxo alcohol portfolio for plasticizer and surfactant applications. Most recently, a major Chinese refining and chemical company has moved to build a world-scale isononyl alcohol facility using licensed technology, with startup targeted for 2026, signaling a meaningful addition to regional supply.
Isononanoic Acid Market
Differentiation Themes and Competitive Advantages
Across these players, differentiation converges on a few recurring themes. Process control and grade purity are foundational, particularly for customers in sensitive applications where specification consistency reduces downstream risk. Sustainability certification and traceable sourcing are increasingly weighted in supplier selection, especially where end customers require documented circular economy alignment. Commercial agility matters as well: producers that can balance large-volume plasticizer supply with specialty grades and provide technical support are better equipped to retain customers during formulation changes.
Regional presence and logistics efficiency also shape advantage. Suppliers with production assets close to fast-growing demand centers can reduce lead times and freight exposure, while those with global distribution networks can serve multinational customers more consistently. Finally, technology licensing and partnership models are enabling new capacity to enter the market with established process knowledge, accelerating scale-up and reducing execution risk relative to wholly custom development paths.
PW Consulting
Evolving Market Structure
The competitive structure is gradually shifting from a purely incumbent-centric model to one that balances established scale with targeted new entry. On one side, large incumbents are defending their positions through certification, application focus, and integration benefits. On the other, new capacity in Asia and Southeast Asia is expanding regional supply and intensifying competition for both volume and specialty demand. This does not necessarily imply a race to the bottom; rather, it suggests a market where differentiation narrows the field. Customers are likely to consolidate spending with suppliers that can demonstrate reliable certification, consistent grade quality, and strong technical support, while price competition intensifies in commoditized segments.
Over time, this dynamic may encourage further consolidation among smaller players lacking scale or certification readiness, while rewarding those that can combine capacity with application expertise. The emergence of large, licensed facilities also raises the importance of customer qualification pipelines and long-term supply agreements, as new volumes must be absorbed into established formulation ecosystems.
Worldwide Isononyl Acrylate Market
Forward Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define the market’s trajectory and open practical opportunities for aligned businesses.
Sustainability-Linked Supply as a Commercial Baseline
Certified, traceable production is expected to move from advantage to baseline expectation in many customer segments. As procurement teams embed sustainability criteria into supplier evaluation, producers with valid certifications and documented circular sourcing will face lower barriers to qualification and retention. Commercial opportunities here include premium-grade offerings that pair performance with compliance, long-term supply arrangements that reward certified continuity, and regional partnerships that reduce the logistical footprint of sustainable supply. The risk is that capability gaps in certification or traceability could limit access to certain customer segments, especially where end-market requirements are stringent.
Grade Specialization and Application-Focused Targeting
The market is likely to reward narrower, application-specific grade strategies over undifferentiated volume plays. In plasticizer formulations, high-purity and performance-tuned grades will remain important where formulators seek predictable processing and end-product characteristics. In personal care, fragrance, and lubricant applications, specialty grades that meet specific sensory, stability, or efficiency requirements can command stronger positioning. Businesses that invest in grade flexibility, technical service, and customer co-development are better placed to capture value in these segments. The uncertainty lies in the pace of formulation change: if alternative chemistries gain traction faster than expected in certain applications, suppliers must be ready to adapt grade portfolios without overcommitting to legacy demand assumptions.
Regional Capacity Rebalancing and Supply Chain Reconfiguration
New capacity additions in East Asia and Southeast Asia will continue to reshape supply geography, creating opportunities for regional price competitiveness, faster service, and reduced logistics risk for nearby customers. For buyers, this can translate into more options for local sourcing and improved resilience. For suppliers, it raises the stakes in qualification speed, distribution capability, and customer relationship depth. The risk is that rapid capacity additions could create temporary oversupply in specific regions or grades, pressuring margins unless offset by demand growth or differentiated offerings. Strategic positioning will depend on aligning capacity with demand centers while maintaining cost discipline and certification readiness.
Actionable Guidance for Decision-Makers
Different stakeholders face distinct priorities, but a few strategic actions apply broadly and can help convert market trends into tangible outcomes.
-
Manufacturing and supply leaders should prioritize certification continuity and grade flexibility as core commercial assets. Maintaining valid sustainability certification, strengthening documentation for regulatory compliance, and expanding the ability to supply application-specific grades can improve qualification speed and customer retention. Where possible, align production and logistics with regional demand growth to reduce lead times and freight exposure.
-
Investors and corporate development teams should evaluate opportunities through the lens of differentiation rather than scale alone. Capacity additions that pair licensed process technology with sustainability credentials and application focus are more likely to secure qualified demand than undifferentiated volume projects. Attention to customer qualification pipelines, regional demand timing, and downstream formulation trends can materially affect the risk-adjusted returns of new capacity or partnership investments.
-
Procurement and sourcing professionals should build supplier evaluation frameworks that weigh certified continuity, grade consistency, and technical service alongside price. In a market where regulatory compliance and sustainability documentation are increasingly important, multi-source strategies that include both scaled incumbents and regionally positioned suppliers can improve resilience. For critical applications, securing long-term arrangements with suppliers able to demonstrate stable certification and consistent specifications can reduce disruption risk and support formulation stability.
The isononyl alcohol market is entering a phase where growth is real but value capture depends on execution quality. Sustainability certification, grade specialization, regional supply strategy, and application-focused technical support are becoming central to competitive success. Businesses that treat these elements as strategic priorities, rather than operational afterthoughts, will be better positioned to navigate demand shifts, regulatory evolution, and new capacity entry.
For organizations seeking deeper segmentation data, regional demand profiles, and customized scenario analysis, PW Consulting’s full market research report provides detailed breakdowns and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Isononyl Alcohol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Forging Presses Market 2026-2032: Inside the 4.3% CAGR and $281M Expansion
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Forging Presses Market
Market Overview and Core Challenges
The global forging presses market has demonstrated resilient, steady growth over the past half-decade, expanding from approximately 145.78 million USD in 2020 to an estimated 208.45 million USD in 2025. This trajectory reflects an underlying compound annual growth rate of 4.3 percent through the forecast period ending in 2032, when revenues are projected to reach 280.9 million USD. The market's expansion is not explosive, but it is structurally supported by fundamental industrial needs: the transformation of raw metal into high-strength, precision-shaped components remains indispensable across transportation, energy, and manufacturing sectors. Growth is being shaped less by cyclical surges and more by a steady accumulation of capacity upgrades, modernization programs, and the gradual migration toward higher-value forming technologies.
A defining characteristic of the current landscape is the widening gap between mature regional markets and those experiencing accelerated industrial investment. North America and Europe continue to anchor significant portions of market value, but Asia Pacific has emerged as the dominant geographic contributor to total market size, reflecting large-scale manufacturing expansion, infrastructure development, and growing domestic demand for forged components across automotive, heavy equipment, and industrial machinery supply chains. Latin America and the Middle East and Africa represent smaller but strategically relevant pockets of activity, often tied to localized industrial policy, resource-based manufacturing, and targeted capital projects. This geographic distribution is reshaping how equipment suppliers think about regional service footprints, localized support, and the balance between standardized offerings and region-specific configuration requirements.
Beneath the growth narrative, three structural challenges are redefining competitive dynamics and forcing strategic recalibration among manufacturers and end-users alike.
Fragmented Value Chains and Regional Capacity Gaps
While aggregate market figures suggest orderly growth, the underlying supply chain remains uneven. Many forging operations face bottlenecks in sourcing high-quality dies, specialized auxiliary equipment, and integrated automation modules. These gaps are not merely procurement inconveniences; they create execution risk for large press installations and complicate delivery timelines for operators trying to align new capacity with production schedules. The result is a market in which vendors capable of bundling presses with dies, handling systems, and control integration are gaining an advantage over those offering machine-only solutions. For end-users, this fragmentation raises the stakes of vendor selection, because the total installed capability of a forging line now depends on more than the press itself.
Energy Intensity and Efficiency Mandates
Forging presses are energy-intensive assets, and environmental as well as operational pressures are pushing the industry toward measurable efficiency gains. Regulatory expectations and internal sustainability targets increasingly require facilities to adopt technologies that deliver substantial reductions in energy consumption relative to conventional systems. This shift is not simply a compliance exercise. It is becoming a financial and operational differentiator, especially in regions where electricity costs, carbon exposure, or industrial energy policies are tightening. Presses that can recover kinetic energy, modulate power delivery more precisely, or integrate hybrid hydraulic-electric architectures are moving from niche innovation to practical necessity for operators seeking lower operating costs and greater production predictability.
Cold Forging Machine Market
Labor Constraints and Automation Pressure
Another persistent challenge is the availability of skilled labor for press operation, die setup, and process supervision. In several major forging markets, workforce constraints are accelerating investment in automation, digital control systems, and tool-less changeover strategies that reduce dependence on specialized manual intervention. This trend is reshaping equipment requirements: buyers are increasingly prioritizing press platforms that can integrate easily with automated material handling, in-process monitoring, and adaptive control logic. At the same time, the transition introduces a new form of complexity. Automation is not automatically plug-and-play, and the value of a press investment increasingly depends on how well it fits within a broader digitized production environment rather than on raw tonnage or stroke speed alone.
Key Drivers Shaping Market Evolution
The market's growth and direction are being pulled by a small set of powerful drivers that reinforce one another. These forces are not isolated trends; they interact to create pressure on legacy designs, reward certain technology pathways, and influence where capital is deployed next.
Mechanical Presses Market
Technology Innovation in Press Architecture and Energy Recovery
One of the most significant enablers of market change is the ongoing refinement of press architectures. Mechanical, hydraulic, and servo-based systems continue to coexist, but the competitive center of gravity is shifting toward designs that combine performance with lower energy input and greater process flexibility. Advanced systems now incorporate energy recovery mechanisms, hybrid drive configurations, and more responsive control architectures that allow manufacturers to run higher stroke rates while reducing waste heat and idle power draw. These innovations are not merely engineering achievements; they have commercial implications. They expand the range of applications that can be economically served by a single press platform, improve consistency in closed-die and open-die operations, and help manufacturers justify capital expenditure in an environment where operating cost and sustainability performance are under closer scrutiny. Recent large-scale installations illustrate how these technologies are moving from pilot demonstrations into production use. A major global press supplier recently began production on what is described as the world's largest forging press equipped with a kinetic energy recovering system, signaling that energy recovery is being engineered into high-capacity assets rather than treated as a retrofit concept. Around the same time frame, another delivery highlighted a full hybrid hydraulic-electric press achieving meaningful energy reduction at an automotive facility, reinforcing the point that hybrid drive strategies are becoming commercially relevant for Tier-1 production environments.
Policy, Regulation, and Industrial Modernization Directives
Policy and regulatory frameworks are increasingly shaping technical expectations and investment timing. Energy efficiency mandates are pushing forging operations to incorporate technologies that deliver substantial consumption reductions compared with conventional systems, and these requirements are influencing both new equipment selection and retrofit strategies. In parallel, industrial modernization programs in several regions are encouraging capacity upgrades that emphasize automation, digital traceability, and process consistency. Forging press suppliers are responding by designing products that align more closely with compliance-related performance targets while also supporting broader modernization goals such as reducedManual intervention, better repeatability, and higher throughput stability. This regulatory and policy context matters because it affects not only whether a press is purchased, but what specifications are considered acceptable in the first place, and how quickly operators are willing to replace or augment older equipment.
Demand-Side Shifts in Automotive and Aerospace Production
Demand patterns from end-use sectors remain central to market direction. Automotive production continues to exert strong pull on forging demand, driven by the need for structural components, safety-critical parts, and lightweighting initiatives that still rely on forged geometries for strength-to-weight performance. Aerospace and related high-integrity applications also contribute meaningfully, where material properties, tolerance control, and process reliability are especially important. These sectors share a common orientation: they are not simply buying tonnage; they are buying predictable quality, repeatable process windows, and the ability to integrate forging into broader automated production flows. As a result, demand-side behavior is shifting toward suppliers and press configurations that can support higher volumes without sacrificing control, and that can demonstrate clear pathway to lower scrap, reduced rework, and tighter process adherence. The commissioning of a fully automatic closed-die forging press at a chain manufacturing operation in China illustrates how high stroke-rate automation is being applied to production environments that prioritize throughput and consistency, a pattern that is likely to become more common as manufacturers pursue cost efficiency and capacity utilization.
Supply Chain Restructuring and Cost Dynamics
Cost structures across the forging ecosystem are being reshaped by material usage patterns, labor economics, and the broader push toward integrated solutions. Carbon steel remains the dominant raw material basis in forging due to its balance of cost and strength, which keeps material sourcing and scrap management central to operational economics. At the same time, labor shortages in forging operations are encouraging greater reliance on automated press systems and digital controls to reduce personnel constraints. Together, these factors are nudging the market toward a model in which total cost of ownership, uptime, and process automation are weighed more heavily than initial purchase price. For suppliers, this means that value propositions are increasingly tied to integration, service responsiveness, and the ability to help customers manage energy, labor, and throughput simultaneously. For buyers, the implication is that the most competitive offer may not be the one with the lowest headline price, but the one that reduces operational drag over the asset's life cycle.
Competitive Landscape and Leading Strategies
The forging press market is competitive, but it is not perfectly consolidated. The top three competitors hold roughly 30 percent of market share, while the top five account for approximately 35 percent. This concentration suggests a landscape in which scale and reputation matter, yet substantial room remains for specialized players, regional experts, and firms that differentiate through technology, application focus, or integration capability. The competitive field is populated by a mix of established Western manufacturers, European technology leaders, Japanese equipment developers, and U.S.-based specialists serving a range of mechanical, hydraulic, warm-hot, and servo press applications.
Strategic Positioning Among Leading Players
A useful way to read the competitive field is by the strategic emphasis each group brings to the market. Some manufacturers have carved out strong identities around custom hydraulic solutions for open-die and closed-die applications, positioning themselves as flexible problem-solvers for customers with non-standard tonnage, configuration, or process requirements. These firms compete on engineering responsiveness, application-specific design, and the ability to adapt a press to the customer's production intent rather than selling a purely standardized machine. Other players focus on standard and custom hydraulic hot forging presses with high tonnage capabilities, appealing to customers who need large-scale forming capacity and want a defined technical baseline with room for customization. Still others extend their portfolios across mechanical, hydraulic, and servo technologies, often as part of broader industrial groups, which allows them to offer cross-technology guidance and to match press type to the production rhythm and process constraints of a given application. In parallel, some suppliers emphasize mechanical and servo press solutions for high-volume production, where speed, repeatability, and integration with automated lines are especially valuable. There is also a meaningful segment of firms that supply forging presses and related industrial forming equipment while positioning themselves as practical partners for metal forming operations, often competing on responsiveness, service support, and regional availability. Finally, a separate tier of custom hydraulic and servo press specialists supports extremely large forming requirements, giving high-tonnage customers access to tailored solutions that go beyond common commercial configurations.
The strategic takeaway is that competition is increasingly multidimensional. While tonnage, brand heritage, and machine class still matter, differentiation is being redefined by how well a vendor can align press technology with energy performance, automation readiness, application-specific process control, and delivery of a complete forming solution. The companies that appear best positioned are those that can articulate a clear technical identity while still offering enough flexibility to meet varying customer requirements across regions and end-use sectors.
PW Consulting
Recent Developments as Indicators of Direction
Recent activity among leading equipment suppliers offers a window into where the market is heading. One of the most notable signals is the growing emphasis on energy recovery and hybrid drive technologies in flagship installations. The start of production on a world-scale forging press featuring kinetic energy recovery, and the delivery of a hybrid hydraulic-electric press with documented energy reduction, both point to a direction in which efficiency is being designed into major assets at the engineering level rather than added later. Another important indicator is the successful commissioning of a fully automatic closed-die forging press achieving high stroke rates at a manufacturing site in China, which reflects the market's accelerating interest in automation, throughput maximization, and integrated closed-die forming capability. Participation in industry technical conferences and exhibitions also remains relevant, as it signals continued investment in customer engagement, technology demonstration, and ecosystem visibility. Taken together, these developments suggest that the competitive dialogue is shifting from machine capability alone toward integrated performance, energy behavior, automation compatibility, and the ability to execute complex installations in demanding production environments.
Market Evolution: Consolidation, Fragmentation, and New Entry
Looking ahead, the competitive structure is likely to evolve along several paths at once. Consolidation pressure exists at the top, where larger, globally capable suppliers can leverage breadth of technology, after-sales networks, and the ability to serve multinational customers with consistent standards. At the same time, fragmentation persists at the regional and application level, where local expertise, shorter decision cycles, and specialized configurations can create durable niches. New entry and repositioning are also possible, especially for firms that bring credible expertise in servo drive technology, energy-efficient press design, or integrated automation packages. The market is not simply moving toward a winner-takes-all structure; it is moving toward a layered competitive environment in which global scale, regional presence, and technology differentiation each create distinct forms of advantage.
Future Outlook and Strategic Opportunities
Based on current market data and visible technology and demand trajectories, three trends stand out as particularly important for the next three to five years.
Efficiency as a Core Buying Criterion
Energy performance is expected to move from an important attribute to a core buying criterion for many forging press purchases. The combination of efficiency mandates, operating cost pressure, and demonstrated hybrid and energy-recovery solutions is likely to make energy behavior a more explicit part of procurement evaluation. For commercial strategy, this creates opportunities for suppliers that can quantify energy savings, demonstrate compatibility with existing facility constraints, and offer solutions that do not sacrifice forming performance. It also creates an opportunity for operators to align equipment selection with broader cost-reduction and sustainability goals, especially where press replacements or major upgrades are already on the horizon. The uncertainty here lies in how quickly different regions and customer segments translate efficiency expectations into purchasing behavior, and whether standardized efficiency benchmarking becomes common enough to simplify comparisons across competing press technologies.
Automation-Integrated Press Platforms
A second major trend is the continued migration toward press platforms designed for integration with automated material handling, in-process monitoring, and adaptive control. The push comes from labor constraints, throughput ambitions, and the desire for more consistent process outcomes. Over the next several years, the most attractive press solutions are likely to be those that can function as part of a coordinated production system rather than as isolated mechanical assets. This opens commercial opportunities for vendors that can offer smoother integration pathways, clearer automation interfaces, and support for faster changeovers and lower manual dependency. For end-users, the opportunity is to reduce variability and increase asset utilization, but the risk is that automation ambition outpaces the readiness of the surrounding process, maintenance, and skills infrastructure. The market will likely reward customers and suppliers that treat automation as a system-level decision, not just a machine feature.
Regional Demand Divergence and Application Specialization
A third trend is the widening of regional demand profiles and the corresponding value of application specialization. While the market as a whole is growing at a moderate pace, demand intensity varies by region and by end-use sector. Areas experiencing broad industrial expansion are likely to drive higher volumes of standard and semi-custom equipment demand, while more mature markets may focus on replacement, modernization, and higher-value specialized forming capabilities. In parallel, applications in automotive, aerospace, and high-integrity industrial components are likely to continue supporting demand for presses that can deliver strong process control and repeatable quality. This environment favors suppliers and service strategies that can tailor offerings to regional realities and application-specific requirements. It also creates a risk: companies that rely too heavily on a single market or a single application may be exposed if local investment cycles shift or if sector demand patterns change faster than expected.
Actionable Guidance for Decision Makers
For manufacturers evaluating forging press strategy, the most important move is to align equipment selection with the operational priorities that will matter most over the asset's life. That means weighing energy performance, automation compatibility, service availability, and application fit alongside tonnage and price. Manufacturers should also consider whether a press platform can support future needs such as hybrid drive upgrades, better process monitoring, or integration with material handling without requiring a full replacement later. Suppliers and producers that take a total-cost and process-consistency view are more likely to emerge with installations that perform well under real production conditions rather than only under ideal specification conditions.
For investors, the opportunity lies in identifying the segments where technology differentiation, automation readiness, and regional demand alignment create durable advantages. The market's moderate overall growth does not mean uniform opportunity; value is likely to concentrate around vendors and end-users that can demonstrate measurable efficiency gains, serve high-integrity applications, or integrate press assets into broader automated production systems. Investors should also watch for signs of competitive repositioning around energy recovery and hybrid technologies, since these areas appear to be moving from demonstration to deployment. As with any industrial equipment sector, execution risk, installation complexity, and regional demand variability should be factored into any opportunity assessment.
For procurement and operations leaders, the priority is to treat press procurement as a systems decision. Transparency around energy consumption, automation interfaces, maintenance demands, and changeover complexity should be part of the evaluation process, not optional add-ons. Procurement teams should also seek evidence that proposed solutions have been validated in similar application environments, and they should ensure that vendor capabilities extend beyond equipment supply to include support for integration, commissioning, and ongoing performance optimization. In a market where operating constraints and workforce realities increasingly shape outcomes, the strongest purchasing decisions are likely to be those that balance technical capability with long-term operational practicality.
The forging presses market is not defined by sudden disruption, but by a steady accumulation of technology, efficiency, automation, and regional demand shifts that are reshaping what buyers expect and what suppliers must deliver. For decision makers who need to move beyond high-level market size figures and understand segment-specific dynamics, competitive positioning, and application-driven demand patterns, deeper market intelligence can make the difference between a reasonable capital plan and a strategically robust one. More detailed breakdowns, company-level profiles, and segment-focused scenario analysis are available in the full research report, where the broader macro context is translated into actionable detail for specific business decisions.
For detailed analysis of this topic, please visit the official page: Forging Presses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Induction Cooktop Market: How 5.6% CAGR and Asia Pacific Demand Reshape 2032
By PW Consulting, 2026-09-21
Induction Cooktop Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global induction cooktop market has entered a period of sustained expansion, with total industry revenue climbing from USD 10.2 billion in 2020 to an estimated USD 23.6 billion in 2025. The trajectory reflects a compound annual growth rate of 5.6 percent through 2032, a pace that signals structural rather than cyclical momentum. By the end of the forecast window, revenue is projected to approach USD 34.7 billion, driven by a steady shift in residential and commercial kitchens away from traditional gas and coil electric surfaces. This growth is not uniform across all segments, however. The market is increasingly shaped by diverging regional adoption curves, pricing pressure in entry-level categories, and a competitive field where the top three players control roughly 36 percent of revenue and the top five hold approximately 45 percent.
For executives and investors watching the sector, the headline numbers obscure several inflection points that will determine who captures value in the coming years. First, the transition from early-adopter households to mainstream consumers has exposed gaps in installer readiness, electrical infrastructure, and consumer education. Many retrofit projects stall because older homes lack the dedicated circuits or panel capacity required for high-wattage induction surfaces. Second, the commercial segment is growing but faces a distinct set of hurdles: kitchen operators must reconcile higher upfront equipment costs with labor savings, ventilation reductions, and heat-load benefits that are not always straightforward to quantify in a single payback period. Third, the supply chain for core components, particularly ceramic glass and induction coils, remains concentrated in a small number of sourcing regions, creating vulnerability for manufacturers who have not diversified or stocked strategic inventory.
These challenges are not insurmountable, but they do require a more granular approach to product planning, channel strategy, and risk management. Companies that treat induction as a simple swap-in replacement for gas or electric cooktops will likely underinvest in the installation support, warranty structures, and total-cost messaging that mainstream buyers and commercial operators need.
Stainless Steel Cookware Market
Key Drivers Shaping the Market
Technology Innovation and Breakthroughs
Induction cooktops are no longer defined solely by speed and efficiency. Recent product introductions demonstrate a clear push toward surface durability, granular temperature control, and outdoor applications that extend the technology beyond the indoor kitchen. A March 2026 launch introduced a matte finish engineered to reduce visible scratches by a factor of five, directly addressing one of the most common consumer objections to glass-ceramic surfaces. In August 2025, a premium brand unveiled a temperature-controlled induction cooktop that had earned recognition at a major kitchen and bath industry show, signaling that precision cooking features are becoming a differentiator rather than a niche luxury. Earlier, in February 2025, the industry saw the first built-in outdoor induction cooktop capable of precise control across a 150°F to 450°F range, opening a new use case for patios, restaurants with open-air concepts, and multi-zone residential setups.
These innovations matter because they broaden the addressable market. Scratch-resistant surfaces reduce the perceived maintenance burden for families and high-traffic commercial kitchens. Fine-grained temperature control supports culinary outcomes that appeal to passionate home cooks and professional chefs alike. Outdoor-capable units create opportunities in markets where gas infrastructure is restricted, costly, or undesirable from a safety and air-quality standpoint. For manufacturers, the strategic implication is clear: the next wave of volume growth will come from features that solve practical pain points, not from raw wattage alone.
Policy and Regulatory Environment
Government and utility initiatives are steadily reshaping the economics of adoption. In June 2025, the Global LEAP Awards released a buyer's guide for induction cooktops designed to help governments and manufacturers identify high-quality, energy-efficient models. This kind of curated reference material lowers the search cost for procurement teams and public-sector buyers who may otherwise hesitate without trusted benchmarks. Meanwhile, regional incentive programs are beginning to put direct financial support behind residential upgrades. A program effective from January 2026 offers rebates of up to $500 for ENERGY STAR certified induction cooktops, a meaningful reduction that can tip the decision for price-sensitive households.
PW Consulting
On the efficiency front, public messaging from the U.S. Department of Energy continues to emphasize that induction appliances can be up to 10 percent more energy-efficient than conventional electric smooth-top ranges and roughly three times more efficient than gas stoves. This narrative is increasingly relevant in markets where building codes, climate targets, and indoor air-quality concerns are converging. The practical effect is twofold: policy support reduces the effective price gap for consumers, and regulatory alignment gives manufacturers a more predictable demand environment in which to plan production and channel investment.
Demand-Side Shifts in Consumer and Commercial Behavior
The demand story is more nuanced than a single narrative of electrified kitchens. In residential settings, the strongest pull comes from buyers who value faster heating, cooler surrounding surfaces, and easier cleanup, alongside a growing segment motivated by indoor air quality and lower ambient heat in the kitchen. In commercial environments, the value proposition leans on operational factors: reduced ventilation requirements, lower cooling loads, and precise heat modulation that can improve consistency and reduce waste. Commercial adoption is still being calibrated, however, because the equipment cost premium and the need to retrain staff on new workflows can slow rollout even when the operational case is sound.
What unites these demand shifts is a move from abstract efficiency claims to concrete, task-specific benefits. Consumers and operators respond faster when the message is tied to a daily experience—how quickly a pot comes to a boil, how little residual heat remains on the surface, how little smoke or combustion byproduct lingers in the room. Marketing and sales teams that can translate technical performance into these everyday outcomes are gaining an edge in conversion.
Supply Chain and Cost Structure Dynamics
Component sourcing remains a strategic pressure point. Ceramic glass and induction coils used in cooktops are still largely imported from China, a concentration that exposes manufacturers to shipping volatility, tariff uncertainty, and lead-time risk. The practical consequence is that cost structures can shift quickly when trade conditions tighten or when demand spikes outpace available capacity. Companies that rely on single-source or just-in-time logistics for critical components face the greatest exposure, especially during product launches or seasonal demand surges.
The cost story is not purely a risk factor; it also creates a differentiation opportunity. Manufacturers that secure multi-region sourcing, build buffer inventory for key inputs, or invest in supplier partnerships with clearer quality and delivery commitments can stabilize margins and protect launch timelines. In a market where premium surface coatings, temperature-control electronics, and outdoor-rated components are becoming more common, the ability to reliably source and integrate these elements is increasingly part of the competitive formula.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of large appliance majors and specialized commercial players, each with a distinct route to value. GE Appliances markets a full line of induction cooktops, including a profile series built around precision control and connected features, positioning the brand at the intersection of performance and smart-home integration. Samsung Electronics brings Flex Zone and power boost technologies to the table, emphasizing flexible zoning and rapid heating for efficient home cooking. Miele & Cie competes in the premium tier with an emphasis on durability and long-term reliability, a positioning that resonates with buyers who view the cooktop as a long-lived kitchen investment. Whirlpool Corporation spans multiple brands, leveraging JennAir, KitchenAid, and Whirlpool to cover a wide price and style spectrum while offering advanced temperature control and wipe-clean surfaces.
Electrolux Group, through Frigidaire, focuses on surface engineering, most notably with the introduction of a matte surface designed to reduce visible scratches and preserve appearance over time. BSH Hausgeräte operates across Bosch, Thermador, and Gaggenau, offering high-output and full-surface options that serve both mainstream and luxury segments. The Vollrath Company occupies a specialized niche with commercial-grade induction cooktops built for professional foodservice and restaurant environments, where ruggedness and serviceability matter as much as cooking performance.
These players illustrate three strategic archetypes. The first is broad-scale differentiation through ecosystem and brand breadth, where a portfolio of brands and connected features aims to capture consumers across price tiers. The second is premium durability and control, where the pitch is long service life, refined cooking precision, and surfaces that hold up to daily use. The third is vertical specialization, where a company concentrates on commercial-grade engineering and the specific operational requirements of foodservice operators. Each archetype is defensible, but each also carries different risks: broad portfolios can dilute focus if execution falters across brands, premium positioning depends on consistently delivering perceived quality, and commercial specialization requires strong service and support networks to sustain customer relationships.
The market structure is evolving along several lines. Consolidation pressure is likely to remain moderate but real, as larger groups seek to strengthen channel coverage and component procurement leverage. At the same time, there is room for targeted fragmentation in outdoor, commercial, and ultra-premium niches where specialized features command attention. New entrants are less likely to win on commodity segments and more likely to gain traction by pairing a clear feature advantage with a credible installation or service proposition. Recent launches underscore this dynamic: matte surface durability, temperature-controlled cooking, and outdoor-built-in capability are not incremental tweaks, they are market-expanding moves that reset expectations for what an induction cooktop can do.
Worldwide Induction Coils Market
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape where value accrues. First, premiumization through practicality will continue to gain ground. Scratch-resistant matte finishes, temperature precision, and outdoor capability are turning induction from a performance upgrade into a lifestyle and operational upgrade. Manufacturers that can deliver these features at a defensible cost position will be able to command stronger margins and better brand loyalty than those competing only on price.
Second, policy-supported adoption will become a more reliable demand driver in select regions. The combination of efficiency messaging, curated quality guides, and rebate programs reduces friction for mainstream buyers and public-sector purchasers. Companies that build offerings to align with recognized certification standards and that can clearly communicate eligible incentive value will have an easier path to conversion. This is especially relevant where energy costs, air-quality regulations, and electrification targets are reinforcing each other.
Third, supply-chain resilience will move from a back-office concern to a competitive differentiator. As advanced surface treatments, control electronics, and specialized form factors become more common, the ability to source reliably and manage component risk will influence launch speed, warranty exposure, and ultimately customer satisfaction. Firms that diversify sourcing, strengthen supplier relationships, and plan for lead-time variability will be better positioned to sustain growth through trade or logistics disruptions.
These trends create concrete commercial opportunities. Premium residential lines can be built around surface durability and precision cooking features that justify higher price points without relying solely on brand heritage. Commercial offerings can target operators who need robust equipment, predictable service, and clear documentation of operational savings through reduced heat load and ventilation demands. Outdoor and multi-zone solutions can open new installation scenarios in markets where gas is restricted or where homeowners want flexible cooking spaces. Each opportunity, however, carries its own set of risks: premium features must deliver measurable quality improvements, commercial sales must be backed by installation and service capacity, and outdoor products must perform reliably in variable environmental conditions.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the features and use cases that are expanding the market rather than merely defending existing share. Surface durability, temperature precision, and outdoor-rated designs are no longer niche experiments; they are signals of where consumer expectations are moving. At the same time, sourcing strategies for ceramic glass and induction coils should be revisited to reduce exposure to concentrated import dependency. Building redundancy into critical component supply, clarifying quality commitments with suppliers, and ensuring launch timing is supported by inventory buffers can protect both margin and brand reputation.
For investors, the most informative question is not whether induction will continue to grow, but where the value is being created and captured. Portfolio breadth, premium durability positioning, and commercial specialization each offer defensible paths, but they require different execution capabilities and carry different margin profiles. The recent wave of product launches suggests that differentiation through practical features is a credible growth lever, and that companies able to pair innovation with reliable supply and channel execution are better placed to convert market growth into durable returns.
For procurement and kitchen operators, the decision framework should move beyond upfront price and toward total cost and operational fit. Incentives and rebate programs can materially improve economic outcomes when models meet recognized efficiency standards, and commercial buyers should weigh ventilation, cooling, and workflow benefits alongside equipment cost. Selecting products with strong surface engineering and clear service support can reduce long-term maintenance exposure, while outdoor or multi-zone options can unlock flexible layouts that gas or conventional electric surfaces may not support as cleanly.
Detailed segment-level sizing, regional growth patterns, and company-specific positioning data can sharpen these decisions further. The full research report provides the granular breakdowns and customized recommendations needed to translate these strategic trends into specific investment, product, and sourcing choices.
For detailed analysis of this topic, please visit the official page: Induction Cooktop Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Wedding Dress Market: Navigating Growth, Innovation, and Strategic Positioning
Market Snapshot and Core Challenges
The wedding dress market has entered a phase of steady, structurally driven expansion. Revenue grew from approximately 120.0 million USD in 2020 to 186.0 million USD in 2025, reflecting a compound annual growth rate of 6.08 percent across the historical period. The trajectory is expected to continue, reaching an estimated 280.7 million USD by 2032. This growth is not merely a post-pandemic rebound; it signals a maturing consumer base willing to allocate discretionary spending to wedding apparel, supported by broader economic recovery and shifting social habits around engagement and celebration.
Despite the favorable top-line momentum, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, market concentration remains moderate, with the top three players holding roughly 25 percent of revenue and the top five capturing about 30 percent. This fragmentation means scale advantages are limited, and leadership cannot rely on dominance alone. Instead, differentiation, brand trust, and operational resilience determine share gains. Second, the apparel supply chain continues to navigate cost volatility, material availability, and lead-time uncertainty. Manufacturers and designers must balance premium craftsmanship expectations with the pressure to deliver predictably, especially as wedding calendars become more compressed and customization requests grow. Third, the market is experiencing a shift in how gowns are sourced and used. The relative weight of off-the-rack and customized offerings, alongside usage patterns spanning personal purchase, rental, and photographic studio needs, indicates that consumers are no longer choosing based on category alone. They are evaluating total experience, flexibility, and perceived value. Companies that treat these categories as siloed segments risk missing cross-category demand signals.
Wedding Ring Market
For executives, the practical implication is clear: healthy growth does not automatically translate into profitable growth. The winners will be those who address structural friction in sourcing, inventory, and customer experience while building brand narratives that justify price points and repeat engagement.
Key Drivers Shaping Market Dynamics
Several forces are converging to reshape how value is created in the wedding dress market. Understanding these drivers is essential for anticipating where competitive advantage will emerge.
Technological Innovation and Operational Breakthroughs
Digital design tools, fit simulation, and data-informed inventory planning are reducing the cost of experimentation while improving speed to market. Designers can prototype more variations with fewer physical samples, and retailers can align stock levels more closely with demand patterns. These capabilities matter because the wedding dress category has traditionally relied on intuition and seasonal collections. Technology is now enabling more responsive design cycles, better sizing accuracy, and fewer unsold units. For manufacturers, the same tools support more efficient production scheduling and clearer communication with buyers, which is especially valuable in a market where customization and detail-oriented craftsmanship carry premium expectations.
Party Costumes Market
Policy and Regulatory Environment
Operational transparency, labor standards, and material sourcing requirements are becoming more visible across the apparel sector. While the wedding dress market is not subject to a single defining regulation, broader expectations around responsible sourcing and production practices are influencing procurement decisions. Brands and factories that can document sourcing practices, maintain consistent quality controls, and demonstrate reliable compliance are increasingly preferred by retailers and international buyers. This trend does not fundamentally alter demand, but it raises the barrier for informal or opaque supply chains and rewards operators with disciplined processes and traceable operations.
Demand-Side Shifts in Consumer and Business Behavior
Consumers are approaching wedding apparel with more deliberate criteria. Personal purchase remains a major driver, but the purchase decision is increasingly shaped by fit, style longevity, sustainability considerations, and the overall service experience rather than brand name alone. At the same time, rental and photographic studio applications continue to represent meaningful demand pools, reflecting a broader willingness to treat wedding apparel as part of a flexible celebration ecosystem rather than a single-use asset. This is pushing businesses to think beyond the gown as a standalone product and toward integrated offerings that combine styling, access, and presentation.
On the business side, buyer preferences are also changing. Retailers and distribution partners want predictable replenishment, clearer differentiation, and strong visual identity. The market’s moderate concentration means many brands compete on aesthetics and localization, but the most resilient operators are those that connect product quality with measurable service reliability.
Supply Chain and Cost Structure Evolution
The cost environment remains a central concern. Material prices, labor conditions, shipping variability, and production lead times all influence margin stability. In response, many operators are reassessing make-versus-buy decisions, supplier concentration, and inventory depth. The practical shift is toward greater diversification and more disciplined planning. Rather than relying on a single production model, leading participants are building flexibility into sourcing and capacity, allowing them to respond to regional demand changes and minimize disruption. This flexibility is becoming a strategic asset, particularly for companies that must serve both premium custom work and higher-volume lines without compromising delivery performance.
Competitive Landscape and Leading Strategies
The competitive field is broad and geographically diverse, spanning established American-designed brands, European manufacturing capacity, Asian production capabilities, and specialized luxury or contemporary players. This diversity is one of the market’s defining features. It creates opportunities for niche differentiation, but it also raises the need for clear positioning.
Strategic Positioning Among Key Players
Several themes emerge when looking at how leading companies compete. American-designed brands tend to emphasize design identity, detail, and perceived craftsmanship. Some highlight handmade construction or in-house production, using that narrative to support premium pricing and loyalty. Others focus on contemporary aesthetics or romantic detailing to attract buyers looking for distinctiveness rather than conventional styles. Luxury-oriented brands build their value proposition around exclusivity, fit, and collection storytelling, often reinforced through events and seasonal launches that keep the brand in front of buyers and press.
Meanwhile, manufacturing-centric participants compete on scale, reliability, and customization support. Large production facilities in Europe and Asia serve as critical capacity nodes for broader industry demand, offering wholesale and made-to-order capabilities that allow brands and retailers to access consistent output. Their advantage lies in volume flexibility, repeatable quality, and the ability to support a range of design specifications. In parallel, some brands are leaning into modern, sustainable, or niche aesthetic directions to stand out in a crowded field, recognizing that differentiation often comes from a coherent point of view rather than from broad assortment alone.
PW Consulting
Differentiation as the Core Competitive Lever
Because market concentration is moderate, no single company dominates the category through size alone. That makes positioning especially important. The strongest operators combine a recognizable design language with dependable execution. They do not simply sell a gown; they sell a coherent experience that includes fit, presentation, delivery, and brand trust. Events such as trade show attendance, collection launches, and designer-focused gatherings play a visible role in maintaining that presence. Recent industry activity illustrates this rhythm: Ricca Sposa appeared at Barcelona Bridal Fashion Week in April 2026, Anne Barge introduced its Fall 2026 collection at New York Bridal Fashion Week in May 2026, Kaya Wedding attended European Bridal Week in April 2026, and Allure Bridals hosted designer events including Once Upon a Dress in May 2026. These moments are not merely calendar items; they are mechanisms for reinforcing brand relevance, testing demand cues, and maintaining relationships with retailers, press, and buyers.
How the Landscape Is Evolving
The market is evolving along multiple paths at once. On one side, there is room for continued fragmentation, as new designers and regional brands enter with targeted aesthetics or direct-to-consumer models. On the other side, consolidation pressure exists for players that need scale in production, distribution, or brand reach. The most likely outcome is not a simple winnowing, but a layered market in which a few broadly recognized names anchor consumer awareness while many specialized players compete in distinct niches. New entrants that can articulate a clear design identity, demonstrate reliable fulfillment, and build digital visibility will have a realistic path to relevance. Established players, meanwhile, will need to protect their positioning by refreshing collections, strengthening supply discipline, and deepening relationships with the channels that matter most to their customers.
Outlook for the Next Three to Five Years
Looking ahead, three trends are likely to define strategic opportunities and risks.
- Design and sourcing will become more integrated. As digital tools and production planning improve, brands that can connect design intent with manufacturing capability more tightly will gain speed and consistency. This integration supports both premium custom work and broader line efficiency, reducing the tension between uniqueness and scalability.
- Consumer expectations will keep moving toward experience-rich purchasing. Fit, personalization, presentation, and post-purchase service will matter as much as the gown itself. Companies that create a smoother journey from discovery to delivery will be better positioned to defend margins and build repeat engagement, including through rental and studio-related demand where appropriate.
- Regional production and supply diversification will remain strategic priorities. The market’s growth will continue to depend on reliable capacity and predictable lead times. Businesses that concentrate all sourcing in one channel or region may face unnecessary exposure, while those that build a balanced supplier base and maintain contingency options will be more resilient to cost and logistics shocks.
These trends open practical opportunities. Design-led brands can deepen loyalty by strengthening fit, service, and collection coherence rather than relying solely on aesthetic novelty. Manufacturers and wholesalers can capture value by becoming more responsive partners, offering clear customization pathways, and demonstrating dependable output. Retail and distribution players can use stronger supplier relationships and better assortment planning to reduce inventory risk while maintaining visual freshness. At the same time, uncertainty remains. Economic fluctuations can affect discretionary spending, costume and accessory demand can shift as celebration habits evolve, and competitive pressure can intensify if too many brands chase the same aesthetic or price point. The market’s growth is durable, but profitability will still depend on disciplined execution.
Strategic Recommendations for Decision-Makers
Different participants will need different priorities, but several actions apply broadly.
For Manufacturers and Brand Operators
Invest in the capabilities that connect design to delivery. That means clearer production planning, flexible sourcing, and fit or sizing improvements that reduce returns and rework. Build a distinctive design position that can be communicated consistently across channels, and treat events and seasonal launches as strategic touchpoints rather than optional marketing activities. Consider where customization, wholesale, and own-brand offerings can coexist without diluting operational focus.
For Investors
Focus on operators with a credible differentiation story and evidence of execution discipline. In a moderately concentrated market, scale alone is less decisive than brand clarity, supply reliability, and channel relationships. Evaluate whether a company’s design identity is sustainable, whether its production model can support demand without compromising quality, and whether its go-to-market approach aligns with changing consumer behavior. Look for signs that the business can manage cost volatility while preserving margin integrity.
For Retailers and Procurement Teams
Prioritize partners that can deliver consistency, transparency, and flexibility. Assortment decisions should balance recognizable style leadership with inventory discipline, and sourcing strategies should not over-concentrate risk in a single supplier or region. Where rental, studio, or multi-use demand is relevant to the customer base, partner selection should reflect the ability to support varied use cases, not just standard retail distribution. Commercial terms and delivery reliability will matter as much as design appeal when planning for seasonal peaks.
Strategic decisions in this market are most effective when informed by detailed segmentation, regional dynamics, and competitive benchmarks. Broad trends indicate direction, but precise choices about product mix, sourcing, pricing architecture, and channel focus require deeper data. Readers seeking a more granular view of segment splits, company positioning, and forward demand scenarios can explore the full PW Consulting Wedding Dress Market research report for expanded analysis and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Wedding Dress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beyond the 6.09% CAGR: What’s Really Driving the $11.34B Mascara Market Through 2032
By PW Consulting, 2026-09-21
The Mascara Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2026–2032)
The global mascara market has matured into a high-contrast landscape where volume growth coexists with intensifying structural pressures. Over the historical period from 2020 to 2025, the category expanded from approximately 5.2 billion USD to 7.5 billion USD, reflecting steady consumer demand and repeated product innovation cycles. The trajectory continues into the forecast window through 2032, with the market projected to reach 11.34 billion USD and a compound annual growth rate of 6.09 percent. These figures are not just a measure of incremental sales; they signal a category that is broadening its functional promises, migrating across channels, and being reshaped by sustainability mandates and packaging engineering. For executives and investors, the central question is no longer whether mascara will grow, but which value pools will capture disproportionate share and how fast the cost and compliance curves will move.
Beneath the headline expansion sits a market that is consolidating around a small number of global players while simultaneously fragmenting at the formulation, applicator, and packaging levels. The top three participants command roughly 65 percent of category revenue, and the top five extend that share to nearly 78 percent. This concentration indicates that scale advantages in acquisition, distribution, and brand architecture remain powerful, yet the same concentration also invites targeted disruption from niche formulators, regional manufacturers, and contract partners that can move faster on ingredient innovation, applicator design, and sustainable packaging. The market’s evolution is therefore best understood as a dual dynamic: broad-based growth on the outside, competitive differentiation on the inside.
Market Snapshot: Growth with Consolidation
The category’s growth curve has been supported by multiple reinforcing forces: repeat purchase behavior in daily wear, demand for specialized effects such as lengthening, volume, and curl retention, and a broadening pipeline of prestige and mass-market SKUs. Yet the distribution of revenue concentration also underscores a strategic reality. Scale players benefit from global supply visibility, retail relationships, and cross-brand leverage, but they must continually reinvest in formulation, claims substantiation, and packaging upgrades to defend shelf space and e-commerce visibility. Mid-tier and private-label manufacturers, by contrast, compete on speed, customization, and cost-efficient production, positioning themselves as critical nodes for brands that want to expand their mascara assortments without building in-house capacity.
For decision-makers, this snapshot translates into a clear takeaway: growth is real, but it is not evenly distributed across players, formats, or geographies. The opportunity lies in identifying which sub-segments of the value chain are most exposed to margin expansion, which formats are most likely to command premium pricing, and where entry barriers are low enough to reward agile innovation rather than brute scale.
Current Structural Challenges and Turning Points
The category faces three interconnected challenges that are reshaping how companies plan capacity, R&D, and go-to-market strategy. First, formulation and applicator performance are increasingly scrutinized by consumers who expect lash-care benefits, precise application, and long-lasting wear without smudging or flaking. Achieving these claims simultaneously creates engineering tension: richer formulas can compromise brush glide, while lighter formulas may reduce pigment intensity or curl retention. Companies that can integrate lash-conditioning attributes with high-pigment delivery and ergonomic application will be better positioned to defend premium price points.
Second, sustainability and material compliance are moving from marketing narratives to operational constraints. The packaging and applicator segments are under pressure to reduce fossil-based plastics, lower carbon intensity, and increase recycled content. This transition is not cosmetic; it affects tooling, supplier qualification, quality control, and cost structures. Where sustainable materials were once a differentiation layer, they are now becoming a baseline expectation in many retail and channel environments. Firms that delay material transitions risk facing procurement friction and brand perception gaps, while those that move early can secure supplier relationships and design leadership.
Lipstick Market
Third, competitive intensity is compressing the room for undifferentiated entry. The high concentration at the top means that new claims, packaging novelty, and branded storytelling must be unusually sharp to gain attention. At the same time, contract manufacturers and private-label suppliers are expanding their capabilities, making it easier for brands to launch with credible production backing. The result is a market where speed-to-shelf and formulation distinctiveness matter as much as scale. Pure price competition is increasingly risky because it erodes the investment needed for sustained innovation and compliance.
Key Drivers Reshaping the Mascara Category
The market’s direction is being pulled by a mix of technology, regulation, consumer behavior, and supply economics. Understanding how these forces interact is essential for assessing where durable advantage can be built.
Innovation in Formulation and Applicator Engineering
Performance expectations have expanded beyond basic volume and length. Consumers increasingly look for brush designs that improve precision and product deposition, formulas that support lash condition, and finishes that balance wear time with natural movement. Brush geometry and fiber selection directly influence how mascara coats lashes, how easily it separates clumped product, and how well it holds a curl. Innovation in this area is becoming a tangible source of differentiation rather than a purely aesthetic exercise.
Recent activity in the applicator space reflects this shift. At major industry events, suppliers have showcased packaging and applicator technologies with stronger sustainability profiles and design novelty. One German manufacturer presented a collection built around new brush designs and shadow printing decoration on packaging made from 100 percent post-consumer recycled plastic, an approach that also reduces CO₂ emissions by up to 26 percent. A UK-based packaging supplier introduced a cellulose-derived renewable fiber applicator intended as a renewable alternative to synthetic materials for mascara and brow products. These developments are significant because they combine performance engineering with material transition, showing that sustainability and application quality can be advanced together rather than traded off.
For manufacturers and brand owners, the implication is clear: applicator and packaging innovation is becoming a competitive lever that affects both consumer perception and operational sustainability. Companies that treat brush design and material science as core R&D priorities can create more defensible product architectures and reduce exposure to future material restrictions.
Regulatory and Sustainability Pressure as a Design Constraint
Sustainability commitments are increasingly embedded in brand and supply strategies rather than treated as separate CSR initiatives. In the mascara category, this means greater attention to formulation origin, biodegradability or natural derivation targets, recyclable packaging, and lower-carbon manufacturing outcomes. Public commitments from major groups have set ambitious timelines for making a high share of mascara formulations biodegradable or naturally derived, reinforcing a direction that is likely to influence sourcing standards, ingredient selection, and supplier qualification across the industry.
This regulatory and reputational environment creates both risk and opportunity. On the risk side, companies dependent on legacy synthetic formulations or non-recyclable packaging may face rising compliance costs and potential channel resistance. On the opportunity side, brands that align formulation, packaging, and communications early can build authenticity in a category where consumers are increasingly attentive to material claims. Importantly, credibility depends on consistent execution across the value chain, not on isolated packaging swaps. A sustainable brush paired with an unchanged formula or a vague messaging strategy can undercut the intended effect.
Consumer and Channel Behavior Shifts
Demand patterns are evolving around use context, not just product type. Daily wear remains the dominant usage environment, which sustains high baseline demand and repeated purchase cycles. At the same time, event and professional makeup applications continue to support premium SKUs and specialized finishes. The practical effect is that the category is served by a dual rhythm: a high-frequency core that rewards reliability, ease of use, and value, and a higher-margin periphery that rewards performance claims, packaging prestige, and trend responsiveness.
Channel dynamics reinforce this bifurcation. E-commerce and digitally native brands have lowered the barrier for launches and made it easier for smaller labels to reach niche audiences. Retail environments, however, still reward shelf impact, repeat conversion, and strong claims substantiation. In practice, this means that brands must reconcile two demands: the consumer-facing promise that drives first purchase, and the consistent performance that drives repurchase and recommendation. Mascara is a category where disappointing performance is difficult to hide, so formulation reliability and applicator consistency are not just product attributes; they are commercial safeguards.
Supply Chain and Cost Structure Pressures
Material availability, packaging input costs, and production flexibility are becoming more prominent in strategic planning. As brands shift toward recycled and renewable materials, they also shift their dependency map, which can introduce new qualification cycles and short-term cost variability. At the same time, manufacturers that can offer a broad texture range, multiple packaging options, and scalable private-label production are increasingly valuable partners for brands managing portfolio complexity.
This environment favors companies that can balance cost discipline with innovation readiness. In practical terms, that means maintaining a supplier base capable of meeting sustainability specifications, investing in process stability to reduce rework and waste, and designing product architectures that can be adapted across markets without excessive rework. For procurement and operations leaders, the goal is not only to manage today’s input costs, but to build a supply architecture that can absorb material transitions without compromising quality or delivery.
Competitive Landscape and the Shape of Advantage
Scale Leaders and Their Strategic Postures
The market’s leading participants are pursuing different but overlapping forms of advantage. One global group anchors its mascara portfolio across mass and prestige brands, using strong brand architecture to cover a wide range of performance claims and price points. Another large corporation competes in the premium and clinical-influenced space with an emphasis on wear technology and curl retention across several established labels. A third major consumer goods company focuses on accessible volume and lengthening performance through mass-market brands, leveraging distribution breadth and price accessibility.
These scale players share common strengths: global reach, significant R&D resources, established retail relationships, and the ability to cross-leverage brand equity across regions. Their strategic challenge is to keep portfolios fresh enough to maintain relevance while maintaining the consistency required to defend volume. In a concentrated market, leadership is less about presence and more about continuous renewal of claims, formats, and packaging stories.
Prestige Positioning and Regional Specialists
On the prestige side, luxury houses and regional specialists compete through differentiated application mechanisms, refined aesthetic signatures, and targeted lash-care narratives. Some players emphasize advanced brush technology and long-lasting pigmentation to justify premium positioning; others focus on precise application and conditioning benefits in Asian markets, where preferences for curl, length, and clean formulation can be especially pronounced. There are also K-beauty-aligned developers working on curling and lengthening effects that respond to regional styling expectations.
This segment is less about raw scale and more about design credibility, application elegance, and regional nuance. For premium brands, the opportunity lies in making performance claims feel both sophisticated and demonstrable, while for regional specialists the opportunity lies in translating local preferences into exportable innovation.
The Expanding Role of Contract and Private-Label Manufacturing
A significant portion of category expansion is enabled by manufacturers that provide end-to-end production, custom formulas, and diverse applicator and packaging options. These partners support a wide spectrum of brand strategies, from budget-priced launches to more premium private-label projects. Their value proposition is increasingly tied to speed, flexibility, and the ability to produce multiple texture ranges without requiring the brand to build its own factory footprint.
Several manufacturers in this space operate with long track records in color cosmetics and a strong export orientation, while others offer customizable formulas and packaging support for direct and private-label markets. This layer of the industry is strategically important because it lowers the execution risk for new product development and allows brands to test concepts with less capital intensity. For investors and brands evaluating partnerships, the key is to assess a supplier’s capability not just in volume output, but in claim-ready formulation control, packaging consistency, and sustainable material readiness.
PW Consulting
How the Landscape Is Evolving
The competitive field is not simply consolidating; it is reconfiguring around capability clusters. At one end, global brands seek scale, portfolio coverage, and sustainability credibility. At the other, contract manufacturers and applicator suppliers create the infrastructure that enables more launches, faster iteration, and more material options. Between them, private-label and regional players can win by offering either cost-efficient execution or distinctive formulation and packaging combinations that larger players may not prioritize immediately.
The most likely trajectory is continued concentration among the largest branded players, alongside a vibrant mid-tier and supplier ecosystem that expands the number of viable market entrants. This means the market will keep generating both acquisition targets and partnership opportunities. The brands and investors that benefit most will be those that can distinguish between genuine capability and surface-level novelty when evaluating potential collaborations or acquisitions.
Outlook: Three Trends Shaping 2026–2032
Trend 1: Performance-Material Integration as a New Standard
The most durable opportunity in the category is the convergence of performance engineering and sustainable material design. Brush architecture, fiber selection, formula delivery, and recyclable or renewable packaging are increasingly evaluated together, not in isolation. Products that can combine lash condition, precise application, and credible material transitions will have an advantage in both consumer acceptance and long-term regulatory resilience. The commercial payoff is not just premium pricing; it is reduced exposure to future input constraints and stronger brand trust in a category where performance disappointment is highly visible.
The accompanying risk is execution complexity. Integrating new materials may require tooling changes, supplier requalification, and reformulation work that affects cost and lead time. Brands that underestimate these operational demands may find sustainability positioning difficult to sustain at scale.
Trend 2: Claim Substantiation and Credibility as Commercial Moats
As claims around volume, length, curl hold, and lash care multiply, substantiation becomes a competitive necessity. Consumers and retail partners increasingly expect supported statements rather than aspirational language alone. In practice, this trend elevates the importance of testing, consistency, and formulation discipline. Companies that build robust evidence pipelines can defend price and shelf space more effectively, while those relying on vague promises will face growing pressure as the category becomes more crowded and more scrutinized.
A key risk here is overclaiming relative to actual performance. In mascara, weak substantiation can quickly translate into reviews, repurchase issues, and brand erosion. The upside is similarly strong: credible, well-communicated performance can drive both trial and loyalty, especially in daily-use categories where repetition matters.
Trend 3: Regional Specialization and Exportable Innovation
Preferences for curl, length, conditioning, and finish are not uniform across markets, and the category’s growth will continue to be shaped by regional taste profiles as well as global brand reach. Asian markets, for example, have shown strong interest in precision application and conditioning-oriented benefits, while other regions may prioritize long-wear, waterproof resilience, or volume. This diversity favors companies that can localize formulas and brush designs without losing production efficiency, and it creates export opportunities for regional innovators who can translate local preferences into formats that travel well.
Face Mask Market
The main uncertainty is globalization versus localization balance. Over-standardizing can blunt regional relevance, while over-fragmenting can raise cost and complexity. The winning model is likely to combine a core platform with region-specific adaptations, allowing scale where possible and differentiation where necessary.
Strategic Implications for Decision-Makers
The mascara category is expanding, but the value is being created by companies that align innovation, sustainability, and execution discipline rather than by those that rely on growth alone. The following priorities are most relevant across common stakeholder groups.
- For manufacturers and brand owners, prioritize applicator and packaging innovation as core product strategy, not as a secondary packaging decision. Treat brush design, fiber choice, and material transitions as levers that influence both performance perception and long-term compliance readiness.
- For investors, distinguish between branded scale that is being renewed through credible formulation and packaging programs and scale that is resting on legacy assets. The stronger opportunities are likely in platforms that can demonstrate sustainable material readiness, substantiated performance, and flexible manufacturing partnerships.
- For procurement and supply chain leaders, build resilience into material sourcing by qualifying suppliers capable of meeting recycled and renewable specifications without sacrificing quality consistency. Map the transition risks early so that sustainability targets do not create unexpected production bottlenecks.
Across all three perspectives, timely and detailed market intelligence is valuable because the category is moving on multiple fronts at once: formulation expectations, applicator technology, packaging materials, and concentration dynamics. Decisions made without a clear view of where capacity, differentiation, and regulatory pressure are heading can lead to missed entries, underestimated costs, or weak claim positioning. A more complete picture of segment-level dynamics, regional variation, and supplier capability typically separates reactive planning from proactive positioning.
For teams that need a deeper breakdown of segmentation details, regional patterns, and competitive capability mapping, the full PW Consulting market report provides expanded data and customized analytical context to support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Mascara Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


