



Chemotherapy-Induced Peripheral Neuropathy (CIPN) Treatment Market — Strategic Brief (PW Consulting)
Why this study matters for 2026 decision-makers
As oncology care continues to extend survival, the clinical and commercial urgency of addressing chemotherapy-induced peripheral neuropathy (CIPN) escalates. Our market study, grounded in a 2025 base year and a seven-year forecast horizon (2026–2032), translates epidemiology, regulatory signals, clinical readouts, and competitive dynamics into executable options for biopharma and investment leaders preparing strategies in 2026.
Chemotherapy Induced Peripheral Neuropathy Treatment Market
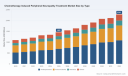
At the macro level, the CIPN treatment market demonstrates steady expansion: a documented increase from an assessed market of USD 1,100 Million in 2020 to USD 1,460 Million in 2025, and a forecast trajectory to approximately USD 2,283 Million by 2032, representing a compound annual growth rate (CAGR) of 6.5% across the forecast period. These headline figures anchor the valuation envelope and are central to capital allocation, partnership timing, and commercialization planning.
Chemotherapy Induced Peripheral Neuropathy Treatment Market
What sets this report apart — actionable, not academic
- Practical revenue forecasting: probability-adjusted revenue curves for marketed and late-stage pipeline assets (model inputs and scenario logic explained, high-sensitivity levers identified).
- Decision-ready clinical timelines: an annotated calendar of near-term catalysts (e.g., pivotal and mid-stage readouts through 2026–2027) that materially affect valuation inflection points.
- Regulatory roadmaps: analysis of the FDA’s January 2025 draft guidance and implications for endpoint selection, prevention vs treatment claims, and accelerated approval pathways.
- Commercial go/no-go frameworks: recommended playbooks for launch sequencing, payer engagement, and pricing strategies under differing clinical efficacy scenarios.
- M&A and partnering playbook: prioritized target profiles, synergy archetypes, and an acquisition timing matrix tied to clinical milestones and market concentration dynamics.
- Reimbursement stress-testing: modeled payer thresholds and budget-impact simulations to stress-test pricing under diverse uptake scenarios.
Methodology and confidence drivers
Our approach combines a bottom-up revenue build with top-down market checks. Key inputs include: validated oncology treatment volumes, CIPN incidence by chemotherapy regimen, standard-of-care utilization trends, and an exhaustive pipeline review. We apply probability-of-success adjustments aligned to phase-specific historic win rates, and we stress-test assumptions through scenario analysis. The report’s historical window (2020–2025) was used to calibrate market response to prior therapeutic innovations and to validate growth assumptions underlying the 6.5% CAGR.
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Market structure is meaningful: the CIPN market exhibits notable concentration among a small set of late-stage and near-market players — our analysis indicates that the top three companies capture a substantial majority of current revenue-share, and the top five firms account for an even larger portion. This concentration amplifies the commercial impact of single-asset readouts and strategic alliances — a reality that investors and business development teams must explicitly incorporate into valuation and negotiation strategies.
Near-term dynamics to watch in 2026
- Clinical readouts with asymmetric upside: Several sponsors are expected to report pivotal or late-stage results in 2026. Positive outcomes could materially accelerate market adoption and reshape incumbent value propositions; conversely, neutral or negative readouts could suppress near-term investment appetite.
- Regulatory posture: The FDA’s draft guidance on CIPN (Jan 2025) clarifies expectations for prevention versus treatment endpoints and creates clearer pathways for accelerated or expedited development for agents that demonstrate clinically meaningful improvements on validated functional endpoints.
- Designations and IND activations: Fast Track and IND clearances granted in 2025–2026 reduce regulatory tail risk for certain assets and concentrate investor attention on trial enrollment and early safety/efficacy signals.
- Commercial readiness vs clinical risk: Sponsors with near-term Phase 2/3 readouts must balance the cost of commercial preparedness (manufacturing scale-up, payer dossiers, field force planning) against the probability-adjusted benefit of a successful result.
Competitive landscape — what the preview reveals (and what it withholds)
Our market map focuses on a curated set of active developers shaping near-term outcomes. Notable programmatic developments summarized in the report preview include:
- Novel mechanism programs advancing through Phase 2 and beyond, including selective Nav1.7 inhibitors and SARM1 antagonists the industry views as potentially disease-modifying.
- Peptide and biologic approaches entering early human trials with IND clearance and targeted funding, indicating diversified modality approaches may converge on clinical validation windows in 2026.
- Established regulatory momentum — Fast Track designations and IND acceptances that materially lower regulatory friction for select programs.
Representative company profiles and recent developments discussed in the full report: leading clinical-stage sponsors with active Phase 2/3 programs, firms that have licensed technologies into broader development partnerships, and novel entrants leveraging unique mechanisms (ion-channel blockade, neuronal repair pathways, receptor agonism, and SARM1 inhibition). For a full company-by-company dossier, including proprietary valuation sensitivity and stakeholder maps, consult the complete report: the preview intentionally omits detailed segment-level revenues and split disclosures to preserve commercial confidentiality and to encourage direct engagement with our analysts.
How to translate insights into 2026 strategic moves
- Asset prioritization: Prioritize assets with regulatory de-risking (Fast Track, IND clearance) and clear mechanistic differentiation for near-term resource allocation. For de-risked assets, accelerate commercial readiness in parallel with confirmatory safety/efficacy readouts.
- Partnership timing: Use pivotal readout timelines to structure contingency-based deal terms — milestones and contingent payments enable partnering while protecting downside if readouts disappoint.
- Clinical development design: Favor adaptive and enrichment strategies to accelerate time-to-signal and to sharpen value propositions for payers (e.g., demonstrating benefit in prevention of sensory deficits vs symptomatic management).
- Commercial staging: Given market concentration among a few leaders, consider niche-first launches (high-volume oncology centers or indication-specific prevention programs) to build clinical traction before broader rollout.
- Regulatory and payer engagement: Engage early with regulatory agencies and payers using the new FDA draft guidance as a framing device to align on acceptable endpoints and real-world evidence commitments.
Risks, uncertainties, and our mitigation playbook
CIPN development faces several non-trivial risks: heterogeneous patient populations and chemotherapy regimens, variable endpoint sensitivity, and the inherent uncertainty of translating neuropathic symptom improvement into durable QoL gains that justify premium pricing. The report translates these sources of uncertainty into quantified downside scenarios and prescribes mitigation strategies — from adaptive trial contingencies to staged launch investments tied to independent milestones.
In addition, the market’s elevated concentration amplifies single-failure impacts. Our contingency models show how a negative pivotal readout from a top-three player can depress adoption curves, creating acquisition windows for differentiated second movers with compelling secondary endpoint data.
What you will find in the full report (practical table of contents)
- Executive summary and strategic implications for 2026 decision cycles
- Market sizing and forecast (2020–2032) with probability-weighted scenario outputs and sensitivity analyses
- Granular pipeline assessment: mechanism, phase, timelines, PoS, and commercial-readiness scoring
- Regulatory landscape and guidance interpretation with agency interaction templates
- Commercial go-to-market playbooks with pricing, market-access, and field-force recommendations
- M&A and partnering landscape with prioritized target archetypes and deal-structuring guidance
- Operational checklists for clinical operations, manufacturing scale-up, and post-approval evidence generation
- Detailed company profiles, trial trackers, and primary-source citations
Final perspective
For executives making 2026 allocation decisions, the CIPN market represents a contest between near-term clinical catalysts and medium-term commercial consolidation. Our analysis quantifies the prize (USD 1.46 Billion market in 2025 expanding toward USD ~2.28 Billion by 2032 under a 6.5% CAGR), identifies the levers that move value in either direction, and prescribes concrete actions to manage asymmetric risk. Whether you are prioritizing an acquisition, structuring a licensing deal, or preparing a launch, the right blend of clinical timing, regulatory engagement, and payer strategy will determine whether your program captures disproportionate share in a market that is both concentrated and primed for disruption.
Next steps
This preview is designed to surface the strategic framing and near-term signals that should inform 2026 choices. For the full dataset, scenario models, and executable templates — including the confidential segment-level outputs and company-specific financials withheld here — contact PW Consulting or visit the report landing page to access the full Chemotherapy-Induced Peripheral Neuropathy Treatment Market study and schedule a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ODT Market to reach USD 344.8 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-07-22
Orally Disintegrating Tablet (ODT) Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused industry brief to orient executive teams on the strategic choices they must make in 2026 informed by our full Orally Disintegrating Tablet Market study. This is a high-conviction preview: we expose the directional macro picture, regulatory inflection points and competitive dynamics that will shape winners and laggards — while intentionally withholding the full, granular segment datasets available in the complete report to preserve the value of our proprietary analysis.
Orally Disintegrating Tablet Market
Macro lens: market trajectory and what it means for corporate strategy
The ODT market is on a clear expansion path. Using 2025 as the report base year, PW Consulting’s topline estimates put the global market at approximately USD 215.0 Million in 2025, with a robust compound annual growth rate (CAGR) of roughly 8.5% through our 2026–2032 forecast horizon. By 2032 the market is projected to approach the mid‑hundreds of millions of USD — a continuation of the steady recovery and acceleration observed across the 2020–2025 historical window.
Orally Disintegrating Tablet Market
Why this matters in 2026: growth at this pace converts niche technology advantages into real revenue opportunities for firms that time investments in formulation platforms, manufacturing capacity and regulatory strategy correctly. Conversely, companies that treat ODTs as a low-priority incremental channel risk ceding access to fast-growing therapeutic niches and to CDMO relationships that will be capacity-constrained in the near term.
Orally Disintegrating Tablet Market
Core regulatory and technical inflection points
-
Regulatory tightening and guidance updates: Late‑2025 product‑specific guidance from a major regulator updated pathways for several ODT candidate molecules. These documents clarify study designs for bioequivalence (including the practicalities of “with water / without water” comparisons) and materially affect time-to-market for generics and reformulations. Expect earlier regulatory interactions to reduce downstream attrition and shorten approval timelines.
-
Design constraints that drive formulation choices: Long‑standing standards continue to dictate practical product boundaries (for example, maximum unit mass and disintegration performance targets), which in turn favor certain technologies and excipient platforms over others for high-dose or difficult APIs.
-
Patent and pipeline activity: Recent patent awards and active formulation development programs signal a fresh wave of branded ODT initiatives that will compete directly with generics and nutraceutical ODT suppliers — creating both licensing opportunities and new competitive pressure.
What the full PW Consulting report delivers (practical, transaction‑ready content)
-
Topline market model with historical series (2020–2025) and base‑case/alternative forecasts through 2032, including sensitivity testing and scenario-based unit economics.
-
Commercial segmentation framework and go‑to‑market playbooks for branded pharma, generics, and nutraceutical segments — including payer/reimbursement pathways and pricing levers by region.
-
Regulatory playbook: product‑specific guidance interpretation, recommended study designs for bioequivalence (water/no‑water arms), and a milestone table for agency interactions to de‑risk approvals.
-
Manufacturing and CDMO mapping: capacity benchmarks, technology capabilities (fast-dispersing polymers, freeze‑dry, molding and direct compression platforms), inspection readiness checklists and estimated capex for greenfield vs. brownfield scaling.
-
Supply chain vulnerability matrix for critical excipients, with recommended dual-sourcing strategies and cost‑control levers.
-
Competitive intelligence dossiers on leading platforms and suppliers, plus an actionable M&A and partnership target shortlist based on strategic fit, capacity and IP ownership.
-
Risk register and mitigation playbooks addressing regulatory shifts, raw‑material volatility and manufacturing scale‑up challenges, with trigger points for contingency actions.
-
Hands‑on financial templates for investment appraisal — NPV, IRR, and payback under alternate uptake and reimbursement scenarios — designed for internal capital committees and bid teams.
Competitive landscape: capabilities to watch (strategic takeaways)
The ODT value chain today spans formulation platform owners, excipient suppliers, contract manufacturers and a mix of branded originators and nutraceutical specialists. A few strategic archetypes emerge:
-
Platform owners with scale CDMO capabilities: Players offering established ODT platforms and large cGMP production footprints are uniquely positioned to capture both branded and generic demand. High‑volume manufacturing capacity enables them to support global launches and to offer turnkey supply — a distinct strategic advantage when customers seek rapid scale‑up.
-
Specialized CDMOs and formulation innovators: Companies that hold validated rapid-disintegration platforms and that have demonstrated bioequivalence through ANDA filings are attractive partners for double‑sided value creation — they reduce clinical and regulatory risk for sponsors while commanding premium contract terms.
-
Excipients and two‑component platform suppliers: Firms that provide formulation building blocks and integrated platforms can exert strong influence on formulation costs and time-to-market. Their roadmap for functional excipients (e.g., taste-masking, mouthfeel modifiers, fast-wetting polymers) will materially affect which ODT approaches are commercially viable for higher-dose APIs.
-
Branded innovators and nutraceutical specialists: Originators with validated ODT prescriptions and nutraceutical manufacturers that customize ODTs create parallel demand pools. Their commercial strategies (brand vs. volume, payer engagement, over‑the‑counter positioning) shape channel-specific uptake curves.
Implication: the market exhibits moderate concentration at the top end, leaving meaningful whitespace for mid‑sized players that can secure differentiated technology or guaranteed CDMO capacity. This structure favors strategic partnerships (technology licensing, toll manufacturing) and selective bolt-on acquisitions in 2026–2027.
Recent events with immediate strategic impact
-
Product‑specific guidance updates from late 2025 have lowered ambiguity for certain generic pathways — this accelerates filing timetables for sponsors who have pre‑aligned study designs with regulators.
-
Patent awards and ongoing formulation development efforts announced in 2026 indicate renewed brand activity in selected CNS and specialty therapy areas — a key demand driver for high-performance ODT platforms.
-
Raw‑material cost discipline remains a decisive competitive lever: companies that lock in multi‑supplier agreements and develop formulation permissiveness to multiple excipient grades will sustain margin resilience.
Recommended strategic moves for 2026 (prioritized, near‑term actions)
-
Prioritize therapeutic focus. Use our scenario outputs to rank indication corridors by expected payer willingness-to-pay and time-to-commercialization. For many sponsors, accelerating CNS ODT initiatives yields the highest probability-adjusted returns; for others, nutraceutical ODTs offer lower regulatory friction and faster revenue ramp.
-
Secure CDMO availability now. Locking capacity with platform-capable contract manufacturers or investing in a modest brownfield line mitigates a primary bottleneck that emerges as demand scales.
-
De-risk regulatory pathways. Engage with regulators early on study design, leveraging the latest product‑specific guidances and PW Consulting’s template briefing packages to minimize clinical surprises.
-
Hedge excipient exposure. Implement dual‑sourcing and qualify alternative excipient grades to maintain margin under volatile raw‑material pricing scenarios.
-
Evaluate technology licensing vs. in‑house development. Compare the time and cost to validate a licensed platform against internal development; for many mid‑sized sponsors, licensing a validated ODT platform yields faster and more predictable market entry.
-
Consider targeted M&A to consolidate supply or acquire differentiated formulation IP, using CR and capacity benchmarks to size the opportunity.
-
Build patient‑centric differentiation. Invest in mouthfeel, taste‑masking and adherence support packaging — small product design improvements materially affect OTC and pediatric acceptance rates.
How PW Consulting supports decision makers in 2026
Our full ODT study is structured to be immediately actionable: bespoke forecast modules, regulatory playbooks, supplier and CDMO matchmaking, M&A screening criteria, and step‑by‑step launch readiness checklists. We work with corporate development, R&D, manufacturing and commercial teams to translate the study’s scenarios into project roadmaps, investment cases and negotiated supplier contracts — all calibrated to the near‑term competitive and regulatory landscape.
To execute on the opportunities and mitigate the risks outlined above, organizations should pair an internal tactical plan (six‑ to eighteen‑month horizon) with a strategic roadmap (three‑ to five‑year horizon). The detailed segment tables, regional breakdowns, channel forecasts, and candidate target lists that underpin these recommendations are available in the full PW Consulting Orally Disintegrating Tablet Market report and accompanying financial models.
Next steps
For teams evaluating ODT investments, partnerships, or M&A in 2026, the window to secure advantageous CDMO terms and to shape regulatory strategy is narrow. PW Consulting can deliver a tailored briefing that maps the full dataset to your portfolio, prioritizes initiatives by expected value, and provides negotiation playbooks for suppliers and potential targets. Access the full report to obtain the comprehensive segment-level forecasts, competitive scorecards, and financial templates that are intentionally not reproduced in this preview.
For detailed analysis of this topic, please visit the official page: Orally Disintegrating Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

Agarose Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
As companies calibrate strategy for 2026, understanding the agarose market’s trajectory is no longer optional — it is strategic. PW Consulting’s forthcoming Agarose Market study synthesizes historic performance, supply-chain stress tests and forward-looking scenarios to equip executives with the insights needed to set sourcing, R&D, capacity and M&A priorities. The market has expanded steadily over the past half-decade, rising from a mid‑three‑figure base in 2020 to a materially larger footprint in our 2025 base year; our modelling then projects continued growth through 2032 driven by bioprocessing, molecular diagnostics and adjacent life‑science demand. On the forecast horizon (2026–2032) we project a compounded annual growth rate of 6.98%, underscoring persistent upside for differentiated suppliers and vertically integrated players.
Agarose Market
Why this matters for 2026 corporate choices
- Sourcing resilience: Rising downstream demand and upstream volatility are changing procurement economics. Companies must weigh single‑source discounts against the strategic risk of concentrated raw material flows.
- Product portfolio prioritization: Not all agarose grades capture equal strategic value. A targeted product strategy—balancing commodity gels and high‑margin specialty resins—will materially affect gross margins and channel dynamics.
- Capacity and footprint decisions: Where you invest in manufacturing or enter into tolling/contract manufacturing relationships will determine your cost base and time‑to‑market for specialized grades.
- M&A and partnership playbook: With the market showing continued expansion and mid‑market consolidation potential, strategic acquisitions and partnerships can accelerate access to high‑growth subsegments and proprietary affinity chemistries.
Market trajectory — the headline numbers
Our analysis places 2025 as the base year for tactical planning. The market has grown meaningfully since 2020 and is expected to continue expanding through the forecast window, culminating in a significantly larger market by 2032. That multi‑year expansion, captured by a forecast CAGR of 6.98% for 2026–2032, is a structural signal: suppliers with differentiated technology, secure raw material strategies and targeted commercial plays stand to outperform. At the same time, the market’s concentration metrics indicate both opportunity and competitive pressure. The three‑largest players account for roughly a third of global revenues, while the five‑player concentration sits below a majority threshold — a profile that supports selective consolidation and leaves room for agile challengers to scale.
Agarose Market
What the full report contains — practical, action‑oriented deliverables
This study is designed as a decision support toolkit for executives, heads of strategy, procurement leads and business development teams. Highlights include:
Agarose Market
- Robust market sizing and topline forecasts with scenario variants that stress macro, raw‑material and regulatory outcomes.
- Segment maps by type, application and region (presented with demand drivers and elasticities) to prioritize where to invest commercial energy.
- Supply‑chain diagnostic: cost build‑ups, supplier capacity maps, bottleneck sensitivity and short/medium‑term raw material exposure analyses.
- Price and margin benchmarking across product grades and end‑use channels, with a focus on tradeoffs between specialty agarose resins and commodity electrophoresis grades.
- Strategic options matrices for capex, contract manufacturing, licensing and M&A, quantified with payback and break‑even ranges under different demand trajectories.
- Regulatory and geopolitical risk register with mitigation measures — essential for procurement and compliance teams operating across multiple jurisdictions.
- Commercial playbooks for market entry and expansion: buyer personas, value propositions and channel strategies for scientific distributors, OEMs and direct laboratory sales.
- Appendices: methods, data sources, interview log and an M&A/partnership database for active deal sourcing.
Competitive landscape — who matters and why
The agarose ecosystem blends global life‑science leaders, specialized resin manufacturers and mid‑sized niche players. Each plays a distinct role in shaping technological direction and market access:
- Agarose Bead Technologies (ABT) (Spain) — A focused provider of custom agarose resins aimed at bioprocessing and advanced therapies. ABT’s recent facility expansion and trade‑show cadence indicate a deliberate commercialization push into higher‑value chromatography applications.
- Purolite (Ecolab) (UK/US) — Known for patented jetting technologies and affinity resin innovation, Purolite’s collaborative launches with bioprocess partners underscore its strategy of technology coupling to accelerate adoption in monoclonal antibody purification.
- Lonza (Switzerland) — With established grades targeted at nucleic acid electrophoresis, Lonza is positioned to serve high‑volume laboratory demand while leveraging brand trust in regulated markets.
- Bio‑Rad Laboratories (US) — A supplier of certified powders and precast gels, Bio‑Rad’s breadth across educational, clinical and industrial customers provides scale advantages in distribution and reference testing.
- Thermo Fisher Scientific (US) — Competes with UltraPure grades and integrated precast gel systems, combining product quality with extensive channel reach to capture routine and high‑throughput workflows.
Recent corporate moves reinforce strategic themes that matter for 2026 planning: capacity scaling by specialty resin players, targeted product introductions by chromatography incumbents, and a blend of trade‑show and partnership plays to access OEM and bioprocess customers. These dynamics suggest that differentiated technology and direct access to end‑use workflows will drive premium positioning more than volume alone.
Industry dynamics and noise — what keeps margins and supply risk‑sensitive?
Three systemic pressures are shaping near‑term decision frameworks:
- Raw material volatility: Seaweed‑derived feedstocks remain a fundamental input. Policy moves that expand or restrict seaweed production—such as national roadmaps or classification changes for seaweed extracts—create both opportunity and episodic price volatility across producers and regions.
- Geopolitical and trade barriers: Heightened tariff activity and shifting import/export rules between major producing nations and key markets have already increased operational costs for some manufacturers and will influence location and inventory strategies.
- Energy and logistics cost pressures: Elevated fuel prices and transport friction since 2024 have propagated through the supply chain, raising landed costs for both raw inputs and finished agarose products.
For 2026, these factors argue for a layered risk‑management approach: diversified sourcing, strategic inventory cushions, and hedged partnerships with upstream suppliers. Additionally, companies should monitor national policies that aim to accelerate domestic seaweed production — such interventions can alter competitive dynamics and create near‑term arbitrage opportunities.
Strategic playbook for executives in 2026
Translate market intelligence into actionable priorities using a three‑track approach:
- Defend core margins: Optimize manufacturing yields, adopt lean processing for commodity grades and renegotiate long‑term contracts with key feedstock suppliers where possible.
- Invest selectively in differentiation: Direct R&D toward high‑value affinity chemistries and low‑volume, high‑margin resins that are less sensitive to commoditized price competition.
- Use partnerships to accelerate scale: Consider co‑development deals with contract manufacturing organizations or channel partners to expedite market access while limiting capital intensity.
What this preview withholds — and why you should consult the full study
True to the “trailer” principle, this preview demonstrates the analytical depth and strategic framing that underpin our full study, but intentionally omits granular segment matrices, price decks, per‑region forecast breakdowns and proprietary supplier cost curves. Those detailed tables and calibrated scenarios are core to making implementable decisions — they include rank‑ordered supplier scorecards, SKU‑level margin impacts, and purchase‑price sensitivities that cannot be responsibly summarized in a public preview.
How to use the full report in 2026 planning cycles
- Incorporate the report’s scenario outputs into Q2 capital allocation reviews and procurement renegotiations.
- Use the supplier scorecards and technical evaluations to inform product prioritization for FY2027 R&D planning.
- Leverage the regulatory risk register to update compliance playbooks and to design contingency logistics strategies for raw material shocks.
- Apply the M&A and partnership matrices to populate tactical deal lists for early‑stage outreach and due diligence.
Closing — what PW Consulting delivers
Our Agarose Market study is structured to help you convert market intelligence into higher‑confidence decisions in 2026. It blends time‑series market sizing, concentration analysis, supplier benchmarking and actionable strategic options—grounded in field interviews and primary data. If your organization is preparing to invest, divest, or defend market position in agarose, the full study provides the necessary line‑of‑sight on where to deploy capital and which operational levers will create the most durable advantage.
For immediate next steps, PW Consulting can brief your executive team with a tailored 90‑minute workshop using excerpts from the full deliverable to align choices on sourcing, product roadmaps and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Agarose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Booster Pump Market to reach USD 306.47 Million by 2032 at 4.45% CAGR
By PW Consulting, 2026-07-22
Booster Pump Market — 2026 Strategic Briefing
Introduction
As PW Consulting’s lead industry analyst, I present a focused strategic perspective on the global booster pump market that is designed to inform executive decisions in 2026. Our latest study synthesizes historical performance, near-term disruptions, and a seven-year forecast horizon to convert market intelligence into executable strategy. The market has demonstrated steady expansion through the last half-decade and — under a baseline scenario — continues to grow at a mid-single-digit compound annual growth rate through the early 2030s. For leaders planning capital allocation, new product launches, channel investments, or M&A activity, this briefing highlights the practical implications of that trajectory while directing you to our full report for granular segmentation and model outputs.
Booster Pump Market
Market trajectory and macro outlook
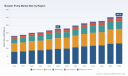
From the 2020 baseline to the 2025 reporting year, the booster pump market has shown resilience amid supply-chain volatility and shifting end‑market demand. Using 2025 as our base year, our forecast to 2032 shows continued expansion, driven by a combination of infrastructure reinvestment, building‑efficiency retrofits, and increasing adoption of variable‑speed and digital control systems. The market’s compound annual growth rate (CAGR) in our core scenario is 4.45%, reflecting steady, predictable expansion rather than episodic spikes.
Booster Pump Market
For strategic planners, the implications are clear: demand is large enough to support differentiated product families and service models, yet growth is measured — favoring investments that improve margins (energy efficiency, digital controls, modular systems) and recurring revenue (service contracts, parts, lifecycle management) over undifferentiated volume plays.
Booster Pump Market
Why this matters for 2026 corporate decisions
- Capital allocation must balance growth and efficiency: With an established growth runway but modest CAGR, the highest ROI investments are those that reduce life‑cycle cost for customers (e.g., energy‑saving variable‑speed drives) or create lock‑in via after‑sales services.
- Product strategy should prioritize differentiation: Energy performance, embedded controls, and modular packaged systems are the vectors that create premium positioning against commoditized centrifugal units.
- Procurement and supply‑chain design need contingency layers: Recent project timelines and vendor announcements show that specialists and package suppliers can deliver tailored solutions faster than broad OEMs when logistics are stressed — an important consideration for large infrastructure projects.
- Regulatory compliance is now a design constraint: Regional minimum pressure, updated pump standards, and building energy calculators are increasingly incorporated into specifications; early engagement with standards bodies and code consultants reduces rework risk.
- M&A and partnership targets should be service- and niche‑technology focused: Given market fragmentation and the premium on lifecycle revenue, acquisitions that add service capability, digital telematics, or access to specific vertical channels (municipal, high‑rise, irrigation) are compelling.
What PW Consulting’s full report delivers (practical contents)
- Market sizing and validated historical time series (2020–2025) and scenario-based forecasts (2026–2032) with sensitivity testing.
- Granular segmentation by region, pump type, and application — with demand drivers and adoption curves for each segment. Note: our briefing intentionally omits core split tables; the report contains the complete breakdowns and model files.
- Competitive landscape and capability mapping of leading OEMs and specialist suppliers, including product portfolios, channel reach, and aftermarket strength.
- Pricing and margin benchmarking, purchase‑decision matrices for key buyer cohorts (municipal engineers, MEP contractors, OEM specifiers), and procurement playbooks.
- Technology and innovation roadmaps, including electrification, variable‑speed integration, digital controls/telemetry, and service‑oriented product design guidelines.
- Regulatory impact assessment and a standards watch tied to procurement specifications and product development milestones.
- Actionable go‑to‑market playbooks: how to launch a packaged system, scale a service offering, or integrate telematics into existing product families.
- M&A screening criteria and a shortlist of strategic archetypes (aftermarket consolidators, niche OEMs, digital control enablers) with valuation levers and integration risk checklists.
Competitive landscape — strategic implications
The market structure is best described as fragmented with a meaningful tier of global full‑range suppliers and a broad long tail of regional specialists and package integrators. Rather than disclosing exhaustive split statistics here, the most important strategic orientation is this: the leading firms are differentiating through breadth of offering and systems capability, while nimble regional players compete on customization, speed, and service.
- Global full‑range OEMs (e.g., Grundfos, Xylem, Wilo, Pentair): These players leverage R&D scale, branded packaged systems, and broad distribution. Their strategic advantage lies in energy‑efficient platforms, global aftermarket networks, and brand trust — making them default choices for large commercial and institutional procurements. Expect continued incremental innovation around smart controls and energy optimization.
- Specialist package suppliers and OEMs (e.g., Gorman‑Rupp, Penn Pump, US Pump Corp, Nickerson): These firms are the go‑to for bespoke booster stations, rapid project delivery, and serviceability. Their strength is customization; their path to scale is either geographic expansion or partnerships with larger distributors.
- Value and replacement-focused suppliers (e.g., Walrus of America, APEC Water Systems): These competitors compete on plug‑and‑play convenience and price/availability for residential and light commercial segments. Margin pressure is real here; differentiation comes from channel exclusivity and SKU rationalization.
- Technology and service innovators (e.g., Franklin Electric, Towle‑Whitney): Movement toward smart, variable‑speed packages with digital monitoring is concentrated among companies that can bundle control hardware, software, and service. The winner’s playbook is combining hardware reliability with a subscription or SaaS service layer.
Recent industry movements underscore these strategic dynamics: new multistage and variable‑speed product launches in 2026, price list updates from major suppliers, and completed custom installations signal active product refresh cycles and steady project demand. Several municipalities and institutions are also issuing RFPs for full station upgrades, emphasizing turnkey delivery and commissioning capability.
Regulatory and standards pulse — operational ramifications
- Minimum pressure regulations and building energy calculators are increasingly embedded in procurement specs; product teams must validate hydraulic performance under these constraints early in design.
- Standards updates for turbine and submersible equipment have spillover effects for booster station certification and interoperability; manufacturers should align type‑testing and documentation roadmaps accordingly.
- Industry conferences and standards forums remain critical go‑to venues to influence specifications and stay ahead of code changes that affect product acceptance and warranty exposure.
Critical strategic moves for executives in 2026
- Prioritize product upgrades that lower customer TCO: Focus R&D on variable‑speed drives, motor efficiency, and hydraulic optimization; demonstrate lifecycle savings through third‑party validation.
- Build service and digital revenue streams: Pilot telematics + predictive maintenance offers in select markets to prove unit economics before scaling to broader channels.
- Refine go‑to‑market segmentation: Separate propositions for municipal/infrastructure projects, commercial building systems, and residential replacements — each needs tailored sales motions and warranty structures.
- Use M&A to close capability gaps: Target acquisitions that add rapid commissioning teams, aftermarket parts networks, or software control expertise rather than broad revenue plays alone.
- Harden supply continuity: Diversify key component sourcing and build modular platform designs that tolerate lead‑time variability without redesign.
- Model multiple demand scenarios: Use the PW Consulting forecast models to stress‑test pricing, service penetration, and capex plans across conservative, base, and upside demand trajectories.
How to use this PW Consulting report
Our report is designed as a decision‑support tool across functions. Product teams receive prescriptive design constraints and competitor feature maps; commercial leaders get pricing benchmarks, channel optimization levers, and RFP win strategies; strategy and corporate development teams obtain M&A screening frameworks and valuations tied to aftermarket accretion. Procurement and supply‑chain managers can run parts‑level sensitivity analyses against our forecast scenarios to size buffer inventories and contract terms.
Closing — why read the full study
This briefing highlights the strategic contours that matter in 2026: steady market growth at a mid‑single‑digit CAGR, rising importance of energy and digital differentiation, a fragmented competitive field where systems and services win margins, and regulatory pressures that are reshaping specs. If your objective is to refine product roadmaps, prioritize service investments, or evaluate acquisition targets, the granular segmentation, regional demand drivers, pricing matrices, and proprietary scenario models in our full Booster Pump Market study are essential. The public summary signals where advantage can be won; the complete report supplies the segmented data, model files, and recommended playbooks you need to act with confidence.
Contact PW Consulting or visit our research page to access the full dataset, model workbook, and tailored advisory packages that translate this intelligence into a prioritized 12–24 month execution plan.
For detailed analysis of this topic, please visit the official page: Booster Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Encrypted USB Flash Drives Market to Grow at 7.5% CAGR (2026–2032)
By PW Consulting, 2026-07-22

Encrypted USB Flash Drives Market: Strategic Briefing for 2026 Decision-Makers
As organizations accelerate digital transformation and tighten controls around data portability, encrypted USB flash drives have evolved from niche compliance tools into strategic peripherals for information governance. This briefing previews PW Consulting’s comprehensive market study—base year 2025, historical analysis 2020–2025, and forecast 2026–2032—highlighting the trends, competitive dynamics, regulatory inflection points, and practical recommendations that will matter most to procurement leaders, CISOs, and product strategists in 2026. To preserve the report’s commercial value, this piece surfaces the analytical scaffolding and strategic conclusions while directing readers to the full report for the granular segment-level intelligence and modeled scenarios.
Encrypted USB Flash Drives Market
Market Snapshot: Scale, Momentum, and Structural Profile
The global encrypted USB flash drives market is on a steady expansion trajectory. From a 2025 base of USD 200.0 Million, our model projects the market to grow at a compound annual growth rate (CAGR) of 7.5% over the 2026–2032 forecast window, reaching approximately USD 330.0 Million by 2032. The historical trend (2020–2025) shows accelerating adoption as organizations moved beyond ad-hoc encryption solutions toward certified, centrally managed, and tamper-resistant devices.
Encrypted USB Flash Drives Market
Two structural characteristics are decisive for strategy:
Encrypted USB Flash Drives Market
- Demand is highly security-driven: purchases are generally procurement-led by security teams and influenced by compliance requirements, not purely price-sensitive consumer demand.
- Supplier concentration is significant: the market is dominated by a handful of specialists and established storage OEMs, creating a competitive landscape where certification, provenance, and management ecosystems matter as much as raw performance.
Why This Study Matters to 2026 Enterprise Decisions
For 2026 planning cycles, encrypted USB drives intersect multiple decision domains—device provisioning, data loss prevention (DLP) programs, endpoint management, and regulated-procurement roadmaps. Our study delivers three decision-useful outcomes:
- Priority allocation: a clear mapping of where encrypted removable media will deliver the highest risk-reduction per dollar across enterprise functions and use-cases.
- Procurement playbook: comparative evaluation criteria that move beyond “encryption strength” to include certifications (FIPS/NIST), lifecycle management, supply chain provenance, and remote administration capabilities.
- Roadmap alignment: scenario-based demand forecasts that help CISOs and procurement teams size CAPEX and subscription spends for managed device fleets, including expected replacement cycles under realistic attrition and threat assumptions.
Key Growth Drivers and Strategic Risks
- Regulatory push and procurement requirements: Recent updates to federal and state guidance—most prominently mandates around 256‑bit AES for removable storage and NIST guidance requiring self-encrypting media for sensitive federal workloads—are accelerating enterprise and government procurement cycles. FIPS 140-3 Level 3 validation, in particular, acts as a gate for high-assurance government and defense use-cases.
- Enterprise governance and supply-chain hardening: Buyers are placing a premium on devices that integrate with endpoint management and that have transparent supply-chain provenance and tamper-evident hardware. Remote provisioning, audit logs, and centralized key management materially change TCO calculations.
- Technological substitution and commoditization risks: Improvements in secure cloud file-sharing and pervasive endpoint encryption could constrain long-term consumer demand. Simultaneously, product-level differentiation around ruggedization, hardware security modules, and zero-software designs will determine winner-take-most outcomes in enterprise/government segments.
- Threat environment: Sophisticated exfiltration and the targeting of removable media in insider scenarios increase demand for drives with hardware-enforced authentication, anti-tamper features, and remote-wipe capabilities.
Competitive Landscape: Who Matters and Why
The market blends specialist security vendors with established storage OEM brands. Our competitive analysis emphasizes product provenance, certification pedigree, management ecosystems, and route-to-market for enterprise and government procurement.
- Kingston Technology Company, Inc. (Fountain Valley, CA) — A leader with its IronKey line, Kingston couples AES‑256 hardware encryption variants and enterprise features (e.g., Locker+ 50 G2, D500S). Recent product launches illustrate a push to stay credentialed in government procurement through FIPS certifications and enterprise-oriented feature sets.
- Apricorn (Poway, CA) — Known for software-free, hardware-encrypted keys (Aegis series) and ruggedized designs. Apricorn’s emphasis on environmental hardening and submission pathways for FIPS validation positions it strongly in industrial and field-heavy use-cases.
- DataLocker Inc. (United States) — Focuses on certified devices with remote management (SafeConsole) and compliance-centered marketing (HIPAA, GDPR, CMMC). Product innovations prioritizing remote wipe and multi-certification broaden appeal to regulated buyers.
- Kanguru Solutions (United States) — Notable for government-certified drives and integrated endpoint protection, Kanguru targets public-sector procurement with tailored compliance support.
- iStorage (United Kingdom) — Delivers PIN-protected hardware-encrypted drives (datAshur PRO series) with an emphasis on simple, auditable secure-transfer workflows—appealing to multinational organizations with cross-border data controls.
- Clevy (United States) — A specialist offering enterprise-grade hardware-encrypted USB drives and management tooling that cater to MSPs and security-first buyers.
- Western Digital / SanDisk (San Jose, CA) — Brings scale, channel reach, and brand familiarity. Their encrypted offerings leverage integrated secure-access software and appeal in situations where brand trust and distribution are decision drivers.
Collectively, these vendors drive a competitive dynamic where certification, management integration, and product ruggedness are primary axes of differentiation. Notably, the market displays a high degree of concentration among top suppliers, reinforcing the importance of OEM and channel strategy when contracting for fleets.
Regulation, Certification, and Procurement Dynamics
Regulatory developments are not background noise—they are deterministic. Three threads to prioritize in 2026:
- State and federal technical standards increasingly mandate AES-256 (or stronger) for removable media; procurement teams must validate both algorithm strength and implementation (e.g., AES XTS hardware modules).
- NIST and FIPS certification regimes (notably FIPS 140-3 Level 3) are de facto procurement gates for defense, federal agencies, and many critical-infrastructure operators—certification status materially affects eligible supplier lists.
- Operational controls—centralized key management, remote-wipe, and audit logging—are becoming normative requirements in RFPs, particularly where GDPR, HIPAA, or contract-driven data protection obligations apply.
Understanding these dynamics is essential to avoid supplier lock-in pitfalls and to craft procurement language that balances assurance with commercial flexibility.
What PW Consulting’s Report Contains (Practical, Actionable Workstreams)
Our full study is organized to be immediately operational for procurement, security architecture, and product strategy teams. Key deliverables include:
- Executive-ready market sizing and revenue trajectory (2020–2032) with scenario sensitivity for macroeconomic shocks and accelerated regulatory adoption.
- Decision matrices for vendor shortlisting: certification status, management platform compatibility, lifecycle TCO modeling, and supply-chain risk scoring.
- Procurement templates and sample RFP language aligned to NIST/FIPS expectations and modern security operations requirements (e.g., remote wipe, hardware authentication, attestation).
- Competitive battlecards for the leading vendors—feature maps, route-to-market analysis, channel strengths, and likely enterprise/government fit.
- Implementation playbooks for IT and security operations that cover provisioning, inventorying, key rotation, incident playbooks for suspected exfiltration, and end-of-life sanitization.
To protect analytical value for subscribers and corporate clients, the report reserves the full granular segmentation tables and per-segment revenue forecasts for the source document. Those elements are essential for detailed budgetary allocations and are accessible through the PW Consulting distribution channel.
Practical Recommendations for 2026 Procurement and Security Leaders
- Align procurement timelines with certification cycles. If your use-case requires high assurance (government/defense/critical infrastructure), prioritize suppliers with active FIPS 140-3 Level 3 validation or a demonstrable roadmap to it.
- Embed management and auditability into contracts. Hardware encryption alone is insufficient; demand remote management, tamper-evidence reporting, and integration with your existing endpoint and identity stacks.
- Run supplier supply-chain assessments. For organizations with stringent provenance needs, incorporate factory attestation and traceability clauses into purchase orders to mitigate counterfeit and insertion risks.
- Adopt a lifecycle mindset. Treat encrypted drives as managed assets: central enrollment, periodic rekeying, supervised decommissioning, and incident procedures to support forensics.
- Build hybrid strategies. Where cloud-first secure file access competes with removable media, define clear use-case gates to avoid diffuse spending and security drift.
Conclusion and Next Steps
The encrypted USB flash drive market in 2026 is a security-first, certification-driven battleground where procurement decisions have outsized implications for compliance posture and operational resilience. PW Consulting’s full report translates market-scale forecasts, vendor capabilities, regulatory mandates, and operational playbooks into actionable steps for executive and technical stakeholders.
For access to the complete dataset, segment-level forecasts, vendor scorecards, and the procurement templates referenced here—along with bespoke briefings for your organization’s specific use-cases—please consult the full PW Consulting Encrypted USB Flash Drives Market report via our distribution portal.
For detailed analysis of this topic, please visit the official page: Encrypted USB Flash Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicon Wafer Market to Reach USD 209.6 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-22

Silicon Wafer Market 2026: Strategic Outlook for Decision‑Makers
As semiconductor roadmaps accelerate into an AI‑and‑edge era, silicon wafers remain the foundational substrate on which future chips — from high‑bandwidth memory to advanced logic and power devices — will be built. PW Consulting’s latest Silicon Wafer Market study (base year 2025) synthesizes five years of historical dynamics (2020–2025) with a detailed forecast (2026–2032) to translate market signals into boardroom‑ready decisions for 2026. The global market reached USD 135.7 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.5% across our forecast window, reaching an estimated USD 209.6 Million by 2032. This report is built for executives who must reconcile near‑term capacity choices with multi‑year technology transitions.
Silicon Wafer Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a pivotal year for wafer suppliers and semiconductor buyers. Supply chain re‑shoring policies, landmark facility investments, and a step‑change in demand for advanced epitaxial and high‑density wafers mean procurement, CapEx allocation, and qualification timelines decided in 2026 will determine competitiveness through the next product cycle.
Silicon Wafer Market -
Macro momentum, measured: After steady growth from 2020 to 2025, the market shows sustained expansion driven by higher wafer area shipments and more complex wafer types. Industry shipment data corroborates the momentum — device manufacturers and equipment makers are increasing commitments to advanced wafer formats to support AI accelerators and memory stacking.
Silicon Wafer Market -
Strategic tradeoffs: With elevated capital intensity for 300 mm and epitaxial lines, firms face tradeoffs between speed to market and long‑term operating leverage. Our study frames those tradeoffs quantitatively and overlays realistic qualification lead times so executives can prioritize projects that materially improve margin and capability.
Key market signals and what they imply
-
Shipment trajectory and demand concentration: Independent industry shipment trackers reported continued volume growth through 2025 and into early 2026, signaling resilient demand for silicon area and for advanced variants favored by AI and memory applications. For planners, this translates to a tighter window for supplier qualification and contract negotiations if seeking guaranteed supply for 2027 product ramps.
-
Policy and regional industrial policy are reshaping the supply map. National targets and state‑level incentives are accelerating local wafer capacity programs, while trade‑policy and subsidy frameworks increase the value of geographically diversified sourcing strategies. Firms that evaluate scenario outcomes for regional sourcing will reduce execution risk.
-
Upstream constraints matter: Semiconductor‑grade polysilicon supply remains a critical upstream risk. Energy‑intensive production and geographic concentration of feedstock processing create point vulnerabilities that can ripple through wafer lead times and costs — a vital consideration for procurement hedging and vertical integration assessments.
-
Segment complexity is rising: The mix is shifting toward larger diameters and more sophisticated process flows (e.g., epitaxial, SOI, and specialty wafers). This changes manufacturing cost curves, qualification timelines, and capital allocation models for both suppliers and buyers.
Competitive landscape — who holds the levers?
The silicon wafer industry remains concentrated among a handful of global suppliers that control a substantial portion of capacity and technology leadership. Leading players covered in our analysis include Shin‑Etsu Chemical (Tokyo), SUMCO (Tokyo), Siltronic (Munich), GlobalWafers (Hsinchu), SK Siltron (Gumi), Wafer Works (Taipei), Zhonghuan (Yixing), and Okmetic (Vantaa). These firms differ in end‑market focus, geography of production footprint, technology depth (prime, epi, SOI, annealed products), and customer mix.
Recent company movements underscore strategic priorities:
-
Facility commissioning and expansion: Select incumbents have brought new 300 mm epitaxial capacity online in Southeast Asia and completed customer qualifications — shortening delivery times for some advanced wafers and signaling readiness to serve next‑generation logic and memory.
-
Construction delays and re‑scoping: At least one major supplier has deferred build‑outs in response to shifting demand and project economics, illustrating the persistent execution risk in capital projects and the importance of flexible investment staging.
-
Government‑backed initiatives: Public‑private programs and terms of engagement in certain markets are accelerating local investments, while also creating potential non‑market competitive pressures that global buyers must incorporate into sourcing strategies.
Report contents — what actionable outputs you’ll get
PW Consulting’s Silicon Wafer Market study combines rigorous market modeling with pragmatic decision support. Key deliverables include:
-
Top‑down market sizing and scenario forecasts (base year 2025), with sensitivity runs for high‑demand and supply‑constrained futures.
-
Supply‑side mapping: facility footprints, technology capabilities, commissioning timelines, and equipment bottleneck analysis to anticipate lead‑time shifts.
-
Cost and margin benchmarking across wafer types and diameters to inform CapEx prioritization and pricing strategies.
-
Risk matrix and mitigation playbook: polysilicon sourcing stress tests, geopolitical scenarios, and inventory strategies tuned to different corporate risk appetites.
-
Buyer playbooks: procurement negotiation levers, multi‑sourcing templates, qualification roadmaps, and supplier partnership models for OEMs and IDM procurement teams.
-
Investment cases and M&A screeners for financial sponsors and strategic buyers, including accretion/dilution heuristics and post‑deal integration priorities.
-
Executive dashboards and model files enabling real‑time what‑if analysis for board presentations and CapEx committees.
Strategic recommendations for 2026
-
Prioritize qualification of at least two independent suppliers for any advanced wafer type critical to your product roadmap. Supplier diversification now reduces the probability of mid‑stream single‑source disruption during 2027–2028 product ramps.
-
Assess staged investment in internal wafer capabilities only when forward‑looking TCO (including energy and feedstock risk) consistently outperforms secure external procurement across multiple scenarios.
-
Lock in polysilicon supply agreements or strategic partnerships where wafer margins are sensitive to feedstock volatility. Hedging and bilateral supply agreements mitigate energy‑driven cost shocks.
-
Embed regulatory scenario planning into sourcing decisions. Domestic content targets and subsidy programs will alter competitive dynamics; proactive engagement with policymakers and alignment with national industrial programs can be a differentiator.
-
For investors: prioritize companies demonstrating clear pathway to advanced wafer technologies (epi, SOI) and a credible execution track record on 300 mm capacity — these attributes will matter more than sheer scale alone as complexity rises.
-
Manufacturing partners should accelerate collaboration on qualification engineering to compress time‑to‑production, leveraging co‑development agreements where beneficial.
What to expect in the near term
Our modeling shows a continuation of the growth trajectory that characterized 2020–2025, underpinned by increased wafer area shipments and a steady shift toward more sophisticated wafer types demanded by AI systems and power devices. However, that growth is not uniform: supply shocks, project execution variability, and policy interventions will create windows of tightness that can be material for time‑sensitive product launches. Companies that combine tactical purchasing agility with strategic capacity plans will convert short‑term market volatility into a durable competitive advantage.
How PW Consulting helps
PW Consulting pairs macro forecasting with executable playbooks. Our Silicon Wafer Market study provides not only the headline market trajectory (base year 2025; projected CAGR 6.5% through 2032) but also the operational templates and risk scenarios that procurement, product, and corporate development leaders need to act in 2026. We deliberately structure the work to support rapid decision cycles — from initial board‑level readouts to detailed supplier negotiation decks.
Next steps — access the full intelligence
This introductory analysis highlights the strategic value we deliver while reserving the granular segmentation and proprietary datasets that underpin supplier‑level and region‑level recommendations. For the full report — including interactive models, supplier scorecards, and downloadable forecast files that break down capacity, cost curves, and scenario outputs — visit our report page or contact PW Consulting’s industry team to schedule a briefing. In a market where timing and access matter, having the full dataset in hand is the tactical advantage you need for 2026.
For detailed analysis of this topic, please visit the official page: Silicon Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Gases Market to Reach USD 167.3 Billion by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-22

Industrial Gases Market: Strategic Primer for 2026 Decision-Makers
This preview synthesizes PW Consulting’s new Industrial Gases Market study—designed to inform board-level choices and operational trade-offs in 2026. The industry is larger and more dynamic than many assume: after steady recovery and expansion from 2020 through our base year (2025), the market is on a multi-year growth trajectory, expanding at a compound annual growth rate of roughly 6.5% in our forecast window (2026–2032). In absolute terms the global market moves from a strong USD 108 billion base in 2025 toward a material enlargement by 2032. This primer highlights the study’s strategic value, the dynamics that will shape capital and sourcing decisions in the year ahead, and why executives should treat the complete dataset as a near-term operational priority.
Industrial Gases Market
Market snapshot (what the numbers imply, not just the numbers)
From 2020 through 2025 the industrial gases market posted resilient recovery from pandemic headwinds, supported by capex in energy and semiconductor value chains and by rising healthcare and food-grade demand. Our base-year analysis (2025) captures structural shifts—most notably the early migration toward low-carbon hydrogen and site-level resiliency in semiconductor clusters—that inform the 2026 decision calendar. The forecast period (2026–2032) shows a continuation of healthy, above-average growth driven by three macro forces: industrial electrification and decarbonization investments, secular demand from high-value manufacturing (semiconductors, chemicals, metallurgy), and the ongoing modernization of logistics and on-site supply models.
Industrial Gases Market
Market concentration is meaningful for strategy: the top-three producers capture a majority share, and the top-five widen that concentration materially—an important fact for buyers and for entrants evaluating competitive intensity and pricing power.
Industrial Gases Market
Why this study matters for 2026 decisions
- Capex prioritization: Capital planners must choose between incremental air separation capacity and green hydrogen/electrolyzer investments. The report maps demand scenarios and IRR sensitivities under different electricity-cost and carbon-regulation paths.
- Sourcing strategy: Procurement teams face trade-offs between long-term dedicated supply agreements, on-site ASU installations, and merchant/packaged-supply approaches. We provide playbooks for contract design, risk allocation, and price-indexing that reflect current concentration dynamics.
- M&A and partnership screening: Private equity and corporate M&A teams can use our competitive overlays and valuation proxies to screen targets and to size bolt-on opportunities in specialty gases and regional logistics.
- Regulatory compliance & product strategy: For healthcare and electronics customers, stricter purity and safety standards require closer supplier integration and quality-control investments—an area where supplier differentiation will matter more in procurement discussions.
High-impact insights you can act on in 90 days
- Reframe 2026 procurement RFPs to include energy-cost pass-through clauses and delivery contingencies tied to power disruptions—especially for cryogenic and electrolyzer-backed supply.
- Run a 3-scenario investment screen (Base / High-Cost Energy / Accelerated Carbon-Pricing) for any electrochemical hydrogen projects before final board approval; our scenario module attaches probability-weighted NPV ranges.
- For semiconductor and specialty-manufacturing buyers, mandate supplier capacity-booking options in supply agreements to secure ramp support during new fab commissioning windows.
- Implement a supplier-benchmark dashboard that tracks three KPIs we identify as leading indicators: installed electrolyzer capacity commitments, on-site ASU uptime guarantees, and bundled logistics footprint.
What the full report contains (practical, decision-ready sections)
- Methodology and transparent market sizing: base-year (2025), historical analysis (2020–2025), and a granular forecasting engine (2026–2032) with scenario toggles for energy price, carbon costs, and demand shocks.
- Operational dynamics chapter: input-cost modelling (electricity, natural gas feedstock), labor and maintenance cost drivers, cryogenic vs. PSA economics, and sensitivity tables for plant economics.
- Commercial playbooks: contract templates, price-indexing mechanisms, inventory and safety-stock strategies, and negotiation levers by buyer archetype (energy, metals, electronics, healthcare).
- Decarbonization & technology pathways: comparative analysis of electrolyzer families, upscaling timelines, integration with renewable PPAs, and capex/O&M profiles under alternative regulatory regimes.
- Competitive benchmarking: strategy maps, capability heatmaps, M&A transaction summaries, and supplier scorecards across capabilities such as on-site services, specialty gases, and project engineering.
- Risk matrix and early-warning indicators: energy price risk, raw-material supply constraints, regulatory shocks (including carbon border adjustment mechanisms), and talent/labor availability.
- Executive playbook: 12–18 month tactical steps for C-suite and a set of board-level scenarios (best practice timelines and deliverables).
Note: the preview deliberately omits the full segmentation tables and detailed regional/application splits; those granular datasets and downloadable models are available in the full subscription report.
Competitive landscape — who moves first matters
The industrial gases arena is dominated by a handful of global platform players and several regional specialists. The leading incumbents combine large-scale production assets, extensive logistics networks, and growing engineering capabilities for turn-key projects—qualities that create high switching costs for large industrial buyers. Our study profiles each major operator, highlighting strategic intent, where they win, and where opportunities exist for challengers and buyers to improve contract economics.
- Air Liquide (France): A leader in large-scale supply agreements and industrial partnerships, with a clear push into electrolyzer-backed decarbonization projects. Their recent long-term supply deals in semiconductors and investment in electrolyzer capacity signal an integrated approach to low-carbon industrial gas supply.
- Air Products and Chemicals (USA): Strong in project execution and logistics; recent facility expansions underline continued investment in capacity and regional service centers—important when assessing near-term ramp capability for large manufacturing clients.
- Linde PLC (Ireland): A mix of engineering proficiency and large-scale supply commitments, with strategic focus on supporting semiconductor and steel industry decarbonization requirements. Public supply commitments in high-technology clusters increase their strategic relevance.
- Messer Group (Germany): A regional heavyweight with focused strengths in industrial process gases and a flexible commercial model that appeals to mid-market manufacturers seeking tailored on-site solutions.
- Matheson Tri-Gas (USA), Nippon Sanso (Japan), Iwatani (Japan), BASF (Germany): These players bring specialty, medical, and by-product gas capabilities that are increasingly valuable in electronics, healthcare, and chemical value chains—areas where purity, certification, and integrated services command premiums.
For buyers and investors the key is to map supplier capabilities against your critical use-cases (e.g., ultra-high-purity for semiconductors vs. bulk cryogenic oxygen for steel) and to treat supplier announcements—new long-term agreements, large electrolyzer projects, and facility expansions—as advance signals of capacity availability and pricing pressure.
Near-term catalysts and operational headwinds
- Raw material and energy volatility: Natural gas remains a common feedstock for several production pathways and electricity consumption for cryogenic air separation is a dominant operating expense. Fluctuations in these inputs materially affect plant-level margins and contract terms.
- Regulatory pressure: Heightened purity and safety standards (notably in healthcare and electronics) increase barriers to entry for small suppliers and raise certification costs. Separately, carbon policy instruments in major markets are beginning to reprice outsourced hydrogen and other carbon-intensive sales.
- Labor and cost inflation: Post-pandemic labor market dynamics and energy-driven inflation have compressed near-term profitability for several producers, prompting efficiency drives and renegotiation of supplier agreements.
- Technology momentum: Electrolyzers and integrated renewables are moving from demonstration to early-commercial scale. Where large producers commit to electrolyzer buildouts and long-term offtake agreements, they reshape the counterparty landscape for buyers seeking low-carbon supply.
Recent market moves—major supply agreements with semiconductor manufacturers, large electrolyzer projects, and targeted facility expansions—are not isolated events. They signal a broader rebalancing: producers are locking downstream demand and buyers are buying security of supply and low-CO2 credentials. The full report links each public development to capacity models and to our risk-adjusted pricing forecast.
How to use this research in a boardroom or procurement review
- Start with a 90-day sourcing sprint informed by our supplier scorecards and scenario templates—prioritize actions that reduce single-supplier exposure and that embed energy-cost hedges.
- Use the decarbonization module to stress-test capex proposals for green hydrogen and to align expected payback with corporate net-zero targets and projected carbon-pricing trajectories.
- In M&A, apply our competitive heatmaps and valuation multipliers to test price expectations for specialty-gas assets and regional logistics platforms.
- Adopt our risk-dashboard (included in the full report) to trigger contract re-opener clauses if key inputs or regulatory frameworks shift materially.
Next steps and how to get the full intelligence
This preview is intended to accelerate the right strategic conversations in 2026. To implement the playbooks, access the scenario models, and view the proprietary regional and application-level datasets that inform our forecasts and supplier scores, download the full Industrial Gases Market report. The detailed segment tables, contract templates, and downloadable Excel models are gated in the full report to ensure decision-makers have the complete evidence base for board presentations and procurement tenders.
For leadership teams, the report converts industry complexity into a practical agenda: secure supply, price certainty, decarbonization alignment, and scenario-ready investment decisions. In an industry where capacity commitments and regulatory shifts can change winners quickly, having a data-driven, playbook-oriented view is non-negotiable in 2026.
For detailed analysis of this topic, please visit the official page: Industrial Gases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Kitchen Ventilation Market at USD 1,630M in 2025; 6.8% CAGR to 2032
By PW Consulting, 2026-07-22
Commercial Kitchen Ventilation Systems Market — Strategic Preview for 2026 Decision-Makers
As global foodservice footprints reconfigure in response to shifting consumption patterns, energy policy pressure, and tighter fire and health codes, commercial kitchen ventilation is moving from a commoditized mechanical discipline to a strategic lever for operators, designers, and investors. This preview synthesizes the core, decision-grade insights from PW Consulting’s full market study to outline why 2026 is a pivotal year for executives shaping product roadmaps, procurement strategies, and M&A agendas in the commercial kitchen ventilation systems market.
Commercial Kitchen Ventilation Systems Market
Market snapshot: growth trajectory and concentration
The commercial kitchen ventilation market has demonstrated resilient expansion through the early 2020s, growing from roughly USD 1.15 billion in 2020 to about USD 1.63 billion in 2025 (base year). Our forecast conservatively assumes a compound annual growth rate (CAGR) of 6.8% over the 2026–2032 period, guiding the market to an expected size of roughly USD 2.58 billion by 2032. These headline dynamics reflect a mix of new-build restaurant growth, intensified retrofit activity driven by energy codes, and accelerating adoption of demand-driven controls and integrated IAQ solutions.
Commercial Kitchen Ventilation Systems Market
Market structure remains moderately concentrated: the top three vendors account for a majority share of the organized market, and the top five reach a stronger, but not monopolistic, presence. This concentration profile creates a landscape where scale delivers advantages in distribution, OEM-manufacturing, and large project specification — while meaningful opportunities still exist for niche innovators and specialist installers to capture profitable share.
Commercial Kitchen Ventilation Systems Market
Why 2026 matters: strategic inflection points
- Regulatory tipping points — Several jurisdictions are moving beyond prescriptive ventilation requirements toward performance-based mandates that explicitly reward energy-saving technologies such as Demand Control Kitchen Ventilation (DCKV). Proposed code changes in leading states are poised to change procurement economics and lifecycle TCO calculations.
- Operational economics — Rising energy costs and operator focus on lifecycle cost are shortening payback thresholds for integrated DCKV, heat recovery, and make-up air solutions. For design firms and specifiers, measurable operating-cost reductions are becoming as persuasive as capex comparisons.
- Digital integration — The shift from stand-alone hardware to controls-enabled solutions (sensors, analytics, BMS integration) is enabling new service revenue models such as performance-as-a-service, predictive maintenance, and value-aligned retrofits.
- Retrofit momentum — Aging equipment fleets and renewed investment in off-premise and hybrid service formats (cloud kitchens, food trucks, commissaries) create a near-term retrofit wave that is tractable for suppliers with strong installation and service capabilities.
Regulatory and safety environment: constraints and catalysts
Multiple codes and standards are central to short-term decision-making. NFPA 96 and the FDA Food Code continue to define fire protection and public health requirements for exhaust systems, while model mechanical codes (e.g., the Uniform Mechanical Code) set installation safety baselines. At the same time, energy policy — including proposals from state energy regulators — is reframing ventilation as an energy efficiency opportunity rather than a simple compliance cost. For market participants this means two concurrent priorities: ensuring absolute compliance with safety and health standards, and proactively aligning product and service offers with energy-code trajectories that may mandate DCKV or equivalent performance in leading markets.
Technology and product trends shaping supplier advantage
- DCKV and sensor-driven ventilation: proven paybacks and expanding code acceptance are turning DCKV from “nice-to-have” to near-essential in many specifications.
- Integrated make-up air and energy recovery: as operators focus on total HVAC impacts, combined solutions that reduce building heating/cooling loads gain traction.
- Controls and connectivity: interoperability with building management systems and remote performance monitoring unlocks service margins and improves lifecycle performance.
- Fire suppression and grease management evolution: modular, easier-to-install systems reduce downtime and total installed cost — a decisive factor for fast service chains and commissaries.
Competitive landscape — capabilities that matter in 2026
The competitive set combines large OEMs with national footprints and specialized regional manufacturers and integrators. Leading players demonstrate distinct positioning:
- CaptiveAire Systems, Inc. — A scale manufacturer with broad product breadth across hoods, fans, and grease management. Its integrated product suite and nationwide distribution give it an advantage in large chain accounts and turnkey projects.
- Greenheck Fan Corporation — Strength lies in engineered fan systems, make-up air units, and energy recovery expertise. Greenheck’s technical reputation makes it a preferred partner for projects emphasizing HVAC integration and efficiency.
- Systemair AB — Emphasizes high-performance exhaust systems and smart airflow controls, positioning itself toward customers prioritizing air quality and advanced control strategies.
- Gaylord Industries — A leader in demand-control kitchen ventilation (DCKV) and custom hood fabrication; well-suited to retrofit and high-efficiency projects where precise modulation of airflow is a differentiator.
- FAST Kitchen Hoods and NAKS — Regional manufacturers that offer compliance-focused, quick-turn hood solutions and value to local installers who demand reliability and Code expertise.
- Chef’s Deal Restaurant Equipment — Evolving from equipment supply into engineered ventilation services with a December 2025 expansion that broadened its service portfolio to fully engineered systems and custom packages — an example of channel players moving upmarket by adding design-engineer-install capabilities.
- Melink Corporation — Known for Intelli-Hood controls and energy-focused solutions; represents the digital, analytics-enabled end of the market and provides a template for value-added software/services monetization.
These players illustrate the two primary value paths in the industry: OEM-led scale (product breadth and distribution) and solution-led specialization (controls, services, retrofit expertise). Both paths create attractive entry points for partnerships, white-labeling, and bolt-on acquisitions.
Strategic imperatives for 2026 decision-makers
- Product and offering strategy: prioritize modular, controls-ready platforms that simplify installation and allow incremental upgrades (sensor retrofits, connectivity modules). This reduces buyer friction and future-proofs installations against evolving codes.
- Commercial model innovation: develop service and subscription offers that monetize ongoing performance (energy savings sharing, preventative maintenance contracts, analytics-based service tiers).
- Distribution and installer economics: invest in certified installer networks and fast-response service teams. Retrofit projects reward vendors who can guarantee minimal downtime and reliable commissioning.
- Compliance as a sales lever: embed compliance assurance in sales collateral — demonstrable NFPA 96 and local code alignment accelerates specification and reduces procurement risk for chains and institutions.
- M&A and partnership playbook: pursue tuck-ins that add local installation density, DCKV/control software, or make-up air expertise. The current concentration suggests room for accretive acquisitions that improve route-to-market and aftermarket capabilities.
- Risk management: hedge raw-material and supply-chain volatility by qualifying alternate stainless and sheet-metal suppliers and by standardizing key components across product families to reduce SKU complexity.
What the report delivers — practical, executable tools
PW Consulting’s full market study is built for application by procurement, product, and corporate strategy teams. Key deliverables include:
- Validated market sizing and conservative-to-accelerated forecasts (2026–2032) with scenario sensitivity for energy policy accelerations.
- Regulatory impact analysis and a policy watch matrix identifying high-probability code changes and their adoption timelines.
- Commercial playbooks: pricing, installation cost models, and payback calculators tailored to new-build vs. retrofit economics.
- Vendor scorecards and capability maps to accelerate partner selection and M&A screening.
- Operational checklists for compliance, commissioning, and service contracts that reduce project risk and warranty exposure.
- Case studies and templates that allow rapid pilot design for DCKV retrofits and integrated make-up-air deployments.
To preserve the strategic value of this preview and to maintain a single, authoritative reference for buyers and advisors, granular segmentation data (region, product, application splits) and detailed vendor revenue figures are intentionally omitted from this public summary. The full dataset is included in the complete report and supports precise targeting, investment sizing, and competitive benchmarking.
How to use the analysis in 90 days
- Quarter 1 (Assessment): Run the provided payback and TCO models on a representative store cluster to quantify retrofit economics under current utility rates and projected 12–24 month energy price scenarios.
- Quarter 2 (Pilot & Partnerships): Launch a DCKV + analytics pilot with a controls provider and a local installer; use the report’s vendor scorecards to select partners and structure service-level agreements.
- Quarter 3 (Scale & Capitalize): Lock in supplier agreements with performance warranties and service SLAs; use the policy watch matrix to pre-emptively align spec sheets with likely code updates.
Closing — the strategic opportunity
The convergence of energy policy, digital controls, and retrofit demand creates a unique window for sellers and operators to transform ventilation from a compliance line item into a measurable contributor to operating margin and brand sustainability. With a mid-single-digit CAGR driving the market toward multi-billion-dollar scale, the companies that combine product durability, control intelligence, and a scalable service model will capture outsized returns.
For executives preparing 2026 budgets and strategic plans, the full PW Consulting report provides the granular analysis, executable tools, and vendor-level insights required to convert uncertainty into competitive advantage.
Next step
Access the complete study for the detailed regional/product/application splits, full vendor scorecards, and the downloadable financial models that support procurement decision-making and M&A diligence. PW Consulting’s research team is available to brief executive teams and to run a customized scenario analysis tailored to your operating footprint.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


