



The PVB Film Market at a Strategic Inflection Point: Growth, Innovation, and Competitive Realignment
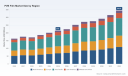
The poly vinyl butyral (PVB) film market has entered a phase of sustained expansion, with global revenue projected to climb from approximately 215.0 million USD in 2025 to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98% across the 2026–2032 forecast window. This trajectory builds on a recovery and acceleration pattern observed from 2020 through 2025, during which the market moved from 163.15 million USD to its current scale despite intermittent supply chain disruptions and macroeconomic volatility. The underlying growth is not merely a bounce-back from pandemic-era constraints; it signals a structural shift driven by performance requirements, regulatory pressures, and evolving end-use expectations. For executives and investors, the PVB film sector presents a concentrated yet dynamically evolving landscape where technological differentiation, sustainability credentialing, and supply chain resilience are becoming the primary axes of competition.
At the same time, the market is not sailing into calm waters. Three interlocking challenges define the current operating environment. First, raw material volatility and input cost pressure continue to test margin structures. Key precursors for PVB film production, including butyraldehyde and polyvinyl alcohol, remain exposed to petrochemical price cycles, logistics friction, and currency translation effects. Recent disclosures indicate that exchange rate fluctuations and fuel cost movements have imposed material headwinds on operating profit for major producers, with one leading manufacturer reporting a negative impact quantified in the billions of its local currency during its most recent fiscal reporting period. Second, the industry is navigating a tightening sustainability and transparency mandate. Customers and regulators are increasingly scrutinizing the carbon footprint of interlayers, pushing producers to adopt certified bio-based or recycled content, renewable energy usage, and third-party verification frameworks. Third, demand is bifurcating across application segments, with some verticals demanding higher structural performance and others prioritizing aesthetic customization or cost efficiency. This divergence forces manufacturers to manage multiple product architectures simultaneously, complicating capacity planning and R&D allocation.
Navigating the Core Challenges
The margin challenge is not simply a cost-pass-through exercise. Producers that rely on undifferentiated standard PVB film face intensifying price sensitivity, especially in applications where interlayer performance requirements are modest. At the same time, the shift toward high-performance variants, which command premium positioning, requires incremental investments in formulation science, processing control, and application-specific validation. These investments are non-trivial, and the return profile depends on the ability to secure design wins in automotive programs, specification adoption in architectural projects, and qualification in photovoltaic laminates. The sustainability mandate adds another layer of complexity. Certification achievements and the integration of recycled resin content are becoming table stakes in certain customer conversations, particularly in Europe and North America, where procurement teams are embedding environmental criteria into supplier qualification processes. Producers that treat sustainability as a compliance checkbox rather than a product and process strategy risk losing specification relevance over time.
Demand bifurcation is equally consequential. Automotive applications continue to drive a substantial share of volume, propelled by evolving vehicle architectures, safety expectations, and the gradual redesign of interiors and glazing systems. Architectural usage remains a steady and growing contributor, supported by building codes, renovation activity, and a growing appetite for specialized visual effects in premium and commercial projects. The photovoltaic segment, while smaller in relative terms, is gaining attention as solar module makers explore improved encapsulation and durability characteristics. The strategic implication is clear: growth is available, but it is unevenly distributed, and capturing it requires targeted product roadmaps rather than broad-based volume plays.
Key Drivers Reshaping the PVB Film Market
Three to four core drivers are interacting to reshape the competitive and commercial dynamics of the PVB film market. These drivers do not operate in isolation; they reinforce one another and collectively raise the bar for what constitutes a viable market position.
Technological Innovation and Performance Breakthroughs
Performance differentiation is moving from a nice-to-have to a decisive purchase criterion. In laminated safety glass, the interlayer's role is expanding beyond basic structural bonding and optical clarity.Automotive OEMs and Tier suppliers are seeking interlayers that contribute to acoustic comfort, impact resistance, and shape retention under stress, while architectural specifiers are looking for films that enable thinner glass packages, improved load-bearing characteristics, and distinctive visual finishes. Recent product introductions illustrate this direction. In the spring of 2024, a major producer launched a next-generation interlayer engineered for improved structural capacity, resistance, toughness, and elasticity, signaling a push toward higher-performance standards in safety glass applications. Later in the year, another incumbent introduced a low-carbon film variant that incorporated recycled resin content and leveraged renewable energy in its production process. By the following year, a European-focused manufacturer unveiled a specialized interlayer designed to deliver a refined visual effect suited to minimalistic architectural designs. These launches collectively demonstrate that innovation is branching into both performance engineering and aesthetic customization, broadening the value proposition beyond traditional transparency and adhesion.
The strategic takeaway is that R&D is becoming a direct revenue lever. Manufacturers that can shorten qualification cycles, align product attributes with end-use validation protocols, and communicate performance benefits in customer-relevant terms are better positioned to secure long-term specification loyalty. Conversely, firms that stagnate on product architecture risk being squeezed between premium innovators and cost-oriented competitors.
Policy, Regulation, and Sustainability Credentials
Regulatory and sustainability dynamics are increasingly shaping procurement decisions and competitive access. Certification frameworks that verify the bio-based or recycled content of materials, as well as the sustainability of manufacturing operations, are gaining traction in customer qualification checklists. Recent certification milestones have covered PVB film products and major production sites across Europe, the United States, and Asia, reflecting a deliberate effort by leading players to institutionalize sustainability credentials across their global footprint. This is not merely a public relations exercise; it is becoming a gateway to certain projects and programs where environmental criteria are embedded in sourcing policy. At the same time, producers are deploying financial and operational instruments to manage input volatility, including derivative tools to hedge exposure on strategic raw materials. The combination of sustainability certification and cost-risk management is creating a more resilient operating model, but it also raises the investment threshold for staying competitive.
For decision-makers, the implication is that sustainability is converging with commercial risk management. Procurement teams are weighing not only price and performance but also the compliance and reputational risk associated with material sourcing. Manufacturers that can provide traceable, verified content and energy sourcing data are gaining an advantage in specification discussions, particularly in regions where regulatory and customer expectations are advancing most quickly.
Demand-Side Shifts in Automotive, Architecture, and Energy Applications
Demand-side behavior is evolving across the three primary application areas, each with distinct drivers. In automotive, glazing strategies are being influenced by vehicle electrification, interior redesign, noise and vibration refinement, and the ongoing push for lighter, safer, and more aesthetically cohesive cabin environments. These trends support continued demand for interlayers that can meet stricter performance profiles while enabling designers to achieve new visual and tactile outcomes. In architecture, the drivers are more varied: building energy codes, renovation and retrofit activity, security and safety requirements, and a growing interest in bespoke finishes for commercial and premium residential projects. The photovoltaic application, while representing a smaller share of current demand, is attracting attention as module manufacturers and integrators evaluate encapsulation options that can contribute to longevity, optical consistency, and processing compatibility. The common thread is that customers are becoming more application-literate and are expecting film suppliers to speak to specific use-case requirements rather than offering generic interlayer solutions.
This specificity changes the commercial dynamic. Winning in automotive often requires long lead times, rigorous testing, and program-aligned supply commitments. Winning in architecture frequently depends on specification relationships, visual and performance differentiation, and the ability to support architects and fabricators with consistent quality and aesthetic options. Winning in photovoltaic contexts depends on validation against module-level durability and processing requirements. Each path requires a tailored go-to-market model, and the firms that can orchestrate these models coherently are better positioned to convert demand into durable revenue.
Supply Chain and Cost Structure Evolution
The supply side is being reshaped by the interplay of input volatility, capacity decisions, and regional localization pressures. Key raw materials remain sensitive to petrochemical cycles and logistics costs, and currency movements can materially affect operating results for globally exposed producers. In response, leading manufacturers are pursuing a combination of hedging strategies, production optimization, and selective capacity expansion or rationalization. The objective is to protect margins without sacrificing service levels or quality consistency. There is also a growing emphasis on reducing the carbon intensity of production, which can involve energy sourcing changes, process efficiency improvements, and the integration of recycled or bio-based feedstocks where technically and commercially viable. These efforts are not isolated initiatives; they are increasingly woven into product positioning and customer discussions, blurring the line between operational efficiency and market-facing value creation.
The practical consequence is that cost leadership alone is becoming harder to sustain as a differentiator. While efficiency remains essential, the more durable advantages are emerging from the combination of performance innovation, verified sustainability attributes, and reliable supply assurance. Producers that can deliver this combination are able to command more favorable commercial terms and build deeper relationships with specifiers and procurement organizations.
Competitive Landscape and Leading Strategies
The PVB film market is characterized by a high degree of concentration, with the top three producers accounting for approximately 79% of market value and the top five representing around 85%. This concentration reflects the scale, technical know-how, and qualification infrastructure required to compete effectively across automotive and architectural applications. It also means that competitive dynamics are shaped by a relatively small number of players whose product portfolios, geographic reach, and sustainability commitments directly influence market direction.
Strategic Positioning of Leading Players
Several incumbent companies illustrate the divergent yet overlapping strategies now unfolding. One U.S.-based producer has built a strong association with laminated safety glass interlayers for both automotive and architectural markets, leveraging established brand recognition and a broad application footprint. Recent moves have combined product innovation with sustainability positioning, including the introduction of a low-carbon film variant that incorporates recycled resin content and uses renewable energy in production. The same company has also relied on derivative instruments to manage volatility in the cost of strategic raw materials, highlighting a dual focus on product differentiation and cost-risk control. Another major player, headquartered in Japan, maintains a globally recognized interlayer portfolio and has pursued a parallel path of performance and sustainability advancement. This includes the launch of a next-generation stiff interlayer designed for improved structural capacity and the achievement of sustainability certification covering products and major plants in Europe, the United States, and Asia. A Taiwanese producer contributes a distinct angle through its focus on polyvinyl butyral resins and film for safety glass interlayers, adhesives, and printing inks, reflecting a broader materials orientation that can support integrated supply advantages. A Belgium-based manufacturer has carved out a specialized position in high-quality PVB film for architectural laminated safety glass, with recent attention to refined visual effects tailored for minimalistic design contexts.
These profiles reveal a market in which leaders are not merely competing on volume but are differentiating along multiple axes: performance engineering, aesthetic customization, sustainability verification, and supply chain resilience. The strategic implication is that competitive advantage is becoming multidimensional. A single strength, such as cost efficiency or brand recognition, is less sufficient on its own than it once was. Instead, the most defensible positions combine at least two of the following: application-specific performance leadership, credible sustainability credentials, and reliable, localized supply capability.
Market Structure Evolution: Consolidation, Differentiation, and Entry Dynamics
Given the high concentration and the technical barriers associated with qualification, scale, and application validation, the market is likely to see continued consolidation pressure among smaller or less differentiated participants. At the same time, the bifurcation of demand and the emergence of specialized product attributes are creating space for targeted differentiation, even within a concentrated landscape. New entry remains challenging because of the need to secure design wins, pass validation protocols, and establish supply reliability across demanding customer segments. However, niche opportunities may arise in specialized architectural finishes, high-performance interlayers for specific automotive programs, or application-tailored solutions for photovoltaic encapsulation, where focused innovation and strong specification relationships can offset scale disadvantages. The broader trend is one of strategic segmentation: the market is not becoming uniformly consolidated into a single winners-take-all structure, but rather into a set of performance and application niches where distinct value propositions can command premium positioning.
VCI Film Market
For observers of competitive dynamics, the key question is not whether concentration will persist, but how value will be distributed within that concentrated structure. Leaders that can translate product innovation into specification wins and sustainability credentials into procurement preference will likely capture a disproportionate share of the incremental growth projected through the end of the decade and into the early 2030s.
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the PVB film market is likely to be shaped by trends that connect technological ambition, sustainability expectations, and application-specific demand. These trends carry both opportunity and risk, and they should inform near-term strategic planning.
Performance-Led Premiumization Accelerates
The push toward higher-performance interlayers is expected to intensify as automotive and architectural customers raise their expectations for structural capacity, acoustic behavior, durability, and design flexibility. This trend favors producers that can validate advanced attributes in relevant applications and secure design or specification wins early in program or project cycles. The commercial opportunity lies in building a portfolio of differentiated variants that address specific performance gaps, supported by technical service and application engineering. The risk is that premiumization outpaces the ability to scale qualified production or that customers resist premium pricing in cost-sensitive segments, forcing difficult trade-offs between margin and volume.
Sustainability Becomes a Specification Factor, Not a Differentiator
Sustainability credentials are on a trajectory from optional advantage to expected attribute in several regions and customer segments. Certification coverage across major production sites, the use of recycled or bio-based content, and renewable energy integration are increasingly part of supplier evaluations. The opportunity is to embed sustainability into product identity and process design in ways that are verifiable and customer-relevant, thereby reducing friction in qualification and strengthening preference in competitive bids. The uncertainty lies in the pace and uniformity of adoption. If expectations diverge significantly by region or application, producers may face complex portfolio and compliance decisions. If standards tighten faster than anticipated, firms that have not invested early may find themselves excluded from certain opportunities or forced into catch-up investments at higher cost.
Supply Chain Localization and Cost Discipline Reshape Competitive Resilience
Input volatility, currency exposure, and logistics complexity are likely to keep cost and supply resilience in focus. Producers will continue to pursue a mix of hedging, process efficiency, energy sourcing changes, and selective capacity adjustments. The opportunity for resilient operators is to combine cost discipline with reliable service and consistent quality, building trust with customers who are themselves managing procurement risk. The risk is that overinvestment in capacity in a softening segment or underinvestment in qualifying new variants can distort the portfolio and weaken competitive positioning. Additionally, regional cost structures and regulatory environments may create uneven profitability across geographies, requiring disciplined portfolio management rather than blanket expansion.
PW Consulting Chemical & Energy Research Center
Actionable Implications for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the specific performance and aesthetic requirements of high-value applications while institutionalizing sustainability credentials across production sites. This means treating R&D as a commercial engine, not a back-office function, and ensuring that new variants are supported by validation data, technical service, and clear positioning. It also means building cost-risk management into the operating model, using hedging and process optimization to protect margins without compromising quality or service. Companies that can demonstrate measurable performance benefits and credible sustainability attributes are more likely to secure specification loyalty and defend premium positioning.
For investors, the strategic signal is that growth is real but unevenly distributed across applications and product tiers. The most attractive exposure is likely to be found in producers that combine application-relevant innovation with verified sustainability and disciplined cost management, rather than in undifferentiated volume plays. Due diligence should focus on qualification pipelines, certification coverage, raw material exposure, and the ability to convert product launches into specification wins. Portfolio valuation should account for the possibility that premiumization and sustainability adoption will accelerate in some regions and segments faster than others, creating divergence in growth and margin profiles across the competitive set.
For procurement and sourcing leaders, the practical guidance is to evaluate suppliers on a broader set of criteria that includes performance validation, sustainability verification, and supply assurance, not just unit price. The most resilient sourcing relationships will be those in which the supplier can demonstrate traceability, consistent quality, and the ability to support application-specific requirements over the life of a program or project. Engaging early in design and specification cycles, and aligning on sustainability and performance expectations upfront, can reduce downstream risk and improve total value.
For all of these audiences, the pace of change in the PVB film market argues for timely, granular intelligence. High-level growth figures and concentration ratios provide context, but the commercial decisions that matter most—program qualification, specification strategy, capacity allocation, sustainability investment, and sourcing commitments—depend on detailed segmentation data, regional demand patterns, and company-level trajectories. Accessing deeper, structured analysis can shorten the distance between market awareness and actionable strategy, enabling more precise prioritization of investments, partnerships, and risk mitigation.
PV Ribbon Market
For detailed analysis of this topic, please visit the official page: PVB Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sodium Permanganate Market: Why 4.6% CAGR and Water Treatment Demand Change Everything
By PW Consulting, 2026-09-21
Sodium Permanganate Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
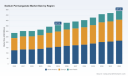
The global sodium permanganate market is navigating a period of structural transformation, defined by steady expansion against a backdrop of regulatory tightening, raw material volatility, and evolving end-use requirements. Over the historical period spanning 2020 through 2025, market revenue demonstrated consistent upward movement, reflecting both post-pandemic industrial recovery and sustained investment in critical infrastructure. The base year of 2025 marks an inflection point where demand growth has begun to outpace earlier cyclical patterns, driven by capital expenditure programs in water infrastructure and electronics manufacturing. The forecast window through 2032 projects a compound annual growth rate of 4.6 percent, suggesting that the market will continue to expand at a moderate but resilient pace, supported by long-cycle investments rather than short-term discretionary spending.
Scale alone, however, does not define the strategic landscape. The market exhibits a pronounced concentration profile, with the top three firms controlling approximately seventy percent of revenue and the top five firms capturing roughly three-quarters of total share. This structure implies limited competitive fragmentation, high barriers to entry around certification and distribution networks, and a pricing environment where incumbents can exert meaningful influence over contract terms. At the same time, concentrated markets are vulnerable to supply shocks and regulatory adjustments that can cascade quickly through the value chain. The current environment presents several interrelated challenges that decision-makers must address.
First, raw material cost volatility has become a persistent pressure point. Manganese-based inputs underpin sodium permanganate production, and recent pricing movements in related chemical streams have introduced margin uncertainty. Quarter-over-quarter increases in manganese sulfate pricing, linked in part to higher sulfuric acid costs, illustrate how upstream inputs can compress profitability even when end-market demand remains robust. Second, supply disruptions tied to mining operations have reinforced the fragility of raw material availability. Weather-related interruptions at manganese-producing sites have periodically tightened supply, pushing ore prices higher and creating timing mismatches between procurement cycles and production schedules. These dynamics elevate the strategic importance of supplier diversification, inventory planning, and long-term contracting.
Third, regulatory frameworks are reshaping competitiveness in ways that go beyond simple compliance. Designations that elevate high-purity manganese to a strategic material status introduce new considerations around supply security, traceability, and alignment with broader policy priorities. In practice, this means procurement decisions increasingly factor in resilience and continuity alongside price and quality. Organizations that can demonstrate certified supply chains, documented compliance, and stable sourcing arrangements gain an advantage in bidding environments where reliability carries tangible commercial weight. Taken together, these challenges do not threaten the market’s trajectory, but they do reward firms that treat supply chain resilience and regulatory readiness as core capabilities rather than operational afterthoughts.
Key Drivers of Market Change
Technological Innovation and Product Differentiation
Innovation in sodium permanganate markets is less about radical chemistry shifts and more about precision, purity, and application fit. High-purity grades have gained traction in end-use segments where contamination sensitivity is critical, particularly in electronics manufacturing and specialized industrial processes. The availability of purity levels approaching ultra-high specifications reflects a broader trend toward customization: buyers are increasingly unwilling to accept commodity-grade solutions when performance margins and process reliability are at stake. This shift favors suppliers capable of delivering consistent quality with rigorous documentation and testing regimes.
Sodium Percarbonate Market
In parallel, liquid-formulation expertise continues to differentiate incumbents in water treatment applications. NSF-certified grades and compliance with AWWA standards have become baseline expectations in municipal and government procurement, not optional enhancements. Suppliers that can provide certified products, clear safety data documentation, and application support are better positioned to secure long-term contracts. The strategic implication is clear: technical credibility and certification infrastructure now function as competitive moats. In a concentrated market, the firms that invest early in quality systems and application-specific grade development are more likely to preserve pricing power and customer loyalty over time.
Policy and Regulatory Environment
Policy developments are increasingly influencing where capital flows and how supply chains are evaluated. The elevation of high-purity manganese within critical raw materials frameworks has made supply security a strategic priority for downstream industries and public-sector buyers alike. When manganese is explicitly recognized as a material important to supply security, procurement teams and project developers pay closer attention to sourcing origins, price stability, and the continuity of available grades. This does not simply add a compliance layer; it changes the decision calculus for large-volume contracts and infrastructure programs.
Simultaneously, government support for domestic production capacity in battery-grade and industrial manganese streams signals a longer-term shift toward supply localization in key geographies. Grant programs and policy incentives aimed at building production facilities reflect a broader emphasis on reducing dependence on imported inputs for strategic applications. For sodium permanganate markets, this creates a dual effect. On one hand, policy-driven investment in manganese production capacity could improve long-term availability and moderate input cost volatility. On the other hand, transitional periods may still be marked by tightness, regional disparities, and competition for intermediate materials. Companies that maintain visibility into these policy dynamics can better time procurement commitments, capacity planning, and partnership structures.
Manganese Sulphate Market
Demand-Side Shifts in Water Treatment and Electronics
Demand growth continues to be anchored by water treatment applications, where sodium permanganate remains a valued oxidizing agent for odor control, iron and manganese removal, and broader oxidation processes. Infrastructure budgets, public health priorities, and tightening water quality standards all contribute to sustained procurement needs in this segment. Importantly, large municipal and government contracts often follow multi-year planning cycles, meaning demand in this area is relatively stable but highly dependent on certification compliance, specification alignment, and trust in supplier reliability. Contract awards that reference NSF and AWWA standards exemplify how procurement processes reward documented conformity and supply consistency.
In the electronics segment, demand is shaped by process sensitivity and purity requirements rather than volume alone. High-specification applications reward suppliers capable of delivering tightly controlled grades with comprehensive quality documentation. As electronics manufacturing continues to emphasize reliability and contamination control, the value proposition of specialty-grade sodium permanganate strengthens. The broader demand picture includes additional application areas that add incremental growth and diversify end-use exposure, reducing reliance on any single vertical. For commercial strategy, the key insight is that demand-side strength varies by segment quality thresholds, procurement structures, and certification dependencies. Success depends on matching product architecture to the specific requirements of each major application rather than treating the market as a homogeneous whole.
Supply Chain and Cost Structure Dynamics
Cost structures in this market are heavily influenced by manganese availability, chemical input pricing, and the logistics of specialized distribution. Recent quarter-over-quarter increases in manganese sulfate pricing illustrate how quickly input economics can shift, especially when driven by higher costs for essential precursor chemicals such as sulfuric acid. These movements affect not only production costs but also the timing of contract negotiations and the structure of pricing terms. In concentrated markets, suppliers with established sourcing relationships and inventory buffers may be better positioned to manage short-term volatility without passing all costs downstream.
Supply disruptions from manganese mining operations further complicate cost planning. When production interruptions occur due to environmental incidents or operational constraints, ore prices can rise and availability can tighten, forcing downstream producers and distributors to adjust procurement strategies. Events such as mine suspensions linked to cyclone damage have shown how quickly physical supply conditions can change. The result is a market where resilience is increasingly priced into sourcing decisions. Buyers are willing to pay for assurance, and suppliers that can offer dependable continuity, transparent documentation, and proactive risk management gain leverage. Over time, this dynamic rewards organizations that treat supply chain design as a strategic function, integrating supplier diversification, contractual flexibility, and scenario planning into everyday operations.
Competitive Landscape and Leading Strategies
The competitive structure of the sodium permanganate market is defined by a small group of established U.S.-based producers and distributors with strong positioning in water treatment, government procurement, specialty-grade supply, and bulk distribution. This concentration reflects the importance of certification, application expertise, and supply reliability. Rather than competing primarily on price, leading firms differentiate through product grades, compliance documentation, distribution reach, and customer relationships built around recurring contract cycles.
Carus Corporation stands out as a major producer and supplier of liquid sodium permanganate for water treatment applications, including NSF-certified grades. Its strategic positioning centers on alignment with municipal and industrial water treatment requirements, where certification and product consistency are decisive. By maintaining a focus on certified grades and application-oriented supply, the company reinforces its role in high-value public-sector and industrial procurement environments. In a market where contract awards increasingly reference NSF and AWWA standards, that certification-oriented posture is a meaningful competitive asset.
Hawkins, Inc. operates as a domestic manufacturer, blender, and distributor with a B2B-only sales model focused on municipal and government water treatment. Its strategy emphasizes local production and distribution reliability, targeting customers that prioritize continuity of supply and direct commercial relationships. The B2B-only orientation allows the firm to concentrate on specification-driven buyers rather than broader retail-style channels. This model supports stable demand attachment to public-sector and institutional customers where procurement processes favor established distribution partners with documented compliance capabilities.
Valudor Products, LLC supplies 40 percent sodium permanganate solution certified for water treatment with full safety data documentation. Its differentiation is rooted in product specification clarity and documentation completeness, which matter in procurement settings where compliance and transparency are non-negotiable. Suppliers that make safety data sheets and certification information readily accessible reduce friction in the purchasing process and strengthen trust with buyers who must satisfy internal and external audit requirements. In concentrated markets, even incremental improvements in documentation and specification clarity can influence supplier selection.
American Elements positions itself around high-purity offerings, providing sodium permanganate at purity levels up to 99.999 percent for commercial, research, and industrial uses. This strategy targets segments where purity thresholds drive value rather than cost minimization alone. High-purity specialization creates a different competitive logic: customers in electronics and advanced industrial applications often prioritize grade integrity and documentation over bulk commodity pricing. By focusing on ultra-high purity capability, the company serves demand that is less sensitive to commodity price fluctuations and more sensitive to performance assurance.
Rock Chemicals, Inc. operates as a trusted bulk supplier with emphasis on reliable sourcing and compliance documentation. Its positioning reflects a practical, reliability-first value proposition: customers in bulk procurement environments value consistency, sourcing transparency, and the ability to meet compliance requirements without administrative delay. In a market where raw material volatility and supply interruptions are real risks, that emphasis on dependable sourcing and documentation provides a practical competitive edge, especially for procurement teams seeking to reduce uncertainty in recurring supply contracts.
Recent procurement activity highlights how these competitive dynamics play out in practice. Contract awards such as the 2025 supply agreement for sodium permanganate under NSF and AWWA standards demonstrate that public-sector buyers continue to prioritize certified compliance and specification alignment. Such contracts reinforce the value of firms that can meet documented standards and sustain reliable delivery. In a concentrated market, these wins are not merely transactional; they signal a broader pattern where certification readiness and procurement compatibility shape share dynamics over multi-year horizons. The competitive landscape is likely to evolve through selective integration, deeper specialization by purity or application, and the continued importance of distribution and documentation capabilities. New entrants will face steep barriers unless they can credibly replicate certification infrastructure, supply reliability, and customer trust.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several interconnected trends are likely to shape commercial strategy in sodium permanganate markets. The first is a reinforcement of certification and compliance as competitive drivers. As water infrastructure procurement remains anchored in public-sector standards and industrial buyers demand documented traceability, firms with robust certification portfolios and clear application-specific grades will be better positioned to win and retain contracts. The opportunity here lies in strengthening application alignment, expanding certified grade availability where feasible, and reducing friction in the buyer’s compliance review process. Organizations that can provide clearly documented, specification-matched products will find it easier to command premium positioning in procurement cycles where risk avoidance matters.
A second trend is the continued tension between demand resilience and raw material volatility. Infrastructure spending and electronics-related demand are expected to provide underlying support, but input cost fluctuations tied to manganese sulfate pricing and mining disruptions will likely remain a recurring theme. This creates commercial opportunities for firms that can secure longer-term sourcing arrangements, build inventory buffers where appropriate, and design pricing structures that balance stability with flexibility. For buyers, the opportunity is to reduce exposure through diversification, strategic contracting, and clearer visibility into upstream pricing signals. For suppliers, the opportunity is to differentiate through reliability, documentation, and service quality in a market where continuity can be as valuable as unit price.
The third trend is the growing influence of strategic raw material policy on supply chain behavior. As manganese gains recognition within critical materials frameworks and public investment supports domestic production development, procurement and production strategies may gradually shift toward greater supply security, regional diversification, and alignment with policy priorities. This creates opportunities for firms that can articulate supply resilience, traceability, and continuity as part of their commercial value proposition. At the same time, transitional uncertainty may persist, particularly during periods when new capacity is being developed but has not yet stabilized availability. Decision-makers should therefore plan for a market environment where policy, sourcing, and pricing interact more closely than in the past.
These trends carry potential risks and uncertainties. Raw material price swings can compress margins or trigger renegotiation pressure if contracts lack flexibility. Regulatory changes can alter compliance expectations faster than product or documentation systems can adapt. Supply disruptions may expose overreliance on limited sourcing channels. In addition, market concentration means that shifts in the strategy or capacity of a small number of incumbents can affect overall availability and pricing dynamics. The commercial opportunity is not simply to forecast growth, but to build operational and commercial buffers that allow firms to respond decisively when conditions change.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to reinforce differentiation through grade specialization, certification readiness, and supply reliability. Investment in high-purity capability, certified water treatment grades, and rigorous documentation can support premium positioning in application-sensitive segments. Equally important is proactive management of input costs and sourcing risk. Diversifying supplier relationships, maintaining visibility into manganese-related pricing trends, and structuring contracts with appropriate flexibility can protect margins without sacrificing customer trust. Manufacturers should also consider how application-specific support, technical documentation, and compliance clarity can reduce friction in customer qualification processes, especially where procurement cycles are long and specification-driven.
For investors, the market presents a profile of steady growth with concentrated leadership and strategic sensitivity to raw material and regulatory dynamics. Due diligence should focus on supply chain resilience, certification positioning, and exposure to input cost volatility rather than on top-line growth alone. Companies with strong compliance documentation, recurring government or municipal contracts, and credible sourcing strategies are better equipped to withstand disruptions and defend pricing. At the same time, investors should monitor the pace of policy-driven capacity development and any shifts in manganese availability that could affect cost structures or regional supply patterns. In concentrated markets, competitive advantage often depends on reliability and credibility as much as scale, so qualitative assessments of operational maturity can be as important as financial metrics.
For procurement teams and buyers, the strategic priority is to reduce exposure to volatility while preserving quality and compliance. Diversifying approved suppliers, aligning purchasing cycles with upstream cost signals, and prioritizing vendors with robust certification and documentation can improve contract stability. Where possible, long-term agreements should incorporate mechanisms that address raw material price movements without sacrificing service quality or specification integrity. Procurement strategies should also account for the increasing importance of supply security and continuity in public-sector and industrial environments, where auditability and reliability can outweigh marginal price differences. In this context, detailed segment-level intelligence on grade demand, certification dependencies, and sourcing risk can materially improve sourcing decisions.
For organizations seeking a more granular view of segment dynamics, regional demand patterns, and contracting trends, deeper analysis can clarify where value is created and where risk concentrates. A detailed research report can provide the segmented data, competitive mapping, and scenario context needed to support pricing, capacity, and sourcing decisions with greater precision. Given the pace of regulatory and raw material developments, timely access to structured market intelligence is not merely an analytical exercise; it is a practical input to strategy execution. For decision-makers who need to translate market signals into procurement, investment, or product strategy, a fuller examination of the data and competitive dynamics can help ensure that action plans are grounded in current conditions rather than assumptions.
PW Consulting Chemical & Energy Research Center
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Natural Astaxanthin Market: Why 9.1% CAGR & Shifting Demand Dynamics Redefine Growth
By PW Consulting, 2026-09-21
The Natural Astaxanthin Market: Strategic Trends and Commercial Opportunities
The natural astaxanthin sector has evolved from a niche antioxidant into a strategically significant ingredient market, driven by converging forces in health and wellness, aquaculture growth, and formulation innovation. Between 2020 and 2025, global revenue expanded from approximately 248.56 million to 372.0 million, reflecting a compound annual growth rate of 9.1 percent. Looking ahead to 2032, the trajectory points toward 686.45 million, with the forecast period (2026-2032) expected to sustain momentum as applications diversify and production systems mature. This growth is not uniform across sources, formats, or end-use categories, and the strategic value for decision-makers lies in understanding where scale, differentiation, and regulatory clarity intersect.
For executives, investors, and procurement teams, the market’s appeal rests on three characteristics: a rich antioxidant profile that commands premium positioning in human nutrition, a biologically active pigment that serves functional roles in animal health, and a supply base that is transitioning from fragmented cultivation to increasingly engineered production environments. Yet the sector is also navigating structural tensions around feedstock economics, regional regulatory divergence, and the balance between batch consistency and cost efficiency. The following analysis maps the current landscape, the forces reshaping it, the competitive postures defining it, and the strategic moves that will separate winners from followers over the next three to five years.
Market Snapshot and Core Tensions
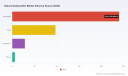
The macro picture is straightforward: demand is expanding, and the revenue curve is steepening as downstream applications broaden. What makes this market strategically interesting is not the headline growth alone, but the way value is distributed across production methods and form factors. Microalgae-derived astaxanthin represents the dominant share of the market, reflecting years of cultivation refinement and the ingredient’s positioning as a clean, plant-based antioxidant. Yeast-based routes account for a meaningful secondary share, offering distinct scalability and cost profiles. Smaller contributions come from krill and shrimp-derived sources, along with other niche inputs. The split matters because each source carries different cost structures, purity expectations, and application fit, which in turn shape pricing power and customer acquisition strategies.
On the formulation side, powder continues to lead in market share, underscoring its versatility across nutraceutical blends, feed premixes, and cosmetic bases. Oil-based formats remain important where bioavailability and sensory performance are priorities, while softgel and other consumer-ready forms occupy a smaller but growing niche as finished-product manufacturers seek convenience and perceived premium quality. Regionally, the market is balanced rather than concentrated in a single hub, with North America, Europe, and Asia Pacific each representing substantial demand centers, and Latin America plus the Middle East and Africa contributing more specialized but increasingly active demand. This geographic spread creates both diversification benefits and complexity in regulatory navigation.
Several structural tensions define the current inflection point. First, feedstock economics remain a persistent pressure point. Natural astaxanthin from Haematococcus pluvialis powder is the primary upstream feedstock for commercial production, with global output estimated at around 800 metric tons annually. This concentration creates sensitivity to cultivation yield, harvest timing, contamination risk, and energy inputs. Companies that can stabilize biomass supply and reduce per-unit production cost gain a durable advantage, but the pathway is capital-intensive and technically demanding.
Second, regulatory divergence is shaping where and how ingredients can be positioned. In the European Union, EFSA concluded in December 2025 that proposed uses of algal meal and oleoresin from Haematococcus pluvialis at levels exceeding the FEEDAP ADI of 0.034 mg/kg body weight per day cannot be established for non-food-supplement applications. At the same time, the powder with 5.0%–5.6% w/w ATX and oleoresin with 10%–12% w/w ATX has been restricted in the EU to food supplements since 1995 under novel food rules. These boundaries create a clear ceiling for certain feed and food uses in Europe, while simultaneously reinforcing the strategic importance of food supplement channels and premium nutraceutical positioning. AstaReal AB also submitted an application in December 2025 for novel food authorization covering algal meal, red viscous oleoresin, and water-dispersible formulations, signaling that the regulatory map is still being redrawn and that clarity, once achieved, can unlock new commercial pathways.
Third, the market is balancing scale against differentiation. With a CR3 of 42.5 percent and CR5 of 56.8 percent, the sector is moderately consolidated, but the room for regional specialists, formulation innovators, and application-specific suppliers remains meaningful. The tension lies in whether growth will be captured by producers who compete primarily on volume and cost, or by those who build defensible positioning through purity claims, traceability, application expertise, and regulatory readiness.
Key Drivers Reshaping the Market
Technology Innovation and Process Maturation
Production technology is moving from artisanal cultivation toward engineered control. Closed-system photobioreactors, improved strain performance, and tighter contamination management are reducing variability in biomass quality and astaxanthin yield. These advances matter because astaxanthin’s value proposition depends heavily on purity, isomer profile, and oxidative stability. Manufacturers that can deliver consistent specifications across batches gain credibility with formulators and finished-product brands, especially in nutraceuticals and cosmetics where claims and consumer trust are tightly linked to ingredient quality. At the same time, open-pond systems continue to play a role where cost efficiency and scale are paramount, particularly for feed-oriented volumes. The strategic question is not which system wins outright, but how each producer aligns technology choice with target applications and margin expectations.
Formulation technology is also advancing the commercial narrative. Water-dispersible and stabilized variants, beadlet integration, and oleoresin refinement expand the ingredient’s usability across matrices that historically posed dispersion or stability challenges. These improvements reduce formulation friction for customers and create opportunities for higher-value, application-tailored offerings rather than commodity-style transactions.
Policy and Regulatory Environment
Regulation is both a constraint and a catalyst. In Europe, the boundaries around feed and broader food uses are being clarified through EFSA opinions, which compresses certain expansion pathways while reinforcing the value of compliance-ready supply. In parallel, novel food authorization efforts signal potential future openings, especially if data packages support broader usage levels or new formulation types. For market participants, the strategic implication is that regulatory readiness is becoming a differentiator. Companies that proactively build dossiers, maintain documentation for traceability and safety, and align labeling and claims with regional requirements can move faster when opportunities open, and avoid disruption when restrictions tighten.
Beyond Europe, regulatory and certification dynamics in destination markets influence purchasing decisions in nutraceuticals, food and beverages, and aquaculture. Organic certification, GRAS status for food use, and contamination control documentation increasingly serve as gatekeeping criteria for buyers who need to defend ingredient choices to regulators, retailers, and end consumers. Regulatory alignment is therefore not simply a compliance exercise; it is a commercial enabler.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, three shifts are particularly relevant. First, the nutraceutical segment continues to anchor demand for natural astaxanthin, supported by consumer interest in antioxidant support, eye health, skin health, and sports recovery formulations. This segment rewards clarity of benefit, clean-label positioning, and brand trust, which in turn favors suppliers that can provide documentation, consistency, and application support. Second, aquaculture and animal feed represent a large and growing demand pool, where astaxanthin’s functional role in pigmentation and health supports adoption in shrimp, salmon, and other species. Here, cost-per-unit performance, batch reliability, and regulatory compliance for feed applications are central, and pricing sensitivity is higher than in premium human nutrition. Third, cosmetics and food and beverage applications, while smaller in share, create high-visibility branding opportunities and can command premium positioning when combined with compelling sensory and stability attributes.
The broader behavioral trend is a move toward ingredients with documented origin, sustainable production stories, and transparency. Buyers are increasingly hesitant to treat natural astaxanthin as a interchangeable input; they want assurance that sourcing, extraction, and final specifications meet the requirements of their specific market and claim structure.
Fucoxanthin (CAS 3351-86-8) Market
Supply Chain and Cost Structure Evolution
Cost structure dynamics are shifting as production volumes scale and operational efficiency improves. Recent developments illustrate this clearly. In June 2025, Cyanotech Corporation reported meaningful improvement in gross margin for fiscal 2025, with increasing production volumes of BioAstin Hawaiian Astaxanthin driving lower per-unit costs. This is a useful signal that scale, when combined with process maturity, can translate into margin expansion rather than merely top-line growth. In May 2025, Beijing Gingko Group announced expansion of astaxanthin manufacturing facilities in Yunnan Province, including a new research laboratory to support its AstaZine natural astaxanthin line. Capacity expansion of this kind indicates confidence in demand durability and a push to strengthen both volume and technical capabilities. Meanwhile, in July 2024, Algatechnologies introduced AstaPure 5% natural astaxanthin for softgels, extending its product line with all-natural extracts. Moves like this show how suppliers are layering formulation-specific offerings onto core production capabilities to capture more value.
The broader supply chain implication is that advantage is increasingly determined by integrated control over cultivation, extraction, and finishing, or by strong partnerships that achieve the same effect. Fragmented, transactional supply chains create exposure to quality variation and price volatility, while integrated or closely coordinated models support specification reliability, margin retention, and faster response to customer needs. Energy costs, water management, and contamination control remain critical cost drivers, especially for microalgae-based systems, and will continue to separate efficient operators from less optimized ones.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market’s competitive core includes a mix of established producers with proprietary cultivation and extraction systems, regional specialists with strong application focus, and larger nutrition and ingredient groups leveraging astaxanthin as part of broader portfolios. The strategic distinction lies less in participation alone and more in how each company constructs defensibility.
AstaReal Inc. operates with a clear brand-centered strategy around natural astaxanthin from Haematococcus pluvialis microalgae, supported by patented cultivation systems and contributions to standards development. Its emphasis on branded extracts, oleoresin, and powder across nutraceutical, cosmetic, and food applications reflects a premium, documentation-rich approach that targets customers seeking reliability and claim support.
Cyanotech Corporation has built a long-standing position around integrated Haematococcus pluvialis cultivation and extraction, with patented open-pond technology and GRAS certification for food use. Its BioAstin Hawaiian Astaxanthin line illustrates how regional identity, certification, and production scale can combine into a recognizable offering. Recent margin improvement tied to higher production volumes reinforces the value of scaling mature processes efficiently.
Algatechnologies Ltd. focuses on high-purity natural astaxanthin from closed-system cultivation, supplying premium extracts and oleoresin with strict contamination control for nutraceuticals, cosmetics, and aquaculture. Its emphasis on purity and controlled environments aligns with buyers who prioritize specification consistency and risk reduction, particularly in sensitive applications.
Beijing Gingko Group stands out as a large-scale producer of natural astaxanthin from Haematococcus pluvialis, offering certified organic biomass, powder, and extracts for global nutraceutical and feed markets. Its scale, ongoing facility expansion, and research investment position it to compete on volume, cost, and broad application coverage, while also building technical depth.
Algalif Iceland operates a large-scale photobioreactor facility and supplies sustainable Haematococcus-derived extracts under its own brand for premium nutraceutical applications. Its strategy highlights how geographic identity, controlled production, and sustainability narratives can support premium positioning in targeted downstream markets.
Fuji Chemical Industry contributes through natural astaxanthin manufacturing via its AstaReal subsidiary, providing high-purity extracts, beadlets, and formulations for human consumption and related applications. This reflects a formulation-oriented model that adds value through finished or semi-finished formats tailored to end-use requirements.
Divis Laboratories Limited participates as a supplier of natural astaxanthin extracts and derivatives, with focus on nutraceutical and cosmetic grades and sustainable sourcing. Its role illustrates the importance of specialty extraction and derivative capabilities in markets where customization and grade differentiation matter.
Astaxanthin (CAS 472-61-7) Market
Differentiation, Consolidation, and New Entry Dynamics
Differentiation is coalescing around several axes: purity and specification control, application-specific formulation support, regulatory readiness, sustainability and traceability claims, and the ability to scale without sacrificing consistency. The most resilient players tend to combine at least two of these strengths rather than competing on a single dimension. For example, a producer may pair controlled cultivation with strong documentation, or combine scale with brand and certification advantages that help customers justify ingredient choices to their own stakeholders.
The market is not moving toward extreme concentration in the near term, but selective integration is likely. Expect more partnerships between cultivation specialists and formulation or distribution networks, more regional capacity investments aligned with local demand and regulatory conditions, and more vertical coordination where producers seek to control feedstock, extraction, and finishing to protect margin and quality. At the same time, new entrants will continue to appear where they can offer a credible technology edge, a defensible sustainability story, or access to an underserved application. The barrier is not simply capital; it is the ability to deliver consistent quality, navigate regulatory complexity, and build buyer trust in a market where claims and contamination risk carry real consequences.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to define the market’s evolution.
-
Application diversification with a premium core. Nutraceuticals will remain the anchor, but growth will increasingly come from better-matched formulations, stabilized variants, and application-specific grades that reduce customer friction and support stronger positioning. Cosmetics and food and beverage uses will remain smaller in share but can deliver outsized brand value when paired with sensory quality and regulatory compliance.
-
Regulatory clarity as a competitive filter. As novel food and feed-related assessments progress, the regulatory map will become clearer in some regions and more constrained in others. Companies that have already invested in documentation, safety data, and compliant positioning will be better placed to expand into newly authorized uses or defend existing channels when restrictions crystallize.
PW Consulting -
Margin improvement through scale and process control. The recent margin improvement reported by established producers suggests that scale, when combined with mature cultivation and extraction processes, can convert volume growth into profitability. Capacity expansions and research investments indicate that leading players are preparing for sustained demand rather than treating growth as a short-cycle opportunity.
-
Sustainability and traceability as purchase criteria. Buyers are increasingly weighing origin, energy and water intensity, and supply transparency. Producers that can substantiate sustainability claims and provide traceable batches will gain advantage in premium segments and in procurement environments where reputational risk matters.
These trends translate into concrete commercial opportunities. For producers, the opportunity lies in aligning capacity and technology with the applications that offer the best combination of margin, growth, and defensibility, rather than chasing all segments equally. For ingredient buyers and formulators, there is an opportunity to secure reliable supply of specification-consistent astaxanthin that supports stronger claims, cleaner labels, and more stable procurement costs. For investors, the appealing thesis centers on operators that combine process maturity, regulatory readiness, and application focus with a credible path to margin expansion as volumes scale.
Potential risks and uncertainties should not be understated. Feedstock availability and cultivation risk can affect supply consistency and pricing, particularly if contamination events or yield variability intensify. Regulatory outcomes may narrow certain applications in key regions, especially where feed and broader food uses face tighter limits. Competitive intensity could compress margins if supply expands faster than demand in specific formats or regions. And claim substantiation expectations may rise, increasing the cost of doing business for suppliers that cannot provide robust documentation and traceability. These risks do not negate the growth outlook, but they do mean that execution quality will determine who captures value.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to match technology and capacity strategy to the applications where differentiation is most defensible. If the target is premium nutraceuticals and cosmetics, investment in controlled cultivation, purity assurance, and documentation is likely to pay off more than pure volume expansion. If the target includes aquaculture and feed, the focus should be on cost efficiency, batch reliability, and compliance with regional feed rules, while preserving enough quality consistency to maintain customer trust. In both cases, formulation-specific offerings and finished or semi-finished formats can help capture more value than commodity supply alone.
For investors, the most compelling opportunities are likely to be found in operators that demonstrate a combination of process maturity, credible regulatory readiness, and a clear application focus. Capacity expansion is meaningful only when paired with the ability to convert volume into margin, and regulatory navigation is increasingly part of the valuation story. Due diligence should examine not just scale and geography, but also contamination control, documentation quality, formulation capability, and the durability of customer relationships in segments where specification consistency matters.
For procurement teams and formulators, the strategic move is to treat natural astaxanthin as a specification-driven ingredient rather than a interchangeable input. Locking in supply partnerships with suppliers that can provide consistent batches, transparent origin, and application support will reduce reformulation risk and strengthen claim confidence. Diversifying across sources and formats where appropriate can also mitigate exposure to regional regulatory shifts or feedstock constraints, especially when planning for longer-term product roadmaps.
The market’s next phase will reward participants who combine technical discipline with commercial clarity. As regulatory boundaries become sharper, production systems become more engineered, and buyers demand stronger documentation and sustainability assurance, the winners will be those who can deliver consistent quality at scale while aligning their offerings to the applications that matter most. For decision-makers seeking to move from broad market awareness to actionable planning, deeper segmentation, supplier benchmarking, and region-specific regulatory mapping will be essential. PW Consulting’s full research report on the natural astaxanthin market provides that level of detail, including segmented demand dynamics, competitive benchmarking, and tailored recommendations designed to support investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Machine Stretch Film Market: Why 5.5% CAGR from 2026 to 2032 Redefines Packaging Strategy
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Machine Stretch Film Market
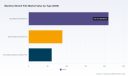
The machine stretch film market has entered a period of structural transformation, moving beyond incremental volume growth to a phase where material science, regulatory pressure, and supply chain resilience redefine competitive advantage. Valued at approximately $360 million in 2025, the market has expanded from roughly $280 million in 2020, reflecting a compound annual growth rate of 5.5 percent through the 2026-2032 forecast horizon. This trajectory is not merely a function of increased pallet wrapping activity; it signals a deeper shift in how logistics operators, manufacturers, and retailers approach load containment, material efficiency, and end-of-life accountability. The market's composition reveals a clear hierarchy in product architecture and application demand, with cast extrusion technologies and logistics-driven use cases commanding the largest revenue shares. Yet the headline figures only scratch the surface. Beneath the growth curve lies a landscape where raw material volatility, extended producer responsibility mandates, and performance differentiation are forcing incumbents and new entrants alike to recalibrate their operating models.
Rebuilding Margins in a Volatile Input Environment
One of the most persistent challenges shaping strategic decision-making is the pricing instability of primary and recycled polyethylene feedstocks. In May 2026, linear low-density polyethylene prices in North America hovered between $1.13 and $1.16 per kilogram, while regional increases of 8.7 to 12.6 percent were reported across Asia and Europe. This input pressure compounds with tighter availability of recycled LLDPE pellets, which traded between 55 and 60 cents per kilogram in 2025 and faced continued upward pressure into 2026 due to supply constraints. For film producers, this environment erodes the traditional cost-pass-through mechanism, particularly in commoditized blown film segments where differentiation is limited. Companies that rely on volume-based pricing without performance or sustainability premiums are seeing margin compression, while those with integrated resin strategies or advanced extrusion capabilities are better positioned to absorb fluctuations without sacrificing competitiveness.
Regulatory Compliance as a Design Constraint, Not an Afterthought
The regulatory landscape has shifted from voluntary sustainability commitments to mandatory material sourcing and reporting requirements. As of August 2025, five U.S. states mandate post-consumer recycled content in plastic packaging, with stretch film falling under flexible packaging targets within extended producer responsibility frameworks. Minnesota's Packaging Waste and Cost Reduction Act, implemented in phases through 2025 and 2026, requires producers to comply with EPR plans that explicitly cover stretch film. Simultaneously, EU and U.S. EPR schemes active in 2026 include mandatory recycled content goals that directly influence production formulations and material procurement. These regulations are no longer peripheral compliance exercises; they are redesigning the economics of film production. Manufacturers must balance recycled content integration with tensile strength, cling, and puncture resistance requirements, while avoiding penalties or market access restrictions in jurisdictions with tightening standards. The operational implication is clear: compliance is becoming a product development parameter, not a post-production adjustment.
Performance Expectations Outpacing Traditional Formulations
A third inflection point lies in the growing disconnect between standardized film specifications and the operational realities of automated wrapping lines. High-throughput distribution centers, robotic palletizers, and precision load containment requirements demand films that maintain stability at high pre-stretch ratios, resist punctures during high-stack storage, and deliver consistent cling without excessive material usage. Traditional blown films often struggle to meet these combined performance thresholds, creating sustained demand for cast and pre-stretched alternatives that offer tighter gauge control, higher elongation, and reduced consumption per pallet. The challenge for producers is to engineer formulations that satisfy these operational demands while navigating recycled content mandates and input cost volatility. Companies that treat performance and sustainability as competing priorities are losing ground to those that integrate both into a single product architecture.
Key Drivers Reshaping Market Dynamics
The market's trajectory is being pulled by four interconnected forces that are redefining how machine stretch films are engineered, sourced, and deployed. Understanding these drivers is essential for executives evaluating capacity investments, procurement strategies, or portfolio positioning.
Advanced Extrusion and Multi-Layer Architecture
Technological progress in nano-layer extrusion and precision gauge control is fundamentally altering the performance ceiling of machine-applied stretch films. Multi-layer coextrusion enables manufacturers to distribute material properties across functional layers, achieving higher stretch ratios and improved load containment without increasing total film weight. Recent product launches demonstrate this shift in action. A major producer commissioned a new 55-layer nano-layer extrusion line in Ohio, delivering machine stretch films with up to 350 percent stretch and approximately 25 percent material reduction. Another specialist introduced pre-stretched film lines incorporating 35 percent post-consumer recycled content while maintaining tensile strength at 22 MPa for machine applications. These developments illustrate a broader industry movement: performance and material efficiency are no longer trade-offs but co-engineered outcomes. For downstream users, this translates into fewer film changes, lower consumption per wrap cycle, and more predictable load stability on automated lines.
Extended Producer Responsibility and Recycled Content Mandates
Policy frameworks are accelerating the integration of recycled polyethylene into machine-grade films, transforming what was once a niche sustainability offering into a compliance-driven baseline. With multiple U.S. states and EU jurisdictions enforcing recycled content targets within EPR schemes, producers are reformulating products to meet minimum thresholds without compromising machine performance. One integrated packaging group launched pre-stretched lines with 35 percent PCR content, while two other major producers introduced stretch film lines featuring 30 percent post-consumer recycled content for high load stability. These milestones reflect a structural shift: recycled content is becoming a spec requirement, not a marketing differentiator. The operational impact extends beyond formulation. Procurement teams must secure consistent recycled resin supply, quality control protocols must adapt to variable feedstock characteristics, and sales teams must articulate performance equivalence to customers transitioning from virgin-only films.
Demand-Side Pressure for Load Containment and Throughput Optimization
End-users are increasingly prioritizing films that reduce waste, minimize changeover downtime, and maintain integrity under high-stack or long-transit conditions. Logistics and distribution operations, which represent the largest application share, are operating with thinner margin buffers and higher throughput expectations, making film consumption a visible cost lever. Food and beverage applications add further complexity, requiring films that balance cling, clarity, and regulatory compliance for perishable or branded goods. Agriculture and industrial packaging sectors demand puncture resistance and weather tolerance, while still seeking material efficiency gains. The common thread across these segments is a preference for films that deliver predictable performance at lower total usage, rather than simply lower price per kilogram. This behavior is reshaping purchasing criteria: total cost per wrapped pallet, line efficiency, and load rejection rates are gaining weight over raw material price alone.
Feedstock Sourcing and Supply Chain Recalibration
The combination of virgin resin price increases and recycled pellet supply constraints is forcing companies to rethink sourcing strategies. Regional price divergence means that producers with geographically diversified resin procurement or localized recycling partnerships can mitigate cost shocks more effectively than those dependent on single-region supply chains. Some manufacturers are integrating recycled polyethylene directly into machine-grade products through new resin blending protocols, while others are investing in closed-loop recovery programs with large logistics customers. The broader implication is that supply chain resilience is becoming a competitive differentiator. Companies that secure predictable access to qualified recycled and virgin feedstocks, while maintaining formulation flexibility, are better equipped to sustain pricing stability and service reliability amid market turbulence.
Worldwide Puncture Resistance Stretch Film Market
Competitive Landscape and Strategic Positioning
The machine stretch film market is characterized by a concentrated core of established producers alongside specialized manufacturers and regional suppliers navigating distinct competitive niches. The top three players collectively account for approximately 55 percent of market revenue, while the top five extend their share to around 70 percent. This concentration reflects the technical barriers to high-performance extrusion, the importance of integrated resin and film production capabilities, and the value of long-term relationships with large logistics and industrial customers. Yet the landscape is not static. Product launches, formulation innovation, and regulatory-driven reformulation are creating pockets of differentiation that allow smaller or regional players to compete on performance specificity rather than sheer scale.
Performance Engineering as the Primary Differentiator
Leading manufacturers are competing on measurable performance attributes rather than generic film availability. One producer emphasizes nano-layer extrusion lines that deliver up to 350 percent stretch with material reduction, targeting automated pallet wrapping operations where film consumption and load stability are critical. Another manufacturer highlights Rite-Gauging technology for consistent pre-stretch and reduced usage, alongside high-cling and high-load containment variants designed for demanding distribution environments. A specialist producer focuses on clarity, stretch performance, and high-strength applications tailored to automated wrapping systems, while a separate player offers series films engineered for pre-stretch levels exceeding 300 percent, high load containment, and puncture resistance. These positioning strategies reflect a shared insight: customers are willing to pay for reliability, reduced consumption, and line compatibility, provided the performance claims are verifiable and consistent.
PLA Biodegradable Stretch Film Market
Sustainability Integration as a Operational Imperative
Sustainability is increasingly embedded into product portfolios rather than marketed as a separate line. Producers are launching films with 30 percent post-consumer recycled content, integrating recycled polyethylene into machine-grade products through new resin protocols, and aligning formulations with EPR and recycled content mandates. One European supplier emphasizes sustainability and performance in its machine-applied stretch films, while a global packaging group positions its machine stretch films within an integrated portfolio focused on performance and cost efficiency. This convergence of sustainability and performance is reshaping competitive dynamics. Companies that treat recycled content integration as a core engineering challenge, supported by consistent feedstock access and robust quality assurance, are building defensible positions. Those that rely on superficial sustainability claims without performance validation risk losing credibility with procurement teams that must meet both cost and compliance targets.
Market Evolution: Consolidation Pressure and Niche Differentiation
The market is experiencing simultaneous forces of consolidation and fragmentation. Scale advantages in resin procurement, extrusion capacity, and distribution networks favor larger producers, particularly in mature regions where automated wrapping infrastructure is widespread. At the same time, regional suppliers and specialists are carving out positions by focusing on specific performance needs, localized service, or regulatory-aligned formulations. New entrants face high technical and compliance barriers, but opportunities exist for companies that can address underserved application requirements, offer verifiable performance improvements, or provide flexible supply arrangements in regions with growing logistics infrastructure. The likely trajectory is a market where a concentrated core sets baseline performance and pricing expectations, while specialized players compete on formulation precision, application-specific engineering, and regional responsiveness.
Forward Outlook: Three Critical Trends for 2026-2032
The next several years will be defined by how quickly producers, investors, and procurement leaders adapt to the intersection of performance demands, regulatory constraints, and input cost dynamics. Three trends are likely to shape strategic outcomes.
Recycled Content as a Baseline, Not a Premium
Mandatory recycled content targets will continue to normalize PCR integration across machine stretch film portfolios. As more jurisdictions enforce minimum thresholds and EPR frameworks tighten, films without qualified recycled content will face procurement disadvantages or market access limitations. This trend creates opportunities for producers with proven formulation stability, consistent recycled resin supply, and transparent compliance documentation. It also introduces risk for companies that overpromise on recycled content without ensuring tensile strength, cling, and puncture resistance remain within specification. The commercial opportunity lies in offering films that meet or exceed regulatory requirements while delivering measurable performance parity or improvement, thereby converting compliance from a cost center into a competitive asset.
PW Consulting
Material Efficiency and Automated Line Optimization
The push toward higher stretch ratios, tighter gauge control, and reduced consumption per pallet will intensify as distribution centers seek to lower total wrapping costs and improve line throughput. Films that enable consistent pre-stretch, minimize changeover variability, and maintain load stability under automated operation will see sustained demand. Producers investing in multi-layer extrusion, precision dispensing compatibility, and application-specific formulations are well positioned to capture this shift. The risk lies in over-engineering films for narrow use cases without ensuring broad compatibility across wrapping equipment and load types. Success will depend on balancing performance specificity with practical deployability across diverse operational environments.
Regional Divergence in Regulatory and Supply Dynamics
Regulatory mandates, recycled resin availability, and virgin resin pricing will continue to diverge across regions, creating uneven competitive conditions. North America and Europe are likely to see faster adoption of EPR-aligned formulations and recycled content integration, while Asia Pacific and emerging markets may experience more gradual regulatory rollout but stronger volume growth driven by expanding logistics infrastructure. LLDPE price increases of 8.7 to 12.6 percent in Asia and Europe, alongside North American price levels around $1.13 to $1.16 per kilogram, illustrate the regional cost landscape that producers must navigate. Companies with flexible sourcing strategies, localized production, or regionally tailored product lines will be better equipped to manage these divergences. The uncertainty centers on the pace and uniformity of regulatory enforcement, the stability of recycled resin supply, and the potential for trade or tariff shifts that could disrupt feedstock flows.
Strategic Actions for Decision Makers
Translating these trends into actionable strategy requires different priorities depending on a company's role in the value chain. The following recommendations highlight where focused effort can yield the strongest returns.
For film manufacturers and producers: Prioritize formulation engineering that treats recycled content and performance as integrated design parameters. Invest in extrusion capabilities that enable higher stretch ratios, consistent gauge control, and material reduction without sacrificing load containment or puncture resistance. Secure diversified resin sourcing to mitigate regional price volatility, and develop transparent compliance documentation that supports procurement teams navigating EPR and recycled content mandates. Differentiate through verifiable performance claims and application-specific solutions rather than volume-based pricing alone.
For investors and portfolio strategists: Evaluate exposure to producers with demonstrated capabilities in advanced extrusion, recycled content integration, and regional supply resilience. Favor companies that can articulate clear performance advantages, maintain formulation flexibility amid input cost fluctuations, and align product portfolios with regulatory trajectories. Monitor consolidation dynamics and niche differentiation opportunities, particularly in regions where logistics infrastructure is expanding and automated wrapping adoption is accelerating. Assess risk around recycled resin supply constraints, virgin resin price divergence, and regulatory enforcement variability.
For procurement leaders and logistics operators: Shift evaluation criteria from price per kilogram to total cost per wrapped pallet, incorporating film consumption, line efficiency, load rejection rates, and compliance readiness. Prioritize suppliers that provide consistent performance at high pre-stretch levels, maintain quality across recycled and virgin blends, and offer documentation that supports EPR and recycled content reporting. Engage early with formulation changes to ensure compatibility with existing wrapping equipment and load profiles, and consider supplier partnerships that provide feedstock transparency and supply stability amid market volatility.
The machine stretch film market is moving into a phase where technical precision, regulatory alignment, and supply chain resilience determine competitive outcomes. The companies that succeed will be those that treat performance, sustainability, and cost efficiency as interconnected objectives rather than competing priorities. For executives seeking granular segmentation data, regional pricing dynamics, competitor benchmarking, and customized strategic scenarios, the full research report provides the detailed framework needed to translate these market-wide insights into precise operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Machine Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cold Milling Machine Market: 6.26% CAGR and the Strategic Shifts Reshaping 2026–2032 Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Cold Milling Machine Market
The global cold milling machine market has entered a phase of sustained expansion, driven by aging infrastructure, tightening environmental mandates, and a strategic shift toward high-efficiency pavement rehabilitation. Valued at approximately $215 million in 2025, the market has grown at a compound annual growth rate of 6.26 percent over the 2020 to 2025 period and is projected to reach $345 million by 2032. This trajectory reflects more than cyclical road maintenance spending; it signals a structural transformation in how contractors approach surface rehabilitation, material recycling, and emissions compliance. The next seven years will be defined by technological differentiation, regulatory alignment, and regional demand rebalancing.
Reconciliation of Physical Infrastructure Reality and Environmental Mandates
The market's underlying growth is rooted in a pragmatic reality: governments and private developers cannot afford to rebuild entire pavement networks from scratch. Instead, they rely on cold milling as a targeted, cost-effective method to remove deteriorated layers, prepare binding surfaces, and recover reusable aggregates. This operational logic has remained consistent, but the execution environment has changed dramatically. Contractors now face overlapping pressures: tighter municipal budgets, stricter noise and emission limits at urban job sites, and client expectations for project completion times that align with modern logistics windows. Machinery that simply removes asphalt or concrete is no longer sufficient. The winning equipment must integrate precise depth control, consistent output, and verifiable sustainability metrics while maintaining operational flexibility across multiple pavement types.
At the same time, the market confronts fragmentation in adoption readiness. Developed regions with mature road networks are prioritizing fine milling, surface rehabilitation, and emissions-reduced operations. Emerging markets are still scaling basic rehabilitation capacity, often balancing imported high-performance equipment against domestically manufactured alternatives. Navigating this divide requires a clear view of where regulatory pressure converts into procurement behavior, and where cost sensitivity still dictates purchasing decisions.
Key Drivers Shaping Market Dynamics
Technological Innovation and the Automation of Precision Milling
The most consequential shift in the market is the transition from mechanical power to controlled, data-enabled precision. Modern cold milling machines increasingly embed intelligent drum speed regulation, grade and slope tracking, and operator-assist systems that reduce variability in cut depth and material consistency. These capabilities directly affect downstream paving quality and the efficiency of material recycling. When a milling pass produces predictable particle size and uniform surface preparation, contractors spend less time on corrective work and more time maintaining throughput.
Recent product introductions illustrate this trajectory. Wirtgen Group's W 210 XF and W 250 XF models, unveiled in early 2025, emphasize high-output milling combined with advanced automation. The W 250 XF was presented as a high-capacity platform with dual-engine architecture and refined milling technology, targeting large-scale rehabilitation where output and consistency determine project economics. Alongside larger platforms, the same manufacturer introduced the W 50 Re battery-electric small milling machine and an updated generation of recyclers designed for lower specific emissions. This pairing of large-scale high-power machines with compact electrified alternatives reflects a broader industry recognition: different job profiles require different power and control architectures, and electrification is entering the market not as a single solution but as a modular option.
From a commercial standpoint, automation is not merely a feature upgrade. It is becoming a procurement criterion. Contractors evaluating bids increasingly weigh whether a machine can reduce operator fatigue, improve cut consistency across long runs, and provide feedback loops that support maintenance planning. Equipment that integrates these functions into a coherent workflow offers a practical advantage in labor-constrained environments and in projects where site access limits the margin for error.
Worldwide Milling Machine Market
Regulatory Pressure and Emissions Compliance as Procurement Catalysts
Environmental regulation has moved from a compliance backdrop to an active determinant of machine selection. European and global frameworks continue to tighten carbon emission expectations for construction equipment, with enforcement and reporting requirements making real-time emissions visibility more valuable. In this environment, cold milling machines that generate transparent performance data and meet advanced emission standards are better positioned for public tenders and large contractor fleets.
Recent regulatory-aligned developments demonstrate how manufacturers are responding. Wirtgen's latest large milling machines incorporate EU Stage 5 and US EPA Tier 4f emission standards alongside real-time CO2 tracking through performance monitoring systems. Caterpillar's PM Series cold planers are designed around Tier 4 Final and Stage V compliant engines to support sustainable construction and reduce operating cost exposure tied to emissions compliance. Rather than treating emissions as an abstract requirement, leading manufacturers are connecting compliance to operating economics: fuel efficiency, maintenance intervals, and fewer regulatory disruptions on urban or sensitive job sites.
This dynamic matters for strategic planning because it introduces a second layer of value beyond raw capacity. Machines that document emissions performance, reduce specific fuel consumption, and support fleet reporting are easier to justify in tender processes where environmental scoring is part of the evaluation. Over the forecast period, this trend is likely to widen the gap between equipment that meets minimum compliance and equipment that actively supports sustainability reporting and cost control.
Demand-Side Shifts Toward Rehabilitation, Recycling, and Lifecycle Thinking
Demand is increasingly shaped by a lifecycle view of pavement assets rather than a replacement mindset. Municipalities, roadway authorities, and large contractors are focusing on rehabilitation strategies that extend service life, recover aggregates, and reduce the need for virgin material inputs. Cold milling sits at the center of this shift because it enables precise removal of distressed layers and produces milled material that can be reintroduced into recycling streams or base layers.
This demand evolution changes how buyers evaluate machines. Output capacity remains important, but it must be balanced against the ability to handle different materials, switch between coarse and fine milling tasks, and support downstream recycling workflows. Contractors operating in regions with high volumes of asphalt rehabilitation are prioritizing consistent milling quality and rapid setup changes, while concrete rehabilitation users need equipment that manages more abrasive surfaces and maintains drum performance over extended usage. The practical implication is that demand is fragmenting by application logic even as overall market volume rises.
A second demand-side pressure is job-site logistics. Urban rehabilitation projects increasingly require equipment that can operate within constrained access windows, minimize noise impact, and adapt to tighter footprints. This favors machines that combine maneuverability with reliable output and that can integrate into coordinated paving and recycling operations without becoming a bottleneck. In practical terms, the strongest commercial opportunities are emerging where cold milling equipment is sold not as a standalone tool but as part of an integrated rehabilitation process.
Supply Chain Realities and Cost Structure Reframing
Equipment economics are also being reshaped by supply chain considerations and operating cost structures. Engine availability, component sourcing, and the cost of maintaining compliance with evolving emission systems all influence total cost of ownership. High-horsepower platforms, in particular, depend on reliable engine supply and service networks that can support advanced exhaust aftertreatment and diagnostic systems. Any disruption in these areas affects uptime and can alter the attractiveness of certain machine architectures.
At the same time, fuel efficiency has become a direct commercial lever rather than a secondary benefit. Advanced drum speed control and optimized transmission systems can deliver measurable fuel savings, which matters in markets where operating costs are under scrutiny and where contractors run machines for long shifts. Fuel consumption is no longer just an engineering metric; it is a tender differentiator and a fleet budgeting variable. In that sense, cost structure is moving from a static procurement concern to a dynamic performance target.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players holding approximately 24.6 percent of the market and the top five reaching around 26.2 percent. This level of concentration suggests that scale, brand recognition, and technology leadership are rewarded, but it also leaves meaningful room for differentiated regional participants, application specialists, and new entrants targeting specific job profiles or price-performance segments. Competition is increasingly defined less by raw size and more by the ability to deliver compliant, efficient, and operationally intelligent machines that match local demand patterns.
Wirtgen Group stands out for portfolio breadth and technology integration. Its lineup spans compact models to large platforms, with recent additions emphasizing automation, mill assist controls, and performance tracking for milling operations. The company's 2025 introductions, including the W 210 XF and W 250 XF, reinforce a high-performance large-machine strategy while its battery-electric small milling machine and updated recycler generation indicate a parallel push toward lower specific emissions and electrified compact equipment. The strategic signal is clear: the company is positioning across multiple power and scale points, using automation and emissions visibility as differentiators.
Caterpillar contributes a different kind of strength: large-engine reliability, emissions compliance, and telematics integration. Its PM Series half-lane cold planers, including models such as PM825 and PM620, are built around high-horsepower engines and Tier 4 Final compliance, with telematics support aimed at fleet management and operational efficiency. Caterpillar's positioning benefits from its broader construction equipment ecosystem, where service networks, parts logistics, and machine data integration can extend value beyond the cold planer itself. For contractors managing multiple asset types, that ecosystem appeal can be decisive.
Regional and application-focused players continue to shape competitive dynamics in specialized ways. Bomag, Dynapac, Volvo Construction Equipment, Sakai, Roadtec, and CMI Roadbuilding each maintain cold milling offerings aligned with particular operating profiles or regional expectations. Roadtec's RX Series cold planers, for example, were updated in early 2025 with higher-horsepower Caterpillar Tier 4 Final engines to target higher production and reliability. These participants often compete on feature-fit, service responsiveness, and application alignment rather than attempting to lead on sheer portfolio scale.
In Asia, SANY Group, XCMG Group, LiuGong, and Shantui represent a distinct competitive dynamic. Their SCM, XM, 5100-2/SM, and SM series machines demonstrate strong capability in road construction and infrastructure applications, with a focus on cost-effective high-performance equipment for local and export markets. The strategic implication is that competition is not only about premium features; it is also about whether manufacturers can balance compliance, durability, and price in ways that match the procurement realities of fast-growing infrastructure regions.
Several competitive trends are emerging. First, there is a clear convergence around compliance-driven engineering, with manufacturers treating emission standards and fuel efficiency as baseline expectations rather than optional enhancements. Second, product launches are increasingly paired with digital value propositions, whether through performance tracking, telematics, or operator-assist features. Third, the market is not consolidating into a single winner-takes-most pattern; instead, it is fragmenting by application, power architecture, and region. That means competitive advantage will depend on matching machine characteristics to specific procurement priorities, not simply on offering the largest or most expensive platform.
Future Trends and Commercial Implications
Electrification and Alternative Powertrains Will Expand by Job Profile
Electric and low-emission configurations are entering the market in targeted forms rather than as blanket replacements. Compact milling tasks, urban rehabilitation, and environments with strict site emissions limits are likely to be the earliest adoption zones. Over the next three to five years, expect battery-electric and hybrid-enabled machines to broaden where site constraints, noise restrictions, or localized sustainability requirements make conventional diesel operation less attractive. Commercial opportunity lies not just in selling an alternative powertrain but in defining the applications where it delivers a credible cost and operational case. Manufacturers and distributors that understand which job profiles justify electrified equipment, and how to support charging, deployment, and maintenance, will be better positioned to shape demand rather than react to it.
Cold Planers Market
Automation and Data Feedback Will Become Table Stakes for High-Value Tenders
Real-time milling control, grade support, and performance data capture are moving from premium differentiators to expected features in competitive procurement. As tender evaluation increasingly includes operating efficiency, emissions documentation, and process consistency, machines without meaningful data capabilities risk losing relevance in higher-value contracts. The commercial implication is that equipment value may shift from purchase price toward lifecycle performance and reporting utility. This favors manufacturers and service providers that can package machine performance with fleet diagnostics, maintenance insight, and verifiable operating metrics. It also creates an opening for service-led revenue models, where monitoring, diagnostics, and process optimization become part of the customer relationship.
Regional Demand Divergence Will Deepen Selection Logic
Market growth will not unfold uniformly. Regions with strict emission environments, mature rehabilitation practices, and dense urban projects will favor automated, compliant, and often electrified solutions. Regions focused on capacity expansion and cost efficiency will still reward durable, high-output machines that deliver reliable performance at a competitive total cost of ownership. This divergence means that successful commercial strategies will require regional calibration: product mix, service coverage, financing support, and application messaging all need to align with local procurement priorities. Companies that attempt a single global narrative across all markets will likely leave value on the table.
These trends carry uncertainty. Emissions frameworks may accelerate or shift implementation timelines. Electrification may progress faster in some geographies while remaining limited in others due to infrastructure and cost constraints. Fuel price volatility, component supply conditions, and changes in public infrastructure spending can all reshape the pace of adoption. Commercial planning should therefore treat these trends as directional indicators rather than fixed predictions, and build flexibility into product, service, and market-entry decisions.
Strategic Actions for Decision Makers
For manufacturers and equipment suppliers, the priority is to align product architecture with the real purchasing drivers of the next cycle. That means maintaining a credible path on emissions compliance, treating automation and data capture as core value elements instead of accessories, and explicitly mapping which machine sizes, power options, and features fit which applications and regions. Pricing and service strategies should reflect total cost of ownership, not only upfront specifications. Where feasible, offering bundled diagnostics, maintenance planning support, and emissions reporting capabilities can strengthen customer retention and differentiate offers in competitive bids.
PW Consulting Automotive & Machinery Research Center
For investors and strategic partners, the opportunity is to focus on the segments where regulatory pressure, rehabilitation demand, and technology adoption intersect most strongly. Equipment that combines compliance, fuel efficiency, and operational data is likely to command stronger positioning in tenders and fleet renewals. Vertical relevance matters as much as product specifications: distribution strength, service coverage, parts logistics, and the ability to support electrified or digitally integrated machines are becoming part of the investment thesis. Monitoring the pace of electrification adoption, the stability of emission compliance requirements, and regional procurement behavior will help identify where demand is real and where it is still aspirational.
For procurement leaders and contractors, the practical goal is to evaluate cold milling equipment against operational context rather than headline capacity alone. Project selection should consider cut precision, material recovery needs, site-access constraints, emissions documentation requirements, and the cost implications of fuel efficiency and maintenance intervals. When renewing fleets or entering multi-year rehabilitation programs, buyers benefit from specifying performance expectations that include consistency, reporting, and service support, not just milling width or engine power. Choosing equipment that fits the workflow reduces rework, improves scheduling predictability, and strengthens the business case for rehabilitation-focused projects.
In a market where specifications, compliance, and application fit increasingly determine winning offers, broad market awareness is useful but not enough. Detailed segmentation data, regional procurement patterns, competitive benchmarking, and product-level performance comparisons are what translate strategic direction into practical decisions. For that level of segmentation and actionable recommendation, interested parties can review the complete report.
For detailed analysis of this topic, please visit the official page: Cold Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microgrid Technology Market: Why an 18.5% CAGR to $73.9B Redefines Energy Infrastructure Through 2032
By PW Consulting, 2026-09-21
Beyond Grid Dependency: Strategic Trends and Commercial Opportunities in the Microgrid Technology Market
The microgrid technology market is undergoing a structural transformation. Valued at approximately 12.5 billion USD in 2020, the sector expanded to 22.7 billion USD by 2025 and is projected to reach 73.9 billion USD by 2032, reflecting a compound annual growth rate of 18.5 percent over the forecast period. This trajectory signals more than incremental adoption; it indicates a shift from pilot-scale experimentation toward mainstream infrastructure deployment. As distributed energy resources mature and operational priorities evolve, microgrids are transitioning from niche resilience solutions to foundational components of modern energy architecture. For enterprise leaders, the implication is clear: microgrid integration now intersects with capital allocation, regulatory navigation, supply chain strategy, and operational continuity.
The current phase of market development is characterized by accelerated technical validation, yet the pathway from concept to commercial scale remains uneven. Several structural friction points define the present landscape. First, the economics of deployment vary significantly depending on site complexity, load criticality, and regional regulatory frameworks. While standardized configurations benefit from predictable cost curves, customized installations for hospitals, industrial campuses, and critical facilities require substantial engineering investment and multi-stakeholder coordination. Second, the transition toward bidirectional power flows and inverter-based architectures introduces new operational dependencies. Legacy interconnection standards, fragmented approval processes, and evolving cybersecurity expectations create coordination layers that can delay project timelines. Third, the market remains moderately concentrated, indicating that scale advantages, proprietary control systems, and integrated service offerings continue to shape competitive positioning. These dynamics collectively suggest that market growth will increasingly favor organizations capable of aligning technical performance with regulatory clarity, financial structuring, and long-term service reliability.
Key Drivers Shaping Market Trajectory
Technological Innovation and System-Level Integration
The maturation of microgrid technology is being driven less by any single breakthrough and more by the integration of previously siloed capabilities. Advanced energy management systems now coordinate distributed generation, storage, and load-shifting with greater precision, enabling facilities to maintain critical operations during grid disturbances. Controller architectures have improved response times for islanding and reconnection, while hybrid configurations increasingly combine solar, battery storage, and alternative generation pathways to reduce reliance on any single resource. These capabilities are especially relevant in environments where continuity is non-negotiable. Recent projects illustrate this trajectory: one of the largest hospital-based renewable microgrid systems in the United States came online with integrated solar generation, long-duration battery storage, and fuel cell backup designed for emergency power continuity. Within months, the installation transitioned into operational backup mode, demonstrating how integrated microgrid platforms can move from construction to active resilience support while contributing to regional renewable transition objectives. Technological progress is therefore not only enhancing system performance but also expanding the envelope of use cases where microgrids can deliver measurable operational value.
Policy and Regulatory Evolution
Regulatory frameworks are becoming both an enabler and a constraint. On one side, public-sector emphasis on grid resilience, decarbonization, and energy security is encouraging distributed infrastructure investment. On the other, the absence of uniform interconnection standards and the complexity of multi-party approvals can complicate deployment, particularly for single-property installations that must coordinate with internal facilities teams, financial stakeholders, and external authorities including utilities, planning departments, and fire marshals. A recent community guide addressing regulatory barriers highlighted how these coordination requirements can slow project execution for hospitals and other critical facilities, especially when stakeholder alignment and jurisdictional approvals are not mapped early in the development cycle. At the same time, new certification initiatives are beginning to establish baseline expectations for device-level security and interoperability. The introduction of an industry-wide cybersecurity certification program for microgrids, inverter-based devices, and distributed energy resources reflects a broader shift toward standardized safeguards as systems become more digitally managed and networked. For market participants, regulatory developments are no longer background conditions; they are active design parameters that influence architecture choices, procurement timelines, and deployment risk.
Demand-Side Realignment Across Sectors
Demand for microgrid solutions is being reshaped by changing expectations around cost predictability, operational continuity, and sustainability performance. Commercial and industrial operators are increasingly evaluating on-site generation and storage as a means to reduce exposure to grid volatility and support corporate energy objectives. Healthcare institutions, in particular, have emerged as a strategically important segment because their load profiles include mission-critical services that cannot tolerate extended outages. Recent deployments have paired solar arrays with combined heat and power systems to deliver meaningful cost reductions alongside carbon footprint improvements, demonstrating how microgrid installations can serve both financial and operational mandates. In parallel, the growth of remote and constrained infrastructure settings continues to support off-grid and hybrid configurations where grid dependence is impractical or too costly. The common thread across these demand patterns is a move from passive consumption toward active energy management, where facilities treat generation, storage, and control systems as part of a broader continuity and efficiency strategy rather than as standalone capital projects.
Supply Chain and Cost Structure Dynamics
Cost structures across the microgrid value chain are evolving as component maturity, manufacturing scale, and system integration practices improve. Still, cost trajectories are not uniform. Construction expenses can vary substantially by generation mix, storage technology, and site-specific engineering requirements, particularly when advanced energy management optimization is needed to support sensitive loads during outages. Hospital-grade installations, for example, may involve higher per-megawatt investment thresholds because of the need to maintain continuity for intensive care units, operating environments, and other critical functions. At the same time, the long-term financial case for microgrids is increasingly strengthened by their ability to reduce dependency on external supply conditions and provide more predictable generation cost profiles. In certain configurations, operators have realized substantial energy cost reductions by shifting toward fixed generation capabilities and lowering exposure to grid pricing variability. These economic dynamics create a nuanced deployment environment: while upfront capital requirements can be meaningful, lifecycle economics and resilience benefits are becoming more quantifiable, encouraging a longer-range view of return on investment.
Competitive Landscape and Strategic Positioning
Differentiated Value Propositions Among Leading Participants
The competitive environment is shaped by a mix of established industrial players and specialized technology providers, each emphasizing distinct aspects of the microgrid value chain. ABB has positioned itself around integrated microgrid technology solutions that span controllers, energy management systems, and hybrid renewable integration, emphasizing reliable power supply across varied operating conditions. Siemens focuses on microgrid controllers and integrated power solutions designed for seamless islanding and scalability, with particular relevance to critical facilities that require dependable operational transitions. Schneider Electric emphasizes platform-based approaches that combine energy management with renewable integration, targeting commercial and critical infrastructure applications. Eaton differentiates through energy storage systems and DC microgrid solutions aimed at efficient power distribution and backup performance. Honeywell concentrates on energy management and control systems optimized for critical facility resilience, while GE Vernova provides advanced controllers and hybrid solutions oriented toward utility and industrial use cases. S&C Electric Company has built its profile around ultra-fast islanding capabilities that support seamless power continuity, and Bloom Energy offers solid oxide fuel cell technology as an always-on clean generation pathway without combustion. On the project and deployment side, organizations such as Faraday Microgrids and Ameresco have developed focused approaches around hospital-based renewable systems and solar canopy configurations delivered under power purchase arrangements, reflecting the growing importance of tailored deployment models in sensitive institutional environments.
Market Structure and Evolution Patterns
Market concentration suggests that scale, integration depth, and service continuity remain influential in shaping competitive advantage. Organizations with broad component portfolios, established control architectures, and the ability to manage complex interconnection requirements often hold an advantage in higher-stakes deployments. At the same time, the landscape is not consolidating into a single model. Instead, it is evolving along multiple axes: some incumbents are deepening system-level integration and software-driven management capabilities, while specialized entrants continue to compete on niche performance characteristics, such as rapid islanding, fuel cell integration, or sector-specific design expertise. The result is a market in which differentiation increasingly depends on the ability to combine hardware reliability, software intelligence, cybersecurity readiness, and financial structuring flexibility. New entrants and project developers are likely to continue carving out positions where specialized load requirements, regional regulatory knowledge, or novel procurement structures create room for tailored solutions. Over time, the market may see further consolidation among integrated platform providers, alongside continued fragmentation in specialized applications where customization and stakeholder management are central to success.
Microgrid Market
Forward-Looking Trends and Commercial Implications
Scaling of Sector-Specific Microgrid Architectures
Over the next three to five years, one of the most consequential trends is likely to be the expansion of microgrid designs optimized for specific institutional and industrial load profiles rather than generic configurations. Healthcare facilities, data-centric campuses, manufacturing sites, and critical public infrastructure each impose distinct requirements on redundancy, response time, load prioritization, and fuel or storage mix. As deployment experience accumulates, architectures are expected to become more standardized within these segments while retaining the flexibility needed for site-specific constraints. The commercial opportunity lies in developing repeatable design templates, financing structures, and operational service models that reduce project risk and accelerate execution. Organizations that can package proven architectures with predictable performance parameters and clear approval pathways will be better positioned to capture demand in sectors where continuity and compliance are paramount. A related risk is that sector-specific standards and approval expectations may diverge across jurisdictions, increasing complexity for multi-site operators and slowing replication unless coordination frameworks improve.
Integration of Cybersecurity and Interoperability as Core Requirements
As microgrids become more digitally managed and interconnected, cybersecurity and interoperability are expected to move from auxiliary considerations to core procurement criteria. Certification programs and baseline security expectations introduced for inverter-based devices and distributed energy resources indicate that buyers will increasingly evaluate control systems not only on performance but also on vulnerability management, update pathways, and vendor accountability. This shift creates opportunities for suppliers that can demonstrate robust security architectures, transparent certification status, and compatibility with broader facility management and grid-interconnection requirements. It also raises the stakes for system designers, because fragmented device ecosystems or opaque security practices can become integration liabilities. A key uncertainty is the pace at which standards, testing protocols, and procurement specifications will harmonize across regions and customer segments. Until then, cybersecurity readiness may function as both a competitive advantage and a compliance hurdle, depending on the market and project type.
PW Consulting Information & Electronics Research Center
Financial Structuring and Lifecycle Value Optimization
The financial narrative around microgrids is likely to become more sophisticated as operators weigh upfront capital against long-term resilience and cost predictability. In settings where grid dependency carries operational or budgetary risk, microgrids can support fixed-cost generation profiles and reduce exposure to external supply volatility. This makes lifecycle modeling, performance guarantees, and service agreements increasingly important in project evaluation. Financing approaches such as power purchase structures, resilience-based procurement, and shared infrastructure models may broaden access for organizations that prefer operational expenditure frameworks over traditional capital investment. The opportunity for suppliers and developers will lie in aligning technology choices with financial outcomes, including maintenance costs, degradation profiles, storage replacement cycles, and control system longevity. The risk is that unrealistic expectations around savings or performance could undermine project credibility if real-world operating conditions, regulatory constraints, or load complexities are underestimated. Sustainable adoption will depend on transparent modeling and disciplined interpretation of site-specific economics.
Micro Turbine Market
Strategic Implications for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize integration depth over component-only positioning. Architectures that combine control, storage coordination, renewable integration, and cybersecurity readiness will increasingly shape procurement decisions in critical and commercial environments.
- Build repeatable segment playbooks. Tailored design templates for hospitals, industrial facilities, and commercial campuses can reduce sales cycle friction and improve deployment predictability if they account for approval pathways, load prioritization, and local interconnection requirements.
- Treat security and certification as product attributes. Demonstrated compliance with emerging cybersecurity baselines and interoperability expectations can become a differentiator, especially where buyers must justify resilience investments to internal audit, compliance, or governance stakeholders.
For Investors and Capital Allocators
- Evaluate markets through the lens of deployment complexity, not just addressable demand. Segments with high continuity requirements and manageable approval pathways may offer more reliable project conversion than highly fragmented or regulation-constrained environments.
- Watch for consolidation signals among integrated platform providers and specialized deployers. Scale advantages in control software, service networks, and financing partnerships may drive concentration in some segments, while niche expertise remains valuable in others.
- Underwrite lifecycle economics carefully. Savings potential, resilience value, and operational risk reduction can be meaningful, but returns depend on realistic assumptions around engineering costs, storage and component longevity, and ongoing management requirements.
For Procurement Leaders and Facility Operators
- Map regulatory and stakeholder dependencies early. Single-property deployments can face coordination challenges with internal teams and external authorities, so early alignment across facilities, finance, planning, utilities, and safety stakeholders is essential to avoid timeline delays.
- Define critical load priorities before sizing solutions. The value of a microgrid depends heavily on how well its architecture supports the loads that matter most during an outage, making load analysis and redundancy planning central to project design.
- Include cybersecurity and service continuity in evaluation criteria. Procurement decisions should account for device security baselines, management updates, vendor support models, and the operational implications of islanding and reconnection performance.
The microgrid technology market is expanding within a landscape defined by technical integration, regulatory maturation, and increasingly demanding operational expectations. Growth is being shaped not only by the appeal of distributed generation and storage, but also by the need for resilient, secure, and financially defensible energy architectures. For organizations evaluating entry, expansion, or procurement decisions, the most valuable next step is to move beyond headline market sizing and examine the segmentation, cost structures, regulatory pathways, and competitive dynamics that determine project viability in specific contexts. Detailed segmentation data, company-level positioning assessments, and customized strategic analysis can sharpen these decisions and reduce execution risk. PW Consulting offers comprehensive research supporting deeper evaluation of these dimensions for decision-makers seeking a fuller understanding of where value is being created and how to act on it.
For detailed analysis of this topic, please visit the official page: Microgrid Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cloud Gaming Market: Why 28.25% CAGR Redefines Gaming Infrastructure Through 2032
By PW Consulting, 2026-09-21
Cloud Gaming Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The cloud gaming market has transitioned from an experimental concept to a commercially viable sector over the past half-decade. From a base of $1.25 billion in 2020, the sector reached $8.72 billion by 2025, reflecting a compound annual growth rate of 28.25 percent. Forecasts project the market will surpass $11 billion in 2026 and scale to approximately $49.47 billion by 2032. This trajectory signals more than incremental adoption; it indicates a structural shift in how content is delivered, consumed, and monetized across consumer electronics and digital entertainment ecosystems.
Such rapid expansion, however, rests on fragile foundations. The industry currently confronts three critical challenges that will define competitive outcomes over the next several years. First, infrastructure scalability remains uneven. Delivering consistently high-fidelity experiences requires dense edge computing coverage and robust broadband capacity, yet network quality varies dramatically across geographies. Regions with advanced telecommunications infrastructure are experiencing accelerated adoption, while markets dependent on legacy networks face persistent latency and bandwidth constraints that undermine user retention.
Second, content economics and licensing complexity continue to pressure unit profitability. Cloud gaming platforms must negotiate rights agreements with publishers, manage localization requirements, and align game catalogs with regional preferences. These negotiations consume significant operational resources and create friction when attempting to scale service offerings globally. Platforms that rely heavily on licensed third-party titles face margin compression unless they can demonstrate clear value differentiation to rights holders.
Third, user acquisition costs and retention dynamics present a persistent challenge. While initial trial adoption has grown, converting free-tier or trial users into sustained subscribers requires continuous investment in service quality, exclusive content, and ecosystem integration. Churn remains elevated in markets where alternative entertainment options compete for disposable income and screen time. Platforms that fail to build sticky user relationships through hardware integration, social features, or personalized experiences risk cyclical reacquisition cycles that erode lifetime value.
Key Drivers Accelerating Market Growth
Technological Innovation and Streaming Optimization
Advances in encoding algorithms, GPU virtualization, and edge computing have substantially reduced the technical barriers that once limited cloud gaming viability. Modern streaming pipelines now deliver higher resolutions and frame rates with lower latency, widening the addressable device base beyond traditional gaming hardware. The integration of artificial intelligence into streaming optimization, demonstrated by recent platform enhancements from NVIDIA in early 2026, illustrates how algorithmic improvements can dynamically adjust quality parameters based on network conditions and device capabilities. These technical breakthroughs reduce the dependency on high-end local hardware and enable premium experiences on smartphones, tablets, and televisions that previously could not support demanding titles.
Policy and Regulatory Environment
The regulatory landscape is undergoing rapid reconfiguration, with implications for infrastructure investment and market entry strategies. In mid-2025, the Federal Communications Commission moved to eliminate net neutrality rules and remove broadband provider restrictions as part of a broader deregulatory initiative. This shift alters the competitive dynamics for content delivery, potentially reducing compliance burdens for cloud gaming operators while raising questions about long-term network neutrality and prioritization practices. Simultaneously, European policymakers are pursuing digital sovereignty objectives. The European Commission's March 2026 proposal for a Technological Sovereignty Package and the €75 million allocation to the EURO-3C federated telco-edge-cloud project signal a strategic push to strengthen regional cloud infrastructure autonomy. These initiatives create both opportunities for localized infrastructure partnerships and compliance complexity for operators navigating divergent regulatory regimes across continents.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer expectations increasingly favor convenience, cross-device continuity, and instant access over ownership of discrete hardware. Gamers are demonstrating willingness to stream titles across smartphones, tablets, PCs, and connected televisions, reducing the threshold for entry into interactive entertainment. This behavior aligns with broader digital consumption trends where subscription access replaces one-time purchases, and where content libraries are expected to be available anywhere. Enterprise and educational sectors are also exploring cloud-based interactive environments for training, simulation, and collaborative applications, extending demand beyond consumer gaming and creating adjacent revenue streams for platforms that can adapt their streaming infrastructure to non-gaming use cases.
Gaming Market
Supply Chain and Cost Structure Evolution
Data center energy demand is reshaping operating cost calculations for cloud-intensive services. U.S. data centers are projected to nearly double their combined energy consumption from approximately 80 gigawatts in 2025 to 150 gigawatts by 2028. For cloud gaming operators, this trend translates into higher infrastructure costs unless mitigated through efficient cooling technologies, renewable energy sourcing, and workload optimization. Companies that invest in energy-efficient architectures and strategic power procurement will gain cost advantages that compound over time, particularly as scale increases and marginal compute costs become a more significant factor in service profitability.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation
The market features a mix of platform-scale incumbents, hardware-integrated operators, and specialized streaming providers. Microsoft has expanded Xbox Cloud Gaming access through device optimizations and Azure edge node improvements, broadening reach to existing hardware ecosystems while leveraging its subscription content library. This approach emphasizes ecosystem leverage, using cloud streaming as an extension of a broader gaming and services portfolio rather than a standalone revenue center. NVIDIA differentiates through technical performance, offering RTX-powered virtual GPUs that enable high-fidelity streaming at elevated resolutions and frame rates. Its recent platform enhancements focus on AI-driven quality optimization and broader device compatibility, positioning performance fidelity as a core value proposition for enthusiasts and performance-sensitive users.
Amazon Luna continues to integrate cloud gaming with Fire TV hardware, creating a direct streaming pathway for subscribers within a controlled device environment. This hardware-software alignment reduces friction for users already embedded in Amazon's consumer electronics ecosystem. Sony has pursued a parallel strategy by enabling cloud streaming of PlayStation titles to its Portal handheld device without requiring a console, effectively decoupling premium content access from dedicated gaming hardware. Blacknut has pursued a distribution-focused model, securing pre-installation partnerships on devices such as the Logitech G Cloud handheld, which provides immediate access to a large catalog of premium titles and reduces adoption barriers for hardware partners seeking to differentiate their products. Boosteroid operates as a multi-platform streaming service emphasizing broad device support and session quality, targeting users who prioritize accessibility across heterogeneous device environments rather than deep integration with a single hardware ecosystem.
Market Structure Evolution
Concentration trends indicate a maturing market where leading operators capture a disproportionate share of value. The top three providers account for approximately 57.3 percent of market revenue, while the top five reach 74.2 percent. This concentration reflects the advantages of scale in infrastructure investment, content licensing, and user acquisition. However, the landscape is not static. Hardware integration partnerships are creating niche entry points for specialized platforms, while telecommunications operators are beginning to bundle gaming services with network packages, as seen in recent 5G gaming offerings from European carriers. These developments suggest a trajectory toward both consolidation at the top and fragmentation at the edges, where device manufacturers, network providers, and regional platforms can carve out defensible positions through integration, localization, or niche performance specialization.
New entrants face steep barriers in content rights, infrastructure scale, and brand trust, but opportunities exist for operators that align cloud gaming with adjacent value propositions. Device manufacturers can use pre-installed streaming platforms to enhance hardware appeal. Telecoms can differentiate broadband offerings with optimized gaming pathways. Regional platforms can compete on localization, language support, and publisher relationships that global incumbents may prioritize less aggressively. The strategic question for each participant is whether to compete on scale, on integration depth, or on specialized performance and service quality.
Future Trends and Commercial Opportunities
Edge-Native Infrastructure and Network-Service Bundling
Over the next three to five years, cloud gaming success will increasingly depend on proximity-aware infrastructure and network-level service optimization. As 5G standalone networks expand and edge computing nodes proliferate, operators that coordinate streaming delivery with telecommunications partners will gain latency and reliability advantages. Bundled offerings that pair broadband or mobile plans with gaming subscriptions will lower acquisition costs and increase stickiness, particularly in markets where telecoms hold strong consumer relationships. Commercial opportunities will emerge for platforms that design their service architecture to leverage these partnerships, including co-branded packages, zero-rating arrangements where permissible, and network-aware quality scaling that adapts experience parameters to connection characteristics.
Hardware-Software Convergence and Ecosystem Lock-In
The boundary between cloud gaming services and consumer hardware will continue to blur. Handheld devices, smart televisions, and connected set-top boxes will increasingly ship with streaming platforms pre-integrated, reducing the friction of initial adoption and creating default access pathways. This convergence benefits hardware manufacturers seeking differentiation and service providers seeking scaled distribution. The commercial implication is clear: platforms that secure pre-installation or deep integration agreements with device makers will capture a larger share of incremental users, while those relying solely on app-store discovery or web-based onboarding will face higher acquisition costs and lower conversion rates. Strategic partnerships with hardware OEMs, including co-marketing and joint optimization efforts, will become a decisive competitive lever.
AI-Driven Personalization and Adaptive Streaming Economics
Artificial intelligence will play an expanding role in both user experience and operational efficiency. Adaptive streaming algorithms will optimize bitrate, resolution, and frame delivery in real time based on network conditions, device capabilities, and user preferences. On the content side, AI-assisted curation and recommendation systems will improve discovery, reducing the friction that leads to trial abandonment. These capabilities create opportunities to increase engagement and reduce churn without proportional increases in content licensing spend. However, the same technologies raise expectations for service quality, and platforms that lag in adaptive optimization may experience disproportionate user dissatisfaction as baseline expectations rise across the market.
Risk Factors and Uncertainties
Several uncertainties could alter the trajectory outlined above. Regulatory divergence between regions may complicate global service architectures, particularly as digital sovereignty initiatives encourage localized infrastructure requirements. Energy cost escalation for data centers could compress margins unless offset by efficiency gains or favorable power contracts. Content rights negotiations may become more expensive as publishers recognize the strategic value of cloud distribution and demand higher revenue shares or exclusivity terms. Finally, competitive intensity could trigger price compression in subscription tiers, forcing platforms to differentiate through performance, integration, or exclusive content rather than price alone. Operators that build diversified revenue streams and maintain flexibility in infrastructure and licensing strategies will be better positioned to navigate these variables.
Strategic Recommendations for Decision Makers
For Platform Operators and Device Manufacturers
Prioritize integration depth over standalone reach. Embedding cloud gaming capabilities into hardware product lines, operating system environments, or network service bundles creates inherent distribution advantages that pure software-play strategies struggle to replicate. Invest in adaptive streaming quality and device-specific optimization to ensure that the user experience meets expectations across heterogeneous conditions. Where possible, pursue partnerships with telecommunications providers to align service delivery with network capabilities and to access bundled customer acquisition channels. For hardware manufacturers, treat pre-installed streaming platforms as a product differentiator and negotiate terms that ensure catalog relevance and technical compatibility over the device lifecycle.
For Investors and Strategic Capital Allocators
Evaluate operators based on infrastructure efficiency, content licensing sustainability, and ecosystem integration rather than headline user growth alone. Metrics such as cost per streaming hour, retention curves by acquisition channel, and the proportion of revenue derived from integrated hardware or network partnerships offer clearer signals of durable competitive advantage than top-line subscriber counts. Favor business models that combine recurring subscription revenue with ancillary monetization paths, including hardware margins, network bundling fees, or enterprise and education extensions. Monitor regulatory developments in key regions, as digital sovereignty and infrastructure policies will influence where capital can be deployed most efficiently and which operators gain preferential access to local edge resources.
Gaming Laptop Market
For Procurement and Partnership Decision Makers
When selecting cloud gaming service providers or infrastructure partners, assess streaming reliability under variable network conditions, the flexibility of content catalogs, and the operator's ability to support multiple device form factors. Prioritize partners that demonstrate a clear roadmap for adaptive quality optimization and that maintain transparent performance reporting. For organizations exploring cloud gaming as a component of broader digital entertainment or training strategies, consider the long-term implications of vendor lock-in and negotiate terms that preserve portability and integration flexibility. Track infrastructure energy commitments and sustainability practices as indicators of long-term cost discipline and operational resilience.
PW Consulting
The cloud gaming market is entering a phase where differentiation will be determined less by the mere availability of streaming and more by the quality of integration, the efficiency of delivery, and the durability of user relationships. Decision makers who align their strategies with these structural drivers will be better positioned to capture value as the market scales toward the end of the decade. For organizations requiring detailed segmentation data, regional breakdowns, competitive benchmarking, and customized scenario analysis, comprehensive research resources are available to support deeper evaluation and strategic planning.
For detailed analysis of this topic, please visit the official page: Cloud Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Patient Data Management Systems Market 2026: Why 11.2% CAGR And ICU Adoption Redefine Growth
By PW Consulting, 2026-09-21
The Patient Data Management Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The global patient data management systems (PDMS) market has entered a phase of accelerated structural transformation. Valued at approximately 527.36 million USD in 2020, the market has grown to an estimated 888.06 million USD by 2025, reflecting a compound annual growth rate of 11.2 percent through the forecast horizon extending to 2032. By the end of that period, total market revenue is projected to surpass 1.85 billion USD. This trajectory is not merely a reflection of incremental IT spending; it signals a fundamental reorientation of how clinical data is captured, integrated, and operationalized across care settings.
The growth curve reveals distinct inflection points. The period from 2020 to 2023 delivered steady expansion, while the 2024 to 2025 window accelerated as hospitals confronted compounding pressures: staffing constraints, regulatory mandates, and the operational urgency of interoperable data flows. Projections for 2026 through 2032 indicate that revenue will compound at a pace that outpaces many traditional healthcare IT segments, driven by consolidation of clinical workflows, cloud migration, and the formalization of PDMS as regulated medical device infrastructure.
Yet the headline figures obscure a market that is actively reconstituting itself. Growth is uneven across deployment models, clinical environments, and geographic regions. Vendors are navigating a landscape where interoperability expectations, cybersecurity exposure, and regulatory classification requirements are reshaping procurement criteria. For executives and investors, the strategic question is no longer whether PDMS adoption will continue, but how value will be captured amid shifting integration standards, mounting security liabilities, and evolving reimbursement and funding mechanisms.
Market Snapshot: Scale, Trajectory, and Structural Tensions
The market's expansion from roughly 527 million USD in 2020 to nearly 888 million USD in 2025 reflects a compound growth rate of 11.2 percent, with forecasts extending to 2032 indicating a pathway toward 1.85 billion USD. This trajectory is anchored by several structural forces: the normalization of PDMS as a clinical documentation and device integration layer, the formalization of risk management and approval processes under hospital IT regulations, and the simplification of functional requirements within industry standards. Together, these factors have lowered adoption friction while simultaneously raising the baseline expectation for what a compliant, production-grade system must deliver.
PW Consulting
Concentration patterns further clarify the market's maturity. The leading vendors collectively account for approximately half of total revenue, with the top three and top five firms each representing roughly 50 percent of the market. This concentration suggests a landscape where established players hold significant share, yet the remaining half is distributed across regional specialists, niche integrators, and emerging cloud-native entrants. The implication for strategy is clear: scale advantages exist, but they are not insurmountable when differentiated clinical workflows, localized compliance needs, or cloud-first deployment models create openings for targeted positioning.
The current market is also defined by three interlocking challenges that are reshaping vendor and buyer behavior alike.
- Interoperability expectations are outpacing legacy integration architectures. Hospitals increasingly demand seamless connectivity across monitors, ventilators, infusion pumps, and electronic patient records, yet many installed bases were designed around single-function documentation rather than hospital-wide data orchestration.
- Cybersecurity and operational resilience have become procurement determinants. The exposure of cloud-based electronic patient record platforms to ransomware incidents has elevated security architecture, backup readiness, and incident response capabilities from technical considerations to board-level risk management criteria.
- Regulatory classification and funding mechanisms are simultaneously enabling and constraining adoption. PDMS are classified as medical devices requiring risk management and approval processes, while funding instruments such as hospital future acts have catalyzed deployments in specific regions. This dual dynamic accelerates certain rollouts while imposing compliance costs and timeline uncertainties elsewhere.
These tensions do not slow the market; they redistribute value. Vendors that can reconcile interoperability, security, and regulatory compliance within coherent deployment models are gaining negotiating leverage, while those relying on fragmented, point-solution messaging are facing longer evaluation cycles and more stringent proof-of-value requirements.
Key Drivers Shaping the Next Wave of Growth
The market's trajectory is being propelled by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a momentum loop that is likely to sustain double-digit growth through the late 2020s.
Patient Engagement Software Market
Technology innovation and integration maturity. The shift from isolated documentation tools to integrated clinical data layers is the most visible technological driver. PDMS platforms are increasingly expected to connect diverse bedside devices, normalize data streams, and feed structured information into broader hospital information and electronic patient record environments. Recent operational deployments illustrate this consolidation: centralized standardized documentation systems are now being implemented across multiple provincial hospitals, embedding PDMS into anaesthesia and intensive care workflows with the explicit goal of improving data quality and cross-hospital communication. At the same time, integration showcases at major industry events are emphasizing closed-loop processes that link media and documentation solutions directly into PDMS and hospital information systems, reducing manual handoffs and supporting continuity of care.
Policy and regulatory environment. Regulatory dynamics are acting as both a catalyst and a filter. PDMS are classified as medical devices and must undergo approval processes that include risk management under hospital IT regulations, which raises the barrier to entry for immature solutions but strengthens confidence in vetted platforms. At the same time, functional requirements for patient data management systems have been simplified in standards, lowering the implementation burden for baseline compliance. New guidelines, laws, and regulations are being directly integrated into PDMS standard content, meaning that vendors must treat regulatory updates as continuous product obligations rather than periodic certification events. This environment rewards platforms with disciplined change management and penalizes those that treat compliance as a static checklist.
Demand-side behavior and clinical workflow pressure. Hospitals are confronting staff shortages alongside budget constraints, which makes PDMS adoption less about optional digitization and more about workflow survival. Complex clinical environments require documentation, device traceability, medication management, and nutritional or pediatric percentile tracking without adding administrative burden. The demand signal is shifting accordingly: buyers are prioritizing systems that can centralize documentation, improve data quality, and reduce the cognitive load on clinical staff. This demand-side pressure is particularly acute in intensive care and anaesthesia settings, where device density and data volume make manual reconciliation impractical.
Cost structure and deployment model evolution. The cost equation is being reshaped by cloud transformation and the operational economics of platform maintenance. Cloud-based hospital information and electronic patient record systems are moving into production, with major medical centers completing launches and phasing out legacy platforms over multi-year transition windows. This shift alters total cost of ownership calculations, introducing subscription and hosting considerations while reducing on-premises maintenance overhead. However, it also introduces dependency on vendor security posture and continuity planning, as evidenced by incidents where ransomware attacks disrupted electronic patient record portals across a large share of hospital organizations using a specific platform. The cost conversation has therefore expanded from license and implementation to include resilience, data protection, and recovery readiness.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by a small group of established vendors with deep clinical integration expertise, complemented by regional specialists and integration-focused entrants. The leaders have built their positioning around distinct clinical use cases, device connectivity breadth, and the ability to embed PDMS within broader hospital information and monitoring environments.
German-based vendors illustrate the depth of specialization emerging in the market. One prominent player focuses on certified PDMS integrated with its hospital information system, emphasizing ICU device connectivity, medication management, nutritional balance, and pediatric percentile features. This configuration targets high-acuity environments where documentation precision and cross-referencing across clinical parameters are essential. Another German firm offers a PDMS suite integrated with acute care monitoring systems for ICU, operating room, and neonatal intensive care settings, with an emphasis on centralized data management, prescription traceability, and optimization of patient care. A third German provider centers its offering on anaesthesia and intensive care departments, delivering centralized documentation, improved data quality, and cross-hospital communication capabilities. These profiles share a common thread: they are designed for environments where device density, regulatory scrutiny, and data continuity requirements are highest.
In the Netherlands, a different integration philosophy is gaining traction. A vendor has advanced a hospital-wide electronic patient record solution with PDMS capabilities that communicate across monitors, ventilators, and infusion pumps throughout the facility. This approach reflects a broader enterprise integration mindset, where PDMS is treated as a connective layer within a unified digital infrastructure rather than a departmental add-on. The emphasis on hospital-wide device communication aligns with buyer expectations for fewer integration silos and more consistent data semantics across care units.
Recent developments illustrate how these positions are being reinforced and tested in practice. One vendor completed a PDMS deployment across anaesthesia and intensive care departments at a state hospital, extending a centralized standardized documentation model to multiple provincial hospitals. Another vendor's cloud-based hospital information and electronic patient record platform reached production at a major medical center, with a phased transition away from legacy systems extending through the following year. Concurrently, a ransomware incident affecting a widely used electronic patient record portal disrupted operations for a substantial portion of hospital organizations, underscoring the operational and reputational stakes tied to platform security. Integration-focused demonstrations have further highlighted the push toward closed-loop processes and point-of-care hardware and monitoring integration, signaling that PDMS is increasingly evaluated as part of a broader clinical technology ecosystem rather than a standalone documentation tool.
Patient Record Management Market
The market is evolving along three overlapping paths. First, consolidation pressure is growing as buyers prefer fewer, more capable platforms that can cover multiple departments and device types, reducing integration overhead and vendor management complexity. Second, differentiation is sharpening around clinical specificity, with vendors competing on anaesthesia, ICU, neonatal, and medication management capabilities rather than generic data capture. Third, new entrants and integration specialists are probing niches where cloud-native architecture, streamlined compliance updates, or specialized device interoperability can offset the incumbency advantages of larger players. The net effect is a market where share is defended through integration depth and compliance readiness, while growth is increasingly contested in segments where deployment model, security posture, and workflow fit matter more than brand recognition alone.
Forward Outlook: Three Trends That Will Define 2026 to 2032
The market's next phase will be shaped by the interaction of integration expectations, security realities, and regulatory continuity. Three trends are likely to dominate strategic planning for the coming years.
- Integration will become the primary value proposition, not a feature. As PDMS is expected to connect devices, documentation, and broader hospital information environments, the competitive advantage will shift from data capture to data orchestration. Platforms that can normalize device outputs, maintain consistent semantics across departments, and support cross-hospital communication will command stronger positioning. The opportunity lies in designing for interoperability as a default architecture, with standardized interfaces and continuous alignment to evolving functional requirements.
- Security and resilience will reprice risk and procurement criteria. High-profile disruptions to electronic patient record platforms have made cybersecurity a central element of vendor evaluation. Buyers will increasingly prioritize architectures with robust access controls, segmented operations, tested recovery processes, and transparent incident readiness. For vendors, the commercial implication is that security maturity may become a differentiator that shortens sales cycles for risk-averse buyers while exposing weaker platforms to prolonged scrutiny. The uncertainty is that threat landscapes and regulatory expectations will continue to evolve, requiring ongoing investment that may pressure margins if not managed efficiently.
- Regulatory integration will shift from periodic certification to continuous compliance. With new guidelines and regulations being embedded directly into PDMS standard content, vendors must treat compliance as an operational discipline. This dynamic favors platforms with structured update mechanisms, clear traceability between regulatory changes and product content, and the ability to demonstrate risk management continuity. The business opportunity is to reduce the lag between regulatory change and product readiness, which can become a decisive factor in public procurement and hospital IT approvals. The risk is that vendors unable to absorb this continuous load will face rework, delays, and competitive disadvantage.
These trends intersect with commercial models in ways that will matter for both suppliers and buyers. Deployment architectures will increasingly blend on-premises device connectivity with cloud-hosted record and documentation layers, creating hybrid environments that demand careful orchestration of data flow, access control, and maintenance responsibilities. Funding and regulatory incentives will continue to influence regional adoption patterns, making some geographies more responsive to near-term expansion while others remain constrained by budget cycles and implementation capacity. The overarching opportunity is to align product roadmaps and commercial narratives with the reality that PDMS is becoming a regulated, integrated, and security-sensitive component of clinical infrastructure rather than a discretionary IT enhancement.
Strategic Recommendations for Decision Makers
The market's trajectory offers distinct implications for manufacturers, investors, and procurement leaders. Each group faces a different set of priorities, but all benefit from treating PDMS as a continuously evolving clinical data and compliance platform rather than a static software purchase.
For manufacturers and platform vendors. Prioritize integration architecture and security readiness as core product investments, not ancillary capabilities. Buyers are evaluating device connectivity breadth, documentation centralization, and the ability to embed regulatory updates into standard content, so differentiation should be built around clinical workflow fit, interoperability reliability, and demonstrable risk management continuity. Where possible, position PDMS as part of a hospital-wide data strategy that reduces silos, supports cross-department documentation, and aligns with evolving electronic patient record environments. Continuous compliance mechanisms and transparent update practices can become meaningful commercial advantages in procurement cycles that increasingly weight regulatory maturity.
For investors and strategic backers. Focus on vendors whose value proposition is tied to integration depth, clinical specificity, and resilience rather than pricing alone. The concentration dynamics suggest that scale incumbents retain advantages, but the distributed share outside the leaders indicates room for differentiated platforms that address cloud migration, security maturity, and specialized workflows in anaesthesia, ICU, and neonatal settings. Monitor deployment milestones, platform transition timelines, and security incident responses as leading indicators of operational credibility. Be mindful that margin profiles can be affected by the ongoing investment required for compliance updates, integration maintenance, and security hardening, making operating discipline as important as growth potential.
For hospital leaders and procurement teams. Treat PDMS selection as a multi-year operational decision that should be evaluated against integration scope, security architecture, compliance continuity, and clinical workflow alignment. Favor platforms that can communicate across monitors, ventilators, infusion pumps, and electronic patient records without creating new documentation silos, and verify that risk management and approval processes are clearly defined and maintained. Weigh the total cost of ownership including hosting, maintenance, resilience, and incident recovery rather than focusing narrowly on initial implementation cost. Demand evidence of how regulatory updates are incorporated into standard content and how the platform supports centralized documentation with improved data quality across departments.
Timely, granular intelligence is essential because the market is changing on multiple fronts at once: integration expectations, security realities, regulatory content, and deployment models are all shifting within the same procurement and planning cycles. Detailed segment data, regional dynamics, and vendor-specific implementation patterns can materially affect go-to-market priorities, investment theses, and purchasing decisions. For decision makers who need deeper segmentation, competitive benchmarking, and customized scenario planning, PW Consulting's full research report provides extended data and tailored guidance to support execution.
For detailed analysis of this topic, please visit the official page: Patient Data Management Systems (PDMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


