



Palletizing Machine Market 2026: Why 6.12% CAGR Signals Broader Automation Shift
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Palletizing Machine Market
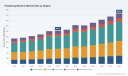
The palletizing machine market is navigating a period of structural transformation, moving beyond simple mechanization toward intelligent, adaptive automation. Over the historical window from 2020 through 2025, the sector expanded from approximately $234.5 million to $307.9 million, reflecting sustained capital investment in post-packaging material handling. This momentum is expected to carry forward through the 2026–2032 forecast horizon, with a compound annual growth rate of 6.12 percent pushing the market toward the $466.6 million mark by the end of the projection period. The trajectory is not merely a function of volume expansion; it is being reshaped by shifting labor economics, evolving safety frameworks, and the convergence of robotics with artificial intelligence. For executives and investors, the critical question is no longer whether to automate palletizing, but how to align equipment strategies with a landscape where conventional, robotic, and mixed configurations are competing on flexibility, integration depth, and total cost of ownership rather than throughput alone.
Core Challenges and Inflection Points
The industry is currently grappling with three interrelated challenges that are forcing strategic recalibrations across equipment manufacturers, system integrators, and end-users. First, the traditional dichotomy between conventional and robotic palletizers is blurring as mixed configurations and collaborative robots gain traction for low-to-medium volume operations. Buyers are increasingly evaluating mixed palletizers as a compromise between the simplicity of fixed automation and the flexibility of robotic cells, which complicates vendor selection and demands clearer total cost models. Second, safety standardization is tightening globally. Recent updates to industrial robot safety frameworks, including the ISO 10218-2025 revision published in March 2025 and the EN 415-4:2025 standard issued in December 2025, introduce differentiated robot classes for palletizing safety assessments and establish safety requirements spanning installation through operation. Compliance is no longer a checkbox exercise; it influences cell design, integration timelines, and lifecycle service obligations. Third, the valuation of automation is being recalibrated by labor economics. With median hourly wages for palletizer operators in the United States reaching $34.80 in 2026 and average fully-loaded costs approaching $55,000 per worker annually, the financial case for automation is stronger than ever, but so is the expectation for systems that reduce changeover complexity, minimize operator intervention, and deliver predictable uptime.
Worldwide Robotic Palletizers Market
These inflection points converge to reshape procurement criteria. Organizations are shifting from unit-price comparisons toward evaluating integration readiness, cross-line configurability, and the ability of equipment to coexist with broader warehouse automation ecosystems. The market is also witnessing a concentration dynamic where a limited set of players controls a meaningful share of revenue, yet the dispersion of mid-tier specialists and regional integrators creates pockets of agility and customization that large incumbents cannot always replicate quickly.
Key Drivers Reshaping the Market
Technological Innovation and Collaborative Flexibility
Technological advances are redefining what palletizing equipment can do in high-mix environments. Collaborative robot families are expanding beyond light assistance into industrial-grade palletizing applications, driven by ergonomic improvements, simplified programming, and safety architectures that reduce the need for extensive guarding. Recent product activity illustrates this direction. In May 2025, FAB America introduced wrist buttons across its CRX cobot lineup to enhance palletizing ergonomics, and by April 2026 debuted the CRX-3iA collaborative robot with new capabilities for palletizing and related tasks. Around the same period, ABB Robotics launched its PoWa cobot family for industrial-grade collaborative palletizing and subsequently rolled out updates to enhance performance. These developments signal a broader trend: collaborative systems are no longer peripheral solutions confined to low-speed tasks, but are increasingly positioned for scalable adoption where mixed SKUs, frequent changeovers, and space constraints make traditional large-cell robotics less attractive.
Palletizer Market
At the same time, mixed palletizing is benefiting from AI-driven decisioning and tighter integration with conveying infrastructure. FlexLink's AI-driven mixed palletizer, showcased at PACK EXPO Las Vegas in September 2025, highlights how software logic can improve stacking efficiency and safety while reducing manual reconfiguration. This shift is significant because mixed configurations have historically been constrained by complex setup routines and limited scalability. AI-enabled approaches lower the operational friction of running multiple product formats on a single line, which is particularly valuable for producers handling variable case sizes, promotional packs, and seasonal assortments.
Regulatory and Standardization Momentum
Regulatory and standards activity is acting as both a constraint and a catalyst. The publication of ISO 10218:2025 in March 2025, with differentiated robot classes for palletizing safety assessments, introduces a more granular safety evaluation framework that aligns system design with application risk profiles. The EN 415-4:2025 standard further establishes safety requirements for palletizers and depalletizers across installation and operation phases. For manufacturers, these updates compel earlier consideration of safety architecture in the product development cycle and influence how cells are commissioned and validated. For buyers, the emerging standards raise the importance of documented compliance, service support, and cross-border acceptance of safety certifications when evaluating global equipment portfolios.
Standards are also shaping integration strategies. As safety requirements become more application-specific, vendors that can provide pre-validated safety configurations, modular guarding options, and clear documentation are gaining a competitive edge in tender evaluations. This dynamic favors suppliers with integrated engineering capabilities and service networks that can support localized compliance without sacrificing throughput design objectives.
Demand-Side Shifts in Food, Beverage, E-Commerce, and Retail
Demand-side behavior is diversifying the use cases for palletizing equipment. Food and beverage production continues to drive substantial volume, but the nature of the demand is changing as lines accommodate more packaging formats, shorter runs, and faster SKU turnover. E-commerce and retail operations are expanding the role of palletizing beyond traditional distribution centers into fulfillment environments where mixed loads, layer integrity, and protection of high-value goods matter more than maximum line speed. These shifts increase the value of systems that can manage overhang constraints, bundle and tier configurations, and rapid format changes without sacrificing stability.
The commercial implication is that throughput alone is no longer the primary differentiator. Buyers are increasingly prioritizing adaptability, ergonomics, and the ability to integrate palletizing into broader warehouse and line-side automation. Companies such as Krones AG, which delivers complete palletizing systems for beverage and food production lines, and BEUMER Group, which provides palletizing and depalletizing solutions for bulk goods and packaged products, illustrate how complete-system thinking is gaining traction for sectors with complex product handling requirements. Meanwhile, palletizer specialists like Columbia Machine, with bundle and tier capabilities, and Symach, with conventional high-speed stacking without overhang, continue to compete on application-specific performance profiles.
Labor Economics and Total Cost of Ownership Reassessment
Labor cost dynamics are accelerating the reassessment of automation economics. The elevated cost of manual palletizer operation is compressing payback horizons for well-designed automation, but it also raises expectations for systems that reduce operator dependency and minimize downtime. As a result, the total cost of ownership calculus now includes not just acquisition cost, but integration complexity, changeover time, maintenance burden, and the degree to which a system can be redeployed across lines or product families. This environment favors equipment that offers modular scalability, intuitive interfaces, and serviceable architectures.
This driver is particularly impactful for mid-sized enterprises that previously found large robotic cells financially out of reach or operationally excessive. Collaborative and mixed configurations, when paired with compact automation cells and rapid deployment models, broaden the addressable market and create opportunities for vendors that can deliver predictable performance at lower integration overhead. The trend is visible in the emergence of versatile, scalable automation offerings and cobot-based compact systems from players such as Schneider Packaging Equipment and Vention, alongside integration-focused providers like TopTier and NOVA Automation.
Competitive Landscape and Evolving Strategies
Differentiation Through Integration, Payload, and Flexibility
The competitive field combines global robotics giants, complete-line specialists, and regional palletizer manufacturers, each pursuing distinct strategic positions. ABB provides robotic palletizing solutions including the IRB 760 high-speed full-layer palletizer and OmniCore controllers, anchoring its strategy in high throughput and control architecture. KUKA AG competes with the KR QUANTEC PA series, emphasizing enhanced payload and multi-line configurations for operations that require robust handling and flexible deployment across multiple packaging lines. FANUC Corporation manufactures industrial and cobot palletizing robots, including the CRX series with user-friendly wrist controls, aligning its approach with ease of use and broad application coverage. Yaskawa Electric Corporation supplies palletizing robots tailored for food and consumer goods applications with integrated systems, leveraging application-specific engineering and system-level delivery.
Beyond the robotics manufacturers, system-level and application-focused suppliers are carving out strong positions. Krones AG delivers complete palletizing systems for beverage and food production lines, positioning itself around end-to-end line integration. BEUMER Group offers palletizing and depalletizing systems for bulk goods and packaged products, appealing to sectors where material handling spans a wide range of formats. Honeywell Intelligrated extends the conversation into warehouse automation, providing integrated palletizing and broader material handling solutions. On the conventional and specialized side, A-B-C Packaging Machine Corporation manufactures high-performance palletizers for case and layer forming, Columbia Machine produces palletizing systems with bundle and tier capabilities for diverse industries, and Symach sells conventional palletizers featuring high-speed stacking without overhang. Schneider Packaging Equipment develops palletizing cells including cobot-based compact automation systems, while FlexLink supplies AI-driven mixed palletizing solutions integrated with conveying systems. Vention offers Rapid Series palletizers for versatile and scalable automation, TopTier provides low-infeed and conventional/robotic palletizing solutions for integration, and NOVA Automation manufactures industrial palletizing cells such as the IPC-25 for case handling.
Some of the most notable strategic signals are coming from product and event activity that emphasizes ergonomics, compact deployment, and AI-enabled flexibility. ABB Robotics' PoWa cobot family and subsequent performance updates, FANUC America's CRX wrist-button enhancements and the CRX-3iA debut, and FlexLink's AI-driven mixed palletizer featured at PACK EXPO Las Vegas in September 2025 collectively point to a market where usability and adaptability are becoming central value propositions. Marchesini's display of the WKR Compact Palletizer and introduction of new single or dual robotic palletizer options further illustrate how compact footprint and dual-configurability are being prioritized for environments where space and line flexibility matter. Honeywell's participation in PACK EXPO Las Vegas with warehouse automation solutions extending beyond palletizing highlights the growing relevance of ecosystem-level integration for buyers seeking cohesive material handling strategies.
Market Structure Evolution: Consolidation Pressure and Niche Agility
The competitive structure is evolving along two directions simultaneously. One is consolidation pressure at the upper end, where broad robotics portfolios, control platforms, and global service networks create advantages in large-scale deployments and cross-market standardization. The other is continued agility among specialized manufacturers and integrators who can configure cells for narrow applications, respond quickly to regional requirements, and tailor changeover procedures to local product mixes. This bifurcation creates a market where large portfolios compete on scale, reliability, and integration breadth, while specialists compete on configurability, application expertise, and faster deployment cycles.
The recent standards and event activity reinforces this dynamic. As safety requirements become more application-specific, suppliers with strong documentation, modular safety design, and cross-regional compliance support are better positioned to win multi-site and multi-market projects. At the same time, AI-driven mixed palletizing and cobot-based compact cells are reducing barriers for smaller and mid-tier operations, expanding the pool of potential adopters and increasing competition among vendors that can deliver straightforward integration without sacrificing performance. The outcome is likely to be a more segmented competitive environment where incumbents strengthen ecosystem positions while challengers win on usability, footprint, and application fit.
Future Trends and Commercial Opportunities
Trend 1: Collaborative and Mixed Configurations as Mainstream Options
Over the next three to five years, collaborative robots and mixed palletizing configurations are likely to move from specialized solutions to mainstream choices for many mid-volume and high-mix operations. The combination of ergonomic improvements, intuitive interfaces, and AI-assisted stacking logic is reducing the operational burden of frequent changeovers and small-batch production. For commercial strategy, this trend opens opportunities in sectors where product variability and space constraints previously limited the business case for automation. Vendors and integrators that can standardize modular cells, simplify commissioning, and provide clear guidance on safety compliance will be well placed to capture demand from organizations seeking automation without the complexity of large-scale robotic installations.
PW Consulting Automotive & Machinery Research Center
Trend 2: Ecosystem-Level Integration and Warehouse Automation Convergence
Palletizing is increasingly evaluated not as an isolated line function, but as part of broader warehouse and production automation. Buyers are looking for smoother interfaces with conveyance, warehouse management, and line-side material flow, which rewards suppliers that can offer integrated solutions and coherent service models. This convergence creates commercial opportunities for companies that can connect palletizing performance to overall material handling efficiency, reduce handoff friction, and support data-driven optimization across the workflow. It also raises the importance of open interfaces, interoperability, and serviceability, since downstream integration quality often determines whether a system delivers its intended throughput and flexibility in practice.
Trend 3: Compliance-Driven Design and Regional Deployment Considerations
The updated safety standards and differentiated robot classes are expected to shape product roadmaps and deployment strategies for the foreseeable future. As compliance documentation, modular safety design, and regional validation become more central to procurement decisions, opportunities will grow for suppliers that can provide pre-configured safety options, clear instruction sets, and support for local requirements. At the same time, regional deployment will remain sensitive to labor costs, facility layouts, and product mix, meaning that one-size-fits-all solutions will continue to face adoption limits. Companies that can balance global consistency with regional customization will have an advantage in multi-market rollouts and in facilities where safety, footprint, and changeover requirements differ significantly across sites.
Strategic Recommendations for Decision-Makers
For Equipment Manufacturers and System Integrators
Focus product and service portfolios on usability, modularity, and compliance readiness. The market is increasingly rewarding equipment that simplifies commissioning, supports rapid format changes, and integrates cleanly with conveying and warehouse automation. Invest in documentation and safety architectures that align with the differentiated robot classes and installation-to-operation requirements emerging from recent standards. Differentiation will increasingly come from how easily a solution can be deployed across lines, maintained over time, and redeployed as product mixes evolve.
For Investors Evaluating Automation and Robotics Exposure
Prioritize businesses that demonstrate integration depth, serviceability, and a credible path to serving mid-volume, high-mix demand. The growth trajectory is supported by a steady compound annual rate, but value capture will favor companies that can convert technological flexibility into repeatable deployment models and clear total cost of ownership advantages. Pay attention to players that are strengthening ecosystem positioning, AI-enabled mixed palletizing capabilities, and cobot-based compact solutions, as these areas are broadening the addressable market beyond traditional high-volume applications.
For Procurement and Operations Leaders Evaluating Palletizing Investments
Base evaluations on total cost of ownership, changeover complexity, safety compliance, and integration fit rather than peak throughput alone. As labor costs stay elevated and product variety increases, the value of palletizing equipment will depend heavily on how well it reduces manual intervention, supports mixed configurations, and aligns with existing material handling infrastructure. Request documented safety compliance, modular configuration options, and clearly defined service support before finalizing decisions, especially for multi-site or multi-region deployments where standard consistency and local adaptability both matter.
Closing Perspective
The palletizing machine market is entering a phase in which flexibility, integration, and compliance readiness will matter as much as raw throughput. Continued expansion toward the mid-$400 million range by the end of the forecast period reflects structural demand for automated material handling, but the winners will be those who can deliver predictable performance across changing product mixes, tighter safety expectations, and broader automation ecosystems. For organizations seeking deeper segmentation, regional granularity, and application-specific benchmarks, the full research report offers more detailed breakdowns and tailored recommendations to support investment timing, portfolio planning, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Palletizing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Marine Audio System Market: How 5.8% CAGR and OEM Demand Shaped 2026 Growth
By PW Consulting, 2026-09-21
Navigating the Marine Audio System Market: Strategic Trends and Commercial Opportunities
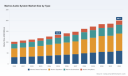
The marine audio system market has evolved from a niche accessory category into a strategically significant segment of the broader recreational and commercial marine electronics ecosystem. Driven by rising boat ownership, increasing expectations for premium onboard experiences, and rapid innovation in weather-resistant audio engineering, the sector has demonstrated consistent expansion over the past five years. With total market revenue climbing from approximately $102.15 million in 2020 to $133.5 million in 2025, and a projected trajectory toward $200.1 million by 2032, the industry is posting a compound annual growth rate of 5.8%. This growth is not merely a reflection of steady consumer spending; it signals a structural shift in how marine vessels are designed, equipped, and experienced.
For executives, investors, and procurement leaders, the market presents a compelling but complex landscape. Growth has been broad-based across component types, with marine speakers commanding the largest share of revenue, followed by stereo receivers, subwoofers, and amplifiers. End-use dynamics are heavily weighted toward original equipment manufacturer (OEM) partnerships, though aftermarket demand remains a meaningful secondary channel. Geographically, the market is distributed across mature and emerging regions, with Asia Pacific, North America, and Europe each representing substantial revenue pools, while Latin America and the Middle East and Africa contribute smaller but growing segments. Despite the optimistic trajectory, the market remains moderately fragmented, with the top three firms accounting for roughly 25.4% of revenue and the top five reaching approximately 35.6%. This concentration level suggests room for both consolidation and disruptive positioning, depending on product architecture, channel strategy, and integration capabilities.
Core Challenges and Inflection Points
The marine audio sector operates at the intersection of harsh environmental demands, stringent quality expectations, and rapidly shifting consumer preferences. Three structural challenges are shaping the competitive landscape and creating decisive inflection points for firms that can respond with agility.
-
Environmental durability versus cost optimization: Marine-grade audio components must withstand prolonged exposure to salt spray, ultraviolet radiation, humidity, and vibration. This requires specialized enclosure materials, UV-stable polymers, corrosion-resistant terminals, and robust sealing architectures. As boat builders and consumers increasingly expect premium acoustic performance alongside durability, suppliers face mounting pressure to balance material and manufacturing costs without compromising reliability. Custom rotomolding and injection-molded polymer processes, along with marine-certified quality control protocols, elevate production complexity and limit the ease of low-cost commoditization.
-
Integration complexity and interoperability standards: Modern marine vessels are becoming tightly networked environments where audio systems must communicate with chartplotters, navigation displays, engine telemetry, and onboard entertainment hubs. Compatibility with established marine networking protocols has become a baseline expectation rather than a differentiator. Products that cannot seamlessly interface with broader vessel electronics risk exclusion from premium OEM platforms and aftermarket installer preferences. This creates a technical barrier that rewards firms with modular architectures, proven integration pathways, and active participation in marine electronics ecosystems.
-
Channel fragmentation and brand differentiation: The market serves both high-end custom installations and volume-driven consumer segments, each with distinct pricing, service, and performance expectations. Aftermarket demand introduces variability in installer skills, regional distribution networks, and brand visibility, while OEM relationships require long lead times, certification rigor, and scalable production consistency. Firms that rely solely on price competition or generic consumer-audio adaptations often struggle to maintain margins, whereas those that cultivate clearly defined performance positioning and marine-specific engineering narratives tend to secure more resilient demand.
Key Drivers of Market Evolution
Technological Innovation and Performance Breakthroughs
Audio technology tailored for marine environments has advanced beyond basic weatherproofing. Digital signal processing, networked audio architectures, and real-time speaker modeling are enabling higher-fidelity reproduction in spaces where acoustic challenges—such as engine noise, wind, and uneven cabin geometry—have historically limited performance. Recent product launches highlight this trajectory. At a major marine industry event in October 2025, Hertz Marine unveiled a DSP amplifier featuring A2B digital audio networking and real-time loudspeaker modeling, signaling a move toward smarter, more adaptive sound tuning for demanding onboard conditions. Alongside this, the introduction of new marine speaker and subwoofer lines underscored the industry's push to combine precise acoustic engineering with reinforced marine-grade construction.
Beyond amplification and tuning, the integration of directional audio concepts into production boat platforms illustrates how technology is reshaping product expectations. For the 2026 model year, certain boat manufacturers introduced built-in directional audio systems across their fleets, moving marine audio from retrofitted add-ons toward designed-in experiences. This shift is significant because it embeds audio performance into vessel value propositions at the point of sale, elevating the strategic importance of audio suppliers in early-stage boat design and procurement.
Policy, Regulation, and Quality Assurance Dynamics
Regulatory frameworks and certification expectations do not dominate marine audio as they might in automotive or aerospace, but quality and durability standards exert meaningful influence on product development, supplier selection, and market access. Marine audio products are increasingly expected to adhere to ISO 9001:2015 quality management practices to demonstrate consistent durability certification for marine conditions. While this may appear to be a procedural detail, it has real commercial implications: certification readiness affects OEM approval cycles, installer confidence, and the credibility of warranty and service promises.
At the same time, interoperability requirements are shaping product roadmaps. NMEA 2000 network compatibility has become a practical necessity for integrating marine audio with chartplotters and other vessel electronics. This is not merely a technical footnote; it defines which products can be specified into integrated systems and which must compete as standalone substitutes. Suppliers that build NMEA 2000 alignment into their product architecture from the outset gain smoother pathways into OEM platforms and professional installation channels, while those that treat compatibility as an afterthought face higher integration friction and narrower addressable demand.
Demand-Side Shifts in Consumer and Commercial Behavior
Consumer expectations in the marine sector increasingly mirror those in automotive and premium consumer electronics: seamless usability, high audio quality, and integration with broader digital experiences. Boat owners and operators are no longer content with basic background sound; they seek immersive, zone-capable audio that performs reliably across different vessel zones, from open decks to enclosed cabins. This demand is reinforced by the proliferation of leisure boating, the growing popularity of customized vessel builds, and the willingness of enthusiasts to invest in upgrades that enhance both recreation and perceived vessel value.
On the commercial side, boat builders are under pressure to differentiate models in a competitive manufacturing environment. Integrated audio has become part of that differentiation strategy, especially in mid-to-high-tier recreational vessels where onboard experience influences purchasing decisions. The trend toward factory-installed directional audio and integrated entertainment systems reflects a broader move toward treating audio as a core feature rather than a peripheral accessory. This shift expands the strategic relevance of suppliers that can deliver both component performance and design flexibility to meet model-specific requirements.
Supply Chain and Cost Structure Dynamics
The cost structure of marine audio is shaped by material selection, specialized manufacturing processes, and the need for consistent durability under harsh conditions. Enclosures and cones require polymers engineered for UV and salt resistance, while connectors, terminals, and sealing components must endure prolonged exposure without degradation. These requirements increase input costs and complicate sourcing compared with standard consumer audio. As a result, supply chains that can secure reliable material grades, maintain process discipline, and validate durability at scale gain a meaningful advantage.
At the same time, the landscape is being influenced by the expansion of custom OEM/ODM capabilities among manufacturers outside traditional market centers. Notably, a Chinese manufacturer announced expanded custom OEM/ODM capabilities for marine audio systems targeting U.S. distributors, reflecting a broader trend of specialized production capacity becoming available to support foreign channel partners. This does not simply represent lower-cost sourcing; it signals the emergence of alternative manufacturing pathways that can be tailored to marine durability requirements while offering flexible volumes and customization. For buyers and competitors alike, this creates both opportunity and strategic risk: opportunities to access specialized production and cost flexibility, alongside risks related to quality consistency, lead-time reliability, and channel control.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation Among Core Players
The marine audio market features a mix of performance-focused specialists, premium brands with broad product portfolios, and suppliers with strong integration or customization capabilities. The competitive logic is not uniform; firms are competing on different axes, and understanding those axes is essential for interpreting market momentum.
-
Performance specialists and marine-native engineering: Companies such as Wet Sounds and JL Audio have built reputations around high-performance marine audio engineered specifically for demanding environments. Their product portfolios typically span speakers, subwoofers, amplifiers, and tower or integrated systems, with emphasis on withstand capabilities and acoustic output suited to open-water and high-noise settings. Their differentiation often rests on a clear marine-first design philosophy, which appeals to enthusiasts, installers, and OEM partners seeking credible performance narratives.
-
Integrated ecosystems and electronics alignment: Suppliers with ties to broader marine electronics platforms can leverage interoperability and installer familiarity as strategic advantages. Garmin's Fusion line, for example, positions advanced marine audio entertainment systems within a networked vessel context, benefiting from alignment with chartplotters and other marine electronics. This ecosystem-oriented approach reduces integration friction for buyers who prioritize unified systems over discrete components.
-
Premium audio credence and cross-environment brand strength: Brands with strong heritage in consumer or mobile audio, such as Rockford Fosgate and BOSS Audio Systems, extend into marine with marine-grade construction and full-system offerings. Their strategy often relies on translating brand recognition and acoustic tuning expertise into the marine segment, while reinforcing durability features such as UV-treated materials, sealed architectures, and weather-resistant components. This can accelerate market acceptance among consumers who already trust the brand in other contexts.
PW Consulting -
Customization and ODM/OEM-enabled supply: China Future Sound illustrates a different competitive model: specialized marine audio OEM/ODM production built around salt spray, UV exposure, and marine durability requirements. Its positioning emphasizes flexibility in speakers, subwoofers, amplifiers, and enclosures for partners seeking tailored solutions. This model is particularly relevant for distributors and brands looking to scale custom products without holding all manufacturing in-house, and it highlights the growing importance of supplier capability in enabling channel and product strategy.
-
Material and acoustic engineering focus: Other players, such as Hertz Marine, Kicker Marine Audio, Poly-Planar, and Maxxsonics, compete on combinations of durability, acoustic quality, and marine-specific component design. Recent product activity, including new speaker and subwoofer lines and the use of UV-treated injection-molded cones and Santoprene surrounds, reflects a continuing emphasis on material durability and acoustic refinement. Where these firms differentiate is often in the specifics of construction, tuning philosophy, and how well they address the tradeoffs between performance, resilience, and cost.
Evolution of Market Structure
The market's moderate concentration suggests it is past the earliest fragmentation stage but not yet dominated by a few scale players. This structure creates multiple plausible evolutionary paths. One is gradual consolidation through OEM partnerships, distribution agreements, and selective acquisitions, particularly as integrated systems and certification readiness become more important. Another is continued segmentation, where performance specialists, ecosystem-integrated suppliers, and customization-focused manufacturers each serve distinct value propositions with limited direct overlap. A third is the entry of capable OEM/ODM partners that enable new brand and distribution models, potentially intensifying competition in specific channels while expanding overall product variety.
A key structural shift already underway is the move from aftermarket-led upgrades toward more embedded OEM design wins. As boat builders incorporate audio into model identity and vessel experience, the sales cycle lengthens and technical requirements tighten, favoring suppliers with proven integration records, scalable manufacturing quality, and the ability to meet model-specific acoustic and durability targets. This does not eliminate aftermarket demand, but it changes where value accrues: suppliers with strong OEM relationships and installer trust gain a more durable growth base, while those dependent on price-sensitive retail channels must work harder to defend margins.
Future Trends and Commercial Implications
Trend 1: Networked, software-defined audio becomes standard in higher-tier vessels
The combination of digital networking architectures, DSP-based tuning, and real-time modeling points toward marine audio systems that are more adaptive and easier to integrate with vessel electronics. Over the next three to five years, this trend is likely to deepen, especially in premium recreational boats and commercial leisure vessels where unified control, zone-based playback, and cleaner installation matter. The commercial implication is straightforward: suppliers that offer open, compatible architectures and tunable performance will be better positioned for OEM specification and professional installation, while closed or hard-to-integrate products may face growing exclusion risk.
Motorcycle Audio Systems Market
Trend 2: Durability and certification as differentiators, not baseline checkboxes
As buyers become more informed about marine environmental stress, durability validation and quality systems will increasingly influence purchasing decisions and channel preferences. This trend favors suppliers that can clearly demonstrate marine-grade construction, consistent process control, and credible warranty and service frameworks. The opportunity lies not just in meeting standards but in making durability understandable and verifiable to installers, dealers, and end users. Suppliers that can connect material choices, testing discipline, and real-world performance into a coherent narrative will have an edge in premium and mid-premium segments.
Trend 3: Customization and flexible manufacturing expand product and channel options
The expansion of custom OEM/ODM capacity, combined with growing demand for tailored speaker, subwoofer, and amplifier configurations, is likely to increase product variety and accelerate model-specific design cycles. For distributors and brands, flexible manufacturing partners can shorten time-to-market and support smaller-volume custom programs. For incumbents, this introduces both opportunity and pressure: opportunity to collaborate and scale specialized offerings, and pressure to maintain quality, lead-time, and cost advantages in the face of new supply options. The result may be a more pluralistic market in which customization capability becomes a strategic asset across multiple business models.
Risks and Uncertainties
Several factors could alter the trajectory of these trends. Material cost volatility and the expense of marine-grade polymers and corrosion-resistant components can compress margins if not managed through design efficiency or sourcing strategy. Interoperability expectations may shift as vessel electronics evolve, potentially requiring redesigns or retrofit strategies for products not built on adaptable architectures. Channel dynamics also remain uncertain: as OEM integration grows, aftermarket demand could become more polarized, with strong performance in premium upgrades and weaker growth in commoditized segments. Finally, the entry of new manufacturing partners can improve flexibility but also raises questions about quality consistency, warranty support, and long-term supply reliability, all of which can affect brand and distributor confidence.
Strategic Actions for Decision Makers
For Marine Audio Manufacturers and Suppliers
-
Treat durability and integration as co-equal priorities in product planning. Weather resistance alone is no longer enough; products must also align with networked vessel architectures and installer workflows. Prioritize architectures that simplify specification into OEM platforms and reduce integration friction for professional installers.
-
Invest in clear, credible performance narratives supported by materials, tuning, and process discipline. Margins are increasingly defended by differentiation that customers can understand and trust, whether through acoustic performance, robustness under real marine conditions, or predictable service outcomes.
-
Use flexible manufacturing and ODM partnerships strategically, not just for cost. Evaluate partners on quality consistency, certification readiness, communication, and ability to support custom programs at scale, especially if targeting U.S. distribution or OEM-adjacent channels.
Worldwide Home Audio System Market
For Investors and Strategic Buyers
-
Look beyond headline revenue growth and assess which companies are gaining share through OEM relationships, ecosystem alignment, and product architectures that reduce integration risk. Revenue is important, but the durability of that revenue depends on specification wins, installer trust, and repeatable quality.
-
Value certification and durability assurance as indicators of long-term competitiveness. Suppliers with mature quality systems and marine-specific validation are better equipped to secure OEM approval and sustain brand credibility in demanding environments.
-
Monitor the customization and ODM landscape for both partnership opportunities and competitive disruption. New manufacturing capabilities can lower barriers to entry for niche brands and accelerate product diversity, which may reshape channel dynamics and margin structures over time.
For Procurement Leaders and Channel Partners
-
Specify with interoperability and serviceability in mind. Products that align with established marine networking standards and offer straightforward installation paths reduce downstream risk and improve dealer and installer satisfaction.
-
Balance brand recognition with marine-native engineering validation. Familiar brands can reduce adoption friction, but marine-specific durability, tuning, and component construction should remain central evaluation criteria, especially for harsher environments and higher-use vessels.
-
Demand transparent material and construction specifications. Understanding enclosure materials, surround technologies, sealing approaches, and corrosion resistance helps procurement teams compare products meaningfully and forecast total cost of ownership more accurately.
The marine audio system market is entering a phase in which growth is increasingly tied to integration, durability credibility, and the ability to serve both OEM design cycles and aftermarket customization. The firms that will capture the most resilient value are those that can align product architecture with vessel electronics, communicate marine-grade performance with substance, and operate with the manufacturing discipline required for demanding environments. For decision makers seeking to move from broad market awareness to precise segment, channel, and product-level planning, a more detailed view of segmentation splits, regional dynamics, competitive benchmarks, and scenario-based forecasts can sharpen execution. The full research report provides that deeper breakdown, including granular sizing across product types, applications, and regions, alongside expanded competitive analysis and tailored strategic recommendations for specific business objectives.
For detailed analysis of this topic, please visit the official page: Marine Audio System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Peroxide Market: Why Asia Pacific's Dominance Changes Growth Through 2032
By PW Consulting, 2026-09-21
Hydrogen Peroxide Market: Strategic Trends and Commercial Opportunities Through 2032
The Market in Context: Growth Trajectory and Structural Challenges
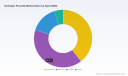
Hydrogen peroxide (H2O2) continues to occupy a strategic position in industrial chemistry, evolving from a commodity chemical into a differentiated input with specialized grades, sustainability credentials, and expanding application breadth. The market has demonstrated consistent expansion over the past five years, moving from approximately 3,073.45 million USD in 2020 to 3,624.4 million USD in 2025. Forward projections indicate the market will cross 3,864.68 million USD in 2026 and reach 5,096.5 million USD by 2032, translating to a compound annual growth rate of 5.2 percent over the 2026–2032 period. This trajectory reflects steady demand expansion rather than a one-off surge, signaling that hydrogen peroxide is increasingly embedded in long-cycle industrial and consumer value chains.
PW Consulting Chemical & Energy Research Center
Despite the upward baseline, the market sits at a crossroads. Three structural challenges are reshaping how producers, buyers, and investors approach the sector. First, demand is fragmenting across increasingly specialized applications that require distinct purity specifications, packaging formats, and supply reliability standards. The days of treating hydrogen peroxide as a uniform bulk chemical are fading; buyers in electronics, food processing, and water treatment now demand grade-specific performance that standard inventories cannot consistently deliver. Second, regulatory frameworks are tightening and expanding simultaneously. Agencies are redefining permissible uses, safety thresholds, and environmental expectations, which forces producers to adapt formulations, documentation, and logistics while creating both compliance burdens and first-mover advantages. Third, cost structures remain exposed to energy intensity, transportation constraints, and regional capacity imbalances. Producers that fail to align asset footprints with demand geography or to manage logistics intelligently risk margin compression even as headline market growth persists.
For executives, the key takeaway is that aggregate growth can mask uneven operational realities. A 5.2 percent CAGR suggests broad expansion, but the strategic question is where incremental growth concentrates, which customer segments reward differentiation, and how quickly regulatory and technical shifts alter competitive positioning. Market participants that treat hydrogen peroxide as a standardized volume play may find themselves exposed to price volatility, margin erosion, and displaced share by suppliers who adapt faster to application-specific needs and regional demand patterns.
Core Drivers Reshaping Demand and Supply Dynamics
Technological Innovation and Grade Differentiation
The most consequential shift in the hydrogen peroxide market is the accelerating divergence between bulk grades and specialty grades with engineered performance profiles. High-purity and electronic-grade variants are increasingly critical for semiconductor fabrication, advanced water treatment, and sensitive processing environments where trace impurities can disrupt yield or compliance. This technical premium is not merely a laboratory concern; it has become a commercial differentiator that determines which suppliers win contracts in high-value downstream markets. Capacity expansions focused on electronic-grade output, including recent initiatives in China targeting semiconductor demand, illustrate how producers are aligning production capabilities with applications that command stronger margins and more durable customer relationships.
At the same time, process innovation is reshaping the cost and sustainability equation. Producers are experimenting with operational improvements, selective capacity debottlenecking, and integrated site strategies that reduce energy intensity and logistics friction. The commercial impact is twofold: differentiation improves pricing power in specialty segments, while process efficiency can cushion margins against input cost volatility. The practical implication for buyers is that supplier technical capability, quality consistency, and site-level reliability are becoming as important as the base chemical itself.
Policy, Regulation, and the Expanding Use-Case Horizon
Regulatory change is no longer a background issue; it is actively widening the addressable use cases for hydrogen peroxide while simultaneously raising compliance expectations. A notable example is the amendment of food additive regulations by the FDA, which expanded permitted uses of hydrogen peroxide as an antimicrobial agent, oxidizing and reducing agent, bleaching agent, and agent for removing sulfur dioxide in food production, including use in modified whey at very low concentrations. This type of adjustment changes the commercial calculus for food processors, sanitation operators, and ingredient suppliers, because it formalizes new application pathways that can increase demand while also requiring rigorous documentation, handling controls, and traceability.
Electronic Grade Hydrogen Peroxide Market
Beyond food applications, environmental and industrial regulations continue to influence demand for water treatment and disinfection solutions. As water quality standards tighten and industrial operators face greater scrutiny around effluents and process hygiene, hydrogen peroxide’s role as an oxidant and disinfectant becomes more strategically relevant. For competitors, the regulatory environment creates a dual opportunity: expanded use cases can lift volume, but only firms with strong compliance capability, clear safety messaging, and reliable grade certification can convert that potential into durable market share.
Demand-Side Shifts Across Industrial and Consumer Segments
Demand is being reshaped by the combined effect of industrial modernization, hygiene expectations, and downstream product innovation. Pulp and paper remains a foundational application area, but the market is no longer defined solely by traditional bulk bleaching cycles. Electronics manufacturing, water treatment, personal care, food and beverage processing, and mining are all creating incremental demand streams with distinct technical requirements. In particular, sectors that rely on process purity, contamination control, and consistent oxidative performance are increasing their dependence on differentiated hydrogen peroxide supplies.
On the consumer-facing side, expectations around sanitation, product safety, and ingredient transparency are influencing downstream formulations. Personal care and food-related applications are especially sensitive to grade reliability and handling standards. These demand-side shifts mean that hydrogen peroxide is increasingly evaluated not just as a reactive chemical but as a process enabler with reputational and operational implications. Buyers are paying closer attention to supply continuity, documentation, and the perceived risk profile of their supplier base, which favors producers that can deliver consistency across complex procurement cycles.
Supply Chain Geometry and Cost Structure Pressures
The geography of production and consumption is becoming a more important source of competitive advantage. Hydrogen peroxide is sensitive to transportation constraints, regional capacity balance, and local demand clustering. Where production capacity aligns with high-growth application demand, suppliers can reduce logistics exposure and improve responsiveness. Where misalignment exists, exporters and importers face higher cost, longer lead times, and greater vulnerability to disruption. This is especially relevant in markets where specialized grades are required, since routing the right grade to the right customer at the right time is more operationally demanding than bulk commodity distribution.
Cost structures are also being influenced by the interaction between energy use, capacity utilization, and product mix. Producers can improve resilience by shifting the portfolio toward higher-margin specialty grades while optimizing bulk operations for reliability and scale efficiency. For buyers, the strategic issue is that cost dynamics are no longer purely a function of raw material movements; they increasingly reflect supplier decisions about asset allocation, grade strategy, packaging, and service levels. This makes supplier selection a more nuanced strategic decision than simple price comparison.
Competition Landscape and Leading Strategies
Strategic Positionings Among Key Players
The competitive field reflects a mix of global scale producers and specialized manufacturers pursuing distinct value propositions. Solvay has reinforced its leadership emphasis on high-purity grades for demanding industrial and electronic applications, including a capacity expansion in Zhenjiang, China that doubled annual output of high-purity electronic-grade hydrogen peroxide to serve semiconductor demand. This move highlights a clear strategic intent: align capacity with high-value downstream markets where technical performance and supply reliability justify stronger positioning.
Arkema brings a long-standing global footprint with broad grade coverage across chemical synthesis, cleaning and disinfection, cosmetics, electronics, food, mining, pharmaceuticals, pulp and paper, and textiles. Its value proposition rests on product breadth, application experience, and certified operational standards that support a wide customer base. For many industrial and consumer-adjacent buyers, that combination translates into convenience, risk reduction, and multi-application sourcing.
Nouryon has positioned itself around sustainability-linked differentiation, including the launch of a low-carbon product line intended to lower the carbon footprint relative to conventional supply. In a market where downstream buyers increasingly face their own emissions targets and procurement expectations, such an offering can become a meaningful advantage, especially for customers who need to document supply chain footprint performance as part of their own reporting.
Mitsubishi Gas Chemical Company holds a prominent position in super-pure and high-purity hydrogen peroxide and has expanded its geographic footprint with production sites in Japan and the United States. Its strength lies in serving end markets where purity is non-negotiable, particularly semiconductors and electronics. In these segments, supplier qualification, consistency, and technical support can matter more than commodity price differentials.
Evonik continues to emphasize specialty applications, including solar cells, semiconductors, food packaging, and photovoltaics, and has moved forward with joint venture-aligned capacity in China. The 20,000-ton specialty facility targeting photovoltaics, semiconductors, and food packaging illustrates how producers are building dedicated capacity for segments where specification control and application focus create defensible commercial positions.
Other participants, including OCI Company Ltd, Sitara Peroxide Limited, Akzo Nobel, BASF, Gujarat Alkalies & Chemicals Ltd., and National Peroxide Limited, contribute important regional supply and application coverage, particularly in industrial, pulp and paper, textile, and bleaching contexts. Their roles often revolve around localized availability, segment specialization, and cost-competitive bulk supply. The strategic implication is that competition is not monolithic: some players compete on global grade breadth and technical reliability, while others compete on regional availability, segment focus, or cost efficiency.
Structural Evolution: Integration, Fragmentation, and Entry Risk
The market is simultaneously consolidating at the top tier and fragmenting at the application and regional levels. Market concentration remains meaningful, with the top three firms accounting for roughly 42 percent of revenue and the top five close to 52 percent. This level of concentration indicates that scale, integrated asset bases, and established grade portfolios still matter, particularly for large buyers seeking supply assurance. At the same time, the concentration figures also leave substantial share for regional and specialty players who can outperform by focusing on specific segments, geographies, or grade requirements.
The evolution of competitive strategy suggests three parallel dynamics. First, scale players are investing in ability to serve high-value segments rather than competing solely on bulk volume. Second, specialty and regional suppliers are building defensible niches by emphasizing grade specifics, compliance capability, or local responsiveness. Third, new entries and joint ventures are concentrating on application-linked demand, especially where semiconductor, electronics, photovoltaic, food packaging, or low-carbon differentiation create higher barriers to entry but also higher payoff for successful positioning. The overall trend is toward a more layered competitive environment, where the same chemical can be supplied through multiple business models with different margin profiles and customer relationships.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Trend 1: Specialty and High-Purity Grades Will Capture Disproportionate Value
Over the next several years, incremental revenue growth is likely to concentrate disproportionately in high-purity, electronic-grade, and sustainability-differentiated products rather than in undifferentiated bulk supply. The rationale is straightforward: demand in semiconductors, electronics, advanced water treatment, and sensitive processing environments rewards specification control, quality assurance, and supply reliability. As downstream industries modernize and become more sensitive to contamination, yield, and process control, the commercial premium for the right grade will become harder for commodity-focused suppliers to match. For producers, this means that portfolio strategy, site specialization, and technical service capability will be more important than volume alone. For buyers, it means procurement planning should account for grade specificity and qualification cycles rather than assuming interchangeable supply.
Trend 2: Application Expansion Will Be Shaped by Regulatory and Hygiene-Driven Demand
Regulatory developments and hygiene expectations are likely to keep broadening hydrogen peroxide’s role in food, water treatment, disinfection, and process sanitation. The expanded FDA scope for food-related uses is a concrete signal that applications can move from marginal to material when regulatory permissions align with functional need. In parallel, water treatment and industrial sanitation demands often grow as standards tighten and operating environments become more compliance-intensive. The strategic opportunity lies in anticipating where these use cases become recurring rather than opportunistic. The associated risk is that regulatory interpretation, documentation requirements, and approval timelines can vary by jurisdiction and application, meaning that entry into new use cases may require more than product availability; it may require qualification, support infrastructure, and consistent compliance positioning.
Trend 3: Regional Capacity Alignment Will Separate Resilient Suppliers from Exposed Ones
A third trend is the growing importance of matching production footprint to localized demand clusters, especially where specialty grades and responsiveness matter. Capacity expansions and joint ventures in regions with strong electronics, photovoltaic, food packaging, or industrial demand indicate that suppliers are betting on proximity advantages, reduced logistics friction, and faster service. Where regional alignment is achieved, suppliers can improve reliability and margin stability. Where it is not, firms may face higher exposure to transport constraints, lead-time variability, and cost pressure. For procurement organizations, this trend reinforces the importance of dual-sourcing strategies, regional backup options, and supplier assessment that goes beyond price into reliability and geographic fit.
Strategic Implications and Operational Priorities
Hydrogen peroxide is moving from a largely commoditized input to a portfolio of differentiated products with application-specific value. That transition has direct implications for how different stakeholders should position themselves.
For Manufacturers and Producers
- Align capacity investments with grade differentiation rather than treating all output as interchangeable. High-purity and specialty segments offer stronger differentiation potential, but only if supported by consistent quality systems, application knowledge, and qualification support.
- Build sustainability and compliance into product value propositions in a way that is verifiable. Low-carbon profiles, documented handling standards, and grade certifications can become purchasing criteria for downstream customers facing their own regulatory and emissions expectations.
- Optimize the asset footprint for regional demand responsiveness and logistics resilience. In a market where the right grade must reach the right customer with minimal friction, site strategy and distribution design can be as important as chemical production capability.
For Investors and Strategic Developers
- Assess exposure to application-linked demand rather than relying on headline market volume. Growth in electronics, food processing, water treatment, and sustainability-differentiated supply is likely to matter more than uniform bulk expansion.
- Look for evidence of defensible positioning: specialized grades, qualification trust, regional alignment, and the ability to support customer compliance needs. These attributes tend to correlate with more durable pricing power and customer retention.
- Monitor regulatory changes as demand-shaping events, not just compliance issues. Permitted-use expansions, sanitation expectations, and industrial standards can alter demand trajectories faster than traditional cyclical factors.
For Procurement, Operations, and Supply Chain Leaders
- Treat hydrogen peroxide sourcing as a specification and reliability decision, not only a cost decision. Grade consistency, documentation, lead-time reliability, and supplier responsiveness increasingly influence operational risk in sensitive applications.
- Evaluate supplier portfolios for regional coverage and backup capacity. Where application requirements are strict or production continuity is critical, multi-source strategies and geographic diversification can reduce exposure to disruption.
- Incorporate sustainability and regulatory compliance attributes into supplier evaluation where relevant. As downstream reporting and procurement expectations evolve, supply chain attributes may become purchasing criteria rather than optional considerations.
Why Detailed Segmentation Still Matters
Aggregate market growth provides only a partial map of where value is created and where risk concentrates. The commercial reality is that hydrogen peroxide demand behaves differently by region, application, and grade, and those differences shape pricing, qualification requirements, logistics cost, and competitive vulnerability. The broad expansion projected through 2032 masks the fact that some segments will migrate toward premium, specification-driven supply while others remain more cost-competitive and volume-sensitive. Understanding those dynamics requires segment-level clarity on demand drivers, grade requirements, regulatory exposure, and regional supply alignment.
Decision-makers who rely solely on headline figures risk misjudging where margins are durable, where new capacity will compete most effectively, and where procurement exposure is highest. A more granular view supports better capital allocation, supplier selection, and product strategy. For organizations that need to move from general market awareness to specific, actionable decisions, deeper segmentation and customized scenario analysis can help translate market direction into operational priorities.
PW Consulting maintains a detailed hydrogen peroxide market research service designed for executives, strategic planners, investors, and procurement leaders who need segment-level clarity on demand, competition, and forward risks. For readers interested in a closer look at regional dynamics, grade-specific demand patterns, and tailored strategic options, the full research report provides expanded data, company-level developments, and segmentation detail beyond this executive overview.
Hydrogen Market
For detailed analysis of this topic, please visit the official page: Hydrogen Peroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Magnetic Drill Press Market 2026: Why 6.2% CAGR and Infrastructure Spending Reshape Competition
By PW Consulting, 2026-09-21
The Magnetic Drill Press Market: Strategic Trends and Commercial Opportunities Through 2032
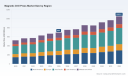
The magnetic drill press market has navigated a period of measured expansion, characterized by steady revenue growth, shifting regional footprints, and evolving product architectures. Between 2020 and 2025, the sector grew from roughly $522.77 million to approximately $694.0 million, reflecting a compound annual growth rate of 6.2 percent through the forecast horizon extending to 2032. By the end of the projection window, revenue is expected to approach $1.05 billion, signaling a market that is maturing but still capable of meaningful value creation. This trajectory is not driven by uniform demand across all segments. Instead, it reflects concentrated spending in specific types, applications, and geographies, alongside a competitive field where the top three firms capture about 55 percent of revenue and the top five hold approximately 67 percent. For executives and investors, the opportunity lies in understanding where growth is concentrating, what is reshaping cost and capability structures, and how established players are positioning themselves against nimble entrants and regional manufacturers.
Market Snapshot and Structural Realities
The market's size and pace are meaningful, but the more telling story is in its shape. Revenue expansion has been consistent rather than explosive, suggesting that adoption is broadening modestly while core end users continue to refresh and upgrade equipment. The regional distribution shows a market that is globally dispersed yet unevenly developed. Asia Pacific carries the largest revenue share, followed by North America, with Europe, Latin America, and the Middle East and Africa forming a more fragmented tail. This dispersion matters because it indicates that competitive dynamics, service requirements, and product preferences differ materially by region. A strategy that works in a mature, code-driven market may underperform in a price-sensitive, high-growth environment where portability and service responsiveness carry more weight than premium brand equity.
The type mix further clarifies where value is migrating. Pneumatic and air-powered systems command the largest revenue share, underscoring the continued relevance of shop and field setups that prioritize control, duty cycle, and integration with existing compressed-air infrastructure. Cordless and battery-powered units represent the next-largest block, reflecting the field's appetite for mobility and reduced setup friction. Electric and hydraulic offerings occupy smaller but important niches, often tied to specialized throughput needs or environments where power availability and precision are decisive. The application side reinforces a construction- and infrastructure-centric demand base, with general industrial use forming a meaningful but smaller layer. Together, these patterns suggest that the market is not a monolith; it is a collection of use cases with distinct buying criteria, lifecycle expectations, and replacement cadences.
Magnetic Pumps Market
Two structural realities frame the next phase. First, the market is moderately concentrated, which typically translates into visible brand leadership and channel leverage at the top, while leaving room for specialized players to win on application fit, regional service, or price-to-performance. Second, the growth path is likely to be uneven, shaped by project pipelines, equipment replacement cycles, and the relative cost of doing business in different regions. For decision-makers, this means that aggregate figures are useful for orientation, but segment-level dynamics determine where to invest, partner, or reposition.
Key Challenges and Inflection Points
The market is passing through a set of pressures that will separate resilient operators from those reliant on legacy assumptions. Three stand out.
First, input cost volatility is reshaping economics at the component and finished-goods level. Hot-rolled coil steel prices averaged around $851 per net ton during 2025, up from $772 in 2024, while busheling scrap prices averaged approximately $424 per long ton, above the ten-year average of $385. These movements affect both the cost base for manufacturers and the broader construction and industrial demand environment in which end users operate. When steel and scrap pricing trend upward, project budgets come under scrutiny, replacement decisions are delayed or reconsidered, and manufacturers face pressure to absorb costs without eroding margin. For magnetic drill press vendors, the challenge is twofold: manage bill-of-materials exposure while preserving the value proposition that justifies purchase in a cost-conscious buying climate.
Second, the magnet and motor supply chain is experiencing regulatory and price pressures that touch core product performance. Rare earth elements, including neodymium oxide, saw price increases exceeding 20 percent between 2024 and 2025. Since high-strength permanent magnets are central to holding force, portability, and usability on inclined or uneven surfaces, any sustained input cost escalation can influence design trade-offs. The designation of U.S. copper as a critical mineral by the U.S. Geological Survey in 2025 adds another layer of scrutiny for winding materials and electrical components. These dynamics do not necessarily disrupt production, but they raise the importance of sourcing resilience, material substitution research, and inventory planning. For buyers, they signal that lead times, warranty terms, and total cost of ownership may become more variable, especially for higher-specification units.
Third, the market is encountering an applicability inflection as crews demand lighter, more agile tools for confined and hard-to-reach work. Structural steel fabrication increasingly takes place in environments where footprint, maneuverability, and setup speed matter as much as raw capacity. This is prompting vendors to emphasize low-profile designs, switchable magnet systems, and compact kits that can operate where larger stationary machines cannot. The challenge is to deliver these benefits without sacrificing hole quality, duty cycle, or durability. Companies that solve this balance well are gaining traction in field-heavy roles, while those anchored to heavier, less adaptable platforms risk losing share in scenarios where access constraints dominate the buying decision.
Core Drivers Reshaping the Market
Demand and capability are being pulled in several directions at once. Four drivers stand out as particularly consequential.
PW Consulting
Technology innovation is the most visible. The transition toward brushless motor architectures, higher hole-per-charge performance in cordless kits, and more efficient magnet control is changing what field teams expect from a portable magnetic drill. DeWALT's promotion of 18V cordless magnetic drill press upgrade kits with brushless motors and high hole-per-charge capacity for professional jobsite use, highlighted in April 2026, illustrates the direction: customers are being asked to consider battery platforms not as compromises, but as capable, productive alternatives for structural steel work. Meanwhile, Champion Cutting Tool's field-tested promotion of the RB30 LittleBrute and SB35 SmartBrute in March 2026 emphasizes lightweight design for tight spaces and hard-to-reach areas, reinforcing the broader shift toward compact, application-tuned solutions. These product narratives matter because they signal to buyers that portability and performance can coexist, expanding the set of jobs where a magnetic drill is preferred over heavier alternatives.
Regulatory and material contexts are shaping design and sourcing strategies. The rare earth price increases and copper's critical mineral status are nudging manufacturers to consider magnet architecture efficiency, winding design, and supply diversification more seriously. Even where immediate substitution is limited, the direction of travel favors firms that can demonstrate supply transparency, steady availability, and design flexibility. In practice, this means that product roadmaps increasingly incorporate material risk as a design input rather than treating it as a procurement afterthought. For procurement teams, supplier credibility on sourcing and continuity is becoming a differentiator alongside price and feature sets.
Demand-side behavior is changing as project teams optimize for labor productivity and setup flexibility. In construction and infrastructure, crews are under pressure to reduce repositioning time, minimize auxiliary equipment, and maintain throughput in constrained sites. Magnetic drills that can be deployed quickly, repositioned easily, and operated safely on varied steel profiles address these priorities directly. Rajlaxmi Machine Tools' March 2026 launch of a 25mm capacity portable magnetic drilling machine with switchable magnet options, 20-25mm air versions, and custom center finder modules, fully manufactured in India, reflects a regional response to these needs. The move highlights how local manufacturing can tailor offerings to specific capacity ranges, magnet behaviors, and accessory combinations that align with regional job patterns and cost expectations.
Supply chain and cost structures are being re-evaluated across the value chain. Elevated steel and scrap prices affect not only manufacturers' bills of materials but also the broader construction and maintenance spending environment. At the same time, the concentration of revenue among leading firms suggests that scale, channel strength, and brand trust remain powerful advantages. Yet the presence of regional manufacturers and specialized entrants indicates that cost-efficient local production, focused application kits, and responsive service can create viable competitive positions. The net effect is a market where scale matters, but precision in segment targeting and supply discipline can be equally decisive.
Competitive Positioning and Market Evolution
The competitive field blends large multi-tool brands, specialized magnetic drill manufacturers, and regional producers with targeted application focus. Each group is pursuing a distinct path to relevance.
Large tool platforms such as DeWALT and Milwaukee Tool leverage broad professional distribution, battery ecosystems, and brand recognition to position magnetic drills as part of integrated jobsite tool sets. DeWALT's cordless and corded magnetic drill presses, including the DWE1622K and 20V MAX brushless DCD1623/DCD1624 models with up to 2-inch hole capacity in structural steel, are designed to fit within an existing cordless workflow. Milwaukee Tool's 18V FUEL and brushless magnetic drill presses and kits with high-torque annular cutter operation target on-site metalworking where torque, durability, and battery compatibility matter. The strategic logic here is ecosystem leverage: buyers who already standardize on a battery platform see incremental value in adding a magnetic drill that shares batteries, chargers, and field support.
Specialist manufacturers compete on application fit, capacity ranges, and accessory integration. Hougen Manufacturing's dedicated line of magnetic drills, including the HMD2X2 and HMD900 along with fabricator kits supporting 1.5-2 inch annular cutter capacity for structural steel fabrication, positions the company around deep familiarity with steel work and cutter compatibility. CS Unitec's portable magnetic drills in the MAB series, combined with annular cutters and core drill systems for industrial and underwater applications, extends the use case envelope into environments where corrosion resistance, specialized drilling, and portability intersect. Evolution Power Tools' portable magnetic drill presses for bridges, beams, and framework, built around a tri-spoke spindle and dovetail slides, target heavy structural work where rigidity and repeatable alignment are critical. Champion Cutting Tool's RB30 LittleBrute, SB35 SmartBrute, and AC35 MiniBrute low-profile magnetic drill presses lean into maneuverability and tight-space work, complementing the broader industry emphasis on compact designs.
European and Asia-based manufacturers bring different strengths. BDS Maschinen GmbH offers premium magnetic drilling machines with more than 30 models supporting twist drilling, core drilling, tapping, and reaming across 1.5-3 inch capacities, appealing to buyers who need a broader machining toolkit within a magnetic platform. Euroboor USA provides magnetic drilling machines and annular cutters for metalworking, construction, and maintenance, backed by ISO 9001:2015 certification, which matters for procurement teams that weight quality system maturity in supplier selection. WEISS MACHINERY CO., LTD integrates magnetic drilling machines with CNC and lathe platforms for oil, gas, and power generation applications, illustrating a more specialized, higher-value path where magnetic drilling is part of a larger precision manufacturing workflow rather than a standalone field tool.
The market is evolving along several axes. Consolidation pressure exists at the top, where brand leaders can compound advantages in distribution, aftermarket parts, and training. At the same time, differentiation is increasing at the application level, where capacity ranges, magnet behavior, cutter compatibility, and mobility features create distinct buying reasons. New and regional entrants, such as Rajlaxmi Machine Tools, are demonstrating that localized manufacturing and customized accessory packages can address specific capacity and magnet requirements efficiently. This does not imply that the market is fragmenting into chaos; rather, it is becoming more segmented, with clear winners in each slice based on fit, service, and total cost of ownership. For incumbents, the strategic question is whether to defend broadly through ecosystem strength or to deepen application specificity where margins and loyalty are strongest.
Three Trends Shaping the Next Three to Five Years
The next phase is likely to be defined by capability migration, sourcing discipline, and application-led segmentation.
First, cordless and battery-compatible magnetic drilling will continue to gain relevance in field-heavy environments. The direction of product promotion and engineering attention points toward brushless motors, improved hole-per-charge performance, and kits that align with existing platform ecosystems. The commercial implication is that buyers will increasingly compare magnetic drills not only on drilling capacity and magnet strength, but also on battery compatibility, runtime consistency, and integration with other jobsite tools. Manufacturers that can deliver reliable cordless performance without sacrificing structural steel capability will expand their addressable field use cases, while those that treat cordless as a lower-tier option risk ceding ground in mobile work.
Second, material sourcing and input cost management will become more central to product strategy and buyer evaluation. With rare earth prices up sharply and copper designated as a critical mineral, companies that can demonstrate supply resilience, transparent sourcing, and efficient magnet and motor design will have an advantage in tender evaluations and long-term planning. This trend also raises the importance of warranty terms, spare parts availability, and service responsiveness, since buyers will want assurance that performance and support remain stable even as input markets fluctuate. For investors, the companies that communicate supply discipline credibly and execute on it are better positioned to defend margins through cycles.
Third, application-specific segmentation will sharpen. The market is already showing distinct demand patterns across structural steel fabrication, bridges, beams, framework, underwater and industrial settings, and integrated CNC-intensive workflows. Over the next few years, success will increasingly depend on matching capacity, magnet behavior, cutter systems, and accessories to the job at hand. Low-profile, switchable-magnet, and tight-space designs will continue to find strong uptake where access is constrained, while higher-capacity, multi-function platforms will remain relevant where versatility and throughput justify the footprint. The commercial opportunity lies in building clear product narratives for each use case and ensuring that service, accessories, and training reinforce the fit. The risk is that broad, undifferentiated offerings lose relevance as buyers become more deliberate about matching tools to specific constraints and productivity targets.
Worldwide Micro Drill for PCB Market
Implications for Different Decision-Makers
Manufacturers and brand owners should treat application fit and supply resilience as strategic priorities, not operational details. That means sharpening product stories around mobility, cutter compatibility, and magnet performance for the jobs that matter most in each region, while also investing in sourcing transparency and material efficiency. Where battery ecosystems matter, integration and runtime credibility should be front and center. Where structural steel fabrication dominates, annular cutter capacity, setup speed, and stability on varied profiles should anchor the value proposition. Where specialized environments such as underwater or precision machining applications are in play, certification, accessory systems, and platform integration become the differentiators. The companies that succeed will be those that can articulate a clear fit for each major use case and back it with dependable service and parts availability.
Investors and strategic partners should focus on where scale and where specificity each create advantage. Scale players with strong distribution, brand trust, and battery or platform ecosystems are well placed to capture share in markets where buyers value integration and support. Specialist and regional manufacturers can create durable positions by aligning capacity ranges, magnet behaviors, and accessory packages to local job patterns and by delivering responsive service. The key is to assess whether a given player's strengths map to the segments where spending is concentrated and where replacement cycles are most active. In a market with moderate concentration and clear segmentation, both broad and narrow strategies can work, but only if they are executed with discipline and backed by credible supply and service arrangements.
Procurement teams and end-user organizations should evaluate magnetic drills against total job conditions rather than headline specifications alone. Magnet holding reliability on the actual steel profiles in use, setup and repositioning speed, cutter compatibility, battery platform fit if applicable, and service proximity all influence real-world productivity and cost. Given input cost volatility and critical mineral designations, supplier continuity, warranty clarity, and spare parts availability should carry more weight in selection. For teams operating in tight spaces or on varied structural work, low-profile and switchable-magnet options may deliver more value than larger stationary-class machines. For those in precision, integrated, or harsh-environment settings, certification, accessory breadth, and platform compatibility may matter more. The goal is to align the tool to the job, the site, and the support ecosystem, rather than optimizing for a single spec in isolation.
Where to Go Next
The magnetic drill press market is expanding at a steady pace, but the real leverage lies in understanding which types, applications, and regions are driving value, how input and regulatory pressures are reshaping design and sourcing, and where leading companies are placing their bets. The trends point toward greater mobility and battery integration, stronger emphasis on supply resilience and material efficiency, and sharper application-led segmentation. For organizations deciding where to compete, invest, or buy, these dynamics create both opportunity and the need for precise, current intelligence. Detailed segment-level sizes, regional trajectories, competitive share movements, and scenario-based outlooks can materially improve planning quality and reduce execution risk. For those seeking a deeper, data-rich view of the market, the full PW Consulting research report provides the granular breakdowns and customized guidance needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Magnetic Drill Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Kiosk Market 2026: Why 15.6% CAGR and Asia Pacific Expansion Change Everything
By PW Consulting, 2026-09-21
The Kiosk Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global kiosk market has evolved from a niche self-service experiment into a foundational layer of modern retail, financial services, hospitality, and public sector infrastructure. With a base-year market valuation of approximately USD 394.9 million in 2025 and a projected trajectory to USD 1,089.4 million by 2032, the sector is expanding at a compound annual growth rate of 15.6% across the 2026–2032 forecast window. Historical momentum reinforces this trajectory: the market moved from USD 191.3 million in 2020 to USD 343.89 million in 2024, reflecting a structural shift rather than a cyclical spike. This growth is not merely a function of unit proliferation. It represents a broader realignment in how organizations design customer touchpoints, manage labor allocation, and deploy connected hardware at scale. Understanding where the market stands today, what is driving its acceleration, and how incumbents are positioning themselves is essential for executives navigating procurement decisions, capital allocation, and product roadmap planning.
Despite the optimistic trajectory, the kiosk sector is confronting a set of structural tensions that will define competitive outcomes over the next several years. First, hardware reliability and total cost of ownership have emerged as critical pressure points. Deployments are increasingly expected to operate continuously in high-traffic environments, yet component cost volatility and supply chain friction are compressing margins for manufacturers and raising the bar for operational durability. Second, the regulatory and standards landscape is tightening around payment security, accessibility, and network modernization, forcing vendors to align hardware architecture with compliance requirements that vary across jurisdictions. Third, the market is experiencing a strategic fork in the road between standardized, high-volume deployments and highly customized, vertical-specific solutions. Companies that attempt to serve both models without clear architectural boundaries risk dilution, while those that commit to a distinct value proposition are capturing defensible share. These dynamics are not temporary headwinds; they are reshaping the basis of competition.
Key Drivers Reshaping the Kiosk Market
Technology Innovation and Hardware-Software Convergence
The most consequential driver of market expansion is the convergence of hardened hardware, embedded computing, and intelligent software layers. Kiosk deployments are no longer standalone terminals; they are becoming managed nodes within broader digital ecosystems. Recent product activity illustrates this shift clearly. In February 2026, KIOSK Information Systems launched ergonomic Windfall Series kiosks built with AOPEN hardened processing units, a move explicitly aimed at addressing reliability concerns in digital front-door deployments. That same company expanded its software ecosystem in March 2026 through a partnership with OpenTech Alliance to deploy INSOMNIAC self-storage software on the Windfall Series, signaling a broader trend toward bundling purpose-built applications with durable hardware platforms. The implication for the market is straightforward: competitive advantage is increasingly determined by how seamlessly hardware, operating software, and vertical applications integrate, rather than by hardware specifications alone.
Beyond core hardware, digital payment architecture is reshaping the design constraints of kiosk systems. PCI PIN on Glass rules now apply to kiosk hardware supporting contactless payments, requiring manufacturers to embed secure cryptographic handling directly into the display and input chain. This regulatory-technical intersection is pushing vendors to rethink bill-of-materials architecture, certification cycles, and long-term software support. Companies that treat compliance as an afterthought face retrofit costs and deployment delays, while those that design for secure payment workflows from the outset are shortening time-to-market and reducing integration risk for end customers.
Self-service Kiosk Market
Policy, Regulatory, and Infrastructure Dynamics
Regulatory and infrastructure developments are simultaneously easing some constraints while introducing new cost structures. On the connectivity side, the FCC’s March 5, 2026 Report and Order reduced regulatory burdens on network modernization for broadband infrastructure, a change that supports more reliable back-end connectivity for distributed kiosk fleets. Improved connectivity lowers the operational risk of cloud-managed kiosks and remote monitoring, which in turn makes large-scale deployments more viable for retail, hospitality, and public-sector operators. This is a meaningful enabler, particularly for organizations that depend on centralized fleet management and real-time software updates.
At the same time, hardware cost pressures are intensifying. Semiconductor tariffs on components raised build and operating costs for kiosk hardware in 2026, squeezing manufacturers that rely on imported processing units, displays, and peripheral controllers. Compounding this, regional infrastructure policies are reshaping the broader technology cost environment. In Alberta, a new policy effective December 31, 2026 requires data centers drawing 75 MW or higher to pay a 2% levy on computer hardware, and states advanced grid infrastructure accountability policies in 2026 are requiring data centers to offset upgrade costs. While these measures target large-scale data infrastructure, they reflect a broader policy environment in which compute and hardware expenditures are increasingly scrutinized. For kiosk vendors and enterprise buyers alike, this environment reinforces the importance of total-cost modeling, energy efficiency, and lifecycle planning rather than focusing solely on upfront unit pricing.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, the kiosk market is being pulled forward by two reinforcing behavioral shifts. Consumers and business customers increasingly expect fast, consistent, and contactless self-service options, particularly in QSR, retail, and financial services environments where queue reduction and transaction speed directly influence satisfaction and throughput. Enterprises, meanwhile, are reevaluating labor deployment models. Self-service kiosks are no longer viewed simply as cost-reduction tools; they are increasingly positioned as service-quality multipliers that free skilled staff for higher-value interactions while standardizing routine transactions. This reframing broadens the addressable use cases and supports adoption beyond traditional high-volume settings.
Accessibility is another demand-side force that is moving from compliance checkbox to competitive differentiator. In August 2025, LG Electronics USA unveiled Gen 2 accessible self-ordering kiosks developed with a Tech for All consultant, designed for users with vision, mobility, and hearing disabilities. This product direction signals a broader market expectation: inclusive design is becoming a baseline requirement rather than a niche feature. Organizations deploying kiosks in public-facing roles are increasingly evaluated on how well their self-service infrastructure serves a full spectrum of users, and vendors that embed accessibility into hardware ergonomics, software navigation, and payment workflows are gaining an advantage in regulated and high-visibility environments.
Supply Chain and Cost Structure Evolution
The cost structure of kiosk manufacturing and deployment is undergoing a measurable transition. Component tariffs, processing unit availability, and durable enclosure requirements are pushing manufacturers to reconsider sourcing strategies, standardization levels, and build-vs-integrate decisions. At the same time, the rise of hosted and software-driven add-ons is changing how value is captured across the stack. In November 2025, Datacap Systems launched a Virtual Gift Card program as a hosted digital gift card add-on for kiosk deployments, an example of how software services can layer onto hardware platforms to create recurring revenue and enhance the end-user experience without requiring a full hardware redesign. This hybrid model—durable hardware combined with modular software services—offers a path to offset hardware margin pressure while improving customer stickiness. For manufacturers, the strategic question is whether to build these software capabilities internally, partner for them, or integrate third-party hosted services into a managed offering.
Competitive Landscape and Leading Strategies
The kiosk market is characterized by a mix of specialized hardware manufacturers, vertically focused solution providers, and broader technology companies extending into self-service deployments. Market concentration reflects a moderately consolidated environment, with the top three players holding roughly 60% of market share and the top five approaching 65%. This concentration suggests that scale, brand trust, and deployment ecosystems matter, but it also leaves meaningful room for specialized players that serve distinct verticals or accessibility needs. The competitive dynamics are best understood by examining how leading companies differentiate rather than by treating the market as a single commodity battleground.
NIOSK Information Systems exemplifies a deployment-oriented strategy centered on design, manufacturing, monitoring, and support across retail, self-storage, healthcare, government, and hospitality. Its February 2026 Windfall Series launch and March 2026 OpenTech Alliance partnership reflect a clear emphasis on reliability and application-specific integration, particularly in self-storage and digital front-door use cases. This approach positions the company as an end-to-end partner for organizations that want a single point of accountability for hardware durability and software ecosystem compatibility. Elo Touch Solutions, by contrast, anchors its offering in self-service kiosks and touchscreens for retail, QSR, and healthcare, leaning on display and interface expertise that matters in high-interaction environments. Its competitive leverage lies in touch fidelity, ergonomic design, and application familiarity across sectors where user interaction quality directly affects throughput and satisfaction.
LG Electronics USA has carved out a distinctive position around accessibility with its Gen 2 self-ordering kiosks designed for vision, mobility, and hearing disabilities. This is not merely a product feature but a strategic positioning that aligns with regulatory expectations and inclusive service mandates. Diebold Nixdorf brings a different angle, providing intelligent kiosks for banking, retail, and the public sector with IoT and cloud management capabilities. Its strength is in managed infrastructure thinking: kiosks as connected, monitorable assets within a broader fleet, which appeals to organizations that prioritize remote oversight, predictive maintenance, and integration with existing enterprise systems. NCR Corporation complements this landscape with AI-powered self-service and contactless kiosks for retail and hospitality, leaning into intelligent transaction handling and contactless experience design. Together, these players illustrate a market where differentiation is increasingly defined by the combination of hardware durability, software intelligence, accessibility, and fleet management maturity.
The broader field further highlights the fragmentation of specialized use cases. Companies such as Redyref, Olea Kiosks, MetroClick, Advanced Kiosks, Pyramid Computer, Acrelec, Coates Group, Meridian, ZIVELO, Embross, Neumo, AOPEN, Posiflex, and HiStone each emphasize distinct value propositions, from interactive digital building directories and ADA-compliant self-service units to hardened processing units, Android-based kiosk computers, and QSR-focused self-ordering hardware. Acrelec’s position as a large global hardware and software supplier for self-ordering in QSR and retail underscores how vertical specialization can scale internationally, while Neumo’s focus on DMV and government self-service kiosks shows how public-sector requirements create durable, regulation-driven demand. HiStone’s expansion from a primarily domestic Chinese market into international channels points to the growing cross-border flow of kiosk hardware and the increasing relevance of cost-competitive manufacturing in the global supply picture.
The competitive evolution is moving along three observable paths. First, there is consolidation pressure among suppliers that can offer integrated hardware, software, and managed services at scale, particularly in retail, QSR, and banking. Second, there is continued differentiation among niche leaders serving accessibility, public-sector, and bespoke environments where customization and compliance outweigh volume economics. Third, new entrants and adjacent technology providers are exploring the space through modular computing, Android-based platforms, and hosted software add-ons, lowering barriers for organizations that want to assemble solutions rather than buy fully integrated units. The likely outcome is a layered market: a concentrated core of scaled providers competing on reliability, fleet management, and vertical breadth, surrounded by specialized manufacturers and software partners competing on accessibility, custom design, and application-specific functionality.
Kiosk Printer Market
Future Trends and Commercial Opportunities (2026–2032)
Trend 1: Managed, Cloud-Integrated Kiosk Fleets Become the Default Expectation
As deployments scale, the operational model is shifting from standalone installation to managed fleet infrastructure. Cloud-managed monitoring, remote updates, and IoT-enabled diagnostics are becoming baseline expectations rather than premium features. The practical effect is that buyers will increasingly evaluate kiosk investments through the lens of uptime, maintenance cost, and software lifecycle support, not just unit price. For manufacturers, this creates an opportunity to build managed service layers that improve stickiness and reduce support fragmentation. For enterprise buyers, it opens the door to predictable operating models and faster issue resolution across distributed locations. The risk is that vendors without robust backend management capabilities will face growing pressure as customers compare total operational performance rather than hardware specs at purchase time.
PW Consulting Information & Electronics Research Center
Trend 2: Accessibility and Inclusive Design Move from Compliance to Brand Value
Accessibility will increasingly function as both a regulatory requirement and a commercial differentiator. Product activity such as LG’s Gen 2 accessible self-ordering kiosks indicates where the market is heading: inclusive ergonomics, multimodal interaction, and payment workflows designed for a broader range of users. As public-facing deployments expand in retail, hospitality, transportation, and government settings, organizations that treat accessibility as a design standard rather than a retrofit will reduce compliance exposure and improve user experience quality. The commercial opportunity lies in developing modular accessibility features that can be integrated across product lines without fragmenting manufacturing scale. The uncertainty is in how quickly standards and customer expectations will converge across regions, which could create uneven compliance timelines and redesign pressure for vendors with global footprints.
Trend 3: Software-Layered Revenue Models Offset Hardware Cost Pressure
With semiconductor tariffs and broader hardware cost pressures reshaping build economics, the market is likely to see more hosted software add-ons, digital payment enhancements, and application-specific services layered onto kiosk platforms. Datacap’s hosted digital gift card add-on is a useful signal of this direction: value is increasingly created through software services that enhance the transaction experience and create recurring engagement without requiring a full hardware redesign. Over the next several years, this trend should encourage more partnerships between hardware manufacturers and software providers, as well as more packaged solutions that combine durable hardware with modular services. The strategic opportunity is to design hardware platforms that can accommodate third-party software integration cleanly, reducing customization cost while enabling faster feature deployment. The risk is fragmentation if integration standards remain inconsistent, which could raise implementation complexity and slow adoption in larger enterprise environments.
Strategic Recommendations for Decision Makers
For Kiosk Manufacturers and Solution Providers
Prioritize architectural clarity between standardized high-volume platforms and customized vertical solutions. The pressure on hardware costs and the rising importance of fleet management make it risky to blur the line between mass-deployable units and bespoke builds. Companies should define a core hardware roadmap that supports modular software integration, accessibility features, and secure payment workflows, then selectively layer vertical applications through partnerships or hosted services. Product activity such as the Windfall Series launch and the INSOMNIAC software partnership demonstrates the value of pairing durable hardware with a focused software ecosystem, and that model is likely to become more relevant as buyers compare total cost of ownership across multi-year deployments.
Equally important is designing for compliance and lifecycle support from the outset. PCI PIN on Glass requirements, accessibility expectations, and connectivity modernization all influence hardware and software choices. Manufacturers that internalize these constraints early can reduce retrofit risk, shorten certification cycles, and present a more dependable value proposition to enterprise buyers managing large, distributed fleets.
For Investors Evaluating the Kiosk Sector
Assess companies based on their ability to manage the hardware-software-service balance rather than on unit volume alone. The most durable growth stories are likely to come from players that can combine reliable hardware platforms with recurring software or managed-service elements, because that mix improves resilience against component cost volatility and creates stronger customer retention. Vertical specialization also deserves attention: accessibility-focused designs, government and public-sector deployments, and QSR self-ordering solutions each have distinct demand drivers and compliance profiles that can support steadier demand than undifferentiated self-service hardware. Investors should also monitor supply-side risk, particularly around component tariffs and regional hardware levies, since these factors can affect build costs, margin structure, and the timing of price adjustments across the value chain.
For Enterprise Buyers and Procurement Teams
Evaluate kiosk investments as multi-year operational commitments, not one-time hardware purchases. The relevant metrics should include uptime performance, remote management capability, accessibility compliance, secure payment architecture, and the supplier’s ability to support software updates and application integration over time. Buying decisions should weigh the trade-off between standardized platforms, which typically offer better scale economics and simpler support, and custom solutions, which may better fit specialized environments but can increase maintenance complexity and lifecycle cost. Procurement teams should also clarify which software services will be hosted, which will be managed internally, and how payment and accessibility requirements will be maintained as standards evolve.
Given the pace of change in hardware cost structures, regulatory expectations, and software-enabled feature sets, detailed segmentation data and customized deployment guidance can materially improve planning accuracy. PW Consulting’s complete research report provides deeper breakdowns across regions, application segments, and solution types, along with tailored recommendations for procurement strategy, vendor evaluation, and investment prioritization. For decision makers looking to translate these market-level trends into specific procurement choices or capital allocation plans, the full report offers the granular intelligence needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hemp Fiber Market: How 18.5% CAGR and Shifting Demand Redefine the 2032 Outlook
By PW Consulting, 2026-09-21
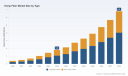
The Hemp Fiber Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview: A Sector in Rapid Transition
The global hemp fiber market has evolved from a niche agricultural byproduct into a strategically significant industrial commodity. Between 2020 and 2025, revenue expanded steadily, crossing the threshold from under half a billion USD to $1.8 billion. The trajectory suggests a compound annual growth rate of approximately 18.5 percent through 2032, with the market projected to reach $6.8 billion by the end of the forecast period. This expansion is not merely a continuation of historical growth patterns; it reflects structural shifts in material sourcing, regulatory clarity, and end-market demand that are reshaping the industry's fundamentals.
Several dynamics explain the acceleration. Production volumes have scaled meaningfully, as evidenced by U.S. fiber hemp open-field output reaching 67.3 million pounds in 2025, an 11 percent increase over the prior year, with an average value of $0.20 per pound. At the same time, regulatory frameworks are stabilizing after years of uncertainty. The USDA's decision to delay enforcement of the requirement that all hemp be tested by DEA-registered laboratories until December 31, 2026, provides a transitional window that reduces compliance pressure on producers in the near term. Furthermore, draft language in the 2026 Farm Bill clarifies the federal definition of industrial hemp as an agricultural commodity and signals a reduction in regulatory burdens for growers and processors. These developments collectively lower barriers to scale and encourage investment in processing infrastructure.
Despite the positive momentum, the sector faces three critical challenges that will determine which players capture value and which fall behind. First, consistent fiber quality remains elusive across supply chains. Variability in decortication methods, retting practices, and crop management leads to divergent grades of bast and core fibers, complicating downstream adoption in applications that require precise material specifications. Second, supply chain fragmentation persists. Many growers lack reliable off-take agreements, while processors struggle to secure steady volumes of consistent raw material. This mismatch creates price volatility and undermines long-term planning for manufacturers seeking to integrate hemp fiber into their product lines. Third, competition from established natural and synthetic alternatives continues to pressure cost parity. Hemp fiber must demonstrate not only environmental or performance advantages but also reliable economics that justify substitution in commercial settings.
Key Drivers: What Is Propelling the Market Forward
The market's trajectory is shaped by an intersection of technology, policy, consumer behavior, and supply chain restructuring. Each driver reinforces the others, creating a compound effect that favors companies able to align across multiple dimensions.
Technological Innovation in Fiber Extraction and Processing
Advancements in decortication and fiber refinement are among the most tangible drivers of market growth. Traditional mechanical separation methods often yield fibers with inconsistent length, strength, or surface characteristics, limiting their suitability for higher-value applications. Newer processing approaches, including low-impact mechanical and bio-assisted technologies, are improving the yield and quality of textile-grade bast fibers while reducing waste streams. Companies such as Canvaloop have introduced product lines that transform agricultural and bast waste into textile-grade hemp fibers and yarns, demonstrating that waste valorization can simultaneously address cost and sustainability objectives. Such innovations expand the addressable market by making hemp fiber viable for applications that previously required more expensive or less available alternatives.
Innovation is also evident in composite and construction material applications. Processors are developing material formulations that leverage hemp hurd and bast fiber for insulation, paneling, and lightweight automotive components. These formulations depend on consistent input quality, which incentivizes closer coordination between growers, decorticators, and end-product manufacturers. The trend toward integrated processing facilities reflects this reality, as vertical integration reduces the friction of coordinating multiple supply chain stages and allows for tighter quality control.
Policy and Regulatory Clarity as an Enabler
Regulatory uncertainty has historically constrained investment in hemp fiber infrastructure. The recent policy signals mark a shift toward greater predictability. The 2026 Farm Bill draft language that clarifies the federal definition of industrial hemp as an agricultural commodity reduces ambiguity for growers and accelerates onboarding of new production capacity. The USDA's enforcement delay on DEA-registered laboratory testing through the end of 2026 offers a practical relief window, giving processors and producers time to align compliance processes without immediate disruption. At the state level, requirements such as Virginia's retail hemp product registration, effective November 15, 2024, illustrate that subnational regulation remains a relevant consideration, particularly for companies distributing finished goods. Overall, the direction of policy is toward normalization, which supports more confident capital allocation and long-term planning.
Demand-Side Shifts Across Textiles, Automotive, and Construction
End-market demand is expanding beyond traditional niches. In textiles, brands and manufacturers are seeking regenerative and lower-impact fiber inputs to meet sustainability commitments and respond to consumer preferences. Hemp's attributes, including relatively low water intensity and the ability to grow with fewer chemical inputs, align with these priorities. In automotive composites, lightweighting and material strength drive interest in natural fiber reinforcements that can reduce vehicle weight and improve sustainability profiles. Construction materials represent another growth avenue, with hemp-based composites and hempcrete gaining traction for insulation, wall systems, and other building applications where thermal performance and carbon footprint are valued. Across these segments, the common thread is a preference for materials that can demonstrate both performance and credible sustainability credentials.
Supply Chain Reconfiguration and Cost Dynamics
Supply chains are being reconfigured to reduce dependence on fragmented, opportunistic sourcing. Vertically integrated operators are scaling decortication and processing capacity to secure more predictable input streams and to offer consistent product grades. This shift is significant because consistent supply is often more important to industrial buyers than marginal cost differences. At the same time, the cost structure is influenced by the economics of raw material production. With U.S. fiber hemp production valued at an average of $0.20 per pound in 2025, the sector continues to work toward cost levels that enable broader substitution. Improvements in yield, harvesting efficiency, and processing throughput will be central to closing any remaining gap with incumbent materials. Partnerships that link U.S. growers with international manufacturing hubs are also emerging as a strategic mechanism to access processing expertise and end-market demand simultaneously.
Competitive Landscape: Strategic Positioning and Evolution
The market remains relatively unconcentrated, with the top three firms accounting for approximately 25 percent of revenue and the top five for about 35 percent. This fragmentation indicates that scale advantages are still emerging and that positioning, rather than incumbency, will define winning strategies. Several distinct strategic archetypes are visible among leading participants.
Vertically integrated producers are building end-to-end control from cultivation through processing. Hemp Inc., with the largest U.S. decortication facility, exemplifies this approach, producing fiber for textiles, composites, and hempcrete. Vertical integration reduces dependency on third-party processors and enables tighter quality management, which is valuable for buyers requiring repeatable material specifications. Similarly, American Hemp, LLC has expanded decortication and processing capacity to serve textile, composite, and construction applications, signaling a focus on multi-application throughput rather than a single niche. This breadth can be advantageous when demand cycles differ across applications, as it allows capacity to be allocated where margins and orders are strongest.
Processors focused on technical fiber and export supply chains represent another strategic profile. IND HEMP, LLC decorticates U.S.-grown hemp straw to produce bales of technical bast fiber, premium refined or cottonized hemp fibers, and hurd in various particle sizes, serving both domestic and export markets. Its recent activities highlight the importance of partnership-driven expansion. In April 2026, the company signed a memorandum of understanding with Summit International Trading and Thien Phuoc Ramie Group to integrate U.S.-grown hemp fiber into Vietnam's textile manufacturing supply chain. A prior engagement at TechTextil North America 2025 in Atlanta, where the company showcased new hemp fiber solutions, indicates a deliberate effort to build visibility among textile industry buyers. These moves underscore a strategy that combines product differentiation with supply chain partnerships to access high-value textile markets.
Innovation-led processors are emerging around waste-to-fiber and low-impact technology. Canvaloop's November 2025 launch of a new line of textile-grade hemp fibers and yarns using low-impact waste-to-fiber technology illustrates how technology can redefine cost and sustainability profiles. By converting waste streams into marketable fiber, such companies can potentially lower input costs and improve margin resilience, while also appealing to buyers with strong sustainability mandates. This approach may also reduce competition for prime crop inputs, since it leverages material that might otherwise be discarded.
International players add geographic and application diversity. Ecofibre Ltd. produces and sells hemp-derived fibers and yarn for textiles and industrial applications, supplying both U.S. and Australian markets, which demonstrates cross-market operational capability. Dun Agro Hemp Group operates as a hemp fiber and grain processor and supplier for European and global markets, while Cavac Biomateriaux focuses on hemp fiber-based materials and composites for construction and industrial sectors in France. These firms highlight the global nature of demand and the importance of regional processing footprints to serve local construction, textile, and composite markets efficiently. Other U.S. processors such as BastCore, Inc., BaFa, and Konoplex LLC contribute to industrial and composite supply, reinforcing the breadth of the processing base and the ongoing specialization by application.
The competitive landscape is evolving along several axes. Integration is accelerating as processors acquire or build decortication capacity to secure inputs and ensure quality. At the same time, specialization is increasing, with firms differentiating by fiber type, application focus, or geographic market. New entrants are likely to continue arriving, particularly in regions where policy support and processing infrastructure align. The net effect is a market that is moving from fragmentation toward selective consolidation, but one in which multiple viable business models can coexist if they secure reliable supply, consistent quality, and clear customer value propositions.
Future Outlook: Trends That Will Shape the Next 3 to 5 Years
Three trends are likely to define the market's evolution through the early 2030s.
First, quality standardization and specification maturity will become increasingly important. As textile, automotive, and construction buyers integrate hemp fiber into regular procurement, they will require consistent grades, test data, and traceable supply. Processors that invest in quality systems, grading protocols, and documentation will be better positioned to secure long-term contracts, while those that supply inconsistent material will face marginalization. This trend favors operators with scale, integrated control, or strong technical partnerships, and it raises the bar for all participants.
PW Consulting
Second, geographic arbitrage and cross-border supply chain linkages will intensify. The integration of U.S.-grown fiber into manufacturing hubs in Asia, as illustrated by recent partnership activity, reflects a broader pattern of matching production regions with processing and fabrication expertise. Companies that can navigate logistics, customs, and qualityConsistency across borders will gain access to larger end markets and more diversified revenue streams. This trend also creates opportunities for regional processors that can serve as intermediaries, blending local feedstock with international demand.
Third, policy and compliance dynamics will continue to influence investment timing and operating costs. The current enforcement delay and the direction of the Farm Bill create a near-term environment that is more favorable for expansion, but state-level requirements and future federal rulemaking remain variables. Firms that build compliance flexibility into their operations, including adaptable testing and registration processes, will be less exposed to disruption if requirements tighten. The risk is that regulatory changes, while broadly constructive, could introduce new costs or administrative burdens that affect margins, particularly for smaller operators.
A related uncertainty is the persistence of cost gaps with incumbent materials. Even with strong demand, hemp fiber adoption will depend on achieving credible economics at scale. If processing yields, harvesting efficiency, or logistics costs do not improve sufficiently, adoption may remain selective rather than broad-based. This risk is particularly relevant in price-sensitive applications where sustainability benefits alone may not justify a premium.
Strategic Recommendations for Decision-Makers
For manufacturers evaluating hemp fiber integration, the priority is to secure reliable, specification-aligned supply before scaling product commitments. Engaging with processors that offer documented grades, consistent decortication output, and clear traceability will reduce the risk of quality variability disrupting production. Where possible, manufacturers should establish multi-source arrangements or partnership-based supply to mitigate dependence on a single chain, and they should validate performance in end-use conditions early to avoid late-stage rework or rejection.
For investors, the most compelling opportunities lie where processing capacity, quality control, and demand access converge. Vertically integrated operators with expanding decortication throughput, low-impact or waste-to-fiber technology, and established channels into textile, composite, or construction markets offer a combination of scale and differentiation. Investors should also monitor partnership activity that links feedstock origins to manufacturing hubs, since these arrangements can accelerate volume growth and reduce market risk. At the same time, due diligence should weigh regulatory exposure, state-level registration requirements for downstream products, and the pace of cost improvement relative to alternatives.
Hemp Market
For procurement and sourcing teams, the focus should be on total value rather than unit price alone. Hemp fiber's advantages in sustainability, weight reduction, and material performance can translate into downstream savings or brand value, but only if supply consistency and specification fit are confirmed. Procurement strategies should include technical trials, clear grading requirements, and contingency plans for supply variability, particularly during the transition from pilot to volume use. Building relationships with processors that demonstrate quality systems and transparent communication will reduce friction as volumes increase.
Across these audiences, the common imperative is to act with both urgency and discipline. The market is expanding quickly, and early positioning can secure access to supply, partnerships, and customer relationships that become harder to establish as the sector matures. At the same time, not all growth is equally valuable; the winners will be those who build defensible advantages in quality, supply reliability, and application fit rather than simply participating in volume expansion.
Hemp Seeds Market
For decision-makers seeking deeper segmentation data, company-level financials, regulatory timelines, and tailored scenario planning, a comprehensive research report can provide the granularity needed to translate these trends into concrete investment and sourcing decisions. The strategic direction is clear, but the details of segment economics, competitive capability, and regional readiness will determine execution success, making detailed intelligence a critical input for the next phase of planning.
For detailed analysis of this topic, please visit the official page: Hemp Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Strategic Shift in Smartphone Power Management ICs: Navigating Growth, Complexity, and Competitive Realignment
The smartphone power management IC (PMIC) market has entered a phase of steady, structurally driven expansion. Total revenue across the sector reached approximately 185.0 million in 2025, building on a consistent climb from 140.0 million in 2020. Over the 2026–2032 forecast horizon, the market is projected to grow at a compound annual growth rate of 5.5 percent, reaching 267.0 million by 2032. This trajectory reflects more than incremental handset volume growth. It signals a fundamental reallocation of value within mobile power architectures, where efficiency, integration, and thermal-aware design are quietly reshaping procurement priorities, product roadmaps, and competitive positioning.
Market Context and Structural Challenges
The revenue curve over the past five years shows a market that has absorbed supply chain volatility, component shortages, and shifting OEM priorities without losing momentum. Growth has been broad-based, but not uniform. The underlying dynamics point to a sector that is consolidating technical requirements while fragmenting competitive approaches. Several structural challenges define the current inflection point.
First, power density and thermal constraints are tightening faster than conventional discrete approaches can accommodate. As smartphone processors, display panels, and RF subsystems draw higher peak currents and operate across wider voltage ranges, PMICs must deliver more precise sequencing, faster transient response, and lower quiescent loss. The burden on system designers is rising, and the margin for error in battery life and thermal performance is shrinking.
Second, the competitive base is broad and increasingly layered. Market concentration remains moderate, with the top three participants holding roughly 22.5 percent of revenue and the top five reaching about 28.5 percent. This distribution indicates a market that is not dominated by a single architecture or vendor, but instead shaped by multiple design houses, foundry relationships, and region-specific OEM requirements. The result is a landscape where differentiation depends less on scale alone and more on the ability to integrate power management with application processors, charging protocols, and system-level firmware.
Third, procurement cycles and platform lifecycles are creating timing friction. Handset OEMs are extending platform validation windows, demanding longer availability commitments, and tightening qualification procedures for power components that sit close to the battery and core rails. Suppliers that cannot guarantee continuity, documentation consistency, and design-in support risk losing position even when their technical specifications are competitive.
Core Drivers Reshaping the Market
Several interlinked forces are accelerating change in smartphone power management. Understanding these drivers is essential for anyone making sourcing, investment, or product planning decisions.
Technology innovation is moving from incremental efficiency gains to architectural integration. Multi-channel PMICs, battery management blocks, and voltage regulation stages are increasingly combined into fewer packages with more programmable control. This integration reduces board space, simplifies power sequencing, and allows OEMs to tailor rail behavior to specific workload profiles. At the same time, fast-charge support, power-path management, and adaptive voltage delivery are becoming baseline expectations rather than premium features. The practical effect is that PMIC selection now influences not only battery endurance, but also user perception of charging speed, thermal comfort, and device reliability.
Power Management IC (PMIC) Market
Policy and regulatory pressure is reinforcing the efficiency trajectory. Energy consumption standards, battery safety expectations, and e-waste considerations are pushing manufacturers toward designs that minimize loss, extend usable battery life, and simplify end-of-life handling. While regulations vary by region, the directional signal is consistent: mobile devices must do more with less energy, and power management is a primary lever for compliance. This environment rewards suppliers that can provide documented efficiency curves, predictable thermal behavior, and evidence of robust fault protection.
Demand-side behavior is also changing the value equation. Consumers expect devices that hold charge longer under mixed usage, recharge quickly without excessive heat, and maintain consistent performance across battery states. Enterprise and premium consumer segments add further requirements, including longer product support windows, tighter supply continuity, and more transparent component provenance. These expectations increase the stakes for PMIC designers, because power management is increasingly visible to end users through charging behavior, thermal performance, and charge-cycle longevity.
Supply chain and cost structure dynamics continue to shape sourcing strategies. Component availability, packaging constraints, and the cost of qualifying alternative parts have made resilience a first-order concern. OEMs and contract manufacturers are diversifying supplier bases where possible, while also seeking partners that can provide stable lead times, clear revision control, and design flexibility. In this environment, cost competitiveness is still important, but it is increasingly weighed against risk mitigation, technical support, and the ability to sustain designs through multiple product generations.
Competitive Landscape and Strategic Positioning
The market features a diverse set of participants, each pursuing a distinct path to relevance. The strategic differences among them reveal where value is being created and how the competitive map is evolving.
Texas Instruments maintains a broad portfolio spanning multi-output PMICs for smartphone battery charging, voltage regulation, and power sequencing. Its positioning rests on depth of reference design, long-standing mobile phone PMIC heritage, and continued development of modern battery management solutions. For system architects, this breadth translates into optionality across charging topologies and rail configurations, supported by a documentation and design-in ecosystem that reduces integration risk.
Analog Devices emphasizes fast-charge support and power-path management, with PMICs integrated alongside battery chargers and low-dropout regulators in mobile platforms. Its differentiation lies in precision power delivery and a focus on charge behavior that aligns with user experience expectations. This approach appeals to designs where charge timing, battery health, and stable operation across load transients are prioritized.
NXP Semiconductors offers configurable power sequencing and fault protection optimized for smartphone CPUs, GPUs, and memory rails. Its value proposition centers on flexibility and protection in handheld environments, where rail ordering and fault handling can materially affect system stability. This makes NXP relevant for platforms that require tailored sequencing across heterogeneous processing blocks.
Renesas Electronics, including its Dialog Semiconductor capabilities, supplies multi-channel PMICs and sub-PMICs for smartphones, tablets, and RF modules, with advanced buck-boost and power distribution solutions. The strategic emphasis is on distribution efficiency and multi-rail control, which supports complex handheld architectures that must balance performance, leakage, and thermal headroom.
ON Semiconductor focuses on efficiency and integration in mobile power management for consumer electronics. Its approach targets loss reduction and functional consolidation, which matters in designs where board area and energy waste are tightly constrained. Richtek Technology contributes PMICs for portable and handheld devices, including buck-boost converters and battery charge controllers, with a practical focus on charging control and conversion efficiency in smartphone applications.
ROHM Semiconductor provides linear and switching regulators along with power management switch ICs tailored for mobile phones and displays. Its portfolio supports designs that need a mix of regulation styles and switching elements, particularly where display and handset rail requirements intersect. Skyworks Solutions is associated with PMICs in next-generation smartphones, including wireless networking and power delivery solutions, positioning power management closer to connectivity and RF subsystem needs.
Qualcomm Technologies integrates Snapdragon SoCs with Power Managers for optimized power delivery, fast charging, and efficiency. Its advantage comes from tight coupling between application processors and power management, enabling coordinated behavior across compute, charging, and delivery paths. MediaTek develops PMICs for smartphones and IoT, including multi-buck and LDO-based power distribution and charging solutions, with a focus on scalable integration across broad handheld and connected device portfolios.
These profiles illustrate a market where differentiation is multidimensional. Some players compete on integration breadth and reference design maturity. Others compete on precision charging, sequencing flexibility, or processor-coupled optimization. The practical implication for decision makers is that PMIC selection is no longer a single-specification purchase. It is a platform decision that affects charging experience, thermal behavior, validation effort, and long-term design continuity.
The competitive structure is evolving along three directions. Consolidation is occurring where suppliers can bundle power management with adjacent functions and reduce total integration cost. Differentiation is intensifying where charging speed, efficiency, and protection features become decisive in premium segments. New entry and regional specialization remain possible where local support, cost structures, and design-in relationships create niches that broader portfolios do not fully address. The moderate concentration levels suggest that the market will remain competitive, but that coordinated advantages in integration, support, and platform alignment will increasingly separate leaders from followers.
Forward Trends and Commercial Implications
Looking ahead across the 2026–2032 period, three trends are likely to shape commercial outcomes.
Integrated, programmable power architectures will become more central to smartphone design. As rail counts, workload variability, and charging expectations increase, PMICs that offer configurable sequencing, adaptive regulation, and tighter coordination with processors and charging protocols will gain preference. The commercial opportunity lies in reducing validation complexity, improving thermal performance, and enabling faster design cycles for OEMs that need to support multiple handset variants from a common power architecture. Suppliers and partner ecosystems that can provide flexible configuration options, clear firmware or control interfaces, and predictable behavior across operating conditions will be better positioned to capture design wins.
Efficiency and thermal-aware design will move from optimization goals to qualification gates. With battery life, charging comfort, and regulatory expectations all trending upward, PMICs that minimize loss, manage transients cleanly, and support stable operation under fast-charge conditions will become harder to substitute. This creates opportunity for vendors that can document efficiency across load profiles, provide robust protection features, and help OEMs meet both performance and compliance targets. The risk is that efficiency claims become commoditized unless supported by measurable system-level outcomes and reproducible validation data.
Supply resilience and lifecycle continuity will increasingly influence sourcing decisions. As platform cycles lengthen and qualification costs rise, procurement teams will favor suppliers that can demonstrate stable availability, disciplined revision control, and the ability to support designs over multiple generations. The commercial implication is that relationship depth, technical support, and continuity planning may become as important as unit pricing. This trend also raises the bar for smaller or less established participants, while rewarding suppliers that can commit to long-lived design support and transparent change management.
Worldwide Consumer Electronics Power Management IC Market
These trends are not guaranteed to unfold uniformly. Risks include component pricing volatility, shifting OEM platform strategies, and the possibility that integration advantages concentrate value among a smaller set of platform-aligned suppliers. There is also uncertainty around how quickly charging protocols, battery technologies, and regulatory expectations will evolve, which could alter the relative importance of specific PMIC features. Decision makers should therefore treat power management strategy as a living assessment rather than a fixed specification exercise.
PW Consulting
Actions for Executives, Investors, and Procurement Teams
For handset and component manufacturers, the priority is to align power management choices with platform strategy rather than treat PMICs as interchangeable commodities. That means evaluating integration depth, sequencing flexibility, fast-charge behavior, and supplier support alongside unit cost. Designs that can reuse a common PMIC architecture across multiple models, while retaining enough programmability to tune rail behavior, will typically reduce validation burden and improve lifecycle economics. Manufacturers should also weigh the value of tighter coordination between processor platforms and power delivery, especially where charging experience and thermal performance are differentiators.
For investors, the relevant question is where value is likely to accrue as integration and efficiency requirements intensify. Companies that can combine multi-channel control, battery management, and regulation in cohesive solutions, while maintaining strong design-in support and stable product lifecycles, are better placed to defend positioning in a moderately concentrated market. Attention should also be paid to suppliers whose roadmaps align with fast-charge adoption, thermal-aware design, and platform-level integration, since these are the areas where commercial differentiation is most likely to widen. Portfolio exposure should be assessed with an eye on continuity risk, qualification lead times, and the ability to sustain designs through multiple product generations.
For procurement and sourcing leaders, the practical focus should be on resilience and traceability without sacrificing technical fit. Qualifying multiple sources where feasible, verifying revision-control discipline, and requiring clear documentation for configuration and protection features can reduce downstream risk. Procurement teams should also evaluate supplier capacity to support long-lived platforms, because the cost of re-qualification and design changes often outweighs narrow unit-price advantages. In parallel, sourcing strategies should reflect the growing importance of charging behavior and thermal performance in end-user satisfaction, since these attributes are increasingly tied to PMIC selection.
Across these roles, the common theme is that smartphone power management is becoming more strategic, less commodity-like, and more tightly linked to platform outcomes. The market’s growth trajectory is steady, but the real value is shifting toward architectures and suppliers that can reduce integration risk, improve efficiency and charging behavior, and sustain designs through changing requirements. Detailed segmentation data, region- and type-level revenue splits, application breakdowns, and supplier-level assessments can sharpen these decisions significantly. For teams that need granular sizing, competitive mapping, and tailored sourcing or investment implications, the full research report provides the deeper quantitative and strategic detail needed to move from market-level direction to actionable plans.
For detailed analysis of this topic, please visit the official page: Smartphone Power Management Ics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Shea Butter Market
The global shea butter market has evolved from a niche ingredient in specialty cosmetics into a strategically significant commodity spanning personal care, food, and pharmaceutical applications. Valued at approximately USD 970.0 million in 2025, the market has demonstrated consistent expansion over the past five years, accelerating from USD 655.2 million in 2020. Forward projections indicate continued growth, with the market expected to surpass USD 1.6 billion by 2032, reflecting a compound annual growth rate of 8.2 percent through the forecast period ending in 2032.
This trajectory reflects more than incremental demand growth. It signals a structural shift in how shea butter is sourced, processed, regulated, and positioned across end-use markets. For executives and investors evaluating exposure to natural ingredients, the shea butter sector offers compelling upside, but it also presents a complex landscape shaped by regional policy interventions, supply chain reconfiguration, and evolving consumer expectations.
PW Consulting's market intelligence on this sector highlights that the opportunities ahead will not accrue uniformly. Companies that understand the interplay between production geography, processing capability, regulatory compliance, and application-specific demand will be best positioned to capture value. This analysis examines the current market structure, the forces reshaping competitive dynamics, and the strategic moves required to navigate the next phase of growth.
Market Landscape and Core Challenges
The shea butter market operates at the intersection of agricultural commodity trading and value-added specialty ingredients. Over the historical period from 2020 to 2025, the market expanded steadily, driven by rising demand for plant-based and naturally derived ingredients across cosmetics, food formulations, and pharmaceutical applications. The forecast period through 2032 projects continued expansion, with the market reaching an estimated USD 1.69 billion by the end of the forecast horizon.
While the top-line growth narrative is clear, the operational reality for market participants is more nuanced. Three structural challenges define the current inflection point.
Supply Chain Concentration and Raw Material Volatility
Shea butter production remains heavily concentrated in specific West and Central African regions, creating geographic dependency that introduces both price volatility and supply continuity risk. The crop's seasonal nature, combined with variable yields and the predominance of smallholder farming, means that raw material availability can fluctuate significantly between harvest cycles. This structural characteristic has historically forced downstream buyers to balance cost efficiency against supply security, often through long-term contracting or geographic diversification of sourcing portfolios.
Compounding this challenge, the gap between raw kernel availability and processed butter output creates bottlenecks. Entities that control refining and fractionation capacity can extract disproportionate value, while those dependent on spot-market purchases face margin compression during periods of tight supply. The market's medium concentration levels, with the top three firms holding a notable share and the top five firms controlling a larger portion of traded volume, indicate that scale and vertical integration confer meaningful advantages.
Regulatory and Policy Fragmentation
The regulatory environment for shea butter varies substantially by destination market and by application. Food-grade shea butter entering the European Union, for example, must comply with mandatory labeling requirements, hygiene standards, and hazard analysis and critical control points systems. Cosmetic and pharmaceutical applications impose their own quality and traceability expectations. This fragmentation increases compliance costs and creates barriers for smaller producers or exporters who lack the institutional capacity to navigate multiple regulatory regimes simultaneously.
More significantly, recent policy actions in key producing countries are reshaping the value-capture dynamics within the supply chain. Governments in the region are increasingly focused on capturing more domestic value by restricting raw nut exports and encouraging local processing. These interventions introduce both opportunity and disruption: they can stimulate investment in local refining infrastructure, but they also create short-term market dislocation, pricing uncertainty, and the need for buyers to renegotiate supply arrangements.
Quality Consistency and Standardization Gaps
Despite growing demand, the shea butter market continues to contend with variability in quality, purity, and processing standards across the supply base. Unrefined and raw variants, which represent a substantial portion of traded volume, differ widely in terms of moisture content, free fatty acid levels, and impurity profiles. For manufacturers in cosmetics and personal care, where consistency and stability are paramount, this variability complicates formulation and can increase quality control overhead. For food and pharmaceutical applications, the bar is even higher, requiring documented traceability and adherence to precise specifications.
Standardization is improving, but the pace is uneven. The presence of minimum price mechanisms tied to quality specifications in some producing markets reflects an effort to align incentives, but widespread adoption of uniform grading and certification remains a work in progress. Companies that invest in supplier qualification, incoming inspection protocols, and collaborative quality improvement with upstream partners can differentiate themselves, but this requires sustained commitment rather than transactional sourcing.
Key Drivers Reshaping the Market
Policy Interventions and the Shift Toward Domestic Value Addition
One of the most consequential developments in the shea butter market is the emergence of policy measures designed to retain more value within producing countries. In July 2025, a minimum price for raw shea kernels was established, set at GH₵9.01 per kilogram, with specific quality parameters covering moisture content, free fatty acids, and impurity levels. This mechanism creates a pricing floor linked to quality, aiming to provide more predictable returns for producers while incentivizing better grading practices.
Shortly thereafter, Nigeria implemented a ban on exports of raw shea nuts, with the stated objective of shifting from raw nut exports toward domestic production of refined shea butter, oil, and derivatives. The ban, initially set for a six-month review period, was reported to have triggered an immediate drop in domestic prices, reflecting the sudden redirection of supply within the local market. Analysts noted that Nigeria accounts for a significant share of global raw shea nut production, and that a substantial portion of that output had historically been exported in unprocessed form.
These policy moves are not isolated. They represent a broader trend among producing nations seeking to capture more value along the supply chain. For downstream buyers and processors, this means that sourcing strategies can no longer assume seamless access to raw materials at historical price levels. Instead, companies must evaluate opportunities to engage with local processing capacity, invest in partnership structures that align incentives, or factor in the cost of compliance with new trade and quality regimes.
Technological and Processing Advancements
Processing technology is a critical lever in the shea butter value chain. The distinction between raw, unrefined butter and refined, fractionated products is not merely a matter of purity; it reflects differences in application suitability, shelf stability, odor and color profile, and cost structure. Refinement and fractionation enable producers to tailor shea butter for specific end uses, including high-stability cosmetic formulations and food applications that require consistent functional properties.
Companies that have invested in refining infrastructure and value-added fractionation are better positioned to serve demanding customers in the food and cosmetic sectors. By converting raw kernels into standardized butter and derivative products, these entities can command higher margins and build longer-term supply relationships. Conversely, reliance on manual or low-scale processing limits the ability to meet the consistency and volume requirements of large industrial buyers.
The technological trajectory also includes improvements in quality testing, traceability systems, and process control. As destination markets impose more stringent requirements, the ability to document and verify product attributes becomes a competitive differentiator. Investments in laboratory capacity, certification, and digital traceability are increasingly relevant for suppliers aiming to access premium segments.
Consumer and Formulation Trends Driving Demand
On the demand side, the shift toward naturally derived, plant-based, and sustainably sourced ingredients continues to reshape formulations across cosmetics, personal care, food, and pharmaceutical products. Shea butter's profile as a multifunctional, naturally occurring lipid aligns with consumer preferences for clean-label and botanical ingredients. In cosmetics and personal care, it is valued for its emollient properties and is used across a range of products, from moisturizers and balms to hair care formulations.
In food and beverage applications, shea butter and its derivatives serve functional roles where stable, plant-based fats are required. The pharmaceutical segment utilizes shea butter in topical formulations and other applications where biocompatibility and consistency are important. Across these segments, the trend is not simply toward natural ingredients in general, but toward ingredients with documented provenance, consistent quality, and the ability to meet application-specific performance criteria.
This demand evolution has implications for how shea butter is positioned and priced. Buyers in premium segments are increasingly willing to pay for verified quality, traceability, and compliance documentation. At the same time, cost-sensitive applications continue to drive volume demand for more commodity-oriented grades. The coexistence of these demand tiers means that the market is not monolithic; success depends on matching product attributes to the right customer segments and application requirements.
Supply Chain Restructuring and Cost Dynamics
The cost structure of shea butter is influenced by multiple factors, including raw kernel pricing, labor and processing costs, logistics, and the cost of meeting regulatory and quality requirements. Recent policy changes in producing countries have introduced new variables into this equation. Minimum price mechanisms can stabilize producer income but may also affect the economics of export-oriented supply chains. Export restrictions on raw nuts redirect supply domestically, which can lower local raw material prices in the short term but also create uncertainty about future availability for international buyers.
For processors and converters, these dynamics create both pressure and opportunity. On one hand, sourcing disruptions and policy uncertainty can increase the cost of securing consistent supply. On the other hand, the push toward domestic processing creates openings for entities that can invest in refining capacity, enter into structured offtake arrangements, or provide technical and commercial support to local producers. The companies that navigate this environment effectively will be those that treat supply chain strategy as a dynamic capability rather than a static procurement function.
Cost dynamics also vary by region and application. Markets with strong local processing ecosystems may offer more predictable input costs for domestic manufacturers, while international buyers may face higher logistical and compliance costs. Understanding these regional and application-specific differences is essential for accurate margin planning and competitive positioning.
Competitive Landscape and Leading Strategies
The shea butter market features a diverse set of participants, from large multinational processors with established supply chains to regional specialists and origin-country producers focused on organic and manually processed products. The competitive landscape reflects different strategic choices regarding scale, vertical integration, product focus, and geographic reach.
Differentiated Strategic Positions
AAK operates with a clear focus on processing and exporting shea kernels and butter derivatives from West Africa, maintaining major supply chains that serve manufacturers in Europe and North America. This position emphasizes scale, supply chain reliability, and the ability to serve demanding downstream customers with consistent product flow. By controlling significant portions of the sourcing and export process, AAK can offer volume stability and quality assurance that are critical for large industrial buyers.
Loders Croklaan has built its positioning around refining shea kernels into crude butter and value-added fractions tailored for food and cosmetic applications. This strategy focuses on the midstream of the value chain, where processing expertise and fractionation capability create differentiation. By offering products that meet specific functional requirements, Loders Croklaan addresses customers who need more than commodity-grade butter, including those in food formulations and high-performance cosmetics.
Almond Oil Market
The Savannah Fruits Company represents a different model, emphasizing organic shea nut sourcing and manual processing at the village level. This approach is oriented around organic certification, rural livelihoods, and export of unrefined butter. The strategic value of this model lies in its alignment with sustainability and social impact expectations, as well as its ability to serve niche markets that prioritize origin authenticity and organic status. The trade-off is scale and consistency relative to larger industrial processors.
VedaOils operates in the wholesale and bulk export segment, focusing on organic and unrefined shea butter for cosmetic and personal care markets. This positioning targets cost-conscious buyers who still require organic or natural credentials, bridging the gap between premium certification and volume supply. The emphasis on wholesale and manufacturing allows VedaOils to serve a broad customer base while maintaining a focus on natural and organic attributes.
Market Structure Evolution
The competitive landscape is evolving along several dimensions. Consolidation pressure exists in segments where scale, refining capacity, and export infrastructure confer advantages. Larger processors with integrated supply chains and compliance capabilities are well placed to capture share from smaller, less capitalized players, particularly in food and pharmaceutical applications where regulatory requirements raise the bar for entry.
At the same time, differentiation and fragmentation persist in niches such as organic, fair-trade, and village-processed products. These segments reward brand story, certification, and direct relationships with producer communities. New entrants that can combine authenticity with reliable quality and documentation may find opportunities, especially as consumer and corporate procurement teams place greater weight on sustainability and provenance.
A third dynamic is the potential for vertical coordination between origin-country processors and downstream buyers. As producing countries encourage domestic refining, opportunities arise for partnerships that align local processing investment with long-term offtake commitments. Such arrangements can reduce supply risk for buyers while providing the capital and offtake certainty that local processors need to expand capacity. The extent to which this model scales will depend on policy stability, investment climate, and the willingness of both sides to commit over multi-year horizons.
Forward Trends and Strategic Implications
Trend 1: Deepening of Domestic Processing and Value Capture in Origin Countries
The policy direction evident in recent interventions points toward a sustained push for domestic processing in key producing countries. If export restrictions on raw nuts become more entrenched or are replicated in other markets, the supply chain will gradually shift toward more refined and fractionated products originating in the region. This creates opportunities for investors and companies that can support or participate in local refining capacity, quality infrastructure, and certification systems.
For downstream buyers, this trend implies that sourcing strategies will need to incorporate more engagement with origin-country processing ecosystems. Long-term contracts, joint ventures, or technical assistance arrangements may become more common as a way to secure supply and influence quality. The commercial opportunity lies in building resilient, multi-year relationships that align incentives across the value chain, rather than relying on spot-market transactions that are vulnerable to policy shocks.
Trend 2: Increasing Importance of Quality, Traceability, and Compliance Documentation
As destination market requirements tighten and application segments demand more consistent attributes, the value of quality assurance and traceability will continue to rise. Companies that can provide documented evidence of product characteristics, processing conditions, and supply chain integrity will be better positioned to access premium segments and command price premiums. This is particularly relevant for food and pharmaceutical applications, where regulatory expectations are highest.
The strategic implication is that investments in quality systems, certification, and traceability are not merely compliance costs; they are enablers of market access and differentiation. For suppliers, this means building the institutional capacity to meet varied requirements across customers and markets. For buyers, it means incorporating quality and documentation capabilities into supplier evaluation and development programs.
Mango Butter Market
Trend 3: Segmentation Between Commodity and Premium Value Chains
The shea butter market is likely to continue diverging into distinct value chains: one oriented toward volume, cost efficiency, and commodity-grade supply, and another oriented toward premium quality, certification, and application-specific performance. This segmentation mirrors broader trends in natural ingredients markets, where buyers increasingly differentiate between baseline commodity supply and value-added, verified products.
PW Consulting
For market participants, the strategic question is where to compete. Companies that operate primarily in the commodity tier will face pressure on margins and will need to compete on cost, reliability, and scale. Those that position in the premium tier will need to demonstrate consistent quality, relevant certifications, and the ability to meet specific formulation or regulatory needs. Hybrid strategies that span both tiers are possible but require operational sophistication to manage the different cost structures and customer expectations involved.
Risk Considerations
Several risks warrant attention. Policy uncertainty in producing countries could lead to further trade restrictions, price volatility, or shifts in export patterns that disrupt established supply chains. Quality and standardization gaps could persist, creating friction in premium segments and increasing the cost of quality assurance. Competition for supply could intensify as more players seek to secure processing capacity or long-term sourcing arrangements, potentially driving up input costs. Finally, demand-side preferences could shift if alternative natural ingredients gain traction or if formulation trends evolve in ways that reduce reliance on shea butter in certain applications.
These risks do not negate the growth outlook, but they underscore the importance of proactive strategy. Companies that monitor policy developments, diversify sourcing where feasible, invest in quality and traceability, and align product offerings with the right application segments will be better equipped to manage uncertainty while capturing growth.
Strategic Recommendations for Decision Makers
The shea butter market's growth trajectory and evolving structure create distinct imperatives for different types of stakeholders. The following recommendations are intended to guide strategic planning and resource allocation.
For Manufacturers and Processors
- Evaluate supply chain resilience in light of recent policy interventions. Companies dependent on raw kernel imports should assess the risk of export restrictions and consider diversifying sourcing geographies, developing alternative supply routes, or engaging with origin-country processors to secure refined supply.
- Invest in product positioning that matches application requirements. Align product grades, quality documentation, and processing attributes with the specific needs of cosmetics, food, or pharmaceutical customers. Where relevant, build capability in refinement and fractionation to access higher-value segments.
- Strengthen quality systems and traceability. Documented quality consistency and supply chain transparency will increasingly determine access to premium customers and compliance with destination-market requirements. Treat these capabilities as strategic assets rather than overhead.
For Investors
- Assess opportunities in origin-country processing and quality infrastructure. The policy push toward domestic value addition creates potential for investments in refining capacity, testing laboratories, certification support, and logistics that enable local processors to meet export-grade standards.
- Differentiate between commodity-scale plays and premium-segment opportunities. Investment theses should account for the distinct economics of volume-driven commodity supply versus certification-intensive, traceability-rich premium products. The risk-return profiles differ materially.
- Monitor policy trajectories and their second-order effects. Export restrictions, minimum price mechanisms, and quality-linked pricing can alter competitive dynamics quickly. Investors should factor policy risk into valuation assumptions and consider scenarios that reflect a range of possible regulatory outcomes.
For Procurement and Sourcing Leaders
- Move beyond transactional sourcing where supply security matters. For critical applications, structured relationships with suppliers, multi-year agreements, or collaborative quality development can reduce exposure to price shocks and supply interruptions.
- Incorporate policy and regulatory monitoring into sourcing strategy. Changes in origin-country policy, destination-market regulations, and quality requirements should be tracked systematically and integrated into supplier selection and contract design.
- Balance cost objectives with quality and compliance needs. In applications where consistency, documentation, and certification are essential, the total cost of ownership may favor suppliers with stronger quality systems, even if unit prices are higher. Procurement decisions should reflect this broader calculus.
Navigating the Next Phase
The shea butter market is entering a period in which growth potential and structural complexity are both increasing. The macro trajectory points to continued expansion, with the market progressing toward the USD 1.6 billion range by the early 2030s. Yet the path to capturing this growth is shaped by policy interventions in producing countries, the maturation of processing and quality infrastructure, and the evolving expectations of customers across cosmetics, food, and pharmaceutical applications.
Success in this environment requires more than awareness of top-line trends. It demands granular understanding of regional supply dynamics, the implications of policy changes for sourcing and pricing, the competitive positioning of key players, and the specific requirements of each application segment. The companies that thrive will be those that combine market-level insight with operational execution: securing resilient supply, delivering consistent quality, and aligning product offerings with the right customer tiers.
For decision makers seeking deeper segmentation data, regional supply analysis, competitor benchmarking, and customized strategic scenarios, a comprehensive research companion is available that extends the analysis presented here with detailed quantitative and qualitative coverage. Access to that level of granularity can materially improve the quality of sourcing decisions, investment theses, and competitive positioning in a market where the difference between generic exposure and targeted advantage is increasingly significant.
For detailed analysis of this topic, please visit the official page: Shea Butter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


