



PW Consulting: Worldwide 3D Automated Optical Inspection (AOI) Equipment in PCB Market Poised to Hit USD 2,312.7 Million by 2032 on 11.2% CAGR — Asia‑Pacific Leads with USD 681.1 Million
By PW Consulting, 2026-07-16
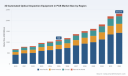
Worldwide 3D Automated Optical Inspection Equipment in PCB Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to present a focused executive preview of our latest market research: Worldwide 3D Automated Optical Inspection (AOI) Equipment in the PCB Market. This briefing distills the report’s strategic value for executives making capital‑allocation, sourcing, and product‑roadmap decisions in 2026 — while preserving the granular segment intelligence available in the full report.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Market snapshot: where the market sits as you enter 2026
Our analysis uses 2025 as the base year. In 2025 the global 3D AOI equipment market for PCB inspection is estimated at roughly USD 1.1 billion. Under our base case scenarios, the market is expected to expand at a compounded annual growth rate (CAGR) of approximately 11.2% through the 2026–2032 forecast window, driving the market toward roughly USD 2.3 billion by 2032. This trajectory reflects rapid adoption in higher‑reliability PCB segments, densification of SMT assemblies, and the migration of inspection from 2D optical to true‑3D methods to meet tighter process tolerances.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Why this matters for 2026 corporate decisions
- CapEx timing and sizing: The near‑term growth rate and underlying technology refresh cycles argue for staggered but committed capital deployment. Companies that delay upgrades risk higher rework rates and longer time‑to‑market for HDI or automotive grade boards.
- Make vs. buy and localization: Supply‑chain constraints and trade policy noise are materially affecting lead times and landed costs for high‑resolution sensors and optics. Firms should reassess the balance between in‑house inspection capability and outsourced contract inspection to control cycle time and warranty exposure.
- Technology selection under new standards: Updated industry accuracy requirements are elevating minimum performance baselines — signaling that not all legacy 3D or hybrid AOI platforms will remain compliant for high‑reliability applications without firmware, optics or sensor upgrades.
- M&A and supplier partnerships: The market shows significant concentration: the leading vendors capture a dominant share of supply. This drives opportunity for bolt‑on acquisitions and strategic alliances to quickly broaden feature sets (AI analytics, AXI integration) or to secure supply of scarce optics components.
What the PW Consulting report delivers — practical content for immediate action
The full report is structured as an operational guide for decision‑makers, not just an academic forecast. Key deliverables include:
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
- Transparent market sizing and growth scenarios (base, upside, downside) tied to demand drivers by end‑use cohort and PCB complexity tier.
- Vendor benchmarking matrix: capability maps that evaluate throughput, detection sensitivity, field‑upgradeability, software openness (APIs), and typical TCO inputs.
- Procurement playbook: negotiation levers, expected lead times under alternate supply scenarios, and sample RFx clauses to mitigate optical/sensor shortages and export control exposure.
- CapEx ROI models and payback calculators customizable to production mix and defect cost profiles, including sensitivity to price inflation in optics and sensor modules.
- Regulatory and standards checklist tailored to high‑reliability and automotive programs (what to test and certify, and how to document compliance).
- Scenario planning and mitigation strategies for trade restrictions, tariffs, and component shortages — with recommended near‑term actions and 24‑ to 36‑month contingency playbooks.
- Curated M&A and partner target shortlist with rationale (technology, geography, supply chain leverage), plus an integration risk heatmap.
For confidentiality and commercial value, the report’s granular regional, technology and end‑use splits are available through the full publication. This preview intentionally omits those detailed tables to guide stakeholders to the primary resource for procurement and strategic planning.
Competitive landscape — who matters and why
The equipment vendor ecosystem is mature but dynamic: leading incumbents continue to invest in sensor fidelity, AI analytics and hybrid inspection (AOI + AXI) functionality. The market’s top suppliers combine deep domain knowledge in SMT inspection with disciplined go‑to‑market execution. Key players covered in our competitive analysis include:
- Koh Young Technology (Seoul) — Market leader in high‑throughput true‑3D imaging with platforms designed for high‑speed SMT lines. Recent product launches signal continued emphasis on embedded AI for faster false‑call reduction and throughput tradeoffs. Strategic strength: strong installed base and sophisticated service networks. Execution risk: dependence on leading‑edge optics suppliers and rising component lead times.
- CyberOptics Corporation (Minneapolis) — Known for multi‑reflection suppression and high‑precision 3D platforms. The company has pushed into ultra‑small component inspection (01005) with recent platform upgrades. Strategic strength: sensor innovation and vertical integration in optics. Consideration: positioning for customers needing very small component detection at high yields.
- Viscom AG (Hannover) — European vendor focused on high‑resolution optics for HDI and multi‑layer PCB production lines. Viscom’s systems are aimed at high‑volume factories that demand consistent throughput/precision balance. Strategic strength: strong alignment with European Tier 1 electronics manufacturers; tariff exposure is a consideration for non‑EU imports.
- Test Research, Inc. (TRI) (Taipei) — Competitive on AI‑driven analytics and cost‑efficient automation for regional EMS and OEMs. TRI’s offerings are notable for their emphasis on solder paste and placement verification. Strategic strength: agility and competitive pricing; risk: scaling service and global support footprint.
- SAKI Corporation (Tokyo) — Focused on precision height measurement, leveraging gimbal‑less camera designs and compliance with industry standards. SAKI’s recent certification updates indicate an ambition to capture higher‑reliability segments. Strategic strength: standards alignment and engineering pedigree.
- Mirtec Corporation (Oxford, CT) — Integrates high‑resolution imaging and laser profiling, often used for post‑reflow validation. Strategic strength: camera resolution and profiling integration; consideration: competition on AI post‑processing and platform openness.
- Nordson Test & Inspection (Carlsbad) — Builds hybrid systems that combine AOI and AXI capabilities for high‑mix environments. Strategic strength: integrated NPI and inspection workflows for varied production mixes; consideration: higher unit pricing but lower long‑term inspection footprint.
Collectively, the top vendors capture a significant portion of market revenue, underscoring consolidation dynamics and high barriers for late entrants. For procurement teams, vendor selection increasingly centers on post‑sale support, upgrade pathways and compliance features, not just headline detection rates.
Industry dynamics shaping vendor and buyer strategies
- Component supply pressures: In Q4 2025 high‑resolution 3D camera module lead times averaged roughly 16–20 weeks due to semiconductor and optics shortages. This is changing procurement cadence and driving advanced orders and supplier risk clauses.
- Standards tightening: The IPC 2025 updates now include stricter 3D height measurement accuracy expectations (on the order of single micron tolerances for high‑reliability inspection). Buyers must validate measurement uncertainty budgets when comparing equipment.
- Trade and tariff frictions: Export controls on advanced imaging sensors and newly implemented tariffs in some regions materially affected shipment flows in 2025. Import tariffs and controls are an input into landed cost models and should be built into 2026 capital planning.
- Price inflation in optics: Average equipment pricing rose year‑over‑year in 2025, reflecting optics inflation and tighter component markets. This has compressed short‑term procurement windows and increased emphasis on lifecycle cost versus upfront price.
Recommended moves for 2026 — a pragmatic playbook
- Prioritize modular upgrade paths: Favor platforms that support sensor swaps and software upgrades to extend service life and respond to tightening standards without full replacement.
- Hedge supply risk: Negotiate long‑lead contracts for critical optics components, identify dual‑sourcing options, and consider consignment or pooled inventory approaches with key suppliers.
- Embed inspection earlier: Shift inspection left (pre‑reflow AOI) where possible to reduce rework costs and accelerate process feedback loops for complex assemblies.
- Require standards‑validated performance: Make compliance evidence (test reports, repeatability studies) a mandatory part of procurement scoring for high‑reliability contracts.
- Model tariff and control impacts: Run sensitivity analyses on landed costs and supply timelines using our scenario templates to stress‑test procurement and capital plans for 2026–2027.
- Evaluate M&A selectively: For OEMs and EMS providers intent on insulating supply or accelerating capability, small acquisitions of specialized sensor or AI companies can deliver rapid differentiation — but ensure integration planning is rigorous.
Conclusion — using insight to decide in 2026
The 3D AOI market for PCB inspection is transitioning from improvement‑driven replacement to mission‑critical infrastructure in many high‑reliability manufacturing contexts. For 2026, the combination of steady market growth, standards tightening, component scarcity, and trade complexity creates both risk and opportunity. Our report translates these macro forces into rigorous procurement, investment and M&A guidance designed to be operationally actionable.
To access the full dataset, vendor scores, segmented forecasts and customizable CapEx models referenced in this preview, visit PW Consulting’s detailed report page or contact our practice for a briefing tailored to your production profile. The granular segmentation tables and vendor financials are available exclusively in the full report and accompanying Excel models.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BARC Market to Reach USD 1,516.7 Million by 2032 at 6.72% CAGR, Led by Asia Pacific and Organic BARC (Top‑3 Firms Hold 65.4%)
By PW Consulting, 2026-07-16
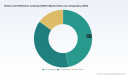
Worldwide Bottom Anti-Reflective Coatings (BARC) Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market study on Worldwide Bottom Anti-Reflective Coatings (BARC) provides a precisely targeted briefing for executives who must make high-stakes decisions in 2026. Built on a 2025 base and a comprehensive historical review (2020–2025), our forecast through 2032 models technology transitions, supply-chain stressors, regulation, and competitive dynamics to produce an investment-grade view of the market. This release is designed as a strategic “preview”: it exposes the analytical framework and key takeaways, while preserving the granular segment-level datasets and interactive models for report subscribers.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Market at a glance
- Base year and scope: The study uses 2025 as the base year, with historical analysis covering 2020–2025 and a forward-looking forecast for 2026–2032.
- Growth trajectory: Our model projects the global BARC market to expand at a compound annual growth rate (CAGR) of approximately 6.72% over the forecast period, reflecting steady capacity additions and demand tied to advanced lithography transitions.
- Magnitude: By 2025 the BARC market had reached the high hundreds of millions (USD, Million) in annual revenues, and our central forecast path reaches well into the mid‑billions by 2032 under the core scenario. Subscribers receive the full year-by-year series and sensitivity cases.
- Concentration: Market concentration is material — the three largest suppliers account for a clear majority of global revenues, and the top five approach near‑ubiquitous supplier presence across major fab regions. This structure creates both supply risk and predictable levers for pricing and partnership strategies.
Why this report matters for 2026 decisions
BARC is a small but strategically essential input in lithography stacks. Decisions you make in 2026 about supplier selection, chemistry investments, and geographic sourcing will have multi‑year consequences for throughput, yield, and capital productivity. PW Consulting’s report translates market psychology and technical trajectories into actionable guidance for:
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
- CapEx and fab siting: timing capacity expansions versus tightening raw material markets.
- Procurement: structuring contracts that hedge tariff and transport risks while securing premium grades for advanced nodes.
- R&D prioritization: identifying formulation gaps tied to EU regulatory shifts and high‑NA/EUV process requirements.
- M&A and alliance screening: spotting targets and partnership types that accelerate access to critical chemistries or regional footprint.
Key dynamics shaping BARC in 2026
Our analysis highlights five dynamics that will dominate boardroom discussions this year:
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
- Technology-led demand heterogeneity: The migration to higher‑resolution lithography (including continued EUV adoption and early high‑NA pilots) is altering specification sets for BARC chemistries. Vendors that have early compatibility with next‑generation exposure systems capture premium share and stronger co‑development relationships with leading foundries.
- Raw material and input volatility: Resin monomers and key solvent families experienced meaningful price uplifts in recent cycles. Supply tightness and an approximately mid‑single‑digit YoY increase in certain monomer costs have tightened margins for formulators who cannot pass through increases or redesign formulations quickly.
- Regulatory pressure and reformulation costs: Chemical regulation — notably restricted solvent lists under EU frameworks — forces product reformulations for any vendor selling into European fabs. Compliance timelines and reformulation R&D capacity are now core sourcing criteria for global consumers.
- Trade and logistics frictions: Recent tariff actions and route disruptions (with per‑kg surcharges on select lanes) are non‑trivial when scaled to multi‑ton annual flows. Procurement strategies must incorporate freight and tariff scenarios to avoid sudden landed cost inflation.
- Supplier concentration and capacity expansion: A small set of established chemical manufacturers dominates supply. Recent capacity investments and product launches by incumbents are accelerating the pace of change — creating windows for opportunistic entrants but raising barriers for late movers.
Competitive landscape — who matters and why
BARC is served by a mix of specialized chemical formulators and large, integrated chemical players. The market structure favors firms that combine deep lithography expertise with scale manufacturing and tight quality systems. Key competitive observations:
- Incumbents with technical depth: A handful of established suppliers are differentiated by proven process compatibility across ArF, KrF and 193nm/EUV stacks and by long-term relationships with leading foundries. These players command preferential qualification pipelines and are first to market for node‑critical chemistry changes.
- Consolidation and integration: Several legacy suppliers have been absorbed into larger specialties portfolios, enabling greater R&D investment and distribution reach. The effect is twofold — improved development velocity for complex formulations, and higher thresholds for new competitors to gain qual traction.
- Recent strategic moves: Notable market events include product introductions tailored for emerging lithography platforms and targeted capacity expansions aimed at next‑generation nodes. These developments reinforce the incumbents’ lead in supplying advanced fabs while also signaling where volume will grow over the near term.
Our full report includes detailed vendor profiles, capability matrices, and a supplier risk heatmap — information that is intentionally excluded from this preview to preserve differentiation for subscribers.
What PW Consulting’s report delivers (operational and strategic toolset)
Beyond narrative context, the study equips decision-makers with practical tools to act in 2026:
- Proprietary revenue model: A downloadable financial model that generates top‑line forecasts across multiple scenarios (base, downside, upside), with sensitivity levers for raw material price shock, tariff implementations, and adoption curves for advanced lithography.
- Supplier benchmarking: A structured scorecard covering formulation breadth, quality systems, capacity footprint, regulatory compliance readiness, and commercial terms — enabling rapid shortlists for procurement pilots.
- Scenario playbooks: Playbooks for procurement, R&D, and M&A that specify timelines, decision gates, and target KPIs tied to process yield, time-to-qualification, and landed cost thresholds.
- Regulatory and cost impact assessment: Quantitative modeling of reformulation costs and the resulting margin pressure under alternative regulatory timelines.
- Deal flow and investment screening: A prioritized list of adjacencies and target profiles for private equity or corporate M&A based on strategic fit and achievable synergies.
Strategic imperatives for 2026 — recommended actions
Based on our analysis, PW Consulting recommends that players along the value chain adopt a three‑pronged approach this year:
- Diversify sourcing with qualification speed: Contract structures should prioritize multi‑source qualification to mitigate single‑supplier risk, while paying a small premium for suppliers with proven reformulation capabilities for regulated markets.
- Invest selectively in formulation capability: For chemical producers, prioritizing R&D projects that reduce reliance on constrained monomers and deliver REACH‑compliant solvent systems will translate into commercial access and price flexibility.
- Align commercial incentives with foundry roadmaps: Suppliers who co‑develop formulations and offer predictable throughput and qualification timelines earn structural pricing power. Fabs should use milestone‑based procurement agreements to align incentives.
Implications for non‑supplier stakeholders
Foundries, OSATs, equipment suppliers and investors all have distinct actions to take in 2026:
- Foundries should integrate BARC strategy into node migration plans, ensuring chemistry supply choices do not create yield or qualification bottlenecks.
- Equipment vendors can leverage partnerships with BARC formulators to co‑validate processes and shorten integration cycles for new exposure systems.
- Investors and corporate development teams should use our M&A screening criteria to identify targets that offer both formulation IP and manufacturing scale, where value creation can be achieved through consolidation or bolt-on integration.
Conclusion — why read the full report
This preview outlines the strategic shape of the BARC market entering 2026: steady growth driven by lithography evolution, concentrated supply, and an operating environment complicated by input cost volatility, regulation, and logistics friction. PW Consulting’s full study supplies the granular segmentation, supplier-level financials, and scenario models needed to execute confident procurement, R&D, and M&A decisions. For teams tasked with protecting yield, managing landed cost, and capturing upside from next‑generation nodes, the full dataset and operational templates are indispensable.
To access the complete report, interactive models, and a tailored briefing for your executive team, visit the PW Consulting report page or contact our industry practice leads. This document is a strategic preview; granular segment tables, regional breakdowns and supplier scorecards are available only in the subscriber package.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polylactic Acid (PLA) Straw Market Set to More Than Double From USD 1.15B in 2025 to USD 2.54B by 2032, Growing at a 12% CAGR
By PW Consulting, 2026-07-16
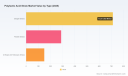
Worldwide Polylactic Acid (PLA) Straw Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Overview
As sustainability-driven regulation and fast-evolving procurement requirements reshape disposable foodservice, the polylactic acid (PLA) straw market has moved from niche alternative to strategic supply chain consideration for foodservice operators, disposable goods manufacturers, ingredient suppliers and private-label buyers. Our latest PW Consulting report — base year 2025, forecasting 2026–2032 — quantifies a market that has grown rapidly over the past five years and is projected to continue expanding at an accelerated pace. The headline: global market value moved from roughly USD 520 million in 2020 to USD 1,150 million in 2025, and is forecast to reach approximately USD 2.54 billion by 2032, reflecting a strong compound annual growth rate of about 12% through the forecast window.
Worldwide Polylactic Acid Straw Market
Why this matters for 2026 decision-makers
- Strategic purchasing: Buyers face a market with rapid demand growth and pronounced supplier fragmentation. The three- and five-firm concentration ratios indicate a low to moderate concentration level, making supplier selection and risk management central to cost and service outcomes.
- Product strategy: Material grades, extrusion-compatibility and certification status are no longer table stakes — they are differentiators in tenders and retail listings.
- Regulatory compliance: Jurisdictions with single-use plastic restrictions and compostability standards are altering product specifications and labeling requirements. Companies that align materials, certification and take-back/composting partnerships before procurement cycles will gain commercial advantage.
What the PW Consulting report delivers (practical, go-to-market tools)
We designed the report as an operational roadmap for 2026 planning cycles. Core deliverables include:
Worldwide Polylactic Acid Straw Market
- An integrated market model (historic 2020–2025, forecast 2026–2032) with sensitivity scenarios for feedstock pricing and regulatory adoption rates.
- A supplier heatmap and strategic sourcing playbook that prioritizes risk-adjusted cost, capacity growth trajectories, certification coverage and geographic sourcing risks.
- A product portfolio scorecard enabling rapid alignment of R&D and procurement objectives: extrusion performance, thermal tolerance, compostability certification and retail positioning.
- Regulatory compliance checklists and market-entry requirements by jurisdiction — practical templates for labeling, documentation and certification sequencing.
- Commercial adoption frameworks — pricing levers, channel-specific value propositions and pilot program blueprints for Q1–Q3 2026 rollouts.
- An M&A and partnership screening matrix identifying capability gaps and transaction criteria for buyers seeking to consolidate supply or secure technology differentiation.
Data-driven market trajectory (high-level)
The market’s recent trajectory makes two things clear to strategic planners: demand momentum is real, and unit economics will be strongly influenced by upstream feedstock dynamics and capacity additions. Our model shows market value more than doubling over the forecast horizon, underpinned by continued regulatory substitution away from fossil-based single-use plastics and growing commercial adoption among foodservice and retail brands. However, growth is lumpy and subject to short-term feedstock price shocks and localized policy shifts — factors we stress-test in three scenarios included in the report.
Worldwide Polylactic Acid Straw Market
Competitive landscape — what incumbents and challengers are doing
The competitive landscape remains fragmented with a mix of resin producers, converter-specialists and vertically integrated players. Key strategic moves observed among industry participants point to an emphasis on resin capacity, tailored grades for extrusion, and certification.
- TotalEnergies Corbion — leveraging its Luminy PLA portfolio to offer extrusion-optimized grades. Recent product launches geared to improve clarity and strength signal an approach focused on converting performance risk into commercial advantage for converters and brand owners.
- NatureWorks — continues to pursue capacity expansion to meet compostable-product demand, with investments signaling confidence in sustained market growth. Capacity moves will materially affect mid-term resin availability and pricing dynamics.
- Biome Bioplastics — concentrating on certification and compliance for foodservice applications, reinforcing the critical role of validated end-of-life claims in buyer adoption.
- Regional converters and brands (including players from India and the US) are building product portfolios for both domestic consumption and export, but face cost differentials driven by feedstock availability and trade barriers.
Collectively, these dynamics suggest an industry where upstream resin innovation and downstream conversion capability are both source points of competitive advantage. Our company profiles and strategic assessments in the report provide scenario-based supplier shortlists and negotiation levers tailored for both procurement and corporate development teams.
Supply chain and cost dynamics
Feedstock volatility and logistics constraints are the dominant near-term economic drivers. Agricultural yield variability and supply chain disruptions have pushed feedstock costs higher in recent cycles, while regional trade measures have introduced location-specific cost premiums for import-reliant buyers. At the same time, announced capacity expansions at major resin manufacturers create a timeline for potential easing — but the market will likely overshoot and undershoot as new capacity comes online and converters re-tool.
For procurement teams, the implications are straightforward: implement dynamic contract structures with indexed pricing components, diversify supplier pools across origin and process technology, and prioritize long-term partnerships that include co-investment in recycling or composting infrastructure.
Regulation, certification and infrastructure realities
Regulation is both a tailwind and a constraint. Single-use plastic bans and compostability standards have accelerated PLA adoption in several markets, but compliance requirements differ by jurisdiction and are dependent on the availability of industrial composting capacity. For manufacturers and retailers, certification timing and aligned waste-stream partnerships are prerequisite investments for successful market rollouts.
Strategic actions we recommend for 2026
- Align procurement cycles with capacity timelines. Use the report’s capacity roadmap to phase offtake agreements and minimize exposure to spot feedstock spikes.
- Reassess product specifications through an “extrusion-to-end-of-life” lens. Prioritize PLA grades that reduce conversion line changeover costs and satisfy key market certifications.
- Negotiate multi-dimensional contracts: combine pricing collars, volume flexibility and technical support clauses to manage production ramp risks.
- Invest selectively in local composting partnerships and labeling programs to close the end-of-life claim loop — this reduces customer friction and supports premium positioning.
- Consider bolt-on M&A or strategic partnerships to secure specialty conversion capabilities or regional distribution, particularly where tariffs or logistics create structural cost gaps.
Key risks and scenario planning
We detail three actionable scenarios in the report: a favorable adoption path with stable feedstock pricing, a volatile supply shock scenario driven by agricultural disruption, and a protectionist trade environment that raises import parity prices for certain origin markets. For each scenario we provide contingency plays — from hedging and inventory strategies to targeted capacity investments and geographic diversification — so executives can operationalize risk mitigation in 2026 planning cycles.
Why PW Consulting’s analysis is different
Our approach combines a market-sizing engine with operational playbooks and supplier-level intelligence. That means decision-makers get both the why (market drivers, regulatory vector) and the how (contract templates, pilot designs, R&D prioritization). Importantly, the report is built to be actionable: spreadsheet-ready models, negotiation playbooks and an M&A screening matrix are provided to accelerate implementation.
Next steps
If your 2026 strategy depends on reliable supply, defensible certification claims, or a clear commercialization path for compostable straws, the intelligence and tools in our report will materially shorten your decision cycle. To preserve commercial sensitivity and to drive direct engagement, we present high-level findings here and retain detailed subsegment-level datasets, region-by-region pricing and the supplier heatmap in the full report.
Contact PW Consulting to request the full Worldwide Polylactic Acid Straw Market report, the underlying models and a bespoke briefing session tailored to your role — procurement, R&D, corporate development or investor relations.
For detailed analysis of this topic, please visit the official page: Worldwide Polylactic Acid Straw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Shielding the Future: PW Consulting Forecasts Industrial-Grade Borated Polyethylene Market to Reach USD 309.07 Million by 2032 at a 5.18% CAGR
By PW Consulting, 2026-07-16
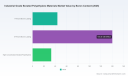
Industrial Grade Borated Polyethylene Materials Market: Strategic Outlook for 2026 — PW Consulting Release
PW Consulting today publishes an executive overview of our new market research report on Industrial Grade Borated Polyethylene Materials, offering a focused briefing for executive teams preparing strategy and capital-allocation decisions in 2026. The analysis distils a complex, technically driven market into the strategic choices that will matter this year — from procurement and product roadmaps to M&A and regulatory compliance — while preserving the full, model-level detail behind a secure paywall.
Industrial Grade Borated Polyethylene Materials Market
Why this report matters for 2026 decisions
-
Macro clarity in a niche, safety-critical market: Our base-year sizing shows that the borated polyethylene market crossed the USD 200 million mark in 2024 and reached approximately USD 217 million in 2025, growing to an estimated USD 226 million in 2026. From a structural perspective, the market follows a steady mid-single-digit expansion with a compound annual growth rate (CAGR) of roughly 5.18% over the forecast window through 2032.
Industrial Grade Borated Polyethylene Materials Market -
Timing matters: For corporates and buyers renewing long-lead shielding contracts, 2026 is a planning inflection—capital projects in nuclear, medical radiation facilities, defense, and advanced research expect multi-year procurement cycles. Our report translates forecast trajectories into procurement windows and supplier-selection signals for immediate action.
Industrial Grade Borated Polyethylene Materials Market -
Risk and opportunity are concentrated: Market concentration metrics demonstrate that leading firms command a meaningful share of sales — a three-firm concentration ratio and a five-firm concentration ratio indicate a market where global and regional champions set technical standards, but specialized players and new entrants can still capture niche value through process or formulation differentiation.
Data-driven view without the noise
This briefing synthesizes the aggregated market scale and growth path so senior leaders can calibrate budgets and strategic bets. We deliberately present the high-level market trajectory and structural indicators while withholding granular regional and application splits from the public summary — those granular allocations are included in full within the primary report and the data pack available via the report landing page.
What the full report delivers (practical, operational, and executable)
-
Validated market sizing and forward model: Year-by-year historicals (2020–2025) and a detailed forecast (2026–2032) with scenario sensitivity to raw-material and regulatory shifts.
-
Supplier and technology matrix: Independent profiles and comparative scorecards for incumbent manufacturers and major fabricators, ranked on technical capability, certifications, geographic reach, and custom-fabrication services.
-
Procurement playbook: Tender design templates, quality-spec checklists (including reference to military and nuclear-grade specifications), and a total cost of ownership model that incorporates material composition, machining losses, transport and handling, and lifespan factors.
-
Product development guidance: Benchmarks for boron-loading strategies, trade-offs among hydrogen density, mechanical properties, and long-term aging; roadmap options for high-concentration polymers and compound formulations that address criticality control, weight, and manufacturability.
-
Regulatory and compliance compendium: Cross-reference of military and nuclear standards that commonly apply to borated polyethylene in naval and commercial installations, and a risk-mitigation checklist for certification pathways.
-
Commercial scenarios and M&A framework: Valuation levers for bolt-on acquisitions and strategic partnerships, informed by concentration dynamics and margin drivers in fabrication, distribution and system-integration services.
-
Raw material and cost dynamics: Forward-looking assessment of feedstock availability, premium differentials for higher boron-content products, and practical recommendations for hedging and supplier diversification.
Key market dynamics shaping 2026 strategy
-
Steady end-market demand: Growth is driven by ongoing capital investments in nuclear maintenance and new builds, expansion of medical radiotherapy capacity, continued activity in research facilities and defense programs, and lifecycle replacements in long-duration storage systems. These demand pools create predictable volume corridors that favor suppliers with reliable sourcing and certified quality systems.
-
Certification and spec-driven procurement: Compliance with established military and nuclear specifications is a gating factor. Buyers increasingly require documented traceability, certified boron loadings, and evidence of aging performance — creating premium opportunities for suppliers that sustain accredited production and testing capabilities.
-
Material-cost and formulation premium: High-boron or specialty formulations command higher margins but come with technical and capital-intensity implications in compounding and fabrication. Procurement teams must balance the performance premium against lifecycle and weight constraints.
-
Concentration creates tactical pathways: With the market neither fully consolidated nor atomized, mid-sized specialist suppliers can capture share through service differentiation (rapid cutting, stocking, on-site fabrication) and geographic responsiveness, while larger manufacturers defend through scale, spec leadership and channel relationships.
Competitive landscape — what to watch in 2026
Our supplier analysis highlights a set of vendors that typify different strategic postures in the market:
-
Technical-brand leaders with specification focus: Firms that have built recognized product lines and proprietary processes, meeting demanding flatness, dimensional, and military/nuclear standards. These players leverage trademarked offerings and production processes to command specification-driven contracts.
-
Service-oriented fabricators: Companies combining inventory management, CNC/water-jet cutting, and custom machining to serve laboratories, hospitals and research facilities requiring bespoke shielding geometries and quick turnarounds.
-
High-volume, configurable manufacturers: Producers with capability to vary boron concentration across a range of products and to export at scale. Their strategic advantages include flexible bill-of-materials, cost-effective compounding and established distribution channels.
-
Global entrants and contract manufacturers: Firms from lower-cost jurisdictions that gain traction through competitive pricing and the ability to meet standard grades; their growth often depends on achieving accredited testing and establishing regional stocking facilities.
Representative firms evaluated in the report include established North American technical suppliers, Canadian specialists with strong service portfolios, U.S.-based fabricators with military/nuclear certifications, and China-based compounding manufacturers offering broad boron-loading options. Each is scored across capability, certification, service, and scale metrics to guide sourcing and partnership decisions.
Recent industry developments to factor into 2026 plans
-
Trade-show visibility and market signaling: Leading manufacturers are using industry events to showcase product variants and to reassert brand positioning to procurement audiences.
-
Strategic partnerships and advocacy: Suppliers are aligning with nuclear industry initiatives and national programs to secure pipelines tied to reactor lifecycles and refurbishment campaigns.
-
Specification anchoring: Industry references to established military and NRC guidance continue to anchor product acceptance and define minimum procurement requirements; proactive conformance to these standards shortens sales cycles.
Actionable recommendations for 2026
-
Re-scope 18–36 month procurement plans to reflect stable mid-single-digit market growth: Lock in multi-year supply arrangements now to secure capacity and avoid premium surges as projects ramp.
-
Prioritize supplier certification as a selection criterion: When performance and price are comparable, certified traceability and compliance with recognized standards reduce project risk and schedule slippage.
-
Deploy a dual-sourcing strategy for critical formulations: Combine a specification-leading incumbent for high-certainty lots with a flexible, lower-cost supplier for volume buffering and contingency supply.
-
Assess value-accretive M&A and commercial partnerships: Buyers with fabrication and logistics capabilities can expand margin capture and shorten lead-times by integrating downstream services.
-
Incorporate material-ageing and lifespan modeling into capital planning: Design replacement cycles and warranty structures that reflect conservative hydrogen-density degradation assumptions used in regulatory safety cases.
How to use the full PW Consulting report
The public briefing you are reading is intended as a strategic roadmap: it signals where the market is headed and which decisions matter in 2026. For procurement teams, engineering leaders and corporate strategists requiring the granular inputs — including regional demand allocations, application-level forecasts, price-sensitivity matrices and the complete supplier scorecard — the full report and the underlying data set are available via our report portal.
Access to the full materials enables you to:
-
Run scenario analyses on supplier mix and boron-loading strategies;
-
Quantify potential cost savings from consolidation or insourcing;
-
Map certification gaps against contract requirements; and
-
Build defensible, board-ready justification for capital allocation and M&A activity tied to shielding component value chains.
Closing: Strategic inference without revealing the playbook
As 2026 unfolds, the borated polyethylene market offers incremental expansion and concentrated pockets of premium margin for firms that combine certified production, fabrication services and supply reliability. PW Consulting’s report packages the technical, commercial and regulatory intelligence you need to convert that macro trajectory — a market now surpassing the USD 200 million threshold and growing at roughly a 5.18% CAGR across the forecast — into defensible strategic moves. For the full dataset, supplier scorecards and executable procurement templates, please request access to the complete report via our website.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Microbial Fuel Cell Market Set to Expand at an 11.25% CAGR Through 2032
By PW Consulting, 2026-07-16
PW Consulting: Strategic Preview — Worldwide Microbial Fuel Cell Market (2026 Outlook)
PW Consulting today publishes an executive preview of our forthcoming Worldwide Microbial Fuel Cell (MFC) Market report — a focused intelligence product designed to inform corporate strategy, procurement, and investment decisions entering 2026. Drawing on a rigorous historical analysis (2020–2025) and a detailed 2026–2032 forecast horizon, the study synthesizes technological maturity, regulatory drivers, supply‑chain economics, and competitive positioning to create a practical playbook for C-suite and business‑unit leaders exploring MFC commercial opportunities.
Worldwide Microbial Fuel Cell Market
Top‑line trajectory: what the numbers mean for planning
The microbial fuel cell market has moved beyond academic curiosity into commercially relevant pilots and early deployments. Our base‑year analysis shows industry revenue rising steadily over 2020–2025, culminating at USD 17.65 million in 2025. We project the market to reach USD 19.93 million in 2026 and expand to USD 37.23 million by 2032, corresponding to a compound annual growth rate (CAGR) of 11.25% across the forecast period. These topline dynamics reflect a compound response to three simultaneous forces: regulatory emphasis on energy‑efficient wastewater treatment, incremental improvements in electrode and reactor engineering, and a growing set of viable use cases beyond pure research demonstrations.
Worldwide Microbial Fuel Cell Market
For decision‑makers, these macro trajectories translate into a narrow window to capture first‑mover advantages in productized applications, secure strategic supply ties, and shape deployment standards before the market consolidates. Market concentration today is moderate: the three largest players account for roughly 38.5% of reported commercial activity, while the five leading participants represent just over half of market engagement — a structure that favors alliances, roll‑up strategies, and targeted IP licensing.
Worldwide Microbial Fuel Cell Market
Why 2026 is a pivotal year for corporate strategy
-
Regulatory inflections. Energy‑efficiency mandates in key jurisdictions are starting to include technology‑neutral criteria that reward resource recovery and low‑footprint secondary treatment options. Companies that position MFCs within broader wastewater decarbonization and energy‑recovery programs will unlock public‑sector procurement and subsidy pathways.
-
From pilot to scale-ready validations. The commercial constraint that currently limits many MFC deployments to pilot installations — notably electrode fouling and historically low sustained power output — is being actively addressed by a new generation of continuous‑flow reactor designs and maintenance protocols. Those who run high‑quality, metric‑driven pilots in 2026 will have the empirical basis to negotiate first commercial contracts in 2027–2028.
-
Supply‑chain windows. Critical inputs such as carbon cloth electrodes have transparent unit pricing in catalog markets today (a market reference range is approximately USD 45–75 per m²). Early procurement and inventory hedging can materially influence project unit economics during the transition from pilot to multi‑site deployment.
Market dynamics shaping strategy and capital allocation
Three operational dynamics will determine winners and losers:
-
Performance envelope. Recent lab‑to‑field demonstrations report continuous‑flow MFCs achieving power densities up to 5 W/m³ in wastewater reactors — a performance threshold that changes the calculus for onsite energy recovery and hybridization with other low‑grade energy systems. Targeting that envelope through design iterations and adaptive control strategies should be a near‑term R&D priority for vendors and integrators.
-
Cost and modularity. Modular, containerized architectures that simplify commissioning and maintenance are rapidly emerging as the preferred commercial form factor. Modularization reduces perceived deployment risk for municipal and industrial buyers and enables standardized service agreements.
-
Regulatory alignment. Jurisdictions with explicit urban wastewater efficiency mandates create a pricing premise for MFCs by valuing lower lifecycle energy consumption. Strategic market entries should prioritize territories where procurement rules and subsidy mechanisms align with resource‑recovery business cases.
Competitive landscape — strategic implications from incumbent & specialist players
The MFC ecosystem today is a mix of small specialists and engineering integrators. Our research profiles the companies currently shaping commercial narratives and technology roadmaps:
-
Aquacycl Ltd. (Didcot, UK) — developing USABR™ bioelectrochemical reactors focused on energy recovery from high‑strength industrial wastewater. Strategic implication: Aquacycl demonstrates how verticalized reactor engineering tailored to concentrated streams can create clear commercial paybacks for industrial off‑takers.
-
Plant‑e B.V. (Wageningen, Netherlands) — commercializing plant‑microbial fuel cell systems that harvest electricity from rhizosphere organic matter. Strategic implication: Plant‑e showcases niche, decentralized generation use cases (e.g., sensor power, micro‑grids) that open non‑utility procurement channels and unique revenue overlays.
-
Microbenergy S.L. (Valladolid, Spain) — producer of BEE‑BOX® modular MFC units for decentralized wastewater treatment and concurrent electricity generation. Strategic implication: Microbenergy highlights the importance of plug‑and‑play productization and repeatable O&M models for municipal micro‑projects.
-
Nijhuis Saur Industries (Doetinchem, Netherlands) — offering BeeVe® membrane‑free bioelectrochemical systems based on MFC principles for COD removal and energy production. Strategic implication: Established water engineering firms entering the space accelerate the path from pilot contracts to large municipal projects via existing client relationships.
Collectively, these players illustrate different viable go‑to‑market routes: specialization in concentrated industrial streams, novel biological integration for off‑grid power, productized modular units for decentralized sanitation, and incumbent engineering houses leveraging client portfolios. Competitive advantage will accrue to firms that pair robust field evidence with scalable service models and protected IP around electrodes, reactor geometries, and maintenance diagnostics.
Commercialization roadmap — practical guidance for 2026 decision cycles
-
Pilot prioritization: Select pilot sites that maximize learning in parameters that materially affect LCoE (loading variability, solids handling, salinity). Define KPIs: continuous power density, COD removal, maintenance interval, and O&M cost per m³.
-
Procurement & supply security: Lock short‑term contracts for critical consumables (e.g., carbon cloth) and explore dual‑sourcing to mitigate price and lead‑time volatility.
-
Partnerships & bundling: Engineer partnerships with water utilities, EPCs, and specialized integrators to convert pilots into performance‑tied service agreements rather than one‑off sales.
-
IP & differentiation: Prioritize IP filings around reactor scaling techniques, anti‑fouling strategies, and automated maintenance protocols — these are likely to be the primary value drivers as the market consolidates.
-
Investment sizing: Use staged investment approaches (seed → demonstrator → commercial) tied to milestone gating based on field KPI attainment to limit capital exposure while preserving upside.
Report scope — what’s included (and what we withhold in this preview)
Our full report is structured to serve operational and investment audiences with actionable tools and plug‑and‑play templates. Key deliverables include:
-
Time‑series market sizing and modeled forecasts (2026–2032) with scenario analysis and sensitivity runs.
-
Technology segmentation and maturity mapping across reactor types and application verticals, with engineering performance benchmarks.
-
Supply‑chain cost build‑ups and procurement playbooks (including raw material price references and implications for project economics).
-
Company dossiers and strategic option matrices for market participants, including M&A candidate screening and partnership archetypes.
-
Regulatory landscape assessment and project‑level subsidy/permit implications in priority jurisdictions.
-
Operational checklists, pilot KPI templates, contract clause illustrations, and sample project‑level NPV models.
To preserve exclusive commercial value for subscribers, the preview intentionally omits granular subsegment tables and downloadable datasets (e.g., application‑level revenue breakdowns and region‑by‑region dollar splits). These detailed analytics are available only in the full report and dataset package.
FAQs — technical constraints and mitigations
-
Are MFCs commercially ready today? MFCs are commercially viable for targeted use cases and controlled sites. However, many deployments remain at pilot scale; industry data indicates pilot installations are generally under 1 kW due to electrode fouling and sustained power output challenges. Successful commercialization depends on demonstrated long‑run reliability and maintenance economics.
-
What are the cost levers? Key levers are electrode materials, reactor modularity, and O&M cadence. Current catalog pricing provides a reference point for carbon cloth and similar materials, and engineering choices around replaceability and cleaning regimes have outsized impacts on lifecycle cost.
-
Which performance benchmarks matter? For wastewater energy recovery applications, power density in continuous operation and stable COD removal rates are decisive. Recent technical briefings cite continuous‑flow reactor power densities approaching the multi‑W/m³ range as meaningful thresholds for commercial consideration.
Concluding recommendations for 2026 planning cycles
For executives and investment committees, the strategic imperative in 2026 is to convert exploratory curiosity into evidence‑based positioning. That means: run focused pilots that generate repeatable KPIs; secure supply‑chain exposure for critical materials; negotiate partnerships that reduce go‑to‑market friction; and preserve optionality through staged capital commitments. Companies that rigorously manage these vectors — balancing technical validation with commercial integration — will be best placed to capture disproportionate value as the market grows at an expected CAGR of 11.25% through 2032.
For a full breakdown of segment models, downloadable datasets, country‑level regulatory maps, and proprietary competitor scorecards, access the complete Worldwide Microbial Fuel Cell Market report from PW Consulting or contact our report team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Microbial Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Parallel Weld Heads Market to Expand at a 6.24% CAGR (2026–2032), Reaching USD 294.06 Million by 2032PW Consulting: Worldwide Breathable Waterproof Fabrics Market to Reach USD 12,874.4 Million by 2032, Growing at a 7.5% CAGR
By PW Consulting, 2026-07-16
Worldwide Parallel Weld Heads Market — Strategic Imperatives for 2026
PW Consulting today releases a strategic preview of our upcoming Worldwide Parallel Weld Heads Market report, a practitioner-focused study designed to inform boardroom and operational decisions throughout 2026. Using 2025 as the base year, our analysis shows the market has expanded meaningfully over the past half-decade (from roughly USD 145 million in 2020 to approximately USD 192.5 million in 2025) and is projected to grow at a compound annual growth rate of 6.24% through the 2026–2032 forecast window, reaching roughly USD 294 million by 2032. This release is a curated executive briefing: it surfaces the trends, risks, and pragmatic levers that will determine competitive advantage next year while directing technical and procurement stakeholders to the full report for the underlying segment tables and supplier-level data.
Worldwide Parallel Weld Heads Market
Why this matters in 2026: from capital allocation to product roadmaps
Parallel weld heads — specialized tooling that enables micro resistance spot welding where access is constrained — are increasingly strategic components in manufacturing lines that underpin electrification, miniaturized medical devices, and high-volume electronics. The expected mid-single-digit CAGR and near-term demand trajectories translate into tangible implications for capital planning, supplier management, and product roadmaps. For executives, three decision horizons crystallize for 2026:
Worldwide Parallel Weld Heads Market
- Short-term operations: inventory, consumables, and supplier continuity playbooks to mitigate raw-material shocks and line downtime.
- Medium-term capacity: selective automation and tooling investments to capture rising volumes without compromising precision.
- Strategic M&A and partnerships: bolt-on capabilities or distribution arrangements to secure access to critical micro-welding technologies and aftermarket consumables.
Market dynamics creating the 2026 operating environment
Our field research and primary interviews identify a small set of amplifying forces that will shape vendor economics and buyer strategies in 2026:
Worldwide Parallel Weld Heads Market
- Electrification-driven demand: Battery pack manufacturing and other electrification use cases continue to push precision micro-welding into the manufacturing critical path. Parallel gap (series) welding remains the practical solution when access is limited to one side of a joint, reinforcing the tool’s strategic value in many assembly flows.
- Raw-material volatility: Copper and specialty alloy price swings — a direct effect of “the electrification of everything” — have already introduced procurement pain. Industry sources indicate that broader consumables markets experienced notable contract disruptions, with a meaningful proportion of procurement agreements affected and alloy wire lead times extending materially. These conditions increase the operating cost volatility for both suppliers and line operators.
- Integration of multi‑technology workflows: Manufacturers are combining resistance welding, laser and hybrid processes to achieve throughput and quality objectives. Vendors and integrators who enable clean, modular integration are winning OEM specifications and system-level contracts.
- Regulatory and quality expectations: Sectors such as medical, automotive and aerospace continue to demand traceability, repeatability and validated process controls, increasing the value of weld heads that support robust measurement, feedback and easy calibration.
Technology and product trends to watch
In 2026, competitive differentiation will increasingly come from three technical directions:
- Low‑force precision models — electromagnetic and micro linear motion heads that enable welding of delicate foils and fine wires — will be essential for advanced cells and sensors.
- Pneumatic and motorized systems that prioritize operator ergonomics and repeatability will continue to be the backbone for many high-volume assembly lines.
- Modularity and integration readiness — mechanical interfaces, electrical controls, and software APIs — are now explicit procurement requirements, not nice‑to‑haves. Suppliers offering validated integration kits or proven compatibility with capacitive discharge and laser sources will enjoy shortened qualification cycles.
Competitive landscape — who to watch (and why)
The parallel weld heads ecosystem is a mixture of specialized manufacturers, integrators/distributors, and technology suppliers. Our market conversations and technical desk research identified several companies that are shaping product availability and application development:
- Sunstone Welders (Payson, Utah, USA — https://www.sunstonewelders.com): A primary manufacturer of parallel weld heads, Sunstone’s pneumatic and manual WH2 / WH2125 series are commonly specified for battery tab welding, pack assembly and fine wire/foil operations. The firm has recently broadened its positioning with public-facing product comparisons and partnerships with research institutes to accelerate micro-welding adoption.
- AMADA WELD TECH (Monrovia, California, USA — https://amadaweldtech.com): An established supplier offering a full line of resistance weld heads and actuators (motorized, servo, pneumatic and manual) used across electronics, medical and automotive applications; recognized for technical depth in series/parallel gap welding configurations.
- TJ Snow (Chattanooga, Tennessee, USA — https://tjsnow.com): A distributor and systems integrator of parallel weld heads, known for packaging micro-heads into capacitive discharge systems for battery pack manufacturing and micro-joining lines.
- Advanced Integrated Technologies (A-I-T) (Arizona, USA — https://www.a-i-t.com): A supplier that distributes Sunstone micro weld heads, including electromagnetic linear motion models designed for very low-force welding—critical in precision micro-joining.
- C-Welding (Distributor — https://www.c-welding.com): A distribution partner that connects parallel weld head manufacturers to aerospace, automotive, electronics and medical customers, often handling application engineering and aftermarket support.
Recent vendor activity underscores the shift toward integrated workflows and collaborative R&D: Sunstone published a benchtop laser welder comparison in August 2025 highlighting integration options, and previously announced partnerships with AWS RWMA and EWI to accelerate applied research and process validation. These moves are emblematic of a broader pattern: suppliers are not only selling hardware, they are offering validated process ecosystems.
Supply‑chain risk and procurement playbook for 2026
Procurement teams should expect tighter coupling between consumables availability and machine uptime. Based on our supplier interviews and market monitoring, important operational countermeasures include:
- Dual-sourcing critical electrodes and alloy wire with geographically diverse suppliers to reduce single‑point risks instigated by raw-material price shocks.
- Implementing short-cycle hedging or price-pass clauses for copper-linked consumables where feasible, and adopting a rolling safety-stock policy tied to lead‑time variability.
- Negotiating service-level agreements that include process support, spare-part kits and rapid calibration services to protect line yield during qualification ramp-ups.
What PW Consulting’s full report delivers (practical, actionable content)
The full report — built for procurement directors, operations VPs and product managers — combines quantitative market sizing with tools that translate insight into action. Highlights include:
- Clear methodology and confidence envelopes for demand projections, including upside/downside scenarios and sensitivity to commodity swings.
- Buyer’s guides and a supplier scorecard that evaluate vendors on integration readiness, application breadth, aftermarket economics and service coverage.
- Technical maturity maps for parallel weld head variants and an implementation playbook that prescribes qualification checkpoints for medical, battery and aerospace deployments.
- Operational tools: a life‑cycle TCO calculator, consumables consumption models, and an RFx template tailored to micro-welding equipment acquisitions.
- M&A and partnership screening matrices: early‑warning indicators for targets that deliver strategic access to technology or regional channels.
To preserve the report’s value as a decision-making asset, the full segment tables, regional splits, exact supplier share estimates and downloadable models are available only with the complete product. This briefing is intentionally high‑signal but non-exhaustive — designed to help executives prioritize the deeper analyses they should commission first.
Practical strategic recommendations for 2026
- Align capital expenditure cycles to validated use cases: prioritize purchases where validated TCO and quality improvements are documented rather than speculative capacity buys.
- Insist on integration proof: require vendors to provide validated integration packages and sample process recipes for your cell/pack designs as part of the purchase agreement.
- Lock in consumables and spares strategies: negotiate combined equipment-and-consumables contracts with performance clauses to stabilize costs and supply.
- Invest in low‑force micro‑weld capability where product lines include delicate foils, sensors or thin tab material—this reduces scrap and inspection overhead.
- Establish a short-list of qualified integrators: global OEMs will favor suppliers who can provide turnkey installation, operator training and traceability systems.
- Scan for partnership and tuck‑in targets: evaluate small toolmakers and regional distributors for acquisition to accelerate market access or secure aftermarket streams.
Closing note — how to use this preview
For 2026, parallel weld heads are more than a purchase order line item; they are a lever for line yield, product differentiation and aftersales revenue. PW Consulting’s forthcoming report provides the granular data, supplier assessments and executable tools that procurement and operations teams need to de‑risk expansion and extract value from the market’s projected growth. Access the full dataset and downloadable toolset to review the detailed segment and regional analytics that informed this briefing.
To obtain the complete Worldwide Parallel Weld Heads Market report and model pack, or to commission a tailored advisory engagement (scenario planning, supplier on‑boarding playbook, or M&A diligence), contact PW Consulting’s Advanced Manufacturing practice.
For detailed analysis of this topic, please visit the official page: Worldwide Parallel Weld Heads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Insect Repellent Supplies Market Reaches USD 4,850 Million in 2025, Poised for 6.3% CAGR Through 2026–2032
By PW Consulting, 2026-07-16
Worldwide Insect Repellent Supplies Market — Strategic Outlook for 2026
PW Consulting’s new market study on Worldwide Insect Repellent Supplies offers a pragmatic and forward-looking roadmap for commercial leaders planning for 2026. Built on a comprehensive historical panel (2020–2025) and a detailed forecast (2026–2032), the report quantifies a market that reached USD 4,850 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.3% over the forecast window. By 2026 the market is forecast to cross the USD 5.2 billion threshold, with a multi-year trajectory that points to sustained expansion through 2032. This release is purpose-built to convert strategic uncertainty into concrete choices: product investments, supply-chain commitments, regulatory positioning, and M&A prioritization.
Worldwide Insect Repellent Supplies Market
Why this report matters for 2026 decision-making
-
Actionable, not academic: The study is designed for executives and investors who must make resource-allocation choices in 2026. It translates market momentum and regulatory shifts into investment levers — R&D priorities, capacity planning, channel strategy, and acquisition targets — with scenario-based financial implications.
Worldwide Insect Repellent Supplies Market -
Risk-aware playbooks: We map supplier concentration, active-ingredient availability, and regulatory touchpoints into a supplier-risk matrix and procurement playbook that guide near-term sourcing (spot vs. contract) and hedging strategies for key actives.
Worldwide Insect Repellent Supplies Market -
Commercial execution focus: The report contains go-to-market modules tailored to different product formats and route-to-customer models (retail, e‑commerce, professional pest management), enabling commercial teams to convert category growth into margin-accretive revenue.
Market trajectory and strategic takeaways
The insect repellent supplies market shows steady recovery and acceleration following the early-2020s volatility. After consistent expansion during 2020–2025, 2025 marked a pivotal base year (USD 4,850M) from which the market enters a structurally stronger phase. The stated 6.3% CAGR reflects a combination of secular and tactical drivers: rising consumer awareness of vector-borne diseases, expanded travel and outdoor recreation, growing adoption of spatial repellents and rechargeable devices, and a notable premiumization trend toward higher-value formats and natural formulations.
Strategic implications for 2026:
-
Prioritize portfolio balance — platforms that combine durable hardware (spatial devices, rechargeable units) with consumables create recurring revenue opportunities and higher lifetime value.
-
Invest selectively in natural active ingredients and clean-label positioning. Consumer demand for plant-based solutions is real, but efficacy, supply security, and regulatory acceptance must be validated in market-specific pilots.
-
Embed regulatory scenario planning in product roadmaps. Efficacy testing requirements and labeling constraints increasingly shape time-to-market and promotional claims.
Competitive landscape — what executives need to know
The market exhibits moderate concentration: the three-largest firms account for a meaningful share of global value, while the top five consolidate well over half of the total industry revenue. That concentration creates a two-speed competitive environment — scale incumbents that leverage global brands and distribution, and nimble specialists that capture niche technical or channel advantages.
-
Reckitt Benckiser Group plc — Global brand reach and multi-format strength (topical and spatial) make it the benchmark for integrated brand-to-shelf execution. Expect continued investments in marketing and geographic expansion strategies.
-
S.C. Johnson & Son, Inc. — Deep expertise in spatial repellents and recent capacity investments in regions like East Africa highlight a playbook focused on local manufacturing to serve growth markets cost-effectively.
-
Spectrum Brands & Sawyer Products — These players differentiate via product performance claims (DEET, picaridin, performance formulations) and outdoor/specialist channels; they represent aggregation targets for mainstreaming high-efficacy formulations.
-
Godrej Consumer Products & Dabur India — Strong regional scale and portfolio breadth in household and herbal segments make them important partners or competitors in emerging markets where household coils, sprays and lotions remain the largest consumption vectors.
-
Thermacell & Coghlan’s — Device-led and outdoor-specialist incumbents are capturing consumer interest with usability and battery-life improvements; these firms are attractive acquisition targets for consumer-goods players seeking hardware-consumable models.
-
Specialists and ingredient suppliers (Citrefine, LANXESS/Saltigo, Sumitomo) — Control of key actives (natural PMD/Citriodiol and synthetics like picaridin) underpins formulation capability and time-to-market across regions.
Recent corporate moves underline predictable strategic patterns: upstream consolidation and capability builds, faster product innovation cycles, and targeted capacity expansions in high-growth markets. Notable developments include a major agricultural/biological player acquiring biological-control capability, new DEET‑free consumer launches, capacity expansions in Africa by a leading household-goods manufacturer, and refreshed device launches with longer battery life. These moves confirm that both ingredient innovation and device convenience will be focal battlegrounds through 2026.
Regulatory and raw-material dynamics that will shape 2026
-
Testing and claims: U.S. regulatory guidance now specifies standardized efficacy testing against key mosquito genera for skin-applied repellents; compliance pathways and dossier preparation affect launch timelines and commercial claims.
-
Labeling nuances and age advisories: Specific provisions around certain natural actives create differentiated labeling and positioning opportunities in family-oriented segments. Understanding these nuances is critical to packaging and marketing strategy.
-
EU biocidal approvals: Ongoing dossier requirements under EU frameworks create a barrier to rapid launches in Europe and favor companies with regulatory dossier management capabilities or partnerships with specialist suppliers.
-
Active-ingredient supply: Citriodiol® (lemon-eucalyptus based PMD) and picaridin (Saltidin®/Icaridin) remain strategically important inputs. Securing reliable supply, validating alternative suppliers, and planning for long lead-times are immediate procurement priorities.
What the PW Consulting report delivers — practical modules
Our report is intentionally operational. It combines strategic high-level insight with tools and templates that teams can apply directly in 2026 planning cycles. Key modules include:
-
Executive summary and investment thesis tailored for C-suite briefings.
-
Segment- and country-level scenario models (base, upside, downside) with sensitivity analysis for pricing, raw-material cost swings, and regulatory-delay assumptions.
-
Commercial playbooks by channel and product format (topical, spatial devices, coils/mats, wipes), including sample promotional mixes and margin roadmaps.
-
Supplier and ingredient risk matrix with recommended contracting strategies for Citriodiol, picaridin, pyrethroid inputs, and emerging biological actives.
-
M&A shortlist and diligence checklist for targets that accelerate route-to-market, add device IP, or secure active-ingredient control.
-
Regulatory action plan and dossier checklist for U.S. and EU pathways, plus label-risk heatmap for family/children claims.
-
Operational capacity and capex playbook to size manufacturing and fill/finish needs for different growth scenarios.
-
Excel-based financial model you can plug your P&L assumptions into, and KPI dashboard templates for go/no-go decision gates.
Importantly, while the report surface-level narratives highlight regional and segment directionality, the detailed segmented forecasts, country-by-country allocations, and granular pricing curves are intentionally reserved for the full report. This “trailer” approach ensures executives see the strategic shape and tools, and can then access the underlying data for transaction- or plant-level decisions.
Actionable recommendations for 2026 planning
-
Secure strategic raw-material positions: Negotiate supply agreements and optionality for PMD and picaridin; evaluate vertical integration where margins justify capital.
-
Prioritize device-plus-consumable business models: Invest in rechargeable spatial devices and consumable cartridges to lock in recurring revenue and consumer stickiness.
-
Accelerate label- and claim-compliant natural product pilots in target markets, with RCT-style field efficacy validation to support premium pricing.
-
Embed regulatory timelines into product launch gates: Use dossier milestones as gating criteria for marketing spend and distribution ramps.
-
Consider bolt-on acquisitions to acquire biological-control expertise or device IP; M&A can be a faster route to diversify away from single-active reliance.
Next steps — how to use this study
For strategy teams, the study is a decision-ready document: use the included scenario models in budget planning, deploy the supplier-risk heatmap in procurement negotiations, and apply the channel playbooks to refine 2026 commercial investment. For investors and M&A teams, the report’s diligence appendices and target shortlists accelerate transaction screening and valuation work.
To review the full dataset, segmented forecasts, and to obtain the proprietary Excel models and playbooks described here, access the complete Worldwide Insect Repellent Supplies Market report on PW Consulting’s report page. The full report contains the granular regional, product-format and channel splits required for transaction-level decisions, along with the primary-source annexes and dossier templates referenced above.
For detailed analysis of this topic, please visit the official page: Worldwide Insect Repellent Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ammonium Polyvanadate (APV) Market Poised for a Robust 8.9% CAGR Through 2032
By PW Consulting, 2026-07-16
Worldwide Ammonium Polyvanadate (APV) Market — Strategic Implications for 2026 Corporate Decision-Making
Executive summary
The ammonium polyvanadate (APV) market is transitioning from a recovery phase into an investment-intensive growth cycle. PW Consulting's latest research — anchored on a 2025 base year and a forecast window through 2032 — shows the industry expanding from USD 312.45 Million in 2020 to USD 455.12 Million in 2025, and our scenario-driven model projects it reaching USD 826.67 Million by 2032. The trajectory implies a compound annual growth rate (CAGR) of 8.9% across the forecast period. For executives finalizing 2026 budgets and three- to five-year strategic plans, this report maps where value will concentrate, what operational risks require mitigation, and which commercial plays are most likely to generate differentiated returns.
Worldwide Ammonium Polyvanadate (APV) Market
Why this matters for 2026 planning
-
Capital allocation: The pace of market expansion makes 2026 a pivotal year for capex prioritization — where incremental capacity, process upgrades, or purity-differentiated product lines can materially affect market share in the next cycle.
Worldwide Ammonium Polyvanadate (APV) Market -
Supply security: Raw material dynamics and geopolitics are reshaping feedstock access. Procurement strategies and long-term offtake agreements negotiated in 2026 will influence margin profiles through 2030.
Worldwide Ammonium Polyvanadate (APV) Market -
Product strategy: Demand is bifurcating between bulk technical-grade APV for metallurgical uses and higher-margin, specialty-grade APV for catalysts, battery chemistries, and chemical intermediates — positioning and capability investments decided in 2026 will determine participation in higher-value segments.
Market trajectory and growth drivers
Our analysis synthesizes demand-side drivers (steel alloying, catalyst manufacturing, emerging energy storage applications) with supply-side realities (feedstock availability, processing constraints, and capital intensity of upgrading routes). The APV market has shown steady growth historically, with accelerating expansion forecast post-2026 driven by two converging factors: continued ferrovanadium demand from alloy and steel producers and a maturing pipeline of specialty applications that value controlled impurity profiles and tighter particle size distributions.
Price dynamics and utilization rates are sensitive to feedstock swings. Consequently, scenario stress tests in the report demonstrate how a range of raw-material supply disruptions or policy shifts can amplify volatility, turning otherwise stable margin pools into strategic battlegrounds.
Supply chain and raw material context
Understanding vanadium supply fundamentals is core to APV strategy. Global contained-vanadium production remains concentrated and exposed to a small number of high-volume producers. Recent estimates peg total global production at roughly 100,000 metric tons of contained vanadium in 2023, with a dominant national producer accounting for the majority of output. Geopolitical measures and sanctions have reduced production from some traditional suppliers, while regulatory developments — including the inclusion of vanadium on the European Union’s Critical Raw Materials list — are elevating the strategic importance of upstream sourcing.
These structural realities translate into three tangible operational priorities for 2026:
-
Secure diversified feedstock sources and invest in feedstock-flexible processing routes to reduce single-source exposure.
-
Increase transparency in the supply chain through supplier audits and traceability systems to support contractual and regulatory compliance.
-
Pursue strategic partnerships—long-term offtakes, joint ventures, or minority investments—with ore producers or midstream processors to lock-in margins and capacity.
Segmentation and where the real opportunities lie (high level)
The APV market is multi-dimensional: regional demand footprints, grade differentiation (technical vs. high-purity), and end-use applications each follow distinct growth patterns. Rather than a single monolithic opportunity, the market offers multiple playbooks:
-
Scale plays focused on metallurgical-grade APV that compete on cost, logistics efficiency, and scale across established steel and ferrovanadium supply chains.
-
Specialty plays concentrating on high-purity grades for catalysts and advanced chemical applications, which reward investments in purification and quality control systems.
-
Platform plays tied to energy-storage ecosystems — particularly where APV intermediates intersect with vanadium redox flow battery value chains — that can command strategic partnerships and premium pricing over time.
Detailed, region- and application-level splits are included in our full model; this release intentionally highlights the directionality of opportunity while preserving the granular segmentation behind the report paywall for subscribers and clients.
Competitive landscape — who matters and why
The industry exhibits a moderate level of concentration. The top three APV producers account for approximately 42% of market share, while the top five account for roughly 58%, indicating meaningful advantages for incumbents but also substantial room for challengers and niche specialists. The companies to monitor fall into three strategic archetypes:
-
Large, vertically integrated miners/processors — These players control upstream feedstock flows and leverage scale to supply metallurgical markets. Example: EVRAZ plc (Moscow, Russia), a major vanadium producer operating facilities that feed ferrovanadium and steel industries.
-
Regionally integrated heavy-industry groups — These producers convert vanadium-bearing ores and slags into APV and downstream V2O5/ferrovanadium for internal consumption and external sales. Example: Panzhihua Iron and Steel Group Vanadium Titanium New Material Technology Co., Ltd. (Panzhihua, Sichuan, China), which benefits from proximity to ore and integrated processing chains.
-
Specialist refiners and chemical suppliers — These companies supply commercial and high-purity APV for catalysts, specialty chemicals, and niche industrial applications. Examples: Chengde Xinhua Hebei Vanadium Products Co., Ltd. (Chengde, Hebei, China), Hebei Jianlong Vanadium Products Co., Ltd. (Qian'an, Hebei, China), and Treibacher Industrie AG (Althofen, Austria).
Each archetype presents distinct implications for partners, customers, and competitors. Vertical integrators will defend feedstock margins and logistics advantages; specialists will compete on product quality and regulatory compliance. For 2026, we expect consolidation pressure around midstream assets and selective capacity investments where purity upgrades unlock higher-margin end-markets.
Regulatory, ESG, and geopolitics — practical impacts
Three regulatory and ESG themes will shape near-term commercial choices:
-
Critical minerals policy: With vanadium recognized by major jurisdictions as a strategic raw material, companies should anticipate incentives for local processing and potential trade frictions affecting supply economics.
-
Emissions and waste management: Upgrading to lower-emission processing routes and implementing robust slag and tailings management will be decisive for market access in regulated markets.
-
Traceability and responsible sourcing: Buyers of high-purity APV will increasingly require chain-of-custody documentation, creating a premium for producers who can certify ethical and low-carbon supply chains.
What the report delivers — practical, transaction-ready tools
PW Consulting’s full APV market study is designed for executives, investors, and business-development teams preparing decisions in 2026. Key deliverables include:
-
Proprietary demand-supply model with base-year calibration (2025), historical time-series, and scenario outputs through 2032, enabling sensitivity testing of feedstock shocks and policy scenarios.
-
Commercial due-diligence templates and valuation multiples tailored to APV-facing assets, supporting M&A or joint-venture negotiations.
-
Supplier scorecards, capex-outlook matrices, and prioritized mitigation playbooks for supply-chain resilience.
-
Regional strategic maps and go-to-market options that align product grade with downstream customers and regulatory regimes.
-
Actionable 18-month and 36-month roadmaps for capacity investments, purification projects, and partnership structures that drive near-term differentiation.
Recommended actions for 2026 (exec checklist)
-
Finalize a prioritized capex list that distinguishes between low-cost debottlenecking and higher-return upgrade projects tied to specialty-grade APV.
-
Negotiate or renew feedstock contracts with clauses for force majeure and price-flexibility; include co-investment language where possible.
-
Initiate supplier and customer pilots for traceability and low-carbon credentialing to pre-empt regulatory requirements in key export markets.
-
Develop contingency scenarios and liquidity cushions calibrated to raw-material supply shocks and regional policy shifts.
-
Assess acquisition targets and technical partnerships among mid-tier refiners that can rapidly upgrade product purity with limited capital outlay.
How to use this research
The report is structured as both a strategic playbook and a practical toolkit. Use the high-level market trajectories and our scenario outputs to stress-test board-level strategies. Apply the commercial templates and supplier scorecards to due diligence and contract negotiations. And use the proprietary demand-supply model to quantify the P&L impact of alternate decisions on capacity timing, product mix, and procurement policy.
We intentionally present directional insights in this public release while reserving the full, disaggregated matrix of regional and application splits, price curves, and supplier-by-supplier assessments for subscribers and commissioned clients. This allows decision-makers to access the depth required for transaction execution and operational planning while preserving the report’s value as a primary source.
Conclusion
As organizations set budgets and strategic priorities for 2026, the APV market offers both cyclical and structural opportunities. The market’s projected expansion, underpinned by an 8.9% CAGR into 2032, is compelling, but the pathway to differentiated returns depends on feedstock strategy, grade-positioning, and proactive management of regulatory and ESG requirements. PW Consulting’s APV study equips leaders with the scenarios, financial models, and commercial tools to convert market growth into durable competitive advantage. For complete segmentation, supplier-level detail, and the full modeling suite, access the full report through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Ammonium Polyvanadate (APV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


