



PW Consulting: Worldwide Luxury Car Coachbuilding Market to Grow at 9.15% CAGR, Surging to USD 2,122.6 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Luxury Car Coachbuilding Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s new market study — base year 2025, forecasting 2026–2032 — delivers a decision-grade vantage point for executives, investors and strategic teams operating in the ultra-luxury automotive space. The report synthesizes five years of historical dynamics (2020–2025) into forward-looking scenarios and actionable playbooks. At a headline level, the market is expanding at a sustained pace (9.15% CAGR on our forecast horizon) and is projected to more than double from the mid‑2020s to the end of the decade, reinforcing coachbuilding as a commercially meaningful and strategically transformative segment for premium OEMs, ateliers, and suppliers alike.
Worldwide Luxury Car Coachbuilding Market
Why 2026 Is a Pivotal Year
2026 marks an inflection: electrification, bespoke ownership experiences, and novel client engagement models converge with falling material costs and advanced composites to reshape economics and delivery models. New product programs launched in early 2026 exemplify this shift — coachbuilt vehicles are no longer solely handcrafted, coachbuilt one‑offs; they are increasingly limited-series electrified packages bundled with multi‑year client experiences. This evolution alters demand profiles, margins and ecosystem partnerships, and it creates near-term windows for strategic moves in product architecture, supply contracts, and experiential services.
Worldwide Luxury Car Coachbuilding Market
Key Macroeconomic Signals Embedded in the Report
- Market trajectory: The market baseline in 2025 is firmly established and our scenario set projects healthy compound growth through 2032. We model demand escalation driven by premiumization, electrified coachbuilt programs, and rising high-net-worth consumer appetite for tailored mobility.
- Structure and concentration: The sector remains concentrated among a small cohort of legacy coachbuilders and high-performance houses, leaving distinct white space for nimble new entrants and vertically integrated OEM initiatives. Competitive concentration metrics in the study underscore why strategic partnerships and selective M&A are high-leverage moves in 2026.
- Supply-side dynamics: Materials and technology cost curves — notably a marked decline in aerospace-grade carbon fiber prices over the last decade — materially improve the unit economics of composite-intensive coachbodies, while aluminum retains advantages for traditional hand-formed craftsmanship.
What the Report Contains — Practical, Executable Modules
- Decision Frameworks: A set of reproducible frameworks to evaluate coachbuild opportunities by profit pool, capability adjacency, and risk-adjusted returns. Each framework comes with decision thresholds calibrated to the 2026 market environment.
- Go-to-Market Playbooks: Segment-specific GTM playbooks (OEM coachbuild programs, studio-led commissions, and aftermarket high-margin conversions) including channel economics, client acquisition levers, and pricing architectures that preserve perceived exclusivity while protecting margin.
- Manufacturing & Supply Chain Blueprints: Step‑by‑step guidance for hybrid manufacturing models that combine artisan handcrafting with small‑series digital workflows — plus sourcing strategies for composites and specialty aluminum that mitigate lead‑time and price volatility risks.
- M&A and Partnership Scorecards: A prioritized deal roadmap identifying target archetypes and integration templates to capture scale benefits without eroding brand cachet. Includes valuation sensitivities and integration red flags unique to coachbuilding.
- Scenario Suite & Financial Models: Eight forward scenarios (from conservative continuity to high‑adoption electrified coachbuild programs) with embedded P&L and balance sheet impacts for OEMs and independent ateliers across 2026–2032.
- Regulatory & Sustainability Pathways: Compliance-response playbooks aligned to tightening global emissions standards, demonstrating how lightweighting and material substitution can reduce lifecycle emissions while preserving bespoke aesthetics.
Competitive Landscape — What Leaders and Challengers Are Doing Now
The report maps the competitive universe across legacy coachbuilders, OEM internal studios, specialist tuners, and boutique design houses. Several dynamics stand out:
Worldwide Luxury Car Coachbuilding Market
- Legacy ateliers are evolving into curated product businesses. Long-respected houses are monetizing heritage through limited-series programs and client experience offerings that extend beyond vehicle delivery.
- OEMs are moving from bespoke one-offs to invite-only, small-batch coachbuild collections integrated into broader brand ecosystems — a shift that trades pure scarcity for repeatable, experience-led revenue streams.
- Aftermarket specialists and tuners remain important talent pools and agile competitors; they often provide rapid response to client customization requests and have developed carbon-intensive modification capabilities that appeal to performance clients.
Illustrative examples in the study include new program launches that combine coachbuilt product with multi‑year client programming, signaling how top-tier players are reframing the addressable market. Our profiles evaluate strategic positioning, execution risks, and partnership opportunities for leading names across Europe and beyond.
Technology and Materials: Strategic Levers for Cost, Weight and Aesthetics
Material technology is no longer a tactical input; it is a strategic variable. The report documents the shifting cost and capability landscape: while traditional aluminum practices remain foundational for hand-formed aesthetics, composite materials — particularly advanced carbon constructs — are the fastest-growing route to create structurally efficient, sculptural bodies. The declining price trajectory for aerospace-grade carbon fiber materially improves viability for limited-series coachbuilt programs, enabling structural creativity that was previously cost-prohibitive.
We also examine digital fabrication and metrology advances that allow bespoke dimensions to be executed at significantly lower iteration cost, enabling studios to offer guaranteed fit-and-finish at scale-sensitive price points.
Regulatory and Sustainability Implications
Escalating global emissions standards and the luxury consumer shift toward sustainable provenance are reshaping coachbuilding choices. Lightweighting via composites and aluminum is increasingly a compliance strategy as much as a performance or design choice. Our regulatory module outlines pathways to certify bespoke bodies and manage end-of-life considerations — a key differentiator for buyers and a source of reputational leverage for manufacturers.
Strategic Recommendations for 2026 Execution
- Prioritize modular coachbuild platforms: For OEMs, invest in flexible platform elements that enable coachbuilt differentiation without duplicative development costs. Modular electrical architectures and body-in-white interfaces reduce unit costs for small series.
- Lock in composite supply arrangements: For ateliers and suppliers, secure mid-term offtakes and technical partnerships with composite suppliers to hedge against capacity squeezes and to negotiate favorable pricing as demand scales.
- Monetize client experiences: Move beyond transactional commissions to subscription-like experiences that bundle concierge services, bespoke servicing, and lifestyle activations — these increase lifetime value and reduce customer acquisition costs for limited‑run programs.
- Use selective collaboration to preserve scarcity: Joint ventures between OEM studios and independent coachbuilders can combine brand reach with artisanal cachet without diluting exclusivity.
- Prepare for certification complexity: Early investment in homologation pathways for electrified coachbuilt vehicles avoids market delays and protects perceived value for clients demanding road-legal, turnkey vehicles.
How PW Consulting Helps
This report is a practical toolkit — not just a narrative. Each chapter includes plug-and-play deliverables (prioritized checklists, model templates, supplier scorecards and scenario dashboards) enabling leaders to convert insight into 90‑, 180‑ and 360‑day action plans. We pair market sizing and concentration analysis with on-the-ground interviews and supplier assessments so recommendations are grounded in operational realities.
Next Steps
For executives planning capital allocation, partnership strategies, or product launches in 2026, the PW Consulting Market Report provides the data, structuring logic and tactical playbooks to execute with confidence. The public summary establishes the market’s growth trajectory and concentration dynamics; the full report contains the granular decision tools and scenario models removed from this communiqué to protect sensitive segment detail and to ensure clients derive exclusive strategic advantage.
To access the full set of deliverables — including modeled P&Ls, supplier negotiation templates, and bespoke scenario workshops — visit the PW Consulting report page and request the Worldwide Luxury Car Coachbuilding Market full study and advisory engagement options.
For detailed analysis of this topic, please visit the official page: Worldwide Luxury Car Coachbuilding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Canoe‑Kayak Accessories Market Valued at USD 840.0 Million in 2025 — Poised for Continued Growth
By PW Consulting, 2026-07-15
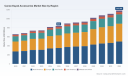
Worldwide Canoe‑Kayak Accessories Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on Worldwide Canoe‑Kayak Accessories establishes a clear, actionable line of sight for executives planning investments, product road maps, and go‑to‑market moves in 2026. The accessory market has matured into a steady-growth niche: after expanding from roughly USD 658 million in 2020 to USD 840 million in our 2025 base year, the industry is projected to grow at a compound annual growth rate (CAGR) of approximately 5.0% over the 2026–2032 forecast window, reaching an estimated USD 1.18 billion by 2032. That trajectory masks a complex, fragmented competitive structure and a supply chain exposed to several high‑impact risks—facts that make disciplined strategic choices in 2026 both necessary and rewarding.
Worldwide Canoe-Kayak Accessories Market
Why this matters for 2026 strategy
-
Predictable overall growth creates bandwidth for strategic investments. A healthy mid‑single‑digit CAGR permits deliberate expansion—new SKUs, premiumization, and channel experiments—without assuming runaway demand.
Worldwide Canoe-Kayak Accessories Market -
Market fragmentation amplifies the payoff from focused M&A, distribution partnerships, and platform plays. The market’s top three players account for less than one‑fifth of total sales, while top five concentration remains below one quarter—creating opportunity for consolidation and rapid share gains through targeted moves.
Worldwide Canoe-Kayak Accessories Market -
Supply‑side volatility means product and margin strategies must be tightly integrated with procurement and manufacturing planning. Emerging cost pressures and regulatory requirements will determine whether firms win on unit economics or lose margin to input inflation and compliance costs.
Market snapshot (2020–2032)
PW Consulting’s longitudinal database captures the market’s recovery and maturation across the 2020–2025 historical window and delivers scenario‑based forecasts to 2032. Key anchor points: the market stood at roughly USD 658 million in 2020, reached USD 840 million in 2025 (our base year), and is forecast to grow to about USD 896 million in 2026 and to approximately USD 1.18 billion by 2032 under our central case. These series underpin the report’s investment models, NPV scenarios, and break‑even analyses tailored for product and channel investments in 2026.
Competitive landscape — what to watch
The industry is populated by specialized manufacturers and accessory platforms that compete on product innovation, channel reach, and OEM/aftermarket relationships. PW Consulting profiles the leading names shaping product and go‑to‑market trends:
-
YakGear (Charleston, SC): known for outriggers, rod holders, and modular track systems that prioritize stability and utility for fishing kayaks.
-
Railblaza (Auckland): a modular QuikMount ecosystem offering rod holders, camera mounts and lighting solutions for track‑equipped boats—recently launched a TracLoader accessory showcased at Outdoor Retailer.
-
Scotty (Sumas, WA): long‑standing supplier of downriggers, bait boards and mounting solutions that service serious angling applications.
-
RAM Mounts (West Des Moines, IA): dominates rugged electronics mounts and has extended SKUs calibrated for kayak vibration profiles.
-
Wilderness Systems and Perception Kayaks (Greenville, NC): leverage brand and OEM relationships to distribute crate systems, deck rigging, and comfort upgrades.
-
Old Town Canoe, Harmony Gear, NRS and Aquaglide: each serves distinct user segments (recreational, sea, whitewater, inflatable) with products from thwarts and yokes to spray skirts and repair kits.
Recent product activity—new outriggers, track loaders, bait boards and vibration‑tolerant phone mounts—indicates R&D investment is concentrated in modularity, fishing performance, and electronics integration. PW Consulting’s competitive matrices map these launches against customer willingness‑to‑pay and channel penetration to identify the most scalable propositions for 2026.
Supply chain and regulatory dynamics: immediate 2026 priorities
-
Raw materials: petrochemical feedstock volatility has driven a notable increase in nylon webbing costs across 2024–2026. Our industry inputs indicate a ~12% rise in nylon webbing prices, directly affecting deck rigging and strap cost lines. Procurement strategies that hedge or diversify raw material sources are now a competitive lever.
-
Labor and production: injection molding labor costs in Vietnam climbed around 8% in late 2025—squeezing margins for manufacturers dependent on Southeast Asian tooling. Near‑term tactics include tighter tolerancing, upgraded automation investments, and selective nearshoring for higher‑value SKUs.
-
Regulation and compliance: commercial rental operators in the U.S. are now subject to clear safety equipment mandates from the US Coast Guard, increasing demand for certified PFD and whistle packages in rental fleets. Meanwhile, EU regulatory updates mandate lead‑free certifications for accessory weights under REACH—requiring cost and supply changes for products aimed at European customers.
Practical intelligence included in the PW Consulting report
The study is designed to be immediately operational for business leaders planning 2026 execution. The report includes:
-
Bottom‑up market model and sensitivity tables (USD Million basis, 2020–2032) with scenario toggles for raw material and labor shocks.
-
Segment‑level playbooks (product, channel, commercial rentals) with evidence‑based ROI curves—note: the public summary omits granular regional and application split tables; full access requires the report download page.
-
Go‑to‑market blueprints by channel—specialty retail, online platforms, and national big‑box—and SKU rationalization frameworks that optimize SKU breadth versus inventory turns.
-
Supply‑chain heatmaps, alternative sourcing options, and cost‑mitigation tactics (material substitution, design for manufacturability, strategic stockpiles).
-
Regulatory compliance checklist and country‑by‑country certification timelines, including REACH implications and USCG guidance for rental operations.
-
Targeted M&A screen and a prioritized list of bolt‑on capabilities that deliver faster route‑to‑market in fishing and electronics‑integration segments.
Actionable strategic plays for 2026
-
Insulate margins with a materials strategy: lock in blended nylon contracts, qualify alternative textiles, and redesign high‑volume straps to reduce material intensity by 5–10% per unit.
-
Double down on modular systems: track‑based and quick‑attach systems increase attachable revenue per hull and raise switching costs. Consider licensing or co‑development deals that expand an accessory ecosystem.
-
Target rental and commercial fleets: USCG rental equipment mandates create a stable B2B volume channel for certified accessory bundles—win this segment with service‑intensive offerings and fleet maintenance programs.
-
Balance channel investments: accelerate DTC and online platforms for premium & accessory bundles while preserving specialty-retailer relationships for discovery and demo. Use marketplace data to refine assortment in near real‑time.
-
Prepare for regulatory costs: budget for certification and testing, and accelerate lead‑free reengineering for EU market continuity. Early compliance reduces time‑to‑shelf and avoids disruptive delists.
-
Consider consolidation where scale matters: with low top‑tier concentration, acquisitive moves that add distribution or niche tech (e.g., camera mounts, electronics damping) can immediately improve margins and expand addressable market.
How PW Consulting’s report supports execution
We built tools that translate the forecast into capital allocation decisions: capex sizing for tooling and automation, an investment prioritization matrix tied to NPV and payback under multiple cost‑shock scenarios, and SKU rationalization calculators that show the P&L impact of removing underperforming parts. For commercial teams, we provide account‑level scripts and pricing negotiation templates tailored for rental operators and big‑box buyers. The full digital appendix includes downloadable models in USD Million units and a workshop agenda for aligning product, procurement, and sales teams around a 90‑day action plan.
What we intentionally leave for report subscribers
This release follows a “trailer” model: we expose the analytical framework, key vectors, and strategic plays to help leaders assess the market’s strategic logic, but we withhold granular regional, application and channel split tables, SKU‑level volumes, and subscriber‑only competitor scorecards. Those core subsegment datasets are available through the report’s access page and are necessary for precise investment sizing and market entry sequencing.
Next steps for executives
-
Use the market anchors (USD 840M base year, CAGR ~5.0% to 2032) to test your 2026 topline and resource plans against our scenarios.
-
Prioritize short‑term actions that reduce input exposure (material contracts and alternate suppliers) and fast‑track compliance for target geographies.
-
Book a strategic workshop with PW Consulting’s Canoe‑Kayak Accessories practice to translate the report into a 90‑day commercial and operational plan aligned with your balance‑sheet constraints.
Conclusion
The canoe‑kayak accessories market in 2026 is neither a winner‑take‑all arena nor a static niche. It is a fragmented, innovation‑driven sector with predictable overall growth but a set of supply‑chain and regulatory inflection points that will determine who out‑margins and out‑grows peers. PW Consulting’s report delivers the models, playbooks, and risk mitigations executives need to convert the market’s steady growth into superior returns—while the granular regional and SKU intelligence required for implementation remains available exclusively in the full report.
To access the full report, the detailed segment tables, and the subscriber tools that operationalize these recommendations, please visit PW Consulting’s Worldwide Canoe‑Kayak Accessories Market page.
For detailed analysis of this topic, please visit the official page: Worldwide Canoe-Kayak Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Conductive Fibers Market Set to Reach USD 2,073.81 Million by 2032, Growing at a 7.5% CAGR
By PW Consulting, 2026-07-15
Worldwide Conductive Fibers Market — Strategic Outlook for 2026 Decision-Making
As enterprises position for next‑stage growth across smart textiles, wearable electronics, EMI shielding and industrial safety, PW Consulting’s latest Worldwide Conductive Fibers Market report delivers the practical intelligence leaders need to make high‑conviction 2026 decisions. The market we modelled shows a clear, durable expansion trajectory: after accelerating through 2020–2025 to an estimated USD 1,250.0 Million in 2025, the sector is projected to grow at a compound annual rate of 7.5% through our 2026–2032 forecast window, reaching just over USD 2,073.8 Million by 2032. At the same time, industry concentration remains modest (top 3 producers ≈22.5%; top 5 ≈34.8%), underscoring a competitive landscape where innovation and supply mastery can rapidly shift advantage.
Worldwide Conductive Fibers Market
Why 2026 is a Pivotal Year for Strategic Action
-
Technology inflection: Improvements in fiber conductivity, composite integration and washability are enabling a new class of durable, comfortable e‑textiles and EMI solutions. Winning in 2026 requires bridging lab advances and scalable manufacturing.
Worldwide Conductive Fibers Market -
Commercialization window: OEMs in medical devices, automotive, defence and consumer wearables are moving from pilot programs to procurement cycles. Companies that can demonstrate repeatable quality and supply reliability will capture disproportionate share.
Worldwide Conductive Fibers Market -
Supply and raw material dynamics: The industry still relies on silver‑coated and stainless‑steel conductive solutions. Stainless steel offers a notable cost trade‑off against silver for textile integration; procurement strategies that optimize alloy choice and coating process are deciding factors for gross margins.
-
Regulatory and standards pressure: Evolving requirements around electrical safety, washability and durability are raising barriers to entry for new suppliers and creating certification premiums for compliant products.
What the PW Consulting Report Delivers — Practical, Decision‑Ready Content
-
Proprietary market model: Full historical view (2020–2025) and a seven‑year forecast (2026–2032) with scenario bands, sensitivity testing and upside/downside trigger points tied to key inputs such as raw material pricing and wearable adoption rates.
-
Actionable go‑to‑market playbooks: Customer archetypes, procurement decision trees, pricing strategy templates and pilot‑to‑scale roadmaps tailored for conductive fiber suppliers and textile integrators.
-
Supply chain and sourcing atlas: Tiered supplier mapping, cost‑to‑serve analyses, lead‑time risk heatmaps and alternative sourcing strategies that quantify resilience trade‑offs.
-
Regulatory and testing matrix: Certification pathways and test protocols for electrical conductivity, washability and durability across major jurisdictions—designed for accelerating product approval and procurement acceptance.
-
IP, R&D and product roadmaps: Landscape of enabling technologies, patent clustering by capability, and prioritized R&D bets with estimated time‑to‑market and cost envelopes.
-
M&A and partnership screens: A short list of strategic acquisition and partnering targets, valuation heuristics and integration risk checklists to support inorganic growth plays.
-
Customizable decision tools: Excel‑based models and dashboards that allow commercial, R&D and finance teams to stress‑test initiatives under client‑specific assumptions.
Note: The report includes granular regional, type and application segmentations and an asset‑level company database. To preserve the strategic value of that granular intelligence (and to respect confidentiality of proprietary sources), those segment tables and company performance figures are not reproduced here; they are available in full in the source report.
Competitive Landscape — Profiles and Strategic Implications
-
Toray Industries, Inc. (Tokyo, Japan | https://www.toray.com): Leveraging deep polymer and textile engineering expertise, Toray is well positioned to scale high‑performance conductive fibers into smart textile platforms and complex EMI applications. Their R&D‑to‑scale capability is a model for competitors seeking vertical integration.
-
Teijin Limited (Tokyo, Japan | https://www.teijin.com): Teijin’s emphasis on medical and automotive conductive solutions makes them a strategic partner for OEMs requiring certified, durable materials. Their sustainability focus also aligns with buyer demand for lifecycle‑aware sourcing.
-
Bekaert (Zwevegem, Belgium | https://www.bekaert.com): Through its Bekinox® stainless steel offerings, Bekaert demonstrates how metallic fiber technology can deliver durable EMI shielding and data transmission while offering cost‑effective alternatives to silver‑based systems.
-
3M Company (St. Paul, MN, USA | https://www.3m.com): 3M’s materials portfolio and industry relationships make them a natural supplier for high‑performance industrial and EMI products, and their scale enables rapid qualification across sectors.
-
DuPont de Nemours, Inc. (Wilmington, DE, USA | https://www.dupont.com): DuPont’s advanced materials and integrated solutions are particularly relevant where conductive fibers must interface with complex electronics and protective garments.
-
Specialist producers (Seiren, Shakespeare Polymers & Filaments, Syscom/Agsis, Shieldex, Haining Taierxin, Eeonyx, Swift Textile Metalizing, Kolon): These players, often more narrowly focused, are the engine room for niche innovation—from silver‑plated antimicrobial yarns to carbon‑suffused electrostatic dissipative fibers. Their agility is an acquisition and partnership magnet for larger players.
Recent market moves underscore the dual thrust of product innovation and market positioning. Haining Taierxin’s early‑2026 repositioning highlights how suppliers are consolidating leadership in functional textiles and EMI shielding. Earlier, in 2025, DexMat’s introduction of a high‑strength conductive yarn (Galvorn C) illustrated the relentless material performance improvements that elevate application envelopes for wearables and industrial use. Collectively, these developments emphasize the importance of monitoring both product launches and strategic repositioning across the value chain.
Strategic Implications by Stakeholder
-
Manufacturers of conductive fibers: Prioritize scalable production processes and certification pipelines. Differentiate through validated washability and mechanical durability—buyer procurement panels increasingly require documented lifecycle performance.
-
Textile integrators and OEMs: Lock in supply through dual‑sourcing strategies that balance silver‑coated performance with stainless‑steel cost robustness. Invest in co‑engineering arrangements to reduce qualification cycles.
-
Material suppliers and chemistries firms: Focus on coatings and surface treatments that improve adhesion and washability, and develop thinner, lower‑resistivity coatings to slash weight without compromising comfort.
-
Investors and acquirers: Seek scale‑adjacent targets that can accelerate qualification into medical and automotive OEM programs. The fragmented market offers multiple roll‑up opportunities to create vertical, margin‑enhancing platforms.
-
Standards bodies and regulators: Accelerate harmonization of conductivity and durability testing protocols to reduce market friction and enable cross‑border product acceptance.
Operational Imperatives for 2026
-
Certify early, scale late: Start certification and washability testing during pilot phases to avoid multi‑month delays when scaling to production.
-
Design for manufacturability: Co‑engineer materials with textile partners—design decisions that save 10–20% in conversion cost often come from early collaboration.
-
Hedge raw‑material exposure: Maintain at least two qualified alloy/coating suppliers and model cost pass‑throughs in commercial contracts.
-
Build demonstrator programs: Real end‑user feedback (e.g., wear trials under standardized wash cycles) outperforms lab metrics when convincing procurement teams.
-
Track competitor IP and M&A signals: Use patent clustering and corporate filings to detect capability plays before they manifest in product launches.
How Executives Should Use the Full PW Consulting Report
Our report is designed as a working toolkit: commercial leaders will find pricing and go‑to‑market templates; R&D and product teams can adopt the patent and materials roadmaps; finance and corporate development teams will use the M&A screens and scenario models. For boards and C‑suite committees, the market’s mid‑decade momentum and the modest concentration metrics create a clear strategic imperative—move from exploratory pilots to defensible scale before the next wave of consolidation.
For clients ready to act in 2026, PW Consulting offers tailored deep‑dives: custom segmentation by application and region, supplier due diligence, and transaction support. The full dataset, including granular regional and application forecasts, company performance tables and the interactive forecast model, is available in the published report and through our client services team.
Closing Perspective
Conductive fibers are at an inflection point where materials science improvements, standards maturation and rising end‑market demand converge to create sizeable commercial opportunity. The market’s projected growth to 2032 reflects both organic demand and the unlocking of new application classes. For decision makers who must prioritize investments, build resilient supply chains and win OEM qualifications in 2026, the difference between a good and a great year will be the quality of the intelligence behind their bets. PW Consulting’s Worldwide Conductive Fibers Market report converts disparate signals into actionable choices—without surrendering the granular detail buyers must access directly from the source.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Epoxy Glass Market to Climb from USD 2,842.6 Million in 2025 to USD 4,218.88 Million by 2032 at 5.82% CAGR — FR-4 and Asia Pacific Lead
By PW Consulting, 2026-07-15
Worldwide Industrial Epoxy Glass Market — Strategic Imperatives for 2026 (PW Consulting Report Preview)
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Industrial Epoxy Glass Market report (base year 2025, forecast period 2026–2032). This executive preview synthesizes the report’s high-impact findings and explains how procurement leaders, product strategists and corporate development teams should use the insights to shape decisions in 2026. The industrial epoxy glass market is neither static nor uniform: after a period of recovery and structural rebalancing, our top-line projection shows the market growing from roughly USD 2,842.6 Million in 2025 to an anticipated USD 4,218.9 Million by 2032, representing a compounded annual growth rate (CAGR) of approximately 5.82% across the forecast window. This growth trajectory underpins a narrow set of strategic choices—timely, resolutely actionable and explored in the full report.
Worldwide Industrial Epoxy Glass Market
Why 2026 is a Strategic Inflection Point
-
Convergence of demand drivers: Electrification, advanced PCB densities, aerospace and defense modernization, and the proliferation of automotive electronics continue to lift aggregate demand for glass-reinforced epoxy materials. These sectors are moving beyond volume to require differentiated performance (thermal stability, flame retardancy, dielectric properties), shifting supplier selection criteria from price-only to capability-focused evaluations.
Worldwide Industrial Epoxy Glass Market -
Input-cost volatility: Epoxy resin remains the primary upstream feedstock for epoxy glass laminates. Recent spot and regional price dynamics—for example, Northeast Asia resin prices observed around USD 2.62/kg (April 2026) and reported China regional price points earlier in 2026—have materially compressed industry gross margins in certain quarters and forced pass-through, hedging, and recipe optimization strategies. Our report models multiple resin-price scenarios and their P&L impacts at plant and product levels.
Worldwide Industrial Epoxy Glass Market -
Concentration and consolidation signals: Market concentration metrics show a mid-market leaning toward a handful of global and regional players: the top three firms do not dominate the industry outright, and the top five collectively control a meaningful but not overwhelming share. This structure creates space for vertical integration, bolt-on M&A, and capacity plays—particularly in markets where lead times and certifications create barriers to entry.
What PW Consulting’s Report Delivers — Practically
The full report is designed as an operational playbook for 2026 decision cycles. It does more than describe market size and direction; it equips teams to act. Key deliverables include:
- Demand-supply balance model with scenario toggles for resin price, automotive electrification pace, and aerospace production rates.
- Unit-cost builds and total-cost-of-ownership (TCO) templates for laminate and prepreg product families, with inputs for resin grades, glass styles, energy intensity, and labor mixes.
- Supplier scorecards and capability matrices that map technical certifications (UL 94 V-0, RoHS/REACH compliance, MIL/NEMA ratings), capacity footprints, and route-to-market strength—structured for rapid vendor shortlists in sourcing events.
- Regulatory and standards checklist tailored to electronics, industrial insulation and aerospace use cases; compliance gates and testing timelines to support new-product qualification.
- Manufacturing and CAPEX playbook: greenfield vs brownfield breakevens, typical cycle-times, and retrofit cost bands paired with productivity levers.
- M&A playbook and valuation comparables, focused on bolt-on targets, consolidation thresholds, and integration risks unique to composite laminate manufacturing.
- Commercial go-to-market guidance—pricing frameworks, margin optimization levers, and channel strategies for OEM direct sales, distributor-led approaches, and contract manufacturing partnerships.
Strategic Decision Levers for 2026
-
Raw-material risk management: Establish tiered procurement commitments and financial hedges for resin exposure. The report provides a practical matrix that links short‑term spot risk to medium-term contracts and long-term strategic supply relationships.
-
Product and process premiumization: Differentiate through technical certifications, high-temperature laminates and visually critical flame-retardant prepregs. We map premium margin bands and outline a 6–12 month qualification timeline for key OEM segments.
-
Capacity and footprint decisions: Decisions to expand, consolidate or partner should be informed by scenario-specific utilization thresholds. The report’s plant-level breakeven templates show when capacity additions meaningfully dilute fixed-costs versus when they risk market oversupply.
-
Supply-chain diversification and nearshoring: Regional lead times and certification regimes make selective nearshoring attractive for high-reliability customers. We quantify the tradeoffs between landed-cost increases and on-time-in-full (OTIF) benefits.
-
M&A and strategic partnerships: With mid-range concentration, there are actionable opportunities for acquisitive players to secure tech capabilities or local scale. Our M&A playbook highlights diligence pitfalls—intellectual property, resin supplier lock-ins, and legacy environmental liabilities.
-
Sustainability and procurement policy: Compliance with RoHS/REACH and meeting UL flame-retardancy standards are table stakes. The report translates compliance timelines into procurement certifications and supplier audit checklists.
Competitive Landscape — Who to Watch
The report’s competitive analysis focuses on capability and strategic posture rather than raw market share alone. A summary of players to monitor:
-
Ventec International Group (Taiwan) — A recognized leader in high-performance copper-clad laminates and prepregs. Ventec’s product breadth and technical depth make it a go-to for demanding PCB and insulation applications; watch its advanced substrate development and global distribution partnerships.
-
Isola Group (United States) — Specializes in copper-clad laminates and high-reliability epoxy glass systems. Isola’s strength lies in qualifying materials for complex electronic platforms and in long-standing OEM relationships that create sticky demand.
-
Atlas Fibre, Franklin Fibre-Lamitex, Current Inc., and Iten Industries (United States) — These North American manufacturers are notable for in-house machining capabilities, MIL/NEMA compliance focus and close relationships with industrial and defense buyers. Their agility on custom shapes and tight-qualification turnaround is a competitive differentiator.
-
Hexcel Corporation & Park Aerospace (United States) — While broader composite specialists, both maintain glass-reinforced epoxy platforms tailored for aerospace and industrial structural use. Their track records in aerospace qualification and supply-chain rigor are strategic assets.
-
SIDA (China joint venture) — Represents large-scale domestic manufacturing with ongoing capacity expansion efforts supporting annual production at significant scale. SIDA’s investments are shaping regional supply dynamics and creating sourcing options for cost-sensitive appliance and industrial buyers.
-
Hony Engineering Plastics (China) — Recently updated product catalogs and specification sets underline a push to meet international IEC and domestic GB standards; their portfolio is increasingly relevant for regional OEMs seeking compliant, localized supply.
Recent industry moves underscore distinct strategic patterns: SHD Composites’ April 2026 launch of a flame-retardant, visually clear epoxy prepreg signals product-level premiumization; Hony’s late-2025 catalog refresh reflects certification-driven commercialization; and SIDA’s capacity expansion highlights regional scale plays. Taken together, these activities validate our forecast scenarios and the need for agility in sourcing and portfolio strategy.
How Clients Should Use This Preview—and the Full Report
-
Procurement leaders: Use the embedded TCO templates to re-run supplier cost models under the new resin-price regimes and to design resilient contract structures for 18–36 month procurement cycles.
-
Product and qualification teams: Map your product roadmap against the certification timeline and the qualification gate checklist to accelerate market entry for premium grades.
-
Corporate development: Leverage the M&A valuation comparables and integration risk matrix in the full report to prioritize targets that unlock technical differentiation or regional scale.
-
Manufacturing/operations: Apply the CAPEX playbooks and productivity benchmarks to evaluate retrofit versus greenfield options and to optimize working-capital tied to resin inventory strategies.
Accessing the Full Intelligence
This preview intentionally emphasizes strategic direction and actionable levers while reserving detailed segmentation tables, supplier scorecards and scenario-model worksheets for report subscribers. For executives preparing capital and procurement decisions in 2026, those datasets are the difference between tactical fixes and durable strategic advantage. To unlock the full dataset—regional and application splits, product-level pricing curves, plant-level cost builds and downloadable procurement templates—please visit our report page or contact PW Consulting’s advisory team for a tailored briefing. Our analysts stand ready to translate the report’s scenarios into a customized decision pack for board-level and operational use.
In summary: the industrial epoxy glass market is on a multi-year growth path supported by durable end-market demand, but margin and supply risks are concentrated in raw-material variability and certification-driven lead times. Companies that combine disciplined procurement, targeted technical differentiation and selective capacity plays will disproportionately capture the upside between 2026 and 2032. PW Consulting’s full Worldwide Industrial Epoxy Glass Market report provides the playbooks and models necessary to execute on that thesis.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Epoxy Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Skin Care Products Tubes Market to Grow at 5.45% CAGR, Reaching USD 26.83 Billion by 2032
By PW Consulting, 2026-07-15
Worldwide Skin Care Products Tubes Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on the Worldwide Skin Care Products Tubes Market provides an actionable intelligence package for executives planning investments, sourcing strategies, product launches, and M&A activity in 2026 and beyond. Our analysis models the market from 2020–2025 with a forward projection through 2032. At the macro level, the market is poised to expand from roughly USD 18.5 billion in 2025 to approximately USD 26.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.45% over the forecast window. Market concentration remains moderate — the top three suppliers account for about 28.5% of demand and the top five about 39.1% — signaling a competitive field with room for both scale players and specialized challengers.
Worldwide Skin Care Products Tubes Market
Why this briefing matters for 2026 strategies
-
Timing and resource allocation: The 5.45% CAGR signals steady, not runaway, growth. That requires a balanced approach between capacity expansion and operational discipline: tactical investments in innovation and sustainability will deliver disproportionate returns relative to blunt capacity plays.
Worldwide Skin Care Products Tubes Market -
Supply chain levers matter more than ever: Volatility in feedstock prices and trade policy means procurement and pricing models will determine margin outcomes for both manufacturers and brand owners. Our scenario analyses quantify the impact of raw material shocks and tariff regimes on landed costs.
Worldwide Skin Care Products Tubes Market -
Regulatory and consumer expectations are driving product and packaging redesign. Meeting recyclability targets and "clean‑beauty" claims will be table stakes; companies that operationalize these requirements fastest will capture shelf and direct‑to‑consumer share.
How PW Consulting’s report supports executive decisions
This report is designed as a practical decision support tool rather than an academic exercise. Key operational deliverables include:
-
Demand forecasting and scenario planning — base, upside and downside cases along with sensitivity to raw material price paths and regulatory milestones.
-
Commercial playbooks — segmented go‑to‑market options for brand owners (e.g., premium versus mass channels), channel margin simulations, and pricing elasticity models to inform promotional strategies.
-
Supplier and technology mapping — an annotated landscape of incumbent and emerging suppliers, airless and dispensing innovations, mono‑material solutions, and barrier technology trade‑offs.
-
Cost-to-serve models — port and tariff stress tests, landed‑cost calculators for onshore versus offshore sourcing, and contract negotiation templates to capture working capital and freight optimization opportunities.
-
Regulatory roadmaps and compliance checklists — jurisdictional requirements, timelines, and compliance cost estimators designed for procurement, legal, and R&D teams.
-
M&A and partnership playbooks — criteria for bolt‑on targets, valuation levers tied to sustainability credentials, and integration risk matrices informed by concentration metrics and supplier footprints.
Competitive landscape — what incumbents and challengers are doing
The market is populated by established packaging conglomerates and specialist players. Each brings distinct capabilities that shape competitive dynamics and partner selection.
-
Albéa Group (Gennevilliers, France) — a global leader across laminated, plastic and aluminum tubes, Albéa is notable for advancing mono‑material recyclable tubes and rapid commercialization of differentiated closures (e.g., recent launches spotlighting recyclable snap-top concepts). For brands prioritizing circularity, Albéa is often the first vendor considered for scale implementations.
-
Silgan Holdings Inc. (Stamford, CT, USA) — through its dispensing division, Silgan is strong on engineered dispensing systems and plastic tube variants that focus on usability and dosage control. Their strengths lie in dispensing innovation and integration with contract packers.
-
AptarGroup Inc. (Crystal Lake, IL, USA) — Aptar’s airless and pump tube technologies are tailored for clean‑beauty and premium skincare formulations, reducing preservative needs and extending shelf life. They are a go‑to partner for formulations sensitive to oxidation.
-
Amcor plc (Zurich, Switzerland) — Amcor competes on flexible, high‑barrier tube solutions and has been aggressive in recyclable material innovations. They are a key partner where barrier performance and sustainability must coexist.
-
Berry Global Group Inc. (Evansville, IN, USA) — Berry emphasizes lightweight and sustainability certification credentials; recent sustainability certifications strengthen their commercial proposition for customers under regulatory pressure to demonstrate recycled content and LCA gains.
-
Huhtamäki Oyj (Espoo, Finland) — notable for laminate and mono‑material options with an emphasis on recyclability and circular value chains targeted at European brands preparing for packaging regulations.
-
Virospack S.A. (Barcelona, Spain) — a specialist in premium airless systems, Virospack serves high‑end skincare brands seeking differentiated tactile and dispensing experiences.
-
Intrapac International Pty Ltd (Keysborough, Australia) — a regional specialist offering customized tubing and dispenser solutions, Intrapac plays a strategic role for brands seeking APAC or Australian supply anchors.
Recent vendor moves reinforce the dual race for sustainability and functional innovation. Examples include recyclable snap‑top launches, airless tube showcases at industry trade events, and sustainability certifications — all pointing to where capital and R&D are being allocated.
Market dynamics and risk signals to monitor in 2026
-
Raw material and input costs — HDPE resin prices and other polymer cost trends materially affect tube economics. For example, HDPE averaged roughly €1,450/MT in Europe in late 2025, tightening margins for plastic‑centric offerings and accelerating the cost case for mono‑material recyclability or aluminum substitution in some use cases.
-
Regulatory inflection points — the EU Packaging and Packaging Waste Regulation sets aggressive recycled‑content targets that will force design and supply changes by 2030. Brands selling into regulated markets should recalibrate supplier scorecards to reflect compliance timelines.
-
Consumer sustainability demand — clean‑beauty and sustainability preferences are growing rapidly (industry surveys show double‑digit yearly increases in demand for sustainable tubes), which elevates the commercial premium for recyclable and low‑carbon packaging options.
-
Trade and tariff exposure — current US tariffs on certain imports remain significant and can erode the cost advantage of lower‑cost offshore suppliers; companies should model tariff‑inclusive landed costs before finalizing sourcing decisions.
-
Regulatory nuances on closures and safety — jurisdictional requirements (for instance, child‑resistant closures for larger volume tubes in some markets) should be embedded into product specs early in development to avoid late redesigns.
Practical recommendations for 2026 planning cycles
-
Prioritize supplier flexibility: add at least one alternative source with different feedstock exposure (e.g., one polymer specialist and one laminate/aluminum supplier) to hedge resin price and tariff risks.
-
Fast‑track sustainability MVPs: deploy mono‑material or high‑recycled‑content tube pilots on high‑visibility SKUs to secure early shelf placement and gather consumer acceptance metrics.
-
Embed regulatory timelines into SKU roadmaps: align product launches with compliance milestones (e.g., recycled content targets) to avoid costly reformulation or repackaging after the fact.
-
Leverage packaging as a margin lever: use dispensing tech (airless, metered pumps) to justify premiumization and reduce preservative loads, supporting price realization and incremental margin.
-
Prepare M&A screens around niche specialists (airless, premium dispensing, or regionally dominant players) where consolidation can capture integration synergies and quick capacity.
What the full report contains — and what we’re intentionally holding back here
The PW Consulting report contains granular analytics: SKU‑level demand forecasts, regional trade flow models, a full supplier scorecard, cost pass‑through simulations, detailed segmentation by region, material and application, and a prioritized list of tactical moves for procurement and R&D teams. In keeping with our “trailer” approach, this briefing purposely omits the detailed regional and application splits and the line‑item segmentation tables that clients use to make procurement and capital decisions. Those segmented datasets and supplier benchmarking matrices are available in the full report and through our advisory engagements.
Next steps and how to engage
-
Download the full report or contact PW Consulting to schedule a tailored briefing workshop. We can convert the market model into client‑specific scenario runs (e.g., SKU‑level P&L under alternate resin price paths) and a 90‑day tactical roadmap for supplier engagement.
-
For procurement and R&D teams preparing 2026 budgets, we recommend an immediate 30‑day sprint to validate supplier capacity, assess total landed cost with tariffs, and initiate at least one recyclable tube pilot on a strategic SKU.
In an environment where packaging choices connect brand positioning, regulatory compliance, and supply chain resilience, the ability to translate market forecasts into executable supplier and product strategies will determine winners in 2026. PW Consulting’s Worldwide Skin Care Products Tubes Market report delivers both the macro view and the operational tools to act decisively — contact us to access the full intelligence package and customized scenario work tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care Products Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Low‑VOC Coating Additives Market to Reach USD 7,208.15 Million in 2025 and Expand at a 6.42% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Low-VOC Coating Additives Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new market intelligence brief on the Worldwide Low-VOC Coating Additives Market synthesizes five years of historical performance and a seven-year outlook to 2032, delivering the strategic context senior executives need as they set priorities for 2026. The market reached USD 7,208.15 Million in 2025 (base year 2025) after a period of uneven but resilient growth from 2020–2025, and our model projects expansion at a compound annual growth rate (CAGR) of 6.42% through 2032, culminating in an expected market size of approximately USD 11,142.59 Million by 2032.
Worldwide Low-VOC Coating Additives Market
Why this report matters for corporate strategy in 2026
- Regulatory inflection points are creating product windows and compliance risk simultaneously. Companies that translate regulatory foresight into product and commercial execution will capture outsized share as markets reprice low-VOC performance.
- Technology and feedstock transitions—toward bio-based coalescents, biosurfactants, and next-generation multifunctional additives—are compressing product life cycles and increasing the value of integrated R&D roadmaps.
- Market structure is competitive but far from concentrated: the three-largest suppliers account for roughly 31.4% of the market and the five-largest about 44.8%, signaling persistent opportunity for mid-tier players and new entrants with differentiated technology or channel access.
- Capital allocation decisions in 2026—R&D spend, M&A, and capacity investments—must balance near-term compliance demand with longer-term shifts to waterborne, high-solids and UV-curable systems. This report translates macro forecasts into a set of prioritized investment hypotheses designed for executive decision cycles this year.
Top-line market trajectory and what it implies
After a recovery from mid-cycle volatility, total market value shows an accelerating path from USD 7,776.63 Million in 2026 to USD 11,142.59 Million by 2032 under our central scenario. This pace—reflecting a 6.42% CAGR—combines steady expansion of architectural and industrial coatings demand with above-average growth in segments where regulators and OEMs demand reduced emissions. For 2026 planning, the arithmetic of the forecast translates into three practical imperatives: protect existing revenue through compliance-ready SKUs, capture share through performance-differentiated additives, and future-proof portfolios by funding sustainable-feedstock initiatives.
Worldwide Low-VOC Coating Additives Market
Regulatory dynamics: a strategic stress test
The regulatory environment is now a primary determinant of product viability and route-to-market. Recent policy shifts—such as amendments to U.S. EPA aerosol coating standards that expand regulated species and introduce new reactivity factors, the persistent influence of California’s SCAQMD limits in shaping national formulations, and the EU Deco-Paint Directive’s continued harmonizing effect—create both compliance costs and incremental demand for validated low-VOC solutions. ASTM’s standardized VOC test methods (e.g., ASTM D6886 for waterborne coatings) are increasingly embedded into procurement specs, making independent validation and transparent documentation a commercial differentiator.
Worldwide Low-VOC Coating Additives Market
For 2026, executives must treat regulation not as a backward-looking constraint but as a forward signal: products designed to meet the most stringent standards will enjoy broader market acceptability and can command price premia in institutional procurement channels.
Raw material and technology trends to watch
- Feedstock diversification: Manufacturers are deploying vegetable oil-derived polyols, biosurfactants and other renewable components to meet VOC and carbon-intensity objectives. These inputs reduce emissions but introduce formulation complexity—opportunities for additive makers who can demonstrate performance parity without cost drag.
- Multifunctionality: The most commercially successful innovations in 2025–2026 are multifunctional coalescents and rheology systems that reduce SKU complexity and enable formulators to hit VOC limits while preserving application properties.
- Waterborne and high-solids acceleration: Technology investment is concentrated on enabling waterborne technologies and high-solids systems, especially where automotive OEMs and institutional specifiers narrow acceptable VOC envelopes.
Competitive landscape — who matters and why
The supplier map couples a set of global incumbents with a dynamic tier of regional specialists. Global chemical leaders such as BASF SE and Evonik occupy positions of technical breadth and global reach, offering portfolios that span defoamers, rheology modifiers, wetting agents and surface modifiers tailored for waterborne and high-solids systems. Dow Inc. and Eastman address both commoditized and specialty channels with acrylic emulsions and coalescents designed for low-VOC formulations. European specialty players—Allnex, Arkema, ALTANA (BYK), LANXESS and others—have leaned into differentiated resin-additive combinations and targeted expansions in performance waterborne systems. Mid-market and regional specialists, including Elementis, Seqens, Nouryon and Huntsman, continue to capture niche pockets where technical service and formulation support determine supplier choice.
Recent competitive moves underscore the theme that in 2026, product announcements and portfolio expansions are strategic signals: LANXESS’s April 2026 launch of a next‑generation multifunctional low‑VOC coalescent (Koalex MFX) demonstrates how new chemistries can be timed to trade shows and OEM testing cycles, while Dow’s 2026 expansion of acrylic emulsions and Evonik’s prior launches of mass-balanced TEGO products underscore the importance of sustainability credentials and certification in buyer selection.
Practical content of the PW Consulting report (what’s inside)
- Methodical market sizing and forecasting (historical 2020–2025; forecast 2026–2032) with scenario analysis that stresses regulatory and feedstock shocks.
- Competitive heat maps and supplier capability matrices that evaluate R&D depth, geographic reach, sustainability credentials, and commercial execution—designed for use in vendor sourcing and M&A screening.
- Regulatory impact models that translate evolving VOC rules into formulation cost and timeline implications for architectural, industrial and automotive coatings supply chains.
- Go-to-market playbooks for the OEM, formulator and industrial distributor channels, including channel economics and win-win partnership models.
- Priority investment roadmaps: recommended R&D focus areas, payback expectations for pilot production, and a triage of near-term vs. strategic opportunities to deploy capital in 2026 and beyond.
To preserve the integrity of the advisory mission and align with the “trailer” principle, the report deliberately does not reproduce every line-item split in the public summary. Detailed subsegment allocations, regional/application share tables and company-by-company revenue breakdowns are included in the full report and interactive datasets available on our site for clients conducting supplier due diligence or preparing investment memoranda.
Strategic recommendations for executives planning 2026 actions
- Embed regulatory scenario planning into product roadmaps. Prioritize formulations that meet the strictest foreseeable standards (e.g., SCAQMD-influenced limits) to avoid stranded SKUs and retain national footprint access.
- Pursue product modularity: invest in multifunctional additives that reduce formulation complexity and inventory burden for coaters and OEMs, thereby shortening customer validation cycles.
- De-risk feedstock through dual-sourcing and qualification of renewable alternatives. Perform targeted performance-cost tradeoffs to identify where bio-based inputs are commercially viable now vs. 2028–2030.
- Accelerate certification and independent testing. ASTM and third-party validations are becoming procurement gates—early certification buys access and de-risks buyer adoption.
- Use M&A and JV selectively to close capability gaps—particularly in bio-based chemistries, application testing infrastructure, and regional manufacturing footprint—to move up the value chain without overstretching balance sheets.
How PW Consulting’s deliverables help execute
Clients using our report receive not only market projections but practical deliverables: a supplier short-list optimized to the client’s strategic priorities, a compliance-ready product checklist mapped to key regional regulations, and a prioritized capex/R&D timetable calibrated to our forecast scenarios. For boards and investment committees, the forecast model provides sensitivity toggles to test down-cycle raw material shocks or accelerated regulatory tightening and to quantify value at stake from different strategic choices.
Closing: a call to action for 2026
As the low-VOC coating additives market moves toward a USD 11+ billion horizon by 2032, 2026 is a pivotal execution year. Regulatory pressure, raw material transitions and multifunctional additive technologies are converging to reward companies that combine technical leadership with regulatory foresight and agile commercial models. PW Consulting’s Worldwide Low‑VOC Coating Additives Market report equips decision-makers with the evidence base—and the executable playbook—they need to convert forecast trajectories into profitable, defensible growth.
To access the full dataset, segment breakouts, supplier scorecards and the interactive forecasting tool, visit the PW Consulting research page for the Worldwide Low‑VOC Coating Additives Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Low-VOC Coating Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Elemental Fluorine Market to Grow at a 6.18% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Elemental Fluorine Market — Strategic Outlook and Action Playbook for 2026
PW Consulting’s latest market study on Worldwide Elemental Fluorine provides a focused, decision-ready strategic resource for executives planning capital allocation, supply-chain resilience, and go-to-market moves in 2026. The report synthesizes five years of historical performance, a rigorous seven-year forecast, and a pragmatic set of playbooks tailored to suppliers, end‑users, financiers, and public-sector stakeholders. Readers will find the analysis rich in actionable guidance while intentionally withholding proprietary sub‑segment tables and granular revenue splits — a design choice that prioritizes confidentiality and drives stakeholders to the full report for transaction-ready detail.
Worldwide Elemental Fluorine Market
Why Elemental Fluorine Matters to 2026 Strategy
Elemental fluorine (F2) is a specialty gas whose market behavior disproportionately influences high-value value chains: semiconductors, advanced materials, specialty chemicals, and nuclear fuel processing. Across 2020–2025 the market demonstrated resilience and recovery dynamics, expanding from approximately USD 685.4 Million in 2020 to USD 928.5 Million in 2025. Our forecast projects continued expansion through 2032, with a 2026 starting point above USD 970 Million and terminal demand approaching USD 1.4 Billion by 2032 — an implied compound annual growth rate (CAGR) of 6.18% across the forecast window.
Worldwide Elemental Fluorine Market
These headline figures encapsulate three strategic realities for 2026 decision‑makers:
Worldwide Elemental Fluorine Market
- Demand persistence in critical industrial and high‑tech applications elevates fluorine from commodity status to strategic input.
- Supply risk is asymmetric — concentrated producer bases, high regulatory overhead, and feedstock pressure create episodic scarcity that can cascade through downstream industries.
- Market consolidation is material: the top three suppliers account for roughly 64.2% of capacity, and the top five approach 79.6%, making partnership and counterparty selection core to risk management.
What the Report Contains — Practical Modules for 2026 Execution
The study is structured as a compact toolkit for executives who must convert market intelligence into decisions within the next 12–18 months. Major modules include:
- Market sizing and trend diagnostics: methodology, confidence bands, and sensitivity tests that reconcile historical shipments with plant-level capacity.
- Supply‑chain maps and node risk scoring: live inventories, transport constraint overlays (UN/DOT/ADR implications), and choke-point charts for feedstock and cylinders.
- Regulatory and permitting playbook: jurisdictional timelines for hazardous‑materials handling, EU REACH implications, and compliance timelines linked to capital projects.
- Competitive landscaping and vendor due diligence templates: capabilities, certifications, and commercial terms to use in RFx and JV negotiations.
- Scenario planning and stress tests: upside/downside demand cases, force majeure, raw‑material shock, and policy closures with quantified P&L impacts and mitigation levers.
- Investment and M&A screening: financial thresholds, integration risk factors, and a short‑list framework for bolt‑on versus greenfield expansion.
- Procurement playbook and contract archetypes: dual‑sourcing clauses, inventory buffers, price‑indexation structures, and performance benchmarks for long‑term supply.
Competitive Landscape — Strategic Profiles and Implications
The elemental fluorine market exhibits a mixed structure of large, diversified industrial gases companies alongside specialized regional players. Our competitive analysis focuses on emblematic firms whose capabilities shape market dynamics:
- Air Products and Chemicals, Inc. (Lehigh Valley, PA; www.airproducts.com) — A global supplier whose ultra‑high‑purity F2 offerings are tightly integrated with advanced semiconductor supply chains. Strengths: global logistics, purity certifications, and deep customer relationships in electronics. Strategic emphasis for 2026: leverage long‑term offtake agreements and co‑development contracts with wafer fabs to lock in demand while supporting customers’ process miniaturization cycles.
- Solvay SA (Brussels; www.solvay.com) — Industrial chemical incumbent with electrolytic production assets. Strengths: vertical integration into fluorochemical intermediates and diversified end uses. Strategic challenge: operational resilience — the 2022 force majeure on HF production highlighted vulnerability in single‑site exposures. For 2026, Solvay and peers must accelerate distributed sourcing and invest in redundancy or risk‑sharing mechanisms with key customers.
- Pelchem SOC Ltd (Pelindaba, South Africa; www.pelchem.com) — A dedicated F2 producer with a unique scale position. Strengths: focused capacity and established nuclear‑grade supply chains. The company’s recovery to full capacity after scheduled maintenance in 2021 underscores the market sensitivity to uptime and the premium value of reliability. Strategic implication: customers evaluating mid‑term contracts will prioritize producers with demonstrable uptime and transparent maintenance governance.
- Kanto Denka Kogyo Co., Ltd. (Tokyo; www.kanto-denka.co.jp) — Regional specialist with a technology focus on electronics and solar applications. Competitive edge: technical customization for precision etching and photovoltaic fluorination processes. For 2026, Kanto Denka’s roadmap for niche process gases and co‑innovation with OEMs represents a defensible strategy amid rising purity demands.
- Stella Chemifa Corporation (Osaka; www.stella-chemifa.co.jp) — Producer with a balanced portfolio across semiconductor cleaning gases, battery materials, and pharmaceutical intermediates. Strategic posture: diversification across end markets cushions cyclical risk, but specialization in high‑value applications requires continuous investment in purity and materials handling.
Collectively, these firms illustrate two clear strategic archetypes that matter for 2026: (1) scale and integrated logistics players that compete on reliability and contract security, and (2) specialized producers that compete on purity, customization, and technical support. Both archetypes will command pricing power at different points in the cycle; the smart buyer will mix counterparty types strategically.
Supply‑Side and Regulatory Dynamics Shaping Near‑Term Risk
Our research highlights several market drivers that will materially affect procurement and investment decisions in 2026:
- Feedstock pressure: fluorspar and anhydrous hydrogen fluoride (HF) price volatility has tightened input margins and raised incentive for vertical integration or long‑term feedstock contracts. Spot price spikes observed in recent years make short‑term procurement exposure expensive and operationally risky.
- Geopolitical concentration: a limited set of jurisdictions dominate upstream fluorspar extraction, and export controls or quota shifts can transmit rapidly into HF and F2 availability. Supply‑chain diversification and inventory strategies are therefore non‑optional.
- Transport & handling regulation: F2’s classification under international hazardous‑materials regimes necessitates specialized cylinders and approved logistics chains. Compliance timelines and capital requirements for safe handling are important gating factors for new capacity.
- Chemical regulation: jurisdictions continue to reassess authorizations and acceptable uses due to reactivity and toxicity profiles. Firms should anticipate evolving authorizations and embed regulatory roadmaps into site selection and product development timelines.
Strategic Recommendations for 2026 Decision Makers
For CEOs, supply‑chain chiefs, and PE sponsors active in 2026, our priority recommendations are:
- Dual‑track supply strategy: combine strategic long‑term offtake contracts with at least one alternative supplier type (a dedicated specialist and a diversified industrial gases firm) to balance price and continuity.
- Feedstock contracts and hedges: negotiate indexed HF or fluorspar arrangements with volume collars and force‑majeure clarity. Consider equity or JV stakes in upstream fluorspar mining where regulatory and return profiles are acceptable.
- Invest in reliability engineering: allocate CAPEX to redundancy, preventative maintenance, and rapid restart capability; the market premiums for uptime justify elevated OPEX and CAPEX in many use cases.
- Regulatory-first project planning: fast‑track permitting workstreams early and budget for transport certification and cylinder fleet upgrades in capital plans to avoid multi‑month launch delays.
- Targeted M&A for capability gaps: use M&A primarily to obtain missing purity grades, specialized logistics, or regional market access rather than broad capacity plays; the CR3/CR5 concentration suggests bolt‑ons can deliver reach with manageable integration risk.
- R&D and substitution pathways: fund applied research into lower‑F2‑intensity chemistries, closed‑loop systems, and recycling of fluorinated streams where regulatory or end‑market economics permit.
Use Cases — How the Report Helps Different Stakeholders in 2026
- Procurement leaders: a ready set of RFx templates, weighted supplier scorecards, and contract clauses calibrated to hazardous‑materials risk.
- Operations & engineering: capex prioritization models and plant siting heuristics that weigh transport cost, permitting timelines, and feedstock security.
- M&A and investors: valuation adjustments for scarcity premia, an acquisition screening checklist, and integration playbooks addressing safety culture and regulatory compliance.
- Policy & compliance teams: country‑level authorization timelines and a compliance roadmap linking EU REACH, UN/ADR transport, and local permitting requirements.
Closing — Where to Go for the Full Intelligence
PW Consulting’s Worldwide Elemental Fluorine Market report offers a blend of quantified market projection (headline market size trajectory and a 6.18% CAGR across the forecast window), operationally focused risk matrices, and negotiation‑ready templates to support decisive action in 2026. To preserve proprietary insights and client value, the report intentionally omits detailed sub‑segment tables in executive summaries; companies and investors seeking transaction‑ready data, geo‑specific scenario outputs, and supplier‑level revenue splits should consult the full report and proprietary appendices available through our subscription portal.
For organizations that view elemental fluorine as a strategic input, 2026 is a year to convert market intelligence into binding commercial protections: long‑term offtakes, selective vertical integration, and targeted investments in plant reliability. PW Consulting’s report provides both the high‑level market thesis and the granular decision tools required to make those moves with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Elemental Fluorine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Methylparaben Market Poised to Reach USD 112.19 Million by 2032, Growing at a 4.5% CAGR
By PW Consulting, 2026-07-15
Worldwide Methylparaben Market 2026 Strategic Outlook: What Executives Need to Know
PW Consulting’s new Worldwide Methylparaben Market report (base year 2025) delivers a focused, decision-grade view of an often-underestimated ingredient that sits at the intersection of personal care, pharmaceuticals and certain food-preservation applications. Our analysis synthesizes the historical period 2020–2025 and delivers a seven-year forecast (2026–2032) underpinned by a proprietary demand-supply model. At a glance: the market reached USD 82.45 Million (2025, Million USD) and is modeled to expand at a compound annual growth rate of 4.5% through the 2026–2032 horizon, reaching an estimated USD 112.19 Million by 2032. This briefing highlights how those macro dynamics should shape 2026 strategic choices for manufacturers, brand owners, distributors and investors.
Worldwide Methylparaben Market
Why this market matters in 2026
-
Methylparaben remains a cost-effective, broadly used preservative with entrenched application footprints in cosmetics, pharmaceuticals and select food uses. Even incremental shifts in formulation policy or raw material costs cascade through procurement, quality, and regulatory functions.
Worldwide Methylparaben Market -
The market exhibits moderate concentration: the three largest suppliers account for a meaningful share of global supply, while the top five approach a majority position — a structural feature that directly affects negotiation leverage, availability risk and consolidation opportunities.
Worldwide Methylparaben Market -
Recent regulatory shifts, trade actions and upstream feedstock volatility have materially changed the risk profile for buyers and producers — making 2026 a pivotal year for supply-chain reconfiguration and product stewardship investments.
What PW Consulting’s report contains (practical deliverables)
-
Comprehensive market model (historical demand 2020–2025; base year 2025) and seven-year forecast (2026–2032) with scenario outputs calibrated to regulatory, feedstock and trade permutations.
-
Price and cost structure analysis, including feedstock margin sensitivity and a forward-looking raw-material outlook tied to phenol and derivative markets.
-
Regulatory heatmap and compliance playbook covering key jurisdictions, limits, labeling obligations and plausible policy trajectories that would affect formulation and market access.
-
Commercial playbooks tailored to manufacturers, brand owners and distributors: procurement strategies, dual-sourcing templates, premium-grade product play, and margin-protection tactics.
-
Supply-base diagnostics: supplier profiles, plant-capacity mapping, quality-certification crosswalks (e.g., cosmetic vs pharmaceutical grades), and a shortlist of acquisition/partnering targets for consolidation-minded players.
-
Actionable M&A and investment framework with valuation sensitivities under different demand and regulatory scenarios, plus an interactive scenario-builder workbook for internal use.
Key macro and market dynamics shaping 2026 decisions
-
Regulatory tightening in major markets remains a real and immediate risk. Existing EU rules constrain methylparaben concentrations in cosmetics and require labeling tied to potential endocrine-disruption concerns, while select national authorities have already introduced product-specific restrictions. These requirements increase compliance costs and can shift demand into alternative preservatives or higher-purity grades with clearer regulatory documentation.
-
Trade and tariff developments have concrete commercial effects. Recent preliminary anti-dumping measures targeting specific import flows have altered commercial incentives for buyers and importers, changing landed-cost calculations and prompting some buyers to re-evaluate near-term sourcing strategies.
-
Upstream feedstock stressors materially influence margins. A meaningful increase in the price of p-hydroxybenzoic acid — the primary feedstock — has been observed, driven by tighter supplies of phenol derivatives. These input cost moves are transmitted to finished-product pricing and compress margins when pass-through is limited by contract structures or competitive pressure.
-
Product stewardship and reputational risk are now commercial imperatives. For brand owners, explicit labeling requirements and heightened consumer scrutiny around parabens mean that transparency, documentation and validated safety dossiers can be differentiators in shelf placement and private-label sourcing.
Competitive landscape: what to watch
The market’s supplier base ranges from large diversified chemical companies to specialty manufacturers and regional exporters. Several large, vertically integrated suppliers occupy the mid-to-high end of the purity spectrum and are differentiated by certification, regulatory compliance and branded ingredient solutions. Smaller, regionally focused suppliers emphasize cost and volume availability.
-
Major multinational chemical companies are leveraging compliance certifications and expanded low-impurity grades to target regulated pharmaceutical and premium cosmetic segments. Recent certification updates and product-catalog expansions are explicitly designed to capture buyers seeking regulatory certainty and reduced impurity profiles.
-
Specialty and laboratory-grade producers supply USP/NF grade material to pharmaceutical and clinical users. Their strategic advantage lies in regulatory documentation, batch traceability and the ability to supply to regulated markets under strict quality systems.
-
Export-oriented producers from Asia continue to play a price-competitive role in industrial and cost-sensitive cosmetic channels, but they face headwinds when jurisdictional trade measures or regulatory restrictions on certain end-uses are tightened.
Selected recent industry actions are illustrative: compliance certification updates in Europe and expanded low-impurity product lines announced in 2024 demonstrate how incumbent suppliers are prioritizing regulatory assurance and product-differentiation. Executives evaluating supply partners should weigh these developments when assessing supplier risk and long-term contracts.
Strategic scenarios and recommended 2026 playbook
We outline three plausible scenarios and the high-impact moves that unlock resilience and upside.
-
Baseline (our central case; CAGR around 4.5% through 2032): Prioritize supply security and cost discipline. Actions: secure multi-year agreements with tier-1 suppliers with supply guarantees, include indexed pricing provisions tied to feedstock benchmarks, and implement an early-warning indicator system for raw-material price spikes.
-
Downside (regulatory escalation or trade fragmentation): Focus on regulatory-safe grades and market diversification. Actions: invest in qualifying higher-purity grades for pharmacopeial use, accelerate dossier submissions and regulatory audits, and restructure geographic exposure to minimize vulnerability to single-jurisdiction actions.
-
Upside (accelerated reformulation or premiumization): Capture margin by supplying differentiated, certifiable solutions. Actions: develop low-impurity, certified cosmetic/pharmaceutical-grade offerings, pursue co-development with brand partners for “clean label” positioning, and consider selective bolt-on acquisitions to gain capacity and technical know-how.
Operational priorities for 2026
-
Supply-chain de-risking: implement dual-sourcing for critical feedstocks, evaluate nearshoring where trade measures increase landed costs, and renegotiate contract terms to include cost-sharing clauses for materially adverse feedstock moves.
-
Regulatory & product stewardship: maintain a living compliance file for principal markets, invest in impurity-reduction process steps where cost-effective, and align labeling and communication strategies to pre-empt consumer and regulator scrutiny.
-
Commercial & price strategy: segment customers by regulatory exposure and willingness-to-pay for certified grades; use differentiated pricing for premium, traceable lots versus commoditized volumes.
-
M&A and partnership posture: target mid-tier players with compliant production assets and validated quality systems; explore toll-manufacturing agreements to flex capacity without heavy capital outlays.
Why PW Consulting’s analysis is actionable for 2026
Our report combines hard market-sizing (historical 2020–2025; base year 2025) and a transparent forecast framework (2026–2032) with jurisdictional regulatory mapping and supplier-level profiling. The product includes an interactive model that allows executives to re-run scenarios using custom assumptions on feedstock prices, regulatory developments and trade measures. Importantly, while this release outlines the strategic implications and methodologies, detailed segmentation tables, regional and application-level shares, and line-item supply figures are purposefully reserved for subscribers — the exact inputs that corporate strategy teams and procurement functions require to operationalize these recommendations.
Next steps
-
Shortlist: if you manage sourcing, quality or regulatory strategy, initiate a 45–60 minute briefing with our chemicals practice to map immediate exposure and obtain a tailored scenario run for your portfolio.
-
Deep-dive: obtain the full report and the interactive workbook to access the granular segmentation, plant-level capacity mapping and supplier scorecards that are not included in this executive briefing.
PW Consulting’s Worldwide Methylparaben Market report is positioned to be a practical tool for 2026 planning: it identifies where risk is concentrated, quantifies the likely scale of near-term market moves, and prescribes the commercial and operational responses that protect margin and enable selective growth. For access to the full data set, hidden segmentation detail and supplier-level tables that underpin these strategic recommendations, visit our report page or contact our chemicals team for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Methylparaben Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


