



PW Consulting Forecasts 4.8% CAGR for Worldwide Oil Hose Market During 2026–2032
By PW Consulting, 2026-07-15
Worldwide Oil Hose Market 2026 Preview: Strategic Imperatives for Corporate Decision-Makers
As PW Consulting publishes its comprehensive Worldwide Oil Hose Market report, this executive briefing outlines the report’s strategic value for leaders planning actions in 2026. The global oil hose market—measured in USD Million and benchmarked to 2025 as the base year—is entering a transitional phase. After reaching an estimated market size of USD 3,925.8 Million in 2025, our model anticipates continued expansion across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 4.8%, reaching roughly USD 5,450.7 Million by 2032. For companies weighing capex, supply-chain realignment, M&A, or product development in 2026, the report crystallizes the operational levers and risk triggers that will determine winners and laggards.
Worldwide Oil Hose Market
Why 2026 Is a Pivotal Year
Our dataset shows 2026 as a hinge year: near-term headwinds exert pressure on volumes and margins, while secular demand drivers for oil & gas exploration, marine bunkering, and industrial fluid transfer continue to underpin medium-term growth. This juxtaposition creates a narrow window in 2026 for strategic repositioning—either to shore up resilience or to accelerate capture of higher-margin niches. The PW Consulting report transforms market dynamics into a decision roadmap for executive teams, enabling prioritized investments that align with a 4.8% CAGR growth trajectory through 2032.
Worldwide Oil Hose Market
Report Highlights: What Makes This Research Actionable
- Market sizing and trend analysis anchored to a robust historical series (2020–2025) and an explicit forecast period (2026–2032), including scenario pathways that reflect commodity shocks and regulatory shifts.
- Commercial playbooks for purchasing, manufacturing, and aftermarket service optimization—translated into KPI triggers and timing recommendations for 2026 spending cycles.
- Supply-chain stress-testing templates that quantify margin exposure to raw-material volatility, logistics interruptions, and regional certification requirements.
- Competitive benchmarking and capability maps (product, geographic reach, certifications) that enable rapid partner selection, alliance formation, or bolt-on acquisition screening without disclosing proprietary segment-level numbers in this preview.
- Execution checklists for product qualification and regulatory compliance for high-risk end-markets such as offshore operations and refuelling systems.
Market Dynamics and Structural Drivers
The long-term demand rationale for oil hoses remains intact: energy sector activity, port and bunkering throughput, petrochemical processing upgrades, and industrial fluid handling requirements continue to drive OEM and aftermarket demand. That said, 2026 will be characterized by three interacting dynamics:
Worldwide Oil Hose Market
- Raw-material cost pressure. Synthetic rubber and nitrile-based elastomers—the primary inputs for many oil hose constructions—have exhibited meaningful price volatility into 2026. For example, synthetic rubber benchmarks rose substantially year-over-year in early 2026, and NBR pricing has shown sharp regional spikes amid supply anxieties. These cost movements compress margins for commodity hose portfolios and elevate the value proposition of design and material optimization.
- Regulatory and certification complexity. Oil hose products intended for fuel and mineral oil handling must meet established standards (for example, industry EN standards and API/OCIMF guidance in offshore contexts). Increasingly, customers demand documented lifecycle performance—traceability, test records, and class approvals—which favors manufacturers with robust quality systems and digital documentation capabilities.
- Demand heterogeneity across applications. Growth is not uniform: high-specification segments (offshore, bunkering, and specialized refinery services) command premium pricing and longer qualification cycles, while commoditized transfer hoses face pricing pressure. This divergence creates strategic choices between volume-led scale and margin-led specialization.
Supply-Side Realities: Fragmentation, Scale and Opportunity
The oil hose market is commercially fragmented. A mix of global industrial OEMs, regional specialists, and independent hose manufacturers coexist, creating both competitive intensity and partnership opportunities. Fragmentation means that regional players with deep local service networks and certifications can preserve healthy margins despite the presence of multinational rivals.
Key strategic implications for suppliers:
- Invest selectively in certification and test capability to access higher-margin, high-barrier segments (e.g., offshore and bunkering).
- Pursue modular manufacturing footprints and near-shore inventory to mitigate raw-material cost pass-through and logistics risk.
- Diversify elastomer sourcing and accelerate substitution or compound engineering where regulatory regimes permit—an approach that can stabilize input cost exposure.
Competitive Landscape: Who Matters and Why
Our competitive analysis focuses on firms that combine broad product portfolios, engineering depth, and global distribution networks. Leading industrial groups and specialized manufacturers each bring different advantages:
- Large industrial conglomerates deliver scale, global service networks, and cross-selling into adjacent product lines—useful when customers prefer single-source suppliers for complex projects.
- Regional specialists and independent thermoplastic or reinforced-hose manufacturers offer agility, quicker qualification turnaround, and customization for local standards or extreme operating environments.
- Technology-focused players that invest in materials science, manufacturing automation, and digital quality records differentiate by reducing total cost of ownership for end-users.
The PW Consulting report profiles the spectrum of competitors and provides capability matrices (product families, certification footprint, facility geographies, and aftermarket service reach). This enables procurement and corporate development teams to rank potential suppliers and targets against their strategic priorities for 2026 without revealing confidential contract-level data in this public summary.
Raw Materials and Margin Sensitivity
Raw-material trajectories are a near-term constraint on profitability. Market indicators through early 2026 show elevated synthetic rubber prices and notable increases in nitrile butadiene rubber (NBR) benchmarks—dynamics driven by feedstock tightness, regional demand rebounds, and geopolitical supply concerns. For manufacturers, the result is an urgent need for dynamic pricing clauses, hedging strategies, and product reformulation pathways to protect margins while sustaining competitiveness.
Regulation and Certification: Non-Negotiable for Premium Segments
Compliance with fuel and mineral oil standards is a baseline expectation in many industrial and transport segments. For high-risk applications, customers increasingly demand third-party verification and lifecycle traceability. The report lays out an implementation timeline for certification investments and the expected payback in terms of access to higher-value contracts—actionable for procurement, engineering, and quality leaders planning 2026 budgets.
Scenarios and Decision Triggers Through 2032
To translate forecast numbers into boardroom actions, our research models three plausible scenarios—baseline, constrained-inputs, and accelerated-demand—each mapped to specific decision triggers. For example, a sustained spike in elastomer costs or a new regulatory requirement for offshore hoses would activate contingency plans around inventory deployment, customer repricing, and supplier consolidation.
- Baseline: steady recovery after the immediate 2026 transitional pressures, supporting the consensus CAGR into 2032.
- Constrained-inputs: prolonged raw-material stress reduces margins and curtails lower-value product volumes, favoring premium niches and regionalized production.
- Accelerated-demand: a stronger-than-expected uptick in offshore and bunkering activity compresses lead times, elevates premium pricing, and fast-tracks qualification cycles for new suppliers.
How Executives Should Use This Report in 2026
For executive teams, the PW Consulting report is designed as a working tool—not just a repository of data. Use it to:
- Prioritize capex: decide whether to invest in certification labs, new compounding capability, or distribution hubs based on the scenario matrix and ROI thresholds provided.
- Design procurement strategies: adopt dynamic contracts and dual-sourcing frameworks informed by our supplier risk scores and raw-material sensitivity analyses.
- Target M&A and alliances: filter potential acquisition candidates and technology partners by capability gaps and regional service depth identified in our competitive maps.
- Frame pricing and go-to-market playbooks: implement segmented pricing and service bundling for premium applications to protect margins when commodity pressures persist.
What the Full Report Contains (Practical Detail)
- Comprehensive market model (2020–2032) with downloadable datasets and scenario toggles.
- Segment-level diagnostic tools and supplier scorecards to support vendor selection and contract negotiations.
- Detailed regulatory and materials appendix, including supply-chain stress-test templates and suggested contractual language to manage pass-through of input-cost shocks.
- Action-oriented recommendations and a 12–18 month implementation roadmap tailored to different revenue and margin objectives.
PW Consulting’s Worldwide Oil Hose Market report offers the precise combination of macro forecasting, tactical tools, and competitive intelligence that corporate leaders need to convert the 2026 inflection into a durable advantage. The public briefing above highlights the strategic contours and priority actions—but the full report contains the granular models, supplier assessments, and executable templates that decision-makers will rely on to operationalize strategy.
Next Steps
For executives preparing 2026 budgets, sourcing strategies, or acquisition screens, PW Consulting’s report provides immediate utility. To access the full dataset, supplier scorecards, and implementation guides—along with a custom briefing tailored to your company’s position within the value chain—visit the report page or contact our industry team to schedule a strategy session.
For detailed analysis of this topic, please visit the official page: Worldwide Oil Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Column Bioimpedance Analyzer Market Poised to Surge to USD 907.86 Million by 2032 on a 9.02% CAGR
By PW Consulting, 2026-07-15
Worldwide Column Bioimpedance Analyzer Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market intelligence on the Worldwide Column Bioimpedance Analyzer market synthesizes five years of historical performance and a forward-looking forecast through 2032, providing a high-confidence foundation for executive decisions in 2026. Our analysis shows the industry continuing on a resilient growth trajectory—market size expanded through the 2020–2025 base period and is projected to grow at a compound annual growth rate (CAGR) of 9.02% over the 2026–2032 forecast window. By 2032 the global market is expected to approach a near doubling from the 2025 base, underscoring both opportunity and urgency for leadership teams planning product, regulatory, and commercial strategies this year.
Worldwide Column Bioimpedance Analyzer Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a tipping point. Buyers across clinical, research and consumer-facing settings are explicitly prioritizing measurement fidelity, regulatory assurance and data interoperability. Our findings show market momentum that rewards firms able to combine clinically validated hardware with robust software and ecosystem partnerships.
Worldwide Column Bioimpedance Analyzer Market -
Capital allocation: With predictable mid-to-high single digit growth, the category is attractive for targeted R&D, M&A, and channel investment. Our model quantifies trade-offs between organic product investment and inorganic scale options—guidance that is immediately actionable for 2026 budgeting cycles.
Worldwide Column Bioimpedance Analyzer Market -
Regulatory pull-through: Recent regulatory activity and reimbursement clarity have catalyzed commercial adoption in certain clinical segments; understanding the interplay of product classification, evidence generation and payer positioning will be decisive for go-to-market success in 2026.
Core takeaways — high-level, decision-focused
-
Market momentum is broad-based. After a multi-year expansion to the 2025 base year, forecast growth at ~9% CAGR through 2032 implies sustained demand across hospital, wellness and home-health channels; this is not a niche bounce, but a structurally enlarging market.
-
Concentration and competitive advantage: The market exhibits moderate concentration among leading firms (aggregate share of the top three and top five suppliers indicates material incumbency advantages). That concentration elevates the importance of differentiation through clinical validation, software services and global regulatory footprints.
-
Software-as-a-service and analytics are a rising value driver. Devices alone no longer secure premium positioning—buyers increasingly value cloud analytics, longitudinal tracking, and integration into electronic health records and fitness ecosystems.
What the PW Consulting report contains (practical, executive-ready)
-
Market sizing and forecast model: A transparent, auditable model covering 2020–2025 historicals and 2026–2032 forecasts. The model can be re-run under alternate macro and adoption scenarios to stress-test strategic options.
-
Market dynamics and adoption drivers: In-depth analysis of buying criteria by end-user cluster, technology preferences (single-frequency vs. multi-frequency/BIS approaches), and channel economics—framed to aid prioritization of product roadmaps and sales investments.
-
Regulatory and reimbursement playbook: Line-item guidance on device classification expectations (U.S. FDA 510(k) pathways and EU Class IIa implications), ISO 13485 requirements, and payer coding/reimbursement touchpoints relevant to lymphedema and related clinical indications.
-
Competitive positioning and capabilities assessment: Comparative profiles of leading suppliers, capability maps (hardware, software, services), and decision matrices for partnership, licensing or acquisition targets.
-
Go-to-market and commercial readiness plans: Tactical recommendations for channel development, pricing architecture, KOL engagement and clinical validation studies calibrated to shorten sales cycles across clinical and consumer channels.
-
Scenario-based strategic options: Three executable strategic pathways—(1) Clinical Excellence, (2) Platform & Data Monetization, and (3) Cost & Channel Scale—each with investment levers, timeline estimates and quantified break-evens. (Note: detailed segment-level datapoints and company revenue splits are reserved for the full report.)
Regulatory and reimbursement environment — what you need on day one
-
Regulatory regimes remain a gating factor for clinical adoption. Bioimpedance analyzers intended for medical diagnostics are subject to U.S. FDA Class II controls (510(k)) and CE marking as Class IIa devices in the EU, with ISO 13485 recognized as the quality management benchmark for manufacturers targeting medical markets.
-
Reimbursement is selective but impactful. Specific CPT coding pathways exist for certain BIS applications (e.g., extracellular fluid assessment in lymphedema), and payer-level coverage decisions materially affect clinician uptake in ambulatory and oncology aftercare markets.
-
Regulatory signals at the start of 2026 matter. Notably, a major BIS software platform received updated 510(k) clearance in January 2026—an example of how software updates and validation can unlock additional clinical use-cases and broaden addressable markets for companies that can demonstrate traceable clinical value.
Competitive landscape — profiles and strategic implications
The field is populated by well-established device manufacturers with distinct go-to-market plays. PW Consulting’s competitive review focuses on product differentiation, evidence generation, and channel reach rather than headline market shares alone.
-
InBody Co., Ltd. (Seoul): A brand synonymous with multi-frequency segmental analysis, InBody’s portfolio emphasizes clinical-grade measurement across standing/column form factors. Strategic implication: Companies competing in research and high-acuity clinical settings must match or exceed the depth of segmental analytics and the research partnerships that sustain trust with hospital systems.
-
Tanita Corporation (Tokyo): Tanita’s column and clinical lines target professional and clinical customers with multi-frequency variants and modular kits. Strategic implication: Modular physical platforms that serve both clinic and fitness channels can capture a broader revenue mix, but require rigorous calibration and service networks.
-
Charder Electronic (Taichung): A cost-competitive supplier with clinical and professional models, Charder is positioned to serve price-sensitive markets and channel partners seeking white-label opportunities. Strategic implication: Competitive entrants should anticipate margin pressure in commoditized channels and differentiate on software, warranty and integration.
-
seca GmbH (Hamburg): Known for medical validation and alignment with reference standards (MRI/4C), seca’s approach underscores the premium value of validated accuracy. Strategic implication: Investing in independent validation studies can materially accelerate procurement among hospital tender processes.
-
Marsden Weighing Machine Group (UK) and selected Chinese manufacturers: These players serve regulated clinical segments and high-volume routine settings. Strategic implication: Scale in distribution and certification proficiency is a viable alternative to near-term R&D differentiation for companies aiming at hospital procurement lists.
Strategic recommendations for executives in 2026
-
Prioritize clinical evidence that aligns to purchaser decision rules. Rapid, targeted studies demonstrating reproducibility versus reference methods (e.g., multi-compartment validation) unlock premium positioning and shorten procurement cycles.
-
Bundle software and services. Offerings that include analytics, longitudinal patient dashboards and integration APIs command higher renewals and create switching costs. A subscription-led model merits pilot programs in 2026.
-
Design regulatory-first roadmaps. Early engagement with regulatory bodies (FDA, notified bodies) and alignment to ISO 13485 will reduce time-to-market risk—critically important for clinical sales cycles and large-system tenders.
-
Targeted channel plays over broad geographic expansion. With incumbent concentration among the top suppliers, focused, well-capitalized channel plays (e.g., strategic partnerships with EHR vendors or regional clinical distributors) often outpace diffuse distribution efforts.
-
Consider bolt-on M&A to access complementary software or service capabilities. Given the market’s moderate concentration, acquiring analytics platforms or validated clinical software accelerates capability assembly compared to multi-year internal development.
Methodology and rigor
PW Consulting’s estimates combine bottom-up device revenue modeling, end-user adoption curves, supplier vetting and primary interviews with purchasing decision-makers across clinical and wellness segments. Our forecast scenarios incorporate sensitivity to reimbursement dynamics, regulatory clearance pacing and emergent software monetization. The report also provides a downloadable, transparent financial model to test alternative assumptions tailored to corporate risk profiles.
Next steps — how to use this intelligence in 2026
-
Board-level strategic planning: Use our scenario tool to quantify ROI of competing capital allocations (R&D vs. M&A vs. commercial expansion) and to stress-test 2026 budgets.
-
Product roadmap alignment: Map your development milestones to regulatory check-points and evidence requirements defined in the report to de-risk procurement timelines.
-
Commercial pilots: Launch subscription pilots that bundle devices with analytics in targeted clinical pathways to validate willingness-to-pay and refine go-to-market economics.
Conclusion — strategic urgency and the value of the full report
The Worldwide Column Bioimpedance Analyzer market is moving from a device-centric industry toward a platform-and-data economy. PW Consulting’s research shows clear, investable pathways to capture disproportionate value—if executives act with regulatory discipline, prioritized evidence generation and a software-led commercial strategy in 2026. This preview surfaces the strategic levers and market dynamics; the full report contains the granular segmentation, modeled scenarios, and supplier revenue maps that boards and product leaders will need to finalize 2026 commitments.
To access the complete dataset, scenario models and supplier benchmarking that underpin these conclusions, request the full Worldwide Column Bioimpedance Analyzer Market report from PW Consulting. The report is structured to support immediate decision-making for investment committees, product teams and commercial leadership.
For detailed analysis of this topic, please visit the official page: Worldwide Column Bioimpedance Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Non‑Thermal Food Processing Market to Reach USD 10,680.4 Million by 2032, Growing at a 10.0% CAGR
By PW Consulting, 2026-07-15
Worldwide Non-Thermal Food Processing Market: Strategic Outlook for 2026 Decision-Making
Executive summary
As companies prepare capital and product roadmaps for 2026, PW Consulting’s latest Worldwide Non-Thermal Food Processing Market report offers a strategic compass grounded in rigorous market-sizing and forward-looking scenario analysis. Using 2025 as the baseline and a historical window from 2020–2025, the study projects the market to expand at a robust compound annual growth rate (CAGR) of 10.0% over the 2026–2032 forecast period. That trajectory doubles down on the strategic relevance of non-thermal technologies—High Pressure Processing (HPP), Pulsed Electric Fields (PEF), ultrasound, cold plasma and adjunct methods—for food preservation, quality retention and product differentiation.
Worldwide Non-Thermal Food Processing Market
Why this report matters for 2026 decisions
-
Timing capex and pilots: With the market passing defined inflection points in the mid-2020s, executives need actionable inputs to decide which technologies to pilot, scale or defer through 2026.
Worldwide Non-Thermal Food Processing Market -
Supplier selection and negotiation: Procurement teams require vendor benchmarking and TCO models to extract value from equipment suppliers and integrators as adoption moves from niche to mainstream.
Worldwide Non-Thermal Food Processing Market -
Regulatory and market-entry strategy: Growing acceptance of non-thermal methods by major regulators reshapes market-access rules and export pathways; companies must align product dossiers and testing plans to unlock new geographies.
-
M&A and partnership screening: The combination of accelerating demand and concentrated supplier markets creates windows for bolt-on acquisitions and strategic alliances—our competitive maps identify where value capture is most plausible.
What’s in the report: practical, actionable outputs
The study goes beyond narrative to deliver tools and templates that senior leaders can deploy immediately:
-
Market sizing with scenario brackets: a base case aligned to 2025 market realities, plus conservative and upside scenarios through 2032 supported by sensitivity testing.
-
Technology deep-dives: end-to-end economics for HPP, PEF, ultrasound and cold plasma, including throughput envelopes, typical CAPEX/OPEX ranges, yield impacts and margin implications for common product categories.
-
Commercial benchmarking: supplier scorecards, lifecycle cost models, commissioning timelines and availability statistics to support procurement RFPs.
-
Regulatory playbook: an actionable matrix mapping major regulatory regimes, certification checkpoints, and documentation templates to accelerate approvals and cross-border trade.
-
Buyer decision frameworks: step-by-step guides for pilots, scale-up triggers and go/no-go criteria tied to ROI thresholds and brand risk tolerances.
-
Investment-ready cases: three leveled use-cases (incremental efficiency, premiumization, export-led growth) with modeled P&L impact and payback periods.
Market pulse and macro signals shaping 2026 choices
The market is now at an inflection where adoption is driven by both demand-side premiumization and supply-side readiness. Our analysis quantifies the overall market evolution from the 2020 baseline through 2025 and models a path to more than double the 2025 scale by the end of the forecast period under the base-case CAGR of 10.0%—a rate that creates meaningful commercial windows within a two- to three-year investment horizon.
Key dynamics to build into 2026 planning include:
-
Regulatory validation: Major regulators have begun to formalize non-thermal pathways. For example, FDA recognition of HPP as an equivalent pasteurization method for certain juices and EU-level acceptance of non-thermal pathogen-reduction approaches materially lower the regulatory friction for commercial launches.
-
Export and compliance complexity: Cross-border trade introduces specific duties; in some product flows export into the EU invokes additional novel-food or equivalence requirements that should be embedded in go-to-market timelines.
-
Input-cost volatility: Raw-material price swings—illustrated by recent commodity movements for processing-grade fruits—alter unit economics for many non-thermal applications and should be stress-tested in business cases.
-
Labor and operational costs: Regional labor-cost differentials affect where automation and capital intensity make the most sense; rising wages in developed markets are increasing the attractiveness of higher-throughput, automated non-thermal lines.
Competitive landscape: where to place your bets
The supplier ecosystem is transitioning from single-technology specialists to integrated systems providers. Market concentration metrics indicate a moderate-to-high level of incumbent strength among top vendors, creating differentiated opportunities for end-users depending on their strategic priorities—speed to market, lowest TCO, or highest yield.
-
Hiperbaric (Burgos, Spain) remains the global reference for HPP equipment. Recent product iterations focus on yield optimization and throughput efficiency for juice and protein applications—an important consideration for brands chasing margin recovery.
-
JBT FoodTech (Chaska, Minnesota) combines HPP systems with full-line integration and has been actively expanding manufacturing footprints to support regional demand, signaling an emphasis on local service and reduced deployment lead-times.
-
Multivac Group (Germany) couples HPP capabilities with packaging systems, creating an integrated value proposition for makers who prioritize packaging-enabled shelf-life gains and simplified supplier relationships.
-
Elea Technology and Pulsemaster (Germany, Netherlands) lead on PEF innovations. Their technology is increasingly relevant for producers focused on cell-disruption use-cases—extraction, minimal-processing vegetable lines and texture-modulated products.
-
Steriflow (Thyssenkrupp) provides a hybrid offering that spans traditional autoclaves to HPP, addressing customers seeking flexibility across thermal and non-thermal portfolios.
Recent vendor activity—product launches to improve yield, trade-show demonstrations focused on vertical use-cases, and regional facility expansions—shows suppliers are optimizing both product features and commercial footprints. For buyers, the vendor decision is now a multi-dimensional trade-off between technical fit, service footprint, and total cost of ownership over a five- to seven-year horizon.
Strategic playbook for 2026
Executives will face three recurring strategic choices in 2026. PW Consulting’s report translates these into executable moves:
-
Selective scaling: Prioritize pilot-to-scale paths for product lines where non-thermal processing unlocks clear consumer or channel premiums. Use short-list TCO and pilot KPIs to avoid over-investment ahead of market validation.
-
Partnership-first market entry: Where regulatory or export complexity is high, pursue co-development or toll-manufacturing relationships to accelerate time-to-shelf while controlling capital deployment.
-
Capability consolidation: For companies with multiple small plants, consider consolidating into fewer, higher-utilization centers equipped with advanced non-thermal systems—our ROI scenarios quantify payback under typical utilization curves.
-
M&A and supplier plays: Identify bolt-on acquisitions that secure feedstock, proprietary formulations or regional distribution; for equipment suppliers, vertical integration into packaging or service creates defensible commercial moats.
Methodology and confidence
The report’s findings rest on a triangulated methodology: bottom-up equipment and consumable revenue mapping, primary interviews across OEMs and end-users, regulatory dossier reviews and transactional evidence from recent supplier contracts. We present multiple scenarios and sensitivity bounds to isolate which assumptions materially change strategic outcomes—helping executives prioritize which levers to test in 2026.
To preserve competitive advantage for our clients, detailed granular splits (technology-by-application-by-region slices, supplier-specific revenue breakouts and modeled contract-level economics) are intentionally summarized in this release and are available in full through our data portal. This “trailer” approach is designed to show analytical depth while protecting the proprietary datasets that enable actionable decision-making.
How to use this insight immediately
-
Run an internal rapid-assessment using our buyer decision framework to classify product lines into pilot, scale or shelve categories within 30 days.
-
Engage shortlisted suppliers for three-way RFIs/RFPs using our standard scoring templates to compare TCO on a like-for-like basis.
-
Adjust product launch timelines to reflect regulatory checkpoints highlighted in the regulatory playbook to avoid costly relaunches.
-
Scope a two-site consolidation pilot where labor and throughput economics suggest near-term payback—our investment cases provide the templates.
Next steps and access to full intelligence
PW Consulting’s Worldwide Non-Thermal Food Processing Market report is designed to be immediately operational for strategy, procurement and R&D teams. The full report includes the confidential datasets, supplier scorecards, downloadable financial models and regulatory dossier templates that underpin the conclusions summarized here. For decision-makers ready to convert this intelligence into action in 2026, please visit PW Consulting’s report page to access the complete study and supporting data tools.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Thermal Food Processing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Reformer Unit Market to Expand from USD 864.5 Million in 2025 to USD 1,383.65 Million by 2032 at a 6.95% CAGR — Asia Pacific, Steam Methane Reformers and Hydrogen Production Lead; Top 3 Account for 42.15%
By PW Consulting, 2026-07-15
Worldwide Reformer Unit Market — Strategic Briefing for 2026 Decisions
Executive summary
As industrial decarbonization accelerates and demand for low-carbon hydrogen and derivatives scales, reformer units sit at the crossroads of energy transition and legacy hydrocarbon value chains. PW Consulting’s latest Worldwide Reformer Unit Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market sizing, technology trajectories, supply‑chain exposures, and vendor economics into a single decision-grade deliverable for boards, project teams, and corporate strategy functions. The market that was approximately USD 864.5 Million in 2025 is projected to grow at a CAGR of 6.95% through the 2026–2032 forecast window, reaching more than USD 1.38 Billion by 2032 — a pace that makes 2026 a pivotal year for lock‑in of long‑lead equipment and partnership structures.
Worldwide Reformer Unit Market
Why this matters for corporate decision‑making in 2026
-
Timing of capital commitments: With multi‑year procurement horizons for reformer furnaces, catalyst supply, and engineered components, firms deciding in 2026 will either secure advantage on pricing and delivery or face higher risk and premium lead times into 2027–2028.
Worldwide Reformer Unit Market -
Technology pathway clarity: Choices between conventional fuel-fired designs, electrified steam reformers (e‑REFORMER), and autothermal configurations have radically different CAPEX/OPEX profiles and decarbonization footprints — our modelling quantifies those trade-offs at plant and portfolio levels.
Worldwide Reformer Unit Market -
Regulatory and market exposure: Stricter GHG regimes and emerging carbon pricing materially affect lifetime project returns for conventional reformers; a 2026 FID horizon is often the breakpoint for whether to invest in retrofit‑ready designs or pursue near‑term electrification and CCS integration.
Market sizing and trajectory (high level)
Our bottom‑up market model reconciles historic sales from 2020 to 2025 and overlays forward project pipelines, announced low‑carbon hydrogen/ammonia initiatives, and traditional refinery/upgrading demand. The market expanded from roughly USD 620 Million in 2020 to USD 864.5 Million in 2025. Under central assumptions — moderated commodity cycles, phased regulatory tightening, and continued hydrogen economy support — we estimate a 6.95% CAGR through 2032, with notable acceleration in later years driven by retrofit waves and second‑generation low‑carbon projects.
Detailed breakdowns by region, type and application are included in the full report. In this briefing we intentionally highlight trends and implications while reserving the granular split tables for the source report to enable decision‑makers to validate vendor offers against the full dataset.
Technology and decarbonization dynamics
-
Electrification: The e‑REFORMER is moving from demonstration to early commercial deployment. Peer‑reviewed studies indicate potential direct flue gas CO2 reductions up to ~91.6% in retrofitted ammonia plants, coupled with thermal efficiency improvements (e.g., moving from mid‑85% ranges to nearly 89% in specific cases). Our techno‑economic modules quantify electricity supply contracts, on‑site renewables integration, and grid decarbonization sensitivities.
-
Autothermal and hybrid designs: For projects prioritizing compact footprint and integration with low‑carbon feedstocks, autothermal reforming and hybrid SMR‑ATR topologies are now competitive when combined with CCS. We model CAPEX escalation scenarios and capture rate trade‑offs across real project templates.
-
Catalysts and materials: Catalyst longevity and reformer tube metallurgy materially influence maintenance cycles and total cost of ownership. Our benchmarking includes catalyst regeneration economics and alloy life‑cycle assumptions that feed into multi‑scenario LCOH/LCOA outputs.
Competitive landscape — what the leaders are doing
Market concentration is moderate: the top three and five suppliers together represent a meaningful portion of the addressable market, underscoring the role of engineering scale and licensing IP in bid outcomes. Vendors are pursuing differentiated pathways:
-
Linde Engineering has leveraged modularization and small on‑site solutions to capture decarbonization‑related demand and signed strategic supply agreements for low‑carbon ammonia projects — a playbook focused on flexible delivery and service‑backed lifetime value.
-
Honeywell UOP and Axens continue to defend and extend catalytic reforming cores through licensing, catalyst systems, and retrofit packages tailored to refinery modernization objectives.
-
KBR and Technip Energies combine EPC scale with process IP for large hydrogen/syngas trains; their wins hinge on integrated CCS readiness and contractor guarantees tied to reformer performance.
-
Specialist suppliers such as Johnson Matthey (catalysts), MetalTek and Kubota (high‑temperature metallurgy), and engineering service houses like Wood and L&T fill critical supply‑chain nodes; their role is often decisive for reliability and life‑cycle cost metrics.
Recent industry movements validate these strategic shifts: a leading catalyst and process firm presented electrification pathways at a major conference in late 2025; a top European engineering firm reported record small‑site project wins in early 2025; and a global gases major entered a long‑term supply agreement tied to an autothermal reforming‑based low‑carbon ammonia facility mid‑2025. These developments are signals of two converging trends: portfolio diversification among incumbents, and a rising demand for appliances and service models that de‑risk owners’ transition paths.
Supply chain, cost drivers and material risks
-
Raw materials: Steel input costs — important for pressure vessels and reformer tubes — were at or near the bottom of the cyclical trough in early 2026. Our procurement scenarios show constrained upside in 2026 with a more meaningful recovery from 2027, implying that contracts signed in 2026 can lock lower alloy prices but must be balanced against delivery timelines.
-
Long‑lead items: Reformer furnaces, specialty alloys, and catalyst systems carry multi‑quarter lead times. Delays in these nodes amplify schedule risk for projects targeting early hydrogen/ ammonia ramps.
-
Service and aftermarket: Tube life extension technologies and predictive maintenance offered by niche providers meaningfully affect lifetime economics; owners should require detailed service SLAs or consider bundled performance contracts.
Regulatory and financing context
Stricter GHG regulations and carbon pricing increasingly alter project IRR math. Policymakers are also supporting electrification pilots and low‑carbon hydrogen incentives in multiple jurisdictions. Financing partners are applying differentiated risk premiums for fossil‑intensive plant designs versus low‑carbon‑ready configurations. Our scenarios evaluate the combined impact of carbon price corridors, subsidy profiles, and offtake‑contract structures on project bankability.
What the report contains — operationally focused deliverables
The report is designed to be immediately actionable for 2026 planning cycles. Key elements include:
-
Granular historical and forecast market sizing (by region, type, and application) with downloadable tables and interactive charts.
-
Vendor scorecards and procurement playbooks: capability maps, risk matrices, contract clauses to protect against alloy and catalyst supply disruption, and recommended bidding frameworks for EPC/Vendor scope splits.
-
Techno‑economic models: configurable CAPEX/OPEX templates, LCOH/LCOA calculators, and sensitivity sweeps for electrification, CCS, and fuel price scenarios.
-
Retrofit and retrofit‑ready design guidance: stepwise pathways to electrification and CCS integration, including expected downtime, regulatory approvals, and staged investment approaches.
-
Case studies and reference plant dossiers: anonymized project data, failure modes, and turnkey performance metrics that illuminate real procurement outcomes.
-
Project pipeline and prospects tracker: validated near‑term tenders and medium‑term opportunities with probability‑adjusted revenue impact (full dataset available in the source report).
Strategic recommendations for 2026
-
Prioritize procurement lead items in 2026 to capture lower alloy prices and avoid 2027 supply‑chain tightening; employ staged purchase options for catalysts and tubes to retain flexibility.
-
Design new assets “retrofit‑first”: favor process configurations and plant layouts that allow staged electrification or CCS add‑ons without excessive rework.
-
Negotiate vendor contracts with performance‑linked milestones and indexed pricing collars for steel and catalyst inputs to share material cost volatility with suppliers.
-
Deploy a portfolio hedging strategy: balance conventional fuel‑based reformer projects with targeted electrified pilots where offtake and power tariffs are favorable.
-
Engage early with financiers and regulators to shape acceptable carbon assumptions in project models — financing terms are increasingly conditional on explicit decarbonization roadmaps.
How to use this analysis
Executives and project teams should treat 2026 as a decision inflection point: the timing of engineering orders, catalyst procurement, and strategic partnerships will materially affect cost and emissions trajectories for a decade. The full PW Consulting report provides the granular segmentation, downloadable models, and supplier scorecards you need to convert the insights above into executable tenders and board memoranda.
Next steps
We have intentionally presented high‑level market sizing and strategic implications here while withholding detailed regional, type and application splits from this briefing to preserve the full business value of the underlying dataset. For access to the complete dataset, interactive models, and proprietary supplier assessments, please consult the full Worldwide Reformer Unit Market report on our website or contact your PW Consulting account representative.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Integral Waterproofing Compound Market to Reach USD 6,043.68 Million by 2032PW Consulting Forecasts Worldwide Areca Nut Market to Expand at a 3.88% CAGR Through 2032
By PW Consulting, 2026-07-15
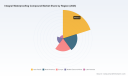
Worldwide Integral Waterproofing Compound Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting is pleased to release a senior-level executive preview of our forthcoming Worldwide Integral Waterproofing Compound Market report. This briefing synthesizes the report’s most consequential strategic guidance for corporate leaders preparing decisions in 2026 — from product and procurement strategy to M&A and regulatory compliance. The narrative below demonstrates the depth of our analysis while intentionally withholding the detailed segment-level tables and price matrices that appear in the full report. To access the complete datasets, supplier scorecards, and downloadable Excel models, please refer to the PW Consulting report page.
Worldwide Integral Waterproofing Compound Market
Market at a glance — trajectory and near-term outlook
The integral waterproofing compound market has shown steady resilience through a period of cyclical construction activity and supply-chain turbulence. Our consolidated market model places the industry at approximately USD 4.22 billion in the 2025 base year, following a full five-year historical reconstruction (2020–2025) and validated through primary interviews with ready‑mix producers, specification engineers, and major admixture manufacturers.
Worldwide Integral Waterproofing Compound Market
Looking ahead, PW Consulting’s top-line forecast projects expansion over the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.28%, producing a market that exceeds USD 6.04 billion by 2032. This steady growth path is driven by ongoing infrastructure renewals, urbanization in high-growth markets, and growing specification rates for durability and low-maintenance concrete in both new-build and refurbishment programmes.
Worldwide Integral Waterproofing Compound Market
Market concentration metrics indicate a moderately consolidated supplier base: the three largest suppliers account for a material share of industry revenue, and the five‑firm concentration increases the degree of influence held by incumbent global players. This structure creates both barriers and openings — scale is critical for distribution and technical service, yet differentiated chemistry and warranty propositions continue to unlock niche opportunities for agile innovators.
Why 2026 is a strategic inflection point
-
Specification and durability expectations are rising. Owners and asset managers are increasingly valuing lifecycle cost over first cost, driving higher uptake of integral solutions that reduce long-term maintenance and leakage risk.
-
Raw material dynamics remain a central risk variable. Energy-driven cost swings and episodic surges in specialty inputs — notably silicone derivatives in recent years — have exposed manufacturer P&Ls to volatility and underline the need for disciplined procurement and hedging frameworks.
-
Regulatory and ESG requirements are reshaping formulations. The move toward low‑VOC and bio-derived hydrophobic agents to meet green building schemes and regional product stewardship rules is accelerating formulation R&D and supplier qualification cycles.
-
Operational adoption trends are favoring formulations that integrate with automated dosing at ready‑mix plants and precast facilities, changing the commercial negotiations between admixture suppliers and concrete producers.
What the PW Consulting report delivers — practical, decision-ready content
Our report is designed as an implementation toolkit for commercial leaders and engineering teams. Highlights include:
-
Methodology and reproducible market model: full transparency on data sources, assumptions, and sensitivity runs so investors and strategists can re-run scenarios against bespoke variables.
-
Revenue and demand forecast (2026–2032) with scenario envelopes for high-growth and downside cases, plus a downloadable Excel model that allows users to test price, mix, and regional demand levers.
-
Supplier scorecards and a technology matrix comparing crystalline, liquid and powdered chemistries on performance attributes (permeability reduction, compatibility with SCMs, curing interactions, dosing requirements), application best-practices, warranty structures, and commercial terms.
-
Procurement playbook: hedging strategies, contract clauses for pass-throughs and change orders, supplier qualification checklists, and a template raw-material risk-adjusted pricing mechanism.
-
Regulatory tracker and formulation risk register, mapping major green building schemes and anticipated regulatory shifts that influence allowable chemistries and labelling obligations.
-
Go-to-market blueprints for incumbents and challengers: channel design, specification campaigns with engineering bodies, bundling with admixtures and curing agents, and digital tools for specification capture at point-of-sale.
-
M&A and partnership guidance: target archetypes (technology innovators, regional distributors, specialty formulators), valuation frameworks that reflect durability premiums and warranty-backed revenue, and integration checklists for technical teams.
-
Case studies and readiness diagnostics: five practical implementations (infrastructure, commercial envelope repair, precast, basement waterproofing, and tunnel linings) with measured performance outcomes and KPIs for warranty claims and maintenance savings.
Competitive landscape — core companies and strategic implications
The market is characterized by a mixture of global chemical majors, specialist crystalline technology houses, and regional formulators. Below we summarize the strategic positioning of the principal players featured in the report:
-
Sika AG (Baar, Switzerland) — A global leader with a broad admixture portfolio and deep distribution. Offers multiple integral waterproofing product lines dating back to early formulations; strong in technical support and global project references ( https://www.sika.com/).
-
Kryton International Inc. (Vancouver, Canada) — A crystalline-specialist with the original Krystol internal membrane heritage; strong intellectual property and a reputation for long-term durability in demanding infrastructure applications ( https://www.kryton.com/).
-
Xypex Chemical Corporation (Richmond, Canada) — Focused on crystalline integral systems designed to become part of the concrete matrix, differentiated by product positioning that minimizes reliance on surface membranes ( https://www.xypex.com/).
-
The Euclid Chemical Company (Cleveland, USA) — Offers powdered hydrophobic blends and has a strong track record in North American infrastructure and repair markets ( https://www.euclidchemical.com/).
-
Anti‑Hydro International (USA) — A legacy brand with century-long applications in concrete and masonry waterproofing ( https://www.anti-hydro.com/).
-
Pioneer Fibre / Pioneer (Hong Kong) — A regional innovator supplying crystalline-integral systems for major bridges and tunnels across Asia and beyond ( https://www.pioneerfibre.com/).
-
Chem Concrete Pty Ltd (Australia) — Developer of hybrid admixture concepts combining densification, repellents, and nanotechnology, marketed with long-term performance warranties ( https://chemconcreteusa.com/).
-
BASF SE (Ludwigshafen, Germany) — Leverages global construction chemicals capability and the MasterLife line to serve durability-focused segments ( https://www.basf.com/).
-
Mapei SpA, Fosroc International, Pidilite Industries, Penetron International — Each brings complementary strengths in regional reach, product breadth, and channel relationships that influence specification dynamics at the local level ( https://www.mapei.com/, https://www.fosroc.com/, https://www.pidilite.com/, https://www.penetron.com/).
Strategic implication: scale and technical service are table stakes for large infrastructure programmes, while differentiated chemistries and warranty-backed performance remain powerful vectors for challenger growth — especially when paired with regional distribution partnerships.
2026 playbook — ten actionable moves for leaders
-
Institutionalize dynamic raw-material procurement: blend indexation clauses, multi-supplier sourcing for specialty intermediates, and rolling six‑to‑12‑month hedge positions where feasible.
-
Prioritize formulary roadmaps that accelerate low‑VOC/bio‑based hydrophobic agents to capture green-building specification uplift and mitigate regulatory risk.
-
Design commercial offers for ready‑mix and precast customers that combine automated dosing compatibility with technical training and co-marketing for specification adoption.
-
Introduce warranty tiers linked to performance testing and monitored field metrics — translate durability into a saleable value proposition.
-
Deploy a targeted M&A approach focused on crystalline IP, nanotech additives, or distribution footprints in high-growth construction markets; use our report’s valuation templates to stress-test synergies.
-
Implement a specification-outreach programme with engineering societies and major consultants to shorten qualification cycles and reduce commercial friction.
-
Operationalize a product-cost-to-serve model to inform pricing, channel incentives, and after-sales resource allocation.
-
Invest in digital tools for specification capture and warranty claim management to reduce friction and improve customer retention.
-
Run quarterly scenario plays that stress-test business plans against raw-material spikes, energy price shocks, and a construction slowdown.
-
Commit to an R&D-to-commercialization pipeline with clear go/no-go gates tied to regulatory compliance and demonstrable lifecycle cost benefits.
Risks and early‑warning indicators
Key risks to monitor include commodity and specialty chemical price shocks (with silicone markets a recent example), energy cost volatility affecting feedstock pricing, abrupt regulatory changes around VOCs and bio-based labelling, and construction sector cyclicality linked to public spending. We recommend a dashboard that tracks raw-material price indices, lead times for specialty intermediates, specification uptakes among top 100 engineering consultancies, and warranty claim frequency with rolling 12‑month visibility.
Conclusion — how to use this briefing
For executives charged with 2026 planning, the PW Consulting report is structured to convert market intelligence into executable initiatives — from procurement redesign to portfolio repositioning and M&A screening. This preview demonstrates our analytical depth and the pragmatic orientation of the deliverables while reserving the segment-level tables, per-region breakdowns, and downloadable models for the full report. Those datasets are essential for operational planning and financial modelling and are available on our report page.
To request the full Worldwide Integral Waterproofing Compound Market report, including the full set of Excel models, supplier scorecards, and scenario runs, contact PW Consulting or visit our report portal. Our team stands ready to provide tailored briefings and hands-on support for strategic planning workshops in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Integral Waterproofing Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Complicated UTI Treatment Market to Expand at a 6.5% CAGR
By PW Consulting, 2026-07-15
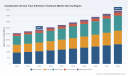
Worldwide Complicated Urinary Tract Infections Treatment Market — Strategic Intelligence for 2026 Decision-Makers
Overview
PW Consulting’s new market study on the Worldwide Complicated Urinary Tract Infections (cUTI) Treatment market delivers a forward-looking playbook designed for commercial, clinical, and corporate strategy teams preparing decisions in 2026. Built on a 2020–2025 historical base and using 2025 as the base year, the report models the market through 2032. The market is projected to grow at a 6.5% CAGR across the 2026–2032 forecast window, rising from an estimated USD 2,850.5 Million in 2025 to USD 4,429.6 Million by 2032. These topline dynamics reflect a confluence of durable demand, regulatory tailwinds for priority antibacterial programs and an active pipeline reshaping treatment mixes.
Worldwide Complicated Urinary Tract Infections Treatment Market
Why this report matters for 2026
-
Actionable timing: The report translates macro momentum into operational timelines — where to accelerate clinical investment, when to prioritize market access, and when to conserve capital ahead of expected pricing and competitive shifts.
Worldwide Complicated Urinary Tract Infections Treatment Market -
Risk-first commercial planning: With antibiotic supply fragility and shifting hospital procurement trends, our risk matrices let teams quantify supply-side disruption impact on revenue trajectories and patient access.
Worldwide Complicated Urinary Tract Infections Treatment Market -
Regulatory and reimbursement foresight: The study synthesizes recent regulatory designations, approvals, and payer moves into scenario-tested reimbursement pathways that materially affect 2026 launch economics.
-
M&A and partnership readiness: By combining competitive mapping with endogenous scenario models, the report flags the most accretive deal types and identifies viable partner archetypes for bolt-on or transformational transactions.
-
Commercial playbooks: Practical go-to-market recommendations — channel prioritization, key account segmentation, and value-communication templates — are calibrated to the mid-decade landscape.
What the report contains — practical deliverables
-
Integrated market-sizing model (historical 2020–2025; forecast 2026–2032) with adjustable drivers for incidence, treatment mix, pricing, and penetration.
-
Scenario planning engine that lets users test alternative clinical outcomes, regulatory timelines and pricing scenarios to produce P&L and cash flow implications.
-
Competitive landscape and pipeline tracker with standardized profiles, strategic assessment grids and event-impact scoring for recent approvals and late-stage trials.
-
Regulatory & reimbursement playbook: QIDP and other priority pathways, payer negotiation levers, formulary and hospital tender playbooks.
-
Supply chain and API risk matrix, including mitigation pathways and inventory policy recommendations tied to demand volatility.
-
Commercialization toolkits — segmented account targeting, medical affairs sequencing, and value dossiers tailored to inpatient and outpatient channels.
-
Executive-ready slide set and an editable Excel financial model to support board deliberations, investor Q&A and deal diligence.
Market dynamics shaping 2026 strategy
Three converging dynamics define the near-term strategic landscape. First, the clinical imperative — rising antimicrobial resistance profiles and the need for agents effective against multidrug-resistant pathogens — continues to sustain demand for novel and combination therapies. Second, regulatory and policy tailwinds have accelerated development; priority designations and recent approvals have shortened pathways for certain candidates, altering the timing of commercial entry. Third, supply-side fragility — highlighted by API shortages reported in recent years — introduces execution risk that can materially affect availability and pricing in hospitals and outpatient settings.
These dynamics interact with payer behavior. Public and private payers are increasingly focused on value-for-money in acute infectious disease care, driving tighter formulary controls, tender-based hospital procurement, and greater use of utilization-management tools. Simultaneously, oral late-stage assets and potential switches from IV to oral regimens create opportunities to capture outpatient volume and lower total cost of care — but only for products that can demonstrate non-inferiority on clinical and health-economic endpoints.
Recent industry developments and what they imply
-
Regulatory approvals of targeted therapies and full approvals of previously accelerated agents have de-risked parts of the competitive set, allowing incumbents to stabilize hospital adoption — but they also reset commercial expectations for pricing and tender competition.
-
Late-stage positive trial readouts for orally available carbapenem-class prodrugs expand potential outpatient market addressability, shifting the competitive calculus for established IV-first portfolios.
-
Priority designations such as QIDP materially shorten time-to-market and provide exclusivity incentives, but teams must pair regulatory wins with robust payer evidence generation to secure access and favorable reimbursement.
-
Patent expiries on core combination agents are approaching in the medium term, creating an inflection point for generic pressure — companies must model generic-entry scenarios and develop defense strategies now.
-
API supply constraints remain a persistent operational risk; contingency sourcing and API hedging strategies are no longer optional for 2026 launches.
Competitive landscape — focused strategic read
The competitive environment is best described as moderately concentrated: a handful of established biopharma companies anchor hospital formularies with approved combination antibiotics and extended-spectrum agents, while a cohort of smaller innovators pursues oral and novel-combination approaches. Our concentration metrics confirm that top-tier firms command meaningful but not dominant shares of the addressable market, leaving substantive room for entrants that can demonstrate differentiated clinical or economic value.
-
Merck & Co., Inc.: Strengths include an established hospital-facing commercial infrastructure and an approved cephalosporin-based combination that remains a standard option in many formularies. Strategic priorities should include life-cycle management, payer outcomes data, and defending hospital access against oral entrants.
-
GlaxoSmithKline plc: With a cephalosporin–β-lactamase inhibitor combination approved for limited-option patients, GSK’s playbook emphasizes targeted stewardship partnerships with major hospital systems and EMA-aligned regulatory positioning.
-
Pfizer Inc.: An experienced commercial organization and an approved combination place Pfizer in direct competition with other large incumbents; their leverage in hospital procurement channels is a core advantage.
-
Allergan (AbbVie Inc.): Though historically focused on skin and other indications, the company’s assets have off-label or supportive roles in cUTI; AbbVie’s strategic flexibility can be an asset in portfolio realignment and hospital penetration tactics.
-
Basilea Pharmaceutica Ltd.: A smaller, partnership-driven player that can become an outsized partner for combination strategies or geographic expansion given focused R&D collaborations.
-
Spero Therapeutics: Late-stage oral agents with priority designations introduce a potential disruption to channel mix — the commercial strategy for oral carbapenem-class drugs must prioritize outpatient pathways and payer evidence generation early.
-
VenatoRx/Entasis-aligned programs: Recent approvals for targeted agents against resistant pathogens create a niche but clinically critical positioning; these assets are essential to hospital formulary decision-making where resistant Acinetobacter and similar organisms are a concern.
Strategic implications and recommended actions for 2026
-
Immediate (0–12 months): Stress-test 2026 launch plans under multiple supply-shock scenarios; build minimum inventory commitments with API suppliers; accelerate real-world evidence (RWE) programs targeted at the largest hospital systems and Medicare administrators.
-
Near-term (12–24 months): Invest in payer economics packages that quantify total cost of care benefits (e.g., reduced length-of-stay, avoidance of escalation) and prepare for formulary negotiations with tiered contracting strategies.
-
Medium-term (24–36 months): For companies with oral late-stage candidates or switches, prioritize outpatient access pathways — align labeling strategies, bolster primary care engagement and create bundled payment narratives where possible.
-
Strategic continuity (ongoing): Monitor leading indicators — pipeline milestone readouts, regulatory designations, patent expiration timelines and API shortage alerts — and incorporate them into quarterly strategy reviews to trigger pre-defined commercial or portfolio actions.
-
M&A and partnerships: Use the report’s opportunity heatmaps to identify inorganic targets that provide either novel oral chemistry, API security, or hospital commercialization scale. Small-to-mid cap assets with differentiated resistance profiles are likely to be the most accretive.
How PW Consulting’s analysis supports board-level and operational decisions
This report is built to bridge strategy and execution. We combine primary interviews with hospital pharmacists, payers and clinical investigators, with a flexible financial model that ties epidemiology, treatment mix and pricing into revenue and margin outcomes. Rather than asking teams to accept static forecasts, our approach provides a toolkit to stress-test strategy under realistic clinical, regulatory and supply disruptions — the exact inputs that will determine commercial success or failure in 2026.
Next steps
Leaders preparing decisions for 2026 should focus on three priorities now: secure supply resilience, accelerate payer evidence generation and finalize hospital commercialization plays for any planned launches. PW Consulting’s full report contains the underlying segment-level intelligence, proprietary scenario models and executable playbooks needed to operationalize these priorities. For teams wanting to convert the 6.5% CAGR pathway and the forecast scenarios into board-ready action plans, our report and accompanying tools provide the shortest route from insight to audited decision.
To access the full dataset, segment-level analysis and the downloadable financial model, please visit our report page or contact your PW Consulting representative for a customized briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: International Business Travel Insurance Market Set to Expand at a 7.85% CAGR, Signaling Robust Growth
By PW Consulting, 2026-07-15
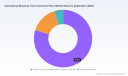
International Business Travel Insurance Plans Market — Strategic Imperatives for 2026 (PW Consulting Report Preview)
As multinational organizations re‑scale international operations and the cadence of cross‑border meetings, assignments and client travel accelerates, corporate travel protection has transitioned from a cost line to a strategic risk and compliance imperative. PW Consulting’s new market study — with a 2025 base year, a detailed historical review (2020–2025) and forward projections through 2032 — shows an international business travel insurance market that reached approximately USD 18,500 Million in 2025 and is forecast to expand at a compound annual growth rate of 7.85% over the 2026–2032 period. This preview summarizes the report’s strategic value for corporate decision‑makers in 2026 while deliberately withholding granular segment tables to reserve the full intelligence for report subscribers.
International Business Travel Insurance Plans Market
Why 2026 Is a Turning Point for Corporate Travel Risk Management
- Duty of care has moved from HR policy to board‑level exposure management. Regulators and stakeholders increasingly expect employers to demonstrate robust protection frameworks for employees traveling internationally on company business.
- Travel volumes and trip complexity are rebounding. With multi‑market operating models and hybrid work patterns, the profile of business travel is more diverse — short frequent trips, extended international assignments, and complex itineraries requiring tailored protection.
- Service expectations have evolved. Buyers demand integrated solutions — medical evacuation, global assistance, telemedicine, mental‑health support and digital claims processing — rather than stand‑alone indemnities.
- Distribution and partnership ecosystems are reshaping: incumbents partner with affinity channels, underwriters deploy selective capacity with third parties, and insurtechs press for embedded, API‑first solutions.
What the PW Consulting Report Delivers — Practical, Executable Intelligence
Our market study is constructed as an executive playbook for procurement heads, risk officers, global mobility leads, insurer strategists and M&A advisors. It blends quantitative market sizing and trend modeling with actionable tools and templates that leaders can deploy immediately:
International Business Travel Insurance Plans Market
- Executive summary with scenario outcomes mapped to strategic decision levers (consolidation, specialization, digital investment).
- Market dynamics and demand drivers: granular narratives on duty‑of‑care regulation, corporate purchasing behavior, and the evolving product stack for business travelers.
- Forecast model (2026–2032) based on a rigorous bottom‑up build and sensitivity testing; key macro assumptions are transparent so readers can re‑run scenarios against their own operating metrics.
- Buyer persona and procurement playbooks — how large corporates, mid‑market buyers, and specialist affinity groups evaluate suppliers and structure master policies.
- Distribution mapping and channel economics — broker and affinity partner dynamics, digital intermediaries, and direct corporate procurement pathways.
- Operational toolkits: RFP templates, vendor scorecards, claims SLA benchmarks and an incident response checklist aligned to duty‑of‑care standards.
- M&A and partnership playbook — where value is created (underwriting scale, distribution reach, embedded services) and how to structure deals to capture synergies quickly.
Methodology and Data Integrity
The report uses 2025 as the base year and synthesizes historical performance (2020–2025) with a forecast horizon through 2032. Our 7.85% CAGR projection is derived from a triangulated approach: proprietary revenue tracking, carrier and broker disclosures, corporate buyer surveys, and primary interviews across underwriting, broking and global mobility teams. Sensitivity analyses are included for alternative demand recovery paths and pricing regimes so decision‑makers can stress‑test procurement or M&A scenarios against conservative and accelerated outcomes.
International Business Travel Insurance Plans Market
Competitive Landscape — Leaders, Differentiators and Strategic Moves
The market exhibits moderate concentration, with the three largest participants controlling a meaningful but not dominant share and the top five representing under half of total market revenue. This structure creates a dual dynamic: incumbent scale advantages (global networks, claims platforms, distribution relationships) co‑exist with opportunities for nimble challengers to capture specialist mandates.
- Allianz Partners (US operations headquartered in Richmond, VA): a full‑service incumbent with a strong affinity and retail channel footprint. Recent strategic activity — including affinity underwriting partnerships, industry council participation and executive appointments — signals a renewed push to deepen commercial travel offerings and thought leadership around traveler confidence and policy integration.
- International Medical Group (IMG) (Indianapolis, IN): specialist strength in international medical and evacuation services for employer groups. Their group options for globally assigned employees position them well for multinational mobility programs where integrated medical and repatriation services are mission critical.
- Seven Corners (Carmel, IN): nimble in product customization and tailored solutions for frequent business travelers and corporate programs; a meaningful contender for mid‑market and affinity channel mandates.
- Travelex Insurance Services (Omaha, NE) and Travel Guard (AIG) (Stevens Point, WI): blend broad distribution with established business travel product suites suitable for standardized corporate policies and scalable program administration.
- Berkshire Hathaway Travel Protection (Stevens Point, WI): known for streamlined claims processes and digital claims experiences that appeal to corporates seeking efficient service delivery.
- Blue Cross Blue Shield Global Solutions: leverages global provider networks and centralized administration capabilities to serve large employers and expatriate populations.
Collectively, these players illustrate different strategic archetypes: global integrated carriers focusing on breadth and compliance; specialised medical and evacuation providers emphasizing clinical services; and digitally native players prioritizing customer experience and claims speed. The competitive narrative in 2026 will be about partnerships, selective underwriting capacity, and differentiation through embedded services rather than pure price competition alone.
Strategic Guidance for Corporate Decision‑Makers
- Align insurance procurement with duty‑of‑care maturity. Treat coverage selection as part of a broader traveler safety and incident response program; contract terms should include clear operational KPIs and escalation pathways.
- Prioritize integrated service models for complex travel profiles. For companies with frequent or high‑risk international travel, evaluate vendors on their ability to combine medical, assistance, and digital case management into a single operational workflow.
- Run total cost‑of‑ownership scenarios, not just premiums. Evaluate the impact of claims handling speed, network adequacy, evacuation capability and program administration on effective cost and traveler uptime.
- Use pilots to de‑risk platform transitions. Begin with a controlled roll‑out that measures claims latency, user experience, and policy compliance before enterprise‑wide adoption.
- Monitor emerging partner ecosystems. Underwriting capacity placed through affinity and retailer channels, and alliances with telehealth and security providers, will drive rapid product innovation — remain connected to those channels to surface new capabilities early.
- Consider M&A or strategic partnerships to fill capability gaps. For insurers, gaining specialist medical or digital claims capabilities can be faster through acquisition or minority investments than through organic build.
Operational Playbook — What You Can Deploy Immediately
- RFP and vendor scorecard templates calibrated to duty‑of‑care, medical evacuation capability, and digital claims KPIs.
- TCO calculator that models premium, administrative fees, expected claim frequency and indirect costs associated with travel disruption.
- Incident response checklist aligned to corporate governance and cross‑border regulatory requirements.
- Distribution evaluation grid to compare broker, affinity partner and direct procurement routes by speed, cost and control.
- Claims SLA benchmark set and a sample contract addendum for guaranteed response times and escalation governance.
What We Are Holding Back — And Why You Should Download the Full Report
This preview is intentionally selective. To preserve competitive advantage for our clients and to respect the proprietary nature of certain inputs, we have excluded detailed breakdowns of regional and application subsegments, as well as company market share tables and disaggregated revenue figures. The full PW Consulting report contains those tables and interactive models so that procurement teams can export data into their sourcing systems, run customized scenarios, and view granular supplier scorecards.
Closing Perspective
2026 will be a year in which strategic clarity in travel risk management delivers measurable value: fewer disruptions, improved traveller safety, and demonstrable compliance with emerging duty‑of‑care expectations. PW Consulting’s market study translates market size and growth dynamics — underpinned by an estimated USD 18.5 billion market base in 2025 and a robust mid‑to‑high single‑digit CAGR into the next decade — into pragmatic, actionable programs for buyers and suppliers. Whether you are re‑negotiating a corporate master policy, evaluating a potential acquisition, or designing an embedded insurer partnership, the playbooks and tools in our report are engineered to accelerate decision velocity and reduce execution risk.
To access the full dataset, company market shares, regional and application breakdowns, and downloadable templates, visit the PW Consulting report page and request the International Business Travel Insurance Plans Market study (2025 base year, forecast through 2032).
For detailed analysis of this topic, please visit the official page: International Business Travel Insurance Plans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide WIPS Market Poised for Rapid Expansion with a 14.2% CAGR Through 2032
By PW Consulting, 2026-07-15
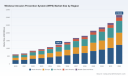
Worldwide Wireless Intrusion Prevention System (WIPS) Market — Strategic Imperatives for 2026
PW Consulting’s latest market study on the Worldwide Wireless Intrusion Prevention System (WIPS) market synthesizes five years of historical performance and a seven‑year forecast to deliver a decision-grade view that security leaders, procurement teams, channel partners, and investors need to plan for 2026. The global WIPS market reached a meaningful scale in 2025, and under a 14.2% compound annual growth rate (CAGR) the market trajectory points to more than doubling by the end of our forecast window. This briefing summarizes the report’s strategic value while deliberately reserving granular segment tables and proprietary vendor scoring to the full report hosted on our website.
Worldwide Wireless Intrusion Prevention System (WIPS) Market
Why 2026 Is a Critical Year for WIPS Investment
-
Regulatory momentum has moved WIPS from “best practice” to “must‑have” in many sectors. Recent updates to payment, healthcare, and critical‑services compliance frameworks are explicitly tying wireless monitoring to compliance regimes, increasing both the speed and scale of procurement cycles across regulated industries.
Worldwide Wireless Intrusion Prevention System (WIPS) Market -
Technology inflection points are expanding the attack surface. The broader authorization and commercial deployment of new spectrum (notably 6 GHz bands) and the rapid rollout of Wi‑Fi 6E and beyond increase the need for continuous spectrum and RF monitoring capabilities that traditional network security stacks were not designed to provide.
Worldwide Wireless Intrusion Prevention System (WIPS) Market -
Vendor innovation is accelerating in parallel. Leading infrastructure and security vendors have been integrating advanced WIPS capabilities—ranging from cloud‑native anomaly detection to embedded marker‑packet techniques—into their access points, controllers, and cloud management planes, shifting buyer decisions toward platform‑centric evaluations.
-
Market structure and competitive dynamics suggest a moderately consolidated vendor field, with top providers holding a material share of market revenue—enough to influence product roadmaps, but not so concentrated as to preclude nimble new entrants or consolidation plays.
What the PW Consulting Report Delivers (Practical, Operational, Actionable)
-
Strategic market sizing and trajectories: a validated historical series through 2025 and a seven‑year forecast that supports budget planning and scenario analysis for 2026–2032.
-
Decision frameworks for CISOs and procurement officers: vendor selection matrices, integration checklists, and a practical buyer’s scorecard calibrated for enterprise, government, and service‑provider needs.
-
Implementation playbooks: step‑by‑step guidance for PoC design, deployment sequencing (spectrum monitoring, policy enforcement, incident response), and operationalizing continuous detection to minimize false positives.
-
Commercial models and TCO templates: cloud vs. on‑prem cost comparisons, managed service options, and contract negotiation levers to secure predictable outcomes while containing ongoing operational expenses.
-
Regulatory mapping: concrete compliance pathways that align WIPS capabilities to obligations under major standards and directives, enabling risk‑based procurement prioritization.
-
Vendor benchmarking and competitive scenarios: qualitative and quantitative analysis of incumbent and challenger strategies, roadmaps, and go‑to‑market plays—helpful for sourcing, partnership, and M&A diligence.
Competitive Landscape: Who Matters — and Why
The report profiles the ecosystem of platform and specialist providers that shape WIPS capability sets today. Key themes in vendor differentiation include depth of integration with WLAN infrastructure, cloud intelligence and automation, detection accuracy vs. false‑positive rates, and operational tooling for SOCs and NOCs.
-
Cisco Systems Inc. — Leverages deep integration between wireless infrastructure and centralized management platforms to deliver continuous RF monitoring and automated containment workflows. Recent expansions in cloud‑managed anomaly detection reinforce its platform position.
-
HPE Aruba Networking — Focuses on embedded RFProtect capabilities integrated into enterprise WLAN stacks, with centralized management that appeals to large campus and distributed‑enterprise deployments.
-
Fortinet, Inc. — Pushes integrated threat prevention by folding WIPS capabilities into a unified security OS, emphasizing automation and high‑accuracy detection for security teams that prefer consolidated control planes.
-
Extreme Networks — Positions WIPS features within its wireless portfolio for ongoing policy enforcement and enterprise‑grade rogue detection, appealing to buyers seeking deep wireless analytics.
-
WatchGuard Technologies — Differentiates via cloud‑managed simplicity and patented detection techniques tailored for low false‑positive operations in SMB and distributed enterprise footprints.
-
Check Point Software Technologies — Extends platform security through integrated wireless threat detection in its broader security fabric, attractive to organizations standardizing on a single security vendor.
-
NetScout Systems and IBM Corporation — Offer WIPS capabilities as part of larger portfolios focused respectively on network performance and enterprise security services, positioning for customers who prioritize operational visibility and managed services.
-
Ruckus Networks (CommScope) and Arista Networks — Provide WIPS techniques via controllers and cloud platforms that emphasize device classification and automated policy actions, catering to high‑density and campus‑style environments.
Regulatory and Standards Catalysts
-
Payment and privacy standards now expect wireless monitoring where sensitive transactions occur; organizations in payments and healthcare must accelerate deployment timelines to remain compliant.
-
National guidance for classified and government systems has evolved to include WIDS/WIPS annexes—raising the bar for procurement specifications and certification requirements in the public sector.
-
Spectrum policy and new band authorizations increase the technical complexity of monitoring. Enterprises must align WIPS capabilities with modern RF environments, including multi‑band and mixed legacy/next‑gen deployments.
Recommended Actions for Enterprise Decision‑Makers in 2026
-
Map regulatory timelines to procurement roadmaps. Prioritize deployments where non‑compliance generates material exposure (payments, healthcare, critical infrastructure).
-
Adopt an integration‑first posture: prefer WIPS solutions that natively integrate with existing WLAN and security telemetry to reduce operational friction and false positives.
-
Design realistic PoCs that validate both detection fidelity and operational playbooks—especially automated containment workflows and SOC handover processes.
-
Evaluate cloud vs. on‑prem tradeoffs through a TCO and risk lens: cloud delivers faster innovation cycles and centralized analytics, while on‑prem can be preferable for high‑security or regulatory‑restricted environments.
-
Incorporate spectrum monitoring into asset management and IoT governance. Treat RF visibility as a first‑class telemetry source for your security operations center.
-
For channel partners and MSPs: package WIPS as a managed capability with SLAs, playbooks, and continuous optimization services to capture recurring revenue and relieve in‑house burden.
Critical Questions to Ask Potential Vendors
-
How does your solution integrate with existing WLAN controllers, network controllers and SIEM/SOAR stacks?
-
What is your measured detection accuracy and what operational controls reduce false positives in production?
-
Which regulatory certifications or published audits support government and regulated enterprise procurements?
-
How do you deliver updates for new spectrum and protocol changes (e.g., Wi‑Fi 6E/7)?
-
Can you demonstrate a TCO comparison and an example PoC plan aligned to our environment?
Why PW Consulting’s Analysis Matters for 2026
Our report combines a rigorous market model, expert vendor due diligence, and hands‑on operational guidance to help organizations make defensible WIPS investment choices in 2026. We quantify market scale and growth dynamics to support budget conversations and M&A screening, while our vendor and implementation frameworks are designed to shorten procurement cycles and de‑risk rollouts.
Importantly, while this briefing highlights high‑impact findings, the full report contains the granular intelligence security, procurement, and corporate development teams require—detailed segmentation, vendor scorecards, scenario models, and downloadable TCO tools. For teams that must move from strategy to execution this year, that granular material is the difference between a compliant checkbox and an operationally mature WIPS capability.
Next Steps
-
Download the full Worldwide WIPS Market report to access proprietary segment tables, vendor rankings, and the interactive financial model that supports procurement and M&A decisions in 2026.
-
Engage PW Consulting for a tailored briefing—our practitioners can map the report findings to your environment and produce a prioritized road‑map for rapid, measurable risk reduction.
As wireless ecosystems become more central to enterprise operations and more heavily regulated, WIPS moves from optional hardening to strategic control. For organizations evaluating investments in 2026, the right approach combines vendor integration, operational readiness, and regulatory alignment—areas where PW Consulting’s market study provides both the market context and the practical tools to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Intrusion Prevention System (WIPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


