



PW Consulting Forecasts 5.11% CAGR for Worldwide Fleet Maintenance Services; Market to Reach USD 358,110 Million by 2032
By PW Consulting, 2026-07-15
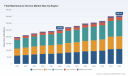
Worldwide Fleet Maintenance Service Market: Strategic Imperatives for 2026
Executive summary
As fleets of all sizes confront higher labor costs, tighter emissions regimes, and accelerating technology adoption, the global market for fleet maintenance services is shifting from transactional repairs toward integrated, intelligence‑driven service models. PW Consulting's latest market study finds the worldwide fleet maintenance services market reached approximately USD 252.5 billion in 2025 and is forecast to grow at a 5.11% compound annual growth rate (CAGR) across our 2026–2032 projection window—exceeding USD 271.4 billion in 2026 and approaching USD 358.1 billion by 2032. These headline figures frame an environment where strategic choices made in 2026 will largely determine market positioning for the remainder of the decade.
Worldwide Fleet Maintenance Service Market
Why this report matters to 2026 decision‑makers
-
Regulatory inflection points: 2026 brings material shifts in compliance obligations—such as changes aligning certain inspections with federal standards and the FMCSA’s overhaul of roadside/CSA categories—that will alter service volumes, work order timing, and the cost of non‑compliance. Understanding how these rule changes propagate through maintenance processes is essential for operational and capital planning.
Worldwide Fleet Maintenance Service Market -
Cost and capacity pressures: technician shortages and rising labor rates have driven meaningful increases in repair costs and service latency. This dynamic is accelerating adoption of remote diagnostics, mobile repair, and higher‑value predictive services that reduce labor dependency per repair event.
Worldwide Fleet Maintenance Service Market -
Technology convergence: telematics, AI diagnostics, and integrated claims/repair ecosystems are transforming where, when, and how maintenance is executed. 2026 is a tipping point for commercial deployment of these capabilities at scale, changing vendor selection criteria from feature lists to ecosystem interoperability and realized downtime reduction.
What PW Consulting’s report delivers (practical, operational insights)
This study is built as a decision tool for executives and practitioners. Beyond the headline market model and forecasts, the report contains:
-
A repeatable ROI framework and sample business case templates for prioritizing investments in telematics, predictive maintenance, and mobile service programs.
-
Operational playbooks for transitioning from preventive to predictive maintenance workflows, including work order redesign, parts‑flow adjustments, and technician reskilling roadmaps.
-
Vendor engagement scorecards and integration checklists that assess capabilities across data ingestion, analytics, service orchestration, and claims/repair reconciliation.
-
Regulatory readiness checklists mapped to enforcement changes expected in 2026, helping fleets quantify compliance cost exposure and retest/downtime impacts.
-
Scenario stress tests showing how changes in labor rates, vehicle electrification trajectories, and regulatory fees affect unit economics and service demand through 2032.
Market structure and competitive dynamics
The market remains fragmented: the top three providers account for a modest share of overall revenue, and the five‑firm concentration is limited—demonstrating that scale matters, but local service networks and software ecosystems are decisive. This fragmentation preserves opportunities for specialist mobile providers, regional service networks, and software platforms that can tie maintenance outcomes to operational KPIs.
Key competitor archetypes we analyze in the report include cloud‑native platform players, telematics incumbents, full‑service fleet operators, and mobile/onsite specialists. Representative firms covered include Fleetio, Geotab, Verizon Connect, Samsara, Trimble, Teletrac Navman, Motive, Ryder, Penske, Element, ARI (Holman), Wheels, FleetNet America, Dickinson Fleet Services, and Wrench. Our analysis focuses on strategic positioning—product capability, data strategy, go‑to‑market model, and partnership leverage—rather than a simple feature matrix.
Notable recent moves shaping 2026 competition
-
Fleetio’s open beta of an AI‑powered Service Advisor accelerates high‑volume repair approvals and is designed to reduce administrative bottlenecks in busy maintenance operations.
-
Teletrac Navman’s introduction of cloud‑based Multi IQ Camera functionality underscores the growing importance of safety‑linked maintenance triggers drawn from AI video analytics.
-
Platform integrations such as Solera’s fleet platform are consolidating claims, repair, and maintenance data—lowering reconciliation friction and enabling new risk‑sharing service models.
-
Selective acquisitions and modular product launches across the ecosystem signal an acceleration in vertical integration between telematics, diagnostics, and execution networks.
Strategic plays for 2026—what to prioritize
-
For fleet operators: move from episodic, reactive maintenance to a prioritized hybrid model—retain preventive discipline for high‑risk assets, scale predictive analytics for repeat failures, and expand mobile repairs for low‑complexity work to reduce downtime. Use the report’s ROI templates to pilot predictive bundles on a 6–12 month cadence.
-
For maintenance networks and independents: invest in digital dispatch and parts‑availability orchestration to capture mobile service demand. Partner with telematics/data players to become the preferred execution arm within software ecosystems.
-
For software and telematics vendors: differentiate on cross‑platform interoperability and closed‑loop repair economics rather than raw telematics metrics. Demonstrate measurable reductions in mean time to repair (MTTR) and total cost per mile (TCPM) in commercial pilots.
-
For OEMs and lessors: embed maintenance offerings into leasing and warranty packages to secure recurring revenue and control repair quality—especially as vehicle architectures (e.g., electrified powertrains) impose different maintenance cadences.
-
For investors and M&A strategists: prioritize targets that combine strong field execution networks with data assets and integration capabilities—companies that can convert telematics signals into predictable service demand will command multiple premiums.
Regulatory and operational triggers to monitor in 2026
-
Regulatory shifts that reclassify inspection regimes or reframe violation categories—these change inspection volumes and the economics of rapid repair programs.
-
Local compliance programs that add per‑asset fees and retest costs—these are direct profit levers for third‑party maintenance providers offering turnkey compliance warranty services.
-
Labor market indicators—technician availability and wage pressure directly affect the ROI of automation and mobile repair strategies. Monitor hiring costs, turnover rates, and training throughput.
Scenarios and decision support
PW Consulting models three actionable scenarios in the report—Baseline (institutional adoption of telematics and phased predictive deployments), Upside (accelerated automation and partnership consolidation), and Stress (prolonged technician shortages and aggressive regulatory costs). Each scenario includes trigger thresholds, financial impacts on unit economics, and tactical responses (e.g., fleet pooling, service bundling, or vertical integration). These scenarios enable CFOs and COOs to stress‑test capital allocation choices and vendor commitments for 2026.
How to use this report in board and budget cycles
Use our study as a bridge between strategy and execution. The materials are structured to support three common 2026 use cases:
-
Budget prioritization—rank technology, mobile service expansion, and compliance investments using our ROI templates to justify CapEx/Opex mixes.
-
Partner selection—apply our vendor scorecards and integration checklist during RFPs to ensure end‑to‑end outcomes not just point solutions.
-
M&A screening—filter targets with field service density plus data assets, and evaluate accretive service cross‑selling opportunities against integration risk.
Final note—what you won’t find here (and where to go next)
To preserve competitive integrity and to respect client confidentiality, this release intentionally omits detailed granular breakdowns by region, vehicle class, and service subsegment. The full report includes those segment-level models, exhaustive vendor benchmarking, contract win‑rate data, and downloadable decision models that PW Consulting clients use directly in boardrooms and sourcing committees.
For executive teams preparing 2026 budgets and strategic roadmaps, this report provides the playbooks, scenario tools, and vendor intelligence needed to turn market growth into durable advantage. To access the complete dataset, detailed segmentation, and the suite of operational tools, request PW Consulting’s full Worldwide Fleet Maintenance Service Market report through our research portal.
— PW Consulting, Global Transport & Mobility Practice
For detailed analysis of this topic, please visit the official page: Worldwide Fleet Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Customs Brokerage Services Market to Expand at a 6.4% CAGR Through 2032PW Consulting: Worldwide Food Encapsulating Technology Market Poised for Rapid Expansion — 8.12% CAGR Forecast Through 2032
By PW Consulting, 2026-07-15
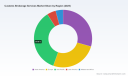
Worldwide Customs Brokerage Services Market 2026: Strategic Intelligence Briefing
PW Consulting is pleased to release an executive briefing summarizing the strategic implications of our new Worldwide Customs Brokerage Services Market report. Built from a proprietary dataset spanning 2020–2025 and forward-looking scenario modelling through 2032, this analysis translates market-level metrics, regulatory shifts, and provider strategies into actionable guidance for executives planning investments and operational changes in 2026.
Worldwide Customs Brokerage Services Market
Why this report matters for 2026 decision-makers
The global customs brokerage services market stands as a critical linchpin in cross-border trade. PW Consulting estimates the market at approximately USD 16.25 billion in 2025, and our baseline projection assumes a compound annual growth rate of 6.4% across the 2026–2032 forecast window. That growth is being driven by a combination of trade volume recovery, continuing supply chain complexity, and the accelerating digitization of compliance workflows.
Worldwide Customs Brokerage Services Market
For senior leaders—logistics heads, trade compliance officers, private equity investors, and technology vendors—these headline numbers are not an end in themselves. The report converts macro trends into investment priorities, operating playbooks, technology adoption roadmaps and regulatory risk matrices, enabling confident decisions in 2026 in an environment of evolving regulation, concentrated yet competitive supplier structures, and shifting client needs.
Worldwide Customs Brokerage Services Market
Depth and practical value: what we deliver (without revealing the proprietary slices)
- Market sizing and scenarios: A transparent base-year audit (2025), historical reconciliation (2020–2025), and three forecast scenarios to stress-test growth assumptions under different trade, regulatory and technology adoption trajectories.
- Provider economics: Unit economics benchmarks, margin ladders by service bundle, and customer lifetime value proxies to guide outsourcing vs. insourcing choices.
- Operational playbooks: Step-by-step templates for integrating brokerage with ERP/WMS, standard operating procedures for exception handling, and time-to-compliance metrics tied to digital tools.
- Technology evaluation framework: A structured rubric to assess compliance automation, AI-powered document verification, Trade Management Software and API-first customs platforms, aligned to ROI and TCO timelines.
- Regulatory impact modelling: Customisable templates that quantify direct regulatory costs—such as permit fees and average monthly compliance spend—and the second-order effects of changes in customs agency processes.
- Strategic M&A and partnership playbook: Deal screening criteria, integration risks, and value-capture levers for buyers and founders in the customs brokerage ecosystem.
Market structure and competition: the strategic terrain
The brokerage market is structurally fragmented with meaningful scale advantages for integrated logistics players and specialized regional champions. Our concentration analysis shows that the top global firms do not dominate the market to the extent seen in some other logistics segments—leaving room for disruptive entrants, technology-enabled challengers, and targeted consolidation.
Key provider archetypes and strategic implications:
- Integrated logistics leaders (global freight forwarders and postal/parcel giants) offer end-to-end value propositions by bundling customs services with ocean/air forwarding and last-mile networks. Their strategic advantage lies in cross-sell, single-invoice convenience and the ability to embed compliance earlier in the transport chain. Examples include large global forwarding and parcel networks that prioritize digital integration with customers’ transportation management systems.
- Technology-first platforms are embedding brokerage capabilities into cross-border commerce stacks, reducing friction for e-commerce and marketplace use cases. Recent acquisition activity in 2026 demonstrates this trend, with platforms integrating brokerage to own the customer experience from checkout to delivery clearance.
- Regional specialists and dedicated brokers continue to command trust from complex importers—especially in regulated industries—by offering deep local compliance expertise and tailored advisory services. These players often excel in high-touch account management and bespoke filing strategies that digital-first providers still struggle to replicate end-to-end.
- Hybrid models combine consultative compliance offerings, software tools and traditional entry filing. These hybrids often present attractive margins and make them logical targets for private equity and strategic partnerships.
Competitor snapshot: strategic takeaways
- Large-scale integrators leverage global networks and platforms to embed customs earlier in the supply chain. Their play focuses on scale, standardization and platform-enabled visibility.
- Courier and express carriers emphasize speed-to-clearance and bundled end-to-end solutions for time-sensitive shipments, competing effectively on customer experience and digital tracking.
- Freight forwarders and logistics groups differentiate on global footprint and multi-modal consolidation, enabling competitive pricing for complex trade lanes.
- Dedicated customs brokers and boutique advisers hold an important niche in handling regulatory complexity, tailored compliance strategies, and value-added consultancy, particularly in regulated industry verticals.
For executives evaluating partners or acquisition targets in 2026, three criteria consistently differentiate winners: the ability to deliver seamless digital integration with client systems, demonstrable regulatory expertise in target jurisdictions, and scalable operating models that lower per-shipment compliance costs as volume grows.
Regulatory and operational dynamics shaping 2026
The brokerage industry in 2026 is operating against a backdrop of active regulatory change and rising compliance costs. Specific drivers include modernization of customs broker regulations in key markets, updated automated systems from customs authorities, and incremental fee adjustments. Practitioners also face mounting per-account and per-permit administrative costs—factors that influence service pricing, margin pressure and the economics of small-batch cross-border trade.
Notable developments you should factor into 2026 planning:
- Customs administrations are expanding automated entry and payment systems, which create both opportunities and short-term friction as brokers migrate processes and integrate APIs.
- Regulatory compliance is becoming more transactionally granular—requiring more sophisticated document verification, provenance checks and automated audit trails. This trend accelerates demand for AI-driven compliance software and reduces manual processing costs for early adopters.
- Policy changes affecting trade restrictiveness in certain jurisdictions have material implications for routing, routing costs and the attractiveness of alternative sourcing strategies.
- Administrative fees and sector-level compliance allocation (for example, the ongoing requirement for annual permit user fees) are predictable line-item pressures that should be budgeted into any outsourcing tender or internal cost model.
Recent market moves and immediate implications
- The acquisition of a brokerage capability by a cross-border commerce platform in early 2026 exemplifies how commerce platforms are internalizing clearance to reduce friction for end users—heightening competition for low-complexity, volume-driven brokerage work.
- Updates from major customs authorities regarding automated payment and entry systems are accelerating adoption timelines for brokers who must certify systems and rework settlement processes.
- Association guidance on account ownership and portal access requires brokers and importers to review account governance, with short implementation windows that can create near-term operational risk if ignored.
Boardroom priorities and near-term playbook for 2026
PW Consulting recommends that executives translate the market outlook into five immediate actions:
- Undertake a two-week "readiness sprint" to assess systems connectivity with major customs platforms and ensure API readiness for automated entry and payments.
- Re-run unit economics with updated regulatory cost assumptions (including permit fees and average monthly compliance allocations) to validate outsourcing thresholds and pricing.
- Prioritise investments in AI-driven document verification and rule-based compliance engines to reduce exception rates and tighten SLA commitments.
- Design partnership pilots with technology platforms to capture e-commerce and small-parcel flows without over-investing in asset-heavy capabilities.
- Establish a regulatory watch cell to track customs agency process changes and association advisories, translating them into account-level action plans and customer communications.
How PW Consulting’s report supports execution
The full report provides playbooks, spreadsheets and scenario templates that map directly onto the actions above. It contains practitioner-focused modules—implementation timelines, procurement checklists, integration test plans and regulatory impact calculators—so leadership teams can move from strategy to execution within months, not quarters.
We intentionally withhold granular regional and application-level splits in this briefing to preserve the strategic exclusivity of the full dataset. The detailed segmentation, provider scorecards and downloadable implementation tools are available via our report portal for clients and subscribers seeking the complete intelligence package.
Next steps
For executives preparing 2026 budgets or evaluating M&A, partnership and technology choices, the PW Consulting Worldwide Customs Brokerage Services Market report offers the empirical foundation and execution toolset needed to convert market growth into profitable, low-risk action. Contact our insights team to schedule a briefing and obtain a tailored extract aligned to your portfolio, trade lanes and strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Customs Brokerage Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 1‑Decanol Market Set to Grow from USD 280.8 Million in 2025 to USD 436.36 Million by 2032 at a 6.5% CAGR — Asia‑Pacific Leads with USD 120.69 Million
By PW Consulting, 2026-07-15
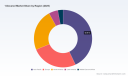
Worldwide 1‑Decanol Market — Strategic Outlook for 2026: PW Consulting Preview
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
The global 1‑decanol market stands at a pivotal inflection point. PW Consulting’s new market study — covering historical performance (2020–2025) and a forward-looking forecast window (2026–2032) — shows that the industry has expanded from a solid base in 2020 and reached an estimated USD 280.8 Million in 2025. Under current assumptions, the market is projected to sustain a compound annual growth rate (CAGR) of approximately 6.5% over the 2026–2032 forecast period, and PwC-calibrated modeling points to a market approaching the mid‑400s (USD Million) by 2032.
Worldwide 1-Decanol Market
Why this matters for corporate decision‑makers in 2026
- Momentum plus disruption: While the market’s headline growth is compelling, the near‑term strategic landscape is defined less by total demand and more by cost volatility, regulatory re‑scoping, and supply‑chain restructuring. Companies that align procurement, product strategy, and regulatory programmes in Q1–Q2 2026 will gain disproportionate advantage.
- Margin sensitivity: Feedstock and upstream intermediate price moves are now primary drivers of short‑cycle margin variation. The report quantifies this sensitivity and offers hedging and sourcing playbooks tailored to different cost‑and‑quality profiles.
- Compliance as a de‑risking opportunity: New and evolving regulatory actions in key markets convert compliance into a competitive moat for producers who act early — and a market access risk for those that don’t.
Market dynamics shaping 2026 strategies
Our analysis synthesizes macroeconomic demand with micro‑level shocks. Two sets of forces deserve immediate attention:
Worldwide 1-Decanol Market
- Feedstock and upstream cost shocks. Recent commodity movements — including a notable rise in coconut oil pricing and materially higher lauric acid levels — have already shifted conversion economics for natural 1‑decanol producers. These dynamics increase the premium on feedstock flexibility, integrated sourcing strategies, and alternative raw material pathways (including selective use of synthetic routes) to protect margins.
- Regulatory and trade changes. The European regulatory calendar requires updated exposure scenarios for surfactant uses by mid‑2026, while targeted trade measures — including tariff adjustments on fatty alcohol imports implemented in early 2026 — are realigning regional supply flows. At the same time, U.S. and state‑level labeling initiatives are raising product governance requirements for consumer applications. These developments make scenario‑based planning and rapid compliance roadmaps essential for both suppliers and downstream formulators.
Competitive landscape: positioning and short‑term moves
The market is moderately concentrated: our concentration analysis indicates that the top three and top five producers capture a meaningful portion of industry capacity, and competitive behavior among these incumbents will materially influence pricing and availability in 2026.
Worldwide 1-Decanol Market
- BASF SE (Ludwigshafen, Germany). A long‑standing producer offering 1‑decanol as part of a broader fatty alcohol platform. BASF’s strengths lie in integrated customer channels and application engineering for surfactants and specialty additives. Strategic priority: translate application know‑how into differentiated value propositions in regulated markets.
- Evonik Industries AG (Essen, Germany). Serves consumer and industrial end‑markets and has recently strengthened its sustainability credentials through certification programmes. Strategic priority: leverage sustainability certification to secure higher‑margin European volumes as REACH obligations tighten.
- KLK Oleo (Shah Alam, Malaysia). A major oleochemical player that announced capacity expansion late in 2024 aimed at Asia‑Pacific demand. Strategic priority: optimize ramp timing against feedstock cycles to avoid margin dilution during scale‑up.
- Musim Mas Group (Singapore). Focused on mid‑cut fatty alcohols and recently launched a high‑purity grade for pharmaceutical excipients. Strategic priority: capture specialty niches with premium product specifications and documentation to support regulated applications.
- PT Sinar Mas Oleochemical (Jakarta, Indonesia). Export‑oriented producer with reach into detergents, textiles, and polymer additives. Strategic priority: fortify trade and logistics strategies in light of tariff movements and freight volatility.
- Eco Services Operations, LLC (Houston, USA; formerly Sasol). A synthetic producer using the Ziegler process, servicing applications where high purity is required. Strategic priority: market synthetic routes as an alternative when natural feedstock scarcity elevates prices.
- Godrej Industries Limited (Mumbai, India). A dual‑market participant supplying domestic and export customers in soaps and lubricants. Strategic priority: integrate downstream consumer insights to move up the value chain.
Recent corporate actions underscore these strategic vectors: KLK Oleo’s late‑2024 capacity expansion explicitly targets Asia‑Pacific demand, Evonik’s RSPO mass balance certification (September 2024) strengthens market access in sustainability‑focused European channels, and Musim Mas’ introduction of a pharm‑grade 1‑decanol (June 2024) signals a push into higher‑value regulated segments. Each move has implications for contract strategy, pricing architecture, and partnership choices in 2026.
Risk map and tactical playbook for 2026
We recommend deploying a concise, actionable framework across sourcing, product, and commercial functions:
- Sourcing: diversify feedstock contracts to include both oleochemical and synthetic supply options; institute trigger points tied to feedstock indices for proactive renegotiation; and pursue co‑sourcing alliances in origin markets where price volatility has risen.
- Product & innovation: prioritize grade differentiation and documentation (e.g., RSPO, pharmaceutical excipient dossiers) that unlock premium channels and reduce exposure to commodity‑grade price swings.
- Regulatory & quality: fast‑track REACH exposure scenario updates and California labeling readiness for consumer SKUs; integrate regulatory timelines into commercial launch plans to avoid market interruptions.
- Commercial & pricing: move from annual to quarterly indexation models where feasible; redesign contractual minimums to balance fill rate expectations with supplier capacity realities.
What PW Consulting’s report delivers — practical contents (high level)
The full report is engineered for immediate use by C‑suite and commercial leaders preparing 2026 playbooks. Key deliverables include:
- Validated historical market size and a transparent forecast model (2026–2032) with sensitivity scenarios tied to feedstock price pathways and regulatory outcomes.
- Competitive intelligence dossiers on leading producers, including strategic positioning, capacity maps, recent investments, and likely next moves.
- Regulatory impact matrix covering EU, U.S. federal and state, and major Asian regulatory evolutions, linked to compliance checklists and cost impact estimates.
- Sourcing and margin modelling tools that quantify margin exposure across natural and synthetic production routes and provide hedging and sourcing playbooks.
- Commercial go‑to‑market templates for launching differentiated grades (sustainability‑certified, pharmaceutical‑grade, high‑purity industrial) and negotiating contracts under new tariff regimes.
- M&A and partnership screening: a prioritized list of targets and capability gaps, plus an acquisition valuation framework reflecting current concentration and growth prospects.
Note: to preserve commercial integrity and encourage client engagement, detailed regional/application splits, supplier scorecards, and line‑by‑line pricing tables are reserved for the full report.
Use cases: five decisions PW Consulting helps clients make in 2026
- Should we reconfigure our feedstock mix to mitigate coconut oil price volatility? (Includes breakeven and payback thresholds.)
- Which export markets require immediate labeling or documentation changes to maintain shelf access under new trade and regulatory constraints?
- Do we commit to capacity expansions or prioritize operational flexibility and tolling arrangements to manage demand uncertainty?
- How do sustainability certifications (e.g., RSPO mass balance) affect contract premiums and customer retention in EMEA and other regulated markets?
- Which potential acquisition targets or JV partners meaningfully de‑risk our supply chain while improving product mix and margin profile?
Methodology & data integrity
Our findings are based on a multi‑source methodology: bottom‑up primary interviews with producers and buyers, transactional price and shipment datasets, feedstock cost analytics, and regulatory filings. We stress‑tested the forecast against alternative scenarios — including acute feedstock shocks, accelerated substitution in select downstream applications, and trade‑policy shifts — to ensure robust guidance for strategic planning cycles in 2026.
Conclusion — action roadmap for the next 12 months
The 1‑decanol market’s headline growth masks a more complex strategic landscape. Firms that integrate procurement adaptability, product differentiation, and proactive regulatory programs will capture the upside of a market growing at roughly a mid‑single digit CAGR through 2032. Conversely, those that delay recalibration risk margin erosion, constrained market access, and lost share as competitors capitalize on certification and specialty moves.
PW Consulting’s full Worldwide 1‑Decanol Market report provides the granular segmentation, supplier analytics, and actionable tools required to convert these insights into immediate decisions. For executives evaluating capital allocation, M&A, or commercial model redesign in 2026, this study is designed to be a playbook — not just a forecast.
Next steps
- Download the comprehensive report for detailed regional and application intelligence, supplier scorecards, and the full set of modelling tools.
- Contact PW Consulting’s Chemicals & Advanced Materials team to schedule a strategy workshop that applies the report’s scenarios to your portfolio.
For detailed analysis of this topic, please visit the official page: Worldwide 1-Decanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Caustic Calcined Magnesia Market Poised to Reach USD 1,170.89 Million by 2032
By PW Consulting, 2026-07-15
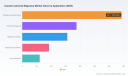
Worldwide Caustic Calcined Magnesia Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s newest market research release on the Worldwide Caustic Calcined Magnesia (CCM) market provides an actionable intelligence package tailored for executive teams planning capital allocation, commercial strategy, and supply‑chain resilience in 2026. Built on a base year of 2025 and a forecast horizon extending through 2032, the study quantifies an industry growing at a mid-single-digit pace (CAGR 4.85% over 2026–2032) from an estimated USD 840.5 Million in 2025 toward the high‑hundreds of millions by 2026 and beyond. This briefing summarizes why the report is a strategic instrument for 2026 decisions while deliberately reserving the detailed regional and application splits for subscribers who download the full model.
Worldwide Caustic Calcined Magnesia Market
Why this report matters for 2026 strategy
- Decision-grade market sizing: The market’s steady expansion and the underlying demand drivers create specific windows for price recovery, capacity investments, and product premiumization in 2026. Executives who need to justify capex, M&A or new product launches will find the report’s scenario outputs directly usable in board materials and investor briefs.
- Regulatory and sourcing clarity: Tightening impurity rules, evolving tariffs and shifting freight economics mean that procurement and regulatory affairs teams must act on detailed, near-term signals rather than legacy assumptions. Our study integrates those dynamics into commercial scenarios.
- Competitive positioning: The CCM marketplace is neither fully commoditized nor a closed oligopoly. Company-level intelligence and concentration metrics in the report enable firms to calibrate offensive and defensive moves — from strategic alliances to selective capacity additions.
What the report delivers — practical, boardroom-ready tools
- Transparent market-sizing methodology with annual historicals (2020–2025) and a granular forecast (2026–2032), including sensitivity testing across price, feedstock cost and demand shocks.
- Interactive financial model (Excel) that allows scenario toggles for price pass-through, magnesite feedstock cost, freight shocks and tariff regimes.
- Supply chain maps and plant-level capacity intelligence for leading producers, enabling rapid supplier risk scoring and near-shore sourcing analysis.
- Regulatory impact assessments (EU REACH, US import measures, international potable-water certifications) and a compliance-gap checklist for product and process upgrades.
- Competitive profiles and capability matrices for the major CCM producers, with an M&A heatmap identifying high-value targets and JV corridors.
- Go-to-market playbooks for premium grades, technical-services monetization, and tendering strategies for large-offtake customers (water utilities, fertilizer formulators, industrial processors).
- Pricing & commercial negotiation templates designed to operationalize rapid cost-recovery while protecting long-term customer relationships.
Market dynamics shaping 2026 decisions
The CCM market’s growth is underpinned by steady end‑use demand across fertilizers, water treatment, chemical processing and construction-related applications. Our mid‑term forecast—anchored by an industry CAGR of 4.85% for 2026–2032—reflects both organic demand growth and structural supply-side frictions. Several near-term dynamics require particular attention:
Worldwide Caustic Calcined Magnesia Market
- Feedstock inflation: Global magnesite pricing experienced upward pressure recently, a factor that erodes margins for producers without pass-through mechanisms. Procurement teams must consider indexed contracts and longer-term offtake arrangements to stabilize input costs.
- Regulatory tightening: Newer impurity thresholds in major jurisdictions increase the technical bar for CCM sold into chemical and potable-water applications. This elevates the value of low‑impurity product lines and in-line quality analytics at production sites.
- Trade and tariff regimes: Recent import duties and trade measures are changing cost parity between regions and shifting trade flows. Commercial teams should re-evaluate supplier scorecards and landed-cost models to reflect the new tariff landscape.
- Logistics volatility: Elevated ocean freight rates and geopolitical chokepoints have increased landed costs and transit time risk for bulk magnesia shipments. Firms should reassess inventory buffers and alternative routing.
- Health & safety classification: While CCM is classified as non‑hazardous under global GHS guidance, regulatory dust-control limits require operational investments in handling and worker protection—areas that have both cost and reputational implications.
Competitive landscape — what the players are signaling
The CCM sector shows moderate market concentration: the three largest firms account for a substantive but not dominant share of global volumes, with the top five holding just over half the market. That structure creates scope for regional leaders to exert pricing influence, while leaving niches open for differentiated players.
Worldwide Caustic Calcined Magnesia Market
- Martin Marietta Magnesia Specialties (US) — A notable capacity expansion announced in late 2024 underscores a strategic bet on water-treatment demand. This move signals that established producers are prepared to back growth segments with brownfield investment.
- Premier Magnesia (US) — Recent potable-water certifications expand addressable markets and justify premium pricing for certified product lines. Certification is an increasingly important commercial lever in 2026.
- Grecian Magnesite (Greece) — New product launches that target low‑iron, low‑impurity specifications show how supplier R&D can unlock higher-value wastewater and specialty chemical applications.
- RHI Magnesita, Baymag, Magnesita Refratários, Haicheng Houying, Qinghua Refractory, Industrias Penoles, Ube — These incumbents collectively illustrate different strategic archetypes: integrated upstream sourcing, regional export focus, premium specialty grades, and technology-led differentiation. Their competing moves — product reformulation, trade-show visibility, and capacity optimization — are the practical levers to watch in 2026.
For buyers, the implication is clear: supplier selection is no longer a pure cost exercise. Technical capability (low‑impurity grades, consistent reactivity), certification status, logistics footprint and tariff exposure all matter for total landed cost and contract durability.
Risk signals and operational priorities for 2026
- Short-term price shocks: Prepare for episodic magnesite cost spikes and freight dislocations. Hedging, tiered supplier contracts and customer price escalators are recommended tactical defenses.
- Regulatory compliance: Achieve and publicize certifications relevant to potable-water and food/feed use cases; implement analytical QC to demonstrate impurity control if serving chemical and environmental clients.
- Supply diversification: Reduce single-source exposure by establishing alternative supplier lanes and near-shore stocking hubs; consider logistics partnerships for transshipment flexibility.
- Operational upgrades: Invest in dust-control systems and occupational safety programs to meet local occupational limits and reduce operational risk.
How to use the report — a 90-day and 12-month playbook
- 90-day actions: Run the report’s interactive model using your own feedstock and freight assumptions; convene a cross-functional supplier-risk workshop; prioritize certification gaps for high-value product lines; renegotiate short-term contracts with explicit pass-through clauses.
- 12-month initiatives: Evaluate brownfield expansions vs. tolling/JV arrangements in constrained regions; launch a premium low‑impurity product line where certification and quality analytics deliver margin uplift; execute targeted M&A screening using our M&A heatmap to identify accretive regional platforms or specialty-chemical capabilities.
Conclusion — the strategic edge for 2026
The CCM market in 2026 will reward companies that translate near-term intelligence into disciplined commercial and operational moves. PW Consulting’s report converts macro indicators—steady mid-single-digit growth, changing feedstock economics, regulatory tightening, and logistical pressure—into executable options for procurement, operations, product management and corporate development teams. We have designed the deliverables to be immediately operationalizable by executive teams preparing board cases, negotiating supply agreements, or screening strategic investments.
For complete regional and application-level breakdowns, plant-level supply maps, and the downloadable interactive model that powers the scenarios summarized here, please consult the full Worldwide Caustic Calcined Magnesia Market report on our website. The detailed segmentation and primary-source datasets are available there to support 2026 decision-making with the precision your leadership requires.
For detailed analysis of this topic, please visit the official page: Worldwide Caustic Calcined Magnesia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carob Chocolate Bars Market Poised to Reach USD 349.77 Million by 2032 as Organic Bars Gain Traction
By PW Consulting, 2026-07-15
Carob Chocolate Bars Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
PW Consulting’s new market intelligence brief on Carob Chocolate Bars—anchored on a 2025 base year and projecting through 2032—translates emerging consumer and supply-side shifts into a compact strategic playbook for corporate decision-makers. This release outlines why carob bars are moving from niche novelty toward a scalable specialty category, the structural risks and strategic opportunities that will matter most in 2026, and the exact types of commercial tests and governance changes we recommend to capture value. The full dataset and granular segment breakouts are reserved for the complete report; this communique highlights high-conviction insights while preserving the deeper numbers as lead-generation assets.
Carob Chocolate Bars Market
Market Snapshot: Growth Trajectory and What It Means for 2026
The carob chocolate bars market has grown steadily from a clearly defined specialty base in 2020 to a materially larger commercial footprint by 2025. Our modelling indicates the market reached about USD 215 million in 2025 and is forecasted to expand at a compound annual growth rate (CAGR) of roughly 7.2% through the 2026–2032 forecast horizon, reaching an estimated USD 350 million range by 2032. That sustained growth signals two important strategic realities for 2026:
Carob Chocolate Bars Market
- Scale is becoming achievable. The economics that once limited carob bars to small-batch artisanal producers are shifting—enlarged distribution and ingredient innovation make a commercial-grade, margin-accretive offering feasible for mid-sized food companies.
- Timing matters. With early mainstream channels now open and ingredient technologies improving taste and functionality, 2026 will be a pivotal year to test expansion plays before the category moves from specialty to adjacent mainstream shelves.
Key Market Dynamics Shaping Strategy
We organize the dynamics that should inform 2026 strategy into three clusters—supply & input cost, consumer & regulatory signals, and product & go-to-market innovation. Each cluster has direct implications for pricing, sourcing, R&D prioritization, and channel investment.
Carob Chocolate Bars Market
- Supply-side and input costs: Carob raw material prices and export/import spreads are proving volatile and geographically concentrated. Recent trade-level observations show material price variability that will require buyers to adopt multi-sourcing, contracting terms that blend spot and forward cover, and supplier development programs to protect margin through 2026. Commercial teams should embed scenario-based cost modelling into every SKU P&L.
- Consumer & regulatory signals: Demand drivers for carob products are anchored in clean-label, plant-based, and reduced-sugar preferences. Carob formulations commonly deliver substantially lower sugar than traditional chocolate, which opens health positioning and reformulation plays. At the same time, imported botanical products are subject to national labeling requirements in key markets; regulatory compliance—including nutrition facts and origin disclosure—must be baked into market-entry timelines, especially where labeling regimes differ materially by market.
- Product & ingredient innovation: Advances in flavor and functional ingredients are rapidly improving carob’s sensory parity versus cocoa. Recent R&D breakthroughs—ranging from flavor-boosting techniques to the emergence of prebiotic carob-derived ingredients tailored to gut-health claims—create white-space for differentiated SKUs that can command price premiums and broaden consumer appeal beyond vegan/health niches.
Competitive Landscape: From Artisanal Roots to Strategic Contenders
The competitive field remains diverse and entrepreneurial. Several specialist brands have established credible propositions that illustrate the strategic options available to incumbents and new entrants alike. Key company archetypes and implications include:
- Artisanal originators with product authenticity premium: Producers that emphasize farm-to-bar provenance and organic credentials are winning affinity among “value-driven” consumers. Their brand strength is an asset in specialty channels, but limited scale creates openings for strategic partnerships or acquisition by larger food groups.
- Channel-focused challengers expanding mainstream reach: Brands that combine vegan/clean-label positioning with distribution expansion into health retailers and national chains are proving the category can migrate off the specialty shelf. Recent retail listing wins by regional players validate a playbook of concentrated channel penetration followed by geographic roll-out.
- Ingredient & tech innovators: New ingredient launches and university-driven flavor enhancement techniques are lowering the sensory barriers that historically constrained adoption. These innovations shift the competition from purely brand-to-brand to supplier ecosystems that can co-develop formulations with manufacturers.
Notable company developments—such as retail listing expansions by established brands into prominent health retail chains, R&D partnerships producing taste-enhancement methods, and new ingredient introductions targeting gut-health claims—underscore an active, fast-learning sector. For corporate strategists, these activities form a roadmap of feasible go-to-market moves and potential partnership targets in 2026.
Report Deliverables: What the Full PW Consulting Report Provides (Practical, Decision-Ready)
Our full market study is designed as a toolbox for executives and business-unit leaders preparing 2026 plans. Key deliverables include:
- Robust historical and forecast market sizing (2020–2032) and scenario models to stress-test pricing, margin, and channel choices under multiple commodity and demand outcomes.
- Decision frameworks for market entry and scale-up, covering license-to-operate, labeling compliance, and retailer acceptance risk matrices.
- Actionable channel playbooks—retail, specialty health, and direct-to-consumer—each with merchandising, assortment, and promotional levers tailored to conversion economics.
- Product innovation blueprints linking flavor-tech advances and functional ingredients to prioritized roadmap initiatives (e.g., reduced-sugar launches, prebiotic positioning, and sustainable packaging pilots).
- A curated list of potential partners and acquisition targets organized by capability (sourcing, flavor-tech, retail reach), plus red-team analyses to illuminate execution pitfalls.
Importantly, while the report contains detailed segment-level breakouts and distribution-weighted forecasts, this summary intentionally omits those granular figures to preserve the report as the canonical source for strategic planning and investor diligence.
Recommended 2026 Moves—Operational and Strategic Priorities
Based on our analysis, PW Consulting recommends a short set of prioritized actions for companies seeking to establish or expand in the carob bars category in 2026.
- Initiate a 12-month market test in two adjacent channels: Use a tight SKU roster (one mainstream, one premium) to optimize assortment and promotional elasticity. Track conversion and repeat purchase KPIs, and use real-time P&L gating criteria to scale.
- Lock in multi-source supply agreements with staged forward coverage: Given the observed wholesale variability in carob raw-material markets, procurement should combine shorter-term spot access for flexibility with longer-term contracts for core volume to stabilize unit costs.
- Co-invest in flavor enhancement and functional claims: Pursue joint R&D or licensing of flavor-boosting techniques and prebiotic ingredients that can provide clear consumer differentiators—taste parity and gut-health positioning will increase conversion beyond niche buyers.
- Embed labeling compliance and packaging sustainability into product development timelines: Regulatory requirements for plant-origin imports and rising retailer sustainability standards mean packaging and labeling decisions must be front-loaded in product roll-outs.
- Design acquisition and partnership scouting criteria: Target partners that deliver one of three capabilities—scale sourcing, flavor/ingredient IP, or retailer access—to accelerate go-to-market while preserving capital efficiency.
Risk and Mitigation Framework
Three high-probability risks could derail a late-2026 acceleration strategy if unaddressed:
- Supply-constrained cost shocks: Mitigate by diversifying origins, negotiating volume options, and hedging via ingredient substitutes where possible.
- Sensory acceptance plateau: Overlay any roll-out with rapid iteration panels and A/B sensory tests. Adopt new flavor-tech selectively to avoid over-engineering core products.
- Channel misalignment: Avoid a “spray and pray” distribution approach. Use data from initial channel pilots to build validated expansion casebooks for retail buyers.
Conclusion: Why 2026 Is the Year to Move from Experimentation to Scale
Carob chocolate bars have advanced from a curiosity to a category with credible growth potential. The market’s trajectory—supported by a clear CAGR and multi-year projected expansion—creates a narrow window for companies to test, learn, and scale before the next wave of mainstream adoption. PW Consulting’s full report equips leaders with the numbers, the playbooks, and the risk frameworks required to make confident 2026 decisions.
To access the complete dataset, segment-level breakouts, and our practical implementation templates—including channel playbooks and supplier scorecards—please consult the full Carob Chocolate Bars Market report on the PW Consulting website. Our team is available to present tailored briefings and to work with commercial teams to turn insights into executable 2026 roadmaps.
For detailed analysis of this topic, please visit the official page: Carob Chocolate Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Military Two-person Rotorcraft Market to Reach USD 12,731.48 Million by 2032, Growing at a 4.35% CAGR
By PW Consulting, 2026-07-15
PW Consulting: Strategic Briefing — Worldwide Military Two‑person Rotorcraft Market (2026 Outlook)
PW Consulting today publishes an executive briefing accompanying our new Worldwide Military Two‑person Rotorcraft Market report — an operationally focused briefing designed to equip defense planners, OEM strategy teams, MRO investors and sovereign acquisition offices with the evidence, scenarios and decision tools they need to act in 2026. Our analysis shows the global two‑person military rotorcraft market reached USD 9,450.0 Million in the 2025 base year and is forecast to expand at a 4.35% CAGR across the 2026–2032 horizon, reaching approximately USD 12,731.48 Million by 2032. This growth trajectory is neither uniform nor risk‑free: it is concentrated among incumbent OEMs, influenced by material supply constraints, and highly sensitive to program timing and geopolitical shifts.
Worldwide Military Two-person Rotorcraft Market
What the report delivers — practical intelligence, not platitudes
- Actionable market sizing and forward curves: A transparent base‑year inventory (2020–2025) and modelled forecasts (2026–2032) in USD Million, with scenario lifts and downside cases calibrated to procurement cycles and operational attrition assumptions.
- Procurement decision frameworks: Time‑phased acquisition playbooks that translate strategic objectives into tractable procurement options — buy, retrofit, or extend — with clear trigger points for near‑term (0–3 years) vs. medium‑term (3–10 years) decisions.
- Supplier and capability heatmaps: Qualitative and quantitative benchmarking for prime OEMs and tier‑1 suppliers (platform, sensors, mission systems, engines, sustainment partners), including a scorecard methodology you can apply to live bid evaluations.
- Supply chain risk and mitigation toolkit: Prioritised supplier maps and mitigation plans for critical inputs (materials, composites, avionics), along with hedging strategies and industrial partnership templates for securing capacity.
- Cost‑of‑ownership and sustainment modelling: Multi‑node TCO templates covering acquisition, retrofit windows, depot capacity, manpower and lifecycle sustainment under alternative usage profiles.
- Technology trajectories and NGRC implications: A strategic view of near‑term upgrades versus disruptive pathways (high‑speed compound concepts, advanced ISTAR integrations) and their procurement implications for alliance and sovereign programs.
Why 2026 is a decisive year for procurement and industrial strategy
Several converging dynamics make 2026 an inflection point. First, a clear recovery and modernization cycle has driven structural demand: the market’s base‑year value of USD 9,450.0 Million provides the launchpad for steady expansion, but the realized opportunity for any one player depends on timing, industrial partnerships and supply resilience. Second, program‑level developments — national option exercises and tranche orders — are compressing decision windows for prime contractors and suppliers. Third, multilateral capability programs and next‑generation studies are beginning to crystallize requirements that will shape medium‑lift and medium‑speed rotorcraft strategies into the 2030s.
Worldwide Military Two-person Rotorcraft Market
For buyers, OEMs and investors, three strategic lessons are immediate: (1) act to derisk critical path items in 2026 (materials, composite capacity, MRO scaling), (2) prioritize platform flexibility and modularity to capture retrofit and training markets, and (3) align near‑term procurement with medium‑term industrial partnerships tied to future capability programs.
Worldwide Military Two-person Rotorcraft Market
Competitive landscape — incumbents, specialisations and strategic moves
- Airbus Helicopters (Marignane, France): A dominant multi‑role player with light and multi‑role platforms that are widely fielded in training, reconnaissance and light attack roles. Recent contract activity and concept work have reinforced Airbus’s position as a lead supplier for European modernization. Notably, Airbus has reported multiple national tranche decisions and publicly advanced next‑generation rotorcraft concepts in collaboration with major systems partners, signaling an intent to lock in industrial participation across allied programs.
- Bell Textron (Fort Worth, Texas, USA): Focused on light utility and training segments with platforms actively used in forward training and light utility roles. Bell’s commercial and training derivatives continue to be a channel into emerging and allied markets where affordability and simple sustainment are primary drivers.
- Leonardo Helicopters (Rome, Italy): Maintains a portfolio oriented to light twins and single‑engine trainers with export‑competitive offerings for NATO and partner fleets. Leonardo’s strategy emphasizes multi‑mission commonality and industrial cooperation across European programs.
- Russian Helicopters / Rostec (Moscow, Russia): Fields dedicated two‑crew attack and anti‑armor platforms; their fleet mix and doctrine emphasise heavy attack and survivability. For non‑Western customers, these platforms remain relevant, while sanctions and geopolitical constraints shape export pathways.
- Boeing (Arlington, Virginia, USA): Anchored by dedicated attack platforms and deep integration with high‑end weapons and sensor suites. Boeing’s offerings are central where networked lethality and integrated sustainment ecosystems dominate requirements.
Across the market, concentration is meaningful: a handful of OEMs capture the lion’s share of revenue and program awards. That concentration raises both opportunity and barrier effects — top‑tier primes can leverage scale for sustainment contracts and derivative programmes, while new entrants face higher entry costs and the need for industrial partnerships.
Supply‑side frictions: materials, composites and production cadence
Material and composite supply are now strategic variables in program execution. The aerospace titanium market, which serves key airframe and rotor components, registered substantive valuation growth in the mid‑2020s and continues to see above‑average demand from military rotorcraft programmes. Concurrently, composite‑material bottlenecks — driven by carbon‑fiber supply constraints, autoclave throughput and skilled labor availability — have been identified as a multi‑year production limiter for rotorcraft scaling. Our supply‑side sensitivity models show that a protracted composite bottleneck adds schedule risk and materially increases per‑unit procurement and retrofit costs unless mitigated through alternative sourcing, localized production investments, or redesign choices favouring metals in specific subsystems.
Program and alliance dynamics — NGRC and national modernization
Multinational next‑generation assessments and alliance studies are beginning to set the frame for medium‑lift replacements in the 2035–2040 window. Participation in these studies and early concept work provides OEMs and industrial partners with preferential access to requirement streams and follow‑on design contracts. For governments, engagement in alliance programmes represents a tradeoff between interoperability and domestic industrial participation; our scenario models quantify the value of early participation versus late procurement from a sovereign industrial base perspective.
Recommended 2026 priorities — a pragmatic five‑point plan
- Lock in critical supply relationships now: Secure titanium and composite throughput through multi‑year off‑take agreements, dual‑sourcing strategies and targeted floor‑space investments in composites capacity.
- Stress‑test acquisition timelines: Use the report’s timing models to align budgetary phasing with production capacity; avoid unsupported fleet gaps by planning retrofit and sustainment purchases in parallel with new platform procurements.
- Accelerate MRO and depot readiness: Treat sustainment investments as strategic force‑multipliers — depot capacity and training pipeline decisions made in 2026 will determine availability across the next decade.
- Engage in NGRC pathways: If national requirements align, enter consortium and concept phases early to capture industrial workshare and ensure sovereign options for critical subsystems.
- Prioritise modularity and upgradeability: Prioritise platforms and sensor suites that support low‑cost incremental upgrades to extend platform relevance amid rapid avionics and weapons integration cycles.
How to use the full report — what’s intentionally withheld here
This briefing presents the strategic implications, headline market sizing and a sampling of our operational recommendations. To preserve the utility of the briefing as a gateway to the full intelligence package, detailed sub‑segment tables (regional and application splits by revenue and unit flows), per‑platform unit economics, and proprietary supplier scoring matrices are available only in the complete report and the accompanying interactive workbook. The full deliverable includes downloadable models that allow you to run custom scenarios, adjust assumptions (procurement tempo, attrition, material price shocks), and produce bespoke outputs for budget‑cycle submissions or board‑level investment cases.
Deliverables and engagement options
- Full report (PDF) with methodology appendix and 2020–2032 model workbook (USD Million denominated).
- Interactive Excel model and scenario dashboards licensed for corporate use.
- On‑site strategy workshops and bespoke supplier/partner due‑diligence support.
- Quarterly update subscriptions to track orders, contract options and supply‑chain shocks through 2032.
PW Consulting’s Worldwide Military Two‑person Rotorcraft Market report is designed to convert raw data into executable action plans for calendar‑year 2026 decision cycles. The market’s base‑year scale (USD 9,450.0 Million in 2025) and a 4.35% forecast CAGR underline steady expansion; our focus is on helping clients translate that macro growth into defensible acquisition strategies, resilient supply chains and winning industrial partnerships. For procurement officers, strategy leads and investors seeking the granular splits, unit economics, and supplier scorecards that underpin our conclusions, the full report and interactive models are available through our publication portal.
For detailed analysis of this topic, please visit the official page: Worldwide Military Two-person Rotorcraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Natural Gelling Agent Market Set to Hit USD 14.12 Billion by 2032, Backed by a 6.42% CAGR
By PW Consulting, 2026-07-15
Worldwide Natural Gelling Agent Market — Strategic Outlook for 2026: A PW Consulting Preview
Executive snapshot
As food, pharmaceutical, personal care and industrial formulators continue to shift toward cleaner labels, plant-based textures and stable supply chains, the global market for natural gelling agents has become a strategic battleground. PW Consulting’s latest market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) finds the industry at an inflection point. The global market reached approximately USD 9,132.4 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.42% through 2032, approaching an estimated USD 14,117.2 Million by the end of the forecast window.
Worldwide Natural Gelling Agent Market
This preview highlights why that trajectory matters for 2026 decision-making, what competitive moves are reshaping the landscape, and which practical tools executives will need to convert market trends into defensible strategies. It demonstrates the depth of our analysis while intentionally withholding the granular segment-level tables and supplier-level scorecards—those are included in the full report available on our website.
Worldwide Natural Gelling Agent Market
Why 2026 is a tactical year for market-share and margin capture
-
Demand dynamics are maturing. Clean-label momentum and plant-based product innovation continue to drive incremental demand across food & beverage, nutraceuticals and personal care. At the same time, specialty applications in pharma (e.g., controlled-release matrices) are increasing the value-per-kilogram of higher-purity gelling agents.
Worldwide Natural Gelling Agent Market -
Supply-side volatility is elevating procurement as a strategic lever. Seaweed-derived inputs (carrageenan, alginates) remain geographically concentrated, exposing supply chains to weather, harvest cycles and trade-flow shifts. Recent quarter-to-quarter price pressures on carrageenan—compounded by strong export demand and tighter red seaweed availability—underline the commercial exposure of manufacturers who lack diversified sourcing or contractual hedges. Sodium alginate markets have also experienced episodic spikes; our analysis flagged a material pricing event in Turkey during mid-2025 that underscores vulnerability to regional harvest fluctuations.
-
Regulatory and trade changes are creating asymmetric advantages. In 2025, several hydrocolloid-related materials were exempted from new reciprocal US tariffs, easing near-term input cost pressure for North America-based processors. These policy moves alter near-term sourcing economics and should factor into 12–24 month sourcing roadmaps.
Competitive landscape — consolidation, capacity and capability
The market remains moderately concentrated: the leading three players account for a meaningful share of demand, and the top five capture a majority presence—creating both scale advantages and space for focused challengers. Recent strategic moves underline two concurrent dynamics: (1) consolidation at scale and (2) targeted capacity investments aimed at specialty grades and sustainability credentials.
-
Tate & Lyle’s acquisition of CP Kelco in 2024 is a landmark consolidation, significantly enhancing pectin and specialty gum capabilities and strengthening integrated go-to-market options for large food and beverage customers. For many buyers this shifts the balance from commodity supply toward bundled ingredient-and-application offerings.
-
Investment into regional manufacturing sits alongside consolidation. Jungbunzlauer’s announced investment to build a xanthan gum facility in Canada, and Cargill’s capacity expansion for pectin in Brazil, both indicate players optimizing proximity-to-demand, sustainable sourcing and local regulatory compliance.
-
Specialist producers—particularly those focused on gelatin, high-purity pectin, and seaweed-derived hydrocolloids—remain critical partners for formulators requiring technical service and regulatory support. These specialty providers often command margin premiums and can be attractive targets for strategic acquisition or long-term supply agreements.
Practical content in the full PW Consulting report (what’s actionable)
Our research is designed for executives who need more than market averages. The full report includes an integrated toolkit that supports decisions across procurement, R&D, M&A and regulatory affairs. Key practical deliverables include:
-
Market sizing and trajectories (validated historicals, 2026–2032 scenarios), with sensitivity analyses that model raw-material shocks, tariff permutations and demand elasticity by end-use.
-
Supplier benchmarking and capability matrices that assess technical depth, geographic footprint, sustainability credentials and substitute-risk. (Note: supplier scorecards and line-item benchmarks are included in the full report.)
-
Raw-material risk maps and procurement playbooks—detailing diversification strategies, contractual hedging options, and inventory optimization templates tailored to perishability and seasonality of agricultural feedstocks.
-
Product-and-portfolio roadmaps for formulators, aligning gelling-agent selection with clean-label claims, processing compatibility and cost-to-serve. We include decision trees for switching agents or adjusting formulations under price shocks.
-
Go-to-market and M&A scenario workbooks: playbooks for vertical integration, bolt-on acquisitions, or strategic partnerships—each assessed against regulatory risk, capex intensity and expected time-to-value.
Strategic implications and recommended actions for 2026
-
Procurement must shift from transactional spot buys to hybrid sourcing strategies. For 2026, we recommend layered contracts that combine long-term offtake for stability, short-term flexible volumes for opportunity capture, and options tied to raw-material indices where feasible.
-
R&D and product teams should prioritize multi-hydrocolloid formulation platforms. Investing in formulation libraries that enable rapid substitution between gelatin, pectin, carrageenan, xanthan and emerging bio-derived gels will reduce time-to-market risk when specific inputs tighten or prices spike.
-
Capex and footprint decisions need a near-term lens on sustainability and proximity. Capacity announcements across North America and Latin America indicate incentives for onshore or nearshore manufacturing—reducing logistics risk and improving ESG narratives for end customers.
-
M&A and partnership focus should be on capability rather than pure scale. Targets that offer specialty grades, technical service teams, or unique feedstock control yield better integration value than volumetric deals alone.
-
Brand and regulatory teams must prepare for tightening claims and traceability expectations. As sustainability and provenance claims become commercial differentiators, traceable supply chains for seaweed and citrus/fruit co-products will be essential to justify premium positioning.
Risk factors and scenario planning
Beyond headline growth, our analysis models several downside and upside scenarios that materially affect profitability and strategy:
-
Downside: Prolonged supply disruption in seaweed harvest regions or concentrated export controls could raise costs and force reformulation for price-sensitive categories.
-
Upside: Broader adoption of plant-based, high-protein, or novel dairy alternatives could expand the addressable market faster than baseline projections, particularly where texturizing performance is a barrier to consumer acceptance.
-
Regulatory pivot: Tariff changes and exemptions already observed in 2025–2026 create variable cost windows—companies that synchronize procurement and manufacturing decisions to these windows can realize both margin and service improvements.
How strategic buyers should use this intelligence in 2026
Leaders evaluating investments, partnerships or portfolio reshaping in 2026 should use the report to:
-
Validate target selection through supplier scorecards and scenario P&L impacts;
-
Design procurement contracts that balance security and flexibility, using our risk-mapped hedging templates;
-
Prioritize R&D and capex investments that lower substitution costs and accelerate product rollout in growth segments;
-
Benchmark commercial propositions against competitors who have integrated raw-material security with application support.
Concluding perspective
The natural gelling agent market is no longer a discreet commodity space—it's an intersecting set of agricultural supply chains, specialty chemistry capabilities and consumer-driven application markets. Reaching roughly USD 9.1 billion in 2025 and forecast to grow at 6.42% annually to around USD 14.1 billion by 2032, the sector offers substantial upside for those who can manage supply risk, differentiate technically and move decisively on consolidation opportunities. Key recent developments—large-scale acquisition activity, targeted capacity investments, and raw-material price dislocations—signal that 2026 will reward companies that combine operational resilience with nimble commercial responses.
PW Consulting’s full Worldwide Natural Gelling Agent Market report provides the data, supplier-level insight and executable playbooks that boards, procurement chiefs and R&D leaders need to convert market growth into durable advantage. For access to the complete dataset, segment breakouts, supplier scorecards and scenario models, please visit the report landing page on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Gelling Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Twist Dispensing Closure Market to Grow from USD 480.5 Million in 2025 to USD 678.83 Million by 2032 at a 5.06% CAGR
By PW Consulting, 2026-07-15
Worldwide Twist Dispensing Closure Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s senior strategic adviser and chief industry analyst, I present a concentrated executive briefing derived from our new market study: Worldwide Twist Dispensing Closure Market (base year 2025; historical window 2020–2025; forecast 2026–2032). This release is built as a tactical briefing for CEOs, product leaders, supply‑chain chiefs and corporate development teams who must take decisive action in 2026. The intent here is to demonstrate the practical value of the full report while reserving granular sub‑segment tables and regional splits for subscribers.
Worldwide Twist Dispensing Closure Market
Executive summary — what the numbers mean for strategy
The twist dispensing closure market has shown steady expansion through the first half of the decade. Our bottom‑up sizing places the global market at approximately USD 480.5 Million in 2025, up from the low‑to‑mid hundreds in 2020, and on a path to roughly USD 509 Million in 2026. Under the central forecast assumptions the market reaches nearly USD 679 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.06% over the projection window.
Worldwide Twist Dispensing Closure Market
Those headline figures mask an important strategic message: growth is consistent but not explosive, and value is being redistributed along the chain—toward sustainability attributes, application‑specific functionality (child‑resistance, tamper evidence, gas‑tight seals), and integration with high‑speed automated application systems. For decision‑makers, this means growth opportunities are attainable but differentiated, and execution needs to be tightly aligned with product design, raw material sourcing and regulatory positioning.
Worldwide Twist Dispensing Closure Market
Why 2026 is an inflection point
- Regulatory acceleration: Extended Producer Responsibility (EPR) programs in the EU and expanding frameworks in North America, alongside the EU’s Single‑Use Plastics measures, have already shifted purchase specifications toward mono‑material, tethered and recyclable closure formats. Compliance timelines and retailer mandates create immediate product and supply obligations for many OEMs and co‑packers in 2026.
- Sustainability as a purchase trigger: Brand owners and retailers are converting sustainability commitments into technical demands—mandating PCR content, specifying overcap designs that maintain recyclability, and prioritizing closures that avoid mixed‑material assemblies.
- Input cost volatility and supply chains: The raw material base—primarily polypropylene (PP) and high‑density polyethylene (HDPE)—remains the single largest cost and availability risk. Manufacturers must adopt hedging, long‑term off‑take or backward integration options to avoid margin erosion.
- Innovation and commercialization cadence: Recent and near‑term product introductions show two concurrent tracks: incremental performance enhancements (better seals, child‑resistant features) and system‑level innovations (tethered designs; multi‑material hybrids with PCR). These are driving differentiated contract wins but also raising line conversion needs at packaging plants.
What the full report provides — practical assets for 2026 execution
We designed the report explicitly as an operational playbook, not an academic exercise. Key deliverables include:
- Layered market model: historical (2020–2025) build and a flexible forecast engine (2026–2032) that supports scenario toggles for regulatory, raw material and adoption curves.
- Price‑sensitivity and margin stress tests: configurable inputs for resin prices, energy, labour and freight to quantify margin impact across product families.
- Supply‑side mapping: capacity inventories, standard machine footprints, high‑speed application lines and change‑over times to evaluate investment needs and time‑to‑market.
- Customer and channel playbooks: buyer personas for food & beverage, personal care, household/industrial and pharmaceutical segments with procurement scoring and contract templates.
- Sustainability compliance roadmap: step‑by‑step actions to meet EPR/tethered closure requirements, PCR adoption pathways, and lifecycle assessment templates for client procurement teams.
- M&A and portfolio optimisation toolkit: target screening criteria, synergy assumptions, integration checklists and valuation sensitivities specific to closure manufacturing assets.
- Competitive playbook: profiles, capability matrices and scenario‑based strategies for the major suppliers and challengers—sufficient to support strategic decisions without exposing raw segmentation tables here.
- Data pack and model workbook: downloadable, auditable spreadsheets supporting every chart and table cited in the report (available to subscribers).
Competitive landscape — tactical takeaways
The market is moderately consolidated: the top three suppliers control roughly a third of global market revenue, and the top five fall under half of the total market. That structure creates both partner and target opportunities for incumbents and challengers. Our analysis of leading players yields several actionable insights:
- Silgan Holdings Inc. leverages established Twist‑Off® and PT positional brands and has operational scale in mono‑material solutions. Strategic advantage: deep customer relationships in liquid food and non‑carbonated beverage channels—priority action for rivals is to differentiate on design and service speed rather than price alone.
- AptarGroup Inc. is pushing the sustainability narrative with recent product launches that combine consumer convenience and child‑resistance. Strategic opportunity: partner with Aptar on co‑development deals for cross‑category launches or acquire niche IP where market access is limited.
- Berry Global, Amcor, and TriMas represent scale players with broad packaging portfolios; their closures business benefits from cross‑sell into existing customer relationships. Competitors should expect aggressive pricing and bundling in large food and personal‑care contracts.
- CSI, O.Berk, Mold‑Rite (MRP) and Guala are differentiated by application engineering, speed‑application competency, and regional manufacturing footprints. For fast niche wins—such as tethered or gas‑tight seals—these firms are often the incumbents of choice.
- Specialist challengers (regional manufacturers or design houses) can capture share by focusing on retrofit solutions and rapid prototyping for specific regulatory windows (e.g., tethered closure conversions demanded by retailers).
2026 strategic playbook — priority actions for executives
- Define portfolio intent: Decide whether to play at scale (volume, commodity margins) or to pursue premium, differentiated closures (value add via functionality or sustainability). Each requires different capex, sales compensation and technical capabilities.
- Operationalize recyclability: Convert 12–18 month product roadmaps into quarter‑by‑quarter deliverables—validate mono‑material designs, secure PCR supply, and qualify recycling compatibility through validated waste‑stream pilots.
- Hedge raw material risk: Implement dual sourcing, hedged purchase contracts and strategic partnerships with resin producers; evaluate vertical options where economics justify capex.
- Prepare for line conversions: Prioritize investments in tooling and high‑speed application changeovers; include capex/take‑rate assumptions in commercial negotiations with brand customers.
- Accelerate commercial pilots: Run co‑development pilots with tier‑one customers to lock design wins and create switching costs—use short‑cycle pilots to demonstrate cost‑neutral sustainability upgrades.
- Assess M&A selectively: Look for targets that provide access to PCR supply, accelerate tethered closure IP, or add high‑speed application competence. Use our M&A toolkit to size returns under the market growth assumptions provided in the full report.
Three pragmatic scenarios for 2026
- Conservative optimisation: Focus on cost and productivity—improve yield and reduce SKUs across commodity closures while maintaining selective investments in compliance conversions.
- Sustainability pivot: Invest in mono‑material and higher PCR content product lines, accept short‑term margin compression to capture long‑term differentiated contracts with sustainability‑focused retailers.
- Growth via consolidation: Acquire regional production capacity, bolt on application expertise, and realize synergies in logistics and tooling to accelerate penetration in prioritized end‑markets.
Methodology and confidence
The study uses a blended bottom‑up and top‑down methodology: production and shipment data from primary sources, validated by more than 50 supplier and buyer interviews, reconciled with secondary statistics and trade flows. Our model includes sensitivity analyses for resin price swings, regulatory adoption rates (tethering mandates and EPR timelines) and market substitution dynamics. For corporate planning we provide both central and two stress‑case forecasts so teams can simulate procurement, pricing and capex outcomes under realistic conditions.
Concluding recommendation
2026 will reward companies that can simultaneously manage short‑term margin pressure from raw material volatility and execute product transformations demanded by regulators and brand OEMs. The growth trajectory—5.06% CAGR to 2032 in our central case—creates meaningful upside for companies that align product, supply and commercial models around sustainability and application performance.
This briefing intentionally highlights strategic implications and omits the detailed regional and application‑level splits that our clients use to build execution plans. To access the full data pack, segmented tables, and the downloadable modelling workbook—along with supplier scorecards and the M&A playbook—visit the report landing page or contact PW Consulting. Our team is available to run a customized 90‑minute workshop to translate these findings into a 12‑month operational roadmap tailored to your business.
For detailed analysis of this topic, please visit the official page: Worldwide Twist Dispensing Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


