



PW Consulting: Worldwide Cobalt Acetate Solution Market Set to Reach USD 627.3 Million by 2032, Growing at a 5.71% CAGR (2026–2032)
By PW Consulting, 2026-07-15
Worldwide Cobalt Acetate Solution Market: Strategic Preview for 2026 Decision‑Making
PW Consulting today releases a strategic preview of our forthcoming Worldwide Cobalt Acetate Solution Market report (base year 2025). This briefing is designed as a “trailer”: it delivers evidence‑based insight, decision frameworks and tactical guidance for 2026, while preserving proprietary segment tables and the interactive models behind our conclusions. Corporates, investors and policy teams should treat this as a concise, operational lens on a market that is mid‑cycle, supply‑constrained and undergoing regulatory rerating.
Worldwide Cobalt Acetate Solution Market
Market snapshot: trajectory and concentration
Between 2020 and 2025 the global cobalt acetate solution market expanded materially, moving from the low hundreds of millions of USD to a base‑year size of approximately USD 425.5 Million. Under our baseline forecast, the market is projected to grow to roughly USD 627.3 Million by 2032, representing a compound annual growth rate (CAGR) of about 5.71% over the 2026–2032 forecast window. Market concentration is moderate: the top three players account for under two‑fifths of the market (CR3 ~38.4%), while the top five capture just over half (CR5 ~52.15%), a structure that supports both scale advantages and meaningful opportunities for regional and specialty producers.
Worldwide Cobalt Acetate Solution Market
What will shape 2026 decisions?
- Raw material volatility: Cobalt feedstock moved from a structural surplus to deficit dynamics in 2025. Cobalt metal pricing more than doubled through 2025 and entered 2026 near US$56,414 per metric ton, while hydroxide feedstock spiked even more sharply. This rapid feedstock repricing is now the dominant margin and sourcing risk for both integrated producers and toll processors.
- Supply re‑balancing from the DRC: Post‑2025 policy changes in the Democratic Republic of Congo have introduced export quotas intended to rebalance upstream flows. The effects are being transmitted down the value chain and are visible in tightened spot availability and longer lead times for certain contract structures.
- Regulatory evolution in key markets: Europe’s regulatory posture is active. In January 2026, one major producer secured an updated REACH registration for cobalt acetate solution that opens new permitted use conditions—an important precedent for pharmaceutical and advanced materials applications. At the same time, regulators are continuing roadmap evaluations on cobalt compounds, which raises compliance questions for formulation and distribution strategies.
- Capacity moves and product differentiation: New capacity additions and on‑site production plans announced by producers in 2025–2026 are altering supplier economics. We note both large‑scale additions by integrated processors and targeted investments in ultra‑high‑purity product lines for electronics and pharma intermediates.
- Demand composition and purity segmentation: End‑use demand remains heterogeneous—industrial oxidation catalysis, coating driers, electroplating and specialty materials each have distinct purity and logistics requirements. The premium attached to high‑purity grades and regulatory‑cleared chemistries is growing, altering how buyers structure sourcing and testing regimes.
Why this report is strategically valuable for 2026
- Turn insight into procurement advantage: Buyers who understand feedstock sensitivities and supplier cost drivers can re‑price long‑term contracts, design hedges and implement tiered sourcing to reduce exposure to spot spikes.
- Target capital allocation: Producers and private equity must prioritize investments—whether in capacity, high‑purity lines, or recycling/feedstock integration—to capture margin uplift without overexposing to cyclical risk.
- Navigate regulatory complexity: Regulatory clearance (and denial) can create rapid product re‑segmentation. The report translates regulatory developments into practical compliance checklists and go‑to‑market adjustments for commercial and R&D teams.
- Inform M&A and JV strategy: Mid‑market consolidation and upstream integration are the most credible routes to margin expansion. We provide an acquisition playbook mapped to value creation levers in processing, logistics and specialty grade development.
- Operationalize scenario analytics: The market is sensitive to a small set of variables (feedstock cost, DRC export policy, and regional regulatory changes). Our scenario toolkit converts those variables into actionable P&L and balance‑sheet stress tests.
Report contents — the practical toolkit inside
The full PW Consulting study is constructed for immediate application by commercial, procurement, technical and corporate strategy teams. Key deliverables include:
Worldwide Cobalt Acetate Solution Market
- Executive synthesis and 7‑year base, upside and downside forecasts with documented assumptions;
- Supply‑demand balance models, including annualized capacity and utilization curves, with sensitivity levers for feedstock cost and trade flows;
- Price‑build and margin simulation model in an interactive Excel workbook (licensed with the report) so teams can test contract scenarios and supplier bids;
- Supplier benchmarking and risk matrix covering integrated refiners, specialty chemical houses, toll processors and regional producers; company profiles include strategic positioning, product scope, geographic reach and recent CAPEX or product moves;
- Regulatory and trade compliance matrix focused on REACH, export controls and country‑specific testing requirements, together with a buyer’s due‑diligence checklist;
- Commercial playbook with contracting templates, accepted test methods for quality disputes, and logistics risk mitigants;
- Detailed annexes and proprietary trade flow visualizations (regional and application splits are presented in the licensed dataset; summary trends are discussed in the public report); and
- Primary research atlas—interview list and methodology disclosure spanning producers, converters, traders and end‑users across the value chain.
Note: this public release intentionally omits the granular regional, grade and application split tables and the downloadable model inputs; these are available only in the licensed report and online portal.
Competitive landscape: what to watch among suppliers
- Umicore N.V. (Belgium) — A technology‑oriented supplier focusing on high‑purity and customized cobalt salts; recent REACH dossier updates expand permitted applications in Europe and are likely to premiumize their higher‑purity portfolio.
- Zhejiang Huayou Cobalt — A large integrated processor that commissioned a significant new cobalt chemicals line in early 2026, expanding available industrial and specialty acetate supplies and changing regional sourcing dynamics.
- China Molybdenum (CMOC) — Announced plans for adjacent processing capacity near upstream mining assets to capture value‑add, a move that could improve feedstock security for their downstream customers.
- Sumitomo Metal Mining — Investing in ultra‑low impurity grades targeted at electronics and pharmaceutical intermediates, responding to increasing demand for trace‑clean chemistries.
- Specialty and regional producers — Companies such as Shepherd Chemical, Palm International, Mechema/Coremax, Avantor, Freeport Cobalt and established Indian and Chinese manufacturers continue to compete on service, customization and regional logistics. Their presence supports flexible supply options for buyers with complex specifications.
These firms represent different strategic archetypes—technology‑and‑compliance leaders, scale integrators, and agile regional specialists. For buyers, the optimal supplier mix will increasingly be hybrid: a scale supplier for baseline tonnage and a specialty partner for high‑purity or rapid‑response needs.
Actionable recommendations for C‑suite and procurement leaders
- Adopt a three‑tier sourcing strategy: secure baseline volumes with integrated producers, assign specialty volumes to high‑purity suppliers, and maintain a tactical pool of regional suppliers for spot volatility.
- Institute feedstock cost pass‑through or indexed pricing clauses for new contracts to avoid full margin erosion during commodity spikes.
- Accelerate qualification of alternative suppliers and material substitution pilots where feasible; shorten supplier qualification cycles through standardized testing and shared audit protocols.
- Perform a targeted capital review for 2026: prioritize investments that de‑risk feedstock access, improve recovery/recycling of cobalt from spent catalysts, or enable premium‑grade production.
- Embed regulatory monitoring into procurement and R&D workflows: regulatory rulings can change product acceptability quickly and materially.
- Use the report’s scenario models to stress‑test balance sheets and contract portfolios across plausible 2026–2028 supply shocks.
Principal risks and uncertainty
- Upstream policy shifts: Export quotas or local content rules disrupt flows and reprice markets.
- Regulatory reclassification: More restrictive chemical controls or use‑case prohibitions could displace demand toward alternatives or higher‑compliance producers.
- Feedstock price spikes: Rapid cobalt/hydroxide cost inflation compresses margins for non‑integrated players unless pass‑through mechanisms exist.
- Technical substitution: Advances in non‑cobalt catalyst chemistries or reduced cobalt formulations could influence medium‑term demand trajectories.
Next steps and how to obtain the full analysis
PW Consulting’s full Worldwide Cobalt Acetate Solution Market report contains the proprietary datasets, regional and application split tables, supplier capacity maps, and the interactive Excel model necessary to operationalize the strategies summarized here. For procurement teams, R&D leaders, corporate development and investors preparing 2026 plans, the licensed report is intentionally structured to convert market intelligence into executable actions. Visit the PW Consulting website to review the license options and to request a sample of the methodology and a limited data extract.
For immediate advisory support — scenario workshops, supplier negotiation playbooks, or custom modeling — PW Consulting’s chemicals and materials practice offers tailored engagement packages to align supply‑chain choices with strategic objectives in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cobalt Acetate Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Auto Steering for Tractor System Market to Grow from USD 1,465.2 Million in 2025 to USD 3,337.53 Million by 2032 at a 12.48% CAGR
By PW Consulting, 2026-07-15
PW Consulting Releases Strategic Briefing: Worldwide Auto Steering for Tractor System Market — The 2026 Playbook for Deliberate Investment
PW Consulting today published a focused industry briefing accompanying our full market research report, Worldwide Auto Steering for Tractor System Market. Built on a base year of 2025 with a historical lens from 2020–2025 and a forward-looking forecast to 2032, this analysis isolates the structural forces shaping capital allocation, product roadmaps, and competitive positioning in precision agricultural steering systems. The market is on a clear growth trajectory — exhibiting a robust compound annual growth rate (CAGR) of 12.48% across the forecast window — and our 2025 baseline and multi-year projections provide the empirical foundation necessary for confident 2026 decision‑making.
Worldwide Auto Steering for Tractor System Market
Why this briefing matters for 2026 corporate strategy
- Timing and conviction: 2026 will be a pivotal year for firms deciding whether to scale internal capabilities, partner for retrofit channels, or consolidate through M&A. The market momentum quantified in our report removes ambiguity from near-term capacity and R&D choices.
- Risk‑adjusted capital allocation: With adoption accelerating, leaders must balance CAPEX for hardware (e.g., hydraulic and electric steer units) with software and services (sensor fusion, GNSS subscriptions, fleet telematics). Our scenario models show how varying technology mixes and pricing assumptions change payback horizons.
- Regulatory and interoperability clarity: Standards such as ISO 18497-1:2024 and evolving emissions and vehicle regulations are changing engineering trade-offs. Our briefing translates these standards into practical product and compliance actions for 2026 roadmaps.
Headline market dynamics (an operational view — high level)
The auto‑steering tractor market has moved from niche adoption to mainstream deployment in just a few agricultural cycles. Macro indicators included in the full report reveal a market that more than doubled in scale from the early 2020s to the 2025 base, with continued expansion projected to 2032. That trajectory — underpinned by a 12.48% CAGR across the forecasted period — is being driven by three converging vectors:
Worldwide Auto Steering for Tractor System Market
- Technology maturity: RTK GNSS, tightly integrated IMU sensor suites, and steer‑by‑wire options have reached cost and reliability thresholds that broaden addressable use cases, from precision row cropping to complex implements.
- Productization of retrofit offerings: A growing ecosystem of retrofit kits and mixed‑fleet interoperability solutions means operators can capture precision benefits without full fleet replacement.
- Commercial imperatives: Labor constraints, sustainability targets, and the drive to reduce operational overlap have sharpened the ROI case for steering automation across farm sizes.
What our report delivers — practical tools, not just charts
PW Consulting’s Worldwide Auto Steering for Tractor System Market report is designed for line managers and C-suite strategists who need executable outputs, not only descriptive analytics. In addition to a layered market forecast and competitive benchmarking, the report includes:
Worldwide Auto Steering for Tractor System Market
- Decision‑grade scenario matrices that map demand, pricing, and technology adoption for five investment profiles (incumbent OEM, Tier‑1 supplier, retrofit specialist, agtech software player, and private equity investor).
- Commercial diligence templates — revenue-sensitivity models, margin waterfall analyses, and CAPEX/OpEx calculators — preconfigured for rapid stress testing of acquisition targets or new product launches.
- Vendor scorecards and integration checklists evaluating sensor accuracy (including RTK and IMU performance), ISOBUS and CAN interoperability, and retrofit fitment complexity to reduce technical surprises in pilots.
- Supply chain heatmaps and risk scenarios assessing semiconductor and precision sensor availability under different demand shocks, plus mitigation playbooks for procurement teams.
- Customer segmentation frameworks and go‑to‑market playbooks that translate adoption barriers into targeted channel strategies for OEM, dealer, and retrofit routes.
Competitive landscape — what leading players are doing and why it matters
The market is neither atomized nor monopolized. Measured concentration indicates a moderately concentrated structure, where the top three and top five groups exert meaningful influence on platform standards, distribution, and technology pathways. This creates both opportunities and constraints for new entrants. Key strategic takeaways regarding the major players covered in the full report include:
- John Deere: Deeply integrated factory systems and a seamless ecosystem approach make Deere the reference point for OEM-embedded precision. Competitive moves that prioritize backward compatibility with dealer networks and subscription monetization are likely to preserve their installed‑base advantage.
- CNH Industrial / Raven: CNH’s dual brand strategy and Raven’s guidance expertise enable cross‑brand technology reuse and a strong retrofit-to-OEM channel. Integration of Raven technologies into Case IH and New Holland product lines changes the calculus for independent retrofit specialists.
- AGCO (Fendt, Massey Ferguson, Valtra): Emphasis on ISO-compliant interfaces and modularity gives AGCO flexibility in multi-vendor environments — a strategic posture that appeals to mixed-fleet operators and large service organizations.
- Trimble, Topcon, Hexagon: These precision‑tech specialists have built strong mixed‑fleet and OEM partnership models. Their value lies in accuracy, support ecosystems, and GNSS competency rather than tractor manufacturing, positioning them as natural partners for both OEMs and retrofit channels.
- CLAAS, AG Leader, CHC Navigation: CLAAS leverages integrated control systems, while precision-electronics firms and retrofit specialists are pushing cost‑effective RTK and multi‑constellation GNSS solutions to broaden market reach.
Recent product movements are illustrative of the competitive playbook: new high‑accuracy GNSS boards and upgraded steering kits introduced in late 2025 and early 2026 signal that suppliers are competing on sensor quality, ease of retrofit, and ISOBUS compatibility. These developments reduce technical barriers for adoption and increase the importance of lifecycle service offerings as differentiators.
Standards, accuracy expectations, and regulatory levers
- ISO 18497‑1:2024 establishes industry safety requirements for highly automated agricultural machines; our report translates the standard into discrete product and testing checklists to help engineering teams align development and certification efforts.
- Field practice has converged around RTK‑level precision combined with IMU terrain compensation, commonly delivering sub‑5 cm repeatability in operational conditions. The report maps how different accuracy tiers affect economics across crop types and implement widths.
- Macro regulatory shifts — for example, heavy‑duty vehicle emissions standards that influence powertrain and electronics integration timelines — are covered in our policy impact scenarios so executives can anticipate indirect compliance costs and redesign requirements through 2032.
Actionable recommendations for 2026
- Prioritize interoperability over proprietary lock‑in: Invest in ISOBUS and multi‑constellation GNSS compatibility to keep channel options open and accelerate retrofit adoption.
- Balance hardware excellence with service monetization: Differentiate through field analytics, precision subscriptions, and guaranteed uptime SLA packages rather than solely on sensor specs.
- Use staged pilots tied to real P&L metrics: Require pilots to deliver measured overlap reduction, time savings, and input efficiency gains before committing to fleet rollouts.
- Prepare for standards-driven certification: Adopt ISO 18497‑aligned testing early; certification roadblocks are a leading cause of delayed launches in our field interviews.
- Design M&A criteria around integration risk: Our due diligence checklist highlights the top five technical and commercial red flags that increase integration cost and timeline for acquisitions in this space.
What we deliberately withhold — and why
To respect commercial confidentiality and to follow the “trailer” principle, this briefing intentionally illustrates strategy and high‑level market traction without publishing the full segmented revenue tables and granular region/application percentages. The full report contains those detailed breakdowns, exhaustive company profiles, and downloadable financial models that enable transaction support and operational planning. PW Consulting’s approach is to establish confidence through visible methodology and actionable frameworks while directing clients to the source deliverable for the granular inputs needed to execute deals and deployments.
How to use this briefing with your 2026 planning cycle
- Integrate the report’s scenario outputs into your budget cycle to stress‑test R&D spend at three accuracy and price points.
- Use the vendor scorecards to fast‑track shortlist creation for pilots, and require ISO‑aligned validation as part of any procurement contract.
- If evaluating M&A, apply our integration risk matrix during initial screens to prioritize targets that minimize platform migration costs.
PW Consulting’s Worldwide Auto Steering for Tractor System Market report is available now. For access to the complete dataset, regional and application forecasts, company market shares, and the suite of practical tools described above, please consult the full report landing page. Our analysts are available for bespoke briefings and tailored due diligence projects to support board decisions and 2026 execution plans.
— PW Consulting, Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Worldwide Auto Steering for Tractor System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Glass Bending Machine Market to Reach USD 758.23 Million by 2032, Expanding at a 5.38% CAGR
By PW Consulting, 2026-07-15
Worldwide Glass Bending Machine Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market research on the Worldwide Glass Bending Machine Market presents a focused, actionable intelligence package designed to support capital allocation, supplier selection, and product strategy decisions as companies plan for 2026 and beyond. Built on a robust base year of 2025 and a six‑year forecast window (2026–2032), the study reconciles historical performance (2020–2025) with scenario analyses and tactical roadmaps that translate market dynamics into boardroom actions.
Worldwide Glass Bending Machine Market
Market at a glance (high‑level)
- Base year: 2025; historical window: 2020–2025; forecast period: 2026–2032.
- Reported market (global revenues, USD Million): the industry expanded from a multi‑hundred million base in 2020 to USD 525.4 Million in 2025 and is projected to grow to USD 758.23 Million by 2032 under the central scenario.
- Compound Annual Growth Rate (2026–2032): 5.38% (central case).
- Market concentration: the industry shows moderate consolidation with a CR3 of 38.5% and a CR5 of 52.1% — a structure that both enables regional champions and leaves room for disruptive entrants and strategic M&A.
These topline figures establish both the scale and the predictable, steady expansion that characterize the next strategic planning cycle. The market is sufficiently large to justify meaningful capex, but sufficiently fragmented that supplier selection and technology differentiation will materially influence unit economics.
Worldwide Glass Bending Machine Market
Why this report matters for 2026 decisions
- Translate growth into timing: With predictable mid‑single‑digit CAGR, the primary strategic question for 2026 is not whether to invest, but how to pace investments across automation, energy efficiency, and product flexibility to optimize payback.
- Procurement and supplier risk: Raw material and energy price volatility is already compressing margins across glass processing value chains. Our risk‑adjusted supplier ranking and procurement playbooks let procurement teams structure contracts and lead times that reduce exposure.
- Regulatory readiness: Stricter energy consumption rules are accelerating demand for more efficient bending furnaces and process controls. The report quantifies regulatory impact scenarios and the breakeven for energy‑efficiency upgrades.
- Competitive positioning: The moderately concentrated market rewards scale and IP (process automation, tooling‑free bending), but there is space for regional specialists and solution providers focused on retrofit and aftermarket services.
- M&A and partnership intelligence: For corporate development teams, the study identifies types of targets (automation specialists, infrared/infra‑furnace innovators, regional manufacturing footholds) likely to unlock near‑term synergies.
What’s inside the report — practical deliverables for executives and practitioners
- Executive playbook: Five investment thesis scenarios and a decision matrix mapping business models to recommended timing (immediate, 12–24 months, 24–48 months).
- Market sizing & forecast models: Bottom‑up and top‑down reconciled revenue forecasts (USD Million) with sensitivity runs for commodity and energy price shocks.
- Supplier diagnostics: Comparative vendor scorecards (technology, automation maturity, service footprint, installation case studies) and contract negotiation checklists.
- CapEx and TCO tools: Practical calculators to model total cost of ownership for new lines vs retrofits, incorporating energy consumption, tooling, floor footprint, and throughput scenarios.
- Regulatory & sustainability assessments: Region‑agnostic frameworks to estimate compliance costs and ROI on energy‑saving retrofits under different policy trajectories.
- Risk matrix and mitigation playbooks: Supplier disruption scenarios, raw material price pass‑through playbooks, spare‑parts strategies, and key KPIs for continuous monitoring.
- Case studies & implementation roadmaps: Real‑world examples — including large‑format architectural installations and automotive windshield programs — that validate timelines, workforce training needs, and typical commissioning risks.
- Strategic M&A shortlist: Profiles of target archetypes and a prioritized shortlist of private companies and niche manufacturers (detailed target dossiers available in the full report).
Five strategic actions for 2026
- Prioritize automation that preserves flexibility.
Given the market’s steady growth and fragmented demand across architectural, automotive and specialty glass uses, the most durable investments are those that allow rapid product mix changes (multi‑format handling, programmable bending sequences) without excessive tooling costs. Our TCO scenarios show automation can shorten payback even when throughput gains are modest, provided flexibility is engineered in from day one.
Worldwide Glass Bending Machine Market - Accelerate energy‑efficiency retrofits.
Regulatory pressure and energy price volatility make energy‑intensive furnaces a long‑term cost liability. We quantify retrofit breakevens for common furnace classes; in many cases, modest capital outlays produce multi‑year energy savings and hedge regulatory risk.
- Design supply strategies for volatility.
Volatile silica and energy inputs mean procurement must move from spot buying to blended strategies: long‑term contracts for core volumes, indexed spot for peak needs, and local inventory buffers for critical spares. The report includes sample contract language and trigger points for inventory replenishment.
- Guard against single‑source dependence.
With CR5 above 50%, single‑source dependencies persist in many OEM footprints. Where uptime is mission‑critical (automotive windshield lines; specialty architectural production), dual sourcing plus preventive maintenance agreements materially reduce downtime risk.
- Leverage partnerships for rapid capability build‑out.
For companies seeking to enter curved‑glass markets quickly, partnerships with specialized furnace makers or retrofit integrators can bridge capability gaps with lower upfront capex than greenfield builds. The report maps partnership types to likely time‑to‑market and dilution of margin upside.
Competitive landscape — who to watch (high‑level)
The industry combines global engineering houses, regional champions, and a cohort of specialist innovators. Below are high‑level profiles of vendors whose strategies and recent moves will shape supplier markets in 2026:
- Changzhou ZT Machine Co., Ltd. (China)
Strengths: turnkey solutions for large‑format and complex curved glass, proven architectural projects (including furnaces used on landmark structures). Strategic value: strong delivery capability for large, bespoke architectural programs and integrated lamination offerings.
- CMS Glass Machinery (Turkey)
Strengths: integrated bending and tempering furnaces enabling curved tempered glass production. Strategic value: competitive integrated systems for mid‑to‑large architectural projects.
- LandGlass Technology (Luoyang, China)
Strengths: intelligent automotive glass bending and tempering offerings. Strategic value: solid partner for OEMs scaling windshield and laminated glass production.
- Glaston Corporation (Finland)
Strengths: tooling‑free processes, product families for automotive and architectural bending (e.g., ScreenMax). Recent installation: ScreenMax furnace deployed for windshield production at Finn Lamex (June 2025), demonstrating applicability to large automotive programs.
- Glasstech, Inc. (USA)
Strengths: high‑capacity automotive deep‑bend systems with energy‑efficiency profiles. Strategic value: attractive for high‑volume OEM lines seeking throughput and reduced energy consumption.
- European engineering houses (Mappi, LiSEC, Bottero, Bavelloni)
Strengths: high‑precision automation, customization, and strong service networks across EMEA. Strategic value: premium solutions where precision and integration are prioritized.
- Chinese volume and retrofit suppliers (Luoyang Lever, Shandong Eworld, Liaoda)
Strengths: price competitiveness and regional support. Strategic value: attractive for price‑sensitive programs and rapid equipment expansion in emerging markets.
- Casso‑Solar Technologies (USA)
Strengths: infrared furnace specialists serving niche sectors (architectural, aerospace, ballistic). Strategic value: technology partner for specialized bending requirements where conventional furnacing is sub‑optimal.
Collectively, vendor strengths map to strategic choices companies must make in 2026: buy for throughput and scale, license for specialty processes, or partner for rapid capability expansion.
Methodology & data integrity
- Data sources: the report synthesizes primary interviews across OEMs, tier‑1 glass processors, and furnace manufacturers; a structured database of historical shipments and revenues (2020–2025); and macro overlays for energy and raw‑material price scenarios.
- Currency & units: all revenue figures reported in USD Million. Base year: 2025.
- Forecast approach: bottom‑up capacity modeling combined with scenario stress tests for commodity and regulatory shocks; sensitivity bounds accompany all forecast outputs.
- What we withhold here: to preserve the utility of the report as an actionable purchase, detailed regional, type‑by‑type and application‑level revenue splits are summarized in the full report and Excel workbooks — these granular datasets are intentionally not disclosed in this announcement.
Conclusion — how to use this intelligence in 2026
For executives preparing 2026 budgets and 3‑year strategic plans, this PW Consulting study reframes the glass bending machine market as a set of tactical choices rather than binary decisions. The sector’s steady growth, moderate concentration, and technology‑driven differentiation create a playbook where timing, supplier choice, and energy strategy matter more than headline market share. Use the report to quantify tradeoffs between retrofit and greenfield builds, to stress‑test suppliers under commodity shocks, and to prioritize investments that protect throughput while reducing regulatory exposure.
To access the full dataset, vendor dossiers, Excel models and the complete strategic playbook — including the segment‑level breakdowns and region/application revenue matrices — visit our report page and download the Worldwide Glass Bending Machine Market report from PW Consulting. The full package is designed to convert market understanding into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Bending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Clamp Market to Reach USD 4,319.9 Million in 2025; Asia‑Pacific Leads with USD 1,796.24M as Market Expands at 4.6% CAGR through 2032
By PW Consulting, 2026-07-15
Worldwide Automotive Clamp Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Worldwide Automotive Clamp Market study (base year 2025, forecast 2026–2032) equips senior leaders with the market intelligence required to make high‑stakes commercial, engineering, and M&A decisions in 2026. The global market demonstrated resilience through 2020–2025, expanding from roughly USD 3.45 billion in 2020 to USD 4.32 billion in 2025, and is projected to grow at a 4.6% compound annual growth rate over the 2026–2032 forecast window. By 2032 the market is expected to approach USD 5.92 billion, reflecting steady demand driven by vehicle production growth, thermal management complexity, and electrification-led packaging changes.
Worldwide Automotive Clamp Market
Why this report matters for 2026 strategy
- Operational leaders need forward-looking cost models: our analysis quantifies how raw-material volatility and manufacturing automation alter unit economics for clamp producers and OEM suppliers.
- Product and R&D heads require a prioritized technology roadmap: the study maps which clamp technologies will be mission‑critical across thermal, high‑pressure, and high‑temperature subsystems over the next five to seven years.
- M&A and corporate development teams need a screening framework: we identify value pools and the consolidation dynamics that make clamp manufacturers attractive targets for Tier‑1s and private equity.
Core market dynamics and strategic implications
The market’s mid-single-digit CAGR masks a complex set of forces that will shape supplier economics and OEM specifications in 2026 and beyond. Three dynamics deserve attention:
Worldwide Automotive Clamp Market
- Input cost volatility and margin pressure.
Steel and stainless steel account for a large portion of production cost for most clamp types; our sector analysis indicates raw‑material exposure can swing manufacturing costs meaningfully, with price volatility capable of raising direct costs by double‑digit percentages in stressed scenarios. For procurement and cost‑to‑serve models, 2026 should be treated as a pivot year to implement hedging strategies, long‑term contracts, and design choices that reduce material intensity.
Worldwide Automotive Clamp Market - Design evolution driven by thermal, vibration, and lightweighting requirements.
Thermal management complexity—particularly in turbocharged engines, hybrid systems, and EV cooling architectures—is accelerating adoption of constant‑tension and spring‑loaded solutions that compensate for thermal expansion and contraction. High‑temperature profile clamps that can withstand extreme exhaust and turbocharger environments—engineered to resist localized temperatures approaching 900°C—are driving premiumization in specific product lines. Simultaneously, vehicle lightweighting mandates are creating demand for alternative alloys and stamped/laser‑cut designs that lower mass without compromising sealing integrity.
- Regulatory & quality gates raise the bar for suppliers.
Automotive clamp suppliers must demonstrate compliance with automotive quality systems and component standards (notably IATF 16949 and performance requirements such as SAE J1508 for worm‑drive types). For OEM sourcing teams, the 2026 procurement checklist must prioritize validated manufacturing processes, traceability, and evidence of high‑temperature performance under cyclic vibration.
Competitive landscape — what to watch in 2026
The clamp market exhibits a moderate level of supplier concentration: the top three manufacturers account for a meaningful share of global supply, and the top five further consolidate the competitive set. This structure creates both opportunities and risks for buyers and investors—scale matters for automated production, while nimble specialists win in application‑specific niches.
- NORMA Group (Germany)
NORMA remains a technology leader in engineered joining solutions across worm‑drive, constant‑tension, profile, and V‑band clamps. Its strategy emphasizes OEM integration and modular product platforms for fluid systems, cooling, and exhaust. Recent investments in automation have expanded capacity and improved unit economics—moves that make NORMA a bellwether for industrialization in the sector.
- Oetiker Group (Switzerland)
Oetiker is focused on ear clamps, low‑profile solutions, and rapid assembly designs optimized for vibration resistance. Their value proposition centers on assembly efficiency and robust sealing in compact packaging—attributes attractive to vehicle manufacturers seeking line‑speed gains.
- Ideal‑Tridon Group (United States)
With a long history in worm gear, T‑bolt, and constant‑tension clamps, Ideal‑Tridon positions itself around heavy‑duty and high‑reliability applications. Expansion of distribution channels is enhancing their international reach and after‑sales service footprint—a competitive lever for global OEM platforms.
- Other notable players
Established names such as Murray Corporation, Breeze Clamps (NORMA Americas), Clampco Products, Mikalor, Rotor Clip, Jolly Clamps, Anhui KSeal/King Seal, and Auto Clamp Co. bring complementary strengths: manufacturing scale, specialized product profiles (V‑bands, T‑bolts, perforated worm drives), cost competitiveness in regional markets, and certifications for automotive quality systems. Several suppliers concentrate on niche technical advantages—high‑temperature metallurgy, self‑compensating bands, or ultra‑low profile designs—that allow them to command technical specification compensation from OEMs.
Recent moves that foreshadow 2026 dynamics
- Mubea’s lightweight clamp launches signal how materials engineering can materially reduce component mass and affect vehicle‑level fuel economy or EV range.
- Capacity expansions among leading manufacturers are driving a greater share of production under automated, high‑repeatability lines, compressing lead times and enabling higher quality consistency.
- Distribution and channel expansions by major clamps groups are narrowing the gap between regional demand and global supply, altering the logic for local inventory versus centralized sourcing.
What the PW Consulting report delivers — practical modules for 2026 action
Our report is designed as an operational playbook rather than a high‑level survey. The deliverables are arranged to be directly usable in boardroom and procurement workshops:
- Granular market sizing and validated topline forecasts through 2032 (base year 2025), including sensitivity scenarios for raw‑material shocks and powertrain mix shifts.
- Product technology maps that align clamp types to subsystem use‑cases (thermal management, exhaust, fuel, steering/suspension, braking), with engineering guidance on when to migrate to constant‑tension or high‑temperature solutions.
- Supplier scorecards and benchmarking templates covering quality certifications, automation level, capacity, and regional footprint—structured to expedite supplier rationalization and dual‑source strategies.
- Cost‑to‑manufacture models and material‑intensity matrices that allow procurement teams to simulate material pass‑through, alloy substitution, and cost mitigation measures under different steel price trajectories.
- Supply‑chain risk maps including single‑sourcing exposures, lead‑time elasticity, and inventory recommendations calibrated for OEM production planning horizons.
- M&A and partnership playbooks: target profiles, valuation heuristics, and integration checklists tailored to clamp manufacturers and complementary fastener/joining technology providers.
- Regulatory and compliance matrix keyed to IATF 16949 and SAE performance standards, with test protocols and documentation templates to accelerate OEM qualification.
- Commercial negotiation levers and contracting templates that embed performance‑based incentives (quality, on‑time delivery, warranty claims) and raw‑material pass‑through mechanics.
How different stakeholders should use this intelligence in 2026
- OEMs and Tier‑1 engineering
Use the product technology maps to specify clamps that reduce warranty exposure and simplify assembly—prioritize suppliers with high‑temperature validated products for exhaust and turbocharger interfaces and favor constant‑tension designs where thermal cycling is severe.
- Clamp manufacturers
Focus capex on automation and material R&D. The economics of scale and repeatability increasingly determine competitive positioning; companies that invest in lighter alloys and automated stamping/assembly will expand margins and win new OEM platforms.
- Procurement & supply chain
Adopt multi‑tier sourcing strategies, secure hedges or long‑term contracts for critical metal inputs, and implement supplier performance dashboards informed by our scorecards to reduce disruption risk.
- Private equity and corporate development
Prioritize targets with differentiated technology (high‑temp metallurgy, constant‑tension IP) and proven OEM qualification pipelines. Consolidation opportunities exist where medium‑sized suppliers can be aggregated to build global scale and broaden product portfolios.
Market structure and competitive tension
The market displays a moderate level of concentration: the top three suppliers account for a significant share of volumes and the top five deepen that lead further. This structure creates a two‑tier landscape—large groups competing on scale, automation, and breadth of product platforms, while specialized suppliers compete on technical differentiation, quick turn prototyping, and regional service. That bifurcation matters for negotiation dynamics and M&A valuation multiples.
Next steps and how to use the full report
This briefing intentionally highlights strategic themes and actionable frameworks while omitting the granular split tables, regional breakdowns, and detailed company share tables that underpin our modeling. The full PW Consulting report contains those datasets, downloadable decision‑support spreadsheets, and supplier scorecards that operational teams can plug directly into procurement systems and engineering roadmaps.
For executive briefings, scenario workshops, or tailored consulting engagements to translate the study’s findings into a 90‑day action plan, PW Consulting offers bespoke advisory packages that pair market data with implementation support.
To access the full report and accompanying toolkits, please visit the PW Consulting report page or contact our industry team for a private briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Clamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 3D TOF Market to Skyrocket to USD 21,165.17 Million by 2032 — Up from USD 6,450.5 Million in 2025 at an 18.5% CAGR
By PW Consulting, 2026-07-15
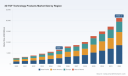
Worldwide 3D Time-of-Flight (ToF) Technology Products Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief for the Worldwide 3D ToF Technology Products Market delivers a concise but rigorous preview of trends that will shape capital allocation, product roadmaps, and M&A activity in 2026. Built on a base year of 2025 and a historical run from 2020–2025, our analysis projects an accelerated expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 18.5%. The total addressable market has moved from an early-stage base in 2020 into a multi-billion dollar industry by 2025 and is forecast to more than triple by the end of the forecast period—evidence of both large-scale adoption and rapid technology maturation. This release is a strategic primer: it surfaces the signal from the noise, highlights near-term inflection points, and outlines the concrete actions executive teams should consider in 2026. Detailed segment tables and regional breakouts are reserved for the full report.
Worldwide 3D TOF Technology Products Market
Executive snapshot: What every leader needs to know
-
Robust market momentum: After a five-year growth phase, 2026 marks the point where product diversification and scale deployments drive margin improvement across sensors, illumination hardware, and optical subsystems. The trajectory implies significant opportunity for firms that can bridge system integration and volume manufacturing.
Worldwide 3D TOF Technology Products Market -
Consolidation with opportunity: Market concentration is meaningful but not prohibitive—our analysis shows a top-three share below saturation and a top-five share that reflects increasing consolidation. Established semiconductor and sensor houses lead, but technical specialization and systems know-how create runway for new entrants and targeted acquisitions.
Worldwide 3D TOF Technology Products Market -
Technology bottlenecks shape winners: Resolution limits in current indirect ToF architectures, ambient-light robustness in direct ToF, and illumination source supply constraints are the technical chokepoints that will determine competitive positioning in 2026.
-
Standards and safety are table stakes: Automotive safety standards and interface standardization are already influencing product roadmaps and procurement requirements. Early certification and standards participation shorten time-to-market for priority verticals.
Why this preview matters for 2026 strategy
As capital allocation committees and product heads plan 2026 initiatives, the core strategic question is not “Will ToF matter?” but “Where on the stack and in which use cases should we compete?” Our market model—rooted in primary interviews, shipment-level device intelligence, supplier cost modeling, and validated revenue forecasts—translates market growth into actionable thresholds for commercialization, R&D spending, and supply-chain investment. For incumbents, the critical decisions revolve around defending systems-level value (software, calibration, and integration). For new entrants, the window to capture differentiated niches is narrow but tangible if teams address the technical bottlenecks we identify and align with emerging safety and privacy requirements.
Report deliverables: Practical tools inside
-
Market-sizing model (2020–2032): an editable forecast model (USD, millions) with scenario toggles for adoption curves and price erosion—designed to plug directly into finance and strategy planning.
-
Go-to-market playbooks: vertical-specific commercialization guides for consumer electronics, automotive, industrial/healthcare, and robotics platforms—each with buyer personas, procurement timelines, and integration checklists.
-
Supplier and component maps: a layered view of the ToF value chain—sensors, illumination, optics, and system integrators—paired with supplier scorecards and negotiated cost benchmarks (reserved for full report subscribers).
-
Technology risk matrix and validation protocols: reproducible test procedures for ambient light resilience, range accuracy, and laser safety compliance; firmware/hardware mitigation patterns for SPAD and readout constraints.
-
Regulatory and standards playbook: a checklist for automotive functional safety (including ISO-driven expectations), interface compliance (e.g., low-latency high-bandwidth links), and privacy-by-design implementation aligned with emerging ethical guidelines.
-
Competitive scorecards and strategic pathways: qualitative and quantitative positioning of leading vendors, suggested partnership archetypes, and an M&A heatmap tuned to 2026 valuations and integration complexity.
Competitive dynamics — what leading firms are signaling
Our vendor analysis synthesizes recent product launches, demos, and strategic moves to identify where incumbents are investing and how challengers are exploiting niches. Notable patterns include:
-
Platform leaders (sensor IC houses): Companies with broad silicon portfolios are extending ToF capabilities through multi-zone and stacked CMOS approaches, emphasizing ambient-light immunity and automotive-grade qualification to secure higher ASPs and longer design wins.
-
Opto-mechatronic specialists: Firms focused on camera modules and illumination sources are becoming indispensable partners for systems integrators, particularly where laser modulation and lens/filter co-design materially improve performance under sunlight and high-dynamic-range scenes.
-
Application-focused OEMs and integrators: Camera and module manufacturers that pair ToF hardware with application software (calibration, point-cloud processing, sensor fusion) are capturing value beyond component sales, especially in industrial automation and robotics.
Representative company signals from our review:
-
STMicroelectronics has continued to iterate on its multi-zone direct ToF family to improve ambient-light immunity—an important product strategy for consumer and robotics customers who need predictable outdoor performance.
-
ams OSRAM’s multi-zone offerings and compact packages are oriented toward gesture and proximity use cases, signaling the persistent importance of low-power, low-footprint sensors in mobile and automotive interiors.
-
Infineon’s demonstrations of indirect ToF for 3D perception underline the push to higher-resolution depth sensing suitable for ADAS and machine perception, with safety and reliability as commercial prerequisites.
-
Specialists such as pmdtechnologies and camera vendors (Basler, Lucid Vision Labs) are carving out industrial and AR/VR niches by integrating ToF into reference designs and high-throughput point-cloud cameras for factory automation.
-
Semiconductor and module players in the United States and Asia continue to advance front-facing and stacked CMOS options, reflecting the premium placed on integration density for mobile and automotive applications.
Technology, standards, and regulatory forces to prioritize
Our fieldwork highlights four near-term constraints that will determine winners and losers in 2026:
-
Resolution ceiling for indirect ToF: Current SPAD-array and readout architectures limit practical VGA-class indirect ToF resolution; breakthroughs in parallel readout and on-chip aggregation are high-impact R&D targets.
-
Ambient light and laser modulation: Direct ToF implementations that combine optimized modulation schemes with robust illumination sources materially reduce error under sunlight—these characteristics are differentiators in outdoor and automotive contexts.
-
Automotive functional safety and certification: Compliance with automotive safety frameworks is non-negotiable for ADAS adoption and requires dedicated engineering timelines and validation budgets.
-
Interface and integration standards: Adoption of modern sensor interfaces for low-latency transfer is accelerating integration cycles; firms engaged in standards bodies gain first-mover interoperability advantages.
Actionable recommendations for 2026
-
Prioritize integration capabilities over component ownership. Invest in software, calibration toolchains, and reference designs that reduce customer integration costs and expand system-level margins.
-
Secure illumination source supply and diversify optics partners. Illumination and lens/filter performance are as impactful as sensor choice when deploying in high-ambient environments.
-
Begin early certification tracks for automotive-targeted products. Start safety validation in 2026 for programs that aim at production timelines in the subsequent 24–36 months.
-
Invest selectively in SPAD/readout innovations or partner via licensing to pursue higher-resolution indirect ToF. This is a mid-term R&D bet with high potential upside in ADAS and industrial inspection.
-
Monitor consolidation rationales and prepare M&A playbooks. The current concentration levels favor well-timed acquisitions of niche camera/module firms and specialized optics suppliers to accelerate product breadth.
-
Embed privacy and ethical design in product architecture. Implement opt-in depth sensing and controls on raw point-cloud export to align with evolving expectations and ethical guidelines.
About the full report and how to access
PW Consulting’s full Worldwide 3D ToF Technology Products Market report includes the complete, downloadable forecast model (USD, millions), detailed vendor scorecards, sub-segment-level revenue breakdowns, and supplier negotiation benchmarks. The report’s base year is 2025, covering historical performance from 2020–2025 and an eight-year forecast through 2032 at an 18.5% CAGR. To preserve the strategic value of the dataset for subscribers, detailed regional and application breakouts are available only with the full report purchase. Visit PW Consulting’s reports page to request the executive summary, view sample findings, or arrange a briefing with our senior analysts.
For strategy teams preparing 2026 budgets, this preview should serve as a decision catalyst: deploy capital where integration and certification barriers are surmountable, shore up supply chains in optics and illumination, and consider M&A to accelerate system capabilities. The full report provides the calibrated numbers and vendor-level analytics needed to convert these strategic intentions into executable plans.
For detailed analysis of this topic, please visit the official page: Worldwide 3D TOF Technology Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Lemon Juice Concentrates Market to Expand at a 5.45% CAGR Through 2032
By PW Consulting, 2026-07-15
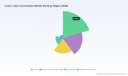
Worldwide Lemon Juice Concentrates Market — Strategic Outlook for 2026: PW Consulting Report Preview
Opening summary
PW Consulting’s latest market study on the Worldwide Lemon Juice Concentrates market provides a practical, decision-oriented briefing for senior executives planning for 2026. The report combines rigorous market sizing, forward-looking scenario modeling and a pragmatic playbook of commercial and operational actions leaders can deploy in response to the evolving supply, price and regulatory environment. This preview highlights the strategic value of the full study while preserving the granular datasets and proprietary scenarios that are available only in the complete report.
Worldwide Lemon Juice Concentrates Market
Quick macro snapshot
Using 2025 as the base year and a historical window from 2020–2025, our analysis shows sustained market growth driven by diversified end-use demand and structural supply-side dynamics. The market expanded materially over the historical period and, per our central scenario, is expected to grow at a 5.45% CAGR through a 2026–2032 forecast horizon. To provide context, the total market stood in the high hundreds of millions of USD in 2025 and is projected to progress substantially by the end of the forecast period — a level that creates both opportunity and strategic stress for suppliers and buyers alike.
Worldwide Lemon Juice Concentrates Market
Why 2026 is an inflection year
-
Input-price shock and supply volatility: Southern European and other suppliers reported a step-change in bulk industrial lemon juice quotations for the 2026 campaign, reflecting a combination of delayed harvests, weather events and constrained supply chains. These dynamics have pushed spot and contract prices materially higher than typical pre-disruption levels, changing negotiated commercial terms and margin mechanics across the value chain.
Worldwide Lemon Juice Concentrates Market -
Regulatory and trade-policy friction: Recent amendments and continuations in antidumping and tariff arrangements affecting trade flows have preserved reference price frameworks into 2025 and beyond. For companies that source internationally, the interaction of seasonal tariffs and antidumping frameworks adds complexity to routing, contractual hedging and landed-cost calculations.
-
Quality and compliance vigilance: Food-safety alerts in select markets concerning undeclared preservatives highlight an ongoing need for end-to-end traceability, robust supplier audits and rigorous incoming-material testing — especially for companies pursuing premium or export-focused channels.
What the PW Consulting report delivers (practical, actionable content)
-
Transparent market-sizing methodology and reconciled historical data (2020–2025) together with a multi-scenario forecast (2026–2032) calibrated to observable price and volume signals.
-
Supply-chain risk matrix mapping suppliers, farming regions and logistical choke points, with concrete mitigation options and expected cost impacts under three stress scenarios.
-
Commercial playbooks for buyers and processors: contracting templates (indexation, volume-flex clauses), tendering guidance, and negotiation tactics aligned to prevailing concentration and supplier power dynamics.
-
Margin and pricing-translation tools: a set of downloadable models that translate upstream price moves into finished-product margin impacts across common formulations and applications.
-
Regulatory tracker and compliance checklist tailored to major export/import corridors, including food-safety alert protocols and tariff/antidumping monitoring.
-
Competitive intelligence dossiers and prioritized M&A and partnership targets, with scenario-based valuation checklists.
Competitive landscape — synthesis and implications
The sector exhibits a moderate level of concentration: the top three players account for roughly one-third of the market while the top five approach half of total market share. This structure creates zones of influence where leading processors and ingredient houses can shape price and innovation flows, while a meaningful long tail continues to supply regional and niche end markets.
Key industry players covered in the report include established European and Latin American processors, specialty organic producers, integrated global ingredient houses, and regional exporters in Asia. Several firms stand out for distinct strategic orientations:
-
European processors with close proximity to Mediterranean orchards are pushing formulation and emulsion solutions aimed at high-performance beverage systems — a trend accelerated by recent product-portfolio expansions showcased at trade forums.
-
Large integrated ingredient suppliers and global citrus processors are leveraging scale to offer value-added services (blend development, cold-chain logistics, private-label manufacturing) to multinational food and beverage customers.
-
Specialist organic producers retain premium positioning in natural and clean-label segments; their leadership in organic supply chains and certification frameworks is an important differentiator for health-focused OEMs.
-
Regional exporters and aseptic-capable manufacturers in Asia are expanding capacity to serve both local industrial demand and global packers seeking cost-competitive sources — a dynamic that is altering traditional sourcing maps.
Strategic imperatives for 2026
-
Diversify sourcing without diluting quality: create tiered supply portfolios combining long-term anchor suppliers, regional flex suppliers and contingent spot suppliers. Prioritize counterparties with traceability and certification credentials to reduce compliance costs.
-
Embed price-indexation and risk-sharing in contracts: deploy blended indexing (raw-material indices + fixed spread) and escalation clauses to protect margins while maintaining competitive offers to customers.
-
Accelerate ingredient innovation: invest in emulsion technology and formulation capabilities that reduce ingredient intensity per finished unit or unlock higher-margin beverage applications.
-
Operationalize food-safety resilience: upgrade incoming QC, supplier audit cadence and rapid recall playbooks to limit reputational and regulatory downside.
-
Pursue selective consolidation and partnerships: the market’s concentration profile suggests value can be realized via bolt-on acquisitions and strategic supply alliances that secure volumes and technology advantages.
Operational levers — where to focus implementation in 90–180 days
-
Re-run procurement tenders with a two-track structure: long-term anchor volumes and a quarterly spot-hedge pool. Assess landed-cost scenarios under at least three price paths from our forecast toolkit.
-
Revise inventory policy to balance working-capital efficiency with continuity-of-supply needs; identify components suitable for hedging or financial derivatives where available.
-
Fast-track supplier audits for organic and high-risk suppliers; deploy third-party lab testing for preservative and contaminant screening on incoming batches.
-
Invest incrementally in formulation R&D for lower-concentration, higher-value applications that reduce exposure to bulk juice price swings.
M&A and partnership themes
Given the market’s structure, the most compelling external growth plays over the next 12–24 months will center on: (1) acquiring regional processors that supply key seasonal windows, (2) partnering with ingredient houses that can deliver blended or emulsified solutions for value-added beverage categories, and (3) investing in organic-specialist platforms to capture premium pricing and differentiated shelf space. The report ranks potential targets and synergies by integration complexity and expected payback horizon.
Concluding guidance — what decision-makers should prioritize now
For executive teams, 2026 should be treated as a planning year where the objective is twofold: harden the supply base and capture margin upside through product differentiation. Tactical moves (contract redesign, targeted capex, QA enhancements) will protect against downside, while strategic initiatives (innovation, M&A, sustainability positioning) will create outsized returns once the market normalizes around new structural price levels.
How to access the complete intelligence
This preview outlines the strategic framework and high-level implications from PW Consulting’s Worldwide Lemon Juice Concentrates Market report. The full study contains the proprietary datasets, regional and application-level breakdowns, supplier scorecards, downloadable financial models and confidential appendices that underpin the scenarios summarized above. For procurement leaders, R&D heads and corporate development teams planning for 2026, the complete report is the operational playbook required to convert market volatility into competitive advantage. To obtain the full report and the accompanying toolkit, please visit the PW Consulting publications page or contact our industry team for a briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Lemon Juice Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide CNS Stimulants Market Poised to Grow at a 6.25% CAGR Through 2032
By PW Consulting, 2026-07-15
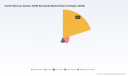
PW Consulting Releases Strategic Preview: Worldwide CNS Stimulants Market — A Decision-Grade Brief for 2026
PW Consulting’s forthcoming Worldwide Central Nervous System (CNS) Stimulants Market report delivers an operationally focused, executive-ready synthesis of the forces shaping commercial performance and strategic choices for 2026 and beyond. Built on a 2025 base, a five‑year historical window (2020–2025) and a granular forecast horizon (2026–2032), the study combines quantitative market sizing with qualitative, actionable counsel. The global market — which expanded from roughly USD 27.9 billion in 2023 to approximately USD 31.4 billion in 2025 — is projected to grow to the high‑forties (USD ~47.9 billion) by 2032, representing a 6.25% CAGR across the forecast period. This preview outlines why this intelligence matters for boardrooms, portfolios, and M&A pipelines in 2026 — while reserving the report’s proprietary segment tables and detailed financials for subscribers.
Worldwide Central Nervous System (CNS) Stimulants Market
Why this report matters for 2026 strategic decisions
-
Strategy under constraint: Regulatory and supply constraints are reshaping capacity economics. A recent FDA labeling mandate (July 2025) for extended‑release amphetamine and methylphenidate products and DEA quota adjustments (October 2025) have moved risk from clinical development and pricing into supply planning and portfolio sequencing. Our report frames these forces and provides decision trees to prioritize investment when quotas, labeling, and reimbursement pressures converge.
Worldwide Central Nervous System (CNS) Stimulants Market -
Market momentum with predictable growth: With an expected 6.25% CAGR over 2026–2032, the category offers steady topline growth but with shifting margin dynamics. The research translates that macro growth into practical scenarios for revenue and capacity planning, without disclosing proprietary subsegment breakouts in this preview.
Worldwide Central Nervous System (CNS) Stimulants Market -
Concentration and opportunity: Market concentration metrics signal a balance between branded incumbents and a robust generics/contract manufacturing ecosystem. This creates specific playbooks for incumbents defending share and for agile entrants evaluating niche formulations, delivery formats, or geographic plays.
What the full report contains (practical, implementation‑oriented)
-
Forecast models and scenario suites — base, downside (regulatory tightening / quota reductions), and upside (improved supply resilience / formulary expansion) — with workstreams for finance and commercial teams to translate scenarios into CAPEX, inventory, and salesforce resource plans.
-
Competitive playbooks — company‑level decision matrices that map product portfolios to tactical moves (line extensions, lifecycle management, controlled‑substance stewardship) and recommend optimal responses for 12 archetypal competitors (brand leaders, specialty formulators, and high-volume generics manufacturers).
-
Regulatory impact analysis — structured implications of recent FDA label changes, DEA quota dynamics, and potential payer reforms such as proposed benchmarking efforts, with compliance checklists and stakeholder engagement templates for 2026.
-
Supply chain risk heatmap — API concentration analysis, single‑source exposures, and alternative sourcing strategies (nearshoring, dual‑sourcing, and strategic inventory buffers) prioritized by probability and commercial impact.
-
Commercial & reimbursement playbooks — formulary access strategies, payer negotiation frameworks, and price sensitivity matrices tailored to stimulants within broader CNS contracting initiatives.
-
M&A and partnership pipeline — target screening criteria, valuation heuristics, and an annotated list of potential bolt‑ons and divestiture targets that align to three strategic objectives: capacity, formulation differentiation, and geographic reach.
-
Practical annexes — primary research methodology, interview transcripts, commercial model templates, and an evidence‑backed list of KPIs for ongoing program monitoring.
Competitive landscape: who matters and what they’re doing
The category blends durable branded franchises and a deep generics base. Established multinational pharmaceutical companies continue to anchor the market with recognized brands and extended‑release portfolios, while generics manufacturers and specialized formulators capture significant volume through price competitiveness and reformulation plays.
-
Large global incumbents maintain brand equity via extended‑release and lifecycle management strategies. Their playbooks emphasize label stewardship, adult indication expansion, and formulary contracting.
-
Specialty developers and small‑cap innovators are differentiating through new delivery formats (transdermal, delayed‑release, liquid formulations) and abuse‑deterrent or prodrug approaches aimed at payer and prescriber concerns.
-
Generics players and CDMOs focus on volume supply and scale, but are exposed to API concentration risk and quota variability — a dynamic that opens short‑term opportunities for price capture and contract renegotiation.
Among the companies we analyzed — spanning brand owners, specialty formulators, and large generics manufacturers — strategies fall into three clusters: protect and extend (brand incumbents), consolidate and scale (generics / CDMOs), and specialize (delivery innovation and life‑cycle niche plays). The full report maps each of these firms to specific tactical recommendations and scenario responses suitable for 2026 execution.
Regulation, supply, and quality: the operational trinity for 2026
-
Regulatory shifts have immediate commercial implications. The FDA’s expanded labeling guidance for extended‑release stimulants introduces new clinical risk management requirements that affect pediatric positioning and promotional strategy. The full report offers a compliance playbook that aligns label changes to messaging, post‑market evidence generation, and lifecycle priorities.
-
Quota and production dynamics are now a more material input into forecasting. DEA quota adjustments in 2025 and supplier requests have altered the production planning calculus. Our modeling tool lets teams stress‑test revenue and stock strategies across quota scenarios and identify breakeven thresholds for contract manufacturing expansions.
-
Quality surveillance is back in focus. Recent FDA sampling results that affirmed extended‑release methylphenidate batches highlight how quality confidence can become a source of commercial advantage. The report includes monitoring triggers and contractual clauses to protect supply continuity and reputational exposure.
Strategic implications and short list of 2026 actions
-
Prioritize supply resilience. Short‑term procurement and mid‑term CAPEX decisions should be informed by API concentration maps; dual‑sourcing and strategic inventory are cost centers that now pay off in continuity and pricing leverage.
-
Reframe portfolio tradeoffs. Use scenario outputs to rank formulations and indications by expected risk‑adjusted contribution; defer low‑return line extensions and accelerate those that reduce reliance on constrained inputs.
-
Accelerate label and safety‑driven evidence generation. Expanded pediatric warnings elevate the value of post‑market safety programs and real‑world evidence to preserve prescriber confidence and payer positioning.
-
Recalibrate commercial models for payers. Anticipate payer benchmarks and include stimulant classes in contracting strategies that account for potential CMS benchmarking initiatives; our reimbursement playbook includes negotiation scripts and economic models for 2026 formulary cycles.
-
Hunt for strategic M&A and partnerships. Opportunities are clearest where capacity and specialized delivery capability converge; the report shortlists targets and valuation approaches keyed to different acquiror objectives.
How executive teams should use this intelligence
Boards and executive teams will find the report immediately usable for three priorities in 2026: (1) converting macro growth into specific capacity and investment decisions with quantified downside protections, (2) integrating regulatory and quota dynamics into commercial launch sequencing and pricing negotiations, and (3) identifying acquisition or alliance targets that accelerate defensible differentiation. The deliverables are designed to be working documents — downloadable models, negotiation kits, and compliance checklists — so leadership teams can move from insight to execution within 30–90 days.
Next steps and accessing the full intelligence
This preview is curated to demonstrate the report’s analytical depth and practical orientation while preserving the proprietary segment tables, company scorecards, and downloadable financial models that subscribers rely on. To obtain the complete Worldwide CNS Stimulants Market report — including the full segmentation analysis, downloadable forecast models for 2026–2032, and the competitor playbooks referenced above — please visit PW Consulting’s market research portal or contact our sales team. For executives seeking bespoke briefings, scenario customization, or rapid commercial due diligence support aligned to 2026 board cycles, PW Consulting offers short‑turn advisory engagements that operationalize the report’s recommendations.
PW Consulting remains committed to converting market intelligence into actionable, risk‑aware strategies. In a category where regulatory signals, supply volatility, and payer reform are converging, companies that translate forecast insight into operational decisions will secure competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rotary and RF Rotary Joints Market Set to Expand at a 5.1% CAGR, New Market Insights Report Reveals
By PW Consulting, 2026-07-15
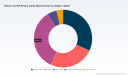
Worldwide Rotary and RF Rotary Joints Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study on Worldwide Rotary and RF Rotary Joints is a decision-grade intelligence product designed to orient executive teams, M&A desks, product leaders, and procurement functions as they set 2026 priorities. The study synthesizes a seven-year market evolution (2020–2025) and delivers a detailed, scenario-based forecast through 2032. At the aggregate level, the market expanded from roughly USD 785.4 Million in 2020 to about USD 985.3 Million in 2025 and is projected to continue its upward trajectory, reaching an estimated USD 1,395.7 Million by 2032 under a baseline compound annual growth rate (CAGR) of 5.1%. These headline figures frame a market that is large enough to support multiple business models — from global platform plays to narrowly focused niche specialists — while still offering space for consolidation and new entrants with differentiated capabilities.
Worldwide Rotary and RF Rotary Joints Market
Why 2026 is the inflection point
Several structural and tactical factors converge in 2026 to make it a pivotal planning year:
Worldwide Rotary and RF Rotary Joints Market
- Macro momentum: The market’s steady compound growth provides a predictable environment for multi-year investments in R&D, test infrastructure, and manufacturing automation.
- Technology convergence: RF joints, mechanical rotary unions, and fiber-optic rotary solutions are increasingly integrated with digital condition monitoring and multi-function slip ring combinations, creating bundled product-service value propositions.
- Supply-side dynamics: Raw material price moderation entering 2026 (notably steel and aluminium) eases near-term cost pressure but raises strategic questions around sourcing, hedging, and design-for-material-efficiency.
- Regulatory and quality thresholds: Customers in aerospace, defense, and space continue to demand AS9100/ISO9001-aligned suppliers, making certification and traceable supply chains a practical gate to premium projects.
For executives planning 2026 budgets and roadmaps, these dynamics translate into three actionable priorities: prioritize modular product architectures that enable rapid cross-selling; invest selectively in digital condition monitoring as a product differentiator; and adopt procurement strategies that balance short-term material-cost advantages with long-term supplier resilience.
Worldwide Rotary and RF Rotary Joints Market
What the report delivers — practical outputs for 2026 decisions
PW Consulting designed the report to move beyond high-level market sizing. The deliverables are explicitly tactical and tailored to accelerate decision cycles in 2026:
- Market scenarios and sensitivity matrices — baseline, upside, and downside runs that quantify revenue and margin impacts across plausible macro, technology, and procurement shocks.
- Actionable 90–180 day playbooks — prioritized initiatives for product management, commercial teams, and procurement to capture near-term incremental revenue and margin.
- Supplier and competitor scorecards — a repeatable framework for assessing engineering depth, certification status, installed-base footprint, aftermarket revenue potential, and MRO capabilities.
- CapEx & manufacturing roadmap — decision points for automation, test-lab investments, and material-substitution programs to reduce lifecycle costs and speed time-to-market for lightweight designs.
- Go-to-market and service models — segment-targeted pricing templates, bundling options (hardware + predictive maintenance), and retrofit/upgrade programs for installed bases.
- M&A and partnership playbook — prioritized target archetypes, valuation multipliers observed in the sector, and integration risk checklists tuned to the market’s concentration profile.
- Data assets — downloadable financial-model workbook and market model that allow users to run custom scenarios for specific go-to-market assumptions.
We intentionally withhold granular segment disclosure in this release. The report contains detailed subsegment forecasts, regional allocations, and application-level breakouts that drive the tactical recommendations above — information available through the official report portal for subscribers and license holders.
Competitive landscape — positioning and strategic implications
The sector is characterized by a mix of global platform leaders, engineering-centric specialists, and regional players that serve verticals from industrial automation to space. Measured concentration indicates room for both scale advantages and niche differentiation: the top three suppliers account for a measurable share of the market, while the top five widen that share further, leaving meaningful opportunity for mid-sized incumbents and innovative newcomers.
- Deublin Company (United States): A global leader in rotary unions, notable for broad standard and custom sealing technologies across heavy industry and semiconductor tooling. Recent trade-show visibility and strategic acquisitions underline its intent to maintain a platform position across automation segments.
- Moog Inc. (United States): Strong in precision motion and fluid control, Moog’s integrated slip ring/rotary union propositions (e.g., combined units designed for cobots and mobile platforms) exemplify product convergence that captures system-level value.
- Spinner GmbH (Germany) and EVERAXIS (France): European specialists with deep RF credentials in radar, satellite, and high-reliability applications. Their engineering-first strategies address markets where performance and environmental qualification command price premiums.
- Diamond Antenna and Microwave Corporation and Link Microtek (United Kingdom / United States): Focused on RF rotary joints for defense and satcom-on-the-move applications. These companies show how certification and repair/overhaul services create sticky aftermarket revenue.
- Moflon Technology (China) and several regional rotary-union vendors: Competitive on cost and local agility; their presence accelerates deployment in high-volume industrial applications and creates sourcing alternatives for OEMs looking to re-shore or dual-source.
- Other notable players — Kadant, Pasternack, Spectrum Control, Rotary Systems Inc., RF‑Lambda, Dynamic Sealing Technologies, Christian Maier — together create a supplier ecosystem where partnerships and co-development can shorten time-to-certification for specialized systems.
Strategic implication: firms must choose between two defensible plays — (1) platform leadership via scale, integrated product portfolios, and aftermarket services; or (2) focused leadership via ultra-high-performance RF, fiber-optic, or high-channel-count solutions paired with premium qualification pathways. Hybrid strategies are feasible but require rigorous go-to-market orchestration and capital discipline.
Key market drivers, risks, and technology trends
- Drivers: Growth in satellite communications, phased-array radar deployments, and advanced medical imaging are increasing demand for compact, high-frequency, multi-channel RF rotary joints and hybrid rotating subsystems.
- Digitalization: IoT-based condition monitoring is moving from pilot to mainstream in industrial and radar applications, enabling predictive maintenance offerings that materially improve lifetime service margins.
- Supply risks: Raw-material volatility matters — steel and aluminium remain important inputs. Current market intelligence points to moderated steel prices and aluminium price normalization around mid-2026 levels, which will influence design trade-offs between durability and weight.
- Regulatory/qualification: AS9100 and ISO9001 remain de facto entry criteria for defense, space, and aviation customers. Certification timelines and supplier-proven processes are frequent procurement gates for high-value contracts.
- Consolidation opportunity: The market concentration measures indicate acquisition economics that can accelerate capability builds (e.g., RF design, repair & overhaul, fiber-optic integration) and expand aftermarket footprints.
Recent industry moves that signal strategic direction
- Exhibit & product activity: Prominent suppliers showcased automation and semiconductor-focused rotary solutions at industry shows in 2024–2025, signaling a push into higher-growth industrial automation and precision manufacturing segments.
- M&A & capability consolidation: Recent acquisitions by established suppliers reflect an appetite to acquire aftermarket repair capabilities and complementary technologies rather than build them organically.
- Certification & mission readiness: Suppliers serving space and defense reaffirmed their AS9100/ISO9001 credentials and invested in qualification capabilities — a clear reminder that long sales cycles in premium segments reward upfront investment in quality systems.
How to use this intelligence in 2026 planning
Recommended executive actions based on report findings:
- Product strategy: Prioritize modular, upgradable architectures that enable optional digital monitoring and multi-channel RF configurations to cross-sell into satcom, radar, and medical markets.
- Sourcing & cost: Implement a two-track material strategy — opportunistic procurement to capture short-term price softness, plus strategic contracts or secondary suppliers for critical alloy inputs.
- Commercial & aftersales: Move from transactional sales to outcome-based offerings (uptime guarantees, predictive maintenance subscriptions) to lift lifetime revenue per installed unit.
- M&A & partnerships: Use the report’s target archetypes and valuation heuristics to identify bolt-on acquisitions that bring certification, repair capabilities, or niche RF engineering talent.
- Risk & compliance: Map certification timelines into product roadmaps early to avoid downstream schedule slippages on high-value defense and space contracts.
Next steps and how to access the full intelligence
This release is a strategic preview. The full PW Consulting report contains the granular subsegment forecasts, regional and application-level breakdowns, supplier-level revenue estimates, and an interactive financial model that underpins the tactical playbooks referenced above. For teams preparing 2026 budgets, procurement strategies, or M&A pipelines, the report converts market-level direction into actionable, time-bound initiatives.
Contact PW Consulting to obtain the complete report and our bespoke briefing packages — including scenario workshops and one-on-one sessions with our lead analysts to tailor recommendations to your organization’s starting position.
For detailed analysis of this topic, please visit the official page: Worldwide Rotary and RF Rotary Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


