



PW Consulting: Worldwide TRIS Buffer Market Poised for 6.32% CAGR in 2026–2032, Signaling Strong Growth Outlook
By PW Consulting, 2026-07-15
Worldwide TRIS Buffer Market — Strategic Outlook for 2026 Decision-Making
PW Consulting today releases an executive briefing summary of our new Worldwide TRIS Buffer Market report, delivering an actionable line of sight for corporate leaders, procurement teams, and investors shaping plans for 2026 and beyond. The global TRIS buffer market reached approximately USD 324.5 million in our 2025 base year and is forecast to expand at a compound annual growth rate (CAGR) of 6.32% through the 2026–2032 horizon, lifting total market value materially by the end of the projection window. This briefing synthesizes the report’s strategic implications while preserving the proprietary, granular segment intelligence available in the full study.
Worldwide TRIS Buffer Market
Why this report is essential for 2026 strategy
TRIS (tris(hydroxymethyl)aminomethane) and TRIS-HCl are foundational reagents across life-science research, diagnostics, and bioprocessing. Small shifts in supply, quality standards, or trade policy have outsized effects on product continuity, regulatory compliance, and margin capture in downstream applications. Our study combines demand-side modelling, supply-chain due diligence, and scenario analysis to produce guidance that is immediately usable in 2026 planning cycles.
Worldwide TRIS Buffer Market
- Macro traction: After a period of steady expansion from 2020–2025, the market enters a mid-single-digit growth phase driven by bioprocessing build-out, diagnostic throughput, and renewed investment in academic and industrial R&D.
- Concentration and negotiation leverage: Market concentration is meaningful—our analysis shows a top-three/top-five concentration profile that creates supplier-side leverage for firms that understand supplier economics and capacity footprints.
- Supply tightness and buffer economics: Global production capacity and consumption metrics indicate available headroom in aggregate but localized stress points and quality-tier mismatches that can create price and availability volatility at the point of use.
Market dynamics that will shape 2026 outcomes
Three structural dynamics stand out for executives planning 2026 budgets and capex:
Worldwide TRIS Buffer Market
- Trade and regulatory risk: Recent trade actions and petitions have elevated the probability of tariffs, quota changes, and protracted anti-dumping procedures. Firms must assume shorter planning horizons for import-dependent supply chains and build contingency routes and cost scenarios into procurement models.
- Raw-material and input-cost volatility: A meaningful share of TRIS producers identify raw-material cost swings as a production-limiting factor. This implies that pricing models should incorporate volatility bands and that procurement should consider indexed contracts or hedging mechanisms where feasible.
- Quality segmentation and premiumisation: Demand is bifurcating between research-grade, bioprocess-grade, and regulated cGMP supply. Players able to assure multicompendial and ISO-aligned quality at scale capture premium win rates in biopharma and diagnostics, creating margin differentials that justify targeted investments.
Competitive landscape — who moves the market
The TRIS buffer ecosystem is a mix of global life-science distributors, specialized chemical manufacturers, and regional commodity producers. Our company-level analysis evaluates manufacturing footprint, quality credentials, channel strength, and strategic initiatives. Highlights from the competitive review include:
- Integrated manufacturers with dual-site or multi-tier production: Companies that own upstream synthesis and downstream buffer preparation position themselves to manage quality, lead times, and regulatory documentation more effectively. Recent capacity expansions and new product introductions from integrated players have increased resilience for customers who prioritize single-sourced quality assurance.
- Specialist regional producers: Several Asia-based producers supply high-volume, competitive-cost TRIS grades into global distribution networks. Their role in base-material supply underpins cost-effective channels, but their commercial impact will depend on evolving trade measures and quality-certification investments.
- Global distributors and brand leaders: Large life-science distributors and reagent brands continue to dominate end-user channels, offering convenience, regulatory documentation, and bundled solutions—capabilities that are especially valued by clinical, diagnostic, and academic buyers.
Notable recent market moves we analyze in depth (and the strategic implications for 2026) include:
- Capacity and capability expansions at U.S. and European production sites by leading integrated firms, strengthening regional supply security for research- and life-science-grade buffers.
- Distribution agreements that re-shape North American channel dynamics and reduce friction for laboratory and bioprocessing customers seeking validated suppliers.
- Trade petitions filed in early 2026 that could result in tariffs or countervailing measures—these have immediate procurement and sourcing implications for companies reliant on certain import routes.
What the PW Consulting report contains — practical, executable content
This study is designed as a hands-on decision tool for 2026 planning. The report’s components include:
- Transparent market sizing and forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) with revenue denominated in Million USD and scenario-based outputs for conservative, base, and upside pathways.
- Supply-chain mapping and capacity audit that highlights active production nodes, documented quality certifications, and single points of failure at the supplier and logistics levels.
- Company scorecards for the leading global suppliers, assessing manufacturing redundancy, product-grade breadth (research → cGMP), distribution networks, and strategic initiatives such as capacity build-outs and exclusive channel agreements.
- Price and margin sensitivity matrices, alongside procurement playbooks (contract templates, quality acceptance checklists, and vendor-monitoring KPIs) tailored to labs, CDMOs, and in-house bioprocess teams.
- Regulatory and trade scenarios, including modeled P&L impacts of tariff introductions, import restrictions, or sudden raw-material cost shocks.
- M&A and partnership screening criteria and an investment thesis framework for corporates evaluating vertical integration, bolt-on acquisitions, or captive supply arrangements.
Strategic recommendations for executives acting in 2026
Applying the report’s findings, PW Consulting recommends a set of prioritized actions that are both pragmatic and defensible under multiple market scenarios:
- Short-term (0–12 months): Secure multi-sourced supply agreements with at least one quality-certified, geographically diversified supplier; negotiate year-over-year price collars; and validate incoming lots against a standardized QC protocol to reduce operational disruption risk.
- Medium-term (12–24 months): Invest in supplier development programs (quality upgrades, audit support) or exclusive distribution partnerships to lock preferential access to high-purity grades required by biopharma customers.
- Policy and advocacy: Proactively monitor trade petitions and engage with trade advisors—companies with significant import exposure should model tariff scenarios and consider import re-routing or localized buffer preparation as mitigants.
- Portfolio and product strategy: Differentiate on quality documentation, traceability, and customized buffer formulations for therapeutic and diagnostic applications—premiumization is a defensible route to higher margins where regulatory requirements are strict.
- Capital allocation: For manufacturers, prioritize investments in dual-site redundancy and analytical testing capacity; for distributors and CDMOs, allocate capex for localized buffer preparation (WFI/compliance-grade lines) to capture near-term demand shifts.
Using the full PW Consulting report
The full report is engineered to be a working tool for sourcing managers, corporate strategists, and M&A teams. Clients gain access to interactive models, supplier scorecards, and a regulatory-impact simulator that allows rapid evaluation of tariff outcomes and raw-material price shocks. Our "what-if" dashboards let users run bespoke scenarios and export procurement- and P&L-ready outputs to support board-level decisions in 2026.
Final perspective — why act now
The TRIS buffer market sits at the intersection of chemical commodity dynamics and stringent life-science quality expectations. The market’s steady base-year size and the mid-single-digit CAGR through the forecast period signal robust, sustained demand—but the near-term environment is being reshaped by policy interventions, cost volatility, and selective capacity additions. Companies that enter 2026 with a disciplined supplier playbook, clarity on quality-tier economics, and pre-defined contingency scenarios will convert market uncertainty into competitive advantage.
PW Consulting’s Worldwide TRIS Buffer Market report delivers the empirically grounded, decision-ready analysis required to do just that. For the detailed segment tables, supplier-by-supplier financial and capacity profiles, and the interactive forecasting model referenced in this briefing, please consult the full report available through our publications portal.
For detailed analysis of this topic, please visit the official page: Worldwide TRIS Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Semiconductor Magnetic Sensor Market Set to Expand at a 9.0% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Semiconductor Magnetic Sensor Market — Strategic Primer for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Semiconductor Magnetic Sensor Market (base year 2025) equips executives with the strategic intelligence needed to make high-stakes product, supply-chain, and M&A decisions in 2026. The market is on a multi-year expansion trajectory — growing from roughly USD 2.15 billion in 2020 to an estimated USD 3.28 billion in 2025, and projected to reach approximately USD 6.0 billion by 2032 at a 9.0% CAGR across the 2026–2032 forecast window. This research brief highlights the practical implications of those macro trends, the competitive dynamics shaping supplier choices, and the operational playbooks that leaders should adopt this year.
Worldwide Semiconductor Magnetic Sensor Market
Why this study matters for 2026
-
Acceleration and bifurcation: The market’s near-term growth is being driven by accelerating demand in electrified mobility, industrial automation, and next-generation consumer sensing, while advanced applications are concentrating value in higher-performance technologies. Executives who understand where value is consolidating will avoid costly technology bets.
Worldwide Semiconductor Magnetic Sensor Market -
Supply-chain fragility: New trade and export controls, concentrated processing of critical magnet materials, and tariff shifts have created acute sourcing risk for sensor manufacturers and OEMs. Procurement and sourcing strategies that ignore these structural constraints will face lead-time spikes and margin erosion.
Worldwide Semiconductor Magnetic Sensor Market -
Consolidation opportunities: Market concentration metrics indicate meaningful share for the top vendors, creating both competitive pressure and M&A potential. Well-timed partnerships or bolt-on acquisitions can secure capability gaps and accelerate time-to-market.
What the report delivers — operational, decision-ready intelligence
-
Market sizing and scenario forecasts to 2032: a baseline plus upside and downside scenarios that stress supply shocks, tariff regimes, and demand slowdowns so teams can build contingency budgets and product launch timelines.
-
Technology trade-off matrices: actionable guidance on Hall-effect vs. various magnetoresistive technologies (including performance, cost, manufacturability, and qualification timelines) to inform BOM decisions and roadmap sequencing.
-
Supply-chain risk mapping: granular supplier topology, single-point-of-failure diagnostics, and an input-material exposure index for rare-earth and specialty material dependencies — designed for procurement to execute mitigation tactics in 90–180 day windows.
-
Regulatory impact dashboard: step-by-step playbooks for compliance and market access under recent measures — including assessments of export controls, tariffs, and foreign-direct-product-style licensing — tailored to North American, European, and Asia-Pacific operating models.
-
Commercial and go-to-market playbooks: pricing sensitivity models, channel optimization strategies, and buyer persona analysis for automotive OEMs, industrial suppliers, and high-volume consumer platforms.
-
M&A and partnership shortlist: vetted target profiles and integration risk scoring, focused on technology fills (high-sensitivity TMR/GMR capability), wafer-level integration, and material-sourcing control.
-
Procurement toolkit: contract clauses, hedging strategies for magnet and rare-earth price volatility, and supplier qualification templates designed to be executed within Q1–Q3 2026 procurement cycles.
Competitive landscape — who matters and why
The market is oligopolistic enough that moves by leading suppliers reshape product and supply dynamics. PW Consulting’s analysis profiles the incumbent and emerging specialists that matter to buyers and investors in 2026.
-
Allegro MicroSystems, Inc. — Strengths: deep automotive-qualified portfolio across Hall and TMR, and a fast-follow product cadence (notably a high-bandwidth TMR current sensor introduced in late 2025). Strategic implication: ideal partner for OEMs requiring automotive-grade current sensing and for firms seeking immediate access to TMR IP post-acquisition integrations.
-
Infineon Technologies AG — Strengths: broad portfolio under a unified sensor platform approach and a strong automotive systems play. Strategic implication: a go-to supplier for integrated system-level qualification and long-lifecycle automotive programs.
-
NXP Semiconductors — Strengths: automotive-focused MR and low-power Hall solutions coupled with strong ECU ecosystem ties. Strategic implication: preferred for energy-constrained vehicle and IoT applications where software and MCU integration matters.
-
Asahi Kasei Microdevices (AKM) — Strengths: tri-axis and consumer-grade TMR/Hall devices optimized for compact, high-integration consumer and industrial products. Strategic implication: high fit for consumer platform suppliers seeking miniaturized multi-axis sensing.
-
TDK Corporation — Strengths: material and sensor integration—recently introduced a TMR angle sensor optimized for safety-critical automotive and industrial systems. Strategic implication: valuable for customers needing supplier-level materials expertise tied to sensor performance.
-
Melexis — Strengths: integrated 3D magnetic position sensors with strong automotive and industrial traction. Strategic implication: high-quality option for position sensing needs with established qualification processes.
-
STMicroelectronics — Strengths: multi-sensor reference designs and ultra-low-power 3-axis magnetic sensors, supporting cross-sensor fusion strategies. Strategic implication: choice partner for multi-sensor architectures and system integration at scale.
-
Honeywell International — Strengths: legacy aerospace/industrial pedigree and reliable Hall-effect offerings. Strategic implication: incumbent in safety and certified sectors where heritage qualification is required.
-
Texas Instruments — Strengths: widely adopted Hall-effect ICs and strong industrial channel presence. Strategic implication: pragmatic choice for high-volume, cost-sensitive industrial programs.
-
ABLIC Inc. — Strengths: compact Hall switch/latch ICs tailored for general-use and automotive switch applications. Strategic implication: tactical supplier for cost-optimized switching functions.
-
Tower Semiconductor — Strengths: foundry services enabling integration of high-temperature Hall sensors and TMR elements with CMOS for specialized high-sensitivity markets. Strategic implication: critical partner when wafer-level integration or specialty process control is required.
Recent product and market developments to watch in 2026
-
Several leading vendors have refreshed their product stacks in 2024–2025 with TMR and ultra-low-power multi-axis designs, and new high-bandwidth TMR current sensors emerged in late 2025 — indicating a technology migration toward higher-performance magnetoresistive solutions in demanding applications.
-
Concurrently, regulatory and trade moves (including export controls and tariffs implemented in 2025–2026) are reshaping procurement math and favoring suppliers with diversified, non-exclusive upstream sources or localized manufacturing footprints.
-
Raw material dynamics — particularly concentrated rare-earth processing capacity and export licensing for heavy rare earths — remain structural negatives for any strategy that assumes frictionless magnet supply. Battery pack price declines in 2024 have eased some cost pressure in electrified systems, but magnet and rare-earth exposure is still a distinct vector of volatility.
Strategic recommendations for corporate leaders in 2026
-
Adopt a two-track technology strategy: defend current product roadmaps where qualification cycles are long (e.g., automotive), while selectively piloting higher-performance magnetoresistive solutions (TMR/GMR) in adjacent fast-follower platforms to capture premium value.
-
Prioritize supply resilience: execute dual-sourcing for critical magnet and wafer inputs, negotiate longer-term agreements with indexed pricing, and evaluate nearshoring or licensed local assembly to mitigate tariff and export risks.
-
Use scenario planning to price for volatility: incorporate regulatory-triggered cost adders and lead-time buffers into commercial bids; preserve margin by structuring tiered pricing linked to material-cost pass-through mechanisms.
-
Targeted M&A and partnerships: prioritize acquisitions that deliver scarce capabilities (high-sensitivity TMR IP, wafer integration) or reduce upstream exposure (magnet processing, specialty materials). For non-strategic businesses, consider divestiture to free capital for capability plays.
-
Accelerate systems-level competence: OEMs and Tier-1s should insist on supplier co-engineering and system reference designs to reduce integration cycles and lower qualification risk—vendor co-development is now a competitive advantage.
-
Operationalize regulatory intelligence: create a rapid-response compliance cell to translate export control and tariff updates into procurement and product deployment decisions on a weekly cadence.
How PW Consulting’s report helps you act in 2026
This market study is designed as an executable toolkit — not an academic exercise. For leadership teams the report provides the forecast foundation, the supplier playbook, and the procurement and M&A decision templates needed to convert the projected 9.0% CAGR through 2032 into profitable growth. Because the highest-value, deal-closing details (including precise segment-by-segment shares, regional splits, and company-level revenue triangulation) are maintained as premium deliverables, PW Consulting’s full report includes downloadable models, supplier heatmaps, and executable contract language to implement the recommendations rapidly.
Next steps
-
Download the full report and the accompanying Excel model from PW Consulting to access the detailed segmentation, supplier scorecards, and scenario-based financial models required to build your 2026 plans.
-
Contact our advisory team for a tailored briefing: we provide board-level presentations, hands-on procurement workshops, and integration roadmaps that convert insight into action within 60–120 days.
PW Consulting’s Worldwide Semiconductor Magnetic Sensor Market study gives executives the forecasting clarity, risk-adjusted supplier playbooks, and M&A roadmaps necessary to navigate 2026’s fast-evolving landscape. The macro trajectory is clear — significant growth and rebalancing lie ahead — but success will be determined by those who pair market insight with rapid operational and procurement execution.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Baggage Packaging Service Market to Reach USD 1,453.93 Million by 2032 at a 6.51% CAGR, Asia‑Pacific Leading with USD 322.25M
By PW Consulting, 2026-07-15
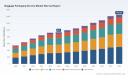
Worldwide Baggage Packaging Service Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s new market study—anchored on a 2025 base year and forecasting through 2032—provides a focused, decision‑ready view of the worldwide baggage packaging service market at a moment of structural change. Between 2020 and 2025 the market expanded materially, and our modelling projects sustained expansion through the forecast horizon at a compounded annual growth rate of 6.51%, reaching a market size in the mid‑hundreds of millions in 2025 and continuing to grow toward the low billions by 2032. For executives planning capital allocation, procurement strategy, M&A, or operational transformation in 2026, the report translates those headline dynamics into concrete choices and quantified scenarios—without losing sight of the tactical actions that deliver results within 12–36 months.
Worldwide Baggage Packaging Service Market
Why 2026 is a Pivotal Year
Three converging forces make 2026 a strategic inflection point for baggage packaging services: recovering and reconfiguring travel demand, accelerating sustainability and regulatory pressures, and technology upgrades at the point of service.
Worldwide Baggage Packaging Service Market
- Demand normalization with segmentation opportunities: Passenger volumes and international travel continue to recover post‑pandemic, but growth is uneven by route and service offering—creating pockets of premium demand (value‑added protection and tracking) alongside cost‑sensitive segments.
- Regulatory and sustainability inflection: Extended Producer Responsibility (EPR) regimes (notably in several U.S. states and multiple international jurisdictions) are shifting lifecycle costs onto producers and providers. Many operators are committing to biodegradable or fully recyclable films as part of their 2025–2027 sustainability roadmaps.
- Technology meets efficiency: Automation, machine upgrades and digital add‑ons (e.g., NFC tracking) are now productive levers to reduce materials consumption and unlock ancillary revenue streams.
For leadership teams, the practical implication is this: firms that treat 2026 as a year for targeted investment (efficiency + sustainability + digital) will capture disproportionate margin expansion and pricing power as travel demand stabilizes.
Worldwide Baggage Packaging Service Market
What the PW Consulting Report Delivers
This study is designed as a hands‑on toolkit for corporate strategists, procurement heads, investors, and airport operators. Key deliverables include:
- Proprietary market sizing and a transparent forecasting model (2026–2032) that maps demand drivers to revenue outcomes under multiple scenarios.
- Cost‑and‑margin archetypes for service operators (from compact single‑terminal kiosks to large franchise networks), including a deployable CapEx/Opex calculator for wrapping equipment.
- Regulatory impact assessment, synthesising global EPR trajectories and practical compliance pathways for packaging providers and airports.
- Commercial playbooks: contract negotiation checklists, bundling and pricing strategies, loyalty‑program integrations, and retail merchandising templates for terminal footprints.
- Vendor and technology evaluation frameworks—covering wrapping machines, film types (LDPE/LLDPE and biodegradable options), digital tracking hardware and software, and lifecycle assessment tools.
- An actionable M&A and partnership guide: due diligence templates, valuation sensitivities, and integration roadmaps for targets across the value chain (service operators, film suppliers, and equipment OEMs).
The analysis balances macro fidelity with operational relevance: readers will find both the headline market trajectory and the tactical steps needed to convert that trajectory into financial performance.
Competitive Landscape — Who Matters and Why
The market features a mix of global incumbents, regional specialists and local operators. Our competitive analysis synthesises primary research, operator interviews, and on‑site assessments. Representative company profiles included in the report:
- Safe Bag S.p.A. (TraWell) — An established global leader in airport baggage protection and tracing services. Recent product innovation (launched early 2025) introduced an automatic wrapping platform integrating NFC tracking and a significant material‑use improvement—key indicators of how incumbents are protecting margins through technology and sustainability claims.
- Secure Wrap — U.S. based operator offering TSA‑authorized services and customer‑friendly policies (e.g., complimentary rewraps after inspection). Their model highlights the value of compliance and customer trust in premium retail positioning.
- BagWrap — UK/European player focused on durable protection across airports and rail stations, with emphasis on ultra‑resistant films that also address weather and hygiene considerations.
- Wrap N’ Fly & TrueStar Group (Wrap and Fly) — Operators known for terminal throughput and franchise scalability. They exemplify two commercial models: high‑velocity terminal operations and franchised network expansion.
- Seal & Go — Notable for rapid sustainability moves, having rolled out biodegradable film services across UK airport locations in 2025; an example of first‑mover green positioning within established geographies.
- Encalm Enwrap — Indian operator offering biodegradable film options, underscoring the regional innovation response to local sustainability and regulatory pressures.
- Excess Baggage Company — Operator with a hygiene and security focus, leveraging ultra‑resistant films at major UK airports and selected overseas locations.
Collectively, top incumbents demonstrate three consistent strategic priorities: tighter operational efficiency through automation, public‑facing sustainability commitments, and incremental revenue development via digital services and insurance/bundling partnerships.
Segment and Supply Dynamics to Watch
At the segment level, the industry remains materially driven by film type and equipment productivity. Baggage wrapping primarily uses stretch films based on LDPE or LLDPE; shifts toward biodegradable or 100% recyclable films are accelerating, driven by airport procurement criteria and consumer expectations. Separately, raw material cycles matter: plastics packaging film pricing is volatile—illustrated by the US Producer Price Index for Plastics Packaging Film and Sheet Manufacturing, which reached 185.768 in March 2026—creating immediate cost‑pass‑through and hedging considerations for service providers.
Risk and Opportunity Matrix
- Risks: accelerating regulatory costs via EPR regimes; film price volatility; terminal access and concession fee pressure; reputational risk if sustainability promises are not backed by lifecycle evidence.
- Opportunities: premiumization through verified sustainable offers; ancillary revenue from digital tracking and claims management; cost savings from newer automatic wrapping platforms that materially reduce film consumption; consolidation plays where disciplined operators can scale fixed costs across more terminals.
Our report quantifies these levers: it models how a mid‑sized operator can improve unit margins through a single combination of machine upgrades, film substitution and revised pricing—while also modelling downside scenarios tied to sustained plastics price elevation or escalated EPR fees.
Recommended 2026 Playbook — Practical Next Steps
- Immediate (0–6 months): conduct a contract and cost audit focused on film procurement and concession economics; pilot biodegradable film with clear lifecycle disclosure and customer communication; run a proof‑of‑concept for NFC‑based tracking on high‑value routes.
- Near term (6–18 months): prioritize capital retrofit of wrapping fleets where ROI < 24 months (using our CapEx/Opex calculator); renegotiate supplier agreements with indexed pricing clauses tied to polymer indices; implement a customer upsell funnel (protection + tracking + insurance).
- Medium term (18–36 months): explore consolidation or strategic partnerships to secure film supply or equipment financing; integrate sustainability certification into procurement tenders; develop a modular software stack for claims and tracking that can be white‑labeled to airport partners.
Why This Report Matters to Executives in 2026
Our study is built to shorten the path from insight to implementation. It combines granular operational testing (equipment throughput, film consumption measurements), proprietary demand modelling through 2032, legal/regulatory scenario planning for EPR regimes, and commercial playbooks that have been road‑tested with airport partners and service operators. The result is not just a market forecast but a step‑by‑step guide you can use to prioritize investments, negotiate contracts, and evaluate M&A targets in 2026.
For readers seeking the complete dataset—detailed segmentation, regional and application breakdowns, modeled P&L impacts at operator level, and a downloadable interactive financial model—please consult the full PW Consulting report. The public brief above demonstrates the depth and practical orientation of our work; the full report contains the granular tabulations and appendices required for transaction‑level decision making.
PW Consulting remains available to run bespoke scenario workshops, underwriting exercises, or procurement negotiations informed by the report’s models and field findings. In a market where small changes in film usage, machine efficiency, or regulatory cost allocation can swing returns, a disciplined, data‑driven approach in 2026 will separate winners from laggards.
For detailed analysis of this topic, please visit the official page: Worldwide Baggage Packaging Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Single Point Anchor Reservoir Market to Rise from USD 1,420.5 Million in 2025 to USD 2,059.5 Million by 2032 at a 5.45% CAGR (2026–2032)
By PW Consulting, 2026-07-15
Worldwide Single Point Anchor Reservoir Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Single Point Anchor Reservoir (SPAR) market frames an industry at an inflection point. Our analysis shows the market expanded from USD 1,089.45 Million in 2020 to USD 1,420.50 Million in 2025 (base year), and is projected to grow to USD 2,059.53 Million by 2032. Across the 2026–2032 forecast window our models point to a compounded annual growth rate (CAGR) of 5.45%. These topline dynamics reflect the combined influence of extended deepwater hydrocarbons activity, the maturation of floating offshore renewables, and a reconfiguration of supply chains and manufacturing footprints.
Worldwide Single Point Anchor Reservoir Market
This press brief is designed as a strategic “trailer”: it demonstrates the depth and operational rigor of the full PW Consulting report while intentionally withholding granular segment-level disclosures to preserve the value of the complete analysis. Senior executives, strategy teams, and investment committees will find the perspectives below immediately actionable as they prepare capital allocation and partnership decisions in 2026.
Worldwide Single Point Anchor Reservoir Market
Why 2026 is a pivotal year for SPAR stakeholders
- Capex and project timing convergence: Several large-scale offshore projects initiated in the mid-2020s enter procurement and FEED phases in 2026–2027, compressing demand for long-lead equipment and specialist fabricators. Alignment (or misalignment) with these cycles will materially affect supplier bargaining power and project economics.
- Technology and design bifurcation: Truss, classic and cell SPAR architectures are each being optimized for different risk profiles—weight, fabrication complexity and lifecycle OPEX. Strategic product choices now determine competitiveness over the asset life, not just at handover.
- Energy transition impact: The growing role of floating offshore wind introduces new addressable demand and requires adaptations in anchoring strategies, interface standards and service models. Companies that treat renewables as a complementary market rather than a footnote will gain strategic optionality.
- Concentration and consolidation pressures: The market exhibits a meaningful degree of concentration (CR3 ~42.5%, CR5 ~61.25%), indicating scale advantages for incumbent leaders, while leaving space for consolidation plays, specialist entrants and vertically integrated challengers.
Key implications for executive decision-making
- Portfolio prioritization: Firms must re-evaluate product portfolios to balance near-term revenue capture against long-term service and retrofit opportunities. Prioritize designs and contracts that optimize total lifecycle returns rather than headline CAPEX reductions.
- Procurement and supplier strategies: With supply chain friction expected to persist in 2026, secure long-lead items through strategic volume agreements, co-investment partnerships, and capacity reservation clauses. Supplier scorecards and financial stress-testing are now essential bargaining tools.
- Manufacturing footprint and localization: Time-sensitive projects favor modular fabrication and localized assembly hubs. Assess trade-offs between centralized economies of scale and regional speed-to-install advantages in contract adjudication.
- R&D and materials innovation: Materials science (advanced steels and composites) and novel joining/welding techniques can alter weight and cost trade-offs. Invest selectively in demonstrable technology readiness levels that shorten schedule and reduce lifecycle costs.
- Service-led monetization: The installed base creates annuity streams—inspection, maintenance, retrofits and digital monitoring. Firms should productize lifecycle services and integrate them into bid economics rather than treating them as afterthoughts.
- M&A and alliance playbooks: Given market concentration, opportunistic M&A, bolt-on acquisitions and strategic JVs can accelerate capability access. Focus deal diligence on manufacturing know-how, long-term contracts, and addressable serviceable markets.
What PW Consulting’s full report delivers (practical, ready-to-use content)
- Robust top-line market sizing (historical 2020–2025, base year 2025) and granular forecasting for 2026–2032, including sensitivity to oil & gas pricing scenarios and renewables uptake.
- Scenario-based demand modeling with three distinct market paths (conservative, central, accelerated) and corresponding procurement timelines to help procurement and planning teams stress-test capacity needs.
- Commercial decision-support tools: downloadable CAPEX/OPEX models, break-even analyses, and bid-versus-build calculators aligned to standard project contracting mechanics.
- Supplier benchmarking templates and a procurement playbook that operational teams can use to evaluate fit-for-purpose fabrication partners, including financial resilience and delivery on-time metrics.
- Risk matrices and mitigation checklists covering geopolitical exposures, export controls, raw material inflation, and regulatory shifts related to offshore operations and decommissioning standards.
- A playable M&A diligence module: target screening criteria, valuation adjustment guides, integration scorecards, and synergy capture templates tuned to the SPAR market.
- Case studies and build-to-operate roadmaps from recent projects (anonymized) that distill lessons on schedule compression, interface management and cost overruns.
- Executive dashboards and an interactive data pack for board briefings—plug-and-play charts and scenario tables to support capex committees, investment memos and lender presentations.
Competitive landscape — what concentration means and how to act
The market’s measured concentration (CR3 ~42.5%; CR5 ~61.25%) signals that scale confers meaningful advantages—manufacturing leverage, integrated project delivery, and stronger negotiating positions with operators and EPC contractors. However, concentration also creates strategic openings:
Worldwide Single Point Anchor Reservoir Market
- Specialists can win on niche value: Firms that specialize in retrofit solutions, rapid-delivery kits, or bespoke interfaces for renewables projects can secure premium margins even without top-tier scale.
- Partnerships overcome scale gaps: Non-integrated players can pursue alliances with yard capacity owners, logistics providers and financing houses to offer turnkey propositions that mirror incumbent strengths.
- Vertical integration for margin control: Leading players will continue to pursue upstream and downstream integration—fabrication, mooring systems, long-term service contracts—to protect margins and stabilize revenue.
Operational priorities for teams executing 2026 strategies
- Fast-track validation of supply pipelines for key long-lead items and secure conditional allocations in 2026 contracts.
- Standardize interfaces and modularize sub-assemblies to reduce on-site schedule risk and enable parallel manufacturing streams.
- Embed digital twins and condition monitoring into new projects to create serviceable data estates and justify premium servicing contracts.
- Conduct systematic workforce planning: welding, composite assembly, offshore hook-up crews and digital engineering skills are decisive constraints.
- Adopt a staged investment approach where prototype builds de-risk full-scale tooling and allow early commercial references for buyers and lenders.
- Use procurement clauses to transfer specific inflation and schedule risks back to suppliers where feasible, while balancing contractor appetite to win work.
How to use this report in boardrooms and investment committees
Leaders can deploy the PW Consulting report to inform three critical processes for 2026:
- Scenario-led capital allocation: Integrate the report’s demand scenarios into capital planning cycles and use the downloadable models to quantify NPV impacts across alternative project timing assumptions.
- Negotiation and procurement strategies: Leverage supplier benchmarking outputs and procurement playbooks when negotiating conditional awards and capacity reservations.
- M&A and partnership diligence: Use the M&A module to establish target screens and to quantify synergy capture timelines—this reduces transaction execution risk and speeds post-deal integration.
Next steps — accessing the complete intelligence
This preview highlights the strategic choices that will define winners and laggards in the SPAR market as companies set course for 2026. The full PW Consulting report contains the proprietary models, playbooks and client-ready templates referenced above—materials designed to be operationalized immediately by strategy, commercial and operations teams.
To obtain the complete report, interactive data pack and to arrange a tailored executive briefing, visit the PW Consulting website or contact your account lead. For clients seeking hands-on support, PW Consulting offers customized workshops that translate the report’s outputs into board-level decision memos, procurement RFP templates and integration roadmaps.
PW Consulting’s outlook is clear: the SPAR market presents a mix of continuity and disruption. Companies that combine disciplined portfolio choices, supply-chain foresight, and pragmatic technology adoption will convert the projected growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Single Point Anchor Reservoir Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide HEA, HEMA, HPA & HPMA Market to Expand at a 5.28% CAGR Through 2032
By PW Consulting, 2026-07-15
Global HEA, HPA, HEMA & HPMA Market: Strategic Imperatives for 2026
Executive summary
The global market for hydroxy-functional acrylates and methacrylates—HEA, HPA, HEMA and HPMA—has entered a phase of steady, structurally-driven expansion. PW Consulting’s latest Worldwide HEA, HPA, HEMA, & HPMA Market study (base year 2025; historical run 2020–2025; forecast 2026–2032) shows the market at USD 1,530 Million in 2025 and projects growth to approximately USD 2,193 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.28% across the forecast window. Concentration metrics indicate a market where the top three and top five suppliers exert meaningful pricing and capacity influence (CR3 ~45.5%; CR5 ~62.3%), but a diverse cohort of regional and specialty producers continues to shape innovation and niche supply dynamics.
Worldwide HEA, HPA, HEMA, & HPMA Market
Why this report matters for 2026 decision-making
- Procurement and price risk management: Feedstock and upstream monomer dynamics are creating asymmetric cost pressures that materially affect margins across formulations and value chains. Procurement strategies built on static assumptions will underperform in 2026.
- Capacity and investment timing: New and expanded capacities—both from large incumbents and ambitious regional players—are altering utilization rates and near-term pricing. Timing capex or brownfield expansions requires scenario-tested forecasts and supplier-stability analysis.
- Regulatory compliance and product stewardship: Changes to emissions control regulations and renewed scrutiny of biomaterials used in medical applications mandate proactive compliance programs and material-risk mapping.
- M&A and partnership plays: With meaningful consolidation among leaders and fast-growing regional competitors, targeted acquisitions or strategic alliances can accelerate access to specialty grades, geographic markets, and downstream formulations.
Macro signals shaping 2026 strategy
The market profile in 2025–2026 is the result of intersecting macro forces. Raw material feedstocks that drive acrylate and methacrylate pricing have shown volatility: acrylic acid experienced sharp month-over-month swings in 2025 even as year-over-year trajectories moderated, and methacrylic acid saw regional quarter-to-quarter softening in late 2025 tied to export flows. Simultaneously, new global capacities and propylene feedstock trends introduced downward pressure on bulk monomer prices in H2 2025.
Worldwide HEA, HPA, HEMA, & HPMA Market
Regulatory shifts such as the US EPA’s HON emissions-control measures—now operating with temporary relief mechanisms for certain stationary sources—are reshaping permit timelines, capital expenditure planning, and emissions-reporting requirements for chemical manufacturing sites. In the medical-device domain, ongoing biocompatibility reviews of pHEMA and related materials underscore the need for rigorous material-data dossiers and proactive engagement with regulators and OEM customers.
Worldwide HEA, HPA, HEMA, & HPMA Market
Competitive landscape — how leading players are positioning
The market is anchored by global chemical majors and several specialized regional producers. Incumbents maintain advantages in scale, integrated feedstock access, and global distribution; specialty suppliers compete on high-purity grades, low-sensitization chemistries, and close technical support to formulators.
- Dow Inc. (Midland, Michigan) remains a cornerstone supplier with broad portfolio coverage across HEA/HPA/HEMA/HPMA and deep integration into coatings, adhesives, and resin value chains. Its scale and technical service capability are primary differentiators for multinational formulators.
- BASF SE (Ludwigshafen) continues to leverage technology-led offerings and has used price adjustments to manage margin erosion from energy and feedstock pressure—an indicator of how majors will balance commercial discipline with market share protection.
- Mitsubishi Chemical Group and Nippon Shokubai (Japan) have differentiated through high-purity, application-specific grades—especially for electronics, photoresists and medical uses—where regulatory and performance barriers raise switching costs.
- Evonik and Röhm (Germany) prioritize specialty methacrylate lines and branded resin systems, targeting formulators that require reactive diluents and tailored reactive-monomer blends.
- Wanhua Chemical (China) and other Chinese producers have rapidly scaled capacity and are actively pursuing both domestic and export opportunities; Wanhua’s announced capacity expansion for methacrylate grades in 2025 is an example of how regional scale-up is pressuring global utilization and pricing.
- Smaller and specialty producers—ranging from Dechem to Polysciences and regional Chinese manufacturers—are increasingly important for niche grades, research-focused supplies, and shorter lead-time service models.
Recent developments worth noting
- Capacity expansions from large regional players are shifting the supply balance and creating localized price deflationary pockets in H2 2025–2026.
- Price management actions by major producers reflect efforts to offset elevated energy and feedstock costs; these measures influence contract cycles and force buyers to reassess indexation clauses.
- Upstream feedstock volatility and regulatory updates continue to generate near-term commercial shocks; companies with flexible sourcing and robust hedging frameworks are positioned to outperform peers.
What PW Consulting’s report delivers (operational, decision-ready content)
Our study is designed for commercial and technical executives who must convert market intelligence into operational decisions in 2026. Core deliverables include:
- Proprietary, reconciled market size and long-run forecast models (USD Million basis), with base- and scenario-based outputs for 2026–2032 that stress-test demand under alternative GDP, construction, electronics and medical-device growth pathways.
- Supply-side mapping and a supplier heatmap that ranks manufacturers by scale, specialty capability, technical service, lead-time performance and regulatory standing—presented in an actionable supplier-score format for sourcing teams.
- Price-sensitivity and margin-stress tools that model the pass-through of acrylic- and methacrylic-acid cost shocks into finished goods under multiple contractual indexation schemes.
- Regulatory impact playbook covering emissions-control requirements, permitting timelines, and material-specific medical-device scrutiny—designed to prioritize compliance investments and documentation efforts.
- M&A and partnership screening: proprietary signals highlighting acquisition targets and JV candidates, including estimated strategic fit, integration risks and value-creation levers.
- Commercial playbooks for coatings, adhesives and medical-device OEMs: go-to-market tactics, formulation migration roadmaps to specialty grades, and customer-contract clauses to mitigate pass-through risk.
- CapEx decision toolkit: ROI calculators, utilization-sensitivity analyses and phased investment roadmaps that help finance and operations teams sequence capacity commitments.
Note: consistent with our “trailer” approach to this release, we present comprehensive, decision-ready insight in the full report. Detailed regional and application splits, supplier-specific volumes, and granular price decks are intentionally omitted from this public summary to preserve the actionable value of the primary deliverable.
Strategic plays for executives in 2026
- Refine procurement strategy: Move beyond single-index contracts. Implement multi-factor indexation, shorter reset periods for spot-exposed purchases and strategic forward-booking for specialty grades.
- Prioritize specialty portfolios: Allocate R&D and commercial resources toward low-sensitization and medical-grade chemistries where switching costs and regulatory barriers protect margins.
- Leverage supplier scorecards: Use performance-weighted scorecards to rebalance sourcing across global majors and nimble regional suppliers to optimize cost, service and regulatory risk.
- Stress-test capex decisions: Use scenario-based utilization and price models to phase expansions, retaining optionality against feedstock and demand cycles.
- Prepare for regulatory headwinds: Fast-track emissions-compliance timelines and strengthen materials data dossiers for medical applications to reduce approval and audit risk.
- Pursue targeted M&A: Acquire capability (high-purity grades, niche formulations) rather than scale alone; tuck-ins that provide technical service and customer intimacy can offer rapid payback.
How to use the full PW Consulting report
This press summary highlights the structural drivers, competitive dynamics and pragmatic plays that will define winners and laggards in 2026. PW Consulting’s full report provides the calibrated inputs and executable tools that procurement, commercial, regulatory and corporate development teams need to operationalize these plays—complete with downloadable spreadsheets, supplier matrices, contract templates and scenario models.
For teams preparing budgets, capex proposals, or M&A diligence in 2026, the report converts market-scale forecasts and concentration metrics into immediate, executable activities. If your decisions hinge on feedstock exposure, supplier resilience, regulatory timelines or specialty-grade adoption curves, the full report contains the granular intelligence and modelled outcomes required to justify and defend those choices to boards and investors.
Closing
As the HEA/HPA/HEMA/HPMA complex moves into a growth phase characterized by selective specialization and regional capacity shifts, executives who pair rigorous supply-side analysis with scenario-tested pricing and regulatory playbooks will capture disproportionate value. PW Consulting’s Worldwide HEA, HPA, HEMA, & HPMA Market report translates market-scale dynamics and concentration metrics into practical, accountable actions for 2026. To access detailed segmentation, supplier-level metrics, and the decision-ready tools referenced above, please refer to the full report and supporting data package.
For detailed analysis of this topic, please visit the official page: Worldwide HEA, HPA, HEMA, & HPMA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Managed Security Services Systems Market to Reach USD 40.5 Billion in 2025, New Report Reveals
By PW Consulting, 2026-07-15
Managed Security Services System Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting today publishes a focused industry briefing drawn from our full Managed Security Services System Market research (base year 2025, historical window 2020–2025, forecast 2026–2032). The managed security services market is at an inflection point: it reached a global scale measured in tens of billions of USD in 2025 and, under our central-case forecast, will more than double over the coming decade — a trajectory reflected in an 11.5% compound annual growth rate (CAGR) across 2026–2032. These macro dynamics have profound implications for how enterprises, public-sector buyers, and vendors should prioritize investment, sourcing, and capability development in 2026.
Managed Security Services System Market
Why this report matters for 2026 decisions
- Capital allocation: With sustained double‑digit growth expected, CIOs and CISOs must decide which security capabilities to build vs. buy to optimize ROI and time‑to‑value.
- Vendor selection and contracting: The market’s growth masks a fragmented competitive landscape. Buyers need criteria that reconcile scale, technical coverage and service economics.
- Regulatory risk and operational resilience: New energy, data sovereignty and bulk-data rules are already altering cost and compliance levers for managed security operations.
- M&A and partnership strategies: Growth creates both consolidation pressure and opportunities for bolt‑on services; disciplined due diligence requires sector-specific comparables and scenario testing.
- Service design for hybrid estates: Cloud, edge and on‑prem footprints demand differentiated delivery models with observable KPIs and vendor SLAs tied to telemetry and automation.
What the report delivers — practical, operational intelligence
The full PW Consulting report is designed to be prescriptive for decision makers. Highlights of the operational deliverables included are:
Managed Security Services System Market
- Executive decision framework: A one‑page playbook to determine build vs. buy based on risk appetite, regulatory exposure and cost curves.
- Scenario‑driven market model: A modular forecast engine (base 2025, forecast 2026–2032) with high/central/low cases and sensitivity levers for pricing, customer churn and SOC automation adoption.
- Vendor assessment toolkit: Standardized scorecards and buying guides covering technical breadth, 24/7 operations capability, compliance posture (including FedRAMP/GovCloud readiness), and integration risk.
- Go‑to‑market playbooks: Actionable templates for service bundling, margin optimization and channel partnerships across enterprise and mid‑market segments.
- Operational playbooks: SOC staffing models, automation roadmaps, playbooks for ransomware readiness and sample SOW/contract language to mitigate energy pass‑through and localization risks.
- TCO and ROI models: Procurement calculators that let buyers compare internal SOC build vs. third‑party managed detection & response (MDR) and managed network security alternatives.
- Regulatory and compliance mapping: Matrixed view of salient regulatory developments and their operational implications for data handling, cross‑border transfers and contractual obligations.
Data, methodology and what we’re not showing here
Our analysis triangulates three streams: a bottom‑up aggregation of provider deployments and service revenue (validated by vendor disclosures and public filings), telemetry and incident trends gathered from operational SOC partners, and primary interviews with 120+ buyer and provider executives over 2024–2026. The dataset anchors on a 2025 base year and projects 2026–2032 with scenario testing for macroeconomic variance and technology adoption curves. The market’s projected 11.5% CAGR is an output of this multi‑vector approach.
Managed Security Services System Market
Consistent with the “trailer” principle of this release, we intentionally omit the detailed segmentation tables, regional/application‑level shares and pricing bandings from this communication to preserve the integrity of the report’s proprietary analysis. Interested readers are invited to access the complete dataset and appendices on our source page.
Market dynamics shaping strategic choices in 2026
- Cloud and hybrid complexity: As cloud native workloads and distributed edge environments proliferate, buyers are demanding managed services that can unify telemetry across hybrid estates — shifting evaluation criteria from point‑products to platform‑level integration and run‑book automation.
- Automation and AI in the SOC: Investment in AI‑assisted detection, orchestration and response continues to accelerate. Our field work shows automation materially reduces mean time to detect (MTTD) and mean time to respond (MTTR) but requires rigorous model governance and labeled telemetry to be effective.
- Supply economics under stress: Regulatory activity in early 2026 — including numerous data center‑related bills and executive guidance on energy cost responsibilities for large operators — is increasing the operating cost base for providers that rely on large-scale data center footprints. Contractual language that allows for energy cost adjustments or alternative delivery modalities will become a standard negotiating point.
- Data sovereignty and cross‑border friction: Trade and regulatory engagements continue to challenge unconstrained cross‑border managed services. Buyers need architectures and contractual clauses that balance operational continuity with jurisdictional controls over sensitive datasets.
- Fragmented competitive structure: While several global platform players retain strength in scale and integration, a vigorous cohort of pure‑play MSSPs and specialized MDR vendors continues to win based on speed, vertical focus and customized threat intelligence. This fragmentation is a structural feature buyers can exploit to negotiate differentiated commercial terms.
Competitive landscape — strategic positioning of core providers
Our vendor analysis synthesizes technology posture, delivery readiness, compliance credentials and recent go‑to‑market moves. Below are high‑level strategic observations on key players.
- IBM Security — Enterprise‑grade breadth and deep hybrid cloud integration remain IBM’s differentiators. Companies seeking global reach, compliance breadth and cross‑product integration (including consulting uplift) will keep IBM on shortlists.
- Verizon — Strengths lie in network‑centric services and distributed mitigation capability (DDoS, SASE integration). Buyers with network‑intensive estates and global connectivity needs should weigh Verizon’s packaged network‑security value.
- LevelBlue — As a pure‑play MSSP emerging from established constituents, LevelBlue combines MDR focus with government‑oriented credentials (including FedRAMP‑adjacent positioning). It is an option for organizations seeking vendor agility with recognized operational certifications.
- Tata Communications — Global managed security reach with network‑integrated monitoring appeals to multinational enterprises pursuing unified telemetries across service provider backbones.
- Secureworks — A platform‑driven MDR approach (Taegis XDR) makes Secureworks an attractive vendor where analytics and integrated case management matter most.
- Arctic Wolf — The concierge SOC model continues to resonate with mid‑market and SME buyers who need managed detection and response delivered as a people‑led service with predictable outcomes.
- eSentire — Specialist MDR provider with 24/7 expert SOC delivery; strong on rapid incident handling and use‑case driven coverage for high‑risk verticals.
Overall, the competitive structure retains meaningful scope for mid‑tier and specialist vendors to grow even as scale players pursue platform consolidation. Buyers will need to balance platform completeness against integration risk and total cost of ownership.
Strategic recommendations for 2026 — five priority moves
- Adopt a hybrid sourcing posture: Combine core in‑house threat governance with outsourced 24/7 MDR for volume detection and specialized retained partners for high‑sensitivity assets.
- Insist on telemetry contracts and SLAs: Require access to raw telemetry, standardized event taxonomies and measurable SLAs to avoid vendor lock‑in and to enable multi‑vendor orchestration.
- Re‑price for energy and regulatory risk: Build contractual clauses and contingency budgets to reflect the evolving cost profile of data center operations and energy passthroughs.
- Prioritize automation and model governance: Invest in playbooks for model validation, drift detection and human oversight to realize productivity gains without elevating false positives.
- Use M&A tactically: For vendors and buyers pursuing consolidation, prioritize acquisitions that add telemetry, vertical threat intel, or regulatory credentials over generic capacity expansion.
How enterprise leaders should use the full PW Consulting report
- Validate internal assumptions: Use our scenario engine to stress‑test in‑flight programs against different adoption and pricing trajectories.
- Run procurement pilots: Deploy the vendor assessment toolkit in 60–90 day vendor pilots to capture empirical performance and cost data.
- Inform board‑level risk briefings: Translate market growth and regulatory exposure into concise financial implications and timelines for executive committees.
- Operationalize compliance: Leverage the compliance mapping and contract playbooks to update SOWs and incident response obligations ahead of tightened regulatory regimes.
PW Consulting’s Managed Security Services System Market report is intended to be an actionable instrument for 2026 planning. This briefing highlights the strategic contours and executive takeaways; it omits the granular segmentation and proprietary supplier scores that live in the full deliverable. To access the complete dataset, segment breakdowns, vendor scorecards and scenario models, please refer to the PW Consulting report page or contact your PW Consulting advisor.
For detailed analysis of this topic, please visit the official page: Managed Security Services System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Paper Cup Sleeve Market Worth USD 642.5 Million in 2025, Set to Reach USD 916.2 Million by 2032 at a 5.19% CAGR — Corrugated Paper and North America Lead
By PW Consulting, 2026-07-15
Worldwide Paper Cup Sleeve Market: Strategic Insights for 2026 Decision-Makers
As companies finalize budgets and product roadmaps for 2026, the paper cup sleeve market presents a clear but nuanced opportunity: steady growth driven by foodservice expansion, sustainability mandates and material-cost dynamics that will reward proactive commercial and operational strategies. PW Consulting’s latest Worldwide Paper Cup Sleeve Market report (base year 2025, forecast period 2026–2032) quantifies that trajectory — the market expanded materially from the start of the decade and is projected to continue compounding at a mid-single-digit CAGR (5.19%) through 2032, reaching roughly USD 916 million by the end of the forecast. What follows is an executive distillation of the report’s strategic value to corporate decision-makers in 2026 — purposefully deep on implications, deliberately light on proprietary segment tables to encourage readers to access the full study for transaction‑grade detail.
Worldwide Paper Cup Sleeve Market
Why this market matters for 2026
-
Convergence of sustainability and regulation — Packaging rules in key jurisdictions and buyer expectations are compressing product lifecycles and redirecting purchasing criteria from price‑only to lifecycle cost and compliance readiness.
Worldwide Paper Cup Sleeve Market -
Predictable, investable growth — With a projected CAGR in the mid‑single digits across 2026–2032, cup sleeves remain an attractive incremental revenue stream for paper‑packaging players, branded coffee chains, and specialty converters that can scale without heavy capex.
Worldwide Paper Cup Sleeve Market -
Fragmented supply base — Market concentration is low compared with many other packaging categories (CR3 and CR5 measures indicate the sector remains decentralized). That fragmentation creates room for nimble suppliers to gain share via customization, sustainability credentials, and logistic excellence.
-
Price and input risk — Raw material volatility is real and uneven across regions (evidence from Q1 2026 kraft-paper price observations shows a material spread between major markets). This creates opportunities for cost arbitrage, blended sourcing strategies, and pass‑through pricing mechanisms.
What the report delivers — practical tools for 2026 action
Our research was designed for operators deciding where to allocate resources this calendar year. The report is not an academic exercise; it is a playbook. Highlights include:
-
Robust market-sizing and scenario modelling: baseline and three downside/upside scenarios for volume, price, and regulatory shock. These scenarios include sensitivity matrices so procurement, pricing and finance teams can stress‑test P&L impact under different pass‑through and adoption assumptions.
-
Regulatory impact modelling: bespoke modules that map the EU Packaging and Packaging Waste Regulation (effective from August 2026), multi‑state U.S. EPR regimes and California SB 54 trajectories into unit economics. The models quantify how modulated EPR fees and compostability mandates change landed cost and margin by product architecture.
-
Raw material and cost playbook: granular cost‑build templates that incorporate regional kraft and corrugated price inputs, energy, labor and freight. Users can input proprietary supplier quotes to produce supplier‑level margins and breakeven buy‑back points.
-
Product redesign ROI: engineering‑to‑commercial templates that evaluate alternative constructions (e.g., corrugated vs. kraft vs. embossing finishes; plant‑based linings versus conventional PE) based on recyclability, thermal performance and total landed cost.
-
Commercial and procurement toolkits: RFP templates, supplier scorecards focusing on sustainability credentials (FSC, compostable certifications), capacity mapping, minimum order economics and recommended contracting clauses for price‑indexation and EPR fee allocation.
-
M&A and partnership screening: a prioritized list of target profiles and a valuation overlay for tuck‑ins and regional converters that would help global players attain scale quickly in resilient segments.
Competitive landscape — who to watch and why
The market is served by a mix of global packaging majors, regional converters and specialist branding vendors. Leading firms demonstrate three strategic postures worth emulating or countering:
-
Integrated sustainability innovators — Companies that tie product launches to credible sustainability claims and systems (e.g., compostable linings or recycled content) are capturing premium placements with café chains and multinational quick‑service operators. Recent product introductions in 2025 underlined this trend and show how new material architectures can become a launch pad for cross‑category upsell.
-
Channel specialists and customizers — Several U.S. and China‑based players focus on rapid, brand‑centric customization (printed sleeves, promotional runs) and maintain differentiated value through responsiveness, digital print capacity and low minimums. These suppliers are attractive partners for retailers seeking co‑branding and local inventory flexibility.
-
Scale converters with integrated foodservice portfolios — Large packaging incumbents leverage distribution to major foodservice accounts, bundling sleeves with cups and lids to drive procurement consolidation. Strategic partnerships with national coffee chains or distributor networks materially de‑risk volume volatility.
Notable recent developments underscore these strategic postures: a major European supplier released fully compostable cup solutions in 2025, complementing insulated sleeve lines; a leading U.S. manufacturer announced a strategic partnership with a national coffee retailer to co‑develop insulated, recyclable cup systems; and an industry initiative launched in 2025 to pilot closed‑loop recycling programs in select municipalities. These moves highlight the acceleration of product‑level sustainability and collaboration between manufacturers, retailers and local stakeholders.
Market dynamics that will determine winners in 2026
-
Regulatory alignment: firms that can demonstrate product designs compatible with EPR scorecards and modulated fee regimes will preserve margin and retain access to priority tenders in regulated markets.
-
Cost engineering and sourcing: given the observed regional spread in kraft paper costs, organizations that implement blended sourcing, local converting and material substitution will protect margins and improve lead times.
-
Brand and co‑marketing capability: the sleeve is increasingly a branding surface. Suppliers offering integrated artwork, limited‑edition print runs and fast turnaround create stickiness with coffee chains and promotional calendars.
-
Operational resilience: low market concentration means opportunities for scale capture exist, but only for suppliers that can balance quality certifications, capacity and traceable supply chains.
Recommended 90‑day agenda for 2026
-
Procurement: implement the report’s supplier scorecard and RFP templates to run a renegotiation or dual‑sourcing exercise focused on EPR‑compliant alternatives and indexed pricing clauses linked to kraft benchmarks.
-
Product development: run a rapid three‑option piloting program (baseline, compostable‑lined, corrugated‑insulated) with at least two retail partners to gather thermals, recyclability validation and consumer feedback.
-
Commercial: pilot a premium “sustainability sleeve” SKU with branded co‑marketing; test price elasticity and measure take‑rate to inform roll‑out and margin models.
-
M&A/opportunities: screen regional converters that offer complementary design or print capabilities as bolt‑on candidates for volume capture in targeted markets.
Closing — the strategic value of full visibility
For 2026 corporate strategy and operating plans, the paper cup sleeve market is a classic example of a modestly growing, structurally changing category where timely, data‑driven moves create outsized returns. Our report synthesizes the quantitative forecasts, regulatory mappings, cost‑builds and supplier diagnostic tools that will answer the key business questions: How should we design product lines to meet upcoming regulatory thresholds? Where can we defensibly optimize cost without sacrificing compliance? Which partners best accelerate go‑to‑market at scale?
This article has surfaced the critical signals and the practical implications. To access the full segment tables, regional and application breakdowns, company financial snapshots, and the downloadable modelling templates referenced here, visit the PW Consulting report page. The full report contains the detailed, transaction‑grade intelligence that executives, procurement leaders and product teams will use to finalize 2026 commitments with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Cup Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Laboratory Glass Container Market Set to Reach USD 6,157.6 Million by 2032, Expanding at a 5.42% CAGR
By PW Consulting, 2026-07-15
Worldwide Laboratory Glass Container Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market briefing on the Worldwide Laboratory Glass Container Market synthesizes five years of historical performance (2020–2025) and delivers a forward-looking view across the 2026–2032 forecast window. The market has demonstrated resilient expansion through the pandemic recovery, climbing from a mid‑single billion base in 2020 to a substantially larger ecosystem by the 2025 base year, and our top‑line forecast projects continued growth to reach over USD 6.1 billion by 2032 at a compound annual growth rate (CAGR) of 5.42% across the forecast period. For executives planning capital, sourcing, or M&A moves in 2026, the intelligence in this report converts market momentum into concrete strategic options.
Worldwide Laboratory Glass Container Market
Why this report matters for 2026 strategy
- Actionable market sizing with scenario-ready models. The briefing provides a validated top‑down market trajectory and scenario variants that stress-test growth against raw‑material price shocks, demand shocks in end‑markets, and accelerated substitution by engineered plastics. This enables CFOs and corporate development teams to quantify downside risk before deploying capital.
- Supply‑chain and input‑cost diagnostics. Borosilicate remains the dominant technical grade for laboratory containers due to its superior thermal shock and chemical resistance. Our study includes a detailed materials map — from boron inputs through soda ash and lime — and a sensitivity model that demonstrates how rising boron costs can pressure margins across manufacturing footprints.
- Competitive and concentration insights. The sector shows a moderate-to-high level of concentration: the three largest players control a material portion of the market and the top five capture more than half. That structure creates distinct opportunities for challengers to capture niches or for mid‑tier players to pursue consolidation strategies.
- Commercial playbooks that work. For product and commercial leaders, we translate market dynamics into go‑to‑market tactics: premiumization of borosilicate offers, bundled sterile-ready solutions, value-based pricing for specialty volumetric ware, and distributor partnership models to accelerate access to target labs and pharma customers.
Report contents — what you will find
- Proven market-sizing methodology and reconciled historicals (2020–2025), with an auditable forecast run to 2032.
- Demand-driver analysis across pharmaceuticals, diagnostics, academic research, and industrial labs, with scenario overlays for pandemic and macro downturn stress-tests.
- Supply‑chain heatmap and supplier risk matrix, including concentration of critical inputs and logistics chokepoints that influence lead times and working capital.
- Competitive benchmarking and capability mapping for leading manufacturers and significant regional suppliers, highlighting product portfolios, R&D positions, and route-to-market strengths.
- Commercial levers and procurement playbook: tactical sourcing options, contract structures, and price-protection strategies tailored to laboratory consumables.
- M&A and partnership playbook: screening criteria for targets, valuation sensitivities, and integration risk checklists, based on observed deal activity and gap analysis.
- Regulatory and compliance checklist linked to regional pharmacopeia and diagnostic standards that affect container qualification and time-to-market.
- Executive dashboards and Excel-ready models for NPV, break‑even, and cost-to-serve calculations, including a vendor scorecard template for supplier selection.
Competitive landscape: who matters and why
The market structure is populated by global incumbents, European tradition brands, and agile regional manufacturers. Global leaders are differentiated by scale, brand trust, and technical pedigree in borosilicate production. Niche players excel in custom apparatus, rapid prototyping or specialized cell culture systems, and often compete on lead time and service. Key strategic profiles covered in detail include:
Worldwide Laboratory Glass Container Market
- Global technology and brand leaders — companies with long heritage brands and deep technical IP in laboratory glassware that serve multinational pharmaceutical and industrial customers.
- European precision specialists — firms that focus on volumetric accuracy, high‑precision borosilicate ware, and pharmaceutical container-grade products. Their core strengths are product reliability and regulatory alignment for drug packaging.
- Regional champions and low-cost manufacturers — suppliers that combine broad catalogues with localized service models to serve educational institutions and regional lab markets at competitive price points.
- Custom and engineered glasshouses — smaller manufacturers and engineering shops that produce bespoke apparatus and serve high-value R&D and industrial clients.
Recent market moves illustrate strategic intent: a notable Indian manufacturer has expanded beyond commodity glassware into analytical vials, filtration products and pharma primary packaging through targeted acquisitions, signaling a deliberate pivot up the value chain. Separately, expansion of distribution agreements between instrumentation groups and major scientific distributors in the United States underscores the continued importance of channel strategies to reach end users rapidly.
Worldwide Laboratory Glass Container Market
Structural themes shaping decisions in 2026
- Premiumization vs. commoditization. Demand for high‑performance borosilicate for critical lab and pharmaceutical uses supports a two‑tier market: premium quality and cost-competitive commodity segments. Product positioning and Value‑Added Services (VAS) will determine margin trajectories.
- Input cost volatility. Boron feedstock and related inputs have placed upward pressure on production costs relative to soda‑lime alternatives. Procurement strategies, hedging options, and supplier partnerships will be decisive for margin protection.
- Single‑use plastics competition. Engineered plastics and single‑use systems continue to encroach on some laboratory workflows. Glass producers competing in these adjacent spaces are investing in value propositions around reusability, lifecycle cost and purity advantages.
- Regulatory and quality demands. Escalating regulatory scrutiny — especially for pharmaceutical primary containers — raises barriers to entry and increases qualification timelines, favoring established, compliant suppliers.
- Servitization and digitalization. Traceability, serialized vials, and integrated inventory solutions are becoming differentiators for customers seeking compliance and supply predictability.
Strategic playbook — priority moves for 2026
- Run scenario‑based capital allocation. Use the report’s sensitivity models to size CAPEX under different boron‑price and demand scenarios before committing to new furnace investments or greenfield capacity.
- Secure critical input channels. Establish dual‑sourced boron supply agreements, consider long‑term purchase contracts, and evaluate backward integration opportunistically if it materially improves margin resiliency.
- Differentiate through services. Bundle pre‑sterilized products, fast‑track qualification kits for pharma clients, and introduce traceability services to create switching costs and premium pricing opportunities.
- Pursue targeted M&A and partnerships. Prioritize acquisitions that add analytical vial capabilities, sterile packaging, or filtration competencies rather than chasing scale alone; integration playbooks in this report reduce execution risk.
- Optimize manufacturing footprint. Rebalance near‑market production for quick delivery to high‑value customers while leveraging cost‑efficient sites for commodity lines.
- Invest selectively in R&D. Focus on coatings, thermal‑shock resistant formulations, and closure compatibility to protect premium segments from plastic substitution.
How to use this intelligence
Executives should treat this briefing as the operational bridge between macro strategy and 2026 execution. Procurement teams can use the input‑cost models to renegotiate supplier terms; product leaders can apply the segmentation logic to prioritize SKUs for premiumization or cost‑reduction; M&A teams can use the valuation frameworks and vendor scorecards to accelerate due diligence while minimizing integration surprises.
For teams preparing board materials, the report’s executive dashboards offer ready visuals and stress scenarios for capital planning rounds. For commercial leaders, the companion go‑to‑market playbook contains channel scorecards and tactical pricing levers proven to increase penetration with diagnostic and pharma buyers.
Next steps and where to find the details
This article provides a strategic preview of the full Worldwide Laboratory Glass Container Market report. PW Consulting’s full study contains the granular segment tables, regional demand breakdowns, vendor scorecards, and downloadable financial models that underpin the recommendations above. To access the detailed intelligence required for transaction execution, sourcing negotiations, or product roadmap finalization, consult the full report and our tailored advisory engagements.
Our analysts and senior advisors are available to walk through bespoke scenario runs, supplier stress‑tests, or M&A target screens that align with your strategic priorities for 2026. Contact PW Consulting to schedule a briefing and translate these insights into a prioritized, executable plan.
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


