



PW Consulting: Worldwide Education Computing Devices Market Poised to Expand at a Robust 14.5% CAGR — Digital Classrooms Drive Demand Through 2032
By PW Consulting, 2026-07-15
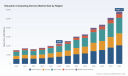
Worldwide Education Computing Devices Market — Strategic Preview for 2026 Decision‑Makers
As education systems worldwide enter a new procurement cycle in 2026, PW Consulting’s latest market study provides a timely, actionable intelligence package for executives who must align device strategy to learning outcomes, budget cycles and emerging technology risks. Our research shows the global education computing devices market accelerating from a 2025 base toward sustained expansion through 2032, underpinned by a projected compound annual growth rate (CAGR) of 14.5% over the 2026–2032 forecast window. The momentum reflected in our topline sizing — with the market crossing the USD 22.45 billion threshold in 2025 and continuing to expand rapidly thereafter — creates both opportunity and strategic complexity for vendors, school systems and investors alike.
Worldwide Education Computing Devices Market
Why this report matters for 2026
-
Timing of procurement cycles: 2026 will be a pivotal year for many districts and higher education institutions renewing 1:1 and shared device programs. Our study connects macro growth trends to practical procurement calendars, helping buyers synchronize RFPs, pilot programs and refresh schedules with expected supplier roadmaps and component availability.
Worldwide Education Computing Devices Market -
AI and connectivity convergence: Devices are no longer merely endpoints — they are gateways to cloud AI services and managed classroom ecosystems. The report explains how AI-enabled device features, OS-level integrations and classroom management tools are reshaping total cost of ownership and support models.
Worldwide Education Computing Devices Market -
Regulatory and infrastructure uncertainty: Recent judicial and policy shifts are altering the connectivity landscape. Our analysis interprets those shifts and quantifies strategic exposure so leaders can make defensible choices on zero‑rating, mobile data strategies and public‑private partnerships.
Report scope and practical deliverables
PW Consulting’s Worldwide Education Computing Devices Market report combines robust market sizing and scenario forecasting with highly practical tools for procurement and operations teams. Key deliverables included in the publication:
-
Market sizing and seven‑year forecasts (2026–2032) built from bottom‑up shipment and ASP models, reconciled to top‑down macro drivers and validated by vendor interviews.
-
Scenario frameworks that test demand under alternate assumptions for connectivity policy, device-as-a-service adoption, and classroom AI uptake.
-
TCO and lifecycle models that translate device specs, warranty choices and management platforms into multi-year budget scenarios tailored for K‑12 and higher education procurement cycles.
-
Vendor scorecards and go‑to‑market playbooks highlighting capability gaps, service propositions and supply chain resiliencies for major OEMs and ecosystem partners.
-
Playbooks for closing the digital divide: procurement templates, carrier engagement checklists, and operational models for large‑scale LTE/5G deployments and device staging.
-
Regulatory impact assessment and mitigation strategies: tailored guidance on zero‑rating programs, state‑level broadband regulation and energy‑related grid upgrades that affect deployment costs.
-
Case studies and pilot templates covering real implementations, change management plans for teacher adoption, and metrics to measure learning ROI.
Competitive landscape — what to watch in 2026
The market shows a moderate degree of vendor concentration: the top three vendors account for a meaningful plurality of supply, while the top five vendors represent a commanding share of the addressable market. This creates a two‑tier competitive dynamic where global OEMs set baseline platform capabilities and scale advantages, while tier‑two vendors and specialists compete on differentiation such as ruggedization, accessibility for special educational needs (SEND), or AI-enabled classroom services.
Our vendor intelligence examines product positioning and go‑to‑market strengths across the competitive set. Highlights include:
-
Long‑established OEMs that have built education‑specific SKUs focused on durability, manageability and serviceability — these players continue to win large institutional contracts where scale and lifecycle support are decisive.
-
Manufacturers emphasizing affordability and classroom‑centric features — they remain attractive to cost‑constrained districts and frequently lead in Chromebook and value laptop segments.
-
Platform owners and OS providers that shape the ecosystem through management consoles and AI services, influencing procurement decisions beyond hardware specifications.
Recent industry movements that will influence 2026 decisions are highlighted in the report. Examples include January 2026 product introductions by major OEMs that bring Wi‑Fi 7, AI‑enhanced devices and SEND‑focused designs to market; and large municipal deployments that demonstrate new connectivity-first procurement approaches. These real‑world events inform our vendor risk assessments and partnership recommendations.
Connectivity, regulation and infrastructure — risk factors that matter
Two regulatory developments and one major industry commitment dramatically change the risk calculus for device programs:
-
A notable judicial decision altered federal broadband classification in the United States, shifting enforcement dynamics and increasing the role of states and legislatures. For education buyers this raises uncertainty about future pricing and the permissibility of zero‑rating or prioritization programs intended to protect digital learning traffic.
-
Public interest exceptions in some jurisdictions preserve the ability to prioritize educational content — a pathway for school systems to secure usable bandwidth for learners. The report examines legal contours and policy levers that procurement teams should monitor before committing to long‑term carrier agreements.
-
Major cloud and technology companies have publicly committed to underwriting new power generation and grid upgrades for data center expansion. While this reduces some upward pressure on residential rates, it also signals an industry shift where energy‑related infrastructure costs are increasingly material to total deployment economics for cloud‑backed education services.
Combined, these elements change how institutions should evaluate carrier partnerships, device selection and content delivery strategies. Our models quantify the sensitivity of device TCO to connectivity cost escalations and to different regulatory outcomes, enabling procurement teams to stress‑test budgets and contract clauses.
Strategic implications and actionable recommendations for 2026
-
Adopt scenario‑based procurement. Do not base multi‑year contracts on a single forecast. Use scenario outputs to specify flexible renewal windows, connectivity fallbacks and price indexing tied to proven cost drivers.
-
Design device portfolios for manageability and teacher workflows. Prioritize platforms that minimize IT overhead through zero‑touch enrollment, standardized management tooling, and predictable warranty/service chains.
-
Build carrier relationships early. With connectivity an explicit part of many device programs (including large municipal LTE/5G rollouts), negotiate pilot‑to‑scale pathways and carve‑outs for zero‑rating where legally permissible.
-
Factor AI and accessibility into adoption roadmaps. Devices with on‑device AI acceleration or curated cloud integrations change software procurement and professional development needs — include teacher upskilling and content licensing in total program budgeting.
-
Prioritize lifecycle sustainability. The combination of supply chain pressures and energy‑related infrastructure costs favors longer refresh cycles, refurbishment programs and as‑a‑service models that can transfer risk and reduce upfront capital requirements.
-
Insist on data‑driven vendor scorecards. Require prospective suppliers to disclose deployable metrics — mean time to repair, zero‑touch enrollment rates, carrier interoperability test results — and benchmark those in contract SLAs.
What the full report unlocks
This preview outlines the strategic themes that will dominate education device decisions in 2026: accelerating market scale, AI and connectivity convergence, regulatory uncertainty and a competitive field shaped by a handful of large OEMs and an active ecosystem of specialists. PW Consulting’s full report delivers the operational detail to act on these themes, including downloadable procurement templates, editable TCO models, a proprietary vendor scoring matrix, and region‑level implementation playbooks. Critical granular intelligence — regional demand mixes, device‑type share curves and the full vendor scorecard data — are intentionally withheld in this summary to protect commercial sensitivity and to direct decision‑makers to the source documentation where they can access validated, auditable tables and models.
Next steps for leaders
Leaders preparing 2026 budgets and procurement strategies should prioritize scenario planning, accelerate carrier and vendor pilots, and align IT, curriculum and finance stakeholders behind a multi‑year deployment framework. PW Consulting is offering tailored briefings and workshop sessions to translate our market forecasts and tools into organization‑specific action plans. For organizations that require immediate tactical support — from RFP language and supplier evaluation to pilot design and SLA negotiation — our advisory teams are standing by to deliver rapid, evidence‑based assistance.
Access the full Worldwide Education Computing Devices Market report for the complete datasets, vendor scorecards and executable playbooks that will enable confident, defensible decisions in 2026 and beyond. Detailed regional splits, device‑type scenarios and the full quantitative appendices are available exclusively in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Education Computing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Outdoor Sound Barriers Market Set to Grow at a 5.06% CAGR Through 2032
By PW Consulting, 2026-07-15
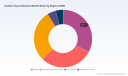
Worldwide Outdoor Sound Barriers Market — 2026 Strategic Preview
PW Consulting today releases an executive preview of its forthcoming Worldwide Outdoor Sound Barriers Market report, delivering forward-leaning analysis designed to shape corporate and public-sector decisions in 2026. This preview outlines the market’s macro trajectory, emergent risks and opportunities, and the practical intelligence executives will need to convert acoustic strategy into measurable project outcomes. It intentionally showcases the depth and applicability of the study while reserving the segmented data and full benchmarking tools for the full report.
Worldwide Outdoor Sound Barriers Market
Why this report matters for 2026 decisions
-
Actionable timing: The outdoor sound barriers market enters 2026 from a position of steady expansion — PW Consulting’s base-year assessment pegs global market revenue at approximately USD 6.45 billion in 2025, with a multi-year compound annual growth rate (CAGR) of roughly 5.06% through our forecast horizon. This trajectory creates immediate windows for procurement, retrofit programs and product innovation that decision-makers should not miss.
Worldwide Outdoor Sound Barriers Market -
Regulatory inflection: Recent updates to outdoor noise measurement standards and EU-level regulations have accelerated demand for verifiable attenuation performance and transparent reporting. Buyers and suppliers who can demonstrate compliance and auditable performance will capture outsized share in tender processes.
Worldwide Outdoor Sound Barriers Market -
Cost and supply-chain sensitivity: Volatility in core raw materials — notably steel — is reshaping vendor economics and favoring design strategies that emphasize modularity, alternative materials and lifecycle cost optimization.
Snapshot of the market trajectory
After recovering from pandemic-era disruptions, the market reached a near-term milestone in 2025. PW Consulting’s modeling shows the market expanding further through the 2026–2032 forecast window, supported by infrastructure renewal programs, urban densification, industrial decarbonization projects and increasing expectations for acoustic comfort in residential and mixed-use developments. While growth is steady rather than exponential, the market's profile favors firms that can combine engineering rigor with procurement-friendly commercial models such as hire/purchase, modular supply and outcomes-based contracting.
Key macro drivers and their strategic implications
-
Standards and compliance: The 2024–2025 cycle saw important updates to outdoor noise engineering practices (notably ISO 9613-2 revisions) and implementation of new reporting requirements across EU member states. Companies must translate these technical changes into project-level risk matrices and updated specification templates. Clients should require accredited modeling and measurement evidence as part of tender documentation to reduce post-installation liability.
-
Raw material dynamics: Engineering News-Record data and industry price forecasts indicate a meaningful rise in steel costs through 2025, with price stabilization at mid-2025 levels. Procurement teams should adopt hedging strategies, multi-sourcing and design-for-material-substitution to mitigate input-cost exposure. Suppliers that present transparent commodity pass-through clauses and lifecycle cost analyses will win longer-term contracts.
-
Product innovation and materials mix: Demand is shifting toward solutions that balance performance, aesthetics and durability — from high-performance absorptive walls to lightweight composite and transparent systems. Manufacturers able to certify acoustic performance while reducing embodied carbon or installation time will be advantaged in public and private tenders.
-
Temporary and rental models: The rise of portable acoustic barriers for construction and event applications introduces recurring-revenue opportunities and alters procurement dynamics for short-term works. Rental providers with robust logistics and rapid-deploy systems create alternative channels to traditional capital procurement.
Competitive landscape — what to expect
The market exhibits a low-to-moderate level of concentration: the top three and top five players together account for a minority share, underscoring a fragmented competitive environment and significant regional incumbency effects. For strategic buyers and investors, this fragmentation creates multiple pathways: consolidate through M&A, partner via white-label agreements, or specialize in niche high-performance segments.
Our company-level analysis in the full report profiles established incumbents and fast-moving specialists, mapping capabilities, service models and recent strategic moves. Highlights from our corporate review include:
-
Sound Fighter Systems (United States) — Longstanding expertise in fully absorptive, high-performance outdoor walls. Their emphasis on demonstrable dB reductions for highways and industrial projects positions them well for infrastructure contracts that prioritize acoustic performance.
-
AIL Sound Walls (Canada) — A turn-key provider that blends absorptive and reflective solutions, serving municipal and residential categories where ease of integration and compliance are as important as attenuation.
-
Echo Barrier (United Kingdom) — A leader in portable and temporary acoustic barriers with hire and purchase models; their business model exemplifies the recurring-revenue opportunity in short-duration applications such as construction, events and demolition.
-
Kinetics Noise Control, IAC Acoustics, Noise Barriers and ArtUSA — Each brings differentiated product portfolios and regional strengths, from lightweight panel systems to Noishield and QuietLine product families tailored to exterior environments and industrial applications.
-
Acoustiblok, Acoustic Sciences Corporation and Sound Seal — Specialists in retrofit systems, fence-integrated absorptive inserts and fabric/assembly-based solutions that cater to residential, commercial and small industrial deployments.
Recent corporate moves — product launches, trade-show demonstrations and content updates — signal a marketplace intent on proving performance, diversifying delivery models and addressing procurement friction points. PW Consulting’s report translates these developments into vendor scorecards and strategic engagement playbooks so buyers can shortlist suppliers against measurable RFP criteria.
Practical intelligence and tools included in the full report
PW Consulting’s full study is built for decision activation. Among the operational tools and deliverables that underpin the report’s utility are:
-
Robust market-sizing and demand scenarios using multiple adoption curves—enabling capital planners to stress-test budgets under conservative, base-case and accelerated deployment assumptions.
-
Procurement playbooks and specification templates aligned to the latest measurement standards and regulatory frameworks—designed for infrastructure owners, municipal buyers and private developers.
-
Lifecycle cost models and TCO calculators that compare material classes, erection methods and maintenance regimes—helping buyers quantify operating expense trade-offs and carbon-intensity considerations.
-
Vendor performance scorecards, M&A maps and an integration roadmap for acquirers looking to consolidate capabilities across materials, installation and measurement services.
-
Implementation checklists and risk matrices for temporary barrier deployments, retrofits, and large linear infrastructure projects (e.g., highways, rail corridors, plant perimeters).
Strategic recommendations for 2026
-
Procurement modernization: Adopt outcomes-based contracting where feasible. Require pre- and post-installation acoustic verification aligned to updated ISO and EU measurement regimes to reduce warranty claims and to create performance benchmarks.
-
Material and supplier diversification: Lock in options across metal, composite and transparent systems while building relationships with rental specialists for short-term needs. Design specifications should allow substitution without compromising measured performance.
-
Invest in modularization and logistics: For large linear projects, modular panel systems that reduce on-site labor and installation time materially decrease schedule risk and enable faster noise mitigation delivery.
-
Pursue targeted M&A and partnerships: Given the market’s fragmentation, complementary acquisitions (e.g., a high-performance panel maker plus a logistics-enabled rental operator) can accelerate growth and entry into adjacent geographies.
-
Design for resilience and sustainability: Embed maintenance pathways and recyclability into product specifications. Procurement teams should value lifecycle carbon metrics and serviceability as part of total cost evaluation.
Risks and contingencies
-
Commodity shocks: Sudden moves in steel and polymer pricing can compress margins or prompt specification swaps — include contractual mechanisms for material-cost pass-throughs or fixed-price hedging for long-term frameworks.
-
Regulatory misalignment: Differing national implementations of measurement standards create project-level compliance complexity; require vendors to demonstrate local accreditation and provide harmonized modeling inputs.
-
Performance verification: Without robust third-party measurement programs, buyers risk accepting sub-optimal installations. Insist on independent acoustic testing clauses in contracts and royalties for performance warranties.
What the full report delivers (and how it supports execution)
PW Consulting’s complete Worldwide Outdoor Sound Barriers Market report goes beyond descriptive forecasting; it equips practitioners with the tools needed to act. The full package contains the detailed segmented market analysis, proprietary vendor benchmarking, regional deployment scenarios, procurement templates, and downloadable financial models that underpin the executive recommendations summarized here. For investors, the report outlines priority investment themes and potential consolidation targets informed by our supply-side due diligence. For public owners and contractors, the report provides specification libraries and installation cost indices tied to current commodity dynamics.
To preserve the integrity of vendor-sensitive benchmarks and client-grade model outputs, this preview deliberately omits granular regional and application splits — these are fully documented and interactive in the complete report, which also includes downloadable spreadsheets and scenario workbooks.
Next steps
Organizations evaluating noise mitigation portfolios, drafting procurement documents for infrastructure projects, or sizing investment programs for acoustic product lines should use this preview as the strategic starting point for 2026 planning. PW Consulting’s analysis translates market momentum, regulatory change and supplier dynamics into operational actions and deal-ready intelligence.
For access to the complete dataset, vendor scorecards, and the procurement toolset, please visit the PW Consulting report landing page and download the full Worldwide Outdoor Sound Barriers Market study. The full report contains the segmented data, company benchmarking, and executable templates that will convert insight into outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Sound Barriers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Modern AI Infrastructure Market Headed to USD 1.68 Trillion by 2032, New Report Finds
By PW Consulting, 2026-07-15
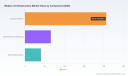
Worldwide Modern AI Infrastructure Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
Executive summary
Modern AI infrastructure is no longer an experimental line item — it is the backbone of strategic competitiveness. Our new PW Consulting market study, grounded on a 2025 base year and five-year historical tracking (2020–2025), projects the global modern AI infrastructure market to expand at a 27.14% CAGR through 2032. The market value we model grows from roughly USD 312.6 Billion in 2025 to an expected USD 397.4 Billion in 2026 and continues on a steep trajectory toward approximately USD 1.68 Trillion by 2032. For leaders making budget, procurement and geographic deployment decisions in 2026, this report translates those macro trends into executable choices — without oversimplifying trade-offs or obscuring operational risk.
Worldwide Modern AI Infrastructure Market
Why 2026 is a strategic inflection point
Two converging forces are creating a unique planning window for 2026. First, hyperscalers and leading cloud providers are accelerating capital programs: combined capex guidance from the largest cloud operators signals an unprecedented spending wave focused on AI infrastructure. Second, the pace of innovation in accelerators, networking silicon and system-level co-design has raised both performance ceilings and integration complexity for on-prem and cloud deployments.
Worldwide Modern AI Infrastructure Market
What this means for enterprise leaders: decisions you take in 2026 about vendor commitments, colocation vs. owned capacity, and power/networking investments will determine your cost curve and time-to-market for the next 3–5 years. Our analysis shows the market growing from mid‑2020s scale to a multi‑trillion-dollar ecosystem over the forecast period — a scale where small timing differences in procurement, site selection, or cooling strategy compound into outsized economic outcomes.
Worldwide Modern AI Infrastructure Market
What the PW Consulting report delivers — practical, decision-ready content
- Actionable strategic frameworks: vendor selection matrices, procurement timing playbooks, and supplier negotiation templates tailored to AI‑first infrastructure.
- TCO and scenario models: modular financial models that map CapEx/OpEx drivers (compute, power, cooling, interconnect) across build, lease and hybrid pathways.
- Deployment playbooks: step-by-step guides for hyperscale, enterprise campus, and edge AI deployments that reconcile performance goals with energy and space constraints.
- Site and capacity planning tools: decision heuristics for assessing power availability, grid interconnection risk, and lead‑time exposures for critical long‑lead items.
- Vendor scorecards and supplier risk heatmaps: comparative assessments across core hardware, networking, foundry and systems integrators — including strengths, service models and IP dependencies.
- Regulatory and supply‑chain checkpoints: compliance pathways to navigate export controls, licensing risks, and cross-border hardware flows.
We intentionally structure the report as a playbook rather than a purely academic forecast — every analytical insight is accompanied by recommended next steps for CIOs, CTOs, CFOs, and infrastructure program leads.
Competitive landscape — who matters and why
The modern AI infrastructure ecosystem is concentrated and increasingly vertically integrated. Market concentration measures underline this dynamic: the top three suppliers account for a substantial majority of market share, and the top five capture an even larger portion—creating both provider leverage and systemic interdependencies.
- NVIDIA Corporation — A dominant force across accelerators, networking and software stacks; their GPU and software ecosystem remains central to large-scale training and inference platforms.
- Advanced Micro Devices (AMD) — Competing with accelerator designs and optimized platforms for high‑performance AI clusters, particularly in HPC-aligned deployments.
- Intel Corporation — Offering a heterogeneous set of CPUs and accelerators with a focus on integrated data-center solutions and inference-performance economics.
- Broadcom and Arista Networks — Critical suppliers of the high-speed interconnect and switching fabrics that enable cluster scale and low-latency topologies.
- Hyperscalers (AWS, Microsoft Azure, Google Cloud, Oracle) — Providers of managed AI infrastructure and custom silicon whose capacity decisions shape supply-and-demand cycles for hardware and services.
- Foundries and system specialists (TSMC, Cerebras, Groq, CoreWeave, Vertiv, Equinix) — These firms enable the manufacturing scale, purpose-built accelerators, cooling and colocation services required for rapid scale-out.
For suppliers and buyers alike, the strategic questions are whether to align with an integrated hyperscaler ecosystem, pursue diversified multi‑vendor sourcing to mitigate single‑supplier risk, or invest in proprietary accelerators and systems to capture differential performance/efficiency. Our vendor scorecards in the full report map these trade-offs against risk tolerance, performance objectives and time-to-deployment constraints.
Structural constraints and regulatory headwinds you cannot ignore
Several non-market factors will materially affect timelines and costs in 2026:
- Export controls and AI‑specific licensing regimes are now a permanent planning variable. Updated controls on advanced compute and high‑scale model weights impose licensing friction on cross‑border transfers and partnerships — adding compliance overhead to procurement and collaboration strategies.
- Electrical infrastructure and power availability are primary bottlenecks. Transformer lead times, grid interconnection queues and permitting timelines introduce multi-year schedule risk; industry modeling shows a material portion of planned near‑term capacity may slip into later years as utilities and permitting agencies catch up.
- Material intensity matters: high-density AI sites are copper- and water‑intensive. Sourcing constraints for cabling and cooling hardware, plus environmental performance benchmarks (PUE, WUE, CUE defined in ISO/IEC standards), will influence site economics and permitting outcomes.
- Standards and benchmarking are maturing. Use of ISO/IEC performance metrics is rapidly becoming a gating factor for corporate sustainability commitments and vendor selection.
Leaders must treat non‑IT stakeholders — utilities, regulators, real‑estate partners — as equal participants in AI infrastructure planning to avoid costly rework and schedule slippage.
Recent market signals to monitor in 2026
- Hyperscaler capex acceleration: combined guidance from leading cloud operators points to an unusually large AI‑directed capital program for 2026 — a demand signal that will stress supply chains for accelerators, networking silicon and rack-level systems.
- NVIDIA and major AI developers are deepening supply and partnership agreements, accelerating the adoption of full‑stack vendor solutions while raising the stakes on supplier availability and priority allocations.
- Major enterprise cloud providers and select specialized providers are pursuing sizable capacity expansions and financing plans to lock in upstream supply and meet anchor customer demand.
- Emerging IP and modular systems: patent activity and modular‑design announcements signal growing interest in distributed and edge‑centric AI data centers built on modular GPU cartridges and liquid cooling — an area where timing and standards will determine who wins the modular battle.
Each of these signals is explored in the report with timelines, risk quantified and dependency maps that show how one supplier's allocation decision can ripple across customers and regions.
Strategic imperatives — a 2026 playbook for decision‑makers
Based on our synthesis of market growth, supplier concentration, and operational constraints, we recommend a focused set of actions for 2026:
- Adopt a power‑first roadmap: prioritize early engagement with utilities and regulators, lock long‑lead transformers and schedule interconnection applications within your project timelines.
- Hedge supplier risk: structure multi‑tiered procurement where strategic capacity is secured with primary suppliers while tactical demand is fulfilled through spot, colo and cloud-burst options.
- Design for modularity and upgradeability: prefer rack and pod designs that enable iterative refreshes of accelerators and networking without full site rebuilds.
- Operationalize compliance: integrate export‑control and model‑weight licensing checks into procurement and cross-border collaboration workflows to avoid inadvertent delays.
- Quantify sustainability exposure: use standard KPIs (PUE/WUE/CUE) to compare vendor and site options, and incorporate carbon cost into long‑term TCO analyses.
- Scenario plan for timing variance: run upside/downside scenarios that capture 18–36 month schedule variance on capacity deliveries and grid availability; align contractual protections and SLAs accordingly.
How to use the full PW Consulting report
This press brief is a strategic preview. The full Worldwide Modern AI Infrastructure Market study contains the granular tools and confidential annexes decision teams need to execute in 2026: detailed vendor scorecards, customizable TCO spreadsheets, procurement timeline templates, risk matrices for supply‑chain and regulatory exposures, and interactive scenario models that translate macro growth into specific capacity and cost outcomes for your organization.
We intentionally withhold granular regional and application splits from this public summary so that practitioners and procurement teams access the full, actionable intelligence via the official report portal. If your 2026 planning cycle includes capital allocation for AI infrastructure, the dataset and playbooks in the report will materially shorten your decision time and reduce execution risk.
Conclusion — act with urgency, but with design
The next 12–18 months are decisive. With market scale accelerating from hundreds of billions in 2025 toward the trillions by the early 2030s, organizations that synchronize vendor commitments, power planning and compliance will capture disproportionate advantage. PW Consulting’s report is designed to help you convert macro momentum into defensible, executable infrastructure strategies for 2026 and beyond.
For access to the full methodology, datasets, vendor heatmaps and practical playbooks, please consult the PW Consulting report landing page and contact our advisory team to schedule a briefing tailored to your program priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Modern AI Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Achondrogenesis Market Poised to Rise from USD 155.0 Million in 2025 to USD 226.75 Million by 2032 at a 5.59% CAGR
By PW Consulting, 2026-07-15
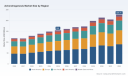
Worldwide Achondrogenesis Market: Strategic Imperatives for 2026
PW Consulting is pleased to release an executive preview of our Worldwide Achondrogenesis Market study — a practical, decision-focused intelligence product designed to equip life‑science and medical technology executives for the strategic choices that will matter in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report models the market in USD (revenue unit: Million) and projects a compound annual growth rate (CAGR) of 5.59% across the forecast period. From a base-year market size of USD 155.0 Million in 2025, our baseline forecast anticipates continued expansion, reaching an estimated USD 226.75 Million by 2032 under the core scenario.
Worldwide Achondrogenesis Market
Why this matters to C‑suite teams in 2026
-
The achondrogenesis market sits at the intersection of rare-disease diagnostics, prenatal care, and specialty pathology. That combination creates unique commercialization dynamics — high clinical value per patient, constrained patient volumes, and outsized importance of reimbursement and guideline adoption. Our study translates those dynamics into actionable priorities for product, commercial and corporate strategy through 2026 and beyond.
Worldwide Achondrogenesis Market -
The forecast trajectory (CAGR 5.59%) is robust enough to justify targeted investments, yet modest relative to many broad genetic or imaging markets — meaning capital deployment must be selective and highly evidence-driven.
Worldwide Achondrogenesis Market -
PW Consulting’s approach focuses on where value accrues across the chain: diagnostic innovation, validated clinical utility, payer acceptance, and scalable delivery models for low‑volume, high‑complexity care.
Report composition — practical deliverables
This study is structured to move teams from insight to execution. Major deliverables include:
-
Top‑line market sizing and forecast (2020–2032) with sensitivity and scenario analysis that quantifies upside/ downside paths tied to key variables (diagnostic adoption rates, reimbursement inflection points, and clinical guideline updates).
-
Market structure and concentration analysis that profiles systemic competitive forces and identifies white‑space opportunities for new entrants or incumbent expansion.
-
A stakeholder map and access playbook covering clinicians, reference labs, payers, and patient advocacy groups — with concrete tactics for evidence generation, KOL engagement, and reimbursement negotiation.
-
Regulatory and payer landscape assessment, including timelines and milestones likely to affect market access across major jurisdictions.
-
Commercial go‑to‑market playbooks: channel strategies, pricing frameworks for rare‑disease tests and services, and contract models for centers of excellence and reference laboratories.
-
M&A and partnership candidate screening methodology and a prioritized list of archetypal targets (technology providers, specialty service labs, and academic spinouts) suitable for different strategic intents — scale, capability, or geographic footprint.
-
Operational checklists for scaling diagnostics and pathology services for low-volume, high‑complexity conditions, including quality systems, sample logistics, and CAP/CLIA compliance considerations.
Market dynamics shaping 2026 decisions
-
Diagnostics innovation: Advances in genetic testing platforms, sequencing cost curves, and imaging resolution are lowering technical barriers to earlier and more accurate detection. Management teams must decide whether to pursue platform parity or invest in differentiated value (speed, interpretive algorithms, integrated reporting) that payers and clinicians will reward.
-
Evidence and guideline formation: For a rare and severe condition, a handful of high‑quality clinical studies and health‑economic dossiers can shift payer coverage and referral pathways. Companies that prioritize prospective evidence generation — tied to clinically meaningful endpoints and cost offsets — will unlock disproportionate commercial value.
-
Reimbursement and market access: Reimbursement variability remains the primary gating factor to scale. The path to sustainable revenue depends less on raw clinical sensitivity and more on demonstrable clinical utility, coding strategy, and early payer engagement.
-
Clinical workflow integration: Adoption is driven by how seamlessly a diagnostic or service fits into prenatal and perinatal care pathways. Solutions that reduce time‑to‑diagnosis and administrative friction (single‑report formats, streamlined sample logistics, teleconsultation backstops) materially improve uptake.
-
Concentration and competitive intensity: The market is neither atomized nor monopolistic. A moderate concentration profile indicates incumbent advantages in scale and relationships, but also room for focused challengers who can deliver differentiated clinical or operational value.
-
Policy and ethics landscape: Regulatory changes around prenatal testing, data privacy, and cross‑border sample shipment can alter market dynamics quickly. Strategic teams should maintain regulatory intelligence feeds and contingency plans for scenario responses.
Competitive landscape — strategic implications (without revealing proprietary data)
Our analysis shows moderate market concentration, with the combined revenues of the top three and five participants representing a material but non‑dominant share of the market. This structure creates three archetypal strategic positions:
-
Scale incumbents — who leverage channel relationships, breadth of services, and reimbursement expertise to defend margins;
-
Specialist challengers — nimble players who offer niche technical differentiation or superior clinical workflows; and
-
Adjunct innovators — primarily technology and platform providers whose IP can be embedded within lab services or hospital workflows.
For potential entrants and investors, the tactical takeaway is clear: identify where a firm’s capabilities convert into defensible value (speed, accuracy, cost‑of‑service, or payer acceptance) and build go‑to‑market models that neutralize incumbent strengths (for example, via partnership sales rather than direct competition). The full report provides a detailed evaluation framework and a set of anonymized capability‑to‑opportunity mapping tools to prioritize targets and partners.
Priority strategic actions for 2026
-
Prioritize clinical evidence that speaks to payers: Invest in studies that demonstrate not just diagnostic accuracy but how testing changes management and offsets downstream costs.
-
Commit to focused commercialization pilots: Test one or two clinical settings (e.g., tertiary prenatal centers or national reference networks) and iterate commercial model based on early payer and clinician feedback.
-
Design reimbursement‑first pricing: Use value‑based and bundled payment constructs to accelerate coverage decisions while protecting margins in low‑volume pathways.
-
Build interoperability and reporting standards: Clinicians adopt tools that reduce ambiguity. Standardized, actionable reporting that integrates with existing EHR workflows accelerates clinical utility realization.
-
Use M&A selectively to accelerate capability: Consider bolt‑on acquisitions to obtain specialized lab capacity, proprietary interpretive algorithms, or geographic access, rather than broad multi‑segment consolidation.
-
Establish a regulatory and payer war‑room: Proactively map approval timelines, coding updates, and payer evidence requirements to de‑risk launch sequencing across jurisdictions.
How to use this study in corporate planning
Executives should treat the PW Consulting report as a strategic playbook rather than a passive market snapshot. Specific applications include:
-
Capital allocation — prioritize resource deployment to initiatives with clear paths to payer acceptance and scalable operational models.
-
Portfolio prioritization — align R&D milestones and go‑to‑market investments to the scenarios that produce the largest revenue and strategic leverage over the forecast horizon.
-
M&A screening — apply the report’s screening matrix to sieve targets that meaningfully change market share or accelerate capability delivery.
-
Investor and board communications — use the forecast and scenario analysis to set realistic growth expectations and transparent milestone‑based investment cases.
Methodology — transparency on how the forecast was built
The report combines primary interviews across clinical, laboratory, and payer stakeholders, systematic review of published clinical literature, and a bottoms‑up market model that reconciles incidence, diagnostic pathways, and realistic adoption curves. Multiple sensitivity scenarios were modeled to reflect upside from accelerated guideline adoption and downside from reimbursement pressure or regulatory constraints. For transparency, the report includes a detailed appendix describing assumptions, data sources, and the modeling engine used to derive the 2026–2032 projections.
Next steps — getting the full intelligence
This press release is intentionally high‑level: it demonstrates the analytical rigor behind our conclusions while withholding granular segment and company‑level datasets that are exclusive to the full PW Consulting report. Clients and interested stakeholders are invited to access the complete study to obtain:
-
Detailed regional, type and end‑user segmentation tables and growth pathways;
-
Granular competitor benchmarking, capability heatmaps and anonymized acquisition targets;
-
Operational templates for pilot commercialization and payer submission dossiers;
-
Customized scenario outputs aligned to alternative strategic options.
PW Consulting stands ready to support executive teams in translating the report’s insights into a 100‑day action plan or longer‑term strategic program. For access to the full Worldwide Achondrogenesis Market report and advisory engagements tailored to your priorities, please visit the report landing page or contact our industry practice leaders.
For detailed analysis of this topic, please visit the official page: Worldwide Achondrogenesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Proctoscope Market Set to Expand at a 5.48% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Proctoscope Market — Strategic Trailer for 2026 Decision-Makers
PW Consulting’s latest market study, “Worldwide Proctoscope Market, 2026–2032,” is purpose-built to inform executive decisions in 2026. Drawing on a six-year historical baseline (2020–2025) and an actionable forecast window (2026–2032), the report synthesizes commercial, clinical, regulatory, and operational intelligence to guide product strategy, M&A screening, and commercialization plans. The global proctoscope market reached an estimated USD 245.5 Million in the base year (2025) and — under PW Consulting’s central scenario — is projected to grow at a compound annual growth rate (CAGR) of approximately 5.48% through 2032, reaching a materially larger addressable market by the end of the forecast period.
Worldwide Proctoscope Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year for many device firms as reimbursement, infection-control economics, and sterilization standards converge to reshape buying behavior across acute and outpatient settings. Our report isolates the inflection points that will determine winners and laggards.
Worldwide Proctoscope Market -
Decision focus: The analysis is tailored for leadership teams weighing investments in product line rationalization (disposable vs. reusable), aftermarket revenues (sterilization consumables, optics upgrades), and channel expansion into ambulatory surgical centers and outpatient clinics.
Worldwide Proctoscope Market -
Risk materiality: We translate regulatory and standards dynamics — including device classification, sterilization validation, and CDC reprocessing expectations — into quantifiable program implications for capital allocation, operating cadence, and go-to-market timing.
Key macro takeaways for boards and strategy teams
-
Steady, predictable market expansion: After a mid-cycle recovery from the pandemic years, the market is on a steady growth trajectory. This provides a stable backdrop for multi-year product investments and bolt-on acquisitions that can be amortized against reliable top-line expansion.
-
Polarized purchasing logic across care settings: Hospitals, ambulatory surgery centers (ASCs), and outpatient clinics are each converging on different value levers — cost-per-procedure, throughput, and infection-control risk management respectively. Manufacturers must map value propositions to these levers rather than rely on a one-size-fits-all commercial argument.
-
Material and process resilience matter: The predominance of medical-grade stainless steel (e.g., AISI 316L) for reusable instruments and the thermal demands of autoclave sterilization impose engineering and supply-chain constraints. Firms that lock in robust materials sourcing and provide validated sterilization protocols gain a durable competitive edge.
What’s inside the report (practical, actionable modules)
-
Executive dashboards: A concise, board-ready view of market size, trajectory, and three alternative scenarios with sensitivity to utilization rates and outpatient migration.
-
Commercial playbooks: Go-to-market blueprints for hospital sales, ASC-focused distribution, and value-based partnerships with large IDNs. Each playbook includes recommended pricing architectures, contracting tactics, and key performance indicators for the first 18 months of execution.
-
Product strategy frameworks: Decision trees for disposable vs. reusable portfolios that integrate clinical workflow, sterilization cost modeling, and lifetime-value calculations for capital equipment and consumables.
-
Regulatory and quality checklist: Practical checklists mapped to FDA device classification (Class I; product code FDT — 510(k) exempt where applicable), ISO 13485 quality management expectations, and ISO 17665 sterilization validation requirements.
-
Operational toolkits: Sterilization validation templates, CDC-aligned high-level disinfection protocols, vendor qualification scorecards, and a procurement RFx template for hospitals and ASCs.
-
Commercial diligence: Valuation multiples, margin profiles and go/no-go gates for M&A opportunities; plus standardized competitor battlecards to support integration planning and cross-selling strategies.
Competitive landscape — who matters and why
The market is moderately concentrated with a set of established medical-device incumbents and a handful of specialized manufacturers. Our qualitative concentration assessment indicates that a small group of global manufacturers collectively command a meaningful share of the market, leaving room for focused challengers and regionally dominant players.
-
Olympus Corporation (Tokyo): A legacy endoscopy leader with a strong portfolio in rigid anorectal instruments. Olympus’s strengths lie in clinical credibility, installed base relationships in gastroenterology, and integrated optics — positioning it well for bundled capital-equipment conversations with large hospital systems.
-
Karl Storz SE & Co. KG (Tuttlingen): Known for optical integration and reusable-system engineering. Karl Storz’s emphasis on high-quality optics and modular systems aligns with customers prioritizing long-term total cost of ownership and reprocessing ecosystems.
-
Richard Wolf GmbH (Knittlingen): A specialist in proctological visualization with established product families for direct rectal examination. The firm competes on surgical-grade instrument durability and clinician ergonomics.
-
PENTAX Medical (HOYA) (Tokyo): PENTAX leverages its endoscopy heritage to service colorectal applications. Its compatibility strategy — integrating proctoscopes into broader endoscopy platforms — is a commercial differentiator in integrated suite sales.
-
Baxter International / Welch Allyn (Deerfield, IL): A prominent supplier of disposable proctoscopes (e.g., single-use KleenSpec). Baxter’s proposition is infection-control simplicity and operational throughput benefits for outpatient and emergency settings.
-
HEINE Optotechnik (Herrsching): Focused on illumination and diagnostic sets, HEINE’s LED-enhanced proctoscopes address markets where visualization quality is the primary purchase criterion.
-
B. Braun Melsungen AG (Melsungen): A broad surgical instrument player offering stainless-steel proctoscopes suited for hospitals and surgical suites. B. Braun competes on margins, distribution reach, and clinical-service bundles.
-
Wallach Surgical Devices (Trumbull, CT): A competitive niche player delivering both disposable and reusable options for gynecological and proctological procedures — often winning with flexible SKU strategies tailored to outpatient clinics.
PW Consulting’s competitive matrices in the full report align product features, service models, and channel strategies against buyer archetypes — enabling acquirers, private-equity teams, and business-unit leaders to pinpoint where to attack or defend in 2026.
Regulatory, standards, and reimbursement context
-
Regulatory posture: In the U.S., proctoscopes are generally Class I with product code FDT and may be 510(k) exempt in many configurations. That regulatory simplicity reduces time-to-market for incremental hardware iterations but does not absolve manufacturers from rigorous quality systems and sterility validation.
-
Standards and sterilization: Compliance with ISO 13485 and validation against ISO 17665 for steam sterilization are baseline expectations. Reusable instruments must be validated for autoclave temperatures representative of hospital workflows, and engineering choices (e.g., AISI 316L stainless) materially influence long-term sterilization performance.
-
Clinical reprocessing risk: CDC guidance on high-level disinfection for reusable proctoscopes remains a critical constraint. Non-compliance raises infection-control liabilities and can materially depress device utilization in sensitive outpatient channels.
-
Reimbursement dynamics: Proctoscopy procedures are mapped to established CPT codes; today’s reimbursement environment creates a pragmatic ceiling on device pricing in low-acuity settings. Commercial strategies that capture operational savings, rather than relying solely on device premiuming, win faster adoption.
Strategic implications and near-term actions for 2026
-
Prioritize a segmented GTM: Recast commercial teams by buyer type rather than by product family. Hospitals value lifecycle support and capital integration; ASCs demand throughput and ease-of-use; clinics prioritize cost-per-procedure and infection control.
-
Develop a sterilization and validation proposition: Invest in vendor-agnostic sterilization validation packs and customer training to lower institutional adoption barriers for reusable systems.
-
Lock material supply and quality margins: Secure long-lead supply for medical-grade stainless and negotiate manufacturing contracts that include sterilization-stress testing to prevent late-stage engineering failures.
-
Design for hybrid portfolios: Offer interoperable product families that permit customers to migrate between disposable and reusable models without retraining or procurement friction. This reduces churn and creates upsell paths for consumables and optics services.
-
Use M&A tactically: Target bolt-on acquisitions that fill a distribution gap (e.g., ASC channels), add complementary consumables, or broaden single-use offerings to capture infection-control-driven adoptions quickly.
How PW Consulting supports execution
Beyond the market sizing and forecast, PW Consulting supplies executable deliverables: negotiation playbooks, integration checklists for acquisition targets, sterilization and reprocessing SOP templates, and a prioritized list of clinical partnerships that accelerate trials and formulary acceptance. Our market and competitive intelligence packs are designed to be operationally embedded within commercial plans for immediate 90–180 day impact.
Next step — where to get the complete intelligence
This article is a strategic preview designed to surface the key forces shaping the proctoscope market as you build 2026 plans. To access the full dataset, granular segmentation, competitive scorecards, and our 12-month implementation roadmap, please visit the PW Consulting report page. The full report contains the segment-level metrics, regional breakouts, and downloadable toolkits necessary to convert insight into action.
For tailored briefings, M&A screening, or to commission a customized regional deep-dive that aligns directly with your 2026 priorities, PW Consulting’s healthcare devices practice is available for confidential engagements.
For detailed analysis of this topic, please visit the official page: Worldwide Proctoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Augmented Bone Graft Market Forecast to Reach USD 6.30 Billion by 2032 at a 6.18% CAGR
By PW Consulting, 2026-07-15
PW Consulting Releases Strategic Brief: Worldwide Augmented Bone Graft Market — The 2026 Decision Playbook
PW Consulting today publishes a strategic industry brief accompanying our comprehensive Worldwide Augmented Bone Graft Market report, structured to help executives, corporate development teams, and investors make high‑conviction decisions as they enter 2026. Anchored on the 2025 base year, our analysis shows the market expanding from roughly USD 3.1 billion in 2020 to USD 4.14 billion in 2025, and we forecast continued growth at a compound annual growth rate (CAGR) of approximately 6.18% through the 2026–2032 horizon, reaching an estimated USD 6.30 billion by 2032. This brief highlights the actionable insights and strategic levers the full report provides — while deliberately reserving granular segment-level disclosures to the full report to preserve competitive value for subscribers.
Worldwide Augmented Bone Graft Market
Why this report matters to 2026 strategy
-
Timing: 2026 is a pivot year for many players. Incremental reimbursement shifts, new hospital procurement strategies, and a wave of clinical data updates are converging to create both consolidation and product differentiation opportunities. Our forecast and scenario analyses quantify the risk/reward tradeoffs for near-term investments versus longer-term platform plays.
Worldwide Augmented Bone Graft Market -
Evidence-driven entry points: The market is neither a commodity nor a narrow niche — it is an innovation arena that rewards clinically validated technologies, clear supply chain resilience, and targeted commercial models. The report’s proprietary go‑to‑market matrices map evidence generation cadence to revenue capture timelines to inform clinical, regulatory, and commercial sequencing decisions.
Worldwide Augmented Bone Graft Market -
Concentration matters: The market exhibits a meaningful degree of concentration — our concentration metrics show the top three firms account for just under half of the market, while the top five control roughly two-thirds — signaling both barriers and runway for challengers with differentiated offerings or superior clinical data.
What the full report delivers (practical, operational intelligence)
-
Executive playbooks: 10 bespoke playbooks tailored to specific corporate archetypes — incumbent medtech leaders, mid‑cap specialists, private equity sponsors, and early-stage developers — each outlining prioritized initiatives, required evidence, and a 24‑month roadmap to commercial inflection.
-
Demand-model toolkit: A downloadable, modifiable revenue model keyed to clinical adoption curves, procurement cycles, and reimbursement sensitivity. Users can stress‑test pricing, adoption lag, and market access scenarios to derive ROI breakpoints for new product introductions and M&A targets.
-
Regulatory & reimbursement playbook: Actionable guidance grounded in current regulatory classifications and reimbursement landscapes, including device class considerations and DRG/CPT interactions. The brief synthesizes how 510(k) pathways and public payer dynamics will influence launch sequencing and hospital contracting tactics in 2026.
-
Clinical evidence prioritization matrix: A ranked list of the most value-accretive clinical endpoints and study designs by indication and channel (hospital, ASC, dental), enabling efficient allocation of limited R&D budgets toward studies that materially change payer coverage and purchasing committees’ decisions.
-
Supplier & manufacturing diagnostics: Risk assessment templates for sterilization, supply continuity, and material cost volatility, including mitigation strategies for raw material exposures and third‑party tissue processors.
Competitive landscape: who to watch and why
The space blends large, diversified medtech incumbents and focused graft specialists. Leading global firms continue to leverage scale, installed relationships, and portfolio breadth. Notable strategic profiles in our analysis include:
-
Medtronic — a market leader with a clinically established recombinant BMP product. Its scale and multi‑year hospital agreements can set benchmarks for pricing and formulary placement, but regulatory and safety considerations for biologic-augmented products require ongoing evidence management.
-
Stryker — positioning synthetic bioactive substitutes with advanced carrier chemistry to address orthopedic voids, emphasizing ease of use and supply reliability for surgeons in high-volume settings.
-
Zimmer Biomet & DePuy Synthes — large orthopedic platform players that integrate synthetic matrices and DBM offerings into broad implant and trauma portfolios, focusing on bundle selling to OR teams and comprehensive clinical pathways.
-
Specialist players (Orthofix, Integra LifeSciences, Globus Medical, Xtant, RTI Surgical, AlloSource, Cerapedics) — these firms compete on product differentiation (e.g., viable cell allografts, peptide augmentation, nanostructured hydroxyapatite), specialized clinical claims, and nimble commercial execution in targeted indications.
Recent corporate moves underline the market’s twin dynamics of consolidation and targeted expansion: clinical study releases that materially affect adoption, regulatory clearances unlocking new geographies, and distribution deals that rapidly scale access. For example, in 2024 several firms announced significant partnerships and clinical updates that the report analyzes in depth to show how such events typically translate into share shifts over 12–36 months.
Market dynamics that will shape 2026 outcomes
-
Regulatory posture: Most bone graft substitutes fall under established device classifications with clear 510(k) pathways. That said, the intersection of biologic augmentation and device classification creates strategic choices: invest in biologic-grade evidence or pursue device equivalence for faster market entry.
-
Reimbursement complexity: Public payer and DRG dynamics vary by procedure setting and graft type. Payer sensitivity to per‑procedure spend means pricing strategies must be aligned with demonstrable clinical or economic benefits — our reimbursement impact maps show where premium pricing is defendable.
-
Supply chain & sterilization: Allograft sourcing and processing standards drive buyer selection. Compliance with established sterilization doses and chain‑of‑custody protocols is a table-stake; suppliers that can demonstrate resilient logistics and validated sterilization processes reduce hospital procurement friction.
-
Material cost and manufacturing economics: Synthetic materials such as beta‑TCP remain cost drivers; controlling raw material exposure and improving yield are critical levers to protect margins without compromising clinical performance.
-
Safety risk profile: Products with biologic augmentation retain a higher bar for post‑market surveillance. Well‑publicized safety advisories affect adoption curves, so firms must pair product chemistry advances with rigorous risk management and clinician education programs.
Strategic recommendations for 2026 (executive checklist)
-
Prioritize clinical programs that shorten the time to meaningful payer coverage or enable premium pricing: single pivotal studies that demonstrate superiority on fusion or revision avoidance deliver outsized commercial returns.
-
Evaluate tuck‑in M&A to secure sterile allograft supply, fill complementary indication gaps, or acquire differentiated synthetic chemistries — our model identifies valuation bands where such deals are accretive within two years.
-
Negotiate multi‑year hospital contracts with staged pricing tied to real-world outcome metrics; hospitals are increasingly receptive to outcome‑based arrangements that shift procurement decisions away from single‑transaction pricing.
-
Invest in sterilization and cold-chain proof points for allograft suppliers; a small capex allocation to demonstrable supply resilience can materially lower contracting friction with large systems.
-
Design post‑market evidence programs up front: registry integration, pragmatic trials, and real-world evidence packages accelerate uptake and mitigate safety‑perception liabilities in biologic-augmented segments.
Risk factors and what to monitor
-
Regulatory reinterpretation of device vs. biologic boundaries could alter approval timelines and evidence requirements; monitor policy signals and FDA guidances closely.
-
Reimbursement shifts or DRG bundling could compress per‑procedure economics; scenario models in the report show thresholds where commercialization becomes unprofitable without price or utilization improvements.
-
Safety communications for bioderived or BMP-based products can depress adoption rates; proactive risk management and clinician engagement reduce downside exposure.
How to use this brief and where to find the full intelligence
This briefing is a curated executive distillation of the larger market study. The full PW Consulting Worldwide Augmented Bone Graft Market report contains the detailed segmentation, regional and application breakdowns, supplier scorecards, financial models, scenario stress‑tests, and the downloadable demand‑model toolkit referenced above. In adherence to our “trailer” approach, we intentionally omit the granular segment-level datapoints here to preserve the competitive advantage of subscribers and to drive direct engagement with our analysts for bespoke modeling.
For teams preparing budgets, M&A pipelines, or clinical development plans for 2026, the full report and our consulting workshops provide the operational playbooks, evidence sequencing, and negotiation templates needed to convert market insights into measurable outcomes. Contact PW Consulting to schedule a briefing or to obtain access to the full report and accompanying financial models.
Conclusion
The augmented bone graft market is maturing into a high‑value, clinically driven market where evidence, supply reliability, and commercial agility determine winners. With total market size expanding materially from 2020 through 2025 and a robust mid‑single‑digit CAGR projected for the 2026–2032 period, companies that pair product differentiation with disciplined evidence and access strategies will capture disproportionate value. PW Consulting’s full report equips decision makers with the models, playbooks, and scenario analyses needed to act confidently in 2026 — and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Augmented Bone Graft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Okra Seeds Market Poised for 8.15% CAGR — Forecast to Reach USD 661.86 Million by 2032 with Asia Pacific Leading at USD 248.11 Million
By PW Consulting, 2026-07-15
Worldwide Okra Seeds Market 2026: Strategic Preview for Executive Decision-Making
Executive Snapshot
As global food systems reorient toward resilient, high-value horticulture, the worldwide market for okra seeds has moved from niche to strategic crop within vegetable seed portfolios. PW Consulting’s latest market study — covering historical performance (2020–2025), using 2025 as the base year, and providing a detailed forecast through 2032 — finds sustained expansion with a compound annual growth rate (CAGR) of 8.15% over the projection period. The market more than recovered from early-decade volatility and is on a trajectory that will materially influence seed suppliers, input manufacturers, and downstream processors by 2026 and beyond.
Worldwide Okra Seeds Market
Why 2026 Is a Pivotal Year for Strategic Choices
Three converging dynamics make 2026 a decision inflection point for companies in and around the okra value chain:
Worldwide Okra Seeds Market
- Commercialization momentum: Breeding advances and the rapid adoption of hybrid varieties have accelerated productivity catch-up in key warm-climate producing regions.
- Competitive consolidation: A measurable increase in M&A and strategic partnerships is reshaping supplier footprints and breeding pipelines, compressing windows for market entry.
- Input and regulatory pressure: Fertilizer availability, irrigation practices, and national variety registration programs are altering the cost and speed of route-to-market for new cultivars.
Market Trajectory — A High-Level View
PW Consulting’s topline analysis tracks a clear recovery and growth arc. From the low-to-mid 200s (USD Million) in the early 2020s the market expanded to a stronger base by 2025, and our deterministic and scenario models show continued expansion toward the end of the forecast horizon. This expansion is not uniform: it is driven primarily by hybrid-seed adoption, intensification of protected and irrigated systems in select producing corridors, and higher-value commercialization pathways for smallholder and commercial growers.
Worldwide Okra Seeds Market
What the Report Delivers — Practical, Decision-Ready Content
The study is intentionally operational. Executives will find content designed to convert insight into action, including:
- Demand drivers and elasticity assessment — dissecting consumer, processor, and institutional procurement signals that accelerate okra seed uptake.
- Grower economics and input sensitivity — granular scenarios showing how fertilizer costs, irrigation cadence, and labor constraints change variety profitability under realistic price paths.
- Go-to-market playbooks — channel strategies and pricing frameworks for launching varieties in emerging and established markets, with risk-adjusted timelines for registration and scaling.
- M&A and partnership screening — a ranked, evidence-backed shortlist of acquisition and licensing targets, plus integration templates based on observed post-deal value capture.
- Regulatory and seed-health roadmaps — compliance checklists and timeline maps for variety release, seed certification, and phytosanitary clearance across priority jurisdictions.
- Scenario planning toolkit — three ready-to-run scenarios (base, accelerated adoption, and constrained inputs) with P&L and cash-flow implications for seed companies and agribusiness investors.
Competitive Landscape — Who Matters and Why
The market is moderately concentrated: the top three firms hold a substantial share of commercial hybrid activity, and the top five amplify that share further. This concentration drives both opportunity and competitive risk. Key players profiled in the report include global multinationals and specialized regional champions:
- Syngenta Group (Switzerland) — a leader in hybrid breeding with focus on disease resistance and tropical adaptation for commercial vegetable production worldwide.
- Bayer AG / Nunhems (Germany) — active in virus-resistant seed development and early-harvest varieties, with strong seed-quality positioning.
- Advanta Seeds (UPL) (India) — sizeable hybrid portfolio and deep regional distribution in Asia and Africa, emphasizing locally adapted, disease-tolerant hybrids.
- Sakata Seed Corporation and Takii (Japan) — breeding depth and product launches tailored for African and Asian producers.
- East-West Seed (Thailand) — specialization in tropical vegetables and strong smallholder outreach and extension capability.
- A competitive cohort of Indian seed houses (including Mahyco, Nuziveedu, Kaveri, and others) — commanding domestic scale and increasingly active in export-oriented strategies.
- Specialty and heirloom suppliers (US and niche Europe providers) — addressing small-scale, heirloom, and premium-market demand.
Our report provides comparative capability matrices, R&D investment estimates, and go-to-market speed scores for each player — enabling acquirers and competitors to map realistic threat and partnership corridors without exposing proprietary breeding or revenue line items.
Recent Developments Shaping 2026 Choices
- Portfolio consolidation through acquisition has accelerated: recent strategic buys broaden vegetable seed pipelines and shorten breeding-to-market timelines — an outcome that increases the value of scalable seed multiplication assets.
- International breeding programs have renewed focus on okra: coordinated releases and working groups are establishing pipeline standards and pre-competitive germplasm exchanges, with implications for licensing and trait-deployment strategies.
- Market introductions of regionally adapted hybrids — from commercial firms and research centers — are already changing adoption curves in Africa and parts of Asia, compressing the commercialization timeline for followers.
Input, Regulatory and Operational Dynamics to Monitor
Operational realities materially affect varietal performance and adoption economics. Key dynamics detailed in the report include:
- Fertilizer and irrigation practices: Empirical agronomy shows that balanced macronutrient application and periodic supplemental irrigation materially improve fruit set and yields under smallholder systems — making irrigation and fertilizer access strategic levers for seed companies considering bundled propositions.
- Labor and gender dynamics: High hired-labor costs and limited access to credit constrain some segments of grower populations, particularly female smallholders. Seed strategies that reduce labor intensity or enable mechanizable practices will gain traction.
- Regulatory pathways: National variety releases and seed registration processes remain a gating factor; investments in regulatory liaisons and targeted trial programs can cut 12–24 months off market entry in priority countries.
- Domestic input investments: Public programs and private fertilizer production expansions in major markets are lowering input costs in certain jurisdictions — a tailwind for varietal adoption that companies must model regionally.
Strategic Playbook for 2026
Companies that move from passive monitoring to affirmative strategy in 2026 will capture disproportionate value. PW Consulting recommends the following priority plays:
- Accelerate tiered-breeding launches: Combine a “rapid-deployment” hybrid for immediate channel capture with a longer-term elite line that targets processing and export quality. Use staged IP and licensing to monetize early yields while protecting flagship germplasm.
- Bundle seeds with agronomy services: Offer input credit, optimized fertilizer packages, and irrigation scheduling to improve grower economics and lock in seed loyalty.
- Pursue bolt-on acquisitions for scale in seed multiplication and distribution hubs rather than broad-spectrum M&A; this reduces integration risk and speeds market supply during peak seasons.
- Invest in public–private breeding consortia: Participating in pre-competitive platforms grants early sight of favorable germplasm and regulatory advocacy benefits in markets where variety approval is a bottleneck.
- Use scenario modeling for capital allocation: Stress-test pipeline investments against fertilizer price shocks, labor shortages, and delayed registrations to prioritize flexible, low-capex deployment options.
Report Access and Strategic Value
PW Consulting’s Worldwide Okra Seeds Market report is built as a practical decision-support tool for CEOs, corporate strategy teams, and institutional investors planning moves in 2026. It combines market-sizing and CAGR-based forecasts with playbooks, M&A screens, and regulatory roadmaps — all calibrated to meet the exigencies of that planning year. While this preview highlights high-level trajectories and competitive themes, the full report contains the specific segmentation analyses, pricing matrices, regional rollout sequencing, and company-level benchmarking that are essential for transaction diligence and roll-out planning.
Conclusion — Time-Sensitive Opportunity
Okra seed markets are at an inflection where breeding progress, commercial consolidation, and input dynamics create both opportunity and urgency. By 2026, firms that have aligned germplasm strategy, channel partnerships, and regulatory readiness will define competitive advantage. PW Consulting’s full study provides the actionable maps and models required to make those choices with confidence.
To evaluate tailored strategic options and receive the complete dataset, segmentation matrices, and company dashboards referenced in this preview, please consult the full PW Consulting Worldwide Okra Seeds Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Okra Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Gracey Curette Market Poised to Grow at 6.85% CAGR, Reaching USD 341.86 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Gracey Curette Market — Strategic Outlook 2026: Executive Release
Introduction
PW Consulting’s new market study, Worldwide Gracey Curette Market (base year 2025; forecast period 2026–2032), provides an action-oriented intelligence package designed to inform boardroom decisions and commercial plans in 2026. The report synthesizes historical performance, forward-looking forecasts, regulatory and clinical dynamics, and a practitioner-focused competitive playbook — all curated to help manufacturers, distributors, dental service organizations, and private equity investors convert market signals into executable value.
Worldwide Gracey Curette Market
Market snapshot: scale, trajectory and near-term implications
Gracey curettes remain a defined but strategically important category within periodontal instruments. From 2020 through the 2025 base year the market demonstrated steady expansion driven by recovery in elective dental procedures, increasing clinical awareness of periodontal disease management, and incremental adoption of instrument enhancements that extend lifecycle and clinical ergonomics. On a baseline of 2025, the category is projected to resume top-line momentum across the 2026–2032 forecast window at a compound annual growth rate of approximately 6.85%, with the market approaching a materially larger size by the end of the period. These macro dynamics create a predictable runway for investment in product innovation, service models (e.g., re-sharpening and refurbishment), and channel optimization to capture outsized share versus inert incumbents.
Worldwide Gracey Curette Market
Regulatory, standardization and clinical reprocessing context
- Regulatory classification: Gracey curettes are positioned as low-risk class I medical devices in key jurisdictions; for example, they are exempt from premarket 510(k) notification under the referenced FDA classification. This lowers barriers to market entry for new designs, but also raises the bar for commercialization teams to differentiate through manufacturing quality and clinical evidence rather than regulatory exclusivity.
- Standards and materials: Instrument manufacturers generally align product specifications to international surgical instrument standards and commonly utilize medical-grade stainless steel to meet durability and corrosion resistance expectations. This standardized baseline enables suppliers to compete on coating technologies, heat treatment, and handle ergonomics.
- Sterilization and reprocessing: Steam autoclaving remains the de facto reprocessing method in clinical settings. Operational decisions around instrument lifecycle — frequency of sharpening, sterilization throughput, and instrument set composition — materially affect clinic-level purchasing patterns and total cost of ownership (TCO).
- Reimbursement and utilization: Periodontal procedures that require manual curettes are embedded in established CDT codes and clinical care pathways, which sustains baseline demand while creating pockets of opportunity where bundled care models or preventive programs expand utilization.
What the PW Consulting report delivers — practical outputs for 2026 action
This study was developed as a practitioner’s manual rather than a purely descriptive report. Core deliverables include:
Worldwide Gracey Curette Market
- Transparent market-sizing methodology and a downloadable model that supports scenario analysis and sensitivity testing for price, adoption and service revenue levers.
- Actionable buyer personas for procurement decision-makers in private dental clinics, hospital dental departments and academic/research institutions — with tender templates and selection checklists aligned to sterilization workflows and clinical ergonomics.
- Competitive playbooks for manufacturers and distributors: product positioning, route-to-market play variants (direct, distributor, OEM partnerships), and sample commercial arrangements to trial in 2026.
- Supplier scorecards and capability matrices, enabling rapid shortlisting of contract and OEM partners based on manufacturing quality, supply continuity, and after-sales services (e.g., sharpening programs, training).
- Pricing and margin benchmarking across product tiers and service bundles — model-ready inputs designed to inform 2026 budget cycles without disclosing micro-level segment data in this release.
- M&A and partnership screening criteria, including target archetypes (niche precision manufacturers, regional distribution scale players, aftercare service providers) and illustrative valuation sensitivities.
- Regulatory and sterilization compliance checklists intended for procurement and clinical operations teams to accelerate onboarding and reduce adoption friction.
Competitive landscape — who matters and why
The market combines legacy instrument houses with specialized innovators. Our competitive assessment profiles companies that shape clinician preference through differentiated value propositions. Representative players highlighted in the report include:
- Hu-Friedy Group (Chicago, Illinois) — a premium-tier portfolio that focuses on high-precision Gracey variants and a broad clinical marketing footprint. Their product family emphasizes fine-edge geometries and clinician training programs to preserve procedural efficacy.
- LM-Dental (Kuopio, Finland) — known for coated instruments (diamond-like carbon and similar technologies) and ergonomic handles designed to reduce hand fatigue and extend cutting life, aligning with clinics that prioritize occupational health and long-run TCO.
- American Eagle Instruments (Mount Vernon, Washington) — differentiates on ultra-light, hollow-handle designs and proprietary sharpening technologies, supporting buyers that value repeated-edge performance and reduced instrument mass for repetitive procedures.
- Paradise Dental Technologies (Colton, California) — offers color-coded instrument families with miniaturized shapes for hard-to-reach anatomy, supporting clinical workflows that require rapid identification and procedural efficiency.
- Nordent Manufacturing (Woodinville, Washington), G. Hartzell & Son (Auburn, Washington), Young Dental (Earth City, Missouri), and Kerr Dental (Orange, California) — each brings a distinct mix of heat-treatment processes, traditional craftsmanship, and distribution access that matter differently across private practice, hospital and academic channels.
Our analysis emphasizes that competition is not a binary ‘price vs. premium’ axis; rather, it is multi-dimensional — involving edge-retention technology, handle ergonomics, after-sale sharpening services, clinical training and distribution reach. The practical implication for 2026 is that differentiated go-to-market moves yield superior margin expansion compared to participating in generalized price competition.
Key innovation and commercial trends to watch in 2026
- Edge longevity technologies: Coatings, advanced heat treatments and sharpening services are converting what were once commoditized consumables into multi-year assets for clinics, shifting conversations from unit price to lifecycle cost.
- Ergonomics and clinician health: Hollow handles, lighter materials, and tactile designs are increasingly marketed as productivity and occupational-health enhancers, a message that resonates in high-volume practices and corporate dental groups.
- Service-led differentiation: Manufacturers that bundle sharpening, inspection, and sterilization consumables with instrument sales create recurring revenue and lock-in — a commercially attractive model for both large suppliers and niche specialists.
- Channel digitization: Direct-to-practice e-commerce and digital catalogues with replenishment reminders reduce procurement friction and create opportunities for subscription models targeted at private clinics.
Strategic recommendations for 2026 decision-makers
For senior executives and procurement leaders planning investments or commercial pivots in 2026, the PW Consulting study translates market signals into prioritized, time-bound actions:
- Adopt TCO procurement criteria: Move beyond unit cost to include edge retention, service availability (sharpening/repair), sterilization throughput impact and clinical downtime. Shortlist suppliers on composite TCO metrics during RFPs.
- Pursue product-service bundles: Manufacturers should pilot sharpening-as-a-service and bundled sterilization consumables to capture incremental recurring revenue and deepen customer relationships.
- Segment go-to-market by buyer archetype: Tailor commercial offers for high-frequency private clinics (focus on ergonomics and subscription replenishment) versus institutional buyers (emphasize compliance, fleet pricing and traceability).
- Invest selectively in differentiation: Prioritize coatings, heat treatment or handle ergonomics that demonstrably improve lifecycle and clinician comfort — capture early-adopter clinics via trials supported by data and clinician testimonials.
- Mitigate supply risk through multi-source strategies: For buyers, dual-sourcing critical instruments and qualifying regional manufacturers for redundancy are pragmatic steps to protect operations in 2026.
- Evaluate M&A targets that extend service capabilities: Private equity and trade buyers should evaluate targets that provide complementary service revenues (re-sharpening, inspection) to increase recurring EBITDA.
- Validate compliance and sterilization protocols early in procurement cycles: Ensure instrument specifications align with ISO and sterilization best practices to avoid adoption delays in clinical settings.
Why PW Consulting’s report matters for 2026
Decisions taken in 2026 will be shaped by a market that is predictable in macro trajectory but nuanced at the product and channel level. The forecast tenor — underpinned by a mid-single-digit CAGR — signals steady growth sufficient to justify targeted investments, but not so rapid as to excuse poor go-to-market execution. Our report provides the tactical blueprints, financial models and vendor-grade scorecards you need to convert a stable market outlook into measurable commercial advantage.
Next steps and access
This executive release highlights strategic takeaways and directional analysis. For full subsegment detail, downloadable forecasting models, supplier scorecards, and bespoke scenario builds that you can deploy in next year’s planning cycle, please visit PW Consulting’s Worldwide Gracey Curette Market report page. The full study includes confidential appendices that disclose granular segmentation, channel economics and clinical utilization models — indispensable inputs for any stakeholder preparing for 2026 market action.
Contact PW Consulting for a tailored briefing or to commission 1:1 advisory that applies these findings directly to your commercial objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Gracey Curette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


