



PW Consulting: Cerebrovascular Accident Drug Market Hits USD 16,850 Million in 2025, New Report Reveals
By PW Consulting, 2026-07-13
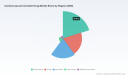
Cerebrovascular Accident Drug Market — 2026 Strategic Preview
PW Consulting today publishes an executive preview of our forthcoming Cerebrovascular Accident (CVA) Drug Market report — a focused, decision-grade briefing designed to arm senior executives, investors, and health-system leaders with the commercial intelligence they need to make high-consequence choices in 2026. Using 2025 as the base year and a seven-year forecast through 2032, our modelling shows the global CVA drug market at USD 16,850 million in 2025 and expanding at a compound annual growth rate (CAGR) of 6.45% to reach approximately USD 26,099 million by 2032. This preview highlights the strategic inflection points embedded in that growth trajectory while intentionally withholding the granular subsegment tables and regional splits contained in the full report; those datasets are available only through the complete publication.
Cerebrovascular Accident Drug Market
What senior leaders should take away
-
Market momentum is structural, not cyclical — growth is driven by an intersection of therapeutic innovation (new thrombolytics and oral anticoagulants), evolving acute-stroke practice guidelines, and ongoing investments in secondary prevention.
Cerebrovascular Accident Drug Market -
Regulatory and guideline catalysts in 2025–2026 materially change near-term commercial dynamics: the March 2025 FDA approval of tenecteplase (TNKase) for acute ischemic stroke and the February 2026 American Heart Association guideline update that endorses tenecteplase as an alternative to alteplase expand the set of reimbursable, guideline-concordant thrombolytic options.
Cerebrovascular Accident Drug Market -
Consolidation at the top of the value chain is meaningful — our concentration metrics indicate that the top three and five firms together capture a dominant share of commercial value, shaping pricing, access and hospital adoption patterns.
-
New mechanisms of action (notably Factor XIa inhibitors) are progressing into late-stage programs with favourable Phase 3 readouts, creating near-term opportunities in secondary prevention that will reconfigure formulary decisions and partnership strategies.
Why this matters for 2026 decision-making
-
Launch sequencing and clinical-readiness: For first- or next-in-class thrombolytic launches, 2026 is a pivot year. Tenecteplase’s single-bolus dosing and the extended thrombectomy window endorsed in recent guidelines change in-hospital workflows — and therefore the commercial levers that drive uptake. Companies must prioritize acute-care channel readiness (emergency medicine, neurology, interventional radiology) and real-world evidence (RWE) generation to accelerate adoption.
-
Payer and hospital contracting: With thrombolytics now including multiple guideline-backed options, payers and health systems will negotiate around pathway costs, administration logistics, and outcomes. Manufacturers that can demonstrate pathway efficiencies, total cost-of-care benefits, and lower hospital length-of-stay will win favorable formulary placement.
-
Secondary prevention redefinition: Positive Phase 3 signals for Factor XIa inhibitors create a bifurcated market — established anticoagulants maintain a broad preventive role while novel agents pursue label expansions on risk-reduction endpoints. Strategic alliances between developers and cardiovascular partners can accelerate market access and strengthen lifecycle value.
-
Supply-chain and manufacturing risk: Thrombolytic active ingredients (recombinant tPA variants) rely on biologic manufacturing capacity; scaling constraints and quality risk will influence procurement strategies and M&A timing.
Competitive landscape — who’s shaping the market
The competitive map is being redrawn by a mix of legacy thrombolytic producers and innovators pursuing secondary-prevention pathways. Incumbent developers of alteplase and tenecteplase have immediate advantages in hospital relationships and distribution. At the same time, major pharmaceutical groups with large cardiovascular portfolios — and biotechs focused on coagulation biology — are advancing next-generation oral agents and combination strategies that seek to meaningfully reduce recurrence risk.
-
Genentech (Roche Group): Holds the unique commercial position of having two FDA-approved thrombolytics for acute ischemic stroke, and the March 2025 approval of TNKase (tenecteplase) as a single 5-second IV bolus is a disruptive clinical convenience that shifts in-hospital protocols.
-
Boehringer Ingelheim: Continues to be an established thrombolytic supplier outside certain territories, maintaining deep clinician relationships that matter for rapid adoption in regional markets.
-
Bayer and other large pharmas (BMS, Pfizer, AstraZeneca, Sanofi, Daiichi Sankyo, Novartis, Johnson & Johnson): These firms are active across anticoagulant and antiplatelet portfolios and are positioned to exploit synergies between prevention and acute care. Bayer’s positive Phase 3 OCEANIC-STROKE results (asundexian + antiplatelet) in November 2025 exemplify the tactical advantage of combining novel MOAs with established regimens.
Our concentration analysis shows a market where the top three and five firms account for a substantial share of commercial value, producing competitive dynamics that favour scale, integrated portfolios, and rapid access capabilities. For smaller innovators, the path to commercial relevance will frequently run through strategic partnerships, licensing, or targeted regional launches.
Report contents — practical, transaction-ready deliverables
The full PW Consulting CVA Drug Market report is designed for operational use by commercial teams, corporate development, and health-system planners. Key deliverables include:
-
A validated top-down market model with base-year 2025 sizing and 2026–2032 forecasts, plus scenario-sensitive outputs to stress-test regulatory, pricing, and uptake assumptions.
-
Pipeline and clinical-milestone tracker mapped to commercial outcomes, with timelines, probability-of-success adjustments, and headline competitive reactions for near-term regulatory events.
-
Go-to-market readiness checklists for acute-care launches (hospital pathway integration, emergency department kits, training programs, and RWE protocols).
-
Reimbursement and contracting playbooks tailored to major payer archetypes and typical hospital procurement processes.
-
Manufacturing and supply-risk matrix highlighting biologic capacity constraints, critical raw-material dependencies, and recommended mitigation steps.
-
M&A and partnership heatmaps identifying logical counter-parties by therapeutic focus, asset maturity, and commercial fit (note: the preview omits the detailed target scorecards).
-
Interactive dashboards and downloadable datasets (full subsegment tables and regional splits are included in the licensed deliverable).
Five strategic moves for 2026
-
Prioritize guideline-aligned evidence generation: Invest immediately in pragmatic RWE and registry studies that demonstrate tenecteplase or novel anticoagulants’ impact on door-to-needle times, reperfusion rates, and net hospital costs.
-
Design hospital-first commercial models: Focus sales resources on stroke centers and integrated stroke teams, offer protocol-support services, and bundle training with supply contracts to overcome inertia in acute-care adoption.
-
Secure biologic manufacturing capacity: For firms reliant on recombinant tPA variants, commit to capacity reservations or contract-manufacturing partnerships now to avoid downstream supply bottlenecks as uptake accelerates.
-
Engage payers with total-cost-of-care narratives: Build modeling that quantifies cost offsets from reduced disability, shorter lengths of stay, and fewer readmissions — then use that evidence in contracting and value-based arrangements.
-
Consider strategic combos and co-development: For developers of secondary-prevention agents, early alignment with antiplatelet or device partners can provide complementary clinical claims and faster payer recognition.
Why PW Consulting’s analysis is different
Our approach combines rigorous epidemiology, commercial-readiness metrics, and actionable scenario planning. We purposely link clinical milestones to commercial inflection points so that licensing teams, BD executives, and hospital strategy groups can convert clinical wins into sustainable revenue streams. The full report includes source-verified event timelines, a proprietary adoption-lag model, and an executable launch roadmap — elements crafted to reduce time-to-decision and increase the probability of successful market entry.
Next steps — access and engagement
This preview intentionally excludes detailed subsegment tables and regional breakdowns to preserve the full analytical value of the report for licensed users. To access the complete dataset, interactive models, and the proprietary competitive scorecards, visit PW Consulting’s report page or contact our strategy team to schedule a tailored briefing and scenario workshop. For executives preparing 2026 budgets and M&A pipelines, early engagement yields the greatest optionality.
Contact: strategic-insights@pwconsulting.com | Report access: https://www.pwconsulting.com/reports/cva-drug-market-2026
As clinicians, regulators, and payers update practice and policy in response to recent approvals and trial readouts, the window to shape product positioning, contracting, and partnership strategies is narrow. PW Consulting’s CVA Drug Market report translates recent clinical progress and market dynamics into a clear set of commercial actions — enabling leaders to convert 2026 turns of the market into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Cerebrovascular Accident Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Automotive Connecting Rod Bush Market to Grow at a 3.82% CAGR Through 2032
By PW Consulting, 2026-07-13
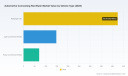
Automotive Connecting Rod Bush Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market intelligence briefing offers a forward-looking, executive-grade appraisal of the global Automotive Connecting Rod Bush market. Built on a 2025 base year, our analysis synthesizes historical performance (2020–2025) and a granular forecast window (2026–2032) to translate market dynamics into actionable choices for OEMs, suppliers, aftermarket players and strategic investors. This preview highlights the report’s strategic value for calendar‑year 2026 planning while deliberately withholding the full segmented tables and proprietary model outputs to encourage review of the complete dossier.
Automotive Connecting Rod Bush Market
Market snapshot — what the headline numbers tell you
-
Market scale and trajectory: The global market stands on a steady expansion path. From a measured market value of USD 642.5 Million in our 2025 base year, the model projects growth at a 3.82% compound annual growth rate (CAGR) across 2026–2032, reaching an estimated USD 835.28 Million by 2032. The market is already showing consistent year‑on‑year gains in the 2023–2025 period that underpin our near‑term baseline.
Automotive Connecting Rod Bush Market -
Concentration and competitive structure: Market concentration is moderate. The top three firms collectively account for a meaningful share of industry revenues, and the top five raise that share appreciably — a structure that supports both scale advantages and pockets of regional/technical specialization.
Automotive Connecting Rod Bush Market -
Forecast horizon: Our scenario suite covers a central case (3.82% CAGR), conservative and upside cases, and sensitivity runs that stress raw‑material price shocks, accelerated electrification, and regulatory-driven replacement demand.
Why this report matters for 2026 strategy
-
Decision timing: 2026 is a pivotal year for capital allocation and product roadmaps. OEMs and Tier‑1/2 suppliers will finalize mid‑cycle product updates and capacity plans; our modeling quantifies the addressable market envelope and highlights where marginal investments deliver the highest ROI under plausible market paths.
-
Risk‑informed sourcing: Raw‑material composition and supply continuity materially affect margin and availability. The report’s procurement stress tests and supplier tiering allow procurement leaders to prioritize dual‑sourcing, hedging, or strategic inventory deployment ahead of potential material squeezes.
-
Regulatory contagion and aftermarket opportunity: Recent airworthiness directives and tightening emissions standards create both compliance costs and aftermarket demand pockets. The report maps regulatory events to demand pulses and prescribes commercial approaches to capture replacement and retrofit demand without compromising OEM channels.
Key strategic implications — recommended plays for 2026
-
Prioritize material and tribology innovation: Advances in bi‑metal and tri‑metal alloys, high‑tin aluminum formulations, and low‑friction surface treatments materially affect fuel efficiency and emissions. Suppliers with validated, low‑wear solutions are positioned to win OEM design‑ins and preferred aftermarket status.
-
Calibrate capacity expansion to regional demand drivers: Given the market’s moderate CAGR, capacity investments should be staged and linked to secured offtake or modular manufacturing strategies. Greenfield capacity is advisable only where long‑term contracts or differentiated technology protect utilization.
-
Leverage aftermarket channels as a margin and resilience lever: Regulatory-driven replacement mandates and repair kit rollouts create high-margin, short‑cycle revenue that can offset upstream cyclicality. A balanced OEM‑aftermarket go‑to‑market strategy reduces exposure to new‑vehicle cycles.
-
Embed regulatory intelligence into product lifecycles: Active monitoring of airworthiness and emissions directives — including recent directives that mandate replacement of specific bushings in certain engine families — should be integrated into product update timelines to preempt compliance disruptions.
-
Adopt flexible sourcing and alloy rationalization: Material mix (bronze, steel‑backed aluminum, brass, etc.) drives both performance and cost. Standardizing alloy families across platforms where performance permits simplifies procurement and improves supplier leverage.
Competitive landscape — tactical takeaways
Our competitive mapping synthesizes product portfolios, geographic footprints, and route‑to‑market strengths across leading incumbents and notable regional manufacturers. High‑level observations include:
-
Global engineering leaders (example: MAHLE GmbH) differentiate through deep OEM relationships, integration into engine systems, and investments in low‑friction, high‑durability bearings tailored to internal combustion platforms.
-
Legacy powertrain specialists (example: Federal‑Mogul / Tenneco) continue to extract value from aftermarket scale and aftermarket‑OEM crossovers, particularly where bi‑metal and tri‑metal technologies address high‑duty commercial engines.
-
High‑performance and niche specialists (example: King Engine Bearings, K1 Technologies) maintain premium positions through tolerance precision and proven performance under extreme loads — important for motorsport, performance aftermarket and heavy‑duty segments.
-
Regional champions and cost‑competitive producers (several Asia and India‑based manufacturers) compete on cost, speed to market, and catalog breadth. Many have upgraded quality systems (IATF/ISO certifications) to capture OEM and aftermarket share simultaneously.
For 2026 playbooks, the analysis recommends distinct approaches for scale players (protect OEM share, invest in materials tech), regional manufacturers (move up the quality curve, secure long‑term contracts), and aftermarket specialists (monetize regulatory replacement windows and repair kits).
Regulatory and materials context — dynamics to watch
-
Regulatory event impact: Recent airworthiness directives related to specific engine models illustrate how targeted regulatory action can create abrupt replacement demand and compliance costs. Our report includes a regulatory tracker that quantifies the near‑term demand uplift and the longer‑term compliance burden by engine family.
-
Material composition and supply risk: Connecting rod bushings remain primarily manufactured from bi‑metal steel‑backed bronze, high‑tin aluminum alloys and brass. Price and availability volatility in copper and aluminum markets, plus regional alloy processing constraints, are modeled to show margin sensitivity across supplier types.
-
Emissions and efficiency pressure: Stringent fuel efficiency and emission mandates globally are increasing the value of low‑friction bushing designs. Our friction‑reduction benefit model translates tribology improvements into measurable fuel and emission gains at fleet level — a key negotiation lever for OEMs and suppliers.
What’s inside the full PW Consulting report (actionable components)
-
Proprietary market model (USD Million base) with historical series (2020–2025) and forecast (2026–2032) under central, conservative and upside scenarios.
-
Segmentation frameworks by region, material type and vehicle class, with elasticities, growth drivers and leading indicators (note: full segment tables and discreet values are retained in the paid report).
-
Supplier scorecards and capability matrices covering engineering depth, capacity, quality certifications, lead times and aftermarket reach.
-
Manufacturing cost and margin benchmarks, including BOM-level sensitivity to alloy price movements and labor/capex assumptions.
-
Regulatory tracker and impact matrix that ties airworthiness directives and emissions mandates to near‑term replacement demand and long‑term design shifts.
-
Go‑to‑market playbooks for OEMs, Tier suppliers and aftermarket players: pricing strategies, contract terms, service propositions and M&A/opportunity heatmaps.
-
Scenario planning tools and a business‑case calculator designed for C‑suite and transaction teams to run quick valuations under different adoption, regulatory and material‑price paths.
How to use this preview in your 2026 planning cycle
-
For strategy teams: Run the report’s scenario suite against your product roadmaps to determine the marginal value of material upgrades or manufacturing capacity expansions.
-
For procurement: Use the supplier scorecards and material sensitivity runs to prioritize dual‑sourcing, strategic inventory, and alloy rationalization before contract renewals.
-
For M&A and corporate development: The concentration metrics and competitive profiles identify targets that either consolidate scale or fill technical gaps; our valuation tool helps quantify synergies under the central and upside cases.
Closing — an invitation to deeper intelligence
This preview demonstrates the analytical depth PW Consulting brings to the Automotive Connecting Rod Bush market: a calibrated market model, supplier and materials intelligence, regulatory foresight, and translated commercial actions. For teams making allocation, sourcing, product or M&A decisions in 2026, the full report supplies the proprietary segmented datasets, playbooks and financial models necessary to act with conviction.
Access to the complete report will provide the precise segment tables, regional and material‑type breakdowns, and downloadable model files that are intentionally withheld here. Contact PW Consulting or visit our report page to obtain the full market study and supporting tools for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Automotive Connecting Rod Bush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Aircraft In-Seat Power Systems Market Poised to Reach USD 229.62 Million by 2032, Growing at a 4.85% CAGR
By PW Consulting, 2026-07-13
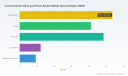
Commercial Aircraft In-Seat Power System Market — Strategic Outlook and Imperatives for 2026
PW Consulting’s latest market research on Commercial Aircraft In-Seat Power Systems delivers a forward-looking, executable playbook for airlines, OEMs, cabin systems suppliers, and investors preparing strategic decisions in 2026. Grounded in a comprehensive historical review (2020–2025) and a granular forecast through 2032, the study synthesizes market trajectory, regulatory drivers, supply-chain dynamics, and vendor capability mapping to convert market intelligence into boardroom-ready action.
Commercial Aircraft In Seat Power System Market
Market trajectory: recovery, near-term growth, and the mid‑term runway
The in‑seat power systems market has transitioned from pandemic-era contraction to steady expansion. Our base-year analysis (2025) captures market value after a multi‑year recovery, and the forecast period (2026–2032) models continued demand growth under multiple demand and regulatory scenarios. At the start of the forecast horizon, the market is projected to grow further year-on-year, with a compound annual growth rate of 4.85% across the 2026–2032 window, producing meaningful expansion by 2032. These macro metrics underpin the report’s scenario models that translate topline growth into linefit, retrofit, and serviceable‑unit demand for different fleet strategies.
Commercial Aircraft In Seat Power System Market
Why 2026 is a pivotal year for strategic decisions
-
Regulatory convergence and standards adoption: 2026 is shaping up as the year when universal USB‑C and high‑power delivery standards materially influence specification and certification timelines. Suppliers that secure early compliance and certification pathways will command tactical advantage in OEM linefit programs and large retrofit tenders.
Commercial Aircraft In Seat Power System Market -
Product differentiation becomes product survival: As seat‑level power moves from a premium feature to baseline passenger expectation, vendors must shift from “feature lists” to systems thinking — power architecture, thermal footprint, certification cost, and maintainability will determine win rates.
-
Supply‑chain inflection points: Material constraints and higher component costs force design tradeoffs (higher‑voltage distribution, conductor optimization). Procurement and engineering teams making sourcing and design choices in 2026 will lock in costs and obsolescence risk over multi‑year fleet programs.
Key dynamics shaping supplier and buyer decisions
-
Standards and regulation: A sustained regulatory push toward universal USB‑C standards and certification pathways is simplifying passenger experience but raising the engineering bar for thermal management and safety approvals for high‑power delivery (60–100W device support).
-
BYOD normalization: Bring‑Your‑Own‑Device behavior drives seat‑level power from optional add‑on to baseline infrastructure. This changes purchase economics—airlines must budget for broader deployments and lifecycle support rather than isolated premium rows.
-
Material and architecture innovation: Copper supply constraints are accelerating the transition to higher‑voltage distribution architectures that use less conductive material while maintaining power throughput. The net effect: re‑engineering investments now yield recurring weight, space, and installation efficiencies.
-
Form factor and efficiency mandates: Fuel‑efficiency and cabin‑weight requirements favor slimline converters and compact modules; designs that reduce cavity space and optimize mass per seat will benefit certification and installation cadences for both narrowbody and widebody fleets.
-
Retrofit economics vs. linefit planning: The report quantifies how retrofit windows, cabin downtime, and installation labor rates interact with device power density and modularity to shape ROI for retrofit campaigns. For many operators, staged retrofit programs aligned with scheduled maintenance deliver superior NPV vs. opportunistic installations.
Competitive landscape — who’s moving the market and why it matters
The vendor landscape combines large systems integrators with specialist module manufacturers. Established cabin and avionics suppliers retain strength through OEM relationships, systems integration capabilities, and global support footprints. At the same time, niche innovators are leveraging modular hardware and software interfaces to win retrofit and specialty contracts.
-
Astronics Corporation — A leading supplier with broad linefit and retrofit pedigree. Recent product introductions reinforce its strategy of offering high‑power USB‑C outlets and validated drop‑in modules for fleet commonality. Procurement teams should watch Astronics for mature integration packages and accelerated certification timelines.
-
Collins Aerospace — Provides tightly integrated cabin power and data‑port solutions, emphasizing IFE-seat integration. Collins’ advantage is systems depth and OEM relationships, useful for operators seeking one‑stop platforms that reduce supplier count and integration risk.
-
Panasonic Avionics — Coupling IFE capability with high‑power USB‑C delivery creates a bundled value proposition for widebody and premium narrowbody installations. Recent service entry of systems offering up to high‑watt charging underscores the premium integration route.
-
Burrana — Positioning its RISE platform as a modern cabin backbone reflects a strategy to compete on modularity and lifecycle services. Airlines favoring quick, lower‑disruption retrofits should evaluate Burrana’s positioning against incumbent integrators.
-
IFPL — A specialist with deep in‑seat module volume experience; its heritage in compact outlets and interface solutions makes it a logical partner for volume retrofit programs and custom passenger‑interface solutions.
-
Mid‑Continent / True Blue Power — Focused on TSO‑certified USB power systems and chargers, True Blue targets safety‑conscious buyers and niche cockpit/cabin power applications where certification pedigree is decisive.
-
KID‑Systeme and Astrodyne TDI — Represent specialized engineering capability in cabin electronics and power conversion modules, respectively. Their strengths are in customized solutions where standard packages do not fit operational constraints.
Recent vendor activity (product launches, trade show positioning, and first‑in‑service deployments) confirms an acceleration of commercial dynamics: new dual USB‑C outlets entering the market, platform positioning at major aircraft interiors shows, and first services of high‑watt solutions with airline customers. Buyers should treat these moves as signals of how vendors prioritize modularity, certification speed, and lifecycle support.
What the PW Consulting report delivers — practical outputs for 2026 decisions
This study is designed as a decision support kit rather than an academic compendium. Deliverables include:
-
Executive dashboard summarizing market size (base year 2025), forecast (2026–2032), and high‑level scenarios driven by regulatory and material inputs (CAGR for forecast period included).
-
Supplier benchmarking and procurement scorecards covering integration capability, certification velocity, retrofit readiness, TCO drivers, and aftermarket support models.
-
Actionable linefit vs retrofit decision trees and NPV models that reflect installation labor, cabin downtime, and module commonality.
-
Technology roadmap and component risk heatmaps: USB‑C power delivery thresholds, converter efficiency expectations, thermal management constraints, and alternative conductor strategies.
-
Supply‑chain playbook addressing sourcing strategies for copper alternatives, distributor hedging, and long‑lead item mitigation.
-
Implementation checklists for OEMs and airlines: procurement clauses, certification checkpoints, integration test plans, and supplier SLAs.
-
Customizable slide pack and briefing materials for investor, board, and procurement committees.
To preserve competitive value for subscribers, the report intentionally withholds publicly replicable granular segmentation tables in this press overview; detailed regional and application splits, vendor market shares, and unit‑price matrices are available in the full report.
Strategic recommendations for 2026 — where to act first
-
Lock USB‑C roadmaps into product and procurement specifications: Mandate compatibility and certification milestones in procurement RFPs to avoid costly retrofit rework as passenger expectations and regulations converge.
-
Architect for higher‑voltage distribution: Re‑evaluate power distribution topologies to capitalize on material efficiencies and reduce conductor mass while maintaining safety margins.
-
Prioritize modular, serviceable designs: Modular outlets and centralized converters reduce downtime and enable staged retrofits. Include maintainability and spare‑part availability as decision criteria.
-
Hedge supplier risk with dual‑sourcing and certification co‑investment: Where critical components face constrained supply, secure second‑source agreements and co‑fund certification pathways to reduce single‑vendor dependency.
-
Use retrofit windows strategically: Synchronize power upgrades with scheduled maintenance to optimize labor utilization and cabin downtime, improving ROI for retrofit programs.
-
Embed lifecycle cost metrics in CAPEX approvals: Move beyond unit price—use our TCO templates to incorporate certification, installation, weight penalty, and obsolescence risk.
How to use this research in your 2026 planning cycle
Procurement leaders, product teams, and investment committees can use the report as the foundation for three immediate actions in 2026:
-
Run a 90‑day supplier selection sprint using our procurement scorecard to shortlist candidates for linefit and large retrofit packages.
-
Model one or two retrofit scenarios using our NPV templates to determine the optimal scope and timing relative to maintenance events.
-
Initiate co‑engineering or certification partnerships with vendors that demonstrate both modular hardware and lifecycle support capabilities to lower time‑to‑service for new‑power specifications.
Next steps and how to engage
PW Consulting’s Commercial Aircraft In‑Seat Power System Market report combines market sizing (base year 2025), a 2026–2032 forecast with an explicit CAGR, vendor scorecards, and implementation tools designed for immediate use in procurement and product roadmaps. For executive briefings, customized scenario modeling, or to obtain the full report with detailed segment tables and supplier market shares, contact PW Consulting to schedule a briefing and receive subscriber access.
For detailed analysis of this topic, please visit the official page: Commercial Aircraft In Seat Power System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smoke Evacuation Tubing Market to Climb from USD 235.05 Million in 2025 to USD 380.4 Million by 2032 at a 7.12% CAGR
By PW Consulting, 2026-07-13
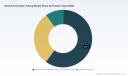
Smoke Evacuation Tubing Market 2026: Strategic Signals for Executive Decision-Making
Executive summary
PW Consulting’s new Smoke Evacuation Tubing Market report synthesizes five years of historical performance (2020–2025) and provides a forward-looking forecast through 2026–2032. The global market expanded materially from the start of the decade and reached USD 235.05 Million in our 2025 base year. Under our forecast scenarios, the market accelerates to roughly USD 380.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.12% across the 2026–2032 horizon. These macro dynamics create a multi-faceted strategic agenda for device manufacturers, distributers, hospital procurement teams, and private equity investors preparing critical decisions in 2026.
Smoke Evacuation Tubing Market
Why this market matters in 2026
-
Structural growth. The product category is no longer a niche accessory: consistent year-on-year expansion and healthy mid-single-digit-to-high-single-digit CAGR dynamics are turning smoke evacuation tubing into a predictable revenue stream that complements larger systems sales and disposable consumable portfolios.
Smoke Evacuation Tubing Market -
Regulatory momentum. Regulatory pressure—both statutory and institutional—has heightened the imperative to manage surgical plume. More than a third of U.S. states have enacted laws requiring smoke evacuation in operating rooms, and devices in this space fall under recognized FDA Class II requirements for electrosurgical accessories. Compliance cost and procurement timelines will be a central consideration for rollouts in 2026.
Smoke Evacuation Tubing Market -
Product innovation is shifting purchasing behavior. Design advances (e.g., tapered corrugated profiles, single-extrusion materials, integrated tubing kits) are improving usability and infection control, enabling suppliers to capture premium positions even as hospitals optimize consumable spend.
Market trajectory — the numbers you need to plan around
Executives planning budgets and M&A strategies for 2026 should anchor decisions to three high-level facts from our study: the market’s base size in 2025 (USD 235.05 Million), the immediate uplift in 2026, and the projected rise to approximately USD 380.4 Million by 2032. Those figures, combined with a 7.12% CAGR for the forecast window, provide a quantifiable foundation for scenario modelling—whether your focus is organic growth, bolt-on acquisitions, or strategic partnerships with OR systems vendors.
Key demand drivers and risk factors
-
Regulatory and institutional mandates. Rising legal and occupational-safety expectations are increasing baseline demand for compliant evacuation solutions, especially in jurisdictions with explicit requirements.
-
Shift toward disposables and integrated consumables. Hospitals balancing infection control and cost efficiency are selectively adopting integrated tubing kits and single-use options that streamline workflow with electrosurgical pencils and smoke evacuators.
-
Procurement rationalization. Larger health systems are centralizing purchasing; this favors suppliers who can offer validated compatibility across major smoke evacuator platforms and can demonstrate supply-chain resilience.
-
Price sensitivity vs. clinical preference. Devices with demonstrable usability or clinical benefit can command a premium; however, commoditization remains a real threat if suppliers compete only on price.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three vendors together account for a meaningful share of the market, while a broader set of manufacturers constitutes a substantial competitive tail. CR3 and CR5 metrics indicate room for consolidation and for service differentiation beyond price.
-
CONMED Corporation (Largo, Florida) — Strengths: breadth of portfolio, compatibility with established evacuator platforms, and a deep distribution network. Strategic play: leverage platform compatibility to negotiate formulary placements with large hospital systems and bundle tubing with consumable and capital equipment sales.
-
Medtronic plc (Dublin) — Strengths: productized RapidVac offerings and laparoscopic variants with control features. Strategic play: integrate tubing design with procedural workflows to drive higher share in electrosurgery-centric specialties and to cross-sell into existing installed bases.
-
CLS-Surgimedics (USA) — Strengths: sterile/non-sterile breadth and accessory ecosystem (pencil wands). Strategic play: emphasize specialty-specific solutions and direct-clinician engagement to defend margin against low-cost imports.
-
I.C. Medical, Inc. (Phoenix, Arizona) — Strengths: U.S.-based manufacturing and laparoscopic sterile sets. Strategic play: position “made-in-country” supply reliability as a procurement differentiator, especially for large health systems prioritizing supply resiliency.
-
DeRoyal Industries , Aspen Surgical , Stryker , CooperSurgical , and Buffalo Filter (CONMED) — Each brings unique channel relationships, system compatibility, or product integration capabilities. Notably, Stryker’s late-2024 regulatory clearance for a smoke-evacuation-enabled device underscores how system-level integration can shift demand toward vendors that can offer instrument-level evacuation solutions.
Strategic implications and recommended actions for 2026
Our analysis yields five pragmatic priorities for executives preparing 2026 roadmaps:
-
Re-seat product strategy around workflow outcomes. Buyers increasingly evaluate tubing on clinical workflow and staff time savings, not just unit cost. Product R&D should emphasize ease-of-use, connector compatibility, and packaging that reduces OR setup time.
-
Build compatibility and validation playbooks. Suppliers that can demonstrate validated compatibility with major smoke evacuators and electrosurgical systems will unlock preferred supplier agreements with integrated health systems.
-
Consider bolt-on consolidation selectively. Given the market’s moderate concentration, serial acquisitions of niche tubing and accessory makers can quickly increase share and margin if integration captures procurement synergies and reduces SKU complexity.
-
Operationalize regulatory and procurement readiness. Ensure product dossiers and 21 CFR compliance artifacts are complete and accessible; regulatory friction is a top source of tender disqualification in 2025–2026 procurement cycles.
-
Differentiate via supply-chain resilience and clinical evidence. Investments in redundancy, U.S.-based manufacturing options, and clinician-led evidence generation (time-in-OR, aerosol reduction metrics) materially improve contracting outcomes with large buyers.
Where the report provides operational advantage
This PW Consulting report is expressly designed as a decision-support tool for 2026. It contains:
-
Actionable market models and scenario tables that map unit-volume, ASP, and revenue sensitivities against regulatory and adoption scenarios (note: detailed segment-level tables and region/application splits are included in the full report and accessible through our data portal).
-
Competitive scorecards and vendor heat maps that evaluate product breadth, system compatibility, manufacturing footprint, and evidence base—constructed to support supplier selection and M&A screening.
-
Regulatory and procurement playbooks that translate FDA Class II device requirements and state-level legislative trends into checklists for product development, clinical trials, and tender responses.
-
Commercial playbooks with go-to-market tactics for three archetypal players—global OEMs, regional specialists, and private-label players—covering channel strategies, pricing levers, and partnership frameworks.
-
Supply-chain stress tests and contingency plans to quantify the cost of disruption and to prioritize domestic-sourcing investments versus offshore optimization.
Use cases where the report delivers immediate ROI
-
Procurement teams preparing 2026 contract renewals: use our compatibility matrices and TCO models to negotiate better terms and fewer SKUs.
-
Corporate development teams evaluating tuck-ins: apply our M&A screening criteria and synergies model to shortlist targets that move the needle on CR3/CR5 concentration and distribution reach.
-
Product and R&D leaders: leverage our usability and clinical evidence frameworks to prioritize product roadmaps that command price premiums.
-
Private equity sponsors: stress-test exit scenarios using our forecast range and sensitivity runs to set valuation and hold-period expectations.
Next steps for executives
For leaders planning capital allocation and commercial initiatives in 2026, the near-term priorities are clear: (1) reconcile product roadmaps with regulatory evidence needs, (2) codify compatibility and supply guarantees for large health-system clients, and (3) evaluate M&A candidates using the report’s revenue-per-SKU and channel-synergy models.
PW Consulting’s report functions as a short-cut to readiness—delivering actionable templates and data that accelerate decision cycles while preserving the granular segmentation and regional figures behind our paywall. If you are preparing a 2026 growth plan, procurement RFx, or acquisition thesis, integrating these market-calibrated inputs will materially reduce execution risk.
Conclusion
The smoke evacuation tubing market is transitioning from niche consumable to strategic portfolio asset. With a base of USD 235.05 Million in 2025 and a guided path toward approximately USD 380.4 Million by 2032 at a 7.12% CAGR, the category merits prioritized attention in 2026 planning cycles. PW Consulting’s report surfaces the competitive, regulatory, and product levers that determine who captures the growth and who competes on eroding margins. For the complete segmentation breakdowns, vendor matrices, and procurement-ready tools that support execution, download the full report from PW Consulting’s market intelligence portal.
For detailed analysis of this topic, please visit the official page: Smoke Evacuation Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.15% CAGR for Food Packaging Absorbent Pads Market Through 2032 as Asia‑Pacific Emerges as Leading Region
By PW Consulting, 2026-07-13
Food Packaging Absorbent Pads Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting presents a forward‑looking briefing drawn from our comprehensive Food Packaging Absorbent Pads Market report (base year 2025). This briefing distils the commercial and competitive imperatives that will shape supplier and buyer decisions in 2026. It demonstrates the analytical depth and practical orientation of our research while intentionally omitting the granular segment tables and price decks that are available only in the full report.
Food Packaging Absorbent Pads Market
Market snapshot: scale, trajectory and what it means
The global market for food packaging absorbent pads has moved from a mid‑single‑billion dollar category in the early 2020s to a robust market exceeding USD 2.15 billion in 2025. Our model projects continued expansion through the forecast window (2026–2032) to roughly USD 3.06 billion by 2032, reflecting a compound annual growth rate of approximately 5.15%. That pace is sufficient to require active repositioning by manufacturers, packagers and retailers — particularly where product differentiation, sustainability and regulatory compliance intersect.
Food Packaging Absorbent Pads Market
Growth is not uniform by application, material or geography; the market is characterized by pockets of rapid innovation (biodegradable and bio‑based pads, higher‑capacity formats, odour‑control systems) and persistent operational complexity (multilayer supply chains, food safety certification regimes, and packaging-film compatibility). Our report quantifies those pockets and translates them into actionable investment and procurement options for 2026.
Food Packaging Absorbent Pads Market
Dynamics shaping 2026 decisions
-
Regulatory pressure and product classification: European regulation treats superabsorbent polymers (SAPs) in non‑sealed absorbers as active packaging devices, bringing additional performance and leakage‑prevention obligations. In parallel, U.S. food contact approval and FSIS guidance continue to govern material acceptance. These rules create both barriers and premium opportunities for compliant suppliers.
-
Sustainability and single‑use plastics policy: retailer and municipal commitments to reduce single‑use plastics are accelerating adoption of cellulose‑based and compostable pads, particularly in markets where plant‑based alternatives are gaining acceptance. Manufacturers face trade‑offs between cost, performance and end‑of‑life claims.
-
Innovation in product performance: recent product launches and R&D have focused on faster absorption rates, higher liquid retention, integrated odour control and antimicrobial layers. These features are increasingly table stakes for meat and seafood packaging and create differentiation avenues for premium supply contracts.
-
Commercial dynamics: retail batch sizes, private‑label specifications, and foodservice channel requirements are compressing lead times and raising demand for certified, consistent supply. Buyers are evolving from price‑only sourcing to multi‑criteria scorecards that account for certified safety, sustainability, and logistics resilience.
Competitive landscape — concentration, capability and recent moves
The absorbent pad market is moderately fragmented: our concentration analysis shows that the top three suppliers account for a minority share of global revenue, while the top five increase that share meaningfully but do not create a tight oligopoly. That competitive topology supports continued M&A and partnership activity, as well as opportunities for regional specialists and differentiated, sustainability‑focused challengers.
-
Novipax (Oak Brook, Illinois, USA) — A leading U.S. manufacturer with multiple SQF‑certified facilities. Novipax’s core strength is scale and reliability in protein absorbent pads for meat, poultry and seafood, making it a primary partner for large retail chains seeking supply security.
-
Sirane Ltd (Telford, UK) — Specialist in the Dri‑Fresh family of pads with extended capabilities in odour control, antimicrobial options and custom absorbency. Sirane’s recent investment in its Telford facility (expansion announced January 2025) signals capacity commitment to meet rising European demand for performance and speciality formats.
-
Elliott Absorbent Products Ltd (Littleborough, UK) — A long‑standing BRCGS‑certified producer offering breadth across meat and fresh foods; Elliott combines regulatory credentials with supplier flexibility that appeals to private label programs.
-
Aptar Food Protection (USA) — Markets the FreshWell system and focuses on patented, food‑safe materials compliant with FDA and EU requirements. Aptar’s value proposition centres on integrated system performance and regulatory assurance for global brand owners.
-
McAirlaid’s Vliesstoffe GmbH (Germany) — Known for airlaid nonwovens, McAirlaid’s has pushed the innovation frontier with biodegradable pads that promise materially faster absorption (product innovation announced October 2025). This underlines the competitive premium for combined performance and sustainability.
-
Dimer GmbH (Germany) — Offers a wide range of formats and colours with an emphasis on suction capacity and format flexibility; well placed for regional processors seeking customization.
-
Tipack Group (Jiangsu, China) — A major Chinese manufacturer and exporter with multiple food‑grade certifications; Tipack is a strategic supplier for global brands seeking cost‑competitive supply and Asian manufacturing capacity.
-
Cellcomb AB (Sweden) — Concentrates on sustainable, cellulose‑based pads and launched a bio‑based, plastic‑free line (announcement active since late 2024). Cellcomb represents the new wave of entrants that convert sustainability into a clear product differentiation strategy.
These players display diverse strategic postures: scale and supply reliability (Novipax, Tipack), certification and private‑label service (Elliott, Sirane), system and technology licensing (Aptar), and sustainability‑led niche offering (Cellcomb, McAirlaid’s). That heterogeneity produces tactically different responses to the same market pressures — from capacity investments and facility expansions to product line pivots.
What the report delivers — practical assets for 2026 planning
PW Consulting’s full report is designed as a commercial toolkit rather than an academic exercise. Key components include:
-
Proprietary market model with annual historicals (2020–2025) and scenario forecasts (2026–2032) by material family, application and geography — provided in an interactive Excel workbook so teams can re‑run scenarios with their own assumptions.
-
Supply‑side mapping and capacity atlas, including certified facilities, lead times, and supplier scorecards to support vendor selection and dual‑sourcing strategies.
-
Regulatory risk matrix and product classification guide (EU SAP rules, U.S. FDA/FSIS expectations), with compliance playbooks for product reformulation and labelling.
-
Raw material cost‑curve analysis and sensitivity scenarios (cellulose, SAP feedstocks, silica gel, film laminates) to enable hedging and procurement contracting.
-
Commercial go‑to‑market modules: retailer specification templates, specification versus cost tradeoff tables, pilot design templates, and commercial negotiation playbooks.
-
M&A screening and value‑creation roadmaps for acquirers, with juxtaposed case studies of recent facility expansions and product launches from leading suppliers.
Note: specific line‑by‑line segmentation tables, regional and application revenue splits, and granular price decks are intentionally excluded from this briefing to preserve the value of the primary report and to direct stakeholders to the full dataset.
Actionable 2026 recommendations
-
Manufacturers: Prioritise investment in cellulose and compostable lines where commercial premiums exist, but retain SAP capability for high‑retention segments. Validate biodegradability claims through third‑party certification and model unit economics under multiple policy scenarios.
-
Procurement & retailers: Shift to multi‑dimensional supplier scorecards that weight certification, supply security, and sustainability alongside price; run 12–24 month pilot programs for new pad formats with clear shelf‑life and purge metrics.
-
Investors & consolidators: Target bolt‑on acquisitions of regional specialists with differentiated technologies or certification footprints. The market’s moderate fragmentation and the presence of innovation leaders create clear arbitrage for roll‑up strategies focused on scale + technical capability.
-
R&D and product teams: Focus on faster absorption rates, improved retention per unit area, integrated odour control and antimicrobial efficacy; ensure new formulations are compliant with EU and U.S. classification regimes before commercial launch.
-
Supply chain managers: Hedge exposure to cellulose and film resin volatility, diversify sourcing across certified suppliers, and audit inbound film compatibility to avoid product failure at pack lines.
Key risks and mitigations
-
Regulatory shifts: Rapid reclassification or tighter active‑packaging rules can raise compliance costs. Mitigation: maintain regulatory monitoring, early engagement with authorities, and adopt conservative design margins.
-
Raw material price shocks: Volatile cellulose or polymer prices can compress margins. Mitigation: indexation clauses, forward buying programs, and blended material designs.
-
Performance substitution: New active packaging solutions or alternative preservation technologies could displace pads in select use cases. Mitigation: invest in performance R&D and defend value via integrated product‑service offerings.
-
Supply concentration: Facility outages at key certified suppliers can disrupt retail programs. Mitigation: dual sourcing, regional backups and contractual service levels.
Why PW Consulting’s report matters for 2026
Decisions in 2026 will determine which suppliers capture growth, how quickly brands meet sustainability commitments, and which investors create value through consolidation. Our report blends a quantified market model (historicals and scenarios), supplier due diligence, regulatory playbooks and commercial tools so that executives can move from insight to action in months, not quarters.
If your 2026 strategy depends on credible, implementable intelligence about product performance, regulatory risk, supplier capability and commercial levers, PW Consulting’s full Food Packaging Absorbent Pads Market report provides the evidence base and the playbooks. The full dataset contains the detailed regional and application splits, unit‑price decks and supplier scorecards omitted from this briefing; available via our report portal.
For access to the full report, interactive models and bespoke advisory engagements to support your 2026 planning, please visit the PW Consulting report page or contact our Food Packaging practice.
For detailed analysis of this topic, please visit the official page: Food Packaging Absorbent Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Rankine Cycle Waste Heat-to-Power Market Poised to Reach ~USD 9.75 Billion by 2032, Growing at a 10.65% CAGR
By PW Consulting, 2026-07-13
Organic Rankine Cycle Waste Heat to Power: A 2026 Strategic Preview — PW Consulting Market Insight
As industrial decarbonization accelerates and energy economics reshape capex allocation, the Organic Rankine Cycle (ORC) waste heat to power (WHtP) market is entering a phase of strategic maturation. PW Consulting’s forthcoming market research report — based on a 2020–2025 historical review and a 2026–2032 forecast horizon — quantifies this shift and translates it into immediate decision rules for executives planning 2026 investments.
Organic Rankine Cycle Waste Heat To Power Market
Market snapshot: decisive momentum, measurable opportunity
- The ORC WHtP market reached USD 4,800.0 Million in 2025 (base year) after a sustained multi-year recovery and expansion from 2020 levels, reflecting growing industrial deployments and maturing technology stacks.
- Our forecast projects a compound annual growth rate (CAGR) of 10.65% over 2026–2032, with the market more than doubling by the end of the forecast period. This trajectory reflects a mix of retrofit demand, greenfield integration, and accelerating deployments at energy-intensive industrial sites and compressor stations.
- Market concentration remains moderate: the top three OEMs account for roughly one quarter of the market, and the top five for just over one third. This structure favors both established leaders and nimble specialists pursuing vertical niches and regional anchors.
Why this matters for 2026 corporate strategy
For corporate strategy, 2026 is less about technological discovery and more about execution. Our analysis identifies three immediate strategic imperatives:
Organic Rankine Cycle Waste Heat To Power Market
- Prioritize bankable projects — accelerate projects where payback and operating profiles align with corporate risk appetite. Industrial payback windows in sectors like cement commonly fall in the 4–8 year range under current electricity price regimes; understanding site-specific duty cycles and heat-quality profiles is now the gating factor.
- Design for regulatory resilience — the regulatory landscape is shifting (notably through initiatives such as the EU Clean Industrial Deal). Equally important are pending chemical-policy developments (e.g., potential restrictions on certain PFAS/HFC working fluids) that will drive fluid selection, retrofit complexity, and long-term maintenance cost assumptions.
- Match scale and modularity to market entry strategy — the market growth profile favors modular ORC solutions for lower-temperature and distributed sources, while larger turbogenerator offerings capture centralized, high-grade waste heat opportunities. Procurement, financing and contracting models should reflect this duality.
What PW Consulting’s report delivers (practical, actionable content)
The report is constructed as an operational playbook for 2026 decision-makers. Key practical deliverables include:
Organic Rankine Cycle Waste Heat To Power Market
- Proprietary market-sizing and growth scenarios (2020–2032), with sensitivities to electricity pricing, carbon pricing, and heat-source availability that drive IRR and payback timelines.
- A decision matrix for technology selection by heat quality, operating hours and site constraints — designed for engineering, procurement, and corporate development teams to prioritize pilot vs. scale deployments.
- Standardized financial models (adjustable templates) to stress-test CAPEX/OPEX, O&M regimes, and alternative contracting structures (EPC, EPC+O&M, PPA, energy-as-a-service).
- Regulatory and fluid-transition risk mapping, including mitigation playbooks for transitioning away from at-risk working fluids and guidance on certification/compliance pathways.
- Commercial due diligence checklists for technology partners, OEM selection and M&A targets — covering IP posture, supply-chain concentration, service footprint and installed-base performance metrics.
Note: To preserve strategic value for subscribers and partners, detailed subsegment tables (regional, capacity and application splitouts) and granular company revenue allocations are presented in the full report only.
Competitive landscape — who to watch and why
The ORC WHtP competitive map blends global incumbents with specialized challengers. Our qualitative and comparative analysis centers on capabilities that matter for 2026: technology modularity, heat-source flexibility, installed-base support, and enterprise sales channels.
- Ormat Technologies Inc. (Reno, Nevada) — Strength: proven REG installations and integrated ORC converter technology. Strategic value: robust service footprint and project financing experience make Ormat a go-to partner for utility-scale industrial recovery where long-term O&M and performance guarantees are required.
- Turboden S.p.A. (Mitsubishi Heavy Industries Group, Brescia, Italy) — Strength: high-capacity ORC turbogenerators and project scalability. Strategic value: ability to deliver multi-megawatt plants and to win upstream-of-grid industrial contracts; recent commissioning of a large North American plant and additional compressor-station contracts underscore their aggressive capacity expansion in the region.
- Exergy International Srl (near Milan) — Strength: Radial Outflow Turbine (ROT) innovation and mid-range unit deployment experience. Strategic value: strong fit for cement and chemical sectors where bespoke turbine architectures improve lifecycle economics.
- ElectraTherm Inc. (BITZER Group) — Strength: low-temperature solutions (down to ~70°C) and modular Power+ generators. Strategic value: access to low-grade heat sources and simpler integration paths for brownfield plants and smaller industrial facilities.
- Orcan Energy AG, ENOGIA SAS, Calnetix Technologies, Alfa Laval AB — Collectively, these suppliers advance modularity, micro-ORC capability, high-speed turbo-generation, and heat-exchanger integration. Strategic value: they enable tailored solutions for maritime, micro-grid, and distributed industrial applications that larger vendors may under-serve.
Recent market movements sharpen competitive dynamics. Notably, Turboden’s commissioning of a multi-megawatt ORC plant in North America and subsequent contract awards for compressor-station projects illustrate demand concentration around baseload, turbine-exhaust recovery opportunities. Parallel deployments by tier-two innovators demonstrate a bifurcated market: large-scale industrial projects versus distributed, low-temperature micro-ORC plays.
Risk map and mitigation levers
- Regulatory / fluid risk: Anticipate restrictions on certain synthetic working fluids. Mitigation: accelerate qualification and pilot deployment of natural refrigerants and new working-fluid topologies; include contractual clauses for fluid replacement and performance guarantees.
- Project economics: Volatile electricity prices and operating hours drive payback variability. Mitigation: structure PPA or energy-as-a-service agreements, leverage merchant hedges, and prioritize high-capacity-factor sites (e.g., compressor stations, continuous-process plants).
- Supply chain & service: Specialized components (turbines, magnetic bearings) and localized service capacity can constrain uptime. Mitigation: secure multi-sourced supply agreements and invest in regional service hubs with performance SLAs.
- Market fragmentation: Moderate concentration implies room for partnerships, carve-outs, and niche plays. Mitigation: evaluate bolt-on acquisitions for service networks or technology gaps, and pursue strategic partnerships with heat-intensive industrial customers.
Operational playbook for 2026 execution
To convert the market opportunity into realized value in 2026, PW Consulting recommends a phased, risk-calibrated execution path:
- Phase 1 — Rapid screening: Use heat-mapping to identify top 5–10 candidate sites by heat availability, duty cycle, and permitting environment.
- Phase 2 — Proof of economics: Deploy pilot(s) with adjustable financial models and entry contracts (short-term PPA or EaaS) to validate performance and establish reference cases for CAPEX approval.
- Phase 3 — Scale & standardize: Lock in standardized procurement bundles, performance-based O&M contracts, and fluid-compliance roadmaps for rollout across an industrial estate or fleet.
- Phase 4 — Strategic expansion: Pursue M&A or JV opportunities to strengthen regional service footprints or acquire complementary micro-ORC/macro-ORC technology for product breadth.
How PW Consulting’s insight supports board-level decisions in 2026
Boards and C-suites require three types of confidence to commit capital in 2026: accurate market sizing, defensible technology choice, and executable commercial models. PW Consulting’s report synthesizes these into a single deliverable — combining validated market growth (CAGR 10.65%), scenario-tested financial templates, and supplier diligence frameworks — to reduce time-to-decision and de-risk early commitments.
Importantly, while this briefing highlights market scale and competitive direction, the full report contains the granular segmentation, regional and application-level analytics, and vendor revenue breakdowns required for procurement RFPs and capital approvals. Those detailed exhibits and model files are intentionally gated to preserve commercial value for subscribers.
Next step — where to get the full intelligence
PW Consulting’s Organic Rankine Cycle Waste Heat to Power Market report is positioned as the operational playbook for 2026. For procurement officers, project developers, corporate strategists and private equity teams evaluating entry or scale investments, the full report provides the actionable templates, segment analytics and vendor scorecards necessary to move from pilot to portfolio. Contact PW Consulting or visit our report page to access subscriber-only exhibits, downloadable financial models, and vendor diligence appendices.
For detailed analysis of this topic, please visit the official page: Organic Rankine Cycle Waste Heat To Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photolithography Equipment Market to Reach USD 32.45 Billion in 2025 as EUV and Asia‑Pacific Dominate
By PW Consulting, 2026-07-13
Photolithography Equipment Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As global semiconductor investment accelerates into AI, high-performance computing, and edge devices, photolithography equipment remains the most capital-intensive and strategically critical segment of the fab supply chain. PW Consulting’s forthcoming Photolithography Equipment Market Research (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) synthesizes macro drivers, technology roadmaps, supplier capabilities and regulatory risk into an actionable framework for executives planning 2026 capital and partner strategies.
Photolithography Equipment Market Research
Key headline: the market is on a sustained expansion trajectory — growing from an already large installed and replacement base in 2025 to roughly double by the end of the forecast horizon — driven by node transitions, capacity buildouts and ongoing node scaling. Our model, built on a 10.45% compound annual growth rate (CAGR) for the 2026–2032 period, yields a 2025 market size of USD 32,450 Million (revenue unit: Million, currency: USD) and a projected market approaching USD 65,065 Million by 2032. These aggregates encapsulate system shipments, upgrades and services across EUV, DUV and complementary patterning technologies.
Photolithography Equipment Market Research
Why this preview matters to 2026 strategy
- Capital allocation: firms committing to 2026 fab investments must reconcile multi-year lead times for advanced lithography with uncertainty from export controls and localized supply initiatives.
- Supplier selection and risk mitigation: with very high market concentration among a handful of suppliers, a robust supplier-risk playbook is critical to avoid production bottlenecks and geopolitical exposure.
- Technology roadmap alignment: buyers and ecosystem participants must balance near-term throughput needs (DUV/ArFi) with medium-term High-NA EUV adoption and service footprints.
Market outlook and macro foundations
Our 2026 outlook is grounded in three measurable macro dynamics: fab capacity growth, node-driven replacement cycles, and regulatory constraints. Industry plans indicate a near-term wafer fab capacity expansion (notably driven by AI and HPC demand) that PW Consulting has incorporated into scenario models. These capacity expansions are front-loaded into the 2026–2028 period and exert outsized demand on immersion DUV and EUV tool availability, spares and service engineers.
Photolithography Equipment Market Research
Regulatory and supply risk layers materially shape deployment feasibility. Recent export control tightening by the US Bureau of Industry and Security on advanced photolithography tools below ~7nm raises both timing risk and potential for supply fragmentation. Concurrently, supplier-side resource constraints — for example, optics production and specialty gases used in EUV sources — have driven cost pressures and cadence uncertainty. Our base-case financial projection reflects these frictions while the upside case assumes eased export constraints and an accelerated High-NA EUV ramp.
Competitive landscape: what to watch in 2026
The photolithography market shows extreme concentration at the supplier level. A very small set of dominant vendors control nearly the entire technology stack for advanced nodes, and that concentration translates into bargaining power, differentiated service ecosystems and long technology lead times. The CR3 and CR5 metrics in our analysis underscore this reality: the top three and top five vendors collectively command the vast majority of supply and aftermarket services.
- ASML Holding N.V. (Veldhoven, Netherlands) — The undisputed leader in EUV and high-end DUV platforms, ASML’s roadmap toward High-NA EUV is central to industry scaling beyond 3nm. Recent product shipments of High-NA EUV systems for leading-edge process development illustrate how tooling availability governs node timelines. For buyers, ASML’s platform cadence and service footprint will dictate migration pathways and capex phasing.
- Nikon Corporation (Tokyo, Japan) — Nikon’s NSR-series and well-established DUV scanners remain strategic workhorses for logic, memory and specialty fabs at mature nodes. Nikon’s incremental system showcases at trade events reflect a play on stability and throughput optimization where EUV adoption is phased.
- Canon Inc. (Tokyo, Japan) — Canon’s focus on ArF immersion upgrades and complementary patterning techniques (including nanoimprint) positions it as a nimble provider for HVM upgrades and differentiated node strategies, particularly for fabs seeking cost-effective throughput gains.
- Shanghai Micro Electronics Equipment (SMEE) (Shanghai, China) — SMEE’s DUV immersion tools are a strategic enabler for domestic fab programs, aligned to China’s localization targets. While performance differentials versus leading-edge suppliers remain, SMEE’s roadmap matters for regional capacity and procurement diversification strategies.
Strategic implication: supplier selection is no longer a pure technical decision. It is a composite of technology fit, supply-chain sovereignty, regulatory exposure and long-term service partnerships. PW Consulting’s vendor-risk matrix in the full report ties supplier capabilities to discrete procurement playbooks for OEMs, IDMs and fabless/OSAT ecosystems.
Operational dynamics and system-level constraints
Behind the headline CAGR lie operational constraints that will determine realized outcomes in 2026:
- Optics capacity: advanced multilayer optics production — a critical input for EUV — has limited ramp cadence. Major optics manufacturers have been increasing capacity, but High-NA tooling targets remain constrained on an annual basis.
- Specialty consumables: supply bottlenecks in items like helium isotopes for EUV sources and specialty gases introduce variable OPEX and can delay tool acceptance.
- Regulatory gating: export controls can delay or reroute shipments, forcing alternative sourcing or second-source strategies and sometimes triggering requalification costs.
These operational realities amplify the importance of service contracts, spare-parts strategies and skills development in 2026 — not as optional extras but as core components of capital planning.
What the PW Consulting report contains (practical, actionable content)
PW Consulting designed the full Photolithography Equipment Market Research report as a decision-useful toolkit for 2026 planning. It includes:
- Market modeling: bottom-up and top-down models reconciled against supplier shipment disclosures, with scenarios for regulatory tightening, High-NA adoption rates and capacity variance. (Base year: 2025; forecast 2026–2032; CAGR 10.45% used for primary baseline.)
- Executive playbooks: procurement, supplier risk mitigation, upgrade vs. new-tool decision flows, and CAPEX phasing templates tailored for IDMs, foundries and advanced packaging players.
- Competitive profiles: deep vendor dossiers covering product roadmaps, installed base dynamics, aftermarket revenue levers and partnership ecosystems for the major suppliers.
- Operational annexes: spare-parts inventories, service-capacity mapping, qualification timelines and cost-to-serve benchmarks for EUV vs. DUV deployments.
- Regulatory and geopolitical scenarios: quantified impact matrices illustrating how export policy shifts and localization drives alter supplier choices, lead times and total cost of ownership.
- Supply-chain stress tests: sensitivity analyses for optics capacity, specialty gas pricing and skilled-service headcount shortages, with mitigation strategies and contingency playbooks.
Note: to preserve commercial confidentiality and to protect the strategic value of the analysis, detailed regional and application-level splits (the granular segmentation figures and percentage allocations) are intentionally summarized at a high level in this preview; full segment-level tables and interactive dashboards are available in the paid report.
Actionable recommendations for 2026
- Adopt a two-track procurement strategy: secure baseline DUV capacity for near-term volume while reserving optionality for EUV/High-NA placements tied to node confirmation and regulatory clearances.
- Prioritize service and spare-part contracts at the time of purchase: our scenario stress tests show that lifecycle availability and responsiveness materially affect effective throughput in years 1–3 post-installation.
- Develop geopolitical hedges: diversify supplier relationships and invest selectively in regionalized service capabilities where export risk is elevated.
- Stress-test supply chains: quantify the impact of key input constraints (optics, gases, skilled field engineers) on your factory ramp plans and incorporate buffer strategies into EBITDA forecasts.
- Engage in collaborative partnerships: consider co-development or long-term service agreements with leading suppliers to secure prioritized delivery windows and accelerated technology transfers where feasible.
Preview of recent industry movements relevant to 2026 execution
- ASML’s delivery of a commercial High-NA EUV system for advanced process development underscores the technology’s strategic role for sub-3nm node workstreams and the limited cadence of production-grade High-NA units.
- Major DUV vendors continue iterative product upgrades—reflecting a market that will sustain both advanced EUV investment and high-throughput DUV deployments for the foreseeable planning horizon.
- Upstream capacity and material news — including optics manufacturers scaling multilayer coating lines and documented specialty-gas supply constraints — should be treated as scheduling risk factors in any 2026 procurement calendar.
Final note — how to use this preview
This article provides a calibrated strategic lens on the photolithography equipment market, designed to inform board-level discussions, procurement cycles and R&D alignment for 2026. For procurement teams, the vendor playbooks and TCO models are immediately actionable. For strategy and corporate development teams, the regulatory scenarios and supply-chain stress tests enable robust M&A and partnership screening.
To access the complete, interactive dataset, detailed segmentation tables, regional and application-level forecasts, and downloadable procurement templates, visit the PW Consulting report landing page. The full report contains the granular intelligence necessary to convert the high-level strategies in this preview into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Photolithography Equipment Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pathogen Detection Market to Hit USD 9,499.07 Million by 2032 at 7.8% CAGR (Forecast 2026–2032), Led by PCR
By PW Consulting, 2026-07-13
Pathogen Detection Market Outlook: Strategic Imperatives for 2026 — PW Consulting Report Highlights
Executive snapshot
PW Consulting's Pathogen Detection Market Report (base year 2025; historical window 2020–2025; forecast period 2026–2032) provides a forward-looking, actionable foundation for enterprise decision-making heading into 2026. Our analysis finds the global market at approximately USD 5,615 Million in 2025, with a projected compound annual growth rate (CAGR) of 7.8% through 2032, when the market is expected to approach roughly USD 9,499 Million. Market concentration is moderate: the top three players account for a meaningful share of the market while the top five increase that concentration further — a structure that favors both scale-driven plays and targeted innovation by specialist entrants.
Pathogen Detection Market
Why this report matters for 2026 decision cycles
-
Translate macro momentum into executable initiatives: Our forecast and scenario analyses convert headline growth into sequenced priorities for product development, distribution, and commercial partnerships.
Pathogen Detection Market -
Bridge regulatory and reimbursement complexity: The roadmap we provide helps firms prioritize dossiers and payer engagements that materially affect near-term access and margins.
Pathogen Detection Market -
De-risk supply and margin pressures: Proprietary supplier-risk and cost-sensitivity modules identify where procurement and vertical integration yield the strongest returns under 2024–2026 supply volatility.
-
Benchmark competitive intent: Our competitor maps and capability matrices allow management teams to identify white-space opportunities and credible acquisition or partnership targets.
What the report delivers — practical, decision-ready tools
-
Five-year and long-range revenue forecasts aligned to multiple go-to-market scenarios, stress-tested against supply shocks and regulatory shifts.
-
Segment- and technology-level growth drivers and adoption curves (PCR, immunoassays, NGS, isothermal amplification, mass spectrometry and others) with use-case prioritization for clinical, food safety, pharmaceutical QC, and environmental testing.
-
Regulatory roadmap and payer-playbook: prioritized pathways for CLIA-waived and CE-IVD strategies, plus reimbursement impact assessments tied to representative CPT and national codes.
-
Supplier and raw-material heatmaps that quantify exposure to reagent and consumables price shocks and identify mitigation levers (dual sourcing, hedging, local manufacturing).
-
Commercial models that optimize hardware-to-consumables economics, including service-led frameworks and subscription-based reagent monetization.
-
M&A and partnership screen: a ranked list of tuck-in targets, strategic partner archetypes, and likely consolidation scenarios — with sensitivity to antitrust and regional regulatory constraints.
-
Executive playbooks and 90/180/365-day action plans for product, commercial, and regulatory teams designed to accelerate time-to-revenue.
Market dynamics shaping 2026 decisions
Three dynamics dominate near-term strategy: regulatory access, reimbursement design, and supply-chain cost pressure.
-
Regulatory access: Point-of-care expansion remains gated by specific regulatory statuses (e.g., CLIA-waived in the U.S.). Securing simplified-use clearances materially expands addressable channels (physician offices, urgent care, non-traditional sites) and shortens sales cycles for low-complexity diagnostics.
-
Reimbursement: Changes in reimbursement can shift clinical and commercial economics quickly. For example, updated payment codes and fee schedules for high-volume tests materially affect provider adoption thresholds and price elasticity in 2025–2026 planning.
-
Input-cost volatility: Medical-grade reagents and single-use plastics experienced notable cost escalation in recent years, elevating the importance of margin-protection measures such as local sourcing, supplier contracts indexed to volumes, and design-for-cost in consumables.
-
Global access and procurement: WHO prequalification expansion for rapid tests increases market opportunity in low-resource settings but also raises the bar for quality, supply assurance, and price-pressure from public tenders.
Competitive landscape — what to watch
The competitive field is composed of diversified diagnostics giants, specialized molecular-platform vendors, and nimble assay innovators. Each group brings distinct vectors of value and risk:
-
Large diagnostics OEMs (e.g., Roche, Abbott, Thermo Fisher, BD) — These firms combine installed instrument footprints, broad assay portfolios, and strong regulatory pathways. Their strategic moves focus on point-of-care marks, higher-throughput platforms, and bundled service contracts. Recent CE and clinical-readout milestones from major OEMs reinforce their ability to accelerate commercialization where regulatory clearance and reimbursement alignment exist.
-
Molecular-platform specialists (e.g., Danaher/Cepheid, Bio‑Rad, Qiagen) — Their strength is rapid molecular workflows and assay multiplexing. Regulatory clearances and targeted product launches in 2024–2025 show continued innovation at the platform assay interface; these firms remain prime partners or acquisition targets for organizations seeking rapid access to validated multiplex capabilities.
-
Assay innovators and isothermal/alternate-technology players (e.g., Meridian, Hologic, Luminex/DiaSorin) — Focused on niche pathogens and faster time-to-result, these players can command clinical adoption in focused indications and are often attractive for licensing or co-development with manufacturers seeking differentiated cartridge content.
Recent company milestones illustrate strategic trajectories that will influence 2026 competition: targeted FDA clearances for new on-demand assays, multiplex panel launches that expand clinical breadth, CE-IVD point-of-care authorizations, strong clinical trial readouts for sensitivity/specificity claims, and distribution deals that accelerate hospital adoption. These moves tighten the window for newcomers to establish clinical trust and payer coverage.
Strategic imperatives for 2026 — recommended plays by stakeholder
-
Instrument manufacturers : Prioritize CLIA-waived and decentralized-use design wins; bundle consumables with service/analytics to protect margins; accelerate modular cartridge strategies to broaden assay attach rates.
-
Reagent and consumables suppliers : Execute dual-sourcing and local-fill strategies in 2026 to reduce exposure to input-cost shocks; develop lower-cost formulations and SKU rationalization for high-volume assays.
-
Clinical lab networks and hospital systems : Model total-cost-of-ownership across on-site, POC, and reference testing pathways; negotiate volume-based reagent rebates and prioritize multiplex panels that reduce downstream workflow costs.
-
Public health and procurement bodies : Leverage WHO prequalification to consolidate tenders and incentivize manufacturers to align pricing and supply commitments for low-resource markets.
-
Private investors and corporate development : Target asset classes that combine high recurring-revenue consumables with differentiated platform lock-in; prioritize targets with clean regulatory pathways and demonstrated clinical utility data.
Immediate actions for Q1–Q4 2026
-
Fast-track regulatory filing strategies for point-of-care pathways and align clinical protocols to payer evidence requirements.
-
Complete supplier risk audits and implement selective near-shoring for critical reagent lines.
-
Negotiate pilot reimbursement arrangements or coverage-with-evidence development to de-risk market launches.
-
Initiate 90-day commercial pilots with integrated pricing and service bundles to prove unit economics before broad rollouts.
How PW Consulting supports your 2026 agenda
PW Consulting offers bespoke advisory services that translate this report’s insights into executable programs: custom market-sizing that reflects your product mix, regulatory-pathway design and dossier support, payer-engagement strategies tailored to national systems, supplier-risk remediation playbooks, and M&A due diligence and valuation for targeted assets. Our strategic workshops convert high-level findings into board-ready operating plans with KPI tracking for the first 12 months post-engagement.
Next steps — where to get the full intelligence
This release is an executive preview designed to surface the strategic logic and operational levers that will matter in 2026. The full PW Consulting Pathogen Detection Market Report contains granular regional and application-level forecasts, technology-specific adoption curves, detailed competitor profiles, and data tables that underpin the scenarios summarized here. To access the complete analysis, data tables, and downloadable playbooks, please visit the PW Consulting report page and request the full report.
For detailed analysis of this topic, please visit the official page: Pathogen Detection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


