



PW Consulting: Green Superfood Market Set to Expand at a 6.95% CAGR Through 2032, Report Says
By PW Consulting, 2026-07-13
Green Superfood Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive summary
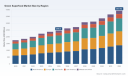
PW Consulting’s new Green Superfood Market report (base year 2025; forecast period 2026–2032) synthesizes quantitative market sizing, competitive intelligence, regulatory dynamics, and actionable go-to-market frameworks to help executives make high-consequence decisions in 2026. The global market, having expanded through the first half of the decade, reached a material scale by 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.95% across the 2026–2032 forecast window. This expansion reflects both continued consumer demand for nutrient-dense plant-based supplements and an intensifying need for robust quality, supply chain resilience, and differentiated product positioning.
Green Superfood Market
Why this report matters for 2026 planning
2026 will be a year of selective consolidation and rules-based differentiation in green superfoods. Companies will not only compete on formulation and brand storytelling, but increasingly on certifications, traceability, and contamination-proof manufacturing. Our report provides the empirical foundation and the practical playbook that decision-makers need to: prioritize R&D investments, structure procurement contracts for raw materials, rationalize SKUs and channel strategies, and assess M&A targets against realistic synergies and regulatory exposures.
Green Superfood Market
Market trajectory and macro view
After steady growth through 2020–2025, the green superfood market has entered a higher-confidence phase. The market scale reported for 2025 confirms a robust consumer base and a resilient retail channel mix. Under our central forecast, the market is set to expand meaningfully through 2032, underpinned by health-conscious consumption, premiumization trends, and growing e-commerce penetration. The modeled CAGR of 6.95% frames a planning horizon in which mid-term investments in quality systems and brand trust are likely to deliver outsized returns relative to short-term promotional spend.
Green Superfood Market
Key demand and supply drivers
- Consumer health positioning: Continued appetite for daily nutrition and preventive wellness supports recurring purchase behavior for green powders and blends.
- Formulation depth: Ingredient stacks that combine greens, probiotics, adaptogens, and functional botanicals are moving from novelty into expected product features.
- Certification and trust signals: With dietary supplements regulated as foods in many jurisdictions (and lacking pre-market approval), third-party certifications such as NSF and USDA Organic have become decisive purchase filters for mainstream buyers.
- Raw material dynamics: Ingredients such as spirulina remain foundational because of their nutrient density and generally recognized as safe (GRAS) status, but sourcing concentration and crop/regenerative practices are shaping supplier selection and cost profiles.
- Channel complexity: Online retail continues to enable direct-to-consumer scale and product iteration, while brick-and-mortar channels still drive trial and reach among value-conscious cohorts.
Competitive landscape — actionable takeaways
The market remains fragmented: the three- and five-firm concentration ratios indicate limited dominance by a few national brands, leaving room for regional specialists and private label entrants. Strategic implications for incumbents and challengers differ:
- Amazing Grass (Newport Beach, CA): A well-established player with a clear organic and plant-based positioning. Strengths include consumer recognition and an accessible portfolio of supergreen blends. Tactical advice: double down on supply chain transparency and expand clinical substantiation for flagship SKUs to defend shelf and digital visibility.
- Garden of Life (Palm Beach Gardens, FL): Known for nutrient-dense raw organic formulations and broad distribution. Strengths in formulation credibility and retail relationships. Tactical advice: leverage brand trust to pilot subscription models and enhance clinic-to-consumer education to lift lifetime value.
- AG1 / Athletic Greens (Carson City, NV): Positioned as a premium, research-forward daily greens drink with extensive ingredient layering and sports certifications. Recent product updates emphasize probiotics and flavor innovations. Tactical advice: reinforce clinical claims with published trials and consider tiered SKUs to broaden addressable consumer segments without diluting premium perception.
- Navitas Organics, Sunfood, Terrasoul, Suncore Foods: These ingredient- and product-focused firms play critical roles across the value chain. They excel with organic sourcing claims and supply of bulk ingredients. Tactical advice: companies that control upstream sourcing should monetize traceability (e.g., traceable QR codes, regenerative sourcing premiums) to capture margin and strengthen buyer relationships.
Recent shock events and regulatory noise
Early 2026 recalls tied to potential Salmonella contamination in several green superfood products have materially shifted the risk calculus. These events spotlight the dual realities that (1) recalls can rapidly erode consumer trust across brands and categories, and (2) quality systems and upstream testing protocols are now primary competitive differentiators.
- Regulatory environment: dietary supplements remain regulated as food in key markets, meaning products are not subject to pre-approval before market entry. In this context, third-party certifications (e.g., NSF Certified for Sport, USDA Organic) serve as market signals that materially influence consumer purchase intent and retail listing decisions.
- Operational responses: manufacturers and brand owners must prioritize hazard analysis, supplier audits, and retention testing. Investment in audit-ready documentation and rapid-response recall playbooks is no longer optional for national-scale players.
Practical contents in the PW Consulting report (what’s inside)
The report combines market-level analytics with executable tools for practitioners. Highlights include:
- Full market model (historical and forecast) with sensitivity scenarios and downside stress cases to support budgeting and valuation exercises.
- Quality and compliance playbook: templates for supplier qualification, lot-release testing, and recall scenario planning tailored to green powder supply chains.
- Formulation benchmarking matrix that compares ingredient stacks, functional claims, and certification footprints across representative competitive sets.
- Go-to-market blueprints for four archetypal strategies: premium DTC, mainstream retail scaling, ingredient-supplier monetization, and private-label consolidation.
- M&A target-screening algorithm and synergy calculators for potential roll-up strategies in manufacturing, ingredient sourcing, and direct-to-consumer brand consolidation.
- Channel economics models that quantify acquisition cost, repeat purchase rates, and lifetime value by channel archetype (for planning marketing and inventory allocation).
- Executive risk register and mitigation roadmap addressing contamination, raw-material shortages, price volatility, and regulatory shifts.
Strategic playbook for 2026 priorities
- Quality-first capital allocation: Allocate capex to testing labs, traceability systems, and supplier diversification before expanding SKU breadth.
- Certification roadmap: Fast-track certifications that align with target consumer segments—sports certifications for athlete-focused mixes, USDA Organic and regenerative claims for premium wellness audiences.
- Channel mix optimization: Use tiered SKUs to separate trial/entry products from subscription-grade SKUs; invest in retention mechanics for DTC while maintaining strategic retail partnerships for reach.
- M&A and partnership criteria: Prioritize targets that provide vertical control of high-risk raw inputs (e.g., spirulina sourcing) or that add validated manufacturing capacity with strong audit histories.
- Brand trust engineering: Publish third-party test results, implement transparent lot tracking, and use evidence-based marketing (clinical endpoints, not only ingredient lists).
Risk assessment and mitigations
The sector’s key near-term risks are operational (contamination, supplier disruption), regulatory (inconsistent labeling rules across markets), and reputational (high-profile recalls). Mitigants recommended by our analysis include:
- Mandatory supplier scorecards and dual-sourcing strategies for critical ingredients.
- Investment in in-house or partnered analytical testing capacity to reduce time-to-detection and liability exposure.
- Insurance structuring and contractual liability clauses to protect from downstream recall costs.
- Active consumer communication strategies that emphasize traceability and third-party validation.
How to use this report in boardroom decisions
Executives should use the PW Consulting model to stress-test scenarios (e.g., contamination-induced demand shocks, ingredient price surges, accelerated certification uptake) and to align capital allocation with the most defensible long-term value drivers: quality systems, traceable sourcing, and credible scientific substantiation of claims. For private equity and corporate development teams, the report’s valuation and synergy modules enable rapid triage of targets according to realistic integration costs and upside on margin improvement.
Trailer note — where to find the granular tables
To respect the “trailer” approach: this press release intentionally demonstrates analytical depth while withholding granular segment-level tables, regional and application breakouts, and specific price- and channel-level revenue figures. The full PW Consulting Green Superfood Market report contains those detailed tables, downloadable models, and company scorecards. Visit the PW Consulting site to access the complete dataset, Excel model, and the full list of practical templates and checklists described above.
Final thought
2026 will favor organizations that convert market growth into durable competitive advantage by institutionalizing quality, delivering evidence-led formulations, and aligning distribution strategies with consumer trust signals. PW Consulting’s Green Superfood Market report equips leaders with the evidence base and operational templates to make those trade-offs with confidence.
For detailed analysis of this topic, please visit the official page: Green Superfood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Drone Inspection System Market to Expand at 18.5% CAGR, Reach USD 57.26 Billion by 2032
By PW Consulting, 2026-07-13
PW Consulting: Strategic Preview — Drone Inspection System Market Intelligence for 2026 Decision-Makers
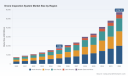
PW Consulting today publishes an executive preview of our in-depth market research on the global Drone Inspection System Market. The report synthesizes proprietary modeling, vendor benchmarking, regulatory scenario analysis, and implementation playbooks designed to inform capital allocation, procurement, and operational scale-up decisions in 2026. Our market model shows sustained, high‑growth dynamics—a compound annual growth rate (CAGR) of 18.5% over the forecast window—driving the market from USD 7,450 Million in 2020 to an estimated USD 17,450 Million in 2025 and pointing toward a multi‑decade industry build-out with total market value expected to exceed USD 57,256 Million by 2032.
Drone Inspection System Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year for enterprise adoption. Regulatory clarity, incremental performance improvements in autonomy, and the maturation of Drone‑in‑a‑Box and analytics platforms are converging to make repeatable, scalable inspection programs commercially viable.
Drone Inspection System Market -
Decision focus: Capital and operating expenditure choices made in 2026 will determine whether organizations capture early cost‑to‑serve advantages or face expensive retrofits to comply with evolving BVLOS and Remote ID requirements.
Drone Inspection System Market -
Risk/reward profile: High growth (18.5% CAGR) creates M&A and partnership windows, but operators must balance speed-to-market against operational constraints (notably battery endurance, mission continuity, and data integrity) and rising regulatory enforcement.
What the report delivers (practical and operationally focused)
-
Forward‑looking market model and scenario variants: Base, accelerated automation, and conservative regulatory scenarios with clear assumptions and sensitivity analyses to inform budgeting and valuation work.
-
Vendor diagnostic and selection framework: Comparative scorecards across autonomy, sensor suites, data pipelines, service models, and financial terms to shorten shortlist cycles and reduce procurement risk.
-
Implementation playbooks: Step‑by‑step templates for pilot-to-scale journeys, including KPI definitions, sample flight‑operation SOPs, safety cases, and procurement/RFP language.
-
Regulatory impact modules: Mapped implications of current FAA/EASA developments, including Remote ID enforcement, proposed Part 108 performance rules for BVLOS, and SORA updates that incorporate AI risk assessments.
-
Commercial archetypes and ROI calculators: Use‑case matrices (capex vs. opex, internal capability vs. outsourced service) and time‑to‑payback scenarios built for energy, infrastructure, and heavy‑industry portfolios.
-
Data governance and integration playbook: Templates for integrating aerial data into asset management systems, ensuring chain-of-custody, model governance, and compliance with industrial IT/OT policies.
-
M&A and partnership playbook: Target profiles, diligence checklists, and valuation levers for rollup strategies or capability acquisitions in autonomy and analytics.
Market dynamics shaping planning for 2026
-
Adoption enablers: Rapid advances in onboard AI, higher resolution multispectral and thermal sensors, and the proliferation of cloud and edge analytics are enabling richer, faster inspections with lower human exposure to risk.
-
Operational constraints: Battery endurance ceilings (commonly 20–40 minutes in current hardware) remain a practical limit on mission geometry, influencing platform selection, staging strategy, and the economics of continuous monitoring.
-
Regulatory inflection: The FAA’s 2026 enforcement updates and ongoing Part 108 NPRM activity, alongside EASA’s SORA enhancements for AI risk, are tightening operational compliance obligations—requiring organizations to bake regulatory risk mitigation into procurement and pilot programs.
-
Service model evolution: The market continues to shift from one‑off service engagements toward subscription and autonomous Drone‑in‑a‑Box models that emphasize continuous monitoring, predictable SLAs, and analytics monetization.
-
Concentration and competitive dynamics: Market concentration is meaningful but not prohibitive—top providers collectively control a meaningful share of revenue, leaving room for specialized players and system integrators to flourish in vertical niches and by delivering full‑stack services.
Competitive landscape — strategic implications for vendors and buyers
Our analysis benchmarks incumbent and emerging players across platform capability, autonomy stack maturity, sensor portfolio, service delivery model, and enterprise integration readiness. Below we synthesize strategic postures and buyer takeaways for leading vendors.
-
SZ DJI Technology Co., Ltd. — Dominant in hardware scale and payload breadth. Strength: enterprise platforms with integrated visual/thermal/RTK payloads and tight interoperability with inspection software. Buyer takeaway: strong hardware TCO and broad parts/support ecosystem; evaluate integration depth with your asset‑management systems and data ownership provisions.
-
SkySpecs, Inc. — Niche leader in wind-turbine autonomy and blade diagnostics. Strength: domain‑specific analytics and high‑quality data capture. Buyer takeaway: ideal for renewable‑asset owners seeking deep domain analytics; consider partnership models that combine their specialist workflows with your field operations.
-
Cyberhawk Innovations Limited — Specialist in aerial inspections for critical infrastructure with a mature data‑management platform (iHawk). Strength: turnkey inspection programs and regulatory pedigree. Buyer takeaway: compelling for operators needing end‑to‑end service and compliance documentation.
-
Skydio, Inc. — Distinctive in autonomy and obstacle avoidance with repeatable mission profiles. Strength: robust AI navigation and capture for complex assets like bridges and utilities. Buyer takeaway: reduces skilled‑pilot dependence for structured inspection routines.
-
Flyability SA — Leader in collision‑tolerant indoor platforms. Strength: access to confined and hazardous spaces where traditional drones cannot operate. Buyer takeaway: essential technology for petrochemical, mining, and confined‑space inspection programs.
-
Percepto Ltd. — Innovator in autonomous Drone‑in‑a‑Box systems and continuous industrial monitoring. Strength: automation and persistent site coverage. Buyer takeaway: evaluate for 24/7 monitoring use cases and high‑frequency inspection requirements.
-
Terra Drone Corporation — Broad service footprint including indoor platforms and cloud inspection tools. Strength: strong regional delivery and integrated cloud offerings. Buyer takeaway: cost‑effective indoor solutions and platform-to‑cloud workflows can accelerate pilot rollouts.
-
Censys Technologies Corporation — Focus on long‑range BVLOS with operational demonstrations. Strength: extended‑range missions and public proof‑points for corridor inspection. Buyer takeaway: strategic partner for wide‑area, infrastructure‑scale programs where BVLOS is required.
-
Drone Volt SA & AeroVironment, Inc. — Established OEMs with industrial portfolios. Strength: diversified platforms and legacy aerospace relationships. Buyer takeaway: evaluate for proven reliability and enterprise procurement cycles.
Recent industry moves reinforce the speed of operational innovation: a 2026 public demonstration of a 79‑mile BVLOS mission highlighted the feasibility of extended corridor inspections, while new indoor inspection platforms launched in 2025 broadened affordable access to confined‑space capabilities. These events underscore that technology readiness is rising in parallel with regulatory evolution—creating opportunities for early adopters who align investments with compliance and operations planning.
Actionable recommendations for 2026
-
Run portfolio‑level pilots, not point tests: Design pilots that mirror scale requirements—mission cadence, handover between sites, and data ingestion into asset management systems—to avoid later scope creep.
-
Prioritize operational resilience: Plan multi‑platform redundancy and charging/staging architectures to mitigate battery endurance limits and environmental variability.
-
Embed regulatory compliance into procurement: Make demonstrable compliance with Remote ID, detect‑and‑avoid, and applicable BVLOS rules a mandatory element of RFPs.
-
Use analytics and governance as a lock‑in: Ensure vendors provide exportable data, model traceability, and APIs for enterprise integration to avoid long‑term vendor lock‑in.
-
Explore partnership and M&A pathways: Consider bolt‑on acquisitions or strategic partnerships to internalize autonomy software, analytics, or persistent monitoring capabilities.
-
Budget for change management: Allocate resources for training, SOPs, and cross‑functional governance—inspection digitization is as much an organizational change as a technology adoption.
How to access the full intelligence
This preview highlights strategic conclusions and practical frameworks from PW Consulting’s full Drone Inspection System Market Report. The detailed model outputs (including regional and application-level revenue splits, vendor scorecards with weighted sub‑criteria, and downloadable procurement templates) are reserved for subscribers and clients. If your 2026 planning requires line‑by‑line forecasts, scenario outputs, or a vendor short‑list tailored to your asset portfolio, PW Consulting can provide a customised briefing and implementation roadmap.
For enterprise briefings, bespoke vendor evaluation, or to purchase the full report and associated toolkits, visit our report page or contact PW Consulting’s industry practice. Our team combines strategy consulting rigor with hands‑on operational know‑how to help organizations convert market growth into defensible, scalable programs.
About PW Consulting
PW Consulting is a strategy advisory firm specialising in industrial digitization, autonomy, and asset lifecycle optimization. We advise boards and operating teams on market entry, vendor selection, and scale‑up execution across energy, utilities, infrastructure, and heavy industry.
For detailed analysis of this topic, please visit the official page: Drone Inspection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Speech-to-Text Market Set to Expand at a 16.5% CAGR Through 2032
By PW Consulting, 2026-07-13
Speech To Text Software And Service Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present the executive preview of our Speech To Text Software And Service Market report — a practical, decision‑centric study designed to inform corporate strategies and vendor choices in 2026. This preview highlights the report’s strategic value for enterprise leaders, summarises high‑level market dynamics, and translates recent technical and regulatory shifts into actionable advice. To preserve the value of the full analysis, we deliberately withhold detailed segment spreadsheets and granular regional/application figures; these are available only in the full report.
Speech To Text Software And Service Market
Why this report matters for 2026 decisions
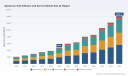
Speech‑to‑text (STT) is moving from a point technology to core infrastructure for customer engagement, operational analytics, and regulated workflows. Our report quantifies that transition at scale: from a multi‑billion dollar market in the mid‑2020s, the STT market is projected to continue at a robust compound annual growth rate (CAGR) of 16.5% across the 2026–2032 forecast window. This trajectory reflects a convergence of factors — improvements in model accuracy, the embedding of STT into conversational AI stacks, and increased enterprise willingness to automate voice workflows — that collectively make STT a strategic procurement and architectural priority for 2026.
Speech To Text Software And Service Market
For CXOs and procurement leads this means two imperatives: treat STT as a platform decision (not a one‑off service) and plan for rapid capability scaling. The market’s increasing scale and vendor concentration (with leading vendors controlling a meaningful share of industry revenue) create both opportunities — predictable innovation roadmaps and ecosystem integrations — and challenges — vendor lock‑in, pricing pressure, and platform risk.
Speech To Text Software And Service Market
High‑level market posture
- Market momentum: PW Consulting’s market model shows sustained acceleration since 2020 and continuing into 2026 and beyond, with the market expanding several fold over the decade as enterprises operationalise voice data.
- Competitive structure: The market exhibits partial concentration: the top three and top five providers account for a sizable portion of revenue, indicating a balance between large cloud platforms and nimble specialist vendors.
- Commercial dynamics: API pricing has stabilized under competitive pressure, but infrastructure cost pressures (notably GPU inference expenses) and rising demand for generative capabilities are altering supplier margins and go‑to‑market tactics.
What the PW Consulting report delivers (practical, hands‑on contents)
- Proven market model and methodology — transparent assumptions, historical calibration (2020–2025), and reproducible forecasting through 2032.
- Executive decision playbook — buy/build decision matrix, procurement checklists, vendor risk heatmaps, and a supplier selection scorecard tailored to enterprise priorities (accuracy, latency, privacy, scalability, total cost of ownership).
- TCO and pricing scenarios — interactive templates and sensitivity analyses that model API pricing, on‑prem vs cloud trade‑offs, inference compute costs, and licensing. (Note: the report reserves granular segment-level cost tables for subscribers.)
- Implementation roadmaps — phased adoption plans for contact centers, clinical transcription, legal dictation, media workflows, and edge/IoT deployments; integration patterns with LLMs and analytics services.
- Compliance and privacy toolkit — mapping of regulatory requirements (GDPR, HIPAA, EU AI Act) to product controls, sample contractual language, and a checklist for privacy‑by‑design STT deployments.
- Vendor shortlists and scenario playbooks — curated vendor sets for each enterprise archetype, plus migration strategies to mitigate lock‑in and ensure multivendor resilience.
- Board‑level risk briefings and investor insights — concise slide decks and talking points that translate technical tradeoffs into financial and strategic implications.
Competitive landscape — how incumbents and specialists shape 2026 choices
The competitive map is anchored by hyperscalers, enterprise specialists, and edge vendors. Each cohort brings different strategic value: hyperscalers offer scale, integration and global infrastructure; specialists provide focused accuracy, vertical expertise and faster customization; edge players deliver privacy and offline capabilities.
- Google Cloud — Strengths: broad multilingual coverage, state‑of‑the‑art universal models and deep integration across data and analytics stacks. Strategic implication: ideal for enterprises prioritising global scale, rapid feature adoption and tight integration with cloud analytics. Watch for rising expectations around model explainability and cost control as usage expands.
- Microsoft Azure (including Nuance) — Strengths: enterprise healthcare and regulated‑vertical pedigree following the Nuance acquisition, plus seamless integration with productivity suites and compliance tooling. Strategic implication: a compelling choice for regulated workflows (medical, legal) where vendor alignment with healthcare compliance and enterprise identity is material.
- Amazon Web Services (Transcribe) — Strengths: mature streaming/batch offerings, call analytics and customizable vocabularies. Strategic implication: strong for contact center, analytics and high‑volume streaming use cases tied to broader AWS footprints.
- Nuance Communications — Strengths: domain expertise in clinical dictation and professional voice recognition; integrated offerings now amplified through strategic partnerships. Strategic implication: preferred where domain accuracy and workflow embedding matter more than raw scale.
- IBM Watson — Strengths: customization options and enterprise deployment flexibility with a history in enterprise AI. Strategic implication: suitable where bespoke acoustic/custom language models and enterprise governance are priorities.
- Speechmatics, AssemblyAI, Deepgram, Otter.ai, Rev.ai — Strengths: specialist accuracy, developer‑friendly APIs, and feature differentiation (summarization, entity detection, low latency). Strategic implication: these vendors are useful as primary providers for targeted use cases or as strategic fallback vendors to reduce lock‑in risk.
- Picovoice, SoundHound — Strengths: on‑device inference, privacy‑first architectures and automotive/IoT integrations. Strategic implication: essential partners for edge, disconnected or privacy‑sensitive deployments.
Recent product and market movements to watch
- Model and feature upgrades: industry leaders continue to introduce universal, multitask models and LLM‑aligned post‑processing (e.g., summarization and entity extraction). These advances materially reduce workflow integration effort and expand the addressable use cases.
- Strategic M&A: the market has seen large strategic moves to acquire vertical expertise and accelerate monetization of voice data in regulated sectors — an indicator that enterprise buyers should expect consolidation around differentiated IP and industry relationships.
- Infrastructure cost pressure: GPU inference costs rose as demand for generative workloads increased, which is feeding through into vendor pricing strategies and multi‑tier product offers that segment premium real‑time services from lower‑cost batch products.
Regulatory, privacy and cost headwinds — operational implications
- Regulation: The EU AI Act’s classification of certain real‑time biometric categorisation systems as high‑risk requires enterprises to embed risk assessments, transparency and governance in any STT deployment that could be used for biometric inference.
- Data protection: Under GDPR, voice data that qualifies as biometric information may require explicit consent and heightened safeguards. Enterprises operating across jurisdictions must design consent flows and data retention policies accordingly.
- Sectoral compliance: HIPAA continues to demand encryption, access controls and auditable processing for medical transcription — selecting vendors with verified compliance controls is non‑negotiable for healthcare deployments.
- Cost dynamics: While API pricing for STT has stabilized in the low cents per minute for commodity transcription, the marginal cost of adding advanced post‑processing, low latency SLAs or on‑device capabilities can materially shift TCO. Our report models these variations across adoption archetypes.
Actionable recommendations for 2026 planning
- Adopt a platform mindset: Assess STT as a platform decision — define target architectures (cloud native, hybrid, edge) and require vendors to demonstrate integration tests with your voice data pipeline.
- Prioritise use cases by ROI and risk: Start with high‑value, low‑risk pilots (e.g., internal meeting capture, media captioning) before expanding into regulated or customer‑facing automations that require additional governance.
- Design for multivendor resilience: Use specialist vendors for vertical accuracy and hyperscalers for scale; include portability and export conditions in contracts to avoid lock‑in.
- Embed compliance by design: Map GDPR, the EU AI Act and sectoral regulations into your procurement and deployment gates; require vendors to supply compliance attestations and runbooks.
- Model TCO beyond unit pricing: Include inference compute, integration effort, retraining cadence, and post‑processing (LLM) costs in procurement scenarios rather than relying on per‑minute API fees alone.
Next steps and how PW Consulting helps
PW Consulting’s full Speech To Text Software And Service Market report provides the detailed segment analyses, vendor scorecards, downloadable financial models and implementation templates referenced above. For enterprise leaders preparing 2026 budgets and platform roadmaps, the report translates market scale, concentration metrics and regulatory realities into concrete procurement clauses, migration plans and risk mitigations.
Access to the full dataset and operational toolkits is available on our report page. PW Consulting’s advisory team is also available to conduct bespoke vendor screenings, TCO workshops, and governance audits to accelerate safe, high‑impact STT deployments.
For detailed analysis of this topic, please visit the official page: Speech To Text Software And Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wastewater Treatment Reactor Market to Grow at a 6.45% CAGR from 2026 to 2032
By PW Consulting, 2026-07-13
PW Consulting Releases Strategic Market Brief: Wastewater Treatment Reactor Market — Essential Intelligence for 2026 Decision-Making
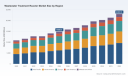
PW Consulting today publishes an executive market brief accompanying our full Wastewater Treatment Reactor Market report (base year 2025). The brief synthesizes the market trajectory, competitive dynamics, regulatory headwinds, and operational cost drivers that will determine winning strategies in 2026 and beyond. The global wastewater treatment reactor market reached USD 14,850.5 Million in 2025 and, on the strength of tightening discharge standards, rising industrial reuse mandates, and accelerating membrane adoption, is forecast to expand to roughly USD 23,001.5 Million by 2032 — a compound annual growth rate (CAGR) of 6.45% over the 2026–2032 forecast horizon.
Wastewater Treatment Reactor Market
Why this report matters to executives planning in 2026
-
Actionable planning horizon: The report aligns scenario-based forecasts to procurement and capital planning cycles that begin in 2026 — enabling CFOs and municipal/industrial utilities to phase CapEx and pilot programs in step with expected tender waves.
Wastewater Treatment Reactor Market -
Risk-adjusted budgeting: We translate macro trends (regulatory tightening, raw-material volatility, membrane cost differentials) into stress-tested CapEx/Opex models to inform financing, leasing vs. buy decisions, and contract structuring for long-life assets.
Wastewater Treatment Reactor Market -
Vendor selection clarity: A pragmatic vendor assessment framework reduces due diligence time by prioritizing suppliers on technology fit, delivery track record, service footprint and modularity for fast deployment.
-
Competitive positioning: Operators and OEMs can convert market growth into commercial advantage by aligning product roadmaps with proven adoption vectors (membrane systems, hybrid biofilm solutions, packaged reactors and treatment-for-reuse configurations).
What the PW Consulting report delivers (practical content overview)
-
Proprietary market sizing and top-line forecasts (2026–2032) with scenario overlays for three regulatory intensities and two energy-price environments.
-
Technology adoption curves and Total Cost of Ownership (TCO) models for common reactor typologies — designed for rapid customization in CapEx committees and tender specification documents.
-
Procurement playbooks and RFP templates tailored for municipal utilities and industrial buyers (food & beverage, petrochemicals, pharmaceuticals, oil & gas) with scoring matrices for: performance, lifecycle service, spare parts, and energy efficiency.
-
Vendor dossiers and capability heatmaps (including manufacturing footprint, membrane partnerships, packaged plant capability, and after-sales coverage) to compress vendor short-listing from months to weeks.
-
Cost sensitivity analyses that quantify the impact of raw-material swings and membrane-premium adoption on Opex and payback timelines.
-
Case studies and deployment checklists covering advanced oxidation + membrane integrations for emerging-contaminant abatement and zero-liquid-discharge (ZLD) retrofits.
Market structure & competitive implications
The market remains commercially fragmented, with specialization and system modularity more important than scale in many procurement settings. Our concentration analysis shows that the top three vendors collectively account for under one-fifth of the market, and the top five for roughly one-quarter — a profile that favors both established global integrators and well-capitalized niche specialists that can deliver engineered solutions for complex effluents.
-
Implication for buyers: Fragmentation increases supplier choice but heightens procurement risk — performance warranties, supply-chain resiliency and long-term service agreements should be contractual priorities.
-
Implication for vendors: There is room for strategic consolidation (technology tuck-ins, geography-driven M&A) and for premium positioning through differentiated membrane technologies, PFAS-capable advanced oxidation, and packaged modular reactors for decentralized markets.
Key supplier profiles — what to watch in 2026
-
Veolia Water Technologies (Saint-Maurice, France) — global integrator with extensive MBR and ultrafiltration product lines and recent deployments focused on PFAS and advanced oxidation.
-
SUEZ (La Défense, France) — breadth in membrane and ion-exchange-based solutions with a strong pipeline in industrial treatment and reuse applications.
-
Xylem Inc. (Rye Brook, NY, USA) — pump and system specialist integrating high-efficiency hydraulics, UV disinfection, and packaged MBRs for aerobic processes.
-
Evoqua Water Technologies (Pittsburgh, PA, USA) — systems integrator with MBR, RO and filtration portfolios geared to industrial buyers requiring compact footprints.
-
Aquatech International (Canonsburg, PA, USA) — specialist in ZLD and membrane-thermal hybrids for chemically challenging wastewater streams.
-
Ovivo (Montreal, Canada) — long-standing equipment provider with experience across municipal, industrial and energy sectors.
-
Smith & Loveless, Kubota, Headworks International, Aqua-Aerobic Systems, Parkson, CWT, World Water Works, WSI International, H2O Innovation — each brings differentiated strengths from operator-friendly packaged MBRs to IFAS/MBBR specialization, and are active participants in regional modernization projects.
Technology, cost dynamics and operating risks you need to model
-
Membrane economics: Adoption of biodegradable/“green” membrane materials is accelerating because of lower sludge production and lifecycle benefits; expect a 20–30% premium at purchase for these alternatives. Buyers must model the premium against reduced solids handling costs and extended disposal liabilities.
-
Chemical cost volatility: Acrylamide-based flocculant pricing has shown material quarterly swings in recent years; our models quantify how a 15–20% volatility band translates into Opex changes for coagulation/flocculation-dependent processes.
-
PFAS and emerging contaminants: The growing regulatory focus on PFAS has pushed combined advanced oxidation + membrane retrofits to the top of capital priorities for many utilities. Facilities that anticipate tighter PFAS limits in 2026 will reduce delivery risk and rework costs by specifying oxidant compatibility and membrane-stage replaceability in initial designs.
-
Energy & resource recovery: Embedded energy and anaerobic digestion opportunities materially affect payback for high-strength industrial streams. Our TCO workstreams enable cross-functional teams to evaluate energy-recovery credits within project finance models.
Regulatory inflection points and procurement timing
-
Stricter effluent and reuse mandates are the primary growth lever — increasing enforcement of reuse and ZLD requirements is driving membrane-led reactor adoption across industrial sectors.
-
Marine and specialized applications must account for industry-specific certification updates (e.g., IMO and U.S. Coast Guard requirements) that can influence equipment specifications and vendor eligibility.
-
Practical consequence for 2026 planning: Municipal utilities that initiated upgrades in late 2025 will enter contracting and commissioning phases through 2026; suppliers with local installation capacity and spare-parts inventories will secure outsized share of near-term projects.
How to use this report in your 2026 playbook — a five-step checklist
-
1) Re-run your CapEx pipeline against the three regulatory scenarios in the report to determine which projects to accelerate, defer, or convert to pilot-and-scale approaches.
-
2) Short-list vendors using our capability heatmap and require lifecycle cost submissions that include membrane-replacement schedules and chemical-consumption baselines.
-
3) Include membrane-premium sensitivity and acrylamide/chemical volatility in Opex forecasts submitted to treasury; secure supply contracts or hedges where appropriate.
-
4) Design RFPs for PFAS-capable systems with staged commissioning milestones and defined acceptance criteria for advanced oxidation and permeate quality.
-
5) Evaluate M&A or partnership opportunities with niche specialists to accelerate market entry into decentralized or high-strength industrial segments.
Recent market signals (selected developments)
-
June 2025 — Veolia North America commissioned a major PFAS treatment facility, underscoring the push toward integrated oxidation + membrane architectures for contaminated wastewater.
-
June 2025 — Strategic consolidation continued with upstream players acquiring packaged-treatment capabilities, increasing pressure on mid-market systems integrators to either specialize or scale.
-
2024–2025 — Multiple municipal utilities initiated plant modernization procurements that will sustain demand for biological reactors and nutrient-removal upgrades through 2026.
What we are intentionally withholding in this press release
To preserve the integrity of client-grade intelligence and to encourage direct engagement with the full analysis, this briefing intentionally omits detailed regional and application-level revenue splits, fine-grained vendor market shares, and customer-level contract values. The full report contains those granular deliverables — including downloadable financial models, vendor scorecards, and RFP templates — and is available via PW Consulting’s report portal.
Next steps and how to obtain the full briefing
Executives looking to convert insights into procurement-ready actions for 2026 should download the full Wastewater Treatment Reactor Market report or contact PW Consulting’s sector team for a tailored briefing and model workshop. The full dossier includes editable TCO models, a procurement playbook, and a vendor short-listing toolkit designed to accelerate decision cycles in the coming 12 months.
About PW Consulting
PW Consulting is a strategy and industry research firm advising utilities, industrial end-users, and equipment OEMs on water and environmental technologies. Our sector teams combine frontline project experience with proprietary market modeling to deliver insight-ready tools for commercial and technical leadership teams.
For detailed analysis of this topic, please visit the official page: Wastewater Treatment Reactor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Substrate Market for Hard Disk Drives Set to Expand at a 5.85% CAGR During 2026–2032
By PW Consulting, 2026-07-13
Glass Substrates for Hard Disk Drives — Strategic Outlook to 2032: A PW Consulting Preview
PW Consulting’s new market study on glass substrates for hard disk drives (HDDs) frames a clear growth trajectory and a compact competitive structure that will shape supplier strategy, OEM roadmaps, and procurement decisions through 2026 and beyond. Using 2025 as our base year and a 2026–2032 forecast horizon, the market expands from a historical USD 380 million in 2020 to USD 520 million in 2025 and is projected to reach roughly USD 774 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.85% across the forecast period. This preview highlights why the report is strategically actionable for executives planning capex, sourcing, and product roadmaps in 2026 while preserving the granular intelligence reserved for the full report.
Glass Substrate For Hard Disk Drives Market
Why this report matters for 2026 decision-makers
-
Timing capital and capacity: The market’s mid-single-digit CAGR masks inflection points driven by nearline demand cycles, higher platter counts, and technology transitions (e.g., HAMR readiness). Understanding the cadence of demand vs. lead times for glass-substrate capacity is essential to avoid over- or under-investing.
Glass Substrate For Hard Disk Drives Market -
Supplier concentration and negotiating leverage: The substrate supply chain is highly concentrated (our analysis shows the top three firms control a dominant share and the top five control an overwhelming majority). Executives need scenario-driven procurement playbooks that factor in supply-side tightness, qualification cycles, and strategic collaboration options.
Glass Substrate For Hard Disk Drives Market -
Design-for-supply and product strategy: Decisions about platter counts, drive thickness, thermal budgets (HAMR/LAMR), and form factors are materially affected by glass substrate capabilities. Early alignment between system architects and substrate suppliers shortens qualification times and reduces time-to-market for higher-density HDDs.
-
Risk-adjusted cost planning: Raw material volatility and environmental constraints in glass manufacturing introduce appreciable cost and schedule risk. Procurement and finance teams must incorporate sensitivity scenarios into 2026 budgets and multi-year forecasts.
Key themes shaping the market
-
Nearline storage demand continues to underpin growth. Cloud and hyperscale requirements for cost-per-TB and power efficiency sustain HDD adoption where cost-effective bulk storage is prioritized over pure performance.
-
Glass substrates enable technical progress. Glass provides rigidity, dimensional stability, and thermal resilience needed for higher platter counts, thinner stacks, and emerging heat-assisted recording designs — enabling OEMs to push areal density without compromising mechanical stability.
-
Supplier concentration drives strategic dependencies. A small set of capable substrate producers shapes qualification timelines, pricing behavior, and capacity availability — making supply-side intelligence a critical input to corporate strategy.
-
Raw material and regulatory pressure. Inputs such as soda ash and the energy intensity of furnaces are both cost levers and regulatory targets. Environmental regulation on CO2 and related emissions is catalyzing investments in cleaner technologies and recycled-content strategies across glass production.
-
Product milestones are accelerating ecosystem change. Recent OEM and component milestones are validating glass-based approaches for higher-capacity nearline drives, creating adoption windows that suppliers and system integrators must act upon quickly.
What the PW Consulting report delivers — practical, execution-ready modules
-
Executive brief and decision-trees tuned for 2026: One-page guidance for CEOs, CFOs, and VPs of Product that maps actions to three strategic postures (expand, partner, hedge).
-
Market sizing and forecast model (2020–2032): Transparent methodology and downloadable model with base-year calibration, demand drivers, and scenario toggles to test upside/downside assumptions.
-
Supply-chain map and capacity tracker: Facility-level visibility, typical lead times, and a timeline of announced and planned capex — enabling procurement to model delivery risk windows.
-
Cost-build and sensitivity analysis: Line-item cost models showing how inputs (raw materials, energy, yield curves) affect substrate unit economics and OEM bill-of-materials.
-
Competitive benchmarking and supplier scorecards: Capability, quality, technology roadmap, capacity, and commercial behavior assessments for incumbent players, plus an M&A/partnership scoreboard.
-
Technology adoption playbook: Qualification pathways for glass substrates across form factors and recording technologies, plus common failure modes observed during pilot runs.
-
Risk scenarios and mitigation strategies: Contingency planning templates for supply shock, raw material spikes, regulatory shifts, and demand compression.
-
Commercial and procurement templates: Model contracts, strategic sourcing checklists, and negotiation levers tailored to high-concentration supplier markets.
Competitive landscape — what matters and why
Our competitive analysis spotlights the single global-scale substrate manufacturer that dominates production for multiple HDD form factors and segments. This supplier’s technical leadership — particularly in producing high-quality glass that supports higher platter counts, thinner designs, and heat-tolerant recording technologies — gives it outsized influence over OEM design cycles and qualification timelines. Recent industry moves underscore this dynamic: the supplier announced a significant capacity expansion investment in Vietnam (announced April 2026), intended to align output with nearline HDD demand growth and operationalize scale advantages by the late 2020s.
At the same time, OEMs are validating glass-based platform architectures: recent product milestones and sampling programs from major HDD manufacturers indicate that glass substrates are moving from advanced qualification into early production for higher-capacity nearline products. These technical confirmations compress adoption risk but increase the value of fast, reliable substrate supply.
Market concentration numbers underscore a structural reality: a small group of firms capture the overwhelming majority of supply. For buyers, this means that strategic sourcing is not about spot-price wins but about securing alignment on capacity commitments, co-development roadmaps, and contingency sourcing in the event of supply disruptions.
Supply-chain and input-cost signals to watch in 2026
-
Soda ash pricing and availability: Soda ash is a primary flux in glass production and has a material impact on substrate costs and producer margins. Market intelligence in early 2026 shows divergent signals: one source reported Chinese domestic trading at about 2,600 RMB/ton in early May 2026 (Sunsirs), while broader datasets reflected a softening trend with levels nearer to 1,200 CNY/ton earlier in the year (Industry Market Data, Feb 2026). The disparity highlights regional spreads and the need for real-time procurement monitoring.
-
Energy and emissions regulation: Stricter environmental requirements in major markets increase operating costs for furnace-driven glass production and drive capital investment into lower-emission technologies and recycled content handling.
-
Capex timelines: Announced capacity expansions should be tracked against actual commissioning schedules. Even well-capitalized projects can slip, creating tightness windows that affect pricing and availability for OEMs and contract manufacturers.
-
OEM adoption rates: Monitor sampling-to-production conversion metrics and the rate at which system integrators increase platter counts and thinner-stack designs — these directly translate into substrate volume demand.
Concrete actions for executives during 2026
-
For procurement leaders: Recast supplier engagements around capacity commitments and co-development clauses rather than purely unit-price negotiations. Introduce raw-material pass-through clauses and establish hedging or index-linked mechanisms where appropriate.
-
For product and engineering: Prioritize early cross-functional qualification programs with substrate suppliers to reduce time-to-production for new high-capacity SKUs. Allocate engineering resources to thermal and vibration testing specific to glass-based platters.
-
For corporate development: Use the current concentration to rationalize M&A and partnership screens — targets include finishing/processing assets, niche substrate refiners, and vertically adjacent suppliers that could offer partial despecialization or near-term capacity relief.
-
For finance and strategy: Build stress-tested forecasts that incorporate raw-material price swings and regulatory capex. Maintain contingency reserves or flexible capital plans to accelerate alternative sourcing or supplier expansions if market tightness materializes.
Next steps — where to get the full intelligence
This preview outlines the strategic contours PW Consulting’s full Glass Substrate for HDDs Market report covers. The full study contains the detailed models, supplier scorecards, and scenario tools your leadership team will need to convert insight into action in 2026. To access the complete dataset, downloadable financial models, and execution templates — including the granular segmentation, capex timelines, and strategic playbooks — please visit the PW Consulting reports page or contact our research team to arrange a briefing.
PW Consulting’s analysis is built to transform market intelligence into executable strategy. In a market where a handful of suppliers and evolving technology milestones determine the pace of innovation and capacity, the right insight — delivered at the right time — is the differentiator between meeting enterprise storage demand profitably or falling behind.
For detailed analysis of this topic, please visit the official page: Glass Substrate For Hard Disk Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aviation Oxygen Systems Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market research brief on the Aviation Oxygen Systems market positions executives to make informed, high‑impact decisions in 2026. The market has moved from a recovery phase into a sustained expansion driven by fleet modernization, tightened airworthiness oversight, and expanding aftermarket demand. Our base‑year synthesis (2025) and forward projections (2026–2032) show a robust trajectory — the market expands from an early‑decade base in 2020 through to a materially larger opportunity by 2032, with a compound annual growth rate (CAGR) of 6.8% across the forecast horizon. This briefing highlights the strategic implications of that growth, the competitive dynamics you must monitor, and the practical actions that will protect and grow revenue and margins this coming year.
Aviation Oxygen Systems Market
Market trajectory and what it means for 2026
-
Recovery to growth: After a multi‑year recovery in the early 2020s, the market reached a meaningful inflection point in 2024–2025 as airlines, business aviation operators, and defense fleets accelerated oxygen system upgrades and MRO activity.
Aviation Oxygen Systems Market -
Scale and momentum: Our model quantifies the market’s march upward through 2025 and projects continued expansion across 2026–2032. That expansion is driven by a mix of OEM fitment on new platforms, retrofits and upgrades (including on‑board oxygen generators and advanced delivery systems), regulatory compliance cycles, and aftermarket maintenance demand.
Aviation Oxygen Systems Market -
Concentration and competitive pressure: The sector exhibits moderate concentration — the top three players capture roughly half of the market, and the five largest vendors command well over sixty percent. This structure creates a dual opportunity for established suppliers to extract scale economies and for challengers to win niche share through service differentiation or technology specialization.
Strategic implications for 2026 corporate planning
-
Prioritize MRO and service‑based revenue. As fleets age and regulatory regimes (airworthiness directives, hydrostatic testing cycles, and purity standards) drive recurring work, aftersales service becomes a high‑margin, sticky revenue stream. Leading players will convert installed base visibility into scheduled MRO programs, subscription services for oxygen cylinder rotation and testing, and bundled compliance offerings.
-
Accelerate certification roadmaps. Regulatory actions in 2025–2026 have demonstrated that airworthiness authorities are actively reassessing portable breathing equipment and operational instructions. Firms that pre‑emptively invest in design validation, AD‑driven replacements, and transparent traceability for oxygen equipment will shorten time‑to‑market and reduce retrofit risk.
-
Invest in next‑gen delivery technologies. Pulse‑demand delivery, compact OBOGS implementations for specific aircraft classes, and smart regulator platforms with integrated sensors for purity and leak detection are adoption vectors with two benefits: product differentiation and longer lifecycle revenue through software and analytics services.
-
Build supply‑chain resilience for critical components. Cylinders, valves, regulators, and mask assemblies are subject to lead‑time variability and regulatory test requirements. Companies should develop diversified sourcing, in‑region repair stations, and forward test capacity to avoid revenue loss from grounding or deferred maintenance.
-
Pursue targeted M&A and partnerships. The market’s concentration profile favors bolt‑on acquisitions that expand MRO footprints, add FAA/EASA repair station approvals, or bring complementary technologies (pulse systems, sensor platforms). The Aerox acquisition activity in early 2025 typifies how strategic MRO capacity deals can immediately deepen service capabilities.
Competitive landscape — what to watch
Our report profiles incumbent OEMs, specialized manufacturers, and defense‑grade suppliers. Key players we analyze include Aerox Aviation Oxygen Systems, Safran Aerosystems (AVOX Systems), Collins Aerospace (RTX), Precise Flight (formerly Nelson Oxygen), Mountain High Equipment & Supply, Meggitt (now integrated under Parker Hannifin for certain capabilities), and Honeywell Aerospace. These vendors differ in several strategic dimensions:
-
Product breadth: Some firms compete across passenger, crew and military lines with integrated PSU/OBOGS solutions; others focus on portable and GA‑oriented systems where aftermarket and DIY installers remain important.
-
Service ecosystems: Leaders with repair‑station networks and certified MRO capabilities can monetize regulatory compliance cycles and cylinder testing obligations more effectively.
-
Regulatory exposure: Airworthiness directives and PBE rulings create short‑term product replacement demand but also raise certification costs. Recent ADs affecting portable breathing equipment underscore the need for proactive compliance programs and recall mitigation playbooks.
-
Defense vs. civil balance: Firms with defense OBOGS and precision regulator experience enjoy higher technical barriers to entry and often benefit from multi‑year procurement programs; civil suppliers rely more on airline retrofit cycles and GA adoption.
Regulation, safety and operational drivers
-
Operational mandates: International and civil aviation regulators enforce specific crew and passenger oxygen use thresholds, as well as oxygen purity and moisture requirements that differ from medical or industrial oxygen. These rules drive both product specification and recurring maintenance obligations (e.g., hydrostatic testing of cylinders).
-
Airworthiness actions: Recent EASA and FAA actions on portable breathing equipment illustrate how even a small subset of product failures can trigger fleet‑wide interventions. Companies must embed regulatory surveillance and rapid response capabilities into product management and customer communications.
What’s in the PW Consulting report (practical value for 2026)
This research is designed as an operational tool for strategy teams and commercial leaders. Highlights include:
-
Proprietary market model: A transparent, auditable model that reconciles historical performance (2020–2025) with a scenario‑based 2026–2032 forecast (anchored to a 6.8% CAGR). The model supports sensitivity testing for fuel price shocks, regulatory cadence, and retrofit acceleration.
-
Customer economics & procurement playbooks: Unit economics for OEMs and MROs, typical service contract structures, and recommended commercial terms to protect margins while increasing fleet penetration.
-
Competitive scorecards and vendor playbooks: Benchmarking across technology, certifications, MRO footprint, and service capabilities — useful for vendor selection and partnership negotiations.
-
Regulatory impact analyses: Detailed scenarios that quantify the near‑term revenue uplift from AD compliance and the long‑term cost of elevated certification requirements, with recommended mitigation steps.
-
Implementation roadmaps: Prioritized initiatives, estimated investment ranges, and KPIs for 12‑, 24‑, and 36‑month horizons to convert strategic intent into measurable outcomes.
Note: To preserve the tactical value of the report as a practical purchase decision for our clients, this public briefing intentionally omits granular regional and application segment tables and dollarized splits. The full intelligence pack contains those detailed breakdowns, company revenues, and product‑level forecasts.
Recommended near‑term actions (a checklist for 2026)
-
Audit your installed‑base visibility and certification status; prioritize customers with imminent hydrostatic or AD compliance windows.
-
Allocate capex to expand FAA/EASA‑approved repair stations or partner with certified MROs to capture cylinder rotation and testing pools.
-
Accelerate product roadmap items that reduce life‑cycle cost for operators (lighter cylinders, pulse‑demand electronics, predictive maintenance sensors).
-
Build regulatory monitoring and recall response teams; predefine logistics for rapid replacement campaigns in case of ADs or PBEs impacts.
-
Assess M&A targets that close service gaps, expand regional presence, or add platform certifications — prioritize deals that deliver EBITDA‑accretive service revenue within 12–18 months.
How to access the full intelligence
PW Consulting’s full Aviation Oxygen Systems Market report includes the exhaustive datasets, granular regional and application breakdowns, company financials, and downloadable models that are excluded from this briefing. Organizations planning capital allocations, supply‑chain investments, or M&A activity in 2026 will find the complete package essential to de‑risk decisions and capture growth opportunities.
For access to the full report, vendor scorecards, and the forecast model (including downloadable scenario variants), contact PW Consulting’s industry practice or visit our report page to request a sample chapter and purchase options.
— PW Consulting, Strategic Advisory & Industry Research
For detailed analysis of this topic, please visit the official page: Aviation Oxygen Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Healthcare Regulatory Affairs Outsourcing Market: Strategic Imperatives for 2026 — PW Consulting Insights
As regulatory complexity, digital mandates and AI-enabled tooling converge, outsourcing of regulatory affairs is transitioning from a cost-driven administrative choice to a strategic lever for product lifecycle velocity and regulatory resilience. PW Consulting’s new Healthcare Regulatory Affairs Outsourcing Market report (base year 2025) synthesizes historical performance (2020–2025), forward-looking projections for 2026–2032 and practical playbooks that senior leaders should use to align sourcing, technology and M&A decisions for 2026 and beyond.
Healthcare Regulatory Affairs Outsourcing Market
Market trajectory: growth, concentration and what it means for strategy
The market for regulatory affairs outsourcing has demonstrated robust expansion during the last five years, with the total market expanding through the 2025 base year and our forecast pointing to a sustained compound annual growth rate (CAGR) of approximately 11.5% across the 2026–2032 forecast window. Under that trajectory, the market size more than doubles over the forecast horizon, reflecting a structural uplift in demand for outsourced regulatory capabilities driven by digital submission mandates, biologics/advanced-therapy complexity and geographic expansion of clinical and commercial programs.
Healthcare Regulatory Affairs Outsourcing Market
Market concentration remains moderate: the top three providers account for just over one-third of market share, and the top five approach roughly half the market. This configuration produces both competitive intensity among established global integrators and opportunity space for specialist and regional players—creating distinct strategic choices for buyers and investors in 2026.
Healthcare Regulatory Affairs Outsourcing Market
Why this report matters for 2026 decision-makers
-
Regulatory acceleration is now mandatory: the industrywide transition to updated electronic submission standards and the proliferation of region-specific technical requirements mean that timeliness and technical compliance are direct enablers of launch windows and revenue realization. 2026 procurement strategies must prioritize providers with proven e-submission readiness and scalable electronic common technical document (eCTD) capabilities.
-
AI and automation are reshaping service economics: vendors have rapidly integrated generative and task-specific AI into submission authoring, intelligence gathering and lifecycle maintenance. Buyers will need to evaluate not only the existence of AI tools but their validated impact on cycle time, quality and audit readiness.
-
Regulatory complexity is geographically differentiated: changing expectations in major authorities and emerging markets (including evolving clinical-data and CMC requirements) create asymmetric value for vendors with targeted local expertise and cross-jurisdictional experience.
-
Outsourcing is becoming strategic, not tactical: Leading biopharma and MedTech companies are moving from isolated, transaction-based outsourcing to portfolio-level outsourcing models (e.g., FSP, center-of-excellence partnerships and embedded teams) that require governance, KPI design and integrated technology roadmaps.
What the PW Consulting report delivers — practical, decision-ready content
Designed for senior leaders in regulatory, development operations, procurement and corporate development, the report blends market-level analytics with hands-on tools you can apply in 2026. Highlights include:
-
Market sizing and scenario modelling: baseline and upside scenarios reflecting policy shifts, AI adoption curves and regional trial expansion—useful for budgeting and outsourcing strategy alignment.
-
Buy-side playbooks: vendor selection scorecards, RFP templates tailored to eCTD 4.0 and AI-enabled capabilities, and evaluation frameworks for FSP versus project-based contracting.
-
Technology assessment framework: independent criteria to assess regulatory intelligence platforms, NLP-driven compilation tools and agent-based automation, including questions to surface validation, audit trails and vendor lock-in risks.
-
Operational templates: KPI sets for time-to-submission, query resolution SLAs, quality control sampling plans, and governance charters to embed outsourced teams into internal regulatory workflows.
-
M&A and partnership playbooks: target screening criteria, valuation sensitivities for technology-led service providers, and integration checklists to preserve regulatory knowledge and IP.
-
Risk registers and mitigation plans: practical steps to manage regulatory policy shocks, data integrity incidents and third-party continuity risks.
To preserve the integrity of client decision pathways, the report intentionally provides high-level market and competitive guidance in this release while reserving detailed segment-level breakdowns, vendor scorecards and proprietary financial models for full report subscribers.
Competitive landscape — how leading suppliers are positioning for 2026
The vendor field combines large clinical development integrators, specialized regulatory boutiques and regionally dominant players. We observe three workable strategic postures:
-
Integrated solutions providers that bundle regulatory with clinical development and commercialization support, investing heavily in AI and platformization to reduce cycle times and increase cross-selling (examples from the market include organizations that have publicly launched AI agents or enterprise AI assistants during 2025).
-
Specialist regulatory firms focusing on deep technical capabilities (e.g., CMC, medical-device-specific submissions, post-approval maintenance) and boutique advisory services that command premium rates for complex or contested pathways.
-
Regional experts and technology-first entrants that translate local regulatory know-how and automation into scaleable service offerings for international clients seeking market entry or dual-jurisdiction strategies.
Recent vendor moves underscore these dynamics: major players have announced AI and automation partnerships and platform launches during 2025 to support eCTD automation and regulatory intelligence; others continue to expand full-service FSP models and lifecycle maintenance offerings. For decision-makers, assessing a provider’s technology roadmap and domain depth is now as important as evaluating historical delivery metrics.
Market dynamics and near-term risks
-
Regulatory policy timing and technical mandates (e.g., the post-2025 electronic submission environment) create implementation urgency and short-term demand spikes for capable vendors.
-
AI validation and trust: rapid tooling adoption raises questions about validation, reproducibility and regulator acceptance of AI-assisted artifacts—buyers must insist on explainability, audit trails and vendor liability constructs.
-
Geographic divergence: differing expectations across major authorities and rapid evolution of certain markets (notably the PRC) increase the value of vendors that combine local regulatory knowledge with global submission experience.
-
Commercial pressure: consolidation and competition between global integrators and niche suppliers will continue to compress margins for commoditized activities while creating premium pricing for complex or strategic services.
-
Talent and knowledge transfer risk: effective outsourcing requires robust governance to avoid loss of institutional knowledge and to ensure continuity through personnel churn or vendor transitions.
Strategic imperatives for 2026 — recommended actions
-
Prioritize vendor eCTD and AI readiness in near-term evaluations: include technical validation milestones and regulatory acceptance criteria as contract preconditions.
-
Adopt hybrid engagement models: preserve a small, high-skill internal regulatory core while outsourcing scalable, repeatable workstreams—this balances control with operational leverage.
-
Implement vendor scorecards that blend delivery metrics with technology maturity and regulatory audit performance; update them quarterly to capture rapid changes in vendor capability.
-
Use pilot programs to de-risk AI-enabled services: run controlled pilots on non-launch-critical submissions to validate throughput and auditability before scaling across portfolios.
-
Built M&A/partnership scouting into the corporate development pipeline: target candidates that provide either technology differentiation (automation, regulatory RIM platforms) or localized regulatory depth in growth markets.
-
Elevate regulatory outsourcing governance: create a cross-functional center of excellence with procurement, legal, quality and regulatory leads to manage KPI enforcement and knowledge retention.
How PW Consulting supports your 2026 decisions
Our report combines market-level forecasts, provider mapping and operational playbooks explicitly built to inform sourcing decisions, technology investments and M&A priorities in 2026. The analysis is grounded in up-to-date market activity—including published vendor technology launches and partnerships—and calibrated against the regulatory shifts that are already affecting submission strategies and product timelines.
We present the strategic implications of a market that is growing rapidly and becoming technologically differentiated, while preserving an evidence-based approach to vendor selection and operational design. For executives making budgetary and sourcing decisions in 2026, the report provides the concrete inputs and executable templates needed to move from intention to implementation.
Next steps — access and verification
This overview conveys the strategic posture and tactical imperatives that PW Consulting recommends for 2026. For the proprietary segment-level data, vendor scorecards, downloadable templates (RFPs, KPI dashboards, pilot protocols) and detailed scenario models referenced above, please consult the full Healthcare Regulatory Affairs Outsourcing Market report on our website. The complete report contains the granular intelligence and financial models that procurement, regulatory and corporate development teams will require to operationalize the strategies summarized here.
Contact PW Consulting to schedule a briefing with our regulatory affairs outsourcing practice to review tailored scenarios for your portfolio and to receive an abbreviated vendor comparison aligned to your therapeutic and geographic priorities.
For detailed analysis of this topic, please visit the official page: Healthcare Regulatory Affairs Outsourcing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ultra Fine Copper Market — Strategic Briefing for 2026: Actionable Intelligence from PW Consulting
Executive snapshot
The global Ultra Fine Copper market is at a strategic inflection point. After a consistent expansion from USD 2,185.4 Million in 2020 to USD 2,855.65 Million in 2025 (base year), PW Consulting’s market model projects continued growth to approximately USD 4,148.54 Million by 2032. Our forecast embeds a compounded annual growth rate (CAGR) of 5.48% over the 2026–2032 period. For corporate leaders planning investments, procurement strategies, or M&A in 2026, this report converts headline growth into concrete decisions — while preserving guarded competitive detail to incentivize a full-read of the proprietary dataset.
Ultra Fine Copper Market
Why this report matters for 2026 decision-making
- Timing of capital allocation: Our analysis maps near-term demand drivers and input-cost volatility to identify windows where greenfield or brownfield investments are most likely to deliver differentiated returns.
- Supply-chain resilience: We quantify how feedstock price shocks and trade measures propagate into finished ultra-fine copper product margins and outline hedging and supplier diversification playbooks.
- Regulatory readiness: With nano- and ultra-fine copper increasingly regulated, compliance posture will be a competitive barrier. Our report translates regulatory milestones into operational checkpoints for 2026 planning.
- M&A and partnership signaling: Given industry concentration metrics, consolidation dynamics are a realistic route to scale. PW Consulting provides a tactical framework to prioritize targets and structure deals without overpaying for short-term capacity gains.
What the report delivers — practical, executable content
The PW Consulting Ultra Fine Copper Market report was designed for functional leaders (strategy, procurement, R&D, legal, and operations) and boards. It contains:
Ultra Fine Copper Market
- Top-down market sizing and a 2026–2032 forecast model (USD Million) with scenario toggles for macroeconomic and input-price shocks.
- Supply-cost decomposition that isolates feedstock exposure, energy intensity, and downstream processing costs to reveal the primary margin levers.
- A vendor assessment toolkit: scorecards, negotiation playbooks, and decision matrices to prioritize suppliers based on quality, technology, geographic risk, and scalability.
- Regulatory compliance matrix: mapping of key regulatory regimes (including EU REACH and GHS handling/transport obligations) against product forms and end-use pathways.
- Commercial go-to-market playbooks for productized copper powders and wire: channel strategies, pricing tactics, and sample commercialization calendars.
- Scenario planning modules: stress-tests for tariff shocks, feedstock spikes, and accelerated EV/5G adoption trajectories.
Note: the report intentionally omits public reproduction of granular regional and application-level revenue splits in this press summary; these are presented only in the full report to paying subscribers and strategic partners.
Ultra Fine Copper Market
Market dynamics that will shape 2026 strategies
- Input-cost volatility: LME Grade A copper price movements — including the 2024 peak — materially affect powder and ultra-fine wire production costs. Our model shows how pass-through rates differ by process technology and contract tenor.
- Treatment and refining spreads: Changes in concentrate treatment charges have compressed margins for certain refiners but opened arbitrage for players with integrated refining-to-powder capabilities.
- Trade and tariff friction: Ongoing tariff measures on copper powders from specific origins introduce non-linear cost penalties and incentivize near-shoring of strategic volumes for tariff-sensitive customers.
- Regulatory tightening: The categorization of nano copper under REACH-style requirements and GHS-driven SDS obligations elevates the cost of market entry and raises the bar for documentation and testing — benefitting established players while raising barriers to low-cost entrants.
- End-market pull: Rapid adoption of high-density electronics, EV powertrains, and precision medical devices sustains structural demand for ultra-fine copper grades, though the shape of demand varies by product form and specification.
Competitive landscape and strategic implications
The Ultra Fine Copper market shows moderate concentration: the top three players control roughly 38.45% of the market while the top five account for about 52.12%. This balance creates pockets of supplier power but also room for disruptors that combine technical capability with scale.
- Technology specialists (Japan & Europe): Companies producing superfine copper powders and atomized products (e.g., Osaka- and Tokyo-based manufacturers, and select Swiss firms) compete on particle-size control, purity, and process reproducibility. Their strategic edge is high-quality product for advanced electronics and additive manufacturing; partnerships or licensing can accelerate capability transfer for firms seeking premium product lines.
- China-based producers: Several suppliers offer a wide particle-size range and cost advantages. They are strategically important for scale buys but their market access and competitiveness can be affected by trade measures and quality certification demands. For multinational buyers, dual-sourcing and compliance audits are critical to maintain continuity without regulatory exposure.
- Service and custom suppliers (US & contract manufacturers): Custom, high-purity specialty suppliers focus on small-batch R&D and high-spec grades for research and niche industrial uses. They are preferred partners for co-development and rapid prototyping but may not yet compete on scale.
Strategic playbook for 2026 — a prioritized action plan
PW Consulting recommends a phased approach keyed to near-term risk mitigation, medium-term capability build, and longer-term structural positioning.
- 0–90 days — Risk triage:
- Initiate a supplier risk audit focused on tariff exposure, lead times, and compliance documentation (especially REACH and GHS SDS completeness).
- Lock short-term copper hedges where exposure is unhedged and cost pass-through to customers is limited.
- Activate contingency stock plans for critical grades where single-source dependence exists.
- 3–12 months — Operational and commercial moves:
- Pursue strategic supply agreements with tiered capacity commitments and built-in quality audits to ensure continuity without carrying full inventory risk.
- Invest in process improvement pilots to improve yield on ultra-fine fraction recovery; even modest recovery gains materially affect unit economics.
- Prioritize product certification efforts in regulated jurisdictions to remove go-to-market friction for advanced applications.
- 12–36 months — Structural repositioning:
- Evaluate bolt-on acquisitions of complementary powder or wire capacity to capture margin compression and accelerate market share gains — focus on targets with proprietary atomization or spheroidization technology.
- Deploy R&D resources to develop higher-purity or application-specific formulations that can command premium pricing and create switching costs.
- Consider geographic rebalancing of production to mitigate tariff and logistics risk, guided by a cost-to-serve analysis included in the full PW model.
Regulatory and trade considerations — immediate compliance checklist
- Confirm classification of product forms against nanomaterial definitions in key jurisdictions; if classified, align test and registration programs to REACH-style expectations.
- Standardize Safety Data Sheets and transport documentation to GHS Revision 10 standards to reduce handling and shipping disruptions.
- Review tariff exposure for critical SKUs and recalculate landed cost models; evaluate re-routing or near-shore options for tariff-sensitive customers.
How PW Consulting’s dataset informs action (but preserves strategic exclusivity)
Our report includes the full numerical breakdowns, supplier scorecards, and regional/application-level forecasts that executive teams need to finalize budgets and select go-to-market tactics. This press release purposefully omits the granular regional and application revenue shares and product-type splits to maintain proprietary insight for report subscribers. Clients who engage with PW Consulting receive model access, scenario-run support, and a live workshop to translate findings into board-ready investment cases.
Conclusion and next steps
The Ultra Fine Copper market offers growth and margin expansion opportunities for 2026 entrants that pair technical capability with disciplined risk management. The market’s trajectory—from USD 2,855.65 Million in 2025 to a projected USD 4,148.54 Million by 2032 at a 5.48% CAGR—creates a planning horizon where operational improvements, compliance leadership, and selective capacity moves can deliver outsized returns. To convert this directional intelligence into executable enterprise decisions, access to the full PW Consulting report and model is required; our full release contains the granular segment data and partner-target lists omitted here.
For access to the complete report, model files, and bespoke advisory engagements, visit the PW Consulting report page or contact our industry team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Ultra Fine Copper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


