



PW Consulting: Prostate Cancer Diagnostics & Treatment Market Poised to Reach USD 117,684.46 Million by 2032, Growing at a 9.85% CAGR
By PW Consulting, 2026-07-13
Prostate Cancer Diagnostics And Treatment Market — Strategic Outlook For 2026: Why This Report Will Shape Your Next Move
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic primer on our new market study, "Prostate Cancer Diagnostics And Treatment Market." This briefing synthesizes the implications senior leadership teams must weigh in 2026 — from commercial strategy and portfolio prioritization to M&A screening and reimbursement planning. The analysis demonstrates why the coming 12–18 months represent a pivotal window for companies across pharmaceuticals, diagnostics, imaging, and radiopharmaceuticals, while intentionally withholding granular segment-level figures to encourage direct access to the full report for operational execution.
Prostate Cancer Diagnostics And Treatment Market
Executive snapshot: market trajectory and why 2026 matters
The prostate cancer diagnostics and treatment market has shown resilient growth through the first half of the decade and stands at a meaningful inflection point going into 2026. Our base-year calibration (2025) and forecast to 2032 reflect a compound annual growth rate (CAGR) of approximately 9.85% over the forecast horizon. That trajectory is driven by three converging forces: regulatory momentum that moves effective therapies earlier into treatment algorithms, accelerating uptake of precision diagnostics (genomic and PSMA-based imaging), and the commercial maturation of radioligand therapies.
Prostate Cancer Diagnostics And Treatment Market
For executive teams, the practical implication is clear: strategies optimized for 2026 should be designed around accelerating commercialization levers (label expansion execution, diagnostic partnerships, and reimbursement dossiers) rather than relying on historical launch playbooks. This report is tailored to convert those macro signals into executable plans.
Prostate Cancer Diagnostics And Treatment Market
Key market dynamics shaping commercial outcomes
-
Regulatory direction favors precision-enabled indications. Recent approvals and filings increasingly link therapeutic indications to companion diagnostics—especially for BRCA-mutated disease and PSMA-expression status. This regulatory posture raises the bar for payer acceptance and clinical pathway adoption, but it also creates premium positioning for companies that can deliver integrated diagnostic-therapeutic solutions.
-
Shift to earlier lines of therapy. Approved label expansions and late-stage data have pushed several agents into earlier disease settings. The strategic consequence is that lifecycle-management and combination-development programs now have outsized impact on market share and long-term revenue curves.
-
Radioligand therapy commercial model is maturing. With expanded indications and growing reimbursement precedents, radioligand therapies are moving from niche specialty settings toward broader adoption—contingent on imaging infrastructure (PSMA PET) and payer confidence in real-world outcomes.
-
Pricing and access pressure from upcoming generic entrants. Key androgen receptor inhibitors face patent cliffs across major markets in the next 12–18 months. This will create downward price pressure and force originator companies to accelerate differentiation through combination regimens, new indications, or value-based contracting.
Recent regulatory and clinical milestones — what they mean for 2026 strategy
-
FDA approvals and indication expansions through 2025–2026 underscore the agency’s willingness to approve precision-targeted regimens and radioligand therapies. Examples include expanded radioligand indications and approvals for PARP-containing regimens in BRCA-mutated disease. For commercial teams, these milestones translate into immediate priorities: launch sequencing, diagnostic partner selection, and payer evidence generation.
-
Late-stage clinical data presentations in 2026 (including high-profile Phase 3 readouts for next-generation androgen receptor inhibitors) will re-shape prescriber preferences and formulary negotiations. Companies that can demonstrate early real-world evidence and economic modeling will capture preferred positions during 2026 contracting cycles.
Competitive landscape: how leading firms are positioning
The competitive field is marked by a blend of large integrated pharmaceutical players, diagnostic specialists, and imaging/radiopharmaceutical companies. Market concentration is neither highly fragmented nor monopolistic; a handful of multinational firms control meaningful share while a diverse set of specialist players capture diagnostic and imaging niches. Competitive dynamics in 2026 will be determined by three tactical axes: therapeutic differentiation, diagnostic integration, and channel/infrastructure control for radioligand delivery.
-
Integrated pharma leaders (e.g., Johnson & Johnson, Pfizer, Astellas, Bayer, AstraZeneca). These companies are leveraging broad oncology franchises and combination-development capabilities to move therapies earlier into treatment paradigms. Recent approvals and regulatory filings reflect deliberate efforts to secure first-mover advantage in precision subsets and combination regimens. Their playbook emphasizes label expansion, companion diagnostic co-development, and aggressive payer engagement.
-
Radioligand and targeted therapy innovators (e.g., Novartis, Telix). With radioligand approvals maturing, these firms focus on scaling delivery capacity, PSMA-imaging partnerships, and health-economic evidence to support reimbursement. Expect to see increased investments in site-of-care networks and centralized distribution solutions to reduce rollout friction.
-
Diagnostics and imaging leaders (e.g., Roche, Siemens Healthineers, GE HealthCare, Abbott, Myriad, MDxHealth). These players occupy critical chokepoints: accurate molecular profiling and high-sensitivity PSMA imaging. Their strategic moves—ranging from companion diagnostic development to bundled diagnostic+therapy service offerings—will materially affect uptake curves for precision therapies.
-
Specialty and diagnostic disruptors (e.g., Lantheus, OPKO, MDxHealth). These firms are focused on carve-outs within screening, risk stratification, and PSMA-supporting agents. Their agility in generating clinical validation data and establishing referral pathways will determine their ability to be included in bundled care models.
What the PW Consulting report contains — practical chapters you can act on
We built the study as a decision-ready tool for commercial, medical, and corporate development leaders. Key deliverables include:
-
Market-sizing and scenario forecasts (base-year 2025 with 2026–2032 outlook), including upside/downside scenarios tied to regulatory and competitive inflection points.
-
Go-to-market playbooks for therapeutic launches and diagnostic partnerships, detailing channel models, KOL engagement sequencing, and formulary-entry tactics.
-
Reimbursement and HTA playbooks with country-level reimbursement gate maps and exemplar dossier structures (note: full payor model tables are available in the report).
-
Pipeline and competitor intelligence trackers with clinical timelines, trial-readout impact simulations, and probability-weighted revenue scenarios.
-
M&A and partnership screening framework: a prioritized list of biotech and diagnostic targets (including financial sensitivity models and integration risk checklists).
-
Commercial and operational readiness checklists for radioligand therapy adoption, including site certification workflows, logistics design, and evidence-generation playbooks.
Top strategic recommendations for 2026 decision-makers
-
Prioritize integrated diagnostic-therapeutic value propositions. Regulatory and payer trends increasingly reward bundled evidence. Companies that invest early in companion diagnostic validation and co-marketing capabilities will shorten time-to-reimbursement and protect price.
-
Defend and differentiate before patent expirations bite. For originator firms facing imminent generic entry, accelerate indication expansion and combination development that create meaningful clinical differentiation and new lines of protected revenue.
-
Invest in PSMA imaging capacity as a market-access enabler. Radioligand therapies depend on robust PSMA-PET availability. Payer conversations should be paired with initiatives to scale imaging capacity and to generate real-world outcomes demonstrating downstream economic benefits.
-
Use M&A to fill diagnostic and delivery gaps quickly. Time-limited windows exist to acquire or partner with diagnostic specialists and radiopharmaceutical service providers that can be integrated into a therapeutic launch model.
-
Design payer-facing evidence generation now, not later. Value-based contracts and indication-based reimbursement will be decided in 2026 for launches in subsequent years; initiate health-economic and outcomes research programs immediately.
Why this report matters for boardrooms and deal teams
Our market model quantifies the scale and speed of opportunity through 2032 and translates those macros into actionable investment thresholds, go/no-go gates for indications, and prioritized clinical-development pairings. Whether you are a commercial lead planning a 2026 launch, an investor evaluating assets in oncology, or an M&A team screening targets, the report provides the templates and forward-looking scenarios necessary to make confident decisions under uncertainty.
Next steps — access the full intelligence
This article highlights strategic implications and topline trajectory signals to inform 2026 planning. For transaction-grade intelligence — including granular regional forecasts, treatment-type revenue splits, payer-modeling templates, and a ranked shortlist of acquisition targets — download the full report from PW Consulting’s market research portal. The complete report includes the scenario models, spreadsheet workbooks, and playbooks that operational teams need to convert strategy into results.
Contact PW Consulting today to arrange a briefing with our lead analysts and receive the data package that will underpin your 2026 prostate cancer strategy.
For detailed analysis of this topic, please visit the official page: Prostate Cancer Diagnostics And Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Artificial Lens Market Poised to Grow at a 5.48% CAGR During 2026–2032
By PW Consulting, 2026-07-13
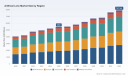
Artificial Lens Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
Executive summary
PW Consulting’s latest Artificial Lens Market report (base year 2025) delivers a data-driven blueprint for executives, investors, and clinical leaders preparing strategic decisions in 2026 and beyond. Our proprietary model projects the global artificial lens market to rise from USD 5,450 Million in 2025 to roughly USD 7,917 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window. These headline figures confirm a durable, mid-single-digit growth trajectory underpinned by product innovation, expanding premium uptake, and evolving care delivery economics.
Artificial Lens Market
Why this report matters for 2026 decision-making
-
Actionable foresight where it counts: The 2026 strategic landscape combines accelerating premium lens adoption with changing reimbursement mechanics and new regulatory codes—forcing firms to reassess pricing, channel, and clinical evidence strategies now, not later.
Artificial Lens Market -
Concentration implies influence: The market exhibits high concentration among a few global leaders (CR3 ~68.5%; CR5 ~82.3%), which amplifies the importance of partnership, selective M&A, and differentiated clinical data to gain share.
Artificial Lens Market -
Timing is critical: Regulatory approvals and reimbursement updates that landed in late 2025 and early 2026 materially alter near-term commercial windows. Our report decodes these shifts into executable go-to-market playbooks.
What’s inside — practical, prioritized intelligence
This research was built from a rigorous blend of primary interviews with surgeons, hospital procurement officers, ASC administrators, and medtech strategy leads; proprietary sales-channel and pricing datasets; and clinical/regulatory filings. The deliverables are structured to be immediately operational:
-
Executive dashboards with scenario-based revenue impact models and sensitivity analysis tied to price, uptake, and reimbursement permutations.
-
A validated go-to-market framework for premium IOLs covering account segmentation, contracting levers for hospitals vs. ambulatory surgery centers, and surgeon engagement pathways.
-
Regulatory and coding playbook that translates new CPT and Medicare developments into revenue and operating scenarios for 2026 planning cycles.
-
Competitive landscaping and M&A heat maps identifying targets that unlock distribution, IP, or clinical differentiation—ranked by strategic fit and integration complexity.
-
Commercial readiness checklists for product launches, including data-generation priorities, KOL engagement sequencing, and OR logistics optimization to accelerate adoption.
Competitive dynamics: incumbents, challengers, and tactical implications
The market’s competitive topology is dominated by established ophthalmic platform holders alongside a well-funded set of niche innovators. Global leaders maintain portfolio breadth across monofocal and premium segments and benefit from integrated surgical ecosystems; several mid-sized and emerging vendors are exploiting material science, lens optics, and niche indications to gain footholds.
Representative strategic positioning observed in the market:
-
Large integrated players focus on premium portfolio depth and surgical ecosystem integration to protect ASPs and margins; they also continue to invest in evidence generation for premium designs.
-
Specialist vendors pursue regulatory-first strategies—securing approvals in key markets to catalyze surgeon awareness and payer conversations, then scaling distribution through partnerships or targeted acquisitions.
-
Regional champions leverage material and manufacturing cost advantages alongside focused clinician networks to contest share in price-sensitive channels.
Key company developments in late 2025–early 2026 underscore the speed of change and provide near-term tactical signals:
-
BVI Medical’s FDA approval (October 2025) and subsequent first US implantations (February 2026) for its FINEVISION HP trifocal lens demonstrate how regulatory milestones can rapidly translate into clinical adoption windows when paired with targeted commercialization.
-
Johnson & Johnson Vision’s March 2026 FDA approval of an EDOF offering positioned without a contrast-sensitivity warning illustrates the importance of differentiated safety and performance claims in payer and surgeon procurement discussions.
-
Bausch + Lomb’s late-2025 approval of a full-range IOL highlights the continuing push from incumbents to shore up their premium pipelines while managing payer scrutiny.
Market dynamics and policy levers to watch in 2026
Beyond product-level competition, subtle but material policy and reimbursement shifts will shape commercial outcomes in 2026:
-
Outpatient payment dynamics—recent adjustments to ASC payment rates for cataract surgery reflect cost containment pressures that can compress margins in high-volume settings and change the calculus on premium lens uptake at ASCs.
-
Coding innovation—introduction of a new CPT Category III code related to insertion and scleral fixation of a capsular-bag prosthesis creates both clarity for novel procedures and a temporary window where coding strategy can influence adoption and billing practices.
-
Fee-schedule changes—updates to Medicare conversion factors and work RVUs for cataract CPTs alter physician incentives and may shift case routing between hospitals and ASCs, affecting channel economics for lens suppliers.
Strategic playbook for 2026
Based on our analysis, PW Consulting recommends that leaders and investors adopt a three-track approach for 2026 planning cycles:
-
Protect and prioritize high-value clinical evidence: Fast-track prospective registries and head-to-head studies that address the two deciding factors for surgeons and payers—functional outcomes (e.g., intermediate vision and spectacle independence) and objective safety profiles (contrast sensitivity metrics).
-
Reconfigure commercial models for mixed-provider geographies: Redesign contracting templates to reflect ASC economics and bundle options that preserve value capture while removing adoption friction. Consider targeted rebate structures tied to demonstrated clinical outcomes.
-
Pursue selective inorganic moves: Focus M&A or licensing on capabilities that accelerate evidence generation, unique optical or material IP, or direct distribution channels into underpenetrated procedural settings.
Operational priorities and quick wins
-
Surgeon enablement: Deploy modular training kits and surgeon-to-surgeon ambassador programs to shorten the learning curve for premium optics and to mitigate first-case hesitancy.
-
OR logistics: Standardize instrument and lens tray workflows to reduce incremental OR time and support throughput in ASCs where time is directly tied to margins.
-
Pricing agility: Implement dynamic pricing pilots across representative accounts to quantify elasticity and to identify where strategic discounting can be offset by volume and service upsells.
Risks, uncertainties, and monitoring indicators
Our forecast assumes steady uptake of premium and enhanced-optic lenses and continued clinical acceptance of newer EDOF/trifocal designs. The principal risks that could modify the trajectory include accelerated reimbursement cuts, unexpected safety signals, or a rapid commoditization of premium optics via low-cost entrants. We recommend establishing a 6–9 month dashboard that tracks four leading indicators: regulatory approvals in major markets, payer coverage decisions for premium lenses, ASC vs. hospital case mix shifts, and surgeon preference surveys.
Conclusion — the strategic value of PW Consulting’s intelligence
For 2026, firms must translate product innovation into repeatable commercial advantage against a backdrop of concentrated competition and tighter reimbursement. PW Consulting’s Artificial Lens Market report synthesizes macro trajectory (USD 5.45 Billion in 2025 growing at a 5.48% CAGR to 2032), granular commercial playbooks, and competitor scenario analysis to enable decisive action. The report demonstrates where to invest finite commercial and R&D resources, how to sequence regulatory and evidence-building activities, and which partnership or M&A moves are likely to create disproportionate value.
To preserve investigative depth and competitive confidentiality, detailed regional and product-split figures and all proprietary model outputs are available exclusively in the full report. Access the complete analysis, interactive models, and our top-tier market-entry templates via PW Consulting’s Artificial Lens Market report page.
For detailed analysis of this topic, please visit the official page: Artificial Lens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Government & Military SATCOM Market to Hit USD 17.52 Billion by 2032, Growing at a 7.0% CAGR (2026–2032)
By PW Consulting, 2026-07-13
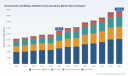
Government and Military Satellite Communications Market: Strategic Imperatives for 2026
Executive preview
PW Consulting’s latest market study on Government and Military Satellite Communications (GOV/MIL SATCOM) frames an industry at an inflection point. The market—valued at roughly USD 10,912 million (~$10.9 billion) in our 2025 base year—is modelled to expand to approximately USD 17,522 million (~$17.5 billion) by 2032, representing a 7.0% compound annual growth rate across the 2026–2032 forecast window. These headline metrics mask an active reshuffling of capability, procurement and industrial priorities driven by geopolitical stress, rapid LEO/MEO/GEO architectural change, and renewed defence investment cycles.
Government And Military Satellite Communications Market
Why this report matters for 2026 decision-makers
- Actionable foresight: Our analysis translates macro growth trends into actionable levers for procurement, program-planning and M&A through 2026 and beyond.
- Timing the transition: 2026 is a pivotal year for choices between legacy MILSATCOM sustainment, hybrid commercial partnerships, and accelerated adoption of proliferated small-satellite architectures.
- Risk-to-return clarity: We map how concentrated supplier footprints and program-level commitments alter negotiation dynamics, delivery risk and cost-of-access for governments and prime contractors.
High-level market shape
The market is neither atomised nor monopolised; top-tier primes and a cohort of satellite service providers jointly drive capability. Our concentration analysis shows a combined share for the three largest suppliers in the high‑thirties (CR3 ≈ 38.5%) and the five largest suppliers in the mid‑fifties (CR5 ≈ 54.2%), underscoring an oligopolistic competitor set with meaningful room for niche entrants and disruptive platform suppliers. For buyers, this creates a balance: deep bench capability and scale from incumbents, with innovation upside in select suppliers and new constellation entrants.
Government And Military Satellite Communications Market
Key dynamics shaping 2026 strategy
- Program-led demand: Major protected- and strategic-SATCOM programs awarded or progressed in 2024–2026 are re-shaping investment envelopes and technical requirements. These programs are catalysing demand for hardened payloads, anti-jam architectures and assured crosslinking across orbits.
- Commercial-military convergence: Expanding LEO/MEO capability from commercial operators—combined with government interest in hybrid procurement—means agencies can procure high-throughput capacity and tactical low-latency services without fully replicating sovereign constellations. Procurement offices must, however, adapt contracting vehicles and risk allocation models to capture those benefits.
- Terminal modernisation and edge resilience: Tactical forces are upgrading terminals to support anti-jam waveforms, multiband operation and multi-orbit handover. This drives lifecycle sustainment, upgrade and training requirements that procurement teams must bake into total-cost-of-ownership calculations.
- Regulatory and alliance levers: Export-control reforms and allied-centred licensing adjustments are lowering friction for cooperative procurement among close allies—shifting supplier selection and industrial participation considerations for 2026 program planning.
Competitive landscape — strategic positioning of core suppliers
Below is a concise strategist’s read on leading firms and what their positioning means for buyers and investors in 2026. For procurement officers, these profiles indicate potential prime partners, subcontracting networks and technology access points.
Government And Military Satellite Communications Market
- Lockheed Martin Corporation — Deep in protected MILSATCOM payloads, terminals and resilient architectures. Expect continued strength on strategic programmes where integration, mission assurance and sustainment carry a premium.
- Northrop Grumman Corporation — Focused on jam-resistant payloads and ground systems; well suited for recapitalisation and prototype-to-production pathways that governments prioritise for assured communications.
- The Boeing Company — A prime for strategic GEO programmes and large satellite buses; favoured where scale, mission assurance and long-term sustainment contracts are decisive.
- Viasat Inc. — High-capacity managed services, secure networking and terminal solutions; a logical partner for hybrid commercial–government models and for buyers seeking managed-data solutions tied to terminal modernization.
- Thales Group and Airbus Defence and Space — European engineering anchors with strong positions in sovereign and allied procurements; critical where European industrial participation, export considerations and interoperability with allied forces matter.
- L3Harris Technologies and RTX (Raytheon) — Tactical terminal and sustainment specialists; attractive for forces focused on ruggedised edge devices and backward-compatible sustainment of legacy fleets.
- SES S.A., Intelsat, Iridium — Service-centric operators providing multi-orbit capacity and specialised managed services; enable rapid capacity ramp via commercial contracts while sovereign programmes progress.
- SpaceX — Starlink/Starshield capability creates new low-latency, proliferated options; procurement teams must weigh rapid capability against resilience and assured access requirements.
- Cobham, Gilat, Astranis — Niche specialists in rugged terminals, deployable systems and small GEO platforms; ideal partners for agile field capability and sovereign-capability augmentation.
Recent programme and contract signals
Programmatic milestones in 2024–2026 offer a real-time signal of where budgets and priorities are flowing—protected geosynchronous concepts, strategic satellite procurements and tactical LEO demonstrations are all active. These moves validate three concurrent market trajectories: continued investment in hardened GEO capability; accelerated demonstrations and tasking for LEO tactical services; and an expanding market for terminals and integrator services. For buyers, the near-term implication is that platform diversification and contractual flexibility are non-negotiable.
What PW Consulting’s report delivers (practical, procurement‑ready content)
- Forward-looking base-case and alternative scenarios for 2026–2032, with sensitivity analyses that translate macro CAGR into programme budget implications.
- Supplier scorecards and procurement playbooks that map capability, delivery risk and partnership pathways for primes, tier‑2s and pure-play service providers.
- Market structure and concentration analysis (CR3/CR5) that informs competitive tension modelling and negotiation strategies.
- Technology roadmaps and capability transition matrices for GEO, MEO and LEO architectures, including terminal modernisation sequencing and integration checkpoints.
- Contracting templates, SLA baselines and sustainment cost drivers to fast-track RFP and IDIQ design informed by recent government programmes.
- Investment and M&A diagnostic frameworks for private‑equity and strategic buyers evaluating specialty suppliers, ground-segment integrators and small-sat platform developers.
- An industry risk register and policy tracker highlighting export-control shifts, procurement office behavior, and alliance-level procurement enablers.
Note: the full report contains detailed segmentation tables, per-platform and per-component forecasts, and granular supplier financial benchmarking. Those tables are intentionally omitted from this summary to encourage direct consultation of the complete dataset.
Strategic recommendations for 2026
- Adopt hybrid sourcing: Combine sovereign programme investment with commercial capacity purchase agreements to accelerate capability delivery while maintaining strategic options.
- Pursue modularity in procurements: Structure contracts to allow technology insertion and crosslink upgrades, minimising obsolescence risk across lifecycle windows.
- Dual-track terminal strategy: Fund backward-compatible upgrades for fielded terminals while piloting next-gen multi-orbit/anti-jam units for priority units and missions.
- Leverage allied procurement channels: Use export-control liberalisation and allied procurement vehicles to broaden supplier pools and reduce sole-source dependence.
- Price resilience into agreements: Include performance incentives and contingency capacity clauses tied to mission assurance metrics and surge demand.
- Operationalise testbeds: Prioritise operational demonstrations (LEO/MEO crosslinking, manoeuvrable GEO trials) to de-risk rapid transition programs before large‑scale procurement commitments.
How PW Consulting supports your 2026 decision cycle
Clients engaging PW Consulting receive a combination of quantitative forecasting, supplier due diligence and procurement playbooks tailored to programmatic timelines. Our deliverables are oriented toward executable milestones—RFP drafting, source selection, budget phasing and sustainment planning—to ensure market intelligence translates into defensible acquisition decisions for 2026.
Close
The GOV/MIL SATCOM market is growing steadily and becoming more strategically complex. The headline CAGR and topline growth show opportunity; the real competitive advantage in 2026 will accrue to organisations that translate those macro trends into adaptable procurement architectures, modular capability investment, and alliance-enabled sourcing. PW Consulting’s full report provides the data, scenarios and templates to operationalise those choices—full segmentation tables, supplier financials and granular forecasts are available in the complete study.
For access to the complete market dataset, supplier benchmarks and procurement templates, visit the PW Consulting report page or contact our Government & Defence practice for a briefing tailored to your program timeline.
For detailed analysis of this topic, please visit the official page: Government And Military Satellite Communications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shared Micromobility Market Set to Expand at 8.25% CAGR — From USD 16.5B in 2025 to USD 28.74B by 2032
By PW Consulting, 2026-07-13
Shared Micromobility Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new market research briefing distills the strategic imperatives that will determine winners and laggards in shared micromobility as global urban transport re-enters a phase of structural expansion. Our full report (base year 2025; forecast 2026–2032) synthesizes market sizing, competitive playbooks, regulatory scenarios, and investor-grade operating models to equip C-suite and corporate strategy teams for high-conviction decisions in 2026. In short: the sector is large, growing, and increasingly driven by operational excellence rather than pure network scale.
Shared Micromobility Market
Market snapshot: growth trajectory and what it implies
By our assessment, the global shared micromobility market reached approximately USD 16.5 billion in 2025 and is forecast to expand at a compound annual growth rate of 8.25% through the 2026–2032 period — approaching the upper tens of billions by the end of the forecast horizon. That trajectory reflects a multi-year recovery and consolidation phase (2020–2025) followed by steady, higher-quality growth driven by electrification, fleet reliability, and municipal partnership models.
Shared Micromobility Market
- Demand is increasingly driven by trips that are too short for cars but beyond comfortable walking distance — a structural tailwind for e-bikes and e-scooters.
- Unit economics are improving as battery costs decline and vehicles are redesigned for serviceability and lower total cost of ownership.
- Market concentration has settled into a mid-level consolidation pattern: incumbents retain meaningful share, but there remains ample room for regional scale-ups and niche specialists to capture value.
Why this matters for 2026 strategic planning
For executive teams allocating capital and attention in 2026, three high-level implications should shape strategy:
Shared Micromobility Market
- Transition from growth-at-any-cost to profitability-at-scale. Investment decisions must prioritize operating margins and predictable unit economics, not only geographic footprint.
- Regulatory and municipal relationships are a strategic moat. Operators who invest in transparent data-sharing, parking infrastructure, and safety programs will access preferential permits and lower enforcement risk.
- Technology and service modularity reduce capital intensity. Swappable batteries, on-vehicle telematics, and a service-first vehicle architecture materially change fleet lifecycle economics.
Report contents — practical tools and actionable deliverables
Our report is designed as a decision-ready playbook, not an academic exercise. Key deliverables include:
- Market sizing and demand scenarios: three macro scenarios (conservative, base, upside) with sensitivity analyses to urban adoption, fare elasticity, and regulatory tightness.
- Unit-economics models: granular templates that allow users to test vehicle TCO, break-even utilization, and payback periods under different procurement and maintenance strategies.
- Fleet optimization toolkit: heuristics and a sample optimization algorithm for vehicle mix, deployment cadence, and rebalancing strategies that minimize walk-away rates and maximize revenue per asset.
- Procurement and supplier playbook: RFP templates, warranty and spare-parts clauses, and commercial negotiation levers for batteries, chassis, and telematics suppliers.
- Pilot-to-scale roadmap: KPI scorecards, sample pilot timelines, go/no-go decision gates, and stakeholder engagement templates for city governments and transit authorities.
- Regulatory playbook: compliance checklists, data-sharing frameworks, municipal partnership case studies, and a licensing risk matrix aligned with common city requirements.
- Technology roadmap: assessment of battery chemistries, modular swap systems, OTA software architectures, and recommended near-term investments to protect asset value.
- Scenario-based M&A and capital strategy guidance: valuation sensitivities, earn-out structures, and integration templates for roll-up strategies or strategic partnerships with ride-hailing and transit operators.
Competitive landscape — what incumbents and fast-movers are doing
The competitive environment is shaped by a mix of multinational operators, regional champions, and public-private partnerships. Our analysis profiles leading players and extracts replicable tactics and risks:
- Lime (San Francisco): Scaling via fleet refreshes and improved battery systems while deepening city-level partnerships to secure multi-year operating agreements. Recent fleet expansions emphasize higher mean-time-between-failure and swappable power units.
- Bird (Santa Monica): Re-capitalization and market acceleration in priority metros, with renewed focus on unit profitability and operational efficiency following fundraising rounds.
- Tier Mobility (Berlin): Platform integration and strategic partnerships to extend urban reach while leveraging multi-modal offerings (scooters, bikes, mopeds) to increase household share of trips.
- Dott (Amsterdam): Product-led differentiation through more repairable hardware and anti-vandalism features, targeting cities where vehicle durability reduces cost of service.
- Bolt (Tallinn) and regional ride-hail platforms: Integrating micromobility into broader mobility-as-a-service propositions, creating bundled trip choices and cross-sell opportunities.
- Shared bike incumbents and public systems (e.g., Nextbike, Citi Bike operators): Leaning into public-private partnership contracts and e-bike conversions to improve trip lengths and yield management.
Our situational analysis shows incumbents are increasingly competing on operational excellence (maintenance networks, spare-part logistics, and telematics insights) rather than raw city count. That shift opens acquisition and niche-penetration opportunities for well-capitalized challengers and service providers.
Key market dynamics and risk vectors for 2026
- Regulatory regimes: Established jurisdictions have codified speed limits, parking requirements, and age rules. Operators should plan for differentiated compliance costs across city clusters and model permit-renewal timelines as a discrete risk factor.
- Raw material and component pricing: Continued declines in battery pack costs improve fleet economics, but supply-chain concentration for critical components (e.g., BMS, semiconductors) remains a sourcing risk.
- Labor and service costs: Skilled technician shortages and rising regional labor costs are increasing maintenance overheads; investment in simplified field-repairability and training programs is an immediate mitigation.
- Safety and standards: Adoption of common safety standards for shared e-bikes and scooters reduces litigation risk but increases minimum vehicle spec costs. Operators must balance compliance with competitive differentiation.
- Municipal policy and public sentiment: Negative press cycles around parking and pedestrian conflicts can trigger swift regulatory action; proactive parking infrastructure and data-driven safety initiatives are defensive essentials.
Priority actions for executive teams in 2026
Leaders should convert insights into an operating agenda with clear KPIs. We recommend a top-five checklist:
- Rebase unit-economics models quarterly and tie capital deployment to demonstrated TCO improvements (not just ridership growth).
- Pursue modular fleet investments (serviceable chassis, swappable batteries, OTA capabilities) to reduce downtime and extend asset life.
- Negotiate multi-year municipal data-sharing and parking agreements with explicit KPIs and revenue/penalty clauses to align incentives with city partners.
- Invest in regional maintenance hubs and technician training to control rising labor costs and improve fleet uptime.
- Design two-to-three pilot variants for rapid experimentation (price, vehicle mix, parking policy) with pre-defined statistical success criteria and scale triggers.
Why PW Consulting’s report is different
We position this study as a practitioner’s manual rather than a descriptive industry overview. The report combines robust market sizing and outlooks with executable playbooks, templates, and models that corporate strategy, operations, and M&A teams can use immediately. We intentionally surface strategic sensitivity points while withholding detailed segmentation tables and proprietary split-values in this public summary to preserve client advantage — full tables, scenario spreadsheets, and model inputs are available in the complete report.
Next steps
For corporate leadership teams preparing budgets and 2026 roadmaps, the timing to translate strategic hypotheses into investable pilots is now. Access the full PW Consulting Shared Micromobility Market report to retrieve the complete scenario models, downloadable unit-economics templates, and city-specific regulatory playbooks that will convert insight into action.
Contact PW Consulting to arrange a briefing and tailored model walk-through for your portfolio or operations team.
For detailed analysis of this topic, please visit the official page: Shared Micromobility Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Card Readers Market to Soar to USD 4,240.96 Million by 2032, Driven by a 10.45% CAGR
By PW Consulting, 2026-07-13
Smart Card Readers Market — Strategic Insights for 2026 Decisions
PW Consulting releases a focused industry brief derived from our full Smart Card Readers Market research report (base year 2025). The market has accelerated from its early-decade base and reached an inflection point: global revenues approached USD 2.11 billion in 2025 and, under our central scenario, are projected to expand at a compound annual growth rate of 10.45% over the 2026–2032 forecast window. By 2032 the market is expected to more than double relative to 2025 levels. For security architects, procurement leaders, and product strategists, this represents a clear moment to convert macro momentum into defensible program-level decisions.
Smart Card Readers Market
Why this report matters for enterprise decision-makers in 2026
-
Stronger demand, more variability. The smart card reader market is growing rapidly, but growth is neither uniform nor risk-free. Growth is being driven by accelerated eID and government programs, renewed investment in payment and POS modernization, and enterprise moves toward stronger authentication (PKI, FIDO). At the same time, regulatory requirements, local certification regimes, and interoperability updates create short windows for compliant procurement.
Smart Card Readers Market -
Standards and certifications are reshaping procurement filters. ISO/IEC 7816 and ISO/IEC 14443 remain foundational for contact and contactless communications; compliance frameworks such as FIPS 201 and national approvals lists materially affect vendor eligibility for government business. Recent standard-level enhancements—most notably the NFC Forum’s Certification Release CR15 to support extended read range—change device selection criteria for applications requiring convenience without compromising security.
Smart Card Readers Market -
Vendor concentration and supplier profiles influence sourcing risk. The market exhibits a mid-level concentration: the top three and top five vendors together account for a meaningful portion of industry revenue, but a substantial long tail of specialized OEMs and regional suppliers persists. That mix creates both opportunities (competitive pricing, niche innovation) and hazards (fragmented support, variable compliance).
-
Practical procurement windows are narrowing. Several recent industry events and certifications (e.g., high-profile product showcases and national government compliance approvals announced in 2025–2026) illustrate that regulatory alignment and demonstrable interoperability will be purchase blockers unless addressed early in RFPs.
What the PW Consulting report delivers — practical, action-oriented content
-
Actionable buyer guidance: procurement checklists and RFP language tailored to government, BFSI, healthcare, enterprise access, and retail/transportation use cases—designed to reduce evaluation time and reduce failed pilots.
-
Technology decision frameworks: simple, field-tested matrices that map use case requirements (authentication strength, offline capability, read range, form factor) to preferred interface architectures (contact / contactless / hybrid / FIDO) and recommended security certifications.
-
Vendor scorecards and negotiation playbooks: comparative frameworks that weigh compliance pedigree, lifecycle support, software ecosystem, and total cost of ownership—allowing procurement teams to move beyond sticker price to negotiated SLAs that matter.
-
Integration and migration roadmaps: staged plans for replacing legacy readers (including cabling and network upgrade considerations), pilot-to-scale templates, and migration checklists to reduce downtime and ensure traceable identity transitions.
-
Risk & compliance matrices: consolidated views of regional regulatory requirements (examples include government-approved product lists, national certification needs, and import/market-entry rules) and mitigation tactics for supply-chain and standards drift.
-
Financial tools: TCO models, replacement timing calculators, and scenario-based budget templates to align technology choices with capital cycles and security roadmaps.
Competitive landscape — synthesis and strategic implications
The market comprises global platform vendors, payment-terminal OEMs, specialized reader manufacturers, and integrated identity systems providers. Our analysis synthesizes vendor strengths across technology, compliance, distribution, and go-to-market.
-
Platform vendors and identity specialists: Companies with deep cryptographic and identity portfolios (examples include vendors with established PKI/FIDO offerings) are positioned to win deployments where high-assurance authentication, long-term lifecycle support, and integration with government eID or enterprise PKI are decisive factors. These suppliers often lead on certifications, and their roadmaps align with enterprise security teams’ risk appetites.
-
Access-control and physical security leaders: Vendors that pair smart card readers with broader access platforms provide compelling value for campus and facility programs where single-vendor integration reduces operational complexity—particularly when devices are listed on government approval lists that demand FIPS 201 or equivalent compliance.
-
Payment and POS OEMs: Payment-focused manufacturers and terminal integrators bring scale and payment certifications (EMV, PCI) that shorten time-to-market for retail and transportation programs. Their advantage is rapid certification cycles and established distribution to merchants.
-
Regional specialists and low-cost OEMs: A vibrant regional supply base supplies certified hardware at competitive prices—important for large-volume rollouts where procurement must balance device cost against lifetime support. However, buyers must validate firmware governance and long-term software support prior to committing.
Recent industry events illustrate these dynamics: a leading reader vendor showcased new contactless and FIDO-enabled models at an Africa-focused identity event in April 2026, while the same supplier simultaneously secured government compatibility approvals in Japan for multiple NFC models. Separately, the NFC Forum’s late-2025 extension to contactless read-range standards materially affects how designers and specifiers balance user convenience versus security controls.
Recommended 6-point decision playbook for 2026
-
1. Compliance-first shortlisting: Make regulatory fit the initial filter. For government and regulated verticals, exclude suppliers that cannot demonstrate required national or international approvals. Confirm inclusion on applicable approved product lists before advancing to PoC.
-
2. Map authentication needs to interface and standards: Use our read-out matrix to translate desired assurance level into interface choices (contact/contactless/hybrid/FIDO), required standards support (ISO/IEC 7816, ISO/IEC 14443, EMV, PC/SC), and cryptographic capabilities (PKI, secure element management).
-
3. Stage pilots with integration gates: Run short, instrumented pilots that focus on interoperability with backend identity systems, firmware update processes, and physical access wiring (prepare for Category cabling and network upgrades where readers move to two-way RS-485 or TCP/IP).
-
4. Quantify lifecycle cost and support: Move beyond CAPEX; demand SLAs on firmware updates, vulnerability disclosures, and software compatibility. Include end-of-life timelines in contracts and require escrowed firmware for mission-critical programs.
-
5. Diversify supplier risk intelligently: Use a preferred-supplier model that balances a primary global vendor with vetted regional suppliers for volume or geographic coverage. Insist on supply-chain transparency and secondary-sourcing commitments for critical components.
-
6. Future-proof for interoperability and user experience: Consider emerging capabilities—extended read ranges under the updated NFC certification, FIDO hardware tokens, and mobile-device wallet interoperability—when specifying hardware that should remain relevant through multiple refresh cycles.
What success looks like in 18 months
Organizations that adopt an integrated procurement strategy—one that prioritizes compliance, sets explicit integration gates, and measures vendor support beyond initial delivery—will turn 2026 investments into operational advantages. Successful programs will achieve faster rollouts, reduced incident response time for vulnerabilities, and lower total cost of ownership through predictable update cycles and contractual protections.
Next steps — why you should consult the full PW report
This release outlines the core strategic implications and practical frameworks that corporate and public-sector buyers need to start 2026 with confidence. The full PW Consulting Smart Card Readers Market report contains the granular datasets, regional forecasts, vendor scorecards, segment-level growth trajectories, and downloadable procurement templates that organizations require to act. We intentionally limit segmentation tables and detailed vendor revenue data in this communiqué to preserve the substantive competitive intelligence available in the full report—available via our website.
For procurement teams, security architects, and product leaders preparing tactical 2026 budgets and roadmaps, the full report converts market indicators into executable plans. Contact PW Consulting to schedule a briefing, obtain sample scorecards, or request purchaser-oriented RFP language tailored to your jurisdiction and use case.
For detailed analysis of this topic, please visit the official page: Smart Card Readers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Sustainable Pet Food Packaging Market Poised for 8.12% CAGR from 2026–2032
By PW Consulting, 2026-07-13
Sustainable Pet Food Packaging Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes an executive briefing drawn from our forthcoming Sustainable Pet Food Packaging Market report (base year 2025). As businesses prepare 2026 budgets and capital plans, this note highlights the strategic value of the full report: a pragmatic, decision-ready toolkit that translates market-scale projections, regulatory momentum, raw-material dynamics and supplier innovation into actionable choices for packaging, procurement, product and sustainability leaders.
Sustainable Pet Food Packaging Market
Why 2026 is a Pivotal Year
The sustainable pet food packaging market has reached critical mass. Our topline estimate: the market stood at approximately USD 3.52 billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of c. 8.1% over the 2026–2032 period, reaching roughly USD 6.08 billion by 2032. These macro fundamentals — steady growth driven by premiumization, regulatory pressure and retailer sustainability commitments — create a narrow window for executives to translate intent into competitive advantage.
Sustainable Pet Food Packaging Market
For corporate strategists, the implication is clear: 2026 is the inflection year to move from pilots and sustainability pledges to scaled packaging transitions that materially affect cost, brand trust and shelf presence.
Sustainable Pet Food Packaging Market
What the Report Delivers — Practical Content for Boardroom Decisions
- Actionable playbooks: Step-by-step decision frameworks for packaging portfolio rationalization, prioritizing SKUs for redesign, and sequencing rollouts to minimize disruption to supply and inventory.
- Investment cases and TCO models: CapEx vs. OpEx trade-offs for converting lines to mono-materials, retrofit vs. rebuild scenarios, and sensitivity analysis that incorporates recycled-content price volatility.
- Supplier and partner scorecards: Operational, sustainability and commercial KPIs to evaluate converters, material suppliers and co-packers — including an RFP template tailored to sustainable pet food packaging requirements.
- Regulatory compliance matrix: State- and country-level EPR readiness checklists, reporting timelines and practical measures to internalize producer obligations into pricing and procurement.
- Lifecycle and quality assurance tools: LCA templates and consumer-communication guidelines to substantiate environmental claims without compromising food safety or shelf life.
- M&A and alliance playbook: Criteria and screening tools for tuck-in acquisitions, joint ventures or strategic supply partnerships focused on material science, recycling access and barrier performance.
These deliverables are designed for immediate use by sustainability leads, procurement heads and operations teams preparing 2026 capital expenditure approvals and supplier negotiations.
Market Structure and Competitive Landscape — What We Observed
The market displays moderate concentration: the top three suppliers account for under one-third of market share while the top five collectively hold a little over two-fifths. This structure creates both competitive intensity and opportunity for differentiated offerings in sustainability and service.
Key players we profile in depth include global flexible and rigid packaging leaders that are actively commercializing recyclable, mono-material and paper-based solutions. Representative companies covered in the report are Amcor plc, Mondi plc, ProAmpac LLC, Berry Global Group, Sonoco, Huhtamaki, Printpack, Greiner Packaging, Constantia Flexibles, Crown Holdings, Smurfit Kappa and Silgan Holdings. Our analysis synthesizes product portfolios, route-to-market, technical capabilities and readiness for scale.
- Innovation signals: Several incumbent suppliers launched or expanded recyclable and lightweight high-barrier solutions in early 2026 to address premium pet food brands seeking shelf performance with improved end-of-life credentials.
- Paper and mono-material traction: Paper-based laminates and mono-PE/PP systems are moving from pilot to commercialization as converters solve mechanical strength and barrier challenges.
- Hybrid competition: Rigid formats remain relevant for wet pet food while flexible formats continue to dominate dry pet food; product format strategy will therefore remain a differentiator tied to brand positioning and cost-to-serve.
Our competitive profiles not only map capability but also evaluate buyers’ practical choices: time-to-market, change management complexity, and supplier risk (single-source vs. multi-sourcing). For procurement teams, the report includes negotiation playbooks and switching-cost calculators tailored to packaging conversions.
Regulatory and Raw-Material Dynamics Shaping 2026 Decisions
- Extended Producer Responsibility (EPR) and reporting: Several sub-national and national EPR regimes advanced through 2025–2026, requiring producer registration, data reporting and preparation for fee obligations. These policies pivot packaging from an operational cost to a regulated line-item that influences SKU profitability and supplier contracts.
- Geographic regulatory variability: With multiple U.S. states implementing packaging producer responsibility programs in 2025–2026 and international mandates on recycled content emerging, multinationals must embed compliance scenarios into product launch and packaging decisions.
- Recycled-content pricing volatility: Recycled PET prices climbed materially in late 2025, reflecting constrained supply and rising demand from packaging converters prioritizing recycled content. Our commercial models quantify the sensitivity of margin to rPET price swings and identify hedging and sourcing levers.
In short: regulatory compliance, recycled-content availability and material cost volatility are co-evolving pressures that materially affect 2026 procurement and product decisions. The report offers concrete mitigation strategies from takt-time investments to long-term off-take agreements with recyclers.
Strategic Priorities and Recommendations for 2026
- Prioritize SKU rationalization and pilot-to-scale pathways: Identify the top 20–30 SKUs by revenue and margin impact and run focused pilots that validate recyclability, shelf life and consumer acceptance before broader rollouts.
- Lock supply for recycled feedstock: Negotiate multi-year offtake agreements with rPET/rPP suppliers or invest in circular supply partnerships to reduce exposure to spot-price shocks.
- Embed regulatory costs early: Build EPR and compliance fee scenarios into product pricing models now; test selective cost pass-through strategies with trading partners and retailers.
- Design for recyclability and clarity of claims: Move toward mono-material constructions where feasible and adopt standardized consumer-facing labels and verification to reduce reputational risk and greenwashing scrutiny.
- Evaluate manufacturing investments: Use our TCO templates to compare retrofits vs. line replacements, considering throughput, waste, and traceability requirements for recycled content.
- Use M&A and partnerships to accelerate capability: Consider bolt-on acquisitions or strategic alliances for material science, recycling access or regional converting capacity — especially where first-mover scale yields premium shelf placement.
Recent Developments to Monitor
- Major converters launched next-generation recyclable flexible solutions in early 2026, underscoring the shift from proof-of-concept to commercial availability for premium pet food segments.
- Paper-based portfolio expansions by leading packaging groups signal that paper laminates are becoming a credible alternative for many dry formulations.
- Industry convenings such as the Sustainability Pavilion at Global Pet Expo 2026 are accelerating supplier-retailer-brand collaboration on material standards and recycling infrastructure.
How PW Consulting’s Report Helps Executives Act
Our report is deliberately practical: beyond market sizing and scenario forecasts, it equips executives with templates, analytics and negotiating language that shorten implementation cycles. Clients can expect:
- Turnkey decision matrices that align sustainability goals with P&L constraints;
- Vendor selection frameworks that weight recyclability, barrier performance and scalability;
- Regulatory playbooks with timelines and sample compliance narratives for stakeholder communications;
- Operational roadmaps for converting lines, staged to fit 2026 procurement cycles and 2027 production ramps.
Conclusion — The Strategic Payoff for 2026
For pet food brands, retailers and packaging manufacturers, 2026 is the year to convert ambition into deterministic plans that lock in advantage. The market’s trajectory — from roughly USD 3.52 billion in 2025 to an estimated USD 6.08 billion by 2032 at an ~8.1% CAGR — confirms durable growth, but success will accrue to organizations that systematically address regulatory risk, secure circular feedstock, and align packaging innovation with consumer trust.
PW Consulting’s full Sustainable Pet Food Packaging Market report provides the granular tools, supplier intelligence and scenario modeling necessary to make those moves with confidence. For executives ready to convert strategy into capital decisions and supplier contracts in 2026, the full report and our advisory services clarify the most value-accretive paths.
Learn More
To access the full intelligence package, including the operational templates and supplier scorecards that underpin our recommendations, visit the PW Consulting publications page or contact our industry team to arrange a briefing and tailored decision workshop.
For detailed analysis of this topic, please visit the official page: Sustainable Pet Food Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Casting & Splinting Market Set to Expand at a 6.18% CAGR, Industry Momentum Builds
By PW Consulting, 2026-07-13
Casting and Splinting Market — Strategic Preview for 2026: Operational Insights to Guide Winning Decisions
Executive summary
PW Consulting's latest industry briefing on the global Casting and Splinting market synthesizes proprietary modeling, supplier-level intelligence, reimbursement and regulatory analysis, and practical go-to-market playbooks to inform executive decisions in 2026. The market demonstrates steady, mid-single-digit growth: from a 2025 base of roughly USD 3.01 billion, our forecast models show a sustained expansion at a compound annual growth rate of about 6.18% through the 2026–2032 horizon. This trajectory is driven by material innovation, procedural shifts in emergency and outpatient care, and gradual adoption of personalized solutions such as 3D-printed splints.
Casting And Splinting Market
Why this briefing matters for 2026 decisions
- Timing: 2026 is the inflection point when new materials, coding clarity, and scalable manufacturing techniques (including additive manufacturing) converge to change procurement economics and clinical workflows.
- Operational focus: The report is designed not as a high-level market narrative but as a decision-ready tool — it translates market growth and competitive moves into prioritized initiatives for product, commercial, and M&A teams.
- Risk-return framing: We quantify scenario outcomes driven by material-cost swings, reimbursement pressure, and channel consolidation so leadership can stress-test capital allocation and pricing strategies.
Market sizing and growth — what the numbers tell you (and what they don’t)
Our bottom-up model places the global Casting and Splinting market at approximately USD 3.01 billion in 2025, moving toward an estimated market size in the later years of the forecast window consistent with robust mid-single-digit growth (CAGR ~6.18%). This growth is neither uniform nor purely volume-driven: it reflects a mix of continued demand for traditional immobilization, a shift toward higher-value materials and semi-custom solutions, and increasing utilization in outpatient and sports-medicine settings.
Casting And Splinting Market
We intentionally preserve granularity in the full report — segment, regional and channel splits, and pricing curves are presented there for licensed subscribers — because those details are the actionable inputs for tender modeling, sales-targeting and product roadmaps. This preview highlights directional drivers and strategic choices without disclosing the proprietary segmentation matrices that subscribers receive.
Casting And Splinting Market
Key market dynamics shaping 2026 strategy
- Material and product innovation: Fiberglass and newer thermoplastics continue displacing legacy plaster in many clinical settings due to superior strength-to-weight ratios and faster setting times. Concurrently, breathable fabrics, bio-based resins and thermo-responsive materials are improving patient comfort and lowering adverse-event rates.
- Customization and additive methods: 3D-printed custom splints are transitioning from pilot projects to scalable care pathways for anatomically complex injuries. Early 2026 product introductions by major OEMs indicate movement from prototyping to integrated clinical trials and reimbursement pilots.
- Regulatory and reimbursement clarity: Casting and splinting products remain regulated under established medical device pathways (e.g., 510(k) in the U.S.). Reimbursement mapping — including HCPCS coding nuances — materially affects commercial viability; correct coding and documentation are increasingly a commercial competency, not just a billing one.
- Channel evolution and procurement: Hospitals and outpatient clinics are pressuring suppliers on total cost of care and service levels. Distribution partnerships and direct-service models (on-site molding, same-day customization) are differentiating factors in tender awards.
- Consolidation and concentration: Market concentration is meaningful at the top, with the three largest players accounting for a substantial share and the five largest for a majority share — a dynamic that influences supplier bargaining power, price corridors, and M&A rationale.
Competitive landscape — strategic implications for incumbents and challengers
The market is characterized by a mix of diversified medtech conglomerates, specialized orthopedics companies, manufacturers of raw and semi-finished materials, and strong regional distributors. The recent cadence of activity illustrates how leading players position themselves:
- 3M Company: Continues to lead on materials science and channel reach. Its spring–2025 launch of an advanced semi-rigid casting tape with bio-based resin and thermo-responsive properties signals a push toward premium, patient-centric disposables. Strategic implication: incumbents must match material advantages with evidence on patient outcomes to command price premia.
- Zimmer Biomet: Moving into personalized care with 3D-printed custom splints reflects a strategic pivot toward value-added services and device differentiation. Implication: companies that can integrate CAD-to-clinic workflows gain both clinical credibility and stickier revenue streams.
- DJO Global / Enovis and Össur: Focus on rehabilitation and extremities positions them well for partnerships with outpatient and sports medicine networks. Implication: OEMs should expand clinical education and rehabilitation bundles to capture downstream care value.
- BSN Medical (Essity) and DeRoyal: Product launches and distribution partnerships in 2024–2025 demonstrate a two-pronged approach — product modularity for emergency care and deeper channel access for hospitals. Implication: modular systems that reduce inventory complexity are attractive to procurement teams.
- Stryker, Smith & Nephew, B. Braun: Leverage scale and hospital relationships to bundle casting and splinting into broader orthopedic trauma offerings. Implication: smaller specialists must identify niche clinical adjacencies or superior unit economics to defend share.
- Distribution and private-label players (e.g., Medline): Their breadth and price focus will continue to squeeze commoditized SKUs while presenting partnership opportunities for manufacturers seeking scale.
Recent developments to watch (operational takeaways)
- Product innovation (2025): Multiple new product introductions emphasize breathability, fast cure times and patient comfort. Action: accelerate clinical evidence generation (e.g., reduced complication rates, faster recovery metrics) to support formulary inclusion.
- Partnerships and channel expansion (late 2025): Strategic distribution alliances are lowering entry barriers in hospitals and clinics. Action: evaluate selective distribution partnerships versus direct-sales investment through a net present value lens.
- Clinical customization (early 2026): Adoption of 3D printing is moving from pilot to deployment at scale for select indications. Action: pilot reimbursement pilots and cost models in high-value centers to establish unit economics before broad rollout.
What the PW Consulting report contains — practical, operational modules
The full report is structured as an execution playbook for 2026 and beyond. Key modules include:
- Methodology appendix and transparent forecast model (base year 2025), scenario variants and sensitivity tables that leadership teams can re-run with their inputs.
- Demand-driver analysis and procurement behavior matrices for acute care, outpatient and sports medicine settings.
- Regulatory and reimbursement guide: pathway maps for device clearance and coder’s playbook for HCPCS alignment and documentation requirements.
- Competitive benchmarking with capability heatmaps (R&D, manufacturing, channel, clinical evidence), plus detailed profiles of leading and challenger firms.
- Go-to-market playbooks: contract-negotiation levers, inventory-optimization tactics, hospital-service bundles, and pricing strategies for both premium and value segments.
- Supply-chain risk register and raw-material stress tests, including mitigation options for fiberglass and thermoplastic suppliers.
- M&A and partnership scorecards: criteria to identify accretive targets, rollout scenarios, and integration checklists.
- Case studies and pilot templates for deploying 3D-printed splints and fast-curing modular systems in clinical settings.
Concrete recommendations for executive teams in 2026
- Prioritize material innovation that demonstrably improves clinical outcomes and patient experience. Use evidence as the primary justification for price differentiation.
- Invest in reimbursement and coding capabilities now — accurate HCPCS mapping and documentation drive realized pricing, particularly where newer materials or custom devices are involved.
- Pilot 3D printing in targeted centers of excellence with clear KPIs (cost per device, lead time, patient satisfaction) before scaling manufacturing investments.
- Consider strategic alliances with distribution partners to accelerate access to outpatient channels while negotiating service-level agreements that protect margins.
- Use M&A to close capability gaps (e.g., rapid-curing resins, digital scanning workflows, regional manufacturing) rather than only to chase incremental volume.
- Diversify raw-material sourcing and build hedging strategies into supplier contracts to shield margins from commodity swings.
- Design commercial incentives around total cost of care and clinical outcomes — procurement teams are increasingly receptive to bundled proposals that reduce downstream costs.
Risk considerations and countermeasures
- Reimbursement pressure: Monitor coding updates and pursue pilots with payers to secure favorable coverage language.
- Regulatory shifts: For novel materials and additive-manufactured devices, plan for premarket documentation early to avoid time-to-market delays.
- Channel disruption: If distributors pursue aggressive private-label strategies, prepare defensive pricing and differentiated service offerings.
- Clinical adoption inertia: Invest in clinician training and real-world evidence to shorten adoption cycles for new device classes.
Conclusion — how to use this preview
This industry preview is intended as a strategic compass for leadership teams making allocation, product and M&A decisions in 2026. The sector’s macro trajectory is favorable: a clear growth runway and concentrated competition create compelling opportunities for focused innovators and disciplined consolidators. The full PW Consulting report contains the scenario models, segment-level analytics, supplier scorecards and executable playbooks needed to convert strategic intent into measurable commercial outcomes. For companies seeking to translate the market’s growth into sustainable advantage, the difference between reacting and leading will be determined by rapid evidence generation, nimble channel strategy, and disciplined use of M&A to fill capability gaps.
Next step
Access to the full report provides the detailed segmentation, pricing curves, granular regional and channel splits, and the downloadable financial model required for board-level decision-making. PW Consulting clients and prospective subscribers may contact our research team for licensing and briefings.
For detailed analysis of this topic, please visit the official page: Casting And Splinting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Soldier Combat System Market Set to Grow at 6.45% CAGR — New Report Unveils Strategic Opportunities
By PW Consulting, 2026-07-13
Soldier Combat System Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest Soldier Combat System Market report positions defence leaders, suppliers and investors to make decisive, risk-balanced choices in 2026. Using 2025 as the analytical baseline and projecting across a 2026–2032 forecast window, the study quantifies a clear expansion trajectory: the global market is growing at a mid-single-digit compound annual growth rate (CAGR) of 6.45%, underpinning sustained demand for integrated soldier capabilities through the next decade. This growth is driven by accelerated digitization of infantry forces, renewed modernization programmes among major militaries, and technology convergence in sensors, power management and communications.
Soldier Combat System Market
Why 2026 is an inflection year for buyers and suppliers
Two trends converge in 2026 to make it a strategic hinge year. First, a wave of programme awards and fielding efforts—focused on modular, networked soldier systems—has moved from concept to scale deployment. Second, emerging technology enablers (multispectral sensing, e-textiles, centralised power hubs and edge-enabled C4I) are now mature enough to materially change procurement trade-offs between capability, soldier burden and lifecycle cost. For defence planners, this means acquisition cycles will require stronger emphasis on integration risk, sustainment pathways and export/regulatory planning. For industry, it means competition will increasingly center on system-of-systems integration, partner ecosystems and service-delivery models rather than on single-component bids.
Soldier Combat System Market
Key market dynamics and what they mean for strategy
-
Demand drivers: Modernization and force interoperability are primary market engines. Governments prioritizing rapid digitization of ground forces are accelerating investments in situational awareness, command-and-control (C4I), and survivability enhancements.
Soldier Combat System Market -
Technology consolidation: Suppliers that bundle sensors, communications and power management into open, modular architectures are winning preference from programme primes and integrators. Open standards enable vehicle integration and coalition operations while also creating differentiation opportunities through software and data services.
-
Market structure: The sector shows measurable concentration among established primes, with the top few players controlling an outsized share of addressable procurement volumes. This concentration increases the importance of teaming, industrial partnerships, and targeted niche plays for mid-sized and specialist firms.
-
Operational constraints: Power & data management, soldier load and export controls remain the three pragmatic blockers to rapid scale-up. Programs that explicitly solve those constraints—through e-textiles, centralized power hubs, or managed export-compliant architectures—will accelerate fielding.
What PW Consulting’s report delivers (practical, procurement-ready intelligence)
-
Actionable programme briefings: A playbook for programme managers that maps common acquisition architectures, procurement decision gates and risk mitigations across the 2026–2032 horizon.
-
Integration readiness assessments: Practical checklists and technical criteria for evaluating openness, vehicle interoperabilty, and power/data distribution maturity in supplier solutions.
-
Commercial playbook: Go-to-market strategies for primes, system integrators and specialists — including recommended teaming arrangements, sustainment offers, and revenue models that capture software and data monetisation.
-
Supply-chain risk matrix: Concentration points for critical components, likely bottlenecks in battery and semiconductor supply, and mitigation options including dual-sourcing and strategic inventory policies.
-
Regulatory & export briefing: Practical steps to design ITAR-aware architectures, manage technical data flows, and structure export-compliant industrial partnerships for coalition programmes.
-
Investment signal framework: Criteria investors and corporate strategists can use to prioritise opportunities — technology readiness, contract pipeline timing, and commercial defensibility.
Competitive landscape — thematic takeaways
The competitive field combines global primes with agile specialists. Large systems integrators bring credentialed delivery capability, scale in defence contracting and access to programme-level interfaces. Specialist firms contribute rapid innovation in sensors, camouflage technologies, personal protection and energy systems. Recent competitive moves illustrate several strategic patterns:
-
Platform-level integration as a market wedge: Established primes are positioning integrated soldier systems as a cornerstone of broader land digitization programmes, pushing modular suites that support sensor-to-shooter chains and vehicle connectivity.
-
Component specialists scaling via teaming: Firms focused on personal protection, optronics or textiles are forming targeted alliances to offer combined kits that meet full-system requirements while preserving their IP and manufacturing roles.
-
Rapid prototyping and OTAs: Contracting mechanisms that allow faster iteration (including Other Transaction Authorities or framework approaches) reduce time-to-field for promising capabilities, increasing the value of adaptable development processes.
Notable recent programme and industry movements
Across 2025–2026, several high-profile moves illustrate the pace of market activity: major primes have secured flagship digitization mandates for national infantry forces; component specialists have announced teaming agreements to supply integrated kits for modernisation programmes; and next-generation head-borne mission command systems have progressed from prototypes to funded development contracts. These developments confirm the trend from evaluation to large-scale procurement in several markets, and underline the importance of readiness to meet multi-year delivery and sustainment demands.
Regulatory, standards and operational constraints
Export controls and technical-data restrictions remain a defining operational constraint. Systems incorporating defence articles (night vision, sensing suites, advanced communications) are subject to export licensing frameworks that influence architecture choices and partner selection. Equally important are standards and interoperability requirements: open architectures, common data models and vehicle interfaces are now procurement prerequisites in alliance contexts. Procurement teams must therefore balance capability ambition against exportability, information-assurance, and coalition-use constraints.
Technology inflection points to watch
-
Energy & power management: Centralised battery solutions, energy-harvesting textiles, and smart distribution hubs are the critical enablers of multi-sensor soldier loads. Programmes that reduce soldier burden while supporting higher sensor counts will be economic winners.
-
Multispectral sensing and fusion: Combining visible, NIR and thermal sensors with edge fusion and assisted targeting materially increases situational awareness. Integration of AI-driven data thinning at the edge will be a discriminator for fielded systems.
-
Networked C4I and sensor-to-shooter loops: Real-time data-sharing and reduced kill-chain latency are shifting value to systems that can reliably operate in contested, denied and degraded environments.
-
Materials & survivability: Advances in lightweight armour materials and multispectral camouflage are changing protection-cost trade-offs for dismounted soldiers.
Recommendations for 2026 decision-makers
-
For procurement authorities: Prioritise open architecture mandates and sustainment pathways in RFPs; require export-compliance roadmaps as part of bids; and stage procurements to allow technology insertion across the lifecycle.
-
For systems integrators and primes: Invest in modular software frameworks, digital twin sustainment models and partner ecosystems that combine protection, sensing and power sub-systems into field-proven kits.
-
For specialist suppliers: Pursue dual tracks — deepen niche technical superiority while forming industrial partnerships that provide access to programme-level procurement channels.
-
For investors and M&A teams: Target suppliers that demonstrate scalable manufacturing, serviceable revenue streams (sustainment/software) and architectures designed for export-compliant deployment across allied customers.
Methodology highlights and market coverage (what we do and do not disclose here)
The PW Consulting report combines bottom-up programme analysis, supplier financial and capability reviews, and scenario-driven forecasting tied to observable procurement pipelines. The published executive summary highlights total market scale and growth trajectory; the full report contains detailed segmentation, country- and application-level forecasts, supplier share models, and an indexed assessment of programmatic risk. In keeping with our “trailer” approach, this announcement surfaces the strategic implications and headline macro metrics needed for immediate decision-making while reserving full segmentation tables and supplier-level revenue breakdowns for the full report.
How to obtain the full intelligence
For procurement teams, supplier strategists and investors requiring the underlying segmentation, country-level forecasts, supplier share models and the complete set of programme briefings, PW Consulting’s full Soldier Combat System Market report includes downloadable datasets and an analyst Q&A. Visit the PW Consulting reports page to access the full study and to schedule a briefing with our senior analyst team. The full package provides the granular inputs necessary to operationalise the strategic recommendations outlined above.
Closing note
2026 will reward organisations that translate system-level thinking into executable acquisition and industrial strategies. With a sustained market expansion at a 6.45% CAGR over the forecast window and clear concentration among established primes, the competitive battleground is now defined as much by integration, sustainment and export-readiness as by sensor performance. PW Consulting’s report is designed to be the practical companion for those choices—showing not just where the market is headed, but how to win in it.
For detailed analysis of this topic, please visit the official page: Soldier Combat System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


