



PW Consulting: Reciprocating Compressor Market for Oil & Gas Set to Expand at a 3.52% CAGR Through 2032, Report Finds
By PW Consulting, 2026-07-13
Reciprocating Compressor For Oil & Gas Market — 2026 Strategic Preview
Executive snapshot
PW Consulting’s latest market intelligence on reciprocating compressors for the oil & gas sector frames an industry at the intersection of incremental growth, regulatory tightening, and a strategic pivot toward low‑carbon fuels. With a 2025 market base of USD 4,121.31 Million and a modeled compound annual growth rate of 3.52% for the 2026–2032 forecast window, our analysis shows steady expansion driven by refurbishment cycles, capacity optimization in midstream systems, and nascent demand for hydrogen‑capable compression solutions. By 2032 the market is projected to exceed USD 5.2 Billion under the central scenario, but the underlying pathways vary materially by technology choice, service model, and regulatory posture.
Reciprocating Compressor For Oil Gas Market
Why this report matters to 2026 corporate decision‑makers
-
Decision readiness: The report translates macro growth into board‑level decision triggers — capex thresholds, retrofit versus replace break‑even windows, and aftermarket service ROI under alternative price/regulatory scenarios.
Reciprocating Compressor For Oil Gas Market -
Risk calibration: It integrates materials, regulatory and operational risk vectors (including steel cost volatility and U.S. EPA NSPS requirements) into scenario models so procurement, engineering and finance teams can quantify exposure over typical compressor life cycles.
Reciprocating Compressor For Oil Gas Market -
Transition planning: It provides a practical roadmap for hydrogen and CO2 readiness, showing how incremental engineering choices today affect lifetime costs and market access tomorrow.
-
M&A & partnership targeting: The intelligence is structured to highlight capability gaps in portfolios and to prioritize targets in aftermarket services, controls, and hydrogen‑capable compression technologies.
What’s in the report — practical, operational content
-
Market sizing and multi‑scenario forecasts (2020–2032) with sensitivity runs capturing commodity‑price and regulatory shocks.
-
Technology assessment comparing high‑speed, low‑speed and modular reciprocating architectures, including retrofit pathways and reliability tradeoffs.
-
Comprehensive value‑chain mapping covering OEMs, integrators, aftermarket service providers, and spare‑parts economics.
-
CapEx/Opex modeling templates and TCO calculators tailored to upstream, midstream and downstream use cases (interactive Excel / dashboard deliverables available to licensees).
-
Regulatory compliance playbook — practical checklists for NSPS OOOOb obligations, ISO 13707 alignment, and emissions monitoring strategies.
-
Supply‑chain risk heatmaps with raw‑material sensitivity (notably steel) and recommended procurement hedging strategies.
-
Competitive landscaping and M&A playbook highlighting strategic moves, capability maps, and integration risk checklists.
Competitive landscape — what to watch in 2026
The reciprocating compressor supplier field remains populated by established engineering leaders and niche specialists. Our qualitative analysis of leading participants highlights the strategic postures most likely to shape competitive dynamics next year:
-
Ariel Corporation — Positioned as a leading separable compressor manufacturer with broad applicability across the oil & gas fullstream. Recent product demonstrations emphasize smart‑packaging (digital monitoring and variable clearance innovations) and hydrogen mobility options. For buyers, Ariel represents a low‑technical‑risk partner for standardization and scale upgrades.
-
Baker Hughes — Focused on API 618‑class compressors with modular, multi‑cylinder frames for high‑pressure services. Its strengths in reliability and maintenance ease make it a preferred choice where uptime and low pulsation are mission critical.
-
Burckhardt Compression AG — A go‑to for customized, modular systems and an early mover in hydrogen and CO2 service readiness. Their commercial positioning is attractive to operators pursuing fuel‑type diversification and bespoke process solutions.
-
Siemens Energy (Dresser‑Rand) — Combines advanced valve technology and capacity control with deep OEM engineering capability. Expect competitive emphasis on performance tuning and lifecycle optimization.
-
Ingersoll Rand, Howden, Atlas Copco, MAN Energy, Neuman & Esser, Borsig — Each brings differentiated strengths: high‑pressure platforms, retrofit/upgrade expertise, oil‑free variants, offshore capabilities, and tight engineering customization. Buyers should map these capability differences against their reliability, emissions, and lifecycle cost priorities.
Recent industry moves underline two strategic themes: expansion of local service footprints and visible bets on low‑carbon readiness. Examples include new regional service centers and high‑profile trade‑show demonstrations of hydrogen‑capable hardware configured for oil & gas workflows.
Market dynamics & regulatory context
-
Material and fabrication costs: Steel price stabilization through mid‑2025 has moderated but not eliminated fabrication cost risk. Procurement leaders should model +/- scenarios for plate and alloy steel inputs when forecasting project costs and long‑lead equipment orders.
-
Emissions and compliance: NSPS OOOOb provisions impose strict rod‑packing flow limits and monitoring/maintenance obligations that materially affect operating expense and maintenance cadence for compressor fleets in regulated jurisdictions. Compliance costs and failure to comply carry both financial and permitting consequences.
-
Standards and reliability: ISO 13707 remains a foundational design and materials standard; aligning procurement specifications to it reduces integration risk, especially for cross‑jurisdictional projects.
-
Energy transition: There is growing commercial demand for compressors that can serve hydrogen, CO2 and blended fuel streams. Manufacturers and operators face engineering tradeoffs between immediate cost efficiencies and future‑proofing for mixed‑fuel service conditions.
Strategic implications for 2026 planning cycles
For executives setting 2026 priorities, the following actions convert insight into implementable steps:
-
Adopt scenario‑based capex gating: Use the report’s scenario outputs to set trigger thresholds (commodity price, regulatory changes, steel cost inflection) that govern go/no‑go for greenfield compressors and major retrofits.
-
Prioritize aftermarket and field service investments: Given the growing importance of uptime and emissions reporting, building or partnering for regional service centers reduces downtime risk and creates recurring revenue streams.
-
Define a hydrogen‑readiness timeline: Establish retrofit standards and spare‑parts roadmaps now — small engineering choices (materials, valve designs, clearances) have outsized impacts on future conversion cost.
-
Lock in material supply strategies: Negotiate long‑lead contracts, index clauses or forward purchases for critical steel inputs to stabilize capital project estimates.
-
Elevate emissions monitoring: Invest in digital rod‑packing monitoring and predictive maintenance to meet regulatory obligations cost‑effectively while reducing unscheduled outages.
-
Targeted M&A and partnerships: Seek bolt‑on acquisitions in controls, aftermarket services, or hydrogen‑specific compression modules to close capability gaps quickly.
What this report does not reveal — and why
In keeping with a “preview” approach, this briefing demonstrates the analytical depth and practical orientation of PW Consulting’s deliverable while withholding the detailed segmented tables, regional and application breakdowns, and proprietary scenario matrices that subscribers rely on for transaction‑level decisions. Those granular datapoints — including split‑level forecasts, regionally disaggregated cost curves and customer‑level competitive positioning — are available in the full report package and interactive dashboards.
Next steps
For strategy teams preparing 2026 budgets, procurement roadmaps, or M&A pipelines, PW Consulting’s full report provides the detailed segment modeling, downloadable TCO templates, and supplier scorecards needed to operationalize the recommendations above. To review the complete segmented forecasts, scenario workbooks, and custom consulting options, please consult the PW Consulting report access channel.
For detailed analysis of this topic, please visit the official page: Reciprocating Compressor For Oil Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Endocrine Disease Treatment Market Poised for 8.75% CAGR Through 2032
By PW Consulting, 2026-07-13
Rare Endocrine Disease Treatment Market: Strategic Outlook and Action Playbook for 2026
PW Consulting’s new Rare Endocrine Disease Treatment Market report — based on a 2025 base year and a 2026–2032 forecast window — delivers a decision-grade narrative for biopharma executives, investors and policy teams preparing for the next wave of launches and dealmaking. The market reached approximately USD 16,450 million in 2025 and, under our central scenario, is projected to approach USD 29,592 million by 2032, representing a compound annual growth rate of 8.75% across the forecast period. This release summarizes the strategic implications we believe will matter most to teams making resource-allocation, portfolio and commercial-access choices in 2026, while preserving the report’s full datasets and segmentation for clients who access the full study.
Rare Endocrine Disease Treatment Market
Why 2026 is a Strategic Inflection Point
The confluence of recent regulatory approvals, novel delivery modalities and expanded pediatric labeling is shifting competitive dynamics in rare endocrinology. In the last 18–24 months the market has seen the first oral somatostatin receptor ligand approved, broadened pediatric approvals for once-weekly growth hormone, and the first new adjunctive therapy for congenital adrenal hyperplasia in decades. These events materially change go-to-market economics, patient adherence trajectories and payer negotiation levers — and they create windows for incumbents and entrants to reshape category leadership.
Rare Endocrine Disease Treatment Market
What the Report Delivers (Practical, Transaction-Ready Content)
- Actionable commercial forecast model (driver-based, scenario-enabled) with sensitivity levers for pricing, uptake and label expansion assumptions.
- Pipeline and clinical roadmap tracker aligned to launch-readiness timelines and regulatory milestones, including risk-adjusted peak sales scenarios.
- Go-to-market playbooks by therapy modality (oral, long-acting injectables, recombinant hormones), including sample patient journey maps and channel strategies.
- Payer-access playbook: evidence generation requirements, likely reimbursement pathways, HTA touchpoints and budget-impact templates.
- Partnering and M&A scout: prioritized acquisition targets and collaboration archetypes by technology and clinical stage.
- Country-agnostic commercialization checklists and a launch-risk heatmap (manufacturing, distribution, clinical, regulatory and reimbursement risks).
- KOL synthesis and advocacy mapping to accelerate uptake in specialist centers and pediatric networks.
Market Dynamics that Will Drive Boardroom Decisions
- Modality disruption. Shifts from frequent injections to oral or less-frequent dosing reduce patient burden and expand addressable populations, but also change cost-per-patient economics and adherence-related value propositions.
- Label expansion and pediatric growth. Expanded pediatric indications unlock materially larger patient pools and longer therapy durations, favoring organizations with pediatric clinical development and manufacturing scale.
- Regulatory and incentive tailwinds. Orphan designations, Fast Track pathways and other incentives are shortening development timelines while enhancing exclusivity economics — a clear rationale for upstream investment in late-stage assets.
- Payer scrutiny and evidence demands. Despite orphan incentives, payers increasingly demand robust real-world and health-economic evidence for long-term therapies — early evidence-generation planning is now a commercial imperative.
- Moderate market concentration. The category is neither highly fragmented nor locked; the balance between innovative mid-cap players and larger specialty/pharma incumbents creates attractive targets for partnerships and selective M&A.
Competitive Landscape: Strategic Positions and Playbooks
The current competitive set combines established pharma with specialist rare-disease biotechs. Below we synthesize strategic positioning and implications for 2026:
Rare Endocrine Disease Treatment Market
- Ascendis Pharma (Copenhagen) — TransCon delivery platforms give Ascendis leverage in long-acting formulations across multiple endocrine indications. Strategy implication: partnership or licensing for TransCon-enabled assets can accelerate payer conversations on adherence and total-cost-of-care benefits.
- Novo Nordisk (Bagsværd) — With a once‑weekly growth hormone that has recently expanded pediatric use, Novo is positioned to extend leadership in growth-disorder therapeutics. Strategy implication: competitors and partners should model extended-duration patient lifecycles and prepare pediatric-specific value dossiers.
- Recordati Rare Diseases (Milan) — Focused specialty capabilities and a presence in pituitary/adrenal disorders make Recordati a durable commercial player in niche centers. Strategy implication: tactical licensing or distribution agreements in select territories could be high-roi moves for companies with complementary assets.
- Neurocrine Biosciences (San Diego) — The introduction of a new adjunctive therapy for congenital adrenal hyperplasia redefines standard-of-care conversations. Strategy implication: competitors must reassess comparator strategies, and partners should fast-track head-to-head and registry-based evidence.
- Ipsen (Paris) & Pfizer (New York) — Both bring specialty commercialization experience for pituitary and hormone-replacement therapies; their scale is an advantage in payer negotiation and global launch execution. Strategy implication: expect aggressive market-defense tactics in territories where they have existing relationships.
- Spruce Biosciences & MBX Biosciences (US) — Small-molecule approaches to HPA-axis disorders represent attractive add-ons or bolt-ons for larger players seeking oral, daily therapies. Strategy implication: high-value partnering opportunities exist for mid-stage developers.
- AstraZeneca / Alexion (Cambridge) — Advancing therapies for hypoparathyroidism with expedited regulatory support, AstraZeneca demonstrates how big pharma can re-enter highly specialized endocrine niches. Strategy implication: innovators should expect stronger competition for orphan designations and accelerated development pathways.
Notable Recent Developments and Strategic Consequences
- Broader pediatric approvals and new oral options have already altered expected uptake curves; companies must refresh launch forecasts and clinical-education plans accordingly.
- Approvals of first-in-class or first-new-in-decades therapies change standard-of-care baselines and evidence benchmarks — impacting pricing, formulary placement and comparative-effectiveness strategy.
- Regulatory designations (orphan, Fast Track) materially improve development economics but also attract competition — timing and exclusivity windows should be central to licensing and M&A negotiations.
Recommended 90‑Day and 12‑Month Actions for 2026
- 90-Day sprint
- Stress-test your forecast model against the latest approval and label scenarios; include oral- vs injectable-adoption curves.
- Initiate payer evidence-gap mapping to identify the top three real-world studies or economic models needed for formulary acceptance.
- Open dialogue with targeted partners for late‑stage assets that complement your modality mix (oral, long-acting, recombinant).
- 12‑Month roadmap
- Secure launch-readiness funding and build a pediatric clinical-education program if your asset has or may pursue pediatric labeling.
- Operationalize a registry and RWE program timed to market access submissions; pre-specify health-economic endpoints.
- Execute a targeted M&A/partnering pipeline using our deal-scout framework to prioritize accretive assets and capabilities.
How PW Consulting’s Report Reduces Execution Risk
The value of this report lies in actionable synthesis: we translate clinical milestones into commercial timelines, regulatory designations into exclusivity windows, and patient-adherence innovations into pricing and contracting strategies. Our forecast model is delivery-ready — clients can plug in alternate assumptions, run sensitivity analyses and generate market scenarios tailored to licensing negotiations or investor diligence. For teams evaluating acquisition targets, the report’s deal-scout templates and risk heatmaps compress months of diligence into a structured, repeatable process.
Closing: What Leaders Should Do Next
For boards and executive teams setting 2026 priorities: treat the rare endocrine category as a rapidly re-shaping space where modality innovation, label expansion and payer evidence strategy will determine which players scale and which stall. Use the next quarter to align clinical, commercial and access functions around a single, stress-tested view of the market; use the next 12 months to convert that view into executed launches, partnerships and evidence programs.
PW Consulting’s full Rare Endocrine Disease Treatment Market report contains the complete datasets, scenario-ready models and detailed segmentation that underpin these recommendations. To access the comprehensive forecast tables, competitor scorecards and our interactive launch-scenario tool, visit PW Consulting’s report portal or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Rare Endocrine Disease Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HPLC and UHPLC Columns Market Poised to Grow at a 6.61% CAGR Through 2032
By PW Consulting, 2026-07-13
HPLC and UHPLC Columns Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new HPLC and UHPLC Columns Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market-scale measurement, competitive dynamics, supply-chain sensitivities and regulatory drivers into a decision-grade toolkit for executives planning moves in 2026. The global market reached roughly USD 2.82 billion in 2025 and, with a compound annual growth rate of 6.61% through our forecast window, is positioned to surpass USD 4.4 billion by 2032. This briefing highlights the report’s practical value for strategic planning while intentionally withholding granular segment-level tables and precise regional/application splits — those detailed datasets and modeller outputs are available in the full report.
Hplc And Uhplc Columns Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivotal year for capital allocation and product roadmaps across life sciences, environmental testing and industrial QA labs. The combination of accelerating UHPLC adoption, heightened regulatory sensitivity and evolving resin supply dynamics creates asymmetric opportunities for firms that align R&D, procurement and commercial execution.
Hplc And Uhplc Columns Market -
Clarity on scale: Our consolidated, audited market-sizing clarifies where aggregate opportunity resides and how it shifts under conservative, base and accelerated demand scenarios — enabling CFOs to stress-test CAPEX and inventory strategies across a multi-year horizon.
Hplc And Uhplc Columns Market -
Actionable intelligence: The report translates market movement into operational options — from raw-material hedging playbooks to prioritized product adjacencies (e.g., sub-2 µm chemistries, hybrid phases, and preparative-to-process column continuum).
Market trajectory and practical implications
The industry’s steady mid-single-digit CAGR masks meaningful structural shifts that will materially affect 2026 decisions. First, regulatory expectations and method harmonization in pharmaceutical and environmental labs are driving a progressive upgrade toward UHPLC-grade chemistries and sub-2 µm particle technologies — creating demand for higher-performance columns and corresponding lifecycle services (method transfer, qualification, and consumables management). Second, bioanalytical and oligonucleotide workflows are generating specialized column requirements (surface chemistries, pore sizes and stability profiles) that favor suppliers able to combine advanced stationary phases with robust analytical support.
For procurement and operations teams, two supply-side realities are decisive: raw-material price and production capacity. In late 2025, Northeast Asia silica gel pricing edged higher (approximately a mid-single-digit percent increase relative to the prior year), and global porous silica capacity supports roughly on the order of a million-plus column-equivalents annually. These inputs translate to volatile input-cost exposure for column producers and create windows for buyers to secure multi-year agreements or collaborate on toll production to lock-in margin profiles.
Regulatory and methodological drivers
Regulatory bodies and standardized methods are exerting direct influence on laboratory column choice. Heightened expectations for sensitivity and resolution in pharmaceutical QC are accelerating adoption of UHPLC platforms and hybrid chemistries. Parallelly, environmental agencies continue to reference established column classes (for example, longstanding C18-based requirements in pesticide and PFAS workflows), anchoring steady demand for validated column types while creating opportunities for differentiated offerings that reduce method development time or improve robustness.
Competitive landscape — what the market structure implies
The market demonstrates moderate concentration: the top three vendors account for roughly the lower 40-percent range of market share while the top five approach the low 60-percent range. This structure supports both scale advantages for incumbent platform vendors and pockets of specialist opportunity for focused challengers.
-
Agilent Technologies (Santa Clara, USA) — broad portfolio strategy combining legacy bonded phases with newly launched ultra-inert offerings targeted at biotherapeutics and oligonucleotide workflows. Strength: deep product breadth and instrument integration; strategic play: extend application-specific support and consumable-as-a-service models.
-
Waters Corporation (Milford, USA) — invests in hybrid surface and surface-engineering approaches and produces its own resins; recent launches expand both preparative and protein-affinity columns for bioprocess QC. Strength: end-to-end platform ownership; strategic play: leverage method standardization and premium service contracts.
-
Thermo Fisher Scientific (Waltham, USA) — competitive across pharmaceutical and environmental segments via multiple branded chemistries; strength in global distribution and cross-selling into existing instrument installed base.
-
Shimadzu, Merck (MilliporeSigma), Danaher/Phenomenex — each presents complementary strengths in system compatibility, superficially porous particles and core-shell technologies; these players continue to push performance differentials while protecting margins through proprietary phase formulations.
-
Specialists and regional players (e.g., Tosoh, Restek, Bio-Rad, YMC, Daicel and others) — maintain positions in ion-exchange, SEC, chiral and process-scale columns; attractive partners for co-development or niche M&A when speed-to-market for specialized chemistries is required.
Our competitive chapter blends capability matrices, supply-security risk scores, and product roadmaps benchmarked against validated performance claims. Recent vendor activity underscores the strategic dynamics: product introductions in 2025 targeted at biotherapeutics (Agilent’s ultra-inert series; Waters’ protein-affinity lines), and process-focused entries (Bio‑Rad’s larger-diameter process columns), which point to a bifurcating market — high-throughput analytical UHPLC demand coexisting with growing requirements for downstream/process chromatography.
What the PW Consulting report contains — operational elements
-
Integrated market-size model (2020–2032) with scenario toggles and sensitivity to raw-material and regulatory shocks.
-
Competitor playbooks: product line maps, patent posture summaries, go-to-market vectors and supplier counterparty risk scores.
-
Segmentation analytics (by technology, application and region) with downloadable CSVs and pivot-ready sheets — note: detailed segment numbers are omitted from this public briefing and available in the full report.
-
Procurement and manufacturing playbooks: cost-to-serve models, silica and resin sourcing strategies, contract templates, and inventory hedging scenarios.
-
Regulatory and method-impacts dossier: mapping of agency method requirements to column specifications, and a prioritized list of method-conversion opportunities for lab service providers.
-
Commercial strategies: channel optimization, bundling/consumable subscription concepts, and key account expansion plans for instrument OEMs and CROs.
-
Executable M&A and partnership framework with target-screening criteria (technology fit, capacity gravity, route-to-market synergies).
How strategic leaders should use the findings in 2026
-
Product strategy: Prioritize investments in hybrid chemistries, ultra-inert surfaces and column formats that reduce method transfer time for biotherapeutics and oligonucleotide assays. Use our product-adoption curves and willingness-to-pay analysis to decide which features to fully fund versus prototype.
-
Commercial & pricing: Consider value-based pricing for validated, method-certified columns and premium support. Leverage the report’s channel-level insights to optimize direct vs distributor coverage in key laboratory verticals.
-
Supply-chain & operations: Hedge silica exposure through multi-sourcing and strategic inventory buffers; evaluate toll-manufacturing or captive resin capacity if predictable volume and margin upside exists.
-
M&A and partnerships: Use our target-screening matrices to identify bolt-on specialists (e.g., chiral or SEC specialists) that can accelerate access to high-growth application niches without heavy R&D spend.
-
Laboratory services & CROs: Build differentiated services around method transfer, column qualification and consumable lifecycle management to secure recurring revenue streams.
Conclusion — what we recommend you do next
For executives making budgetary and portfolio decisions in 2026, the instrumental questions are: where will you invest to capture premium UHPLC demand, how will you protect margin against raw-material volatility, and which partnership or M&A moves accelerate access to application-specific expertise? PW Consulting’s HPLC and UHPLC Columns Market report converts those strategic questions into prioritized actions, underpinned by a validated market model and competitor intelligence.
For full access to the segmentation tables, vendor scorecards, scenario models and the downloadable Excel workbook that power these recommendations, please consult the complete report page. The public briefing above is intentionally high-level to signal readiness and preserve the detailed, actionable datasets for subscribing clients and authorized readers.
For detailed analysis of this topic, please visit the official page: Hplc And Uhplc Columns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Hepatitis Test Diagnosis Market to Reach USD 5,104.07 Million by 2032, Expanding at a 6.2% CAGR
By PW Consulting, 2026-07-13
Hepatitis Test Diagnosis Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest market research synthesizes the critical evidence executives need to align product, regulatory and commercial strategies in the hepatitis diagnostics space as they enter 2026. Anchored on a comprehensive time series and forward forecast, the study finds that the global hepatitis test diagnosis market reached approximately USD 3,350 Million (base year 2025) and is forecast to expand to roughly USD 5,104 Million by 2032, representing a compound annual growth rate (CAGR) of 6.2% over the 2026–2032 forecast window. This growth trajectory, combined with shifting regulatory and reimbursement landscapes, makes 2026 a pivotal planning year for life‑science leaders, laboratory networks, payers and investors.
Hepatitis Test Diagnosis Market
Why this report matters for 2026 strategy
-
Actionable foresight: The market is moving beyond incremental product upgrades toward systemic changes driven by point‑of‑care molecular testing, multiplex rapid diagnostics and new screening recommendations. Executives who recalibrate now will capture the largest share of the next growth phase.
Hepatitis Test Diagnosis Market -
Regulatory inflection points: Recent regulatory reclassifications and approvals change development timelines, capital allocation and go‑to‑market sequencing — making precise impact analysis indispensable for product roadmaps and submission strategies.
Hepatitis Test Diagnosis Market -
Commercial leverage: As reimbursement criteria evolve and screening protocols broaden, the window to secure favorable coverage, build lab partnerships and scale distribution is limited. The report translates macro trends into concrete commercial priorities for 2026.
What the report delivers (practical, decision‑ready content)
-
Market sizing and trend analysis (historical base: 2020–2025; forecast period: 2026–2032) with downloadable financial models in USD (Million).
-
Segmentation frameworks by region, test type and end‑user with scenario‑driven demand modeling (note: granular subsegment figures are reserved for the full report to preserve proprietary insights and to guide stakeholder conversations).
-
Competitive benchmarking and capability mapping for leading suppliers across molecular, immunoassay and rapid formats.
-
Regulatory and reimbursement trackers that quantify timing and materiality of policy moves across major markets.
-
Commercial playbooks: product positioning, pricing sensitivity analysis, channel strategies, and lab‑network partnership templates.
-
Risk register and mitigation actions covering supply chain shocks, regulatory uncertainty and payer reimbursement shifts.
Key market dynamics shaping 2026 decisions
-
Technology diffusion: The near‑term commercial story is twofold — continued dominance of centralized immunoassays in high‑volume settings and accelerated adoption of decentralized molecular/POC assays for screening and linkage to care. Point‑of‑care RNA testing and multiplex rapid diagnostics are changing screening workflows and shortening diagnosis‑to‑treatment timelines.
-
Regulatory momentum: Notable regulatory events have lowered barriers to market for some classes of hepatitis assays and clarified pathways for others. For example, recent reclassification of certain HBV assay devices in major markets reduces regulatory timelines for follow‑on entrants, while high‑profile approvals and waivers for POC molecular HCV tests validate the clinical utility of decentralized RNA testing.
-
Screening policy evolution: Expanded public health guidance — including recommendations for broader HBV screening panels — will reshape test demand composition and create opportunities for both multiplex rapid diagnostics and comprehensive laboratory‑based screening algorithms.
-
Reimbursement realignment: Updates to payer coverage criteria mean pricing power will vary by test format and clinical indication; developers must calibrate evidence generation to reimbursement endpoints, not just regulatory clearance.
-
Consolidation and concentration: Market concentration metrics indicate a moderately concentrated supplier base at the top end, with room for specialist and mid‑sized players to win niche segments through differentiated technology or service models.
Competitive landscape — strategic implications
The market is anchored by several global diagnostics companies that combine installed platform footprints, reagent portfolios and service capabilities. Major incumbents offer comprehensive immunoassay platforms, high‑throughput molecular systems, and a growing set of rapid, point‑of‑care options. Recent corporate and regulatory developments demonstrate how quickly competitive advantage can shift:
-
Large platform providers maintain scale advantages for high‑volume clinical laboratories through integrated immunoassay and molecular portfolios, enabling bundled offers that hospitals and reference labs find attractive for cost and workflow simplicity.
-
Specialist molecular and POC players have proven they can accelerate diagnosis and linkage to care when regulatory pathways permit CLIA waivers or comparable decentralization allowances. Those firms can rapidly scale through strategic partnerships with laboratory networks and non‑traditional care settings.
-
Regulatory and quality milestones materially affect market access. Recent approvals and prequalifications for multiplex rapid and POC molecular tests demonstrate how product endorsements by regulators and global health agencies increase adoption velocity among public health purchasers.
-
Market concentration measures (CR3 ~48.4%; CR5 ~64.2%) point to meaningful leadership at the top, but also to an addressable market for technology‑led challengers and regionally focused players. This structure implies both competitive barriers and tactical entry points for innovators.
Selected recent events have immediate strategic relevance: high‑profile regulatory approvals and WHO prequalification of multiplex rapid tests validate both clinical and procurement pathways for combined screening approaches; meanwhile, regulatory reclassification in major markets reduces uncertainty for certain assay classes; and payer policy updates adjust the economics for screening across indications. Each of these developments is analyzed in the report to map time‑to‑impact on revenue and adoption curves.
Strategic recommendations for 2026 (what to do next)
-
For product developers: Prioritize regulatory intelligence and modular design. Align clinical evidence plans with payer endpoints and target WHO prequalification where procurement from public health programs is strategic.
-
For platform incumbents: Defend high‑throughput share while investing selectively in decentralized molecular and multiplex rapid capabilities through partnerships, in‑licensing or targeted M&A.
-
For laboratory networks and hospitals: Rebalance procurement toward a mixed portfolio — maintain centralized throughput for confirmatory testing while piloting POC molecular solutions in high‑yield clinical pathways to reduce time to diagnosis.
-
For payers and health systems: Use the next 12 months to update coverage criteria and contracting approaches that incentivize validated rapid linkage‑to‑care solutions, rather than purely lowest‑cost testing.
-
For investors and private equity: Look for assets that combine clinical differentiation with regulatory clarity and addressable contract pipelines; mid‑market consolidation vehicles with platform synergies remain compelling.
How PW Consulting helps — tools and engagement models
-
Data‑driven financial models and scenario planning customized to client portfolios and geographies.
-
Regulatory impact assessments and submission roadmaps tied to commercial rollout sequencing.
-
Commercial playbooks with channel strategies, pricing sensitivity analysis and partnership templates.
-
Due diligence services for M&A and licensing, including competitive threat mapping and integration planning.
-
Executive workshops to translate market forecasts into 90‑, 180‑ and 365‑day action plans.
PW Consulting’s Hepatitis Test Diagnosis Market report is intentionally crafted to be a strategic catalyst for 2026 planning cycles. The full report contains the granular segmentation, regional breakout, product‑level forecasts and downloadable models that you will need to operationalize the recommendations above. For access to the complete dataset, company scorecards, and bespoke advisory engagements, please visit our report landing page or contact PW Consulting’s healthcare team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Hepatitis Test Diagnosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Broadband Router Market to Grow at 7.15% CAGR (2026–2032), Reaching USD 36,486.1 Million by 2032
By PW Consulting, 2026-07-13
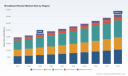
Broadband Router Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As broadband architectures, home connectivity expectations and regulatory regimes shift in near real time, corporate leaders need crisp, actionable intelligence that balances market-scale clarity with tactical discretion. PW Consulting’s latest Broadband Router Market report (base year 2025) delivers that combination: a data-grounded view of the sector’s trajectory — a global market that grew from roughly USD 19.6 billion in 2023 to USD 22.5 billion in 2025 and is forecast to expand at a steady compound annual growth rate of c. 7.15% across 2026–2032 — paired with operator-focused playbooks that protect competitive advantage while preserving commercially sensitive detail for report subscribers.
Broadband Router Market
Why this report matters for 2026 corporate decision-making
-
Timing: 2026 is a pivot year. Infrastructure deployment patterns (fiber reach and fixed wireless scale-ups), a wave of Wi‑generation upgrades, and newly intensified regulatory scrutiny are converging to reshape procurement, product roadmaps and channel strategies.
Broadband Router Market -
Scale and growth clarity: Our topline market sizing and forecast provide a reliable macro frame for capital planning and product investment. With the market expanding consistently into the early 2030s, executives can quantify portfolio growth potential while aligning to risk tolerances.
Broadband Router Market -
Action orientation: The report is designed as a decision tool — not just a descriptive study. It translates market signals into prioritized initiatives across R&D, manufacturing footprint, channel deployment, and M&A scouting.
Market outlook — what the numbers say (and what they don’t)
Our modeled forecast — built on historical patterns (2020–2025), operator CAPEX signals, technology migration rates and regulatory scenarios — points to persistent, mid-single-digit to upper single-digit CAGR expansion through 2032. This reflects sustained demand for upgraded home and enterprise edge devices, continued service provider investments in fiber and fixed wireless, and cyclical refresh waves tied to new Wi‑generation life cycles.
Importantly, while the aggregate opportunity widens, value capture will not be uniform: product differentiation (multi-gig throughput, mesh scalability, integrated security, managed services) and supply-chain resilience will determine margin trajectories. The report emphasizes where aggregate growth can be translated into outsized returns and where it risks becoming commoditized volume.
Regulatory and macro dynamics shaping strategy
-
National security and equipment approvals: Recent regulatory moves in some major markets have expanded lists of equipment subject to heightened authorization or conditional approvals. These policies materially affect the ability of vendors to introduce new consumer-grade devices without additional compliance steps and can change procurement windows for service providers.
-
Judicial and policy shifts on broadband classification: Changes in the regulatory doctrine governing broadband services are altering the contours of federal oversight and state-level policy levers. Market participants must model multiple regulatory scenarios into product and pricing strategies.
-
Infrastructure economics: Fiber is now serviceable to a majority of households in a leading market, but deployment costs — from labor to make-ready permitting — have risen markedly, changing the economics of capex-driven expansion. Simultaneously, spectrum policy and auctions are creating a growing runway for fixed wireless broadband as a strategic alternative.
-
Procurement and subsidy programs: Updates to major broadband subsidy programs emphasize technology neutrality and cost-effectiveness, accelerating competitive bids where suppliers can demonstrate rapid, low-cost installations.
Competitive landscape — strategic implications for core players
The router market today blends large enterprise-focused vendors with nimble consumer and platform players. A few strategic patterns emerge that are validated across our benchmarking and vendor interviews:
-
Cisco Systems: Strong enterprise and service-provider positioning, including cloud-native broadband routing platforms. Their prime strategic advantage is integration across access, aggregation and cloud orchestration layers. For Cisco, the near-term playbook centers on accelerating cloud-managed feature sets and deepening partnerships with large operators to convert capital spend into recurring software revenue.
-
TP‑Link / NETGEAR / ASUS / D‑Link / Belkin (Linksys) / Amazon (eero): These consumer and prosumer vendors compete intensely on feature-to-price ratios, brand trust and channel reach. As Wi‑generation upgrades (Wi‑6/6E → Wi‑7) and mesh adoption expand, differentiation will be driven by software ecosystems (security, parental controls, subscription services) and supply-chain agility. Regulatory constraints on imported consumer-grade equipment further elevate localization and compliance as priorities.
-
Huawei: Continues to be a supplier of advanced broadband gateways and ONTs globally. Geopolitical and regulatory headwinds impact market access in some markets; where accessible, Huawei competes on integration and cost, influencing price benchmarks for fiber and fixed wireless gateway devices.
-
Ubiquiti: Focused on scalable network management and hybrid consumer–SMB propositions. Their strengths in simplified enterprise-like management for SMB and venues make them a strategic partner for managed service rollouts.
Across the vendor set, several imperatives recur: (1) build regulatory-compliant SKUs and a compliance roadmap, (2) develop subscription-native services to lift lifetime value, (3) prioritize modular hardware platforms to accelerate new Wi‑generation introductions, and (4) secure diversified component sourcing to mitigate tariff and authorization disruptions.
Recent industry movements and tactical read-throughs
-
Regulatory lists and conditional approvals: The recent expansion of equipment lists requiring additional approvals has created both risk and opportunity. Vendors with exemption pathways or domestic-compliant product lines can convert short-term disruption into competitive share gains.
-
Product innovations — industrial and gateway: The introduction of TAA-compliant industrial 5G routers and demonstrations of next‑gen XGSPON gateways underscore two parallel trends: edge compute integration and readiness for extreme-density broadband endpoints. Service providers and enterprise adopters should re-evaluate edge compute roadmaps in tandem with access equipment refresh cycles.
-
Spectrum and fixed wireless: Planned spectrum auctions and growing interest in upper mid-band assets will expand fixed wireless viability, especially where fiber deployment faces steep incremental costs. Vendors that can deliver integrated customer premises equipment (CPE) for both fiber and FWA will hold strategic advantage.
What the PW Consulting report contains — operationally useful sections
-
Topline market sizing and 2026–2032 forecasting model with scenario toggles for regulatory and deployment variability.
-
Demand-driver analysis: household connectivity trends, gaming and OTT consumption, enterprise SD‑WAN and IoT access patterns.
-
Vendor benchmarking and go-to-market scorecards covering product architecture, software strategy, channel strength and compliance posture (note: granular segment shares and per-region revenue breakdowns are reserved in the full dataset to preserve commercial sensitivity).
-
Regulatory impact matrix mapping probable policy outcomes to product launch, certification and channel timing.
-
Supply‑chain and sourcing playbook with mitigation options for equipment authorizations, tariffs and supplier concentration risks.
-
M&A and partnership heatmap highlighting target archetypes and valuation sensitivities under different growth scenarios.
-
Actionable roadmaps for product teams, procurement and operator strategy groups — including a 90‑day playbook for urgent compliance and market access moves.
Recommended strategic moves for 2026 (prioritized)
-
Immediate compliance triage: Audit product lines against emergent authorization lists and secure conditional pathways or TAA/compliant alternatives where exposure is material.
-
Platform modularization: Invest in common hardware platforms that can be rapidly reconfigured for multiple regulatory markets and Wi generations to shorten time‑to‑market and lower SKU proliferation costs.
-
Monetize software: Bundle security, parental controls, and cloud management as subscription offerings to offset hardware margin pressure and stabilize revenue predictability.
-
Diversify access play: For network operators, pair fiber buildouts with fixed wireless pilots in cost-challenged geographies; for vendors, present converged CPE propositions for both access technologies.
-
Channel recalibration: Shift reseller incentives toward managed‑service enablement and recurring-revenue conversions rather than one‑time device pushes.
Concluding perspective — the strategic overlay
The broadband router market presents a classic “growth with complexity” opportunity. Aggregate demand and a predictable mid‑to‑late‑2030s expansion curve create a sizeable market context for investment, but regulatory shifts, infrastructure economics and technology transitions rework the routes to capture. PW Consulting’s Broadband Router Market report equips leaders with the contextualized forecasts, vendor intelligence and executable playbooks needed to convert growth into durable advantage — while reserving the granular segmentation intelligence that informs deal-level decisions for report subscribers.
Next steps
For leadership teams preparing budgets, product roadmaps or M&A pipelines in 2026, the report is designed to be a working document — not a summary. Access to the full dataset and vendor scorecards (including scenario models and the tactical 90‑day playbook) is available on our report landing page. Schedule a one-on-one briefing with PW Consulting’s broadband practice to translate the findings into a bespoke action plan for your organization.
For detailed analysis of this topic, please visit the official page: Broadband Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Tactics Simulator Market Poised to Expand at a 7.42% CAGR Through 2032, Fueling Multi‑Domain Training Innovation
By PW Consulting, 2026-07-13
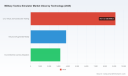
Military Tactics Simulator Market — Strategic Briefing for 2026 Decision-Makers
As geopolitical competition deepens and defence organizations accelerate digital transformation of training, military tactics simulators have moved from niche capability to strategic infrastructure. PW Consulting's new Military Tactics Simulator Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) synthesizes quantitative market trajectory, vendor and technology dynamics, and an operational playbook designed to inform capital allocation, procurement strategy, and capability roadmaps for 2026. The market is expanding steadily: from roughly USD 11,250 million in 2020 it reached about USD 16,150 million in 2025 and is forecast to grow to roughly USD 26,654 million by 2032 at a compound annual growth rate of 7.42% over the 2026–2032 window. This briefing highlights the report’s strategic value while preserving the granular breakdowns that make the full study a must-download for program managers and C-suite decision-makers.
Military Tactics Simulator Market
Why this market matters in 2026
- Training fidelity now directly affects operational readiness: high-fidelity LVC (live-virtual-constructive) environments, AI-enhanced adversary modeling, and VR/AR-enabled squad and crew training reduce time-to-mission and lower lifecycle costs for platforms.
- Interoperability and standards adoption are procurement accelerants: compliance with NATO and DoD modelling & simulation norms materially expands program eligibility for multinational exercises and coalition procurements.
- Budget cycles and capability refreshes planned in 2026 will prioritize platforms that deliver measurable VV&A (verification, validation and accreditation) outcomes — making validated simulation solutions more competitive.
Market trajectory and what the headline numbers mean
The market’s trajectory from 2020 through 2025 shows resilient growth driven by defence modernization programs, augmentation of training pipelines post-pandemic, and expanding use of virtualized training across platforms. Our 2026–2032 forecast — a 7.42% CAGR — reflects steady demand for systems that combine LVC integration, AI-driven scenario generation, and immersive VR/AR for tactical-level training. The projected increase to an estimated USD 26,654 million by 2032 underscores that investment in simulation is transitioning from program-level add-ons to core capability lines in defence budgets.
Military Tactics Simulator Market
Practically, this means program officers preparing FY2026 to FY2028 budgets should treat simulator acquisition and associated sustainment (software updates, cyber hardening, model VV&A, and hardware refresh) as multi-year, scalable contracts rather than one-off purchases. Capital planners should expect a mix of direct procurement, partnership models, and subscription-style software services becoming prevalent.
Military Tactics Simulator Market
Report contents — what the full study delivers (practical, executable)
PW Consulting’s full report is designed as an execution-ready briefing for procurement and capability planners. It includes:
- Scenario-based procurement templates aligned to capability outcomes (e.g., platoon-level combined arms rehearsal, urban fight, maritime boarding operations)
- Vendor scorecards and capability matrices that compare LVC maturity, AI/ML tooling, VR/AR fidelity, and VV&A workflows (note: granular vendor scores and regional splits are available in the full report)
- Technology adoption roadmaps and interoperability checklists tied to NATO/DoD standards
- Risk register with mitigation actions for supply-chain chokepoints (compute hardware, specialist sensors, and tactile/haptic subsystems)
- M&A and partnership playbook highlighting where scale, IP, or software specialization produce near-term competitive advantage
Competitive landscape — who moves the market
The market sits in a mid-consolidation phase: three- and five-firm concentration ratios indicate a meaningful presence of large systems integrators while leaving space for specialist software houses and niche hardware suppliers. That structure creates win-windows for both prime contractors and focused innovators.
- CAE Inc. (Montreal, Canada) — CAE’s strength is integrated LVC environments and long-standing defence training contracts. Their advantage is an end-to-end delivery posture: hardware, mission-rehearsal software, and live-virtual orchestration. For customers prioritizing federation and multi-domain mission rehearsal, CAE is a logical anchor vendor.
- Rheinmetall AG (Düsseldorf, Germany) — Competitive in land-force simulators and XR-enabled training. Rheinmetall brings systems engineering depth and a strong legacy in tactical vehicle and combat-systems modeling, which appeals to armies modernizing vehicle fleets and driver/combat crew training pipelines.
- Thales Group (Paris, France) — Thales leverages C2-simulation integration and a focus on command-and-control rehearsal. Their offerings are attractive where doctrine and C2 interoperability are the selection drivers, particularly for integrated multinational exercises.
- Lockheed Martin Corporation (Bethesda, USA) — Lockheed Martin’s immersive tactical suites pair deep platform integration with defence prime-level program execution. Their strength is in full-spectrum mission-rehearsal systems for joint force applications.
- BAE Systems (London, UK) — With solutions oriented toward tactical engagement and combined-arms scenarios, BAE’s One Arc-style architectures are compelling for forces emphasizing integrated arms training and analytics-driven after-action review.
- L3Harris Technologies (Melbourne, USA) — Noted for maritime and ground tactical simulators and crew synchronization capabilities, L3Harris is a player in both platform-based and distributed training networks.
- Saab AB (Stockholm, Sweden) — Saab brings AR-centric tactical simulators and modular systems well-suited for incremental upgrades and coalition interoperability programs.
- Bohemia Interactive Simulations (Orlando, USA) — The VBS family remains a reference for realistic tactical training software; Bohemia’s strength is fidelity and modular scenario generation that supports combined-arms and C2 training.
- FAAC Incorporated (Ann Arbor, USA) — FAAC focuses on tactical vehicle and route-clearance simulators. Their niche focus is attractive to ground forces with high operational tempo and specific vehicle training needs.
- HAVELSAN Inc. (Ankara, Turkey) — Offers tactical warfare simulators and command training systems; regionally influential and competitive in export markets with interoperable, cost-effective solutions.
- Cubic Corporation (San Diego, USA) — Cubic’s emphasis on live, virtual and constructive training with tactical engagement pacing positions it well in training ranges and tactical engagement fusion.
Recent demonstrations and standardization activity — including public product demonstrations at DSET 2025 and NATO’s Simulation Interoperability Workshop — show vendors racing on two axes: fidelity of experience and standards-based interoperability. Our full competitor brief maps each vendor to those axes and provides tactical recommendations for partner selection depending on capability priorities.
Regulatory and standards dynamics you cannot ignore
- NATO and DoD standards (including HLA-based interoperability guidance and C2SIM profiles) are becoming procurement gating factors. Compliance accelerates multinational exercise participation and eases coalition sustainment.
- DoD Instruction on VV&A (updated 2024) tightens the evidentiary bar for models and simulations to be used in decision-support and training — expect longer lead times for acceptance unless VV&A is part of initial delivery.
- Standards alignment also reduces integration risk for LVC federations, which is critical for joint force readiness and cost-effective multi-user training ranges.
Supply-chain and technology constraints — practical implications
High-fidelity simulation is compute- and data-intensive: real-time terrain rendering, high-resolution 3D models, low-latency networking for distributed LVC federations, and haptic/VR hardware are all bottlenecks. Procurement teams should bake in lifecycle costs for specialized hardware and secure supply lines for GPUs, sensors, and haptic peripherals. The report’s supply-chain annex identifies substitution pathways and sourcing strategies to de-risk implementations.
Strategic playbook for 2026
- Prioritize interoperability-first procurements: require conformance to NATO/DoD profiles and include federated acceptance tests as contractual milestones.
- Procure VV&A as a deliverable: make verification and validation a priced, scheduled deliverable with independent third-party evidence required for acceptance.
- Balance primes and niche providers: pair systems integrators for federation and sustainment with specialist software vendors for scenario fidelity and AI adversary modeling.
- Structure contracts for continuous delivery: prefer modular contracts with software-baselines, security-hardening cycles, and scheduled hardware refresh options.
- Invest in human capital: field training for simulation technicians, scenario designers, and VV&A specialists will amplify ROI and accelerate operational acceptance.
Risks and mitigations
- Regulatory non-compliance: mitigate by early standards mapping and independent VV&A planning.
- Supply-chain shortages: mitigate by multi-sourcing critical compute and haptic components and by contractually anchoring BOM availability.
- Integration complexity: require sandboxed federation tests and staged integration gates.
- Vendor lock-in: favor open-standards, modular architectures, and enforceable data export/portability clauses.
Next steps — how to use the full PW Consulting report
For program directors and C-suite leaders preparing 2026 decisions, the full report offers the actionable artifacts needed to convert strategic intent into executable programs: vendor shortlists, procurement templates, standards compliance checklists, risk registers, and scenario-based ROI models. We deliberately withhold the granular regional and platform splits in this briefing to preserve the competitive utility of the full dataset. The complete study includes detailed regional and platform-level forecasts, vendor scoring matrices, and scenario-by-scenario cost models that are essential for bid specification and budget justification.
PW Consulting’s Military Tactics Simulator Market report is the operational intelligence asset that procurement offices, capability planners, and defence investors will use to shape FY2026 acquisitions and multi-year modernization strategies. For access to the full dataset, vendor scorecards, and the implementation playbook, visit PW Consulting’s report page or contact our defence analytics team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Military Tactics Simulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aviation Simulators Market Poised for a 5.48% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
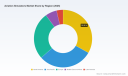
Aviation Simulators Market: Strategic Outlook for 2026 — PW Consulting
PW Consulting’s latest Aviation Simulators Market briefing synthesizes five years of observed market behavior (2020–2025) with a forward-looking forecast through 2032 to equip senior executives with the insights they need for decisive, risk-aware investment and partnership decisions in 2026. Built on an extensive proprietary database and primary interviews across OEMs, training providers and regulators, this analysis highlights the structural forces reshaping simulator demand, vendor positioning, regulation and technology adoption — while reserving detailed segment-level tables for readers of the full report.
Aviation Simulators Market
Market trajectory: scale, pace and structural drivers
The global aviation simulators market demonstrates steady, resilient growth as airlines, defense agencies and training organisations accelerate investment to reduce flight hours, lower costs and meet evolving certification requirements. After a multi-year recovery across 2020–2025, the market enters 2026 from a substantially larger base and continues on a moderate growth path through 2032, with a compound annual growth rate of 5.48% across the forecast period. By the end of the forecast horizon the market is material — reflecting the combined effect of fleet renewals, advanced-technology adoption (eVTOL, XR/MR), and ongoing defense modernization programs.
Aviation Simulators Market
Key demand drivers underpinning this trajectory include: persistent pilot training capacity constraints that push airlines toward simulation-heavy syllabi; regulator-led acceptance of mixed reality and VR-based devices; growth in urban air mobility and eVTOL type-specific training requirements; and the drive to reduce carbon and operating cost through increased simulator hours. On the supply side, visual system advances, modular motion platforms and software-enabled digital-twinning have reduced entry barriers for new solution archetypes while also creating opportunities for incumbent OEMs to upsell lifecycle services.
Aviation Simulators Market
What this means to executives in 2026 — practical strategic levers
-
Procurement timing and capital planning: With steady compound growth expected, procurement teams should align simulator CapEx with fleet type-entry and regulatory qualification schedules rather than short-term price cycles. Early engagement with certification authorities for new platform types (e.g., eVTOL) reduces qualification lag and accelerates time-to-training.
-
CapEx vs. simulation-as-a-service: Many operators will face a choice between owning full-flight assets and contracting training capacity. Our analysis provides use-case driven TCO matrices that show breakeven horizons under different utilization and certification scenarios to inform that choice.
-
Vendor selection criteria beyond price: During 2026 procurement, prioritize suppliers with demonstrable certification pathways, scalable visual and motion architectures, lifecycle service offerings and integration capability with airline training management systems. Interoperability and modular upgrade paths are high-value attributes as curricula evolve.
-
Regulatory playbook: Regulators are increasingly receptive to MR/VR devices and to reciprocal validation frameworks. Firms need a proactive certification and evidence strategy — including test protocols and data packages — to shorten approval timelines and avoid hold-ups that delay training readiness.
-
Training-center footprint and network strategy: Decisions about investing in geographically distributed training centers should be informed by demand clustering, cost of trainee relocation, and the ability to deploy portable or roll-on roll-off simulator solutions to reduce lead times.
-
Digital transformation and skills: Operators must balance investments in physical simulators with investments in software, instructor training, and data analytics capabilities that capture training outcomes and close the loop on recurrent and upset recovery training.
-
M&A and partnership windows: Moderate market concentration and an active vendor landscape create opportunities for strategic acquisitions and partnerships — especially for firms that can bolt on software, visual system IP or regional training networks to core manufacturing capabilities.
Competitive landscape — roles, recent moves and disruption vectors
The sector combines a handful of established global OEMs with agile niche players and an accelerating cohort of XR-native entrants. Market concentration is meaningful: the top three suppliers capture a majority share of market revenues, while the top five firms command an even larger portion, indicating both high barriers to entry at full-flight simulator parity and room for adjacent innovation.
Representative positioning and recent developments to watch in 2026:
-
CAE Inc. — Continues to lead in civil and military simulation with investments across high-fidelity full-flight simulators and new eVTOL capability. Recent deliveries and contracts underline CAE’s strategy to pair hardware with advanced visual systems and instructor ecosystems to secure long-term training relationships.
-
FlightSafety International — Strong presence through integrated training centres and a deep catalogue of device types. Their model of combining simulator manufacture and end-to-end training delivery remains a durable competitive moat.
-
L3Harris Technologies — Historically a key supplier of full-flight simulators for several types, the company’s strategic moves (including divestiture of commercial aviation solutions in 2025) have reshaped its future go-to-market posture and opened strategic windows for competitors in certain product lines.
-
Thales Group — Differentiates through helicopter simulation and high-fidelity fixed-wing offerings, often selected where integration with avionics and defense systems is required.
-
TRU Simulation + Training — Innovation focus on modular and roll-on roll-off architectures reduces deployment friction for customers needing flexible training capacity.
-
Specialists and challengers (Frasca, Indra, HAVELSAN, Loft Dynamics, Elite, SIMCOM) — Each brings targeted capabilities: general aviation fidelity, defense program footprints, country-level OEM relationships, VR/XR-native approaches, and certified, type-specific training devices. Loft Dynamics and other VR-first vendors are accelerating regulator acceptance curves for immersive devices.
Recent industry milestones reinforce evolving norms: type-specific simulator certifications (including new widebody qualifications and light-turboprop devices) and the qualification of MR/VR devices by regulators have lowered the friction for alternative training architectures. These developments shorten time-to-deployment for innovative approaches but also require careful evidentiary work to meet operational acceptance criteria.
What PW Consulting’s report delivers (high-level overview)
Our full Aviation Simulators Market report is structured to be directly operational for senior leaders evaluating investments in 2026. It includes:
-
Executive dashboards with company-agnostic strategic imperatives and scenario-based financial impacts for 2026–2032 decisions.
-
Demand-side buyer archetypes and utilization models to align procurement with realistic training-hours and certification timelines.
-
Vendor scorecards and capability matrices covering certification experience, visual/motion architectures, upgrade pathways and service economics.
-
Regulatory and standards playbook mapping FAA/EASA developments, mixed-reality acceptance cases, and recommended evidence packages to accelerate qualification.
-
TCO and sensitivity models (CapEx/Opex, utilization, certification risk, and personnel costs) that can be tailored to your fleet and training strategy.
-
Implementation roadmaps for in-house training centre investments, outsourcing, hybrid training networks, and digital-twin adoption.
-
M&A / partnership target shortlists and integration risk checklists for buyers seeking inorganic growth or capability buys.
-
Interactive datasets and forecast tables (note: detailed regional and application-level segment tables are available in the full report and supporting data portal).
How to use this briefing in 90 days
-
Week 1–2: Run a rapid TCO exercise against your current training portfolio to identify near-term cost saves from increased simulator utilization or contracting options.
-
Week 3–6: Shortlist 2–3 vendors based on certification fit and upgradeability and issue a focused RFI addressing modularity, visual systems, and service SLAs.
-
Month 3: Convene regulator engagement and an evidence-gathering plan if adopting MR/VR or novel device architectures to ensure qualification windows align with training needs.
PW Consulting’s assessment is intentionally selective in this public briefing: while it provides the strategic framing and actionable playbooks executives need for 2026, granular region-by-region and application-level forecasts, vendor scorecards and downloadable data tables are contained in the full report and the interactive client portal. For procurement teams, training directors and corporate strategists preparing budgets and board-level business cases in 2026, the full dataset is the indispensable next step.
To discuss a tailored briefing for your organisation or to obtain the full Aviation Simulators Market report (including the complete forecast model and vendor analytics), contact PW Consulting’s aviation practice. Our team will map the findings to your fleet, regulatory exposure and training model to produce a prioritized implementation plan for 2026.
For detailed analysis of this topic, please visit the official page: Aviation Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Solar Inverter Market Poised for a 9.06% CAGR During 2026–2032
By PW Consulting, 2026-07-13
Solar Inverter Market 2026: Strategic Intelligence for Decisions that Matter
As global decarbonization accelerates and power systems evolve, the solar inverter market has shifted from a components market to a strategic systems market. PW Consulting’s new Solar Inverter Market report (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with the actionable intelligence they need to shape supply, product and go-to-market choices in 2026. The market we model grows from USD 24.5 Billion in 2025 to roughly USD 43.5 Billion by 2032, representing a compound annual growth rate of 9.06% across the forecast horizon. This release is a strategic “trailer”: it outlines the decisive trends, competitive moves and operational playbooks buyers and sellers must master—while reserving the full segment-level datasets for subscribers who require the complete modeling and downloadable decision tools.
Solar Inverter Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year. Policy extensions, grid-code updates and component-cost inflections converge to create windows of accelerated deployment, procurement re‑structuring and technology substitution. The report translates these inflection points into decision-ready scenarios for capital planners and product teams.
Solar Inverter Market -
Scale and momentum: The market’s structural growth—underpinned by a near-doubling of addressable revenue from the 2020 base to 2032—makes inverter selection a multi-year source of margin capture or erosion. Our scenario outputs let CFOs quantify the long-term P&L impacts of alternative supplier strategies and product investments.
Solar Inverter Market -
Concentration dynamics: The market exhibits moderate concentration—top three suppliers account for roughly one-third of global shipments while the top five approach half the market—creating differentiated risks and opportunities across procurement, innovation partnerships and M&A pipelines.
What the report contains — practical content for execution
-
Proprietary market model (2020–2032): Granular revenue and shipment modeling with scenario toggles for commodity prices, tariff regimes and subsidy policy. Models are provided in spreadsheet form and can be adapted to corporate inputs.
-
Technology and cost curves: Comparative BOM and manufacturing cost curves for central, string and module‑level power electronics, updated to reflect recent SiC MOSFET supply dynamics and yield improvements.
-
Regulatory and grid-code matrix: Cross-jurisdictional mapping of new and pending rules (including recent IEC and regional grid-code changes) with clear compliance action lists for OEMs, project developers and integrators.
-
Supplier risk heatmap: A dynamic vendor scoring system that incorporates concentration metrics, supply‑chain exposure, tariff sensitivity and product roadmaps to prioritize sourcing options.
-
Commercial playbooks: Tender templates, warranty/availability clauses, and O&M procurement strategies designed to protect returns in multi-year PPAs and asset portfolios.
-
Use-case TCO and LCOI models: Total cost of ownership and levelized cost of inverter (LCOI) calculators that integrate capex, efficiency deltas, lifetime reliability assumptions and local grid services revenues.
Market dynamics shaping 2026 choices
-
Component-cost deflation and the SiC inflection: Scaled production has driven significant downward pressure on SiC MOSFET pricing in late 2025, reshaping cost parity timelines for higher-efficiency topologies. Manufacturers and system integrators must reassess near-term BOM mixes and the premium they assign to efficiency gains.
-
Regulation and compliance: Global standards updates (notably recent IEC safety revisions) and regional grid-code mandates (including low-voltage and fault-ride-through requirements) are changing product certification paths and time-to-market. OEMs must accelerate design-for-compliance to avoid retrofit costs.
-
Policy tailwinds and policy risk: In major markets, extended investment tax credits and other incentives continue to underpin demand through the decade, yet shifts in tariff policies and trade barriers can rapidly reconfigure cost competitiveness. Project developers should stress-test financing plans under alternate tariff and subsidy outcomes.
-
Grid services and system value: Inverters are increasingly revenue-producing grid assets (synthetic inertia, frequency response, smart farm aggregation). Product roadmaps that couple power electronics with software platforms unlock new monetization paths for asset owners and OEMs alike.
Competitive landscape — read the signals, not just the headlines
The competitive field remains a mix of high-volume suppliers and technology-specialists. Recent corporate moves reveal a clear pattern: incumbents are optimizing efficiency and scale, while challengers focus on modularization, software differentiation and distributed architectures.
-
Sungrow: Continuing to push scale and efficiency with high-performance string inverters that target both utility and distributed markets. Recent product introductions underscore a push to win larger utility-scale share without abandoning residential traction.
-
Huawei: Rapid commercial wins in large-scale projects attest to the attractiveness of AI-optimized string inverter platforms for plant-level performance enhancement—an advantage where integrated digital services are valued.
-
SMA & SolarEdge: Represent divergent plays—SMA leaning on proven heavy-duty central and hybrid offerings for storage-enabled plants; SolarEdge doubling down on module-level power electronics and high-efficiency inverter cores to capture rooftop and commercial value pools.
-
Enphase and other microinverter specialists: Growing deployments in community-scale and dense residential applications show that module-level architectures can yield superior yield, monitoring and safety attributes—particularly where grid constraints and behind-the-meter services matter.
-
European and diversified players (Fronius, Fimer, Power Electronics, Ingeteam, Siemens, Schneider): Competing on integration with storage, grid-stability features and service contracts; these players are attractive partners for developers targeting grid-code-heavy geographies.
Collectively, these dynamics form an environment where product differentiation—efficiency, reliability, software and service—matters as much as price. The market’s top three vendors capture roughly one-third of shipments, and the top five approach half the market, leaving material share for regional specialists and new entrants to exploit niche advantages.
Recent industry developments that should influence 2026 planning
-
Product and efficiency milestones: Multiple suppliers announced high-efficiency inverter platforms in 2024–2025, signaling a next wave of performance-driven replacement cycles that could compress O&M and energy-loss costs for asset owners.
-
Large-scale commercial traction: Significant module and inverter orders in major projects demonstrate that procurement decisions are increasingly centralized around performance guarantees and whole-of-plant optimisation rather than component price alone.
-
Policy and trade shifts: Extended investment tax credits in certain jurisdictions and elevated tariff levels in others create asymmetric incentives—advantaged markets will attract large-scale deployments, while tariffed markets will favor local sourcing and manufacturing acceleration.
Strategic recommendations for executives in 2026
-
For OEMs: Invest in software-enabled differentiation and certification pipelines. Prioritize SiC-ready platforms and accelerate compliance testing against the latest IEC and regional grid-code requirements to shorten customer procurement cycles.
-
For developers and IPPs: Use scenario-based procurement (multi-sourcing via layered contracts) to hedge tariff and component risks. Negotiate outcome-based performance clauses that share upside from efficiency and grid-service revenues.
-
For financiers and asset managers: Insist on LCOI and service-level stress-tests as part of diligence. Capital providers should require supplier concentration analyses and contingency plans for warranty and spare-parts access in tariff-exposed regions.
-
For policy-makers and system operators: Focus on harmonizing grid-code requirements with certification timelines and providing predictable subsidy horizons to reduce market volatility and attract long-term manufacturing investment.
How to use PW Consulting’s deliverables
-
Adopt the market model to run at least three procurement scenarios: baseline policy, accelerated subsidy, and tariff-constrained. Use outputs to set multi-year supplier sourcing bands and inventory strategies.
-
Apply the supplier heatmap in RFQs to weight commercial terms against supply-risk exposures and certification readiness.
-
Integrate the TCO and LCOI calculators into capital allocation and PPA negotiations to capture the full value of efficiency and grid services over asset life.
Closing—what this “trailer” delivers and what you’ll find in the full report
This briefing highlights the strategic inflection points executives must address in 2026: robust compound growth, shifting cost structures, tighter regulatory demands and an evolving competitive map where software and grid services are as decisive as hardware. PW Consulting’s full Solar Inverter Market report delivers the complete datasets, downloadable models, supplier scorecards and jurisdictional compliance matrices that practitioners use to make binding procurement, product and investment decisions. For teams preparing 2026 budgets, capital plans and product roadmaps, the report turns complexity into executable options.
Subscribe to the full report to access the segment-level forecasts, downloadable scenario models and the supplier benchmarking toolkit needed to operationalize the recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Solar Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


