



PW Consulting: Electroporation Buffer Market Set to Rise from USD 225.88 Million in 2025 to USD 366.32 Million by 2032 at a 7.15% CAGR
By PW Consulting, 2026-07-13
Electroporation Buffer Market: Strategic Imperatives for 2026 — A PW Consulting Advance Brief
As global life‑science organizations prepare budgets, supplier agreements, and R&D roadmaps for 2026, PW Consulting’s new Electroporation Buffer Market report delivers an evidence‑based, decision‑ready perspective tailored to senior executives. Grounded on a 2025 base year and a historical analysis covering 2020–2025, the study projects the market through 2032 and quantifies a measured, durable expansion: the market is expected to grow from approximately USD 225.9 Million in 2025 to roughly USD 366.3 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.15% for the 2026–2032 forecast period. This brief summarizes the report’s strategic value while preserving the granular segment-level analytics that stakeholders must access directly in the full report.
Electroporation Buffer Market
Why this report matters for 2026 decision cycles
-
Capital allocation and portfolio prioritization — The electroporation buffer market sits at the intersection of academic research, biopharma manufacturing, and evolving clinical workflows. Our revenue and growth modeling provides CFOs and portfolio managers with probabilistic scenarios that link buffer demand to bioprocess adoption, cell therapy clinical milestones, and reagent sourcing constraints.
Electroporation Buffer Market -
Supply‑chain risk calibration — The study translates upstream commodity and trade developments into forward‑looking supply‑risk scores for buffer formulations, enabling procurement to calibrate hedging, dual‑sourcing, and inventory strategies ahead of 2026 contract renewals.
Electroporation Buffer Market -
Regulatory gating and commercial readiness — For product and quality leaders, the report maps RUO/GMP boundaries, compliance milestones, and certification pathways that materially affect time‑to‑market for clinical and manufacturing buffer grades.
-
M&A and partnership screening — Strategic and financial buyers receive a short‑list framework for assessing targets, informed by market concentration metrics, competitive positioning, and margin drivers unique to buffer manufacturing.
Report scope and practical deliverables
The report is structured to be immediately usable by corporate strategy, procurement, and business development teams. Core deliverables include:
-
Market sizing and trend decomposition — a year‑by‑year historical series (2020–2025) and a granular forecasting engine for 2026–2032 that isolates demand drivers across product types, end‑users, and distribution channels.
-
Scenario models — three stressed scenarios (supply disruption, accelerated clinical adoption, and trade‑policy shock) with quantified impacts on volumes, pricing, and supplier viability.
-
Price‑and‑cost analytics — material cost pass‑through matrices that link key raw inputs to finished‑goods margins and suggested pricing levers for manufacturers.
-
Regulatory and compliance playbook — actionable checklists for converting Research‑Use‑Only (RUO) formulations to GMP‑compliant equivalents, including documentation, testing, and certification timelines.
-
Commercial go‑to‑market templates — differentiated channel strategies for OEMs, distributors, and direct sales in academic vs biopharma segments.
-
Supplier due diligence toolkit — an operational checklist and scoring model for evaluating contract manufacturers, with emphasis on quality certifications, capacity resilience, and contamination control.
Key market dynamics executives must track
-
Commodity pressure and ingredient availability — A recent spike in spot pricing for mannitol, a widely used osmotic stabilizer, highlights the market’s exposure to feedstock volatility. Our analysis maps the pass‑through of such price movements into buffer costs under varied contractual mixes (fixed‑price, indexed, short‑term spot) and suggests mitigation strategies including multi‑source qualification and formula reformulation options.
-
Regulatory tightening in the EU — Updated restrictions under REACH (Annex XVII) have tightened impurity thresholds relevant to sugar alcohols used in cell culture reagents. Manufacturers must reconcile formulation purity with cost targets; the report examines trade‑offs and compliance pathways that preserve transfection performance while meeting new impurity ceilings.
-
Trade policy and tariffs — Recent tariff recalibrations affecting chemical buffer classifications have increased landed costs on certain imports. The study quantifies the short‑term margin impacts and provides a customs classification playbook to reduce tariff exposure and latent audit risk.
-
Regulatory status boundaries — The FDA’s guidance on RUO materials creates a clear compliance boundary: electroporation buffers labeled as RUO are not suitable for GMP manufacturing or clinical trials. Our compliance roadmap helps manufacturers and end users transition products and labeling to meet clinical application requirements.
Competitive landscape: who moves the market
The electroporation buffer market exhibits moderate concentration: the aggregate market share of the top three suppliers is meaningful, with the top five accounting for a larger majority. This structure creates both barriers and opportunities — established vendors benefit from scale and validated supply chains, while niche innovators can capture value through formulation differentiation and application‑specific claims.
-
Merck KGaA (MilliporeSigma) — With established electroporation solutions optimized for mammalian transfection workflows, Merck leverages broad commercial reach and recent quality investments (including a 2024 ISO 13485 certification for a US production line) to solidify its enterprise relationships in both research and biotech manufacturing.
-
Thermo Fisher Scientific — Thermo Fisher’s portfolio includes buffers designed for high‑throughput and automated electroporation systems. Recent SKU launches targeting large‑run workflows signal a strategic push into scale‑oriented sample preparation and automated labs.
-
Lonza Group — Lonza’s play centers on tailored buffers for hard‑to‑transfect cells and stem‑cell platforms. Product updates that enhance stability for advanced electroporation systems underscore Lonza’s orientation toward clinical and manufacturing use cases.
-
Bio‑Rad Laboratories — A long‑standing provider of buffers compatible with a broad range of electroporation equipment, Bio‑Rad competes on interoperability and technical support across bacterial, mammalian, and plant applications.
-
BTX (Harvard Bioscience) — Focused on system‑compatible buffer kits, BTX targets niche research and microbial applications where system pairing and protocol fidelity drive purchase decisions.
For executives evaluating partnerships or acquisitions, the report contains a comparative matrix that scores these incumbents across R&D intensity, channel coverage, regulatory readiness, and margin resilience. That matrix is intentionally withheld from this brief to preserve advisory value in the full report.
Strategic recommendations for 2026
-
Operational: implement a two‑tier sourcing model. Qualify at least one geographically diversified second source for critical feedstocks and select a secondary contract manufacturer within 12–18 months to reduce single‑point failure exposure.
-
Commercial: segment customers by application maturity (discovery, translational, GMP) and align SKUs and pricing to willingness‑to‑pay, bundling buffers with service offerings (protocol support, stability data) for premium capture.
-
Regulatory: accelerate conversion of lead formulations from RUO to GMP where strategic customers indicate near‑term clinical translation; build clinical‑grade documentation packages in parallel with process scale‑up.
-
R&D: prioritize formulation stability and reduction of impurity sensitivities to address both REACH constraints and raw‑material substitution opportunities. Investing in stability can materially reduce logistic and inventory costs downstream.
-
M&A and alliances: target specialty formulators with demonstrated GMP transition capability and niche cell‑type expertise. Use earn‑outs tied to validated clinical use to bridge valuation gaps.
What the full report contains (select highlights)
-
Detailed 2020–2025 historical demand tables and the 2026–2032 forecast model with downloadable scenarios.
-
Segment performance analytics and channel economics (note: detailed regional and application breakdowns are excluded from this brief and available in the full deliverable).
-
Supplier scorecards, due diligence templates, and a validated list of potential contract manufacturing partners by capability and geography.
-
Buyer playbooks for procurement teams, including negotiation levers, sample clauses for supply contracts, and inventory optimization heuristics.
How PW Consulting’s analysis is distinct
Our methodology blends bottom‑up manufacturing capacity checks with top‑down adoption curves anchored to cell‑therapy pipelines and academic research output. We add value by converting regulatory and commodity "noise" into quantified business impacts — for example, translating mannitol price shifts and tariff changes into cost per kit impacts across scenarios. The result is a pragmatic forecast and a set of executable strategies that reduce uncertainty for 2026 operational plans.
Next steps for stakeholders
-
Senior executives: use the report’s scenario outputs to stress‑test 2026 budgets and capital allocation.
-
Procurement and supply‑chain leaders: adopt the sourcing and inventory playbooks to build resilience against commodity and trade shocks.
-
R&D and product teams: consult the GMP conversion roadmap to align development pipelines with clinical commercialization requirements.
To access the full Electroporation Buffer Market report — which includes the complete segment matrices, supplier scorecards, and proprietary scenario‑model files — please visit PW Consulting’s report page or contact our industry desk for a tailored executive briefing. The full report contains the granular data and concrete tables companies need to operationalize the strategies summarized here.
For detailed analysis of this topic, please visit the official page: Electroporation Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Potassium Cocoyl Hydrolyzed Collagen Market to Expand at 5.25% CAGR (2026–2032)PW Consulting: Handheld Microphones Market Poised for 5.42% CAGR During 2026–2032, New Insights Report Finds
By PW Consulting, 2026-07-13
Potassium Cocoyl Hydrolyzed Collagen Market Outlook — 2026 Strategic Briefing
PW Consulting presents an executive preview of our new market study on Potassium Cocoyl Hydrolyzed Collagen. Built on a robust historical series (2020–2025, base year 2025) and a forward-looking forecast to 2032 (2026–2032), the study quantifies market growth, maps competitive dynamics and translates technical and regulatory developments into concrete commercial options. At the macro level the market is projected to expand from USD 225.4 Million (base year 2025) to roughly USD 322.5 Million by 2032, representing a compound annual growth rate (CAGR) of 5.25% over the forecast period. This briefing highlights the actionable intelligence in the full report and the strategic choices companies must prioritize in 2026.
Potassium Cocoyl Hydrolyzed Collagen Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 is a pivot year where procurement cycles, reformulation roadmaps and regulatory reviews align — making forward-looking supplier strategy imperative.
Potassium Cocoyl Hydrolyzed Collagen Market -
Risk vs. Opportunity: The market’s steady mid-single-digit CAGR masks material near‑term volatility driven by raw-material shocks and regulatory reappraisals. Companies that act early to secure supply, validate alternatives and certify compliance will capture outsized share.
Potassium Cocoyl Hydrolyzed Collagen Market -
Commercial levers: The report converts market sizing into executable playbooks — supplier scorecards, formulation decision trees, and M&A heatmaps — enabling commercial teams to prioritize investments and partnerships that improve margins and speed-to-market.
Market trajectory and structural dynamics
Our base-series shows a clear recovery and re-acceleration following pandemic-era and supply-disruption episodes: the market rose from USD 174.5 Million in 2020 to USD 225.4 Million in 2025, with visible short-term fluctuation around 2022–2024. Looking ahead, the projected climb to roughly USD 322.5 Million by 2032 at a 5.25% CAGR indicates sustained demand expansion, driven by formulators’ preference for mild, multifunctional surfactant-collagen conjugates across personal-care categories.
However, beneath the headline growth are three structural dynamics that will shape winners and losers in 2026:
-
Raw-material volatility — climate-driven supply shocks have already tightened coconut derivatives markets and pushed crude coconut oil pricing into significantly elevated ranges. These shocks materially affect cost curves for cocoyl-derived ingredients and create urgency for multi-origin sourcing and inventory strategies.
-
Regulatory reappraisal — 2025 saw intensified scrutiny from safety panels and regulatory bodies. Recent reopened assessments on cocoyl hydrolyzed collagen ingredients demand additional sensitization and impurity data; concurrently, regulatory moves that reduce labeling frictions for coconut derivatives are reshaping product claims and SKU economics.
-
Formulation and consumer trends — demand for milder surfactants and ingredient transparency is accelerating uptake in higher-value personal-care segments (cleansing, hair-care and targeted serums). Suppliers that combine performance claims with verified sustainability and upcycling narratives gain traction with premium brands.
Competitive landscape — what leading suppliers are doing
The market exhibits moderate concentration, with top-three and top-five supplier aggregates indicating a balance between incumbent strength and meaningful room for regional or differentiated challengers. Key suppliers exemplify distinct strategic postures:
-
BASF Personal Care (Germany) — Focus: platformization and formulary support. Product positioning emphasizes mildness and multifunctionality for shower gels, shampoos and body cleansers. Recent datasheet and platform updates reflect an emphasis on market-ready documentation and compliance clarity to shorten qualification timelines for brand formulators.
-
SEIWA KASEI CO., LTD. (Japan) — Focus: ingredient innovation and sustainability narratives. Their Promois series and HAZUMI-HADA offering demonstrate a strategy of leveraging upcycled raw materials (e.g., fish-scale collagen) and anti-aging claims to move beyond commodity surfactant positioning into higher-margin specialty applications.
-
Active Concepts (USA) — Focus: nimble, application-led commercialization. Their AC Foaming Collagen line targets formulators seeking ISO-compliant, mild-foaming collagenates that deliver hair conditioning and sensory benefits. Small, agile suppliers are proving effective at capturing formulators’ interest through rapid sampling and formulation support.
Recent industry moves underscore the competitive tempo: tier-1 suppliers are refreshing technical documentation to accelerate procurement approvals; innovators are expanding sustainable provenance stories; and safety panel activity is prompting suppliers to enhance traceability and impurity control disclosures. Together these trends are compressing time-to-market for compliant, differentiated formulations but raise the bar for due diligence.
Key risks and strategic responses for 2026
Our study identifies five risk vectors and prescribes pragmatic corporate responses companies can implement in 2026 to protect margins and accelerate growth.
-
Supply concentration and raw-material shocks — Response: establish multi-basin sourcing, invest in strategic stockpiles for critical grades, and negotiate index-linked contracts with suppliers to smooth cost pass-throughs.
-
Regulatory uncertainty — Response: early engagement with safety panels, joint supplier-client data-sharing agreements, and expanded in-house or third-party toxicology verification to de‑risk launch timelines.
-
Price volatility — Response: deploy flexible formulation matrices that allow graded substitution between liquid and powder formats and alternative cocoyl feedstocks, coupled with hedging where feasible.
-
Market access and differentiation — Response: invest in certified sustainability claims (upcycling, traceability) and co‑development pilots with lead brands to create locked-in specifications and favored-supplier status.
-
Competitive displacement — Response: pursue bolt-on acquisitions of niche specialty suppliers or formulation labs to accelerate capability build and capture adjacent higher-margin applications (serums, targeted hair treatments).
What’s in the full PW Consulting study (operational highlights)
The full report is designed for immediate operational use by procurement, R&D, regulatory and corporate development teams. Deliverables include:
-
Proprietary market-sizing model (2020–2032) with scenario modules — base, constrained-supply and accelerated-adoption pathways.
-
Supplier diagnostic toolkit — detailed scorecards, documentation templates and a recommended supplier audit checklist to streamline qualification.
-
Regulatory playbook — summary of recent safety-panel findings, suggested test matrices to meet emerging sensitization requirements and a stakeholder engagement plan for regulators and trade bodies.
-
Value-chain and margin waterfall — cost build-up analysis from raw coconut derivatives to finished ingredient, identifying key margin capture opportunities and cost-reduction levers.
-
Commercial roadmaps — channel and pricing strategies for penetration into premium personal-care segments, and GTM frameworks for ingredient suppliers, co-manufacturers and private-label brands.
-
Innovation pipeline maps — competitive technology benchmarking (including upcycled collagen derivatives), end-use case studies and sample formulations that balance cost and sensory performance.
-
Risk and contingency planning — inventory playbooks, contract templates, and M&A target lists prioritized by strategic fit and integration complexity.
Executive recommendations — immediate actions for 2026
-
Procurement: lock multi-source supply agreements for critical grades and include audit+data clauses to guarantee impurity and molecular-weight disclosure.
-
R&D: institute a parallel-formulation program to qualify alternative cocoyl feedstocks and explore upcycled collagen variants for premium positioning.
-
Regulatory & QA: prepare a unified dossier to respond to safety-panel data requests and fund targeted sensitization testing to keep launches on schedule.
-
Commercial: pilot co-branded formulations with lead retailers emphasizing mildness and sustainability; prioritize channels where margin uplift is highest.
-
Corporate Development: evaluate tuck-in acquisitions of specialty ingredient firms or formulation labs that provide immediate access to higher-margin end‑uses.
Concluding perspective
Potassium Cocoyl Hydrolyzed Collagen sits at the intersection of performance-driven formulation and shifting sustainability and regulatory expectations. The market’s projected mid-single-digit CAGR masks a period of strategic reallocation: winners in 2026 will be those who convert supplier, regulatory and formulation uncertainty into durable advantages through better data, stronger supplier partnerships and focused product differentiation.
PW Consulting’s market study turns noisy inputs — climate-driven raw material shocks, safety-panel reassessments, and supplier innovation — into clear, executable strategies. This briefing provides the roadmap; the full report contains the proprietary models, supplier dossiers and tactical playbooks required to operationalize the strategy. For procurement teams, R&D leaders and corporate strategists preparing budgets and roadmaps for 2026, the report is an essential commercial instrument to convert market insight into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Potassium Cocoyl Hydrolyzed Collagen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refractory Bricks Market Poised to Reach USD 29.43 Billion by 2032, Expanding at a 4.62% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Refractory Bricks Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
Executive summary
PW Consulting’s new Refractory Bricks Market brief provides a compact, decision-ready view for corporate leaders, procurement chiefs, engineering directors, and private equity teams preparing strategy for 2026. The sector is on a steady expansion path — the global market has grown from roughly USD 17.1 billion in 2020 to about USD 21.45 billion in 2025, and is projected to approach USD 29.4 billion by the end of the 2030s — underpinned by a mid-single-digit compound annual growth rate (CAGR) of roughly 4.6% across the forecast horizon. That steady expansion masks accelerated change in supply chains, raw-material risk, decarbonization, and product-technology mixes. Our brief synthesizes those dynamics into operational guidance and strategic options for near-term investment and 2026 planning cycles.
Refractory Bricks Market
Why this brief matters for 2026 decision-makers
-
Actionable timeline: Our analysis translates a macro growth trajectory into calendarized trigger points for procurement renegotiations, capacity decisions, and R&D milestones you should consider for 2026 and the subsequent three-year execution window.
Refractory Bricks Market -
Risk-to-return clarity: The brief maps where raw-material volatility, trade-policy shifts, and regulatory pressure concentrate downside risk versus where premium product mixes and technical innovation unlock higher margins.
Refractory Bricks Market -
Deal and partnership playbook: Whether you are evaluating bolt-on M&A, JV structures, or strategic sourcing partnerships, the brief evaluates transaction archetypes and provides a scorecard to prioritize targets and partners.
What the report contains — practical, deployment-ready content
-
Market sizing and medium-term outlook: A concise top-line growth trajectory with scenario overlays (base, constrained supply, accelerated decarbonization) to stress-test revenue and utilization plans.
-
Supply-chain heatmap and supplier segmentation: Identification of single-source exposures, logistics chokepoints, and near-term build-out needs across raw-material networks — with prioritized mitigation actions.
-
Raw-material sensitivity models: Excel-ready cost decks that let you run price-shock and substitution scenarios for alumina, magnesia and silica inputs and understand margin impact by product family.
-
Capex and plant optimization toolkit: A modular ROI calculator for retrofit vs greenfield choices, plus a checklist for capacity-expansion approvals that aligns with emissions and permitting constraints.
-
Commercial playbooks: Negotiation levers for long-term contracts, indexation clauses, and inventory hedging strategies designed for buyers and vertically-integrated producers.
-
Regulatory and ESG compliance templates: Practical guidance to align plant operations with current emissions frameworks and an operational roadmap for low-carbon refractory solutions.
-
M&A and partnership screening matrix: A quantitative rubric to prioritize acquisition targets and alliance partners based on technical fit, geographic risk, and integration complexity.
Market dynamics shaping strategic choices
Four structural factors will determine winners through 2026: raw-material exposure, alignment with decarbonization pathways, the ability to deliver high-performance bricks for demanding metal- and glassmaking processes, and supply-chain resilience. Raw materials remain the dominant cost driver, subject to periodic supply shocks and trade-policy shifts that can rapidly alter landed costs. Meanwhile, stakeholders across the value chain — from steelmakers to cement and glass producers — are accelerating demand for refractory solutions that enable lower-carbon production and longer lining lives to reduce total furnace downtime.
Policy and regulatory regimes are tightening in major markets, increasing the compliance burden on large-scale manufacturers and creating a premium for suppliers with robust emissions management and circularity programs. At the same time, global steel production remaining near the 2-billion-tonne scale continues to underpin steady baseline demand, but growth pockets are shifting as end-users seek higher availability and technical performance rather than simple price-based sourcing.
Strategic implications and recommended actions for 2026
-
Procurement and supplier strategy: Move from spot sourcing to layered contracts that combine medium-term indexed supply agreements with capacity reservation clauses. Build tiered supplier scorecards that weigh technical capability and decarbonization credentials as heavily as price.
-
Hedge raw-material risk: Implement hedging and inventory strategies using the report’s sensitivity models — particularly for alumina and magnesia — to protect margins across plausible price shock scenarios.
-
Prioritize retrofit and productivity projects: For owners/operators, prioritize linings and refractory combinations that extend campaign life and reduce downtime; these projects typically deliver higher near-term IRR than greenfield capacity in most scenarios.
-
Capitalize on decarbonization premium: Invest selectively in product lines and process solutions that align with customers’ carbon-reduction commitments. Players highlighting verified lower-carbon solutions are already securing strategic tenders.
-
M&A and partnerships: Use our M&A rubric to identify regional players with strong technical IP or access to critical raw-material sources. Prioritize targets where integration synergies reduce supply-cost exposure or accelerate adoption of advanced bricks.
-
Regulatory-readiness: Establish a compliance playbook to manage emissions rules and trade policy shifts. Even modest changes in jurisdictional regulation can force lead times and capital requirements that affect 2026 budgets.
Competitive landscape — where incumbents are positioned
The sector combines global leaders with deep vertical integration and regional specialists focused on cost-competitive supply and fast service. Leading players emphasize production breadth (shaped and unshaped refractories), technical solutions for steel and non-ferrous applications, and manufacturing footprints across multiple continents. Others differentiate through specialty products, strong local service presence, or lean, custom-solution capabilities targeted at specific furnace types.
-
Global integrators: Firms with integrated mining-to-brick operations are investing in decarbonization projects and advanced product platforms. Their scale supports R&D and client co-development, making them preferred partners for large steel and glassmakers focused on predictable supply and technical assurance.
-
Specialists and regional champions: Several regionally-focused manufacturers combine fast lead times with customization and local service, a compelling value proposition for mid-sized producers with tight furnace turnaround schedules.
-
Innovation and service-led players: Specialist companies are winning share where performance and longevity of linings are mission-critical. Their business models lean heavily on application engineering and aftermarket services rather than commoditized product sales.
Recent market activity illustrates these trends: strategic acquisitions and targeted capacity expansions are being used to shore up regional inventories and service capabilities, while leading manufacturers showcase decarbonization initiatives to secure long-term contracts with sustainability-minded buyers. These moves suggest that 2026 will increasingly favor suppliers who can simultaneously demonstrate technical performance, service reliability, and credible emissions reductions.
How to use PW Consulting’s brief in your 2026 planning
-
Board-level scenario workshops: Use the brief’s scenario outputs to test balance-sheet and cash-flow outcomes under alternative demand and input-cost paths before committing to large capex or M&A.
-
Procurement playbooks: Implement the layered contracting templates and supplier scorecards during 2026 tender cycles to lock in supply while retaining flexibility for capacity shifts.
-
Commercial and technical alignment: Use the report’s product-performance comparison framework to align sales teams and technical account managers on value-based pricing and total-cost-of-ownership messaging.
-
Investor diligence: Private equity and corporate development teams can apply our M&A screening matrix to pre-qualify targets with durable competitive advantages and manageable integration risk.
Conclusion — a compact roadmap for 2026
The refractory bricks market offers predictable, mid-single-digit expansion and resilient demand anchored by heavy industries, but the strategic contest in 2026 will be decided by who manages raw-material exposure, demonstrates credible low-carbon pathways, and couples product performance with superior service. PW Consulting’s brief provides the tactical toolset — from sensitivity models to procurement playbooks and M&A rubrics — that leaders need to convert market growth into sustainable competitive advantage.
Next steps
This release highlights the brief’s strategic thrust and practical outputs while omitting the full segmentation and detailed datasets that corporate planners and deal teams rely on. For access to the complete dataset, segmentation analytics, and the full suite of implementation tools (including downloadable models and checklists), please visit the report landing page referenced in our distribution materials.
For detailed analysis of this topic, please visit the official page: Refractory Bricks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.48% CAGR for Prefabricated Security Booth Market Through 2032
By PW Consulting, 2026-07-13
Prefabricated Security Booth Market 2026 Outlook: Strategic Imperatives for Buyers, Manufacturers and Investors
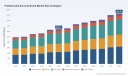
PW Consulting’s latest Prefabricated Security Booth Market study—anchored on a 2025 base year and projecting through 2032—translates eight years of historical observation (2020–2025) and robust scenario analysis into an actionable playbook for 2026 decision-makers. Our topline model shows the global market expanding at a 5.48% CAGR across the forecast window, with total industry revenues growing from mid‑2020s base levels to a materially higher run‑rate by 2032 (values reported in USD Million in the full report). This release summarizes the strategic takeaways senior procurement, product, operations and corporate development leaders need now, while reserving the granular regional and end‑use splits for subscribers to the full report.
Prefabricated Security Booth Market
Why this report matters for 2026 decisions
-
Demand is steady and mission‑critical. Security booths are no longer a simple shelter—requirements for ballistic protection, access control integration and code compliance have elevated procurement from capex line item to strategic security infrastructure.
Prefabricated Security Booth Market -
Cost pressure is real and persistent. Material and construction input inflation is reshaping supplier economics and contract negotiation tactics, affecting both OEM margins and buyer total cost of ownership.
Prefabricated Security Booth Market -
Fragmentation creates opportunity. The market’s competitive structure supports differentiated product strategies, selective consolidation, and targeted roll‑outs across verticals where value capture is highest.
-
Regulation and certification are non‑negotiable. Procurement strategies must bake in ballistic standards, structural codes and site‑specific compliance to avoid costly retrofits.
Macro dynamics shaping supplier and buyer strategy
-
Measured growth but asymmetric cost drivers — Our baseline projects mid‑single digit CAGR to 2032 (5.48%), reflecting steady replacement cycles, infrastructure investment and heightened security spend in key verticals. That growth coexists with disproportionate input cost pressure arising from metals and construction materials.
-
Material inflation and supply‑chain stress — U.S. steel mill prices rose by about 17% year‑over‑year through December 2025, while aluminum mill shapes climbed north of 30% in the same window; industry reports place aluminum averages near $2,800/ton in 2026. Nonresidential construction input prices also accelerated into early 2026. These factors materially impact BOM cost, lead times and underwriting assumptions for long‑term projects (Associated General Contractors of America; Construction Dive / ABC analyses, 2025–2026).
-
Regulatory and ballistic standards increase technical complexity — High‑risk applications increasingly demand compliance with ballistic protection standards (UL 752 Levels 1–4) and structural framing standards such as ASTM A500; specialized government facilities reference additional criteria (e.g., ICD 705). Certification timelines and engineering documentation are therefore core procurement considerations (manufacturer specifications and standards sources).
-
Product evolution and integration — Beyond material and ballistic choices (steel, aluminum, fiberglass/composites), value differentiation now derives from modularity, integrated access control, remote monitoring, HVAC and occupant ergonomics. Buyers prize turnkey solutions that shorten site commissioning time.
Competitive landscape: concentrated strengths within a fragmented market
The prefabricated security booth market is fragmented: the largest three firms capture under one‑fifth of the market and the top five under one‑quarter—metrics that point to regional champions, specialized niche leaders and a long tail of local fabricators. This structure favors both focused organic growth and targeted M&A.
-
B.I.G. Enterprises — Longstanding premium builder with deep experience in bullet‑resistant and code‑compliant booths for high‑security sites and Fortune 500 clients. Strengths: custom engineering, high‑end materials and longstanding client relationships.
-
PortaFab — Offers standardized heavy‑duty booths across a range of platform sizes emphasizing rapid installation and environmental resistance. Strengths: repeatable manufacturing and quick delivery for commercial projects.
-
Delta Scientific — Known for fully prefabricated, assembled deliveries including Level‑4 ballistic models for critical infrastructure. Strengths: tight specifications and high‑security credentials for airports and government installations.
-
Par‑Kut International, Little Buildings, Guardian Booth, Porta‑King, Austin Mohawk, Panel Built and others — Each brings differentiated combinations of material expertise (steel, aluminum, composites), delivery models (panelized vs fully assembled), customization depth, and service footprints (domestic and international shipping).
-
Niche specialists such as Mardan Fabrication and Karmod deliver material‑specific differentiation (aluminum, fiberglass) that can provide cost or environmental advantages in harsh or regulated settings.
Practical implications for procurement, manufacturing and product strategy
-
Procurement playbook adjustments — Move short‑term contracts to indexed or hedged pricing, secure strategic inventory for long‑lead items, and require supplier reporting on material procurement and lead‑time visibility. Where possible, shift to modular BOMs that allow substitution between materials without re‑engineering.
-
Design for modularity — Standardize interfaces for access control, HVAC and ballistic panels so upgrades and field retrofits can be executed with minimal disruption. Modularization reduces site labor, lowers shipping costs and shortens installation cycles—key advantages when demand is dispersed geographically.
-
Invest in certification and documentation — Firms that internalize ballistic testing, UL/ASTM compliance processes and code documentation will shorten sales cycles in regulated verticals and command premium pricing.
-
Rationalize supply footprint — Nearshoring or multi‑plant approaches for key components can reduce exposure to raw‑material shocks and freight volatility, particularly for large or fully assembled deliveries.
-
Service and aftermarket monetization — Warranties, preventive maintenance contracts and remote‑monitoring subscriptions materially increase lifetime revenue per installed unit and improve customer retention.
Go‑to‑market and product priorities for 2026
-
Prioritize vertical specialization — Security booths sold into airports, defense, utilities and high‑value industrial sites require different certification, testing and logistic approaches than units sold into commercial campuses or residential complexes.
-
Balance custom and standard offers — A tiered product line (standard off‑the‑shelf modules + configurable premium units with ballistic options) optimizes factory throughput and margin capture.
-
Differentiate on speed and total cost of ownership — Buyers increasingly select vendors who can demonstrate lower lifecycle costs via durable materials, energy‑efficient HVAC and simplified maintenance access.
-
Use digital tools to accelerate specification and procurement — Interactive configurators, lead‑time dashboards and contractual templates speed negotiation and reduce errors.
M&A and investment perspective
The combination of steady market growth (5.48% CAGR), fragmented share, and rising technical barriers (ballistic testing, certification infrastructure) makes the sector attractive to strategic acquirers and financial buyers seeking roll‑up opportunities. Targets with proprietary ballistic designs, rapid manufacturing systems or embedded service revenue are likely to command valuation premiums. Conversely, targets with single‑region exposure and thin documentation packages present execution risk and require operational remediation post‑acquisition.
What the full PW Consulting report delivers (operational outputs)
-
Transparent market model with historical series and scenario forecasts to 2032 (base year 2025), including sensitivity testing to material‑price and construction‑input shocks.
-
Supplier benchmarking toolkit—capability matrices covering materials, ballistic levels, delivery models and aftermarket service offerings.
-
Procurement playbook and contract clauses to manage pass‑throughs, lead‑time risk and performance warranties.
-
Cost pass‑through modelling that quantifies the impact of steel and aluminum price trajectories on BO M and pricing strategies.
-
Regulatory and certification matrix (UL 752, ASTM references, ICD and government facility requirements) with timelines and testing cost estimates.
-
Investment and M&A scorecards highlighting target attributes, valuation multipliers and integration playbooks.
-
Scenario planning templates and an executive‑level one‑page decision guide for 2026 budget and procurement cycles.
How to use this analysis in your 2026 planning
-
Buyers should lock in availability and hedging clauses for critical materials, move toward modular specifications, and require suppliers to demonstrate compliance documentation up front.
-
Manufacturers must prioritize factory flexibility, pursue certification investments, and develop service offerings that capture recurring revenue.
-
Investors should screen for targets with documented technical credentials, backlog visibility, and diversified end‑market exposure; expect due diligence to focus heavily on supplier contracts and certification records.
PW Consulting’s Prefabricated Security Booth Market report is designed as a decision‑grade tool for 2026 planning cycles. The synopsis above highlights the strategic contours—growth trajectory, cost headwinds, and competitive dynamics—while preserving the detailed regional, material and end‑use splits for subscribers. For the complete dataset, granular segmentation, vendor scorecards and downloadable models, please consult the full report on the PW Consulting website or contact our research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Prefabricated Security Booth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cosmetic-Grade Guar Gum Market Set for Steady Expansion at 5.82% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
Cosmetic Grade Guar Gum Market — Strategic Intelligence for 2026 Decision-Making
Executive summary
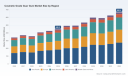
As PW Consulting’s lead industry analyst, I present a distilled strategic view of our new Cosmetic Grade Guar Gum Market study — a practitioner’s intelligence product designed to inform procurement, R&D, and corporate strategy decisions across the personal care value chain in 2026. The global market enters the forecast horizon from a 2025 base of USD 448.5 Million (report base year 2025), and our model projects an ascent to roughly USD 666.4 Million by 2032, tracking a compound annual growth rate (CAGR) of 5.82% over the 2026–2032 forecast period. The historical series (2020–2025) confirms an established recovery and expansion profile that underpins both near-term tactical choices and medium-term strategic plays.
Cosmetic Grade Guar Gum Market
Why this report matters for 2026
-
Actionable timing: 2026 is a pivot year for buyers and producers — raw material price normalization, tightening sustainability requirements, and concentrated supplier footprints create windows for contractual resets and capability investments.
Cosmetic Grade Guar Gum Market -
Decision readiness: the study translates macro growth (market scale and the 5.82% CAGR) into scenario-based procurement and investment thresholds, enabling CFOs and procurement leads to quantify risk-adjusted working-capital and inventory commitments.
Cosmetic Grade Guar Gum Market -
Regulatory and claims risk: cosmetics-grade guar gum is now judged not only on rheology but also on microbial purity, traceability, and eco-certification compatibility — thresholds that materially affect formulation timelines and market access in premium segments.
Report composition — what practitioners get
Designed as a “boardroom-to-bench” toolkit, the report blends market sizing, forward-looking price scenarios, supplier benchmarking, and product-level implications. Key deliverables include:
-
Authoritative market model (historical 2020–2025; forecast 2026–2032) with downloadable Excel workstreams to run sensitivity tests against price, yield and demand shocks.
-
Scenario price-paths informed by observed market movements (Q3 2025 spot data and early‑2026 outlooks) and by primary supplier capability statements.
-
Supplier scorecards assessing microbial purity, traceability, capacity, certifications (ISO/GMP, COSMOS/ECOCERT compatibility), and geographic risk.
-
Regulatory and formulation playbook: compliance checklists, recommended analytical assays, and a roadmap to secure eco‑certified claims for EU/US channels.
-
Commercial playbook: recommended contracting strategies (short vs long term), inventory buffers, and a go-to-market checklist for ingredient suppliers targeting cosmetic formulators.
-
Investment appendix: capital requirements and payback scenarios for brownfield upgrades, small-scale purification capacity, and vertical integration options.
Note: this communication adopts a “trailer” approach — the report contains granular regional and application breakdowns, price tables and vendor-level revenue splits that are intentionally omitted here to preserve the actionable value of the full document.
Market dynamics shaping 2026 strategy
-
Demand-growth drivers: Consumers’ sustained preference for natural, sensorial, and stable formulations is expanding cosmetic-grade guar usage across hair, skin and bath products; combined with premiumization, this underpins the underlying CAGR in our forecast.
-
Supply-side concentration and opportunity: The market shows moderate concentration among top suppliers, indicating both supplier leverage and identifiable acquisition targets for strategic buyers seeking secured access to high-purity grades.
-
Price volatility: Industry-observed pricing dynamics saw guar gum spot levels reach around USD 1,546/MT in September 2025, with a Q1 2026 outlook near USD 1,473/MT. Parallel movements in guar seed prices in Indian mandis were reported in early 2026. These inputs feed our cost pass-through modeling and suggest hedging and contract-duration optimization as near-term priorities.
-
Regulatory and certification thresholds: Cosmetic-grade specifications increasingly require demonstrable microbial purity and documented compliance to international hygiene and eco-certification standards (ISO, GMP, COSMOS/ECOCERT). This shifts value toward suppliers with robust QA/QC and traceability systems.
-
Sustainability lens: Guar’s agronomy — a drought-resistant crop requiring limited irrigation — gives it comparative sustainability credentials versus many synthetic hydrocolloids. This is a strategic lever for formulators pursuing “naturally derived” claims.
Competitive landscape — strategic takeaways
The competitive map is dominated by established guar processors and a smaller set of geographically differentiated players with distinctive strategic propositions. Key profiles and implications:
-
Altrafine Gums (India) — market reputation for high-purity cosmetic grades and compliance-readiness. Their public positioning on eco-certification and microbial standards signals they are a priority supply partner for premium personal care brands.
-
Supreme Gums, Sunita Hydrocolloids, Rama Gum, Hindustan Gums, Lucid Group, Shree Ram Industries, Agro Gums — Indian producers that combine scale with deep upstream sourcing expertise. India’s dominant production role means these firms are critical nodes in any regional sourcing strategy.
-
Guar Resources (Brownfield, Texas, USA) — the strategic value of a USA-grown, USDA-certified organic guar supplier is twofold: supply‑chain resilience for North American formulators and fast-track access for organic & clean-label claims. Their reported capacity statements make them attractive for firms seeking domestic-origin assurances.
-
AEP Colloids, Ampak, Economy Polymers — US-based suppliers and importers who play distributor/refiner roles; useful for formulators seeking smaller lot sizes, technical support services, and blended supply options.
-
Market concentration metrics (top-3/top-5) indicate a balance between dominant incumbents and an accessible mid-tier, which creates opportunities for differentiated entrants and contract consolidation by large personal-care groups.
Recent signals to act on in 2026
-
Supplier positioning: Firms such as Altrafine publicly articulated strengthened cosmetic grade positioning and eco-certification alignment in late 2025 — a signal that premium, compliance‑ready volumes will be constrained unless buyers commit earlier.
-
Domestic organic capability: Guar Resources’ June 2025 capability statement (USDA-certified, commercially scaled) materially changes the sourcing calculus for North American formulators prioritizing origin claims.
-
Price normalization: The trajectory from Q3 2025 to early 2026 suggests a window to renegotiate contracts before demand re-acceleration later in the forecast horizon.
Recommended 2026 strategic moves (practical checklist)
-
Diversify contracts by origin and grade: Combine strategic agreements with high-purity certified suppliers and shorter tactical buys from regional distributors to smooth cost exposure.
-
Prioritize suppliers with documented QA and eco-certification pathways: For premium segments, accept a price premium in exchange for traceability and certification that shorten time-to-market for claim-sensitive SKUs.
-
Hedge raw-material exposure: Implement a layered hedging approach (forward contracts, buffer inventory tied to validated shelf-stable grades) informed by our price-path scenarios.
-
Invest in formulation readiness: Allocate R&D hours to switch tests and microbial challenge studies early — compliance rework costs and launch delays are the largest hidden drains on margin.
-
Evaluate near-shore partnerships or minority equity in processing: For large CPGs, minority stakes or offtake-linked investments in processing assets (incl. brownfield upgrades) secure preferential access at controlled economics.
-
Operationalize sustainability claims: Map the supply chain for “grower to bottle” storytelling; leverage guar’s low-water profile where credible and supported by traceability.
How to use this study inside your organization
Procurement teams will find the supplier scorecards and price scenarios immediately actionable for 2026 contract cycles. R&D and regulatory functions will use the formulation and compliance modules to accelerate launch timelines. Corporate development teams can apply the investment appendix and supplier profiles to shortlist acquisition or joint-venture targets. The integrated model enables scenario testing at SKU, brand and enterprise levels.
Next steps — access to the full intelligence
This article is a preview of the report’s strategic insight. The full PW Consulting study contains complete regional and application-level revenue splits, granular vendor revenue benchmarking, downloadable financial models, and a detailed regulatory compliance annex that we intentionally withhold here to preserve its commercial value. Clients and subscribers can download the full report or request a tailored briefing that maps our findings to your corporate P&L.
For an executive briefing or to secure the full dataset and vendor scorecards, please contact PW Consulting’s research desk. Our team will provide the complete workbook, scenario runs customized to your exposure, and a one-hour strategic debrief tailored to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Cosmetic Grade Guar Gum Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: EDTA Solution Market to Expand at a 4.38% CAGR Through 2032
By PW Consulting, 2026-07-13
Edta Solution Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
Executive summary
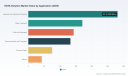
As global supply chains recalibrate and regulatory scrutiny intensifies, the EDTA solution market is entering a phase where strategic decisions made in 2026 will determine competitive leadership through the end of the decade. PW Consulting’s latest Edta Solution Market research—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the market poised for steady expansion at a 4.38% compound annual growth rate. After a period of modest volatility in the first half of the decade, total industry revenues reached USD 845.5 Million in 2025 and are forecast to approach roughly USD 1.14 Billion by 2032.
Edta Solution Market
Why this report matters for 2026 decision-making
-
Actionable horizon: The report translates macro projections into 18-month and 36-month tactical priorities for procurement, product development, and regulatory compliance—timeframes that align with typical corporate planning cycles for 2026.
Edta Solution Market -
Risk vs. opportunity mapping: We overlay commodity, regulatory and trade shocks onto demand trajectories to show where margins are most at risk and where premiumization or substitution can capture value.
Edta Solution Market -
Competitive clarity without data overload: We synthesize concentration metrics and firm-level positioning to clarify who can scale quickly, who is most exposed to feedstock inflation, and where consolidation is likely—while intentionally withholding granular segment tables to preserve the report’s commercial intelligence value.
Market trajectory and near-term dynamics
The EDTA solution market exhibited resilience through 2020–2025 with demand recovery pockets across industrial cleaning, water treatment and specialty end-markets. Our baseline forecast expects the market to grow at a steady mid-single-digit CAGR through 2032, reflecting steady demand from industrial water treatment and specialty formulations, tempered by substitution pressures and regulatory limits in certain consumer applications.
Key drivers for 2026 include: (1) feedstock cost dynamics—recent uplifts in formaldehyde pricing are already pressuring manufacturing margins; (2) regulatory tightening in major markets, which is shifting formulation strategies and supplier qualification timelines; and (3) trade-policy interventions that are re-routing sourcing and inventory planning. PW Consulting’s scenario suite quantifies the P&L sensitivity of each of these drivers to help companies prioritize interventions.
Regulation, raw materials and trade—implications for procurement and R&D
-
Regulatory headwinds: Recent limits on EDTA concentrations in detergents and heightened labeling obligations in leading subnational markets mean formulators and consumer goods companies must accelerate reformulation roadmaps or secure compliant supply channels. For 2026 budget cycles, plan for extended compliance timelines and incremental testing costs.
-
Feedstock inflation: A notable rise in formaldehyde pricing has increased variable costs for EDTA synthesis. Buyers with thin supplier diversification are at greatest risk; manufacturers with integrated upstream capabilities or long-term feedstock contracts retain a margin advantage.
-
Trade and tariffs: Import duties imposed on certain origin shipments have already altered cross-border flows and created near-term arbitrage opportunities. Procurement teams should re-evaluate total landed cost models and intensify supplier qualification processes in 2026.
Competitive landscape — who to watch
The market presents a mid-to-high level of concentration. The top three firms account for a substantial share of industry revenue, with the top five controlling a clear majority. This structure produces a competitive dynamic where scale matters for global water-treatment contracts and formulation credentials matter for specialty and high-purity niches.
-
Dow Inc. (Midland, MI, USA): A market incumbent with strong industrial water treatment credentials. Recent certification wins for potable water applications enhance its go-to-market credibility for municipal and commercial water projects—an important strategic advantage for winning multi-year contracts.
-
BASF SE (Ludwigshafen, Germany): Maintains a capacity-led strategy, having recently expanded production capability to meet detergent demand. BASF’s global commercial reach and channel relationships make it a preferred partner for large CPG firms that require scale and co-development.
-
Nouryon (Amsterdam, Netherlands): Demonstrating an innovation play, Nouryon’s recent biodegradable chelate launch signals a deliberate push into sustainability-oriented formulations—an approach that resonates with European personal-care customers facing strict regulatory scrutiny.
-
Jungbunzlauer and regional specialty producers: Well-positioned in food and nutraceutical segments where ingredient-grade and supply reliability are paramount. Their product focus helps them command better margin on specialty applications.
-
Laboratory and distribution players (Merck/Sigma-Aldrich, Avantor/VWR) : Command niches in high-purity, research and biotech supply chains, where product quality and traceability trump commodity pricing.
-
Other system players (Mitsubishi Gas Chemical, Huntsman) : Focused plays in electronics cleaning and scale inhibition, respectively, that make them indispensable in targeted downstream ecosystems.
Recent strategic moves and what they signal
-
Nouryon’s mid-2025 launch of a biodegradable chelate alternative highlights an R&D-driven response to formulation restrictions in the EU and an early-mover stance on sustainability differentiation.
-
Dow’s 2025 potable-water certification reinforces the trend of suppliers seeking regulatory credentials to secure municipal and commercial water contracts—moves that materially de-risk long-cycle sales efforts.
-
BASF’s capacity expansion to address detergent demand underscores how established producers are investing to protect share in core commodity applications, while also preparing for demand rebound scenarios.
Report contents — practical modules inside
PW Consulting’s Edta Solution Market report is designed as a decision toolkit rather than an academic exercise. Key modules include:
-
Market sizing and validated demand forecasts (2020–2032) with scenario modeling for commodity and regulatory shocks.
-
Supplier risk matrix and short-listing framework for strategic sourcing, including supplier financial health checks and capacity elasticity scoring.
-
Regulatory compliance playbook tailored to the most consequential jurisdictions, with reformulation impact estimates and a testing timeline template.
-
Pricing sensitivity dashboard that maps margin impact across feedstock price bands and duty regimes.
-
Commercial playbooks for manufacturers and specialty formulators: channel strategies, bundling options, and premiumization pathways.
-
M&A and partnership radar: prioritized targets and deal theses for consolidation and technology acquisition, including valuation multiples observed in recent transactions.
How buyers, producers and investors should act in 2026
-
Buyers (CPG, industrial users): Fast-track multi-sourcing pilots and contractual hedges. Include compliance milestones in supplier SLAs and allocate budget for alternative-chelate testing.
-
Producers: Protect margins through feedstock integration or hedging; accelerate high-purity and bio-alternative product lines; and pursue certifications that open municipal and food-grade channels.
-
Investors and M&A teams: Prioritize targets that combine technical differentiation (high purity, eco-alternatives) with stable contractual revenue. Be wary of assets exposed to feedstock shocks without pricing pass-through mechanisms.
Governance and scenario planning — a checklist for 2026
-
Update risk register entries for trade-policy and raw-material shocks; quantify P&L exposure under conservative and adverse commodity scenarios.
-
Mandate reformulation timelines for consumer-facing teams where regional restrictions apply; align marketing and supply functions to avoid product withdrawals.
-
Institute supplier continuity exercises with top- and second-tier suppliers, including capacity reallocation triggers and rolling inventory targets.
What we intentionally withheld and why
In this public briefing we surface strategic conclusions, firm-level positioning and macro projections to enable high-quality executive dialogue. To preserve the commercial value of the primary research, detailed segment-level tables (regional splits, application shares and granular pricing matrices) are reserved for the full report. This “trailer” approach is deliberate: organizations that require the exact segmentation, downloadable datasets and supplier-level scorecards should consult the full PW Consulting Edta Solution Market report and supporting data workbook.
Conclusion — the 2026 strategic horizon
For companies operating in or adjacent to the EDTA solution ecosystem, 2026 is a year to reallocate strategic focus from passive sourcing and tactical compliance to proactive product and channel management. With market revenues recovering to a larger base and a multi-year CAGR of roughly 4.38%, the upside is accessible but conditional: successful players will combine supply resilience, regulatory agility and targeted innovation. PW Consulting’s Edta Solution Market intelligence is built to convert those conditions into executable choices—shortlists for suppliers, product roadmaps, and M&A playbooks that will shape competitive outcomes through 2032.
Next steps
-
Download the full report and dataset to access complete segmentation, downloadable tables and supplier scorecards.
-
Contact our advisory desk for a tailored 90-minute executive briefing and a customized 12–18 month action plan aligned to your role (procurement, R&D, corporate strategy, or investor diligence).
For detailed analysis of this topic, please visit the official page: Edta Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tripterygium Glycosides Tablets Market Forecast to Reach USD 298.58 Million by 2032
By PW Consulting, 2026-07-13
Tripterygium Glycosides Tablets Market: Strategic Preview for 2026 Decisions
PW Consulting presents a forward-looking industry briefing on the Tripterygium Glycosides Tablets (TGT) market. This briefing synthesizes our newly completed market study (base year 2025, historical 2020–2025, forecast 2026–2032) and distills the strategic implications that matter for executives, investors, and policy-makers preparing for 2026. The analysis reveals a market on a steady growth trajectory driven by clinical demand within China, evolving scientific understanding, and concentrated manufacturing dynamics — while continuing to face safety, quality, and regulatory constraints that limit global roll-out.
Tripterygium Glycosides Tablets Market
Why this preview matters for 2026
-
Decision levers in 2026 will be less about market existence and more about competitive positioning, quality assurance, and pathway-to-internationalization. Our report equips leadership teams with the actionable frameworks required to make those choices under constrained regulatory visibility.
Tripterygium Glycosides Tablets Market -
With the global attention on autoimmune therapy innovation, TGT presents both a high-risk and high-opportunity profile: an established clinical footprint domestically, but persistent toxicity and quality-control concerns that make commercialization strategy and clinical development pathway design critical.
Tripterygium Glycosides Tablets Market -
For capital allocators, the timing of investments in manufacturing upgrades, clinical safety programs, and chemistry-quality standardization initiatives will determine 3–5 year returns. This briefing outlines the strategic trade-offs and priority initiatives for 2026.
Market trajectory and headline metrics
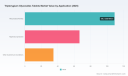
At the macro level, the TGT market demonstrates steady recovery and expansion following short-term fluctuations. PW Consulting’s market model places the 2025 market size at approximately 210.5 Million USD. Under our central scenario, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 5.12% across the 2026–2032 forecast window, reaching an anticipated market value of just under 300 Million USD by 2032.
These aggregate figures underscore two important realities for 2026: first, market growth is significant enough to justify strategic investment in product quality and clinical evidence generation; second, the pace is measured — favoring disciplined, risk-managed capital deployment rather than aggressive expansion without remediation of known safety and supply-chain issues.
What the full report delivers (practical, executive-ready content)
PW Consulting’s full TGT market report goes beyond high-level charts. It contains practitioner-focused deliverables designed to be usable in boardrooms and corporate planning cycles:
-
Decision matrices for choosing between investments in GMP upgrades, analytical-method standardization, and R&D into toxicity mitigation strategies.
-
Clinical prioritization frameworks that align development programs with reimbursement pathways and domestic guideline positioning.
-
Supplier risk-scoring tools and an auditable methodology for assessing batch-to-batch chemical consistency and raw material traceability.
-
A phased go-to-market playbook for cross-border ambitions, including regulatory gap analyses, evidence generation roadmaps, and stepwise market-entry options.
-
Scenario-based financial models which quantify the impacts of alternative regulatory outcomes, safety-data releases, and pricing/reimbursement shifts.
Note: This preview intentionally omits the detailed regional, distribution-channel, and application-level splits contained in the full report. Those granular datasets, scenarios, and downloadable models are available on the source page.
Competitive landscape — players, positioning, and actionable intel
The TGT manufacturing landscape is concentrated and dominated by established domestic producers that combine clinical-supply relationships with legacy manufacturing capacity. Leading manufacturers in our assessment include Jiangsu Meitong Pharmaceutical, Zhejiang DND, Hunan Qianjin Pharmaceutical, Huangshi Feiyun Pharmaceutical, Shanghai Fudan Forward S&T, and Ningbo Liwah Pharmaceutical. These firms collectively shape supply dynamics, clinical study availability, and pricing pressure for standard TGT products.
-
Market structure: The market displays a moderate-to-high concentration among a small number of incumbents. That concentration creates both barriers and levers: incumbents can influence quality norms and clinical access, but they are also vulnerable to reputational risk if adverse-safety signals or quality inconsistencies are publicized.
-
Operational focus: Several manufacturers prioritize cost-effective domestic production and supply for clinical research; others are increasingly investing in standardization and analytical controls to reduce product heterogeneity.
-
Strategic moves to watch: product-supply agreements tied to clinical trials, investments in analytical-method validation, and partnership activity with research institutions aiming to mitigate toxicity concerns.
Our full report contains a company-by-company strategic assessment, sourcing footprints, margin-pressure analysis, and a short-list of acquisition/partnership candidates based on capability gaps and regulatory-readiness scoring.
Regulatory, clinical, and quality dynamics shaping 2026 strategy
TGT occupies a complex regulatory and clinical environment:
-
Regulatory scope: TGT is approved and widely used within China for rheumatoid arthritis and other autoimmune indications, but it lacks approvals outside China due to safety and quality-control concerns. For firms contemplating international expansion, 2026 strategy must prioritize robust toxicology, pharmacovigilance, and standardized manufacturing protocols.
-
Clinical positioning: TGT appears in domestic clinical guidelines as either a first-line or an add-on therapy in certain autoimmune contexts. This entrenched clinical use is a strategic asset but also binds manufacturers to higher standards of pharmacovigilance and post-market surveillance.
-
Safety profile: Peer-reviewed literature highlights hepatotoxicity, reproductive toxicity, and idiosyncratic drug-induced liver injury as material risks. These safety considerations directly influence labeling, monitoring requirements, and commercial messaging.
-
Quality heterogeneity: Analytical studies have identified significant variability in chemical composition across manufacturers — for example, consistent fingerprinting efforts have revealed dozens of shared and variable chromatographic peaks. This heterogeneity drives regulatory concern and complicates interchangeability claims.
For 2026, the imperative is clear: firms must invest in chemistry, manufacturing, and controls (CMC) excellence and clinical risk mitigation before pursuing scaled commercialization beyond domestic markets.
Recent developments to monitor going into 2026
-
Research momentum: A February 2026 review synthesized advances in mechanism elucidation, toxicity-reduction strategies, and clinical-applicability studies — signaling elevated scientific attention and potential pathways to safer formulations.
-
Clinical-supply linkages: In early 2025, one major manufacturer supplied TGT for a preclinical model of autoimmune encephalomyelitis, demonstrating continued use of TGT in experimental and translational research.
-
Implication: These developments expand the evidence base but also raise the bar for manufacturers: translational research activity increases scrutiny of product composition and safety characteristics.
Strategic recommendations for 2026
-
Prioritize quality harmonization programs: Invest in validated analytical fingerprints, batch-release criteria, and third-party reference standards. Firms that can credibly demonstrate product consistency will command strategic optionality.
-
Build clinical-safety evidence rather than relying solely on real-world domestic usage: Sponsor prospective pharmacovigilance studies and targeted toxicology programs to de-risk regulatory conversations outside China.
-
Leverage concentration dynamics tactically: Incumbents should consider defensive moves — securing supply agreements with leading clinical centers — while challengers should explore differentiation through demonstrable quality and safety improvements.
-
Prepare phased internationalization blueprints: Adopt a staged path to external markets that sequences enhanced CMC, focused clinical data packages, and regulatory engagement rather than immediate broad-market applications.
-
Engage payers and guideline committees proactively: For markets where reimbursement is formalized, early liaison with guideline bodies and payers will be critical to maintain domestic positioning and to support any abroad reimbursement cases.
How PW Consulting supports your 2026 playbook
PW Consulting’s full-market deliverable contains the operational tools you need to convert insight into execution: customizable financial models, supplier risk matrices, analytical-method templates, and a staged regulatory-engagement playbook aligned to the most likely 2026–2028 pathways. We also provide a confidential advisory offering to help boards and executive teams prioritize investment choices across manufacturing, clinical, and market-access tracks.
This preview is intentionally selective. Our analysis demonstrates the market’s attractive growth profile at the aggregate level and highlights the structural constraints that will determine winners and losers in 2026. For immediate access to the full dataset, granular region- and application-level splits, and the downloadable strategic toolkit, please consult the report landing page.
Closing note
Tripterygium Glycosides Tablets sit at the intersection of traditional clinical use and modern regulatory expectations. In 2026, the most successful organizations will be those that treat TGT not merely as a commodity but as a complex biologically active product requiring rigorous control, clear clinical strategies, and disciplined capital allocation. PW Consulting’s full report provides the playbook to do exactly that.
For detailed analysis of this topic, please visit the official page: Tripterygium Glycosides Tablets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Magnesium & Magnesium Alloy Market Tops USD 5,250 Million in 2025, Poised for 6.25% CAGR to USD 8,025 Million by 2032
By PW Consulting, 2026-07-13
PW Consulting Releases Strategic Market Report: Magnesium And Magnesium Alloy Market — 2026 Strategic Outlook
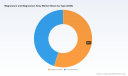
PW Consulting today published its flagship market intelligence release, "Magnesium And Magnesium Alloy Market — 2026 Strategic Outlook," designed specifically to equip corporate leadership teams, investors, and policy-makers with the decision-grade analysis they need for capital allocation, sourcing strategy, and risk management in 2026. Built on a 2025 base and a 2026–2032 forecast horizon, the report quantifies a market growing at a 6.25% CAGR and lays out the strategic implications of a projected expansion from a mid‑2020s market base to a multi‑billion dollar industry by 2032.
Magnesium And Magnesium Alloy Market
Why this report matters for 2026 decision-makers
- Actionable foresight: The report translates macro trajectory and near-term shocks into concrete milestones that should trigger or pause upstream and downstream investment decisions in 2026.
- Supply‑chain stress testing: It reconciles global concentration, raw material dependencies, and trade measures into scenario models that show when and where sourcing switches or inventory build‑outs are commercially justified.
- Regulatory & policy navigation: Given recent shifts in critical minerals policy and trade actions, the report provides a regulatory playbook for procurement and public affairs teams.
- Investment readiness: Private equity and corporate development functions receive a prioritized list of midstream and technology targets, with techno‑economic filters and IRR sensitivity analysis tailored to 2026 financing conditions.
What’s inside — depth without overexposure
- Executive summary and investment thesis synthesizing historical performance (2020–2025) and our base‑case forecast (2026–2032).
- Market sizing and growth drivers with transparent methodology, including price, volume and demand decomposition across the forecast period.
- Demand dynamics and application pathways — covering automotive lightweighting, aerospace and defense, electronics and die‑casting — with driver scorecards that prioritize near‑term vs. structural demand.
- Supply‑side technical dossier: primary production routes (including thermal reduction and electrolytic/brine routes), upstream feedstock dynamics (dolomite and other inputs), and new‑technology development paths.
- Comprehensive competitive landscape and capability maps with CR3 and CR5 concentration metrics, capability matrices, and M&A target shortlists.
- Price modeling and scenario stress tests incorporating tariff shocks, spot price swings, and feedstock scarcity.
- Practical playbooks: supplier diversification roadmaps, offtake and JV negotiation templates, low‑carbon production transition plans, and contingency checklists for OEMs and converters.
- Interactive deliverables: downloadable financial models, supplier scorecards, scenario dashboards and a risk register tailored for 2026 execution planning.
Market dynamics shaping strategic choices in 2026
Several structural and cyclical forces converge to make 2026 a pivotal year for corporate strategy around magnesium.
Magnesium And Magnesium Alloy Market
- Robust but navigable growth: Our forecast embeds a steady mid‑single digit CAGR (6.25%) across 2026–2032, reflecting both healthy end‑market demand and supply constraints that will keep supplier margins and price volatility meaningful for buyers and investors alike.
- Geopolitical concentration and policy responses: With the bulk of primary magnesium supply concentrated in a single producing geography, Western markets have pursued de‑risking measures. Magnesium’s addition to the USGS Critical Minerals List in 2025 and the reinstatement of trade measures in 2025 (which precipitated a near‑term spot increase of about 17% for affected imports) materially change sourcing economics and compel nearshoring and strategic inventory policies.
- Price signals and cost baselines: Market participants should prepare around a new cost reference level: US import prices for high‑purity primary magnesium averaged approximately $3.13 per pound into late 2025, with regional spreads and volatility expected as tariff and feedstock dynamics play out.
- Raw material and process risk: The reliance of Pidgeon process producers on dolomite and the environmental profile of different primary routes mean that feedstock access and permitting timelines will be decisive for new capacity schedules.
- Emerging alternative capacity and financing flows: The industry is witnessing targeted initiatives to build non‑Chinese capacity and cleaner production routes. Recent commercial moves include project financing indications and JV term sheets aimed at expanding brine‑based and fly‑ash derived production, signaling a credible pathway to diversify global supply over the coming five years.
Competitive landscape — strategic implications for market participants
The market exhibits a mixed structure: measurable concentration among leading suppliers, but with meaningful space for technology and location‑based entrants to capture value. Our CR3 and CR5 metrics indicate a concentrated top tier that exerts pricing and technology influence, while mid‑tier and regional players shape local supply dynamics and specialization.
Magnesium And Magnesium Alloy Market
- Established primary producers: Companies with proprietary feedstock access or brine extraction footprints remain advantaged for high‑purity supply to aerospace and defense. These players are natural partners for long‑term offtake and technical collaboration but can also be supply bottlenecks during environmental or operational stress.
- Technology and recycling players: Firms that combine alloy development with recycling and low‑carbon production (including electrolytic and secondary recovery routes) are positioned to capture premium demand from OEMs pursuing scope‑3 emissions reductions.
- Die‑casting specialists and integrators: Vertical integrators that offer high‑precision component manufacturing create stickiness with OEMs and can capture margin by optimizing alloys for process yield and weight reduction.
- Regional producers and emerging projects: New projects and financing milestones in non‑dominant regions indicate strategic opportunities for governments and private capital to co‑invest in capacity that supports industrial policy goals while offering commercial returns.
Representative strategic profiles and moves discussed in the report:
- Primary brine‑based producers maintaining aerospace‑grade supply chains and managing water and permitting constraints.
- Thermal‑reduction producers in resource‑rich jurisdictions serving global die‑casting demand.
- Recycling and alloy specialists offering decarbonization pathways attractive to OEMs under regulatory pressure to report and reduce scope‑3 emissions.
- Project finance events and JV term sheets that reveal where new capacity is likely to emerge and which technology pathways are attracting capital.
Recent industry developments that should directly influence 2026 decisions
- Joint venture term sheets and project partnerships targeting domestic production in previously under‑served jurisdictions — an early sign that capital is allocating to alternative supply chains.
- Operational adjustments at legacy brine operations to mitigate environmental and hydrological constraints — indicating potential near‑term supply tightness and the need for contingency sourcing.
- Significant project financing indications for low‑carbon primary production demonstrations — a signal that financiers see route viability and that early movers could achieve differentiated market access for low‑carbon product streams.
Six practical recommendations for corporate leaders in 2026
- Lock first‑mover optionality: Execute pilot offtake agreements with chargeable seller options that convert to firm volumes if price and policy triggers materialize; this preserves upside optionality while capping near‑term exposure.
- Dual‑track sourcing: Combine short‑term spot coverage with medium‑term contracts from geographically diversified suppliers; integrate clause sets that address tariff, force majeure, and sustainability certification risk.
- Invest in recycling and circularity: Prioritize in‑house scrap capture and supplier recycling partnerships to reduce reliance on primary feedstock and to meet OEM ESG commitments cost‑effectively.
- Embed scenario triggers into capex decisions: Use the report’s modeled price and availability scenarios to define minimum IRR thresholds and staged‑investment gates for new capacity or retrofits.
- Engage in technology partnerships: Collaborate with alloy developers and process licensors to harden supply chains via co‑development, licensing, or minority equity stakes.
- Advocate strategically: Align procurement and public affairs to influence predictable policy outcomes on trade measures and critical minerals programs that materially affect cost and availability.
Next steps — how to use this report in your 2026 planning cycle
Procurement teams should incorporate our scenario outputs into Q2 supplier reviews; corporate development should use the M&A shortlist and valuation banding to prioritize diligences; product and engineering teams should work with alloy specialists identified in the report to validate weight‑saving opportunities that preserve cost and manufacturability. Investors and policy clients will find the risk register and the project financing overlays especially useful for underwriting and program design.
PW Consulting’s "Magnesium And Magnesium Alloy Market — 2026 Strategic Outlook" is intentionally detailed where it counts (market sizing, price and scenario models, competitive strategy, and playbooks) and intentionally selective where proprietary granularity resides (detailed segmentation line items and raw dataset tables). This “trailer” approach ensures readers can validate strategic fit and see the migration path for decisions, while encouraging direct engagement to obtain the full datasets and interactive tools that enable transaction‑level execution.
To request the full report package, interactive models, or a bespoke client briefing tailored to your company’s position in the value chain, visit PW Consulting’s research portal or contact our industry practice lead for magnesium and advanced alloys. Our team stands ready to translate the findings into board‑level recommendations and execution roadmaps for 2026.
For detailed analysis of this topic, please visit the official page: Magnesium And Magnesium Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


