



Intellectual Property Rights Royalty Management Market: Strategic Imperatives for 2026
As organisations enter 2026, intellectual property (IP) and royalty management are moving from cost-center administration to strategic revenue and risk levers. PW Consulting’s latest market study shows a market that has more than doubled in scale since the start of the decade and is forecast to continue expanding at a robust compound annual growth rate (CAGR) of 9.22% across the 2026–2032 horizon. In monetary terms, the sector reached roughly USD 7.25 billion in 2025 and is projected to exceed USD 13.4 billion by 2032. That trajectory fundamentally changes the calculus for procurement, technology investment, and organisational design for IP-intensive enterprises, law firms, and research institutions.
Intellectual Property Rights Royalty Management Market
Why 2026 is an inflection point
- Regulatory acceleration: Multiple new state-level privacy regimes in the United States and clarified international AI and data rules (including compliance implications from the EU AI Act and recent DOJ constraints on select cross-border data transactions) materially affect how IP data and royalty systems can be operated and outsourced.
- AI moving from pilot to production: Vendors now embed AI into valuation, infringement detection, and licensing analytics, creating new capability differentials—and new governance obligations—across provider portfolios.
- Complexity of portfolios: Sustained growth in patent and trademark filings globally is increasing portfolio scale and transaction volume, demanding automation, auditable royalty calculation, and integration with enterprise systems.
- Commercial model innovation: Subscription and consumption-based pricing have emerged alongside traditional perpetual and per-seat models, changing TCO and vendor selection dynamics.
What this report delivers to executive decision-makers
This study is written to be directly actionable for leaders making 2026 investment and sourcing decisions. It combines market-sizing and scenario-based forecasts with practical tools that move beyond descriptive industry analysis into execution guidance. Highlights include:
Intellectual Property Rights Royalty Management Market
- Clear near-term market sizing and seven-year forecasts that let CFOs and corporate development teams stress-test ROI under multiple adoption and pricing scenarios.
- Vendor positioning and capability maps tied to procurement use-cases (enterprise portfolio management, licensing & royalties, media & entertainment rights, and technology transfer), designed to shorten vendor selection cycles.
- Risk matrices and control templates addressing privacy law fragmentation, AI explainability and liability, and international data-transfer constraints—ready to be adapted into RFPs and contracts.
- TCO and migration playbooks that quantify people, process, and technology costs—especially the persistent line-item of specialised labour for compliance, data governance, and AI oversight.
- Operational checklists—data migration, entitlement and audit trails, contract clause libraries, and KPI dashboards—designed to reduce implementation time and audit exposure.
Competitive landscape: who matters and why
The sector is simultaneously consolidating around a group of global platforms while leaving room for specialised, vertical-focused providers. Market concentration is moderate: the largest three vendors account for less than roughly 30% of market spend, and the five largest vendors represent under 40%—a structure that favours both scale and niche differentiation.
Intellectual Property Rights Royalty Management Market
- Anaqua Inc. (United States) — https://www.anaqua.com
Anaqua’s integrated IP management platforms are notable for end-to-end workflows from docketing to portfolio analytics and royalty workflows. Recent product evolution—most notably an AI-enhanced release and the introduction of consumption-based pricing—signals a push to align vendor value capture with customer outcomes and portfolio activity. Procurement teams should evaluate the trade-offs between usage-based economics and predictability in budgeting. - Clarivate PLC (UK; US operations) — https://clarivate.com
Clarivate remains a capability anchor through its IP management suites and strong analytics. Strategic partnerships announced in 2025—linking invention-generation AI and design-infringement detection—illustrate a pattern of inorganic capability assembly that boosts analytic differentiation for brand- and design-sensitive customers. - Questel (France) — https://www.questel.com
Questel’s Equinox products continue to combine docketing and analytics with an emphasis on AI-assisted search and workflow automation, making it a contender for organisations prioritising integrated patent-to-licensing workflows. - PatSnap (Singapore) — https://www.patsnap.com
PatSnap’s AI-native intelligence and search capabilities are particularly relevant for teams seeking rapid, data-driven valuation and competitive intelligence to support licensing strategy. - Dennemeyer (Luxembourg) — https://www.dennemeyer.com
With a strong services layer in renewals and global portfolio administration, Dennemeyer is often selected where regulatory-compliant, multi-jurisdictional administration is paramount. - LexisNexis / RELX (UK/US) — https://www.lexisnexis.com
Offers analytics and IP tracking tools that tie into broader legal and research workflows; beneficial for law firms and corporate legal teams aiming to consolidate intelligence stacks. - Wellspring, Rightsline, FilmTrack, FADEL, Vistex, Klopotek
These vendors represent specialised paths: technology transfer and licensing (Wellspring), media and entertainment rights and royalties (Rightsline, FilmTrack, FADEL, Klopotek), and enterprise-integrated monetisation (Vistex). Selection depends heavily on vertical fit and integration priorities.
Recent vendor moves that will shape procurement choices in 2026
- Anaqua’s 2025 release of an AI-powered platform and adoption of consumption-based pricing changes procurement negotiation points: SLAs, active-family metrics, and auditability of AI-driven decisions should be contractual imperatives.
- Clarivate’s partnerships to embed invention-generation and computer-vision capabilities reflect an ecosystem play: buyers should assess partner roadmaps and data-sharing models to avoid fragmentation of analytics across suppliers.
- New platform entrants and upgrades (e.g., regional platform launches) continue to raise the bar for integration, UX, and analytics depth—creating retrofit risks for legacy deployments.
Operational and compliance priorities embedded in the report
Our fieldwork and vendor assessments show that the single largest controllable cost in IP rights and royalty systems is specialised human labour—compliance officers, data engineers, and AI stewards. The report therefore places heavy emphasis on:
- Governance frameworks for AI components (data lineage, decision explainability, and liability allocation).
- Contract clauses required to comply with new US state privacy requirements and constraints originating from recent DOJ rules on cross-border data handling.
- Data architecture patterns that enable secure cross-border operations while minimising expensive bespoke integrations (e.g., federated query models, privacy-preserving analytics).
- Audit and reconciliation protocols for royalties to reduce leakage and litigation exposure.
Risks, blind spots and mitigation playbook
- Regulatory fragmentation: Plan for the superset of requirements. The report includes contractual and technical mitigations to avoid rework as local laws take effect.
- AI opacity: Require vendor-provided explainability layers and independent model validation for valuation and infringement modules.
- Vendor lock-in and data portability: Enforce exportable data models and clear SLAs for bulk data extraction and reconciliation.
- Human capital scarcity: Where in-house expertise is limited, use phased outsourcing or managed services as a bridge while upskilling IP operations teams.
Recommended 90-day and 12-month actions for CxOs and IP leaders
- 90 days: Conduct a prioritized risk review focusing on data flows that implicate new privacy and cross-border rules; demand vendor attestations on data handling and AI governance.
- 90 days: Run a targeted TCO proof-of-concept comparing consumption-based vs. subscription models for high-volume portfolios.
- 6–12 months: Consolidate disparate royalty and rights workflows into a single governance model; adopt a standard contract annex for AI and privacy responsibilities.
- 12 months: Re-benchmark vendor ecosystem performance using the report’s vendor scorecards and move to an outcome-based procurement model (KPIs tied to realized licensing revenue, audit exceptions, and time-to-licence).
How to use the full PW Consulting report
The public executive summary signals where disruption and opportunity are converging; the full PW Consulting study supplies the operational details your teams will need to act. It contains vendor scorecards, negotiation playbooks, migration checklists, sample contract language addressing AI and privacy, and Excel-ready TCO and ROI models that can be dropped into budgeting and sourcing processes.
We intentionally limit the public dissemination of granular segment-level splits and proprietary benchmark tables in this press release to protect the analytical integrity of the study and to ensure that our clients — whether corporate IP leaders, law firms, or institutional licensors — receive the full, validated dataset and templates. For immediate access to the complete dataset, vendor comparisons, and appendix materials that underpin our forecasts and practical frameworks, please refer to the PW Consulting report page or contact our advisory team directly.
PW Consulting remains available to brief executive teams with a focused, 90-minute strategic workshop that translates the report’s insights into a bespoke 18-month roadmap for your organisation.
For detailed analysis of this topic, please visit the official page: Intellectual Property Rights Royalty Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DL-10‑Camphorsulfonic Acid Market to Reach USD 121.29 Million by 2032, Expanding at a 5.12% CAGR
By PW Consulting, 2026-07-13
DL-10-Camphorsulfonic Acid Market — Strategic Imperatives for 2026 (PW Consulting Preview)
As specialized chemical inputs tighten their link to pharmaceutical synthesis, asymmetric catalysis and advanced materials, DL-10-Camphorsulfonic Acid (DL-10-CSA) has moved from a niche reagent to a strategic commodity for many life-science and specialty-chemicals players. PW Consulting’s forthcoming DL-10-Camphorsulfonic Acid Market report (base year 2025) synthesizes five years of historical data and a seven-year forecast to deliver the market intelligence corporate leaders will rely on when making portfolio, sourcing and M&A decisions in 2026. This article highlights the report’s strategic value while reserving the granular segment outputs for the full release.
DL-10-Camphorsulfonic Acid Market
Why 2026 Is a Decision Point
Several intersecting dynamics make 2026 a turning point for stakeholders in DL-10-CSA: a steady uptick in demand from pharmaceutical intermediates and chiral resolution work, ongoing capacity rationalization among specialty chemical suppliers, and shifts in procurement approaches (longer-term contracts, dual-sourcing, and local stocking strategies). These dynamics mean that procurement strategies decided in early 2026 will materially affect cost of goods sold, supply continuity and R&D throughput through the rest of the decade.
DL-10-Camphorsulfonic Acid Market
Market Snapshot — Macro View
At the macro level, the global DL-10-CSA market has expanded meaningfully over the past half decade — growing from roughly USD 67.3 Million in 2020 to USD 85.5 Million in 2025. PW Consulting’s base-case projection foresees a compound annual growth rate (CAGR) of approximately 5.12% for the 2026–2032 forecast window, taking the market to roughly USD 121.3 Million by 2032 under the central scenario. These numbers reflect sustained end-market demand and modest improvements in pricing and product mix rather than a single demand shock.
DL-10-Camphorsulfonic Acid Market
What the PW Consulting Report Contains (Practical, Actionable Tools)
- Executive dashboard: A one-page, actionable summary for C-suite decision-making, including sensitivity to price shifts, capacity outages and regulatory changes.
- Demand modelling toolkit: Scenario-based forecasts calibrated to pharma R&D cycles, generic launches, and catalyst uptake — with Monte Carlo sensitivity outputs for procurement and inventory planning.
- Supplier assessment matrix: A comparative evaluation of material quality, range of grades offered, lead times, regulatory compliance footprint and commercial flexibility for all active suppliers.
- Commercial playbook: Recommended contracting structures (spot vs. term vs. hedged), pricing negotiation levers and escalation clauses tailored to different buyer archetypes.
- Regulatory & compliance sweep: Mapping of current and anticipated regulatory constraints affecting production, transport and use — with mitigants and audit checklists.
- M&A & partnership shortlist: Identified mid-market targets and bolt-on assets whose acquisition would deliver immediate route-to-market or technical capability advantages.
- Risk register & early-warning indicators: Leading KPIs for supply disruption, feedstock volatility and demand-side shifts to trigger contingency actions.
These components are built to be operationally deployable by procurement, business development and corporate strategy teams. The full report contains scorecards, supplier worksheets and downloadable model templates — resources we intentionally withhold from this preview to direct readers to the authoritative source.
Competitive Landscape — Who Matters and Why
The DL-10-CSA market exhibits a moderate degree of concentration. The top-three suppliers account for a material share of global supply, and the top-five further increase that concentration — a structure that favors established players with broad distribution and quality assurance capabilities while leaving room for specialist, regional suppliers.
- Global life-science conglomerates: Companies with integrated distribution networks and strong regulatory/compliance infrastructures dominate in reliability and trust. Their ability to supply consistent, high-purity material at scale makes them default partners for pharmaceutical companies and large contract manufacturers.
- Specialty reagent producers: These firms compete on technical service, breadth of pack sizes and rapid response for R&D customers. They often develop close relationships with academic and small-biotech customers who value short lead times and flexibility.
- Regional distributors and local suppliers: In markets where logistics or import regulatory friction is high, regional players capture volume despite smaller scale — they play a critical role in continuity strategies and emergency response.
Our supplier assessment in the full report benchmarks commercial terms, sample-to-production support, certificate-of-analysis consistency and scale-readiness. For strategic buyers, partnering with at least one global player and one responsive regional partner emerges as a repeatable best practice.
Strategic Implications for 2026 — Five Priority Actions
- Reassess inventory strategy: Convert single-month coverage policies into a tiered buffer approach — prioritize safety stock for SKUs tied to critical clinical timelines and keep lean inventories for exploratory R&D materials.
- Re-negotiate contracts now: Lock in multi-year commitments with volume bands and price collars where your consumption is predictable; request performance SLAs tied to COAs and lead time windows.
- Dual-source with intent: Source at least one supplier with global compliance reach and one agile regional partner; document dual-source switching procedures and sample re-qualification timelines.
- Embed DL-10-CSA into R&D cost models: Include reagent cost sensitivity into go/no-go decisions for chiral resolution pathways — a small reagent cost delta can cascade into meaningful project IRR impact.
- Pursue targeted M&A or JV plays: For mid-size chemical companies seeking higher margin downstream specialization, acquiring regional production or packaging capability for DL-10-CSA can shorten cycles to profitability.
Risk Scenarios and Early-Warning Signals
Our scenario work identifies three principal risk vectors: feedstock and energy price shocks, regulatory changes affecting production/transport, and consolidation among major suppliers. For each vector, the report lists leading indicators you can monitor in real time — e.g., freight rate spikes, permit changes in key production jurisdictions, and shifts in supplier lead-time reporting. We provide trigger thresholds and recommended contingency playbooks so that teams can move from detection to execution within weeks, not months.
How Executives Should Use This Preview — and Where to Find the Full Intelligence
This preview is intended as a strategic briefing: it clarifies market direction, highlights where value can be captured or eroded, and lays out tactical moves for 2026. The full PW Consulting DL-10-Camphorsulfonic Acid Market report supplies the precise, segment-level intelligence that underpins supplier scorecards, pricing models and the M&A shortlist — including downloadable Excel models and supplier COA comparators.
If your decisions in 2026 will touch procurement terms, clinical pipelines, or specialty-chemicals positioning, the full report will materially shorten your decision cycle and reduce execution risk. Contact PW Consulting to access the complete dataset, region and application splits, and the executable templates referenced above.
Conclusion
DL-10-Camphorsulfonic Acid is no longer just a laboratory reagent — it is a strategic lever in asymmetric synthesis and chiral resolution, with implications across procurement, R&D and corporate development. PW Consulting’s analysis shows a steady growth trajectory through 2032 supported by underlying demand fundamentals and a moderately concentrated supplier base. For executives planning near-term actions, the priorities are clear: shore up supply continuity, align contractual risk to project timelines, and incorporate reagent economics into development-stage decision-making. The full PW Consulting report provides the granular, operational detail required to implement these steps with confidence.
To obtain the complete report, including regional and application-level breakdowns, supplier scorecards, downloadable models and our M&A shortlist, please visit PW Consulting’s report page or contact our strategic insights team for a briefing session.
For detailed analysis of this topic, please visit the official page: DL-10-Camphorsulfonic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MEMS Hydrophones Market to Nearly Double from USD 200.18 Million in 2025 to USD 394.59 Million by 2032 at a 10.18% CAGR
By PW Consulting, 2026-07-13
MEMS Hydrophones Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As organizations reassess technology roadmaps and procurement priorities for 2026, MEMS hydrophones have emerged from niche research labs toward commercial relevance. Our latest PW Consulting market study projects the global MEMS hydrophones market to continue a strong upward trajectory, building on a five‑year historical expansion and a forecast that carries the market from an estimated USD 200.18 Million in 2025 to roughly USD 394.59 Million by 2032, at a compound annual growth rate (CAGR) of 10.18% over the 2026–2032 forecast window.
Mems Hydrophones Market
This briefing highlights the report’s strategic value for executives, investors, product managers, and procurement leads contemplating near‑term investment or partnership moves. It is written as a high‑signal “trailer”: it demonstrates the depth of our analysis and the practical insights available in the full report while intentionally withholding some granular segment figures to invite a direct review of the published study for operational decisions.
Mems Hydrophones Market
Why this market matters in 2026
-
Technology inflection: Miniaturization, MEMS fabrication advances, and system‑level integration are lowering size, weight, power and cost (SWaP-C) barriers that once confined high‑performance hydrophones to traditional piezoelectric designs.
Mems Hydrophones Market -
Commercial and defense demand vectors: Government sensor modernization programs, renewed investment in subsea exploration and monitoring, and the expansion of autonomous underwater systems are driving demand for compact, networkable acoustic sensors.
-
Regulatory and measurement frameworks: Ongoing IEC standards (notably the IEC 62127 series) shape test and calibration requirements for ultrasonic and medical ultrasonic hydrophone applications — a critical gating factor for suppliers targeting regulated markets.
Market dynamics and growth drivers (data‑driven view)
The market’s historical trajectory shows clear acceleration from 2020 through 2025, reflecting both increased deployments and widening application breadth. Our base‑year analysis (2025) and the forecast to 2032 reflect a robust mid‑teens cumulative growth outcome in absolute terms, underpinned by a 10.18% CAGR for the forecast period. For 2026 planning cycles, this trajectory means that decisions made this year on technology bets, supply chain commitments, and partner selection will compound materially over the next six years.
Key drivers supporting that growth include sensor integration into distributed monitoring networks, the push for low‑cost arrays for environmental and commercial subsea sensing, and continued R&D progress that narrows performance gaps between MEMS and incumbent hydrophone technologies.
Technology & standards — what to watch
-
Standards compliance: Any supplier seeking to win defense, medical or research contracts must demonstrate testability and calibration aligned with IEC 62127 series requirements. The report provides a practical checklist to align product validation programs with these standards and avoid common procurement rejections.
-
Research vs. commercialization: Notable laboratory breakthroughs (for example, a November 2025 prototype reported by MIT Lincoln Laboratory that achieved promising sensitivity using a repurposed MEMS microphone architecture in a custom polymer cavity) show the potential for low‑cost MEMS hydrophones. However, independent market verification indicates many MEMS designs remain at prototype or early demonstration stages for underwater use.
-
Test and verification playbook: The report contains recommended characterization protocols, tolerance budgets, and accelerated aging test designs tailored to MEMS‑based acoustic sensors to shorten qualification cycles.
Competitive landscape — implications for sourcing and M&A
The sector shows a mixed structure: a set of established acoustic equipment companies with broad product catalogs and a group of emerging specialists and contract manufacturers focused on MEMS development. Market concentration is meaningful — the top suppliers control a plurality of the market, with the top five firms accounting for over half of industry revenue — which has implications for pricing power, supplier risk, and consolidation strategies.
-
Teledyne Marine (Teledyne Technologies) — United States: A long‑standing supplier of precision hydrophones and transducers with extensive catalog and service capabilities for marine and defense customers. Teledyne’s engineering depth and validated performance products make it a preferred vendor for applications where proven performance and lifecycle support outweigh early adoption of novel MEMS architectures. Link: https://www.teledynemarine.com
-
Ocean Sonics — Canada: Commercial provider of digital, streaming hydrophone systems designed for real‑time acoustic monitoring. Their platform focus (data acquisition, streaming and analytics) highlights a profitable route to market: pairing sensor hardware with subscription or services models for continuous monitoring deployments. Link: https://oceansonics.com
-
GeoSpectrum Technologies — Canada: Known for wideband omnidirectional hydrophones and integrated preamplifier solutions for surveillance and research. Firms like GeoSpectrum illustrate the high‑performance end of the product spectrum where ruggedness and signal fidelity are decisive.
-
MEMSound Pte Ltd., Guangzhou Chenfang, Digi Tech — Singapore and China: These firms are cited repeatedly in sector analyses as suppliers developing or offering MEMS hydrophone products. Our field validation finds heterogeneous commercialization progress: some offer prototype or small‑volume systems, while others focus on component supply and contract manufacture. For buyers considering near‑term procurement, understanding supplier roadmaps and sample‑to‑production ramp plans will be essential.
Strategic recommendations for 2026
-
Classify opportunities by risk tolerance: For programs requiring guaranteed, standards‑certified performance in 2026, prioritize validated suppliers with track records in hydroacoustics. For exploratory programs that can accept higher technical risk in exchange for lower unit cost or new capability, selectively partner with MEMS specialists and labs demonstrating credible prototypes.
-
Pursue dual‑track procurement: Adopt parallel qualification paths — one optimized for incumbent technology to meet immediate delivery timelines, and one for MEMS pilots to accelerate path‑to‑production. This hedges against supplier delays while keeping optionality for disruptive cost and SWaP gains.
-
Embed standards expertise into RFPs: Require IEC 62127‑aligned test evidence where applicable, and insist on transparent calibration practices and measurement histories as part of technical bids.
-
Invest in systems integration and data stacks: The largest near‑term value pools often accrue to firms that bundle sensors with edge processing and cloud analytics. Consider strategic partnerships or in‑house builds that move beyond raw sensor supply to serviceable monitoring solutions.
-
Assess consolidation and vertical integration plays: Given the market’s concentration profile, selectively target acquisition or strategic investments in firms that can accelerate time‑to‑market for MEMS devices (e.g., companies with manufacturing scale, IP portfolios or strong domain validation trials).
What the PW Consulting report delivers (operationally useful contents)
The full report is designed as a practical toolkit for near‑term strategy and implementation. Key deliverables include:
-
Market sizing and seven‑year forecast models with scenario sensitivity and supplier‑level revenue projections.
-
Commercial viability diagnostic for MEMS vs. incumbent hydrophone technologies, including performance tradeoffs, unit economics, and cost‑at‑scale models.
-
Supplier profiles and qualification scorecards that assess technical maturity, manufacturing capability, compliance posture, and sample‑to‑production timelines.
-
Procurement checklists, RFP language templates, and calibration/test protocols mapped to IEC 62127 guidance.
-
IP landscape summary and patent fences that help identify white‑space and potential licensing targets.
-
Case studies and early deployment lessons from commercial and research pilots (non‑confidential), plus a playbook for pilot-to-production transitions.
Risk factors and watch items
-
Technology maturity: Several high‑profile MEMS efforts are at prototype stages; buyers should expect longer qualification cycles and increased engineering support commitments when engaging these suppliers.
-
Standards and regulatory gating: Compliance demands in medical and defense procurement can delay adoption unless validation plans are built into contracts from day one.
-
Supply chain concentration: Critical subcomponents and specialty packaging may create single‑source risks; qualifying second suppliers or designing for alternate parts is prudent.
-
Market timing: Rapid advances could compress cost curves, but aggressive timing bets may lead to legacy inventory risk if MEMS solutions underperform against incumbent systems.
How PW Consulting helps
Clients seeking to operationalize a MEMS hydrophone strategy in 2026 can engage PW Consulting for tailored services: supplier due diligence, pilot design and management, standards compliance roadmaps, M&A target screening, and integrated go‑to‑market planning. Our workshop‑based approach converts the report’s insights into executable project plans with KPIs and stop/go criteria aligned to your risk appetite.
Next steps (teaser)
The full MEMS Hydrophones Market report contains the granular segmentation, region and application breakdowns, supplier revenue models, and downloadable financial templates that enable deal‑level decisions. For access to the complete dataset, segmentation tables and supplier scorecards — and to schedule a strategy workshop tailored to your organization — please refer to the PW Consulting release page. The material in that report will empower procurement leaders, CTOs and corporate development teams to convert 2026’s market momentum into measurable outcomes while managing technical and regulatory risk.
For detailed analysis of this topic, please visit the official page: Mems Hydrophones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Turbine Discs Broaching Machines Market Poised for 6.0% CAGR Through 2032
By PW Consulting, 2026-07-13
Turbine Discs Broaching Machines Market — Strategic Outlook for 2026 Decisions
PW Consulting’s new Turbine Discs Broaching Machines Market briefing provides a focused, decision-ready view for executives planning capital allocation, supplier strategy, and technology adoption in 2026. Our analysis shows the global market as a multi-hundred-million USD sector that has expanded steadily through the early 2020s and is forecast to continue growing at a compounded annual growth rate (CAGR) of approximately 6.0% across the 2026–2032 projection window. Specifically, the market moves from an estimated USD 435.8 million in 2025 toward a mid-600s million USD total by 2032 — a trajectory that compresses opportunity and risk into the immediate planning horizon.
Turbine Discs Broaching Machines Market
Why 2026 is a Strategic Inflection Point
-
Demand-side momentum. Commercial aviation recovery combined with continued investment in gas and steam turbines for power generation are increasing requirements for precision fir‑tree and dovetail broaching on turbine discs. This intensifies demand for machines that can handle high-strength, heat-resistant alloys at tight tolerances.
Turbine Discs Broaching Machines Market -
Materials and process intensity. Turbine discs are frequently produced from nickel‑based superalloys (e.g., Inconel-class materials) that mandate high-force, highly controlled broaching systems and tooling. This specialization elevates total cost of ownership (TCO) and supplier stickiness.
Turbine Discs Broaching Machines Market -
Regulatory gating. Aerospace broaching for engine components remains tightly regulated: NADCAP accreditation and equivalent quality programs are essentially prerequisite for contractors participating in aero engine supply chains. Compliance timelines should be built into procurement and qualification plans for 2026 projects.
-
Industry structure. The market exhibits significant concentration among a small number of specialist providers — a driver of both pricing power and strategic partner emphasis. Firms evaluating machinery purchases will need to weigh supplier resiliency and aftermarket capability alongside initial price.
What this Report Delivers — Practical, Actionable Content
-
Market sizing and outlook: global totals and trend analysis (base year 2025; forecast 2026–2032), with scenario stress-testing for demand shocks and supply disruptions.
-
Segmentation mapping: machine types (vertical vs. horizontal), application classes (aerospace engine manufacturing, power generation, industrial gas turbines), and regional dynamics — presented in a way that supports deployment sequencing and go‑to‑market prioritization. Note: detailed segment tables and line‑item splits are reserved for full report subscribers.
-
Vendor scorecards and capability matrices: technology scope, automation readiness, process monitoring, maximum part envelope, aftermarket support, and NADCAP/quality certification status.
-
CapEx decision framework: TCO modelling templates that capture machine acquisition, tooling lifecycle, NADCAP/qualification costs, cycle-time impacts, and expected uptime under alternative production scenarios.
-
Supply‑chain risk assessment: raw-material exposure, single‑source supplier flags, and reman/used equipment pathways to shorten lead times.
-
Technology roadmaps and adoption playbooks: automation and Industry 4.0 integration, in‑process metrology, broach condition monitoring, and retrofit opportunities for legacy assets.
-
Case studies and procurement checklists: real-world examples of broaching cell redesign, automation of disc handling, and contracted service models that reduced cycle time or improved qualification lead times.
Key Market Dynamics and Strategic Implications
-
Consolidation and concentration. With the top-tier players capturing a dominant share of the market, large OEMs and strategic MROs face a trade‑off between supplier specialization (higher performance and integration) and supplier dependency (commercial leverage and supply risk). Our market concentration metrics signal that partnering strategies and long‑term service contracts should form a central pillar of procurement plans.
-
Aftermarket and services as differentiation. Suppliers that build credible service footprints — including NADCAP‑adherent processes, on‑site maintenance, spare broach inventories, and rapid reconditioning — win repeat business and can command premium pricing. Expect aftermarket revenue to be a growing part of supplier economics through 2032.
-
Capital intensity vs. agility. New machine purchases are high-capex commitments. For buyers with variable volumes, used or remanufactured equipment, modular retrofit packages, and third‑party broaching services offer pragmatic ways to balance capacity with capital preservation.
-
Skill and tooling constraints. Advanced broaching requires specialist tooling design and life‑cycle management. Investment in tooling engineering, process monitoring, and in‑house expertise will materially affect cycle time, yield, and qualification speed.
-
Technology enablement. Integration of process monitoring, predictive maintenance, and automated loading/unloading is moving from differentiator to baseline expectation. Suppliers that demonstrate PLC-to-cloud telemetry, analytics, and closed-loop SPC will be preferred by quality‑sensitive buyers.
Competitive Landscape — Who Matters and Why
-
FORST Technologie GmbH & Co. KG (Germany) — FORST’s compact, high‑rigidity lines (horizontal and vertical series) are engineered specifically for external broaching of dovetail and fir‑tree profiles on turbine and compressor discs. Their emphasis on process monitoring, automation options, and capacity for large disc diameters makes them a natural partner for OEMs seeking integrated production cells and strong European supply chain credentials. Recent trade show participation underscores an active product‑development pipeline.
-
Broaching Machine Specialties (BMS, USA) — BMS’s capability to source, remanufacture, and supply both new and used large horizontal machines (including legacy models) positions it uniquely for North American customers pursuing rapid capacity expansion or cost‑efficient asset acquisition. Their high‑visibility engagement with policymakers and community outreach reflects a strategic focus on domestic manufacturing continuity.
-
Arthur Klink GmbH (Germany) — A specialty manufacturer with expertise across special broaching, surface broaching, and tooling. Arthur Klink is well placed for bespoke applications where part geometries or production processes depart from standard configurations.
-
Colonial Tool Group (USA) — Colonial combines CNC broaching platforms (including multi‑axis horizontal designs) with aerospace production know‑how. Their support for large stroke systems and tailored configurations aligns with tier suppliers and MROs seeking scalable horizontal broaching capacity.
-
Nachi‑Fujikoshi Corp. / Nachi America (Japan) — Known for vertical processing machines capable of heavy cutting and high accuracy, Nachi’s product set is attractive where vertical broaching aligns with existing cell layouts or specific process flows. Their tooling for fir‑tree grooves is an important capability for aero-focused plants.
-
Pioneer Broach Company (USA) — Beyond machine manufacture, Pioneer’s combination of broaching services and NADCAP‑aligned process credentials makes it a go‑to partner for engine component makers requiring accredited subcontracting or technical support during qualification phases.
-
Taizhou Chengchun Automation Equipment (China) — Offers competitively priced turbine disc broaching machines emphasizing groove broaching with electrical and hydraulic systems. Their value proposition is relevant for cost‑sensitive programs and regions where local sourcing is prioritized.
Two recent vendor developments to note: Broaching Machine Specialties hosted a U.S. congressional engagement as part of a manufacturing advocacy initiative, signaling political and industrial relevance for domestic broaching manufacturing; FORST’s participation at a major production-technology trade fair underscores continued vendor investment in product visibility and incremental innovation.
Recommended 2026 Actions — For OEMs, Tier Suppliers, MROs, and Investors
-
Embed scenario-based CapEx planning. Build base, upside, and downside CapEx scenarios into 2026 budgets that account for lead times, NADCAP qualification costs, and tooling ramp‑up. Use TCO templates to compare new vs. reman/used acquisitions.
-
Prioritize supplier selection criteria beyond price. Evaluate process monitoring, automation readiness, aftermarket footprint, and qualification support as first-order selection factors.
-
Invest in tooling and process engineering capability. Shorter tooling cycles and better broach life‑cycle management are high‑ROI levers for yield improvement and cost control.
-
Negotiate long‑term service partnerships. Given market concentration and aftermarket value, structured service agreements (SLA + spares + guaranteed lead times) reduce operational risk and protect time‑to‑market.
-
Use phased automation and retrofit strategies. Where immediate full‑line automation is unaffordable, deploy modular retrofits for handling and in‑process inspection to capture early productivity gains.
-
Consider dual‑track sourcing. Combine a primary specialist provider for mission‑critical capacity with a secondary, cost‑efficient supplier or reman provider to buffer lead‑time risk.
Get the Full Intelligence
This briefing highlights the strategic contours of the Turbine Discs Broaching Machines Market and why 2026 decisions will disproportionately influence value capture across the next technology cycle. PW Consulting’s full report contains the detailed segmentation tables, machine-level specifications, supplier scorecards, downloadable TCO models, and supplier negotiation playbooks that operational and procurement teams need to execute with confidence. Core segment tables and the proprietary vendor scoring dataset are intentionally omitted from this summary — they are available in the full report.
To access the complete market model, vendor matrices, and downloadable tools that underpin our recommendations, visit PW Consulting’s research portal or contact our client services team to request the full Turbine Discs Broaching Machines Market report and tailored briefings for your procurement or investment committee.
For detailed analysis of this topic, please visit the official page: Turbine Discs Broaching Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 4.61% CAGR for Residue Hydrodesulfurization Catalyst Market Through 2032
By PW Consulting, 2026-07-13
Residue Hydrodesulfurization Catalyst Market: Strategic Imperatives for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Residue Hydrodesulfurization (R-HDS) Catalyst Market report (base year: 2025; historical review: 2020–2025; forecast: 2026–2032) delivers a focused, decision-grade view for executives planning capital allocation, procurement, and technology strategies in the refining and catalyst-supply ecosystem. Our analysis shows a resilient market trajectory — a mid-single-digit compound annual growth rate (CAGR) of 4.61% over the 2026–2032 forecast window — with the market valued at roughly USD 3.9 billion in 2025 and trending toward the mid–single‑billion range by 2032 under the baseline scenario.
Residue Hydrodesulfurization Catalyst Market
Why this matters for 2026 planning cycles
Refiners, catalyst manufacturers, private equity investors and strategy teams will face a confluence of pressures in 2026 that make forward-looking, granular intelligence indispensable. Tighter global ultra‑low sulfur fuel standards continue to underpin demand for high-activity NiMo and CoMo R‑HDS catalysts capable of processing sour and heavy residues. At the same time, raw‑material volatility (notably molybdenum spot swings observed in 2025) and concentrated upstream supply dynamics are creating cost and supply risks that reverberate through margin models, capital project economics, and inventory strategies.
Residue Hydrodesulfurization Catalyst Market
What the report delivers (practical content)
- Market sizing and method notes: transparent build-up from refinery feedstock flows to installed reactor capacities, with sensitivity cases for feedstock quality and regulatory tightening.
- Forward-looking demand scenarios: baseline, accelerated regulation, and softening-refinery cases that enable rapid stress-testing of capital plans and contract structures.
- Value-chain and margin analytics: component cost drivers (including raw material pricing dynamics), manufacturing cost benchmarks, and refinery-level margin impact per incremental HDS performance.
- Technology and product positioning: qualitative and comparative assessments of fixed‑bed, ebullating‑bed and slurry technologies, with decision frameworks for selection based on feedstock, uptime, and downstream quality targets.
- Supply-chain resilience playbook: procurement hedging strategies, supplier qualification matrices, and inventory optimization models calibrated for 2026 procurement cycles.
- Competitive intelligence: concise, business‑relevant profiles of leading catalyst suppliers, recent M&A developments, partnership models, and route-to-market strategies.
- Investment and M&A guidance: deal-readiness checklists, valuation drivers for catalyst technology assets, and integration risk factors for acquirers and targets.
Market structure and competitive dynamics — what we found
The R‑HDS catalyst market displays oligopolistic tendencies with a relatively high degree of concentration among the top suppliers. This concentration translates into differentiated bargaining power across manufacturers and creates distinct strategic options for buyers: long-term supply agreements with incumbents, co-development partnerships for tailored catalyst formulations, or vertical integration in captive catalyst production. Our competitive framework evaluates players on four axes: technological performance (HDS/HDN/HDCCR), feedstock breadth (atmospheric and vacuum residues), manufacturing scale and geographic footprint, and aftermarket service capability (reactivation, monitoring, lifecycle management).
Residue Hydrodesulfurization Catalyst Market
Key industry participants profiled in the report include multinational catalyst and technology houses as well as integrated national producers. Recent transaction activity has accelerated consolidation and capability re‑alignment — notably, a late‑2025 acquisition that materially strengthened a supplier’s position in fixed and ebullated bed resid hydroprocessing. These moves are reshaping commercial negotiation dynamics and creating opportunities for strategic partnerships and bolt‑on acquisitions aimed at complete solution offerings (catalyst + process licensing + aftermarket services).
Raw material and cost pressures — actionable implications
Two cost realities stand out for 2026 procurement and capital planning:
- Metal supply volatility: Molybdenum experienced pronounced spot volatility in 2025, generating margin pressure for formulators who rely on concentrated supply sources. Buyers should assume periodic price shocks remain likely without diversified sourcing or hedging programs.
- Formulation premiums: Standard base‑metal catalyst inputs trade within a defined price band; specialty formulations designed for residue applications command material premiums relative to standard grades. These premiums meaningfully affect lifecycle cost of ownership and should be incorporated into unit economics of upgrade projects.
Regulatory and feedstock dynamics driving technology choice
Regulatory tightening toward ultra‑low sulfur products is the primary structural demand driver for high‑activity R‑HDS catalysts. For 2026 decision-makers this translates into three practical imperatives:
- Prioritize catalyst formulations and reactor technologies that deliver deep desulfurization without catastrophic sacrifice of conversion or catalyst life when processing sour, high‑CCR residues.
- Embed performance‑based contracts and KPIs into supplier engagements to align lifetime cost‑of‑ownership incentives — uptime, cycle life, and regenerator performance matter as much as initial activity ratings.
- Implement feedstock surveillance programs and blending controls to reduce catalyst poisoning risk and optimize regeneration cycles.
Strategic options for 2026 — recommended actions
Based on scenario analysis and supplier assessment, PW Consulting recommends the following high‑impact actions for organizations setting strategy in 2026:
- Procurement and commercial strategy: Move from spot purchases to hybrid contracting — combine shorter indexed supply contracts with strategic buffer stocks and supplier performance incentives. This dampens exposure to metal price spikes and manufacturer lead‑time risk.
- Technology selection: Match reactor choice to long‑term feedstock profile. For refineries expecting sustained heavy/resid inputs, prioritize ebullating and slurry solutions where conversion flexibility and fouling tolerance justify higher capital intensity; for incremental sulfur reduction on lighter residues, advanced fixed‑bed formulations may provide the best return.
- M&A and partnership playbook: For incumbents and new entrants alike, target bolt-on capabilities in aftermarket services (reactivation, monitoring) and catalyst recycling to protect margins and unlock post‑sales revenue streams.
- R&D and product differentiation: Invest in formulations that reduce susceptibility to metal contaminants and that lower hydrogen consumption per unit of sulfur removed — this is a direct lever on refinery operating costs.
- Risk mitigation: Deploy commodity hedging for key input metals and diversify supplier base across geographies to reduce single‑source exposures.
Case study highlight (illustrative)
Refinery X (North Africa, illustrative): by redesigning its procurement and switching to a performance‑tied catalyst contract, the refinery de‑risked molybdenum price exposure and extended catalyst cycle life via a supplier co‑development program — outcomes included improved sulfur removal consistency and smoother capex phasing for a downstream upgrading unit. Details of the model and sensitivity analysis are provided in the full report for replication.
What we are not disclosing here (and why)
This release is intentionally a strategic “trailer.” While we present the macro market sizing, growth trajectory, and high‑level concentration metrics, the full report contains granular segmentation by region, detailed application and type split values, supplier market shares, pricing forecasts, and downloadable data tables that are indispensable for detailed procurement, investment, and engineering work. We withhold those line‑by‑line figures in this public release to preserve the commercial utility of the full dataset and to ensure readers engage with the complete analysis when executing 2026 strategies.
How to use our intelligence in 2026 decision cycles
Decision-makers should treat the report as both a diagnostic and playbook. Use it to:
- Validate your capex timing — run our regulatory and feedstock scenarios against your project IRR assumptions.
- Design supplier contracts — adopt our recommended KPI structure and renegotiation triggers tied to raw material benchmarks.
- Prioritize R&D agendas and M&A targets — focus on formulations and service capabilities that materially change lifetime economics.
Next steps and access
PW Consulting’s Residue Hydrodesulfurization Catalyst Market report is designed to be immediately actionable for 2026 planning. The full report includes the datasets, scorecards, and implementation templates referenced in this announcement. For access to the complete segmentation, company scorecards, forecast tables and downloadable models, please visit the report landing page or contact our market intelligence desk to schedule a briefing tailored to your organization’s priorities.
PW Consulting — helping clients convert complex market dynamics into executable advantage as they navigate the 2026 planning horizon and beyond.
For detailed analysis of this topic, please visit the official page: Residue Hydrodesulfurization Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnesia Partially Stabilized Zirconia Market Poised for Steady Expansion — 5.45% CAGR Projected Through 2032
By PW Consulting, 2026-07-13
Magnesia Partially Stabilized Zirconia Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market study on Magnesia Partially Stabilized Zirconia (Mg-PSZ) delivers a concise, actionable intelligence package designed to inform capital allocation, sourcing strategy, product roadmaps, and M&A decisions in 2026. Built on a rigorous historical base (2020–2025) and a forward-looking forecast window (2026–2032), the study projects a steady expansion of the Mg-PSZ market at a compound annual growth rate (CAGR) of 5.45% through the forecast horizon. With the market estimated at approximately USD 219.0 Million in the base year 2025 and forecast to rise meaningfully by 2032, the report synthesizes demand drivers, supply-side risks, standards implications, and competitive dynamics into pragmatic guidance for commercial and technical leaders.
Magnesia Partially Stabilized Zirconia Market
Why this report matters for 2026 strategy
- Timing for strategic moves: 2026 will be a pivot year for many Mg-PSZ participants. Macro growth is predictable, but supply-side shocks and standards-related opportunities can create outsized value for well-prepared players.
- Actionable risk management: Our analysis isolates the raw-material and logistics vectors most likely to affect cost and availability, enabling procurement teams to move from ad hoc buying to hedged, multi-sourcing strategies.
- Commercial differentiation: The technical divergence between general industrial and high-purity/specialty uses is accelerating. Executives who align certification, production practices, and customer segmentation will defend margin better than those pursuing volume alone.
What the study contains — practical tools and deliverables
- Demand-scenario models (conservative, base, accelerated) covering 2026–2032, with sensitivity levers for key end-markets and macro variables.
- Supply-risk matrix mapping zircon feedstock exposure, geographical concentration, and substitution pathways; includes short-, medium-, and long-term mitigation roadmaps.
- Value-chain cost build-ups and margin waterfalls for core product families — designed to support price negotiations, tolling agreements, and vertical-integration assessments.
- Competitive benchmarking and capability heatmaps across technology, quality certifications, vertical integration, precision finishing, and aftermarket services.
- Commercial playbook: go-to-market tactics for premium vs. commodity segments, recommended account coverage models, and channel strategies for industrial and high-purity applications.
- M&A and partnership screening framework: acquisition targets, bolt-on capabilities, and value-extraction tactics tailored to both strategic and financial buyers.
- Regulatory and standards impact assessment, including implications of the reapproved ASTM specification for high-purity dense Mg-PSZ relevant to surgical implants.
Market context and supply-side dynamics
The projected CAGR of 5.45% reflects a market that is neither nascent nor commoditized — it is maturing. Growth is being driven by steady industrial demand for wear- and corrosion-resistant components, selective replacement of metallic parts with engineered ceramics, and specialized high-purity applications where regulatory compliance and long-term reliability justify premium pricing.
Magnesia Partially Stabilized Zirconia Market
However, material upstream constraints are an increasingly decisive factor. Premium-grade zircon sand — the principal feedstock for zirconia ceramics — traded at a level near USD 2,000 per metric ton through 2025, and industry-visible supply patterns point to a medium-term tightening beyond 2026 as a share of mature mining operations approach decline. Global zircon exports are highly concentrated, creating potential vulnerability to regional disruptions. These realities change supplier-selection calculus: margin protection now requires active feedstock strategy, not passive purchasing.
Magnesia Partially Stabilized Zirconia Market
Competitive landscape — what the leaders are doing
The Mg-PSZ market displays moderate concentration: the top three firms account for a notable portion of industry revenue while the top five collectively represent more than half the market. This structure produces both competitive pressure and consolidation opportunities.
- CoorsTek (United States, https://www.coorstek.com) — Positions Mg-PSZ under product platforms designed for severe-service mechanical environments. Their focus on engineered Dura-Z™ components underscores a vertical capability set: materials development, application engineering, and finished-component supply for valves and rotating parts. For incumbent customers, this means high-reliability supply and integrated design support.
- Morgan Advanced Materials / Nilcra® Zirconia (United Kingdom; operations in Australia, https://www.morgantechnicalceramics.com) — Distinguishes itself through high-toughness grades and long-term reliability metrics used to replace metals and carbides in heavy industrial sectors. Morgan’s focus on Weibull strength performance and application-specific grades (e.g., thermal shock tolerant variants) makes it a preferred partner where predictable lifespan and failure-mode insight are essential.
- Refractron Technologies (United States, https://refractron.com) — Emphasizes US-made precision ground parts and microstructure-tuned Mg-PSZ (Izory®HD) for best-in-class wear and corrosion resistance. Their messaging centers on supply-chain resilience and precision finishing for demanding wire-drawing and pump environments.
- Superior Technical Ceramics (STC) (United States, https://ceramics.net) — Focuses on transformation-toughened MSZ materials with thermal stability and ceramic-to-metal assembly expertise, creating differentiation for high-temp and down-hole applications.
- C-Mac International LLC (United States, https://cmacintl.com) — Concentrates on valve and pump components, oil & gas down-hole tooling, and cyclic fatigue-resistant parts — offering application-tailored components for OEMs seeking metal-to-ceramic migration.
- Zircoa Inc. (United States, https://zircoa.com) — Specializes in tailored MgO-PSZ compositions and engineered feedstocks for crucibles, grinding media, and upstream production materials; positions itself as a materials innovator for high-temperature specialty applications.
- Bangalore Ceramics (India, https://bangaloreceramics.com) — Provides custom-formed Mg-PSZ and YSZ solutions for customer-specific demands, adding regional capacity and customization capability to the global supply base.
Recent industry signals to watch in 2026
- Product application updates and materials publications continue to expand the addressable specialty market. Notably, a 2026 publication highlighted Zircoa’s Composition 3001 MgO-PSZ crucibles for high-temperature PGM melting applications, underlining the opportunity in metallurgical recycling and refining.
- Manufacturers have broadened their product catalogs: recent releases emphasize high-temperature tubular and form-factor components capable of operating beyond traditional alumina limits, indicating incremental displacement in thermal and chemical stability niches.
- Standards and certification remain active levers. ASTM’s reapproval of the specification for high-purity Mg-PSZ intended for surgical implant use crystallizes a pathway for medical-market entry but also raises the bar for manufacturers seeking to supply these segments.
Strategic implications and recommended next steps for 2026
- Procurement and inventory: Move from single-source relationships to flexible triage: a primary long-term supplier, a regional alternate, and a contingency partner with tolling or third-party finishing. Consider strategic inventory cushions for critical feedstock and finished parts during 2026 as risks of zircon supply tightening rise.
- Technology and product strategy: Differentiate along functional outcomes (wear life, thermal-shock tolerance, precision surface finish) rather than on generic ceramic claims. Prioritize certification pathways for high-purity and medical-grade product lines where premiums are structural.
- Manufacturing footprint: Reassess near-term onshoring or regionalization for critical components to de-risk logistics and shorten lead times for key customers in heavy industry and oil & gas.
- M&A and partnerships: Use the moderate concentration of the market to hunt for bolt-on targets that strengthen feedstock control, finishing capability, or high-purity credentials. Structured earn-outs tied to technology transfer or qualification milestones can align incentives.
- Commercial and pricing: Implement tiered pricing that captures value for engineered, high-reliability applications while preserving competitiveness in commodity wear parts. Quantified lifecycle cost models will be essential to justify up-front premiums.
How PW Consulting supports buyers and investors
Our Mg-PSZ study is structured to accelerate board- and management-level decisions in 2026. Beyond the market sizing and scenario forecasts, we provide a playbook with executable recommendations: sourcing contracts with feedstock clauses, capex sizing templates, go-to-market launch plans for high-purity lines, and a prioritized list of acquisition targets and partnership archetypes. For investors, we offer a valuation outlook under three growth scenarios and an acquisition integration checklist that highlights where post-merger synergies are most likely to materialize.
Closing — the opportunity window in 2026
Mg-PSZ is at a crossroads: predictable, steady growth is coupled with a tightening and geographically concentrated upstream supply base and rising standards-led premium demand. Firms that treat 2026 as a strategic year—codifying feedstock strategy, accelerating high-purity certifications, and selectively expanding in precision finishing—will capture disproportionate value as the market matures.
For a full breakdown of segmentation, granular regional and application forecasts, detailed competitive scorecards, and the proprietary models referenced in this preview, please consult the full PW Consulting Magnesia Partially Stabilized Zirconia Market report on our website. The published report contains the segment-level data, downloadable tools, and appendices necessary to operationalize the strategies summarized here.
For detailed analysis of this topic, please visit the official page: Magnesia Partially Stabilized Zirconia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: AI Speech Generation Systems Market to Skyrocket at 18.5% CAGR from 2026–2032
By PW Consulting, 2026-07-13

Ai Speech Generation System Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive teaser
As enterprises accelerate voice-first initiatives across customer experience, learning, accessibility and automation, the Ai speech generation system market has shifted from experimental to mission-critical. PW Consulting’s new market research (base year 2025; forecast period 2026–2032) shows the sector expanding at an 18.5% compound annual growth rate, rising from a nascent industry valuation in 2020 to a multi‑billion dollar market by 2025, and projected to exceed ten billion USD by 2032. This preview outlines the report’s strategic value for decision-makers in 2026 — the practical choices, implementation trade-offs, and risk controls that separate pilots from production-grade voice initiatives — while reserving the detailed segmentation and proprietary scorecards for the full release.
Ai Speech Generation System Market
Market snapshot and what it implies for 2026 planning
PW Consulting’s historical analysis shows rapid adoption across enterprise verticals between 2020 and 2025, driven by improvements in naturalness, multilingual capabilities, and developer-friendly APIs. In 2025 the market reached a tipping point: investments moved beyond point solutions into platform-level deployments, and vendor ecosystems matured to offer both cloud-first and secure on-premise options. Our 2026 baseline modeling projects continued expansion at an 18.5% CAGR through 2032, reflecting accelerating use cases such as automated contact centers, localized content creation, and assistive technologies.
Ai Speech Generation System Market
For 2026 enterprise planning, the implications are clear:
Ai Speech Generation System Market
- Voice AI is no longer optional for digital CX and training strategies; it is a material component of customer experience and content workflows.
- Decisions about deployment architecture (cloud, hybrid, on‑premise), vendor lock‑in, and compliance posture should be made now to avoid rework as regulation and enterprise requirements converge.
- Cost structures and unit economics are rapidly standardizing — meaning procurement can negotiate on defined quality tiers rather than vague “voice AI” premiums.
Key trends and operational dynamics
Our sector analysis synthesizes technology trajectories, regulatory shifts, and economics that will shape vendor selection and implementation tactics in 2026:
- Technology maturation: New model releases and open-weight initiatives have materially improved expressive control, multilingual coverage, and latency. This increases the viability of real-time agentic voice assistants and large-scale dubbing workflows.
- Regulatory overlay: The EU AI Act provisions slated to take effect around August 2026 introduce specific transparency and risk assessment requirements for high-risk voice AI use cases. Enterprises with EU footprints must embed governance and documentation into procurement and implementation lifecycles.
- Compliance as a differentiator: SOC 2, GDPR, and data residency capabilities are now primary selection criteria for enterprise buyers managing sensitive content; security posture often outweighs feature sets in RFP evaluations.
- Economics and production cost reduction: Adopting AI speech generation can reduce audio production labor and studio costs by up to 70% versus traditional human recording workflows. At the component level, TTS runtime costs commonly range between roughly $0.01 and $0.25 per minute depending on fidelity and delivery model, making per-minute economics a usable benchmark in ROI modeling.
- Concentration and competition: The market shows moderate concentration — leading providers collectively command a meaningful share, but a competitive field of specialist and hyperscaler offerings persists, creating both partnership and competition dynamics.
Competitive landscape — who matters and why
Our vendor review distills relative strengths across specialist pure‑players, mid‑market platforms, and hyperscalers. PW Consulting’s assessment identifies three pragmatic vendor archetypes for procurement teams to consider:
- Hyperscaler platforms (scale and integration): Major cloud providers deliver broad language coverage, deep platform integration with AI/ML tooling, and enterprise SLAs that suit large-scale deployments. Recent product updates from hyperscalers underscore a race on expressive control and watermarking for provenance.
- Specialist synthetic-voice innovators (quality and feature depth): Niche firms emphasize ultra‑realistic voice cloning, expressive models, and creative workflows directed at media, education, and marketing use cases. Their strengths include rapid feature iteration, specialty voices, and creative tooling tailored to content teams.
- Enterprise-grade hybrid providers (security and control): Vendors offering both cloud and on-premise deployments bridge security and compliance gaps for regulated industries and contact centers, often bundling governance features like watermarking and deepfake detection.
Representative players evaluated in the report include a cross-section of the above archetypes — from hyperscalers to focused startups. Each profile in the full report contains capability matrices covering model quality, latency, language breadth, integration ease, compliance certifications, pricing transparency, and go-to-market motion. Recent market moves we analyze in-depth include a new open-weight frontier TTS release from a leading research lab, a strategic enterprise partnership integrating high-fidelity TTS into orchestration platforms, and hyperscaler releases that add granular audio tags and watermarking. These developments alter procurement leverage and should shape 2026 vendor roadmaps.
What the PW Consulting report delivers (practical contents)
The full PW Consulting study is designed as an operational playbook for buyers and strategists. Core deliverables include:
- Market sizing and forecast model (2020–2032) with scenario analysis and sensitivity to adoption, regulation, and pricing.
- Vendor scorecards and a stratified vendor map that aligns vendor archetypes to enterprise use cases and compliance needs.
- Implementation checklists for pilots and production deployments — covering latency SLAs, voice licensing, voice cloning consent, watermarking, and observation/monitoring frameworks.
- Procurement templates and RFP language optimized for quality tiers, regional deployment constraints, and security attestations.
- Unit-economics and TCO calculators that incorporate per-minute runtime costs, expected content volume, localization needs, and talent redeployment savings.
- Use‑case ROI playbooks for customer service automation, e‑learning scalability, accessibility tooling, and media localization, including KPIs and success thresholds.
- Regulatory and ethical risk framework tailored to the EU AI Act and global privacy regimes, with required documentation artifacts and audit-ready templates.
Note: To preserve commercial confidentiality and the integrity of our modeling, detailed segment-level numeric splits, proprietary vendor weightings, and the master forecast spreadsheet are available only within the full report package.
How to use these insights to decide in 2026
Executives and technology leaders can convert the report’s insights into concrete 2026 actions using a three-step decision framework:
- Assess strategic fit: Map voice AI use cases to the company’s customer experience, regulatory exposure, and content strategy. Prioritize use cases where voice reduces cost or increases revenue predictably within 12–24 months.
- Define guardrails: Establish mandatory security, data residency, and provenance requirements (e.g., watermarking, consent workflows, SOC 2/GDPR alignment) before vendor engagement to avoid late-stage rework.
- Pilot to scale path: Start with modular pilots that prove integration and voice quality at production scale, instrument usage and user acceptance metrics, then move to negotiated enterprise contracts that reflect expected volumes and SLA tiers.
Strategic risk considerations
Key risks we flag for 2026 decision-makers:
- Regulatory misalignment: Underestimating compliance obligations in the EU and other jurisdictions can delay rollouts and increase legal costs.
- Data provenance and reputational exposure: Poorly governed voice cloning poses brand and trust risks, particularly in customer-facing contexts.
- Vendor fragmentation vs lock-in: Balancing rapid feature adoption (often with smaller innovators) against the stability and contractual protections of hyperscalers is a critical procurement trade-off.
Concluding guidance and next steps
PW Consulting’s preview shows that 2026 is the year to move from experimentation to disciplined deployment of Ai speech generation. The market’s trajectory — from roughly one billion in early‑stage valuations to a multi‑billion dollar industry by 2025 and further expansion through 2032 at an 18.5% CAGR — creates a strategic imperative: build voice capability now, but do so with governance, cost discipline, and vendor strategy embedded.
For enterprise leaders preparing budgets and roadmaps in 2026, our report provides the operational playbooks, vendor assessments, and scenario models needed to make defensible investments. The complete report contains the granular segmentation, vendor scorecards, and downloadable forecast models that inform procurement, legal, and technology roadmaps — available on PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Ai Speech Generation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Double Base Propellant Market Set to Expand at a 5.1% CAGR Through 2032
By PW Consulting, 2026-07-13
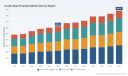
Double Base Propellant Market — Strategic Outlook for 2026: Actionable Intelligence for Procurement, M&A and Capacity Planning
Executive snapshot
PW Consulting’s new market study on Double Base Propellant (DBP) delivers a focused, decision-ready view for 2026 planning cycles. Using a 2020–2025 historical baseline and a 2026–2032 forecasting horizon, the report quantifies an addressable global market that we estimate at USD 625.5 Million in the 2025 base year and projecting to approximately USD 886.0 Million by 2032 — an implied compound annual growth rate of 5.1% (USD; revenue units in Million). Alongside numerical projections, the study exposes the operational levers, supplier footprints, technology inflection points and regulatory constraints that will determine winners and laggards in the coming procurement and industrialization rounds.
Double Base Propellant Market
Why this matters for 2026 decision-makers
- Budget cycles and capital allocation: defense and industrial buyers must align 2026 CAPEX and inventory policies with a market expanding at ~5% CAGR through 2032 to avoid either supply shortfalls or stranded inventory.
- Near-term supply risk versus long-term capacity expansion: capacity investments announced through 2025 change bargaining dynamics in 2026; organizations that lock multi-year supply now will obtain different pricing and security outcomes than late movers.
- Regulatory and export-control compliance: DBP’s primary constituents are subject to export controls and military QA standards; failure to internalize compliance into contracts raises both program-risk and reputational risk.
Demand and supply dynamics shaping 2026 strategy
The market is being driven by three overlapping forces: defense ammunition replenishment and modernization; sovereignization of energetics supply chains; and technology-led productivity gains in propellant manufacturing. Defense demand remains the principal growth lever as governments replenish stocks and pursue next‑generation munitions. At the same time, manufacturers and prime contractors are accelerating domestic and allied production capacity to reduce dependency on single-source supply chains.
Double Base Propellant Market
- Capacity developments matter now. Recent industrial moves — including large plant expansions and new joint venture greenfields announced through 2025 — materially increase available throughput in specific corridors and influence pricing negotiations in 2026.
- Technology choices affect lifecycle economics. Solventless manufacturing approaches for certain high‑caloric DBP grades deliver ballistic stability advantages and lower solvent handling costs, but require distinct capital and process capabilities; decisions to adopt or source these technologies will impact unit economics and qualification timelines.
- Raw material concentration is a practical vulnerability. Nitrocellulose and nitroglycerin are the primary input vectors; secured upstream sites and supplier relationships reduce program risk but introduce geopolitical exposure when feedstock is concentrated geographically.
Competitive landscape — what the major players reveal about market structure
The DBP industry demonstrates moderate concentration (CR3 ≈ 42.8%; CR5 ≈ 58.4%), indicating several dominant incumbents alongside capable regional players. The competitive map is a mix of legacy defense suppliers, state-backed manufacturers and specialized process-equipment providers offering turnkey plants. Key strategic observations:
Double Base Propellant Market
- Catalysts from European incumbents: Established European producers have invested in both production scale and technological differentiation. These suppliers combine deep ballistic expertise with integrated nitration and propellant manufacturing capabilities — positioning them as preferred partners for high-stakes military programs that require stringent certification and traceability.
- Verticalized offerings and turnkey approaches: Some firms offer end-to-end plant delivery models (including spherical DBP plants), enabling governments and new market entrants to accelerate sovereign capacity with a single supplier engagement. Such turnkey vendors are attractive to buyers seeking rapid industrialization with reduced supplier coordination risk.
- Regional and niche players maintain operational agility: Government-owned and regionally focused manufacturers continue to supply a substantial portion of demand for standard DBP grades, particularly where national procurement policies prioritize local sourcing.
- Prime integrators and system houses remain influential: Large defense primes and ordnance divisions retain advantages in program-level contracting and specification definition; their in-house propellant qualifications and longstanding client relationships lower time-to-contract for integrated munitions programs.
Representative company capabilities covered in the study include extruded and cast DBP formulations for ejection systems, rocket motors and gun systems; solventless high‑caloric grades for tank gun applications; spherical and flake powders for small- and medium-caliber ammunition; and turnkey plant suppliers for rapid onshore production build-out. The report also annotates public strategic moves — such as capacity expansions, international collaborations and JV launches — and interprets their implications for supplier bargaining power and regional security of supply.
Regulatory and quality environment — constraints that shape supplier selection
- Export controls: DBP constituents are routinely subject to national export-control regimes and the Commerce Control List. Contractual clauses and supplier vetting must explicitly address classification, licensing timelines and denial contingencies.
- Quality and certifications: Military-grade DBP production is governed by recognized quality standards; operators typically maintain ISO 9001 and AQAP-equivalent certifications as a baseline for defense qualification and procurement compliance.
- Feedstock traceability: Given nitrocellulose’s centrality to DBP, sourcing strategies that secure feedstock continuity (including multi-site sourcing and contractually obligated inventories) materially reduce program risk.
What PW Consulting’s report includes (practical deliverables)
Built for commercial and government buyers, the study is intentionally operational. Highlights include:
- Top-line market forecasts (2026–2032) and scenario analyses under alternate demand and supply stress tests;
- Supplier capability matrices and a qualitative technology readiness assessment for extruded, cast and solventless DBP technologies;
- Transaction playbook for forward-buy commitments, capacity offtake agreements and JV structuring;
- Procurement templates and RFP checklists reflecting export-control and QA requirements;
- Supply‑chain risk heatmaps and mitigation actions (dual‑sourcing, strategic inventory, backward integration options);
- Quantitative valuation models for M&A and greenfield investments, with sensitivity testing across feedstock prices and certification timelines.
To preserve strategic confidentiality and encourage direct engagement, the report presents an executive-level synthesis in this press release and reserves granular regional/application splits, supplier ranking tables and contract-by-contract benchmarking for the full document available on PW Consulting’s portal.
Actionable recommendations for 2026
- Lock near-term security through layered contracting: combine limited-duration spot purchases with structured offtake agreements tied to escalation clauses and force‑majeure protections. This balances price exposure with supply certainty while new capacity comes online.
- Prioritize qualification pipelines for solventless DBP where ballistic performance forecasts justify the investment — especially for large-caliber and tank applications that benefit most from high‑caloric formulations.
- Accelerate supplier due diligence on export control readiness and certified quality systems; demand demonstration of AQAP/ISO-compliant processes as part of standard contracting pre-conditions.
- Assess JV or minority investments in turnkey plant providers to secure preferential build slots and technology transfer terms without bearing full project risk.
- Embed feedstock diversification clauses in contracts and establish strategic inventory buffers at national or program level to mitigate upstream nitration bottlenecks.
- Use the 2026 budget window to pilot technology automation and remote monitoring systems that reduce operational risks and shorten qualification timelines for new production lines.
Implications for M&A, procurement and industrial policy
For acquirers and policy-makers, DBP represents a strategically important but specialized segment: it demands a blend of chemical-processing know-how, military qualification expertise and secure logistics. The current competitive configuration (moderate concentration among top players, active capacity expansions and cross-border collaborations) creates windows for bolt-on acquisitions that add capacity or specialized technology, as well as for public-private arrangements that accelerate sovereign production. Procurement strategies that ignore certification and export-control lead times will face program slippage and potential cost overruns.
Next steps — how to use this intelligence in 2026
- Procurement teams: request our supplier short‑list and the RFP templates to compress vendor qualification timelines by 30–50%.
- M&A teams: obtain the report’s valuation model and candidate screening matrix to prioritize targets with solventless capability or turnkey plant IP.
- Policy-makers and program offices: use the supply‑chain heatmap to design strategic inventory and accelerate local capacity via JVs or CAPEX incentives.
Conclusion and call to action
PW Consulting’s Double Base Propellant market study delivers a pragmatic synthesis of projected growth, supplier capabilities and actionable mitigations tailored to 2026 decision-makers. With the market expanding from a 2025 base of USD 625.5 Million toward approximately USD 886.0 Million by 2032 at a 5.1% CAGR, decisions made in 2026 about sourcing, capacity investments and technology adoption will determine program resilience and cost trajectories for the rest of the decade.
For access to the full report — including the complete regional and application-level segmentation, supplier rankings, contract templates and the full set of quantitative tables reserved from this executive summary — visit PW Consulting’s market publications page or contact our industry desk to request the complete study and tailored briefings for procurement, M&A or industrial policy teams.
For detailed analysis of this topic, please visit the official page: Double Base Propellant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


