



PW Consulting: Helium Leak Detector Rental Market Set to Expand at 7.79% CAGR Through 2032, Led by Portable Units
By PW Consulting, 2026-07-13
Helium Leak Detector Rental Services Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new market brief on Helium Leak Detector Rental Services frames the market as a high-growth, mission-critical niche within industrial testing and non-destructive testing (NDT) services. Built on a historical analysis through 2025 (base year) and a forward-looking forecast to 2032, the study projects sustained expansion at a compound annual growth rate (CAGR) of roughly 7.8%. That trajectory reflects accelerating demand from capital-intensive sectors, regulatory tailwinds for hydrogen-related testing, and persistent operational pressures—most notably helium supply constraints and scarcity of trained field technicians.
Helium Leak Detector Rental Services Market
Why this matters for 2026 strategic planning
For equipment OEMs, rental houses, utilities, defense primes, EV and battery manufacturers, and infrastructure owners, the rental layer of the leak-detection value chain is rapidly shifting from a convenience to a strategic enabler. Short-term rentals reduce capital outlay and provide fast access to the latest mass spectrometer-based systems; mid-term contracts reshape maintenance planning; and long-term partnerships can embed testing capabilities into product validation and warranty regimes. Our macro view — anchored on a 2025 baseline and our projection window beginning in 2026 — gives corporate leadership a quantified runway to design procurement policies, service-level agreements, and capacity investments that align with a near-8% growth environment.
Helium Leak Detector Rental Services Market
Market trajectory and macro drivers
Key demand drivers identified in the analysis include the semiconductor/electronics cycle, the rapid scale-up of EV battery manufacturing, aerospace and defense maintenance cycles, and new regulatory regimes that explicitly permit helium-based testing for certain hydrogen vehicle and storage systems. At the same time, industry-wide helium supply dynamics and cost pressures are reshaping test modalities: we document widespread adoption of diluted-helium techniques, closed-loop recovery solutions, and hybrid tracer strategies. These adaptations are already affecting utilization patterns and operator economics—insights that are critical for 2026 budget cycles.
Helium Leak Detector Rental Services Market
Report deliverables — what’s inside (practical, actionable content)
- Market sizing and validated growth projection from the historical period through a multi-year forecast window beginning 2026, enabling scenario planning for capex and opex.
- Commercial playbooks for rental providers and end-users: procurement templates, rental-vs-own decision matrices, and break-even analyses that account for helium recovery and dilution strategies.
- Operational readiness checklists for field services: technician competency frameworks, rapid-response deployment standards, and maintenance-to-replacement decision guides for mass-spectrometer systems.
- Regulatory impact notes and compliance mapping: concise summaries of recent rule changes affecting hydrogen vehicle testing and compressed hydrogen storage system protocols, with implication matrices for OEMs and test houses.
- Vendor benchmarking and service-level scoring: qualitative and semi-quantitative assessments against speed-of-deployment, global reach, device diversity, and aftermarket support—designed for procurement teams evaluating rental partners.
- Risk scenarios and mitigation playbooks: helium supply shock models, labor-skill shortages, and contingency strategies such as inventory pooling and strategic rental partnerships.
Competitive landscape — practical reading for procurement and M&A teams
The rental market combines global OEM-supported options with specialized rental houses and regional service providers. Our analysis profiles leading participants that span pure rental and field-service specialists through to OEMs offering short-term allocations. Examples include established rental and equipment-servicing houses that operate fleets across major vacuum technology brands; specialist field-service teams that pair mass spectrometer rentals with on-site leak diagnosis and repair; and manufacturers that augment sales with rental and backup programs.
Operational strengths we highlight—without exposing proprietary segment shares—are the ability to provide worldwide deployments, breadth of supported instrument models, turn-key field service (including technicians certified for mass spectrometer operation), and flexible rental terms (weekly to monthly). Recent vendor activity demonstrates the market’s emphasis on flexible fleet availability and enhanced field capability: for example, rental-program updates that emphasize weekly/monthly terms, and service bulletins that promote expanded field-service offerings and faster dispatch windows.
Regulatory and technology inflection points
Two regulatory developments are particularly material for 2026 planning. First, recent updates to vehicle safety standards permit the controlled use of inert gases, including helium, for closure and leak testing in hydrogen vehicle systems—this change creates near-term testing demand as OEMs validate designs to new compliance thresholds. Second, post-crash test protocols for compressed hydrogen storage systems now allow helium as a test gas within specified volumetric limits, which further institutionalizes helium-based testing in safety validation programs.
From a technology standpoint, the interplay of helium scarcity and the need for high-sensitivity detection is accelerating two convergent responses: (1) operational designs that minimize helium use via dilution and recovery, and (2) rental fleets shifting toward units and service models that support closed-loop testing. These technical adaptations have economic implications—rental pricing, utilization rates, and service-pack structuring—that are core inputs in our financial templates and procurement playbooks.
Operational and commercial implications for service providers
- Fleet optimization: Providers should prioritize flexible inventory mixes that balance portable sniffer units and bench/box units for in-facility testing, while embedding recovery accessories into every rental kit.
- Skills and service delivery: Investment in technician training, certified mass-spectrometer operation, and rapid-deployment field teams translates directly to reduced customer downtime and higher contract renewal rates.
- Pricing architecture: Adopt modular pricing—separating equipment rental, technician hours, helium consumption, and recovery services—to align incentives and reduce exposure to raw-material price swings.
- Partnerships and channel: Strategic alliances with OEMs for access to next-generation analyzers and with logistics partners for expedited cross-border deployments will be differentiators in 2026.
Strategic recommendations for buyers and investors
For buyers (industrial end-users and OEMs): embed rental as a tactical line item in design validation and warranty testing programs to reduce cycle time and capital lock-up. Negotiate rental contracts that include helium recovery options and technician certification clauses to protect uptime and technical quality.
For investors and M&A teams: target assets that combine fleet depth with service capability—companies that offer both rental inventory and certified field services are positioned to capture higher-margin recurring revenue. Due diligence should prioritize operational metrics such as turnaround-time, technician headcount/training, and recovery-capable inventory rather than pure device-count alone.
The PW Consulting edge and next steps
Our report couples quantitative market sizing and a 2026-to-2032 forecast timeline with hands-on commercial tools to convert insight into action. It is expressly designed to support procurement cycles, go-to-market refinement, and M&A screening in time for 2026 planning windows. To respect competitive sensitivities and to preserve the tactical value for readers, detailed regional and application-level splits, along with full vendor scorecards and downloadable financial models, are available only in the full report.
Call to action
For teams executing 2026 budgets, operational readiness plans, or strategic acquisitions in the leak-detection value chain, PW Consulting’s full Helium Leak Detector Rental Services Market report delivers the data, commercial playbooks, and supplier assessments needed to de-risk decisions. Access to the complete dataset, granular segment breakdowns, and procurement-ready templates is available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Helium Leak Detector Rental Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Bone Cement for Spine Market Tops USD 895 Million in 2025
By PW Consulting, 2026-07-13
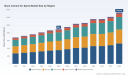
Bone Cement for Spine Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s latest market study on bone cement for spine (base year 2025) delivers a compact, decision-ready roadmap for executives planning 2026 actions. At a global level the market sits at roughly USD 895 million in 2025 and — under our base-case assumptions — is forecast to grow to more than USD 1.3 billion by 2032, representing a mid-single-digit compound annual growth rate (CAGR). That trajectory is notable for supply-chain sensitivity, technology-led product differentiation (viscosity profiles, antibiotic-loaded formulations, delivery systems), and a reimbursement environment that favors standardized augmentation procedures. This release highlights the strategic takeaways from the full report while intentionally withholding certain granular segment-level figures to preserve the report’s role as a commercial intelligence product.
Bone Cement for Spine Market
Market dynamics shaping 2026 decisions
-
Clinical demand and procedure mix — The clinical drivers behind vertebral augmentation remain robust: an aging population, sustained incidence of osteoporotic and pathological vertebral compression fractures, and a continued preference among interventional spine specialists for minimally invasive stabilization techniques. Device adoption is being influenced as much by operator workflow and injection control as by material properties.
Bone Cement for Spine Market -
Product innovation — Two technical threads dominate supplier investment: controllable viscosity (including ultra-high-viscosity formulations optimized for anterior column support) and adjunct functionality (e.g., antibiotic-loaded PMMA for combined infection risk mitigation). Radio-opacity and working/injection windows are increasingly marketed as clinical differentiators.
Bone Cement for Spine Market -
Regulatory & reimbursement context — PMMA bone cements used in vertebral augmentation remain regulated under established Class II pathways in major jurisdictions, with special controls and sterilization expectations shaping dossier requirements. In the US, common percutaneous vertebral augmentation procedures are covered under established CPT codes that include cavity creation and cement injection with imaging guidance — a practical advantage for adoption but one that still requires payer-level diligence for new product introductions.
-
Quality, sterilization and materials risk — Manufacturers face rigorous sterilization validation expectations (e.g., documented methods, sterility assurance levels, pyrogenicity testing). On the materials front, standard PMMA formulations continue to exceed ISO mechanical baselines, but raw material sourcing and monomer handling present latency risks that must be managed in supplier contracts and manufacturing operations.
What the full PW Consulting report delivers (practical contents)
-
Proprietary market model with transparent assumptions — multi-scenario forecasts covering 2026–2032 and sensitivity testing for key inputs (procedure volumes, pricing erosion, market entry timing).
-
Regulatory playbook — classification mapping, recommended 510(k)/equivalent strategies, essential documentation checklists (including sterility and pyrogenicity pathways) and timings to market in major regions.
-
Reimbursement and coding guide — payer levers, procedural code implications, and hospital-level bundle impacts for percutaneous vertebral augmentation.
-
Clinical evidence compendium — outcome metrics, comparator data for high- vs low-viscosity formulations, and guidance on randomized vs registry-driven evidence programs to support product claims.
-
Commercial playbooks — go-to-market options by tier (incumbent OEM, challenger, start-up), distributor selection criteria, tender playbooks and pricing negotiation frameworks.
-
Supplier & manufacturing checklist — material qualification criteria, sterilization vendor shortlist templates, and inventory resilience strategies for monomer and radiopaque additives.
-
M&A and partnership scanner — prioritized target profiles, valuation sensitivities, and integration risks for bolt-on acquisitions versus co-development alliances.
Competitive landscape — practical implications for 2026
The market is characterized by a mix of large medtech incumbents and specialized suppliers. Global orthopedics and spine players maintain scale advantages through integrated portfolios and distribution networks, while smaller specialists compete on niche innovations and faster regulatory cycles. Key competitive themes we emphasize:
-
Stryker — leverages a spine-focused product suite with high-viscosity and clinically positioned cements; strength lies in integrated sales channels and long-standing trust with interventional spine clinicians.
-
Medtronic — combines legacy vertebral augmentation platforms with established PMMA offerings; regulatory experience and global reach support rapid rollouts of incremental product improvements.
-
Zimmer Biomet — increasingly targeting differentiated clinical niches (e.g., antibiotic-loaded cements) and leveraging orthopedic scale to cross-sell into spine.
-
DePuy Synthes (J&J) — consistent PMMA portfolio compatibility with spine workflows; pricing and procurement relationships with hospitals are core strengths.
-
Heraeus & Tecres — European-origin suppliers that compete on formulation specificity (high-viscosity, radiopacity) and regulatory craft for EU and broader markets.
-
Merit, IZI Medical, Xelite Biomed and others — smaller, nimble players focusing on differentiated delivery systems, RF-modulated cement systems, or recently cleared products to penetrate the US market.
Recent regulatory and product developments underline near-term shifts in competitive positioning: several entrants obtained US clearances in late 2024–2025 and new antibiotic PMMA launches in 2025 signal pockets of rapid product refresh. These moves increase clinical choice and can compress pricing unless matched by demonstrable outcome advantages.
Strategic recommendations for 2026
-
Prioritize clinical differentiation backed by evidence — invest in prospective registries or limited randomized studies that show procedure-time savings, leak reduction, or infection mitigation; these datapoints materially improve contracting outcomes with hospital systems.
-
Pursue regulatory efficiency with sterilization-first design — embed validated sterilization pathways early (including SAL documentation and pyrogen testing) to avoid late-stage delays and to reduce time-to-market risk.
-
Design resilient supply chains — secure secondary suppliers for critical monomers and radiopaque additives and include inventory buffering in commercial contracts to mitigate spikes in demand for vertebral augmentation seasons.
-
Segment go-to-market by hospital archetype — academic centers value clinical data and novel delivery systems; community hospitals prioritize cost, packaging and ease-of-use; tailor pricing and service bundles accordingly.
-
Explore adjacent value propositions — antibiotic-loaded PMMA, combined scaffold/adhesive approaches, or bundled augmentation systems (implant + cement) can unlock premium positioning if supported by clinical benefit.
-
Prepare for consolidation plays — use 2026 to identify bolt-on targets that provide formulation IP, regulatory dossiers, or regional distribution as part of defensible share gain strategies.
90–120 day tactical plan for executive teams
-
Complete a portfolio stress test: map each SKU against regulatory readiness, sterilization validation, and reimbursement exposure.
-
Kick off a focused registry protocol with 6–12 month interim endpoints to build hospital adoption cases.
-
Negotiate conditional supply agreements with secondary monomer suppliers and establish safety stock triggers.
-
Run pricing simulations by hospital archetype and prepare targeted contracting pilots for high-volume systems.
-
Scan for acquisition or partnership targets that close capability or geographic gaps and pre-draft integration playbooks.
Why this PW Consulting report is essential for 2026 planning
Leadership decisions in 2026 will be made at the intersection of clinical value, regulatory readiness and supply resilience. PW Consulting’s report combines a transparent, model-driven forecast with concrete operational tools — regulatory checklists, reimbursement playbooks, supplier templates, and M&A screening frameworks — to accelerate executive decision cycles and reduce execution risk. We surface not only where growth is likely to occur, but which commercial and technical levers move the needle on share and margin.
Next steps and how to access the intelligence
This briefing intentionally highlights the strategic framing, practical levers and competitive moves that will matter in 2026 without reproducing the report’s detailed segment-level tables and targetable numeric splits. For board-ready slides, market model access, or a tailored advisory workshop that maps these insights to your portfolio and risk appetite, contact PW Consulting for the full market study and executive-briefing package.
For detailed analysis of this topic, please visit the official page: Bone Cement for Spine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Magnesium Bisglycinate API Market to Expand at an 8.12% CAGR During 2026–2032
By PW Consulting, 2026-07-13
Magnesium Bisglycinate API Market: Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market research — the Magnesium Bisglycinate API Market Report (base year 2025, forecast period 2026–2032) — provides executive teams, business development leaders, and supply‑chain strategists with a concise, actionable roadmap for decisions to be taken in 2026. The global market has expanded steadily from USD 118.11 Million in 2020 to USD 174.50 Million in 2025 and is projected to reach USD 301.41 Million by 2032, representing a compound annual growth rate (CAGR) of 8.12% over the forecast horizon. This release summarizes the report’s strategic value, highlights the competitive environment, and outlines the practical tools included in the full study — while intentionally withholding granular sub‑segment tables so stakeholders must consult the full report for complete, proprietary segmentation and regional breakdowns.
Magnesium Bisglycinate API Market
Why this report matters in 2026
- Decision velocity: The magnesium bisglycinate value chain is at an inflection point where formulation trends (bioavailability, GI tolerability, longevity/sleep positioning) intersect with tightening raw‑material dynamics and evolving quality standards. Our report equips executives to move from reactive sourcing to proactive commercial strategies within the 2026 planning window.
- Resource prioritization: With clear topline growth and an identified mid‑single‑digit to high‑single‑digit CAGR, the study helps prioritize R&D spend, manufacturing scale‑up, and M&A screening across corporate and private equity portfolios.
- Risk calibration: The research synthesizes supplier concentration metrics, certification coverage and material‑cost signals to quantify operational risk and inform contingency planning for 2026 procurement cycles.
Market dynamics and drivers
The market’s steady expansion is underpinned by three structural dynamics: (1) a persistent premiumization of magnesium ingredients toward chelated, high‑tolerability forms that deliver demonstrable clinical and consumer benefits; (2) formulary diversification as dietary supplement, medical food and pharmaceutical channels each push for higher purity grades and documented supply chains; and (3) downstream product innovation that leverages magnesium bisglycinate’s profile for sleep, recovery and age‑management positioning.
Magnesium Bisglycinate API Market
On the supply side, material‑price volatility and upstream magnesium commodity trends are already influencing commercial terms and inventory strategies. Notable indicators in recent quarters include elevated magnesium hydroxide pricing and month‑on‑month increases in magnesium metal quotations — all of which translate to compressed margin windows for producers that do not enjoy scale or manufacturing efficiency. Separately, the broader magnesium compounds market is projected to sustain multi‑year expansion, reinforcing long‑term demand for refined, application‑ready APIs such as magnesium bisglycinate.
Magnesium Bisglycinate API Market
Competitive landscape — what executive teams need to know
The market structure is best described as moderately concentrated: the top three players account for a meaningful share of supply, while the top five further extend market control, leaving room for regional producers and specialty suppliers to coexist. This mix creates a market where scale and brand reputation matter, but opportunities remain for differentiated entrants focused on certification, clinical substantiation, or integrated service offerings.
- Established European specialty producers have positioned premium, fully reacted chelates with a strong emphasis on documented manufacturing standards and clinical tolerability claims. Their product stories resonate with pharmaceutical and medical‑food formulators who require tight batch consistency and third‑party certifications.
- Large Indian API manufacturers have reinforced the market’s supply base by offering cGMP‑aligned product sets and an emphasis on compliance documentation (including DMF/USDMF and EU GMP portfolios). These suppliers are strategically important for cost‑competitive sourcing and rapid order fulfillment in APAC and emergent markets.
- US‑based technology licensors and branded chelate providers differentiate through proprietary chelation platforms and clinical research, targeting the nutraceutical and premium supplement segments where absorption and GI tolerability drive purchasing decisions.
- Smaller, GMP‑audited manufacturers and exporters remain relevant for regional formulators and as alternate sources during supply disruptions; their agility in custom‑packaging and niche regulatory coverage remains a competitive asset.
Recent corporate movements further crystallize strategic positioning for 2026: certification renewals and food‑safety accreditations reinforce supply reliability claims; targeted product positioning (e.g., sleep and longevity formulations) illustrates how ingredient owners are aligning with downstream marketing trends; and R&D publications from select producers underscore the importance of clinical and bioavailability evidence as a commercial moat.
Implications for commercial strategy and M&A
- Supplier segmentation: Buyers should classify suppliers across three axes — technical differentiation (proprietary chelation, particle form), regulatory/certification footprint, and commercial flexibility (MOQs, lead times). This triage enables a dual‑track sourcing strategy combining preferred partners and tactical alternates.
- Pricing & margin management: Given upstream commodity signals, manufacturers with vertical integration or hedging strategies can sustain margin, while formulators should examine pass‑through mechanisms and product premiumization to protect archetypal margins.
- M&A and partnership playbook: Targets that combine documented regulatory dossiers, geographic diversification, and niche clinical claims are most attractive. For private equity, bolt‑on plays that add GMP capacity or expand certification portfolios can accelerate access to higher‑value pharma and medical‑food channels.
Operational and regulatory considerations
Quality and traceability remain decisive differentiators. The market rewards suppliers who can demonstrate robust manufacturing systems (cGMP, WHO/ISO frameworks, batch traceability and DMF/CEP filings). For pharmaceutical and medical‑food customers, consistent certification and audit readiness are non‑negotiable. Our fieldwork highlights that buyers are increasingly incorporating supplier audit scores, certificate longevity, and third‑party testing into multi‑year sourcing contracts — not merely as compliance checks but as commercial negotiation levers.
From a manufacturing perspective, formulators should consider particle form, hygroscopicity, and stability profiles as early inputs to product design — these upstream decisions materially affect downstream processing costs and product shelf life. The report’s operations chapter includes practical checklists and factory acceptance criteria for procurement teams evaluating new suppliers in 2026.
What the PW Consulting report delivers (practical takeaways)
- Topline projection model: An interactive revenue model covering 2026–2032 with scenario toggles for commodity stress, certification-driven premiuming, and adoption curves across end‑use categories.
- Supplier scorecards: Proprietary benchmarking that compares manufacturing certifications, dossier maturity, clinical evidence, capacity flexibility and commercial terms — designed for rapid vendor short‑listing.
- Commercial playbooks: Negotiation scripts and contracting templates that reflect current price dynamics, lead‑time realities and quality assurance obligations.
- Risk scenarios and contingency playbooks: Supply disruption simulations tied to raw‑material price shocks and capacity outages, with recommended mitigation pathways (dual sourcing, safety stocks, toll‑manufacturing arrangements).
- Regulatory and documentation tracker: A living checklist of DMF/USDMF/CEP filings, FSSC/ISO certificates and publication milestones to prioritize supplier engagement and due diligence.
To preserve competitive edge, the report withholds proprietary sub‑segment tables and the granular regional/application breakdowns from this summary. These tables (including purity‑grade and application‑level breakdowns, regional forecasts and supplier share estimates) are part of the full deliverable and are essential for tactical procurement and investment decisions.
Next steps for executives in 2026
- Procurement leaders: Use the supplier scorecards and risk scenarios to finalize your 2026 dual‑sourcing strategy and to define acceptable inventory buffer levels.
- Business development and BD‑M&A teams: Screen acquisition/opportunity lists against the report’s M&A playbook and perform accelerated due diligence on targets with strong certification portfolios or proprietary chelation technologies.
- R&D and product teams: Prioritize formulation tests that validate claimed bioavailability benefits and stability under your packaging systems — early validation will accelerate go‑to‑market timelines.
Accessing the full intelligence
PW Consulting’s Magnesium Bisglycinate API Market Report is designed as an operational instrument: it combines market projection models, supplier intelligence and executable playbooks to inform 2026 budgets, sourcing mandates and investment decisions. Readers of this summary should consult the full report to access the detailed sub‑segment forecasts, regional and application splits, and the supplier‑level dossiers that we intentionally omitted here to protect proprietary analysis.
For executives who require a briefing or a tailored workshop to translate the report’s findings into a 90‑day action plan, PW Consulting offers dedicated advisory sessions and customized supplier due‑diligence engagements.
For detailed analysis of this topic, please visit the official page: Magnesium Bisglycinate API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 3.8% CAGR for TDI 80/20 Market (2026–2032) in New Market Insights Report
By PW Consulting, 2026-07-13
TDI 80/20 Market — TDI 80/20: Strategic Imperatives for 2026 Decision‑Makers (TDI 80/20 Market — TDI 80/20 Market Report, TDI 80/20 Market — TDI 80/20 Market Research)
Executive summary
PW Consulting’s TDI 80/20 Market — TDI 80/20 Market Report (base year 2025; historical window 2020–2025; forecast period 2026–2032) delivers a focused, decision‑grade playbook for corporate strategy, capital allocation, and procurement optimization in the global TDI 80/20 value chain. The market is valued at approximately USD 2,850 million in 2025 and, under our central scenario, grows at a compound annual growth rate (CAGR) of 3.8% to reach roughly USD 3,700 million by 2032. The near‑term profile includes a modest post‑2025 rebalancing before recovery into the late 2020s driven by capacity additions, energy and feedstock volatility, and regulatory pressure.
TDI 80/20 Market
Why this report matters for 2026 planning
-
Actionable timing: Our cross‑check of recent capacity moves, modernization programs and trade policy shifts identifies specific windows in 2026 when sourcing, hedging and investment decisions will capture outsized value — particularly for foam converters, CASE formulators and upstream feedstock integrators.
TDI 80/20 Market -
Risk triage: We quantify seven operational and market risks (feedstock cost shocks, localized trade barriers, safety/regulatory compliance, concentrated supply, energy transition exposure, technology obsolescence, and logistics bottlenecks) and prioritize mitigation measures that fit typical corporate risk appetites.
TDI 80/20 Market -
Competitive signals: The report synthesizes primary and secondary research on incumbent producers, revealing how recent capacity and efficiency actions reshape regional sourcing dynamics and margin pools in 2026–2028.
Market trajectory — what the headline numbers hide
The headline CAGR of 3.8% to 2032 masks a two‑phase trajectory that should directly influence 2026 decisions. After a near‑term inventory and price adjustment, driven by feedstock volatility and selective capacity startups, the market re‑accelerates as demand for flexible polyurethane foam and other polyurethane segments regain momentum. Importantly, the market concentration is material: the top three producers account for a majority share of capacity, and the top five approach four‑fifths of supply — a structural factor that amplifies the impact of individual producer investments and outages on global availability and pricing.
Primary demand and cost drivers (what matters in 2026)
-
Feedstock price dynamics: Toluene price pressure is a direct, measurable input to TDI 80/20 manufacturing economics. Recent northeast Asia price moves—sharp appreciation in the referenced period—translate into single‑digit to double‑digit percentage shifts in cash‑cost curves for exposed producers. Procurement teams must build scenario hedges and supplier scorecards that account for at least three realistic toluene paths over 12–24 months.
-
Energy and decarbonization initiatives: Plant modernizations that capture reaction energy for steam generation materially change unit economics and CO2 intensity. Facilities that lower energy and emissions profiles will enjoy regulatory and off‑taker advantages in markets where downstream purchasers are imposing carbon criteria.
-
Regulatory and occupational safety: TDI remains tightly regulated globally as a respiratory sensitizer. Occupational exposure limits from agencies such as OSHA and guideline values like those from ACGIH create compliance cost floors. Companies must treat occupational safety and REACH‑style chemical management as strategic investments — not just compliance items — because they affect licensing, insurance, and customer acceptance.
-
Trade policy and protectionism: Antidumping and other trade measures can create sudden regional dislocations in supply and pricing. Ongoing duties in major markets are already influencing sourcing decisions and will remain a lever for domestic policy makers through 2026.
Competitive landscape — what recent moves tell us
The competitive map is being redrawn by two simultaneous dynamics: (1) large, integrated capacity additions from resource‑rich incumbents and (2) targeted efficiency investments in legacy plants. Our firm view, based on primary interviews and plant‑level disclosures, is that these moves produce asymmetric advantages for both global exporters and regionally focused suppliers.
-
Large Chinese integrated producers: Recent capacity startups significantly expand global outbound availability from certain Chinese producers. These investments are purpose‑built to serve both domestic foam chains and export markets. For buyers and investors, this means short to medium‑term pricing pressure in exposed corridors but an eventual leveling as trade barriers and freight dynamics reassert themselves.
-
European energy/efficiency upgrades: Select European players have completed modernization projects that reduce energy intensity and emissions per tonne. These projects change competitive positioning by lowering variable cost and improving access to customers with sustainability procurement mandates.
-
Regional producers and market protection: Local producers in major consumption markets retain strategic advantages through proximity, regulatory familiarity and, in several cases, targeted trade defense policies that sustain higher local realizations.
Spotlight: tactical developments to watch in 2026
-
Capacity startups that came online in late 2025 will be the proximate trigger for a short‑term supply cadence reset; monitoring ramp rates is essential for procurement timing.
-
Plant modernizations that recycle reaction heat into steam and other utilities materially reduce energy exposure and CO2 output; these projects are the differentiator for long‑term cost leadership.
-
Trade remedies enacted through 2026 will continue to reallocate supplier‑buyer relationships and may force relocation or reshoring discussions among exposed downstream players.
Implications for 2026 corporate decision‑making
-
Procurement: Move from transactional spot buying to layered coverage: short‑term tactical pools, medium‑term indexed contracts tied to energy/feedstock benchmarks, and strategic supply agreements with performance and service metrics. Include clauses for force majeure, trade duty pass‑throughs, and sustainability attributes.
-
Operations & CAPEX: Prioritize retrofit opportunities that deliver rapid energy and emission paybacks. Greenfield or brownfield investments should be timed to capture windows when incumbent ramp‑ups temporarily depress input prices and labor availability.
-
M&A and JV strategy: Target bolt‑on positions in logistics hubs and feedstock integration rather than only seeking new polymer capacity. Minority stakes with offtake rights in modernized facilities yield outsized optionality while limiting capital exposure.
-
Regulatory & safety governance: Strengthen chemical safety programs and product stewardship capabilities. Compliance excellence is now a commercial differentiator in tender processes where purchasers insist on supplier safety records and low‑emission footprints.
What the PW Consulting TDI 80/20 Market report contains (practical deliverables)
-
Quantitative market model (2020–2032) with base case, upside and downside scenarios, sensitivity runs for feedstock and energy, and a policy shock module designed for CFO stress testing.
-
Supplier scorecards and mapped value chains for strategic sourcing, including plant‑level capability, retrofit potential and logistics latency analysis.
-
Commercial playbooks for buyers, manufacturers and investors — containing contract language templates, risk allocation recommendations and a prioritized list of mitigations for the top seven risks identified.
-
Competitive profiles of the major producers with operational summaries and strategic intent indicators based on announced capacity, modernization projects, and public filings.
-
Regulatory and occupational safety annexes that summarize relevant limits, compliance costs and engagement templates for global regulators and trade authorities.
How PW Consulting’s insight is different
We combine plant‑level engineering economics with procurement scenario planning and regulatory foresight. Rather than merely publishing descriptive segmentation, our report offers executable guidance: when to hedge, when to invest, and which supplier strategies will preserve margin through feedstock and policy cycles. To preserve commercial sensitivity and to encourage a calibration with real operational parameters, detailed region/application split tables and producer‑specific financials are available exclusively in the full report download and interactive dashboard.
Next steps for executives and investors
-
Review the scenario appendix and run the policy‑shock module against your current procurement book to identify exposure timing in 2026.
-
Engage with a short advisory to model a retrofit vs. new‑build decision under the energy and emissions sensitivities set out in the report.
-
Use supplier scorecards to re‑negotiate 12–24 month contracts with clauses for trade remedy pass‑through and sustainability credits.
Accessing the full intelligence
This release frames the strategic implications from PW Consulting’s TDI 80/20 Market — TDI 80/20 Market Report. The full report contains the complete segmentation tables, plant‑level data, producer‑specific metrics and the downloadable market model that drive the recommendations summarized here. For licensing, enterprise access and bespoke advisory services to operationalize these findings in 2026, please visit the TDI 80/20 Market report page or contact our industry desk for a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: TDI 80/20 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Open Circuit Combustible Gas Detector Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on the Open Circuit Combustible Gas Detector market provides a focused, decision-grade vantage point for corporate leaders planning capital allocation, product strategy, and M&A activity in 2026. Anchored to a 2025 base year with a historical window covering 2020–2025 and a forecast horizon stretching 2026–2032, the study projects a steady expansion at a compound annual growth rate (CAGR) of 6.85% across the forecast window. The market has grown from roughly USD 142 Million in 2020 to about USD 201 Million in 2025, and our base forecast anticipates it reaching in excess of USD 320 Million by 2032. These headline figures frame a clear growth trajectory—but beneath them lie operational and strategic inflection points that will determine winners and laggards in 2026 and beyond.
Open Circuit Combustible Gas Detector Market
Why this matters for 2026 corporate decision-makers
- Safety compliance is increasingly non-negotiable. Performance standards and approvals (for example, industry-recognized criteria such as ANSI/ISA and FM approvals) are driving procurement toward devices with demonstrable field reliability and certification pedigrees.
- Technology differentiation is accelerating. Infrared open-path systems retain broad industrial relevance, while laser-based and other advanced detection modalities are competing on sensitivity, false-alarm rejection, and lifecycle cost.
- Supply-side dynamics are squeezing margins. Inflationary pressure on raw materials and sensor components is affecting manufacturing cost curves and time-to-market for next-gen products.
- Market structure allows for selective consolidation. The market concentration metrics indicate a moderate cluster of leading vendors alongside a robust long tail of specialist suppliers—creating M&A and alliance opportunities for scale, channel depth, and technology access.
Key strategic implications (executive summary)
- Prioritize certified product lines for core accounts. Buyers increasingly privilege devices with proven field performance and relevant certifications—invest in testing, certification, and transparent reliability data.
- Shift from CAPEX-only selling to lifecycle value propositions. Differentiation through service contracts, predictive maintenance, and remote diagnostics will create recurring revenue that offsets raw-material-driven margin compression.
- Accelerate selective investment in next-gen modalities. Laser-based and advanced IR sensors promise technical advantages in select use cases; pilot deployments in high-value sites will shape 2027+ procurement cycles.
- Hedge supply-chain exposure. Near-term inflation and component scarcity demand supplier consolidation, strategic sourcing, and inventory strategies to protect delivery commitments.
- Scan the M&A horizon. Moderate market concentration and technology gaps among incumbents make acquisitions of niche innovators and regional channel partners an efficient route to scale.
What the PW Consulting report delivers (practical contents)
- A transparent, model-backed market sizing and forecast (2026–2032) with scenario variants that stress-test upside and downside cases against energy transition, regulatory tightening, and raw-material volatility.
- A deployable commercial playbook: customer segmentation, procurement triggers, pricing sensitivity templates, and recommended service-pack architectures to convert pilots into recurring revenue.
- Competitive benchmarking and positioning grids that combine product capabilities, certification status, installed-base reach, and channel strength into investable insights (note: detailed sub-segment share tables and raw values are reserved for subscribers).
- Technology roadmaps and R&D priorities, including integration checklists for laser, infrared, catalytic, and hybrid detection approaches and practical test protocols for field validation.
- Supply-chain risk maps and a cost-driver model that quantify the impact of raw-material price moves on unit economics and margin scenarios.
- A curated shortlist of acquisition and partnership targets based on capability fit, commercial reach, and valuation heuristics.
Competitive landscape: profiles and strategic takeaways
- Emerson (Rosemount / Spectrex) — Emerson’s portfolio is anchored by field-proven infrared open-path products that serve harsh hydrocarbon environments. Its strength is an installed base and deep OEM/enterprise channel relationships. Strategic takeaway: incumbency and integration depth make Emerson a de facto partner or a competitor to be matched on service and certification rather than price.
- MSA Safety — With offerings spanning infrared detectors and next-gen connected portable devices, MSA is pushing both product innovation and connectivity. Recent product introductions in connected detection underscore its move to embed monitoring into broader safety ecosystems. Strategic takeaway: position against MSA by accelerating connected diagnostics and offering superior false-alarm rejection in industrial deployments.
- Teledyne Gas & Flame Detection — Teledyne’s preview of next-generation devices and laser-based detectors signals aggressive technology investment. Expect targeted wins where sensitivity to specific gas species or long-range detection is critical. Strategic takeaway: monitor new product launches closely and prioritize technical trials in customers with demanding detection specifications.
- GDS Corp — As a distributor and systems integrator, GDS is a key channel partner for manufacturers looking to broaden reach in industrial segments. Strategic takeaway: channel partnerships with distributors like GDS accelerate deployment in segmented industrial pockets—evaluate exclusive or prioritized distribution agreements where appropriate.
- Det-Tronics (UTC Group) — Det-Tronics’ open-path solutions are oriented toward continuous hydrocarbon monitoring with an emphasis on system reliability. Strategic takeaway: compete on demonstrable uptime, reduced false positive rates, and integrative capability with site safety systems.
Regulatory and supply-side dynamics to watch in 2026
- Standards compliance is a table-stakes requirement. Meeting established performance requirements and approvals materially affects buyer shortlists and insurance acceptance; manufacturers should accelerate certification timelines and publish third-party test results.
- Raw-material cost inflation is not transitory for all vendors. Rising component and sensor costs compress gross margins and create incentives for product redesign or price escalation; proactive cost-to-serve analysis and supplier hedging are practical mitigants.
- False-alarm rejection and data integrity will be differentiators. Buyers reward devices that reduce nuisance trips because these devices lower total cost of ownership and site disruption risk.
Market concentration and competitive opportunity
Market concentration metrics indicate a moderate degree of aggregation: the three largest firms account for a meaningful minority of market share, while the top five capture a clear majority. This structure implies that well-executed scale plays—whether through organic channel expansion or targeted tuck-ins—can rapidly change competitive dynamics. For incumbents, the task is defending margin and installed-base services; for challengers, the opportunity is to offer differentiated technology or local service excellence to win share.
Open Circuit Combustible Gas Detector Market
90-day action plan for executive teams
- Initiate certification fast-tracks for priority products and publish independent test results to shorten procurement cycles.
- Run cost-to-serve and component-sensitivity stress tests; identify top 3 cost levers to protect gross margin under +10% raw-material inflation scenarios.
- Set up 2–3 field pilots for next-gen sensors with strategic customers to gather performance and service data under real operating conditions.
- Conduct a rapid channel health check: top distributors, integrators, and service partners—identify single points of failure and redundancy plans.
- Compile a short M&A watchlist of 6–8 targets (technology specialists, regional leaders, service platforms) and commence initial diligence on cultural and systems fit.
How to use the full PW Consulting study
This briefing is intentionally selective—a “trailer” that surfaces the most consequential strategic insights while withholding granular sub-segment tables and confidential company scorecards. The full report contains the underlying market model, detailed segmentation by region, type, and application, complete competitive scorecards, pricing matrices, and downloadable datasets that operational teams can use in procurement, R&D prioritization, and M&A underwriting. Organizations that need executable plans—detailed product roadmaps, go-to-market playbooks, and a prioritized list of acquisition targets with valuation heuristics—will find those deliverables in the full study.
Open Circuit Combustible Gas Detector Market
Next steps
- Request the full report and dataset to access the withheld sub-segment detail and company-level scorecards.
- Engage PW Consulting for a tailored two-week diagnostic: we will translate the market model into a bespoke strategic plan aligned to your portfolio, channels, and balance sheet.
PW Consulting — We combine field-tested industry insight, rigorous modeling, and practical playbooks to help safety-technology firms and industrial operators translate market growth into profitable, sustainable advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Open Circuit Combustible Gas Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Nappa Leather Market Poised for 5.22% CAGR, Signaling Robust Growth Through 2032
By PW Consulting, 2026-07-13
Nappa Leather Market — Strategic Outlook 2026: Navigating Growth, Supply Risk, and Sustainable Differentiation
Executive summary
PW Consulting’s new Nappa Leather Market report delivers an actionable intelligence package tailored for executives making procurement, product, and M&A decisions in 2026. The global Nappa leather market has demonstrated steady expansion — growing from approximately USD 2.52 billion in 2020 to about USD 3.22 billion in 2025 — and our baseline forecast projects continued expansion to roughly USD 4.59 billion by 2032 under a 5.22% CAGR. This trajectory reflects ongoing demand across automotive interiors, furniture and upholstery, premium fashion, and footwear, combined with technology-driven substitution dynamics in advanced synthetic Nappa alternatives.
Nappa Leather Market
Why this report matters for 2026 corporate decision-making
- Timing: 2026 is a pivot year. OEM product specifications are shifting (notably in premium vehicle segments) and regulatory thresholds for chemical use and traceability will materially affect sourcing and capital plans.
- Strategic levers: The market remains fragmented (low top-three/top-five concentration), meaning buyers can still capture supplier leverage — but only if they act with precise, data-driven supplier segmentation and contract design.
- Risk / opportunity balance: Natural Nappa retains brand equity in luxury segments while high-performance synthetic Nappa is gaining OEM acceptance; companies must decide where and when to pivot, hedge, or dual-source.
Market trajectory and forecast — what the headline numbers tell you
Our macro model integrates historical performance (2020–2025) and scenario-based forecasts for 2026–2032. Key takeaways: the market is growing at a mid-single-digit CAGR (5.22% across the forecast horizon), driven by premiumization in automotive and furniture segments, the expanding middle-high consumer cohorts in select emerging markets, and increasing specification of premium upholstery in lifestyle and transport applications.
Nappa Leather Market
For decision-makers, these headline figures are not an end in themselves but a directional foundation: they validate investment in capacity optimization, justify selective premiumization of product lines, and quantify upside for elastic pricing strategies tied to brand and sustainability credentials.
Nappa Leather Market
What’s inside the report — practical, executable deliverables
- Proprietary market-sizing and scenario models (base case, OEM-adoption upside, rapid-substitution downside) with transparent assumptions so clients can run custom sensitivity tests.
- Supplier scorecards and procurement playbooks — inclusive of quality, lead-time, sustainability certifications, traceability maturity, and cost-to-serve benchmarks — designed for fast integration into SRM systems.
- Unit-economics comparisons: natural versus synthetic Nappa across CAPEX, OPEX, lifecycle emissions estimates, and working-capital implications (we show pivot points where synthetic becomes cost-advantageous at scale).
- Regulatory impact assessments and compliance checklists (chemical restrictions, certification timelines, supplier audit templates) with specific action items tied to known 2026 regulatory milestones.
- M&A and JV diligence templates: valuation sensitivities, integration risk heatmaps, and bolt-on targets by capability (high-volume supply, specialty tanning, traceability tech).
- Commercial tools: sample contract clauses to allocate price, quality, and sustainability risks; inventory hedging templates; and SKU-level sourcing decision frameworks.
Competitive landscape — how leading players are positioned
The Nappa leather sector remains characterized by many specialized tanneries, regional champions, and a handful of internationally recognized suppliers. Market concentration is low (CR3 ~18.5%, CR5 ~24.35%), underscoring a competitive ecosystem of niche leaders rather than dominant global oligopolies. This structure shapes strategic options for buyers and investors in 2026:
- ECCO Leather (Denmark) — Strength: premium sustainable Nappa solutions with advanced tanning and traceability. Strategic advantage: vertically integrated R&D and strong footwear-to-automotive cross-selling potential; watch for partnerships that move traceability from marketing to verified supply chain control.
- Gruppo Mastrotto & Dani (Italy) — Strength: Italian craftsmanship and finishes for luxury automotive and fashion. Strategic advantage: heritage positioning allows price premiums and co-development with premium OEM lines.
- Heller-Leder, Elmo Sweden, Boxmark — Strengths: automotive-grade performance, environmental compliance, and finish engineering. Strategic imperative: deepen OEM integrations and certify against evolving interior air-quality and chemical restrictions.
- Horween, Wickett & Craig, Hermann Oak, Scottish Leather Group — Strengths: premium, small-batch, and specialty leathers serving luxury accessories and aviation/interiors niche markets. Strategic play: defend brand premium while scaling traceability and eco-claims.
- JBS Couros, Durli Leathers (Brazil), Kartik Leather (India), Jinjiang Guotai and Quanzhou Solamni (China), Wai Hing (HK/China), KOKTASLAR (Turkey) — Strengths: scale manufacturing, export orientation, and competitive cost structures. Strategic note: these players are critical to managing global capacity and price volatility.
Across the board, expect consolidation opportunities for buyers seeking secure capacity via long-term partnerships and for private-equity investors targeting vertically integrated platforms that combine finish technology with sustainability credentials.
Industry dynamics and regulatory signals you cannot ignore
- Processing chemistry and compliance: chrome tanning remains the dominant process to achieve Nappa’s characteristic soft grain and suppleness. However, environmental and chemical governance is rising in importance — certifications like ISO 14001 and OEKO-TEX are table-stakes for premium contracts.
- Regulatory inflection: U.S. EPA’s 2024 rule banning distribution of articles containing PIP (3:1) in commerce from October 31, 2026 introduces an operational cliff for manufacturers and tanneries that rely on legacy processing equipment or inputs. Firms must audit chemical inventories, map potential exposures, and have substitution plans in place well ahead of that date.
- Raw material economics: cowhide base prices vary by grade and region; typical market references show low-to-mid single-digit USD per square foot ranges for cowhide inputs. Buyers with flexible sourcing strategies and hedging instruments will mitigate margin pressure during supply tightness.
- OEM adoption signals: recent vehicle introductions and concept integrations demonstrate both continuing demand for natural Nappa and growing legitimization of synthetic Nappa alternatives. These OEM moves are early indicators for specification engineers and procurement teams evaluating pilot programs in 2026.
Practical 2026 playbook — recommended actions by function
- Chief Procurement Officer: initiate a supplier risk heatmap and secure diversified supply lanes. Negotiate conditional contracts that include price collars and quality KPIs tied to sustainability certification milestones.
- Head of Product / Design: define clear application rules for natural vs synthetic Nappa. Run controlled pilots with synthetic Nappa in non-flagship SKUs to validate customer perception and durability claims before broader roll-outs.
- Head of Sustainability & Compliance: complete a chemical inventory and supplier audit before Q3 2026 to avoid PIP exposure. Prioritize suppliers with ISO 14001/OEKO-TEX and documented animal welfare traceability for premium assortments.
- M&A / Strategy teams: use our diligence templates to screen for tuck-ins that add finish technology, traceability platforms, or regional capacity in growth corridors; target assets that raise CRV (customer retention value) rather than raw volume.
- Finance / Treasury: model working-capital impacts of longer lead times and recommend targeted inventory hedging for critical hide grades to smooth input-price volatility.
How to use this report — the “trailer” and where to go next
This release is intentionally designed as a strategic trailer: it demonstrates the analytical depth and operational orientation of PW Consulting’s full study while withholding detailed regional and application-level splits that are reserved for the full report and client workshops. Subscribers and clients will receive:
- Full regional and application breakdowns, segmented supplier economics, and SKU-level pricing curves.
- Interactive Excel models to run sensitivity tests against your specific volumes, geographic footprints, and product mixes.
- Access to bespoke advisory sessions to translate the findings into executable sourcing contracts, product roadmaps, and M&A screens tailored to your risk appetite and growth ambitions.
Closing — decision points and immediate next steps for 2026
2026 will separate organizations that react tactically from those that re-shape their leather strategies. The market is sizable and growing, but value will migrate to firms that combine procurement discipline, sustainability compliance, and product differentiation — while remaining agile to OEM specification shifts and synthetic leather innovations. Use our report to convert headline market growth into a prioritized, time-bound action plan for procurement, product, and corporate development.
To access the full dataset (regional/application splits, supplier scorecards, and the interactive forecast model) and to schedule a briefing with PW Consulting’s leather and automotive interiors practice, visit our report page or contact your PW account executive.
For detailed analysis of this topic, please visit the official page: Nappa Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Castor Oil Modified Polyol Market Poised to Expand at 7.02% CAGR, Reaching USD 492.7 Million by 2032
By PW Consulting, 2026-07-13
Castor Oil Modified Polyol Market — Strategic Outlook for 2026: An Executive Preview
Executive summary
PW Consulting’s latest Castor Oil Modified Polyol Market study frames a fast-evolving value chain that is shifting from niche bio-based experimentation toward industrial-scale adoption. The global market, which PW Consulting tracks on a USD Million revenue basis, expanded from an estimated USD 218.4M in 2020 to USD 306.4M in our 2025 base year and is forecast to continue rising through the 2026–2032 horizon, reaching an estimated USD 492.7M by 2032. This trajectory implies a compound annual growth rate of approximately 7.02% over the forecast period — a growth profile that is large enough to justify strategic resource allocation but still concentrated enough to reward targeted moves on technology and supply chain.
Castor Oil Modified Polyol Market
Why this preview matters for 2026 decision‑makers
-
Investment timing — The mid-single-digit-to-high-single-digit CAGR underlines a window in which first-mover or fast-scaler advantages translate into long-term commercial relationships with formulator OEMs, particularly in coatings, adhesives and polyurethane systems.
Castor Oil Modified Polyol Market -
Raw material risk management — Castor seed and oil remain the systemically critical feedstock. Global castor oil market volumes were approximately 965–978 KMT in 2025, with India continuing as the dominant supplier. Buyers and producers must bake in volatility: our prices and procurement scenarios show material quarter-to-quarter swings that affect gross margins and competitive positioning.
Castor Oil Modified Polyol Market -
Regulatory arbitrage — Stricter VOC/VOC‑adjacent policies in the EU and progressive procurement preferences (bio-preferred incentives) are creating demand pull for certified bio-content chemistries. At the same time, policy changes such as China’s April 1, 2026 cancellation of the VAT export rebate for polyether polyols will alter relative cost differentials and could re-shape trade flows and import parity economics through 2026–2027.
-
Consolidation and supplier concentration — The market exhibits moderate concentration: the three largest suppliers account for a meaningful share of the market, with the top five approaching half of reported revenues. Strategic buyers should therefore map dependency and optionality across the supply base now.
-
Technology and go‑to‑market choices — Differentiation is increasingly achieved via low‑viscosity, high bio-content grades, waterborne variants, and grades engineered for specific CASE and foam formulations. Product stewardship (certifications, documentation, formulation support) is becoming as important as price in commercial win rates.
Market dynamics and implications
The market’s growth is driven by three overlapping forces: demand-side policy and procurement preferences that favor renewable inputs; formulation-led substitution in established polyurethane and CASE supply chains; and industrial players moving to secure castor-based capacity as feedstock economics become better understood. Environmental regulation — from EU REACH and the Green Deal to US TSCA/EPA guidance and procurement standards — is accelerating adoption among formulators that must meet VOC limits and demonstrate bio-based credentials.
Supply-side dynamics remain anchored in agricultural cycles and geopolitics. India’s dominant position in castor seed supply creates both opportunity and vulnerability: when yields or harvest acreage change, FOB price indices and regional trading spreads react quickly. Our scenario workbench models show that average castor oil price swings materially affect margins for both modified polyol producers and downstream formulators, and they amplify incentives for vertical integration or long‑term offtake agreements.
Competitive landscape — strategic takeaways
Market participants fall broadly into three strategic archetypes: global chemical majors with portfolio breadth and certification capabilities; regional castor-specialist producers with proximity to feedstock and cost advantages; and nimble formulators supplying tailored grades and services. Key companies to watch:
-
Alberdingk Boley GmbH (Krefeld, Germany) — Their ALBODUR® portfolio and the July 2025 technology documentation update signal a play focused on high-solid, solvent-free systems and downstream formulation support. The emphasis on certified biobased content and application guidelines is a template for premium positioning in corrosion protection and industrial floor coatings.
-
Jayant Agro‑Organics / Vithal Castor Polyols (Jhagadia, India JV) — Recent capacity announcements (site opening in November 2025) reinforce the strategic value of feedstock proximity. Their vertically integrated model is a core risk-mitigation and cost-leadership enabler for downstream customers looking for stable supply.
-
BASF SE — As a global major, BASF’s natural-oil polyols and branded solutions (e.g., SOVERMOL®, Lupranol Balance series) combine performance claims with global commercial reach and technical service. Their playbook underscores the importance of combining product performance with compliance certification.
-
Stepan Company — Focused grades and reactivity control (STEPANPOL® family) position them to win in controlled production environments and reactive polyurethane systems where processing consistency matters.
-
Regional and specialist players (Eagle Specialty Products, Gokul Overseas, Emirachem, Modi Oil Mill) — These suppliers compete on specialized grade ranges, custom blending, and agility. Their value is highest for customers requiring tailored low-volume formulations, local logistics advantages, or specific sustainability narratives.
What the PW Consulting report delivers (practical modules)
This study is designed as a directly actionable briefing for commercial leaders, product managers, procurement teams, and corporate development groups preparing decisions in 2026. Core modules include:
-
Market sizing and proven methodology — full historical reconciliation 2020–2025 and top‑down/bottom‑up triangulation for the 2026–2032 forecast.
-
Supply chain and cost build-up — feedstock-to-finished-good cost models, sensitivity analyses to castor oil price scenarios, and suggested hedging/contract structures.
-
Regulatory and certification matrix — mapping of REACH/TSCA/Green Deal implications, bio-preferred certification pathways, and compliance timelines.
-
Competitive benchmarking — vendor scorecards, capability heatmaps, recent developments and capacity tracker (including the July 2025 & November 2025 updates), and tactical playbooks for supplier negotiations.
-
Commercial playbooks — go-to-market templates for premium bio-content grades, waterborne strategies, and CASE/foam-focused application roadmaps.
-
M&A and partnership scouting — target criteria, valuation sensitivities, and a short‑list of mid-market acquisition and JV opportunities aligned to scale and feedstock integration.
-
Client-ready slide packs and data extracts — configurable datasets for board-level briefings and investment committees.
How to use this preview in 2026 planning
-
Procurement managers should re-run supplier stress-tests using the report’s price‑sensitivity templates and model the impact of China’s April 2026 VAT rebate cancellation on regional import parity and landed costs.
-
R&D and product leadership must prioritize two tracks: (1) enhancing formulation work to convert existing polyurethane systems to high‑bio-content castor polyols without performance trade‑offs, and (2) developing lower‑VOC, waterborne offerings supported by technical documentation and lifecycle claims.
-
Corporate development teams should evaluate smaller regional producers for bolt‑on capacities that improve feedstock optionality, or for access to application-specific formulations and customer book advantages.
-
Regulatory/compliance teams need to fast-track certification dossiers where required — procurement preferences and tender processes increasingly include bio-content proof points.
What we are intentionally withholding here — and why
In this executive preview we present market trajectory, strategic implications, and company-level signals; however, granular regional and application split tables, price-by-region series, and detailed segment-level revenue figures have been reserved for the full report and interactive datasets. This “preview” approach preserves the strategic value of the primary research while providing enough insight to inform near-term planning. For teams that require the complete tables, downloadable models, and bespoke regional breakdowns, PW Consulting provides a dedicated data pack and client workshop options.
Next steps
For 2026 planning cycles, a concentrated effort in Q1 will capture the highest value: update procurement contracts to incorporate hedging triggers, prioritize a two-phase R&D roadmap (fast followers for immediate wins; platform investments for 2028+), and accelerate supplier audits against bio-content and traceability criteria. PW Consulting is available to run a focused 48–72 hour rapid workshop to translate the report’s scenarios into an operational action plan tailored to your company’s footprint and risk tolerance.
To access the full dataset, proprietary segmentation, and the interactive cost models referenced in this preview, please visit our report page or contact your PW Consulting account lead to arrange a briefing and data license.
For detailed analysis of this topic, please visit the official page: Castor Oil Modified Polyol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infrared Light Therapy Device Market to Reach USD 616.32 Million by 2032, Growing at a 7.15% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Infrared Light Therapy Device Market — Strategic Outlook for 2026
PW Consulting’s new market brief on Infrared Light Therapy Devices equips executives with the evidence and tactical playbook needed to make high-conviction decisions in 2026. Built on a 2025 base year and a seven-year forecast window (2026–2032), the study projects continued expansion at a compounded annual growth rate (CAGR) of 7.15%. After a strong recovery through 2020–2025 (market value reached approximately USD 380 Million in 2025), the market is expected to expand materially through the forecast period, passing the USD 400 Million threshold in 2026 and approaching the mid‑hundreds of millions by 2032. This brief summarizes the report’s strategic value while deliberately reserving granular splits and financials to the full report—intentionally designed to prompt direct engagement with PW Consulting for the complete dataset, models, and vendor scorecards.
Infrared Light Therapy Device Market
Why this analysis matters for 2026 corporate strategy
- Timing of market entry: The sub‑segment growth dynamics and macro trajectory show that 2026 is a decisive year for product launches and regulatory initiatives. Firms that move from prototype to clinical validation now can capture disproportionate share as clinics and health systems scale adoption.
- Regulatory differentiation: FDA 510(k) requirements for Class II devices and the growing emphasis on clear therapeutic indications create barriers that favor players with clinical programs and regulatory experience.
- Reimbursement levers: Existing billing codes and therapy session allowances create a commercialization path for clinic-focused offerings; savvy payor strategies materially improve unit economics.
- Supply‑chain risk and cost structure: High‑power near‑infrared LEDs (especially ~850nm units) are a material portion of device BOM — our sector analysis shows these components can drive 20–30% of BOM — making supplier strategy and cost management a priority.
- Fragmented competitive landscape: Market concentration remains modest, indicating fertile ground for consolidation, partnerships, and white‑label opportunities for medical OEMs and clinical players.
What’s in the PW Consulting report (practical, decision-ready content)
- Executive summary with investment thesis and go/no‑go decision checkpoints for 2026.
- Market sizing and forecast model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario and sensitivity analysis.
- Segment methodology and assumptions (type, application, and regional frameworks) with downloadable model worksheets—note: detailed segment tables and revenue splits are available only in the full report.
- Commercialization playbooks for direct‑to‑consumer, clinic, and hospital channels including pricing models and reimbursement capture strategies.
- Vendor benchmarking and go‑to‑partner scorecards based on product capability, clinical evidence, regulatory status, distribution strength, and manufacturing readiness.
- Regulatory and reimbursement mapping: 510(k) pathways, applicable CPT codes, and payer engagement templates.
- Supply‑chain risk matrix and supplier negotiation playbook focused on high‑power LED sourcing, BOM optimization, and inventory strategies.
- M&A target shortlist, value‑creation levers, and integration risk checklists for roll‑up strategies in a fragmented market.
- Appendices: clinical evidence compendium, IP landscape snapshot, and raw data export for custom modeling.
Competitive landscape — who’s shaping the market
The market is currently driven by a mix of consumer wellness brands, clinical device manufacturers, and specialty medical laser companies. No single player dominates; the three‑ and five‑firm concentration ratios indicate a market that remains open to entrants with clinical credibility or differentiated go‑to‑market approaches.
Infrared Light Therapy Device Market
- Infraredi (USA) — Focused on portable panels for pain relief and recovery with devices covering the 660–850nm range. Competitive strengths: portability and targeted pain solutions for athlete recovery.
- Mito Red Light (USA) — Consumer and clinical panels with recent product upgrades. Strategic note: launched the MitoPRO+ series (Oct 2025), enhancing near‑infrared output to improve depth of penetration—an important move for clinic‑grade positioning.
- Joovv (USA) — Modular full‑body systems with near‑infrared capability. Strategic note: received FDA Class II clearance for a portable device in June 2025, adding an important regulatory credential for OTC pain indications.
- PlatinumLED Therapy Lights (USA) — High‑power BIOMAX panels combining red and near‑infrared LEDs; credible in both wellness and therapeutic use cases.
- Novaa Lab (USA) — Wearable devices like iTorus aimed at joint and targeted relief; represents the miniaturized/wearable axis of product strategy.
- Celluma (USA) — Clinic‑focused, FDA‑cleared LED devices with an evidence base for acne, aging, and pain; published data (March 2025) showing significant efficacy in arthritis pain reduction is a marketable clinical asset.
- NovoTHOR (UK) — Whole‑body bed systems for clinical recovery; notable for strategic distribution deals with hospital chains (e.g., November 2024), illustrating a hospital‑partnership route to scale.
- THOR Photomedicine (UK) — Portable and clinical near‑infrared lasers targeting wound healing and neurological indications; strengths include clinical depth and laser expertise.
- Multi Radiance Medical (USA) — Combines super‑pulsed laser with infrared LEDs for non‑invasive pain therapy; notable for device hybridization strategies.
- Erchonia (USA) — FDA‑cleared low‑level laser therapy devices with infrared wavelengths; strong clinical positioning in musculoskeletal therapy.
Key market dynamics and tactical implications
- Regulation is a gating factor: Non‑invasive infrared therapy devices are typically Class II and often require 510(k) clearance for pain indications. Firms that design clinical studies aligned to FDA expectations shorten time‑to‑market and reduce recall risk.
- Reimbursement unlocks clinical demand: Existing CPT codes and Medicare/physical‑therapy allowances create a repeatable revenue stream for clinic‑deployed systems; capture requires documented outcomes and clear billing pathways.
- Clinical evidence is becoming table stakes: High‑quality trials and peer‑reviewed results accelerate adoption among clinicians and payors. Recent positive outcomes (e.g., arthritis pain reductions) materially de‑risk hospital conversations.
- Component economics matter: Medical‑grade, high‑power LEDs (notably those near 850nm) are a key cost driver. Locking preferred pricing and secondary suppliers is essential to protect margins and avoid passthrough price shocks.
- Fragmentation = opportunity: With relatively low top‑tier concentration, incumbents and new entrants can grow via differentiation (wearables, whole‑body beds, hybrid laser/LED solutions) or consolidation.
Practical 2026 playbook — five recommended actions for executives
- Finalize your regulatory roadmap now: Decide between OTC, clinic, or hospital‑grade positioning and initiate the 510(k) and documentary programs aligned to that pathway.
- Invest in targeted clinical programs: Prioritize one high‑value indication (e.g., musculoskeletal pain or wound healing) to build a repeatable clinical case and payer argument.
- Secure LED supply and BOM resilience: Negotiate long‑term contracts with LED suppliers, validate secondary sources, and model BOM sensitivity in pricing scenarios.
- Design hybrid go‑to‑market channels: Combine DTC for consumer wellness with clinician partnerships for reimbursement capture; pilot hospital deployments with KOLs to accelerate adoption.
- Prepare for consolidation: Use the relatively low CR3/CR5 concentration to proactively screen acquisition targets—wearables, clinical bed makers, or companies with FDA clearances—to accelerate capability build‑out.
Why purchase the full PW Consulting report
This brief demonstrates the kind of actionable insight embedded in PW Consulting’s full report: robust scenarios, downloadable financial models, granular segmentation (by region, type, and application), vendor financial and product scorecards, go‑to‑market templates, and an M&A shortlist. To preserve the strategic value of our proprietary analysis, we have withheld the detailed numerical splits, regional revenue tables, and vendor revenue breakdowns from this summary. The full report includes those items plus Excel‑ready models you can drop into your planning cycle.
Infrared Light Therapy Device Market
For product teams, regulatory leads, corporate development groups, and investors planning activity in 2026, the full PW Consulting Infrared Light Therapy Device Market report is designed to reduce execution risk, sharpen strategic choices, and shorten time to market. Contact PW Consulting to obtain the complete dataset, vendor dossiers, and our 90‑day implementation roadmap.
For detailed analysis of this topic, please visit the official page: Infrared Light Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


