



Isoparaffin Solvents Market: Why 3.5% CAGR and $1.14B Trajectory Mask Hidden Shifts
By PW Consulting, 2026-09-21
Isoparaffin Solvents Market: Navigating the Strategic Crossroads of Sustainability, Compliance, and Growth
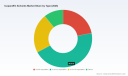
The isoparaffin solvents market has entered a phase of measured maturation, shaped by tightening environmental mandates, evolving application demands, and a competitive landscape that rewards precision and compliance. After reaching a valuation of approximately 905.16 million USD in 2025, the sector is projected to expand at a compound annual growth rate of 3.5 percent through 2032, culminating in a market size near 1,144.78 million USD. This trajectory reflects more than steady demand growth; it signals a structural shift in how formulators, manufacturers, and regulators evaluate solvent performance, safety, and sustainability.
While the broader market moves forward on a moderate growth curve, the underlying dynamics are anything but uniform. Revenue distribution across regions and applications reveals a market that is geographically diversified but application-concentrated, with heavy reliance on industrial and specialty formulations that demand high-purity, low-odor hydrocarbon solvents. The competitive field remains moderately fragmented, with the top three players capturing roughly 28.3 percent of market share and the top five holding about 32.1 percent. Such concentration suggests that scale, technical differentiation, and regional capacity positioning matter significantly, yet they also leave space for niche players and innovative entrants to compete on performance, compliance, and supply reliability.
As 2025 transitions into the forecast period, the isoparaffin solvents market is being reshaped by environmental compliance, feedstock economics, and application-specific performance requirements. These forces are not isolated; they intersect to create both constraints and openings for companies that can align product portfolios with emerging regulatory and operational realities.
Market Landscape: Performance, Pressure Points, and the 2026-2032 Trajectory
A Market Defined by Steady Expansion and Structural Complexity
The isoparaffin solvents market has demonstrated consistent expansion across the 2020-2025 period, supported by enduring demand in paints and coatings, metalworking fluids, agrochemicals, cleaning formulations, pharmaceuticals, and personal care. This breadth of use underscores the versatility of isoparaffinic hydrocarbons as low-aromatic, low-odor alternatives to traditional solvent systems. However, breadth does not imply uniformity. Demand patterns vary by end-use performance requirements, regional manufacturing footprints, and regulatory exposure, creating a market where growth is unevenly distributed across segments and geographies.
Forecasting through 2032 suggests continued expansion, but also highlights a market that must balance volume growth with margin discipline. Feedstock-linked cost volatility and regulatory compliance costs place pressure on producer economics, while downstream customers increasingly prioritize product consistency, purity, and documentation. In this environment, market growth is less a simple function of demand volume and more a result of value capture through differentiated grades, technical support, and supply reliability.
Critical Challenges and Inflection Points
Several structural challenges are reshaping the competitive and operational landscape for isoparaffin solvent producers and users.
- Feedstock volatility and margin sensitivity: The production economics of isoparaffin solvents are closely tied to hydrocarbon feedstock dynamics. Price swings, availability constraints, and energy cost fluctuations can compress margins and complicate long-term pricing strategies. This sensitivity forces producers to manage cost structures carefully while maintaining product quality that meets stringent application specifications.
- Regulatory tightening on VOCs and aromatic content: Environmental regulation continues to redefine the acceptable boundary for solvent use. In multiple regions, including parts of South America, restrictions on volatile organic compound emissions and aromatic content have become more rigorous, especially for paints, coatings, and adhesives. These rules accelerate the shift toward high-purity isoparaffin grades but also increase compliance burdens and formulation complexity for downstream users.
- Performance versus sustainability trade-offs: Downstream formulators face a dual mandate. They need solvents that deliver consistent dissolution, evaporation, and rheological behavior, while also meeting sustainability goals and regulatory limits. Balancing performance, odor, toxicity perception, and carbon footprint is becoming a core product selection criterion rather than a secondary consideration.
These challenges are not merely obstacles. They are inflection points that reward players with strong technical portfolios, dependable supply, and clear regulatory alignment. Companies unable to navigate these pressures risk margin erosion, substitution risk, or loss of share in applications where compliance is a prerequisite.
Key Drivers Reshaping the Isoparaffin Solvents Market
Regulatory and Environmental Mandates as a Growth Accelerator
Environmental regulation is one of the most influential forces behind current market dynamics. In the United States, EPA VOC limits and in Europe, the Solvent Emissions Directive continue to steer formulators away from higher-aromatic solvent systems toward high-purity, low-aromatic alternatives. Isoparaffin solvents, with their low odor and reduced aromatic content, are increasingly positioned as compliant substitutes in applications where emissions limits and workplace safety requirements are tightening.
This regulatory pressure is particularly visible in regions where paint, coating, and adhesive manufacturers must meet stricter emission thresholds. In South America, for example, countries such as Brazil and Argentina have moved to tighten VOC emission standards between 2023 and 2025, mandating reduced aromatic content in solvents used across paints, coatings, and adhesives. Such measures do not simply constrain the market; they redirect it. Demand flows toward solvent grades that can satisfy compliance requirements without sacrificing application performance, and isoparaffins are well placed to benefit from that redirection.
Product Innovation Centered on Purity, Odor, and Application Fit
Technological progress in isoparaffin solvents is increasingly focused on refining product attributes rather than simply expanding volume. Leading suppliers are updating technical documentation, emphasizing low odor, low aromatic content, and narrow boiling ranges, and aligning products with specific formulation needs in coatings, cleaning, metalworking, and personal care. This is not cosmetic repositioning; it reflects a real shift in market expectations. Formulators want solvents that reduce odor complaints, improve workplace conditions, and enable cleaner formulations while preserving solvency performance.
Recent product and documentation updates from major players illustrate this direction. ExxonMobil Chemical updated the technical datasheet for Isopar M, highlighting low aromatic content. Shell Chemicals released an updated product datasheet for ShellSol, emphasizing low odor and suitability for surface coatings. These actions signal that competitive advantage is increasingly linked to grade-level differentiation and technical clarity, not just brand recognition. When downstream customers compare solvent options, the ability to demonstrate purity, consistency, and application-specific fit can be decisive.
Demand-Side Shifts in Coatings, Metalworking, and Specialty Formulations
Demand for isoparaffin solvents is being reshaped by changing expectations in major application categories. Paints and coatings remain a central use case, but the drivers within this segment are evolving. Coatings formulators are under pressure to reduce VOC emissions, improve indoor air quality, and support sustainability claims. Metalworking fluids and industrial cleaning applications continue to value low-odor, effective hydrocarbon solvents that support degreasing, parts cleaning, and process consistency. Agrochemical formulations also contribute to demand, where solvent choice can influence product stability, handling, and regulatory acceptability.
At the same time, personal care and pharmaceutical applications, while smaller in absolute terms, represent high-value segments where purity, odor control, and regulatory documentation matter disproportionately. In these markets, even modest volume growth can be strategically meaningful because the margin and differentiation potential is higher. The broader implication is that demand growth is not only a volume story; it is increasingly a value story, with certain applications generating stronger pull for premium, high-purity grades.
Capacity Adjustments and Regional Supply Positioning
Supply-side dynamics are also influencing market direction. Recent capacity actions by major producers point to a focus on regional availability and application-oriented supply reliability. In February 2025, Shell Chemicals inaugurated a new isoparaffin solvent production plant in Brazil, increasing local capacity by 30 percent. In March 2025, Chevron Phillips Chemical increased its manufacturing capacity for isoparaffin solvents. These developments matter because regional production can shorten supply chains, reduce logistical risk, and better serve local regulatory and application requirements.
For buyers, the practical implication is greater importance placed on supply continuity and regional support. For producers, the lesson is that capacity deployment is most effective when aligned with local demand intensity, compliance conditions, and distribution capabilities. As capacity expands in key regions, competition may intensify on service level, formulation support, and availability rather than price alone.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
How Leading Players Are Shaping the Field
The competitive landscape in isoparaffin solvents is shaped by large chemical and energy-linked companies with broad hydrocarbon portfolios and strong technical reputations. These players compete not only on scale, but on product clarity, application support, and regulatory alignment. Several firms stand out for distinct positioning.
Solvent Naphtha Market
- Shell Chemicals has built a strong identity around ShellSol isoparaffins, emphasizing high-purity synthetic hydrocarbon solvents with narrow boiling ranges and low impurities. The brand is associated with coatings, inks, dry cleaning, and industrial applications, and recent updates have reinforced low-odor performance and surface coating suitability. Its February 2025 plant inauguration in Brazil also demonstrates a strategy of strengthening regional supply and local capacity.
- Chevron Phillips Chemical Company is recognized for Soltrol isoparaffin solvents, including Soltrol 130, which are positioned as low-odor and compatible with parts cleaning, degreasing, paints, inks, and agrochemical formulations. The March 2025 capacity increase signals continued investment in meeting demand for versatile, compliant solvent grades.
- ExxonMobil Chemical markets Isopar fluids with a focus on high purity, low aromatic content, and odorless properties for personal care, coatings, cleaning, and metalworking. The July 2025 technical datasheet update for Isopar M underscores a strategy of reinforcing product differentiation through documented purity and application-specific attributes.
- Braskem S.A. and TotalEnergies SE both participate in the market through broader hydrocarbon and chemical portfolios, supplying isoparaffin solvents for industrial and specialty applications, including paints and coatings. Their relevance lies in portfolio breadth and the ability to integrate solvent offerings within larger supply relationships.
- INEOS Group, Idemitsu Kosan, Calumet Specialty Products Partners, Sasol Limited, and SK Global Chemical each bring regional or specialized strengths. INEOS focuses on industrial cleaning, coatings, and personal care; Idemitsu Kosan supplies IP Clean and IP Solvent products; Calumet emphasizes industrial cleaning and coatings; Sasol participates through its chemical portfolio; and SK Global Chemical offers ISOL isoparaffins for industrial solvents and formulations.
What connects these players is a shared recognition that isoparaffin solvents are no longer commoditized cleaning or dissolving agents alone. They are increasingly evaluated as engineered chemical inputs with specific performance, safety, and compliance profiles. In this context, technical documentation, application expertise, and consistent quality become central competitive tools.
Strategic Positioning and Differentiation Levers
Leading companies are pursuing differentiation through several interlocking levers.
De-Aromatic Solvents Market
- Purity and low-aromatic positioning: In markets where VOC limits and aromatic content restrictions are tightening, high-purity grades gain an advantage. Suppliers that can clearly document low aromatic content and odor performance strengthen their relevance for compliant formulations.
- Application-focused product architecture: Rather than offering a single generic solvent, successful players tailor grades to specific uses such as coatings, metalworking, cleaning, personal care, and agrochemicals. This application alignment improves customer fit and reduces substitution risk.
- Regional capacity and supply visibility: Local production and reliable logistics reduce vulnerability to freight volatility and can improve responsiveness to regional regulatory changes. Brazil’s capacity expansion and broader capacity increases elsewhere illustrate the strategic value of placing supply closer to demand.
- Technical communication and datasheet clarity: Updated datasheets and product documentation are not administrative tasks; they are market-facing signals. Clear specifications help formulators validate compliance, compare alternatives, and justify solvent selection to internal and external stakeholders.
Together, these levers create a competitive environment where advantage is built through reliability, specificity, and compliance readiness rather than through broad volume claims alone.
Market Evolution: Consolidation, Fragmentation, and Entrant Dynamics
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. On one hand, large integrated players benefit from scale, feedstock access, and portfolio breadth, which can support pricing resilience and global reach. On the other hand, the presence of multiple capable regional and specialty suppliers means that differentiation by region, application, and grade remains viable.
Over the next several years, the landscape may evolve along three directions. First, selective consolidation could occur as players seek to strengthen geographic coverage, product ranges, or application expertise. Second, fragmentation may persist or deepen in high-value specialty niches where purity, odor, and documentation command premiums. Third, new entrants or expanding regional producers may gain ground by addressing local compliance needs and supply reliability more nimbly than global incumbents. The outcome will depend on how well companies align capacity, product grades, technical support, and regulatory preparedness with regional demand patterns.
Future Outlook: Three Trends Shaping the 2026-2032 Window
Trend 1: Compliance-Driven Grade Migration Toward High-Purity Isoparaffins
As VOC limits and aromatic content rules continue to tighten across multiple regions, a clear trend is the migration toward high-purity isoparaffin grades that can satisfy regulatory requirements while maintaining formulation performance. This shift is not just a regulatory response; it is becoming a procurement and product development preference. Formulators are increasingly choosing solvents that reduce compliance risk, lower odor concerns, and support sustainability narratives.
The commercial implication is that demand may grow more strongly for specific premium grades than for the market as a whole. Producers and buyers alike should expect a bifurcation in which high-purity, well-documented products capture disproportionate value, while undifferentiated grades face greater substitution pressure. The opportunity lies in aligning product portfolios with the grades that regulatory and performance trends are pulling toward.
Trend 2: Regional Supply Diversification and Near-Market Capacity
Another likely trend is continued regional diversification of supply. Recent capacity expansions in South America and capacity increases elsewhere suggest that producers are looking to reduce exposure to long supply chains and better serve local demand and compliance conditions. Over the forecast period, regional availability may become a more important purchase criterion, especially in markets where logistics cost, lead time, and regulatory context vary significantly.
For buyers, this trend creates opportunities to diversify supply sources and reduce dependency on a single route. For producers, it emphasizes the value of localized capacity, distribution partnerships, and application support that match regional market conditions. The risk is that overexpansion in one region could create localized oversupply, while underinvestment in another could leave demand underserved and open the door to imports or competitor entry.
Trend 3: Application-Specific Value Creation in Coatings, Cleaning, and Specialty Use
A third trend is the growing importance of application-specific value creation. Paints and coatings will remain a dominant demand pool, but the most strategic growth may come from tailored solutions that address odor, purity, and regulatory documentation in coatings, metalworking fluids, cleaning, and specialty formulations such as personal care and pharmaceuticals. These segments reward precision, consistency, and technical support, and they can generate stronger margins than bulk-oriented applications.
This trend opens opportunities for suppliers that can provide not just solvent volume, but formulation guidance, compliance documentation, and grade optimization. It also creates risk for players that compete primarily on price without offering the technical assurance that formulators increasingly require. In practice, the market is likely to reward those who treat isoparaffins as part of a broader solution rather than as a standalone commodity.
Strategic Implications and Action Guidance for Decision Makers
For Manufacturers and Producers
Producers should prioritize grade-level differentiation and regulatory readiness. As compliance becomes a stronger purchase driver, the ability to provide high-purity, low-aromatic, low-odor solvents with clear documentation will matter more than broad product claims. Capacity investments should be evaluated not only for volume potential but also for regional fit, feedstock exposure, and the ability to serve compliance-sensitive applications. Technical communication, including updated datasheets and application guidance, should be treated as a competitive asset that helps customers justify solvent selection and reduce formulation risk.
For Investors and Financial Stakeholders
Investors should look beyond aggregate market growth and focus on where value is concentrating. Segments and grades tied to regulatory compliance, odor reduction, and high-purity requirements are more likely to deliver durable demand and margin resilience than undifferentiated bulk solvent exposure. Regional supply dynamics also matter: capacity expansions and local production can strengthen competitive positioning, but they also create execution risk if demand growth is uneven. A careful assessment of feedstock exposure, regulatory alignment, and application mix is essential when evaluating companies in this space.
For Procurement and Formulation Teams
Procurement and formulation decision-makers should treat isoparaffin selection as a strategic variable rather than a tactical purchase. Compliance documentation, aromatic content, odor profile, and supply reliability should be weighted alongside price. Because regulatory requirements and application performance needs differ by region and formulation, it is wise to validate supplier capability across the specific grades and use cases that matter most. Diversifying supply sources and seeking suppliers with strong regional presence can reduce vulnerability to logistics disruptions and regulatory shifts.
Why Timely, Granular Intelligence Matters
The isoparaffin solvents market is moving through a period in which aggregate growth numbers tell only part of the story. Regulatory pressure, grade-level differentiation, regional capacity shifts, and application-specific demand are creating a landscape where timing, specificity, and supply positioning determine outcomes. For companies making investment, production, or procurement decisions, access to detailed segmentation data, regional breakdowns, and company-level movement tracking can materially improve decision quality. Broad directional awareness is useful, but the real advantage lies in understanding which grades, regions, and applications are gaining or losing traction, and how competitors are adjusting capacity and product positioning in response.
For organizations that need deeper coverage of market size by segment, regional demand patterns, competitive activity, and customized strategic recommendations, a comprehensive market research report can provide the structured detail required to move from general insight to concrete action. Detailed data, scenario-ready segmentation, and forward-looking assessment are particularly valuable when planning capacity, evaluating suppliers, or positioning product portfolios for compliance-led demand shifts.
Conclusion
The isoparaffin solvents market is not experiencing a sudden disruption; it is undergoing a deliberate restructuring shaped by environmental compliance, product purity expectations, regional supply strategy, and application-specific performance needs. The forecast growth path through 2032 suggests a market that continues to expand, but the more important story is where value is being created and where competitive advantage is being built. High-purity, low-odor, compliance-aligned grades are gaining relevance, regional capacity is becoming a strategic differentiator, and technical clarity is increasingly part of the commercial battleground.
PW Consulting Automotive & Machinery Research Center
For executives, investors, and procurement leaders, the practical question is no longer whether isoparaffin solvents remain important, but how to position for the next phase of demand migration, regulatory pressure, and supplier competition. Companies that align their strategies with these trends, and that invest in the intelligence needed to track them closely, are better placed to capture value in a market where growth and differentiation are increasingly inseparable.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Kitchen Ventilation Systems Market: Why 6.8% CAGR Signals Major Shifts
By PW Consulting, 2026-09-21
Commercial Kitchen Ventilation Systems Market: Strategic Trends and Commercial Opportunities Through 2032
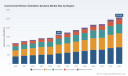
The commercial kitchen ventilation systems market is entering a phase of structural transformation, driven by tightening environmental mandates, accelerating energy-efficiency expectations, and a fundamental shift in how foodservice operators approach kitchen infrastructure. Valued at approximately $1.63 billion in 2025, the market is projected to expand at a compound annual growth rate of 6.8 percent through 2032, crossing the $2.58 billion threshold by the end of the forecast period. The growth trajectory reflects more than incremental replacement demand; it signals a rebalancing of how commercial kitchens are designed, regulated, and optimized for operational cost and compliance performance.
Historical momentum has been steady rather than explosive, with annual revenue progressing from $1.15 billion in 2020 toward the mid-$1.6 billion range by 2025. The acceleration in the 2025-2032 window is rooted in a confluence of regulatory upgrades, retrofit activity in aging foodservice footprints, and manufacturer-level innovation that is converting ventilation from a passive exhaust utility into an active energy and air-quality management asset. For executives, planners, and capital allocators, the strategic question is no longer whether the market will grow, but which sub-segments, geographies, and competitive positions will capture disproportionate value as standards tighten and operating economics shift.
Navigating the Current Inflection Point
Three structural challenges are reshaping how commercial kitchen ventilation markets evolve and how players position themselves within them.
The first is the regulatory ratchet. Kitchen ventilation has historically been governed by a patchwork of fire-safety, mechanical, and food-code requirements. The current trajectory moves beyond containment toward active performance standards. Recent proposals from the California Energy Commission point toward code changes designed to improve energy efficiency and reduce greenhouse gas emissions in commercial kitchens, including the potential introduction of mandatory Demand Control Kitchen Ventilation (DCKV) requirements as the next progression beyond existing standards. When jurisdictional frameworks begin to tie ventilation performance to energy usage and emissions, the market shifts from discretionary spend to compliance-driven investment, which changes the sales cycle, specification logic, and competitive differentiation for manufacturers and service providers alike.
The second challenge is the growing gap between installed base reality and modern performance expectations. Many commercial kitchens continue to operate with legacy exhaust hoods, fixed-speed fans, and non-integrated air management systems that were specified under older mechanical codes and pre-efficiency cost assumptions. Retrofitting these environments requires more than equipment swaps; it demands airflow engineering, grease management coordination, fire suppression compatibility, and controls integration. This elevates project complexity and favors suppliers that can deliver engineered solutions rather than commodity components. It also raises the stakes for installers and service networks, since performance guarantees increasingly depend on proper commissioning and ongoing maintenance.
The third challenge is cost structure volatility interacting with energy economics. Electrical pricing, refrigeration loads, cooking equipment heat output, and building envelope performance all influence the total cost of ownership for kitchen ventilation. A system that performs adequately from a compliance standpoint may still impose avoidable energy expenditure if airflow is not modulated to actual cooking load. As operators face sustained pressure on margins, the economic case for smarter ventilation becomes more compelling, but it also demands clearer quantification of savings, more credible performance data, and integration with broader kitchen energy strategies. The market is therefore moving toward solutions that can demonstrate a measurable link between ventilation control and operating cost reduction.
Key Drivers Behind Market Expansion
Technology Innovation and Demand-Controlled Ventilation
The most consequential technology trend in commercial kitchen ventilation is the shift toward demand-controlled operation. Instead of running exhaust and makeup air at fixed capacities, DCKV systems adjust airflow based on real-time cooking activity, thermal load, or contaminant detection. This approach directly addresses the energy penalty of over-ventilation, which has long been an overlooked source of waste in commercial kitchens. By matching ventilation output to operational demand, facilities can reduce fan energy consumption, lower heating and cooling losses, and improve hood capture efficiency under variable cooking conditions.
This innovation is not occurring in isolation. It is converging with broader building controls, digital commissioning tools, and smarter air-flow management architectures. Providers such as Systemair and Melink illustrate the direction of travel with offerings that combine exhaust performance with smart flow controls and demand-controlled ventilation solutions, while companies with DCKV-focused portfolios such as Gaylord and Melink emphasize modulation as a core value proposition. The strategic implication is clear: ventilation hardware is increasingly evaluated not only by capture area, material durability, and fire-safety conformance, but also by how effectively it integrates with controls that minimize idle energy use.
Residential Ventilation Systems Market
Regulatory Pressure as a Market Accelerator
Regulation is becoming a primary catalyst for both new construction specifications and retrofit programs. The FDA Food Code requires commercial kitchen exhaust systems to capture and contain heat, smoke, grease, and vapors to protect public health, while NFPA 96 sets mandatory requirements for ventilation control and fire protection in commercial cooking operations. These frameworks establish the floor for safe ventilation design. The emerging layer is the energy and emissions dimension, where jurisdictions are exploring requirements that go beyond containment and address efficiency performance.
At the installation and mechanical design level, updated model codes such as the 2021 Uniform Mechanical Code provide the baseline requirements for safe installation of commercial kitchen ventilation and exhaust systems. As local jurisdictions adopt, modify, or layer additional performance expectations on top of these standards, the specification environment becomes more formalized and more consequential. For manufacturers, this creates a dual opportunity: compliance assurance remains a licensing requirement for market participation, but added-value solutions that help operators meet evolving efficiency expectations can command stronger positioning and more resilient demand.
Demand-Side Shifts in Foodservice Operations
The application landscape reflects a broad, diversified demand base rather than reliance on a single end-use channel. Restaurants and cafes continue to represent the largest application share, supported by ongoing build-out, refresh cycles, and the need to upgrade older ventilation installations. Hotels and hospitality facilities contribute a substantial secondary demand stream, where ventilation is tied not only to kitchen safety but also to guest-facing comfort, indoor air quality, and multi-use facility performance. Corporate and industrial canteens, educational institutes, and hospitals and healthcare facilities each bring distinct operating requirements and procurement cycles, broadening the market’s resilience and reducing dependence on any single sector’s investment timing.
Operationally, the demand story is being shaped by labor, throughput, and risk management considerations. Kitchens are under pressure to improve consistency, reduce downtime, and simplify maintenance. Ventilation systems that are easier to commission, cleaner to service, and better aligned with variable cooking loads can improve day-to-day reliability while reducing the operational burden on kitchen staff and facility teams. In institutional and healthcare settings, the air-quality and containment rationale is especially strong, reinforcing ventilation as part of broader facility safety and environmental control strategies.
Supply Chain and Cost Structure Dynamics
Cost structures in commercial kitchen ventilation are influenced by material inputs, fabrication complexity, ratings and certification requirements, and the labor associated with installation and service. For hoods and ducting assemblies, material selection, fabrication tolerances, and fire-rated components can materially affect both pricing and delivery timelines. For controls and makeup air systems, value is increasingly determined by integration capability, sensor reliability, and software-mediated performance optimization rather than by hardware alone.
This changing cost-and-value equation is nudging the market toward more bundled and engineered offers. Suppliers that can coordinate hood design, exhaust and supply airflow, grease management, fire suppression coordination, and controls into a coherent specification are better positioned to manage total project risk and capture more of the value chain. At the same time, component-level suppliers that can deliver certified, cost-competitive hardware with reliable lead times retain an important role, especially in retrofit and maintenance-driven demand. The competitive edge is moving toward coordination, specification support, and documented performance.
Competitive Landscape and Positioning Strategies
The market is characterized by a concentrated set of established manufacturers and a broader tier of regional and application-focused players. Concentration at the top reflects the importance of scale, certification depth, engineered product portfolios, and service reach in winning specification-driven projects. At the same time, fragmentation persists because commercial kitchen ventilation is not a single product category; it spans exhaust hoods, fans and ducting systems, makeup air units, controls and accessories, and installation services, with different competitors leading in different slices.
CaptiveAire Systems stands out as a broad-line manufacturer of commercial kitchen ventilation systems, including exhaust hoods, fans, grease management, and complete HVAC solutions for foodservice operations. Its positioning emphasizes a full-system capability that can address the integrated nature of modern kitchen design, where exhaust, makeup air, and grease handling must work together. Greenheck Fan Corporation similarly occupies a wide portfolio position, offering exhaust hoods, fans, make-up air units, and energy recovery ventilation for restaurants and foodservice. The strategic significance of this breadth is that it allows specification of complementary components under a more unified performance logic, which can reduce integration risk and simplify procurement for larger projects.
Systemair AB brings an advanced-exhaust and air-purification orientation, with high-performance air purifiers, smart air flow controls, and demand-controlled ventilation solutions. This places the company closer to the efficiency and controls frontier, where value is created through modulation, filtration, and system intelligence rather than through hardware volume alone. Gaylord Industries focuses on Demand Control Kitchen Ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice, reinforcing a differentiated stance around active ventilation control and custom engineering. FAST Kitchen Hoods contributes a more specialized, regionally anchored presence as a Canadian manufacturer of cULus-rated commercial kitchen hoods, exhaust systems, island hoods, and low-ceiling hoods for restaurants, illustrating how rating compliance and form-factor specialization can anchor a defensible niche.
Chef’s Deal Restaurant Equipment operates with a service-intensive model as a supplier and installer of comprehensive commercial kitchen ventilation systems, including engineered hoods, make-up air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. Its recent expansion of its Commercial Kitchen Hood Service portfolio to include fully engineered ventilation systems, professional consultation, customized hood packages, make-up air units, ventless exhaust, Type 1 grease hoods, Type 2 condensate hoods, food truck hoods, pizza oven hoods, fire suppression, and exhaust hood filters and accessories for restaurants, food trucks, retailers, and institutional kitchens reflects a deliberate move toward broader solution coverage and consultative specification support. North American Kitchen Solutions maintains a multi-site U.S. footprint with manufacturing of commercial kitchen hoods, exhaust and supply fans, fire suppression, and portable ventless hood systems, showing how geographic and product diversification can support both project-based and supply-driven demand.
How Leaders Differentiate
Across these players, differentiation tends to cluster around several strategic levers. The first is portfolio breadth versus specialization. Full-line providers compete on integration, specification ease, and project-scale capability. Specialists compete on performance depth, rating expertise, or application fit. The second lever is controls and efficiency capability. As energy and emissions expectations rise, manufacturers that can demonstrate meaningful demand-controlled operation, reliable airflow modulation, and credible energy outcomes are better positioned for specification advantage. The third lever is installation and service reach. Ventilation performance depends heavily on proper sizing, duct routing, commissioning, and ongoing maintenance, so providers with strong field capacity can convert product capability into realized performance. The fourth lever is compliance and ratings fluency. In a market shaped by mechanical codes, fire-safety standards, and food-code requirements, the ability to navigate certification and demonstrate conformance is a basic but essential competitive precondition.
Market Structure Evolution
The competitive structure is likely to evolve along three lines. First, integration pressure will increase as operators and specifiers seek fewer interfaces between hood, fan, makeup air, controls, and suppression. This favors companies that can deliver coordinated designs and may encourage selective partnerships or acquisitions that close capability gaps. Second, the controls and efficiency layer will become more valuable, creating openings for players that can bring software-mediated ventilation management, better sensor integration, and verifiable savings narratives into the market. Third, regional and application-focused specialists will continue to find room to compete, especially where local code interpretation, rating requirements, or niche form factors such as low-ceiling or mobile-food applications create specificity that larger portfolios do not automatically address.
Future Trends and Commercial Opportunities
Efficiency Mandates Will Move From Optional to Expected
The most consequential near-to-medium-term trend is the normalization of demand-controlled and efficiency-oriented ventilation as a standard expectation rather than a premium option. With regulatory discussions increasingly pointing toward mandatory DCKV-style requirements in leading jurisdictions, and with model codes and food-safety standards already establishing the containment baseline, the market is heading toward a two-layer framework: safe capture and fire protection as the foundation, and active efficiency performance as the differentiating expectation. Commercial opportunity lies in products and services that can make demand-controlled operation reliable, easy to commission, and simple to verify after installation. Manufacturers and integrators that can reduce the friction of controls adoption—through clearer specification tools, more robust sensor performance, and stronger field support—will be well placed to convert regulatory momentum into specification share.
Retrofit and Performance Upgrades Will Outpace Pure New-Construction Demand
Given the size and age of existing foodservice footprints, a significant portion of future demand will come from upgrading or replacing ventilation systems that no longer meet current performance, safety, or efficiency expectations. Retrofit demand is more fragmented and more service-intensive than new construction, but it also creates opportunities for engineered assessments, phased replacement programs, and controls retrofits that improve energy performance without full kitchen rebuilds. The commercial opportunity here is in bundled upgrade packages that pair hood or fan replacement with airflow rebalancing, controls integration, and grease management review. Providers that can quantify pre- and post-upgrade performance and reduce operational disruption will have an advantage in this segment.
PW Consulting Automotive & Machinery Research Center
Smart Air Management and Integrated Kitchen Energy Design Will Gain Share
Ventilation is increasingly being evaluated as part of the broader kitchen energy and air-quality system rather than as a standalone exhaust function. This creates a trend toward tighter integration between exhaust, makeup air, temperature control, and demand modulation, with controls acting as the connective tissue. The opportunity is for suppliers that can position kitchen ventilation as an energy-management asset with measurable impact on fan power, thermal load, and indoor comfort. It also opens the door to more sophisticated service models, including performance monitoring, scheduled commissioning checks, and data-informed maintenance. As operators look for ways to manage operating costs and meet internal sustainability expectations, integrated air management solutions will become more relevant and more defensible.
Risks and Uncertainties
The outlook carries meaningful uncertainty. Code adoption is uneven across jurisdictions, so the pace and shape of mandatory efficiency requirements will vary, creating a patchwork rather than a uniform transition. Economic conditions can shift the timing of restaurant build-outs, hospitality renovations, and institutional procurement cycles, affecting demand volatility. Supply chain and input cost pressures can influence hardware pricing and project economics, particularly for fabrication-intensive components. Finally, the promised energy and operational savings from controls-based ventilation depend on correct design, installation, and ongoing calibration; if realized performance falls short of expectations, trust in efficiency narratives can erode. Participants should therefore treat performance validation, service quality, and transparent specification as strategic necessities rather than supporting functions.
Actionable Recommendations for Decision-Makers
For Manufacturers and Solution Providers
Position around integration, not just equipment. The market is rewarding providers that can coordinate hood design, airflow balance, controls, grease management, and fire protection into a coherent offer. Invest in specification support, commissioning expertise, and post-installation performance validation so that efficiency claims are credible and repeatable. Where portfolio breadth is not achievable, build clear differentiation around a specialized strength such as demand-controlled control logic, rating compliance for a specific form factor, or a service model that reduces install and maintenance friction. Monitor regulatory signals closely, especially jurisdictional moves toward efficiency-oriented kitchen ventilation requirements, and prepare specification tools and product configurations that align with the next code progression.
Worldwide Commercial Kitchen Fire Suppression System Market
For Investors and Capital Allocators
Evaluate exposure to the efficiency and controls layer as a distinct value driver. Pure hardware volume plays may continue to perform, but the higher-margin, higher-differentiation opportunity is increasingly tied to demand-controlled ventilation, integration services, and performance verification. Consider the mix of new-construction exposure versus retrofit and service exposure in any target, since retrofit-heavy models can be more resilient to construction-cycle volatility while demanding stronger field and service capabilities. Assess regulatory sensitivity as part of the investment thesis: companies aligned with the direction of tightening efficiency expectations are better positioned than those dependent on discretionary, low-performance specifications. In due diligence, probe installation quality, commissioning processes, and the evidence base for energy or operating-cost claims, because these factors increasingly determine whether a product wins repeat specification.
For Procurement and Facility Decision-Makers
Treat kitchen ventilation as a total-cost and compliance asset, not merely a capex line item. Specify with attention to demand-controlled capability, proper airflow design, grease management integration, and fire-safety conformance, and require clear commissioning and performance verification before project closeout. Evaluate suppliers on their ability to deliver engineered solutions and documented post-installation performance, not only on unit pricing. Where existing systems are underperforming, consider targeted retrofits that improve modulation and control before committing to full replacements, and align ventilation decisions with broader kitchen energy and maintenance strategies to capture operational savings over time.
The commercial kitchen ventilation market is moving from a compliance-and-commodity orientation toward a performance-and-integration orientation. That shift creates winners among companies that can combine certification strength, engineering depth, controls capability, and service reliability, while leaving narrower or purely transactional models exposed to margin and specification pressure. As efficiency expectations mature and retrofit demand expands, the strategic value of timely, granular market intelligence becomes harder to overstate. Decision-makers who understand where regulation is heading, how controls are reshaping operating economics, and which competitive positions are gaining specification advantage will be better equipped to allocate capital, prioritize product roadmaps, and structure procurement around the next phase of market growth.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PRP Market Analysis: How 10.5% CAGR to $1B Reshapes Orthopedics and Aesthetics
By PW Consulting, 2026-09-21
The Platelet-Rich Plasma Market: Strategic Trends and Commercial Opportunities in Autologous Biologics
The global platelet-rich plasma (PRP) market has evolved from a niche regenerative modality into a structured commercial ecosystem, driven by clinical adoption across orthopedics, sports medicine, aesthetics, and wound care. With historical revenue expanding from approximately $236.5 million in 2020 to $512.0 million in 2025, and a projected trajectory toward $1,032.3 million by 2032, the sector reflects a compound annual growth rate of 10.5 percent. This growth is neither uniform nor accidental. It emerges from a convergence of technological maturation, shifting reimbursement pathways, regulatory clarification, and demand-side preferences that favor autologous, minimally processed biologics. For executives, investors, and procurement leaders, the current moment represents a transition from early experimentation to scaled commercialization. The challenge lies in navigating a fragmented supply base, inconsistent coverage models, and evolving clinical evidence while capturing value in segments where efficacy, workflow integration, and reimbursement alignment intersect.
The market structure reveals a moderately concentrated landscape, with the top three players accounting for roughly 47.2 percent of revenue and the top five reaching 52.8 percent. This concentration suggests that scale, regulatory clearance, and system integration confer meaningful advantages, yet substantial runway remains for differentiated technologies and regional expansion. Growth is not evenly distributed across applications or geographies. Orthopedic and sports medicine use cases continue to anchor demand, while aesthetic and wound care applications present distinct reimbursement and clinical-evidence dynamics. The following analysis examines the forces shaping this transition, the strategic postures of leading participants, and the practical implications for decision-makers seeking to capitalize on the next phase of market development.
Plasma Protein Therapeutics Market
Market Snapshot: Growth Trajectory and Structural Realities
Over the 2020–2025 period, the PRP market expanded at a pace that outpaced many adjacent medical device and biologics segments. Revenue climbed from $236.5 million to $512.0 million, and forward projections indicate continued expansion through 2032, with annual figures moving from $579.7 million in 2026 to $1,032.3 million in 2032. This trajectory implies a sustained 10.5 percent CAGR, reflecting both underlying volume growth and incremental adoption of point-of-care preparation systems. The market’s composition spans multiple product formats, including pure PRP, leukocyte-rich variants, platelet-rich fibrin, and ancillary systems, alongside application breadth that covers orthopedic reconstruction, sports injury management, cosmetic procedures, and chronic wound care.
Despite the favorable headline numbers, the market operates within a set of structural constraints that shape commercial strategy. First, clinical evidence remains uneven across indications, with stronger data in select musculoskeletal and wound applications and more limited consensus in aesthetic and certain orthopedic injection contexts. Second, reimbursement pathways are partial and indication-specific, creating adoption friction in settings where providers cannot reliably pass through preparation costs. Third, regulatory classification creates a dual-track environment: FDA-cleared preparation devices enable compliant autologous use, while off-label applications depend on provider discretion and often lack broad coverage. Together, these realities mean that market growth is increasingly tied to workflow efficiency, evidence generation, and reimbursement alignment rather than to scientific novelty alone.
Key Challenges and Inflection Points
The PRP sector stands at several inflection points that will determine which participants capture durable value. One central challenge is the evidence-to-reimbursement gap. While point-of-care systems have improved consistency and reduced preparation variability, payers and institutions increasingly require indication-specific data, standardized protocols, and transparent cost accounting. Without these, adoption remains concentrated in cash-pay, sports medicine, and high-income aesthetic segments, limiting broader institutional uptake.
A second challenge involves cost structure and sterilization logistics. Single-use processing components, hemapheresis kits, and point-of-care consumables depend on gamma sterilization and small-batch manufacturing, which elevate unit costs and constrain margin flexibility. Suppliers must balance clinical-grade reliability with economic scalability, particularly as volume expectations rise and hospital procurement teams normalize total-cost-of-ownership assessments.
A third inflection point is regulatory clarity versus clinical flexibility. Autologous PRP devices are classified as Class II under 21 CFR 864.9245 and require 510(k) clearance, while PRP itself is regulated as a blood product by FDA CBER and is generally considered investigational for most non-wound applications. This framework ensures compliance for cleared autologous use but leaves many orthopedic and aesthetic injections in a provider-discretion zone without broad insurance coverage. The result is a market where device clearance, coding specificity, and clinical protocol design are increasingly intertwined commercial variables rather than purely regulatory checkboxes.
Core Drivers of Market Change
Technology Innovation and Workflow Integration
The most consequential technological shift is the move toward point-of-care systems that combine high platelet yields, customizable formulations, and rapid preparation workflows. Automated separation platforms, double-syringe kits, and single-spin systems have reduced preparation time and improved reproducibility, making PRP more viable in busy clinical environments. Systems that enable up to 18x platelet concentration at the point of care, or that deliver supraphysiologic concentrating with customizable formulations, address two practical barriers: clinical consistency and operational throughput. These capabilities matter because adoption in orthopedics and sports medicine often hinges on whether preparation can be embedded into existing procedure workflows without disrupting scheduling or staffing.
Technology differentiation is also moving toward application-specific optimization. In wound care, fibrin-based matrices and gel preparations that support exuding cutaneous wounds represent a distinct value proposition from injection-focused systems used in musculoskeletal settings. This specialization is creating a broader ecosystem in which device architecture, kit composition, and preparation protocol are increasingly matched to clinical use cases rather than sold as generic autologous blood products.
Policy and Regulatory Environment
Regulatory and coding developments are reshaping commercial viability. FDA clearance of PRP preparation systems establishes a compliance pathway for autologous use, while the broader classification of PRP as a blood product under FDA CBER keeps many non-wound applications in an investigational category. This duality means that device-level clearance does not automatically translate into coverage for every indication. Instead, commercial success increasingly depends on aligning cleared indications with coding structures and payer policies.
Worldwide Platelet Rich Plasma (PRP) Kit Market
Reimbursement dynamics are evolving in parallel. For chronic non-healing diabetic wounds, Medicare covers autologous PRP prepared with FDA-cleared devices under HCPCS G0465, with required invoice documentation for the PRP supply kit and an in-house processing fee. This creates a structured, if narrow, coverage pathway that rewards cleared devices and documented supply chains. At the same time, Category III coding such as 0232T applies to PRP injections across sites, including image guidance, harvesting, and preparation, with some payers requiring separate billing for supplies. These coding nuances affect provider economics and influence which systems are preferred in outpatient and institutional settings.
Demand-Side Shifts in Provider and Consumer Behavior
Demand is being reshaped by a preference for autologous biologics that minimize immunogenicity concerns and align with regenerative care models. In sports medicine and orthopedics, providers seek options that can be deployed during same-session procedures, reducing reliance on off-site processing and supporting rapid turnaround. In aesthetics, consumer interest in minimally invasive rejuvenation continues to drive volume, though this segment remains more sensitive to evidence messaging, pricing transparency, and outcomes consistency. In wound care, the demand driver is clinical necessity: chronic ulcers and non-healing wounds create a persistent care burden, and autologous PRP-based matrices offer a biologically aligned adjunct where standard dressings and therapies may be insufficient.
Across these settings, the common thread is a growing expectation that PRP should be reproducible, documented, and economically legible. Providers and procurement teams increasingly evaluate systems not only on platelet concentration claims but also on sterility assurance, kit reliability, ease of use, and compatibility with existing billing and documentation workflows.
Supply Chain and Cost Structure Evolution
Supply chain economics are becoming a strategic variable. Gamma sterilization requirements and small-batch manufacturing for single-use kits raise input costs, which can compress margins for manufacturers and increase total cost for providers. This environment favors participants that can standardize kit architectures, secure reliable sterilization pathways, and design systems that minimize waste or redundant consumables. It also rewards vertical alignment between device platforms and consumable supply, since fragmentation can introduce variability in both cost and clinical performance.
At the same time, distribution partnerships are altering market access. Agreements that place PRP systems under established brand channels can accelerate reach in specific clinical segments, particularly where wound care or orthopedic procurement is consolidated. Such arrangements can reduce the commercial burden on smaller manufacturers while expanding the availability of cleared systems within trusted distribution networks.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Participants
The competitive set reflects a mix of device-focused manufacturers, biologics integrators, and specialty developers pursuing differentiated preparation architectures. Several participants have built their positioning around point-of-care concentration performance and workflow reliability. EmCyte Corporation emphasizes a supraphysiologic concentrating system for point-of-care autologous PRP preparation with customizable formulations and high platelet yields, appealing to settings that value concentration control and formulation flexibility. Arthrex, Inc. focuses on an automated PRP system and double-syringe kits designed for orthopedic applications, enabling high platelet concentration at the point of care and integrating preparation into procedure workflows. Zimmer Biomet emphasizes integrated PRP systems and biologics kits that support orthopedic reconstruction and soft-tissue procedures, leveraging the advantages of an established orthopedic portfolio. Terumo BCT targets point-of-care PRP systems and related kits for rapid autologous preparation, with an emphasis on workflow speed and clinical usability.
PW Consulting
In parallel, several developers have pursued application-specific differentiation. Regen Lab S.A. focuses on PRP kits and systems optimized for clinical use in regenerative medicine applications, aligning product design with practitioner workflows. Royal Biologics has concentrated on fibrin-based PRP and PRF systems for wound management and bone graft handling, including a PRF wound matrix that recently received FDA clearance for management of exuding cutaneous wounds, including diabetic and venous ulcers. Nuo Therapeutics, Inc. has built a wound care and biodynamic therapy focus, with its PRP system distributed through private-label arrangements to Smith+Nephew in the U.S. wound care market. Gale Force Aesthetics, LLC emphasizes a single-spin system designed for high-volume platelet capture and rapid preparation, while Forever Labs, Inc. focuses on an automated separator for safe, rapid autologous PRP preparation at the point of care. Royal Wound-X, Inc. concentrates on a PRF-matrix system for rapid PRP gel preparation from peripheral blood for wound management.
These positions illustrate two strategic paths. One path concentrates on concentration performance, automation, and orthopedic or sports medicine integration, where procedural efficiency and reproducibility are paramount. The other path emphasizes wound care and regenerative applications, where matrix properties, clearance status, and reimbursement compatibility can create more defined commercial pathways. Both paths require disciplined alignment between device capability, kit economics, and clinical protocol design.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is evolving along multiple axes. Consolidation pressure is rising where scale, distribution reach, and regulatory clearance create advantages, particularly in segments where procurement is centralized or where private-label distribution can rapidly expand availability. Differentiation is intensifying around workflow integration, concentration consistency, and indication-specific design, as generic autologous blood preparation becomes less distinctive in a maturing market. At the same time, new entrants continue to appear, often bringing novel spin architectures, automated separation concepts, or niche wound care formulations that challenge established incumbents on speed, yield, or use-case fit.
A notable dynamic is the increasing importance of commercial alignment beyond pure product performance. Recent developments such as exclusive private-label distribution agreements in wound care and FDA clearances for specific wound matrix indications demonstrate how regulatory milestones and channel partnerships can reshape market access. In wound care especially, clearance for exuding cutaneous wounds and diabetic or venous ulcers can materially change the commercial profile of a system by enabling more defensible positioning within reimbursement-eligible pathways. In orthopedics and aesthetics, the absence of broad coverage for many off-label applications means that competitive advantage often depends on provider education, protocol standardization, and total cost management rather than on clearance alone.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Indication-Specific Commercialization Becomes the Norm
The next phase of growth will likely reward participants that align device design, coding strategy, and clinical evidence with specific indications rather than treating PRP as a single homogeneous category. Wound care offers a concrete example: where cleared devices and defined coverage pathways exist, commercialization can be structured around documented supply chains, processing fees, and matrix-based protocols. In musculoskeletal and aesthetic settings, growth may remain stronger in cash-pay and sports medicine channels unless evidence and coding evolve further. The commercial implication is clear: companies that build indication-specific value propositions, including protocol support and billing compatibility, are better positioned to convert adoption into repeatable revenue.
Trend 2: Automation and Workflow Integration Will Separate Leaders from Laggards
Point-of-care automation, rapid preparation, and high-yield concentration are increasingly baseline expectations rather than differentiators. The next competitive frontier is end-to-end workflow integration: systems that minimize hands-on time, reduce variability, and fit cleanly into existing clinical routines. This matters because clinical adoption is often constrained by operational friction as much as by clinical interest. Manufacturers that can demonstrate reliable kit performance, straightforward preparation steps, and compatibility with institutional procurement and documentation requirements will have an advantage in converting trial use into sustained adoption.
Trend 3: Reimbursement Architecture and Cost Transparency Will Shape Segment Economics
As payers, institutions, and providers scrutinize cost, the economics of PRP will depend more heavily on coding clarity, supply-chain documentation, and processing-fee structures. Narrow coverage pathways can be commercially attractive where they are well-defined, but they also demand rigorous invoice and kit documentation. In segments where coverage is limited, cost transparency and predictable kit economics will influence whether providers continue to adopt PRP or redirect spend to alternative biologics or procedures. The risk is that uneven reimbursement and variable sterilization-driven costs create instability in margin planning and adoption forecasting.
Opportunities and Uncertainties
These trends open several commercial opportunities. There is room for differentiated systems that combine automation with application-specific performance, particularly where wound care clearance or orthopedic workflow integration can be clearly demonstrated. Distribution partnerships and private-label arrangements can accelerate access in consolidated procurement environments. There is also opportunity in standardizing kit economics and sterilization pathways to improve margin resilience. At the same time, uncertainties remain: evidence gaps in select indications, reliance on provider discretion for many off-label applications, and cost pressures from gamma sterilization and small-batch manufacturing can all temper growth expectations. Participants should also monitor regulatory developments, since device clearance does not automatically broaden coverage, and coding practices may continue to diverge across payers and regions.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Developers
- Align product development with indication-specific workflow needs, prioritizing automation, reproducibility, and kit reliability over concentration claims alone.
- Invest in documentation-ready supply chains and clear billing compatibility, especially where coverage pathways such as wound care codes create structured economic models.
- Pursue distribution partnerships or private-label channels where procurement is consolidated, using cleared indications and proven reproducibility to gain entry into institutional workflows.
- Plan for cost structure resilience by standardizing single-use components, securing reliable sterilization pathways, and reducing consumable waste wherever possible.
For Investors
- Evaluate companies on the strength of their regulatory positioning, reimbursement alignment, and workflow integration rather than on market-level growth narratives alone.
- Favor business models that can convert clinical interest into repeatable economics, including recurring kit demand, stable sterilization and manufacturing pathways, and defensible channel access.
- Monitor segment-specific dynamics closely, since wound care, orthopedics, sports medicine, and aesthetics each face different evidence, coverage, and pricing constraints.
- Assess whether a company’s differentiation is durable in the face of automation becoming a baseline expectation, and whether its cost structure can withstand single-use kit economics.
For Procurement and Clinical Leaders
- Evaluate PRP systems against total cost of ownership, including kit reliability, preparation time, sterility assurance, and billing documentation requirements.
- Match system selection to the intended indication and clinical protocol, recognizing that wound care, orthopedic, and aesthetic applications often require different performance and coverage considerations.
- Require transparent documentation for supply kits, processing fees, and device clearance status to support compliance and reimbursement where applicable.
- Prioritize vendor support that includes protocol guidance, staff training, and consistent kit availability, since workflow friction can undermine adoption even when clinical interest is strong.
The PRP market is moving from broad enthusiasm to disciplined commercialization. Growth is increasingly determined by the intersection of cleared device pathways, reimbursement compatibility, workflow integration, and cost transparency. In that environment, the most valuable intelligence is segment-specific: how clearance status interacts with coding, how kit economics behave under sterilization and small-batch constraints, and where distribution partnerships can open durable access. Detailed segmentation data, competitive benchmarking, and customized scenario planning can help decision-makers translate these dynamics into concrete investment, product, and procurement choices. For leaders seeking a fuller view of the market’s subsegments, regional trajectories, and company-level positioning, accessing the complete research dataset and methodology notes provides the granularity needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Platelet Rich Plasma (PRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
ESP Market 2026–2032: Why 6.4% CAGR and Power Generation Dominance Redefine Strategy
By PW Consulting, 2026-09-21
Navigating the Electrostatic Precipitators Market: Strategic Trends and Commercial Opportunities Through 2032
The electrostatic precipitator (ESP) market is entering a phase of measured but meaningful expansion, driven by tightening emissions standards, aging infrastructure demands, and incremental technological upgrades. Between 2020 and 2025, the global market grew from 6,500.0 million USD to 8,300.0 million USD, reflecting steady demand across utility and industrial sectors. Looking ahead to the 2026-2032 forecast period, the trajectory points toward a compound annual growth rate of 6.4%, with revenue projected to reach 12,790.0 million USD by 2032. This growth is not uniform. It is concentrated among a handful of established players, as reflected in a CR3 of 38.2% and CR5 of 55.0%, indicating that scale, technical expertise, and long-term service relationships continue to shape competitive dynamics. The market’s structure favors firms that can deliver not only hardware but also lifecycle support, performance upgrades, and integration with broader emission control systems.
Behind the headline numbers lie structural tensions that will define how companies position themselves over the next several years. The first challenge centers on the balance between capital intensity and operational efficiency. Advanced ESP configurations increasingly rely on digital control modules, corrosion-resistant materials, and hybrid filtration approaches, all of which raise upfront investment. At the same time, electrical energy consumption in large-scale installations remains substantial, translating into ongoing operating costs that plant operators must justify against performance gains. The second challenge is regulatory fragmentation. While federal and regional standards continue to push particulate limits downward, the pace and specifics of compliance requirements vary by jurisdiction and by industrial application, creating uneven demand cycles and complicating long-term planning. The third challenge involves the shift from greenfield installations to retrofit and rebuild activity. Many existing plants are prioritizing incremental upgrades that restore or exceed original collection efficiency without full system replacement, reshaping procurement patterns and service expectations.
Market Structure and the Shift Toward Service-Enabled Solutions
The ESP market’s evolution is increasingly defined by how suppliers manage the entire asset lifecycle rather than by initial equipment sales alone. Rebuild contracts, performance optimization, and integration with flue gas treatment systems are gaining weight in commercial negotiations. Companies that can demonstrate consistent collection efficiency, lower operating expenditure, and predictable maintenance intervals are finding stronger positioning in both utility and industrial segments. This shift is visible in recent contract activity and network expansion moves, where the emphasis is on extending service reach, supporting existing installations, and delivering measurable efficiency improvements. For decision-makers, the implication is clear: competitive advantage is moving from hardware specification to total cost of ownership and performance reliability over time.
Key Drivers Reshaping the ESP Market
Regulatory Pressure as a Baseline Demand Catalyst
Emissions regulations are the most consistent force behind ESP demand, and recent regulatory actions reinforce that trajectory. In the United States, the EPA’s Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, accelerating the deployment of ESP systems that can meet or exceed those limits. At the same time, federal regulations on particulate matter emissions from industrial sources continue to compel facilities to adopt ESP technologies for compliance. These requirements do not merely create one-time purchase cycles; they establish a compliance floor that encourages operators to invest in systems capable of sustained performance, particularly where future tightening is anticipated. For suppliers, this environment rewards proven high-efficiency collection capability and the ability to document compliance outcomes.
Technological Innovation: Efficiency, Control, and Integration
Technological progress in ESP systems is increasingly focused on improving collection efficiency while moderating energy use and simplifying integration with downstream gas cleaning. High-efficiency collection up to 99.9% is now a benchmark that several leading providers reference, and achieving that level consistently often depends on advanced electrode design, better discharge management, and refined control logic. Equally important is the move toward smarter operation. AI-enhanced control systems and digital monitoring are being embedded into ESP platforms to adjust operating parameters in response to load changes, dust characteristics, and process conditions. This reduces wasted energy, stabilizes performance, and improves predictability for plant operators. Integration with flue gas conditioning and NOx reduction technologies further extends the value of ESP installations, especially in coal-fired utility settings where multi-pollutant control is a priority.
Recent developments illustrate how these innovations are being commercialized. Babcock & Wilcox secured more than 18 million USD in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, emphasizing collection efficiency up to 99.9%, a clear signal that performance-led upgrades remain commercially attractive. FLSmidth expanded its service center network with a new facility in Dammam, Saudi Arabia, to support advanced emission control technologies including electrostatic precipitators, reflecting a strategy of positioning service capability closer to key industrial demand centers. Mitsubishi Heavy Industries delivered an ESP unit for a 700,000-tonne chemical pulp project in China, while Valmet shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler with completion targeted by the end of 2025. These activities show that demand is not limited to power generation; pulp and paper, chemical pulp production, and broader industrial recovery systems are also active deployment areas where ESP performance matters.
Demand-Side Shifts Across Power and Industrial Applications
Demand for ESP systems continues to be anchored by power generation, particularly where coal-fired and biomass-linked facilities must meet strict particulate limits or extend the viable operating life of existing assets. Beyond power, industrial applications are expanding the addressable market. Cement and lime processing, waste-to-energy and biomass, chemical and petrochemical operations, and specialized sectors such as pulp and paper recovery boilers all present distinct dust characteristics and operating conditions that shape ESP selection. The commercial implication is that a single ESP architecture rarely fits all applications. Suppliers that can tailor electrode design, gas flow management, and cleaning methods to specific process environments are better positioned to capture demand across multiple verticals. This is also where wet and dry system choices become strategically important, with selection driven by dust properties, moisture content, and downstream process constraints.
PW Consulting
Cost, Energy, and Supply Chain Considerations
Despite the positive demand outlook, cost and energy dynamics remain central to commercial decision-making. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment. Electrical energy consumption in electrostatic precipitators can also be substantial, with resulting high operating costs for large-scale installations. These factors encourage a more disciplined approach to procurement, where operators evaluate not only collection performance but also energy profile, maintenance intervals, and 부품 or material availability over the system’s lifespan. Supply chain considerations are becoming more prominent as well, particularly for specialized materials and control hardware. Providers that can streamline sourcing, localize support, and reduce downtime through predictable maintenance planning are likely to gain preference in competitive bidding situations.
Competitive Landscape and How Leading Players Differentiate
The ESP market is moderately concentrated, with a limited group of established companies holding meaningful share and long-standing relationships across utility and industrial markets. Market leadership is less about unit volume alone and more about the breadth of application coverage, demonstrated efficiency, service reach, and the ability to offer integrated emission control solutions. Several firms have built their positioning around high-efficiency systems, rebuild and retrofit capabilities, and sector-specific expertise. For example, some leaders emphasize wet and dry ESP systems for utility and industrial power generation with global installation experience, while others specialize in advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Custom wet and dry ESP manufacturing for power, cement, and steel applications remains a differentiator for firms serving heavy industrial environments, and AI-enhanced control systems are increasingly part of the value proposition for providers targeting cement and industrial applications.
Worldwide Dry Electrostatic Precipitator Market
Company activity over the past two years highlights three strategic themes. First, performance-led rebuilds are a commercially meaningful pathway, as shown by major rebuild contracts focused on restoring or improving collection efficiency in existing plants. Second, geographic and service expansion is being used to reduce response times and strengthen relationships in important demand regions, including the Middle East. Third, sector-specific project wins in pulp, chemical pulp, and recovery boiler environments indicate that specialization can open doors beyond the largest power generation markets. Together, these moves suggest a market where incumbents are reinforcing their positions through service proximity, proven efficiency claims, and application-specific execution rather than relying solely on equipment pricing.
Consolidation, Fragmentation, and Entry Dynamics
The ESP market is not experiencing dramatic consolidation at the top, but it is showing signs of functional consolidation around capabilities. Buyers increasingly value suppliers that can handle design, installation, commissioning, and ongoing optimization under a coordinated framework. At the same time, niche players remain relevant where specialized applications, local support needs, or custom engineering demands create room for focused offerings. New entry is challenging but not impossible, especially where a company brings a clear technical advantage, such as a novel control approach, improved energy management, or a distinctive material solution that lowers lifecycle cost. In practice, the most resilient competitors are those that combine technical credibility with commercial flexibility, allowing them to serve both large-scale utility projects and smaller industrial retrofits without losing operational focus.
Forward Outlook: Trends Likely to Shape the Next 3-5 Years
Trend 1: Efficiency and Energy Management Will Become the Central Battleground
As regulations tighten and operating costs remain under scrutiny, the most important competitive differentiator will be the ability to deliver high collection efficiency without inflating energy consumption. Systems that can modulate power use intelligently, sustain efficiency across variable loads, and integrate with broader plant controls will be favored in both new installations and upgrades. This trend creates commercial opportunities for providers that can quantify energy savings, reduce maintenance burden, and show compliance durability over time. It also raises the stakes for suppliers still relying on static operating profiles, since plants are increasingly reluctant to accept high operating costs as a fixed requirement.
Electrostatic Chucks (ESCs) Market
Trend 2: Retrofit, Rebuild, and Life Extension Will Outweigh Greenfield Demand in Many Markets
In many regions, the near-term opportunity lies less in replacing entire systems and more in restoring performance, adapting to new fuel or process conditions, and extending service life. Rebuild contracts and targeted upgrades are likely to remain a significant share of activity, especially where plants need to meet current standards or prepare for future limits without committing to full replacement. This shift rewards vendors with strong field service capabilities, modular upgrade paths, and the ability to diagnose existing installations efficiently. For investors and manufacturers, it suggests that service-oriented revenue streams and upgrade kits may be as strategically important as flagship new-system sales.
Trend 3: Regional Service Footprints and Application Specialization Will Determine Access to Demand
Demand is geographically and sectorally uneven, and access to projects will increasingly depend on local presence and application knowledge. Expansion of service centers, local support teams, and region-specific engineering capacity can reduce friction in procurement and commissioning while improving responsiveness during operation. At the same time, companies that understand the dust and process nuances of specific industries will be better positioned to win in segments such as cement, waste-to-energy, chemical, and pulp and paper applications. The commercial opportunity here is to build repeatable sector playbooks rather than treating each project as a standalone customization exercise.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Regulatory timelines may shift, particularly if compliance deadlines are adjusted or if enforcement emphasis changes across jurisdictions. Energy pricing and availability can affect operating economics, especially for large installations where power use is a major cost element. Material availability and lead times for specialized components may influence project scheduling and total cost. Finally, changes in fuel mix, plant retirement decisions, and the balance between coal, biomass, and alternative generation pathways can reshape where ESP demand appears and how quickly it materializes. Companies that monitor these variables closely will be better prepared to adjust pipeline planning and service capacity.
Strategic Recommendations for Decision-Makers
For ESP Manufacturers and Solution Providers
- Prioritize total-cost-of-ownership positioning by documenting efficiency outcomes, energy behavior, and maintenance predictability, not just collection performance at a point in time.
- Invest in service and rebuild capabilities, since retrofit and upgrade activity is likely to remain a durable source of revenue and customer contact.
- Build application-specific engineering playbooks for cement, waste-to-energy, chemical, and pulp and paper environments, where process conditions shape system selection and value claims.
For Investors and Strategic Partners
- Evaluate providers based on their ability to sustain high-efficiency claims in the field, expand service reach, and capture multi-pollutant integration opportunities rather than equipment scale alone.
- Watch for commercial signals in rebuild activity, regional service expansion, and sector project wins, as these often indicate where demand is becoming more concrete.
- Assess exposure to energy-intensive operating profiles and specialized material supply, since these factors influence margin stability and project execution risk over the forecast period.
For Plant Operators and Procurement Teams
- Select ESP solutions with a clear view of lifecycle cost, including energy consumption, maintenance intervals, and the feasibility of future upgrades as regulations or processes change.
- Use rebuild and retrofit pathways where feasible to meet current compliance targets while preserving capital flexibility for other plant priorities.
- Request performance evidence tied to operating conditions similar to your own, especially for dust characteristics, load variability, and integration with existing gas treatment systems.
The ESP market is moving toward a more performance-intensive, service-oriented, and application-aware phase of growth. That shift rewards companies that can combine proven collection efficiency with smarter operation, local support, and credible lifecycle economics. For organizations seeking to navigate this environment with greater precision, deeper segmentation data, company-level benchmarks, and customized strategic guidance can clarify where to commit resources and how to sequence next steps. Access the full PW Consulting report on the Electrostatic Precipitators market to explore detailed segmentation, competitive profiles, and forward-looking scenarios built for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chemotherapy Induced Peripheral Neuropathy Treatment Market: 6.5% CAGR from 2026-2032
By PW Consulting, 2026-09-21
Chemotherapy-Induced Peripheral Neuropathy Treatment Market: Strategic Trends and Commercial Opportunities
The chemotherapy-induced peripheral neuropathy (CIPN) treatment market has reached a critical inflection point. With a total market value of approximately $1.46 billion in 2025 and a projected trajectory to exceed $2.28 billion by 2032, the sector reflects a compound annual growth rate of 6.5 percent over the 2026-2032 period. This expansion is not merely a function of rising oncology volumes. It represents a structural shift in how the pharmaceutical industry approaches symptom management, neurological preservation, and quality-of-life endpoints in cancer care. Chemotherapy remains one of the most widely deployed modalities in oncology, and neuropathy stands among its most persistent and debilitating side effects. Patients receiving platinum-based agents, taxanes, and vinca alkaloids frequently experience progressive sensory loss, pain, balance impairment, and treatment-limiting dose reductions. The market for interventions addressing these outcomes has evolved from a fragmented landscape of off-label symptomatic therapies into a structured pipeline of mechanism-targeted candidates, increasingly shaped by regulatory guidance and clinical evidence standards.
Yet the scale of opportunity is matched by complexity. Stakeholders approaching this space must navigate a market where clinical differentiation, regulatory pathways, pricing dynamics, and oncology practice patterns intersect in non-linear ways. The next phase of growth will likely reward players who can translate mechanism plausibility into robust trial design, align with evolving oncology workflows, and articulate value propositions that resonate beyond symptom relief alone. Understanding where the market stands today, what forces are reshaping it, how competitors are positioning themselves, and where strategic opportunities are likely to emerge provides a necessary foundation for informed decision-making.
Market Landscape and Core Challenges
The CIPN treatment space is characterized by moderate market concentration and a therapeutic mix that still leans heavily on existing symptomatic classes, particularly antidepressants and anticonvulsants, alongside a smaller but strategically important segment of narcotics and emerging alternatives. This composition reflects both historical prescribing habits and the limited number of approved, mechanism-specific interventions. While the broader market size demonstrates steady expansion, the underlying structure reveals a sector that is simultaneously mature in its standard-of-care elements and early-stage in its innovation pipeline. That duality creates both stability and uncertainty, as legacy therapies continue to anchor clinical practice while newer candidates attempt to redefine therapeutic expectations.
A first challenge lies in clinical endpoint definition and trial design. CIPN presents across a spectrum of sensory, motor, and autonomic symptoms, and the field has historically struggled to standardize how improvement, stabilization, or prevention should be measured. Different chemotherapy regimens, cumulative dosing patterns, and patient baseline risk profiles complicate the creation of uniform trial populations. Sponsors that rely on broad symptom scales without mechanistic alignment or clearly defined responder thresholds risk generating data that is difficult to position clinically or commercially. The challenge is not simply demonstrating statistical change. It is demonstrating clinically meaningful change that oncologists, neurologists, and payers can act upon.
A second challenge is the persistent alignment gap between existing symptomatic classes and the underlying neurobiology of nerve injury. Current treatments often address perceived symptom pathways without directly interrupting axonal degeneration, ion channel dysfunction, or inflammatory signaling associated with specific chemotherapeutic agents. As understanding of CIPN mechanisms matures, therapies that are not linked to a plausible biological rationale may face growing pressure in clinical discussion and formulary positioning. This does not render all symptomatic options obsolete, but it does raise the bar for differentiation. The market increasingly favors interventions that can articulate not only what they treat, but why they should work in a particular chemotherapy context.
PW Consulting Health Care Research Center
A third challenge involves the oncology treatment environment itself. Dose adjustments, regimen substitutions, and individualized risk-benefit calculations can influence both the incidence of neuropathy and the perceived value of adjunctive interventions. In practice, neuropathy management does not exist in isolation. It competes for attention alongside tumor response, survival endpoints, and other supportive care priorities. Treatments that can integrate into existing oncology workflows, offer predictable safety profiles, and demonstrate a credible link to preserving chemotherapy delivery are more likely to gain adoption than those positioned as standalone neurological interventions with limited integration into cancer care pathways.
Key Drivers Shaping the Market
Several interconnected factors are accelerating momentum in the CIPN treatment market, and their influence is likely to intensify over the next several years. Rather than acting independently, these forces are reinforcing one another, reshaping both pipeline priorities and commercial expectations.
One of the most consequential drivers is the shift toward mechanistic and targeted approaches. A growing portion of the pipeline is focused on molecular pathways with clearer links to nerve injury, signaling dysregulation, or peripheral nerve repair. Candidates addressing specific ion channels, receptor-mediated protective pathways, and topical delivery strategies reflect an effort to move beyond nonspecific symptom modulation. This trend matters commercially because it creates opportunities for sharper messaging, more defensible clinical narratives, and potential differentiation in a crowded supportive care environment. At the same time, it raises the technical requirement for biomarker strategy, subgroup definition, and endpoint clarity. Sponsors that can connect a mechanism to a meaningful clinical readout are better positioned to justify investment and partnership interest.
Regulatory guidance and pathway signals are a second major driver. The issuance of FDA draft guidance for developing drug and biological products for the prevention and treatment of CIPN has helped establish a more explicit framework for expectations around trial design, population definition, and outcome measurement. Complementary regulatory actions, including Fast Track designations and IND clearances for candidates targeting CIPN, indicate that the agency is engaging with the area more actively. This environment reduces some ambiguity for developers and can improve the perceived credibility of programs that are designed with regulatory expectations in mind. For commercial stakeholders, the implication is that programs aligned early with guidance are more likely to navigate development with fewer late-stage surprises and clearer dialogue with regulators.
A third driver is the changing demand profile within oncology. As cancer therapies improve and patients live longer, the burden of chronic treatment-related effects is becoming more visible. Neuropathy that persists beyond active chemotherapy or limits future treatment options carries significant downstream implications for physical function, independence, and quality of life. This has increased attention to interventions that can prevent symptomatic progression, reduce dose-limiting toxicity, or support patients through longer treatment courses. Demand is not only coming from patient advocacy and clinician concern. It is also being shaped by the broader oncology goal of preserving treatment continuity and minimizing long-term functional impairment.
Supply-side and reimbursement dynamics also play a role, though often in less visible ways. The relative availability of generic symptomatic therapies exerts competitive pressure on pricing and adoption for newer agents, while reimbursement expectations increasingly favor evidence that connects treatment to functional outcomes, reduced downstream costs, or maintained chemotherapy delivery. Cost structures are therefore influenced by both the competitive shadow of established options and the evidentiary requirements of payers and health systems. Programs that can demonstrate practical value in real-world oncology settings are more likely to achieve sustainable market positioning than those relying solely on clinical signals without integration into care economics.
Competitive Landscape and Leading Strategies
The competitive environment reflects a spectrum of developmental maturity and strategic focus. Some companies are advancing candidates with clearer regulatory momentum or later-stage clinical activity, while others are operating in earlier phases or have paused further development after earlier signals. What distinguishes the more strategically positioned players is not only the stage of their programs, but the coherence of their therapeutic rationale, the alignment of their trial design with oncology context, and their ability to use regulatory or partnership leverage to accelerate confidence in their approach.
Dogwood Therapeutics illustrates a company building momentum through a combination of clinical progress and strategic licensing activity. The Halneuron program has moved forward in Phase 2b with reported interim findings and substantial enrollment progress, while the SP16 program has advanced through licensing from Serpin Pharma with IND clearance and planned Phase 1b activity. This dual-track structure suggests an emphasis on diversifying mechanism exposure while maintaining forward progress in a lead candidate. From a strategic standpoint, the company appears to be positioning around both clinical data generation and partnership-enabled capability expansion, which can be valuable in a market where single-asset dependence carries execution risk.
Asahi Kasei Pharma’s ART-123 program takes a prevention-oriented approach in a defined oncology population, focusing on sensory symptom prevention in colorectal cancer patients receiving oxaliplatin. This positioning is strategically notable because prevention can be harder to demonstrate than treatment, but it may also offer stronger clinical integration if the evidence supports a clear reduction in neuropathy burden within a specific chemotherapy context. Targeting a well-defined regimen and patient group can reduce some of the heterogeneity challenges that complicate broader CIPN studies, though it also narrows the initial commercial footprint.
Neuropathy Pain Treatment Market
Sironax’s SIR2501 program has drawn attention through Fast Track designation, signaling regulatory recognition of potential unmet need and development efficiency value. In a market where endpoint complexity can slow progress, regulatory designations can provide useful leverage for development planning, clinical engagement, and partnership conversations. WinSanTor’s topical pirenzepine program, meanwhile, reflects an alternative delivery strategy and a broader peripheral neuropathy focus, with ongoing work extending beyond CIPN. Topical approaches may be attractive if they can reduce systemic exposure or offer localized benefit, but adoption will depend on evidence that supports clinical differentiation and practical usability.
Serpin Pharma’s SP16 program reinforces the growing importance of early-stage financing and academic or institutional support in shaping pipeline viability. The receipt of grant funding to support a Phase 1b trial highlights how non-dilutive resources can help earlier programs reach critical developmental checkpoints. For investors and partners, this is a reminder that the CIPN market includes meaningful activity not only from large-scale commercial developers, but also from smaller, mechanism-focused groups whose evolution may influence future licensing and acquisition dynamics.
Across these players, a few competitive themes emerge. First, there is a clear trend toward programs that are more tightly tied to specific mechanisms or delivery modalities, with the intent of differentiating from nonspecific symptom management. Second, regulatory engagement and guidance alignment are increasingly part of strategic positioning, particularly for companies looking to reduce development risk or improve the credibility of their programs in clinical and investor discussions. Third, the landscape remains open enough for new entrants to find niches, but crowded enough that differentiation must be supported by more than mechanistic plausibility. Credible clinical design, context-specific positioning, and practical integration into oncology care will likely determine which programs translate into durable commercial advantage rather than short-term pipeline interest.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the direction of the CIPN treatment market. These are not mutually exclusive, and each carries distinct commercial implications.
One likely trend is a sharper separation between prevention-focused and treatment-focused interventions. As clinical programs mature, stakeholders may increasingly differentiate between agents intended to reduce the onset or progression of neuropathy during chemotherapy and those intended to manage established symptoms. This distinction matters for trial design, regulatory positioning, and clinical adoption. Prevention programs may target specific regimens or high-risk populations, while treatment programs may need to demonstrate meaningful benefit in patients with existing neurological impairment. The commercial implication is that value propositions will need to be tailored more precisely to the clinical context in which the intervention is used. Broad, undifferentiated claims may be less effective than narrowly supported, use-case-specific positioning.
A second trend is the increasing importance of topical and targeted delivery approaches alongside systemic therapies. Topical strategies may gain attention if they can offer focused benefit with favorable tolerability or reduced systemic exposure, especially in a population where polypharmacy and cumulative toxicity are concerns. However, clinical adoption will depend on whether these approaches can demonstrate consistent efficacy, ease of use, and integration into oncology supportive care routines. The commercial opportunity is not just in developing a new formulation. It is in proving that the delivery method creates meaningful clinical or operational advantages that clinicians and patients will accept in practice.
A third trend is growing pressure to connect CIPN interventions with functional and care-continuity outcomes. As payer and health system expectations evolve, evidence that goes beyond symptom scores may become more important. Demonstrating associations with maintained chemotherapy dosing, reduced supportive care utilization, or improved day-to-day function could strengthen commercial viability for certain programs. The risk is that companies relying solely on conventional symptom endpoints without a clear link to broader outcomes may find adoption more difficult or reimbursement discussions more complex. This creates a strategic imperative to design evidence generation around the full clinical and economic context of use.
At the same time, uncertainty remains. Trial results may vary by chemotherapy class, baseline risk, and endpoint definition, and not every mechanistic hypothesis will translate into durable clinical benefit. Competitive dynamics may also shift through partnerships, licensing, or consolidation, particularly as earlier-stage programs reach pivotal milestones. Stakeholders should therefore plan for a market that is growing but fragmented in credibility, where selection of partners, programs, or investment targets requires careful assessment of trial design, intended use case, and alignment with oncology practice.
Strategic Recommendations for Decision-Makers
For manufacturers and developers, the priority is to design programs with clear clinical context and regulatory alignment from the outset. This includes defining the intended chemotherapy setting, the relevant patient population, and the endpoint strategy in a way that supports both clinical credibility and commercialization. Mechanism-based differentiation is valuable, but it must be paired with evidence that can withstand scrutiny in real-world oncology settings. Developers should also consider how they will position their intervention relative to existing symptomatic options and whether they can articulate a distinct value proposition around tolerability, delivery, or care integration.
For investors, the opportunity lies in distinguishing programs with defensible execution roadmaps from those that depend primarily on early enthusiasm. Attention should be paid to enrollment feasibility, endpoint clarity, regulatory engagement, and the strength of clinical rationale within a specific chemotherapy context. Programs that combine mechanism interest with sound trial design and credible milestones may offer stronger risk-adjusted prospects than those that emphasize scientific promise without a clear path to clinically actionable evidence. Early-stage licensing and partnership activity may also create optionality, particularly if it enables better-capitalized or more operationally experienced groups to accelerate development.
For procurement and formulary decision-makers, the focus should be on evidence that supports practical adoption and value relative to current care patterns. This means evaluating not only efficacy signals but also safety, ease of integration, and any demonstrated impact on treatment continuity or functional outcomes. As new agents emerge, structured assessment frameworks can help determine which interventions warrant adoption, under what conditions, and where further evidence is needed before broader use. The availability of more standardized guidance and maturing clinical data should support more disciplined evaluation over time.
Worldwide Advanced Cancer Pain Management Market
In a market expanding toward $2.28 billion by 2032, the strategic question is not whether demand for effective CIPN intervention will continue to grow, but which programs, partnerships, and evidence strategies will separate durable value creation from transient pipeline interest. Detailed segmentation data, pipeline benchmarking, and scenario analysis can help organizations move from general market awareness to specific, actionable decisions. Readers interested in deeper breakdowns of market segments, competitive benchmarks, and customized strategic implications can explore the full report available through PW Consulting for more detailed segmentation data and tailored guidance.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insect Feed Market: How 16.4% CAGR and Aquaculture Demand Reshape 2032 Outlook
By PW Consulting, 2026-09-21
The Insect Feed Market: Strategic Trends and Commercial Opportunities Through 2032
The insect feed sector is transitioning from niche sustainability play to mainstream protein infrastructure. With the global market valued at approximately $147 million in 2025 and projected to reach $425.8 million by 2032, the sector is expanding at a compound annual growth rate of 16.4 percent. This trajectory reflects more than incremental demand growth. It signals a structural recalibration of animal nutrition supply chains, driven by regulatory opening, substrate economics, and the scaling of bioconversion technology. For executives and investors, the question has shifted from whether insect protein will gain traction to how capital, capability, and partnerships will be allocated as the market matures.
Market Landscape and Core Challenges
The revenue arc over the past half-decade illustrates steady acceleration, with growth compounding as production capacity converts from pilot scale to commercial throughput. By the close of the forecast window, the market is on a path toward nearly triple its 2025 baseline. That expansion is uneven rather than uniform, shaped by regional regulatory readiness, feed formulation economics, and the pace at which manufacturing networks achieve cost parity with conventional protein sources. Understanding where the market is heading requires looking past headline figures to the structural constraints that will determine which players capture value.
Navigating Structural Constraints
Several inflection points are shaping the operational reality of the industry. First, substrate sourcing and waste-stream consistency remain foundational bottlenecks. Insect feed production depends on upcycled organic inputs such as food processing byproducts, and the economics of collection, pretreatment, and contamination control vary widely by geography and season. While this model can reduce material costs substantially relative to conventional protein sourcing, the operational discipline required to maintain consistent substrate quality across multiple intake streams is non-trivial. Facilities that fail to standardize input quality encounter downstream variability in yield, nutrient profiles, and regulatory compliance.
Second, regulatory adoption is advancing but remains fragmented. In the European Union, rules governing insect protein in aquaculture are established, and approval pathways for poultry and swine applications have progressed under updated feed frameworks. In the United States, regulatory clearances have extended for select insect proteins in poultry and pet food categories. The pace and scope of these approvals differ by jurisdiction and protein type, creating uneven commercialization timelines. Companies that can navigate multiple regulatory regimes simultaneously, or that align product development with the fastest-opening categories, gain a meaningful time advantage.
Aqua Feed Market
Third, scaling biology is as much an engineering challenge as a biological one. Temperature control, humidity management, disease mitigation, and harvesting logistics all influence yield stability and unit economics. Early-stage producers often underestimate the capex intensity of climate-controlled environments and the operational complexity of continuous rearing systems. As the market moves toward larger facilities, the gap between companies with proven process control and those still refining biological workflows will become more visible in margin performance and supply reliability.
Key Drivers Reshaping the Sector
Several forces are converging to accelerate adoption and reshape competitive dynamics. These drivers are not isolated; they reinforce each other and create a clearer line of sight to commercial scale for operators who align technology, compliance, and customer demand.
Bioconversion and Process Technology
The most consequential technical progress lies in improving rearing efficiency, feedstock flexibility, and downstream processing consistency. Proprietary rearing systems, automation in harvesting and separation, and process controls that stabilize larval growth cycles are reducing variability in protein and lipid outputs. This matters because feed formulators require repeatable nutrient profiles, contamination thresholds, and functional properties. Companies that treat insect production as a manufacturing process rather than an agricultural experiment are gaining credibility with B2B buyers who evaluate suppliers on reliability as much as sustainability credentials.
The commercial significance of this shift is clear when viewed alongside recent market activity. Innovafeed has expanded its operational footprint with a U.S. facility in Decatur, Illinois, marking a step toward localized production in a market where feedstock availability and regulatory timing support scale-up. This move illustrates how technology-enabled producers are positioning themselves closer to end markets in order to reduce logistics friction and respond more quickly to regional demand signals.
Regulatory Opening and Category Expansion
Regulation remains the central gatekeeper for category expansion. Approvals for aquaculture have already enabled commercial use of insect proteins in fish feed, while newer regulatory movements in the EU and U.S. have extended possibilities into poultry and swine nutrition and, in certain contexts, pet food. These changes do not merely open new addressable segments; they reshape feed formulation economics by creating alternatives to soy and fishmeal in categories where substitution pressure is strongest.
The regulatory trajectory also influences procurement behavior. Feed manufacturers and integrators that have been waiting for regulatory clarity are now beginning to test inclusion rates, evaluate supply continuity, and negotiate multi-year arrangements. Protix, for example, signed a multi-year supply agreement with Skretting for black soldier fly meal in salmon feed formulations, a move that signals how regulatory maturity is translating into committed offtake and category-specific product development.
Demand-Side Shifts in Animal Nutrition and Pet Care
Demand is being pulled by multiple end-use pressures. In aquaculture, the need for sustainable protein inputs continues to intensify as marine ingredient supply faces volatility and environmental scrutiny. In poultry and swine nutrition, producers are exploring insect protein not only for sustainability positioning but also for functional benefits and supply diversification. In pet food, consumer interest in novel protein sources and premium formulation is expanding the addressable market for insect-based ingredients, particularly where regulatory clearance and brand acceptance progress together.
This diversification matters strategically because it reduces dependence on any single category’s adoption cycle. Companies with portfolios that span aquaculture, livestock nutrition, and pet food can shift commercialization emphasis as regulatory timing and customer readiness vary by region. The effect is a more resilient demand base and a stronger foundation for long-term contract structures.
Cost Structure and Substrate Economics
The economic case for insect feed is closely tied to substrate cost and plant efficiency. Because insect production can utilize upcycled organic waste streams, input costs can be materially lower than those of conventional protein sources when collection and pretreatment are managed effectively. Life cycle assessments comparing insect-based inputs with soy or fishmeal indicate substantial differences in land and water requirements and lower associated greenhouse gas emissions, reinforcing the sustainability narrative that supports procurement decisions.
However, cost advantage is not automatic. It depends on logistics networks, preprocessing capability, and the ability to maintain consistent substrate composition at scale. Facilities that integrate substrate procurement, pretreatment, and rearing into a coordinated operational model are better positioned to protect margins as volumes increase. This is where competitive differentiation increasingly emerges: not simply in the insect species used, but in the industrial design of the entire value chain.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of established producers accounting for a meaningful share of revenue and an expanding set of regional and specialized entrants competing on niche formulations, geography, or substrate strategies. The strategic posture of leading companies reveals how value is being captured in a market still defining its standards.
Differentiation Through Scale, Technology, and Of ftake
Several patterns distinguish the more advanced players. Protix has built a profile around high-quality insect solutions spanning feed, pet food, aquaculture, and plant care, with a focus on black soldier fly larvae and broad application coverage. Its multi-year agreement with Skretting illustrates a strategy centered on committed customer relationships and category-specific formulation support, which helps stabilize demand and fund capacity expansion.
Innovafeed has emphasized proprietary rearing technology and geographic expansion, including its U.S. facility in Illinois. This reflects a strategy of combining technical differentiation with direct market access, reducing reliance on export logistics and positioning closer to large North American feed markets. Entobel has pursued a similar operational discipline, with long-standing production in Vietnam and a recent certification milestone that reinforces its positioning around sustainability and governance as commercial signals for B2B buyers.
Pet Food Insect Protein Market
Other companies are carving distinct lanes. Beta Hatch has focused on mealworm-based production within a regenerative agriculture framing, highlighting a different species and system design from the black soldier fly-dominant core of the market. Nutrition Technologies, now operating under the Sentara Group name following expansion, has continued to build around black soldier fly ingredients for aquaculture, agriculture, and animal feed, illustrating how rebranding and organizational scaling can accompany capacity growth. Hexafly and nextProtein have emphasized the bioconversion of food waste into protein, oil, and fertilizer, aligning product portfolios with circular-economy value propositions that appeal to customers seeking integrated sustainability outcomes.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape is evolving along several axes. Scale industrialization is concentrating production among companies able to fund large facilities, standardize processes, and secure stable substrate supply. At the same time, specialization remains viable in niches such as pet food formulations, functional ingredients, plant care products, and regional supply arrangements where logistics and regulatory timing favor local production.
New entry continues, but the bar is rising. Early entrants could often compete on concept and pilot output; newer entrants must demonstrate process reliability, regulatory compliance, cost control, and defensible customer relationships. This dynamic is likely to reward operators that combine biological capability with manufacturing discipline and commercial execution. It also suggests that partnerships, offtake agreements, and integration with existing feed supply chains will become more important than standalone brand positioning.
Forward Outlook: Three Strategic Trends for 2026–2032
Looking ahead, several trends are likely to define how value accrues in the insect feed market over the next several years.
Trend 1: Regional Production Clusters and Feedstock-Proximity Manufacturing
Production is likely to consolidate around feedstock availability, regulatory readiness, and end-market demand rather than forming a single global center of gravity. Regions with strong waste-stream infrastructure, supportive feed regulations, and large aquaculture or livestock sectors will attract capacity. This has direct commercial implications: companies that align facility siting with substrate economics and customer proximity will lower logistics costs and improve supply reliability, while those dependent on long-distance substrate or product movement may face margin pressure as the market scales.
Trend 2: Formulation Integration and Category-Specific Product Design
Insect ingredients will increasingly be valued not simply as generic protein but as formulated inputs tailored to specific species, life stages, and functional requirements. As feed manufacturers gain experience with inclusion rates and nutrient performance, demand will shift toward consistent specifications, traceability, and technical support. The commercial opportunity lies in building product architectures around customer formulations rather than selling undifferentiated bulk ingredients. Suppliers that invest in application engineering and quality assurance will be better positioned to defend pricing and deepen relationships.
Trend 3: Regulatory Normalization and Procurement Mainstreaming
As approvals expand and standards mature, insect protein is likely to move from special-case procurement to routine supplier evaluation. That transition will favor operators with established compliance records, auditable quality systems, and supply continuity. It also introduces risk: regulatory timing can shift, inclusion limits can change, and category approvals may not proceed uniformly. Companies that assume a linear regulatory path without scenario planning may misallocate capacity or overcommit to segments that open more slowly than expected.
Associated uncertainties include substrate consistency at scale, biological process control during rapid expansion, and the risk that sustainability narratives alone will not sustain procurement decisions if cost or performance gaps remain. The market’s trajectory is strong, but execution quality will determine which participants convert growth into durable margins.
Implications and Actions for Decision Makers
For executives and investors evaluating the insect feed market, the strategic task is to match ambition with operational readiness and to prioritize the decisions that convert market momentum into competitive advantage.
PW Consulting Health Care Research Center
For Producers and Technology Developers
- Prioritize process control and substrate logistics as the foundation of scale-up. Consistent quality and cost stability matter more to B2B buyers than incremental sustainability claims, so investment should flow toward rearing consistency, harvesting efficiency, and integrated feedstock management.
- Align capacity deployment with regional regulatory timing and customer demand. Expanding too quickly into segments with uncertain approval pathways can create underutilized assets, while sequencing expansion around opening categories supports revenue absorption and learning-curve gains.
- Build formulation support and application data. As customers move from trial to routine use, technical service capability becomes a differentiator. Developing species-specific and application-specific evidence strengthens customer retention and pricing power.
For Investors and Capital Allocators
- Evaluate biological capability alongside manufacturing discipline. The most attractive opportunities are likely to be with teams that can demonstrate repeatable yield, contamination control, and cost trajectory rather than concept-level promise.
- Assess demand visibility through offtake structure and customer diversification. Contracts, pilot-to-commercial conversion rates, and exposure across aquaculture, livestock, and pet food can indicate resilience if one category’s adoption slows.
- Model regulatory and substrate scenarios, not just base-case growth. Because approvals, inclusion limits, and feedstock availability can vary by region, sensitivity analysis around timing and input costs is essential for realistic return expectations.
For Procurement and Feed Formulators
- Treat insect ingredients as part of a supply diversification and sustainability strategy, but validate them through performance trials and supply reliability assessment. The strategic value lies in reducing exposure to conventional ingredient volatility while maintaining nutrient specification and consistency.
- Engage early with suppliers on specification design and traceability. Collaboration on inclusion rates, quality parameters, and auditability can accelerate integration and reduce reformulation risk.
- Structure sourcing with regulatory awareness. Procurement plans should account for category-specific approvals and potential changes in inclusion limits so that supply commitments align with regulatory reality in each market.
Closing Perspective
The insect feed market is entering a phase where growth is increasingly determined by execution rather than narrative. The revenue trajectory through 2032 points to a substantial expansion in addressable demand, but the distribution of value will depend on how effectively companies manage substrate economics, regulatory complexity, process control, and customer integration. For organizations building, funding, or sourcing from this sector, the opportunity is not simply to participate in a high-growth category but to shape a supply chain that can deliver consistent quality at competitive cost while meeting the sustainability expectations of modern animal nutrition. Detailed segmentation, regional dynamics, and company-level benchmarking can sharpen these decisions further, and a full research report can provide the supporting data and structured frameworks needed for planning at the segment and facility level.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Robotic Polishing Machine Market: Why the 12.6% Growth Trajectory Redefines Competition
By PW Consulting, 2026-09-21
Robotic Polishing Machine Market: Strategic Shifts, Competitive Dynamics, and Value Creation Horizons
The global market for robotic polishing machines is entering a phase of accelerated structural transformation. Between 2020 and 2025, market revenue expanded from approximately $163 million to $215 million, reflecting sustained adoption across precision manufacturing and surface finishing workflows. The trajectory forward indicates a compound annual growth rate of 12.6% through 2032, with projected revenue approaching $345 million by the end of the forecast horizon. This growth is not merely a function of incremental automation adoption; it reflects a fundamental rethinking of how surface quality, throughput, and labor constraints interact in modern production environments. For executive teams and capital allocators, the implication is clear: robotic polishing is transitioning from a niche productivity tool to a strategic capability that shapes product quality, operational resilience, and competitive positioning.
Market Snapshot and Structural Challenges
The market’s expansion over the past half-decade has been broad-based, with steady year-over-year increases that signal deepening integration rather than speculative cycles. Revenue climbed from roughly $174 million in 2021 to nearly $208 million in 2024, before stabilizing near $215 million in 2025. The forward path suggests continued momentum, with the market expected to cross $250 million by 2027 and approach $290 million around 2030. Yet this headline trajectory masks a more nuanced reality. Growth is uneven across use cases, and the market is navigating several inflection points that will separate winners from laggards.
One of the most pressing challenges is the tension between standardization and application-specific customization. Polishing requirements vary dramatically by material, geometry, tolerance thresholds, and finish specifications. A solution that performs exceptionally on high-volume automotive components may struggle with delicate electronics housings or irregularly shaped stone surfaces. Manufacturers are therefore forced to balance the cost efficiencies of modular, repeatable systems against the precision demanded by specialized workflows. This creates a strategic fork: companies that over-index on rigid automation risk losing high-margin niches, while those that overengineer custom solutions may sacrifice scalability and total cost of ownership advantages.
A second challenge lies in workforce transition and operational integration. Deploying robotic polishing is not simply a hardware purchase; it requires reconfiguration of upstream and downstream processes, recalibration of quality control protocols, and upskilling of operators who must interface with systems that blend mechanical execution with sensor-driven adaptation. Facilities with strong internal automation competency are absorbing these transitions relatively smoothly, but organizations with fragmented production planning or limited engineering bandwidth are experiencing longer payback periods and higher initial friction. The market is increasingly rewarding operators who treat robotic polishing as a process transformation initiative rather than a point solution.
A third challenge is the evolving regulatory and safety environment. Industrial robotics deployments are subject to stringent operational safety requirements, and robotic polishing systems introduce additional complexity due to dynamic force application, tool wear, and interaction with delicate or irregular workpieces. Compliance frameworks now emphasize risk assessments, protective measures, and system-level integration checks. While these standards are essential for safe, scalable deployment, they also raise the barrier to entry for smaller integrators and increase the importance of designing for compliance from the outset rather than retrofitting it after the fact.
Core Drivers Reshaping the Market
Several interconnected forces are accelerating the shift toward robotic polishing, and each carries distinct strategic implications for how companies should position themselves.
Technology Innovation and Adaptive Control
The most consequential technical shift is the move from static, pre-programmed finishing routines to adaptive, sensor-informed polishing. Advanced systems increasingly combine multi-axis motion with force control, vision-based inspection, and closed-loop feedback that adjusts pressure, speed, and tool engagement in real time. This capability directly addresses one of the long-standing limitations of automation in surface finishing: the inability to maintain consistent quality when workpieces vary or when tool wear introduces drift. AI-enabled platforms are pushing this further by scanning surfaces, mapping deviations, and automating path generation without extensive manual programming. The result is faster setup, reduced rework, and more repeatable finishes on complex geometries. For manufacturers, the strategic takeaway is that value is increasingly created not just by the robot arm itself, but by the intelligence layer that governs how polishing decisions are made during production.
Regulatory and Safety Expectations
As robotic systems become more capable and more widely deployed, safety and compliance expectations are becoming a defining element of market acceptance. Governing standards for industrial robots now require structured risk assessments and protective measures that account for force-controlled interactions, tool changes, and human proximity in shared workspaces. This is particularly relevant in polishing applications where unpredictable material response and tool wear can create operational variability. Systems designed with integrated safety logic, documented risk controls, and modular compliance features are gaining preference, especially in regulated industries and in deployments where multiple stakeholders must validate automation before scaling. Compliance is no longer a checkbox; it is becoming a competitive differentiator that influences procurement decisions, deployment speed, and long-term operational risk.
Demand-Side Shifts in Quality, Throughput, and Consistency
On the demand side, manufacturers are under increasing pressure to deliver higher consistency at lower defect rates while maintaining throughput. Automotive production, electronics assembly, hardware tooling, and household product manufacturing all place distinct demands on surface finish, but they share a common requirement: quality cannot be treated as a variable that is inspected in at the end of the line. It must be engineered into the process. Robotic polishing supports this shift by reducing dependence on manual skill variability, enabling repeatable finishes across shifts and facilities, and freeing skilled workers for higher-value tasks. At the same time, end customers and OEM partners are increasingly specifying finish tolerances and appearance standards that are difficult to meet reliably with manual or semi-automated methods. This demand-side pressure is expanding the addressable use case set beyond high-volume commodity finishing into precision and brand-sensitive applications where finish quality directly affects perceived value and downstream performance.
Supply Chain and Cost Structure Dynamics
Cost structures are also evolving in ways that reshape ROI calculations for automation. Labor availability, wage dynamics, and training burdens continue to push manufacturers toward solutions that reduce dependence on highly skilled manual finishing labor. At the same time, improvements in component availability, tooling ecosystems, and system integration practices are gradually lowering the total cost of deployment for well-scoped projects. The most compelling economics are emerging where robotic polishing is used not only to replace labor but to compress cycle times, reduce scrap and rework, and stabilize output quality across production runs. Companies that evaluate ROI narrowly through headcount replacement often underestimate the operational value of consistency, uptime, and reduced quality leakage. The market is increasingly favoring deployments that are justified through a broader set of operational benefits rather than labor cost alone.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of established automation suppliers, specialized tooling and finishing companies, and newer entrants bringing software-centric approaches to surface finishing. Several firms stand out for the way they are positioning their offerings around different value propositions.
Acme Manufacturing has built a strong focus on robotic polishing machines with advanced belt polishing heads, targeting high-volume producers that need repeatable finishes on complex shapes. Its strategic emphasis is on throughput and consistency for demanding production environments, where the ability to maintain finish quality across large batches is a core purchasing driver. This positioning reflects a broader trend: in high-volume segments, reliability and repeatability are often more valuable than flexibility, and suppliers that can demonstrate proven performance at scale gain traction.
Mirka Ltd offers a more complete system view, combining robotic polishing and sanding systems with tools and automation solutions for industrial surface finishing. By presenting an integrated tool-plus-automation proposition, Mirka addresses customers who want fewer integration handoffs and a more coordinated hardware ecosystem. This approach reduces ambiguity in tool selection, process setup, and maintenance planning, which can be especially valuable for organizations that prefer to simplify supplier complexity and standardize finishing workflows.
GrayMatter Robotics has differentiated itself with AI-powered robotic polishing systems that scan surfaces and automate polishing to support manufacturing capacity and quality enhancement. This software-led approach centers on reducing programming effort and enabling faster adaptation to variation, which appeals to environments where part diversity or setup changeovers make conventional programming costly. The strategy highlights a growing market segmentation: systems that emphasize intelligence, scanning, and automated path generation are gaining relevance wherever flexibility and responsiveness are prioritized over fixed, high-volume routines.
Dinosaw Machine manufactures 6-axis robotic arms and systems for stone grinding and polishing, with a focus on force control and precision tooling. Its emphasis on precision control and material-specific applications illustrates the importance of domain specialization. In materials such as stone, where structural variability and surface behavior can differ significantly from metallic or synthetic workpieces, force-controlled accuracy and tooling precision are central to performance. This specialization also aligns with the broader regulatory and safety expectations for industrial robots, where force control and protective integration are increasingly viewed as prerequisites for reliable deployment.
American Siepmann Corporation supplies automated CNC polishing machines and robotic systems for high-precision industrial finishing. Its positioning reflects demand for tightly controlled processes in environments where tolerance, repeatability, and integration with CNC workflows matter. The company’s focus on precision industrial finishing underscores the fact that robotic polishing is not a single market but a family of use cases, each with its own performance priorities and procurement logic.
Recent market developments reinforce these strategic directions. In late 2025, Dinosaw Machine presented a detailed analysis of stone polishing robot technology, emphasizing 6-axis force control and safety integration. That activity reflects a broader industry emphasis on controlling force dynamically while meeting safety expectations for industrial robotics. Meanwhile, Mirka Ltd updated its robotic solutions materials to highlight automated polishing, sanding, and grinding systems, signaling continued investment in integrated finishing offerings and a desire to make automation more accessible across a wider set of applications. These kinds of moves suggest that leading players are expanding system completeness, reinforcing safety and control capabilities, and refining the way they communicate value to customers who are evaluating automation across multiple use cases.
PW Consulting
The market structure itself is moderately concentrated, with the top firms accounting for a majority of revenue. This concentration does not imply stagnation; rather, it suggests that scale, integration depth, and brand trust still matter in a market where deployment risk and process reliability are significant concerns. At the same time, the landscape is open enough to permit differentiation through technology depth, application specialization, and software-enabled flexibility. New entrants and niche specialists can compete by solving specific finishing problems better than broader incumbents, particularly in high-value or technically demanding segments. Consolidation is likely to continue where larger players seek to broaden their system capabilities, but fragmentation will persist where application diversity and regional manufacturing patterns reward localized specialization.
Outlook: Key Trends for the Next Three to Five Years
Looking ahead, several trends are likely to shape how the market evolves and where commercial opportunities will concentrate.
-
Adaptive, intelligence-led finishing will become a baseline expectation rather than a premium feature. Systems that can scan, measure, and adjust polishing behavior in real time will increasingly be favored because they reduce programming burden, improve robustness to variation, and support faster changeovers. Over the next few years, the strategic question will shift from whether to adopt robotic polishing to how much adaptive control is necessary for a given application and how to integrate that capability into quality workflows.
-
Application specialization will intensify, with suppliers and end users aligning solutions more tightly to material and process requirements. Polishing for automotive components, electronics, hardware tools, household products, and stone or specialty materials each carries distinct demands. Companies that build deep domain expertise, tool ecosystems, and demonstration cases in specific verticals are likely to earn stronger customer trust and pricing power than those that attempt to serve all segments with generic solutions. This trend creates opportunities for focused innovators and for established players that can credibly claim leadership in a defined application set.
-
Integration and compliance will increasingly operate as joint value drivers. As deployments scale, customers will care not only about the polishing module but about how it connects to upstream machining, downstream inspection, tooling maintenance, and operational safety. Systems that are designed with documented safety integration, risk-control logic, and interoperability in mind will face lower deployment friction and will be easier to scale across facilities. In practice, this means that the most successful offerings will be those that reduce the total integration burden rather than simply optimizing a single machine’s performance.
These trends create clear commercial opportunities, but they also carry risks. One risk is overinvestment in automation before process maturity is sufficient to absorb it. Facilities that lack stable upstream processes, clear quality specifications, or operational discipline may experience disappointing results even with capable hardware. Another risk is market fragmentation driven by application diversity: too much customization can erode scalability, while too little can leave high-value segments underserved. A third risk is the pace of regulatory and safety expectations, which may continue to evolve and raise the standard for what counts as a deployable system. Organizations that treat safety, integration, and process design as afterthoughts will face higher costs and slower adoption curves.
Strategic Implications for Decision Makers
For manufacturers evaluating robotic polishing, the first priority should be to define the operational problem with precision. The strongest business cases typically emerge where finishing variability, rework, or throughput constraints are well understood and where automation can be introduced into a process that already has clear quality targets and stable upstream conditions. Rather than starting with the hardware, leaders should start with the finish specification, the tolerance for variation, the frequency of changeovers, and the cost of quality leakage. That framing makes it easier to determine whether a repeatable high-volume system, an adaptive AI-driven platform, or a precision-focused CNC-integrated solution is the better fit.
For investors and strategic planners, the opportunity lies in identifying where value is being created along the chain. Revenue growth is meaningful, but the more important question is where margins, differentiation, and recurring value are forming. Companies that control the combination of hardware, tooling, adaptive software, and integration know-how are likely to capture more durable value than those competing primarily on unit pricing. Equally important is the ability to demonstrate measurable outcomes in targeted applications. Investors should favor exposure to players that can connect their technology to defensible use cases, repeatable deployments, and clear operational benefits, rather than to broad claims that are not anchored in specific finishing problems.
Worldwide Glass Polishing Powder Market
For procurement and operations leaders, the emphasis should be on total deployment risk rather than initial sticker price. That means evaluating tooling ecosystems, programming and changeover burden, safety and compliance posture, and the service and maintenance model alongside the core machine. A system that appears marginally more expensive may offer materially lower integration risk and faster ramp-up if it reduces programming time, simplifies tooling management, or embeds safety and quality logic more effectively. Procurement decisions that incorporate these factors tend to produce more reliable outcomes and fewer hidden costs after deployment.
For all of these audiences, the value of detailed, current market intelligence is rising. The market is moving quickly enough that broad assumptions about adoption, pricing, and competitive positioning can become outdated within a short period. Segment-level demand patterns, technology substitutions, regulatory expectations, and supplier strategies can differ significantly across regions and applications, and these differences shape where opportunities are real and where they are overstated. Organizations that use detailed, structured intelligence to map their specific application, cost structure, and competitive environment are better positioned to calibrate investment timing, prioritize use cases, and avoid committing to solutions that do not fit their operational reality.
As the robotic polishing market continues its shift from incremental automation to capability-driven competitiveness, the leaders who benefit most will be those who approach it as a strategic decision rather than a tactical purchase. The combination of adaptive technology, application specialization, safety-aware integration, and disciplined ROI framing will determine which organizations capture durable value. For decision makers seeking a deeper view of segment-level dynamics, regional variation, and tailored scenario planning, the full PW Consulting research report on the robotic polishing machine market provides a more detailed foundation for those decisions.
Robotic Polishing Cells Market
For detailed analysis of this topic, please visit the official page: Robotic Polishing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fibrinogen Concentrates Market: Why a 5.96% CAGR Reshapes the $704.96M Outlook by 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Fibrinogen Concentrates Market
The global fibrinogen concentrates market has evolved from a specialized niche into a strategically significant segment within the broader plasma-derived therapeutics landscape. Market valuation reached approximately USD 468.38 million in 2025, reflecting a compound annual growth rate of 5.96 percent over the historical evaluation period and positioning the sector for continued expansion through 2032, when projected revenues approach USD 705 million. This trajectory is not merely a function of demographic demand or clinical adoption; it reflects structural shifts in surgical standards, regulatory pathways, manufacturing efficiency, and the economics of hemostatic care. For executives navigating biologics markets, fibrinogen concentrates present a case study in how concentrated therapeutic classes can scale while navigating plasma supply constraints, reimbursement complexity, and competitive differentiation.
PW Consulting
At the same time, the market is not without friction. Growth trajectories must be weighed against manufacturing bottlenecks, cost barriers for end users, and the evolving reimbursement environment that determines real-world utilization. Understanding where value is being created, which strategic moves are compounding advantage, and where uncertainty remains is essential for companies allocating capital, shaping product roadmaps, or evaluating partnership and acquisition targets in hemostasis and plasma-derived therapies.
Market Dynamics and Core Challenges
The current market structure reflects a mature but still expanding therapeutic category. Demand is distributed across surgical bleeding management, congenital fibrinogen deficiency, and a broad set of acquired and specialized applications. The product mix continues to favor powdered formulations, while liquid presentations are gaining incremental traction as reconstitution and storage considerations are addressed through formulation innovation. Geographically, developed markets continue to anchor the largest revenue shares, but the growth profile increasingly depends on expanded access in regions where hemophilia and bleeding disorder infrastructure is maturing.
Human Fibrinogen Market
Several forces are converging to define the near-term inflection points for the industry:
- Plasma supply and fractionation economics remain the dominant cost constraint. Fibrinogen-rich plasma inputs account for more than half of total production costs, which means that supply chain resilience, yield optimization, and donor plasma economics directly influence pricing power and margin stability.
- Reimbursement and coding frameworks are evolving rapidly in key markets. Recent HCPCS designations and expanding clinical approvals are reshaping the administrative and financial pathways that hospitals and payers use to authorize fibrinogen concentrate use, influencing both volume and substitution patterns.
- Clinical adoption is expanding beyond congenital indications into acquired fibrinogen deficiency and acute bleeding settings, but evidence requirements, institutional protocols, and cost consciousness create uneven adoption curves across health systems.
These dynamics create a market that rewards operators who can align product formulation, regulatory strategy, and market access planning rather than treating each as a separate silo. The ability to navigate plasma cost volatility while securing reimbursement clarity is becoming a competitive differentiator rather than a baseline expectation.
Key Drivers Shaping the Market
Technological Innovation and Formulary Differentiation
Innovation in fibrinogen concentrates is increasingly centered on presentation formats, viral inactivation robustness, reconstitution convenience, and indication expansion. Manufacturers are advancing refined purification and pathogen reduction processes that support confidence in efficacy and safety, while new packaging options are designed to meet the operational needs of surgical theaters and emergency settings. The introduction of specialized gram-level presentations reflects a broader trend toward tailoring product formats to clinical workflows and dosing requirements. These advances are not cosmetic; they affect procurement decisions, storage logistics, dosing precision, and the speed with which fibrinogen can be deployed in time-sensitive bleeding scenarios.
From a commercial standpoint, formulation and presentation strategy has become a lever for market access. Products that reduce handling complexity, improve dosing flexibility, or support specific patient populations can gain preference even in a category where therapeutic class equivalence is often assumed. The practical implication is that innovation must be paired with evidence generation and reimbursement alignment to translate clinical value into market share.
Regulatory and Reimbursement Dynamics
Regulatory progress continues to expand the addressable patient population. Recent approvals in the United States have broadened the use of fibrinogen concentrates for acquired fibrinogen deficiency and acute bleeding episodes, while separate regulatory actions have reinforced product-specific coding pathways. These developments matter because they influence prescribing confidence, hospital procurement policies, and payer coverage decisions. A product that moves from a narrower congenital indication into acquired and acute bleeding settings can unlock substantially larger utilization, provided the supporting evidence and coding environment enable consistent reimbursement.
The same regulatory environment introduces complexity. Stringent plasma collection, testing, and fractionation requirements raise the barrier to entry and increase the operational burden for manufacturers. Simultaneously, payers and health systems are scrutinizing cost-effectiveness, dosing efficiency, and the relationship between fibrinogen concentrate use and broader hemostatic management protocols. Companies that proactively shape clinical evidence, real-world utilization data, and coding narratives are better positioned to mitigate reimbursement friction and sustain volume growth.
Demand-Side Transformation in Surgical and Bleeding Care
Demand for fibrinogen concentrates is being shaped by several interrelated clinical and institutional trends. Surgical bleeding management remains a central application, supported by growing recognition of fibrinogen’s role in perioperative hemostasis and the desire to reduce transfusion-related risks and complications. At the same time, congenital fibrinogen deficiency continues to anchor a consistent base of demand, while acquired fibrinogen deficiency is emerging as an area of expanding clinical interest across trauma, cardiac, obstetric, and critical care settings.
Hospital procurement behavior is also shifting. Procurement teams are increasingly balancing clinical efficacy, supply reliability, presentation convenience, and total cost of care. In many institutions, formulary decisions are not made solely on price per gram; they incorporate workflow fit, stability, reconstitution requirements, and the availability of dosing options that match patient weight and bleeding severity. This suggests that demand growth will not be uniform across products or settings. Instead, adoption will favor manufacturers who can demonstrate clinical reliability, practical usability, and a clear value proposition relative to alternatives in the hemostatic toolkit.
Supply Chain and Cost Structure Pressures
Cost structure remains a defining feature of the market. The economics of plasma fractionation mean that plasma acquisition and processing represent the largest share of manufacturing cost, with fibrinogen-rich materials contributing a substantial portion of total expense. This creates sensitivity to plasma supply variability, donor availability, fractionation yields, and overhead associated with compliance and testing. For manufacturers, the challenge is not simply reducing unit cost; it is managing a cost stack that is partially exposed to external supply dynamics while maintaining consistent product availability and quality.
The cost implication for end users is equally important. At typical dosing levels, fibrinogen concentrate therapy can represent a meaningful expense for hospitals, particularly in lower-income regions or resource-constrained settings. That pricing pressure does not eliminate demand, but it shapes substitution decisions, protocol design, and the pace at which fibrinogen concentrate use expands beyond well-resourced centers. Commercial strategies that account for tiered access, presentation efficiency, and strong pharmacoeconomic justification are more likely to sustain growth across diverse market conditions.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of established plasma-derived biologics manufacturers alongside regional players seeking to establish or expand fibrinogen concentrate offerings. Leading organizations differentiate themselves through combinations of indication breadth, presentation options, regulatory milestones, manufacturing scale, and market access positioning. Rather than competing on a single dimension, successful players are aligning product portfolios with clinical workflows and reimbursement realities.
Several strategic positions are evident in the current landscape:
- Indication expansion as a growth lever. Companies that secure approvals for acquired fibrinogen deficiency or acute bleeding episodes broaden the clinical contexts in which their products can be used, increasing the addressable volume beyond congenital deficiency alone.
- Presentation flexibility as an operational advantage. Introducing dosing options and formulations tailored to specific settings can reduce friction in procurement, compounding, and bedside administration, strengthening hospital preference and formulary retention.
- Regulatory and coding alignment as a commercial enabler. Clear coding pathways and reimbursement language can reduce administrative barriers and accelerate institutional adoption, especially when paired with clinical evidence that supports appropriate use.
- Plasma-derived manufacturing credibility and supply resilience. Established fractionation capabilities and robust quality systems matter in a category where consistency, safety, and supply continuity are paramount for both clinicians and purchasers.
Recent developments illustrate how regulatory and product-level moves are reshaping competitive positioning. In late 2025, a major plasma therapeutics company secured FDA approval for a fibrinogen concentrate in acute bleeding episodes for pediatric and adult patients with congenital fibrinogen deficiency. Shortly thereafter, in early 2026, another key player gained FDA approval for a new 2-gram presentation of its fibrinogen concentrate for bleeding patients with acquired fibrinogen deficiency, building on earlier expanded approval activity in the prior year. These milestones are not isolated product events; they signal a broader shift toward wider clinical use, more flexible dosing formats, and increased competitive intensity around indication coverage and market access.
The market concentration profile suggests that scale and regulatory experience still matter, with a relatively concentrated share structure among leading participants. However, the landscape is also evolving through targeted launches, indication-specific differentiation, and regional capacity development. New entrants and regional manufacturers can compete by focusing on specific geographies, cost-efficient presentations, or locally relevant indications, particularly where access gaps remain or where procurement dynamics favor regional supply resilience. Consolidation may continue over time as larger players seek to strengthen portfolio depth and manufacturing reach, but differentiation through formulation, indication strategy, and market access capability will remain central to winning share.
Future Trends and Commercial Implications
Broader Clinical Use Will Drive Volume, but Distribution Will Be Uneven
Over the next three to five years, the most consequential trend is likely to be the continued migration of fibrinogen concentrate use beyond narrowly defined congenital indications into acquired deficiency and acute bleeding management. This broadening reflects both regulatory momentum and clinical interest in targeted fibrinogen replacement. The commercial implication is that total volume potential increases, but adoption will depend on local protocols, evidence dissemination, and reimbursement clarity. Markets with mature bleeding disorder infrastructure and established surgical hemostasis pathways are likely to absorb new indications faster, while regions where plasma-derived therapy access remains constrained will see more gradual uptake. Companies that invest in clinical education, guideline engagement, and site-level implementation support can convert indication expansion into sustained utilization more effectively than those relying on label expansion alone.
Presentation Innovation and Workflow Fit Will Influence Preference
As the category matures, product format will increasingly serve as a differentiator. Liquid formulations, specialized gram presentations, and packaging designed for rapid deployment in surgical and emergency settings can reduce logistical friction and improve fit within institutional workflows. This does not eliminate the importance of clinical efficacy and safety, but it adds a practical layer to procurement and formulary decisions. The trend favors manufacturers that treat product design as part of the value proposition, aligning presentation choices with real-world usage patterns. For hospitals and health systems, the opportunity lies in standardizing fibrinogen concentrate use in a way that supports both clinical outcomes and operational efficiency.
Cost, Access, and Reimbursement Will Remain Strategic Variables
Cost pressures are unlikely to disappear. Plasma-dependent manufacturing economics will continue to expose the category to input cost volatility, while high per-dose treatment costs will keep affordability and pharmacoeconomic justification in focus for payers and hospital administrators. The trend here is not a simple price war; it is a more sophisticated market access environment in which coding, coverage, evidence, and total cost of care arguments influence adoption. For manufacturers, the strategic response should include robust health economics support, dosing efficiency narratives, and proactive engagement with reimbursement frameworks. For investors, the durability of margins will depend on yield management, supply resilience, and the ability to secure favorable access arrangements rather than on volume growth alone.
Hemodialysis Concentrates Market
Potential Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Plasma supply disruptions, donor availability constraints, or fractionation bottlenecks can affect availability and cost. Reimbursement changes, stricter utilization management, or shifts in payer policy could slow expansion in specific settings. Competitive intensity may increase as new presentations, regional entrants, or alternative hemostatic therapies influence treatment choices. In addition, clinical evidence expectations may evolve, requiring more robust real-world data to support use outside traditional indications. These risks do not negate the growth outlook, but they highlight the need for contingency planning around supply, access, and evidence strategy.
Actionable Guidance for Decision Makers
The fibrinogen concentrates market rewards strategic discipline across product, regulatory, and access dimensions. For executives and investors, four priorities stand out.
- For manufacturers, align formulation innovation with indication strategy and reimbursement planning. Product launches should be built around clinical workflow fit, dosing flexibility, and a credible market access narrative, not solely around regulatory milestones.
- For investors, focus on supply resilience, fractionation efficiency, and access-enabled growth. Companies that can manage plasma cost exposure, maintain consistent availability, and convert indication expansion into reimbursed utilization are better positioned for durable value creation.
- For procurement and clinical leaders, evaluate fibrinogen concentrate options based on total workflow impact and total cost of care, including presentation efficiency, dosing suitability, and evidence supporting appropriate use in relevant patient populations.
- For all stakeholders, treat market access and evidence development as ongoing capabilities. Reimbursement pathways, coding frameworks, and clinical adoption patterns are shifting quickly, and timely intelligence can reduce execution risk and improve planning accuracy.
Given the pace of regulatory updates, presentation innovation, and reimbursement evolution, decisions made on incomplete market intelligence carry avoidable risk. For organizations that need deeper segmentation, pricing and reimbursement detail, competitive benchmarks, and scenario planning across regions and indications, more granular analysis can help translate these trends into actionable plans. Detailed data sets, company-specific evaluations, and tailored commercial scenarios are available through PW Consulting’s full Fibrinogen Concentrates Market report, which provides the structured intelligence needed to support product strategy, investment decisions, and procurement planning with greater precision.
For detailed analysis of this topic, please visit the official page: Fibrinogen Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


