



PW Consulting: Amorphous Metal Sheets Market to Reach USD 4,099.1 Million by 2032 at a 9.4% CAGR — Asia-Pacific Commands USD 1,160.46M Share
By PW Consulting, 2026-07-13
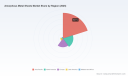
Amorphous Metal Sheets Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s Amorphous Metal Sheets Market report (base year 2025) synthesizes seven years of historical performance with a forward-looking forecast to 2032, equipping executives with the market intelligence required to make decisive 2026 investments. The market reached approximately USD 2.19 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 9.4% across the 2026–2032 forecast window, culminating in a multi‑billion dollar market by 2032. The growth trajectory is underpinned by accelerating demand across power distribution, e-mobility, and power electronics, combined with concentrated manufacturing footprints and continued product innovation in soft magnetic materials.
Amorphous Metal Sheets Market
Why 2026 is a pivot point for corporate strategy
-
Regulatory and ESG pressure: Amorphous metal technologies offer measurable energy-efficiency gains in transformers and motors, enabling manufacturers and utilities to meet stricter energy and CO2 reduction targets. For companies planning capital allocation in 2026, the ability to demonstrate lower core losses will be a differentiator in tendering and public procurement.
Amorphous Metal Sheets Market -
Supply-chain and trade-policy shocks: Recent policy shifts—most notably strengthened U.S. tariffs on metal products—have altered import economics for metallic precursors and finished sheets. Companies must model tariff scenarios and re-evaluate near-term sourcing and localization strategies before committing to long‑lead capital projects.
Amorphous Metal Sheets Market -
Industrial-scale capacity dynamics: Capacity expansions and new lines brought online by major producers substantially change the supply-demand balance. These moves increase volume availability but also raise competitive pressure on pricing and product differentiation.
-
Technology and product innovation: Advances in laminated bonded ribbons, high-density packing for xEV motors, and high-precision bulk amorphous processing are shifting addressable use cases — from large distribution transformers to precision components in mobility and medical devices.
What the PW Consulting report delivers (practical, executable content)
-
Robust market sizing and scenario forecasts: granular historical analysis (2020–2025) and probabilistic scenarios for 2026–2032 that stress-test demand under alternative macro, policy, and technology assumptions.
-
Actionable demand-supply matrix: forward-looking capacity maps, lead times, and utilization curves to inform procurement timing, contract length, and hedging strategies.
-
Strategic sourcing playbook: decision frameworks for make vs buy, regional vs localized supply, and supplier qualification scorecards (technical, financial, ESG).
-
Technology and manufacturing economics: comparative analysis of processing routes (rapid solidification ribbons, laminated bonded constructions, bulk metallic glass), unit cost drivers, capital intensity, and scale thresholds.
-
Commercial go-to-market tactics: pricing sensitivity models, value-based propositions for OEMs, and sector-specific entry strategies for EV, renewables, and power distribution OEMs.
-
M&A and partnership screening: prioritized list of bolt-on targets and JV structures, with acquisition synergies and dilutive risk profiles evaluated under multiple financing scenarios.
-
Regulatory impact templates: tariff and standards impact calculators to quantify near-term margin risk and change procurement KPIs accordingly.
Competitive landscape — how to read the market
The market structure sits between concentrated leadership and broad industrial participation. The top three producers control a meaningful share of global supply (CR3 ~58.4%), and the top five are responsible for roughly 72.2% of availability — a concentration that creates both supplier power and clear M&A/partnership opportunities for challengers.
-
Metglas Inc. (Conway, SC, USA) — A global leader in amorphous ribbon production and well-positioned in transformer and motor core segments. Metglas’s legacy in rapid-solidification ribbon manufacturing makes it a reference supplier for high-performance transformer cores.
-
Proterial, Ltd. (Tokyo, Japan) — Focused on laminated bonded ribbons and product forms tailored to xEV motors and efficient transformers. Recent launches emphasize packing density and manufacturability improvements, signaling OEM-centric product roadmaps.
-
VACUUMSCHMELZE GmbH & Co. KG (Hanau, Germany) — Specializes in high-permeability Fe- and Co-based amorphous alloys and stamped parts, catering to precision electronics and power applications where permeability and loss profile are critical.
-
China-based leaders (Qingdao Yunlu, AT&M, Shenzhen SAT, etc.) — These firms have aggressively expanded capacity and are competing on scale and cost-for-performance, particularly in distribution transformer cores. One major Chinese producer recently commissioned large new production lines, materially increasing annual capacity.
-
High-precision and BMG specialists (Heraeus Amloy, Amorphology, Liquidmetal, Orbray) — These players are focused on bulk amorphous glass processing, additive and precision molding for high-value components in aerospace, medical, and premium industrial products, creating pockets of high-margin opportunity away from commodity transformer volumes.
Recent strategic moves exemplify market direction: capacity expansion in China has improved availability and put pricing pressure on commodity transformer cores; laminated bonded ribbon innovations from Japanese players are designed to capture xEV motor content; and cross‑sector asset acquisitions have broadened technology stacks, indicating consolidation and diversification of capabilities.
Five immediate strategic actions for 2026
-
Re-run your procurement models with a 50% tariff tail-risk scenario for critical metal inputs and finished imports. Shorten supplier qualification cycles and establish dual-sourcing where economics justify buffer stock.
-
Prioritize investments where material performance unlocks price premiums — e.g., motor core designs that reduce inverter losses or transformer cores targeting distribution upgrade tenders with ESG scoring. Use our value-capture templates to model ROI at product-level.
-
Pursue strategic partnerships with laminated-bond and BMG specialists to accelerate time-to-market for high-density motor cores and precision components rather than attempting full in-house development.
-
Evaluate brownfield capacity additions near key OEM clusters to mitigate tariff exposure and gain logistics advantages. Our capacity-mapping module identifies pinch-points and ideal geographies for localization.
-
Embed energy-efficiency and lifecycle carbon reductions into procurement RFPs. Demonstrable reductions in core losses can be monetized through tender scoring and long-term service contracts in utility and grid modernization programs.
How clients are using this report to guide 2026 decisions
-
CTOs and product leadership run our technology-attainment timelines to prioritize R&D spend between incremental ribbon improvements and higher-risk bulk amorphous applications.
-
Procurement teams adopt our supplier-scorecards and tariff impact models to redesign contracts and inventory buffers, cutting exposure to single-supplier or single-region risk.
-
Corporate development teams apply our M&A screening to identify targets that provide immediate technical capability (e.g., bonded ribbons, high-precision BMG) versus those that deliver scale economics.
-
Power utilities and OEMs use the report’s loss-reduction benchmarks to strengthen capital-approval cases for transformer retrofits and new purchases that promise lifecycle OPEX savings.
What we intentionally withhold (and why)
Consistent with the “trailer” approach, this brief demonstrates the analytical depth and practical frameworks contained in the full PW Consulting report while intentionally omitting granular region-, material-, and application-level split values. Those segmentation details, interactive datasets, and downloadable financial models are available exclusively on the report landing page for clients and subscribers. This preserves our data licensing integrity and ensures decision-makers access fully auditable inputs and scenario controls when they engage with the full deliverable.
Next steps
If you are evaluating capital allocations, supplier strategies, or M&A activity related to amorphous metal sheets in 2026, PW Consulting’s full report provides the models, supplier dossiers, and scenario toolkits to convert insight into action. Contact our industry team to schedule a briefing or to obtain access to the complete dataset, segmentation matrices, and executable templates tailored to your organization’s risk profile.
For detailed analysis of this topic, please visit the official page: Amorphous Metal Sheets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Photosensitive Polyimide for Semiconductors Poised to Grow at 9% CAGR During 2026–2032
By PW Consulting, 2026-07-13
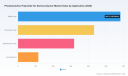
Photosensitive Polyimide for Semiconductor Market: Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on Photosensitive Polyimide (PSPI) for the semiconductor industry delivers a rigorous, actionable roadmap for executives making capital‑allocation, sourcing, and product strategy decisions in 2026. The market has demonstrated robust recovery and expansion over the past half decade, rising from under USD 900 million in 2020 to approximately USD 1.45 billion in 2025. Our forecast model, calibrated to supply, demand and regulatory inflection points, projects a continued compound annual growth (CAGR) of roughly 9.0% through the 2026–2032 horizon, taking the market to the mid‑USD 2.6 billion range by 2032.
Photosensitive Polyimide For Semiconductor Market
Why this matters for 2026 planning
Photosensitive polyimide functions as a critical enabling material across packaging, interconnect, passivation and MEMS process steps. The material’s technical evolution (thicker, higher‑aspect‑ratio patterning, PFAS/NMP‑free chemistries, film‑type options) and the semiconductor industry’s appetite for advanced packaging and heterogeneous integration are converging to make PSPI a strategic procurement and R&D priority for device makers, substrate suppliers and materials firms alike.
Photosensitive Polyimide For Semiconductor Market
Market trajectory and how PW Consulting modeled risk
Our base‑case model integrates historical trends from 2020–2025 with bottom‑up overlays for production capacity, qualification lead times, raw‑material price volatility and regional demand shifts. Key takeaways from the model that influence 2026 decisions:
Photosensitive Polyimide For Semiconductor Market
- The market saw sustained, double‑digit growth early in the decade and normalized to a strong mid‑single to high‑single growth path by 2025. This momentum underpins our 9.0% CAGR through 2032.
- Supply tightness episodes and raw material price swings (notably in 2025) materially affect near‑term margins and supplier fill rates, creating a premium for secured supply agreements and validated second‑source options.
- Regulatory transitions (REACH, RoHS and local chemical control laws) are accelerating reformulation on two fronts: elimination of NMP and PFAS, and reduction of volatile organic compounds (VOCs). These transitions create both substitution risk and new product opportunities.
Industry dynamics shaping 2026 strategic choices
- Product innovation is moving the performance envelope. Recent launches and scale‑ups target thicker films, ultra‑high aspect ratios, PFAS‑free formulations and film‑type PSPI for panel‑level processes — attributes that unlock novel packaging topologies and MEMS architectures.
- Capacity investments and consolidation are changing who can reliably supply at scale. Several tier‑one chemical manufacturers and strategic joint ventures have announced plant expansions and new production lines to shorten lead times and support advanced packaging ramp‑ups.
- Regulatory and sustainability pressures are no longer peripheral. Compliance with limits on NMP and PFAS, together with customer demand for low‑VOC solutions, are commoditizing “conventional” chemistries and elevating reformulated alternatives.
- Market concentration is high: the top three suppliers capture a substantial majority of market share, and the top five command an even larger share. This concentration creates distinct bargaining and competitive dynamics — entrants and niche players can win by focusing on differentiated chemistries, qualification support, or localized supply footprints.
Competitive landscape — what recent moves tell us
Our industry surveillance tracked multiple strategic moves in 2025–2026 that illuminate vendor positioning and the near‑term battle for product leadership:
- Major incumbents pushed product diversification and supply expansion: new PFAS‑free and NMP‑free formulations, film‑type variants for panel processes, and thicker film/high‑aspect‑ratio PSPI optimized for next‑gen RDL and MEMS.
- Capacity plays are real and targeted. Select manufacturers completed new plants or announced multi‑year investments to scale PSPI output and shorten qualification lead times for substrate and OSAT partners.
- Joint ventures and legacy material specialists are leveraging combined R&D and go‑to‑market muscle to defend large OEM relationships while enabling faster sample cycles for advanced packaging customers.
Collectively, these developments reduce time‑to‑market for differentiated PSPI variants but raise the bar on supplier selection: qualification timelines, environmental compliance, scale economics and technical support now determine contract awards as much as unit price.
Strategic implications and recommended actions for 2026
Executives should treat PSPI strategy as integral to semiconductor packaging and interconnect roadmaps. Below are prioritized, practical moves for 2026:
- Secure staged supply agreements: negotiate multi‑tier contracts with primary and validated secondary suppliers that include capacity reservation, qualification milestones, and price collars to manage short‑term volatility.
- Invest in accelerated qualification programs: co‑develop test vehicles and accelerated reliability protocols with suppliers to reduce qualification lead time from months to weeks for critical use cases.
- Embed regulatory foresight into procurement: require supplier commitments for NMP/PFAS‑free formulations and documented compliance pathways for REACH/ROHS, and include reformulation timelines in supplier SLAs.
- Pursue modular sourcing: split strategic buys between global leaders for scale and specialized suppliers for differentiated chemistries (e.g., extreme aspect‑ratio, film‑type) to balance risk and innovation access.
- Align capex and product roadmaps: substrate makers and OSATs should synchronize laminator and lithography investments with supplier product roadmaps to maximize yield and avoid stranded manufacturing capability.
- Explore selective partnerships and tuck‑ins: for materials firms and PE investors, targeted M&A or minority partnerships with specialty PSPI developers can accelerate market entry and add proprietary IP for next‑gen chemistries.
What PW Consulting’s report delivers — practical tools for 2026 execution
The full PW Consulting market report is structured to move an executive from insight to implementation. Highlights include:
- A transparent, auditable forecast model covering 2026–2032 with scenario toggles for demand mix, qualification timelines and raw‑material cost shocks.
- Supplier scorecards that evaluate technical competence, capacity scalability, environmental compliance posture, qualification throughput and commercial terms (redacted summary available in this brief; full scorecards in the report).
- Technology readiness assessments mapping PSPI variants (negative/positive tone, film vs. liquid, PFAS/NMP‑free chemistries) to packaging use cases and qualification complexity.
- Commercial playbooks for OEMs, substrate suppliers and materials companies that cover sourcing strategies, cost modeling, rebate and volume incentive design, and launch sequencing to minimize time‑to‑revenue.
- A risk register with mitigation playbooks for price volatility, regulatory transition, supplier single‑point‑of‑failure and qualification delays — each tied to operational KPIs for procurement, quality and product management teams.
- M&A and partnership candidate shortlists with high‑level rationale — including technology gaps they fill and likely valuation multiples (detailed targets and financials are in the full report).
Case signals from the vendor landscape
Recent company actions illustrate the strategic patterns we see across the industry. Manufacturers are accelerating product development for PFAS/NMP‑free chemistries, launching film‑type PSPI for panel processes, and bringing high‑aspect‑ratio formulations into mass production. Simultaneously, capacity investments and supply network expansion are being prioritized to service advanced packaging ramp‑ups and AI‑related demand. For procurement and strategy teams, these moves translate into narrowed windows for supplier qualification and first‑mover advantage for those who can align manufacturing readiness with new material attributes.
How to use this report
For C‑suite and functional leaders planning 2026 investments, the report is a decision support kit: it quantifies market scale and growth drivers, validates supplier claims through independent scoring, and provides executable sourcing and product playbooks. Use the model to stress‑test capital plans, the supplier matrices to shape RFx strategies, and the risk‑mitigation playbooks to design contingency budgets and alternative‑sourcing timelines.
Conclusion and next steps
Photosensitive polyimide has moved from a niche specialty material to a strategically important enabler of packaging and MEMS innovation. With the overall market expanding from the low‑hundreds of millions in 2020 to around USD 1.45 billion in 2025 and forecast to grow at about 9.0% annually through 2032, 2026 is a pivotal year for locking in capability, securing compliant chemistries and aligning supply chains. PW Consulting’s report gives leaders the empirical basis and the operational playbooks to convert that market opportunity into competitive advantage.
To access the full dataset, supplier scorecards, scenario model and executable playbooks, please visit the report page on PW Consulting’s website or contact our research team for a briefing and model license.
For detailed analysis of this topic, please visit the official page: Photosensitive Polyimide For Semiconductor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SiC & TaC Coated Graphite Market Poised for 11.2% CAGR Through 2032
By PW Consulting, 2026-07-13
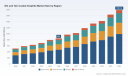
PW Consulting: Strategic Outlook — SiC and TaC Coated Graphite Market (2026 Strategic Brief)
Executive summary
As global semiconductor and compound semiconductor manufacturing intensifies through 2026 and beyond, SiC- and TaC-coated graphite materials are set to play a pivotal role in enabling higher throughput, tighter process control, and extended consumable life in critical wafer processing equipment. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — shows the total market expanding from approximately USD 850.0 Million in 2025 to USD 1,787.12 Million by 2032, reflecting a compound annual growth rate (CAGR) of 11.2% across the forecast horizon. Historical momentum is strong: our model traces growth from about USD 512.14 Million in 2020 to USD 850.0 Million in 2025, underscoring durable demand drivers and rising technology adoption.
SiC and TaC Coated Graphite Market
Why this matters for 2026 decision-makers
- High-growth window: With an expected near-term step-up in 2026 demand, procurement, engineering, and corporate development teams must recalibrate sourcing, capacity, and pricing strategies now to avoid being reactive in a tight supply environment.
- Consolidated supplier base: Market concentration metrics indicate a concentrated supplier landscape (top‑3 firms controlling a clear majority and top‑5 firms commanding more than three‑quarters of market supply). This shapes bargaining leverage, lead‑time risk, and the feasibility of supplier diversification strategies.
- Policy and tariff risk: New and reinstated tariffs on graphite inputs materially change landed cost math for coated graphite consumers and producers; 2026 will be a pivotal year for re‑pricing, nearshoring, and tariff mitigation tactics.
What PW Consulting’s report delivers (practical, operational insights)
This study was designed as an actionable playbook for senior managers and strategists. Key deliverables include:
SiC and TaC Coated Graphite Market
- Top-down market sizing and dynamic forecast model (2026–2032) with scenario toggles for demand shocks, tariff adjustments, and capacity ramp timelines.
- Supply‑chain mapping that identifies single‑source risks, tiered supplier alternatives, and critical raw‑material chokepoints for coated graphite production.
- Detailed competitive diagnostic for leading manufacturers (technology capability, geographic footprint, capacity posture, and go‑to‑market focus) with playbooks for partnership, procurement, and M&A approaches.
- Commercial frameworks: price‑sensitivity analysis, contract structures (consignment, hedge, long‑term offtake), and inventory optimization templates aligned to fab cadence and equipment installation pipelines.
- Regulatory and trade-impact assessment, including tariff stress‑tests and recommended mitigation levers (localization thresholds, alternate feedstocks, and duty drawback mechanisms).
- Capex and technology decision matrices for OEMs and fab operators evaluating SiC vs TaC coatings by process application, lifetime economics, and contamination tolerance.
Competitive landscape — what we found and why it matters
The SiC and TaC coated graphite market blends established global specialists with rapid industrialization among regional challengers. Our qualitative and quantitative analysis profiles leading suppliers across Japan, Europe, North America and China, mapping their technological differentiators, capacity footprints, and strategic intent.
SiC and TaC Coated Graphite Market
- Toyo Tanso Co., Ltd. (Japan) — A technology leader with proprietary CVD capabilities and branded SiC/TaC offerings. Their strategic expansion in TaC capacity and premium positioning on high‑temperature applications makes them a critical partner for customers prioritising lifetime and thermal resilience. For 2026, expect Toyo Tanso to selectively prioritize high‑mix, high‑value customers while exploring tighter regional partnerships to offset tariff headwinds.
- SGL Carbon (Germany) — Strong in pedigree and product breadth for wafer processing and crystal growth. European customers valuing supply continuity and regulatory compliance see SGL as a preferred incumbent; however, European fabs and OEMs must evaluate total cost versus regional alternatives as tariff and logistics factors shift global economics.
- Schunk Xycarb Technology (Schunk Group) — Focused on susceptors, carriers and consumables across diverse equipment classes (EPI, RTP, CVD, PVD). Schunk’s engineering depth and equipment‑system integration capabilities make them an attractive collaborator for OEMs seeking co‑engineered consumables that reduce cycle time variability.
- Mersen (France) — A supplier positioning its SiC and TaC coated components as purity‑first solutions for demanding semiconductor processes. Their offering suits customers where contamination control and material traceability are decisive procurement criteria.
- China‑based manufacturers (multiple firms) — A cluster of manufacturers has scaled rapidly, offering competitive pricing and localized service in Asia. These firms are increasingly capable on technology (CVD and pyrolytic coatings), but buyers should evaluate qualification timelines, reproducibility, and IP‑related concerns when displacing incumbent sources.
- North American specialists — Several US‑based suppliers focus on rapid prototyping, specialized TaC trays and high‑purity coatings that target regional fabs and LED/PV segments. Their flexibility is attractive for co‑development and short lead‑time windows but may command a premium.
Recent strategic moves reinforce these dynamics. A notable 2025 acquisition [Materion, July 2025] expanded capacity for tantalum solutions in Asia — indicative of consolidation and strategic asset capture aimed at securing proximity to major semiconductor hubs. Earlier, select incumbents announced capacity expansions for TaC products, signaling tiered differentiation between SiC and TaC in high‑temperature and durability‑sensitive applications.
Regulatory and raw‑material signals — actionable intelligence
Two policy levers materially affect near‑term strategy:
- Tariffs: A reinstated tariff regime schedules a significant duty on certain graphite imports effective in early 2026; other graphite categories have been under tariff since mid‑2024. The combined effect is to raise landed input costs, reshape sourcing incentives, and accelerate nearshoring conversations.
- Feedstock availability: Synthetic and natural graphite availability, combined with price volatility, require multi‑pronged procurement strategies — multi‑sourcing, qualified alternate chemistries, and longer‑term supply contracts with indexation clauses.
For 2026 planning, companies should run three practical exercises: (1) landed cost re‑calibration that factors in tariff schedules and transit/insurance fluctuations; (2) supplier dual‑qualification for critical product families; and (3) an inventory hedging simulation to balance working capital and risk of supply interruptions during qualification cycles.
Strategic recommendations for 2026
PW Consulting recommends the following actions, prioritized by impact and ease of implementation:
- Short term (0–9 months) — Perform immediate landed‑cost and margin sensitivity analyses incorporating the 2026 tariff schedule. Lock critical long‑lead orders where price exposure or supply risk is highest. Begin supplier audits for single‑source components.
- Medium term (9–18 months) — Implement dual‑sourcing strategies for susceptors and trays used in high‑value process nodes. Negotiate contractual features that share risk (volume flex, rebate corridors, and multi‑year price collars). For OEMs, embed coated graphite qualification timelines into product roadmaps to avoid retrofit penalties.
- Long term (18–36 months) — Evaluate strategic investments: greenfield capacity in low‑tariff jurisdictions, JV or minority investments in technology‑leading suppliers, and acquisitions that secure feedstock or advanced CVD capabilities. Use the market’s concentration profile to identify bolt‑on M&A targets that can fast‑track scale and margin capture.
How PW Consulting’s intelligence reduces execution risk
Our report combines a transparent forecast model with a practical toolkit: templated RFQ frameworks that speed qualification, a supplier‑risk heatmap for procurement prioritization, and an M&A playbook tailored to capture synergies in coated graphite production. Importantly for 2026 decision cycles, the report includes scenario analyses that quantify the impact of tariff shifts and raw‑material shocks on P&L and cash‑flow under multiple demand-growth trajectories.
Final note — why this is a “must‑have” for 2026 planners
With the market roughly doubling in size over the coming six years under the central forecast and concentrated supplier dynamics, decisions made in 2026 will disproportionately affect competitive positioning through the decade. Whether the objective is to secure supply for ramping fabs, to optimize consumable lifetime economics, or to pursue strategic consolidation — the intelligence in PW Consulting’s study provides the empirical foundation and execution frameworks necessary to move from reactive procurement to proactive strategic sourcing.
Get the full analysis
This press summary highlights directional market sizing, competitive themes, and actionable recommendations. To preserve the strategic value of segment-level market intelligence, we have deliberately withheld detailed regional, type and application split figures from this release. PW Consulting’s full report contains those segmentation breakdowns, supplier share tables, supplier scorecards, and downloadable forecast models that will be essential to operationalize the strategies outlined above. Contact our research team or visit the PW Consulting website to request the full SiC and TaC Coated Graphite Market report and schedule a strategic briefing tailored to your organization.
For detailed analysis of this topic, please visit the official page: SiC and TaC Coated Graphite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Automated Ophthalmic Perimeters Market to Reach USD 545.34 Million by 2032
By PW Consulting, 2026-07-13
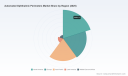
PW Consulting Strategic Preview: Automated Ophthalmic Perimeters Market — What 2026 Decision‑Makers Need to Know
PW Consulting’s latest market intelligence on Automated Ophthalmic Perimeters delivers the forward-looking, decision‑grade perspective that device manufacturers, hospital groups, diagnostic chains, private equity investors and public health planners will use to shape 2026 priorities. Anchored on a 2025 base year and a historical view (2020–2025), our forecast runs through 2032. The market shows steady expansion from the mid‑2020s and is projected to grow at a compound annual growth rate (CAGR) of 5.31% through the forecast horizon, reflecting both hardware refresh cycles and pockets of disruptive product innovation. Market concentration is meaningful: the top three vendors account for roughly 58% of market value, and the top five capture about 72%, signalling a market where incumbency and brand trust still matter, but where differentiated technology can move share.
Automated Ophthalmic Perimeters Market
Top‑level trajectory and why it matters in 2026
-
Steady, investable growth: The global market has expanded consistently in the early 2020s and continues to offer a low‑to‑mid single‑digit growth runway. For capital equipment manufacturers, this profile favours strategic investments that prioritize margin preservation, selective feature innovation, and after‑sales services rather than large volume gambles.
Automated Ophthalmic Perimeters Market -
Technology as the principal growth lever: Adoption of integrated imaging, AI‑driven progression analytics, retinal‑tracking objective perimetry, and VR/portable testing formats is accelerating. These innovations improve throughput, diagnostic confidence and patient experience — three levers that justify premium pricing and recurring software service models.
Automated Ophthalmic Perimeters Market -
Reimbursement and hospital capital behaviour: Existing CPT codes continue to underwrite automated perimetry activity in major markets, and prevailing payer economics support hospital investment in perimeter systems when bundled with workflow gains or clear diagnostic advantages. PW Consulting’s modelling incorporates real‑world fee structures and typical hospital CapEx cycles to estimate adoption timing across buyer types.
Dynamics shaping procurement and R&D choices
-
Clinical demand drivers: Demographic ageing and rising awareness of glaucoma and retinal disease screening sustain baseline demand. Beyond prevalence, diagnostic pathway changes — earlier imaging, combined structural‑functional assessment and telemonitoring — determine which device features become “must‑have” versus “nice‑to‑have.”
-
Regulatory and commercial inflection points: Objective perimetry platforms that combine retinal tracking with automated analysis have reached major regulatory milestones, removing a prior barrier to broad adoption. For product teams, a regulatory‑first development strategy is increasingly table stakes in high‑value markets.
-
Workflow and throughput economics: Faster testing protocols and binocular or virtual approaches reduce technician time and increase daily test capacity — directly improving ROI for hospitals and large clinic groups. Vendors that can demonstrate validated time‑savings and seamless EMR integration will gain procurement leverage.
-
Service and software monetization: As hardware commoditization intensifies, recurring revenue from analytics, progression monitoring subscriptions, and remote support becomes a critical margin driver. Contract structures aligning price to utilization or outcomes are emerging as competitive differentiators.
Competitive landscape — incumbents, challengers and strategy cues
The market remains anchored by several established medtech firms that combine brand recognition with entrenched installed bases. At the same time, focused innovators are introducing feature sets that materially change clinical workflows. Key strategic takeaways from vendor positioning:
-
Carl Zeiss Meditec AG — Zeiss retains a leadership role through an established platform that is broadly accepted as a clinical standard for glaucoma management. For buyers, Zeiss’s ecosystem approach (device + analytics + service) is a low‑risk choice; for competitors, displacing such a platform requires demonstrable, peer‑validated clinical advantage or significant TCO benefits.
-
Haag‑Streit AG — With systems that support both static and kinetic perimetry and a reputation for robust clinical analytics, Haag‑Streit competes on clinical depth. Their focus suits specialty ophthalmic centres that require broad diagnostic capability.
-
Topcon Corporation — Topcon’s emphasis on speed and workflow (notably faster testing protocols) makes it attractive to high‑volume clinics and integrated eye care chains. Vendors targeting hospitals should expect procurement panels to prioritise validated throughput improvements.
-
Konan Medical — Regulatory wins for objective perimetry (CE Mark under MDR and earlier FDA 510(k) clearance) mark a potential turning point. Objective measurement with retinal tracking materially reduces patient‑dependence of tests; this technology is a strategic priority for fleets pursuing telemonitoring and decentralised diagnostics.
-
Centervue (iCare) and Optopol — These vendors illustrate two viable strategies: integration of active retinal imaging to combine structural and functional assessments, and competitive pricing with modern software, respectively. Both approaches underpin viable plays in mid‑market practices and emerging geographies.
-
Smaller innovators (VR/portable players) — Virtual and portable perimeter solutions address point‑of‑care and home monitoring use cases. They are particularly relevant to telehealth strategies and cross‑sell opportunities within primary care networks.
What the full PW Consulting report delivers (practical contents)
-
Proven market sizing and multi‑scenario forecasts (2026–2032) aligned to typical procurement cycles and product replacement curves.
-
Vendor scorecards with strategic positioning, go‑to‑market tactics and product roadmaps (qualitative benchmarking to inform partnership or competitive moves).
-
Actionable buyer playbooks for hospitals, clinic chains and diagnostic centers: total cost of ownership frameworks, procurement negotiation levers, and deployment sequencing to maximise utilization.
-
Regulatory and reimbursement mapping for major markets, including practical implications of CPT code coverage and typical fee levels that influence payback periods.
-
Technology adoption timelines and impact assessments for AI analytics, retinal tracking/objective perimetry and VR/portable platforms, enabling prioritised R&D roadmaps.
-
M&A and partnership targets with screening filters tailored for strategic acquirers and financial buyers, plus integration checklists to de‑risk post‑deal value capture.
Immediate strategic recommendations for 2026
-
For manufacturers: prioritize modular architectures that allow field upgrades (software + optional retinal tracking modules). This preserves installed‑base economics while enabling premium add‑ons tied to subscription services.
-
For hospital systems and large clinic groups: align procurement decisions with throughput and interoperability criteria (validated time savings, EMR/DI integration), not just headline device specs. Use pilot deployments to quantify practice‑level ROI before wide rollout.
-
For investors: target companies that combine an established installed base with a credible roadmap to recurring software revenue, or focused innovators with regulatory approvals for objective perimetry and defensible IP.
-
For service providers and software partners: pursue partnerships that embed progression analytics and telemonitoring workflows into existing perimeter platforms — clinical workflows are the path to premium pricing.
How to use this preview in your 2026 planning
Consider this document a strategic map: the market’s steady CAGR and concentrated vendor structure mean that 2026 is a year to sharpen positioning rather than make broad, speculative investments. Use the following practical sequence in your planning cycle:
-
Q1: Run cross‑functional workshops to translate clinical improvements (faster tests, objective metrics, integrated imaging) into procurement requirements and R&D feature backlogs.
-
Q2: Execute focused pilots with vendors demonstrating measurable throughput or diagnostic gains. Capture baseline KPIs and measure delta payback under local reimbursement scenarios (note: typical physician fee schedules influence device payback; industry references place common payment levels in a range that materially affects hospital ROI calculations).
-
Q3–Q4: Convert successful pilots into phased rollouts, or, for manufacturers, pivot commercial models to subscription bundles supported by validated clinical outcomes and remote monitoring services.
Methodology and confidence
PW Consulting’s market model combines historical shipment and revenue analysis (2020–2025), primary interviews with clinicians and procurement leads, vendor financials and product launch schedules, and payer/regulatory mapping. Scenario sensitivity analyses test technology adoption rates and hospital replacement cycles to produce a central forecast and alternate upside/downside cases. The resulting output prioritises strategic insight and executionable recommendations over exhaustive public‑domain datapoints — consistent with the “trusted advisor” approach our clients rely on.
Next steps and where to get the full intelligence
This preview outlines the strategic choices 2026 decision‑makers must make to capture value as the automated perimetry market evolves. To access the full dataset, vendor scorecards, procurement playbooks and the proprietary modelling that supports our forecast, please download the complete Automated Ophthalmic Perimeters Market report from PW Consulting’s report portal or contact your PW Consulting representative. The full report contains the granular annexes and confidential vendor benchmarking that we intentionally withhold from public summaries but that are essential for transaction diligence, product roadmapping and procurement negotiations.
PW Consulting — translating market dynamics into strategic advantage for ophthalmic device markets.
For detailed analysis of this topic, please visit the official page: Automated Ophthalmic Perimeters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiberglass Composite Rail Ties Market Set to Grow at a 6.29% CAGR Through 2032
By PW Consulting, 2026-07-13
Fiberglass Composite Rail Ties Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s new market research brief on Fiberglass Composite Rail Ties positions senior executives and procurement leaders to make decisive, risk‑calibrated moves in 2026. The market for fiberglass-reinforced composite ties has developed from a niche sustainable alternative into a commercially viable class of track components. Our analysis shows the market expanding from approximately USD 242.4 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.29% through 2032, reaching roughly USD 371.8 Million by the end of the forecast window. The market remains moderately concentrated, with the top three and five suppliers accounting for meaningful shares — a dynamic that creates both supply-side leverage and opportunity for well‑timed entrants.
Fiberglass Composite Rail Ties Market
What’s inside the PW Consulting report
- Concise executive synthesis for board-level decision-making: implications for capex, sourcing, and sustainability commitments in 2026.
- Methodology and assumptions: transparent scenario construction covering base-year 2025, historical series (2020–2025) and a 2026–2032 forecast horizon.
- Supply-chain and raw-material risk maps: granular supplier lists, input cost drivers, and contingency pathways for glass fiber, recycled HDPE and other feedstocks.
- Regulatory and standards matrix: compliance checklists aligned with major railway engineering authorities and certification pathways for North America and international systems.
- Commercial playbook: procurement templates, pilot‑to‑scale scorecards, and contract clauses to manage lifecycle performance and end‑of‑life recycling obligations.
- Competitive intelligence dossiers: profiles and capability assessments for incumbent composite tie manufacturers and emerging challengers, emphasizing manufacturing technology, IP posture, and reference installations.
- Capital allocation and ROI models: sensitivity testing against raw material price volatility, energy input scenarios, and accelerated adoption cases driven by replacement demand in high‑decay corridors.
Market snapshot — growth and concentration
The fiberglass composite rail tie market has transitioned to steady growth after an early-adopter phase. Our topline indicates a clear expansion trajectory: from mid‑hundreds of millions in annual revenue in the mid‑2020s to well into the high hundreds by the early 2030s under PW Consulting’s base scenarios. The reported 6.29% CAGR reflects both rising adoption in replacement cycles and incremental penetration into high-performance applications where durability and environmental benefits command a premium.
Fiberglass Composite Rail Ties Market
Market concentration is material: the three largest providers control a substantial portion of supply, and the top five firms capture an even larger share. For prospective investors and railroad operators, this concentration implies that strategic partnerships, manufacturing scale, or proprietary material formulations will be differentiators in 2026 and beyond.
Fiberglass Composite Rail Ties Market
Competitive landscape — what to watch
- Evertrak LLC (St. Louis, Missouri, USA) : Develops GFRP ties engineered from recycled polyolefins and glass fiber, positioning products for heavy‑haul North American corridors. Strategic capital injections and partnership activity in 2025 indicate a push to expand production capacity and vertically integrate recycling feeds.
- EFG TieTek / TieTek Global (Houston, Texas, USA) : Longstanding manufacturer with a product portfolio spanning cross ties, switch ties and specialty applications. Their patented formulations and ISO 9001 quality system make them a reference supplier for operators seeking field-proven alternatives to wood.
- Triton Ties (affiliate of Granite Peak Plastics / Triton Group) : Leverages extrusion technology and decades of plastics recycling experience to produce fiber-reinforced polymer ties. Recent corporate communications emphasize engineered mainline solutions and custom tie geometries for OEMs and contractors.
- AGICO Rail (Anyang, China) and Pioonier GmbH (Germany) : Regional specialists with product families tailored to metro systems and European rail operator requirements; their presence underscores that certification and regional standards are gatekeepers to market entry.
Recent company and industry developments should inform 2026 strategy: strategic investment and manufacturing scale‑up announcements, product and website refreshes signaling repositioning, and independent technical research into high glass‑fibre content HDPE composites that materially affect stiffness and long‑term flexural performance. Executives must track both corporate moves and R&D breakthroughs — together they shape supplier selection, contract negotiation levers, and product roadmaps.
Technology, raw materials and regulatory dynamics
Three interlocking dynamics will influence project economics in 2026:
- Raw-material cost volatility: Fiberglass and recycled plastics remain the largest variable in per‑unit manufacturing cost. Market datapoints show conflicting near‑term behavior — late‑2025 indices recorded moderating fiberglass prices in some markets, while early‑2026 reports indicate upward pressure due to energy and supply tightness. The net effect is greater procurement risk and the need for hedging or supplier‑partner arrangements.
- Formulation innovation: Technical advances in recycled HDPE composites reinforced with elevated glass fiber fractions and mineral fillers are improving flexural modulus and stiffness, narrowing the performance gap with traditional hardwood ties. These developments change life‑cycle cost math and the certification path for mainline applications.
- Standards and field validation: Compliance with railway engineering bodies (for example, the dimensional and mechanical criteria set by major engineering guides) is non‑negotiable. Equally important are documented, multi‑year field trials demonstrating fastening performance, lateral resistance, and long‑term track geometry behavior.
Strategic implications for 2026 decision-makers
For executives planning budgets, pilots or procurement strategies in 2026, PW Consulting highlights five strategic imperatives:
- Prioritise certified suppliers and documented field performance: Insist on third‑party testing and operational references before awarding scale contracts. Certification timelines can be a multi‑quarter gating factor.
- Lock in feedstock security: Negotiate multi‑year offtake or supply agreements for fiberglass and recycled polyolefins, or partner with recyclers to create captive feedstock pipelines that reduce price volatility and improve sustainability credentials.
- Stage investments via pilot‑to‑scale pathways: Design procurement strategies that begin with controlled pilot deployments in targeted high‑decay zones, measured by pre‑defined KPIs (track geometry, lifecycle maintenance costs, fastening retention), before committing to network‑wide rollouts.
- Embed end‑of‑life recycling clauses: Capture value and manage reputational risk by structuring supplier contracts with take‑back or guaranteed recyclability obligations.
- Monitor and test advanced formulations: Allocate R&D or co‑development budgets to validate new composite formulations that promise improved stiffness or lower cost — early adopters can gain a performance edge or preferenced supplier status.
Operational playbook — six tactical moves for 2026
- Due diligence sprint: Execute a 90‑day supplier vetting process focused on manufacturing capacity, QA systems, reference installations, and supply-chain traceability.
- Performance trial design: Develop a standardized field trial template with baseline measurements, instrumentation, and 12–36 month monitoring to produce defensible comparative data versus wood and concrete ties.
- Cost sensitivity modelling: Build scenario models that stress raw material inputs and energy; use these to set price floors in long‑form procurement agreements.
- Partner for recycling feedstock: Create joint‑venture or off‑take arrangements with tire and plastics recyclers to capture lower‑cost, reliable inputs and secure circularity claims.
- Certification runway management: Map certification milestones (testing, lab validation, field acceptance) into the procurement schedule to avoid rollout delays.
- Strategic investment checklist: For investors considering minority stakes or strategic bets, prioritize companies with demonstrable IP, validated manufacturing scale, and direct relationships with major rail operators.
Risks and mitigation
Key risks for 2026 include raw-material price shocks, certification delays, and under‑performing field trials that could slow operator adoption. Mitigation actions are straightforward and executable: diversify feedstock sources, secure contractual take‑or‑pay windows with staggered delivery options, and structure supplier performance guarantees tied to measurable lifecycle outcomes.
Why PW Consulting’s report matters now
Decision windows in 2026 will close quickly for organizations that delay. The convergence of stronger commercial demand, ongoing material innovation, and renewed capital interest by strategic investors makes this year pivotal. PW Consulting’s report translates raw market growth metrics and competitive movements into executable strategies: from procurement templates to investment screening tools. We provide the diagnostic work and the tactical playbook; what remains is the executive decision to act.
Access and next steps
This release is a concise preview highlighting the strategic value of the full study. The comprehensive report contains the granular segmentation tables, supplier scorecards, contract language examples and modelled P&L scenarios that are intentionally withheld here to preserve the analytical depth reserved for report subscribers. To obtain the full dataset, proprietary segmentation breakdowns, and executable annexes that support 2026 decision-making, visit PW Consulting’s report page or contact our client services team for a briefing and data license options.
For detailed analysis of this topic, please visit the official page: Fiberglass Composite Rail Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low Alpha Spherical Alumina Market Set to Expand at a 14.02% CAGR Through 2032
By PW Consulting, 2026-07-13
Low Alpha Spherical Alumina Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
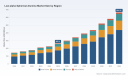
PW Consulting’s forthcoming Low Alpha Spherical Alumina Market report (base year 2025; forecast 2026–2032) consolidates proprietary supply-chain mapping, commercial intelligence, and scenario-driven recommendations aimed at informing executive decisions throughout 2026. The market is demonstrably on a multi-year expansion path: our model places 2025 as a pivotal base (USD 265.4 Million) and projects robust growth through the forecast window at a compound annual growth rate of 14.02%, with the market more than doubling toward the end of the forecast horizon. These headline metrics underline why low-alpha spherical alumina is moving from a specialty input to a strategic commodity for semiconductor packaging, thermal management and other high-performance electronics applications.
Low Alpha Spherical Alumina Market
Why this matters for 2026 decisions
- Speed of qualification matters: Lead times for new material qualification in advanced packaging and memory stacks are compressing. Companies that align testing, supply assurance, and co-development in H1–H2 2026 will secure the earliest commercial footholds.
- Margin and risk management: With midstream consolidation and high market concentration among a small number of incumbent suppliers, buyers and investors must plan for supplier concentration risk and pricing volatility.
- Raw-materials and policy drivers are reshaping economics: Input-price volatility, trade policy and regional production imbalances are creating near-term windows to lock favorable terms or to justify upstream integration.
Market dynamics: drivers, constraints and tailwinds
The transition to higher-density memory, advanced packaging, and electrified mobility is the primary demand engine: applications needing ultra-low alpha performance and high thermal conductivity are expanding capacity and advancing qualification timelines. On the supply side, the market remains concentrated among a small number of technology-differentiated producers, which supports premium pricing but also creates vulnerability to capacity bottlenecks.
Low Alpha Spherical Alumina Market
Key external dynamics to watch in 2026:
Low Alpha Spherical Alumina Market
- Raw-material pricing: Aluminum-hydroxide pricing in Northeast Asia eased to roughly USD 0.24/kg in March 2026 — down notably from late-2025 — reflecting softer downstream demand and easing upstream alumina/bauxite costs. Regional spreads remain meaningful: European indices recorded materially higher levels in the same period, underscoring persistent geographic cost dispersion.
- Alumina supply balance: U.S. alumina production and substantial import volumes in 2025 indicate the North American market’s dependence on imported feedstock and sensitivity to freight and tariff shifts; the average import unit value in recent reporting is a strategic input for cost models.
- Policy & tariff exposure: Trade measures (including Section 232 effects on aluminum and derivatives) have contributed to regional premiums in raw aluminum markets, translating into differentiated downstream input costs for producers and converters.
- Concentration & capability: Market concentration metrics indicate that a handful of players account for the majority of supply. That structural reality elevates supplier negotiation dynamics and makes qualification of secondary sources a strategic imperative.
Competitive landscape — capabilities and strategic postures
Our competitive analysis focuses on technology leadership, capacity posture, downstream go-to-market and the ability to support long qualification cycles. The companies we benchmark include Japan-based specialists, European integrated producers, and rapidly scaling Chinese suppliers. Key observations:
- Technology-led incumbents: Firms leveraging proprietary production technologies (e.g., vaporized metal combustion, fusion & separation processes) maintain product differentiation in ultra-low alpha performance and tight morphology control. Their strategic advantage is not only in product specs but in the vertical know-how necessary to sustain yield and consistency for sensitive semiconductor applications.
- Integrated players targeting scale: Established chemical incumbents and specialty mineral firms have signaled commercial production ramps and mid-term sales targets tied to both low-alpha alumina and complementary engineered fillers. Their approach is to combine manufacturing scale with multi-product portfolios to capture share in thermal interface and molding compound segments.
- Regional challengers: Emerging suppliers from China are actively qualifying multi-batch lots with advanced packaging customers and promoting stable mass-supply propositions. Their speed-to-market and cost orientation present a credible second-source pathway for global buyers — especially where localization or cost pressures dominate.
- Service and application focus: Some producers emphasize TIM and power module markets with engineered particle-size distributions to maximize packing density and thermal conductivity; others target encapsulants and EMC for advanced memory where alpha-ray performance is mission-critical.
Recent industry moves to monitor
- Commercial production ramps by large chemical manufacturers confirm that low-alpha spherical alumina is crossing into scaled manufacturing for thermal molding compounds and substrate materials — a shift with implications for multi-year supply availability.
- Intensified R&D by technology specialists aimed at HBM-class memory and AI-accelerator packaging indicates that the next phase of demand will be driven by ultra-tight alpha and contamination controls, requiring co-engineering between filler makers and compound formulators.
- Downstream qualification trajectories are shortening in some segments but remain prolonged in mission-critical semiconductor applications — creating staggered demand waves for qualified material.
Strategic playbook for 2026
For executives making choices in 2026, PW Consulting recommends a multi-dimensional strategy combining procurement discipline, technical collaboration, and optionality in capacity and sourcing. Key levers:
- Prioritize dual-track qualification: Run parallel qualification programs with a primary technology-led supplier and one validated regional second source. This reduces go-to-market risk without forfeiting quality requirements.
- Negotiate multi-year offtakes with staged volume and price review clauses tied to transparent indices (feedstock and alumina prices). Where feasible, include conversion performance SLAs rather than purely volumetric commitments.
- Invest in joint development agreements (JDAs) for particle morphology and surface-treatment co-optimization, especially for TIMs and EMCs; co-development shortens qualification and improves first-pass yields.
- Hedge raw-material exposure selectively: Short-term volatility in aluminum-hydroxide and alumina import pricing argues for hedging or indexed contracts for major rollouts scheduled within 12–24 months.
- Consider upstream moves selectively: For OEMs with large, predictable volumes, strategic equity stakes or long-term supply partnerships with specialty producers can secure priority allocation and influence technical roadmaps.
- Embed supply-chain stress tests into your 2026 capital planning: Scenario models should include supplier outage, regional production curtailments, and tariff shocks to determine buffer inventory and dual-sourcing thresholds.
What PW Consulting’s full report delivers (practical content)
The published analysis is designed for commercial, procurement, and product development leaders. Highlights include:
- Proprietary demand model (2026–2032) segmented by application and technology maturity — delivered with interactive scenario toggles so clients can test demand implications under different adoption curves.
- Supply-side capacity maps, quantified supplier scorecards, and a concentration heat map showing where single-point dependencies exist and where surge capacity can be sourced.
- Cost-to-serve and landed-cost modules incorporating regional feedstock indices, tariff overlays and logistics cost curves to support negotiation and make-or-buy decisions.
- Qualification timelines and risk matrices for semiconductor encapsulants, TIMs and high-frequency substrates — including recommended test protocols and milestone checkpoints.
- Partner & M&A shortlists based on capability fit, geographic complementarity, and integration difficulty — accompanied by modelled valuation sensitivities under three demand scenarios.
- An actionable 90–180 day playbook for buyers and OEMs translating insights into procurement actions, engineering priorities and capital allocation decisions.
How to use this intelligence in 2026
Executives should treat the report as both a reference and an execution tool. Practical first steps we recommend for 2026:
- Run a rapid supplier risk assessment comparing current supplier shares to the report’s concentration analysis; prioritize mitigation for any single-sourced critical pathways.
- Initiate JDAs with at least one technology-focused supplier to lock early design wins for high-value packaging programs scheduled for H2–H2 2027 ramp.
- Adjust procurement KPIs to reward suppliers that provide verifiable long-term feedstock cost transparency and that accept performance-based pricing terms tied to first-pass yield improvements.
Why PW Consulting’s preview — and why now
We built this preview to orient decision-makers on the high-level strategic levers: growth trajectory, supply concentration, raw-material dynamics, and the competitive plays shaping 2026 outcomes. The full report contains the granular models, supplier-level assessments and executable templates that procurement, engineering and corporate development teams will use to convert strategy into action.
Next steps & availability
PW Consulting is publishing the full Low Alpha Spherical Alumina Market report with client-ready models, supplier scorecards, and a customizable board-deck template. The preview above intentionally omits certain proprietary segment-level breakdowns and supplier-level financials to preserve the practical value of the paid report. To access the complete report, scenario tools, and a briefing with our senior analysts, please contact PW Consulting via our official channels.
PW Consulting — We translate materials-market complexity into executable competitive advantage. In a market defined by concentration, tight technical requirements and supply-side friction, early, well-informed moves in 2026 will determine who captures the value created across the next expansion cycle.
For detailed analysis of this topic, please visit the official page: Low Alpha Spherical Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PVDF‑TrFE Resin Market Set to Grow at a 12.18% CAGR Through 2026–2032, PW Consulting Forecasts
By PW Consulting, 2026-07-13
PVDF‑TrFE Resin Market: Strategic Preview for 2026 Decision Makers
Executive summary
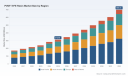
PW Consulting’s forthcoming PVDF‑TrFE Resin Market report positions executive teams to make high‑impact choices in 2026 that will shape competitiveness through 2032. The market has accelerated from a measured base in 2020 (USD 172.5 Million) to an expanded 2025 baseline (USD 312.45 Million), and our forecast projects sustained expansion across 2026–2032 at a 12.18% CAGR, reaching roughly USD 698.65 Million by 2032. This trajectory creates a window for proactive capacity planning, vertical integration, strategic partnerships, and selective M&A — but it also raises near‑term supply‑chain, feedstock and regulatory risks that demand targeted mitigation.
PVDF-TrFE Resin Market
Why 2026 is a strategic inflection point
-
Commercial scaling decisions made in 2026 will determine which players capture the majority of incremental value through the period to 2032. The market more than doubles in size from the 2025 base to our 2032 projection, meaning first‑mover advantages on capacity, grades and go‑to‑market models will compound.
PVDF-TrFE Resin Market -
The sector is highly concentrated: the top three firms account for roughly 72.5% of established market share and the top five about 88.4%. Such concentration creates both barriers to entry and opportunities for challengers who adopt differentiated technical, cost or sustainability positions.
PVDF-TrFE Resin Market -
Operational realities — notably feedstock cost volatility and the capital intensity of specialized polymerization — imply that timing, scale and supply assurances are as important as product innovation.
Market trajectory and practical implications
From a structural perspective, PVDF‑TrFE sits at the intersection of advanced materials and electrified systems (sensors, actuators, ultrasound, flexible electronics and energy harvesting). The historical series (2020–2025) shows steady, demand‑led growth as applications migrate from R&D into higher‑volume industrial and medical deployments. The forecast window (2026–2032) reflects both organic demand drivers and the impact of capacity decisions made in the near term.
Key takeaways for 2026 planning:
-
Scale to capture growth: Firms that secure material offtake, increase throughput, or form preferential supply relationships in 2026 will benefit from compounding demand to 2032.
-
Focus on margin resilience: Manufacturing of PVDF‑TrFE typically carries a 25–40% cost premium versus conventional fluoropolymers due to specialized polymerization. Margin protection strategies (efficiency, product premiuming, contractual pass‑throughs) are necessary.
-
Supply risk management: Volatility in VDF monomer pricing materially affects unit economics. Hedging, long‑term supply agreements and diversifying feedstock sources should be part of any 2026 procurement playbook.
Competitive landscape — what to watch
The market is anchored by a handful of well‑established suppliers with complementary strengths. Understanding each player’s strategic posture helps buyers and investors assess where competitive pressure and partnership opportunities will arise:
-
Arkema Piezotech (France, https://piezotech.arkema.com) — A leader in electroactive P(VDF‑TrFE) copolymers across powders, inks and films. Recent capacity expansion activity signals an intent to secure industrial applications in EVs, energy storage and printed electronics.
-
Solvay (Belgium, https://www.solvay.com) — Brings scale and formulation expertise in PVDF‑based fluoropolymers for high‑performance piezo and ferroelectric applications. Their strength lies in integration across polymer chemistry and application engineering.
-
Kureha Corporation (Japan, https://www.kureha.co.jp) — Mature fluoropolymer manufacturing capabilities and regional integration in Asia position Kureha to serve high‑reliability electronics and medical supply chains.
-
PolyK Technologies (USA, https://www.polyk-lab.com) — Specialist supplier focused on R&D and small‑to‑bulk volumes; an attractive partner for early‑stage product development and prototype supply chains.
-
Peraglobe (USA, https://www.peraglobe.com) — Premium PVDF and PVDF‑TrFE provider with emphasis on films, sensors and transducers for medical and ultrasound markets.
Competitive dynamics will be influenced by capacity additions (notably Arkema’s announced increase in early 2025), targeted product differentiation (grades, inks, films) and non‑price competition (sustainability credentials, regulatory compliance, supply security).
Operational and supply‑chain considerations
-
Raw material exposure: VDF monomer price swings are a primary upstream risk. Firms must model scenarios for sustained high prices and stress test customer contracts to assess elasticity of demand.
-
Cost structure: The polymerization process required for PVDF‑TrFE contributes to a 25–40% manufacturing cost uplift versus standard fluoropolymers. Capital investments that reduce conversion costs — catalyst/process optimization, energy efficiency, and continuous processing — can alter competitive positions.
-
Regulatory and sustainability drivers: Stringent environmental regulations in key European markets (e.g., Germany, France) are accelerating interest in cleaner feedstocks and lower‑emissions processes. Achieving green certifications and transparent lifecycle data will unlock premium procurement channels, particularly in medical and automotive applications.
-
Inventory strategies: Given concentration and tight lead times for specialty grades, just‑in‑time models should be balanced with strategic safety stocks or contracted capacity to avoid missed revenue opportunities during demand surges.
M&A, partnership and R&D playbook for 2026
Based on our scenario analysis, we recommend a differentiated set of actions tailored to corporate size and ambition:
-
For incumbent producers: prioritize brownfield capacity optimization, selective bolt‑on acquisitions that strengthen application expertise (film coating, inkjet inks, extrusion capabilities), and long‑term feedstock agreements.
-
For challengers and private equity: pursue platforms that deliver niche application know‑how (medical transducers, printed electronics) and integrate with manufacturers that can scale while preserving margin.
-
For OEMs and systems integrators: secure captive supply via JV or offtake contracts, and invest in co‑development to lock in custom grades and processing methods that provide product differentiation.
-
Across players: accelerate R&D into lower‑cost polymerization routes and substitute chemistries to mitigate monomer volatility; demonstrate sustainability credentials to access premium demand segments.
What PW Consulting’s report delivers (practical contents)
Our full market study (base year 2025; historical window 2020–2025; forecast 2026–2032) is engineered as an operational toolkit for 2026 decisions. Key deliverables include:
-
Detailed market sizing and forecast models (USD Million) with scenario sensitivity to VDF pricing, capacity additions and regulatory tightening.
-
Demand segmentation by form factor and application with growth levers and buyer‑use cases — presented in a proprietary decision matrix that maps margin, scale and technical risk.
-
Competitive benchmarking and capability maps for leading suppliers, highlighting technology portfolios, regional footprints and strategic moves.
-
Supplier & feedstock risk heatmaps, procurement negotiation playbooks, and sample contract structures for long‑term offtake and tolling arrangements.
-
Investment and M&A playbooks: target selection filters, valuation frameworks adapted to concentration realities, and integration checklists focused on quality control and regulatory compliance.
-
Implementation roadmaps — 90/180/365 day tactical plans for scaling, cost reduction and certification timelines.
Note: In keeping with our “trailer” principle, this release showcases the report’s strategic depth while intentionally withholding core granular segmentation data (regional/application percent shares and certain proprietary unit economics). Full tables, worksheet access and candidate target lists are available in the full report on our website.
Recommended next steps for executives in 2026
-
Initiate scenario planning workshops in Q1 2026 to align capital allocation with the most likely VDF price and regulatory scenarios.
-
Lock in strategic procurement and offtake arrangements where possible; prioritize counterparties that offer co‑development and risk sharing.
-
Pilot process improvements that reduce polymerization costs; consider engaging technology partners or government grants to offset capex for greener processes.
-
Evaluate targeted M&A: focus on capability gaps (films, printable inks, medical approvals) rather than broad revenue scale alone.
Closing — the strategic value of timely intelligence
PVDF‑TrFE resin is transitioning from a specialist material to a strategically critical feedstock for next‑generation sensors, medical devices and flexible electronics. The market’s projected compound growth (12.18% CAGR, 2026–2032) and the current concentration profile create asymmetric opportunities for well‑timed moves in 2026. Our report converts that market view into action: executable procurement approaches, modular investment frameworks, and a detailed competitor playbook you can deploy immediately.
To access the full dataset, granular segmentation, model workbooks and our shortlist of acquisition/partner candidates, please visit the report page on PW Consulting’s website or contact our industry team for a briefing. For speed, begin with the supplier links and recent development noted in this preview: Arkema Piezotech ( https://piezotech.arkema.com), Solvay ( https://www.solvay.com), Kureha ( https://www.kureha.co.jp), PolyK Technologies ( https://www.polyk-lab.com) and Peraglobe ( https://www.peraglobe.com).
For detailed analysis of this topic, please visit the official page: PVDF-TrFE Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BT Laminate Market to Expand at a Strong 7.25% CAGR Through 2032
By PW Consulting, 2026-07-13
BT Laminate Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive snapshot
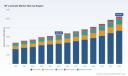
PW Consulting’s latest BT Laminate Market report (base year: 2025; forecast period: 2026–2032) equips senior executives with forward-looking, actionable intelligence to shape procurement, product, and investment decisions in 2026. Our analysis shows the global BT laminate market expanded from roughly USD 2.35 billion in 2020 to about USD 3.21 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 7.25% through 2032—driving the market toward just over USD 5.24 billion by the end of the forecast period. The market’s high supply concentration (top-3 firms controlling over 80% and top-5 over 90%) magnifies supplier leverage and creates systemic risks that require proactive executive responses.
BT Laminate Market
Why this report matters for 2026 decisions
2026 is shaping up to be a hinge year: raw-material inflation, supply tightness in specialty glass cloth, and discrete supplier price adjustments have created a classic squeeze on margins and availability. Executives evaluating sourcing strategies, product roadmaps (particularly halogen-free and low-loss grades), or capital projects must understand not only demand trajectories but also the dynamics of supplier power, input-cost pass-through, and regulatory tailwinds. Our study synthesizes market-scale projections with tactical playbooks that can be executed in the next 6–18 months—precisely the horizon where many procurement and product decisions will lock in value or cost exposure.
BT Laminate Market
What’s in the report (practical deliverables)
- Market sizing and trend decomposition: five-year historical performance and a detailed 2026–2032 forecast model, built from bottom-up demand drivers and validated by primary supply-side interviews.
- Price-sensitivity and input-cost scenarios: calibrated stress tests modeling copper foil, electronic-grade glass cloth, specialty-resin, logistics, and labor cost shocks and their pass-through into laminate prices and OEM COGS.
- Supplier benchmarking toolkit: capability maps, technology archetypes (low-warp, halogen-free, low-transmission-loss), manufacturing footprints, and an execution-risk score for critical suppliers.
- Supply-chain resilience playbook: eight tactical levers—dual sourcing, inventory hedging, contractual clauses for cost pass-through, and nearshoring decision matrices—tailored to BT laminates.
- Commercial and product strategy templates: go-to-market options for OEMs, substrate manufacturers, and electronic material suppliers to capture premium segments (e.g., high-frequency, FC-BGA, LED packaging).
- M&A and capacity-investment screen: a short-list of target profiles, valuation checkpoint metrics, and synergy models for vertical integration or strategic capacity expansion.
- Regulatory and sustainability risk assessment: compliance pathways for halogen-free grades and lifecycle impact considerations relevant to Tier-1 OEM procurement policies.
Market dynamics you need on your radar
- Upstream cost inflation: 2025–2026 saw marked increases in copper foil, specialty resins, and electronic-grade glass cloth. These upward pressures are not transient input noise but drivers that reshape procurement strategies and product pricing across the value chain.
- Supplier pricing behavior: the market’s concentrated supplier base magnifies the impact of any single producer’s pricing move. A notable example in early 2026 demonstrated how a major supplier’s uniform price increase can rapidly rebase customer cost assumptions and trigger commercial contract renegotiations.
- Regulatory and specification shifts: accelerated demand for halogen-free BT laminates stems from both regulation and OEM ESG commitments. This technical requirement is becoming a new non-price selection criterion among higher-value customers.
- Supply tightness risk: specialty fiberglass cloth availability tightened during late-2025, coinciding with elevated semiconductor and memory demand. This illustrates how adjacent industry cycles (e.g., a memory supercycle, AI-driven server demand) can transmit stress into substrate availability.
Competitive landscape — what the report reveals (high-level)
The market is dominated by established materials specialists and large-scale laminate producers who combine resin IP, capacity control, and channel relationships. Leading firms have differentiated along several axes: proprietary BT resin chemistries (low-warp, low-loss), global production footprints (to support local procurement and logistics resiliency), and tailored product portfolios for memory, RF/logic, and packaging applications.
BT Laminate Market
Notable strategic themes among incumbents include: continued product innovation (next-generation low-warpage and low-transmission-loss grades), selective capacity investments in Southeast Asia and East Asia, and a renewed focus on premium, compliance-driven product lines (halogen-free, high-reliability automotive/aerospace grades). The result is a market where technology leadership and scale both matter—making partnership strategies and supplier selection pivotal.
Strategic implications and recommended plays for C-suite and procurement leaders (2026 action list)
- Immediate (0–3 months): Re-run cost-pass-through clauses and pricing triggers with your suppliers; prioritize contract provisions that protect margins during episodic raw-material shocks.
- Near-term (3–9 months): Implement a tiered inventory policy for critical BT laminate grades—combine safety stock for high-risk SKUs with rapid-order mechanisms for mainstream SKUs to balance cash and service levels.
- Procurement diversification: Map strategic single points of failure across the top-3 supplier relationships; qualify secondary suppliers even where primary relationships are long-standing.
- Technical hedging: Accelerate cross-qualification of halogen-free and low-loss alternatives in your product validation pipelines so substitution risk is minimized during supply disruptions.
- Commercial strategy: Re-examine price-to-performance segmentation—justify premium pricing for ASIL/automotive and RF grades while negotiating volume discounts for consumer-volume laminates.
- Capex & M&A screening: For manufacturers, evaluate brownfield capacity expansion in lower-cost jurisdictions and assess targeted bolt-on acquisitions that close capability gaps (resin synthesis, copper-cladding, or prepreg production).
- Risk transfer: Consider indexed pricing agreements or shared-cost models with key OEMs to smooth margin volatility across the ecosystem.
- ESG & compliance: Prioritize halogen-free roadmap investments to stay ahead of tightening environmental specifications that materially affect customer qualifying choices.
Scenario thinking: three plausible 2026 outcomes and tactical responses
- High-cost pass-through scenario: Sustained raw-material inflation leads to permanent upward price resets among major suppliers. Tactical response: secure multi-year supply contracts with fixed-volume commitments and negotiated escalation formulas; pursue localized production to reduce logistics exposure.
- Demand shock in a segment (e.g., memory slowdown): Rapid demand retraction could free up capacity but compress prices. Tactical response: reallocate capacity to growing subsegments (RF, automotive) and accelerate product conversion where process compatibility permits.
- Regulatory acceleration toward halogen-free: Sudden adoption by Tier-1 OEMs creates premium windows for compliant suppliers. Tactical response: fast-track qualification of halogen-free grades and align marketing/pricing to capture the premium while competitors retrofit.
How executives should use this report
- Board briefings: use our executive summaries and scenario decks to align the board on procurement contingency budgets and capital spend priorities for 2026.
- Procurement playbooks: operationalize the supplier benchmarking and cost-model worksheets to negotiate improved commercial terms and reduce single-source exposure.
- R&D and product strategy: leverage the technology archetypes and qualification roadmaps to prioritize investments in low-warp, low-loss, and halogen-free chemistries.
- M&A diligence: apply our target-screen criteria and valuation overlays when evaluating acquisitions or joint ventures focused on midstream specialization (e.g., prepregs, CRS, copper-clad laminates).
Closing — the strategic choice for 2026
The BT laminate market is transitioning from steady growth to a structurally riskier phase where supplier concentration, raw-material inflation, and regulatory shifts interact. For decision-makers, the choice is clear: adopt a proactive, scenario-driven strategy now or face higher cost of correction later. PW Consulting’s BT Laminate Market report delivers the integrated market-sizing, supplier intelligence, and playbooks that executives need to convert uncertainty into strategic advantage in 2026.
For full access to the report’s segment-level models, supplier scorecards, and downloadable scenario tools, consult the PW Consulting market intelligence portal.
For detailed analysis of this topic, please visit the official page: BT Laminate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


