



PW Consulting: Semiconductor TMAH Developer Market Poised for Robust Expansion — 8.01% CAGR Forecast for 2026–2032
By PW Consulting, 2026-07-13
Semiconductor TMAH Developer Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
PW Consulting’s forthcoming Semiconductor TMAH Developer Market report equips senior executives and investment committees with the forward-looking intelligence required to make high-consequence decisions in 2026. The global TMAH developer market, a critical enabling segment for photolithography in semiconductor and display fabs, stands at an inflection point: after expanding through the 2020–2025 period, the market is projected to grow at a compound annual growth rate (CAGR) of 8.01% over the 2026–2032 forecast window. Our base-year assessment (2025) values the market at USD 1,155.4 Million and our modeled scenarios show continued expansion to a strategic size by 2032, driven by advanced-node adoption, increased use in advanced packaging, and shifts in waste-management and recycling practices.
Semiconductor TMAH Developer Market
Why this matters for 2026 decision-making
-
Procurement and supply-chain leaders: 2026 will be the year to move from reactive sourcing to resilient architecture. Policies, tariffs, and near-shoring dynamics have already reshaped vendor selection—our analysis highlights the tactical levers that reduce single-supplier exposure without compromising ultra-purity requirements.
Semiconductor TMAH Developer Market -
Manufacturing and process owners: device node transitions and advanced packaging choices will alter developer chemistry requirements and consumption profiles. The report translates these trends into actionable litho-process risk matrices and change-management plans for fabs planning node migrations in 2026–2028.
Semiconductor TMAH Developer Market -
Investors and M&A teams: with meaningful market concentration at the supplier level, there are strategic windows for value creation through capacity investments, consolidation, and targeted vertical integration—our scenario modelling quantifies upside under several capacity and recycling adoption cases.
Market outlook — what the headline numbers tell you (and what they don’t)
The headline trajectory is unambiguous: steady, above-market growth supported by continued semiconductor content per device and a resurgence in display and advanced-packaging volumes in select geographies. The market trajectory from the 2025 base through 2032 implies not only growth in absolute demand but higher strategic value for suppliers that can demonstrate ultra-pure production, transparent supply chains, and waste-treatment or recycling capabilities. While we disclose high-level market size and the 8.01% CAGR to orient strategic planning, the report deliberately withholds detailed sub-segment financials in this preview to preserve the competitive edge contained in our full analytics.
What the full report contains — practical, executable content
-
Market forecasting and scenario analysis: base, upside, and downside scenarios through 2032 with sensitivity to node adoption, packaging adoption, and recycling penetration.
-
Supplier assessment and scorecards: proven methodology evaluating product purity, multi-site redundancy, regulatory compliance, geographic risk, and cost-to-qualify metrics.
-
Procurement playbook: tactical sourcing templates, qualification timelines for ultra-pure TMAH, and negotiation levers specific to long-lead chemical contracts.
-
Capex & capacity planning toolkits: shortlists of strategic investments (purification, sealed production lines, TMAC integration) with ROI thresholds tailored to various demand-growth paths.
-
Waste and circularity pathways: technology assessment of recycling, on-site treatment, and third-party off-gas/waste handling options, plus a regulatory-impact matrix.
-
Regulatory and trade impact playbook: compliance checklists, tariff-impact simulations, and recommended near-shoring vs. diversification strategies for 2026 procurement cycles.
-
Executive-ready slides and cut-to-the-chase recommendations that operationalize the analysis for CFOs, Heads of Manufacturing, and Chief Procurement Officers.
Competitive landscape — who matters and why
The TMAH developer market is meaningfully consolidated: the top three suppliers capture a substantial portion of market volume, and the top five control a clear majority. This concentration creates both stability for qualified buyers and opportunity for disruptive entrants that can address capacity, purity, or circularity gaps.
-
SACHEM, Inc. (United States) — a long-established supplier known for high-purity aqueous solutions and a geographically dispersed manufacturing footprint. Strengths: trusted quality credentials and diversified production in key fab regions. Strategic questions for 2026: how will SACHEM deepen supply assurance and engage in recycling partnerships?
-
Tokuyama Corporation (Japan) — producer of positive-type photoresist developer series with regional shipping bases positioned to support advanced fabs. Strengths: close R&D ties to Asian foundries and proven product lines. Strategic questions: will Tokuyama scale capacity or pursue joint ventures to manage tariff-driven near-shoring?
-
Moses Lake Industries (MLI, United States) — notable for sealed, chlorine-free integrated processes and direct connection to TMAC refineries. Strengths: manufacturing processes designed for ultra-purity and low contamination risk. Strategic implications: buyers prioritizing ultra-high purity will place premium value on such integrated production models.
-
Chang Chun Group (Taiwan) — a major raw-material supplier with scale in electronic-grade TMAH. Strengths: upstream position and feedstock security for regional developer producers. For 2026, upstream integration remains a primary defense against supply shocks.
-
Tokyo Ohka Kogyo (TOK), Tama Chemicals, Kanto Chemical, Dravyaom, Fujifilm Electronic Materials, Merck KGaA — each brings complementary strengths: formulation expertise, node-focused R&D, regional logistics and global distribution footprints. Their strategic moves—capacity expansions, product reformulations, and customer co-development—should be front-of-mind for buyers negotiating multi-year agreements in 2026.
Key industry dynamics changing procurement and process risk in 2026
-
Recycling and circularity are no longer theoretical. Leading foundries are piloting and scaling recycling to remove a material share of virgin purchases over the coming decade. This changes long-term demand elasticity and creates new counterparty risk considerations (e.g., qualification of recycled streams).
-
Tariffs and trade policy have accelerated the logic of near-shoring. Recent measures implemented in major markets have already prompted investments in additional purification facilities and reshaped logistics cost assumptions in many sourcing models.
-
Production technology matters: chlorine-free, sealed integrated manufacturing architectures are now a baseline requirement for suppliers targeting advanced-node fabs. Buyers will increasingly require process audits and traceable chain-of-custody documentation as part of qualification.
-
Waste management complexity has risen: TMAH-containing waste streams require specialized treatment and carry legal and environmental risk if managed improperly. Qualified third-party waste handlers and on-site recycling reduce both cost and compliance exposure.
Strategic playbook for 2026
-
Map criticality, then prioritize qualification. Treat ultra-pure TMAH as a dual-risk asset (supply and contamination). For critical fabs, qualify at least two suppliers with distinct supply chains and complementary risk profiles.
-
Embed circularity options into long-term contracts. Include clauses for recycled-product qualification, price offsets, and shared R&D for closed-loop processing to capture supply-side efficiencies.
-
Align capex decisions with scenario thresholds. Delay irreversible investments until near-term indicators (policy stability, recycling adoption rates, node migration cadence) cross defined thresholds—our report provides the trigger values used in PW Consulting’s models.
-
Negotiate capacity reservation rather than only spot volume. Where supplier capacity is constrained, secure prioritized access via reservation agreements tied to joint-quality roadmaps.
How PW Consulting’s report helps you act
This report is designed as a decision-operational tool, not merely a desk study. We combine proprietary forecasting, supplier due-diligence frameworks, and executable procurement templates so that 2026 plans move from strategy to contractual action within a quarter. Our client-facing deliverables include scenario-model spreadsheets, supplier scorecards, and executive slide decks that compress weeks of internal analysis into board-ready recommendations.
Closing — the invitation
As semiconductor supply chains pivot in response to policy, sustainability, and technology inflection points, the TMAH developer market will be a small-but-strategically-critical battleground for fabs and chemical suppliers alike. PW Consulting’s Semiconductor TMAH Developer Market report provides the context, tools, and supplier intelligence to convert 2026 uncertainty into competitive advantage. For full sub-segment analytics, supplier-specific benchmarking, and the operational templates referenced above, visit the PW Consulting report page to download the comprehensive study and supporting toolkits.
For detailed analysis of this topic, please visit the official page: Semiconductor TMAH Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nitroguanidine Market to Rise from USD 565.4 Million in 2025 to USD 758.17 Million by 2032 at a 4.28% CAGR
By PW Consulting, 2026-07-13
Nitroguanidine Market 2026: Strategic Imperatives for Resilient Growth — PW Consulting Industry Brief
PW Consulting’s latest Nitroguanidine Market report — covering historical performance (2020–2025) and forward-looking scenarios for 2026–2032 — arrives at a pivotal moment for producers, buyers and investors navigating raw-material volatility, regulatory headwinds and defense-driven demand cycles. Our analysis shows the global nitroguanidine market has expanded steadily from the early 2020s and is positioned to continue growing through the next planning cycle, projecting a compound annual growth rate (CAGR) of 4.28% across the 2026–2032 forecast window (all values USD Million). The market’s trajectory underlines both opportunity and strategic complexity for 2026 corporate planning.
Nitroguanidine Market
Why this report matters for 2026 decision-makers
-
Actionable timing: Our forecast model translates macro growth into timing signals for capacity investments, contract negotiations and inventory strategies. The market’s momentum into 2026 means firms must decide now whether to accelerate brownfield expansions, pursue feedstock integration, or secure long-term offtake to avoid being marginalised in the next two-year contracting cycle.
Nitroguanidine Market -
Risk-adjusted scenarios: We deliver three calibrated scenarios — baseline, upside (defense & tactical stockpiling), and downside (agrochemical demand contraction from regulatory tightening) — to stress-test capital plans and M&A priorities under divergent price and demand paths.
Nitroguanidine Market -
Competitive and concentration dynamics: The market displays moderate concentration (CR3 ~52.4%; CR5 ~68.8%), meaning regional champions and specialty players can exert real pricing and specification influence. Our intelligence on incumbent capabilities and expansion plans is essential for companies determining whether to compete, partner, or specialize.
Key findings at a glance (what we reveal — and what we intentionally withhold)
-
Macro growth: The global nitroguanidine market advanced through 2020–2025 and is projected to continue expanding to the end of our forecast horizon, reflecting steady demand across energetics, certain industrial intermediates and pockets of agrochemical applications.
-
Structural drivers: Defense procurement patterns, volatility in upstream precursors, and evolving pesticide regulatory regimes create diverging incentives across product qualities (e.g., solvent-grade versus propellant-grade). Our report quantifies the elasticity of demand by end-use and sensitivity to regulatory shocks — detailed segment-level tables are available in the full report.
-
What we don’t disclose here: To preserve the commercial value of our research (and to respect client-level confidentiality), this brief intentionally omits the granular regional and application-level split figures and unit-level price trajectories. These are presented in the detailed datasets and interactive dashboards on the report portal.
Report contents — practical modules designed for managers and strategists
-
Market sizing & historical reconstruction (2020–2025): reconciled company shipment data, customs flows, and producer disclosures to establish a verified baseline.
-
Supply-demand model and short-term balancing (2026–2028): dynamic inventory logic, lead times, and feedstock conversion constraints to simulate realistic tightness episodes around capacity additions.
-
Price and margin analytics: blended costing (feedstock + conversion + safety/compliance premiums) with sensitivity to urea/ammonium nitrate and concentrated-acid feedstock inputs.
-
Regulatory impact matrix: region-by-region assessment of pesticide restrictions and energetic material controls, with scenario-specific demand curves for sensitive applications.
-
Competitive landscaping & supplier profiles: capability mapping (purity grades, grain sizes, backward integration), partnership levers and an M&A target shortlist for strategic buyers.
-
Investment and commercial playbooks: go-to-market options for capacity owners, contract templates to secure feedstock and customers, and a prioritised list of operational improvements to shorten ramp-up cycles.
-
Risk register & mitigation playbook: practical actions to address feedstock bottlenecks, regulatory shocks, logistics constraints and workforce/safety compliance risks.
Competitive dynamics — implications for strategy
Our competitive scan synthesises public filings, capacity announcements and site-level capabilities to produce a near-term map of strategic maneuvering.
-
Backward-integration wins. Producers with upstream control of guanidine nitrate or strong access to primary feedstocks enjoy structural cost and security advantages. Recent investment plans by a major European player — the company disclosed its largest-ever investment in Nitroguanidine capacity and related guanidine nitrate facilities, with new output scheduled to come online in H2 2026 — will alter the supply landscape for high-purity grades. For buyers focused on defense or airbag-quality material, this shifts bargaining leverage and may compress spot premiums.
-
Specialty vs commodity differentiation. US and European specialty manufacturers continue to prioritise high-purity, tight-spec product lines for energetic and automotive safety applications, while several Asia-based producers concentrate on scale and agrochemical intermediates. Firms must choose whether to pursue margin-rich specialty niches (requiring quality assurance, certification and security-of-supply commitments) or compete on cost into commoditised channels.
-
Regional supply chains and cross-border risk. Integrated facilities sited near feedstock sources or with multi-location production footprints reduce single-point-of-failure exposure, an increasingly valuable attribute for defense-related procurement. Expect selective premium contracting and geographic diversification to accelerate in 2026.
-
Consolidation potential. Given the market’s concentrated profile, there is room for consolidation via bolt-on acquisitions and strategic partnerships, particularly to secure high-quality production assets in regulated jurisdictions. Our deal-scenario analyses identify acquisition targets that would meaningfully change a buyer’s access to strategic customers and move the needle on CR metrics.
Raw-material and regulatory dynamics to watch in 2026
-
Feedstock chain vulnerability. Nitroguanidine’s primary precursor is guanidine nitrate, produced from urea and ammonium nitrate via catalytic pathways. Interruptions or cost spikes in these upstream streams propagate rapidly into conversion economics and can flip spot markets within months. Our modelling includes feedstock stress tests and recommended hedging approaches.
-
Regulatory friction in agrochemicals. Areas with tightened controls on nitroguanidine-substituted neonicotinoids have materially reshaped demand profiles for certain intermediates. Companies exposed to agrochemical end-markets must quantify regulatory exposure, pursue product diversification, or build mitigation strategies such as reformulation partnerships and geographic reallocation.
-
Safety, environmental & permitting hurdles. Scale-ups for high-purity grades face stricter environmental permitting and occupational safety requirements; those lead times must be built into 2026 CAPEX schedules.
Top strategic moves we recommend for 2026
-
Secure upstream: Pursue tolling agreements, long-term feedstock contracts, or minority investments in guanidine nitrate capacity to de-risk conversion margins and protect lead times.
-
Segment consciously: Decide whether to pursue the premium specialty channels (defense, airbags, high-purity intermediates) or defend share in lower-margin agrochemical supply. Each choice requires different R&D, certification, and commercial investments.
-
Time expansions to demand windows: If contemplating greenfield or major brownfield projects, target construction schedules that align with forecasted tightening windows; avoid bringing capacity online during periods of regulatory-induced demand softness in agrochemicals.
-
Negotiate differentiated contracts: For high-spec customers, lock in clauses that protect margins under feedstock inflation and that recognise security-of-supply premiums; for commoditised buyers, prioritise volume and logistics optimisation.
-
Monitor policy and engage proactively: Maintain regulatory monitoring and engage in evidence-based dialogue on pollinator health and pesticide stewardship to preserve market access.
Frequently asked strategic questions (short answers)
-
Q: Should producers accelerate capacity investments in 2026? A: Only after stress-testing plans across our three scenarios. Firms with secure feedstock or defence contracts can justify accelerated expansion; others should prioritise supply security and contract coverage before irreversible CAPEX.
-
Q: Is vertical integration always the right answer? A: Not universally. Vertical moves make sense where conversion economics and security-of-supply materially improve ROI. In commodity-exposed business lines, tolling or long-term procurement agreements may deliver comparable benefit with lower capital intensity.
-
Q: How material is regulatory risk? A: Substantive for certain agrochemical pathways. Allocate capital and R&D to alternative formulations and non-sensitive end-markets if exposure is concentrated.
Next steps and how to access the full intelligence
This brief outlines the strategic implications derived from PW Consulting’s Nitroguanidine Market study — intended to help executives set priorities for 2026. Our full report delivers the confidential, segment-level data, interactive forecast models, supplier scorecards and executable playbooks that procurement leaders, corporate development teams and plant operations managers require to act decisively.
To obtain the comprehensive datasets, scenario workbooks and bespoke advisory packages, visit the PW Consulting report page or contact our Nitroguanidine practice lead. We intentionally withhold detailed regional/application splits and unit-level price schedules from this public summary to protect the commercial value of our primary research; subscribers receive full access including downloadable tables and an analyst briefing tailored to your strategic questions.
For detailed analysis of this topic, please visit the official page: Nitroguanidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Plastic Enclosure Market Projected to Grow at a 6.0% CAGR Through 2032
By PW Consulting, 2026-07-13
Electronic Plastic Enclosure Market: Strategic Insights for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused briefing drawn from our newest market research on the Electronic Plastic Enclosure market. This preview is designed to help executives, product leaders, procurement heads, and M&A teams prioritize decisions in 2026. It demonstrates the report’s analytical depth and operational utility while intentionally withholding detailed segmentation tables so that practitioners will consult the full report for the granular figures that underpin tactical plans.
Electronic Plastic Enclosure Market
Executive snapshot: why 2026 is a pivot year
The electronic plastic enclosure market has moved beyond recovery toward structurally stronger demand. Our base-year analysis (2025) places global market value in the mid‑single‑digit billions (USD, revenue units in millions), and the market is forecast to expand at roughly a 6.0% CAGR across the 2026–2032 forecast window. That trajectory reflects a combination of accelerating end‑market adoption (notably in industrial, automotive electronics and consumer segments), incremental premiumization (NEMA/IP ratings, EMI shielding, Class A finishes), and design-for-manufacture consolidation among upstream suppliers.
Electronic Plastic Enclosure Market
For corporate leaders, 2026 represents the year to shift from defensive cost management to selective investment: invest where design, compliance and supply‑chain advantage translate to durable margin expansion and market share gains.
Electronic Plastic Enclosure Market
High‑level market dynamics
- Growth drivers: Increased electronics integration across consumer, industrial and automotive systems; demand for lighter, corrosion‑resistant housings; and a rising premium on enclosures that offer environmental and EMI protection.
- Price and raw material volatility: Material markets are bifurcating. ABS resin recently experienced upward pressure from feedstock constraints and turnarounds, while polycarbonate recorded notable price easing into early 2026. These divergent moves materially alter component cost math and should inform material selection decisions for 2026 product programs.
- Regulatory and sustainability constraints: New reporting regimes and product‑chemical limits (for example, national plastics registries and international electronics eco‑criteria restricting bromine/chlorine levels) are moving compliance from a back‑office checkbox to a commercial differentiator.
- Supply‑chain geopolitics: Trade policy changes and tariff adjustments affecting flows from key jurisdictions have increased the value of dual and regional sourcing strategies for enclosure manufacturers and their OEM customers.
What this means for corporate strategy in 2026
Leaders must translate macro trends into three concurrent programs:
- Material and cost engineering: Re‑examine material bills of materials (BOMs) with a view to optimizing for both unit cost and compliance risk. For products with high environmental exposure or price sensitivity, polycarbonate’s recent price softness may create a window for substitution trials. Conversely, ABS price upticks require short‑term hedging or locked‑price contracts for critical SKUs.
- Design for differentiate and modularity: Prioritize enclosure platforms that support modular customization (faceplate inserts, standardized mounting rails, EMI gaskets, sealing options) so that product teams can address multiple end markets without duplicative tool spend.
- Supply‑chain resilience: Implement layered sourcing (regional + offshore) and accelerate supplier qualification for near‑shoring and tool‑less manufacturing partners to maintain time‑to‑market while controlling CAPEX risk.
Competitive landscape — themes, not scorecards
The market remains moderately fragmented: a broad set of specialized manufacturers (from US‑based cottage innovators to European ergonomics specialists) compete alongside injection‑molders and thermoforming shops serving OEM needs. Several commercial archetypes emerge from our competitive review:
- US makers emphasizing local manufacture and NEMA/IP robustness: Firms that stress domestic production and NEMA-rated offerings are leveraging on‑shore lead times, vertical integration and customer confidence in supply continuity. Recent product launches and line expansions from such manufacturers signal a play toward ruggedized outdoor and industrial end uses.
- Ergonomics and industrial design specialists: European and design‑focused manufacturers emphasize handheld and human‑interface enclosures with high personalization and fit‑finish — an advantage for medical devices and premium industrial controls.
- High‑mix, short‑run customizers and tool‑less providers: Newer service models that remove traditional tooling barriers enable medical and low‑volume industrial OEMs to shorten time‑to‑prototype and commercialization, a growing differentiator for product teams with aggressive roadmaps.
- Large catalog suppliers with broad SKUs: Companies offering wide off‑the‑shelf portfolios serve a critical role for engineering teams looking to reduce design spend and accelerate test cycles, particularly in consumer electronics and basic industrial controls.
Recent vendor activity underscores these themes. In 2025–2026 several market participants expanded product lines (new NEMA rated series, additional size options, new IP67 designs), which points to continued vendor competition on specification breadth rather than purely on price. This competitive posture raises the bar for OEMs: enclosure selection is increasingly about matching nuanced performance attributes (EMI/RFI shielding, ingress protection, environmental ratings) to end‑use profiles.
What the PW Consulting report contains — practical, actionable deliverables
Our full report is designed as a working tool for 2026 implementation, not just a descriptive narrative. Key practical elements include:
- A transparent, auditable market model with historical series and a 2026–2032 forecast at global and national levels; scenario runs allow you to stress material price shocks and tariff changes.
- Strategic supplier assessment templates and an RFP playbook tailored to enclosure procurement (including scoring matrices for lead time, tooling cost, certifications, and sustainability credentials).
- Material substitution and cost‑impact calculator that models ABS vs. polycarbonate vs. engineering plastics across volumes and regional cost bases.
- Go‑to‑market playbooks for OEMs and enclosure suppliers (new product launches, channel tactics, contract manufacturing options, and after‑sales service models).
- Compliance checklists and eco‑design pathways aligned to current registries and international eco‑criteria to fast‑track product registration and avoid rework.
- Deal‑scouting lists and capability maps to support M&A or partnership searches — targeted by manufacturing process (injection, thermoforming, sheet molding), certification portfolio, and service model (off‑the‑shelf, custom, tool‑less).
Because we recognize that execution is often constrained by the need for confidential supplier and pricing intelligence, the report combines open data with proprietary vendor assessments and interview insights to provide a practical action plan for 2026.
Recommended 90‑day action plan for executives
- Weeks 1–4 — Rapid diagnostics: Use the report’s supplier scorecard to rank your current enclosure sources. Identify one high‑risk single‑source part and begin qualification of an alternate vendor.
- Weeks 5–8 — Design & procurement alignment: Run three material‑substitution scenarios for your top 10 SKUs to quantify cost and compliance impacts. Prioritize modular redesign on two high‑volume platforms to defer tooling spend.
- Weeks 9–12 — Strategic supplier engagements: Negotiate fixed‑price short‑term contracts for critical ABS demand or consider forward procurement for key feedstocks. Pilot a tool‑less or low‑tooling production partner for a near‑term product launch to measure lead‑time and quality tradeoffs.
Signals to monitor in 2026
- Material feedstock announcements and plant turnarounds—these will affect ABS availability and pricing more acutely than polycarbonate in the near term.
- Tariff and trade policy notices affecting component imports—adjust sourcing maps within 30–90 days of formal notifications.
- Certification and registry compliance requirements—missed filings are a commercial and reputational risk for globalized OEMs.
- Vendor product roadmaps—additions of NEMA/IP, EMI shielding, or tool‑less service offerings are leading indicators of where competition will concentrate over the next 18–24 months.
Conclusion — the strategic value of the report for 2026
For 2026, the central strategic choice for players in the electronic plastic enclosure ecosystem is whether to treat the year as a continuation of cost containment or as the inflection point to invest in resilient sourcing, design modularity and compliance‑led product differentiation. Our report provides the data, risk scenarios and executable tools to make that choice with confidence. It synthesizes market‑level forecasts (anchored by a solid mid‑single‑digit CAGR), vendor capabilities and real‑world cost inputs so that leadership teams can prioritize capital and operating moves that protect margins and accelerate share gains.
If you are preparing a 2026 operating plan, a product roadmap refresh, or evaluating M&A targets, this report is structured to convert insight into a 90‑day action agenda and a three‑year operational roadmap. For the complete segmentation data, firm‑level profiles, and downloadable operational tools referenced above, refer to the full report on our website.
For detailed analysis of this topic, please visit the official page: Electronic Plastic Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 3D Topological Insulator Market Poised for Rapid Expansion at 22.46% CAGR, Fueling Quantum Computing and Spintronics Advances
By PW Consulting, 2026-07-13
Three Dimensional Topological Insulator Market — Strategic Outlook for 2026: PW Consulting Release
PW Consulting today publishes an executive briefing drawn from our new Three Dimensional Topological Insulator Market study (base year 2025; forecast period 2026–2032). This analysis synthesizes historical performance (2020–2025), our proprietary scenario projections, and a targeted competitive-supply review designed to help corporate leaders, technology investors, and supply-chain managers set priorities for 2026. The headline: the market is entering a high-velocity growth phase, expanding from an estimated USD 82.45 million in 2025 to roughly USD 340.54 million by 2032 at a compounded annual growth rate (CAGR) of 22.46% — a trajectory that will create both strategic opportunities and operational constraints for market participants.
Three Dimensional Topological Insulator Market
Why this matters for 2026 decision-makers
-
Investment timing: With an observed historical increase from the low tens of millions in 2020 to USD 82.45 million in 2025, and a steep forecast path thereafter, companies face a classic “first-mover vs. fast-follower” calculus. Early capacity and integration choices made in 2026 will have outsized returns as adjacent industries (quantum-enabled systems, spintronics-enabled memory and sensors, and specialty optoelectronic components) commercialize at scale.
Three Dimensional Topological Insulator Market -
Supply-chain fragility: Critical precursor materials and specialty chalcogenides exhibit price volatility and export control sensitivity. These dynamics can convert a technically successful product into a commercially unprofitable one if procurement is not addressed as a strategic priority.
Three Dimensional Topological Insulator Market -
Consolidation window: Market concentration metrics reflect a moderately consolidated supplier base (our market concentration analysis shows a CR3 of ~44% and a CR5 of ~62%), implying that partnerships, strategic sourcing agreements, and selective M&A can materially change competitive positioning within a short period.
What the PW Consulting report delivers (practical, board-ready content)
-
Robust market model: We provide a transparent top‑down and bottom‑up revenue model covering 2020–2032 with sensitivity scenarios tied to adoption rates in key technology adjacencies. The model isolates demand drivers by technology readiness, device-tier, and institutional vs. industrial research channels.
-
Scenario-driven strategy playbooks: Three investable scenarios (Constrained Supply, Accelerated Commercialization, and Defensive Build‑Out) describe specific action plans for OEMs, materials suppliers, and investors. Each playbook outlines capex timing, contractual terms to pursue, and go-to-market sequencing to protect margin under different market conditions.
-
Supply-chain risk map: A prioritized heat-map covering raw-material exposure (including tellurium and bismuth derivatives), single-source dependencies, logistics bottlenecks, and regions of regulatory sensitivity. This section includes practical mitigations — dual-sourcing checklists, inventory hedging approaches, and contract clauses for end‑use verification delays.
-
Commercial and technical diligence templates: Standardized vendor scorecards for crystal and thin-film suppliers, test specifications for device integration, and sample acceptance protocols to accelerate qualification while limiting technical debt.
-
M&A and partnership diagnostics: Target selection filters, valuation multipliers tailored to intellectual property quality and scale-up risk, and an integration checklist emphasizing fab-compatibility, contamination control, and IP transfer risks.
-
Regulatory and trade compliance framework: Practical guidance for companies navigating export controls, licensing timelines, and end-user verification requirements that have emerged in 2024–2025.
Key market dynamics and near-term (2026) implications
-
Acceleration in commercialization: The growth path we model is driven by parallel advances in device architectures and translation of lab-scale materials into reproducible thin films and crystals. For 2026, firms should prioritize pilot-scale reproducibility and device integration rather than incremental materials R&D alone.
-
Raw‑material cost and availability: Tellurium and related chalcogenide feedstocks have shown marked price and export volatility recently, creating immediate procurement risk for companies producing bismuth telluride-based compounds. Our report quantifies the sensitivity of gross margins to changes in precursor pricing and recommends procurement contracts and alternative-material exploration paths that are implementable in 2026.
-
Regulatory timing risk: Export licensing and verification requirements in key supplier countries have introduced multi‑week to multi‑month timelines in some trade flows. For manufacturers and system integrators, this means building multi-sourced inventories and factoring regulatory lead-times into product launch schedules now, not later.
-
Concentration and strategic leverage: The current CR3/CR5 footprint implies that a small number of high-quality suppliers account for a significant share of market supply. This creates both bargaining power for those suppliers and acquisition/partnership opportunities for larger buyers seeking to secure supply or to accelerate scale-up.
Competitive landscape — practical takeaways
Our competitive audit reviews leading materials and components suppliers across crystal growth, evaporation and sputtering targets, CVD and film-deposition providers, and distribution channels. We profile incumbent specialists and emerging players to help buyers and investors assess technical fit and operational risk.
-
Specialist single-crystal producers (e.g., regional crystal labs and focused compound houses): These players excel at supplying research-grade materials with well-characterized topology and minimal defects. Their compounds are indispensable for early-stage device validation; however, they are typically capacity-limited and command premium pricing. Strategic options for device OEMs include long-term supply agreements and joint scale-up ventures to secure priority access.
-
Integrated materials manufacturers and substrate suppliers: Firms that offer a portfolio of sputtering targets, evaporation materials and thin-film capabilities play a critical role in bridging lab results to manufacturing. For players deploying pilot fabs in 2026, vertically integrated suppliers reduce qualification time but may create longer-term vendor lock-in.
-
Distributors and solution providers: Channel partners that combine inventory depth with technical support reduce adoption friction for new entrants and research institutions. Their value proposition in 2026 is tied to rapid sample availability and local technical assistance for integration.
Examples from our supplier profiles (non-exhaustive; representative capabilities):
-
High-quality single-crystal specialists supply prototypical 3D topological insulator crystals and quaternary alloys that are the gold standard for device R&D.
-
Materials manufacturers market high-purity bismuth chalcogenides in multiple form factors — powders, crystals, sputtering targets — supporting both research and low-volume device production.
-
Advanced materials firms offer wafer-scale deposition and CVD film products aimed at accelerating device integration and reproducibility at scale.
Actionable recommendations for 2026
-
Operationalize a two-track procurement strategy: secure immediate priority access to critical feedstocks through short-term strategic agreements while funding development of alternative chemistries or recycling pathways that reduce long-term exposure.
-
Prioritize manufacturability in product roadmaps: shift resources from exploratory pure-material R&D to reproducibility, contamination control, and device qualification processes that shorten time-to-revenue.
-
Use targeted M&A and strategic alliances to control upstream and midstream capability: identify acquisition targets that materially increase supply resilience or accelerate time-to-market for integrated device prototypes.
-
Embed regulatory timing into go-to-market planning: factor export licensing and verification processes into procurement and launch schedules and build contingency playbooks for border or sourcing disruptions.
-
Create an investor-friendly commercialization dossier: combine technical roadmaps, supply-chain mitigations, and scaled revenue projections (our report’s model provides the templates) to shorten investor due diligence cycles in 2026.
How this briefing fits into your 2026 strategic cycle
For executives setting budgets and milestones in 2026, the PW Consulting report is designed to be actionable within 90 days of readout. It supplies the quantitative market model required for capital allocation, a prioritized supplier shortlist and qualification roadmap, and a tiered set of strategic responses tied to credible upside and downside scenarios. In short: it moves topological-insulator strategy from “science project” to “commercial line item.”
Next steps and where to get the full intelligence
We have intentionally positioned this release as a strategic preview: it highlights the market trajectory, competitive dynamics, and near-term actions without disclosing detailed segmentation matrices or proprietary financial schedules. Subscribers and licensed clients receive the full datasets, including the granular regional and application segment models, supplier scorecards, and downloadable scenario models that support board-level decision papers.
To obtain the complete report, model files, and supplier appendices — and to arrange a bespoke briefing for your executive or investment committee — please visit PW Consulting’s market reports page or contact your account representative. Our team stands ready to deliver a focused 90‑minute workshop tailored to your organization’s role in the three-dimensional topological insulator value chain.
For detailed analysis of this topic, please visit the official page: Three Dimensional Topological Insulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carboxymethyl Tamarind Gum (CMT) Market Set to Expand at 6.49% CAGR, Reaching USD 28.74 Million by 2032
By PW Consulting, 2026-07-13
Carboxymethyl Tamarind Gum (CMT) Market: Strategic Briefing for 2026 — PW Consulting Industry Insight
Executive summary
PW Consulting’s latest market study on Carboxymethyl Tamarind Gum (CMT) synthesizes five years of historical performance (2020–2025) and delivers a forward-looking, scenario-based forecast for 2026–2032. The global market reached USD 18.5 Million in 2025 and is modeled to grow at a compound annual growth rate (CAGR) of 6.49% through the forecast window, reaching an estimated USD 28.7 Million by 2032. This briefing highlights the practical implications of those macro-trends for executive decisions in 2026 — from procurement strategy and capacity planning to product development, regulatory assurance, and M&A scouting — while preserving the report’s full analytical datasets for subscribers.
Carboxymethyl Tamarind Gum (CMT) Market
Why the 2026 planning cycle matters for CMT stakeholders
- Demand inflection and margin pressure: CMT’s steady historical growth and accelerated mid-term forecast reflect expanding end-use demand in textile auxiliaries, specialty paper, and industrial fluids. Buyers and producers must align short-cycle inventories with a structurally growing market while protecting margins against raw-material volatility.
- Supply-side concentration and opportunity: The market shows moderate concentration (CR3 ≈ 38.4%; CR5 ≈ 52.15%), indicating a cluster of capable suppliers alongside a long tail of regional producers and distributors. For strategic buyers, this structure enables targeted supplier consolidation, premium sourcing relationships, and selective vertical integration.
- Regulatory and raw-material context: India remains the primary raw-material basin, with national tamarind production forming the feedstock base. Regulatory clarity — including recognition of tamarind kernel powder in manufacturing applications — reduces one regulatory tail-risk for industrial users, but chemical-processing inputs and environmental compliance require closer scrutiny.
Market dynamics that will drive 2026 decisions
- Reliable baseline growth, actionable levers: With the market expanding from roughly USD 13.5 Million in 2020 to USD 18.5 Million in 2025 and projected to exceed USD 28 Million by 2032, the macro trajectory is clear: incremental capacity, differentiated grades, and downstream formulation innovation will capture outsized returns.
- Raw-material supply chain realities: The tamarind-to-kernel supply chain is capital-light but seasonally variable. Industry-standard processing steps (seed selection, dehusking, milling, sieving, followed by alkali-mediated etherification with monochloroacetic acid) create leverage points for quality improvement and cost control. Firms that secure upstream kernel-processing capability or long-term feedstock contracts will reduce volatility and improve margin predictability.
- Regulatory and quality assurance: Existing safety recognition for tamarind kernel powder in manufacturing/processing applications simplifies risk assessment for industrial uses, but producers converting to purified grades for personal care, pharmaceuticals, or food-contact uses must meet stricter documentation, traceability, and impurity controls.
- End-use tailoring and product segmentation: Market expansion will be realized through grade differentiation (technical vs. purified grades) and application-specific formulations (high-viscosity textile thickeners, paper-sizing formulations, oilfield fluid additives). Strategic R&D and co-development with anchor customers are critical to capture premium pricing for specialized grades.
Competitive landscape — strategic takeaways
Our supplier mapping identifies a dual-structure market: experienced, scale-oriented Indian manufacturers with integrated supply chains and a network of global distributors enabling reach into North America, Europe, and emerging markets. Key players and their strategic positions include:
Carboxymethyl Tamarind Gum (CMT) Market
- Indian Hydrocolloids: A market leader with a product portfolio of customizable CMT grades covering textile printing, cosmetics, and oil & gas. Strengths: breadth of grades, export capability, technical support services. Strategic implication: ideal partner for co-development and long-term supply contracts for buyers seeking grade customization.
- Adachi Group: Specializes in textile printing thickeners emphasizing color fastness and wash-off properties. Strengths: process control and cost-competitive grades. Strategic implication: strong tactical supplier for large-volume textile formulators prioritizing cost-performance.
- Sudev International: Differentiates on specified viscosity and international quality standards. Strengths: reproducible functional metrics attractive to formulators. Strategic implication: suitable for suppliers seeking consistent rheology and controlled batch-to-batch performance.
- Chhaya Industries: Offers high-viscosity grades optimized for synthetic fiber printing. Strengths: niche product engineering and stability. Strategic implication: target supplier for premium textile applications and rotary printing processes.
- Global distributors (e.g., Wego Chemical Group, Riverland Trading): These players provide market access, inventory buffering, and logistical services across continents. Strategic implication: use distributors to mitigate supply shocks, expedite market entry, or pilot new grades without large minimum purchases.
- Regional and specialist manufacturers: A broad base of producers (Altrafine Gums, Premcem, Shivam Exim, and others) create sourcing optionality but vary widely on quality systems, export capability, and technical support. Strategic implication: rigorous supplier qualification and staged onboarding are essential.
Operational and strategic actions recommended for 2026
- Procurement & sourcing: Implement a dual-sourcing strategy that pairs a primary, technically capable manufacturer with a distributor or regional secondary supplier. Negotiate volume-flex clauses with price-indexing tied to raw-material markers to share volatility risk.
- Product & R&D: Prioritize development of purified and specialty grades for higher-margin end uses (cosmetics, pharma excipients, specialty adhesives). Invest in small-batch co-development programs to shorten lead times for customer qualification.
- Manufacturing & capex planning: For producers, consider modular upgrades in kernel processing and in alkylation/quenching controls to improve impurity profiles and yield. For buyers, evaluate backward integration into kernel procurement or toll-processing partnerships to control feedstock quality.
- Quality, compliance & traceability: Strengthen supplier audits focused on chemical-handling controls, residual reagent limits (e.g., haloacetic acid derivatives), and documentation required for higher-grade approvals. Map regulatory pathways for intended end-uses early in the product-signoff process.
- M&A & partnership screening: Given moderate market concentration, mid-market acquisitions can expedite capacity, extend product portfolios, and secure qualified suppliers. Use value-creation checklists that assess technical capabilities, export compliance, and customer concentration.
What our full report delivers (practical, action-ready content)
The PW Consulting CMT report is designed for executives and functional leaders who need to convert market insight into decisions in 2026. Deliverables include:
Carboxymethyl Tamarind Gum (CMT) Market
- Historical market sizing (2020–2025) and bottom-up forecasts (2026–2032) with scenario analysis and sensitivity modeling.
- Supplier scorecards and a validated buyer-supplier matrix covering technical capability, geographic reach, quality systems, and commercial terms.
- Procurement playbooks: contract clause templates, hedging strategies for feedstock volatility, and inventory optimization models.
- Regulatory and compliance primer: documentation requirements by end-use, impurity risk mitigation, and recommended testing protocols for purified grades.
- R&D prioritization framework and cost-to-serve models for launching specialty grades in textiles, paper, cosmetics, and industrial fluids.
- M&A screening tool with a shortlist of strategic acquisition/partner archetypes and illustrative valuation sensitivities.
- Operational checklists for on-site audits, quality acceptance testing, and environmental compliance for chemical modification processes.
Case implications — brief scenarios for 2026 decision makers
- Buyer (textile chemical house): Lock multi-year supply from a technical-grade manufacturer while co-developing a mid-viscosity CMT optimized for reactive dyes. Use distributor inventory to manage short-term demand spikes.
- Producer (mid-sized Indian manufacturer): Invest in kernel-processing capacity and impurity-reduction steps to move up the value chain into purified grades for cosmetics and food-contact applications; pursue selective export partnerships to diversify market risk.
- Investor / acquirer: Target mid-tier producers with proven QC systems and export footprints; consolidate regional capabilities to capture scale benefits in R&D and logistics.
Next steps and how PW Consulting supports execution
PW Consulting combines sector expertise with hands-on operational tools to accelerate strategy-to-execution. For 2026 planning we offer tailored support packages: supplier due diligence and audits, negotiated supplier agreements, co-development roadmaps, and transaction advisory for industry consolidation. Our industry database and interactive models are regularly updated to incorporate feedstock price signals, regulatory changes, and new product approvals.
Call to action
This briefing is an executive distillation of our full CMT market study. To access the comprehensive data tables, supplier scorecards, scenario models, and operational playbooks referenced here, please visit the PW Consulting publications page or contact our sales team to request the complete report. The full report contains the granular segmentation and tactical appendices that procurement, R&D, and corporate development teams require to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Carboxymethyl Tamarind Gum (CMT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Part Refurbishment Repairs Market to Grow at 7.85% CAGR, Reaching USD 8,230.93 Million by 2032
By PW Consulting, 2026-07-13
Semiconductor Part Refurbishment & Repairs Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting is pleased to announce the release of our latest market research briefing: "Semiconductor Part Refurbishment & Repairs Market." Built on a base year of 2025 with historical analysis covering 2020–2025 and forecasts through 2032, this report synthesizes primary research, supplier audits, repair-centre site visits, and proprietary financial models to help executives, investors, and operations leaders make high‑confidence decisions in 2026 and beyond.
Semiconductor Part Refurbishment Repairs Market
Macro outlook: resilient growth, increasing strategic importance
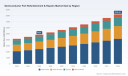
The second half of the 2020s is shaping up as a pivotal period for aftermarket services in semiconductor manufacturing. Our market model shows the global semiconductor part refurbishment and repairs market expanded from an estimated USD 4,169.67 Million in 2023 to USD 4,850.00 Million in 2025 (base year), with an expected compound annual growth rate (CAGR) of 7.85% across the 2026–2032 forecast window. Under our central scenario the market is projected to approach the USD 8.2 billion range by 2032.
Semiconductor Part Refurbishment Repairs Market
Two countervailing structural forces underpin this trajectory. On one hand, chip industry capex and fab expansion — aggregated capital commitments into new fabrication and assembly capacity — are driving stronger demand for spare parts, field servicing, and life‑extension work. On the other hand, supply chain pressures, geopolitical controls, and new trade/regulatory frictions are elevating the economic value of refurbished and repair‑based solutions as firms seek resilience and cost efficiency.
Semiconductor Part Refurbishment Repairs Market
Why this report matters for 2026 strategy
- Decision timeliness: With accelerating lead‑time volatility and material price swings in early 2026, repair and refurbishment strategies have become immediate levers for meeting production targets without incurring the full cost or delay of new equipment procurement.
- Operational playbooks: The report translates market sizing into executable operational guidance — repair vs. replace evaluation matrices, total cost of ownership (TCO) templates, and lifecycle ROI calculators designed for capital planners and MRO managers.
- Regulatory scenario planning: We provide scenario overlays that quantify the commercial impact of the new U.S. Section 232 proclamation effective January 2026 — notably the tariff regime and its repair exemptions — and ongoing export control dynamics, enabling compliance-aware sourcing and servicing decisions.
Key market dynamics and near‑term noise
- Pricing pressure and component scarcity: Multiple chip suppliers announced price increases in April 2026 in the range of ~15–35% as AI‑driven compute demand sustains higher ASPs. These input cost trajectories increase the marginal economic attractiveness of refurbishment options where technical integrity can be assured.
- Lead‑time risk: Select semiconductors are exhibiting lead times trending toward 30–42 weeks in early 2026, with certain power and analog components extending even further. Repair and refurbishment pathways shorten effective replacement cycles and reduce line downtime exposure.
- Policy and trade overlays: U.S. export controls and licensing requirements continue to shape cross‑border maintenance and technology transfer patterns. Simultaneously, the 25% tariff measure enacted under Section 232 (with carve‑outs for in‑country repairs and certain R&D activities) materially changes sourcing economics for imported replacement parts.
- Fab investment tailwinds: Industry consortiums report a multi‑hundred‑billion‑dollar pipeline of new manufacturing projects since major semiconductor incentives were implemented, supporting sustained aftermarket demand across the forecast horizon.
What the PW Consulting report contains (practical, operational intelligence)
- Proprietary market model (2020–2032) with scenario layers (base, constrained supply, accelerated capex) and sensitivity levers for price and lead‑time shocks.
- Repair economics toolkit: step‑by‑step calculators for repair vs. replace decisions, refurbishment cost benchmarking, warranty and SLA scenarios, and expected downtime exposure analyses.
- Supplier performance scorecards and capability maps covering test rig capabilities, quality processes (e.g., traceable rework logs, cleanroom refurbishment), lead‑time profiles, and RMA handling practices.
- Operational playbooks for fabs and service centers: inbound inspection templates, parts cleanliness and contamination mitigation standards, refurbishment QC checkpoints, and OEM interface checklists for legacy platforms.
- Regulatory and compliance playbook: guidance on navigating export controls, tariff exemptions for repair activities, and audit preparation for cross‑border servicing arrangements.
- Investment and M&A decision frameworks: valuation adjustments for refurbishment revenues, earn‑out structures linked to service KPIs, and integration checklists for acquiring independent service organizations (ISOs).
- Executive dashboards and data appendices: interactive charts for market trajectories (by year), aggregate concentration metrics, and spend multipliers for budget planning. (Note: core disaggregated segment tables are reserved for full‑report clients.)
Competitive landscape: capability clusters and strategic moves
The market remains moderately fragmented — our concentration analysis indicates that the top three players account for roughly one‑third of market value while the top five approach the low‑40% range. That structure creates room for specialized service providers, regional consolidated players, and strategic partnerships between OEMs and ISOs.
- IES Semiconductor Parts (Bristol, UK) — A specialist in repair and testing for a broad array of production parts. Its emphasis on extending legacy and obsolete equipment life, combined with warranty offerings, positions it as a preferred partner for customers seeking predictable lifecycle extension on older platforms.
- PSI Semicon Services (Livonia, MI) — Offers comprehensive repair, refurbishment and remanufacturing across electromechanical and electronic subsystems. PSI’s deep bench on robotics, controllers and power systems makes it attractive for fabs with heterogeneous installed bases.
- SemiGroup (Dallas, TX) — Focuses on refurbishing equipment to OEM specifications with rigorous testing and installation services. Its turnkey approach (refurbish + install + warranty) suits buyers prioritizing single‑source risk transfer.
- Capitol Area Technology (Austin, TX) — A distributor‐led model that combines parts distribution with repair services, effective for customers wanting integrated spare parts flows tied to repair turnaround metrics.
- Ichor Systems (Fremont, CA) — Brings design engineering and field services to complex refurbishments (notably single‑chamber etch tools), enabling higher‑value retrofits and productivity upgrades as part of refurbishment packages.
- Semiconductor Support Services Co. (Austin, TX) & Conation Technologies (USA) — Niche specialists with deep OEM equipment experience (AMAT, Lam, TEL, KLA‑Tencor), valuable for customers seeking domain expertise on specific tool families.
Recent industry moves confirm the strategic pivot toward sustainable, resilient aftermarket models. Notably, an eco‑focused refurbishment facility launched in Singapore in early 2025 demonstrates material recovery and cleaning innovations that can reduce consumables spend and environmental footprint. Meanwhile, large manufacturing investment pipelines in North America and beyond are shifting where and how service providers position capacity and technical resources.
Strategic implications and recommendations for 2026 planning
- For fab operators: Implement a prioritized portfolio of repairable components using the report’s TCO and downtime models. Treat repair‑capable subsystems as strategic inventory to reduce exposure to long lead times and tariff volatility.
- For OEMs: Revisit service‑led monetization models — warranties, certified reman programs, and authorized refurbishment channels — to capture aftermarket value while managing IP and compliance risk under export control regimes.
- For service providers and ISOs: Invest selectively in test‑bed capabilities and traceability systems that meet OEM and fab audit expectations. Consider strategic alliances or bolt‑on acquisitions to scale capabilities in high‑value tool families.
- For investors and M&A teams: Use the concentration and scenario outputs to identify consolidation targets that can scale regional service density, shorten logistics cycles, and unlock margin through site rationalization.
- For procurement and supply chain leaders: Leverage repair exemptions in new tariff regimes and design contractual KPIs with service providers for turnaround, contamination risk, and first‑pass yield of refurbished parts.
Accessing the full intelligence
This briefing intentionally highlights strategic takeaways while preserving the detailed, table‑level intelligence that is most valuable to commercial and operations teams. The full PW Consulting report contains the complete disaggregated datasets, supplier scorecards, downloadable model files, and custom scenario support that organizations need to operationalize the recommendations above.
To request the full report, license the underlying market model, or schedule a private briefing with our Senior Industry Analysts, visit the PW Consulting publications portal or contact our client services team. For organizations seeking an immediate tactical advantage in 2026, we also offer short‑form bespoke analyses tailored to a firm’s installed base, procurement exposure, or planned capex program.
PW Consulting — Insight to action for semiconductor aftermarket resilience.
For detailed analysis of this topic, please visit the official page: Semiconductor Part Refurbishment Repairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Leucoxene Market Poised for Robust Growth at a 5.4% CAGR Through 2032
By PW Consulting, 2026-07-13
Leucoxene Market 2026: Strategic Imperatives for Procurement, Processing and Portfolio Leaders
PW Consulting’s new Leucoxene Market report — base year 2025, forecast 2026–2032 — delivers the actionable intelligence that industrial buyers, feedstock processors, and corporate strategists need to shape decisions throughout 2026. Anchored in primary-source price signals, production reviews and field-level certifications, the study reconciles near-term supply shocks with a multi-year structural outlook. This release summarizes the report’s strategic value and highlights the decision pathways it is designed to unlock — while preserving the proprietary segment-level detail available in the full report.
Leucoxene Market
Market trajectory at a glance
The leucoxene market expanded steadily through the first half of the decade, rising from roughly USD 165.2 Million (2020) to USD 215.1 Million in 2025 (USD, revenue unit: Million). Our forecast for 2026 anticipates continued growth to approximately USD 232.8 Million, underpinned by a 2026–2032 compound annual growth rate (CAGR) of 5.4%, and reaching an expected market size north of USD 310 Million by 2032.
Leucoxene Market
Those headline dynamics reflect intersecting forces: substitution pressure among titanium feedstocks, evolving welding and pigment demand patterns, and the uneven distribution of high-grade primary deposits. The market exhibits a measurable concentration among a small group of producers, which in turn creates both price resilience and episodic volatility for buyers and downstream processors.
Leucoxene Market
Why this matters for 2026 decision-makers
- Procurement and supply security: With market concentration favoring a handful of integrated and upstream producers, 2026 is a high-leverage year to re‑price contractual terms, re-examine destination-hedging strategies, and diversify offtake to mitigate single-source exposure.
- Feedstock selection and process engineering: Leucoxene’s role as a high‑TiO₂ natural feedstock places it in direct technical competition with rutile and slag inputs. Process engineers and product teams must incorporate variable grade profiles into kiln and finishing designs to sustain pigment yields and welding flux performance.
- Capital allocation and M&A timing: The market’s 5.4% forecast CAGR, combined with episodic low-quality supply events, creates asymmetric value for well-timed buy-side consolidation, bolt-on processing capacity, and strategic investments in beneficiation technologies.
Key dynamics shaping 2026
- Price baselines and short-cycle signals: Public commodity references point to a 2025 FOB Australia price benchmark of about USD 400 per metric ton for ilmenite and leucoxene bulk loads. Such benchmarks are informative for short‑cycle procurement, but buyers should layer grade, logistics and treatment premiums when negotiating long-term contracts.
- Quality dispersion and margin compression: Recent production reviews have signaled the market consequences of lower-quality leucoxene entering premium supply chains, exerting downward pressure on certain titanium feedstock price bands and nudging downstream processors to optimize blending and upgrade strategies.
- ESG and certification as commercial differentiators: Field-level sustainability achievements (for example, IRMA performance recognition at major coastal operations) are rapidly shifting from reputational niceties to commercial levers that can influence sourcing mandates and lender covenants.
- Geopolitical flows and import dependencies: Trade flows remain important: a meaningful share of global ilmenite production and intermediate concentrates continue to be routed through very specific origin corridors, necessitating scenario planning for logistics disruption or trade-policy shifts in 2026.
Competitive landscape — what leaders, challengers and traders mean for strategy
The leucoxene value chain is populated by vertically integrated miners, state-owned operators, specialist project developers and merchant traders. PW Consulting’s analysis synthesizes company-level production footprints, product grade strategies and commercial positioning to reveal where value accrues.
- Iwatani Corporation (Japan) — via its subsidiary operations, Iwatani controls high‑quality primary leucoxene deposits that command premium positioning for high‑value pigment and welding feedstock markets. Strategic takeaway: premium deposit access supports margin control and provides leverage in long-term offtakes. ( https://www.iwatani.co.jp)
- The Kerala Minerals & Metals Limited (India) — as a state‑owned supplier, KMML anchors regional feedstock availability and offers strategic relief for downstream Indian pigment and welding industries. Strategic takeaway: national suppliers can be critical partners for localized supply security and regulatory navigation. ( https://www.kmml.com)
- Eramet / Grande Côte Operations (France / Senegal) — markets a high‑TiO₂ leucoxene product with targeted campaigns into welding applications; also notable for recent sustainability certification milestones. Strategic takeaway: certification can unlock new industrial offtake pools and support price differentiation. ( https://www.eramet.com)
- Iluka Resources (Australia) — a major sands producer whose production quality variability has had knock-on effects for pricing dynamics. Strategic takeaway: monitor producer quality disclosures — periodic quality fluctuations from large suppliers can reshape short-term bargaining power. ( https://www.iluka.com)
- Tronox Holdings Plc (United States) — integrated feedstock-to-pigment players like Tronox internalize feedstock risk, creating a competitive moat in pigment supply chains but also amplifying exposure to concentrate-price swings. Strategic takeaway: vertical integration is an effective hedge, but it requires disciplined capital allocation. ( https://www.tronox.com)
- Astron Limited, Kenmare Resources, Arima Minerals Processing, Mineral Global Trading — project developers, regional operators and merchant traders together provide flexibility to the supply base, functioning as swing suppliers or niche premium channels. Strategic takeaway: trading partners and project-stage players offer tactical routes to fill shortfalls or source specialized sands. ( https://astronlimited.com.au, https://www.kenmareresources.com, https://arimaminerals.com, https://mineral-global.trading)
What PW Consulting’s report delivers (practical, non-redundant outputs)
Our full study is built for decision velocity. It translates market signals into operational actions and investment priorities without exposing the proprietary segment tables that clients purchase with the report. Notable deliverables include:
- Forward-looking price-deck scenarios and sensitivity models (short-cycle and structural), mapped to buyer risk profiles.
- Supplier risk heatmaps integrating production quality volatility, certification status, and logistics exposure.
- Technology and process playbook: beneficiation, upgrade and blend strategies that maximize TiO₂ yield across typical downstream process routes.
- M&A and partnership targets: prioritized list of project-stage assets and merchant networks by strategic fit and execution risk (confidential annexes include contact-ready diligence starting points).
- Regulatory and ESG tracker linking certification status to lender and customer procurement policies, with recommended compliance pathways.
- Practical negotiation templates and contracting clauses for medium‑term offtakes to capture grade and logistics variability protections.
How to use the report to shape your 2026 playbook
- Buyers: Use the report’s price-deck and supplier heatmap to renegotiate 2026 contracts with clauses that balance price indexation and grade‑based adjustments.
- Processors and pigment-makers: Prioritize engineering runs that test feedstock blends highlighted in the playbook; invest selectively in beneficiation where NPV sensitivity is strongest.
- Investors and corporate development: Target bolt-on assets and trading platforms that provide counter-cyclic optionality; leverage the M&A annex to accelerate due diligence.
- Financial institutions: Align lending covenants with the ESG tracker and certification milestones to reduce portfolio transition risk.
Operational checklist for Q1–Q3 2026
- Reassess counterparty concentration: quantify the share of supply tied to the top producers and stress-test alternatives against logistics scenarios.
- Lock-in partial protection against short-cycle price swings using a mix of spot, capped forwards and capacity reservation agreements.
- Implement on-site sampling and grade reconciliation protocols tied to payment mechanisms to avoid downstream yield erosion from unexpected quality shifts.
- Engage with certified suppliers to secure ESG-alpha in procurement terms that are acceptable to both lenders and end-customers.
Final note — what you’ll only find in the full report
To preserve the commercial value of the report for subscribers, this summary intentionally omits the detailed regional and application-level split tables, and the precise financials tied to individual segments and scenarios. Those granular datasets — which convert the market-level trajectory into product-by-product and route-by-route investment decisions — are included in the paid report and its modeling workbook.
If your 2026 strategy depends on securing feedstock, defending margins, or capturing consolidation value in the titanium value chain, PW Consulting’s Leucoxene Market 2026–2032 report is designed to be an operational catalyst. For access to the full dataset, proprietary segment models, and client‑only advisory slots, visit PW Consulting’s report page or contact our industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Leucoxene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Rotator Cuff Injury Therapy Market to Grow from USD 1,949.82 Million in 2025 to USD 2,951.21 Million by 2032 at a 6.1% CAGR
By PW Consulting, 2026-07-13
Rotator Cuff Injury Therapy Market — Strategic Preview for 2026 Decision-Makers
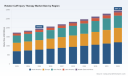
PW Consulting’s latest market intelligence on Rotator Cuff Injury Therapy reframes the competitive horizon for medtech, orthopedics and provider organizations entering 2026. Built on a base year of 2025 and a historical window covering 2020–2025, our analysis projects a steady expansion at a 6.1% CAGR through 2032 — taking the market from an estimated USD 1,949.82 Million in 2025 toward roughly USD 2,951.21 Million by 2032. For executives weighing R&D prioritization, commercial investment, or M&A through the coming year, this report functions as both thermometer and roadmap: it diagnoses structural forces and prescribes pragmatic moves without disclosing all proprietary segment-level modeling in this preview.
Rotator Cuff Injury Therapy Market
Why this preview matters for 2026 strategic planning
-
Investment horizon clarity: The market’s mid-single-digit CAGR signals durable demand driven by aging demographics, rising surgical volumes, and expanding biologics adoption. This underpins capital allocation decisions — from clinical programs to sales footprint expansion.
Rotator Cuff Injury Therapy Market -
Regulatory and reimbursement inflection points: Recent guideline and clearance activity is reshaping clinical pathways and payer conversations; executives must realign clinical evidence strategies and reimbursement playbooks now, not later.
Rotator Cuff Injury Therapy Market -
Competitive posture and consolidation window: Market concentration metrics show meaningful presence by leading incumbents while leaving room for specialized entrants to capture niche share through differentiation or partnerships.
Key macro takeaways
-
Growth profile: The market is projected to continue growing at a 6.1% CAGR over the 2026–2032 forecast period, reflecting both replacement demand and expanded indications for augmentation technologies.
-
Concentration: Our competitive metrics indicate a mixed structure — the top three companies hold a meaningful share while the top five account for a clear majority of industry revenues. This produces both competitive pressure in core device categories and opportunities in adjacent biologic/augmentation niches.
-
Clinical economics: Updated clinical guidance and cost-effectiveness evidence increasingly favor repair strategies that incorporate biologics and advanced fixation techniques; lifetime societal savings versus nonoperative care are material for payer negotiations.
Industry dynamics shaping 2026 choices
-
Guideline-driven adoption: The AAOS 2025 Clinical Practice Guideline explicitly emphasizes bioinductive implants to reduce re-tear rates. This shifts clinical preference curves and raises the bar for product clinical evidence packages.
-
Regulatory momentum for augmentation devices: Multiple 510(k) clearances in 2025–2026 for reinforcement matrices and augmentation kits lower barriers to commercial entry for biologics and implant adjuncts — but also intensify competition around claims and label differentiation.
-
Payer nuance: Medicare reimbursement pathways remain complex. For example, modifier 22 (increased procedural complexity) succeeds in only a minority of arthroscopic rotator cuff cases — an operational reality that affects price realization and commercial value propositions.
-
Procedure economics: Hospital list prices for arthroscopic repairs—and published cost-effectiveness analyses—create a compelling commercial narrative for products that demonstrably reduce re-tear, reoperation and downstream societal costs.
Competitive landscape — what to watch
The market features several well-positioned incumbents and growing specialist players. Our strategic assessment focuses on how product portfolios, channel strategies and clinical evidence are likely to determine winners in 2026.
-
Arthrex, Inc. — Strengths: broad arthroscopic systems and knotless/knotted repair platforms with integrated augmentation options. Strategy implication: incumbency in instrumentation enables cross-sell of biologic adjuncts; potential acquirers should evaluate integration synergies.
-
Smith & Nephew plc — Strengths: bioinductive implant leadership and active engagement at key orthopedics forums. Strategy implication: visibility in clinical guidelines and trade shows amplifies adoption; competitors should anticipate accelerated clinician uptake where reimbursement supports it.
-
Stryker Corporation — Strengths: anchor technologies and alternative solutions (e.g., spacer devices) for massive irreparable tears. Strategy implication: portfolio breadth enables segmentation across simple to complex cases; partnerships with specialty biologic innovators could further extend reach.
-
Zimmer Biomet and Johnson & Johnson (DePuy Synthes) — Strengths: comprehensive implant and instrumentation portfolios, deep hospital relationships. Strategy implication: incumbency advantage in hospital purchasing requires challengers to offer clear incremental clinical or economic value.
-
CONMED, Atreon Orthopedics, Integra LifeSciences and others — Strengths: focused augmentation and biologic matrices, recent regulatory clearances. Strategy implication: these specialists are attractive targets for larger players seeking to fill biologic/augmentation gaps.
Recent tactical events underscore an accelerating tempo: Smith & Nephew’s high‑profile presence at AAOS 2026, Atreon’s 2025 FDA clearance and CONMED’s 2025 device approvals all signal that product innovation and regulatory wins will continue to drive share shifts in 2026.
Strategic imperatives for 2026
-
Prioritize evidence generation that maps to guideline endpoints. With clinical guidelines elevating bioinductive implants, companies must invest in outcomes studies that demonstrate reduced re-tear and cost-effectiveness versus alternatives.
-
Design reimbursement-first clinical programs. Given payer scrutiny (e.g., modifier 22 utilization dynamics), align trials and real-world evidence to reimbursement benchmarks and develop coding/coverage playbooks early in the commercialization path.
-
Segment GTM by clinical complexity. Differentiate offerings across simple repairs, complex tears and irreparable cases (including spacers and augmentation). Tailor messaging and distribution (ASC vs hospital vs specialist clinic) to unit economics and procurement behaviors.
-
Use partnership and M&A as fast-track options. The biologics and matrix space is consolidating; strategic acquisitions or co-development arrangements accelerate product breadth and clinical validation.
-
Operationalize value-based contracting pilots. Demonstrating reduced reoperation rates and lifetime cost savings creates leverage with payers and IDNs; pilot agreements can unlock preferential access and pricing premiums.
What PW Consulting’s full report delivers (practical, executable content)
-
Detailed 2026–2032 forecast model with sensitivity scenarios and key drivers, plus historical trend decomposition for 2020–2025.
-
Commercial playbooks by treatment type and end-user, including go-to-market tactics for hospitals, ambulatory surgery centers and physiotherapy channels.
-
Regulatory and reimbursement roadmaps tailored to the U.S. and major international markets, highlighting approval pathways, coding strategies and payer engagement templates.
-
Competitive benchmarking that scores technology portfolios against clinical, economic and operational attributes — and identifies M&A and partnership opportunities.
-
Clinical evidence matrix linking product claims to guideline-relevant endpoints and suggested trial designs to support market access.
-
Risk register and mitigation playbook addressing supply-chain, regulatory, price erosion and competitive entry scenarios.
Note: This preview intentionally omits granular regional and application-level splits and our full pricing sensitivity tables. Those segment-level models and underlying assumptions are included in the full report and online data portal to support transaction diligence and market-entry planning.
Immediate actions for executives in 2026
-
For R&D leaders: fast-track at least one mid-size clinical study that aligns endpoints with AAOS guideline recommendations and payer value metrics.
-
For commercial leaders: pilot value-based contracting in targeted IDNs where case volume and reimbursement complexity enable measurable KPIs.
-
For corporate development teams: prioritize M&A targets that provide biologic augmentation capability or label-extension potential; expect competitive auction activity for differentiated matrices.
-
For hospital/ASC operators: re-evaluate product formularies and pathway bundles to capture demonstrated reductions in reoperation and downstream costs.
Conclusion — the strategic choice
Entering 2026, the Rotator Cuff Injury Therapy market is neither a speculative frontier nor a saturated commodity field. It is a predictable-growth market with windows of rapid differentiation driven by guideline alignment, augmentation technologies and payer economics. Companies that synchronize clinical evidence, regulatory strategy and commercial models will capture outsized returns; those that delay will face margin compression and entrenched incumbents. PW Consulting’s full report supplies the segmented modeling, granular pricing analysis and operational playbooks necessary to convert this market trajectory into concrete enterprise value.
To access the full data-packed report, regional and treatment-level forecasts, and executable go-to-market templates, please visit our report page or contact PW Consulting’s healthcare strategy team.
For detailed analysis of this topic, please visit the official page: Rotator Cuff Injury Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


