



PW Consulting: Automotive Ethernet Market Poised for 19.5% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Automotive Ethernet Market 2026: Strategic Imperatives for Executives Preparing for a Networked Vehicle Future
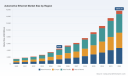
As vehicles transition from distributed electrical architectures to software-defined platforms, Automotive Ethernet has moved from niche experiment to strategic infrastructure. PW Consulting’s upcoming Automotive Ethernet Market research—anchored on a 2025 base year and projecting through 2032—captures this tectonic shift with a rigorous blend of primary research, techno-commercial modeling, and scenario planning. The market we track expanded from roughly $1.5 billion in 2020 to about $4.5 billion in 2025 and is forecast to accelerate at a compound annual growth rate (CAGR) of 19.52% in the 2026–2032 window, reaching an estimated $15.7+ billion by 2032. For leadership teams finalizing 2026 roadmaps, procurement plans, and partnership strategies, this report is designed to be an operational tool—not a marketing brochure.
Automotive Ethernet Market
Why 2026 is a Strategic Inflection Point
-
Bandwidth becomes a governance problem: As ADAS, infotainment, and centralized compute converge, the cost and topology implications of moving to 100BASE-T1/1000BASE-T1—and increasingly 10GBASE-T1—are no longer purely technical. They inform vehicle architecture, supplier selection, and OPEX planning.
Automotive Ethernet Market -
Standards + regulation compress timelines: New and updated standards (ISO 10681 series, OPEN Alliance committees) and regulatory requirements (notably cybersecurity mandates such as UN ECE R155) are creating hard gates for type approval and limiting design freedom for legacy, proprietary bus systems.
Automotive Ethernet Market -
Supplier consolidation and specialization: Market concentration metrics indicate a competitive landscape where a small group of firms account for the majority of supply leadership—creating both dependency risk and M&A opportunity.
What the Report Delivers (Practical, Actionable Content)
-
Executive roadmaps: A prioritized set of short-, medium- and long-term actions for OEMs, Tier-1s and semiconductor suppliers tied to adoption scenarios (conservative, base, accelerated).
-
Scenario-based financial modeling: Sensitivity analyses that translate PHY, switch and software cost declines into vehicle BOM and total cost of ownership outcomes across centralized and zonal architectures.
-
Vendor benchmarking and competitive matrix: Capability maps covering PHYs, MAC-PHY integration, switch throughput, deterministic networking, software stacks and testing toolchains—benchmarks that inform make/buy decisions.
-
Regulatory and standards impact assessment: Timing and design implications of ISO, IEEE, OPEN Alliance work items and UN ECE cybersecurity requirements.
-
Testing, validation and certification playbooks: Practical steps and checklists for lab and in-vehicle verification, including deterministic-networking test cases and EMI mitigation guidance for higher-speed PHYs.
-
Supply-chain and procurement playbook: A risk matrix for single-source dependencies, long-lead component risks, and contract constructs for co-development and IP sharing.
-
Vendor and partner engagement templates: Negotiation levers for joint development agreements, NRE structures, and revenue-share models tied to gateway and domain-controller deployments.
Core Market Dynamics and Technology Constraints
-
Multi-tier standards landscape: OPEN Alliance work on multi-drop and high-speed profiles (TC8/TC10), ISO’s evolving phy requirements and IEEE legacy constraints shape allowable topologies and permissible PHY choices.
-
EMI and signal integrity are not solved problems: 1000BASE-T1 and beyond require sophisticated DSP techniques and carefully specified cable/connectors. These technical constraints translate to supplier differentiation and increase the value of validated reference designs.
-
Cybersecurity is now a procurement filter: UN ECE R155 and OEM cyber policies have elevated secure boot, segment isolation, and log/audit capabilities to mandatory design elements—impacting software, hardware and lifecycle services.
-
Functional safety and power design: Power-over-data-line approaches remain constrained by ISO 26262 safety isolation requirements—limiting some low-cost sensor consolidation strategies and shifting design choices toward dedicated power architectures.
Competitive Landscape—How Key Players Are Positioning
The market is shaped by semiconductor incumbents, specialist switch vendors, and tool providers. Competitive dynamics are defined less by single-product wins and more by ecosystem plays: PHY performance + software stacks + test/validation capabilities + OEM relationships. Notable strategic positions include:
-
Broadcom Inc. —leveraging scale in PHYs and switches, Broadcom’s recent compliance progress with high-speed profiles underscores a push into 10G-class automotive Ethernet, where certification breadth matters for tiered supply strategies.
-
Marvell Technology —demonstrated vehicle integrations highlight the commercial traction of their higher-speed PHYs; integration into OEM platforms acts as a leading indicator for accelerated high-bandwidth ADAS adoption.
-
NXP Semiconductors —continues to marry PHY and SoC capabilities, positioning itself for zonal and domain-controller plays with products tailored for SDV architectures and OEM-grade switch solutions.
-
Texas Instruments and Microchip —target cost-performance and volume gateway applications, emphasizing robust 100BASE-T1 implementations for mass-market segments where price sensitivity dominates.
-
Analog Devices —focusing on specialized PHYs for long-reach sensor networks, providing design advantages in architectures that favor distributed sensor topologies.
-
Renesas —moving to integrate 10G-class Ethernet into SoCs in collaboration with automotive suppliers, placing them at the confluence of compute and network consolidation strategies.
-
TTTech Auto, Vector, Intrepid —specialists in deterministic networking, test & validation and diagnostics. Their tools and software are increasing in strategic value as OEMs require production-grade verification and in-field diagnostics for Ethernet stacks.
Recent vendor activity through 2025—product launches, vehicle integrations and compliance certifications—signals an acceleration toward higher-rate Ethernet in production vehicles. These moves validate the market’s upwards trajectory, but they also raise the bar for verification and supply-chain coordination.
Strategic Recommendations for 2026 Decision-Makers
-
Adopt a two-track architecture strategy: Validate a zonal baseline for near-term cost control while maintaining a phased path to centralized compute for ADAS and domain consolidation. Use PoC programs to stress-test both supply and cybersecurity postures.
-
Prioritize supplier qualification for PHYs and switches with proven EMI performance and compliance records. Where possible, secure dual-sourced design wins or contingency agreements to mitigate single-vendor risk.
-
Invest in in-house or co-developed validation capabilities. The complexity of high-speed automotive Ethernet makes third-party test tools and deterministic-networking stacks mission-critical—delay here increases recall and field-failure risk.
-
Align procurement windows with standardization timelines. Certification and regulatory gating will dictate production readiness; early alignment prevents costly late-stage redesigns.
-
Factor cybersecurity and functional safety into supplier KPIs and contracts. UN ECE R155 and ISO 26262 constraints translate into recurring lifecycle obligations and potential warranty exposure.
-
Consider non-linear revenue streams: software-enabled features, OTA update services, and managed diagnostic offerings can offset hardware margin pressure as component prices decline.
What We Withhold (and Why)
To preserve the report’s strategic utility and to respect the “trailer” principle, we deliberately do not publish granular regional, application or component revenue splits in this introduction. The full report contains an exhaustive breakdown by region, component and application—complete with downloadable Excel models, supplier scorecards and primary-interview transcripts. This granularity is essential for supplier selection, capex modeling and M&A diligence, and is available through PW Consulting’s full deliverable.
Concluding Note
For 2026 planning cycles, Automotive Ethernet is not an incremental engineering choice—it is a portfolio-level decision that impacts product architecture, supplier ecosystems, regulatory compliance, and long-term service models. With a market expanding from multi‑billion dollars today to a projected multi‑billion scale by 2032 at a near‑20% CAGR, the opportunity and the risk are both pronounced. PW Consulting’s Automotive Ethernet research gives leadership teams the frameworks, metrics and tactical playbooks necessary to convert network transition into competitive advantage.
Access the full report to obtain the detailed segmentations, vendor matrices, scenario models and procurement templates necessary to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: Automotive Ethernet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Noise Meter Market to reach USD 2,144.55M by 2032 at 5.85% CAGR - PW Consulting
By PW Consulting, 2026-07-13
Digital Noise Meter / Decibel Meter Market: Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concentrated, practice‑oriented preview of our new Digital Noise Meter Decibel Meter Market study. This piece is designed to orient executive teams making 2026 investments — showing the strategic contours of the market, the forces that will shape near‑term returns, and the practical levers companies should prioritize. We deliberately present high‑level, data‑driven insight here while omitting the granular segment tables and regional splits that are included in the full report—to preserve the “trailer” experience and direct decision‑makers to the full study for transaction‑level intelligence.
Digital Noise Meter Decibel Meter Market
Market at a Glance: Macro Trajectory and Strategic Implication
-
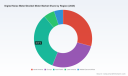
Base year dynamics: The digital noise meter market is materially larger today than five years ago, with the market reaching USD 1,440.15 Million in our 2025 base year.
Digital Noise Meter Decibel Meter Market -
Forward view: Under our central scenario, the market grows at a 5.85% CAGR across the 2026–2032 forecast window, reaching approximately USD 2,144.55 Million by 2032.
Digital Noise Meter Decibel Meter Market -
Concentration: Market concentration suggests room for both established OEMs and focused challengers—the top three firms control a meaningful share while the top five increase that footprint further, indicating a mix of specialization and consolidation pressures.
What this means for 2026 decisions: the market is large enough to reward focused scale plays (product platform expansion, service and SaaS tethering) while remaining sufficiently fragmented to allow disciplined entrants and partnerships to capture niche, higher‑margin positions. Capital allocation should therefore prefer strategies that combine product differentiation, data monetization, and channel acceleration.
Key Market Dynamics Executives Need to Embed in 2026 Strategy
-
Regulatory and standards pull: Occupational and environmental regulation remains the primary demand anchor. OSHA thresholds for hearing conservation programs and peak exposure limits continue to drive procurement cycles among industrial and public‑sector buyers. Simultaneously, IEC 61672 performance classifications and the updated ISO 9612 guidance are tightening admissibility criteria for measurement devices—raising the technical bar for market credibility.
-
Product evolution: Buyers are increasingly comparing instruments not just on baseline accuracy (Class 1 vs. Class 2) but on integrated functionality—wireless telemetry, native logging, edge analytics, and lifecycle calibration/traceability services. The market premium is migrating toward systems that reduce buyer total cost of ownership (TCO) through automation and cloud integration.
-
Industrial digitization and smart cities: There is clear momentum for embedding noise sensors into broader IoT and smart factory architectures. Partnerships between metrology equipment providers and factory systems integrators demonstrate a near‑term channel for sensor OEMs to monetize recurring services and software wrappers around measurement endpoints.
-
Procurement sophistication: Large buyers are moving from one‑off capex purchases to mixed models—capex for certified instruments complemented by subscription services for analytics, compliance reporting, and multi‑site fleet management.
What’s Inside the Full Report (Practical, Actionable Content)
Our study is built for corporate strategists, product leaders, and procurement heads who must act in 2026. The full deliverable extends beyond market sizing to deliver executable items you can use in boardrooms and program plans:
-
Validated market sizing and trend drivers (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity scenarios for regulation‑driven spikes and faster IoT adoption.
-
Decision frameworks for product portfolio strategy—when to prioritize Class 1 accuracy versus cost‑optimized Class 2 deployments, and the breakpoints where software and services increase lifetime value.
-
Go‑to‑market playbooks by buyer archetype (industrial compliance, environmental monitoring programs, building acoustics, transportation authorities, occupational health managers), including RFP checklists and procurement negotiation levers.
-
Commercial models and pricing templates for hybrid offerings (instrument + SaaS + calibration services), with NPV simulations and subscription elasticity inputs tailored to different end‑user segments.
-
Integration and systems engineering guidelines for embedding noise sensing into smart factory and smart city deployments—sensor selection matrices, data pipelines, edge vs cloud processing tradeoffs, and calibration governance to meet IEC/ISO requirements.
-
Regulatory compliance map that translates OSHA, IEC, and ISO requirements into vendor product specs and enterprise deployment checklists—designed to speed procurement sign‑off and reduce audit risk.
-
Due‑diligence toolkit for M&A and partnership scouting—valuation multiples observed in recent transactions, integration risk checklists, and prioritized capability gaps to close through bolt‑on acquisition or alliance.
Competitive Landscape: Who Matters and Why
The market remains anchored by incumbent metrology and instrumentation specialists, with product and distribution strengths that differ by buyer profile. The report profiles leading firms and evaluates them against five commercialization dimensions: measurement pedigree, product breadth, channel reach, systems integration capability, and service/SaaS proficiency.
-
Brüel & Kjær (Nærum, Denmark) — Renowned for precision Class 1 instruments and deep acoustic expertise; strong pedigree in environmental and research applications with advanced wireless and analysis features. Their brand equity supports premium pricing in regulated deployments.
-
Extech Instruments (Nashua, NH, USA) — Competes on affordability and field usability; good fit for occupational safety teams and smaller environmental programs that prioritize cost and portability.
-
PCE Instruments (Meschede, Germany) — Offers a broad range across Class 1/2 segments and emphasizes industrial applications; well‑placed to compete on product breadth in EMEA manufacturing markets.
-
REED Instruments (Wilmington, NC, USA) — Focused on portable, easy‑to‑use devices for occupational and educational settings; strength in rapid deployment and basic data logging.
-
Larson Davis (Provo, UT, USA) — Strong in advanced occupational and environmental monitoring with recent product launches (e.g., Spartan 821IH) that emphasize integrated dose metrics and professional workflows—indicative of a strategy to deepen ties with occupational health purchasers.
-
Casella (Bedford, UK) — Known for compliance‑oriented instruments and national market penetration in occupational noise; frequently selected for regulated workplace programs.
-
Svantek (Warsaw, Poland) — Positioned in the high‑end professional and industrial analyzer space; strong engineering capability for complex measurement scenarios.
-
RION (Tokyo, Japan) — Provides precision meters conforming closely to local (JIS) and international standards; a preferred supplier in markets with stringent standardization demands.
-
Pulsar Instruments (Filey, UK) — Focuses on workplace monitoring and personal dosimetry—an area set to expand as hearing conservation programs digitize.
Recent vendor moves underscore the market’s push toward integrated solutions and faster time‑to‑value. Notable examples include Larson Davis’s product launch for occupational dose metrics in 2025, new low‑cost pocket meters entering adjacent channels, and partnerships to integrate sound monitoring into smart factory systems. These developments illustrate two converging themes: hardware differentiation remains necessary, but margin expansion increasingly depends on services, connectivity, and validated data workflows.
Strategic Recommendations for Executives Planning in 2026
-
Prioritize “platform‑led” product roadmaps: invest in firmware and cloud APIs that enable multi‑vendor interoperability. Buyers are rewarding vendors who reduce integration friction with factory systems and environmental dashboards.
-
Design hybrid commercial models: pilot subscription‑based compliance reporting and calibration services alongside traditional instrument sales to capture recurring revenue and improve customer retention.
-
Target compliance‑driven procurement windows: align product certification roadmaps (IEC/ISO) to anticipated regulatory review cycles in customers’ jurisdictions to be “procure‑ready” when budgets open.
-
Use targeted partnerships to accelerate scale: form integrations with metrology partners, smart factory integrators, and occupational health platforms rather than attempting full in‑house stacks immediately.
-
Focus on proof points: deliver case studies that quantify reduced audit cycle time, lower noise‑related incidents, and saved remediation costs—these financial outcomes are the most effective sales accelerants in 2026 procurement processes.
-
Prepare M&A playbooks for capability gaps: where time‑to‑market matters, prioritize tuck‑ins that add analytics, wireless telemetry, or channel depth rather than purely incremental sensor improvements.
Why PW Consulting’s Study Is a 2026 Imperative
For 2026 decision cycles, the combination of a clear macro growth trajectory, tightened regulatory and standards expectations, and accelerating digital integration creates a narrow window of asymmetry for strategic players. Acting without precise market timing, buyer segmentation, and commercial models exposes firms to missed procurement windows and suboptimal capital allocation.
Our full report supplies the missing granularity—validated segment forecasts, buyer willingness‑to‑pay benchmarks, pricing ladders, and downloadable procurement checklists—that transform the high‑level recommendations above into boardroom decisions and investment memos.
Next Steps
If you are evaluating product roadmap investments, channel partnerships, or potential acquisitions in the digital noise measurement space this year, PW Consulting can provide a tailored briefing that includes the granular segment data, regional and application splits, and executable financial models omitted from this preview. Contact our market team to schedule a private walk‑through of the full study and a 60‑minute strategic alignment workshop for your leadership team.
For detailed analysis of this topic, please visit the official page: Digital Noise Meter Decibel Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sleep Apnea Masks Market to Reach USD 5,452.49M by 2032 at 8.15% CAGR
By PW Consulting, 2026-07-13
Sleep Apnea Masks Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused, action‑oriented introduction to our full Sleep Apnea Masks Market study. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory and reimbursement context, and the practical tools included in the full report — structured to inform boardroom decisions, product roadmaps, M&A screens, and commercial playbooks for 2026. Core, granular subsegment tables and precise split figures have been intentionally withheld from this preview to preserve the report’s commercial value; the sections summarized here are designed to show the depth of our analysis and the decision‑ready outputs you will find in the full deliverable.
Sleep Apnea Masks Market
Why this study matters for 2026
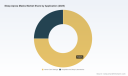
- Market momentum: The global sleep apnea masks market has demonstrated consistent expansion across the past half‑decade and is forecast to continue that trajectory into the early 2030s. From roughly USD 2.06 billion in 2020, the market reached about USD 3.15 billion by the 2025 base year and is projected to exceed USD 5.45 billion by 2032. The forecast period (2026–2032) carries an illustrative compound annual growth rate of 8.15%.
- Timing alignment: 2026 is a pivotal year for strategic moves — early adopters of AI‑enabled comfort systems, modular mask platforms, and institutional sales expansion will capture disproportionate share as demand shifts from hospital‑centric channels to hybrid home‑and‑institutional care pathways.
- Risk and opportunity concentration: Market concentration metrics indicate a highly consolidated competitive landscape (CR3 at 78.4%, CR5 at 89.6%). This creates predictable competitive dynamics but also opens windows for fast followers and niche challengers to exploit under‑served segments and service gaps.
Macro drivers shaping 2026–2032
- Demographics and diagnosis: Rising OSA awareness, broader screening, and telehealth‑enabled diagnosis sustain a steady addressable base. Home sleep testing and remote titration are shifting therapy initiation timelines and supplier touchpoints.
- Product innovation: Recent technological advances — from minimal‑contact nasal pillow designs to AI‑driven comfort personalization paired with integrated therapy devices — are changing patient adherence dynamics and creating new differentiation levers for incumbents and entrants alike.
- Regulatory & reimbursement overlay: Masks are FDA Class II devices in the U.S., generally requiring 510(k) clearance. Reimbursement remains a powerful determinant of commercial success; public payors (e.g., Medicare) support mask coverage under HCPCS codes with defined replacement rhythms, generating recurring demand for consumables and servicing models.
- Supply chain and input risk: Medical‑grade silicone remains the dominant cushion material due to biocompatibility and durability requirements. Pricing and availability of silicone and other key components can directly influence margins and time‑to‑market for new product introductions.
Competitive landscape — incumbents, challengers and what to watch in 2026
The competitive set is axiomatic: several global incumbents control large swathes of volume through integrated device‑mask ecosystems and strong clinical relationships, while a steady stream of challengers and regional suppliers pursue niche differentiation.
Sleep Apnea Masks Market
- ResMed (San Diego, CA) — strategy: ecosystem integration. ResMed continues to leverage device–mask compatibility and software hooks; its late‑2025 clearance for Smart Comfort AI‑enabled personalized comfort settings underscores the strategic pivot toward software‑mediated adherence. Expect ResMed to prioritize cross‑sell into existing installed bases and to sophisticate its recurring revenue from consumables and subscription services.
- Fisher & Paykel Healthcare (Auckland, NZ) — strategy: cushion and fit engineering. Known for engineering advances in cushions and headgear, their recent product introductions signal continued focus on comfort as a primary adherence lever. They compete by incremental product differentiation rather than broad ecosystem locking.
- Philips Respironics (Amsterdam, NL / US ops) — strategy: brand and channel scale. Philips maintains strength via well‑known consumer brands and broad distribution, focusing on both hospital and home channels with modular mask designs.
- New entrants and challengers — Inogen, REMSleep, React Health, Bleep, BMC (and legacy OEMs like Drive DeVilbiss): each pursues distinct plays. Inogen’s 2026 Aurora launch marks a classic device‑adjacent entry, using brand recognition in respiratory devices to penetrate CPAP accessory spend. REMSleep’s expanded FDA 510(k) clearance for its DeltaWave nasal pillow system (early 2026) is strategically significant — it broadens institutional addressability and demonstrates that targeted regulatory wins can rapidly change the competitive calculus for smaller players.
Implication for 2026: incumbents will defend via integrated software and service propositions; challengers will pursue regulatory niches, price‑performance pockets, and service‑led differentiation. Companies that align product, reimbursement, and distribution strategies will widen their moat faster than those focusing on single levers.
Sleep Apnea Masks Market
Report contents — what the full study delivers (practical, executable assets)
Our full report provides a suite of operational tools designed to accelerate strategy execution in 2026:
- Market sizing and forecast models (2020–2032) with scenario engines to model serviceable addressable market under alternative diagnosis and reimbursement trajectories.
- Segmentation analytics — by region, by product type, and by application — including channel maps, replacement rhythms, and consumable economics. (Note: granular split tables are available in the full report.)
- Competitive benchmarking — product matrix comparing fit/comfort features, materials, device compatibility, distribution reach, regulatory filings, and patent footprints.
- Go‑to‑market playbooks — differentiation strategies for incumbents, challenger entry plans, hospital sales acceleration, and direct‑to‑consumer pathways with KPIs and launch checklists.
- Reimbursement & regulatory roadmap — HCPCS code mapping, typical replacement schedules, 510(k) pathways, and an assessment template for U.S. and major international markets.
- Supply chain & sourcing diagnostics — supplier concentration maps for silicone and critical subcomponents, cost‑pass and nearshoring scenarios, and quality control checkpoints tailored for medical‑grade elastomers.
- M&A and partnership screening tools — prioritized target lists, valuation multiples observed in recent transactions, and integration risk checklists focused on R&D, regulatory, and channel consolidation synergies.
- Risk matrix and contingency playbooks — covering product recalls, reimbursement changes, component shortages, and litigation scenarios.
Actionable strategic priorities for executives in 2026
- Prioritize ecosystem value over one‑off product launches. The data shows accelerating returns to players that can link masks to adherence analytics, device firmware features, and subscription services.
- Convert regulatory clearances into commercial advantages. REMSleep’s recent expanded clearance illustrates how targeted 510(k) wins unlock institutional tenders. Build a prioritized regulatory roadmap that sequences filings to match highest‑value channels.
- Design consumable economics. Replacement rhythms and reimbursement create a predictable consumables revenue stream; optimize cushion durability, direct replacement programs, and bundled pricing to capture recurring value.
- Mitigate material risk. Secure multi‑source agreements for medical‑grade silicone, consider strategic inventory buffering, and evaluate alternative materials subject to clinical equivalence testing to reduce single‑vendor exposure.
- Explore disciplined M&A for capability gaps. With high market concentration among top players, bolt‑on acquisitions that add novel comfort technologies, software capabilities, or distribution in under‑penetrated regions can accelerate share gains.
- Invest in clinician and patient education. Adoption and adherence are behaviorally driven; targeted programs that reduce friction at initiation (fitting, remote follow‑up, tailored comfort settings) materially improve retention and lifetime value.
Risks to monitor closely in 2026
- Regulatory tightening or deviations in 510(k) policy that could extend approval timelines and raise development costs.
- Reimbursement pressure or code consolidation that alters replacement economics for interfaces — scenario modelling in our full report quantifies the commercial impact under multiple reimbursement pathways.
- Supply shocks and raw material price volatility for medical‑grade silicone, which can compress margins and delay launches if not proactively managed.
- Product quality events. Given the personal and clinical nature of masks, recalls or safety incidents can rapidly erode trust; robust post‑market surveillance and supplier QA are essential defensive investments.
Conclusion — what leaders should do next
For executives making 2026 resource allocation decisions, the question is not “Will the sleep apnea masks market grow?” — the macro trajectory and forecast clarity in our study answer that affirmatively. The strategic challenge is deciding where to place bets within a concentrated market that rewards integration, regulatory savvy, and durable consumables economics. PW Consulting’s full report provides the models, maps, and playbooks to translate that macro confidence into executable strategy: from product roadmaps that align with reimbursement cycles to M&A screens that target capability gaps.
This briefing intentionally highlights the analytic depth and the decision‑ready outputs you will receive. To access the complete market splits, company scorecards, downloadable financial models, and the scenario engine that underpins our forecasts, visit the full report page on PW Consulting’s site.
For detailed analysis of this topic, please visit the official page: Sleep Apnea Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Purity L-Glutamine Market to Reach USD 418.28 Million by 2032 at 7.91% CAGR
By PW Consulting, 2026-07-13
High-Purity L‑Glutamine Market: Strategic Imperatives for 2026 Decision‑Making
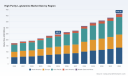
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present an executive preview of our new market study on High‑Purity L‑Glutamine. The study synthesizes a five‑year historical view (2020–2025, base year 2025) and delivers a forward forecast across 2026–2032. At the macro level, the global market—measured in USD Million—is growing robustly, with the 2025 base-year valuation and a forecast path that takes the market materially higher through 2032, driven by a compound annual growth rate (CAGR) of 7.91% across the forecast window. This preview is designed to demonstrate the depth of our analysis and the practical, transaction‑grade guidance embedded in the full report, while intentionally reserving detailed segment and share tables for subscribers and direct engagements.
High Purity L Glutamine Market
Why this study matters to corporate leaders in 2026
-
Strategic timing: 2026 is shaping up to be a hinge year—policy shifts, raw material movements, and capacity investments announced in 2024–2025 are now influencing supply and pricing dynamics.
High Purity L Glutamine Market -
Decision relevance: procurement, capacity planning, regulatory filings, and M&A activity planned this year will crystallize exposure to supply risk or competitive advantage for the next seven years.
High Purity L Glutamine Market -
Actionability: our study converts market forecasts into prioritized options and financial outcomes—so executives can move from data to board-ready decisions within weeks.
Market trajectory and structural drivers
High‑purity L‑glutamine sits at the intersection of biologics manufacturing, cell therapy and cultured cell workflows, clinical nutrition, and the broader nutraceuticals market. Across the historical period to 2025 and into our 2026–2032 forecast, demand growth is underpinned by the expansion of cell culture media and injectable formulations for biologics, alongside continued uptake in clinical nutrition and dietary supplement channels.
Two structural facts are particularly consequential for 2026 planning. First, fermentation‑based manufacture dominates global production—industry data indicate this pathway accounts for the vast majority of supply—implying that upstream feedstock and fermentation capacity cycles drive cost and availability. Second, upstream raw material markets have become more volatile: glutamic acid and other key feedstocks saw price adjustments early in 2026 amid inventory imbalances and softer downstream demand in certain producing regions. Those movements materially affect feedstock cost pass‑through and margin dynamics for suppliers and buyers alike.
Supply chain and capacity dynamics — what to watch in 2026
-
Capacity shifts: recent announcements from large-scale manufacturers indicate an acceleration of capacity expansion outside traditional sourcing hubs. These moves change logistics and lead‑time calculus for global buyers.
-
Quality and certification premium: suppliers with cGMP, USDMF/CEP/JDMF and low‑endotoxin manufacturing capabilities command strategic importance for parenteral and cell‑therapy use cases. Investing to secure these grades is no longer optional for players targeting high‑value segments.
-
Regional trade policy: ongoing trade measures and tariff reviews affecting pharmaceutical ingredients—particularly actions under recent trade investigations—create an overlay of policy risk that can favour local or near‑shore production investment.
Competitive landscape — players, positions, and implications
The marketplace comprises global incumbents with deep fermentation expertise, regional champions with scale and cost advantages, and specialty manufacturers focused on injectable‑grade and research‑grade product lines. Leading multinational producers leverage microbial fermentation technology and robust regulatory filings to serve pharmaceutical and cell culture customers; specialty cGMP firms emphasize low‑endotoxin, low‑metal specifications required by parenteral applications. Several Asian manufacturers are expanding export capacity and product ranges, while regional API and excipient producers in India and Europe strengthen their compliance profiles through active regulatory filings.
-
What it means for buyers: procurement strategy should differentiate between commodity supply and mission‑critical, certified grades. Long‑term contracts, quality audits, and dual‑sourcing arrangements will be critical for clients dependent on parenteral or clinical‑grade material.
-
What it means for investors: quality of earnings will increasingly be tied to regulatory certification and product‑mix rather than absolute capacity. Buyers of producers must value regulatory dossiers, customer concentration, and the ability to upgrade production to parenteral specifications.
Regulatory and policy horizon
Regulatory developments in 2025–2026 have direct strategic implications. Investigations and tariffs targeting pharmaceutical imports introduce complexity for supply chains that rely on cross‑border trade of amino‑acid intermediates and finished L‑glutamine. Some exemptions for certain vitamins and amino acids remain possible, but the policy landscape is fluid. Companies should model tariff‑sensitive scenarios, and consider onshore or nearshore capacity as an insurance strategy where price elasticity and clinical timelines justify the investment.
Risk matrix for 2026 corporate decisions
-
Supply risk: single‑source dependencies, capacity overhang in low‑cost regions, and lead‑time variability for certified grades.
-
Demand risk: cyclical volume swings in cell therapy and bioprocessing programs, and channel substitution in nutraceuticals driven by ingredient alternatives.
-
Policy risk: tariff regimes and import controls that can raise landed costs or force re‑qualification of suppliers.
-
Quality & compliance risk: contamination events or manufacturing non‑compliance leading to batch rejects and costly remediation.
-
Commodity feedstock risk: volatility in glutamic acid and fermentation substrates altering margins and incentive to idle or expand lines.
Practical strategic playbook for 2026
-
Prioritize supplier segmentation: class suppliers by product grade, regulatory coverage, and contingency capacity. Lock in offtake for critical certified grades and maintain tactical frameworks for commodity buys.
-
Dual‑source and nearshore where clinical timelines or tariff exposures make continuity paramount. For high‑value parenteral applications, prioritize suppliers with low‑endotoxin credentials and active regulatory filings.
-
Adopt a staged CAPEX approach: de‑risk greenfield investments with tolling, JV, or capacity reservation agreements before committing full plant spend.
-
Pursue targeted M&A for missing capabilities—quality certifications, regulatory dossiers, or local market access—rather than scale alone.
-
Implement raw material monitoring and hedging: integrate feedstock price dashboards into procurement and product‑margin modelling to enable timely contractual decisions.
-
Differentiate through service: supply chain transparency, guaranteed traceability, and technical support for cell culture and formulation customers create stickiness and premium pricing opportunities.
What PW Consulting’s report delivers (practical and reserved)
Our full study converts the market’s macro momentum into decision‑grade outputs for corporate and investor stakeholders. Key deliverables include:
-
Scenario‑based revenue and margin models across 2026–2032, allowing users to stress test tariff, feedstock and demand shocks against capex and working capital decisions.
-
Supplier benchmarking and procurement playbooks that score manufacturers on certification, traceability, capacity flexibility, and cost position.
-
Regulatory risk dashboards and re‑qualification timelines for key grades and geographies—valuable for supply continuity planning.
-
Commercial templates for offtake contracts, tolling agreements, and JV term sheets designed for rapid execution.
-
Executive briefing slides and tailored, confidential advisory for M&A diligence or strategic sourcing implementations.
Note: this preview demonstrates the analytical depth of our study while intentionally withholding granular segmentation tables and company revenue splits that subscribers and bespoke clients access through the full report and supporting spreadsheets.
Final recommendation — how to act in 2026
For companies exposed to high‑purity L‑glutamine: treat 2026 as a year to convert strategic options into structural protection. That means formalizing supplier segmentation, executing priority certification upgrades where needed, and establishing contingency capacity via contracts or partnerships. For investors and acquirers, focus on capability gaps rather than pure volume—regulatory dossiers, low‑endotoxin manufacturing, and direct customer relationships in cell therapy channels will carry disproportionate value.
PW Consulting is ready to provide the full report, the underlying Excel models, and a tailored briefing that maps these strategic recommendations to your specific exposure and timelines. For access to the detailed datasets, segmentation breakdowns, and supplier scorecards, please visit the PW Consulting research portal or contact our industry team for a confidential briefing.
For detailed analysis of this topic, please visit the official page: High Purity L Glutamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IoT in Energy to reach USD 76.8 Billion by 2032 at 13.08% CAGR
By PW Consulting, 2026-07-13
IoT in Energy 2026: A Strategic Preview for Decision Makers
Executive snapshot
The Internet of Things (IoT) is no longer an experimental layer in energy systems — it is a structural element reshaping how generation, transmission, distribution and consumption are planned, operated and monetized. Our latest PW Consulting market study, with a base year of 2025 and a forecast through 2032, maps this transformation and translates it into practical decision frameworks for 2026. The market has already moved from USD 17.5 Billion in 2020 to roughly USD 32.4 Billion in 2025 and is projected to reach approximately USD 76.8 Billion by 2032, implying a robust compound annual growth rate of about 13.08% over the forecast period. These macro dynamics make 2026 a pivotal year for capturing strategic advantage — the choices you make now will determine whether you lead or lag as deployments scale.
Internet Of Things Iot In Energy Market
Why 2026 matters: inflection points and timing
Two simultaneous forces converge in 2026. First, capital flows into clean energy and grid modernization have accelerated — global energy investment is set to reach roughly USD 3.3 trillion in 2025, with a sizeable portion directed at renewables, grid, storage and related infrastructure that are natural hosts for IoT-enabled control and analytics. Second, connectivity and edge compute economics (driven by wide-area protocols, low-cost modules and hardened edge platforms) have passed critical thresholds, enabling utility-grade use cases at scale. The result is a maturation window where proof-of-concept pilots must convert into sustained rollouts — and where architectural, commercial and regulatory choices become irreversible at scale.
Internet Of Things Iot In Energy Market
What the numbers tell you (not everything we measured)
- Historical momentum: the market nearly doubled over five years to 2025, reflecting accelerating deployment of sensors, connectivity and analytics across energy value chains.
- Forecast trajectory: our forecast to 2032 anticipates more than doubling from the 2025 base, driven by greater telemetry density, software-led monetization and an expanding set of edge-cloud services.
- Market structure: despite significant activity from major industrial players and new entrants, concentration remains low — a structural feature that favors partnerships, vertical specialization and niche strategies.
Strategic implications for corporate leaders
For executive teams, the headline is straightforward: invest selectively and move deliberately. The following implications should shape strategic planning for 2026.
Internet Of Things Iot In Energy Market
- Prioritize architecture, not point solutions. The winners will be those who can guarantee secure, interoperable data flows from edge devices to cloud-native analytics, and who can demonstrate deterministic outcomes (reliability, loss reduction, flexibility markets participation) rather than generic efficiency claims.
- Embed regulatory and policy scenarios into roadmaps. Executive actions and interconnection policies — for example, grid reliability mandates and clean energy procurement rules — will materially affect deployment cadence and allowable business models across jurisdictions.
- Shift from capex pilots to opex platforms. Many utilities will prefer managed-service or outcome-based commercial models to accelerate adoption while conserving capital. Vendors should build flexible pricing and SLA constructs to capture this demand.
- Design for lifecycle economics. Procurement decisions in 2026 must be evaluated against seven- to ten-year total cost of ownership perspectives that include software updates, cyber resilience, calibration and data value extraction.
Operational levers for scaling IoT programs
Operational excellence becomes the bottleneck once pilots move to regional or national scale. In 2026, organizations should focus on three execution levers:
- Standardized validation gates: create a light but rigorous set of design, security and performance gates that any vendor solution must pass before being allowed in production.
- Edge-first data strategies: balance where analytics run. Use edge processing to reduce latency and network cost, and reserve cloud layers for model training, historical analytics and cross-domain orchestration.
- Interoperability and supplier diversity: avoid single-vendor lock-in by adopting open standards where possible and building integration layers that can onboard multiple device types and protocols.
Competition and capability mapping
The competitive landscape is populated by industrial incumbents, networking specialists and metering-focused vendors. Each archetype brings different strengths and commercial models. Below we summarize the strategic posture of ten leading vendors and their implications for buyers and partners.
- Siemens AG (Munich) — Strength: end-to-end digital twins and grid automation. Strategic posture: platform-led, with deep integration into transmission and distribution projects; ideal partner for utilities seeking systems integration and long-term digitalization programs.
- Schneider Electric SE (Rueil-Malmaison) — Strength: energy management architecture and building-grid convergence. Strategic posture: solution bundler focused on energy efficiency and renewable integration within commercial and industrial estates.
- ABB Ltd. (Zurich) — Strength: asset performance and grid stability solutions. Strategic posture: positioned to win on reliability and legacy grid modernization, especially where electro-mechanical asset expertise matters.
- General Electric (GE Vernova) (Cambridge, MA) — Strength: industrial IoT platforms and ADMS. Strategic posture: targets utilities seeking operational analytics and asset optimization across generation and distribution.
- Honeywell International (Charlotte, NC) — Strength: building and industrial energy systems with a strong performance optimization platform. Strategic posture: effective in industrial and commercial environments where process integration and safety overlap with energy use.
- Cisco Systems (San Jose, CA) — Strength: networking, secure edge compute and industrial connectivity. Strategic posture: infrastructure-first vendor for large utilities and operators prioritizing cyber-hardened connectivity.
- Hitachi Energy (Zurich) — Strength: digital substations and grid automation. Strategic posture: enterprise-grade offerings for transmission and distribution modernization, recently recognized as a market leader in industrial IoT platforms for energy.
- Itron Inc. (Liberty Lake, WA) — Strength: smart metering and AMI with deep utility relationships. Strategic posture: go-to supplier for large-scale metering programs and meter-to-cloud data services.
- Landis+Gyr AG (Zug) — Strength: grid-edge intelligence and smart metering. Strategic posture: focused on distribution edge solutions and integration with utility OMS/MDMS stacks.
- Semtech (formerly Sierra Wireless) (Camarillo, CA) — Strength: cellular and LPWAN modules for utility applications. Strategic posture: key connectivity supplier enabling low-cost device rollouts at scale.
Recent signals you should monitor in 2026
- Massive-scale connectivity platforms: LoRaWAN deployments surpassed 125 million devices globally and continue to expand rapidly — utilities remain a leading vertical. This validates low-power wide-area networks as credible production architectures for grid edge telemetry.
- Standards and edge projects: LF Edge initiatives and similar open projects are moving from pilots to production use cases (for example, verifiable carbon measurement in bio-gas plants), making open edge stacks a commercial consideration — not just academic interest.
- Policy drivers: national and regional policy (including executive orders focused on grid reliability and security) will shape procurement priorities and accelerate funding for grid digitalization programs.
Investment and M&A posture
Given the market’s growth trajectory and fragmented supplier base, 2026 is a year for targeted inorganic moves and capability fills rather than large-scale consolidation. Strategic acquirers should prioritize:
- Edge compute and device management capabilities that close the operational gap between device fleets and cloud orchestration.
- Data rights and analytics IP that can convert telemetry into recurring revenue streams (e.g., predictive maintenance, flexibility services participation).
- Channel and utility relationships that accelerate procurement cycles and reduce pilots-to-production friction.
What’s in the PW Consulting report (practical, actionable deliverables)
Our full study is built for strategy teams and implementers. Key operational deliverables include:
- A validated top-down market model and scenario analyses through 2032 that quantify adoption drivers and sensitivity to policy and commodity trends.
- Vendor scorecards and capability matrices mapping product, service and go-to-market strengths to utility and industrial buyer needs.
- Playbooks for procurement, pilot-to-scale transitions, and outcome-based contracting templates tailored to energy sector risk appetites.
- Technical architecture blueprints that prescribe edge/cloud partitioning, cyber controls and interoperability patterns across common protocols and legacy interfaces.
- Case studies and TCO frameworks from live deployments that expose hidden cost drivers and identify high-impact efficiency levers.
How to use this intelligence in 90 days
Leaders should convert insight into action with a focused 90-day program: 1) align executive sponsors and define 12–36 month outcomes; 2) run a rapid vendor bake-off using the PW Consulting validation gates; 3) design a pilot pipeline with clear scale triggers and funding mechanisms; and 4) lock in strategic partnerships for connectivity, cybersecurity and data monetization. Rapid execution in 2026 will capture first-mover advantages in flexibility markets, DER orchestration and resilience services.
Closing — the trailer, not the film
This preview highlights why IoT will be a defining component of energy strategy in 2026 and beyond. It surfaces the strategic trade-offs, execution levers and competitor moves that matter now. The full PW Consulting report contains the granular segment economics, vendor benchmarks and decision tools required to operationalize these insights — including downloadable models and procurement templates designed for immediate use. Accessing the complete study will give you the segment-level intelligence and executable artifacts to convert 2026 momentum into sustained market leadership.
For detailed analysis of this topic, please visit the official page: Internet Of Things Iot In Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dried Fruit Ingredients Market Poised for 5.45% CAGR Through 2032
By PW Consulting, 2026-07-13
Dried Fruit Ingredients Market — Strategic Briefing for 2026 Decisions
Executive snapshot
As of the 2025 baseline, the global dried fruit ingredients market stands at approximately USD 9.55 billion (2025, USD Million basis). Our forecast model projects a steady expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.45%, driving the market toward roughly USD 13.8 billion by 2032. Market concentration remains modest: the top three suppliers account for roughly 22.4% of the market and the top five for about 34.15%, underscoring a highly fragmented value chain with meaningful room for consolidation, vertical integration, and differentiated positioning.
Dried Fruit Ingredients Market
Why this market matters for 2026 strategic choices
-
Nutrition-driven reformulation: Manufacturers are reformulating baked goods, cereals, snacks, and dairy innovations to reduce added sugars, increase fiber and natural ingredients — positioning dried fruits both as an ingredient and as a functional claim.
Dried Fruit Ingredients Market -
Cost and raw-material volatility: Grower returns, weather-driven crop swings, and regional production shifts have elevated supply risk. For example, multi-year data and grower surveys indicate material swings in returns for key grape and prune crops, increasing the value of hedged or vertically integrated supply strategies.
Dried Fruit Ingredients Market -
Regulatory and reputational pressure: Label transparency requirements and renewed focus on added sugars (FDA labeling updates) plus sporadic recall events mean manufacturers must build compliance and traceability into product roadmaps from formulation to shelf.
-
Consolidation opportunity: Fragmentation and modest overall concentration create acquisition and scale-play opportunities for players who can execute plant rationalization, cold-chain investments, or targeted geographic expansion.
Key strategic questions companies must resolve in 2026
- Do we prioritize cost efficiency (scale, commodity sourcing) or product differentiation (varietal, provenance, low-moisture technologies)?
- How will evolving labeling rules and consumer expectations on added sugars affect recipe engineering and pricing strategies?
- Which parts of the supply chain should be digitized for traceability and recalls mitigation, and where should capital be allocated first?
- For ingredient buyers: should you lock multi-year supply contracts, diversify suppliers across geographies, or pursue supplier partnerships with innovation co-investment?
What our PW Consulting report delivers (practical content)
- Executive dashboards: interactive top-line market model with scenario toggles for commodity shocks, tariff shifts, and demand elasticity.
- Segment and application roadmaps: methodology-driven frameworks that translate macro demand into practical SKU and formulation implications for bakery, cereal, snacks, dairy and beverage segments (note: detailed numeric segmentation tables are reserved for the full report).
- Supply chain and cost-to-serve models: plant-level cost drivers, cold-chain sensitivity, and a ranked list of supply nodes by risk and cost exposure.
- Regulatory & recalls playbook: compliance checklist, labeling impact maps, and an audit-ready traceability template to reduce recall lead times and reputational costs.
- Innovation tracker & formulation playbook: documented sensory impact matrices, recommended dosage bands, and case studies of sugar-reduction substitutions and low-moisture blends.
- M&A and partnership tissue: target screening criteria, valuation priors, and five illustrative integration scenarios focused on scale, capability buy, and regional entry.
- Supplier scorecards and negotiation scripts: KPI templates, risk-adjusted pricing models, and contracting guardrails for long-term offtakes.
Competitive landscape — interpreting the incumbents
The dried fruit ingredients industry is populated by specialist suppliers with differentiated capabilities — from varietal sourcing to value-added processing (dicing, infusion, purees). Below is a concise strategic read on the core companies analyzed in our study.
-
Graceland Fruit, Inc. (Tipton, Michigan) — Strengths: flexible diced and infused low-moisture blends for bakery and snack customers; strong product development cadence (recently showcased low-moisture diced blends at IFT FIRST Expo). Strategic implication: attractive partner for co-development pilots where moisture control and texture retention are critical; potential vulnerability is scale for global programs.
-
Traina Foods (Escalon, California) — Strengths: sun-dried specialty fruits with a depth in apricots, peaches, pears and plums and continued investments in certifications (recent certification update). Strategic implication: well-suited for customers prioritizing provenance and traditional sun-dried sensory profiles; a likely consolidation candidate for buyers seeking category breadth.
-
Sun-Maid Growers of California (Kingsburg, California) — Strengths: market leadership in raisin ingredients and broad manufacturing reach. Strategic implication: national and global scale in raisin sourcing and product forms makes Sun-Maid a default partner for high-volume bakery and cereal applications.
-
Sunsweet Growers, Inc. (Yuba City, California) — Strengths: category leadership in prune-derived ingredients and active product innovation (launch of Sunsweet Amaz!n™ Bits for baking). Strategic implication: strong fit for functional food formulations and nutrition-bar segments where prunes provide unique textural and labeling advantages.
-
Mariani Packing Company (Vacaville, California) — Strengths: premium dried fruit positioning across apricots, nectarines, cherries; deep relationships in yogurt and cereal channels. Risk note: past recall activity has highlighted the need for strengthened traceability protocols and supplier risk mitigation.
-
Ocean Spray Cranberries, Inc. (Lakeville-Middleboro, Massachusetts) — Strengths: branded power and a focused offering of sweetened/unsweetened dried cranberries for muffins, trail mixes and confections. Strategic implication: Ocean Spray’s brand equity reduces go-to-market friction for co-branded ingredient launches.
-
Monterey Bay Foods / Valley Fig Growers (Salinas, California) — Strengths: specialization in mission figs and tailored ingredient forms for bakery and dairy. Strategic implication: niche supplier with attractive margins for premium, provenance-led product claims.
Market dynamics and external shocks to model in 2026
- Trade policy: recent retaliatory tariffs and trade frictions can meaningfully re-route trade flows and change landed costs for certain fruit forms — scenario planning must include tariff escalations and rapid re-sourcing options.
- Crop variability: weather-driven declines in specific tree-fruit yields (e.g., prune production contraction in recent crop years) underline the value of multi-origin supply portfolios and dynamic safety stocks.
- Labeling & health policy: FDA labeling updates around added sugars and serving sizes remain a design constraint for new product launches — product teams must bake label-forward formulations earlier in development cycles.
- Food safety & recall risk: episodic recalls underscore the requirement for serialized traceability, rapid root-cause analytics, and mapped recall cost assumptions in business cases.
Where the hidden value (and risk) lives
Two strategic tensions determine winners over the next 24 months: (1) the ability to convert commodity-grade fruit into differentiated, shelf-stable ingredient formats that address sugar reduction and texture demands; and (2) the capacity to manage supply volatility through either vertical integration or agile multi-geography sourcing. The low-to-moderate market concentration means new entrants with focused capability (e.g., low-moisture technologies, infusion processes, or branded co-development) can rapidly scale with the right commercial partnerships.
90–180 day playbook for 2026
- Run a supplier stress test: scenario-run current suppliers against crop, tariff and recall events; identify a shortlist of “rescue” alternate suppliers for each critical SKU.
- Initiate 2–3 NPD pilots that substitute reduced-sugar sweeteners with targeted dried fruit inclusions, using PW’s sensory impact matrix as the control.
- Invest in traceability pilots: incremental serialization plus a data-integration sprint with top co-manufacturers to reduce recall lead time to under 48 hours.
- Screen M&A targets with a triage model: capability accretion (processing tech), geographic coverage, and margin uplift potential — pursue rapid diligence on 3–5 targets.
- Establish an innovation partnership with a specialty supplier (low-moisture or infusion capability) to co-develop a commercial-scale reduced-sugar product.
Why PW Consulting — unique value in this study
- Primary-sourced supplier scorecards, plant-level cost models and negotiated price benchmarks.
- A dynamic scenario engine that models tariff, crop and demand shocks and translates them into P&L and unit-cost impacts.
- Actionable playbooks (supply risk mitigation, reformulation suites, labeling compliance) that are ready for deployment by product, procurement and M&A teams.
- Competitive intelligence that blends public filings, trade-show intelligence, recall databases and first-hand interviews with supplier leadership.
Next steps
This briefing introduces the strategic imperatives we see shaping decisions in 2026. For the full data tables, segmented demand maps, supplier scorecards and downloadable scenario model that quantify those imperatives, access the complete PW Consulting Dried Fruit Ingredients Market report. The report contains the granular segmentation, regional and application breakdowns, and company scorecards necessary to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Dried Fruit Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Inorganic Feed Mycotoxins Binders & Modifiers Market Outlook - 5.15% CAGR to 2032
By PW Consulting, 2026-07-13
Inorganic Feed Mycotoxins Binders and Modifiers: Strategic Preview for 2026 Decision-Making
Executive teaser
The inorganic mycotoxin binders and modifiers market sits at the intersection of animal health, feed security and commodity mineral supply chains. As feed producers, integrators and ingredient suppliers prepare strategies for 2026, they need a compact, decision-grade view that links market momentum, regulatory constraints, material sourcing and competitive moves to actionable playbooks. This preview synthesizes the key market trajectory and strategic implications from PW Consulting’s full Inorganic Feed Mycotoxins Binders and Modifiers Market study, highlighting why the dataset and our scenario-based recommendations are essential to near-term corporate choices—while intentionally reserving the detailed segment-level tables and proprietary scoring that drive investment-grade decisions for the full report.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Why 2026 is a strategic inflection point
2026 is the first full forecast year beyond our 2025 base. Companies will be making multi-year commitments—capacity investments, long-term supply contracts, new product rollouts and M&A decisions—that lock in risk exposures across raw materials (mined clays and carbonaceous inputs), regulatory compliance and customer adoption cycles. Our analysis shows the market has already expanded from its 2020 baseline and continues on a steady growth path. That trajectory means decisions taken in 2026 will compound through the remainder of the forecast period and materially affect relative positioning by 2032.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Market trajectory and macro assumptions
Key macro facts to anchor strategic planning:
Inorganic Feed Mycotoxins Binders And Modifiers Market
- The market, measured on an industry-accepted revenue basis, recorded steady growth through the first half of the decade and reached a clear mid-single-digit scale by the 2025 base year.
- Forward-looking projections assume a compound annual growth rate of approximately 5.15% over the 2026–2032 forecast window, reflecting a combination of continued mycotoxin risk awareness, expanding adoption in formulated feeds, and incremental product innovation focused on spectrum performance and delivery formats.
- Under these base assumptions the global market value progresses materially through the forecast horizon, reflecting both organic growth and accelerating uptake in higher-value feed mixes and geographies with intensifying regulatory scrutiny.
These macro anchors are embedded in the full model we use to stress-test scenarios (demand shocks, raw-material cost volatility, regulatory tightening). The granular scenario matrices—alongside sensitivity outputs by price, uptake rates and substitution elasticities—are available in the full study to support board-level decisions and budgetary planning.
Competitive landscape: what incumbents and challengers are doing
The market structure combines global specialty ingredient players, clay miners with feed divisions, and niche formulators. Several players are visible in the market for inorganic binders and are executing distinct strategic plays:
- Amlan International (Oil‑Dri Corporation of America) — focused on proprietary mineral formulations designed for targeted mycotoxin profiles; recent activity includes product introductions and strategic market partnerships to accelerate regional distribution and proof-of-performance studies.
- Kemin Industries — leverages portfolio breadth and established feed additive channels to push activated adsorbent solutions across feed chains, pairing technical advisory services with product bundles for integrators.
- Tolsa — positions itself as a mineral supplier with specialized blends that combine different clay and carbon components, competing on raw-material integration and quality consistency.
- Bentoli Inc. — a specialized clay-based supplier emphasizing practical toxin-control products for livestock and poultry customers, often competing on the basis of application support and localized supply chains.
Competitive moves to watch into 2026 include co-marketing partnerships in high-growth geographies, broadened product portfolios that combine inorganic binders with enzyme or probiotic adjuncts, and commercial validation programs (on-farm trials and third‑party efficacy testing) designed to overcome buyer skepticism about efficacy and nutrient interaction.
Regulatory and raw-material dynamics that will shape strategy
Two structural themes determine the playing field for 2026 decisions:
- Regulatory clarity and constraints: Certain inorganic binders (notably specific bentonite grades) enjoy explicit regulatory acceptance for targeted mycotoxin mitigation in key jurisdictions. However, regulators mandate evidence of efficacy without compromising nutrient bioavailability and animal safety. Compliance protocols and dossier readiness are therefore prerequisites for any scale-up.
- Raw-material sourcing: Inorganic binders are predominantly based on mined aluminosilicates and related minerals—bentonite, montmorillonite, sepiolite, zeolites—and sometimes activated carbons. Supply-chain bottlenecks, mining permit cycles, and quality variability materially affect cost, margin and product consistency, and require upstream hedging or vertical integration choices.
Our full report includes a risk heatmap that prioritizes geographies and mineral sources by supply risk, environmental permitting tightness, and freight-cost volatility—tools that will be critical to procurement strategy for 2026 contracts.
What the full report delivers (practical, transaction-ready content)
PW Consulting’s study is structured to convert market intelligence into executable actions. Highlights of the deliverables you can expect in the full report include:
- A detailed, audited market model (historical 2020–2025; base year 2025) and granular forecasts through 2032 with scenario toggles for commodity price, adoption rates and regulatory shifts.
- A competitive matrix profiling incumbents and challengers on product architecture, channel strategy, intellectual property and commercial traction—plus a proprietary attractiveness-ranking for potential acquisition targets.
- Regulatory mapping across major markets including documentation templates and recommended study designs to demonstrate efficacy and safety without undermining nutrient uptake.
- Supply-chain and procurement playbooks: mineral sourcing scorecards, contingency plans, and suggested contractual clauses to limit quality variability and freight exposure.
- Commercial go-to-market modules for three archetypal companies (global incumbent, regional challenger, mineral supplier) with pricing strategies, sample P&L impact analyses, and trial roll-out roadmaps.
- Operational checklists and on-farm trial protocols that meet regulatory expectations and maximize the probability of persuasive efficacy evidence for feed customers.
Note: The full report contains the full segmentation tables, regional and application shares, price elasticities, and unit economics that underpin the headline forecasts. We intentionally omit those fine-grained tables here to preserve the strategic advantage embedded in the proprietary model.
Recommended strategic moves for 2026
For executives preparing capital, commercial and regulatory plans next year, the analysis points to a compact set of priority actions:
- Secure feedstock continuity: negotiate multi-year offtake or invest selectively in upstream reserves or partnerships to lock-in grade-consistent clay and activated carbon supply; include quality acceptance criteria tied to adsorption metrics.
- De-risk regulatory path: initiate dossier assembly and sponsor targeted efficacy trials in markets where approval frameworks require demonstration of lack of negative nutrient interaction; align trial designs with recognized authorities to accelerate registration.
- Differentiated product positioning: invest in formulation science to move beyond single-mechanism binders—combine adsorption with modifiers that broaden spectrum or improve pellet stability; prioritize formulations that demonstrate minimal nutrient sequestration.
- Commercial validation and channel enablement: fund independent field trials, create sample-to-scale programs for large feed mills, and structure distributor incentive programs that convert technical superiority into commercial trial uptake.
- M&A and partnership scouting: use 2026 as a sourcing year for bolt-on acquisitions that add niche mineral sources, regional registration dossiers, or proprietary processing technologies that raise barriers to entry.
How purchasers and investors should use these insights
Feed manufacturers should treat the market model as a decision-support engine: stress-test price passthrough, analyze substitution risk against organic adsorbents and adsorptive blends, and prioritize capital allocation to product lines with defensible performance claims. Ingredient suppliers and miners should focus on supply security, vertical handshake opportunities and co-development agreements with feed formulators.
Investors should use the competitive diagnostic to identify candidates for consolidation, prioritizing businesses with validated field data and established distribution to accelerate integration value. For transaction teams, our commercial due diligence module provides the evidence-based checks that materially reduce execution risk.
Next steps and how to access the full intelligence
This preview frames the strategic stakes and immediate actions relevant to 2026. The full PW Consulting report contains the comprehensive segment-by-segment economics, regulatory dossier templates, supplier scorecards and M&A target lists required to operationalize the recommended actions. For organizations preparing budgets, regulatory roadmaps or M&A pipelines for 2026, the full dataset and advisory support will materially shorten time-to-decision and reduce implementation risk.
Contact PW Consulting to arrange access to the full report and to commission a tailored briefing that maps the findings directly to your asset base, product portfolio and regional priorities.
For detailed analysis of this topic, please visit the official page: Inorganic Feed Mycotoxins Binders And Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HFO Data-Center Fluids Market to Hit USD 1,947.03M by 2032 (CAGR 18.02%)
By PW Consulting, 2026-07-13
HFO Cooling Fluids for Data Centers: A Strategic Preview for 2026 Decision-Makers
Executive snapshot
The market for hydrofluoroolefin (HFO) cooling fluids tailored to data center thermal management has moved from niche experimentation to strategic mainstreaming. Our analysis uses 2025 as the base year and tracks an accelerated trajectory driven by density-led cooling needs, tighter emissions regulations, and industrial-scale product qualifications. The global market reached approximately USD 610.5 Million in 2025 and is forecast to expand sharply into 2026 and beyond — with the near-term step change visible in a projected market size of roughly USD 738.3 Million in 2026 and an aggregate 2026–2032 compound annual growth rate of 18.02%, reaching nearly USD 1.95 Billion by 2032. These headline figures underline both urgency and opportunity for 2026 corporate planning cycles.
Hfo Cooling Fluids For Data Center Market
Why this study matters for 2026 corporate decisions
-
Regulatory timing: Emerging standards and rules (including recent U.S. EPA measures, the Kigali-driven HFC phasedown and EU F‑Gas direction) are compressing windows for compliant product selection and factory charges. For companies deciding on equipment refreshes, procurement windows in 2026 will determine whether assets fall under transitional allowances or face full compliance obligations.
Hfo Cooling Fluids For Data Center Market -
Procurement and qualification: Several HFO chemistries and architectures (two‑phase immersion, single‑phase immersion, direct‑to‑chip, chilled-loop systems) are commercially available but require distinct qualification protocols. The pace at which hyperscalers and OEMs complete interoperability testing will determine early-adopter cost advantages.
Hfo Cooling Fluids For Data Center Market -
Supply-chain resilience: HFO production is reliant on specific fluorinated feedstocks and olefins; price volatility and capacity investments will materially affect supplier economics and total cost of ownership. Tactical procurement and long-lead contracting will be essential for 2026 deployments.
-
Vendor selection and partnerships: The market already shows concentration among a few leaders — our concentration metrics indicate a high three‑firm share and even higher five‑firm share — creating a landscape where strategic partnership and early qualification with suppliers may yield outsized competitive advantages.
What the report delivers (practical, operational content)
This research is designed for executives who must convert technical cooling choices into financial and operational outcomes. Core deliverables include:
-
Market sizing and forward scenarios with clear decision triggers for 2026 procurement cycles;
-
Vendor and technology due‑diligence frameworks — qualification checklists, materials compatibility matrices, and failure‑mode guidance for immersion and direct‑contact architectures;
-
Techno‑economic models and sensitivity analyses that translate HFO chemistry, price volatility, and energy savings into multi‑year cashflow impacts;
-
Regulatory matrix mapping key compliance milestones (U.S., EU, APAC) against deployment and manufacturing timelines;
-
Supply‑chain risk maps with mitigation playbooks (dual sourcing, toll‑manufacturing partnerships, hedging strategies, and CAPEX timing recommendations);
-
Commercial playbooks for suppliers and OEMs on packaging, qualification support services, and channel strategies to accelerate adoption among colo operators and hyperscalers;
-
Investor briefs and M&A scorecards to assess consolidation opportunities and technology licensing potential.
Competitive landscape — who matters in 2026 and why
The vendor field consists of established refrigerant and specialty‑chemicals houses, niche immersion‑fluid specialists, and HVAC incumbents adapting refrigerant portfolios. Leading positions are occupied by firms with integrated capabilities across chemistry, regulatory affairs, and commercial scale‑up. Notable profiles:
-
The Chemours Company — positioned as a high‑visibility supplier of two‑phase dielectric fluids (Opteon™ 2P50) and pursuing manufacturing scale and ecosystem partnerships. Recent product qualifications with major OEMs and strategic manufacturing agreements underscore an aggressive go‑to‑market push and provide signals on standards for SSD and electronics compatibility.
-
Solstice Advanced Materials (formerly Honeywell Advanced Materials) — offers Solstice® E‑Cooling lines and has demonstrated the commercial dynamics of raw material exposure; recent pricing adjustments reflected input cost pressures and highlight the importance of supplier cost transparency in long‑term agreements.
-
Arkema S.A. — emphasizes low‑GWP HFO/HCFO blends (notably 1233zd variants) and has invested in production capacity expansions to support chiller and thermal‑management demand — a strategic move that reduces lead‑time risk for downstream integrators.
-
TMC Industries — a specialized entrant focused on dielectric fluids for two‑phase immersion, providing differentiation through targeted thermal stability and non‑flammability characteristics appropriate for sensitive electronics stacks.
-
Daikin Industries — leverages refrigerant and HVAC expertise to move into immersion and refrigerant solutions for data centers, offering an OEM perspective that integrates refrigerant lifecycle management and service networks.
Collectively, the market exhibits a concentrated supplier base (with a large majority of share held by the top three and top five suppliers). For buyers, this means negotiating leverage is asymmetric across regions and product architectures — early qualification and secured supply contracts will be competitive advantages for 2026 projects.
Regulatory and raw‑material dynamics that will shape 2026 outcomes
-
Regulation: U.S. and international policy movements are setting explicit GWP corridors and phasedown timelines. U.S. EPA technology transition rules and EU F‑Gas expectations are already influencing design choices; these regulatory milestones are not distant — they should be treated as procurement constraints as much as compliance items.
-
Raw material volatility: HFO production depends on specific fluorinated feedstocks and olefins. Industry disclosures in 2025 exposed notable input cost movements and periodic supplier price adjustments, underscoring the need for financial stress‑testing procurement plans.
-
Capacity build: Recent capacity expansions by key chemical suppliers signal a response to demand but also suggest a timing gap between capital projects and near‑term demand spikes — timing of CAPEX announcements and commissioning matters for 2026 deployments.
Practical scenarios and decisions for 2026 planners
The report models multiple adoption pathways — conservative, accelerated, and transformative — with clear triggers and recommended actions for each. In practical terms:
-
Conservative: Prioritize compatibility testing, staggered rollouts, and contractual flexibility. Recommended for operators constrained by capital or regulatory uncertainty.
-
Accelerated: Pursue co‑development pilots with leading suppliers and secure multi‑year supply agreements. Suitable for hyperscalers seeking performance and density advantages.
-
Transformative: Commit to broad architecture shifts (immersion-first design) and invest in vertical integration or strategic partnerships to lock in supply and IP advantages. Appropriate for integrators aiming to lead market design standards.
Each pathway is paired in the full study with procurement timelines, risk registries, and a checklist for vendor selection and commercial negotiation points — designed to be immediately operational for 2026 decision windows.
Immediate tactical recommendations for 2026
-
Initiate qualification partnerships now: Product trials and SSD/component compatibility testing announced by manufacturers provide templates for rapid in‑house validation — don’t treat vendor demos as sufficient evidence.
-
Lock in supply options: Use staged purchase commitments and explore toll‑manufacturing or captive blending arrangements to reduce exposure to raw‑material spikes.
-
Integrate regulatory timelines into CAPEX planning: Consider whether planned deployments should aim for pre‑transition allowances or be designed to meet the next‑generation low‑GWP floors.
-
Stress‑test total cost of ownership: Account for end‑of‑life handling, disposal compliance, and potential trade‑offs between energy savings and fluid procurement costs.
How PW Consulting’s study supports your 2026 playbook
This research is structured as a decision‑enablement toolkit. Beyond headline market sizing and growth trajectories, it equips teams with operational templates (test protocols, procurement term sheets, CAPEX/OPEX calculators) and strategic maps (technology roadmaps, partner matrices, regulatory impact timelines). The material is explicitly designed to translate technical fluid choices into board‑level investment rationales and procurement‑grade contracts.
Next steps — where to find the missing pieces
Consider this article a strategic trailer: it surfaces the essential market dynamics, vendor moves, and immediate actions for 2026 planning while preserving the report’s detailed segmentations, contract templates, and full financial models for subscribers. If your 2026 strategy depends on precise regional, product and architecture breakdowns, or you require downloadable qualification checklists and scenario model spreadsheets, the full report and supporting data pack deliver those assets in actionable form.
For detailed analysis of this topic, please visit the official page: Hfo Cooling Fluids For Data Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


