



Rechargeable Handheld Metal Detector Market: $240.5M in 2025, 6.25% CAGR to $367.6M by 2032
By PW Consulting, 2026-07-13
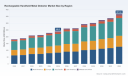
Rechargeable Handheld Metal Detector Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our latest market research on the Rechargeable Handheld Metal Detector industry. This briefing is designed for procurement leads, product strategists, investors, and security operators who must make high-stakes decisions in 2026. It synthesizes market-scale dynamics, competitive posture, technology inflection points, and practical actions — while intentionally withholding the granular segment tables and model-level forecasts available in the full report to preserve its tactical value.
Rechargeable Handheld Metal Detector Market
Market at a Glance: Direction and Scale
- Market scale: By the end of the report base year, the global rechargeable handheld metal detector market reached a substantive size measured in the hundreds of millions (USD, revenue units used). The industry is on a multi-year expansion path driven by heightened public security priorities and renewed capital investments in screening infrastructure.
- Growth trajectory: PW Consulting’s forecast horizon points to mid-single digit compound annual growth. The market is expected to grow at a steady pace through the 2026–2032 window, reflecting recurring replacement cycles, technology refreshes, and expanded adoption across non-traditional venues.
- Concentration: Competitive concentration is meaningful but not prohibitive. A cluster of established manufacturers controls a significant portion of global revenues, leaving room for focused challengers and regional specialists to capture niche opportunities.
Why 2026 Is a Strategic Inflection Point
- Certification convergence: With updated NIJ draft standards and increased public-sector procurement scrutiny, 2026 is primed for a certification-driven wave of purchases and device retirements. Vendors who can demonstrate compliance early will secure preferred-bidder status in major tenders.
- Battery and charging standards: Lithium-ion energy packs and USB-C charging are becoming baseline expectations. Product lifecycles will be increasingly judged on operational hours per charge, charging convenience, and maintenance cost — not just raw sensitivity.
- Commoditization risk vs. value capture: Hardware specification is converging (sensitivity, weight, IP rating). Differentiation will shift to lifecycle services, software-enabled diagnostics, ergonomic design, and bundled commercial models (warranty, replacement programs, training).
Key Market Dynamics
- Demand diversification: Traditional buyers — airports, correctional facilities, and government buildings — remain core. However, growth in events, education, and certain industrial segments is broadening the end-market footprint and changing procurement cycles.
- Technology trajectory: Multifrequency sensing, waterproofing for harsh environments, and vibration-based feedback are now table stakes in mid to high tiers. Higher-end models increasingly tout NIJ-standard compliance and extended run-times (some exceeding 100 hours), which influence total cost of ownership assessments.
- Supply-side pressures: Lithium-ion battery availability and certification timelines for new standards represent the primary near-term supply risks. Manufacturers operating single-source battery lines or relying on long cross-border supply chains are exposed to lead-time and price volatility.
- Regulatory influence: New and draft standards (notably NIJ 0602 updates) are reshaping procurement specs. Buyers are favoring NIJ-compliant units and field-calibration minimization features to reduce maintenance overhead.
Competitive Landscape: What the Leaders and Challengers Are Doing
The market’s competitive fabric blends legacy OEMs with agile regional players. Key archetypes and recent moves illustrate strategic positioning:
Rechargeable Handheld Metal Detector Market
- Established global OEMs: Firms with long-standing supply contracts for aviation and government buyers emphasize certification, durability, and service networks. Their strength lies in procurement relationships, warranty infrastructure, and brand trust.
- Specialist high-performance vendors: Select European and U.S. companies compete on NIJ-certified performance and tailored law-enforcement features. Their investments in compliance and ruggedization make them preferred in high-risk, mission-critical deployments.
- Cost-competitive OEMs from Asia: Several Chinese manufacturers aggressively pursue volume opportunities with competitive pricing, USB-C convenience, and localized channel strategies. Their agility and cost structure favor large-volume, lower-margin institutional buyers and private sector event managers.
- Recent product signals: Market leaders are refreshing portfolios — from ergonomic, IP-rated flagship units to law-enforcement-specific variants with multifrequency sensing and improved battery management. These launches underscore a bifurcation: commoditized low-end replacements versus premium, service-backed units for critical infrastructure.
Strategic Implications for Manufacturers
- Prioritize NIJ compliance and pre-certification: Invest in aligned testing early. Compliance will expedite access to large public tenders and reduce price competition.
- Diversify battery sourcing and standardize charging interfaces: Lock in supply via alternative suppliers, dual-sourcing contracts, or vertical integration for battery packs. Offer USB-C as a standard to meet operational expectations and reduce friction in recharging logistics.
- Shift go-to-market from product to platform: Build digital services — device health telemetry, usage analytics, and predictive maintenance — as margins in hardware compress. Subscription and managed-service models can smooth revenue and deepen customer relationships.
- Defend premium positioning with service SLAs: For airport and government customers, response time, calibration-free operation, and field-swappable battery options are decisive. Service contracts are a competitive moat.
- Explore bolt-on acquisitions in APAC: Regional OEMs with low-cost manufacturing and channel access are attractive targets to accelerate capacity and reduce lead times for global bids.
Strategic Implications for Buyers and Operators
- Procurement playbook for 2026: Reframe RFPs to prioritize total cost of ownership metrics — run-time per charge, maintenance intervals, field-calibration needs, and end-of-life battery replacement costs — rather than purchase price alone.
- Specify lifecycle services: Include remote diagnostics, replacement battery provisioning, and training bundles in contracts. These additions lower downtime and simplify procurement governance.
- Leverage phased replacement strategies: For large fleets, consider staged upgrades tied to certification milestones. This reduces capital shock and aligns device rollouts to regulatory timing.
- Demand interoperability and data standards: Insist on telemetry-friendly devices with standardized APIs for asset management systems, enabling centralized monitoring and predictive maintenance.
Risk Map — What to Watch in 2026
- Standard updates and procurement pauses: Draft standard rollouts can temporarily slow purchasing as buyers await new compliance baselines.
- Battery supply fluctuations: Price spikes or lead-time increases for lithium-ion cells will compress margins and could trigger substitution risks for lower-grade batteries with shorter lifecycles.
- Counterfeit/gray-market challenge: Price-sensitive channels may introduce unauthorized units that underperform in the field, damaging trust and increasing false-acceptance incidents.
- Service capacity constraints: Rapidly expanding installed bases without corresponding service investments create operational risk and reputational exposure for vendors.
Actionable Priorities — A 90-Day Playbook for 2026
- For manufacturers: Complete NIJ-alignment audits and publish a compliance roadmap; secure at least two battery suppliers; pilot a telemetry-enabled service offering with 3–5 anchor customers.
- For investors: Screen for targets with strong service revenue, certification-ready product lines, and regional manufacturing that shortens logistics lead times; prioritize assets with existing public-sector contract footprints.
- For buyers/operators: Update procurement templates to emphasize TCO and certification; run a fleet audit to classify units for immediate retirement versus phased upgrade; negotiate service-level KPIs tied to device uptime and battery replacement.
What PW Consulting’s Full Report Delivers
The complete Rechargeable Handheld Metal Detector Market report provides practical, executable intelligence designed for immediate integration into 2026 plans. Highlights include:
Rechargeable Handheld Metal Detector Market
- Detailed market sizing and forecasts with scenario modeling and sensitivity analysis across 2026–2032.
- Competitive benchmarking with capability matrices, channel maps, and profile deep-dives of leading vendors.
- Buyer personas and procurement templates that procurement teams can adapt for RFPs and tender evaluations.
- Manufacturing and supply-chain heatmaps identifying single-source risks, near-shoring opportunities, and battery-sourcing strategies.
- Practical go-to-market playbooks for premium and volume segments, including pricing levers, bundling strategies, and aftermarket monetization paths.
- M&A screening criteria and a shortlist of strategic acquisition targets and partnership profiles by region and capability.
Concluding Guidance
The rechargeable handheld metal detector market in 2026 sits at the intersection of regulatory tightening, technology convergence, and enduring demand for reliable screening. For incumbents, the path to defend margins and accelerate growth runs through certification, battery resilience, and services. For challengers and investors, opportunities exist in regional consolidation, software augmentation, and targeted bolt-on acquisitions. For buyers, the tactical advantage accrues to teams that reframe procurement around operational uptime, lifecycle cost, and compliance readiness.
PW Consulting’s full analysis contains the granular models, vendor scorecards, and procurement-ready templates needed to convert these insights into action. To access the complete dataset and interactive strategic tools, please visit the report portal.
For detailed analysis of this topic, please visit the official page: Rechargeable Handheld Metal Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Body Repair Fillers Market at USD 3,600M (2025), 4.85% CAGR to 2032
By PW Consulting, 2026-07-13
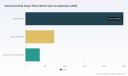
Automotive Body Repair Fillers Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing to orient senior executives, corporate strategy teams, and M&A practitioners ahead of critical 2026 planning cycles. This piece previews our full Automotive Body Repair Fillers Market study (base year 2025; historical horizon 2020–2025; forecast 2026–2032) and highlights the decision-useful insights within. We purposely surface analytical depth while preserving the granular segment-level data and proprietary scenarios contained in the full report — consider this a trailer that demonstrates method and value, and a prompt to access the complete dataset for transaction- and operations-level action.
Automotive Body Repair Fillers Market
Market trajectory: what the headline numbers mean for strategy
Over the 2020–2025 historical window, the global automotive body repair fillers market demonstrated resilient expansion as repair demand rebounded from pandemic impacts and product innovation improved workshop productivity. Our base-year view estimates the market reached USD 3,600 Million in 2025. Looking forward under our central scenario, the market progresses at a compound annual growth rate (CAGR) of approximately 4.85% across the forecast window 2026–2032, reaching a projected USD 5,015.4 Million by 2032.
Automotive Body Repair Fillers Market
These topline dynamics matter beyond the headline: modest but steady growth combined with pockets of differentiated innovation creates an environment where scale and specialty both win. For incumbent manufacturers, this implies an imperative to defend breadth across product formats while selectively investing in next-generation chemistries and channel models that deliver margin lift. For private equity and strategic buyers, the expansion supports buy-and-build theses aimed at technology consolidation and downstream access.
Automotive Body Repair Fillers Market
Industry structure and competitive math
The market’s concentration metrics indicate moderate fragmentation with meaningful leadership pockets. The three-largest players account for less than a third of industry revenue (CR3 ~28.5%), while the five-largest capture roughly four in ten dollars (CR5 ~41.2%). Such structure creates a dual strategic pathway: (1) regional or application-focused challengers can defend profitable niches through service and formulation differentiation; (2) larger players can pursue scale synergies, channel exclusives, and recipe standardization to drive unit economics.
Competitor positioning is already evolving along these lines. Major global names combine strong R&D platforms, distribution reach, and OEM/channel relationships, while a set of regional and specialist formulators compete on lightweight, workability, or fast-cure propositions. Examples profiled in our report include:
- ITW Evercoat (Cleveland, OH) — Deep professional OEM/collision credentials and a product portfolio emphasizing lightweight compounds engineered for easy sanding and minimal pinholes; recent product refreshes and new UV- and fast-cure variants signal a clear focus on shop throughput and finish quality.
- 3M (St. Paul, MN) — Leverages vacuum-processed formulas and cross-material adhesion claim sets (steel, aluminum, fiberglass) as competitive differentiators; brand equity supports both trade and retail channels.
- U.S. Chemical & Plastics (USC) (Ohio) — Known for workability and spreadability in professional palettes; appeals to high-volume collision workshops prioritizing application speed.
- Bondo (3M) — Iconic trade/DIY brand with deep awareness across independent shops and aftermarket channels.
- U-POL (UK) and AkzoNobel (Netherlands) — Emphasize high-performance finishing and refinish-compatible chemistries, including UV-curable options.
- SYNEW (China) — Represents the growing cohort of Asia-origin suppliers scaling capability for global distribution partners and price-competitive product families.
Notably, product and pack innovations — lightweight fillers, vacuum-processed systems, and UV-cure primers/fillers — are central levers for differentiation. ITW Evercoat’s product launches at SEMA in late 2025 are an early indicator of supplier emphasis on throughput-enhancing chemistries designed to shorten cycle time and improve surface finish consistency.
Supply-side dynamics and regulatory risk: the strategic implications
Three cross-cutting themes dominate the supply-side risk profile and should frame 2026 planning: raw material volatility, regulatory scrutiny on chemistry, and feedstock exposure to oil-cycle swings.
- Raw material volatility — Unsaturated polyester resin pricing experienced swings exceeding 40% between 2020 and 2025, driven by petrochemical feedstock volatility. This amplitude forced formulators to adopt dynamic raw-material sourcing, forward-purchasing, and substitution playbooks. In our full report we quantify margin sensitivity to common resin and filler cost scenarios and model hedging-related CAPEX for large formulators.
- Chemical regulation — Ongoing evaluation of key monomers (notably styrene) by European regulatory authorities presents a material downside risk for polyester-dominant fillers. Potential classification as a substance of very high concern (SVHC) would introduce authorization and usage constraints in key markets and accelerate R&D migration toward styrene-reduced or styrene-free recipes. Our scenario modules model the commercial impact of phased regulatory restrictions and estimate timelines for reformulation investment and market substitution rates.
- Oil-market exposure — Petroleum-based components remain vulnerable to price shocks stemming from macro oil-market instability. We outline practical levers — formulation diversification, blended sourcing, and agile contract structures — that mitigate input-price pass-through and protect gross margins in mid-cycle downturns.
Demand-side drivers and structural shifts
Repair volume fundamentals remain the single largest determinant of near-term demand. Vehicle parc age, miles driven, and accident frequency are the proximal demand engines; beyond these, three structural shifts deserve strategic attention:
- Material mix evolution — Broader adoption of aluminum, high-strength steels, and composite components in vehicles changes the adhesion and finishing requirements of fillers. Suppliers with validated cross-substrate performance and technical support for body shops gain share potential.
- Workshop productivity focus — Collision repair chains and high-throughput independents continue to prioritize products that reduce cycle time (fast-cure systems, UV cure) and rework. Product portfolios that materially cut booth time or sanding hours command premium pricing power.
- Environmental and worker-safety preferences — Low-VOC and water-based alternatives, and systems that reduce airborne particulates and hazardous monomer exposure, earn preference among chains with sustainability and compliance programs.
What the full PW Consulting study delivers — practical, transaction-ready output
This market briefing is deliberate in scope. The full PW Consulting report provides the operational detail and decision-ready modules that executives need to act in 2026:
- Granular market sizing and segmentations by product chemistry and application with historical and forecast volumes and revenues (2020–2032).
- Segment-level price and margin benchmarking, including sensitivity to primary resin and filler input prices.
- Competitive landscaping with capability maps, channel footprints, and M&A heat-maps highlighting inorganic targets by strategic rationale.
- Supply-chain stress-testing models and recommended hedging/sourcing strategies for common exposure scenarios.
- Regulatory impact simulations (including potential SVHC pathways) and stepwise compliance/transition playbooks.
- Commercial playbooks for premiumization, formulation migration, and workshop adoption pathways including pilot structures and ROI profiles.
- Investment case appendices for private equity and corporate development teams, including accretion/dilution modeling under multiple roll-up scenarios.
- Primary interviews with supply-chain executives, collision repair network managers, and leading formulators underpinning qualitative assumptions.
Strategic recommendations for 2026 planning
Based on our synthesis, executive teams and investors should prioritize three complementary moves in 2026:
- De-risk raw-material exposure — Implement a staged hedging and multi-sourcing program for polyester resins and key additives, combined with targeted reformulation capacity for styrene-reduced chemistries.
- Accelerate shop-centric innovations — Invest in or partner for UV-cure and fast-cure technologies that demonstrably reduce cycle time and rework. Pilot programs with national collision chains convert product claims into procurement commitments.
- Pursue focused consolidation — Pursue tuck-in targets that add specialty formulations, regional channel access, or proprietary cure technologies. Given current concentration metrics, selective roll-ups can rapidly improve scale economics and broaden technology portfolios.
Next steps — where PW Consulting adds value
For teams preparing budgets, M&A pipelines, or R&D commitments in 2026, the full PW Consulting study provides the quantitative underpinnings required to: prioritize CAPEX, size reformulation budgets, select acquisition targets with clear synergy pathways, and stress-test go-to-market pilots. The analysis marries primary market research with scenario modeling to transform strategic hypotheses into executable roadmaps.
If your 2026 planning cycle hinges on differentiated assumptions about regulatory timing, raw material cost trajectories, or competitive moves, our report’s scenario modules and transaction-focused annexes will be directly actionable. Access to the complete dataset and segment-level modeling is available through the PW Consulting market portal and will be essential for teams intending to execute on the recommendations above.
To obtain the full report, models, and tailored briefings for corporate or investor teams, contact PW Consulting for access and to schedule a strategy workshop.
For detailed analysis of this topic, please visit the official page: Automotive Body Repair Fillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gas Humidity Sensors Market to Reach $2.43B by 2032 at 7.51% CAGR
By PW Consulting, 2026-07-13
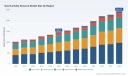
Gas Humidity Sensors Market 2026 — Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present an executive preview of our newest market study on Gas Humidity Sensors. This briefing distills the research’s strategic value for corporate leaders planning actions in 2026, highlights the market trajectory, and identifies the operational levers that will determine winners over the next planning cycle. The goal: demonstrate the depth of our analysis while reserving the granular segment-level datapoints for the full report.
Gas Humidity Sensors Market
Market at a Glance — The Macro Frame
The gas humidity sensors market is on a multi-year expansion path. After a steady recovery across the early 2020s, the market base in our 2025 reference year stands near the mid‑single‑billion dollar mark (USD, revenue unit: Million). Under our central forecast — grounded in historical 2020–2025 performance and validated demand drivers — the market grows at a compound annual growth rate of approximately 7.51% through our 2026–2032 forecast horizon, with the 2032 market approaching roughly USD 2.43 billion. Market concentration is moderate: the top three firms account for about 32.4% of industry revenues, and the top five about 48.2%, indicating meaningful room for both scale-driven incumbents and specialized challengers.
Gas Humidity Sensors Market
Why This Matters for 2026 Strategic Planning
- Revenue predictability with tactical inflection points: The underlying CAGR provides a baseline for budget planning, but 2026 is characterized by discrete catalysts — product upgrades to meet safety standards, OEM design-wins in automotive sensing, and integrated multi-sensor modules for IoT — that can materially accelerate adoption in targeted verticals.
- Margin and procurement pressure: Supply-chain frictions remain a structural risk. Our research flags a notable increase in lead times for certain specialty electronic materials used in sensing modules; clients should expect procurement volatility unless they actively diversify suppliers or secure strategic inventory positions.
- Regulatory and safety-driven demand: Functional-safety certification requirements (e.g., ASIL-level readiness in automotive perception and LiDAR systems) are creating premium segments within the market where suppliers can command differentiation and pricing power.
What the Full Report Delivers — Actionable, Practically Oriented Content
This study is designed to be operationally prescriptive for executives and commercial teams. Key deliverables include:
Gas Humidity Sensors Market
- Forward-looking market sizing and scenario models (base, upside, downside) that you can plug directly into corporate planning tools. Models are parameterized for demand shocks, technology adoption, and regulatory shifts.
- Commercial playbooks for OEM engagement: prioritized verticals, value-proposition templates, and recommended channel strategies for capturing design wins in automotive, HVAC, industrial controls, and healthcare applications.
- Supply-chain resilience toolkit: supplier segmentation, dual-sourcing constructs, recommended inventory buffers, and cost-to-serve analysis to mitigate lead-time and rare-material exposure.
- Technology roadmap and R&D scorecards: comparative assessment of MEMS, digital sensor integration, and hybrid sensing approaches with time-to-market and IP risk indicators.
- M&A and partnership map: target archetypes for bolt-on acquisitions, JV models for co-development with automotive Tier 1s, and licensing opportunities with complementary semiconductor partners.
- Regulatory impact matrix: compliance timelines, certification cost estimates, and go/no-go decision thresholds for adopting ASIL and other region-specific standards.
Competitive Landscape — Who to Watch and Why
The industry mixes established sensor specialists, diversified industrial conglomerates, and semiconductor players. The competitive dynamics are nuanced: incumbents with high-precision heritage enjoy credibility in industrial and life-sciences segments, while semiconductor and electronics OEMs are leveraging integration and scale to acquire share in consumer and automotive adjacencies.
- Sensirion AG (Stäfa, Switzerland) — Maintains a technology leadership posture in high-precision digital humidity sensors and has recently highlighted safety-rated (ASIL) product developments and several automotive design-wins. Sensirion’s moves underscore the strategic premium available for suppliers that certify sensors for functional-safety environments.
- Honeywell International — Leverages its building technologies portfolio to sustain strong placements in HVAC and building automation, where integrated environmental sensing is a staple of retrofit and new-build projects.
- Texas Instruments — Brings semiconductor scale and power-efficiency credentials to digital humidity sensing, forcing a commercial playbook that bundles sensors with broader embedded-system solutions.
- Bosch Sensortec — Focused on MEMS-enabled combo sensors for consumer, wearable and IoT platforms; their strategy highlights the value of sensor fusion in constrained form factors.
- Amphenol, TE Connectivity, Vaisala, and E+E Elektronik — These firms represent a mix of robust industrial offerings, aerospace/defense channel access, and high-accuracy instrumentation, making them attractive partners for customers that require environmental-grade performance, long-term support, or sector-specific certifications.
Recent corporate actions accelerate these themes: product launches integrating humidity elements into broader environmental sensors, distribution agreements to reach aerospace and defense OEMs, and investor presentations calling out ASIL-rated sensor roadmaps are all signs the competitive bar is rising in 2025–2026.
Key Dynamics Shaping Competitive Advantage
- Integration wins: The market increasingly rewards vendors that can deliver combined temperature, humidity, pressure, and gas sensing in compact, calibrated modules suitable for IoT and automotive platforms.
- Safety and lifetime support: Designers and procurement teams in regulated industries now factor multi‑year support and safety certification into supplier selection. Products promising extended legacy support windows command strategic value.
- Supply chain friction: Geopolitical tariff actions and rare-material bottlenecks have increased procurement complexity; firms that secure upstream continuity via multi-region sourcing or backward integration will realize a pricing and reliability edge.
Strategic Imperatives for 2026 — What Executives Should Do Now
- Prioritize ASIL and certification roadmaps: If you supply or depend on sensors for automotive or safety-critical systems, accelerate certification planning. Early movers will capture design wins and create switching costs.
- Hedge supply risk with tactical inventory and dual-sourcing: Our supply-chain analysis quantifies lead-time volatility for critical components; firms should combine limited strategic stockpiles with validated alternate suppliers to avoid production stoppages.
- Adopt a product differentiation playbook: Invest in sensor fusion, calibration services, and edge-compute software to move from component supplier to systems partner — this expands TAM per device and deepens customer stickiness.
- Embed commercial flexibility: Offer tiered SLAs and long-term support contracts for enterprise and industrial customers, monetizing durability and lifetime assurance as a premium service.
- Explore focused inorganic moves: Use M&A selectively to acquire niche IP (e.g., MEMS or coating technologies), channel access, or certifications — faster than building in-house capability.
How to Use This Research in Your 2026 Planning Cycle
Integrate our forecast and scenario outputs into three core planning processes this quarter:
- Capital allocation: benchmark R&D and manufacturing investments against the market growth envelope and allocate to initiatives with >2x return under our central case.
- Commercial strategy: use the OEM engagement frameworks to prioritize design-win opportunities where certification and integration create outsized value.
- Risk management: apply the supply-chain toolkit to stress-test your sourcing and develop contingency playbooks tied to specific supplier disruption probabilities.
Final Observations — The Strategic Horizon
By 2026, the gas humidity sensor market will still be shaped by technological integration, regulatory pressure, and supply-chain realignment. Firms that combine certification readiness, supply resilience, and product differentiation will capture disproportionate value as the market scales toward the early-2030s. The market’s mid-term CAGR and concentration metrics suggest enough growth to reward both incumbent scale and focused innovators — but execution risk remains high for those that wait to react.
For executives preparing 2026 budgets and go-to-market plans, our full PW Consulting report provides the granular segmentation, regional demand maps, supplier scorecards, and downloadable financial models required to convert insight into action. This preview reveals the strategic contours; the complete study contains the detailed tables, heat maps, and scenario workbooks you will need to operationalize these recommendations.
Next Steps
- Contact PW Consulting to access the full report and downloadable scenario models.
- Request a tailored briefing with our sensor-market specialists to align our findings to your product roadmap, procurement strategy, or M&A pipeline.
PW Consulting’s Gas Humidity Sensors Market study is engineered to be a direct input into 2026 decision-making — pragmatic, defensible, and calibrated to the execution challenges that separate strategic plans from realized outcomes.
For detailed analysis of this topic, please visit the official page: Gas Humidity Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polymer Gel Market to Reach USD 33.94 Billion by 2032 at 7.5% CAGR
By PW Consulting, 2026-07-13
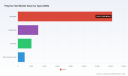
Polymer Gel Market — Strategic Outlook for 2026 Decisions
Executive snapshot
By 2025 the global polymer gel market had matured into a multi‑billion dollar industry, and our base‑year assessment places total market revenue at just over USD 20.4 billion. PW Consulting’s modelling projects a sustained mid‑single‑digit expansion at a compound annual growth rate of 7.5% across the 2026–2032 forecast window, lifting the market toward roughly USD 34.0 billion by 2032. That momentum is neither uniform nor accidental: it is driven by converging forces in healthcare, hygiene, agriculture, personal care, and industrial applications that reward both scale and technical differentiation.
Polymer Gel Market
Why this research matters for 2026 decision-making
- Capital allocation: Clear demand trajectories and scenario outputs enable CFOs and corporate development teams to prioritise brownfield expansions, pilot plants, or strategic M&A with higher conviction.
- Supply‑chain risk management: Volatility in key upstream feedstocks and shifting trade policies require procurement strategies calibrated to 18–36 month planning horizons rather than purely spot decisions.
- Product portfolio strategy: The market rewards companies that can segment offerings into commoditised SAP volumes and higher‑margin, formulated specialty gels for clinical, cosmetic and advanced industrial use cases.
- Regulatory preparedness: New restrictions on microplastics and PFAS are material to formulation roadmaps; being first‑mover on compliant formulations is a commercial advantage.
- Commercial go‑to‑market: Channel selection, contract lengths and co‑innovation partnerships differ by end‑use; our analysis translates that into actionable sales playbooks.
Data‑driven lens: what the numbers tell us (high level)
The headline growth profile (CAGR 7.5% for 2026–2032) reflects two linked realities: persistent end‑market expansion in hygiene and healthcare, and accelerating adoption in non‑traditional segments such as thermal management and specialty agriculture. Historical trends from 2020–2025 show steady recovery and re‑rating after pandemic disruptions, while our scenario work identifies asymmetric outcomes under alternate macroeconomic and raw‑material price paths.
Polymer Gel Market
Market concentration is meaningful but not prohibitive: the three largest players control a material share of demand, and the top five approaches a near‑majority position. This structure creates both opportunity and tension — incumbents can leverage scale economics, but mid‑tier and specialist firms can carve defensible niches through formulation IP and application‑specific service models.
Polymer Gel Market
Critical market dynamics and near‑term risks
- Feedstock volatility: Acrylic‑acid based supplies remain the principal upstream input. Recent price cycles have shown double‑digit percentage swings in regional markets over 12 months; procurement teams must model both price and availability scenarios into product margin analyses.
- Regulatory headwinds: EU measures targeting intentionally added microplastics and proposed PFAS restrictions are already influencing formulation choices and supplier disclosure requirements. Companies that delay reformulation run reputational and commercial risk in major end‑market jurisdictions.
- Trade and tariff exposure: New tariff regimes introduced in 2025 applied to polymer and chemical imports at non‑trivial ad‑valorem rates, compressing optionality for cross‑border sourcing and increasing the value of local production footprints.
- Technology substitution and premiumisation: Advances in antimicrobial hydrogels, aerogel‑enhanced thermal products, and engineered organogels are creating differentiated premium segments that command higher ASPs and demand closer collaboration between R&D and sales.
Competitive landscape — what the market leaders are doing
The market topology blends global chemical majors, specialty polymer houses, regional champions and application‑driven players. Several strategic behaviors stand out and should inform competitor response plans:
- BASF SE (Ludwigshafen) — leveraging scale in SAP and polymer gel production, BASF has recently completed a targeted efficiency and sustainability upgrade at a key North American site. That move is consistent with a strategy to improve unit economics while shrinking the carbon footprint of high‑volume grades.
- Evonik Industries AG (Essen) — focusing on higher‑performance gel formulations, Evonik’s recent launch of an antimicrobial super‑absorbent product for wound care exemplifies a playbook centred on clinical differentiation and premiumisation.
- Nippon Shokubai and Sumitomo Seika (Osaka) — both Japanese incumbents are expanding capacity and accelerating pilot programs in Asia, reflecting a bet on regional demand growth in hygiene and incontinence products and a desire to shorten lead times for regional customers.
- LG Chem and Dow Inc. — these players are integrating polymer gel offerings with adjacent material platforms (e.g., acrylic systems, specialty additives) to present bundled solutions for OEMs in consumer and industrial markets.
- Specialists such as Ashland , SNF , and Cabot — compete on niche application expertise (personal care, water treatment, aerogel thermal solutions). Their agility in product development and customer intimacy makes them attractive partners or targets for larger strategic investors.
- Regional suppliers (e.g., Chemtex, Saudi Arabian Amiantit) — play to local market needs with tailored formulations and distribution networks; they are often the front line for agriculture and construction applications.
Recent strategic moves worth noting
- BASF completed a capacity and efficiency upgrade in Texas aimed at better polymer performance and a lower carbon footprint — a signal that incumbents are willing to invest to defend share in mature volumes while improving sustainability metrics.
- Evonik’s product launch for antimicrobial wound‑care gels highlights the margin opportunity in medical specialties and the value of early clinical validation.
- Sumitomo Seika’s twin actions — regional hydrogel expansion and a new SAP pilot plant — underscore a two‑track strategy: meet near‑term demand growth while de‑risking next‑generation formulations prior to large‑scale rollout.
Strategic implications and recommended 2026 moves
- Prioritise “supply assurance + price flexibility” in procurement. Hedging programmes, multi‑sourcing and selective upstream integration for acrylic‑acid derivatives will materially protect gross margins under volatile feedstock scenarios.
- Differentiate via formulation IP rather than competing on commodity volumes alone. Invest in R&D to translate regulatory constraints into product advantages (e.g., microplastics‑free, PFAS‑free, bio‑based polymers).
- Map capacity expansion to real, contractable demand. Use our scenario outputs to size brownfield expansions vs greenfield projects; shorter lead‑time brownfield projects often dominate ROI in the 2026 investment window.
- Pursue bolt‑on M&A to fill capability gaps — targets that offer clinical validation, application engineering teams, or regional distribution can accelerate market access with lower execution risk than greenfield growth.
- Revisit pricing and commercial terms in light of tariffs and regionalisation. Longer‑dated contracts with indexation clauses and flexible volume bands will mitigate margin leakage.
- Embed regulatory roadmaps into product development lifecycles. Cross‑functional teams comprising regulatory, R&D and commercial should be mandated to certify first‑to‑market compliant formulations for high‑value end uses.
What the full PW Consulting report delivers (practical, board‑ready assets)
- Dynamic market model with historicals (2020–2025) and probabilistic forecasts (2026–2032), including sensitivity tables and scenario comparators you can plug into investment cases.
- Financial impact toolkit: margin modelling templates that combine feedstock price curves, tariff scenarios and product mix to quantify EBITDA exposure.
- Supplier scorecards and heat maps (capability, cost, capacity, compliance readiness), with acquisition attractiveness indices for M&A screening.
- Technology and product roadmap: maturity matrices for hydrogels, organogels, aerogels and emergent hybrids, showing time‑to‑market and IP risk profiles.
- Regulatory impact matrix linking specific measures (e.g., EU microplastics rules, proposed PFAS restrictions) to product classes, reformulation lead times and certification costs.
- Commercial playbooks: go‑to‑market strategies for premium medical gels, scaled SAP volumes, and new industrial applications (thermal, battery, water treatment), including recommended channel structures and contract framing.
- M&A and partnership shortlist with deal rationales, high‑level valuation comparators and integration risk checklists.
- Implementation roadmap and 100‑day action plans tailored for CEOs, Heads of Strategy, and Procurement leads to convert insight into deliverable initiatives during 2026.
Using this research in the boardroom
- Convert the market scenarios into capital allocation choices: use the PW model to stress test NPV outcomes of expansion, refurbishment or acquisition alternatives.
- Brief procurement and commercial teams with a condensed playbook from the report to renegotiate supplier contracts and update pricing mechanisms.
- Rapidly prioritise R&D projects that both mitigate regulatory risk and open access to higher‑margin specialty segments.
- Use the M&A screening outputs as a pre‑qualified pipeline for corporate development — enabling quicker, lower‑risk deal execution when market windows appear.
Concluding note — an actionable preview
PW Consulting’s Polymer Gel Market research is intentionally engineered as a decision‑support tool for 2026. It combines macro forecasts (base‑year 2025, CAGR 7.5% to 2032), scenario stress testing, supplier due diligence and regulatory impact mapping into a single, operationally oriented suite. This article is a strategic preview: it surfaces the critical trends, competitive moves and high‑impact choices you need to consider now, while preserving the full segmentation granularity, interactive models and targetable datasets for subscribers of the complete report.
For boards, investors and commercial leaders preparing budget cycles or M&A roadmaps in 2026, the right next step is access to the complete dataset and the downloadable model — these contain the detailed segment breakdowns, regional demand curves and company‑level volumes that turn strategy into executable plans.
For detailed analysis of this topic, please visit the official page: Polymer Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Backup System Market to Reach USD 15,083M by 2032 at 11.25% CAGR
By PW Consulting, 2026-07-13
Cloud Backup System Market — Strategic Preview for 2026 Decision Makers
Executive snapshot
As enterprises plan capital and operating budgets for 2026, cloud backup is no longer a point product; it is a strategic capability that intersects cybersecurity, compliance, sustainability and service continuity. Our new PW Consulting study positions the Cloud Backup System market as a dynamically expanding sector — growing from a mid-single-digit billion-dollar base in the early 2020s to an addressable market that crosses the multi‑billion‑dollar threshold by the end of the decade. Specifically, the market expanded from approximately USD 5.78 billion in 2023 to roughly USD 7.15 billion in 2025, and under a central forecast scenario it grows at a compound annual growth rate (CAGR) of 11.25% to reach about USD 15.08 billion by 2032.
Cloud Backup System Market
Why this study matters for 2026 decisions
-
Budget prioritization: With an 11.25% CAGR baked into our baseline forecast, cloud backup budgets will compete with adjacent investments (e.g., DR orchestration, data governance and cyber insurance). Procurement teams need a defensible rationale for spend allocation that ties to recovery time objectives (RTOs), regulatory exposure and total cost of ownership (TCO).
Cloud Backup System Market -
Vendor selection and partnership strategy: The market is mixed — a set of large cloud platform incumbents and a vigorous set of specialised vendors. Our concentration analysis shows the top three vendors account for a meaningful but not dominant share of market revenues (market concentration metrics are included in the full report). This balance creates opportunities for both scale players and focused specialists, depending on an organisation’s risk profile and operational model.
Cloud Backup System Market -
Policy and sustainability alignment: Energy and infrastructure constraints — and new reporting mandates — mean backup architecture decisions have implications beyond recovery performance. Expect procurement requirements in 2026 to include energy efficiency and data locality clauses alongside SLAs and cybersecurity controls.
Market trajectory and strategic implications
The mid‑2020s are a hinge point. Demand for cloud backup is being driven by several converging forces: an acceleration of SaaS and cloud-native workloads; rising ransomware and data‑integrity threats; and regulatory pressure on data sovereignty and operational resilience. Over the forecast horizon, we see three macro trajectories that buyers and providers must plan for simultaneously:
-
Volume and cadence: Data volumes continue to rise, and business recovery expectations compress backup cadences. Providers that can deliver efficient, frequent backups without linear cost increases will displace legacy models.
-
Platform convergence: Backup functionality is folding into broader data management and cyber resilience stacks. Expect acquisitions and broadened product roadmaps as vendors pursue one‑stop solutions for backup, recovery, detection and compliance.
-
Infrastructure friction: Real-world constraints — from rising data center construction costs to electricity consumption metrics that are now regulated in multiple jurisdictions — will shape where and how backups are stored and replicated.
Competitive landscape — what the leading players signal for 2026
The competitive set includes hyperscalers, legacy enterprise software vendors and a cadre of cloud‑native specialists. Our analysis highlights tactical themes illustrated by recent vendor moves:
-
Hyperscaler integration and native services. Major cloud platforms continue to expand native backup and recovery services as part of their cloud ecosystems, emphasizing automated policy orchestration, multi‑region availability and deep platform integration. For enterprise buyers, this increases the attractiveness of “backup as an integrated service” but raises questions about cross‑cloud portability and vendor lock‑in.
-
Feature parity and differentiation. Established backup specialists are racing to embed cybersecurity primitives (e.g., immutable vaults, air‑gap architectures, ransomware scanners) alongside governance controls to serve enterprise compliance needs. Recent product updates from vendors have notably extended ransomware detection coverage and multi‑cloud scanning capabilities.
-
Partnership ecosystems and recognition plays. Strategic alliances between infrastructure and data management vendors are becoming a primary route to scale. Recognition and partner awards reflect who the hyperscalers are choosing to co‑deliver resilience solutions — an important market signal for buyers selecting partners for large deployments.
-
Consolidation pressure and survivorship. Mid‑tier consolidation will likely continue as vendors pursue breadth (adding data management, DR orchestration and cloud cost optimisation) or depth (specialising in SaaS backup, endpoint protection or immutable cloud vaults).
Recent vendor trends to watch
-
Expanded cybersecurity integration: Vendors are not only backing up data but scanning for integrity deviations and embedding recovery playbooks that align with incident response.
-
Higher-frequency and multi‑region recovery capabilities: Faster snapshot cadences and multi‑region vaulting are moving from advanced options to buyer expectations, particularly for critical compute and database workloads.
-
Platform partnerships: Advances in partner programs and co‑engineering efforts are accelerating product maturity for hybrid and cloud‑native deployments.
-
Continuous product iteration: Regular releases are reducing feature gaps between hyperscaler-native services and specialist vendors, making product evaluation a live exercise instead of a point‑in‑time check.
Regulatory, cost and infrastructure pressures shaping supplier and buyer choices
External forces materially affect the economics and design of backup architectures:
-
Energy and reporting mandates: Regulatory frameworks now require reporting of power and water efficiency metrics for data centers in some major markets. This increases the importance of PUE/WUE considerations in backup site selection and may shift preferences toward efficient object storage strategies and cold‑tier policies.
-
Data sovereignty and privacy: Increasingly, local regulation drives demand for regionally co‑located or edge backup nodes. Buyers must reconcile data residency requirements with the operational benefits of centralised multi‑region vaults.
-
Infrastructure costs: Rising data center construction and power costs raise the economic threshold for storing large volumes on-premises, accelerating adoption of cloud‑centric and hybrid models that optimise for both cost and recovery SLAs.
What the PW Consulting report delivers (practical, actionable content)
We designed this study as an execution toolkit for technology leaders, procurement teams and corporate strategists. Key deliverables include:
-
Market sizing and scenario models — with a clear baseline and alternate scenarios that stress inflation, energy shocks and rapid RTO compression.
-
Vendor universe and comparative scorecards — covering functional capability, cyber resilience, multi‑cloud support and commercial models.
-
Operational playbooks — recovery runbooks, SLA negotiation checklists, and implementation migration paths for lift‑and‑shift, hybrid and native reintegration approaches.
-
TCO and procurement frameworks — including example cost models that incorporate energy and data egress dynamics, and contract amendment templates to protect buyers against vendor lock‑in.
-
Regulatory impact assessments — jurisdictional analysis templates that translate data sovereignty and energy reporting rules into actionable architecture decisions.
-
Strategic options matrix — acquisition targets, partnership archetypes and capability investment priorities based on buyer risk appetite and cloud maturity.
Note: The public preview intentionally omits granular subsegment breakdowns and regional percentage splits. Those detailed tables, vendor scorecards and downloadable models are available in the full report and interactive dashboard.
How to use the study in your 2026 planning cycle
-
Quarterly roadmaps: Use our cadence and cost scenarios to stress test your operating plan and to create contingency budgets aligned with different threat and regulation outcomes.
-
Vendor shortlisting: Start with our high‑level vendor archetypes and pair them with the scorecard to arrive at a 3‑vendor shortlist for technical proofs of concept (POCs).
-
Procurement and legal alignment: Incorporate the report’s recommended clauses on data portability, immutable storage and energy efficiency into RFPs and master agreements.
-
M&A and partner scouting: Leverage our strategic options matrix to identify bolt‑on acquisitions and partnership targets that accelerate time‑to‑market for resilience features.
Final perspective — the decision lens for 2026
Cloud backup is maturing from commodity storage to a strategic resilience discipline. For 2026, boards and technology executives should evaluate investments through three lenses: operational resilience (Can we recover within business tolerances?), regulatory alignment (Can we prove compliance and data locality?), and economic sustainability (Do our backup architectures scale without untenable increases in energy or capital cost?).
PW Consulting’s Cloud Backup System Market study provides both the macro market trajectory and the tactical playbooks to answer these questions. The preview above is designed to orient your leadership team; the full report contains the granular datasets, vendor scorecards and downloadable models required to execute a defensible 2026 strategy. For access to the complete analysis and interactive tools, please visit our research page.
For detailed analysis of this topic, please visit the official page: Cloud Backup System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Carpal Tunnel Syndrome Treatment Market: Strategic Insights for 2026 Decision‑Making
As PW Consulting’s senior industry analyst, I present an evidence‑based briefing designed to orient executive teams to the strategic inflection points shaping the Carpal Tunnel Syndrome (CTS) treatment market in 2026. This briefing synthesizes historical performance, near‑term trajectory, regulatory and reimbursement inflections, technology vectors, and competitive behaviors that should be central to boardroom discussions. It intentionally signals the report’s depth while reserving granular segment tables for subscribers — a deliberate “teaser” to catalyze informed engagement with our full market study.
Carpal Tunnel Syndrome Treatment Market
Executive summary
The CTS treatment market has moved from a niche procedural arena to a diversified, innovation‑driven specialty market. Between 2020 and 2025, the market expanded noticeably — reflecting both clinical adoption of minimally invasive techniques and improvements in diagnostic workflows. Our base‑year analysis shows steady growth culminating in 2025, and our forecast projects continued expansion through 2032 at a compound annual growth rate (CAGR) of 6.12% (USD, revenue unit: Million). Market concentration metrics indicate a moderately consolidated landscape (CR3 ≈ 34.3%, CR5 ≈ 51.1%), which creates both competitive barriers and entry opportunities for focused innovators.
Carpal Tunnel Syndrome Treatment Market
Market trajectory and what it means for 2026 strategy
Macro trajectory matters because it determines the scale of commercial investment and the timing of returns. The market’s steady CAGR of ~6.1% through the forecast window aligns with broader orthopedic and ambulatory surgery growth trends, but it is the composition of that growth — driven by device innovation, procedural shifts, and reimbursement change — that dictates differentiated strategy.
Carpal Tunnel Syndrome Treatment Market
-
Clinically, there is a clear shift toward less invasive and image‑guided procedures that shorten recovery time and enable ambulatory settings. This trend supports device suppliers that can demonstrate safety, reproducibility, and scalable training models.
-
Economically, payor and coding changes in 2026 materially alter the reimbursement calculus for percutaneous and endoscopic approaches. Reimbursement clarity will be a gating factor for adoption in outpatient environments.
-
Regulatory dynamics and evidence generation will disproportionately favor entrants that can rapidly convert approvals into peer‑reviewed outcomes and payer‑facing value dossiers.
Recent regulatory and reimbursement inflections
-
New procedural coding: Effective January 1, 2026, a Category I CPT code was established for percutaneous carpal tunnel decompression (CPT 64728). Its zero‑day global period and valuation methodology (day‑of‑service focus with separate reporting of post‑procedure visits) change the economics for office‑based procedures and ambulatory surgical centers. Manufacturers and providers must align procedural documentation and billing workflows to capture appropriate revenue.
-
Endoscopy reimbursement: Some endoscopic systems have associa ted reimbursement under existing endoscopy codes; device makers that can map clinical workflows to established coding pathways will accelerate adoption in Medicare populations.
-
Regulatory signal: Recent 510(k) clearances for ultrasound‑guided and endoscopic release systems, together with supportive independent publications, are lowering the clinical adoption friction for image‑guided approaches — but regulatory scrutiny persists, as demonstrated by an FDA warning to an unapproved device vendor in 2025. Robust labeling, claims substantiation, and post‑market surveillance programs are non‑negotiable.
Technology vectors to watch in 2026
-
Ultrasound‑guided release: Real‑time visualization is becoming a differentiator. Systems that tightly integrate imaging, ergonomics, and single‑use safety features are positioned to displace blind techniques in select practice settings.
-
Miniaturized endoscopy and percutaneous platforms: Lower‑trauma options with reduced recovery time align with payer and patient preferences for fast return to function. The market is rewarding devices that reduce procedure time and post‑op resource use.
-
Diagnostic AI and point‑of‑care tools: Handheld ultrasound with neural nets that automate median nerve metrics is shifting diagnostic throughput from referral centers to primary care and specialty clinics, creating earlier intervention opportunities.
-
Consumables and single‑use ecosystems: Commercial models that bundle capital light entry with recurring consumables can accelerate footprint expansion into ambulatory centers and specialty clinics.
Competitive landscape: who’s shaping adoption and why it matters
The competitive set spans global orthopedic OEMs, niche device innovators, and diagnostics vendors. Established medtech firms bring scale, distribution and clinician relationships; smaller players contribute focused innovations that can rapidly change practice patterns.
-
Large OEMs: Companies with broad orthopedic or minimally invasive surgery portfolios leverage installed salesforces and integrated systems to push endoscopic and instrument‑based solutions into hospitals and ambulatory surgical centers. Their strengths lie in reimbursement navigation, multi‑channel distribution, and bundled clinical training.
-
Specialty innovators: Firms focused on ultrasound‑guided or percutaneous technologies are converting clinical interest into regulatory clearances and peer‑reviewed evidence. These entrants excel in niche technical performance and lower upfront capital requirements, making them attractive to ambulatory settings.
-
Diagnostics and AI players: Vendors offering handheld ultrasound with median nerve analytics are not just diagnostic suppliers; they are demand creators — enabling earlier detection and referral pathways that expand addressable procedure counts.
Notable recent milestones to incorporate into 2026 planning:
-
Regulatory clearances in 2025–2026 for image‑guided release systems and median nerve AI tools, which reduce clinical adoption friction for ultrasound‑based pathways.
-
Independent publication activity validating ultrasound‑guided release through the 2026 literature, providing payers and clinicians with outcome data needed for broader uptake.
-
Regulatory enforcement actions against vendors making unapproved therapeutic claims, reminding market participants that compliant claims and robust evidence frameworks are critical to sustainable commercialization.
Strategic implications and recommended actions for 2026
Executives should prioritize a focused set of actions that translate market trajectory and regulatory signals into competitive advantage.
-
Build a reimbursement playbook: Map product claims to CPT and ICD codes, simulate payer coverage scenarios, and prepare procedural documentation templates that capture day‑of‑service value. For percutaneous approaches, ensure billing workflows reflect the 0‑day global period and separate post‑op visit reporting.
-
Invest in clinical evidence and publication strategy: Rapidly generate peer‑reviewed outcomes and health economics analyses. Independent registry data demonstrating real‑world recovery, complication rates, and resource utilization will be decisive in 2026–2027.
-
Prioritize training and scale: Devices that reduce procedural variability through modular training — simulator, proctoring, and digital content — will shorten the sales cycle, especially with ambulatory surgical centers and specialty clinics.
-
Explore partnerships and distribution flex: Small innovators should consider alliances with established OEMs for market access, while incumbent players should scout acquisition or licensing opportunities to fill capability gaps in image guidance and AI diagnostics.
-
Operationalize ambulatory and office‑based models: Commercial strategies, pricing, and clinical support must be tailored for lower‑cost settings where procedural volumes and throughput economics differ from inpatient hospitals.
-
Mitigate regulatory downside: Maintain conservative claims, rigorously document indications, and set up proactive post‑market surveillance to avoid enforcement that can quickly erode market trust.
What the PW Consulting report delivers (high‑practicality checklist)
-
Five‑year and extended‑forecast scenarios incorporating reimbursement sensitivity and adoption curves for image‑guided/percutaneous technologies.
-
Competitive intelligence dossiers on leading OEMs and niche innovators, including capability maps, go‑to‑market strengths, and M&A watch points.
-
Revenue and unit forecasts (historical 2020–2025 baseline and 2026–2032 outlook) with scenario toggles for coding, reimbursement, and adoption speed.
-
Commercial playbooks: coding alignment templates, payer value scripts, clinician training program outlines, and pricing frameworks for hospital vs. ambulatory settings.
-
Risk register and regulatory watchlist: probable enforcement vectors, evidence gaps by claim type, and clinical endpoints most persuasive to payers.
Why this analysis matters to decision‑makers in 2026
2026 is a transition year: new procedure coding, multiple recent device clearances, and the emergence of diagnostic AI converge to change who performs CTS procedures and where they take place. Strategic choices made in 2026 — on evidence generation, reimbursement positioning, and channel strategy — will disproportionately determine market share and return on investment over the remainder of the planning horizon.
With market concentration levels indicating room for focused competitors to capture meaningful share, the winners will be those that convert clinical innovation into payer‑aligned value propositions and scalable go‑to‑market models.
Next steps (how to use our intelligence)
-
Use the PW forecast scenarios to stress‑test your product roadmap and capital allocation plans under multiple coding and adoption assumptions.
-
Deploy the reimbursement templates in pilot markets to validate coding capture and revenue realization for percutaneous and endoscopic workflows.
-
Engage PW Consulting for a tailored competitive intercept study or a rapid evidence gap assessment to prioritize pivotal clinical investments.
Final note — what we intentionally withheld
This briefing intentionally omits granular regional and treatment‑type breakouts and specific segment revenue tables. Those detailed segmentations, granular competitive shares and modelled pricing assumptions are included in the full PW Consulting Carpal Tunnel Syndrome Treatment Market report and interactive dashboards. Access to that intelligence provides the precise inputs your commercial, regulatory, and clinical development teams need to operationalize the strategies outlined here.
To translate these strategic insights into an executable plan for 2026, contact PW Consulting to obtain the full market dataset, scenario models, and bespoke advisory support.
For detailed analysis of this topic, please visit the official page: Carpal Tunnel Syndrome Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mp System On A Chip (SoC) Market — Strategic Outlook for 2026 Decision‑Makers
As companies recalibrate product roadmaps, capital allocation, and supply‑chain strategies for 2026, the Mp System On A Chip (SoC) market is a linchpin that will determine competitive advantage across consumer electronics, telecommunications, automotive and industrial systems. PW Consulting’s latest market study synthesizes seven years of historical data and a seven‑year forward forecast to give executives a precise, actionable view of where investment and strategic effort will produce the highest returns. The market has expanded materially in recent years — rising from approximately USD 128,110 million in 2020 to roughly USD 195,500 million in 2025 — and our base‑case projection places the market above USD 215,000 million in 2026 with a compound annual growth rate of 9.25% through 2032, reaching an expected USD 363,159 million at the end of the forecast window. These headline dynamics create both opportunity and complexity for strategic decision‑makers in 2026.
Mp System On A Chip Market
Why this study matters for 2026 decisions
-
Timing of technology inflection points: 2026 is the first year many leading foundries and designers will roll out 2nm‑class products at scale. This will reshape performance, power and integration economics for flagship SoCs and high‑end edge devices.
Mp System On A Chip Market -
Strategic policy tailwinds and headwinds: public funding programs and export control regimes are simultaneously accelerating domestic capacity in some markets while constraining cross‑border technology flows. Firms must navigate incentives, compliance risk and the new economics of localized supply chains.
Mp System On A Chip Market -
Consolidation pressure vs. fragmentation opportunity: the market exhibits moderate concentration among global leaders, but technology specialization (imaging, automotive-grade safety, mixed‑signal integration) leaves room for targeted entrants and M&A plays.
-
Packaging and integration shifts: advanced packaging and standardized chiplet interconnects are changing the value chain — companies that adopt heterogeneous integration early will shorten time‑to‑market for differentiated performance.
What the report delivers — practical, decision‑grade insight
-
Robust market sizing and scenario models: transparent methodology that reconciles historical revenues (2020–2025) with three forecast scenarios (base, upside, downside) across 2026–2032, enabling stress‑tested volume and revenue planning.
-
Go‑to‑market playbooks: prioritized GTM options for semiconductor vendors, OEMs and system integrators by technology stack and buyer persona, including product positioning, channel choices and pricing levers.
-
Supply‑chain and manufacturing roadmaps: evaluation of node transition timelines, advanced packaging adoption curves, and high‑margin assembly strategies, with a focus on risk mitigation under export control regimes.
-
Technology and IP strategy: assessment of chiplet adoption, UCIe standardization impacts, and how to structure partnerships with foundries and packaging specialists to capture performance cost improvements.
-
Commercial due diligence toolkit: vendor scorecards, M&A screening criteria, and integration checklists to accelerate target selection and post‑acquisition value capture.
-
Regulatory and compliance matrix: practical guidance for export control exposure analysis, navigating incentives (including national chip funding programs), and building a defensible compliance posture.
-
Risk and contingency planning: scenario‑based operational playbooks for yield shocks, geo‑political supply interruptions and sudden demand shifts in automotive or telecommunications segments.
Competitive landscape — what the leaders are doing and why it matters
The competitive field spans vertically integrated platform owners, fabless specialists, diversified semiconductor giants and niche systems vendors. The market’s top three players collectively command a meaningful portion of aggregate revenue, while the top five account for a dominant slice of industry revenue — a structure that supports both scale advantages and differentiated niche strategies. Key strategic positioning to watch in 2026:
-
Qualcomm Technologies, Inc.: Continues to leverage modem and connectivity IP alongside high‑performance application processors to defend its mobile and expanding automotive footprint. Its integrated approach to connectivity and heterogeneous compute remains a commercial advantage for OEM partnerships.
-
Apple Inc.: Vertical integration of SoC design and system architecture drives substantial per‑device differentiation. Its control of silicon and software stacks makes it a benchmark for performance per watt and user experience optimization.
-
MediaTek Inc.: A proven operator in cost‑performance tradeoffs for mainstream mobile and consumer segments; its recent tape‑out on advanced process technology signals an intent to close the gap on flagship performance while preserving aggressive cost structures for high‑volume markets.
-
Samsung Electronics: Dual role as designer and foundry provides flexibility in aligning SoC design to manufacturing advances and memory integration including HBM, valuable for both mobile and high‑performance segments.
-
AMD and Intel: Both are converting traditional CPU franchises into broader SoC strategies for data center, edge and PC markets, with implications for platform consolidation and software ecosystem lock‑in.
-
NVIDIA: Focused on GPU‑centric SoCs for automotive and edge AI; its strengths in deep learning acceleration make it a go‑to for workloads that prioritize parallel compute and model inference at the edge.
-
Broadcom, NXP, STMicroelectronics, Texas Instruments: Each occupies differentiated niches in networking, automotive, industrial and analog/mixed‑signal SoCs. Their breadth of product portfolios delivers resilience against single‑market downturns.
-
OMNIVISION and Socionext: Examples of specialized IP and systems expertise — from imaging sensor SoCs to custom automotive solutions — that enable targeted wins where domain knowledge and integration matter most.
Industry dynamics shaping strategic choices in 2026
-
Node adoption and packaging: The industry’s march toward 2nm‑class process nodes and wider deployment of advanced packaging (including large‑reticle interposers supporting HBM) will change the performance/cost frontier. Decision‑makers should assess where node upgrades materially improve product value versus where multi‑die integration yields better TCO.
-
Standardization and modularization: The emergence of chiplet standards is lowering barriers to heterogeneous integration but increasing the importance of IP orchestration and ecosystem partnerships.
-
Policy and supply‑chain realignment: Export control regimes and national incentives are reconfiguring supply footprints. Firms must develop localized manufacturing options or secure strategic supply agreements to avoid market access constraints.
-
Domain‑specific acceleration: Automotive L2–L4, edge AI, and telecommunications (5G/6G evolution) are driving differentiated SoC requirements — from functional safety certification to determinism and long‑term availability commitments.
Strategic imperatives for 2026 — recommended action checklist
-
Prioritize investment where node and packaging advances unlock clear product differentiation; defer blanket node upgrades where chiplet or packaging alternatives deliver similar performance at lower capital spend.
-
Harden regulatory playbooks: map export control exposure to product roadmaps, and align R&D footprints to incentive programs and compliant manufacturing partners.
-
Forge ecosystem partnerships: early adoption of chiplet standards and joint engineering agreements with foundries and packaging houses will accelerate time‑to‑market for heterogeneous SoCs.
-
De‑risk supply: diversify high‑risk suppliers, secure long‑lead materials, and design for multi‑sourcing of critical IP blocks where possible.
-
Targeted M&A: prioritize tuck‑ins for missing capabilities (imaging ISPs, automotive safety IP, mixed‑signal expertise) over large horizontal purchases that dilute focus.
-
Commercial readiness: establish price‑performance tiers aligned to buyer personas and produce modular product families that simplify platform migration for OEM customers.
How PW Consulting’s study helps operationalize these imperatives
This research is designed as a decision‑support engine: detailed financial models, LCOE style cost curves for node and packaging options, vendor scorecards, and stepwise GTM templates are included so that product and corporate strategy teams can convert insight into executable plans within quarters, not years. Importantly, this introduction intentionally omits granular regional and application splits and the vendor‑level financial tables — those sensitive, high‑value datasets are available in the full report and the accompanying interactive dashboard for subscribers.
For executives preparing 2026 budgets, negotiating supplier agreements, or screening M&A targets, the combination of a 9.25% CAGR base case, our scenario stress tests, and the technology‑policy overlay provided in the full study will materially improve the quality and defensibility of strategic choices.
Next steps
-
Download the full report and interactive models to access regional and application breakouts, vendor financials, and a prioritized list of acquisition targets and partnership candidates.
-
Engage PW Consulting for a tailored workshop: scenario planning, capex optimization, and regulatory risk quantification specific to your product portfolio.
PW Consulting’s Mp System On A Chip Market study is structured to convert complexity into executable strategy for 2026 — providing a roadmap that balances technological ambition, regulatory realism and commercial discipline. For access to the granular intelligence and tools that support concrete investment and partnership decisions, please consult the full report.
For detailed analysis of this topic, please visit the official page: Mp System On A Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial-Grade Trichlorosilane Market Poised for 8.12% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Industrial-Grade Trichlorosilane Market: Strategic Imperatives for 2026
This preview synthesizes PW Consulting’s latest Industrial Grade Trichlorosilane (TCS) market study — a practitioner’s guide designed to inform capital allocation, procurement strategy, and supply-chain resilience planning as firms enter 2026. Below we surface the macro trends, competitive dynamics, supply- and demand-side risks, and the practical decision levers executives should be testing now. Note: this article intentionally showcases our analytical depth while withholding granular segment-level figures and tables to encourage direct access to the full study for transaction-grade intelligence.
Industrial Grade Trichlorosilane Market
Market at a Glance: Scale, Momentum, and Near-Term Trajectory
By PW Consulting’s baseline (2025), the industrial-grade TCS market stands at roughly USD 6.45 billion and is forecast to grow to approximately USD 6.93 billion in 2026, accelerating along an 8.12% compound annual growth rate through our 2026–2032 forecast horizon. By 2032 the market is projected to exceed USD 11 billion under our central case. That combination of sizeable base and persistent double‑digit-ish expansion creates a strategic imperative for both incumbents and new entrants to refine their positioning now — both to capture growth and to insulate margins against commodity and regulatory shocks.
Industrial Grade Trichlorosilane Market
Why This Report Matters for 2026 Decisions
-
Investment prioritization: The growth profile supports selective capacity additions, but only where plant economics reflect evolving feedstock and environmental costs. Our report flags where incremental CAPEX is accretive versus where operational excellence will generate higher returns.
Industrial Grade Trichlorosilane Market -
Procurement and hedging: Feedstock volatility and localized trade measures mean that raw-material procurement strategies will have outsized impact on cash flows in 2026. The study provides procurement playbooks based on price scenarios and contract structures.
-
M&A and partnerships: Consolidation and vertical integration are already altering value capture. We outline target archetypes and synergies to prioritize in near-term deals.
-
Regulatory and ESG readiness: Environmental compliance costs and tighter reporting regimes are non-trivial. The report quantifies the operational impact of major regulatory regimes and proposes mitigation pathways.
Core Dynamics Shaping 2026
-
Feedstock and price signals: Metallurgical silicon remains the primary input for TCS via hydrochlorination. Northeast Asian spot references for metallurgical-grade silicon reached about USD 1.45/kg in late‑2025 with quarter-on-quarter upticks, while Chinese industrial-silicon domestic price bands continued to show wide variance. Those inputs drive cost curves for most producers; small percentage movements in feedstock prices materially change factory-gate margins.
-
Technology and energy intensity: Advances in reactor design and energy-efficient processes — notably fluidized-bed reactor (FBR) implementations — are already delivering step‑changes in energy consumption and unit economics. Where energy is a material share of production cost, FBR-based operations re-rate long-run cost competitiveness.
-
Regulation and trade policy: Tighter environmental compliance in regulatory regimes such as the EU’s chemical frameworks has raised operating costs and introduced potential downtime exposure. Concurrently, trade remedies and export-control decisions in key markets can re-route supply chains over short horizons; these dynamics matter for feedstock sourcing, plant location choices, and inventory strategy.
-
Demand-side pull: Polysilicon demand for solar and semiconductor end-markets, coupled with stable requirements from silicone value chains, remains the principal growth engine. Differentiation between industrial-grade and higher-purity electronic/solar-grade TCS is a recurring theme for value capture.
Supply Structure, Concentration, and the Strategic Consequences
The market exhibits moderate concentration: the top three suppliers account for a meaningful share of global output while the top five capture an even larger portion of supply. This structure creates three tactical realities for 2026 planning: pricing power for integrated players, counterparty concentration risk for buyers, and transaction opportunities for vertically minded investors.
Leading producers combine integrated polysilicon and chlorosilane value chains, focused investments in purification technologies, and regional capacity plays. Recent corporate developments illustrate the strategic responses shaping the sector:
-
Wacker Chemie expanded purification capability at a major European site to serve semiconductor customers, signaling a move to capture higher-margin, high-purity TCS demand adjacent to local chip manufacturing growth.
-
Hemlock Semiconductor secured significant public funding to underpin new polysilicon facilities in the U.S., strengthening domestic upstream capacity and de‑risking supply for North American buyers amid reshoring incentives.
-
OCI and other Asia-focused producers have increased regional capacity to meet polysilicon feedstock demand from Southeast Asia — a reminder that cost-competitive regional hubs will continue to attract large-volume flows.
-
GCL‑Poly’s deployment of FBR-based production in Inner Mongolia underscores how energy- and capital‑efficiency drives can shift competitiveness and tilt investment returns in favor of advanced process adopters.
Additional established chemical players and diversified producers remain relevant as suppliers of industrial-grade TCS and as potential consolidation partners; our full profiles map plant footprints, purity capabilities, and low-emissions investments for each major player.
Demand Composition and Grade Differentiation
Understanding who consumes industrial-grade TCS — and for what purpose — is essential. The polysilicon industry is the primary demand anchor, but secondary uses in coupling agents and other chemical intermediates create a multi‑tiered demand stack. The important operational implication for purchasers and producers alike is that grade mix and routing decisions (i.e., directing TCS to purification streams for higher‑value electronic grades versus direct feed to polysilicon lines) materially affect logistic and margin outcomes.
For 2026, decision-makers should test scenarios where demand rebalances (for example, stronger semiconductor capex versus a moderated solar build-out), because trade and regional policy can produce asymmetric demand shocks across regions and applications.
Pricing and Risk Management Playbook
-
Lock in differentiated contracts for feedstock: Given volatility in metallurgical silicon references and the observed ranges in Chinese industrial-silicon prices, long-term forward contracts combined with indexed clauses provide a balanced approach.
-
Prioritize energy-efficiency investments where IRR stack supports CAPEX: FBR and other efficiency gains have strategic value beyond cost — they are defensible against potential carbon/energy surcharges and improve resilience to power-price swings.
-
Diversify routes to market: Buyers that rely on a small set of suppliers should consider multi-sourcing, tolling arrangements, or equity stakes in upstream production to secure feedstock availability and price predictability.
-
Quantify regulatory exposure: Producers serving markets with stringent chemical regulation must build compliance buffers into operating models and scenario-led capital plans to avoid costly stoppages.
Strategic Playbook — Actions for 2026
-
For producers: Prioritize selective purification capability and value‑chain integration where markets reward higher‑purity output. Allocate incremental CAPEX towards energy-saving process upgrades and emissions controls to avoid regulatory obsolescence.
-
For buyers (polysilicon and silicones): Secure multi-year supply contracts with embedded flexibility, and explore upstream partnerships or captive production as insurance against trade and feedstock disruptions.
-
For investors and M&A teams: Focus on targets with either proprietary purification technologies, advantaged feedstock access, or FBR adoption; model three scenarios (base, upside, downside) with stress tests for feedstock price spikes and regulatory shutdowns.
-
For policymakers and industry associations: Prioritize predictable regulatory timelines and targeted incentives for low‑emission production technologies to avoid unintended domestic supply shrinkage.
What PW Consulting’s Full Report Delivers
Our full Industrial Grade Trichlorosilane report is structured for immediate operational use and strategic planning. Key deliverables include:
-
A probabilistic demand model through 2032 with scenario toggles for solar and semiconductor trajectories.
-
Supply-side asset maps, plant-level cost curves, and an index of purification and reactor technologies.
-
Price-sensitivity analyses and procurement playbooks linked to feedstock-price scenarios and trade-policy outcomes.
-
Regulatory and ESG impact matrices with mitigation options and compliance cost ranges.
-
Granular company profiles, recent development tracking, and an M&A pipeline with accretion/dilution modeling templates.
To respect this preview’s “trailer” role, we have intentionally not reproduced segment-level tables and region/application breakdowns here. The full report contains those granular splits, downloadable datasets, and the underlying models that power the forecasts.
Closing — Immediate Next Steps for 2026 Planning
Entering 2026, firms should treat the TCS market not as a single commodity bet, but as a multi-dimensional set of choices across purity gradations, geographic supply options, and technology paths. The headline growth and concentration metrics make clear that capacity discipline, feedstock management, and technology-driven cost advantages will determine winners. PW Consulting’s study equips decision-makers with the quantitative scenarios and executable playbooks needed to convert market growth into durable value — access the full report to obtain the granular segmentation, plant-level economics, and deal-screening tools required for transaction execution and tactical planning.
For detailed analysis of this topic, please visit the official page: Industrial Grade Trichlorosilane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


