



PW Consulting: Water Recycling & Reuse Market to Reach USD 47,349.62M by 2032 (11.25% CAGR)
By PW Consulting, 2026-07-13
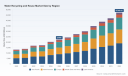
Water Recycling and Reuse Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-grade preview of our full Water Recycling and Reuse Market study — designed to fast-track C-suite and corporate strategy teams in 2026. This piece demonstrates the depth of our analysis and the concrete strategic implications emerging today, while preserving proprietary segment-level intelligence to encourage direct access to the full report and interactive tools.
Water Recycling And Reuse Market
Market Snapshot: Scale, Trajectory, and the Investment Imperative
The global water recycling and reuse market has transitioned from a niche sustainability play to a major infrastructure and industrial investment theme. Our base-year assessment shows the market reached approximately USD 22.45 billion in 2025. Under a central-case projection, the market expands at a compound annual growth rate (CAGR) of 11.25% across our 2026–2032 forecast horizon, nearly doubling to an estimated USD 47.35 billion by 2032. This trajectory reflects the combined effect of policy acceleration, industrial demand for closed-loop water systems, urban-scale recycling programs, and growing commercial viability of advanced treatment technologies.
Water Recycling And Reuse Market
Strategic Drivers That Will Shape Corporate Decisions in 2026
- Regulatory acceleration and mandate-driven demand. New policy frameworks and standards are proliferating. Notable examples include the US EPA’s Water Reuse Action Plan 2.0, which explicitly targets industry verticals such as data centers and energy; state-level mandates increasing reuse of produced water in oil & gas; and adoption of testing/qualification standards for onsite reuse systems. These create predictable demand corridors for firms able to meet compliance thresholds and demonstrate validated treatment performance.
- Large-scale municipal and industrial projects as market pull. Major programmes — from municipal purified-recycled-water initiatives to industrial reuse facilities built under long-term O&M contracts — are crystallizing the market into investable, bankable assets. Project milestones in 2025–2026 have converted theoretical demand into executable pipelines.
- Technology maturation and cost dynamics. Membrane-based systems, modular MBRs, and multi-barrier tertiary treatment are now proven at scale. Capital-intensity remains a consideration: industry benchmarks continue to quote capital cost ranges for membrane bioreactor systems and advanced tertiary treatment in per-gallon terms, which materially affect project-level IRR and procurement choice between centralized and decentralized architectures.
- Commercial models shifting to services and outcomes. The value pool is moving from equipment sales toward integrated offerings — performance guarantees, long-term service contracts, and digital-enabled lifecycle optimization. Acquirers and platform investors are seeking recurring-revenue streams tied to O&M and analytics.
- Fragmented supplier base with rising consolidation pressure. Market concentration metrics show meaningful room for consolidation: leading vendors account for a material but not dominant share, leaving strategic space for M&A, roll-up plays, and strategic partnerships between technology specialists and global operators.
What the PW Consulting Report Delivers — Actionable, Not Academic
Our full report is structured to convert market intelligence into executable initiatives. Highlights include:
Water Recycling And Reuse Market
- Proprietary market sizing and three scenario-based forecasts (conservative, central, disruption) with sensitivity analysis to policy and capital-cost variables.
- Demand-driver mapping by use-case (municipal programs, industrial reuse, produced water, onsite greywater), translating regulatory signals and capital cycles into addressable opportunity curves.
- Technology assessment framework that ranks treatment pathways by total cost of ownership, regulatory fit, footprint, and time-to-deploy — with deployment playbooks for centralized vs. decentralized models.
- Supplier and competitive intelligence, including strategic profiles and capability heatmaps for global and regional challengers. (Profiles of core companies included in the public synopsis; full comparative matrices are in the report.)
- Investment and procurement toolkits: project-level financial models, contractor RFP templates, O&M contracting options, risk allocation matrices, and a regulatory tracker for major markets.
- Ten detailed case studies that distill lessons from recent project wins, large-scale municipal programs, and industrial ZLD implementations — each with implementation timelines and supplier ecosystem maps.
Competitive Landscape — Who Matters and Why
The market is competitive and strategically diverse: global operators with integrated water-management capabilities are competing alongside specialized membrane and modular-system vendors. Key players we profile in depth include Veolia, Xylem Inc., SUEZ Water Technologies & Solutions, Ecolab (Nalco Water), DuPont Water Solutions, Pentair, Aquatech, Kubota, ALFA LAVAL, Hitachi, Siemens, Fluence, Kurita, Culligan, and Consolidated Water. Our report evaluates each firm across three strategic vectors: technology stack and IP, go-to-market model (project EPC vs. recurring O&M vs. product sales), and corporate capability to scale across geographies and verticals.
- Veolia continues to leverage its project-development and long-term O&M expertise to secure consortium-scale industrial reuse contracts, exemplified by large industrial plant agreements signed in 2025.
- Xylem’s platform expansion via acquisition is a defining move — combining fluid-handling, membranes, and analytics shifts the value proposition toward integrated lifecycle services and data-driven performance guarantees.
- SUEZ and Ecolab remain strong in modular solutions and customized industrial programs; their strength lies in multi-barrier approaches and chemical/biological process integration.
- Specialists — from membrane manufacturers to ZLD system integrators and modular decentralized providers — are the most likely acquisition targets or partners for larger engineering and services firms seeking rapid capability scaling.
Recent, tangible developments underscore these dynamics: a major acquisition completed in early 2026 that enlarged a membranes-and-analytics platform; milestone project agreements and contract awards for large-scale industrial and municipal plants in 2025–2026; and municipal programs advancing environmental approvals — all of which convert stated strategies into near-term addressable revenue.
Strategic Playbook for Executives in 2026
- Prioritize use cases with policy-backed demand. Immediate priorities should be projects and contracts anchored to regulatory mandates or long-term municipal programmes. These are the highest-confidence revenue streams for capex deployment and investor pitches.
- Design offerings around lifecycle economics, not just capex. Given the capital intensity of advanced treatment, winning in 2026 requires service-centric pricing, performance guarantees, and ability to reduce total cost of ownership through predictive maintenance and process optimization.
- Pursue targeted M&A and partnerships. Buyers should acquire modular-treatment specialists, membrane IP, or analytics providers to create bundled solutions. Sellers should seek strategic buyers that can deliver large-scale O&M contracts to convert product revenues into recurring streams.
- Use pilots to derisk and prove commercial models. Structure limited pilots with clear KPIs and scale-up triggers tied to financing milestones; consider shared-risk, incentive-aligned contracts to accelerate customer adoption.
- Embed digital to monetize performance data. Invest in remote monitoring and analytics to enable outcome-based contracts and to protect margins as hardware becomes commoditized.
- Monitor cost benchmarks and procurement timing. Capex-per-unit benchmarks for membrane bioreactors and tertiary treatment remain central inputs to bid strategy and ROI calculations — incorporate these ranges into tender pricing and lifecycle models.
- Engage regulators early and shape standards. Proactive engagement on standards and testing protocols will accelerate approvals and give first-mover advantages in nascent reuse categories (e.g., industrial reuse for data centers, produced water mandates).
Why PW Consulting’s Report is Valuable for 2026 Decisions
This study is not an academic compendium; it is a hands-on, transaction-oriented playbook. It gives corporate strategists and investment committees the forecasts, vendor scorecards, and risk-adjusted financial models needed to: prioritize capital allocation, design deals that convert projects into annuity-like income, position organizations for consolidation waves, and operationalize regulatory change. We surface where policy and project execution intersect to create bankable opportunities — and where capability gaps will determine winners and losers.
For decision-makers preparing budgets, negotiating partnerships, or evaluating M&A opportunities in 2026, the choice is twofold: rely on high-level public narratives — or equip your team with the granular scenarios, commercial templates, and supplier assessments that materially improve project selection, pricing discipline, and negotiation outcomes. Our report delivers the latter.
Next Steps
Access to the full PW Consulting Water Recycling and Reuse Market report provides the detailed, segment-level models, vendor matrices, and interactive ROI tools referenced above. For executives ready to convert the 2026 market dynamics into a clear growth agenda — whether through organic investment, partnership, or acquisition — the report is the operational map and the decision support system you need.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Balanced Salt Buffer Market to Reach USD 1,388.7M by 2032 at 7.4% CAGR
By PW Consulting, 2026-07-13
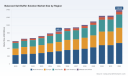
Balanced Salt Buffer Solution Market: Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present an executive introduction to our Balanced Salt Buffer Solution Market study — a practitioner's guide designed to shape high‑stakes decisions in 2026. This piece outlines the strategic value of the study, highlights the market’s macro trajectory, surfaces the structural forces and supplier dynamics that will matter this year, and sketches the actionable frameworks embedded in the full report. To preserve the report’s commercial value and encourage direct engagement with our core deliverable, we intentionally do not publish the granular segment tables and proprietary model outputs here.
Balanced Salt Buffer Solution Market
Why this study matters for 2026 decision-makers
Balanced salt buffer solutions (BSS) are foundational consumables across cell culture, bioprocessing, regenerative medicine, and diagnostic workflows. The market is no longer a low‑margin, low‑visibility line item on procurement lists — it is a strategic lever. Our analysis shows the market reached roughly USD 842.5 Million in 2025 and is projected to expand to about USD 923.2 Million in 2026, continuing on a compound annual growth path of approximately 7.4% through our forecast horizon. By 2032, the market is projected to exceed USD 1.38 Billion, reflecting sustained, modality-driven demand and increasing commercialization of cell‑based therapies.
Balanced Salt Buffer Solution Market
What this trajectory means for executives in 2026: - Procurement leaders must treat BSS suppliers as strategic partners rather than spot vendors. - R&D and product teams need to factor solution specifications (sterility, endotoxin, ion balance) into early design and scale-up choices. - Corporate strategists should re-evaluate M&A and capacity playbooks: volume growth and margin uplift are driven by both product differentiation and supply reliability.
Balanced Salt Buffer Solution Market
Market structure and concentration — implications for strategy
The BSS market exhibits a moderate concentration profile: the top three players account for a material share of market value, and the top five firms capture a majority of market revenue. This structure creates a dual reality. On the one hand, established global suppliers provide predictability, validated quality systems and regulatory alignment; on the other hand, mid‑tier and regional vendors are agile, cost-competitive and increasingly attractive to cell therapy developers seeking customized, cGMP‑grade formulations.
- Implication for procurement: blend long‑term contracts with global suppliers to secure validated inventory and contingency supply from local or specialized manufacturers to protect against single‑point failures.
- Implication for investors: consolidation opportunities remain, particularly where a buyer can combine manufacturing scale with niche formulation capabilities (custom buffers for CGT — cell and gene therapy).
- Implication for manufacturers: invest selectively in certified capacity (cGMP/ISO) and analytical documentation to win blue‑chip clients and premium pricing.
Competitive landscape — what the leading suppliers reveal
Our qualitative review of leading suppliers underscores four distinct competitive plays: global integrated life‑science platforms, laboratory reagent specialists, contract/custom manufacturers, and regionally focused low‑cost producers. Representative players exemplify these strategies:
- Global platforms (e.g., Thermo Fisher Scientific) leverage brand, scale manufacturing, and deep regulatory documentation to serve large pharma and core research institutions with a broad portfolio of stock and custom BSS formats.
- Laboratory reagent and materials companies (e.g., Cytiva / HyClone, Sigma‑Aldrich / Merck) compete on product breadth, sterile‑filtered formats and channel reach into academic and industry labs.
- Specialist manufacturers (e.g., Corning, Sartorius) differentiate through validated device and media systems, frequently bundling BSS with ancillary consumables and instrumentation to increase wallet share.
- Custom/formulation specialists and regional players (e.g., Boston BioProducts, Nucleus Biologics, Procell) win contracts where tailored specifications, lower endotoxin thresholds or cGMP‑grade documentation are required, notably in cell and gene therapy supply chains.
For procurement and R&D teams, supplier selection should be a risk‑weighted choice: does the project require validated global continuity, or is customization and speed of development the dominant priority? Our report provides a supplier scorecard and sourcing decision tree to operationalize this trade‑off.
Supply chain dynamics and raw material sensitivity
BSS production is deceptively simple in composition but complex in risk. Sodium chloride, buffers (e.g., phosphate, bicarbonate), and filtration/packaging inputs represent concentrated upstream exposure. Recent commodity and regional dynamics — including seasonal volatility in European feedstock markets and transient price softening in North America — highlight how seemingly peripheral factors can compress margins or disrupt supply windows.
Strategic recommendations: - Build visibility into upstream feedstock availability and price indices (salt, salts for pH control, packaging components). - Adopt hedging and multi‑sourcing where volumes justify the operational overhead. - For manufacturers, prioritize energy efficiency and local sourcing in regions where logistic or energy cost volatility drives margin erosion.
Regulatory and quality expectations — the non‑negotiables
BSS used in cell culture and bioprocessing increasingly cross regulatory thresholds. Buyers must demand cGMP manufacturing, ISO‑certified quality systems, and robust analytical release testing (osmolality, pH, endotoxin, sterility). Our analysis confirms those capabilities are table stakes for suppliers seeking to serve clinical and late‑stage programs.
- Product labeling caveat: many BSS formulations remain labeled for “research use only”; converting these into clinical‑grade materials requires documentation, validated change controls, and potential reformulation — decisions that should be budgeted early in 2026 program plans.
- Quality investment payback: suppliers that achieve ISO 13485 and validated GMP lines can command premium terms and shorten technical transfer timelines for biopharma partners.
Report deliverables — what you get from the full study
PW Consulting’s full market study is structured to be immediately usable by commercial, procurement, and strategy teams. Key deliverables include:
- An interactive financial model projecting market size across 2026–2032 with scenario toggles for adoption curves in cell therapy and diagnostic segments.
- A supplier matrix and scorecard that quantifies capability across quality systems, custom formulation, fill‑finish, geographic coverage and commercial flexibility.
- Procurement playbooks including contracting templates, KPIs for supplier performance, and a contingency sourcing blueprint.
- Go‑to‑market frameworks for suppliers — pricing ladders, channel strategies, and technical collateral templates tailored to CROs, CMOs and therapy developers.
- A risk register covering feedstock concentration, geopolitical logistics, and regulatory shifts — coupled with mitigation pathways and capex sensitivity analysis.
Note: The report contains granular segmentation, regional and application-level breakdowns, and downloadable datasets. Those detailed tables, which are essential for operational planning and investment memos, are intentionally excluded from this public preview to preserve client value and to guide stakeholders to the primary report portal.
Decision playbook for 2026 — three pragmatic moves
Based on our analysis, executives should prioritize three actionable moves this year:
- Reclassify BSS spend in procurement: shift from commodity sourcing to strategic category management, incorporating quality tiers and demand forecasting into contract terms.
- De‑risk clinical supply chains: mandate audited cGMP capabilities and dual sourcing clauses for any supplier supporting IND‑enabling or clinical programs.
- Explore targeted consolidation or partnership: pursue bolt‑on acquisitions that add customizable formulation capability or regional manufacturing footprint if your growth scenario assumes accelerated CGT commercialization.
How to use the full report in board and investment conversations
When presenting to boards or investors, use the PW Consulting study as a fact‑based adjunct to strategic narratives: supplement your internal forecasts with our market model, extract supplier scorecards to validate vendor choices, and use scenario outputs to stress‑test capex or M&A assumptions. The report is organized to produce slide‑ready exhibits and an executive appendix that aligns with typical diligence checklists.
Closing — where to go next
The Balanced Salt Buffer Solution market is transitioning from a stable consumables category to a strategically contested domain. Companies that treat BSS as part of a larger therapeutic and manufacturing ecosystem — and that invest in quality, vertical integration or strategic partnerships — will capture disproportionate value as cell‑based modalities scale.
For procurement leaders, R&D heads, and corporate strategists preparing for 2026, PW Consulting’s full study delivers the data, templates and playbooks to convert market projections into executable plans. To access the complete segmentation tables, supplier scoring models and the interactive forecast, please refer to the full report page listed in PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Balanced Salt Buffer Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luciferase Assay Market to Reach USD 992.33M by 2032 at 6.95% CAGR
By PW Consulting, 2026-07-13
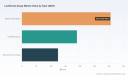
Luciferase Assay Market: Strategic Preview for 2026 Decision-Makers
Executive teaser
As laboratories, biotechs, and instrument platform providers recalibrate priorities for 2026, luciferase assays remain a bellwether technology for gene expression, high‑throughput screening (HTS), and early‑stage drug discovery. PW Consulting’s latest market research—anchored on 2025 as the base year and forecasting through 2032—shows a market expanding at a steady compound annual growth rate (CAGR) of 6.95%. The market size trajectory and technology inflection points we summarize here are intended to inform strategic choices for the coming 12–36 months. This preview highlights the directional opportunities and competitive dynamics; full segmentation, regional allocations, and transaction‑grade datasets are reserved for the comprehensive report to preserve its actionable value.
Luciferase Assay Market
Market snapshot and trajectory
By our base year (2025) the luciferase assay market stood at approximately USD 620 million (USD, Million). Under the central forecast, the market is expected to grow into the mid‑hundreds of millions by 2026 and approach roughly USD 1 billion by the end of the forecast window in 2032. The near 7% CAGR reflects a combination of ongoing demand for reporter gene assays, expanding use of bioluminescence imaging in translational research, and sustained spend in drug discovery screening campaigns.
Luciferase Assay Market
Why this market matters to corporate strategists in 2026
- Demand resilience: Luciferase assays continue to be a cost‑effective, high‑signal platform for reporter gene studies and HTS. That combination of sensitivity, throughput, and established workflows makes the category a defendable recurrent revenue line for reagents manufacturers and a strategic consumable for pharma/biotech R&D arms.
- Technology inflection: Innovations—particularly in enhanced luciferase reporters and spectral engineering—are re‑shaping product differentiation. Players who control next‑generation reporters and complementary detection chemistries capture pricing power and heightened user stickiness.
- Regulatory clarity (and limits): Most luciferase assay kits are designated as Research Use Only (RUO). This status preserves a broad, low‑barrier market for research and drug discovery but constrains direct clinical diagnostic commercialization, altering route‑to‑market strategies for firms eyeing clinical utility.
- Consolidation and concentration: The market exhibits moderate concentration among leading life‑science reagent and instrumentation companies. This dynamic affects partnership opportunities, distribution access, and M&A valuation benchmarks.
Primary demand drivers and near‑term trends
- Drug discovery throughput: Biopharma’s ongoing appetite for cell‑based and reporter assays in early screening campaigns continues to be the largest single source of demand—particularly for robust, scalable luminescence readouts compatible with automated platforms.
- Spectral and sensitivity advances: The emergence of enhanced luciferases and red‑shifted reporters expands assay applicability to multiplexing and in‑vivo imaging. Recent product signals from leading vendors indicate intensified competition around two‑color assays and improved tissue penetration for live‑animal studies.
- Platform bundling: Vendors increasingly bundle assay chemistry with validated detection protocols and software workflows, reducing friction for end users and enabling premium pricing for validated, reproducible solutions.
- Academic and translational research funding: Funding cycles in academia and translational centers continue to influence purchasing patterns; strategic vendors are prioritizing flexible SKUs and educational collaborations to capture long‑term adoption.
Competitive landscape—what to watch
The field is populated by a mix of large reagent/instrument conglomerates and focused assay specialists. The market’s top tier combines deep R&D pipelines, global distribution, and broad product portfolios; smaller players emphasize niche performance or value. The top three firms capture a meaningful share of the market and the top five tighten that concentration further—creating distinct strategic behaviors across incumbents and challengers.
Luciferase Assay Market
- Promega Corporation (Madison, WI) — Promega’s leadership in luciferase systems is rooted in its NanoLuc family and dual‑luciferase platforms. Its recent presentation of a red‑shifted NanoPrism reporter and two‑color bioluminescence approaches signals a tactical push into multiplexed and deeper‑tissue imaging applications. Strategically, Promega is positioning itself to convert sensitivity advantages into broader platform lock‑in by pairing advanced reporters with validated assay kits and automation‑friendly formats.
- Thermo Fisher Scientific Inc. (Waltham, MA) — Thermo Fisher’s strength is distribution scale and portfolio breadth. Its reporter assay lines span classic firefly and Renilla systems through to Gaussia and Cypridina offerings, which it leverages to serve large institutional and commercial screening customers. For market entrants, Thermo Fisher’s reach represents both a channel obstacle and a potential commercialization partner.
- Revvity Inc. (formerly PerkinElmer; Waltham, MA) — Revvity’s emphasis on high‑throughput detection chemistries positions it well for integrated HTS workflows. Its product family targets users seeking throughput and automation compatibility—an attractive proposition for CROs and large pharma screening centers.
- Biotium Inc. (Fremont, CA) — A specialist approach, Biotium competes on assay optimization and cost‑effectiveness for reporter gene kits. Small, focused vendors like Biotium can outmaneuver larger rivals in targeted segments by moving fast on reagent improvements and customer support.
- Abcam plc (Cambridge, UK) — Abcam leverages its life‑science reagent ecosystem to cross‑sell luciferase substrates and related detection tools into cell biology and molecular biology workflows, emphasizing ease of use and reagent quality.
- Merck KGaA / MilliporeSigma (Darmstadt, Germany) — Integrating luciferase reagents into a broader luminescence portfolio gives Merck scale advantages in supply chains and product bundling for research customers.
Strategic takeaways by corporate role
- For product and R&D leaders: Prioritize investments in reporter sensitivity and spectral diversification (multiplexing, red‑shifted variants) that demonstrably reduce assay failure rates and enable new use cases (e.g., two‑color readouts, in‑vivo models). Validate with cross‑platform benchmarking and independent third‑party studies to shorten adoption cycles.
- For commercial leaders: Differentiate through bundled workflows (reagent + validated protocol + software) and targeted channel strategies—academic, biotech, CROs, and pharma require different value propositions. Consider tiered SKUs to balance price sensitivity with premium adoption.
- For corporate development and strategy teams: The market’s mid‑single‑digit CAGR and concentrated supplier base make M&A and partnership plays viable for acquiring niche technologies or accelerating distribution. Focus diligence on IP clarity for novel reporter chemistries, manufacturability, and RUO regulatory positioning.
- For procurement and lab operations: Evaluate total cost of ownership, including assay robustness, lot‑to‑lot consistency, and vendor support for automation; these factors frequently outweigh nominal reagent price in high‑throughput environments.
Risks, mitigants, and scenario considerations
- Regulatory and labeling constraints: The RUO designation frames a clear boundary: kits are not for diagnostic clinical decision‑making without separate validation and regulatory pathways. Firms seeking clinical applications must invest early in regulatory strategy and clinical assay validation.
- Commoditization pressure: Core chemistries can become commoditized. Mitigate by developing value‑added services (protocols, automation integration, data analysis pipelines) and protecting novel reporters through IP.
- Technology substitution: Alternative reporter systems and label‑free technologies could encroach on specific use cases. Maintain a watchlist for disruptive readout technologies and prioritize interoperability where practical.
- Supply and scale risk: For firms with global ambitions, securing reagent supply chains and scalable manufacturing for enzyme and substrate components is a non‑trivial operational investment.
What the full PW Consulting report contains (practical, deal‑ready materials)
The comprehensive report provides transaction‑grade insight and practitioner tools for 2026 strategy execution, including:
- Granular segmentation by region, type, and application with time‑series revenue tables and scenario variants (base, conservative, upside).
- Quantitative forecasts through 2032 with sensitivity analysis and model access (spreadsheet) for custom assumptions.
- Competitive diligence packs: detailed company profiles, product mapping, go‑to‑market models, recent product launches, and partnership histories.
- Commercial playbooks: pricing benchmarks, channel strategies, clinical translation checklists, and sample commercial decks for rapid deployment.
- M&A and partnership screening: valuation comps, deal multiples observed in reagent and life‑science tools transactions, and an IP due‑diligence checklist for reporter chemistries.
- Primary research insights: interviews with end users across academic, biotech, and pharma labs, plus supplier‑side manufacturing capacity assessments and distribution maps.
How to use this preview in your 2026 planning
Use the directional insights here to prioritize where to allocate scarce resources—R&D bets on next‑generation reporters, commercial investments in bundled workflows, or corporate development targets to shore up distribution or unique chemistries. The category’s stable growth profile (mid‑single‑digit CAGR) supports both organic market expansion strategies and bolt‑on M&A as credible routes to accelerate presence.
Final note — where to go next
This briefing intentionally omits granular regional and segment revenue breakdowns and the full numerical annex so that purchasing organizations, corporate development teams, and product leaders obtain the transaction‑ready datasets directly from PW Consulting. For a complete set of charts, scenario models, and downloadable tools that translate this strategic preview into executable plans for 2026, consult the full Luciferase Assay Market study available through our report page.
For detailed analysis of this topic, please visit the official page: Luciferase Assay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Selective Soldering Market to Hit USD 922.6M by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-13
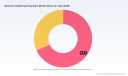
Selective Soldering Equipment Market: Strategic Intelligence for Executive Decisions in 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an incisive preview of our latest Selective Soldering Equipment Market study — a practical briefing designed to inform capital allocation, product strategy, supply-chain prioritization, and M&A decision-making throughout 2026. This article emphasizes the strategic value of the research while deliberately withholding the granular sub-segment figures that reside in the full report to preserve the incentive to engage with our complete analysis.
Selective Soldering Equipment Market
Executive snapshot: why this matters to 2026 decision-makers
Selective soldering is no longer a niche workshop capability; it is a foundational technology for high-reliability, mixed-technology PCB assembly across automotive electrification, advanced industrial controls, telecom infrastructure and increasingly demanding consumer electronics. Our base-year view (2025) positions the global selective soldering equipment market at approximately USD 582.1 Million, with a projected 2026 market step-up to roughly USD 663.2 Million and a compound annual growth rate (CAGR) of 6.8% through our 2026–2032 forecast window. Those topline numbers quantify a recovery and acceleration trajectory that corporate leaders must internalize when planning CAPEX cycles, equipment refresh programs, and factory modernization roadmaps in 2026.
Selective Soldering Equipment Market
Market trajectory and the mechanics behind the growth
-
Recovery and momentum: The market exhibited pandemic-era volatility during 2020–2022, followed by stabilization and renewed investment through 2023–2025. The forecast to 2032 anticipates steady expansion driven by miniaturization, lead-free requirements, and rising complexity in mixed-technology assemblies.
Selective Soldering Equipment Market -
Consolidation and concentration: Market concentration is non-trivial: the leading three suppliers control close to half the market, while the top five approach two-thirds of market share. This balance of scale and specialized engineering capacity shapes pricing, service coverage and innovation cycles for buyers and investors.
-
Structural demand drivers: Adoption is being propelled by three structural shifts — miniaturized components that require focused heat control, regulatory and lead-free soldering mandates, and the growth of electric vehicle (EV) and ADAS electronics which demand selective accuracy and low-void solder joints.
Why 2026 is a pivot year for equipment and operations strategy
For OEMs, EMS providers, and equipment vendors, 2026 represents a decision inflection: deferment of equipment investment risks falling behind in throughput and process yield versus competitors; premature replacement risks under-utilized assets and eroded returns. Our study frames that tradeoff through three executable decision lenses:
-
Capital allocation: Use forward-looking demand curves and scenario stress-tests to time major inline selective soldering investments. Short-cycle production needs can still be met with modular or standalone platforms, while strategic high-volume lines justify integrated, multi-station in-line systems.
-
Operational efficiency: Selective soldering’s cost profile (notably lower flux and solder consumption and reduced nitrogen use) can materially alter TCO compared with conventional wave soldering — a critical lever when margins are under pressure.
-
Quality & compliance: The technology supports compliance with IPC-level industry standards and can achieve void and reliability targets necessary for aerospace, medical and automotive electronics, making selective soldering a risk-management investment as much as a throughput play.
Practical, actionable content inside the full report
Our Selective Soldering Equipment Market study was assembled specifically for operational leaders and strategic investors. Key pragmatic deliverables include:
-
Decision-ready financial models — TCO calculators that contrast CAPEX, OPEX, consumables, and service across equipment classes and production profiles.
-
Vendor scorecards — engineering, aftermarket support, global service footprint, and retrofit compatibility metrics to accelerate shortlisting and procurement.
-
Technology roadmaps — comparative analysis of inline multi-station architectures versus standalone/batch systems, including modular upgrade paths and automation integration considerations.
-
Scenario playbooks — three to five demand and supply scenarios with sensitivity analysis for raw-material price swings, labor constraints, and regulatory tightening.
-
M&A and partnership lenses — playbooks for strategic and financial buyers highlighting integration risks, service-synergy opportunities, and quickly accretive bolt-ons.
-
Service & spares optimization — inventory policies and aftermarket strategies to reduce downtime and guarantee process repeatability across multi-site rollouts.
Competitive landscape: who matters and why
The competitive field blends long-established OEMs with focused niche specialists. Our study contains detailed vendor profiles, but the strategic highlights follow.
-
Kurtz Ersa GmbH (Germany) — A market leader with modular VERSAFLOW and ECOSELECT platforms. Strengths: broad platform range from entry-level to high-volume, electromagnetic pump technology and multi-nozzle adaptability that supports throughput scaling.
-
Nordson SELECT (United States) — Offers a complete spectrum (standalone, inline, multi-station) with a deep global service network. Competitive edge: turnkey solutions and aftermarket coverage for high-volume electronics manufacturers.
-
SEHO Systems GmbH (Germany) — Strong in integrated fluxing, preheating and soldering zones aimed at productivity and yield. Notable for platform-level engineering to support higher first-pass yields.
-
Pillarhouse International Ltd (UK) — Pioneer of selective soldering with a high-patent count; competitive in high-engineering-standard, reliability-focused segments.
-
JUKI Corporation & Apollo Seiko (Japan) — Provide batch and inline platforms, respectively, with particular relevance to through-hole legacy transitions and dual-pot innovations for precision soldering.
-
US and regional specialists (DDM Novastar, RPS Automation, TM Soldering Solutions, Hentec, VennTek-SASinno, INERTEC) — Offer cost-effective, niche and retrofit solutions that improve access to selective soldering across small and medium-sized EMS providers.
Recent vendor movements underscore competitive dynamics: multiple product launches and trade show showcases in late 2025 and early 2026 signal accelerating feature competition and an emphasis on throughput and modularity. Our full profiles catalog disclosed product launches, service expansions and regional go-to-market tactics in granular detail.
Key operational and regulatory context
-
Raw materials: The solder flux market — a critical consumable for selective processes — was estimated at roughly USD 3.12 billion in 2025 and is itself a growth market. Understanding flux segmentation and supply-chain concentration is essential for reliable OEE planning.
-
Process efficiency: Empirical process studies and vendor claims point to substantial reductions in solder usage and nitrogen consumption for selective soldering versus wave approaches. These efficiencies directly influence operating margins and environmental footprint.
-
Standards & reliability: Selective soldering is a practical enabler of compliance with IPC-level requirements and lower void percentages demanded by aerospace, medical and automotive assemblies — translating into lower warranty risk and higher product reliability.
Risk factors and scenario planning
While demand fundamentals remain constructive, 2026 strategies must include contingency playbooks addressing:
-
Raw-material volatility and supply chain disruptions for fluxes and specialty alloys.
-
Geopolitical shifts affecting capital-equipment sourcing and service footprints.
-
Rapid technology substitution or unexpected shifts in production architectures — for instance, a faster-than-anticipated move to fully automated inline cells that renders some legacy standalone investments sub-optimal.
Actionable strategic recommendations for 2026
-
For OEMs and Tier-1 manufacturers: Prioritize selective soldering investments on product lines where reliability premiums or regulatory compliance deliver quantifiable margin uplift. Use staged adoption: start with pilot inline cells on critical SKUs before committing to full-line conversions.
-
For EMS providers: Build a flexible equipment portfolio that mixes compact standalone systems for short runs and modular inline stations for predictable, high-volume customers. Strengthen service contracts and spare-parts availability to turn uptime into a competitive differentiator.
-
For equipment vendors: Invest in service orchestration, remote diagnostics, and modular upgradeability. Product differentiation will hinge on throughput scaling, ease-of-retrofit, and lifecycle service economics.
-
For investors & M&A teams: Seek targets that offer either niche technological IP (e.g., unique pump or nozzle technologies) or service-reach that can be rapidly integrated into a global aftermarket network; focus on assets that improve gross margin predictability in rolling 12–24 month horizons.
What the full PW Consulting report unlocks
The complete study contains the operational models, supplier scorecards, and scenario analytics required to convert these strategic signals into executable plans. To respect proprietary value and maintain the “selective” nature of this preview, we have withheld the granular regional and application splits from this article — those tables and the interactive modeling tools are available within the full report package and on our data portal.
Next steps
If you are responsible for CAPEX planning, factory modernization, procurement of selective soldering systems, or evaluating investment targets in 2026, the PW Consulting Selective Soldering Equipment Market study provides the operational blueprints and financial models you need. Contact our team or visit the report landing page to obtain the full dataset, vendor scorecards, and the TCO calculator.
For detailed analysis of this topic, please visit the official page: Selective Soldering Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Logistics Software Market to Reach USD 58,052.5M by 2032 (14.5% CAGR)
By PW Consulting, 2026-07-13
Cloud Logistics Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive snapshot
As organizations reset supply‑chain priorities for the post‑pandemic, AI‑enabled decade, cloud logistics software has moved from “nice to have” to a board‑level imperative. PW Consulting’s latest study—anchored on a 2025 base year and a six‑year historical run (2020–2025) with a forward forecast covering 2026–2032—documents a market that has more than doubled in momentum over the past half‑decade and is set to expand at a sustained compound annual growth rate of approximately 14.5% through the forecast horizon. This research synthesizes macro sizing, competitive dynamics, regulatory forces, and operational playbooks into a single, execution‑focused reference for CIOs, supply‑chain chiefs, and procurement leaders planning for 2026.
Cloud Logistics Software Market
Why this research matters for decisions in 2026
-
Investment timing and ROI: With rapid growth and rising vendor sophistication, enterprise buyers must align procurement windows, pilot cadences, and migration budgets to capture both short‑term efficiency and medium‑term strategic advantage.
Cloud Logistics Software Market -
Risk management: Escalating cloud hosting cost pressure and evolving regulatory requirements (data transfer documentation, AI transparency mandates, and heightened vendor risk expectations) are reshaping total cost of ownership and contractual terms.
Cloud Logistics Software Market -
Vendor selection and ecosystem planning: The market is large and growing fast, but remains only moderately concentrated—creating choices between integrated platform plays, best‑of‑breed specialists, and new entrants focused on AI or last‑mile orchestration.
Market trajectory and macro dynamics
Our topline sizing places the cloud logistics software market firmly in a high‑growth category as we enter 2026. After a period of accelerated adoption across transport management, warehousing, freight forwarding, and visibility services, the market’s baseline in 2025 provides the springboard for robust expansion through 2032—driven by rising e‑commerce volumes, omnichannel fulfillment complexity, and the application of AI/advanced analytics to network optimization.
Two external forces deserve special emphasis because they will materially affect vendor economics and enterprise deployment decisions in 2026:
-
Cloud hosting and infrastructure cost pressure: Major cloud and hardware suppliers signaled notable price adjustments in late‑stage 2025 and into 2026. Enterprises evaluating SaaS offers must treat host‑cost volatility as a line‑item risk when modelling multi‑year TCO and when negotiating pass‑throughs or fixed‑price elements in vendor agreements.
-
Regulatory and compliance tightening: GDPR enforcement continuity around cross‑border transfers, plus the operational demands of the EU AI Act for systems that process personal data, mean that buyers and vendors must now bake transfer impact assessments, SCC documentation, and model‑level transparency into contracts and implementation plans.
What the full report delivers (practical, operational, and boardroom ready)
PW Consulting designed this study to do more than describe trends; it is built to be applied. The full deliverable includes:
-
Topline market sizing and validated demand model (historical 2020–2025, forecast 2026–2032) with scenario stress‑testing for macroeconomic and cost‑inflation paths.
-
A market concentration and competitive landscape assessment enabling go‑to‑market targeting and M&A diligence, including CR3/CR5 concentration context to frame consolidation risk and white‑space opportunities.
-
Vendor scorecards and capability matrices mapping functional depth (TMS, WMS, freight forwarding, visibility), cloud‑native maturity, data fabric architectures, and partner ecosystems—useful for shortlisting and RFP design.
-
Implementation playbooks and migration roadmaps tailored to enterprise archetypes (global manufacturers, retailers, 3PLs, and asset‑light freight forwarders), including phased KPIs, integration patterns, and change‑management checklists.
-
Procurement templates: contract clauses for cloud cost pass‑throughs, service credits tied to delivery and event metrics, data governance and AI transparency obligations, and vendor exit/portability provisions.
-
Financial models and TCO templates (capex/opex tradeoffs, incremental margin impact, and sensitivity to hosting price inflation) that can be dropped into internal capital asks.
-
Security and compliance controls: zero‑trust architecture recommendations, third‑party risk assessment checklists, and operational controls aligned with current regulatory expectations.
Competitive landscape: how to read vendor differentiation
The vendor ecosystem in cloud logistics can be viewed through three pragmatic lenses: integrated ERP clouds, best‑of‑breed logistics suites, and specialist freight/forwarding platforms. Each category follows distinct commercial and technical tradeoffs buyers must weigh against their operating model.
-
Integrated ERP clouds (examples among incumbents): These providers leverage broad installed bases and offer end‑to‑end enterprise process continuity—from order to cash through logistics execution. Their strengths are in unified data models and single‑vendor support; tradeoffs include potential slower innovation cycles on logistics‑specific features and higher switching costs.
-
Best‑of‑breed logistics suites: Vendors focused on warehouse, transportation, and optimization bring deeper operational functionality and faster release cadences for logistics innovation. Their differentiation often lies in domain expertise, flexible deployment, and partner ecosystems for execution (carrier integrations, TMS/TM). However, integration effort and cross‑functional coordination are procurement considerations.
-
Freight‑forwarding and niche specialists: Platforms optimized for forwarding, customs, and cross‑border documentation deliver workflow efficiency and compliance strength for international trade flows. They can be attractive to freight forwarders and 3PLs but may require more extensive ERP interfaces for global shippers.
Notable competitive cues from recent market activity and our vendor review:
-
Longstanding logistics software vendors continue to defend enterprise footprints through integrated suites and ecosystem play—pushing customers toward bundled cloud‑managed offerings.
-
Cloud‑native, AI‑first entrants are accelerating capabilities for last‑mile orchestration and dynamic routing, intensifying competition in urban delivery and final‑mile SLAs.
-
Recognition and award activity among niche vendors underscores the continuing market appetite for specialized solutions that deliver rapid time‑to‑value in focused use cases such as freight forwarding and trade compliance.
-
Overall concentration metrics indicate meaningful market share for leading players, but enough fragmentation remains to permit strategic partnerships, regional champions, and acquisition opportunities.
Recent signals: product launches, recognition, and what they imply
Our monitoring of industry developments through early 2026 highlighted two signals worth noting for strategy teams:
-
A prominent last‑mile platform unveiled a unified AI‑driven logistics system that consolidates execution, analytics, and automation in a single cloud‑native stack—an explicit bet on bringing orchestration and optimisation closer to the delivery edge.
-
Specialist forwarding platforms continue to receive industry recognition for product maturity and customer satisfaction, emphasizing that vertical depth and executional fit still win deals, particularly for complex cross‑border flows.
Procurement and implementation counsel for 2026
Enterprises preparing to select or renew cloud logistics solutions in 2026 should institutionalize six practices immediately:
-
Treat hosting cost volatility as procurement risk—require transparent pass‑through mechanisms, caps, or multi‑year fixed elements where possible, and simulate cost shocks in TCO models.
-
Demand AI model documentation and risk assessments as part of RFP responses—this anticipates regulatory expectations and reduces downstream remediation costs.
-
Define composable integration boundaries—standardize on APIs and data models to avoid lock‑in and to enable best‑of‑breed composition.
-
Adopt zero‑trust and continuous monitoring requirements in security annexes, and make third‑party audit evidence a contractual prerequisite.
-
Prioritize early wins with focused pilots (e.g., route optimization, dock scheduling, customs automation) that generate measurable ROI within 6–9 months.
-
Preserve exit optionality—require structured data exports, runbook transfer support, and interoperability guarantees to safeguard future strategic pivots.
Strategic scenarios and recommended next steps
Based on our scenario modeling, enterprises should align vendor choices to one of three strategic paths:
-
Defensive consolidation: For firms seeking single‑vendor simplicity and deep ERP alignment, prioritize integrated clouds with defined roadmaps for logistics capability growth.
-
Operational differentiation: For companies competing on fulfillment speed and cost, adopt best‑of‑breed logistics suites and invest in API‑first integration and data fabrics.
-
Edge innovation: For urban delivery and last‑mile leaders, pilot AI‑driven orchestration platforms and develop carrier/partner networks that can be orchestrated through a single control tower.
Conclusion and how to use this briefing
This introduction provides the strategic framing enterprise leaders need to prioritize cloud logistics investments for 2026. The full PW Consulting report expands each of these themes with granular models, vendor scorecards, contractual language, and implementation templates that operational teams can use immediately. If your goal is to accelerate time‑to‑value while controlling cost and regulatory risk, the complete research package and downloadable tools will provide the practitioner‑level detail you need to act in 2026—without the need to reinvent frameworks or rebuild financial models from scratch.
To access the full dataset, segmentation models, and actionable playbooks referenced here, please consult the PW Consulting report portal for the Cloud Logistics Software Market 2026 edition.
For detailed analysis of this topic, please visit the official page: Cloud Logistics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fish Nets Market to Hit USD 3,501.15M by 2032 at 6.45% CAGR
By PW Consulting, 2026-07-13
Fish Nets Market — Strategic Outlook for 2026: A PW Consulting Industry Brief
By 2025 the global fish nets market had matured into a multi‑billion dollar industry, underpinned by steady demand across commercial fishing, aquaculture and recreational segments and a clear technological shift in materials and end‑of‑life strategies. Our modeling, which uses 2025 as the base year and projects through 2032, indicates a compound annual growth rate (CAGR) of 6.45% across the forecast window. For corporate leaders planning budgets, R&D roadmaps, or M&A activity in 2026, the strategic inflection points identified in this brief should determine where to allocate capital and where to defer investment.
Fish Nets Market
Why this market matters in 2026
-
Durable demand with premiumization potential: The market is growing at a mid‑single digit CAGR, driven both by traditional consumption patterns and rising professionalisation within aquaculture. This translates into predictable baseline volumes, with margins increasingly driven by product differentiation rather than commodity pricing alone.
Fish Nets Market -
Sustainability as a structural force: Regulatory and buyer pressure to reduce ghost gear and microplastic impact is accelerating adoption of recycled, regenerable and biodegradable options. Early pilots and product launches have moved beyond the lab — they are now relevant to go‑to‑market timing and procurement specifications for 2026 contracts.
Fish Nets Market -
Materials and service convergence: The rise of high‑performance polymers (e.g., HDPE/UHMWPE) and circular nylons is changing the lifecycle profile of nets: lighter, longer‑lasting nets alter replacement cadence, logistics costs and aftermarket services revenue.
-
Concentration and competitive dynamics: The three‑ and five‑firm concentration metrics show a market where leading specialists matter, but room remains for nimble regional players and technology partners to capture share through innovation and vertical integration.
Key market drivers and near‑term shocks to watch
-
Regulatory acceleration: Tighter national and port regulations on ghost gear disposal, plus procurement mandates for recycled content in several major buyer segments, will turn sustainability compliance into a procurement checklist item rather than an optional feature.
-
Material innovation: Approximately one third of newly manufactured nets in recent industry sampling incorporated HDPE or UHMWPE fibers, delivering meaningful gains in durability and weight reduction. Parallel developments in marine‑biodegradable polymers and regenerated nylons will reframe lifecycle cost analysis for 2026 purchasing cycles.
-
Supply chain and input cost volatility: Fibers, additives and finished twine remain exposed to petrochemical cycles and logistics constraints. Firms that secure upstream agreements or vertically integrate polymer supply will hold a margin advantage.
-
Circularity and recycling economics: Recycling discarded nets back into nylon has quantifiable environmental and cost advantages; lifecycle accounting now factors significant CO2 and externality avoidance when comparing solutions.
What PW Consulting’s Fish Nets Market report delivers — practical content for decision makers
-
Top‑down and bottom‑up market sizing with transparent assumptions: our 2020–2025 historical reconciliations and 2026–2032 forecast model include demand drivers, replacement cycles and price curves expressed in USD (millions) — full model available in the report’s download package.
-
Segmentation framework: modular analysis by type (knotted vs. knotless), application (commercial fishing, aquaculture, recreational) and regional demand drivers — the report includes our proprietary elasticity matrices and sensitivity scenarios.
-
Competitive scorecards and supplier heatmaps: in‑depth profiles of incumbent manufacturers, challenger specialists and material innovators with strategic recommendations for partnering, sourcing and supplier consolidation.
-
Technology & sustainability audit: lifecycle comparisons (durability, weight, recyclability), pilot case studies, and a regulatory tracker that translates policy into procurement actions.
-
Commercial playbooks and procurement tools: RFP templates, TCO calculators (material vs. service tradeoffs), replacement‑cycle optimization models and go‑to‑market blueprints tailored to OEMs, distributors and aquaculture operators.
-
Scenario planning and deal pipeline support: three downside/upside scenarios for demand and pricing, plus M&A targets identified by strategic fit and EBITDA uplift potential.
Competitive landscape — what leading firms are doing and why it matters
-
Nitto Seimo Co., Ltd. (Tokyo, Japan): A broad portfolio player across knotted and knotless solutions with strong product engineering capability. Recent corporate communications emphasize technology and customer solutions — a signal that the firm is repositioning to compete on premium, integrated offerings rather than volume alone.
-
King Chou Marine Technology Co., Ltd. (Kaohsiung, Taiwan): Established specialist with deep manufacturing expertise in purse seine and aquaculture nets. Their strengths are scale in regional markets and customization capabilities, making them a preferred OEM partner for buyers seeking tailored nets and cage systems.
-
Garware Technical Fibres Limited (Pune, India): A materials‑driven competitor focused on HDPE and performance rope technologies. They represent the archetype of a materials supplier that can capture value as fibers become the differentiator in total cost and durability calculations.
-
Miller Net Company Inc. and Memphis Net & Twine Company Inc. (Memphis, USA): North American manufacturers and distributors that excel in custom solutions and aftermarket servicing. Their channel strengths and service networks are strategic assets as replacement cycles lengthen but service complexity grows.
-
AKVA group (Egersund Net), Badinotti Group, Momoi Fishing Net Mfg. Co., Ltd.: These regional and product specialists combine advanced aquaculture net systems, purse seining expertise and integrated synthetic fibre capabilities. Their competitive playbooks focus on vertical solutions for aquaculture farms and industrial fleets.
-
Material and circularity entrants (e.g., Aquafil/Diopas collaborations, GAIA Biomaterials pilots): innovators in regenerative nylon and marine‑biodegradable polymers are already moving from pilot to commercial proofs. Their partnerships with net manufacturers create asymmetric opportunities: firms that secure first‑mover supply agreements will own the sustainability story for major buyers.
Notable recent developments to factor into 2026 plans
-
Product and pilot activity: Pilots of biodegradable PBS‑based nets in African commercial fisheries and launches of fully circular aquaculture nets from regenerated nylon indicate that sustainable alternatives are commercially viable and will be on procurement radar in 2026.
-
Digital and brand repositioning: Several established manufacturers have refreshed their customer‑facing platforms to emphasize technology and services — an indicator that selling features alone is giving way to selling outcomes (reduced downtime, lower total cost, regulatory compliance).
-
Material performance gains: Industry sampling shows a meaningful slice of new production adopting HDPE/UHMWPE fibers, offering higher durability and lower weight — these technical improvements materially affect logistics, handling and vessel fuel implications.
-
Environmental accounting: Recycled nylon pathways are being quantified with lifecycle benefits (significant CO2 avoidance and externality cost reductions per tonne) — this is influencing buyer decisions where sustainability is procurement criteria.
Strategic recommendations for 2026 — a concise playbook
-
For manufacturers: Prioritize product variants that align with circularity mandates and secure upstream polymer partnerships. Invest selectively in demonstration pilots with flagship buyers to accelerate specification adoption.
-
For material suppliers: Focus on certification, traceability and cost‑to‑recycle economics; offer bundled supply agreements that reduce buyer switching friction.
-
For aquaculture operators and fleet owners: Shift procurement evaluation from unit price to total cost of ownership — include replacement cadence, logistics and end‑of‑life handling in bid evaluations.
-
For distributors and service providers: Expand aftermarket services (repair, certified recycling collection) as a hedge against longer net lifespans and a revenue stream as product sales commoditise.
-
For investors and private equity: Screen targets for technology partnerships and sustainable product roadmaps — assets that combine manufacturing scale with access to circular material sources will show disproportionate value uplift.
How to use this brief and next steps
This introduction is a strategic preview: it highlights the macro trajectory, the forces reshaping supplier economics, and the competitive moves that will determine winners in 2026. The full PW Consulting Fish Nets Market report contains granular segment modeling, downloadable forecast spreadsheets, supplier scorecards, procurement templates and scenario stress tests. If you are allocating capital, negotiating multi‑year supply contracts, or setting product roadmaps for 2026, the complete report and its analytical appendices will convert these strategic insights into executable plans.
For access to the full dataset, proprietary models and supplier heatmaps — including our detailed breakdowns by type, application and region — consult the PW Consulting publication page for the Fish Nets Market study. Our team is available to walk through the model, run bespoke scenarios for your portfolio, or help craft an M&A or partnership thesis calibrated to the 2026 decision timeline.
For detailed analysis of this topic, please visit the official page: Fish Nets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Purity Tungsten Market to 2032 — USD 1,001.64M, 6.5% CAGR
By PW Consulting, 2026-07-13
High Purity Tungsten Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest High Purity Tungsten Market study is designed as a decision‑grade intelligence package for corporate strategists, procurement leaders, and investors gearing up for the 2026 planning cycle. Built on a full historical series (2020–2025) and a forward forecast (2026–2032), the analysis combines a robust demand model, supply‑side mapping, and scenario stress‑tests to translate commodity dynamics into executable business options.
High Purity Tungsten Market
Why this study matters in 2026
-
Strategic inflection. The high purity tungsten market is transitioning from a niche industrial material into a strategic raw material for advanced electronics, semiconductor sputtering targets, and select aerospace/medical applications. That transition creates both volatility and structurally higher long‑term value—requiring distinct strategic choices for suppliers, consumers, and financiers.
High Purity Tungsten Market -
Policy and trade shocks. Recent policy moves—tariff increases and export controls—have altered supply economics and rendered previously robust sourcing strategies fragile. Procurement teams and corporate strategists must reconcile short‑term price volatility with longer term supply security objectives.
High Purity Tungsten Market -
Capital allocation decisions. With the market on a growth trajectory and increasing interest in upstream project development, 2026 is a pivotal year to decide on greenfield investments, offtake agreements, and M&A plays that will determine access to high‑purity feedstocks for the decade ahead.
Market snapshot — the macro view
Our macro model tracks the high purity tungsten market from roughly USD 462 million in 2020 to approximately USD 645 million in 2025, driven by stronger electronics demand and constrained feedstock flows. We project the market to expand at a compound annual growth rate (CAGR) of about 6.5% over the 2026–2032 forecast window, reaching roughly USD 1.0 billion by 2032 under the baseline scenario. These headline numbers mask significant structural shifts beneath the surface—changes in buyer concentration, grade mix, feedstock sourcing, and the role of geopolitical policy—that materially affect margin pools across the value chain.
Key market dynamics reshaping strategy
-
Feedstock tightness and price volatility. Ammonium paratungstate (APT), the primary intermediate for high purity production, experienced acute price moves driven by supply controls and trade measures—creating immediate margin pressure for processors and downstream buyers. Rotterdam and domestic price indicators tracked sharp increases through 2025–2026, underscoring the need for explicit raw‑material risk management in contracts and forecasting.
-
Regulatory and trade interventions. Major jurisdictional actions—most notably increased tariffs on imports from China in the U.S., and Chinese export controls on selected tungsten intermediates—have elevated the cost basis for cross‑border flows and accelerated regionalization of processing capacity. These interventions change commercial calculus for sourcing and capital projects and require continuous monitoring in supplier selection frameworks.
-
Supply response and new project pipeline. The supply side is responding: new mining production and advanced project developments in multiple jurisdictions, together with targeted public funding for domestic capacity in several markets, will change availability over the medium term. However, upstream lead times and metallurgy constraints mean that supply elasticity will remain limited in the near term.
-
Consolidation and concentration. The market exhibits moderate concentration: incumbent manufacturers and integrated material houses retain dominant shares of high‑purity manufacturing capabilities. This concentration supports pricing discipline but also raises counterparty risk for large raw‑material consumers.
What the PW Consulting report delivers (practical, operational modules)
-
Interactive demand model — build your own scenarios by application, purity grade, and procurement horizon (baseline, upside, downside).
-
Supply chain map — from concentrate to ultra‑high purity metal and finished components, identifying single points of failure and alternative routing options.
-
Price and feedstock sensitivity matrices — quantify margin exposure across realistic APT price trajectories and tariff permutations.
-
Regulatory watchlist and export‑control matrix — jurisdictional rules and likely policy pathways that impact trade flows and permitting timelines.
-
Company profiles and capability heatmap — strengths, technological differentiators, capacity footprints, and counterparty risk indicators (detailed supplier dossiers included for leading market participants).
-
Project evaluation templates — capex/opex heuristics, payback thresholds, and blended cost of supply models tailored for greenfield and brownfield investments.
-
Commercial playbooks — procurement levers, hedging blueprints, offtake negotiation frameworks, and M&A screening criteria focused on 2026 execution.
Competitive landscape — strategic reads on core participants
-
Elmet Technologies LLC (Lewiston, ME, USA) — Fully integrated U.S. manufacturer with reduction‑based powder making and downstream mill products. Elmet’s integration gives it defensible margin control and fast response times to North American demand surges. Strategic implication: attractive partner for short‑term offtake and for firms seeking to shorten supply lines, but scale limitations may constrain large program commitments without capacity expansion.
-
Buffalo Tungsten Inc. (Depew, NY, USA) — Independent specialist focused on ultra‑high purity powders and tungsten carbide powders. Buffalo’s product purity and niche customer relationships make it a preferred supplier for high‑value electronics work; however, independents remain exposed to feedstock cost shocks and freight disruptions.
-
Global Tungsten & Powders (GTP) — Plansee Group affiliate — A major integrated materials house with broad downstream capabilities, positioned to capture value across the chain (powder, chemicals, components). GTP’s global footprint and downstream product mix reduce single‑point exposure, making it a logical counterparty for OEMs seeking supply continuity and technical partnerships.
-
H.C. Starck / Plansee Group / A.L.M.T. / JX Nippon / Xiamen / Chongyi Zhangyuan / Masan High‑Tech — A mix of European, Japanese, Chinese and Southeast Asian manufacturers covering a range of technological capabilities—from specialty powders and wires to large‑scale powder production. The competitive set presents a spectrum of tradeoffs between cost, quality, speed, and geopolitical exposure. Strategic buyers must weigh price against security and qualification lead times for critical applications.
Recent developments that change the game
-
Project momentum in exploration and development has picked up—new staking and land expansions in North America and project approvals in Europe create optionality for future feedstock supply lines.
-
Trade and regulatory measures enacted since late 2024 and into 2025 have meaningfully tightened cross‑border flows of key intermediates and prompted buyers to re‑evaluate sourcing and inventory policies.
-
Public funding and strategic programs in mine jurisdictions are reducing some sovereign risk, but not eliminating short‑term price spikes driven by immediate constraints in processing and transport.
Actionable plays for corporate leaders in 2026
-
Adopt a two‑tier procurement strategy: secure a core of qualified, long‑term suppliers (to cover critical needs) and maintain a flexible margin of opportunistic purchasing to exploit spot dislocations.
-
Hedge selectively using contract structures that share raw‑material risk—indexation clauses, blended pricing corridors, and multi‑year offtake with escape provisions for extreme policy moves.
-
Prioritize qualification pipelines: accelerate qualification of alternative suppliers and regional sources (even at a premium) for mission‑critical components to shorten response time in supply shocks.
-
Assess vertical integration selectively: for manufacturers with scale, upstream processing or strategic equity stakes in concentrate projects can be accretive—model conservatively and stress‑test on delayed ramp scenarios.
-
Target bolt‑on M&A where it reduces counterparty risk or speeds time‑to‑market for higher‑purity grades; for investors, look for platform assets with repeatable processing technology and locked‑in offtake.
-
Invest in materials R&D that substitutes high‑cost grades or improves recovery—small improvements in yield or downstream processing can materially change unit economics over multi‑year production runs.
Why PW Consulting’s study is different
Beyond conventional market sizing, our study ties macro dynamics to micro decisions through an integrated demand/supply/risk model and an actionable toolkit for 2026. We combine granular supplier intelligence, a dynamic pricing sensitivity engine, and regulatory scenario mapping so that commercial, procurement, and corporate development teams can run "what‑if" strategies and produce investment‑grade outputs suitable for Board review.
Note: this briefing emphasizes strategic takeaways and constrained disclosure by design. Core subsegment tables, granular regional shares, and application‑level revenue splits are intentionally withheld from this public overview to preserve the report’s commercial integrity. Full access to the segmentation, supplier dossiers, and interactive models is available through the PW Consulting report portal.
Immediate next steps for readers
-
Procurement & Supply Chain leads — request the report’s procurement playbook and the supplier risk heatmap to incorporate into 2026 sourcing cycles.
-
Corporate Strategy & M&A teams — schedule a scenario workshop to test acquisition and investment hypotheses against our baseline and downside cases.
-
Investors & Project Developers — use the project evaluation templates and offtake framework to fast‑screen opportunities in the new supply pipeline.
For organizations that need to convert market signals into executable plans in 2026, this study provides the models, vendor intelligence, and tactical playbooks to act with conviction. Access to the full study, including the underlying segmentation tables, supplier dossiers, and the interactive forecast model, is available via PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micro System Analyzer Market to Hit USD 431.2M by 2032 at 8.36% CAGR
By PW Consulting, 2026-07-13
Micro System Analyzer Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
The Micro System Analyzer (MSA) market sits at an inflection point. After a steady recovery and expansion through the early 2020s, the global market escalated from a modest base in 2020 to a substantially larger industry by 2025, and our forecast shows continued acceleration through 2032. PW Consulting’s baseline model projects a compound annual growth rate (CAGR) of 8.36% across the 2026–2032 forecast horizon, reflecting rising demand for non‑contact optical characterization, tighter product qualification cycles, and broader adoption across high‑value end markets. In absolute terms, the market nearly doubles over the next several years under our central scenario, driven by technology maturation, higher test-throughput requirements at wafer and device level, and expanding applications that demand precise dynamic and topographic measurement.
Micro System Analyzer Market
Why this research matters for 2026 corporate decisions
-
Timing for capital allocation: An 8%+ structural growth trajectory means executives must decide whether to accelerate capital deployment in test equipment, or to pursue capacity-light options (contract test services, partnerships) to capture growth without over-investment.
Micro System Analyzer Market -
R&D and product roadmap prioritization: As measurement capabilities move from single-point probing to integrated, non-contact optical workstations, product teams must weigh embedding measurement-friendly features (test hooks, design-for-measurement) against system cost and manufacturability tradeoffs.
Micro System Analyzer Market -
M&A and partnership strategies: A market with noticeable concentration at the top creates premium for bolt-on capabilities—companies can buy optics competency, software analytics, or expand into wafer-level quality assurance through targeted acquisitions or co-development agreements.
-
Regulatory and reimbursement posture for medical applications: Non-contact dynamic characterization is gaining acceptance in medical device development workflows. Decision makers in med‑tech need to integrate validated measurement protocols early to shorten clinical and regulatory cycles.
What PW Consulting’s Micro System Analyzer Market report delivers
Our study is designed as a practical playbook for leaders making investment, product, and market entry decisions in 2026. The report combines proprietary market sizing and scenario-driven forecasts with market structure diagnostics and tactical tools for execution. Highlights include:
-
A transparent market model—historical time series (2020–2025) and forward-looking scenarios for 2026–2032—allowing financial planners to stress test capital plans against upside/downside demand trajectories.
-
Technology deep dives that decode performance envelopes (frequency, spatial resolution, throughput) and map product families to typical use cases (R&D, wafer‑level inspection, reliability testing).
-
Action-oriented go‑to‑market modules—buyer personas, procurement decision trees, and commercial playbooks for OEMs, test houses, and academic labs.
-
Competitive benchmarking and capability matrices that identify where incumbents dominate and where white‑space exists for new entrants or adjacent players.
-
Investment and M&A scoring tools that rank targets against integration risk, time‑to‑market contribution, and margin accretion potential.
-
Risk registers and mitigation roadmaps covering supply chain fragility, software validation, and evolving regulatory scrutiny—especially for biomedical applications.
To preserve the value of the dataset for our subscribers, this public overview purposely omits granular regional and application segment figures. The full report includes those breakdowns alongside downloadable financial models and primary‑research transcripts.
Competitive landscape: focus on Polytec and market structure
Market structure matters for strategy. Our concentration analysis indicates the market is neither highly fragmented nor monopolized—top vendors capture a meaningful share of demand, creating advantages in scale, installed base, and aftermarket services. That balance produces both stability for incumbent margins and windows of opportunity for innovative entrants.
Polytec GmbH emerges as the most visible incumbent in the MSA category. The company’s MSA series—positioned as all‑in‑one, optical, non‑contact workstations—serves static and dynamic three‑dimensional characterization needs across MEMS and microsystems development. Key strategic implications from Polytec’s footprint:
-
Product breadth and depth: Polytec’s lineup spans instruments optimized for high‑frequency vibration analysis through to comprehensive surface topography mapping. For buyers, this creates a compelling single‑vendor option for multi‑stage workflows (R&D → wafer test → reliability).
-
Clinical and biomedical relevancy: Polytec explicitly supports non‑contact characterization of biomedical samples and medical MEMS devices. For med‑tech firms, the ability to validate dynamic behavior without mass loading is a material advantage for device verification and regulatory filing strategies.
-
Channel and service moat: Mature instrumentation vendors like Polytec typically benefit from installed‑base lock‑in via calibration, software updates, and training—elements that increase switching costs for key R&D and production customers.
-
Competitive posture: New entrants should plan to undercut incumbents on either cost or data‑centric features (analytics, integration with PLM/ALM systems). Incumbents will likely respond by deepening software ecosystems and expanding test services.
Key market dynamics and risks to model into 2026 planning
-
Adoption versus commoditization: As optical and data‑processing components scale, certain measurement functions may commoditize, compressing hardware margins but raising value of software and services.
-
Regulatory tailwinds and constraints: Non‑contact measurement supports medical device validation without introducing measurement artifacts—a strategic benefit—but it also introduces scrutiny over traceability and validation protocols. Companies must prepare for tighter documentation and auditability in clinical pathways.
-
Supply chain concentration: Specialized opto‑electronic components and high‑precision mechanics remain concentrated among a handful of suppliers. Procurement strategies should include multi‑sourcing or long‑lead contracting for critical parts.
-
Consolidation dynamics: Given meaningful share captured by leading vendors, strategic acquisition activity is likely around software analytics, automated inspection integration, and wafer‑level throughput improvements.
2026 playbook: recommended actions for executives
-
Integrate measurement strategy into product design cycles. Treat non‑contact characterization capabilities as first‑class design requirements to reduce iteration and accelerate qualification.
-
Prioritize pilot deployments with clear KPIs. Run small, cross‑functional pilots that pair MSA vendors with manufacturing test engineers to validate throughput, yield impact, and process integration before scaling procurement.
-
Hedge hardware risk by buying modularity. Specify instruments with modular optics and upgradeable software so you can extend useful life and protect against early obsolescence.
-
Evaluate M&A or partnership for rapid capability acquisition. For those seeking near‑term entry into wafer‑level testing, acquiring analytics or service capabilities offers faster path to market than in‑house development.
-
Lock in regulatory certainty early. For medical device programs, mandate validated measurement protocols and traceable calibration practices during preclinical stages to de‑risk later submission delays.
How to use this report in Q1 2026
Leadership teams should treat the report as an execution tool rather than a theoretical brief. Immediate uses include: model-driven capital budgeting that ties equipment buys to revenue scenarios; configuration checklists for procurement that articulate must‑have technical specs; target lists for M&A screening; and regulatory playbooks for medical device qualification. Each deliverable in the report is paired with templates—RFP language, ROI calculators, and pilot test plans—to move from decision to deployment within a single fiscal quarter.
Conclusion and next steps
The Micro System Analyzer market offers disciplined growth and strategic leverage for organizations that decide early and design measurement strategy into their product and production lifecycles. PW Consulting’s research synthesizes market sizing, technology assessment, competitive insight, and executable playbooks to shorten the path from insight to impact in 2026.
Note: this overview highlights our core findings while intentionally withholding the granular regional and application split data and downloadable financial models that subscribers receive. To access the full dataset, vendor matrices, and the scenario financial model that powers our CAGR and forecast, please visit the report landing page or contact PW Consulting’s industry practice for a demo and sample worksheets.
For detailed analysis of this topic, please visit the official page: Micro System Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


