



PW Consulting: Recovered Carbon Black (RCB) Market to Grow at 11.5% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Recovered Carbon Black (rCB) Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
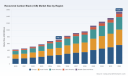
Recovered carbon black (rCB) has moved rapidly from niche sustainability pilots into a commercially material segment of the carbon black industry. Our PW Consulting Recovered Carbon Black Rcb Market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—documents a clear, investment-grade growth trajectory: the rCB market expanded materially between 2020 and 2025 and is projected to compound at a double-digit clip (11.5% CAGR) into the early 2030s. By 2025 the market reached a level that demands serious strategic attention from tire makers, masterbatch formulators, coatings companies and raw-material traders; by 2032 the market is expected to be more than double the size it was in 2020.
Recovered Carbon Black Rcb Market
Why this matters for 2026 corporate strategy
-
Supply security & cost resilience: rCB introduces a new upstream vector that can reduce exposure to fossil-derived feedstock pricing cycles. For companies deciding 2026 procurement strategies, rCB supply agreements and feedstock partnerships can be structured to complement traditional carbon black sourcing while de‑risking long-term cost volatility.
Recovered Carbon Black Rcb Market -
Regulatory arbitrage and market access: policy moves—most notably European recognition of tire pyrolysis as a recovery process and the emergence of ISCC PLUS for circular carbon—create a compliance and commercial pathway for rCB to be treated as a non‑waste, tradeable input. Firms adjusting product specifications or sustainability claims in 2026 will need to embed certification prerequisites into procurement contracts.
Recovered Carbon Black Rcb Market -
Product strategy and margin management: rCB’s current material properties (purity levels that are lower than top‑grade virgin carbon black) create both opportunity and constraint. 2026 decisions will hinge on pragmatic product segmentation—where to deploy rCB blends without compromising performance, and where to retain virgin carbon black for high‑stress applications.
-
M&A and capex prioritization: the rCB value chain is consolidating but far from mature (market concentration shows leading groups do not yet dominate the sector). For corporates evaluating inorganic growth or greenfield investments in 2026, the market offers attractive bolt‑on and joint‑venture prospects, particularly for firms that can marry feedstock access to downstream integration.
Market trajectory — what the headline data says
Our modeling, which synthesizes historical data and primary interviews across the value chain, shows robust expansion from the early 2020s into the 2030s. After a multi‑year ramp from 2020 to 2025, the market’s compound annual growth rate during the forecast window points to sustained demand pull and accelerating commercialization. This macro momentum is driven by three structural forces: increasing tire and rubber recycling rates, industrial adoption for lower‑risk elastomer and non‑tire applications, and policy frameworks that reward circular inputs.
Competitive landscape — who to watch (and why)
The rCB competitive set is populated by technology‑led specialists and strategic initiatives from incumbent tyre and chemical players. Key profiles include:
-
Pyrolyx AG (Germany) — A commercial pyrolysis producer that has moved from demonstration to industrial production. Pyrolyx’s early plant commercialization provides practical evidence that scaled rCB supply can meet industrial reinforcement specifications, supporting integration strategies for downstream users.
-
Black Bear Carbon (Netherlands) / Michelin partnership — Backed by a major tire manufacturer, this operation is emblematic of the “buyer‑backed” approach to feedstock security and quality control. Strategic partnerships of this sort materially shorten commercialization timelines and reduce technical adoption risk for tyre makers.
-
Enviro AB (Sweden) — Focused on certification and compliance, Enviro’s attainment of circularity credentials demonstrates the importance of verified sustainability chains for market acceptance, especially in Europe.
-
Hi‑Green Carbon (India) — A lower‑cost regional producer whose ISCC‑certified production lines and proximity to feedstock pools illustrate the geographic arbitrage and trade flows that will shape regional supply dynamics.
Market concentration remains moderate: the top three and top five suppliers do not yet command an overwhelming share of the market, leaving room for new entrants and consolidation. That balance favors strategic buyers who can secure preferential supply or form joint ventures without paying monopoly premia.
Regulatory and technical dynamics impacting 2026 decisions
-
Regulatory recognition and certification: The EU Waste Framework’s treatment of pyrolysis outputs and the adoption of ISCC PLUS establish a compliance framework that allows rCB to be commercially used and marketed as circular. Companies planning 2026 product claims must lock in certified supply and ensure mass‑balance bookkeeping.
-
Purity and application scope: rCB purity presently sits below the highest‑performance virgin grades. This technical constraint will dictate a phased adoption: early wins will be in non‑critical rubber goods, some plastics/masterbatch formulations and selected coatings/inks, with gradual penetration into higher‑performance tire compounds as R&D advances.
-
Trade and tariffs: Regional fiscal treatments (including import duties in certain jurisdictions) will influence global sourcing strategies. These are tangible near‑term considerations for companies designing 2026 cross‑border procurement programs.
What our report delivers — practical outputs for 2026 action
The PW Consulting Rcb Market report is intentionally built for decision makers who need executable recommendations, not just high‑level commentary. Key deliverables include:
-
Global market model with scenario and sensitivity analysis—enabling buyers and investors to stress‑test demand, feedstock availability and price pathways without exposing proprietary segment splits in this preview.
-
Supplier due‑diligence and scorecard toolkit—covering technology maturity, certification status, feedstock security, and commercial reliability to accelerate vendor selection.
-
Procurement playbook—templates for offtake agreements, quality acceptance criteria, and contract provisions that incorporate certification and traceability clauses.
-
Commercial adoption roadmap—segment‑by‑segment go‑to‑market sequencing, pilot design checklists, and KPI frameworks to measure performance during 2026 rollouts.
-
CapEx and investment decision matrix—an interactive framework for evaluating greenfield vs. JV vs. supplier partnerships, with trigger thresholds for investment readiness calibrated to market growth and concentration dynamics.
-
Regulatory and certification checklist—practical steps to achieve ISCC compliance, engage with authorities and ensure claims are auditable across multiple jurisdictions.
Case actions for 2026 (recommended)
-
Secure short‑to‑mid term offtake: Negotiate staggered offtake volumes with certified suppliers to de‑risk supply while preserving optionality as product acceptance evolves.
-
Embed certification requirements: Make ISCC (or equivalent) certification a contractual condition for sustainability claims and corporate reporting.
-
Run targeted formulation pilots: Prioritize non‑critical rubber and plastics applications where rCB performance parity is closest, then scale into higher‑risk tire applications only after validated performance data and lifecycle assessments.
-
Design a blended sourcing strategy: Combine regional low‑cost producers with strategic local partners to balance price, logistics and regulatory exposure.
-
Allocate a small strategic M&A war chest: Use it to secure minority stakes in technology‑proven producers or recycling networks that provide privileged access to feedstock.
Where the uncertainty lies—and how the report helps
-
Feedstock price volatility and competition for scrap tires: Increased recycling demand can drive feedstock costs. Our forecast scenarios quantify impacts on margin and recommend hedging and vertical integration strategies.
-
Technical parity with virgin carbon black: Current purity gaps limit some tyre tread applications. The report includes an R&D prioritization guide and blending decision matrix to minimize performance tradeoffs.
-
Policy tailwinds and trade friction: Divergent regional treatments create both arbitrage and compliance complexity; our regulatory matrix maps actions by jurisdiction to keep 2026 strategies compliant and efficient.
Final thoughts — the 2026 strategic inflection
Recovered carbon black is no longer a speculative sustainability experiment; it is a maturing industrial commodity with clear pathways to scale and meaningful implications for cost structures, product positioning and sustainability claims. The macro indicators point to rapid expansion through the remainder of the decade, but the commercial story will be written in 2026 by firms that move from assessment to disciplined operational execution—locking in certified supply, proving formulations in prioritized applications, and using structured procurement and investment frameworks to capture upside while managing purity and regulatory constraints.
Next step
This briefing is a curated preview designed to help senior leaders frame 2026 choices. Our full PW Consulting Recovered Carbon Black Rcb Market report contains the granular forecasting, supplier performance benchmarking, contractual templates and scenario models you will need to operationalize the recommendations above. Visit the report page to access the complete dataset, downloadable toolkits and supplier matrices that support immediate execution.
For detailed analysis of this topic, please visit the official page: Recovered Carbon Black Rcb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Diamond Grit Market — 5.2% CAGR to USD 3,065M by 2032
By PW Consulting, 2026-07-13
Synthetic Diamond Grit Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Synthetic Diamond Grit Market study provides a focused, decision-ready view for companies preparing strategy, sourcing, and investment plans in 2026. At a market level, the industry demonstrates steady, resilient growth: from an estimated USD 2,150.5 Million in 2025 to a projected USD 3,065.05 Million by 2032, representing a 5.2% compound annual growth rate across the 2026–2032 forecast window. Our research draws on a 2020–2025 historical baseline and a 2026 forward-looking modelling framework (base year 2025), combining primary interviews, plant-level economics, and trade/regulatory scenario analysis to produce operationally relevant guidance.
Synthetic Diamond Grit Market
Why this matters for 2026
- Market momentum. The mid-single-digit CAGR underlines an industry moving beyond cyclical volatility into structural demand drivers tied to infrastructure, precision manufacturing, and high-performance materials.
- Timing of choices. Capital allocation, capacity expansions, and supply-contract renegotiations executed in 2026 will determine competitive positioning for the next seven years of growth reflected in our forecast.
- Complex levers. Price exposure (feedstock and freight), regulatory shifts, and evolving end-use requirements (from heavy sawing to semiconductor polishing) create a narrow window where operational agility converts to market share gains.
Market trajectory and what the numbers imply
The market’s recent trajectory shows consistent year-on-year expansion through 2025, with the structural drivers expected to sustain growth into the 2030s. Our scenario modelling incorporates baseline demand for industrial abrasives, incremental gains from advanced polishing in electronics, and cyclical influences from construction and mining. While headline figures indicate attractive growth, strategic implications differ by value chain node: raw-material sourcing and energy intensity are critical for producers; supply reliability and product-grade diversification matter most to toolmakers and OEMs.
Synthetic Diamond Grit Market
Competitive landscape — what to watch
The synthetic diamond grit ecosystem includes global leaders with diversified technical portfolios and vertically integrated producers focused on volume and cost. The market exhibits moderate concentration (CR3 and CR5 metrics indicate a cluster of established multinationals alongside numerous regional specialists), which creates both partnership and consolidation opportunities.
Synthetic Diamond Grit Market
- Global technology leaders: Established players with HPHT and CVD capabilities continue to push technical differentiation into electronics and precision grinding applications. New product launches aimed at high-value polishing segments are shifting value away from commodity grit supplies.
- Regional manufacturers: Several Asia-based manufacturers drive scale in construction- and stone-processing grades. Their strengths lie in cost competitiveness and proximity to heavy end markets.
- Specialist suppliers: Firms focusing on high-strength or application-specific grades (e.g., thermal-stable grits for high-speed sawing or high-purity pellets for semiconductor polishing) are capturing premium niches.
Recent notable corporate moves include new high-purity products for semiconductor polishing, capacity expansions targeted at stone-processing demand, and launches of thermally stable grades for high-speed sawing—each signaling where profitable growth is emerging. Our competitive assessment maps these developments against technology roadmaps and customer procurement cycles to identify likely winners and vulnerable incumbents.
Supply chain, cost drivers and operational risk
Three supply-side dynamics will dominate strategic choices in 2026:
- Feedstock and energy intensity. Graphite—which remains a principal feedstock for HPHT synthesis—has shown price volatility; supply-chain sensitivities and feedstock sourcing strategies materially affect production cost curves. HPHT production’s energy consumption is non-trivial and has been highlighted in regulatory and carbon-accounting frameworks.
- Transport and logistics. Ocean freight volatility is impacting landed costs for continent-spanning supply chains. Recent freight-rate increases materially raise shipment economics for low-value, high-weight consignments and alter the optimum location for inventory and toll-processing facilities.
- Trade and regulatory regimes. Tariff regimes and chemical-materials regulations create pricing and compliance layers that must be modelled into sourcing decisions. Import duties and nano-material registration requirements can change go-to-market math quickly for cross-border flows.
Regulatory and environmental dynamics — implications for 2026 planning
Regulatory developments are not peripheral; they reshape cost structures and market access. Key dynamics to account for in strategic planning include:
- Nanomaterial registration requirements in major markets, which affect formulations and mixture approvals for certain abrasive products.
- Tariff and trade measures that can materially alter landed costs for imports from specific countries—necessitating alternative sourcing or local footprint adjustments.
- Energy and carbon accounting frameworks that increasingly influence the competitiveness of HPHT versus alternative synthesis routes and may drive relocation or investment in low-carbon energy at scale.
Sector-specific demand signals
Different end-use sectors present distinct growth, margin, and product-quality profiles:
- Construction and stone-processing remain volume anchors; price sensitivity and delivery reliability govern vendor selection.
- Automotive and aerospace require tighter specifications and traceability, presenting opportunities for premium pricing where certification and supplier quality systems are demonstrable.
- Electronics and semiconductor polishing represent the highest margin growth corridor, but require rigorous R&D, long qualification cycles, and tight supply security.
What PW Consulting’s report delivers — practical, operable outputs
We structure the deliverables to support the decision calendar of C-suite, commercial, and procurement teams in 2026:
- Strategic scenarios and playbooks: three actionable pathways (scale, specialize, partner) with trigger points and capex/ROI sensitivities modelled under alternative cost and regulatory scenarios.
- Commercial tactics: customer-segment scorecards, value-capture levers by application, and pricing playbooks that integrate freight and tariff overlays.
- Supply-chain diagnostics: supplier scorecards, recommended hedging strategies for feedstock, and a roadmap for nearshoring vs. offshore procurement backed by landed-cost modelling.
- M&A and partnership screening: a prioritized list of acquisition and JV archetypes, integration risk profiles, and suggested due-diligence metrics focused on technology, quality systems, and energy footprint.
- Operational benchmarks: plant-level throughput, energy consumption norms, and productivity KPIs to inform capital investment sizing and retrofit decisions.
How to use this research in 2026
Senior leaders should treat the report as a tactical blueprint for the year ahead:
- Procurement teams: re-run supplier TCO with updated freight and compliance assumptions; implement short-term hedges where exposure is highest.
- Business development and R&D: prioritize qualification efforts in semiconductor and high-precision grinding segments where premium margins and long-term contracts justify development spend.
- Finance and strategy: stress-test capital projects against carbon-accounting scenarios and tariff contingencies; use our scenario outputs to set hurdle rates and staging conditions for expansions.
- M&A teams: use the target archetypes and integration playbooks to accelerate screening and reduce transaction timelines.
Risks and early-warning indicators
Key early-warning indicators to monitor through 2026 that would necessitate tactical course corrections:
- Feedstock and energy price spikes or regional supply disruptions.
- New or tightened regulatory requirements for nano-component registration or carbon-embedded tariffs in major consuming regions.
- Sharp freight-rate shifts or port congestion that push landed costs beyond threshold economics.
- Acceleration of technical substitution in specific applications (e.g., new abrasive chemistries or tool designs that reduce diamond consumption per unit).
Competitive watch-list (what we tracked)
Our coverage includes proprietary profiling and strategic positioning for major industry participants—global technology leaders, regional high-volume manufacturers, and specialist suppliers. Recent corporate moves observed in the market include launches of high-purity polishing products targeted at semiconductor applications, capacity expansions focused on stone-processing demand, and new grades engineered for thermal stability in high-speed sawing. These activity clusters highlight where R&D and capex are being deployed, and where partnership or M&A interest is likely to concentrate over the next 12–24 months.
Next steps — how PW Consulting helps you operationalize insight
The full PW Consulting study provides the underlying data tables, sensitivity models, and supplier scorecards required to convert high-level insight into executable plans—without disclosing client-sensitive segmentation or proprietary contract levers in this preview. If your 2026 plan includes capacity decisions, supplier consolidation, or entry into premium polishing markets, our bespoke advisory services can translate the study’s scenarios into a detailed implementation roadmap, including commercial negotiation tactics, capex phasing, and integration checklists.
Closing
The synthetic diamond grit market presents a classic choice for 2026 leaders: commit to selective investment and capability-building now to capture a disproportionate share of the forecast growth window, or risk margin compression as energy, trade, and regulatory realities reshape competitiveness. PW Consulting’s report equips decision-makers with the frameworks and operational tools to make that choice with confidence. For full access to the segmented modelling, supplier-level analysis, and implementation templates referenced here, please consult the complete report on our publication platform.
For detailed analysis of this topic, please visit the official page: Synthetic Diamond Grit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Closeouts Market to Reach USD 454.0B by 2032 at 6.85% CAGR — PW Consulting Insight
By PW Consulting, 2026-07-13
Closeouts Market — 2026 Strategic Brief
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present this executive introduction to our forthcoming Closeouts Market research — a strategic primer intended to orient C-suite leaders, corporate strategists, and private equity investors preparing decisions in 2026. This brief demonstrates the depth of our analysis, highlights the critical forces reshaping the closeouts ecosystem, and outlines the concrete decision levers companies must master. In keeping with the “trailer” principle, we intentionally surface high‑level findings and strategic implications while reserving core subsegment tables and granular breakdowns for the full report and interactive datasets on our source page.
Closeouts Market
Market trajectory: clarity at the macro level
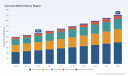
Our base-year analysis (2025) and historical review (2020–2025) underpin a forward-looking forecast spanning 2026–2032. The global closeouts market is on a sustained expansion path, driven by structural overstock generation, accelerating secondary channels, and increasing buyer sophistication. At the macro level, the market expands from the mid‑hundreds of billion USD range in 2023–2025 into a larger market by 2032 under a compound annual growth rate of 6.85%. To provide a sense of scale, our topline trajectory moves from the mid‑200s Billion USD in the early 2020s to a market size exceeding four hundred Billion USD by the end of the forecast period — a growth pattern that demands strategic reorientation by incumbents and new entrants alike.
Closeouts Market
Why this matters for 2026 corporate decisions
- Liquidity as a competitive lever: With elevated overstock levels driven by conservative retail inventory strategies and several high‑profile bankruptcies, the ability to convert slow‑moving inventory into cash faster than peers is a sustainable advantage.
- Channel economics are shifting: Digital auction platforms, B2B marketplaces and programmatic liquidation enable more granular price discovery and selective recovery strategies, altering the return profile of closeouts compared with traditional wholesale and auction channels.
- Policy and cost headwinds: Ongoing U.S. tariff dynamics on consumer imports are affecting landed costs and cross‑border arbitrage economics, creating both risk and opportunity for players who can actively manage regulatory pass‑through and sourcing flexibility.
- Consolidation opportunities: Market concentration is low relative to many consumer‑goods sectors (our concentration metrics show the top three firms account for less than one‑quarter of market share and the top five still represent a minority). This fragmentation leaves room for scale players to consolidate supply relationships and capture disproportionate recovery margins.
What the full report delivers — practical, transaction‑ready content
The full Closeouts Market report is designed to be a working tool for 2026 strategies. Its principal deliverables include:
Closeouts Market
- Robust market model: A reconciled topline model from 2020 through 2032 with scenario outputs, sensitivity analyses, and an extensible spreadsheet that allows teams to test custom assumptions.
- Channel playbooks: Detailed playbooks for online liquidation platforms, auction-based channels, and secondary retail partnerships — including cost-to-serve templates, recommended lot sizing and lot composition strategies, and margin improvement levers.
- Operational diagnostics: KPIs and benchmarking tools for condition grading, disposition velocity, recovery percentiles, and logistics cost drivers — enabling rapid diagnostics of opportunity gaps across a portfolio.
- M&A and partnership roadmap: Criteria matrices and valuation frameworks for roll-up plays, platform acquisitions, and exclusive supplier partnerships, complete with integration checklists and synergy capture plans.
- Regulatory and tariff playbook: Scenario modelling for tariff pass‑through, inventory reclassification tactics, and customs optimization steps to protect margins under shifting trade regimes.
- Digital transformation guide: Tactical guidance on pricing algorithms, condition‑scoring automation (vision and data ingestion), fraud detection, and marketplace UX improvements that demonstrably lift realized recovery rates.
- Sustainability and resale strategy: ESG-aligned frameworks for maximizing asset reuse, refurbish-and-resell flows, and responsible disposal options that reduce reputational and regulatory exposure.
Competitive landscape — where the money flows and who to watch
The competitive map of the closeouts industry combines native online marketplaces, auction specialists, pallet and truckload wholesalers, and mixed merchandise distributors. Notable operators profiled in our research include:
- Direct Liquidation (United States) — An industry leader that partners with national retailers and manufacturers to channel name‑brand overstock, returns and surplus through auction and wholesale routes.
- B-Stock (United States, bstock.com) — A specialized online wholesale marketplace connecting professional buyers with large‑scale overstock and returns from major retailers and e‑commerce platforms.
- Liquidation.com (United States, liquidation.com) — An auction‑centric platform with deep volumes in surplus consumer goods from broad retailer and manufacturer networks.
- BULQ (United States, bulq.com) — A supplier of palletized liquidation inventory focused on predictable lot profiles for resellers and secondary retailers.
- Overstock Trader, Total Surplus Solutions, Countryside Closeouts, Kole Imports, Global Distributors, UpLiquidation — A set of national wholesalers and distributors that participate across B2B channels, private sales and bulk distribution networks.
Our concentration metrics are revealing: the top three firms capture under 20% of the market and the top five sit below one quarter. That market fragmentation is a double‑edged sword — it lowers barriers to entry for specialized, tech-enabled challengers while presenting attractive consolidation and scale-up economics for strategic acquirers. In practice, the most successful players combine deep supplier relationships (retail and manufacturer), proprietary demand pools (repeat buyer networks), and data-enabled pricing engines.
Key 2026 strategic plays — prioritized, actionable, measurable
Based on our analysis and fieldwork through Q1 2026 (including insights from industry events such as ASD Market Week), we recommend leaders prioritize the following plays and metrics:
- Secure diversified supply corridors: Build direct procurement agreements with retailers and manufacturers, include first‑look clauses on returns, and develop a special situations desk to source distressed inventory from bankruptcy estates.
- Invest in digital price discovery: Deploy dynamic auction mechanisms and machine learning pricing models that optimize lot composition and timing to maximize recovery, with A/B testing across platforms to quantify uplift.
- Reconfigure logistics for reverse flows: Create regional consolidation hubs and hub‑and‑spoke reverse supply chains to reduce handling and accelerate conversion to sale — measure improvements in inventory velocity and landed disposal costs.
- Hedge regulatory exposure: Implement tariff‑aware sourcing and pass‑through policies, and run scenario stress tests on landed cost sensitivity as part of quarterly commercial reviews.
- Monetize data: Package buyer demand signals, condition insights and price discovery history into value‑added services for suppliers — a new revenue stream and a sticky supplier lock‑in mechanism.
- Pursue tuck‑ins with clear synergy paths: Focus M&A on targets that deliver immediate operational leverage (buyer pools, warehouse footprint, tech capabilities), and use our integration scorecards to prioritize deals by payback speed.
- Embed ESG and consumer‑facing provenance: Leverage refurbishment, certification, and provenance tracking to access premium secondary channels and reduce disposal liabilities.
How to use this research in your 2026 planning cadence
Applying the report is practical and repeatable across investment and operating agendas:
- For portfolio companies: use our benchmarking tools in Q1 planning to set KPI targets (recovery %, inventory days, average lot price) and to construct three plausible scenarios for 2026 operational budgets.
- For corporate strategists: map supplier and buyer relationships against the competitive map to identify exclusivity opportunities and strategic partnerships where margin pools are concentrated.
- For private equity and M&A teams: apply our valuation multiples and synergy templates to target screening, and use the report’s diligence checklist to accelerate deal execution.
Sources, scope and a final note on access
The insights summarized here draw from a blended evidence base: reconciled market models, primary interviews with platform operators and large buyers, supply chain datasets, public filings, and field intelligence gathered at industry gatherings (including ASD Market Week, March 2026). We explicitly model tariff and trade scenarios aligned with public economic analysis and industry filings to reflect current policy uncertainty.
In line with the “trailer” principle, this brief intentionally omits detailed regional and product‑category splits, company‑level share tables, and the full set of downloadable models. Those granular datasets, along with interactive dashboards and the complete methodological appendix, are available in the full Closeouts Market report on our source page. Accessing that content will provide the subsegment economics and deal‑level detail necessary to execute any of the strategic plays outlined above with confidence.
PW Consulting’s Closeouts Market report is built to be operational: a living toolkit for 2026 decisions. If your team is preparing to reposition supply chains, pursue platform M&A, or monetize secondary inventory flows this year, this research will be the backbone of those efforts.
For detailed analysis of this topic, please visit the official page: Closeouts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive DSP Amplifier Market to Expand at 8.75% CAGR Through 2032
By PW Consulting, 2026-07-13
Automotive DSP Amplifier Market — Strategic Briefing for 2026 Decision-Making
As the automotive cockpit evolves from a passive cabin to an intelligent sensory environment, digital signal processing (DSP) amplifiers are becoming a cornerstone technology — not just for premium audio aficionados but for OEMs reshaping in-vehicle experiences. PW Consulting’s latest Automotive DSP Amplifier Market research consolidates five years of historical performance and a seven-year forecast to 2032, delivering decision-grade intelligence for product leaders, supply chain heads, and corporate development teams preparing for pivotal choices in 2026.
Automotive Dsp Amplifier Market
Market snapshot: growth trajectory and concentration
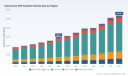
The market for automotive DSP amplifiers has expanded rapidly over the last half-decade, reflecting stronger content per vehicle, accelerating EV adoption, and a shift toward software-defined cabin experiences. Our base-year assessment for 2025 positions the global market in the low‑billions (USD, Million units aggregated as revenue), having nearly doubled since 2020. Looking forward, we forecast a compounded annual growth rate (CAGR) of 8.75% through 2032, with the market projected to roughly reach the mid‑five‑billion USD range by the end of the forecast horizon.
Automotive Dsp Amplifier Market
This is not an undifferentiated, commoditized market. Market concentration data in the study shows a clear tiering: the three largest suppliers command a meaningful plurality of supplier revenue, and the top five firms together control a majority stake. That structure creates both risks and opportunities for challengers, component suppliers, and OEM integrators.
Automotive Dsp Amplifier Market
Why this research matters for 2026 strategic choices
- Timing R&D and feature roadmaps: The 8.75% CAGR and the underlying adoption curves indicate a window in 2026–2028 where investment in next‑generation DSP features (high-frequency Class‑D optimization, AI/ML-enhanced sound personalization, and deterministic low-latency processing for active noise control) will deliver the greatest incremental returns.
- Prioritizing supply chain resilience: Semiconductor volatility, mature-node shortages, and rare-earth constraints are shaping lead times and BOM risk profiles. Our research quantifies likely disruption scenarios and models the tradeoffs between vertical integration, multi-sourcing, and strategic inventory.
- Go-to-market segmentation for OEMs and aftermarket players: Automotive manufacturers face competing pressures to monetize software-defined audio experiences while preserving OEM cost targets. The report translates market growth into concrete product and pricing archetypes suitable for OEM integration versus premium aftermarket channels.
- M&A and partnership timing: Given the market’s moderate concentration, 2026 may be a pivotal year for acquisitive scale plays — particularly for electronics companies seeking to combine DSP IP with system-level audio brands or semiconductor producers aiming to secure application reference designs.
What’s inside the PW Consulting report — practical deliverables
We designed this study as an execution tool rather than an academic exercise. The report contains:
- Top-down market sizing (historical and forecast), with scenario pathways tied to EV penetration, smart‑cockpit adoption, and aftermarket replacement cycles.
- Actionable go-to-market playbooks for OEM suppliers and Tier‑1s, including channel economics, bundling strategies, and sample commercial term sheets for supplier negotiations.
- Competitive benchmarking templates and a proprietary “DSP Capability Stack” that scores vendors across processing power, power-efficiency, integration, software ecosystems, and calibration tooling.
- Supply chain stress tests and a mitigations matrix: part criticality maps, alternate supplier lists, and cost-to-serve models for strategic inventory and long-lead procurement.
- Regulatory and compliance checklist: practical steps to achieve AEC‑Q qualifications, functional safety alignment, and recommendations for test labs and partner certification paths.
- Financial playbooks for corporate development: valuation comparables, integration checklists for acquisitions, and synergy models for cross-selling between semiconductor and system brands.
- Customizable dashboards and downloadable financial models that let teams run “what-if” scenarios (price erosion, content-per-vehicle shifts, and supply disruptions) to stress-test 2026 budgets and capex plans.
Competitive landscape — what the leading names reveal
The competitive map combines acoustics-focused brands, car-audio specialists, and semiconductor heavyweights. PW Consulting’s qualitative and quantitative benchmarking highlights distinct strategic clusters.
- High-end audio brands (system integrators and aftermarket leaders): Companies such as Audiotec Fischer, Audison, Alpine, Mosconi, ARC Audio, and AudioControl focus on premium sound quality, integrated tuning workflows, and strong brand recognition among enthusiasts and premium OEM programs. Recent industry recognition — including awards for best-in-class DSP products and software tools — highlights the continued demand for differentiated tuning and end-customer experiences.
- Semiconductor and DSP platform providers: STMicroelectronics, Texas Instruments, Analog Devices, and NXP represent the platform layer. Their launches in 2024–2025 (new Class‑D devices, higher-frequency amplifiers for smart cockpits, and advanced DSP cores with AI/ML acceleration) are enabling a tectonic shift: audio is becoming a software-centric feature, with the silicon vendor playing a larger role in system differentiation.
- Strategic implications: Premium integrators must accelerate their software ecosystems (calibration tools, auto-tuning algorithms, user personalization) to maintain margin and defend against silicon vendors bundling reference designs. Conversely, platform suppliers need to build go-to-market muscle with Tier‑1s and OEMs to capture system-level value beyond chip revenue.
Regulatory, supply-chain, and raw‑material considerations
Regulatory and qualification friction is a real operational constraint. Automotive components must meet AEC‑Q and functional safety expectations for reliability in harsh vehicle environments — a development and testing overhead that affects time-to-market and cost. On the supply side, persistent semiconductor volatility and rare‑earth material stresses are expected to continue through 2026, making proactive supplier mapping, dual-sourcing strategies, and long‑lead contracting essential for program stability.
Eight strategic imperatives for 2026
- Embed software-first roadmaps: prioritize DSP platforms that enable over-the-air tuning and post-production personalization.
- Lock critical silicon via strategic partnerships: secure supply for mature-node MCUs and power ICs through multi-year commitments or equity partnerships where necessary.
- Modularize hardware to hedge BOM risk: design a common amplifier module that can be upgraded via firmware to span trim levels.
- Invest in tuning ecosystems: calibration tooling and user personalization features materially increase perceived value and defend margin.
- Differentiate through AI/ML: allocate R&D to perceptual audio features and cabin-aware sound control that leverage in-cabin sensors and vehicle networks.
- Pursue bolt-on acquisitions selectively: target audio‑software firms or boutique integrators that can be scaled within OEM programs.
- Align compliance early: factor AEC‑Q and functional-safety timelines into program gating to avoid late-stage delays.
- Stress-test commercial models: use the downloadable scenario tools in the report to simulate pricing, content, and supply disruptions for 2026 budgeting cycles.
How to use this briefing in your 2026 planning cycle
Procurement teams should use the report’s supply‑chain scenarios to establish preferred supplier lists and inventory buffers; product leaders should adopt the DSP Capability Stack to prioritize feature investments; corporate development teams will find the M&A playbooks and valuation comparables useful for assessing targets and timing bids. The report’s scenario tool enables rapid recalibration of business plans against realistic shifts in adoption and supply risk.
What we intentionally withhold here — and why
To preserve the report’s value as an operational dataset, this briefing intentionally omits detailed regional, type, and application splits, as well as downloadable segment-level spreadsheets. Those core subsegment datasets, commercial elasticities, and the full model outputs are included in the paid report and interactive dashboards. The selective disclosure here is deliberate: we show market trajectory, concentration dynamics, and strategic implications to demonstrate insight depth while reserving granular intelligence for practitioners executing 2026 programs.
Final perspective
For executives calibrating 2026 investments, the central signal is clear: the DSP amplifier market is growing at a double-digit pace relative to many traditional cabin components, driven by higher content per vehicle and the commoditization of basic amplification combined with a premium on software and personalization. Firms that align silicon strategy, software capability, and supply-chain resilience in 2026 will capture disproportionately higher returns as the market matures toward 2032.
For immediate access to the full forecasting model, segment breakouts, supplier scorecards, and the scenario simulator for board-level decision exercises, consult the PW Consulting Automotive DSP Amplifier Market report. Our team can also deliver a tailored executive workshop to translate these insights into a 90‑day action plan aligned with your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Automotive Dsp Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heavy Industry Hydraulic Systems Market to Grow at 4.85% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Heavy Industry Hydraulic System Market — Strategic Intelligence for 2026 Decision-Makers
As capital budgets reopen and heavy industry operators accelerate decarbonization and digitalization plans, hydraulic systems remain an indispensable element of the global heavy equipment value chain. PW Consulting’s new market study — anchored on a 2025 base year and projecting through 2032 — quantifies that importance and translates it into executable strategic options. The market is set to expand at a steady mid-single-digit pace (4.85% CAGR for the 2026–2032 forecast window), moving from a large multi‑billion-dollar base in 2025 toward materially higher aggregate revenue by 2032. For C-suite leaders, corporate strategists, and business development teams, the practical question in 2026 is not whether hydraulics matter, but how to allocate scarce capital and talent to capture resilient, margin-accretive growth while managing rising regulatory and input-cost volatility.
Heavy Industry Hydraulic System Market
Why this study matters in 2026
-
Timing and trajectory: The forecast period (2026–2032) captures a decisive phase in the heavy-equipment refresh cycle. Capex programs, electrification pilots, and retrofit projects that are decided in 2026 will reach execution or scale within our forecast horizon — making early strategic choices high-leverage.
Heavy Industry Hydraulic System Market -
Policy and standards acceleration: New standards such as ISO 18464:2025, together with energy-efficiency mandates, materially change product design constraints. Manufacturers that internalize these constraints now will reduce rework and margin erosion later.
Heavy Industry Hydraulic System Market -
Input-cost and supply risk: Steel-price volatility and concentrated raw-material supply chains continue to pressure component costs and supplier reliability. Procurement and product-design strategies developed this year will determine the robustness of supply for the next 5–7 years.
-
Technology inflection: The industry is balancing proven hydraulic architectures with hybrid and electrified options (including electrified hydraulic power units — eHPUs) and increasingly connected control layers. The pace and economics of these transitions are uneven across application classes; our study provides the decision frameworks to prioritize investments.
Market structure and competitive dynamics — what to watch
Our analysis shows a market that blends global incumbents with regionally strong specialists. Market concentration is moderate: the top three firms account for roughly one-third of the market while the top five capture under half. This structure creates a dual pathway for competitive advantage — scale-based plays from the leading incumbents and focused differentiation opportunities for nimble specialists.
Key established players continue to set technology and quality benchmarks: large engineering OEMs and system integrators are investing in connected controls, higher-pressure architectures, and energy-optimization packages. Select independent suppliers are pursuing narrow but deep plays on filtration and wear-resistant components, or on integrated electro-hydraulic subsystems tailored to off-highway and mining applications. Newer entrants and regional champions accelerate adoption through trade-show launches and targeted OEM partnerships — recent product reveals and awards in major 2026 shows demonstrate the ongoing innovation cycle.
-
Strategic positioning matters more than ever: firms that combine systems engineering, software-enabled controls, and service-based revenue models will capture a disproportionate share of aftersales and lifecycle margin.
-
M&A and partnership activity will be selective: buyers are targeting capabilities in electrified power units, system integration, and digital services more than low-margin commodity components.
-
Regional go-to-market remains relevant: global scale helps with R&D and supply chain resilience, but local engineering and aftermarket presence determine success in heavy industries with site-specific requirements.
Technology and regulatory tailwinds that shape winners
Three linked trends will define competitive outcomes across the forecast horizon:
-
Energy efficiency and compliance: With ISO 18464:2025 and strengthening emissions/efficiency mandates, product roadmaps must incorporate energy-optimized circuit design and loss-reduction technologies. Early adopters can exploit first-mover advantages in bidding for large retrofit and greenfield projects.
-
Electrification and hybrid architectures: eHPUs and hybrid hydraulic-electric drivetrains reduce on-site emissions and offer lifecycle cost benefits in many duty cycles. Commercial viability depends on component reliability, integration skill, and TCO-based sales models that account for fuel, maintenance, and downtime.
-
Digitally enabled reliability: Predictive maintenance, remote diagnostics, and control-layer optimization translate into lower OPEX and higher attachment uptime — and thus into monetizable service contracts. Companies that marry hydraulic expertise with software platforms will be best positioned to grow aftermarket revenues.
Recent market signals — what the shows and awards reveal
Targeted industry events in early 2026 offered useful directional signals. Several exhibitors showcased next-generation mobile hydraulics and purpose-built cylinder and pump solutions at major North American trade shows; an electrified hydraulic power unit secured a top new-product award at a leading agricultural expo. These public demonstrations — from both established suppliers and newer specialists — confirm rising customer interest in electrified subsystems, application-specific performance tuning, and integrated testing platforms. For strategists, these signals imply that product maturity, customer validation, and price points are aligning to enable broader commercial adoption in the near term.
What the PW Consulting report delivers (practical contents)
Our study is designed to be hands-on and decision-oriented for 2026 corporate planning cycles. Highlights include:
-
Transparent market sizing and forecast methodology, including base-year reconciliation and scenario-based projections across a 2026–2032 forecast horizon.
-
End-user demand drivers and procurement behavior profiles: capital vs. operating cost sensitivities, retrofit decision triggers, and service-interval economics.
-
Technology deep dives: comparative TCO analyses for conventional hydraulics, hybrid architectures, and electrified hydraulic power units; control-layer integration and cybersecurity considerations for connected systems.
-
Value-chain mapping and supplier risk assessment that identify choke points (raw materials, filtration, control semiconductors), mitigation levers, and strategic sourcing playbooks.
-
Competitive benchmarking and capability matrices across system suppliers, component specialists, and OEM integrators, coupled with M&A and partnership screening templates.
-
Commercial playbooks for market entry and scale: channel strategies, aftermarket enhancement tactics, pricing frameworks, and retrofit program designs tailored to heavy-industrial customers.
-
Executive-ready decision tools: investment prioritization frameworks, sensitivity analyses for steel-price shocks and regulatory tightening, and phased implementation roadmaps for 2026 capital plans.
Note: The full report contains granular splits, component- and regional-level scenarios, proprietary segmental tables and financial templates that are intentionally omitted from this preview to preserve the report’s exclusive value.
How to convert insight into 2026 actions
-
Rebalance R&D toward integration: Shift incremental R&D budgets from component improvement to system-level integration (electro-hydraulic controls, eHPU uptime, and digital diagnostics) to increase capture of lifecycle value.
-
Hedge raw-material exposure: Implement a two-tier procurement approach — strategic long-term steel contracts for core production and tactical spot positions for opportunistic sourcing — and update bill-of-materials designs to reduce steel intensity where feasible.
-
Prioritize retrofit economics: Develop retrofit bundles that emphasize short payback for high-utilization assets in mining and infrastructure — backed by financing or outcome-based contracts to lower buyer resistance.
-
Build aftermarket-as-a-service propositions: Monetize predictive-maintenance insights through subscription models that combine remote monitoring, parts-on-demand logistics, and uptime guarantees.
-
Design M&A with capability inflection in mind: Target acquisitions that offer direct capability jumps in electrified subsystems, software platforms, or specialized filtration and wear components rather than pure-volume roll-ups.
Final takeaways for 2026 strategic planning
Hydraulics will remain central to heavy-industry productivity through 2032, but the basis of competition is shifting. Firms that integrate energy-efficient engineering, electrified subsystems, and software-enabled lifecycle services will win premium returns. Conversely, players relying on commodity differentiation face margin compression and acquisition vulnerability unless they pursue structural change. The market’s moderate concentration means there is room for both scale plays and focused specialists, but successful execution requires clarity on regulatory scenarios, raw-material risk, and the economics of electrified alternatives.
PW Consulting’s Heavy Industry Hydraulic System Market study provides the empirical foundation — robust market sizing, scenario modeling, and operational playbooks — to convert these insights into action. For executives preparing 2026 capital allocations, technology roadmaps, or M&A targets, the study offers a pragmatic, prioritized path to secure competitive advantage in a market growing at a 4.85% CAGR through 2032.
To access the full set of segment-level intelligence, competitive scorecards, and investment-ready templates, visit the PW Consulting report page for this study.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biomass Power Equipment Market to reach USD 201.46B by 2032 (6.99% CAGR)
By PW Consulting, 2026-07-13
Biomass Power Equipment Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our full Biomass Power Equipment Market study — a practical intelligence package designed to inform capital allocation, partnership selection, and technology choices as organizations finalize strategies for 2026. Our analysis is grounded in a comprehensive market model (base year 2025, forecast 2026–2032) and shows the global market expanding from USD 125,458.26 Million in 2025 to USD 201,458.54 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.99%. This trajectory, and the structural dynamics behind it, will materially influence project economics, procurement timelines, and M&A activity over the next three years.
Biomass Power Equipment Market
Why 2026 Is an Operational and Strategic Inflection Point
- Policy-driven demand acceleration. Recent and prospective policy interventions—ranging from strengthened renewable targets in major economic blocs to tax incentives and investment credits—have created a near-term window for project developers and OEMs to lock in favorable financing and subsidy conditions. Timing investments to capture these policy windows is a high-return move in 2026.
- Carbon and energy-market economics are reshaping fuel choice. Elevated carbon prices in emissions trading systems and more aggressive national decarbonization roadmaps increase the economic case for biomass retrofit and replacement of fossil-fired capacity in jurisdictions where sustainability credentials are accepted for biomass feedstocks.
- Feedstock and component cost volatility matters. Commercial wood pellet and other biomass feedstock prices, plus the unit costs for key equipment (e.g., grate stoker systems), have shown meaningful bid-ask spreads in recent project tenders; supply-chain negotiations and contracting strategies in 2026 will materially affect long-term project IRRs.
- Technology performance is advancing quickly. Efficiency improvements and hybridization strategies demonstrated by incumbent OEMs compress payback periods for higher-capex, higher-efficiency solutions. Buyers that optimize for lifecycle cost rather than first-cost will capture superior margins or lower levelized cost of energy (LCOE).
What PW Consulting’s Full Report Delivers (Practical, Implementable)
- Robust top-down market sizing and forecast: granular annual modeling from 2026–2032 with scenario variants tied to policy and commodity shocks.
- Technology and feedstock decision frameworks: actionable matrices that map technology archetypes (combustion, fluidized bed, gasification, anaerobic digestion) to typical plant scales, operational profiles, and feedstock elasticity — enabling quick narrowing of viable options for a given project mandate.
- Procurement & CapEx/O&M playbooks: standardized bid templates, cost benchmarking, and assembly-level component cost ranges to accelerate vendor selection and negotiate fixed-price EPC contracts.
- Policy & incentive integration tools: jurisdictional incentive trackers and templates that translate headline subsidies and tax credits into project-level cashflow impacts and investor-return scenarios.
- Supply chain risk maps: prioritized mitigation strategies for feedstock sourcing, component lead times, and logistics, including contingency procurement paths that preserve project timelines.
- Commercial and contracting models: off-take, tolling, and co-generation commercial term sheets, plus model financial covenants that reflect biomass-specific risks.
- M&A and partnership playbook: valuation frameworks for bolt-on acquisitions and JV structures that accelerate market entry while de-risking supply and permitting exposures.
The above deliverables are designed as executable tools — not just narrative — so commercial teams can move from strategy to procurement and execution with clarity and speed. To preserve competitive value and to respect client confidentiality thresholds, the public preview intentionally omits certain segment-level monetary and regional share tables; the full report contains those stratified datasets and downloadable models.
Biomass Power Equipment Market
Competitive Landscape: Players, Positions, and Tactical Moves to Watch
- Valmet (Espoo, Finland) — Strengths: full-plant capability spanning boilers, turbines, and flue gas cleaning for multiple combustion platforms. Tactical implication: attractive partner for developers seeking turnkey delivery and advanced emissions compliance. Recent commissioning of a biomass-fired CHP plant demonstrates continued commercial execution on mid-to-large scale projects.
- ANDRITZ (Graz, Austria) — Strengths: fluidized bed combustion expertise and turnkey deliveries. Tactical implication: suited for projects focused on efficient biomass utilization and fuel flexibility; maintain ANDRITZ on shortlists where fuel variability is expected, as evidenced by recent European orders.
- Babcock & Wilcox (Akron, USA) — Strengths: grate and hybrid stoker technologies optimized for co-firing and dedicated biomass. Tactical implication: strong candidate for retrofit projects and for clients prioritizing modular staging; recent grid connections validate commercial reliability.
- Mitsubishi Power (Yokohama, Japan) — Strengths: integrated high-efficiency steam turbines and advanced combustion systems. Tactical implication: preferred where top-tier thermal efficiency and long-term performance guarantees are procurement priorities; recent efficiency milestones highlight R&D-to-market velocity.
- Siemens Energy (Munich, Germany) & GE Vernova (Cambridge, USA) — Strengths: turbine optimization and systems integration for variable fuel inputs and hybrid configurations. Tactical implication: ideal partners where integration with broader grid assets or hybrid gas/steam cycles is envisioned.
- Kraftwerke Mannheim (Mannheim, Germany) — Strengths: operator-supplier model with European co-generation experience. Tactical implication: partner of choice for utilities and municipalities pursuing operational know-how and O&M excellence.
- Zibo Zichai New Energy (Zibo, China) — Strengths: cost-competitive gasifiers and equipment for small-to-medium plants. Tactical implication: strong contender for distributed generation projects where capital efficiency and local content are decisive.
Market concentration metrics indicate an industry that remains moderately fragmented, leaving room for consolidation and alliance strategies. Incumbents are using a mix of turnkey project wins, efficiency innovations, and selective geographic plays to expand footprints — presenting opportunities for M&A, technology licensing, and OEM-developer partnerships.
Biomass Power Equipment Market
Key Dynamics That Will Drive 2026 Decisions
- Policy and incentives: National investment credits and renewable targets materially change the NPV calculus for new-build projects and repowering initiatives. Structuring bids to capture those windows is critical.
- Carbon pricing: Elevated allowance prices increase the competitiveness of biomass solutions against fossil alternatives; buyers should model carbon-price sensitivities across 5–10 year horizons.
- Feedstock markets: Feedstock cost and availability will be a gating factor for project sizing and contract tenors. Hedging, vertical integration, or long-duration supply agreements should be prioritized in 2026 procurement strategies.
- Component supply and CapEx: Equipment lead times and the unit economics of core systems (e.g., grate stoker modules) will shape project schedules and financing structures; early procurement windows reduce schedule risk.
- Operational efficiency and retrofits: Efficiency upgrades and hybridization pathways materially change lifetime returns — businesses should evaluate retrofit options for existing assets as potential quick wins.
Actionable Strategic Imperatives for Executives
- Prioritize feedstock security through long-term contracts, strategic inventories, or upstream investments. Short-term savings on feedstock can erode returns if supply reliability is compromised.
- Opt for technology decisions that align with long-term fuel availability and grid-service requirements; favor solutions that offer modular scalability and retrofit pathways.
- Lock in EPC and major-equipment lead times in 2026 to avoid inflationary and supply-chain exposure; consider contractor-financed milestones tied to performance guarantees.
- Design financing structures that capture available tax credits and grants, and stress-test models for carbon-price volatility and fuel-cost inflation scenarios.
- Use M&A and JV structures to accelerate entry in fragmented markets where local operating know-how and permitting relationships are decisive.
Decision Scenarios — How to Use This Intelligence
- Utility decarbonization track: Prioritize high-efficiency steam turbines and long-term feedstock contracts; evaluate retrofits to existing coal plants as a near-term emissions reduction lever.
- Independent power producer track: Emphasize modular plant options and flexible off-take agreements; structure financing to capture available investment tax credits and subsidies.
- OEM and equipment supplier track: Focus R&D on fuel flexibility and emissions control, and pursue strategic alliances to offer turnkey solutions that reduce buyer integration risk.
Each of these scenarios is supported in the full report by modelled P&L, sensitivity runs, supplier scorecards, and a prioritized action list for the next 12–18 months.
Next Steps — Where This Preview Leaves You
This preview synthesizes the high-level market trajectory, competitive patterns, and tactical pathways that will shape biomass power equipment investment and procurement decisions in 2026. It intentionally highlights strategic levers and refrains from publishing the full segment-level figures and regional breakouts — those detailed tables, downloadable financial models, and supplier scorecards are part of the full PW Consulting report.
If your team is preparing capital plans, supplier RFPs, or M&A strategies for 2026, the full report will accelerate decision-making by providing the calibrated models and operational playbooks necessary to convert strategy into executable projects. Visit our report page to access the complete dataset, scenario models, and procurement templates (full access includes editable financial models and vendor evaluation tools).
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fender Flare Trim Market to Grow at 5.45% CAGR through 2032
By PW Consulting, 2026-07-13
Fender Flare Trim Market — Strategic Preview for 2026 Decision-Makers
Executive preview
As vehicle personalization and regulatory-driven robustness converge, the global Fender Flare Trim market is entering a phase of steady, structural growth. Our 2025-base study at PW Consulting projects a compound annual growth rate (CAGR) of 5.45% across the 2026–2032 forecast window, with the market expanding from roughly USD 1.0 billion in 2020 to about USD 2.0 billion by 2032. For executives planning capital allocation, product roadmaps, or M&A activity in 2026, the strategic choices made now will determine who captures margin-rich aftermarket and OEM-adjacent opportunities over the next business cycle.
Fender Flare Trim Market
Why this report matters in 2026
-
Actionability for multiple stakeholders — OEM purchasing leads, tier-1/2 suppliers, aftermarket brands, and private equity — the report translates macro momentum into granular decision levers: where to invest, where to consolidate, and where to price for profitability.
Fender Flare Trim Market -
Timing — 2026 is a hinge year: EV adoption and light-vehicle refresh cycles create new specification requirements for trim materials, sealing performance, and installation methods. Early movers who align product portfolios to these mechanical and regulatory shifts will both defend OEM contracts and gain aftermarket share.
Fender Flare Trim Market -
Risk reduction — the study combines supply-chain scenario stress tests with raw-material exposure maps, enabling procurement teams to quantify trade-offs between cost volatility and supplier resilience.
Market trajectory — what the headline numbers tell us
The trajectory is clear: steady expansion with episodic acceleration tied to vehicle production and aftermarket spending cycles. Our base-year calibration (2025) and historic series (2020–2025) underpin a robust forecast to 2032. The mid-single-digit CAGR reflects a blend of recurring replacement demand, rising personalization trends in mature markets, and increasing specification requirements for EV platforms and off-road-oriented light trucks. Importantly, the growth is not uniform — pockets of rapid adoption sit alongside established, comparatively slower segments.
Segmentation and product strategy (preview)
Fender flare trim is not monolithic. Key material classes — ABS plastic, polyurethane, fiberglass, steel, and engineered rubbers such as EPDM — each present distinct cost structures, tooling needs, installation mechanics, and margin profiles. Equally, channels bifurcate between OEM-specified accessories, aftermarket personalization, and commercial/industrial uses. In this preview we outline strategic considerations for each material and channel without disclosing the line-by-line segmentation tables contained in the full report.
-
Materials strategy — ABS and polyurethane typically offer rapid injection-molding scale and lower per-unit costs; EPDM rubber and specialty seals command premium pricing where sealing, vibration, or regulatory flame-performance is required. Fiberglass and metal trims remain niche but valuable in premium and specialty vehicle programs.
-
Installation and value capture — peel-and-stick adhesive systems (3M-grade tapes and acrylic foam tapes) and snap-in/slide-seal designs alter both warranty profiles and aftermarket install economics. Suppliers with validated adhesive systems or integrated sealing solutions capture a higher share of OEM-spec business.
-
Channel sequencing — for companies expanding from aftermarket into OEM supply, the pathway frequently involves demonstrating material compliance and manufacturing traceability, then moving from accessory SKUs to platform-specific accessory contracts.
Supply chain and raw material dynamics
Raw material exposure is a strategic pivot for 2026. EPDM rubber supply chains benefit from broad manufacturing footprints and established sources, but volatility in feedstock and energy costs can compress supplier margins. The synthetic rubber market itself is expanding in lockstep with broader automotive and EV demand: industry estimates place the synthetic rubber industry around USD 30.4 billion in 2025 with projections toward roughly USD 41.6 billion by 2032. That structural demand trajectory implies sustained upward pressure on elastomeric pricing over the medium term unless new capacity is commissioned.
For procurement teams, the report contains a supplier-risk matrix that maps single-source exposure, lead-time sensitivity, and hedging options. We also model the impact of adhesive tape shortages and propose specific mitigation steps — dual-sourcing, qualified alternative adhesives, and inventory strategies keyed to lead-time elasticity.
Regulation and standards
Compliance remains a gating item for OEM contracts. Components that use rubber and polymeric materials frequently must meet flammability and material safety standards (for example, flammability regulations that govern automotive interiors and exposed components). Conformity to these standards is not optional for OEM supply and materially affects supplier selection. The full report includes a compliance checklist and a practical guide for certifying materials to common regulatory regimes.
Competitive landscape — what established players and specialists are doing
The Fender Flare Trim market is concentrated enough for incumbents to exert pricing and technology pressure, but fragmented enough to present entry and consolidation opportunities. Our competitive concentration metrics indicate a market that is neither a tight oligopoly nor a pure commodity field — the top three and top five providers control meaningful but not overwhelming shares, making strategic partnerships and differentiation viable routes to scale.
-
Trim-Lok, Inc. — A technology-forward supplier with strong adhesive-based sealing solutions and a comprehensive catalog strategy. Their 2025 catalog refresh and product introductions (including a Cut-to-Length Slide Seal Kit) showcase a playbook focused on modular, install-friendly components that reduce fitment liability. Key implication: rivals should prioritize ease-of-installation innovations to neutralize Trim-Lok’s aftermarket convenience advantage.
-
Trimco — Focused on flexible plastic trims with ozone-resistant adhesives; their value proposition centers on durability in exterior applications and conformability to complex curvatures. For OEM buyers, Trimco’s offering reduces rework risk on body seams and tight radii.
-
Johnson Bros. Roll Forming Co. — A custom roll-form specialist; their strength lies in bespoke profiles and shorter-run flexibility — an attractive supplier for niche vehicle programs and low-volume specialty flares.
-
Bushwacker — A household name in the accessory segment with integrated replacement edge trim options. Their aftermarket reach and brand equity mean product launches can quickly shift consumer expectations and influence OEM accessory strategies.
-
Air Design — Focuses on OE-style and low-profile flares, often via OEM accessory channels. Their channel alignment strategy is instructive for suppliers seeking adjacencies into factory-fit programs.
-
Steel Rubber — Niche leader in EPDM-based edge trim with peel-and-stick tape solutions; well placed where environmental resistance and longevity are prioritized.
-
Putco — Premium stainless-steel trim specialist; their metal-focused SKUs serve higher-margin, visually distinctive segments where perceived quality drives purchase decisions.
Recent developments to watch
-
Trim-Lok’s Catalog 800 release and subsequent metric/multilingual editions (2025) signal a deliberate push to support global OEM and aftermarket channels with clearer specification tools and product modularity.
-
The October 2025 Cut-to-Length Slide Seal Kit introduction marks an important trend: suppliers are moving from component-only offers toward systemized, install-friendly solutions that reduce OEM assembly time and aftermarket installation errors.
Strategic playbook for 2026
-
For OEMs — institute a materials harmonization program that creates a preferred list for trim materials (balancing cost, regulatory compliance, and durability). Use the report’s scoring model to rank suppliers on fitment risk and innovation capability.
-
For suppliers — prioritize two pathways: (1) deepen adhesive and sealing IP to bundle with trim products, and (2) develop modular kits that cut installation time and warranty exposure. Both approaches measurably increase the likelihood of winning OEM accessory contracts.
-
For investors — identify mid-market manufacturers with strong engineering IP or specialized tooling as attractive consolidation targets. Our M&A playbook identifies valuation multipliers driven by patented adhesive integrations and OEM-qualified testing records.
-
For aftermarket brands — lean into fitment guarantees and installation simplicity. Marketing strategies that emphasize “no-gap” fit and certified adhesive systems convert hesitant buyers faster than price-led promotions.
What the full PW Consulting report delivers
-
Validated market sizing and a base-year model (2025) calibrated with primary research and supplier interviews.
-
Scenario-driven forecasts to 2032 with sensitivity to vehicle production, EV penetration, and raw-material price shocks.
-
Granular region, material, and application segmentation (note: full breakdowns and regional/application shares are contained in the report’s data annex and are intentionally omitted from this preview).
-
Competitive profiles, product-matrix benchmarking, and go-to-market templates for OEM and aftermarket channels.
-
Actionable strategic recommendations, roadmap templates, and a 12–24 month operating plan to capture incremental market share.
How to use this preview — next steps
This preview is designed to orient decision-makers and surface the strategic choices that matter in 2026. For procurement, product, or investment teams needing the line-level segmentation, supplier scorecards, or the full scenario models, the complete report provides the data tables, primary-research transcripts, and implementation-ready roadmaps required to act with confidence. PW Consulting’s methodology and appendices provide traceability for every assumption and sensitivity modeled.
Closing note
The Fender Flare Trim market sits at the intersection of material science, installation engineering, and consumer-driven aesthetics. Growth is steady, pockets of premium margin exist for differentiated materials and installation systems, and supplier strategy will determine who benefits from the 2026 inflection in vehicle architectures. To convert this strategic preview into executable plans, access the full PW Consulting report for the data and templates that operational teams will use to execute in 2026.
For detailed analysis of this topic, please visit the official page: Fender Flare Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Corn Flour Market to Reach USD 8.63 Billion by 2032 at 4.25% CAGR
By PW Consulting, 2026-07-13
Corn Flour Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Industry Brief
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Corn Flour Market
Executive snapshot
The global corn flour market is entering a period of steady, structurally-driven growth. After a multi-year historical review (2020–2025), our baseline analysis identifies the market at approximately USD 6.45 Billion in 2025 (base year). Under conservative demand- and supply-side assumptions, the market is projected to expand to roughly USD 8.63 Billion by 2032, reflecting a compound annual growth rate (CAGR) of about 4.25% over the 2026–2032 forecast window.
Corn Flour Market
This industry brief previews the full PW Consulting Corn Flour Market study and translates our quantitative findings into pragmatic strategic guidance for 2026 corporate decision-making. We intentionally reveal directional market dynamics, methodology rigor, and practical use cases while withholding detailed sub-segmentation datapoints to preserve the study’s exclusive value for subscribers.
Corn Flour Market
Why this matters for 2026 strategy
- Portfolio prioritization: Growth is predictable but not uniform — stable mid-single-digit expansion means firms must choose where to invest for higher returns versus protecting volume-driven businesses.
- Capex & capacity planning: Manufacturers and ingredient suppliers need forward-looking demand curves and input-price scenarios to time mill upgrades, capacity expansions, or contract manufacturing partnerships without overexposure to cyclical inventory risk.
- Procurement & price risk: Corn price dynamics remain a primary margin lever; procurement strategies (fixed contracts, indexed purchasing, hedge overlays) will materially influence 2026 earnings sensitivity.
- Innovation & premiumization: Premium, specialty, and functional applications offer margin uplift — but they require R&D, labeling, and targeted distribution investments aligned to consumer trends.
- Regulatory & trade-readiness: Recent regulatory shifts and tariff developments mean supply-chain flexibility and compliance readiness are non-negotiable for exporters and multinational processors.
What the full report delivers — practical, action-oriented content
Our full Corn Flour Market report is structured to convert macro insight into executable initiatives. Key deliverables include:
- Transparent market-sizing methodology with bottom-up and top-down reconciliations, sensitivity testing, and alternate scenarios for high/low demand outcomes.
- Seven-year forecasting models (2026–2032) with monthly-to-annual cadence options for demand planning and capex phasing.
- Supply-chain maps by milling configuration and logistics archetype, highlighting lead times, critical bottlenecks, and cost-to-serve benchmarks.
- Input-price scenario suite: spot, forward, and stress-case trajectories for corn and energy that feed margin-scenario matrices for manufacturers and ingredient buyers.
- Go-to-market playbooks for ingredients (e.g., industrial, retail, foodservice), including route-to-market options, co-manufacturing criteria, and private-label risk assessments.
- M&A & partnership target screening framework: a scored universe of strategic fits based on product portfolio, geography, capacity, and ESG alignment.
- Regulatory compliance checklist and labeling implications across key jurisdictions, plus an assessment of how trade-policy shifts could alter sourcing economics.
- Operational improvement diagnostics: recommendations for yield uplift at wet- and dry-milling operations, energy optimization, and waste valorization opportunities.
Market dynamics shaping 2026 choices
Several ongoing dynamics will determine which players capture disproportionate value in 2026 and beyond:
- Input-price volatility: USDA’s projection of a season-average corn price for 2025/26 and contemporaneous futures pricing indicate continued sensitivity to harvest outcomes and macro demand (including feed and ethanol). Firms must model procurement under both normalized and stress-price regimes.
- Regulatory clarity: Standards of identity and labeling requirements (e.g., national food codes) remain a structural constraint for product reformulation and cross-border trade. Compliance-driven reformulation timelines must be built into product-development roadmaps.
- Trade-policy friction: Recent tariff activity and legal rulings have injected uncertainty into import/export economics; supply-chain reworking (nearshoring, multi-sourcing) is a prudent defensive measure.
- Sustainability and traceability: Buyer preference is accelerating toward regenerative sourcing, lower-carbon milling, and documented supply chains. Sustainability credentials are increasingly table stakes for large retail and foodservice contracts.
Competitive landscape — who to watch and what they signal
The corn flour market sits at the intersection of large agribusiness integrators, specialized ingredient innovators, and regional/heritage millers. Each cohort brings distinct capabilities and strategic intent that will influence competition, partnership opportunities, and consolidation dynamics in 2026.
- Global processors (Archer Daniels Midland, Cargill, Bunge): These firms leverage scale, integrated origination, and diversified end markets. Their strengths are in supply security, contract logistics, and large-scale food-ingredient solutions. Recent sustainability initiatives and new-plant investments reflect a dual focus on decarbonization and feedstock-to-fuel economics — moves that can compress supplier risk for buyers but also escalate competitive intensity in commoditized channels.
- Ingredient specialists (Ingredion, Grain Millers): These companies compete on formulation expertise, functional performance, and ingredient customization. They are natural partners for consumer-packaged goods firms seeking clean-label texture and shelf-life solutions. Expect continued product development around texturizing functionalities and starch-protein blends that enable reformulation away from higher-cost inputs.
- Heritage and nixtamal-focused producers (Gruma, Azteca Milling, Minsa): With deep know-how in traditional masa and nixtamalized flours, these players dominate cultural and premium segments. Their IP in processing and recipe adaptation creates high barriers for entrants aiming at heritage categories, and they are attractive targets for CPGs aiming to secure authenticity credentials.
- Specialty and retail-focused mills (Bob’s Red Mill, King Arthur Baking, regional millers): These firms command premium positioning through organic, non-GMO, and gluten-free claims. They are well positioned to capture retail and specialty foodservice premiums, though scale limitations may prompt contract manufacturing or distribution alliances to meet broader demand.
- Regional & contract processors (SEMO Milling, LifeLine Foods, Mittal Cornezza): These players offer flexible tolling, private-label, and B2B supply solutions. Their value lies in agility and cost-competitive regional fulfillment; they often form the backbone of contingency supply strategies for larger buyers.
The mix of scale, specialty, and regional players suggests a market where strategic collaborations — rather than pure acquisitions — may deliver the most immediate value in 2026. Examples include co-located milling partnerships with retailers, sustainability-linked offtake agreements, and joint R&D on functional flours.
Recent developments with strategic implications
- Major processor sustainability programs — for example, large global processors introducing regeneratively sourced flours milled with renewable electricity — will accelerate buyer requirements for origin verification and may shift premium capture toward vertically integrated suppliers.
- New downstream or adjacent-capacity announcements (e.g., processing and ethanol facilities) can alter local corn balances and logistics flows; firms should re-evaluate feedstock availability and tolling economics in affected corridors.
- Commodity-price signals and futures levels through early 2026 emphasize the value of dynamic hedging frameworks and flexible supply contracts to protect margins during price swings.
- Trade-policy and court rulings that modify tariff regimes create windows for import growth in some supply-constrained markets — an opportunity for agile exporters and tolling providers.
Strategic recommendations for 2026 (prioritized)
- Build adaptive sourcing playbooks: Implement multi-tier supplier strategies that combine long-term offtake with short-term spot levers and hedges tied to price triggers.
- Invest selectively in premium innovation: Allocate R&D and commercial resources to high-margin, specialty blends and labeling claims favored by retail and foodservice channels.
- Partner for sustainability: Form origin-level partnerships to secure regenerative or low-carbon inputs; align commercial incentives with farm-level practices to lock in premiums.
- Operationalize scenario planning: Use the report’s forecast and stress scenarios to sequence capex, manage working capital, and design contingency logistics pathways.
- Explore targeted alliances: For mid-size players, pursue co-manufacturing, distribution-sharing, or minority investments with specialty millers to access capabilities without full integration risk.
How PW Consulting’s study supports execution
Our full report operationalizes the above recommendations with the tools procurement, finance, and commercial teams need to act in 2026: granular forecasting models, supplier-scorecard templates, scenario-ready P&L impacts, and a screened M&A/partnership universe. Subscribers receive both the evidence base and the execution checklists required to move from strategy to measurable outcomes within twelve months.
Next steps
PW Consulting’s Corn Flour Market study is designed as a decision-support asset for 2026. If your organization is evaluating capacity investments, re-shaping procurement, launching premium products, or exploring M&A in the corn value chain, the full report will provide the detailed segmentation, financial models, and supplier-level diligence you need. Contact our client services team to arrange a briefing, data-room access, or a tailored advisory workshop that maps findings to your strategic priorities.
Note: This preview emphasizes high-level market sizing, growth trajectory, competitive positioning, and actionable implications while withholding detailed sub-segment data reserved for the full report subscription.
For detailed analysis of this topic, please visit the official page: Corn Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


