



PW Consulting: Liquid Phenolic Resin Market at USD 7,411.35M in 2025; 5.01% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Liquid Phenolic Resin Market 2026: Strategic Compass for Executive Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer on the Liquid Phenolic Resin market that frames the strategic choices facing manufacturers, downstream integrators, investors and policy teams in 2026. This is a forward-looking, decision-focused synopsis designed to show the analytical depth of our full study while preserving the detailed segment tables and proprietary models that drive prescriptive action. Consider this a high-resolution map with the detailed coordinates available in the full report.
Liquid Phenolic Resin Market
Why this market matters to 2026 strategy
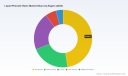
Liquid phenolic resins sit at an intersection of durable-goods manufacturing, construction materials, automotive lightweighting and high-temperature industrial processing. Between 2020 and 2025 the global market expanded materially, reflecting recovery in construction and targeted industrial demand. Our base-year sizing indicates a market of USD 7,411.35 Million in 2025. Looking forward, our forecast model projects the market will grow at a compounded annual rate of 5.01% across the 2026–2032 horizon, reaching approximately USD 10,435.47 Million by 2032. That growth trajectory creates a multi-year runway for strategic investment but also raises stakes around feedstock exposure, regulatory compliance and competitive positioning.
Liquid Phenolic Resin Market
Five structural dynamics shaping decision trade-offs
-
Demand diversification vs. concentration risk. End-use demand drivers (construction, insulation, foundry, laminates/coatings and friction materials) are uneven in cyclical sensitivity and margin profile. Firms must balance investments toward higher-growth structural uses—such as advanced composites for automotive lightweighting—with the steady base provided by traditional wood product and refractory markets.
Liquid Phenolic Resin Market -
Raw material volatility and cost pass-through. Phenol is the principal upstream feedstock. Pricing signals through early 2026 demonstrate renewed tightening: Northeast Asia phenol spot prices reached about USD 1.01/kg in March 2026 (an 8.6% increase from December 2025 and a 3.1% monthly rise), pressured by maintenance outages and stronger downstream resin operating rates. These dynamics mean feedstock hedging, bilateral supply agreements and flexible formulation strategies are now core commercial capabilities.
-
Regulatory and sustainability premium. Stricter formaldehyde emission standards and related air quality regulations are elevating compliance costs—our synthesis of region-level regulatory impact models indicates compliance-driven cost increases in the neighborhood of 8–12% for producers of conventional formulations. Concurrently, buyers increasingly prize certified low-emission and circular-material variants, creating a dual imperative: regulatory compliance and product differentiation through sustainability credentials (e.g., ISCC PLUS).
-
Supply-chain fragmentation and geopolitics. The sector shows moderate aggregation at the top: our concentration analysis indicates the market remains neither fully consolidated nor atomized (three-company concentration and five-company concentration metrics point to a moderate-leading-player landscape). Tariff actions, such as U.S. reciprocal measures implemented in 2025 that affected certain resin-related imports, can abruptly shift cost competitiveness and reroute trade flows, incentivizing nearshoring and multi-regional footprints.
-
Product and process innovation as margin lever. Incremental improvements—lower-emission resoles, waterborne systems, and process yields—translate directly into commercial share when paired with robust application development (e.g., adhesives with reduced formaldehyde release for engineered wood). Certification achievements and validated sustainability claims materially accelerate buyer adoption in Europe and premium segments.
Competitive landscape: strategic implications for incumbent and new entrants
The competitive set combines global chemical integrators, regionally specialized producers and technically focused toll manufacturers. Key strategic archetypes we analyzed include:
-
Global integrators: Companies with large-scale, vertically integrated chemical platforms and global distribution capability are positioned to absorb feedstock volatility, invest in low-emission product lines and offer bundled solutions to large OEMs. Their strategic options include selective capacity expansion in growth corridors and value-capture via downstream formulation licensing.
-
Regional specialists: European-focused and Asia-specialized players emphasize proximity to key customers and regulatory competence. Their competitive edge is speed-to-market for region-specific formulations and certification services; their primary strategic vulnerabilities are feedstock import exposure and limited scale when competing for global OEM contracts.
-
Custom and toll producers: Dedicated contract manufacturers and ISO-certified tollers provide flexible small-batch supply and rapid formulation iteration—an attractive route for engineering houses and mid-sized firms seeking lower capital intensity. Scaling these relationships into longer-term partnerships is an underutilized strategy for premium capture.
Representative firm-level observations from our review:
-
Hexion Inc. – Broad resoles capability and global reach make it a natural supply partner for multi-national wood and composites OEMs. Strategy: deepen value-added adhesive platforms and negotiate long-term phenol-offtake arrangements to shield margins.
-
Prefere Resins Holding GmbH – European specialization gives it regulatory fluency; prioritize certification-led differentiation and selective capacity to serve higher-margin construction and insulation segments.
-
Sumitomo Bakelite – The company’s ISCC PLUS certification (achieved in late 2025 for some operations) is a strategic advantage in European sustainability-conscious markets; accelerate certified-supply commercialization and target automotive electronics and coatings customers that value circularity.
-
BASF and DIC – Large-scale integration enables aggressive product development; opportunity lies in leveraging BASF’s downstream formulation assets and DIC’s Asian expansions to capture premium industrial applications.
-
Capital Resin, Georgia-Pacific Chemicals, Bakelite Synthetics, Jinan Shengquan, SI Group – These players represent a mix of contract manufacturing strength, regional volume supply and technical niche expertise. Their strategic move sets include expanding tolling footprint, consolidating regional supply agreements, and aligning product roadmaps with OEM decarbonization goals.
What our full study delivers (practical, transaction-ready content)
The PW Consulting report is structured to convert insight into action. Key operational and strategic deliverables include:
- Validated market sizing and multi-scenario forecasts (base and upside iterations) covering 2020–2032 with our 2025 base year and 2026–2032 projection horizon.
- Feedstock price modeling and sensitivity matrices showing margin exposure across pricing, tariff and regulatory shock scenarios.
- Regulatory impact assessment and compliance-cost playbooks for major jurisdictions—detailing engineering, formulation and certification pathways to meet formaldehyde and related standards.
- Competitive benchmarking with playbook recommendations by strategic archetype (scale integrator, regional specialist, toll manufacturer).
- Deal pipeline: prioritized M&A targets and partnership hypotheses, screening using synergies, capacity fit and regulatory exposure.
- Commercial go-to-market templates for premium positioning (sustainability certification, low-emission claims, co-development with OEMs).
- Operational recommendations on capacity siting, tolling partnerships, and raw material logistics hedging.
Note: This preview deliberately omits granular regional and application-split tables and the proprietary unit economics that underpin our buy/sell recommendations—these are available in the full report and interactive data annex.
Actionable recommendations for 2026 planning cycles
-
Hedge and diversify phenol exposure. Lock incremental phenol volumes through multi-year contracts in tandem with flexible formula options to protect margins during episodic price spikes.
-
Prioritize low-emission formulations and certification. Dedicate R&D and capital to bring ISCC PLUS–compatible and low-formaldehyde product lines to market; certification accelerates market access in Europe and premium OEM segments.
-
Reassess footprint under tariff risk. Evaluate nearshoring or regional manufacturing agreements in response to trade measures that can impose up to meaningful tariff levels; consider tolling partnerships to maintain customer continuity.
-
Use M&A and partnerships to buy capabilities. Acquire or partner for formulation know-how, certification pipelines and local regulatory expertise rather than relying solely on organic development—this shortens time-to-revenue.
-
Implement dynamic pricing linked to feedstock indices. Where contract structures allow, adopt transparent indexation to pass-through material cost swings while preserving customer relationships.
Closing perspective
The liquid phenolic resin market presents a balanced risk-reward profile for 2026 decision-makers: predictable, mid-single-digit growth aggregated at the global level but with concentrated value creation available to players who manage feedstock volatility, regulatory compliance and product differentiation. Our full PW Consulting market study converts the broad opportunities highlighted above into executable strategies, quantified scenarios and a prioritized action plan tailored to your role—supplier, OEM, investor or policy advisor. For the numerical tables, segment-level economics and the interactive decision-support model that power the tactical recommendations in this brief, please consult the full report via PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Precision Copper Foil Market — USD 21,167.3M by 2032, 8.64% CAGR
By PW Consulting, 2026-07-13
High Precision Copper Foil Market — Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
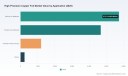
PW Consulting’s High Precision Copper Foil Market study provides a strategic compass for companies that must make decisive capital, procurement and product choices in 2026. Using 2025 as the base year, our top‑line market model shows an industry that has grown materially through the 2020–2025 historical window and is forecast to continue expanding at a compound annual growth rate (CAGR) of 8.64% across the 2026–2032 horizon. In revenue terms (USD, Million), the market moves from a substantial 2025 base toward a materially larger addressable opportunity by 2032 — underpinning both near‑term tactical choices and multi‑year strategic investments.
High Precision Copper Foil Market
Why this study matters in 2026
-
Demand structuralization: The market is being reshaped by simultaneous secular forces — electrification of mobility, miniaturization and density increases in printed circuit boards, the growth of advanced AI and communications hardware that require ultra‑smooth, low‑roughness foils, and the continuing adoption of lithium‑ion and next‑generation battery formats. These trends are durable and create differentiated value pools for specific foil technologies.
High Precision Copper Foil Market -
Supply fragility and cost volatility: Raw material dynamics—most notably copper feedstock price volatility—are exerting a visible influence on cost structures and commercial behavior across the value chain. Producers have already signaled price adjustments in 2026, and upstream treatment/refining charge swings are introducing asymmetric risk to producers and buyers alike.
High Precision Copper Foil Market -
Regulatory and sustainability pressures: Advanced jurisdictions have tightened environmental requirements, pushing manufacturers to invest in emissions‑reduction measures, renewable energy sourcing and recycled copper usage. Compliance choices now directly affect capital planning, cost competitiveness and market access for certain high‑end applications.
-
Consolidation and niche specialization: The competitive landscape shows a mix of global leaders investing in ultra‑smooth and ultra‑thin technologies alongside regional specialists focusing on battery grade and flexible circuit applications. The market is neither a pure monopoly nor atomized: concentration metrics point to meaningful leadership but with room for differentiated entrants.
What PW Consulting’s report delivers (practical, decision‑ready content)
Our research is designed to be operationally useful to procurement, product leadership, corporate strategy and M&A teams. Key deliverables include:
-
An audited market‑size model (base year 2025) and a point‑by‑point forecast through 2032 with scenario variants tied to copper price paths, EV penetration curves and board design cycles.
-
Cost‑to‑produce and break‑even curves for electrodeposited versus rolled foil pathways, including sensitivity analysis to cathode price swings and energy cost assumptions.
-
Supplier heatmaps and capability matrices highlighting technology differentiators (ultra‑thin foils, ultra‑smooth surfaces, precision thickness control), facility footprints and recent capacity moves.
-
Commercial playbooks for procurement teams: hedging trigger points, contract structures, acceptable lead‑time buffers and escalation clauses to protect against rapid raw material-driven price moves.
-
Regulatory and sustainability impact matrix: capital expenditure implications of emissions requirements, recommended carbon reduction investments and payback estimates under multiple policy regimes.
-
M&A and partnership diagnostic: target profiles, valuation sensitivities and integration checklists for buyers seeking either vertical integration into rolling/electrolytic production or bolt‑on specialty capability.
-
Go‑to‑market playbooks for technology owners: product positioning, co‑development pathways with OEMs (batteries, AI accelerators, HDI boards) and specification negotiation templates.
Competitive landscape — what leading players signal for 2026
The industry map is populated by long‑established materials houses and focused specialty suppliers. Leading firms distinguish themselves through IP in ultra‑smooth and ultra‑thin foil production, control of critical process steps, and targeted capacity investments.
-
Mitsui Mining & Smelting (Mitsui Kinzoku) continues to pursue premium MicroThin and ultra‑smooth product strategies and has signaled commercial price increases in early 2026 while rolling out capacity expansions for its proprietary VSP™ technology. These moves underscore a willingness to defend margins and to scale proprietary, high‑value products.
-
JX Nippon and Furukawa maintain technology‑led positions in both electrodeposited and rolled foils, emphasizing precision thickness control and high‑frequency performance—areas where end‑users are increasingly willing to pay for demonstrable technical advantage.
-
European and regional specialists such as Circuit Foil Luxembourg, Wieland (rolled foil) and Solus are doubling down on tight‑tolerance and ultra‑low roughness niches, supporting high‑frequency and AI accelerator applications where surface quality is a commercial differentiator.
-
Asian manufacturers, including established and emerging Chinese, Korean and Taiwanese firms, are strategically important to global supply given their large manufacturing footprints and accelerating capability upgrades directed at both battery grade and high‑precision electronics segments.
Market concentration metrics indicate a moderate-but-meaningful level of aggregation among the top players. This structure produces competitive dynamics where technology leadership and commercial agility matter as much as scale—creating opportunities for focused entrants to win niche premium positions while larger players protect broadscale OEM relationships.
Recent market signals executives must heed in 2026
-
Price actions by major suppliers in early 2026 reflect immediate margin pressure from raw material and labor costs; commercial teams should expect further supplier‑initiated repricing unless copper feedstock trajectories moderate.
-
Capacity investments announced by technology leaders indicate a deliberate move to capture growing volumes in ultra‑smooth and ultra‑thin segments; late entrants should assess the risk of downward pressure on premium spreads if capacity growth outpaces niche demand.
-
Product portfolio refreshes and updated catalogs point to rapid iteration in tolerance and surface finish specifications—buyers must update qualification processes to avoid supply constraints on next‑generation designs.
Strategic imperatives & recommended actions for 2026
To translate market intelligence into competitive advantage, executive teams should prioritize a mix of defensive and offensive moves:
-
Build a procurement “early warning” system tied to raw material and supplier signals. Define contract escalation clauses and a hedging playbook tied to specific copper price thresholds and supplier liquidity signals.
-
Reassess product roadmaps: accelerate co‑development with foil suppliers on ultra‑thin/ultra‑smooth specifications where willingness‑to‑pay is demonstrable; defer commoditized transitions where margin erosion risk is high.
-
Calibrate capacity investments to scenario outcomes. Use PW Consulting’s demand‑by‑application scenarios to time capacity additions and to size them for premium versus commodity mixes.
-
Pursue supply diversification and dual‑sourcing for critical specifications. Where performance risk is high (AI accelerators, certain battery foils), secure qualification of at least two geographically diverse suppliers.
-
Embed sustainability as a commercial differentiator: investments in recycled copper sourcing and renewable energy not only mitigate regulatory risk but are increasingly requested by OEM procurement teams.
-
Explore targeted M&A to acquire specialty capabilities rather than broadscale volume. The most accretive deals in the near term will be technology or specification plays that shorten time‑to‑market for premium applications.
How to use this study in 90 days
-
Procurement: implement the supplier scorecard and commence renegotiation pilots with top suppliers using the price‑trigger templates in the report.
-
R&D/Product: run a technical gap analysis against the foil technology roadmaps and prioritize two co‑development projects for ultra‑thin/ultra‑smooth foils.
-
Corporate Strategy: model two M&A scenarios using the report’s valuation sensitivities and target lists; commence discreet outreach if criteria match.
Next steps and access to the full intelligence
The analysis above demonstrates the type of strategic depth PW Consulting brings to high precision copper foil decisions in 2026. The full report contains proprietary, transaction‑grade intelligence — including detailed segmentation by application and region, supplier scorecards, precise cost curves, and downloadable scenario models — intentionally withheld here to preserve the commercial utility of our subscription offering.
Reach out to PW Consulting to obtain the full dataset, supplier benchmarking tables, and the model templates you can deploy immediately to stress‑test 2026 investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: High Precision Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TV ODM Market 3.8% CAGR to 2032; Asia‑Pacific leads at USD 19,084M
By PW Consulting, 2026-07-13
TV ODM Market 2026: Strategic Preview for Boardrooms and Procurement Leaders
Executive summary
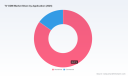
As companies prepare budgets and strategic plans for 2026, the TV ODM market presents a mix of steady growth, concentrated supplier power, and episodic cost shocks. Our PW Consulting market research—anchored to a 2025 base year and a 2026–2032 forecast horizon—projects a compound annual growth rate (CAGR) of 3.8% through the forecast window. The global TV ODM market reached roughly USD 42,500 Million in 2025 and is expected to continue expanding under modest, demand-driven dynamics and periodic supply-side pressures.
Tv Odm Market
This short briefing is designed as a “trailer” of the full study: it demonstrates the analytical depth and the practical value delivered to decision-makers, while deliberately withholding the granular segment tables and regional splits that sit inside the full report. If you need those detailed breakdowns, supplier scorecards, and downloadable models, the full release provides them.
Tv Odm Market
Why this market matters for 2026 decisions
-
Capital allocation: With market growth modest but persistent, executives must choose between volume-driven investments (capacity and scale) and margin-focused plays (higher-value displays and feature-rich smart TVs). The full report maps these trade-offs across multiple scenarios so CFOs can stress-test capex decisions against panel-price volatility and potential trade-policy headwinds.
Tv Odm Market -
Supply resilience: TV panels and associated ICs remain the dominant cost drivers in TV manufacturing; panels can represent roughly two-fifths or more of BOM cost. Short-term price spikes for large-size panels and memory components materially alter supplier economics and contract terms. Procurement teams need clear playbooks for hedging and for negotiating pass-through clauses—tools that are included in our full study.
-
Competitive positioning: Market concentration is material—leading OEM/ODM groups capture a substantial share of shipments—which affects negotiation leverage, lead times, and the strategic value of single-supplier relationships. The study quantifies concentration dynamics and provides a supplier-prioritization framework for strategic sourcing.
Market trajectory and the near-term drivers
The TV ODM industry is neither in rapid disruption nor in stagnation; it is maturing. Our historical view (2020–2025) and forecast (2026–2032) show a market that absorbs technological transitions—Mini-LED, QLED, OLED and AI-enabled smart stacks—while volumes move with end-market demand and replacement cycles. The steady CAGR of 3.8% disguises meaningful tactical volatility: episodic panel price steps, regional policy shifts, and a push toward higher-margin differentiated SKUs create windows of both risk and opportunity.
Key near-term drivers to watch in 2026 include raw-material and IC cost inflation (we observed early-2026 panel price upticks for larger formats), regulatory moves on trade policy that may affect component flows, and continued capacity expansion among leading ODMs and panel makers. These factors combine to create a market environment where timing and supplier mix can materially affect 2026 P&L outcomes.
What the full report delivers (practical outputs)
-
Scenario-based revenue and cost models calibrated to a 2025 base and extended through 2032—useful for board-level forecasts and sensitivity testing.
-
Supplier heatmaps and a risk-scored OEM/ODM shortlist that translate concentration metrics into procurement action items (RFP priorities, dual-sourcing thresholds, and contingency partners).
-
Contract negotiation playbook including clauses for price pass-through, capacity reservations, and IP protection for white-label and licensed-brand relationships.
-
Capex and capacity overlay: where new or ramped factories change delivery risk by product family and lead time—presented as decision trees rather than headline region shares.
-
M&A and partnership decision frameworks that link synergies to integration complexity and payback under different panel-price regimes.
-
Supply-chain stress tests and recommended inventory strategies for different risk appetites—from “cost-minimal” to “resilience-first”.
Competitive landscape: who matters and why
The TV ODM ecosystem blends pure-play contract manufacturers with major display groups and large EMS houses. Several firms stand out because of scale, geographic footprint, or strategic moves that influence the marketplace in 2026.
-
MOKA (TCL MOKA) — Emerged as a turnkey ODM partner for advanced smart-TV platforms. Its close integration with established supply chains enables rapid go-to-market for licensed brands and supports high-volume launches with integrated software stacks—an attractive proposition for OEMs seeking to outsource both hardware and platform services.
-
AMTC — Focused on international markets, with strategic factory expansions intended to serve North America and global retail channels. Their capacity plays and trade-lane orientation make them a candidate for brands prioritizing logistics efficiency.
-
HKC — A top-tier contract supplier and panel partner with recent greenfield commissioning adding meaningful production capability. For customers needing scale and proven supplier relationships with retailer-facing brands, HKC is a primary option.
-
Express Luck — Rapidly expanding production parks designed to scale ODM shipments; attractive for mid-size brands that need flexible MOQ and swifter ramp profiles.
-
TPV Technology, BOE VT, Foxconn, Innolux, and other tier-one suppliers — These players combine OEM, panel manufacturing, and EMS strengths. Their role varies from full turnkey ODM to component supplier and contract assembly partner. Understanding which role a supplier prefers is critical when negotiating IP, warranty, and after-sales responsibilities.
-
Smaller, highly agile ODMs — They serve niche customers with shorter lead times and extreme SKU flexibility; useful for pilots and test-market launches that might be uneconomic with large-scale suppliers.
Our full report contains strategic profiles and decision matrices for each named player, including governance structures, preferred customer types, and contract negotiation levers. The preview intentionally omits the granular supplier scorecards and capacity tables to preserve the incentive to access the full dataset.
Supply-chain and cost dynamics to model in 2026
-
Panel-cost sensitivity: Display panels are the single largest line item in TV BOMs. Even modest unit-price moves for 65–75 inch panels or memory can swing margins enough to require contract re-pricing or promotional adjustments. The research supplies a panel-price shock model you can plug into your P&L.
-
Tariff and trade risk: Policy conversations in key markets introduce execution risk for cross-border sourcing. We model tariff-tail scenarios and their impact on landed cost, and provide sourcing decision rules that align with different corporate risk tolerances.
-
Concentration and lead-time risk: With a meaningful share of volumes held by a few large suppliers, single-point failures or capacity reallocations can create supply squeezes. The report includes supplier-reallocation playbooks and contingency sourcing pathways.
Strategic actions recommended for 2026
-
Embed scenario planning into procurement cycles: Run at least three scenarios (baseline, panel-price spike, and tariff shock) before committing to multi-year supply contracts or new product launches.
-
Prioritize supplier segmentation by strategic value, not just price: Reserve long-term capacity with 1–2 strategic partners while keeping agile suppliers on shorter, higher-margin projects.
-
Negotiate flexible cost-pass-through mechanisms and capacity reservation terms that protect margins without permanently locking in unfavorable rates.
-
Localize where it reduces trade risk: For brands with exposure to tariff scenarios, selectively shifting assembly or component sourcing closer to end markets can be defensible despite higher fixed costs.
-
Invest in platform and software differentiation: With hardware margins under pressure, owning or licensing smart-TV platforms and user experiences becomes a durable source of differentiation and aftermarket revenue.
How to use this report in your 2026 planning cycle
Boards, CEOs, and procurement leads will find the report most valuable when it is used as an input to three canonical decision processes: capex approval, supplier consolidation/expansion planning, and product portfolio optimization. Each of these processes benefits from the report’s scenario outputs, supplier heatmaps, contract clauses and cost-shock templates.
If your role is supply-chain, use our stress-test tools to validate safety-stock and lead-time assumptions. If your role is corporate development, use the M&A playbooks and valuation sensitivity matrices to test acquisition rationales under different panel-price and demand scenarios.
Conclusion and next step
The TV ODM market in 2026 is an arena of steady growth complicated by episodic cost drivers and a concentrated supplier base. Decisions made in the next 6–12 months—about capex, supplier strategy, and product differentiation—will determine who gains margin and who absorbs cost pressure. Our full market report provides the segment-level breakdowns, supplier scorecards, downloadable models, and negotiation playbooks necessary to translate insight into action. For access to the complete datasets and operational toolkits, please follow the link to the full TV ODM Market release.
For detailed analysis of this topic, please visit the official page: Tv Odm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyurethane Adhesives for Shoes Market to Grow at 5.85% CAGR Through 2032
By PW Consulting, 2026-07-13
Polyurethane Adhesive for Shoes Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-level strategic primer drawn from our full Polyurethane Adhesive for Shoes Market study. This preview is designed to orient senior executives and corporate strategy teams toward the inflection points they must address in 2026. It synthesizes market trajectory, competitive dynamics, regulatory and raw-material risks, and immediate tactical moves — while intentionally withholding the granular segment tables and region/application splits that form the licensed core of our paid report.
Polyurethane Adhesive For Shoes Market
Market trajectory and why 2026 matters
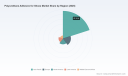
The polyurethane adhesive for shoes market has transitioned from recovery to steady expansion. Our analysis shows the global market expanded substantially between 2020 and 2025 and stands at approximately USD 1,795 million in 2025. Under base-case assumptions the market is forecast to grow at a compound annual growth rate (CAGR) of roughly 5.85% through the 2026–2032 horizon, reaching approximately USD 2,673 million by 2032. That growth rate, combined with shifting product and regulatory dynamics, makes 2026 a decision-rich year for suppliers, footwear OEMs, and private equity investors evaluating production footprint, R&D priorities, and M&A opportunities.
Polyurethane Adhesive For Shoes Market
What this study delivers (operational highlights)
- Forward-looking market sizing and a validated 2020–2025 historical dataset mapped to a 2026–2032 forecast model calibrated against primary interviews and price series.
- Competitive scorecards that evaluate technology capabilities, channel reach, and industrial partnerships for the market’s leading players (detailed supplier profiles are included in the full report).
- Actionable commercial playbooks — pricing scenarios, margin sensitivity to raw-material swings, and go-to-market templates for technical service and co-development deals with footwear OEMs.
- Regulatory and input-cost risk maps: REACH, VOC restrictions, tariff impacts, and isocyanate / polyol price volatility modeled across three supply-chain scenarios.
- M&A and JV prescriptive insights — target archetypes, valuation back-of-envelope templates, and integration/redesign checklists for adhesive formulators and downstream conversion specialists.
Dynamics shaping strategic choices in 2026
- Material and input-price volatility: Primary isocyanates (MDI, TDI) and polyols remain subject to feedstock-linked price swings. Historical crude oil cycles have translated into margin pressure for adhesive formulators; our model quantifies margin sensitivity under alternative raw-material price paths.
- Regulatory push to low-VOC and waterborne systems: Stricter environmental rules and the European Green Deal continue to accelerate substitution away from high-VOC solvent systems. This is not merely compliance — it changes production flows, capital investment needs, and aftercare for manufacturing lines.
- Sustainability as market access: Adoption of bio-based polyols and low-emissions formulations is becoming a procurement requirement among major footwear brands. Sustainability claims now carry measurable commercial value in supplier scorecards.
- Trade and tariff noise: Recent tariff adjustments on certain polyols and isocyanates have increased landed costs for some import-dependent manufacturers, prompting near-term reshoring and supplier diversification discussions.
- Product performance evolution: Hot-melt, water-based, and reactive chemistries each have distinct operational and labor implications. Innovations are focusing on faster cure cycles, bonding of engineered uppers and multi-material midsoles, and durability under athletic stressors.
Competitive landscape — signals and implications
The market is moderately concentrated: our concentration metrics indicate the top three suppliers capture a meaningful share, and the top five hold a majority position — a structure that supports both collaboration and targeted consolidation. The competitive set includes multinational chemical majors, specialized adhesive formulators, and regional technical champions. Each group presents different strategic implications:
Polyurethane Adhesive For Shoes Market
- Multinational chemical leaders (e.g., Henkel, BASF, Covestro, Arkema/Bostik): These players leverage scale in raw-material supply, broad R&D engines, and an ability to supply integrated systems (resins, TPU, dispersions). Recent product positioning highlights reduced production steps, low-energy curing, and increased use of waterborne systems — all aligned to customers seeking total cost of ownership reductions.
- Specialized adhesive formulators (e.g., H.B. Fuller, Lubrizol, NANPAO, Taiwan PU specialists): These companies compete on formulation expertise, application engineering, and service. Portfolio expansions and bio-based product introductions indicate a race to convert legacy solvent demand into higher-margin, differentiated offerings.
- Regional and emerging suppliers: Several regional producers are scaling capability with solvent-resistant and thermoplastic grades, competing on price and proximity. Their presence increases buyer leverage in certain manufacturing clusters and creates local sourcing alternatives during supply shocks.
Recent corporate moves underscore strategic fault-lines: Henkel’s emphasis on polyurethane hot melts for sports shoes, Lubrizol’s expansion of bio-based TPU lines, and market repositioning by specialized resins suppliers indicate a dual trend — performance-driven innovation (faster, stronger bonds for engineered footwear) and sustainability-driven product pivots. For incumbents and challengers alike, three practical corollaries follow: invest in application engineering resources, prove sustainability claims with third-party metrics, and align pricing strategy to raw-material hedging plans.
Practical implications for 2026 corporate strategy
- Supply-chain resilience: Build dual or multi-sourced supply agreements for MDI/TDI and critical polyols, and include passthrough clauses matched to contract-tenor. Consider strategic inventory buffering only where cost-of-carry beats the risk-adjusted margin erosion from disruptions.
- Product portfolio and R&D allocation: Prioritize waterborne and reactive systems that meet low-VOC regulations while funding incremental hot-melt performance chemistry. Allocate R&D spend to reduce cure times and improve adhesion to engineered uppers and recycled substrates.
- Commercial and go-to-market: Differentiate through OEM co-development, adhesion performance guarantees, and lifecycle emissions data. Technical service capability — in-line trials, application training, and rapid formulation tweak support — is increasingly a commercial differentiator.
- Pricing and margin management: Move from fixed-price contracts to indexed or hybrid models that share raw-material cost risks with buyers. Use the study’s scenario outputs to set contractual bands and to model margin corridors under different feedstock price trajectories.
- M&A and partnerships: Opportunistic acquisitions of regional formulators with strong customer relationships can rapidly expand addressable markets and application knowledge; JV structures with TPU/raw-material producers reduce feedstock exposure.
- Regulatory readiness: Invest in REACH-compliant formulations and VOC monitoring capabilities. Early compliance can be turned into a marketable advantage with sustainability-conscious brands.
How to use the full report in 90 days
- Week 1–2: Run the report’s supplier scorecards against your current vendor list to identify three underperforming supply relationships and two high-opportunity supplier partners.
- Week 3–6: Use our cost-sensitivity workbook to model FY26 budgets under three raw-material price scenarios; refresh pricing strategy and contract templates accordingly.
- Week 7–12: Pilot a product switch or co-development with a technical alliance partner; deploy the regulatory heatmap to prioritize which manufacturing lines require retrofits for VOC compliance.
Closing note — what we are intentionally withholding here
To preserve the “trailer” value of this preview, we have intentionally omitted exhaustive regional and application-level numerical splits, full supplier scoring matrices, and downloadable forecast tables. These gated elements include granular breakouts by region, type (water-based, solvent-based, hot-melt), and application (athletic, casual, formal, work), as well as model inputs used for scenario testing. If your team needs the detailed segmentation, unit-level pricing forecasts, or the supplier scorecards (including contactable tiered supplier lists and proprietary valuation guidance), the full deliverable provides those decisive inputs.
Next steps
If your 2026 planning must allocate capital, redesign supply footprints, or reposition a product portfolio around low-VOC and bio-based chemistries, the full PW Consulting report will convert this high-level intelligence into executable initiatives. Contact our analyst team to schedule a one-hour briefing where we will walk through the forecast models, supplier scorecards, and the prioritized 12–24 month action plan tailored to your role in the footwear value chain.
Selected corporate profiles and recent developments referenced in this preview reflect public disclosures and sector interviews through March 2025; our full report provides the citations and primary-source documentation necessary for investment committee review and procurement negotiations.
For detailed analysis of this topic, please visit the official page: Polyurethane Adhesive For Shoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Atmosphere Furnace Market Poised for 7.85% CAGR Through 2032
By PW Consulting, 2026-07-13
Vacuum Atmosphere Furnace Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
The Vacuum Atmosphere Furnace market is entering a structurally attractive phase. After steady recovery during 2020–2025, the market reached approximately USD 612.45 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of about 7.85% through our 2026–2032 forecast horizon. By 2032, the market is on track to exceed the USD 1 billion threshold, creating an expanded envelope of opportunity across industrial heat‑treating, brazing, sintering, and advanced materials processing segments.
Vacuum Atmosphere Furnace Market
This briefing is designed as a strategic “trailer” for PW Consulting’s full Vacuum Atmosphere Furnace Market study: it surfaces the decisions, risks, and competitive vectors that matter to corporate leaders in 2026 while intentionally withholding detailed sub‑segment numbers and regional splits to preserve the value of the full report.
Vacuum Atmosphere Furnace Market
Why this matters for 2026 decision cycles
-
Capital budgeting: A sustained near‑8% CAGR reshapes CAPEX planning — vendors, integrators, and large OEMs must align multi‑year spend with a market that is doubling the scale of aftermarket and services demand by the early 2030s.
Vacuum Atmosphere Furnace Market -
Supply‑chain resilience: Raw material constraints and concentrated supplier footprints are already creating execution risk for system manufacturers and end users buying furnaces in 2026–2027.
-
Regulatory timing: New energy‑efficiency and emissions mandates in major markets (notably Europe) are compressing the useful specification window for existing furnace designs; compliant product roadmaps must be prioritized now to avoid mid‑cycle rework.
-
M&A and partnership playbooks: The market concentration metrics indicate meaningful room for consolidation and capability purchases to accelerate access to high value niches (e.g., high‑pressure gas quenching, ultra‑high‑temperature R&D systems).
Market dynamics — what is driving growth
-
Technology upgrade cycle: The move toward precision metallurgy, additive manufacturing post‑processing, and higher‑value aerospace and semiconductor components is shifting demand to more sophisticated vacuum atmosphere systems. Buyers increasingly prioritize tight atmosphere control, repeatable thermal profiles, and integrated quench systems.
-
Service and aftermarket economics: As installed base grows, aftermarket services (spares, retrofits, hot‑zone replacements, qualification services) become a margin‑rich revenue stream. Organizations that design for serviceability gain outsized lifecycle economics.
-
Supply inputs and cost inflation: High‑purity graphite — a critical hot‑zone and insulation material — is under supply pressure from export controls and raw‑material bottlenecks. These constraints are elevating lead times and creating substitution and design‑for‑supply tradeoffs.
-
Regulatory pressures: Energy efficiency and emissions rules — particularly in Europe — are accelerating adoption of cleaner furnace technologies and better thermal management, forcing incumbents to update product roadmaps and customers to re‑qualify equipment earlier.
Competitive landscape — who matters and why
The sector is populated by established furnace OEMs with differentiated engineering stacks, regional service footprints, and legacy customer relationships. Market concentration is moderate: the top three players account for roughly 38.5% of market share while the top five account for about 52.8% — a structure that supports both scale advantages and targeted niche competition.
-
Ispen (Cherry Valley, IL, USA): A broad product line with the TITAN series positions them as a go‑to for aerospace and medical process customers requiring validated thermal processes. Strengths: validated process families, strong aftermarket and qualification expertise.
-
Solar Manufacturing (Sellersville, PA, USA): Known for energy‑efficient designs and high‑pressure gas quenching systems. Recent activity shows capability deployment in aerospace supply chains. Strengths: high‑performance quench systems, energy optimization focus.
-
Centorr Vacuum Industries (Nashua, NH, USA): Offers extreme temperature ranges and specialized systems for R&D and sintering. Strengths: bespoke high‑temperature solutions and deep R&D customer relationships.
-
SECO/WARWICK (Meadville, PA / Group: Poland): Delivers high vacuum furnaces and systems for precision brazing and hardening, with strong reach in industrial and nuclear segments. Strengths: systems engineering, global manufacturing footprint.
-
AVS Inc. (Ayer, MA, USA): Focused on custom high‑temperature and pressure furnaces tuned to spec requirements — attractive to specialist OEMs and research labs.
-
ECM Technologies (Grenoble, France): Longstanding European presence with capabilities in brazing, sintering and quenching — competitive where European regulatory compliance and local service are decisive.
-
Camco Furnace (San Carlos, CA, USA): Specialist in hydrogen and high vacuum furnaces up to 2300°C — strong in metallurgical and advanced material applications.
-
ALD‑Holcroft (Wixom, MI, USA): Provides advanced vacuum furnace technologies tailored to automotive and precision heat treatment processes.
Recent vendor motions underline the market’s operational tempo: installations and certifications through late 2025 and into 2026 demonstrate ongoing capacity investment and quality positioning by service providers. These public actions — new high‑pressure installations, large system shipments into aerospace suppliers, upgrades to hot zones, and merit‑level Nadcap certifications — validate both demand and the premium placed on certified process capability.
What the full PW Consulting report delivers (practical, decision‑ready content)
Our full study is built to be operational for executives, plant managers, procurement leads, and investors. Key deliverables include:
-
Executive decision frameworks: CAPEX prioritization templates that quantify payback windows under multiple demand ■scenarios and energy cost trajectories.
-
Risk and mitigation playbook: Tactical steps to de‑risk graphite shortages, including dual‑sourcing strategies, inventory hedging, and validated substitute materials mapping.
-
Vendor assessment toolkit: Scorecards and negotiation levers based on technical fit, service footprint, certification capability, and total cost of ownership.
-
Procurement timing matrix: When to order from standard builds vs. custom systems to align delivery, qualification, and production ramps (including critical lead‑time buffers).
-
Product roadmaps and retrofit guides: Practical design changelists to meet imminent energy‑efficiency regulations and reduce lifecycle emissions without sacrificing throughput.
-
Aftermarket monetization playbook: Strategies for OEMs and service players to capture higher margin through spares, qualification services, digital monitoring, and performance‑based contracts.
-
Investment and M&A shortlist: Criteria‑driven targets for buyers seeking to acquire capability (e.g., HP gas quench, ultra‑high‑temp sintering) with indicative valuation ranges and integration risks.
Actionable recommendations for 2026
-
Lock in supply diversity now: Buyers should execute dual‑source agreements and strategic inventory buffers for graphite and other critical inputs to protect 2026 build schedules and reduce price exposure.
-
Accelerate energy‑compliant upgrades: Manufacturers selling into Europe and other regulated markets should fast‑track low‑emissions product upgrades and customer retrofit kits to capture replacement cycles.
-
Prioritize service‑first economics: Newly installed systems should be specified for modular hot‑zone swaps, remote diagnostics, and spare part standardization to maximize lifecycle margins.
-
Time CAPEX for the ramp: Stagger capital commitments to align with the 2026–2032 growth trajectory — early adopters of advanced quench and vacuum brazing technologies can achieve premium pricing and shorter qualification windows.
-
Build partnership ecosystems: OEMs and suppliers should form strategic alliances with specifiers in aerospace and semiconductors to co‑develop validated thermal cycles and reduce customer time‑to‑market.
Risks and watchlist through 2026
-
Prolonged graphite supply constraints and export controls that materially lengthen lead times and increase system prices.
-
Tightened regional regulations that require retrofits or early obsolescence of non‑compliant designs, increasing total lifecycle costs for some installed bases.
-
Qualification bottlenecks in aerospace and semiconductor segments — which may delay customer adoption of new furnace models despite availability.
-
Competitive shaving of margins as mid‑sized players target aftermarket and services to offset slowing new‑build growth in some geographies.
Concluding perspective — how to use this preview
For executives preparing 2026 strategy decks, this preview should be read as the operational intelligence layer that informs three decisions: where to commit capital, how to shield manufacturing timelines from raw‑material volatility, and which vendor capabilities will deliver the fastest path to qualified production. The underlying market momentum — represented by mid‑2020s scale and an approximately 7.85% CAGR through 2032 — validates continued investment while also demanding disciplined risk management.
PW Consulting’s full report contains the granular regional, type, and application breakdowns, quantitative scenario models, supplier scorecards, and procurement playbooks that translate this high‑level direction into executable plans. Accessing the complete study will provide the detailed inputs necessary for procurement specifications, CAPEX approvals, M&A due diligence, and operational hedging strategies.
For detailed analysis of this topic, please visit the official page: Vacuum Atmosphere Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steering Wheel Adjustment Motors — USD 2,110.88M by 2032 at 6.19% CAGR
By PW Consulting, 2026-07-13
Automotive Steering Wheel Adjustment Motor Market — Strategic Preview for 2026 Decision-Makers
As vehicles evolve from mechanical assemblies to integrated smart cabins, the humble steering wheel adjustment motor is becoming a strategic component. Our latest PW Consulting study positions this market as a distinct growth node within the broader vehicle electrification and human-machine interface (HMI) wave: the global market stood at approximately USD 1.39 billion in 2025 and is forecast to expand to roughly USD 2.11 billion by 2032, growing at a compound annual growth rate (CAGR) of 6.19% through the 2026–2032 forecast window. For corporate leaders planning investments, procurement strategies, product roadmaps or M&A activity in 2026, this study delivers the actionable context needed to convert opportunity into advantage.
Automotive Steering Wheel Adjustment Motor Market
Why this market matters for 2026 strategic choices
-
Convergence of cabin electrification and advanced driving functions: Steering adjustment actuators are no longer a convenience feature; they play a role in automated ingress/egress, memory-based personalization, and even steer-by-wire architectures that reshape interior packaging. Decisions on motor topology, control integration and supplier relationships now affect vehicle architecture and customer experience.
Automotive Steering Wheel Adjustment Motor Market -
Commodity and supply-chain inflection points: Compact high-torque motors increasingly rely on NdFeB rare-earth magnets. Recent 2025 developments — including domestic NdPr supply agreements and qualification of U.S.-produced NdPr oxide into automotive-grade magnet production — materially change sourcing calculus for OEMs and tier suppliers in 2026.
Automotive Steering Wheel Adjustment Motor Market -
Consolidation and competitive positioning: The market exhibits moderate concentration; the top three players control a meaningful share, and the top five consolidate a clear majority. That dynamic creates windows for strategic partnerships, volume-driven pricing plays, and selective M&A to secure capability or margin.
-
Regulatory and safety lift: Emerging standards for steer-by-wire systems (notably ISO 19725 under publication during 2024–2025) mean that 2026 product and supplier selections must account for system-level validation and compliance timelines, not just component cost and performance.
What PW Consulting’s report delivers — practical content for 2026 action
-
Forward-looking market sizing and scenario modelling: A base-year anchor in 2025 with forecasts to 2032, including high/medium/low adoption scenarios that map directly to EV penetration, autonomous driving feature sets and regional OEM program timelines.
-
Technology and design decision framework: A detailed assessment of motor topologies (brushed vs brushless), actuation form-factors (linear vs spindle/hollow-shaft), control electronics integration, and crash- and noise-performance trade-offs — presented as decision matrices tailored to OEM, tier-1, and supplier use cases.
-
Supplier benchmarking and playbooks: Comparative scorecards covering capability, program wins, manufacturing footprint, and integration expertise. Benchmarks are presented with recommended sourcing strategies — direct supply, JV/strategic equity, or multi-source backup — depending on strategic priorities.
-
Materials and procurement risk module: Analysis of NdPr/NdFeB supply pathways, price-sensitivity scenarios and mitigation tactics including long-term offtakes, vertical integration, and design options that reduce rare-earth intensity without compromising torque density.
-
Regulatory and systems safety checklist: Compliance pathways for emerging standards (including steer-by-wire safety requirements), recommended testing programs and timelines to align product launches with certification milestones.
-
Commercial models and pricing sensitivity: Templates for total cost of ownership (TCO) including integration costs, warranty exposure and program allocation that allow procurement and product teams to stress-test supplier proposals.
-
Deal and portfolio playbook: M&A targets, partnership archetypes and integration plans built from scenario analysis — enabling rapid decision-making in 2026 when consolidation windows open.
Market dynamics to watch in 2026
-
Material sovereignty and magnet markets: 2025 transactions and technical milestones — such as domestic NdPr supply agreements and the commercialization of U.S.-produced NdPr oxide into automotive-grade NdFeB magnets — have reduced single-source risk. Nevertheless, price volatility remains a core purchasing risk into 2026; our procurement module models price bands and hedging strategies to protect margin.
-
Shift to more integrated actuator subsystems: OEMs increasingly seek suppliers capable of delivering not just motors but validated actuator subassemblies with embedded controls, memory functions and diagnostics. This trend favors suppliers with cross-domain system competence or those willing to partner with electronics specialists.
-
Regulatory gating for steer-by-wire adoption: As ISO 19725 becomes authoritative for certain vehicle classes, OEMs that plan to introduce steer-by-wire features must prioritize suppliers with documented system-safety engineering processes and demonstrable compliance roadmaps.
-
Program cadence and volume timing: The market’s projected expansion from the 2025 base through 2032 at a 6.19% CAGR is not linear across vehicle segments or geographies. Program award timing and first-fit positions in vehicle platforms will determine which suppliers capture disproportionate share of incremental revenue. Our report maps those program windows to OEM roadmaps to help teams prioritize 2026 engagement plans.
Competitive landscape — players to know and why they matter
-
Johnson Electric (Hong Kong) — strengths: dedicated steering adjuster motors with automatic linear and height adjustment, and user-centric modes (intelligent/welcome) that align with smart-cabin and EV applications. Their product focus makes them a go-to for OEMs prioritizing seamless entry/egress experiences.
-
Bosch Mobility (Germany) — strengths: broad electric drive portfolio (including hollow-shaft and spindle solutions) offering mature functions such as easy entry/exit, memory, low-noise designs and crash resistance across 12/24V platforms. Bosch’s systems expertise positions it well for safety-critical and integrated solutions.
-
NSK (Japan) — strengths: engineered tilt and telescopic columns using advanced plastic technologies for impact energy absorption and position memory. NSK’s materials and mechanical know-how are attractive to programs where crash performance and weight savings are prioritized.
-
thyssenkrupp (Germany) — strengths: infinitely variable electrical height/length adjusters for luxury segments, utilizing lightweight aluminum/magnesium and high crash-safety designs. Their premium positioning serves high-margin vehicle lines seeking sophisticated user features.
-
Brose (Germany) — strengths: integration of motorized adjusters within a broader electric motors & drives portfolio, with a track record of providing compact, integrated solutions for steering columns.
-
Nexteer Automotive (United States) — strengths: systems-level steering columns and intermediate shafts with capabilities for steer-by-wire and stowable columns. Nexteer is notable for supplying architectures that enable novel interior layouts and automated driving features.
-
JTEKT (Japan) — strengths: steering systems with electronic power steering and adjustment-related tuning expertise; attractive to OEMs seeking tight integration between steering feel and adjustment mechanics.
Collectively, the top three and top five suppliers wield concentrated market influence — an important fact when negotiating volume, intellectual property sharing and platform commitments. Our study’s competitor scorecards and negotiation playbooks provide program-specific guidance without publishing commercially sensitive detail in this preview.
Strategic plays we recommend for 2026
-
Lock early on magnet supply paths: Negotiate offtake or strategic partnerships with magnet producers or qualified converters, or design product variants that reduce rare-earth intensity. Time-to-contract in 2026 will materially affect component cost curves into 2027 and beyond.
-
Prioritize system-capable suppliers: Favor partners who can deliver validated actuator subassemblies with software and diagnostics — this reduces integration risk and compresses vehicle validation timelines.
-
Define compliance and testing milestones in supplier contracts: Embed ISO 19725-aligned milestones and third-party verification into early-stage contracts to de-risk steer-by-wire program timelines.
-
Use modular sourcing to balance innovation and security: Combine strategic single-sourcing for performance-critical variants with second-source agreements for mainstream volumes to maintain resilience without sacrificing capability.
-
Monitor consolidation targets: With market concentration favoring a handful of suppliers, 2026 is likely to see partnership and M&A activity — be prepared with criteria for when to pursue bolt-on acquisitions versus technology partnerships.
How to use this preview and next steps
This article is a strategic preview designed to highlight why the steering wheel adjustment motor market deserves board-level attention in 2026. It showcases the depth of the PW Consulting analysis — including scenario-based forecasts, supplier scorecards, materials risk models, and compliance playbooks — while intentionally omitting the granular segment tables and program-level numeric matrices that are reserved for the full report.
For procurement leaders, product chiefs and corporate strategists planning 2026 actions, the full study provides the playbooks and financial models needed to make decisive moves: secure material pathways, prioritize supplier engagements, specify safety and validation milestones, and assess M&A opportunities against quantified demand scenarios. Accessing the complete report will unlock the segmented forecasts, program-timing maps and vendor negotiation templates that convert the strategic directions outlined here into executable plans.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Adjustment Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Purity Methyl Acetate Market — USD 309.62M by 2032, 5.48% CAGR
By PW Consulting, 2026-07-13
High Purity Methyl Acetate Market — Strategic Preview for 2026 Corporate Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our forthcoming High Purity Methyl Acetate Market research. This briefing surfaces the strategic implications executives must internalize heading into 2026, anchored in the report’s quantitative framework and scenario work. It demonstrates the analytical depth behind our findings while intentionally withholding granular segment tables and proprietary unit economics — the premium content that drives visits to the full study.
High Purity Methyl Acetate Market
Market snapshot: macro trajectory and what it means
High-purity methyl acetate has recorded steady expansion through the recent five-year window, rising from a global market in the low hundreds of USD million in 2020 to a 2025 base of approximately USD 213 million. Our forecasted compound annual growth rate (CAGR) of 5.48% through the 2026–2032 horizon points to a market that remains niche but durable, scaling toward a projected market size by 2032 that materially exceeds the 2025 base.
High Purity Methyl Acetate Market
For corporate leaders, two immediate takeaways emerge from this macro trajectory. First, the market is large enough to justify targeted commercial and supply-chain plays — but not so large as to allow passive strategies. Second, the growth profile favors suppliers and downstream users who can capture value through product specification, reliability of supply, and regulatory alignment rather than scale alone.
High Purity Methyl Acetate Market
Key dynamics shaping supplier and buyer strategy
-
Feedstock and margin sensitivity: Methanol and acetic acid constitute the dominant cost components of methyl acetate manufacture. For high-purity grades, additional purification and handling steps amplify raw-material sensitivity. Volatility in these feedstocks can compress margins quickly; our report offers scenario-level sensitivity maps tying feedstock swings to margin outcomes across manufacturer archetypes.
-
Near-term price pressure in China and implications: Recent supply-side disruptions and cost pressures in China have increased acetic acid and methanol market volatility. These dynamics translate to transitory cost inflation for methyl acetate producers and underscore the strategic value of diversified feedstock sourcing, hedging programs, and optionality in purification throughput.
-
Regulatory tailwinds for application demand: High-purity methyl acetate benefits from favorable regulatory positioning in key end markets. In the U.S., it remains VOC-exempt under applicable EPA guidance, which continues to incentivize its use in environmentally oriented coatings, cleaners, and adhesives. Anticipate regulatory alignment to persist as a structural demand support in developed markets.
-
Purity as a differentiator: The delta between standard and high-purity grades is more than a specification — it is a commercial moat. High-purity product lines underpin access to pharmaceutical intermediates, electronics cleaning, and precision coatings where contamination tolerance is minimal. Suppliers that can articulate validated manufacturing controls and certificate-of-analysis traceability command preferential commercial positioning.
Competitive landscape — positioning implications for 2026
The market is neither atomized nor tightly monopolized: a group of established chemical majors and specialist producers hold substantive share, while regional players and lab-supply brands address niche and local demand. The competitive map splits into three broad strategic archetypes: global integrated majors, specialty/pharma-grade suppliers, and large-scale regional producers with cost advantage.
-
Global integrated majors (Eastman Chemical, Celanese, BASF): These firms leverage integrated acetate value chains, stringent environmental and quality controls, and global customer relationships to sell high-purity grades into coatings, adhesives, and chemical intermediates. Their strategic strengths are certifiable supply continuity, product stewardship, and scale-driven innovation in formulation support. For buyers, these vendors offer lower supply risk but often command premium contractual terms.
-
Specialty and life-science suppliers (Merck KGaA / MilliporeSigma, Thermo Fisher Scientific): These companies compete on ultra-high-purity specifications, documentation (e.g., pharma/analysis-grade certificates), and service-levels tailored to R&D and regulated manufacturing. Their go-to-market focuses on traceability, small-batch flexibility, and proximity to lab and pharmaceutical customers — attributes that are mission-critical for regulated end-uses.
-
Large-scale regional producers (Anhui Ruibai and comparable integrated acetate producers): Certain vertically integrated producers in Asia have developed cost-advantaged capacity and breadth of acetate derivatives, enabling competitive pricing for electron-grade and industrial-high-purity grades. Their scale can pressure margins for non-differentiated product lines in cost-sensitive regions, while their expansion plans influence global supply balance.
Strategic implication: procurement organizations should differentiate supplier selection by use-case — aligning ultra-high-purity purchases with specialty providers while pursuing cost-and-security trade-offs with integrated players. For producers, the path to premium positioning lies in validated quality systems, regional servicing capability, and targeted product variants for electronics, pharma, and precision coatings.
What our full report provides — a practitioner’s brief
The report translates market projections into executable intelligence for commercial, supply-chain, and M&A decision-makers. Highlights include:
- Robust demand model: A top-down market model from 2020 through 2032, with base-year calibration, scenario runs, and sensitivity testing tied to feedstock and end-market assumptions.
- Supplier and manufacturing dossier: Operating profiles and strategic assessments of leading producers (including product positioning, certification footprints, capacity archetypes, and investment signals).
- Price and margin scenario library: Forward-looking cost maps showing how acetic acid and methanol moves cascade into producer margins under varying purification intensities.
- Go-to-market and customer segmentation playbooks: Differentiated commercial strategies for suppliers versus buyers, including channel design, technical service requirements, and contract structures that protect margin while enabling growth.
- Risk matrix and mitigation playbook: Practical mitigation measures for feedstock volatility, regulatory shifts, and supply disruptions, complete with contingency checklist and prioritized mitigation investments.
- M&A and capex decision tools: Transaction screeners, payback windows for purification capacity add-ons, and integration checklists tailored to players considering upstream or downstream consolidation.
Each analytical module is supported by an evidence base of primary interviews, trade data, and proprietary modeling. The report is deliberately pragmatic: every section concludes with an "Action Radar" — a ranked list of the next three moves executives should consider within 3, 6, and 12 months.
Actionable recommendations for 2026 planning
-
For producers: Prioritize investments in purification and analytical capabilities that enable premium-grade certifications. Consider staged capacity additions tied to offtake commitments rather than speculative greenfield expansion. Evaluate upstream hedging partnerships for methanol and acetic acid exposure and explore product bundling with adjacent acetate derivatives.
-
For downstream manufacturers (coatings, adhesives, pharma, electronics): Establish dual-sourcing frameworks that match supplier capability to quality requirement, with contractual clauses that address force majeure and feedstock pass-throughs. Where contamination intolerance is high, prefer suppliers with documented pharma/lab credentials and regional inventory support.
-
For investors and M&A teams: Target assets that either (a) offer validated access to high-purity manufacturing with certificates and audited processes, or (b) provide feedstock integration that compresses cost exposure. Be cautious of assets reliant on commoditized grade sales without visible technical differentiation.
Methodology and market concentration note
Our modelling synthesizes historical market flows (2020–2025), bottom-up supply assessments, and end-market demand drivers through 2032. The competitive landscape shows a market where leading firms collectively command a meaningful plurality of demand — creating both competitive pressure and opportunities for specialist entrants. For executives, this means scale matters, but so does specification control and service-level differentiation.
Why this preview — and why now
Entering 2026, firms face a convergence of factors: feedstock volatility that can alter cost curves quickly; regulatory regimes that advantage certain solvents; and an end-market mix that rewards precision and traceability. Our report equips decision-makers with the quantitative scenarios, supplier insights, and tactical playbooks required to translate forecast trajectories into defensible, revenue-protective choices.
To access the full dataset, regional and application-level segmentation, detailed supplier benchmarking, and the Action Radar that operationalizes these findings, please consult the complete High Purity Methyl Acetate Market report on the PW Consulting research portal. The premium analysis contains the discrete segmentation tables and unit-cost schedules that are deliberately omitted from this preview.
For detailed analysis of this topic, please visit the official page: High Purity Methyl Acetate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hectorite Clays Market to Reach USD 1,185.5M in 2025, Growing at 4.82% CAGR
By PW Consulting, 2026-07-13
Hectorite Clays Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused, decision-oriented preview of our full Hectorite Clays Market study. This preview synthesizes the macro trajectory, structural dynamics, and actionable strategic implications that will matter for boardrooms and commercial teams planning for 2026. It is designed to demonstrate the analytical depth of our research while reserving granular segment-level data and proprietary scenarios for the full report.
Hectorite Clays Market
Market at a Glance: Growth and the Strategic Implication
Hectorite remains a specialty industrial mineral with a clear and stable growth profile. Our bottom-up sizing shows the market expanding from a mid-single‑hundreds USD million base in 2020 to an estimated USD 1,185.5 Million in 2025, with a near-term forecast of roughly USD 1,253 Million in 2026 and a long‑run projection approaching USD 1,646 Million by 2032. That trajectory implies a compound annual growth rate in the high‑single digits over the full forecast window (4.82% CAGR across the modelling horizon), driven by steady demand in specialty formulators and a rising premium for high‑performance natural and modified hectorite products.
Hectorite Clays Market
Strategic takeaway for 2026: growth is reliable rather than explosive. This creates a planning environment where investments in supply security, product differentiation and regulatory/sustainability alignment typically yield higher and more predictable returns than speculative capacity plays.
Hectorite Clays Market
Why Hectorite? Structural Drivers and Competitive Implications
- Unique material properties: Hectorite’s rheological, suspension, and adsorption characteristics make it indispensable in high‑margin applications—cosmetics, specialty coatings, drilling fluids and select industrial adhesives. These end uses reward performance and certification over commodity price competition.
- Constrained primary supply: Natural high‑grade hectorite sources are geographically limited, with one major commercial high‑grade mine serving global markets. That structural scarcity elevates the strategic value of upstream assets and long‑term offtake arrangements.
- Mix of natural and synthetic pathways: Producers offer a spectrum from mined natural hectorite to engineered synthetic and organo‑modified grades. Each pathway carries different margin profiles, capital commitments, and sustainability narratives, creating distinct strategic options for market entry or consolidation.
- Regulatory and sustainability overlay: Cosmetic safety assessments and accelerating environmental scrutiny in mining jurisdictions favor suppliers who can demonstrate both product safety (e.g., cosmetic-use concentrations validated by independent review) and responsible extraction/processing practices.
Competitive Landscape — Who Matters and Why
The supplier landscape is characterized by a mix of integrated incumbents, regional formulators and specialist processors. A relatively small group of global and regional players controls the lion’s share of commercial hectorite supply and downstream rheology solutions. Key dynamics we highlight:
- Upstream owner-operators: Firms that control high‑grade natural deposits possess an outsized strategic lever. Ownership of primary ore source(s) reduces substitution risk and enhances negotiating power for premium supply contracts.
- Formulation leaders and branded additives: Producers that pair mineral access with branded, application‑specific formulations (e.g., additive families targeted at personal care and coatings) capture a disproportionate share of value through R&D‑driven differentiation and technical service.
- Regional manufacturers and supply chains: Several Asia‑based manufacturers supply engineered and organo‑modified hectorite grades at scale, supporting rapid formulation cycles in high-growth consumer and industrial markets.
Recent market activity reinforced these structural contours. Leading additive firms have rolled out new hectorite product lines tailored to high‑growth personal care segments, while academic and industrial R&D has produced novel synthesis routes for mesoporous and modified hectorite—opening new application adjacencies such as adsorption and targeted delivery systems. For commercial strategists, these trends translate into both offensive and defensive pathways: invest in formulation IP to capture premium margins or secure upstream capacity to protect supply and cost base.
Risk Map: What Keeps CFOs and Procurement Directors Awake
- Supply concentration risk: Limited geographic sources create exposure to single‑asset disruptions and raise the value of dual‑sourcing, long‑term offtake and vertical partnerships.
- Price and input volatility: While hectorite is not a high‑volume commodity, related clay markets and logistics cycles influence landed cost. Traders and industrial buyers should model scenarios for transportation, energy and environmental compliance costs.
- Regulatory and ESG compliance: Mining environmental permitting and chemical safety frameworks are tightening across North America and Europe. Firms lacking transparent sustainability practices face market access friction among large formulators and retailers.
- Substitution and technological disruption: Advances in synthetic and organically modified hectorite, along with alternative rheology technologies, can shift value‑capture to innovation‑savvy competitors.
What the Full PW Consulting Report Delivers (Operationally Focused)
Our full study is calibrated to inform commercial and investment decisions for 2026 and beyond. Core deliverables include:
- Robust market sizing and scenario forecasts with transparent methodology and sensitivity analysis across pricing, demand elasticity and substitution paths.
- Supply‑chain heatmap and vulnerability scoring for upstream assets, logistics corridors and processing nodes—designed to support procurement risk mitigation and offtake strategy.
- Competitive intelligence dossiers on leading and disruptive players, combining product portfolios, technical capabilities, asset ownership and go‑to‑market positioning.
- Commercial playbooks tailored to three corporate archetypes: (a) upstream asset owner/operator; (b) formulation and branded additive company; (c) downstream manufacturer/end‑user—each with prioritized tactics for 12–36 month implementation.
- M&A and partnership screening framework that ranks targets by strategic fit, integration risk and realistic synergies under conservative and aggressive scenarios.
- Regulatory and ESG tracker focused on cosmetics safety standards, mining environmental compliance and relevant trade contexts affecting inputs and logistics.
- Technical deep dive on innovation pathways, including organo‑modification chemistry and emergent synthesis methods like steam‑assisted crystallization (SAC) that could alter cost and performance dynamics.
Strategic Moves for 2026 — Prioritized, Pragmatic Recommendations
To convert market insight into measurable advantage in 2026, we recommend executives prioritize three parallel tracks:
- Secure supply, then optimize: Negotiate multi‑year offtake agreements with high‑grade suppliers or pursue minority equity stakes in upstream assets. For formulators, short‑term spot buying is unattractive without parallel efforts to qualify secondary suppliers.
- Invest selectively in product‑led differentiation: Allocate R&D budget to organo‑modification and formulation services that deliver demonstrable performance and compliance benefits—areas where customers will pay premiums. Technical service and co‑development shorten adoption cycles.
- Operationalize sustainability as market access: Develop and publish verifiable sustainability metrics (chain‑of‑custody, emission intensity, reclamation plans). For many buyers in cosmetics and coatings, sustainability is already a procurement filter rather than a marketing garnish.
Secondary recommendations include exploring bolt‑on acquisitions in regional processing to improve turn times for Asia‑based customers, and establishing a monitoring program for emergent synthesis processes that could change the long‑term mix of natural versus engineered hectorite supply.
Execution Checklist for Boards and Commercial Leads (90–180 day horizon)
- Audit current supply contracts and map single‑point failure exposures; prioritize escalation for any single‑source items tied to critical SKUs.
- Initiate one pilot co‑development with a branded additive firm to lock technical specs and accelerate customer adoption.
- Commission a lightweight ESG due diligence on upstream suppliers to assess alignment with target accounts’ procurement policies.
- Run a three‑scenario profitability model (base, upside, downside) for your hectorite‑dependent product lines to quantify sensitivity to raw material movements and switching costs.
Closing: Why This Matters for 2026
Hectorite’s market dynamics in 2026 present a classical alignment problem with a strategic premium: modest, dependable growth coupled with concentrated supply and rising regulatory/sustainability expectation. That combination rewards firms that move from transactional buying to strategic sourcing, from generic formulations to co‑developed, certified solutions, and from ad‑hoc R&D to targeted product platforms. Our full report equips leadership teams with the empirical modelling, competitor playbooks and operational checklists required to convert these market characteristics into defensible commercial advantage.
For access to the full dataset, segmentation granularity, modelled scenarios and company‑level playbooks that underpin these recommendations, request the complete PW Consulting Hectorite Clays Market report. The full study contains the proprietary segment-level intelligence and tactical templates necessary to execute the 2026 moves described above.
For detailed analysis of this topic, please visit the official page: Hectorite Clays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


