



PW Consulting: Ground Handling Services Market to Reach USD 56.8B by 2032 at 7.9% CAGR
By PW Consulting, 2026-07-12
Ground Handling Services Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a focused briefing on the ground handling services market designed to inform executive choices in 2026. This preview synthesizes our latest market modelling (base year 2025) and competitive intelligence into a practical, decision‑oriented narrative. Readers will gain the strategic context and prioritized actions needed to navigate a market that is expanding steadily yet experiencing structural change driven by regulation, digitalization, and shifting carrier economics.
Ground Handling Services Market
Market at a glance: growth trajectory and structural cues
The ground handling services market has rebounded strongly from the pandemic trough. Our historical series shows expansion from roughly USD 24 billion in 2020 to USD 33.5 billion in 2025. Looking forward, the market is forecast to grow at a compound annual growth rate (CAGR) of 7.9% during 2026–2032, reaching approximately USD 56.8 billion by 2032. This growth profile reflects a blend of passenger recovery, sustained uplift in air cargo flows, and steady outsourcing demand from carriers and airports.
Ground Handling Services Market
Two structural features are particularly important for strategy in 2026: first, meaningful concentration among scale incumbents that capture a large share of revenue; second, accelerating non‑linear value drivers — notably technology platforms, regulatory compliance regimes, and new commercial contracting practices — that are re‑shaping unit economics across service lines.
Ground Handling Services Market
Why this study matters for decisions in 2026
- Regulatory inflection points: New EU and UK requirements for the provision and oversight of ground handling services are moving from consultation to enforcement. These rules introduce certification, compliance and self‑declaration steps with near‑term deadlines, forcing providers and their airline partners to re‑engineer governance, training and audit trails.
- Commercial pressure and margin re‑rating: Airlines are revisiting outsourcing models, pricing structures and performance metrics. Contract renegotiations and route network changes are creating winners and losers among established providers and regional specialists.
- Technology and operational transformation: Investments in resource optimization, baggage reconciliation systems, and shared data platforms are creating a two‑speed market: operators who digitize capture productivity gains rapidly while laggards face margin compression.
- Cargo and ancillary growth vectors: E‑commerce tailwinds and growth in freighter operations are producing outsized revenue opportunities, but also require different asset mixes, skillsets and throughput models compared with passenger handling.
Report scope — practical outputs you can apply immediately
Our full research is structured to move beyond benchmarking and into operational and commercial playbooks. Key deliverables include:
- Top‑down market sizing (2020–2025 historical, 2026–2032 forecast) with scenario buckets for faster/slower recovery paths.
- Segmentation by region, service type and application (kept at a high level here to preserve proprietary granularity in the full report).
- Provider profitability matrix, cost‑per‑turn models and normalized SG&A overlays for peer comparison.
- Service‑level KPI benchmarks (turnaround times, baggage mishandling rates, ramp productivity) and a digital‑adoption maturity model for operations teams.
- Regulatory compliance checklist and an implementation timeline tied to EU/UK milestone dates, designed for use in operational readiness programs.
- Commercial playbook: bid‑defense templates, contract clause prioritization, and scenario‑based price modelling for tenders and renegotiations.
- M&A and partnership decision framework — target archetypes, valuation sensitivities and integration checklists — tailored to mid‑market and strategic bolt‑on transactions.
Competition: strategic positioning and recent moves
The market is shaped by global integrators, regionally dominant players and specialist technology providers. Understanding each archetype’s playbook is critical for strategic responses.
- Swissport International AG — A scale leader with a broad global footprint and multi‑certification profile. Recent contract wins and regional rollouts demonstrate a continued emphasis on large‑scale network expansion and contract consolidation with global and flag carriers. For incumbents and challengers alike, Swissport’s strategy underscores the importance of combined scale and standardized, certificated operations when competing for major airline agreements.
- dnata — An integrated services operator with a strong base in the Middle East. dnata’s model blends ground handling with cargo and travel services, offering resilience through diversification and long‑term airline partnerships. Their approach is instructive for operators seeking to deepen vertical integration and cross‑sell ancillary services.
- Worldwide Flight Services (WFS) — A specialist in both ground and cargo operations with focused growth in high‑throughput nodes. WFS highlights the commercial leverage available from aligning cargo capabilities with freighter network growth and logistics customers.
- Menzies Aviation — A prominent competitor that is actively investing in next‑generation operational technologies. Recent rollouts of advanced baggage reconciliation and resource planning systems signal a strategy of performance differentiation via digital enablement and targeted airline partnerships.
- Aviapartner and regional specialists — Independent providers that maintain deep local relationships at major hubs. Their agility in tailoring service levels and pricing remains a strategic advantage in contested tenders where incumbents may be constrained by scale and cost structures.
- 5Continents and regional-focused operators — Anchored in specific geographies, these players reveal opportunities in markets with under‑served capacity or where regulatory complexity favors local providers.
- SITA — A pivotal technology partner, supplying data platforms and operational solutions that increasingly sit at the center of collaborative airport ecosystems. For many operators, engaging with platform providers like SITA is less a back‑office choice than a strategic necessity to access airline/airport data and to enable industry‑level interoperability.
Market concentration metrics confirm an environment where the leading few capture the majority of revenue, creating high barriers to scale. Nevertheless, the combination of regional specialization, technology partnerships, and performance‑led contracting continues to open pockets of opportunity for focused entrants and well‑executed roll‑ups.
Top strategic implications and prioritized actions for 2026
Executives should translate the market realities into a clear set of near‑term and medium‑term initiatives. Our recommendation framework breaks down into coherent, actionable priorities:
- Regulatory readiness (immediate to 12 months): Establish a cross‑functional compliance program that maps EU/UK requirements against your operating procedures, contracts and training curricula. Use a risk‑based approach to prioritize certifications and self‑declaration paths.
- Digitize to defend margins (0–24 months): Prioritize investments that deliver clear unit‑cost reductions (resource scheduling, digital ramp coordination, baggage RFID/BRS). Pilot small, measurable deployments before scaling across hubs.
- Commercial re‑engineering (0–18 months): Revisit contract structures to align incentives around on‑time performance, asset utilization and ancillary upsides. Develop tailored bid strategies for large network contracts versus opportunistic regional tenders.
- Targeted M&A and partnerships (12–36 months): Use M&A to fill capability gaps (technology, cargo handling, regional access) rather than to chase scale alone. Consider JV structures for rapid market entry where regulatory or labor dynamics make outright acquisition risky.
- Workforce and labor strategy (ongoing): Invest in training, multi‑skilling and accredited competency systems to meet both regulatory requirements and the flexibility needed for peak recovery periods.
- Sustainability and energy transition (18–48 months): Begin aligning fleet and ground equipment replacement plans with decarbonization trajectories — this will increasingly influence contract awards and airport concession terms.
Operational playbook — three horizons
- Quick wins (0–6 months): Standardize SOPs, tighten KPIs on mishandling and turnaround delays, and launch low‑cost digitization pilots at high‑volume gates.
- Build capability (6–24 months): Deploy scalable resource optimization platforms, certify training programs for compliance, and negotiate technology partnerships with platform providers.
- Strategic re‑positioning (24–36 months): Execute selective bolt‑on acquisitions, develop cross‑border service bundles aligned to airline network strategies, and institutionalize continuous improvement via data‑driven operations centers.
Getting the full picture
This preview highlights the strategic themes that will shape successful ground handling strategies in 2026. The full PW Consulting report contains the detailed segmentation, proprietary unit‑cost models, KPI dashboards and regulatory checklists that executives and transaction teams need to operationalize these recommendations. Our analysis intentionally provides high‑level direction here while reserving granular splits, scenario worksheets and model inputs for the full study to preserve exclusivity and to ensure decision‑grade utility.
For leaders preparing budgets, negotiating multi‑year contracts, or evaluating acquisitions in 2026, this research converts macro growth and regulatory change into concrete choices — enabling you to prioritize investments, structure partnerships, and defend margins as the market scales toward the USD 50+ billion horizon signaled in our forecasts. Contact PW Consulting to access the full dataset, regional breakdowns and executable playbooks used to underpin this strategic briefing.
For detailed analysis of this topic, please visit the official page: Ground Handling Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Identity Resolution Software Market to Reach USD 2.42M by 2032 at 9.9% CAGR
By PW Consulting, 2026-07-12
Identity Resolution Software Market 2026: Strategic Imperatives for Decision Makers
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present an executive preview of our latest market research on the Identity Resolution Software (IRS) market. This briefing is designed to articulate the strategic value of the full report for enterprise and investor decisions in 2026: the choices that will determine competitive positioning, customer economics, compliance posture, and technology architecture over the next business cycle.
Identity Resolution Software Market
Why this research matters for 2026 decision cycles
Identity resolution is no longer a niche data-science exercise. It is an operational capability that underpins personalized customer experiences, fraud prevention, compliance, measurement and cross-channel orchestration. In 2026, procurement and product teams face a narrow window of action: privacy regulation, signal deprecation and accelerating expectations for real-time interactions are compressing the timeline to deploy robust, auditable identity fabrics.
Identity Resolution Software Market
Our research equips executives to prioritize investments that materially change unit economics and risk exposure. We translate market-level dynamics into vendor-agnostic decision frameworks, a procurement playbook, and scenario-tested ROI models so that boards, CIOs and CMOs can act with conviction rather than react to vendor narratives.
Identity Resolution Software Market
Market trajectory: what the headline numbers tell you
-
The IRS market is on a sustained growth path with an annualized growth rate of approximately 9.9% across the forecast window. This trajectory reflects accelerating demand for deterministic linking, hybrid matching architectures, and enterprise-grade data governance.
-
At the base year (2025) the addressable market is measured in the mid-single‑digit millions (USD, revenue unit Million) and our model projects expansion into the low‑single‑digit millions by the end of the forecast horizon. The combination of steady market size growth and fragmentation creates pockets of strategic opportunity for both software vendors and systems integrators.
-
Market concentration is meaningful but not prohibitive: the top three vendors account for under half of the market while the top five capture a clear majority — a structure that sustains competitive differentiation yet allows disruptive entrants to claim share through specialized capabilities or go‑to‑market innovation.
Key dynamics shaping vendor selection and architecture
-
Privacy and regulation: GDPR, CCPA and the emergence of AI governance frameworks are not theoretical constraints. Vendors are being evaluated on privacy-by-design, auditable matching algorithms, and capabilities to support consent orchestration. Compliance is table stakes; explainability and audit trails have become procurement differentiators.
-
Signal deprecation and cookieless environments: The industry faces a structural shift as third‑party identifiers and passive signals decline in reliability. Expect hybrid solutions — combining deterministic identifiers, first‑party orchestration and probabilistic inference where appropriate — to dominate short‑term deployments.
-
Cloud economics and operational cost model: Cloud hosting and API licensing are primary cost drivers for deployments. Procurement must evaluate total cost of ownership across scale scenarios, including data ingress/egress, model retraining frequency, and real‑time API usage patterns.
-
Demand for explainable matching and auditable pipelines: With regulators scrutinizing automated decision-making, enterprises will favor platforms that provide traceability from raw signals to resolved identities, including algorithmic versioning and human‑readable provenance.
-
Integration with customer data architectures: Identity solutions are increasingly assessed by how seamlessly they integrate with CDPs, DMPs, martech stacks and enterprise data lakes, and whether they enable two‑way synchronization with downstream activation systems.
What the PW Consulting report delivers (practical, operational intelligence)
-
Methodology appendix and model transparency — our base-year assumptions, historical calibration and scenario levers are documented so buyers can adapt the model to their environment.
-
Market sizing and forecast — a rigorous top‑down and bottom‑up synthesis that distinguishes addressable market versus committed spend.
-
Procurement playbook — RFx templates, SLAs for match quality and latency, TCO worksheets, and negotiation tactics for licensing and cloud costs.
-
Vendor scorecards and capability matrix — comparative assessment across technical capabilities (deterministic/probabilistic matching, graph depth, API latency), deployment models, privacy features and enterprise readiness.
-
Implementation playbooks — blueprints for proof‑of‑concepts, data hygiene routines, onboarding checklists and runbooks to operationalize identity resolution at scale.
-
Use cases and value cases — quantified examples for personalization lift, attribution accuracy improvement, fraud reduction, and customer lifetime value extension.
-
M&A and ecosystem guidance — strategic criteria for partnering, niche acquisitions and integration risk mitigation to accelerate capability build.
Competitive landscape — who matters and why
The vendor field is a mix of specialized identity‑centric firms, data management stalwarts and cloud‑native entrants. Each cluster brings different strengths that align with distinct buyer profiles:
-
LiveRamp (San Francisco, CA) — A market leader known for its identity graph and interoperability across advertising and measurement ecosystems. Strong in deterministic linking and enterprise integrations; well suited for firms prioritizing scale and cross‑platform reach.
-
Informatica (Redwood City, CA) — A legacy data management vendor that offers identity resolution as part of a broader data governance and MDM suite. Appeals to enterprises seeking integrated data management and governance capabilities alongside identity matching.
-
Zeta Global (New York, NY) — Positioning identity resolution as part of a broader customer engagement and activation platform; attractive to marketers seeking combined identity and activation workflows without stitching multiple vendors.
-
Amperity — Specialized in customer data unification for large enterprises; recognized for strong deterministic matching and enterprise readiness. Often chosen where customer‑centric use cases are prioritized over advertising integration.
-
Hightouch (San Francisco, CA) — A modern CDP/Reverse-ETL oriented player; its recent introduction of adaptive identity resolution reflects a market push toward flexible deterministic/probabilistic hybrid models suited to real‑time activation needs.
-
FullContact, Infutor (Austin, TX), Throtle (Red Bank, NJ), Tapad, NetOwl, Meiro, Wunderkind — These providers occupy differentiated niches: data enrichment and identity graphs, consumer data files, tag and signal-based resolution for cookieless contexts, AI-driven matching and server-side tracking enhancements. Their value is often realized in point solutions, specialized integrations or advanced features such as cross-device graphs and privacy-centric APIs.
Recent vendor developments underscore the direction of product evolution: Throtle’s enhanced tag for cookie‑free environments, Hightouch’s adaptive identity launch, Wunderkind’s cross‑device and server‑side tracking enhancements, and Infutor’s strategic rebranding post‑acquisition. These moves validate the market’s pivot toward cookieless resilience, real‑time activation and enterprise-grade packaging.
Strategic choices for 2026: recommended actions
-
Immediate (next 6 months) — Run dual-path proofs of concept that validate both deterministic matching against your master identifiers and probabilistic augmentation for edge cases. Insist on auditable match logs and regulatory readiness in RFPs.
-
Medium term (6–18 months) — Align identity strategy to your primary use cases (personalization, fraud, compliance). Where activation speed is critical, prioritize platforms with low API latency and robust reverse‑ETL capabilities. Where governance is primary, prioritize vendors with MDM and lineage features.
-
Long term (18–36 months) — Consider strategic M&A or partnerships to acquire capability gaps, particularly around first‑party ingestion, consent orchestration and deterministic householding. Build internal expertise in algorithm explainability and data provenance to reduce vendor lock‑in risk.
-
Procurement checklist — Require model explainability clauses, SLA metrics for match accuracy and latency, portability commitments for resolved identifiers, and explicit costs for cloud hosting at scale.
How PW Consulting’s full report accelerates execution (and why you’ll need it)
The full PW Consulting study is designed as an operational companion for 2026 decision cycles — not an academic exercise. It includes downloadable models, vendor scorecards, an RFx toolkit, scenario-based TCO outputs and playbooks that convert vendor capabilities into measurable business outcomes. We surface risk-adjusted forecasts and provide the decision criteria that translate market growth signals into procurement, product, and M&A moves.
Consider this preview a strategic trailer: we’ve demonstrated the logic, the direction of travel and the vendor contours. The granular intelligence — the interactive segment dashboards, the full vendor scoring matrices, and the raw forecast workbook that allows you to test alternative assumptions — is reserved for the complete report and its client workshop deliverables.
Next steps
If you are prioritizing identity resolution in 2026 — whether to defend privacy compliance, regain measurement fidelity in a cookieless world, or convert customer signals into profitable personalization — PW Consulting’s full report and accompanying advisory engagement are designed to reduce uncertainty and accelerate time to value. Contact our team to schedule a tailored briefing and to receive the full data model and procurement kit.
For detailed analysis of this topic, please visit the official page: Identity Resolution Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Voltage Insulating Gloves Market to Reach USD 232.08 Million by 2032 (6.1% CAGR)
By PW Consulting, 2026-07-12
High Voltage Insulating Gloves Market: Strategic Briefing for 2026 Decisions
As utilities, contractors, OEMs and safety directors plan capital allocation and operational priorities for 2026, the high voltage insulating gloves market presents a measured growth runway underpinned by regulatory certainty, concentrated supply, and persistent material dependencies. This briefing, drawn from PW Consulting’s latest High Voltage Insulating Gloves Market study (base year 2025), synthesizes the strategic implications senior leaders must weigh now. It showcases the analytical depth available in the full report while deliberately omitting proprietary segment-level figures to direct decision-makers to the source for transaction-grade detail.
High Voltage Insulating Gloves Market
Market snapshot: what the headline numbers mean for 2026
The global market for high voltage insulating gloves has expanded steadily through the first half of the decade and continues to exhibit healthy momentum: using 2025 as the analytical baseline, the market grows at a compound annual growth rate (CAGR) of 6.1% into the forecast window. The trajectory reflects a combination of recurring replacement demand driven by mandated dielectric testing and asset maintenance, incremental demand from accelerating renewable-energy infrastructure buildouts, and periodic procurement cycles among large utilities.
High Voltage Insulating Gloves Market
For corporate strategists, two takeaways are immediate. First, predictable growth at the headline level enables multi-year sourcing contracts and phased capacity investments without the macro volatility that forces defensive stances. Second, the market is sufficiently concentrated to make supplier selection and competitive positioning material to margin performance—our concentration analysis shows a meaningful share held by the largest manufacturers, reinforcing the strategic importance of supplier risk management.
High Voltage Insulating Gloves Market
Why this study matters for 2026 decisions
- Capital allocation: The market’s steady CAGR supports investment bets on manufacturing capacity, in-house testing labs, or equity stakes in regional suppliers—each yielding different risk/return profiles evaluated in the full study.
- Procurement strategy: The report models replacement cycles and compliance-driven demand to inform optimal contract length, safety stock, and pooled procurement opportunities across utility consortia.
- Product & R&D prioritization: Detailed demand-driver analysis helps prioritize development of ergonomic, higher-dielectric, or composite offerings targeted to growth applications such as distributed renewables and electrified industrial processes.
- Regulatory compliance & litigation risk: The study translates standards and testing cadence into operational checklists that reduce audit exposure and work-stoppage risk.
Core market dynamics shaping 2026 strategy
- Standards and testing are non-negotiable operational factors. OSHA guidance and ASTM D120 / IEC 60903 conformance frame not only product specs but also employer testing programs; the frequency and traceability of dielectric tests are line-item cost drivers that the report quantifies for multiple operational archetypes.
- Segment-specific regulations matter. Specialized regimes—for example, mining rules that mandate monthly testing for certain classes of gloves—create predictable, recurring replacement demand and elevate the value of vendor-managed inventory and certified-testing-as-a-service models.
- Natural rubber remains the dielectric benchmark. Industry data confirms natural rubber’s superior dielectric properties (exceeding 25 kV/mm in standard test conditions), which underpins its dominant role in high-voltage insulating gloves. That material concentration introduces supply-side exposure to rubber price and provenance risks, a theme the report models across scenarios.
- Product differentiation is evolving. Traditional all-rubber constructions continue to dominate for highest-voltage classes, while composite and hybrid constructions gain traction where ergonomics, dexterity and wear-life improvements deliver measurable operational benefits.
- Concentration enables and constrains strategic options. The market’s top manufacturers account for a majority share—our concentration metrics indicate that the three- and five-firm shares are material—which creates pricing discipline, but also opens opportunities for challengers focusing on service models, certification speed, or niche applications.
Competitive landscape: what incumbents and challengers signal
The market comprises a mix of global incumbents, regional specialists, and vertically integrated safety suppliers. Selected company profiles in the report illuminate strategic postures and tactical playbooks:
- Salisbury (Chicago, IL) — A long-established rubber glove manufacturer with deep penetration into U.S. investor-owned utilities. Salisbury’s ASTM- and IEC-certified product lines and entrenched customer relationships illustrate the defensibility of standard-compliant, high-trust supply in regulated markets. Notably, their scale within utilities creates both supplier advantage and counterparty concentration risk for buyers who over-index to a single source.
- Ansell (Melbourne, Australia) — Positions product development at the intersection of comfort and protection. Ansell’s ActivArmr® line exemplifies a premium play that targets ergonomics and durability, which can reduce total cost of ownership via longer in-service life and fewer fit-related work stoppages.
- PIP (Protective Industrial Products, Rochester, NY) — Offers broad class-range gloves with an emphasis on North American standards and distribution networks. Their catalog approach highlights the strategic value of channel reach and inventory depth for contractors and distributors.
- CATU Electrical (France) — A supplier focused on high-voltage Class 4 capability and international standard conformity, underscoring the importance of technical accreditation for cross-border projects and high-voltage industrial infrastructure.
- C&G Safety (China), Yotsugi (Japan), Stanco (U.S.) — These regional players demonstrate alternate strategies: cost-competitive manufacturing, rapid third-party testing and certification, and specialization in localized standards and service offerings.
Taken together, these profiles point to a dual-path competitive landscape: scale and certification secure the largest contracts, while localized service, testing agility, and ergonomic differentiation create entry points for focused competitors. The full report includes comparative scoring, go-to-market archetypes and supplier diligence checklists for buyers.
Report deliverables: what’s in the practical toolkit
PW Consulting’s study is designed as an operational playbook for buyers, product leaders and investors. Key practical deliverables include:
- Scenario-based market sizing and a transparent forecasting model that maps replacement cycles, standards-driven testing intervals, and application growth into demand curves for 2026–2032.
- Regulatory impact mapping that translates OSHA, ASTM, IEC and industry-specific rules into procurement and testing requirements for different end markets.
- Supplier risk matrix and audit templates covering certification, quality systems, testing cadence and geographic supply risk.
- Product roadmap recommendations: where to invest in composite hybrids, ergonomic liners, and lifecycle-extending coatings to capture higher-margin pockets.
- Procurement playbooks: recommended contract structures, inventory buffers, and testing-service outsourcing options to reduce on-balance-sheet working capital.
- M&A and partnership screening tool: prioritizes targets by technical capability, certification coverage and customer footprint to identify logical tuck-ins or minority investment candidates.
- Operational checklists for dielectric testing programs, vendor-managed inventory pilots, and field training tied to compliance evidence trails.
- Appendices with primary interviews, lab-testing protocols and a glossary of standards and classes for executive reference.
Action roadmap for executives (prioritized for 2026)
- Immediate (0–6 months): Run supplier rationalization workshops using the report’s supplier risk matrix; pilot vendor-managed inventory with one regional utility to validate costs and responsiveness; ensure internal testing programs align with ASTM/IEC/OSHA expectations and capture traceability data for audits.
- Near-term (6–18 months): Invest in ergonomics and lifecycle trials of composite/hybrid gloves for targeted workgroups (e.g., renewable field technicians); negotiate multi-year contracts with built-in service levels and testing support; evaluate strategic minority stakes in regional testing labs or glove manufacturers to secure capacity and certification agility.
- Medium-term (18–48 months): Build or partner for in-house dielectric testing capability where volumes justify; standardize glove procurement across business units to capture scale discounts; pursue product differentiation through co-development with specialty suppliers to address renewables and distributed-energy use cases.
Closing guidance
For leaders making 2026 allocation choices, the market presents an attractive blend of predictability and tactical inflection points. Headline growth provides room for disciplined investment, but material concentration, standards-driven replacement cycles and reliance on natural rubber create strategic trade-offs that require calibrated action. PW Consulting’s full report delivers the empirical foundation, scenario models and executable playbooks to convert these insights into defensible decisions.
Note: this briefing intentionally omits granular regional and application split figures and full segment-level tables—these are included in the complete report and linked dataset. For transaction-ready intelligence, supplier scorecards, and downloadable forecasting models, access the full High Voltage Insulating Gloves Market report on our website.
For detailed analysis of this topic, please visit the official page: High Voltage Insulating Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wood Chippers Market 2026 — Strategic Preview for Executive Decision-Makers
Executive summary
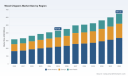
As a capital- and regulation-intensive segment of the broader forestry and biomass equipment market, wood chippers present a distinctive blend of mature demand and tactical disruption. Our 2025-base study shows the global wood chippers market expanded from roughly USD 318 million in 2020 to USD 427.5 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of 6.1% across the 2026–2032 forecast window — reaching an estimated USD 647 million by 2032. For corporate strategists planning capacity, product portfolios, M&A, or go-to-market strategies in 2026, these metrics are the macro scaffold on which more granular choices must be built.
Wood Chippers Market
Why this research matters for 2026 decisions
- Timing matters: 2026 is a hinge year. Regulatory headwinds (Tier 4 Final / EU Stage V) have been internalized by many OEMs and late adopters now face a steeper cost curve for compliant diesel units. Our report quantifies the cost and maintenance implications across machine classes and maps adoption pathways for low-emission alternatives.
- Capital allocation clarity: With mid-term growth at ~6.1% CAGR, executives must reconcile steady market expansion with pockets of disruption (electrification, digital services). The study provides ROI scenarios that help prioritize R&D vs. aftermarket investments.
- Risk-adjusted roadmap: Supply-chain pressure points — from knife and anvil wear rates to after-treatment component scarcity — materially affect TCO. We translate these operational risks into financial sensitivities and procurement safeguards ready for 2026 contracting cycles.
Market trajectory and structural dynamics
The market’s recent compound expansion is driven by converging forces: continued demand from land-clearing, biomass and pulp & paper segments; replacement cycles in municipal and arborist fleets; and technology-driven differentiation among OEMs. However, the headline growth number masks uneven economics across product tiers — low-cost entry machines demonstrate materially higher maintenance intensity and slower throughput, while premium industrial systems trade on uptime, modularity and serviceability.
Wood Chippers Market
Critical structural dynamics that will shape strategic options in 2026 include:
Wood Chippers Market
- Regulation-driven cost inflation: Emission after-treatment (diesel particulate filters, SCR systems) has increased upfront costs and ongoing maintenance for diesel platforms. Compliance timelines and retrofit economics are modeled in the report.
- TCO and maintenance economics: Our benchmarking finds that entry-level machines can incur substantially higher blade and anvil replacement frequencies, with knock-on effects for feed rates and lifecycle cost. Procurement decisions that focus solely on purchase price risk higher lifetime spend.
- Standardization and safety: EN 13525, AS/NZS 4024.1 and ISO 11448 remain binding for machine design and operation. Manufacturers that embed these standards early limit downstream liability and accelerate access to regulated markets.
- Product bifurcation: Demand is bifurcating into high-capacity industrial chippers for biomass and pulp operations, and compact, low-emission or electric solutions for arboriculture and urban applications. Each segment has distinct go-to-market and service requirements.
Competitive landscape — what the majors signal
The competitive map combines legacy OEM strengths (industrial scale, dealer networks) with agile regional specialists focused on niche requirements (compact tracked units, PTO-towed machines, or premium self-propelled designs). Our competitive chapter profiles leading OEMs and identifies the strategic implications of their recent moves without disclosing transaction-level or segment share tables reserved for the full report.
Highlights from company-level patterns:
- Product leadership and differentiation: Firms such as Vermeer emphasize proprietary crushing and feed technologies for throughput and consistency, while others (e.g., Morbark, Terex/CBI) reinforce high-capacity drum and whole-tree solutions tailored for biomass and industrial applications. These technology choices materially affect buyer segments, maintenance regimes and aftermarket opportunities.
- Warranty and service as competitive weapons: Extended warranty programs and parts availability (for example, multi-year or hour-based guarantees) are being used to offset premium pricing and to lock-in fleet operators.
- Geography-driven playbooks: Some manufacturers prioritize road-towable and compact chippers for arborists and municipalities, while others focus on tub grinders and industrial chippers for mills and land-clearing contractors. The report evaluates each player’s manufacturing footprint, channel depth and product roadmap to assess scalability.
- Recent strategic moves worth attention: Product launches of large-capacity whole-tree chippers and compact professional models, an OEM acquisition that consolidates complementary technologies, a contract award for a bespoke drum chipper to a major mill, and supplier appointments for critical wear parts — together, these developments indicate both ongoing product innovation and ecosystem strengthening among incumbents.
From insights to action — what executives can do in 2026
We designed this study as a playbook for the decisions that matter in the coming 12–24 months. Below are the practical outputs and how to use them.
- Portfolio & product decisions: Use our demand segmentation and elasticity models to decide whether to prioritize electrified compact units, invest in high-capacity whole-tree lines, or pursue modular architectures that lower service downtime.
- Pricing & go-to-market: Benchmarks for dealer margins, service revenue potential and replacement-part pricing enable data-driven pricing strategies and subscription models (e.g., knife-management contracts, uptime guarantees).
- Supply chain and sourcing: The report maps critical single-sourced components (after-treatment modules, high-grade steels for knives) and recommends near-term hedging, dual-sourcing, or local manufacturing options aligned with 2026 procurement cycles.
- M&A and partnerships screening: A targeted list of bolt-on opportunities and capability gaps is provided, scoring targets by strategic fit, integration complexity and likely synergies for both OEMs and investors.
- Compliance & safety roadmap: The study translates EN, ISO and national emission frameworks into an actionable compliance timetable and cost schedule so product teams can prioritize design changes ahead of regulatory enforcement windows.
What we do not publish here — and why you should request the full analysis
To preserve the commercial integrity of the intelligence and to encourage direct engagement, this preview intentionally omits the detailed segmentation tables, regional and end-use splits, and the full competitive concentration matrices. The complete report contains:
- Granular segmentation across geography, type and application with modeled revenue paths and elasticities;
- Consolidation metrics and concentration ratios with implication matrices for new entrants vs incumbents;
- Full financial-model workbooks (USD million base, forecasted P&Ls for product lines and scenario-adjusted capex plans);
- Vendor-level SWOTs and an executable 90-day market-entry checklist for OEMs, distributors and private equity investors.
Practical scenario examples (samples from the report)
- Scenario A — Premium industrial focus: A mid-sized OEM redirects 60–70% of R&D to high-capacity drum and whole-tree platforms and pursues a service-first warranty play. Our scenario model shows how this strategy affects utilization thresholds and aftermarket revenue over a 5-year horizon.
- Scenario B — Electrification and urban niche: A distributor pivots toward compact electric and low-emission petrol models for municipal and arborist fleets, pairing machines with battery-as-a-service offerings to reduce operator up-front cost and increase retention.
- Scenario C — Parts and service consolidation: An aftermarket specialist negotiates exclusive supply of knives and wear components to capture recurring revenues; our sensitivity analysis indicates the point at which parts margin begins to offset declining machine sales in a mature market.
Final guidance for 2026 planning
Executives should treat the 2026 planning cycle as an inflection point: the market is not a binary growth story, but a mosaic of stable core demand and fast-evolving subsegments. Strategic clarity requires marrying the macro growth trajectory (6.1% CAGR) with granular insights on regulatory cost, maintenance economics and competing OEM roadmaps. Where to compete, at what price, and how to lock-in aftermarket revenue will determine winners.
To access the full suite of models, segmentation data, competitor concentration metrics, and the executable 12–24 month playbook that underpins these executive recommendations, please consult the complete Wood Chippers Market report from PW Consulting. Our full analysis supplies the confidential line-item breakouts and scenario workbooks that boards and investment committees will need to make rigorous 2026 commitments.
For detailed analysis of this topic, please visit the official page: Wood Chippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Voltage DC Circuit Breaker Market to Reach USD 320.2M by 2032 at 7.0% CAGR
By PW Consulting, 2026-07-12
Low Voltage DC Circuit Breakers: Strategic Outlook for 2026 Decision-Making
Executive preview
The Low Voltage DC Circuit Breaker market is transitioning from niche engineering challenge to strategic battleground for utilities, inverter makers, balance-of-system vendors and industrial OEMs. Between 2020 and 2025 the market expanded from USD 142.3 Million to USD 200.0 Million (base year 2025), and our forecast projects a continuation of that momentum to approximately USD 320.2 Million by 2032 at a 7.0% CAGR over 2026–2032. That trajectory masks important inflection points: material-cost volatility, standards updates, and rapid product evolution around higher-voltage DC distribution and solid-state protection create both risk and opportunity for firms that need to commit capital in 2026.
Low Voltage DC Circuit Breaker Market
Why this research matters to 2026 corporate plans
-
Capital allocation: With the market expanding meaningfully through the forecast horizon, companies that finalize manufacturing CAPEX, tooling spend or capacity-sharing agreements in 2026 will capture the early-adopter premium in high-growth niches.
Low Voltage DC Circuit Breaker Market -
Product roadmap timing: The convergence of higher-voltage PV strings, energy storage deployments, and faster EV DC charging protocols creates a narrow window where product specification choices made now determine certification cycles and go-to-market readiness into 2027–2028.
Low Voltage DC Circuit Breaker Market -
Supply chain posture: Raw material shocks in 2025 and the cascading cost effects on manufacturing economics mean procurement strategies and hedging approaches decided in 2026 materially affect gross margins into 2028.
Market trajectory and macro drivers
Our historical build (2020–2025) shows steady adoption across renewable and industrial applications—growth accelerated notably as storage and fast-charging use cases matured. The forecast (2026–2032) embeds a 7.0% CAGR that reflects continued end-market expansion as well as gradual migration toward higher-voltage DC topologies and greater electrification of transportation and industrial automation.
Key demand drivers evaluated in the study include the accelerating roll-out of battery energy storage systems (BESS), increasing PV string voltages and inverter architectures, and the mainstreaming of DC fast-charging. Conversely, cost-side pressures—from base commodity shifts to new certification requirements—shape practical pricing and margin outcomes for manufacturers and distributors.
Competitive landscape: who matters and why
The report profiles leading and emerging suppliers, assessing strategic positioning, product portfolios, channel models and near-term capacity moves. Market concentration is moderate: the top three suppliers account for roughly 54% of identifiable market revenue while the top five account for about 65%—enough to influence pricing dynamics but leaving space for regional specialists and innovative entrants.
-
ABB (Switzerland) — A full-spectrum provider with conventional MCBs/MCCBs and solid-state offerings tailored to solar and storage DC distribution. ABB’s portfolio is notable for broad channel reach and system integration capability (link: https://new.abb.com/low-voltage/direct-current-systems).
-
Eaton Corporation (Ireland) — A major global supplier of DC-rated molded case breakers, including solutions designed specifically for PV and BESS applications, with proven designs up to 1000 VDC (link: https://www.eaton.com).
-
Siemens AG (Germany) — Focused on modern low-voltage installations with tried-and-tested series targeting renewables, data centers and industrial use (link: https://www.siemens.com).
-
Mitsubishi Electric (Japan) — Advanced breaking technologies for machinery and electrical equipment; a supplier with deep industrial OEM relationships (link: https://www.mitsubishielectric.com/fa/products/lvd/lvcb/index.html).
-
LS ELECTRIC (South Korea) , Fuji Electric (Japan) , CHINT Group (China) , Hager Group (Germany) , and Chinese OEMs such as Beny and Chinasuntree — each brings distinct advantages, from smart-power integration and cost-competitive manufacturing to specialized enclosures and PV-focused product sets (see company sites cited in report).
Recent tactical moves matter. Fuji Electric’s 2025 investment to expand transmission & distribution capacity—with operations ramping in FY 2026—reshapes regional supply availability. Several OEMs used 2025–2026 trade shows to preview higher-voltage and IP-rated solutions (notably 1500 V capabilities), signaling intent to compete on both performance and system compatibility.
Supply chain and cost dynamics
Material composition and price volatility are no longer secondary issues. Our cost-model deep dives show copper is a dominant raw-material line item—accounting for roughly 45% of material costs in low-voltage electrical equipment—with silver and copper together representing an even larger share of critical metal exposure. Since July 2025, silver prices have surged substantially (well over 400%), while copper has also experienced steep increases (>140%). These moves have immediate margin implications for conventional contact-based breakers and even more pronounced effects for products where precious metals are used in contacts or plating.
For procurement and operations leaders, the combination of concentrated supplier base for certain specialty subcomponents, upward material pressure and long lead times for precision tooling produces three practical levers we quantify in the report: (1) design-for-material-efficiency pathways, (2) alternative contact alloys and coating strategies, and (3) inventory/forward-buy frameworks tailored to hedging costs without overexposure.
Regulatory and standards outlook
Standards evolve rapidly and directly influence product architecture and time-to-market. EN IEC 60898-3:2025 introduces clearer expectations for household DC breakers up to 440V, while industry deployments continue to require compliance with UL 489 B and IEC 60947-2 for solar PV and energy storage systems. Our regulatory risk scenarios examine certification timelines, required lab modifications, and the cost of incremental testing for higher-voltage ratings—all crucial for product managers and compliance teams planning 2026 releases.
Strategic implications and actionable recommendations for 2026
-
Prioritize modularity: Build product roadmaps that allow incremental voltage and interrupting-capacity upgrades without a full redesign. This reduces certification cycles and amortizes test costs across families.
-
Lock targeted capacity early: For companies intending to scale, secure manufacturing slots or partnerships in 2026—especially for enclosures and high-precision contacts—before 2027 demand surges.
-
Hedge raw-material exposure: Combine strategic sourcing with design choices that reduce precious-metal usage, and explore long-term offtake agreements for copper and alternative alloys.
-
Invest in standards readiness: Dedicate a certification roadmap tied to the product launch cadence—missing a standards milestone can delay market entry by quarters and hand share to more agile competitors.
-
M&A and partnership playbooks: Consider bolt-on acquisitions for system integration capabilities (e.g., relays, sensing electronics) or partnerships for manufacturing scale; the report includes diligence templates and valuation sensitivities focused on 2026 timing.
Report content: what you will find inside
The full PW Consulting study is organized to be immediately operational for strategy, product and commercial teams. It contains:
-
Market sizing (USD Million) and historical trend analysis (2020–2025) with a base year of 2025, plus a detailed forecast through 2032 with scenario sensitivity to material prices and standards adoption.
-
Competitive benchmarking across product capabilities, channel strategies, price positioning and near-term capacity events—covering both global leaders and regional specialists.
-
Supply-chain cost models that quantify exposure to copper and silver, and design trade-offs to preserve margin under high-price scenarios.
-
Regulatory and certification timelines, mapped to product architectures and time-to-market impacts.
-
Actionable go-to-market playbooks for OEMs, distributors and EPCs including pricing strategies, channel incentives and systems-integration approaches tailored to 2026 deployment windows.
-
Risk matrices and scenario planning templates designed to support 2026 board-level investment decisions—concisely mapping probabilities, impacts and mitigations.
To preserve commercial value and to respect our clients’ need for proprietary segmentation, this introduction intentionally omits granular regional, type and application splits. The full report contains those segment-level data and the underlying model that powers our forecasts.
How to use this study in 90 days
-
Month 1 — Align: Run the report’s scenario workshop with product, procurement and business leaders to align on which scenario(s) your company will prioritize.
-
Month 2 — Commit: Finalize CAPEX and sourcing decisions for critical-path components, and begin certification scheduling for planned product updates in 2027.
-
Month 3 — Execute: Implement hedging and inventory plans, initiate any targeted M&A or strategic partnership discussions, and deploy the go-to-market testing plans included in the study.
Conclusion and next steps
For firms making binding strategic choices in 2026, the intersection of robust market growth (USD 200.0 Million in 2025 to an expected USD 320.2 Million by 2032 at a 7.0% CAGR), material-cost volatility, and evolving standards creates a compressed set of decision points. The full PW Consulting Low Voltage DC Circuit Breaker Market report provides the granular segmentation, supplier-level intelligence and executable playbooks required to convert market momentum into profitable growth. For access to detailed segment splits, supplier scorecards, and our model workpapers, consult the source report page and schedule a briefing with our industry team.
For detailed analysis of this topic, please visit the official page: Low Voltage DC Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Communications to hit USD 56,800M by 2032 (6.8% CAGR)
By PW Consulting, 2026-07-12
Military Communications Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Military Communications Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) offers an actionable synthesis designed to guide executive decisions in 2026. Anchored in robust bottom‑up modeling, the study traces the market through a period of structural transition and projects continued expansion at a compound annual growth rate (CAGR) of 6.8%. In aggregate terms the market sits comfortably in the multi‑tens of billions (USD, revenue unit: Million) in 2025 and — based on scenario-validated drivers — is forecast to grow materially by 2032. This briefing explains why that trajectory matters, what levers will shape supplier and buyer outcomes over the next 18 months, and how to extract operational advantage from the full report.
Military Communications Market
Why this study matters now
2026 is a decision‑heavy year for stakeholders across defense primes, tiered suppliers, satellite operators, and government procurement offices. Investment cycles are accelerating around three intersecting inflections: the shift toward proliferated and protected small‑satellite architectures; the industry adoption of high‑throughput optical interconnections and anti‑jam technologies; and the tightening nexus between spectrum policy and procurement funding. Our research quantifies the economic implications of these inflections (base year metrics, historical growth patterns, and forecast trajectories are embedded in the report’s models) and translates them into near‑term commercial and programmatic actions.
Military Communications Market
- Macro posture: The market’s mid‑single digit CAGR signals steady demand and encourages capacity investments, but it also requires disciplined portfolio prioritization to avoid misallocated capital.
- Competitive structure: Concentration metrics show the top three firms control a significant portion of market revenue while the top five expand that share further, creating a market where scale matters but niches remain accessible to specialized innovators.
- Program timing: Multiple government programs and IDIQ frameworks initiated in 2024–2026 create procurement windows that favor early movers with validated demonstration assets and partner ecosystems.
Core market dynamics and technology inflection points
Our analysis synthesizes procurement announcements, corporate moves, and regulatory shifts to explain demand and supply evolution.
Military Communications Market
- Proliferation of protected small‑satellite constellations: Program awards and IDIQ pools created in 2025–2026 reinforce a system architecture that prizes distributed resilience and anti‑jamming capabilities. This drives demand across satellite manufacturing, hosted payload services, ground segment anti‑spoofing, and RF hardening.
- Optical and hybrid networking: Progress on optical inter‑satellite links and the acquisition of key optical terminal vendors by launch and integrator players is creating a value chain where photonics expertise materially changes cost and performance equations for long‑haul military comms.
- Hybridization of commercial and dedicated military networks: Operators are increasingly pitching hybrid service models combining commercial constellations with DoD overlays. This trend alters contracting approaches and supports alternative revenue models for satellite operators and service integrators.
- Spectrum policy as a strategic variable: Recent congressional and federal actions are reshaping the spectrum pipeline and reimbursement mechanics; procurement teams must now reconcile auction dynamics, relocation cost recovery frameworks, and the absence of fully documented interagency spectrum‑sharing plans in their risk models.
Competitive landscape — what matters to bidders and partners
Our competitive analysis focuses on a curated set of companies that illustrate three strategic archetypes: prime system integrators, vertically integrated satellite and terminal developers, and specialized subsystem providers. Each archetype faces distinct opportunity and risk profiles.
- Prime integrators (examples reviewed): Firms with legacy systems engineering depth and prime contract experience retain advantage in large‑scale modernization programs. Their ability to package end‑to‑end solutions and to hold critical path responsibility for national continuity and NC3 modernization is a differentiator.
- Platform and operator entrants: Companies building or operating small satellites and hybrid service layers are disrupting traditional supplier relationships. Their advantage lies in rapid iteration, lower per‑unit capital intensity, and service‑level flexibility attractive to both program offices and allied partners.
- Specialist technology providers: Optical terminal vendors, anti‑jam modem manufacturers, and tactical comms hardware suppliers are the innovation engines. Consolidation moves and targeted acquisitions have expanded their industrial reach, enabling them to supply both government programs and new commercial backbones.
Strategically, winners will be those who master systems integration across radiofrequency, photonics, and software layers while navigating multi‑award IDIQs, teaming arrangements, and export/compliance constraints.
What the report contains — practical deliverables
The full study is structured to be immediately operational for commercial strategy teams, M&A investors, and procurement leads. Highlights include:
- Top‑line market sizing and a transparent, reproduceable model (base year 2025; historical window 2020–2025; forecast 2026–2032) with downloadable datasets in USD (Million).
- Scenario‑based forecasts under alternative policy and budget pathways, enabling rapid sensitivity testing of program win rates, pricing pressure, and technology adoption curves.
- Vendor profiles and capability maps that go beyond public press releases to assess program relevance, integration risk, and partnership fit—without exposing confidential commercial splits in the preview.
- Procurement playbooks that translate program timelines and contract vehicle structures into bidding and teaming recommendations, including go‑to‑market approaches for IDIQ pools and prototype opportunities.
- An operator and supplier heatmap that flags where price competition, technical differentiation, or regulatory constraints are likely to compress margins.
- Investment and M&A scoring frameworks with target shortlists and integration red‑flags tailored for investors seeking to enter or expand in military communications supply chains.
- Regulatory and spectrum risk modules that incorporate recent legislative changes, auction mechanics, and reimbursement frameworks—critical for financial planning and program cost‑of‑ownership estimates.
Policy and regulatory context — the unseen constraint
Policy developments in 2024–2026 have elevated spectrum strategy from a technical consideration to a core budgetary and programmatic risk. Recent legislation established a spectrum pipeline and identified bands for reallocation and study. At the same time, federal guidance on spectrum‑sharing mechanisms remains incomplete, and government actors have signaled that auction proceeds must cover federal relocation and sharing costs with defined reimbursement rules. For program planners, this creates two imperatives: model the cost of spectrum transitions conservatively, and engage early with spectrum policy teams to avoid schedule and funding surprises.
Strategic recommendations for 2026
- Prioritize modular, demonstrable capability: Win probability in multi‑award procurements favors teams that can present a demonstrator or flight‑proven subsystem tied to a clear path to scale.
- Build hybrid revenue pathways: Combine service contracts with hardware sales and managed service elements to stabilize cash flow against procurement timing variability.
- Invest in optical and anti‑spoofing competencies: These technologies are gatekeepers to next‑generation architectures and command premium margin in integration phases.
- Calibrate partnership strategies to concentration realities: The market is dominated by a few large primes, but targeted partnerships with incumbents or co‑development with specialist vendors yields differentiated access to program pipelines.
- Embed policy scenario planning: Invest in a small, focused capability to track spectrum policy, auction cues, and reimbursement rules—this reduces bid‑to‑contract timeline risk and protects program margins.
Risk profile — what could derail plans
- Policy uncertainty: Incomplete interagency guidance on spectrum sharing and pipeline timing can create program slips or unanticipated relocation costs.
- Supply chain constraints: Optical terminal production, specialized RF components, and certain semiconductor lines remain chokepoints that can inflate lead times.
- Budget volatility: Shifts in defense appropriation priorities or reallocation to other domains could compress award opportunities in the short term.
- Competitive consolidation: M&A activity among specialist vendors can rapidly change competitive dynamics and create new integration dependencies.
How to use this briefing and next steps
This article is a strategic preview intended to surface the directional forces and practical recommendations that will shape successful plays in 2026. It intentionally omits granular regional and application revenue splits to preserve the commercial incentive for the full dataset. PW Consulting’s full Military Communications Market report contains the detailed segmentation, downloadable financial models in USD (Million), supplier scorecards, and scenario workbooks that allow you to:
- Quantify addressable market share by program and geographies for inclusion in investment memos;
- Create evidence‑based win strategies with sensitivity testing for pricing and program delays;
- Identify mid‑market acquisition targets and model accretive integration paths;
- Build procurement timetables tied to policy milestones and auction outcomes.
For executives mapping 2026 resource allocation, this study provides both the high‑level market architecture and the operational playbooks to convert forecasts into funded programs. To access the complete dataset, segmented forecasts, and supplier playbooks, please refer to the full PW Consulting Military Communications Market report available through our publications portal.
For detailed analysis of this topic, please visit the official page: Military Communications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
IPL Hair Removal Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive snapshot
As aesthetic medicine continues to migrate from specialist clinics to multi‑channel delivery models, the IPL (Intense Pulsed Light) hair removal market is moving from niche adoption toward sustained commercial scale. Using 2025 as the base year, PW Consulting projects the global market at roughly USD 100 Million in 2025, expanding at a compound annual growth rate (CAGR) of 8.5% through the forecast horizon (2026–2032). By the end of the forecast period the market is expected to be materially larger, reflecting accelerating adoption in both professional and home‑use contexts and continued technological maturation of IPL platforms.
IPL (Intense Pulsed Light) Hair Removal Market
This briefing outlines why the 2026 planning cycle is pivotal: product roadmaps, regulatory investment, channel partnerships and M&A theses established now will determine competitive position across the next six years. The full PW Consulting IPL Hair Removal Market report contains the detailed datasets, segment breakouts, vendor scorecards and tactical playbooks required to execute—this article intentionally highlights strategic implications while withholding the granular splits that are available in the paid report.
IPL (Intense Pulsed Light) Hair Removal Market
Why this research matters for 2026 strategic planning
- Investment prioritization: The market’s mid‑single‑digit to high‑single‑digit CAGR requires selective capital allocation—knowing which product enhancements and geographies drive outsized returns is essential.
- Regulatory timing: FDA and EU milestones affect time‑to‑market; clearance strategies must be synchronized with commercial launches to avoid revenue leakage.
- Channel transformation: Clinics, med spas and at‑home offerings are converging; manufacturers and service providers must redesign distribution, training and post‑sales models to capture blended demand.
- Competitive differentiation: Leading vendors are shifting from single‑function devices to platform plays that bundle clinical versatility, data capture and consumables—firms that ignore platform economics risk margin compression.
Market dynamics shaping near‑term strategy
The IPL hair removal market is being shaped by four interdependent dynamics that should inform every board‑level discussion in 2026.
IPL (Intense Pulsed Light) Hair Removal Market
- Technology evolution and clinical outcomes: Innovations such as optimized pulse modulation, SHR (super hair removal) techniques, contact cooling and integrated safety sensors are reducing procedure time, minimizing discomfort and expanding treatable skin types. These improvements accelerate in‑clinic throughput and support premium pricing for differentiated platforms.
- Channel convergence and consumer behavior: Demand is shifting from episodic, clinic‑only treatments to hybrid pathways that include professional services and validated home‑use devices. Consumer willingness to pay for convenience and safety is increasing, but providers retain influence through clinical supervision and recurring service revenue.
- Regulatory pressure and safety standards: FDA 510(k) clearances for permanent hair reduction and updated EU MDR requirements have raised the bar for device documentation, electrical safety and clinical evidence. Home‑use devices now face stricter requirements around low‑fluence safety sensors and human factors engineering. Vendors that build regulatory robustness into product design can shorten approval timelines and reduce post‑market risk.
- Competitive intensity and market concentration: The market shows a clear leadership tier of established OEMs and newer entrants leveraging regulatory clearances to scale rapidly. While incumbent brands benefit from installed bases and clinician trust, low‑cost OEMs are increasing price pressure in mature channels and accelerating feature parity in entry segments.
Regulatory and reimbursement context (short, practical takeaways)
- FDA pathways: Professional and home‑use IPL systems intended for permanent hair reduction require careful alignment to 510(k) predicates and radiation safety standards; early engagement with regulators reduces rework risk.
- EU compliance: CE marking under MDR plus a Declaration of Conformity and ISO‑aligned electrical safety testing remain prerequisites for EU commercialization; supply chain documentation and clinical evaluation reports are often the gating factors.
- Reimbursement reality: IPL hair removal is predominantly cosmetic and self‑pay in most jurisdictions; providers must therefore optimize direct‑to‑consumer pricing and financing options rather than relying on third‑party reimbursement codes.
Competitive landscape: how market leaders are positioning
The competitive picture is defined by a handful of globally recognized platforms and a rising cohort of validated new entrants. Key characteristics of the competitive set include platform extensibility, clinical evidence, channel reach and strategic partnerships.
- Lumenis (Yokneam, Israel) — a technology pioneer known for OPT™ (Optimal Pulse Technology) and broad clinical platforms that address multiple aesthetic indications. Lumenis leverages long clinical track records and multi‑indication devices to defend premium positioning.
- Candela (Marlborough, MA, USA) — an incumbent with a deep installed base and FDA‑cleared solutions. Recent partnership activity has demonstrated Candela’s go‑to‑market emphasis on expanding clinic networks and increasing utilization per site.
- Alma Lasers (Caesarea, Israel) — focuses on fast, low‑discomfort SHR approaches and clinic efficiency. Alma’s product packaging is engineered to lower the operator learning curve and maximize throughput.
- Cynosure (Westford, MA, USA) — positions its Xelera platform and laser offerings as integrated tools for multi‑procedure practices, emphasizing workflow integration and training services.
In 2025 and 2026 the market also saw regulatory milestones where multiple new entrants obtained FDA clearances—demonstrating that product entrants with rigorous clinical dossiers can rapidly access the U.S. market. Parallel commercial moves include major clinic networks augmenting fleets with additional platforms, reinforcing the point that partnerships with national providers accelerate adoption curves.
What the PW Consulting report delivers (practical, operational outputs)
The full IPL Hair Removal Market report is designed for direct operational use by product teams, regulatory affairs, corporate development and commercial leadership. Key deliverables include:
- Historical market sizing (2020–2025) and scenario forecasts (2026–2032) with device‑level and channel‑level demand models to support NPV and ROI calculations.
- Competitive vendor scorecards and go‑to‑market playbooks that benchmark product features, clinical evidence, installed base and dealer network strength.
- Regulatory and compliance matrix (FDA 510(k) considerations, EU MDR checklists, human factors testing templates) to accelerate submissions and minimize non‑conformities.
- Commercial strategies tailored to clinics, med spas and home‑use channels—including pricing elasticity analysis, subscription and consumable models, and training/service economics.
- M&A and partnership screening toolsets identifying inorganic targets by capability gaps, geography and regulatory status.
- Practical annexes: sample clinical protocols, risk mitigation checklists, procurement decision trees, and a dataset appendix for integration into internal BI tools.
Note: To preserve the strategic value of this preview we have intentionally withheld the granular regional and application splits, unit price schedules and the full vendor share table. These detailed data products are available in the full PW Consulting report.
Top strategic recommendations for 2026
- Prioritize platform modularity: Build devices that support feature‑bundling (cooling, pulse profiles, software upgrades) to capture upsell and extend product lifecycle without full hardware replacement.
- Invest in a regulatory‑first product development lifecycle: Integrate regulatory, clinical and risk teams from concept to launch. Early human factors testing and predicate mapping shortens 510(k) timelines and reduces post‑market corrective actions.
- Design channel‑specific value propositions: For clinics and med spas emphasize throughput, warranty and consumables economics; for home‑use emphasize safety sensors, UX and data privacy to build consumer trust.
- Move from device sales to recurring revenue models: Consider consumables, service contracts, software subscriptions and training packages to stabilize margin and increase customer lifetime value.
- Execute selective partnerships: Collaborate with major clinic networks and telehealth platforms to create funnel visibility and ensure device utilization at scale—deal structures should align incentives around throughput and repeat visits.
- Monitor low‑cost OEM entries: Maintain a two‑track response: defend premium segments through superior clinical evidence and customer service while evaluating cost reduction or mid‑market product variants.
Decision framework and next steps
To convert market insights into executable plans in 2026, PW Consulting recommends a five‑step decision framework:
- Diagnose: Validate your current addressable market using the report’s demand model and compare to internal forecasting assumptions.
- Prioritize: Identify high‑return product and channel investments using scenario analyses and sensitivity testing provided in the report.
- Prepare: Align R&D, regulatory, clinical and commercial teams on a single product launch roadmap with regulatory milestones mapped to revenue targets.
- Execute: Deploy partnerships, pilot commercial launches, and convert early adopter data into dossier content for accelerated scaling.
- Optimize: Use the report’s performance KPIs and market intelligence to iterate pricing, consumable strategies and service offerings on a quarterly cadence.
PW Consulting’s IPL Hair Removal Market report is built to be the operational backbone of 2026 planning cycles. For executives preparing capital allocation, M&A diligence or product launch strategies, the report provides the quantitative foundation and tactical playbooks necessary to compete effectively.
To access the complete datasets, vendor scorecards and downloadable playbooks, please visit the PW Consulting IPL Hair Removal Market report page where the full intelligence package is available.
For detailed analysis of this topic, please visit the official page: IPL (Intense Pulsed Light) Hair Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ship-to-Shore (STS) Container Cranes Market USD 3,000M in 2025; 5.2% CAGR (2026–32)
By PW Consulting, 2026-07-12
Ship-to-Shore (STS) Container Cranes Market: Strategic Outlook for 2026 Decision-Making
Executive preview
The global Ship-to-Shore (STS) container cranes market has demonstrated steady expansion through the early 2020s and enters 2026 from a position of structural growth and renewed capital intensity. In our base-year assessment (2025) the market reached approximately USD 3,000 Million (revenue, Million USD), up from roughly USD 2,500 Million in 2020. Our model projects a compound annual growth rate (CAGR) of about 5.2% across the 2026–2032 forecast window, driving the market toward an anticipated USD 4,253 Million by 2032 under the baseline scenario.
Ship-to-Shore (STS) Container Cranes Market
This briefing is intended as a strategic “preview”: it captures the data-driven trends, competitive dynamics, and procurement levers that will matter for boardroom decisions in 2026, while intentionally withholding the granular regional and application split tables reserved for the full PW Consulting report and interactive datasheet.
Ship-to-Shore (STS) Container Cranes Market
Why this matters for 2026 purchasers and investors
- Capital allocation and timing: Port terminals, marine investors and OEMs must align crane procurement and retrofit cycles with longer lead-times and rising capital costs. The combination of steady underlying demand and protracted delivery schedules creates windows where early commitment improves access and price certainty.
- Contract design and risk transfer: With stretch in delivery timelines and tariff volatility, contract terms that clearly allocate escalation, delay penalty and scope-change risk are now differentiators in tender outcomes.
- Service and lifetime value: As fleets grow and vessel dimensions increase, lifecycle costs — not only purchase price — determine terminal productivity. Maintenance contracts, digital diagnostics, and spare-parts logistics are elevated priorities.
Key market dynamics shaping 2026 strategies
Three macro dynamics dominate the STS market heading into 2026:
Ship-to-Shore (STS) Container Cranes Market
- Vessel upscaling and operational productivity — The push toward larger vessels and denser yard operations continues to favor higher-capacity cranes, dual-trolley concepts and feature-rich control systems that compress vessel turnaround.
- Supply-chain and manufacturing pressure — Producers and buyers alike grapple with longer manufacturing cycles. Average global delivery schedules extended materially between 2022 and 2024, driven by steel-price and PLC-cost inflation as well as capacity constraints in fabrication and electrical subsystems.
- Regulatory and trade friction — Trade measures and tariff actions introduced noise into sourcing strategies, increasing the premium on diversified procurement footprints and local-assembly options.
Operational evidence underlines these dynamics. Industry surveys reported continued deliveries in the low hundreds of STS units globally in recent years, and trends in lift-class selection and boom outreach reflect how terminal planners are trading capacity for reach. These market signals translate directly into vendor selection criteria: uptime guarantees, anti-sway and automation features, electric-drive options and modularity now outrank simple upfront price in many tenders.
Price and delivery realities: what procurement teams must know
Purchase price ranges remain wide, reflecting model complexity and optionality. STS crane prices typically span from lower-cost Panamax-class units to premium super post-Panamax builds — the variability largely reflects lift capacity, outreach, electrification and automation packages. Importantly, manufacturing lead-times lengthened in the mid-2020s: our analysis cites an extension from roughly 11 months to 15 months on average during 2022–2024, a function of a near-term spike in steel and PLC costs and constrained workshop capacity.
Trade policy can materially change landed cost. Recent Section 301 measures and related import tariffs on certain origins have added a non-trivial incremental cost to some major U.S. terminal projects, forcing re-evaluation of sourcing, value-engineering and potential capital reallocation.
Competitive landscape — who matters and why
The STS market demonstrates concentrated leadership by established OEMs with deep installed bases and broad global service networks. Market concentration metrics indicate that the industry’s top three vendors control a majority share of new-build activity, with the top five extending that dominance further. For procurement teams, this creates a specific dynamic: while a shortlist of incumbents offers scale and predictable delivery, emerging and regional suppliers compete aggressively on price, customization and local support.
- Konecranes (Helsinki, Finland) — Focused on high-reliability STS designs; differentiators include proprietary electric motors, gearing and control systems and a large installed base supporting fast ship turnaround. ( https://www.konecranes.com)
- Liebherr (Bulle, Switzerland) — Premium STS cranes with advanced anti-sway, fully electric variants and dual-trolley options; long-standing manufacturing footprint and recent high-profile deliveries to major European terminals. ( https://www.liebherr.com)
- ZPMC (Shanghai, China) — Global reach with flagship STS deployments across six continents; recognized domestically for manufacturing excellence and sizeable production capacity. ( https://www.zpmc.com)
- SANY Group (Changsha, China) — Competitive pricing and strong Asia-Pacific relationships with increasing emphasis on customization and local support. ( https://www.sanyglobal.com)
- Paceco Corp. (Cypress, California, USA) — Focus on large PORTAINER® STS gantry cranes, emphasizing trolley speed and bespoke designs for North American and select global terminals. ( https://pacecocorp.com)
- Hyundai Samho (South Korea) — Integrated heavy-industry portfolio with STS offerings tied into broader port-equipment supply chains. ( https://www.hyundai-heavy.com)
- Mitsui Engineering & Shipbuilding / PACECO (Tokyo, Japan) — Known for robust PORTAINER® designs with a focus on productivity and lifecycle reliability. ( https://www.mes.co.jp)
- Henan Weihua (Henan Province, China) — Experienced regional manufacturer with multi-decade design and production capability for STS units. ( https://www.henanweihua.com)
- Anupam Industries (India) — Targeting global terminals with competitive, regionally tailored STS solutions. ( https://www.anupamindustries.com)
Recent deal-flow and deliveries illustrate competitive positioning: premium OEMs secured new supply contracts and key deliveries in late 2025 for strategic terminals; flagship projects in emerging markets continue to attract Chinese and regional suppliers. Industry associations’ surveys in 2024 captured unit deliveries and shifting lift-class preferences, reinforcing that the product mix is moving toward higher-capacity, longer-reach equipment.
Practical report takeaways — what PW Consulting delivers
For executives preparing 2026 procurement cycles, the full PW Consulting Ship-to-Shore market study provides five practical outputs designed to inform decisions and accelerate execution:
- Forward-looking demand model: Scenario-based forecasting (2026–2032) with sensitivity to vessel-size trajectories, terminal throughput growth and capex pacing. The model is delivered in an interactive spreadsheet so teams can stress-test assumptions.
- Supplier scorecards and procurement playbooks: Comparative supplier assessment across technical capability, on-time delivery history, service network quality and total cost of ownership (TCO) implications; negotiation templates and contract clauses tailored to mitigate lead-time and tariff risk.
- Unit economics and TCO frameworks: End-to-end cost modelling that captures purchase price, import duty exposures, spare-parts logistics, energy consumption (electric vs diesel/electric hybrid options) and typical maintenance profiles.
- Supply-chain and risk maps: Factory-capacity overlays, single-point-of-failure analysis for critical subsystems, and contingency playbooks for accelerated delivery or local-assembly strategies.
- M&A and Capex screening tools: Valuation benchmarks, integration-risk flags and a shortlist of strategic targets where vertical integration or aftermarket capability could change competitive dynamics.
Note: this preview intentionally omits the full segmentation tables and unit-level pricing ladders (regional splits, application-by-type breakdowns and supplier-by-model price matrices), which are accessible in the full report and accompanying data workbook.
How to apply these insights in 2026 — a short action checklist
- Align procurement windows with current average lead-times; place orders with realistic acceptance dates and incentivize early delivery where needed.
- Build tariff and escalation clauses into contracts; evaluate local assembly or phased delivery if duties materially increase landed cost.
- Prioritize lifecycle uptime through longer service agreements and digital-monitoring add-ons; quantify TCO rather than chasing headline discounts.
- Maintain multi-supplier shot lists for major tenders; use PW Consulting’s supplier scorecards to validate technical claims against historical delivery performance.
- Stress-test capex scenarios against vessel size evolution and terminal throughput; stagger investments to retain flexibility for retrofits and automation upgrades.
Next steps and where to get the full intelligence
This executive preview synthesizes the strategic and operational signals that will shape STS procurement and investment decisions in 2026. The full PW Consulting Ship-to-Shore (STS) Container Cranes Market report includes the complete regional and application segmentation, model assumptions, unit-price ladders, supplier scorecards and an interactive forecast workbook designed for CFOs, procurement leads and terminal operators. To access the comprehensive analysis, data tables and proprietary scenario tools, please follow the link on our report page or contact a PW Consulting advisor for a guided walk-through of the dataset and model outputs.
For detailed analysis of this topic, please visit the official page: Ship-to-Shore (STS) Container Cranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


