



PW Consulting: Semiconductor Electrostatic Chuck Market to grow at 5.1% CAGR
By PW Consulting, 2026-07-12
Semiconductor Electrostatic Chuck Market — Strategic Outlook for 2026 Decision-Makers
The semiconductor electrostatic chuck (ESC) market is entering a period where incremental technology improvements, supply-chain friction, and customer qualification dynamics will determine winners and losers. This briefing synthesizes the directional intelligence from PW Consulting’s latest market study to equip executives, procurement leaders, and product strategists with the decision levers that matter in 2026. We intentionally provide a high-resolution strategic view while withholding granular segment- and region-level splits to preserve the full analytical value of the underlying research and motivate targeted follow-up.
Semiconductor Electrostatic Chuck Market
Market snapshot: position and trajectory
Between 2020 and 2025 the ESC market expanded from roughly USD 764.5 Million to approximately USD 975.65 Million, reflecting steady demand tied to wafer processing and advanced-node ramp activity. With a 2026–2032 forecast CAGR of 5.1%, the market is projected to pass the USD 1,000 Million threshold in the near term and approach a materially larger market by 2032. This growth profile is neither explosive nor stagnant — it is the kind of sustained, modest expansion that rewards disciplined strategic plays in manufacturing scale, IP differentiation, and supply resiliency.
Semiconductor Electrostatic Chuck Market
Why this research matters for 2026 decisions
-
Timing capital allocation: With demand growth predictable but not exponential, 2026 is a year to be surgical about CapEx. The right move is to prioritize modular investments and supplier co-development agreements that preserve optionality for advanced-node or high-mix fabs rather than committing to large, inflexible lines.
Semiconductor Electrostatic Chuck Market -
Supplier and qualification strategy: ESCs remain subject to long qualification timelines at leading-edge fabs (commonly 12–24 months). Procurement teams must start second-source qualification cycles in 2026 if they aim to change or diversify suppliers by 2028. Our research highlights qualification as a gating issue that directly constrains pricing power and supplier entry.
-
Risk-adjusted sourcing: The market concentration is meaningfully skewed toward a small set of established equipment and ceramics suppliers (the study reports a top-three concentration and a top-five concentration that underline high incumbent power). For decision-makers, this implies negotiating beyond price — seek technical co-engineering, longer-term material commitments, and shared risk models.
-
R&D and product positioning: Incremental improvements in hold force, thermal uniformity, and plasma resistance are the primary differentiators today. Investments in these areas deliver outsized commercial returns when paired with process integration partnerships at strategic fabs.
Core dynamics shaping the market
-
Technology evolution: ESC design is progressing along three axes — electrostatic performance, thermal management, and contamination control. Suppliers are introducing innovations ranging from RF-optimized and cryogenic-compatible chucks to hybrid ceramic-polymer constructions that reduce mass and improve alignment. These refinements translate to tighter process windows and higher switching costs for fab operators.
-
Materials and supply pressure: High-purity aluminum nitride, specialty oxides, and advanced coatings are critical inputs. The supplier base for certain high-grade materials is geographically concentrated, creating exposure to geopolitical tensions, tariffs, and export controls — a factor that must be priced into sourcing and inventory strategies.
-
Regulatory and trade environment: Export controls and technology decoupling between major markets are introducing permit and compliance layers that complicate cross-border procurement. In this environment, localized manufacturing or qualifying domestic secondary suppliers can be a value-preserving strategy.
-
Fabs’ qualification inertia: Long qualification timelines blunt price volatility and raise the bar for new entrants. The implication for incumbents is protection; for challengers, it means investing in pilot partnerships and shared integration risk to shorten adoption hurdles.
Competitive landscape — strategic profiles and tactical moves
The competitive field mixes global equipment OEMs with specialized ceramics and materials houses. The leading suppliers combine system-level integration capabilities with materials expertise, producing an incumbent advantage that extends beyond product specifications.
-
Applied Materials, Inc. — As a major equipment OEM, Applied Materials leverages platform integration to offer ESC modules bundled with etch, CVD and PVD tools. Their recent product initiative focuses on higher hold force and improved thermal uniformity, which can shorten customer integration cycles. For suppliers and buyers alike, partnering with platform OEMs remains a high-leverage way to accelerate process qualification.
-
Tokyo Electron Limited (TEL) — TEL is positioning RF-optimized ESCs for sub-3nm and advanced fabrication. Their approach emphasizes process uniformity and thermal stability, making them a preferred option for advanced-node ramp customers and a formidable competitor on performance-sensitive applications.
-
Lam Research Corporation — Lam has invested in cryogenic-compatible ESCs and cold-resistant ceramics to address etch processes used in 3D NAND and advanced nodes. Their focus on application-specific materials engineering underscores how niche capabilities can secure design wins in segments with extreme environment requirements.
-
Ceramics and materials specialists (Kyocera, NTK CERATEC, NGK, Sumitomo Osaka Cement, Tsukuba Seiko, TOTO, Shinko, Creative Technology) — These suppliers concentrate on high-purity ceramics, coatings, and process-specific chuck features like dual-zone control, plasma-repellent surfaces, and self-cleaning capabilities. Several have expanded product lines or capacity recently, reflecting steady OEM demand for differentiated materials.
-
Entegris — As a materials and components supplier, Entegris occupies a unique positional advantage by providing integrated materials and contamination-control solutions that complement ESC performance, particularly in high-purity process environments.
Recent product launches from major OEMs and material-house expansions (notably launches in early 2025 and product-line growth in 2024) reinforce that vendor competition is centered on performance gains and integration depth rather than on commoditized pricing.
Practical, actionable insights for 2026
-
Start immediate dual-sourcing pilots for any ESCs that will be qualified in the 2027–2028 window. Qualification lead times mandate that decisions made in 2026 determine supplier flexibility in 2028.
-
Negotiate supplier agreements that include technical co-development clauses and reciprocal IP milestones. These clauses convert a supplier relationship into a competitive barrier for rivals and shorten cycle times for iterative product improvements.
-
Lock in strategic material supply contracts with clauses for capacity reservation or priority allocation to mitigate geopolitical disruption risks for specialty ceramics and coatings.
-
Invest selectively in in-house testbeds to accelerate qualification and reduce dependency on fab time for early-stage validation. Even modest capital trade-offs that enable quicker validation can yield outsized commercial advantages.
-
Embed scenario planning into procurement and product roadmaps. Model permutations of export-control intensity, tariff shocks, and supply interruptions to stress-test supplier portfolios and inventory policies.
-
Assess M&A or strategic JV opportunities with specialized ceramics houses if your strategy requires rapid vertical integration or secured access to niche materials and coatings.
What the full report delivers (practical elements)
PWC’s full Semiconductor Electrostatic Chuck Market report contains operationally focused deliverables designed for immediate use by corporate strategy, procurement, and R&D teams. Highlights include:
-
A detailed TAM and SAM view with year-by-year market sizing and scenario-based forecasts calibrated to device node and fab investment cycles.
-
Vendor heatmaps and supplier scorecards that evaluate technical differentiation, qualification timelines, capacity constraints, and supply-chain exposure.
-
Actionable go-to-market playbooks for OEMs, materials suppliers, and system integrators, including partnership and pricing strategies for 2026–2028.
-
Risk matrices and mitigation roadmaps for raw-material concentration, trade policy shifts, and long customer qualification cycles.
-
Operational models for inventory optimization and contract design to protect margins under varying supply-disruption scenarios.
Note: while this briefing summarizes strategic implications and market trajectory, it intentionally omits granular regional and application splits and certain proprietary competitive metrics. Those detailed tables, interactive dashboards, and supplier-level revenue models are available in the full report and are essential for executable procurement and investment plans.
Call to action
For organizations that must make capital, procurement, or product decisions in 2026, coupling scenario-adjusted forecasts with supplier-level intelligence is non-negotiable. PW Consulting’s full study provides the granular segmentation and supplier analytics required to convert directional insight into executable strategy. Contact PW Consulting to obtain the complete dataset, vendor scorecards, and implementation playbooks that translate the broad market signals summarized here into prescriptive action.
For detailed analysis of this topic, please visit the official page: Semiconductor Electrostatic Chuck Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ethernet Connectors to hit USD 1,091.5M by 2032 at 7.1% CAGR
By PW Consulting, 2026-07-12
Industrial Ethernet Connectors Market — Strategic Preview for 2026 Decisions
As industrial networks accelerate toward higher speeds, denser device counts and greater environmental ruggedization, the choice of physical connectivity becomes a strategic decision — not a commodity purchase. This PW Consulting market briefing introduces our full Industrial Ethernet Connectors Market study (base year 2025), designed to equip boards, product executives and supply-chain leaders with the actionable intelligence required to make high‑stakes decisions in 2026 and beyond.
Industrial Ethernet Connectors Market
Market snapshot — scale, momentum and the near-term horizon
Our bottom-up model values the global Industrial Ethernet connectors market at approximately USD 674.5 Million in 2025, with the sector accelerating at a compound annual growth rate (CAGR) of 7.1% across our 2026–2032 forecast window. That trajectory places the market comfortably above USD 1 billion by the early 2030s, driven by the confluence of factory digitization, single‑pair Ethernet adoption, and the push for hardened, field‑installable interfaces.
Industrial Ethernet Connectors Market
For 2026 specifically, our preliminary estimate positions the market just over USD 714 Million — a critical milestone for buyers and suppliers who must translate strategic objectives into sourcing and R&D commitments during the coming procurement cycles.
Industrial Ethernet Connectors Market
Why this study matters for 2026 enterprise decisions
- Timing of platform investments: With industrial OEMs and system integrators planning multi‑year product roadmaps, connector choice now locks downstream platform capabilities (data rates, IP protection, field‑serviceability). Our study maps the technical and commercial tradeoffs so procurement can align purchases with 5‑year technology plans.
- Supply‑chain risk mitigation: Material and manufacturing constraints are recurring risk vectors for connector supply. The report synthesizes supplier footprints, raw‑material considerations and aftermarket service models essential to negotiating resilient contracts in 2026.
- Standards and interoperability: Adoption curves for single‑pair Ethernet standards and emerging industrial‑grade variants will shape interoperability and unit economics. The research decodes the standards landscape and its implications for retrofit vs. greenfield strategies.
- Competitive positioning for automation vendors: For automation OEMs, incorporating the right connector technology can be a differentiator in solution reliability and total cost of ownership. The study provides playbooks for embedding connectivity into bundled hardware/software offers.
What the full report contains — practical deliverables
- Granular, modeled market forecasts (2026–2032) across commercial vectors, with sensitivity scenarios reflecting macroeconomic and technology adoption variance.
- Go‑to‑market frameworks for product managers and procurement teams, including cost‑benefit templates for field‑installable vs. factory‑terminated solutions.
- Supplier scorecards that assess technical breadth, manufacturing footprint, lead‑time reliability and aftermarket support — created to inform RFP shortlists.
- Standards impact analysis that connects IEC, Alliance roadmaps and proprietary protocols to practical product acceptance timelines for industrial end‑users.
- Strategic M&A and partnership playbook highlighting consolidation vectors, entry thresholds and integration pitfalls for new entrants and incumbents.
Note: This preview intentionally omits the report’s full segmented tables and per‑segment forecasts. Those datasets, essential for procurement tenders and capex approvals, are available in the full study.
Strategic themes shaping vendor and buyer decisions in 2026
- From speed to intelligence: The Ethernet Alliance 2026 roadmap elevates AI‑driven networking as a macro driver — a shift that forces connector choices to be evaluated not just on port speed, but on sustained throughput, signal integrity under interference and lifecycle reliability in edge compute nodes.
- Single‑pair Ethernet as a cost/weight lever: Standards such as IEC 63171‑6 are advancing single‑pair solutions into industrial contexts. This is lowering wiring complexity for certain sensor and actuator classes, creating new product design tradeoffs between cost, weight and future upgrade paths.
- Field‑installability and serviceability: Increased demand for uptime and reduced mean time to repair is driving interest in field‑terminable and push‑pull contact systems. Buyers should balance the premium for serviceability against deployment frequency and expected field‑service cadence.
- Ruggedization standards matter: Industrial end‑users are prioritizing IP‑rated and vibration‑resistant connectors. Material selection, such as polycarbonate variants used in certain ix Industrial form factors, has real implications for heat tolerance, impact resistance and long‑term dimensional stability.
Competitive landscape — who matters and why
The Industrial Ethernet connectors market remains functionally fragmented, with the top suppliers collectively accounting for a modest share of the market (the three‑firm concentration is around the mid‑twenties percentile). This fragmentation keeps competitive dynamics active across product innovation, channel strategy and service models.
- TE Connectivity Ltd. (Schaffhausen, Switzerland — https://www.te.com): A comprehensive portfolio spanning RJ45, Mini I/O and M8/M12 with field‑installable options and IP20–IP67 ratings. TE’s scale and protocol support (including higher‑speed Ethernet variants) make it a default supplier for complex automation suites.
- Amphenol Corporation (Wallisellen, Switzerland — https://www.amphenol-cs.com): Aggressively pursuing IEC 63171‑6 single‑pair solutions alongside high‑speed RJ45/M12 offerings — positioning to capture cost‑sensitive factory‑automation use cases seeking 10G performance on reduced pair counts.
- Belden Inc. (St. Louis, USA — https://www.belden.com): Leveraging Hirschmann and Lumberg brands for rugged industrial copper RJ45 connectors; their strength lies in legacy automation retrofit markets and deep channel relationships with system integrators.
- Phoenix Contact Ltd. (Blomberg, Germany — https://www.phoenixcontact.com): Known for plug‑in RJ45 and M12 systems capable of up to 10 Gbit/s; strong certification portfolios help accelerate adoption in regulated industries.
- Hirose Electric (Tokyo, Japan — https://www.hirose.com): Offers compact industrial Ethernet interfaces suitable for space‑constrained equipment, attractive to OEMs prioritizing miniaturization.
- HARTING Technology Group (Espelkamp, Germany — https://www.harting.com): The ix Industrial® family and related innovations (e.g., Captain IX) emphasize robust, industrial‑grade form factors and user‑focused field installation features.
- Eaton Corporation (Dublin, Ireland — https://www.eaton.com), Siemens AG (Munich, Germany — https://www.siemens.com), Rockwell Automation (Milwaukee, USA — https://www.rockwellautomation.com): These automation platforms integrate connectors into broader hardware ecosystems; their advantage is systems‑level integration and service bundling rather than connector‑only leadership.
Recent industry activity illustrates where the market’s energy is concentrated: HARTING’s Industrial Ethernet Week (February 2026) emphasized smart device design and field installation ergonomics for ix Industrial connectors, while Amphenol’s presence at DesignCon 2026 highlighted next‑generation IEC 63171‑6 single‑pair solutions.
Supply chain, materials and regulatory considerations
- Material choices matter: Engineered thermoplastics such as polycarbonate deliver impact resistance and dimensional stability for certain industrial form factors, but they also introduce specific molding and flammability constraints relevant to UL/IEC compliance.
- Certification as a time‑to‑market gate: Conformity to industrial communication standards and third‑party testing reduce adoption friction for end‑users but add lead time and cost for suppliers. Procurement timelines in 2026 must factor certification milestones into deployment schedules.
- Component sourcing risks: Connector subcomponents and plated contacts remain sensitive to base‑metal and noble metal pricing cycles. Strategic buyers should model multi‑sourcing and inventory buffers to protect critical production lines.
M&A and investment signal — what to watch in 2026
With moderate market concentration, M&A activity is likely to be targeted and capability‑driven. Expect acquisitive moves aimed at:
- Obtaining single‑pair Ethernet competencies and IP portfolios;
- Securing specialized field‑installable manufacturing and validation capabilities;
- Gaining entry into high‑value aftermarket field services or captive channel relationships with automation platform vendors.
Private equity and strategic buyers will favor bolt‑on deals that accelerate route‑to‑market for next‑generation connector formats while preserving existing OEM customer relationships.
How to use PW Consulting’s full study in your 2026 planning
- Procurement leaders: Use the supplier scorecards and SKU mapping to build two‑year sourcing plans with hedged supply options and contract SLAs tied to certification timelines.
- Product and R&D teams: Leverage the standards adoption timeline and technology roadmaps to prioritize connector integration on product roadmaps, minimizing future rework.
- Corporate development: Use our M&A playbook and valuation sensitivities to identify targets and prepare integration scenarios that preserve customer‑facing differentiators.
- CEOs and board directors: The market sizing, growth profile and concentration metrics inform capital allocation between organic innovation, partnerships and inorganic expansion.
Next steps — where this preview leads
This briefing demonstrates the strategic contours and operational levers that will determine winners in 2026. For teams drafting procurement specifications, prioritizing product features for next‑generation automation platforms, or evaluating acquisition targets, the full PW Consulting report contains the segmented forecasts, supplier assessments and executable playbooks required to move from intent to action.
Accessing the detailed tables and scenario models will remove ambiguity around segment exposures, regional demand patterns and SKU‑level pricing dynamics — information we intentionally reserve for the full study to support your 2026 decision milestones.
For detailed analysis of this topic, please visit the official page: Industrial Ethernet Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AWG Market to Reach USD 300 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-07-12
Arrayed Waveguide Grating (AWG) Market: Strategic Outlook for 2026 Decision‑Makers
As AWG-enabled photonics moves from niche telecom applications into mainstream data‑center interconnects, coherent optics, and integrated photonic platforms, 2026 will be a pivotal year for corporate strategy. This briefing — drawn from PW Consulting’s latest AWG Market research (base year 2025; historical 2020–2025; forecast 2026–2032) — synthesizes the practical intelligence executives need to convert technical signals into commercial advantage.
Arrayed Waveguide Grating (AWG) Market
Data‑driven snapshot you can act on
-
Measured in USD (Million), the AWG market expanded materially through the early 2020s, growing from the low‑hundreds of millions to a base‑year size of USD 170 Million in 2025.
Arrayed Waveguide Grating (AWG) Market -
Our forecast horizon (2026–2032) assumes a compound annual growth rate (CAGR) of 8.5%, with the market tracking toward an approximate USD 300 Million size by 2032 under the base scenario.
Arrayed Waveguide Grating (AWG) Market -
Market concentration remains moderate: the top three suppliers account for roughly 30% of global share, while the top five reach about 45% — a structure that favors nimble specialists and opportunistic consolidation alike.
These headline metrics are intended to inform capital allocation, product roadmaps, and M&A screening in 2026. The full report contains the granular segmentation, pricing bands, and channel economics required to convert these directional numbers into executable plans.
Why this research matters for 2026 decisions
-
Standards and regulation are converging on AWG performance thresholds. Recent standards work (e.g., channel grids and spacing) and operator specifications for insertion loss and crosstalk are establishing pass/fail gates that will determine which modules scale in hyperscale deployments.
-
Thermal management is a commercial battleground. Athermal AWG solutions remove active temperature control from the bill of materials and operations, creating a durable OPEX advantage for outdoor and uncontrolled environments. The implications span product engineering, procurement, and field operations.
-
Manufacturing complexity and labor intensity remain high. Wafer‑scale AWG fabrication requires cleanroom capacity, specialized photonic engineers, and strict process control — a barrier that constrains rapid commoditization and shapes supplier selection.
-
Growth is uneven across end‑use drivers. Internet backbone upgrades, data center interconnects, and enterprise optical fabric programs are each on different adoption curves. Strategic planners must align product features (e.g., channel spacing, athermal behavior, uniformity) with the precise requirements of target use cases.
Key dynamics shaping 2026–2032
-
Standards alignment: ITU‑T grids and Ethernet developments (e.g., large‑bandwidth datacenter optics) are driving demand for specified channel spacings and filter performance. Suppliers that pre‑qualify products to these standards shorten buying cycles and reduce qualification risk.
-
Regulatory and procurement requirements: Data center interconnect specifications increasingly mandate low insertion‑loss uniformity and stringent crosstalk limits for cascaded AWG chains. These technical barometers are now commercial gates for hyperscalers and telecom operators.
-
Technology tradeoffs: Substrate choice (silica, PLC, polymer, silicon photonics) defines the trade space: cost, thermal behavior, channel density, and integration potential. Different substrates appeal to different buyers — and companies that can span more than one technology stack have new cross‑selling opportunities.
-
Manufacturing and supply risk: High precision fabrication concentrates value around foundries with appropriate tooling and skills. Outsourcing strategies, IP protection, and dual‑sourcing are critical levers for manufacturing‑heavy players.
Competitive landscape — what to watch in 2026
The AWG supplier ecosystem is composed of distinct archetypes: silicon‑photonics integrators, PLC and silica module specialists, polymer/SoS athermal vendors, and niche optics houses. Below we summarize strategic postures for key players featured in our global coverage.
-
Aloe Semiconductor (Middletown, NJ, USA) — Focused on silicon photonic integrated circuits that embed AWG functions alongside active components. Strengths: integration density, roadmap alignment with coherent optics and transceiver OEMs. Strategic risks: foundry dependences and thermal sensitivity at scale.
-
Bright Photonics (Eindhoven, Netherlands) — IP and prototyping specialist offering AWG cores and modules for custom foundry runs. Strengths: rapid prototyping, access to European photonic ecosystems, and IP flexibility. Strategic play: act as an innovation bridge between universities/foundries and systems OEMs.
-
Agilechip Photonics (Zhongshan, China) — Manufactures PLC‑based AWGs, including athermal variants for DWDM, CWDM, and data‑center optics. Strengths: manufacturing scale and cost competitiveness in high‑volume segments. Watch: globalization efforts and customer qualification timelines outside local markets.
-
SENKO Advanced Components (Japan) — Producer of polymer and SoS athermal AWG modules with a focus on DWDM mux/demux uniformity. Strengths: field‑proven athermal designs and strong OEM relationships in Asia. Opportunity: lead in outdoor/uncontrolled deployments where OPEX matters most.
-
AC Photonics (United States) — Silica‑on‑silicon athermal AWG specialist targeting 100/150 GHz DWDM coherent markets. Strengths: high channel uniformity and alignment to coherent telecom requirements. Strategic runway: move up the value chain into subsystem integration for coherent transceivers.
-
engionic Fiber Optics (Germany) — Niche high‑performance photonic component specialist. Strengths: deep engineering capabilities and tailored solutions for demanding optical subsystems. Strategic fit: attractive partner for customized, high‑margin applications.
Collectively, these players demonstrate the sector’s heterogeneity: technology specialization, geography, and business model diversity. For buyers and investors in 2026, supplier selection will hinge on technology fit, qualification velocity, and the supplier’s ability to manage manufacturing and supply risk.
What PW Consulting’s full report contains (practical deliverables)
-
Market sizing and forward forecasts (2026–2032) with scenario sensitivity analyses that stress test CAGR assumptions against supply disruptions, standard shifts, and hyperscaler adoption — enabling realistic upside/downside planning.
-
Segmented demand drivers by use case, with a procurement playbook for qualifying AWG modules against operational KPIs (including insertion loss uniformity and crosstalk thresholds mandated by data center specifications).
-
Technology maps that compare substrate tradeoffs (silicon photonics, silica, PLC, polymer/SoS), product roadmaps, and cost drivers to inform product‑level decisions and make/buy debates.
-
Supplier scorecards, benchmarking, and a prioritized M&A target list — with commercial due diligence templates and red‑flag indicators for intellectual property, foundry access, and qualification backlog.
-
Operational guidance: sample RFP language, test‑plan checklists tethered to IEEE/ITU‑T norms, and capex/OPEX models that quantify the lifetime savings of athermal modules in uncontrolled environments.
-
Scenario playbooks for 2026 procurement cycles: supplier negotiation levers, dual‑sourcing roadmaps, and pilot program designs to de‑risk deployment at scale.
Actionable recommendations for 2026
-
For OEMs and subsystem integrators: prioritize athermal solutions where the lifetime energy and thermal management cost outweigh incremental BOM savings. Pre‑qualify at least two substrate technologies to avoid single‑technology risk.
-
For hyperscalers and carriers: insist on supplier compliance to industry performance gates and include staged acceptance tied to field metrics (insertion loss, crosstalk) to accelerate vendor accountability.
-
For investors and private equity: target consolidation candidates that own differentiated IP or exclusive foundry access. The market’s CR3/CR5 profile indicates room for bolt‑on value creation without competing on low‑margin commoditized products.
-
For foundries and contract manufacturers: invest in wafer‑scale process control and workforce development — these are persistent supply constraints that will command premium contracting terms with OEMs.
Intentional withholding — why you should read the full study
In keeping with our “trailer” approach, this article deliberately highlights strategy, dynamics, and actionable themes while withholding granular subsegment tables, regional breakdowns, and unit‑price banding that are essential for procurement negotiation and precise financial modeling. The full PW Consulting AWG Market report supplies those confidential line items, detailed supplier cost models, and buyer‑specific scenario outputs to convert strategic intent into executable plans.
Next steps
-
Use the high‑level intelligence here to set internal priorities for 2026 (standards alignment, athermal pilots, supplier due diligence).
-
Engage PW Consulting for a tailored briefing that maps the report’s granular data to your product roadmap, procurement calendar, and M&A thesis.
AWG technology is no longer a peripheral component — it is a gating factor for future optical architectures. In 2026, the right combination of standards readiness, manufacturing resilience, and product differentiation will separate leaders from followers. PW Consulting’s full study provides the segmented facts and decision tools you need to act with conviction.
For detailed analysis of this topic, please visit the official page: Arrayed Waveguide Grating (AWG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vehicle-to-Grid (V2G) Market 2026: Strategic Imperatives for Corporates — A PW Consulting Preview
As the energy transition accelerates, Vehicle-to-Grid (V2G) has moved from niche pilots to the threshold of commercial scale. Our PW Consulting Vehicle-to-Grid Market study (base year 2025) synthesizes quantitative forecasting, policy overlays, commercial pilots and supplier due diligence into a decision-grade guide for corporate leaders planning capital allocation, product roadmaps, and market entry in 2026. This preview explains why V2G should be on every energy, mobility and asset-management executive’s 2026 agenda — and how our full study equips organizations to act with confidence.
Vehicle-to-Grid (V2G) Market
Why 2026 is the Inflection Year
Two converging forces create a unique window for V2G value capture in 2026: regulatory standardization and improving economics. Binding technical requirements that mandate bidirectional communication in new/renovated charging infrastructure are scheduled to take effect across major jurisdictions, effectively turning “nice to have” bidirectionality into a compliance and market-access requirement. Separately, recent policy moves — for example the removal of double grid fees in key markets — materially improve the commercial case for exporting vehicle-stored energy back to the network.
Vehicle-to-Grid (V2G) Market
Price signals are supportive. Global residential electricity rates and wholesale futures in 2026 have produced realistic revenue pathways for aggregate V2G fleets to monetize arbitrage and ancillary services. These conditions convert theoretical V2G value into executable business cases for utilities, aggregators, OEMs and large fleet owners.
Vehicle-to-Grid (V2G) Market
Market Momentum — The Macro Picture
Our bottom-up model traces the V2G market from early commercial traction in 2020 through the 2025 base year, and projects forward across a 2026–2032 forecast horizon. The market expanded from the low hundreds of millions (USD, revenue unit: Million) in 2020 to roughly USD 215.0 Million by the 2025 base year; projected growth accelerates thereafter, reaching an estimated USD 344.8 Million by 2032. The forecast is driven by a compound annual growth rate (CAGR) of approximately 6.98% over the modeled forecast period — a pace signaling steady, platform-enabled adoption rather than exponential consumer-led uptake.
Two implications follow: first, V2G is not a rapid, consumer-driven gold rush; it is a multi-stakeholder systems play that rewards strategic positioning and partnerships. Second, early movers who secure grid access, aggregation capacity, and regulatory alignment will capture durable, higher-margin revenue streams as the market matures.
Competitive Landscape — Who Matters and Why
The V2G ecosystem today is characterized by meaningful technical differentiation and a fragmented supplier base. Market concentration metrics confirm a low consolidation state: the top-three and top-five providers hold modest combined shares, reflecting room for partnership, consolidation and regional champions. For corporates this means the competitive battlefield will be defined less by price alone and more by integration capability, regulatory footprint, and data/aggregation competence.
- Technology providers and aggregators: Players such as Nuvve (GIVe platform) and Virta emphasize fleet aggregation, bidirectional control stacks and virtual power plant services — capabilities essential for monetizing grid services. Recent organizational moves (e.g., Nuvve’s deployments and local leadership appointments in Japan in 2026) underscore a push into critical new geographies.
- Hardware and industrial integrators: ABB and The Mobility House specialize in bidirectional charging hardware and integrated systems — from chargers to V2G control software — enabling scale deployments for commercial, industrial and fleet customers. Standalone hardware competence without software and aggregation partnerships will limit addressable value.
- OEMs and ecosystem partners: Vehicle manufacturers and utilities (e.g., Nissan launching affordable bidirectional charging solutions, and energy groups such as E.ON and Enel) are closing the loop between vehicles, tariffs and customer propositions. Examples in early 2026 show OEMs and energy companies bringing market-ready bundles to residential and commercial customers.
- Retail energy innovators: New tariff and platform experiments by energy retailers (e.g., Octopus Energy’s Powerloop) illustrate the consumer-facing business model evolution: V2G as a differentiated retail product combining hardware incentives, smart tariffs and customer engagement.
These firms are all active in the field through product launches, deployments and commercial pilots — but none alone dominates the space today. That presents an opening for thoughtful strategic engagement, whether through JV models, white-label partnerships, or targeted M&A focused on aggregation, software IP and market access.
What the PW Consulting Report Contains — Practical Deliverables
Our full study is designed as an executable toolkit for 2026 decision-making. Highlights include:
- Forecast model with scenario branches (baseline, accelerated policy adoption, and slow consumer uptake) and sensitivity levers for energy prices, vehicle-to-charger adoption rates, and tariff structures.
- End-to-end value chain analysis mapping revenue pools by use case (e.g., residential arbitrage, ancillary services, demand-side management), supplier roles, and margin profiles.
- Commercial playbooks: go-to-market options for OEMs, utilities, fleet operators and retailers including pricing templates, partner scorecards, pilot-to-scale transition checklists, and B2B contract clauses for aggregation and energy settlement.
- Regulatory and compliance matrix tied to product design — including implementation pathways for ISO 15118-20 and jurisdictional fee structures — to accelerate product certification and tariff approval processes.
- Technology assessment and interoperability map: charger and vehicle compatibility matrices, cyber-security best practices, and data governance frameworks required for grid services participation.
- Vendor diligence annex: comparative profiles, recent developments, patent and IP snapshots, and M&A heatmaps identifying likely consolidation targets.
- Financial tools: TCO calculators for fleet and residential deployments, capital expenditure planning templates, and investment cases capturing bidirectional hardware costs, software-as-a-service revenue, and O&M assumptions.
The full report contains granular regional and application splits, vendor scorecards and downloadable models. In this preview we intentionally withhold those segmented figures to preserve the value of the detailed datasets and proprietary scoring methods included in the subscription edition.
Practical Strategic Recommendations for 2026 Decision-Makers
- Utilities and system operators: Prioritize partnership pilots with aggregators that can demonstrate real-time dispatch and settlement capability. Use 2026 commercial pilots to validate revenue stacking (ancillary + arbitrage + capacity) and to influence tariff design that supports bidirectional participation.
- OEMs: Embed V2G capability into product roadmaps where it aligns to customer value and regional regulation. Consider white-label charging partnerships and enable flexible warranty/maintenance models for bidirectional hardware to lower customer adoption friction.
- Fleet operators and large energy buyers: Test aggregation contracts that offer predictable revenue streams; use short-term procurement to build operational experience and refine fleet management practices before committing to large-scale capital expenditure.
- Charge-point operators and hardware vendors: Invest in software layers and open APIs for marketplace participation. Hardware-only strategies are increasingly fragile: the monetizable economics of V2G come from orchestration, settlement and QoS guarantees.
- Investors and corporate development: Focus M&A on companies that combine aggregation software with documented grid revenue performance and regulatory footprints in priority markets. Early-stage investments should prioritize IP around bidirectional control algorithms, cyber-resilient communications, and settlement engines.
Risk & Mitigation — What to Watch in 2026
- Regulatory timing and implementation risk: Mandates and technical standards are evolving; companies should build flexible architectures that can adapt to ISO 15118-20 implementations and AFIR timelines without costly hardware retrofits.
- Revenue stacking dependence on price signals: V2G returns are sensitive to electricity price volatility and ancillary market design. Mitigation: secure pre-commercial agreements with grid operators and explore revenue guarantee structures during pilot stages.
- Interoperability and cybersecurity: As multiple vendors and vehicle platforms interact, interoperability failures or breaches could stall deployments. Recommended mitigation includes vendor certification requirements, layered security designs, and third-party interoperability testing.
- Customer acceptance and behavioral risk: Residential adoption depends on perceived battery degradation risk and simplicity of proposition. Transparent warranty terms and intuitive tariffing are essential.
Signals from the Field — 2026 Developments Worth Noting
- OEM-led consumer product launches (e.g., Nissan’s affordable bidirectional chargers in early 2026) are shifting V2G from research labs into retail channels.
- Energy-utility collaborations (e.g., BMW/E.ON residential V2G commercial offers launched in Germany) demonstrate how tariff innovation can accelerate customer take-up when paired with OEM hardware commitments.
- Localized deployments (for example, bidirectional charger installations using Quasar 2 technology) show real-world interoperability tests between hardware vendors and vehicle models — useful early lessons for scale rollouts.
- Corporate moves into key markets (e.g., Nuvve’s organizational expansion in Japan) reveal where operator confidence in local market structures is rising.
Conclusion — What PW Consulting Recommends for 2026
V2G in 2026 is a strategic opportunity best pursued with a systems view. The macro trajectory — reflected in our forecasted growth to the end of the decade and a near-7% CAGR — favors orchestrators who can align vehicle OEMs, charge-point vendors, energy retailers, and grid operators. For executives deciding budgets and partnerships this year, PW Consulting recommends a three-track approach: (1) secure pilot-level technical and commercial proof points in priority markets; (2) build or partner for aggregation and settlement capabilities; and (3) embed regulatory foresight into product design to avoid costly rework when standards take effect.
Our full report provides the actionable segmentation, vendor scorecards, and financial models necessary to translate these strategic imperatives into procurement decisions and investment theses. For teams preparing 2026 capital plans, the report functions as both roadmap and risk register — designed to shorten time-to-value while preserving optionality as the market consolidates.
Next Steps
Contact PW Consulting to access the complete V2G Market study, including the downloadable forecast model, regional and application splits, detailed vendor profiles and custom advisory options tailored for executives preparing 2026 strategies. The market is at an inflection point — firms that prepare now will be best positioned to convert nascent grid services into recurring, defensible revenue streams.
For detailed analysis of this topic, please visit the official page: Vehicle-to-Grid (V2G) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Scrap Lifting Magnets Market to Reach USD 290.5 Million by 2032 (5.7% CAGR)
By PW Consulting, 2026-07-12
Scrap Lifting Magnets Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present an executive preview of our new market research on the global scrap lifting magnets sector. This essay highlights the report’s strategic value for corporate leaders making capital-allocation, product, and M&A decisions in 2026. It is written as a professional trailer: we reveal the analytical framework, market trajectory, competitive dynamics, and the pragmatic tools executives need — while preserving the granular, transaction-ready data inside the full report.
Scrap Lifting Magnets Market
Why this study matters in 2026
- Base and scope: Our study uses 2025 as the base year, captures historical trends from 2020–2025, and models multiple scenarios through a 2026–2032 forecast horizon.
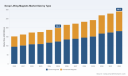
- Market momentum: The market has shown steady growth through the historical period and is forecast to continue expanding at a compound annual growth rate (CAGR) of 5.7% over the forecast window.
- Decision contexts covered: procurement optimization, product roadmap prioritization, capacity planning, aftermarket and service expansion, channel strategy, and transaction screening for strategic or financial buyers.
For procurement teams and asset managers, timing of equipment replacement and the selection of technology (electro-permanent vs. electromagnetic vs. permanent systems) is increasingly value-critical. For corporate development and private equity, the sector’s growth profile, pockets of consolidation, and technology-driven differentiation create specific M&A and partnership opportunities that require precise demand and margin modeling — which our report provides.
Scrap Lifting Magnets Market
Market trajectory at a glance
Readers will find in the full report a rigorous time series that traces market value through the pandemic and recovery years, demonstrating how demand normalized and then accelerated under new regulatory and operational dynamics. To orient strategic thinking: the global market moved from the low hundreds of millions (USD) at the start of the decade to a larger base by 2025, and is projected to grow meaningfully by the early 2030s under our base-case assumptions. The 5.7% CAGR reflects a mix of steady replacement cycles, expanding recycling and scrap-handling activity, and technology-driven conversions in mobile and stationary applications.
Scrap Lifting Magnets Market
Key demand and supply dynamics shaping 2026 choices
- Regulatory pressure and circular-economy mandates. Governments across multiple regions are tightening waste-management and recycling targets, pushing industrial operators to invest in higher-throughput and safer scrap-handling systems.
- Commodity price volatility. Steel scrap pricing has migrated into the mid-hundreds per ton range in recent years, increasing the economic incentive to recover more metal per lift and shorten handling cycles — both of which favor investment in advanced lifting magnets and automation.
- Labor and operating-cost pressures. Rising labor and service costs are accelerating the shift to systems that reduce manual load handling time and deliver higher uptime through modular, battery-assisted, or electro-permanent technologies.
- Energy and operational efficiency. Battery-powered and electro-permanent solutions are gaining share because they combine operational flexibility with lower downtime versus some legacy electrically powered alternatives, influencing total cost of ownership (TCO) calculations.
- Safety and OEM-driven standards. Large end-users — notably automotive and heavy industry OEMs — increasingly specify lifting equipment to meet stringent quality, traceability, and risk-management standards, reinforcing the value of established suppliers with certification and long-term service footprints.
Technology and product trends to prioritize
Technology trends in the sector have clear strategic implications for product development and procurement: modular electromagnets with remote switching, electro-permanent units that maintain magnetic holding without continuous power, battery-operated mobile systems that enable longer operating windows, and sensorized units for predictive maintenance. Each approach carries different CapEx vs. OpEx trade-offs, and the optimal choice depends on rhythm-of-use, maintenance infrastructure, and safety requirements — all modeled in the full report’s TCO and sensitivity tools.
Competitive landscape — what structure means for strategy
The market exhibits moderate concentration: the largest players together account for a substantial share, but meaningful pockets of niche specialist activity remain. That structure has three strategic takeaways:
- Incumbent advantage: Established manufacturers with broad product lines and global service networks can capture premium margins on safety-certified, high-duty-cycle systems and aftermarket service contracts.
- White-space for specialists: Companies that focus on a narrow application (e.g., shovel-mounted units, skid-steer systems, or compact battery-powered lifters) can build defensible niches that remain attractive to consolidators.
- Channel and partnership play: Local service partners, OEM integrators, and distributors continue to be key growth levers for firms seeking to scale penetration in industrial end markets with complex service demands.
Selected companies profiled in our competitive analysis include manufacturers and OEMs that illustrate these strategic archetypes:
- Walker Magnetics (Boyne City, Michigan) — recognized for product breadth across lighter and heavier scrap-handling families designed for steel mills and recycling applications.
- SGM Magnetics (Manerbio, Italy) — an engineering-driven player known for proprietary electro lifting magnet designs that reduce side magnetic attraction and improve handling safety.
- Sinfonia Technology (Japan) — focused on shovel-mounted and integrated systems prioritizing secure load transfer and operational efficiency.
- Gensco Equipment (Canada) — offers hydraulic and skid-steer solutions with strong appeal to demolition and site-level recycling operations.
- DIMET (United States) — producers of a portfolio of electromagnets for scrap and turnings with global sales reach and presence at regional trade shows.
- HVR MAG (China), Bunting Magnetics (United States), and Magnetool, Inc. (United States) — each illustrating different strategic bets: electro-permanent technologies, separation and lifting integration, and mobile battery-powered lifting systems, respectively.
Activity signals in the market reinforce an active product and trade-show calendar, highlighting continued investment in visibility and new-product rollout: recent exhibitor participation and demonstrations by manufacturers in major industry expos underscore the speed of iterative product development and the centrality of field demonstrations to sales cycles.
What the PW Consulting report delivers — practical, actionable outputs
We designed this study to be immediately operational for executives and deal teams. Key deliverables include:
- Robust market sizing and baseline demand curves (2020–2025), plus scenario-based forecasts to 2032 using alternative macroeconomic and commodity assumptions.
- Vendor and product mapping with a decision matrix that links operating profile (lift cycles per hour, duty class, mobility requirement) to recommended technologies and supplier archetypes.
- TCO and sensitivity models that estimate CapEx, energy use, maintenance, and downtime impacts across electrified, electro-permanent, and battery systems.
- Go-to-market playbooks for market entrants and incumbents — channel strategies, pricing frameworks, and aftermarket service bundles that maximize lifetime value.
- M&A screening tools: scorecards, valuation sensitivities, and integration risk checklists customized for both strategic acquirers and financial sponsors.
- Risk matrix and regulatory mapping that align compliance requirements across major jurisdictions with procurement timelines and certification roadmaps.
- Primary interview summaries, expert-opinion synthesis, and a methodology appendix that documents data sources, assumptions, and modeling approaches.
To respect the “trailer” principle, we present the analytical structure and outcomes here, while detailed segment-level splits, regional roll-ups, and the downloadable datasets that underpin our forecasts are available only in the full report package.
How executives should use this intelligence in 2026
- CapEx & procurement: Use the report’s TCO modules to decide between retrofit, replacement, or reconfiguration of fleets — prioritizing projects that shorten payback under plausible scrap-price scenarios.
- Product roadmap and R&D: Prioritize battery management, sensor integration, and modular serviceability where the model shows the highest incremental value per dollar spent.
- Channel strategy: Evaluate partnerships with regional maintenance providers and OEMs to secure long-term service revenue and compliance credentials.
- M&A & JV screening: Identify consolidation targets that offer complementary product capabilities or service footprints; use our M&A scorecards to size integration upside and downside risks.
- Pilot programs: Run targeted field pilots for electro-permanent and battery-assisted platforms to validate productivity uplift and serviceability metrics before full-scale rollouts.
Conclusion — where this report fits in your 2026 playbook
As scrap flows increase and industrial operators pursue higher throughput with lower operating costs, the scrap lifting magnets market sits at the intersection of regulatory demand, energy-efficiency priorities, and technology-driven differentiation. The sector’s steady CAGR and forecasted market expansion create a compelling environment for both incremental investment and selective consolidation. PW Consulting’s full study converts those dynamics into operational guidance — from tactical procurement checklists to strategic M&A screens and validated TCO models.
For teams preparing 2026 budgets, product launch roadmaps, or transactional diligence, the full report provides the granular segmentation, regional demand profiles, and downloadable financial models you will need. Access the complete research package on our site to unlock the datasets and the tactical annexes that make these strategic recommendations executable.
For detailed analysis of this topic, please visit the official page: Scrap Lifting Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UGC Software Market to Hit USD 10.99B by 2032 with 10.6% CAGR — PW Consulting
By PW Consulting, 2026-07-12
User Generated Content (UGC) Software Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Industry Analyst, I present an executive preview of our new market research on the User Generated Content (UGC) Software market. This briefing is designed as a strategic “trailer”: it surfaces the essential macro trends, competitive positions, and actionable levers that should inform enterprise decisions in 2026, while intentionally withholding certain proprietary segment tables and vendor scorecards reserved for the full report.
User Generated Content (UGC) Software Market
Why this research matters for 2026
UGC software is no longer a niche marketing tool — it has become a foundational layer of contemporary commerce, customer experience, and brand trust architecture. Organizations making platform, vendor, and data governance decisions in 2026 must reconcile three concurrent shifts: accelerating AI-driven content collection and personalization, increasing regulatory scrutiny on AI/curated content, and the rising commercial value of shoppable, permissioned visual media.
User Generated Content (UGC) Software Market
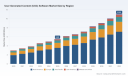
Our modeled market trajectory captures these dynamics. From a clearly observable expansion across 2020–2025, the market reached a material inflection point in 2025 (base year) and is forecast to grow at a 10.6% compound annual growth rate over the 2026–2032 horizon. The outcome is a near-doubling of market scale through the forecast period, underscoring both intensifying vendor activity and expanding buyer demand for integrated UGC capabilities.
User Generated Content (UGC) Software Market
High-level market picture (what leaders need to know)
- Growth profile: The market has expanded steadily through 2020–2025 and transitions into a mature acceleration phase in 2026, driven by enterprise adoption of UGC as a conversion and retention tool.
- Concentration: Market concentration is meaningful but not prohibitive — three vendors account collectively for a majority share of commercial activity, with the top five increasing that footprint. This creates a dual environment of stable incumbency and targeted opportunity for challengers with differentiated capabilities.
- Value drivers: The principal ROI levers for buyers are content authenticity and rights management, shoppable integrations that shorten commerce funnels, and AI-assisted moderation and tagging that reduce operational cost.
Dynamics shaping vendor selection and implementation
- AI as paradox: AI both unlocks scale (automated tagging, sentiment, visual recognition) and introduces new risks (hallucinations, synthetic content). Buyers must evaluate vendor approaches to provenance, explainability, and human-in-the-loop workflows.
- Regulatory noise and compliance priorities: Recent regulatory moves — for example, new rules requiring rapid removal of demonstrably harmful AI-generated content and explicit labeling of AI-curated media in some jurisdictions — elevate compliance from checklist to core capability. Vendors’ content governance, audit trails, and localization support will be decisive.
- Integration tax: UGC value accrues only when tightly integrated with commerce stacks, CDPs, and CX platforms. Procurement assessments should weight API quality, latency SLAs, and headless/rendering options equally with feature lists.
- Rights & moderation economics: Clear, auditable rights acquisition and automated moderation workflows materially affect total cost of ownership and legal exposure—features that have moved from “nice-to-have” to “must-have.”
Competitive landscape — strategic snapshots
The competitive set is diverse: from legacy e-commerce review platforms to AI-first personalization vendors and visual-content specialists. Below are targeted assessments of the primary vendors covered in our study. These snapshots synthesize public positioning, product focus, and strategic implications for enterprise buyers.
- Bazaarvoice (Austin, Texas) — Bazaarvoice is positioned as a robust e-commerce UGC collection and syndication platform. Its strengths are mature review workflows, retailer integrations, and an extensive syndication network. Strategic fit: organizations prioritizing scale of review distribution and cross-retailer consistency. Considerations: evaluate roadmap for AI curation and visual UGC expansion.
- Yotpo (New York, New York) — Yotpo presents an AI-augmented UGC stack covering reviews, social, and visual commerce. Strengths include tight e-commerce UX integrations and marketing automation. Strategic fit: DTC brands seeking embedded loyalty and conversion optimization. Considerations: probe for provenance controls and moderation latency under peak loads.
- Taggbox (Covina, California) — Taggbox emphasizes social feed widgets, reviews, and shoppable content aggregation across platforms. Strengths are flexibility in display formats and channel-agnostic aggregation. Strategic fit: event-driven, campaign-centric use cases and experiential marketing. Considerations: assess enterprise-grade governance and platform SLAs for high-traffic deployments.
- Emplifi (Columbus, Ohio) — Emplifi integrates UGC with social analytics, commerce, and broader CX capabilities. Strengths include an analytics-centric approach and cross-channel orchestration. Strategic fit: enterprises that require UGC insight to feed loyalty, CX, and service functions. Considerations: clarify data ownership models and cross-module interoperability.
- Nosto (Helsinki, Finland) — Nosto is recognized for AI-powered commerce experience and visual UGC personalization. Strengths include recommendation engines and visual merchandising tied to UGC. Strategic fit: retailers investing heavily in personalization at scale. Considerations: request transparency on model training data and regional regulatory compliance readiness.
- PowerReviews (Chicago, Illinois) — PowerReviews focuses on ratings and reviews with conversion optimization and syndication capabilities. Strengths lie in review authenticity features and conversion analytics. Strategic fit: brands focused on review-led conversion strategies with large SKU catalogs. Considerations: understand how visual UGC and influencer-driven content are supported.
- Crowdriff (Toronto, Ontario) — Crowdriff specializes in visual content discovery, management, and publishing, with particular traction in travel, hospitality, and retail. Strengths include visual search and rights-cleared publishing. Strategic fit: destination marketing and retail brands that rely on aspirational imagery. Considerations: evaluate commerce linkage maturity for direct shoppability.
Recent events and regulatory signals to watch in 2026
- Platform innovation: New entrants and product launches continue to change the competitive calculus. For example, early-2026 product introductions aimed at capturing text-based experience data are expanding the types of consumer narratives that can be monetized or moderated.
- Regulatory accelerants: Jurisdictions are moving quickly to impose obligations around AI-generated content — including removal timeframes for harmful content and mandatory labeling of AI-curated media. These measures shift vendor evaluations toward demonstrable auditability and localization features.
- Operational implications: The combined effect of product innovation and regulation increases the premium on vendors that can demonstrate low-latency moderation, strong provenance, and clear rights management across country boundaries.
What the full report delivers (practical, actionable components)
Our full market study is built for practitioners and C-suite decision-makers who need to turn insight into execution in 2026. Deliverables include:
- Comprehensive market sizing and forecast (2020–2032) with sensitivity scenarios and CAGR decomposition by driver.
- Competitive landscaping that pairs vendor capabilities with use-case fit, implementation complexity, and buying signals.
- Go-to-market and procurement playbooks: RFP templates, vendor scorecards, and negotiation levers tailored to enterprise priorities.
- Technical integration blueprints and API evaluation checklists for commerce, CDP, CMS, and moderation pipelines.
- Actionable ROI and TCO models with benchmarked assumptions for content moderation, rights clearance, and shoppable conversion uplift.
- Regulatory compliance annex with jurisdictional heatmaps, sample contractual clauses, and audit trail templates aligned to 2026 regulations.
- Deployment roadmaps and pilot designs to validate value quickly while managing legal and operational risk.
- Curated executive briefs and one-page decision frameworks for board and procurement committees.
How to use this briefing to act in 2026
- Prioritize a rights-first evaluation: Require vendors to demonstrate rights acquisition, verifiable provenance, and chain-of-custody for visual assets as a gating criterion.
- Make AI governance concrete: Insist on explainability, human-in-the-loop review thresholds, and remediation SLAs tied to regulatory timeframes in your contracts.
- Prize integration over point features: Choose vendors that reduce integration lift and offer clear pathways into your commerce and CX ecosystems.
- Pilot for legal and commercial outcomes: Structure initial engagements as limited-scope pilots with measurable conversion and compliance KPIs before rolling out wholesale.
Closing — a strategic prompt
The UGC software market in 2026 sits at an inflection of opportunity and obligation. Growth is robust — reflecting sustained enterprise investment — but the competitive and regulatory environments are evolving rapidly. This briefing surfaces the strategic signposts leaders must use to select vendors, design pilots, and scale responsibly.
For the complete segmentation tables, provider scorecards, and the proprietary appendices that translate these insights into executable procurement and integration artifacts, access the full PW Consulting report. Our research includes the granular data and templates required to turn the market’s projected 10.6% CAGR and the full 2020–2032 sizing into a concrete 12–18 month action plan for your organization.
For detailed analysis of this topic, please visit the official page: User Generated Content (UGC) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Millimeter-Wave Radar Market to Reach $5.84B by 2032 at 11% CAGR
By PW Consulting, 2026-07-12
Automotive Millimeter-Wave Radar Market: Strategic Preview for 2026 Decision-Making
By PW Consulting — Senior Strategy Advisor & Chief Industry Analyst
Automotive Millimeter Wave Radar Market
Executive snapshot
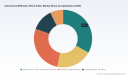
The global automotive millimeter-wave radar market has moved from niche safety enabler to core sensor backbone for production-level ADAS and nascent automated driving. Our research—anchored on a 2025 base year and extending through a detailed 2026–2032 forecast horizon—shows the market roughly doubling from the mid‑2020s baseline to the end of the decade, tracking a compound annual growth rate (CAGR) of approximately 11%. After an incremental recovery from 2020, the installed and revenue base accelerated into 2024–2025, with continued secular demand expected through 2032 as regulatory mandates, OEM feature parity, and system-level integration converge.
Automotive Millimeter Wave Radar Market
Why this matters for 2026 strategic planning
-
Timing matters: 2026 is the decision inflection point for suppliers, OEMs, tier‑1 integrators, and investors. Contracts negotiated, fabs allocated, and module roadmaps defined in 2026 will determine market share and margin capture across the 2027–2030 window when volume ramps and compliance-driven adoption collide.
Automotive Millimeter Wave Radar Market -
Regulatory tailwinds will crystallize demand: Binding regulatory milestones—most notably compulsory AEB rules in major markets and expanded ADAS test protocols—are translating policy into procurement. For organizations that anticipate the timing and specification of these regulations, the opportunity is not only in unit volume but in upgraded functional requirements and higher ASPs for more capable radar subsystems.
-
Margin profile and concentration: The market is already concentrated. The top-tier suppliers collectively control a majority of market revenues, creating a strategic landscape where partnerships, IP leverage, and scalable manufacturing are decisive. Firms looking to enter or expand in 2026 must plan for either premium differentiation or cost leadership at scale.
Market trajectory — what the headline numbers tell us
From a revenue base that grew steadily through 2020–2025, the market shows continued momentum into the forecast period. By 2025 the market has reached a mid‑single‑billion dollar scale (USD denominated, base year 2025), and the PW Consulting forecasts point to a near doubling of market revenues by 2032. That trajectory—driven by both unit growth and increasing per-module capability—creates a multi-year window for strategic capture, but it is punctuated by inflection points driven by regulation, standardization, and technology migration.
Regulatory and geopolitical dynamics shaping 2026 decisions
-
Mandates on vehicle safety systems: Regulatory moves to require features such as automatic emergency braking (AEB) and expanded ADAS performance criteria are shortening OEM procurement lead times and broadening the TAM for robust radar systems. Companies that have product roadmaps aligned with the stricter test protocols will be preferred suppliers for high-volume platforms.
-
Federal harmonization of automated vehicle rules: Efforts to create federal frameworks for automated driving reduce the risk of fragmented state-level standards, simplifying compliance roadmaps for OEMs and enabling clearer investment cases for suppliers in 2026.
-
Geopolitical supply constraints: Heightened controls on production equipment and critical semiconductor transfers introduce supply-chain risk and protect advantages for regionalized manufacturing strategies. Firms must incorporate scenarios for constrained access to certain radar production capital and critical ICs into their 2026 sourcing and capacity plans.
Competitive landscape — capability profiles and strategic moves
The industry’s competitive topology is defined by a mix of established automotive OEM suppliers, semiconductor leaders, and specialized SoC entrants. A concentrated top tier holds a majority of revenues, but product-level differentiation and systems-integration capabilities are increasingly decisive.
-
Established automotive Tier‑1s — Companies with deep OEM relationships and radar module portfolios continue to defend share through platform scalability, system validation, and vertical integration. Their advantages include proven qualification cycles, safety certifications, and bundled ADAS systems offerings that reduce OEM integration risk.
-
Semiconductor and SoC specialists — Pure‑play IC vendors and radar SoC start‑ups are pushing the performance envelope (higher antenna counts, integrated 4D imaging, advanced point‑cloud generation). Their disruptive potential is real, but realization depends on production-readiness and automotive-grade qualification.
-
Regional manufacturers — Localized production and targeted product variants are emerging in high-growth markets. These players benefit from proximity to OEMs and reduced logistical friction, especially where trade controls complicate cross-border supply chains.
Recent product and certification activity in 2025–2026 underscores these dynamics: major suppliers launched 4D imaging radar platforms and next‑generation millimeter‑wave SoCs; production rollouts in strategic regions moved from pilot to volume; and selected SoC vendors achieved industry certifications that accelerate ecosystem interoperability. These moves are not isolated product updates—they represent an industry push to combine range, angular resolution, and processing capability into single radar modules that can serve multiple ADAS functions simultaneously.
Technology and product evolution — what to expect
-
Convergence to higher-frequency, higher-channel configurations for critical ADAS functions. This is enabling richer environmental perception at longer ranges and with finer angular resolution, which matters for lane-level automation and pedestrian/obstacle classification.
-
System‑level integration: radar is increasingly being delivered as part of sensor fusion stacks, where SoC performance, software stacks, and data pre‑processing determine the effective value to OEMs. Suppliers who can provide validated sensor-fusion modules reduce OEM integration timelines and command premium positioning.
-
Certification and safety engineering: Automotive functional safety (ISO 26262) and interoperability standards are a gating factor for adoption. Certification achievements shorten time-to-production and open doors to high-tier platform contracts.
Strategic playbook for 2026 — actionable choices by role
-
OEMs : Lock down multi‑year supply agreements that embed roadmaps for incremental capability upgrades, ensure dual sourcing for critical SoCs, and negotiate software‑license terms that preserve long‑term margin potential.
-
Tier‑1 suppliers : Invest selectively in SoC partnerships, pursue modularization that standardizes interfaces across platforms, and accelerate certification to reduce OEM integration friction.
-
Semiconductor firms : Prioritize automotive qualification pipelines, build reference platforms that accelerate adoption, and secure strategic foundry commitments to mitigate geopolitical supply risks.
-
Investors & private equity : Target assets where technology maturity aligns with strong OEM bookings or where regional manufacturing provides an entry barrier; test downside scenarios for supply-chain constraints and regulatory timing sensitivity.
What our full PW Consulting report delivers (practical, operational intelligence)
The published study is designed for decision-makers who need both strategic context and executable plans. Key deliverables include:
-
Bottom‑up market sizing and demand scenarios across 2026–2032 with sensitivity analyses that model regulatory timelines, OEM adoption curves, and ASP evolution.
-
Supplier benchmarking covering product roadmaps, certification status, manufacturing footprint, and go‑to‑market positioning—identified strengths, blind spots, and partnership opportunities.
-
Technology roadmaps and cost‑curve analysis that map antenna counts, SoC node migration, and bill‑of‑materials sensitivities to margin outcomes.
-
Commercial playbooks for OEM procurement teams and Tier‑1 strategy leads: negotiation levers, sourcing checklists, and timing matrices to align product launches with regulatory milestones.
-
M&A and JV target lists informed by capability gaps, regional access needs, and IP portfolios—paired with valuation frameworks stress‑tested against multiple adoption scenarios.
Trailer note — the signal, not the raw data
In the spirit of a strategic “trailer,” this article highlights the most consequential trends and the tactical choices that matter in 2026. To preserve the research value and to support executable planning, granular regional splits, application-level market shares, per-type revenue breakdowns, price curves, and OEM program mappings are reserved for the full report. PW Consulting clients and subscribers will receive the complete datasets, model workbooks, and supplier scorecards required for implementation.
Conclusion — positioning for the next wave
Millimeter-wave radar is no longer an accessory; it is a core architectural decision for vehicle safety and automated driving roadmaps. With market revenues on a clear growth path through 2032 and concentration among a few strategic suppliers, 2026 offers a narrow but decisive window to secure long-term advantage. Companies that align product roadmaps to regulatory calendars, invest in certification and production scale, and hedge geopolitical supply risks will capture outsized returns. For executives preparing budgets, partnerships, or acquisition strategies this year, the PW Consulting Automotive Millimeter-Wave Radar Market study provides the scenario‑tested intelligence and practical toolset to convert insight into action.
Next steps
Access the full report for the datasets, supplier scorecards, and scenario models required to operationalize a 2026 strategy. PW Consulting subscriptions include analyst briefings and custom modeling sessions to translate the findings into board-ready recommendations.
For detailed analysis of this topic, please visit the official page: Automotive Millimeter Wave Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SMS Medical Nonwoven Market at USD 402.46M in 2025 — 5.75% CAGR Ahead
By PW Consulting, 2026-07-12
SMS Medical Nonwoven Fabric Market — Strategic Outlook and Decision Playbook for 2026
Executive preview
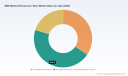
As healthcare systems, PPE manufacturers, and hospital procurement teams recalibrate for a post‑pandemic steady state, the SMS (spunbond–meltblown–spunbond) medical nonwoven fabric market is entering a phase defined by steady growth, concentrated supply, and a new set of regulatory and sustainability pressures. Our PW Consulting market study — based on a 2025 base year with historical tracking from 2020–2025 and forward projections through 2032 — shows a resilient market trajectory underpinned by a compound annual growth rate (CAGR) of roughly 5.75% over the forecast horizon. Global revenue has expanded meaningfully over the past five years and is expected to continue its upward climb through 2032.
SMS Medical Nonwoven Fabric Market
Why this research matters for 2026 decisions
- Timing: 2026 is the inflection year when incremental demand drivers (elective procedures rebound, routine PPE procurement normalization, and renewed focus on biodegradables) meet the cyclical effects of capacity additions announced in 2024–2025. The study translates those interactions into decision-ready scenarios.
- Capital allocation: Companies considering greenfield lines, capacity upgrades, or converting existing meltblown assets to SMS lines need forward‑looking demand curves and utilization sensitivity models — not just historical size figures. Our model provides scenario-based utilization thresholds tied to price and raw‑material volatility.
- Regulatory readiness: With recent FDA clarifications and 510(k) clearances relevant to SMS constructions, 2026 procurement and compliance strategies must change. The report maps regulatory pathways and the risk/reward of pursuing classification changes or exemptions.
Market trajectory and macro drivers
From a macro standpoint, the SMS medical nonwoven segment has moved from emergency-driven spikes to predictable, healthcare-driven growth. The study quantifies that transition: after the rapid demand shocks of the early 2020s, annual market revenues have expanded and are projected to continue growing at mid-single-digit rates through the end of the decade. This is driven by a confluence of forces:
SMS Medical Nonwoven Fabric Market
- Structural healthcare demand — routine surgeries, outpatient care growth, and expanding access in developing markets.
- Product innovation — manufacturers are introducing SMS variants that balance barrier performance with breathability and comfort, widening the addressable applications beyond traditional gowns and drapes.
- Sustainability and circularity — biodegradable blends and recyclable constructions are becoming procurement differentiators, influencing both OEM selection and premium pricing potential.
- Regulatory de‑risking — clearer FDA guidance on exemptions for certain nonwoven medical devices and recent 510(k) clearances reduce time‑to‑market uncertainty for modification of SMS constructions.
Competitive landscape — what the market structure means for strategy
The market exhibits moderate concentration with the top three players controlling a substantial share and the top five an even larger portion. That structure produces distinct competitive dynamics:
SMS Medical Nonwoven Fabric Market
- Scale advantages: Large global producers have the balance-sheet capacity to invest in multi‑regional capacities and sustainability R&D, enabling them to capture enterprise OEM contracts and hospital system frameworks.
- Regional specialist plays: Mid‑sized and local producers compete by offering customization, faster lead times, or lower cost bases in localized markets.
- Collaborative innovation: The trend toward co‑development partnerships and cross‑licensing (notable between multinational material suppliers and performance‑fabric specialists) is accelerating differentiated product launches.
Key players profiled in the study include established global integrators and regional specialists. The report assesses each on dimensions that matter for strategic counterpart selection and competitive response: manufacturing footprint, product portfolio breadth (including SMMS and reinforced laminates), sustainability roadmap, regulatory clearances, and customer segmentation focus.
Recent industry moves and regulatory context — implications for 2026
- Strategic partnerships and product launches: Several strategic collaborations and new product introductions in 2024–2025 signal a shift from capacity‑race tactics to capability‑led competition. Notably, collaborations targeting sustainable SMS formulations and high‑performance barrier fabrics suggest that technical differentiation — not purely price — will drive premium procurement decisions.
- Capacity expansions: Announcements of manufacturing expansions by leading firms point to upcoming capacity additions that will moderate raw‑material inflation pass‑throughs but will also pressure utilization for smaller producers unless demand growth accelerates as forecasted.
- Regulatory clarity: Recent FDA notices and 510(k) activities have reduced some approval risk for specific SMS constructions, while regional certifications (e.g., CE conformity of blood/biological sample collection materials) open adjacent market opportunities for material suppliers. Commercial teams need to align product claims, testing packages, and submission strategies to exploit these windows.
Strategic playbook for 2026
For executives planning actions in 2026, the study translates macro forecasts and competitive intelligence into a set of prioritized strategic moves. Examples include:
- Capacity and footprint decisions: Use our utilization-trigger matrix to decide between incremental capacity (module expansion), asset retrofits (converting meltblown to SMS lines), or contract manufacturing partnerships. The matrix highlights breakpoints where internal capacity becomes accretive versus outsourcing.
- Product portfolio and differentiation: Prioritize investment in SMS variants that offer validated barrier-breathability trade-offs and in biodegradable/polyolefin blends that meet hospital sustainability procurement criteria. The study includes concept-to-commercial timelines and cost implication models.
- Partnerships and M&A targets: Identify targets that fill capability gaps — whether raw‑material resilience (regional polymer supplies), specialty meltblown technology, or validated regulatory dossiers — and use our valuation overlay to size accretive deals under multiple demand scenarios.
- Regulatory and quality readiness: Align R&D and regulatory teams to the simplified entry pathways for select SMS device classes; prepare 510(k) or equivalent dossiers for high‑value product extensions to minimize launch delays.
- Procurement and supply resilience: Rebalance supplier mix and contract tenors to mitigate polymer feedstock volatility; consider vertical integration or strategic long‑term offtakes for meltblown intermediates where scale advantages justify CAPEX.
What’s in the full report (practical, executable content)
The full PW Consulting report is structured to support immediate decision-making and phased strategy execution. Highlights include:
- Bottom‑up market sizing and validated growth scenarios through 2032, including sensitivity to adoption rates for biodegradable and reinforced SMS constructions.
- Utilization and capacity maps incorporating announced expansions and plausible new builds, with breakeven and payback analyses for different capex pathways.
- Competitive benchmarking across manufacturing footprint, product capabilities, regulatory clearances, and sustainability credentials — enabling prioritization of partners and competitors.
- Segment playbooks (go‑to‑market, pricing, and procurement strategies) for hospital systems, OEMs, and national health agencies — presented as executable 90‑, 180‑, and 360‑day plans.
- M&A screening tool: a short list of target archetypes and valuation ranges tied to synergy and integration complexity.
- Regulatory navigators: step‑by‑step guidance for leveraging recent FDA clarifications and CE conformity precedents to accelerate market entry.
Note: To preserve strategic advantage and respect commercial sensitivity, our public executive summary intentionally omits detailed sub‑segment revenue splits, regional share tables, and explicit pricing ladders. These are included in the full dataset and interactive dashboards available on our report portal.
How to use these insights in boardroom conversations
- Frame capital requests with scenario‑tested utilization outcomes: present conservative, central, and aggressive demand cases derived from the study.
- Use competitive profiles to justify partnership versus build decisions: show how capability gaps will impact time‑to‑contract for large health systems.
- Prioritize regulatory investment: align 510(k) and certification timelines to product launch windows where margin recovery is highest.
- Embed sustainability metrics into procurement negotiation: leverage hospital ESG mandates to capture premium pricing for certified biodegradable or recyclable SMS options.
Closing — a call to action for 2026
The SMS medical nonwoven fabric market is no longer a pure-volume play — it has evolved into a multi‑dimensional battleground where technology, sustainability, regulatory positioning, and regional footprint determine who captures value. Our analysis shows a clear path for companies that can synchronize capacity deployment with differentiated product offerings and regulatory readiness. For executives preparing 2026 plans, the immediate priority is to convert market visibility into executable roadmaps: align capex, partner selection, and compliance investments to the demand scenarios that best fit your risk appetite.
For full access to the detailed breakdowns, sub‑segment forecasts, regional demand analytics, and our interactive scenario tools, request the complete PW Consulting SMS Medical Nonwoven Fabric Market report and dataset.
For detailed analysis of this topic, please visit the official page: SMS Medical Nonwoven Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


