



PW Consulting: Electric Heating Cable Systems Market to Reach USD 3,372M by 2032 at 7.0% CAGR
By PW Consulting, 2026-07-12
Electric Heating Cable Systems Market — Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
As companies position portfolios and capital allocation for 2026, the electric heating cable systems market offers a mix of steady expansion and structural shifts that demand disciplined, near‑term strategic choices. Our PW Consulting analysis uses 2025 as the operational baseline and traces market development across 2020–2025, then projects through a scenario‑aware forecast horizon of 2026–2032. At the macro level the market has grown from under USD 1.5 billion in 2020 to roughly USD 2.1 billion in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of approximately 7.0% across the 2026–2032 forecast window, approaching the mid‑USD 3‑billion range by 2032.
Electric Heating Cable Systems Market
Why this research matters for 2026 decisions
-
Investment prioritisation: The report translates high‑level growth into actionable signals for CapEx timing, product R&D, and geographic deployment. The 7% CAGR and the trajectory since 2020 create clear windows for rolling out differentiated offerings and capturing rising demand without over‑saturating low‑margin channels.
Electric Heating Cable Systems Market -
M&A and portfolio shaping: Consolidation metrics in the market point to moderate concentration among the leading suppliers. PW Consulting’s benchmarking and acquisition playbooks equip buyers and sellers with valuation levers, integration checklists and post‑deal value capture roadmaps tailored to this industry.
Electric Heating Cable Systems Market -
Regulatory and cost shock readiness: Our scenario analysis models the impact of recent regulatory shifts and raw material volatility on unit economics and procurement strategies — critical inputs for procurement, pricing and contract negotiation in 2026.
-
Commercial model redesign: For businesses moving from pure component sales to services and systems, the study identifies practical approaches to capture recurring revenue through monitoring, predictive maintenance and outcome‑based contracting.
Market dynamics you cannot ignore
The market momentum is underpinned by sustained industrial thermostatic and freeze‑protection demand, parallel growth in building electrification, and expanding process‑temperature maintenance needs in emerging energy applications. However, this growth is juxtaposed with several disruptive forces that materially affect strategy:
-
Raw material price volatility: Escalating nickel and other alloy costs have increased production costs, particularly for mineral‑insulated constructions. Manufacturers face compressed margins unless cost recovery mechanisms or technical substitutions are implemented.
-
Regulatory tightening: Recent European regulatory updates have removed certain exemptions related to floor‑heating devices, broadening compliance scope and creating certification and labeling requirements that can delay time‑to‑market for non‑compliant SKUs.
-
Tariff and classification changes: Updates to HS codes for insulated electric conductors have implications for cross‑border logistics, customs valuation and landed cost models—effects that are already surfacing in pricing and sourcing deliberations.
-
Sectoral demand shifts: Emerging applications — notably in hydrogen production and related industrial processing — are driving product innovation and new safety certifications. Industry participants exhibiting early technical solutions at hydrogen and energy transition forums are starting to differentiate.
What the PW Consulting report contains (practical, deal‑ready intelligence)
-
Comprehensive market sizing and trend analysis: Yearly historicals (2020–2025), baseline 2025 metrics and scenario forecasts through 2032 with sensitivity to price, adoption and regulatory shocks.
-
Competitive intelligence pack: Profiles of leading platform and regional players, capability matrices, go‑to‑market footprints and channel economics to support win/loss and partnership decisions.
-
Profitability and cost models: Bill‑of‑materials driven cost build‑ups (including raw material stress tests), margin ladders and recommended pricing strategies to preserve margin under pass‑through limits.
-
Regulatory and compliance tracker: Mapping of critical standards, recent rule changes and compliance timelines with a practical “must‑do” checklist for product teams and regulatory affairs.
-
Supply chain resilience playbook: Supplier risk scoring, dual‑sourcing templates, near‑shoring impact assessments and inventory policies designed to reduce lead‑time risk without excess working capital draw.
-
Commercial and product roadmaps: Prioritized innovations (e.g., systems integration, IoT monitoring, hazardous‑area certifications) and an investment‑tier matrix showing expected payback under multiple uptake scenarios.
-
M&A and corporate development toolset: Target screening criteria, valuation comparables, integration milestones and three detailed synergy cases for potential consolidation plays.
-
Installation, service and lifecycle guidance: Field‑tested recommendations to reduce installation time, extend operational life and lower total cost of ownership for end customers—critical for OEM and contractor sales strategies.
Competitive landscape — who matters and why
The competitive set blends global platforms, specialised system providers and regional manufacturers. Market leadership has been built by companies that combine product breadth, hazardous‑area credentials, and integrated system capabilities. Key players covered in the report include:
-
nVent (RAYCHEM) — a global systems brand focusing on self‑regulating solutions and full heat‑tracing systems for freeze protection and process control.
-
Thermon — a major provider of heat tracing and temperature maintenance systems for industrial and commercial clients, with service capabilities that support long‑life contracts.
-
Chromalox and Emerson — larger industrial technology players whose portfolios and channel reach influence standards and system‐level expectations.
-
European specialists such as Bartec and Eltherm — firms with strong hazardous‑area product credentials and regulatory know‑how.
-
Chinese and North American manufacturers — a group of agile suppliers focused on cost‑competitive offerings, regional responsiveness and growing export footprints.
Our competitive matrices assess product technology (self‑regulating, constant wattage, mineral‑insulated and other architectures), certification breadth, manufacturing scale, aftermarket service availability and channel access. The report also quantifies market concentration indicators to inform strategy: the three‑firm and five‑firm concentration ratios show that leading suppliers collectively command a meaningful portion of the market, creating both entry barriers and M&A opportunities.
Recent industry movements and emergent signals
-
Product and brand activity: Market participants are investing in product extensions and brand initiatives targeted at hydrogen and other low‑carbon industrial processes; trade show presence and new product introductions during 2025–2026 underscore a push into adjacent energy sectors.
-
Policy tailwinds and headwinds: The broadening of regulatory scope for floor heating products in Europe and updated HS codes for heating cables are practical changes with near‑term commercial ramifications — from labeling to customs classification to product design.
-
Input cost pressure: Nickel and related alloy price moves have immediate repercussions for mineral‑insulated product lines, prompting cost mitigation actions such as design re‑specification, supplier renegotiation, and selective price adjustment strategies.
Strategic implications and recommended actions for 2026
-
Prioritise modular product platforms: Invest in product commonality that allows rapid SKU adaptation for different safety domains and thermal performance needs; modular platforms reduce development cost and accelerate certification timelines.
-
Implement procurement hedges and input‑indexing clauses: Given metal price volatility, include material price‑indexing in new supply agreements or adopt phased procurement to manage exposure.
-
Accelerate compliance programs: Treat recent regulatory changes as a market access issue. Certify core SKUs against the tightened European framework and align product labeling and documentation processes to eliminate shipment delays.
-
Go‑to‑market via systems + services: Differentiate on monitoring, diagnostics and service contracts that shift customer conversations from capital cost to lifecycle value and recurring revenue.
-
Screen M&A with a strategic lens: Targets should offer technical capabilities (hazardous‑area certified solutions, mineral‑insulated know‑how) or geographic market access that complements your portfolio; use our valuation templates to stress‑test synergies.
-
Develop hydrogen‑ready variants: For players seeking growth in industrial process heat and energy transition sectors, prioritized proof‑of‑concepts and field pilots in hydrogen and related applications can unlock early mover advantages.
How to use this study in your 2026 planning cycle
Supply chain leaders will find the cost stress tests and supplier risk maps immediately actionable. Product teams can use the certification timelines and technical benchmarking to set R&D roadmaps and budget requests. Strategy and corporate development executives will benefit from the M&A playbooks and market concentration analysis to prioritize targets and partnership structures. Finally, commercial teams can adapt the installation and lifecycle guidance to sharpen value propositions and accelerate conversion in tender processes.
Next steps
PW Consulting’s Electric Heating Cable Systems Market study is structured to be a working tool — not an academic exercise. It offers the data and frameworks for board‑level decisions, commercial playbooks for sales teams, and operations guidance for procurement and manufacturing. This article intentionally highlights high‑level findings and actionable implications while withholding detailed segment tables and granular regional splits to preserve the competitive value of the underlying dataset. For access to the full dataset, scenario worksheets and bespoke advisory engagement options, please visit the report landing page or contact our sector practice leads to schedule a tailored briefing.
For detailed analysis of this topic, please visit the official page: Electric Heating Cable Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Premium Audio Market Poised for 5.63% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Automotive Premium Audio Systems Market — Strategic Outlook for 2026 Decisions
Executive trailer: why this research matters in 2026
As OEMs and suppliers enter a new rhythm of software-enabled differentiation and immersive content partnerships, premium in-car audio is no longer a niche amenity — it is a strategic battleground for brand affinity, EV acoustic masking strategies, and recurring revenue opportunities. PW Consulting’s Automotive Premium Audio Systems Market study synthesizes historical performance, near-term shocks, and a seven‑year forecast to equip C‑suite and business‑unit leaders with the evidence and frameworks needed to make defensible 2026 decisions.
Automotive Premium Audio Systems Market
At a glance: the global market recovered from pandemic-era volatility to reach an estimated USD 4.5 billion (base year 2025), with the study projecting a steady compound annual growth rate of 5.63% through our forecast horizon. Underlying that headline growth is a dynamic interplay of immersive audio adoption, consolidation among premium suppliers, and the rapid entanglement of audio with infotainment and cloud services. Our report translates these macro signals into practical go-to-market options without exposing the granular commercial intelligence that defines competitive advantage — intentionally reserving full segmentation and channel-level detail for the complete report.
Automotive Premium Audio Systems Market
What this research delivers (practical, decision-grade content)
- Actionable market sizing and trend attribution — a clear chronology from 2020 through 2025 and a scenario‑based forecast to 2032 that isolates demand drivers (technology adoption, vehicle mix, aftermarket dynamics) from one‑off shocks.
- Strategic playbooks for OEMs, Tier‑1s, audio specialists, and aftermarket players — including partnership archetypes, revenue models (hardware premiuming vs. software/subscription capture), and prioritized target segments.
- Competitive landscape mapping — a synthesis of capability, go‑to‑market intent, and recent strategic moves across the leading suppliers and technology partners, designed to illuminate white spaces and risk corridors.
- Commercial frameworks — pricing vs. perceived value matrices, supplier selection scorecards, TCO templates for bundled audio‑infotainment packages, and an integration checklist for immersive audio features (object‑based mixing, spatialization, and vehicle‑specific tuning).
- Supply‑chain and sourcing risk assessment — component concentration, strategic raw‑material considerations, and mitigation strategies for the premium audio bill of materials.
- Illustrative case studies and launch playbooks — detailing how leading luxury brands and selected mainstream OEMs introduced immersive features (e.g., Dolby Atmos integrations) without disclosing proprietary contract terms or segment revenue splits.
Market trajectory and what it implies for 2026 planning
The market’s trajectory through 2025 shows recovery and re‑acceleration, resulting in a mid‑single digit CAGR over the forecast period. For executives this means two simultaneous realities: first, a predictable base of hardware demand that continues to expand as vehicle complexity and consumer expectation rise; second, that marginal value creation is increasingly found beyond loudspeaker counts — in software, acoustic tuning ecosystems, personalized audio, and platform partnerships.
Automotive Premium Audio Systems Market
Consequently, 2026 should be treated as a pivotal operational year: companies with strong hardware heritage must accelerate their software and content strategies; software‑first firms must prove hardware integration competencies or secure closer OEM alliances; and aftermarket players must recalibrate value propositions as factory‑fitted immersive options proliferate.
Five strategic themes shaping the premium audio agenda
- Immersive audio as a mainstream differentiator — Object‑based formats and spatial audio are migrating from flagship models into broader portfolios through platform partnerships and infotainment integrations. The technology is no longer decorative; it is a design requirement for brands that sell emotional differentiation.
- Software and content economics — Audio experiences are now services: asset pipelines, licensing (e.g., Atmos), personalization engines, and OTA tuning represent recurring revenue levers that materially change lifetime customer economics.
- Consolidation and capability layering — The premium supply base is consolidating around a few leaders that combine global OEM reach with an extended brand portfolio and content partnerships. Market concentration metrics indicate material share held by the top suppliers, influencing negotiation dynamics for new entrants.
- Platformization of audio — Infotainment platforms and smartphone integrations (Apple CarPlay/Android Auto) are critical distribution vectors for spatial audio; OEMs are evaluating whether to embed capabilities in vehicle platforms or to defer differentiation to branded audio partners.
- Aftermarket versus factory-fit interplay — A growing set of consumers seeks upgraded sound via aftermarket products, but the rapid factory adoption of immersive standards narrows certain aftermarket opportunities while creating new niches (e.g., retrofittable spatial processors, personalized sound profiles).
Competitive landscape: who matters and why
The premium automotive audio ecosystem is diverse: legacy high‑fidelity brands, technology platforms, consumer electronics conglomerates, and specialist OEM integrators. The study profiles each major participant, assessing where they play (vehicle classes, OEM anchor relationships), their architectural strength (acoustics, DSP, software services), and indicators of future intent (acquisitions, partnerships, product launches).
- HARMAN International (Stamford, CT) — A cornerstone supplier in the automotive premium space, HARMAN’s brand breadth and recent portfolio expansion through strategic acquisitions position it as a one‑stop partner for OEMs seeking both brand cachet and scale integration. Expect continued emphasis on immersive system integration and bundled software services.
- Bose Corporation (Framingham, MA) — Bose’s SeatCentric and active noise management capabilities give it a unique value proposition for comfort‑focused premium experiences. Demonstrations at major trade shows and OEM relationships underline its role as a supplier that bridges acoustical engineering and user personalization.
- Bowers & Wilkins (UK) and Burmester (Germany) — High‑fidelity specialists that anchor luxury brand collaborations; their differentiation rests on studio‑grade transducers, bespoke vehicle tuning, and an artisanal product narrative that supports premium price points.
- Dynaudio, McIntosh Group, Pioneer, Panasonic, Sony, ALPS ALPINE — These players vary across OEM focus, aftermarket offerings, and component specialization. Together they form the competitive middle and upper tiers where innovation in speaker design, amplifier integration, and platform interoperability occurs.
- Dolby Laboratories (San Francisco) — As a technology and licensing partner, Dolby is an accelerant: its Atmos ecosystem has been adopted by dozens of manufacturers and over a hundred vehicle models, and recent OEM partnerships demonstrate how audio IP can determine product positioning across entire vehicle portfolios.
Recent developments — from Burmester’s series introduction of object‑based immersive “Audiofields” to Dolby’s public roll‑outs with OEMs and Pioneer’s aftermarket spatial audio receiver — signal two concurrent movements: immersive audio is becoming a baseline expectation, and suppliers are racing to own the software and playback stack that determines how consumers experience that immersion.
How to convert insight into 2026 action — recommended plays
- Prioritize platform partnerships over one‑off feature wins. Negotiations should secure rights to update tuning, profile delivery, and data‑driven personalization — not only hardware placement.
- Design an “audio as service” experiment. Test subscription or pay‑per‑feature models on a limited fleet or configurator SKU to understand monetization elasticity before a broad commercial rollout.
- Reassess supplier risk with concentration in mind. Given the market’s consolidation, build contingency pathways (dual sourcing, white‑label DSP stacks) for critical audio components and software licenses.
- Leverage brand equity through co‑development. Luxury OEMs and tier‑1 integrators should exploit co‑branded audio experiences to extract higher trim attach rates while protecting margins via shared IP and service agreements.
- Invest selectively in content and UX. Customer‑facing features — personalized sound profiles, acoustic presets for EV cabin noise, and integrated voice‑activated audio services — yield disproportionate perceived value relative to incremental hardware costs.
What we deliberately withhold here — and why
To respect commercial sensitivity and to preserve the strategic advantage for subscribing clients, this introduction does not disclose the full regional and application‑level split, nor the transaction‑level pricing matrices and contract templates included in the full study. Those granular segmentation tables and supplier contract exemplars are central to executing precise go‑to‑market moves and are available through the complete report package.
Final note — making 2026 the year you capture acoustic advantage
Premium automotive audio now sits at the intersection of hardware excellence, software services, and content licensing. The market’s mid‑single digit growth masks an important truth: the highest value is created by firms that rearchitect the offering from a set of bundled electro‑acoustic components into a platform platform-plus‑services proposition. For executives mapping 2026 priorities, this research provides the diagnostic, the competitive context, and the tactical playbooks needed to convert product differentiation into durable commercial returns.
To unlock the detailed segmentation, supplier scorecards, and executable contract templates referenced above, access the full PW Consulting Automotive Premium Audio Systems Market study and our bespoke advisory services for tailored 2026 strategies.
For detailed analysis of this topic, please visit the official page: Automotive Premium Audio Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rho Associated Protein Kinase 2 Market Poised for 5.6% CAGR Through 2032
By PW Consulting, 2026-07-12
Rho Associated Protein Kinase 2 (ROCK2) Market — Strategic Briefing for 2026 Decision-Makers
As we enter 2026, the Rho Associated Protein Kinase 2 (ROCK2) market is transitioning from a research-focused niche into a clinically consequential therapeutic segment. PW Consulting’s latest market study (base year 2025) captures this inflection: the global market reached a measured milestone in 2025 and is projected to expand through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.6%. This briefing explains why that trajectory matters to corporate leaders, what strategic moves will be decisive in 2026, and how our full report converts insight into actionable plans for commercialization, R&D prioritization, and partnership strategy.
Rho Associated Protein Kinase 2 Market
Why 2026 Is a Strategic Pivot Year
-
From research tools to approved therapeutics: The past half-decade has seen ROCK2 evolve from a predominantly preclinical target to one with approved agents and advanced clinical candidates. That evolution compresses timelines for market entry, reimbursement negotiations, and clinical adoption — compressions that amplify both opportunity and risk for late movers.
Rho Associated Protein Kinase 2 Market -
Market momentum with measured maturity: After steady historical growth through 2020–2025, the market shows a clear upwards trajectory into 2026 and beyond. That dynamic favors organizations that can convert scientific expertise into scalable supply chains and differentiated clinical positioning.
Rho Associated Protein Kinase 2 Market -
Consolidation signals and competitive breathing room: Market concentration metrics indicate a market led by a few notable incumbent names but with substantial share still up for grabs — creating attractive windows for targeted partnerships, out-licensing, or focused product launches rather than broad-spectrum competition.
What the Numbers Mean for Strategy (without giving away the playbook)
At the macro level, the market’s CAGR and the compound growth observed through the base year demonstrate a predictable, moderate expansion. For strategy teams, that validates investments in late-stage clinical programs and scale-up of manufacturing capacity — provided there is a clear route to differentiated clinical benefit or a compelling commercial proposition. Crucially, our analysis shows that absolute market growth is driven by a mix of approved therapeutics, specialty ophthalmic products, and expanding research reagents and assay demand. We intentionally withhold granular subsegment figures in this briefing to preserve the strategic value of segmentation for subscribers; however, the report contains the precise breakdowns necessary for go/no-go decisions, licensing valuations, and territory prioritization.
Report Scope — Practical, Executable, and Designed for 2026 Action
-
Market sizing and modeling: 2020–2025 historical reconstruction, a validated 2025 baseline, and a scenario-driven forecast for 2026–2032 that integrates clinical readouts, approval timelines, and pricing assumptions.
-
Commercialization playbooks: Step-by-step guidance on channel strategies (direct vs. partner-led), payer engagement templates for specialty indications, and launch sequencing recommendations to maximize uptake while minimizing market cannibalization.
-
R&D and portfolio prioritization tools: A decision matrix for selecting between indications, combination strategies, and formulation investments based on clinical probability, time to market, and expected lifetime value.
-
Manufacturing and supply recommendations: Scalable API and formulation capacity planning, COGS sensitivity scenarios, and contract manufacturing organization (CMO) selection criteria tailored to ROCK2 modalities.
-
Regulatory and reimbursement pathways: Comparative pathway analyses across major regulatory jurisdictions, plus a reimbursement risk register and recommended evidence generation plans to mitigate payor pushback.
-
Deal and valuation frameworks: Benchmarked M&A comps, licensing term templates, and a negotiation playbook that translate the market forecast into deal structures aligned with 2026 value creation timelines.
Competitive Landscape — Who Matters and Why
Our competitive analysis focuses on incumbent developers, research suppliers, and assay providers that define the upstream and downstream economics of the ROCK2 market. Collective assessment of these players informs partnership priorities, potential acquisition targets, and threats from adjacent therapeutic platforms.
-
Aerie Pharmaceuticals (Durham, NC, USA) — With a commercialized ROCK2-targeted ophthalmic product and a combination formulation in-market, Aerie exemplifies how niche therapeutic focus can translate into steady specialty revenues and channel advantage in ophthalmology. Their experience in ophthalmic development and distribution is a case study in targeting a high-barrier specialty channel where formulary access and clinician familiarity matter.
-
Kadmon Pharmaceuticals / Sanofi (New York / Paris) — The development and commercialization pathway of belumosudil (Rezurock) illustrates the classic biotech-to-big-pharma lifecycle. Kadmon’s clinical program demonstrated clinical feasibility in an immune-mediated indication; subsequent acquisition and commercialization by a large pharmaceutical company accelerated global market access and reimbursement discussions. This sequence highlights M&A as a credible exit for developers and a rapid market-entry route for established pharma players.
-
STEMCELL Technologies (Vancouver, Canada) — As a research-reagent supplier, STEMCELL’s selective ROCK2 inhibitor for in vitro studies represents the demand tail that funds early discovery. High-quality research tools reduce risk in translational programs and shorten lead identification cycles.
-
Promega Corporation (Madison, WI, USA) — Promega’s enzyme systems and assay kits underpin robust target validation and high-throughput screening. For companies investing in drug discovery, access to validated assay platforms significantly reduces time-to-candidate and offers reproducible comparators for lead optimization.
-
Cell Signaling Technology (Danvers, MA, USA) — Providers of antibodies and kinase activity kits, such firms fill the crucial reagent and assay gap that links basic research to translational studies. Their catalog and validation data can materially accelerate IND-enabling studies.
Strategic Implications for 2026 — Where to Play and How to Win
-
Prioritize high-value, defensible indications: With limited development capital, prioritize indications where a ROCK2 mechanism offers clear incremental benefit or where combination therapy substantially improves response rates. Our report maps indication-level competitive density against clinical feasibility to support prioritization.
-
Integrate research-supply partnerships early: Securing validated assay systems and reagent supply agreements reduces scientific risk and strengthens timelines for IND filings. Consider precompetitive consortia to share validation burdens in complex translational workstreams.
-
Design launches for specialty channels: For ophthalmic and select immunology indications, tailored channel strategies (specialty pharmacies, focused KOL networks) outperform broad sales approaches. Early payer engagement and real-world evidence planning are essential to achieve acceptable net pricing.
-
Evaluate M&A and licensing as acceleration tactics: Given the observed market concentration and demonstrated acquisition pathways, licensing or selling programs that de-risk preclinical/early clinical assets may yield superior returns compared to de novo commercialization.
-
Stress-test upside and downside scenarios: The 5.6% CAGR represents a baseline; sensitivity analyses in our report quantify the commercial impact of faster approvals, adverse trial outcomes, and pricing variability — critical inputs for board-level capital allocation decisions in 2026.
Risk Matrix — What Could Derail Value Creation
-
Clinical readouts that fail to demonstrate meaningful clinical benefit relative to standard-of-care or class competitors.
-
Reimbursement constraints for specialty-priced therapies in core markets unless comparative-effectiveness data are generated.
-
Supply chain concentration for key reagents or API precursors that could delay scale-up or increase COGS.
-
Competitive entry of differentiated modalities (e.g., bispecifics or novel small molecules) that change the therapeutic calculus in priority indications.
How PW Consulting’s Full Report Converts Insight into Action
The full Rho Associated Protein Kinase 2 Market report contains the calibrated numbers, granular segmentation, and executable templates that C-suite and business development teams need to execute in 2026. Subscribers receive:
-
Detailed subsegment breakdowns and regional demand curves — enabling precise ROI modeling for clinical investments and market entry plays.
-
License and acquisition comparables, customized to company stage and asset maturity, to inform negotiation ranges and deal structures.
-
Evidence-generation roadmaps mapped to payer decision points — translating clinical trial designs into commercial-readiness milestones.
-
Vendor and supplier scorecards to fast-track reagent and assay sourcing, with contingency plans for supply interruptions.
Final Thought — Seize the 2026 Inflection with Intelligence, Not Just Capital
ROCK2 offers a compelling intersection of validated biology, approved products, and an active pipeline — a combination that rewards well-targeted capital and strategic partnerships. The market’s steady growth profile provides downside protection, but optimal value creation in 2026 will hinge on clinical differentiation, payor-aligned evidence strategies, and tactical use of M&A or licensing. PW Consulting’s comprehensive study is designed to be the decision-grade resource leaders use to convert macro forecasts into boardroom mandates and operational plans.
For executives ready to convert these insights into a 90-day action plan and a five-year growth blueprint, the full report provides the granular segmentation, scenario models, and market access tools necessary to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Rho Associated Protein Kinase 2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial RTU Market: 4.2% CAGR to USD 1,060.39M by 2032; Asia Pacific $326.77M
By PW Consulting, 2026-07-12
Industrial Remote Terminal Unit (RTU) Market — Strategic Outlook for 2026 Enterprise Decision-Making
As PW Consulting’s lead industry analyst, I present a concise, strategy-first briefing that frames our full Industrial Remote Terminal Unit (RTU) Market study for executives planning decisions in 2026. This briefing demonstrates the analytical depth and practical orientation of the research while deliberately withholding granular segment datapoints and proprietary tables to guide readers to the full report for detailed validation.
Industrial Remote Terminal Unit (RTU) Market
Market trajectory at a glance — what the numbers imply
The RTU market has shown steady expansion through the early 2020s and continues on a modest growth trajectory. Our base-year assessment for 2025 places the global market near USD 801 million, rising at a compound annual growth rate (CAGR) of approximately 4.2% over the 2026–2032 forecast window, reaching just over USD 1.06 billion by 2032. Historical trend analysis shows sustained recovery and investment cycles since 2020, reflecting a combination of legacy-system refreshes, targeted digitalization in industrial verticals, and increasing portfolio mixes that include edge-enabled and wireless-capable RTUs.
Industrial Remote Terminal Unit (RTU) Market
Why this matters for 2026: the market size and mid-single-digit CAGR indicate an environment where disciplined prioritization of capex and differentiated product/service strategies win. Large incumbents and focused specialists alike will chase incremental growth—creating selective opportunity windows for strategic buyers, system integrators, and technology partners.
Industrial Remote Terminal Unit (RTU) Market
Market structure and competitive dynamics — fragmentation with platform concentration
The market is structurally fragmented: the share held by the largest three and five firms is modest, signaling ample room for regional specialists, system integrators, and component vendors to compete. This fragmentation creates strategic consequences:
- Price and specification competition remain intense at the low end, favoring scale players and contract manufacturers.
- At the high end, platform interoperability, cybersecurity, and lifecycle services are primary differentiators.
- M&A and partnership playbooks are the likely medium-term levers for top-tier players to accelerate access to niche capabilities and regional footprints.
Key market participants we track include global automation and control leaders, telecom and communications specialists, industrial computing vendors, and regional RTU manufacturers and integrators. The following qualitative profiles summarize the strategic postures we see in the market (this is an analytical snapshot, not an exhaustive vendor scorecard).
- ABB (Zurich): Leverages broad grid and automation franchises to position RTUs within larger distribution and substations solutions; focus on system-level integration and lifecycle services.
- General Electric (Schenectady): Integrates RTUs into broader asset management and industrial digitalization offers, emphasizing analytics and legacy modernization pathways.
- Schneider Electric (Rueil‑Malmaison): Uses EcoStruxure and system-level offerings to bind RTUs into energy management and process-automation value propositions.
- Honeywell (Charlotte): Positions RTUs as part of its process automation and remote monitoring suites, strong in regulated industries requiring proven safety and compliance traces.
- Siemens (Munich): Offers RTUs within grid automation and industrial digitalization stacks, with emphasis on interoperability and engineering tools.
- Emerson (St. Louis): Focuses on process industries and integration with DCS platforms; competitive where lifecycle services and vendor-managed solutions are required.
- Rockwell Automation (Milwaukee): Competes via control-system integration and scalable automation architectures suited to North American process and discrete markets.
- Motorola Solutions (Chicago): Brings communications and ruggedized networking strengths—relevant where mission-critical remote communications are a core requirement.
- Advantech & Moxa (Taipei): Position as industrial-computing and IIoT gateway specialists that translate RTU data into edge compute and connectivity solutions.
- Yokogawa (Tokyo): Integrates RTUs with DCS and process-control expertise, strong in long-cycle capital projects.
- Red Lion (York) & Fanox (Barcelona): Niche specialists in protocol conversion, remote monitoring, and protection components—important partners for retrofit programs.
- Arteche, Iskra Sistemi, SEL, Dongfang Electronics: Regional and technical specialists providing measurement, protection, and rugged RTU solutions tailored to local grid and industrial standards.
- INTECH Process Automation, Kalki Communication Technologies: Systems integrators and communications specialists that convert vendor stacks into working field deployments at scale.
Strategically, incumbents lean on platform integration and services to expand TAM per customer, while smaller vendors compete on price, agility, and regional compliance expertise. Expect an uptick in alliances pairing global platforms with regional integrators over the next 18–24 months.
Demand drivers and headwinds — shaping priorities in 2026
- Digitalization & IIoT adoption: Edge analytics, remote asset management, and data-driven O&M are primary demand drivers. RTUs that natively support secure edge processing and common industrial protocols gain procurement preference.
- Asset modernization: Utilities and industrial operators with long tail of legacy RTUs will pursue staged refreshes to balance reliability and ROI.
- Cybersecurity mandates: Regulatory and insurer expectations force RTU purchases to include hardened communication stacks and patch-management guarantees.
- Wireless uptake vs. wired reliability: Wireless RTUs unlock lower-install-cost remote monitoring, but mission-critical applications still demand deterministic wired options; product roadmaps must accommodate both.
- Supply chain & materials volatility: Semiconductor supply-chain constraints, and the rising compliance and cost pressures around sustainable packaging and materials, affect lead times and TCO modeling.
Note on regulatory context: broader environmental and packaging regulations in major markets are increasingly relevant to hardware vendors’ supply chains. For example, recent EU and UK directives and taxes on packaging and recycled-content requirements have raised supplier compliance burdens and, in some cases, near-term cost exposure for plastic enclosures and packaging. In Europe, recycled-PET pricing has been higher than virgin PET through 2020–2025 in certain categories—an issue that hardware procurement teams should model into total lifecycle costs and supplier audits.
Strategic playbook for 2026 — recommended actions
- Adopt a two-speed procurement model: fast pilots for wireless/edge RTU use cases and long-lead tender tracks for mission-critical wired deployments.
- Prioritize interoperability and lifecycle services in vendor selection to reduce obsolescence risk and lower long-term TCO.
- Embed cybersecurity and patch-management SLAs into procurement contracts; require supplier transparency on supply-chain resilience.
- Design retrofit-first architectures where practical—use vendor-agnostic protocol gateways and edge compute nodes to extend legacy asset life while enabling phased data enrichment.
- Maintain an M&A/partnership watchlist: regional integrators and niche technology providers offer rapid capability fills for cloud/edge analytics and communications.
- Model regulatory cost exposure linked to packaging and materials compliance as part of capex justification for new hardware rollouts.
What the PW Consulting RTU report delivers (practical content)
Our full study is built for immediate operational use by procurement, OT/IT architects, and corporate strategy teams. Highlights include:
- Market sizing and 2020–2032 forecast with scenario variants and sensitivity to key drivers (base-year 2025 anchoring).
- Segmentation frameworks (by product type, application, and region), plus addressable-market maps for prioritizing growth plays — note: granular segment tables are available in the full report.
- Vendor benchmarking across technical, commercial, and delivery dimensions (capability heatmaps and RFP-ready supplier shortlists).
- Go-to-market playbooks: retrofit vs greenfield decision trees, pilot designs, and integration checklists.
- Financial tools: TCO and ROI templates for procurement justification, and capital planning scenarios under different obsolescence/maintenance assumptions.
- Risk matrix and mitigation playbook covering supply chain, regulatory, and cybersecurity exposures.
- Primary research annex: interview summaries with buyers, integrators, and vendor product leads, plus methodology notes and data sources.
Closing — why use this insight in 2026
By 2026, typical enterprise agendas will combine tighter capital discipline with an increased need to extract operational value from existing assets. The RTU market’s modest growth yet fragmented supplier landscape means that a targeted strategy—combining selective capex, supplier rationalization, and partnerships for analytics and cybersecurity—will generate outsized returns versus blanket replacement programs.
This briefing provides the strategic spine; the full PW Consulting RTU Market report supplies the granular segmentation, interactive models, and vendor-level benchmarking necessary to operationalize these recommendations. We intentionally withheld detailed subsegment tables and proprietary mappings here to ensure readers consult the full dataset for procurement and investment-grade decisions.
To access the comprehensive dataset, vendor scorecards, and downloadable decision tools, please consult the full PW Consulting report and supporting digital workbook.
For detailed analysis of this topic, please visit the official page: Industrial Remote Terminal Unit (RTU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Impact Crusher Market 2026: Strategic Preview for Decision‑Makers
Introduction — Why this preview matters for 2026 planning
As organizations reset capital allocation, supply‑chain priorities, and product‑mix strategies for 2026, an accurate read on the impact crusher market is no longer optional. PW Consulting’s latest market study (base year 2025, forecast 2026–2032) synthesizes demand trajectories, regulatory headwinds, input‑cost volatility, and vendor positioning to convert noise into actionable choices. This preview highlights the study’s strategic takeaways while preserving the granular sub‑segment intelligence that we reserve for the full report—intentionally positioning this piece as a high‑trust trailer that equips executives to prioritize next steps, not to replace the full dataset and scenario models.
Impact Crusher Market
Market trajectory and macro context
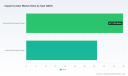
The impact crusher market has moved from a niche replacement cycle into a phase of steady, investment‑grade growth. After recovering through the early 2020s, the market reached an estimated USD 86.2 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.9% across the 2026–2032 forecast window. By 2026 the market is expected to exceed USD 90 Million, with continued expansion through the late 2020s driven by infrastructure activity, recycling mandates, and equipment fleet renewals in mining and aggregates operations.
Impact Crusher Market
For corporate leadership, two far‑reaching implications follow: first, predictable top‑line growth validates multi‑year product development and aftermarket investments; second, the rate of growth is modest enough that competitive advantage will accrue to firms who combine operational excellence, aftermarket capture, and regulatory compliance—rather than to those relying solely on rapid top‑line expansion.
Impact Crusher Market
What is changing beneath the headline numbers
- Shift from pure throughput to lifecycle economics: Buyers increasingly evaluate crushers on total cost of ownership (TCO), factoring energy consumption, wear‑part longevity, uptime, and modularity for multi‑site redeployment.
- Mobility and configurability premium: Mobile and semi‑mobile platforms with faster set‑up, simplified transportability, and modular screening/secondary crushing options are commanding procurement attention in contract tendering and rental markets.
- Sustainability and emissions compliance: Equipment that enables recycling and reduces fleet emissions is being prioritized in public projects and large private contractors’ procurement frameworks.
Regulatory, material‑cost and safety dynamics that will shape 2026 decisions
Procurement, product engineering, and aftermarket strategies must be stress‑tested against a trio of external dynamics that are material to margins and project timelines.
- Standards and compliance: Mobile crushers are increasingly governed by ISO 21873‑1 terminology and commercial requirements; design, testing, and labeling processes must reflect these standards to secure bids and pass regulatory audits.
- Wear‑part specifications: ASTM A128 specifications for austenitic manganese steel affect materials sourcing and supplier qualification. Companies that lock in compliant alloy supply lines and offer validated wear‑part warranties will secure a pricing and availability advantage.
- Input‑cost volatility: Manganese ore prices are linked to broader steel and infrastructure cycles; recently prices moved lower month‑over‑month (to roughly CNY 32.25/mtu in June 2026), but longer‑term demand drivers—urbanization and energy technologies—support price upside risk. Sourcing strategies and hedging policies should be revisited now, not later.
- Workplace and emissions safety: MSHA and regional mobile equipment emission rules are tightening in key markets. Compliance capability (documentation, testing, retrofit paths) is a differentiator in public tenders and long‑term supply contracts.
Competitive landscape — who matters and why
The impact crusher market sits in a moderately concentrated competitive structure. The top three players collectively command a meaningful share of the market, and the top five extend that footprint further—creating both consolidation opportunities and niche openings for specialist players. For decision‑makers, the dynamic is clear: incumbents with broad portfolios are focusing on uptime, modularity, and lifecycle services, while niche and regional manufacturers are leveraging agility and local service networks.
Key vendor behaviors we observed in 2026 that will inform procurement and partnership strategies:
- Product line refreshes with transportability and configurability improvements — exemplified by a major OEM’s launch of a new horizontal impact series designed for easier road transport and site configuration, showcased at a major UK trade show in mid‑2026.
- Rotor and materials engineering advances — a leading Austrian manufacturer introduced next‑generation mobile impact units with rotors engineered for 17–25% higher inertia, paired with automated control systems to increase uptime for aggregate producers.
- Scale and capacity pushes — another OEM debuted a high‑capacity mobile impact crusher capable of headline feed sizes and throughput that target large quarry operations and aggressive recycling programs; these launches signal that vendors are pushing both ends of the market: high throughput and high mobility.
Representative companies demonstrating these strategic postures include global OEMs and specialist mobile‑plant vendors. Their recent product moves and regional positioning illustrate three distinct competitive playbooks: full‑spectrum OEMs pushing integrated systems and services; European mobile specialists emphasizing rotor and control innovation; and North American track‑specialists focusing on on‑site crushing and rental market needs. Each playbook has implications for procurement (e.g., bundling vs. best‑of‑breed), service partnerships, and aftermarket capture.
Report contents — what the full study delivers (practical, operational, and tactical layers)
PW Consulting’s full Impact Crusher Market report provides layered intelligence designed for commercial, product, and strategic planning teams. Highlights include:
- Market sizing and validated time series (2020–2025) and deterministic scenarios for 2026–2032 with sensitivity to commodity cycles and infrastructure spend.
- Scenario modeling (base, upside, downside) that quantifies impacts of regulatory changes, manganese price shocks, and accelerated recycling mandates on market demand and margin pools.
- Competitive diagnostic including vendor profiles, recent product introductions, technology scorecards (mobility, energy efficiency, modularity), and go‑to‑market vectors for each vendor archetype.
- Procurement playbook: decision matrices to evaluate buy vs. rent vs. lease, total cost of ownership calculators, and a supplier‑selection checklist that aligns with ISO and ASTM compliance requirements.
- Aftermarket and services roadmap: prioritized opportunities for spare‑parts margins, predictive maintenance programs, retrofit offerings, and digital‑services monetization pathways.
- Commercial annex: tender language templates, sample specification bundles, and a pricing framework to benchmark capital and spare‑parts offers against market medians.
Note: The report contains detailed regional, type, and application-level splits and unit economics that we do not publish in this preview. Those granular tables and interactive dashboards are available exclusively in the full report to preserve the competitive value of the segment-level intelligence.
Strategic recommendations for 2026 — five high‑impact moves
- Prioritize lifecycle economics in RFPs. Move procurement evaluation away from headline throughput metrics and toward validated uptime, wear‑part life, and energy usage under customer‑relevant duty cycles.
- Lock in compliant materials suppliers. Given ASTM and ISO alignment and the sensitivity to manganese pricing, create multi‑year agreements or option‑based contracts with qualified alloy suppliers to stabilize aftermarket margins.
- Modularization and retrofit pathways. Invest in modular secondary crushing and screening options, and design retrofit kits that enable existing fleets to meet evolving emissions and safety regulations without full replacement.
- Aftermarket service packages as a revenue lever. Build or partner for predictive maintenance, fleet telematics, and guaranteed‑uptime contracts—these convert installed base into repeatable revenue and higher margin streams.
- Scenario‑based capex timing. Use the report’s scenario outputs to time significant capital deployments: accelerate in upside infrastructure scenarios, but stage purchases through rental partnerships when downside commodity risk is elevated.
Closing — how to use this preview
This preview is intended to orient executive priorities and identify the critical questions to ask in 2026 planning cycles: where to invest in R&D, how to structure supply agreements, which supplier archetypes to partner with, and how to monetize installed fleets. If your organization is evaluating procurement strategies, product roadmaps, or aftermarket growth targets, PW Consulting’s full report provides the model outputs, segment‑level splits, and supplier scorecards needed to translate these strategic recommendations into executable plans.
For access to the complete dataset, downloadable dashboards, and the supplier benchmarking annex (including the regional, application, and type‑level breakdowns that underpin our recommendations), please consult the full Impact Crusher Market report on our website.
For detailed analysis of this topic, please visit the official page: Impact Crusher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Retro-Reflective Materials Market at USD 10,000M in 2025; 5.5% CAGR
By PW Consulting, 2026-07-12
Retro-Reflective Materials Market: Strategic Primer for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, forward-looking primer designed to orient executive teams, corporate development units, and policy strategists preparing for critical decisions in 2026. This piece synthesizes the macro trajectory, competitive dynamics, regulatory inflections, and pragmatic use-cases contained in our full Retro-Reflective Materials Market study — enough to inform strategic questions today, but intentionally selective to preserve the full intelligence available in the complete report.
Retro-Reflective Materials Market
Market snapshot: momentum and magnitude
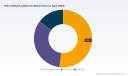
The retro-reflective materials market is mature yet evolving. Using 2025 as our baseline, PW Consulting models the global market at USD 10,000 Million in 2025 and projects a compound annual growth rate (CAGR) of 5.5% through the 2026–2032 forecast window. On that trajectory, the market is expected to grow from roughly USD 7.8 Billion in 2020 to an anticipated approximately USD 14.5 Billion by 2032. That steady, above-inflation expansion underscores long-term structural demand drivers — traffic safety upgrades, regulatory tightening on nighttime conspicuity, and the incremental adoption of higher-performance sheeting and glass-bead technologies across public and private infrastructure.
Retro-Reflective Materials Market
Why this matters for 2026 decision cycles
-
Capital allocation: The combination of mid-single-digit CAGR and concentrated manufacturer positions suggests selective capital deployment. Companies must balance near-term operational investments against strategic bets on premium product lines such as microprismatic films and high-intensity sheeting.
Retro-Reflective Materials Market -
Portfolio prioritization: Product and channel choices made in 2026 will determine market share trajectories across the decade. The market’s scale and steady growth support expansion strategies, but success will hinge on technical differentiation, supply security, and regulatory alignment.
-
Regulatory hedging: Standards and procurement lists remain powerful demand levers. Firms that accelerate compliance, certification, and DOT-level approvals will be positioned to capture outsized share as jurisdictions update nighttime conspicuity requirements.
What the full PW Consulting report delivers (practical and actionable)
The complete study translates macro forecasts into tactical guidance. Highlights include:
-
Decision-ready financial models: downloadable templates that allow management teams to stress-test revenue outcomes under alternative adoption curves, margin scenarios, and CAPEX programs aligned to the 2026 planning cycle.
-
Go-to-market playbooks: channel segmentation, tender-beating strategies, and OEM/distributor engagement frameworks tailored to different end-users (transportation authorities, fleet operators, industrial safety suppliers).
-
Manufacturing and sourcing benchmarks: cost and lead-time diagnostics for glass beads, microprismatic films, adhesives, and coating systems, including supplier scorecards and near-shoring scenarios to mitigate supply-chain risk.
-
Regulatory compliance tracker: an operational register of global standards and procurement constraints with suggested certification roadmaps for achieving DOT and EU conformity within 12–24 months.
-
M&A playbook: prioritized target archetypes with valuation heuristics and integration checklists designed for both strategic buyers and private equity investors seeking exposure to durable infrastructure safety markets.
Competitive landscape — concentration and positioning
The market structure is moderately concentrated: our analysis shows the top three firms control a majority share, with the top five raising that concentration further. That asymmetry creates both barriers and opportunities. Incumbents benefit from scale, distribution footprints, and long-standing channel relationships. Emerging players and specialists can still capture value by focusing on niche performance advantages, faster certification cycles, or service-based propositions.
-
Avery Dennison Corporation (Ohio, USA) — well-established in high-performance sheeting for traffic signs, work zones, and rail safety. Avery Dennison’s deep channel relationships and materials science capabilities position it to defend premium sign and vehicle-conspicuity segments. Explore their reflective portfolio at: https://reflectives.averydennison.com.
-
3M Company (Minnesota, USA) — market legacy in microprismatic films and Diamond Grade solutions for high-visibility applications. 3M’s R&D scale and global service capabilities make it a default partner for large infrastructure programs. Reference: https://www.3m.com/3M/en_US/road-safety-us/.
-
ORAFOL Europe GmbH (Oranienburg, Germany) — specialist in sheeting and adhesive systems with growing capability in traffic safety and vehicle conspicuity. The firm has extended its Asia-Pacific reach through recent strategic acquisitions and manufacturing investments. See: https://www.orafol.com.
-
Nippon Carbide Industries (Tokyo, Japan) — focus on high-intensity sheeting and films for signage; well-placed to serve markets that prioritize specification-led procurement and durability.
-
ATSM, Inc. (United States) — niche supplier of sheeting for traffic control and safety applications; agility in specification adaptation is its advantage.
-
SWARCO AG (Austria) and Potters Industries, LLC (United States) — noted for glass-bead production for road markings; their technical focus on bead performance and lifecycle characteristics supports critical roadway applications. SWARCO’s and ORAFOL’s lifecycle and certifications are increasingly decisive in public procurement discussions.
-
VisiUltra (United States) — high-performance bead specialist serving thermoplastic and paint applications with targeted performance claims.
Recent sector signals and M&A
Strategic consolidation and capability plays are accelerating. Notably, ORAFOL’s acquisition of Reflomax Co., Ltd. in September 2025 signals intensified competition to secure Asia-Pacific manufacturing footholds and to internalize reflective-technology IP. Such moves are typical when incumbents seek to accelerate market access while managing lead times and certification timelines regionally. Expect additional bolt-on activity in coatings, adhesive technologies, and specialty bead manufacturing over the next 18–36 months.
Regulatory and standards dynamics — the demand lever
Regulatory regimes and authoritative procurement lists remain primary demand drivers. Key dynamics to monitor:
-
State-level approval lists continue to influence procurement windows. For example, as of June 2026, California DOT maintains an Authorized Material List for high-performance retroreflective glass beads with authorizations extending through mid-2027. Such lists create discrete bidding opportunities and barriers for suppliers without pre-qualification.
-
European producers are increasingly subject to lifecycle and environmental standards; leading producers now hold ISO 9001, ISO 14001, and ISO 50001 certifications alongside compliance to construction product regulations — credentials that factor into public tenders and corporate sustainability commitments.
-
Technical standards evolve incrementally. ASTM D4956 remains the technical backbone for sign sheeting, and ongoing updates — especially around Type XI and improved nighttime conspicuity classifications — will raise minimum performance thresholds and create a premium tier for advanced materials.
Technology and supply-chain inflection points
Two technological trajectories will shape supplier economics and buyer preferences:
-
Performance differentiation through microprismatic architectures and higher-intensity sheeting is enlarging the share of premium-spec installations (signage, emergency vehicle conspicuity). Buyers weigh lifecycle cost and safety performance, which can justify price premiums where procurement frameworks allow.
-
Glass-bead production and downstream incorporation into paints and thermoplastics remain sensitive to raw-material and energy price volatility. Firms with regionalized production or vertical integration (bead + paint/coating) will have margin resilience against supply shocks.
Risks, scenarios, and recommended corporate responses for 2026
-
Risk: Rapid standard upgrades could obsolesce legacy inventories. Response: Accelerate certification programs and adopt roll-forward clauses in supply contracts to manage inventory risk.
-
Risk: Concentration among leading suppliers may pressure margins for smaller players. Response: Pursue niche specialization, service differentiation, or strategic alliances to access tender pipelines.
-
Risk: Geopolitical and energy disruptions can affect bead and film production. Response: Develop dual-source strategies, prioritize local content where cost-effective, and model total landed cost across supply scenarios.
How to use PW Consulting’s analysis in your 2026 planning
Leaders should use the study to convert market intelligence into action plans across three horizons:
-
Horizon 1 (0–12 months): Operationalize compliance roadmaps, qualify suppliers for high-priority tenders, and run margin-sensitivity analyses tied to product-mix shifts.
-
Horizon 2 (12–36 months): Execute capability investments where certification timelines align with expected tender cycles; pursue tuck-in acquisitions that close capability gaps or secure regional manufacturing capacity.
-
Horizon 3 (36+ months): Build long-term supply resilience and innovation partnerships focused on next-generation reflective materials that optimize sustainability, lifecycle cost, and manufacturability.
Final note — the value of the complete dataset
This primer exposes the structural contours and decision levers executives need in 2026. The full PW Consulting Retro-Reflective Materials Market report provides the granular segmentation, regional and application breakdowns, lean-cost models, and tender-level intelligence necessary to execute with confidence. If your 2026 planning requires scenario-calibrated financials, supplier scorecards, or an M&A target short-list, the complete dataset and playbooks are available on our report landing page. For teams prioritizing capital deployment, procurement optimization, or regulatory preparedness, the full report will convert market momentum into measurable strategic advantage.
For detailed analysis of this topic, please visit the official page: Retro-Reflective Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silage Corn Seed Market to Reach USD 344.8 Million by 2032 at 7.21% CAGR
By PW Consulting, 2026-07-12
Silage Corn Seed Market — Strategic Preview for 2026 Decision-Makers
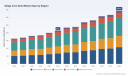
As global dairy and livestock systems face mounting pressure to improve feed efficiency, lower production costs, and mitigate climate risk, the silage corn seed market stands at a strategic inflection point. Our latest PW Consulting study — built on a 2020–2025 historical base and forward-looking to 2032 — shows the market expanding at a compound annual growth rate of 7.21%. The research synthesizes macro sizing, scenario-driven forecasts, supplier positioning, cost and regulatory shocks, and practical playbooks that companies must adopt to convert growth into profitable share gains in 2026 and beyond.
Silage Corn Seed Market
Why this report matters for 2026
-
Timing: 2026 is the first full planning year after multiple 2025 product launches and regulatory updates that materially affect seed development, risk management, and field economics. Boards and commercial leaders must translate these near-term changes into 3–5 year plans now.
Silage Corn Seed Market -
Market trajectory: The market’s steady historical growth combined with an above-average forecast trajectory implies both continued demand and heightened competitive intensity. Strategic moves in R&D, channel coverage, and pricing executed in 2026 will disproportionately shape outcomes for the remainder of the decade.
Silage Corn Seed Market -
Concentration dynamics: Market concentration at the top tier remains high, creating asymmetric opportunities. Established leaders can leverage scale and trait portfolios, while challengers can win by narrowing focus and exploiting gaps in innovation or service.
What the PW Consulting report delivers (practical, executable content)
-
Robust market architecture: a clear articulation of demand drivers, cost pressures, and adoption levers across the value chain, with modeled scenarios that stress-test pricing, yield, and trait-penetration assumptions.
-
Actionable commercial playbooks: segmented go-to-market options for seed houses and distributors, including prioritized channel investments, differentiated product messaging for dairy vs. beef systems, and farm-level ROI calculators to increase adoption.
-
R&D and product strategy guidance: a diagnosis of trait gaps and breeding priorities (e.g., digestibility, drought tolerance, BMR variants, and gene-edited traits), recommended investment pacing, and partnership archetypes for co-development or licensing.
-
M&A and partnership scorecards: framework for evaluating targets by asset type (germplasm, trait stack, distribution footprint), with sensitivity analyses showing how different deal structures affect short- and long-term return profiles.
-
Commercial risk matrix: regulatory and insurance shifts, supply-chain fragilities, and farm economics translated into contingency playbooks for price shocks, seed shortages, or rapid trait adoption.
Competitive landscape — what to watch in 2026
The market is dominated by a small number of global R&D leaders with deep hybrid pipelines, broad distribution networks, and the capital to commercialize advanced trait packages. That said, a vibrant mid-market and regional specialist cohort remain strategically important — both as customers (through licensing or distribution partnerships) and as acquisition targets.
-
Bayer CropScience: Continues to push breeding advances and has moved into gene editing for drought resilience. Expect Bayer to lean into trait differentiation and stewardship programs that help translate genetic advances into demonstrable on-farm value.
-
Corteva Agriscience: With a broad hybrid portfolio and strong channel relationships, Corteva’s pathway to growth emphasizes integrated trait stacks and farm-centric data services that increase stickiness across the growing season.
-
Syngenta: Focused on digestibility-optimized lines and energy-efficient hybrids; Syngenta’s near-term bets will be on partnerships and co-branded products that accelerate adoption in dairy-intensive geographies.
-
KWS, Limagrain, Brevant, Maizex, Hybrid85 and other regional players: These firms compete on niche specialization — forage-centric breeding, non-GMO portfolios, or value pricing and direct shipping. Their agility and local knowledge make them credible challengers in defined segments.
Recent 2025–early-2026 developments reflect this dynamic: new hybrid launches across multiple firms, drought-tolerant gene-edited lines coming to market, and distribution partnerships that increase route-to-farm reach. Taken together, these signals point to faster product turnover and a higher premium on commercialization excellence.
Cost, regulation and operational dynamics shaping 2026 choices
-
Input cost pressure: Field-level economics are shifting. For 2026, industry averages show a step-up in per-acre planting costs compared with 2025. Management teams must account for this when designing price-pack structures and farmer financing offers.
-
Insurance and regulatory flux: The USDA Risk Management Agency’s updated standards and new pilot insurance programs approved in late 2025 change the risk calculus for both farmers and seed firms. Companies should model the impact of these programs on adoption risk and stocking strategies.
-
Seed unit economics: Kernel-level breeding and scaling efficiencies, including cost per 1,000-kernel metrics in major production geographies, are now core inputs to pricing models and inventory decisions.
Strategic implications and recommended 2026 priorities
Companies that treat 2026 as a pivot year — aligning portfolio, go-to-market, and capital allocation decisions to a mid-term (2028–2030) value capture view — will outperform. Below are prioritized actions for executive teams.
-
Prioritize product-to-market velocity. Compress the commercialization funnel for proven trait packages by reallocating marketing and trial resources toward the highest-response geographies and channels. Fast-follower models that shorten shelf-to-farm time will capture disproportionate share.
-
Rebalance pricing and packaging. With farm-level planting costs elevated, experiment in 2026 with conditional pricing (e.g., performance rebates, split-payment structures, bundled agronomic services) to reduce perceived adoption risk while protecting margins.
-
Make targeted R&D bets plus external leverage. Divide R&D spend between core long-lead breeding and near-term gene-editing or trait-acceleration investments. Complement internal work with structured licensing and co-development to derisk time-to-market.
-
Strengthen distribution economics. Reassess distributor incentives and direct-to-farm capabilities; investments in digital ordering, logistic optimization, and seed-finance products can materially increase farmer loyalty and margin capture.
-
Use M&A strategically. Pursue tuck-ins that enhance trait breadth or regional coverage, and consider bolt-on acquisitions that instantly upgrade commercial capacity rather than purely germplasm consolidation.
-
Plan for regulatory and insurance permutations. Build scenario models that incorporate the updated crop-insurance standards and pilot programs, and design commercial offers that align with farmer risk-management choices.
How this preview is designed to spark action — and what is reserved for the full study
This article is intentionally structured as a strategic “trailer”: it surfaces the key directional forces, competitive moves, and executive-level recommendations that should shape 2026 planning. The full PW Consulting Silage Corn Seed Market report contains the granular inputs and proprietary models that drive these conclusions — including regional demand curves, type- and application-level adoption scenarios, company benchmarking scorecards, investor-ready financials, and downloadable ROI tools for field trials.
Concretely, the full study provides:
-
Model spreadsheets that allow users to run their own sensitivity tests against price, yield, and trait-penetration assumptions.
-
Detailed competitor dossiers and GTM mapping that uncover white-space opportunities within and between geographic clusters.
-
Step-by-step commercialization templates for launching new hybrid lines, including trial design, farmer engagement, and distributor incentive mechanics.
Final note to executives
As the silage corn seed market scales, the window to secure advantaged positions narrows. 2026 will reward companies that combine disciplined capital allocation, sharper commercialization, and flexible risk-management solutions for farmers. Our research quantifies the market’s trajectory, unpacks the near-term shocks, and prescribes the operational moves that convert macro growth into durable competitive advantage. For teams preparing budgets, M&A pipelines, or product roadmaps for 2026, this study is the strategic backbone that turns insight into implementation.
PW Consulting remains available to walk leadership teams through a tailored briefing of our findings, run custom scenarios on your portfolio, and co-develop a 90–180 day execution plan aligned to your ambition in this evolving market.
For detailed analysis of this topic, please visit the official page: Silage Corn Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coffee Concentrates Market to Hit USD 315.7M by 2032 at 5.71% CAGR
By PW Consulting, 2026-07-12
Coffee Concentrates Market — Strategic Outlook for 2026 Decision-Making
As organizations enter 2026, the coffee concentrates market sits at an inflection point defined by steady demand growth, shifting channel economics, and growing regulatory and raw‑material complexity. PW Consulting’s latest Coffee Concentrates Market study synthesizes seven years of market dynamics (2020–2025) and a forward-looking forecast (2026–2032) into an operational playbook for commercial leaders. This introduction outlines the report’s strategic value for 2026 decision cycles, highlights the levers that will determine competitive advantage, and previews the types of analysis and tools included — while preserving the granular segmentation that makes this study proprietary and available through the full report.
Coffee Concentrates Market
Macro snapshot: a resilient growth trajectory that rewards timely positioning
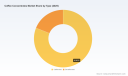
The market demonstrated steady expansion through the historical period, growing from a modest base in 2020 to a market size of approximately 215.0 Million USD in the 2025 base year. Under PW Consulting’s baseline forecast, the market continues to expand at a compound annual growth rate of 5.71% across the 2026–2032 horizon, reaching an expected market size north of 315 Million USD by 2032. The growth profile is neither explosive nor stagnant — it is the kind of predictable expansion that invites structured investment, product-line optimization, and targeted M&A rather than speculative scale‑outs.
Coffee Concentrates Market
Why this matters for 2026 corporate decisions
-
Capital allocation: With mid-single-digit CAGR and steady year‑over‑year expansion, executives can model multi-year returns on product development, automation in liquid-fill/packaging, and channel expansion with a meaningful probability of payback. The market favors selective investment into higher-margin formats and go‑to‑market models that reduce working capital intensity.
Coffee Concentrates Market -
Portfolio prioritization: Incremental demand is visible across multiple end uses (retail, foodservice, RTD/ingredient). However, competitive advantage will accrue to players who optimize SKU portfolios and trade up product narratives (e.g., premiumization, organic, low‑sugar) that align with consumer willingness-to-pay rather than expanding breadth indiscriminately.
-
M&A and JV timing: Market concentration metrics show a moderate-to-high incumbent presence at the top end of the industry. Strategic bolt-ons that fill capability gaps — such as cold‑chain expertise, contract-manufacturing scale, or branded DTC infrastructure — are likely to yield higher value than broad horizontal consolidation in 2026.
Competitive landscape — what incumbents and challengers are doing
The competitive field blends global CPG powerhouses, specialty roasters, ingredient suppliers, and regional co‑packers. Global manufacturers bring distribution scale and ingredient‑level R&D; specialty players supply brand equity, premiumization, and close consumer relationships; contract manufacturers and ingredient houses offer industrial formats and bespoke extract capabilities.
-
Large CPGs and global brands — exemplified by multinational beverage players — are leveraging brand licensing and global channels to accelerate retail and foodservice penetration. Their playbooks prioritize scaling shelf-stable formats, co‑branded product launches, and ingredient solutions sold into RTD manufacturing.
-
Specialty and direct‑to‑consumer players focus on experience, provenance, and premium cold‑brew concentrates. These firms tend to command higher ASPs (average selling prices) per SKU and use DTC subscriptions to secure lifetime value and margin density.
-
Industrial producers and co‑packers compete on cost, format range (e.g., bag‑in‑box, bulk syrup), and food‑service relationships. Their strategic advantage lies in scale manufacturing, formula customization, and logistics for large clients such as quick‑service restaurants and beverage manufacturers.
PW Consulting’s report profiles the core market participants in detail, covering their commercial models, product pipelines, manufacturing footprints, and channel strategies. Recent notable market moves — including a global cold brew concentrate launch by a major multinational partner in 2026 and technology investment in low‑sugar concentrate processing announced in late 2025 — are reshaping competitive dynamics and accelerating premium and health‑oriented product introductions.
Supply and cost dynamics: raw material and regulatory noise you must model
Two supply‑side drivers are particularly salient for 2026 planning.
-
Raw material volatility: Weather and crop cycles continue to inject asymmetry into cost forecasts. While global production forecasts show a net increase year‑over‑year driven by gains in certain producing regions, localized declines — including a notable contraction in Brazil’s production for 2025/26 — raise the probability of short‑term price spikes and margin pressure for ingredient‑intensive formats. Commercial teams must be competent in hedging strategies, blended sourcing, and contract terms that insulate margin during transient shocks.
-
Regulatory and taxation variability: Jurisdictional excise and VAT treatments create pockets of elevated cost and complexity for exporters and ingredient sellers. Multiple markets apply specific excise rules to extracts and concentrates, and these can materially affect product economics for export‑oriented manufacturers and formulators. A proactive regulatory mitigation plan — tariff engineering, reformulating for tax classifications, and selective market entry — can be a differentiator.
Format and channel considerations — where to compete
The market’s economics differ by format and channel. Liquid concentrates and frozen extracts offer operational synergies with centralized manufacturing and foodservice distribution, while powdered forms can reduce logistics costs but require formulation capabilities to match sensory performance. On channels, RTD and foodservice maintain steady institutional demand; retail and DTC channels remain the primary arenas for premiumization and brand-led margin expansion.
PW Consulting’s full study includes a non‑linear decision framework that helps leaders map format choices to channel strategies, capital investments, and SKU rationalization. The framework is designed to be operational — providing scenario templates for supply contracts, shelf program economics, and pilot launch P&Ls — not merely descriptive.
Strategic implications and recommended moves for 2026
-
Adopt a three‑lane portfolio strategy: (1) defend core industrial channels with cost and supply integration, (2) selectively scale premium consumer formats through brand partnerships or DTC pilots, and (3) incubate high‑value innovations (e.g., low‑sugar processing, functional additions) through small‑batch launches to validate willingness‑to‑pay.
-
De‑risk supply through blended sourcing and flexible contracts: Build tolerance for short‑term commodity shocks by expanding origin portfolios and negotiating indexed pricing or floor‑price clauses. For manufacturers, invest in formula flexibility that allows rapid substitution between bean grades without sensory compromise.
-
Lock in regulatory pathways early: Where excise or VAT regimes create adverse economics, evaluate reformulation, reclassification, or targeted market exits/entries. Regulatory tax arbitrage can materially improve net revenues at the country level.
-
Pivot commercialization tactics based on channel economics: For retail, focus on premiumization and on-shelf storytelling; for foodservice and ingredient sales prioritize consistency, cost-per-use, and logistics reliability.
-
Use M&A as capability fills, not scale chases: Prioritize acquisitions that close capability gaps (cold‑chain, co‑packing, specialty cold‑brew expertise, or proprietary extraction tech) rather than simply adding incremental volume to existing manufacturing capacity.
What’s inside PW Consulting’s full study (practical, transaction‑ready contents)
The full report is built for implementation. Key deliverables include:
-
Market sizing and validated forecasts (2020–2032) with scenario variants and sensitivity models suitable for board‑level capital allocation.
-
Commercial playbooks for each format and channel, including unit economics, go‑to‑market canvases, and 18‑month pilot blueprints.
-
Supply‑chain heatmaps and procurement playbooks addressing origins, hedging, and manufacturing footprint optimization.
-
Regulatory matrix across priority markets with mitigation options and tax‑sensitivity analyses.
-
Competitive benchmarking and strategic profiles of core vendors, including capability matrices and suggested partnership archetypes.
-
Transaction support materials: valuation comparables, synergy levers for targets, and integration checklists focused on concentrate businesses.
Why PW Consulting’s view is unique
Our approach blends bottom‑up manufacturing economics with top‑down channel and consumer modeling. We calibrate forecasts with primary interviews across retail, foodservice, and co‑manufacturing stakeholders and validate pricing and volume assumptions against real operational metrics. The result is a forecast and set of playbooks designed to be directly executable by commercial, procurement, and M&A teams in 2026.
Next steps for commercial leaders
-
For C‑suite teams: Use the study to stress‑test capital allocation plans and identify one short‑term (12–18 month) and one medium‑term (24–36 month) strategic initiative to capture share or margin.
-
For procurement and operations: Run a sourcing‑scenario workshop using our supply‑chain models to quantify the P&L impact of origin shifts and hedging strategies under the 2026 price regime.
-
For business development: Map potential bolt‑on targets using our capability‑gap filters and use the included transaction playbooks to accelerate diligence and integration planning.
PW Consulting’s Coffee Concentrates Market report provides the granular segmentation, proprietary forecasts, and playbooks that decision‑makers need to convert the market’s steady growth into durable advantage. For access to the full dataset, segment and regional detail, and the tactical templates referenced above, consult the primary report page and our advisory team to schedule a walk‑through tailored to your firm’s agenda.
For detailed analysis of this topic, please visit the official page: Coffee Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


