



PW Consulting: Worldwide Headphones Without Mic Market Hits $4.8B in 2025, Projects 4.25% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Clarity in an Audio Market Defined by Purity: Inside the 2026 Worldwide Headphones Without Mic Report
The global audio hardware landscape is undergoing a quiet but decisive realignment. As voice assistants, hybrid meeting ecosystems, and always-on connectivity become default expectations, a distinct counter-trend has solidified around devices engineered purely for sound reproduction. Our latest Worldwide Headphones Without Mic Market research isolates this specialized segment, delivering a ten-year analytical window that spans historical baselines from 2020 through 2025 and a forward-looking forecast extending to 2032. For executives, product planners, and supply chain leaders navigating 2026 procurement cycles and portfolio resets, this publication functions as a decision-grade intelligence layer rather than a static market snapshot.
Headphones without microphones occupy a unique position in the broader audio ecosystem. Their value proposition is measured in acoustic fidelity, driver engineering, closed or open-back architecture, and purpose-built ergonomics for monitoring, critical listening, and focused entertainment. They are not optimized for two-way communication; they are optimized for signal purity. That distinction has become commercially significant. Professional studios, home audio enthusiasts, and audiophile communities continue to prioritize passive acoustic designs, while manufacturers face mounting pressure to separate product lines that serve communication-heavy use cases from those that serve performance-first applications. Understanding where revenue concentrates, how product typologies evolve, and which regional dynamics dictate sourcing strategies has never been more essential to capital allocation.
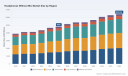
The headline trajectory captured in our analysis reflects sustained, disciplined expansion. The worldwide market for headphones without microphones crossed the 4.8 billion USD threshold in 2025 and is projected to advance toward a range above 6.4 billion USD by the end of the 2032 forecast period, supported by a compound annual growth rate of 4.25 percent. These figures are not abstract totals; they are a structural signal. The growth pace suggests a mature but resilient category, one that expands less through explosive category creation and more through steady replacement demand, premiumization in professional and enthusiast segments, and incremental penetration of high-performance personal audio in home entertainment environments. For 2026 strategy sessions, the implication is clear: this is not a market to treat as a commodity derivative of general headset sales. It behaves according to its own acoustic priorities, procurement cycles, and competitive benchmarks.
What the Report Delivers for 2026 Decision-Making
A market study earns its place on an executive dashboard only when it translates data into operational choices. Our Worldwide Headphones Without Mic Market report is built for that purpose. Rather than offering a single aggregated number, the analysis deconstructs the market into actionable dimensions that align with how companies actually plan, source, and launch.
Structural Breakdown Across Product Typologies and Use Cases
The research disaggregates demand across the core physical architectures that define the segment: over-ear, in-ear, and on-ear form factors. Each architecture carries distinct manufacturing pathways, acoustic tuning priorities, and consumer or professional expectations. Over-ear designs continue to anchor professional and audiophile usage, where enclosure volume, damping materials, and driver spacing directly shape monitoring accuracy and long-session comfort. In-ear monitors sustain a highly specification-driven demand profile tied to stage monitoring, portable critical listening, and compact high-fidelity setups. On-ear configurations occupy a narrower but persistent niche, often balancing portability with acceptable acoustic isolation for focused listening scenarios.
Equally important is the application lens. Revenue flows through professional studio workflows, home entertainment setups, and audiophile listening environments, each with different purchasing cadence, performance tolerance, and willingness to invest in premium components. Studio-oriented procurement revolves around durability, consistency across units, and reference-grade tonal balance. Home entertainment purchases increasingly blend convenience with a desire for richer spatial presentation and reduced distortion at higher listening levels. Audiophile buying behavior is driven by component hierarchy, enclosure craftsmanship, and the perceived transparency of the signal chain. The report explains how these application pathways diverge in volume, margin profile, and product lifecycle expectations, enabling teams to align roadmap priorities with realistic demand pools rather than broad assumptions.
Competitive Positioning Beyond Brand Names
Market share is a starting point, not a conclusion. The report maps the competitive architecture of the segment through the lens of product philosophy, engineering specialization, and go-to-market focus. Entrants such as Sony Corporation, Sennheiser Electronic GmbH & Co. KG, Audio-Technica Corporation, Beyerdynamic GmbH & Co. KG, Grado Labs, AKG Acoustics, Focal-JMlab, and Audeze LLC are examined not as a simple ranking, but as players occupying distinct acoustic and commercial territories. Some compete primarily on studio durability and consistent reference tuning. Others emphasize handcrafted construction, planar magnetic driver technology, or high-end tweeter materials aimed at discerning listening audiences.
The analysis also tracks how these companies are actively shaping the segment through product updates and targeted launches. Recent activity includes the introduction of open-back studio models designed for mixing accuracy, the continued availability of stationary studio headphones alongside USB-enabled variants, the release of closed-back professional models with upgraded driver technology, and catalog refinements for established studio lines in key domestic markets. These moves matter because they signal where incumbents believe performance differentiation remains achievable. For 2026 planners, the competitive section is designed to illuminate which innovation vectors are receiving investment, which product families are being maintained for continuity, and where the segment is seeing a deliberate reinforcement of passive, no-microphone architectures.
Macro Tailwinds and Supply-Side Realities Shaping 2026
Any credible forecast for audio hardware must account for the environment in which products are designed, sourced, and shipped. The report integrates current industry context so that strategy teams can test their assumptions against real operational friction rather than idealized market logic.
- Raw material pressures are reshaping cost structures at the component level. Neodymium magnet pricing has experienced measurable year-over-year escalation, reflecting supply chain constraints linked to rare earth processing. Since high-performance drivers rely heavily on magnetic flux efficiency, cost volatility in this input stream directly affects tuning targets, bill-of-materials planning, and margin defense in premium tiers.
- Manufacturing labor economics continue to adjust across major assembly geographies. Rising average hourly wages in key Vietnamese production hubs alter the traditional cost calculus for large-volume builds. The effect is not uniform across all product types, but it is meaningful for companies balancing cost leadership with consistent quality control in complex acoustic assemblies.
- Regulatory frameworks are becoming more prescriptive. Updated European restrictions on restricted substances in cable and component materials change compliance requirements for products destined for EU markets. For manufacturers operating multi-region supply chains, this is not a marginal administrative detail; it influences material selection, supplier qualification, and time-to-market for revised SKU configurations.
- Trade policy remains a live variable for imported audio hardware. Tariff exposure on certain Chinese-origin headphones continues to influence landed cost calculations for market entry and replenishment strategies. Companies with concentrated sourcing footprints must evaluate whether regional diversification, inventory buffering, or supplier renegotiation will be necessary to protect margin and availability in 2026.
- Lead times for advanced driver technologies have extended in certain high-specification categories, especially where rare earth processing bottlenecks affect specialized magnetic components. This constraint has practical consequences for launch timing, forecasting accuracy, and the ability to respond quickly to competitor announcements.
These dynamics are presented within the report as part of a broader operating environment, not as isolated headlines. The objective is to help decision-makers connect market expansion with the physical realities of production, compliance, and logistics. Growth is only valuable when it can be executed without eroding quality, delaying launches, or undermining cost discipline.
Worldwide Headphones Without Mic Market
Headphone Market
Concentration, Structure, and the Shape of the Competitive Field
The headphones without microphone segment is not equally dispersed across all participants. A meaningful share of revenue is captured by a relatively concentrated group of established manufacturers with strong engineering reputations, long-standing professional-channel relationships, and recognized brand equity in both studio and enthusiast circles. The report quantifies this concentration at the top of the market, providing a realistic picture of how much of the category’s economics are tied to a handful of players versus a broader tail of specialized or regional brands.
This structural insight is particularly useful for 2026 competitive planning. In a moderately concentrated market, pricing behavior, channel access, and innovation signaling can be influenced disproportionately by a few anchor companies. Simultaneously, the presence of differentiated specialists means that total market leadership does not necessarily translate into universal relevance across all applications. A company dominant in professional studio monitoring may compete under different rules than a high-end audiophile brand centered on planar magnetic transducers and handcrafted enclosures. Understanding where each competitor derives defensibility allows strategy teams to avoid generic competitive benchmarking and instead target the rival moves that actually affect their segment, margin structure, and product roadmap.
How the Report Becomes an Operational Tool
The Worldwide Headphones Without Mic Market study is designed to be referenced repeatedly throughout the planning cycle. Its structure supports scenario work, not just static reporting. Product teams can use the segmentation framework to compare form-factor momentum and identify where design investment will have the highest payoff. Procurement and operations leaders can incorporate the supply-side context into sourcing strategies, inventory planning, and cost negotiation timelines. Commercial and marketing leaders can map application-driven demand patterns to position products with the right performance messaging and channel focus.
The report also serves as a shared reference point for cross-functional alignment. In categories where audio performance, component availability, and regulatory compliance interact so closely, strategic misalignment often arises when engineering, sales, and supply chain teams work from different assumptions. By consolidating historical performance, forecast logic, competitive activity, and operating constraints into one coherent view, the research reduces the risk of decisions made on fragmented intelligence. That is especially valuable in 2026, when many organizations are recalibrating portfolios after several years of rapid change in consumer audio habits and manufacturing economics.
Why the Full Intelligence Layer Matters Now
Summarizing the market’s direction is useful; understanding its underlying mechanics is what changes decisions. The core figures, segmentation detail, competitive activity log, and operating-environment analysis are assembled to reveal the interplay between demand behavior and execution risk. When revenue expands steadily, the strategic question is not simply whether growth exists, but where it is coming from, which product lines are absorbing it, and what cost or compliance pressures could alter the return on investment behind each growth path.
This is why the complete report goes beyond a top-line narrative. It provides the structured breakdown, company-level context, and environmental variables that allow teams to pressure-test their own plans. Executives who rely only on aggregate totals may miss the product-type shifts, regional sourcing pressures, and competitive launches that actually reshape the field. Executives who work from the full analytical package can time launches more deliberately, prioritize engineering resources where acoustic differentiation still matters most, and anticipate supply-side constraints before they become schedule risks.
For organizations preparing 2026 budgets, product roadmaps, and channel strategies, the Worldwide Headphones Without Mic Market research offers a focused lens on a segment where sound quality is the product. The publication is built to translate that reality into measurable strategic advantage. The complete dataset, segmentation detail, and competitive activity timeline are available through the full report, where they can be examined in the depth required for confident decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Headphones Without Mic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Concrete Densification Market Hits $985.4M in 2025, Projected 6.15% CAGR to 2032
By PW Consulting, 2026-09-17
Global Concrete Densification Polishing Material Market: Strategic Intelligence for 2026 Corporate Decision-Making
The worldwide market for concrete densification and polishing materials is entering a decisive phase of structural expansion, driven by simultaneous pressures in construction sustainability, industrial floor performance mandates, and rapid shifts in chemical feedstock economics. As organizations map their capital allocation and product development roadmaps for the 2026 through 2032 horizon, relying on retrospective snapshots or fragmented supplier claims is no longer a viable strategy. A rigorous, forward-looking market intelligence framework is now a prerequisite for securing margin resilience, anticipating regulatory inflection points, and positioning formulations against intensifying regional competition.
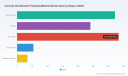
This comprehensive market research delivers precisely that framework. Drawing on verified historical tracking from 2020 through 2025 and an analytically rigorous forecast window extending to 2032, the study translates macro trajectory signals into actionable commercial intelligence. The base valuation for 2025 anchors the analysis, with the overall market size subsequently progressing toward a projected valuation of approximately 1,099.18 million USD in 2026. That opening forecast year marks the beginning of a sustained growth cadence, ultimately converging toward a 1,496.42 million USD valuation by 2032. Across the full evaluation window, the compound annual growth rate registers at 6.15 percent, a figure that reflects not merely cyclical demand but a structural realignment in how contractors, facility managers, and value-chain stakeholders specify, procure, and apply concrete densification chemistry. For strategic planners, this trajectory is more than a directional indicator; it is a quantifiable baseline against which capacity investments, formulation R&D pipelines, and regional market-entry sequencing must be calibrated.
Decoding the Forecast Architecture: What Decision-Makers Actually Gain
High-level revenue projections rarely drive boardroom decisions in isolation. The strategic utility of this research lies in its layered dissection of the market's underlying mechanics. The analysis segments the global landscape across chemical formulation categories, end-use application vectors, and geographic deployment patterns, while explicitly mapping how raw material volatility, certification requirements, and competitive concentration interact to shape pricing behavior and market share dynamics.
Within the formulation landscape, the research tracks the relative commercial weight of lithium silicates, sodium silicates, potassium silicates, and siliconates alongside fluorosilicates. These segments are not evaluated as static product lines; rather, the study examines how each chemistry performs against real-world specification trends, including dustproofing requirements, surface hardness thresholds, light reflectance targets, and compatibility with diamond-abrasive polishing workflows. Similarly, the application analysis dissects demand across industrial and warehousing environments, commercial retail and office installations, residential construction projects, and institutional or public infrastructure deployments. Each vertical is assessed through the lens of procurement cycle characteristics, specifier influence, performance longevity expectations, and the extent to which densification chemistry functions as a value-engineered alternative to thicker surface coatings or replacement slab overlays.
Geographic analysis adds another dimension of tactical relevance. The research evaluates demand distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, contextualizing each region's trajectory against local construction intensity, floor maintenance standards, supply chain proximity, and the pace of adoption for polished concrete as a default specification in both new builds and refurbishment programs. Importantly, the report avoids superficial regional snapshots. Instead, it isolates the operational variables that determine whether a manufacturer, distributor, or end-user can scale profitably within a given territory, including distributor network density, technical support requirements, freight and customs exposure, and the local cost structure of foundational feedstocks.
Competitive Positioning: Mapping the Field Beyond Brand Recognition
The densification and polishing materials market is characterized by a blend of legacy chemical specialists, globally scaled construction material suppliers, and agile formulation innovators. This research maps that landscape systematically, profiling organizations whose product architectures, distribution footprints, and technology roadmaps define current procurement choices and future displacement risks.
The competitive set spans established manufacturers with multi-decade formulation heritage alongside firms leveraging next-generation delivery mechanisms and sustainability certifications to differentiate their offerings. Profiles include entities such as Curecrete Distribution, Inc., W. R. Meadows, Inc., Sika AG, The Euclid Chemical Company, LATICRETE International, Inc., PROSOCO, Adhesives Technology Corporation (ATC) / Convergent, Ecolab, Duraamen Engineered Products, Xtreme Polishing Systems, Hyper Grinder, and Rio Floor. Each profile is evaluated not merely for product lineage but for strategic posture: the extent of integrated system offerings versus standalone densifier sales, the positioning of lithium-silicate versus colloidal-silica or silica-free chemistries, the depth of technical service attached to specification approvals, and the company's exposure to regional raw material pricing swings.
Market concentration metrics included in the study further clarify the structure of competitive rivalry. The analysis captures the consolidated share held by leading participants, highlighting a landscape that remains relatively distributed rather than dominated by a single hegemonic supplier. This fragmentation carries strategic implications. For incumbents, it signals both the necessity of sustained differentiation through performance data, application engineering, and certification readiness, and the opportunity to capture share through channel expansion or M&A targeting of regional specialists. For new entrants and private-label formulators, it underscores the importance of identifying underserved application niches or cost-optimized chemistry pathways rather than attempting undifferentiated head-to-head competition in mature specification categories.
Operational Intelligence: From Formulation Choices to Procurement Resilience
Beyond structural mapping, the research delivers practical tools that translate market conditions into procurement and production decisions. A central focus is placed on the raw material dynamics that directly affect densifier cost structures, formulation economics, and margin predictability. The report integrates current pricing intelligence for foundational feedstocks, including regional sodium silicate benchmarks that analysts tracked in early 2026. Northeast Asia, Europe, India, and North America each present distinct cost baselines, and the study interprets these differentials not as isolated commodity data points but as indicators of regional competitiveness for silicate-dependent densifier manufacturers.
The research also examines how upstream volatility propagates downstream. European soda ash availability constraints and energy-driven cost fluctuations during 2024 and 2025, for example, are analyzed for their impact on silicate production economics and, by extension, on the pricing architecture of dependent concrete densification products. Colloidal silica pathways receive parallel scrutiny, given their reliance on sodium silicate and sulfuric acid inputs and the documented cost escalation patterns observed in prior years. By connecting feedstock behavior to finished-product commercial strategy, the analysis equips procurement leaders with the context needed to negotiate supplier contracts, evaluate inventory hedging windows, and anticipate when regional cost advantages may narrow or reverse.
The study equally emphasizes the operational value of certification and sustainability documentation. Environmental Product Declarations and related compliance instruments are increasingly woven into specification decisions, particularly where projects target LEED v5 alignment, greenhouse gas performance optimization, and broader low-carbon flooring objectives. Recent industry activity underscores this trajectory, including January 2026 announcements by PROSOCO regarding Environmental Product Declarations for multiple concrete densifier formulations intended to support sustainability credits and broader GWP targets in polished concrete installations. The research contextualizes such developments as commercial enablers rather than isolated compliance events, showing how documentation readiness can influence specifier preference, project award probability, and the strategic positioning of product lines in sustainability-sensitive segments.
Worldwide Concrete Densification Polishing Material Market
Why 2026 Represents a Critical Strategic Inflection Point
The current market environment is not defined by a single disruption but by the convergence of several reinforcing forces. Demand for hardened, dust-resistant, and aesthetically optimized concrete flooring continues to expand across industrial throughput environments, commercial tenant improvement programs, and public-sector infrastructure refurbishment. Simultaneously, the specification community is placing greater weight on verifiable environmental documentation, lifecycle performance, and chemical formulations that align with evolving institutional procurement standards. At the same time, feedstock economics remain highly sensitive to energy pricing, logistics bottlenecks, and regional supply imbalances, meaning that margin planning cannot rely on static input-cost assumptions.
Worldwide Glass Polishing Powder Market
Within this environment, strategic decisions made in 2026 will shape competitive positioning well into the latter half of the decade. Capacity expansion, for instance, must be evaluated against the reality that regional demand is uneven and that feedstock cost exposure varies significantly by geography. Product roadmap choices must weigh the performance advantages of established silicate technologies against the differentiation potential of alternative chemistries and spray-on or accelerated-penetration delivery models. Channel strategy must account for the fact that market concentration, while moderate, still leaves meaningful space for specialized players who can combine technical credibility, documentation readiness, and competitive landed cost.
The research is designed to support precisely this kind of multidimensional decision-making. It does not merely assert that growth will continue; it identifies where growth is likely to concentrate, what variables will accelerate or compress it, and how companies can translate market trajectory into durable commercial advantage. Whether the objective is to refine a regional distribution strategy, evaluate a formulation investment, benchmark competitive exposure, or align procurement planning with anticipated raw material and certification shifts, the study supplies the evidentiary foundation required to move from assumption-driven planning to evidence-based execution.
Navigating the Full Intelligence Set
A market of this complexity demands more than summary-level figures and generic trend narratives. The full report unpacks the segmentation interactions, competitive profiling details, regional deployment logic, and raw-material-to-finished-product cost linkages that senior planners need when modeling scenarios, stress-testing assumptions, and prioritizing capital. It also integrates the documentation and regulatory context that increasingly determines which formulations win specification approval in sustainability-conscious project pipelines.
Engaging with the complete research enables stakeholders to move beyond directional confidence into operational precision. Readers will gain clarity on how the 6.15 percent compound annual growth trajectory breaks down across the commercial realities of application demand, formulation economics, and regional execution risk. They will also see how the market's moderate concentration profile interacts with pricing power, channel control, and the strategic importance of certification readiness in a landscape where sustainability documentation is rapidly becoming a commercial differentiator rather than a compliance afterthought.
For executives, analysts, and commercial leaders preparing for the 2026 decision cycle and the years that follow, this research offers a rigorously constructed view of where value is being created, where competitive pressure is intensifying, and how to position formulations, distribution, and procurement strategies accordingly. The complete dataset, segmentation breakdowns, competitive profiles, and forward-looking scenario analysis are available through the full report, providing the depth required to convert market intelligence into measurable enterprise advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Concrete Densification Polishing Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyetherimide Films Market to Hit $843.66 Million by 2032, with 7.12% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for the Polyesterimide Era: Navigating the 2026 Polyetherimide Films Market
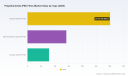
The global Polyetherimide (PEI) films market stands at a critical inflection point. As industries demand higher performance materials capable of withstanding extreme thermal and mechanical stress, PEI films have transitioned from niche specialty inputs to essential components in high-value manufacturing. This report serves as a definitive strategic compass for executives seeking to capitalize on the projected revenue trajectory reaching 843.66 million USD by 2032, evolving from a 521.5 million USD baseline in 2025. Understanding these shifts is not merely an academic exercise but a prerequisite for securing supply chain resilience and identifying high-margin growth vectors in 2026 and beyond.
Macro Trajectory and Growth Dynamics
The market has demonstrated remarkable recovery and expansion following the volatility of the early twenty-first decade. Historical analysis from 2020 through 2025 reveals a compound annual growth rate of 7.12 percent extending into the forecast period of 2026 to 2032. This sustained expansion is underpinned by the material unique ability to maintain structural integrity at temperatures up to 217°C, a property that continues to displace traditional polymers in critical applications. The revenue progression from 460.09 million USD in 2024 to the anticipated 549.14 million USD in 2026 underscores a robust demand environment that rewards early movers with superior material formulations and strategic partnerships. Stakeholders must recognize that this growth is not uniform across all segments. The divergence between standard performance grades and specialized high-temperature or acoustic variants presents distinct risk-return profiles that require nuanced portfolio management.
Segmentation Architecture and Demand Vectors
A granular understanding of product types and application end-uses is vital for optimizing production capacity and R&D expenditure. The market is fundamentally divided into three primary film grades, each serving a specialized industrial function.
- General Grade PEI Film represents the volume backbone of the industry.
- High Temperature Grade PEI Film caters to extreme environment applications where thermal stability is non-negotiable.
- Acoustic Grade PEI Film addresses noise reduction requirements in mobility and consumer electronics.
Parallel to product segmentation, demand is aggregated across four key application clusters. Electronics and Semiconductors constitute a major consumption pillar, driven by miniaturization trends and the need for durable insulation in flexible circuitry. Aerospace and Defense remain a high-value segment, where material certification and flame resistance are paramount. The Automotive sector is increasingly integrating PEI films into lightweighting initiatives and electric vehicle battery management systems. Industrial and Medical applications round out the demand landscape, leveraging the material biocompatibility and chemical resistance for precision equipment and diagnostic devices.
Regional Market Distribution
Geographical dynamics play a decisive role in sourcing strategies and market entry timing. The Asia Pacific region commands the largest share of market activity, reflecting the concentration of electronics manufacturing and rapid industrialization. North America and Europe maintain significant presence, supported by stringent aerospace regulations and advanced medical device ecosystems. The Rest of World region represents an emerging frontier with growing potential for infrastructure development and localized production. Companies must navigate varying regulatory landscapes and logistics costs across these territories to maximize margin realization.
Competitive Landscape and Corporate Profiles
Market concentration is substantial, with the top three competitors accounting for approximately 62.45 percent of total revenue and the top five controlling nearly 78.3 percent. This oligopolistic structure suggests high barriers to entry and emphasizes the importance of supply partnerships for downstream manufacturers.
SABIC, headquartered in Riyadh, Saudi Arabia, maintains its position as a global leader in ULTEM™ polyetherimide films. The company offers thin-gauge films ranging from 0.025 to 2 mm, specifically engineered for aerospace, electronics, and medical applications that require heat resistance up to 217°C. Their technical datasheets confirm that specific grades achieve UL 94 V-0 flame ratings at thicknesses as low as 0.075 mm, fully complying with aerospace FAR 25.853 standards. This certification capability is a critical differentiator for defense and aviation contractors.
Ensinger GmbH, based in Nufringen, Germany, produces TECAPEI™ PEI films and sheets tailored for technical applications. Their product line serves the automotive, electronics, and medical sectors, offering both standard and custom thicknesses to accommodate diverse processing requirements. The European manufacturer emphasis on precise thickness tolerances supports high-volume automotive production lines where consistency is essential.
RTP Company, located in Winona, Minnesota, USA, provides custom-compounded PEI films designed for specialty applications. Their expertise in electrical insulation and flexible circuitry allows them to address niche technical demands that standard off-the-shelf products cannot meet. This customization capability enables rapid prototyping and collaboration with engineering teams during product development phases.
Supply Chain and Raw Material Considerations
Strategic planning must account for feedstock dynamics and regulatory compliance. The market has experienced pressure from raw material cost fluctuations, notably regarding m-Phenylene diamine (MPDA), a key monomer for PEI synthesis. In Asia, MPDA prices rose 12 percent year-over-year to approximately 2,500 USD per metric ton during the third quarter of 2024 due to feedstock tightness. This volatility impacts production costs and requires hedging strategies or long-term supplier agreements to protect profitability.
Worldwide Polyetherimide (PEI) Films Market
Regulatory frameworks continue to shape market access and product specifications. Certain PEI film grades have met EU REACH Annex XVII restrictions on BPA migration for food contact applications, expanding the material utility in packaging and food processing equipment. Additionally, compliance with flame retardancy standards and aerospace certification requirements remains a gatekeeper for entry into high-value sectors. Manufacturers must ensure their product portfolios align with evolving global safety and environmental regulations to avoid market exclusion.
Operational Scope and Executive Utility
This comprehensive study delivers actionable intelligence designed to support cross-functional decision-making. The analysis covers historical performance benchmarks and forward-looking forecasts that enable capacity planning and investment prioritization. Readers will gain access to detailed segmentation evaluations that clarify demand drivers across product types and application sectors. The report also examines competitive positioning, benchmarking key players against performance metrics and geographic reach.
Procurement and supply chain teams will find value in the raw material trend analysis and regulatory updates that inform risk mitigation strategies. R&D and product development stakeholders can leverage the technical specifications and grade comparisons to align material selection with end-user requirements. Sales and marketing organizations benefit from the regional distribution insights that guide market expansion and channel partner selection.
Polyetherimide (PEI) Market
Strategic Imperatives for 2026
As the market advances toward the 2032 horizon, successful organizations will be those that integrate material science expertise with commercial agility. The convergence of electric vehicle adoption, semiconductor packaging complexity, and aerospace fleet modernization creates a favorable demand environment. However, capturing this opportunity requires disciplined execution in procurement, compliance management, and customer collaboration.
Decision-makers who engage with this intelligence early will be better positioned to negotiate favorable terms, anticipate supply constraints, and align product roadmaps with emerging application needs. The data presented herein provides the foundation for building resilient strategies that navigate the complexities of a concentrated global market while capitalizing on the 7.12 percent growth trajectory projected over the forecast period.
About This Research
This analysis is derived from PW Consulting Worldwide Polyetherimide (PEI) Films Market study, offering a complete view of market size, segmentation splits, competitive dynamics, and regional distributions. The full report includes detailed data tables, methodology disclosures, and strategic recommendations tailored for C-suite executives, investors, and industry analysts. For complete access to all segmentation data, company profiles, and forecast models, please refer to the source publication available through our research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Soundproof Ventilator Market to Reach $1,062.44 Million by 2032 at 6.18% CAGR
By PW Consulting, 2026-09-17
The Sound of Silence: Navigating the Worldwide Soundproof Ventilator Market in 2026 and Beyond
The Growing Imperative for Acoustic Comfort
As urbanization accelerates and construction trends shift toward high-density living, the demand for quiet indoor environments has transformed from a luxury to a fundamental requirement. Urban noise pollution, coupled with stricter building codes and a heightened awareness of indoor air quality, is driving a significant structural shift in the ventilation sector. Companies are no longer just selling airflow; they are selling acoustic comfort. This intersection of acoustics and ventilation forms the backbone of the Worldwide Soundproof Ventilator Market, a sector poised for sustained growth over the next decade. For strategic decision-makers, understanding the trajectory of this market is critical. The convergence of regulatory pressure, material science advancements, and consumer preference for healthier, quieter spaces creates a complex landscape where early movers can secure substantial competitive advantages. Our latest comprehensive research, Worldwide Soundproof Ventilator Market, offers a granular analysis of these dynamics, providing the intelligence necessary to navigate the forecast period from 2026 to 2032.
Market Trajectory: A Decade of Steady Growth
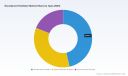
The historical trajectory of the soundproof ventilator market reveals a robust expansion pattern, underpinned by consistent investment in building infrastructure and retrofitting projects. Between 2020 and 2025, the market experienced steady revenue generation, reflecting the post-pandemic emphasis on ventilation in residential and commercial spaces. This historical foundation sets the stage for the forecast period, where the market is projected to continue its upward momentum. Our analysis indicates that the market is on a clear growth path, with a Compound Annual Growth Rate (CAGR) of 6.18% anticipated from 2026 through 2032. This sustained growth is not merely a function of population increase but is driven by deeper structural changes in how buildings are designed and operated. By 2032, the market is expected to reach a significant revenue milestone, highlighting the increasing valuation of acoustic ventilation solutions across diverse economic zones. The financial scale of this opportunity is substantial. During the base year of 2025, the market recorded revenues of USD 698.24 Million. Looking ahead, the projection for 2026 starts at USD 718.72 Million, with growth accelerating as regulatory frameworks tighten and adoption rates increase in noise-sensitive sectors. This upward curve suggests that the market will more than double its 2025 valuation by the end of the forecast period, closing 2032 at USD 1,062.44 Million. Such growth signals a maturing market where scale and efficiency become paramount.
Strategic Segmentation: Where Value is Created
While the aggregate market numbers tell a story of expansion, the true strategic value lies in understanding how value is distributed across product types, applications, and geographies. Our research delves deep into the segmentation splits that define the competitive landscape. In terms of product architecture, the market is dominated by decentralized ventilation solutions that prioritize silence and efficiency. Wall-mounted ventilators represent a significant portion of the market value, reflecting their popularity in renovation projects where window modifications are impractical. Window-mounted units remain a critical segment, particularly for new builds in high-noise urban corridors, while passive acoustic air inlets are gaining traction for their low-energy profile and compliance with stringent acoustic standards. The interplay between these types is evolving as manufacturers introduce hybrid concepts that blend passive insulation with active airflow control. Application-wise, the residential sector continues to be the primary driver of demand. Homeowners are increasingly vocal about noise pollution from traffic and neighbors, making soundproof ventilation a key selling point in real estate development and property upgrading. However, the commercial office sector is emerging as a high-growth area, driven by the need for productive work environments in open-plan offices located in bustling city centers. Healthcare and education facilities also represent a specialized but vital segment, where acoustic comfort is directly linked to patient recovery rates and student concentration levels. The specific revenue contributions and growth rates within each application segment are detailed extensively in the full report to guide targeting strategies. Geographically, the market exhibits a balanced but regionally distinct growth pattern. Europe holds a substantial share of the market, fueled by advanced building regulations and a strong culture of energy-efficient retrofitting. Asia Pacific follows closely, reflecting rapid urbanization and infrastructure development in key economies. North America maintains a robust position, particularly in the commercial and industrial ventilation subsectors. Meanwhile, the Middle East and Africa, as well as Latin America, present emerging opportunities driven by incremental infrastructure investments. The report provides a detailed breakdown of market values across these regions without obscuring the nuanced differences in adoption drivers and barrier levels.
Consolidation and Competitive Dynamics
The competitive landscape of the soundproof ventilator market is characterized by a mix of specialized acoustic technology firms and large-scale ventilation manufacturers. Market concentration metrics indicate a moderately fragmented environment, with a CR3 of 31.25% and a CR5 of 44.82%. This structure suggests that while major players hold significant sway, there is ample room for niche innovators and regional specialists to capture value through differentiation. Leading companies are actively shaping the market through product innovation and strategic presence. German firms, in particular, dominate the high-end acoustic ventilation space. LUNOS Lüftungstechnik GmbH, headquartered in Berlin, specializes in decentralized systems with sound insulation reaching up to 72 dB. Their focus on both heat recovery and non-heat recovery models positions them as a versatile partner for residential new builds and renovations. SIEGENIA GROUP also leverages its German engineering heritage to offer AEROPAC and AEROMAT series, which combine whisper-quiet operation with CO₂ regulation and high acoustic performance, addressing the needs of noise-polluted environments. Ventomaxx GmbH, based in Landshut, provides passive and active decentralized systems designed for full compliance with DIN 4109 sound insulation requirements, offering hybrid concepts for buildings with extreme acoustic demands. In the United Kingdom, Titon Holdings plc manufactures acoustic trickle ventilators and sound attenuating slot vents, with models like the SF Xtra achieving high Dn,e,w ratings essential for modern window and door systems. R.W. Simon Ltd complements this offering with Framevent, Slimline, and humidity-controlled models that deliver sound reduction up to 40 dB closed, catering specifically to noise-sensitive installations. The landscape also includes global industrial players expanding into acoustic solutions. FläktGroup, with global operations, offers sound attenuators and low-noise fans suitable for integration across commercial and industrial applications. TROX GmbH remains a leading provider of sound attenuators and acoustic louvers certified for room air conditioning systems, focusing on low noise and high performance. In the United States, Greenheck Fan Corporation manufactures acoustical louvers and sound curbs that reduce noise transmission while providing ventilation protection in commercial and industrial settings. On the materials and innovation front, Wuxi Sinceriend New Material Technology Co., Ltd. in China focuses on acoustic vents using advanced materials to produce high-quality soundproof products. Recent developments underscore the dynamism of this competitive field. In March 2026, LUNOS Lüftungstechnik GmbH exhibited at SHK+E in Essen, showcasing their latest soundproof ventilation systems and reinforcing their commitment to the European market. Earlier, in May 2025, Soundcoat launched the QuietFlow Acoustic Louvers System, utilizing fire-resistant melamine foam for fan noise reduction in energy infrastructure and cooling applications. These moves highlight the ongoing race to integrate advanced materials and demonstrate capabilities at major industry events.
Regulatory Tailwinds and Industry Context
Regulatory frameworks are acting as powerful accelerants for the soundproof ventilator market. In the United Kingdom, Approved Document F mandates that mechanical ventilation systems be designed and installed to minimize noise, with suggested limits of 30 dB(A) in noise-sensitive rooms such as bedrooms and living rooms. This regulation directly incentivizes the adoption of soundproof ventilators in residential and commercial projects, forcing developers to specify products that meet these acoustic thresholds. In Germany, DIN 4109 sets rigorous sound insulation requirements for ventilation systems in buildings. Companies like Ventomaxx have aligned their product development to ensure full compliance in both passive and active decentralized units, turning regulatory adherence into a competitive differentiator. Meanwhile, in North America, the California 2025 Building Energy Efficiency Standards, effective for permits from 2026, strengthen ventilation requirements alongside energy efficiency measures. This dual focus on air quality and noise control is likely to drive innovation in the Western US market and influence broader regional standards. On the materials front, the industry is increasingly relying on high-performance absorptive media. Acoustic louvers and silencers commonly utilize galvanized steel, aluminum, or melamine foam for sound absorption while maintaining airflow efficiency. The availability and cost of these raw materials, along with advancements in fire resistance and durability, are key factors influencing product design and margin structures. Our report examines these supply chain dynamics in detail, providing insights into how material trends may impact cost structures and product performance over the forecast period.
Report Contents and Strategic Utility
The Worldwide Soundproof Ventilator Market study is designed to be a practical decision-support tool for executives, investors, and product strategists. Beyond the macroeconomic projections and segmentation analysis, the report offers a deep dive into the operational and tactical aspects of the market. Readers will gain access to a comprehensive analysis of market drivers and restraints, helping to anticipate shifts in demand cycles. The study includes a detailed port assessment of key product types and applications, allowing stakeholders to benchmark their portfolio against market realities. Furthermore, the report features an in-depth competitive profiling of major players, analyzing their market positioning, product strategies, and recent moves such as trade show exhibitions and product launches. The forecast model extends through 2032, providing a long-term view that supports capital allocation and R&D planning. By integrating regional breakdowns, type splits, and application-specific trends, the report enables users to identify high-potential niches and assess the risk-reward profile of expansion into new geographies or segments. Whether you are evaluating entry into the market, seeking to optimize your product mix, or monitoring competitor activity, the data and insights contained in this study provide the clarity needed to act with confidence.
Conclusion: Positioning for the Future
The Worldwide Soundproof Ventilator Market is entering a phase of accelerated maturity, driven by regulatory mandates, technological innovation, and an unstoppable consumer demand for quiet, healthy indoor environments. The projected CAGR of 6.18% and the market's trajectory toward exceeding USD 1 Billion by 2032 underscore the magnitude of the opportunity. However, capturing this value requires more than just awareness of the growth trend; it demands a nuanced understanding of segmentation, competitive dynamics, and the regulatory forces shaping product specifications. For stakeholders looking to secure a leadership position in this evolving landscape, the time to act is now. This research serves as a foundational intelligence asset, revealing the hidden currents and overt signals that will define success in the years to come. We invite you to explore the full report to access the complete dataset, detailed forecasts, and strategic recommendations that will empower your decision-making in 2026 and beyond.
Worldwide Soundproof Ventilator Market
Acoustic Vents Market
For detailed analysis of this topic, please visit the official page: Worldwide Soundproof Ventilator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pro Microphone Market to Reach $4.83B by 2032 with 6.01% CAGR
By PW Consulting, 2026-09-17
# Strategic Intelligence for the Voice Era: Unlocking Value in the Worldwide Pro Microphone Market (2026-2032)
Executive Summary: The Strategic Imperative for 2026
In the evolving landscape of professional audio, the microphone remains the foundational interface between human expression and digital permanence. For executives, product leaders, and investors operating in the pro audio ecosystem, understanding the trajectory of this market is no longer optional—it is a strategic imperative. As the industry transitions from purely analog performance tools to integrated digital networking nodes, the Worldwide Pro Microphone Market is undergoing a structural transformation that demands precise intelligence.
This article serves as a strategic preview of PW Consulting's latest comprehensive study, Worldwide Pro Microphone Market. While public headlines often surface high-level figures, the true value for enterprise decision-making lies in the granular segmentation, competitive intensity mapping, and supply chain vulnerability analysis that only a deep-dive report can provide. The following insights outline the macro-environment and strategic contours of the market through 2032, setting the stage for why our full intelligence package is essential for navigating the coming growth cycle.
Market Trajectory and Macro Economic Foundations
The professional microphone sector has demonstrated remarkable resilience and growth potential, driven by the dual engines of traditional live performance recovery and the exploding demand for high-fidelity content creation. Based on our analysis of historical data from 2020 through 2025, the market has consistently outperformed broader consumer electronics expectations, reflecting a sustained investment in professional-grade audio infrastructure.
Worldwide Pro Microphone Market
Our forecast model projects a robust expansion phase from 2026 through 2032. The market is anticipated to grow at a Compound Annual Growth Rate (CAGR) of approximately 6.01% over this forecast period. This growth trajectory suggests that the industry will not merely recover to pre-pandemic levels but will structurally expand its total addressable market. By 2032, total market revenue is projected to reach significant new milestones, driven by the maturation of wireless ecosystems and the professionalization of streaming and podcasting workflows.
Wireless Microphone Market
However, raw growth percentages tell only part of the story. The velocity of this expansion varies significantly across product categories and application verticals. Understanding where the leverage points lie—whether in high-volume dynamic microphones for live reinforcement or precision condenser systems for broadcast—is critical for capital allocation. Our report dissects these growth vectors to identify which segments will generate the highest margin expansion versus simple volume growth.
Segmentation Dynamics: Technology and Application Convergence
The modern pro microphone market is increasingly defined by the convergence of acoustic performance with digital connectivity. While traditional acoustic classification remains relevant, the strategic battleground has shifted toward integration capabilities.
By Technology: The market comprises distinct technology stacks including Condenser, Dynamic, Wireless Systems, and Ribbon/Specialty microphones. Condenser technology continues to dominate high-fidelity studio and broadcast applications where transient response and sensitivity are paramount. Dynamic microphones maintain their stronghold in live sound reinforcement and vocal performance due to durability and handling noise rejection. However, the Wireless Microphone Systems segment represents a high-growth vector, fueled by the need for mobility in live events, corporate conferencing, and broadcast journalism. The strategic interplay between wired precision and wireless flexibility is reshaping product roadmaps across the industry.
By Application: End-user demand is fracturing into specialized verticals. Studio and Broadcasting remains a cornerstone, heavily reliant on precision measurement and studio condensers. Live Performance and Events continues to be a major revenue driver, particularly for dynamic and wireless solutions. A rapidly evolving segment is Corporate and Education, where hybrid meeting environments have permanently altered procurement standards, demanding networked audio solutions that integrate seamlessly with existing IT infrastructure. Meanwhile, Hospitality and Government applications require ruggedized, secure, and often specialized acoustic solutions. The allocation of resources across these application verticals requires a nuanced understanding of procurement cycles and budget sensitivity in each sector.
Competitive Landscape and Strategic Positioning
The pro microphone market is characterized by a mix of established heritage brands and agile innovators. Our analysis identifies a concentrated competitive environment where brand equity, acoustic R&D, and ecosystem integration serve as primary moats. The competitive dynamics are heavily influenced by major players who have entrenched themselves across multiple product categories.
- Shure Inc. (Niles, Illinois, USA): As a global leader, Shure maintains a dominant presence across dynamic, condenser, and wireless categories. Their recent introduction of the KSM11 Wireless Vocal Microphone System with dual-diaphragm condenser technology at the NAMM Show in January 2024 illustrates their strategy of merging studio-grade acoustic quality with wireless convenience. This move signals a direct challenge to the traditional trade-offs between mobility and fidelity.
- Sennheiser Electronic GmbH & Co. KG (Wedemark, Germany): Sennheiser continues to be a critical competitor, offering a broad portfolio from the e 900 series dynamics to MKH condensers and wireless systems. Their strength lies in serving the full spectrum from live performance to broadcast, often leveraging strong brand loyalty in European and Asian markets.
- Neumann GmbH (Berlin, Germany): Neumann specializes in the high-end studio condenser tier, with iconic models like the U 87 Ai and TLM series. Their strategy focuses on premium positioning within professional recording and broadcast, maintaining a reputation for acoustic excellence that commands price premiums.
- Audio-Technica Corp. (Tokyo, Japan): Audio-Technica offers a comprehensive range including the AT4040 condenser and Artist Elite series, alongside 5000/3000 wireless systems. Their inclusion of Dante networking in recent boundary microphone releases, such as the ATDM-0706BN announced in December 2023, highlights a strategic pivot toward networked audio integration for conferencing and pro audio.
- AKG Acoustics (Vienna, Austria): Owned by Harman, AKG leverages the C414 condenser and D5 dynamics alongside WMS wireless systems. Their brand remains a staple in both stage and studio applications, benefiting from broader corporate audio ecosystem synergies.
- DPA Microphones A/S (Kvistgaard, Denmark): DPA is recognized for high-precision miniature and measurement microphones, including the 4006A omnidirectional and 4099 instrument mics. Their recent update to the CORE 6061 subminiature lavalier microphone in October 2023, featuring improved moisture resistance, demonstrates a focus on durability in demanding live and broadcast environments.
- Electro-Voice (Burnsville, Minnesota, USA): As a Bosch brand, Electro-Voice focuses on dynamic microphones like the RE20 and ND series, targeting live sound reinforcement and broadcasting. Their engineering heritage in durability and vocal clarity positions them strongly in fixed installation and touring scenarios.
- Beyerdynamic GmbH & Co. KG (Heilbronn, Germany): Beyerdynamic offers professional dynamic and condenser mics such as the M 88 TG and TG series, along with Opus wireless solutions. Their product strategy balances performance with robust construction for live and studio use.
- RØDE Microphones (Sydney, Australia): RØDE has expanded its footprint significantly in studio condenser microphones like the NT1 and NTG shotgun series, targeting content creation, podcasting, and professional recording. The launch of the NT1 5th Generation in March 2024, featuring ultra-low self-noise and DSP features, underscores their push into intelligent, integrated microphone technologies.
- Other Strategic Players: The market also includes niche and heritage specialists such as Telefunken Elektroakustik (South Windsor, Connecticut, USA), known for reissues and modern recreations of classic tube and FET microphones like the ELA M 251; Lewitt Audio (Vienna, Austria), offering contemporary condensers like the LCT 440 PURE; sE Electronics (Las Vegas, Nevada, USA), providing affordable studio condensers like the V7 and Neptune tube mic; Schoeps GmbH (Karlsruhe, Germany), recognized for precision measurement and studio condensers like the CMC 6 series; Josephson Engineering (Santa Cruz, California, USA), specializing in high-end solid-state and tube microphones; and Earthworks (AEA Audio) (Holliston, Massachusetts, USA), known for omnidirectional and cardioid condensers like the QTC50 for high-fidelity recording.
The market concentration indicates a moderately consolidated environment, where the top players command a significant share of total revenue, yet specialized niche players continue to thrive by targeting high-margin, low-volume segments or specific acoustic needs. Competitive advantage increasingly depends on the ability to offer integrated solutions, robust supply chain management, and rapid adaptation to digital protocol standards.
Macro External Forces Shaping Market Dynamics
Strategic planning for the pro microphone market cannot occur in a vacuum. Several external forces are currently exerting pressure on costs, availability, and compliance frameworks, requiring proactive management by industry stakeholders.
- Raw Material Volatility: The cost structure of microphone manufacturing is sensitive to raw material pricing. Notably, neodymium oxide average prices reached $85.00 per kilogram in 2023, reflecting increases from prior years due to mining constraints. Since China accounts for approximately 60% of global refined rare earth production used in dynamic microphone magnets, this concentration creates significant supply chain exposure. Fluctuations in these inputs directly impact the cost of goods sold for dynamic and magnetic components, squeezing margins or forcing price adjustments.
- Regulatory Compliance: Manufacturers and distributors must navigate strict regulatory environments, including the European Union's RoHS Directive 2011/65/EU, which restricts hazardous substances in electrical equipment. Compliance requires rigorous material substitution and testing protocols, adding complexity to the design and production lifecycle, particularly for global brands operating across multiple jurisdictions.
- Trade Policy and Tariffs: Geopolitical trade dynamics continue to influence market economics. US Section 301 tariffs impose duties of up to 25% on microphones classified under HTS 8518.10 imported from China. For companies with manufacturing footprints or sourcing strategies entangled in these trade flows, tariff exposure can alter competitive positioning and necessitate supply chain reconfiguration to maintain price competitiveness in North American markets.
- Supply Chain Latency: The availability of electronic components remains a critical bottleneck. Electronic component lead times for capacitors and integrated circuits averaged 20 to 25 weeks in the fourth quarter of 2023 for pro audio manufacturers. Extended lead times disrupt production planning, delay product launches, and can create inventory shortages during periods of high demand. Managing these dependencies requires sophisticated supply chain resilience strategies.
Operational Insights: What the Full Report Delivers
While the macro trends and competitive overviews outlined above provide a strategic compass, they represent only the surface layer of market intelligence. PW Consulting's Worldwide Pro Microphone Market report is designed to provide the deep operational data and analytical frameworks required for decisive action. The full study goes beyond high-level aggregates to deliver actionable intelligence across multiple dimensions.
The report provides a comprehensive segmentation analysis that isolates revenue contributions, growth rates, and market share dynamics across all regional and product sub-segments. This allows stakeholders to pinpoint exactly where growth is originating and which sub-markets are under-penetrated or saturated. Furthermore, the study includes a detailed competitive benchmarking module, evaluating key players not just by revenue presence, but by product portfolio depth, technological differentiation, and geographic coverage.
Our methodology incorporates rigorous primary research and validated secondary data to construct a reliable forecast model. Readers of the complete report will gain access to historical data reconstruction covering the baseline period, allowing for the validation of trends against actual performance. The forecast period analysis provides granular projections that account for variable adoption curves in different application sectors. Additionally, the report addresses the impact of external shocks, offering scenario analysis frameworks that help decision-makers stress-test their strategies against supply chain disruptions, tariff changes, and raw material price volatility.
For product managers and R&D leaders, the report includes technology trend assessments that identify emerging acoustic and digital integration patterns, helping to guide innovation pipelines. For procurement and supply chain executives, the analysis offers visibility into cost drivers, component availability risks, and regional manufacturing dynamics. For investors and strategy teams, the competitive landscape mapping and market concentration metrics provide a clear view of barrier to entry and potential consolidation opportunities.
Strategic Conclusion: Positioning for the Growth Horizon
The Worldwide Pro Microphone Market is poised for a sustained growth phase through 2032, underpinned by a projected CAGR reflecting healthy demand expansion across diverse applications and geographies. However, the winners in this cycle will not be determined solely by riding the growth wave. Strategic advantage will accrue to organizations that can navigate the complexities of raw material constraints, regulatory compliance, trade policy uncertainties, and supply chain latency while simultaneously innovating in wireless connectivity and digital integration.
The competitive arena is intensifying, with legacy giants reinforcing their dominance through product launches that blur the lines between studio and live performance, and agile challengers introducing smart features and cost-optimized solutions that expand accessibility. Understanding the precise market share distribution, the growth velocity of specific technology types, and the regional nuances of demand is essential for crafting targeted go-to-market strategies and investment theses.
To fully capitalize on the opportunities within this market, stakeholders require access to the complete intelligence ecosystem. PW Consulting's Worldwide Pro Microphone Market report delivers the comprehensive data, segmentation granularity, competitive profiling, and strategic context necessary to make informed decisions in 2026 and beyond. We invite industry leaders to explore the full study to unlock the detailed market size assessments, regional breakdowns, and application-specific forecasts that will guide your strategy toward measurable success. The voice of the market is clear; the detailed intelligence to act on it is available.
For detailed analysis of this topic, please visit the official page: Worldwide Pro Microphone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isopropyl Biphenyl Heat Transfer Fluid Market to Hit $346.61M by 2032 at 5.48% CAGR
By PW Consulting, 2026-09-17
Strategic Imperatives in the Isopropyl Biphenyl Heat Transfer Fluid Market: A 2026 Outlook
The industrial landscape of 2026 demands a rigorous recalibration of thermal management strategies. As manufacturing processes push toward higher efficiency thresholds and stricter environmental compliance standards, the selection of heat transfer fluids has evolved from a mere operational detail to a critical strategic decision. The Isopropyl Biphenyl Heat Transfer Fluid Market stands at a pivotal juncture, driven by the dual engines of industrial expansion and regulatory shifts away from legacy chemical compounds.
Isopropyl Biphenyl Heat Transfer Fluid Market
For executives, procurement leaders, and R&D strategists, navigating this landscape requires more than surface-level awareness. It demands a granular understanding of market trajectories, competitive maneuvers, and the underlying dynamics shaping supply chains. Our latest market research publication offers a comprehensive beacon for these decisions, synthesizing historical data with forward-looking projections to illuminate the path forward through 2032.
Market Trajectory and Growth Dynamics
The historical performance of the isopropyl biphenyl sector reveals a consistent upward trend, reflecting the growing reliance on synthetic aromatic fluids in high-temperature applications. Between 2020 and 2025, the market demonstrated resilience and steady expansion, setting a robust foundation for the forecast period. The overall market size, valued in millions of USD, has shown a compound annual growth rate (CAGR) of 5.48 percent from 2026 to 2032.
This growth trajectory is not merely a continuation of past trends but a response to evolving industrial needs. The projection indicates that revenue will continue to accumulate significantly over the next seven years. Such sustained growth suggests a healthy demand environment where replacement cycles and new installations contribute equally to market expansion. For stakeholders, this implies that investing in supply chain resilience and product innovation is not optional but essential to capturing share in a burgeoning market.
Segmentation Strategic Overview
Understanding the market requires dissecting its fundamental components. The research provides a detailed breakdown across three primary dimensions: type, application, and region. However, the strategic value lies not just in the numbers, but in interpreting what these segments mean for capacity planning and market entry strategies.
- Product Type Dynamics: The market is bifurcated into Monomer Grade and Technical Grade isopropyl biphenyl. The distinction between these grades dictates their suitability for specific thermal profiles and purity requirements. High-purity monomer grades often command premium positioning in sensitive applications, while technical grades serve broader industrial needs.
- Application Diversity: Demand is distributed across varied end-use sectors, including chemical processing, polyester and fiber manufacturing, waste heat recovery systems, and electronics cooling. Each application presents unique thermal stability requirements and operating temperature ranges, influencing the specific fluid formulations preferred by end-users.
- Regional Variances: Consumption patterns differ significantly across geographies. Established industrial hubs in North America and Europe maintain substantial demand, while the Asia Pacific region exhibits dynamic growth potential driven by expanding manufacturing infrastructure. Latin America and the Middle East and Africa also contribute to the global footprint, albeit at different scales.
Our report delves deep into these segments without exposing the raw data here. The interplay between grade specifications and application requirements creates niches where competitive advantage can be won or lost. Identifying which segments offer the highest margin potential or the fastest growth is a key outcome of this analysis.
Competitive Landscape and Key Players
The market structure is characterized by a moderately concentrated environment. With a CR3 of 68.45 percent and a CR5 of 84.12 percent, the top players hold significant market power, yet there remains room for specialized manufacturers to carve out positions based on technical differentiation and regional presence. The competitive arena is defined by major chemical corporations and specialized producers who invest heavily in product stability and thermal performance.
Eastman Chemical Company remains a cornerstone of the industry, offering the renowned Therminol 62. This high-purity isopropyl biphenyl mixture is designed for low-pressure liquid phase systems, capable of reaching maximum bulk temperatures of 325°C. Their global availability and reputation for exceptional thermal stability make them a benchmark against which competitors are measured.
Nippon Chemical Texas Inc. (NCTI) provides a robust alternative with their SS-300 product. This mixture of di- and tri-isopropyl biphenyl isomers offers thermal stability up to 330°C. It is particularly noted for its suitability in high-temperature and sub-zero conditions, making it versatile for diverse industrial uses across Texas and beyond.
Dalian Richfortune Chemicals Co., Ltd. has established a strong foothold, particularly in projects involving Concentrated Solar Power (CSP). Their RFCTHERM-IPB is equivalent to Therminol-62, supplying reliable long-term operation for low-pressure liquid phase heat transfer systems. Their experience in large-scale industrial applications adds a layer of operational credibility.
Jiangsu Zhongneng Chemical Technology Co., Ltd. leads in biphenyl derivatives with offerings like SCHULTZ S730. Their fluids cover temperature ranges from -20°C to 330°C, addressing a wide spectrum of thermal requirements. As a leading manufacturer, their production capabilities influence supply dynamics in the region.
Manto Chemistry (Jiangsu Manto Chemistry Co., Ltd.) focuses on high-purity synthetic aromatic heat transfer fluids with their Mantherm IBP, equivalent to Therminol 62. They operate with an annual production capacity of 3,000 tons of isopropylbiphenyl, ensuring dedicated supply for systems between -20°C and 350°C. This capacity commitment signals a strong strategy to secure supply chain stability for their clients.
Rütgers GmbH contributes high-quality synthetic heat transfer fluids based on isopropyl biphenyl mixtures with their Ruetasolv BP series. Designed for high-temperature applications up to 350°C, their German engineering standards reinforce the premium segment of the market.
These players illustrate a market where technical specifications such as maximum bulk temperature, thermal stability, and isomer composition are the primary battlegrounds. Strategic partnerships and capacity expansions are key levers used to maintain competitiveness.
Industry Drivers and Regulatory Context
The growth of the isopropyl biphenyl market is inextricably linked to regulatory and environmental shifts. A critical driver is the phase-out of polychlorinated biphenyls (PCBs). Isopropyl biphenyl mixtures have emerged as viable replacements for PCBs in heat transfer and capacitor fluids following historical regulatory phase-outs. This transition is not merely about compliance; it is about ensuring operational continuity with safer, more sustainable chemical alternatives.
The adoption of isopropyl biphenyl as a dielectric insulating fluid in capacitors after the 1978 U.S. EPA ban on PCB manufacture and distribution underscores the long-term viability of this chemical class. This historical context validates the current market momentum, as industries continue to retrofit and upgrade systems to meet modern safety standards.
Furthermore, raw material dynamics play a crucial role. Dedicated production capacities, such as the 3,000 tons annually maintained by key manufacturers for isopropylbiphenyl, highlight the importance of vertical integration and supply security. Fluctuations in raw material availability or cost can ripple through the value chain, affecting pricing and lead times. Understanding these upstream dependencies is vital for risk management.
Operational Intelligence Within the Report
Our comprehensive study goes beyond high-level summaries. It is designed as a decision-support tool that provides actionable intelligence for various stakeholders.
- Capacity and Supply Analysis: Detailed assessments of manufacturing capabilities, including regional production hubs and capacity expansions, allow readers to gauge supply tightness and potential bottlenecks.
- Technology and Product Roadmaps: Insights into R&D trends help companies anticipate future product specifications, such as improvements in thermal stability limits or eco-friendly formulations.
- Pricing and Cost Structures: While specific price points are reserved for the deep dive, the report analyzes cost drivers, including raw material correlations and regional pricing differentials, enabling better budgeting and negotiation strategies.
- Risk Assessment: Evaluation of regulatory risks, supply chain vulnerabilities, and competitive threats provides a holistic view for strategic planning.
Strategic Value for 2026 Decision Makers
In the context of 2026, the insights provided by this research are instrumental for several strategic objectives.
Market Entry and Expansion: For companies looking to enter the market or expand their footprint, the segmentation data highlights high-growth pockets. Understanding the regional demand intensity and the competitive saturation in specific areas allows for targeted investment rather than scattergun approaches.
procurement and Sourcing: Procurement teams can leverage the competitive landscape analysis to identify alternative suppliers, assess vendor reliability, and negotiate better terms based on a clear understanding of capacity constraints and market concentration.
Product Development: R&D departments can align their innovation pipelines with market needs. Knowing which applications are driving demand—such as waste heat recovery or electronics cooling—guides the prioritization of fluid formulations with specific thermal properties.
Investment Planning: Investors and finance leaders can use the growth projections and market concentration metrics to evaluate the attractiveness of the sector. The steady CAGR and the shift toward safer chemicals suggest a stable long-term investment thesis.
Navigating the Future of Thermal Management
The Isopropyl Biphenyl Heat Transfer Fluid Market is more than a commodity sector; it is a critical enabler of industrial efficiency and safety. As regulations tighten and operational temperatures rise, the choice of fluid becomes a determinant of system longevity and performance.
p.p'-Dibromobiphenyl Market
The data indicates a market that is growing steadily but is also complex. The concentration among top players suggests that collaboration or differentiation is key. The regulatory backdrop ensures that demand for compliant fluids will remain robust. The variation in applications means that a one-size-fits-all strategy is insufficient.
Our full report unpacks these complexities with precision. It offers the granular data and analytical frameworks needed to turn market intelligence into competitive action. From detailed historical tables to forecast models and company profiles, every section is crafted to reduce uncertainty and enhance strategic clarity.
For organizations committed to optimizing their thermal management strategies and capitalizing on the opportunities within this specialized chemical market, deep intelligence is the prerequisite for success. The 2026 horizon offers significant potential for those equipped with the right insights. We invite you to access the complete study to unlock the full spectrum of data and analysis required to navigate this evolving landscape with confidence.
For detailed analysis of this topic, please visit the official page: Isopropyl Biphenyl Heat Transfer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MPGF Market Hits $346.48M in 2025, Poised for 6.52% CAGR Through 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the Energy Transition: Navigating the Worldwide Multi-Point Ground Flares Market 2026-2032
The Strategic Imperative for Stakeholders in 2026
As the global energy sector navigates an increasingly complex landscape defined by stringent environmental regulations and operational efficiency demands, the infrastructure supporting safe and compliant waste gas combustion has never been more critical. For executives, investors, and strategic planners operating within the oil, gas, and petrochemical industries, understanding the trajectory of the Worldwide Multi-Point Ground Flares (MPGF) Market is not merely an operational necessity but a strategic imperative. Our latest market research provides a comprehensive lens into this evolving sector, offering the data-driven insights required to make informed decisions in 2026 and beyond. The transition toward cleaner combustion technologies and the relentless pressure to minimize environmental footprints are reshaping the competitive arena, making detailed intelligence on market size, growth rates, and technological shifts essential for maintaining a competitive edge.
This report serves as a vital tool for capital allocation and risk management. With the market demonstrating a consistent upward trajectory, stakeholders need to understand not just the current valuation but the momentum driving future revenue streams. The analysis covers a robust forecast period, allowing organizations to model long-term scenarios based on reliable historical data and projected growth metrics. By integrating macroeconomic indicators with industry-specific dynamics, this research equips leadership teams with the foresight needed to anticipate demand shifts, identify emerging opportunities, and mitigate potential disruptions before they impact the bottom line.
Market Trajectory and Growth Dynamics
Historical Performance and Future Outlook
The concrete evolution of the Multi-Point Ground Flares market over the past half-decade lays the groundwork for a promising future. From a market valuation of approximately 325.27 million USD in 2024, the sector has progressed to reach an estimated 346.48 million USD in 2025. This steady expansion underscores the resilience of the industry despite fluctuating raw material costs and varying regulatory environments across different jurisdictions. Looking ahead, the market is projected to maintain a steady Compound Annual Growth Rate (CAGR) of 6.52 percent throughout the forecast period extending from 2026 to 2032. This growth rate signals a mature yet expanding market where innovation and regulatory compliance are the primary drivers of revenue generation.
By the end of the forecast horizon in 2032, the total market revenue is anticipated to reach significant milestones, surpassing the five-hundred-million-dollar mark. This upward curve reflects the increasing adoption of advanced flaring technologies designed to meet modern emission standards. For stakeholders contemplating investments or capacity expansions, these figures provide a baseline for understanding the scale of the opportunity. However, the aggregate numbers only tell part of the story. The underlying drivers vary significantly across different segments and geographies, necessitating a granular analysis that our full report provides to ensure strategic alignment with specific business units.
Segmentation Analysis and End-User Demand
Diverse Applications Driving Demand
The demand for Multi-Point Ground Flares is diversified across several critical industrial segments, each with unique operational requirements and compliance challenges. The end-user landscape is primarily dominated by sectors that handle large volumes of hydrocarbon waste gases. Key industries utilizing these systems include Oil and Gas Processing, Petrochemical and Chemical manufacturing, and LNG Terminals and Storage. Each of these sectors contributes differently to the overall market volume, driven by specific processing capacities and safety regulations unique to their operations. For instance, the need for reliable combustion solutions in high-volume processing plants contrasts with the specific containment and monitoring requirements found in import and export terminal facilities.
Furthermore, the market is segmented by technology type, primarily distinguishing between High-Pressure Sonic Flares and Low-Pressure Multi-Point Flares. These technological distinctions are crucial for engineering teams and procurement specialists who must match the flare system specifications to the specific waste gas characteristics of their facilities. The balance between these types influences procurement strategies and capital expenditure planning. Understanding the relative weight of these segments in the total market mix helps organizations benchmark their product portfolios against industry standards. Detailed breakdowns of these segmentation splits are available in our comprehensive dataset, allowing for precise targeting of sales and development efforts.
Regional Market Distribution
Global Reach and Regional Variations
Geography plays a pivotal role in the distribution of MPGF installations and revenue generation. The market exhibits a varied landscape across different continents, reflecting the global nature of the energy and chemical industries. Regions with heavy industrial activity and significant upstream and downstream operations show higher concentrations of demand. Key geographic areas included in our analysis span the Middle East and Africa, North America, Asia Pacific, Europe, and Latin America. Each region presents distinct regulatory frameworks and infrastructure development phases that influence market penetration rates and investment cycles.
For example, regions with extensive oil and gas exploration activities naturally drive demand for robust ground flare systems, while areas with stringent environmental protection laws may prioritize specific low-visibility or smokeless technologies. Understanding these regional nuances is essential for multinational corporations planning global rollouts or local firms looking to expand their market share. The spatial distribution of market revenue highlights where the largest concentrations of activity are occurring. However, to fully leverage this information, clients require the detailed regional breakdowns and growth potential assessments provided in the complete version of this market study.
Competitive Landscape and Key Players
Manufacturers Shaping the Industry
The competitive environment within the Multi-Point Ground Flares market is characterized by the presence of several specialized engineering firms that lead the pack in terms of technology and market share. The industry shows a notable level of concentration, with a CR3 of 58.4 percent and a CR5 of 72.15 percent, indicating that a handful of major players hold significant influence over market pricing and innovation standards. Leading companies in this space include Zeeco, Inc., John Zink Hamworthy Combustion, Aereon (part of Cimarron), Honeywell UOP Callidus, and Encore Combustion. These entities are headquartered primarily in the United States, reflecting the strong industrial base supporting combustion technology development.
Each of these companies brings distinct value propositions to the table. Zeeco, Inc. focuses on engineered solutions for highly variable waste gas volumes, emphasizing safety and lowvisibility performance in sensitive areas. John Zink Hamworthy Combustion distinguishes itself with the LRGO portfolio, offering extended lifespan and industryleading flow rates with high destruction efficiency exceeding 99.5 percent. Aereon designs systems for very large flows using array enclosed configurations with multi-stage operation. Honeywell UOP Callidus supplies systems suited for both onshore and offshore gas processing with automated staging systems. Meanwhile, Encore Combustion offers enclosed combustion solutions using proprietary burner technologies for large volumes of hydrocarbons. The rivalry among these firms drives continuous improvement in reliability, emission reduction, and operational efficiency.
Recent Developments and Operational Updates
Market activity is not static, and recent events highlight the dynamic nature of this sector. In mid-2025, Zeeco, Inc. highlighted its Multi-Point Ground Flares as a solution for handling variable waste gas volumes with safe, smokeless, and less-visible flaring, reinforcing the commitment to environmental compliance. Similarly, operational updates such as Shell Chemical Appalachia LLC planning additional camera installations for monitoring MPGF units demonstrate the increasing focus on oversight and accountability in flare operations. Furthermore, project supply activities, such as Ever-power supplying a large capacity multi-point ground flare for a petrochemical complex in 2024, illustrate the ongoing capital expenditure in industrial infrastructure. These events serve as indicators of the broader trends affecting market demand and technology adoption.
Worldwide Multi-Point Ground Flares (MPGF) Market
Regulatory Environment and Industry Dynamics
Compliance as a Growth Driver
Regulatory compliance remains a cornerstone of the MPGF market, influencing design specifications, operational protocols, and market entry barriers. Flare systems must adhere to rigorous standards, including ISO 23251 (API 521) and 40 CFR 60.18, which govern the design and operation of flare systems to ensure safety and environmental protection. Specific products, such as the John Zink LRGO portfolio, are designed to meet API 537 compliance, showcasing the industry's alignment with recognized engineering standards. These regulations ensure that combustion processes minimize harmful emissions and maintain structural integrity under various operating conditions.
Worldwide Flare Fittings Market
Additionally, regulatory bodies continue to refine emission limitation strategies. For instance, the EPA has approved Alternative Means of Emission Limitation for the operation of pressure-assisted Multi-Point Ground Flares at major chemical facilities in Texas, establishing specific monitoring and performance requirements. Such regulatory milestones create both challenges and opportunities for manufacturers and operators. Compliance drives demand for advanced monitoring and control systems, while also necessitating regular updates to existing infrastructure. Understanding the interplay between these regulations and market growth is essential for long-term strategic planning, as non-compliance can result in significant operational risks and financial penalties.
Conclusion: Leveraging Intelligence for Strategic Advantage
The Worldwide Multi-Point Ground Flares Market represents a critical intersection of industrial engineering, environmental stewardship, and strategic investment. As the industry moves through the forecast period to 2032, the ability to navigate regulatory complexities, leverage technological advancements, and understand competitive shifts will define success. The data outlined in this overview provides a high-level perspective, but the depth required for decisive action lies in the detailed segmentation, competitor profiling, and market volatility analysis contained within our full report. For organizations aiming to secure their position in this evolving landscape, accessing the complete intelligence suite is the next logical step. We invite you to explore the full dataset to uncover the specific insights that will drive your strategy forward.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Point Ground Flares (MPGF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Surgical Tray Market to Hit $801.59M by 2032 Driven by 5.81% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for Surgical Tray Markets: Navigating Growth Through 2032
The global surgical tray market stands at a critical inflection point as healthcare delivery models, sterilization science, and supply chain economics converge. Our latest Worldwide Surgical Tray Market research provides decision-makers with a structured, evidence-based view of where value is being created, where pressure is intensifying, and how leading organizations are positioning for the 2026–2032 horizon. This introduction outlines the strategic architecture of the study, demonstrates its relevance to corporate planning, and invites executive teams to access the full intelligence suite for detailed segmentation, competitive benchmarking, and forward-looking scenario analysis.
A Market Defined by Structural Expansion and Operational Complexity
Historical performance shows a market that has consistently expanded through cycles of capacity investment, protocol refinement, and procedural volume growth. From a baseline in the early 2020s, revenue progression has accelerated into a mid-single-digit compound annual growth trajectory forecast to sustain through the end of the decade. The overall market size has climbed steadily from 2020 through 2025, with the latest base-year valuation reflecting sustained demand across both reusable and disposable formats. Forecasts extending to 2032 indicate a continued upward path, with the market expected to move decisively past the 700 million USD threshold before reaching a final projected valuation near 800 million USD.
This scale is not merely a function of procedural volume. The growth profile reflects a combination of sterilization modernization, tray standardization initiatives, and the ongoing tension between infection prevention imperatives and cost containment pressures. Organizations that treat surgical trays as a commoditized logistics item often underestimate the operating leverage embedded in tray design, reprocessing efficiency, material durability, and procedural-specific customization. Our research frames the market through that lens: trays are not passive containers but active components in sterile workflow, turnaround time optimization, and clinical outcomes.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands clarity on three interlocking questions:
- Which material and format choices offer the best balance of lifecycle cost, reprocessing compliance, and user preference across care settings?
- How are concentration patterns, supplier capabilities, and recent product or contract developments reshaping procurement leverage?
- Where do regulatory, reimbursement, and sterilization validation requirements create barriers, enablers, or margin opportunities?
Our study is built to answer these questions with data that can be operationalized. Rather than stopping at high-level market sizing, the analysis connects macro trends to procurement strategy, tray engineering trade-offs, sterile processing economics, and competitive positioning. For manufacturers, the research supports roadmap decisions around material mix, reusable versus disposable portfolio balance, and regional capability deployment. For providers and sterile processing leaders, it informs standardization strategies, vendor evaluation criteria, and total-cost-of-ownership modeling. For investors and corporate development teams, it clarifies where market concentration and innovation activity suggest durable advantages versus crowded segments.
Report Architecture: Practical Intelligence, Not Abstract Synthesis
The Worldwide Surgical Tray Market study is organized to support rapid executive consumption while offering enough depth for cross-functional planning. The report moves from market foundation to actionable segmentation, then integrates competitive intelligence and regulatory context into a coherent decision framework.
What the Study Covers
- Historical market performance and forward-looking projections anchored to a consistent methodology, including a clearly defined base year, retrospective window, and forecast horizon through 2032.
- Segment-level perspective across material choices and tray types, with attention to how stainless steel, plastic, and aluminum applications differ in utilization patterns, reprocessing requirements, and cost structures.
- End-user demand analysis spanning hospitals, ambulatory surgical centers, and specialty clinics, reflecting distinct purchasing behaviors, procedure mixes, and turnaround priorities.
- Regional assessment across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, framed around market maturity, supplier presence, and procedural environment differences.
- Competitive landscape mapping for major participants, including profile context and a set of recent developments that illustrate how product innovation, contract wins, and catalog expansion are shaping the market.
- Regulatory, reimbursement, and sterilization governance considerations that directly affect product classification, validation burden, and procurement economics.
Material and Format Dynamics: The Core Trade-Offs
Material selection remains one of the most consequential design decisions in surgical tray planning. Stainless steel continues to anchor reusable workflows because of durability, compatibility with reprocessing cycles, and long-term cost amortization. Plastic-based solutions serve high-throughput disposable needs where convenience, reduced reprocessing dependency, and single-use safety considerations dominate procurement thinking. Aluminum appears where weight, cost, and specific procedural requirements drive a middle path between permanence and portability.
The broader tray conversation is similarly bifurcated. Reusable trays emphasize reprocessing infrastructure, sterilization validation, and instrument longevity, while disposable trays emphasize workflow simplicity, inventory flexibility, and reduced cleaning variability. The research does not treat either format as universally superior. Instead, it examines where each format is gaining traction based on setting-specific pressures, infection control protocols, and total cost structures. In doing so, the study helps leaders evaluate not just what is being purchased today, but how format preferences may shift as sterilization technology, staffing models, and reimbursement incentives evolve.
Procurement Realities Across Care Settings
End-user segmentation reveals how differently surgical trays are valued depending on the clinical environment. Large hospital systems typically integrate trays into broader sterile processing strategies, where reprocessing throughput, instrument availability, and validation consistency directly affect operating room readiness. Ambulatory surgical centers often prioritize convenience, turnaround speed, and cost predictability, especially in settings where procedural volume is high but on-site reprocessing resources are limited. Specialty clinics sit in a distinct position, with procedure-specific requirements that can make customized or application-focused tray configurations more relevant than generic standardization alone.
Our analysis connects these setting-specific realities to purchasing behavior, service expectations, and contract design. This is crucial because the same tray can function as a cost center in one environment and a workflow enabler in another. Decision-makers who understand these differences are better positioned to negotiate terms, design service agreements, and align product specifications with real operational constraints rather than generic assumptions.
Competitive Landscape: Concentration, Capability, and Recent Moves
The market is not evenly distributed. Competitive concentration is meaningful, with the top three participants and the top five participants together representing a substantial share of overall activity. That concentration suggests that scale, distribution reach, sterilization expertise, and procedural portfolio depth continue to matter. At the same time, specialized players can compete effectively by focusing on niche applications, custom configurations, or highly differentiated sterilization container systems.
Several leading organizations anchor the market. Cardinal Health is widely recognized for custom sterile surgical procedure trays and packs serving operating rooms globally. Medline Industries produces reusable stainless steel and disposable plastic instrument trays with sterilization compatibility in mind, while B. Braun Melsungen AG offers modular stainless steel trays and containers designed for steam and EO sterilization across international markets. Steris contributes rigid sterilization container systems and surgical trays tailored for hospital central sterile processing departments. Teleflex supports specialty surgical trays through its Pilling brand, including perforated and solid bottom instrument trays. Integra LifeSciences serves neurosurgery and orthopedic surgical needs through Miltex instruments and accessories, while Becton, Dickinson and Company integrates surgical trays into procedure kits for vascular and general surgery. Mölnlycke Health Care develops custom procedure trays for wound care and general surgery applications internationally.
What matters strategically is not only who is present, but how these organizations are executing. Recent market activity illustrates the pace of change. In late 2023, Steris plc introduced a next-generation rigid container system intended to enhance sterilization efficiency for surgical trays, signaling continued investment in reprocessing performance. Earlier that year, Cardinal Health secured a multi-year supply agreement with a major US hospital system for custom surgical trays, reinforcing the importance of long-term service relationships and institutional standardization. In late 2022, Medline released an expanded surgical tray catalog featuring new anti-fog and modular designs, demonstrating how product-level innovation can broaden application fit and user appeal.
These developments are not isolated events. They reflect a broader pattern in which suppliers compete on sterilization efficiency, customization capability, material performance, and procurement partnerships. Our report translates such moves into competitive signals that procurement teams, product planners, and strategy leaders can actually use.
Regulatory, Reimbursement, and Sterilization Context
Surgical tray decisions do not happen in a vacuum. They are shaped by standards, device classification, sterilization validation, and payment frameworks that influence both product design and commercial readiness.
Sterilization quality remains foundational. Surgical trays must comply with ISO 17665-1 for moist heat sterilization validation, and reusable trays require validated cleaning protocols per AAMI ST79 to keep bioburden within acceptable limits. These requirements are not administrative footnotes; they determine reprocessing reliability, failure risk, and the operating burden placed on central sterile processing departments. In parallel, most surgical instrument trays are classified as Class II devices under FDA oversight, requiring 510(k) premarket notification for many offerings. That classification influences time-to-market, documentation requirements, and the level of technical rigor needed from manufacturers.
On the financial side, tray economics intersect with reimbursement structures. Surgical trays are included in CMS DRG payments for inpatient procedures under relevant major operating room case categories, which ties tray costs to broader procedure payment logic rather than treating them as standalone consumables. This link matters because it shapes how hospitals evaluate cost, how suppliers frame value, and how procurement teams assess whether a tray solution reduces downstream risk or simply adds visible expense.
Material cost dynamics also affect long-term planning. Medical-grade 316L stainless steel used for reusable trays carries a unit cost that can materially influence durable product economics, especially when procurement teams model total lifecycle cost rather than unit price alone. Combined with sterilization validation, instrument life expectancy, and reprocessing labor, the true cost picture becomes more nuanced than a simple reusable-versus-disposable comparison.
Worldwide Surgical Tray Market
What the Full Report Enables Beyond This Overview
This introduction is deliberately designed to demonstrate analytical depth without revealing the detailed figures and split-level sensitivities that sit inside the complete study. The full report provides:
Sterilization Trays Market
- Granular market size and forecast values across the historical period and the 2026–2032 forecast window.
- Segment-level market values across material types, tray formats, and end-user categories.
- Regional breakdowns that allow leadership to prioritize expansion, sourcing, or partnership moves by geography.
- Contextual competitive evaluation that ties recent product launches, contract awards, and catalog changes to market positioning.
- Practical guidance for interpreting regulatory and sterilization requirements in commercial and operational terms.
By reserving those specifics for the complete report, we ensure that executive readers receive both credibility and curiosity: enough substantive insight to trust the methodology, and enough unresolved detail to justify accessing the full intelligence set.
Where to Focus Next
For teams planning 2026 budgets, product roadmaps, supplier evaluations, or market entry assessments, the immediate value of this research lies in its ability to turn market growth into actionable strategy. The worldwide surgical tray market is not simply expanding; it is evolving in response to sterilization efficiency demands, procedural standardization pressures, and competitive consolidation. Organizations that use this study as a strategic reference point will be better equipped to distinguish short-term procurement noise from structural opportunity.
The complete Worldwide Surgical Tray Market report provides the detailed segmentation, competitive benchmarking, and forecast architecture needed to support those decisions. We recommend aligning planning teams around the full study so that market insight can be translated into concrete actions across product strategy, purchasing strategy, and growth planning.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Tray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


