



PW Consulting: Stainless Steel Cable Ties Market to Reach $390.3M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Frontier: Strategic Intelligence for the Stainless Steel Cable Ties Market (2026-2032)
The industrial fastening sector is undergoing a period of disciplined evolution, driven by a convergence of infrastructure modernization, maritime expansion, and increasingly stringent environmental resilience requirements. Within this landscape, the stainless steel cable ties market has emerged as a critical niche where material science meets operational reliability. Over the past half-decade, the market has demonstrated steady consolidation, with historical valuation climbing from approximately $215 million in 2020 to $252.5 million by 2025. As we turn the page to 2026, the trajectory points toward a base valuation of $260.72 million, with a projected compound annual growth rate positioning the sector to reach $390.3 million by the end of 2032.
These figures represent more than macroeconomic arithmetic. They reflect a structural shift in how engineers, procurement directors, and project managers approach cable management in harsh, corrosive, and high-vibration environments. For decision-makers navigating 2026, understanding the underlying drivers, competitive positioning, and regulatory friction points is no longer optional. It requires a granular, forward-looking intelligence framework. The latest PW Consulting Stainless Steel Cable Ties Market research report has been engineered precisely for this purpose.
Stainless Steel Cable Ties Market
Macro Growth Trajectory and the 2026 Inflection Point
The historical performance between 2020 and 2025 tells a story of resilience and deliberate recalibration. Following a period of market adjustment in 2024, evaluated revenue rebounded to $242.08 million before climbing to $252.5 million in 2025, signaling renewed capital allocation across both replacement and greenfield industrial projects. Looking ahead, the forecast horizon from 2026 through 2032 maps a sustained upward curve, with annual valuations expected to accelerate as downstream adoption deepens in electrical infrastructure, marine platforms, and heavy industrial assembly lines.
The headline CAGR of 6.98 percent underscores a market that is neither speculative nor stagnant, but structurally growing. This rate of expansion demands strategic attention. Organizations that rely on backward-looking procurement benchmarks will quickly find themselves misaligned with material availability, pricing dynamics, and certification requirements that are evolving in real time. The 2026 edition of our market research dissects these trajectories not as isolated numbers, but as interconnected signals that inform capacity planning, supplier negotiations, and regional deployment strategies.
Nylon Cable Ties Market
Competitive Architecture and the Rise of Specialized Offerings
The competitive landscape is defined by a concentrated yet differentiated group of manufacturers that have carved distinct value propositions within the stainless steel cable ties ecosystem. Market concentration data indicates a moderately fragmented structure, with the top three firms collectively capturing a modest share and the top five extending that footprint only slightly further. This dispersion suggests ample room for targeted positioning, but it also demands rigorous evaluation of product engineering, coating technologies, and compliance portfolios.
HellermannTyton, headquartered in Germany, has built its reputation on precision-engineered stainless steel cable ties offered across a spectrum of lengths, widths, and tensile specifications. Their approach emphasizes full polyester coating to prevent contact corrosion, paired with protective polyolefin channels designed to mitigate chafing, vibration, and mechanical shock. In critical infrastructure scenarios, their MBT-Series has achieved full-range UL 62275 certification for short-circuit protection, establishing a compliance benchmark that procurement teams increasingly reference during vendor qualification.
Across the Atlantic, Panduit, based in Illinois, has focused on integrated systems rather than standalone components. Their Pan-Steel System consolidates stainless steel cable ties, banding, mounts, identification solutions, and installation tools into a unified workflow tailored for shipbuilding and severe operating environments. The emphasis on smooth, round edges that prevent cable insulation damage reflects a user-centric engineering philosophy that resonates with OEM integrators and field installation teams.
BAND-IT, operating from California, has concentrated on tensile durability and industrial bundling performance through its Ultra-Lok locking style. This mechanical design prioritizes secure, repeatable fastening in high-stress applications, positioning the brand as a go-to for manufacturers that require consistent clamping force under dynamic load conditions.
On the compliance and regional manufacturing front, Hayata distinguishes itself as a US-owned, ISO 9001-certified producer offering 360-degree coated stainless steel cable ties and banding in multiple sizes. Its status as the only such US-based manufacturer serving harsh environment applications provides a tactical advantage for domestic supply chain resilience and procurement teams prioritizing localized production footprints.
Kable Kontrol has carved a niche around flame-retardant Grade 304 stainless steel cable ties featuring an easy-install, low-profile self-locking ball bearing head, with UL listing that streamlines approval cycles for electrical positioning devices. Meanwhile, HUA WEI INDUSTRIAL CO., LTD., based in Taiwan, has expanded its certification footprint to include UL, CSA, GL, CE, and CQC accreditations, aligning its heavy-duty and ball-lock stainless steel cable ties with severe industrial application standards. Their June 2026 participation in ElectroneX, where they showcased stainless steel and heavy-duty cable ties alongside ball-lock variants and polyamide 12 solar cable ties, illustrates how trade presence and product diversification are being leveraged to capture cross-sector attention.
Additionally, Hangzhou Gordon Electric Co., Ltd. was highlighted in April 2026 as a specialized OEM/ODM manufacturer within the top supplier landscape, reinforcing the growing role of contract and custom manufacturing in meeting project-specific fastening requirements across global industrial deployments.
Material Standards, Regulatory Friction, and the Certification Economy
The operational value of stainless steel cable ties is inseparable from the material grades and regulatory frameworks that govern their deployment. Grade 304 and marine-grade 316 stainless steel form the backbone of the category, offering corrosion resistance and thermal tolerance spanning from -100°F to 1000°F. This thermal and chemical resilience is what enables adoption in environments where polymer-based fasteners degrade, where salt exposure accelerates failure, or where electrical safety mandates fire-retardant performance.
Yet material capability alone does not unlock market access. Certification has become a decisive commercial variable. The UL 62275 alignment achieved by HellermannTyton’s MBT-Series, the UL listing secured by Kable Kontrol under File No. E530766, and the multi-accreditation portfolio maintained by HUA WEI INDUSTRIAL CO., LTD. all reflect a market where compliance is a gatekeeper to project eligibility. ISO 9001 certification, as demonstrated by Hayata’s US-based production line, further signals process maturity that procurement and quality teams weigh heavily when qualifying suppliers for long-term contracts.
For 2026 strategy planning, this certification economy introduces both constraint and opportunity. Organizations that internalize the mapping between application requirements, regional regulatory expectations, and supplier certification portfolios will compress approval timelines and reduce downstream rework risk. Our research report layers these dynamics into a practical compliance-and-selection framework, helping teams evaluate not just what a tie does, but what standards it satisfies and where those standards carry the greatest commercial weight.
Why This Report Is Built for 2026 Decision-Making
Market research that merely recites growth percentages fails the modern strategist. The 2026 Stainless Steel Cable Ties Market report is structured to convert intelligence into action. It delivers an operational blueprint that covers:
- Historical performance mapping and forward forecast modeling that contextualizes the 2026-2032 growth arc without reducing it to a single headline figure, enabling scenario-based planning across procurement cycles and capital budgeting windows.
- A structured examination of type, size, application, and regional segmentation dynamics, presented to illuminate where demand density is concentrating and how product configurations are aligning with end-use requirements, while preserving the strategic discretion necessary for competitive positioning.
- A competitive profiling module that dissects product engineering, coating technologies, locking mechanisms, installation ergonomics, and compliance portfolios across the key manufacturers shaping the category, equipping buyers and sellers with a comparative lens for vendor selection and market entry evaluation.
- An integrated view of market concentration and fragmentation trends, providing context for pricing power, negotiation leverage, and the strategic implications of a moderately dispersed supplier base.
- A regulatory and certification tracker that translates recent UL, CSA, GL, CE, CQC, and ISO 9001 developments into actionable guidance for project qualification, export planning, and risk mitigation.
- Material and performance benchmarks anchored in real-world thermal, corrosion, and flame-retardant requirements, enabling engineering and procurement teams to align specification choices with environmental exposure and safety mandates.
The deliberate architecture of this report reflects a core principle: in a market where certification, coating technology, tensile design, and regional compliance expectations are moving in tandem, decision-makers need an integrated intelligence system, not a fragmented data dump. The report is designed to support sourcing strategy, product portfolio alignment, competitive benchmarking, and market-entry assessment with equal rigor.
The Strategic Case for Deeper Intelligence
As 2026 unfolds, the stainless steel cable ties market will continue to reward organizations that treat fastening not as a commodity afterthought, but as a performance-critical component embedded in larger system reliability. The convergence of infrastructure renewal, marine asset expansion, and electrical safety mandates is expanding the addressable base, while certification scrutiny and material differentiation are raising the barrier to entry for undifferentiated players.
The full research report extends beyond the trajectory outlined here. It maps the segmentation architecture across type, size, application, and regional demand patterns, unpacks the competitive positioning of the companies shaping the category, and provides the analytical scaffolding needed to convert market signals into procurement strategy, product development priorities, and expansion planning. To access the complete segmentation breakdown, forecast scenarios, and competitive deep dives, we invite you to explore the full report on our platform. The intelligence required to navigate 2026with precision is available, and the organizations that secure it first will be best positioned to capture the growth ahead.
For detailed analysis of this topic, please visit the official page: Stainless Steel Cable Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PTFE Venting Membrane Market to Reach $2.69B by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-16
Strategic Venting: Navigating the PTFE Membrane Market in 2026
The global industrial landscape is undergoing a profound transformation, driven by electrification, stringent safety regulations, and evolving material science demands. At the intersection of these trends lies the critical role of PTFE venting membranes. These specialized components are no longer mere accessories; they are essential enablers of battery safety, sterile medical environments, and durable structural systems. As we move through 2026, understanding the trajectory of this market is not just an academic exercise—it is a strategic imperative for stakeholders across the value chain. This analysis draws from our latest comprehensive market research to outline the opportunities and risks defining the sector over the next decade.
The market has witnessed a robust trajectory over the past five years, recovering from global supply chain shocks and accelerating towards new highs. Historical data from 2020 through 2025 indicates a steady upward curve, culminating in a valuation that sets the stage for significant growth in the forecast period. Our analysis projects the global market value to reach approximately 2,050 million USD in 2026, up from 1,883.5 million USD in the base year of 2025. This momentum is expected to continue, with revenues climbing towards 2,689.9 million USD by 2032. Such figures underscore a compound annual growth rate (CAGR) of 5.2 percent during the forecast period from 2026 to 2032. This growth is not linear; it is punctuated by technological shifts and regional dynamics that require nuanced strategic planning.
PTFE Venting Membrane Market
Market Dynamics and Supply Chain Pressures
While the top-line growth figures are promising, the underlying dynamics present a complex picture for procurement and manufacturing leaders. The cost structure for PTFE venting membranes is heavily influenced by raw material volatility. High-grade PTFE resins exhibit price volatility driven by global supply chain disruptions, a trend that analysts have flagged as persistent throughout 2025 and into 2026. This volatility is compounded by geopolitical factors affecting the fluorspar supply chain. Sovereign fluorspar policies in China, which supplies a significant majority of global output, are raising landed costs for North American and European converters by double-digit percentages.
These regulatory and logistical headwinds are forcing adjustments in production planning. Several European compounders have been observed idling a portion of their nameplate PTFE capacity during the first quarter of 2026 to preserve liquidity in response to tightening export licensing and shipment volumes. China's export licensing tightened 2025 shipments to levels below previous years, creating a squeeze on availability for downstream manufacturers. For companies operating in this space, the ability to hedge against raw material price variations—which can fluctuate by a significant margin annually—is becoming a key differentiator in maintaining margin integrity. Our report delves deep into these cost structures, offering models for supply chain resilience that go beyond simple procurement tactics.
Segmentation and Application Drivers
The demand for PTFE venting membranes is not uniform across all sectors. It is being pulled by specific high-value applications that prioritize performance and safety. The report segments the market by type, distinguishing between ePTFE Membrane Vents and Sintered PTFE Membrane Vents. Each type serves distinct functional requirements, with expanded PTFE gaining traction in applications requiring high breathability and chemical resistance, while sintered variants are critical where structural integrity under pressure is paramount.
In terms of application, the breadth of use cases illustrates the material versatility of PTFE. The electric vehicle (EV) battery sector remains a primary growth engine, driven by the absolute necessity for thermal runaway protection and pressure equalization in battery packs. Alongside this, the medical sector continues to demand high-purity venting solutions for sterile devices and drug delivery systems. The automotive industry, broader than just EV batteries, utilizes these membranes for under-the-hood components and lighting systems to protect against moisture and contaminants. Electronics packaging and industrial uses further diversify the revenue base. Chemical packaging and food and beverages packaging represent niche but high-compliance segments where barrier properties are non-negotiable. Understanding the specific growth rates and revenue contributions of each of these segments is crucial for targeting investment, and our full study provides the granular breakdown required to prioritize these verticals effectively.
Geographically, the market is distributed across key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific currently represents a substantial portion of the volume, reflecting the concentration of manufacturing and electronics production. However, North America and Europe maintain strong positions driven by high-value automotive and medical applications. The report analyzes the revenue distribution across these regions without revealing specific percentages in this overview, but the full publication details the regional revenue contributions and growth trajectories, highlighting where local manufacturing capabilities are aligning with demand centers.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of established material science giants and specialized converters. Market concentration remains moderate, with the top three players holding a combined share in the low twenties and the top five accounting for slightly less than thirty percent of the market. This fragmentation suggests opportunities for consolidation or for niche players to secure strong positions through differentiation.
Key companies shaping the industry include Gore & Associates, Inc., known for leading production of expanded PTFE venting membranes for automotive and medical applications. Donaldson Company, Inc. continues to be a pivotal supplier of advanced filtration and venting solutions, recently expanding production capacity in late 2024 to support rising demand from life sciences and industrial processing. Saint-Gobain Performance Plastics has also moved to expand fluoropolymer materials processing capability in early 2025 to address rising specialty filtration demand.
In Asia, Nitto Denko Corporation and Sumitomo Electric Industries, Ltd. are key providers of engineered PTFE membranes for electronics and automotive OEMs. Porex Corporation introduced advanced porous polymer and membrane solutions in mid-2024, targeting medical and industrial customers. Other significant players include Zeus Industrial Products, Marian, Inc., Poly Fluoro Ltd, and Membrane Solutions, LLC, each contributing to the supply chain through conversion, customization, or specialized property engineering such as hydrophobic and oleophobic coatings. The report profiles these entities in detail, analyzing their strategic partnerships, capacity investments, and R&D focus areas to help clients identify potential suppliers or competitors.
Strategic Value of the 2026 Research
For corporate strategists, investors, and product developers, this market research offers more than just historical data. It provides a forward-looking lens calibrated for the 2026 decision-making cycle. The study includes actionable insights on capacity planning, helping manufacturers anticipate where bottlenecks might occur given the current idling of European capacity and tightening of exports. It evaluates the regulatory environment, offering compliance roadmaps for companies navigating fluorspar policies and export licensing changes.
Furthermore, the report assesses the technological roadmap. As EV battery architectures evolve and medical devices become more complex, the specifications for venting membranes are tightening. The research identifies which technical properties are becoming standard versus premium, allowing R&D teams to align their development pipelines with market needs. The segmentation analysis enables precise market sizing for new product launches, ensuring that capital is deployed into the highest potential application areas. Whether you are evaluating entry into the ePTFE space or assessing the risk of raw material price hikes on your sintered product lines, the detailed data tables and forecast models in the full study provide the quantitative backing needed for confidence in your strategy.
Industrial Venting Membrane Market
Conclusion
The PTFE Venting Membrane Market is at a critical juncture where growth potential is high, but so are supply chain risks. The projected expansion to nearly 2,690 million USD by 2032 represents a significant opportunity for those who can navigate the complexities of raw material sourcing and regional regulatory shifts. Companies that leverage detailed intelligence on competitive moves, such as the capacity expansions by Donaldson and Saint-Gobain, will be better positioned to anticipate market shifts. By understanding the specific demands of the EV, medical, and packaging sectors, stakeholders can tailor their offerings to capture value in the most resilient segments. This research serves as a foundational tool for executing that strategy, ensuring that decisions made in 2026 are built on a comprehensive understanding of the market landscape. The full report contains the specific data points, regional splits, and company profiles necessary to operationalize these insights.
For detailed analysis of this topic, please visit the official page: PTFE Venting Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dry Ice Machine Market to Reach $344.8M by 2032, 5.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Cold Front: Strategic Insights for the Dry Ice Machine Market Through 2032
The global industrial landscape is undergoing a silent but significant transformation, driven by the need for sustainable cleaning solutions, stringent cold chain requirements, and the relentless pursuit of operational efficiency. At the heart of this shift lies the Dry Ice Machine Market. As enterprises face increasing pressure to adopt eco-friendly technologies while maintaining rigorous safety standards, understanding the trajectory of dry ice production and blasting equipment becomes not just an option, but a strategic imperative. Our latest market research provides a comprehensive roadmap for stakeholders looking to capitalize on these emerging opportunities between 2026 and 2032.
In an era where data transparency dictates competitive advantage, decision-makers require more than surface-level estimates. They need a granular understanding of how market forces interact, how regulatory frameworks evolve, and where the capital flows are heading. This introduction serves as a high-level overview of the intelligence contained within our full study, designed to equip senior leadership with the context needed to interpret the broader market signals before diving into the specific methodologies and breakdowns available in the complete report.
Macro Economic Trajectory and Growth Signals
Historical data suggests a resilient upward trend for the dry ice machine sector, reflecting broader industrial adoption rates and the substitution of traditional abrasive cleaning methods with cryogenic alternatives. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a solid foundation for forecasting the period extending to 2032. The market has demonstrated consistent expansion, moving from a valuation of approximately 163.15 million USD in 2020 to a projected 215.0 million USD by 2025. This trajectory underscores a mature yet accelerating adoption curve.
Dry Ice Machine Market
Looking forward, the forecast period indicates sustained momentum. The market is expected to reach 231.45 million USD in 2026, climbing steadily to 344.8 million USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 5.5 percent over the forecast horizon. Such a rate suggests a balanced expansion where technological innovation meets steady demand across key verticals. For investors and manufacturers, this CAGR signals a stable environment for capital deployment, albeit one that requires careful monitoring of regional nuances and operational costs.
It is crucial for strategists to recognize that these aggregate figures mask complex underlying drivers. The revenue growth is not uniform across all product categories or geographic zones. While the top-line numbers indicate a healthy market, the distribution of value across different machine types and application sectors varies significantly. Our full report dissects these variations to reveal which specific segments are outpacing the average growth rate and which are facing headwinds due to saturation or regulatory constraints.
Segmentation Landscape: Types and Applications
The market is diversified across several machine types, each catering to distinct production needs and output specifications. The landscape includes pellet dry ice production machines, block dry ice production machines, and slice dry ice production machines. Each type serves a unique function within the supply chain, influencing everything from storage logistics to end-user application efficiency. Understanding the revenue contribution of each category is essential for manufacturers deciding where to focus R&D resources.
Dry Ice Market
Similarly, the application sector drives significant demand variance. Key verticals include food and beverage, cold chain logistics, industrial cleaning, and medical and pharmaceutical uses. The food and beverage sector often leads in volume due to the critical need for temperature control during processing and transport, while industrial cleaning sees strong uptake due to the environmental benefits of dry ice blasting over sand or chemical blasting. Medical applications, though smaller in volume, command high compliance standards that impact machine specification requirements.
However, precise revenue splits and percentage contributions for these segments are sensitive competitive intelligence. In our complete market study, we detail exactly how these segments compare in terms of market share and growth velocity. Access to this level of detail allows procurement officers and product managers to benchmark their internal portfolios against the broader industry standard. Without this granular view, companies risk misallocating resources to slower-growing niches while missing high-potential opportunities in emerging applications.
Regional Market Dynamics and Distribution
Geographic distribution plays a pivotal role in shaping market strategy. The global landscape is divided into key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique mix of regulatory environments, industrial density, and cold chain infrastructure maturity. Historically, North America and Asia Pacific have shown robust activity, reflecting strong industrial bases and varying degrees of adoption in logistics and cleaning sectors.
Europe continues to maintain a significant presence, driven by strict environmental regulations that favor dry ice blasting over chemical alternatives. Meanwhile, emerging markets in Latin America and the Middle East and Africa represent areas of potential expansion, though they come with distinct infrastructural challenges and varying raw material availability. The interplay between these regions creates a complex trade flow and supply chain dynamic that affects pricing and availability of equipment.
Detailed regional revenue figures and growth rates are central to our full analysis. These metrics help multinational corporations determine where to prioritize sales channels and where local manufacturing might offer a competitive edge against imports. For a precise understanding of which regions are contributing the most to the global revenue pool and how their growth rates compare to the global average, stakeholders are encouraged to refer to the complete regional breakdown provided in the full report. This ensures that expansion strategies are grounded in accurate local market intelligence rather than generalized assumptions.
Competitive Landscape and Key Incumbents
The market features a mix of established players and specialized innovators, operating across multiple continents. Concentration levels indicate a moderately fragmented environment, with the top three companies holding approximately 24.6 percent of the market and the top five reaching 26.2 percent. This structure suggests that while there are dominant forces, there is still room for niche players to compete on technology or regional specialization.
Key companies shaping the industry include Cold Jet, LLC based in San Marcos, Texas, known for advanced dry ice production pelletizers and blasting equipment focusing on energy-efficient CO2 utilization. CRYONOMIC in Belgium offers hydraulic drive solutions for crystal-hard pellets and sticks in semi-automated industrial settings. ASCO Carbon Dioxide Ltd from Switzerland specializes in automatic pelletizers capable of multiple thicknesses for food-grade and industrial use. Other notable entities include Artimpex nv and IceTech in the United States, Alfred Kärcher SE & Co. KG in Germany, TOMCO2 Systems, Aquila Triventek, and Ziyang Sida Cryogenic Machine Co., Ltd. in China.
Recent industry movements highlight the dynamic nature of this competition. For instance, Cold Jet has been particularly active, launching a new line of dry ice blasting machines for the food processing industry in August 2025, followed by the introduction of the PR750H industrial pelletizer in November 2025 and the PE 80 High-Efficiency Pelletizer in February 2026. These launches demonstrate a clear focus on efficiency and versatility across pellet sizes. Meanwhile, CRYONOMIC appointed Multico svl. as a distributor for Romania in November 2025, and ICS exhibited at Auto Exotica 2026 in April, signaling ongoing efforts to expand distribution networks and brand visibility in specific verticals like automotive.
Competitor profiling in our full report goes beyond product listings. It analyzes market positioning, recent strategic moves, and the implied focus areas based on public announcements. For investors, understanding the cadence of product launches and distribution expansions provides clues about where each company sees the highest growth potential. This intelligence is vital for partnership due diligence or for identifying acquisition targets that align with long-term strategic goals.
Critical Market Dynamics and Operational Considerations
Beyond pure economics, the dry ice machine market is heavily influenced by regulatory and operational factors that impact total cost of ownership and deployment feasibility. Safety and compliance are not merely checkboxes; they are structural components of the market that define where and how equipment can be utilized. Our research integrates these dynamics to provide a realistic view of market barriers and facilitators.
Regulatory Frameworks and Safety Protocols
Operators must navigate a complex web of safety standards when deploying dry ice production and blasting equipment. A primary requirement is the use of equipment only in properly ventilated spaces that comply with local and national regulatory standards. This constraint impacts facility design and limits the types of environments where dry ice blasting can be implemented without significant infrastructure upgrades.
Exposure limits are another critical factor. Guidelines often dictate that exposure to dry ice must follow specific occupational safety standards, such as maintaining CO2 levels below certain thresholds over an 8-hour workday with continuous monitoring. For example, adherence to OSHA guidelines regarding 5,000 ppm limits requires facilities to invest in monitoring systems, adding to the capital expenditure associated with dry ice technology adoption.
Transportation and logistics also face strict oversight. All dry ice transportation containers must meet DOT regulations for hazardous materials labeling and emission controls. This affects the downstream logistics of companies utilizing dry ice for shipping or cleaning, influencing the choice of production machines that can integrate smoothly with compliant packaging and distribution workflows. Additionally, safety protocols for blasting equipment include the use of insulated containers and compliance with federal regulations on hazardous materials, ensuring that both operators and the environment are protected during industrial cleaning processes.
Raw Material Economics and Supply Chain Volatility
The economics of dry ice production are intrinsically linked to the availability and pricing of CO2 feedstock. Raw material expenses remain subject to fluctuations in CO2 supply, which can be influenced by seasonal demand in other sectors, such as beverages or welding, and broader industrial production cycles. This volatility introduces a variable cost element that manufacturers must factor into their pricing models and long-term contracts.
Current sector analysis indicates that average pellet prices can range significantly, reflecting the interplay between supply constraints and regional demand spikes. For machine operators, this means that the efficiency of the production machine—measured in yield and energy consumption per pound of dry ice—is a critical metric for profitability. Machines that optimize CO2 utilization can mitigate some of the impact of raw material price swings, offering a competitive advantage to operators who invest in higher-efficiency technology.
Our full report delves into the sensitivity analysis regarding raw material costs and how they impact the overall market revenue projections. By understanding the correlation between CO2 pricing trends and machine utilization rates, businesses can develop more robust financial models. This level of insight is necessary for forecasting operational budgets accurately and avoiding margin erosion during periods of supply tightness.
Strategic Implications for 2026 and Beyond
For enterprises operating in or adjacent to the dry ice machine market, the period from 2026 to 2032 offers both challenges and opportunities. The projected growth suggests that demand will not vanish, but the competition for market share will intensify. Success will depend on the ability to interpret data correctly, anticipate regulatory shifts, and align product offerings with the specific needs of high-growth applications.
Strategic decision-makers should consider the following implications based on the macro trends identified:
- Technology Investment: With new product launches focusing on high-output and multi-size capabilities, R&D should prioritize flexibility and energy efficiency to match evolving customer requirements in food processing and industrial cleaning.
- Compliance Integration: Safety regulations are tightening. Equipment that integrates monitoring and ventilation compliance features directly into the production system may gain preference in regulated industries like pharmaceuticals and food safety.
- Regional Strategy: While global growth is steady, regional disparities require tailored approaches. Distributors and sales teams need localized data to identify regions where infrastructure supports dry ice adoption versus those hindered by supply chain or regulatory hurdles.
- Supply Chain Resilience: Given the volatility in CO2 feedstock prices, partnerships with reliable gas suppliers and investment in machines with high conversion efficiency will be key to maintaining margins.
Ultimately, navigating this market requires more than a glance at the headline CAGR. It demands a deep dive into the segmentation splits, competitive maneuvers, and regulatory undercurrents that define the daily operations of the industry. Our comprehensive market research report is designed to provide that depth. It offers the specific breakdowns, detailed company profiles, and forward-looking risk assessments necessary to build a resilient strategy.
To access the full suite of data, including precise regional valuations, detailed application segment sizes, and complete competitive benchmarking, we invite you to review the full publication. The insights contained within are crafted to support informed decision-making, ensuring that your organization is prepared to lead rather than follow in the evolving landscape of dry ice production and blasting technology.
For detailed analysis of this topic, please visit the official page: Dry Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PPS Resin Market to Hit $3.47B by 2032, Driven by 7.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Polyphenylene Sulfide Landscape: Strategic Imperatives for 2026 and Beyond
In an era defined by accelerated material innovation, supply chain volatility, and stringent sustainability mandates, the global Polyphenylene Sulfide (PPS) resin market stands at a critical inflection point. For corporate strategists, procurement leaders, and R&D directors across high-performance engineering sectors, the ability to anticipate demand trajectories, identify emerging capacity shifts, and decode competitive positioning is no longer a luxury. It is a prerequisite for sustained market share and margin protection. Our newly released PPS Resin Market Research Report delivers exactly that: a rigorously validated, forward-looking intelligence framework calibrated to guide executive decision-making through 2032 and beyond.
The macro trajectory tells a compelling story. From a baseline of USD 1,450.0 Million in 2020, the market has consistently compounded upward, reaching USD 2,020.0 Million in 2025. Our baseline forecast projects the sector will exceed USD 2,143.6 Million in 2026 and continue its upward march to USD 3,470.0 Million by 2032. Anchored by a robust compound annual growth rate of 7.8 percent, the expansion is neither accidental nor cyclical. It reflects structural demand drivers, evolving material substitution patterns, and deliberate capacity reallocation by Tier-1 producers who are actively reshaping the competitive architecture. Yet, headline figures only scratch the surface. The real strategic value lies in understanding the mechanics beneath the aggregate numbers: how demand is being reallocated across value chains, where production bottlenecks are forming, and which players are positioning themselves to capture disproportionate share in high-margin end-use segments.
This intelligence brief serves as a strategic preview. It outlines the core analytical pillars embedded in our full study, highlights the competitive dynamics currently redrawing the market map, and demonstrates how procurement and product development teams can leverage granular, actionable data to optimize sourcing strategies, de-risk supply chains, and accelerate time-to-market for next-generation engineered components.
Polysulfone Resin Market
Decoding the Report Architecture: What Decision-Makers Will Gain
Our research methodology is built on a multi-layered analytical framework that moves far beyond top-line market sizing. The full report synthesizes historical trajectory data, forward-looking demand modeling, supply-side capacity mapping, and application-specific consumption patterns into a unified decision-support toolkit. Rather than presenting static snapshots, we track momentum. The historical period from 2020 to 2025 establishes the baseline behavior of the market across economic cycles, raw material fluctuations, and regional demand shocks. The forecast window from 2026 through 2032 extends that modeling into scenario-weighted projections that account for macroeconomic variables, technological adoption curves, and regulatory inflection points.
Throughout the document, readers will encounter structured analytical modules designed for direct operational translation. These include demand-side consumption mapping across major end-use verticals, supply-side capacity and utilization tracking by manufacturing geography, and segmentation analysis that isolates growth vectors within resin type categories and application clusters. Each module is cross-referenced with pricing sensitivity indicators, feedstock dependency assessments, and sustainability compliance tracking. The goal is to equip strategists with a complete operational lens: one that connects macroeconomic demand signals to plant-level capacity decisions, and links regulatory developments to formulation and sourcing strategies.
Crucially, the report is structured to support iterative decision-making. Executives can use it to stress-test procurement portfolios, identify long-term supply continuity risks, evaluate joint-venture or contract-manufacturing opportunities, and benchmark internal performance against industry growth curves. R&D and product development teams will find targeted insights into grade differentiation, thermal and chemical resistance requirements, flow characteristics for high-volume injection molding, and the growing importance of recycled-content variants in meeting corporate sustainability targets.
Competitive Recon: Mapping the Architecture of Market Leadership
Market concentration in the global PPS resin sector remains pronounced, with the top three producers collectively accounting for approximately 65 percent of total revenue and the top five controlling roughly 80 percent. This concentration does not imply stagnation. On the contrary, it reflects deliberate capital allocation, technological specialization, and strategic geographic positioning by a tightly aligned group of performance-material manufacturers who are competing on grade formulation, regulatory certification, recycling capability, and application-specific value engineering.
At the heart of this competitive ecosystem sits Celanese Corporation, whose Fortron® PPS resin portfolio has long been associated with high thermal stability, chemical resistance, and consistent performance in automotive and industrial injection molding applications. Operating from Dallas, Texas, Celanese continues to reinforce its position through grade optimization, processing reliability, and deep integration into Tier-1 supply chains. Across the Atlantic, Solvay S.A. has built a formidable presence through its Ryton® PPS brand and Supreme series grades, targeting high-voltage electrical applications, high-flow engineering requirements, and increasingly, sustainability-certified production pathways. The company's ongoing pursuit of mass-balance certification and its footprint across Texas and Belgium underscore a dual focus on performance and compliance-driven market access.
The Asian manufacturing corridor continues to exert structural influence. Toray Industries, Inc. has systematically expanded its Torelina® PPS resin portfolio to serve high-performance automotive and electronics applications, recently completing a second production line expansion at its Gunsan plant in Korea to reinforce regional capacity resilience. DIC Corporation and Kureha Corporation have maintained steady positioning in industrial and automotive segments, with Kureha placing particular emphasis on high-temperature and flame-resistant grades that align with stringent safety specifications in electrical and transport equipment. Tosoh Corporation serves as a specialized supplier across electrical and high-performance engineering applications, while Polyplastics Co., Ltd. has carved a distinct niche through its DURAFIDE® PPS grades, recently advancing into mechanically recycled-content formulations that respond directly to corporate sustainability mandates and circular-economy procurement standards. Rounding out the competitive matrix, Ensinger GmbH provides compounded PPS materials and precision-machining-ready resin solutions for industrial components, reinforcing Europe's role as a hub for specialized, high-value-added formulations.
Recent operational moves by key players confirm that the competitive landscape is actively recalibration. In May 2025, Syensqo announced a capital investment to expand PPS compounding capability at its Augusta, Georgia manufacturing site for Ryton-branded compounds, signaling a strategic push into North American downstream processing and localized supply chain responsiveness. Later in the year, Toray Industries completed the expansion of its second PPS production line at its Gunsan facility in Korea, reinforcing its capacity footprint and regional supply agility. In January 2026, Polyplastics Co., Ltd. launched two new DURAFIDE® PPS grades made from mechanically recycled content, a move that directly intersects with the growing procurement preference for sustainable resin inputs and circular material sourcing.
These developments are not isolated corporate announcements. They are indicators of structural realignment: capacity is being deliberately placed closer to key demand clusters, compounding and formulation capabilities are being expanded to capture higher-margin downstream value, and sustainability certification is transitioning from a compliance checkbox to a competitive differentiator. Understanding who is expanding, where, and why is essential for any organization seeking to optimize long-term sourcing strategy or position new products in high-growth application corridors.
Structural Dynamics Shaping the 2026 Horizon
The trajectory of the PPS resin market is being shaped by an interlocking set of technical, economic, and regulatory forces. At the raw material level, PPS production relies on the polymerization of dichlorobenzene and sodium sulfide as foundational feedstocks. Pricing and supply continuity for these commodity inputs remain highly sensitive to broader chemical market dynamics, and procurement teams must track these dependencies closely as they translate into resin cost structures and margin variability. In the third quarter of 2025, North American PPS prices rose to approximately USD 11,250 per metric ton, driven by intensified demand pull from the automotive and electronics sectors. This price behavior is not an isolated event; it reflects how demand acceleration in high-value applications can rapidly transmit through regional pricing structures, particularly when capacity expansion timelines lag behind consumption growth.
Regulatory and sustainability frameworks are equally influential. The attainment of ISCC PLUS 2 mass-balance certification for PPS production facilities in Texas and Belgium demonstrates how major producers are institutionalizing sustainable manufacturing pathways. As downstream OEMs and Tier-1 suppliers face mounting corporate sustainability targets and customer-facing carbon disclosure requirements, certified sustainable resin inputs are evolving from a niche preference to a qualifying factor in procurement evaluations. The strategic implication is clear: organizations that embed sustainability compliance into sourcing criteria will not only mitigate reputational and regulatory risk but will also gain preferential access to supply from producers who have already navigated the certification pathway.
On the technology and application side, continuous advancements in resin formulation are expanding the boundaries of where PPS can be deployed. Enhancements in thermal stability, chemical resistance, flow characteristics, and flame-retardant performance are enabling deeper penetration into demanding engineering applications where traditional thermoplastics and lower-performance engineering resins fall short. Simultaneously, the rise of recycled-content grades is creating new procurement dynamics. As mechanically recycled PPS formulations gain commercial traction, buyers are confronted with a more complex sourcing landscape that requires evaluation of material consistency, processing compatibility, certification alignment, and total cost of ownership rather than simple price-per-kilogram comparisons.
Strategic Positioning for 2026 and the Road to 2032
As the market moves from baseline recovery and consolidation into an accelerated growth phase, several strategic imperatives are coming into sharp focus for organizations operating in or adjacent to the PPS value chain. First, supply chain resilience must be treated as a structural capability rather than a short-term risk mitigation exercise. The concentration of capacity among a small group of large-scale producers, combined with regional price sensitivity and feedstock dependency, means that diversification of sourcing relationships, forward contracting strategies, and awareness of capacity expansion timelines are essential to maintaining continuity and cost predictability.
Second, application-specific demand mapping should inform both procurement and product development roadmaps. As automotive electrification, high-performance electronics, aerospace component requirements, and industrial precision-machining demand continue to shape consumption patterns, organizations that understand which end-use verticals are accelerating, which are stabilizing, and which are emerging will be better positioned to align capacity acquisition, inventory planning, and new product introductions.
Third, sustainability is becoming a procurement qualifier, not an aspirational add-on. Certified sustainable production pathways, recycled-content grades, and compliance with evolving regulatory expectations are increasingly influencing supplier selection. Organizations that proactively embed these criteria into supplier qualification, technical evaluation, and contract negotiation will reduce exposure to future compliance shocks while strengthening alignment with downstream customer expectations.
Finally, competitive intelligence must be continuous. The recent capacity expansions, grade launches, and certification milestones among leading producers confirm that the market is structurally dynamic. Tracking these moves, understanding the geographic and application logic behind them, and anticipating their downstream impact on pricing, availability, and formulation options will be a decisive factor in maintaining competitive advantage over the next planning cycle and beyond.
PPS Resin Market
Closing the Intelligence Gap
Headline growth rates and aggregate market sizes provide orientation, but they rarely provide direction. Real strategic advantage comes from understanding the mechanics beneath the numbers: how capacity is being reallocated, how grade differentiation is reshaping application eligibility, how sustainability certification is filtering supplier pools, and how pricing behavior reflects demand shifts in high-value end-use sectors. Our full PPS Resin Market Research Report is designed to close that intelligence gap. It translates historical trajectory, forward-looking modeling, competitive mapping, and structural dynamics into a decision-ready framework that procurement, strategy, and engineering teams can apply directly to sourcing plans, capacity negotiations, product roadmaps, and market-entry evaluations.
For organizations preparing for the 2026 decision cycle, the window to build a comprehensive, evidence-backed view of the PPS resin market is open now. The full report provides the granular segmentation detail, regional and application-level consumption trajectories, pricing sensitivity modeling, competitive positioning analysis, and scenario-weighted forecasts needed to move from reactive monitoring to proactive strategy. We invite you to access the complete study on our website, where you will find the full data architecture, detailed segmentation contours, and executive-ready synthesis required to navigate the next phase of market expansion with confidence.
For detailed analysis of this topic, please visit the official page: PPS Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Piston Engines Market to Hit USD 7,152.97M by 2032 at 5.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Sky: Strategic Intelligence for the Aircraft Piston Engines Market (2026-2032)
The global aviation landscape is undergoing a subtle yet profound transformation. While much attention dominates the headlines regarding sustainable aviation fuels and electric propulsion, the heartbeat of general aviation remains steadfastly dependent on the internal combustion piston engine. For stakeholders, investors, and strategic planners, understanding the trajectory of this mature yet evolving market is not merely an academic exercise—it is a critical component of risk mitigation and growth strategy for the 2026 fiscal year and beyond.
PW Consulting is proud to introduce our comprehensive market intelligence report on the Aircraft Piston Engines Market. This document serves as a strategic compass for navigating the complexities of engine manufacturing, aftermarket support, and regulatory compliance over the forecast period extending to 2032. By synthesizing historical data with forward-looking projections, this study provides the granularity required to make informed capital allocation and product development decisions.
Market Trajectory and Historical Context
The resilience of the piston engine sector is evident when examining the revenue trends over the past half-decade. From 2020 to 2025, the market demonstrated a consistent upward trajectory, recovering from global supply chain disruptions and ramping up to meet renewed demand in general aviation. Revenue figures have climbed steadily, reflecting both increased production rates and healthy pricing power within the supply chain.
Looking forward, the market is projected to expand from an estimated 5,270 million USD in 2026 to approximately 7,153 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent throughout the forecast period. This rate suggests a market that is not only recovering but maturing, driven by replacement cycles, fleet expansion in emerging economies, and technological upgrades in existing airframes. For decision-makers, these top-line figures validate the sector as a stable investment vehicle with predictable long-term returns, though the allocation of these revenues across different segments requires deeper analysis provided in our full report.
Segmentation Dynamics: Types, Applications, and Geography
Understanding where value is generated within the market is crucial for targeting investments. The market is divided into distinct categories based on engine architecture, operational application, and regional demand. While specific percentage splits are detailed within the proprietary sections of our study, the structural composition reveals key preferences among manufacturers and operators.
In terms of engine type, the market is anchored by Horizontally Opposed, Inline, and Radial configurations. The dominance of certain architectures often correlates with specific aircraft categories, influencing supply chain requirements and manufacturing capabilities. Similarly, the application landscape is diversified across Training, Aerial Work, and Private and Recreational segments. The training sector, for instance, remains a critical volume driver due to the perpetual need for pilot certification, whereas aerial work demands durability and specific performance metrics. Private and recreational use continues to be a significant contributor, fueled by hobbyist enthusiasm and personal aviation ownership.
Geographically, the demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, economic conditions, and fleet ages that dictate consumption patterns. Our analysis highlights how regional discrepancies in certification standards and economic growth rates create varied opportunities for engine manufacturers and service providers.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established legacy manufacturers and innovative entrants focusing on alternative fuel capabilities. The market concentration, indicated by a CR5 of 26.2 percent, suggests a moderately fragmented industry where niche players can still carve out significant market share through specialization.
Lycoming Engines, based in Williamsport, Pennsylvania, remains a cornerstone of the industry. Their production of four-, six-, and eight-cylinder piston engines up to 400 horsepower supports a vast array of general aviation, training, and commercial aircraft. Notably, their engines power over half of the world's general aviation fleet, establishing a reputation for reliability that creates high switching costs for operators.
Continental Aerospace Technologies, headquartered in Mobile, Alabama, competes closely with a focus on advanced designs. They manufacture piston engines capable of running on both Jet-A and avgas, accumulating over 12 million flight hours. Their recent moves highlight a strategic pivot towards fuel flexibility and certification in new sectors.
Aircraft Piston Engines Market
BRP-Rotax, located in Austria, serves a specialized niche by developing engines for light sport, ultralight, and training aircraft. Their focus on the lower end of the weight and power spectrum allows them to dominate segments where traditional general aviation engines are too large or costly.
DeltaHawk Engines, based in Racine, Wisconsin, represents the innovative frontier. They manufacture FAA-certified jet-fuel-burning piston engines, such as the DHK180 and DHK6A350. By enabling the use of heavy fuel in piston engines, they address logistical advantages in remote operations and reduce dependency on traditional avgas supplies.
Recent Developments and Technological Shifts
The period leading into 2026 has seen significant activity regarding product launches and certifications that will shape the next cycle of market growth. These events signal a shift towards fuel flexibility and expanded operational envelopes.
In July 2025, Piper Aircraft, Inc. announced the Piper Seminole DX, powered by DeltaHawk's FAA-certified DHK4A180 180-hp heavy fuel engine. The order book opened at EAA AirVenture 2025, marking a tangible entry of heavy-fuel piston technology into multi-engine training and commercial applications. This development is particularly significant given the regulatory backdrop. FAA certification flight testing for the Piper Seminole DX with the DeltaHawk engine commenced in November 2025, with certification expected in Q3 2026. This timeline suggests that full market availability and subsequent fleet integration will accelerate demand in the latter half of the forecast period.
Continental Aerospace Technologies achieved a milestone in April 2026 by receiving EASA approval for the CD-170R Jet-A piston engine for rotorcraft applications. This marks the first certified Jet-A FADEC-controlled helicopter piston engine. By bridging the gap between fixed-wing efficiency and rotary-wing operational needs, this certification opens a new revenue stream that was previously inaccessible to piston engine manufacturers.
Jet Engines Market
Simultaneously, DeltaHawk Engines achieved FAA Type Certification for the DHK180 jet-fuel piston engine in June 2025, with the first flight occurring in a Van's RV-14. This certification validates the technical viability of heavy-fuel piston engines in experimental and general aviation categories, encouraging further adoption among builders and operators seeking fuel security.
These technological strides are supported by broader industry data. The General Aviation Manufacturers Association (GAMA) reported that piston airplane deliveries increased by 4.2 percent in 2024 to 1,772 units. This uptick in unit shipments provides a strong foundational demand signal for engine manufacturers, indicating that airframe production is aligning with engine supply capabilities.
Strategic Implications for 2026 Decision-Makers
For executives and planners preparing budgets and strategies for 2026, several implications arise from this landscape. First, the reliance on avgas remains a strategic vulnerability for many operators, making the adoption of Jet-A capable engines a potential risk mitigation strategy. The certifications achieved by Continental and DeltaHawk in 2025 and 2026 provide viable alternatives that should be evaluated against total cost of ownership and logistics.
Second, the fragmentation of the market means that partnership opportunities exist beyond the top tier. With a CR5 of only 26.2 percent, there is room for specialized manufacturers to thrive, particularly in training and aerial work segments where specific power-to-weight ratios are prioritized over raw horsepower. Supply chain resilience is also paramount; understanding the geographic distribution of demand helps in positioning inventory and service centers to minimize downtime.
Finally, regulatory timelines are critical path items. The expected FAA certification for the Piper Seminole DX in Q3 2026 is a catalyst that could spur orders in the training and commuter segments. Stakeholders should align their procurement and hiring strategies to anticipate the ripple effects of this certification on maintenance training and parts inventory.
Report Scope and Methodology
This strategic insight is derived from a robust methodology that combines primary research with extensive secondary data analysis. The full report offers a deep dive into the factors influencing market growth, including regulatory frameworks, technological innovations, and economic indicators.
Readers of the complete study will gain access to detailed segmentation analysis that breaks down market value by region, type, and application, allowing for precise market sizing. The competitive profiling extends beyond basic company statistics to include strategic positioning, recent M&A activity, and product pipeline assessments. Furthermore, the report addresses the constraints and challenges facing the industry, such as fuel availability, emission standards, and supply chain bottlenecks.
Our analysis covers the forecast period from 2026 to 2032, providing a long-term view that supports capital expenditure planning and technology roadmap development. Whether you are a manufacturer looking to expand your portfolio, an investor assessing market entry barriers, or an operator optimizing fleet composition, the data contained herein is tailored to support those specific objectives.
Conclusion
The Aircraft Piston Engines Market stands at a inflection point where traditional reliability meets modern fuel flexibility. The growth projected through 2032 is not merely a reflection of historical trends but a result of active innovation in engine technology and expanding operational scopes. For organizations aiming to lead in this sector, access to granular, verified data is the differentiator between reactive management and proactive strategy. This report provides the foundation necessary to navigate the coming years with confidence.
For detailed analysis of this topic, please visit the official page: Aircraft Piston Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vehicle Roadside Assistance Market to Hit $42.77B by 2032, 5.3% CAGR
By PW Consulting, 2026-09-16
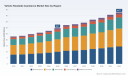
Strategic Imperatives in the Global Vehicle Roadside Assistance Market: A 2026 Outlook
The vehicle roadside assistance industry stands at a critical inflection point as it moves through 2026. Driven by shifting consumer expectations, the electrification of fleets, and an increasingly complex regulatory environment, the sector is undergoing a transformation that demands precise, data-backed strategic planning. For executive leadership teams, investors, and operational decision-makers, navigating this landscape without granular intelligence is no longer viable. Our newly released Vehicle Roadside Assistance Market research report provides the comprehensive analytical framework required to turn market volatility into competitive advantage.
This analysis is not merely a retrospective of market performance. It is a forward-looking strategic instrument designed to inform capital allocation, partnership structuring, geographic expansion, and technology investment decisions through 2032. By synthesizing historical performance data with rigorous forecasting models, the report reveals the structural forces that will define winners and laggards in the coming years.
Market Trajectory: From Historical Resilience to Forecasted Expansion
The global vehicle roadside assistance market has demonstrated consistent growth over the past half-decade, reflecting the essential nature of emergency mobility services in modern transportation ecosystems. Historical data from 2020 through 2025 illustrates a steady upward trajectory, with the market expanding from a baseline revenue of 22.8 billion USD to 29.7 billion USD. This compound growth reflects enduring demand across both consumer and commercial segments, even as the industry contended with supply chain disruptions, labor market tightness, and evolving safety protocols.
Looking ahead, our forecast period spanning 2026 to 2032 projects continued expansion, with the market expected to reach 42.77 billion USD by the end of the forecast window. This growth is anchored by a forecasted compound annual growth rate of 5.3 percent, signaling a mature yet dynamically evolving industry. The midpoint of this trajectory, with 2026 revenue projected at 32.26 billion USD and 2027 at 32.95 billion USD, underscores a market that is not experiencing a transient spike but rather sustaining a methodical climb. For strategic planners, this persistence suggests that roadmap decisions made in 2026 will compound in significance as the market approaches the 40 billion USD threshold toward the decade's end.
Crucially, these top-line figures represent only the surface layer of our analysis. The report deconstructs the underlying drivers, volume-to-value shifts, and regional asymmetries that shape these totals, providing the depth required for actionable strategy. Decision-makers who rely on aggregate numbers alone risk missing the nuanced opportunities hidden within service type dynamics, application-segment behaviors, and geographic growth pockets. The full intelligence is detailed within the complete report, where segmented projections and sensitivity analyses equip leaders to model multiple scenarios with precision.
Industry Dynamics: Labor, Regulation, and Operational Risk
The market does not operate in a vacuum. Several macro-level forces are actively reshaping cost structures, compliance obligations, and service delivery models across the roadside assistance value chain. Understanding these dynamics is essential for building resilient operational strategies that can withstand external shocks.
Labor costs represent a persistent pressure point. According to data released by the U.S. Bureau of Labor Statistics in April 2026, private industry worker compensation costs rose 3.4 percent over the year ending March 2026. For roadside assistance operators, whose business models depend heavily on skilled field personnel, tow truck operators, and dispatch coordinators, rising compensation expenses directly impact margins. Companies that fail to integrate workforce cost escalation into their pricing strategies, route optimization algorithms, or automation roadmaps will find their profitability eroding. Our report examines how leading operators are responding, from technology-enabled dispatch efficiencies to strategic fleet partnerships that redistribute labor intensity.
Regulatory scrutiny is simultaneously intensifying across key jurisdictions. In the United States, Colorado now requires towing carriers to submit operational towing data for the previous calendar year by February 1, 2026, reflecting a broader trend toward data transparency and regulatory oversight. Meanwhile, Maine's working group concluded in January 2026 that formal regulation is needed for the statewide towing and roadside assistance industry under the Board of Motor Vehicle oversight. These developments signal a shift from informal industry self-governance toward structured compliance frameworks. In California, towing and roadside assistance operations are separately classified under code 7227 for insurance reporting purposes, a nuance with significant implications for risk assessment, coverage structuring, and inter-state operational planning. Our report maps these and other regulatory currents, helping organizations anticipate compliance costs and align their operational footprints accordingly.
Operational safety remains a non-trivial concern. Research from the AAA Foundation for Traffic Safety in 2024 highlighted the elevated risk roadside assistance providers face of being struck by vehicles while assisting stranded motorists. This safety dimension influences insurance premiums, workforce retention, and the design of service protocols. Companies that invest in enhanced safety training, improved vehicle visibility technologies, and digital coordination tools that minimize on-site exposure are better positioned to manage both human and financial risk. The report explores how safety-driven innovation intersects with customer experience and cost management.
24 Hour Emergency Roadside Assistance Market
Competitive Landscape: Ecosystem Players and Strategic Positioning
The competitive architecture of the vehicle roadside assistance market is multifaceted, encompassing traditional consumer service providers, white-label digital platforms, insurance-integrated offerings, OEM ownership programs, and specialized networks for niche vehicle segments. This diversity creates both collaboration opportunities and competitive friction, and understanding where each player fits is critical for partnership strategy and market entry decisions.
In North America, AAA remains a primary provider of consumer roadside assistance, leveraging a combination of in-house fleets and independent service providers to deliver emergency towing, tire changes, lockout services, and minor repairs. Its brand recognition and broad membership base position it as adefault reference point in the consumer segment. Alongside AAA, insurance carriers such as Allstate, GEICO, and Progressive offer roadside assistance as optional or integrated coverage within auto insurance policies, embedding emergency services into the broader risk management ecosystem. This insurance-led model creates a distinct value proposition centered on policyholder convenience and bundled pricing.
The digital transformation of roadside assistance is perhaps most evident in the rise of platform operators like Agero, Inc. As a leading white-label digital roadside assistance platform and network operator, Agero serves insurance companies, fleets, and OEMs, processing more than 14 million annual dispatches while integrating deeply into vehicle policies and mobility programs. Agero's strategic momentum in 2026 underscores this direction: in May 2026, the company renewed its multi-year partnership with Hagerty to deliver premium roadside assistance services tailored to enthusiast vehicles through the Hagerty Drivers Club, and simultaneously completed the acquisition of Urgently to expand its tech-driven network across automotive, fleet, rental, and insurance markets. These moves illustrate how platform players are scaling through both partnership depth and consolidated network reach.
Across Europe, the competitive landscape is characterized by network operators and integrated service providers with strong OEM and fleet ties. ARC Europe SA, headquartered in Belgium, operates a European roadside assistance network focused on OEM and fleet digital platforms, providing towing, lockout, and minor repair services with an emphasis on real-time information and electrification compatibility. In February 2026, ARC Europe published analysis on 2026 driver expectations for transparency, real-time ETA visibility, and digital communication, citing electrification as a key driver of changing service requirements. Viking Assistance Group AS, based in Norway, provides roadside assistance including heavy-duty and commercial vehicle support across Europe, with a focus on fleet and insurance partnerships. In Denmark, SOS International A/S delivers global roadside assistance and recovery services primarily for commercial and fleet vehicles, while Falck A/S offers full-service roadside assistance including towing, battery service, and subscription-based vehicle support across Northern Europe. Allianz Partners, headquartered in France, rounds out the European contingent by embedding integrated roadside assistance solutions within insurance and mobility programs, coordinating towing, mechanical assistance, and claims processes.
OEMs represent another strategic axis. Ford Motor Company offers 24/7 roadside assistance and support benefits to owners through warranty and ownership programs. Nissan Motor Corporation provides nationwide 24/7 assistance for vehicle owners, including towing, jump starts, and emergency lockout service. Hyundai Motor Company guarantees five-year 24/7 roadside assistance coverage under its Hyundai Assurance program. Lincoln Motor Company delivers lifetime 24/7 assistance for qualifying vehicles, including fuel delivery and emergency support. Mazda Motor Corporation offers complimentary roadside assistance for new vehicles, covering three years of flat tire, lockout, and towing services. Subaru Corporation provides 24-hour nationwide assistance for owners, covering towing, jump starts, flat tire changes, and gas delivery. These OEM programs illustrate how vehicle manufacturers use roadside assistance as a value-added differentiator, strengthening brand loyalty and ownership experience.
Finally, specialized networks such as Good Sam Enterprise, LLC address underserved segments, providing roadside assistance tailored to RV, marine, and specialty vehicle owners through insurance and membership programs. This segmentation highlights how niche focus can command premium positioning and foster deep customer relationships outside the mainstream passenger and commercial vehicle segments.
Report Scope: Operational Intelligence for Strategic Execution
To translate market awareness into executable strategy, leaders require more than high-level trends. The Vehicle Roadside Assistance Market report delivers a structured, operationally relevant body of intelligence designed for immediate application in planning cycles. The report's architecture ensures that every section serves a decision-making purpose.
Key components of the report include:
- Comprehensive historical market sizing from 2020 through 2025, establishing a validated baseline for trend analysis and model calibration
- Forward-looking revenue forecasts segmented across the 2026 to 2032 horizon, enabling scenario planning and investment prioritization
- A detailed breakdown of service type dynamics, including towing services, tire replacement services, and other service categories, with qualitative and quantitative insights into demand drivers and service mix evolution
- An application-segment analysis covering passenger cars, commercial vehicles, and other application areas, with attention to usage patterns, fleet composition shifts, and commercial versus consumer demand differentials
- A regional assessment that evaluates market maturity, growth catalysts, and competitive intensity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa
- A competitive landscape review that profiles core companies, maps their strategic positioning, and analyzes recent developments such as partnerships, acquisitions, and industry analyses that signal future market direction
- An in-depth examination of industry dynamics, including labor cost trajectories, regulatory developments, safety considerations, and their combined impact on operational design and margin management
- Strategic recommendations tailored to distinct stakeholder roles, including service providers, platform operators, insurers, OEMs, fleet managers, and investors
Each section is built to stand alone as a reference for specific functional teams while also integrating into a cohesive strategic narrative. The report's segmentation analysis, in particular, provides the granularity needed to identify where growth is concentrated, which service categories are gaining relative share, and how application-level demand is shifting in response to vehicle technology evolution and fleet composition changes. These insights are deliberately developed to support resource allocation decisions, partnership targeting, and market entry sequencing.
Why This Intelligence Matters for 2026 Decision-Making
The 2026 operating environment rewards organizations that can align strategic vision with empirically grounded market intelligence. Several factors make this report particularly timely for current decision-making cycles.
First, the convergence of digitalization, electrification, and regulatory change is restructuring how roadside assistance is delivered, priced, and integrated into broader mobility and insurance ecosystems. Organizations that understand these interconnections can design offerings that anticipate rather than react to market shifts. The report's analysis of recent developments, such as Agero's partnership renewal with Hagerty and its acquisition of Urgently, alongside ARC Europe's published analysis on driver expectations and electrification, provides concrete reference points for how industry leaders are positioning themselves in real time.
Second, the forecasted growth trajectory to 2032 creates a window for strategic investment in network expansion, technology infrastructure, and partnership development. However, the distribution of growth is not uniform. Segments and regions will outperform or lag based on structural factors that aggregate numbers cannot reveal. Accessing the full segmentation analysis allows decision-makers to direct capital and operational effort toward the highest-probability opportunities while avoiding areas where competitive saturation or regulatory headwinds may compress returns.
Third, the competitive landscape's breadth means that partnership strategy has become as important as organic capability building. Whether an organization is an insurer seeking embedded assistance solutions, an OEM designing ownership benefits, a fleet manager optimizing total cost of ownership, or a platform operator pursuing network consolidation, identifying the right partners and understanding their strategic incentives is essential. The report's company profiles and recent developments section equip teams to evaluate potential alliances with a clear view of each player's capabilities, market focus, and momentum.
Finally, the operational pressures surrounding labor costs, compliance, and safety are not transient. They represent structural components of the cost and risk equation that must be factored into pricing strategy, service design, and technology investment Roadside assistance providers face elevated risk of being struck by vehicles while assisting stranded motorists, a reality that influences everything from insurance costs to workforce planning. Meanwhile, the 3.4 percent rise in private industry worker compensation costs and the emergence of new regulatory reporting requirements in jurisdictions such as Colorado and Maine demonstrate that cost and compliance management are becoming increasingly sophisticated disciplines. The report translates these dynamics into strategic considerations, helping organizations build operating models that are both efficient and resilient.
Vehicle Roadside Assistance Market
Conclusion: Access the Full Strategic Picture
The vehicle roadside assistance market in 2026 is defined by steady growth, structural transformation, and an intensifying competitive agenda. The headline figures, a market moving from 29.7 billion USD in 2025 toward 42.77 billion USD by 2032 at a compound annual growth rate of 5.3 percent, tell a story of sustained opportunity. But the real strategic value lies beneath the surface, in the segmentation patterns, regional asymmetries, competitive maneuvers, and operational dynamics that determine where value is created and captured.
This article has previewed the scope and strategic relevance of our Vehicle Roadside Assistance Market research. It has outlined the market trajectory, the industry dynamics shaping cost and compliance, the competitive landscape spanning consumer providers, digital platforms, insurers, OEMs, and specialty networks, and the operational intelligence embedded in the full report. What remains are the precise segmentation figures, regional breakdowns, and detailed forecasts that enable confident, specific decision-making.
For executives who need to move from market awareness to executable strategy, the complete report provides the depth, structure, and actionable insight required. We invite you to access the full research to explore the comprehensive segmentation analysis, competitive profiles, regulatory mapping, and forward-looking forecasts that will inform your 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Vehicle Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mesalazine Market Hits $215M in 2025, Projects 3.7% CAGR Through 2032
By PW Consulting, 2026-09-16
Unlocking the Mesalazine Market: Strategic Intelligence for the 2026–2032 Horizon
As inflammatory bowel disease (IBD) continues to impose a growing clinical and economic burden across global healthcare systems, the mesalazine (mesalamine) market stands at a critical inflection point. Between 2020 and 2025, the market expanded steadily from approximately 169.0 million USD to 215.0 million USD, reflecting sustained demand for first-line aminosalicylate therapies and the gradual maturation of regulatory pathways for generic entry. Looking ahead, our latest market research projects the global mesalazine market to reach 224.36 million USD in 2026, with a compound annual growth rate of 3.7% driving the sector toward 277.0 million USD by 2032. For pharmaceutical executives, commercial leaders, and supply chain strategists, these figures are more than macro indicators. They are signals of where capital, regulatory attention, and competitive friction will concentrate over the next seven years.
This article serves as a strategic preview of our comprehensive Mesalazine Market report. It outlines the structural dynamics shaping the sector, highlights the competitive and regulatory forces that will dictate performance in 2026 and beyond, and explains why data-driven scenario planning is no longer optional for firms operating in this space. The full report provides a granular, decision-ready intelligence package. What follows is designed to demonstrate the depth of our analysis while preserving the proprietary segmentation and modeling details that you will need to access directly to build your own action plans.
Why 2026 Demands a Fresh Strategic Lens
The 2026–2032 forecast window is not merely an extension of historical trends. It is a period defined by overlapping shifts in clinical practice, regulatory volatility, and supply chain economics. Over the historical period from 2020 to 2025, the market demonstrated a consistent upward trajectory, with annual revenues climbing from 177.59 million USD in 2021 to 208.96 million USD in 2024, before settling at 215.0 million USD in 2025. This pattern reflects a market that has moved past early-cycle adoption and is now navigating the complexities of generic proliferation, formulation differentiation, and regional supply constraints.
For decision-makers, the strategic question in 2026 is no longer whether mesalazine demand will grow, but how to position product portfolios, sourcing strategies, and regulatory engagement to capture value in a market that is simultaneously expanding and fragmenting. Our report is built around that question. It translates top-line growth into actionable intelligence across dosage forms, clinical applications, and geographic markets, while explicitly mapping the risks and opportunities that generic competition, shortages, and tariff-driven cost pressures introduce into forecasting models.
What Our Research Delivers: Operational Intelligence Beyond Headlines
A market study earns its place in a strategic planning cycle only when it equips teams to make concrete decisions. Our Mesalazine Market report is structured to move beyond narrative description and deliver operational precision. The analytical framework covers the full value chain, from active pharmaceutical ingredient (API) sourcing and regulatory filings to finished dosage form commercialization and patient-level demand drivers.
Mesalazine Market
At the core of the report is a multi-dimensional segmentation architecture that decomposes market size by dosage form, clinical application, and region. Rather than presenting isolated percentage splits, the analysis integrates these dimensions into a cohesive view of where volume concentrates, how formulation preferences vary across indication profiles, and why certain markets exhibit faster revenue conversion than others. This integrated approach allows commercial teams to stress-test product positioning, evaluate go-to-market timing, and identify underserved niches without relying on blunt aggregate metrics.
Equally important is the report’s treatment of competitive dynamics. The mesalazine sector features a diverse ecosystem of API specialists, formulation manufacturers, and branded product owners, many of whom operate across overlapping regulatory territories. Our analysis maps these players not simply by revenue share, but by manufacturing capability, certification portfolios, geographic reach, and recent market actions. That mapping is essential for understanding where supply resilience is strong, where single-source dependencies create exposure, and where new generic entrants are reshaping pricing and access expectations.
The report also incorporates a forward-looking regulatory and supply chain overlay. This includes tracking of recent FDA approvals, European Medicines Agency procedure outcomes, documented product shortages, and trade-policy developments that influence API cost structures. By embedding these variables into the market narrative, the research enables scenario planning that reflects real-world friction rather than idealized linear growth.
Competitive Landscape: From API Specialists to Branded Formulators
The mesalazine competitive landscape is best understood as a layered ecosystem. At the foundation sit API manufacturers and bulk suppliers whose certification portfolios and capacity footprints shape the cost and availability of the active ingredient. Firms such as PharmaZell, Zhejiang Hengkang Pharmaceutical Co. Ltd., LGM Pharma, Metrochem API Private Limited, IOL Chemicals and Pharmaceuticals, CTX Lifesciences, Syntese A/S, Ajinomoto OmniChem N.V., and Zydus Lifesciences represent a broad geographic spread across Europe, China, the United States, and India. Their common thread is a focus on mesalazine API supply supported by regulatory documentation including USDMF and CEP filings, which facilitates cross-border distribution and reduces friction for downstream formulation partners.
Above this API layer, branded and generic finished-product companies compete on formulation technology, release mechanisms, and clinical positioning. Ferring Pharmaceuticals and Tillotts Pharma AG have historically anchored significant branded presence through products such as Pentasa, Mezavant, and Asacol, building recognition in ulcerative colitis and related indications. At the same time, generic entrants such as Amneal Pharmaceuticals Inc. have expanded access through product launches referencing established branded benchmarks, including Amneal’s 2025 introduction of mesalamine 800 mg delayed-release tablets aligned with ASACOL HD for moderately active ulcerative colitis in adults. DifGen Pharmaceuticals further intensified competitive pressure in 2025 when it received FDA approval for generic mesalamine extended-release capsules in 250 mg and 500 mg strengths.
This layered structure creates a market in which competitive advantage does not come from a single lever. API reliability, regulatory timing, formulation differentiation, and supply continuity all interact. For example, branded players must navigate the growing availability of generic alternatives while maintaining inventory resilience, especially when documented shortages affect key dosages. Generic manufacturers, conversely, must manage the tension between volume ambitions and the operational realities of API sourcing, regulatory approvals, and intermittent supply disruptions. The report evaluates these interactions in detail, offering a competitive map that goes beyond simple company listings and instead highlights where strategic pressure is building.
Market Dynamics: Regulation, Shortages, and the New Cost Environment
No analysis of the mesalazine market in 2026 can ignore the operational realities introduced by recent regulatory actions, supply interruptions, and trade-policy shifts. These factors are not peripheral; they are central to forecasting accuracy and strategic risk management.
One of the most visible disruptions has been the intermittent shortage of established mesalazine formulations. In 2025, the marketing authorisation holder Tillotts reported shortages of Asacol 400 mg and 800 mg enteric-coated tablets, a development documented by the Finnish Medicines Agency. Such shortages matter because they affect prescribing continuity, patient trust, and the competitive balance between branded and generic options. The situation also illustrates how localized supply constraints can propagate across markets when a widely used dosage form experiences demand-supply misalignment. Compounding this, broader shortage dynamics have extended into 2026, with reports indicating that generic mesalamine extended-release capsule availability remains constrained with no clear resupply timeline in some channels. For manufacturers and purchasers alike, this underscores the importance of mapping shortage-prone dosages against inventory strategies and alternative sourcing paths.
Regulatory activity is moving in parallel. The European Medicines Agency procedure PSUSA/00001990/202402 for mesalazine concluded with a variation in November 2024, reflecting ongoing regulatory oversight of quality, comparability, and documentation standards across the supply base. For companies engaged in API supply or generic development, such procedures are not abstract compliance events. They influence submission timing, inspection readiness, and the pace at which new product versions can be commercialized. The report integrates these regulatory milestones into the forecast framework so that clients can anticipate approval cycles and compliance burdens rather than react to them.
On the cost side, the API supply chain has faced renewed pressure from trade-policy developments. As of 2025, U.S. Section 301 tariffs and additional reciprocal tariffs on Chinese imports have increased costs for API supply chains, a reality highlighted by suppliers including LGM Pharma. Because mesalazine production depends on intermediary chemistry and cross-border material flows, tariff exposure can affect margin structures, sourcing decisions, and the relative attractiveness of different manufacturing geographies. The analysis treats these cost pressures as a variable that can alter both pricing expectations and regional supply preferences, especially when firms reevaluate concentration risk in their supplier base.
Taken together, these dynamics create a market environment in which growth is real but uneven. Multiple generic approvals and launches have expanded competitive intensity, yet supply interruptions and regulatory variation continue to introduce volatility. For strategy teams, the implication is clear: forecasting should be built on scenarios that incorporate shortage risk, regulatory timing, and cost transmission, rather than on a single baseline trajectory.
Why This Research Matters for 2026 Decision-Making
The value of a market study lies in its ability to reduce uncertainty in the decisions that follow. In the mesalazine sector, that means helping leaders answer questions that are immediate and practical. Where is demand likely to be most resilient over the forecast period? Which dosage forms and indication segments concentrate volume and why? How should API sourcing strategies adapt to tariff exposure and certification requirements? Which competitive moves by branded and generic players are likely to reshape pricing and access in the near term?
Our report is designed to support those decisions with structured data and analytical clarity. It provides a historical foundation covering 2020 through 2025, a forecast framework extending to 2032, and a market concentration profile that helps assess the degree of competition and supplier dependency across the value chain. It also connects macro trends to operational implications, such as the need to evaluate shortage exposure in key formulations, the strategic relevance of USDMF and CEP certifications in enabling international supply, and the importance of monitoring regulatory procedure outcomes that can accelerate or delay market entry.
Because the full segmentation architecture, regional and application-level breakdowns, and proprietary scenario modeling are central to the report’s decision-support function, the deepest analytical layers are reserved for the complete document. The objective is straightforward: give you enough evidence of rigor and relevance here to confirm the study’s fit for your planning cycle, while preserving the detailed intelligence that should inform your final strategy.
How to Use This Report in Your Next Planning Cycle
For commercial leaders, the report can anchor portfolio prioritization by clarifying where volume concentrates and how formulation type and indication profile shape demand trajectories. For supply chain and procurement teams, it offers a basis for evaluating supplier diversification, certification alignment, and tariff-sensitive sourcing decisions. For regulatory and market access stakeholders, the inclusion of recent FDA actions, EMA procedure outcomes, and documented shortages supports more realistic planning around launch timing, inventory buffers, and contingency sourcing.
The research is equally useful for competitive intelligence. By situating API manufacturers, branded marketers, and generic entrants in a shared analytical frame, the report helps teams assess where competitive intensity is rising, where branded products face substitution pressure, and where supply continuity may become a differentiator rather than a baseline expectation.
Conclusion: A Market Growing with Discipline, Competing with Complexity
The mesalazine market is moving from a phase of steady historical expansion into a period defined by procedural scrutiny, generic competition, and supply chain recalibration. That combination makes 2026 a pivotal year for strategic planning. Growth to 224.36 million USD in 2026 and a projected 3.7% CAGR through 2032 provide a credible foundation, but the real strategic work lies in understanding how dosage form preferences, application mix, regulatory events, and sourcing costs reshape value capture across regions and customer segments.
Mesalamine Market
Our full Mesalazine Market research report translates this complexity into a structured intelligence asset. It is built to support portfolio decisions, supply strategy, competitive positioning, and scenario planning with a level of detail that headline figures alone cannot provide. We invite you to access the complete report to obtain the segmentation depth, competitive mapping, and forward-looking analysis needed to turn market growth into disciplined execution.
For detailed analysis of this topic, please visit the official page: Mesalazine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Arts & Crafts Market Hits $56.26B in 2025, 5.6% CAGR to $82.38B by 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value in the Arts and Crafts Market: A 2026 Executive Briefing
The global arts and crafts industry is entering a decisive inflection point. As organizations navigate a landscape shaped by post-pandemic normalization, shifting consumer behaviors, and evolving supply chain dynamics, the ability to anticipate market trajectories has become a critical differentiator. PW Consulting’s latest comprehensive research on the Arts and Crafts Market delivers the analytical rigor and forward-looking intelligence required to transform uncertainty into executable strategy. This briefing outlines the structural forces reshaping the sector, examines the competitive architecture, and demonstrates how decision-makers can harness our 2026–2032 forecast framework to secure sustainable growth in an increasingly fragmented landscape.
Macro Trajectory and Structural Demand Signals
The sector has demonstrated remarkable resilience over the past half-decade, defying broader macroeconomic headwinds that constrained discretionary spending in adjacent consumer categories. Drawing on a rigorous historical baseline spanning 2020 through 2025, our analysis maps a consistent expansion trajectory that sets the foundation for sustained momentum across the forecast horizon. The market has steadily grown from a baseline valuation in the early 2020s to a substantially elevated valuation by 2025, reflecting robust demand across both retail and commercial channels.
This upward trajectory is projected to continue through the end of the decade, with total market valuation anticipated to reach new milestones by 2032. The compound annual growth rate of 5.6 percent underscores a steady, compounding expansion rather than a speculative spike. For executives, this implies that arts and crafts is transitioning from a cyclical lifestyle segment into a structurally supported consumer and commercial category. The persistence of demand is further validated by independent spending indicators, which confirm that consumer outlays for non-essential creative products remained resilient throughout 2025 despite cooling labor markets and lingering inflationary pressures. This divergence from broader discretionary trends suggests deep-seated behavioral shifts: creative engagement is increasingly viewed as a core wellness and community-building driver rather than a discretionary luxury.
Yet macroeconomic stability alone does not dictate strategic advantage. The operational environment is being reshaped by material sourcing constraints, regulatory scrutiny, and channel fragmentation. Nearly a quarter of global manufacturers experienced production schedule delays during 2025 as supply chain disruptions impacted imported raw materials. Simultaneously, a significant portion of consumers reported dissatisfaction with non-certified products sourced through unverified digital marketplaces. These friction points reveal a market that is simultaneously expanding and maturing, where quality assurance, compliance readiness, and supply chain transparency are rapidly becoming competitive moats rather than baseline operational requirements.
Segmentation Architecture and Application Dynamics
Understanding where value concentrates is essential for resource allocation, product positioning, and channel strategy. Our research dissects the market across multiple structural dimensions, revealing distinct demand pools that operate under different velocity and margin profiles. In the product taxonomy, traditional creative mediums continue to command the largest share of revenue, anchored by painting and drawing applications that reflect enduring consumer preference for accessible, expressive formats. Sewing and fabric-based activities represent the next major pillar, benefiting from the sustained DIY and home textile revival. Paper crafts, kid-focused creative kits, specialized arts and crafts tools, and a broader category of ancillary offerings complete the ecosystem, each with unique seasonal patterns, demographic affinities, and retail pathway requirements.
The application split further clarifies strategic priorities. Personal use dominates overall consumption, reflecting the sector’s deep roots in hobbyist, educational, and mindfulness-driven engagement. Commercial applications, while smaller in relative scale, represent a high-value growth vector where institutional procurement, retail merchandising, and professional-grade material specifications create distinct pricing and service expectations. Companies that treat personal and commercial demand as interchangeable risk diluting their value proposition. Instead, successful operators are designing bifurcated product architectures, distribution partnerships, and compliance frameworks that align with the specific purchasing criteria of each application vertical.
Geographic distribution tells a parallel story of maturity and emerging opportunity. North America and Europe continue to anchor substantial portions of total revenue, supported by established retail infrastructure, strong brand recognition, and mature consumer education around creative products. Asia Pacific presents a structurally significant footprint, driven by expanding middle-class participation, localized manufacturing capabilities, and accelerating digital commerce penetration. Latin America and the Middle East and Africa, while smaller in absolute terms, reflect incremental growth vectors where population demographics, informal retail networks, and rising disposable income create early-stage expansion potential. Crucially, these regional profiles are not static; they are being reshaped by cross-border commerce, localized product adaptation, and shifting regulatory environments, requiring executives to move beyond one-size-fits-all geographic assumptions.
Competitive Landscape and Strategic Positioning
The industry’s competitive architecture is characterized by a moderate concentration profile, with the top three players collectively holding a modest share of total market revenue and the top five firms extending that footprint only slightly further. This fragmented baseline indicates that scale alone is insufficient for durable advantage. Instead, differentiation is increasingly driven by brand trust, product innovation cadence, channel agility, and compliance readiness.
Several established players exemplify the strategic postures defining the current cycle. Crayola LLC maintains a dominant position in the children’s creative expression segment, leveraging iconic product architecture and recent campaign-driven innovation such as its 2025 launch of a newly positioned 64-count crayon box designed to reinforce brand heritage while stimulating renewed retail velocity. Faber-Castell AG anchors its positioning in premium art and graphic materials, emphasizing professional drawing instruments and marker systems that cater to both serious hobbyists and educational institutions. STAEDTLER Mars GmbH & Co. KG operates across a broad spectrum of drawing and coloring instruments, with a long-standing reputation for precision engineering and durable creative tools. F.I.L.A. Group extends its footprint through modeling clays, crayons, and related creative products, with brand portfolios that bridge educational and artistic use cases. Newell Brands Inc. operates as a diversified portfolio player, integrating writing instruments, markers, and craft supplies across multiple recognized brand assets, enabling cross-category bundling and broad retail distribution.
These enterprises illustrate two divergent but complementary strategic playbooks. The first prioritizes category leadership within high-visibility product families, using brand equity, packaging innovation, and campaign-led demand generation to defend share and drive trial. The second emphasizes portfolio breadth, channel leverage, and operational scale to capture share across multiple sub-segments and retail formats. For market entrants and mid-tier operators, the strategic implication is clear: competing on volume alone against entrenched portfolios is inefficient. Sustainable positioning requires a clearly defined value narrative, whether anchored in premium material quality, educational alignment, demographic targeting, or supply chain reliability.
Operational Realities and Compliance Imperatives
Strategic planning in this sector must account for a growing layer of operational complexity. Regulatory frameworks are becoming more explicit, particularly in the United States, where manufacturers must align with chronic toxicity labeling requirements and toy safety standards before products reach retail shelves. Compliance is no longer a back-office function; it is a market access prerequisite that directly influences shelf eligibility, retailer confidence, and consumer trust. Organizations that embed regulatory readiness into product development cycles gain a distinct advantage in speed-to-market and risk mitigation.
Quality assurance is equally decisive. The proliferation of unverified online retail channels has introduced significant variability in product authenticity and material safety. Consumer dissatisfaction with non-certified supplies has become a material reputational and retention risk, particularly in categories where parents, educators, and professional creators prioritize predictable performance and safe material composition. Companies that invest in certification transparency, traceability systems, and channel vetting protocols are better positioned to defend margin integrity and reduce returns, while also building the trust capital necessary to expand into higher-value application segments.
Supply chain resilience represents a third operational imperative. Imported material dependencies have exposed production schedules to volatility, forcing manufacturers to reassess sourcing diversification, inventory buffers, and lead-time planning. The firms that treat supply continuity as a strategic capability, rather than a tactical procurement function, will be better equipped to protect launch calendars, maintain retail availability, and respond to demand spikes without compromising margin structure.
How This Research Converts Intelligence into Execution
PW Consulting’s Arts and Crafts Market report is engineered for decision-makers who require more than high-level trend commentary. The study integrates historical performance, forward-looking forecasts, and granular segmentation analysis into a single strategic framework designed to inform product roadmaps, channel investment, pricing architecture, and competitive positioning. Readers will gain access to structured evaluations of market sizing across multiple time horizons, enabling scenario planning that accounts for both base-case momentum and structural inflection points.
Arts and Crafts Market
The report provides a detailed segmentation map that clarifies how revenue distributes across product types, application contexts, and regional demand pools. Rather than presenting static share figures in isolation, the analysis ties each segment to underlying demand drivers, purchasing behavior patterns, and channel dynamics, allowing stakeholders to identify where incremental investment is likely to yield the strongest returns. Competitive profiling extends beyond corporate descriptions to examine strategic posture, product architecture, and market signaling, giving executives a practical lens for benchmarking their own positioning against incumbent playbooks.
Operational context is embedded throughout. Regulatory expectations, consumer quality perceptions, and supply chain friction points are evaluated not as peripheral risks but as strategic variables that influence product design, channel selection, and go-to-market timing. By connecting market structure to execution realities, the research enables teams to prioritize initiatives that are both commercially attractive and operationally feasible.
For organizations evaluating market entry, category expansion, or portfolio optimization, the study offers a structured basis for opportunity sizing and risk assessment. For incumbent players, it provides a diagnostic framework to pressure-test growth assumptions, identify vulnerable share pockets, and align innovation pipelines with the segments most likely to compound value over the forecast period.
Worldwide Harbor Craft Market
Strategic Imperatives for 2026 and Beyond
The next phase of growth in the arts and crafts sector will be defined by how effectively organizations translate market visibility into disciplined execution. Several priorities stand out. First, companies must calibrate portfolio investment to segment velocity rather than historical familiarity, recognizing that demand dynamics differ sharply between personal and commercial applications, as well as across product families. Second, brand trust and compliance readiness must be treated as revenue-enabling assets, particularly as channel fragmentation increases and consumer scrutiny around product safety intensifies. Third, supply chain design should be aligned with market expansion goals, ensuring that sourcing strategies, inventory planning, and launch sequencing can sustain availability during periods of demand acceleration.
Finally, competitive positioning requires honest segmentation of the playing field. With market concentration remaining moderate, the opportunity for targeted share capture exists, but it will accrue to organizations that define a clear value proposition, execute consistently across the chosen channel mix, and invest in the operational foundations that protect margin and reputation over time.
The full scope of our 2026–2032 analysis extends far beyond the directional signals outlined here. Detailed segmentation trajectories, competitive benchmarking, regional demand mapping, and scenario-based revenue pathways are available in the complete report. Executives seeking to convert market momentum into measurable strategic advantage are encouraged to access the full research suite, where the underlying intelligence is structured to support board-level planning, product strategy, and commercial execution with precision.
For detailed analysis of this topic, please visit the official page: Arts and Crafts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


