



PW Consulting: Sodium Hydrosulfide Market to Hit $620M by 2032 with 4.2% CAGR
By PW Consulting, 2026-09-16
Sodium Hydrosulfide Market Strategic Outlook 2026: Navigating Volume Growth and Regulatory Friction
The global sodium hydrosulfide market is entering a pivotal phase where steady volume expansion collides with tightening environmental oversight and fluctuating input costs. For industrial strategists, procurement leaders, and corporate development teams, the 2026 operating environment demands more than backward-looking revenue tracking. It requires a clear understanding of how regional supply architectures, type-specific demand shifts, and application-side procurement behaviors will evolve across the forecast horizon. Our latest Sodium Hydrosulfide Market research publication is engineered to deliver exactly that operational clarity. Drawing on a structured base year of 2025 and a historical review spanning 2020 through 2025, the report extends its analytical lens to 2026–2032, providing decision-makers with a defensible framework for capacity planning, contract negotiations, and competitive positioning.
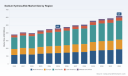
At the macro level, the market trajectory reflects measured but consistent growth. Revenue moved from 380.0 million USD in 2020 to 432.67 million USD in 2023, then continued its upward path to 449.38 million USD in 2024 and 460.0 million USD in 2025. The forecast arc projects this momentum through the end of the decade, with revenues expected to reach 476.99 million USD in 2026 and climb to approximately 620.0 million USD by 2032. This progression translates to a forecast period CAGR of 4.2 percent, a rate that signals durable demand rather than speculative surges. For executives, that growth profile carries a specific strategic implication: sodium hydrosulfide is not a niche volatile chemical, but a workhorse industrial input whose procurement and supply decisions compound over multi-year horizons. The report contextualizes these headline figures within the underlying demand engine, showing where volume is structurally accumulating and where margin exposure is intensifying.
Why 2026 Decision-Making Requires a Different Analytical Lens
The 2026 landscape is defined by a convergence of operational pressures that historical benchmarks alone cannot resolve. Sulfur-based chemical supply chains are navigating stricter transport protocols, closed-loop sulfur handling expectations, and low-emission production requirements. Environmental compliance under REACH and EPA frameworks is no longer a peripheral compliance cost; it is reshaping logistics economics, site selection logic, and supplier qualification standards. At the same time, raw material volatility remains a persistent threat to manufacturing economics. Price movements in sulfur dioxide, sodium hydroxide, and zinc—particularly for zinc-based production routes—can compress margins quickly during commodity spikes, making procurement timing and hedging strategy central to profitability.
Compounding these dynamics, market pricing signals are already showing sensitivity to broader commodity cycles. In the United States, pricing for sodium sulfide products, including sodium hydrosulfide, eased to 518 USD per metric ton in November 2025, reflecting a modest month-over-month decline and a more pronounced year-over-year pullback. While such movements can temporarily relieve procurement budgets, they also mask underlying structural risks: environmental scrutiny of sulfur dioxide emissions as a process byproduct, the generation of sulfite and thiosulfate residues in wastewater streams, and the operational hazards associated with transport and handling. These pressures are especially acute in Europe and North America, where regulatory intensity is reshaping acceptable sourcing models and pushing manufacturers to differentiate on safety, traceability, and environmental performance.
This is where the new report adds decision-grade value. Rather than presenting a flat growth curve, it breaks down the forces that will determine which companies capture share, which procurement teams secure supply resilience, and which operators navigate margin compression without sacrificing service quality. The analysis is designed for teams that must act in 2026 with incomplete visibility into the next seven years, giving them a structured way to test assumptions, prioritize investments, and align commercial strategy with evolving regulatory and operational realities.
What the Report Delivers: Operational Intelligence Over Abstract Trends
The publication is built around actionable modules that connect market structure to business decisions. It begins with a rigorous demand-and-supply framework that maps how sodium hydrosulfide flows across major industrial ecosystems and where procurement behavior is shifting. Instead of stopping at top-line projections, the report unpacks the structural drivers behind volume formation, helping readers understand which demand centers are expanding on fundamentals and which are being shaped by substitution risk, process optimization, or regional compliance costs.
A central strength of the study is its segmentation logic, which translates market complexity into operational categories that procurement, sales, and strategy teams can use directly. The analysis examines the liquid and solid forms of sodium hydrosulfide as distinct value propositions, reflecting the different handling requirements, end-user preferences, and application fit that define purchasing decisions. It also maps demand across core industrial uses, including pulp and paper processing, mining operations, leather and tanning workflows, and water treatment applications. For each segment, the report explores the operational rationale for adoption, the factors influencing specification requirements, and the procurement dynamics that will shape sourcing behavior over the forecast period. This structure allows readers to move quickly from high-level market size to the specific demand pockets most relevant to their portfolios.
Equally important, the report integrates a regulatory and operational risk overlay that many market summaries overlook. It evaluates how environmental compliance, transport constraints, and production-side emissions management are altering the economics of sodium hydrosulfide supply. Rather than treating regulation as a static barrier, the analysis frames it as a competitive variable: firms that invest early in safer handling, closed-loop sulfur systems, and lower-emission processes are building negotiating leverage and customer trust, while those that rely on legacy logistics models face rising friction. For buyers, this distinction influences supplier selection, contract structure, and total cost of ownership assessments. For producers, it shapes capital priorities and product positioning.
The forecast architecture is deliberately built for scenario use. Readers are given the analytical scaffolding to test how changes in raw material costs, regional compliance intensity, and application-side procurement timing could shift outcomes across the 2026–2032 window. This is not a single-point prediction exercise; it is a decision-support tool that helps teams prepare for multiple plausible paths, identify early warning signals, and align internal planning with market realities. The report is structured so that strategy, supply chain, and commercial teams can extract directly applicable insights without wading through disconnected data points.
Competitive Landscape: Consolidation, Differentiation, and the Race for Operational Credibility
The sodium hydrosulfide market is characterized by a moderately concentrated competitive structure, where scale, geographic reach, and application-specific expertise determine who can compete effectively across multiple end-use sectors. With a CR3 of 48.5 percent and a CR5 of 65.2 percent, the market shows meaningful concentration at the top, yet still leaves room for specialized players to win on purity, logistics reliability, and sector-focused service models. In this environment, competitive advantage is increasingly defined not just by output volume but by the ability to deliver consistent specification quality, compliant handling, and dependable supply across long procurement cycles.
Several leading suppliers anchor the market and illustrate the different routes to competitive relevance. Nouryon, based in Amsterdam, Netherlands, manufactures and supplies sodium hydrosulfide solution as a reactive sulfur chemical building block, serving mining, pulp and paper, and polymer production. Its positioning reflects the importance of integrating NaSH supply into broader chemical value chains where consistency and reactive performance matter. Solvay, headquartered in Brussels, Belgium, offers sodium hydrosulfide alongside high-grade sodium sulphide for industrial applications, including mining and chemical intermediates, emphasizing the role of multi-product portfolios in meeting diversified industrial demand. Tessenderlo Kerley, Inc., operating from Phoenix, Arizona, United States, produces and supplies sodium hydrosulfide solution with a focus on mining, the Kraft process, and leather dehairing, highlighting how application-specific expertise can anchor a supplier’s commercial footprint.
Regional specialization and product differentiation continue to shape the competitive field. Moleko, based in Australia, supplies high-purity ekoSURE Sodium Hydrosulfide solution for copper and molybdenum flotation, Kraft process operations, leather tanning, and specialty chemicals. In July 2025, Moleko officially launched a new brand identity for its high-purity sodium hydrosulfide solution, repositioning it as ekoSURE and emphasizing investments in purification technologies, traceability, and environmentally responsible production. That move is instructive: it signals a market where purity, documentation, and sustainability credentials are becoming commercial differentiators rather than optional enhancements.
In China, Shandong Aojin Chemical Technology Co., Ltd., located in Zibo City, Shandong, manufactures sodium hydrosulphide and sodium hydrosulfide for mining, paper making, leather processing, and textile production, illustrating the role of integrated regional manufacturing in serving multiple industrial sectors. Quadra Chemicals Ltd., based in Canada, supplies mining-grade sodium hydrosulfide solution for industrial and mining applications, reinforcing the importance of grade consistency and sector-focused distribution in markets where operational reliability is paramount. BOINTE ENERGY Co., Ltd., operating from Tianjin, China, functions as an active exporter and supplier of sodium hydrosulfide with logistics organized for global shipments, showing how export-oriented players compete on reach, coordination, and supply continuity. Together, these companies reflect a competitive landscape where geographic presence, product grade, application alignment, and logistics capability all influence market standing.
The report evaluates these players within a broader structural context, helping readers understand where concentration creates pricing and supply resilience dynamics, and where fragmentation leaves openings for differentiated entrants. It examines how suppliers are responding to the same operational pressures facing buyers—transport safety, emissions management, raw material exposure, and compliance burden—and how those responses are reshaping competitive advantage. For executives assessing partnerships, sourcing diversification, or market entry, this competitive mapping provides a practical foundation for evaluating who is positioned to sustain supply, who is investing in future-ready production, and where vulnerability may emerge under tighter regulatory or cost conditions.
Liquid Sodium Hydrosulfide Market
Turning Market Intelligence into 2026 Advantage
The strategic value of this research lies in its ability to connect market structure to executable decisions. For procurement teams, the report supports more informed sourcing strategies by clarifying where demand is structurally durable, where specification expectations are tightening, and where compliance and logistics risks will influence total cost of ownership. For producers and distributors, it offers a framework for prioritizing capacity, grade development, and regional positioning in a market where margin protection increasingly depends on operational discipline and differentiated service. For investors and corporate development groups, the analysis provides a grounded view of where consolidation pressures, application growth, and regulatory-driven barriers may shape future competitive dynamics.
The 2026–2032 outlook is not merely a projection exercise. It is a decision architecture for managing a chemical market that is growing at a steady pace while becoming more complex to serve. The report translates that complexity into structured insight: how the market is sized, how it is segmented, who competes and why, and which operational forces will matter most over the forecast period. By integrating historical performance, forward estimates, competitive mapping, and regulatory context into a single analytical package, the study gives teams a practical basis for aligning procurement, production, and commercial strategy with the realities of the next phase of market development.
Sodium Hydrosulfide Market
For organizations that need to move from high-level awareness to actionable intelligence, the full report provides the deeper segmentation detail, competitive benchmarking, and scenario-ready analysis necessary to support confident 2026 decision-making. The macro direction is clear; the strategic edge comes from understanding where to act, what to weigh, and how to prepare for the operational and regulatory shifts already reshaping the sodium hydrosulfide market.
For detailed analysis of this topic, please visit the official page: Sodium Hydrosulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tubular Steel Wind Tower Market Hits $8.31B in 2025, 7.3% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Steel Skeleton of Wind Energy: Strategic Insights for the Tubular Steel Wind Tower Market 2026-2032
Executive Preface: Why This Intelligence Matters Now
The global energy transition is no longer a theoretical trajectory; it is a supply chain imperative. As wind farm developers push for higher capacity factors and greater hub heights, the demand for robust tubular steel wind towers has entered a critical inflection point. Our latest comprehensive study, covering historical performance from 2020 through 2025 and a detailed forecast extending to 2032, provides the analytical rigor required to navigate this complex landscape. This article serves as a strategic preview of that research, designed to equip corporate strategy teams, procurement leaders, and investors with a clear understanding of the market forces at play.
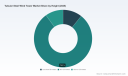
In 2026, decision-making cannot rely on outdated assumptions. The market has demonstrated consistent growth, with revenue figures climbing from approximately 5.84 billion USD in 2020 to a projected 8.66 billion USD in 2026. Looking further ahead, the trajectory points toward 13.61 billion USD by 2032. This represents a compound annual growth rate of 7.3 percent over the forecast period. These numbers are more than statistics; they represent the scale of capital deployment required to meet renewable energy targets. However, understanding the aggregate size is only the starting point. The true value of this report lies in dissecting the underlying drivers, constraints, and competitive maneuvers that will determine market share in the coming years.
Readers should note that while this overview highlights the strategic framework, specific segmentation breakdowns, detailed regional revenue figures, and proprietary competitive scoring are reserved for the full report. This approach ensures that stakeholders who require actionable intelligence for precise investment or sourcing decisions have a compelling reason to engage with the complete dataset.
Market Resilience and Growth Trajectory
The period from 2020 to 2025 established a foundation of stability despite global supply chain disruptions. The market size expanded from 5.84 billion USD to 8.31 billion USD over this historical window, reflecting a steady uptake in wind energy infrastructure. The forecast period from 2026 to 2032 anticipates a continuation of this momentum, with the market expected to breach the 10 billion USD threshold by 2028 and reach 13.61 billion USD by the end of the forecast horizon.
Several macro factors support this outlook. First, the ongoing repowering of older wind farms requires replacement towers that meet modern standards for height and durability. Second, new project approvals in key markets are driving demand for onshore installations, which remain the dominant application type within the tubular steel segment. While offshore wind presents a high-growth opportunity, the sheer volume of onshore deployments continues to anchor the market size.
However, growth is not linear. Project developers must contend with significant variability in input costs. Steel constitutes a substantial portion of tower construction expenses, and volatility in raw material pricing between 660 and 890 USD per ton observed in recent years continues to ripple through project budgets. This cost sensitivity makes accurate forecasting and strategic sourcing essential for maintaining margin integrity. Our report analyzes how these cost structures influence bidding strategies and project viability across different regions.
Structural Segments and Technical Trends
Understanding the market requires looking beyond total revenue to the technical specifications that drive demand. The industry is currently defined by a preference for mid-to-high hub heights. Towers in the 80 to 120 meters range represent a significant portion of the market value, as they offer the optimal balance between energy capture efficiency and transportation logistics. Towers below 80 meters are seeing reduced relative demand as turbines grow larger, while structures above 120 meters are gaining traction for specific high-wind sites, often requiring specialized engineering solutions.
Innovation in tower design is also reshaping the competitive landscape. Traditional tubular steel designs are being augmented by hybrid models. For instance, recent product launches have introduced hybrid steel towers that combine modular segmented steel with tubular sections to achieve higher hub heights without compromising structural integrity. These technological shifts are not merely engineering feats; they alter the supply chain requirements and open new avenues for manufacturers who can adapt their production capabilities.
The report provides a granular analysis of how these technical segments evolve over the forecast period. It examines the trade-offs between cost, logistics, and performance for different tower heights and application types. By understanding these technical drivers, stakeholders can better anticipate future demand patterns and align their production capacities accordingly.
Competitive Landscape and Concentration
The tubular steel wind tower market is characterized by a high degree of concentration. The top three players command a significant share of the market, while the top five entities further consolidate this position. This concentration implies that market dynamics are heavily influenced by the strategic moves of a few key industrial players. Our research profiles several of these critical companies, analyzing their operational footprints, product portfolios, and strategic positioning.
In North America, companies such as Arcosa Wind Towers and Broadwind Energy remain pivotal. Arcosa focuses on manufacturing and supplying tubular steel towers for onshore wind farms across the region, leveraging its location in Dallas, Texas, to serve a broad domestic market. Broadwind Energy, based in Cicero, Illinois, produces tubular steel towers and repowering adapters for turbine OEMs in the United States, positioning itself as a key partner for turbine manufacturers seeking reliable supply chain integration.
Asia Pacific presents a different competitive dynamic, with strong manufacturing bases in South Korea and China. CS Wind Corporation, headquartered in Seoul, supplies tubular steel wind towers and has secured full supply contracts for major US wind projects, highlighting the global nature of modern wind supply chains. In China, Titan Wind Energy in Suzhou and Shanghai Taisheng Wind Power Equipment Co., Ltd. are specialized manufacturers serving both onshore and offshore applications. Qingdao Tianneng Heavy Industries Co., Ltd. is also noted for its emphasis on offshore capabilities, reflecting the region's push into deeper water wind resources.
Europe remains a hub for technological innovation and high-quality manufacturing. ENERCON GmbH, based in Aurich, Germany, provides tubular steel wind towers for its own turbine platforms and hybrid designs. The company's recent introduction of a Hybrid Steel Tower demonstrates the ongoing innovation in this space, aiming to combine the benefits of modular segmentation with the strength of tubular sections for higher hub heights.
The report dives deep into the financial health, capacity expansions, and strategic partnerships of these key players. It also examines recent developments, such as the launch of a new wind tower manufacturing facility in Yanbu, Saudi Arabia, by Al Yamamah Steel Industries in late 2025. This move signals an effort to expand local supply chains in the Middle East, reducing reliance on imported components and potentially altering regional logistics costs.
Regulatory Environment and Trade Dynamics
No strategic analysis of the tubular steel wind tower market is complete without a rigorous examination of the regulatory landscape. Trade policies and anti-dumping duties have become central variables in project economics, particularly in the United States. The US International Trade Commission has recently issued determinations in five-year sunset reviews for utility-scale wind towers from Canada, Indonesia, South Korea, and Vietnam. The commission determined that revoking antidumping duty orders on these imports would likely lead to the continuation or recurrence of material injury to the domestic industry. This decision reinforces the protective trade measures that have been in place, affecting sourcing strategies for developers who might have considered these regions for cost savings.
Furthermore, the US Department of Commerce has amended final determinations on anti-dumping duties for utility-scale wind towers from Spain, setting a rate of 28.55 percent. Such specific duty rates can dramatically alter the landed cost of imported towers, making domestic or non-tariffed supply options more attractive. Additionally, a new federal tariff of 25 percent on imported steel-derivative products, including wind towers, announced in 2025, is already threatening specific projects. Reports indicate that nine wind projects in British Columbia face increased costs due to this tariff, highlighting the cross-border implications of US trade policy on neighboring markets.
These regulatory factors create a complex matrix for compliance and risk management. Companies must navigate not only the direct costs of tariffs and duties but also the potential for retaliatory measures and supply chain disruptions. Our report provides a detailed mapping of these regulatory risks, offering insights into how different regions are affected and what mitigation strategies are being employed by leading market participants. Understanding the legal and political context is as crucial as understanding the technical specifications of the towers themselves.
Why You Need the Full Report
While this overview underscores the magnitude and complexity of the tubular steel wind tower market, it only scratches the surface of the intelligence available in our full study. The market is too dynamic, and the stakes too high, to rely on high-level summaries for critical decision-making. The full report offers a depth of analysis that transforms general market awareness into actionable strategy.
Access to the complete research enables stakeholders to benchmark their performance against detailed market size data segmented by region and application. It provides the specific revenue figures and growth rates for each segment, allowing for precise target setting and resource allocation. The competitive analysis goes beyond company profiles to include market share estimates, strategic moves, and potential vulnerabilities. This level of detail is essential for identifying partnership opportunities, assessing competitive threats, and planning capacity expansions.
Tubular Steel Wind Tower Market
Moreover, the report includes a comprehensive analysis of raw material trends, supply chain risks, and regulatory updates, providing a holistic view of the operating environment. For investors, this data supports valuation models and risk assessments. For manufacturers, it informs production planning and pricing strategies. For developers, it aids in procurement negotiations and project feasibility studies.
In a market projected to reach 13.61 billion USD by 2032 with a CAGR of 7.3 percent, the difference between success and missed opportunity often lies in the granularity of the data. The full report is designed to provide that granularity. We invite you to explore the complete study to unlock the full potential of these insights and ensure your organization is equipped with the intelligence needed to thrive in the evolving wind energy landscape.
Worldwide Wind Turbine Tower Market
For detailed analysis of this topic, please visit the official page: Tubular Steel Wind Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Content Market Hits $191.55B in 2025, Projected to Reach $761.75B by 2032
By PW Consulting, 2026-09-16
Navigating the Surge: A Strategic Framework for the Digital Content Market Through 2032
The global digital content ecosystem is undergoing a structural transformation that demands immediate strategic attention. As we move deeper into the 2026 fiscal cycle, enterprise leaders face a complex intersection of accelerating addressable demand, evolving regulatory expectations, and rapid technological substitution across creation, distribution, and monetization layers. At PW Consulting, we have synthesized multi-year historical performance with forward-looking structural indicators to deliver a comprehensive assessment of how this market will evolve through 2032, and what disciplined capital allocation and capability investment require in response.
The opportunity set is substantial, but it is not uniformly distributed. Organizations that continue to treat content as a tactical output channel will find themselves outpaced by competitors who recognize it as a core infrastructure investment. This research note outlines the macroeconomic trajectory, competitive fault lines, regulatory friction points, and operational leverage points that should shape board-level discussion in the coming quarters.
Market Trajectory and the 2026 Inflection Point
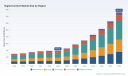
The historical record from 2020 through 2025 reveals a market that experienced rapid expansion followed by a period of measured correction and consolidation. Revenue climbed from a baseline of 149.4 billion USD in 2020 to a peak near 193.12 billion USD in 2024, before settling at approximately 191.55 billion USD in 2025. This 2025 adjustment reflects a combination of macroeconomic recalibration, platform-level monetization optimization, and early cost-reduction pressures from automation adoption. Rather than signaling demand erosion, this phase represents a maturation inflection where volume-driven growth gives way to value-driven growth.
Looking forward, the forecast period from 2026 through 2032 projects a sustained upward arc, starting at 227.63 billion USD in 2026 and scaling toward 761.75 billion USD by 2032. The implied compound annual growth rate of 5.1 percent over the forecast horizon may appear measured on the surface, yet it understates the structural reallocation occurring beneath the aggregate figure. Growth will not be evenly distributed across formats, channels, or geographies. Certain content modalities will capture disproportionate share as production economics shift, while legacy consumption patterns face compression from agentic workflows and AI-native generation pipelines.
For decision-makers, the critical takeaway is timing. Entering new content investment cycles without segmentation intelligence risks capital misallocation into formats or platforms that will face margin erosion within the forecast window. Conversely, organizations that align capability building with the segments showing durable monetization resilience can capture both top-line expansion and operating leverage.
What the Research Delivers: Actionable Intelligence Beyond the Headline
This study is designed as a decision-support instrument, not a static size-and-growth summary. It translates market architecture into operational implication across multiple planning horizons. The report framework is organized to answer four questions that recur in boardrooms and strategy functions alike: where is value accumulating, who controls the enabling infrastructure, what constraints will reshape cost and compliance structures, and how should a portfolio of content initiatives be sequenced.
The segmentation architecture maps content types, application environments, and regional demand profiles to identify where scale advantages and growth momentum diverge. Rather than presenting undifferentiated totals, the analysis isolates structural drivers such as production cost curves, audience engagement durability, platform dependency risk, and monetization pathway maturity. This allows strategy teams to distinguish between segments that are expanding on the strength of fundamental consumption shifts and those that are temporarily inflated by promotional cycles or platform subsidy dynamics.
The competitive landscape review examines the strategic positioning, technology roadmaps, and ecosystem leverage of leading platform and creation-oriented players. The assessment focuses on how each organization is shaping the supply side of content production, the degree to which integrated toolchains are creating switching costs, and where emerging interoperability or licensing models may alter competitive moats. This lens is particularly important for enterprises evaluating partnership structures, vendor consolidation, or build-versus-buy decisions for content operations.
The report also incorporates cross-cutting industry dynamics that influence execution risk. Regulatory developments around accessibility, content transparency, and platform accountability are not peripheral compliance issues; they are becoming design constraints that affect development timelines, cost structures, and market access. By mapping these requirements against current capability maturity, the research enables teams to forecast implementation burden and prioritize remediation or redesign efforts before they become growth bottlenecks.
Finally, the study integrates recent commercial and intellectual property developments that signal how the infrastructure layer of content delivery, rights management, and creator compensation is being reconstituted. These developments matter because they alter the downstream economics of distribution and monetization, influencing how value is captured once content reaches end users.
Digital Notes Market
Competitive Architecture and the Battle for Creation Leverage
The competitive field is increasingly defined by organizations that can compress the distance between idea, production, and distribution while preserving quality and brand consistency. Several platform-scale players are extending their influence through integrated creation suites that combine workflow tooling, storage, versioning, and AI-assisted generation within a single operational environment.
Microsoft Corporation has positioned its suite around productivity and content operations, embedding creation, storage, and management capabilities across familiar interface environments. Its strategy emphasizes continuity between professional documentation, presentation, and video editing workflows, which reduces friction for enterprise content teams that already operate within its productivity ecosystem. The integration of assistant-oriented creation features further accelerates draft-to-final timelines for internal and external content assets.
Digital Content Market
Alphabet Inc. has pursued a parallel path through collaborative workspace tooling and video production assistance, emphasizing AI-supported editing and management within cloud-native environments. Its approach leverages widespread adoption of its collaboration and communication infrastructure, aiming to make content creation a natural extension of daily operational workflows rather than a separate production discipline.
Adobe Inc. continues to anchor its position in professional-grade content creation, with a focus on high-fidelity visual production, compositing, and managed asset workflows. The integration of generative capabilities into its core creative environment is reshaping production economics by reducing manual iteration cycles, particularly for creative teams working under cost and turnaround pressure. Adobe's trajectory signals a market where professional creation tools are becoming more accessible through AI augmentation, expanding the producer base while simultaneously raising the bar for differentiated output quality.
Canva Inc. has expanded its relevance beyond lightweight graphic design into broader content generation, including video and conversational, agentic design workflows. Its recent introduction of a foundation-model-driven design layer reflects a broader industry shift toward prompt-mediated production with layered, editable outputs. This lowers the skill threshold for content creation, which expands participation but also intensifies competition for audience attention in already saturated channels.
Beyond these established players, the infrastructure and rights-management layer is beginning to attract targeted innovation. Recent patent activity and structured commercial intake initiatives from emerging infrastructure-oriented providers indicate growing attention to verified content delivery, stateful media handling, and rights-controlled access. These developments suggest that the market is moving toward more explicit mechanisms for tracking delivery, enforcing access conditions, and aligning creator compensation with verifiable consumption. For content-dependent enterprises, this infrastructure evolution may eventually influence platform selection, licensing strategy, and revenue-sharing expectations.
Structural Dynamics Shaping Cost, Compliance, and Content Design
Market growth does not occur in a regulatory vacuum. A series of accessibility and content-accountability mandates is reshaping how digital content must be designed, deployed, and monitored. In the United States, accessibility standards adopted by federal health and justice agencies established expectations aligned with web content accessibility guidelines at a defined compliance level for web and mobile content. This creates a durable design requirement that affects user interface decisions, media asset preparation, and testing workflows across content operations.
In parallel, the European accessibility framework introduced compliance obligations for digital products and services, including websites and applications, with deadlines that have already come into force for relevant organizations. For companies operating across multiple jurisdictions, these requirements introduce a multi-layered compliance map that must be reconciled during product and content development rather than retrofitted afterward. Failure to internalize these constraints early can lead to rework, delayed launches, and elevated assurance costs.
Beyond accessibility, content accountability expectations are expanding. Policy guidance from child health and development authorities has emphasized the importance of transparent metrics around content intended for younger audiences, signaling a likely trajectory toward more structured reporting and content governance in specific segments. For platforms and brands with significant youth-facing content exposure, this introduces an additional governance and disclosure layer that should be factored into operating models.
Production economics are also shifting. Recent industry analysis from a major creative software provider highlights growing demand for AI-augmented workflows aimed at reducing creation time and cost. This is not merely a productivity narrative; it is a structural pressure on the cost base of content production. Teams that successfully integrate assisted generation, asset reuse, and automated iteration can expand output volume without proportionate headcount growth. Teams that do not adapt risk margin compression as production expectations rise while budget constraints remain tight.
Strategic Priorities for 2026 Decision-Making
Translating these dynamics into action requires a disciplined approach that balances growth ambition with execution realism. The following priorities should anchor near-term planning.
- Align content investment with segment-level resilience rather than aggregate market momentum, since growth concentration varies materially across formats and application environments
- Evaluate creation and distribution toolchains for integration depth, switching cost exposure, and AI workflow compatibility, recognizing that vendor selection increasingly shapes long-term operating economics
- Build accessibility and content governance requirements into design and development cycles from the outset, treating them as product constraints rather than retrospective compliance tasks
- Assess licensing, rights management, and delivery-verification developments as potential sources of future monetization structure, particularly where content distribution depends on third-party platforms or partner networks
- Sequence capability investments so that AI-assisted production enhances differentiation rather than merely compressing cost, since lower production barriers will intensify competition for audience attention
- Monitor competitive moves in both creation tooling and delivery infrastructure, because shifts in either layer can alter the economics of content reach, retention, and revenue capture
The 2026 planning cycle is not simply a matter of forecasting demand; it is a matter of positioning portfolios, partnerships, and operating models against a market that is expanding while simultaneously reorganizing itself around automation, regulation, and infrastructure change. Organizations that approach the market with segmented intelligence, compliance-aware design, and strategic clarity on where value will accrue will be better placed to convert growth into durable advantage.
The complete analysis, including detailed segmentation trajectories, competitive positioning matrices, and regional demand breakdowns, is available through our full Digital Content Market research release. We encourage strategy and commercial leadership teams to review the full dataset to inform capital allocation, platform strategy, and content operating model decisions for the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Digital Content Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stainless Steel Cable Ties Market to Reach $390.3M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Frontier: Strategic Intelligence for the Stainless Steel Cable Ties Market (2026-2032)
The industrial fastening sector is undergoing a period of disciplined evolution, driven by a convergence of infrastructure modernization, maritime expansion, and increasingly stringent environmental resilience requirements. Within this landscape, the stainless steel cable ties market has emerged as a critical niche where material science meets operational reliability. Over the past half-decade, the market has demonstrated steady consolidation, with historical valuation climbing from approximately $215 million in 2020 to $252.5 million by 2025. As we turn the page to 2026, the trajectory points toward a base valuation of $260.72 million, with a projected compound annual growth rate positioning the sector to reach $390.3 million by the end of 2032.
These figures represent more than macroeconomic arithmetic. They reflect a structural shift in how engineers, procurement directors, and project managers approach cable management in harsh, corrosive, and high-vibration environments. For decision-makers navigating 2026, understanding the underlying drivers, competitive positioning, and regulatory friction points is no longer optional. It requires a granular, forward-looking intelligence framework. The latest PW Consulting Stainless Steel Cable Ties Market research report has been engineered precisely for this purpose.
Stainless Steel Cable Ties Market
Macro Growth Trajectory and the 2026 Inflection Point
The historical performance between 2020 and 2025 tells a story of resilience and deliberate recalibration. Following a period of market adjustment in 2024, evaluated revenue rebounded to $242.08 million before climbing to $252.5 million in 2025, signaling renewed capital allocation across both replacement and greenfield industrial projects. Looking ahead, the forecast horizon from 2026 through 2032 maps a sustained upward curve, with annual valuations expected to accelerate as downstream adoption deepens in electrical infrastructure, marine platforms, and heavy industrial assembly lines.
The headline CAGR of 6.98 percent underscores a market that is neither speculative nor stagnant, but structurally growing. This rate of expansion demands strategic attention. Organizations that rely on backward-looking procurement benchmarks will quickly find themselves misaligned with material availability, pricing dynamics, and certification requirements that are evolving in real time. The 2026 edition of our market research dissects these trajectories not as isolated numbers, but as interconnected signals that inform capacity planning, supplier negotiations, and regional deployment strategies.
Nylon Cable Ties Market
Competitive Architecture and the Rise of Specialized Offerings
The competitive landscape is defined by a concentrated yet differentiated group of manufacturers that have carved distinct value propositions within the stainless steel cable ties ecosystem. Market concentration data indicates a moderately fragmented structure, with the top three firms collectively capturing a modest share and the top five extending that footprint only slightly further. This dispersion suggests ample room for targeted positioning, but it also demands rigorous evaluation of product engineering, coating technologies, and compliance portfolios.
HellermannTyton, headquartered in Germany, has built its reputation on precision-engineered stainless steel cable ties offered across a spectrum of lengths, widths, and tensile specifications. Their approach emphasizes full polyester coating to prevent contact corrosion, paired with protective polyolefin channels designed to mitigate chafing, vibration, and mechanical shock. In critical infrastructure scenarios, their MBT-Series has achieved full-range UL 62275 certification for short-circuit protection, establishing a compliance benchmark that procurement teams increasingly reference during vendor qualification.
Across the Atlantic, Panduit, based in Illinois, has focused on integrated systems rather than standalone components. Their Pan-Steel System consolidates stainless steel cable ties, banding, mounts, identification solutions, and installation tools into a unified workflow tailored for shipbuilding and severe operating environments. The emphasis on smooth, round edges that prevent cable insulation damage reflects a user-centric engineering philosophy that resonates with OEM integrators and field installation teams.
BAND-IT, operating from California, has concentrated on tensile durability and industrial bundling performance through its Ultra-Lok locking style. This mechanical design prioritizes secure, repeatable fastening in high-stress applications, positioning the brand as a go-to for manufacturers that require consistent clamping force under dynamic load conditions.
On the compliance and regional manufacturing front, Hayata distinguishes itself as a US-owned, ISO 9001-certified producer offering 360-degree coated stainless steel cable ties and banding in multiple sizes. Its status as the only such US-based manufacturer serving harsh environment applications provides a tactical advantage for domestic supply chain resilience and procurement teams prioritizing localized production footprints.
Kable Kontrol has carved a niche around flame-retardant Grade 304 stainless steel cable ties featuring an easy-install, low-profile self-locking ball bearing head, with UL listing that streamlines approval cycles for electrical positioning devices. Meanwhile, HUA WEI INDUSTRIAL CO., LTD., based in Taiwan, has expanded its certification footprint to include UL, CSA, GL, CE, and CQC accreditations, aligning its heavy-duty and ball-lock stainless steel cable ties with severe industrial application standards. Their June 2026 participation in ElectroneX, where they showcased stainless steel and heavy-duty cable ties alongside ball-lock variants and polyamide 12 solar cable ties, illustrates how trade presence and product diversification are being leveraged to capture cross-sector attention.
Additionally, Hangzhou Gordon Electric Co., Ltd. was highlighted in April 2026 as a specialized OEM/ODM manufacturer within the top supplier landscape, reinforcing the growing role of contract and custom manufacturing in meeting project-specific fastening requirements across global industrial deployments.
Material Standards, Regulatory Friction, and the Certification Economy
The operational value of stainless steel cable ties is inseparable from the material grades and regulatory frameworks that govern their deployment. Grade 304 and marine-grade 316 stainless steel form the backbone of the category, offering corrosion resistance and thermal tolerance spanning from -100°F to 1000°F. This thermal and chemical resilience is what enables adoption in environments where polymer-based fasteners degrade, where salt exposure accelerates failure, or where electrical safety mandates fire-retardant performance.
Yet material capability alone does not unlock market access. Certification has become a decisive commercial variable. The UL 62275 alignment achieved by HellermannTyton’s MBT-Series, the UL listing secured by Kable Kontrol under File No. E530766, and the multi-accreditation portfolio maintained by HUA WEI INDUSTRIAL CO., LTD. all reflect a market where compliance is a gatekeeper to project eligibility. ISO 9001 certification, as demonstrated by Hayata’s US-based production line, further signals process maturity that procurement and quality teams weigh heavily when qualifying suppliers for long-term contracts.
For 2026 strategy planning, this certification economy introduces both constraint and opportunity. Organizations that internalize the mapping between application requirements, regional regulatory expectations, and supplier certification portfolios will compress approval timelines and reduce downstream rework risk. Our research report layers these dynamics into a practical compliance-and-selection framework, helping teams evaluate not just what a tie does, but what standards it satisfies and where those standards carry the greatest commercial weight.
Why This Report Is Built for 2026 Decision-Making
Market research that merely recites growth percentages fails the modern strategist. The 2026 Stainless Steel Cable Ties Market report is structured to convert intelligence into action. It delivers an operational blueprint that covers:
- Historical performance mapping and forward forecast modeling that contextualizes the 2026-2032 growth arc without reducing it to a single headline figure, enabling scenario-based planning across procurement cycles and capital budgeting windows.
- A structured examination of type, size, application, and regional segmentation dynamics, presented to illuminate where demand density is concentrating and how product configurations are aligning with end-use requirements, while preserving the strategic discretion necessary for competitive positioning.
- A competitive profiling module that dissects product engineering, coating technologies, locking mechanisms, installation ergonomics, and compliance portfolios across the key manufacturers shaping the category, equipping buyers and sellers with a comparative lens for vendor selection and market entry evaluation.
- An integrated view of market concentration and fragmentation trends, providing context for pricing power, negotiation leverage, and the strategic implications of a moderately dispersed supplier base.
- A regulatory and certification tracker that translates recent UL, CSA, GL, CE, CQC, and ISO 9001 developments into actionable guidance for project qualification, export planning, and risk mitigation.
- Material and performance benchmarks anchored in real-world thermal, corrosion, and flame-retardant requirements, enabling engineering and procurement teams to align specification choices with environmental exposure and safety mandates.
The deliberate architecture of this report reflects a core principle: in a market where certification, coating technology, tensile design, and regional compliance expectations are moving in tandem, decision-makers need an integrated intelligence system, not a fragmented data dump. The report is designed to support sourcing strategy, product portfolio alignment, competitive benchmarking, and market-entry assessment with equal rigor.
The Strategic Case for Deeper Intelligence
As 2026 unfolds, the stainless steel cable ties market will continue to reward organizations that treat fastening not as a commodity afterthought, but as a performance-critical component embedded in larger system reliability. The convergence of infrastructure renewal, marine asset expansion, and electrical safety mandates is expanding the addressable base, while certification scrutiny and material differentiation are raising the barrier to entry for undifferentiated players.
The full research report extends beyond the trajectory outlined here. It maps the segmentation architecture across type, size, application, and regional demand patterns, unpacks the competitive positioning of the companies shaping the category, and provides the analytical scaffolding needed to convert market signals into procurement strategy, product development priorities, and expansion planning. To access the complete segmentation breakdown, forecast scenarios, and competitive deep dives, we invite you to explore the full report on our platform. The intelligence required to navigate 2026with precision is available, and the organizations that secure it first will be best positioned to capture the growth ahead.
For detailed analysis of this topic, please visit the official page: Stainless Steel Cable Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PTFE Venting Membrane Market to Reach $2.69B by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-16
Strategic Venting: Navigating the PTFE Membrane Market in 2026
The global industrial landscape is undergoing a profound transformation, driven by electrification, stringent safety regulations, and evolving material science demands. At the intersection of these trends lies the critical role of PTFE venting membranes. These specialized components are no longer mere accessories; they are essential enablers of battery safety, sterile medical environments, and durable structural systems. As we move through 2026, understanding the trajectory of this market is not just an academic exercise—it is a strategic imperative for stakeholders across the value chain. This analysis draws from our latest comprehensive market research to outline the opportunities and risks defining the sector over the next decade.
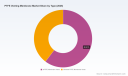
The market has witnessed a robust trajectory over the past five years, recovering from global supply chain shocks and accelerating towards new highs. Historical data from 2020 through 2025 indicates a steady upward curve, culminating in a valuation that sets the stage for significant growth in the forecast period. Our analysis projects the global market value to reach approximately 2,050 million USD in 2026, up from 1,883.5 million USD in the base year of 2025. This momentum is expected to continue, with revenues climbing towards 2,689.9 million USD by 2032. Such figures underscore a compound annual growth rate (CAGR) of 5.2 percent during the forecast period from 2026 to 2032. This growth is not linear; it is punctuated by technological shifts and regional dynamics that require nuanced strategic planning.
PTFE Venting Membrane Market
Market Dynamics and Supply Chain Pressures
While the top-line growth figures are promising, the underlying dynamics present a complex picture for procurement and manufacturing leaders. The cost structure for PTFE venting membranes is heavily influenced by raw material volatility. High-grade PTFE resins exhibit price volatility driven by global supply chain disruptions, a trend that analysts have flagged as persistent throughout 2025 and into 2026. This volatility is compounded by geopolitical factors affecting the fluorspar supply chain. Sovereign fluorspar policies in China, which supplies a significant majority of global output, are raising landed costs for North American and European converters by double-digit percentages.
These regulatory and logistical headwinds are forcing adjustments in production planning. Several European compounders have been observed idling a portion of their nameplate PTFE capacity during the first quarter of 2026 to preserve liquidity in response to tightening export licensing and shipment volumes. China's export licensing tightened 2025 shipments to levels below previous years, creating a squeeze on availability for downstream manufacturers. For companies operating in this space, the ability to hedge against raw material price variations—which can fluctuate by a significant margin annually—is becoming a key differentiator in maintaining margin integrity. Our report delves deep into these cost structures, offering models for supply chain resilience that go beyond simple procurement tactics.
Segmentation and Application Drivers
The demand for PTFE venting membranes is not uniform across all sectors. It is being pulled by specific high-value applications that prioritize performance and safety. The report segments the market by type, distinguishing between ePTFE Membrane Vents and Sintered PTFE Membrane Vents. Each type serves distinct functional requirements, with expanded PTFE gaining traction in applications requiring high breathability and chemical resistance, while sintered variants are critical where structural integrity under pressure is paramount.
In terms of application, the breadth of use cases illustrates the material versatility of PTFE. The electric vehicle (EV) battery sector remains a primary growth engine, driven by the absolute necessity for thermal runaway protection and pressure equalization in battery packs. Alongside this, the medical sector continues to demand high-purity venting solutions for sterile devices and drug delivery systems. The automotive industry, broader than just EV batteries, utilizes these membranes for under-the-hood components and lighting systems to protect against moisture and contaminants. Electronics packaging and industrial uses further diversify the revenue base. Chemical packaging and food and beverages packaging represent niche but high-compliance segments where barrier properties are non-negotiable. Understanding the specific growth rates and revenue contributions of each of these segments is crucial for targeting investment, and our full study provides the granular breakdown required to prioritize these verticals effectively.
Geographically, the market is distributed across key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific currently represents a substantial portion of the volume, reflecting the concentration of manufacturing and electronics production. However, North America and Europe maintain strong positions driven by high-value automotive and medical applications. The report analyzes the revenue distribution across these regions without revealing specific percentages in this overview, but the full publication details the regional revenue contributions and growth trajectories, highlighting where local manufacturing capabilities are aligning with demand centers.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of established material science giants and specialized converters. Market concentration remains moderate, with the top three players holding a combined share in the low twenties and the top five accounting for slightly less than thirty percent of the market. This fragmentation suggests opportunities for consolidation or for niche players to secure strong positions through differentiation.
Key companies shaping the industry include Gore & Associates, Inc., known for leading production of expanded PTFE venting membranes for automotive and medical applications. Donaldson Company, Inc. continues to be a pivotal supplier of advanced filtration and venting solutions, recently expanding production capacity in late 2024 to support rising demand from life sciences and industrial processing. Saint-Gobain Performance Plastics has also moved to expand fluoropolymer materials processing capability in early 2025 to address rising specialty filtration demand.
In Asia, Nitto Denko Corporation and Sumitomo Electric Industries, Ltd. are key providers of engineered PTFE membranes for electronics and automotive OEMs. Porex Corporation introduced advanced porous polymer and membrane solutions in mid-2024, targeting medical and industrial customers. Other significant players include Zeus Industrial Products, Marian, Inc., Poly Fluoro Ltd, and Membrane Solutions, LLC, each contributing to the supply chain through conversion, customization, or specialized property engineering such as hydrophobic and oleophobic coatings. The report profiles these entities in detail, analyzing their strategic partnerships, capacity investments, and R&D focus areas to help clients identify potential suppliers or competitors.
Strategic Value of the 2026 Research
For corporate strategists, investors, and product developers, this market research offers more than just historical data. It provides a forward-looking lens calibrated for the 2026 decision-making cycle. The study includes actionable insights on capacity planning, helping manufacturers anticipate where bottlenecks might occur given the current idling of European capacity and tightening of exports. It evaluates the regulatory environment, offering compliance roadmaps for companies navigating fluorspar policies and export licensing changes.
Furthermore, the report assesses the technological roadmap. As EV battery architectures evolve and medical devices become more complex, the specifications for venting membranes are tightening. The research identifies which technical properties are becoming standard versus premium, allowing R&D teams to align their development pipelines with market needs. The segmentation analysis enables precise market sizing for new product launches, ensuring that capital is deployed into the highest potential application areas. Whether you are evaluating entry into the ePTFE space or assessing the risk of raw material price hikes on your sintered product lines, the detailed data tables and forecast models in the full study provide the quantitative backing needed for confidence in your strategy.
Industrial Venting Membrane Market
Conclusion
The PTFE Venting Membrane Market is at a critical juncture where growth potential is high, but so are supply chain risks. The projected expansion to nearly 2,690 million USD by 2032 represents a significant opportunity for those who can navigate the complexities of raw material sourcing and regional regulatory shifts. Companies that leverage detailed intelligence on competitive moves, such as the capacity expansions by Donaldson and Saint-Gobain, will be better positioned to anticipate market shifts. By understanding the specific demands of the EV, medical, and packaging sectors, stakeholders can tailor their offerings to capture value in the most resilient segments. This research serves as a foundational tool for executing that strategy, ensuring that decisions made in 2026 are built on a comprehensive understanding of the market landscape. The full report contains the specific data points, regional splits, and company profiles necessary to operationalize these insights.
For detailed analysis of this topic, please visit the official page: PTFE Venting Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dry Ice Machine Market to Reach $344.8M by 2032, 5.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Cold Front: Strategic Insights for the Dry Ice Machine Market Through 2032
The global industrial landscape is undergoing a silent but significant transformation, driven by the need for sustainable cleaning solutions, stringent cold chain requirements, and the relentless pursuit of operational efficiency. At the heart of this shift lies the Dry Ice Machine Market. As enterprises face increasing pressure to adopt eco-friendly technologies while maintaining rigorous safety standards, understanding the trajectory of dry ice production and blasting equipment becomes not just an option, but a strategic imperative. Our latest market research provides a comprehensive roadmap for stakeholders looking to capitalize on these emerging opportunities between 2026 and 2032.
In an era where data transparency dictates competitive advantage, decision-makers require more than surface-level estimates. They need a granular understanding of how market forces interact, how regulatory frameworks evolve, and where the capital flows are heading. This introduction serves as a high-level overview of the intelligence contained within our full study, designed to equip senior leadership with the context needed to interpret the broader market signals before diving into the specific methodologies and breakdowns available in the complete report.
Macro Economic Trajectory and Growth Signals
Historical data suggests a resilient upward trend for the dry ice machine sector, reflecting broader industrial adoption rates and the substitution of traditional abrasive cleaning methods with cryogenic alternatives. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a solid foundation for forecasting the period extending to 2032. The market has demonstrated consistent expansion, moving from a valuation of approximately 163.15 million USD in 2020 to a projected 215.0 million USD by 2025. This trajectory underscores a mature yet accelerating adoption curve.
Dry Ice Machine Market
Looking forward, the forecast period indicates sustained momentum. The market is expected to reach 231.45 million USD in 2026, climbing steadily to 344.8 million USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 5.5 percent over the forecast horizon. Such a rate suggests a balanced expansion where technological innovation meets steady demand across key verticals. For investors and manufacturers, this CAGR signals a stable environment for capital deployment, albeit one that requires careful monitoring of regional nuances and operational costs.
It is crucial for strategists to recognize that these aggregate figures mask complex underlying drivers. The revenue growth is not uniform across all product categories or geographic zones. While the top-line numbers indicate a healthy market, the distribution of value across different machine types and application sectors varies significantly. Our full report dissects these variations to reveal which specific segments are outpacing the average growth rate and which are facing headwinds due to saturation or regulatory constraints.
Segmentation Landscape: Types and Applications
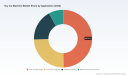
The market is diversified across several machine types, each catering to distinct production needs and output specifications. The landscape includes pellet dry ice production machines, block dry ice production machines, and slice dry ice production machines. Each type serves a unique function within the supply chain, influencing everything from storage logistics to end-user application efficiency. Understanding the revenue contribution of each category is essential for manufacturers deciding where to focus R&D resources.
Dry Ice Market
Similarly, the application sector drives significant demand variance. Key verticals include food and beverage, cold chain logistics, industrial cleaning, and medical and pharmaceutical uses. The food and beverage sector often leads in volume due to the critical need for temperature control during processing and transport, while industrial cleaning sees strong uptake due to the environmental benefits of dry ice blasting over sand or chemical blasting. Medical applications, though smaller in volume, command high compliance standards that impact machine specification requirements.
However, precise revenue splits and percentage contributions for these segments are sensitive competitive intelligence. In our complete market study, we detail exactly how these segments compare in terms of market share and growth velocity. Access to this level of detail allows procurement officers and product managers to benchmark their internal portfolios against the broader industry standard. Without this granular view, companies risk misallocating resources to slower-growing niches while missing high-potential opportunities in emerging applications.
Regional Market Dynamics and Distribution
Geographic distribution plays a pivotal role in shaping market strategy. The global landscape is divided into key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique mix of regulatory environments, industrial density, and cold chain infrastructure maturity. Historically, North America and Asia Pacific have shown robust activity, reflecting strong industrial bases and varying degrees of adoption in logistics and cleaning sectors.
Europe continues to maintain a significant presence, driven by strict environmental regulations that favor dry ice blasting over chemical alternatives. Meanwhile, emerging markets in Latin America and the Middle East and Africa represent areas of potential expansion, though they come with distinct infrastructural challenges and varying raw material availability. The interplay between these regions creates a complex trade flow and supply chain dynamic that affects pricing and availability of equipment.
Detailed regional revenue figures and growth rates are central to our full analysis. These metrics help multinational corporations determine where to prioritize sales channels and where local manufacturing might offer a competitive edge against imports. For a precise understanding of which regions are contributing the most to the global revenue pool and how their growth rates compare to the global average, stakeholders are encouraged to refer to the complete regional breakdown provided in the full report. This ensures that expansion strategies are grounded in accurate local market intelligence rather than generalized assumptions.
Competitive Landscape and Key Incumbents
The market features a mix of established players and specialized innovators, operating across multiple continents. Concentration levels indicate a moderately fragmented environment, with the top three companies holding approximately 24.6 percent of the market and the top five reaching 26.2 percent. This structure suggests that while there are dominant forces, there is still room for niche players to compete on technology or regional specialization.
Key companies shaping the industry include Cold Jet, LLC based in San Marcos, Texas, known for advanced dry ice production pelletizers and blasting equipment focusing on energy-efficient CO2 utilization. CRYONOMIC in Belgium offers hydraulic drive solutions for crystal-hard pellets and sticks in semi-automated industrial settings. ASCO Carbon Dioxide Ltd from Switzerland specializes in automatic pelletizers capable of multiple thicknesses for food-grade and industrial use. Other notable entities include Artimpex nv and IceTech in the United States, Alfred Kärcher SE & Co. KG in Germany, TOMCO2 Systems, Aquila Triventek, and Ziyang Sida Cryogenic Machine Co., Ltd. in China.
Recent industry movements highlight the dynamic nature of this competition. For instance, Cold Jet has been particularly active, launching a new line of dry ice blasting machines for the food processing industry in August 2025, followed by the introduction of the PR750H industrial pelletizer in November 2025 and the PE 80 High-Efficiency Pelletizer in February 2026. These launches demonstrate a clear focus on efficiency and versatility across pellet sizes. Meanwhile, CRYONOMIC appointed Multico svl. as a distributor for Romania in November 2025, and ICS exhibited at Auto Exotica 2026 in April, signaling ongoing efforts to expand distribution networks and brand visibility in specific verticals like automotive.
Competitor profiling in our full report goes beyond product listings. It analyzes market positioning, recent strategic moves, and the implied focus areas based on public announcements. For investors, understanding the cadence of product launches and distribution expansions provides clues about where each company sees the highest growth potential. This intelligence is vital for partnership due diligence or for identifying acquisition targets that align with long-term strategic goals.
Critical Market Dynamics and Operational Considerations
Beyond pure economics, the dry ice machine market is heavily influenced by regulatory and operational factors that impact total cost of ownership and deployment feasibility. Safety and compliance are not merely checkboxes; they are structural components of the market that define where and how equipment can be utilized. Our research integrates these dynamics to provide a realistic view of market barriers and facilitators.
Regulatory Frameworks and Safety Protocols
Operators must navigate a complex web of safety standards when deploying dry ice production and blasting equipment. A primary requirement is the use of equipment only in properly ventilated spaces that comply with local and national regulatory standards. This constraint impacts facility design and limits the types of environments where dry ice blasting can be implemented without significant infrastructure upgrades.
Exposure limits are another critical factor. Guidelines often dictate that exposure to dry ice must follow specific occupational safety standards, such as maintaining CO2 levels below certain thresholds over an 8-hour workday with continuous monitoring. For example, adherence to OSHA guidelines regarding 5,000 ppm limits requires facilities to invest in monitoring systems, adding to the capital expenditure associated with dry ice technology adoption.
Transportation and logistics also face strict oversight. All dry ice transportation containers must meet DOT regulations for hazardous materials labeling and emission controls. This affects the downstream logistics of companies utilizing dry ice for shipping or cleaning, influencing the choice of production machines that can integrate smoothly with compliant packaging and distribution workflows. Additionally, safety protocols for blasting equipment include the use of insulated containers and compliance with federal regulations on hazardous materials, ensuring that both operators and the environment are protected during industrial cleaning processes.
Raw Material Economics and Supply Chain Volatility
The economics of dry ice production are intrinsically linked to the availability and pricing of CO2 feedstock. Raw material expenses remain subject to fluctuations in CO2 supply, which can be influenced by seasonal demand in other sectors, such as beverages or welding, and broader industrial production cycles. This volatility introduces a variable cost element that manufacturers must factor into their pricing models and long-term contracts.
Current sector analysis indicates that average pellet prices can range significantly, reflecting the interplay between supply constraints and regional demand spikes. For machine operators, this means that the efficiency of the production machine—measured in yield and energy consumption per pound of dry ice—is a critical metric for profitability. Machines that optimize CO2 utilization can mitigate some of the impact of raw material price swings, offering a competitive advantage to operators who invest in higher-efficiency technology.
Our full report delves into the sensitivity analysis regarding raw material costs and how they impact the overall market revenue projections. By understanding the correlation between CO2 pricing trends and machine utilization rates, businesses can develop more robust financial models. This level of insight is necessary for forecasting operational budgets accurately and avoiding margin erosion during periods of supply tightness.
Strategic Implications for 2026 and Beyond
For enterprises operating in or adjacent to the dry ice machine market, the period from 2026 to 2032 offers both challenges and opportunities. The projected growth suggests that demand will not vanish, but the competition for market share will intensify. Success will depend on the ability to interpret data correctly, anticipate regulatory shifts, and align product offerings with the specific needs of high-growth applications.
Strategic decision-makers should consider the following implications based on the macro trends identified:
- Technology Investment: With new product launches focusing on high-output and multi-size capabilities, R&D should prioritize flexibility and energy efficiency to match evolving customer requirements in food processing and industrial cleaning.
- Compliance Integration: Safety regulations are tightening. Equipment that integrates monitoring and ventilation compliance features directly into the production system may gain preference in regulated industries like pharmaceuticals and food safety.
- Regional Strategy: While global growth is steady, regional disparities require tailored approaches. Distributors and sales teams need localized data to identify regions where infrastructure supports dry ice adoption versus those hindered by supply chain or regulatory hurdles.
- Supply Chain Resilience: Given the volatility in CO2 feedstock prices, partnerships with reliable gas suppliers and investment in machines with high conversion efficiency will be key to maintaining margins.
Ultimately, navigating this market requires more than a glance at the headline CAGR. It demands a deep dive into the segmentation splits, competitive maneuvers, and regulatory undercurrents that define the daily operations of the industry. Our comprehensive market research report is designed to provide that depth. It offers the specific breakdowns, detailed company profiles, and forward-looking risk assessments necessary to build a resilient strategy.
To access the full suite of data, including precise regional valuations, detailed application segment sizes, and complete competitive benchmarking, we invite you to review the full publication. The insights contained within are crafted to support informed decision-making, ensuring that your organization is prepared to lead rather than follow in the evolving landscape of dry ice production and blasting technology.
For detailed analysis of this topic, please visit the official page: Dry Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PPS Resin Market to Hit $3.47B by 2032, Driven by 7.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Polyphenylene Sulfide Landscape: Strategic Imperatives for 2026 and Beyond
In an era defined by accelerated material innovation, supply chain volatility, and stringent sustainability mandates, the global Polyphenylene Sulfide (PPS) resin market stands at a critical inflection point. For corporate strategists, procurement leaders, and R&D directors across high-performance engineering sectors, the ability to anticipate demand trajectories, identify emerging capacity shifts, and decode competitive positioning is no longer a luxury. It is a prerequisite for sustained market share and margin protection. Our newly released PPS Resin Market Research Report delivers exactly that: a rigorously validated, forward-looking intelligence framework calibrated to guide executive decision-making through 2032 and beyond.
The macro trajectory tells a compelling story. From a baseline of USD 1,450.0 Million in 2020, the market has consistently compounded upward, reaching USD 2,020.0 Million in 2025. Our baseline forecast projects the sector will exceed USD 2,143.6 Million in 2026 and continue its upward march to USD 3,470.0 Million by 2032. Anchored by a robust compound annual growth rate of 7.8 percent, the expansion is neither accidental nor cyclical. It reflects structural demand drivers, evolving material substitution patterns, and deliberate capacity reallocation by Tier-1 producers who are actively reshaping the competitive architecture. Yet, headline figures only scratch the surface. The real strategic value lies in understanding the mechanics beneath the aggregate numbers: how demand is being reallocated across value chains, where production bottlenecks are forming, and which players are positioning themselves to capture disproportionate share in high-margin end-use segments.
This intelligence brief serves as a strategic preview. It outlines the core analytical pillars embedded in our full study, highlights the competitive dynamics currently redrawing the market map, and demonstrates how procurement and product development teams can leverage granular, actionable data to optimize sourcing strategies, de-risk supply chains, and accelerate time-to-market for next-generation engineered components.
Polysulfone Resin Market
Decoding the Report Architecture: What Decision-Makers Will Gain
Our research methodology is built on a multi-layered analytical framework that moves far beyond top-line market sizing. The full report synthesizes historical trajectory data, forward-looking demand modeling, supply-side capacity mapping, and application-specific consumption patterns into a unified decision-support toolkit. Rather than presenting static snapshots, we track momentum. The historical period from 2020 to 2025 establishes the baseline behavior of the market across economic cycles, raw material fluctuations, and regional demand shocks. The forecast window from 2026 through 2032 extends that modeling into scenario-weighted projections that account for macroeconomic variables, technological adoption curves, and regulatory inflection points.
Throughout the document, readers will encounter structured analytical modules designed for direct operational translation. These include demand-side consumption mapping across major end-use verticals, supply-side capacity and utilization tracking by manufacturing geography, and segmentation analysis that isolates growth vectors within resin type categories and application clusters. Each module is cross-referenced with pricing sensitivity indicators, feedstock dependency assessments, and sustainability compliance tracking. The goal is to equip strategists with a complete operational lens: one that connects macroeconomic demand signals to plant-level capacity decisions, and links regulatory developments to formulation and sourcing strategies.
Crucially, the report is structured to support iterative decision-making. Executives can use it to stress-test procurement portfolios, identify long-term supply continuity risks, evaluate joint-venture or contract-manufacturing opportunities, and benchmark internal performance against industry growth curves. R&D and product development teams will find targeted insights into grade differentiation, thermal and chemical resistance requirements, flow characteristics for high-volume injection molding, and the growing importance of recycled-content variants in meeting corporate sustainability targets.
Competitive Recon: Mapping the Architecture of Market Leadership
Market concentration in the global PPS resin sector remains pronounced, with the top three producers collectively accounting for approximately 65 percent of total revenue and the top five controlling roughly 80 percent. This concentration does not imply stagnation. On the contrary, it reflects deliberate capital allocation, technological specialization, and strategic geographic positioning by a tightly aligned group of performance-material manufacturers who are competing on grade formulation, regulatory certification, recycling capability, and application-specific value engineering.
At the heart of this competitive ecosystem sits Celanese Corporation, whose Fortron® PPS resin portfolio has long been associated with high thermal stability, chemical resistance, and consistent performance in automotive and industrial injection molding applications. Operating from Dallas, Texas, Celanese continues to reinforce its position through grade optimization, processing reliability, and deep integration into Tier-1 supply chains. Across the Atlantic, Solvay S.A. has built a formidable presence through its Ryton® PPS brand and Supreme series grades, targeting high-voltage electrical applications, high-flow engineering requirements, and increasingly, sustainability-certified production pathways. The company's ongoing pursuit of mass-balance certification and its footprint across Texas and Belgium underscore a dual focus on performance and compliance-driven market access.
The Asian manufacturing corridor continues to exert structural influence. Toray Industries, Inc. has systematically expanded its Torelina® PPS resin portfolio to serve high-performance automotive and electronics applications, recently completing a second production line expansion at its Gunsan plant in Korea to reinforce regional capacity resilience. DIC Corporation and Kureha Corporation have maintained steady positioning in industrial and automotive segments, with Kureha placing particular emphasis on high-temperature and flame-resistant grades that align with stringent safety specifications in electrical and transport equipment. Tosoh Corporation serves as a specialized supplier across electrical and high-performance engineering applications, while Polyplastics Co., Ltd. has carved a distinct niche through its DURAFIDE® PPS grades, recently advancing into mechanically recycled-content formulations that respond directly to corporate sustainability mandates and circular-economy procurement standards. Rounding out the competitive matrix, Ensinger GmbH provides compounded PPS materials and precision-machining-ready resin solutions for industrial components, reinforcing Europe's role as a hub for specialized, high-value-added formulations.
Recent operational moves by key players confirm that the competitive landscape is actively recalibration. In May 2025, Syensqo announced a capital investment to expand PPS compounding capability at its Augusta, Georgia manufacturing site for Ryton-branded compounds, signaling a strategic push into North American downstream processing and localized supply chain responsiveness. Later in the year, Toray Industries completed the expansion of its second PPS production line at its Gunsan facility in Korea, reinforcing its capacity footprint and regional supply agility. In January 2026, Polyplastics Co., Ltd. launched two new DURAFIDE® PPS grades made from mechanically recycled content, a move that directly intersects with the growing procurement preference for sustainable resin inputs and circular material sourcing.
These developments are not isolated corporate announcements. They are indicators of structural realignment: capacity is being deliberately placed closer to key demand clusters, compounding and formulation capabilities are being expanded to capture higher-margin downstream value, and sustainability certification is transitioning from a compliance checkbox to a competitive differentiator. Understanding who is expanding, where, and why is essential for any organization seeking to optimize long-term sourcing strategy or position new products in high-growth application corridors.
Structural Dynamics Shaping the 2026 Horizon
The trajectory of the PPS resin market is being shaped by an interlocking set of technical, economic, and regulatory forces. At the raw material level, PPS production relies on the polymerization of dichlorobenzene and sodium sulfide as foundational feedstocks. Pricing and supply continuity for these commodity inputs remain highly sensitive to broader chemical market dynamics, and procurement teams must track these dependencies closely as they translate into resin cost structures and margin variability. In the third quarter of 2025, North American PPS prices rose to approximately USD 11,250 per metric ton, driven by intensified demand pull from the automotive and electronics sectors. This price behavior is not an isolated event; it reflects how demand acceleration in high-value applications can rapidly transmit through regional pricing structures, particularly when capacity expansion timelines lag behind consumption growth.
Regulatory and sustainability frameworks are equally influential. The attainment of ISCC PLUS 2 mass-balance certification for PPS production facilities in Texas and Belgium demonstrates how major producers are institutionalizing sustainable manufacturing pathways. As downstream OEMs and Tier-1 suppliers face mounting corporate sustainability targets and customer-facing carbon disclosure requirements, certified sustainable resin inputs are evolving from a niche preference to a qualifying factor in procurement evaluations. The strategic implication is clear: organizations that embed sustainability compliance into sourcing criteria will not only mitigate reputational and regulatory risk but will also gain preferential access to supply from producers who have already navigated the certification pathway.
On the technology and application side, continuous advancements in resin formulation are expanding the boundaries of where PPS can be deployed. Enhancements in thermal stability, chemical resistance, flow characteristics, and flame-retardant performance are enabling deeper penetration into demanding engineering applications where traditional thermoplastics and lower-performance engineering resins fall short. Simultaneously, the rise of recycled-content grades is creating new procurement dynamics. As mechanically recycled PPS formulations gain commercial traction, buyers are confronted with a more complex sourcing landscape that requires evaluation of material consistency, processing compatibility, certification alignment, and total cost of ownership rather than simple price-per-kilogram comparisons.
Strategic Positioning for 2026 and the Road to 2032
As the market moves from baseline recovery and consolidation into an accelerated growth phase, several strategic imperatives are coming into sharp focus for organizations operating in or adjacent to the PPS value chain. First, supply chain resilience must be treated as a structural capability rather than a short-term risk mitigation exercise. The concentration of capacity among a small group of large-scale producers, combined with regional price sensitivity and feedstock dependency, means that diversification of sourcing relationships, forward contracting strategies, and awareness of capacity expansion timelines are essential to maintaining continuity and cost predictability.
Second, application-specific demand mapping should inform both procurement and product development roadmaps. As automotive electrification, high-performance electronics, aerospace component requirements, and industrial precision-machining demand continue to shape consumption patterns, organizations that understand which end-use verticals are accelerating, which are stabilizing, and which are emerging will be better positioned to align capacity acquisition, inventory planning, and new product introductions.
Third, sustainability is becoming a procurement qualifier, not an aspirational add-on. Certified sustainable production pathways, recycled-content grades, and compliance with evolving regulatory expectations are increasingly influencing supplier selection. Organizations that proactively embed these criteria into supplier qualification, technical evaluation, and contract negotiation will reduce exposure to future compliance shocks while strengthening alignment with downstream customer expectations.
Finally, competitive intelligence must be continuous. The recent capacity expansions, grade launches, and certification milestones among leading producers confirm that the market is structurally dynamic. Tracking these moves, understanding the geographic and application logic behind them, and anticipating their downstream impact on pricing, availability, and formulation options will be a decisive factor in maintaining competitive advantage over the next planning cycle and beyond.
PPS Resin Market
Closing the Intelligence Gap
Headline growth rates and aggregate market sizes provide orientation, but they rarely provide direction. Real strategic advantage comes from understanding the mechanics beneath the numbers: how capacity is being reallocated, how grade differentiation is reshaping application eligibility, how sustainability certification is filtering supplier pools, and how pricing behavior reflects demand shifts in high-value end-use sectors. Our full PPS Resin Market Research Report is designed to close that intelligence gap. It translates historical trajectory, forward-looking modeling, competitive mapping, and structural dynamics into a decision-ready framework that procurement, strategy, and engineering teams can apply directly to sourcing plans, capacity negotiations, product roadmaps, and market-entry evaluations.
For organizations preparing for the 2026 decision cycle, the window to build a comprehensive, evidence-backed view of the PPS resin market is open now. The full report provides the granular segmentation detail, regional and application-level consumption trajectories, pricing sensitivity modeling, competitive positioning analysis, and scenario-weighted forecasts needed to move from reactive monitoring to proactive strategy. We invite you to access the complete study on our website, where you will find the full data architecture, detailed segmentation contours, and executive-ready synthesis required to navigate the next phase of market expansion with confidence.
For detailed analysis of this topic, please visit the official page: PPS Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Piston Engines Market to Hit USD 7,152.97M by 2032 at 5.2% CAGR
By PW Consulting, 2026-09-16
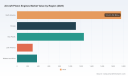
Navigating the Sky: Strategic Intelligence for the Aircraft Piston Engines Market (2026-2032)
The global aviation landscape is undergoing a subtle yet profound transformation. While much attention dominates the headlines regarding sustainable aviation fuels and electric propulsion, the heartbeat of general aviation remains steadfastly dependent on the internal combustion piston engine. For stakeholders, investors, and strategic planners, understanding the trajectory of this mature yet evolving market is not merely an academic exercise—it is a critical component of risk mitigation and growth strategy for the 2026 fiscal year and beyond.
PW Consulting is proud to introduce our comprehensive market intelligence report on the Aircraft Piston Engines Market. This document serves as a strategic compass for navigating the complexities of engine manufacturing, aftermarket support, and regulatory compliance over the forecast period extending to 2032. By synthesizing historical data with forward-looking projections, this study provides the granularity required to make informed capital allocation and product development decisions.
Market Trajectory and Historical Context
The resilience of the piston engine sector is evident when examining the revenue trends over the past half-decade. From 2020 to 2025, the market demonstrated a consistent upward trajectory, recovering from global supply chain disruptions and ramping up to meet renewed demand in general aviation. Revenue figures have climbed steadily, reflecting both increased production rates and healthy pricing power within the supply chain.
Looking forward, the market is projected to expand from an estimated 5,270 million USD in 2026 to approximately 7,153 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent throughout the forecast period. This rate suggests a market that is not only recovering but maturing, driven by replacement cycles, fleet expansion in emerging economies, and technological upgrades in existing airframes. For decision-makers, these top-line figures validate the sector as a stable investment vehicle with predictable long-term returns, though the allocation of these revenues across different segments requires deeper analysis provided in our full report.
Segmentation Dynamics: Types, Applications, and Geography
Understanding where value is generated within the market is crucial for targeting investments. The market is divided into distinct categories based on engine architecture, operational application, and regional demand. While specific percentage splits are detailed within the proprietary sections of our study, the structural composition reveals key preferences among manufacturers and operators.
In terms of engine type, the market is anchored by Horizontally Opposed, Inline, and Radial configurations. The dominance of certain architectures often correlates with specific aircraft categories, influencing supply chain requirements and manufacturing capabilities. Similarly, the application landscape is diversified across Training, Aerial Work, and Private and Recreational segments. The training sector, for instance, remains a critical volume driver due to the perpetual need for pilot certification, whereas aerial work demands durability and specific performance metrics. Private and recreational use continues to be a significant contributor, fueled by hobbyist enthusiasm and personal aviation ownership.
Geographically, the demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, economic conditions, and fleet ages that dictate consumption patterns. Our analysis highlights how regional discrepancies in certification standards and economic growth rates create varied opportunities for engine manufacturers and service providers.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established legacy manufacturers and innovative entrants focusing on alternative fuel capabilities. The market concentration, indicated by a CR5 of 26.2 percent, suggests a moderately fragmented industry where niche players can still carve out significant market share through specialization.
Lycoming Engines, based in Williamsport, Pennsylvania, remains a cornerstone of the industry. Their production of four-, six-, and eight-cylinder piston engines up to 400 horsepower supports a vast array of general aviation, training, and commercial aircraft. Notably, their engines power over half of the world's general aviation fleet, establishing a reputation for reliability that creates high switching costs for operators.
Continental Aerospace Technologies, headquartered in Mobile, Alabama, competes closely with a focus on advanced designs. They manufacture piston engines capable of running on both Jet-A and avgas, accumulating over 12 million flight hours. Their recent moves highlight a strategic pivot towards fuel flexibility and certification in new sectors.
Aircraft Piston Engines Market
BRP-Rotax, located in Austria, serves a specialized niche by developing engines for light sport, ultralight, and training aircraft. Their focus on the lower end of the weight and power spectrum allows them to dominate segments where traditional general aviation engines are too large or costly.
DeltaHawk Engines, based in Racine, Wisconsin, represents the innovative frontier. They manufacture FAA-certified jet-fuel-burning piston engines, such as the DHK180 and DHK6A350. By enabling the use of heavy fuel in piston engines, they address logistical advantages in remote operations and reduce dependency on traditional avgas supplies.
Recent Developments and Technological Shifts
The period leading into 2026 has seen significant activity regarding product launches and certifications that will shape the next cycle of market growth. These events signal a shift towards fuel flexibility and expanded operational envelopes.
In July 2025, Piper Aircraft, Inc. announced the Piper Seminole DX, powered by DeltaHawk's FAA-certified DHK4A180 180-hp heavy fuel engine. The order book opened at EAA AirVenture 2025, marking a tangible entry of heavy-fuel piston technology into multi-engine training and commercial applications. This development is particularly significant given the regulatory backdrop. FAA certification flight testing for the Piper Seminole DX with the DeltaHawk engine commenced in November 2025, with certification expected in Q3 2026. This timeline suggests that full market availability and subsequent fleet integration will accelerate demand in the latter half of the forecast period.
Continental Aerospace Technologies achieved a milestone in April 2026 by receiving EASA approval for the CD-170R Jet-A piston engine for rotorcraft applications. This marks the first certified Jet-A FADEC-controlled helicopter piston engine. By bridging the gap between fixed-wing efficiency and rotary-wing operational needs, this certification opens a new revenue stream that was previously inaccessible to piston engine manufacturers.
Jet Engines Market
Simultaneously, DeltaHawk Engines achieved FAA Type Certification for the DHK180 jet-fuel piston engine in June 2025, with the first flight occurring in a Van's RV-14. This certification validates the technical viability of heavy-fuel piston engines in experimental and general aviation categories, encouraging further adoption among builders and operators seeking fuel security.
These technological strides are supported by broader industry data. The General Aviation Manufacturers Association (GAMA) reported that piston airplane deliveries increased by 4.2 percent in 2024 to 1,772 units. This uptick in unit shipments provides a strong foundational demand signal for engine manufacturers, indicating that airframe production is aligning with engine supply capabilities.
Strategic Implications for 2026 Decision-Makers
For executives and planners preparing budgets and strategies for 2026, several implications arise from this landscape. First, the reliance on avgas remains a strategic vulnerability for many operators, making the adoption of Jet-A capable engines a potential risk mitigation strategy. The certifications achieved by Continental and DeltaHawk in 2025 and 2026 provide viable alternatives that should be evaluated against total cost of ownership and logistics.
Second, the fragmentation of the market means that partnership opportunities exist beyond the top tier. With a CR5 of only 26.2 percent, there is room for specialized manufacturers to thrive, particularly in training and aerial work segments where specific power-to-weight ratios are prioritized over raw horsepower. Supply chain resilience is also paramount; understanding the geographic distribution of demand helps in positioning inventory and service centers to minimize downtime.
Finally, regulatory timelines are critical path items. The expected FAA certification for the Piper Seminole DX in Q3 2026 is a catalyst that could spur orders in the training and commuter segments. Stakeholders should align their procurement and hiring strategies to anticipate the ripple effects of this certification on maintenance training and parts inventory.
Report Scope and Methodology
This strategic insight is derived from a robust methodology that combines primary research with extensive secondary data analysis. The full report offers a deep dive into the factors influencing market growth, including regulatory frameworks, technological innovations, and economic indicators.
Readers of the complete study will gain access to detailed segmentation analysis that breaks down market value by region, type, and application, allowing for precise market sizing. The competitive profiling extends beyond basic company statistics to include strategic positioning, recent M&A activity, and product pipeline assessments. Furthermore, the report addresses the constraints and challenges facing the industry, such as fuel availability, emission standards, and supply chain bottlenecks.
Our analysis covers the forecast period from 2026 to 2032, providing a long-term view that supports capital expenditure planning and technology roadmap development. Whether you are a manufacturer looking to expand your portfolio, an investor assessing market entry barriers, or an operator optimizing fleet composition, the data contained herein is tailored to support those specific objectives.
Conclusion
The Aircraft Piston Engines Market stands at a inflection point where traditional reliability meets modern fuel flexibility. The growth projected through 2032 is not merely a reflection of historical trends but a result of active innovation in engine technology and expanding operational scopes. For organizations aiming to lead in this sector, access to granular, verified data is the differentiator between reactive management and proactive strategy. This report provides the foundation necessary to navigate the coming years with confidence.
For detailed analysis of this topic, please visit the official page: Aircraft Piston Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


