



PW Consulting: Industrial Hose Market Hits $14.35B in 2025 with 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
Industrial Hose Market Outlook 2026: Strategic Intelligence for Enterprise Decision Makers
The industrial hose market stands at a critical inflection point as the global economy navigates shifting supply chain dynamics, evolving regulatory frameworks, and sustained capital investment across heavy industry. Our latest comprehensive market research, Industrial Hose Market Analysis 2026, delivers the strategic intelligence needed to navigate this complex landscape. This report is not merely a data compilation, but a decision-support engine designed for executives, procurement leaders, and strategic planners who require actionable foresight rather than retrospective summaries. With a forecast horizon extending through 2032, our analysis captures both the immediate pressures shaping 2026 operations and the structural shifts that will define competitive advantage over the next half-decade.
Market Trajectory and Structural Growth Patterns
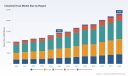
The industrial hose sector has demonstrated consistent revenue expansion over the past half-decade, with historical performance data from 2020 through 2025 establishing a clear trajectory of resilience and demand acceleration. Total market valuation has progressed from a baseline of 10,278.0 million USD in 2020, reaching 11,011.88 million USD in 2021, and advancing through 11,654.77 million USD in 2022, 12,007.18 million USD in 2023, 13,227.84 million USD in 2024, before culminating at 14,352.0 million USD in 2025. This historical arc reflects sustained capital deployment across fluid transfer infrastructure, equipment modernization cycles, and infrastructure development initiatives globally.
The forecast period from 2026 through 2032 projects continued expansion, anchored by a compound annual growth rate of 6.98 percent. Revenue is expected to reach 14,864.94 million USD in 2026, scaling toward 16,623.63 million USD by 2027, 18,166.93 million USD in 2028, 18,307.89 million USD in 2029, 20,276.98 million USD in 2030, 21,952.85 million USD in 2031, and ultimately 23,169.0 million USD by 2032. These figures represent nominal market size in USD millions, reflecting the aggregate value of hose products, assemblies, and associated fluid handling components across all industrial applications. The sustained growth rate underscores a market that continues to expand beyond cyclical recovery, driven by underlying industrial activity and technological modernization.
Importantly, our methodology isolates growth drivers from noise, enabling stakeholders to distinguish between temporary demand spikes and durable structural expansion. The 6.98 percent CAGR encompasses multiple interacting variables, including raw material cost volatility, geographic supply chain reconfiguration, regulatory compliance costs, and the ongoing shift toward high-performance composite and thermoplastic materials. executives who rely solely on headline growth figures risk misallocating resources; our analysis deconstructs these layers to reveal where sustainable value creation resides.
2026 Strategic Context: Pricing Pressures, Standards, and Operational Realities
The current operating environment is defined by intersecting cost and compliance pressures that directly influence procurement budgets, manufacturing margins, and product specification decisions. As of early 2026, stainless steel prices have stabilized near 1,995 USD per ton, a level that directly impacts hydraulic hose production costs and influences the economics of metal-reinforced assemblies. Simultaneously, natural rubber benchmark pricing has fluctuated between approximately 1.61 and 2.23 USD per kilogram, while synthetic rubber FOB pricing in China registered around 2,267 USD per ton in January 2026. These input cost dynamics do not merely affect short-term pricing; they reshape the competitive positioning of material categories, forcing manufacturers and buyers alike to reevaluate specification strategies, inventory management approaches, and total cost of ownership calculations.
Regulatory and standards evolution adds another critical dimension. The newly defined EN 854:2026 specifications establish updated requirements for textile reinforced rubber hydraulic hoses and assemblies intended for industrial and commercial applications, creating a compliance imperative that will influence product selection, certification processes, and market access for suppliers who have not aligned their portfolios accordingly. Concurrently, OSHA regulations continue to set binding workplace safety rules for hose handling and pressure systems in industrial settings, reinforcing the operational importance of durable, compliant assemblies that reduce incident risk and support audit readiness. These standards are not peripheral considerations; they embed themselves into procurement criteria, supplier qualification processes, and liability frameworks across multiple sectors.
Industrial Hose Market
Worldwide Industrial Flexible Hose Market
Trade show activity during early 2026 further illustrates the industry's active engagement with these dynamics. Companies including Salem-Republic Rubber Company, NRP Jones, Tubes International, and Elastohose have all maintained visible booth presences at major industry gatherings such as CONEXPO-CON/AGG 2026 and FLUID POWER 2026, showcasing product innovations, engaging with end-users, and signaling strategic priorities around durability, material advancement, and application-specific engineering. This sustained exhibition activity reflects an industry in active dialogue with its customer base, adapting to technical requirements and competitive expectations in real time.
Core Research Dimensions: What the Report Delivers
Our analysis is structured to provide immediate tactical value alongside long-term strategic orientation. Rather than presenting isolated data points, the report integrates quantitative benchmarking with qualitative assessment to produce a decision framework applicable across corporate functions.
Quantitative Benchmarking and Historical Reconstruction
The research reconstructs historical market performance from 2020 through 2025, calibrating base-year 2025 figures before projecting forward through 2032. This structure allows users to validate internal assumptions against audited market trajectories, identify periods of outperformance or underperformance relative to industry trends, and model scenario-based forecasts with confidence in the underlying baseline. All figures are expressed in USD millions, ensuring consistency with global financial reporting conventions and facilitating direct integration into strategic planning models.
Application and Product Category Landscape
The report maps revenue distribution across hydraulic hoses, air and water hoses, suction and discharge hoses, chemical hoses, and food and beverage hoses, while simultaneously tracking demand intensity across oil and gas, construction and infrastructure, automotive, agriculture, mining, chemicals, and food and beverage applications. By presenting these dimensions as interlocking rather than independent, our analysis reveals how material selection, performance requirements, and end-market purchasing cycles interact to shape revenue concentration and growth velocity within each product and application stream. Readers gain visibility into which categories are structurally positioned for sustained expansion and which face margin compression, substitution risk, or regulatory headwinds.
Geographic Demand Architecture
Market activity spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region, each exhibiting distinct procurement patterns, infrastructure development pacing, and industrial output profiles. Our geographic assessment avoids simplistic ranking exercises in favor of examining how regional industrial structures, trade flows, and local manufacturing capacity interact to produce divergent growth paths. This regional layering enables multinational operators to prioritize market entry timing, distribution investments, and localized product strategies with greater precision.
Competitive Position Mapping and Strategic Posture Assessment
The competitive landscape includes established multinational manufacturers and specialized fabricators whose strategic positioning, product breadth, and regional reach vary considerably. Our analysis profiles organizations including Parker Hannifin Corporation, Gates Corporation, Danfoss, Continental AG, Kuriyama of America, Inc., Flexaust Inc., Southeastern Hose, Inc., and NRP Jones, examining their product portfolios, operational focus areas, and apparent strategic emphasis on fluid transfer, pressure systems, and specialized industrial applications. Rather than providing static company descriptions, we assess how each player's portfolio architecture and market orientation suggest vulnerability to pricing pressure, capacity to capture premium specification opportunities, and likelihood of influencing industry standards adoption.
Supply Chain, Procurement, and Cost Drivers
Recognizing that input costs and logistics realities fundamentally affect commercial outcomes, the report integrates raw material pricing intelligence, production cost considerations, and procurement cycle dynamics into its strategic recommendations. By linking stainless steel and rubber pricing movements to segment margins and product substitution patterns, we equip procurement teams and finance leaders with the context needed to negotiate with suppliers, time purchases, and evaluate make-versus-buy decisions more effectively.
Competitive Dynamics: Concentration, Differentiation, and M&A Potential
Market concentration metrics indicate a moderately fragmented but increasingly competitive environment, with CR3 at 24.6 percent and CR5 at 26.2 percent. These figures signal that while no single entity commands dominant market control, the top tier of suppliers collectively holds meaningful share, and the distance between leading players and the broader tail of manufacturers remains structurally significant. For strategic planners, this concentration profile suggests several actionable implications. First, pricing power is unlikely to be exercised uniformly across the market, meaning that differentiation through application engineering, certification compliance, delivery reliability, and technical support will likely determine which suppliers succeed in capturing premium positions. Second, the moderate concentration leaves room for consolidation, partnership formation, and vertical integration moves that could alter competitive balances over the forecast horizon. Third, smaller and mid-tier fabricators that specialize in custom assemblies, oilfield applications, or niche material configurations may find opportunities to compete on responsiveness and engineering service rather than price alone, particularly as end-users increasingly prioritize specification integrity and operational safety.
The strategic posture of leading and mid-tier players reflects the broader tension between scale economies and specialization. Multinational manufacturers typically compete on portfolio breadth, international distribution reach, and alignment with major industrial standards, while regional or application-focused fabricators often emphasize custom engineering, rapid turnaround, and proximity to specific end markets. Our analysis examines how these strategies are likely to perform as raw material volatility persists and as regulatory updates such as EN 854:2026 raise the baseline for compliance. Companies that have invested in material science capabilities, certified manufacturing processes, and application-specific testing infrastructure are better positioned to defend margins and capture share from less differentiated competitors.
2026 Decision Framework: Translating Market Intelligence into Action
The report is designed to answer the strategic questions that matter most to enterprise decision makers in 2026 and beyond. Rather than offering generic observations, we structure the analysis around actionable decision points.
- Where should procurement and sourcing investments be directed given current raw material pricing, input volatility, and compliance-driven specification requirements?
- Which product categories and application segments present the most attractive risk-adjusted growth exposure over the 2026 to 2032 window, and how should capital allocation reflect those opportunities?
- How do geographic demand patterns affect distribution strategy, local manufacturing decisions, and market entry timing for both incumbent operators and new entrants?
- What competitive vulnerabilities and strengths are embedded in current supplier portfolios, and how should that assessment inform partnership, sourcing, and potential acquisition evaluations?
- In what ways do evolving standards and safety regulations reshape the total cost of ownership calculus for industrial hose systems, and which suppliers are best positioned to support compliance-driven purchasing requirements?
Each of these questions is addressed through integrated quantitative data, qualitative market assessment, and competitive profiling that together provide a coherent basis for strategic planning. Our objective is to enable leaders to move from uncertainty to structured decision making, using evidence that accounts for both near-term operating realities and longer-term structural trends.
Concluding Perspective
The industrial hose market in 2026 is defined by durable growth momentum, material cost complexity, regulatory refinement, and an active competitive landscape that rewards differentiation and technical capability. The trajectory from a 14,352.0 million USD base in 2025 toward an estimated 23,169.0 million USD by 2032 reflects an industry where sustained capital spending, infrastructure development, and fluid handling modernization converge to support demand. Yet beneath these headline figures lies a richer analytical environment, one in which product category dynamics, application-specific demand intensity, regional variation, cost-driven substitution, and competitive positioning collectively determine where value is created and retained. Our full Industrial Hose Market report delivers the detailed segmentation analysis, scenario modeling, competitive profiling, and procurement intelligence required to act on this complexity with confidence. For executives and strategic planners who need more than macro-level summaries, the complete study provides the resolution necessary to inform sourcing strategy, investment prioritization, partnership evaluation, and risk management through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refractory Metals Market Hits $7.0 Billion in 2025, Projected to Reach $8.39 Billion by 2032
By PW Consulting, 2026-09-16
Securing Critical Edges: Strategic Intelligence for the Refractory Metals Market Through 2032
Refractory metals form the backbone of high-performance engineering, enabling capabilities in aerospace, electronics, and industrial manufacturing that no other material class can match. As geopolitical tensions reshape supply chains and advanced manufacturing drives new demand vectors, understanding the trajectory of this specialized market has become a strategic imperative for executives, investors, and procurement leaders. The latest market research from PW Consulting delivers a comprehensive, data-driven assessment of the global refractory metals landscape, projecting market evolution from the base year of 2025 through the forecast horizon of 2032. This article previews the strategic insights contained within the full report, highlighting the structural dynamics, competitive forces, and regulatory headwinds that will define decision-making in the years ahead.
Market Architecture: Growth Trajectory and Structural Foundations
The global refractory metals market has demonstrated steady expansion over the historical period from 2020 to 2025, progressing from a revenue base of 5.8 billion USD to a projected 7.0 billion USD by 2025. This growth reflects sustained demand from high-value end-use sectors alongside incremental capacity additions and evolving material specifications. Looking forward, the forecast period spanning 2026 to 2032 indicates continued market development, with overall revenue projected to advance toward 8.39 billion USD by the terminal forecast year. The compound annual growth rate across the forecast window registers at 2.7 percent, representing a measured but resilient expansion profile characteristic of a mature, capital-intensive materials sector.
This growth trajectory is neither uniform nor guaranteed. It reflects the interplay of structural demand drivers, supply-side constraints, pricing dynamics, and regional trade policy shifts. The report dissects these layers systematically, providing decision-makers with a framework to evaluate where value will concentrate, which segments will outperform, and how external shocks may alter baseline projections. Rather than offering a static snapshot, the analysis maps the conditional pathways that market participants are likely to navigate, emphasizing the importance of scenario planning and supply chain flexibility.
Refractory Metals Market
Segmentation Dynamics: Where Value Is Created and Competitive Pressure Intensifies
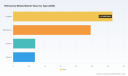
The market segmentation architecture examined in the research reveals several structural characteristics that are critical for strategic positioning. By material type, the market is anchored by tungsten and molybdenum, which together dominate revenue share and underpin the majority of industrial and advanced manufacturing applications. Tantalum and niobium represent smaller but strategically vital subsegments, often serving niche, high-specification roles in electronics, aerospace, and specialty alloys. The report details how these material categories differ not only in absolute scale but in pricing sensitivity, supply concentration, technological substitution risk, and end-market growth profiles.
From an application perspective, aerospace and defense, alongside electronics and semiconductors, constitute the primary demand engines for refractory metals. These sectors demand high purity, consistent quality, and certified supply chains, creating premium positioning for suppliers who can meet stringent qualification requirements. The steel industry remains a meaningful consumption channel, though its growth dynamics are more closely tied to broader industrial cycles and infrastructure investment patterns. The full report breaks down these application profiles with granular attention to demand drivers, material specifications, and the competitive implications of shifting procurement strategies across each vertical.
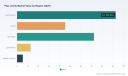
Regionally, the analysis captures a globally distributed market with meaningful participation across North America, Europe, and Asia Pacific, alongside smaller but strategically relevant activity in Latin America and the Middle East and Africa. The geographic distribution of production capacity, processing infrastructure, and end-market consumption shapes trade flows, tariff exposure, and competitive dynamics in ways that the report examines in depth. Readers of the full publication will find a detailed mapping of regional supply-demand balances, import dependency trends, and the localized effects of trade policy actions that are already altering market behavior.
Competitive Landscape: Concentration, Vertical Integration, and Strategic Maneuvering
Market concentration in the refractory metals sector registers at a CR3 of 38 percent and a CR5 of 45 percent, indicating a moderately consolidated landscape where a handful of large, globally integrated players command significant share, while a broad base of regional specialists, niche processors, and recyclers compete on service, quality, and application expertise. The competitive environment is further shaped by the presence of major primary producers, sophisticated downstream fabricators, and an active secondary processing and recycling ecosystem that is increasingly relevant as supply security and sustainability considerations intensify.
The research provides detailed company profiles and strategic assessments for a comprehensive set of participants spanning North America, Europe, China, Brazil, and Chile. Key North American entities include established producers and fabricators such as Cleveland Tungsten, Inc., Cronimet Specialty Metals USA, Inc., Elmet Technologies LLC, Global Tungsten & Powders LLC, Hyperion Materials & Technologies, Innovative Carbide LLC, Kennametal Inc., Lineage Metallurgical, Molymet Corporation, Niagara Refining LLC, PLANSEE USA LLC, Rhenium Alloys Inc., Thomas & Skinner, Inc., Umicore Canada Inc., and Vista Metals. These organizations represent a cross-section of the industry's capabilities, from primary production and powder metallurgy to specialty alloys, carbide products, and secondary recovery.
On the global stage, the competitive field includes significant primary producers and material specialists such as Jinduicheng Molybdenum Co., Ltd. and Xiamen Tungsten Industry Co., Ltd. in China, CBMM in Brazil as a leading niobium producer, Molymet in Chile, the Plansee Group in Austria, Treibacher Industrie AG, ATI, H.C. Starck Tungsten GmbH in Germany, Ningxia Orient Tantalum Industry, and Climax Molybdenum in the United States. The full report evaluates these players across dimensions including capacity positioning, product breadth, technological capabilities, geographic reach, and strategic responsiveness to supply chain and regulatory shifts.
Recent corporate activity underscores the dynamic nature of this competitive environment. In August 2025, Molymet incorporated Molymet Alloys, LLC in Delaware to advance higher value-added products and related activities, signaling a deliberate move up the value chain. In October 2025, Molymet completed the acquisition of all rights and shares of Rhenium Alloys, Inc., expanding its footprint across molybdenum, tungsten, rhenium, and semiconductor-related product lines. These moves illustrate how established players are consolidating capabilities to capture margin, broaden application coverage, and strengthen supply chain control. The report analyzes such developments not as isolated events but as indicators of broader strategic themes reshaping industry structure.
Market Dynamics: Regulation, Trade Policy, and Supply Chain Realignment
The refractory metals market is operating in an environment where regulatory frameworks, trade policy actions, and raw material pricing dynamics are exerting increasingly direct influence on competitive outcomes. Several developments captured in the research illustrate the nature and pace of these shifts. As of November 2025, the average monthly price for tantalum ore stood at 180 USD per kilogram of Ta2O5 content, reflecting the premium attached to secure, qualified supply in a market with concentrated production and growing demand from electronics and defense applications. In 2025, U.S. tantalum apparent consumption increased 58 percent to 890 tons, accompanied by corresponding rises in imports, highlighting the sensitivity of domestic demand to supply availability and pricing.
Trade policy actions are introducing new volatility and cost structures into the market. In February 2025, China implemented new export controls on selected tungsten items, contributing to sharp price rises for tungsten concentrates and reinforcing concerns about supply concentration for a material that is central to multiple high-value applications. Concurrently, U.S. Section 301 tariffs on tungsten products from China increased to 25 percent effective January 1, 2025, altering the cost calculus for importers and incentivizing efforts to diversify sourcing or develop domestic and allied-supply alternatives. The research also notes that U.S. imports for tungsten concentrates showed increased reliance on China, with data from 2021 to 2024 indicating a 26 percent share amid ongoing supply constraints, underscoring the persistence of dependency even as policy and strategic efforts push toward greater supply autonomy.
These dynamics are not merely background conditions; they are actively reshaping procurement strategies, capacity investment decisions, and competitive positioning. The report integrates these factors into its market assessment, providing a structured evaluation of how regulatory and trade developments influence price formation, supply security, regional competitiveness, and the strategic calculus of major buyers and producers alike. Decision-makers relying on the full publication will find these insights contextualized within scenario frameworks that account for the range of plausible policy and supply outcomes over the forecast period.
Strategic Developments: Capacity, Recycling, and Defense-Driven Demand
Recent activity across the industry points to a clear strategic thrust toward capacity enhancement, supply chain domestication, and the valorization of secondary materials. In November 2025, 6K Additive received a 1.95 million USD Phase II government contract to produce certified tungsten, niobium, and other refractory metal powders from domestic military scrap for defense applications, illustrating the growing intersection of advanced manufacturing, recycling, and national security priorities. Also in November 2025, the U.S. Defense Logistics Agency awarded an 8.6 million USD delivery order for tantalum ingots and secured up to 100 million USD for domestic tantalum processing from ore, reinforcing the strategic importance of tantalum for defense and aerospace applications and signaling sustained government commitment to building resilient domestic supply capabilities.
Further reflecting the push toward supply chain resilience and circular material flows, Plansee Group announced and advanced a U.S. capacity expansion project in February 2026 focused on tungsten recycling and refractory metals production. This development, alongside the broader activity in secondary processing and recycling among firms such as Lineage Metallurgical, Niagara Refining LLC, and Vista Metals, indicates that recycling and material recovery are moving from peripheral considerations to central components of supply strategy. The full report assesses these developments within the context of long-term market evolution, examining how capacity additions, recycling scale-up, and defense-driven procurement intersect with commercial demand growth and competitive dynamics.
Why This Research Matters for 2026 Decision-Making
The refractory metals market presents a distinctive strategic challenge: it is simultaneously a mature, structurally stable materials sector and a rapidly evolving environment shaped by trade policy, supply concentration, technological demand shifts, and heightened attention to supply security. Navigating this landscape requires more than high-level market sizing or generic demand narratives. It demands a precise understanding of segment-level growth drivers, competitive positioning, pricing and cost dynamics, regulatory exposure, and the strategic implications of recent corporate and policy developments.
Refractories Market
The PW Consulting Refractory Metals Market research is designed to meet that need. It combines rigorous historical analysis, a structured forecast framework extending to 2032, detailed segmentation and regional assessment, comprehensive competitive profiling, and integrated analysis of the regulatory and trade dynamics that are actively reshaping the market. The full report goes beyond the macro trajectory to provide actionable intelligence on where value is being created, which competitive moves are reshaping industry structure, and how buyers, producers, and investors can position themselves to manage risk and capture opportunity.
For executives and strategists operating in 2026, the difference between reactive positioning and proactive advantage lies in the quality of intelligence available. The insights previewed here are drawn from a broader body of analysis that drills into the specifics of material-level demand profiles, application-driven pricing dynamics, regional supply-demand balances, competitive capabilities, and the strategic significance of recent contract awards, capacity expansions, acquisitions, and regulatory actions. To access the complete dataset, segmentation detail, competitive assessment, and scenario-based forecasts that underpin these conclusions, we invite you to explore the full report through the source webpage. The comprehensive intelligence contained within is intended to serve as a foundational reference for strategic planning, procurement strategy, investment evaluation, and competitive positioning across the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Refractory Metals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Temperature Controllers Market to Hit $3,132.63M by 2032, 4.6% CAGR
By PW Consulting, 2026-09-16
Navigating Precision: Strategic Insights for the Industrial Temperature Controllers Market in 2026
Executive Summary: The Case for Strategic Foresight
In the complex landscape of industrial automation, temperature control remains a foundational element of operational efficiency, product quality, and safety. As we move beyond the base year of 2025, enterprise leaders face a critical juncture. The trajectory of the Industrial Temperature Controllers Market is not merely a function of technological advancement but a reflection of broader macroeconomic shifts, regulatory pressures, and evolving manufacturing demands. Our latest comprehensive market study is designed to equip stakeholders with the granular intelligence necessary to navigate this evolving terrain.
This article serves as a strategic primer, outlining the scope, methodology, and competitive dynamics analyzed in our full report. While we highlight key market forces and structural trends here, the proprietary segmentation data, detailed revenue forecasts, and specific risk assessments contained within the complete publication remain exclusive to our subscribers. The objective is to demonstrate the depth of our analysis while underscoring the necessity of accessing the full intelligence package for actionable decision-making.
Market Trajectory and Growth Vectors
The historical performance of the industrial temperature control sector indicates a steady expansion, driven by the relentless need for precision in processing industries. Our analysis covers historical data spanning from 2020 through 2025, establishing a robust baseline for forecasting the period from 2026 to 2032. The market has demonstrated resilience and consistent upward momentum, reflecting the integral role of thermal management in modern industrial operations.
Looking forward, the forecast period anticipates continued growth, underpinned by a compound annual growth rate that signals sustained investment in automation technologies. This growth is not uniform across all vectors; it is propelled by specific technological shifts and regional industrialization efforts. Understanding the magnitude of this expansion requires a nuanced view of how different controller types and application sectors contribute to the overall revenue pool. While the aggregate market size figures point to a significant valuation by the end of the forecast period, the strategic value lies in dissecting the drivers behind these numbers.
Key growth vectors include the modernization of legacy manufacturing infrastructure and the adoption of smart control systems in emerging economies. However, capturing these opportunities requires more than top-line figures. It demands an understanding of the interplay between supply chain dynamics, component availability, and the specific thermal requirements of high-growth sectors such as energy and advanced manufacturing.
Irrigation Controllers Market
Competitive Landscape and Key Players
The market structure is characterized by a mixture of established global conglomerates and specialized regional players. Our report provides an in-depth profiling of key companies that are shaping the competitive environment. Understanding the strategic positioning of these entities is vital for companies looking to benchmark their performance or identify potential partnership opportunities.
Among the leaders, Omron Corporation stands out with a strong focus on PID process controllers. Their offerings are deeply integrated into industrial automation and manufacturing workflows, emphasizing precision regulation that aligns with high-standard automation protocols. Headquartered in Kyoto, Japan, Omron continues to leverage its global footprint to deliver solutions that cater to complex industrial requirements.
Similarly, Watlow Electric Manufacturing Company maintains a significant presence, particularly in the realm of precision temperature controllers and thermal management systems. Based in the United States, Watlow's portfolio extends to multi-loop process controllers, addressing applications where multiple thermal zones must be managed simultaneously. Their approach underscores the importance of reliability in harsh industrial environments.
On the other side of the spectrum, Yudian Temperature Control Technology Co., Ltd. represents a pivotal player in the global supply chain, headquartered in Xiamen, China. Yudian has distinguished itself not only through product volume but through regulatory and standards leadership. Notably, Yudian was the first in the instrumentation industry to achieve UL certification as of 2012, a milestone that opened doors to stringent international markets. Furthermore, the company has led the drafting of the core Chinese national standard GB/T 20819.1-2015 for Controllers with Analogue Signals for Industrial Process Control Systems. This involvement in standards setting signals a long-term commitment to compliance and interoperability. Their products are exported to over 150 countries and regions, highlighting their extensive global distribution network.
Additionally, Wuxi Keen Technology Co., Ltd. (Cakeen) is increasingly relevant, particularly for integrated PID temperature controllers and semiconductor-related heating solutions. Based in Wuxi, Jiangsu Province, their growth reflects the broader trend of specialized manufacturers catering to high-tech manufacturing needs where precise thermal control is critical for component integrity.
The competitive dynamics are further influenced by market concentration. Our analysis indicates a moderately concentrated market where top players hold significant share, creating both barriers to entry and opportunities for consolidation. Understanding the strategic moves of these key firms—from product launches to geographic expansion—is essential for anticipating market shifts.
Segmentation and Application Drivers
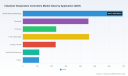
A core component of our research is the detailed breakdown of the market by type and application. The choice of controller technology often dictates the efficiency and cost-effectiveness of an industrial process. The market is segmented into categories such as On/Off Controllers, Proportional Controllers, and PID Controllers. Each category serves distinct operational needs, from simple heating tasks to complex, variable Process control loops requiring high precision.
In terms of application, the demand is spread across a diverse range of industries. Sectors such as Metals Mining & Metallurgy, Chemicals, and Food & Beverages represent significant consumption hubs due to the critical nature of temperature in material processing and safety compliance. Energy & Power and Oil & Gas also remain steady contributors, driven by infrastructure maintenance and operational safety requirements. General Manufacturing and other sectors provide additional volume, reflecting the ubiquitous need for thermal management across the industrial base.
While aggregate figures provide a view of total market size, the strategic insight lies in recognizing how these segments interact. For instance, the shift towards automation in food processing may drive demand for specific controller types that differ from those preferred in metallurgy. Our full report delves into these nuances, providing the specific revenue breakdowns and growth rates for each segment without the noise often found in generalized industry summaries.
Regional Dynamics and Market Concentration
Geographically, the market exhibits distinct characteristics influenced by local industrial policies, manufacturing capacity, and adoption rates of advanced automation. The analysis covers five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Industrial Temperature Controllers Market
Asia Pacific often emerges as a critical hub due to the density of manufacturing activity and rapid industrialization. However, mature markets in North America and Europe continue to drive demand through upgrades and replacements of existing infrastructure. Latin America and the Middle East and Africa present growth opportunities linked to resource extraction and energy sector developments.
Market concentration metrics suggest that while the market is accessible, scale and distribution networks play a crucial role in securing market share. Companies operating in this space must navigate varying regulatory environments and supply chain complexities unique to each region. Our report analyzes these regional disparities to help stakeholders identify where to focus their commercial efforts.
Regulatory and Compliance Influences
Regulatory frameworks and industry standards significantly impact product development and market access. Compliance is no longer optional; it is a competitive differentiator. As noted in our findings, certain manufacturers have moved early to secure certifications that facilitate international trade. For example, achieving UL certification can be a gateway to North American markets, while adherence to national standards like GB/T in China ensures domestic competitiveness and export compliance.
These regulatory milestones affect not only the manufacturers but also the end-users who require assurance of safety and reliability. In sectors like chemicals and energy, non-compliance can lead to severe operational risks. Therefore, our market study incorporates an analysis of how regulatory trends are shaping product specifications and procurement criteria. This includes tracking standards development and certification achievements that may alter the competitive balance.
Methodological Rigor and Data Integrity
To ensure the reliability of our insights, the report employs a multi-faceted research methodology. This includes extensive primary interviews with industry stakeholders, suppliers, and end-users, supplemented by secondary research from credible industry databases and financial reports. The data is validated through triangulation to minimize bias and ensure accuracy.
Our base year analysis establishes the current market state, while the forecast period utilizes trend analysis and modeling to project future performance. We account for variables such as economic fluctuations, technological disruptions, and supply chain constraints. This rigorous approach ensures that the insights provided are robust enough to support high-stakes strategic planning.
Strategic Value for 2026 Decision Makers
Why does this matter for your organization in 2026? In an environment where capital allocation must be precise, understanding the market trajectory of industrial temperature controllers can inform investment decisions, product development roadmaps, and supply chain strategies.
- Investment Planning: Identify high-growth segments before they become saturated.
- Competitive Benchmarking: Understand where key players are focusing their R&D and sales efforts.
- Risk Mitigation: Anticipate regulatory changes and supply chain disruptions that could impact operations.
- Market Entry Strategy: Evaluate regional potentials based on detailed demand analysis rather than generic assumptions.
The full report provides the specific data points required to execute these strategies. It moves beyond general trends to offer actionable intelligence on revenue potentials, market shares, and specific growth rates across all analyzed dimensions.
Conclusion: Accessing the Full Intelligence
The Industrial Temperature Controllers Market is poised for continued evolution, driven by technological refinement and industrial demand. However, navigating this landscape requires more than surface-level observations. It demands a deep dive into segmentation, competitive moves, and regional specifics.
This article has outlined the scope and strategic relevance of our latest study. To access the complete repository of data—including detailed segmentation revenues, specific CAGR breakdowns by segment, and comprehensive company profiles—we invite you to consult the full report. Equip your team with the precise intelligence needed to lead in 2026 and beyond. The future of industrial precision belongs to those who plan with data-driven confidence.
For detailed analysis of this topic, please visit the official page: Industrial Temperature Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pipe Joints Market Hits $228.6M in 2025, Projected to Reach $327.9M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Pipe Joints Market 2026-2032: Navigating Growth, Competition, and Regulatory Shifts
The global pipe joints market stands at a pivotal juncture as organizations prepare for the 2026 fiscal year and beyond. Infrastructure spending, industrial expansion, and evolving safety regulations are converging to reshape demand patterns across multiple sectors. For executives, procurement leaders, and strategic planners, the ability to anticipate these shifts is not merely an advantage, it is a necessity. Our latest Pipe Joints Market research delivers a comprehensive, data-driven blueprint designed to inform capital allocation, product positioning, and competitive strategy through 2032.
This insight briefing outlines the macro trajectory, competitive architecture, and emerging dynamics that will define the market landscape. It is structured to demonstrate the analytical rigor and actionable depth embedded in the full report, while intentionally reserving granular segmentation figures, regional breakdowns, and application-specific revenue allocations for the complete dataset available on our platform.
Macro Trajectory: A Resilient Growth Arc Across the Forecast Horizon
Drawing on historical performance from 2020 through 2025 and extending into a seven-year forecast period spanning 2026 to 2032, the market demonstrates a consistent upward trajectory. The overall revenue base, measured in USD millions, has progressed from 173.5 in 2020 to 181.33 in 2021, 187.78 in 2022, and 209.06 in 2023. The pace of expansion accelerated notably in 2024 and 2025, with recorded revenues of 209.42 and 228.6 respectively, reflecting stronger industrial activity, renewed construction momentum, and recovering supply chain conditions.
The forecast window projects sustained growth, with the market expected to reach 243.46 in 2026, followed by 255.59 in 2027, 269.9 in 2028, 290.04 in 2029, 293.41 in 2030, 308.93 in 2031, and a projected 327.9 by 2032. This pathway corresponds to a compound annual growth rate of 5.35 percent across the forecast horizon, signaling a market that is expanding at a steady, investable pace rather than experiencing volatile spikes. For strategic planners, this CAGR provides a reliable baseline for capacity planning, inventory forecasting, and long-term partnership structuring.
Importantly, the absolute scale of the market and the consistency of its growth underscore the foundational role that pipe joints and couplings play across critical infrastructure and industrial ecosystems. As organizations map their 2026 objectives, understanding how this trajectory aligns with regional development cycles, application-specific demand surges, and material cost normalization becomes a central component of scenario planning.
What the Report Delivers: Operational Content Designed for Execution
The full Pipe Joints Market study goes beyond top-line projections to equip decision-makers with structured, implementation-ready intelligence. The report is organized around several core analytical pillars, each calibrated to support distinct enterprise functions:
- Market sizing and forward modeling: Historical baselines and forecast pathways are presented with methodological transparency, enabling teams to anchor budgeting and demand planning in validated trajectories rather than speculative estimates.
- Segmentation architecture: The analysis dissects the market across product types, application verticals, and geographic regions. While aggregate growth signals are clear, the report provides the segmented context necessary to identify where demand is concentrating, which product categories are outpacing the broader curve, and how application-driven procurement patterns differ across industries.
- Competitive landscape and concentration metrics: Market structure is evaluated through concentration indicators, revealing the degree of fragmentation versus consolidation. This framework helps organizations assess entry barriers, partnership opportunities, and the strategic implications of operating in a market where the top three players hold a measured share and the top five maintain a slightly broader but still moderate footprint.
- Pricing and cost environment analysis: Unit economics are examined in the context of material inputs, manufacturing complexity, and specification tiers. The report situates price ranges for standard metal and alloy fittings within broader cost dynamics, giving procurement and pricing teams a reference frame for negotiations, margin planning, and make-versus-buy decisions.
- Regulatory and compliance mapping: Emerging codes and installation mandates are tracked to highlight how policy shifts influence material selection, approval workflows, and project timelines. This section is particularly relevant for firms operating in jurisdictions where nonmetallic joint specifications and manufacturer installation protocols are becoming more stringent.
- Recent industry developments and event intelligence: Product launches, trade show activity, and supplier announcements are synthesized to provide a live pulse on innovation cadence and market engagement. This ensures that strategy teams are aware of near-term product introductions and industry gatherings that may influence competitive positioning or procurement cycles.
Competitive Landscape: Key Players and the Structure of Market Participation
The pipe joints sector is characterized by a mix of established manufacturers, specialized engineering firms, and regional suppliers, each competing on dimensions such as joint integrity, installation efficiency, diameter range, and application-specific performance. The report profiles several core companies whose product portfolios and recent moves illustrate the competitive dynamics shaping the market.
Northwest Pipe Company, headquartered in Bellingham, Washington, focuses on engineered steel water pipe solutions with watertight joint systems, including its InfraShield® platform and custom mechanical couplings designed to preserve pipeline integrity under demanding service conditions. Victaulic, based in Easton, Pennsylvania, manufactures grooved mechanical pipe couplings and joining systems that emphasize faster, safer installation across industrial applications, and has continued to expand its fire protection portfolio with recent coupling introductions targeting rigid pipe joints in sprinkler systems. Teekay Couplings, operating from the United Kingdom, produces mechanical pipe couplings spanning a wide diameter range, with an emphasis on space, weight, and installation efficiency for diverse project requirements.
American Cast Iron Pipe Company, located in Birmingham, Alabama, offers restrained joint solutions such as Flex-Ring and Field Flex-Ring designs for ductile iron pipe, addressing endwise separation risks under thrust conditions. Holz Rubber Company, based in the United States, manufactures custom and standard expansion joints that absorb thermal movement and accommodate misalignment in piping systems, supporting reliability across variable operational environments.
These profiles are not isolated company snapshots; they are embedded within a broader concentration analysis that quantifies how market share is distributed and what that distribution implies for competitive strategy. In a market where the top three participants collectively hold approximately 22.8 percent and the top five reach roughly 28.5 percent, the landscape remains relatively fragmented at the top, leaving meaningful room for specialized players, regional specialists, and innovation-driven entrants to compete on performance, service, and application focus rather than scale alone.
Recent activity reinforces this dynamic. In early 2026, Victaulic introduced its style 009v FireLock coupling for rigid pipe joints in sprinkler systems, reflecting continued product development in fire protection and mechanical coupling segments. On the industry engagement front, Iran PIVEX held a January 2026 trade show featuring pipe joints and fittings from international suppliers, while the TUBE Trade Fair in Düsseldorf, scheduled for April 2026, is expected to showcase a broad array of pipe joints and coupling exhibitors. These events signal active supplier participation and sustained interest in cross-border sourcing, technology demonstration, and partnership formation.
Market Dynamics and Contextual Forces Shaping 2026 Decision-Making
Beyond sizing and competition, the research integrates the contextual forces that influence how the market behaves in practice. One notable development is the normalization of raw material costs. Steel prices for pipe joints and couplings are moderating in 2026 following earlier declines, as base metal costs stabilize. This shift has direct implications for manufacturing margins, supplier pricing strategies, and procurement timing, particularly for organizations that delayed purchasing decisions during periods of price volatility.
Pipe Joints Market
Artificial Joints Market
Regulatory evolution is equally consequential. The 2025 Ohio Fire Code mandates that nonmetallic pipe joints must be approved and installed in accordance with manufacturer instructions, reinforcing the importance of compliance documentation, approved product listings, and installer training. For firms operating in or supplying to jurisdictions with similar code trajectories, this type of requirement can affect product selection, project approval timelines, and the relative attractiveness of metallic versus nonmetallic joint solutions in specific applications.
Cost structures also vary meaningfully across specification tiers. General steel or metal pipe joints typically range from approximately USD 30 to over USD 200 per unit, while high-specification alloy fittings can reach between USD 500 and USD 2,000. These ranges illustrate how performance requirements, material grades, and application criticality drive pricing dispersion. For strategic planners, the key insight is that average market growth does not imply uniform profitability across all product categories; instead, value capture often depends on positioning within higher-specification segments, optimizing supply chain efficiency, or differentiating through installation reliability and joint performance.
Together, these dynamics create a market environment where growth is broad-based but execution is highly segmented. Companies that succeed in 2026 and beyond will be those that align their product portfolios with application demand, monitor material cost trends closely, and maintain agility in response to code changes and installation standards.
Why This Research Matters for 2026 Enterprise Decisions
As organizations finalize 2026 strategies, the pipe joints market presents both opportunity and complexity. The projected expansion from 243.46 in 2026 toward 327.9 by 2032, supported by a 5.35 percent CAGR, indicates that demand will continue to grow at a meaningful pace. however, growth at the aggregate level masks important variation across regions, product types, and end-use sectors. Without segmented visibility, companies risk overcommitting to underperforming categories, underestimating regional demand intensity, or misaligning pricing and inventory strategies with actual procurement behavior.
This research is designed to reduce that uncertainty. By combining macro forecasting with structured segmentation, competitive profiling, concentration metrics, and contextual intelligence on materials, regulation, and recent industry activity, the report provides a decision-ready framework for multiple functional teams:
- Strategy and corporate development: Evaluate where to invest, which application verticals offer the strongest near-term tailwinds, and how market concentration shapes partnership and acquisition logic.
- Sales and commercial leadership: Identify high-potential segments, tailor value propositions around joint integrity, installation efficiency, and compliance readiness, and align go-to-market plans with regional demand patterns.
- Procurement and supply chain: Time purchases in response to material cost normalization, assess supplier diversity and concentration risk, and benchmark unit economics against specification tiers.
- Product and engineering: Prioritize development toward mechanical coupling innovations, restrained joint technologies, expansion joint solutions, and fire protection systems where recent launches and trade show activity indicate active market interest.
The full report also contains the detailed regional and application-level segmentation data, granular revenue allocations, and deeper competitive benchmarking that are essential for precise planning. Those specifics are intentionally reserved for the complete dataset, ensuring that teams accessing the full study receive the uncompromised intelligence needed for targeted execution.
Looking Ahead: Positioning for Durable Advantage
The pipe joints market is not simply expanding; it is evolving in ways that reward precision, compliance awareness, and application-specific engineering. As steel costs stabilize, fire and installation codes tighten, and major suppliers continue to introduce specialized coupling and joint technologies, the competitive edge will belong to organizations that can translate market-level growth into segment-level action.
Our Pipe Joints Market research provides the foundation for that translation. It equips leadership with the historical context, forecast confidence, competitive structure, and dynamic intelligence required to make informed decisions throughout 2026 and across the remainder of the forecast period. For teams ready to move from high-level outlook to detailed planning, the complete report offers the segmentation depth, regional specificity, and application-level revenue context necessary to operationalize strategy with precision.
The 2026 market environment will reward those who prepare with data, act with segmentation discipline, and monitor the regulatory and material shifts that shape real-world demand. This study is built to support that preparation from the first strategic review through to execution.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the 2-in-1 Laptop Market: Navigating Growth, Disruption, and Competitive Realignment in 2026
The 2-in-1 laptop category has evolved from a niche premium segment into a foundational hardware architecture for modern computing. As form factors continue to blur the boundaries between productivity, creativity, and mobile workflows, enterprise buyers, channel partners, and OEM strategists require more than surface-level trend summaries. They need structured, forward-looking intelligence that connects macroeconomic trajectories, component-level disruptions, and competitive maneuvering into actionable decision frameworks. PW Consulting's latest market research on the 2-in-1 Laptops Market is built precisely for that purpose: to convert complex industry signals into clear strategic direction for 2026 and beyond.
The Strategic Imperative of a Data-Backed Market View
Over the past half-decade, the category has demonstrated consistent expansion, moving from a baseline of approximately 2,590 million USD in 2020 to an estimated 3,340 million USD in 2025. That progression reflects more than incremental demand; it signals a structural shift in how organizations and individual users evaluate device versatility, input flexibility, and display interactivity. The forecast window extending through 2032 projects a compound annual growth rate of 7.0 percent, with market valuation anticipated to reach roughly 5,357 million USD by the end of the period. These figures are not abstract statistics. They represent the scale of capital allocation, product roadmap prioritization, and regional capacity planning that stakeholders must address in the current planning cycle.
For executives evaluating portfolio investments, inventory commitments, or channel strategies, the key question is no longer whether the 2-in-1 category will continue to expand, but how growth will be distributed across architectures, use cases, and supply ecosystems. A 7.0 percent CAGR in a mature hardware segment suggests sustained transition rather than speculative hype. It implies that convertible and detachable designs are becoming default considerations in specific procurement segments, while also rewarding manufacturers that can align processor roadmaps, display technologies, and service models with evolving user expectations. PW Consulting's research translates this trajectory into a structured lens for scenario planning, allowing decision-makers to test assumptions against validated historical patterns and forward projections.
Report Architecture: From Macro Trajectory to Operational Readiness
The research is organized to support both strategic oversight and tactical execution. Rather than presenting a single narrative arc, the report decomposes the market into analyzable layers that reflect how real organizations make hardware decisions. The foundation rests on historical tracking from 2020 through the 2025 base year, followed by a forecast horizon spanning 2026 to 2032. This dual structure enables readers to benchmark recent performance, identify inflection points, and calibrate medium-term expectations with confidence.
Beyond top-line sizing, the report examines the architecture split between convertible and detachable designs, mapping how each form factor addresses distinct usage profiles, thermal constraints, and input preferences. It also assesses demand patterns across consumer and commercial environments, highlighting where procurement cycles, total cost of ownership calculations, and device longevity requirements diverge. Regional coverage is integrated as a strategic layer rather than a static table, allowing readers to understand how localized purchasing behavior, distribution maturity, and policy environments shape deployment velocity.
The analytical framework further incorporates competitive positioning, supply chain sensitivity, and technology adoption timing. Readers will find structured evaluations of product line breadth, feature differentiation, and go-to-market emphasis across leading manufacturers. Equally important, the report connects these commercial signals to upstream realities such as display and touch integration, semiconductor sourcing pressures, and tariff-driven cost dynamics. The objective is to give strategists a complete operating picture: what is selling, why it is selling, where production risk is accumulating, and which capabilities are most likely to determine market share in the next planning cycle.
Competitive Landscape: Architectural Diversification and AI-Enabled Positioning
The 2-in-1 laptop arena is defined by a concentrated group of established OEMs that are competing simultaneously on hardware versatility, display quality, processor integration, and software-enabled productivity. Market concentration remains high, with the top firms collectively commanding a substantial share of category revenue. This concentration does not imply stagnation. Instead, it reflects an intense competition over micro-differentiation: hinge engineering, touch and pen responsiveness, battery endurance, screen resolution and color accuracy, and increasingly, the integration of AI-centric processing capabilities.
Dell continues to maintain a broad convertible portfolio across mainstream and performance-oriented segments, pairing touch and pen-ready configurations with current-generation Intel Core Ultra platforms. Its lineup illustrates a pragmatic approach to the category: multiple screen sizes and price tiers, consistent enterprise serviceability, and clear positioning for users who need convertible flexibility without abandoning traditional laptop ergonomics.
HP has emphasized the intersection of manageability, display quality, and AI features, particularly in business-facing convertible lines. By combining OLED touchscreen options with AI-forward branding and enterprise-grade chassis design, HP targets procurement teams that want device versatility alongside security, manageability, and visual quality for presentation-heavy or content-review workflows.
ASUS has pursued a more segmented strategy, spanning creative-oriented convertibles, lightweight gaming-capable flip systems, business flip models, and Chromebook options. The breadth of its portfolio reflects a deliberate effort to capture different purchase motivations under one roof, from color-accurate displays for professional creators to 360-degree hinge designs for education and general productivity environments.
2-In-1 Laptops Market
Acer's presence in the category highlights value-conscious engineering and, more recently, a focus on next-generation processor platforms. Its convertible offerings span budget-friendly spin designs, business travel models, and AI-branded flip systems. This range demonstrates how aggressively the category is being extended into multiple price and performance bands, making 2-in-1 configurations accessible to a wider set of buyers.
Lenovo has leaned into the convergence of design refinement, OLED touchscreen adoption, and AI PC narratives. Its convertible and detachable-oriented lines target both premium consumer segments and commercial buyers seeking balanced ergonomics and modern input experiences. The emphasis on Copilot+ features and OLED implementation shows how manufacturers are using software and display quality as leverage in a category where hardware form factors are increasingly familiar to consumers.
Samsung has positioned its Galaxy Book 360 lineup around high-end display technology and integrated ecosystem appeal. With Super AMOLED touchscreens and Intel Core Ultra platforms, these devices reinforce the idea that 2-in-1 devices can serve as premium productivity and media tools rather than merely compromise form factors. The strategy aligns with a broader push toward visually rich, AI-capable devices that perform well in both tablet and laptop modes.
Microsoft remains a defining presence through its Surface line, particularly with detachable-oriented devices powered by advanced silicon options. Its high-end detachable offerings underscore the enduring relevance of detachables in scenarios where tablet-first usage, portability, and pen-based interaction take priority. At the same time, the broader competitive conversation shows that detachable and convertible designs are not interchangeable; each serves distinct workflow assumptions and purchase criteria.
Taken together, these players reveal a market where success depends less on announcing a new form factor and more on executing consistently across display quality, battery performance, thermal management, support ecosystems, and supply reliability. PW Consulting's research evaluates these competitive signals in a way that helps stakeholders identify where differentiation is genuine and where product narratives risk blending into commodity positioning.
Industry Dynamics: Supply Chain Realignment, Component Innovation, and Tariff-Driven Economics
The category's growth trajectory is unfolding against a backdrop of meaningful operational friction. Recent sector analysis points to tariff-related pressures and export restrictions affecting advanced semiconductor components, prompting manufacturers to diversify sourcing and accelerate localization strategies. These developments are not incremental conveniences; they reshape cost structures, lead-time expectations, and regional production planning. For 2-in-1 laptops, which depend on integrated display, touch, and processing ecosystems, any disruption in component availability can cascade quickly into product timing and margin performance.
Tariff actions and retaliatory measures from trade partners have added further complexity by raising production costs for consumer goods, including 2-in-1 laptops, with estimates indicating cost increases in a broad double-digit range. Alongside that, supply chain disruptions have become a recurring risk factor rather than an occasional exception. Semiconductor and display sourcing remain especially sensitive, and the U.S. General Services Administration has noted that such disruptions have translated into longer lead times and higher costs for critical laptop components. In a category where hinge design, touch integration, and thin-chassis thermal constraints already demand precise component coordination, these pressures can influence everything from bill-of-material planning to channel inventory strategy.
Gaming Laptop Market
Despite these headwinds, component-level innovation continues to open differentiation opportunities. Himax Technologies' move into mass production of OLED Touch IC for IT applications is a notable example. By enhancing integrated display and touch performance with industry-leading characteristics, such component advances can improve the user experience that manufacturers rely on to justify premium pricing and reinforce product identity. At the device level, recent introductions such as AI-focused convertible systems powered by next-generation Snapdragon platforms illustrate how manufacturers are translating NPU capability, extended battery life, and multi-monitor support into tangible value propositions. These product developments matter because they show that the category is still evolving in ways that go beyond hinge rotation or screen size alone.
For strategic planners, the implication is clear: market expansion is real, but it is being filtered through a more complicated operating environment. Revenue opportunity must be weighed against sourcing resilience, tariff exposure, logistics risk, and the cost of localizing or dual-sourcing critical inputs. PW Consulting's report addresses these tensions directly, giving readers a structured way to evaluate where demand is durable and where execution risk may erode expected returns.
Why This Research Matters for 2026 Decision-Making
In 2026, hardware strategy is no longer about forecasting a single growth curve. It is about aligning product mix, channel behavior, procurement expectations, and supply chain options within a market that is simultaneously expanding and fragmenting in its competitive logic. The 2-in-1 laptop category exemplifies this challenge. It offers clear long-term demand support, yet it also requires careful interpretation of form-factor preferences, commercial versus consumer buying patterns, regional purchasing conditions, and component-level constraints.
This research is designed to reduce uncertainty at exactly those decision points. It provides a disciplined framework for interpreting historical performance, evaluating forward projections, and understanding how competitive and operational variables interact. Readers gain clarity on where the market is heading in aggregate, how major players are positioning themselves, and which structural pressures are most likely to influence cost, availability, and differentiation in the near term. Just as importantly, the report is built to support internal discussion: it gives product leaders, procurement teams, channel strategists, and investors a common reference point for debating scenario outcomes and prioritizing investments.
The full study goes further than the overview presented here. It contains the detailed segmentation logic, competitive profiles, regional interpretations, and operational risk analysis needed to convert high-level market direction into executable plans. To access the complete dataset, segmentation breakdowns, and strategic recommendations underpinning this analysis, visit the source report page and obtain the full intelligence package. In a market where timing, positioning, and supply resilience determine competitive outcomes, that deeper view is the difference between reactive planning and confident strategic action.
For detailed analysis of this topic, please visit the official page: 2-In-1 Laptops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports 5.55% CAGR for Progressing Cavity Pumps Market to Reach $2,036.03 Million by 2032
By PW Consulting, 2026-09-16
Navigating the Future of Fluid Handling: Strategic Insights from the Progressing Cavity Pumps Market Forecast 2026-2032
The global industrial landscape is undergoing a profound transformation driven by efficiency demands, regulatory shifts, and the relentless need for reliable fluid management solutions. For stakeholders in the progressing cavity pump (PCP) sector, the period from 2026 through 2032 represents a critical window of opportunity and challenge. PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip leadership teams with the actionable intelligence required to navigate this evolving terrain.
As enterprises finalize their strategic roadmaps for the upcoming fiscal years, understanding the macroeconomic currents shaping the PCP market is no longer optional—it is imperative. This briefing serves as an introduction to our deep-dive analysis, outlining the trajectory of market growth, the competitive dynamics at play, and the operational variables that will define profitability in the years ahead. While this article provides a high-level overview of the strategic landscape, the full report contains the granular segmentation and proprietary data necessary for precise capital allocation and market entry strategies.
Market Trajectory and Growth Horizons
The progressing cavity pump market has demonstrated resilience and steady expansion over the past half-decade. Our analysis tracks performance from 2020 through the base year of 2025, providing a robust historical foundation for forecasting future trends. The market has grown consistently, driven by increased industrialization and the expanding application of PCP technology in demanding environments ranging from heavy oil extraction to precise food processing.
Looking toward the forecast period of 2026 to 2032, the momentum is expected to continue. The market is projected to reach significant revenue milestones by the end of the forecast window. This growth is not merely a function of inflation but reflects genuine adoption rates and technological modernization across key sectors. The compound annual growth rate (CAGR) indicates a steady upward trajectory, suggesting that demand for specialized fluid handling equipment will outpace broader industrial sluggishness in certain segments.
For strategic planners, these figures underscore the importance of timing. Entering or expanding within this market requires alignment with the growth curves identified in our study. The data suggests that while the early years of the forecast period may see moderate expansion, the later years present accelerated opportunities as infrastructure projects mature and new technologies gain widespread acceptance. Understanding the inflection points in this revenue curve is essential for optimizing inventory, production capacity, and investment timelines.
Segmentation Dynamics and Operational Drivers
The versatility of progressing cavity pumps is reflected in their diverse deployment across various configurations and end-use industries. Our research dissects the market into critical dimensions, including pump type and application sector. This segmentation is vital because growth is not uniform across all categories. Some configurations are experiencing faster adoption due to specific industry trends, such as the shift toward more efficient artificial lift methods in oilfields or the increasing stringent hygiene standards in food processing.
-
Technological Configurations
The market is categorized by stage configurations, each serving distinct performance requirements. Single-stage, double-stage, and four-stage pumps cater to different pressure and viscosity needs. Our analysis reveals how the balance among these configurations is shifting. For instance, higher-stage configurations may see increased demand in applications requiring greater head pressure, while single-stage units remain vital for specific low-pressure, high-flow scenarios. The choice of configuration directly impacts maintenance schedules and operational expenditure, making this segment analysis crucial for product portfolio planning.
-
Industry Applications
End-user application is a primary driver of demand. Key sectors include Oil and Gas, Water and Wastewater, Chemical and Petrochemical, Food and Beverage, and Others. Each sector presents unique challenges and regulatory requirements. The Oil and Gas sector continues to be a major contributor, particularly in artificial lift solutions where reliability in harsh downhole conditions is paramount. Simultaneously, the Water and Wastewater sector is gaining traction due to environmental regulations and the need for handling abrasive slurries and viscous fluids without degradation.
The Food and Beverage industry represents a high-growth niche where hygienic designs compliant with international standards are non-negotiable. Chemical processing also remains a steadfast consumer of PCP technology, driven by the need to handle shear-sensitive materials. Our report details the revenue contributions and growth rates of each application area, helping clients identify which verticals offer the highest return on investment for their specific capabilities.
Competitive Landscape and Strategic Positioning
The global PCP market is characterized by a mix of specialized manufacturers and diversified industrial giants. Market concentration metrics indicate a moderate level of consolidation, with the top three players holding a significant share, though ample room remains for niche competitors and regional specialists. Understanding the competitive hierarchy is essential for benchmarking performance and identifying partnership or acquisition opportunities.
Process Gas Compressor Market
Key Market Participants
Several companies define the current competitive landscape, each bringing distinct strengths to the table:
- PCM Group (France): A leader in progressing cavity pumps with a global presence in over 90 countries. Their portfolio includes the EcoMoineau MX, HyCare, and Moineau A series. Recent activities highlight their focus on oily water treatment and hygienic meat transfer solutions, showcasing adaptability across industrial and sanitary applications.
- NETZSCH Pumps & Systems (Germany): Recognized as a global leader in NEMO progressing cavity pumps. They serve chemical, environmental, mining, and oil and gas sectors. Recent innovations focus on hermetic seal upgrades that allow safer handling of toxic liquids without maintenance, addressing critical safety regulations.
- SEEPEX (Germany): A specialist in standard progressive cavity pumps, hopper pumps, and API 676 models. They are notable for integrating digital control systems, catering to abrasive, shear-sensitive, and viscous fluids across multiple industries.
- NOV Process & Flow Technologies (United States): Providers of Mono and Moyno technologies. Their emphasis lies in oilfield artificial lift, heavy oil, and high-sand applications, positioning them strongly within the energy extraction segment.
- Weatherford International (United States): Suppliers of PCP systems and artificial lift solutions tailored for oil and gas wells. They offer material options designed to withstand harsh downhole conditions, competing directly in the upstream energy space.
- ChampionX Corporation (United States): Developers of PCP pumping systems including SMARTEN VSD and HiCone models. Their focus is heavily oriented toward oilfield applications and artificial lift technologies.
- Sulzer Ltd (Switzerland): Providers of progressing cavity pump solutions for chemical processing, energy, and industrial sectors, leveraging a broad engineering heritage.
- Roto Pumps Limited (India): Manufacturers of high-pressure progressive cavity pumps for chemical, mining, wastewater, and power plant applications, representing strong growth potential in emerging markets.
- ITT Bornemann GmbH (Germany): Suppliers of Bornemann progressing cavity pumps focused on hygienic, sanitary, and industrial fluid handling, competing in the high-sanitation niche.
- Nova Rotors Srl (Italy): Producers of Diamond progressing cavity pumps and related grinders. Recent participation in food and beverage exhibitions underscores their commitment to this sector.
- Flexon-All Srl (Romania): Manufacturers of custom progressive cavity pumps with 22 standard types, offering flexibility for flows ranging from 1.6 to 135 m³/day.
Beyond the established giants, the landscape includes regional players who compete on customization and cost-efficiency. Strategic decisions regarding partnerships or market entry must consider the specific strengths of these competitors, such as NETZSCH's recent advancements in hermetic seals or PCM's focus on reducing maintenance downtime through maintenance-in-place designs.
Industry Dynamics and Risk Factors
No strategic plan is complete without a thorough assessment of the external forces that could impact operations. Our report integrates several critical dynamics that are currently shaping the PCP market environment. These factors influence not only the cost of goods sold but also the regulatory compliance burden and the overall value proposition offered to customers.
Supply Chain and Material Volatility
One of the most significant challenges facing manufacturers is the volatility of raw materials. The elastomer raw materials and specialized polymers used in stators are subject to price swings that can impact the bottom line. Industry data suggests these fluctuations can cause annual price variations touching double digits. Since stator costs can form a significant portion of the total pump value, even minor changes in material pricing can ripple through to final equipment costs. Furthermore, quarterly fluctuations of up to 15% in elastomeric stator materials have been observed due to supply chain factors. Effective procurement strategies and supplier diversification are therefore critical competencies for maintaining margin stability.
Regulatory and Safety Standards
Regulatory pressure is mounting, particularly regarding safety and hygiene. New hermetic seal upgrades for progressing cavity pumps are enabling safer handling of toxic liquids and gases without the need for frequent maintenance. This innovation aligns with stricter occupational health and safety regulations in chemical and energy sectors. Additionally, in the food and beverage sector, hygienic and sanitary progressing cavity pumps must comply with EHEDG and FDA standards. Compliance is not just a legal requirement but a competitive differentiator. Companies that fail to adapt to these standards risk losing access to high-value market segments.
Operational Efficiency and Labor Costs
Labor costs and downtime are persistent concerns for operators. Maintenance-in-place designs, such as those highlighted by PCM Group, reduce pump removal downtime and associated labor requirements. In an environment where skilled labor is increasingly scarce and expensive, equipment that minimizes intervention offers a compelling economic advantage. This trend is driving purchasing decisions toward technologies that promise longer service intervals and easier onsite maintenance. Strategic planners must weigh the initial capital expenditure against these long-term operational savings when evaluating market opportunities.
Strategic Implications for 2026 Decision Makers
As organizations move into 2026, the insights derived from this market research will inform several key strategic pillars. First, market entry and expansion decisions must be data-driven. Knowing which regions and applications are growing fastest allows for targeted marketing and distribution efforts. Second, product development roadmaps should align with the shifting demand between single-stage, double-stage, and four-stage configurations, as well as the increasing integration of digital controls and hermetic seals.
Progressing Cavity Pumps Market
Third, risk management strategies need to account for raw material volatility. Hedging strategies or long-term supply contracts may become necessary to protect margins. Finally, M&A activity remains a viable path for consolidation. With a moderate concentration level, there is potential for acquiring niche players to gain access to specific regional markets or application expertise, such as the hygienic food processing sector or high-sand oilfield applications.
Conclusion and Access to Full Intelligence
The Progressing Cavity Pumps Market is poised for steady growth, underpinned by industrial expansion and technological innovation. However, realizing value in this market requires more than a superficial understanding of global totals. It demands a deep grasp of segmentation shifts, competitive maneuvers, and the nuanced dynamics of supply chains and regulations.
This article has outlined the strategic framework and high-level trends defining the sector. Yet, the full depth of our analysis contains the specific segmentation data, regional breakdowns, and detailed company profiles necessary to build a robust business case. The complete report offers the granular intelligence required to validate assumptions and finalize investment decisions with confidence.
For executives and analysts seeking to secure a competitive advantage in the 2026-2032 period, PW Consulting's full market research report provides the essential toolkit. We invite you to access the complete study to unlock the detailed forecasts, segmentation splits, and strategic recommendations that will drive your organization's success in the evolving landscape of progressing cavity pump technology.
For detailed analysis of this topic, please visit the official page: Progressing Cavity Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Playground Turf Market Hits $187.7M in 2025, 7.54% CAGR to $309.6M by 2032
By PW Consulting, 2026-09-16
Beyond the Green Carpet: Strategic Insights for the Playground Artificial Grass Turf Market in 2026
Introduction: The Strategic Imperative for 2026
As the global landscape for recreational infrastructure evolves, the playground artificial grass turf market stands at a pivotal juncture. For stakeholders ranging from municipal planners to private manufacturers, understanding the trajectory of this sector is no longer optional; it is a critical component of risk management and capital allocation strategy. PW Consulting's latest market research study offers a comprehensive examination of this industry, designed to equip decision-makers with the intelligence required to navigate the complexities of the 2026 to 2032 forecast period.
This report is not merely a collection of figures. It is a strategic roadmap intended to clarify growth vectors, regulatory hurdles, and competitive pressures. By analyzing historical performance from 2020 through 2025 alongside forward-looking projections, organizations can better position themselves to capitalize on emerging opportunities while mitigating potential downsides. The following analysis highlights the key themes explored in our full study, demonstrating why this intelligence is vital for corporate strategy in the coming fiscal year.
Macro Market Overview: Growth Trajectory and Historical Context
The playground artificial grass turf sector has demonstrated remarkable resilience and expansion over the past half-decade. Historical data indicates a steady climb in market revenue, reflecting increased adoption rates across various recreational and educational settings. From a base market size in 2020, the industry has progressed through 2021 and 2022, continuing its upward trend into 2023, 2024, and reaching a significant valuation in 2025. This historical performance sets a robust foundation for the current outlook.
Looking toward the immediate future, the projected market size for 2026 represents a substantial increase from the previous year, signaling continued momentum. The forecast extends through 2032, offering a long-term view for infrastructure planning. The compound annual growth rate (CAGR) calculated for the 2026 to 2032 period stands at 7.54 percent. This growth rate is a key indicator of market health, suggesting that investment in this sector remains attractive despite broader economic fluctuations. Such top-line growth underscores the necessity for businesses to secure their supply chains and refine their product offerings to meet escalating demand.
Segmentation Dynamics: Type, Application, and Regional Nuances
Understanding where growth originates is just as important as knowing how much the market is growing. Our research dissects the market into primary segmentation categories, including product type and end-user application. While specific percentage breakdowns are reserved for the full dataset, we observe that certain synthetic materials dominate the landscape. The industry is primarily characterized by the use of polyolefin and polyester films, with other specialized types comprising a smaller portion of the total mix. The dominance of polyolefin film highlights the industry's preference for durability and safety features inherent in this material class.
In terms of application, the market is driven significantly by school playground installations. This segment represents a major revenue contributor, followed by public playground initiatives and other miscellaneous applications. The distinction between school and public sector demand is crucial for companies targeting specific procurement channels. Government-led public projects often have different bidding requirements compared to private school districts or residential complexes. Additionally, the report analyzes regional performance, noting that North America, Europe, and Asia Pacific represent the largest revenue centers. Each region presents unique growth drivers, from demographic shifts to urban development projects. Latin America and the Middle East and Africa also contribute to the global total, offering emerging opportunities for expansionist strategies.
Artificial Grass Turf Market
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is defined by a mix of established manufacturers and specialized producers who focus on certified quality and safety standards. Higher market concentration can be observed through metrics such as the CR3 and CR5 values, indicating that while the market is not a monopoly, key players hold significant influence. To achieve success, companies must differentiate themselves through product certification, innovation, and supply chain reliability.
Several core companies exemplify the standards required to thrive in this environment. Controlled Products, headquartered in Dalton, Georgia, operates as a vertically integrated manufacturer. They are known for producing IPEMA-certified playground artificial grass turf products. Their standard lines, such as PL929 and PL981, utilize specific thatch systems and fiber shapes like Omega and S-shaped fibers. They also offer private-label options for commercial playground applications, allowing partners to brand products appropriately. This vertical integration provides them with control over quality and cost structures.
Another significant player is XGrass, based in the United States. They specialize in manufacturing IPEMA-certified artificial grass playground surfacing systems. Their product portfolio includes lines such as XGrass Prime, Ultra Natural, and Premier Natural. A key feature of their offerings is the inclusion of PolyGreen shock-absorbing foam padding and antimicrobial infill. These features address critical safety and hygiene concerns, which are paramount for facilities hosting children.
Smart Turf is also a prominent manufacturer in the space, with operations in the USA. They focus on playground artificial grass turf featuring built-in Microban antimicrobial technology. This is specifically designed for heavy-traffic contact sports and playground areas. The inclusion of antimicrobial technology responds to growing health and safety expectations, making their products suitable for high-use environments. These companies illustrate the market demand for certified, safety-focused products that withstand rigorous use.
Industry Dynamics: Regulation, Materials, and Standards
Dynamic regulatory changes are reshaping the operational landscape for manufacturers and suppliers. Compliance is no longer a static requirement but an evolving process that requires constant monitoring. A critical regulation involves IPEMA certification, which is required for commercial playground surfacing systems using artificial grass to meet ASTM F1292 impact attenuation standards. This standard ensures that the surfacing adequately cushions falls, reducing the risk of serious injury. Manufacturers must maintain this certification to access commercial contracts, making compliance a gatekeeper for revenue streams in the public and institutional sectors.
On the materials side, the construction of playground artificial grass turf is primarily based on polyethylene fibers. This material choice is driven by performance characteristics and cost considerations. Industry data suggests that polyethylene-based playground turf materials cost between $2.20 and $4.10 per square foot. Managing raw material costs within this range is essential for maintaining margin health. Fluctuations in raw material pricing or supply availability can directly impact the final cost to consumers and the profitability of installers and manufacturers.
Recent developments highlight the increasing focus on chemical safety and standardized testing. In May 2026, the Synthetic Turf Council published a new ASTM F3782-26 standard for sampling and testing synthetic turf fiber and fabric for the presence of PFAS. This certification achievement represents a shift toward greater transparency and environmental responsibility. The standard provides a standardized practice for sampling and testing synthetic turf for these per- and polyfluoroalkyl substances. Compliance with ASTM F3782-26 will likely become a differentiator for brands seeking to appeal to environmentally conscious consumers and regulators. Businesses must anticipate how these testing protocols will affect production processes and supply chain sourcing.
Strategic Value for Decision Makers
Access to detailed market intelligence provides a distinct advantage in strategic planning. For corporate leaders and investors, the full report offers proprietary data that goes beyond public summaries. The value of this research lies in its granularity and actionable insights. While high-level figures provide context, the detailed segmentation splits and company-specific analyses allow for precise scenario planning.
Understanding the specific revenue contributions of regions like North America or Asia Pacific, along with the exact market shares of application segments such as school versus public playgrounds, enables targeted marketing and distribution strategies. Knowing the precise market concentration metrics helps in evaluating market entry barriers and merger acquisition opportunities. Furthermore, the detailed breakdown of material costs and regulatory timelines allows operations teams to budget more accurately for the 2026 fiscal year and beyond.
Playground Artificial Grass Turf Market
The report also serves as a benchmark for performance. Companies can compare their internal growth metrics and regional penetration against the industry averages provided. This benchmarking is essential for setting realistic KPIs and adjusting strategic goals. In a market growing at nearly 8 percent annually, missing a trend or misinterpreting a regulatory shift can result in lost market share. The insights contained in this study are designed to prevent such oversights.
Conclusion: Navigating the Future
The playground artificial grass turf market presents a landscape of opportunity tempered by regulatory complexity. With a forecast period extending to 2032 and a strong growth trajectory established from 2020 to 2025, the sector is poised for continued expansion. However, success in 2026 and beyond will depend on the ability to adapt to new standards like ASTM F3782-26, manage material costs, and compete effectively against landscape leaders.
PW Consulting's Playground Artificial Grass Turf Market Research delivers the depth required to make informed decisions. By integrating historical data, future projections, and a detailed analysis of competitive and regulatory dynamics, this study provides the comprehensive view necessary for long-term planning. For organizations ready to move beyond surface-level information, the full report offers the critical intelligence needed to harness the momentum of this evolving market. We invite you to explore the complete findings to secure the strategic advantage you need.
For detailed analysis of this topic, please visit the official page: Playground Artificial Grass Turf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Preclinical Tomography Market to Hit $490.93M by 2032, Growing at 9.14% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Preclinical Tomography System Market Through 2032
The preclinical imaging sector is entering a decisive inflection point. Over the past half-decade, tomographic platforms have evolved from specialized academic tools into core infrastructure for drug discovery, toxicology, and translational biology. For executive teams, capital allocators, and R&D leaders, understanding this trajectory is no longer optional. It is a prerequisite for informed investment, pipeline prioritization, and competitive positioning. Our newly published research on the Preclinical Tomography System Market captures this transformation with granular precision, mapping historical performance, forward-looking forecasts, competitive dynamics, and regulatory shifts that will shape enterprise decisions well into the next decade.
Preclinical Tomography System Market
This article offers a strategic preview of the study, illustrating how the analysis connects macro-level market evolution to actionable, boardroom-ready insights. While the full report delivers exhaustive segment-level data, vendor benchmarks, and scenario modeling, the following overview demonstrates the analytical depth, operational relevance, and decision-support architecture that define our methodology.
Historical Trajectory and Forward Growth Architecture
The market has demonstrated consistent expansion from 2020 through the base year of 2025, building on sustained adoption across research institutions, hospital-affiliated laboratories, and pharmaceutical discovery units. Revenue progression over this six-year window reflects compounding demand for high-resolution, in vivo imaging that reduces reliance on terminal histopathology and accelerates iterative study design. The revenue baseline established at the end of 2025 provides a stable foundation for the projection phase, which extends through 2032.
Over the forecast horizon, the market is projected to advance at a compound annual growth rate of 9.14%, measured in USD millions. This trajectory is not purely linear; it reflects accelerating replacement cycles, broader integration of multimodal tomography platforms, and increasing procurement standardization across enterprise research portfolios. The forward curve captures both volume-driven expansion and value migration toward higher-resolution, workflow-integrated systems that reduce total cost of ownership while improving data reproducibility.
For decision-makers, the strategic implication is clear. Budget planning, capital expenditure approval, and vendor evaluation must account for a market that is scaling steadily rather than experiencing speculative spikes. Forecasting through 2032 enables procurement leaders to model phased rollout strategies, R&D directors to align imaging capacity with pipeline timelines, and investors to assess long-term demand resilience across therapeutic and academic end-users.
Structural Drivers Reshaping Procurement and Research Workflows
Several structural forces are converging to amplify demand for preclinical tomography systems. First, the industry-wide shift toward in vivo, longitudinal imaging is reducing study attrition and improving translational fidelity. High-resolution micro-CT and emission tomography platforms now enable repeated measurements in the same subject, supporting pharmacokinetic modeling, bone and dental microarchitecture assessment, soft tissue characterization, and disease progression tracking with greater statistical confidence.
Second, regulatory expectations around imaging biomarkers are becoming more prescriptive. Guidance from major health authorities increasingly positions tomographic imaging as essential for pharmacokinetic and toxicity assessments within investigational new drug frameworks. Parallel recommendations emphasize standardized protocols for good laboratory practice compliance, reproducible data generation, and multimodal assessment strategies for novel therapeutics, including gene therapies and cellular products. For sponsors and contract research organizations, these expectations elevate imaging from a supportive technique to a compliance-critical workflow component.
Third, ethical and documentation requirements governing animal model usage continue to tighten. Legislative frameworks in the United States and European Union impose rigorous oversight on preclinical animal studies, which in turn incentivizes adoption of imaging platforms that enable fewer subjects, richer datasets, and stronger documentation trails. Institutions that standardize on validated tomography systems are better positioned to satisfy oversight requirements while preserving research throughput.
Finally, workflow integration and multimodal convergence are reshaping procurement criteria. End-users increasingly evaluate systems not only on raw resolution, but on interoperability with reconstruction software, informatics pipelines, automated analysis modules, and multi-modality configurations that combine structural and functional imaging. This evolution favors vendors that deliver compact benchtop performance alongside enterprise-grade scalability, clinical compliance alignment, and continuous software enhancement.
Competitive Positioning and Recent Market Developments
The competitive landscape is concentrated, with leading vendors differentiating through hardware innovation, regulatory milestones, and ecosystem partnerships. Three organizations illustrate the strategic directions currently shaping the market.
Bruker Corporation
Headquartered in Billerica, Massachusetts, Bruker has expanded its preclinical imaging portfolio with advanced micro-CT platforms designed for high-resolution in vivo imaging of small animals and biological samples. Its product lineage, including the X4 POSEIDON, SKYSCAN 1273, and SKYSCAN 2214 CMOS Edition systems, targets detailed structural imaging across bone, dental, and soft tissue applications. In February 2025, Bruker launched the X4 POSEIDON advanced X-ray microscope with micro-CT functionality, delivering compact benchtop performance and enhanced image quality for preclinical life-science workflows. This release reinforces a broader competitive shift toward high-performance systems that fit within constrained laboratory footprints while preserving research-grade imaging fidelity.
SCANCO Medical AG
Based in Bassersdorf, Switzerland, Scanco Medical maintains a focused presence in preclinical micro-CT through platforms engineered for in vivo small-animal studies. Its vivaCT 80 in vivo micro-CT scanner is positioned around a large field-of-view and high-resolution imaging capability, supporting longitudinal study designs and detailed structural assessment. Scanco’s strategy reflects sustained emphasis on specialty preclinical imaging where resolution, reproducibility, and workflow consistency carry outsized importance for academic and translational research teams.
Mediso Medical Imaging Systems
Operating from Budapest, Hungary, Mediso has built its competitive identity around multimodal tomography systems that combine structural and functional imaging for molecular preclinical research. The nanoScan family encompasses preclinical PET/CT, SPECT/CT, and multi-modality configurations designed to support molecular imaging applications. In December 2025, Mediso received FDA 510(k) clearance for the AnyScan 3.0 NM Scanner Family, encompassing PET/CT and SPECT/CT systems suitable for preclinical research applications. This regulatory milestone is strategically significant because emission tomography clearances increasingly hinge on recognized performance and safety standards, raising the barrier to entry for new competitors while strengthening the compliant positioning of established vendors.
Beyond these core players, the broader ecosystem includes partnerships and collaborations that expand imaging infrastructure and co-develop advanced workflows. For example, a December 2024 strategic collaboration between Nikon Metrology and Taipei Medical University established a joint micro-CT imaging center and initiated co-development of advanced preclinical imaging workflows. Moves of this kind signal growing institutional investment in shared imaging capacity, standardized acquisition protocols, and cross-functional research integration.
Regulatory and Compliance Architecture as a Market Catalyst
Regulatory and ethical frameworks are no longer peripheral considerations; they are shaping product requirements, procurement criteria, and time-to-deployment. Clearance pathways for emission computed tomography systems, including recent submissions for preclinical scanner families, reference compliance with recognized standards for performance and safety. These expectations influence not only vendor validation processes but also institutional purchasing decisions, where demonstrable compliance reduces operational risk and supports smoother study approval.
Simultaneously, guidance around imaging biomarkers in preclinical studies is pushing organizations toward standardized protocols that support GLP compliance and reproducible data in drug development submissions. Updated international guidelines for preclinical imaging emphasize multimodal assessment strategies for novel therapeutics, reinforcing the value of platforms that can integrate structural, functional, and molecular readouts within consistent workflows. For sponsors, CROs, and academic centers, this translates into stronger demand for systems that minimize protocol variability and help maintain auditable documentation across study phases.
The interaction between regulatory evolution and procurement strategy is particularly important for enterprise buyers. When evaluating platforms, organizations increasingly consider not just immediate imaging performance, but also long-term alignment with evolving standards for safety, biomarker validation, multimodal integration, and animal welfare documentation. In this environment, the ability to forecast which system architectures will remain compliant and adaptable through the end of the decade becomes a genuine competitive advantage.
Why This Research Matters for 2026 Decision-Making
Market intelligence in this sector must do more than describe growth. It must help leadership teams anticipate capital needs, align technology roadmaps, and interpret competitive signals with confidence. Our Preclinical Tomography System Market study is designed for that practical purpose, translating historical performance and forward projections into structured decision support for 2026 and beyond.
The report provides comprehensive coverage across the full market architecture, including revenue evolution from historical years through the forecast horizon, segment-level breakdowns by region, system type, and application, and competitive profiling of key participants. It examines procurement drivers, regulatory catalysts, technology adoption patterns, and the implications of recent product launches, clearances, and strategic collaborations. Importantly, the analysis is organized to support use cases that matter to executives: budget allocation, vendor evaluation, capacity planning, partnership assessment, and risk-adjusted market entry or expansion strategy.
Several elements distinguish the study from generic market summaries. First, the forecast structure enables multi-year planning under a consistent growth framework, allowing organizations to model different adoption and replacement scenarios rather than relying on point estimates. Second, competitive profiling connects product offerings to real-world strategic moves, including benchtop performance innovations, multimodal system expansions, and regulatory clearances that alter market access dynamics. Third, regulatory context is woven directly into market dynamics, helping readers understand why compliance, standardization, and documentation requirements are influencing demand patterns and procurement cycles.
For 2026 specifically, the research supports several high-value actions. R&D and imaging operations leaders can use the forecast and segmentation framework to justify phased capital deployment and align imaging capacity with pipeline milestones. Procurement teams can benchmark system types and end-user application demand to refine request-for-proposal criteria and evaluate total cost of ownership across competing platforms. Business development and corporate strategy teams can interpret competitive moves, partnership activity, and regulatory timing to anticipate market consolidation, identify white-space opportunities, and prepare for evolving buyer expectations.
By integrating macro growth trends with operational realities, the report helps transform uncertainty into structured planning. Readers gain clarity on how revenue progression, system type adoption, application demand, and regional dynamics interact over the forecast period, while maintaining the flexibility to stress-test assumptions according to internal priorities and research pipelines.
What the Full Study Delivers
While this preview outlines the strategic framework, the complete report provides the detailed intelligence required for precise execution. The full analysis includes:
- Historical market sizing and forward projections through the end of the forecast period, expressed in consistent revenue units to support budget modeling and scenario comparison.
- Segment-level breakdowns that help clarify where demand is concentrated across geography, system type, and end-use application, enabling targeted planning without exposing enterprise strategy to one-size-fits-all assumptions.
- Competitive assessments that connect vendor portfolios, recent launches, regulatory developments, and collaboration activity to actionable positioning insights.
- Regulatory and compliance analysis that contextualizes clearance requirements, imaging biomarker expectations, GLP considerations, and animal welfare documentation within procurement and workflow decisions.
- Strategic interpretation of market concentration and competitive dynamics, helping readers understand how leadership positions, differentiation levers, and ecosystem partnerships shape near-term competition.
This is precisely the type of evidence base that supports confident decisions in 2026, when organizations must reconcile accelerating imaging adoption with compliance expectations, budget discipline, and the need to future-proof laboratory infrastructure.
Moving from Insight to Action
The Preclinical Tomography System Market is expanding with measurable momentum, but the real strategic challenge lies in interpreting that momentum correctly. Growth alone does not dictate successful investment; the value comes from understanding where demand is forming, which system architectures are gaining traction, how regulatory requirements are reshaping procurement, and which competitive moves signal longer-term positioning shifts.
Our research is built to answer those questions with discipline and specificity. It offers the analytical structure needed to plan capital deployment, refine vendor selection, align imaging strategy with R&D timelines, and anticipate compliance-driven changes in buyer behavior. For executives who need more than broad market narratives, the full report delivers the depth, segmentation, and competitive intelligence required to act decisively.
Computed Tomography System Market
To access the complete market analysis, detailed segment data, and executive-ready strategic recommendations, visit the full report page and secure the comprehensive intelligence package designed for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Preclinical Tomography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


