



PW Consulting: Modular Data Centers Hit \$36.37B in 2025, Forecast 17.11% CAGR to \$109.88B by 2032
By PW Consulting, 2026-09-16
Modular Data Centers Market 2026: Strategic Intelligence for Enterprise Decision-Making
The digital infrastructure landscape is undergoing a structural transformation. As enterprises confront exponential data growth, AI-driven compute demands, and persistent supply chain volatility, traditional data center construction models are increasingly misaligned with operational realities. Modular data centers have emerged not as a convenience, but as a strategic imperative. Our latest comprehensive market research on the Modular Data Centers Market is designed to translate this inflection point into actionable intelligence for executive decision-makers, infrastructure planners, and investment strategists.
Drawing on historical data spanning 2020 through 2025 and a forward-looking forecast horizon extending to 2032, this report maps the trajectory of a market that has evolved from a niche deployment alternative to a mainstream architectural standard. The narrative is clear: modularization is no longer reactive. It is reshaping how organizations approach capacity planning, risk mitigation, and scalability in an era where speed-to-deployment and infrastructure agility determine competitive positioning.
The Structural Inflection Point: Why 2026 Is a Defining Year
The market has demonstrated consistent, compounding growth over the past half-decade, with revenue expanding from approximately 16.51 billion USD in 2020 to an estimated 36.37 billion USD in 2025. The trajectory does not plateau. Forecasts indicate a continued acceleration, with the market projected to reach 43.82 billion USD in 2026 and climbing toward 109.88 billion USD by 2032. This growth reflects a compound annual growth rate of 17.11 percent across the 2026–2032 period, underscoring a sustained shift rather than a temporary cycle.
Several converging forces are compressing traditional procurement and construction timelines. AI and high-performance computing workloads demand higher power density and more sophisticated thermal management. Geographic dispersion of compute, driven by edge computing requirements and data sovereignty considerations, favors deployable, standardized infrastructure over ground-up construction. Simultaneously, regulatory frameworks and industry standards are maturing to accommodate prefabricated and containerized systems, reducing historical friction around compliance, safety certification, and interoperability.
Modular Data Centers Market
For enterprise leaders, the implication is straightforward: modular data centers are no longer a contingency option. They are becoming the default architecture for organizations that must balance speed, scalability, and capital efficiency. Understanding the nuances of this shift requires more than headline growth figures. It requires a rigorous, segment-level understanding of how deployment models, application drivers, and regional dynamics interact to shape risk and return.
Decoding the Market Architecture: What This Research Uncovers
Our Modular Data Centers Market research is structured to move beyond macro trends and deliver operational clarity. The report dissects the market across multiple dimensions, enabling stakeholders to evaluate strategic fit, investment prioritization, and competitive exposure with precision.
Prefabricated And Modular Data Centers Market
Deployment Models and Architectural Strategy
The market is segmented by deployment architecture, reflecting fundamentally different approaches to scaling infrastructure. Containerized systems offer highly mobile, self-contained environments optimized for rapid deployment and constrained footprints. Prefabricated data centers provide a modular, repeatable construction methodology that blends factory-controlled quality with site-specific adaptability. All-in-one datacenter configurations consolidate power, cooling, IT, and management layers into unified deployments designed for efficiency and accelerated commissioning. Each model presents distinct trade-offs in terms of lead time, scalability limits, capital intensity, and operational complexity. The research evaluates these architectures not in isolation, but in the context of workload requirements, site constraints, and lifecycle economics.
Application-Driven Demand Patterns
Demand is not uniform across industries. Telecommunications continues to drive significant adoption as network architectures evolve toward distributed, low-latency infrastructure. Finance, healthcare, education and research, and a broad set of other enterprise applications each impose unique requirements around reliability, compliance, density, and expansion flexibility. By mapping application-level demand dynamics, the report reveals where modular deployments are gaining structural advantage and where traditional build-out models still compete effectively.
Regional Deployment Dynamics
Geographic variation plays a critical role in shaping deployment strategy. Different regions exhibit distinct maturity curves, regulatory environments, supply chain conditions, and capital availability. North America reflects a mature, technology-forward market with strong enterprise and AI-driven demand. Europe demonstrates steady adoption shaped by sustainability mandates and infrastructure modernization priorities. Asia Pacific captures rapid growth driven by digital expansion, data localization trends, and expanding cloud and edge footprints. Latin America and the Middle East and Africa represent emerging opportunities where modular deployment can mitigate construction risk, address infrastructure gaps, and accelerate time-to-operation in environments where conventional development cycles face heightened friction. The report contextualizes these regional differences without reducing them to static figures, instead emphasizing the strategic implications for site selection, partnership models, and deployment sequencing.
Competitive Landscape: Strategic Positioning and Market Concentration
The modular data center ecosystem is characterized by a mix of established infrastructure leaders, specialized modular integrators, and technology providers expanding into converged infrastructure solutions. Market concentration indicates a moderately consolidated environment, with the top three competitors collectively capturing a substantial share of revenue and the top five extending that influence further. This concentration reflects both the capital and engineering intensity of modular offerings and the advantage held by players with integrated capabilities across power, cooling, IT, and deployment services.
Leading Competitors and Strategic Differentiation
Several core companies define the current competitive landscape, each pursuing distinct strategic angles:
- Vertiv emphasizes prefabricated modular data center solutions that integrate power, cooling, and IT modules for rapid deployment, with a clear focus on high-performance workloads and AI/HPC requirements.
- Schneider Electric positions EcoStruxure modular data center solutions around adaptable, high-performance designs capable of addressing complex infrastructure needs across diverse locations and operating environments.
- ABB offers modular, scalable, and prefabricated solutions aimed at accelerating colocation deployment and improving return on investment while preserving flexibility for future scaling.
- Eaton delivers SmartRack modular data center solutions that consolidate IT rack, cooling, and service enclosures within a single enclosure to optimize performance and reduce deployment timelines.
- Flex focuses on AI infrastructure platforms with pre-engineered modular designs that integrate power, cooling, and compute, targeting accelerated deployment timelines.
- Dell Technologies supports modularized integrated racks designed for edge and high-density environments, extending modular data center concepts beyond traditional facility constraints.
- M.C. Dean contributes specialized modular support rack systems and installation methods for overhead-mounted electrical and telecommunications components, addressing deployment efficiency at the infrastructure layer.
- Haskell Modular Solutions provides custom modular data center solutions built on factory-controlled fabrication, emphasizing efficiency, flexibility, and scalability.
The competitive narrative is not simply about who offers modular products. It is about who can responsibly integrate design, fabrication, deployment, and ongoing operational support while aligning with workload-specific performance demands. The research evaluates these players through the lens of technology positioning, deployment speed claims, scalability frameworks, and strategic alignment with the fastest-growing demand drivers.
Recent Strategic Movements Shaping 2026 Dynamics
Market momentum is being reinforced by concrete product and partnership developments. Eaton expanded its modular data center offering in collaboration with Flexnode to accelerate AI factory deployment, integrating power backup, racks, and cable management with the stated goal of reducing deployment schedules by a meaningful margin. Vertiv introduced a global solution built around modular design for high-performance data centers, targeting deployment scales relevant to AI and HPC requirements. Siemens launched a turnkey modular edge data center in partnership with other infrastructure providers, supporting deployment timelines suited to both permanent and interim operational needs. These moves reflect a broader industry shift: modular data centers are increasingly being engineered as integrated, workload-aware platforms rather than standalone enclosures.
Regulatory, Standardization, and Supply Chain Forces Redefining Deployment Risk
Strategic planning in this market must account for more than technology and pricing. Regulatory evolution, standardization efforts, and supply chain realities are actively shaping deployment risk and time-to-value.
Evolving Standards and Safety Expectations
The revised UL 2755:2025 outline of investigation for prefabricated modular data center systems and related modular units reflects an industry response to the operational profile of modern modular deployments, including AI-driven workloads. Updated safety and performance expectations influence design choices, certification pathways, and procurement validation. Firms that align early with emerging standards can reduce compliance friction and accelerate project approval cycles.
Intellectual Property and Deployment Method Innovation
Innovation is not limited to product hardware. Patent activity around modular support rack systems and installation methods highlights a growing focus on streamlining electrical configuration and accelerating delivery on large-scale campuses. Such developments matter because deployment efficiency is increasingly a competitive differentiator. When capacity must scale rapidly, the speed and repeatability of installation methodology can determine whether modular infrastructure delivers on its strategic promise.
Supply Chain Resilience and Standardization-Driven Efficiency
Modular deployments can reduce construction risk in regions facing supply chain constraints by shifting a greater share of fabrication and integration into controlled factory environments. At the same time, open standardization initiatives are working to improve interoperability and deployment speed across power, cooling, IT, and all-in-one modules. These factors are especially relevant for organizations planning multi-site rollouts or operating in environments where project predictability is as important as final performance.
Strategic Applications for Enterprise Decision-Makers
This research is intended to support decisions across multiple organizational functions. For infrastructure and facilities leaders, it provides a framework to evaluate deployment models against workload roadmaps, site constraints, and expansion scenarios. For procurement and sourcing teams, it contextualizes supplier capabilities, integration depth, and the strategic implications of concentration in the supplier base. For investment and corporate strategy teams, it clarifies where demand is structurally strengthening and where adoption remains contingent on regulatory, capital, or operational conditions.
Crucially, the report avoids the temptation to reduce a complex market to oversimplified segmentation percentages or isolated dollar figures. Enterprise decisions in this space depend on understanding the relationship between architecture, application demand, regional conditions, deployment speed, and long-term scalability. That is the analytical lens this research applies throughout.
Navigating the Path Forward Through Precision Intelligence
The Modular Data Centers Market is expanding at a pace that rewards organizations capable of making informed, timely decisions. Growth to 43.82 billion USD in 2026 and further expansion toward the end of the decade signals more than market opportunity. It signals a structural reordering of how compute infrastructure is designed, deployed, and scaled.
The full research report provides the detailed segmentation analysis, competitive benchmarking, regional and application-level insight, and forward-looking scenario context necessary to act with confidence. It is designed for leaders who need more than directional trends. It is built for those who must justify capital allocation, choose deployment architectures, anticipate supplier and regulatory shifts, and align infrastructure strategy with enterprise growth plans. The complete intelligence package is available through our full report, where the core segmentation data, detailed competitor analysis, and deployment scenario frameworks can be reviewed in full.
In a market defined by speed, scale, and structural change, precision intelligence is not optional. It is the foundation of sound strategy.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Combine Harvesters Market to Reach $180 Million by 2032 Amid 4.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Combine Harvesters Market: Strategic Intelligence for 2026 and Beyond
The global agricultural machinery sector stands at a critical inflection point, driven by the convergence of labor shortages, regulatory incentives, and rapid technological adoption. As we move through 2026, understanding the trajectory of the combine harvesters market is essential for stakeholders ranging from equipment manufacturers to large-scale farming enterprises. PW Consulting's latest market research study offers a comprehensive roadmap of this evolving landscape, providing the granular intelligence necessary to navigate volatility and capitalize on emerging opportunities.
This article serves as an executive overview of the study's strategic value. It highlights the macro-economic trajectory, the competitive forces reshaping the industry, and the operational dynamics that will define profitability over the next seven years. By synthesizing historical performance with forward-looking analysis, this research equips decision-makers with the context needed to align capital allocation, product development, and market entry strategies with realistic growth expectations.
Market Trajectory: From Recovery to Sustained Growth
The combine harvesters market has demonstrated resilience through recent economic fluctuations, transitioning from a period of post-pandemic adjustment into a phase of steady expansion. Historical data from 2020 to 2025 reveals a market that has consistently grown in value, reflecting the agricultural sector's ongoing need for efficiency and scale. The total revenue generated by the global combine harvesters market has shown a robust upward trend, setting a strong foundation for the forecast period extending to 2032.
Our analysis projects that this momentum will continue, with the market expected to reach substantial valuation levels by the end of the forecast horizon. The compound annual growth rate (CAGR) during the 2026-2032 period is estimated at 4.5%, indicating a healthy, sustained expansion rather than a speculative bubble. This growth is not merely a function of price inflation but is underpinned by tangible increases in unit deployment, technological upgrades, and expanding agricultural output in key regions.
Combine Harvesters Market
For enterprise strategists, this trajectory suggests a long-term opportunity window. The market size in the base year of 2025 establishes a significant benchmark, and the progression through 2026, 2027, and beyond indicates consistent year-over-year increments. However, capturing this value requires more than passive observation. The study delves into the nuances of this growth, examining how shifts in commodity prices, trade policies, and farm consolidation rates influence demand cycles. By understanding the velocity of this growth, companies can better time their investment cycles and production scheduling to match market absorption rates.
Navigating Competitive Dynamics and Industry Concentration
The competitive landscape of the combine harvesters market is characterized by a mix of established global giants and specialized regional players. Our research provides a detailed profiling of key market participants, analyzing their strategic positioning, product portfolios, and recent operational milestones. Understanding the maneuvering of these core enterprises is vital for assessing market share potential and identifying gaps in the current offering landscape.
Leading the pack is John Deere, headquartered in Moline, Illinois. The company continues to push the boundaries of precision agriculture with its S-Series and X9 combine harvesters. Recent developments highlight their focus on automation and diverse crop support. For instance, in February 2026, John Deere showcased the S4 combine harvester at the Show Rural Coopavel 2026, targeting small properties and rugged terrains with features like Machine Sync autopilot. This move underscores a strategy to penetrate niche segments while maintaining dominance in high-volume sectors through AI-driven harvesting support.
In Europe, CLAAS KGaA mbH, based in Harsewinkel, Germany, remains a formidable force. The company celebrated a significant production milestone in October 2024, with the 500,000th combine harvester rolling off its global production lines. Their portfolio, including the Lexion, TRION, and Dominator series, emphasizes scale and reliability. This anniversary edition and the volume achievement signal strong brand loyalty and manufacturing capacity that competitors must account for when planning regional expansions.
CNH Industrial N.V., operating from Amsterdam, Netherlands, continues to leverage the New Holland brand to serve large-scale farming operations. Their CR10 and CR11 models are positioned around high power and efficiency, addressing the needs of growers who prioritize throughput. Similarly, AGCO Corporation, based in Duluth, Georgia, maintains a strong presence through its Massey Ferguson and Gleaner brands, offering a diverse range of solutions that cater to varying farm sizes and crop types. These brands are integral to the market fabric, and our study analyzes their specific strengths and potential vulnerabilities in the face of changing consumer preferences.
In the Asia Pacific region, Kubota Corporation of Osaka, Japan, occupies a unique strategic position. Specializing in rice and wheat combine harvesters, Kubota has sold over 30,000 units annually, demonstrating deep penetration in specific crop markets. Their focus on unmanned autonomous models highlights the region's rapid adoption of labor-saving technologies. This regional specialization contrasts with the global breadth of Western manufacturers, creating a complex competitive environment where local expertise and global scale often intersect.
Market concentration data indicates that the top three players hold a significant portion of the market, while the top five collectively command nearly half of the total revenue. This concentration suggests high barriers to entry and the importance of scale, yet it also leaves room for specialized players who can offer differentiated technology or superior service networks in underserved areas.
Key Market Drivers and Operational Risks
A successful strategy in the combine harvesters market requires a clear understanding of the forces propelling demand and the risks that could impede it. Our study integrates recent industry context to provide a holistic view of the market dynamics that will influence performance in 2026 and beyond.
Technological Adoption and Labor Constraints
Labor availability remains a pressing constraint for the agricultural sector. Recent reports indicate that US farmers face a labor shortfall of approximately 20% for harvesting operations. This deficit is a primary driver for the increasing demand for autonomous and semi-autonomous combine harvester systems. Manufacturers like Kubota are responding with unmanned models, while others are integrating advanced autopilot and AI features to maximize the efficiency of existing labor pools. For buyers, this trend shifts the value proposition from simple mechanical performance to total operational efficiency and labor cost mitigation. Investing in technology-rich machinery is becoming a strategic imperative to ensure harvest completion amidst workforce instability.
Grain Combine Harvester Market
Regulatory Incentives and Sustainability
Regulatory frameworks are increasingly shaping procurement decisions. In the United States, the Environmental Quality Incentives Program (EQIP) provides subsidies for machinery upgrades, including combine harvesters, to encourage the adoption of eco-friendly models. This program effectively reduces the total cost of ownership for compliant equipment, incentivizing farmers to upgrade older fleets. Strategic planners must account for these subsidies when modeling market demand, as policy changes or funding availability can create sudden spikes in specific segments. Furthermore, the push towards sustainability is influencing design requirements, with emissions standards and fuel efficiency becoming key differentiators in competitive tenders.
Cost Structures and Maintenance Economics
Capital expenditure and ongoing operational costs are critical considerations for both manufacturers and end-users. The average price of a new self-propelled combine harvester typically ranges significantly depending on specifications and brand, representing a major investment for agricultural businesses. Beyond the purchase price, ownership costs are substantial. Studies suggest that annual maintenance costs for high-end combine harvesters can exceed $15,000. This reality places a premium on durability, serviceability, and parts availability. Companies that can offer lower total cost of ownership through robust engineering or predictive maintenance solutions gain a competitive edge. Our research examines how these cost factors influence buyer behavior across different farm sizes and economic regions.
Sales Volatility and Market Sentiment
While the long-term trend is positive, short-term volatility can impact planning. Recent data from the Association of Equipment Manufacturers showed that US retail sales of self-propelled combine harvesters in April 2026 were reported at 428 units, a significant decrease compared to the previous year's figures. Such fluctuations highlight the sensitivity of the market to broader economic conditions, commodity prices, and seasonal factors. Understanding the root causes of such dips—whether they stem from inventory adjustments, financing costs, or temporary demand shifts—is crucial for accurate forecasting. Our study provides the analytical framework to distinguish between noise and structural shifts in sales patterns.
Report Scope and Strategic Utility
To support these strategic insights, the PW Consulting market research study offers a depth of analysis designed for immediate operational application. The report goes beyond high-level summaries to provide actionable intelligence across multiple dimensions.
The analysis covers a comprehensive segmentation structure, allowing stakeholders to isolate performance drivers within specific categories. We examine the market by type, distinguishing between self-propelled units and tractor-powered alternatives, as well as other specialized configurations. This breakdown is essential for manufacturers targeting specific technological segments and for buyers evaluating the right equipment class for their operations. Furthermore, the study analyzes application segments, detailing how demand varies across cereal crops, corn, and other agricultural outputs. This granularity helps in aligning product features with crop-specific harvesting requirements and in identifying high-growth application areas.
Geographic analysis is another cornerstone of the research. We provide a detailed view of market performance across key regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities, from infrastructure maturity and subsidy landscapes to crop mix and farm structure. By understanding regional nuances, companies can tailor their go-to-market strategies, optimize supply chains, and prioritize investments where returns are most likely.
The report also includes a thorough competitive landscape assessment. Beyond the profiles of major players, we analyze market concentration metrics to gauge the level of competition and the potential for consolidation. This data helps in benchmarking performance and understanding the market power dynamics. Additionally, the study incorporates recent developments and news intelligence, ensuring that the analysis reflects the most current events, such as product launches, production milestones, and sales reports that may impact market perception and strategy.
Conclusion: Making Data-Driven Decisions in 2026
The combine harvesters market offers significant potential for growth, but realizing this potential requires more than intuition. It demands a rigorous understanding of historical trends, competitive actions, and the complex web of drivers influencing demand. The 4.5% CAGR projected for the forecast period underscores the opportunity, but the path to capturing value is paved with specific challenges related to labor, regulation, and cost management.
This market research study by PW Consulting is designed to be a strategic asset for leadership teams, investors, and product managers. It provides the evidence base needed to validate assumptions, identify risks, and uncover hidden opportunities. Whether you are evaluating market entry, planning capacity expansions, or refining your product roadmap, the insights contained within this report offer the clarity required to act with confidence.
For a complete view of the data, including detailed segmentation splits, regional revenue figures, and in-depth competitor benchmarking, we invite you to access the full report. The executive summary provided here highlights the breadth of the analysis, but the full intelligence package delivers the specific numbers and strategic recommendations necessary to drive your 2026 decisions. Explore the full study to secure the comprehensive market intelligence your organization needs to lead in the evolving agricultural machinery landscape.
For detailed analysis of this topic, please visit the official page: Combine Harvesters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AIN Market Hits $166.02M in 2025, Projected 5.5% CAGR Through 2032
By PW Consulting, 2026-09-16
The Thermal Imperative: Why Aluminum Nitride Market Intelligence Defines Strategic Advantage in 2026
At PW Consulting, we recognize that in advanced thermal management, material performance is no longer just a technical specification, it is a strategic differentiator. As power densities climb, semiconductor packages shrink, and electrification accelerates across mobility and infrastructure, Aluminum Nitride has emerged as the substrate material of choice for engineers who cannot compromise on thermal conductivity, electrical insulation, or long-term reliability. Our latest Aluminum Nitride Market market research is designed to convert this complex, fast-moving landscape into a clear, decision-ready intelligence asset for executives, product leaders, and supply chain strategists operating in 2026 and beyond.
This report is not a generic market scan. It is a structured strategic navigation tool built to help organizations anticipate demand shifts, assess competitive positioning, evaluate supplier risk, and align portfolio investments with the trajectory of a market that is evolving under both technical and geopolitical pressure. Below, we outline the framing, scope, and strategic logic behind this analysis, while preserving the detailed segmentation and quantified forecasts for the full study.
The Strategic Context for 2026 Decision-Makers
The timing of this research is deliberate. By 2026, the Aluminum Nitride market operates at the intersection of rising end-use demand and increasing supply-side complexity. From an aggregate perspective, the global market reached an estimated USD 166.02 million in 2025, building on a multi-year expansion that traces back to a 2020 baseline of USD 131.42 million. This trajectory reflects sustained, measurable growth rather than a transient cycle. Looking forward, our forecast period for this study spans 2026 through 2032, with the CAGR projected at 5.5%.
Why the Numbers Matter, Even When They Do Not Tell the Whole Story
Executive teams often ask a simple question: is this material category gaining structural momentum, or is growth being inflated by a narrow application pocket? The macro trend answers that question with clarity. The market has moved from USD 140.56 million in 2021 to USD 145.47 million in 2022, then USD 149.79 million in 2023, followed by a more pronounced step-up to USD 164.44 million in 2024. That sequence matters because it shows resilience across different demand environments and suggests that adoption is broadening rather than concentrating only in a single hype-driven segment.
Our forecast model continues this arc, projecting the market at approximately USD 170.03 million in 2026, advancing to USD 184.71 million in 2027, USD 200.95 million in 2028, USD 206.42 million in 2029, USD 213.70 million in 2030, USD 225.94 million in 2031, and USD 239.11 million by 2032. These figures form the analytical backbone of the study, but they are only the starting point. The strategic value lies in understanding the forces shaping each phase of that path and in identifying where commercial opportunities will be won or lost.
Aluminum Nitride (AIN) Market
Where Real Decision Insight Comes From
For a market defined by high-performance ceramics, substrate engineering, and application-specific thermal requirements, broad market sizing alone is insufficient. PW Consulting built this report to help leaders answer the questions that actually drive capital allocation and product strategy:
- Which material forms are gaining traction for different engineering constraints, and how should manufacturers think about capacity mixed across powder, granules, and substrates?
- Where is demand intensifying most strongly across power electronics, microelectronics, and adjacent application pools, and what does that mean for downstream sourcing priorities?
- Which geographic markets are expanding on the strength of local end-use demand, industrial ecosystems, and supplier proximity, and where do logistics, regulation, and export control dynamics reshape the playing field?
- How concentrated is the competitive base, and what does supplier concentration mean for procurement resilience, technology access, and negotiation leverage?
The report addresses these issues through an integrated analytical framework that connects market structure, application requirements, regional dynamics, and company-level positioning. Our intent is to give readers a usable map of the market, one that supports scenario planning, supplier evaluation, and go-to-market decisions without forcing them to infer relationships from disconnected datasets.
Aluminum Nitride Ceramic Heaters Market
Market Structure and Concentration: The Hidden Risk Layer
One of the most important themes in this research is the degree of market concentration. A market can grow steadily on paper yet still expose buyers and investors to concentration risk if a small group of suppliers controls a disproportionate share of high-quality output. In this study, we examine a landscape in which the top three companies account for an estimated 65.2% of market revenue, while the top five companies reach approximately 71.5%.
From a strategic standpoint, this concentration changes the nature of the buying and partnering conversation. It affects lead-time reliability, qualification cycles, technical support depth, and the negotiation dynamics around proprietary formulations or substrate grades. It also raises the stakes for organizations that depend on differentiated thermal performance and cannot afford disruption in supply consistency. Rather than treating concentration as a static statistic, the report uses it as a lens for assessing supplier viability, technology access, and the practical implications of building a sourcing strategy in a market where a limited number of players shape a large portion of available supply.
Competitive Landscape: Capability, Focus, and Timing
The Aluminum Nitride competitive set is not a homogeneous group. It spans established ceramic manufacturers, substrates specialists, and companies pushing single-crystal material development into commercial applications. The study profiles several core participants whose activities help define the market's direction, including CoorsTek, CeramTec GmbH, KYOCERA Corporation, Crystal IS, HexaTech Inc., Tokuyama Corporation, Precision Ceramics, and Accumet Materials Co.
Each of these companies brings a distinct angle to the market. CoorsTek develops custom-engineered aluminum nitride ceramics and substrates tailored for thermal management, semiconductor, and electronics applications. CeramTec GmbH offers Alunit aluminum nitride substrates and heat sinks designed for high thermal conductivity and electrical insulation, with emphasis on power electronics and microelectronics. KYOCERA Corporation manufactures aluminum nitride substrates and packages with a strong focus on design flexibility and thermal and electrical properties for semiconductor and electronic components. Tokuyama Corporation supplies high-purity aluminum nitride powder and granules used in sintered bodies and heat-dissipation materials for semiconductors and electronics. Precision Ceramics machines aluminum nitride components and prototypes across multiple grades for thermal management and electrical insulation uses. Accumet Materials Co. supplies aluminum nitride powders and materials for technical ceramic applications.
Beyond the established substrate and powder supply base, the research also tracks the growing relevance of single-crystal development. Crystal IS produces bulk single-crystal aluminum nitride substrates, including 100 mm diameter options, for UVC LEDs, RF, and power semiconductor applications. HexaTech Inc. develops and produces single-crystal aluminum nitride substrates for power and RF device technologies. These capabilities matter because they point toward higher-performance substrate classes that can reshape qualification windows, device performance ceilings, and competitive differentiation over time.
Recent Moves That Signal Strategic Direction
Market intelligence is most useful when it connects company actions to forward-looking implications. In this study, we incorporate a set of notable recent developments that illustrate how suppliers are scaling, refining, and repositioning their offerings. In February 2026, HexaTech Inc. launched a 3-inch, or 76.2 mm, diameter single-crystal aluminum nitride substrate product for commercial-scale power and RF device technologies. That announcement signaled a move from development-scale output toward broader commercialization. In July 2025, HexaTech also introduced an optimized nitrogen-face aluminum nitride substrate for power and RF device development, reinforcing a pattern of iterative performance optimization rather than one-time product launches.
In April 2026, Crystal IS announced an expanded focus on AlN substrates and a new pilot production line for 100 mm aluminum nitride substrates, pointing to increased emphasis on scalable single-crystal supply for high-value device applications. In the same month, KYOCERA Corporation released a comprehensive guide to aluminum nitride packages and substrates highlighting properties and applications, an action that reflects both technical positioning and customer-facing education in a market where material selection is closely tied to engineering confidence.
These developments are not isolated news items. They are indicators of where capability investment is going, which form factors are being prioritized, and how suppliers are preparing for higher-performance and higher-volume device requirements. The report uses this evidence to help readers assess which players are building near-term commercial momentum and which are betting on longer-horizon differentiation.
Demand Dynamics and Application Realities
The core demand story for Aluminum Nitride is tied to thermal management in environments where conventional materials struggle to keep pace with heat flux, miniaturization, and reliability expectations. In the study, we analyze how demand distributes across application areas such as power electronics and microelectronics, along with a smaller pool of other uses. The report examines how these application categories create different purchasing behavior, qualification requirements, and performance thresholds.
Power electronics and microelectronics, in particular, place distinct demands on substrate quality, surface characteristics, thermal performance, and consistency. The research explores the strategic consequences of that split: how application requirements shape preferred material forms, influence supplier selection, and affect the balance between standardized volume supply and application-specific engineering support. By linking application context to supply logic, the study helps readers understand why demand growth is never merely a function of end-market size. It is also a function of technical fit, development cycles, and the maturity of manufacturing and qualification pathways.
Regional Dynamics and the Supply-Regulation Intersection
In a market of this nature, geography matters not only because demand is distributed unevenly, but also because supply chains and regulatory environments differ sharply by region. The report assesses regional market structures and the implications of localized demand, manufacturing presence, and industrial ecosystem development. Rather than treating regional splits as isolated revenue buckets, the analysis connects them to practical questions of sourcing proximity, logistics exposure, and the strategic value of regional supplier relationships.
At the same time, the study integrates an increasingly important layer of market dynamics: regulatory and export-control pressure. Aluminum Nitride substrates are subject to licensing considerations in certain contexts, particularly where end uses intersect with military applications or sanctioned-entity exposure. The research highlights that suppliers and buyers alike must navigate US export administration requirements, with AlN substrates classified under the Export Administration Regulations as controlled items requiring licensing for certain military and sanctioned applications. Relatedly, Japanese and US export licensing requirements for AlN substrates have become material considerations for international trade, especially for sensitive end uses.
The regulatory environment is further complicated by broader supply-chain pressures. High-purity aluminum and nitrogen raw materials face volatility linked to supply-chain disruptions, and US-China tensions along with export restrictions on critical raw materials such as high-purity aluminum and nitrogen compounds influence how supply chains are configured. The market is also affected by the limited global supply of high-purity raw materials, which can constrain share capture and shape competitive outcomes. These are not background issues; they are operational realities that affect cost structure, lead times, supplier selection, and long-term market access.
Why This Research Is Built for 2026 Strategy
PW Consulting developed this research to support decisions that have to hold up under uncertainty. In 2026, organizations are not simply asking where the market is going. They are asking how to position for growth while managing concentration risk, raw-material volatility, regulatory exposure, and the increasing performance demands of end applications. The report is structured to help with exactly those questions.
It provides a cohesive view of market scale and trajectory, segmentation logic across type and application, regional context, competitive concentration, company-level positioning, and the operational dynamics that shape procurement and product strategy. Equally important, it is designed to be actionable. Readers can use it to pressure-test assumptions about demand durability, supplier reliability, and the commercial meaning of technical advances such as larger-diameter single-crystal substrates or optimized substrate faces.
What the Full Study Delivers
In the complete report, these themes are developed with the depth and specificity required for executive and operational use. The study combines market sizing and forecast analysis with segmentation evaluation, competitive assessment, and a structured review of the forces reshaping supply and demand. It is built to serve multiple internal audiences at once: strategy teams evaluating market entry or expansion, procurement leaders assessing supplier risk and concentration exposure, product teams aligning roadmaps with material availability and performance trends, and investors or advisors seeking a rigorous view of market structure.
The full research also preserves the detailed quantitative architecture behind the analysis. That includes historical performance from 2020 through 2025, forward projections across the 2026 to 2032 forecast window, and the underlying segmentation and company-level context needed to interpret those figures with confidence. The goal is not to overwhelm with data, but to provide a disciplined evidentiary foundation for decisions that depend on more than directional intuition.
Conclusion: A Market Where Intelligence Determines Execution
Aluminum Nitride is no longer a niche thermal material in search of a market. It is a strategically important substrate and material category whose growth is being shaped by device performance requirements, supplier concentration, raw-material constraints, and regulatory complexity. In that environment, strategic advantage belongs to organizations that understand not just the headline numbers, but the structure beneath them.
PW Consulting's Aluminum Nitride Market study is designed to give decision-makers that structural understanding. It translates a multi-year growth trajectory and a 5.5% forecast CAGR into a practical intelligence framework for 2026 and the years ahead. For leaders who need to move from general awareness to specific, defensible action, the full report provides the segmentation, company-level detail, competitive context, and market-dynamic analysis required to act with confidence.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride (AIN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AFIS Market Hits $348M in 2025, Forecasts 7.5% CAGR to Reach $566M by 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave of Identity Verification: Strategic Imperatives in the Automated Fingerprint Identification Systems Market
Executive Overview for Corporate Decision-Makers
In an era defined by accelerating digital transformation and the relentless pursuit of security, the Automated Fingerprint Identification Systems (AFIS) sector stands at a critical inflection point. For enterprise leaders, public sector officials, and technology investors, the ability to accurately map the trajectory of this market is not merely a matter of academic interest; it is a prerequisite for effective capital allocation, partnership strategy, and competitive positioning. Our latest comprehensive market research delivers a granular, forward-looking examination of the AFIS landscape, designed specifically to equip organizations with the intelligence required to navigate the complexities of 2026 and the subsequent seven-year forecast window through 2032. This publication serves as a definitive guide, translating raw market kinematics into actionable strategic frameworks.
The global fingerprint identification ecosystem is undergoing a profound structural evolution. Legacy on-premise architectures are rapidly yielding ground to cloud-native, AI-enhanced platforms capable of processing multimodal biometric data with unprecedented speed and accuracy. This transition is not uniform; it is shaped by divergent regulatory environments, varying degrees of digital infrastructure maturity, and distinct operational mandates across law enforcement, border control, and commercial identity verification. Understanding where value is created, which participants hold sustainable advantages, and how technological substitution will reshape demand curves requires more than surface-level observation. It demands rigorous historical reconstruction, precise baseline calibration, and scenario-driven forecasting. That is precisely the mandate of this analysis.
Market Trajectory and the Foundation for 2026 Decision-Making
Strategic foresight begins with a clear comprehension of historical momentum and its projection into the near term. Over the baseline period spanning 2020 through 2025, the AFIS market demonstrated consistent expansion, reflecting sustained demand from government agencies, security contractors, and financial institutions seeking robust identity assurance mechanisms. The cumulative revenue run-rate has steadily climbed, establishing a robust foundation that positions the sector for continued growth as digital identity becomes increasingly embedded in both public administration and private sector operations.
Looking forward, the forecast window from 2026 to 2032 outlines a clear growth arc that will test the agility of market participants. The market is projected to expand from its 2026 baseline to a substantially larger valuation by the close of the decade, driven by compounding adoption rates and the continuous modernization of biometric infrastructure. At the heart of this projection lies a sustained compound annual growth rate of 7.5 percent, a figure that signals steady, defensible expansion rather than speculative volatility. For corporate strategists, this growth profile carries critical implications. It suggests that demand will remain structurally supported by long-term procurement cycles, public safety mandates, and the global push toward seamless yet secure identity verification. Simultaneously, it indicates that competitive intensity will likely increase as new entrants and established players alike race to capture market share through product differentiation and ecosystem lock-in.
The strategic value of this macro trajectory for 2026 planning cannot be overstated. Organizations that treat the market as a monolithic opportunity risk misallocating resources. Instead, leaders must parse the growth narrative into regionally nuanced implementation realities, application-specific procurement triggers, and technology-tier preferences. The 7.5 percent annual expansion provides the overarching rhythm, but it is the underlying composition of that growth which determines where tactical investments yield disproportionate returns. Decision-makers must therefore anchor their 2026 roadmaps in a nuanced understanding of which segments are accelerating, which are plateauing under regulatory or technical constraints, and where substitution threats from alternative biometric modalities are most pronounced.
Automated Fingerprint Identification Systems (AFIS) Market
Operational and Technological Context Shaping Demand
The contemporary AFIS marketplace is defined by a convergence of technological sophistication and operational pragmatism. Modern installations are no longer judged solely by raw matching throughput; they are evaluated against a matrix of criteria that includes interoperability with legacy justice information systems, compliance with stringent data sovereignty requirements, scalability across heterogeneous device fleets, and the capacity to support multibiometric fusion. The shift from offline, batch-oriented processing toward live scan and cloud-integrated architectures has fundamentally altered procurement dynamics. Agencies and enterprises are increasingly prioritizing modular deployments that can be incrementally scaled, integrated with existing case management workflows, and updated with algorithmic improvements without requiring wholesale hardware replacement.
Within this operational landscape, several demand vectors warrant close attention as organizations formulate their 2026 strategies. Law enforcement and public security agencies continue to represent the core consumption base, driven by the imperative for faster case resolution, latent print matching, and cross-jurisdictional data sharing. Criminal investigations and border management functions form complementary demand channels, each with distinct latency tolerances, accuracy thresholds, and regulatory guardrails. Meanwhile, commercial applications in financial services, physical access control, and enterprise identity management are expanding the addressable user base, introducing new pricing dynamics and creating opportunities for vendors that can bridge public-sector rigor with private-sector user experience expectations.
Technological differentiation is increasingly concentrated in algorithmic efficiency, template interoperability, and cloud orchestration. The platforms that will capture premium positioning are those that can demonstrate consistent matching performance across diverse sensor qualities, support real-time querying at scale, and provide transparent audit trails aligned with evolving privacy frameworks. For strategy teams, this means evaluating vendor offerings not merely on feature checklists but on architectural resilience, integration latency, and total cost of ownership across the deployment lifecycle. The market is moving toward solutions that function as identity engines rather than isolated identification utilities, and this conceptual shift will dictate purchasing criteria throughout the forecast period.
Competitive Architecture and Strategic Positioning
The AFIS competitive landscape is characterized by a mix of entrenched multinational technology firms, specialized biometric pure-plays, and regional champions with deep domain expertise in specific justice or civil identity ecosystems. Market concentration data indicates a moderately consolidated environment, where the top three participants command a meaningful share of global revenue and the top five collectively account for a majority of total market output. This concentration level carries strategic significance. It suggests that scale advantages in algorithm development, global support infrastructure, and cross-border compliance certification provide tangible moats, while also leaving sufficient whitespace for agile specialists to compete on niche performance metrics, deployment flexibility, or regional partnership networks.
Leading participants have built their positions around distinct value propositions that reflect their organizational heritage and technological focus. NEC Corporation has anchored its strategy around its Integra-ID AFIS/ABIS platform, leveraging advanced fingerprint matching algorithms tailored for law enforcement and border security workflows. Fujitsu Limited has pursued a cloud-forward posture, delivering platforms that integrate AI-enhanced matching with applications spanning financial institutions and public security domains. HID Global Corporation has emphasized modular architecture and operational reliability, offering livescan management software alongside FBI-certified scanner hardware designed for government and law enforcement deployments. IDEMIA has focused on cloud-native identity infrastructure with its STORM ABIS system and Case AFIS offering, targeting latent fingerprint identification and multibiometric search capabilities. DERMALOG Identification Systems GmbH has concentrated on core AFIS and ABIS software development, prioritizing high-speed matching algorithms for both civil and criminal identification use cases.
The competitive field also includes specialized players with strong regional or functional positioning. Papillon Systems supplies AFPIS multibiometric AFIS for forensic and law enforcement contexts, extending support to palmprint and fingerprint modalities. Sonda Technologies Ltd. delivers biometric fingerprint identification systems and AFIS solutions tailored to government and commercial applications. M2SYS Technology offers scalable cloudABIS and AFIS platforms built around hyper-threaded matching servers designed for large-scale biometric databases. Crossmatch Technologies Inc. manufactures fingerprint scanners and AFIS integration solutions that maintain certification alignment with FBI NGI systems. SUPREMA provides BioMini and complementary fingerprint scanners alongside AFIS-compatible solutions oriented toward identity and border control. Innovatrics develops high-performance ABIS architectures with multimodal support designed for enterprise biometric identification. The duplicated presence of Suprema Inc. in corporate registries underscores the intensity of focus on advanced algorithmic integration and scanner compatibility for law enforcement applications.
For 2026 strategic planning, this competitive map suggests several actionable insights. First, procurement teams should evaluate vendors against their ability to support modular scaling and cross-system interoperability, as hybrid deployments become the norm rather than the exception. Second, organizations seeking long-term partnerships should assess each provider's track record in algorithm updates, regulatory adaptation, and support responsiveness across complex multi-site installations. Third, competitive pressure will likely intensify around pricing transparency, service-level commitments, and integration ease, making vendor evaluation a multidimensional exercise rather than a single-axis cost comparison. The moderately concentrated structure of the market means that both incumbents and challengers will be actively reshaping their portfolios, making continuous competitive intelligence a core component of 2026 procurement and partnership strategy.
Strategic Application of This Research for 2026 Planning
The true utility of a market research publication lies not in the elegance of its narrative but in the precision with which it informs decision cycles. This AFIS market study is structured to function as an operational reference for multiple stakeholder groups, each of which requires a distinct lens on the same underlying dataset. For technology procurement leaders, the analysis provides a structured framework for comparing architectural approaches, understanding the trade-offs between live scan and offline processing pathways, and mapping vendor capabilities to organization-specific security and compliance requirements. For corporate development and investment teams, the report offers a calibrated view of growth vectors, enabling more disciplined evaluation of partnership opportunities, acquisition targets, and market entry timing. For public sector strategists, the research contextualizes demand drivers within evolving operational mandates, supporting more resilient budgeting and capability roadmap planning.
A critical design principle of this publication is its emphasis on segmentation intelligence without exposing the granular percentages and localized revenue figures that would otherwise allow competitors to reverse-engineer strategic assumptions. Readers will gain a clear understanding of how the market divides across regional deployment patterns, technology-type preferences, and application-driven procurement behaviors. The report details the relative positioning of each segment, the operational characteristics that define demand in each category, and the strategic implications of segment-specific growth trajectories. However, to preserve the analytical premium and maintain the competitive neutrality of downstream sourcing decisions, the full breakdown of regional contributions, type-level revenue distributions, and application-specific allocations is reserved for the complete dataset accessible through the source publication. This approach ensures that organizations using the study gain directional clarity and prioritization guidance while retaining the incentive to acquire the full intelligence package for precise budgeting and forecasting.
Face Recognition Systems Market
Practically, the research supports 2026 planning in several concrete ways. It enables organizations to benchmark their current technology posture against prevailing market architectures and identify integration or scalability gaps before procurement cycles begin. It informs go-to-market and partnership strategies by clarifying which vendor archetypes align best with specific deployment contexts and customer expectations. It assists in scenario planning by outlining how shifts in regulatory standards, sensor technology, or cloud adoption rates could alter demand intensity across different segments. And it provides a common analytical language for cross-functional teams, ensuring that technology, security, finance, and operations stakeholders evaluate AFIS investments against a shared, evidence-based framework rather than fragmented assumptions.
Conclusion: Turning Market Intelligence into Structural Advantage
The AFIS market in 2026 rewards organizations that combine strategic patience with analytical precision. The headline trajectory points toward sustained expansion, supported by a 7.5 percent compound annual growth rate and a market base that has already matured through several cycles of technological upgrade and institutional adoption. Yet the strategic opportunities hidden within that macro narrative are far more varied. Segment-level demand signals, vendor-specific architectural strengths, regional implementation realities, and the evolving expectations around cloud integration and multimodal biometrics will collectively determine which organizations capture disproportionate value and which merely participate in a crowded field.
This research publication has been constructed to help decision-makers navigate that complexity with confidence. It synthesizes historical performance, forward-looking projections, competitive positioning, and operational context into a coherent strategic reference. By focusing on the structural forces that will shape procurement, partnership, and technology roadmaps, it enables organizations to move beyond reactive purchasing and toward proactive capability building. For leaders seeking to align their 2026 initiatives with durable market momentum, the complete dataset and detailed segmentation analysis available through the full report provide the precision necessary to convert high-level insight into executable strategy. In a market where matching accuracy, deployment agility, and compliance readiness define competitive outcomes, the cost of insufficient intelligence is measurable. The strategic response begins with a thorough, disciplined engagement with the full research.
For detailed analysis of this topic, please visit the official page: Automated Fingerprint Identification Systems (AFIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Pressure Transducers Market Hits $360M in 2025, Forecast 6.5% CAGR to $535M by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Medical Pressure Transducers Market: Navigating Growth and Complexity through 2032
Executive Overview
The global medical pressure transducers market stands at a critical inflection point where clinical necessity, technological evolution, and regulatory scrutiny converge to shape procurement strategies and product development roadmaps. For healthcare manufacturers, distributors, and hospital systems alike, understanding the trajectory of this sector is no longer optional. It is a fundamental component of risk management and revenue optimization. Our latest comprehensive study on the Medical Pressure Transducers Market offers a granular look into the forces driving value creation and erosion across the forecast horizon.
As we move into 2026, decision-makers are faced with a landscape defined by steady expansion but increasingly complex operational challenges. The market has demonstrated resilience over the past five years, recovering from pandemic-related disruptions and stabilizing into a growth pattern driven by aging demographics, the rising prevalence of cardiovascular conditions, and the continued adoption of minimally invasive monitoring technologies. However, raw growth figures tell only half the story. The real strategic value lies in understanding where margin pressure is building, how regulatory shifts are altering time-to-market, and which geographic corridors offer the most sustainable competitive advantage.
This article serves as a strategic preview of our full market intelligence report. It highlights the macroeconomic trends, competitive dynamics, and regulatory undercurrents that define the sector today. We will outline the operational depth contained within the study and explain why access to the complete dataset is essential for formulating robust strategies in 2026 and beyond.
Market Trajectory and Macroeconomic Context
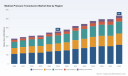
The financial architecture of the medical pressure transducers market reveals a consistent upward trajectory, underpinned by a compound annual growth rate that reflects both recovering demand and structural adoption of advanced monitoring solutions. Between 2020 and 2025, the market expanded from approximately 280 million USD to 360 million USD, signaling a recovery and acceleration phase that has set the stage for the forecast period.
Looking ahead to 2032, the revenue landscape is projected to reach 535 million USD. This growth path is not linear. The forecast period from 2026 to 2032 indicates varying velocities of expansion, with early forecast years showing measured acceleration before gaining momentum in the latter half of the decade. The overall CAGR of 6.5 percent suggests a mature but steadily expanding market, where volume growth is complemented by value-added features and premium product positioning.
It is crucial for stakeholders to recognize that these aggregate numbers mask significant variation across product types, clinical applications, and regional procurement environments. The interplay between established markets with high penetration rates and emerging markets with growing healthcare infrastructure creates a dual-speed environment. Companies that fail to differentiate their go-to-market strategies across these zones risk leaving revenue on the table or overinvesting in low-yield segments. Our full report deconstructs these layers to reveal the specific growth pockets and saturation risks that aggregate data obscures.
Segmentation Dynamics and Demand Drivers
Demand for medical pressure transducers is fundamentally tied to the criticality of hemodynamic monitoring and fluid management in acute care settings. The market is structured around distinct product configurations that serve different clinical workflows, ranging from single-channel solutions for straightforward monitoring to multi-channel systems designed for complex patient management. Each configuration carries different cost structures, manufacturing complexity, and clinical value propositions.
Applications span the spectrum of critical care and perioperative monitoring. Blood pressure monitoring remains a cornerstone application, driven by the ubiquity of invasive arterial pressure measurement in intensive care units and operating rooms. Respiration systems represent another significant demand center, particularly as ventilator management and respiratory support continue to evolve in complexity. Infusion pumps and related fluid delivery systems also rely heavily on accurate pressure sensing to ensure dosing accuracy and patient safety. Beyond these primary uses, specialized applications in surgical and interventional settings contribute to the broader demand picture.
Medical Pressure Transducers Market
From a regional perspective, the market exhibits a diversified footprint. North America continues to hold a substantial share, reflecting high healthcare spending, established critical care infrastructure, and a strong base of domestic manufacturers. Europe maintains a significant presence, though it faces unique regulatory and reimbursement dynamics that influence product adoption cycles. The Asia Pacific region represents a rapidly evolving landscape, where expanding hospital networks, growing medical tourism, and localized manufacturing initiatives are reshaping competitive dynamics. Latin America and the Middle East and Africa, while smaller in absolute terms, present growth opportunities tied to healthcare modernization efforts and increasing access to advanced monitoring technologies.
The strategic implication for 2026 is clear: a one-size-fits-all approach to product launches, pricing, and distribution is increasingly inefficient. Stakeholders must align their portfolios with regional clinical preferences, procurement cycles, and regulatory expectations. The detailed segmentation analysis in our full report provides the specific revenue allocations and growth rates that allow companies to prioritize investments with precision.
Competitive Landscape and Strategic Positioning
The competitive environment in the medical pressure transducers market is characterized by a mix of established multinational players and specialized manufacturers, each carving out niches through product differentiation, clinical evidence, and supply chain reliability. Market concentration metrics indicate that while the top players command meaningful share, the market remains sufficiently fragmented to allow for targeted strategic moves. The combined share of the top three and top five firms underlines the presence of scale advantages, yet also suggests room for agile competitors to capture value in specific applications or regions.
Several key companies define the current competitive benchmark. Edwards Lifesciences Corporation, based in Irvine, California, maintains a prominent position with its TruWave disposable pressure transducers, which are widely recognized for invasive hemodynamic monitoring applications. Their product lineage reflects a focus on integration with broader hemodynamic monitoring ecosystems, appealing to institutions that prioritize workflow compatibility and clinical standardization.
Smiths Medical, headquartered in Minneapolis, Minnesota, offers the TranStar disposable pressure transducer systems, which are designed for hemodynamic monitoring and emphasize reliability in high-acuity settings. Their portfolio underscores the importance of disposable systems in infection control and operational efficiency, a theme that resonates across modern critical care procurement criteria.
ICU Medical, Inc., located in San Clemente, California, provides the Transpac integrated and disposable pressure transducer systems tailored for critical care. Their offering highlights the convergence of sensor accuracy, ease of setup, and compatibility with existing monitoring platforms, factors that are increasingly weighted in hospital buying decisions.
Merit Medical Systems, Inc., based in South Jordan, Utah, contributes the Meritrans pressure transducers and Meritrans DTXPlus disposable systems, expanding the range of options available for procedural and critical care monitoring. Their presence illustrates how diversified medical device companies leverage pressure transducer portfolios to support broader interventional and diagnostic workflows.
Argon Medical Devices, Inc., operating from Plano, Texas, focuses on pressure monitoring lines and transducer kits for interventional procedures. Their specialization points to the growing demand for Procedural-specific monitoring solutions that address the unique requirements of catheterization labs, interventional radiology, and hybrid operating environments.
Competitive dynamics are further shaped by recent developments that signal shifts in accessibility and safety scrutiny. In September 2025, Shanghai Draeger Medical Instrument Co., Ltd. received FDA 510(k) clearance for an IBP transducer adapter cable compatible with multiple major brands, including Argon/BD/Ohmeda, Edwards, and Smiths/TranStar. This clearance highlights a trend toward interoperability and cross-compatibility, which can reduce dependency on single-vendor ecosystems and increase flexibility for hospital procurement teams. At the same time, Edwards Lifesciences' December 2025 adverse event report related to the TruWave disposable pressure transducer, documented in the FDA MAUDE database, serves as a reminder that post-market surveillance and device reliability remain critical differentiators. Incidents of this nature can influence purchasing confidence, quality assurance protocols, and risk management frameworks across the industry.
Regulatory and Operational Pressures Reshaping the Value Chain
Regulatory frameworks are exerting an increasingly pronounced influence on market entry timelines, cost structures, and product lifecycle management. The certification landscape has become more demanding, particularly within the European context. Analysts' insights indicate that the average certification timeline for the EU Medical Device Regulation 2017/745 has expanded from nine months to 18 months between 2021 and 2025. This elongation is accompanied by a cost increase ranging from 35 to 50 percent, placing greater strain on product development budgets and time-to-revenue expectations. For companies planning launches or refreshes in the European market, these shifts necessitate earlier regulatory engagement and more robust documentation strategies.
In parallel, FDA Class II clearance continues to govern the global blood pressure transducers market, ensuring biocompatibility and calibration accuracy. Compliance with these standards is a baseline requirement, but the competitive edge often lies in how manufacturers demonstrate consistency, traceable calibration practices, and post-market performance data. ISO 80601-2-34 governs transducer performance, yet actual calibration practices differ by hospital, manufacturer, and even individual clinician. This variability introduces both a quality assurance challenge and an opportunity for companies that can standardize calibration workflows, provide clear guidance, and reduce ambiguity in clinical settings.
On the supply side, the raw material procurement landscape adds another layer of complexity. The manufacturing of pressure transducers involves the pouring and processing of materials such as silicon, stainless steel, specialty alloys, and plastics sourced from various suppliers. Fluctuations in material availability, pricing, and supplier reliability can affect production continuity and cost margins. Companies that build resilient supplier networks, maintain strategic buffer stocks, and qualify alternative sources are better positioned to navigate supply chain disruptions without compromising delivery commitments.
These operational and regulatory factors combine to create a market environment where success is not solely determined by product performance but also by organizational agility, compliance readiness, and supply chain robustness. The detailed analysis in our report maps these dynamics against market segments and regional profiles, enabling stakeholders to anticipate bottlenecks and align resources accordingly.
What the Full Report Delivers for 2026 Decision-Making
The Medical Pressure Transducers Market study is designed to move beyond surface-level statistics and provide actionable intelligence for strategy formulation, portfolio planning, and competitive positioning. The report integrates demand-side analysis with supply-side dynamics, offering a 360-degree view of the market that supports both short-term tactical adjustments and long-term strategic investments.
Key components of the study include a comprehensive segmentation breakdown that isolates revenue contributions, growth rates, and trajectory patterns across product types, applications, and regions. Rather than presenting static snapshots, the analysis tracks the evolution of each segment over the historical period and projects forward through 2032, highlighting inflection points, saturation risks, and emerging demand pockets. This allows readers to identify which segments offer the most attractive risk-adjusted returns and which require defensive strategies or withdrawal considerations.
The competitive profiling section goes beyond corporate descriptions to assess market positioning, product differentiation, and strategic moves that indicate future intent. By mapping recent regulatory clearances, adverse event disclosures, and compatibility expansions, the report provides early signals of shifting competitive advantages and potential vulnerabilities. This level of detail helps manufacturers refine their value propositions, anticipate competitor responses, and identify partnership or acquisition opportunities that align with market needs.
Additionally, the study embeds regulatory and operational context into the market analysis, ensuring that growth projections are interpreted through the lens of real-world constraints. Certification timelines, cost escalations, calibration variability, and raw material procurement challenges are not treated as peripheral issues; they are integrated into the strategic narrative, showing how they influence product economics, launch sequencing, and regional prioritization. This approach enables readers to stress-test their plans against plausible scenarios and make more informed resource allocation decisions.
Ultimately, the report is structured to answer the questions that matter most to executives, product leaders, and commercial teams: Where is sustainable growth concentrated? Which competitive moves are most likely to disrupt current share distributions? How do regulatory and supply chain dynamics alter the profitability of different segments? And what specific actions should be prioritized in 2026 to capture value while mitigating exposure?
Conclusion: The Case for Comprehensive Market Intelligence
The medical pressure transducers market is entering a phase where growth is achievable but increasingly contingent on strategic precision. Aggregate expansion masks divergent segment trajectories, regional nuances, and shifting competitive threats that can materially affect outcomes if left unaddressed. Companies that rely on high-level summaries or outdated assumptions risk misallocating capital, misreading competitor intent, and underestimating the operational hurdles that shape market access.
Our full Medical Pressure Transducers Market report provides the depth, granularity, and forward-looking context required to navigate this environment with confidence. By revealing the specific revenue distributions, segment growth patterns, and competitive benchmarks that underpin the market's trajectory, the study equips stakeholders with the intelligence needed to optimize product portfolios, refine geographic strategies, and strengthen operational resilience.
Medical Pressure Sensors Market
For organizations preparing for 2026 and the forecast decade ahead, the difference between reactive positioning and proactive leadership lies in the quality of the information guiding critical decisions. Access to the complete market analysis ensures that strategy is built on evidence rather than inference, and that growth opportunities are pursued with clarity, discipline, and a realistic understanding of the landscape. We invite you to explore the full report to unlock the detailed insights that will inform your next strategic moves.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cold Mix Asphalt Additives Market to Hit $701M by 2032, Growing at 4.92% CAGR, Says PW Consulting
By PW Consulting, 2026-09-16
Navigating the Cold Mix Asphalt Additives Market: Strategic Intelligence for 2026 Decision-Makers
The construction materials landscape is undergoing a structural shift, driven by tightening environmental regulations, volatile feedstock costs, and an accelerating demand for sustainable pavement solutions. At the center of this transformation lies the Cold Mix Asphalt Additives Market, a specialized yet rapidly evolving segment that bridges traditional road infrastructure with next-generation green procurement mandates. As organizations plan capital allocation, R&D roadmaps, and market entry strategies for 2026 and beyond, understanding the underlying market mechanics is no longer optional—it is a strategic imperative.
Why 2026 Is a Pivotal Year for Strategic Planning
The trajectory of the cold mix asphalt additives sector reveals a market that has consistently expanded over the past half-decade. Historical revenue data from 2020 through 2025 demonstrates a clear upward inflection, with total market valuation reaching approximately 501 million USD by the base year. Looking ahead, the forecast period spanning 2026 to 2032 projects sustained growth momentum, anchored by a compound annual growth rate of 4.92 percent. This incremental expansion reflects more than cyclical roadbuilding activity; it signals a structural transition toward ambient-temperature application technologies that deliver measurable energy savings and emission reductions compared to conventional hot mix processes.
For corporate strategists, the 2026 horizon presents a convergence of forces. Regulatory frameworks are hardening, supply chain dynamics are recalibrating around feedstock volatility, and procurement standards are increasingly favoring lower-carbon construction methodologies. Companies that treat the cold mix additives space as a peripheral product line risk ceding ground to competitors who are already positioning their portfolios around polymer-modified bio-based formulations, emission-reduction performance metrics, and compliance-ready chemical architectures. The strategic value of precise market intelligence in this environment cannot be overstated. It enables leadership teams to align product development cycles with procurement timelines, anticipate regulatory friction points, and calibrate pricing strategies against premium sustainability credentials.
Decoding the Market Architecture
The cold mix asphalt additives ecosystem is defined by a multi-dimensional segmentation structure that shapes downstream purchasing behavior, manufacturing capacity allocation, and competitive positioning. Understanding how these segments interact with broader industry dynamics provides executives with the contextual framework needed to evaluate growth vectors and risk exposures.
Segmentation Dynamics and Value Distribution
The market divides along three primary axes: geographic footprint, chemical formulation type, and end-use application. Each axis carries distinct commercial implications, yet their interdependencies often dictate which products scale efficiently and which remain niche. Regional demand patterns reflect divergent infrastructure priorities, climatic operating conditions, and regulatory maturity levels. Formulation categories encompass emulsion-based architectures and solvent-based alternatives, each presenting different trade-offs between performance characteristics, handling complexity, and cost structures. Application channels further bifurcate between stockpile maintenance mixes and continuous paving workflows, influencing volume demand, specification requirements, and supplier selection criteria.
Our research deliberately maps these segmentation layers without relegating them to isolated figures. Instead, the analysis traces how regional infrastructure spending cycles, climatic constraints on ambient-temperature application, and the growing specification of recycled material incorporation rates collectively reshape segment attractiveness over the forecast horizon. This holistic view is essential for executives evaluating market entry, capacity expansion, or product portfolio rebalancing.
Forces Reshaping Competitive and Operational Realities
Several cross-cutting dynamics are altering the benchmark for market participation. Sustainability research published in late 2025 highlights that ambient-temperature application of cold mix asphalt additives can yield energy savings in the range of thirty-five to fifty percent, alongside emission reductions of forty to sixty percent relative to conventional hot mix asphalt. These performance differentials are increasingly embedded into procurement scorecards, transforming what was once a cost-centric purchasing decision into a compliance-and-sustainability-driven evaluation.
Simultaneously, regulatory complexity is elevating the barrier to international product deployment. European REACH requirements, California Proposition 65 mandates, and analogous frameworks in Australia and Canada impose substantial toxicological testing and documentation obligations on chemical additives used in cold mix formulations. The compliance burden extends beyond registration costs; it influences time-to-market timelines, regional portfolio prioritization, and the feasibility of exporting formulations developed for one jurisdiction into another.
Cold Mix Asphalt Additives Market
On the cost side, volatility in crude oil and petrochemical feedstock prices continues to exert direct pressure on production economics. Bitumen emulsifiers, amine-based anti-stripping agents, and petroleum-derived adhesion promoters remain sensitive to commodity price swings, forcing manufacturers to balance margin protection with competitive pricing. Against this backdrop, bio-based alternatives are emerging as strategically differentiated offerings. Industry market data from 2025 indicates that these sustainable formulations typically command a price premium of approximately fifteen to twenty-five percent over conventional products, reflecting both raw material economics and the premium that procurement entities place on sustainability credentials.
Green procurement mandates introduced by national and municipal governments across Europe, North America, and Oceania are further accelerating adoption. These mandates incentivize or require lower-emission construction methods, effectively creating policy-driven demand pull that rewards early movers with established compliance documentation and proven field performance.
Competitive Landscape: Positioning, Innovation, and Strategic Differentiation
The market structure reflects a moderately concentrated environment. Concentration metrics indicate that the top three participants account for approximately thirty-seven and a half percent of total revenue, while the top five hold around forty-five percent. This distribution suggests a landscape where established players maintain meaningful scale advantages, yet sufficient fragmentation remains to allow specialized innovators to capture value through differentiated formulations, application-specific performance claims, and sustainability-aligned branding.
Worldwide Cement Additive Market
Strategic Profiles of Key Market Participants
Arkema SA, headquartered in Courbevoie, France, has carved a distinct position around cold mix adhesion and longevity performance. Its ColdGrip portfolio centers on cold mix asphalt additives and adhesion promoters designed to improve cold patch durability by displacing water and enhancing binder-aggregate adhesion. In practical terms, this approach targets a persistent pain point in cold mix applications: moisture-induced failure and reduced service life in stockpile or interim repair scenarios. Arkema’s strategic emphasis on adhesion science positions its offerings as performance-critical consumables rather than commoditized blending agents, enabling a value proposition anchored in durability and reduced rework.
Cargill, based in Minneapolis, Minnesota, has pursued a parallel but chemically distinct path. Its Anova cold mix additives leverage polymer-modified, bio-based formulations that enable up to one hundred percent recycled asphalt pavement incorporation while maintaining low VOCs, supporting year-round application, and improving viscosity and moisture resistance. In May 2026, Cargill introduced an enhanced Anova lineup that reinforced these attributes, signaling a deliberate push toward high-RAP formulations that align with circular economy objectives and tightening emission expectations. Cargill’s approach demonstrates how feedstock innovation and sustainability positioning can be integrated into a single product narrative, appealing to buyers seeking both compliance readiness and performance consistency across seasonal conditions.
Latest Strategic Moves Defining the Innovation Frontier
Beyond established players, the market is being shaped by targeted launches that broaden the technical envelope of what cold mix additives can achieve. In May 2026, Verde Resources unveiled a biochar-infused cold-mix asphalt formulation that successfully sequesters CO₂ while retaining durability under traffic loading. This development illustrates how carbon capture concepts are beginning to intersect with construction materials, creating hybrid value propositions that combine performance, sequestration potential, and regulatory alignment. Such initiatives signal that innovation in this space is no longer confined to adhesion or workability improvements; it is expanding into carbon accounting, material circularity, and multi-attribute sustainability credentials.
What This Research Delivers: Operational Intelligence for Executive Decisions
Our comprehensive market study is designed to convert macroeconomic signals into executable strategy. The report does more than summarize historical growth or project future revenue range; it constructs a decision-ready architecture that connects market sizing to actionable business implications. Throughout the analysis, we reference the overall market scale trajectory—anchored at roughly 501 million USD in the base year and expanding toward a forecasted valuation of approximately 701 million USD by 2032—to frame the magnitude of the opportunity without reducing it to isolated segment figures.
Executives will find a structured examination of how formulation types, application channels, and regional demand environments interact under current regulatory, cost, and sustainability pressures. The study maps the competitive field with enough granularity to identify where incumbents derive defensible advantage and where gaps remain for new entrants or portfolio extensions. It also evaluates the practical consequences of compliance requirements, feedstock volatility, and green procurement mandates on pricing architecture, product launch sequencing, and regional prioritization.
Key Operational Components Included
- A multi-year historical review and forward-looking forecast framework that links revenue trajectory to underlying demand drivers and policy shifts.
- Segment-level analysis that examines how formulation architectures, application workflows, and geographic demand environments shape commercial positioning and growth potential.
- Competitive profiling that assesses how leading participants differentiate through adhesion technology, bio-based formulation chemistry, recycled material compatibility, and sustainability messaging.
- Regulatory and compliance mapping that identifies documentation burdens, testing requirements, and regional market-access considerations influencing product deployment strategies.
- Cost and pricing dynamics analysis that connects feedstock exposure, bio-based premium structures, and procurement incentives to margin and positioning decisions.
- Innovation trajectory assessment that tracks how carbon sequestration concepts, high-RAP compatibility, low-VOC formulations, and year-round application capabilities are redefining product benchmarks.
Strategic Takeaways for 2026 Planning
The Cold Mix Asphalt Additives Market is not merely expanding; it is being rearchitected around sustainability performance, regulatory readiness, and formulation innovation. Companies that treat this evolution as a compliance overhead will find themselves reacting to procurement shifts after the fact. Those that proactively align product development, documentation strategy, and regional market sequencing with the emerging demand environment will be better positioned to convert policy-driven pull into durable share gains.
The research underscores that success in 2026 will depend on how effectively organizations can navigate the intersection of performance claims and verification requirements, feedstock cost exposure and bio-based premium strategies, and regional regulatory divergence and global product architecture. Understanding where concentration already exists, where innovation is creating new value pools, and how application-specific demands differ across stockpile maintenance and continuous paving contexts provides the strategic clarity needed to prioritize investments with greater confidence.
Access the Full Intelligence Architecture
This overview is intentionally designed as a strategic prelude. It illustrates the analytical depth, segmentation logic, competitive mapping, and dynamic assessment that inform our complete market study, while preserving the granular breakdowns, quantitative segment contributions, and detailed forecast tables for the full report. For executives and strategy teams seeking to model regional opportunities, evaluate formulation positioning, assess competitor moves, or build 2026-2032 planning scenarios, the complete research provides the structured intelligence necessary to move from conceptual awareness to operational decision-making.
To access the full market research, including detailed segment analysis, competitive benchmarking, regulatory impact assessment, and multi-year forecast architecture, visit the official PW Consulting research page and secure your copy of the Cold Mix Asphalt Additives Market study.
For detailed analysis of this topic, please visit the official page: Cold Mix Asphalt Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micromanipulators Market to Hit $152.8M by 2032 at 9.3% CAGR
By PW Consulting, 2026-09-16
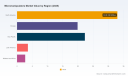
Strategic Imperatives in the Micromanipulators Market: A 2026 Executive Preview
The global landscape for precision instrumentation is undergoing a structural transformation. As life science research accelerates and industrial manufacturing demands tighter tolerances, micromanipulators have evolved from niche laboratory utilities into critical enablers of high-value workflows. Our newly released Micromanipulators Market report provides a comprehensive strategic compass for executives navigating this rapidly expanding sector through 2032.
For decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise. It is a prerequisite for capital allocation, R&D prioritization, supply chain resilience, and competitive positioning. This introductory analysis distills the macro forces shaping the industry, outlines the analytical architecture of our full study, and demonstrates how procurement leaders, investors, and strategic planners can translate market intelligence into actionable advantage.
Market Trajectory and Structural Growth Signals
The micromanipulators market has demonstrated consistent upward momentum over the past half-decade. Valued at approximately 72.97 million USD in 2024 and closing at 81.5 million USD in 2025, the sector has entered a phase of accelerated expansion. Our forecasting model projects the market to reach 88.81 million USD in 2026, scaling steadily toward a projected 152.8 million USD by 2032. This progression reflects a compound annual growth rate of 9.3 percent across the 2026 to 2032 window, signaling sustained demand elasticity rather than short-term cyclical spikes.
Several converging dynamics are underpinning this trajectory. First, R&D investment across neurology, molecular biology, and semiconductor fabrication has intensified the need for high-precision positioning systems capable of sub-micron resolution. Second, the commercialization of assisted reproductive technologies continues to formalize micromanipulation as a standardized clinical workflow. Third, cost-structure innovations are reshaping procurement calculus. Recent sector analysis indicates that a low-cost electric micromanipulator assembled in Japan costs roughly one-fourth the price of a commercial hydraulic unit while requiring no regular maintenance, fundamentally altering the total cost of ownership equation for laboratories and mid-tier manufacturers.
Regulatory frameworks are reinforcing this demand. The International Glossary on Infertility and Fertility Care 2025 explicitly defines micro-operative assisted reproductive techniques utilizing micromanipulation for intracytoplasmic sperm injection and assisted hatching. Such nomenclature standardization is quietly driving procurement standardization across clinical and research institutions, embedding micromanipulators deeper into accredited operational protocols.
Micromanipulators Market
Segment Architecture and Application Intelligence
The market's revenue architecture is anchored by a clear hierarchy of technology types and application domains. Electric micromanipulators command the dominant share of overall revenue, reflecting a broader industry pivot toward automated, programmable positioning systems that integrate seamlessly with digital microscopy and electrophysiology workflows. Hydraulic systems maintain a meaningful presence, particularly in applications demanding exceptional force control and mechanical stability. Manual platforms, while occupying a smaller revenue footprint, continue to serve specialized research environments where tactile precision and low overhead costs remain decisive.
By application, cell micromanipulation represents the core demand engine, capturing the largest portion of total market revenue. This segment spans electrophysiology, patch clamp studies, microinjection, and assisted reproductive workflows, each requiring different combinations of resolution, throughput, and integration complexity. Industrial micromanipulation constitutes a substantial secondary pillar, driven by semiconductor testing, microassembly, and advanced materials characterization. The remaining revenue is distributed across adjacent application spaces that are increasingly intersecting with automated laboratory ecosystems.
Geographically, the market exhibits a multi-polar distribution pattern. North America leads as the largest revenue region, supported by dense concentrations of academic research institutions, biotechnology enterprises, and clinical facilities. Europe holds a strong secondary position, underpinned by robust public research funding and established medical technology manufacturing bases. Asia Pacific represents a fast-growing corridor, where expanding life science infrastructure and regional assembly economics are reshaping both supply and demand dynamics. Latin America and the Middle East and Africa together form an emerging periphery, where adoption is gradually accelerating as research capacity and clinical accessibility improve.
Competitive Landscape and Strategic Positioning
The competitive field is characterized by a moderate concentration structure. The top three players collectively account for approximately 38.5 percent of market revenue, while the top five extend their combined share to roughly 45.2 percent. This architecture suggests a market that is neither fully consolidated nor highly fragmented, creating strategic room for differentiated innovation, regional partnerships, and technology-led disruption.
Sensapex Oy, headquartered in Oulu, Finland, has built its reputation on patented ultraprecise micromanipulators and automated microscope workstations designed for electrophysiology and imaging, with in-house manufacturing reinforcing quality control and supply agility. Sutter Instrument, based in Novato, California, continues to serve the research community with precision manual and motorized micromanipulators optimized for electrophysiology and cell manipulation tasks. Scientifica Ltd, operating from East Sussex, UK, specializes in PatchStar micromanipulators and electromechanical systems tailored for patch clamp and electrophysiology applications, reflecting deep vertical integration into neuroscience workflows.
Siskiyou Corporation, located in Grants Pass, Oregon, delivers high-precision micromanipulators and micropositioners for microscopy and research applications, emphasizing mechanical reliability and modular compatibility. Narishige Group, based in Tokyo, Japan, offers the NTX series of hydraulic and motorized micromanipulators designed for cell manipulation and microinjection, combining established mechanical engineering heritage with evolving automation interfaces. World Precision Instruments, headquartered in Sarasota, Florida, remains a recognized provider of manual micromanipulators for electrode positioning in electrophysiology and neuroscience research. Leica Microsystems, from Wetzlar, Germany, integrates micromanipulator systems into broader microscopy and cell research platforms, leveraging ecosystem synergy rather than standalone instrument positioning. Eppendorf SE, headquartered in Hamburg, Germany, supplies high-precision micromanipulation and injection systems for life science applications, benefiting from strong brand recognition in sample handling and laboratory automation.
Recent corporate activity illustrates how quickly the battlefield is shifting. In mid-2024, Sensapex released Rev 2.0 documentation for its uMp micromanipulation system, including the uMp-TSC2 controller and uMp-3 and uMp-4 micromanipulators, reinforcing its focus on usability and system integration. In late 2024, New Scale Technologies delivered a Modular Insertion System to the Allen Institute for Neural Dynamics, enabling order-taking for next-generation silicon probe micromanipulation, a move that signals growing demand for specialized neural interface instrumentation. Looking into 2026 planning cycles, industry events such as SLAS Europe have already begun featuring sessions on manual micromanipulation in an era of lab automation, underscoring the tension between tactile expertise and automated throughput that will define procurement debates throughout the forecast period.
Operational and Strategic Content of the Full Report
Our complete study goes beyond top-line forecasting to deliver a practical decision-support framework. The report maps the full competitive matrix, profiles the strategic positioning of each major participant, and evaluates how product portfolios, distribution channels, and regional manufacturing footprints intersect with demand growth. It dissects the total cost of ownership differentials across technology types, offering procurement teams a structured approach to evaluating electric, hydraulic, and manual platforms against operational requirements rather than purchase price alone.
The analysis further examines how application-specific requirements create distinct purchasing criteria. Laboratories conducting cell micromanipulation prioritize resolution, repeatability, and integration with imaging or electrophysiology systems. Industrial users weigh throughput, environmental robustness, and compatibility with automated assembly or testing lines. Adjacent application segments introduce additional variables, including regulatory compliance, sterilization protocols, and software interoperability. By isolating these decision drivers, the report enables stakeholders to segment their own demand profiles and align vendor selection accordingly.
Regional expansion pathways are evaluated with attention to infrastructure maturity, research funding cycles, and local assembly economics. The study also addresses supply chain considerations, including component sourcing, service network density, and the implications of maintenance-free electric architectures for long-term operational budgets. Regulatory developments are tracked not as abstract policy commentary but as practical procurement catalysts, showing how evolving clinical definitions and laboratory standards influence purchasing standardization and vendor qualification.
Translating Insight into 2026 Decision Advantage
For executives planning capital deployment in 2026, the strategic implications are clear. First, technology selection should be evaluated through a total lifecycle lens rather than an upfront cost comparison. The growing availability of low-maintenance electric platforms is compressing the long-term cost gap between premium hydraulic systems and economical electric alternatives, particularly for organizations that value operational simplicity and reduced service overhead.
Second, application focus matters. Organizations centered on cell micromanipulation should prioritize vendors with strong integration ecosystems and documented performance in electrophysiology, imaging, and microinjection workflows. Industrial buyers should emphasize positioning repeatability, environmental tolerance, and compatibility with automation pipelines. A generic procurement approach risks overpaying for unnecessary capabilities or underinvesting in critical performance attributes.
Third, geographic strategy should align with regional research intensity and local supply dynamics. North America and Europe remain anchor markets with deep established demand, but Asia Pacific is expanding rapidly as research infrastructure scales and regional assembly options mature. Companies seeking growth should evaluate distribution partnerships, service coverage, and local compliance requirements with the same rigor applied to product development.
Fourth, competitive monitoring should focus on integration velocity and ecosystem breadth. As laboratory automation and neuroscience instrumentation advance, the winners are increasingly those who offer seamless software control, modular upgrade paths, and compatibility with next-generation probes and imaging platforms. Recent product releases and institutional deliveries indicate that the market is moving toward more specialized, workflow-embedded solutions rather than generic positioning tools.
Humanoid Five-finger Manipulators Market
Conclusion and Next Steps
The micromanipulators market is entering a defining growth phase. Steady macroeconomic expansion, application-driven demand intensity, cost-structure innovation, and evolving regulatory clarity are collectively reshaping how institutions evaluate precision positioning equipment. The 9.3 percent compound growth trajectory projected through 2032 reflects a market that is expanding on the strength of real operational needs rather than speculative adoption.
Yet the strategic value of this market cannot be captured through aggregate figures alone. Effective decision-making requires a granular understanding of technology trade-offs, application-specific purchasing criteria, regional expansion dynamics, and the competitive maneuvers that are currently reshaping vendor positioning. Our full Micromanipulators Market report delivers that depth, providing the structured intelligence needed to align procurement, R&D investment, and growth planning with the realities of a rapidly evolving sector.
For leaders who require precise segmentation data, detailed competitor benchmarking, and forward-looking scenario analysis, the complete study offers the unfiltered intelligence necessary to move from awareness to action. The 2026 decision window is open, and the organizations that equip themselves with comprehensive market intelligence will be best positioned to capture value as the micromanipulators market continues its ascent.
For detailed analysis of this topic, please visit the official page: Micromanipulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wellington Boots Market to Hit $1,842.67M by 2032 at 4.8% CAGR
By PW Consulting, 2026-09-16
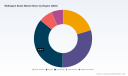
Strategic Intelligence in the Wellington Boots Market: A 2026 Outlook
The global Wellington boots market stands at a critical inflection point as enterprises navigate shifting trade dynamics, material innovation, and evolving consumer expectations. At PW Consulting, we recognize that stakeholders across agriculture, industrial manufacturing, retail, and footwear distribution require more than surface-level trends. They need a rigorously validated, forward-looking framework that translates historical momentum into actionable decision pathways. Our newly released Wellington Boots Market research report delivers precisely that: a comprehensive intelligence asset engineered to support strategic planning throughout the 2026-2032 forecast horizon.
This introductory analysis outlines the strategic rationale behind the study, highlights the operational architecture of the full report, and frames the competitive and macroeconomic forces that will shape procurement, product development, and market entry decisions over the coming years. Readers seeking complete quantitative breakdowns, granular regional demand matrices, and detailed competitor benchmarking will find the full intelligence document essential. The following preview establishes the analytical foundation while directing quantitative deep dives to the complete release.
Market Trajectory and the Strategic Imperative for 2026
The Wellington boots sector has demonstrated consistent expansion across the 2020-2025 historical window, reflecting structural demand from professional working environments, agricultural operations, and the growing consumer preference for weather-ready functional footwear. Our analysis places the 2025 revenue baseline at approximately USD 1,330.0 million, with forward trajectory modeling indicating sustained growth through the end of the decade. The forecast period projects a compound annual growth rate of 4.8 percent, positioning the market to approach USD 1,842.7 million by 2032.
Such trajectory is not merely a function of incremental consumption. It is the cumulative result of durable end-use demand, public and private procurement cycles, and the ongoing repositioning of Wellington-style footwear as both utilitarian equipment and lifestyle-adjacent product. For executives evaluating capacity planning, inventory allocation, or geographic expansion, the central strategic question is no longer whether the category will grow, but where growth concentrates, which material platforms will sustain margin integrity, and how trade policy reshapes sourcing economics. Our report answers these questions through segmented modeling that isolates demand drivers, pricing elasticity, and channel behavior without oversimplifying the operational complexity on the ground.
The forecast architecture covers an eight-year horizon from 2026 through 2032. This duration is deliberate. Short-term projections often miss inflection events such as tariff adjustments, raw material cost shocks, or product lifecycle transitions. An eight-year span enables leadership teams to test scenario-based strategies, evaluate capital deployment timing, and align product roadmaps with multi-cycle procurement calendars. By anchoring the study in historical data from 2020 onward and extending projections with scenario-tested assumptions, the report provides a reliable scaffold for board-level discussions and operating-plan development.
What the Report Delivers: Operational Content for Decision-Makers
Comprehensive market intelligence must translate into executable insight. The Wellington Boots Market research is structured to serve cross-functional teams, from procurement and supply chain leadership to marketing, product development, and corporate strategy. Rather than offering a single aggregate figure, the study decomposes the market into analytically meaningful dimensions that correspond to real operational decisions.
The report provides a detailed examination of the material composition landscape, evaluating how different manufacturing substrates influence cost structures, performance characteristics, and end-user segmentation. It also maps application-driven demand patterns, distinguishing between professional agricultural usage, household and lifestyle consumption, industrial manufacturing environments, outdoor recreation, and additional specialized deployments. This segmentation lens is critical because each vertical exhibits distinct purchasing cycles, durability requirements, price sensitivity, and channel preferences.
Geographically, the study assesses regional demand dynamics to help leadership teams identify where volume concentration is strongest, where growth momentum is accelerating, and where regulatory or logistics constraints may alter entry strategies. The analysis integrates market concentration metrics to contextualize competitive rivalry and distribution leverage, giving stakeholders a clear view of how consolidated the landscape is and where white space or partnership opportunities may reside.
Beyond structural segmentation, the report embeds forward-looking assessments of pricing architecture, supply chain exposure, and product innovation trajectories. The inclusion of scenario modeling enables users to evaluate how changes in raw material costs, freight economics, or duty regimes could shift margin profiles and sourcing strategies. This is particularly valuable in a category where input costs and trade policy are actively reshaping manufacturer pricing behavior and retailer purchasing decisions.
To support implementation, the study incorporates a structured competitive benchmarking section that examines product architecture, positioning, and strategic moves among leading participants. This component is designed to help organizations compare value propositions, anticipate competitive responses, and identify areas where differentiation must be driven by construction quality, material innovation, or channel alignment rather than price alone.
Competitive Landscape: Positioning, Differentiation, and Recent Moves
The Wellington boots market is shaped by a diversified set of participants spanning heritage craftsmanship, professional-grade work and fishing footwear, industrial protective equipment, and consumer-oriented lifestyle products. Our competitive analysis examines how these companies construct their offerings and where strategic activity is intensifying.
Le Chameau, headquartered in Normandy, France, exemplifies a craftsmanship-led approach with iconic handcrafted rubber Wellington boots built around a Chamolux rubber upper and dual-material construction designed for durability and weather resistance. Its recent retail partnership activity in 2025, including the stocking of new Fairfax collaboration Wellington boots at major retailers, signals a deliberate extension into broader consumer distribution while preserving a premium product identity.
Grundéns, based in Canada, focuses on professional-grade rubber and neoprene fishing and work boots, with its Crewman model engineered for commercial durability. The company's 2025 product launch of the Crewman boot after nine months of field testing across Alaska, the Canadian Maritimes, Maine, and Europe demonstrates a testing-intensive development model aligned with demanding environmental and operational conditions.
Xtratuf, operating in the United States under Rocky Brands ownership, maintains a strong presence with durable waterproof rubber work and fishing boots. The brand's positioning reflects a practical, performance-first portfolio that supports commercial and recreational use cases where waterproof integrity and rugged construction are paramount.
Rubbermaid, headquartered in Atlanta, Georgia, contributes a commercial-grade rubber boots and protective footwear line aimed at industrial and facility use. Its offering underscores how facility management, hygiene, and workplace safety requirements shape demand for durable rubber products in institutional settings.
Bogs Footwear, based in Portland, Oregon, emphasizes waterproof rubber and seamless Wellington-style boots for farm, work, and outdoor use. Its construction philosophy highlights the consumer and professional overlap in the category, where comfort and weather protection intersect.
Blundstone, headquartered in Hobart, Australia, offers rugged rubber and leather Wellington boots for work and casual use. The combination of material types reflects a dual-purpose strategy that bridges utility and everyday wear, appealing to users who want durability without sacrificing style versatility.
Aigle, from France, markets unisex rubber Wellington boots with lugged soles and dual-material uppers for outdoor and adventure use. Its design language aligns with the broader outdoor recreation segment, where traction, weatherproofing, and aesthetic coherence matter to active consumers.
Dunlop Boots, based in the United Kingdom, focuses on industrial and professional rubber boots with chemical-resistant features. This specialization illustrates how sector-specific performance requirements, such as chemical handling and workplace safety compliance, drive product engineering decisions and segment-specific demand.
Rockland, operating in the United States, addresses the affordable rubber Wellington boot segment for general consumer and work applications. Its positioning demonstrates that accessibility and broad functionality remain important demand anchors, particularly where price sensitivity is high and usage expectations are standardized.
Tingley Rubber, also based in the United States, supplies durable rubber overshoes and Wellington-style footwear for safety and industrial use. Its product focus reinforces the role of protective footwear in occupational environments where overshoes and specialized rubber constructions serve practical compliance and contamination-control functions.
Together, these participants illustrate a market where differentiation is increasingly defined by material engineering, durability validation, channel strategy, and brand positioning across professional and consumer contexts. The report evaluates these dynamics with a structured competitive framework, enabling clients to benchmark their own product strategies and anticipate how rivals may respond to cost pressures, regulatory changes, and evolving consumer preferences.
Macroeconomic and Regulatory Dynamics Shaping the 2026 Decision Environment
Strategic planning in the Wellington boots market cannot be separated from the broader operating environment. Several interconnected forces are actively reshaping sourcing economics, product development priorities, and margin management.
Chelsea Bootie Market
Trade and duty policy has emerged as a central variable. Recent U.S. customs actions have applied a 37.5 percent ad valorem duty under HTS 6401.99 for waterproof rubber boots originating from China under Executive Order 14389, with effect from February 2026. In parallel, broader U.S. footwear import tariffs introduced in April 2025 raised duties for Vietnamese boots by 46 percent and Indonesian boots by 32 percent, with duties reaching up to 145 percent on certain Chinese imports. These measures directly affect Wellington boots supply chains by altering landed cost calculations, reshaping sourcing geography, and creating pressure on manufacturers and distributors to reassess supplier mixes and inventory positioning.
On the European and UK side, the HS Code 6401.99.00 classification for rubber Wellington boots carries EU import duties of 16 percent and UK duties of 16 percent under 2026 HTS revisions. For companies operating transatlantic supply chains or evaluating European distribution footprints, these duty levels influence margin modeling and demand forecasting at the regional level.
Cost-side pressure is equally significant. Industry-wide exposure to rising raw material and freight costs in 2025 has led manufacturers to increase Wellington boot prices by more than 20 percent in order to maintain margins. This pricing response is not merely a tactical adjustment; it signals a structural shift in the cost base that procurement teams and pricing strategists must incorporate into forward budgets, contract negotiations, and retail price architecture.
Consumer and product development trends are also reshaping the landscape. Eco-friendly materials have featured in roughly half of new product launches for Wellington boots since 2023, driving consumer demand particularly in Europe and North America. This shift is mirrored in broader footwear dynamics, with Wellington-style boots commanding substantial material demand share in consumer footwear and rubber remaining a central substrate. The implication for product teams is clear: sustainability messaging, material substitution, and performance validation are becoming inseparable from commercial competitiveness.
These dynamics are not isolated. Duty changes influence sourcing; sourcing decisions affect material availability and cost; cost pressures affect pricing; pricing interacts with consumer willingness to pay; and consumer preferences increasingly reward material innovation. The report integrates these interdependencies into a coherent analytical narrative so that leadership teams can evaluate second-order effects rather than reacting to single variables in isolation.
Strategic Takeaways for Executive Planning in 2026
As organizations prepare for the 2026 operating year, the Wellington boots market demands a disciplined, evidence-based approach to strategy. Several priorities stand out for executives seeking to align their plans with the market's actual structure and trajectory.
First, sourcing and supply chain strategy must be re-examined in light of evolving duty regimes and freight economics. Companies that rely on single geography sourcing or fixed supplier contracts may face heightened exposure to cost volatility and duty-driven margin compression. Scenario planning that evaluates alternative sourcing paths, inventory buffers, and channel timing can reduce disruption risk and preserve pricing flexibility.
Second, product strategy should account for the growing role of material innovation and performance differentiation. With eco-friendly materials increasingly prevalent in new launches and consumer expectations rising in key regions, product roadmaps that rely solely on legacy constructions may lose relative positioning. Organizations should assess where dual-material construction, weather resistance, chemical resistance, or seamless design can serve as credible differentiators aligned to professional or consumer use cases.
Wellington Boots Market
Third, segmentation discipline is essential. The market's demand is distributed across agriculture, household use, industrial manufacturing, outdoor recreation, and additional applications, each with distinct purchasing behavior and performance requirements. A uniform product or pricing strategy is unlikely to optimize results across these verticals. Leaders should use segmentation insights to tailor product specifications, channel selection, and commercial messaging to the specific operational and emotional drivers within each application group.
Fourth, competitive positioning must be understood in context. The landscape includes companies pursuing craftsmanship-led premium strategies, professional-grade durability narratives, industrial protective applications, and affordable general-use offerings. Understanding where a given organization sits within this spectrum, and how competitors are deploying retail partnerships, product launches, and material innovation, enables more precise strategic choices around brand architecture, channel expansion, and product investment.
Finally, forecast discipline matters. The eight-year projection horizon in the full report is designed to support multi-cycle planning rather than short-term reaction. Organizations that integrate forward demand modeling with cost scenarios and competitive intelligence are better positioned to time capacity investments, rationalize SKU portfolios, and allocate commercial resources where growth probability is highest.
Accessing the Full Intelligence Framework
This overview has outlined the strategic architecture of the Wellington Boots Market research and the decision environment that makes it relevant for 2026 planning. The complete report expands significantly on these themes, providing the detailed market sizing, segmentation breakdowns, regional demand analysis, competitive benchmarking, and scenario-based forecasts needed to translate strategy into execution.
For teams responsible for sourcing, product development, pricing, distribution, or corporate planning, the full study offers the depth required to move from directional awareness to evidence-based action. Given the ongoing influence of tariff structures, raw material economics, and material innovation on both cost and consumer response, organizations that equip themselves with comprehensive market intelligence will be better prepared to manage risk, capture growth, and compete effectively across professional and consumer segments.
The Wellington boots category continues to evolve at the intersection of utility, durability, and consumer lifestyle expectations. In that environment, strategic clarity depends on rigorous analysis, and rigorous analysis depends on complete data. The full PW Consulting report is built to provide exactly that foundation for the decisions ahead.
For detailed analysis of this topic, please visit the official page: Wellington Boots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


