



PW Consulting: Phosphorus Pentasulfide Market Hits $470M in 2025, Eyes $640.8M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Phosphorus Pentasulfide Market: Navigating Growth, Supply Constraints, and Competitive Dynamics Through 2032
Why This Study Matters for 2026 Decision-Makers
The Phosphorus Pentasulfide (P2S5) market is entering a period of structural recalibration. Demand drivers are diverging across end-use sectors, feedstock volatility is reshaping cost architectures, and regulatory regimes are tightening across major trade corridors. For executives planning capital allocation, procurement strategy, and geographic expansion in 2026, surface-level market narratives are no longer sufficient. What is required is a structured, evidence-based view of how the market is likely to evolve across the forecast horizon, where margin pressure will concentrate, and which competitive positions will prove defensible as the industry matures.
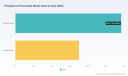
This research study is designed to provide that strategic clarity. Built on a rigorous historical baseline spanning 2020 through 2025 and extended forward across a multi-year forecast period, the analysis translates macro trajectory into decision-ready intelligence. The overall market has demonstrated a steady expansion path over the past half-decade, with revenue progressing from approximately 382.5 million USD in 2020 to an estimated 470.0 million USD in 2025. The forward trajectory suggests continued growth, with the market projected to advance toward the 640 million USD range by the end of the forecast window, supported by a compound annual growth rate of 4.6 percent. While these headline figures establish the scale of the opportunity, the real strategic value lies in understanding the forces shaping growth dispersion, the cost dynamics affecting supply resilience, and the competitive maneuvers that will define market leadership.
This study has been developed specifically to help organizations move beyond generic industry summaries. It is intended for strategy leaders, procurement executives, product managers, and investment analysts who need a coherent framework for interpreting phosphorus pentasulfide market behavior in 2026 and beyond. Rather than offering a static snapshot, the analysis connects demand-side shifts, supply-side constraints, and regulatory pressures into a single interpretive lens. The result is a research asset that can inform internal planning, support external engagement, and sharpen the questions teams should be asking as they evaluate growth options.
A Multi-Dimensional View of Market Structure and Trajectory
Effective strategy depends on segmentation that reflects how value is actually created and consumed. This study examines the phosphorus pentasulfide market through multiple analytical dimensions, enabling readers to assess not only how the market is composed today, but how segmentation logic is likely to influence competitive positioning and demand evolution over time.
The report maps the market across regional landscapes, product-grade distinctions, and application-based demand patterns, then integrates those views with broader industry context. This structure matters because P2S5 is not a uniform commodity market. Different grades serve different technical and commercial requirements, and demand patterns vary meaningfully by application and geography. By analyzing these layers together, the study provides a more credible basis for prioritizing markets, anticipating substitution pressure, and identifying where supply reliability or specification performance will become a decisive differentiator.
Readers will find detailed attention to the kinds of structural questions that often determine execution risk: which segments are expanding on the strength of technical demand rather than volume alone, where application portfolios are diversifying, and how regional demand profiles interact with production geography and logistics constraints. The analysis avoids oversimplified conclusions and instead frames each segment within the operational realities of handling, transportation, and downstream integration. This approach is especially relevant for organizations that must reconcile growth ambitions with the practical complexities of hazardous chemical supply chains.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The phosphorus pentasulfide market is characterized by a concentrated competitive structure, with a relatively small group of established players accounting for a substantial share of overall revenue. This concentration has important strategic implications. It suggests that pricing behavior, capacity decisions, and product differentiation are likely to be influenced by a limited set of players whose investments and market moves can shape sector-wide expectations. For buyers and competitors alike, understanding who holds capability, where capacity is located, and how firms are positioning themselves across grades and applications is essential.
Phosphorus Pentasulfide Market
The study profiles the market’s most consequential participants, including Trecora LLC, Perimeter Solutions, Prasol Chemicals Pvt Ltd, Hubei Xingfa Chemicals Group Co., Ltd., Shandong Sinchem Group Corporation, Liaoning Ruixing Chemical Group Co., Ltd., and Excel Industries Ltd. These companies represent a cross-section of operating models, geographic footprints, and product strategies. Some are oriented toward high-purity or specialty-grade supply for lubricant additives and advanced industrial applications; others compete primarily on scale and cost-competitive industrial-grade volumes across lubricants, agrochemicals, mining reagents, and related intermediate markets.
The strategic significance of these profiles goes beyond corporate description. The study uses them to illustrate how capability, plant footprint, and application focus shape competitive advantage in practice. For example, producers with specialized high-purity offerings are positioned to serve customers where specification reliability, safety, and downstream performance are paramount. At the same time, large-scale industrial-grade producers play a central role in meeting volume demand across lubricant, mining, and agrochemical value chains, where cost efficiency and supply consistency are often the primary drivers. By examining these distinctions, the report helps readers evaluate which types of suppliers are most relevant to their operating context and where supplier diversification or qualification strategies may be warranted.
The competitive analysis also accounts for recent market-moving developments. Notable activity includes the launch of top-grade phosphorus pentasulfide for lubricants with improved packaging designed to address handling and safety considerations, as well as capacity expansion efforts in Asia-Pacific aimed at strengthening supply availability while reducing environmental impact. Such developments are not isolated events; they signal how incumbents are responding to demand evolution, regulatory pressure, and shifting customer expectations. The study places these moves in context so that readers can interpret them as indicators of broader strategic direction rather than as isolated news items.
Industry Dynamics: Cost Structures, Regulation, and Supply Chain Risk
No phosphorus pentasulfide strategy can be built on demand outlooks alone. The market is shaped by a set of operational and regulatory realities that influence cost, availability, and risk exposure across the value chain. This study integrates those dynamics directly into its analytical framework so that decision-makers can assess not just where growth may occur, but how difficult it may be to capture profitably and reliably.
Worldwide Organic Polysulfide Market
One of the most persistent structural pressures comes from feedstock volatility. Fluctuations in the pricing of elemental yellow phosphorus and sulfur create cost uncertainty for producers and can complicate procurement planning for downstream users. Because these inputs are fundamental to phosphorus pentasulfide production, even moderate price movement can influence margins, sourcing decisions, and the economics of capacity utilization. The report examines how these raw material dynamics interact with supply resilience and what they imply for procurement timing, contract structures, and risk mitigation.
Regulatory complexity adds another layer of strategic importance. In Europe, stringent REACH requirements govern the handling and use of hazardous phosphorus compounds, adding compliance costs and shaping how products can be marketed and used across applications. At the same time, phosphorus pentasulfide is classified as a hazardous material under major transport regulations, including ADR, IATA, and IMDG frameworks, which imposes logistics cost burdens and constrains supply chain flexibility in global trade. Environmental and occupational safety rules further require tighter controls on reactivity with air and water in multiple jurisdictions. These factors collectively influence where production is viable, how products move across borders, and what compliance overhead must be built into commercial models.
Taken together, these dynamics underscore why market participation in this sector is not simply a function of demand visibility. It also depends on operational readiness, regulatory competence, and the ability to manage hazardous-material handling at scale. The study addresses these issues in a practical way, helping readers distinguish between markets that appear attractive on paper and those that can be served sustainably within existing operational and compliance capabilities.
What the Study Delivers: Practical Intelligence for Internal and External Decisions
This research report is structured to support a wide range of business decisions without overwhelming readers with undifferentiated data. It provides a comprehensive yet accessible foundation for analyzing the phosphorus pentasulfide market from both strategic and operational perspectives.
Key elements of the study include:
- A detailed market sizing and forecast framework that situates historical development within a forward-looking trajectory, giving executives a credible baseline for scenario planning and investment prioritization.
- A segmentation-oriented analysis that clarifies how the market is structured across regions, grades, and applications, enabling more precise evaluation of demand opportunities and exposure to segment-specific risk.
- In-depth company profiles of leading participants, with emphasis on product focus, geographic presence, and strategic orientation, so that readers can interpret competitive behavior in context rather than in isolation.
- An assessment of industry dynamics, including feedstock cost exposure, regulatory burdens, and transportation constraints, that links market structure to real-world execution challenges.
- A synthesis of recent developments and evolving market signals, helping teams understand how current activity reflects longer-term strategic shifts in product quality, safety, packaging, capacity, and regional supply strategy.
The report is designed to be actionable. It can support procurement strategies by clarifying where supply reliability, grade specification, and supplier diversification matter most. It can inform product and market planning by showing how application and regional demand patterns are likely to evolve. It can strengthen competitive intelligence by revealing how major players are positioning themselves across value chains and what that may imply for pricing, availability, and differentiation over time. For investors and analysts, the study provides a structured basis for interpreting market momentum and assessing the durability of competitive advantages.
Why the Full Report Is Essential for 2026 Planning
The phosphorus pentasulfide market is large enough to matter and complex enough to reward disciplined analysis. High-level numbers can indicate direction, but they do not reveal where competitive intensity will intensify, which segments will depend on technical performance rather than price alone, or how regulatory and logistics constraints will shape the practically accessible market. Those questions require deeper segmentation, company-level insight, and a clear treatment of the forces that influence cost and risk.
This study is built to provide that depth while remaining focused on strategic relevance. It is intended to help organizations move from observation to action: to refine market entry thinking, calibrate procurement strategy, anticipate competitive responses, and prepare for the operational realities that accompany participation in a hazardous-chemical value chain. The detailed segmentation data, regional and application-level breakdowns, and company-specific intelligence that support these conclusions are presented in full within the complete research report.
For teams responsible for 2026 planning, the difference between informed strategy and reactive decision-making often comes down to the quality of the underlying intelligence. This study is designed to close that gap by offering a rigorous, internally coherent view of where the phosphorus pentasulfide market stands today and how it is likely to develop across the forecast period. The complete report provides the detailed market framework, segmentation evidence, and competitive analysis needed to translate these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Phosphorus Pentasulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Linear Actuators Market to Hit $352.21M by 2032, 7.3% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Global Linear Actuators Market: A 2026 Decision-Maker's Guide to Sustained Growth and Competitive Positioning
The linear actuators market stands at a critical inflection point. Over the past five years, the sector has demonstrated remarkable resilience and steady expansion, reflecting the broader industrial push toward automation, precision motion control, and electrification across multiple end-use industries. As we enter 2026, enterprise executives, product planners, and supply chain strategists face a landscape defined by rapid technological iteration, shifting regulatory mandates, and intensifying competitive pressures. The latest Linear Actuators Market research from PW Consulting is designed explicitly to translate these macro-level shifts into actionable intelligence, equipping leadership teams with the analytical rigor required to navigate an increasingly complex environment. This article outlines the strategic architecture of the study, explains why its insights matter for 2026 planning cycles, and demonstrates how decision-makers can leverage its findings to secure durable competitive advantage.
Electric Linear Actuators Market
The Macro Trajectory: Why 2026 Marks a Defining Planning Year
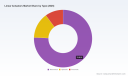
The market's historical progression tells a clear story of disciplined, compounding growth. Between 2020 and 2025, global revenue climbed from approximately $163.15 million to $215.0 million, a trajectory that reflects sustained demand from automation-intensive sectors and the gradual replacement of legacy mechanical systems with more sophisticated actuation solutions. Looking ahead, the forecast window extending through 2032 projects continued upward momentum, with the market expected to reach $352.21 million by the terminal year of the analysis period. This expansion is underpinned by a compound annual growth rate of 7.3 percent, a figure that signals both structural opportunity and the necessity for proactive strategic positioning.
For executives calibrating capital allocation, product roadmaps, or geographic expansion strategies in 2026, these top-line indicators serve as more than background context. They represent a quantifiable growth envelope that must be factored into scenario planning, capacity investment decisions, and partnership evaluations. The research move beyond headline figures to unpack the operational and competitive dynamics that will determine which organizations capture disproportionate value within this expanding market. By framing 2026 as a pivotal planning year, the study equips leaders to anticipate inflection points rather than react to them after market shifts have already occurred.
Navigating Supply-Side Volatility and Evolving Compliance Landscapes
Market expansion does not occur in a vacuum. Organizations operating within the linear actuators ecosystem must contend with a set of dynamics that directly affect cost structures, product design timelines, and compliance postures. Raw material fluctuations represent one of the most persistent challenges. Rare-earth magnets, which feature prominently in high-performance electric actuator designs, have experienced annual price swings of 30 to 40 percent, exacerbated by highly concentrated supply chains. Simultaneously, rising alloy surcharges for corrosion-resistant steel have introduced additional uncertainty into short-term cost forecasting for manufacturers operating on tight OEM contracts. These pressures demand sophisticated procurement strategies and, increasingly, alternative material architectures that can preserve performance without exposing firms to unsustainable input volatility.
Regulatory evolution compounds these supply-side complexities. Recent updates to ISO 10218-1:2025 have restructured safety requirements for robotics, with specific attention to how linear actuators function within partially completed machinery. In parallel, SAE ARP5812 has established a comprehensive set of design, manufacturing performance, and test requirements tailored to linear mechanical actuators deployed in aerospace applications. On the food and beverage side, EHEDG and FDA guidelines continue to mandate hygienic, fail-safe actuation solutions capable of meeting stringent safety standards in bottling and processing environments. For firms that must align product portfolios with multiple regulatory frameworks simultaneously, the compliance landscape has become a strategic differentiator rather than a mere operational checkbox.
The research integrates these dynamics into a cohesive analytical framework, helping readers evaluate how raw material exposure, compliance deadlines, and engineering trade-offs intersect. Instead of treating each factor in isolation, the study maps their combined influence on margin structures, time-to-market timelines, and competitive positioning across different product categories and end-use segments.
Inside the Study: A Practical Blueprint for Strategic Execution
The Linear Actuators Market report is structured to deliver operational relevance, not just descriptive analysis. It opens with a comprehensive market sizing and forecasting module that traces revenue progression across the historical window and projects growth trajectories through 2032. This baseline establishes the quantitative foundation upon which more granular strategic assessments are built. From there, the study examines segmentation patterns across technology types, application verticals, and geographic regions, providing readers with a structured understanding of where demand is concentrating and which sub-markets are accelerating relative to the broader trend.
A substantial portion of the research is dedicated to competitive intelligence. Thirty-two key companies are profiled with attention to their headquarters locations, core product capabilities, and strategic positioning within the value chain. These profiles span established multinational players, specialized niche manufacturers, and distribution-focused intermediaries, offering readers a panoramic view of the competitive field. The study also tracks recent product launches, trade show participation, and capability expansions, enabling readers to monitor how rivals are advancing their portfolios in near real-time. By synthesizing these developments into a coherent competitive map, the research allows strategists to identify whitespace opportunities, anticipate rival moves, and calibrate differentiation strategies accordingly.
Beyond competitive dynamics, the report addresses market concentration metrics, evaluating how revenue is distributed among leading participants and what that implies for barrier-to-entry considerations, pricing power, and partnership strategies. The analysis integrates these structural insights with the raw material and regulatory factors discussed earlier, ensuring that readers understand not only who competes in the market but also the operational constraints and compliance requirements that shape competitive outcomes. This holistic design makes the study useful for a wide range of internal audiences, from engineering leaders assessing technology roadmaps to commercial teams evaluating market entry or expansion scenarios.
The Competitive Arena: Technology Diversification and Regional Capability Hubs
The competitive landscape for linear actuators is characterized by meaningful technological diversification and a geographically dispersed manufacturing base. Electric actuation continues to gain traction as a preferred solution in applications demanding high precision, programmable motion profiles, and integration with digital control architectures. Mechanical systems retain relevance where simplicity, durability, and cost-efficiency are paramount, while hybrid electro-hydraulic designs are emerging as a compelling middle ground for applications requiring both high force density and precise control. Pneumatic solutions maintain a foothold in environments where clean operation, fast cycling, and simplified infrastructure are prioritized.
Firms across North America, Europe, and Asia are each advancing distinct capability clusters. In North America, organizations such as Tolomatic, Actuonix Motion Devices, LINAK, PHD Inc., Rollon, Kyntronics, SMC Corporation, PBC Linear, igus, Progressive Automations, Curtiss-Wright Exlar, Parker Hannifin, and Electromate represent a broad spectrum of specialization, from micro-scale precision devices to heavy-duty industrial systems capable of extreme force outputs. Tolomatic's recent expansion of its RSX series to reach substantially higher force thresholds illustrates how established players are pushing the performance envelope for rugged automation. Actuonix's introduction of ultra-compact micro linear actuators and Oriental Motor's rolled ball type attachment with sub-micron repetitive positioning accuracy reflect the industry's push toward finer resolution and tighter integration in precision applications. In Europe, companies like LINAK, igus, and Rollon continue to strengthen their positions in vehicle integration, polymer-based low-maintenance systems, and belt-driven electric actuation respectively. In Asia, SMC Corporation and THK maintain strong footprints in industrial automation and precision motion systems, while recent introductions from firms like Schaeffler at major trade exhibitions demonstrate the ongoing pace of product innovation across the region.
The research provides detailed profiles and recent development tracking for all major participants, enabling readers to assess capability gaps, identify potential supplier or partnership candidates, and monitor the pace at which competitors are expanding their portfolios. This competitive intelligence is particularly valuable for organizations evaluating M&A targets, supplier qualification processes, or new product development initiatives that require benchmarking against the state of the art.
Translating Insights into 2026 Strategic Decisions
The true value of the Linear Actuators Market study lies in its applicability to concrete decision-making scenarios. For capital investment planning, the growth trajectory and segmentation insights help organizations prioritize which product categories, application verticals, or geographic markets warrant expanded capacity, distribution investment, or R&D focus. For product strategy teams, the competitive profiling and recent development tracking provide a benchmark against which to evaluate internal roadmaps, ensuring that new offerings align with emerging performance expectations and compliance requirements. For procurement and supply chain leaders, the integration of raw material volatility and alloy cost pressures into the broader market analysis supports more resilient sourcing strategies and supplier diversification plans.
For executives considering market entry or expansion, the study's regional and application segmentation provides a structured lens for evaluating demand concentration, competitive saturation, and regulatory complexity across different environments. Rather than relying on generalized assumptions, decision-makers can use the research to identify where addressable demand is strongest, which customer requirements are most stringent, and where incumbents may be vulnerable to differentiated offerings. The market concentration analysis further supports strategic judgments about partnership viability, pricing expectations, and the feasibility of gaining meaningful market share in segments dominated by established players.
Linear Actuators Market
Importantly, the research does not prescribe a single strategic path. Instead, it provides the analytical scaffold upon which organizations can construct internally tailored strategies that reflect their specific capabilities, risk tolerances, and growth ambitions. This flexibility makes the study relevant across a wide range of organizational contexts, from emerging entrants seeking foothold opportunities to incumbents defending and extending their positions.
Why Comprehensive Intelligence Matters Now
The linear actuators market is expanding, but expansion alone does not guarantee competitive success. Organizations that thrive in 2026 and beyond will be those that combine awareness of macro growth trends with deep, granular understanding of technological shifts, regulatory mandates, supply-side constraints, and rival capabilities. The PW Consulting Linear Actuators Market research is built to deliver exactly this combination, translating complex market dynamics into structured, decision-ready intelligence.
The full study contains detailed segmentation data, extended competitor profiles, granular regional and application breakdowns, and comprehensive tracking of recent product and compliance developments that extend well beyond the summary presented here. For executives and strategy teams who require the complete analytical framework to inform 2026 planning cycles, the full report provides the depth necessary to move from strategic awareness to confident execution. Exploring the complete market intelligence equips organizations with the precision insights needed to allocate resources effectively, anticipate competitive moves, and position their product and supply chain strategies for sustained advantage in a market defined by both opportunity and complexity.
For detailed analysis of this topic, please visit the official page: Linear Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Purification Equipment Market Hits $15.5B in 2025, Projected to Reach $22.55B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Blood Purification Equipment Market: Navigating 2026 and Beyond
The global blood purification equipment market stands at a critical inflection point heading into 2026. For executives, investors, and clinical leaders, the choice is no longer whether to monitor this space, but how to extract actionable intelligence from a landscape defined by shifting regulatory frameworks, evolving reimbursement structures, and accelerating technological differentiation. PW Consulting's latest market research on Blood Purification Equipment delivers precisely that intelligence. This report is designed to serve as a foundational strategic asset for decision-makers who require more than surface-level trends. It provides a rigorous, data-grounded view of where the market has been, where it is heading, and how to position organizations to capture value across the forecast horizon.
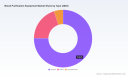
The market's trajectory over the past half-decade tells a story of resilience and structural growth. Valued at approximately 13,000 million USD in 2020, the industry navigated a period of fluctuation before reestablishing a clear upward path. By 2023, valuation had climbed to roughly 14,500 million USD, and the momentum carried through 2024 and 2025, reaching an estimated 15,500 million USD at the close of the base year. Looking forward, our forecast models project the market will surpass the 16,000 million USD threshold in 2026, continuing through a defined 2026-2032 forecast period to reach over 22,500 million USD by the terminal year. The implied compound annual growth rate of 5.5 percent sits comfortably above broader medical device benchmarks, signaling sustained demand driven by demographic shifts, expanded clinical indications, and the modernization of care delivery models. For any enterprise operating in this domain, these figures are not abstract statistics. They represent the scale of opportunity and the urgency of strategic planning.
Why 2026 Demands a Precision Strategy
The year 2026 is not merely another data point on a growth curve. It is a year where regulatory clarity, reimbursement adjustments, and technological adoption cycles intersect in ways that will materially alter competitive dynamics. Organizations that enter 2026 relying on outdated assumptions about market segmentation, product positioning, or geographic prioritization risk misalignment at precisely the moment when capital allocation and R&D focus need to be sharpest. Our research is built to prevent that misalignment. It provides a structured framework for understanding how macro trends translate into operational realities, from procurement behavior to clinical adoption patterns.
Several dynamics underscore the strategic urgency. Regulatory authorities have refined their classifications to better address evolving device capabilities, with recent guidance establishing new controls for hemodialyzers featuring expanded solute removal profiles. Simultaneously, manufacturing standards have been tightened, including updated GMP expectations concerning equipment and detection systems for blood purification products. On the reimbursement side, state-level programs are updating coverage codes and maintenance provisions for dialysis-related equipment, directly influencing provider purchasing behavior and total cost of ownership calculations. These developments do not operate in isolation. They compound, creating a landscape where compliance, clinical efficacy, and economic viability must be evaluated together. Our report maps these interconnections explicitly, enabling leadership teams to anticipate ripple effects rather than react to them after the fact.
Inside the Report: Structure, Depth, and Strategic Utility
PW Consulting's Blood Purification Equipment market research is structured to function as both a reference document and a decision-support tool. Rather than offering a single aggregated view, the analysis is organized to allow readers to drill into the dimensions that matter most to their specific mandates. The report balances macro-level context with granular operational insights, ensuring that strategy teams, product leaders, and market access professionals can each find relevant, actionable content.
The core analytical framework examines the market across multiple axes, including product type, clinical application, and regional dynamics. For each dimension, the report traces historical performance, identifies structural drivers, and projects forward-looking trajectories. Importantly, the analysis avoids the trap of presenting segmentation as a static snapshot. Instead, it contextualizes each segment within the broader ecosystem, examining how drivers such as chronic disease prevalence, acute care requirements, and the growing emphasis on home-based and decentralized treatment models interact to shape demand. Readers will find quantified assessments of how these forces are expected to play out across the forecast period, with careful attention to the timing and magnitude of shifts that could influence purchasing patterns and product mix.
Beyond segmentation, the report includes a comprehensive competitive landscape evaluation. This section goes beyond ranking players by market share to examine how leading companies are differentiating themselves through technology, service models, geographic expansion, and regulatory strategy. The analysis captures recent product introductions, clearance milestones, and commercial rollouts that signal where incumbents and challengers are placing their bets. It also assesses the structural characteristics of the market, including concentration levels and the strategic implications of a landscape where a relatively small group of firms commands a disproportionate share of revenue. Understanding these concentration dynamics is essential for gauging pricing power, partnership opportunities, and barriers to entry.
Competitive Dynamics and the Emerging Innovation Frontier
The competitive environment in blood purification equipment is characterized by a blend of established multinational leadership and specialized innovators pushing the boundaries of what extracorporeal therapies can achieve. Long-standing players have built formidable positions through integrated portfolios that span dialysis machines, disposables, and related consumables, often supported by global service networks and deep regulatory expertise. Their scale advantages are significant, yet the market has not become dormant. Instead, it is being reshaped by companies that are targeting specific clinical needs with novel mechanisms, advanced materials, and differentiated treatment protocols.
Blood Filter Market
Recent industry activity illustrates this dual dynamic. Major incumbents have continued to advance their flagship platforms, with notable rollouts expanding the availability of high-volume hemodiafiltration systems and extending their commercial footprint across key markets. Parallel to these moves, innovators have secured important regulatory clearances that open new avenues for patient access. One prominent example involves the clearance of a dialysis system designed to support high dialysate flow across the full spectrum of end-stage renal disease care, including home use. Such developments point to a broader trend: the blurring of traditional boundaries between institutional and home-based care, and the corresponding need for equipment that can perform reliably across varied settings.
At the same time, a distinct wave of technology-driven entrants is exploring new modalities for blood purification. This includes devices and consumables designed for targeted removal of pathogens and toxins, advanced hemadsorption cartridges aimed at critical care applications, and experimental systems leveraging magnetic nanoparticle approaches for sepsis and other high-acuity indications. These efforts reflect a growing recognition that blood purification is not a monolithic category. Rather, it encompasses a spectrum of clinical challenges, each with distinct performance requirements, regulatory pathways, and reimbursement considerations. Our report analyzes how these emerging players fit into the broader ecosystem, what differentiates their value propositions, and where the most consequential competitive threats and partnership opportunities may arise.
The geographic footprint of competition is equally important. Leading manufacturers are headquartered across multiple regions, each bringing different strengths in engineering, clinical validation, and market access. The interplay between regional innovation clusters and global commercialization strategies shapes how quickly new technologies reach diverse patient populations. By examining the profiles and strategic posturing of key companies, readers gain a clearer understanding of who is likely to lead in specific subsegments and which organizational capabilities will be most valuable in the years ahead.
Market Structure and the Implications for Positioning
Understanding the architecture of the market is essential for effective strategy. The research highlights a concentrated competitive environment in which a core group of firms accounts for a substantial share of industry revenue. This concentration has meaningful implications. For incumbents, it underscores the importance of defending share through continuous innovation, service excellence, and strategic portfolio management. For challengers and new entrants, it points to the need for clear differentiation, whether through technology, niche application focus, cost structure, or partnership models that allow rapid penetration of specific channels.
The report also examines how segmentation intersects with market structure. Certain product categories and clinical applications represent the bulk of current revenue, while others, though smaller today, carry disproportionate strategic significance due to their growth profiles, unmet clinical needs, or alignment with evolving care delivery models. The analysis does not simply enumerate these segments. It evaluates them in terms of strategic relevance, examining the drivers that could accelerate or constrain growth and the competencies required to compete effectively within each. This approach ensures that readers can distinguish between segments that offer incremental volume and those that could fundamentally reshape product strategy and resource allocation.
Supply-side considerations are addressed with equal rigor. Manufacturing standards, quality assurance expectations, and regulatory compliance obligations are no longer peripheral concerns. They are central to commercial viability, particularly as authorities refine guidance for equipment and related production processes. Organizations that anticipate these requirements and embed them into product development and operational planning will be better positioned to navigate audits, maintain market access, and protect brand integrity. The report integrates these factors into its strategic assessment, helping leaders connect regulatory and operational realities to competitive positioning.
From Insight to Execution: How Leaders Should Use This Research
A market research report is only as valuable as the decisions it informs. PW Consulting has designed this study to be practical from the outset. It is intended to support a range of strategic use cases, including portfolio prioritization, market entry evaluation, competitive benchmarking, pricing and reimbursement strategy, and long-range planning. The emphasis throughout is on clarity, comparability, and relevance to executive decision-making.
Several principles guide the report's design. First, it grounds all projections in a rigorous methodology that accounts for historical performance, structural drivers, and forward-looking indicators, rather than relying on simplistic trend extrapolation. Second, it situates quantitative findings within qualitative context, explaining not just what is expected to happen but why it matters and how different scenarios could alter outcomes. Third, it maintains a focus on actionability, ensuring that insights can be translated into concrete next steps, whether that means refining a product roadmap, identifying target geographies, assessing partnership candidates, or stress-testing a commercialization plan against evolving regulatory and reimbursement conditions.
For organizations preparing for 2026 and the broader 2026-2032 forecast period, the research offers a unified reference point. It allows leadership teams to align around a shared understanding of market size, growth trajectory, competitive dynamics, and structural shifts. That alignment is critical. In a market where regulatory updates, reimbursement changes, and technological breakthroughs can alter the calculus quickly, a common strategic baseline reduces the risk of fragmented decision-making and helps ensure that resources are directed toward the highest-value opportunities.
The Strategic Imperative for the Next Phase of Growth
The blood purification equipment market is entering a phase in which scale, technology, and regulatory sophistication will increasingly separate winners from the rest. Growth to more than 22,500 million USD by 2032, supported by a 5.5 percent CAGR, is not automatic. It will be captured by organizations that can read the signals in the data, anticipate the impact of regulatory and reimbursement shifts, and align their capabilities with the evolving needs of clinicians and patients. The window for strategic positioning is open now, but it will not remain wide indefinitely.
Blood Purification Equipment Market
This report is intended to equip leaders with the intelligence required to act with confidence. It combines macro-level market sizing with detailed competitive and structural analysis, delivering a comprehensive view of an industry in transformation. Yet the full depth of the analysis, including the most granular segmentation data, scenario-based forecasts, and proprietary competitive assessments, is reserved for the complete study. For executives and strategy teams who need to make high-stakes decisions in 2026, the complete report provides the level of detail and context necessary to convert insight into execution.
The market will not pause for indecision. Blood purification equipment is central to the care of millions of patients, and the companies that define the next era will be those that combine clinical understanding with commercial discipline. PW Consulting's research is built to help you navigate that future with precision, clarity, and strategic advantage.
For detailed analysis of this topic, please visit the official page: Blood Purification Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Bonded Magnets Market to Hit $905M by 2032, 5.46% CAGR
By PW Consulting, 2026-09-16
Navigating Strategic Opportunities in the Plastic Bonded Magnets Market Through 2032
The global landscape for plastic bonded magnets is entering a phase of mature yet dynamic expansion. As industries ranging from automotive to advanced medical devices increasingly rely on compact, complex magnetic solutions, the demand for polymer-bonded magnetic materials has become a critical focal point for strategic planners. PW Consulting's latest market research report provides a comprehensive lens into this evolving sector, offering decision-makers the intelligence required to navigate supply chain complexities, regulatory shifts, and competitive pressures through the forecast period ending in 2032.
For organizations operating in or entering this space, the difference between reactive management and proactive strategy lies in the granularity of available data. This report moves beyond surface-level estimates to deliver actionable insights derived from rigorous analysis of historical performance and forward-looking indicators. By understanding the trajectory of the market, stakeholders can align their investment portfolios, manufacturing capabilities, and sourcing strategies with the realities of the coming strategic period.
Market Trajectory and Macroeconomic Indicators
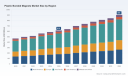
The historical data from 2020 through 2025 establishes a clear baseline for market resilience and growth. Over this six-year period, the market valuation demonstrated consistent upward momentum, reflecting steady adoption rates across key industrial verticals. This historical performance sets the stage for the forecast period extending from 2026 to 2032. Projections indicate that the global market revenue is expected to reach approximately 641.68 USD Million in 2026, continuing a steady climb to reach 905.0 USD Million by the end of the forecast horizon in 2032.
This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 5.46 percent throughout the forecast period. While this rate suggests stable growth rather than explosive disruption, it highlights the sector's role as a reliable component of broader industrial and technological supply chains. The consistency of this growth trajectory implies that demand drivers are structural rather than cyclical, rooted in the ongoing miniaturization of electronic components and the electrification of transport systems. Strategic planners must interpret this CAGR not merely as a financial metric but as an indicator of sustained capital investment opportunities within production capacity and research and development.
Segmentation Dynamics and Value Distribution
Understanding where value is generated within the plastic bonded magnets market is essential for resource allocation. The market is segmented by region, type, and application, each presenting distinct risk and reward profiles. The Asia Pacific region currently stands as the dominant revenue contributor, reflecting its position as both a major manufacturing hub and a center for high-tech electronics consumption. North America follows as a significant market, driven by strong industrial and medical device sectors, while Europe maintains a steady presence supported by automotive manufacturing and engineering excellence. Emerging regions such as Latin America and the Middle East and Africa represent smaller but potentially growing avenues for diversification.
When analyzing the market by type, injection molded magnets account for the largest share of revenue. This preference is driven by the ability to produce complex geometries with high precision, which aligns with the needs of modern sensor and motor applications. Compression molded magnets constitute the second largest segment, offering advantages in specific performance characteristics where isotropy is required. Other types, while representing a smaller portion of the total revenue mix, cater to niche applications that require specialized material properties.
In terms of application, the automotive sector is the primary driver of demand. The shift toward electric vehicles and the proliferation of advanced driver-assistance systems have intensified the need for reliable magnetic components that can withstand harsh operational environments. The electronics industry follows closely, fueled by the continuous demand for consumer gadgets, telecommunications infrastructure, and computing hardware. Medical devices, industrial equipment, and other applications round out the demand profile, each contributing to the overall health of the market in ways that are critical for specialized suppliers.
Competitive Landscape and Strategic Positioning
The market structure indicates a moderate level of concentration, with the top three companies accounting for approximately 42 percent of total market share and the top five firms holding around 48 percent. This concentration suggests that while established players hold significant influence, there remains sufficient fragmentation to allow for strategic entry or expansion by agile competitors. The competitive environment is defined by a mix of global technology giants and specialized manufacturers, each leveraging distinct capabilities to capture value.
Switzerland-based Bomatec AG remains a key player, focusing on injected and pressed plastic-bonded NdFeB magnets using binders such as polyamide 11, 12, or PPS. Their ability to offer complete assemblies provides a competitive edge in delivering turnkey solutions. Similarly, GMB Deutsche Magnetwerke GmbH in Germany specializes in custom-designed injection-molded components using NdFeB, SmCo, or ferrite powders in polyamide or epoxy resin matrices. Their focus on customization allows them to serve clients with highly specific technical requirements.
In the United States, Arnold Magnetic Technologies continues to expand its footprint by offering injection-molded and compression-bonded magnetic components for automotive, industrial, and medical markets. Their recent launch of a new line of high-temperature plastic-bonded magnets designed for aerospace applications in August 2024 demonstrates a commitment to pushing performance boundaries in demanding sectors. Bunting Magnetics Co. and Dexter Magnetic Technologies also maintain strong positions, with Bunting focusing on vertically integrated production including compound preparation, and Dexter specializing in custom assemblies for medical devices, sensors, and aerospace applications.
Asian manufacturers are equally pivotal. Daido Electronics Co., Ltd. in Japan produces isotropic polymer-bonded Nd-Fe-B magnets and radially oriented anisotropic ring magnets with ISO 9001:2015 certification, emphasizing quality and consistency. TDK Corporation leverages its broader electronics portfolio to produce bonded magnets for automotive and electronics applications. In China, Ningbo Yunsheng and DMEGC Magnetics manufacture bonded magnets with emphasis on plastic-bonded types for industrial use, capitalizing on regional supply chain efficiencies. Evitron in Poland and Nichia Corporation, which showcased advancements in bonded SmFeN magnets at MDSM 2025, further illustrate the global reach and technical diversity of the supplier base.
Industry Dynamics and Risk Factors
Strategic planning in this sector must account for significant external pressures that could alter market trajectories. One of the most pressing concerns involves the supply chain security of rare-earth elements. According to data from the U.S. Geological Survey, China accounts for over 60 percent of global rare earth production. This concentration creates inherent supply risks for manufacturers dependent on these materials. In April 2025, China tightened its export controls on rare-earth elements, adding restrictions on exports of products containing even trace amounts of Chinese content. This was followed by more stringent controls imposed in September 2025, which resulted in exports of bonded magnets declining 6.1 percent month-over-month.
These regulatory shifts underscore the vulnerability of global supply chains and highlight the importance of diversification strategies. Companies that rely heavily on single-source sourcing for critical raw materials face increased exposure to geopolitical tension and trade policy volatility. Conversely, the U.S. Department of Defense has committed funding under the Defense Production Act to develop domestic rare earth processing and magnet manufacturing capabilities. This initiative supports local production of plastic bonded magnets and may offer opportunities for suppliers aligned with domestic manufacturing incentives.
Environmental regulations also present a evolving challenge. The European Chemicals Agency (ECHA) has progressively expanded its REACH regulation scope, scrutinizing thermoplastic and thermoset binder systems used in plastic bonded magnets for environmental persistence. As compliance requirements tighten, manufacturers may need to invest in alternative binder technologies or process adjustments to maintain market access in Europe. These regulatory dynamics add a layer of complexity to product development and lifecycle management that must be factored into long-term strategic roadmaps.
Core Content and Analytical Framework of the Report
To support leaders in navigating these complexities, the report provides a multi-faceted analytical framework. It begins with a detailed executive summary that distills key findings and strategic implications for immediate decision-making. The market overview section contextualizes the industry within the broader macroeconomic environment, examining factors such as industrial production rates, automotive sales trends, and electronics consumption patterns that drive demand.
The segmentation analysis offers a granular view of revenue distribution across regions, types, and applications. Rather than simply presenting static numbers, the report examines the growth drivers and constraints within each segment. This approach helps identify which sub-markets offer the highest potential for expansion and which may face headwinds due to technological substitution or regulatory hurdles. The forecast section projects market size and growth rates through 2032, providing baseline scenarios that can be stress-tested against internal planning assumptions.
A significant portion of the report is dedicated to the competitive landscape. It profiles key companies, analyzing their product portfolios, manufacturing capabilities, and recent strategic moves. This includes an assessment of recent developments such as new product launches and expansions that signal shifting priorities among market leaders. By understanding the moves of competitors, organizations can anticipate market reactions and identify gaps in the current supply offering.
Worldwide Flexible NdFeB Market
Furthermore, the report delves into supply chain dynamics, raw material availability, and regulatory impacts. It evaluates the implications of export controls, environmental regulations, and government funding initiatives on cost structures and supply security. This section is critical for operations managers and procurement specialists tasked with mitigating risk in an unstable geopolitical environment. The synthesis of these factors provides a holistic view of the market that goes beyond simple revenue projections.
Strategic Imperatives for Decision Makers
The insights contained in this research are designed to empower specific strategic actions. For manufacturing firms, the data supports decisions regarding capacity expansion, technology investment, and geographic footprint optimization. Understanding the relative performance of injection molded versus compression molded segments can guide capital expenditure toward the production methods most aligned with future demand shifts. Similarly, recognizing the dominance of the automotive and electronics applications helps prioritize resource allocation toward the sectors with the strongest growth signals.
For investors and financial analysts, the report offers a foundation for valuation models and risk assessment. The market concentration data and competitive profiling assist in evaluating the sustainability of market shares and the potential for disruption. The identification of regulatory and supply chain risks allows for a more accurate pricing of risk in investment portfolios. For procurement and supply chain professionals, the analysis of raw material risks and regulatory changes provides the intelligence needed to diversify sourcing strategies and secure long-term contracts that protect against volatility.
The period from 2026 to 2032 will be defined by how well organizations adapt to these interconnected forces. The market is large enough to support multiple winners but competitive enough to reward efficiency and innovation. Companies that leverage the detailed intelligence in this report will be better positioned to optimize their operations, mitigate supply chain risks, and capture value in the high-growth segments of the plastic bonded magnets industry.
Plastic Bonded Magnets Market
Access to the full dataset and detailed interpretive commentary is available through the complete PW Consulting report. By leveraging this comprehensive intelligence, stakeholders can transform uncertainty into a structured plan for growth and resilience in the years ahead.
For detailed analysis of this topic, please visit the official page: Plastic Bonded Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Barcode Reader Market Hits $7.67B in 2025, Forecast to $12.3B by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence in the Barcode Readers Market: Navigating the 2026–2032 Outlook
As digital transformation accelerates across global supply chains, the barcode readers market stands at a critical inflection point. What was once a commoditized peripheral has evolved into a sophisticated interface between physical operations and real-time data ecosystems. For executives navigating 2026 procurement strategies, capital allocation decisions, and technology roadmaps, understanding the structural forces shaping this market is no longer optional. This comprehensive industry analysis delivers a rigorous, data-driven assessment of market trajectories, competitive positioning, and operational dynamics through 2032, providing the analytical foundation required for enterprise-level decision-making.
Macroeconomic Trajectory and Growth Architecture
The market has demonstrated resilient, compounding growth over the past half-decade, with total revenue expanding from approximately $6.91 billion in 2020 to an estimated $7.67 billion in 2025. This historical expansion reflects sustained enterprise adoption across supply chain modernization initiatives, regulatory compliance requirements, and the ongoing digitization of asset tracking workflows. Forecasts extending through the 2026–2032 horizon indicate continued upward momentum, with projected revenue reaching roughly $8.19 billion in 2026 and scaling toward $12.30 billion by 2032. The implied compound annual growth rate of 6.98 percent underscores a market characterized by steady, structurally supported expansion rather than speculative volatility.
This growth trajectory is underpinned by several converging forces. Organizations are increasingly replacing legacy scanning infrastructure with imaging-based and AI-enhanced readers capable of decoding damaged, low-contrast, or high-density codes in variable lighting conditions. Simultaneously, the proliferation of omnichannel fulfillment models, just-in-time inventory practices, and real-time location tracking requirements has elevated barcode scanning from a back-office utility to a mission-critical operational node. Enterprise buyers in 2026 must therefore evaluate scanner portfolios not merely on unit cost, but on interoperability, durability, software integration readiness, and total cost of ownership across multi-year deployment cycles.
Report Scope and Operational Utility
This market research study is engineered to function as a practical decision-support instrument rather than a purely academic overview. The analysis spans multiple dimensional layers, allowing readers to isolate the variables most relevant to their operational context. Coverage includes granular assessments of product architecture categories, deployment environment suitability, and vertical-specific adoption patterns. The report maps the historical performance baseline from 2020 through 2025, establishes forward-looking projections across the 2026–2032 forecast window, and contextualizes these figures within prevailing macroeconomic and regulatory conditions.
Readers will find structured evaluations of technology transitions affecting reader design, including the shift from laser-based illumination to advanced imaging engines, the integration of machine vision capabilities, and the emergence of AI-augmented decoding algorithms that improve read rates in challenging environments. The study also examines procurement considerations such as ruggedization standards, connectivity protocols, firmware lifecycle management, and the extent to which scanner ecosystems integrate with warehouse management systems, enterprise resource planning platforms, and point-of-sale architectures. By consolidating these dimensions into a single analytical framework, the report enables managers to benchmark vendor offerings, model scenario-based investment paths, and identify inflection points where premature or deferred procurement may carry measurable operational risk.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants collectively commanding approximately 25 percent of total revenue and the top five firms accounting for roughly 35 percent. This distribution reflects an environment where established incumbents maintain strong brand equity and installed-base loyalty, while regional specialists and technology-focused entrants compete on feature differentiation, pricing agility, and vertical-specific customization. Understanding the strategic posture of leading suppliers is essential for buyers evaluating long-term partnership stability, service-level commitments, and innovation roadmaps.
Datalogic, headquartered in Bologna, Italy, has cemented its position as a leading manufacturer of CCD and laser-based barcode readers, offering handheld, fixed-mount, and OEM models tailored to retail, manufacturing, and logistics workflows. Its product philosophy emphasizes ergonomic design, read-performance consistency, and broad environmental adaptability. Cognex, based in Natick, Massachusetts, operates at the intersection of industrial barcode reading and machine vision, with its DataMan series spanning fixed-mount, handheld, and verification solutions widely deployed in automation and traceability applications. Cognex's competitive advantage lies in the tight integration of decoding hardware with vision processing algorithms, enabling high-speed identification in precision manufacturing and automotive contexts.
Zebra Technologies, located in Lincolnshire, Illinois, provides a comprehensive range of rugged, ultra-rugged, and general-purpose 1D and 2D scanners designed for retail, healthcare, logistics, and harsh-environment deployments. Zebra's strategy centers on end-to-end device ecosystems, durable construction standards, and deep integration with enterprise mobility platforms. Honeywell, headquartered in Charlotte, North Carolina, manufactures plug-and-play barcode scanners and modules leveraging both laser and imaging technologies, serving general-purpose, industrial, and healthcare applications with an emphasis on ease of integration and standardized configuration options.
Newland AIDC, based in Fuzhou, Fujian, China, has carved out a specialist position in barcode scanners, mobile terminals, and OEM scan engines, increasingly incorporating AI-powered models to serve industrial, retail, and logistics segments. Its growth reflects broader trends in cost-optimized engineering, rapid feature iteration, and expanding distribution reach across emerging and developed markets. Opticon, operating from Renton, Washington, produces 1D laser and 2D imaging barcode scanners, including handheld, fixed-mount, and mobile computer solutions, with a reputation for reliable performance in retail and light-industrial settings. Collectively, these firms illustrate a competitive field where differentiation is achieved through a combination of hardware robustness, software ecosystem maturity, vertical expertise, and supply chain responsiveness.
Industry Dynamics and Regulatory Influences
Market behavior in the barcode readers sector is increasingly shaped by external regulatory pressures, compliance frameworks, and operational events that influence procurement priorities and risk assessments. Recent developments highlight the sensitivity of scanner-dependent operations to pricing accuracy mandates, cross-border trade policy shifts, and manufacturing quality standards. For instance, Zebra Technologies has factored potential tariff-related impacts into its near-term profit outlook, reflecting how trade policy uncertainty can affect component sourcing, final-device pricing, and margin structures for major hardware suppliers. Such dynamics underscore the importance of scenario planning for enterprises with globally distributed supply chains or multi-regional deployment footprints.
Smart Card Readers Market
On the retail compliance front, enforcement actions around price-scanning accuracy have drawn renewed attention to the operational reliability of scanning infrastructure. Regulatory bodies in several jurisdictions have imposed fines and corrective measures on retailers where register-scanner discrepancies resulted in consumer pricing errors, reinforcing the link between scanner performance, software calibration, and audit readiness. In parallel, frameworks such as the Scanner Price Accuracy Code continue to evolve, with updated discount thresholds and enforcement expectations shaping how retailers configure checkout equipment and validate price-display integrity. These regulatory currents create both compliance obligations and procurement incentives, as operators seek hardware and firmware configurations that minimize mismatch risk and facilitate audit documentation.
Manufacturing and quality-assurance standards also exert structural influence on market development. ISO-certified production facilities have become a baseline expectation for many procurement teams, particularly in sectors where device failure carries operational, safety, or regulatory consequences. European market projections further emphasize the role of regulatory compliance in shaping long-term growth trajectories, as buyers align equipment selection with evolving standards related to electromagnetic compatibility, environmental durability, and data-handling expectations. Taken together, these dynamics indicate that purchasing decisions in 2026 and beyond will increasingly weigh compliance readiness and certification status alongside traditional performance metrics.
Barcode Readers Market
Key Decision Frameworks for 2026 and Beyond
Effective market participation in the current cycle requires decision-makers to reconcile several overlapping priorities. First, technology selection must account for the operational environment in which readers will function. Fixed-mount installations in automated production lines or conveyor systems impose different durability, read-angle, and integration requirements than handheld devices used by mobile floor staff or field service teams. Buyers should evaluate whether imaging-based architectures, laser-based architectures, or hybrid configurations best match their code types, label quality, and throughput demands. Second, deployment strategy should consider the increasing prevalence of software-defined features, over-the-air firmware updates, and integration hooks that determine how quickly a scanner fleet can adapt to changing workflows or new barcode symbologies.
Third, supply chain resilience and vendor stability merit close scrutiny. As tariff exposures, component availability, and logistics variables influence lead times and pricing, organizations benefit from mapping vendor manufacturing footprints, service-network coverage, and spare-parts logistics before committing to large-scale rollouts. Fourth, total cost of ownership analysis should extend beyond initial purchase price to encompass training requirements, device lifecycle expectations, battery replacement cycles for mobile units, and the cost of integration with existing management software. Finally, the moderate market concentration observed among leading suppliers suggests that while scale players offer broad portfolios and established support infrastructures, specialized vendors may provide more tailored engineering, faster customization turnaround, and competitive pricing in niche segments.
The strategic implications are clear: barcode readers are no longer interchangeable commodities. They are integral components of data-capture architectures that influence inventory accuracy, order fulfillment speed, compliance posture, and customer experience. Executives who treat scanner procurement as a strategic systems decision, rather than a tactical hardware purchase, will be better positioned to align operational performance with broader digital transformation objectives.
Accessing the Complete Strategic Intelligence
This overview has outlined the structural parameters, competitive forces, and operational considerations that define the barcode readers market as organizations move through 2026 and plan for the decade ahead. The full report expands substantially on these themes, delivering detailed segmentation analysis, forward-looking revenue projections, technology-transition assessments, vendor benchmarking matrices, and scenario-based guidance calibrated to distinct procurement contexts. Readers seeking to translate these macro insights into precise investment decisions, vendor evaluations, and deployment roadmaps are encouraged to access the complete publication. The comprehensive dataset and analytical frameworks contained within provide the depth required to move from general market awareness to actionable, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Barcode Readers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Mineral Water Market to Reach $8.23 Billion by 2032, Growing at 3.2% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the 2026 Boardroom: Navigating the Global Mineral Water Market
As organizations calibrate their strategies for the 2026 fiscal year, the global mineral water sector stands at a complex inflection point. Long viewed as a stable consumer staples segment, the industry now faces converging pressures from regulatory recalibration, supply-chain reconfiguration, and shifting retail architectures. Decision-makers operating in beverage, retail, logistics, and private equity require more than directional commentary; they need a rigorously benchmarked, forward-looking intelligence framework that translates macro trajectories into executable positioning. The latest Mineral Water Market research deliverable from PW Consulting was designed to serve precisely that function. By bridging historical settlement patterns with a structured outlook through 2032, this analysis equips leadership teams with the analytical scaffolding necessary to time capital deployment, assess competitive vulnerabilities, and anticipate structural shifts before they become priced into the market.
A Market Maturing Into Measured Expansion
Over the review horizon of 2020 through 2025, the global mineral water revenue base demonstrated the hallmarks of a category transitioning from hyper-growth to disciplined compounding. Trailing valuations moved from approximately 5.5 billion USD in 2020 to an estimated 6.6 billion USD by 2025, with intermediate years reflecting the familiar volatility of commodity-adjacent consumer goods, supply chain adjustments, and regional demand oscillations. Rather than signaling stagnation, this pattern underscores a market that is consolidating around verified demand drivers: sustained health-conscious consumption, preference for traceable sourcing, and incremental premiumization in mature urban markets. Looking toward the forecast window of 2026 through 2032, the research projects a compound annual growth rate of approximately 3.2 percent, with revenue scaling toward an estimated 8.23 billion USD by the terminal forecast year. The implication for strategic planners is nuanced. A mid-single-digit CAGR is neither a runaway expansion narrative nor a contraction warning; it is a signal that value capture will increasingly depend on share defense, mix optimization, and operational efficiency rather than on aggregate volume tailwinds. Organizations that treat this trajectory as a backdrop for portfolio tuning, rather than a generic growth prophecy, will be better positioned to allocate marketing spend, negotiate distribution terms, and evaluate M&A targets with precision.
Regulatory Architecture and the Redefinition of Market Access
One of the most consequential themes emerging for 2026 strategy is the intensification of regulatory scrutiny across multiple jurisdictions. Standards that once functioned as baseline hygiene requirements are evolving into differentiated market-access levers, altering the cost of compliance and the speed of new-product introductions. In Europe, the latest amendment framework issued by the Irish Ministry of Health in May 2025 tightened definitions around water sampling, clarified market-entry conditions, and formalized officials’ sampling procedures for bottled and containerized waters. While the change originates within a single jurisdiction, its structural logic often influences regional harmonization debates and supplier qualification expectations across broader European supply chains. In parallel, Asia’s regulatory posture is moving toward tighter contaminant thresholds and testing discipline. Japan’s Consumer Affairs Agency proposed combined limits of 50 ng/L for PFOS and PFOA in sterilized or disinfected mineral water products, deliberately aligning bottled standards with tap water benchmarks during early 2025. Meanwhile, India’s FSSAI removed the mandatory BIS certification requirement for packaged drinking water and mineral water effective October 2024, replacing it with a new compulsory Scheme of Testing covering source water, microbiological safety, packaging, and hygiene beginning January 1, 2026. The shift illustrates a broader global pattern: regulators are less interested in blanket certification stamps and more focused on verifiable process integrity, contamination surveillance, and traceability. For corporate strategists, these developments are not merely legal footnotes. They influence plant audit cycles, supplier onboarding timelines, labeling architecture, and the risk profile of short-term capacity expansion. A market study that integrates regulatory trajectory analysis allows leadership to anticipate where compliance costs will concentrate, which product formats face heightened scrutiny, and how certification velocity could affect time-to-market for new SKUs.
Competitive Restructuring and the Strategic Signal of Recent Moves
The competitive landscape is being reshaped not only by long-term brand positioning but by discrete corporate events that reveal where incumbents see structural value, risk concentration, and portfolio fit. Several recent developments warrant close boardroom attention because they offer early indicators of sector consolidation logic and operational recalibration. Nestlé’s separation of its water and premium beverages activities into a standalone business, effective January 1, 2025, reorganized global mineral water brands into a focused entity and set the stage for a formal sale process initiated in January 2026, with the business valued at approximately 5 billion EUR. This sequence signals a strategic intention to unlock balance-sheet flexibility, sharpen category focus, and invite external capital or acquirer architectures into a legacy portfolio encompassing Perrier, San Pellegrino, Acqua Panna, Vittel, and Contrex. For competitors and potential buyers, such a process creates both opportunity and uncertainty: brand portfolios may shift ownership, distribution relationships may be renegotiated, and pricing frameworks may be reset under new ownership mandates. Coca-Cola’s recent operational actions around Topo Chico illustrate a different but equally instructive dynamic. A voluntary recall in mid-2025 involving limited quantities of carbonated Topo Chico in 16.9-ounce glass bottles, attributed to potential Pseudomonas bacterial contamination, emphasized the criticality of microbiological control and traceability in premium packaged water. Followed by a production pause in early 2026 for facility upgrades at the source and manufacturing site in Mexico, with product expected to return to shelves later in 2026, this sequence highlights how supply integrity, source-facility readiness, and brand trust are tightly coupled in the mineral water segment. Even strong global marketers must weather operational interruptions when contamination risk or infrastructure readiness is questioned. Beyond these specific events, the report profiles a focused set of category-leading enterprises including Danone, with its Evian and Volvic portfolio orientation; Nestlé Waters and its global premium still and sparkling lineup; The Coca-Cola Company’s expanding presence through Topo Chico; Fiji Water Company’s premium volcanic-source positioning; and Gerolsteiner Brunnen GmbH & Co. KG with its German sparkling and still offerings. Together, these players represent a cross-section of strategic postures: legacy European provenance, aggressive international distribution, premium brand cultivation, and regional scale advantages. The research examines how these organizations are navigating overlapping imperatives: brand trust maintenance, source protection, retail negotiation leverage, and the balance between natural mineral positioning versus man-made alternatives. The estimated revenue composition underscores this tension, with natural mineral water commanding a substantially larger revenue share than man-made variants. That structural imbalance matters for strategy. It directs attention to provenance storytelling, geological authenticity, and certification narratives, while leaving room for niche positioning around blended or processed offerings in specific price or functional segments.
Demand Pathways, Retail Rearchitecture, and Distribution Strategy
Market access in mineral water is increasingly dictated by channel evolution as much as by product characteristics. The forecast period is being shaped by the reorganization of grocery retail, the expansion of convenience-oriented purchasing, and the continued integration of digital commerce into everyday beverage procurement. Hypermarkets and supermarkets remain a dominant revenue gateway, reflecting the enduring importance of mass retail in driving repeat purchase behavior and basket placement. Yet strategic nuance lies in how this channel interacts with convenience stores, independent grocery stores, e-commerce platforms, and miscellaneous outlets. Convenience retail, in particular, continues to capture incremental impulse and on-the-go demand, while e-commerce provides a structurally smaller but strategically important route for subscription models, premium packs, and regional reach extension. For 2026 planning, the strategic question is not which channel is largest in absolute terms, but how each channel’s margin architecture, shelf dynamics, fulfillment cost, and consumer frequency profile align with a company’s brand tier and geographic footprint. A premium provenance brand may over-index on selective distribution and controlled e-commerce presentation, while a mass-positioned offering may rely more heavily on high-velocity supermarket resets and convenience visibility. The report maps these channel dynamics without reducing them to simplistic share rankings, because effective distribution strategy requires an understanding of purchase rhythm, pack-size economics, and the cost-to-serve associated with each route.
Why This Research Is Built for 2026 Decision-Making
A market study earns its place in the executive workflow when it converts data points into decision architecture. This Mineral Water Market research was constructed around that principle. It is designed not merely to describe where revenue has traveled, but to help leadership teams determine where to commit resources, what assumptions to stress-test, and which risks to structure around. The deliverable integrates several practical components that support operational planning and strategic evaluation. It provides a structured historical baseline through 2025, establishing the demand and revenue context against which the forecast period can be judged. It extends a forward view through 2032, allowing teams to model medium-term capacity, brand investment, and channel development with a common time horizon. It contextualizes regulatory developments as strategic variables rather than background noise, enabling compliance and sourcing teams to align with upcoming testing, sampling, and certification expectations. It profiles the competitive set with attention to brand architecture, recent corporate actions, and operational incidents that reveal underlying vulnerabilities or strengths. It further maps channel dynamics and product-type structure so that managers can align portfolio choices with market access realities. Most importantly, the analysis deliberately preserves the granularity necessary for actionable planning within the full report framework. Macro trajectories, concentration signals, and directional splits are presented to establish scope and credibility, while the detailed regional and application-level figures, exact revenue attributions, and scenario-level sensitivity analysis are reserved for the complete study. This structure reflects a practical reality: the executive summary builds confidence and strategic orientation, but the operational decisions around territory prioritization, pack architecture, supplier selection, and channel investment require the full analytical depth that the report is built to deliver.
Reading Concentration as a Strategic Variable
Market concentration is often treated as a static statistic, but in practice it is a strategic diagnostic. The sector’s estimated CR3 and CR5 concentration levels indicate a landscape that is competitive but not fully fragmented, suggesting that scale players command meaningful influence while still leaving substantial space for regional specialists and premium niche positioning. For a 2026 strategist, this creates a dual imperative. On one side, competing against consolidated brands requires clarity on differentiation: source authenticity, packaging distinction, sustainability storytelling, and channel-specific value propositions. On the other side, the presence of meaningful headroom below the top tier means that targeted regional plays, private-label partnerships, and specialized distribution agreements can still generate attractive returns if they are matched to the right local demand patterns and compliance conditions. Concentration data therefore functions as a map of where to defend, where to attack, and where to avoid direct confrontation until a superior cost or brand position is established.
From Insight to Action: How to Use the Outlook in 2026
Strategists can translate this market outlook into near-term action across several dimensions. First, portfolio reviews should account for the reality that aggregate growth is moderate, meaning that revenue improvement will likely come from mix, pricing precision, and channel optimization rather than from waiting for market-wide expansion. Second, supply-chain and quality assurance planning should incorporate the regulatory direction observed across Europe, Japan, and India, especially the movement toward more rigorous testing, contamination monitoring, and sampling discipline. Third, corporate development teams should monitor ownership transitions and operational adjustments among leading players, since portfolio sales, production pauses, and recall episodes can alter distribution leverage and shelf availability within a single fiscal year. Fourth, brand and communications planning should recognize the structural preference for natural mineral positioning, using provenance, source integrity, and certification narratives as strategic assets rather than optional branding elements. Finally, channel strategy should be calibrated to each route’s economic profile, with deliberate choices about which formats, pack sizes, and fulfillment models fit supermarket velocity, convenience visibility, grocery selectivity, and e-commerce subscription potential.
Conclusion: A Deliberate Market Deserving Deliberate Strategy
The mineral water market entering 2026 is best understood as a category in disciplined evolution. It is large enough to matter for portfolio strategy, dynamic enough to reward those who monitor regulatory and competitive signals early, and concentrated enough to demand clear differentiation rather than undifferentiated scale play. With revenue projected to move from an estimated 6.67 billion USD in 2026 toward an estimated 8.23 billion USD by 2032 at a compound annual growth rate of roughly 3.2 percent, the sector offers steady but procurement-sensitive expansion for organizations prepared to treat it as a strategic platform rather than a passive cash category. The full Mineral Water Market research from PW Consulting provides the detailed segmentation, regional and application-level revenue intelligence, company-specific strategic profiling, and regulatory mapping required to convert this high-level orientation into a concrete 2026 action plan. For executive teams seeking to align capital allocation, brand strategy, supply integrity, and channel execution with the realities of the next forecast cycle, the complete report offers the level of proprietary detail and scenario-ready structure that boardroom decisions demand.
Mineral Water Market
Coconut Water Market
For detailed analysis of this topic, please visit the official page: Mineral Water Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Microbial Coatings Market Set to Hit USD 408 Million by 2032 at 8.95% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Anti-Microbial Coatings Market: Navigating Growth, Compliance, and Competitive Complexity Through 2032
The global landscape for surface protection is undergoing a structural transformation. As industries reconcile post-pandemic hygiene standards with evolving regulatory frameworks and supply chain volatility, the Anti-Microbial Coatings Market has emerged as a critical vector for operational resilience and product differentiation. Our latest comprehensive market research study is designed not merely as a retrospective analysis, but as a forward-looking strategic instrument for executives, R&D leaders, procurement directors, and investors operating across coatings, healthcare, construction, and consumer goods. Spanning a detailed historical reconstruction from 2020 through 2025 and projecting disciplined growth trajectories through 2032, this report distills macro-level momentum, competitive maneuvering, and regulatory inflection points into actionable intelligence tailored to 2026 decision cycles.
Macro Trajectory and the Architecture of Projected Growth
The sector's recent evolution reflects a decisive departure from reactive procurement toward engineered, long-term surface protection. Historical market valuation demonstrates a clear compounding trajectory, with total industry revenue expanding from approximately 155 million USD in 2020 to an estimated 225 million USD by the 2025 base year. This upward inflection has been sustained by broadened application adoption, heightened facility management requirements, and accelerated material science innovation across both commodity and premium product segments. Our forecasting methodology extends this momentum through 2032, anchoring projections on a robust compound annual growth rate of 8.95 percent. Under this trajectory, the aggregate market is positioned to breach the 253 million USD threshold in 2026 and continue its ascent toward 408 million USD by the terminal forecast year.
These headline figures are not abstract indicators; they represent shifting resource allocation priorities across capital-intensive and high-compliance sectors. Yet aggregate size alone masks the structural forces that will determine which players capture sustainable margin expansion versus those trapped in commoditized competition. The report deconstructs revenue dispersion across foundational product architectures, primary end-use verticals, and geographic demand clusters without reducing strategic reality to static percentage tables. Instead, it contextualizes how material substitution decisions, formulation economics, and procurement standardization are recalibrating segment attractiveness. For example, the 2025 surge in silver spot pricing—driven by mining disruptions and speculative inventory positioning—has fundamentally altered cost-of-goods assumptions for formulators reliant on metallic antimicrobial architectures. Simultaneously, entrenched demand in medical healthcare environments, food and beverage processing infrastructure, and building construction applications reflects divergent procurement cycles, validation requirements, and specification-driven purchasing behaviors that cannot be managed through uniform go-to-market strategies.
Regulatory Inflection Points and Compliance as a Competitive Moat
Market expansion does not occur in a regulatory vacuum. The intervening period between historical baseline assessment and mid-forecast horizon has introduced standardized evaluation protocols, procurement mandates, and lifecycle verification requirements that are rapidly transitioning antimicrobial performance from a marketing claim to a verifiable engineering specification. The CEN Workshop on Evaluating Antimicrobial Coatings, initiated in mid-2025, established a collaborative framework for harmonizing assessment methodologies across air filtration efficiency, antiviral mechanism validation, and ecotoxicological profiling. This standardization trajectory will directly influence specification language, laboratory validation costs, and cross-border market access timelines.
Parallel regulatory developments are embedding antimicrobial durability requirements into public procurement and institutional infrastructure. The UK National Health Service has institutionalized a mandatory retesting cycle under ISO 22196 methodology at eighteen-month intervals for antimicrobial coatings deployed within healthcare facilities. In parallel, India's National Cold Chain Mission and revised Good Distribution Practice guidelines, effective from early 2025, now require ISO 21702-certified antiviral coating validation for refrigerated logistics warehouses and vaccine storage environments. These mandates represent a structural pivot: compliance is no longer a periodic audit exercise but an ongoing lifecycle obligation that shapes vendor selection, specification bundling, and long-term service agreements.
Our analysis maps these regulatory vectors against procurement sensitivity, testing infrastructure capacity, and regional enforcement cadence. Leaders who treat certification as a one-time launch milestone will face compounding specification rejection risks and supply chain friction. Conversely, organizations that embed verification protocols, accelerated aging methodologies, and documented field performance into their product architecture will convert compliance into a defensible competitive advantage, particularly in public-sector tenders and multinational facility networks.
Competitive Architecture: Technology Readiness, Portfolio Breadth, and Recent Strategic Moves
The market's competitive fabric is defined by a differentiated spectrum of players spanning specialty additive suppliers, architectural and industrial coating formulators, and broad-platform material science corporations. Market concentration metrics indicate that the top three participants command approximately 27.5 percent of total revenue, while the top five consolidate roughly 38.0 percent, suggesting a landscape where scale advantages coexist with meaningful opportunities for technology-led differentiation and application-specific specialization.
Strategic positioning among leading participants reveals distinct technology theses and commercialization pathways. Microban International continues to anchor its architectural, industrial, and outdoor textile portfolios through a suite of governed protection technologies spanning AkoTech platform integration, Ascera, LapisShield, and H2O Shield formulations, each engineered to deliver 99.99 percent bacterial inhibition. Their forthcoming presence at the American Coatings Show in mid-2026, with technical presentations focused on accelerated laboratory methodologies for algae and antifungal resistance in exterior formulations, signals a deliberate push toward durability validation and environmental aging credibility.
HeiQ has emphasized high-efficacy silver-based and bio-origin additive architectures, positioning its HeiQ SANPURE ready-to-use coating with efficacy exceeding 99.999 percent against bacteria and viruses, complemented by plant-based Life Natural additives designed for integration into paints, powder systems, and coil coating processes. Sherwin-Williams extends antimicrobial compatibility across waterborne, solventborne, and 100 percent UV topcoat systems tailored for furniture, flooring, and public-contact surfaces, with validated 99.99 percent bacteria reduction per JIS Z 2801:2010 testing protocols.
Material and substrate specificity is a recurring theme among emerging and established players alike. BioBond's introduction of biobased urethane antimicrobial coatings through its BioCoat SUP250 architecture, alongside three-layer protective systems developed for concrete, ceramic, wood, and metal substrates, reflects a strategic emphasis on adhesion durability and surface compatibility in demanding infrastructure contexts. AkzoNobel continues to leverage powder coating and architectural paint platforms through Interpon D Antimicrobial Powder Coatings and Dulux Antimicrobial Paint, aligning antimicrobial functionality with established industrial and architectural distribution networks. PPG Industries has advanced antiviral and antimicrobial architectures through its COPPER ARMOR paint technology and antimicrobial powder coating formulations for architectural and industrial surfaces, while The Dow Chemical Company supplies antimicrobial additives and tailored formulations for powder and liquid coating systems across healthcare and general industrial applications.
Specialty chemical and performance material players further expand the ecosystem's breadth. BASF SE contributes architectural, industrial, and automotive-grade protection through its Ultranox and Neopentyl Glycol antimicrobial coating lines. Arch Lonza maintains focus on industrial and healthcare surfaces via its Arch Biocides and antimicrobial coating portfolios. Axalta Coating Systems addresses refinish and industrial applications through Axalta Refinish Antimicrobial Coatings and Imron Antimicrobial Coatings, while 3M provides antimicrobial additives and coating solutions spanning industrial, construction, and consumer applications. RPM International reinforces its position with specialized antimicrobial formulations engineered for industrial and architectural coating environments.
These technology postures are not static. Our report evaluates each participant's formulation flexibility, testing validation posture, distribution reach, and recent strategic signaling, enabling decision-makers to benchmark competitive exposure and anticipate specification displacement risks.
End-Use Fragmentation, Material Economics, and the Cost-Structure Reality
Antimicrobial coating adoption is fundamentally application-driven, and the economic logic of surface protection varies sharply across operating environments. Medical healthcare procurement prioritizes validated pathogen reduction, cleaning chemical compatibility, and lifecycle retesting cadence, often bundling antimicrobial specifications into broader infection control frameworks. Food and beverage processing environments emphasize washdown durability, temperature cycling resilience, and regulatory alignment with sanitation protocols. Building construction and facility management sectors focus on long-term surface preservation, occupant wellness positioning, and integration with architectural finish aesthetics. Each vertical imposes distinct cost-justification structures, specification gatekeepers, and renewal cycles.
Worldwide Smart Antimicrobial Surface Market
Material selection further compounds these dynamics. Silver-based architectures continue to dominate high-efficacy narratives but are directly exposed to commodity volatility, as reflected in early 2025 pricing shocks. Copper-based and alternative inorganic or organic systems offer distinct cost-performance trade-offs, while hybrid formulations and additive-dependent designs shift the balance between upstream raw material exposure and downstream performance validation. The report evaluates these architecture choices through the lens of formulation cost stability, supply continuity risk, and specification acceptability across key procurement environments, rather than presenting them as isolated product categories.
Operational Intelligence Embedded in the Research Architecture
A market study of this scope must deliver more than directional growth commentary. The report is structured to support operational planning across multiple commercial functions. Demand drivers are mapped against procurement trigger events, facility renewal cycles, and specification-writing behavior across priority verticals. Supply-side assessment covers formulation readiness, additive integration pathways, substrate compatibility constraints, and the practical implications of regulatory testing cadence on product launch timing. Competitive benchmarking moves beyond flat revenue attribution to examine technology readiness levels, portfolio coverage across architectural, industrial, healthcare, and consumer surfaces, distribution model advantages, and recent strategic signaling such as trade-show technical disclosures and multi-layer protective system launches.
Anti-Microbial Coatings Market
Regional demand analysis is contextualized through infrastructure investment pacing, healthcare facility modernization cycles, cold-chain logistics expansion, and public-sector procurement standardization, allowing readers to evaluate where localization strategies, partnership models, or specification-aligned product configurations will yield the highest conversion efficiency. The study also incorporates market concentration implications, examining how fragmented mid-tier participation interacts with consolidated upstream material supply and downstream distribution channels.
Strategic Deployment for 2026 and the Forecast Horizon
As organizations enter 2026 planning cycles, the strategic questions are no longer whether antimicrobial surface protection will expand, but how to position portfolios, pricing architectures, validation frameworks, and channel strategies to capture durable value. Decision-makers must determine whether to compete on broad-formulation compatibility and distribution breadth, or to pursue application-specific engineering claims anchored in accelerated aging validation and standardized efficacy testing. Procurement leaders must weigh commodity-exposed metallic systems against alternative chemistries while accounting for verification cadence and tender specification rigidity. R&D and product management teams must align development pipelines with regulatory standardization trajectories, particularly around antiviral mechanism documentation and ecotoxicological profiling.
The report provides the evidentiary foundation for these decisions, linking macro growth momentum to segment-level economic logic, regulatory compliance expectations, and competitive positioning patterns. It is designed for executive teams seeking to integrate antimicrobial coating strategy into broader materials, facility, and product roadmaps with discipline rather than speculation.
Conclusion: From Market Size to Strategic Advantage
The Anti-Microbial Coatings Market is transitioning from a reactive hygiene response category to a mature, specification-driven, compliance-aware industrial sector with clear long-term growth architecture. Sustained value capture will belong to organizations that combine formulation credibility, regulatory readiness, substrate-specific engineering, and procurement-aligned validation into a coherent commercial strategy. Our comprehensive study delivers the depth required to navigate this environment, while preserving proprietary segmentation detail, regional revenue breakdowns, and granular application economics for direct engagement. For executives, investors, and strategy teams requiring complete quantitative segmentation, full competitive profiling, and region-specific procurement intelligence, the full report provides the structured intelligence necessary to convert market momentum into defensible strategic advantage through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Anti-Microbial Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyacrylonitrile Market to Reach $9.59B in 2032 at 3.3% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Global Polyacrylonitrile Market: Navigating Growth, Volatility, and Competitive Consolidation
The polyacrylonitrile (PAN) market stands at a critical inflection point where traditional textile demand intersects with rapidly expanding advanced materials applications. For corporate strategists, procurement leaders, and investment committees operating in 2026, understanding the nuanced trajectory of this sector is no longer optional-it is a prerequisite for resilient supply chain design, capacity planning, and competitive positioning. The latest PW Consulting market research on polyacrylonitrile provides a comprehensive, data-grounded roadmap through this complex landscape, translating historical performance and forward-looking projections into actionable intelligence. This analysis draws exclusively from proprietary modeling and primary industry engagement to equip decision-makers with the clarity required to navigate raw material volatility, regulatory pressure, and accelerating technological substitution.
Market Trajectory and Structural Evolution
Historical performance from 2020 through 2025 reveals a market characterized by steady expansion punctuated by periodic supply disruptions and input cost fluctuations. Revenue progression across this six-year window demonstrates a consistent upward trajectory, with total global market value crossing the seven-billion-dollar threshold and stabilizing at approximately 7,545 million by the end of 2025. This foundational baseline establishes the starting point for the current forecast cycle, which projects continued expansion through 2032. The medium-term outlook anticipates the market scaling to nearly 8,000 million in 2026, followed by sustained growth that pushes valuations toward the mid- to upper-nine-billion range by the end of the decade.
The central growth catalyst across the forecast horizon is a compound annual growth rate of 3.3 percent. While this figure may appear moderate on the surface, its strategic significance lies in the underlying composition of demand drivers. Growth is not uniformly distributed across all application verticals; rather, it is increasingly concentrated in high-performance precursor segments and specialized filtration grades, while traditional textile volumes face margin compression and regional demand oscillations. The trajectory also reflects a market that has matured past its early expansion phase, entering a period where efficiency, formulation optimization, and supply chain integration become the primary differentiators. Companies that fail to align capacity investments with these shifting demand centers risk exposure to overcapacity in legacy segments and underinvestment in high-margin precursor pathways.
Temporal demand modeling within the research framework further highlights the importance of scenario planning. The projected sequence of annual valuations through 2032 illustrates a market that does not grow in a straight line but rather responds dynamically to macroeconomic cycles, feedstock pricing, and regulatory implementation timelines. Decision-makers who rely on single-point forecasts are particularly vulnerable to misallocated capital and misaligned inventory strategies. Our analysis emphasizes dynamic range modeling and stress-testing against input cost shocks, ensuring that strategic plans remain viable across multiple plausible futures.
Demand Architecture and Segment Interplay
The structural composition of PAN demand is fundamentally bifurcated between conventional textile applications and advanced industrial precursors. Traditional acrylic staple fiber and tow grades continue to command substantial volume, driven by apparel, home textiles, and industrial fabric markets. However, the growth narrative is increasingly anchored in specialized applications where PAN serves as a critical enabler of next-generation materials. Precursor-to-carbon-fiber grades represent a growing share of total market value, supported by sustained aerospace build rates, automotive lightweighting mandates, and expanding wind energy compounding requirements.
Filtration applications present another distinct demand node, leveraging PAN's chemical resistance and thermal stability for industrial liquid and gas processing environments. Meanwhile, outdoor and fiber-reinforced concrete applications, though smaller in aggregate volume, demonstrate specialized growth trajectories tied to infrastructure modernization and durability requirements in harsh environmental conditions. The interplay between these segments creates a complex demand matrix where volume shifts in one vertical can rapidly translate into pricing and capacity adjustments across the broader value chain.
From a segmentation perspective, the market exhibits clear structural boundaries across geographic distribution, product typology, and end-use application. Regional demand concentration reflects established manufacturing footprints and localized downstream processing capabilities, while product-type splits highlight the divergence between staple fiber production, tow intermediates, and top-grade specialty formulations. Application-level demand patterns further underscore the transition from commodity-driven consumption toward performance-specified procurement. These structural splits are not static; they evolve in response to capacity additions, trade flow adjustments, and regional compliance mandates. The research framework captures these dynamics through granular modeling that tracks how shifts in one segment propagate through the broader market equilibrium.
Competitive Landscape and Strategic Consolidation
The competitive architecture of the PAN market is defined by a concentrated yet geographically diverse participant base. Market concentration metrics indicate that the top three players collectively command approximately 26 percent of total revenue, while the top five extend their combined share to roughly 30 percent. This moderate concentration level suggests that while scale advantages exist, the market remains sufficiently fragmented to allow specialist players to compete on formulation quality, regional integration, and customer-specific precursor engineering.
Polyacrylonitrile (PAN) Market
The participant landscape spans integrated chemical manufacturers, fiber specialists, and advanced materials conglomerates. Turkish producers have reinforced their regional positioning through ownership restructuring and vertical integration, most notably through the acquisition of remaining equity stakes in joint carbon fiber ventures and the subsequent rebranding of operations to unify precursor and fiber production under a single corporate identity. This move illustrates a broader industry trend toward tighter integration between PAN precursor supply and downstream carbon fiber processing, reducing transactional friction and improving formulation consistency.
European manufacturers continue to emphasize dry-spun fiber technologies and specialized PAN grades tailored for both textile and precursor applications, leveraging established process engineering capabilities and strong compliance infrastructure. In East Asia, major chemical and composite companies maintain significant production footprints, with some operating fully integrated polymerization, spinning, and precursor oxidation workflows under proprietary brand architectures. These vertically aligned operations provide distinct advantages in cost structure, quality control, and supply reliability for aerospace and industrial composite customers. South Korean and Taiwanese participants similarly contribute meaningful capacity, with several firms expanding precursor-grade production to support domestic and export-oriented carbon fiber manufacturing. Japanese specialty chemical suppliers add further depth to the competitive field, focusing on advanced composite precursor grades and collaborative development with end-user composite fabricators.
Recent strategic activity reinforces the consolidation and integration narrative. Ownership transitions, exhibition showcases, and industry day participations have collectively signaled a market preparing for heightened scrutiny around circularity, precursor efficiency, and application-specific performance validation. These developments are not isolated; they reflect a coordinated push by leading participants to align PAN production capabilities with evolving downstream specifications, particularly in carbon fiber precursor markets where consistency, oxidation behavior, and impurity control directly determine final composite performance.
Operating Environment Pressures and Risk Factors
Beyond structural demand and competitive positioning, the PAN operating environment is shaped by persistent input cost volatility, regulatory compliance burdens, and supply chain fragility. Acrylonitrile remains the dominant cost component in PAN manufacturing, representing roughly two-thirds of total production expenses. Price movements in this feedstock therefore transmit rapidly into producer margins, pricing strategies, and end-customer negotiations. Recent quarters have demonstrated sustained elevation in global acrylonitrile pricing, with early-2026 increases largely attributed to rising propylene feedstock costs. In specific regional markets, price surges have been more pronounced, driven by inventory drawdowns and tighter availability of both propylene and ammonia, the upstream inputs that dictate acrylonitrile production economics.
These raw material pressures are compounded by regulatory dynamics. Environmental compliance requirements governing acrylonitrile production in the European Union have increased operational costs for PAN producers, adding a measurable compliance premium to European manufacturing footprints. Such regulatory shifts do not merely affect cost structures; they influence location decisions, capacity expansion timelines, and the competitive balance between regions with differing compliance regimes. Producers with integrated feedstock access, advanced process efficiency, or flexible sourcing strategies are better positioned to absorb these incremental costs without compromising margin targets.
Supply chain resilience has also emerged as a critical operational theme. Historical production disruptions linked to raw material shortages in key manufacturing regions have demonstrated how quickly localized feedstock constraints can cascade into broader output reductions. Facilities exposed to concentrated supplier dependence or single-region feedstock sourcing have experienced production curtailment, reinforcing the strategic importance of diversified procurement, inventory buffering, and demand-forecast alignment. The market research framework incorporates these risk vectors explicitly, enabling planners to evaluate exposure across multiple procurement scenarios and assess the financial implications of input price shocks and regulatory cost escalations.
What the Research Delivers for Decision-Makers
The PW Consulting polyacrylonitrile market study is designed to function as a practical decision-support instrument rather than a static statistical compendium. The research architecture is structured to provide strategic teams with the granularity required to evaluate capacity investments, procurement strategies, competitive positioning, and regional market entry or expansion plans. Core deliverables span multi-period market sizing, segment-level demand modeling, competitive profiling, and operating environment analysis, all calibrated to the current forecast cycle and grounded in primary data collection and proprietary analytical methods.
The report provides detailed segmentation analysis across regional distribution, product typology, and end-use application, enabling users to isolate growth centers, assess volume-to-value translation, and identify segments where margin dynamics diverge from headline growth rates. Competitive intelligence components map incumbent capabilities, strategic movements, and integration trajectories, offering context for partnership evaluation, benchmarking, and threat assessment. Operating environment sections synthesize raw material cost behavior, regulatory impact trajectories, and supply chain vulnerability indicators, equipping procurement and risk management teams with the inputs necessary to design resilient sourcing and pricing strategies.
Strategic planners will find particular value in the scenario-based modeling framework, which translates macro-level trends into actionable planning ranges. Rather than presenting a single deterministic path, the research outlines plausible demand and cost trajectories under varying macroeconomic, feedstock, and regulatory conditions. This approach supports more robust capital allocation, inventory planning, and supplier negotiation strategies. Additionally, the inclusion of recent industry developments and corporate activity timelines provides forward-looking context for interpreting competitor behavior and anticipating shifts in market participation.
Isophthalonitrile (INP) Market
Why 2026 Decisions Require Precision Intelligence
The current market environment demands a higher standard of strategic precision. Growth is real, but it is uneven. Input costs remain volatile, and regulatory costs are incrementally reshaping regional competitiveness. Competitors are consolidating, integrating, and rebranding to align precursor supply with downstream composite requirements. In this context, decisions made in 2026 will determine not only near-term margin performance but also long-term capacity relevance and supplier credibility.
Organizations that treat the polyacrylonitrile market as a static commodity sector will miss the structural shifts occurring in precursor demand, regional cost differentials, and application-specific procurement behavior. Conversely, teams that ground their planning in detailed, scenario-aware market intelligence will be better positioned to time capacity adjustments, optimize procurement contracts, identify partnership opportunities, and anticipate competitive moves before they reshape pricing and availability. The difference between reactive adaptation and proactive strategy often comes down to the quality and timeliness of the underlying intelligence.
Accessing the Full Strategic Picture
This overview captures the structural logic, competitive dynamics, and operating environment pressures that define the polyacrylonitrile market as of 2026. However, the full strategic value of the research lies in its detailed segmentation modeling, comprehensive competitive profiling, scenario-driven planning tools, and precise quantification of demand shifts across regions, product types, and applications. Core growth sensitivities, segment-level valuation trajectories, regional concentration dynamics, and competitor capability assessments are developed in depth within the complete report, providing the quantitative backbone necessary for confident capital allocation, procurement strategy design, and market positioning.
For executives, analysts, and supply chain leaders who require verified market sizing, granular segmentation breakdowns, competitive benchmarking, and forward-looking operating environment analysis, the complete PW Consulting Polyacrylonitrile Market research offers the comprehensive intelligence needed to convert complexity into clarity. Access the full report to obtain the detailed data, scenario frameworks, and strategic assessments that will inform your 2026 and beyond planning decisions.
For detailed analysis of this topic, please visit the official page: Polyacrylonitrile (PAN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


