



PW Consulting: Fullerene Market to Reach $600M by 2032 Amid 7.8% CAGR Growth
By PW Consulting, 2026-09-16
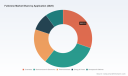
Strategic Intelligence for the Fullerene Market: Navigating Growth, Supply Constraints, and Competitive Shifts Through 2032
The global fullerene market stands at a pivotal inflection point. What began as a niche materials segment has matured into a cross-industry enabler spanning high-purity electronics, advanced cosmetics, pharmaceutical formulations, and next-generation energy systems. For executives and strategy teams operating in 2026, the decisions made today around feedstock security, purity validation, and application diversification will define competitive positioning over the next half-decade. This market research report delivers a structured, data-grounded blueprint for navigating that complexity.
Our analysis traces the market trajectory from its historical baseline through a forward-looking forecast window. The sector reached an estimated valuation of 358.91 million USD in the 2025 base year, building on consistent growth momentum since 2020 when the market was evaluated at 250.0 million USD. The compound annual growth rate of 7.8 percent projects the market toward approximately 600.0 million USD by 2032. This trajectory is not merely a numerical forecast; it reflects structural shifts in manufacturing capability, regulatory evolution, and the migration of fullerene materials into higher-value applications. Understanding where growth concentrates, which purity thresholds are becoming commercially non-negotiable, and how supply-side constraints are reshaping cost structures is essential for capital allocation, partnership strategy, and product roadmapping.
Market Trajectory and Structural Drivers
The historical series from 2020 to 2025 demonstrates a compounding expansion pattern. Revenue scaled from 250.0 million USD in 2020 to 275.27 million USD in 2021, continued to 298.41 million USD in 2022, advanced to 316.88 million USD in 2023, reached 342.75 million USD in 2024, and closed at 358.91 million USD in 2025. This steady progression signals a market that has moved beyond early-stage volatility into a more predictable growth rhythm. The forecast horizon extends that momentum through 2032, with projected annual valuations climbing from 386.43 million USD in 2026 to 406.58 million USD in 2027, 446.49 million USD in 2028, 473.23 million USD in 2029, 506.52 million USD in 2030, 568.88 million USD in 2031, and 600.0 million USD in 2032.
Several interlocking forces underpin this expansion. First, the migration of fullerene-based materials from laboratory-scale research into validated commercial processes is broadening the addressable market. High-purity grades are increasingly specified in optical and electronic formulations where performance thresholds demand consistent molecular quality. Second, regulatory scrutiny around nanomaterials has intensified, reshaping validation requirements and elevating the commercial premium for materials that meet stringent purity benchmarks. Third, feedstock dynamics are introducing new cost and availability considerations that reward manufacturers and buyers who secure resilient supply chains. These drivers do not operate in isolation; they interact to create both margin pressure and differentiation opportunities for organizations that align procurement, R&D, and compliance strategies early.
Supply-Side Realities and Regulatory Headwinds
Graphite remains the foundational feedstock for fullerene production, anchoring the entire value chain to upstream carbon material economics. Recent years have seen tighter export controls on natural graphite, particularly from China, which has constrained global feedstock availability and contributed to elevated supply-chain costs. For procurement and operations leaders, this is not a transient disruption. It represents a structural recalibration that favors diversified sourcing strategies, long-term offtake agreements, and manufacturers with integrated purification capabilities. Companies that rely on single-source feedstock exposure face heightened vulnerability to price volatility and lead-time variability, while those that hedge across geographies and grades can stabilize input costs and protect margin profiles.
On the regulatory front, the FDA has ramped up risk assessments and validation requirements for nanomaterials, a shift that directly influences fullerene procurement specifications. The practical outcome is rising demand for ultra-high-purity fullerene materials at thresholds of 99.5 percent and 99.9 percent or higher, alongside validated purification techniques that can withstand scrutiny in regulated end markets. This trend is especially relevant for pharmaceutical and cosmetic applications, where traceability, batch consistency, and documented purification pathways increasingly determine whether a material qualifies for advanced formulation pipelines. Organizations that treat purity validation as a strategic capability rather than a compliance checkbox will be better positioned to capture premium segments and reduce time-to-market for next-generation products.
The Competitive Landscape and Strategic Positioning
The fullerene market exhibits meaningful concentration, with the top three players accounting for approximately 57.0 percent of market share and the top five expanding that footprint to roughly 63.0 percent. This concentration underscores the importance of understanding not just who the incumbents are, but how their technological capabilities, certification milestones, and application focus shape competitive dynamics. The following companies anchor the current landscape and illustrate the strategic diversity within the sector.
Nano-C, Inc.
Headquartered in Westwood, Massachusetts, United States, Nano-C operates as the leading US manufacturer of high-purity C60, C70 fullerenes, and functionalized derivatives via combustion synthesis. Its product and process orientation is tightly aligned with organic photovoltaics, electronics, and nanotechnology applications. In May 2026, the company achieved ISO 9001:2015 certification for advanced electronic materials including fullerenes, a milestone that reinforces its credibility in quality-sensitive electronic supply chains and signals a deliberate focus on manufacturing consistency and customer qualification requirements.
SES Research Inc.
Based in Houston, Texas, United States, SES Research functions as a manufacturer and distributor of premium C60 fullerenes and derivatives, with a commercial emphasis on wellness, supplements, and research-grade applications. Its positioning highlights the divergence within the market between high-specification industrial materials and consumer-facing or research-oriented product lines, where branding, purity communication, and application-specific testing play outsized roles in commercial success.
Frontier Carbon Corporation
Located in Tokyo, Japan, Frontier Carbon specializes in high-volume combustion-synthesis fullerenes and derivatives designed for cosmetics, pharmaceuticals, and electronics. The company's application breadth reflects a strategic emphasis on scale and multi-segment relevance, aligning volume production with the purity and consistency requirements that regulated and performance-driven end markets demand.
MER Corporation
Operating from Tucson, Arizona, United States, MER Corporation supplies mixed fullerenes including C60 and C70, along with higher-order fullerenes, for research and materials applications. Its portfolio orientation illustrates the continuing importance of research-grade supply and specialty material variants that support R&D pipelines, prototype development, and materials science discovery.
BuckyUSA, Inc.
Also based in the United States, BuckyUSA operates as a market-driven producer of fullerene materials for science and industrial uses. Its commercial model highlights the role of flexible, application-responsive production in serving diverse buyer requirements across academic, industrial, and specialized materials contexts.
Solenne BV
Headquartered in Groningen, the Netherlands, Solenne produces high-quality fullerene derivatives including PCBM grades at scales up to the kilogram level. This capability is particularly relevant for customers that require derivative-grade materials with controlled specifications and scalable batch production, bridging the gap between laboratory research and pilot-scale or early commercial deployment.
Together, these players demonstrate that the competitive landscape is not monolithic. Differentiation emerges through purity thresholds, certification status, production scale, application specialization, and geographic positioning. For buyers and investors alike, understanding which capabilities align with specific end-use requirements is critical to selecting partners, structuring supply agreements, and identifying white-space opportunities where incumbent coverage remains incomplete.
Report Scope and Practical Value for Decision-Makers
This market research report is designed to translate macro trends into actionable intelligence. It provides a comprehensive analytical framework that covers market sizing, growth decomposition, segmentation dynamics, competitive profiling, and forward-looking scenario considerations. Rather than presenting numbers in isolation, the report embeds them within the operational and regulatory contexts that determine how those numbers translate into real-world strategy.
Readers will gain clarity on how the market evolved from 2020 through 2025, why the projected 7.8 percent CAGR is grounded in observable demand and supply dynamics, and which structural factors are likely to accelerate or moderate growth through 2032. The analysis examines how purity requirements, feedstock availability, and application migration interact to shape margin structures and procurement strategies. It also maps the competitive landscape in a way that highlights not just market share, but the strategic implications of certification milestones, geographic footprints, and application-specific capabilities.
For corporate strategy, R&D leadership, procurement, and investment teams, the report serves as a decision-support tool. It helps identify where to prioritize supplier qualification, how to assess the commercial implications of tightening nanomaterial regulations, and which application pathways offer the most credible growth potential. It also provides a structured basis for evaluating partnership opportunities, capacity investments, and market-entry timing.
Cucurbituril Market
What the Full Analysis Delivers
To support robust strategic planning, the complete report goes beyond headline figures and offers granular, segment-level intelligence. The full analysis includes detailed regional performance trends, type-specific valuation and growth patterns across C60, C70, C76, and other fullerene variants, and application-level demand trajectories spanning cosmetics, semiconductor and electronics, pharmaceuticals, energy and power, and aerospace and defense. These breakdowns are essential for understanding where value creation is concentrated and how growth diverges across end markets with different purity, scale, and regulatory profiles.
The report also incorporates competitive benchmarking, recent corporate developments such as Nano-C's ISO 9001:2015 certification achievement in May 2026, and a forward-looking assessment of supply-chain risk factors tied to graphite availability and export-control dynamics. By connecting these operational developments to broader market outcomes, the analysis equips decision-makers with a more durable basis for scenario planning and investment prioritization.
Why This Research Matters for 2026 Strategy
2026 is a year in which intuition alone will not suffice. Feedstock constraints, regulatory validation demands, and the migration of fullerene materials into higher-value applications are reshaping the commercial terrain at a pace that rewards organizations with disciplined market intelligence. The projected expansion toward 600.0 million USD by 2032 is significant, but the strategic question is not simply how large the market will become. It is who will capture disproportionate value within it, under what purity and supply conditions, and through which application pathways.
Accessing the full market research report provides the depth required to answer those questions with confidence. It delivers the segment-level breakdowns, competitive context, and supply-and-regulation dynamics that executives need to align product roadmaps, procurement strategies, and partnership decisions with where the market is actually headed. For teams evaluating capital allocation, supplier qualification, or market-entry timing, this research offers a structured, evidence-based foundation for the decisions that will shape performance through 2032 and beyond.
Fullerene Market
For detailed analysis of this topic, please visit the official page: Fullerene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Carpet Tiles Market to Reach $17.29B by 2032, Growing at 5.12% CAGR
By PW Consulting, 2026-09-16
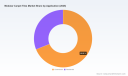
Navigating the Modular Carpet Tiles Market: Strategic Intelligence for 2026 and Beyond
The global flooring landscape is undergoing a structural transformation, driven by evolving workplace requirements, stringent sustainability mandates, and a renewed emphasis on circular material flows. Within this complex environment, modular carpet tiles have emerged as a critical solution for facility managers, architectural specifiers, and commercial real estate developers. As organizations align their procurement strategies with 2026 operational targets, understanding the precise trajectory of this segment is no longer optional. This executive overview introduces our latest market research on the Modular Carpet Tiles Market, outlining why a data-driven, forward-looking intelligence framework is essential for overcoming near-term volatility and capturing long-term value.
A Market Reaching a Strategic Inflection Point
Drawing on six years of historical tracking and a seven-year forward projection, our analysis reveals a market exhibiting consistent, compounding expansion. Between 2020 and 2025, global revenue crossed significant thresholds, with the baseline year registering $12.15 billion. The momentum continues unabated: 2026 is positioned at $13.01 billion, followed by a steady climb that places the market at $17.29 billion by 2032. This trajectory translates to a forecast compound annual growth rate of 5.12 percent, a figure that underscores durable demand rather than cyclical recovery.
For executives, these numbers carry more than macroeconomic relevance. They signal a market where growth is being unevenly distributed, shaped by product architecture, regional procurement policies, and the accelerating institutionalization of environmental product declarations. The reality is that aggregate expansion masks divergent performance across flexible and rigid formats, across commercial and residential end-use channels, and across regulatory jurisdictions that increasingly dictate which suppliers can scale efficiently. Navigating this landscape requires a granular comprehension of where capital is being deployed, which specifications are winning specification approvals, and how trade frameworks are recalibrating cost structures.
What Our Research Delivers: Operational Intelligence for 2026 Decision-Making
The full study is structured to convert macro indicators into actionable strategic playbooks. Rather than presenting static snapshots, the report maps the operational levers that will define competitive positioning over the 2026–2032 horizon. Key components include:
- A comprehensive sizing and forecasting model that decomposes historical performance and projects forward revenue across the entire modular carpet tiles ecosystem, enabling demand planning and capacity allocation with precision.
- Deep-dive segmentation analysis that evaluates product architecture, end-use deployment patterns, and regional consumption profiles, allowing leadership teams to isolate the highest-yield growth corridors and adjust portfolio emphasis accordingly.
- A competitive benchmarking framework that profiles major manufacturers, dissects their product pipelines, sustainability positioning, and commercial execution strategies, giving executives a clear view of where market share is being contested.
- A regulatory and certification tracker that monitors environmental product declarations, cross-border duty structures, and countermeasure tariffs, helping procurement and compliance teams anticipate cost shifts and specification friction before they impact margins.
- Sustainability and circularity mapping that evaluates advances in bio-based backings, recycled content integration, and take-back programs, aligning product development roadmaps with the specifications now dominating institutional tenders.
- Scenario-based guidance for 2026, offering leadership teams tested frameworks to adapt pricing, supply chain routing, and regional market entry strategies amid shifting trade policies and evolving end-user expectations.
Each section is engineered to support concrete decisions: whether evaluating a manufacturing expansion, repositioning a commercial sales force, adjusting logistics partnerships, or preparing for tender specifications that now require verified lifecycle documentation.
Carpet Tiles Market
Competitive Landscape: How Leading Players Are Positioning for the Next Cycle
The modular carpet tiles arena is characterized by a concentrated but highly dynamic competitive field. Our analysis tracks a core cohort of established manufacturers whose product architectures, sustainability commitments, and regional footprints actively shape market directionality. Understanding their strategic posture is essential for any organization planning capacity, pricing, or specification targeting in 2026.
Interface, headquartered in Atlanta, Georgia, continues to anchor its portfolio on modular carpet tiles featuring TacTiles installation systems and CQuest Bio backing technologies. The company’s operational philosophy is tightly coupled with its Mission Zero commitments and the ReEntry recycling program, positioning environmental accountability as a core commercial differentiator rather than a compliance add-on. Mohawk Industries, also based in Calhoun, Georgia, deploys modular offerings across the EcoFlex ONE, Matrix, and NXT lines, pairing commercial resilient flooring expertise with multiple optimized environmental product declarations that streamline specification in regulated procurement environments. Tarkett, operating from Méru, France, extends its modular carpet tile and plank portfolio with the Quiet Edit collection and circular solutions incorporating DESSO backing, specifically engineered for open-plan commercial spaces where acoustic performance and material circularity intersect.
EF Contract Flooring, based in the United States, manufactures the Advance and Nexus modular carpet tile families, utilizing PVC backing systems while maintaining EPD-compliant sustainable pathways that align with institutional procurement thresholds. Tapibel, headquartered in Belgium, emphasizes design flexibility and standardized 50x50 cm formats, delivering sustainable collections that bridge commercial and residential applications without sacrificing specification versatility. Shaw Contract, rooted in Dalton, Georgia, complements its modular carpet tile product line with broadloom options, reinforcing a USA-made performance flooring narrative that resonates with commercial buyers prioritizing supply chain reliability and localized manufacturing.
Recent corporate activity underscores how rapidly competitive positioning is evolving. In mid-2025, EF Contract Flooring refreshed the Nexus modular carpet tile environmental product declaration, updating version and validity dates to maintain compliance through 2029. Shortly thereafter, Interface issued a tufted modular carpet tile declaration for CQuest Bio backing, securing validity through 2030 under a recognized European certification body. EF Contract Flooring also advanced its Advance modular carpet tile documentation with an EPD appendix that remained active well into 2025. By early 2026, Tapibel published its 2026–2027 collection catalog, reinforcing its focus on sustainable modular formats and forward-looking design portfolios.
These movements are not isolated product announcements. They reflect a broader industry recalibration where documented lifecycle performance, material transparency, and portfolio agility are becoming decisive factors in specification wins and regional expansion. The full report quantifies how these developments influence share shifts, pricing tolerance, and the speed at which competitors can capture high-value commercial tenders.
Market Dynamics: Regulation, Certification, and the Redefinition of Trade Flows
The operational environment for modular carpet tiles is being reshaped by a convergence of policy instruments and certification requirements that directly affect cost structures, market access, and specification velocity. Our research integrates these dynamics into a cohesive framework so that executives can anticipate disruption rather than react to it.
Trade policy has emerged as a particularly sensitive variable for North American and cross-border supply chains. Current guidance confirms that US-origin modular carpet tiles classified under HS 5704 can qualify for a zero percent duty rate when imported into Canada under CUSMA/USMCA provisions, provided they satisfy applicable rules of origin. Yet this advantage operates alongside countermeasure measures: Canada has applied a temporary 25 percent tariff on certain US carpets, effective from March 2025. For manufacturers and distributors, this dual reality creates a complex compliance overlay where product classification, country of origin documentation, and final destination routing can materially alter landed cost and margin predictability.
Modular Carpet Tiles Market
Simultaneously, environmental product declarations have transitioned from voluntary differentiation to baseline expectation. Multiple manufacturers updated or issued EPDs throughout 2025, including Interface’s CQuest Bio backing declaration and EF Contract Flooring’s Nexus modular documentation. In Europe, Interface modular carpet tiles are now declared under EN 15804+A2, with issue dates tracked through September 2025. This regulatory and certification cadence matters because it determines which suppliers can efficiently participate in public tenders, institutional fit-outs, and corporate sustainability programs that increasingly demand verified environmental data as a precondition for evaluation.
Beyond compliance, product innovation continues to align with changing spatial requirements. Tarkett’s Quiet Edit carpet tile collection, for example, leverages repurposed materials aesthetics to serve commercial open spaces, reflecting a broader shift where visual identity, acoustic performance, and circular content are evaluated together during specification. These dynamic layers—trade rules, certification timelines, and product narrative evolution—are mapped in detail within the report, with scenario analysis illustrating how shifts in any one variable can cascade through pricing, share, and regional allocation strategies.
Why 2026 Demands a Different Decision Framework
The 2026 outlook is not simply another year in a growth curve. It represents a period in which historical assumptions about demand uniformity, sourcing flexibility, and specification tolerance are being tested simultaneously. Organizations that rely on aggregated market narratives will miss the structural divergences that determine actual performance. The modular carpet tiles market is expanding, but the value creation is increasingly tied to identifiable drivers: documented environmental performance, adaptive product formats, and supply chains capable of navigating overlapping trade and certification requirements.
This report is designed to give leadership teams a clear, quantitative, and strategically actionable foundation. It connects the $13.01 billion entry point of 2026 to the broader 2032 trajectory of $17.29 billion through a disciplined analytical lens, while deliberately preserving the detailed regional, application, and product-level breakdowns for the full intelligence package. That intentionality reflects how high-stakes decisions are made: executives need the directional confidence that the headline numbers provide, but they also require the granular evidence that supports resource allocation, partnership selection, and market-entry sequencing.
Access the Complete Strategic Intelligence
For senior executives, procurement leaders, and strategy teams preparing for the 2026–2032 cycle, the full study delivers the depth required to move from observation to execution. It provides the segmented forecasting detail, competitive scenario mapping, regulatory and certification tracking, and sustainability alignment analysis needed to shape pricing strategy, portfolio prioritization, and regional expansion plans with confidence.
To request the complete Modular Carpet Tiles Market research and gain access to the full dataset, segmentation breakdowns, and proprietary competitive assessments, visit the official research portal. The complete report is structured to serve as a decision-ready intelligence asset, enabling your organization to act on the market’s direction with precision rather than assumption.
For detailed analysis of this topic, please visit the official page: Modular Carpet Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: RF Filters Market Hits $12B in 2025, Poised for 15.7% CAGR Through 2032
By PW Consulting, 2026-09-16
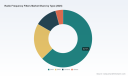
Unlocking the $32.93 Billion Opportunity: A 2026 Strategic Outlook for the RF Filter Market
Radio frequency filters have evolved from passive components to strategic linchpins in the global electronics ecosystem. As we enter 2026, the industry stands at the convergence of explosive connectivity demands and geopolitically driven supply chain restructuring. Our latest research, PW Consulting's Radio Frequency Filters Market Analysis, provides executives with the definitive roadmap to navigate this complex landscape. By examining the trajectory from $12.0 billion in 2025 to a projected $32.93 billion by 2032, this report informs critical investment decisions in manufacturing capacity, supply chain resilience, and product portfolio prioritization.
The Macro Trajectory: A CAGR-Driven Growth Story
The market's expansion over the past five years has been characterized by relentless upward momentum, driven by the rollout of 5G infrastructure and the proliferation of connected devices. Current valuations build upon a historical foundation where revenue grew from $6.2 billion in 2020 to $12.0 billion in 2025, reflecting accelerated adoption rates across critical sectors. Looking forward, our forecast model projects a compound annual growth rate of 15.7% for the 2026-2032 forecast period, signaling a phase of structural expansion rather than transient hype. This growth engine is powered by multi-faceted demand signals, yet the specific allocation of capital across regions and application verticals reveals complex investment vectors that generic trade publications often overlook.
Segmentation Dynamics: Technology, Geography, and Application Vectors
Technology Displacement and Portfolio Shifts
The competitive battlefield is defined by the interplay between surface acoustic wave (SAW) dominance and the rising prominence of bulk acoustic wave (BAW) technologies in high-frequency bands. Ceramic and other specialized topologies continue to serve niche but indispensable roles in aerospace and defense applications. Understanding the precise revenue contribution and growth velocity of each technology type is essential for R&D allocation.
Regional Scrutiny and Localization Trends
Global revenue streams are distributed across major economic zones, with North America and Asia Pacific currently commanding significant share, while Europe and Latin America present distinct growth profiles. However, recent years have seen a tactical pivot toward regional supply-chain diversification, particularly in response to trade friction and export control mechanisms. This localization drive is reshaping procurement strategies for multinational OEMs, moving beyond pure cost optimization to ensure compliance and continuity.
Application Diversification Beyond Consumer Electronics
While consumer electronics remains a substantial revenue driver, the telecommunications infrastructure sector leads in terms of volume, fueled by base station deployments and backhaul upgrades. Automotive applications are experiencing a structural inflection point with the integration of advanced driver-assistance systems and in-vehicle connectivity, while aerospace and defense maintain high barriers to entry but offer lucrative, long-cycle contracts. Identifying the precise growth rates within these segments is vital for resource allocation.
Competitive Landscape: Market Concentration and Strategic Positioning
The market exhibits high concentration, with the top three players controlling over 55% of total revenue and the top five capturing approximately 75%. This oligopolistic structure necessitates careful competitor analysis for any firm seeking to gain share or defend position. Key incumbents such as Microchip Technology Inc. leverage comprehensive portfolios spanning aerospace, defense, communications, IoT, and automotive sectors, utilizing both SAW and discrete filter technologies. Microchip's footprint in Chandler, Arizona, underscores a U.S.-based manufacturing presence that aligns with onshoring trends.
In contrast, companies like Spectrum Control in Fairview, Pennsylvania, specialize in highly customizable RF solutions—including bandpass, lowpass, notch, cavity, ceramic, SAW, and glass filter topologies—that address demanding defense, aerospace, medical, and industrial requirements. TEMWELL Corporation, headquartered in Taipei, focuses on custom 5G RF microwave filters using helical, cavity, SMD, and SAW types to serve wireless communications, drones, automotive, aerospace, and military systems, representing the Asia Pacific manufacturing capability. Microwave Filter Company, Inc. (MFC) in East Syracuse leverages decades of heritage since 1967, producing cavity, coaxial, and waveguide filters tailored for satellite communications and defense. Qorvo, Inc., based in Greensboro, North Carolina, provides SAW and BAW filters supporting cellular, GPS, ISM, Bluetooth, and 5G bands, featuring proprietary LowDrift and NoDrift temperature compensation technologies.
Tuning Ingest for Recent Developments
Recent product and portfolio expansions illustrate the pace of innovation. In June 2024, Spectrum Control launched a new high-Q RF filter family utilizing wafer-scale manufacturing on glass substrates for surface-mount applications covering 500 MHz to 10 GHz, addressing the need for miniaturization and performance in next-generation systems. In October 2024, Qorvo expanded its BAW filter portfolio to support global 5G base station deployments, reinforcing the infrastructure boom. These moves signal that incumbents are aggressively capturing the demand wave, and new entrants or investors must anticipate the technical specifications and supply commitments being locked in by these initiatives.
Regulatory and Geopolitical Headwinds: The New Risk Matrix
No strategic assessment of the RF filter market in 2026 is complete without integrating the regulatory and geopolitical environment. In May 2024, the U.S. Department of Commerce revoked the export license under which Qorvo previously sold 4G and certain integrated circuit products to Huawei, marking a pivotal shift in technology transfer controls. This action has reverberated through supply chains, impacting component availability and end-market strategies for players reliant on specific regional demand. Furthermore, the FCC Second Report and Order in October 2025 prohibits authorization of any modular transmitter listed on the Covered List, tightening regulatory oversight on equipment integration and pushing manufacturers toward certified component architectures. The FCC online Table of Frequency Allocations was updated in April 2026, continuously reshaping spectrum management and filter design requirements for international compliance.
Beyond North America, U.S.-China trade tensions have prompted increased localization and supply-chain diversification efforts for RF filter components, compelling both buyers and suppliers to reassess sourcing strategies that were previously optimized solely for efficiency. Geopolitical tensions and export restrictions are also increasing vulnerability to regional trade barriers for critical materials such as gallium nitride (GaN) and ferroelectric compounds used in RF filter production, introducing raw material risk into the cost and availability models. These dynamics are not abstract; they directly influence capital allocation, inventory planning, and partnership ecosystems.
Inside the Market Research: What Decision-Makers Will Gain
This comprehensive study is designed to provide actionable intelligence rather than superficial market summaries. Executive stakeholders will find detailed breakdowns of market sizing across historical and forecast periods, including granular insights into revenue contributions by technology type, geography, and application segment—data that remains shielded here to encourage focused evaluation through our full report. Readers will also gain access to a thorough competitive benchmarking section, profiling major players with headquarters, technological focus areas, and product offerings, alongside an analysis of recent developments that highlight product launches, portfolio expansions, and strategic shifts.
Radio Frequency Filters Market
Radio Frequency Front-end Module Market
The report includes dedicated sections on market dynamics that untangle the impact of regulatory mandates, trade policies, and material supply constraints, providing a risk assessment framework for supply chain resilience. Furthermore, it maps out the concentration metrics and fragmentation trends that inform M&A potential and entry barriers. Professionals can utilize this intelligence to stress-test investment scenarios, benchmark their portfolio against high-growth niches, and align timing for capacity expansion or technology transitions with the 2026–2032 forecast window.
Conclusion: The Strategic Imperative for 2026
As the RF filter market accelerates from $14.19 billion in 2026 toward $32.93 billion by 2032, the window for decisive strategic positioning is open but narrowing. Companies that fail to integrate macro growth signals with granular segmentation intelligence, competitive maneuvers, and regulatory foresight risk misallocating resources in a market where concentration is high and margins are influenced by complex geopolitical variables. Our research equips leaders with the data-backed clarity needed to navigate this inflection point. We invite you to access the full PW Consulting Radio Frequency Filters Market Analysis to uncover the precise numerical insights, regional breakdowns, and application-specific projections that will anchor your 2026 strategy and beyond.
For detailed analysis of this topic, please visit the official page: Radio Frequency Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non-invasive Ventilation Masks Market Hits $215M in 2025, Projected 7.07% CAGR to 2032
By PW Consulting, 2026-09-16
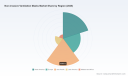
Strategic Imperatives in the Non-invasive Ventilation Masks Market: A 2026 Outlook
The global healthcare landscape is undergoing a profound transformation in respiratory care delivery. As hospitals face mounting pressure to optimize patient outcomes while managing resource constraints, Non-invasive Ventilation (NIV) masks have emerged as a critical interface between patients and life-sustaining therapy. The strategic importance of this market segment cannot be overstated, particularly as we navigate the complex regulatory, clinical, and competitive dynamics of 2026.
Recent market analysis reveals a trajectory of steady expansion that demands attention from executive leadership teams across the medical device ecosystem. The Non-invasive Ventilation Masks Market has demonstrated consistent growth over the historical period from 2020 through 2025, progressing from a valuation of USD 163.15 million to USD 215.0 million by the base year. Looking ahead to the forecast period spanning 2026 through 2032, the market is projected to reach USD 345.24 million, reflecting a compound annual growth rate of 7.07 percent. This sustained upward momentum signals more than mere market expansion—it represents a fundamental shift in how healthcare systems approach respiratory intervention, with significant implications for manufacturers, distributors, and healthcare providers alike.
Understanding the Market Architecture
The structural composition of the NIV masks market reveals distinct segments that each present unique strategic opportunities and challenges. In terms of product typology, the market encompasses nasal masks, full face masks, and total face masks, with each category serving specific clinical requirements and patient comfort parameters. The full face mask segment, including innovations such as bridge-free designs and vented/non-vented options compatible with both single-limb and dual-limb circuits, has garnered particular attention from manufacturers seeking to differentiate their portfolios through enhanced clinical efficacy and user experience.
Application-wise, the market addresses critical therapeutic areas including sleep apnea, chronic obstructive pulmonary disease, and acute respiratory distress syndrome. Each application domain carries distinct clinical priorities, reimbursement considerations, and adoption timelines that shape the competitive landscape. The sleep apnea segment represents a substantial portion of market activity, driven by growing awareness of sleep-disordered breathing and the expanding role of non-invasive ventilation in both home and hospital settings. Meanwhile, the chronic obstructive pulmonary disease and acute respiratory distress syndrome segments reflect the increasing integration of NIV therapy into acute care protocols and long-term respiratory management strategies.
Geographic distribution adds another layer of complexity to market analysis. The North American region has established a significant presence, supported by mature healthcare infrastructure and favorable reimbursement frameworks. European markets continue to demonstrate steady demand, while the Asia Pacific region represents a particularly dynamic growth arena characterized by expanding healthcare access, rising chronic disease prevalence, and increasing adoption of advanced respiratory technologies. Latin America and the Middle East and Africa markets, though currently smaller in scale, present emerging opportunities for organizations with the right strategic positioning and regional expertise.
Navigating Regulatory and Reimbursement Dynamics
The operational environment for NIV mask manufacturers and suppliers in 2026 is defined by an evolving regulatory framework and shifting reimbursement policies that directly impact market access and commercial viability. In the United States, the Centers for Medicare and Medicaid Services has taken notable steps to clarify coverage parameters for non-invasive interfaces. Under the June 2025 CMS policy, masks for home mechanical ventilators are covered when used for more than eight hours in any twenty-four-hour period in volume-targeted mode, or at night with an oronasal mask. Furthermore, the Medicare National Coverage Determination published on June 9, 2025, explicitly covers home respiratory assist devices and home mechanical ventilators with non-invasive interfaces for COPD patients, with NIV masks now included as eligible non-invasive interfaces for respiratory assist devices and home mechanical ventilators in home settings for chronic respiratory failure.
On the regulatory compliance front, single-patient use NIV masks must satisfy a rigorous set of requirements. Manufacturers are expected to secure FDA 510(k) clearance, achieve CE marking under the EU Medical Device Regulation, comply with ISO 10993 biocompatibility standards, and meet applicable sterilization requirements. These compliance obligations create both barriers to entry and competitive moats for established players with the resources and expertise to navigate complex regulatory pathways efficiently.
These dynamics have direct implications for product development roadmaps, go-to-market strategies, and partnership decisions. Organizations that proactively align their innovation pipelines with regulatory expectations and reimbursement realities will be better positioned to capture market share as the policy environment continues to mature.
Competitive Landscape and Innovation Trajectories
The competitive landscape in the NIV masks market is characterized by a mix of global medtech leaders, specialized respiratory care companies, and emerging innovators from diverse geographic markets. The market concentration metrics indicate a moderately fragmented environment, with the top three players accounting for approximately 24.6 percent of market revenue and the top five representing around 26.2 percent. This structure suggests that while scale players hold meaningful positions, there remains substantial room for differentiation, niche leadership, and technology-driven disruption.
Non-invasive Ventilation Masks Market
Fisher & Paykel Healthcare, headquartered in New Zealand, has established a prominent position through its focused portfolio of NIV mask solutions. The company's F&P Visairo bridge-free full face mask and F&P Nivairo full face mask, available in both vented and non-vented configurations and compatible with single- and dual-limb circuits, reflect a deliberate emphasis on clinical versatility and patient comfort. In September 2025, Fisher & Paykel Healthcare received FDA 510(k) clearance for its OptiNIV Vented Full Face Masks in sizes A through C, featuring an optional expiratory filter and compatibility with single-limb circuits for hospital NIV applications. Earlier that year, in February 2025, the company also secured FDA clearance for the Mariana Minerva and Mariana Nimbus ventilators, which provide non-invasive ventilation support for patients above 13 kilograms. These regulatory milestones underscore the company's commitment to expanding its respiratory care ecosystem through iterative innovation and strategic regulatory engagement.
ResMed, based in the United States, continues to leverage its strong brand recognition and clinical reputation in the respiratory device space. Its AirFit F20 NV non-vented full face mask, designed specifically for NIV therapy, exemplifies the company's focus on delivering reliable, clinically validated solutions for hospital and home care environments. In January 2026, REMSleep—a related entity within the ResMed ecosystem—submitted a supplemental 510(k) to the FDA to expand the DeltaWave CPAP mask indications for use with BiPAP and other positive pressure ventilation devices, as well as for institutional single-patient hospital use. This move signals a strategic push to broaden the therapeutic applications of existing mask platforms and strengthen the company's footprint in the NIV mask segment.
Philips, also headquartered in the United States, offers the AF541 NIV mask for hospital NIV applications, featuring interchangeable under-the-nose and over-the-nose options that provide clinicians with flexibility in fitting and therapy delivery. The company's broader ventilation portfolio and global distribution capabilities position it as a significant contender in the market, particularly in scenarios where integrated device ecosystems and multi-product account relationships are valued by procurement decision-makers.
Sleepnet Corporation and Intersurgical, operating from the United States and the United Kingdom respectively, collaborate on the VariFit NIV mask platform, which is available in both non-vented and vented configurations and incorporates AIR gel cushion technology for single-patient hospital use. This partnership model highlights how strategic alliances can accelerate product development, expand geographic reach, and combine complementary manufacturing and commercial capabilities.
Worldwide Non-invasive Ventilation (NIV) Masks Market
Additional players such as ApneaSeal in Australia and Inspirate in Singapore are exploring the custom NIV mask segment, addressing the clinical need for personalized fitting solutions that can improve seal integrity, patient compliance, and therapeutic outcomes. GaleMed Corporation, based in China, provides a broad range of NIV masks for non-invasive ventilation therapy, reflecting the growing presence of manufacturers from the Asia Pacific region in the global respiratory device market.
Strategic Considerations for Executive Decision-Makers
As organizations evaluate their positioning for the 2026 to 2032 forecast period, several strategic priorities merit careful consideration. First, the integration of regulatory intelligence into product planning cycles is no longer optional. The convergence of FDA clearance requirements, EU MDR compliance, biocompatibility standards, and evolving sterilization expectations demands a proactive compliance infrastructure that can anticipate changes and adapt product portfolios accordingly. Second, reimbursement dynamics will continue to shape demand patterns, particularly in home care segments where coverage policies directly influence patient access and purchase volumes. Organizations that develop deep expertise in reimbursement navigation and actively engage with payer stakeholders will gain a competitive advantage in markets where coverage uncertainty persists.
Third, the competitive environment rewards companies that can articulate clear clinical differentiation. Whether through bridge-free mask designs, advanced cushion technologies, customizable fitting options, or compatibility across diverse ventilator circuits, the ability to demonstrate measurable improvements in patient outcomes, caregiver efficiency, or total cost of care will be essential in securing formulary placements, hospital procurement approvals, and diagnostic channel partnerships. Fourth, geographic expansion strategies must be tailored to regional market characteristics, including regulatory maturity, reimbursement infrastructure, distribution channel dynamics, and local competitive intensity. A one-size-fits-all approach to international growth is unlikely to yield optimal returns in a market as heterogeneous as the NIV masks segment.
Finally, the moderate market concentration observed in the current landscape suggests that consolidation, strategic partnerships, and technology licensing agreements may reshape the competitive structure over the forecast period. Organizations should assess their M&A readiness, evaluate potential collaboration opportunities with complementary technology providers, and consider how emerging innovators might disrupt established value chains through novel approaches to mask design, material science, or digital integration.
Why Comprehensive Market Intelligence Matters
The executive decisions required to capture value in the Non-invasive Ventilation Masks Market extend far beyond high-level market sizing and headline growth rates. Successful strategic planning demands granular insights into segment-specific demand drivers, competitive positioning metrics, pricing and reimbursement trends, regulatory pathway nuances, and emerging technology adjacencies that could reshape the market over the next several years. It requires a detailed understanding of how leading manufacturers are structuring their product portfolios, which clinical indications are gaining traction in different care settings, and how procurement dynamics vary across hospital, home care, and sleep clinic channels.
The full market research report provides a comprehensive, data-driven analysis that goes well beyond the macro-level overview presented here. It delivers detailed segmentation analysis, forward-looking forecasts across multiple dimensions, in-depth company profiles that map strategic positioning and recent product and regulatory developments, and a thorough examination of the regulatory and reimbursement frameworks that will govern market access through 2032. The report also includes actionable recommendations for market entry, portfolio optimization, partnership strategy, and competitive response in an environment where technological innovation and regulatory agility are increasingly decisive factors.
For organizations seeking to make informed, confident decisions in the Non-invasive Ventilation Masks Market, the depth and granularity of available intelligence can be the difference between reactive positioning and proactive market leadership. Access the complete research to explore the full scope of market dynamics, competitive insights, and strategic pathways that will define respiratory care innovation in the years ahead.
For detailed analysis of this topic, please visit the official page: Non-invasive Ventilation Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Signage Market Hits $31.09B in 2025, Projected to Reach $53.98B by 2032 at 8.2% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the 2026 Digital Signage Landscape: Why This Market Report Matters
The digital signage market has crossed a critical inflection point. Between 2020 and 2025, global revenues scaled from 18.0 billion USD to 31.09 billion USD, marking a compound trajectory that reflects both post-pandemic recovery and the accelerating digitization of physical spaces. As enterprises map out their capital allocation and technology roadmaps for the 2026 to 2032 forecast period, understanding the underlying mechanics of this expansion is no longer optional. This market research report dissects the structural forces, competitive maneuvers, and regulatory shifts that will define portfolio decisions, vendor partnerships, and deployment strategies for the next seven years. Written to function as a decision-support instrument rather than a superficial market overview, the analysis is engineered to help leadership teams separate durable trends from short-lived hype.
Digital Signage Market
Market Architecture: Growth Patterns and Structural Edges
The headline trajectory is compelling, but the strategic value lies in the distribution of growth across the forecast horizon. Following a base year valuation of 32.82 billion USD in 2026, the market is projected to compound at an annualized rate of 8.2 percent, reaching 53.98 billion USD by 2032. This pace indicates that the sector is moving beyond early-adopter saturation into a phase where enterprise-grade reliability, content orchestration, and network scalability become the primary differentiators. The report frames this expansion through multiple analytical lenses, including hardware versus software mix shifts, deployment latency across commercial verticals, and the growing influence of infrastructure economics on total cost of ownership.
A deliberate omission of granular regional or application-level splits in this overview is intentional. Those splits are where procurement strategies, localization constraints, and channel dynamics create asymmetric opportunities. The full report isolates high-velocity pockets and slow-growth zones so that readers can align budget cycles, pilot programs, and channel partnerships with markets that match their risk tolerance and execution capacity. Rather than treating the market as a monolith, the study decomposes it into actionable layers that reveal where vendors are consolidating share, where pricing pressure is emerging, and where new entrants can still compete on differentiation instead of scale.
Competitive Arena: How Differentiated Capabilities Are Reshaping the Field
The competitive landscape is defined by a concentration ratio that leaves substantial room for specialization. With the top three players holding approximately 25 percent of market revenue and the top five controlling roughly 30 percent, the ecosystem remains broadly contested, allowing firms with focused value propositions to carve out defensible positions. The report profiles ten core companies whose strategic postures illustrate the range of approaches currently shaping buyer expectations and deployment models.
BrightSign continues to anchor its position through an end-to-end architecture centered on proprietary BrightSignOS players, integrated network management, and cloud services tailored for commercial and professional AV applications. Daktronics leverages its heritage in LED and LCD displays, networked public signage, and transportation-focused deployments to address environments where durability and visibility are non-negotiable. Scala has built its reputation on a scalable enterprise software platform that unifies content management with commerce integrations, a positioning that has only grown more relevant as signage networks are asked to perform as revenue-facing touchpoints rather than pure out-of-home displays.
Omnivex Corporation remains distinctive for software that manages and presents real-time information across signage networks in corporate and organizational settings, an approach that emphasizes operational messaging and data-driven scenario handling. Cisco Systems brings networking infrastructure, software-defined solutions, and integration expertise to the category, enabling deployments where connectivity, security, and room-level orchestration determine success. Samsung Electronics contributes commercial displays, spatial signage, and smart ecosystems aimed at retail and public applications, while LG Electronics extends the field with LED, OLED, and indoor/outdoor signage solutions that pair visual quality with Google Cast integration for hospitality and commercial environments.
Panasonic Corporation and Sony Corporation reinforce the professional display tier with signage technologies designed for demanding commercial and public spaces, and NEC Display Solutions rounds out the competitive set with display and signage solutions for enterprise and public applications. The report does not simply catalog product portfolios. It evaluates how each player is positioning against the same procurement requirements, where their roadmaps converge or diverge, and what their recent moves signal about the coming wave of buyer expectations.
2026 Signals: Recent Moves That Hint at the Next Cycle
Recent developments in early 2026 already illustrate the kind of capability escalation that buyers should track before committing to multi-year deployments. In January, BrightSign launched an enhanced BrightSign Control Plus device management solution ahead of InfoComm 2026, extending premium-tier remote management for its signage players and reinforcing the industry tilt toward centralized control and reduced field maintenance overhead. In February, Cisco Systems enabled digital signage functionality on Room Schedulers for Board, Desk, and Room Series devices, supporting non-booking activation and integration with Microsoft Teams Panel modes, a move that expands the addressable surface for signage within collaborative workplace environments.
In April, Scala announced a major release of its core digital signage platform, Scala Enterprise v13.60, enhancing capabilities for content management and enterprise deployments, while Daktronics introduced the Fuelight 5000 fuel price display product at its Sales Expo 2026 alongside product showcases for Galaxy LED signs and LCD networks. These releases are not isolated product updates. They reflect a broader pattern in which software manageability, real-time data integration, and vertical-specific hardware variants are becoming the levers that separate commodity deployments from sticky, long-term contracts. The full report maps each development to its likely impact on procurement cycles, integration requirements, and competitive displacement risk.
Digital Signage Design Services Market
Industry Dynamics: The External Pressures That Will Shape Deployment Economics
Market growth does not happen in a vacuum. Several external conditions are actively reshaping the cost base and compliance environment for digital signage networks. One of the most immediate pressures comes from infrastructure expense. Deployment costs for fiber-optic broadband infrastructure have increased by more than ten percent, with materials and labor driving the increase. Because digital signage performance, latency, and reliability are tightly coupled to network quality, this dynamic has direct implications for site readiness, rollout pacing, and total project economics. The report examines how procurement teams can anticipate these cost curves and adjust deployment sequencing accordingly.
Regulatory and tariff developments add another layer of uncertainty. A February 2026 U.S. Supreme Court ruling invalidated prior IEEPA-based tariffs, resulting in new ten percent global tariffs that affect digital signage hardware imports and deployments. For organizations planning international sourcing, multi-region rollouts, or long-lead hardware procurement, this shift alters landed-cost assumptions and inventory strategies. At the same time, the FDA updated guidance in 2026 to loosen regulatory requirements for certain digital health tools, expanding exemption scopes for low-risk digital signage applications in healthcare settings. This change opens the door to broader use of signage in clinical communication and patient-facing environments, but it also introduces new expectations around content governance and compliance documentation.
Broader infrastructure funding dynamics are also influencing the installation environment. FCC compliance requirements for digital infrastructure, including broadband equity funding under the IIJA, have driven state-level investments exceeding 628 million dollars in Montana alone for network deployments. While this figure reflects a single state, it illustrates the scale of public-sector network activity that can affect site availability, connectivity readiness, and the competitive landscape for commercial signage integrators. The study translates these moving parts into a structured view of risk and opportunity so that decision-makers can model scenarios rather than react after the fact.
What the Report Delivers: A Practical Toolkit for 2026 Decision-Making
This research is designed to support concrete planning rather than abstract observation. The full study combines quantitative forecasting with qualitative assessment of vendor strategy, buyer behavior, and operational constraints. It provides a structured basis for evaluating where digital signage investments can improve customer engagement, streamline communications, and support revenue-facing touchpoints, while also highlighting the operational realities that determine whether deployments scale cleanly or stall in pilot mode.
Readers will find detailed attention to segmentation dynamics, competitive positioning, and deployment feasibility across commercial environments. The analysis is built to answer the questions that typically surface during budget reviews and technology selection: which capability areas are becoming table stakes, which segments are likely to see the most intense pricing or differentiation pressure, and which external factors should be incorporated into risk-adjusted planning. The report also connects market evolution to vendor roadmaps, recent product releases, and regulatory developments so that leaders can assess not only what the market will look like, but what will be required to compete effectively within it.
To preserve analytical precision without overloading this introduction, the overview intentionally refrains from publishing the full set of regional and application-level figures. Those details are central to the report's differentiation because they expose where concentration is greatest, where growth is most defensible, and where specific buyer profiles are likely to dictate procurement terms. The complete intelligence is available on the source page, where the full segmentation analysis, competitive benchmarking, and scenario modeling can be reviewed in context.
Why This Matters for Executive Planning in 2026
The strategic imperative for 2026 is not simply to recognize that digital signage continues to expand. It is to understand how the market's composition, competitive intensity, and external cost environment are changing the terms of participation. The forecast period through 2032 suggests a market large enough to reward disciplined positioning, but only if organizations can align technology selection, deployment economics, and compliance awareness with the realities on the ground.
This report provides the framework to do that with greater confidence. It connects macro growth to the operational details that actually determine outcomes: hardware ecosystem choices, software manageability, network readiness, vendor differentiation, and regulatory exposure. For executives evaluating capital allocation, channel strategy, or product integration roadmaps, the research is structured to reduce uncertainty and support defensible decisions. The complete market intelligence, including segmented forecasts and embedded competitor analysis, is available on the source page for teams that want to move from high-level awareness to actionable planning.
For detailed analysis of this topic, please visit the official page: Digital Signage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Adiabatic Coolers Market to Hit $872M by 2032, 7% CAGR (2026-2032)
By PW Consulting, 2026-09-16
Navigating the Adiabatic Coolers Market: Strategic Intelligence for 2026 and Beyond
The global industrial and commercial cooling landscape is undergoing a fundamental shift. As energy costs rise and environmental regulations tighten, organizations are increasingly turning to adiabatic cooling technologies to balance thermal management requirements with sustainability mandates. PW Consulting's latest market research on the Adiabatic Coolers Market provides a comprehensive strategic roadmap for decision-makers navigating this evolving sector. This analysis synthesizes historical performance data, forward-looking projections, and competitive dynamics to equip stakeholders with actionable intelligence for the 2026-2032 forecast period.
Understanding the trajectory of this market requires more than surface-level observations. The transition from traditional evaporative systems to adiabatic solutions represents a structural change in how industries approach heat rejection, water conservation, and energy efficiency. Our research delves into the underlying drivers, constraints, and opportunities that will define competitive positioning over the next several years.
Market Trajectory and Growth Dynamics
The adiabatic coolers market has demonstrated consistent expansion over the past half-decade, reflecting broader trends in industrial automation, data center proliferation, and commercial building optimization. Historical analysis from 2020 through 2025 reveals a market that has matured significantly, with revenue scaling from approximately 385 million USD to 542 million USD. This growth trajectory underscores the accelerating adoption of water-saving cooling technologies across multiple sectors.
Looking forward, our forecasts indicate sustained momentum through 2032. The market is projected to reach 595.48 million USD in 2026, continuing its upward path to approximately 872.0 million USD by the end of the forecast horizon. This progression reflects a compound annual growth rate of 7.0 percent, signaling robust demand underpinned by technological advancements and regulatory tailwinds. However, growth is not uniform across all segments or regions, and strategic allocation of resources requires nuanced understanding of where value is being created.
Several macroeconomic and operational factors are converging to accelerate this expansion:
- Rising energy prices are driving facility managers to prioritize systems that reduce electrical consumption while maintaining cooling capacity
- Water scarcity concerns in key industrial regions are making low-water-use cooling solutions increasingly attractive compared to conventional evaporative alternatives
- Environmental regulations, including California's Title 24 requirements for CO2 CDUs in supermarket systems effective 2026, are introducing compliance considerations that influence equipment selection and system design
- The Cooling Technology Institute's development of thermal performance certification programs for adiabatic fluid coolers, anticipated to launch under CTI Standard 201, is expected to enhance transparency and standardization in performance claims
Competitive Landscape and Key Players
The adiabatic coolers market exhibits notable concentration, with the top three firms capturing approximately 65 percent of total revenue and the top five accounting for roughly 75 percent. This consolidated structure suggests mature competitive dynamics where scale, technological differentiation, and regional presence play critical roles in market share retention. Our research provides detailed profiling of the companies shaping this landscape, examining their product portfolios, strategic positioning, and recent developments.
In the United States, several established players continue to drive innovation in adiabatic cooling solutions. SPX Cooling Technologies, headquartered in Overland Park, Kansas, offers the Marley and Recold Adiabatic Series, which combines water-saving benefits with energy efficiency for commercial and industrial refrigeration applications. Baltimore Aircoil Company, based in Jessup, Maryland, has gained attention for its TrilliumSeries Adiabatic Cooler and hybrid systems designed for efficient cooling with reduced water and energy consumption. EVAPCO, also located in Baltimore, Maryland, has expanded its eco-Air Series with the Titan, recognized as the largest adiabatic cooler in its lineup, featuring pumpless recirculation and pre-cooling capabilities for process cooling applications.
European manufacturers are equally active in advancing adiabatic cooling technology. MITA Cooling Technologies, based in Italy, provides adiabatic dry coolers with pre-cooling systems tailored for industrial HVAC and energy-efficient operation across Europe and the Americas. Kelvion, headquartered in Germany, offers adiabatic condensers and dry coolers utilizing spray or pad systems capable of achieving 10°C air cooling. Torraval Cooling, from Spain, focuses on compact adiabatic coolers and subcooler series designed to deliver quick return on investment for refrigeration applications. Frigel, based in Florence, Italy, specializes in intelligent process cooling equipment, including adiabatic systems for plastics and broader industrial applications. GEA Group, located in Düsseldorf, Germany, provides process cooling systems with adiabatic solutions for food processing and industrial heat rejection.
Alfa Laval, headquartered in Lund, Sweden, rounds out the competitive field with its Abatigo Adiabatic Liquid Coolers, which incorporate patented pre-cooling sections suitable for data centers and industrial use. These companies represent the vanguard of adiabatic cooling innovation, and our report includes in-depth assessments of their strategic moves, product launches, and market activities.
Recent developments highlight the pace of innovation in this sector. EVAPCO released the Titan in September 2025 as the largest adiabatic cooler in its eco-Air Series, signaling continued investment in scaling capacity for demanding applications. Baltimore Aircoil Company demonstrated its TrilliumSeries Adiabatic Cooler at the 2025 AHR Expo, reinforcing its commitment to showcasing hybrid cooling solutions at major industry events. Meanwhile, the Cooling Technology Institute has been developing a thermal performance certification program for adiabatic fluid coolers, with anticipated launch in the first half of 2025 under CTI Standard 201, covering forced and induced draft adiabatic fluid coolers for water or aqueous glycol solutions. These milestones illustrate the dynamic nature of the market and the importance of staying informed about product evolution and standardization efforts.
Segmentation Insights and Application Trends
The adiabatic coolers market spans multiple technology types and application verticals, each with distinct growth drivers and adoption patterns. Our research segments the market by type, application, and region to provide a granular view of where demand is concentrated and how it is evolving.
Worldwide Adiabatic Demagnetization Refrigerators (ADR) Market
By technology type, the market includes dry air coolers and liquid coolers, both of which serve critical roles in industrial and commercial cooling architectures. Dry air coolers have gained prominence in applications where water conservation is a priority, while liquid coolers remain essential for processes requiring precise temperature control and high thermal capacity. The segmentation analysis reveals how these technologies are being deployed across different end-use scenarios and what factors influence procurement decisions.
In terms of application, industrial and commercial sectors represent the primary demand drivers. Industrial applications, encompassing process cooling, manufacturing heat rejection, and large-scale facility management, account for the dominant share of market revenue. Commercial applications, including data centers, commercial buildings, and retail refrigeration systems, are expanding as organizations seek to comply with energy codes and reduce operating expenses. The interplay between these application segments and regional deployment patterns provides valuable context for market entry strategies and product positioning.
Regional dynamics further shape the competitive environment. North America and Europe represent mature markets with established infrastructure and regulatory frameworks that favor energy-efficient cooling solutions. Asia Pacific, Latin America, and the Middle East and Africa present emerging opportunities where industrialization, data center growth, and climate conditions are driving demand for advanced cooling technologies. Our report examines these regional variations in detail, identifying where growth is accelerating and what barriers exist to adoption.
Strategic Value for 2026 Decision-Making
In an environment characterized by rapid technological change, regulatory uncertainty, and intensifying competition, access to reliable market intelligence is not a luxury—it is a strategic necessity. PW Consulting's Adiabatic Coolers Market report is designed to support decision-makers across multiple functions, from product development and investment planning to competitive positioning and risk assessment.
For executives evaluating market entry or expansion opportunities, the report provides a foundational understanding of market size, growth trajectories, and segmentation dynamics. This macro-level perspective enables informed resource allocation and helps identify the most promising avenues for investment. For product managers and engineering teams, detailed technology assessments and competitive benchmarking offer insights into feature differentiation, performance standards, and emerging customer requirements. Procurement and supply chain leaders can leverage the analysis to anticipate price trends, evaluate supplier landscapes, and mitigate risks associated with raw material costs and component availability.
The report also addresses the regulatory and compliance dimensions that are increasingly shaping purchasing decisions. With standards such as CTI Standard 201 gaining prominence and regional requirements like California's Title 24 imposing new constraints on adiabatic gas coolers in supermarket systems, organizations must navigate a complex compliance landscape. Our research synthesizes these regulatory developments and their implications for product design, system integration, and market access.
Key areas where this research delivers strategic value include:
- Identifying high-growth segments and regions where competitive intensity is still developing, enabling first-mover advantages
- Understanding the technological differentiators that matter most to customers, from pre-cooling capabilities to material specifications such as 304L stainless steel tubing and aluminum fins
- Assessing the impact of water-use considerations on equipment selection, as adiabatic models use water only when ambient conditions and load require it, offering flexibility in operating modes for utility savings
- Evaluating the competitive positioning of key players based on their product portfolios, geographic reach, and recent strategic initiatives
- Anticipating the effects of certification programs and regulatory changes on market dynamics and compliance costs
Why This Research Matters Now
The adiabatic coolers market is at an inflection point. Technological improvements, regulatory shifts, and evolving customer expectations are converging to create both opportunities and challenges for market participants. Organizations that proactively understand these dynamics will be better positioned to capitalize on growth, manage risks, and build sustainable competitive advantages.
Adiabatic Coolers Market
Our report goes beyond high-level summaries to deliver the depth and granularity required for confident decision-making. It integrates historical data, current market conditions, and forward-looking projections into a cohesive analytical framework. By examining the strategies of leading companies, the evolution of technology types, and the forces shaping regional demand, the research provides a comprehensive view of the market ecosystem.
Stakeholders who rely on fragmented information or outdated assumptions risk misallocating resources, missing emerging opportunities, or underestimating competitive threats. PW Consulting's market research equips organizations with the intelligence needed to make informed choices about product development, market expansion, partnership strategies, and investment priorities.
Accessing the Full Intelligence Package
This article provides a strategic overview of the adiabatic coolers market and highlights the core themes explored in our comprehensive research report. However, the full depth of our analysis—including detailed segmentation data, regional breakdowns, competitive assessments, and methodological rigor—requires access to the complete publication. The nuanced insights that drive strategic decisions are embedded throughout the report, and we encourage stakeholders to obtain the full document to ensure they have the most complete picture of market dynamics.
As the adiabatic cooling sector continues to evolve, staying ahead of trends and understanding the competitive landscape will be essential for sustained success. PW Consulting is committed to delivering market intelligence that meets the highest standards of accuracy, relevance, and actionable value. For organizations seeking to navigate the complexities of the 2026-2032 period with confidence, our adiabatic coolers market research offers the foundation for informed, strategic action.
For detailed analysis of this topic, please visit the official page: Adiabatic Coolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Precision Industries Forecasts Cold Heading Machine Market to Hit $4.69B by 2032 With 4.01% CAGR
By PW Consulting, 2026-09-16
Navigating the Cold Heading Machine Market: Strategic Intelligence for 2026 and Beyond
The cold heading machine market stands at a critical inflection point. As manufacturing precision demands escalate and fastener production scales to meet complex industrial needs, decision-makers require more than surface-level forecasts. They need actionable intelligence that connects machine specifications, regional supply chains, application-specific demand drivers, and competitive positioning into a coherent strategic narrative. This introduction frames the Cold Heading Machine Market research report by PW Consulting, a comprehensive study designed to equip C-suite executives, procurement leaders, and strategic planners with the clarity needed for 2026 decision-making and multi-year investment planning.
Why This Research Matters Now
Cold heading remains one of the most efficient manufacturing processes for producing high-volume fasteners, pins, and precision components. The ability to form metal at or near room temperature—without the thermal degradation risks of hot working—offers distinct advantages in dimensional accuracy, material grain structure, and production economics. Yet the machines that execute these processes are evolving rapidly. Multi-die configurations, advanced automation integration, and tighter tolerance capabilities are reshaping procurement criteria across automotive, electronics, industrial equipment, and aerospace supply chains.
Our study delivers a rigorous, data-grounded assessment of the market across a structured historical window and a forward-looking forecast horizon. The analysis spans from 2020 through 2025, capturing the market's recent trajectory, and extends through 2032 to illuminate long-term demand pathways. For 2026 strategists, this temporal range is invaluable: it isolates the post-2025 recovery signals, quantifies the direction and pace of growth, and exposes the structural shifts that will define competitive advantage in the years ahead.
The market measured in this report is expressed in Million USD. From a 2025 base year assessment of 2,923.01 Million USD, the forecast period projects a market that advances to approximately 3,709.16 Million USD in 2026, climbs steadily through the late 2020s, and reaches 4,685.24 Million USD by 2032. The overall compound annual growth rate across the 2026–2032 forecast window registers at 4.01 percent. These macro figures anchor the study, but they are only the starting point. The real strategic value lies in how this growth decomposes across machine types, end-use applications, and geographic corridors—and in the operational insights the report surfaces beneath the headline numbers.
Report Architecture: What Decision-Makers Will Find Inside
This study is structured for immediate practical use. Rather than presenting a static collection of charts, the research is organized around the strategic questions that procurement directors, plant managers, and market entry strategists face when evaluating cold heading equipment investments.
Market Sizing and Historical Trajectory
The report reconstructs the market's behavior from 2020 through 2025, a period marked by shifting production priorities, supply chain adjustments, and variability in capital expenditure cycles. By tracing the path from 3,558.00 Million USD in 2020 through to the 2025 base year assessment, the study identifies the inflection points that shaped buyer behavior and supplier responses. Readers will gain a clear picture of how demand fluctuated, where resilience emerged, and which segments absorbed capacity during softer periods.
Forecast Framework and Growth Drivers
Beyond 2025, the analysis projects a market that regains momentum and expands at a measured, sustained pace. The forecast portion of the report links this trajectory to concrete demand catalysts: fastener volume requirements tied to vehicle electrification and lightweighting, electronics miniaturization driving precision component needs, industrial equipment refurbishments and expansions, and aerospace program ramp-ups. Each driver is mapped to the machine categories and regional demand pools it influences, giving strategists a framework for scenario planning rather than a single-point prediction.
For those evaluating capacity additions, replacement cycles, or technology upgrades, the forecast window through 2032 provides a multi-year canvas. The progression from the 2026 baseline toward the 2032 endpoint reveals where growth concentrates, which years carry the steepest incremental demand, and how the market's composition is expected to evolve. This temporal granularity is essential for aligning procurement lead times, capital budgeting cycles, and production planning with market realities.
Segmentation for Targeted Strategy
One of the study's core strengths is its segmentation architecture. Market demand is analyzed across machine type, end-use application, and geographic region, enabling readers to isolate the pockets of opportunity most relevant to their strategic posture. Whether a company focuses on single-die precision lines or multi-die high-throughput systems, whether its customer base skews toward automotive components, electronics, industrial equipment, or aerospace, and whether it targets mature production hubs or emerging manufacturing corridors, the segmentation layer provides the lens needed to prioritize resources and tailor value propositions.
Importantly, the report avoids the reductive approach of presenting isolated regional or application shares without context. Instead, it situates each segment within the broader demand ecosystem, explaining how subsegments interact, where substitution dynamics occur, and which structural factors will accelerate or temper growth in specific pockets of the market over the forecast period.
Competitive Intelligence and Firm-Level Insights
Market growth is meaningless without understanding who captures it. The competitive landscape section profiles the leading entities shaping the cold heading machine sector, offering readers a grounded view of supplier capabilities, geographic footprints, and market positioning. The study examines established manufacturers and specialized suppliers that collectively define the industry's current architecture, including National Machinery LLC, headquartered in Tiffin, Ohio, recognized globally for advanced cold and warm forming machinery, process technology, and customer support for precision cold forming solutions; Hariton Machinery Company, Inc., based in New York, which supplies new and used cold header machines, multi-station headers, and related cold heading equipment; SACMA Group of Limbiate, Italy, known for cold heading machines including the KSP series headers for fastener production; Chun Yu Group, operating through Chun Zu Machinery Industry Co. Ltd in China, producing cold heading machines and forming equipment for the fastener industry; GFM GmbH Steyr of Steyr, Austria, supplying high-performance cold heading machines and forming systems; Hatebur Umformmaschinen AG of Grenchen, Switzerland, a manufacturer of precision cold heading and forming machines; Asahi Sunac Corporation of Japan, providing cold heading machine solutions for fastener and precision parts production; Wrentham Tool Group LLC of Massachusetts, specializing in cold heading tools and equipment for machine manufacturers; Sakamura USA Inc., a U.S.-based distributor and provider of Sakamura cold heading machines; and HUBEI TRI-RING METALFORMING EQUIPMENT CO. of China, manufacturing metalforming and cold heading equipment.
Beyond firm profiles, the report examines recent market activity that signals evolving competitive intensity. For example, Krevere's participation in the International Fastener Show IFS 2026 in Shanghai, where it showcased cold heading machines including the KRBF-64S model, illustrates the ongoing product introductions and trade presence that keep the competitive environment in motion. Such developments matter for procurement teams tracking supplier innovation cycles and for strategists assessing which players are actively expanding their visibility in key regional venues.
Market Dynamics: Structural Forces Shaping the Landscape
Understanding where the market is going requires grasping the forces that constrain and accelerate it. The report disentangles these dynamics into several interconnected themes.
Cost Efficiency, Precision, and Process Evolution
Cold heading's enduring appeal rests on its ability to deliver high-volume output with tight tolerances and favorable material utilization. As downstream industries push for lighter components, higher strength-to-weight ratios, and greater consistency in fastener performance, machine builders have responded with designs that improve strike accuracy, reduce secondary operations, and integrate process monitoring. The study examines how these technological and process trends are translating into buyer preferences, what trade-offs exist between single-die and multi-die configurations in different production contexts, and where automation and tooling advancements are reshaping total cost of ownership calculations.
Cold Forging Machine Market
Regional Manufacturing Footprints and Demand Geography
The market does not grow uniformly across the globe. Production capacity, fastener consumption patterns, and industrial policy environments differ markedly by region, and these differences shape both demand and competitive entry strategies. The research maps how demand pools align with regional manufacturing strength and where export-oriented equipment flows intersect with local production needs. For organizations evaluating market entry, supplier localization, or regional capacity deployment, this geographic lens is essential for avoiding misallocated investment and for identifying where near-term volume and long-term structural demand diverge.
Cold Heading Machine Market
The study covers the full regional spectrum, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, situating each within the broader demand architecture rather than treating them as isolated silos. Readers will understand not just which regions carry significant volume, but how regional dynamics—industrial base maturity, trade flows, and application mix—interact with machine type and end-use segmentation to create distinct strategic environments.
Standards, Safety, and Compliance as Operating Parameters
Machinery procurement and deployment do not occur in a regulatory vacuum. The report integrates the standards and safety frameworks that shape equipment specification, installation, and operation. ISO 4954-1:2024 specifies requirements for non-alloy and alloy steels intended for cold heading and cold extruding delivered as wire rods and wire, establishing a material-grade reference that ties directly to cold heading process performance. EN 10263:2017 serves as the standard reference for cold heading steel wire grades, including boron-alloyed and alloyed steels, further anchoring material selection to machine capability and output quality. On the safety side, the U.S. Occupational Safety and Health Administration enforces ANSI B11.7-2020 safety requirements for cold headers and cold formers, a framework that remains active and relevant for operators and equipment purchasers alike.
These standards are not peripheral details; they influence machine design expectations, supplier qualification, operator training, and the risk profile of capacity investments. By incorporating this compliance layer, the report equips readers to assess supplier offerings and project requirements with a fuller understanding of the operational environment in which cold heading equipment must perform.
Competitive Concentration and Market Structure
The distribution of market share among leading participants provides a window into the industry's competitive architecture. The study notes that the top three firms collectively account for approximately twenty-five percent of market revenue, while the top five reach roughly thirty percent. This concentration profile suggests a market where scale advantages, technological differentiation, and regional reach matter, but where meaningful headcount of specialized suppliers also persists. For strategists, this balance between concentration and fragmentation has implications for supplier negotiation leverage, partnership selection, and the feasibility of displacing incumbents in targeted segments.
The report examines how this structure is likely to evolve as growth accelerates through the forecast period, where consolidation pressure may intensify, and which types of firms—broad-line manufacturers, application specialists, or regionally anchored suppliers—are best positioned to capture incremental share. Rather than offering a static snapshot, the analysis connects concentration data to the strategic behaviors that will shape competitive outcomes over time.
Translating Insights into 2026 Action
Strategic reports derive their value from how they inform decisions. This study is built with that principle at its core. Across procurement, capacity planning, competitive positioning, and market entry, the research provides a framework for converting market intelligence into concrete action.
For procurement teams, the segmentation and competitive analysis clarify which machine types align with specific application requirements and which suppliers offer credible capability in those niches. The standards and safety context supports more rigorous equipment qualification, reducing the risk of downstream fit or compliance issues. For capacity planners and plant executives, the historical trajectory and forecast pathway inform timing decisions—when to accelerate replacement cycles, where to concentrate automation investments, and how to sequence expansions against anticipated demand increments. For market strategists evaluating expansion or new product lines, the regional and application lenses identify where demand momentum is strongest and where competitive barriers are most navigable.
Crucially, the report's structure is designed to support scenario thinking rather than point forecasts alone. By revealing how demand drivers, machine categories, and regional dynamics interact, it enables decision-makers to test assumptions, stress-test investment plans, and align internal timelines with external market rhythms.
What the Full Study Delivers
This introduction previews the analytical rigor and strategic relevance of the complete Cold Heading Machine Market research. The full report extends this foundation with detailed segmentation analytics, deeper competitive profiling, granular demand-driver mapping, standards and safety integration, and forward-looking scenario considerations that together form a comprehensive decision-support toolkit. It is written for executives who need to move beyond headline market figures and into the operational and strategic detail that determines whether a 2026 investment, procurement decision, or market move lands effectively.
The complete analysis, including the full segmentation breakdowns, firm-level evaluations, regional demand contexts, and the nuanced interpretation of growth drivers across the 2026–2032 horizon, is available through the full report. Readers seeking the precise figures, segment-level decompositions, and the complete competitive landscape assessment are encouraged to access the source study to obtain the complete intelligence package.
In a market where precision, timing, and supplier selection carry outsized consequences, the difference between reactive planning and strategic advantage comes down to the quality of the intelligence underpinning decisions. This research is designed to deliver exactly that—grounded in data, attentive to dynamics, and oriented toward the actions that matter in 2026 and the years that follow.
For detailed analysis of this topic, please visit the official page: Cold Heading Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Noni Juice Market Hits $101.7M in 2025, Projects 8.3% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Noni Juice Market: Strategic Intelligence for 2026 and Beyond
The global wellness beverage landscape is undergoing a structural transformation, and noni juice stands at the intersection of functional nutrition, botanical authenticity, and premiumized consumer habits. As businesses map their 2026 portfolios, supply chains, and market-entry strategies, a clear-eyed understanding of where this category has been, how it is currently behaving, and which forces will shape its trajectory through 2032 is no longer optional. The newly released Noni Juice Market study delivers exactly that clarity, packaged as a decision-grade intelligence asset for executives, investors, and category managers who need to act with conviction rather than guesswork.
This introduction previews the strategic architecture of the full report, demonstrates the analytical rigor it applies to a fast-evolving category, and illustrates why the findings matter for 2026 planning cycles. It is designed as a trailer: enough depth to establish trust, enough structure to reveal what is at stake, and just enough restraint to ensure that the full operational intelligence remains reserved for teams that are ready to deploy it.
The Trajectory: From Post-Pandemic Rebound to Sustained Expansion
The macro story of noni juice over the past half-decade is one of measured acceleration. Between 2020 and 2025, the category moved through a distinct arc: an initial pandemic-era recalibration of health priorities, followed by gradual supply chain stabilization, and culminating in a more confident, repeat-purchase consumer base that treats botanical wellness drinks as habitual rather than experimental. By the close of the base year, the overall market had reached 101.7 million USD, building steadily off the 92.18 million USD posted in 2024 and the 85.66 million USD recorded in 2023. That cumulative climb reflects more than incremental growth; it signals a maturing category in which distribution discipline, product quality consistency, and brand storytelling are beginning to separate durable players from transient entrants.
Noni Juice Market
Looking forward, the forecast window extends through 2032, and the path it traces is equally instructive. The overall market is projected to reach 106.63 million USD in 2026, then advance to 118.21 million USD in 2027, 126.32 million USD in 2028, 136.98 million USD in 2029, and 152.81 million USD in 2030. The longer arc continues upward, reaching 165.22 million USD in 2031 and 176.9 million USD by 2032. These figures translate into a forecast CAGR of 8.3 percent, a rate that is robust enough to justify strategic investment yet grounded enough to demand operational realism. For 2026 decision-makers, the takeaway is not simply that the category is expanding; it is that expansion will be unevenly distributed across formats, channels, and geographies, and that the firms who capture disproportionate value will be those who understand the segmentation logic beneath the headline numbers.
Why This Report Matters for 2026 Decision-Making
A market overview alone does not equip a company to allocate capital, redesign a SKU lineup, renegotiate sourcing contracts, or reposition a brand against incumbents. What executives need is a structured map of demand architecture, competitive posture, regulatory headwinds, and supply-side risk, all calibrated to the specific ways the noni category behaves in practice. This study was built with that operational intent from the outset.
The report is structured to answer the questions that recur in 2026 strategy sessions:
- Where is demand genuinely consolidating, and where is it fragmenting into niche micro-trends that are less durable than they appear?
- How do type preferences, application contexts, and regional purchasing behaviors interact to create pockets of margin advantage?
- Which competitors are winning on authenticity, processing capability, or distribution reach, and what does that imply for entry timing and positioning?
- What supply-side and regulatory shocks are already visible, and how should they be priced into 2026–2028 operating assumptions?
- What concentration patterns exist in the competitive field, and how much room is realistically available for new or expanding participants?
To answer these questions, the study moves beyond static descriptions and into the mechanics of the category. It examines how product type influences adoption among different consumer segments, how application contexts shape repeat-purchase behavior, and how regional demand patterns are being reshaped by both local wellness cultures and the global premiumization of functional beverages. The analysis is deliberately anchored in actionable frameworks rather than abstract commentary, so that procurement teams can read it alongside finance, and marketing teams can align it with channel strategy.
The Competitive Field: Architecture, Not Just Names
One of the most valuable contributions of the report is its treatment of the competitive landscape as a system of strategic archetypes rather than a simple roster of companies. The noni juice market is characterized by relatively low headline concentration, with the top three players accounting for approximately 25.0 percent of revenue and the top five reaching about 28.0 percent. That structure matters: it indicates a category that is not locked into a tight oligopoly, yet still rewards firms that can combine sourcing credibility, processing consistency, and brand legitimacy at scale. In a market this distributed, the ability to narrate origin, demonstrate quality assurance, and maintain reliable volume can be as decisive as pricing tactics.
The study profiles a cross-section of companies whose offerings illustrate the different ways the category is being played. Morinda Holdings, Inc., headquartered in Provo, Utah, exemplifies a vertically oriented, globally distributed flagship model centered on its Tahitian Noni Juice and related noni-based beverages and concentrates, produced through owned processing plants in Tahiti, the U.S., China, Japan, and Germany. That footprint gives the company a distinctive combination of origin storytelling and manufacturing control across multiple jurisdictions.
In parallel, the report examines regional and category-specific innovators who are stretching the definition of noni products. CIMG Inc., based in Beijing, has moved aggressively into plant-based functional beverages, including its Maca Noni energy drink formulated with noni plant extracts for immunity and fatigue relief, supported by award-winning distribution. Hawaiian Noni, operating from Hawaii, focuses on organic noni juice and wellness products rooted in Hawaiian noni farms, with flavor-enhanced variants that address one of the category’s long-standing adoption barriers. Puna Noni, also based in Hawaii, emphasizes pure noni fruit juice, capsules, and complementary products sourced through proprietary Hawaiian supply arrangements. Royal Noni Fiji represents a family-owned, origin-specific model built on local noni plantations, while Noni Biotech in India contributes a nutraceutical-grade angle through noni juice and ingredients positioned for broader beverage and supplement applications.
The international spread continues with Vitis Industries, which approaches the category from West African noni cultivation and supply; Cook Islands Noni, which centers on authentic noni juice and wellness beverages from local farms; Dave’s NONI, which operates within a broader corporate group and includes bottling and private label capabilities; and Virgin Noni Juice and Healing Noni, both Hawaii-based operations emphasizing pure, premium-grade Hawaiian noni juice and wellness solutions from large-scale local cultivation. Together, these profiles reveal a market where sourcing geography, processing philosophy, and product format are not interchangeable details but strategic choices that define competitive positioning.
Recent Moves That Redefine Category Expectations
Competitive analysis becomes most useful when it is tied to concrete action. The report integrates recent developments that show how quickly the category is being reshaped at the product level. In January 2025, CIMG Inc. launched its Maca Noni plant-based energy drink, combining maca and noni extracts to target physical fatigue relief and immune support, and later received recognition as the 2024 China Annual Most Innovative New Consumer Brand. That move matters because it demonstrates how noni is increasingly being embedded inside hybrid functional formats rather than sold only as a standalone traditional juice.
In March 2025, Hawaiian Noni introduced an Organic Flavor-Enhanced Noni Juice built on proprietary processing designed to address the traditional taste profile while preserving bioactive compounds and nutritional benefits. This is precisely the kind of product-level engineering that can alter adoption curves in a category where flavor acceptance has historically constrained mainstream penetration. For 2026 planners, such launches are not isolated anecdotes; they are early indicators of how product design, sensory experience, and functional claims will interact to shape the next wave of volume growth.
Market Dynamics: Supply, Regulation, and Operational Reality
A strategy built on demand assumptions alone is fragile. This study incorporates the operational realities that determine whether growth plans survive contact with supply chains and regulatory environments. One of the most significant near-term pressures comes from raw material volatility. Climate instability and irregular rainfall patterns across Southeast Asia are creating sourcing uncertainties and pushing production costs higher, with industry data pointing to an estimated 12 percent increase in input costs. That kind of pressure does not merely compress margins; it reshapes sourcing geometry, encourages diversification of supply origins, and rewards companies that have invested in traceability and supplier resilience.
On the regulatory and compliance side, the report addresses the growing documentation expectations surrounding noni concentrates, particularly as European importers require comprehensive records that include cultivation documentation and pesticide-residue testing before approving materials. In parallel, the category is also being touched by broader labeling and consumer transparency trends, including the Consumer Affairs Agency in Japan’s publication of voluntary guidelines for front-of-pack nutritional labeling on processed food in March 2026. While voluntary in form, such guidance often functions as a practical benchmark for brands seeking shelf credibility and retail readiness in discerning markets. Taken together, these dynamics underscore that quality assurance, documentation discipline, and labeling clarity are becoming part of the category’s competitive floor rather than optional enhancements.
What the Full Study Unlocks for 2026 Planning
The preview above establishes the analytical frame; the full report supplies the operational map. It is designed for teams that need to convert market awareness into specific commitments: which customer segments warrant dedicated SKUs, which applications show the strongest pull-through, where regional attention should be concentrated, and how to interpret competitive moves without overreacting to noise. The report’s segmentation analysis is built to show how type preferences, application contexts, and regional demand patterns interlock, enabling sharper portfolio decisions than broad category averages can support. It also examines the implications of the competitive concentration profile, helping entrants and incumbents alike understand where there is room to differentiate and where share gains will require genuine advantage rather than incremental marketing.
Worldwide Coffee Concentrate Juice Market
Equally important, the study treats recent product launches and supply-side pressures as strategic signals rather than isolated events. It connects the spread of hybrid functional formats, the ongoing effort to improve taste and bioactive retention, and the cost and compliance pressures influencing sourcing decisions into a single coherent narrative. That integrated perspective is what allows leadership teams to plan with confidence in a category where consumer enthusiasm, input volatility, and regulatory expectations are evolving simultaneously.
A Note on Intelligence Structure and Access
In keeping with the report’s role as a decision-support asset, the public-facing introduction is intentionally focused on framework, trajectory, and strategic relevance, while the granular segmentation figures, detailed regional and application breakdowns, and company-level comparative data are reserved for the full study. That design choice reflects a simple principle: executive summaries should build trust and frame the decision, while the operative numbers should be accessed in the complete research package where they can be read in context and applied with precision. Teams evaluating market entry, capacity expansion, sourcing diversification, or brand positioning will find that the detailed segmentation and company profiles in the full report provide the comparative clarity needed to avoid overgeneralization and to target resources where they will generate the greatest return.
For organizations preparing 2026 strategies, the Noni Juice Market study offers more than a forecast. It provides a structured way to think about a category that is expanding at a robust pace, fragmenting across formats and applications, and becoming increasingly-sensitive to quality, origin, and compliance. The headline direction is encouraging, but the strategic advantage will belong to those who understand the shape of the opportunity beneath the top-line trend. The full report is designed to make that understanding operational.
For detailed analysis of this topic, please visit the official page: Noni Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


